



Category: market research
PW Consulting Global Insight: Worldwide Cosmetic Grade Centella Asiatica Extract Market Valued at 636.32 Million USD in 2025 Drives 7.65 CAGR Forecast Through 2032
By PW Consulting, 2026-09-02
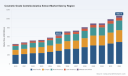
Charting the Green Trajectory: Strategic Intelligence for the Global Cosmetic Grade Centella Asiatica Extract Market
The global beauty industry is currently navigating a paradigm shift where efficacy meets naturality. At the forefront of this evolution is Centella Asiatica, colloquially known as Cica, a botanical ingredient that has transcended its traditional roots to become a cornerstone of modern skincare formulations. For stakeholders operating within the cosmetic ingredient supply chain, understanding the magnitude and direction of this trend is no longer optional; it is a prerequisite for survival and growth. Our latest comprehensive study, the Worldwide Cosmetic Grade Centella Asiatica Extract Market, offers a definitive roadmap for navigating this complex landscape through 2032.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
This research is not merely a collection of numbers. It is a strategic asset designed to inform critical investment decisions, supply chain optimizations, and product development pipelines in 2026 and beyond. By analyzing historical performance from 2020 to 2025 and projecting forward through 2032, we provide a clear lens into the market mechanics that drive value in this sector. The following analysis underscores the strategic value of this intelligence, highlighting the macro-economic drivers, competitive pressures, and operational nuances that define the current market environment.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
Macro-Economic Trajectory and Revenue Pathways
The financial narrative of the cosmetic grade Centella Asiatica extract market is characterized by robust, sustained growth. Our analysis tracks a compelling revenue journey, beginning with a total market valuation of approximately 442.15 million USD in 2020. Over the subsequent five years, the market demonstrated resilience and acceleration despite global supply chain disruptions, culminating in a valuation of 636.32 million USD in 2025. This historical performance sets a strong foundation for the forecast period.
Worldwide Cosmetic Grade Centella Asiatica Extract Market
Looking ahead, the momentum shows no signs of abating. The market is projected to reach 718.28 million USD in 2026, marking a significant step up in value creation. As we extend the horizon to 2032, the trajectory points toward a valuation exceeding 1 billion USD, specifically reaching 1066.19 million USD. This expansion suggests a Compound Annual Growth Rate (CAGR) of 7.65 percent over the forecast period from 2026 to 2032. For executives and investors, these figures represent more than just top-line growth; they indicate a maturing market where scalability becomes a key differentiator. The consistent upward curve implies that demand drivers are structural rather than cyclical, rooted in changing consumer preferences and formulation science rather than fleeting trends.
Supply Chain Dynamics and Sourcing Vulnerabilities
A critical component of strategic planning in this sector involves understanding the upstream constraints that influence downstream availability. The supply of high-purity Centella Asiatica raw material for extraction relies primarily on cultivated sources in Asia. This geographic concentration creates a specific set of dynamics for global manufacturers. India, for instance, accounts for approximately 38 percent of global supply, making the cosmetic-grade extract inherently vulnerable to agricultural yield variations. Weather patterns, crop diseases, and local regulatory changes in sourcing regions can have outsized effects on global pricing and availability.
Furthermore, the industry is witnessing an increasing focus on traceability and sustainable farming practices. As brands face pressure to validate their natural claims, the provenance of the Centella Asiatica biomass becomes a competitive asset. Supply chain resilience is therefore not just about logistics; it is about securing relationships with cultivators who can guarantee consistency in biomass quality. Our report delves into these regional supply nuances without compromising sensitive commercial data, allowing procurement leaders to assess risk exposure in their current vendor networks. The interplay between agricultural output and industrial extraction capacity is a vital lever for cost management and product consistency.
Segmentation Strategy and Product Formulation Heterogeneity
The market is not a monolith. It is fragmented by extraction type, regional demand, and application utility. From a product perspective, the landscape includes distinct categories such as Madecassoside, Asiaticoside, Asiatic Acid, Madecassic Acid, and Standardized Mixed Extracts. Each of these chemical fractions offers different functional benefits, ranging from skin repair to soothing and anti-inflammatory properties. Understanding the relative market weight of these types is crucial for R&D teams deciding which active ingredient to prioritize for specific skin concerns.
Geographically, the demand distribution varies significantly, influenced by local beauty trends and regulatory environments. Similarly, the application landscape spans Skin Care, Hair Care, Makeup and Color Cosmetics, and Oral Care and Others. While skin care remains the dominant driver of demand, the diversification into hair and oral care represents an emerging frontier for growth. Strategic entrants must identify which segments offer the highest margin potential versus those that are volume-driven. Our analysis provides the framework to evaluate these segments based on growth velocity and competitive saturation, enabling companies to allocate resources where the return on investment is maximized. However, the specific percentage splits and revenue figures for these sub-segments are detailed exclusively within the full report to maintain analytical precision for our subscribers.
Competitive Intensity and Strategic Positioning
The competitive landscape is defined by a mix of established global chemical giants and specialized botanical extract manufacturers. Market concentration metrics indicate a moderately fragmented environment, with the top three companies holding a collective share that suggests room for consolidation or niche domination. With a CR3 of 31.45 percent and a CR5 of 42.8 percent, no single entity dominates the entire value chain, allowing specialized players to compete on quality, purity, and technical service.
Key players such as Indena S.p.A. and BASF SE leverage their extensive R&D capabilities and global distribution networks to maintain strong positions. Indena, based in Italy, focuses on high-purity botanical extracts including standardized Centella Asiatica extracts like TECA, emphasizing skin repair and soothing benefits. BASF, headquartered in Germany, incorporates these extracts into broader personal care portfolios, benefiting from synergies across multiple formulation types. Symrise AG and Croda International Plc similarly integrate Centella derivatives into their premium cosmetic offerings, with Croda utilizing its Sederma division to supply specialty ingredients for high-end formulations.
Regional specialization is also evident. In Asia, manufacturers like COSROMA and Wellgreen Technology Co., Ltd. in China are actively marketing high-triterpene contents, such as the Cosroma CICA-T80, catering to the demand for potent active ingredients. Botanic Healthcare in India leverages its proximity to raw material sources to supply extracts with specific asiaticoside concentrations for nutri-cosmetic applications. Meanwhile, companies like Seppic in France are differentiating through technical guidance, releasing detailed guides in late 2025 that emphasize precision and consistency in extracts to support the Cica trend. These recent developments, including product listings by Lipoid Kosmetik AG and new offerings from COSROMA, highlight the pace at which product portfolios are evolving. Understanding the specific strategic moves of these key companies is essential for benchmarking and identifying potential partnership or acquisition opportunities.
Regulatory Frameworks and Standardization Requirements
Compliance is a gatekeeper in the cosmetic ingredient industry. Cosmetic-grade Centella Asiatica extracts must comply with standardization requirements for triterpene content, including asiaticoside, madecassoside, asiatic acid, and madecassic acid. This standardization is critical to support consistent claims in skincare formulations. Without verified potency, marketing claims regarding barrier support or soothing efficacy can be challenged by regulators or scrutinized by informed consumers.
The regulatory landscape is evolving alongside consumer habits. There is a rising demand for natural, soothing, and barrier-repair ingredients in K-beauty, clean beauty, and sensitive skin products. This shift drives the incorporation of standardized cosmetic-grade Centella Asiatica extract. However, this demand also invites stricter scrutiny on ingredient provenance and safety. Our report assesses the regulatory hurdles across key markets, helping compliance officers and product managers anticipate changes that could impact formulation stability or market access. Navigating these requirements requires a partner who understands both the science of the extract and the legal framework of the destination market.
Strategic Imperatives for 2026 Decision Makers
As we move into 2026, the strategic implications for businesses operating in or entering this market are clear. First, supply chain security must be prioritized. Given the agricultural concentration risks, diversifying sourcing locations or investing in vertical integration could mitigate volatility. Second, product differentiation through standardization will be key. With multiple players offering extracts, the ability to guarantee and certify specific triterpene levels will become a primary value proposition.
Third, the expansion into adjacent application categories offers untrodden growth paths. While skin care dominates, the potential in hair care and other segments should not be overlooked. Finally, competitive intelligence must be continuous. The recent activity from major players in late 2025 signals an intensification of marketing and product development efforts. Companies need to stay ahead of these moves to protect their market share or find gaps to exploit.
This summary provides a high-level view of the market's health and direction, but the depth required for execution lies within the full data set. The macro trajectories, segmentation splits, and company profiles described here are merely the surface of a much deeper analytical ocean. To access the granular data necessary for precise forecasting, vendor selection, and market entry strategy, stakeholders are invited to explore the complete Worldwide Cosmetic Grade Centella Asiatica Extract Market research. The full intelligence packaged in this study is designed to convert uncertainty into actionable strategy, ensuring that your organization is positioned to capitalize on the green wave of Cica innovation.
For detailed analysis of this topic, please visit the official page: Worldwide Cosmetic Grade Centella Asiatica Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Worldwide Sendust Core Market to Reach 1.12 Billion by 2032 with 9.2 Percent CAGR from 2026 to 2032
By PW Consulting, 2026-09-02
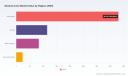
Navigating the Flux: Strategic Imperatives in the Worldwide Sendust Core Market Through 2032
The landscape of power electronics is undergoing a seismic shift, driven by the relentless demands of electrification, renewable energy integration, and high-frequency communication networks. At the heart of this transformation lies a critical component often overlooked until supply chains fracture: the Sendust core. As businesses navigate the complexities of 2026 and beyond, understanding the trajectory of the Worldwide Sendust Core Market is not merely an academic exercise—it is a strategic necessity for supply chain resilience, product design optimization, and competitive positioning.
Worldwide Sendust Core Market
Our latest comprehensive research, the Worldwide Sendust Core Market study, offers a granular view of this evolving sector. This article serves as a strategic preview, outlining the macro-economic forces, competitive tensions, and technological disruptions defined within the full report. We invite industry leaders to examine these insights as a foundation for deeper engagement with the complete intelligence package available on our source page.
Worldwide Sendust Core Market
The Trajectory of Growth: A Decade of Expansion
The Sendust core market has demonstrated robust resilience and growth over the past half-decade, establishing a strong baseline as we enter the forecast period. Between 2020 and 2025, the market evolved from a valuation of approximately 385.2 million USD to 605.15 million USD. This historical performance sets the stage for an ambitious forecast period spanning 2026 to 2032.
Worldwide Sendust Core Market
Our analysis projects a compound annual growth rate (CAGR) of 9.2 percent throughout this forecast window. By 2032, the market is anticipated to reach a valuation exceeding 1.1 billion USD. This trajectory reflects more than just incremental gains; it signals a structural expansion in demand drivers. The jump from the 2025 base year valuation of 605.15 million USD to the 2026 projection of 643.3 million USD indicates immediate momentum that stakeholders must capitalize on before the growth curve steepens further towards the end of the decade.
Such growth is not uniform. It is propelled by specific industrial shifts that require precise navigation. The full report dissects the velocity of this growth across different timeframes, identifying inflection points where investment or procurement decisions will yield the highest strategic return. Understanding the timing of these peaks is crucial for capacity planning and inventory management.
Supply Chain Dynamics and Material Realities
Strategic planning in the magnetic materials sector requires a clear understanding of the physical and regulatory constraints shaping production. Sendust cores, composed primarily of an alloy powder consisting of 85 percent iron, 9 percent silicon, and 6 percent aluminum, represent a specific niche within soft magnetic composites. This composition offers distinct advantages in terms of lower core losses and better thermal properties compared to traditional iron powder cores, making them indispensable for high-frequency applications.
However, the stability of this supply chain is subject to volatility. During 2023, iron-based feedstock prices for magnetic powder cores fluctuated by up to 15 percent, directly impacting production cost stability. For procurement managers, this historical volatility underscores the need for hedging strategies and diversified sourcing, details of which are modeled in our risk assessment section.
Regulatory environments are equally critical. Stringent environmental regulations in China and South Korea require a 20 percent reduction in emissions per ton of powder produced by the end of 2025 for metal magnetic powder core manufacturing. Compliance with these standards is not optional; it defines market access. Simultaneously, trans-Pacific trade dynamics have shifted dramatically. US Section 232 duties on steel and aluminum imports, including derivatives, increased to 50 percent effective June 2025. This includes tariff stacking for steel and aluminum content in products. For buyers in North America, this alters the landed cost calculus significantly, potentially favoring domestic or allied-nation suppliers over those subject to these duties.
The full report provides a detailed matrix of how these regulatory pressures interact with regional manufacturing capabilities, offering a roadmap for compliance and cost mitigation strategies that go beyond surface-level tariff analysis.
Application-Driven Demand: Where the Value Lies
The utility of Sendust cores spans several high-growth verticals. Our segmentation analysis identifies three primary pillars of demand that are driving the 9.2 percent CAGR.
Automotive and EV Electronics represent the largest share of current market value. As electric vehicles become more sophisticated, the need for efficient power conversion and magnetic components in inverters, DC-DC converters, and onboard chargers intensifies. The requirement for components that can handle high saturation levels while minimizing loss at high frequencies positions Sendust cores as a preferred solution.
Renewable Energy Inverters constitute the second major demand driver. The push for solar energy adoption necessitates inverters that operate efficiently at higher switching frequencies. Recent developments highlight this focus; for instance, Micrometals developed Sendust cores specifically for solar inverters that reduced power loss by 12 percent. Such technological improvements directly correlate with the expansion of this segment.
Telecommunications and 5G infrastructure form the third pillar. As networks densify and frequency bands expand, the magnetic components within base stations and network equipment must meet rigorous performance standards without compromising on size or thermal management.
While industrial power supplies remain a steady contributor, the explosive growth is concentrated in the first three categories. The report provides a comparative analysis of how these application segments interact with pricing structures and volume commitments, revealing where the highest margin opportunities exist for suppliers and where the most critical supply risks lie for OEMs.
The Competitive Arena: Incumbents and Emerging Players
The global competitive landscape for Sendust cores is characterized by a mix of established Western manufacturers and a robust cohort of Asian producers. Our market concentration data indicates a moderately consolidated environment, with the top three companies holding a combined market share (CR3) of 42.15 percent and the top five reaching 58.42 percent. This concentration suggests that while there is room for niche players, the bulk of market influence rests with key incumbents.
In the United States, Magnetics (Spang & Company) continues to emphasize quality and thermal properties, manufacturing high-quality Kool Mu (Sendust) powder cores. Similarly, Micrometals offers advanced variants like MS Sendust and SM SenMax, focusing on low loss and high saturation characteristics. Their recent development work on solar inverter cores underscores their commitment to the renewable energy segment.
The Asian manufacturing base is diverse and highly competitive. In China, companies like Pourleroi specialize in high DC Sendust cores and DPH-enhanced variants using fine-grain alloy powders for new energy applications. HSMAG focuses on toroid Sendust power cores for high-frequency applications above 8kHz. Other significant Chinese players include Shaanxi Magason-Tech, Shaanxi Gold-Stone Electronics (GS Magnetics), and Shinhom, all of which focus on various aspects of Sendust core production and customization.
South Korea contributes significant capacity through firms such as Chang Sung Corporation (CSC), which produces Sendust powder cores alongside MPP and High Flux materials. Samwha Electronics and Dongbu Electronic Materials also supply Sendust powdered cores for global applications, while CMSS Technology remains involved in production activities. Taiwan's ACME Electronics stands as a key player in the segment, and India's Vijaya Electronics serves as a manufacturer and exporter for electronic applications. In the US coil winding and specialized component space, Coil Winding Specialist, Inc. (CWS) offers Sendust toroidal cores for specific inductor and choke applications.
Strategic positioning in this market requires more than just identifying these players. It requires understanding their specific technological capabilities, certification statuses, and supply chain reliability. The full report includes detailed profiles and SWOT analyses for these key entities, providing the context needed to negotiate partnerships or assess single-source risks.
Technological Innovations and Certification Milestones
Innovation in the Sendust core market is not limited to material composition; it extends to manufacturing processes, environmental compliance, and product certification. Recent industry developments highlight the direction of travel.
In July 2025, TDK introduced eco-friendly coatings for powder cores, enhancing recyclability by 30 percent in industrial applications. This move aligns with the broader industry push towards sustainability and circular economy principles, potentially setting a new standard for component lifecycle management.
Certification is another critical battleground. In December 2025, Ole Wolff Elektronik A/S released the OWTC157xxxVS-xxx Sendust Toroid Choke series with RoHS, REACH, and AECQ-200 Grade 1 certifications tailored for ESS and PFC applications. Achieving AECQ-200 Grade 1 is particularly significant for automotive-related supply chains, as it validates the component for stringent automotive reliability standards.
These developments illustrate that market leadership is increasingly tied to sustainability credentials and certification breadth. Companies that fail to adapt to these evolving standards risk exclusion from high-value supply chains. Our report tracks these certification milestones and their implications for market entry barriers and competitive advantages.
Strategic Recommendations for 2026 Decision Makers
As organizations finalize their strategies for 2026, several key imperatives emerge from the data.
-
Supply Chain Diversification
Given the volatility in iron-based feedstock prices and the impact of US Section 232 duties, reliance on single-region sourcing is a heightened risk. Diversifying suppliers across different geopolitical zones can mitigate tariff shocks and material price fluctuations.
-
Focus on High-Growth Applications
Resource allocation should prioritize segments with the highest growth elasticity. Automotive EV electronics and Renewable Energy Inverters are projected to outpace general industrial demand. Aligning product roadmaps with these sectors ensures exposure to the strongest revenue streams.
-
Regulatory Compliance as a Value Proposition
With emissions reductions mandated in key manufacturing hubs like China and South Korea, compliance should be viewed as a competitive differentiator. Suppliers who can guarantee lower carbon footprints and adherence to local environmental laws will gain preference in sensitive supply chains.
-
Technology Adoption and Recycling
The introduction of eco-friendly coatings and improved loss-reduction technologies suggests a market trend towards efficiency and sustainability. Evaluating suppliers based on their adoption of these technologies can future-proof product designs against upcoming regulatory tightening.
These recommendations are derived from a synthesis of historical data, regulatory forecasts, and competitive intelligence. However, implementing them effectively requires access to the detailed segmentation splits, regional revenue breakdowns, and specific manufacturer market shares contained in the full study.
A Call for Deep-Dive Intelligence
The Worldwide Sendust Core Market is entering a phase of accelerated maturity. The confluence of electrification, renewable energy expansion, and stringent regulatory frameworks creates a complex environment where general market trends are insufficient for strategic success. Leaders need precise data on regional revenue splits, application-specific growth rates, and the nuanced positioning of competitors to navigate this terrain effectively.
This article has highlighted the macro trajectory, the key players, and the critical external factors influencing the market. Yet, it intentionally omits the granular data points necessary for immediate operational decision-making. The full report provides the specific revenue units for each segmentation, the detailed regional splits beyond the top-line figures, and the comprehensive competitive benchmarking that allows for apples-to-apples comparison of supplier capabilities.
For stakeholders ready to move beyond high-level overviews, the complete Worldwide Sendust Core Market research offers the detailed intelligence required to secure supply chains, identify partnership opportunities, and capture growth in this vital component sector. We invite you to access the full study via our source page to equip your organization with the precise data needed to drive 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Sendust Core Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Influencer Relationship Management Platform Market Hits $12.5 Billion in 2025 and Projects 26.04% CAGR Through 2032
By PW Consulting, 2026-09-01
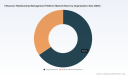
Navigating the Influencer Economy: Strategic Imperatives for the IRMP Market in 2026 and Beyond
The influencer marketing landscape has matured from a discretionary brand experiment into a core revenue operations function. As social commerce, creator-led product launches, and algorithmic content distribution continue to reshape customer acquisition, enterprises are increasingly turning to Influencer Relationship Management Platforms (IRMPs) to systematize discovery, contracting, performance tracking, and long-term creator lifecycle management. PW Consulting’s newly released Worldwide Influencer Relationship Management Platform Market study is designed to equip executive teams, procurement leaders, and growth strategists with the structural intelligence needed to make informed technology investments, vendor selections, and capability-building decisions throughout the 2026–2032 forecast horizon.
Worldwide Influencer Relationship Management Platform Market
This market research is not a surface-level trend summary. It is a decision-grade intelligence asset built to help organizations cut through vendor noise, anticipate platform evolution, and align technology roadmaps with emerging regulatory and commercial realities. Below, we outline the strategic architecture of the study, the operational contents it delivers, and the competitive and regulatory forces that will define platform selection criteria in the coming years.
Worldwide Influencer Relationship Management Platform Market
Why IRMP Intelligence Matters for 2026 Decision-Making
By 2026, influencer marketing is no longer optimized through spreadsheets, ad-hoc outreach, or fragmented analytics dashboards. Scaling creator programs across product categories, regions, and campaign types requires a centralized system of record that can manage relationship touchpoints, compliance documentation, payment workflows, and multi-channel performance attribution. Organizations that treat IRMP adoption as a tactical software purchase rather than a strategic capability investment frequently encounter data silos, inconsistent creator onboarding, and opaque return measurement.
Worldwide Influencer Relationship Management Platform Market
The research underscores that platform selection in this category must be evaluated against three interconnected decision dimensions: operational scalability, data integrity, and ecosystem interoperability. Operational scalability determines whether a platform can support both micro-creator volume programs and enterprise-scale ambassador relationships without degradation in workflow efficiency. Data integrity governs how accurately platforms attribute engagement, validate creator authenticity, and surface fraud signals. Ecosystem interoperability reflects the degree to which a platform can integrate with e-commerce infrastructure, CRM systems, media planning tools, and payment gateways.
The study’s market trajectory analysis provides executives with the context needed to time these investments appropriately. The global influencer relationship management platform market reached an estimated revenue base of approximately $12.5 billion in 2025, expanding from roughly $2.85 billion in 2020. This growth trajectory reflects the compounding effect of creator-driven commerce, broader adoption of performance-linked influencer programs, and the structural shift toward managed relationship workflows rather than one-off sponsored placements. Looking forward, revenue is projected to continue its steep ascent through 2032, with a compound annual growth rate of 26.04 percent across the forecast period.
For decision-makers, this growth rate signals more than market enthusiasm. It indicates sustained platform investment, accelerating feature differentiation, and increasing pressure on legacy tools that cannot support AI-assisted discovery, automated contract management, or cross-channel relationship tracking. Organizations evaluating IRMP vendors in 2026 must therefore assess whether a platform’s roadmap is aligned with this pace of change or whether it is positioned for commoditization.
Inside the PW Consulting Research: Practical Intelligence for Execution
The study is structured to move beyond aggregate market commentary and deliver actionable, implementation-relevant content. It is intended for teams that need to justify budget allocation, compare vendor capabilities, and anticipate where the category is heading. The report’s architecture is built around several core components that directly support enterprise and mid-market planning cycles.
At the foundation of the analysis is a comprehensive market sizing and forecast framework that maps historical performance and forward-looking revenue trajectories across the 2026–2032 period. Rather than presenting isolated figures, the research embeds these numbers within a broader narrative about demand drivers, adoption maturity, and the transition from experimental influencer budgets to formalized creator relationship operations. This framing allows leadership teams to benchmark their internal timing assumptions against market-wide momentum.
The report also examines deployment-mode dynamics in detail. As organizations evaluate whether to prioritize cloud-based delivery or maintain on-premise infrastructure for sensitive campaign and contract data, the study analyzes how architecture choices affect integration flexibility, cost structures, and scalability. This is particularly relevant for enterprises managing large creator networks, multi-region compliance requirements, and complex data governance policies.
Organization-size segmentation is another critical dimension in the research. The analysis differentiates how large enterprises and small-to-medium enterprises approach IRMP adoption, including differences in workflow complexity, procurement behavior, and required feature depth. Large organizations typically demand enterprise-grade relationship orchestration, contract management, and multi-role access controls, while smaller teams often prioritize faster onboarding, cost efficiency, and streamlined discovery-to-outreach workflows. Understanding these divergent requirements helps buyers avoid either overbuying or under-specifying their platform.
Beyond sizing and segmentation, the report delivers practical operational coverage that can be applied directly to platform evaluation and internal rollout planning. This includes:
- Functional capability mapping across influencer discovery, relationship nurturing, campaign orchestration, gifting and product seeding workflows, payment and contract handling, affiliate and performance tracking, and analytics reporting.
- Vendor evaluation frameworks that translate feature claims into decision-relevant comparisons, helping procurement and marketing operations teams assess fit against internal use cases rather than marketing narratives.
- Implementation and adoption considerations that address integration complexity, internal workflow redesign, data migration, and cross-functional ownership between marketing, legal, finance, and operations.
- Procurement and licensing context designed to support negotiations around usage tiers, seat structures, API consumption, and enterprise service agreements.
The study is intentionally designed to help organizations convert market information into operational decisions. It provides the kind of structural clarity needed to assess whether a platform will support not only current campaign demands but also the next phase of creator program maturity, including cross-channel expansion, commerce integration, and automated relationship scoring.
Competitive Landscape: Differentiated Strategies Among Core Platforms
The IRMP category is shaped by a competitive set of vendors that have taken distinct strategic paths. Rather than converging on a single platform model, the market now reflects specialization across enterprise CRM depth, e-commerce integration, AI-assisted performance analytics, and workflow automation. The research analyzes this competitive architecture to help buyers understand not just who is in the market, but how each platform attempts to create value and where differentiation is most credible.
Aspire positions itself as a SaaS platform focused on influencer discovery, relationship management, campaign tracking, and performance analytics across social channels. Its trajectory in the market reflects an emphasis on end-to-end campaign visibility and channel-spanning analytics, appealing to teams that want a unified operational layer for creator programs.
CreatorIQ occupies a more enterprise-oriented position, offering CRM tools for relationship management, contracts, payments, and ROI measurement. The platform’s enterprise focus makes it particularly relevant for organizations that require formalized contracting, financial workflow integration, and structured return measurement across large creator networks.
Grin emphasizes influencer relationship management software that integrates discovery, outreach, gifting, and e-commerce tracking for brands. Its product direction reflects the growing importance of product seeding and commerce-linked creator programs, where the relationship lifecycle extends beyond content publication into product fulfillment and sales attribution.
Influencity brings an AI-powered approach to influencer discovery, CRM, campaign management, and real-time performance reporting. Platforms that center AI in their value proposition are responding to demand for faster creator identification, more dynamic performance monitoring, and improved prioritization of relationship opportunities.
Klear, operating within Meltwater’s broader suite, embeds influencer relationship management into a wider media and analytics ecosystem. Its positioning highlights discovery, engagement tracking, and analytics, appealing to organizations that want influencer workflows connected to broader listening, monitoring, and media intelligence capabilities.
Later Influence approaches the category through an influencer collaboration platform that combines relationship management, marketplace matching, and content approval workflows. This model is especially relevant for teams that need structured content review, brand safety controls, and collaborative approval processes in addition to relationship tracking.
Traackr focuses on influencer CRM for relationship nurturing, performance insights, and enterprise-scale campaign orchestration. Its enterprise orientation and emphasis on long-term relationship management differentiate it for organizations that treat creator programs as sustained partnerships rather than transactional campaigns.
Upfluence offers an all-in-one influencer platform with CRM features for discovery, outreach, payments, and affiliate tracking. Its broad feature set reflects the demand for consolidated workflows that can reduce tool sprawl across multiple stages of the creator engagement lifecycle.
The research situates these vendors within a broader competitive dynamic by examining how product launches, partnerships, and feature updates reshape evaluation criteria. Recent activity illustrates the pace of differentiation in the category. In October 2025, CreatorIQ launched AI-powered influencer fraud detection and relationship scoring enhancements, underscoring the growing importance of authenticity verification and relationship quality signals. In September 2025, Aspire announced integration with Shopify for streamlined influencer gifting and e-commerce tracking, reflecting closer ties between creator platforms and commerce infrastructure. In June 2025, Grin introduced automated contract generation and payment workflows in influencer CRM, signaling movement toward operational automation in creator contracting and compensation. In April 2025, Traackr expanded its platform with multi-channel relationship management for TikTok and YouTube Shorts, demonstrating continued adaptation to short-form video ecosystems and cross-channel relationship orchestration.
For enterprise buyers, these developments matter because they reveal where vendor attention is flowing. Fraud detection, commerce integration, automated contracting, and short-form video coverage are not isolated feature additions; they are indicators of the capabilities that the market increasingly expects as baseline requirements. The study helps organizations interpret these signals within a comparative framework, enabling more disciplined shortlisting and negotiation.
Market Dynamics and Structural Forces Shaping Platform Strategy
The IRMP market is not expanding in a vacuum. Several structural forces are reshaping how organizations design creator programs and how platforms must respond. The research integrates these dynamics to help buyers anticipate where compliance, cost, and creator strategy will influence technology decisions.
Regulatory pressure is one of the most consequential forces in the category. The EU Digital Services Act requires influencer platforms to disclose sponsored content and verify creator authenticity, introducing new obligations around transparency and identity validation. In parallel, FTC Endorsement Guides mandate clear disclosure of material connections in influencer relationships, reinforcing the need for platforms that can store, surface, and manage compliance documentation throughout the campaign lifecycle. These regulatory developments push IRMP adoption beyond convenience and into risk management, making contract storage, disclosure tracking, and authenticity verification more central to platform value.
Infrastructure and analytics costs also influence platform economics, particularly for AI-driven influencer analytics. Cloud computing costs for AI-driven influencer analytics average $0.05 to $0.20 per 1,000 API calls via AWS or GCP. While this cost range may appear modest at the unit level, it becomes strategically relevant when platforms scale high-volume discovery, sentiment evaluation, or performance modeling across large creator datasets. For organizations evaluating total cost of ownership, understanding how vendors manage API consumption, data storage, and compute intensity is essential to forecasting long-term operating expenses.
A third dynamic is the strategic shift in creator selection and relationship design. The market is increasingly shaped by a move toward micro-influencer relationships, with 70 percent of brands prioritizing creators under 100K followers. This trend increases platform demand for high-volume discovery, relationship triage, and workflow efficiency, because managing many smaller-scale relationships requires different operational tooling than managing a small roster of macro creators. Platforms that can support volume onboarding, automated outreach, lightweight contracting, and efficient performance monitoring are better positioned to serve this evolving brand preference.
Together, these dynamics create a market environment in which platform selection must balance compliance readiness, cost efficiency, and workflow scalability. The research addresses these forces not as isolated observations but as integrated inputs to a broader evaluation framework, helping organizations understand how regulatory requirements, infrastructure economics, and creator strategy will shape platform fit over the forecast period.
Market Concentration, Selection Discipline, and Strategic Timing
Despite rapid growth and expanding vendor activity, the IRMP market remains structured around a moderately concentrated competitive field. The research examines market concentration to help buyers understand the balance between established platform presence and ongoing room for specialization. This context is valuable because concentration levels influence pricing leverage, integration expectations, and the likelihood of future consolidation or platform bundling.
For 2026 decision-makers, the key implication is that vendor selection cannot be reduced to feature checklists alone. Enterprise buyers need to evaluate how each platform’s architecture, data handling, compliance support, and integration depth will perform as creator programs grow in complexity. Mid-market buyers must weigh speed of deployment and usability against the risk of outgrowing a platform as their creator strategy matures. In both cases, the study provides the comparative context needed to align vendor shortlists with organizational trajectory rather than short-term campaign needs.
The report also supports timing decisions. In a category expanding at a 26.04 percent CAGR, the cost of delayed evaluation can be significant. Organizations that postpone platform standardization may find themselves accumulating manual processes, fragmented performance data, and compliance gaps that become harder to unwind over time. Conversely, organizations that rush into platform adoption without clear workflow definitions or integration requirements may pay for unused capability or face costly reconfiguration later. The research is designed to help teams strike that balance by framing platform investment as a phased capability build rather than a one-time purchase.
What the Full Study Enables for Your Organization
The Worldwide Influencer Relationship Management Platform Market study is built to support a wide range of executive and operational use cases. It is intended to help strategy leaders understand where the market is going, procurement teams evaluate vendor claims with greater discipline, and marketing operations teams plan implementation in a way that reduces disruption and accelerates time to value.
Specifically, the full research equips organizations to:
- Benchmark internal platform requirements against market-wide adoption patterns and growth trajectories.
- Assess vendor differentiation across discovery, CRM, contract and payment workflows, analytics, fraud detection, and commerce integration.
- Anticipate how regulatory disclosure obligations and creator authenticity verification will affect platform selection and internal process design.
- Evaluate deployment-mode and organization-size fit in the context of integration needs, data governance, and scalability expectations.
- Frame procurement negotiations around realistic usage, API consumption, seat structures, and enterprise service requirements.
- Align influencer program roadmaps with platform capabilities so that relationship management evolves in step with campaign complexity and commerce integration.
Because the category is moving quickly, the most valuable decisions are those made with access to complete segmentation detail, forward-looking scenario context, and vendor-specific evaluation support. The published summary provides the strategic frame; the full report provides the operational depth required to convert that frame into a concrete purchasing and implementation plan.
Conclusion: From Market Awareness to Decisive Action
The influencer relationship management platform market is entering a phase in which technology choice has direct consequences for creator program efficiency, compliance readiness, and performance transparency. Growth has been strong, the competitive field is actively differentiating, and regulatory and operational forces are raising the stakes for platform selection. In this environment, organizations need market intelligence that goes beyond headline figures and supports practical, cross-functional decision-making.
PW Consulting’s Worldwide Influencer Relationship Management Platform Market study is designed for exactly that purpose. It combines market sizing, forecast trajectory, segmentation insight, competitive analysis, and regulatory context into a structured decision-support resource. For leaders responsible for marketing technology, creator programs, procurement, or growth strategy, the research offers a path toward more confident vendor evaluation and more disciplined investment timing.
To access the full segmentation detail, complete vendor profiles, and the full range of forward-looking market intelligence supporting these findings, visit the source page to retrieve the complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Influencer Relationship Management Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Vibration Detector Market to Hit 13080 Million by 2032 Growing at 9.33 CAGR
By PW Consulting, 2026-09-01
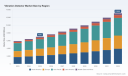
Strategic Imperatives in the Global Vibration Detector Market: Navigating the 2026 Landscape
The global industrial landscape is undergoing a seismic shift. No longer content with reactive repairs and scheduled downtime, enterprises are increasingly turning to condition-based monitoring and predictive maintenance strategies. At the heart of this transformation lies the vibration detector market, a critical enabler for asset integrity, operational efficiency, and safety across heavy industry. As we move through 2026, the strategic value of understanding this market extends far beyond simple procurement; it is about anticipating technological convergence, regulatory pressures, and competitive shifts that will define the next decade of industrial operations.
Worldwide Vibration Detector Market
PW Consulting has compiled a comprehensive Worldwide Vibration Detector Market study, designed specifically to equip decision-makers with the intelligence needed to navigate this complex ecosystem. This report is not merely a collection of statistics; it is a strategic roadmap derived from deep-dive analysis of historical trends, current market dynamics, and forward-looking projections. The following insights offer a preview of the critical themes shaping the industry, urging leaders to look beyond surface-level metrics and grasp the underlying forces driving growth.
Worldwide Vibration Detector Market
Market Trajectory and Financial Landscape
The financial magnitude of the vibration detector market underscores its importance as a strategic investment sector. Drawing from historical data spanning 2020 to 2025, the market has demonstrated consistent expansion, reflecting the growing reliance on sensor technology for machinery health assessment. In the base year of 2025, the overall market revenue reached approximately 7010.0 Million USD. This established foundation sets the stage for a robust forecast period extending from 2026 to 2032.
Worldwide Vibration Detector Market
Projections indicate a steady upward trajectory, with the market expected to climb to 7650.0 Million USD in 2026. By the end of the forecast period in 2032, revenue is anticipated to reach 13080.0 Million USD. This growth path translates to a Compound Annual Growth Rate (CAGR) of 9.33 percent over the forecast horizon. Such performance highlights the market's resilience and its integral role in industrial modernization. However, these aggregate figures represent only the tip of the iceberg. The true strategic value lies in understanding the velocity of growth across different vectors and the factors accelerating adoption in specific operational contexts.
Segmentation Dynamics: Type, Application, and Region
While the total market size provides a macro view, the segmentation data reveals where the opportunities and risks are concentrated. The market is divided across multiple dimensions, including sensor type, end-use application, and geographic region. Each segment presents unique value propositions and adoption curves that require tailored strategic approaches.
In terms of technology, the market encompasses a diverse array of sensor modalities. Piezoelectric accelerometers continue to hold a significant position, driven by their reliability in high-frequency vibration measurement. However, the landscape is increasingly competitive with the presence of piezoresistive vibration sensors, capacitive accelerometers, electromagnetic sensors, and optical laser vibration detectors. The choice of technology often depends on the specific environmental constraints and measurement requirements of the application, ranging from harsh industrial conditions to precision laboratory settings. Understanding the relative maturity and cost structures of these technologies is essential for product strategists and procurement leaders.
Application-wise, the demand is spread across several key industries. Industrial manufacturing remains a primary driver, leveraging vibration data for predictive maintenance of production lines. The automotive and transportation sector utilizes these sensors for vehicle dynamics and engine health, while aerospace and defense applications demand high-reliability solutions for critical components. Additionally, sectors such as oil and gas, energy and power, and medical and healthcare contribute to the demand profile. Each application vertical faces distinct regulatory and operational pressures that influence procurement cycles and technology preferences.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional dynamics are shaped by local industrial bases, investment in automation, and the pace of digital transformation initiatives. While global averages provide a baseline, regional nuances regarding supply chain logistics, local manufacturing capabilities, and specific industrial policies play a crucial role in market entry and expansion strategies.
Competitive Landscape and Key Players
The vibration detector market is characterized by a mix of established industrial giants and specialized technology providers. The competitive environment is moderately concentrated, with the top three players holding a combined market share of approximately 32.4 percent and the top five companies accounting for 45.6 percent. This structure suggests a market where scale and brand reputation matter, yet there remains room for specialized innovators to capture niche segments.
Several key companies define the current competitive arena. SKF, headquartered in Gothenburg, Sweden, is a prominent provider of vibration sensors, analyzers, and monitoring systems, including the SKF Microlog series for predictive maintenance in industrial machinery. Emerson Automation Solutions, based in St. Louis, MO, USA, offers AMS wireless vibration sensors and CSI 2140 machinery analyzers for real-time vibration monitoring in rotating equipment. Fluke Corporation, located in Everett, WA, USA, manufactures handheld vibration meters such as the Fluke 805 and 810 for bearing and machinery health assessment.
Brüel & Kjær (HBK), with headquarters in Nærum, Denmark, supplies VIBROPORT and advanced vibration analyzers for condition monitoring in power plants and manufacturing. Honeywell International, based in Charlotte, NC, USA, delivers vibration monitoring systems including the HM500 series for aerospace and industrial applications. Siemens AG, from Munich, Germany, provides SIMATIC PCS 7 integrated vibration monitoring for process industries and turbine diagnostics. General Electric (GE Bently Nevada), located in Minden, NV, USA, specializes in 3500 series rack-mounted vibration monitoring systems for turbomachinery protection. PCB Piezotronics (IMI Sensors), in Depew, NY, USA, produces industrial accelerometers and vibration sensors like the 608A series for harsh environments. Metrix Vibration, based in Houston, TX, USA, offers proximity sensors and vibration transmitters for oil and gas and power generation equipment. National Instruments (NI), from Austin, TX, USA, develops modular vibration analysis systems using LabVIEW software for custom monitoring solutions.
Recent activities among these players signal the direction of the market. In October 2025, SKF launched the IMx-8 multi-channel vibration monitoring system for advanced predictive maintenance. Emerson showcased the AMS 2140 machinery health analyzer at the ACHEMA 2025 exhibition in June 2025. Fluke released an updated Fluke 805 Vibration Meter with an enhanced laser tachometer in April 2025. In March 2025, HBK achieved ATEX certification for the VIBROPORT 600 vibration analyzer for hazardous areas. These developments highlight a trend toward multi-channel capabilities, enhanced user interfaces, and expanded safety certifications, all of which are critical for operators in demanding environments.
Macro Drivers and Industry Dynamics
The growth of the vibration detector market is propelled by a confluence of macro-level drivers and industry-specific dynamics. A primary catalyst is the adoption of predictive maintenance strategies, driven by Industry 4.0 initiatives. Analysis suggests that predictive maintenance can reduce unplanned downtime by up to 50 percent, making the investment in vibration monitoring systems a compelling proposition for operations managers seeking to maximize asset utilization.
Additionally, regulatory frameworks play a significant role in shaping market demand. Standards such as ISO 20816-2016 govern vibration measurement and evaluation for machinery, requiring limits for rotating equipment. Compliance with these standards often necessitates the deployment of reliable vibration detection solutions, thereby creating a steady baseline demand in regulated industries.
Cost structures also influence market dynamics. On the raw material front, silicon MEMS accelerometer prices stabilized at 15 to 25 USD per unit in Q4 2025 amid a steady semiconductor supply. This stability provides a predictable cost environment for sensor manufacturers and integrators, allowing for more accurate pricing strategies and margin planning. Conversely, labor costs present a different pressure point. Skilled maintenance technician wages rose 4.2 percent year-over-year in the manufacturing sector to an average of 32 USD per hour in 2025. As labor costs increase, the economic case for automation and sensor-based monitoring becomes even stronger, as organizations seek to mitigate reliance on scarce and expensive skilled labor.
Report Structure and Operational Content
The PW Consulting Worldwide Vibration Detector Market study is structured to provide actionable intelligence for a wide range of stakeholders, from strategic planners to procurement specialists. The report delves into granular details that transform high-level market data into operational insights. Readers will find comprehensive analysis of market sizing, growth rates, and segmentation trends, supported by a methodology that ensures accuracy and relevance.
Key components of the report include detailed historical reviews and forecast models that account for various market drivers and restraints. The segmentation analysis breaks down the market by type, application, and region, offering a nuanced view of where growth is concentrated and where competitive intensity is highest. The competitive landscape section profiles major players, examining their product portfolios, strategic moves, and market positioning. This includes an assessment of recent product launches, partnerships, and certifications that indicate shifts in competitive advantage.
Furthermore, the report integrates industry context, including raw material trends, regulatory updates, and macroeconomic factors that influence market behavior. By synthesizing these elements, the study provides a holistic view of the ecosystem. The objective is to empower users to make informed decisions regarding market entry, product development, investment allocation, and risk management. The depth of analysis ensures that stakeholders can benchmark their performance against industry averages and identify gaps in their current strategies.
Strategic Takeaways for 2026 Decision-Makers
As leaders evaluate their strategies for 2026 and beyond, several critical takeaways emerge from the market analysis. First, the convergence of sensor technology with data analytics platforms is accelerating. Companies that can offer integrated solutions combining high-quality vibration detection with actionable insights will gain a competitive edge. Second, the emphasis on safety and compliance, evidenced by certifications like ATEX, is becoming a differentiator in hazardous environments, opening new markets for compliant solutions. Third, the stabilization of component costs combined with rising labor expenses strengthens the ROI narrative for predictive maintenance investments, suggesting a widening adoption base beyond early adopters.
Moreover, the moderate market concentration implies that while large players dominate, there is strategic room for targeted acquisitions or partnerships to enhance capabilities. Understanding the specific strengths of competitors such as SKF, Emerson, and Siemens, alongside specialized players like Fluke and HBK, allows organizations to identify whitespace opportunities. For instance, regions or applications where coverage is fragmented may present avenues for growth for agile entrants or those with localized support networks.
The forecast period through 2032 offers a long-term horizon for planning. With the market expected to grow from 7650.0 Million USD in 2026 to 13080.0 Million USD by 2032, the cumulative opportunity is substantial. However, realizing this value requires a nuanced understanding of the segmentation splits and the dynamics driving growth in each segment. Decisions made today regarding technology selection, supplier relationships, and market focus will have lasting implications as the market matures.
Conclusion and Access to Full Intelligence
The worldwide vibration detector market represents a dynamic intersection of industrial necessity, technological innovation, and economic efficiency. For enterprises operating in 2026, the ability to navigate this market with precision is a strategic imperative. The insights provided in this preview highlight the breadth and depth of the trends shaping the industry, from the growth trajectory and segmentation nuances to the competitive maneuvers of key players and the macro drivers influencing adoption.
However, the complexity of the market demands a level of detail that goes beyond summary observations. To fully leverage the data and analysis presented in the PW Consulting Worldwide Vibration Detector Market study, stakeholders are encouraged to access the complete report. The full document contains the granular segmentation data, detailed company profiles, regional breakdowns, and comprehensive forecast models necessary to build robust strategies. By accessing the complete intelligence, decision-makers can ensure their plans are grounded in the most accurate and up-to-date market evidence, positioning their organizations for success in an evolving industrial landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Vibration Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Shaper Machine Market to Reach USD 1590.34 Million by 2032 with 3.5 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Intelligence for the 2026 Capital Expenditure Cycle: Inside the Worldwide Shaper Machine Market
As manufacturing leaders finalize their capital allocation plans for the 2026 fiscal year, the precision metalworking landscape demands a clear-eyed assessment of where value will be created and where volatility threatens margins. The globally distributed shaper machine sector is entering a phase of measured expansion, shaped by industrial automation mandates, shifting labor economics, and incremental mobility toward smart manufacturing infrastructure. Our latest Worldwide Shaper Machine Market research study provides the analytical architecture required to navigate this environment. By anchoring decision-making in rigorously modeled historical performance and forward-looking demand drivers, procurement leaders, plant managers, and corporate strategists can move beyond reactive purchasing cycles and into proactive capacity planning.
Worldwide Shaper Machine Market
The report is designed as a decision-support instrument rather than a static statistical compendium. It maps the trajectory of the global shaper machine market from a 2025 baseline valuation of 1,250.0 million USD through a forecast horizon extending to 2032, where projected revenue reaches 1,590.34 million USD. Over the historical window spanning 2020 to 2025, the market demonstrated steady consolidation, with 2023 recorded at 1,165.2 million USD and 2024 climbing to 1,207.5 million USD. The forward-looking period from 2026 to 2032 reflects a compound annual growth rate of 3.5 percent, moving through 1,293.75 million USD in 2026, 1,339.03 million USD in 2027, and 1,385.90 million USD in 2028, before continuing a consistent upward path to 1,434.40 million USD in 2029, 1,484.60 million USD in 2030, 1,536.56 million USD in 2031, and ultimately 1,590.34 million USD in 2032. These figures are not abstract benchmarks; they represent the revenue baseline against which regional investments, technology adoption timelines, and competitive positioning must be calibrated.
Worldwide Shaper Machine Market
Why a 3.5 Percent CAGR Still Demands Precision in Capital Planning
A moderate growth rate in a mature industrial equipment category can easily be misread as a low-stakes environment. In reality, a 3.5 percent CAGR across a 2026 to 2032 window places an extraordinary premium on timing, segmentation discipline, and total cost of ownership calculations. Market participants who treat shaper machine procurement as a commodity purchase will find themselves exposed to equipment mismatch, underutilized capacity, and shifting compliance burdens. Conversely, organizations that align their acquisition strategy with granular demand segmentation, regional dynamics, and technology roadmap integration will capture disproportionate operational leverage.
Worldwide Shaper Machine Market
The forecast trajectory does not suggest explosive disruption; it indicates methodical expansion driven by replacement cycles, incremental modernization, and selective capacity additions in high-precision production environments. For decision-makers in 2026, this profile means that strategic value lies not in chasing volume alone but in optimizing the fit between machine capability, production cadence, and end-market demand. The research frames this challenge by breaking the market into actionable structural dimensions while deliberately keeping the most sensitive analytical layers reserved for the full study. This approach ensures that corporate planning teams can validate their internal assumptions before committing to multi-year capital programs.
Report Architecture: Operational Coverage for Procurement, Engineering, and Strategy Teams
The study is structured to serve multiple internal stakeholders simultaneously. For procurement and supply chain leaders, the report delivers a historically grounded view of pricing trajectories, capacity utilization signals, and procurement timing considerations. For engineering and manufacturing operations, it maps application-driven demand patterns across key production verticals, helping teams align machine specifications with part complexity, tolerance requirements, and throughput expectations. For corporate strategy and investor relations teams, the report provides a competitive landscape synthesis, market concentration context, and an assessment of the operational and regulatory forces shaping the industry’s medium-term evolution.
Core Analytical Modules
The research framework is organized around several interlocking modules, each built to convert raw data into executable strategy:
- Market size and trajectory modeling that anchors executive discussions in a validated baseline and transparent forward path, enabling budgeting teams to test scenarios against established revenue envelopes.
- Structural segmentation analysis that examines how different machine configurations and end-use environments are shaping demand, providing the basis for fleet planning, replacement scheduling, and product-mix optimization.
- Regional demand and intensity mapping that identifies where industrial activity, capacity investment, and modernization efforts are concentrated, giving multinational operators a platform for localized sourcing and deployment decisions.
- Competitive positioning and benchmarking that profiles established manufacturers, evaluates their product strategies, and contextualizes recent public activity within broader market momentum.
- Industry dynamics and external pressure assessment that quantifies the impact of material cost movement, labor cost escalation, regulatory compliance, and smart-manufacturing adoption on purchasing decisions and operating economics.
What the Study Is Built to Answer
The report is designed around the questions that repeatedly stall capital planning cycles: where should capacity be added first, which machine architectures best match near-term production requirements, how should organizations weigh automation and connectivity features against upfront cost, and what external cost pressures must be incorporated into lifetime value calculations. By addressing these questions within a single framework, the research removes the need for cross-functional teams to reconcile fragmented spreadsheets and disconnected forecasts.
Competitive Landscape: Dominant Manufacturers and the Battle for Precision Share
Market leadership in the shaper machine sector is not defined solely by historical reputation; it is increasingly determined by the ability to marry precision engineering with automation, connectivity, and application-specific customization. The competitive field reflects a strong concentration of advanced manufacturing capability among Japanese and European producers, complemented by regionally focused specialists that serve distinct end-use requirements. The study profiles the principal market participants and evaluates how their product portfolios, development cadence, and strategic signaling are shaping industry direction.
Leading Japanese Manufacturers and Integrated Precision Systems
Yamazaki Mazak Corporation continues to anchor its reputation around CNC shaper machines and multi-function machining centers engineered for precision metal shaping in automotive and aerospace applications. The company’s recent product trajectory signals a push toward integrated multi-tasking platforms designed to reduce part handling and streamline complex shaping workflows. DMG Mori Co., Ltd. similarly emphasizes horizontal and vertical shaper configurations paired with advanced CNC controls, targeting high-volume industrial production environments where consistency and throughput are paramount. Okuma Corporation distinguishes its offering through gear shapers and universal shapers tailored to gear manufacturing and heavy-duty metalworking applications, reinforcing a positioning around specialized tooling demands rather than generalized machining. Mitsubishi Heavy Industries Machine Tool Co., Ltd. supplies hydraulic shapers and precision shaping machines with a particular emphasis on shipbuilding and energy equipment fabrication, where large-scale structural integrity and controlled material removal are decisive factors.
Regional Specialists and Heavy-Industry Capabilities
Beyond the Japanese leadership cluster, a set of European and Korean manufacturers contributes differentiated capabilities to the competitive mix. Doosan Machine Tools manufactures CNC shapers for mold and die production with a clear emphasis on high-speed shaping capabilities, aligning its portfolio to tooling-intensive sectors where cycle time compression translates directly into margin performance. WaldrichSiegen GmbH & Co. KG specializes in large-scale portal shapers for heavy industry components such as turbine housings, addressing applications where footprint, rigidity, and load-bearing capacity shape purchasing criteria more than unit economics alone. Gretel Maschinen GmbH provides mechanical and CNC shaper machines for woodworking and metal shaping in furniture and toolmaking, bridging material categories with equipment flexibility. Soraluce S.A. develops traveling column shapers for milling and shaping operations in aerospace and energy sectors, emphasizing adaptable work envelopes and multi-axis integration for demanding fabrication requirements.
Recent Corporate Activity as a Signal of Product Momentum
Publicly visible product launches and trade show participation in the recent period provide useful signals about where manufacturers believe demand is heading. In April 2025, DMG Mori showcased a new CNC horizontal shaper model at Hannover Messe with enhanced automation features, underscoring the industry’s broader push toward reduced operator intervention and smoother line integration. In September 2025, Yamazaki Mazak introduced an Integrex shaper-integrated multi-tasking machine for complex part shaping, reinforcing a trend toward consolidating multiple operation types into a single platform to simplify workflow and improve part consistency. In November 2025, Okuma Corporation exhibited GENOS series shapers with AI-driven tool monitoring at IMTS Americas, demonstrating how intelligence and condition monitoring are moving from optional add-ons to core engineering priorities.
These developments are not isolated exhibition highlights. Together, they indicate that manufacturers are investing in automation readiness, process visibility, and integrated part handling as differentiators rather than peripheral upgrades. For corporate buyers in 2026, the strategic implication is clear: the ability to evaluate equipment not only on shaping accuracy but also on integration complexity, data output, and maintenance predictability will increasingly determine which procurement decisions generate long-term value.
Market Dynamics and the Cost Environment Shaping 2026 Decisions
A market forecast can outline where revenue is likely to move, but operational decisions are made inside a live cost and compliance environment. The research incorporates several external pressures that directly affect purchasing timing, equipment selection, and operating budget assumptions, including raw material pricing, labor economics, regulatory expectations, and industrial modernization mandates.
Input Cost and Labor Pressures
Structural cost pressures remain a central theme for equipment planning. Steel prices for machine tool frames rose by 8 percent to 850 dollars per metric ton due to supply chain constraints, a movement that directly affects the cost floor for heavy fabrication and long-lead manufacturing equipment. At the same time, global skilled machinist wages increased 5.2 percent year-over-year amid automation shortages in manufacturing. These two forces create a dual margin challenge: equipment acquisition costs are reacting to input cost inflation, while operators are also facing higher labor costs in environments where skilled technician availability constrains throughput. For planning teams, this means the business case for shaper machine investment increasingly depends on how effectively the equipment can offset labor intensity, reduce rework, and improve repeatable precision without requiring disproportionate post-purchase customization.
Regulatory and Standards-Based Compliance
Regulatory and standards frameworks add another layer of planning discipline. The ISO 230-2:2014 standard governs the test code for machine tools including shapers, requiring annual compliance verification. In practical terms, this pushes compliance from a one-time vendor selection checkpoint into an ongoing operational requirement. Organizations that deploy shaper machines without incorporating compliance verification into their maintenance and quality programs may face hidden risk in audit exposure, process qualification, and customer acceptance cycles. The study treats standards alignment as a recurring operational asset, not a static purchase criterion, and frames it as part of the broader total cost of ownership discussion.
Industry 4.0 and Smart Equipment Adoption
A separate structural driver is reshaping procurement priorities: industry 4.0 mandates are driving 15 percent adoption of smart shapers with IoT sensors by 2026. This shift is not uniform across segments, but it is materially influencing how manufacturers evaluate connectivity, data collection, predictive maintenance potential, and process visibility. Smart-shaping capability is increasingly treated as an enabler of uptime stability and process traceability rather than a premium feature. Buyers are therefore expected to weigh sensor integration, data architecture compatibility, and support pathways as part of the core equipment evaluation rather than as after-the-fact retrofits.
Market Concentration and the Strategic Implications of Fragmented Leadership
The shaper machine market continues to display competitive intensity with meaningful but not overwhelming consolidation. Market concentration remains structured around a moderate share held by leading manufacturers, with the top three players collectively holding 28.5 percent of the market and the top five expanding that share to 35.2 percent. This concentration profile indicates that while established manufacturers command significant influence over product direction and technology cadence, a substantial portion of market activity remains distributed across additional producers serving regional and application-specific niches.
For corporate strategy teams, this structure has two practical implications. First, competitive benchmarking must extend beyond the largest brands; in several application contexts, specialized manufacturers deliver decisive advantages in work envelope, material compatibility, or speed-to-deployment. Second, procurement leverage is best exercised through portfolio thinking rather than single-vendor dependency. Organizations that build multi-source relationships, validate alternative suppliers against technical fit, and maintain flexibility in vendor selection are better positioned to manage price, availability, and technology choice across a multi-year deployment horizon. The full study provides deeper competitive mapping and share context so that buyers can assess where supplier concentration creates risk and where it creates negotiation advantage.
How the Report Supports 2026 Capital Allocation and Procurement Strategy
The Worldwide Shaper Machine Market research is built to convert market context into near-term action. Its value lies in helping organizations align external demand conditions with internal planning needs across several critical dimensions:
- Budget timing and fleet planning grounded in a transparent revenue trajectory and historical context that reduces uncertainty around capacity additions and replacement cycles.
- Application-aligned equipment selection that connects demand distribution across end-use environments to machine specification decisions, helping teams avoid over-engineering or under-specifying for actual production requirements.
- Competitive and supplier evaluation that provides a structured way to assess manufacturers by product direction, application fit, and recent development signaling without relying on marketing narratives alone.
- Operating cost modeling inputs that incorporate input cost inflation, labor escalation, and smart-equipment adoption as variables in decision-making rather than treating them as background noise.
- Compliance and lifecycle management that frames standards adherence and maintenance predictability as value drivers tied to uptime and qualification risk.
The report does not replace internal engineering judgment or plant-level operational knowledge. Instead, it supplies the external market architecture that makes those internal decisions more defensible. By situating procurement, engineering, and strategy teams inside a shared set of market realities, the study shortens the distance between strategic intent and operational execution.
What the Full Study Reveals and Why the Complete Intelligence Matters
This overview is deliberately constructed to demonstrate analytical rigor while preserving the most decision-sensitive layers for the complete publication. The macro trajectory, structural segmentation, competitive profiles, and industry pressure points summarized here establish the context and credibility of the research. The full study extends far beyond that framework. It delivers the detailed segmentation layers, regional intensity breakdowns, application-level demand mapping, competitive share context, and scenario-ready planning inputs that corporate teams require when they move from strategic direction to procurement authorization.
For organizations preparing capital plans for 2026, the difference between a high-level market narrative and a fully integrated market research package is the difference between an informed discussion and a decision-ready brief. The complete report transforms headline figures into actionable segmentation, places competitive dynamics within operational reach, and equips teams to evaluate smart-equipment adoption, compliance readiness, and cost volatility as part of a single planning model.
Conclusion: Positioning for Measured Growth with Strategic Discipline
The worldwide shaper machine market is unfolding within a defined growth path, shaped by modernization mandates, cost pressures, and a competitive landscape that rewards precision, integration, and application-aware equipment selection. A 3.5 percent compound annual growth rate over the 2026 to 2032 period may appear moderate, but in a capital-intensive manufacturing environment it rewards those who plan with discipline and penalizes those who rely on assumptions. The research supply chain of data, segmentation, competitive intelligence, and industry dynamics assembled in this study is designed to support exactly that discipline.
For decision-makers evaluating where to allocate resources, which machine types to prioritize, and how to structure supplier relationships in 2026, the full version of the Worldwide Shaper Machine Market report provides the depth required to turn market awareness into procurement confidence. The complete intelligence framework remains available for teams that need to move from strategic context to specific planning actions, and it is that completeness that makes the study a practical asset for the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Shaper Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide Snack Ball Equipment Market to Hit USD 655.41 Million by 2032 Delivering 6.38 CAGR
By PW Consulting, 2026-09-01
Unlocking Growth in the Global Snack Ball Equipment Market: A 2026 Strategic Outlook
The global snack ball equipment market stands at a pivotal inflection point. Between 2020 and 2025, the sector expanded from 310.5 million USD to 425.11 million USD, reflecting a compound annual growth rate of 6.38 percent as forecasters project revenues to reach 655.41 million USD by 2032. For manufacturers, equipment suppliers, and strategic investors navigating 2026, these figures are not merely historical markers—they are the foundation for capital allocation, capacity planning, and competitive positioning. Our newly released Worldwide Snack Ball Equipment Market research translates this trajectory into an actionable intelligence framework, designed to help leadership teams make informed decisions in an environment characterized by rapid automation adoption, evolving consumer health preferences, and intensifying global competition.
Worldwide Snack Ball Equipment Market
Why This Report Matters for 2026 Decision-Making
The 6.38 percent CAGR observed across the forecast horizon through 2032 masks a more complex operational reality. While headline growth signals expanding demand, the true strategic value lies in understanding where that growth concentrates, how it is distributed across machine architectures, and which operational variables will determine margin capture. The market’s trajectory from 451.05 million USD in 2026 to 584.62 million USD by 2030 reflects sustained investment, but the path is uneven. Regional demand patterns, application specialization, and machine-type preferences each create distinct risk-reward profiles that require granular analysis rather than top-line extrapolation.
Worldwide Snack Ball Equipment Market
Our research equips decision-makers with three critical lenses. First, it maps the structural shifts driving equipment purchasing behavior—specifically the transition from semi-automated lines to fully integrated, sensor-driven production systems capable of handling diverse ingredient matrices. Second, it evaluates how regulatory compliance, material specifications, and food safety standards are reshaping procurement criteria across export-oriented and domestic markets. Third, it assesses competitive positioning by analyzing product portfolios, throughput capabilities, and recent innovation cycles among key market participants. Each lens is designed to translate market data into operational clarity, enabling procurement teams to align equipment selection with production targets, R&D teams to anticipate formulation-driven machinery requirements, and executive leadership to evaluate partnership or acquisition opportunities with precision.
Worldwide Snack Ball Equipment Market
Importantly, the report does not stop at macro-level sizing. It connects revenue trajectories to functional deployment scenarios, illustrating how capacity utilization, changeover flexibility, and automation depth interact to influence total cost of ownership over a five-to-seven-year equipment lifecycle. This multi-layered approach ensures that the intelligence delivered is immediately applicable to budgeting, forecasting, and strategic roadmapping in 2026 and beyond.
Market Architecture: Size, Growth, and Structural Drivers
The revenue arc from 387.84 million USD in 2023 to 425.11 million USD in 2025 demonstrates accelerating momentum, with the forecast period extending that trajectory through 2032. This expansion is not uniform; it is propelled by converging macro trends, operational economics, and regulatory frameworks that together redefine what manufacturers demand from snack ball forming equipment.
Several structural drivers underpin this growth. The rising preference for protein-rich, nutrient-dense, and clean-label snack formats has increased throughput requirements and ingredient-handling complexity. Production lines must now accommodate variable dough consistencies, multiple filling types, and rapid product changeovers without sacrificing yield or hygiene standards. Simultaneously, labor cost pressures across manufacturing hubs have accelerated adoption of integrated automation, where dividing, rounding, forming, and coating processes are consolidated into continuous operations. This consolidation reduces manual intervention, improves consistency, and enables output ranges spanning from 60 pieces per minute in smaller specialized lines to 4,000 pieces per hour in high-volume configurations. Such throughput diversity means that equipment selection is increasingly a function of product portfolio strategy rather than a one-size-fits-all capital purchase.
Compliance and material standards further shape market architecture. Food-grade 304 stainless steel remains the baseline for contact surfaces, while PTFE and Teflon coatings on rollers and molds have become standard expectations for non-stick performance and cleaning efficiency at scale. Export-oriented manufacturers must also navigate certification requirements, including CE markings for European and other regulated markets, which influence supplier eligibility and lead-time planning. These operational specifications are not peripheral concerns; they directly affect equipment compatibility with production goals, maintenance cycles, and cross-border market access.
The market’s consolidated structure—with top-three participants holding a combined share and top-five entities commanding a broader aggregate—indicates that scale, technical differentiation, and service ecosystems matter significantly. Yet consolidation also leaves room for specialized players who excel in particular applications or machine architectures. Understanding where competitive intensity is highest, and where whitespace remains, is essential for both incumbents defending share and new entrants evaluating entry points.
Segmentation Intelligence: Regions, Machine Types, and Applications
Effective 2026 planning requires moving beyond aggregate sizing to understand how demand distributes across segments. The market’s segmentation structure reveals distinct performance characteristics across geographies, machine categories, and end-use applications, each carrying different growth velocities, margin implications, and capital intensity profiles.
- Regional demand patterns reflect varying levels of consumption maturity, production localization, and export orientation. Equipment purchases are influenced by local formulation preferences, labor economics, and compliance environments, meaning that regional strategies must be calibrated to specific operational realities rather than generalized global trends.
- Machine-type segmentation distinguishes between encrusting and forming systems, automatic ball rolling platforms, and coating and polishing units. Each category serves different production objectives, with encrusting and forming equipment capturing significant share due to its versatility in handling filled and unfilled snack balls, while rolling and coating systems address specialized finishing requirements. Throughput capabilities, mold-change flexibility, and integration potential with upstream and downstream units determine where each machine type delivers the strongest return on investment.
- Application segmentation spans protein and energy formats, confectionery and chocolate-based balls, bakery and pastry products, and meat or savory variants. Application mix is a critical determinant of equipment specification, as ingredient rheology, moisture content, and finishing requirements vary substantially. Manufacturers pursuing multi-application lines must balance line flexibility against throughput efficiency, while single-application specialists can optimize for speed, consistency, and changeover simplicity.
These segmentation dynamics are interrelated. A manufacturer’s application focus often dictates regional market entry strategy, which in turn influences machine-type selection and compliance requirements. The report provides a structured mapping of these relationships, enabling teams to evaluate how segment-level opportunities align with internal capabilities and market positioning. Rather than presenting static share breakdowns, the analysis emphasizes operational fit—how segment characteristics translate into equipment specifications, production economics, and competitive differentiation. This approach ensures that segmentation intelligence serves as a practical decision tool rather than a descriptive snapshot.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is shaped by a diverse set of manufacturers whose product portfolios, throughput capabilities, and innovation trajectories define the market’s evolution. Several companies exemplify the strategic directions that are redefining equipment standards and customer expectations.
Shanghai Papa Industrial Co., LTD (PAPA Machinery), headquartered in Shanghai, China, has established a focused presence in automatic encrusting and forming machines tailored for energy balls, protein balls, date balls, and various filled or unfilled snack balls. Its equipment portfolio supports capacities up to 100 pieces per minute, with adjustable weight, size, and ratio controls, integrated powder coating capabilities, and PLC-based automation for high-density, round products such as rum balls, bliss balls, and coconut-coated variants. Construction with 304 stainless steel and scalability from small to industrial volumes position the company as a flexible supplier for producers seeking customizable forming solutions. Recent promotional activity has highlighted automatic energy and protein ball making machines designed for rum tamarind and multi-variant snack formats, signaling an emphasis on product diversity and formulation adaptability.
ANKO Food Machine Co., Ltd., based in Taiwan, offers a different operational paradigm through high-capacity automatic encrusting and forming systems such as the SD-97W, engineered for pistachio balls, energy balls, protein balls, and healthy snack formats. With output reaching 4,000 pieces per hour or 90 kilograms per hour, the platform incorporates IoT monitoring, adjustable filling and thickness controls, and quick mold change functionality to accommodate varied fillings and doughs including nuts, oats, and proteins. This combination of speed, digital oversight, and changeover efficiency reflects a strategy centered on high-volume producers that require both throughput and operational visibility.
Beikn Food Machinery, operating from Kunshan, China, has pursued an integrated line strategy, combining dough dividers, rounders, and powder coating machines into cohesive production systems. Its lines produce 10 to 60 balls per minute across a range of dough types, utilizing food-grade 304 stainless steel construction, consistency-focused sensors, and CE certification to support export readiness. Recent product launches include an advanced integrated line for 10 to 60 balls per minute and a high-speed protein ball manufacturing machine capable of producing thousands of protein balls per hour, underscoring a dual focus on modular flexibility and high-throughput specialization.
Hanyuan Machinery, based in Dongtai City, Jiangsu Province, China, concentrates on servo-controlled molding solutions for nuts and puffed rice snack balls, with equipment such as the HY-ML260 designed for large-scale production at 200 to 260 kilograms per hour. The platform features non-stick PTFE molds, soft pressing mechanisms, and multi-shape capability through mold changes, enabling efficient handling of black sesame, nuts, and puffed rice formats. This design philosophy emphasizes product variety and gentle material handling, which is particularly relevant for delicate or high-value ingredient matrices.
Additional participants contribute to a diversified supply ecosystem. AC Horn Manufacturing, located in Dallas, Texas, USA, produces the Model M563 automatic popcorn ball forming machine, a PLC-controlled, servo-driven system capable of up to 72 sugar popcorn balls or 45 caramel balls per minute, situating snack ball equipment within broader nut and popcorn processing workflows. Shanghai Seny Machinery Co., Ltd. supplies energy and protein ball production lines, including the SY-800 series, for automated forming of protein balls, date balls, and energy balls suited to small and medium factories. Shanghai Yucheng Machinery Co., Ltd. offers peanut butter protein ball making machines and encrusting lines for high-volume automated production of protein and energy snack balls. Together, these companies illustrate a market in which equipment positioning spans capacity tiers, application focus, regional footprint, and integration philosophy.
Strategic positioning in this landscape is not determined by capacity alone. Service networks, documentation and compliance support, mold and tooling ecosystems, and the ability to accommodate rapid formulation changes are increasingly decisive factors in procurement decisions. The report evaluates these dimensions systematically, identifying where incumbents have built defensible advantages and where emerging capabilities may alter competitive dynamics over the forecast period.
Operational and Regulatory Dynamics Shaping Procurement
Equipment purchasing in this market is increasingly governed by a combination of operational efficiency targets, food safety expectations, and export compliance requirements. These dynamics intersect with broader industry trends, shaping not only which machines are selected but also how they are specified, validated, and integrated into production environments.
Material and hygiene specifications have become baseline procurement criteria. Food-grade 304 stainless steel for contact parts and PTFE or Teflon coatings on rollers and molds are now standard expectations for ensuring non-stick performance and cleaning efficiency in high-volume production. These specifications influence wear characteristics, maintenance frequency, and sanitation workflows, all of which feed into total cost of ownership calculations. Manufacturers evaluating equipment must therefore assess not only initial capital cost but also the downstream implications for downtime, cleaning cycles, and ingredient-handling compatibility.
Regulatory alignment is equally critical, particularly for companies targeting international markets. Equipment must comply with global food safety standards, and CE certification has emerged as a practical requirement for export eligibility in several regions. Compliance documentation, validation support, and the ability to adapt configurations to regional regulatory frameworks are now part of the supplier evaluation process. Buyers are increasingly recognizing that certification readiness affects not only market access but also procurement lead times and integration complexity.
Macro demand trends continue to shape equipment capability expectations. Rising consumer interest in healthy, protein-rich, and nutrient-dense snacks is driving adoption of automated encrusting and forming machines capable of handling diverse ingredient profiles including nuts, oats, whey protein, and dried fruits. This shift increases the importance of line flexibility, ingredient-tolerant forming mechanisms, and coating systems that preserve product integrity across varied formulations. At the same time, automation is reducing manual labor requirements by consolidating dividing, rounding, forming, and coating into continuous operations, with capacities ranging from 60 pieces per minute to 4,000 pieces per hour. These throughput ranges reflect a market that serves both specialized, lower-volume producers and large-scale manufacturers, each with distinct automation thresholds and operational priorities.
Recent product developments illustrate how manufacturers are responding to these dynamics. Integrated line launches, high-speed protein ball machines, and promotional expansions into multi-variant snack formats all point to a competitive environment where differentiation is increasingly tied to integration depth, throughput scalability, and application versatility. Procurement teams in 2026 must therefore evaluate suppliers not only on current specifications but also on roadmap alignment, upgrade paths, and the ability to support future product extensions.
What the Report Delivers: From Data to Execution
The Worldwide Snack Ball Equipment Market research is structured to convert complex market information into decision-ready intelligence. It combines macro-level sizing and growth forecasting with segment-specific analysis, competitive profiling, and operational context, creating a single reference point for strategic planning. The report’s architecture is designed to support multiple use cases, from capital budgeting and supplier evaluation to market entry analysis and product portfolio alignment.
At the analytical core, the report provides detailed market sizing across the historical and forecast periods, establishing a credible baseline for scenario modeling and capacity planning. These figures are contextualized within segmentation frameworks that map regional, machine-type, and application dynamics, enabling readers to identify where growth opportunities are most concentrated and how segment characteristics influence equipment requirements. Rather than presenting segmentation as isolated share figures, the analysis connects each segment to operational implications, including throughput expectations, changeover needs, and compliance considerations.
The competitive assessment section profiles key companies with attention to product capabilities, throughput ranges, construction standards, and recent development activity. This profiling is complemented by an evaluation of competitive structure, including concentration indicators that help clarify the balance between scale players and specialized suppliers. By examining recent product launches, promotional initiatives, and technology integrations, the report highlights the innovation directions that are shaping procurement expectations and differentiating supplier offerings.
Operational and regulatory context is woven throughout, ensuring that market analysis is grounded in practical execution factors. Material specifications, certification requirements, automation economics, and application-driven equipment needs are evaluated in relation to procurement strategy, allowing readers to align market intelligence with internal operational constraints and goals. The report also addresses how macro trends translate into equipment adoption patterns, providing a forward-looking perspective on where demand is likely to intensify and what capabilities will become standard expectations.
Crucially, the report is designed to preserve analytical depth while guiding readers toward comprehensive engagement. Core segmentation breakdowns, detailed regional and application revenue distributions, and granular competitive metrics are developed to support precise strategic action, but their full value is realized through the complete research package. This structure ensures that organizational teams can assess the breadth and rigor of the analysis, while accessing the detailed data necessary for implementation-specific decisions.
Conclusion: Positioning for the Next Growth Cycle
The snack ball equipment market’s trajectory—from 425.11 million USD in 2025 to a projected 655.41 million USD by 2032, with a sustained 6.38 percent CAGR across the forecast period—signals a structural expansion that will reward organizations capable of aligning equipment strategy with application demand, automation economics, and compliance readiness. In 2026, the winners will be those who treat equipment selection as a strategic lever rather than a tactical purchase, integrating throughput requirements, ingredient handling, changeover flexibility, and supplier capability into a cohesive capital plan.
Our Worldwide Snack Ball Equipment Market research provides the analytical foundation for that planning. It translates macro growth into segment-level clarity, situates competitive activity within operational realities, and equips decision-makers with the context needed to evaluate opportunities with precision. The full report extends far beyond the overview presented here, offering the detailed segmentation data, competitive metrics, and regional-application intelligence necessary to convert insight into execution. For teams preparing for the next growth cycle, the complete research package is the essential next step.
For detailed analysis of this topic, please visit the official page: Worldwide Snack Ball Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Assembly Line Robot Market to Hit 19770 Million by 2032 at 9.85 Percent CAGR Driven by Asia Pacific
By PW Consulting, 2026-09-01
Strategic Automation: Navigating the Global Assembly Line Robot Market in 2026
The manufacturing landscape is undergoing a tectonic shift, driven by the dual forces of labor economics and technological maturity. For enterprise leaders, capital allocators, and operational strategists, the question is no longer whether to automate, but how to navigate a market that is evolving at an unprecedented velocity. PW Consulting's latest comprehensive study, the Worldwide Assembly Line Robot Market report, offers a critical lens into this transformation. This article serves as a strategic primer, outlining the macro-environment, competitive structures, and operational dynamics defined within our full intelligence brief, designed to empower decision-making throughout the 2026 fiscal year and beyond.
Worldwide Assembly Line Robot Market
The Macro Trajectory: A Market in Acceleration
Understanding the scale and speed of market expansion is the foundational step for any robust strategic plan. Our analysis tracks the revenue trajectory from historical baselines through to the long-term forecast horizon. The data indicates a consistent upward trend in global spending on assembly line robotics. Starting from a base of USD 6,450 Million in 2020, the market has demonstrated resilient growth through the pandemic recovery period, reaching USD 10,250 Million in 2025. This historical performance sets the stage for a projected forecast period spanning 2026 to 2032.
Worldwide Assembly Line Robot Market
Looking forward, the market is expected to breach the USD 11,468 Million threshold in 2026, accelerating towards a final forecast valuation of USD 19,770 Million by 2032. This expansion is underpinned by a robust Compound Annual Growth Rate (CAGR) of 9.85%. For CFOs and strategy heads, this figure signals more than just market health; it indicates a phase of maturation where investment returns are becoming increasingly predictable, yet competition formarket share is intensifying. The transition from the 2025 historical year into the 2026 forecast year represents a pivotal inflection point where adoption rates are expected to widen beyond traditional heavy industry into more diverse manufacturing sectors.
Worldwide Assembly Line Robot Market
Dynamic Forces Shaping Deployment Strategies
Market size alone does not dictate strategy. The underlying drivers of demand are shifting, requiring a nuanced understanding of external pressures. According to recent industry intelligence, labor shortages and rising labor costs remain the primary macro driver for the adoption of assembly line robots. Manufacturers are increasingly turning to automation not merely as a cost-cutting measure, but as a necessity to maintain production capacity in the face of workforce constraints. This dynamic is particularly acute in developed economies where demographic shifts are reducing the availability of skilled manual labor.
Furthermore, the geopolitical and economic context is adding a new layer of complexity. Reshoring initiatives combined with persistent labor shortages are accelerating automation investments. Recent outlook reports suggest that 95% of U.S. industrial organizations are planning new automation implementations over the next three years. This surge in domestic investment alters the regional flow of capital and technology deployment. Simultaneously, regulatory frameworks continue to standardize the industry. ISO standards for industrial robot safety and collaborative operation continue to guide deployment worldwide, ensuring that speed of adoption does not come at the expense of workplace safety. Compliance with these standards is now a baseline requirement for market entry, influencing procurement cycles and integration timelines.
On the supply side, the component market is experiencing its own evolution. Key components in industrial robots, including sensors and gearboxes, have experienced average selling price changes influenced by competition and scale. While volatility exists, the overall component market for industrial robots is forecasted to grow. This suggests that hardware costs may stabilize or decrease relative to value added, improving the total cost of ownership (TCO) calculations for potential buyers. However, supply chain resilience remains a critical consideration for long-term planning.
Segmentation Intelligence: Where Value is Concentrated
Our research dissects the market into critical dimensions—Region, Type, and Application—to reveal where growth is most potent. While specific percentage splits are detailed in the full report, the relative weight of these segments offers immediate strategic direction.
Geographic Distribution
The market is not uniformly distributed. Our data captures the revenue contribution across Asia Pacific, Europe, North America, and the Rest of World. The Asia Pacific region continues to represent a substantial portion of global revenue, reflecting the density of manufacturing infrastructure and the pace of industrial modernization in key economies. Europe and North America follow, driven by high-value manufacturing and the aforementioned reshoring trends. Understanding the specific revenue contributions of each region is vital for companies deciding where to allocate sales resources or manufacturing capacity. The full report provides the precise valuation for each geographic segment, allowing for granular market share analysis.
Technology Types
The hardware landscape is diverse, catering to different precision and flexibility requirements. The market includes Articulated Robots, SCARA Robots, Collaborative Robots, and Cartesian and Parallel Robots. Articulated robots maintain a strong presence due to their versatility in high-speed, high-precision applications. SCARA robots remain critical for high-speed assembly of small components. However, the Collaborative Robots segment is witnessing significant interest due to their ability to be deployed without extensive safety fencing, enabling flexible automation for small and medium batch production. The interplay between these types defines the technological roadmap for manufacturers. Our analysis covers the revenue valuation for each robot type, highlighting which technologies are gaining traction in specific production environments.
Application Verticals
Demand is segmented across Automotive Manufacturing, Electrical and Electronics, Metal and Machinery, Food and Beverage, and Pharmaceuticals and Others. The Automotive sector remains a cornerstone, particularly for body-in-white and component assembly. The Electrical and Electronics sector drives demand for precision handling and cleanroom operations. Meanwhile, sectors like Food and Beverage and Pharmaceuticals are increasingly adopting robotics to meet hygiene standards and variable production demands. The distribution of revenue across these applications indicates where the immediate revenue opportunities lie for robotics vendors and where integration challenges are most prevalent.
Competitive Landscape: Incumbents and Innovation
The assembly line robot market is characterized by a high concentration of top players, yet it remains dynamic with continuous innovation. Our report analyzes the market concentration, noting a CR3 of 42.5% and a CR5 of 61.2%. This indicates that while a few major players dominate the landscape, a significant portion of the market is contested by mid-tier specialists and regional leaders.
Key Market Participants
The competitive arena features a mix of global conglomerates and specialized manufacturers, predominantly headquartered in Japan, Europe, and the United States.
- FANUC Corporation (Yamanashi, Japan): As the world's largest manufacturer of industrial robots, FANUC offers a comprehensive range of articulated and SCARA robots optimized for high-speed, high-precision assembly line applications in automotive, electronics, and general manufacturing.
- ABB Ltd. (Zurich, Switzerland): ABB provides IRB series industrial robots and collaborative robots specifically engineered for flexible assembly lines, with strong integration in automotive and electronics sectors.
- Yaskawa Electric Corporation (Kitakyushu, Japan): Through its Motoman brand, Yaskawa offers high-performance robots for precision assembly tasks, including small-part handling and high-speed assembly in manufacturing lines.
- KUKA AG (Augsburg, Germany): KUKA specializes in robotic systems for assembly lines, particularly in automotive body-in-white and component assembly, featuring advanced KR series robots.
- Universal Robots (Odense, Denmark): Owned by Teradyne, Universal Robots leads in collaborative robots designed for easy deployment on existing assembly lines, enabling flexible automation for small and medium batch production.
Beyond these top-tier entities, the market includes other significant contributors such as Kawasaki Heavy Industries, Mitsubishi Electric Corporation, Denso Wave Incorporated, Epson America Inc., Comau SpA, OMRON Corporation, Yamaha Motor Co., Ltd., DAIHEN Corporation, Hirata Corporation, and Panasonic Corporation. Each brings specific strengths, from welding and material handling to cleanroom operations and vision-integrated systems. The full report provides detailed profiling of these companies, including their strategic positioning and recent product developments.
Recent Strategic Moves
The pace of innovation is visible through recent corporate activities and industry events. In early 2026, multiple robotics manufacturers unveiled latest automation and robotics innovations for manufacturing assembly at CES 2026. These showcases highlighted the trend towards smarter, more connected systems. Later in the year, participation and showcasing of assembly automation and industrial robot solutions occurred at Assembly & Automation Technology 2026 in Bangkok, involving companies including FANUC, ABB, and Yaskawa. Additionally, Yaskawa Motoman presented on factory automation and robot applications at the COSI Science Festival robotics event. These activities underscore the industry's focus on visibility, education, and demonstrating practical application capabilities to a broader audience.
Operational Implications for 2026 Decision Makers
For enterprises operating in or investing within this sector, the implications of these findings are profound. The convergence of high market growth, specific regional strengths, and a concentrated competitive field requires a tailored approach to strategy.
Capital Allocation and ROI
With a forecasted CAGR of 9.85%, the market offers attractive growth potential. However, capital allocation must be justified against specific operational needs. The choice between collaborative and traditional industrial robots depends heavily on the production volume and flexibility requirements. Companies must evaluate the total cost of ownership, considering not just the hardware cost but also integration, maintenance, and safety compliance costs. The data on component pricing trends suggests that timing purchases alongside market cycles could yield cost advantages.
Risk Management
Reliance on a concentrated supply base introduces supply chain risk. With the top five companies controlling over 60% of the market, procurement strategies should consider multi-sourcing where possible or locking in long-term service agreements to ensure continuity. Additionally, regulatory compliance regarding safety standards is non-negotiable. Failure to adhere to ISO standards can result in operational delays and liability issues. Strategic planning must include compliance audits and workforce training programs to manage the human-robot interface safely.
Market Entry and Expansion
For new entrants or companies looking to expand market share, the regional data provides a roadmap. While Asia Pacific offers scale, North America and Europe present opportunities driven by reshoring and high-value manufacturing demands. Understanding the specific application verticals that are growing in each region is key. For instance, electronics assembly may offer different opportunities in Asia compared to automotive assembly in Europe. The detailed segmentation data in the full report allows for precise market sizing to support business cases for regional expansion.
Conclusion: The Value of Comprehensive Intelligence
The Worldwide Assembly Line Robot Market is at a critical juncture. The combination of macroeconomic drivers, technological diversification, and intense competition creates a complex environment for strategic planning. High-level figures provide direction, but they do not replace the need for granular intelligence. Decisions regarding vendor selection, investment timing, and regional focus require access to detailed revenue breakdowns, competitive profiling, and segment-specific growth rates.
PW Consulting's full market research report goes beyond the summaries provided here. It offers the specific valuations for each region, type, and application segment that were referenced but withheld in this overview. It provides deep dives into the financial health and strategic moves of the key companies listed, along with an analysis of the regulatory and component supply environments that will shape the next seven years of the forecast period.
In a market moving towards a USD 19,770 Million future by 2032, the cost of incomplete information is high. To secure a competitive advantage and ensure robust strategic alignment for 2026 and beyond, stakeholders are encouraged to access the complete intelligence package. The full report is available for download at the source webpage, providing the necessary depth to turn market insight into actionable business strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Assembly Line Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Global Cosmetic Synthetic Materials Market to Reach $26.17 Billion by 2032 Growing at 5.12% CAGR
By PW Consulting, 2026-09-01
Strategic Intelligence for the Worldwide Cosmetic Synthetic Materials Market: Navigating Growth, Regulation, and Competitive Pressures Through 2032
The global cosmetic synthetic materials market stands at a critical inflection point. Over the past five years, the sector has demonstrated remarkable resilience, expanding from a base of 14,800.0 million USD in 2020 to 18,450.5 million USD in 2025. This trajectory reflects not only sustained demand across personal care categories but also the industry's accelerating pivot toward engineered, performance-driven ingredients. As we advance into the 2026-2032 forecast period, market momentum is expected to accelerate at a compound annual growth rate of 5.12 percent, ultimately reaching 26,170.11 million USD by 2032. For executives, formulation scientists, procurement leaders, and strategic planners, this is more than a growth story. It is a complex landscape shaped by regulatory evolution, feedstock volatility, technological innovation, and an intensely concentrated competitive field.
Worldwide Cosmetic Synthetic Materials Market
PW Consulting's newly released Worldwide Cosmetic Synthetic Materials Market research study delivers the analytical rigor, granular segmentation, and forward-looking intelligence that organizations require to make confident decisions in 2026 and beyond. This article serves as a strategic preview of the report's scope, methodology, and actionable insights. It highlights the macro forces reshaping the industry and demonstrates why a comprehensive, data-backed view of this market has become indispensable for competitive positioning.
Worldwide Cosmetic Synthetic Materials Market
The Macro Trajectory: Sustained Expansion Against a Complex Backdrop
Examining the historical performance from 2020 through 2025 reveals a market that has weathered supply chain disruptions, inflationary pressure, and shifting consumer preferences without losing its structural growth orientation. After reaching 16,249.78 million USD in 2021, the market experienced a brief moderation to 15,879.13 million USD in 2022 before recovering steadily. By 2023, revenues climbed to 16,985.66 million USD, followed by 17,176.84 million USD in 2024. The 2025 figure of 18,450.5 million USD underscores renewed confidence in synthetic materials as foundational enablers of formulation performance, sensory appeal, and product stability.
Worldwide Cosmetic Synthetic Materials Market
The forecast period from 2026 through 2032 projects a disciplined but meaningful acceleration. Beginning at 18,464.48 million USD in 2026, the market is expected to progress through 19,597.75 million USD in 2027, 20,930.93 million USD in 2028, and 23,142.25 million USD in 2029. The growth curve continues toward 23,517.83 million USD in 2030, 24,318.67 million USD in 2031, and ultimately 26,170.11 million USD in 2032. This trajectory reflects several reinforcing drivers: rising demand for high-performance emollients, rheology modifiers, and conditioning polymers; the expansion of skincare and color cosmetics categories in emerging and developed markets alike; and the ongoing substitution of natural or less predictable ingredients with engineered synthetics that offer batch consistency, functional reliability, and tailored sensory profiles.
Importantly, growth is not uniformly distributed across the value chain. The interplay between product type, application, and regional demand creates pronounced pockets of opportunity and risk. Understanding where value is concentrating, which segments are accelerating, and how regulatory and cost pressures are reshaping margins requires the kind of structured decomposition that only a full-market intelligence study can provide.
Regulatory Realignment and Raw Material Dynamics: The 2026 Decision Environment
No strategic assessment of the cosmetic synthetic materials market in 2026 can ignore the regulatory environment. Compliance has evolved from a checklist exercise to a core determinant of ingredient selection, formulation architecture, and market access. Several developments are already reshaping procurement and R&D priorities.
In Europe, the EU REACH restriction on synthetic polymer microparticles (SPM) now mandates annual emission reporting by manufacturers and downstream users. The first reporting cycle covers 2025 data and is due by May 31, 2026. This requirement introduces new administrative burdens and encourages formulators to evaluate particle size distributions, release pathways, and alternatives where feasible. Simultaneously, the EU Omnibus VIII Regulation prohibits additional CMR substances in cosmetics, with a compliance deadline of May 1, 2026, affecting certain synthetic ingredients and forcing suppliers and brands to reassess ingredient portfolios well ahead of the cutoff.
On the other side of the Atlantic, a growing number of US states have moved to prohibit intentionally added PFAS in cosmetic products. California, Colorado, Maryland, Minnesota, Washington, Maine, and Vermont have enacted restrictions spanning the 2025-2026 window. For synthetic material suppliers and cosmetic manufacturers, the implications are twofold: sourcing transparency has become a commercial prerequisite, and formulation teams must verify that emulsifiers, surfactants, and processing aids do not inadvertently trigger noncompliance.
Raw material economics add another layer of complexity. Propylene glycol prices in Europe reached 1.44 USD/kg in March 2026, supported by balanced supply from propylene oxide hydration and steady demand from the cosmetics sector. While this suggests a stable near-term environment for specific intermediates, the broader feedstock picture remains sensitive. Ethylene and propylene, which serve as primary feedstocks for polyethylene, polypropylene, and other synthetic cosmetic polymers, continue to reflect crude oil and natural gas price volatility into 2026. Margin planning, inventory strategy, and contract structuring must therefore account for cyclical fluctuations rather than assuming flat input costs.
These dynamics are not isolated constraints; they are strategic levers. Companies that integrate regulatory intelligence into ingredient selection, build supply chain visibility around feedstock exposure, and align product development with compliance timelines will secure a distinct advantage. The full report maps these forces against segment-level implications, enabling readers to translate regulatory and cost signals into concrete sourcing and formulation choices.
Competitive Intensity and the Concentration Landscape
Market concentration provides an essential lens for assessing bargaining power, innovation velocity, and barriers to entry. The cosmetic synthetic materials market is moderately concentrated, with the top three players accounting for approximately 32.4 percent of total revenue and the top five capturing around 46.8 percent. This structure indicates that while large, globally integrated suppliers wield meaningful influence, there remains substantial room for specialized players, regional specialists, and formulation-focused innovators to compete on performance, sustainability narratives, and application-specific expertise.
Several leading organizations define the competitive frontier. BASF SE, headquartered in Ludwigshafen, Germany, stands as a global leader supplying synthetic polymers, surfactants, emollients, UV filters, and conditioning agents tailored for cosmetic and personal care formulations. The Dow Chemical Company, based in Midland, Michigan, USA, is a major provider of silicones, including DOWSIL cosmetic powders, alongside polymers, surfactants, and bio-based and synthetic ingredients serving skin care, hair care, sun care, and color cosmetics. Evonik Industries AG, from Essen, Germany, supplies silicones, surfactants such as rhamnolipids, polymers, and specialty actives designed for cosmetic emulsions, conditioning, and sensory performance.
Croda International Plc, located in Snaith, United Kingdom, offers synthetic and specialty esters, silicone derivatives, bio-based polymers, and functional ingredients with a clear focus on skin feel and formulation stability. Lubrizol Corporation, based in Wickliffe, Ohio, USA, provides rheology modifiers, conditioning polymers, emulsifiers, and synthetic ingredients that shape personal care textures and performance. Ashland Global Holdings Inc., from Wilmington, Delaware, USA, specializes in fixative and styling polymers, rheology modifiers, bioadhesives, and conditioning polymers for hair care and skincare cosmetics. Clariant AG, headquartered in Muttenz, Switzerland, supplies synthetic polymers, surfactants, and specialty chemicals for color cosmetics, skincare, and personal care applications.
Wacker Chemie AG, based in Munich, Germany, produces high-purity silicones and silicone elastomers used as synthetic materials in cosmetic formulations for sensory and film-forming properties. Innospec Inc., from Englewood, Colorado, USA, offers custom silicone fluid compounds and specialty synthetic ingredients for cosmetic sensorial effects and performance. 3V Sigma USA, located in Georgetown, South Carolina, USA, manufactures synthetic rheology modifiers, carbomers, polymeric emulsifiers, and thickeners for cosmetic textures and stability. Solvay S.A., headquartered in Brussels, Belgium, provides specialty polymers and surfactants for cosmetic and personal care synthetic material applications.
Recent product activity illustrates how competition is being fought on the front of innovation and commercialization. In December 2025, Dow Inc. continued the commercialization and availability of DOWSIL 9701 Cosmetic Powder, a silicone-based powder for skin care, sun care, and color cosmetics. In April 2025, Evonik Industries AG launched multiple biotech-powered synthetic and functional ingredients, including Vecollage Fortify GP for anti-aging cosmetic applications, showcased at in-cosmetics Global. In February 2026, Ashland Global Holdings Inc. reinforced its portfolio with collapeptyl biofunctional, a hyalupeptide hybrid for cosmetic formulations. These moves signal an industry where differentiation is increasingly tied to biofunctional claims, sensory engineering, and hybrid synthetic-biological approaches.
The complete study goes further, providing company-level profiles, strategic positioning assessments, recent development tracking, and a structured view of how these players compete across product types and applications. For procurement and R&D teams, this competitive mapping is essential to benchmarking supplier capabilities, evaluating substitution options, and anticipating where innovation is likely to emerge next.
Segmentation Architecture: Where Value Is Created and Captured
A market of this scale and diversity cannot be managed effectively through aggregate figures alone. The report deconstructs the worldwide cosmetic synthetic materials market across multiple dimensions, enabling readers to identify high-potential segments, assess relative size and growth trajectories, and align internal strategies with the most relevant demand pockets.
By product type, the analysis covers synthetic polymers, surfactants, synthetic waxes, synthetic pigments and dyes, and preservatives and emollients. Each category carries distinct performance characteristics, formulation roles, regulatory considerations, and cost structures. Synthetic polymers, for instance, anchor texture, film formation, and stability across a wide range of personal care products. Surfactants define cleansing efficacy, foam behavior, and emulsion compatibility. Synthetic waxes contribute to structural integrity and sensory finish in color and care products. Synthetic pigments and dyes are central to color cosmetics and branding expression. Preservatives and emollients address shelf stability, skin compatibility, and consumer-perceived benefit. Understanding how these categories interact with application needs and regional demand is fundamental to formulation strategy, sourcing decisions, and portfolio planning.
By application, the study examines skin care, hair care, makeup and color cosmetics, and fragrances and toiletries. Skin care represents the largest demand pool, reflecting the category's expansive range of leave-on and rinse-off products, its sensitivity to emollient and rheology performance, and its rapid adoption of active delivery systems and sensory modifiers. Hair care follows as a significant application, driven by conditioning polymers, fixatives, and styling agents that must balance hold, feel, and wash-off behavior. Makeup and color cosmetics rely heavily on synthetic waxes, pigments, and film-forming materials to deliver coverage, longevity, and aesthetic consistency. Fragrances and toiletries encompass a broad array of formats where surfactants, emollients, and specialty synthetics support both functional performance and consumer experience.
Regional analysis completes the segmentation framework. The report evaluates demand patterns across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa. Each region presents a distinct combination of consumer preferences, regulatory environments, manufacturing footprints, and growth rates. Asia Pacific reflects large-scale consumption and rapid product innovation. North America and Europe are characterized by stringent regulatory scrutiny, high formulation standards, and strong demand for performance and sustainability attributes. Latin America and the Middle East and Africa offer heterogeneous but expanding opportunities shaped by urbanization, rising disposable incomes, and evolving beauty routines.
Crucially, the study avoids superficial regional or application breakdowns. Instead, it integrates segment-level dynamics with macro trends, regulatory timelines, and competitive activity to reveal where growth is most durable and where risk is most concentrated. The full report contains the detailed segmentation data, including size estimates and forward projections that support category-level planning, target-setting, and investment prioritization.
What the Report Delivers: Operational Intelligence for 2026 Decision-Making
PW Consulting's Worldwide Cosmetic Synthetic Materials Market report is designed to move beyond descriptive market sizing and into the territory of decision-ready intelligence. The study combines historical reconstruction, forecast modeling, segmentation analysis, competitive profiling, and regulatory and cost monitoring into a single integrated framework. This approach allows executives and technical leaders to align strategy across functions, from R&D and procurement to sales, marketing, and regulatory affairs.
The report's structure supports a wide range of practical applications. Formulation and product development teams can use the segmentation and competitive materials to identify ingredient alternatives, benchmark supplier capabilities, and anticipate performance trade-offs. Procurement and supply chain leaders can incorporate feedstock and pricing context, regulatory milestones, and supplier concentration data into sourcing strategy and contract planning. Commercial and strategy teams can leverage regional and application insights to prioritize markets, shape portfolio roadmaps, and assess where synthetic material trends will influence product positioning and consumer perception.
Throughout the study, attention is given to the interplay between technical performance and market dynamics. Synthetic materials are not commodities in the cosmetic sector; they are functional enablers whose value is judged by sensory outcomes, stability, compatibility, and regulatory acceptability. The report reflects this reality by situating market data within the context of formulation behavior, application requirements, and compliance trends. This integrated perspective helps organizations avoid the trap of treating ingredient decisions as purely cost-driven, and instead evaluate them through a lens that includes performance, risk, and strategic fit.
The forecast methodology accounts for historical patterns, demand drivers, regulatory shifts, and feedstock considerations. By projecting the market from 2026 through 2032, the study provides a forward window that supports budgeting, capacity planning, and long-range innovation investments. Readers can assess how different segments are likely to evolve, where growth is expected to concentrate, and what external factors may accelerate or moderate expansion.
Why This Intelligence Matters Now
The 2026 operating environment demands a higher standard of market clarity than ever before. Regulation is tightening on multiple fronts, from microparticle reporting to CMR substance restrictions and PFAS prohibitions. Feedstock costs remain sensitive to energy market volatility, even as specific intermediates such as propylene glycol exhibit relative stability in certain regions. Competitive players are launching hybrid synthetic and biotech-powered ingredients that reset expectations for sensory performance and functional benefit. Meanwhile, market growth at a 5.12 percent CAGR through 2032 indicates that demand will continue to expand, but not uniformly, and not without competitive and compliance risk.
In this context, organizations that rely on fragmented data sources or outdated assumptions risk misallocating resources, overlooking substitution opportunities, or underestimating regulatory exposure. A comprehensive study of the worldwide cosmetic synthetic materials market offers a corrective. It consolidates macro trends, segment dynamics, competitive intelligence, and regulatory signals into a coherent view that supports timely, evidence-based decisions.
The preview above has outlined the strategic logic, market trajectory, regulatory backdrop, competitive structure, and segmentation architecture that define this research. The full report provides the detailed figures, segment-level magnitudes, regional breakdowns, company profiles, and forward-looking analysis that organizations need to translate insight into action. For executives seeking to align formulation strategy, procurement planning, and market positioning with the realities of 2026 and the years ahead, this study offers a structured, rigorous foundation for the next phase of decision-making.
To access the complete dataset, segmentation detail, competitive assessments, and forecast tables that underpin this analysis, we invite you to visit the source page for the Worldwide Cosmetic Synthetic Materials Market research. There, you will find the full intelligence suite designed to support strategic planning, supplier evaluation, and category-level decision-making across the cosmetic synthetic materials landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Cosmetic Synthetic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Releases Global AI Server PCB Market Report Showing 32.14% CAGR and Growth to 67,840 Million USD by 2032
By PW Consulting, 2026-09-01
Navigating the AI Server PCB Inflection Point: Strategic Imperatives for 2026
The infrastructure underpinning the artificial intelligence revolution is undergoing a structural transformation of unprecedented speed. As hyperscale cloud providers, sovereign AI initiatives, and enterprise data centers scale out their compute fleets, the printed circuit board (PCB) stack that physically connects accelerators, memory, and interconnects has emerged as a critical bottleneck and a decisive competitive lever. Our latest Worldwide AI Server PCB Market study, anchored in historical tracking from 2020 through 2025 and extended with a rigorous forward outlook spanning 2026 to 2032, maps this inflection point with the granularity required for capital allocation, supply chain redesign, and technology roadmap planning. This article previews the analytical framework, highlights the operational realities shaping the sector, and explains why disciplined intelligence is no longer optional for executives navigating the next phase of AI infrastructure deployment.
Worldwide AI Server PCB Market
The market trajectory observed over the past half-decade tells a story of exponential adoption meeting physical constraint. Revenue across the global AI server PCB sector expanded from approximately 645.2 million USD in 2020 to a base-year valuation of 12650.0 million USD in 2025, reflecting an order-of-magnitude acceleration as training clusters, inference racks, and high-density networking fabrics became standard configurations rather than experimental deployments. Our forecast model projects the market reaching 16500.97 million USD in 2026 and continuing its steep ascent through 2032, at which point valuation is expected to approach 67840.4 million USD. This expansion is underpinned by a compound annual growth rate of 32.14 percent, a pace that fundamentally alters how procurement teams, substrate manufacturers, and equipment suppliers plan capacity, pricing, and partnership structures. Yet velocity alone is an incomplete narrative. The true strategic challenge lies in understanding where value concentrates, which architectural choices dominate next-generation server designs, and how supply chain topology responds under sustained demand pressure.
Worldwide AI Server PCB Market
The Architecture of the Market: Layers, Components, and Regional Gravity
High-performance AI server PCBs are no longer commodity interconnect boards. They are engineered substrates that must simultaneously satisfy extreme layer counts, signal integrity at multi-gigabit rates, thermal dissipation requirements, and form-factor constraints within densely packed rack architectures. The market naturally segments across multiple axes, each carrying distinct implications for sourcing strategies, qualification cycles, and supplier selection. In terms of complexity, the segment spanning 18 to 28 layers represents the largest revenue pool at 7553.76 million USD, reflecting the industry’s baseline requirement for multilayer routing density in mainstream AI server configurations. Above this threshold, boards exceeding 28 layers contribute 3845.17 million USD, capturing the premium tier where ultra-high density interconnects, advanced backplane architectures, and tightly coupled accelerator mezzanine designs are increasingly mandated by next-generation compute modules. Below 18 layers accounts for 1251.07 million USD, a smaller but strategically relevant bracket often tied to supporting infrastructure, auxiliary compute nodes, and specialized I/O expansion boards.
Worldwide AI Server PCB Market
Component-level segmentation further clarifies where engineering emphasis and procurement dollars flow. GPU accelerator module boards dominate the landscape at 8277.3 million USD, underscoring the centrality of high-bandwidth accelerator packages, thermal-managed interconnects, and dense routing topologies that keep memory and compute tightly coupled. Mainboards and switch boards follow at 3124.92 million USD, representing the backbone of server fabric, power distribution, and chassis-level orchestration. Expansion and power cards round out the structure at 1247.78 million USD, reflecting the growing need for modular power conversion, peripheral connectivity, and rack-scale flexibility. These architectural layers are not static. As accelerator packaging evolves, as high-bandwidth memory architectures tighten physical tolerances, and as rack form factors continue to compress, substrate specifications are being re-optimized for lower impedance, improved thermal pathways, and higher pin-density reliability.
Geography adds another dimension of strategic complexity. Asia Pacific registers as the largest regional demand pool at 6512.04 million USD, reflecting the concentration of advanced packaging ecosystems, cloud infrastructure build-out, and manufacturing capacity that has become deeply integrated with global AI server supply chains. North America follows at 4375.48 million USD, driven by hyperscale deployment cycles, bespoke server engineering, and accelerating regionalization of critical hardware sourcing. Europe contributes 1383.88 million USD, where enterprise AI adoption, automotive-adjacent compute, and sovereign infrastructure initiatives are shaping steadier but increasingly specialized demand. The rest of world accounts for 378.6 million USD, a segment that typically grows through spillover demand, regional data center expansion, and emerging telecom-compute convergence. For executives, the critical insight is not simply which region leads in absolute terms, but how regional concentration interacts with qualification timelines, logistics resilience, and geopolitical sensitivity in ways that can compress or extend time-to-deployment for large-scale AI rollouts.
Competitive Dynamics and the Shape of the Supply Base
The supplier landscape for AI server PCBs is defined by a mix of long-established HDI and multilayer specialists, advanced substrate manufacturers, and regional producers scaling into higher-complexity tiers. Market concentration remains meaningful but not absolute, with the top three players accounting for 48.2 percent of revenue and the top five reaching 63.55 percent. This structure indicates a market where scale, technological maturity, and sustained customer relationships confer durable advantages, yet where selective capacity additions and architectural specialization still create room for targeted disruption.
At the forefront of high-layer count and advanced HDI capability is Zhen Ding Technology Holding, a global leader in multilayer and HDI boards serving AI servers, data centers, and high-speed computing applications, with an emphasis on advanced HDI and flexible or rigid-flex solutions. Unimicron Technology Corporation operates as a major producer of HDI, build-up multilayer, and IC substrates, delivering high-performance boards and substrates optimized for AI servers, HPC, and data center infrastructure. TTM Technologies brings strength in high-end technology PCBs, including RF, advanced HDI, and backplanes, serving AI and data center environments alongside aerospace and defense markets with complex multilayer server boards. Ibiden Co., Ltd. specializes in high-density interconnect and IC substrates, positioning itself as a key supplier of advanced PCBs and substrates for AI accelerators and high-performance server applications. Compeq Manufacturing Co., Ltd. produces multi-layered, HDI, HLC, flexible, and rigid-flex PCBs, including server and computing infrastructure boards for AI and machine learning devices.
European and Asian players extend the competitive field with distinct technological emphases. AT&S Austria Technologie & Systemtechnik AG provides high-performance HDI PCBs, IC substrates, and embedded power solutions tailored for AI and HPC servers and data center applications. Samsung Electro-Mechanics manufactures high-value PCBs and substrates, including multilayer boards for servers and computing systems, alongside AI and IoT applications. Nippon Mektron offers flexible and rigid PCBs with a focus on high-reliability applications such as servers and high-speed data transmission. Tripod Technology Corporation specializes in multilayer PCBs for memory modules, servers, and AI-related high-speed network equipment. Shennan Circuit Co., Ltd. produces high-layer count and high-speed PCBs for servers, AI computing, and telecommunications infrastructure. WUS Printed Circuit supplies AI server and high-speed network switch PCBs with a significant share among overseas cloud and AI customers. DSBJ operates as a large-scale PCB producer with capacity for server and computing boards supporting AI infrastructure. Victory Giant Technology provides PCBs for data center and AI server applications with an emphasis on high-density solutions. Young Poong Electronics manufactures PCBs including for high-end computing and server markets.
What distinguishes this competitive set is not merely scale, but the pace at which each player is aligning capital, process technology, and qualification depth with the specific demands of AI server architectures. The strategic question for procurement and engineering leaders is how to evaluate suppliers not only by current capability, but by their demonstrated trajectory in cost structure, yield maturity, lead-time predictability, and ability to support rapid specification changes without destabilizing long-term supply commitments.
Recent Developments and Material Realities Shaping Deployment Timelines
Market forecasts gain credibility only when anchored in observable operational signals. Over recent months, several developments have highlighted both the intensity of demand and the material constraints that accompany it. Equipment investment has accelerated as manufacturers prepare capacity specifically configured for AI server PCB production. For example, SCHMID Group secured two significant orders for complete wet-process equipment lines dedicated to AI server PCB production, and later reported robust 2025 order intake of about 95 million EUR primarily driven by AI-server board production capacity expansions. In materials innovation, PCBAIR introduced an 8-layer glass core PCB substrate platform with Through Glass Via technology for AI accelerators and high-speed data center servers, with pilot production and customer sampling initiated. In capital deployment, Kingshine injected CNY 240 million into a subsidiary for a high-end server PCB project to address growing AI server demand.
These actions are unfolding against a backdrop of raw material pressure that is reshaping cost models and planning horizons. Copper foil prices for high-end HVLP used in AI server PCBs increased by more than 50 percent amid a global supply gap exceeding 40 percent. Copper-clad laminate prices climbed by as much as 45 percent year-over-year as AI-driven demand for high-performance materials intensified. Lead times for advanced laminates and high-end materials extended from typical 8 to 12 weeks to 20 to 30 weeks due to capacity redirection toward AI server applications. These dynamics mean that material availability, not just board design, increasingly dictates deployment velocity for large-scale AI infrastructure programs.
Policy and trade environment considerations further complicate the planning environment. U.S. tariffs and export controls on semiconductor-related items, including advanced computing components, have contributed to regional concentration risks, with 70 percent of high-end PCB capacity concentrated in Taiwan and South Korea. In parallel, the U.S. Bureau of Industry and Security implemented refinements to export controls on advanced computing and semiconductor manufacturing items, including high bandwidth memory relevant to AI server supply chains. The intersection of equipment lead times, material scarcity, and regulatory evolution makes supply chain scenario planning a board-level concern rather than a tactical procurement exercise.
What the Full Study Delivers: Operational Intelligence for 2026 Decisions
Executive summaries capture direction; detailed market intelligence supports execution. The complete study is structured to move from macro validation to actionable segmentation, competitive profiling, and scenario-informed planning inputs. It integrates historical performance from 2020 through 2025 with a disciplined forecast architecture extending through 2032, allowing teams to test sensitivity around adoption curves, capacity addition timing, and component mix shifts. Rather than presenting a single-point outlook, the analysis is designed to support what-if evaluation across multiple planning variables, including substrate complexity, component-type emphasis, and regional sourcing strategies.
The report provides detailed segmentation breakdowns across layer count, component type, and region, with sufficient depth to inform supplier shortlisting, qualification prioritization, and inventory strategy. It examines competitive positioning, recent capacity and product developments, and the practical implications of market concentration for negotiation leverage and supply assurance. It also embeds industry context around raw material pressures, lead-time elongation, and regulatory exposure so that cost forecasts and risk registers reflect current operating conditions rather than stale assumptions. For teams planning 2026 capex, multi-year contracts, or platform architecture changes, this structure is intended to reduce ambiguity in areas that are often handled with intuition alone.
Importantly, the study is built to support cross-functional alignment. Engineering teams can use the architectural segmentation to understand where complexity is monetized and where specification creep creates downstream cost risk. Procurement and supply chain leaders can map regional demand patterns and concentration dynamics to sourcing resilience and dual-sourcing feasibility. Strategy and finance teams can use the forward trajectory and concentration metrics to frame growth assumptions, investment timing, and competitive positioning in a market that is scaling faster than traditional planning cycles were designed to accommodate.
Strategic Implications for 2026 and Beyond
The 2026 decision environment will be shaped by three intertwined forces. First, demand is compounding at a pace that rewards early architectural clarity. Organizations that define substrate specifications, qualification pathways, and supplier relationships before capacity becomes contested will secure more favorable terms and shorter deployment cycles. Second, material and process constraints are becoming first-order planning variables. Extended lead times for advanced laminates, elevated copper and CCL costs, and equipment cycle timing mean that board availability is increasingly a function of upstream material strategy as much as downstream manufacturing capacity. Third, concentration and regulatory exposure require deliberate supply chain design. With a substantial share of high-end capability located in a limited set of regions, executives must weigh efficiency against resilience, and evaluate how policy evolution could affect sourcing options, qualification pathways, and inventory buffers.
In this environment, the most valuable intelligence is not simply how large the market is, but how it is structured, how it is changing, and where the friction points lie between design intent and production reality. AI server PCBs are not a peripheral hardware category; they are a critical enabler of compute density, signal integrity, thermal management, and rack scalability. Decisions made in 2026 will influence cost structures, supply assurance, and architectural flexibility well into the next forecast cycle.
Conclusion: Why the Complete Intelligence Package Matters
Velocity and complexity are rewriting the rules of AI infrastructure sourcing. The worldwide AI server PCB market is expanding at a pace that places a premium on early visibility, disciplined segmentation, and supplier-level strategic assessment. Our study provides the analytical foundation to move from reactive procurement to proactive capacity and architecture planning, with historical validation, forward trajectory, competitive context, and material reality all integrated into a single decision-support framework.
Because the market is evolving quickly and the operational details matter, we have reserved the full segmentation breakdowns, supplier-level profiles, regional demand patterns, and scenario inputs for the complete report. Those sections are where procurement teams, engineering leaders, and strategy planners will find the specific data required to model sourcing options, evaluate qualification risk, and calibrate investment timing for 2026 and beyond. To access the complete intelligence package, including the detailed market tables, competitive assessments, and forward segmentation that underpin this overview, visit the source page for the Worldwide AI Server PCB Market study.
For detailed analysis of this topic, please visit the official page: Worldwide AI Server PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Fire System Design Market Reaches USD 13,180 Million in 2025 With 8.24 Percent CAGR Predicted Through 2032
By PW Consulting, 2026-09-01
Navigating the Inferno: Strategic Imperatives in the Worldwide Fire System Design Market Through 2032
The built environment is undergoing a radical transformation. As urban density increases and industrial processes become more complex, the margin for error in life safety diminishes. The Worldwide Fire System Design Market is no longer merely a compliance checkbox; it has evolved into a critical layer of risk management, asset protection, and operational resilience. For executives, investors, and engineering leaders, understanding the trajectory of this sector is not optional. It is a prerequisite for sustainable growth.
Worldwide Fire System Design Market
Our latest comprehensive study, the Worldwide Fire System Design Market Research, offers a granular look at the forces shaping this industry from the base year of 2025 through the forecast horizon of 2032. This article serves as a strategic briefing on why this intelligence is vital for 2026 decision-making, highlighting the macroeconomic momentum, the shifting regulatory tide, and the competitive maneuvers defining the landscape.
Worldwide Fire System Design Market
The Macro Trajectory: Sustained Growth Amidst Complexity
The numbers tell a story of robust, uninterrupted expansion. The market has demonstrated remarkable resilience and growth potential over the past five years. In 2020, the global valuation stood at approximately 8,945.3 million USD. By the base year of 2025, that figure has surged to a projected 13,180.0 million USD. This trajectory indicates more than just recovery; it signals a fundamental escalation in demand for sophisticated safety architectures.
Worldwide Fire System Design Market
Looking forward, the momentum does not wane. The forecast period from 2026 to 2032 suggests a continued upward climb. Starting from an estimated 14,214.02 million USD in 2026, the market is poised to reach over 22,942.06 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 8.24 percent. For strategic planners, this rate is significant. It suggests that fire system design is outperforming many traditional construction-related sectors, driven by retrofitting needs, stricter code enforcement, and the integration of smart building technologies.
However, raw market size is only half the equation. The composition of this growth reveals where the true opportunities lie. The market is not monolithic. It is fractured across service types, end-user sectors, and geographies, each with distinct growth drivers and barriers. Understanding the specific weight of fire detection versus suppression, or the nuances of commercial buildings versus infrastructure, requires a depth of analysis that general market reports often miss. Our research dissects these splits to reveal where capital is flowing and where risks are concentrated.
Regulatory Tailwinds and Headwinds: The New Compliance Landscape
In the fire safety industry, regulation is not just a constraint; it is a primary demand driver. The period leading into 2026 and beyond is marked by significant regulatory shifts that will redefine design parameters and service requirements.
NFPA Revisions and Design Verification
The National Fire Protection Association (NFPA) continues to set the global standard for best practices, and recent updates carry substantial implications for designers and consultants. The 2026 edition of NFPA 25 introduces clarifications regarding inspector roles. Specifically, it delineates that evaluating whether a fire protection system is properly designed for the hazard falls outside the scope of routine inspection, testing, and maintenance (ITM) activities. This distinction elevates the importance of the initial design phase. It places a heavier burden on design engineers to ensure systems are fit for purpose from day one, as post-installation ITM cannot rectify fundamental design flaws.
Simultaneously, the NFPA 72 2025 edition sets a maximum ceiling height of 40 feet for traditional smoke detector placement methods. For spaces exceeding this height, the code requires performance-based design and engineering calculations. This is a pivotal shift. It effectively mandates advanced engineering services for high-bay warehouses, atriums, and industrial facilities. Designers can no longer rely on prescriptive code compliance alone; they must employ modeling and simulation to prove efficacy. This regulatory nuance directly stimulates demand for the highest-value service segments within the market.
Environmental Regulations and Gas Suppression
On the sustainability front, the EU F-Gas Regulation (Regulation (EU) 2024/573) is accelerating the phase-down of high-GWP fluorinated gases used in certain gas suppression agents. This creates a dual challenge for the industry. First, it pressures designers to specify alternative agents that meet safety standards without violating environmental mandates. Second, it necessitates the redesign of existing systems in legacy facilities within European jurisdictions. The transition away from traditional clean agents opens avenues for water mist, foam, and hybrid systems, reshaping the revenue mix for suppression-focused firms.
Energy Storage and Lithium-Ion Risks
Perhaps the most dynamic risk profile is emerging from the energy sector. NFPA 855 updates address stricter requirements for energy storage and battery systems (BESS). As the adoption of lithium-ion battery storage accelerates for grid stabilization and electric vehicle charging infrastructure, fire protection system design must adapt. Traditional water-based systems may be insufficient or even dangerous for certain battery chemistries. This has created a specialized niche for explosion protection and special hazard fire protection solutions. The intersection of renewable energy infrastructure and fire safety design is becoming a high-growth pocket within the broader market, demanding specialized knowledge that generalist firms may lack.
Competitive Landscape: Consolidation and Specialization
The market concentration metrics suggest a fragmented but consolidating environment. The CR3 stands at 18.45 percent, while the CR5 reaches 27.12 percent. This indicates that while the top five players hold a significant share, a substantial portion of the market remains distributed among regional specialists and niche engineering firms. This structure creates both opportunity and threat. Large conglomerates are leveraging acquisitions to verticalize their offerings, while specialized consultancies compete on technical depth and code expertise.
Industry Titans and Strategic Moves
Several key players are defining the pace of innovation and consolidation. Johnson Controls International plc, headquartered in Cork, Ireland, continues to leverage its integrated platform. In April 2025, the company unveiled industry-specific bundled fire and life safety solutions tailored for non-acute healthcare and correctional facilities. This move signals a shift toward vertical-specific bundling, moving beyond generic hardware to solution-based selling that addresses the unique life safety needs of vulnerable populations.
Siemens AG, based in Munich, Germany, has aggressively expanded its footprint through acquisition. In late 2024, Siemens completed the acquisition of Danfoss Fire Safety. This strategic move was designed to expand their sustainable fire suppression portfolio, specifically adding high-pressure water mist and low-pressure CO2 technologies. For clients, this means access to a broader suite of eco-friendly suppression options integrated within Siemens broader building automation ecosystem.
Other major entities like Honeywell International Inc. in Charlotte, North Carolina, and Robert Bosch GmbH in Gerlingen, Germany, continue to reinforce their positions through advanced detection technologies and integrated building safety solutions. Bosch integrates fire detection into broader security portfolios, while Honeywell focuses on the convergence of fire alarm, notification, and suppression technologies.
The Specialists: Engineering and Consulting Powerhouses
While the manufacturers hold volume, the design and engineering specialists hold the intellectual capital. JENSEN HUGHES, based in Baltimore, Maryland, specializes in fire engineering and systems design for complex structures. Their focus on risk assessment, performance-based fire protection design, and commissioning is critical for projects where prescriptive code compliance is insufficient. Similarly, WSP in Montreal, Canada, offers global engineering consultancy services covering fire system design and compliance for massive infrastructure projects.
In the United States, Code Consultants, Inc. (CCI) in St. Louis represents the depth of local expertise, providing specialized analysis and consulting with NICET-certified professionals and active NFPA committee involvement. Their participation in standard-setting bodies gives them a forward-looking advantage in interpreting upcoming codes. Meanwhile, Minimax Viking Group and Fike Corporation focus heavily on the suppression end of the spectrum, offering solutions for special hazards and high-risk facilities. Minimax focuses on water mist and special hazard protection, while Fike provides explosion protection and global manufacturing capabilities.
The diversity of this landscape means that buyers must navigate a complex vendor ecosystem. A hospital project might need Johnson Controls for integrated life safety, but a high-tech battery storage facility might require Fike for explosion protection and Jensen Hughes for performance-based design verification. Identifying the right partner for the specific risk profile is a strategic challenge that our research addresses by mapping capabilities against market segments.
Service Segmentation: Where Value is Created
Understanding the breakdown of services is crucial for revenue forecasting and capability development. The market is not just about installing hardware; it is about the intellectual service surrounding the design.
Fire Suppression System Design represents a significant portion of the value chain, given the hardware intensity and the critical nature of active protection systems. However, Fire Detection System Design remains a foundational element, driving recurring revenue through integration with building management systems. The less ubiquitous but highly specialized segments, such as Smoke Control and Exhaust Design and Fire Modeling and Simulation, are where the highest engineering margins often reside.
Smoke control is particularly vital in high-rise commercial buildings and underground infrastructure, where life safety depends on egress time management rather than just fire extinguishment. Fire modeling and simulation, driven by the new NFPA 72 ceiling height requirements, is transitioning from a niche service to a standard requirement for complex geometries. Companies that can offer validated simulation tools and the engineering expertise to interpret them will capture premium value in the 2026-2032 period.
End-User Dynamics: Diversification of Demand
The demand signal comes from varied corners of the economy. Commercial Buildings continue to be a primary driver due to occupancy codes and retrofitting of aging stock. However, the Industrial and Manufacturing sector is seeing renewed interest driven by automation, high-bay storage, and the aforementioned BESS requirements.
Residential Complexes represent a steady, volume-driven segment, particularly in rapidly urbanizing regions where high-density housing mandates robust communal fire safety systems. Meanwhile, Infrastructure and Transport projects, including airports, tunnels, and rail networks, require bespoke design solutions that account for unique evacuation challenges and continuity of operations. Each end-user category carries distinct regulatory requirements, budget cycles, and procurement behaviors. A strategy that works for commercial high-rises may fail in industrial manufacturing settings. Our research provides the breakdown necessary to align go-to-market strategies with the specific nuances of each vertical.
Geographically, the market is balanced across major regions. North America and Europe remain mature markets with strong regulatory enforcement, driving steady demand for upgrades and compliance. Asia Pacific presents a high-growth opportunity linked to urbanization and infrastructure development. The Middle East and Africa, along with Latin America, offer niche but significant opportunities tied to specific large-scale projects and resource extraction industries. Understanding the relative intensity of demand across these regions is essential for multinational firms planning capacity allocation.
Strategic Implications for 2026 Decision-Makers
As we move further into the forecast period, several strategic imperatives emerge for stakeholders in the fire system design market.
First, Integration is Key . The separation between fire safety and general building automation is blurring. Clients expect systems that communicate with HVAC, access control, and energy management. Firms that can offer integrated design solutions will command higher margins and stickier client relationships.
Second, Regulatory Fluency is a Competitive Moat . With NFPA 72 ceiling limits and NFPA 25 design verification clarifications, the ability to interpret and design to complex codes is becoming a primary differentiator. Firms that invest in continuous training and certification for their design teams will reduce liability and win more complex bids. The shift away from routine ITM for design verification means the design phase is the last best chance to ensure safety; errors here are costly and legally perilous.
Third, Sustainability Must be Designed In . The EU F-Gas regulations and global ESG pressures mean that suppression agent selection is no longer just a technical decision but a compliance and reputational one. Designers must be versed in low-GWP alternatives and water mist technologies. Companies lagging in sustainable portfolio offerings risk being excluded from public sector and multinational corporate bids.
Fourth, Special Hazard Expertise is Booming . The rise of energy storage, data centers, and specialized manufacturing creates demand for suppression and protection solutions that go far beyond standard sprinklers. This requires niche expertise in explosion protection and chemical suppression. Firms that can pivot to serve these high-risk, high-value sectors will see disproportionate growth.
Finally, M&A Activity will Continue . With a CR5 of 27.12 percent, there is still room for consolidation. Large players will seek to acquire specialized engineering firms to gain market access and technical capabilities, while smaller firms may seek exit strategies as compliance burdens increase. Understanding valuation drivers and capability gaps is essential for those considering inorganic growth.
Why This Research Matters Now
In a market projected to grow at 8.24 percent CAGR, the difference between success and stagnation lies in the details. Aggregate numbers tell you the market is healthy; segmentation data tells you where to play. Regulatory updates tell you what is legal; case studies and company profiles tell you who can deliver it.
This Worldwide Fire System Design Market Research report goes beyond surface-level metrics. It provides a detailed mapping of service type revenues, end-user spending patterns, and regional intensity without relying on generic industry assumptions. It analyzes the specific capabilities of the key competitors, from Johnson Controls and Siemens to specialized engineering consultancies like WSP and Jensen Hughes. It contextualizes recent developments, such as the Siemens Danfoss acquisition and the latest NFPA standard releases, within the broader market trajectory.
For strategic planners, investors, and C-suite executives, the cost of incomplete intelligence is high. Misallocating resources to declining segments, underestimating regulatory compliance costs, or partnering with vendors lacking specific technical depth can erode competitive advantage. This report is designed to mitigate those risks.
The fire system design market is entering a phase of heightened complexity and opportunity. The convergence of sustainability mandates, advanced engineering requirements, and infrastructure growth creates a rich landscape for those equipped with the right data. We invite you to delve deeper into the full report to access the specific segmentation splits, regional analyses, and competitive benchmarks that will inform your 2026 strategy and beyond. The data is available; the strategic advantage lies in how you use it.
To access the complete dataset, including detailed breakdowns of service types, end-user expenditures, and regional market sizes, please visit the source page. The full intelligence package provides the granularity required to build robust business cases, identify partnership opportunities, and navigate the regulatory shifts defining the next decade of fire safety design.
For detailed analysis of this topic, please visit the official page: Worldwide Fire System Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


