



Category: market research
PW Consulting Report Projects Global Commercial Satellite Customization Market to Reach 17750 Million by 2032 Growing at 16.03 CAGR
By PW Consulting, 2026-09-01
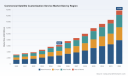
Strategic Imperatives in the Global Commercial Satellite Customization Landscape: A 2026 Market Intelligence Brief
The commercial space sector has graduated from an experimental frontier to a core pillar of global connectivity, defense infrastructure, and earth observation economics. As satellite architectures grow more complex and mission requirements more specific, the demand for tailored satellite solutions has surged. This evolution demands a precise, data-driven understanding of where value is being created, how supply chains are consolidating, and which technological vectors will define competitive advantage through the end of the decade.
Worldwide Commercial Satellite Customization Service Market
Our latest Worldwide Commercial Satellite Customization Service Market research provides a granular, forward-looking blueprint for executives, investors, and policy stakeholders. The study maps the trajectory from a 2025 base of USD 6,280.00 million to a projected USD 17,750.00 million by 2032, underpinned by a sustained compound annual growth rate of 16.03 percent. This briefing synthesizes the macro-economic currents, competitive architectures, and regulatory fault lines that will shape strategic decision-making in 2026 and beyond.
Worldwide Commercial Satellite Customization Service Market
A Market Accelerating on Customization Economics
The historical record from 2020 through 2025 demonstrates a consistent, accelerating expansion in the commercial satellite customization regime. Revenue climbed from USD 3,120.00 million in 2020 to USD 5,692.02 million in 2024, before reaching the 2025 baseline of USD 6,280.00 million. This trajectory reflects more than cyclical investment cycles; it signals a structural shift toward mission-specific engineering. Operators are no longer willing to anchor their constellations to off-the-shelf buses when payload integration, orbit-specific thermal and radiation environments, and sovereign data requirements demand bespoke configurations.
Worldwide Commercial Satellite Customization Service Market
The forecast window from 2026 through 2032 indicates that this customization premium will continue to compound, with market sizing escalating through the late 2020s and accelerating into the early 2030s. Growth is being propelled by the convergence of three dynamics: the proliferation of low-earth orbit and medium-earth orbit architectures, the escalating sophistication of payloads for communication and earth observation, and the growing requirement for end-to-end mission assurance from design through integration and testing. For enterprise leaders, the implication is clear. Procurement strategies that treat satellite services as commoditized capacity are increasingly misaligned with the economics of the market. Value capture is shifting toward partners who can deliver tailored system architectures at scale.
Report Architecture: Operational Intelligence for 2026 Decision Cycles
This report is engineered for immediate operational deployment. Rather than stopping at headline sizing, the analysis dissects the structural drivers, segmentation behaviors, and competitive tactics that determine win rates, pricing power, and deployment velocity. The study is organized to support multiple decision functions across the enterprise.
- Strategic portfolio planning with scenario-tested sizing across the forecast horizon, enabling capital allocation, M&A screening, and capacity-expansion decisions to be stress-tested against plausible demand pathways.
- Segment-level analysis that disentangles demand drivers across satellite size classes and end-user verticals, with attention to how mission profiles, payload complexity, and delivery timelines diverge by segment.
- Competitive benchmarking of incumbent primes, specialized integrators, and agile newcomers, with emphasis on platform strategies, customization breadth, and partnership ecosystems.
- Regulatory and spectrum dynamics mapping that connects international coordination, national policy shifts, data sovereignty requirements, and constellation deployment milestones to operational risk and opportunity.
- Technology and process innovation tracking, including automation in design, rapid production pathways, and mission-solutions models that are reshaping lead times and integration economics.
Each section is designed to translate market intelligence into procurement, partnership, and investment actions that can be executed within the current fiscal cycle. The report deliberately avoids superficial aggregates and instead isolates the levers that determine commercial outcomes in a market where customization is both the growth engine and the primary source of differentiation.
Competitive Architecture: Incumbents, Specialists, and the New Mission-Solutions Model
The supply side of the commercial satellite customization market is defined by a tiered competitive structure. Large aerospace primes bring full-spectrum capabilities spanning design, manufacturing, payload integration, and mission assurance across multiple orbits. Specialized integrators and agile newcomers compete on speed, configurability, and domain-specific expertise, particularly in small satellite and sovereign system builds. The result is a market in which differentiation is increasingly determined by the breadth of customization offered, the reliability of delivery, and the ability to embed advanced technologies into repeatable production pathways.
Airbus Defence and Space, headquartered in Toulouse, France, provides full satellite design, manufacturing, and customization services for commercial GEO, MEO, and LEO missions. Its value proposition centers on tailored payloads, buses, and mission-specific configurations, enabling operators to align platform performance with precise mission requirements across a broad orbital spectrum.
The Boeing Company, based in Chicago, USA, delivers commercial satellite customization through Boeing Satellite Systems. The organization focuses on bespoke GEO and other satellite platforms, offering custom payloads and configurations that serve communication and diversified application sets. Boeing’s positioning underscores the continued relevance of established platforms augmented by mission-specific engineering.
Lockheed Martin Space, headquartered in Bethesda, USA, delivers end-to-end custom satellite solutions that span mission-specific design, integration, and testing for commercial customers. The emphasis on a seamless delivery chain reflects the market’s growing expectation that customization must be accompanied by rigorous verification and operational readiness.
Northrop Grumman, located in Falls Church, USA, supplies customized satellite buses, payloads, and full systems for commercial communications and Earth observation missions. Its portfolio illustrates how customization increasingly extends from the bus layer through to payload and system-level integration to meet mission-unique performance thresholds.
Thales Alenia Space, headquartered in Cannes, France, specializes in custom satellite manufacturing and integration for commercial telecom and observation satellites across various orbits. Its focus on multi-orbit integration highlights the importance of platform adaptability as operators mix and match orbital regimes to optimize coverage, latency, and lifecycle economics.
Maxar Technologies, based in Westminster, USA, provides custom satellite solutions with a focus on high-resolution Earth observation platforms and tailored geospatial capabilities. This specialization demonstrates how segment-specific expertise can command premium positioning when payload performance and data utility are the primary purchase drivers.
Capella Space, headquartered in San Francisco, USA, offers custom satellite and mission solutions that include spacecraft bus customization, payload configuration, and sovereign system builds for commercial and strategic needs. The inclusion of sovereign system builds reflects the market’s sensitivity to data control, national security considerations, and the need for tailored operational architectures.
Umbra, located in Santa Barbara, USA, delivers custom SAR satellite solutions through its Mission Solutions line, including bespoke buses, payloads, constellations, and advanced mission capabilities for commercial customers. The development of a dedicated mission-solutions line signals a strategic move toward full-spectrum customization for synthetic aperture radar applications, where mission-specific performance is especially critical.
Azista USA provides end-to-end custom satellite manufacturing spanning LEO, GEO, CubeSat, and SmallSat platforms tailored to specific mission requirements. Its breadth of platform coverage underscores the market’s demand for integrators who can scale customization across size classes while maintaining mission-aligned performance.
York Space Systems focuses on bespoke and configurable satellite platforms for commercial, government, and defense customers with full-stack customization. The emphasis on configurability positions the company to serve customers who require a balance between standardization and mission-specific tailoring.
ISISpace Group, headquartered in the Netherlands, specializes in small satellite customization, including CubeSat and nanosatellite platforms and mission-specific integrations for commercial applications. Its specialization reflects the continued importance of small satellite architectures as a vehicle for rapid, cost-effective customization in targeted mission profiles.
Collectively, these players illustrate a competitive environment in which incumbents leverage scale, heritage, and multi-orbit capabilities, while specialists capture share through speed, domain depth, and modular configurability. Market concentration remains moderate, with the top three firms representing a meaningful but not dominant share and the top five firms accounting for a majority of activity. This structure leaves room for differentiated entrants that can demonstrate credible customization at competitive lead times and integration standards.
Recent Innovation Vectors and the Shift Toward Rapid, Automated Customization
The customization market is being reshaped by process innovations that reduce design friction and compress delivery timelines. In March 2025, Proteus Space announced a breakthrough in automated high-fidelity structural design for rapid custom satellite buses, simultaneously signing its first commercial payload customer and securing funding. This development points to a broader trend in which automation and high-fidelity modeling are being used to accelerate the earliest stages of bus design while preserving mission-specific performance.
In July 2024, Umbra launched a dedicated Mission Solutions line for building fully operational custom SAR satellite solutions, including buses, payloads, constellations, and advanced mission capabilities for governments and corporations. The move formalizes a mission-solutions model that treats customization as an integrated service rather than a component-level transaction, aligning commercial offerings with the requirements of complex radar-based earth observation missions.
In October 2024, GomSpace North America was selected by Proteus Space for components in an AI-enabled custom satellite bus design platform, MERCURY, targeting rapid ESPA-class satellite production. This collaboration highlights how component suppliers and design-platform innovators are beginning to interlock their capabilities to enable faster, repeatable production of customized buses at commercially relevant scales.
Taken together, these developments indicate that the customization market is moving from bespoke, one-off engineering toward platforms that enable repeatability without sacrificing mission specificity. For buyers, this shift changes the evaluation criteria. The relevant questions now include not only whether a partner can meet a given mission profile, but whether it can do so with a process architecture that supports speed, iteration, and scalable delivery.
Regulatory and Spectrum Dynamics: Structural Constraints and Enablers
Market expansion does not occur in a vacuum. The commercialization of satellite systems operates within an evolving framework of spectrum coordination, orbital resource management, and data governance. These factors influence both the pace of deployment and the design choices that customization providers must accommodate.
The International Telecommunication Union coordinates global radiofrequency spectrum and satellite orbit resources, and ongoing pressure on spectrum allocation is intensifying as commercial satellite systems demand higher data rates. The implications for customization providers are practical: payload architectures, link budgets, and interference mitigation strategies must be designed with an acute awareness of spectrum scarcity and coordination timelines.
In the United States, spectrum policy developments during 2025 and 2026, including legislative and administrative actions, are intended to create additional spectrum pipelines that support commercial satellite deployments and operations. These developments can serve as enablers for capacity expansion and service scaling, but they also require providers and operators to align their roadmaps with the timing and conditions of spectrum access.
Parallel to spectrum considerations, national data sovereignty laws and regulations are increasingly relevant to satellite data handling and operations, particularly for cross-border commercial satellite communications and services. Customization strategies that incorporate data routing, storage, and processing architectures aligned with sovereignty requirements are better positioned to meet procurement requirements in markets where data control is a gating condition.
On the deployment side, major constellation milestones continue to shape demand expectations. For example, planned launches of production satellites for commercial broadband LEO services are setting the pace for capacity rollouts and the associated ecosystem of ground, payload, and customization requirements. These milestones reinforce the importance of aligning customization roadmaps with the operational calendar of large-scale constellation deployments.
Strategic Takeaways for 2026 Planning
For enterprises operating in or adjacent to the commercial satellite customization market, the current environment calls for a disciplined, intelligence-led approach. Several strategic priorities emerge from the market structure and momentum described in this briefing.
- Treat customization as a strategic capability rather than a transactional service. Differentiation increasingly lies in the ability to integrate mission-specific payloads, buses, and system-level configurations with predictable delivery and assurance.
- Align procurement and partnership strategies with segment realities. Demand drivers, performance thresholds, and delivery expectations differ materially by satellite size class and end-user vertical, and strategy should reflect those divergences rather than relying on aggregate assumptions.
- Monitor process innovation as a lead indicator of competitive shift. Automation in design, rapid production pathways, and mission-solutions models are changing the economics of customization and will increasingly determine who can win on both performance and speed.
- Integrate spectrum and data sovereignty considerations into architecture decisions early. Regulatory and policy developments are not merely compliance issues; they shape design choices, partnership eligibility, and market access across regions and customer segments.
- Use scenario-based forecasting to reduce planning risk. A market growing at a double-digit CAGR through the early 2030s will present multiple plausible pathways. Scenario-informed capital allocation and capacity planning provide resilience against demand volatility and technology timing risk.
Access the Full Intelligence Suite
This briefing has outlined the structural growth of the market, the competitive architecture shaping supply-side dynamics, the innovation vectors accelerating customization, and the regulatory currents that influence deployment and design decisions. It has intentionally refrained from disclosing the detailed segmentation values, regional and application-level splits, and company-specific performance metrics that sit at the core of the full study. Those data points are essential for precise market entry, pricing, and partnership decisions, and they are available in the complete report.
The Worldwide Commercial Satellite Customization Service Market research is designed to serve as a decision-grade asset for 2026 planning and execution. It combines macro-sizing, segmentation analysis, competitive profiling, and regulatory mapping into a single, integrated intelligence framework. Leaders who require the granular figures that support board-level commitments, investment committee reviews, and procurement strategy will find them in the full report, where the data is presented with the context and methodological rigor needed for confident action.
For a complete view of market sizing through 2032, detailed segmentation dynamics, full competitive profiles, and the regulatory roadmap that will shape commercial satellite customization over the forecast period, access the full study. The depth of insight contained in the complete report is built to turn market momentum into measurable strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Satellite Customization Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Video Splicer Market to Reach USD 5686.42 Million by 2032 with a 7.42% CAGR Driven by Strong Asia Pacific Demand and Hardware-Based Processor Adoption
By PW Consulting, 2026-09-01
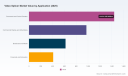
Strategic Foresight in the Worldwide Video Splicer Market: Navigating the 2026–2032 Growth Trajectory
The global video infrastructure landscape is undergoing a structural transformation. As organizations scale command centers, deploy immersive commercial displays, and modernize broadcast workflows, the role of video splicing technology has evolved from a tactical signal-routing function to a strategic enabler of visual continuity, operational reliability, and real-time decision-making. For enterprise leaders navigating capital allocation, vendor selection, and technology roadmaps in 2026, understanding where the market is headed—and why—is no longer optional. It is a prerequisite for competitive positioning.
Worldwide Video Splicer Market
Our latest market intelligence, the Worldwide Video Splicer Market study, provides a comprehensive, data-grounded view of this evolving ecosystem. Spanning historical performance from 2020 through 2025 and extending forecasts to 2032, the report translates macro-level momentum into actionable strategic insight. It is designed for executives who need more than headline figures: they need context, segmentation logic, competitive differentiation, and the operational signals that will shape procurement and investment decisions over the next seven years.
Worldwide Video Splicer Market
This article previews the strategic architecture of the study. It does not reproduce the full dataset. Instead, it frames the market’s directional trajectory, highlights the structural forces at play, and outlines how decision-makers can use the complete report to de-risk strategy and accelerate informed action.
Worldwide Video Splicer Market
Market Trajectory: A Seven-Year Window of Sustained Expansion
The worldwide video splicer market has demonstrated consistent growth through a period marked by shifting display architectures, expanding control-room deployments, and accelerating adoption of integrated visual management platforms. Between 2020 and 2025, the market expanded from a base of approximately 2,380.45 million USD to 3,445.42 million USD, reflecting a compound trajectory shaped by both incremental upgrades and foundational shifts in how organizations design visual infrastructures.
Looking forward, the forecast period from 2026 to 2032 outlines a continuation of this momentum. The study projects a market CAGR of 7.42 percent, with revenue scaling toward the upper range of the forecast window. This growth is not linear across every segment; rather, it reflects a market in which certain technology categories, application environments, and geographic clusters are pulling ahead while others evolve at a more measured pace. That divergence is exactly where strategic clarity becomes valuable.
For 2026 decision-making, the near-term inflection matters most. The projected 2026 revenue level of 3,644.33 million USD represents more than a statistical checkpoint. It signals the market’s transition from recovery-era expansion into a phase where vendors, integrators, and end-users are aligning on next-generation architectures, interoperability standards, and cost-performance trade-offs. Companies that understand which sub-segments are driving this near-term lift—and which are lagging—can prioritize resources with greater precision. The full report unpacks those dynamics without reducing them to surface-level ratios.
Importantly, the forecast does not assume a uniform pace of adoption. The data reveals how growth concentrates in environments where splicing technology is tightly coupled with operational continuity, visualization density, and content flexibility. That concentration pattern carries direct implications for product strategy, channel development, and partnership design. The study’s segmentation framework is built to expose those patterns clearly, while preserving the analytical discipline needed to avoid overgeneralization.
Strategic Value for Enterprise Decision-Making in 2026
A market study earns its place in the executive workflow only when it connects numbers to decisions. The Worldwide Video Splicer Market research is structured around that principle. Rather than presenting an isolated snapshot, it places the market within the operational realities faced by procurement leaders, technology directors, system integrators, and strategy teams.
The report’s value begins with its time horizon. By anchoring historical performance to a forward-looking forecast, it enables organizations to test assumptions against a consistent baseline. Leaders evaluating whether to accelerate deployment, phase investments, or defer certain purchases can compare their internal planning scenarios with the study’s projected trajectory. That comparison is especially useful in 2026, when many organizations are reconciling post-expansion budgets with the need to modernize aging visual infrastructure.
Equally important is the report’s segmentation logic. Market growth is rarely uniform, and meaningful strategy depends on knowing where value is actually being created. The study disaggregates the market along technology types, application environments, and regional footprints, allowing readers to identify where demand is structurally stronger and where it remains conditional on broader infrastructure cycles. This approach supports three core decision functions:
- Portfolio and product alignment: Organizations developing, distributing, or integrating splicing solutions can map their offerings against the segments with the strongest projected pull, adjusting feature emphasis, channel focus, and pricing strategy accordingly.
- Procurement and deployment timing: End-users can use segmentation trends to anticipate where supply dynamics, technology transitions, and competitive intensity are likely to shape pricing, availability, and integration complexity.
- Risk assessment and scenario planning: By separating high-certainty growth areas from more contingent ones, the report helps teams stress-test investment cases against alternative demand pathways instead of relying on a single market narrative.
In practice, the report is also designed to support cross-functional alignment. Strategy, operations, and technical teams often evaluate the same market through different lenses. The study’s structure provides a shared reference point: one that remains analytically rigorous without becoming inaccessible to non-specialists. That balance is critical in 2026, when video splicing decisions increasingly intersect with broader concerns such as control-room modernization, commercial display integration, and broadcast pipeline efficiency.
For readers seeking the complete segmentation detail, the full report deliberately preserves depth while maintaining clarity. It allows decision-makers to explore how the aggregate trajectory decomposes across the major axes that matter to commercial planning—without flattening those distinctions into overly simplified ratios.
Technology Shifts, Application Demand, and Regional Divergence
Video splicing technology today sits at the intersection of hardware performance, software-defined flexibility, and system-level interoperability. The market’s evolution reflects this blend. On one side, processor-centric and hardware-based solutions continue to serve environments where deterministic performance, low latency, and high-channel density remain paramount. On the other, PC-based and IP-distributed architectures are expanding the addressable range of deployment scenarios by offering greater flexibility in integration, scaling, and remote management.
The study’s segmentation captures this technological diversity without treating it as a simple hierarchy. Instead, it frames each type in terms of where it creates the most strategic value. Hardware-oriented processing remains relevant in settings that demand reliable, high-capacity signal handling and predictable performance under sustained operational loads. PC-based and distributed IP approaches, meanwhile, are gaining traction in environments where modularity, reconfiguration speed, and software-driven control are becoming more important than raw processing concentration. This split is not merely technical; it reflects different purchasing priorities, integration expectations, and total-cost considerations.
On the application side, the market’s demand profile is similarly varied. Command and control environments continue to represent a structurally significant portion of demand, reflecting the need for high-availability visualization, multi-source aggregation, and real-time situational awareness. Commercial display and advertising applications contribute another substantial layer, driven by the expansion of large-format visual installations, dynamic content strategies, and experiential media deployments. Broadcast and media applications add a distinct set of requirements, particularly where signal integrity, format handling, and pipeline flexibility are critical. Corporate and education environments round out the demand base with use cases that often emphasize ease of deployment, multi-screen coordination, and cost-effective scaling.
Regional dynamics further shape how these technology and application trends manifest. Different markets are influenced by distinct infrastructure maturity, procurement practices, integration ecosystems, and investment cycles. In some regions, demand is closely tied to large-scale control-room and visualization projects; in others, commercial signage and media-driven installations play a larger role. The study’s regional breakdown is intended to help readers interpret where growth is being led by institutional procurement, where it is being pulled by technology adoption, and where it remains sensitive to broader capital spending patterns.
This layered view matters because the next wave of competitive advantage will likely come from recognizing how these layers interact. A technology type that performs well in one application context may face different adoption barriers in another. A region with strong overall demand may still present uneven opportunities depending on the maturity of local integration channels and the pace of infrastructure modernization. The full report provides the analytical structure needed to navigate those interactions without resorting to broad, undifferentiated market statements.
Competitive Landscape: Differentiation, Positioning, and Emerging Moves
The worldwide video splicer market is shaped by a mix of established visualization specialists, display-control vendors, and technology providers focused on specific signal-processing niches. Competitive advantage in this landscape is increasingly defined not just by hardware performance, but by the ability to deliver integrated control, image optimization, interoperability, and deployment flexibility across diverse customer environments.
Several companies illustrate the breadth of strategic positioning in the market. NovaStar Technology has built a profile around LED display control systems and video splicing processors, with flagship solutions designed for fine-pitch LED applications and advanced image processing. Its emphasis on modular capability and integrated control highlights a direction in which many customers are moving: toward platforms that combine processing, management, and visualization optimization in a more cohesive architecture. Colorlight Cloud Tech Ltd contributes a complementary angle through video processor and splicing solutions that support multi-screen configurations and dynamic content processing, reflecting the growing importance of flexible display matrices in commercial and signaling environments.
Shenzhen Huidu Technology Co., Ltd. operates in the broader display control and multi-image splicing space, with processor families designed for large LED video walls and plug-and-play signal integration. Its focus on third-party equipment control and modular signal cards underscores a practical trend in the market: customers increasingly value solutions that reduce integration friction while preserving compatibility with existing infrastructure. Shenzhen Mooncell Electronics Co., Ltd. offers LED control systems and video splicers oriented toward multi-channel splicing, monitoring, and high-load applications, reinforcing the continuing demand for reliable, high-capacity control in full-color display environments. Xiamen RGBlink Science & Technology Co., Ltd. rounds out the China-based processing segment with a focus on professional video signal processing, including seamless switching, scaling, and splicing for AV and LED display settings.
International players bring a different competitive dimension. Barco is recognized for high-performance video wall controllers and processors designed for control rooms, command centers, and digital signage environments. Its emphasis on seamless management across multiple displays aligns with the needs of organizations that treat video splicing as part of a broader visualization and operational workflow rather than an isolated signal task. Starfish Technologies, meanwhile, represents a software-oriented approach with transport stream splicing solutions geared toward broadcast and media delivery, including frame-accurate handling and support for industry cueing standards. This software-defined angle reflects a parallel trajectory in the market, where certain applications are shifting toward more flexible, pipeline-aware processing models.
Recent company activity further illustrates how the competitive landscape is evolving in real time. In early 2026, Starfish Technologies presented updated releases of its TS Splicer products alongside a new Monitoring Dashboard aimed at improving operational oversight across on-premises, cloud, and hybrid deployment models. That move highlights a broader industry direction: even in segments rooted in signal processing, vendors are increasingly emphasizing visibility, manageability, and deployment flexibility as competitive differentiators.
At the same time, adjacent infrastructure and service dynamics continue to shape the operating environment. Updates to maintenance applications, partner certification programs, and skills-based sponsorship efforts are not merely operational details; they reflect how vendors are investing in service ecosystems, qualification pathways, and long-term customer support structures. For buyers and competitors alike, these actions signal where companies are placing bets on post-sale value, integration preparedness, and market education.
The study’s competitive analysis is built to go beyond company profiles. It situates each player within the broader pressure points of the market: technology mixing, integration expectations, regional channel strength, and the growing importance of total-cost and service considerations. Readers gain a view of how positioning differs across segments, where incumbents face the strongest challenges, and where new entrants or platform-level shifts may alter existing relationships. The full report preserves this analytical depth while keeping the competitive narrative grounded in operational reality rather than abstracted rivalry.
Beyond Demand Numbers: Regulation, Infrastructure Cost, and Market Friction
Market growth does not occur in a vacuum. The trajectory of video splicing demand is influenced by wider infrastructure policy, energy and facility cost dynamics, and regulatory decisions that shape how organizations plan, finance, and deploy large-scale technology environments. These forces are especially relevant when splicing technology is embedded in control rooms, large display installations, and broadcast pipelines that depend on stable operational and physical infrastructure.
Recent regulatory and policy developments provide useful context for understanding where friction—and opportunity—may emerge. In the broadband and connectivity domain, legal rulings affecting the FCC’s authority over net neutrality have introduced uncertainty into the regulatory landscape for internet and mobile broadband providers. While not a direct splicing mandate, such shifts can influence how network operators and content delivery organizations plan their architecture and cost structures, which in turn affects the broader environment in which video infrastructure is deployed and managed.
Infrastructure cost pressures are equally important. Hyperscale data center projects are increasingly associated with very large capital commitments, involving extensive energy, transmission, and networking requirements across large facility footprints. As these projects move forward, the cost of power delivery, transmission-line upgrades, substations, and related infrastructure becomes a material part of the planning equation. That matters for visual infrastructure markets because command centers, media operations, and commercial display environments are often tied—directly or indirectly—to broader facilities and connectivity strategies.
Policy responses are beginning to shape how these costs are allocated. In one notable development, major hyperscale operators committed under a ratepayer protection framework to absorb transmission and distribution upgrade costs without increasing household electricity rates. Meanwhile, regulatory actions in certain jurisdictions have moved to require large data centers to enter long-term power contracts and bear infrastructure-related costs for transmission and substation upgrades. At the federal level, permitting acceleration for qualifying large capital projects has also been used to support high-voltage transmission and networking equipment deployment.
The strategic implication for video splicing markets is indirect but real. When infrastructure procurement cycles shift, when power and transmission costs become more prominent in project economics, and when regulatory expectations alter the pace of facility expansion, the timing and scale of downstream visual infrastructure investments can change as well. Command and control rooms, large-scale display installations, and media delivery environments do not operate independently of these conditions. They are part of a broader investment chain.
The report addresses these dynamics not as peripheral commentary, but as part of the market’s operating context. By acknowledging where regulatory and infrastructure pressures may accelerate, delay, or reshape demand, the study helps decision-makers separate structural growth from cycle-dependent expansion. That distinction is essential for 2026 planning, when organizations must distinguish between enduring adoption trends and short-term project pull driven by external policy or cost conditions.
What the Full Report Delivers: From Executive Summary to Actionable Intelligence
The Worldwide Video Splicer Market study is designed as a working intelligence asset rather than a static overview. It provides the analytical scaffolding needed to support strategic planning, investment review, vendor assessment, and market-entry judgment. The report’s structure reflects that intent, moving from high-level trajectory to segmentation detail, competitive context, and the operational forces that influence market behavior.
At the executive level, the report offers a consolidated view of where the market has been, where it is projected to go, and what that trajectory implies for near-term and mid-term planning. It anchors those observations in a consistent dataset spanning the historical period and the forecast window, allowing readers to evaluate growth against a stable reference frame. For 2026 decision-makers, that continuity is especially valuable because it supports comparison across internal forecasts, procurement calendars, and technology roadmaps.
Beneath the top-line view, the study provides a segmentation framework that enables more precise interpretation of market behavior. Readers can examine how technology types, application environments, and regional dynamics contribute to overall growth, and where the balance of opportunity is shifting. The segmentation is presented with enough depth to support commercial analysis while remaining accessible to cross-functional teams that need a shared understanding of market structure.
The competitive section extends that analysis by placing key companies within the market’s strategic logic. Instead of treating vendor profiles as isolated company summaries, the report connects them to broader themes such as integration expectations, deployment flexibility, service ecosystem development, and segment-specific differentiation. This approach helps buyers compare alternatives with greater context and helps vendors or investors assess where competitive intensity is rising and where positioning remains underappreciated.
The report also integrates regulatory and infrastructure context as part of the market narrative. That inclusion matters because video splicing decisions increasingly intersect with facility planning, connectivity expectations, and broader capital cycles. By addressing those influences directly, the study helps readers avoid overly narrow interpretations of demand and instead evaluate the market through a more complete operational lens.
Crucially, the full report retains the detailed breakdowns that executives and analysts need for concrete planning. It supports questions such as which technology categories are gaining relative momentum, how application demand differs by environment, where regional growth is most concentrated, and how competitive dynamics vary across segments. Those answers are presented in a way that supports scenario analysis, procurement strategy, and product or channel planning without reducing the market to a few headline figures.
For teams preparing 2026 decisions, the study is intended to serve as both a reference and a conversation starter. It gives strategy leaders a defensible basis for investment assumptions, helps procurement teams anticipate where supply and competitive pressure may evolve, and provides technical and operational teams with a clearer picture of the market forces shaping integration requirements and deployment choices.
Conclusion: Using Market Intelligence to De-Risk Strategy in 2026
The worldwide video splicer market is entering a phase in which growth is real but uneven, and in which strategic advantage depends on understanding the structure beneath the aggregate numbers. A 7.42 percent CAGR across the forecast window signals sustained momentum, but the more important question for enterprises is where that momentum is coming from, how durable it is, and what it means for specific technology choices, application priorities, and regional strategies.
This is precisely the space the Worldwide Video Splicer Market study is built to address. It connects historical performance to forward-looking projection, situates technology and application trends within real operational contexts, and frames the competitive landscape in terms of differentiation, service ecosystems, and integration expectations. It also acknowledges the wider infrastructure and regulatory forces that can alter the timing and scale of demand, helping decision-makers separate long-term adoption patterns from short-term project cycles.
For 2026 planning, that combination of breadth and depth is what turns market data into usable strategy. The full report provides the detailed segmentation, company-level context, and operational analysis needed to support procurement, product, channel, and investment decisions with greater confidence. We invite executives, analysts, and planning teams to explore the complete study for the full intelligence set—so that market insight can be translated directly into informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Video Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Releases Worldwide Sandwich Car Heat Shield Market Report with 5.18% CAGR and USD 1,640.5 Million Growth Outlook to 2032
By PW Consulting, 2026-09-01
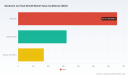
Strategic Intelligence for the Automotive Thermal Management Landscape: Unlocking Value in the Global Sandwich Car Heat Shield Market
As the automotive industry accelerates through its most significant technological transformation in decades, thermal management has emerged as a critical battleground for engineering excellence and supply chain resilience. The sandwich car heat shield market sits at the intersection of regulatory compliance, electrification demands, and lightweighting imperatives. Our recently published Worldwide Sandwich Car Heat Shield Market research delivers the comprehensive intelligence executives need to navigate this evolving terrain through 2032 and beyond.
Worldwide Sandwich Car Heat Shield Market
This market research is not merely a statistical compilation. It is a decision-support instrument designed to help strategic leaders decode competitive pressures, anticipate material shifts, and align product roadmaps with real demand signals. From OEMs sourcing next-generation shielding architectures to tier suppliers recalibrating capacity and material mix, the insights contained in our report provide the structured clarity required to convert uncertainty into advantage.
Worldwide Sandwich Car Heat Shield Market
Why 2026 Is a Pivotal Year for Automotive Heat Shield Strategy
The global sandwich car heat shield market has demonstrated sustained momentum, with total revenue expanding from approximately $890.12 million in 2020 to an estimated $1,150.45 million in 2025. Looking ahead, the market is projected to reach roughly $1,212.98 million in 2026 and continue its growth trajectory toward approximately $1,640.5 million by 2032. This expansion reflects a compound annual growth rate of around 5.18% across the 2026 to 2032 forecast period, signaling a steady, structurally supported demand environment rather than a short-lived cyclical spike.
Worldwide Sandwich Car Heat Shield Market
For decision-makers, these figures underscore a fundamental reality: heat shield requirements are becoming more sophisticated, more diversified, and more integral to vehicle performance. As emission regulations tighten and vehicle architectures evolve, OEMs are increasingly compelled to adopt advanced lightweight materials, multi-layer insulation systems, and sandwich-type structures that deliver thermal protection without sacrificing fuel efficiency, range, or packaging efficiency. The result is an expanding addressable market where performance requirements, cost constraints, and regulatory pressures converge.
What makes 2026 especially consequential is the timing of multiple overlapping forces. Electrification continues to reshape thermal requirements, particularly around battery packs and power electronics. At the same time, internal combustion platforms still require continuous optimization to meet evolving standards. This dual dynamic is creating demand for specialized shielding across multiple vehicle systems, reinforcing the strategic importance of understanding where growth is durable and where competitive differentiation is being built.
Decoding the Market Architecture: Materials, Applications, and Regional Realities
A core strength of this report lies in its ability to map the market's architecture in a way that supports practical strategic choices. The research examines the principal material families driving heat shield production, including aluminum, stainless steel, and ceramic-based or other advanced materials. Each material category represents a distinct value proposition: aluminum-based shields are widely recognized for their lightweight characteristics and heat-resistant performance in sandwich and multi-layer constructions, stainless steel continues to serve applications where durability and high-temperature resilience are paramount, and ceramic or composite-oriented solutions are gaining attention for specialized insulation needs and weight-sensitive designs.
The report also analyzes the primary application segments in which heat shields are deployed. Exhaust systems remain a central demand node, reflecting their ongoing role in managing underbody temperatures and meeting compliance requirements. Turbocharger applications represent another significant area of consumption, driven by the need to protect sensitive components from extreme thermal exposure. Engine compartments continue to generate consistent demand as manufacturers refine packaging and thermal isolation strategies, while underbody and other specialized applications contribute additional growth vectors tied to body architecture, chassis protection, and electrified component shielding.
Importantly, the study places these material and application dynamics within a regional framework. The market's distribution reflects varying degrees of manufacturing activity, vehicle production concentration, and technology adoption patterns across major geographies. Asia Pacific, Europe, and North America represent substantial portions of the market landscape, while Latin America and the Middle East and Africa contribute additional demand tied to regional vehicle production and aftermarket activity. Rather than presenting these as static snapshots, the report interprets them as indicators of where supply capabilities, customer expectations, and competitive intensity are likely to evolve.
This segmentation is especially valuable for companies evaluating capacity allocation, sourcing strategies, and product positioning. Understanding how material preferences, application requirements, and geographic demand interact allows organizations to prioritize investments with greater confidence and avoid overcommitting to segments that may be structurally limited or increasingly price-pressured.
Competitive Dynamics: How Leading Players Are Shaping the Next Generation of Heat Shields
The competitive landscape in this market is defined by a mix of specialized material providers, component manufacturers, and broader automotive supplier groups. Together, these players are influencing standards for thermal performance, weight reduction, acoustic behavior, and cost efficiency. Their strategies reveal where the market is heading and which capabilities are becoming table stakes for sustained participation.
Among the firms examined in the report are Carcoustics International GmbH, Morgan Advanced Materials, Autoneum, ElringKlinger AG, Dana Incorporated, Tenneco Inc., Alkegen, Vibrant Power Inc., JBC Technologies, Inc., and Argent International. These organizations represent a cross-section of the industry's value chain, from engineered materials and customized insulation solutions to multi-layered metallic shields and adhesive-backed thermal systems. Their differing product philosophies illustrate the range of technical routes available to address the same underlying challenge: protecting sensitive vehicle components while keeping weight, cost, and complexity within acceptable bounds.
Several recent developments highlight the pace of innovation in this space. In late 2024, ElringKlinger AG introduced ElroForm TP-ECO and ElroSafe shielding solutions for battery systems, emphasizing thermal propagation protection and EMI shielding at a major industry fair. That move reflects a broader industry pivot toward battery safety as a priority, particularly as electrified platforms increase the stakes for thermal containment. Around the same time, Autoneum opened a new Research & Technology Center in Shanghai focused on new mobility and e-mobility components, including thermal management solutions. This expansion signals the growing importance of localized innovation and faster response to regional vehicle architectures.
Further evidence of product evolution emerged in 2025, when Autoneum Holding AG advanced lightweight fiber-based heat shields offering combined thermal and acoustic insulation with improved recyclability for both ICE and electric vehicles. In parallel, Zircotec unveiled a new range of ceramic coatings aimed at lighter EV battery and heat-shield designs, enabling substitution of heavier steel with coated aluminum or composites. These developments point to a recurring industry theme: material substitution and multi-functional integration are becoming central levers for competitive advantage.
The report interprets these moves within the wider context of market concentration. With a measurable share held by leading participants, the landscape is neither fully fragmented nor dominated by a single entity, creating room for differentiation through product performance, regional reach, service integration, and advanced material technology. For buyers and suppliers alike, understanding which firms are building durable advantages and where gaps remain is essential for negotiating positioning, partnership strategy, and long-term supply planning.
Strategic Forces Reshaping Demand: Electrification, Regulation, and Lightweight Innovation
The growth of the sandwich car heat shield market is not simply a function of more vehicles being produced. It is increasingly shaped by the changing requirements of those vehicles. One of the most impactful dynamics is the rising adoption of plug-in hybrid electric vehicles and battery electric vehicles, which creates specialized demand for lightweight heat shields designed to protect battery packs and electronic components. As thermal management becomes more tightly linked to battery safety, efficiency, and longevity, shielding solutions are expected to play a more prominent role in overall vehicle architecture decisions.
Regulatory pressure is another powerful driver. Stricter emission standards are encouraging OEMs to increase the use of advanced lightweight materials such as aluminum, composites, and multilayer insulation within heat shields. In this environment, the heat shield is no longer just a passive protective element. It is part of a broader system-level effort to reduce mass, optimize performance, and remain compliant without compromising reliability. This shift increases the strategic relevance of suppliers that can deliver multi-functional solutions, whether through fiber-based fillers combined with metallic layers or engineered coatings that enable lighter constructions.
Material innovation is also redefining what heat shields can achieve. Sandwich-type structures often combine high-temperature-resistant fiber fillers with aluminum or metallic layers to improve thermal insulation in automotive applications. Such configurations help balance protection with weight reduction, a crucial consideration in both conventional and electrified platforms. Meanwhile, developments such as adhesive-backed thermal dissipating systems and ceramic-coated alternatives are expanding the menu of options available to design engineers. These solutions can offer weight savings and performance characteristics that differ meaningfully from traditional metal-only approaches.
For businesses, the implication is clear: competitive positioning in this market depends on understanding where material performance, manufacturing capability, and customer requirements intersect. A company that can anticipate which material routes will gain traction in different applications, and in different regions, will be better equipped to shape product specifications, pricing strategy, and supply relationships.
Inside the Report: What Decision-Makers Will Find
The Worldwide Sandwich Car Heat Shield Market research is designed to translate complex market signals into actionable intelligence. It provides a structured assessment of historical performance, current conditions, and forward-looking projections, with a forecast horizon extending through 2032. The report is organized to help executives move from macro understanding to targeted decision-making.
Readers will find detailed market size analysis that situates the industry within a consistent trajectory, including base-year context and forecast estimates that support planning discussions. The research evaluates demand across multiple dimensions, including material types and end-use applications, so that organizations can identify segments that align with their capabilities and growth objectives. Regional analysis is included to support localization strategies, supply network decisions, and market-entry assessments.
The competitive section goes beyond company names to examine how key players are positioned, what distinguishes their product philosophies, and how recent launches and facility investments reflect broader strategic priorities. This coverage is supported by information on recent industry developments, giving readers context on how innovation activity is unfolding in real time. By integrating these developments with market structure and segmentation, the report helps users interpret whether new product introductions and investments represent incremental refinement or meaningful shifts in market direction.
Additional analytical elements address the operational realities that influence purchasing and production decisions. This includes the role of raw material characteristics, such as the lightweight and heat-resistant properties of aluminum-based shields, the layered construction logic behind sandwich-type heat shield structures, and the increasing weight and cost considerations that shape OEM preferences. Regulatory developments and macro trends are also examined as part of the broader demand environment, so that strategic readers can distinguish between temporary fluctuations and structural inflection points.
Crucially, the report is built to support different kinds of strategic work. For product developers, it provides market context around application priorities and material trends. For procurement and supply chain leaders, it helps illuminate where demand is concentrated and how competitive supply dynamics may influence sourcing flexibility. For corporate strategists and investors, it offers the kind of market framing needed to assess growth potential, risk exposure, and differentiation opportunities without relying on fragmented or anecdotal information.
How to Use This Intelligence in 2026 Planning
In a market growing at a measured but persistent pace, the companies that outperform are rarely those simply chasing volume. They are the ones that understand where value is being created and how competing firms are attempting to capture it. The 2026 to 2032 outlook provided in this research is especially useful for organizations planning capacity, portfolio adjustments, and partnership strategies in a period when vehicle platforms are diversifying rather than converging.
OEMs and tier suppliers can use the report to stress-test assumptions about material selection and application targeting, particularly as lightweighting and electrification continue to reshape specifications. Manufacturers of heat shields and advanced thermal materials can use the analysis to identify high-potential segments and assess where their product offerings align with customer priorities such as weight reduction, thermal durability, acoustic performance, and recyclability. Meanwhile, companies evaluating market entry or expansion can use the regional and segmentation insights to target geographies and applications with the strongest strategic fit.
Because the research inhibits only high-level market estimates and deliberately omits granular regional, application, or material-level breakdowns in public-facing summaries, it preserves the full analytical value for readers who engage with the complete study. The published overview establishes credibility and direction, while the detailed segmentation and supporting data remain accessible through the full report. This design ensures that strategic users receive the depth they need without diluting the commercial intelligence that gives the research its competitive edge.
Conclusion: Turning Market Complexity into Strategic Clarity
The global sandwich car heat shield market is evolving in response to a rare combination of forces: tightening regulation, electrification-driven thermal requirements, lightweight material innovation, and increasingly diverse vehicle architectures. In such an environment, informed strategy depends on more than top-line growth expectations. It requires a rigorous understanding of market structure, competitive behavior, and the technical and commercial factors that determine which solutions will win preference in different applications and regions.
Our Worldwide Sandwich Car Heat Shield Market research is built to deliver that understanding. It provides a comprehensive foundation for 2026 decision-making and multi-year planning, combining historical context, forecast trajectory, segmentation interpretation, and competitive analysis into one coherent strategic resource. By engaging with the full report, organizations can move from broad awareness to precise, defensible action across sourcing, product development, market positioning, and investment planning.
For executives seeking to stay ahead in a market where thermal performance, weight, cost, and compliance all matter at once, this research offers the level of insight required to make informed choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Sandwich Car Heat Shield Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global Optical Current Transformer Market Report Projects 7.5% CAGR to Reach 1526.33 Million USD by 2032
By PW Consulting, 2026-09-01
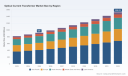
Global Optical Current Transformer Market 2026–2032: Strategic Intelligence for the Next Energy Transition Decade
The worldwide transition toward digitized, decarbonized, and highly resilient power networks is quietly rewriting the rules of high-voltage measurement. At the center of this shift sits a technology that was once considered niche but has now become indispensable to the architecture of modern grids: optical current transformers. As utilities, transmission operators, and industrial developers navigate an environment shaped by renewable integration, offshore HVDC expansion, and stringent sustainability mandates, understanding where this market is heading has moved from technical curiosity to executive necessity. Our latest Worldwide Optical Current Transformer Market study is designed precisely for that purpose: a focused, decision-ready intelligence asset that translates multidimensional market signals into actionable strategy for the 2026–2032 horizon.
Worldwide Optical Current Transformer Market
This report arrives at a moment when the broader energy infrastructure landscape is being reshaped by three overlapping forces. First, the accelerating deployment of high-voltage direct current links, particularly those feeding offshore renewable parks and cross-border interconnections, is demanding measurement solutions that preserve accuracy across wide current and frequency ranges without the drift and saturation limitations that can affect conventional electromagnetic designs. Second, the global push toward digital substation automation is making interoperability, real-time data fidelity, and seamless integration with process bus architectures a baseline procurement requirement rather than a premium add-on. Third, environmental regulation and corporate sustainability commitments are forcing high-voltage equipment manufacturers and buyers to scrutinize not only performance but also the lifecycle footprint of the components they specify, from insulating gases to composite materials. Optical current transformers, with their passive designs, fiber-optic sensing cores, and compatibility with modern communication standards, sit at the intersection of all three trends.
Worldwide Optical Current Transformer Market
Why 2026 Demands a Fresh Strategic Lens
For senior leaders in utilities, OEMs, system integrators, and investment teams, the current market window is not simply about tracking growth. It is about recognizing where structural advantages are being built, where competitive intensity is about to intensify, and where procurement or portfolio decisions made in the next twelve to eighteen months will lock in capabilities for the better part of a decade. The base year of our analysis is 2025, with historical data tracing back to 2020, and the forecast period extends through 2032. This framing allows decision-makers to compare a fully realized post-deployment baseline against a forward trajectory shaped by new project pipelines, technology maturation, and evolving regulatory expectations.
Worldwide Optical Current Transformer Market
The headline trajectory reflects a market that has moved past the experimental phase and entered a period of sustained, infrastructure-led expansion. Drawing on historical revenue patterns and forward project momentum, the worldwide market generated roughly 820 million USD in 2023, advanced to approximately 870 million USD in 2024, and reached an estimated 920 million USD in 2025. From there, the study models steady, compounding growth that brings the market to about 989 million USD in 2026 and continues upward through the end of the forecast period. The implied seven-and-a-half-year growth path is neither explosive nor flat; it is the kind of measured expansion that rewards disciplined positioning, selective partnerships, and early alignment with end-use project cycles. A compound annual growth rate of 7.5 percent underscores that this is a maturing yet still ascending category, where gains are increasingly tied to differentiated value propositions rather than volume alone. For executive teams, that combination matters. It means the total addressable opportunity is substantial enough to justify dedicated commercial attention, while the pace of growth is steady enough that underestimating competitive or supply-chain dynamics can quietly erode margins over time.
Equally important for strategy is the concentration pattern visible across the competitive field. The market remains moderately consolidated, with the top three players accounting for a meaningful share of revenue and the top five consolidating an even larger portion of total activity. This structure sends a clear strategic signal: scale, brand trust, and established substation integration credibility still matter enormously, but there is enough dispersion to create room for specialized challengers, regional champions, and technology-led entrants that can win on particular use cases, delivery models, or cost-performance profiles. The implication for buyers is that supplier evaluation should go beyond headline reputation and drill into application fit, interface compatibility, and lifecycle support. For vendors, it means that differentiation is unlikely to come from a single generic offering; it will come from how well a product family aligns with specific grid architectures, renewable integration scenarios, and sustainability expectations.
The Technology and Application Logic Behind the Growth Curve
Optical current transformers are gaining traction because they answer several long-standing constraints in high-voltage environments simultaneously. Their sensing principles, rooted in the Faraday effect, allow current measurement through optical fibers and glass ring sensors rather than relying solely on traditional magnetic core arrangements. That architecture brings practical advantages in contexts where accuracy, isolation, weight, and maintenance burden are all under scrutiny. At the same time, the components themselves are increasingly tied to specialized optical fibers, composite insulators, and carefully engineered sensor rings, which means the supply base and manufacturing know-how are becoming just as important as the end-product specifications. Any strategy that overlooks the component ecosystem risks missing where future pricing power, lead-time stability, and qualification bottlenecks will emerge.
The application landscape is similarly instructive. Demand is being pulled most strongly by high-voltage direct current transmission systems, where precise current measurement is critical for control, protection, and grid stability across long distances and mixed renewable generation profiles. This is not a trivial segment. HVDC is increasingly the backbone of large-scale offshore renewable integration and interregional power balancing, and the measurement equipment specified on those projects tends to stay in service for decades. A second, structurally important demand pool comes from smart grid infrastructure, where digital substation programs are driving wider adoption of devices that can interoperate cleanly with process bus environments and modern utility data architectures. A third channel, encompassing railways and industrial power systems, continues to provide additional volume and diversification, particularly in geographies and project types where robust, compact, and application-tailored current sensing is needed outside the largest transmission networks.
On the technology side, the market is not monolithic. Fiber optic current sensors represent the larger revenue pool within the product taxonomy and are closely associated with digital substation integration and modular deployment models. Bulk optical current transformers form the second major product family and are often evaluated for high-rating applications where voltage class, current range, and long-term field reliability dominate purchasing criteria. Understanding how these two lines compete, complement, and evolve against one another is central to making sound product roadmap and procurement decisions. The strategic question for many organizations is not simply which category is larger, but which category aligns best with the specific voltage levels, interface requirements, and environmental constraints of their target projects.
Competitive Landscape: Scale, Specialization, and the New Battleground
The field of incumbent and emerging participants reflects a market where global credibility and technological specificity are both being monetized. Several multinational names have built positions by integrating optical current transformer solutions into broader high-voltage instrument transformer and digital substation portfolios. Siemens Energy, for example, offers optical current transformers within its high-voltage instrument transformer and digital substation solutions, aligning measurement hardware with the wider automation context that utilities increasingly demand. ABB remains an active provider of optical current transformers and fiber-optic current sensors, including models positioned for high-voltage applications and digital substation integration, reinforcing its long-standing presence in instrument transformer ecosystems. GE Vernova develops and supplies optical current transformer solutions as part of its instrument transformer portfolio for grid applications, linking current sensing to a broader suite of grid-oriented equipment. Hitachi Energy offers the Free Standing Fiber Optic Current Sensor, an optical current transformer with an IEC 61850-9-2LE digital interface designed for integration into digital substation automation systems, a specification that matters because it connects hardware choice directly to substation communication architecture.
Alongside these broader portfolio players, several companies have carved out specialized positions by focusing more tightly on optical measurement technologies and the needs of demanding high-voltage applications. Arteche provides SDO-OCT and optical current transformers for HVDC applications based on the Faraday effect and a 3x3 interferometer topology, supporting modular design, IEC 61869-9 digital interfaces, both HVDC links for renewable integration and general high-voltage use. That positioning is strategically significant because it ties the product narrative directly to the fastest-growing end-use driver in the market while also emphasizing interface compatibility and modularity. Trench Group supplies Trench Optical Current Transformers rated up to 800 kV and 4000 A, with extensibility to 6000 A, featuring optical sensing technology, composite insulators, nitrogen insulation, passive design, IEC 61850-9-2 process bus interface, and sustainability features including zero GWP insulation. For organizations evaluating suppliers against environmental criteria, that combination of high voltage capability and non-SF6 insulation is a meaningful differentiator, especially when lifecycle emissions and regulatory pressure around conventional insulating gases are taken into account.
The competitive picture is not limited to established Western manufacturers. NR Electric Co., Ltd. provides optical current transformers and related protection and automation solutions for power systems, while Acrel Co., Ltd. manufactures optical current transformers as part of its current transformer and power monitoring product lines. These participants illustrate an important reality: the market is global, and regional manufacturing capability, cost structure, and localized support are becoming increasingly relevant as procurement teams balance performance, delivery assurance, and total cost of ownership. In a moderately concentrated market, competition often plays out not only through headline market share but through project wins in specific voltage classes, regional grid programs, and integrated solution bundles.
Recent activity from the leading players reinforces that the battleground is being shaped as much by documentation, integration readiness, and specification clarity as by product launches alone. In early 2026, Arteche updated or released brochure material for its Optical Current Transformer SDO OCT, highlighting Faraday effect technology and HVDC applications, an adjustment that matters because clearer specification narratives help both procurement teams and engineering groups align on suitability for renewable-integrated HVDC contexts. Around the same time, Trench Group refreshed documentation for its Trench Optical Current Transformers, emphasizing compact design, sustainability under its Regenera label, and digital substation compatibility. These moves are best read as strategic positioning signals. In a market where substation standards, interface expectations, and environmental criteria increasingly govern vendor shortlists, the ability to communicate precisely how a device fits into IEC-aligned digital architectures and sustainability goals can be as commercially powerful as the hardware itself.
Market Dynamics Shaping the 2026–2032 Outlook
Strategic forecasting is only as useful as the dynamics it explains. In this market, several forces are interacting to determine not just how fast growth occurs, but where value accumulates. The first is the renewable-driven expansion of HVDC links, particularly those associated with offshore parks and long-distance renewable integration. As these networks scale, they create persistent demand for current measurement that maintains accuracy across a wide range of currents and frequencies without degradation in performance. That requirement favors technologies that can deliver stable readings in environments where conventional sensors may face tighter constraints. It also ties procurement decisions more closely to long-lived transmission programs, which means early supplier qualification and specification alignment can have multi-year consequences.
The second dynamic is digital substation standardization. Optical current transformers commonly integrate with IEC 61850-9-2 process bus and IEC 61869-9 digital interfaces, and that interoperability is becoming central to substation automation strategies. For buyers, the practical implication is that product selection cannot be separated from communication architecture, data handling workflows, and protection system integration. For suppliers, the implication is that interface maturity, documentation quality, and demonstrated integration pathways are now part of the core value proposition. In a market where digital substation programs can span years of engineering, testing, and phased deployment, standards alignment is not a checkbox; it is a commercial precondition.
The third dynamic is sustainability and environmental responsibility in high-voltage equipment. Traditional SF6-based systems carry a substantial greenhouse gas footprint, while some advanced optical current transformer designs use nitrogen insulation with zero GWP, creating a stark contrast in lifecycle impact. As utilities, regulators, and large industrial customers face increasing pressure to account for embodied emissions and operational environmental performance, insulation choice and overall device footprint are moving from technical details to procurement criteria. That does not mean sustainability automatically dictates every purchase, but it increasingly shapes shortlists, funding approvals, and public-facing project narratives. Companies that can credibly demonstrate environmental advantages while maintaining technical performance and safety standards are positioned to capture a differentiated share of demand.
The fourth dynamic is supply-side reality. Because optical current transformers depend on specialized optical fibers, glass ring sensors, and composite insulators, the supply base for core components is strategically relevant. Even when final assembly and system integration are concentrated among a limited number of firms, the availability, qualification, and cost behavior of critical inputs can influence pricing, lead times, and project certainty. Strategic planners should therefore view the market not only as a landscape of named competitors but also as an ecosystem of materials, manufacturing processes, and certification pathways. Bottlenecks or advancements in component supply can shift commercial outcomes just as much as product specification improvements can.
What Our Worldwide Optical Current Transformer Market Study Delivers
This report is structured to move beyond general commentary and provide the operational intelligence that strategy, product, procurement, and investment teams can use directly. The study builds a coherent view of the market through layered analysis rather than isolated charts, so that readers can understand not just where the market is going but why, and what that implies for decision-making in their specific context.
At the core of the study is a comprehensive market sizing and forecast framework that places historical revenue patterns alongside forward estimates through 2032. This allows readers to see the full shape of the growth curve, identify inflection points, and test how different assumptions about project pipelines, technology adoption, and regional demand might affect outcomes. The framework is presented in a way that supports internal scenario planning, whether the goal is capacity alignment, portfolio prioritization, or investment timing.
The research also provides a structured competitive profiling section that examines the companies shaping the market, their positioning, and the ways they are competing on technology, integration, and application focus. Rather than treating competitors as static names, the analysis connects each player’s capabilities to the practical questions buyers face: which solutions fit digital substation architectures, which are strongest in HVDC contexts, which emphasize sustainability, and which compete on regional delivery or cost-performance balance. This approach is designed to support supplier evaluation, partnership strategy, and competitive benchmarking.
A substantial part of the study is devoted to the operational content that turns high-level market trends into usable insight. Readers will find detailed treatment of product categories, application drivers, interface and standards considerations, and the component ecosystem that supports optical current transformer manufacturing. The report examines how fiber optic current sensors and bulk optical current transformers compare in relevance across different voltage classes and use cases, and it discusses how application demand from HVDC transmission systems, smart grid infrastructure, and railways and industrial settings differs in pace, specification requirements, and procurement behavior. Just as importantly, the study addresses the strategic implications of those differences, helping readers determine where to focus commercial efforts and where to monitor rather than commit.
Regulatory and standards dynamics are treated as part of the competitive environment rather than as background information. Because digital substation integration increasingly hinges on interface compatibility and process bus alignment, the study examines how IEC 61850-9-2 and IEC 61869-9 considerations influence product selection, project timelines, and supplier evaluatio n. Sustainability is similarly treated as a market force with commercial consequences, not merely a narrative theme. The analysis considers how environmental expectations around insulation choices and lifecycle impact affect buyer criteria, and where those expectations are most likely to translate into actual specification shifts.
Recent developments are incorporated to give readers a current-sense of how leading participants are refining their market positions. Updated product documentation, specification emphasis, and application focus from key suppliers are interpreted as indicators of where the market is being pushed toward greater clarity on HVDC suitability, compact design, sustainability labeling, and digital substation compatibility. These signals matter because they often precede shifts in shortlist composition, RFP requirements, and engineering preferences. By placing recent activity in context, the study helps readers distinguish transient marketing noise from durable positioning changes.
The study also includes competitive concentration analysis, which helps explain how market share is distributed and what that means for both buyers and vendors. A moderately concentrated market can create advantages for established players in terms of credibility, reference projects, and integration experience, while still leaving space for specialized players to win on technology fit or regional execution. Understanding that balance is essential for realistic planning. It helps buyers avoid overpaying for brand prestige where application fit is the true driver, and it helps vendors understand where they need to compete on integration capability, documentation, or sustainability credentials in order to break through.
Across all of these components, the report is built with a practical orientation. It is designed for teams that need to make decisions about product roadmap priorities, supplier selection, market entry or expansion, partnership formation, and capital allocation. To support that orientation, the study focuses on the relationships between technology, application demand, standards, sustainability, and competitive behavior, rather than presenting each as an isolated topic. The aim is to give readers a usable map of the market environment, one that can inform both immediate actions and longer-term positioning.
How to Use This Intelligence in 2026
For leadership teams, the most valuable use of this research is not simply to confirm that the market is growing, but to decide what kind of exposure, investment, or caution the growth pattern justifies. Organizations evaluating supplier relationships can use the competitive and application analysis to align product fit with specific project architectures, especially where digital substation integration and HVDC relevance matter. Companies planning product or service expansion can use the segmentation logic to determine whether to prioritize fiber optic current sensors, bulk optical current transformers, or application-specific bundles, and to understand which demand pools offer the most durable revenue characteristics. Investors and strategy teams can use the forecast structure and concentration analysis to assess where scale advantages are entrenched and where niche differentiation still offers credible upside.
Equally important, the study helps organizations anticipate where future competition is likely to intensify. As HVDC expansion continues, as digital substation programs mature, and as sustainability criteria become more embedded in procurement, the suppliers that will capture disproportionate value are likely to be those that can combine technical reliability with clear standards alignment, credible environmental positioning, and strong integration support. That combination is rarely accidental. It is built through specification discipline, component supply strategy, documentation quality, and close attention to the actual requirements of transmission and distribution projects. The report is designed to help readers identify where those capabilities are being assembled and where gaps still remain.
This Worldwide Optical Current Transformer Market study is therefore more than a data update. It is a strategic briefing for navigating a market that is becoming increasingly important to the reliability, digitization, and environmental performance of modern power systems. The full report provides the deeper segmentation detail, competitive profiles, regional and application breakdowns, and forward scenario content needed to make confident decisions. Readers seeking the complete set of estimates, supplier analyses, and actionable implications are encouraged to access the full study through the source page, where the comprehensive intelligence behind this overview is available in detail.
In a market where measurement technology, grid digitization, and sustainability expectations are converging, the organizations that act early with the right evidence will be best positioned to turn market growth into durable advantage. This research is intended to give those organizations the clarity they need to move with confidence throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Current Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Shows Worldwide Portable pH Meter Market Reaching $603.68 Million by 2032 with 5.12% CAGR from 2025
By PW Consulting, 2026-09-01
Strategic Intelligence for 2026: Navigating the Worldwide Portable pH Meter Market
In an era where precision measurement dictates regulatory compliance, product quality, and environmental stewardship, the portable pH meter sector stands as a critical enabler for industries ranging from pharmaceuticals to wastewater management. As we step into 2026, enterprise leaders face a complex landscape defined by technological convergence, stringent regulatory frameworks, and shifting regional demand patterns. This article serves as a strategic primer, distilling key macro trends and competitive dynamics to underscore the necessity of comprehensive market intelligence. While this overview highlights the structural forces shaping the industry, it intentionally omits granular segmentation data to emphasize the value of the full Worldwide Portable pH Meter Market research report. For decision-makers aiming to optimize supply chains, identify partnership opportunities, or benchmark against competitors, access to detailed segmentation splits and forecast specifics is indispensable.
Worldwide Portable pH Meter Market
Market Trajectory and Growth Dynamics
The global demand for portable pH measurement solutions has demonstrated resilience and steady expansion over the past half-decade. Analyzing historical performance from 2020 through 2025 reveals a market that has successfully navigated supply chain disruptions and evolving operational standards. The sector reached a valuation of approximately 425.61 Million USD in the base year of 2025, reflecting a mature yet growing ecosystem. Looking forward, the forecast period spanning 2026 to 2032 projects a compound annual growth rate (CAGR) of 5.12 percent. This growth trajectory suggests that by 2032, the market will approach a valuation exceeding 600 Million USD.
Worldwide Portable pH Meter Market
Such macro-level expansion is not merely a function of population growth or general industrial output; it is driven by specific drivers within water safety, food quality assurance, and environmental monitoring. However, understanding the aggregate revenue figures is only the first step. The true strategic value lies in dissecting how this growth is distributed across different technological formats, application verticals, and geographic territories. Aggregated numbers mask the nuances of regional regulatory pressures and the varying adoption rates of digital versus analog technologies. Therefore, while the overall market size indicates a healthy investment environment, stakeholders must delve deeper into segmentation data to understand where the highest value densities reside. This level of granularity is available exclusively in the full market study, where specific regional contributions and application-based revenue splits are mapped against historical data to isolate high-potential opportunities.
Worldwide Portable pH Meter Market
Technological Shifts and Product Segmentation
The evolution of portable pH meters is characterized by a clear divergence between traditional analog instruments and modern digital solutions. Digital portable pH meters currently dominate the revenue landscape, leveraging advantages such as automated data logging, Bluetooth connectivity, and enhanced calibration protocols. This technological shift is responding to the industry demand for traceability and real-time data integration, particularly in regulated environments like pharmaceutical manufacturing and high-volume water treatment facilities.
Conversely, analog portable pH meters maintain a significant presence, particularly in markets where cost sensitivity is paramount or where simple, robust functionality suffices for intermittent field testing. The coexistence of these two types creates a dual-track competitive environment. Manufacturers must decide whether to compete on high-margin digital features or volume-driven analog reliability. Recent product developments highlight this tension and the subsequent innovation race. For instance, enhancements in waterproofing ratings, such as the updated IP67 certification received by major players for their Orion Star series, signal a push toward ruggedization that benefits both digital and analog segments. Similarly, the introduction of wireless probes and edge computing capabilities in handheld devices indicates a future where portable meters act as nodes in a broader Internet of Things (IoT) network.
The full market research report provides a detailed breakdown of revenue contributions by type, allowing stakeholders to quantify the penetration rate of digital solutions across different sectors. Without this segmentation data, strategic planning regarding R&D investment or product portfolio optimization remains speculative. Leaders need to know not just that digital is growing, but at what pace relative to analog in specific application verticals such as agriculture versus clinical testing.
Application Verticals and Industrial Drivers
Portable pH meters are ubiquitous, yet their importance varies drastically across application segments. Water and wastewater treatment remains a cornerstone application, driven by stringent environmental regulations and the global imperative for clean water access. This sector demands high durability and multi-parameter capabilities, often integrating pH measurement with conductivity, dissolved oxygen, and temperature monitoring. The pharmaceutical and biotechnology industry represents another high-value segment, where compliance and precision are non-negotiable. In this domain, portable meters must adhere to rigorous quality management standards, including ISO 13485 for medical use and IEC 60601-1 safety standards for electrical equipment.
Further diversification is seen in the food and beverage industry, where portability allows for rapid testing along production lines to ensure safety and shelf-life stability. Environmental testing and agriculture also contribute significantly, though often with different procurement cycles and budget structures. A notable constraint in certain high-regulation sectors is the classification of devices. For example, the US FDA classifies benchtop and portable pH meters as Class I exempt devices under 21 CFR 872.3770 for dental use, and portable pH meters are restricted to research and non-invasive diagnostic use only in clinical settings per FDA guidelines. Additionally, there are no specific CPT or DRG reimbursement codes for portable pH meters; they are classified as general lab supplies under hospital budgets. These regulatory nuances influence procurement strategies and market entry barriers.
Understanding the revenue split across these applications is critical for targeted marketing and sales strategies. A company focusing on ruggedized industrial probes may find more aligned opportunities in wastewater management, while a firm specializing in high-precision glass electrodes suitable for medical-grade borosilicate with a lifetime of 12-18 months in continuous use may target pharmaceutical clients. The comprehensive report details these application-based revenue contributions, enabling firms to align their product development roadmaps with the most lucrative verticals.
Regional Landscape and Competitive Concentration
Geographically, the market exhibits a balanced but distinct distribution of demand. North America, Europe, and Asia Pacific collectively represent the bulk of global revenue, each influenced by local regulatory environments and industrial bases. North America and Europe are characterized by mature markets with high adherence to compliance standards, while Asia Pacific presents growth opportunities driven by expanding manufacturing capabilities and infrastructure development in water treatment. Latin America and the Middle East and Africa, while smaller in total volume, offer niche opportunities in specific resource extraction and agricultural sectors.
The competitive landscape is moderately concentrated, with the top three players holding a combined market share of approximately 38.42 percent and the top five players controlling around 54.18 percent. This concentration indicates a market where large incumbents hold significant sway, but there remains sufficient fragmentation for specialized players to compete on technology or regional expertise.
Key competitors include a mix of globally recognized instrument manufacturers and specialized niche providers. Hanna Instruments , based in Woonsocket, RI, USA, offers the HI98100 series portable pH meters with waterproof design, GLP data logging, and CAL Check standards for field and lab use. They recently launched an edge pH meter with Bluetooth module and HALO wireless probes for enhanced portable connectivity. Horiba , headquartered in Kyoto, Japan, provides LAQUAtwin pocket pH meters and LAQUA handheld series with high accuracy electrodes for environmental monitoring and aquaculture. They expanded their catalog with the LAQUAtwin pH-22 meter featuring an improved microelectrode for low-volume samples. Thermo Fisher Scientific , located in Waltham, MA, USA, manufactures the Orion Star A series portable pH meters featuring Bluetooth connectivity and rugged design. They received updated IP67 certification for the Orion Star A326 pH/conductivity portable meter. Mettler Toledo , from Greifensee, Switzerland, supplies FiveGo and SevenExcellence portable pH meters with IP67 rating and intelligent sensor management. They showcased the SevenCompact Duo S210 portable pH meter at MEDICA 2023 with a new InLab Pure Pro electrode.
Other significant players include YSI (Xylem) in Yellow Springs, OH, known for ProDSS and Pro10 portable pH meters integrated with multi-parameter sondes for wastewater and surface water monitoring. Oakton (Cole-Parmer) in Vernon Hills, IL, offers WD series waterproof portable pH meters with data logging and electrode diagnostics for education and lab applications. Extech Instruments (FLIR) in Waltham, MA, delivers PH100 and PH110 waterproof handheld pH meters with ATC and memory storage for HVAC and water treatment. Finally, Milwaukee Instruments in Rocky Mount, NC, provides MW102 and pH600 portable pH meters with dual-level LCD and fast response electrodes for hydroponics and field use.
Analyzing the rivalry among these firms requires more than a list of offerings. It requires an understanding of pricing strategies, distribution networks, and regional market shares. The full study provides the necessary competitive benchmarking data, including market share estimates and strategic moves, to help companies position themselves effectively against these incumbents.
Strategic Imperatives for 2026 Decision Makers
As we move through 2026, several strategic imperatives emerge for stakeholders in the portable pH meter market. First, regulatory compliance is no longer a checkbox but a competitive differentiator. With standards like ISO 13485 and IEC 60601-1 influencing device design and certification, manufacturers must integrate compliance into their product lifecycle early. Second, the shift toward connectivity necessitates investment in software ecosystems. Devices that merely measure pH are becoming commodities; devices that log, transmit, and analyze data are becoming strategic assets. Third, supply chain resilience regarding raw materials, such as medical-grade borosilicate for electrodes, must be managed to prevent disruptions in product availability.
For investors and corporate strategists, the 5.12 percent CAGR indicates a stable growth environment, but the opportunity lies in the pockets of higher growth within specific segments. Identifying whether the growth is driven by replacement cycles, new market entry, or technological upgrades requires the depth of analysis found in the complete market report. The aggregation of historical data from 2020 to 2025 alongside the forecast through 2032 provides a timeline for trend validation that is essential for long-term planning.
Conclusion: The Value of Comprehensive Intelligence
The Worldwide Portable pH Meter Market is at a pivotal juncture where technological innovation meets regulatory scrutiny. While the macro indicators point to robust growth and a mature competitive landscape, the specific pathways to profitability are nuanced. Regional variations, application-specific demands, and the race between analog and digital technologies create a complex decision matrix for industry participants.
This article has outlined the structural framework of the market, highlighting key players, regulatory contexts, and high-level growth trends. However, the precise segmentation splits, detailed regional revenue contributions, and specific market share percentages are critical data points that form the backbone of actionable strategy. To access the full spectrum of intelligence required to navigate 2026 successfully, including the deep-dive analysis into the competitive moves of Hanna Instruments, Horiba, Thermo Fisher Scientific, and their peers, stakeholders are encouraged to consult the full Worldwide Portable pH Meter Market research report. In a market defined by precision, half-measures are insufficient. Comprehensive data is the key to unlocking strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Portable pH Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Predicts Intercontinental Opacifying Agent Market to Reach 27,109.83 Million USD by 2032 with 4.2 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Opacity: Navigating the Worldwide Opacifying Agent Market in 2026 and Beyond
In the complex landscape of industrial materials, few components wield as much influence over product performance and consumer perception as opacifying agents. From the vibrant white of a architectural coating to the subtle coverage of a cosmetic foundation, these materials are the unseen architects of visual quality. As we move deeper into 2026, the Worldwide Opacifying Agent Market stands at a critical inflection point. Characterized by steady growth, shifting regulatory frameworks, and a consolidating competitive landscape, this sector requires nuanced strategic planning. PW Consulting's latest comprehensive market research, titled Worldwide Opacifying Agent Market, offers a definitive guide for stakeholders aiming to secure their position in this evolving ecosystem.
Worldwide Opacifying Agent Market
This article serves as a strategic primer, outlining the macroeconomic currents and structural shifts identified in our full report. It is designed for C-suite executives, procurement leaders, and R&D directors who need to understand not just the size of the opportunity, but the mechanics driving it. While we provide a high-level view of the trajectory here, the granular segmentation, proprietary company profiles, and detailed forecast models reside within the complete research document. Accessing that full intelligence is essential for transforming these macro trends into actionable competitive advantage.
Worldwide Opacifying Agent Market
The Growth Trajectory: Understanding the Scale and Momentum
The fundamental story of the opacifying agent market is one of resilient expansion. Based on historical data from 2020 through 2025 and forecasts extending to 2032, the market demonstrates a consistent upward trajectory. In 2020, the market valuation stood at approximately 16.4 billion USD. By the base year of 2025, this figure has grown to over 20.3 billion USD. This historical performance sets a robust baseline for our forecast period, which projects continued growth through 2032.
Worldwide Opacifying Agent Market
Our analysis indicates that the market will breach the 21 billion USD mark in 2026, reaching an estimated 21.3 billion USD. The forward-looking data suggests that this growth is not merely linear but reflects underlying demand drivers across multiple end-use industries. By the end of the forecast window in 2032, the market is positioned to approach 27.1 billion USD. This progression implies a Compound Annual Growth Rate (CAGR) of 4.2 percent over the forecast period.
For strategic planners, a 4.2 percent CAGR in a mature materials market signals stable demand but also intensifies the need for efficiency. Growth is not guaranteed by default; it must be captured through market share gains or value-added product differentiation. The absolute revenue figures illustrate the sheer scale of the opportunity, yet the distribution of this value is highly specific. Our full report dissects these figures across regions and applications, revealing where the highest margins and fastest growth rates are concentrated, without broadcasting those specific splits publicly.
Key Drivers and Industry Dynamics
The resilience of the opacifying agent market is underpinned by diverse applications that rely on opacity for both functional and aesthetic purposes. The demand is not monolithic; it is distributed across several key sectors that respond differently to economic cycles. Understanding the weight of these sectors is crucial for risk management.
- Paints and Coatings: This segment remains a cornerstone of demand, driven by renovation activities in established markets and infrastructure development in emerging economies. The need for titanium dioxide and other opacifiers here is tied closely to construction cycles and consumer spending on home improvement.
- Plastics: As lightweighting becomes a priority in automotive and packaging, the demand for opacifying polymers and pigments within plastic matrices continues to evolve. Performance requirements here are shifting towards durability and compatibility with recycling streams.
- Personal Care and Cosmetics: A high-value segment where opacity is critical for product efficacy and consumer appeal. Regulatory scrutiny on ingredient safety is highest here, influencing formulation choices significantly.
- Ceramics and Paper: Traditional applications that provide steady baseline demand, though they are increasingly subject to cost pressures and raw material availability constraints.
Beyond application demand, the market dynamics are heavily influenced by regulatory and raw material factors. In 2025 and early 2026, several regulatory decisions have reshaped the landscape. Notably, the European Court of Justice upheld a ruling in August 2025 that titanium dioxide is no longer classified as a category 2 carcinogen in the EU. This regulatory clarity removes a significant uncertainty for EU-based manufacturers and users, potentially stabilizing demand in the European region. Conversely, the addition of titanium dioxide to the Global Automotive Declarable Substance List (GADSL) Reference List on February 1, 2025, introduces new reporting thresholds for automotive supply chains, requiring stricter compliance management.
Furthermore, EU restrictions on titanium dioxide nanoparticles in certain leave-on cosmetics continue to drive reformulation toward compliant opacity systems. These regulatory nuances create both barriers and opportunities for suppliers who can offer compliant alternatives. Simultaneously, raw material costs remain a pivotal concern. Ilmenite prices in the USA reached 351 USD per metric ton in December 2025, reflecting firmer procurement strategies from titanium dioxide producers. USGS data highlights ongoing competition among ilmenite, leucoxene, rutile, and slag as feedstock sources, indicating that cost management will be a key differentiator for producers in the coming years.
Competitive Landscape: Consolidation and Strategic Moves
The opacifying agent market is moderately concentrated, with a significant portion of value controlled by a handful of global players. Our report data indicates a CR3 of 42.8 percent and a CR5 of 58.4 percent. This level of concentration suggests that while there is room for specialized niche players, the bulk of volume and pricing power resides with major integrated producers.
Strategic activity among these key companies has been intense, particularly in the last eighteen months. The market is witnessing a shift in asset ownership and capacity allocation, driven by cost pressures and portfolio optimization.
- The Chemours Company: As a major global producer of Ti-Pure titanium dioxide pigments, Chemours maintains a strong presence across coatings, plastics, and paper. In December 2025, the company implemented global price increases for TiO2 grades in plastics and coatings segments, signaling a focus on margin protection amidst input cost fluctuations.
- Tronox Holdings plc: A vertically integrated producer supplying opacifying pigments worldwide. In January 2026, Tronox announced the permanent closure of its 46,000-metric-ton Fuzhou TiO₂ plant. The decision cited sulfur feedstock cost escalation and oversupply, highlighting the sensitivity of production assets to regional input costs and market saturation.
- KRONOS Worldwide, Inc.: Specializing in titanium dioxide pigments for architectural and industrial coatings, Kronos has actively expanded its asset base. In July 2025, Kronos completed the acquisition of Venator's 50 percent stake in the Louisiana Pigment Company TiO₂ facility, gaining full control. This move consolidates capacity and control over key North American assets.
- LB Group (Lomon Billions): One of the largest Chinese producers of high-performance titanium dioxide pigments. In October 2025, LB Group agreed to divest its UK TiO₂ facility to LB Group as part of portfolio restructuring (Note: Venator agreed to divest its UK TiO₂ facility to LB Group). This cross-border acquisition underscores the global nature of capacity optimization strategies.
- Venator Materials PLC: Following the divestiture of its UK facility, Venator continues to focus on supplying titanium dioxide and functional additives acting as opacifiers in coatings and plastics, restructuring its portfolio to align with core competencies.
- Specialty and Niche Players: Companies like Dow Inc., Evonik Industries AG, Imerys, Arkema SA, and Tayca Corporation play critical roles in diversifying the supply base. Dow offers ROPAQUE opaque polymers as polymeric opacifiers for partial TiO2 replacement, addressing cost and specific performance needs. Evonik provides specialty chemicals and zinc oxide-based or hybrid opacifiers for cosmetics and personal care. Imerys supplies natural mineral-based opacifiers such as ImerCare Opaque for gels and shampoos. Arkema offers chemical solutions including opacifiers for coatings and plastics, while Tayca Corporation produces titanium dioxide and specialty opacifying materials for various industrial and cosmetic applications.
This landscape is not static. The recent developments involving Tronox, Kronos, Venator, and LB Group illustrate a trend toward rationalization and strategic realignment. Companies are closing inefficient units, acquiring control over key facilities, and adjusting pricing strategies to navigate the complex cost environment. Our full report provides detailed profiles on each of these entities, analyzing their historical performance, strategic direction, and potential impact on supply security for buyers.
Segmentation Nuances: Where Value Lies
While the aggregate market numbers provide the macro view, the true strategic insight lies in the segmentation. The market is divided by type, application, and region, each with distinct growth characteristics and competitive dynamics.
In terms of product type, Titanium Dioxide remains the dominant force, commanding a significant share of the revenue due to its unmatched opacity and brightness properties across multiple industries. However, the market is not solely reliant on TiO2. Zircon Silicates, Opaque Polymers, and Other Types constitute substantial portions of the market, each serving specific performance niches. For instance, opaque polymers are gaining traction in applications where TiO2 replacement is desired for cost reduction or specific rheological properties. The interplay between these types is critical for procurement strategy, especially when raw material costs for TiO2 feedstocks fluctuate.
Regionally, the market is global, but performance varies significantly based on local industrialization levels and regulatory environments. Asia Pacific represents a massive volume center, driven by manufacturing output and consumption in paints, plastics, and personal care. Europe and North America represent mature markets where premium grades and compliance with strict regulations are key value drivers. Latin America and the Middle East and Africa offer growth potential linked to infrastructure development and expanding consumer goods sectors.
Similarly, the application split reveals where the growth engines are located. Paints and Coatings remain the largest absorber of opacifying agents, but the Personal Care and Cosmetics segment often commands higher value per unit due to stringent purity and safety requirements. Plastics and Ceramics provide stable volume, while Paper and Packaging face unique challenges related to sustainability and substitution. Our detailed segmentation analysis in the full report quantifies these splits, allowing clients to benchmark their portfolio exposure against market realities.
Strategic Implications for 2026 Decision Makers
The convergence of steady market growth, regulatory clarity in some regions versus complexity in others, and active consolidation among suppliers creates a specific set of imperatives for 2026.
Supply Chain Resilience: With capacity closures such as Tronox's Fuzhou plant and acquisitions like Kronos's full control of Louisiana facilities, the supply map is being redrawn. Buyers need to assess the security of their supply lines. Dependence on single-region sourcing or specific suppliers may introduce risk if geopolitical or cost factors shift further. Diversifying across suppliers with different feedstock strategies (e.g., ilmenite vs. rutile vs. slag) may be prudent.
Regulatory Compliance as a Value Driver: The EU classification ruling and GADSL listing changes are not just compliance hurdles; they are market signals. Suppliers who can proactively assist customers in navigating these regulations—whether through compliant nanoparticle-free formulations or clear documentation for automotive supply chains—can command premium positioning. For formulators in cosmetics, the continued restrictions on nanoparticles mean that investment in alternative opacity systems is a long-term necessity.
Cost Management and Substitution: With ilmenite prices firming and producers like Chemours adjusting prices, cost pressure is evident. The availability of opaque polymers as partial TiO2 replacements, such as those offered by Dow, presents a strategic lever for cost optimization without sacrificing performance. Understanding the technical trade-offs and total cost of ownership is essential for procurement teams facing budget constraints.
Competitive Intelligence: The high market concentration means that the strategic moves of the top five players significantly impact market pricing and availability. Monitoring divestitures, acquisitions, and capacity announcements is no longer optional; it is a core component of market intelligence. Our report tracks these developments in detail, providing context on how each move alters the supply-demand balance.
Conclusion: The Case for Comprehensive Intelligence
The Worldwide Opacifying Agent Market is characterized by a blend of stability and disruption. The underlying demand is robust, supported by fundamental applications in construction, consumer goods, and industrial manufacturing. However, the path to capturing value in this 21.3 billion USD market in 2026 and beyond is fraught with complexities regarding feedstock costs, regulatory compliance, and supplier consolidation.
General market knowledge is insufficient for making high-stakes investment or procurement decisions. The nuances of regional growth rates, the specific financial health and strategic direction of key competitors like LB Group, Venator, and Evonik, and the precise sizing of niche application segments require a depth of data that only comprehensive research can provide. Understanding the 4.2 percent CAGR is one thing; understanding which segments are growing faster than the average and which suppliers are best positioned to serve them is another.
PW Consulting's Worldwide Opacifying Agent Market report is designed to bridge that gap. It moves beyond the headlines of capacity closures and price hikes to provide a structured framework for analysis. The full report includes detailed historical data from 2020 to 2025, granular forecasts through 2032, deep dives into regional dynamics without exposing competitive secrets to the wider public, and exhaustive company profiles that include recent developments and strategic outlooks.
For executives who need to validate their sourcing strategies, evaluate potential partnerships, or identify new market opportunities in cosmetics, coatings, or plastics, this research offers the empirical foundation required for confident decision-making. The macro trends are clear, but the micro-strategies that win in this market depend on access to precise, actionable intelligence. We invite you to access the full report to utilize the complete dataset and analysis necessary to navigate the opacifying agent market with strategic precision.
For detailed analysis of this topic, please visit the official page: Worldwide Opacifying Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Tendinitis Treatment Market to Reach 301.76 Billion USD by 2032 Growing at 4.71 CAGR From 2026
By PW Consulting, 2026-09-01
Strategic Horizons in Tendinopathy Care: Why the 2026 Market Shift Demands Precision Intelligence
The global landscape for tendinitis treatment is entering a decisive inflection point. As healthcare delivery models evolve and surgical philosophies converge around minimally invasive precision, market participants face a dual challenge: capturing growth while navigating an increasingly complex regulatory and reimbursement environment. Our latest Worldwide Tendinitis Treatment Market research was designed not as a static snapshot, but as a forward-looking decision architecture for executives who must allocate capital, shape product roadmaps, and position commercial teams for the 2026 to 2032 horizon.
Worldwide Tendinitis Treatment Market
At a macro level, the market has demonstrated resilient expansion across the historical review window, progressing from approximately 172,450 million USD in 2020 to an estimated 218,650 million USD in 2025. Looking ahead, the forecast period projects a measured but sustained compound annual growth rate of 4.71 percent, guiding revenue trajectories toward the 301,764 million USD range by 2032. These figures do more than chart scale; they signal the maturation of a therapeutic ecosystem where pharmacological management, rehabilitative protocols, energy-based technologies, and surgical interventions compete, complement, and increasingly converge. For strategy teams, the operative question is no longer whether the market will grow, but where relative share will migrate, which clinical pathways will accelerate adoption, and how procurement economics will reshape margin structures.
Worldwide Tendinitis Treatment Market
This report translates those trajectories into actionable intelligence. Rather than offering broad directional commentary, we anchor every insight in segment-level demand signals, competitive maneuvering, and the operational realities of hospitals, ambulatory surgery centers, and outpatient rehabilitation networks. The outcome is a reference framework that supports scenario planning, pricing strategy, partnership evaluation, and geographic prioritization without exposing organizations to the guesswork that often accompanies multi-year clinical device and therapy forecasting.
Worldwide Tendinitis Treatment Market
A Market Rooted in Clinical Diversity and Segment Migration
Tendinitis is not a singular clinical event, and neither is its treatment market. The overall revenue pool is distributed across distinct therapeutic pathways that reflect varying patient populations, procedural preferences, and clinical economics. Medication-based management continues to command a substantial share of the treatment mix, anchored by anti-inflammatory regimens, analgesic protocols, and adjunct pharmacotherapies that remain deeply embedded in early-stage care pathways. Physical therapy, meanwhile, represents a durable and expanding pillar, driven by conservative care mandates,Return-to-function protocols, and the growing integration of structured rehabilitation into post-procedure and non-operative management plans. Shockwave therapy has carved a differentiated position as an energy-based intervention for refractory cases, while surgical treatment maintains a specialized but high-value role for advanced structural compromise and failed conservative management.
Condition-level demand further shapes the strategic map. Achilles, patellar, rotator cuff, and epicondylar presentations each carry distinct procedural frequencies, rehabilitation timelines, and device utilization profiles. The report examines how these clinical indications influence procurement patterns, equipment utilization, and physician preference, while preserving focus on the commercial implications rather than isolated volume counts. This condition-aware lens matters because tendinitis is frequently managed across overlapping care settings, and the same facility may deploy pharmacological, rehabilitative, and procedural options in sequence. Understanding where the revenue pools concentrate, and how they interact across the care continuum, is essential for organizations seeking to align sales territory strategy, channel messaging, and product portfolio emphasis with real-world treatment flows.
Importantly, the segmentation architecture presented in this study is designed to support operational planning, not mere taxonomy. Regional demand is framed through the lens of healthcare infrastructure readiness, procedural capacity, reimbursement familiarity, and clinical adoption velocity. Treatment-type analysis is structured to reveal substitution dynamics, co-utilization patterns, and the circumstances under which one modality compresses or expands adjacent demand. Condition-specific insights help decision makers anticipate where clinical innovation is most likely to translate into commercial traction. Throughout, the report maintains a deliberate boundary: it illuminates the direction, drivers, and structural composition of the market without disclosing the granular percentage splits or discrete regional and application-level revenue figures that belong to the full commercial deliverable. That design choice reflects a practical reality of high-stakes market intelligence. Strategic advantage is created when clients gain sufficient context to ask sharper questions, then obtain the precise figures required to underwrite commitments, model scenarios, and defend investment theses with complete data integrity.
Competitive Maneuvers: Where Incumbents Are Shaping the Next Wave
The competitive environment in tendinitis treatment is defined by firms that combine surgical hardware portfolios, percutaneous systems, biologic augmentation platforms, and suture anchor technologies within a single strategic ecosystem. Several enterprises stand out for the breadth of their tendinopathy-related offerings and the cadence of their recent commercialization activity.
Smith and Nephew has reinforced its position in percutaneous tenotomy and tendon regeneration with the TENEX Health TENEX 2 System and the REGENETEN Bioinductive Implant, each targeting distinct points on the tendinopathy continuum. Arthrex continues to expand its arthroscopic footprint through the SpeedBridge system, MicroTenodesis implants, and tendon repair suture anchors, complemented by targeted suture innovations for upper extremity procedures. Stryker integrates robotic-assisted precision with tendon repair hardware, including Mako robotic-arm assisted systems and NanoKnotless anchors, while also advancing outpatient procedural reach through expanded distribution partnerships with ambulatory surgery centers. DePuy Synthes, operating within Johnson and Johnson MedTech, supplies knotless anchor technologies and the FiberTak system that address rotator cuff and broader tendon repair contexts. Zimmer Biomet contributes biologic augmentation options, including the Regeneten surgical mesh platform and knotless anchor systems, aligning structural reinforcement with tendon healing pathways. CONMED emphasizes minimally invasive repair through all-suture anchor designs and suture management systems, while Wright Medical supports foot and ankle interventions with dedicated tendon systems and bio-composite fixation components. Tenex Health, now embedded within the Stryker ecosystem, maintains a focused identity around ultrasonic tenotomy for outpatient procedures performed without general anesthesia.
Recent commercial activity underscores the pace of differentiation. Regulatory and product milestones have accelerated throughout the latter half of 2024 and into the current planning cycle, reinforcing how tightly product development, clearance timing, and clinical evidence generation are intertwined. Smith and Nephew broadened the resorption profile of its next-generation REGENETEN bioinductive implant following 510(k) clearance, signaling continued emphasis on biologic implant evolution. Arthrex introduced a suture solution tailored to small tendon repairs in upper extremity tendinitis procedures, extending its fixation portfolio into more granular clinical applications. Tenex Health published two-year outcomes data highlighting substantial pain reduction in chronic tendinitis patients treated with its ultrasonic tenotomy system, reinforcing the evidence narrative around non-anesthetic outpatient intervention. Stryker expanded distribution of Mako tendon applications through partnerships with ambulatory surgery centers, illustrating a strategic alignment between procedural precision, site-of-care migration, and scalable access.
These moves are not isolated product updates. They reflect a broader pattern in which competitors pursue differentiation through procedural efficiency, biologic augmentation, outpatient suitability, and fixation innovation simultaneously. For buyers and investors, the implication is that competitive assessment must transcend brand presence and evaluate how each platform interfaces with reimbursement realities, operative workflow, clinician training requirements, and post-market evidence generation. The report provides a structured mapping of these positions, highlighting where portfolio depth, indication focus, and commercialization timing are likely to influence share dynamics in the coming planning cycle.
Dynamics, Barriers, and the Operational Realities of Market Entry
Market expansion does not occur in a vacuum. The tendinitis treatment sector is shaped by regulatory classification, reimbursement architecture, material procurement economics, and the evolving standards of clinical evidence that accompany new devices and therapeutic protocols. These dynamics create both avenues for differentiation and friction points that can determine whether a product reaches adoption at scale.
From a regulatory standpoint, tendon repair scaffolds and related implant technologies are positioned within a device classification framework that requires premarket notification pathways for many categories. In the United States, this context places important emphasis on design controls, performance documentation, and clearance strategy for scaffolds and fixation devices used in tendon repair applications. In Europe, the regulatory environment introduces additional certification obligations for tendon implants, with clinical evaluation expectations that align to recognized guidance on medical device documentation and conformity assessment. These frameworks do not merely represent compliance tasks; they influence time-to-market, labeling scope, and the ability to make expanded clinical claims that support adoption. Strategy teams must incorporate regulatory sequencing into launch planning, because the rhythm of clearance, post-clearance promotion, and real-world evidence generation can materially shape commercial pacing.
Reimbursement structures add another layer of strategic complexity. Tendinitis-related repair procedures operate within fee schedules that establish baseline payment expectations for specific procedural codes, influencing site-of-care economics and the financial calculus of hospitals and ambulatory providers. While the exact reimbursement figure for a given procedure reflects broader Medicare Physician Fee Schedule parameters, the practical insight for commercial strategy is that payment predictability affects procurement decisions, case volume planning, and the attractiveness of procedural solutions in outpatient settings. Where reimbursement supports efficient turnaround and predictable revenue, procedural adoption can accelerate; where payment variability rises, providers may favor more conservative pathways or negotiate more aggressively around device cost.
Procurement economics for consumables and implant components also shape margin design and value proposition. Medical-grade bioabsorbable suture anchors and associated kit components carry per-unit cost ranges that vary with volume, specifications, and supply chain conditions. For manufacturers and distributors alike, these cost structures inform bundling strategy, pricing architecture, and the competitive positioning of procedural kits versus standalone components. A device portfolio may demonstrate clinical appeal, but its commercial trajectory will be influenced by the degree to which it fits into hospital procurement tolerances, sterile supply logistics, and surgeon workflow preferences. The report addresses these dynamics by linking market behavior to the operational constraints that actually govern purchasing decisions, rather than treating demand as a purely clinical phenomenon.
A further market reality lies in the boundaries of labeled use and investigational application. Certain systems are cleared for designated clinical contexts, while additional research protocols may govern use outside those labeled indications. This distinction matters for scientific communication, training, sales behavior, and risk management. Commercial teams must understand the difference between evidence-supported adoption and investigational use, particularly when evaluating newer platforms that are still building the clinical literature around long-term outcomes and expanded indications. The interplay of evidence, clearance, and clinical confidence directly affects how quickly a technology transitions from niche adoption to mainstream utilization.
Inside the Report: What Decision Makers Can Operationalize
This Worldwide Tendinitis Treatment Market study is structured to support concrete business decisions rather than abstract market description. The content architecture is built around decision-relevant modules that collectively provide a complete view of market composition, competitive positioning, and forward-looking dynamics.
- Segment-level analysis across treatment types, clinical conditions, and regional demand structures, organized to reveal where volume, value, and growth momentum are concentrated and how they may shift across the forecast horizon.
- Competitive profiling that maps product portfolios, technology focus, and recent commercialization activity for the key participants shaping the tendinitis treatment landscape.
- Regulatory and reimbursement context intended to inform launch timing, indication strategy, and site-of-care positioning, with attention to the practical implications of device classification, documentation requirements, and procedural payment frameworks.
- Procurement and cost-structure considerations that help organizations anticipate how material economics, kit design, and supply arrangements influence adoption and margin viability.
- Clinical evidence and adoption signals where available, framed to support assessment of durability, pain reduction, procedural efficiency, and the trajectory from early uptake to broader utilization.
- Scenario-oriented interpretation that enables teams to evaluate alternative growth paths, competitive responses, and demand migration without relying on single-point assumptions.
The report is designed with the expectation that different audiences will extract different value. Product leaders can use the segmentation and competitive content to prioritize development focus and positioning. Commercial leaders can translate demand patterns into territory strategy, messaging alignment, and channel planning. Procurement and market access teams can assess how reimbursement and cost dynamics influence adoption pathways. Strategic planning groups can incorporate the forecast framework into multi-year capital allocation and partnership evaluation. In each case, the objective is the same: to provide a structured, defensible foundation for decisions that will be judged over a multi-year horizon.
Why This Intelligence Matters for 2026 Decisions
Entering 2026, organizations operating in tendinitis treatment face a market that is simultaneously expanding and fragmenting in clinically meaningful ways. Growth is supported by procedural innovation, outpatient migration, biologic augmentation interest, and the continued centrality of rehabilitation in tendinopathy care. Yet that growth is unevenly distributed across treatment modalities, conditions, and care settings, and the competitive field is actively differentiating through clearance timing, evidence generation, and distribution strategy. In such an environment, strategic advantage accrues to those who can connect market structure to operational reality.
The 4.71 percent projected compound annual growth rate is not merely a headline statistic. It reflects an underlying market rhythm that will challenge assumptions about capacity planning, inventory strategy, pricing resilience, and competitive response. The trajectory from recent base-year sizing toward the late-2030s forecast range indicates that total demand will continue to expand, but the composition of that demand will shift as clinical preferences, procedural economics, and evidence narratives evolve. Organizations that treat the market as a single block risk misallocating resources; those that understand segment-level migration, competitive intent, and the regulatory and reimbursement constraints that shape adoption are better positioned to prioritize the right opportunities.
A critical element of the report’s value lies in its balance of breadth and discretion. It establishes enough analytical depth to demonstrate methodological rigor and market fluency, while reserving the most granular figures for the full commercial dataset. That approach respects the practical reality of specialized market intelligence: clients benefit from context, frameworks, and directional clarity, but the numbers that underwrite investment decisions, pricing models, and competitive response plans should be delivered in a form that is complete, auditable, and tailored to the client’s own scenario assumptions. The downloadable research is structured to provide that completeness, enabling users to move from market understanding to quantitative planning with confidence.
Closing Perspective
The Worldwide Tendinitis Treatment Market is entering a period in which clinical precision, procedural efficiency, regulatory alignment, and reimbursement realism will jointly determine competitive success. The market’s continued expansion is supported by a diverse therapeutic landscape and an active field of technology providers, but the more consequential story is how demand is being reorganized across treatment pathways, care settings, and clinical indications. Smart strategy in 2026 will depend on reading that reorganization accurately and acting on it with disciplined market intelligence.
This report offers the structural clarity required to do that work. It connects segment behavior to competitive movement, situates product innovation within regulatory and reimbursement constraints, and frames the forecast period in terms that support planning rather than speculation. For executives seeking to evaluate portfolio priorities, refine commercial strategy, and anticipate where share will move across the 2026 to 2032 horizon, the full research delivers the detailed data architecture needed to convert insight into execution.
For detailed analysis of this topic, please visit the official page: Worldwide Tendinitis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide AMC CPU Card Market to Reach 844.22 Million USD by 2032 with 8.24 Percent CAGR
By PW Consulting, 2026-09-01
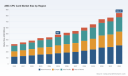
Worldwide AMC CPU Card Market: Strategic Intelligence for 2026 Enterprise Planning
Executive Preview: Why This Market Study Matters Now
The worldwide market for AdvancedMC CPU cards is entering a decisive growth phase, shaped by converging demands in telecommunications, aerospace, industrial automation, and medical computing. As enterprises reassess infrastructure roadmaps for 2026 and beyond, board-level compute modules based on AMC (AdvancedMC) form factors are no longer peripheral components but strategic assets that determine system scalability, thermal resilience, and supply-chain predictability. This article serves as a strategic preview of our newly released Worldwide AMC CPU Card Market research. It outlines the macro trajectory, competitive intensity, and regulatory and raw-material dynamics that executives must track, while deliberately keeping the most granular segmentation data behind the paywall of the full report. The objective is simple: give leadership teams enough context to recognize the strategic stakes, and enough incentive to commission the complete dataset for investment, procurement, and M&A decisions.
Worldwide AMC CPU Card Market
Macro Trajectory: A Multi-Year Expansion Curve
Over the historical window from 2020 through 2025, the AMC CPU card market moved from a mature niche into an accelerated expansion track. Total market revenue climbed from approximately 328.45 million USD in 2020 to 485.0 million USD in 2025, reflecting sustained adoption of MicroTCA and ATCA architectures across edge, telecom, and high-reliability industrial environments. The forecast period from 2026 to 2032 suggests continued momentum, with total revenue projected to rise toward 844.22 million USD by 2032. This translates to a compound annual growth rate of 8.24 percent, a pace that signals structural demand rather than a transient procurement cycle.
Worldwide AMC CPU Card Market
For enterprise planners, the macro numbers answer a foundational question: is this a cyclical upswing or a durable platform shift? The answer leans heavily toward the latter. The sustained step-up in revenue indicates that AMC CPU cards are being embedded into long-lived systems where replacement cycles span years, not quarters. That durability has knock-on effects for capacity planning, vendor negotiation, and architecture selection. Decision-makers need to see not just the headline figures, but the underlying segmentation logic, the architecture mix, and the application profiles that explain where growth is pooling and where margins are tightening. Those details are covered in the full report; here, we focus on the strategic implications of the trajectory itself.
Worldwide AMC CPU Card Market
Segmentation Architecture: Where Growth Concentrates
Growth in the AMC CPU card market is not uniform across regions, processor architectures, or end-use applications. Our analysis segments the market along three axes that matter to procurement and product strategy: region, processor architecture, and application. In 2025, North America accounted for 176.73 million USD of revenue, Europe contributed 131.36 million USD, Asia Pacific represented 137.08 million USD, and the Rest of World region added 39.83 million USD. These regional distributions reveal a market that is broad but not evenly balanced, with North America and Asia Pacific carrying substantial weight and Europe maintaining a strong, specialized position in defense and industrial platforms.
On the architecture side, x86-based solutions generated 294.61 million USD of revenue in 2025, ARM-based modules contributed 112.02 million USD, and PowerPC-based offerings added 78.37 million USD. This architecture split is strategically significant. x86 continues to anchor performance-intensive deployments, while ARM is gaining relevance in power-constrained, multicore edge configurations. PowerPC maintains a dedicated footprint in applications that prioritize deterministic behavior and long-term supply assurance. The report details how each architecture aligns with specific form factors, I/O requirements, and lifecycle expectations, so that engineering leaders can match architectural choice to operational reality rather than defaulting to legacy procurement patterns.
Application-wise, 2025 revenue was distributed across Telecommunications at 208.45 million USD, Aerospace and Defense at 136.89 million USD, Industrial Automation at 91.55 million USD, and Medical Computing at 48.11 million USD. Telecommunications remains the largest application pool, reflecting continued investment in edge routing, baseband processing, and modular chassis designs. Aerospace and Defense follows as a high-reliability segment where AMC CPU cards support mission-critical compute in harsh environments. Industrial Automation and Medical Computing, while smaller in absolute terms, often command premium margin profiles and longer product lifecycles. The complete study breaks these application pools into actionable sub-segments, enabling readers to see which verticals are expanding fastest, which are consolidating, and where specification requirements are changing most rapidly.
Competitive Landscape: Who Shapes Pricing and Roadmaps
The market is moderately concentrated, with the top three firms collectively holding about 41.25 percent of revenue and the top five firms representing approximately 63.8 percent. That concentration level matters because it gives leading suppliers meaningful influence over roadmap timing, specification adoption, and supply availability. Our research profiles several core players whose product strategies define the current state of the market and whose moves signal where the market is heading in 2026 and beyond.
- Kontron AG (Germany): Kontron offers AdvancedMC processor modules such as the AM4010 and AM4022 series, available in single-width or double-width configurations for MicroTCA and ATCA systems. These modules are built around Intel Core processors with ECC memory support and high I/O capability, targeting telecom, industrial, and defense applications. Kontron’s positioning highlights the enduring value of robust I/O and memory integrity in long-lifecycle systems.
- VadaTech (United States): VadaTech provides a broad range of Processor AMC modules, including AMC765 with 11th Gen Intel Core, AMC766, AMC757 with Xeon E3, and AMC753 with Xeon D, among others. These single- or double-width modules support MicroTCA systems and emphasize high-performance computing with PCIe, Ethernet, and storage options. VadaTech’s recent 2025 product activity underscores its focus on expanding performance tiers and form-factor flexibility.
- N.A.T. Europe (NAT) (Germany): NAT specializes in versatile AMC CPU boards for MicroTCA and ATCA, including NAT-AMC-LX2, a 16-core ARM A72 board with high-speed Ethernet and PCIe, and NAT-AMC-COMex, which supports COM Express Type 7 modules with Intel Ethernet and high-bandwidth backplane connectivity. NAT’s portfolio illustrates the growing importance of ARM-based options and backplane-rich designs for compact, high-throughput edge systems.
- EMCOMO Solutions AG (Germany): EMCOMO supplies MicroTCA AMC CPU modules such as AMC758 with Intel Xeon E3 and NVMe, AMC750 with Xeon E5, AMC754 with Xeon D, and EM-AM4024 with Core i7, alongside offerings based on NXP QorIQ or Cavium processors. Features include ECC memory, 10GbE, and industrial temperature ranges, reinforcing the market’s appetite for ruggedized, high-bandwidth compute in demanding environments.
- Advantech Corp. (Taiwan): Advantech is an active provider of embedded computing solutions, including AMC-compatible modules and network mezzanine cards for industrial, telecom, and edge applications, with systems supporting high-core Intel Xeon processors. Advantech’s breadth across embedded platforms makes it a significant reference point for integrators seeking interoperability across larger system ecosystems.
These companies are not evaluated solely on product counts; the report analyzes how their roadmaps intersect with standard ratification, supply constraints, and application-specific certification requirements. The competitive section also maps recent product launches and release cadence, including VadaTech’s May and August 2025 activity around Processor AMC modules, to show how quickly the market is iterating on performance and form factors. The full study provides the deeper competitive benchmarking, win/loss patterns, and distribution channel context that procurement teams need when negotiating multi-year supply agreements.
Market Dynamics: Standards, Supply, and Thermal Design Power
The AMC CPU card market does not evolve in a vacuum. Three dynamic forces are reshaping competitive positioning and sourcing strategy: standards maturation, raw-material and manufacturing pressure, and CPU availability constraints. Each has strategic implications that extend beyond the immediate procurement cycle.
On standards, PICMG ratified the MicroTCA.0 Revision 3.0 specification in 2024, introducing 100 GbE and PCIe Gen 5 fabrics designed to improve system performance by about 4x, expanding thermal design power to support higher-performance processors, and enabling up to 12 slots for demanding edge and server applications. This ratification is a structural catalyst. It raises the performance ceiling for AMC-based systems while simultaneously pushing thermal and power handling higher. Systems that were adequate on earlier revisions may need redesigns to exploit the new fabrics and slot density. Engineering leaders should treat MicroTCA.0 Revision 3.0 not as a minor update but as a platform inflection point that affects architecture choices, thermal management, and long-term interoperability. The report connects this standards shift to specific product strategies and adoption timelines, helping readers anticipate which suppliers are best positioned to deliver compliant, high-performance modules at scale.
On raw materials, TSMC expansion has triggered shortages and price surges for certain filter materials used in wafer manufacturing processes critical to advanced semiconductor production, including CPUs. This dynamic is relevant because AMC CPU cards depend on semiconductor supply health not only for the processor itself but for supporting components and manufacturing consistency across the value chain. When filter materials and related inputs tighten, yield and cost pressure can cascade into module availability and lead-time variability. The full study discusses these supply-side sensitivities and maps them to likely pricing behavior across 2026, so that finance and procurement teams can build more realistic cost scenarios.
On CPU availability, Intel, AMD, and MediaTek are boosting CPU production capacities amid strong demand, yet lead times for certain CPUs have reached up to 1 year with prices continuing to increase. This is a crucial nuance for AMC CPU card planning. Even as capacity expands, specific processor families can remain constrained, and lead-time elongation directly affects system delivery schedules. For organizations designing MicroTCA or ATCA platforms with long integration cycles, the gap between announced capacity increases and actual availability of preferred CPUs can be the difference between a smooth rollout and a delayed deployment. The report translates these lead-time dynamics into sourcing guidance, including when to lock in configurations early, how to qualify alternates, and which architecture ports offer the best resilience in constrained periods.
What the Full Study Delivers for 2026 Decision-Making
This preview establishes the strategic stakes, but the full Worldwide AMC CPU Card Market research is designed to convert those stakes into operational decisions. The report is built for teams that need to move from awareness to action. It delivers practical content across several dimensions that matter to executives, engineers, and procurement leaders alike.
- Revenue trajectory and segmentation detail: The complete study pairs the macro revenue path with granular segmentation across regions, processor architectures, and applications, enabling readers to identify where growth is concentrated, which sub-segments are consolidating, and where specification requirements are evolving. Rather than relying on aggregate numbers alone, decision-makers can see the structure beneath the total.
- Competitive benchmarking and roadmap intelligence: Beyond company profiles, the report evaluates how leading suppliers are positioning their AMC CPU cards relative to standards adoption, thermal and power capabilities, and application-specific certifications. It highlights recent product launches and release cadence, providing context for supplier selection, negotiation leverage, and multi-source planning.
- Standards impact analysis: The study translates the MicroTCA.0 Revision 3.0 ratification into practical implications for performance, thermal design power, slot density, and interoperability. It helps organizations understand which product features will become table stakes and which may create differentiation in the next planning cycle.
- Supply-chain and raw-material scenario planning: The report integrates the TSMC-related filter-material pressures and the CPU lead-time dynamics into sourcing scenarios, so that procurement and finance teams can model cost and availability under different conditions and decide when to secure configurations ahead of demand.
- Application-specific guidance: For telecommunications, aerospace and defense, industrial automation, and medical computing, the full study examines the unique performance, reliability, and certification demands that shape module selection. This helps engineering teams align architecture choices with the operational realities of each vertical rather than applying a one-size-fits-all procurement template.
The report is also structured to support multiple internal use cases. Strategy teams can use it to prioritize market entry or expansion in high-growth segments. Product managers can use it to align module specifications with prevailing architecture mixes and application requirements. Procurement can use it to frame negotiation strategy around concentration levels, lead-time risk, and standards-driven performance expectations. The intention is to provide a single, coherent intelligence base that multiple functions can reference, reducing the gap between market understanding and execution.
Strategic Implications for 2026 Planning Committees
For leadership teams planning 2026 initiatives, the AMC CPU card market presents a set of linked decisions. First, organizations must decide how much to invest in platforms that can exploit the performance and slot-density gains enabled by MicroTCA.0 Revision 3.0. The 4x performance improvement potential and expanded TDP are compelling, but they also raise the importance of thermal design, power delivery, and backplane compatibility. Second, teams need to determine how to manage CPU availability risk while preserving performance targets. As certain processor lead times stretch toward a year and prices continue to rise, the timing of configuration lock-in and the breadth of qualified alternates become critical. Third, the architecture mix should be reviewed in light of application priorities. x86 remains dominant in revenue terms, but ARM and PowerPC maintain meaningful positions in specific reliability, power, and lifecycle scenarios, and the right mix depends on vertical requirements rather than generic preference.
Concentration in the market further sharpens these decisions. With the top three firms holding over 41 percent and the top five firms holding nearly 64 percent, a limited number of suppliers exert meaningful influence over roadmap timing and availability. That does not make the market inaccessible, but it does mean that supplier relationships, qualification pipelines, and second-source strategies deserve explicit attention. The report’s competitive analysis is designed to help teams identify where supplier strength lies, where differentiation is most likely to emerge, and how to structure sourcing plans that balance performance with resilience.
Closing: The Case for Complete Intelligence
The worldwide AMC CPU card market is expanding along a durable growth curve, shaped by standards maturation, raw-material pressure, and CPU availability dynamics that together influence cost, schedule, and architecture choice. The headline trajectory is clear enough to justify strategic attention, but the decisions that matter in 2026 depend on the details: which regions and applications are driving the strongest expansion, how architecture splits are evolving, which suppliers are moving fastest on performance and form-factor breadth, and how standards ratification changes the requirements for thermal design and slot density. This preview is intended to establish the strategic context and demonstrate the analytical rigor behind our Worldwide AMC CPU Card Market study, while leaving the core segmentation data, competitive benchmarking depth, and scenario planning tables for the full report. For organizations that need to translate market momentum into concrete procurement, product, and investment actions, the complete intelligence is the tool that turns awareness into execution.
For detailed analysis of this topic, please visit the official page: Worldwide AMC CPU Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Worldwide Broadband Network Market to Exceed $626 Billion by 2032 Growing at 4.8% CAGR
By PW Consulting, 2026-09-01
Beyond Connectivity: Strategic Intelligence for the Next Era of Global Broadband Infrastructure
The worldwide broadband network market stands at a decisive inflection point in 2026. After a decade of steady capacity expansion and technology migration, service providers, equipment vendors, and infrastructure investors now face a more complex operating environment shaped by intensifying capital requirements, shifting regulatory frameworks, and the accelerating demand from data-intensive applications. Our newly released Worldwide Broadband Network Market research is designed for executives who must move beyond headline growth figures and into the structural dynamics that will determine competitive positioning, capital allocation, and technology roadmaps over the remainder of the decade.
Worldwide Broadband Network Market
This introductory briefing outlines the strategic value of the full study for 2026 decision-making, demonstrates the analytical framework embedded in the report, and highlights the competitive, regulatory, and cost pressures currently reshaping broadband deployment. Consistent with the depth expected by senior leadership teams, this preview provides a rigorous orientation to the market architecture while reserving the granular segmentation, forecast drivers, and company-level benchmarking for the complete publication.
Worldwide Broadband Network Market
A Market Defined by Scale, Maturity, and Structural Transition
Between 2020 and 2025, the global broadband network market progressed from a base of 358.5 billion USD to 451.05 billion USD, reflecting sustained investment in fiber rollouts, fixed wireless access expansion, and legacy technology migrations. The trajectory through the forecast period extends this momentum: the market is projected to reach approximately 457.78 billion USD in 2026, advance to 496.81 billion USD in 2027, and continue scaling toward 626.26 billion USD by 2032. Across the full forecast window, the market is expected to compound at a rate of 4.8 percent, a pace that signals durable demand while also underscoring the operational discipline required to capture value in an increasingly competitive landscape.
Worldwide Broadband Network Market
For enterprise strategists, these numbers matter less as isolated benchmarks than as indicators of where capital, spectrum, and engineering resources are being concentrated. The growth profile suggests that broadband is no longer a peripheral utility investment but a core enabler of residential connectivity, commercial digital transformation, and public-sector service delivery. At the same time, the maturity of certain access technologies means that future gains will increasingly depend on differentiation in fiber architecture, transport efficiency, and service-layer innovation rather than on raw subscriber additions alone.
The full report translates this top-line trajectory into a structured analytical foundation for 2026 planning. Rather than presenting growth as a single curve, the study decomposes the market into the technology pathways, end-user segments, and regional footprints that executives need to evaluate when setting investment priorities, negotiating vendor partnerships, or assessing adjacencies. The objective is to provide a decision-ready map of where value is being created and where margin pressure, deployment complexity, and competitive overlap are likely to intensify.
One of the central contributions of the research is its treatment of concentration and competitive structure. The broadband network market continues to exhibit meaningful consolidation of share, reflecting the scale advantages of major equipment suppliers and large service providers. Understanding how that concentration interacts with regional deployment strategies, technology mix, and service provider business models is essential for any organization evaluating entry, expansion, or partnership opportunities. The report examines these dynamics in detail, enabling readers to calibrate expectations around bargaining power, supply-chain exposure, and long-term market accessibility.
Why 2026 Requires a Different Strategic Lens
The 2026 operating environment differs from prior years in ways that directly affect strategic planning. Deployment economics are under heightened scrutiny, policy frameworks are being recalibrated for AI-era infrastructure needs, and service providers are reorganizing around fiber and converged fixed-mobile offerings at a pace that rewards speed but penalizes inefficient capital deployment. In this context, a market study must do more than forecast demand; it must help leaders evaluate trade-offs in technology selection, build-cost management, partnership structures, and geographic prioritization.
The research responds to that requirement by embedding practical decision modules alongside the macro forecast. It addresses how broadband networks are being scaled across residential, commercial and enterprise, and government and public-sector end users, and it examines the implications of those demand profiles for access technology mix, backhaul requirements, and service design. Executives can use this structure to assess where their portfolios align with market direction and where recalibration may be necessary to protect margins or capture new revenue streams.
Equally important, the study situates deployment activity within the broader institutional landscape shaping the industry. Policy discussions increasingly link broadband infrastructure to hyperscale data centers, AI-driven services, and mission-critical applications, while ongoing programs and permitting frameworks influence the pace and cost of network build-out. The report incorporates these forces into its market dynamics analysis, giving readers a clearer view of how regulatory and structural factors may accelerate, delay, or redirect investment over the forecast period.
Another layer of strategic value comes from the report’s treatment of competitive positioning. Rather than cataloguing vendors and service providers as static entities, the analysis evaluates how leading organizations are competing across fiber access, optical transport, broadband routing, fixed wireless access, and converged service offerings. This approach helps clients understand not only who occupies significant share in the market today, but also where capability overlaps, where differentiation is emerging, and where consolidation or partnership activity may alter the competitive map in the near term.
Inside the Worldwide Broadband Network Market Report
The full study is structured to support multiple audience needs within a single coherent framework. It begins with a comprehensive market overview and forecast architecture, then moves into segmentation analyses that enable targeted strategic interpretation. The report is designed to be used both as a standalone intelligence asset and as a reference point for internal planning sessions, investment committee reviews, and competitive assessments.
Key components of the report include the following areas of analysis:
- A full market forecast with historical context and forward projections that anchor the strategic discussion in quantified demand trajectories rather than anecdotal signals.
- Technology-pathway analysis covering the major access and transport architectures shaping broadband deployment, including the relative scale and role of fiber-to-the-home, cable HFC, DSL, fixed wireless access, and satellite solutions.
- End-user segmentation that distinguishes residential, commercial and enterprise, and government and public-sector demand patterns, helping readers interpret where growth is likely to be concentrated and what service requirements accompany each segment.
- Regional evaluation that frames how broadband infrastructure demand differs across major geographic markets, with attention to deployment maturity, competitive intensity, and investment climate.
- Competitive landscape assessment covering major equipment and infrastructure suppliers as well as leading service providers, with emphasis on capability positioning, deployment focus, and strategic movement.
- Market dynamics review that integrates policy, cost, and operational factors influencing build decisions, including permitting environments, deployment-cost trends, and the interaction between infrastructure investment and emerging data-center and AI-related demand.
- Recent industry developments and event-driven intelligence that capture partnership activity, network expansions, acquisitions, and policy discussions with direct relevance to 2026 planning.
The report also includes practical orientation for how organizations can apply the findings. For vendors, the study supports product-roadmap prioritization, regional go-to-market planning, and competitive benchmarking. For service providers, it informs capital-expenditure sequencing, technology-mix decisions, and market-entry or market-expansion evaluations. For investors and advisors, it provides a structured basis for assessing sector momentum, concentration risk, and the durability of growth across different parts of the broadband ecosystem.
Importantly, the research does not stop at descriptive analysis. It is built to support forward-looking interpretation, enabling readers to test assumptions about demand elasticity, deployment feasibility, and competitive response. That makes the study particularly useful in 2026, when the cost of capital, labor, and materials can materially alter the economics of network expansion and when strategic timing often matters as much as market size.
Competitive Positioning and the Shape of the Market Map
The worldwide broadband network market is contested by a mix of global equipment and optical-transport specialists, broad infrastructure suppliers, and large service providers whose deployment scale directly shapes demand signals. Understanding this landscape requires looking beyond vendor names to the functional roles they play in access, aggregation, transport, and service delivery. The report evaluates these players in a way that highlights where competition is most intense and where distinct capability advantages are being built.
On the equipment and infrastructure side, the analysis examines organizations that anchor key parts of the broadband value chain. Huawei Technologies and ZTE Corporation are assessed in the context of their end-to-end broadband and access-platform offerings, including fiber access, PON systems, and transport equipment that support large-scale fixed and mobile broadband deployments. Nokia and Ericsson are reviewed for their contributions to fixed broadband access, PON and fiber network technology, IP routing, optical transport, and fixed wireless access solutions that help service providers build higher-capacity infrastructure. Cisco Systems is addressed for its role in broadband routing, switching, cable modem termination systems, and optical networking gear across service provider and cable access environments, while Ciena is evaluated for specialized optical networking and coherent DWDM capabilities that are increasingly important in high-capacity backbone and metro transport.
The report also considers companies whose influence extends across fiber connectivity, access components, and broadband network elements. CommScope is analyzed for its fiber connectivity, coaxial, antenna, and access-network infrastructure contributions, including FTTH and HFC components. Corning is examined as a leading supplier of optical fiber, fiber optic cables, and connectivity solutions that remain foundational to FTTH and broader broadband deployments. ADTRAN is included for its fiber access platforms, DSL and PON equipment, and broadband solutions oriented toward service providers and enterprises, while Juniper Networks is assessed for high-performance routing, switching, and security solutions in broadband provider core and edge networks.
On the service-provider side, the research analyzes organizations whose deployment scale and service strategies influence both demand and competitive behavior. AT&T and Verizon are evaluated as major broadband providers with extensive fiber and fixed wireless access offerings across residential and enterprise markets. Comcast is reviewed for its large cable broadband footprint, ongoing fiber expansion, and hybrid fiber-coaxial infrastructure. China Mobile is assessed as a dominant operator with massive FTTH and 5G fixed broadband deployment activity, and Deutsche Telekom is examined as a European leader in fiber broadband with broad FTTH rollout and converged fixed-mobile offerings.
This competitive framing is not intended as a static vendor directory. Instead, the report uses these profiles to illuminate strategic behavior: where companies are competing on scale, where they are differentiating through technology architecture, and where recent moves suggest evolving priorities. By placing equipment, infrastructure, and service-provider activity in a single analytical frame, the study helps clients interpret competitive pressure more precisely and identify where partnership, procurement, or market-entry decisions may be most consequential.
Recent Industry Movements Reshaping Deployment Strategy
The broadband market in 2026 is being shaped not only by long-term forecast trends but also by a series of recent operational and strategic developments. These events provide early signals about how organizations are responding to deployment costs, fiber-footprint goals, and the broader policy conversation around infrastructure and data-intensive services.
A notable example is the April 2026 strategic activity involving T-Mobile, which formed fiber joint ventures with Oak Hill Capital and Wren House to acquire GoNetspeed/Greenlight Networks and i3 Broadband. The move is intended to expand fiber footprint substantially, with reported plans to pass over 1.3 million households by the end of 2026. This kind of partnership-and-acquisition approach reflects a broader industry pattern: service providers are pursuing fiber reach expansion through structured combinations and joint ventures rather than relying solely on organic build-outs. For competitors and suppliers, the implication is that fiber footprint, local market presence, and access to existing infrastructure are becoming increasingly valuable strategic assets.
At the same time, policy and industry dialogue are intensifying around the relationship between broadband infrastructure and next-generation digital demand. In April 2026, the Fiber Broadband Association hosted a Broadband Policy Upload at Fiber Connect 2026 to explore policy frameworks supporting hyperscale data centers, AI-driven services, and fiber infrastructure for mission-critical applications. This discussion underscores that broadband is increasingly evaluated not just as a consumer connectivity service but as critical enabling infrastructure for higher-order computing and data-demand ecosystems. Organizations planning broadband investments should therefore consider how policy alignment, permitting pathways, and infrastructure support may influence long-term build viability.
Recent network-expansion and acquisition activity further illustrate how aggressively operators are pursuing footprint and customer access. In November 2025, Charter Communications expanded its fiber broadband network in Fountain County, Indiana, adding service to more than 2,800 homes and businesses as part of a multi-year rural initiative backed by private investment exceeding 7 billion USD. Separately, in May 2025, AT&T agreed to acquire substantially all of Lumen’s Mass Markets fiber internet business for 5.75 billion USD, an transaction expected to close in the first half of 2026 and accelerate fiber access for millions of locations. These moves highlight the continued emphasis on consolidating and extending fiber-based service reach, particularly where incumbents can leverage scale, existing rights-of-way, and established customer bases.
Beyond corporate activity, the industry is also absorbing new cost and deployment intelligence. Early 2026 reporting drew on the 2025 Fiber Deployment Cost Annual Report, which detailed median U.S. fiber build costs and ongoing deployment activity supporting continued expansion into 2026. That context is important because deployment economics directly affect the pace and selectivity of network investment. When labor, materials, permitting, and make-ready costs rise, operators are forced to prioritize higher-return locations, optimize construction methods, and reassess the timing of expansion programs. The report incorporates these operational realities so that clients can interpret market growth in light of the cost constraints that actually govern execution.
Deployment Economics, Policy, and the Cost Environment
Cost dynamics are now central to broadband strategy. Recent deployment-cost reporting indicates that median labor costs for U.S. fiber deployments reached 12.23 USD per foot for underground builds and 4.50 USD per foot for aerial builds in 2025. Median underground fiber deployment cost overall reached 18.00 USD per foot, while aerial deployment was 8.00 USD per foot. These figures do more than describe construction expense; they frame the economic logic behind technology selection, route design, and market prioritization. In practical terms, they help explain why operators are increasingly attentive to build efficiency, aerial-versus-underground tradeoffs, and the strategic value of existing infrastructure assets.
The broader industry outlook reflects a cautious but still expansionary posture. In a 2025 survey, 88 percent of respondents in the U.S. fiber industry expected deployment costs to rise again in 2026, driven by labor, materials, permitting, and make-ready costs. This expectation has direct strategic implications. If cost pressure persists, then the markets that grow fastest will not necessarily be those with the highest demand in the abstract, but those where operators can deploy efficiently, leverage favorable topology, or secure enabling policy and partnership support. The report uses this cost environment as one of the analytical inputs for interpreting where and how broadband investment is likely to be directed.
On the regulatory and policy side, U.S. fiber deployment continues under frameworks including the BEAD program, while recent policy discussions at Fiber Connect 2026 addressed permitting and infrastructure support for AI and data centers. This combination of long-standing program support and newer technology-driven policy attention suggests that broadband infrastructure is being positioned within a wider national and regional priority set. For organizations planning network investments, the relevant question is not only whether demand exists, but how policy momentum, permitting timelines, and infrastructure-support discussions may shape execution feasibility over the near term.
Taken together, the cost and policy environment reinforces a central theme of the study: market growth cannot be interpreted in isolation from the operational constraints that determine how that growth is realized. The report integrates these factors so that readers can distinguish between headline opportunity and actionable deployment potential.
What 2026 Decision-Makers Should Take Away
The strategic message of this research is that the worldwide broadband network market remains attractive, but it is also becoming more demanding. Growth is expected to continue through the forecast period, yet the composition of that growth, the competitive intensity surrounding it, and the cost conditions governing its execution are all evolving in ways that reward disciplined analysis. Organizations that rely on aggregated market narratives risk over- or under-estimating opportunity in specific technologies, end-user segments, or regions. Those that use a structured, forecast-backed, and competition-aware framework are better positioned to allocate capital, choose partners, and time deployment decisions.
For executives preparing 2026 plans, the full report offers several practical advantages. It connects macro trajectory to segmentation logic, so that growth can be interpreted in operationally meaningful terms. It places competitive actors in functional context, allowing readers to evaluate where pressure is building and where differentiation is attainable. It incorporates recent corporate, policy, and cost developments, giving the forecast a real-world anchor rather than treating it as an abstract projection. And it is designed to support multiple decisions at once, from technology roadmap choices to geographic prioritization and partnership strategy.
This preview has been written to provide a credible, expert-level view of the market’s shape and significance while preserving the detailed segmentation, region-by-region interpretation, and granular benchmarks for the complete study. The full Worldwide Broadband Network Market research extends well beyond the summary figures presented here, offering the deeper breakpoints, comparative analysis, and forward-looking interpretation required for high-stakes planning.
Access the Full Strategic Intelligence
The complete report provides the detailed segmentation analysis, forecast drivers, competitive benchmarking, and deployment-context interpretation needed to convert market insight into concrete strategic action. For leaders responsible for broadband investment, network planning, vendor selection, or market-entry evaluation, the full study is the appropriate reference point for 2026 decision-making. We invite you to access the full Worldwide Broadband Network Market research to obtain the complete dataset, regional and technology-level interpretation, and the comprehensive competitive analysis that support the conclusions outlined in this introduction.
For detailed analysis of this topic, please visit the official page: Worldwide Broadband Network Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Presents New Outlook: Worldwide International Recruitment Services Market Poised to Reach $62,545.98 Million by 2032 with 7.34% CAGR
By PW Consulting, 2026-09-01
Navigating Talent Borders: Strategic Intelligence for the Global Recruitment Services Market 2026–2032
The international recruitment services industry is no longer a reactive support function; it is a strategic imperative for organizations operating in an increasingly borderless and skills-constrained economy. As enterprises recalibrate workforce plans for 2026 and beyond, understanding the structural forces shaping global talent mobility has become a board-level priority. This market intelligence report delivers a rigorous, data-anchored view of the Worldwide International Recruitment Services Market, mapping historical trajectories, forecasting forward momentum, and decoding the regulatory, competitive, and operational dynamics that will determine which organizations thrive in the coming years.
Worldwide International Recruitment Services Market
Our analysis covers the period from 2020 through 2032, anchored by a 2025 base year that reflects post-pandemic normalization, geopolitical realignment, and the maturation of digital recruitment ecosystems. The market has demonstrated remarkable resilience and structural growth, evolving from cyclical staffing demand into a sophisticated, compliance-driven global service layer. For executives, investors, and policy-aware strategists, this report serves as a diagnostic toolkit—translating macro-level trends into executable insights without obscuring the complexity of the terrain.
Worldwide International Recruitment Services Market
Market Trajectory: From Recovery to Sustained Expansion
The global recruitment services market has carved a clear upward path, reflecting the persistent gap between talent demand and domestic supply. Historical data reveals a market that surged through the early 2020s, experienced a brief recalibration, and then resumed its expansion as organizations recognized the strategic necessity of international talent pipelines. By 2025, the market had reached a substantial scale, positioning the industry at an inflection point where growth is increasingly driven by structural labor shortages, cross-border project deployments, and the globalization of specialized skill requirements rather than temporary staffing demand alone.
Worldwide International Recruitment Services Market
Looking ahead, the forecast horizon through 2032 indicates sustained, compounding growth. The market is projected to expand at a steady compound annual growth rate, reflecting durable demand across both permanent placements and flexible staffing models. This trajectory is not merely a function of population growth or economic expansion; it is fundamentally tied to the accelerating mismatch between the skills organizations require and the talent pools available within domestic labor markets. As multinational corporations, mid-market enterprises, and public-sector entities alike pursue global talent strategies, international recruitment services have matured from an operational afterthought into a centralized capability that intersects with risk management, compliance, employer branding, and long-term workforce planning.
Importantly, the growth narrative is nuanced. The market's expansion is not uniform; it is shaped by regional economic maturity, regulatory environments, sector-specific talent intensity, and the pace of digital adoption within recruitment workflows. Understanding these underlying drivers—and how they compound over time—is essential for organizations that must allocate capital, define partnership strategies, and anticipate service-level expectations in the years ahead.
Service Models and Vertical Demand: The Architecture of Global Talent Acquisition
International recruitment services operate across a diversified service ecosystem, each model addressing distinct organizational needs, risk profiles, and time horizons. The market is broadly structured around permanent placement, contractual and temporary staffing, executive search, and recruitment process outsourcing. These service lines do not compete in isolation; they frequently converge within enterprise talent strategies, where organizations balance long-term capability building with short-term agility, leadership succession with project-based surge capacity, and in-house recruiting bandwidth with external specialization.
Permanent placement remains the foundational pillar of the market, driven by organizations seeking durable, culturally integrated talent to anchor operations, fill specialized roles, and support geographic expansion. Contractual and temporary staffing, meanwhile, continues to serve as a critical mechanism for navigating demand volatility, seasonal fluctuations, and project-specific skill requirements without incurring long-term employment liabilities. Executive search operates at the premium end of the spectrum, where leadership selection carries outsized strategic weight and where international mobility is often tied to succession planning, market entry, or organizational transformation. Recruitment process outsourcing has emerged as a structural response to the operational complexity of talent acquisition, allowing organizations to delegate sourcing, screening, compliance coordination, and candidate management to partners with specialized infrastructure and cross-border expertise.
These service models are distributed across a broad spectrum of industry verticals, each with distinct recruitment intensity, compliance complexity, and talent-skill requirements. The IT and telecommunications sector consistently drives some of the strongest demand, reflecting the global shortage of digital, engineering, and technical talent and the pace at which organizations are modernizing legacy infrastructure. Healthcare and life sciences represent another high-intensity vertical, where international recruitment is shaped by clinical workforce shortages, an aging population in many advanced economies, and the global mobility of specialized medical professionals. Manufacturing and engineering demand reflects supply chain reconfiguration, industrialization initiatives, and the need for technical expertise across borders. The BFSI sector, meanwhile, depends heavily on talent capable of navigating regulatory complexity, risk management, and digital transformation, often requiring recruiters who understand both technical competency and jurisdictional nuance.
Beyond these core verticals, a broad base of additional industries continues to rely on international recruitment services for niche expertise, localized market entry, and flexible workforce scaling. What unites these sectors is not identical demand, but a shared dependency on talent accessibility and the need for recruitment partners who can operate with precision across multiple legal, cultural, and administrative environments.
Geographic Distribution and Structural Concentration
The global market is not evenly distributed. Regional demand patterns reflect differences in economic development, labor market flexibility, regulatory frameworks, and the maturity of recruitment ecosystems. North America and Europe continue to represent substantial share of overall market activity, supported by mature corporate sectors, high demand for specialized talent, and well-established cross-border recruitment infrastructures. The Asia Pacific region, meanwhile, has emerged as a powerful growth engine, driven by industrialization, digital transformation, and the increasing globalization of corporate operations across the region. Markets in the Middle East and Africa, as well as Latin America, are smaller in absolute terms but hold strategic relevance for specific labor flows, regional restructuring, and emerging talent corridors.
Strategic interpretation of regional activity requires nuance. Aggregate market scale does not always translate to equal opportunity for all service providers. Local compliance requirements, cultural expectations around candidate representation, visa and mobility frameworks, and the presence of established domestic recruitment ecosystems all influence how international recruitment services are consumed and valued in each geography. The result is a market where global footprint and local delivery capability must coexist for sustained competitive advantage.
The competitive landscape also reflects meaningful structural concentration. A relatively small group of large-scale providers accounts for a notable share of total market revenue, while a broader set of specialized and regional players compete on expertise, sector focus, and service differentiation. This concentration has implications for pricing dynamics, partnership leverage, and the degree to which enterprise buyers can consolidate recruitment-related expenditures across geographies and service lines. At the same time, the presence of strong specialist firms and mid-tier operators ensures that segmentation remains active, particularly in executive search, sector-specific staffing, and compliance-heavy international placements.
Competitive Landscape: Scale, Specialization, and the Battle for Trust
The international recruitment services market is defined by a set of major global players whose strategies reflect divergent approaches to scale, specialization, and cross-border delivery. Understanding these players is essential for organizations evaluating partnership models, benchmarking service expectations, and anticipating industry consolidation or capability expansion.
Adecco Group has built a broad international footprint, offering temporary, permanent, and contract staffing solutions across industries that include IT, engineering, finance, and healthcare. With operations extending across more than sixty countries, the firm's positioning emphasizes breadth of coverage and the ability to support multinational workforce deployments through integrated service lines.
Randstad operates with a similarly global orientation, delivering recruitment, staffing, and HR services that emphasize international talent acquisition, temporary agency work, and workforce solutions. Its presence across dozens of countries reflects a focus on scalable delivery and the ability to match flexible staffing demand with localized market knowledge.
ManpowerGroup provides workforce solutions spanning international recruitment, staffing, and talent management for permanent, temporary, and project-based roles. With operations in more than eighty countries, the company has positioned itself around the idea of end-to-end workforce capability, where recruitment is coupled with broader talent management and deployment services.
Hays plc specializes in specialist recruitment for permanent and temporary positions, with international reach concentrated in sectors such as IT, construction, finance, and engineering. Its model reflects a strong emphasis on market-specific expertise and sector-aligned candidate evaluation.
Robert Half focuses on international recruitment for finance, accounting, IT, and administrative roles, with a footprint that spans numerous countries. Its positioning underscores the importance of specialized skill matching in professional and financial services labor markets.
Korn Ferry distinguishes itself through executive search and international talent acquisition services that are integrated with organizational consulting and leadership assessment. Rather than operating purely as a placement provider, the firm frames talent acquisition as part of a broader capability to shape leadership, organizational design, and executive mobility across borders.
Allegis Group offers staffing and recruitment solutions with significant international capabilities, particularly in engineering, IT, and professional services. Its operating model reflects a combination of scale and sector orientation, enabling it to serve clients with both volume staffing needs and specialized technical requirements.
Kelly Services delivers temporary, permanent, and outsourced staffing with international recruitment support across a range of industries. Its breadth of service lines positions it to respond to diverse workforce demands while maintaining cross-border recruiting capacity.
Michael Page specializes in mid-to-senior level international recruitment across finance, marketing, engineering, and other professional sectors. Its focus on experienced talent and professional career mobility reflects the premium end of international recruitment, where candidate assessment, market intelligence, and employer positioning carry heightened importance.
Together, these firms illustrate the competitive tension shaping the market: global scale versus sector specialization, operational efficiency versus executive advisory depth, and standardized service delivery versus localized compliance and cultural fluency. For enterprise buyers, this competitive diversity is not a distraction; it is the mechanism through which service quality, pricing, innovation, and risk management are continuously recalibrated. The organizations that succeed in 2026 and beyond will be those that can align their talent acquisition strategies with providers whose capabilities match their geographic footprint, sector complexity, and compliance exposure.
Regulatory and Ethical Dynamics Reshaping International Recruitment
The expansion of international recruitment services cannot be understood apart from the regulatory and ethical environment in which it operates. Cross-border talent mobility is increasingly governed by a web of labor protections, data privacy requirements, fee structures, and employer responsibility standards. These forces are not peripheral concerns; they directly affect candidate sourcing strategies, visa and mobility workflows, contractual design, reputation risk, and the long-term sustainability of recruitment partnerships.
One of the most significant regulatory themes in recent years has been the scrutiny of recruitment fees and related costs charged to workers. International labor standards have increasingly emphasized that charging workers for recruitment fees can create financial vulnerability and, in severe cases, contribute to exploitation. Policy coverage in Europe and Central Asia has expanded notably, with a growing majority of reviewed countries adopting policies that prohibit fee-charging for both national and international recruitment. In parts of Africa, legislation on recruitment fees has been applied specifically to international recruitment in countries such as Uganda, Kenya, and Tunisia, with many laws requiring employers to cover transportation costs for relocated workers. These developments reflect a broader shift toward placing compliance and ethical responsibility on employers and recruitment intermediaries rather than on migrant workers themselves.
The financial scale of fee-related exploitation is not trivial. Recruitment fees and related costs have been linked to debt bondage and are estimated to account for a significant share of forced labour cases, extracting billions of dollars annually from migrants in forced labour situations. For international recruitment service providers and their clients, this is not merely a humanitarian concern; it is a compliance, due diligence, and reputational risk issue. Organizations that rely on cross-border talent must ensure that recruitment processes are transparent, fee structures are aligned with ethical recruitment standards, and supply-chain oversight extends to the intermediaries involved in candidate mobilization.
Data privacy regulation adds another layer of operational complexity. Requirements such as GDPR demand transparency, consent, and accountability in handling candidate data throughout recruitment processes. Ongoing enforcement activity and guidance updates have affected cross-border data transfers and automated decision-making in hiring, particularly as organizations increasingly deploy digital screening tools, candidate relationship management platforms, and algorithmic sourcing technologies. recruiters operating across jurisdictions must therefore design workflows that respect local data protection expectations while maintaining consistent candidate experience and operational efficiency.
Sector-specific labor regulation also continues to shape international recruitment dynamics. In certain verticals, government visa routes intended to facilitate essential worker mobility have drawn scrutiny where vulnerability, exploitation, or inconsistent oversight has been reported. In response, regulators and advocacy groups have called for stronger ethical recruitment practices, enhanced monitoring, and mechanisms such as rematching support where placement integrity is compromised. For employers, these developments underscore the importance of ethical sourcing, candidate protection, and careful partner selection in international recruitment ecosystems.
Taken together, these regulatory and ethical dynamics are reshaping the market's operating logic. Compliance is no longer a back-office function; it is embedded in client expectations, intermediary selection, contract design, and the credibility of the recruitment brand itself. Providers that proactively align their processes with evolving labor standards, data protection expectations, and ethical recruitment principles are better positioned to serve clients operating in heightened regulatory scrutiny environments.
Report Framework: What This Analysis Delivers for 2026 Decision-Making
This market research is designed to translate complex industry dynamics into practical strategic guidance. Rather than offering a static snapshot of market size, the report provides a structured, decision-oriented framework that helps leaders anticipate change, evaluate options, and allocate resources with greater confidence. The analysis is organized to support both high-level strategic planning and operational decision-making across multiple stakeholder functions.
At the foundation of the report is a comprehensive market overview that contextualizes historical performance, current scale, and forward-looking growth potential. This section establishes the baseline for understanding how international recruitment services have evolved and why the market is positioned for continued expansion. The historical review traces the path from early-pandemic disruption through recovery and structural recalibration, while the forecast discussion translates that trajectory into a forward outlook that reflects durable demand drivers rather than short-term volatility.
The segmentation analysis breaks the market into actionable dimensions—by region, service type, and industry vertical—so that organizations can evaluate where demand is concentrated, where growth is most likely to accelerate, and where service expectations differ. Rather than treating the market as a single aggregate, this structure enables readers to identify the segments most relevant to their business context, whether they are evaluating market entry, partnership strategy, capacity investment, or competitive positioning.
The competitive landscape assessment examines the major providers shaping the market and the strategic logic behind their operating models. By mapping firm profiles, geographic reach, sector focus, and service breadth, the report helps readers understand how scale, specialization, and cross-border capability interact in practice. This section is particularly useful for organizations comparing vendor ecosystems, assessing consolidation risk, or determining what capabilities they should build internally versus outsource.
The regulatory and dynamic environment discussion synthesizes the policy, compliance, and ethical factors currently influencing international recruitment. This includes the evolving treatment of recruitment fees, data privacy obligations, candidate protection expectations, and the operational consequences of heightened scrutiny in certain labor corridors. By integrating these forces into the market analysis, the report frames compliance not as a separate governance topic but as a strategic variable that affects cost, speed, risk, and competitive differentiation.
In addition to macro and competitive analysis, the report incorporates actionable tools for market interpretation and decision support. These include strategic considerations for enterprise talent acquisition leaders, guidance for assessing provider fit across service lines and geographies, and frameworks for anticipating how regulatory change may alter recruitment workflows and partner selection criteria. The objective is to equip readers with a clear line of sight from high-level market intelligence to operational implications.
Throughout the analysis, the focus remains on insight that can be applied. For corporate strategists, this means a clearer understanding of where international recruitment fits within broader workforce planning and how service models align with talent strategy. For investors and market participants, it means a structured view of growth drivers, competitive differentiation, and the regulatory pressures likely to shape profitability and operating models. For policy-aware organizations, it means a realistic assessment of ethical recruitment expectations and the compliance burden associated with cross-border talent deployment.
Strategic Implications for Leaders Planning Beyond 2026
As organizations enter the 2026 planning cycle, the international recruitment services market presents both opportunity and complexity. The growth trajectory is strong, but growth alone does not guarantee advantage. The companies that extract strategic value from this market will be those that treat international recruitment as a managed capability rather than a transactional purchase.
First, talent strategy and compliance strategy must be integrated. The regulatory environment is becoming more demanding, and organizations that treat ethical recruitment, fee transparency, and data handling as afterthoughts expose themselves to operational disruption and reputational risk. Embedding compliance into vendor selection, contract design, and candidate journey design is no longer optional; it is a competitive safeguard.
Second, service model alignment matters. Not every organization needs the same mix of permanent placement, temporary staffing, executive search, or recruitment process outsourcing. The strategic question is how to combine these services to balance long-term capability, short-term flexibility, and operational control. Providers that offer integrated delivery across these lines can reduce fragmentation, but only if their capabilities match the organization's sector, geography, and scale requirements.
Third, geographic and vertical context should drive partnership and investment decisions. Demand conditions, regulatory exposure, and recruitment complexity differ significantly across markets and industries. A strategy that works in one region or vertical may not translate elsewhere. Leaders should therefore avoid overgeneralizing market growth and instead anchor decisions in segment-specific realities.
Finally, the market is likely to reward providers and clients that prioritize transparency, specialized expertise, and digital-enabled efficiency without sacrificing candidate experience or compliance integrity. As recruitment processes become more technology-driven and more cross-jurisdictional, the differentiating factors will increasingly be trust, accuracy, and the ability to operate responsibly across borders.
The Worldwide International Recruitment Services Market is at a stage where scale, structure, and scrutiny are all intensifying. For leaders navigating workforce strategy in 2026 and the years that follow, comprehensive intelligence is not a luxury; it is a prerequisite for sound decisions. This report provides the analytical foundation needed to understand where the market is heading, who is shaping it, and what it will take to operate effectively within it. The full analysis, segmentation detail, competitive mapping, and forward outlook are available in the complete research release, where decision-makers can access the depth of data and strategic context required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide International Recruitment Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


