



Category: market research
PW Consulting: Worldwide Container Vans Market to rise to USD 15,958.8 Million by 2032 at a 4.35% CAGR — Asia Pacific leads with USD 5,662 Million
By PW Consulting, 2026-08-18
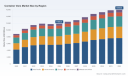
Worldwide Container Vans Market — 2026 Strategic Outlook and Playbook
Executive preview
PW Consulting’s latest market study, operating off a 2025 base and forecasting through 2032, equips corporate leaders with the forward-looking intelligence required to make high-stakes decisions in 2026. The global container vans market, having expanded materially since 2020, reached roughly USD 11.8 billion in 2025 and is projected to surpass USD 12.4 billion in 2026 under a baseline compound annual growth rate of 4.35% over the 2026–2032 forecast window. These headline metrics capture the sector’s resilience and the steady demand underpinning intermodal logistics worldwide — but the strategic value of the report lies in how those dynamics translate into actionable choices for OEMs, carriers, fleet owners, leasing companies, and infrastructure investors.
Polymeric Positive Temperature Coefficient Device Market
Market trajectory and macro drivers
From pandemic-era disruption through subsequent recovery and normalization, the container vans market shows a clear re-anchoring to pre‑pandemic trade patterns with new structural inflections: accelerated e-commerce trade flows, expanded cold‑chain logistics, and the rising use of containers for modular storage and construction. These forces underpin steady volume growth while also shifting the product mix toward higher-specification units in certain use cases.
Black and White Ultrasound System Market
Cost-side dynamics matter: steel remains the dominant input in container manufacturing, and price moves directly affect production economics and contract negotiations. In Q4 2025, benchmark steel prices reflected notable regional variation (with recorded price points near USD 891/MT in the U.S. and USD 804/MT in Germany), underscoring that raw-material exposure and hedging decisions should be core elements of 2026 sourcing strategies. At the same time, international technical and safety frameworks — notably ISO 1496 performance/testing standards and the Convention for Safe Containers (CSC) administered through national authorities — continue to shape product specifications and compliance-related capital needs.
Electrochemical Hydrogen Sulfide Sensor Market
What the PW Consulting report delivers — practical contents designed for 2026 action
- Integrated demand model and scenario maps: high-resolution forecasts across the 2026–2032 horizon with sensitivity runs for trade shocks, steel price swings, and modal-shift scenarios.
- Procurement playbook: time-phased buying strategies, raw-material hedging options, supplier negotiation levers, and contract structures tailored to varying appetite for CAPEX vs. OPEX exposure.
- Supplier and capacity heat maps: assessment of manufacturing concentration, lead-time drivers, and geopolitical risk vectors to inform nearshoring and dual-sourcing decisions.
- Total Cost of Ownership (TCO) templates: lifecycle cost calculators that incorporate maintenance, repair, retrofit, and residual value assumptions for dry, refrigerated, and special-purpose container vans.
- Regulatory and compliance checklist: ISO and CSC alignment steps, inspection cadences, and certification impact matrices for new unit introductions and fleet conversions.
- Aftermarket and service opportunities: repair network optimization, spare parts stocking strategies, and value-add service bundles that enhance asset utilization.
- Strategic M&A and partnership playbook: acquisition targets, JV models, and partnership structures designed to secure capacity, technology, or geographic access.
Competitive landscape — who matters and why
The market demonstrates a high degree of concentration at the top: the three largest manufacturers control a substantial majority of global capacity, and the top five are dominant across production, OEM services, and aftermarket capabilities. That structure has several implications for buyers and challengers alike: suppliers with scale can exert pricing discipline and deliver rapid fulfillment; conversely, buyers that can aggregate demand or offer long-term contracting certainty can unlock preferential allocation and pricing benefits.
- China International Marine Containers (CIMC) — Shenzhen, China : The world’s largest producer, CIMC’s scale and ISO-compliant high-volume production model make it the default sourcing partner for many global shipping lines and leasing firms. Its vertically integrated capabilities — from standard dry vans to reefers and specialty units — position CIMC as a price and capacity anchor in negotiations.
- Dong Fang International Container (DFIC) — Shanghai, China : DFIC focuses on high-throughput dry freight and specialized containers, leveraging Chinese manufacturing efficiencies to serve global intermodal needs. Its factory footprint and logistics integration support competitive lead times for large volume commitments.
- Singamas Container Holdings Ltd. — Hong Kong, China : Known for breadth of product (dry freight, flat-rack, open-top and specialty), Singamas competes on product variety and flexible production runs, making it a strategic supplier for operators requiring diverse fleets.
- CXIC Group Containers Co., Ltd. — Changzhou, China : CXIC’s product set spans dry cargo, tanks and special containers; it is a reliable alternative for companies seeking diversification away from a single large supplier.
- Maersk Container Industry (MCI) — Tinglev, Denmark : MCI is differentiated by its refrigerated and higher-specification refrigerated units, serving customers where cold-chain performance and durability command a premium.
- COSCO Shipping Development — Shanghai, China : As an integrated shipping and container production player, COSCO’s vertical reach supports strategic fleet management synergies between tonnage and container availability.
Understanding these capabilities — and how they map to your product mix and geographic priorities — is essential. PW Consulting’s report combines company profiles, capacity trend analysis, and contract benchmarking so that procurement teams can convert supplier insights into lower TCO and more resilient supply chains.
Strategic implications for 2026 decision-makers
- Prioritize supply resilience: With manufacturing concentrated among a few large producers, build contingency plans that include multi-supplier contracts, staggered delivery windows, and, where feasible, regional sourcing to reduce lead-time risk.
- Hedge raw-material exposure: Given steel’s dominant cost role and recent price volatility, embed material-price pass-through clauses, index-linked pricing, or forward-purchase strategies into 2026 procurement cycles.
- Optimize product mix with TCO focus: Distinguish between life-cycle value and upfront price; refrigerated or higher-spec units may command higher purchase costs but deliver superior lifetime net value where cold-chain or specialized applications exist.
- Leverage concentration for value: If your organization can provide volume certainty, use it to negotiate capacity reservation, priority allocation clauses, and improved warranty/service terms with top-tier suppliers.
- Invest in compliance and inspection readiness: Align procurement and operations with ISO 1496 and CSC requirements to reduce downtime risk and maintain cross-border service validity.
- Pursue modularity and circularity: Design fleets for easier retrofit, repurposing, and end-of-life recovery to capture residual value and meet tightening sustainability expectations from customers and regulators.
- Monetize aftermarket services: Add-on services — from maintenance bundles to telematics-driven uptime guarantees — can materially improve margins and customer stickiness.
How to use this study in your 2026 planning cycle
PW Consulting structured the study for immediate operational use. Examples of executable outputs embedded in the report:
- A procurement calendar that syncs order placement to lead-time windows and steel-price cycles, enabling lower average acquisition costs without sacrificing delivery certainty.
- Fleet refresh prioritization matrices that rank replacement candidates by TCO, regulatory exposure, and residual value recovery potential.
- Negotiation templates and supplier scorecards to secure favorable terms from large incumbents while preserving flexibility to pivot to niche suppliers where needed.
- Scenario playbooks for demand shocks, where the report’s sensitivity models quantify the impact on utilization and freighting costs and propose mitigation measures.
Final takeaways — why this matters for 2026
Entering 2026, the container vans industry offers a blend of steady baseline demand and pockets of strategic opportunity — but both reward preparation. Scale and concentration among a handful of manufacturers create both bargaining risks and opportunities: well-capitalized buyers that can commit to volume will extract advantage, while mid-sized players should pursue specialization, strategic alliances, and service differentiation. Steel-price exposure and compliance obligations are not peripheral; they should be central to procurement, capital allocation, and risk-management conversations next year.
PW Consulting’s Worldwide Container Vans Market report translates market-scale dynamics (including the 2025 baseline and the projected 2026 advancement under a 4.35% forecast CAGR) into an operational playbook. It provides the detailed segment modeling, supplier analytics, and scenario tooling that senior executives need to convert insight into measurable outcomes in 2026 and beyond.
Next steps
For a complete view — including the full segmented datasets, regional and application-level forecasts, and downloadable TCO models — access the full report on PW Consulting’s market research page. Our analysts are available to brief executive teams, support vendor negotiations, and build bespoke scenario runs tailored to your fleet and procurement profile.
For detailed analysis of this topic, please visit the official page: Worldwide Container Vans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Femtosecond OPA Market Poised to Grow at a 6.91% CAGR Through 2032
By PW Consulting, 2026-08-18
PW Consulting Releases Strategic Brief: Worldwide Femtosecond OPA Market — Essential Guidance for 2026 Decision-Makers
PW Consulting today publishes its authoritative market briefing accompanying the new Worldwide Femtosecond Optical Parametric Amplifier (OPA) Market report. Compiled from an intensive 2020–2025 historical analysis and a 2026–2032 forecast horizon, the briefing synthesizes the commercial, technical, and strategic vectors that will shape supplier and buyer choices through 2026 and beyond. Our objective: equip executives with immediately actionable frameworks and risk maps while preserving the proprietary granularity that differentiates the full report.
Low and Medium Density SPI NOR Flash Market
Market at a glance — a reliable growth runway
The femtosecond OPA market has moved from a specialist research niche into a commercially meaningful segment as ultrafast tools migrate from core physics labs into applied spectroscopy, multiphoton imaging, high-harmonic generation, and precision micromachining. PW Consulting’s base-year assessment (2025) places the market at approximately USD 242.5 Million, with a compound annual growth rate (CAGR) of 6.91% over our forecast window. Under our central scenario, the market expands steadily into the early 2030s, reflecting a combination of stronger pump-laser platforms, broadened application adoption, and incremental system-level integration.
Burglary Resistant Safety Doors Market
Two aggregated dynamics define the near-term opportunity set. First, suppliers that solve for integration — packaging stable pump sources, dispersion management, and user-friendly tuning — shorten the path to adoption in applied R&D and light-industrial environments. Second, the maturation of high-average-power Yb-based femtosecond pump lasers and advances in nonlinear crystal engineering materially widen the practical operating envelope for OPA OEMs and integrators, unlocking higher average power, broader tuning, and higher repetition-rate operation.
Worldwide Election Management Software Market
Why this briefing matters for 2026 decisions
- Prioritize technology bets with ROI clarity: The market’s steady CAGR implies selective investment is wiser than blanket expansion. R&D and product teams must choose between competing value plays — ultra-broad tuning vs. compact industrial robustness vs. extreme repetition-rate systems — based on downstream customer economics.
- De-risk supply chains: Material and component constraints, especially nonlinear crystals and synchronized Yb pump lasers, are primary bottlenecks. Strategic sourcing, qualification of alternate crystal suppliers, and dual-sourcing of pump modules should be implemented in 2026 to avoid delivery slippage as demand grows.
- Commercial go-to-market timing: Systems that lower the barrier to non-expert operation (automation, air-cooled/monolithic designs, one-box formats) accelerate adoption in industrial and translational research contexts. Vendors and channels should align product launches and pilot programs to this commercial inflection.
Competitive landscape — what incumbents and challengers signal
The femtosecond OPA ecosystem is concentrated, with a handful of specialized firms establishing leadership in product breadth, application-tailored systems, and integration capabilities. This concentration creates distinct strategic postures: deep-technology incumbents defend by extension of platform capabilities; agile challengers focus on niche applications and faster commercialization.
- Light Conversion (Vilnius): A recognized leader with broad tunable platforms and industrialized OPA modules designed for high repetition rates and Yb-pumped ecosystems. Their emphasis on stability and attachable modules shows a focus on industrial and high-throughput R&D customers.
- APE (Berlin): Positioned on thermal stability and automation for 1 μm pump environments, with product variants optimized for different pulse-length targets — a play designed to appeal to high-throughput spectroscopy and imaging labs seeking reliable operation.
- Coherent (Santa Clara): Integrates one-box, computer-controlled OPAs tailored to popular amplifier platforms, underscoring an integration-first commercial route that resonates with system buyers seeking turnkey solutions.
- EKSPLA (Vilnius): Recent product launches indicate a push into the compact, high-repetition-rate submarket with engineered dispersion compensation — an aggressive move to capture applied-imaging and spectroscopy workflows.
- Spectra-Physics (MKS Instruments): Focuses on ultrafast amplifier-matched NPAs optimized for biomedical and spectroscopy use cases; their approach highlights the importance of alignment with laser OEM ecosystems.
- Amplitude (Bordeaux): Positions air-cooled, high-repetition platforms that emphasize gapless, broad-range coverage and dispersion management — signaling a strategy targeting multi-photon imaging and time-resolved spectroscopy.
- Class 5 Photonics (Hamburg): Specializes in OPCPA approaches and few-cycle/high-power options, pursuing frontier science applications such as attosecond experiments and high-harmonic generation where pulse duration and peak power are critical.
Recent product developments underscore an ongoing bifurcation: vendors are either (a) doubling down on integration and industrialization, or (b) pushing the performance frontier for demanding science applications. Both strategies can be commercially viable — the key is alignment between product architecture and buyer willingness to pay for either ease-of-use or extreme performance.
Operational constraints and regulatory context
- Material supply chain: Nonlinear crystals (such as commonly used BBO, LBO, KTA and emerging chalcohalides) remain a gating factor for wavelength coverage and conversion efficiency. Quality and availability of crystal substrates directly influence both product differentiation and manufacturing lead times.
- Pump-laser infrastructure: The transition to high-average-power, Yb-based femtosecond pumps is a precondition for scaling many mid- and high-repetition-rate OPA architectures. Procurement cycles and technical partnerships with pump-laser OEMs should therefore be a top priority for system manufacturers.
- Standards and export controls: Femtosecond OPAs are typically operated under general laser safety standards; there is no bespoke ISO standard unique to the product family. However, dual-use export controls that govern advanced laser technologies can affect cross-border supply and aftermarket support — a factor that should be baked into 2026 market-entry plans.
What the PW Consulting report delivers — executable intelligence (without the spoilers)
In order to translate macro trends into tangible actions, the full report includes a suite of practical deliverables designed for executives and functional leaders:
- Demand-scenario modelling calibrated to technology adoption curves and pump-laser capacity constraints.
- Vendor benchmarking frameworks and scorecards that evaluate systems on stability, tuning range, ease-of-integration, and total cost of ownership (TCO).
- Go-to-market playbooks for suppliers — from lab-focused OEMs to industrial integrators — with channel strategies and pilot-program templates for accelerating early adoption.
- Supply-chain risk matrices and mitigation templates covering raw-material sourcing, dual-sourcing strategies, and compliance checklists for export controls and laser safety governance.
- Technical decision trees for product managers to select trade-offs between repetition rate, pulse duration, tuning coverage, and thermal management architectures.
- A M&A and partnership screening rubric for corporate development teams aiming to buy capabilities rather than build them, including due-diligence checklists and integration playbooks.
We intentionally refrain from publishing the sub-segment breakdowns in this briefing. Those high-resolution data slices — including regional mixes, application-level revenue trajectories, and product-type unit economics — are packaged within the full report and interactive data exhibits to enable precise business cases and investment memos.
Actionable plays for 2026
- For OEMs and product teams: Formalize a two-track product portfolio: a commercialized “integration-first” line (ease-of-use, air-cooled, one-box) and a science-focused “performance-first” line (few-cycle, high-peak-power). Prioritize modularity so that customers can upgrade pump or dispersion-management modules independently.
- For procurement and system integrators: Lock in multi-year supply agreements for nonlinear crystals and pump modules in 2026. Build in technical acceptance criteria that stress long-term beam quality and synchronization under expected operational loads.
- For investors and corporate development: Use the report’s vendor scorecards to identify targets where proprietary nonlinear-crystal partnerships or pump-laser integration IP create durable moats. Favor targets with repeatable revenue from service and upgrade pathways.
- For research institutions and early adopters: Negotiate pilot programs with vendors offering flexible financing and clear upgrade paths; prioritize platforms that demonstrate both spectral coverage and ease of operation to maximize experimental throughput.
How to use the full report
The full PW Consulting report transforms the high-level trends above into executable projects — from build-versus-buy decision templates to quantified investment cases. Clients use it to:
- Compose 12–36 month product and sourcing roadmaps;
- Underpin capital allocation decisions for R&D, manufacturing scale-up, or M&A;
- Structure channel and partnership agreements that capture translation from lab validation to industrial deployment.
For procurement, engineering, and strategy teams, the differentiator is not that femtosecond OPA demand is growing — it is that the shape of that growth and the necessary operational moves to capture share are both tractable and actionable if pursued deliberately in 2026.
Closing — a selective preview with a clear next step
PW Consulting’s briefing offers a high-confidence roadmap for executives preparing for 2026. We present a nuanced view: the market is sizeable and expanding at a mid-single-digit CAGR, the competitive set is concentrated with well-capitalized specialist players and inventive challengers, and the primary levers for success are supply-chain control, strategic integration, and alignment with pump-laser roadmaps.
To access the full dataset, proprietary segment-level forecasts, vendor scorecards, and downloadable decision-support tools that underpin the recommendations above, please consult the Worldwide Femtosecond OPA Market report available through PW Consulting’s report portal. The complete package contains the subsegment granularity and financial exhibits necessary for rigorous investment, procurement, and product strategy work in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Femtosecond OPA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Soft Tissue Repair Mesh Market to climb from USD 4,500 Million in 2025 to USD 6,681.9 Million by 2032, driven by a 5.81% CAGR
By PW Consulting, 2026-08-18
Worldwide Soft Tissue Repair Mesh Market: Strategic Imperatives for 2026—A PW Consulting Preview
PW Consulting’s latest market study on the Worldwide Soft Tissue Repair Mesh Market (base year 2025) provides a forward-looking intelligence package designed to drive executive decisions in 2026. Anchored by a robust market model and validated with primary interviews across suppliers, hospitals, and payers, the study finds the global market at approximately USD 4,500 Million in 2025 and projects a steady expansion to an estimated USD 6,682 Million by 2032—equivalent to a compound annual growth rate (CAGR) of 5.81% through the forecast window. This preview summarizes the report’s strategic value, high-confidence growth drivers and risks, competitive implications for leading incumbents, and the practical tools executives will find indispensable when shaping 2026 priorities.
Fully Enclosed Cable Carrier Market
Why the 2026 Decision Window Matters
Healthcare buyers and providers face accelerating pressure to balance improved clinical outcomes with cost containment. For device manufacturers and strategic investors, 2026 represents a pivotal inflection point: evolving regulatory expectations, shifting reimbursement rules, and accelerating material and procedural innovation converge at scale. Our analysis shows that the market is neither fragmented opportunistically nor ossified—the top three players account for a majority share of revenue while the top five consolidate an even larger share—creating a competitive landscape in which scale and differentiated clinical evidence matter more than ever.
Expulsion Fuses Market
What the Report Delivers: Practical, Transaction-Ready Intelligence
This report was designed to be directly actionable. It includes:
Water Quality Monitor Market
- Bottom-up revenue modeling (USD Million; historical 2020–2025, forecast 2026–2032) with modular scenario toggles that isolate price, volume, and mix effects.
- Regulatory and reimbursement trackers that map device-class guidance, recent clearances, and payer coding/pricing changes across major markets.
- Commercial playbooks for product launches and portfolio rationalization, including go-to-market tactics by channel (hospital, ASC, outpatient) and by surgeon specialty.
- Supplier scorecards and manufacturing capacity risk matrices to support sourcing and M&A diligence.
- Clinical evidence gap analysis and recommended trial designs to secure favorable labeling and reimbursement trajectories.
- Target screening for strategic partnerships and acquisitions—ranked by clinical fit, technology adjacency, and integration complexity.
Market Dynamics—Drivers, Headwinds, and Timing
Key forces shaping the market in 2026 include:
- Regulatory tightening on labeling transparency and product safety: notable is the FDA’s June 2025 draft guidance advocating standardized package labeling for hernia mesh devices that explicitly calls for clinically relevant mechanical and physical property disclosures. This raises the bar for clinical documentation and may accelerate demand for meshes with clear comparative data and standardized labeling frameworks.
- Ongoing reimbursement realignment: updated Medicare payment rates and coding guidance for hernia repair procedures in 2025 demonstrate how reimbursement granularity can materially affect hospital and ASC economics. Several reinforced tissue matrices have received explicit reimbursement references, creating differentiated commercial advantages for compliant products.
- Product innovation and differentiated materials: the market continues to evolve across synthetic, biologic, and hybrid/composite matrices. New electrospun fiber matrices and fully resorbable options are entering clinical practice, shifting surgeon preferences and long-term value propositions.
- Legal and safety history in specific applications: prior regulatory actions on certain transvaginal pelvic organ prolapse meshes underscore the importance of robust long-term safety data and risk-management planning for pelvic applications.
Competitive Landscape: What 2026 Strategy Teams Must Know
The market’s competitive fabric combines large diversified medtech incumbents with agile specialists and tissue/regenerative firms. Our report profiles the leading participants and assesses strategic posture across product portfolios, regulatory positioning, and go-to-market capability.
- Johnson & Johnson (Ethicon) — With deep legacy presence in abdominal and pelvic reinforcement, Ethicon’s portfolio offers established composite and synthetic options. Strategic considerations: leverage scale for global clinical studies, accelerate labeling clarity in response to FDA guidance, and prioritize value-based contracting in high-volume hernia centers.
- Medtronic (Covidien/Sofradim) — Recent regulatory progress and product clearances highlight Medtronic’s continued investment in lightweight synthetics and composites. Strategic considerations: align new product introductions with reimbursement windows, and emphasize differentiated handling and fixation profiles to sustain hospital preference.
- Becton, Dickinson and Company (BD, formerly Bard/Davol) — BD has moved into absorbable technologies and continues to expand its biologic-synthetic mix. Strategic considerations: build clinical narratives around absorbability and reduced long-term complications; consider strategic studies in ASCs where cost and recovery time matter most.
- Gore Medical — Known for PTFE-based patches, Gore’s strengths are in material science and surgeon familiarity. Strategic considerations: protect market share through evidence generation and targeted education around nuanced handling advantages.
- Specialists and Tissue Firms (TELA Bio, LifeNet Health, Integra, Organogenesis) — These companies drive innovation in reinforced matrices and biologic grafts. Strategic considerations: partnerships with larger distributors or co-development deals can accelerate scale while preserving innovation agility.
- Orthopedic and Surgical Portfolio Players (Stryker, Smith & Nephew, Zimmer Biomet) — Although not pure-play mesh suppliers, these firms can mobilize commercial reach. Strategic considerations: cross-selling into surgical suites and leveraging global distribution networks for newer mesh categories.
- Other strategic players (Cook Medical, Atrium/Getinge) — Mid-sized firms with focused product sets can be attractive consolidation targets or partners for geographic expansion.
Across the competitive set, the top three players control a material majority of market revenue and the top five an even larger share—conditions that favor scale, integrated clinical programs, and supply stability. Yet the level of concentration also leaves niches—innovation-led biologics, resorbable scaffolds, and specialty reinforced matrices—ripe for targeted entry or acquisition.
Notable Recent Developments and their Strategic Consequences
- Regulatory: FDA draft guidance (June 2025) on hernia mesh labeling elevates transparency expectations; manufacturers should prioritize mechanical property disclosure and standardize testing protocols to avoid market friction at launch.
- Regulatory Approvals and Launches: Several 510(k) clearances and product launches in 2025 and 2025–2026 cycles (including new electrospun matrices and absorbable patches) indicate a continuing cadence of incremental innovation. Time-to-evidence and payer engagement must be integrated into launch timelines to capture reimbursement-driven adoption.
- Reimbursement: Updated Medicare coding and payment practice for abdominal hernia procedures in 2025 underscores the need for granular hospital-level economics and ASC-focused pricing strategies. Products already referenced in reimbursement guidance enjoy immediate commercial leverage.
- Safety Context: Historical regulatory actions affecting select transvaginal meshes reiterate that long-term outcomes and real-world safety surveillance are material to both regulatory status and commercial acceptance.
Actionable 2026 Playbook: Four High-Impact Priorities
For 2026, we recommend executive teams focus on four concurrent priorities to maximize upside and mitigate downside:
- Evidence-First Product Strategy: Invest in mid- to long-term clinical studies and real-world evidence programs aligned with the FDA’s labeling expectations. Rapid post-market surveillance and registries will differentiate products in procurement processes.
- Reimbursement-Linked Launch Planning: Align product launches with payer policy cycles and Medicare updates. Build hospital/ASC economic models that quantify incremental value (OR time, readmission avoidance, long-term complications) to support favorable contracting.
- Supply & Manufacturing Resilience: De-risk critical material and contract manufacturing relationships. Scenario-test capacity under regional demand spikes and regulatory-driven recalls; maintain buffer stocks for high-volume SKU families.
- M&A and Partnership Discipline: Target acquisitions that bring clinical differentiation or fill coverage gaps (e.g., biologic matrices, novel resorbable materials). Consider earn-outs tied to reimbursement milestones and post-acquisition clinical endpoints.
How PW Consulting Helps You Execute
PW Consulting’s full report provides the analytical plumbing to operationalize the playbook above: downloadable financial models, surgeon adoption curves by practice setting, an interactive regulatory tracker, reimbursement mapping tables, and a prioritized M&A target list with integration risk scoring. Importantly, the full report preserves granular segmentation and revenue breakdowns by region, mesh type and clinical application—data we intentionally withhold here to encourage confidential access and deeper engagement.
Conclusion: Moving from Insight to Investment
The soft tissue repair mesh market is poised for measured growth driven by clinical innovation, clearer regulatory expectations, and reimbursement dynamics that will reward demonstrable value. With the market sized at roughly USD 4.5 billion in 2025 and trending to the mid-single-digit CAGR we model through 2032, the opportunity favors organizations that combine product differentiation with disciplined evidence generation and commercial rigor.
PW Consulting’s Worldwide Soft Tissue Repair Mesh Market report is designed for leadership teams, corporate strategy functions, and M&A groups preparing for decisive investment choices in 2026. For access to the full dataset, interactive models, and the supplier playbooks referenced in this preview, please contact PW Consulting to arrange secure access to the complete study.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Tissue Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mountain Protection Net Market to Top USD 1,008.64 Million by 2032, Backed by a 6.42% CAGR
By PW Consulting, 2026-08-18
Worldwide Mountain Protection Net Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide Mountain Protection Net Market (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) synthesizes commercial, technical and regulatory intelligence to help infrastructure owners, contractors, investors and policy teams make higher‑confidence decisions in 2026. At the aggregate level the market has crossed the USD 650 million mark in our base year and, under our central forecast, will progress at a compound annual growth rate (CAGR) of 6.42% through 2032 — comfortably moving the sector past the USD 1 billion threshold by the end of the forecast window.
Worldwide Oil Production Software Market
This briefing highlights the strategic value of the full report: rigorous, operationally focused analysis that explains where demand will materialize, how technology and testing regimes are reshaping supplier differentiation, and what procurement and engineering teams must change now to protect budgets, timelines and safety outcomes.
Worldwide Faux Suede Market
Why this market matters for 2026 strategy
-
Convergence of capital programs and regulation: Renewed highway, rail and mining investments in mountainous regions — combined with tightening safety and certification expectations — are converting episodic project demand into predictable pipelines. The consequence for 2026 planning is that mountain protection net solutions are moving from discretionary add‑ons into mandatory design elements for many projects.
Air Cables Market -
Scale and concentration: The market’s mid‑single‑digit CAGR masks structural shifts: while the top tier of suppliers remains influential, with the three largest vendors accounting for a meaningful share of installed capacity and the top five controlling a majority of commercial activity, there is also room for specialized entrants that combine testing capabilities, local execution and lifecycle service offerings.
-
Cost and supply chain exposure: Manufacturers and procurers face material cost volatility. High‑tensile steel — the primary input for many systems — has demonstrated price swings in recent supply disruptions and represents a very large share of manufacturing cost. That dynamic alters tender outcomes, favours vertically integrated suppliers or strategic hedging, and increases the value of flexible contracting approaches.
What the full PW Consulting report delivers (practical inputs for 2026 decisions)
-
Actionable market sizing and forward scenarios — Our base volumes and revenue model are accompanied by three pragmatic scenarios (baseline, constrained supply and accelerated infrastructure) built from bottom‑up project pipelines and policy levers. The scenarios are designed to stress test capital plans and procurement phasing for the next 36 months.
-
Procurement playbook — Standardized tender language, warranty and contractual templates, a price risk allocation matrix and procurement timing recommendations tailored to high‑risk mountain projects.
-
Supplier due diligence kit — A vendor benchmarking framework that combines technical testing capability, certification footprint, full‑scale trial records, installation capacity and aftermarket services into a single scorecard for rapid shortlisting.
-
Supply chain risk map — A granular view of upstream exposure (raw materials, galvanizing capacity, mesh/rope manufacturing), price sensitivity testing and mitigation levers (forward purchases, local manufacture, consortium procurement).
-
Engineering and standards navigator — A practical summary of prevailing test regimes (including the European transition from ETAG 027 to EAD guidance), recommended compliance checkpoints for MEL/SEL testing, and guidance on interpreting full‑scale test reports for barrier selection and certification acceptance.
-
Project intelligence and win themes — A curated pipeline of projects, procurement timelines and contracting patterns, plus tactical recommendations for suppliers to win in specific end‑use segments.
Competitive landscape — who matters and why
The market combines global engineering leaders, specialist European manufacturers, and high‑volume producers in Asia. A handful of companies combine engineering know‑how with documented full‑scale testing and global installation experience, while a broader cohort competes on cost, local presence and execution speed. Key names observed in our analysis include legacy innovators and scaled regional players known for specific system types, flexible barrier testing, and integrated slope stabilization capability.
-
Leaders with test‑proven systems and global track records — Several established suppliers distinguish themselves through large‑scale testing programs and unique product lines for high‑energy events; these firms are often selected where a project requires validation at the upper end of impact energy curves.
-
Engineering integrators and geosynthetics specialists — Firms that combine geotechnical systems with netting and anchoring services are increasingly competitive in long‑term slope stabilization contracts, because owners prize single‑contract responsibility.
-
Volume producers and regional suppliers — Cost‑sensitive projects and high‑throughput rehabilitation programs create opportunity for manufacturers with large monthly output and efficient logistics to serve regional markets.
Recent marketplace activity underscores these dynamics: independent full‑scale testing milestones and field deployments have become choice moments for buyers to validate systems. In the past 18 months the market has seen record absorptive capacities demonstrated in controlled testing environments and real‑world barrier activations that materially influenced bid behaviour and specification language.
Regulation, testing and technical validation (implications for procurement)
Certification regimes remain a central procurement hinge. European guidance (the evolution from ETAG 027 to the EAD framework) continues to set expectations for full‑scale MEL/SEL testing of deformable barriers, and several manufacturers now publish 1:1 scale test results as part of their technical dossiers. Practitioners should treat full‑scale test results and independent verification as procurement must‑haves rather than nice‑to‑haves when selecting systems for high‑energy scenarios.
Supply‑side economics and input risk
Manufacturers and project owners must plan for persistently higher raw‑material sensitivity. Recent market stress produced steel price movements in the order of mid‑tens of percent, and high‑tensile wire and ropes can represent the dominant portion of manufacturing cost. That combination amplifies the value of hedging, consortium purchasing and early procurement commitments, and elevates the importance of lifecycle cost assessment over first‑cost selection.
Strategic playbook for executives in 2026
-
Procurement: Move from lowest‑price buying to total lifecycle contracting. Require demonstrable full‑scale test evidence and include indexed pricing mechanisms to balance supplier risk.
-
Engineering: Specify performance envelopes, not proprietary products. Use objective criteria tied to energy absorption, post‑impact inspectability and maintainability to widen sourcing options without sacrificing safety.
-
Supply‑chain: Lock long‑lead items early and explore regional manufacturing partnerships to shorten logistics and reduce exposure to global steel cycles.
-
Investment and M&A: Seek bolt‑on targets with testing facilities, regional installation capacity or specialist service capabilities; these assets materially increase tender win rates.
-
Operations and maintenance: Adopt condition‑based monitoring and contractual frameworks that align aftermarket incentives — preventive maintenance reduces lifecycle cost and minimizes unplanned closures on critical routes.
How PW Consulting’s study positions your 2026 agenda
Our research translates market size, concentration and scenario analysis into executable recommendations that directly inform 2026 budgets, sourcing strategies and risk management. By focusing on the tactical levers — certification evidence, supplier scorecards, procurement templates and pipeline timing — the report shortens the path from strategy to contract award.
We have deliberately withheld detailed regional and application splits from this public briefing to preserve the report’s operational value. The full research package contains the granular segmentation, vendor revenue benchmarking, a searchable project database and downloadable procurement templates that infrastructure owners and buyer teams will find immediately practical.
Closing: the near term decision agenda
As capital programs ramp and regulators tighten expectations, the commercial difference in 2026 will be made by teams that combine technical scrutiny with robust procurement design. PW Consulting’s Worldwide Mountain Protection Net Market report provides the data, the test‑verified supplier intelligence and the contractual tools that help organizations make defensible choices on supplier selection, budget allocation and risk transfer.
For project teams, investors and procurement leaders preparing their 2026 playbooks, the full report is the operational reference that converts market insight into procurement action. PW Consulting clients receive the segmentation tables, vendor scorecards, full scenario modelling and the procurement playbook necessary to execute over the coming 18–36 months.
For detailed analysis of this topic, please visit the official page: Worldwide Mountain Protection Net Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide H-line Photoresist Market to Reach USD 235.93 Million by 2032, Expanding at a 3.5% CAGR
By PW Consulting, 2026-08-18
Worldwide H-line Photoresist Market: Strategic Preview for 2026 Decision-Makers
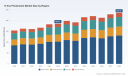
PW Consulting today releases a strategic preview of our forthcoming Worldwide H-line Photoresist Market report, a targeted industry playbook designed to inform executive-level decisions as companies enter 2026. The H-line photoresist market is subtle yet consequential — a materials niche that underpins power semiconductors, MEMS, optoelectronics and a range of advanced packaging flows. Our analysis synthesizes market sizing, supplier dynamics, regulation and supply-chain stressors into operationally useful guidance, while reserving the detailed segmentation tables and financial models for report subscribers.
Driver Training Management Software Market
Market trajectory and what it means for 2026 planning
On a macro basis, the H-line photoresist market is stable and growing. Using 2025 as our base year, PW Consulting estimates the global market at approximately USD 185.4 Million (USD Million, base year 2025), with a projected compound annual growth rate (CAGR) of roughly 3.5% across our 2026–2032 forecast horizon. By the end of the forecast period the market is expected to be materially larger than the 2025 base, reflecting continued, if measured, demand from semiconductor packaging, power device manufacturing and MEMS production.
Industrial Centrifuge Machines Market
For executives planning 2026 capital allocation, R&D prioritization or sourcing strategies, the implication is clear: H-line remains a steady, mission-critical materials segment rather than a breakout growth story. That positioning changes the calculus for investment — favor optimized, defensive plays (supply security, formulation innovation, specialized applications) over broad speculative expansion.
Worldwide Blood and Fluid Warming Unit Market
Why this report is strategically valuable for 2026
- Actionable Forecasting — Our report pairs a bottom-up market model with scenario analyses that stress-test sensitive drivers (demand shocks, regulatory shifts, raw-material volatility). This allows procurement and finance teams to build contingency budgets for 2026.
- Supplier Intelligence — We provide a qualitative and quantitative assessment of incumbent suppliers and emergent specialists. Rather than a simple vendor list, subscribers receive scorecards across technical capability, capacity flexibility, sustainability credentials and commercial behavior.
- Regulatory & Compliance Playbook — H-line formulations are increasingly affected by cross-border rules and chemical restrictions. We translate regulatory language into compliance checklists and timeline gates so product and export managers can prioritize reformulation or sourcing alternatives ahead of enforcement actions.
- Risk & Resilience Tools — The report includes a supply‑chain risk matrix and mitigation roadmap tailored to H-line inputs, helping operations teams design inventory and dual-sourcing strategies calibrated for 2026 realities.
- M&A and Partnership Roadmap — For strategy teams, we identify capability adjacencies and provider archetypes that make attractive bolt-on targets or licensing partners in a concentrated supplier landscape.
Competitive landscape — concentration and implications
The H-line photoresist arena remains concentrated. Leading suppliers command a meaningful share of the market, creating a landscape where a few established players influence pricing, specification norms and technology roadmaps. This concentration matters strategically: it raises the importance of supplier engagement, long-term contracts and technical collaboration agreements for manufacturers that depend on predictable supply and tailored formulations.
Key firms referenced in our coverage include Tokyo Ohka Kogyo (TOK), JSR Corporation, Shin-Etsu Chemical, DuPont de Nemours, Sumitomo Chemical, Fujifilm Electronic Materials, MicroChemicals and Allresist. Each brings a distinct positioning: global scale and legacy product depth, regional capacity expansions, sustainability and regulatory credentials, or niche technology leadership in high-resolution and specialty resists. Recent industry activity underlines how suppliers are investing along different vectors:
- Tokyo Ohka Kogyo has introduced new H-line formulations optimized for high-aspect-ratio etching in power device stacks — a product-led move aimed at premium packaging customers.
- JSR Corporation has expanded production capacity for legacy H-line grades to address packaging demand, signaling confidence in near-term volumes and a desire to protect share where lead times matter.
- Shin-Etsu Chemical’s manufacturing recertifications emphasize low‑VOC and sustainability improvements, a deliberate response to procurement and regulatory pressures.
For buyers, this means negotiation leverage varies by requirement: commodity H-line volumes favor established global suppliers with capacity discipline; specialized, high-performance needs can be addressed through technical partnerships with smaller innovators. Both routes benefit from supplier evaluation matrices and contractual clauses that are included as templates in our full report.
Dynamics reshaping supply, costs and compliance
Three systemic dynamics are shaping the H-line market heading into 2026:
- Raw-material volatility — Feedstock availability and price swings for key intermediates are increasing procurement risk. Where possible, product and sourcing teams should model multiple input-price scenarios and validate alternative formulation pathways to hedge exposure.
- Regulatory tightening and trade friction — Cross-border compliance requirements and trade policy shifts are influencing where and how formulations can be produced and exported. Exporting manufacturers must now bake region-specific compliance steps into product lifecycle plans while monitoring enforcement timelines.
- Demand concentration by application — H-line demand is correlated with growth in select end-markets such as advanced packaging, power electronics and MEMS. Strategic players are aligning product development roadmaps to the technical trends within those consuming industries rather than treating H-line as a generic photolithography material.
Collectively, these forces favor suppliers and buyers who can demonstrate technical agility, regulatory foresight and resilient sourcing. Our report provides a tailored decision matrix so procurement leaders can prioritize which mitigations yield the highest risk-adjusted returns for 2026.
Report contents — what's in the full deliverable
PW Consulting’s Worldwide H-line Photoresist Market report is designed as an executable toolkit for strategy, procurement, operations and R&D teams. Highlights include:
- Market model (2020–2032): Base-year reconciliation, demand drivers, and scenario outputs calibrated to multiple growth paths.
- Supplier scorecards: Comparative assessments across capability, capacity flexibility, sustainability credentials and commercial terms.
- Technical appendix: Formulation families, exposure compatibility notes, process integration guidance and failure-mode case studies.
- Supply‑chain stress tests: Raw‑material sensitivity analysis, supplier disruption scenarios and recommended inventory policies.
- Regulatory impact map: Region-specific compliance requirements, reformulation timelines and export controls with practical actions for product teams.
- Commercial playbooks: Sourcing negotiation scripts, contract clauses for capacity guarantees, and joint-development term sheets tailored to H-line suppliers.
- M&A and partnership intelligence: Candidate archetypes, valuation multipliers, and integration checklists for acquirers or licensing partners.
Importantly, the report couples narrative insight with spreadsheets and templated tools so teams can move quickly from insight to implementation — a decisive advantage for 2026 planning cycles.
Practical strategic recommendations for 2026
- Lock in dual sourcing for critical H-line grades used in production flows where uptime and qualification lead times are long. Use staged contracts that escalate capacity commitments as volume milestones are met.
- Prioritize reformulation readiness for products with regulatory risk exposure. Establish technical surveillance to track region-specific restrictions and a migration plan for restricted chemistries.
- Invest selectively in application-specific resin development where margin uplift is demonstrable (for example, formulations that enable higher aspect ratios or improved adhesion in power device stacks).
- Negotiate technical collaboration agreements with at least one leading supplier and one specialized innovator to balance reliability with access to next‑generation formulations.
- Operationalize a raw‑material monitoring dashboard and run quarterly procurement scenario exercises linked to your 2026 budget process.
What we are deliberately withholding — and why
To preserve the commercial value and integrity of the analysis, this preview intentionally omits granular split tables, region-by-region revenue breakdowns, application-level percentage shares and other core segmentation figures. Those detailed datasets, alongside downloadable models and supplier financial overlays, are included exclusively in the full report and model package. The goal is to provide enough strategic foresight to inform planning while directing practitioners to the full intelligence assets they will need to execute with confidence.
Next steps — how to access the full intelligence
Executives and functional leaders preparing 2026 budgets or strategic roadmaps are invited to access the complete Worldwide H-line Photoresist Market report from PW Consulting. The full deliverable contains the proprietary model, supplier scorecards, scenario outputs and the suite of templates described above. For immediate tactical support, PW Consulting also offers bespoke advisory engagements that can operationalize the report’s recommendations into procurement, R&D and M&A workstreams.
Contact PW Consulting to schedule a briefing and receive a sample executive dashboard. For teams that must finalize sourcing and qualification plans in early 2026, timing is critical: the decisions taken now will materially affect supply security and cost exposure through the year.
Final thought
H-line photoresists are not the headline-grabbing substrate of semiconductor investment cycles, but they are a foundational material whose stability and specification drive yield, qualification and product roadmap choices. For 2026, the intelligent strategy is not to chase rapid expansion in the H-line market, but to secure, specialize and align — securing supply and regulatory compliance, specializing where technical differentiation creates margin, and aligning product roadmaps to the end-market customers that will drive durable demand.
For detailed analysis of this topic, please visit the official page: Worldwide H-line Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vanadium Pentoxide Electrolyte Market to Surge to USD 3,482.24 Million by 2032, Fueled by a 21.45% CAGR
By PW Consulting, 2026-08-18
Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market — Strategic Briefing for 2026 Decision-Makers
Executive Summary
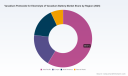
As vanadium redox flow batteries (VRFBs) transition from pilot deployments to commercial-scale grid storage, the market for vanadium pentoxide (V2O5) used in electrolyte formulations has become a strategic battleground. PW Consulting’s latest market study, with a 2025 base year and a forecast window through 2032, quantifies a robust growth path underpinned by rapid deployment of long-duration storage and upstream supply responses. The study projects a compound annual growth rate (CAGR) of 21.45% for the overall market over the forecast period — a trajectory that transforms V2O5 from a specialty chemical into a core enabler of low-carbon electricity systems.
AI Training Cluster Market
Why this matters for 2026 planning
Corporate strategy teams, procurement leads, and investors preparing 2026 budgets face three interacting realities:
Worldwide Nutritionist Software Market
- Demand inflection: Market modelling in our report shows a steep rise in total market value after 2025, driven by utility-scale procurement cycles and electrolyte-as-a-service commercial models;
- Concentration and supplier dynamics: A small group of vertically integrated and specialized producers exerts meaningful influence on midstream availability and quality controls, generating both opportunity and exposure for buyers and project developers;
- Regulatory and standards evolution: Ongoing standards work and trade policy shifts are altering sourcing economics and risk profiles for cross-border supply chains, with implications for localization and inventory strategies.
Market trajectory — the headline numbers
Our top-line sizing shows the industry moving from a niche chemical market into a high-growth segment. Using 2025 as the analytical base, the market expands materially across our forecast horizon, reflecting the maturation of VRFB deployments and the scaling of dedicated electrolyte production capacity. This macro trajectory — underpinned by a projected CAGR of 21.45% — should be treated as directional evidence for boards and investment committees that capacity planning and contractual positions entered in 2026 will shape cost and availability outcomes for years.
Manual Crown Remover Market
What PW Consulting’s report delivers — practical, actionable intelligence
We designed this study to be operationally useful to procurement, technology, and M&A teams. Key deliverables include:
- Dynamic demand-supply modelling calibrated to 2020–2025 historicals and stress-tested across adoption scenarios for 2026–2032;
- A supplier map and qualitative capability assessment highlighting upstream feedstocks, refining routes, and downstream electrolyte know-how;
- Scenario-based cost curves that synthesize feedstock inputs, processing pathways, and capital intensity for new electrolyte plants;
- A decision toolkit for buyers and project developers that ranks hedging options (long-term offtake, tolling, electrolyte leasing) against capital and operating trade-offs;
- Regulatory and standards impact analysis that translates ongoing IEC work and recent trade actions into procurement playbooks;
- A transaction-ready annex for investors and corporate development teams that flags strategic M&A targets and partnership archetypes without displacing due diligence.
These elements are designed to support 90–180 day decision cycles in 2026 — from contract negotiation to plant greenlighting — and to provide the runway for longer-term strategic positioning.
Competitive landscape — who matters, and why
The market is competitive but concentrated. Our concentration analysis indicates that the top three suppliers hold a majority share of market influence, and the top five firms together consolidate a substantial portion of supply — an arrangement that has critical implications for pricing power, quality control, and strategic supply security.
Several company archetypes are particularly relevant to 2026 strategy:
- High-purity specialists: Firms with demonstrated capability to produce battery-grade V2O5 and ultra-high-purity electrolyte are differentiating on quality and certification. These players are attractive partners for developers that require predictable cycle-life and warranty-backed supply.
- Integrated miners with downstream strategies: Primary producers that have integrated into electrolyte supply chains are pursuing commercial models that combine material sales with leasing or electrolyte-as-a-service offerings. Their vertical integration can shorten lead times but may reduce flexibility for buyers seeking multi-sourcing.
- Technology purifiers and recyclers: Companies capable of converting lower-purity feedstocks, recycled streams, or alternative vanadium sources into compliant electrolyte raw materials are important in scenarios where primary feedstock tightness elevates prices.
- Regional industrial players executing scale projects: New, large-capacity plants in established chemical clusters are accelerating local availability, influencing decisions about project siting and localization for critical energy storage projects.
Company spotlights — strategic takeaways
- U.S. Vanadium LLC — A profile of specialization. Recent product expansions and funding align the firm as a premium supplier with dual relevance to defense and energy markets. For U.S.-based buyers, their positioning offers a low-logistic-risk option for high-purity requirements.
- Storion Energy (with Largo JV linkages) — A domestic electrolyte supplier model. The Storion-Largo axis illustrates how upstream mine strength can be paired with downstream chemistry to offer integrated services, including leasing models attractive to project finance structures.
- LB Group and other large-scale chemical producers — Indicative of capacity-led competition. New commissioning activity signals that project-level supply risk is being actively managed by players with industrial-scale ambitions; buyers should factor commissioning timelines and ramp risks into procurement windows.
- Boutique and regional suppliers — Players in China, Europe, and Africa demonstrate differentiated cost and standard compliance profiles; they are potential strategic partners for localized projects but may require rigorous quality and certification pathways to meet international VRFB standards.
Supply chain and raw material dynamics
The upstream feedstock mix remains diverse — primary titanomagnetite ores, slag from steelmaking, and secondary sources such as spent catalysts and refinery residues all feature in the supply base. The diversity benefits overall resilience but introduces heterogeneity in impurity profiles and processing costs. In 2025 the market experienced a softening in commodity-level prices which, combined with pockets of capacity underutilization, created a window for buyers to renegotiate terms. Stakeholders should not assume this softness persists: our scenario work shows a potential recovery in pricing as utilization tightens and VRFB deployments accelerate after late-2026.
Regulation, standards, and trade — the new operating constraints
Trade measures and the development of international electrolyte quality standards are reshaping sourcing calculus. Recent tariff actions and reciprocal trade measures in certain jurisdictions increased near-term uncertainty for cross-border procurements. Simultaneously, IEC and other standards bodies are progressing work to harmonize electrolyte quality specifications. For 2026 planning, companies should incorporate two mitigants into their procurement strategy: (1) build lead-time contingency through diversified qualified suppliers; and (2) prioritize suppliers engaged in certification pathways to reduce acceptance friction at project commissioning.
Risk matrix — what can derail strategy in 2026?
- Supply-side shocks: unforeseen disruptions at integrated mines or at large electrolyte plants can create short-term scarcity;
- Quality failures: inconsistent impurity profiles from alternative feedstocks can translate into performance risk for battery warranties;
- Policy reversals: abrupt trade measures or shifts in subsidy frameworks for storage can compress demand realization timelines;
- Standards divergence: slow harmonization of international electrolyte standards can raise transaction costs for cross-border projects.
Practical recommendations for 2026
Our strategic playbook for executives centered on the 2026 decision window includes:
- Procurement: Establish dual-track offtake strategies — combine multi-year supply contracts with flexible short-term purchases to balance price and availability;
- Localization: Prioritize qualification of at least one local or regional supplier where policy or tariffs present execution risk; where viable, consider co-investment in downstream electrolyte capacity to secure supply;
- Quality & certification: Require supplier participation in IEC or equivalent certification programs as a condition of selection to reduce downstream acceptance risk;
- Inventory architecture: Move from lean to strategic buffer inventories for first-wave utility projects to de-risk commissioning timelines;
- M&A and partnerships: Target partnerships with players that offer integrated models (mine-to-electrolyte or electrolyte leasing) when project finance structures favor predictable lifecycle opex.
Report value proposition and how to engage
PW Consulting’s report provides the quantitative backbone and pragmatic scenarios that allow teams to convert 2026 ambitions into executable plans. It combines system-level demand models, supplier capability dossiers, regulatory pathways, and investment case frameworks in a single read-across. The publication follows a “preview” approach here: this briefing outlines the strategic contours and implications; the full report contains detailed demand-supply matrices, supplier scorecards, and actionable contract templates that purchasers and investors will find indispensable.
Closing — the strategic imperative
For companies active in energy storage, materials supply, or related infrastructure investment, 2026 is not simply another planning year — it is the decision point that will determine who captures the early economics of VRFB-enabled long-duration storage. The market’s strong growth trajectory and concentrated supplier base demand a proactive, analytically grounded response. PW Consulting’s Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market report offers that response: rigorous modelling, clear supplier intelligence, and a pragmatic steering framework to convert growth opportunities into durable advantage.
To access the full report, including proprietary models and supplier scorecards, please visit the PW Consulting website or contact our sector desk for a briefing and customization options tailored to your organization’s 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Asia Pacific Leads Worldwide Railway Expansion Joints Market with USD 223.86 Million Share
By PW Consulting, 2026-08-18
Worldwide Railway Expansion Joints Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Railway Expansion Joints market synthesizes seven years of market flows, supplier evolution and input-cost dynamics into a decision-ready framework for executive teams preparing 2026 capital and procurement plans. The report combines a clear, data-driven view of market scale and momentum with operational playbooks, risk heatmaps and vendor scoring models that translate macro trends into concrete steps for infrastructure owners, EPCs and tier-1 suppliers.
Biotin Binding Plate Market
Market Snapshot: scale, pace and structural features
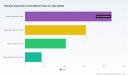
The global market for railway expansion joints has shown steady recovery and expansion through the early 2020s, reaching an estimated market size of USD 520.45 Million in 2025. Under the scenarios modelled in our forecast period (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 5.14%, reaching the upper hundreds of millions in nominal terms by 2032. Our near-term estimate for 2026 positions the market above the 2025 baseline, reflecting a mix of maintenance-driven demand, bridge and viaduct renewals, and targeted investment in capacity and resilience.
Worldwide Pendant Lampshade Market
Two structural observations matter for strategic planning in 2026:
Thermoelectric Converter Market
- Consolidation is meaningful but not dominant. The three largest suppliers account for a material minority of the market, while the top five capture just over half—an industry structure that preserves both bargaining power for sophisticated buyers and opportunities for differentiated niche specialists.
- Demand drivers are multi-modal and lifecycle-oriented. New-build programmes (including high-speed corridors and urban rail capacity projects) sit alongside a steady, higher-volume market for refurbishment and asset preservation on bridges, viaducts and standard track sections. Procurement strategies that treat these demand streams separately will outperform one-size-fits-all approaches.
What this report delivers — practical intelligence, not academic noise
Beyond headline numbers, PW Consulting’s report is explicitly operational. Key deliverables include:
- Decision frameworks for 2026 CAPEX prioritization — a ranked set of investment triggers that help owners allocate scarce capital between replacement, rehabilitation and resilience upgrades.
- Procurement playbooks — contractual templates, specification checklists and total lifecycle cost (LCC) models to structure supplier bids and evaluate long-run value beyond initial price.
- Supplier risk and capability matrix — comparative assessments across mechanical performance, customization lead times, approvals and field-installation experience to help short-list partners for tenders.
- Scenario-based stress testing — price and supply-disruption scenarios (steel price swings, logistics interruptions) with quantified P&L and schedule impacts for representative project archetypes.
- Maintenance optimization modules — sensor-enabled monitoring options, whole-life repair versus replacement thresholds and rapid-response strategies for minimizing traffic disruptions.
Competitive landscape: capabilities, positioning and strategic moves
The market is characterised by a mix of specialized bridge-joint specialists, integrated rail-systems players and regional manufacturers. Our competitive analysis emphasises capability clusters rather than pure market share—because choice is driven by application complexity, approval status and life-cycle guarantees as much as by price.
- Freyssinet (France) — recognized for solutions that prevent ballast ingress on bridge decks and capable of accommodating very large movements (noted installations up to 900 mm). Freyssinet’s long global track-record on railway structures makes them a preferred partner for complex bridge projects where bespoke sealing and movement management are core deliverables.
- voestalpine Railway Systems (Austria) — combines rail expansion joint (REJ) product lines for switchable-rail applications and heavy-duty REJs (e.g. models engineered for substantial axle loads and larger extensions). Their portfolio suits clients seeking integrated rail-system suppliers with proven heavy-axle credentials.
- MAURER (Germany) — a specialist in mat-type expansion joints for railway bridges with Manufacturer-Related Product Qualification (MRPQ) approvals for major operators. Recent technical documentation updates in mid-2025 reinforced their compliance positioning and clarified load-transfer and weather-performance claims—an important differentiator for tenders requiring DB AG-equivalent approvals.
- Mageba (Switzerland) — focuses on stainless-steel, ballast-retaining solutions and has strong references with national operators. Mageba’s emphasis on corrosion-resistant materials and field-proven designs makes them well-suited to harsh-environment or long-service-life specifications.
- D.S. Brown (USA) and L.B. Foster (USA) — both bring decades of engineered-product experience to the North American market, with portfolios extending from bridge joints to insulated rail and trackwork components. Their strengths lie in local project execution and integrated supply for multi-component track contracts.
- Vossloh (Germany) — offers manganese and all-rail configurations and is positioned where clients require full-track-system competence, especially in refurbishment projects blending track components and expansion joint systems.
- CMI Promex (Romania) — a regional manufacturer of rail expansion joints that can deliver competitive lead times and solutions for embedded tracks and standard configurations.
For 2026 RFPs, our vendor-selection guidance balances three pillars: conformity to operator approvals (e.g., MRPQ/DB AG equivalence), proven field performance on comparable bridge/track typologies, and commercial conditions that manage steel-price and lead-time risk.
Supply chain and input-cost considerations — what to watch in 2026
Raw material dynamics are a decisive short-term variable. Steel benchmarks demonstrated measurable upticks into 2026—steel rebar benchmarks, in local-currency terms, rose modestly in early 2026 relative to the prior month and year—while global steel prices in Q1 2026 exhibited range-bound but volatile behaviour driven by raw-material costs, construction demand recovery and inventory cycles. These movements translate into two practical imperatives for buyers:
- Hedge and contract structure: include index-linked pricing, floor/ceiling protections and material-purchase pass-through clauses, while negotiating options for supplier-managed buys on long-lead items where suppliers can secure scale discounts.
- Design and material choices: consider stainless and corrosion-resistant alloys selectively for high-life, low-maintenance bridge joints where higher upfront material cost reduces total life-cycle expense—an approach many European operators are already formalising.
Operationally, major freight and network owners continue to invest heavily in track and capacity: public filings from large North American rail operators show multi-billion-dollar capital programmes in 2026 focused on surfacing, undercutting and capacity expansion. These programmes create predictable replacement volumes and targeted upgrade windows that should be reflected in any supplier sourcing or capacity-allocation decision for 2026.
Key strategic recommendations for 2026
PW Consulting’s pragmatic advice—specially tailored for infrastructure owners, EPCs and procurement leads planning 2026 activity—focuses on three interlocking levers:
- Differentiate procurement by application and lifecycle risk. Treat bridge/viaduct joints, standard track joints and high-speed rail joints as distinct purchasing classes. Each class has different tolerance for movement range, maintenance access and approval regimes. Use tailored RFP templates and LCC models per class.
- Negotiate supplier commitments that manage input-cost volatility. For any 2026 contracts longer than 12 months, embed material-price adjustment mechanisms, and secure supplier commitments on sub-tier transparency and material provenance to avoid downstream disputes.
- Prioritise design-for-maintenance and monitoring. Mandate design features that simplify in-situ replacement of wearing elements and require suppliers to support remote-monitoring piloting. These measures materially reduce line-closure risk and lifecycle spend.
- Use competitive sourcing to capture differentiation, not just price. Short-list suppliers based on approval status, field references for comparable geometry and proven installation productivity metrics. Where possible, run parallel pre-qualification tests to reduce procurement cycle time.
- Plan for capacity and lead-time variability. Where projects are time-sensitive, secure early supplier allocations and consider dual-sourcing for long-lead assemblies to protect schedules.
Why executives should read the full PW Consulting report
The public summary above outlines the strategic levers that matter for 2026. The full report contains the proprietary analytics and tools executives need to turn those insights into contracts and schedules:
- Modelled cash-flow and schedule impacts for 12 procurement archetypes (bridge replacement, viaduct refurbishment, HSR insertion, yard rebuilds).
- Supplier scorecards with technical deep-dives, approvals matrices and installation productivity benchmarks.
- Negotiation playbooks and standard contract clauses covering material-indexing, warranty periods and IP for sensor-enabled monitoring systems.
- Interactive scenario workbooks that allow users to stress-test their procurement plans against steel-price and logistics shocks.
PW Consulting’s role is to bridge the gap between headline market growth and executable plans. The railway expansion joints market is growing modestly but meaningfully—creating a window in 2026 for buyers who can combine disciplined procurement, early supplier engagement and lifecycle-minded specifications. For teams preparing to submit budgets, launch tenders or renegotiate framework agreements in 2026, the full report provides the granular tools omitted here by design: detailed segment-level charts, supplier financials and the exact specification templates that you can apply directly to your projects.
Next steps
- Access the full report to obtain segment-level analytics, downloadable RFP templates and supplier scorecards.
- Book a strategy session with PW Consulting’s rail infrastructure practice to align 2026 procurement and CAPEX calendars with supplier capacity and risk mitigation plans.
PW Consulting remains available to support immediate tender preparation, bidder short-listing and contract-structure workshops. Our analysis converts the market’s steady growth and structural nuances into priority actions that protect budgets, schedules and long-term asset performance in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Railway Expansion Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
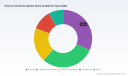
PW Consulting: Worldwide Polymer Substrates Market Reaches USD 16,450 Million in 2025; Poised to Grow at a 6.42% CAGR Through 2026–2032
By PW Consulting, 2026-08-18
Worldwide Polymer Substrates Market: Strategic Outlook for 2026 — PW Consulting Report Preview
PW Consulting’s upcoming Worldwide Polymer Substrates Market report delivers a practitioner-focused, forward-looking playbook for executives shaping product roadmaps, supply chains, and M&A strategies in 2026. The market for polymer substrates has moved from an estimated USD 12,250.45 Million in 2020 to USD 16,450.00 Million in 2025 and, under our base forecast, is projected to reach approximately USD 25,434.38 Million by 2032 — a steady compound annual growth rate (CAGR) of 6.42% across the 2026–2032 forecast window. This trajectory reflects the combined tailwinds of flexible and wearable electronics adoption, next‑generation display architectures, and continued demand from high-security substrate applications.
Worldwide Acetylenic Alcohols Market
Why this report matters for 2026 decision-makers
-
Actionable demand foresight: Our scenario-based demand models translate technology adoption curves (flexible printed circuits, advanced displays, and thin-film photovoltaics) into practical procurement and capacity-planning inputs for 2026 capex cycles.
Wireless HART Communicators Market -
Cost-to-price sensitivity: We map upstream feedstock volatility — historically swinging ±25% annually for key monomers — into finished‑substrate cost models, enabling CFOs and procurement teams to quantify pass‑through exposure and to design hedging or contract structures that balance margin protection and competitiveness.
5-leg IV Stand Market -
Regulatory and compliance playbook: The report consolidates emerging regulatory constraints — from restrictions on specific bonding agents to the phase‑out impacts on plating chemistries — into a compliance-impact matrix that operational teams can use to prioritize remediation investments in 2026.
-
Competitive and concentration diagnostics: With top‑tier firms capturing a meaningful share of the market (top‑3 firms collectively control roughly one‑third and the top‑5 nearly half), our analysis identifies where consolidation, niche specialization, or regional capacity shifts will offer the highest strategic returns.
What we examined — scope and methodologies
The report synthesizes a multi‑method research approach: granular primary interviews across OEMs and converters, bottom‑up plant and capacity mapping, contract‑level price and lead‑time intelligence, and a proprietary demand model calibrated against historical shipment data from 2020–2025 (shown in our historical time series). We overlay commodity feedstock scenarios and regulatory shocks to create three discrete 2026 planning cases — base, upside (accelerated display & flexible electronics adoption), and downside (raw material shock + regulatory tightening) — each with clear tactical prescriptions for procurement, R&D prioritization, and go‑to‑market adjustments.
Core report deliverables (practical, ready for boardrooms)
-
Executive dashboard: consolidated market sizing, growth drivers, and risk heatmap designed for CFOs and strategy leads.
-
Supply‑side maps: plant locations, effective capacity, and expansion timelines for major producers and niche specialists, with actionable supplier scorecards for 2026 sourcing decisions.
-
Price and margin simulator: a parametric model connecting ethylene/propylene/PTA price swings to substrate cost curves and finished‑product margin impact.
-
Regulatory impact matrix: compliance timelines, CAPEX estimates for retrofits, and prioritized remediation options for affected substrate lines.
-
Commercial playbooks: differentiated GTM strategies for substrate incumbents, new entrants, and non‑substrate players seeking adjacency moves (e.g., adhesives, barrier coatings, printing security features).
-
Transaction intelligence: valuation benchmarks, recent deal archetypes, and a shortlist of pragmatic acquisition targets and partners aligned to 2026 strategic themes.
Market dynamics shaping 2026 strategy
Several converging dynamics will dominate boardroom discussions in 2026. First, upstream feedstock volatility remains a structural variable that cannot be ignored: PET, BOPP and polyimide film economics are tightly coupled to ethylene, propylene and PTA price moves. Firms that integrate feedstock risk into commercial contracts or that accelerate alternative‑feedstock R&D will preserve gross margin advantage.
Second, regulatory shifts are reshaping acceptable material and process choices. Recent restrictions on certain solvent bonding agents and tightening requirements related to hexavalent chromium in plating are increasing compliance costs and forcing process re‑engineering. Our regulatory playbook quantifies typical retrofit costs and offers prioritization logic for operators deciding which lines to upgrade in 2026 versus those to phase out.
Finally, price momentum in early 2026 — with announced increases from several upstream suppliers — elevates the need for disciplined price‑pass‑through strategies and value‑based pricing at the converter and OEM levels. Our price scenario outputs give procurement and commercial teams concrete bands for negotiations and inventory strategies.
Competitive landscape — positioning and strategic options
The sector is composed of global diversified chemical and materials giants, specialized film manufacturers, and security‑focused substrate providers. The market concentration metrics indicate a marketplace where scale matters, but differentiated product and service models provide defensible niches. Below are concise strategic reads on key participants that corporate strategists and investors should monitor closely in 2026.
-
DuPont de Nemours, Inc. — A legacy innovator in polyimide and polyester films, DuPont pairs a deep IP portfolio with broad customer access across electronics and automotive. Watch: technology licensing and targeted capacity reallocation for high‑value flexible electronic substrates.
-
3M Company — Competes on optical and performance differentiation; 3M’s strength is system‑level integration (film + functional coating) which is a playbook for moving up the value chain.
-
Toray Industries, Teijin, Sumitomo Chemical, Mitsubishi Chemical — Japanese incumbents that combine polymer film expertise with scale manufacturing; strategic focus is on co‑development with display OEMs and on supply continuity.
-
LG Chem — Oriented to next‑generation display and thermal‑stable applications; a candidate to accelerate inward integration with downstream display partners.
-
Covestro, Avery Dennison — European players that leverage specialty polymer chemistries and branding applications; Covestro favours performance plastics while Avery Dennison targets labeling and flexible electronics niches.
-
CCL Secure (Innovia Films), De La Rue, Landqart, Giesecke+Devrient (Louisenthal), Q&T Hi‑Tech Polymer — Security‑substrate specialists where regulatory, printing, and security‑feature integration create high entry barriers and pricing insulation. Q&T’s recent domestic banknote adoption highlights how regional producers can capture sovereign contracts.
-
Rogers Corporation, Ares Materials — Niche high‑performance substrate suppliers (RF/microwave, optical) that serve differentiated end markets with technical specifications that command premium pricing.
Recent market signals — what to watch in 2026
Early 2026 has already shown the kinds of supply‑side pressures and policy moves that will inform near‑term strategy: several polymer producers announced price increases citing raw material and logistics costs, and engineered‑materials suppliers implemented selective list price hikes. These moves matter beyond short‑term margin mechanics: they compress the time window for OEMs to renegotiate contracts, accelerate supplier qualification for second sources, and justify strategic inventory buffers for critical launches in 2026.
Additionally, the banknote substrate space continues to evolve with successful domestic adoptions by new entrants — underscoring the potential for regional producers to displace incumbents where national security and sovereign procurement policies favour local sourcing. For suppliers, this implies a bifurcated playbook: double down on high‑spec product innovation for global electronics markets while developing compliant, secure, and cost‑competitive offerings for national and regional security markets.
Strategic recommendations for executives in 2026
-
Embed commodity sensitivity into pricing and procurement — move from annual to quarterly review cadences, and test a mix of swaps, capped price contracts, and strategic inventories for critical feedstocks.
-
Prioritize retrofit investments where regulatory change forces line closures; defer greenfield investments into new capacity unless paired with long‑term offtake agreements.
-
Adopt a segmented customer approach: protect high‑margin, technically demanding customers through dedicated capacity and co‑development; pursue volume growth in emerging regions through modular, lower‑capex manufacturing models.
-
Consider targeted M&A or JVs to fill capability gaps — especially around high‑value optical films, high‑temp polyimides, and secure polymer banknote substrates — but use strict synergy and customer‑lock tests before execution.
-
Accelerate sustainability and substitution programs to preempt regulatory risks and to capture premium buyers seeking lower‑impact materials and transparency across the feedstock chain.
Next steps — how to use this research
PW Consulting’s Worldwide Polymer Substrates Market report is designed to be a decision‑grade resource for 2026 strategy cycles. If you are evaluating: capital allocation for new lines, revisions to supplier contracts, M&A targets, or regulatory compliance roadmaps, the report provides the models and playbooks to support board approvals and procurement negotiations. The executive dashboards and the price‑to‑margin simulator are particularly useful for rapid scenario stress‑testing ahead of budgeting rounds.
For full access to the complete segmentation matrices, regional and application breakdowns, and the proprietary financial models that underpin our scenarios, please consult the full report on our website. The preview above is intended to convey the strategic depth and practical orientation you can expect; the detailed segment-level data is available exclusively in the full PW Consulting report.
For detailed analysis of this topic, please visit the official page: Worldwide Polymer Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 9% Nickel Steel Plate Market Expected to Reach USD 3,570.47 Million by 2032, Growing at a 7.5% CAGR
By PW Consulting, 2026-08-18
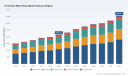
Worldwide 9% Nickel Steel Plate Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward‑looking briefing drawn from our comprehensive Worldwide 9% Nickel Steel Plate Market report (base year 2025). This “trailer” distills the strategic intelligence that senior executives, procurement leads and project sponsors need to make high‑stakes decisions in 2026 — while reserving the granular segmentation datasets and supplier scorecards for the full report.
Worldwide Pharma Grade Calcium Acetate Market
Market snapshot: robust growth, concentrated supply
The 9% nickel steel plate market has moved from niche to strategic criticality over the past half‑decade. Our topline measures show an increase in aggregate market value from the low‑billions in 2020 to over two billion USD in 2025, and a continued upward trajectory through the forecast horizon. Under our base scenario the market advances at a compound annual growth rate of 7.5% from 2026 to 2032, reaching a multi‑billion dollar size by the end of the period.
Worldwide High Resolution 3D Sensors Market
Two structural features stand out with direct implications for 2026 planning. First, market concentration is material: the top three suppliers control a majority share of supply, and the top five firms approach three‑quarters of total capacity. Second, demand drivers remain dominated by cryogenic LNG applications — onshore tanks, marine containment and the processing pipeline network — sustaining high specifications and tight quality acceptance criteria.
Worldwide Cherry Oil Market
Why this matters for 2026 decisions
- Project timing and procurement windows: With lead times for certified 9% nickel plate production, test certification, and logistics measured in months rather than weeks, procurement strategies initiated in late 2025 or early 2026 will determine who secures material for projects commissioned in 2027–2028.
- Capital allocation and supplier consolidation: Given the concentrated supply base, OEMs and EPCs must weigh the trade‑offs between single‑source long‑term agreements (price certainty, capacity reservation) and diversified sourcing (supply security, competitive pricing). Our analysis quantifies where these trade‑offs become value‑creating.
- Risk management across the value chain: Nickel feedstock dynamics and trade policy shocks (notably tariff actions) materially affect landed costs and availability — requiring hedging, contractual pass‑through clauses and alternative material pathways to be embedded in 2026 contracting strategies.
Supply chain realities and raw‑material exposure
Nickel remains the dominant upstream input. Global nickel production is projected to be in the order of a few million metric tons by 2026, which supports broad alloy manufacture, but not without price and availability cycles that can compress margins and redirect flows. For 2026, buyers should plan for continued volatility in nickel premiums and consider layered mitigating actions: strategic stockpiles sized to project pipelines, indexed long‑term purchase agreements with tolling options, and contractual backstops for extreme price events.
Logistics and trade policies amplify these raw material dynamics. Reinstated or expanded tariff measures on steel imports have already begun to change sourcing economics for certain markets; buyers that ignore tariff‑driven landed cost differentials risk supply interruptions or acute cost escalation.
Product and technology shifts to monitor in 2026
- TMCP and lower‑nickel alternatives: New thermomechanically processed (TMCP) grades with reduced nickel content and comparable fracture toughness are moving from demonstration to commercial adoption. Late‑2025 product updates from leading mills highlight substitutions that can lower alloy cost while meeting cryogenic toughness thresholds. However, adoption is application‑specific and demands rigorous qualification programs.
- Thickness and fabrication trends: Manufacturing capabilities for ultra‑thin and heavier plates both matter. Advances in production and vacuum treatment processes are enabling broader plate width/thickness envelopes, which in turn create opportunities for design optimization at the tank and hull level, and for reducing welding labour through fewer seams.
- Material certification and classification society acceptance: Continued emphasis on guaranteed impact properties across orientations, and retained austenite behaviour at cryogenic temperatures, means that material certifications and transverse Charpy guarantees are differentiators in supplier evaluation.
Regulatory and standards environment
Regulatory recognition and classification society acceptance remain central to deployment. The leading cryogenic steel specification (ASTM A553 Type 1) enjoys endorsement within international codes that govern LNG storage and marine fuel systems; retained austenite and fracture toughness performance at −196°C are core validation elements. Concurrently, trade policy changes — including tariff reinstatements effective March 2025 — have already created geographic price dispersion that buyers must plan around.
Competitive landscape — practical takeaways for supplier strategy
The competitive environment features a mix of longstanding Western specialty mills and high‑volume Asian producers. Within this landscape:
- European specialty producers maintain leadership on ultra‑clean metallurgy, broad plate widths, and deep certification records that favor top‑tier marine and LNG contractors who demand transverse impact guarantees and traceable vacuum treatment processes.
- Major Asian integrated mills and specialized Chinese mills combine scale with improving metallurgical capability, and are increasingly competitive on both price and delivery for large infrastructure programs.
- Regulatory acceptance and classification society approvals serve as non‑price gating factors. Suppliers that couple volume with robust quality systems and third‑party approvals secure outsized commercial wins.
For procurement teams evaluating partners in 2026, the decisive criteria are: demonstrated cryogenic performance (including orientation‑specific impact testing), capacity scheduling for project windows, and resilience to nickel feedstock shocks. Our market concentration findings reinforce that strategic partnerships with one or two qualified suppliers often outperform spot‑market tactics when projects must not slip.
Recent market signals that will shape 2026
- Major mill product catalog updates in late‑2024 and 2025 reveal a two‑track product evolution: enhanced documentation of traditional 9% nickel grades with transverse property guarantees, and commercial roll‑outs of reduced‑nickel TMCP alternatives that claim comparable toughness at lower alloy cost.
- Large project awards supplied by regional integrated mills demonstrate that certain national champions can meet full project demands under local content and logistics advantages — reinforcing the imperative to include regional capacity maps in tender evaluations.
- No systemic recalls of standard 9% nickel plates meeting recognized standards have been identified, yet the bar for acceptance remains high; this supports a market where quality premium is sustainable.
Practical playbook for 2026
Based on our synthesis, firms should consider a five‑point playbook when shaping 2026 strategies:
- Start procurement cycles earlier: initiate qualified supplier pre‑selection and long‑lead ordering against firm project milestones to lock supply and price bands.
- Qualify TMCP alternatives where value‑for‑money can be proven: run parallel qualification trials on pilot lots and quantify welding and fabrication impacts before committing volume.
- Hedge nickel exposure tactically: combine indexed long‑term contracts with limited physical buffers sized to the project pipeline.
- Embed classification society checkpoints in contracts: require supplier evidence of orientation‑specific impact properties and third‑party certifications as pre‑conditions for acceptance.
- Design supplier governance for concentrated markets: include capacity reservation clauses, force majeure definitions aligned with trade policy risk, and penalty/reward mechanics for schedule adherence.
What the full PW Consulting report delivers
Our full Worldwide 9% Nickel Steel Plate Market report supplies the operational intelligence teams need to convert these strategic insights into executable plans. Highlights include:
- Proprietary headline forecasts and scenario modelling through 2032, with sensitivity runs for nickel price paths and tariff regimes;
- Supplier heatmaps, plant capability matrices and audited certification trackers for leading mills and regional champions;
- Procurement playbooks and contract templates adapted to high‑spec cryogenic supply, including acceptance testing protocols and capacity reservation clauses;
- Fabrication and weld procedure advisories aligned to plate thickness classes and reduced‑nickel options;
- Project risk assessments and mitigation blueprints tailored to large LNG and marine builds.
In keeping with our “trailer” approach, we are intentionally withholding the granular segmentation tables and supplier scoring that underpin our recommendations — these are available in the full report and interactive datasets that accompany it.
Closing perspective
By 2026 the 9% nickel steel plate market will be defined by a tension between supply concentration and technological substitution. Buyers and investors who act early — securing qualified supplies, stress‑testing alternative alloys, and hard‑wiring regulatory acceptance into contracts — will materially reduce execution risk and capture significant margin and schedule advantages. PW Consulting’s full report provides the tactical roadmaps and the proprietary numbers required to operationalize these strategies. For organizations facing multi‑year projects or strategic exposure to cryogenic materials, the choice in 2026 is between reactive sourcing and deliberate, data‑driven positioning.
To access the complete analysis, datasets and supplier scorecards referenced above, consult the PW Consulting report package and accompanying interactive briefing. The full intelligence suite is designed to convert market foresight into defensible, actionable decisions for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide 9% Nickel Steel Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Otolaryngology Endoscopy Market to Expand at a 6.52% CAGR Through 2032
By PW Consulting, 2026-08-18
Worldwide Otolaryngology Endoscopy Market — Strategic Briefing from PW Consulting
Executive summary
The Worldwide Otolaryngology Endoscopy Market is at an inflection point. Our new market study, anchored on 2025 as the base year and spanning historic performance from 2020–2025 with a forward view to 2026–2032, quantifies a market that we estimate at approximately USD 3,551.5 Million in 2025 and projects steady expansion through 2032. The report models a compound annual growth rate (CAGR) of 6.52% across the 2026–2032 forecast window, culminating in an addressable market above USD 5.5 Billion by 2032.
Worldwide Single Stage High Speed Centrifugal Fan Market
This briefing synthesizes the strategic implications for executives, product leaders, commercial teams, and hospital procurement officers preparing choices in 2026. It highlights growth levers, risk vectors, competitive moves, and actionable frameworks — while intentionally withholding granular sub-segment figures to direct decision-makers to the full report for transaction-ready detail.
Worldwide Off Road Trailer Market
Why this matters for 2026 decision-making
-
Planning horizon alignment: Capital planning cycles at health systems and manufacturers increasingly align with multi-year expenditure and product roadmaps. The market’s mid-single-digit-plus CAGR over 2026–2032 means that 2026 is a pivotal year for locking in platform investments, with meaningful upside for first-mover partners that can secure share in new product categories and integrated systems.
Disposable Silicone Catheter Market -
Portfolio prioritization: With technological convergence (imaging, navigation, single-use disposables, and robotics) reshaping value propositions, firms must re-weight R&D and go-to-market spending to products that drive recurring consumable revenue and system-level differentiation.
-
M&A and partnership timing: The quantified trajectory of the market provides a data-backed foundation for timing bolt-on acquisitions, forming strategic alliances, or accelerating licensing deals to capture capacity- constrained growth in high-adoption healthcare systems.
Market dynamics: what’s driving growth in 2026 and beyond
-
Technology convergence and imaging advances. Extended depth-of-field imaging, higher-resolution processors, and integrated visualization systems are improving diagnostic accuracy and shortening procedure times. Recent regulatory clearances and product launches demonstrate vendor momentum toward richer imaging and hybrid platforms.
-
Single-use and flexible systems adoption. Infection-control priorities and procedural throughput have accelerated interest in disposable flexible rhinolaryngoscopes and ancillary devices. This is reshaping procurement debates — balancing per-use economics against sterilization logistics and clinical workflow efficiency.
-
Navigation, robotics, and systems integration. The FDA’s recent clearances expanding indications for robotic platforms and navigation systems into transoral and skull-base applications create a pathway for bundled offerings (imaging + navigation + robotic assistance) that command premium pricing and stickier customer relationships.
-
CapEx tailwinds from major hospital operators. Large hospital systems continue to guide elevated capital expenditure for medical device infrastructure, creating a favorable window for vendors to scale installations of integrated endoscopy suites and accompanying service contracts.
-
Regulatory and reimbursement signals. Recent regulatory decisions and reimbursement coding adjustments are materially impacting the economics of certain procedures and devices. These shifts are accelerating adoption in cases where procedure-level payments and coding clarity improve hospital margins.
Competitive landscape — strategic positions to watch
The market is populated by established medical-device leaders and specialized endoscopy firms. The competitive environment is characterized by platform sellers chasing systems integration and smaller, focused innovators targeting discrete procedural needs. Key players profiled in our analysis include global diversified med-tech leaders and niche endoscopy specialists; selected companies profiled in the report are:
-
Karl Storz SE & Co. KG — deep heritage in rigid and flexible optics and comprehensive instrument portfolios for otolaryngology.
-
Olympus Corporation — strong imaging and processor capabilities, with strategic moves into single-use flexible rhinolaryngoscopes and enhanced depth-of-field technologies.
-
Stryker Corporation and Medtronic plc — pursuing system-level value through visualization, navigation, and integrated procedural platforms that extend into skull-base and head-and-neck surgery.
-
PENTAX Medical (HOYA), Richard Wolf, Fujifilm — firms emphasizing specialized video naso-pharyngo-laryngoscopes and flexible endoscopy technologies.
-
Ambu A/S — a clear commercial bet on single-use flexible scopes to capture infection-control-driven procedure volume.
-
Boston Scientific, Smith & Nephew, Integra LifeSciences (via Acclarent), XION GmbH — players extending portfolios with accessories, navigation adjuncts, and system components.
Our competitive analysis maps each firm across three strategic dimensions: technology depth (imaging + navigation + disposables), route-to-market (hospital direct, distributors, OEM partnerships), and margin model (capital-driven versus consumables-driven). This permits side-by-side scenario building for rival moves and potential gaps where challengers can create outsized returns.
Recent developments that will shape tactical choices in 2026
-
Product and regulatory milestones: Examples include new clearances for integrated navigation and robotic systems, and the launch of single-use flexible rhinolaryngoscopes in key geographies. These events materially change go-to-market calculus for both incumbents and new entrants.
-
FDA indications expansion for robotic platforms in transoral procedures: This re-writes the playbook for competing in selected ENT surgical segments where robotic assistance can be presented as a surgeon-safety and outcomes differentiator.
-
Reimbursement updates: New payment assignments for automated tympanostomy systems and procedural cross-walks can accelerate adoption where hospital revenue neutrality or uplift exists.
-
CapEx commitments by major health systems: Elevated capital guidance from large hospital operators signals an addressable market for room- and hospital-level upgrades — creating windows to bundle devices with service, training, and financing.
What the full report contains — practical, transaction-ready content
PW Consulting’s full Worldwide Otolaryngology Endoscopy Market report is built for decision-makers who need both strategic insight and executable detail. Key deliverables include:
-
Market sizing and growth modeling: historical series and a granular, scenario-based forecast through 2032, with sensitivity analysis for technology adoption rates and reimbursement shifts.
-
Segment architecture and demand drivers: a commercial taxonomy covering product types, clinical applications, and adoption vectors, plus qualitative demand influencers by hospital type.
-
Vendor benchmarking: capability matrices, go-to-market mapping, announced product pipelines, and M&A activity analysis — with an emphasis on where margins can be defended or expanded.
-
Buyer economics: total cost of ownership models for capital systems vs. single-use disposables, procedure-level reimbursement impact, and procurement negotiation levers.
-
Strategic playbooks: three executable 12–36 month strategies for incumbents, challengers, and new entrants — covering product, pricing, partnerships, and regulatory tactics.
-
Primary research appendices: interview summaries with thought leaders, hospital procurement officers, and key opinion leaders to ground forecasts in clinician workflows and purchasing intent.
To preserve the report’s value as a commercial intelligence product, the public summary intentionally omits detailed sub-segment tables and region-by-application financials; these are included in the full dataset and model delivered to subscribers and clients.
How to convert insight into 2026 action
-
Immediate triage (0–3 months): Use our decision frameworks to identify which SKUs and platforms should be prioritized for accelerated commercialization or rationalization given hospital CapEx trends and regulatory tailwinds.
-
Near-term execution (3–12 months): For product teams, invest in interoperability (imaging + navigation) and consumables that lock in recurring revenue. For commercial teams, target health systems with near-term CapEx guidance and pilot bundled solutions that lower adoption friction.
-
Strategic bets (12–36 months): Consider acquiring or partnering with niche developers of steerable or single-use flexible scopes to shore up the consumables pipeline. Negotiate service-level and data-sharing agreements that make installed bases harder to displace.
Final observations and invitation
The otolaryngology endoscopy market presents a compelling growth narrative: durable demand from diagnostic and therapeutic procedures, technology-driven expansion in value per procedure, and a competitive landscape where systems integration and consumables economics will decide winners. Our modeling shows a market trajectory from the mid–single-digit billion range in 2025 to north of USD 5.5 Billion by 2032 at a 6.52% CAGR — a signal to executives that 2026 is a year to move decisively rather than defensively.
PW Consulting’s full report contains the detailed segment economics, regional mixes, and company-level estimates required for contract negotiations, M&A diligence, and annual budgeting. For access to the complete dataset, model files, and client-only strategic workshops, please consult the report landing page or contact our client services team.
For detailed analysis of this topic, please visit the official page: Worldwide Otolaryngology Endoscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


