



Category: market research
PW Consulting: Worldwide Headless CMS Software Market Set to Grow at a Strong 21.45% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Headless CMS Software Market: Strategic Briefing for 2026 Decision‑Makers
As enterprises accelerate composable digital strategies, headless content platforms have moved from experimental stacks to mission‑critical infrastructure. PW Consulting’s latest Worldwide Headless CMS Software Market report synthesizes five years of historical data (2020–2025) and delivers a forward-looking forecast for 2026–2032. Our models show the market expanding from an emergent sub‑billion-dollar sector in 2020 to a robust market in 2025, and then growing at a forecast compound annual growth rate (CAGR) of 21.45% through 2032. By 2026 the market is projected to cross the USD 1.6 billion threshold, with sustained acceleration expected into the early 2030s.
Benchtop Vickers Hardness Testers Market
Why this briefing matters for 2026 strategic planning
-
Architecture decisions made this year will shape time‑to‑market and cost profiles for multi‑year digital initiatives. The rapid CAGR reflects both substitution of legacy CMS and net‑new demand from omnichannel campaigns and embedded experiences.
Worldwide Programmatic Native Advertising Platform Market -
Vendor choice is no longer purely tactical. Platform selection now determines governance, localization reach, developer productivity, and the ability to embed AI and data services across a distributed content estate.
Worldwide Field Glasses Market -
Regulatory and security trends are converging with technical choices—data residency, zero‑trust operational models and post‑quantum readiness are creating new non‑functional requirements that materially affect cloud and self‑hosted decisions.
What the PW Consulting report delivers (practical, executable)
-
Decision frameworks that map business objectives (brand scale, speed, regional compliance) to platform archetypes and cost drivers. These frameworks turn boardroom goals into procurement specifications.
-
Vendor scorecards combining architectural fit, commercial model, integration surface area, and operational TCO. Each scorecard highlights key tradeoffs—time‑to‑value vs. long‑term control—without exposing confidential customer benchmarks.
-
Migration and coexistence playbooks for common scenarios: legacy CMS lifts, hybrid headless increments, and multi‑brand content rationalization. Each playbook includes stepwise milestones, risk mitigations, and measurable KPIs for the first 180 days.
-
Operational runbooks and security checklists oriented to modern threats: API governance, RBAC patterns, encryption lifecycle management and preparatory steps for post‑quantum cryptography adoption.
-
Commercial negotiation guides and sample SOW clauses for SaaS SLAs, data exportability, and vendor exit strategies—crafted to protect enterprise continuity in dynamic vendor landscapes.
-
Interactive TCO models and sensitivity analyses that let procurement teams test scenarios across API‑call intensity, CDN egress, user seats and self‑hosting staffing assumptions.
Competitive landscape: strategic positioning and implications
The headless CMS arena now comprises a mix of enterprise incumbents, developer‑centric open source projects, and cloud‑native SaaS platforms. Market dynamics remain moderately concentrated: several large vendors lead adoption in enterprise accounts, but innovative open source and cloud entrants continue to erode traditional vendor lock‑in by winning new workloads. The ecosystem is therefore fertile for consolidation, partnerships, and platform specialization.
-
Contentful (Berlin): Enterprise‑grade, API‑first architecture with strong localization and composable content features. Best fit for large organizations that prioritize scale and enterprise integrations; expect Contentful to remain a go‑to when reliability and global reach are non‑negotiable.
-
Sanity (San Francisco): Developer‑focused platform that excels at real‑time collaboration and structured content workflows. Strong TypeScript tooling and flexible data models make Sanity attractive for product‑centric engineering teams embedding content as data.
-
Strapi (Paris): The open‑source self‑hosted leader that offers full control for data‑sovereignty use cases. The 2026 Strapi 5 release—introducing enhanced TypeScript support and Vite integration—reduces friction for enterprise adoption but does not eliminate the operational cost delta versus managed SaaS.
-
Storyblok (Linz): Differentiates through a visual, component‑based editor and strong marketing usability. Recent industry recognition for AI‑enabled features highlights Storyblok’s appeal to organizations where marketer autonomy and governance must coexist.
-
Hygraph (London): GraphQL‑native approach and content federation capabilities serve complex, multi‑brand architectures; a solid technical choice where relational modeling and GraphQL ecosystems are dominant.
-
Prismic (Paris): Maintains momentum among organizations focused on slice‑based page building and non‑technical team workflows. Recent positioning among leading enterprise platforms underscores its utility for page‑centric experiences.
-
Contentstack (San Francisco): Positioned for enterprise DXP and governance, combining advanced visual editing and composable platform capabilities; recognized in multiple analyst evaluations as a strategic visionary.
-
Kontent.ai (Brno): Tailored for enterprise governance and multi‑language workflows with attention to AI‑assisted content operations.
-
Payload, Directus, Agility, Butter: Each addresses particular slices—code‑centric control, database‑driven APIs, speed‑oriented delivery, or simplified blog/page needs. These platforms are often chosen for specific developer or editorial workflows rather than as enterprise standards.
Recent vendor developments reinforce these strategic distinctions. In early 2026, Strapi released a major technical revision focused on TypeScript and build tooling; Prismic was re‑classified among the top enterprise platforms; Storyblok received recognition for its AI‑enabled editor; and Contentstack continued to be highlighted by analyst firms for its enterprise DXP posture. Collectively, these moves signal that vendors are doubling down on either developer ergonomics, marketer usability, or enterprise governance—rarely all three at once.
Regulatory, operational and cost dynamics shaping 2026 decisions
-
Compliance and data residency: GDPR remains table stakes in Europe, and new directives such as NIS2 are imposing stricter obligations. Enterprises must evaluate vendor regional availability and contractual commitments for data locality rather than assuming global SaaS footprints suffice.
-
Security posture: Increasing focus on API security, fine‑grained RBAC and early preparations for post‑quantum cryptography are changing vendor evaluation criteria. “Harvest now, decrypt later” threats are driving enterprises to require longer‑term cryptographic roadmaps from providers.
-
Operational costs and developer time: Self‑hosted open‑source deployments typically demand materially more operational developer effort—our analysis indicates roughly a 45–48% increase in maintenance and patching labor compared with managed SaaS alternatives. This delta must be modeled into multi‑year TCO scenarios alongside hosting, backup and disaster recovery footprints.
-
Usage economics: For SaaS offerings, primary cost levers are API call volume, CDN bandwidth and user seats. Procurement teams should insist on transparent usage tiers and negotiate pilot caps to avoid steep bill shock during growth phases. As an example point of reference, some market providers offer entry tiers around USD 300/month with specified API allowances—pricing transparency is improving but remains uneven.
Strategic imperatives and recommended next steps for 2026
-
Adopt a two‑track procurement approach: fast pilots on managed SaaS for short time‑to‑value, paired with a proof‑of‑concept for self‑hosted or cloud‑native stacks where data sovereignty or customization is mandatory.
-
Prioritize governance early: define content models, localization taxonomies, and RBAC policies before vendor selection. Governance debt is harder to repay than platform debt.
-
Embed security and cryptographic roadmaps into contracts: require vendor commitments on API security standards, incident notification SLAs, and a roadmap for PQC readiness.
-
Quantify developer cost differentials: use the report’s TCO models to test scenarios across high API throughput, heavy personalized experiences, and long‑tail localization needs. Often, lower initial platform spend is eclipsed by higher operational costs over the second and third years.
-
Design for composability and observability: instrument content APIs, CDNs and edge deployments to measure latency, cache efficiency, and personalization costs—these metrics will drive performance‑vs‑cost tradeoffs as usage grows.
-
Plan for AI augmentation: vendors are rapidly integrating AI into authoring and personalization. Evaluate platforms for safe AI features (explainability, governance) rather than novelty alone.
Concluding perspective and call to action
The headless CMS market is entering a maturation phase where architectural fit, operational economics and regulatory alignment determine winners. PW Consulting’s report arms technology and business leaders with the frameworks, playbooks and data‑driven models needed to make defensible platform decisions in 2026. We deliberately present strategic insights and vendor evaluations here while reserving our full, granular segmentations, interactive financial models, and vendor‑level scorecards for the complete research package.
For procurement teams, CTOs, and digital leaders who must finalize architecture choices this year: PW Consulting’s full report provides the empirical models and contract language you need to move from evaluation to execution with confidence. Visit our report page to access the complete dataset, customizable TCO calculators, and vendor scorecards that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Headless CMS Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Vaccine Transport Boxes Market to Reach USD 1,139.6 Million by 2032, Growing at a 6.25% CAGR
By PW Consulting, 2026-08-12
Worldwide Vaccine Transport Boxes Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence on the Worldwide Vaccine Transport Boxes Market delivers a focused, decision-ready briefing for leaders planning supply chain, procurement, and product development strategies in 2026. The market has demonstrated steady expansion through the first half of the decade and is projected to continue at a robust compound annual growth rate of 6.25% into the next planning horizon. Our base-year view (2025) captures recent volatility and stabilization after pandemic-driven demand shocks; the forecast horizon through 2032 highlights durable growth driven by expanded immunization programs, heightened regulatory scrutiny, and technology adoption in cold chain logistics.
Multifunctional Fuel Bladder Market
Why this matters to leaders in 2026
Procurement directors, product managers, and strategy teams face a compressed window in which to align sourcing, certification, and operational investments with long-term immunization objectives. The market’s CAGR of 6.25% signals both opportunity and competitive pressure: demand growth is sufficiently strong to justify capacity and innovation investments, yet concentrated enough in the hands of established suppliers to make timing and partner selection pivotal. The total market expansion between 2020 and 2025—and the continued projected rise toward the end of the forecast period—frames a landscape where the right tactical moves in 2026 will shape market share and margin trajectories for years.
Canopy Light Market
Macro dynamics shaping the market
- Sustained public-sector procurement: National immunization programs and international agencies remain central buyers. Their procurement cycles, funding windows, and specification standards create predictable demand pulses that suppliers and buyers should model into procurement cadence and inventory strategies.
- Regulatory consolidation and WHO PQS requirements: WHO Performance, Quality and Safety (PQS) standards—particularly the E004 category—remain a gating criterion for procurement by UN agencies and many donors. Specifications that require demonstrated cold life at high ambient temperatures and protection against freezing are driving product development priorities.
- Technology and material innovation: Advances in insulation materials, coolant formulations, and monitoring adjuncts (e.g., integrated temperature loggers and tamper-evident seals) are boosting product differentiation. These incremental innovations influence total cost of ownership (TCO) far more than unit price alone, especially for long-range transport and high-value vaccine payloads.
- Service and after-sales ecosystems: Demand is moving beyond boxes toward guaranteed performance across the lifecycle—qualified spares, coolant management, calibration services, and repair networks are increasingly relevant selection criteria.
Regulatory and procurement context
For 2026 planning, regulatory compliance is not a checkbox; it is a strategic axis. WHO PQS prequalification remains a primary procurement filter for UN and donor-funded programs. The PQS requirements that test cold-life performance at elevated ambient temperatures and evaluate freeze-protection performance have reshaped supplier product portfolios. Organizations that underweight PQS conformity risk exclusion from major tenders; those that over-invest in certification without aligning distribution and service infrastructure risk poor utilization of capital expenditures. Balanced strategies that pair certified product lines with validated field performance data and service networks will be advantaged.
Worldwide Screening Equipment Market
Competitive landscape — what to watch
The market exhibits moderate concentration: the top three firms account for a material share of revenue, and the top five increase that concentration further, indicating a competitive environment where a small group of established suppliers retain procurement influence while numerous regional and specialty players capture niche demand. This structure creates differentiated opportunities:
- Established global suppliers secure large institutional contracts through recognized certification, breadth of product lines, and global servicing capability.
- Regional manufacturers compete effectively on lead times, localized service, and price-sensitive segments.
- Specialist entrants — for example, firms focused on ultra-compact carriers or on integrated monitoring solutions — can capture premium niches if they pair product innovation with PQS-aligned validation strategies.
Key companies to monitor include multinational and regional manufacturers that have actively sought WHO PQS alignment and broad customer footprints. Each brings distinct strategic strengths: demonstrated PQS prequalification, focused product portfolios for freeze-prevention or extended cold life, and regional manufacturing footprints that shorten lead times and lower landed cost. Our report examines these players in tactical detail—benchmarking certification status, product breadth, service networks, and route-to-market capabilities—while withholding granular procurement-level share tables in this preview.
What the full report delivers (practical, operational content)
PW Consulting’s full report is designed for executives and functional leaders who must convert insight into 2026 action. It provides modular, implementable deliverables including:
- Decision-grade market sizing and scenario demand models that allow “what-if” testing across budget cycles and funding assumptions.
- Supplier scorecards that synthesize PQS status, field performance evidence, service footprint, lead-time risk, and commercial terms—constructed to support shortlisting for formal tenders.
- Procurement playbooks with sample RFP language, evaluation matrices, and contract clauses focused on warranty, performance guarantees, and replenishment logistics.
- TCO calculators that factor unit cost, coolant consumption, service frequency, replacement rate, and logistics cost to drive economically robust buy-vs-lease decisions.
- Operational blueprints for cold chain planners, including distribution network optimization, staging best practices, and risk mitigations for high ambient temperature environments.
- Regulatory compliance matrices that map WHO PQS requirements to product specifications and test evidence, accelerating prequalification and audit readiness.
- Competitive benchmarking and scenario-driven M&A/partnership frameworks for corporates evaluating entry or expansion strategies in the vaccine transport segment.
Strategic recommendations for 2026
Based on our analysis, PW Consulting recommends leaders prioritize the following actions in 2026 to capitalize on market dynamics:
- Align procurement with certification timelines: Synchronize purchasing calendars with manufacturers’ PQS certification cycles and validation testing windows to minimize qualification risk and avoid supply gaps.
- Adopt TCO-focused sourcing: Move procurement discussions beyond unit price. Use TCO models that capture coolant and service costs, expected lifespan under field conditions, and failure risk to inform both sourcing and inventory policies.
- Invest selectively in servicing networks: For organizations that operate in dispersed geographies, co-investing in regional repair and calibration capacity can materially reduce downtime and improve effective cold-life delivery.
- Fast-track pilot validation: Before large-scale rollouts, execute short-cycle field validations that measure cold-life and freeze-protection under local ambient profiles; incorporate results into final award criteria.
- Consider hybrid procurement strategies: Blend long-term contracts with capacity options and an approved vendor list to respond to demand spikes while preserving price discipline.
How buyers and suppliers can use this report
Buyers will find the report useful to build defensible procurement strategies and to structure tenders that reflect operational realities and regulatory constraints. Suppliers and manufacturers can use the benchmark and gap analyses to prioritize certification investments, refine product value propositions, and shape go-to-market plays for 2026 tenders. Investors will gain a lens on market concentration, potential consolidation opportunities, and the return profiles associated with service-led vs. product-led growth strategies.
About our competitive profiles
The report includes concise, action-oriented company profiles across the ecosystem: long-established global suppliers with broad PQS-aligned portfolios; regional manufacturers that excel in cost and lead-time competitiveness; and specialist firms focused on freeze-preventive or extended cold-life designs. Our evaluation framework rates firms on PQS validation, field performance evidence, after-sales capability, and commercial agility. To respect competitive sensitivity and to preserve commercial value for subscribers, we present headline assessments in this preview and reserve full scorecards and procurement-ready vendor shortlists for report purchasers.
Closing — the strategic window in 2026
As the market continues its steady expansion—having grown meaningfully from the start of the decade and forecast to extend into the next—2026 represents a pivotal planning year. Organizations that operationalize certification alignment, embed total-cost thinking into sourcing, and partner with suppliers that combine PQS validation with field-proven service models will derive disproportionate value. PW Consulting’s full report equips decision-makers with the models, playbooks, and supplier intelligence required to act quickly and confidently.
Next steps
To access the full dataset, supplier scorecards, and procurement playbooks referenced in this briefing, visit the PW Consulting insights portal to download the comprehensive Worldwide Vaccine Transport Boxes Market report. Our team is available to provide tailored briefings and to run scenario workshops that translate market intelligence into actionable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Vaccine Transport Boxes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wood Gas Generator Market Poised for 6.54% CAGR (2026–2032), Forecasting Strong Global Growth
By PW Consulting, 2026-08-12
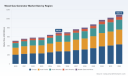
Worldwide Wood Gas Generator Market — Strategic Briefing for 2026
PW Consulting today publishes an executive briefing accompanying our full market study, "Worldwide Wood Gas Generator Market (Base Year: 2025; Forecast: 2026–2032)". The study synthesizes five years of historical performance (2020–2025) with forward projections to 2032, delivering an evidence-based playbook for corporate leaders, investors, utilities and equipment OEMs deciding where to place bets in 2026 and beyond.
Rack Mount Nas Market
Market at a glance — momentum and trajectory
Wood gas generation has moved from niche experimentation toward an operationally mature segment of decentralized low‑carbon energy systems. Our analysis puts the global market at an estimated USD 697 million in 2025, continuing on a compound annual growth path of approximately 6.5% through 2032, when total industry revenues are projected to exceed USD 1.08 billion under the baseline scenario. The trajectory reflects recovering capital spending following early‑decade disruptions, accelerating policy support for distributed biomass CHP, and improved economics as modular and automated systems scale.
Worldwide Biogas Plants Engineering, Procurement and Construction Management (EPCM) Market
Why 2026 is pivotal
- Policy windows are opening. Targeted public finance instruments at national and rural levels are de‑risking larger projects and enabling commercial lenders to underwrite distributed biomass investments. Strategic actors that structure bankable rural energy projects in the next 12–18 months will capture first‑mover advantages.
- Feedstock & logistics optimization becomes decisive. Wood pellets, chips and residues remain the practical fuels for commercial gasifiers; projects that invest early in feedstock quality control and supply‑chain automation lock in superior uptime and realized output.
- Scale and modularization converge. Product roadmaps are moving from bespoke installations toward modular, containerized CHP units — allowing faster deployment, standardized commissioning and tighter O&M contracts.
- Cost competitiveness is maturing. On‑site biomass gasification is already delivering material reductions to fuel-import dependent generation costs in demonstrated projects; investors should expect payback windows amenable to corporate CapEx programs and infrastructure funds.
Actionable strategic insights — what to do in 2026
- Prioritize pilot-to-scale roadmaps. Run 1–3 small pilots that validate local feedstock regimes and integration with existing thermal or electrical loads. Use pilots to establish realistic capacity factors, spare parts profiles and fuel preprocessing needs before committing to multi‑site rollouts.
- Design finance before technology. Structure project finance vehicles that combine public loan guarantees, tax incentives, and offtake contracts. Early engagement with regional development agencies will materially shorten approval cycles.
- Adopt a vendor‑agnostic procurement rubric. Procurement should weight O&M contracts, modular service SLAs, remote monitoring and spare‑parts lead times as heavily as CAPEX. Our report includes a procurement scorecard you can adapt to RFPs.
- Focus on integration with existing energy ecosystems. The most attractive value propositions are hybrid: gasifiers paired with thermal networks, biomass residue processors and seasonal storage reduce stranded asset risk.
- Hedge feedstock risk. Secure diversified feedstock agreements (pellets, chips, residues) and invest in preprocessing capability; consider clustered sourcing across industrial forestry, sawmill residues and agricultural co‑products.
- Explore partnership models. Technology OEMs, EPC contractors and local operators can form cascade agreements where each party specializes — creation of local service hubs is a material competitive advantage.
Report deliverables — practical, decision‑grade content
Our full market study is intentional in its operational utility. It contains:
House Service Cut Out Market
- Market sizing and growth scenarios (base, upside and stress) covering 2020–2032 and sensitivity tests for feedstock price variance and incentive shifts.
- Technology assessment and benchmarking — including equipment maturity, modularization potential and automation readiness.
- Commercial models and CAPEX/OPEX templates — project-level pro formas you can adapt to site specifics and financing structures.
- Vendor profiles and competitive scorecards with side‑by‑side comparisons on system design, service coverage, product roadmaps and reference projects.
- Go‑to‑market playbooks for developers and OEMs — from pilot selection to scale deployment, plus contract templates and tender checklists.
- Risk registers and mitigation strategies for feedstock, permitting, performance decline and end‑market volatility.
- Case studies and commissioning checklists derived from operational projects, highlighting procurement missteps and best practices that materially affect LCoE.
Note: this briefing intentionally omits detailed regional and application split tables — the full dataset and segmented forecasts are available in the report and through our client portal.
Competitive landscape — who is shaping the market
The wood gas generator market remains fragmented: three largest suppliers account for less than a fifth of global revenue, and the top five collectively hold well under a third. This fragmentation creates opportunity for consolidation, strategic partnerships and vertical integration.
- Burkhardt GmbH (Mühlhausen, Germany) — Strengths are modular CHP product lines designed for pellets and chips, continuous process optimization and strong engineering services for decentralized heat and power. Ideal partner for European district heat integrators seeking turnkey solutions.
- Spanner Re² GmbH (Germany) — Positions itself on CO2‑neutral energy from wood waste with global cascading installations for businesses and community heating networks. Its market proposition ties regulatory incentives into customer economics, making it attractive for public‑private collaborations.
- ALL Power Labs (Berkeley, USA) — Focused on small‑scale, modular and increasingly automated gasifiers. Their products appeal to distributed power use‑cases and rapid prototyping, and their open‑engineering ethos accelerates local adaptation.
- Powermax Renewable Energy (Wuxi, China) — Offers a breadth of industrial offerings and long project experience across 100+ deployments. Their scale and product range — extending into multi‑hundred‑kW units — make them a natural supplier for larger industrial and municipal projects.
- Regional and niche players — Companies such as Ankur Scientific, GASEK, Holzenergie Wegscheid, Vulcan Gasifier, Volter and Community Power Corporation occupy important niches: cost‑competitive deployments in emerging markets, specialized electricity‑centric systems, and market access through local service networks.
For most corporate buyers, winning strategies combine global OEM reliability with local service partnerships. Expect differentiated market positions to emerge around digital remote monitoring, feedstock preprocessing, and service‑driven warranty extensions.
Near‑term developments to watch
- Project finance activation. Recent approvals of government loan guarantees for biomass gasification projects signal that lenders are reallocating capital into rural and forestry‑waste energy projects. This de‑risking will accelerate project pipelines where sponsors can present bankable supply chains.
- OEM product rollouts. Leading suppliers are expanding industrial offerings and standardizing product families from tens of kW to multi‑hundreds of kW capacity — a shift that reduces engineering lead time and cost for multi‑site buyers.
- Regulatory alignment. National incentives and EU mechanisms for decentralized biomass CHP are maturing; projects that align with these frameworks secure superior returns and faster permitting.
- Demonstrated economics. Operational projects have documented material operating cost savings relative to diesel generation, with payback horizons that make them compelling for corporate energy managers and infrastructure investors.
How executives should use this report in 2026
- Board & investment committees: Use the market scenarios in the report to stress‑test investment approvals and to allocate a disciplined portion of CapEx to biomass‑based distributed generation.
- Corporate energy & sustainability teams: Leverage the procurement scorecards and case studies to design pilots that earn internal buy‑in and transition to multi‑site rollouts.
- Investors & project developers: Apply the financial templates and risk matrices to shape fund structures and to negotiate incentive‑linked offtake agreements.
- OEMs & service providers: Use the competitive benchmarking to identify white spaces for modular product development, service hubs and digital O&M offerings that extend lifetime margins.
Conclusion — the strategic imperative for 2026
Wood gas generators are no longer an experimental niche; they are becoming a mainstream option for decentralized, low‑carbon thermal and power solutions where feedstock logistics, policy incentives and grid constraints align. 2026 is the year to move from assessment to execution: pilot, de‑risk and scale with partners who can supply both hardware and long‑term operational capability. PW Consulting’s full report offers the granular datasets, vendor evaluations and transaction playbooks required to make those decisions confidently.
For the comprehensive segmented forecasts, supplier scorecards, financial models and downloadable tools referenced in this briefing, please visit our report landing page or contact PW Consulting’s energy team for a client briefing and demo.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Gracey Curette Market Poised to Expand at a 6.85% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Gracey Curette Market: Strategic Outlook and Action Playbook for 2026
Executive summary
PW Consulting’s latest Worldwide Gracey Curette Market report (base year 2025) delivers a focused, decision-oriented perspective for executives planning allocations and competitive moves in 2026. The market for Gracey curettes has demonstrated steady expansion over the 2020–2025 historical window, rising from USD 154.37 Million in 2020 to USD 215.0 Million in 2025, and is projected to continue growing through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of 6.85%, reaching an estimated USD 341.86 Million by 2032. These macro dynamics create both tactical opportunities for established players and strategic inflection points for smaller innovators and new entrants.
Memory Card Data Recovery Service Market
Why this report matters for 2026 decision-making
-
Timing. 2026 represents the first full planning year under the new mid-decade market conditions we model: accelerating adoption of specialty instrument variants, continued emphasis on infection control, and reimbursement stability for periodontal scaling procedures. Decisions on production capacity, product roadmaps, and distribution investments made in 2026 will determine competitive positions through the remainder of the forecast horizon.
Process Analytical Technology (PAT) Software Market -
Risk calibration. Our analysis quantifies the sensitivity of revenues to three critical variables — product mix shifts (standard vs. micro / coated instruments), sterilization and instrument lifecycle costs, and procurement cycles in dental chains — enabling CFOs to stress-test budgets and contingency plans before commitments are made.
Insulation Piercing Clamp Market -
Competitive leverage. The report synthesizes benchmarked capabilities across leading manufacturers and identifies where differentiation is defensible (materials and coatings, handle ergonomics, edge-retention technologies, and channel partnerships).
Market trajectory — what the macro numbers reveal (no segment leakage)
From a macro perspective, the market’s path is clear: a solid structural base in 2020–2025, followed by sustained expansion through 2032. The USD 215.0 Million base in 2025 and the modeled CAGR of 6.85% reflect combined demand drivers such as rising demand for preventive and periodontal care, incremental premiumization (coatings and specialty geometries), and investments by dental service organizations to standardize instrument fleets. While the headline growth is attractive, the report stresses that growth is uneven across product types, geographies, and end-use settings — details that we reserve for subscribers to the full study. Executives should plan around a continued, above-market growth trajectory while preparing for localized pockets of price and procurement pressure.
What the full report delivers — practical, executable content
-
Actionable market sizing and scenario modeling: comprehensive historical (2020–2025) baselines and three forecast scenarios to 2032 (stable growth, accelerated adoption, and constrained demand), including sensitivity matrices for key assumptions.
-
Go-to-market playbook: channel segmentation, distributor economics, pricing ladders, and promotional levers that drive adoption in private dental clinics, hospital settings and academic institutions.
-
Product strategy frameworks: decision trees for portfolio rationalization (when to introduce coated or extended-shank variants), unit economics by product family, and upgrade paths that preserve instrument lifecycle profitability.
-
Procurement and supply-chain diagnostics: inventory-turn and sterilization-capacity benchmarks, supplier risk scoring, and tactical sourcing pathways for raw materials (medical-grade 440A stainless steel and alternative alloys/coatings).
-
Regulatory and compliance playbook: practical checklists and process maps for regulatory classification, sterilization protocols, and reimbursement coding alignment to reduce launch friction.
-
Commercial due diligence assets: competitor scorecards, M&A valuation lenses, and integration checklists for bolt-on acquisitions or private-label agreements.
Competitive landscape — positioning the players that matter
The market is characterized by a mix of global premium brands, specialist European innovators, and established U.S. instrument manufacturers. Market concentration is moderate; leading manufacturers collectively occupy a non-dominant share of the market, leaving meaningful room for differentiation and share shifts.
-
Hu-Friedy Group (Chicago, Illinois, USA) — Recognized for premium offerings such as EverEdge 2.0 and micro-mini Gracey variants, Hu-Friedy competes on technical edge geometry and strong brand presence in professional circles. Strategic imperatives for Hu-Friedy include translating premium product features into quantifiable clinic-level ROI and extending service offerings (sharpening/maintenance programs) to lock in repeat spend.
-
LM-Dental (Kuopio, Finland) — European specialist notable for diamond-like carbon (DLC) coating and ergonomic handle design. LM-Dental’s value proposition centers on extended sharpness and operator comfort. The path to scale involves selective geographic expansion and distributor partnerships that can sell the premium use-case to sophisticated dental practices.
-
American Eagle Instruments (Mount Vernon, Washington, USA) — Positions on lightweight handles and advanced edge-retention technologies. Their story resonates with clinicians focused on reduced fatigue and lower total cost of ownership. Opportunities exist for co-marketing with large dental service organizations that emphasize ergonomics as a performance metric.
-
Paradise Dental Technologies (Colton, California, USA) — Differentiates with color-coded instrument systems improving chair-side workflow and access in complex anatomies. The commercial play is to pair instrument kits with training services to increase unit attachment rates and foster brand loyalty.
-
Nordent Manufacturing, G. Hartzell & Son, Young Dental, Kerr Dental — These companies represent a mix of heritage craftsmanship and broad periodontal instrument portfolios. Strengths include robust manufacturing know-how, heat-treatment processes for edge retention, and distribution through traditional dental dealers. Strategic moves for these players include targeted product modernization and digital marketing to reach younger clinician cohorts.
Dynamics, standards and compliance — the operating constraints
-
Regulatory classification: Gracey curettes are classified as Class I medical devices and are exempt from 510(k) premarket notification under FDA 21 CFR 872.4830. This reduces time-to-market risk for incremental product variants but does not remove the need for rigorous quality systems and record-keeping.
-
Standards: Instruments generally conform to ISO 7153-1:2016 for stainless-steel surgical instruments. Compliance to recognized standards remains a buyer expectation and a gate to certain institutional contracts.
-
Sterilization protocols: Steam autoclaving at 121–134°C for 15–30 minutes is the accepted reprocessing method. Equipment, cycle-time and instrument life yield are variables companies must model when presenting TCO claims to buyers.
-
Reimbursement linkage: Periodontal scaling and root planing procedures utilizing Gracey curettes are reimbursable under CDT code D4341. Manufacturers and distributors who can map product benefits to reimbursable procedures will improve clinician uptake.
-
Materials: Medical-grade 440A stainless steel remains the workhorse material for corrosion resistance and durability; coatings and alternative alloys are evolving as premium differentiators.
Strategic imperatives for executives in 2026 — what to do now
-
Prioritize product-level profitability over SKU proliferation. Use lifecycle-cost models (sterilization cycles, re-sharpening economics, and replacement rate) to decide which new coated or micro instruments to productize.
-
Lock distribution anchors with dental chains and hospital groups. Offer bundled service agreements (sharpening, training, color-coded kits) to create switching costs and predictable repurchase patterns.
-
Invest selectively in differentiation that is defensible and measurable: coatings that demonstrably extend edge life, ergonomic handles that reduce procedure time, and color-coding that lowers chair time. Accompany product claims with clinic-level pilot data demonstrating TCO improvements.
-
Design sterilization and procurement pilots. Partner with key customer accounts to validate autoclave compatibility and instrument throughput, and then use these pilots to build commercial case studies.
-
Consider inorganic options to accelerate capability gaps. Given the market’s moderate concentration and fragmented specialty niches, targeted acquisitions (edge-coating technology, ergonomic handle IP, or regional distributors) can shift market share faster than organic builds.
-
Operationalize regulatory and standards compliance as a sales differentiator. Build quick-reference compliance guides and TCO calculators for procurement teams to speed deal cycles.
How PW Consulting’s report becomes a boardroom tool
This release is intended to be a strategic teaser: it highlights the market’s direction and the specific levers that will matter in 2026 without disclosing the granular segment shares and price ladders that are part of the full dataset. Clients will receive the full suite of deliverables — including detailed regional and application segment models, pricing grids, product-level unit economics, and competitor benchmarking matrices — that enable scenario planning, sales-target setting, and M&A diligence.
Next steps — where to get the full picture
For executive teams preparing budgets, go-to-market plans, or M&A pipelines for 2026, the full Worldwide Gracey Curette Market report is designed as an immediately actionable guide. Contact PW Consulting to access the complete dataset, bespoke modelling, and an implementation workshop tailored to your commercial objectives. Our goal: convert the quantified growth trajectory and competitive insights into a concise, executable 12–18 month plan that protects margin while capturing share in a growing instrument category.
For detailed analysis of this topic, please visit the official page: Worldwide Gracey Curette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide N‑Allylamine Market to Expand at a Robust 5.12% CAGR Through 2032
By PW Consulting, 2026-08-12
PW Consulting Releases Worldwide N‑Allylamine Market Report — Strategic Imperatives for Corporate Decision‑Making in 2026
Executive Synopsis
PW Consulting today publishes its most comprehensive study to date on the Worldwide N‑Allylamine market, a focused analysis designed to inform strategic decisions in 2026 and beyond. Built on a detailed historical review (2020–2025) and a seven‑year forecast (2026–2032), the report combines rigorous quantitative modelling with pragmatic, transaction‑oriented guidance for executives in chemicals, pharmaceuticals, agrochemicals, specialty polymers, and industrial water treatment.
Tissue Slide Market
Why N‑Allylamine Matters Now
N‑Allylamine plays a foundational role as a building block across multiple value chains — notably pharmaceutical intermediates, polymer and resin synthesis, agrochemical routes, and water treatment chemistries. Its dual role as an input in high‑value fine chemicals and as a commodity intermediate makes strategic planning around supply, quality, and regulatory compliance particularly consequential for manufacturers and downstream formulators.
Mobile Emergency Power Systems Market
Market Trajectory: Data‑Driven Takeaways
Our market model shows steady expansion from the low‑forties (USD Million) in 2020 to just over USD 52 Million in 2025 (base year), followed by a renewed growth trajectory through the forecast horizon. PW Consulting projects the market to grow to approximately USD 57.5 Million in 2026 and to surpass USD 74 Million by 2032, corresponding to a compound annual growth rate (CAGR) of 5.12% across the forecast period.
Micro LED Display Chips Market
Key numeric signals embedded in the time series are instructive for 2026 planners:
- Recoveries and inflection: The 2020–2025 period shows recovery from pandemic‑era disruption into a stable base in 2025, which underpins the 2026 uptick modeled in our scenarios.
- Non‑linear demand: The forecast includes scenarios where demand accelerates in particular years due to capacity additions, regulatory approvals in pharma portfolios, or episodic industrial procurement cycles — factors that drive the model’s mid‑to‑late horizon variability.
- Volatility vectors: Short‑term dips and rebounds in the historical series signal susceptibility to upstream feedstock availability, pricing pass‑through, and logistical bottlenecks; these are modeled explicitly in our stress‑testing engine.
What the Report Contains — Practical, Transaction‑Ready Intelligence
PW Consulting’s Worldwide N‑Allylamine report is structured to move an organization from insight to action. The deliverables include:
- Comprehensive historical data (2020–2025) and a transparent forecasting methodology for 2026–2032, including scenario, sensitivity, and Monte Carlo analyses.
- Price and margin modelling at the manufacturer and distributor levels, with breakeven and unit economics templates tailored for contract negotiations.
- Supply chain and feedstock risk maps that identify single‑point failures and candidate mitigation strategies (dual sourcing, tolling, inventory optimization).
- Regulatory and standards overview relevant to production, handling, and cross‑border trade, including recommended compliance checkpoints for manufacturers and buyers.
- Commercial due diligence toolkits and competitor scorecards to support M&A, JV, or off‑take discussions.
- Actionable playbooks — capacity expansion decision trees, purity‑differentiation strategies, and go‑to‑market options for specialty vs. commodity channels.
Competitive Landscape — Who Matters and Why
The market comprises a mix of global specialty suppliers, laboratory distributors and vertically integrated manufacturers. Our competitive analysis focuses on strategic positioning, product quality, channel strength and geographic capability — not just revenue ranks. Four representative players that exemplify differing routes to market are:
- Tokyo Chemical Industry Co., Ltd. (TCI) — Tokyo, Japan: TCI maintains a strong global reach with a product emphasis on high‑purity N‑Allylamine suited to organic synthesis and pharmaceutical intermediate applications. Their channel strength in fine chemicals and consistent product specifications make them a preferred supplier for precision applications.
- Merck KGaA (Sigma‑Aldrich) — Darmstadt, Germany: As a legacy laboratory and bulk supplier, Merck combines trusted quality control and global logistics with capability to service both research and larger scale fine‑chemical needs. Their brand equity in regulated markets is an important strategic asset.
- Thermo Fisher Scientific Inc. (Alfa Aesar) — Waltham, MA, USA: Alfa Aesar’s offering targets lab and small production volumes with emphasis on fast delivery and catalogue availability. This channel is critical for innovators and smaller manufacturers that require rapid prototyping and quality consistency.
- Capot Chemical Co., Ltd. — Hangzhou, China: Capot represents the export‑oriented manufacturing base supplying N‑Allylamine as an intermediate into global supply chains, particularly for resin, agrochemical and some pharmaceutical intermediates. Their cost‑competitive posture and contract manufacturing capabilities are strategically significant for downstream formulators.
Across the market there is a mix of high‑specification suppliers and high‑volume exporters; understanding which player archetype aligns with your portfolio (specialty vs. commodity) is a priority for 2026 procurement strategies.
Strategic Priorities for 2026 Decision‑Makers
Based on the report’s integrated findings, PW Consulting recommends a focused set of actions for corporates planning in 2026:
- Segmentation‑aligned sourcing: Match supplier archetype to product application — prioritize purity and traceability for regulated pharma intermediates; prioritize cost and logistics for large‑scale polymer or resin feeds.
- Secure modular capacity: Evaluate tolling and contract‑manufacturing partners as a way to scale exposure without the capital intensity of greenfield capacity, using the report’s supplier scorecards to shortlist partners.
- Build optionality into feedstock procurement: Where feasible, establish alternative feedstock pathways or hedging arrangements to reduce exposure to price and availability shocks highlighted in our risk maps.
- Invest in quality differentiation: For firms competing in higher‑margin pharma or specialty markets, investments in higher‑purity grades and documentation (e.g., GMP‑like controls) can yield material premium capture.
- Prepare for episodic demand spikes: Use the report’s scenario outputs to model the cash, inventory and working capital impacts of demand surges, and design contractual flex terms with suppliers to limit supply shortfalls.
Regulatory and Sustainability Considerations
Regulatory scrutiny and sustainability expectations are increasingly shaping supplier selection. The report provides a practical matrix for assessing compliance readiness — from hazardous‑materials handling and cross‑border transport requirements to increasingly common supply‑chain environmental and social governance (ESG) checklists. For 2026, companies that can credibly demonstrate control over product specifications and environmental footprint will command negotiating leverage.
Use Cases — How Executive Teams Should Apply the Report
Typical use cases where the report creates immediate value include:
- Commercial due diligence for M&A or minority investments — rapid target screening and risk quantification templates.
- Procurement strategy redesign — supplier rationalization, contract length optimization, and price‑escalation clause modelling.
- R&D and product development prioritization — guidance on which purity grades and derivative chemistries are likely to show better margin potential over the forecast horizon.
- Capital planning — decision support for expanding internal capacity versus outsourcing, backed by cash‑flow impact analysis and break‑even timelines.
Limitations and What Is Intentionally Omitted
This release follows PW Consulting’s “trailer” principle: it communicates the depth and operational relevance of our analysis while preserving the proprietary, segment‑level intelligence that forms the core commercial value of the full report. Detailed regional breakdowns, application‑level shares, exact supplier market shares and granular pricing series are omitted here to encourage direct engagement with the source report, where proprietary datasets, tables, and model files are available.
Next Steps and How to Access the Full Report
PW Consulting’s Worldwide N‑Allylamine Market report is available now. Subscribers and clients can access full datasets, methodological appendices, supplier scorecards, scenario models and a tailored briefing with our senior industry analysts. For procurement teams, strategy groups, corporate development and investors active in downstream sectors, the report provides a compact set of decision tools to make 2026 strategic moves with confidence.
- To request the full report, bespoke data extracts, or a private briefing, please visit PW Consulting’s publications portal (link in the official distribution) or contact your PW engagement lead.
- For buyers and investors contemplating immediate action, request the interactive model to stress‑test supplier switching and capacity investment cases under our calibrated scenarios.
Closing Perspective
N‑Allylamine is a small molecule with outsized strategic importance across several industrial value chains. With a coherent growth path through 2032 and structural drivers in high‑value downstream applications, 2026 will be a pivotal year for firms that move from reactive procurement to proactive strategic design. PW Consulting’s report equips decision‑makers with the quantitative backbone and commercial heuristics required to convert insight into competitive advantage — while the full proprietary dataset provides the segment‑level granularity needed to execute with precision.
For detailed analysis of this topic, please visit the official page: Worldwide N-Allylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Security Software in Telecom Market Poised for Rapid Expansion at 13.01% CAGR During 2026–2032
By PW Consulting, 2026-08-12
Worldwide Security Software in Telecom Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting is publishing a focused industry briefing derived from our comprehensive market study, Worldwide Security Software in Telecom Market (base year 2025). The study synthesizes historical performance (2020–2025), near‑term market movements, and a forward-looking forecast (2026–2032) to provide operators, vendors, investors, and regulators with the strategic intelligence required to act with confidence in 2026. Our topline finding: the telecom security software market is re‑accelerating as operators monetize secure cloud, 5G, AI, and sovereign‑compliance offerings — growing from a 2025 base of USD 15,570 Million and expected to expand at a compounded annual growth rate of 13.01% through 2032, reaching an estimated market value in the low‑to‑mid USD 36,600 Million range by the end of the forecast.
Worldwide Higher Education Student Information Systems Software Market
Why this report matters for 2026 strategic choices
-
Timing and scale: The market’s 2026 inflection point combines increased operator investment in security‑enabled B2B services, vendor product cycles optimized for AI and 5G, and regulatory drivers that accelerate procurement timelines. The report quantifies this surge and models scenario outcomes that matter for budgeting, partnership selection, and M&A timing.
Data Center Renovation Service Market -
From CapEx to outcomes: Telecom buyers no longer purchase security as a discrete line item. They buy risk reduction, regulatory assurance, and business enablement. Our analysis translates market growth into actionable procurement levers, procurement timelines, and measurable KPIs for security projects aligned to revenue generation (enterprise connectivity, private networks, and managed security services).
105Ah LiFePO4 Battery Cell Market -
Vendor and technology roadmaps: The report identifies which technology classes and vendor archetypes will be pivotal in 2026 — from cloud‑native security platforms and SASE/SSE overlays to embedded 5G core security and AI‑driven threat detection — and maps sensible sourcing strategies for each.
What’s inside: practical, executable intelligence
-
Market sizing and robust forecasting: historical analysis (2020–2025) and probabilistic forecasts (2026–2032) with scenario sensitivity to regulatory shifts and technology adoption curves.
-
Go‑to‑market playbooks: vendor selection criteria, decision matrices for buy vs. build vs. partner, and RFP frameworks tailored to telecom operator procurement cycles and compliance needs.
-
Commercial models and TCO frameworks: CapEx/Opex modelling for cloud‑native vs on‑premise deployments, managed service cost comparisons, and revenue uplift scenarios for security‑augmented B2B offers.
-
Risk and regulatory impact assessment: actionable guidance on navigating digital sovereignty, data localization, trusted vendor policies, and emerging mandates such as the EU’s move toward quantum‑safe cryptography in critical communications.
-
Operator case studies and deployment templates: vetted implementation checklists for common telecom use cases (5G core protection, network slicing security, DDoS mitigation for mobile networks, secure edge and IoT onramps) and post‑deployment operational KPIs.
-
Vendor benchmarking and competitive playbooks: qualitative and quantitative scoring across performance, integration ease, roadmap, and compliance posture — designed for CISO and procurement decision support.
-
M&A and partnership signal matrix: identification of likely consolidation targets and partnership archetypes, underpinned by concentration metrics and vendor positioning insights to inform investment theses.
Key market dynamics shaping 2026 strategy
-
Cloud acceleration meets telecom specificity: Operators continue to migrate security functions to cloud‑native control planes while demanding telecom‑grade SLAs, low latency for edge security, and deterministic integration with OSS/BSS. Vendors that bridge cloud agility with carrier‑class reliability will capture share.
-
5G and AI are multiplying attack surfaces — and value: Network slicing, private networks, and AI‑driven network functions introduce both new vulnerabilities and new monetizable security services. The interplay between AI‑enabled network orchestration and AI‑driven security controls is a primary battleground in 2026.
-
Sovereignty, trusted stacks and quantum timelines: Policymakers are actively tightening requirements on vendor trust, data locality, and post‑quantum cryptography. Operators and vendors must plan for compliance pathways that are technology‑agnostic yet defensible in procurement reviews.
-
Persistent adversary activity: Independent threat intelligence indicates that telecom‑targeted campaigns observed in 2025 are persisting into 2026. Operators must prioritize threat hunting, telemetry fusion, and cross‑domain incident response capabilities.
-
Commercial convergence: Telecom providers are packaging security as a differentiator in B2B offers — bundling secure connectivity with managed detection, identity and access services, and security analytics to increase ARPU and stickiness.
Competitive landscape — who matters and why
The market exhibits balanced concentration: the three largest vendors command a meaningful share of market influence while the broader vendor tier provides specialized capabilities and regional strength. This structure creates strategic choice — align with broad‑portfolio incumbents for integrated delivery, or partner with focused specialists for rapid feature differentiation.
-
Cisco Systems — A go‑to provider for operators seeking integrated network security stacks and broad ecosystem interoperability. Cisco’s portfolio remains attractive for service providers that value deep routing and carrier‑grade security integration across RAN, transport, and core domains.
-
Palo Alto Networks — Positioning strongly around AI‑enabled security fabrics and sovereign AI protection frameworks. Recent partnership expansions showcased at industry events underscore a strategy to secure AI factories and operator AI deployments across multiple vendor ecosystems.
-
Fortinet — Focused on high‑performance security appliances and fabric integration. Recent OS releases emphasize AI controls and simplified SASE/SD‑WAN convergence, appealing to operators seeking consolidated management planes and performance at scale.
-
Ericsson & Nokia — As infrastructure incumbents, they embed security into 5G cores, RAN, and management stacks. Their strength lies in deep carrier relationships and turnkey integration for operators modernizing core and edge architectures.
-
Huawei — Continues to offer integrated security across cloud and network fabrics for operators in markets where its solutions remain viable on sovereign and commercial terms.
-
Check Point, Juniper, F5, Trend Micro — These vendors offer differentiated capabilities in perimeter security, high‑performance routing/security convergence, application delivery, and threat intelligence. Their modular approaches are attractive in multivendor operator deployments.
-
Specialists (Allot, P1 Security and others) — Niche vendors focused on telecom protocol security, DDoS mitigation, signaling protections, and attack simulation are critical for operators with advanced threat models and bespoke needs.
Recent market moves — including partnership expansions to protect AI factories, product releases that bake AI controls into security stacks, and independent threat advisories — reinforce that vendor roadmaps and threat trends are converging on AI and regulatory compliance as top priorities for 2026 procurement.
Strategic imperatives for telecom leaders in 2026
-
Adopt a layered, outcomes‑focused architecture: Combine cloud‑native detection with embedded core and RAN protections. Prioritize observability and telemetry fusion for rapid detection and automated remediation.
-
Embed compliance into procurement: Design vendor contracts and architecture choices to anticipate data localization, trusted vendor, and post‑quantum requirements — reducing rework and regulatory risk.
-
Monetize security: Build security bundles into enterprise connectivity and private network offers with clear SLAs and monetizable threat prevention or incident response services.
-
De‑risk supply chains via hybrid sourcing: Combine incumbents for scale and specialist partners for innovation. Use managed service pilots to accelerate time‑to‑value while controlling integration risk.
-
Plan for quantum migration now: Given EU and national targets for quantum‑safe transitions, include cryptographic migration pathways in network transformation roadmaps and vendor evaluations.
How to use our report and next steps
PW Consulting’s Worldwide Security Software in Telecom Market report is designed as an operational playbook for executives who must translate market trends into procurement, architecture, and investment decisions in 2026. The public briefing above highlights the strategic implications and vendor dynamics; the full report contains the granular scenarios, vendor scorecards, implementation checklists, and downloadable modelling spreadsheets that CISOs, CTOs, and strategic investors require.
To preserve the commercial value of our proprietary segmentation and vendor scoring, we have intentionally summarized insights here without publishing detailed regional or solution split figures. Organizations that require the full dataset, decision matrices, and bespoke advisory workshops can access the complete report and supporting deliverables on the PW Consulting website or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Security Software in Telecom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Okra Seeds Market Poised to Grow at 8.15% CAGR Through 2032, Signaling Strong Industry Upswing
By PW Consulting, 2026-08-12
Worldwide Okra Seeds Market: Strategic Imperatives for 2026 — A PW Consulting Brief
PW Consulting today publishes an executive preview of our in-depth Worldwide Okra Seeds Market study (base year 2025, forecast 2026–2032). The global market has demonstrated sustained expansion through the first half of the decade, reaching an estimated USD 382.45 Million in 2025 and tracking a compound annual growth rate of approximately 8.15% into the forecast window. Our forward scenarios show continued momentum, with the market approaching the mid-to-high hundreds of millions of dollars by the end of the 2032 horizon. This briefing highlights the strategic insights in the full report that matter for board-level decisions and investment priorities in 2026 — without disclosing the granular segment tables contained in the paid study.
Worldwide Virtual IT Labs Software Market
Why this report matters for 2026 decision cycles
-
Timing: Seed companies, strategic investors, and institutional buyers are setting budgets and R&D roadmaps now for programs and planting seasons that will scale through 2027–2029. Understanding the macro trajectory and the drivers behind the 8%-plus CAGR is essential to avoid misallocation of capital.
Dual-Detector Gamma Camera Market -
Risk management: Fertilizer and input volatility, labor constraints in high-density producing regions, and accelerating regulatory approvals for new varieties are converging to create both near-term disruption and long-term opportunity. Our study maps these exposures to commercial outcomes.
Worldwide Convertible Jet Pumps Market -
Portfolio prioritization: As the market consolidates around a handful of global and regional champions, companies must choose where to compete (large-scale commercial supply chains vs. smallholder-focused varieties, protected vs. open-field use) — decisions that will lock in returns for multiple seasons.
Market dynamics shaping strategy in 2026
-
Demand and product mix: Hybrid varieties continue to drive productivity gains and adoption among commercial growers, supporting a healthy market expansion. At the same time, renewed varietal releases and public–private breeding programs are improving resilience and market acceptance in emerging production geographies.
-
Consolidation and competitive intensity: The sector displays moderate concentration. Leading multinational seed and agricultural groups command a meaningful share of commercial hybrid pipelines, while a diverse set of regional players fills local niches. M&A, strategic acquisitions, and breeding alliances are accelerating as firms seek scale in R&D and distribution.
-
Input and agronomy pressures: Fertilizer availability and cost, irrigation practices (notably supplemental watering schedules that materially influence yields), and labor constraints — particularly for women smallholders in several producing regions — are structural considerations that influence seed demand profiles and value propositions.
-
Regulatory and public-sector catalysts: Active public breeding programs and variety approvals are shortening commercialization timelines in priority countries. Institutional relaunches and working groups are creating coordinated pipelines of resilient varieties, widening the pool of bankable products for seed companies to commercialize.
Competitive landscape — positioning and strategic moves
The competitive set blends global agricultural leaders, specialized vegetable seed houses, and agile regional players. Below is a synthesized strategic reading of the principal competitors covered in our research.
-
Syngenta Group (Switzerland): Focused R&D in hybrid okra traits such as disease resistance and tropical adaptation positions it well for commercial vegetable production across large-scale value chains.
-
Bayer AG / Nunhems (Germany): Emphasizes quality, early-maturity and virus-resistant varieties; corporate strategy blends global breeding depth with targeted product launches for commercial supply chains.
-
Advanta Seeds / UPL (India): Strong presence in Asia and Africa with a broad hybrid portfolio; growth strategy leverages local adaptation and channel relationships with commercial and smallholder farmers.
-
Sakata Seed Corporation (Japan) & East-West Seed (Thailand): Both specialize in breeding for warm-climate performance and smallholder suitability; their offerings are notable for extended harvest windows and operational simplicity for growers.
-
Large European firms (e.g., Limagrain, Enza Zaden) and established Japanese and Indian companies (Takii, Mahyco, Nuziveedu, Kaveri, and several regional specialists): These firms provide product depth, distribution networks, and ongoing breeding investments that sustain competitive entry barriers.
-
Specialty and heirloom suppliers (e.g., Kitazawa, W. Atlee Burpee): Address the home-garden and niche culinary segments, an increasingly visible revenue stream as consumer interest in specialty produce grows.
Recent strategic events underscore the market momentum: corporate acquisitions that fortify vegetable seed portfolios, public-sector variety releases and program relaunches that broaden resilient trait availability, and commercial product rollouts targeted at key producing countries. These developments collectively accelerate commercialization timelines and shift the competitive salience toward companies that can integrate breeding, supply chain, and go-to-market execution swiftly.
What the PW Consulting report contains — practical modules for action
The full report is structured to be operationally useful for executive teams assessing near-term and medium-term bets. Key deliverables include:
-
Market sizing and forecast models (global and by commercial market archetypes) with sensitives and scenario outputs that can be toggled for alternative yield, price, and adoption assumptions.
-
Concentration and competitive benchmarking with capability heatmaps for breeding, distribution, and on-farm adoption reach.
-
Go-to-market playbooks for product launches: segmentation of buyer archetypes, channel economics, recommended pricing ranges, and sample promotional calendars tailored to planting cycles.
-
Supply chain stress tests and input-risk dashboards that translate fertilizer availability and labor dynamics into margin and volume impacts.
-
Farm-level adoption and ROI calculators designed for extension agents and commercial sales teams to accelerate farmer uptake trials.
-
M&A and partnership frameworks: target screening matrices, valuation comparators, and integration checklists for acquiring breeding assets or distribution footprints.
-
Regulatory and variety-tracker: approvals, public breeding outputs, and key policy levers that will affect commercialization speed in priority markets.
Note: The public preview purposefully omits line-item segment tables, regional share tables, and application-level revenue lines to preserve the report’s commercial data integrity. Those detailed inserts are available to subscribing clients and licensees.
High-level recommendations for 2026 action plans
-
Accelerate trait-led hybrid R&D focused on disease resistance and harvest window extension. Prioritize traits that demonstrably improve mechanization or reduce labor intensity — these attributes yield outsized commercial adoption in constrained labor markets.
-
Pursue targeted inorganic moves (selective acquisitions or minority investments) to secure breeding germplasm and regional seed multiplication capacity rather than broad geographic rollouts that dilute focus.
-
Lock in input supply and mitigate fertilizer cost exposure through strategic procurement partnerships and local production engagement; this reduces margin volatility for seed customers and supports adoption on smaller farms.
-
Deploy dual-channel strategies: maintain large-account commercial offerings for institutional buyers while designing simplified, lower-cost packs and agronomy support for smallholder and peri-urban growers.
-
Partner with public breeding programs and regional research centers to co-develop varieties that meet both yield and resilience goals — these collaborations shorten time-to-market and strengthen social license.
-
Invest in digital extension and distribution pilots that tie seed purchases to bundled advisory services, irrigation scheduling, and input financing to raise per-farmer lifetime value.
How PW Consulting supports your 2026 roadmap
-
Bespoke data subscriptions: full access to the report’s models, downloadable datasets, and periodic updates through 2032.
-
Strategic advisory: M&A due diligence, integration planning, portfolio optimization, and go-to-market activation.
-
Pilot design and field validation: localized adoption trials, ROI studies, and supply chain optimization workshops.
-
Regulatory and stakeholder navigation: support for variety registration strategies and public–private partnership frameworks.
Next steps: For teams shaping budgets, R&D investments, or M&A pipelines in 2026, the comprehensive models and playbooks in our full study will materially shorten decision cycles and reduce execution risk. The PW Consulting report brings together commercial intelligence, agronomic realities, and strategic playbooks so leadership teams can convert the favorable market tailwinds into sustained, defensible value.
We intentionally present a high-level strategic narrative in this preview. For full access to the segment-level data, regional breakouts, and downloadable financial models that underpin our recommendations, please contact PW Consulting to license the report or schedule a briefing with our industry practice leads.
For detailed analysis of this topic, please visit the official page: Worldwide Okra Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Engine Oil Additives Market Poised to Expand at a 3.21% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Automotive Engine Oil Additives Market: Strategic Outlook for 2026 — PW Consulting Preview
As PW Consulting publishes its latest market research on the Worldwide Automotive Engine Oil Additives market, this briefing synthesizes the strategic implications senior executives must weigh as they plan for 2026. Our full report provides granular, transaction-ready intelligence; the following preview highlights the high‑impact signals we expect to reshape supplier economics, product portfolios, and go‑to‑market plays without disclosing the proprietary segment-level datasets reserved for report subscribers.
Worldwide 5G Antennas Market
Market snapshot: measured expansion with structural pressures
After a period of steady recovery through the early 2020s, the global engine oil additives market is projected to continue expanding at a moderate compound annual growth rate (CAGR) of approximately 3.21% through the 2026–2032 forecast window. On an aggregate basis, the market crosses an important threshold in our base-year view, reflecting both the tailwinds from stricter performance and emissions standards and headwinds from raw material cost shocks and volatile base oil markets.
Worldwide Appraisal Service Market
PW Consulting’s model—built on bottom‑up SKU-level demand, OEM licencing calendars, and validated downstream blending activity—shows that market momentum entering 2026 is real but nuanced: growth is sustained, yet increasingly conditioned by regulation, vehicle fleet composition, and concentrated supplier dynamics that amplify both opportunity and risk.
Radio Tower Market
Why this matters for 2026 decision-makers
-
Standards-driven product re‑engineering is now mission‑critical. ILSAC GF‑7’s licensing and the simultaneous introduction of API SQ have created a multi‑track technical roadmap for passenger car and ultra‑low viscosity engine oils. Suppliers that can accelerate formulation platforms to meet fuel‑efficiency, low‑speed pre‑ignition (LSPI) mitigation, and piston cleanliness targets will win OEM and marketer share in 2026.
-
Price volatility in 2026 has changed commercial calculus. Early‑year base oil and additive cost increases—material suppliers publicly signalled finished‑goods price pressure in the mid‑teens percent range—mean margin management and purchasing strategy (including hedging and supplier diversification) will be board‑level priorities.
-
The market structure favors scale and technical breadth. With the top three suppliers accounting for a dominant portion of global revenue and the top five controlling an even larger share, the competitive environment rewards integrated technology providers and penalizes fragmented, low‑margin operators.
Competitive landscape: leaders, challengers, and what to watch in 2026
The industry’s competitive map is intentionally concentrated. PW Consulting’s competitive assessment confirms that global majors—companies with established additive platforms, OEM approvals, and broad IP portfolios—remain advantaged. These players combine formulation expertise (dispersants, VIIs, anti‑wear systems), recognized OEM relationships, and global manufacturing footprints that allow them to meet both performance and compliance timelines.
-
The Lubrizol Corporation: Renowned for additive packages aligned to passenger car and heavy‑duty diesel needs, Lubrizol’s recent rollouts targeting ILSAC GF‑7 compliance underscore its go‑to‑market agility. Expect continued pressure from Lubrizol on rapid formulation updates and customer trials in 2026.
-
Infineum: Backed by major oil‑company parents, Infineum’s focus on fuel efficiency and LSPI mitigation positions it well for GF‑7-era collaborations with OEMs and formulators seeking validated solutions for ultra‑low viscosity grades.
-
Afton Chemical and Chevron Oronite: Both firms balance broad product portfolios with deep OEM approval channels. Their strengths lie in translating regulatory requirements into scalable additive packages and securing approval timelines that matter to global oil marketers.
-
BASF, Evonik, LANXESS, Croda and Vanderbilt: These specialty chemical houses supply critical building blocks—antioxidants, viscosity index improvers, friction modifiers—creating a two‑tier dynamic where formulators purchase both complete packages and component technologies from multiple sources.
-
Regional producers and Chinese incumbents: Domestic manufacturers are growing relevance in certain markets through competitive pricing and localized supply chains, but they face a technology gap on new‑generation performance chemistries unless partnerships or licensing accelerate in 2026.
What this means: incumbency and technology ownership will remain the single biggest moat. However, nimble niche players can carve out durable positions by specializing in bio‑based additives, friction modifiers, or custom formulations for emerging fleet segments.
Regulatory timeline and operating risks
Regulatory updates are the dominant demand shaper for 2026. The ILSAC GF‑7 transition and API’s parallel category (API SQ) create an overlapping implementation timeline that extends into late 2026. PW Consulting’s regulatory matrix shows that the phased overlap was deliberately extended to provide the supply chain breathing room, but it also creates a strategic choice for additive suppliers: accelerate costly re‑formulation investment now for early adopter advantage, or stagger capital deployment and accept first‑mover disadvantages in select markets.
Other operating risks include geopolitical-driven raw material disruptions that have already pushed input costs materially higher. Suppliers and buyers who fail to lock in supply or establish cost‑pass‑through mechanisms will face margin erosion in 2026.
Practical report deliverables that inform 2026 execution
PW Consulting’s comprehensive market study offers a suite of practical tools and outputs for commercial, product, and corporate strategy teams:
-
Proprietary market sizing and forecast model (2026–2032) with scenario toggles for regulation, price shocks, and EV penetration.
-
Supplier benchmarking (technology, certifications, capacity, channel coverage) and a stratified supplier risk heatmap for procurement planning.
-
Regulatory implementation calendar mapped to product development lead times and OEM approval windows—actionable for R&D prioritization.
-
Price‑sensitivity and margin impact analysis tied to raw material movements and manufacturer pass‑through elasticity assumptions.
-
M&A and partnership scorecards identifying target profiles where scale, technology, or regional footprint would create immediate strategic leverage.
-
Playbooks for oil marketers and additive formulators covering launch sequencing, co‑marketing with OEMs, and sample‑to‑approval timelines by jurisdiction.
Note: The preview intentionally omits the full, segmented revenue tables by region, additive type, and vehicle application. These segment‑level numbers and the supporting transaction datasets are available exclusively in the full PW Consulting report.
Strategic recommendations for calendar‑year 2026
-
Make GF‑7 readiness a prioritized, cross‑functional program. R&D, regulatory affairs, and key account teams should collaborate on a six‑to‑nine‑month acceleration plan for API/ILSAC validation trials and customer pilots.
-
Institute dynamic purchasing and pricing strategies. Given recent base oil and additive price upticks, implement hedging, multi‑sourcing, and index‑linked pricing clauses to protect margins while remaining competitive.
-
Target OEM and leading oil marketers with proof‑point packs. Companies that can demonstrate LSPI mitigation, fuel‑economy gains, and piston cleanliness through independent labs will secure early adoption and sticky approvals.
-
Evaluate scale through partnerships. For mid‑sized specialty producers, strategic alliances or minority investments with technology leaders can fast‑track access to GF‑7 IP while avoiding large upfront capex.
-
Prepare operational contingency plans for supply disruption. Scenario playbooks addressing logistics constraints and alternative sourcing in the Middle East and Asia are essential.
Concluding perspective: choices and trade‑offs
2026 will be a year of accelerated technical change and commercial recalibration for the engine oil additives sector. The aggregate market outlook shows continued growth at a modest pace; yet, within that growth lie divergent outcomes determined by technology leadership, supply‑chain resilience, and regulatory alignment. Firms that move early to align formulation roadmaps with GF‑7/API SQ, that actively de‑risk inputs, and that deploy targeted commercial plays with OEMs and oil marketers will consolidate advantage.
PW Consulting’s full report converts these strategic imperatives into executable plans, complete with proprietary segment breakouts, supplier scorecards, and financial scenarios. For companies deciding their 2026 capital, R&D and commercial priorities, the report is designed to shorten decision cycles and reduce execution risk.
How to access the full intelligence
This preview is intended to orient senior leaders and shape 2026 planning conversations. To obtain the full Worldwide Automotive Engine Oil Additives Market report—including the segmented revenue tables, company‑level financial proxies, and the downloadable forecast model—please visit our official report page or contact PW Consulting’s industry practice.
PW Consulting will also be hosting a closed‑door webinar in early Q3 2026 to walk clients through model scenarios and bespoke implications for procurement and R&D roadmaps. Contact your client service representative to request an invitation.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Semiconductor Magnetic Sensor Market to Surge from USD 3,280 Million in 2025 to USD 5,995.97 Million by 2032 on a 9.0% CAGR
By PW Consulting, 2026-08-12
Worldwide Semiconductor Magnetic Sensor Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Semiconductor Magnetic Sensor Market synthesizes five years of historical performance (2020–2025) and a seven-year forecast (2026–2032) into an actionable strategic playbook for executives, product leaders, and investors. The industry enters 2026 from a position of renewed momentum: the market reached approximately USD 3,280 Million (base year 2025) and our bottom-up modeling projects a compound annual growth rate (CAGR) of roughly 9.0% through 2032, with the market approaching a near-doubling by the end of the forecast horizon. This briefing highlights the report’s strategic value without disclosing the proprietary granular splits — a deliberate “trailer” designed to show depth while directing readers to the full report for the detailed intelligence required for transaction-level decisions.
Worldwide Dimethyl Phosphite Market
Why this market matters in 2026
-
Critical enabling role: Magnetic sensors underpin a broad set of high-growth systems — from electrified powertrains and wide‑bandgap power conversion to advanced position, current and angle sensing in industrial automation and consumer devices. Their performance characteristics (bandwidth, sensitivity, size, power) are increasingly determinative of system-level outcomes.
Worldwide Search Engine Marketing (SEM) Tools Market -
Compelling macro momentum: After steady expansion through 2025, our forecasts show sustained double-digit tailwinds in select end-markets and accelerating adoption of high-performance technologies that support higher price realization and value-additive system integration.
Worldwide Retail Task Management Software Market -
Concentration and competitive dynamics: The market exhibits meaningful concentration at the top, creating a strategic calculus for mid‑market suppliers and OEMs contemplating vertical integration, exclusive supply contracts, or targeted M&A to secure capability or capacity.
What the report delivers — practical, transaction-ready outputs
-
Proprietary market sizing model calibrated to 2020–2025 historicals and validated by primary interviews with OEMs, tier‑1 suppliers, foundries and materials providers. The model supports ad-hoc scenario runs for pricing, volume shifts, and technology substitution.
-
Scenario-based forecasts (2026–2032) across demand shock, supply-constrained, and technology-adoption pathways to quantify revenue and margin sensitivities for strategic planning and valuation work.
-
Go‑to‑market playbooks for product managers and BD teams, detailing channel strategies, value-based pricing approaches, and use-case prioritization that materially shorten time-to-revenue for new sensor platforms.
-
Supplier & material risk scorecards that translate geopolitical, regulatory, and rare-earth exposure into quantifiable procurement stress metrics and recommended mitigation actions.
-
Comprehensive competitive benchmark and capability atlas mapping IP, manufacturing footprints, product families and adjacent solutions — designed to support M&A target screening, JV structuring, and licensing negotiations.
Key market signals shaping 2026 strategies
-
Technology premiumization: Adoption is shifting toward higher-performance magnetoresistive technologies and integrated multi-axis solutions that command price premiums and create differentiation opportunities for suppliers able to deliver system-grade references and supplier guarantee metrics.
-
System integration as strategic battleground: OEMs increasingly prize sensor suppliers that provide reference designs, certification-ready modules, and supply assurances — not just die-level components. This favors companies with cross-domain IP (sensor + analog front-end + system calibration).
-
Margin polarization: Cost deflation in adjacent subsystems (e.g., battery pack price declines) and rising value derived from electrification and automation are compressing margins on commodity sensors while expanding margins on high-speed, high-bandwidth and safety-critical solutions.
-
Geopolitical and raw material friction: Recent trade and export policy moves — and concentrated global processing capacity for certain rare earths — materially raise the probability of mid-cycle supply shocks. These dynamics necessitate active hedging, dual-sourcing, and material substitution strategies.
Supply chain and regulatory watch-list
-
Export controls and tariffs: Recent policy measures affecting semiconductor and related materials create new import/export complexity for multi-national supply chains. Companies should reassess sourcing clauses and contract language to reflect adjusted lead times, customs duties, and licensing requirements.
-
Concentration of critical processing: A high share of refined heavy rare earth processing remains geographically concentrated. For product lines that rely on high‑performance magnets or specialized alloys, procurement teams should quantify single‑point dependencies and develop decoupling options.
-
Commercial levers to mitigate risk: Stockpiling strategic components is costly; alternatives include design-for-substitutability, long-term offtake agreements with upstream refiners, and co-investment in alternate processing capacity.
Competitive landscape: how incumbent and emerging players are positioning
The competitive topology is a mix of specialized sensor houses, diversified semiconductor groups, and niche foundries that enable differentiated materials or integration approaches. The top-tier demonstrates both product breadth and deep application expertise, while mid-tier players are exploiting adjacent strengths and targeted innovations.
-
Specialist sensor manufacturers are deploying aggressive product roadmaps that combine advanced TMR/GMR technologies with application-specific analog front-ends and software calibration ecosystems. Their advantage is rapid time-to-market for higher-value use cases and tight OEM relationships.
-
Diversified semiconductor groups leverage scale, cross-divisional design capabilities, and global distribution to bundle magnetic sensing into multi-sensor portfolios for automotive and industrial customers, often providing certified reference designs and supply guarantees.
-
Foundry and materials partners that provide specialized process nodes (e.g., high-temperature GaN-compatible processes, TMR integration with CMOS) are emerging as strategic partners for performance-sensitive customers where in-house fabs are uneconomic.
To illustrate how strategy maps to players (without divulging proprietary rankings), the full report contains detailed company profiles and capability matrices for the leading participants in this sector — covering product architectures, commercial go‑to‑market motions, recent launches, and likely next moves. Recent public activity shows continued product innovation: new ultra‑low‑power 3-axis industrial designs, compact TMR angle sensors optimized for safety, and the first commercial 10 MHz TMR current sensors tailored to wide‑bandgap power electronics. These moves reflect a clear uptick in engineering investment toward higher-frequency, higher-accuracy, and systemized sensor solutions.
Implications for strategic choices in 2026
-
Product roadmap prioritization: If your portfolio includes commodity Hall-effect sensors, 2026 is the year to decide whether to move up‑market into magnetoresistive variants and integrated modules — or to double down on cost leadership with ultra‑low‑cost, high-volume manufacturing strategies.
-
M&A and partnership timing: With top‑tier concentration creating barriers to entry in certain subsegments, mid-size players should evaluate bolt-on acquisitions that add materials, foundry access, or software calibration stacks rather than pursuing organic scale exclusively.
-
Supply-chain restructuring: Design teams must incorporate alternative magnet and rare-earth sourcing into product specifications, and procurement should lock in multi-year agreements for vulnerable components. Consider co-investment vehicles with upstream suppliers to secure capacity and preferential pricing.
-
Commercial contracts and risk allocation: Revisit contractual risk allocation (force majeure, tariffs, export licensing) in new supplier agreements to reflect the elevated regulatory tail‑risk environment.
Who should read the full report
-
CEOs and corporate strategy teams evaluating M&A or vertical integration opportunities in sensors and power electronics.
-
Product and engineering leaders planning 3–5 year roadmaps that must reconcile performance requirements with realistic supply scenarios.
-
Procurement and supply-chain executives seeking prioritized mitigation actions and supplier scorecards tied to material risk exposure.
-
Investment professionals and corporate development teams requiring rigorous, auditable forecasts and scenario outputs to underwrite transactions.
Methodology snapshot and transparency
PW Consulting’s market model integrates bottom‑up bill-of-materials (BOM) analysis, aggregated shipment data, primary interviews, and public company disclosures reconciled to historical revenue. The base year is 2025 and the forecast window is 2026–2032. Our sensitivity suite allows users to re-run the forecast under alternative assumptions for technology substitution rates, material-cost pass-through, and end-market elasticity.
Next steps — how to act on this preview
-
Download the full report to obtain the granular segmentation, supplier rankings, and downloadable forecast model that support transaction diligence and product-strategy decisions.
-
Schedule a PW Consulting workshop to stress-test your 2026 product roadmap or M&A thesis using our scenario engine and supplier risk dashboards.
-
Engage our advisory team for a bespoke supplier risk audit or to develop a strategic sourcing playbook aligned with anticipated regulatory shifts and rare-earth supply volatility.
PW Consulting’s study provides the market-sizing, competitive intelligence, and pragmatic playbooks that senior teams need to make confident, time-sensitive decisions in 2026. The market’s trajectory is clear: sustained growth with differentiated value pools emerging for high-performance, system-oriented magnetic sensing solutions. For the granular segmentation and transaction-grade tables that underpin the strategic recommendations above, please consult the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Achondrogenesis Market to Grow at a 5.59% CAGR, Reaching USD 226.75 Million by 2032 (From USD 155.0 Million in 2025)
By PW Consulting, 2026-08-12
Worldwide Achondrogenesis Market: Strategic Imperatives for 2026 Decision-Makers
As health systems, diagnostic providers, biotechs, and specialty investors prepare plans for 2026, PW Consulting’s new Worldwide Achondrogenesis Market report offers a focused, pragmatic compass for navigating one of the most technically demanding and clinically sensitive rare-disease segments. Grounded in an updated market model with a 2025 base year and a six-year forecast horizon (2026–2032), the study synthesizes historical trends (2020–2025), scenario-driven forecasts and practical decision tools that leaders need to accelerate time-to-impact while managing commercialization risk.
Industrial Flash Memory Chip Market
Why this report matters for 2026 planning
Achondrogenesis is a low-incidence, high-need condition where every diagnostic and therapeutic decision has outsized clinical and economic consequences. Our analysis shows the global market value moving from USD 155.0 Million in 2025 to an estimated USD 226.75 Million by 2032, with an aggregate compound annual growth rate of 5.59% across the forecast window. The path between these anchor points is non-linear—reflecting episodic inflections from technology adoption, regulatory milestones and evolving care pathways—which makes tactical annual planning (not just extrapolation) essential for stakeholders aiming to optimize investment and operating choices in 2026.
Atomic Energy Batteries Market
Key market dynamics shaping near-term strategy
- Technology-driven detection gains: Continued advances in genomics, sequence interpretation and imaging integration are shortening diagnostic timelines. For organizations that can operationalize next-generation testing and post-analytic decision support, there is an opportunity to capture incremental diagnostic volume and to become preferred referral partners.
- Payor and reimbursement evolution: Reimbursement remains a gating factor. Our interviews and payment-mapping exercises indicate growing, but uneven, recognition of the value of early, definitive diagnosis—especially where it reduces downstream invasive procedures or inappropriate interventions. Strategic engagement with payors in 2026 will be decisive for uptake.
- Clinical pathway consolidation: Centers of excellence and academic networks are consolidating expertise, creating referral clusters and standardized protocols. Companies able to align with these networks—through clinical evidence, service-level agreements, or integrated diagnostics—will accelerate market penetration.
- Data and privacy constraints: The requirement for rare-disease registries and cross-jurisdictional data sharing is increasing. Organizations must balance data utility with compliance—investing early in governance frameworks will reduce time-to-launch risks for multisite initiatives.
- Concentration and competitive positioning: The market exhibits a mid-level concentration: the top three players account for a meaningful share of market revenues, while the top five capture just over half. This structure creates room for focused entrants and clinical innovators to carve sustainable niches if they apply clear differentiation and execution discipline.
What the report delivers — practical, execution-oriented content
We designed this report to be a working toolkit for executives, not just a descriptive monograph. Users receive:
Worldwide Manufacturing Intelligence Software Market
- Robust market model: An editable Excel model calibrated to historical activity (2020–2025) and populated with scenario branches for 2026–2032. The model supports sensitivity testing on key levers—diagnostic adoption rates, price points, reimbursement scenarios and referral routing—to generate bespoke forecasts for board-level decisions.
- Decision matrices and go-to-market plays: Field-tested playbooks that link product profiles to optimal commercialization paths (direct hospital partnerships, diagnostic lab networks, reference-center collaborations). Each play includes revenue levers, time-to-adoption estimates and implementation roadmaps tailored for 12–36 month horizons.
- Regulatory and reimbursement playbook: A practical checklist of filing pathways, evidence thresholds and payer engagement sequences with templates for economic dossier construction and real-world evidence strategies specific to prenatal and neonatal diagnostic contexts.
- Stakeholder maps and patient-journey analytics: Detailed maps of the referral and decision nodes that drive diagnostic utilization, with recommended interventions to reduce diagnostic delay and to increase appropriate test ordering among frontline clinicians.
- Risk-adjusted investment cases: Three archetypal investment models—conservative, base, aggressive—each projecting cash-flow timing, break-even horizons and upside triggers for investors and corporate development teams.
- Implementation checklists: Operational due-diligence templates for laboratory scale-up, quality systems, supply chain resilience and clinical trial site selection geared to rare-disease contexts.
Competitive landscape — strategic implications without divulging proprietary splits
Rather than replicate company-by-company revenue tables here, the report synthesizes competitive positioning across capability vectors—diagnostic breadth, clinical partnerships, service delivery, and evidence generation. The market’s concentration metrics indicate a competitive dynamics where the largest players drive volume and standard-setting, but where a credible technical differentiation or a compelling partnership can quickly change the playing field.
- Incumbent advantages: Scale players benefit from established network effects, validated lab processes and existing reimbursement relationships—advantages that compound in early-adopter markets.
- Mid-market opportunity zones: Mid-sized diagnostic innovators and academic spin-outs can capture share by specializing in integrated offerings (e.g., bundled genomic testing plus counseling) and by pursuing regional centers of excellence.
- Disruptor entry paths: New entrants should prioritize clinical evidence and operational reliability over broad geographic coverage. Focused clinical pilots that demonstrate utility and economic benefits are the fastest route to payer acceptance.
Scenario planning: seven plausible 2026 inflection scenarios
The report includes mapped scenarios that translate macro drivers into operational choices for 2026. Examples include:
- Accelerated-tech adoption: Rapid clinical acceptance of combined genomic-imaging protocols—favours diagnostic-first strategies and investments in high-throughput interpretation platforms.
- Reimbursement tightening: Conservative payor behavior shifts testing economics—favours bundled service offerings and risk-sharing agreements with payors and hospitals.
- Registry-enabled discoveries: International registry data yields new genotype-phenotype correlations, opening pathways for targeted therapeutic research collaboration.
Each scenario is coupled with tactical checklists—what to do in months 0–6, 6–18 and 18–36—enabling leaders to move from strategic intent to executable steps quickly.
How to use the report for 2026 decision cycles
- Portfolio prioritization: Use the scenario-adjusted financial model to re-score pipeline and diagnostic investment opportunities—identify which assets should be accelerated, which require de-risking, and which to shelve.
- Clinical partnership strategy: Map and prioritize center-of-excellence partnerships using our diagnostic referral and volume forecasts to maximize early patient identification and generate real-world evidence streams.
- M&A and partnering diligence: Employ the report’s valuation sensitivity tables and operational due-diligence checklists to test acquisition targets and alliance partners under multiple adoption and reimbursement outcomes.
- Regulatory timing and evidence sequencing: Follow the stepwise evidence plan to align regulatory filings, payer submissions and clinical publications—optimizing the sequencing to unlock revenue faster.
What we are intentionally withholding here — and why
True to the “trailer” principle, this public summary demonstrates the analytical depth and practical utility of the study while deliberately withholding core segmented figures and granular revenue splits. Those detailed data — including breakouts by geography, modality and end-user revenue — are included in the full report and interactive model only. This approach protects the immediacy and operational value of the report for subscribers and paying clients who require actionable, granular line-item analyses for investment and operational decisions.
Clients who will extract the most value
- Biotech and diagnostic companies developing next-generation prenatal and neonatal tests.
- Hospital systems and reference labs planning to expand rare-disease diagnostic services.
- Investors and corporate development teams evaluating targeted M&A or strategic partnerships.
- Policy-makers, payors and patient advocacy groups interested in optimizing care pathways for rare skeletal dysplasias.
Next steps and how to access the toolkit
For executive teams finalizing 2026 budgets and strategic plans, the PW Consulting Worldwide Achondrogenesis Market report functions as both a decision-accelerator and a governance resource. The full publication includes the downloadable market model (USD, revenue unit: Million), detailed segmentation, competitor landscaping, regulatory timelines and bespoke recommendation sets tailored to different stakeholder types.
Contact PW Consulting to arrange a walk-through of the model, obtain customized scenario outputs, or commission a rapid deep-dive tailored to your asset or market entry plan. For teams that need to move quickly: our 90-day implementation sprint combines the report outputs with hands-on advisory support to embed the findings into commercial and clinical launch plans.
In an environment where each diagnostic decision reshapes patient trajectories and commercial outcomes, robust, executable market intelligence isn’t optional—it’s mission-critical. PW Consulting’s report equips leaders with the insight and tools to turn 2026 uncertainty into strategic advantage while preserving the proprietary, high-value data that underpin confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Achondrogenesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


