



Category: market research
PW Consulting: Worldwide Sapphire Powder Market Set for 7.25% CAGR Through 2032, Bolstered by Rising High‑Purity Demand
By PW Consulting, 2026-08-12
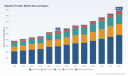
Worldwide Sapphire Powder Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest Worldwide Sapphire Powder Market report synthesizes five years of historical performance, live industry developments through early 2026, and a robust forecast model spanning 2026–2032 to equip executives with decision-ready insight. The global market for sapphire powder expanded from USD 384.07 Million in 2020 to USD 545.0 Million in 2025. Our base-case projection sees continued momentum through the forecast window, with market value rising to USD 889.56 Million by 2032 at a compound annual growth rate (CAGR) of 7.25% for 2026–2032. For 2026, that trajectory creates both time-sensitive opportunities and structural risks: the window to secure differentiated feedstock, lock in offtake arrangements, or capture margin through process innovation is narrow.
Worldwide Liquid Optically Clear Adhesive (LOCA) Market
Why this market matters for 2026 strategy
-
Deep tech dependence. Sapphire powders—particularly high- and ultra-high-purity alumina grades—are foundational inputs for advanced optics, LED substrates, precision abrasives, and semiconductor-related components. Their technical specifications (phase purity, low alpha emissions, particle morphology) materially influence yield, defect rates, and downstream process economics.
Worldwide Audio Engine Software Market -
Demand pattern acceleration. The market’s steady historical rise into 2025 and the projected 7.25% CAGR reflect an intensifying demand mix driven by higher ASPs for specialty grades, new display and sensing form factors, and growing adoption of sapphire in niche semiconductor and optical applications.
Worldwide Bone Marrow Aspiration Device Market -
Concentration and bargaining power. The sector exhibits meaningful concentration among a handful of specialized vendors and integrated crystal growers; this creates a supplier landscape in which strategic partnerships, early qualification cycles, and dual-sourcing strategies determine competitive advantage.
-
Cost & sustainability pressure. Upstream alumina production pathways remain energy intensive—contributing to price volatility and ESG scrutiny—while emerging low-carbon production methods are beginning to shift commercial negotiations and procurement priorities.
Supply-side dynamics to watch in 2026
-
Process innovation as a competitive moat. Proprietary solvent extraction and specialized Bayer enhancements differentiate product purity and emissions intensity. Recent disclosures indicate some newer processes can cut emissions substantially versus conventional routes—an outcome that is already influencing buyer preferences in carbon-constrained value chains.
-
Price signaling and specialized-grade premiums. For ultra-high-purity alpha-phase materials used in sapphire production and critical ceramics, pricing evidence suggests a wide range across grades and forms—reflecting both purity and form-factor premiums. Procurement teams must prepare for grade-sensitive price volatility and structure contracts that protect margin without forfeiting supply security.
-
Regulatory and qualification headwinds. Ultra-low alpha-emission specifications are becoming non-negotiable in select semiconductor and radiation-sensitive ceramic applications. Manufacturers that can certify sub-ppb-level contamination and provide traceable lot histories will capture a persistent technical premium.
-
Feedstock energy constraints. Upstream feedstock routes have sizeable energy footprints; this creates a second-order risk profile where energy cost shifts, decarbonization policies, or supply interruptions can cascade to finished-powder availability and pricing.
Competitive landscape — practical read on market incumbents
-
Polar Performance Materials (formerly Polar Sapphire) — Strength: established technical pedigree in high-purity alumina powders and a product portfolio aligned to consistent, defect-free crystal growth. Strategic implication: incumbents with vertically integrated feedstock-to-crystal capabilities will be focal partners for OEMs seeking single-lot traceability and tight process control.
-
Alpha HPA Ltd — Strength: proprietary low-carbon solvent-extraction routes and an explicit push into ultra-high-purity, low-alpha products. Recent corporate activity through early 2026 (including governmental equity support and upgraded letters of intent from major semiconductor customers, plus commissioning of dispersion manufacturing for CMP slurries) signals rapid scale-up and downstream market capture. Strategic implication: companies that can validate volume, consistency, and regulatory compliance with Alpha HPA’s product set may secure advantaged access to next-generation sapphire feedstock.
-
AdValue Technology LLC — Strength: established supply of high-purity alumina via process enhancements to the conventional Bayer route. Strategic implication: suppliers leveraging well-understood process economics can compete on reliability and price for non-niche grades while selectively moving upstream in the value chain.
-
Juropol / POLYCOR (Poland) — Strength: integrated sapphire crystal growers producing ultra-pure feedstock via patented refining for LED and semiconductor applications. Strategic implication: integrated growers that control feedstock refinement and crystal growth will command choice customers that prioritize quality over lowest-cost sourcing.
-
Goodfellow Corporation — Strength: global distribution and specialty-market reach. Strategic implication: distributors remain essential to R&D and prototyping cycles, shortening qualification timelines for newcomers and enabling geographically dispersed sourcing strategies.
What we recommend organizations prioritize in 2026
-
Procurement: Move from spot buying to strategic offtakes. Cultivate multi-year agreements with technical windows tied to qualification milestones; include clauses addressing purity, lot traceability, and ESG benchmarks to de-risk downstream manufacturing.
-
R&D & Quality: Invest in qualification cycles now. The lead time to qualify ultra-high-purity powders into semiconductor and optical production streams is measured in quarters, not months. Begin co-development pilots to secure first-mover yield advantages in 2027–2028.
-
Supply risk management: Create modular sourcing playbooks. Use a mix of global suppliers, regional capacity, and distributor-backed trial volumes to balance price and continuity—prioritizing suppliers with demonstrated contamination control and lot-level data.
-
Capital deployment: Target process-enabled scale and carbon-efficient routes. For investors and materials companies considering capex, favor technologies and plants that can both reduce energy intensity and support the product grades commanding the highest technical premiums.
-
M&A & partnerships: Pursue bolt-on capabilities focused on purification, shaping (sintering/tableting), and traceable supply chains. The market’s concentrated nature means well-timed, targeted acquisitions can shift negotiating leverage quickly.
What PW Consulting’s report provides (actionable components)
-
Scenario-based demand models and pricing decks covering 2026–2032, stress-tested for energy and regulatory shocks.
-
Supplier scorecards that evaluate purity credentials, qualification readiness, commercial scale, ESG performance, and go-to-market alignment.
-
Procurement playbooks and sample contract language tailored for offtake, tolling, and joint development agreements.
-
CapEx decision frameworks and ROI models for new production routes, including sensitivity runs on energy costs, carbon pricing, and yield differentials.
-
Risk matrix and early-warning indicators—covering feedstock disruptions, regulatory tightening on radiological contaminants, and concentrated buyer behavior—to guide board-level monitoring.
-
M&A playbook with target archetypes, valuation filters, and integration checklists to extract synergies quickly while preserving product quality.
How different stakeholders should use this intelligence in 2026
-
OEMs (optics, LED, semiconductor equipment): Prioritize supplier qualification and insist on lot traceability tied to contamination analytics. Early co-development can lock favorable pricing and preferred access to ultra-high-purity grades.
-
Materials producers: Accelerate decarbonization of processing routes and formalize product families with certified low-alpha and traceable supply documentation to capture the technical premium.
-
Investors & private equity: Seek high-entry-barrier assets (patented purification, integrated crystal growth) and stress-test capex plans against energy-linked operating scenarios and regulatory compliance costs.
-
Policymakers & industrial strategy teams: Understand the strategic import of domestic feedstock and purification capacity; targeted investment or offtake guarantees can accelerate local manufacturing competitiveness.
PW Consulting’s report is built to be a decision catalyst for 2026. We deliberately balance public-facing synthesis with proprietary, commercial-grade data and supplier-level granularity that materially alters strategic outcomes. This article previews the analysis—key trajectories, structural dynamics, and recommended actions—while preserving the segmentation tables, supplier financials, and contract templates that form the report’s actionable core.
For access to the full dataset, regional and application segmentation breakdowns, supplier scorecards, and downloadable decision tools referenced here, please visit our report landing page. PW Consulting’s advisory team stands ready to support bespoke scenario modeling, supplier diligence, and transaction execution to translate insight into measurable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Sapphire Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Heated Wiper Fluid Market Poised to Reach USD 299.01 Million by 2032, Driven by a 6.5% CAGR (2026–2032)
By PW Consulting, 2026-08-12
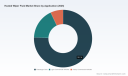
Worldwide Heated Wiper Fluid Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's latest market study on the Worldwide Heated Wiper Fluid Market positions industry leaders and investors to make high-consequence 2026 decisions with clarity and confidence. The total market has expanded steadily — from roughly USD 142 million in 2020 to an estimated USD 192.4 million in 2025 — and our forecast baseline applies a 6.5% CAGR across the 2026–2032 window, guiding a trajectory that reaches approximately USD 299 million by 2032. Those headline dynamics hide a set of tactical inflection points that will determine winners and losers in the next 18–36 months.
Flat-Bottomed Fiberglass Rubber Boat Market
Why 2026 Is an Inflection Point
-
Consolidation and scale: Market concentration is meaningful — the top three players control a substantial share while the top five extend that control materially. This creates a dual posture for incumbents: defend margin through integration, or expand through adjacent services and aftermarket penetration.
Implantable Dosing System Market -
Product-technology crossroads: Heated fluid systems are rapidly evolving beyond simple inline heaters to integrated blade- and nozzle-based solutions, and OEM interest in packaged cold-weather systems is accelerating product portfolios and OEM-aftermarket interplay.
Worldwide Screening Equipment Market -
Component and materials stress: PTC heating element supply competes directly with other automotive thermal markets (EV battery thermal management, seat heaters), while formulations still rely on low-freezing agents such as methanol that carry toxicity, flammability and reclamation liabilities.
-
Regulatory and safety overhangs: Historical safety incidents and current rule-making debates mean regulatory scrutiny and compliance costs are front-of-mind. Product safety design and regulatory preparedness will be decisive in 2026 procurement cycles.
What PW Consulting’s Report Delivers — Practical, Decision-Ready Intelligence
-
Robust market sizing and forecasting model: A transparent, bottom-up Excel model covering 2020–2032 with scenario toggles for adoption rates, pricing trajectories and raw-material shocks — built to be integrated into corporate planning systems.
-
Scenario analysis and stress testing: Three investment-grade scenarios (base, accelerated-adoption, and constrained-adoption) show how changes in regulation, OEM optional-package adoption, and supply-chain disruption materially alter revenue and margin outcomes.
-
Supplier and component heat maps: Practical maps that identify single points of failure in PTC supply, formulation raw-material concentration, and critical subcomponent lead-times — with supplier risk scores and mitigation playbooks.
-
Commercial and product playbooks: Tailored go-to-market strategies for OEM suppliers, aftermarket distributors and chemical formulators including channel positioning, bundling strategies, warranty and servicing models for heated systems.
-
Regulatory & safety dossier: Actionable guidance on compliance paths, test protocols, and design-for-safety changes designed to reduce recall risk and insurance exposure.
-
M&A and partnership prioritization: A ranked set of acquisition and strategic partnership targets by capability gap, speed-to-market, and integration risk to accelerate scale or plug technical gaps.
Note: to preserve competitive integrity and encourage direct engagement, this briefing intentionally omits detailed segment-level datapoints (regional, type and application splits). The full dataset, with downloadable tables and the complete segmentation matrix, is available on the report landing page.
Competitive Landscape — Profiles and Tactical Implications
-
Valeo S.A. (France) — Valeo’s AquaBlade heated wiper blade systems demonstrate how OEM-caliber integrated solutions can reshape customer expectations. Their move into aftermarket availability for heated blades signals a strategy to capture both OEM specification margins and recurring aftermarket revenue. For competitors, Valeo’s play highlights the value of end-to-end system integration and multi-channel distribution.
-
Recochem Inc. (Canada) — As a global fluids manufacturer with temperature-protection formulations, Recochem is positioned to benefit from any shift toward chemistry-led differentiation. Chemical formulators should prioritize low-toxicity, low-flammability winter blends to align with tightening handling and waste regulations.
-
CCI Corporation (Genuine Chemistry) (Japan) — Serving OEMs across mobility segments, CCI demonstrates the strategic value of being a trusted supplier to vehicle manufacturers. Visibility into OEM platforms and early-stage co-development can convert into long-term supply contracts and specification leadership.
-
SPLASH Products Inc. (Factory Motor Parts) and Old World Industries (OWI) (United States) — These aftermarket-focused manufacturers underscore the large and serviceable aftermarket opportunity. Speed-to-shelf, manufacturing footprint, and distribution partnerships determine who captures retrofit and seasonal demand.
-
Kautex Textron and Denso Corporation — As fluid management and thermal-systems specialists, these Tier-1 players are natural partners for OEMs seeking integrated heater modules or vehicle-packaged solutions. Their engineering depth increases switching costs for vehicle manufacturers.
-
AlphaTherm (Donmar/HotShot) and HydroBlast (Kleinn) — Aftermarket heater specialists that show there is product-level differentiation to be won on performance, ease of installation, and thermal efficiency. Their success paths include channel partnerships with service networks and fleet operators.
-
China Hong Wipers — A cost-competitive supplier serving both OEM export and aftermarket channels; critical for teams evaluating offshore sourcing trade-offs against quality and regulatory compliance.
Recent Developments and Market Signals
-
Product launches and aftermarket availability (e.g., Valeo’s heated AquaBlade in 2025) indicate manufacturers are pre-emptively monetizing winter-safety features outside of OEM programs.
-
Trade-show presence and OEM supplier visibility (e.g., CCI at AAPEX 2025) demonstrate that fluid formulators and system suppliers are pursuing cross-channel exposure to accelerate specification wins.
-
Patents and in-vehicle R&D (e.g., Ford’s patent activity) show OEMs are exploring integrated bottle-heating architectures, which could shift BOM ownership and service models over the next vehicle generation cycle.
Key Strategic Recommendations for 2026
-
Secure heater-element supply now. With PTCs in high demand across multiple automotive thermal applications, buyers should implement multi-sourcing strategies, long-lead purchase agreements, and co-investment in capacity where necessary.
-
Accelerate low-risk chemistry development. Formulations that reduce reliance on methanol or lower toxicity profiles will reduce lifecycle liabilities and improve acceptance in regulated markets.
-
Invest in safety and test protocol differentiation. Given historical recalls and regulatory scrutiny, the ability to demonstrate robust thermal control, short-circuit protection and insulation standards is a near-term commercial advantage.
-
Design aftermarket-first offerings for fleets and extreme-weather regions. Subscription, retrofit kits, and fleet-level service packages can monetize a large latent demand pool ahead of broad OEM penetration.
-
Pursue targeted M&A to close capability gaps. Buyers should prioritize targets that provide immediate access to validated heater architectures, proprietary chemistries, or distribution footprints that complement existing channels.
-
Prepare regulatory and warranty playbooks. Proactive recall-avoidance measures, enhanced QA processes and extended-warranty economics will be decisive when negotiating OEM contracts or large fleet tenders.
Scenario Snapshots — How 2026 Choices Change the Curve
-
Base case (our primary forecast): Continued steady adoption driven by incremental OEM optional-package inclusion and aftermarket retrofits, consistent with a 6.5% CAGR over the forecast window.
-
Accelerated adoption: A combination of stricter winter-safety guidance, rising fleet demands, and successful low-toxicity formulations accelerates uptake; this scenario favors vertically integrated suppliers and scaled chemical formulators.
-
Constrained adoption: A high-profile safety incident or abrupt regulatory restriction on certain formulations and components could slow adoption, favoring incumbents with deeper compliance and warranty capabilities while creating acquisition opportunities for disciplined buyers.
How To Use This Intelligence in 2026
-
Board-level planning: Use our downloadable model to stress-test capital allocation, R&D spend and M&A scenarios against the three adoption paths.
-
Procurement and supply chain: Convert the supplier heat maps into procurement contracts and contingency plans that prioritize thermal component security and formulation continuity.
-
Product and commercial leadership: Adopt the provided go-to-market templates to position heated wiper fluids as bundled safety options, with clear warranty and service economics suitable for OEM negotiation or aftermarket rollouts.
PW Consulting’s Worldwide Heated Wiper Fluid Market report is deliberately configured as a decision-tool: it provides the strategic narrative, the validated market size and growth trajectory, supplier and technology maps, and the practical templates that buyers and sellers need for 2026. To access the full segmentation by region, type and application, the complete company scorecards, and the interactive Excel model with scenario toggles, visit the report landing page or contact our team for a private briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Wiper Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Water Separation Systems Market Poised for Expansion with a 5.02% CAGR
By PW Consulting, 2026-08-12
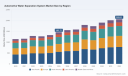
Worldwide Automotive Water Separation System Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Automotive Water Separation System market provides a practical, decision-oriented briefing tailored for executives preparing strategic moves in 2026. Grounded in a five-year historical dataset (2020–2025) and a seven-year forecast window (2026–2032), the report synthesizes regulation-driven demand, supplier positioning, technology risk, and supply-chain pressure into an actionable framework for OEMs, tier suppliers, investors, and aftermarket operators.
First Aid Vest Market
Snapshot: why this matters in 2026
- Market momentum: The market reached an estimated USD 1,461.7 Million in our base year (2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.02% across 2026–2032, driving the addressable market toward roughly USD 2.06 billion by 2032. This trajectory underpins both near-term procurement strategy and longer-range capability investments.
- Decision leverage: For 2026 planning cycles, the interplay of tightening fuel-quality standards, supply-chain cost shocks, and technology maturation makes water separation systems a high-leverage area for reducing engine failures, warranty exposure, and lifecycle operating costs.
- Commercial inflection: The market’s competitive structure—characterised by a moderate top-tier concentration—creates persistent opportunities for differentiated entrants, targeted partnerships, and selective consolidation.
What the report delivers (practical, operational intelligence)
- Executive dashboard: concise KPIs and scenario outcomes tailored for procurement, R&D, and M&A committees.
- Market architecture: end-to-end mapping of the value chain from media suppliers through OEM integration to aftermarket channels—identifying where margin pools and pricing leverage currently exist.
- Regulatory and technical playbook: clear implications of applicable standards and validation requirements, plus a technology risk register (including Euro-level and EPA-driven tests) that links compliance needs to product design choices.
- Supplier benchmarking: qualitative and quantitative performance profiles across the leading players, including technology differentiation, channel reach, and recent go-to-market wins.
- Cost and price modelling: build-your-own templates that allow you to stress-test scenarios for raw-material inflation, production scale, and alternative media choices.
- M&A and partnership roadmap: prioritized targets and value-creation checklists reflecting integration risk and synergies.
Key market dynamics shaping strategy in 2026
- Standards and compliance are non-negotiable. European and US fuel and emissions standards continue to impose rigorous water-content and removal-efficiency requirements—forcing system upgrades or validations for any product intended for regulated markets. Meeting regulatory thresholds is table stakes; doing so with lower life-cycle cost is the real commercial differentiator.
- Raw-material shocks are real and persistent. Tightness in specialty glass microfiber supply chains pushed upstream prices materially in 2024, elevating input cost for coalescing media. Procurement strategies in 2026 must therefore balance technical performance against sourcing resilience—consider dual-sourcing, hedging, and selective redesign to reduce glass dependency where feasible.
- Technology bottlenecks exist at the ultra-low water-removal frontier. Emerging requirements—especially those tied to the newest emissions and fuel-quality regimes—place pressure on polymer membrane coalescers to achieve sub-50 ppm performance. That capability remains a development frontier with meaningful IP and scale economics implications.
- Product-market fit is segment-specific. Heavy-duty duty cycles and nonroad applications continue to sustain high demand for robust separation solutions; meanwhile, gasoline applications remain a limited use-case due to fuel chemistry. This divergence requires differentiated product roadmaps rather than a one-size-fits-all approach.
Competitive landscape: who matters and why
The market exhibits a mixed competitive structure: a handful of global platform players hold meaningful share, while a long tail of specialty and regional suppliers capture niche opportunities. The three-firm and five-firm concentration ratios indicate a market where leading suppliers exert influence but do not dominate all innovation or distribution channels—creating space for tactical partnerships and carve-outs.
Plumbing Fixtures Market
- Donaldson Company — strong in heavy-duty and off-road applications with high-efficiency coalescing technology; recent media upgrades show a focus on adapting to low-sulfur fuels while protecting legacy install bases.
- Parker Hannifin (Racor) — notable for marine and automotive diesel applications and for supplier relationships with large OEMs; supplier nominations with strategic OEMs indicate momentum for new-platform integration.
- Cummins (Fleetguard) — leverages engine-integrated offerings and recent validation work to position as an OEM-aligned supplier; integration into engine systems is a competitive moat for fleet operators seeking single-source warranty alignment.
- Mann+Hummel — focuses on multifunctional filtration modules with integrated separation for passenger and commercial vehicles; partnerships with OEMs signal intent to be embedded in next-generation platforms.
- Mahle, Hengst, Sogefi — European filtration specialists that combine global OEM relationships with modular product portfolios; strengths lie in scale, engineering depth, and localized manufacturing footprints.
- Separ Sweden, Davco (Eaton), Baldwin Filters — provide differentiated technologies or aftermarket-focused solutions; niche innovation and channel reach make them attractive as acquisition targets or engineering partners.
Recent notable developments—new media launches, supplier nominations by OEM fleet programs, ISO validations, and joint development agreements—underscore an environment where product refresh cycles and OEM alignment determine winners. For example, recent media upgrades and OEM supplier nominations serve both as validation of technology readiness and as early indicators of platform-level adoption.
Worldwide Computer Container Technology Market
Strategic implications and recommended actions for 2026
- For OEMs: tighten technical specs to reflect real-world fuel variations and warranty economics. Require validation evidence (not just lab claims) and prioritize suppliers who can demonstrate system-level integration and lifecycle service support.
- For tier suppliers: accelerate investment in media alternatives and hybrid separation architectures that mitigate single-supplier exposure to specialized glass microfiber. Consider licensing or joint development on polymer coalescers where scale can be pooled.
- For investors and M&A teams: prioritize targets with demonstrable OEM contracts, engineering depth (particularly around ultra-low ppm separation), and aftermarket channels. Small- to mid-sized companies with unique separation tech or regional footprint are prime roll-up candidates given the market’s mid-level concentration.
- For aftermarket players: build predictive maintenance and sensor-enabled product propositions. As fuel systems become more instrumented, combining mechanical separation with electronic diagnostics can unlock recurring-service revenues and stickier customer relationships.
- For procurement and operations: model raw-material scenarios (including elevated glass microfiber costs) into total cost of ownership (TCO) calculations and early-sourcing of critical media. Implement supplier scorecards that combine price with delivery resilience and test-validated performance.
Methodology and credibility
PW Consulting’s study synthesizes longitudinal demand modeling (historical 2020–2025), bottom-up supplier revenue analysis, and primary interviews across OEMs, tier suppliers, and aftermarket distributors. Forecasts (2026–2032) incorporate scenario-based sensitivity to regulatory shifts, commodity-price shocks, and technology adoption curves. Competitive benchmarking leverages public disclosures, supplier product portfolios, and validated field test results. All modeling choices, assumptions, and scenario inputs are documented in the full report to enable independent replication.
How to use this briefing in your 2026 planning
- Embed the report’s regulatory and technology timelines into platform-gate checklists for powertrain programs.
- Use the supplier benchmarking and cost templates to run competitive procurement simulations prior to RFPs.
- Leverage the M&A roadmap to prioritize targets that accelerate capability gaps rather than duplicating existing scale.
- Incorporate the sensitivity tables into capital-allocation decisions to stress-test R&D and CAPEX under commodity-price volatility scenarios.
Next steps: where to find the full intelligence
This briefing intentionally previews the study’s strategic takeaways while withholding detailed subsegment matrices and regional splits to protect the analytical value offered in the full deliverable. The complete report includes fine-grained regional and application-level breakdowns, supplier share by subsegment, pricing curves, and downloadable Excel models—all essential for transaction-level diligence and engineering-level product decisions. Visit our report page to access the full dataset, procurement-ready templates, and an executive briefing with our analysts.
PW Consulting stands ready to support tailored workshops, scenario runs, and supplier diligence sessions to convert these insights into 2026-ready action plans.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Water Separation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Polycarbonate Glazing Market to Expand at 5.19% CAGR Through 2032
By PW Consulting, 2026-08-12
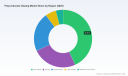
Worldwide Polycarbonate Glazing Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Polycarbonate Glazing Market report. The industry is at an inflection point — shaped by material science advances, regulatory pressure around Bisphenol A (BPA), and shifting capex and trade dynamics. This advisory summarizes the macro trajectory, the competitive battleground, and the pragmatic decision frameworks we recommend for corporate leaders preparing strategic moves in 2026. For readers seeking the full dataset, granular regional and application-level breakouts, and the proprietary financial models, please consult the complete report on our website.
Extracorporeal Membrane Oxygenation Medical Device Market
Macro trajectory: steady expansion with episodic volatility
Polycarbonate glazing has demonstrated resilient expansion through the 2020–2025 period, with the market size moving through a phase of pandemic-related disruptions, a mid-cycle correction, and a recovery that culminates in our 2025 base-year estimate. From that base the market is forecast to grow at a compound annual growth rate (CAGR) of 5.19% across the 2026–2032 forecast horizon. By 2032, the industry is projected to be materially larger than in 2025, reflecting durable end-use demand across construction, automotive, security, and specialty glazing segments.
Worldwide Electroretinogram Market
Two observations matter for boardrooms and corporate strategy teams: first, long-term demand fundamentals remain intact — polycarbonate’s unique mix of impact resistance, optical clarity, and thermal performance continues to unlock specification wins. Second, short-to-medium term value capture will be strongly influenced by supply-side moves (capacity adjustments and feedstock pricing) and regulatory transitions addressing BPA and low-migration material requirements.
Slime Pump Market
What the PW Consulting report delivers — practical, transaction-ready intelligence
- Forward-looking market model (2026–2032) with scenario variants calibrated to raw material shocks, tariff regimes, and adoption curves for next-generation low-migration grades.
- Proprietary price and margin bridge analyses, linking typical converter economics to resin and sheet manufacturing cost drivers, including a sensitivity engine for BPA-based feedstock variances.
- Regulatory impact assessment that maps EU and North American measures into compliance costs, product requalification timelines, and opportunity windows for alternative chemistries.
- Commercial playbooks — go-to-market, channel segmentation, and value-based pricing strategies — tailored for manufacturers, distributors, and large specifiers (architects, OEMs, and systems integrators).
- CapEx and capacity planning guidance with clustered investment scenarios and a readiness checklist for ramping specialty lines (e.g., ISCC-certified materials, optical grades, multiwall platforms).
- Comprehensive M&A and partnership framework with target archetypes, integration risk matrices, and accretion/dilution scorecards.
- Vendor scorecards and technology assessment matrices to support sourcing and qualification decisions, including recycled-content and mass-balance traceability options.
While this release sketches the strategic contours, the full report contains the data tables, supplier scorecards, and downloadable models that decision-makers will need to convert insights into executable plans.
Competitive landscape: dynamics and strategic postures
The polycarbonate glazing market exhibits moderate concentration: a handful of global chemical majors and specialized sheet producers dominate innovation, distribution reach, and brand recognition. Our research identifies recurring strategic archetypes among market leaders — global integrated resin producers, regional sheet specialists, and converters focused on fabrication and system integration. Each archetype faces distinct levers for value creation.
- Integrated resin leaders (example: large European and Korean players) leverage scale in feedstock sourcing and R&D to defend margin through custom grades and patented UV-stabilization or optical treatments. These firms are making selective capacity investments to serve automotive and high-spec architectural segments.
- Sheet-focused specialists (example: established European and Israeli players) compete on formulation diversity, sheet extrusion quality, and rapid customer qualification. Their advantage is speed-to-spec and established relationships with construction and agricultural customers.
- Converter and fabricator groups (North American and regional specialists) capture downstream value by offering finished glazing systems, engineered assemblies, and service levels that simplify adoption for architects and OEMs.
Recent industry moves illustrate these strategic choices. A major capacity expansion in North America has been announced targeting tailor-made grades for automotive and electronics glazing needs, signaling continued upstream investment by integrated players. Certification wins for sustainable sourcing (mass balance/ISCC PLUS) and product launches emphasizing lightweight mechanical performance reflect two complementary responses: (1) compliance and sustainability differentiation, and (2) performance-driven product innovation for transport and rail sectors.
For competitive intelligence, the full report provides a consolidated company matrix that aligns product portfolios, geographic reach, and recent transactions against our commercially actionable scoring system. This allows acquirers and partners to rapidly screen partners by strategic fit rather than raw capacity metrics alone.
Regulatory and raw-material headwinds: what keeps CFOs awake
Regulation is the single most consequential non-market variable for the polycarbonate glazing value chain in 2026. Recent EU measures limiting certain BPA uses — and evolving migration limits — complicate legacy product lines that historically straddled consumer-contact and non-food applications. Although glazing is often outside the most restrictive food-contact scopes, compliance documentation, requalification costs, and customer reassurance efforts will impose programmatic costs, especially for producers who sell into mixed-use applications.
On the raw-material side, BPA price variability remains a risk vector. Regional maintenance events and restocking patterns have driven price spikes in certain markets, and U.S. reciprocal tariffs add another layer of complexity for manufacturers that rely on cross-border resin flows. Our sensitivity scenarios quantify the margin impact of feedstock swings and tariff friction, and outline inventory and hedging strategies to attenuate earnings volatility.
Strategic implications for 2026 — recommendations for boards and executive teams
- Prioritize product requalification programs now. Even where glazing applications are not directly subject to the strictest BPA bans, customers will demand traceability and documentation. A structured requalification roadmap (12–24 months) will reduce specification churn and protect priced lists.
- Adopt a staged capacity strategy. Favor modular or contract-manufacturing options to preserve nimbleness in the face of feedstock and demand uncertainty. Greenfield investments should be contingent on contract backlog or secured off-take agreements in target segments.
- Invest selectively in sustainability certifications and material mass-balance. ISCC-type credentials are becoming table stakes for premium architectural and transport specifications — they command non-trivial price premiums and shorten procurement cycles in some buyer segments.
- Use scenario-based procurement playbooks. Implement hedging and inventory policies tied to predefined price triggers (BPA-linked) and tariff milestones to avoid reactive buying at adverse spreads.
- Differentiate through systems, not sheets alone. Firms that bundle engineered assemblies, value-add fabrication, and specification support create higher switching costs for customers and better resilience against commodity price compression.
- Target M&A for strategic adjacency. Look for bolt-ons that provide geographic access to resilient end-markets, or capabilities in specialty formulations (optical, low-migration, or recycled-content grades) that are expensive to develop organically.
- Strengthen technical sales and specification teams. Educating architects, OEM engineers, and procurement buyers on lifecycle benefits, maintenance costs, and sustainability attributes will convert technical superiority into commercial wins.
Decision triggers and monitoring dashboard
We recommend executive teams monitor a short list of forward-looking indicators that should trigger tactical pivots or capital deployment: (1) feedstock price indices and plant restart/maintenance calendars, (2) trade policy announcements impacting tariff bands, (3) certification milestones and customer RFQs for low-migration grades, (4) backlog and tender activity in rail and architectural projects, and (5) competitor capacity announcements and product launches. The full PW Consulting dashboard supplies data feeds and alert thresholds aligned to each indicator.
Conclusion — the strategic window for 2026
The polycarbonate glazing market’s growth path is clear at the aggregate level: the sector is on a growth trajectory underpinned by persistent end-market need and product advantages that are hard for alternatives to match. However, value capture in 2026 will depend on tactical execution in three areas: managing feedstock and trade exposure, defending and extending technical differentiation via certification and targeted R&D, and adopting commercial models that shift the value proposition from commodity sheets to assembled glazing systems.
This preview is intended to equip senior leaders with the strategic lens required for immediate planning cycles. Our full report contains the underlying data, regional and application breakouts, supplier scorecards, and downloadable financial models to convert these insights into 2026 action plans. Contact PW Consulting to access the complete Worldwide Polycarbonate Glazing Market report and the accompanying decision-support toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sports Lingerie Market Poised for Strong Expansion at 8.98% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Sports Lingerie Market: Strategic Roadmap for 2026 — PW Consulting Release
PW Consulting today publishes an advanced briefing derived from our forthcoming Worldwide Sports Lingerie Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032). The global sports lingerie market reached approximately USD 13.5 billion in 2025 and — driven by secular shifts in active lifestyles, product innovation and retail transformation — is projected to sustain robust growth through the forecast period at a compound annual growth rate (CAGR) of roughly 9%, reaching the low‑to‑mid tens of billions by the end of the decade. This briefing summarizes the strategic implications for executive teams planning 2026 investments, product roadmaps, and channel strategies. As a preview, it demonstrates the analytical depth of the full study while reserving proprietary segment-level figures for subscribers.
Variable Inductance Shunt Reactors Market
Why 2026 Is a Strategic Inflection Point
-
Demand dynamics have matured. Sports lingerie has moved from niche technical apparel into mainstream wardrobes. The category now captures a material portion of overall intimate apparel spend and is a primary growth engine for brands that successfully bridge performance and lifestyle.
Worldwide Aluminum Tape Market -
Product innovation is accelerating. Seamless constructions, advanced knit technologies, and additive manufacturing techniques are shifting the cost and capability frontier — enabling lighter, more supportive, and more fashion-forward products that appeal across use cases.
Worldwide Wasabi Powder Market -
Channel transformation is now structural. Online-first distribution and direct-to-consumer (DTC) models are displacing traditional assortment rules; omnichannel demand orchestration will separate winners from also-rans in 2026.
-
Input and regulatory volatility persists. Synthetic fiber supply chains, recycling ambitions, and chemical-safety scrutiny (notably activewear testing attention in recent years) require active procurement and compliance strategies rather than passive sourcing.
-
Market structure favors both scale and specialization. The market remains relatively fragmented: a small group of global brands drive significant awareness and innovation, but there remains room for niche specialists, regional champions, and vertically integrated newcomers to capture share.
What PW Consulting’s Report Delivers to Decision‑Makers
Our report is designed as an operational playbook for 2026, not just a forecast. It translates market projections into actionable decisions across product, commercial, supply chain and corporate strategy. Highlights include:
-
Robust forecasting with scenario design: baseline, upside and downside demand pathways across the 2026–2032 horizon — enabling capital planning and inventory sizing under alternative macro trajectories.
-
Channel and assortment playbooks: frameworks to optimize SKU mix, price architecture, and margin management across DTC, specialty, department, and online retail partners.
-
Consumer segmentation and journey maps: psychographic and behavioral segments with conversion levers, lifetime-value estimates, and retention playbooks developed from primary interviews and digital-signal analysis.
-
Product development roadmap: prioritized feature sets (support systems, knit construction, sustainable fiber blends, seamless thermals, and 3D manufacturing pilots) tied to willingness-to-pay and route-to-market suggestions.
-
Supply chain and sourcing playbook: a raw-material risk matrix, supplier concentration heatmaps, and nearshoring vs. cost arbitrage scenarios to preserve margin under input volatility.
-
Regulatory and safety compliance primer: testing protocols and quality assurance sequences to mitigate reputational and legal risk associated with chemical residues and labeling claims.
-
M&A and partnership pipeline: quantitative screens to identify tuck-in and scale targets, plus JV structures to accelerate capability buildouts in performance textiles and DTC fulfillment.
-
Implementation blueprints: 90/180/360 day playbooks for pilot launches, retail rollouts, and infrastructure investments with KPIs and cost templates.
Competitive Landscape — What Leaders Are Doing (and What It Means)
The competitive set includes established sportswear powerhouses, specialty active brands, heritage intimate-aparel players and high-value lifestyle entrants. Across this group we observe three repeatable strategic plays:
-
Scale-driven platform play: Global sportswear names are leveraging R&D, brand equity and omnichannel distribution to churn out high-volume performance bras and active intimates that migrate into everyday wardrobes. These players prioritize broad fit ranges, elevated supply resilience, and rapid product refresh cycles.
-
Premium innovation and community play: Premium active-lifestyle brands are investing in ultra-lightweight constructions, comfort-engineered fits and athlete endorsements to justify price premiums and loyalty-driven repeat purchase economics.
-
Value and accessibility play: Large generalists and house‑brand specialists focus on accessible price points, simplified SKUs and wide distribution to capture volume-oriented consumers and new market entrants.
Representative company moves provide instructive examples: a leading premium athleisure brand introduced a high-impact performance bra tested by endurance athletes early in 2025, emphasizing ultrarunning-ready attributes; a major global sportswear firm has piloted 3D-printed structural supports to reduce cut-and-sew complexity and accelerate time to shelf; and the category saw extensive B2B and B2C showcase activity at intimate apparel trade events early in 2026 that underscored collaborative innovation across suppliers and brands.
Strategic implication: incumbents that combine product distinctiveness, distribution discipline and cost-effective innovation capture outsized returns. At the same time, relative market concentration remains modest — top players lift category standards but do not fully dominate — creating opportunities for fast-followers and regional specialists to scale.
Operational Imperatives for 2026: Three Priorities
-
Re-wire product portfolios around margin drivers. Run SKU profitability audits; identify high-return silhouettes and retire low-converting legacy SKUs. Prioritize investments in fit technology, seam-free knits and breathable constructions that deliver measurable benefits to end-users.
-
Secure flexible, transparency-first sourcing. Build multi-sourcing strategies for key performance fibers and embed traceability into supplier contracts. Pilot recycled and lower-impact feedstocks, but connect sustainability claims with verifiable supply chain proof points to avoid greenwashing risk.
-
Operationalize omnichannel demand orchestration. Implement a single source of truth for inventory, use targeted assortment strategies by channel and deploy conversion-centric digital merchandising (fit tools, virtual try-on pilots, and refined size‑guides) to reduce returns and lift AOV.
Risk and Scenario Planning: Preparing for the Upside and the Downside
Our scenario work identifies three plausible outcomes for the 2026–2032 window: a steady-growth baseline aligned to current consumer trends; an upside driven by accelerated active adoption and rapid premiumization; and a downside where input shocks or heightened regulatory actions depress demand. Key mitigations we recommend include:
-
Hedged procurement and capacity options to handle spike costs without eroding retail price competitiveness.
-
Phased commercial investments (pilot → scale) to preserve cash while validating product-market fit across geographies and segments.
-
Proactive compliance programs and third-party testing regimes to preempt consumer-safety escalations and to protect brand equity.
How Executives Should Use This Report in 2026
For leadership teams, this study functions as both a decision-support engine and a roadmap. Use it to prioritize capital allocation, shape product and channel experiments, and inform M&A diligence. For commercial teams it provides the operating playbooks needed to improve sell-through, reduce promotional leakage, and strengthen repeat purchase economics. For sourcing and operations it supplies the risk matrices and supplier playbooks that translate market signals into resilient supply strategies.
About the Full Report (a Strategic Teaser)
The full PW Consulting Worldwide Sports Lingerie Market report contains detailed segment-level forecasts, regional demand analyses, channel revenue splits, product-type growth diagnostics, price and margin models, and primary interview-based competitor scorecards. It also includes appendices with proprietary modeling templates, a vendor shortlist for manufacturing and digital-fit technologies, and an M&A target matrix. We intentionally withhold granular segment tables and confidential model assumptions from this release to preserve the report’s value as a subscription-grade intelligence product.
If your 2026 plan depends on winning in sports lingerie — whether you are a manufacturer, brand, retailer or investor — this study delivers the analytics, playbooks and scenario planning necessary to make high‑conviction choices under uncertainty. To access the full dataset, competitor dashboards and executable 90/180/360 day playbooks, contact PW Consulting or visit our website to request the complete report.
PW Consulting — translating market complexity into strategic clarity for the active-intimates era.
For detailed analysis of this topic, please visit the official page: Worldwide Sports Lingerie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MMP13 Antibody Market at USD 42.5 Million in 2025, Forecast to Reach USD 63.14 Million by 2032 at 5.82% CAGR
By PW Consulting, 2026-08-12
PW Consulting: Strategic Brief — Worldwide MMP13 Antibody Market (2026 Outlook)
As the market for MMP13 antibodies moves from niche reagent to strategic research enabler, organizations making procurement, partnership, and product-development choices in 2026 will need market intelligence that pairs rigorous forecasting with actionable guidance. PW Consulting’s new Worldwide MMP13 Antibody Market report (base year 2025, historical 2020–2025, forecast 2026–2032) delivers that intelligence. The global market is estimated at USD 42.5 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.82% through 2032, when it reaches roughly USD 63.14 Million. This brief summarizes the report’s strategic value for 2026 decision-making while deliberately omitting granular segmentation figures to invite review of the full report for proprietary splits and supplier-level data.
Worldwide Small Molecule Antibodies Market
Why MMP13 Matters to Life-Science Strategy in 2026
-
Scientific relevance: MMP13 (matrix metalloproteinase‑13) is central to extracellular matrix remodeling, with sustained research interest in osteoarthritis, oncology, tissue remodeling and wound healing. These application domains continue to drive demand for validated antibodies across Western blot, IHC, ELISA, and immunocytochemistry workflows.
Worldwide Cloud Private Branch Exchange (PBX) Software Market -
Technology shift: The field is transitioning toward recombinant monoclonal reagents and highly validated monoclonal offerings alongside traditional polyclonal products. This affects product life cycles, pricing dynamics, and supplier differentiation.
Worldwide Cloud Management Suite Market -
Market dynamics: A moderate concentration among leading suppliers provides both competitive threats and consolidation opportunities. Our market concentration analysis (CR3 and CR5 metrics) highlights strategic levers for incumbents and challengers alike.
-
Regulatory framing: All commercial MMP13 antibodies remain research-use-only (RUO). This regulatory status defines go-to-market approaches, claim language, and the pace of clinical translation for developers relying on MMP13-targeted reagents.
What the Report Delivers — Practical, Actionable Modules
-
Executive synthesis — 5‑minute and 30‑minute read versions for C-suite and business unit leads that distill demand drivers, risk matrices, and recommended next steps for 2026.
-
Market sizing & forecast — a year-by-year top-line forecast from 2026–2032 underpinned by a 2020–2025 historical baseline; scenario analyses that stress-test the base case across technology adoption and research funding scenarios.
-
Competitive landscape — comparative profiles and strategic positioning for the industry’s principal suppliers (detailed supplier matrices, capability maps, and innovation heatmaps are included in the full report).
-
Product & validation taxonomy — categorization by antibody modality, validation status, and application suitability, plus guidance on internal validation checklists to reduce assay failure and procurement risk.
-
Go-to-market and commercial playbooks — segmented pricing strategies, channel optimization, bundling and reagent-as-a-service options tailored for reagent suppliers and academic core facilities.
-
Supply-chain resilience & manufacturing — risk assessment and mitigation strategies for raw material dependence, contract manufacturing relationships, and inventory policies tuned to reagent shelf-life and lot-to-lot variability.
-
M&A and partnering framework — identification of value-accretive acquisition targets, strategic partnership archetypes, and integration checklists for expanding immunoreagent portfolios.
-
Regulatory & compliance appendix — practical advisory on labeling, RUO positioning, and global distribution compliance considerations for research-use reagents.
Competitive Landscape — Who Matters and Why
The MMP13 antibody market is served by an ecosystem of global reagent specialists and larger life‑science suppliers. Our report profiles leading players with a view toward procurement, alliance, and competitive response strategies. Highlights include:
-
Abcam (Cambridge, UK) — recognized for a diversified MMP13 portfolio that includes both polyclonal legacy reagents and recombinant monoclonal options validated across multiple applications. Their emphasis on cross‑application validation strengthens purchasing confidence for translational researchers ( https://www.abcam.com).
-
Thermo Fisher Scientific / Invitrogen (Waltham, MA, US) — a broad catalog presence and end-to-end distribution capability. The breadth of SKUs supports scale buyers and platform bundling strategies ( https://www.thermofisher.com).
-
R&D Systems / Bio-Techne (Minneapolis, MN, US) — known for antibodies that detect both pro and active MMP13 forms and for supplementing antibody offers with ELISA quantitation kits important for translational workflows ( https://www.rndsystems.com).
-
Cell Signaling Technology (Danvers, MA, US), Proteintech (Rosemont, IL / China operations), Sigma‑Aldrich / Merck (St. Louis, MO, US), Santa Cruz Biotechnology (Dallas, TX, US), GeneTex (Irvine, CA, US), Bioss (Woburn, MA, US), and Novus Biologicals (Centennial, CO, US) — each brings distinct strengths in clone validation, reagent documentation, technical support, and geographic channel coverage. The full report contains supplier scorecards with strengths, service models, and pricing posture comparisons.
Market Structure & Competitive Implications
Our concentration analysis shows a market where top-tier suppliers command meaningful share, but not one of extreme dominance — creating windows for nimble challengers that offer differentiated validation data, recombinant clones, or superior service. Specifically, PW Consulting’s CR3 and CR5 metrics quantify concentration and inform strategic moves such as focused M&A, exclusive distribution agreements, or platform partnerships to accelerate scale.
Strategic Recommendations for 2026
-
For reagent manufacturers: Prioritize investment in recombinant monoclonal development and expanded orthogonal validations (e.g., paired knockout/knockdown controls, mass‑spec confirmation) to win research customers who equate validation with reliability. Consider modular pricing tied to validation packages.
-
For distributors and academic core facilities: Lock strategic supply agreements with manufacturers that offer consistent lot‑to‑lot documentation and extended technical support. Build a catalog of validated in‑house assays to increase stickiness with end users.
-
For biopharma and translational labs: Treat MMP13 antibody selection as a risk-management decision: require orthogonal validation evidence and supplier traceability before depending on reagents for preclinical decision gates. Plan procurement cycles to reflect the market’s projected steady growth and occasional SKU rationalizations.
-
For investors and corporate development teams: Evaluate targets that offer complementary validation platforms, recombinant capabilities, or geographic channel gaps. The market’s growth profile supports bolt‑on acquisitions that deliver rapid margin expansion through catalogue rationalization and cross‑sell.
How PW Consulting’s Forecast Helps You Prioritize Spend in 2026
The report’s year-by-year forecasts and scenario models enable procurement and R&D leaders to set 12–24 month budgets that reflect realistic growth in reagent demand. By combining the 5.82% CAGR baseline with scenario levers (e.g., research funding shifts, adoption rates for recombinant clones), decision-makers can:
-
Right-size inventory to avoid overstocking short‑shelf reagents;
-
Time product launches to coincide with uptake curves in key research domains;
-
Structure supplier contracts that balance price and guaranteed validation deliverables.
Report Access & Next Steps
This strategic brief is a selective distillation of the larger Worldwide MMP13 Antibody Market study. The full report contains the proprietary segmentation matrices, supplier scorecards, SKU-level catalog analysis, and downloadable data tables that underpin the strategic recommendations summarized here. Organizations that need to operationalize 2026 plans — from procurement and lab management to product development and M&A — should consult the complete report for the granular metrics and supplier comparisons that were intentionally withheld from this public summary.
FAQ (Regulatory & Use Considerations)
-
Are MMP13 antibodies approved for clinical diagnostics or therapy? No. All commercial MMP13 antibodies are designated for research use only (RUO) and are not cleared or approved for diagnostic or therapeutic procedures in humans. This affects labeling, marketing language, and clinical translation timelines.
-
Where are MMP13 antibodies used? Commercial MMP13 reagents are intended for laboratory applications such as Western blot, immunohistochemistry, ELISA, and immunocytochemistry in research exploring extracellular matrix remodeling and related conditions. Users should follow supplier validation guides and apply orthogonal controls where feasible.
PW Consulting’s Worldwide MMP13 Antibody Market report is designed to be the single, defensible source of commercial insight for stakeholders planning resource allocation and strategic moves in 2026. To download the full report, access detailed supplier scorecards, or commission a bespoke briefing tailored to your organization’s priorities, please visit the PW Consulting report page or contact our life‑sciences practice team.
For detailed analysis of this topic, please visit the official page: Worldwide MMP13 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sheep Milk & Infant Formula Market Reaches USD 6.28 Billion in 2025, Set for 9.85% CAGR Through 2026–2032
By PW Consulting, 2026-08-12
Worldwide Sheep Milk and Infant Formula Market: Strategic Guide for 2026 Decision-Making
PW Consulting’s new market study on the Worldwide Sheep Milk and Infant Formula Market equips executives, investors, and policy teams with a tightly focused strategic playbook for 2026. Built on five years of historical data and a rigorous scenario-driven forecast to 2032, the report synthesizes market sizing, competitive dynamics, regulatory shifts, and practical go‑to‑market frameworks that matter for near-term corporate action.
Environmental Reliability Test Services Market
Why this report matters for 2026
The sheep milk and infant formula category is transitioning from niche to structured growth: our market model indicates a strong compound annual growth rate (CAGR) of 9.85% across the 2026–2032 forecast window, against a 2025 base market size of USD 6,280 Million. This trajectory reflects both premiumization in infant nutrition and expanding geographic and channel penetration. For 2026 planning cycles, those signals translate into three operational imperatives:
Automotive RTK GNSS Module Market
- Prioritize regulatory and source‑of‑supply assurance as a front‑line risk management task;
- Define product‑formulation and channel strategies that preserve margin while enabling scale; and
- Identify focused consolidation and partnership plays to capture disproportionate share in a market that already shows moderate concentration at the top (CR3 ≈ 41.3%; CR5 ≈ 56.8%).
How the market is evolving — headline drivers
Demand is being driven by three structural consumer trends: heightened interest in alternative dairy due to perceived digestibility benefits, a premium adult and toddler nutrition market that cross‑subsidizes infant formulation innovation, and the maturation of e‑commerce and specialty retail channels that make smaller‑volume premium SKUs commercially viable. On the supply side, sheep dairy exhibits distinct cost and seasonality characteristics: sheep milk typically commands a price premium versus cow milk, reflecting smaller herd sizes and seasonal yields. That raw‑milk cost differential materially affects unit economics across formulation and contract manufacturing choices.
Worldwide Configure, Price and Quote Application Suites Market
Regulation is now a dominant determinant of commercial risk. The period since late 2025 has seen two regulatory actions with direct consequences for supply strategy and market access. First, China’s regulatory reforms for infant milk—bringing liquid infant formula under the same registration and production controls as powdered formula—have reshaped contract production feasibility and local manufacturing requirements. Second, the European Commission’s reinforced import controls on certain nutritional oils used in infant formula have introduced heightened border inspection regimes and new certificate requirements. These developments are already altering sourcing patterns and accelerating manufacturer decisions on localizing critical supply lines.
Practical implications for 2026 strategy
- Sourcing and vertical exposure: Companies dependent on third‑party supplier networks must quantify exposure to seasonal yield variability and the 40–60% raw‑milk cost premium (relative to cow milk) in their 2026 P&L scenarios. Hedging options include long‑term offtake agreements with premium sheep milk producers, investment in on‑farm productivity programs, and selective vertical integration for high‑margin SKUs.
- Regulatory navigation as a competitive moat: The new controls around liquid formula registration and import checks create higher entry costs for late movers. Firms that invest in regulatory affairs capability, accredited QC labs, and localized production (or certified contract manufacturing partners that meet new registration rules) gain time‑to‑market advantages.
- Channel configuration and premiumization: The premium sheep milk proposition aligns strongly with direct‑to‑consumer and specialty retail channels, and with differentiated toddler/incremental nutrition products. However, scale ambitions require hybrid channel strategies: maintain premium positioning while engineering supply chain efficiencies for supermarket and mass channels where volume growth lives.
- M&A and partnership playbook: Given a moderate top‑end concentration, acquisitive plays focused on provenance (premium NZ sheep milk assets), formulation IP, or capacity in regulated markets (e.g., Asia manufacturing footholds) are attractive. Strategic criteria for 2026 targets should prioritize regulatory-compliant production footprints and validated ingredient traceability.
Competitive landscape — who to watch
The market remains anchored by a mix of legacy dairy groups and nimble specialist producers. Leading players include established New Zealand sheep milk companies that combine farm‑gate control with branded infant formula portfolios, large global dairy groups experimenting with sheep‑based SKUs, and regional specialists driving local innovation. Select profile highlights:
- Spring Sheep Milk Co. (New Zealand) — The largest sheep milking operator in the Southern Hemisphere, supplying premium grass‑fed sheep milk and finished infant formula under recognized labels. Their integrated model—milk supply, powders and nutritional bases—illustrates the scale benefits of upstream control.
- Blue River Dairy (New Zealand) — A brand‑led manufacturer with deep exposure to the China market; provides both consumer‑ready formulations and contract manufacturing services, demonstrating the commercial value of market‑specific formulation and distribution expertise.
- Maui Milk Ltd / Maui Sheep Milk (New Zealand) — A specialist supplier to multinational nutrition brands; their role underscores the strategic value of being a trusted ingredient partner to large infant‑nutrition manufacturers.
- Danone (Nutricia / Karicare) (France) — A global incumbent that has piloted sheep‑based toddler milk drinks and continues to test expanded sheep formula ranges, highlighting the category’s strategic visibility to major dairy groups.
- Regional and specialty producers (Ireland, Canada, China/Netherlands, etc.) — A growing set of national champions and niche suppliers are building regional supply chains and premium propositions; collectively they create sourcing optionality for formulators and brand owners.
Our analysis shows incumbent leaders leveraging integrated supply models and brand equity, while challengers compete through formulation flexibility, contract manufacturing capacities, and targeted regional access. The market’s CR3 and CR5 metrics indicate an industry neither fully fragmented nor tightly consolidated—an ideal constellation for targeted M&A and partnership strategies in 2026.
Regulatory and ingredient risk matrix
Two recent regulatory actions should be part of every 2026 risk register:
- China’s alignment of liquid infant formula with powdered formula registration and production controls (effective end‑2025) raises immediate compliance and local production considerations; contract manufacturing for infant liquid formulas has essentially been restricted, altering existing supply agreements and necessitating fast re‑work of China market entry strategies.
- The European Commission’s intensified checks on certain nutritional oils (early 2026) require importers to secure certificates and accommodate substantial physical check rates at borders—implications include longer lead times, higher compliance costs, and the need to validate alternative suppliers or certified stockpiles.
Consequence planning for 2026 should quantify lead‑time and working capital impact from these two levers and incorporate contingency sourcing forecasts into capital and procurement plans.
What the PW Consulting report delivers (practical contents)
The published study is a hands‑on toolkit for decision makers. Key deliverables include:
- Market sizing with a 2020–2025 historical base and detailed scenario forecasts to 2032, including a base‑case 9.85% CAGR projection for 2026–2032;
- Regulatory navigator and compliance checklists tailored to major jurisdictions (EU, China, Australia/New Zealand), with timelines and certification maps;
- Supply‑chain diagnostic templates that quantify exposure to raw‑milk price premia and seasonal yield volatility, plus suggested hedging and sourcing structures;
- An M&A and partnership playbook that ranks targets by strategic fit (supply, formulation IP, regulatory footprint), with valuation sensitivities under differing regulatory scenarios;
- A go‑to‑market matrix for branded and private label entrants addressing product positioning, channel mix, pricing strategies and packaging formats; and
- Operational checklists for scaling production, including contract manufacturing assessment criteria and a supplier due‑diligence protocol.
Importantly, the report balances strategic narrative with executable templates—models you can drop into 2026 planning cycles to stress‑test investment cases, optimize supply configurations, and accelerate regulatory approvals.
Recommended 90‑ and 180‑day actions for 2026
- Day 0–90: Conduct a regulatory-gap analysis for all current/formulated SKUs vs. China and EU requirements; secure certified inspection and lab partners where needed. Begin supplier audits focused on traceability and seasonal risk.
- Day 90–180: Finalize at least one binding offtake or equity partnership with a premium sheep milk producer; pilot a localized production or certified contract manufacturing arrangement in your priority market; initiate targeted M&A due diligence on one specialty or regional asset.
Conclusion — where value will be captured in 2026
Sheep milk infant nutrition is moving from artisanal to industrially viable—driven by strong growth fundamentals, premium consumer positioning, and an evolving regulatory landscape that raises barriers while creating differentiation opportunities. For 2026, the decisive moves are operational: secure compliant supply, invest in regulatory and quality infrastructure, and selectively pursue partnerships or acquisitions that provide immediate production and traceability advantages. PW Consulting’s report delivers the strategic roadmap and the actionable tools to prioritize those decisions with confidence—while preserving the granular, proprietary segment intelligence that will be available through full report access.
For a preview of the full dataset, proprietary supplier lists, and exclusive scenario models designed for board‑level planning, visit PW Consulting’s Worldwide Sheep Milk and Infant Formula Market page or contact our advisory team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Sheep Milk and Infant Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Enzymes for Biofuels Market Reaches USD 1,885.5 Million in 2025, Poised for 6.51% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Enzymes for Biofuels Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our latest market research: Worldwide Enzymes for Biofuels. This briefing is designed to clarify the strategic levers that will matter for commercial, R&D, and M&A decisions as companies enter 2026 — while intentionally withholding certain granular splits to encourage access to the full report for transaction-grade detail.
Worldwide IRC Software Market
Market trajectory at a glance
Our analysis shows a resilient recovery and sustained growth for the enzymes-to-biofuels sector. The market expanded from roughly USD 1.38 billion in 2020 to an estimated USD 1.89 billion in 2025, reflecting both structural demand for decarbonized transport fuels and episodic volatility tied to feedstock and energy markets. Looking forward, the sector is forecast to grow at a compound annual growth rate (CAGR) of approximately 6.51% through 2032, reaching a projected market size of about USD 2.93 billion by the end of the forecast horizon.
Vision Corrector Market
These headline figures underscore two enduring dynamics: first, enzymes remain a high-value, enabling input in both first- and second-generation biofuel value chains; second, demand is being shaped by policy shifts, feedstock economics, and technology maturation rather than pure commodity cycles. For 2026 planning cycles this means firms should be sizing investments to capture medium-term structural growth rather than short-lived spikes.
Worldwide Automatic Bleeding Valves Market
Why this report matters for 2026 strategic decisions
-
Actionable growth priorities — We map out where enzyme demand will be most sensitive to regulatory signals and technological substitution, enabling commercial teams to prioritize product development, pricing, and upstream feedstock partnerships for 2026 launch windows.
-
Priority investments and capability gaps — The report identifies high-return R&D focus areas (e.g., thermostable cellulases, low-dose cocktail formulations, lipases for mild transesterification) and quantifies the commercial benefit ranges for each investment pathway.
-
M&A and partnership playbook — Given notable concentration among incumbents, the research provides scenario-based playbooks for bolt-on acquisitions, licensing deals, and strategic alliances to accelerate scale or complement portfolios.
-
Supply chain stress-test — We model the impact of upstream commodity swings and enzymatic production costs on gross margins, and provide hedging and procurement tactics tailored to enzyme manufacturers and biofuel integrators.
Report contents — practical, transaction-focused deliverables
-
Market sizing and forward-looking demand scenarios through 2032, with sensitivity analysis around feedstock prices and policy stances.
-
Competitive benchmarking and capability maps across enzyme families, manufacturing scale, and formulation expertise.
-
Commercial playbooks for market entry, channel optimization, and customer segmentation — including go-to-market templates and pricing frameworks.
-
Technology readiness assessments and R&D roadmaps that align enzyme innovation timelines with regulatory and blending milestones.
-
Supply chain modelling that quantifies the share of manufacturing cost driven by fermentation feedstocks and proposes mitigation strategies (procurement, co-location, feedstock contracts).
-
M&A heat maps and valuation heuristics for targets across enzyme type, geographic reach, and captive feedstock exposure.
Market structure and concentration — strategic implications
The enzyme-for-biofuels market exhibits meaningful concentration at the top. Our concentration metrics indicate that the top three firms capture a substantial portion of market revenues, and the top five firms capture an even larger share — a structure that creates both protective moats and strategic entry points. For incumbent firms, this concentration supports disciplined price management and reinvestment in process scale; for challengers, it signals where niche differentiation or technology-led disruption can unlock value.
Put simply: scale and IP matter. Companies that combine fermentation scale, enzyme engineering, and strong sales channels are best positioned to preserve margin as cost pressures fluctuate. At the same time, the degree of concentration creates acquisition opportunities for companies seeking to accelerate access to critical formulation know-how or unique feedstock-adapted enzymes.
Competitive landscape — what incumbents and challengers signal for 2026
-
Novonesis (formerly Novozymes) — With deep heritage in both starch- and fiber-based ethanol enzyme platforms, Novonesis remains a bellwether for best-practice process integration and yield optimization. Their capability to bundle enzymes and process advisory services is a model for revenue capture beyond product sales.
-
Lallemand Biofuels & Distilled Spirits (LBDS) — The strategic acquisition of BASF’s bioenergy enzyme assets strengthens LBDS’ position in grain processing and ethanol co-product optimization. This is a structural move that signals consolidation among firms seeking complementary portfolios and regional footholds.
-
DuPont (Industrial Biosciences / IFF) — DuPont’s enzyme suites, targeted at both starch and lignocellulosic hydrolysis, reflect a dual-pathway strategy: defend high-volume starch markets while participating in the long-term upside of cellulosic conversion.
-
Technology specialists (Codexis, Iogen, Agrivida) — Engineering and feedstock-integrated approaches from these players point to a bifurcated market where tailored, high-performance enzymes command premium pricing in advanced biofuel projects.
-
Lipase-focused players (TransBioDiesel, Amano) — Enzymatic biodiesel remains a niche but strategically important segment, with lipase-based processes offering operational and environmental benefits versus traditional chemical catalysts.
-
Regional and industrial scale specialists (AB Enzymes, DSM-Firmenich, Advanced Enzyme Technologies, Enzyme Supplies Ltd.) — These firms underscore the importance of localized formulation expertise, supply reliability, and service models tailored to regional feedstock mixes and regulatory regimes.
Dynamics shaping near-term demand and margins
-
Feedstock cost sensitivity: Enzyme manufacturing is materially dependent on fermentation feedstocks — with raw material costs commonly representing a substantial portion of production expenses. Commodity price swings, particularly in corn and other starch crops, therefore transmit to enzyme cost bases and pricing negotiations.
-
Policy and regulatory tailwinds: Recent regulatory actions — including updated biofuel volume mandates in major markets — reinforce a multiyear runway for advanced biofuels. Adjustments that favor cellulosic volumes materially influence R&D prioritization and commercial demand for cellulases and new enzyme cocktails.
-
Technology maturation: Incremental improvements in enzyme efficacy, dose reduction, and process integration continue to compress per-liter enzyme costs for ethanol producers, changing the calculus for adoption timing and contract structures.
-
Market consolidation: Acquisitions and portfolio rationalization among leading enzyme suppliers are reshaping competitive dynamics. Recent deals indicate a preference for inorganic growth to secure IP, fill portfolio gaps, and achieve route-to-market scale.
Practical recommendations for leadership teams in 2026
-
Stress-test product portfolios against policy scenarios: Integrate multiple regulatory paths into your demand models (e.g., supportive vs. conservative cellulosic mandates) to set R&D and capex prioritization.
-
Hedge upstream feedstock exposure: Consider procurement contracts, feedstock co-location, or vertical partnerships to stabilize enzyme production margins when agricultural commodity volatility spikes.
-
Pursue selective M&A and licensing: Use concentrated market structure to target bolt-ons that extend your formulation capabilities or grant rapid entry into advanced biofuel segments.
-
Design commercial models that capture value from process advisory: Bundling performance guarantees, lifecycle analyses, and optimization services can increase stickiness and margin compared with raw product sales.
-
Invest in low-dose, high-efficacy chemistries: Marginal improvements in enzyme performance that lower required doses create disproportionate commercial value for both buyers and sellers.
How PW Consulting can accelerate your 2026 plans
Our full report contains transaction-ready appendices, scenario models, and a confidential target list for potential acquisitions or partnerships. It also includes a modular decision-support toolkit — pricing sensitivity models, R&D investment case templates, and an M&A valuation framework — designed to integrate directly into corporate planning cycles for 2026.
Given the combination of predictable structural growth (6.51% CAGR through 2032) and episodic market shocks, the firms that prepare with policy-aware demand models, feedstock risk mitigation, and targeted capability builds will capture the majority of the sector’s upside. For stakeholders preparing capital allocations, portfolio pivots, or strategic deals in 2026, our analysis converts industry complexity into executable choices.
Next steps and how to access the full intelligence
This briefing intentionally omits detailed regional and application-level splits and the transaction-grade segment tables that underpin valuation work. These are available in the full Worldwide Enzymes for Biofuels Market report and the accompanying Excel model. To obtain the complete dataset and our strategic playbooks, visit the PW Consulting report page or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Enzymes for Biofuels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive ISOFIX Mounts Market Poised to Reach USD 1,605.05 Million by 2032 on a 6.25% CAGR
By PW Consulting, 2026-08-12
Worldwide Automotive ISOFIX Mounts Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting today publishes a targeted strategic brief derived from our comprehensive Worldwide Automotive ISOFIX Mounts Market report (base year 2025). The market for ISOFIX mounts — the structural anchorage systems that enable secure, repeatable installation of child restraint systems — is no longer a niche engineering topic. It is a multi‑hundred‑million dollar global market that is expected to expand at a steady compound annual growth rate of 6.25% across 2026–2032, rising from a market size of approximately USD 1,050 million in 2025 to roughly USD 1,605 million by 2032. For C‑suite leaders and business unit heads preparing budgets, product roadmaps, and M&A pipelines in 2026, the implications are immediate: compliance, sourcing and supplier strategy, and test‑led innovation will determine winners and laggards.
Plastic Rigid Intermediate Bulk Containers Market
Why ISOFIX Should Be on Your 2026 Strategic Agenda
-
Regulatory momentum is accelerating. UNECE R129 (i‑Size) has entrenched ISOFIX as the preferred attachment for many child seat categories in markets aligned to UNECE, while the U.S. is advancing related safety mandates: the NHTSA’s FMVSS 213a initiative (side‑impact test enhancements) will materially affect designs for child restraints and the anchors that support them. Additionally, UNECE GRSP discussions in 2025 flagged an evolutionary path for “ISOFIX 3.0,” indicating potential technical and compliance changes over the medium term.
Capillary Columns Market -
Product engineering is converging on higher performance under crash loads. ISOFIX mounts and anchors are predominantly fabricated from high‑strength steels or alloy steels to meet anchorage strength, positioning, and energy‑absorption requirements under ECE and FMVSS standards — a fact that ties product capabilities directly to material sourcing and manufacturing technology choices.
Power Infuser Market -
OEM and aftermarket priorities are diverging and converging simultaneously. OEMs are integrating ISOFIX design into seat structures earlier in vehicle development cycles, and aftermarket demand is driven by retrofit and replacement needs in diverse vehicle fleets. Both channels require suppliers to offer validated, cost‑efficient solutions plus traceability for regulatory and warranty management.
What PW Consulting’s Report Delivers — Practical, Board‑Ready Tools
Our report is positioned as a decision‑making toolkit for executives, not just an academic exercise. Key deliverables include:
-
Market sizing and forecast model with scenario levers — base case aligned to the 6.25% CAGR, with upside/downside scenarios for regulatory acceleration and macro auto production shocks.
-
Demand drivers and adoption timing matrix by vehicle program type and product architecture (OEM integration vs. retrofit/aftermarket plays).
-
Supply‑side mapping and factory build‑out analysis — a granular view of manufacturing capabilities, tooling lead times, and capacity constraints for steel stampings and subassembly lines.
-
Regulatory and validation playbook — compliance checkpoints across ECE R44/R129 and FMVSS, a test matrix for FMVSS 213a side‑impact performance, and a timetable for certification milestones.
-
Commercial templates — pricing corridors, cost‑to‑serve benchmarking, and contracting terms aligned for OEMs and aftermarket distributors.
-
Supplier scorecards and M&A screening framework — independent assessments of engineering competence, product portfolio breadth, quality systems, and go‑to‑market reach.
-
Operational risk heatmap — raw material exposure (high‑strength steel), logistics bottlenecks, and mitigation options including dual‑sourcing and near‑shoring sensitivity analyses.
Competitive Landscape — High‑Level Insights
The supplier ecosystem is a mix of specialized connectors and component houses, automotive subassembly vendors, and larger safety‑component manufacturers. Leading firms profiled in our research include Holmbergs (Sweden), Ningbo Welldon Infant and Child Safety Technology Co., Ltd. (China), IMMI (United States), and Quanzhou Kwok Shing Automotive Subassembly Co., Ltd. (China). Each brings distinct strengths:
-
Holmbergs — niche engineering leadership in ISOFIX/LATCH connectors, tethers and adjusters, with deep relationships to child seat OEMs in Europe and beyond (see: https://www.holmbergs.se).
-
Ningbo Welldon — volume manufacturing expertise in mount points and anchors, positioned to serve high‑volume programs (see: https://www.nbwelldon.com).
-
IMMI — broad compliance and system integration capabilities, with product lines that align to FMVSS, ECE and other global standards (see: https://www.imminet.com).
-
Quanzhou Kwok Shing — automotive subassembly supplier focused on rigid baby car seat components and subassemblies, enabling OEM procurement efficiency (see: https://kwokshing.en.made-in-china.com).
From a market structure perspective, the ISOFIX mounts industry is neither atomized nor monopolistic — leading suppliers control meaningful, defensible positions across certain segments, but opportunities remain for technologically differentiated entrants and regional champions. Recent regulatory moves and standard discussions have raised the strategic value of engineering capability and validated testing assets above simple manufacturing scale.
Key Strategic Imperatives for 2026
-
Embed compliance as a product gateway. Treat ECE R129 and FMVSS 213a test data as mandatory gating items for any new anchor design; accelerate investment in side‑impact test rigs and third‑party validation to reduce program cycle time.
-
Design for modularity. Develop anchor and bracket architectures that can be adapted across seat platforms and vehicle architectures to reduce SKUs and certification cycles.
-
Secure steel supply lines. High‑strength alloy steel lead times and price volatility directly affect cost and delivery. Institute strategic raw‑material contracts, dual‑sourcing and material substitution studies.
-
Differentiate via testing and traceability. Offer traceable, serialized subassemblies to meet OEM warranty, recall and compliance demands — this can be a premium, defensible service for suppliers.
-
Pursue targeted partnerships and bolt‑on acquisitions. If your strategy is growth, prioritize M&A that brings testing capability, design IP for side‑impact performance, or regional manufacturing footprint; if your strategy is defensibility, lock multi‑year OEM contracts with integrated service levels.
-
Prepare aftermarket plays. Retrofit and replacement opportunities require different channel strategies, logistics models, and parts traceability; invest in distributor training and certified install networks.
Scenario Planning — Practical Signals to Monitor
We recommend framing 2026 plans against three internally consistent scenarios in our report: (1) Base — regulatory implementation continues on the current timetable (aligned with the 6.25% CAGR), (2) Upside — accelerated global adoption of stricter side‑impact rules and broader retrofit programs creating faster penetration, and (3) Downside — slower vehicle production or delayed regulatory implementation compressing near‑term demand. Each scenario in the full report is paired with tactical triggers (e.g., final regulatory text dates, lead time changes for steel, and OEM platform timing) to translate signals into immediate actions.
How Boards and Strategy Teams Should Use This Analysis in 2026
-
CapEx and resource allocation: Prioritize spend on testing assets and validation personnel ahead of tooling expansion to avoid stranded investments if regulations shift.
-
M&A and partnership screening: Use our supplier scorecards to shortlist targets that provide testing certificates, IP in side‑impact anchor design, or strategic regional capacity.
-
Procurement negotiations: Leverage the report’s cost‑to‑serve and raw‑material hedging analysis to renegotiate steel contracts and timing clauses with OEMs.
-
Product roadmaps: Map product launches to certification windows; prioritize modular anchor systems that can be economically requalified across programs.
-
Aftermarket growth: Deploy a certified installer and parts traceability program to capture retrofit demand without eroding OEM channel relationships.
Operational Next Steps — A 90‑Day Checklist
-
Run a regulatory readiness audit focused on FMVSS 213a and UNECE R129 gaps.
-
Engage top supplier(s) in a material continuity workshop and secure at least one alternate source for high‑strength steel.
-
Initiate a proof‑of‑concept for serialized traceability on a pilot vehicle program.
-
Identify one M&A target or strategic partner to accelerate access to test‑lab capability or regional capacity; commence confidential due diligence.
Our full Worldwide Automotive ISOFIX Mounts Market report expands each of the areas summarized above with primary‑research driven data, supplier scorecards, and downloadable models you can plug into 2026 planning cycles. To preserve the strategic advantage for subscribers, we have summarized segmentation insights here while reserving detailed subsegment numbers, regional splits, and company share tables for the full report.
For executives ready to convert this intelligence into commercial advantage in 2026 — whether that means de‑risking supply chains, accelerating product validation, or selectively pursuing M&A — PW Consulting’s full report provides the operational templates, regulatory checklists, and financial models required to act. Contact PW Consulting via our corporate portal to request the complete dataset, supplier benchmarking files, and the scenario modelling workbook that underpins the conclusions summarized in this release.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ISOFIX Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Low‑Frequency Geophone Market to Grow at 7.0% CAGR, Reaching USD 244.81 Million by 2032
By PW Consulting, 2026-08-12
Worldwide Low Frequency Geophone Market — Strategic Briefing for 2026 Decisions
Executive summary
The low frequency geophone market is entering a decisive phase for enterprise strategy and capital allocation. Our latest PW Consulting study — covering 2020–2025 historicals and a 2026–2032 forecast horizon — finds the market expanding at a steady compound annual growth rate of approximately 7.0%. After a steady climb from the early-2020s, the global market is projected to continue its compound growth into the early 2030s, moving from a mid-hundreds million USD base in 2025 to materially larger totals by 2032. Market concentration is meaningful: the top three suppliers collectively control a plurality of the market, while the top five account for a clear majority — a competitive landscape that favors scale, product breadth, and integrated service models.
Worldwide Organic Detox Tea Market
Why this report matters for 2026 corporate planning
- Procurement and CapEx timing: Buyers in energy (including carbon capture and storage), mining, and civil infrastructure must align sensor purchases and deployment timelines with multi-year project horizons. Understanding the market’s near-term growth and supplier capacity constraints will materially affect negotiation leverage and inventory strategy in 2026.
- R&D and product roadmaps: Technical advancements in low-frequency response, sensitivity and tilt/temperature tolerance are differentiators. The 2026 decision window is optimal for redirecting R&D budgets toward low-frequency performance improvements and integration with distributed sensing arrays.
- M&A and partnership scouting: With a moderately concentrated supplier base, bolt-on acquisitions and strategic partnerships can rapidly expand technical capability and geographic reach. Our report provides the commercial and technical due diligence framework that privately held and public buyers will use to prioritize targets in 2026.
- Regulatory and compliance planning: Operators involved in induced seismicity monitoring and carbon storage projects increasingly face documentation and monitoring requirements. Certification profiles and quality systems across suppliers should be a gating factor in sourcing decisions.
Market dynamics shaping 2026 choices
Several convergent forces are driving demand for low frequency geophones in the coming planning cycle. First, applications that require extended low-frequency response — deep seismic exploration, carbon storage monitoring, and induced seismicity tracking — are growing in project count and budget commitment. Second, technology integration trends (ruggedized remote deployments, distributed arrays, and high-sensitivity triaxial solutions) are shifting buyer preferences toward suppliers who can offer systems-level solutions rather than standalone transducers. Third, supply-side considerations — availability of precision electromagnetic coils, specialty magnets, and spring elements — introduce lead-time and quality variability that must be managed strategically.
Worldwide Job Costing Software Market
Quality and process standards remain a hygiene factor: leading manufacturers maintain ISO 9001 and environmental/occupational certifications to support industrial-grade production and project compliance. These certifications are often prerequisites on large energy and infrastructure tenders and are therefore incorporated into procurement scorecards.
Bifurcated Covered Stent Market
Competitive landscape — who matters and why
The competitive map is populated by established instrumentation houses, specialist geophone manufacturers, and several regional players that service fast-growing end markets. Key vendors include firms with mature low-frequency portfolios, product launches targeted at specific use cases, and recent strategic collaborations that indicate how the market will structure over the next 18–24 months.
- Geospace Technologies Corporation (Houston, USA): Portfolio breadth and targeted new product introductions — including recent low-frequency models designed for marine and onshore applications — position the firm as a go-to supplier for integrated exploration workflows. Their product strategy underscores an emphasis on systems that support carbon storage and hazard monitoring programs.
- Sercel (Carquefou, France): Long-period and high-sensitivity seismometer capabilities make Sercel a preferred partner for scientific and industrial projects demanding extended low-frequency response. Their product lineage and global service footprint support large-scale programs with demanding quality requirements.
- Seis Tech and Zhaofeng (China): These suppliers combine competitive cost structures with an expanding product range, including triaxial and very-low-frequency offerings. Their presence is an important consideration for operators balancing price, lead-time, and local content requirements.
- Specialists and adjunct suppliers (CSI Supplies, INOVA, Kinemetrics, Nanometrics, Geometrics, PASI SRL): These companies fill niches — from high-sensitivity nodal sensors to ruggedized seismographs and specialized velocity sensors — and are frequently engaged for bespoke projects or as complementary suppliers in multi-vendor procurement strategies.
Recent market moves exemplify the dual trend of product innovation and ecosystem integration. Notably, a leading US supplier launched a new low-frequency model in mid-2024 aimed at marine and onshore exploration, while a prominent seismograph manufacturer announced a strategic partnership to embed rugged, remote-deployed low-frequency sensors into distributed arrays. These developments signal that differentiated hardware alone will no longer be sufficient; ecosystem partnerships and software-enabled services are becoming commercial requisites.
What the PW Consulting report delivers (practical contents)
Our report is engineered for decision-makers who need to convert market intelligence into executable plans during the 2026 budgeting and procurement cycle. Deliverables include:
- Validated market sizing and a transparently modeled forecast through 2032, calibrated to recent project pipelines and technology adoption curves.
- Scenario-based demand models that test sensitivities to commodity cycles, CCS deployment rates, and regulatory tightening around induced seismicity monitoring.
- Supplier scoring and a comparative heatmap across dimensions such as sensitivity, low-frequency floor, ruggedization, certification status, and after-sales service.
- Procurement playbooks and contract templates designed to mitigate lead-time and quality risks tied to component sourcing (coils, magnets, precision springs).
- Supply-chain risk matrix and mitigation strategies including dual-sourcing, local assembly, and strategic inventory positions aligned with multi-year project pipelines.
- M&A and partnership advisory frameworks to prioritize targets based on technical fit, manufacturing capability, and route-to-market synergies.
- Field trial design and validation protocols to accelerate adoption while reducing measurement uncertainty in operational environments.
Strategic imperatives for 2026
- Adopt a prioritized supplier strategy: combine a global prime supplier for scale with regional specialists to optimize cost, compliance, and technical fit.
- Lock in capacity for high-sensitivity, low-frequency models now. Lead times for precision electromagnetic components and magnet sourcing create procurement risk that compounds across project timelines.
- Invest in testbeds and joint R&D with suppliers to accelerate platform integration (sensor + telemetry + analytics), reducing time-to-value for distributed array deployments.
- Design procurement contracts with technical acceptance criteria and certification milestones (including ISO-related compliance) to avoid downstream remediation costs.
- Use scenario stress-testing in budgeting processes — particularly around CCS and induced seismicity use cases — to ensure capital plans remain robust to alternative adoption curves.
- Consider bolt-on acquisitions or exclusive supply agreements to secure niche technologies (e.g., long-period seismometers or triaxial high-sensitivity sensors) that competitors may lack.
How PW Consulting supports your 2026 agenda
PW Consulting brings a combination of sector expertise, technical bench-strength, and transaction experience designed for outcomes-oriented clients. Our services can be scoped to support:
- Strategic sourcing programs, including RFP design, vendor scorecards and reverse-auction simulations;
- Technical due diligence for M&A or JV opportunities with product-level performance validation;
- Supply-chain resilience design, including alternative material sourcing and local assembly strategies for mission-critical projects;
- Regulatory readiness and monitoring frameworks tailored to projects that require continuous seismic observation and documented compliance.
Conclusion — the 2026 decision window
The low frequency geophone market is no longer a niche instrumentation segment; it is a strategic enabler for projects where subsurface certainty and long-period signal fidelity are mission-critical. A moderate, sustained growth trajectory and a concentrated supplier base create both risks and opportunities for buyers, manufacturers, and investors. Our report provides the analytic rigor and executable playbooks required to convert that macro trajectory into 2026 choices that protect project value and create competitive advantage.
For a complete view of our dataset, supplier scorecards, scenario outputs, and the restricted segment-level insights that drive procurement and investment decisions, access the full PW Consulting Worldwide Low Frequency Geophone Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Low Frequency Geophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


