



Category: market research
PW Consulting: Worldwide K–12 Art Course Market Poised to Soar — Report Forecasts 8.52% CAGR
By PW Consulting, 2026-08-12
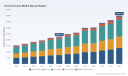
Worldwide K–12 Art Course Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market brief on the Worldwide K–12 Art Course Market synthesizes five years of historical performance and a forward-looking seven-year forecast to deliver a decision-grade view for 2026 planning cycles. The global market expanded from approximately USD 15.4 billion in 2020 to about USD 22.6 billion in 2025, and our modelling projects continued expansion at a compound annual growth rate (CAGR) of 8.52% through the 2026–2032 forecast window, reaching roughly USD 40.1 billion by 2032. This trajectory underscores a durable, investible market driven by digital adoption, curriculum reinvigoration at district level, and new commercial models for supplemental and blended arts learning.
Worldwide Fused Silica Wafers Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a watershed year for K–12 procurement calendars and product roadmaps. Districts and national ministries that budget now will lock in curriculum purchases, edtech integrations, and professional development programs that remain in place for multiple years.
Worldwide Push-to-Talk Over Cellular (PoC) Service Market -
Visibility: The market’s mid-2020s acceleration has reached a point where first-mover posture on platform integrations, teacher upskilling, and privacy-compliant monetization creates sustainable advantage.
Worldwide Food Tracking Technologies Market -
Risk mitigation: Rapid vendor proliferation and low consolidation (CR3 ~11.4%; CR5 ~16.8%) amplify buyer risk. The report gives procurement teams the governance frameworks and vendor scorecards needed to reduce adoption risk while controlling TCO.
What is in the report — practical content and deliverables
PW Consulting designed this brief as an operational toolkit for business leaders, product managers, district buyers, and investors. Key deliverables include:
-
Robust market model: historical tracking (2020–2025) and a granular forecast (2026–2032) with sensitivity scenarios tied to device penetration, per-pupil spending, and curriculum policy shifts.
-
Buyer segmentation and persona plays: profiles for district curriculum directors, virtual school operators, parents who purchase supplemental courses, and independent instructors on marketplace platforms.
-
Go-to-market playbooks: differentiated strategies for publishers, SaaS creative-tool vendors, supplemental class marketplaces, and district services teams — including channel economics and contract levers.
-
Product and pricing frameworks: pricing ladders, freemium-to-premium conversion levers, and bundling strategies that account for both classroom and after-school revenue streams.
-
Compliance & procurement kit: practical checklists for COPPA and FERPA alignment, contract language templates for data stewardship, and vendor audit templates to streamline district review cycles.
-
M&A and partnership map: acquisition targets, partnership archetypes, and a valuation filter that prioritizes recurring revenue, customer stickiness, and data assets.
-
Implementation templates: LMS/API integration patterns, teacher PD curricula, student assessment rubrics tied to art standards, and ROI models to support adoption business cases.
-
Case studies & benchmarks: anonymized district rollouts, platform integrations, and a comparative performance matrix that highlights adoption velocity and pedagogical outcomes.
Note: This press summary intentionally omits granular regional and course-type breakdowns contained in the full report to preserve the integrity of the proprietary datasets; readers will find the full segmentation and downloadable models via the official report page.
Market dynamics shaping 2026 decisions
-
Digitalization of practice: Creative software and digital media tools are now core to K–12 art pedagogy, not niche supplements. Adoption of digital creation workflows is increasing demand for curriculum that blends traditional studio art with media arts competencies.
-
Hybrid delivery normalization: Post-pandemic schooling patterns have institutionalized hybrid and online modalities — buyers now expect turnkey solutions that include synchronous instruction, asynchronous project workflows, and assessment integrations.
-
District-level strategic planning: Major districts are releasing unified arts education plans and data systems to track instruction quality from pre-K through grade 12. These programs create procurement windows for vendors that can demonstrate data-driven learning outcomes.
-
Privacy and regulatory constraints: Updated COPPA and ongoing FERPA enforcement materially affect product design, marketing, and data monetization strategies. Vendors must design consent-first experiences and limit third-party commercial disclosure to maintain trust and compliance.
-
Human capital is the bottleneck: Despite platform advances, certified art educators remain essential. Scalable models that augment teacher capacity (micro-credentialing, PD-as-a-service, and instructor marketplaces) outperform purely automated offerings.
Competitive landscape: what incumbents and specialists are doing
The K–12 art market remains fragmented, with a mix of legacy curriculum providers, edtech incumbents, creative software vendors, niche platforms, and new marketplace entrants. Our competitive analysis examines strategic positioning, product architectures, and go-to-market approaches among representative players:
-
Stride, Inc. (K12) — established leader in online K–12 curriculum with curated art offerings, experiential projects, and community events. Their annual student art competitions and portfolio-centric offerings strengthen engagement and brand affinity among families and districts pursuing fully online schooling options.
-
Connections Academy (Pearson) — leverages public-school partnerships and tuition-free virtual schools to embed arts electives at scale. Their strengths lie in credentialed teacher networks and compliance-ready school operating models.
-
Adobe Inc. — the dominant creative-software incumbent enabling digital art workflows. Strategic moves toward education licensing, classroom integrations, and curriculum-aligned templates make Adobe a partner of choice for digital-and-media arts pathways.
-
Savvas Learning Company — a curriculum and platform player pursuing tighter assessment and content integrations. Platform playbooks that bridge core subjects with arts-aligned competencies are driving interest among districts seeking cohesive learning ecosystems.
-
Hillsdale College K–12 — an example of low-cost, content-rich curriculum providers that emphasize fine arts and the humanities, appealing to districts and families seeking classical approaches and budget predictability.
-
Artsonia — a specialized platform focused on student artwork portfolios and exhibitions. It demonstrates the value of community and showcase features in generating teacher adoption and parent engagement.
-
Outschool — represents the flexible, marketplace-led supplemental model where independent instructors deliver live, niche art classes. Marketplace flexibility can accelerate experimentation and reach underserved demand pockets.
Recent industry activity — including major district arts plans and interoperability partnerships between curriculum and assessment vendors — signals an accelerating shift from pilot projects to large-scale adoption. PW Consulting’s full competitive matrix maps product fit, contract terms, and integration readiness for each archetype.
Implications and recommended actions for 2026 planners
For executives, product leaders, district buyers, and investors, the following strategic moves are high-impact and time-sensitive in 2026:
-
Prioritize privacy-by-design: Build COPPA- and FERPA-centric data flows now. Contracts, consent flows, and vendor audits created in 2026 will still be scrutinized in later renewals.
-
Bundle for teacher enablement: Differentiate not on content alone but on teacher enablement — PD, assessment scaffolds, and turnkey lesson plans that reduce classroom prep time.
-
Invest in interoperability: APIs, LTI/OneRoster compatibility, and portfolio export features shorten procurement cycles and reduce integration costs for districts.
-
Design mixed revenue models: Combine per-seat district deals, school-year subscriptions, and supplemental marketplace offerings to diversify cash flow and capture both core and after-school demand.
-
Seek partnership-first expansion: Publishers and creative-software firms should prioritize channel partnerships with district consortiums and specialty platforms (e.g., portfolio hosting, assessment providers) to accelerate scale.
-
Proof points and measurement: Deploy small-scale pilots tied to measurable outcomes (student engagement, portfolio growth, arts graduation metrics) that can be scaled across purchasing cohorts.
Risk factors and watchlist for 2026
-
Policy shifts: National or state-level adjustments to arts funding and procurement rules can compress or expand addressable budgets rapidly.
-
Teacher labor dynamics: Teacher shortages or certification bottlenecks can cap implementation speed — invest in teacher-adjacent services to mitigate.
-
Data commercialisation limits: Rules that limit third-party data use will reduce some monetization pathways for consumer-facing platforms.
-
Fragmentation: Low market concentration means intense competition on price and feature parity; differentiation through teacher outcomes and district-level integration is essential.
How to use this intelligence
PW Consulting’s brief is structured to be immediately operational: use the market model to stress-test your 2026 topline scenarios, deploy the procurement playbook to accelerate district wins, and use the M&A map to prioritize targets that close capability gaps. The report’s custom templates (contracts, PD curricula, API checklists) are designed to be dropped into RFP responses and pilot agreements.
Next steps
This press summary shares the high-level story and strategic implications; detailed segmentation, regional and course-type splits, and downloadable financial models are intentionally reserved for the full report. Organizations preparing 2026 budgets, product roadmaps, or acquisition plans should review the complete dataset to secure the tactical intelligence necessary for execution.
Contact PW Consulting or visit our report page to access the full Worldwide K–12 Art Course Market report, the underlying market model, and our bespoke advisory engagements for stakeholders seeking rapid, low-risk entry or scaling strategies in this expanding market.
For detailed analysis of this topic, please visit the official page: Worldwide K12 Art Course Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Fast Connection Solutions for Liquid Cooling Systems Market to Reach USD 4,012.79 Million by 2032, Expanding at an 18.25% CAGR
By PW Consulting, 2026-08-12
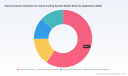
Worldwide Fast Connection Solutions for Liquid Cooling System Market — A Strategic Preview for 2026 Decision-Makers
As enterprises plan capital allocation and product roadmaps for 2026, the fast connection solutions segment for liquid cooling systems is transitioning from niche technical componentry to a critical enabler of performance, uptime, and compliance across data centers, high-performance computing (HPC), electric mobility, and industrial thermal management. Our new market study finds the overall market accelerating from roughly USD 1.24 billion in 2025 and, at a projected compound annual growth rate (CAGR) of 18.25%, moving toward a multibillion-dollar opportunity by the end of the 2026–2032 forecast horizon. For executives weighing deployment strategies, partner selections, or M&A moves next year, this preview outlines the practical implications we expect to drive boardroom decisions.
Worldwide Property Restoration Software Market
Why 2026 Is a Pivotal Year
-
Density and performance demands driven by AI/HPC, coupled with regulatory pressure on energy efficiency, are converging. Industry-standard guidelines and regulations (ASHRAE updates, ISO/IEC metrics, and regional efficiency mandates) are making liquid cooling a prescriptive, not optional, approach for many high-density deployments.
Sterile Abdominal Pads Market -
Direct liquid cooling (DLC) and immersion cooling are delivering measurable energy benefits versus air-cooled designs. These architectures create new technical requirements for connectors: higher steady-state throughputs, minimal pressure-drop, leak-free blind-mateability, and serviceability for zero-downtime maintenance.
Worldwide Restaurant Scheduling Software Market -
Supply-side innovation is accelerating. New polymer valve systems and optimized flow-path designs are entering the market alongside established metal quick-disconnect technologies, enabling system-level trade-offs between weight, purity, manufacturability, and lifecycle cost.
What PW Consulting’s Report Delivers — Practical Tools for Executives
Designed as a working intelligence asset for procurement, product, and corporate strategy teams, the report emphasizes actionable frameworks over academic summaries. Key deliverables include:
-
Market sizing and scenario models calibrated to 2020–2025 historical performance, with a transparent methodology for the 2026–2032 forecast that supports sensitivity analysis by deployment scale and cooling architecture.
-
ROI and TCO calculators that translate connector performance (flow, pressure loss, serviceability) into measurable facility-level metrics (cooling energy, PUE impact, maintenance window exposure).
-
Supplier scorecards and interoperability matrices to support vendor selection: test results, failure-mode analyses, qualification checkpoints, and contract language recommendations.
-
Procurement playbooks for phased rollouts and pilot-to-production transition plans, including acceptance criteria for blind-mate systems and non-spill couplings.
-
Supply chain risk maps highlighting raw material exposure, manufacturing concentration, and logistics constraints—with mitigation options for near-term disruption risk.
Data-Driven Strategic Imperatives
The market’s strong mid-to-high teens CAGR signals that connection technologies are no longer commoditized accessories; they are strategic levers. From our analysis, four imperatives should guide 2026 investment decisions:
-
Prioritize flow-optimized, low-pressure-drop designs. System-level energy and pump efficiency are highly sensitive to connector hydraulics—small improvements in connector loss translate into material savings and lower operating expenses at scale.
-
Insist on validated non-spill and blind-mate solutions for serviceability. Downtime cost models favor connectors that eliminate fluid loss during hot-swaps, enabling in-situ maintenance and modular scaling.
-
Balance material strategy across distribution and chip interfaces. Metals continue to dominate high-pressure, direct-to-chip quick disconnects due to strength and thermal resilience, while modern polymers offer advantages for peripheral distribution networks and leak-tight, lightweight assemblies.
-
Design for standardization and interoperability. Early investment in OCP, vendor-compliance testing, and unified coupling standards reduces integration risk and accelerates time-to-scale.
Competitive Landscape — Who Matters and Why
The supplier ecosystem combines established hydraulics and connector specialists with emergent niche players. Market concentration metrics show the leading three firms capture a substantial slice of the market footprint, and the top five contribute an even larger share—pointing to an industry that is fragmented but consolidating at the higher end around validated, certified designs. For strategy teams, that dynamic implies both partnership opportunities and attention to vendor lock-in risks.
-
CPC (Colder Products Company) — Strength lies in Everis® series non-spill and blind-mate couplings tailored to electronics and data center usage. Their productized reliability testing is a differentiator for integration-driven buyers.
-
Parker Hannifin Quick Coupling Division — Offers dripless designs optimized for server and rack cooling, with strong system-engineering guidance that appeals to conservative enterprise operators focused on energy-efficiency gains.
-
CEJN — High-flow, low-pressure-drop couplings and OCP-compliant products position CEJN as a go-to supplier for CDU-level applications where interchangeability and standards compliance matter.
-
Danfoss (Hansen®) — Emphasizes flow-path optimization to reduce pressure drop—an attractive value proposition for operators focused on pump energy and system diversity.
-
Stäubli — Known for clean-break, high-temperature tolerant solutions; recent miniature connector launches suggest a push into compact optical and dense blade applications.
-
Amphenol, Gates, Specialty Mfg., TITAN Fluid, Motivair — Each brings unique advantages: broad connector portfolios, full-flow direct-to-chip solutions, custom engineering services, OCP/NVIDIA-compliant stainless designs, and specialized dynamic cold-plate systems, respectively.
Recent industry moves underline the market’s momentum. Polymer-based innovations and integrated cooling infrastructure announcements by incumbent industrial suppliers illustrate a dual track of evolution: incremental optimization of existing metal couplings and step-change system reengineering centered on new materials and valve designs.
Supply Chain and Materials Outlook
Material choice is strategic, not merely cost-based. Metals remain the dominant material class for high-pressure, direct coupling interfaces given their mechanical performance and thermal robustness; polymers are gaining ground for distribution infrastructure due to lower weight, chemical purity, and manufacturability advantages. New polymer valve patents and full-scope polymer cooling systems are already shifting procurement conversations, especially where long-run lifecycle, corrosion resistance, or rapid deployment are priorities.
Raw material exposure, manufacturing lead times, and qualification cycles must be factored into 2026 sourcing decisions. Our supply-chain risk matrix maps these variables and proposes hedging strategies—dual-sourcing where feasible, localized inventory buffers for pilot rollouts, and phase-gated qualification to shorten production ramp time.
Actionable Recommendations for 2026
-
Run targeted pilot programs (3–6 months) that validate connector performance against pump curves and failure modes of critical paths. Use pilots to de-risk procurement commitments.
-
Prioritize specification standardization across vendors to reduce integration costs and accelerate interchangeability in modular deployments.
-
Engage suppliers early on compliance testing—demand third-party validation for leak rates, cycle life, and pressure-drop metrics to reduce surprises in deployment.
-
Adopt a tiered sourcing strategy: secure design partnerships with innovators for direct-to-chip interfaces while standardizing distribution hardware on mature platforms to optimize TCO.
-
Monitor consolidation activity—use M&A or strategic alliances to fill capability gaps in blind-mate tech, polymer manufacturing, or qualification services.
How to Use the Full PW Consulting Report
This preview highlights the report’s strategic themes and executive-level recommendations. The full study contains the granular intelligence corporate teams need to convert strategy into procurement and product decisions: downloadable scenario spreadsheets, detailed supplier scorecards and test matrices, build-versus-buy decision trees, product roadmaps, and a confidential M&A watch list. Importantly, granular regional and application-level segmentation tables are available in the complete report for teams that require localized deployment economics and supplier mapping. Our “trailer” approach here intentionally showcases the report’s depth while guiding readers to the comprehensive dataset and tools behind PW Consulting’s recommendations.
For 2026, decisions about supplier selection, pilot prioritization, and system architecture will materially affect total cost of ownership, serviceability, and compliance outcomes. PW Consulting’s Worldwide Fast Connection Solutions for Liquid Cooling System Market report is designed as a working asset to help your team convert these market dynamics into defensible, measurable actions.
Contact PW Consulting to request an executive briefing, obtain the full dataset, or commission a tailored workshop to align cooling-connector strategy with your 2026 capital and product plans.
For detailed analysis of this topic, please visit the official page: Worldwide Fast Connection Solutions for Liquid Cooling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rotating Gamma System Market to Reach USD 507.19 Million by 2032, Expanding at a 5.5% CAGR
By PW Consulting, 2026-08-12
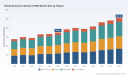
Worldwide Rotating Gamma System (RGS) Market: Strategic Imperatives for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Rotating Gamma System (RGS) market delivers an actionable, executive-ready synthesis designed to inform capital planning, clinical adoption, and corporate strategy throughout 2026. This executive briefing summarizes the strategic value of our full report—highlighting near-term market dynamics, competitive posture, regulatory inflection points, and the practical decision frameworks hospitals, device OEMs, and investors should use when allocating resources next year. To preserve the commercial edge our clients expect, we present high‑level, data‑driven findings here while reserving detailed segment and competitor econometrics for the full report.
Worldwide Toilet Rim Block Market
Why 2026 Is a Pivotal Year
As stereotactic radiosurgery technology and reimbursement frameworks converge, 2026 will be a year when early adopters either consolidate clinical leadership or fall behind on both outcomes and ROI. RGS platforms—driven by rotational cobalt-60 architectures—are moving from niche validation to broad clinical implementation. The window for procurement decisions, network-level clinical pathways, and vendor partnerships is narrow: procurement cycles for capital equipment, site readiness workstreams, and regulatory submissions converge in calendar 2026, creating a decisive planning horizon for health systems and suppliers alike.
Worldwide Multifamily Software Market
Market Outlook: Size, Growth, and Structural Features
Our base-year assessment (2025) and forward-looking model show a market that has recovered from pandemic distortions and is on a steady growth trajectory. The total RGS market expanded meaningfully through 2020–2025 and, according to our forecast, will continue to grow at approximately 5.5% CAGR through the 2026–2032 forecast window. This growth is driven by technology refresh cycles in established centers, new installations in emerging oncology hubs, and expanding extracranial indications.
Embryo Holding Medium Market
Important structural characteristics that shape strategic choices:
- Concentration of supply and differentiated platform strategies: a small number of suppliers retain disproportionate influence over technology roadmaps, clinical partnerships, and service models.
- Capital intensity and service economics: RGS platforms require significant upfront investment but present predictable service and source-replacement profiles compared with alternative modalities.
- Clinical extension potential: primary intracranial use-cases remain the adoption anchor, while controlled expansion into extracranial stereotactic radiotherapy is the most material growth vector.
What Our Report Provides—Practical, Implementable Content
PW Consulting’s full RGS report is built for decision-makers who need to act, not just observe. Key deliverables that drive 2026 decision-making include:
- Proprietary market-sizing and scenario models (base-year 2025; forecast through 2032) that allow users to test alternative adoption, pricing, and reimbursement pathways.
- Vendor benchmarking matrices covering technology attributes, service economics, clinical footprint, regulatory status, and total cost of ownership (TCO) over multi-year horizons.
- Clinical adoption playbooks for hospital systems—covering site selection, OR/radiation oncology integration, patient throughput modeling, and referral network development.
- Regulatory and reimbursement roadmaps that translate 510(k) clearances, NRC licensing nuances, and CPT utilization pathways into procurement and capital-planning actions.
- Risk and contingency playbooks (supply chain, cobalt source logistics, and replacement cost sensitivity analyses) to stress-test investment cases.
- Commercial go-to-market blueprints for OEMs and distributors, including M&A levers, channel strategies, and partnership archetypes with academic centers.
Each of these deliverables is paired with templates, checklists, and a practical “next‑90‑days” implementation plan tailored to whether the reader is a health system, OEM, or private capital investor.
Competitive Landscape: Who Matters and Why
The RGS competitive environment is defined by a mix of established specialist players and agile new entrants. Across the vendor set, differentiation centers on three dimensions: 1) clinical workflow integration (image guidance and targeting), 2) operational footprint and TCO, and 3) regulatory and clinical validation. Leading companies profiled in the report include manufacturers and platform developers that have each carved distinct strategic positions.
- American Radiosurgery Inc. – Known for its Vertex360 and RGS Orbiter platforms, this U.S.-based specialist emphasizes a patient‑centric systems design aimed at head, neck, spine, and body indications. Its value proposition focuses on clinical versatility and streamlined noninvasive workflows.
- Akesis Inc. – With the Galaxy RTi and Gemini360RT platforms, Akesis has positioned itself around continuous-rotation cobalt-60 delivery paired with in-plane image guidance. Recent regulatory and clinical milestones in the U.S. have materially altered adoption risk profiles for buyers evaluating new installations.
- MASEP (INFINI) – Operating from China with an international presence, MASEP targets both intracranial and extracranial applications, emphasizing cost-competitive capital solutions for hospital groups in Asia and markets open to alternative procurement models.
- OUR United (TaiChi, Gamma Master) – Focused on image-guided rotating gamma solutions, OUR United combines platform modularity with regulatory clearances across multiple jurisdictions, enabling cross-market clinical validation strategies.
Recent industry developments that materially affect vendor selection and adoption strategies:
- Akesis’ U.S. regulatory progress has reduced entry friction for its platforms and was followed by the first clinical implementation at a major U.S. cancer center in mid‑2025—an important reference case for U.S. buyers.
- Published clinical retrospective series from China in 2025 provide growing evidence for extracranial stereotactic radiotherapy use-cases, accelerating conversations about expanding indications beyond traditional intracranial targets.
- Prior 510(k) clearances for rotating gamma platforms in multiple jurisdictions have created a framework where reimbursement and hospital adoption are driven more by clinical and economic case than by regulatory uncertainty.
Regulatory, Reimbursement, and Technical Considerations
Three pragmatic facts should shape procurement and capital decisions in 2026:
- Regulatory momentum: Several rotating gamma platforms have secured 510(k) clearances; this means market access risk is lower than it was in prior cycles, but local licensing (NRC and equivalent authorities) and radiation safety planning remain non-trivial.
- Reimbursement pathways: Stereotactic radiosurgery/SBRT procedures performed with cobalt-60 rotating systems are typically covered under existing CPT frameworks in hospital settings; organizations must nonetheless align coding strategies with payers to avoid episodic reimbursement variability.
- Technical profile and operations: Rotating gamma designs commonly employ thirty cobalt-60 sources with total activities in a multi-thousand curie range and rotational delivery to create convergent dose arcs. This architecture shifts certain lifecycle costs—chiefly source management and regulatory compliance—into a predictable service model that can be captured in TCO analyses.
Strategic Recommendations for 2026
For Hospital Systems
- Prioritize early engagement with vendors that offer integrated image-guidance and workflow support: this is the primary determinant of throughput and patient selection economics.
- Use the 90‑day procurement diligence templates in our report to align capital committees, radiation safety, and clinical leadership before RFP issuance.
- Evaluate hybrid deployment models (single academic hub vs. networked installations) using scenario models that stress-test referral volumes and payer mixes.
For OEMs and Distributors
- Differentiate on service models (predictable source management, uptime SLAs) and outcome-linked value propositions rather than on price alone.
- Invest in clinical evidence generation in parallel with regulatory filings—U.S. and China reference cases materially accelerate adoption in secondary markets.
- Consider strategic alliances with academic centers for co-marketing and training to reduce buyer implementation risk.
For Investors
- Focus on platform providers with defensible clinical anchors, recurring service revenue, and clear TCO advantages versus orthogonal modalities.
- Assess regulatory and insurance-reimbursement exposure as primary risk levers when modeling exit scenarios.
- Monitor consolidation signals: the market’s high degree of concentration creates both buy-and-build opportunities and potential regulatory scrutiny.
Risks, Uncertainties, and What We Excluded from This Brief
The RGS market faces execution risks that should be explicitly modeled in any 2026 investment or procurement decision: clinical adoption rates (especially for extracranial indications), local licensing complexity, cobalt source logistics, and payer mix shifts. Our full report quantifies these risk vectors under multiple scenarios and provides sensitivity tables for capital managers and CFOs. To preserve strategic value for subscribers, we have not presented detailed sub-segment revenue breakdowns, regional penetration percentages, or vendor share tables in this summary—those deliverables are included in the full report along with the underlying data and modeling assumptions.
Next Steps
Organizations preparing to make capital, clinical, or investment decisions in 2026 should treat the full PW Consulting RGS report as an operational toolkit rather than a descriptive study. The report combines market forecasts, vendor due diligence, procurement templates, and clinical pathway playbooks—each designed to shorten time to value and reduce execution risk.
To obtain the full dataset, vendor scorecards, and customizable scenario models that support board‑level decision-making, please access the complete report via PW Consulting’s research portal. Subscribers receive a complementary 60‑minute strategy workshop to translate findings into a 2026 action plan tailored to their organization’s role in the RGS ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Rotating Gamma System (RGS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Emergency Road Service Market to Expand at a 5.2% CAGR, Reaching USD 40.64 Billion by 2032PW Consulting Forecasts 8.75% CAGR for Worldwide Aesthetic Phototherapy Lamps Market Through 2032
By PW Consulting, 2026-08-12
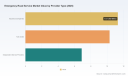
Worldwide Emergency Road Service Market 2026 Outlook: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting today releases an executive briefing accompanying our full-market study on the Worldwide Emergency Road Service Market (base year 2025). As organizations prepare budgets and strategic roadmaps for 2026, this briefing distills the report’s highest‑value takeaways and explains how executive teams — across insurers, automakers, fleet operators, auto clubs and independent service networks — should recalibrate priorities to capture sustained growth in a market expanding at a steady compound annual growth rate (CAGR) of 5.2% through the 2026–2032 forecast horizon.
Containerized Solar Microgrids Market
Why this market matters for 2026 strategic planning
After recovering from pandemic disruptions, the global emergency roadside services market reached approximately USD 28.5 billion in 2025 and is projected to surpass USD 40 billion by 2032. That trajectory — underpinned by a 5.2% CAGR — masks a more complex competitive and operational reality. Decision-makers who treat this as a pure volume play risk margin erosion from rising labor costs, regulatory compliance requirements and shifting reimbursement dynamics. Conversely, organizations that align service design, pricing and partner networks with the technological and regulatory inflection points identified in our report will unlock differentiated growth and profitability.
DR Portable X-ray Systems Market
Key market dynamics shaping 2026 choices
-
Technological enablement is reshaping response economics. Real‑time telematics, AI-driven dispatch, and integrated mobile experiences are shortening time‑to‑service and improving first‑touch resolution. Recent vendor deployments — notably AI routing alliances between B2B platforms and major insurers — underscore how predictive logistics are moving from pilot to scale.
Retail Soft Tags Market -
Electrification is altering service mixes and asset needs. EVs change common failure modes and introduce novel needs such as on-site charging and battery diagnostics. Leading clubs and service providers have begun embedding EV locators and battery health tools within member apps; this is rapidly becoming table stakes for customer satisfaction and retention.
-
Operational cost pressure is intensifying. Labor scarcity and wage inflation for tow and roadside technicians have already translated into higher unit costs. These trends force operators to rethink utilization, routing efficiency and task bundling to preserve margins without compromising SLA commitments.
-
Regulatory and data‑privacy regimes are increasing compliance overhead. Mandates for vehicle and dispatcher GPS tracking, plus tightened data anonymization timelines in multiple jurisdictions, require investments in secure data architectures and processes — with direct implications for vendor selection and contractual frameworks.
-
Reimbursement behaviors are evolving. Insurer reimbursement levels and claim handling practices are a major demand-side lever that affects pricing models across the ecosystem. The interplay between insured benefit design and third‑party service rates will be a primary battleground for margin capture in 2026.
Competitive landscape — what incumbent and challenger moves tell us
The market exhibits a mid‑level concentration: the top three players command a meaningful but not dominant share, and the top five increase that share materially. This structure creates opportunities for both scale players and nimble specialists. Our report examines leading firms across club, insurer-integrated, B2B dispatch and independent service models to surface replicable plays and avoided pitfalls.
-
Consumer-facing auto clubs and insurers continue to leverage membership ecosystems and brand trust to retain recurring revenue streams. Their investments in native mobile capabilities and value-added services have strengthened customer stickiness.
-
B2B platforms that link insurers, OEMs and service networks are increasingly differentiating on orchestration and technology. Strategic partnerships incorporating AI dispatching and predictive routing have already produced measurable improvements in response time and cost per event.
-
Independent and regional service providers remain critical for last‑mile execution despite rising platformization. Those that professionalize operations through standard operating procedures, digital job management and performance analytics are winning higher‑value contracts with insurers and fleets.
Our company profiles of major players examine strategic postures across several dimensions: product and service bundling, technology adoption, network depth, partner ecosystems, pricing model experimentation and recent strategic developments. We highlight several illustrative moves that industry leaders have taken in the last 18 months to adapt to the new operating environment.
Recent market developments that alter the competitive calculus
-
Strategic partnerships between orchestration platforms and major insurers have moved from announcement to operational impact, improving route efficiency and first response metrics.
-
Leading consumer-facing organizations have upgraded mobile and diagnostics capabilities to address EV and battery-related claims at scale, embedding value that reduces downstream repair costs.
-
Innovative pilots — such as using drones for remote breakdown scouting — have demonstrated potential to materially improve response in sparsely populated areas, suggesting a differentiated opportunity for those willing to invest in non‑traditional modalities.
What our report delivers — practical, operational intelligence for 2026
PW Consulting’s full report is structured to enable immediate decision-making. Rather than a static market narrative, the deliverable is a practical toolkit for commercial, operations and M&A teams. Highlights include:
-
Robust market sizing and validated forecasts (2026–2032) that reconcile top‑down trends with bottom‑up activity metrics to inform 3‑ to 5‑year financial planning.
-
Scenario modelling that quantifies upside and downside outcomes under alternative EV adoption, labor cost and regulatory paths — enabling stress‑tested budgets and capital allocation choices.
-
An actionable vendor and partner assessment framework that prioritizes technology, coverage, cost and compliance attributes for insurer, OEM and fleet buyers.
-
Operational playbooks for margin improvement, covering dispatch optimization, mixed‑asset utilization, surge staffing models, and dynamic pricing levers tied to reimbursement schedules.
-
Regulatory and privacy matrix detailing jurisdictional compliance requirements and implementation cost benchmarks, with recommended contractual clauses and data handling standards.
-
M&A and partnership due‑diligence templates tailored to roadside services — from network quality audits to technology and integration risk checklists.
Strategic actions for executive teams in 2026
Based on our synthesis of market trajectory, competitive moves and operational constraints, PW Consulting recommends five priority actions for leaders planning 2026 initiatives:
-
Invest selectively in dispatch orchestration and AI routing. Even modest improvements in route efficiency can offset wage inflation and materially improve unit economics.
-
Embed EV capabilities into core service offers and mobile experiences now. Early adopters will capture customer loyalty and realize lower long‑term cost per incident through better diagnostics and remote triage.
-
Standardize partner performance metrics and enforce SLAs that link payment to verified outcomes. Strong contract governance mitigates variability from fragmented provider networks.
-
Build regulatory and data‑privacy compliance into product design rather than as an afterthought. Jurisdictional differences in GPS tracking and data anonymization timelines require modular, auditable systems.
-
Use scenario planning to size optionality for expansion, M&A or tech investments. With the market on a steady growth curve, strategic capital should be deployed to secure differentiation, not just share.
Who benefits most from the report
The report is expressly designed for senior leaders who need to translate market dynamics into executable plans: chief strategy officers, heads of operations, product leads at insurers and OEMs, M&A teams, and private equity investors evaluating platform and roll‑up opportunities in the roadside ecosystem. It is also a practical manual for regional operators seeking to professionalize and compete for higher‑value contracts.
Next steps
PW Consulting’s full report contains the comprehensive datasets, benchmarking tables and proprietary scenario models that underlie this executive briefing. For companies that must make capital allocation decisions or negotiate network agreements in 2026, the report provides the empirical foundation and executable frameworks required to move from intent to results. To access the full analysis, contact PW Consulting through our official distribution channels to request the report package and supporting advisory services.
PW Consulting’s senior advisory team remains available to perform tailored workshops, rapid due diligence and integration planning to accelerate evidence‑based decision making. Our goal: make 2026 the year your organization turns roadside service complexity into a durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Emergency Road Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pharmaceutical-Grade L‑Carnitine Market Poised to Grow at a 5.45% CAGR During 2026–2032
By PW Consulting, 2026-08-12
Worldwide Pharmaceutical Grade L‑Carnitine Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
PW Consulting’s latest market study on pharmaceutical‑grade L‑carnitine synthesizes seven years of historical performance (2020–2025) and a seven‑year forecast horizon (2026–2032) into an actionable intelligence package for senior executives, procurement leaders, and corporate strategists. The market has demonstrated steady expansion, reaching an estimated global revenue base of approximately USD 245.5 Million in 2025 and progressing at a compound annual growth rate (CAGR) of 5.45% into the forecast window. Our modeling projects continued growth through 2032 under base assumptions, driven by clinical nutrition demand, hospital formulary procurement, and specialty hospital nutrition launches.
Worldwide Non-leather Products Market
Why this report matters to 2026 corporate strategy
- Data‑led timing: 2026 is a pivot year where demand growth intersects with supply constraints. Firms that calibrate their sourcing, capacity, and regulatory readiness in the first half of 2026 will capture disproportionate share and margin.
- Price and margin dynamics: Pharmaceutical‑grade product commands a material premium versus feed‑grade material because of purity, GMP, and endotoxin control requirements. Understanding the drivers of that premium is essential for product positioning and tender planning.
- Concentration and competitive leverage: The market structure exhibits notable concentration among the largest producers, creating both supply risk and partnership opportunities for mid‑sized and regional players seeking stable supply or value‑added collaboration.
- Regulatory gatekeepers: Compliance with pharmacopeial standards and endotoxin limits is non‑negotiable for injectable and clinical applications — gaps in documentation or sterilization controls materially affect market access and reimbursement eligibility.
Market trajectory and 2026 inflection points
Our quantitative base shows a resilient expansion from the pandemic era into a post‑pandemic normal, with the 2025 market base providing the foundation for modestly accelerating demand in 2026. The 5.45% CAGR embedded in our forecast translates into a mid‑single‑digit compound increase year‑over‑year, reflecting three simultaneous forces: (1) steady clinical nutrition adoption in hospital and geriatrics channels; (2) incremental uptake in oral and parenteral therapeutic formulations; and (3) structural supply issues driven by raw material and process bottlenecks in high‑purity manufacturing.
Dual Channel Flame Photometers Market
For decision makers, this means 2026 is less a year of radical expansion and more a year of optimisation — optimising supply chains, forward cover strategies, regulatory dossiers, and go‑to‑market assets to secure premium tenders and hospital formularies.
Vitrification Cooling Box Market
Key dynamics that will shape decisions in 2026
- Supply chain and capacity bottlenecks: Fermentation and high‑purity chemical synthesis capacity is unevenly distributed. Expect elevated lead times and potential spot market volatility unless companies secure multi‑year agreements or pursue vertical integration.
- Regulatory and quality thresholds: Pharmaceutical L‑carnitine must meet USP and EP standards with stringent endotoxin ceilings for injectable grades. Auditable GMP footprints and validated analytics are table stakes for hospital channel access.
- Commercial and reimbursement complexity: Hospital nutrition products command distinct procurement routes and reimbursement mechanisms. Pharmaceutical manufacturers with clinical evidence and hospital marketing experience can unlock premium channels faster than commodity suppliers.
- Strategic consolidation and portfolio shifts: Divestitures and redeployments among major ingredient houses create acquisition windows and partnership opportunities for specialty players focused on clinical nutrition.
Competitive landscape — positioning and strategic implications
The market combines global specialty producers, large life‑science suppliers, and a broad cohort of certified regional manufacturers. Our competitive assessment highlights distinct playbooks:
- Lonza Group (Basel, Switzerland) — Lonza’s Carnipure® franchise leverages decades of high‑purity manufacturing, strong quality credentials, and brand recognition in clinical and nutraceutical spaces. Their value proposition centers on compliance, continuity of supply, and premium therapeutic positioning.
- Northeast Pharmaceutical Group (NEPG) and Chinese industrial leaders — Several large China‑based producers operate integrated chemical and GMP manufacturing chains able to scale rapidly. Their strengths are cost competitiveness and volume flexibility; the strategic questions are documentation depth, export regulatory robustness, and end‑to‑end quality controls required by Western hospital clients.
- European specialty manufacturers (e.g., Alfasigma, Biosint, Merck KGaA) — These firms combine pharmaceutical marketing channels with technical grades suitable for clinical trials and hospital supply. Established distribution networks and investigational support are advantages for product launches in regulated markets.
- Contract manufacturers and distributors (e.g., Rochem, AgEx Pharma, others) — These players fill gaps for companies lacking own capacity, offering quick time‑to‑market but exposing buyers to tiered quality and supply‑risk profiles; robust vendor qualification is mandatory.
Strategically, large buyers will look to de‑risk via diversified sourcing, dual‑sourcing strategies, and strategic stockpiles. Mid‑sized producers should evaluate premium niches (injectable, parenteral clinical nutrition) and value chain moves (e.g., GMP upgrades, analytics labs) to climb the value ladder. Private equity and corporate development teams can exploit recent portfolio changes among global ingredient players to acquire capabilities or distribution platforms at attractive valuations.
Recent developments and near‑term triggers
- Product innovation in clinical nutrition: New formulations incorporating pharmaceutical L‑carnitine, notably semi‑solid and enteric nutrition offerings, are expanding hospital use cases and creating tender opportunities for compliant suppliers.
- Business realignment among ingredient majors: Divestitures and redeployments in adjacent food and health ingredient portfolios are reshaping supply chain partnerships and altering capacity footprints that buyers must monitor closely.
- Commercial momentum at customer level: Growth in human nutrition and health segments among large suppliers signals expanding downstream demand, intensifying competition for high‑quality API volumes.
What PW Consulting’s report delivers (practical, non‑revealing summary)
We designed the research to be immediately actionable while protecting client value. Key deliverables include:
- Forward‑looking revenue model calibrated to 2020–2025 historicals and stress‑tested scenarios through 2032, with sensitivity analyses for demand shocks, raw material price shocks, and GMP capacity outages.
- Supply‑chain heat maps and supplier scorecards: an anonymized, audited view of production nodes, documented regulatory readiness, and likely bottlenecks — enabling procurement teams to prioritize supplier audits and contracting.
- Regulatory compliance playbook: step‑by‑step guidance to meet USP and EP requirements, injectable endotoxin control expectations, and dossier readiness for hospital formulary inclusion.
- Commercial playbooks: tender strategy templates, pricing playbooks that explain the drivers of pharma‑grade premiums, and hospital engagement frameworks for clinical nutrition launches.
- Strategic M&A screening toolkit: screening criteria tied to capacity, quality, and go‑to‑market synergies; valuation stress tests tuned to the current concentration dynamics.
- 90/180/360‑day operational checklists: tactical milestones for procurement, quality assurance, regulatory filing, and manufacturing scale‑up to capture 2026 opportunities.
Practical 2026 decisions — a recommended roadmap
- Within 90 days: Perform a rapid supply‑risk audit, secure forward cover for critical injectable grades, and validate secondary suppliers with documented GMP and endotoxin testing capabilities.
- Within 180 days: Update regulatory dossiers where needed, conduct supplier audits focussing on endotoxin control and batch traceability, and launch targeted hospital evidence generation for priority markets.
- Within 360 days: Execute capacity expansion or alliance agreements as indicated by demand realization; evaluate acquisitions or minority investments in regional GMP manufacturers to vertically integrate critical production nodes.
How executives should use the full report
Use the report as a decision support engine: link the forecast scenarios to procurement contract lengths, test supplier contingency plans against our stress scenarios, and align R&D/medical affairs investments with the clinical nutrition opportunities identified. For those considering inorganic routes, use our M&A toolkit to prioritize targets with validated GMP footprints and hospital channel access.
Conclusion — the strategic edge for 2026
Pharmaceutical‑grade L‑carnitine is entering a phase where measured, operationally disciplined moves win share. The market’s steady base and mid‑single‑digit growth create opportunity without runaway volatility — provided companies act on supply assurance, regulatory excellence, and hospital channel readiness. PW Consulting’s report equips leaders with the scenario models, supplier intelligence, and regulatory playbooks necessary to convert 2026 into a year of durable advantage.
For full datasets, detailed supplier mappings, and the downloadable tactical toolkits referenced above, access the full report on our website. The executive summary and model snapshots provided here are designed to build trust and orient strategy; the complete report contains the granular, auditable inputs needed to operationalize decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Optical Networking IC Market to Grow at a 13.52% CAGR Through 2032 on Surging Data Center Demand
By PW Consulting, 2026-08-12
Worldwide Optical Networking IC Market — Strategic Outlook for 2026: What Leaders Must Know
Executive summary
PW Consulting’s newest market study — the Worldwide Optical Networking IC Market — delivers a forward-looking strategic compass that senior executives, product leaders, and investors will use to structure decisions for 2026 and beyond. Built on a 2020–2025 historical baseline and a 2026–2032 forecasting horizon, the report quantifies a market that has accelerated from the low‑billion range in the early 2020s to an estimated USD 6,450.5 Million in 2025. Under our central scenario the market expands at a compound annual growth rate (CAGR) of 13.52% across the 2026–2032 forecast window, reaching an estimated USD 15,671.12 Million by 2032. That pace reflects structural demand drivers — AI-scale interconnects, co-packaged optics transitions, and densification of cloud and edge fabrics — and creates distinct strategic inflection points for vendors, hyperscalers, and system integrators in 2026.
Worldwide Portable Electric Scooter Market
Why this report matters for 2026 decisions
-
Timing and scale: The market’s projected two‑to‑threefold growth over the forecast period means that design wins and architectural choices made in 2026 will determine revenue trajectories and platform relevance for the better part of the next decade.
Worldwide Bot Management Solution Market -
Structural shifts: The transition from traditional DSP‑centric pluggables to hybrid and co‑packaged optics (CPO), and the parallel rise of linear pluggable and LPO approaches, is changing supplier economics, integration models, and energy profiles across deployments.
Worldwide Electrochemical Flow Cells Market -
Supply‑side consolidation: The market is concentrated — the top three and top five firms control a significant majority of revenue — intensifying competition on roadmap depth, scale manufacturing, and customer partnerships.
Market dynamics shaping 2026 strategy
-
AI workloads are the growth engine. Massive bandwidth demands and strict power budgets in AI clusters are driving migration toward higher lane rates, novel modulation (PAM‑4 and beyond), and integrated photonics. These technical imperatives accelerate adoption of new IC architectures and influence module form factors and system integration timing.
-
Energy and total cost of ownership (TCO) constraints. With U.S. data centers consuming substantial electricity and energy intensity rising with AI deployments, operators are prioritizing architectures that materially reduce joules per bit. Our analysis — consistent with recent industry demonstrations — shows that CPO and linear pluggable approaches can reduce power consumption by a large percentage versus legacy pluggable DSP modules, reshaping procurement criteria and network architecture roadmaps.
-
Infrastructure and deployment economics. Fiber trenching, right‑of‑way, and urban restoration costs remain a major contributor to network economics. Public funding and programs that expand backbone fiber availability are also changing investment horizons for optical transceiver demand in metropolitan and regional networks.
-
Standards, interoperability and multi‑vendor ecosystems. Recent multi‑vendor demonstrations have accelerated the pace at which new electrical and optical interface standards translate into deployable product cycles. Interoperability successes reduce risk for large buyers, but they also compress the window for differentiated value capture by component vendors.
Competitive landscape — capabilities that matter in 2026
Our vendor benchmarking focuses on technology depth, roadmap alignment to AI and telecom requirements, manufacturing scale, and go‑to‑market engagement models. Leading incumbents and challengers demonstrate different approaches to winning in the evolving market:
-
Broadcom Inc. — advancing high‑performance optical DSPs with a focus on very low‑power, high‑lane‑rate PAM4 engines. Recent product sampling of a next‑generation 3nm optical DSP underscores its strategy to enable denser pluggable modules targeting AI interconnects.
-
Marvell Technology — combining coherent and PAM4 DSP expertise with strategic acquisitions to bring plasmonics and silicon photonics performance enhancements into its roadmap, aiming at the 3.2T scale and beyond for high‑speed fabrics.
-
Intel — positioning silicon photonics and CPO integration for close coupling with switching silicon, aligning with hyperscaler interests in minimizing board‑level power and maximizing density.
-
Cisco (including Acacia) — offering integrated optical engines and system‑level solutions, leveraging packet‑optical product roadmaps to tie component evolution to network operator buying cycles.
-
Coherent, Lumentum, Semtech — component and IC specialists that provide drivers, TIAs and photonic building blocks enabling the next generation of 800G/1.6T modules; demonstrations at industry forums validate roadmap momentum.
-
Infinera, Ciena — vertically integrated coherent vendors focused on long‑haul and metro coherent engines, with innovation concentrated in photonic integration and DSP algorithms for transport networks.
-
NVIDIA — moving into CPO and silicon photonics integration alongside switching silicon to create end‑to‑end AI fabric performance advantages.
Recent catalyst events and what they signal for buyers
-
Product launches and demonstrations (early‑ to mid‑2026) reveal that the technical building blocks for 1.6T and beyond are moving from labs to samples, compressing timelines for module OEMs and hyperscalers to evaluate integration trade‑offs.
-
M&A and technology acquisitions are accelerating access to plasmonics, advanced silicon photonics and packaging IP — firms that secure these capabilities early will have optionality across both pluggable and co‑packaged pathways.
-
Multivendor interoperability showcases reduce deployment risk for new interface standards, enabling operators to pilot higher‑rate designs with less concern about vendor lock‑in at the IC level — but they also tighten competitive windows for component differentiation.
Actionable implications for corporate leaders in 2026
-
Product strategy: Prioritize modular roadmaps that allow simultaneous support for advanced DSP pluggables and incremental CPO adoption. Time investments in silicon photonics and high‑speed driver/TIA architectures to align with 12–24 month customer validation cycles.
-
Supply chain and manufacturing: Build flexible capacity plans that hedge between high‑volume wafer runs and specialized packaging. Consider partnerships or minority investments in photonics fabs and advanced packaging foundries to secure differentiation without overcapitalization.
-
Commercial and pricing: Reframe commercial models to account for TCO and energy savings rather than component unit price alone. For buyers, include power, integration cost and footprint as primary procurement levers in 2026 RFPs.
-
M&A and alliance playbook: For both strategic acquirers and challengers, target technology nodes and packaging capabilities that reduce integration risk for CPO and LPO deployments, and accelerate time-to-market for 1.6T+ solutions.
-
Regulatory and infrastructure engagement: For network operators and policy-minded investors, incorporate public funding programs and backbone expansion initiatives into multi‑year demand models — fiber availability materially affects where and how capacity is deployed.
What the PW Consulting report contains (practical components)
The report is designed as an operational toolkit for decision makers. Key deliverables include:
-
Proprietary market sizing and bottom‑up forecast models (2020–2032) with scenario analysis and sensitivity to lane‑rate adoption curves and power‑efficiency thresholds.
-
Vendor scorecards that evaluate techno‑commercial positions across DSPs, TIAs, driver ICs, and silicon photonics, including comparative roadmap mapping and capability gaps.
-
Supply‑chain and manufacturing playbooks that identify choke points, alternate sourcing strategies, and capital intensity estimates for packaging/assembly transitions.
-
Customer decision frameworks and RFP templates that embed energy and TCO metrics as primary procurement criteria.
-
M&A playbooks, scenario valuation models, and integration checklists tailored for acquiring photonics IP or foundry partnerships.
-
Regulatory impact assessment and deployment case studies illustrating how public infrastructure programs and fiber economics affect commercial opportunity maps.
Using this intelligence in 2026
Executives should treat the market trajectory and tactical guidance in the report as inputs into three parallel processes in 2026: (1) product portfolio reprioritization; (2) manufacturing and supply‑chain de‑risking; and (3) commercial model redesign that converts energy and integration advantages into sustainable margin. The timing of integration pilots, the selection of packaging partners, and the shape of alliance portfolios will be determinative for whether an organization captures the high‑growth portion of the optical IC market during the late 2020s.
Closing perspective — the strategic window
With the optical networking IC market set to more than double over the forecast horizon under our base case and with concentration among a handful of large incumbents, 2026 is a pivotal year for both defensible incumbency and credible entry. The technical choices — from DSP node selection to the adoption cadence of CPO and LPO architectures — will lock in cost and performance differentials that are hard to reverse. PW Consulting’s report equips decision makers to translate the macro trajectory (market size, growth rates and concentration dynamics) into concrete plans that manage risk while capturing the most valuable segments of demand.
Next steps
For senior teams developing 2026 roadmaps, PW Consulting offers tailored workshops that map the report’s scenarios to your product, supply‑chain and M&A choices. The full report contains detailed subsegment modeling, vendor share analytics, and downloadable financial models — information we intentionally reserve for subscribers and clients to preserve strategic advantage. To access the complete dataset and schedule an executive briefing, please visit the Worldwide Optical Networking IC Market report page on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Optical Networking IC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pressure‑resistant Sensor Market Poised to Rise from USD 2.44 Billion in 2025 to USD 3.87 Billion by 2032 at a 6.82% CAGR
By PW Consulting, 2026-08-12
Worldwide Pressure-resistant Sensor Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting’s new market study on Worldwide Pressure-resistant Sensors frames the strategic decisions that will define winners in 2026 and beyond. Using a rigorous historical base (2020–2025) and a forward-looking forecast (2026–2032), the report quantifies a market that reached approximately USD 2,439.6 Million (revenue unit: Million USD) in 2025 and is expected to expand to roughly USD 3,871.5 Million by 2032. That trajectory implies a compound annual growth rate (CAGR) of 6.82% over the forecast period — a pace that presents both sustained opportunity and intensifying competitive pressure across product, application and geographies.
Oceanographic Batteries Market
Why this matters for 2026 decision-makers
-
Investment prioritization: The market’s mid-single-digit CAGR signals that incremental capacity and product investments must be tightly aligned with differentiated product characteristics (e.g., biocompatibility, high-pressure tolerance, miniaturization) to secure above-market returns.
Toothbrush Tufting Machine Market -
Portfolio strategy: Device OEMs and sensor manufacturers face a choice between breadth (serving multiple verticals) and depth (specializing in high-value niches such as implantables and downhole monitoring). Our analysis shows meaningful rewards for focused, IP-backed positions where regulatory and reimbursement barriers raise entry costs for latecomers.
Worldwide Sodium Alkane Sulfonate Market -
M&A and partnership timing: Consolidation dynamics are already visible — the market is moderately concentrated (CR3 ≈ 38.45%; CR5 ≈ 52.12%). For investors and corporate development teams, 2026 is a window to acquire targeted capabilities (MEMS fabs, sterilization-ready packaging, or chronic-implant expertise) before competition drives multiples higher.
What the report covers — the practical toolkit inside
Our market study was written as a decision-enabling tool rather than an academic exercise. Deliverables include:
-
Transparent methodology and base-case model: granular revenue build-up from 2020–2025, deterministic forecasts for 2026–2032, and sensitivity scenarios that stress-test price erosion, raw-material shocks, and regulatory outcomes.
-
Go-to-market playbooks for four strategic profiles: (1) large multi-national suppliers, (2) focused MEMS specialists, (3) medical OEM partnerships, and (4) value players targeting industrial and subsea markets.
-
Commercialization roadmap: time-to-market estimates for implantable-class devices, sterilization and biocompatibility requirements, and recommended clinical-validation pathways to accelerate reimbursement.
-
Manufacturing & supply-chain diagnostics: capacity maps, nearshoring implications, and supplier-risk matrices for critical components and sterilization-compatible materials.
-
Regulatory and reimbursement matrix: device-classification checklists, typical certification timelines (e.g., Class III implantables), ISO and product standards alignment, and payer-access scenarios following recent NCD-level changes.
-
Competitive intelligence dossiers: anonymized but actionable benchmarking of market positioning, core IP, and commercialization strengths for leading incumbents and emerging challengers.
-
M&A scorecards and valuation heuristics: deal-preparation templates that translate technical differentiation (e.g., chronic implant survivability, high-pressure media compatibility) into price multiples and integration risks.
Market dynamics and growth levers
The market is being shaped by three simultaneous forces: technology miniaturization (MEMS and thin-film advances), regulatory and reimbursement shifts that favor clinically validated implantables, and hard-environment demand (downhole, subsea, aerospace) requiring extreme pressure-resilience. Together these create distinct value pools — commoditized low-pressure sensing on one hand, and high-margin, certificate- and validation-intensive niches on the other.
-
Technology: MEMS piezoresistive sensors and high-fidelity catheter-tip modules continue to improve signal-to-noise and longevity, enabling chronic implant use-cases and precise hemodynamic monitoring. Fiber-optic and thin-film approaches offer complementary performance profiles where electromagnetic immunity or temperature stability is critical.
-
Regulation & reimbursement: Implantable pulmonary artery pressure sensors receiving national coverage determinations create meaningful clinical adoption pathways. Conversely, Class III device pathways and sterilization validation (Gamma/EO compatibility, USP Class VI materials) impose time and cost that favor incumbents or well-funded entrants.
-
End-market demand: Critical verticals — healthcare (invasive and non-invasive monitoring), oil & gas downhole systems, aerospace engine monitoring, industrial hydraulics and deep-sea exploration — continue to drive specialized sensor requirements where robustness and reliability command price premiums.
Competitive landscape: who’s shaping the market and why it matters
Our report profiles the suppliers whose strategic moves set the tone for 2026. Highlights below synthesize capability vectors rather than proprietary revenue splits.
-
TE Connectivity (Schaffhausen, Switzerland) — breadth in medical-grade solutions and recent capacity expansion: TE’s portfolio spans miniature catheter-tip devices and disposable AAMI-compliant sensors. Their new facility expansion in 2024 signals a capacity-focused play to support integrated microfluidic and sensor assemblies for medical OEMs.
-
Honeywell International (Charlotte, NC, USA) — clinical reliability focus: Honeywell’s strength is in high-precision, clinically proven platforms that are trusted in patient monitoring and respiratory therapy contexts where regulatory pedigree and long-term support matter.
-
Edwards Lifesciences / BD (Irvine, CA / part of BD) — dominance in disposable hemodynamic transducers: The TruWave lineage demonstrates how consumable-linked business models (device + disposables) can create recurring revenue and lock-in in hospital critical care environments.
-
Merit Sensor Systems & Millar Inc. (UT & TX, USA) — MEMS and catheter-tip specialization: Merit’s high-pressure MEMS and Millar’s high-fidelity chronic implant modules underscore the strategic premium of vertical integration and clinical-grade long-term sensor reliability.
-
Utah Medical, Amphenol All Sensors, Sensata, Setra, Metallux, Smiths Medical — niche and complementary plays: These firms excel in segments such as disposable transducers, ultra-low pressure respiratory devices, sterilization-ready housings, and cost-efficient industrial sensor variants.
Recent developments that alter the 2026 playbook
-
Regulatory shift enabling reimbursement: A 2025 national coverage determination for certain implantable pulmonary artery sensors materially improves commercial viability for chronic implant technologies and should accelerate clinical rollouts where clinical-economic evidence is sufficient.
-
Product & capacity moves: Exhibitions and product showcases (e.g., COMPAMED 2025) underline accelerating modularization and developer-kits for MEMS implantables — shorter integration cycles for OEMs but higher competition among suppliers for customization services.
-
Facility investments: Suppliers expanding medical-component capacity (e.g., TE’s 2024 facility) indicate strategic bets on medical device integration rather than pure-component supply, shifting margin pools upstream.
Practical 2026 recommendations — action items by function
-
CEOs & Boards: Use the report’s scenario and M&A scorecards to select one of three strategic stances — scale (capacity and distribution), specialize (clinical/implantable niches), or partner (co-development with OEMs). Each yields different margin and capital implications over a 3–5 year horizon.
-
R&D & Product: Prioritize sterilization-compatible materials, long-term drift testing, and integration-ready sensor modules (electrical/mechanical interfaces) to reduce OEM integration friction and move up the value chain.
-
Commercial & BD: Accelerate clinical evidence generation where reimbursement is a gating factor; negotiate bundled supply-plus-service agreements for hospital settings to capture recurring revenue from disposables.
-
Supply-Chain & Ops: Build dual-sourcing plans for critical raw materials, and evaluate nearshoring or regional manufacturing footprints to mitigate geopolitical or logistics risk for high-value medical production.
-
Corporate Development: Target tuck-in acquisitions that add validated implantable IP, sterilization-certified manufacturing, or clinical trial execution capability to shorten time-to-revenue.
Data transparency and next steps
PW Consulting intentionally presents core macro indicators in this release — historical base (2020–2025), base year 2025, forecast (2026–2032), and the 6.82% CAGR — to ground strategic conversations. To preserve the report’s role as a commercial-grade decision asset, detailed regional, type, and application split figures have been withheld from this summary. The full report contains the segmented revenue tables, proprietary demand drivers by vertical, and the full competitive benchmarking matrix that executives will need to finalize 2026 budgets and M&A pipelines.
How to use this insight
-
Download the full report for the detailed segment models, scenario files and supplier dossiers required for budgeting, R&D planning and acquisition diligence.
-
Engage PW Consulting for a tailored briefing workshop: we will run your executive team through the model, stress-test your strategy against adverse scenarios, and produce a 90‑day action plan aligned to your chosen strategic stance.
For boards and executive teams facing competing capital priorities in 2026, our study converts market momentum into operational priorities and deal-ready intelligence — enabling faster, less-risky moves into the pressure-resistant sensor value chain. To access the comprehensive dataset, segmentation tables and company-level appendices, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Pressure-resistant Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Robust 5.12% CAGR for Worldwide Rod Capacitive Level Gauge Market in 2026–2032
By PW Consulting, 2026-08-12
Worldwide Rod Capacitive Level Gauge Market — 2026 Strategic Preview
Executive snapshot: Why this report matters for 2026 decision-making
As capital planners and operations leaders prepare budgets and technology roadmaps for 2026, the rod capacitive level gauge market is entering a phase where steady growth meets accelerating technical differentiation. PW Consulting’s new market study establishes the evidence base that executives need to convert sensing upgrades from tactical purchases into strategic enablers of reliability, process optimization, and regulatory compliance.
Worldwide Scuba Diving Clothing Market
This is a briefing designed as a decision catalyst. We disclose the high-level market trajectory and competitive dynamics that justify near-term action, while reserving the granular segmentation datasets and supplier scorecards for the full report—intentionally positioning this piece as a professional “trailer” to drive executive engagement.
Waste Paper Drum Pulper Market
Market trajectory: macro metrics that shape strategic choices
Key macro indicators in the study create a clear planning horizon. After a measured recovery through the early 2020s, the global rod capacitive level gauge market reached approximately USD 461.2 Million in our 2025 base year. Under our central scenario the market grows at a 5.12% compound annual growth rate (CAGR) through the 2026–2032 forecast window, reaching roughly USD 654.2 Million by 2032.
Worldwide Desktop KVM Switches Market
Those topline figures reflect both steady demand for proven capacitive sensing in liquids and solids and the premium placed on robustness, hygienic construction, and electronics that enable digital integration. Importantly, market concentration is moderate: the three largest vendors collectively account for under half the market, and the top five approach a clear majority—conditions that preserve competitive entry opportunities while rewarding scale and channel reach.
What the 2026 inflection looks like
-
Demand filters from operational reliability to systems-level value: Buyers increasingly evaluate level gauges not as isolated instruments but as instruments of uptime, data continuity, and predictive maintenance. Procurement teams that insist on lifecycle total cost of ownership (TCO) now capture materially different ROI than those focused on purchase price alone.
-
Regulatory and hygiene drivers raise technical thresholds: Industries with stringent sanitary or corrosive environments—food & beverage, pharmaceuticals, specialty chemicals—are adopting higher-spec insulation and materials that reduce cleaning downtime and sensor replacement cycles.
-
Digital integration is the new baseline: Suppliers that embed HART/fieldbus options, active-shield technologies, and smarter diagnostics are winning specification-led contracts. Commodity providers are pushed toward customization, service bundles, or competing on lead times.
-
Capital sensitivity in adjacent sectors influences order timing: Recent surveys and industry reports show capex constraints across service-intensive sectors (notably healthcare), which can compress replacement cycles or shift demand toward retrofit-friendly, low-disruption solutions.
Practical contents of the PW Consulting report — what you get
This study is built for action. The full deliverable combines quantitative forecasting with hands-on tools for procurement, product, and operations teams. Highlights include:
-
Interactive market model (2020–2032): scenario-enabled forecasts with sensitivity to material cost shifts, regulatory tightening, and digital-adoption ramp rates.
-
Supplier scorecards and procurement playbooks: vendor capability matrices, typical lead times, technology fit by application class, and negotiation levers that matter for 2026-2027 contracts.
-
Application maturity maps: readiness ladders and retrofit templates for water/wastewater, process industries, hygienic environments, and solids handling.
-
Technical due-diligence checklists: insulating material selection, probe geometries, EMI mitigation (active-shield approaches), and diagnostics you should require in RFPs.
-
Regulatory and safety matrix: region-agnostic compliance touchpoints and testing protocols that reduce approval friction across plant expansions.
-
ROI and TCO toolkits: step-by-step calculators for payback windows under varying labor, downtime, and replacement assumptions—built to be adapted to your P&L.
-
M&A and partnership scorecards: strategic fit analyses for targets or partners whose sensor IP, channel access, or systems-integration capability accelerate a platform play.
Competitive landscape — vendor dynamics and strategic takeaways
The market features a mix of long-established instrumentation houses, specialized meter manufacturers, and regional players with local engineering advantages. Our competitive analysis focuses on capability differentiation rather than headline share figures, enabling buyers to match vendor strengths to specific technical and commercial requirements.
-
VEGA Grieshaber KG (Schiltach, Germany): VEGA’s VEGACAL rod probes exemplify material and insulation breadth—PTFE, PE, FEP and ceramic options—positioning them for demanding chemical and high-cleanliness environments. Their road-tested product families and strong channel presence make them a natural incumbent for brownfield upgrades.
-
Endress+Hauser (Reinach, Switzerland): With rod probes tailored for continuous level and interface measurement, Endress+Hauser emphasizes diagnostics and process integration. Their portfolio often wins on specification-driven projects that prioritize accuracy in viscous or build-up prone media.
-
Siemens AG (Munich, Germany): Siemens brings active-shield technology and systems-level optics to the category via the SITRANS LC series and Pointek rod devices. Siemens’ advantage is systems integration—winning projects where level sensors form part of a larger automation or MES upgrade.
-
KOBOLD Instruments (Hofheim, Germany / Pittsburgh, USA): KOBOLD’s flexible probe lengths and industrial-grade transmitters make them competitive for plant-standard rollouts and replacement programs where compatibility and ruggedness are priorities.
-
Dwyer Instruments / Omega Engineering (Michigan City, IN): These vendors play strongly in retrofit and industrial OEM channels, offering straightforward 4–20 mA interfaces and products optimized for oils, solvents, and process waters.
-
NIVELCO Process Control Co. (Budapest, Hungary): NIVELCO’s NIVOCAP offerings—recently refreshed in a 2026 North America product catalog—signal an intensified push into high-sensitivity capacitive solutions. Their catalog release underscores how regional product campaigns can accelerate adoption, especially where sensitivity to low-dielectric media matters.
-
SenTec (Chengdu, China), BinMaster (Lincoln, NE), UWT GmbH (Betzigau, Germany), Baumer (Frauenfeld, Switzerland), and Balluff (Neuhausen, Germany): These players collectively represent a mix of specialized design approaches, silo/bin solutions, point-level detection, and industrial-sensor competitors. Their presence ensures a healthy mid-market and OEM supply chain.
Strategic implications for procurement, product, and operations leaders
For 2026 planning, the study guides three practical moves:
-
Shift supplier selection from product specs alone to system outcomes. Require proposals to include diagnostics, upgrade paths for digital integration, and quantified expected reductions in downtime.
-
Prioritize modularity and retrofittability. Given capital constraints in adjacent industries—particularly healthcare institutions that report restrained capex outlooks—solutions that minimize installation disruption and allow phased upgrades will win in tender processes.
-
Exploit diagnostic data for predictive maintenance pilots. Level instruments with richer diagnostics can be low-friction initial use cases for broader predictive-maintenance programs with measurable near-term savings.
Scenarios that materially change the outlook
Our forecast is built around a central projection, but three alternative scenarios materially alter timing and priorities:
-
High-Integration Upside: Faster adoption of industrial IoT and tighter vendor-plant integration increases premium-sensing uptake and shifts procurement toward bundled hardware-software providers.
-
Cost-Pressure Compression: Prolonged material cost inflation or tightening capex reduces replacement cycles, increasing demand for retrofit-friendly, lower-cost probes but compressing supplier margins.
-
Regulatory Tightening: New sanitary or measurement standards in key end markets force early replacement of legacy probes and favor vendors with compliant insulation materials and certification pipelines.
How PW Consulting recommends using this report in boardroom planning
Three practical uses deliver immediate value:
-
Quarterly procurement checkpoints: embed our supplier scorecards and TCO calculators into RFP evaluation templates to ensure consistent trade-off decisions across facilities.
-
Capital allocation triage: use our scenario outputs to prioritize projects that deliver the fastest payback under constrained capex assumptions.
-
M&A or partnership screening: apply our strategic fit filters to assess potential bolt-on technologies that accelerate your pathway to system-level sensing and analytics.
Conclusion — the decisive window for action
The rod capacitive level gauge market in 2026 is neither a niche nor a commodity; it is a foundation technology evolving into a systems asset. The market’s steady growth and moderate concentration create opportunities for companies that align procurement strategy, product selection, and digital roadmaps. PW Consulting’s study supplies the scenario models, supplier diagnostics, and practical playbooks that convert market intelligence into defensible 2026 investment choices.
For full datasets, interactive models, and the supplier scorecards referenced here, access the complete PW Consulting Worldwide Rod Capacitive Level Gauge Market report and dashboards. The full report contains the granular segmentation, regional and application split analytics, and downloadable tools required to operationalize the strategies outlined in this preview.
For detailed analysis of this topic, please visit the official page: Worldwide Rod Capacitive Level Gauge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Silicon Parts for Etching Market to Expand at a 9.15% CAGR Through 2032, New Report Shows
By PW Consulting, 2026-08-12
Worldwide Silicon Parts for Etching Market: Strategic Insights to Guide 2026 Decisions
PW Consulting today releases a focused executive brief derived from our forthcoming Worldwide Silicon Parts for Etching Market report. As the semiconductor equipment ecosystem accelerates through next‑generation nodes and denser process architectures, silicon parts used in plasma etch—critical wear items such as focus/edge rings, electrodes and related chamber components—are moving from commodity spares to strategic levers of yield, throughput and cost control. Our analysis, grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, quantifies that transition and translates it into practical levers for 2026 planning.
Why this report matters for executive planning in 2026
- Clear growth trajectory: The market demonstrates sustained expansion, reflecting both increased fab equipment intensity and shorter consumable replacement cycles. Our modeling shows a compound annual growth rate (CAGR) of 9.15% across the 2026–2032 forecast window, underscoring predictable upside for suppliers and growing procurement exposure for OEMs and fabs.
- Operational leverage from consumables: Silicon etch parts are high‑frequency consumables in plasma processing. Typical replacement intervals measured in wafer‑runs create a continuous service and supply requirement that directly impacts uptime, cost per wafer and process stability—making procurement strategy a continuous competitive variable.
- Concentration and supplier dynamics: The market exhibits moderate concentration among leading suppliers (top‑3 firms account for a near‑majority share, and top‑5 firms capture roughly two‑thirds of the market). This structure creates both supplier leverage and pockets of opportunity for focused mid‑tier players and regional specialists.
- Strategic timing: 2026 is a pivotal planning year—investments committed now in supplier qualification, co‑development and inventory strategies will determine competitive positioning for the largest tranche of expected demand through 2032.
Macro picture: scale, growth and forecasting lens
Using USD‑denominated revenue measures and a 2025 base year, our market model captures annual evolution across 2020–2025 and projects through 2032. The market expanded meaningfully in the early 2020s and reached a multi‑billion dollar scale by 2025; under our baseline demand and technology assumptions it is projected to exceed the mid‑single digit billions by the end of the forecast period. The 9.15% CAGR we apply reflects underlying drivers—ramping fab utilization, more complex etch chemistries, larger wafer formats in selected lines, and the substitution of higher‑value precision silicon parts to manage tighter uniformity and defect targets.
Key dynamics shaping supplier and buyer strategies
- Technology push: As etch processes evolve to support advanced logic and memory nodes, silicon components increasingly require tighter impurity controls, defect‑free monocrystalline structures and improved dimensional stability. Techniques such as MCZ growth and strict dislocation controls are now prerequisites for parts that must meet long service lives while avoiding particulate generation.
- Consumable economics: Many silicon etch parts are designed as consumables with replacement cadences tied to wafer counts—typical lifetimes are on the order of hundreds of wafers per part—creating predictable recurring revenue for suppliers and recurring cost streams for fabs. Optimizing lifetime through materials and protective coatings has immediate ROI implications.
- Supply chain localization vs. diversification: Production and consumption clusters remain concentrated in the Asia‑Pacific region owing to heavy semiconductor investments and manufacturing footprint. This geographic asymmetry has intensified sourcing risks—procurement teams must balance near‑shoring benefits with diversification to mitigate geo‑political and logistics disruptions.
- Market concentration: With top‑tier suppliers capturing a substantive portion of volume, buyers face a trade‑off between single‑source performance advantages and bargaining power. For entrants and mid‑sized suppliers, targeted capabilities (e.g., low impurity large‑diameter monocrystalline parts) represent credible routes to carve out specialized demand.
Competitive landscape: what the leading players are doing
Our competitive analysis profiles global incumbents and notable regional specialists. Below are strategic snapshots—each company name links to their public profile for additional corporate context.
- Silfex Inc. (Eaton, Ohio, USA) — Specialized in high‑purity custom silicon components, with a focus on precision gas distribution parts and wafer edge rings supplied to major equipment makers. Strengths include deep custom engineering and close OEM partnerships.
- Hana Materials Inc. (Cheonan‑si, South Korea) — Integrated producer covering electrodes and rings, with upstream control from ingot processing. Their vertical integration supports rapid scale and tailored product suites for dry etch processes.
- Mitsubishi Materials Corporation (Japan) — Established supplier of high‑quality silicon parts, leveraging broader materials science capabilities to advance thermal and plasma‑resistant designs.
- CoorsTek (USA) — Offers semiconductor‑grade silicon components, emphasizing focus ring designs and materials engineered to withstand harsh plasma environments and improve uniformity.
- Ningxia Dunyuanjuxin Semiconductor Technology Corporation (DSTC) (Yinchuan, China) — Large domestic manufacturer producing an array of etch components including showerheads and shielding rings, focused on optimizing plasma uniformity.
- Sicreat (China) — Develops monocrystalline silicon components with low impurity content and large wafer capability (products reported up to 485mm), positioning itself for advanced IC etch requirements.
- Other regional suppliers (Semicorex, Thinkon/Fujian Dynafine, Worldex, Techno Quartz, RS Technologies, KC Parts Tech.) — These vendors play critical roles in regional supply, niche product segments and aftermarket servicing.
Practical content in the full report (what executives will find)
Our full report is structured for direct operational use by procurement, manufacturing and strategy teams. Key deliverables include:
- Top‑down market sizing and bottom‑up forecasting model (2020–2032) with scenario analysis for demand shocks and technology adoption paths.
- Supplier scorecards and capability maps—assessing manufacturing footprint, quality certifications, vertical integration, lead times and aftermarket service levels.
- Procurement playbook—supplier selection criteria, negotiation anchors, contract templates, and safety‑stock algorithms tailored to consumable lifecycles.
- Technology assessment—material science briefings (e.g., MCZ growth requirements, dislocation control, impurity thresholds) and their implications for lifetime and defect risk.
- Risk register and mitigation options—geo‑political, raw material, and logistics scenarios with contingency pathways and costed alternatives.
- Operational case studies—real‑world examples showing how incremental investments in higher‑performance silicon parts have translated into yield improvements and total cost reductions.
Actionable strategic recommendations for 2026
- Prioritize supplier qualification for high‑value nodes: Lock in co‑development agreements with suppliers capable of MCZ growth and zero‑dislocation parts to protect advanced node yields. Early qualification shortens ramp time and reduces variation risks.
- Adopt lifecycle economics over unit price: Structure contracts to reflect part lifetime and replacement cadence rather than simple price per piece. Consider outcome‑based SLAs tied to wafer yield or mean time between replacements.
- Design a hybrid sourcing network: Blend a small number of strategic global suppliers with regional partners to balance performance, cost and resilience. Include dual‑sourcing for critical SKUs where possible.
- Invest in predictive replacement analytics: Use in‑line sensor data and process analytics to move from scheduled to condition‑based replacement, extending useful life without compromising process integrity.
- Explore aftermarket and servitization opportunities: Suppliers and OEMs can capture incremental value through refurbishment services, certified remanufacturing and performance guarantees—models that reduce TCO for fabs while creating recurring revenue.
- Monitor consolidation and M&A windows: Given market concentration among top providers, 2026 could be a favorable year to pursue strategic acquisitions or joint ventures to secure critical capabilities and expand geographic reach.
Implications for investors and private equity
With a steady CAGR of 9.15% and recurring consumable demand patterns, the silicon parts for etch market represents a compelling segment for industrial investors seeking predictable cash flows with technical differentiation. The moderate concentration at the top creates clear buy‑and‑build opportunities: add‑on targets with specialty materials capability or regional market access can meaningfully increase enterprise value through integration and margin expansion.
Next steps and how PW Consulting can help
Our full report contains the segment‑level forecasts, supplier scorecards, downloadable datasets and procurement templates that underpin the strategic recommendations above. The brief you are reading is intentionally selective—designed to surface the decision‑critical findings while reserving detailed segment numbers, contract templates and supplier‑level financials for subscribers.
To obtain the complete Worldwide Silicon Parts for Etching Market report—including the granular market breakdowns, model files and deal playbooks—visit our report page or contact PW Consulting’s semiconductor practice. For procurement leaders and C‑suite teams planning 2026 supplier strategies, our advisory engagements can provide rapid diagnostics, supplier selection support, and deal execution assistance tailored to this market’s specific dynamics.
PW Consulting — Senior Strategy & Industry Analysis, Semiconductor Materials and Components Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Silicon Parts for Etching Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide CMP Equipment Market to Rise from USD 3,872.66 Million in 2025 to USD 6,855.16 Million by 2032 at an 8.5% CAGR — Asia Pacific Leads with USD 2,621.97 Million
By PW Consulting, 2026-08-12
Worldwide CMP Equipment Market: Strategic Imperatives for 2026 Decision-Making
Executive Summary
As semiconductor supply chains reconfigure and capital investment cycles accelerate, chemical-mechanical planarization (CMP) equipment sits at the nexus of node scaling, heterogeneous integration, and new-substrate power electronics. Our new PW Consulting Worldwide CMP Equipment Market study (base year 2025; historical period 2020–2025; forecast 2026–2032) provides an actionable intelligence package for executives shaping procurement, R&D, and M&A strategies in 2026 and beyond. The market recorded robust expansion through the 2020s and, using our baseline forecast, the CMP equipment market is projected to expand at a compound annual growth rate (CAGR) of 8.5% over the 2026–2032 horizon, with total market value moving from approximately USD 3.87 billion in 2025 to a materially larger market by 2032.
Worldwide IT Financial Management Tools Market
Why CMP Matters Now: Technology and Demand Drivers
-
Process node scaling and advanced packaging are increasing planarization complexity. Smaller geometries and heterogeneous stacks require tighter thickness control, new slurry chemistries, and multi-zone slurry and pad management. CMP is therefore not a commoditized step; it is an enabler for yield improvement on every leading node and for hybrid bonding in package-level integration.
Worldwide Collections Management Software Market -
Power electronics (SiC and GaN) and compound semiconductor markets are introducing new wafer diameters, substrate hardness profiles, and thinning requirements. These shifts demand specialized grinder-polish and CMP hybrids—opening adjacent addressable markets beyond traditional logic and memory fabs.
Worldwide Public Relations (PR) Software Market -
Fab capacity expansions worldwide—both greenfield and brownfield—and the geographic diversification of manufacturing create non-uniform demand for tools and consumables. Procurement windows, tool deployment timelines, and consumable lifecycles are now critical levers for both OEMs and fabs to optimize total cost of ownership (TCO).
Market Snapshot (High-Level)
Our longitudinal analysis captures the market’s recovery from cyclical headwinds and the structural tailwinds tied to advanced-node and new-substrate demand. Between 2020 and 2025 the market experienced sustained growth, with total global revenue increasing markedly over that period. The 2026–2032 forecast, underpinned by granular equipment replacement cycles, fab ramp schedules, and consumables demand models, yields an 8.5% CAGR—illustrating a sector that is expanding faster than many adjacent equipment markets and remains strategically relevant to capital planners.
What the Report Contains: Practical, Executable Content
PW Consulting’s report is built for decision-makers who must move from insight to action. Highlights include:
-
Proprietary market-sizing and demand curves (historical and forecast), with scenario-driven sensitivity analyses for three CAPEX rhythms (accelerated, baseline, deferred).
-
Bottom-up build of equipment demand by wafer size, tool class, and application profile—coupled with consumable volume forecasts and TCO modelling that captures tool price erosion, consumable recycling impacts, and service revenues.
-
Detailed supplier scorecards and capability maps that evaluate technology maturity (process control, metrology integration, endpoint detection), manufacturing footprint, spare-parts lead times, and aftermarket services.
-
Procurement playbook for fabs and IDMs, including an optimized supplier-split framework, long‑lead component checklist, and timing recommendations for tooling and consumable orders to minimize ramp risk and maximize yield capture.
-
Risk register and mitigation strategies covering raw material exposures, regulatory constraints, and logistics stress tests—integrated with supplier dependency matrices to prioritize diversification actions.
-
M&A and investment due diligence templates—valuations that reflect the high concentration in the supplier base, service attach potential, and consumable annuity models that can lift enterprise multiples.
Competitive Landscape: Who Moves the Needle
The CMP equipment market is concentrated and characterized by a small set of OEMs that combine mature product lines, strong installed bases, and service ecosystems. High concentration metrics indicate that a few leading suppliers control the majority of new tool placements and aftermarket revenues; this supplier topology materially shapes procurement leverage, lead times, and innovation pathways.
-
Applied Materials, Inc. (Santa Clara, CA): A dominant player with platforms optimized for 300mm wafer processing and a heavy emphasis on AI-driven process control for sub-3nm applications. Their integrated approach—linking metrology, process control, and tool automation—makes them a critical partner for logic-focused fabs and advanced nodes.
-
Ebara Corporation (Tokyo): Known for single-wafer systems and strong memory-fab penetration, particularly where multi-zone pressure control and optical endpoint detection are priorities. Ebara’s roadmap emphasizes throughput and repeatability in high-volume memory environments.
-
Tokyo Seimitsu (ACCRETECH) (Tokyo): A niche leader in precision planarization integrated with thinning, grinding, and dicing—services that are increasingly important for advanced packaging and wafer-thinning processes.
-
Lapmaster Wolters (Germany), Revasum (US), and other specialized OEMs: These companies focus on compound semiconductors, SiC/GaN power substrates, and R&D-grade platforms. Their offerings are strategic for fabs targeting EV and power-conversion markets where substrate hardness and surface integrity are paramount.
-
Service and retrofit specialists such as Entrepix (Amtech Systems), Axus Technology, and several precision lapping providers are significant because aftermarket services, refurbished tools, and process development capacity are being used to compress ramp timelines and lower upfront capital intensity.
Supply Chain and Regulatory Dynamics
Two interlocking supply-side factors are reshaping supplier economics and tool availability:
-
Raw material inputs for pads and slurries face structural constraints. Petrochemical-driven polyurethane availability has been uneven in recent years, and procurement teams must model longer lead times and price volatility into consumable contracts.
-
Regulatory moves—particularly restrictions on certain fluorinated chemistries—are accelerating R&D into PFAS‑free pad and slurry formulations. OEMs and consumable suppliers that can de-risk regulatory exposure while delivering equivalent CMP performance gain a competitive edge.
Recent Market Signals and What They Imply
-
New-product introductions aimed at hybrid bonding and advanced packaging slurries signal an industry pivot: consumable chemistry and pad engineering are becoming as strategically important as the hardware itself. Firms that capture early design wins with leading packaging houses will lock in recurring revenue streams.
-
Conferences and symposiums continue to concentrate thought leadership and early technical validation. Public showcases of CMP-related technology at major trade events are reliable leading indicators for near-term adoption in U.S. and Asian fabs.
-
Governmental emphasis on domestic semiconductor capacity has stimulated demand—but it also compresses delivery windows and increases the premium on suppliers with localized manufacturing and service footprints.
Strategic Imperatives for 2026
For executives making capital, sourcing, or R&D decisions in 2026, the following actions should be prioritized:
-
Align procurement timing with wafer fab ramp schedules using scenario-based buffers. Early engagement with preferred OEMs for lead-time lock-in, coupled with staggered consumable contracts, reduces yield risk during critical ramp months.
-
Pursue supplier diversification where possible, but prioritize “fit-for-purpose” partnerships. For advanced logic and high-volume memory lines, tie-ups with established 300mm tool suppliers bring lower integration risk; for SiC/GaN and compound lines, specialty suppliers can deliver differentiated capability.
-
Invest in on-site process-development and service capabilities to accelerate process transfer and reduce dependency on OEM field engineers—this is a force-multiplier during tight ramp windows.
-
Reframe consumables as strategic assets. Long-term supply agreements that include joint R&D clauses, regulatory-compliance roadmaps, and staged pricing can convert a recurring cost center into a predictably managed annuity.
-
Monitor regulatory trajectories aggressively. Companies that anticipate PFAS restrictions and adjust material roadmaps can avoid last-minute reformulations that impair yield and tooling compatibility.
The PW Consulting Value Add
Our report does more than present forecasts. It operationalizes data into purchasing templates, risk-adjusted cash-flow models, and supplier engagement scripts that procurement, operations, and corporate development teams can execute in 90‑day sprints. In a market where a single tool placement or a slurry chemistry mismatch can cost weeks of lost yield, that operational readiness is material.
Note on Data Transparency and Access
To preserve the report’s role as a strategic source for clients, we intentionally adopt a “preview” posture in public briefings: we disclose market-size trajectories, concentration metrics, and macro drivers to inform high-level decision-making, while detailed segmented allocations (by region, application, and equipment sub-class), price curves, and OEM-specific share tables are included exclusively in the full report and associated data packs. These proprietary breakdowns are the tactical inputs that procurement and corporate development teams use to finalize supplier selections and investment sizing.
How to Use this Insight in 2026
Leaders should treat the 2026 planning window as an inflection point. Use the report to:
-
Stress-test capex plans under alternative ramp scenarios;
-
Prioritize supplier engagements that offer end-to-end roadmaps for consumables and tool integration;
-
Evaluate acquisition targets where consumable annuities amplify enterprise value;
-
Design internal capability upgrades (process labs, refurb centers) that reduce external dependency and compress time-to-yield.
Next Steps
PW Consulting’s Worldwide CMP Equipment Market report is designed to be the operational backbone for 2026 strategy. For procurement leaders, R&D heads, and corporate development teams ready to convert forecast insight into executable plans, the full report includes the granular demand models, supplier scorecards, and executable templates referenced above. Accessing the full data pack will enable you to move from strategic intent to tactical implementation with confidence.
Contact PW Consulting for the full report and to schedule a tailored briefing where we will walk through scenario regressions, vendor‑specific implications, and a customized procurement roadmap aligned to your fab ramp timetable.
For detailed analysis of this topic, please visit the official page: Worldwide CMP Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


