



Category: market research
PW Consulting Forecast: Contactless NFC & Mobile Wallets Power Worldwide Vending Machine Payment Market to USD 32,500.5 Million by 2032 at 11.45% CAGR
By PW Consulting, 2026-08-12
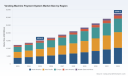
Worldwide Vending Machine Payment System Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market briefing on the Worldwide Vending Machine Payment System Market synthesizes an actionable intelligence set designed to inform enterprise strategy in 2026. Built on a 2025 base year and a robust forecasting horizon through 2032, this analysis combines historical performance (2020–2025), market sizing, a compound annual growth rate (CAGR) of 11.45%, vendor-level competitive assessments, regulatory impact modeling, and practical deployment playbooks. The result is a decision-grade toolkit that helps C-suite leaders, operators, equipment manufacturers, and payment integrators convert growth forecasts into prioritized, low-friction investment programs.
Medical Protective Textiles Market
Why 2026 matters: inflection, not incremental change
-
The market is transitioning from isolated device upgrades to platform-driven modernization. By 2026 the global market is projected to expand materially year-over-year, continuing a trajectory that sees total market value more than double by the end of the forecast window. This pace is driven by converging forces — consumer preference for tap-and-go, operator demand for data-enabled efficiency, and maturation of unattended payment ecosystems.
Visualization of Knowledge System Market -
Operational economics are shifting. Operators that embrace connected, cashless payment systems are reporting measurable reductions in service costs and machine downtime, enabling redeployment of field teams to revenue-enhancing activities. These productivity gains, combined with evolving consumer behavior, accelerate payback timelines for modernization projects initiated in 2026.
Worldwide Vibraphones Market -
Regulatory and security exigencies are tightening. Payment card data compliance (PCI DSS) and regional authentication rules create both cost and capability requirements that should be baked into procurement choices and vendor contracts before pilot rollouts in 2026.
Macro trajectory: what the numbers tell us (high level)
Our market model — anchored on 2025 as the base year — reconciles historical performance (2020–2025) against leading macro drivers to produce a consistent forecast for 2026–2032. The market is expected to grow at an aggregate CAGR of approximately 11.45% during the forecast period. In plain terms, the sector is not merely expanding; it is reshaping the economics of unattended retail: within the near term, total addressable revenue expands meaningfully year-on-year as operators monetize contactless payment features, telemetry services, and value-added software such as loyalty and dynamic pricing engines.
What this PW Consulting report contains (practical, deployment-ready content)
-
Executive dashboards and scenario models: stress-tested growth cases and sensitivity analyses to evaluate vendor selection, lease vs. buy, and capex vs. opex choices.
-
Integration playbooks: step-by-step guidance for retrofitting legacy machines, API and telemetry integration checklists, carrier and eSIM selection guidelines, and sample SLAs for uptime and data fidelity.
-
Procurement frameworks: vendor short-listing matrices, contractual clauses to mitigate shared-responsibility PCI exposure, and negotiated pricing strategies for volume rollouts.
-
ROI calculators and TCO models: operator-validated models that incorporate labor savings from remote monitoring, reductions in cash handling, and revenue uplift from cashless conversion and dynamic pricing.
-
Security and compliance toolkit: an executable roadmap for meeting PCI DSS requirements, including cost-estimates, audit cadence recommendations, and a migration plan for unattended-tokenization strategies.
-
Go-to-market and monetization playbooks: product bundles, subscription models for telemetry and analytics, and partner ecosystem strategies to accelerate market entry.
Strategic implications for enterprise decision-makers (how to act in 2026)
-
Prioritize platform-first procurement. Vendors are increasingly competing on telemetry, analytics, and recurring software revenues, not just the payment terminal. Contract for upgrade paths, data access rights, and interoperability up front.
-
Design pilots to validate operational KPIs, not just technical integration. Measure labor hours per route, refill cycles, and machine uptime before scaling. Operators reported meaningful downtime reductions when telemetry and predictive maintenance were implemented; such operational savings often dwarf raw payment revenue effects in early ROI calculations.
-
Embed compliance costs into capital plans. PCI DSS and related audit obligations are non-trivial. Our report quantifies likely audit and remediation costs under different deployment scales and recommends cost-effective shared-responsibility approaches for third-party managed deployments.
-
Use dynamic pricing and loyalty as revenue accelerators. Data-driven pricing and micro-loyalty programs are proven lever arms for increasing basket size and repeat transactions in unattended retail.
-
Plan for hybrid payment mixes. Contactless payments and mobile wallets are dominant behavioral preferences; however, QR, digital currency options, and integration for credential-based campus cards remain part of an effective multi-pay strategy.
Competitive landscape — who matters and why
The market is moderately concentrated, with top-tier vendors accounting for a material share of installed bases and platform activity. Market concentration metrics indicate that the leading three and five suppliers collectively command a significant share of market presence, reinforcing the importance of assessing both scale and specialization when choosing partners.
Key market participants covered in the report include international platform vendors, legacy payment terminal manufacturers, telemetry specialists, and hybrid IoT/payments integrators. Each player is profiled with respect to product architecture, channel coverage, integration maturity, and commercial models. Examples of profiles included are:
-
Nayax Ltd. (Herzliya, Israel) — end-to-end cashless payment ecosystems, loyalty, and telemetry for global operators.
-
Cantaloupe, Inc. (Malvern, PA, USA) — connected vending management software and cashless devices with strong U.S. channel presence.
-
Crane Payment Innovations (CPI) — established hardware and card reader IP with evolving mobile wallet integrations.
-
Azkoyen Group (Coges) — integrated payment and mechanical systems for OEMs and operators.
-
Vendon, Televend (INTIS), Ingenico, 365 Retail Markets, Heartland (Global Payments), Apriva, HID Global, and Gantner — each representing capability niches from telemetry to RFID/NFC modules and unattended-specific payment terminals.
Recent market intelligence also shows accelerating connectivity: independent trackers report that the number of connected vending machines globally has entered the multi-million range, and vendor-installed bases for leading suppliers are substantial. Operators and OEMs should use the vendor assessment templates in our report to align technology choices with their own scale, channel strategy, and compliance posture.
Regulatory and security dynamics – constraints and opportunities
-
PCI DSS remains a binding constraint. The report explains how shared-responsibility models should be structured contractually and offers practical cost-range estimates and mitigation pathways for both large and small operators.
-
Regional authentication rules (e.g., SCA in Europe) create exceptions for unattended low-value transactions; this regulatory nuance materially affects front-end UX and should influence payment-method prioritization.
-
Security-by-design wins in procurement. Tokenization, point-to-point encryption, and hardware-secured modules materially reduce audit scope and long-term compliance costs; our deployment checklist ranks these controls by cost-to-implement and risk-reduction impact.
Recommended 2026 action roadmap
-
Q1: Run a validated pilot focusing on telemetry, contactless payments, and remote monitoring on a representative route; measure labor and downtime metrics baseline vs. post-deployment.
-
Q2: Negotiate modular commercial terms with primary vendor(s) that include upgrade windows, data portability clauses, and explicit PCI shared-responsibility definitions.
-
Q3: Expand rollouts tied to measurable KPIs (service cost reduction, transaction uplift, uptime) and enable dynamic pricing pilots where consumer elasticity supports it.
-
Q4: Consolidate platform contracts, implement tokenization and end-to-end encryption across deployments, and begin monetization experiments for analytics services to partners.
How to use this briefing — and where to get the full playbook
This article intentionally highlights strategic conclusions and practical pathways without releasing the full set of segmented forecasts, granular vendor scorecards, or deployment cost matrices — those elements are central to the full PW Consulting report and are available through our official release. The complete study contains region- and application-level scenarios, vendor-specific TCO comparisons, and customizable Excel models that translate the macro CAGR and market sizing into site-level investment decisions.
For operators, OEMs, and investors planning capex or partnership moves in 2026, the full report supplies the data-backed, risk-adjusted roadmaps needed to prioritize pilots, negotiate vendor terms, and minimize compliance exposure. Visit PW Consulting’s report page for access to the full dataset, an executive briefing, and tailored advisory engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Vending Machine Payment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide UV Roller Coater Machine Market Forecast to Expand at a 4.85% CAGR, Signaling Robust Global Demand
By PW Consulting, 2026-08-12
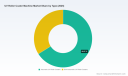
Worldwide UV Roller Coater Machine Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting's new market research briefing on the Worldwide UV Roller Coater Machine Market (base year 2025; historical series 2020–2025; forecast period 2026–2032) synthesizes commercial, technological, and regulatory intelligence that will materially shape capital allocation and go-to-market choices in 2026. The sector has expanded from an estimated USD 255.0 Million in 2020 to roughly USD 320.0 Million in 2025, and our forecast anticipates the market reaching approximately USD 445.8 Million by 2032 — a compound annual growth rate (CAGR) of 4.85% over the projection window. These headline figures hide a more complex landscape of uneven adoption, accelerating technology substitution, and margin pressure driven by input costs and regulation. The purpose of this preview is to distil the strategic implications for OEMs, integrators, end-users, and investors — while directing practitioners to the full report for the underlying segmentation tables, price curves, and vendor scorecards that enable executable plans.
Worldwide Torrefied Pellets Market
Market trajectory — what the numbers conceal (and reveal)
-
Recovery with structural upside. The market’s steady climb from 2020 to 2025 reflects both rebound demand in print and furniture sectors post-pandemic and deeper structural shifts toward energy-efficient, low-emission surface finishing. The forecast path to 2032 assumes continued expansion in industrial finishing and packaging applications even as cyclical headwinds create short-term irregularities.
Worldwide Dew Point Analyzer Market -
Moderate, differentiated growth. A headline CAGR of 4.85% masks significant heterogeneity across application segments and customer archetypes. High-volume, automated lines will capture disproportionate R&D and capex spend, while small-format and specialty coaters remain a meaningful niche for retrofit and service providers.
Surgical Microscope Protective Cover Market -
Fragmentation persists. Market concentration metrics show a fragmented supplier base: the largest three suppliers do not command a dominant share, and the top five together account for roughly a third of market value. That fragmentation preserves opportunity for regional specialists and technology-focused challengers, while also favoring consolidation plays aimed at building full-line capabilities.
Technology and regulatory dynamics shaping 2026 decisions
-
UV-LED disruption accelerates. UV-LED curing platforms are expanding rapidly — independent industry measures suggest a multi-year CAGR in excess of 20% for LED adoption in curing systems — driven by superior energy efficiency, narrower process windows, and regulatory pressure to eliminate mercury lamps. This is a tectonic shift for roller coater OEMs: product roadmaps, aftermarket lamp inventories, and service models must be re-architected to support LED-centric offerings.
-
Supply-side volatility. Raw-material and component dynamics are increasing near-term price noise. Upstream pressure on LED and related components is expected to lift UV-LED module prices in early 2026 (quarterly volatility reported), and procurement teams should model multiple cost scenarios into supplier contracts and CapEx planning.
-
Regulatory catalysts for innovation. REACH and national-level ordinances in Europe are accelerating the development of photoinitiator-free and low-volatile organic compound (VOC) UV-curable formulations. These chemistry shifts create opportunities for OEMs to co-develop certified line solutions and for coating formulators to create “system sales” propositions bundled with curing hardware.
-
Emerging lamp technologies. Industry signals point to upcoming high-power UV LEDs (e.g., multi-hundred mW-class products) designed to replace legacy mercury lamps in curing rigs. Such launches will have immediate implications for retrofit demand, OEM upgrade offerings, and service revenue streams tied to replacement lamp consumables.
Competitive landscape — capabilities to watch in 2026
Our competitive analysis synthesizes product portfolios, geographic reach, and strategic positioning for core vendors operating in the UV roller coater space. Below we summarize each firm’s strategic DNA and the competitive moves that should influence executive planning.
-
American Ultraviolet (United States) : Known for a hardened, made-in-USA approach and the AUV-Coat family re-engineered from legacy technologies. Strengths include customization for print finishing and a service-oriented model that benefits retrofit demand among North American print shops.
-
TEC Lighting (United States) : An established supplier of high-performance lamps and curing modules. Their engineering focus on lamp and system integration positions them as a preferred partner for OEMs transitioning to LED curing solutions.
-
BÜRKLE (Germany) : Offers integrated roller coater and dryer lines with customer-specific concepts for high-quality surface lacquering. Their European footprint and systems expertise make them a natural partner for premium wood and furniture customers subject to stringent environmental rules.
-
Dubois Equipment (United States) : Specializes in roll-coating machinery adaptable to UV, water, and solvent-based chemistries. Their mechanical flexibility and thickness-control features are attractive to converters managing mixed substrate programs.
-
PURETE (China) , SENLIAN (China) , and Kisinhom (China) : These manufacturers emphasize full-line automation and cost-competitive systems targeting wood, furniture, and decorative board producers. Expect their influence to grow in emerging markets and among cost-sensitive mid-tier customers.
-
Bobst Group (Switzerland) and Koenig & Bauer AG (Germany) : Global printing and packaging equipment providers that integrate UV coating modules as part of holistic finishing solutions. Their strength lies in cross-selling to large packaging customers and offering press-integrated curing options.
Recent signals — such as an announced high-power UV-C/UV LED launch in early 2026 and new medium-format roller coater catalogs from regional manufacturers — suggest a bifurcating market: incumbents defending installed bases with retrofit and service programs, and new entrants pushing LED-first, modular systems for fast OEM adoption cycles.
What the full report contains — operationally useful deliverables
PW Consulting’s full market study goes beyond narrative to provide executable intelligence for 2026 planning. Highlights include:
- Detailed market sizing (historical and forecast) with sensitivity bands and scenario-driven pathways tied to LED adoption, raw-material price trajectories, and regulatory implementation timelines.
- Granular segmentation by region, product type, and application, together with regional demand drivers and channel maps (note: segmentation tables and numeric splits are reserved for the full report).
- Vendor benchmarking: capability matrices, product roadmaps, aftermarket economics, and an independent technology readiness index.
- Supply-chain diagnostics: component sourcing maps, single-source risk heatmaps, and short‑cycle mitigation playbooks for OEM procurement teams.
- Commercial playbooks: pricing ladders, bundling strategies for coating+curing, and service-contract templates focused on recurring revenue capture.
- Investment and M&A thesis module: valuation analogues, consolidation scenarios, and integration risk checklists for private equity and strategic acquirers.
- Practical tools: buyer persona profiles, capex planning templates, retrofit payback calculators, and a 5-step procurement checklist for 2026 CapEx cycles.
Strategic implications for OEMs, integrators, and users in 2026
-
OEMs: Prioritise LED integration roadmaps and certify equipment with leading LED-module suppliers. Defensive retrofit offerings for installed bases will sustain aftermarket revenue while LED-native platforms win new-build orders.
-
System integrators and engineering firms: Expand chemistry and controls expertise. Interfacing curing profiles to modern UV-curable formulations — including photoinitiator-free systems demanded by European regulations — will be a competitive differentiator.
-
End-users (furniture, flooring, packaging): Recalculate total cost of ownership with updated energy, consumables, and compliance cost models. Invest selectively in automation where throughput gains and waste reduction translate to sub-24-month paybacks under conservative price scenarios.
-
Investors: Target companies that combine product differentiation (LED expertise, systems integration) with service-led revenue models. Early movers in LED retrofit kits and validated end-to-end coating solutions will command premium exit multiples.
How to use this research in 2026 planning cycles
-
Integrate the report’s scenario outputs into CapEx approval workflows. Use our sensitivity bands to stress-test investment cases against LED price swings and raw-material cost shocks.
-
Adopt the vendor scorecard to structure RFPs and to identify partnership candidates for co-development or selective distribution agreements.
-
Leverage the procurement playbook to renegotiate component contracts with tier-one LED suppliers, and identify hedging strategies for key consumables.
Conclusion — a 2026 action agenda
2026 will be a defining year for the UV roller coater market: technology substitution, tighter regulatory constraints, and supply-side volatility combine to create uneven risk and opportunity. Companies that move early to align product roadmaps with LED curing platforms, that secure resilient supply chains, and that craft service-centric commercial models will capture the best growth pockets identified in our study. PW Consulting’s full report provides the granular segmentation, vendor analytics, and decision tools required to translate market insight into executable strategy — including the region- and application-level data tables that underpin robust CapEx decisions.
Learn more
For access to the complete dataset, vendor scorecards, retrofit economics, and downloadable tools referenced here, please visit the PW Consulting report page for the Worldwide UV Roller Coater Machine Market. Our team is available for bespoke briefings and scenario workshops designed to translate the report’s outputs into a tailored 90‑day action plan for your business.
For detailed analysis of this topic, please visit the official page: Worldwide UV Roller Coater Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Litz Wire Market Hits USD 680 Million in 2025, Report Reveals
By PW Consulting, 2026-08-12
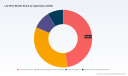
Worldwide Litz Wire Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest Worldwide Litz Wire Market report (base year 2025, historical series 2020–2025, forecast 2026–2032) delivers the actionable industry intelligence senior executives, corporate strategy teams, and investors need to set priorities for 2026. The market—measured on a revenue basis in USD millions—has expanded robustly from roughly $488 million in 2020 to $680 million in 2025 and is forecast to reach approximately $756 million in 2026, growing at a compound annual growth rate (CAGR) of 6.85% over the forecast horizon to exceed $1.08 billion by 2032. This briefing summarizes the strategic implications of those dynamics while preserving the deeper segmentation, regional splits, and deal-level modeling for report subscribers.
Worldwide Instant Communications Security and Compliance Solutions Market
Why this matters for 2026 strategic plans
-
Converging demand vectors: Electrification, wireless power, 5G/telecom miniaturization, and renewables are creating overlapping use-cases that intensify demand for engineered Litz constructions. The aggregate market trajectory shown above masks divergent growth and margin profiles across end-markets—precisely the differentiation we map in the full report.
Scrap Based Electric Arc Furnace Market -
Cost and supply volatility: Escalating copper and specialty enamel costs, extended resin lead times, plus targeted trade measures are compressing near-term supplier capacity and commercial flexibility. These forces will shape supplier selection, inventory policy, and contract structure in 2026.
Worldwide Biopotential Sensors Market -
Competitive consolidation window: Industry concentration metrics indicate a market where the top three firms command a meaningful yet not dominant share, and the top five widen that footprint. That concentration profile creates an opportunistic window for disciplined M&A and capability-driven roll-ups.
Market trajectory and critical macro inputs
-
Historical momentum: The global market expanded from about $488 million in 2020 to $680 million in 2025, reflecting a blend of incremental product redesigns (to reduce skin and proximity losses), new HF applications, and growth in electrified mobility systems.
-
Near-term forecast: Our base-case model projects the market to reach ~ $756 million in 2026 and to grow at a 6.85% CAGR through 2032, culminating above $1.08 billion. We publish three scenario paths (base, upside, downside) and a sensitivity matrix that ties demand to EV adoption curves, wireless-charging commercialization timelines, and renewable inverter deployments.
-
Key cost and supply inputs to watch in 2026: copper costs and specialty enamel availability are the dominant drivers of unit costs; regulatory shifts and tariff regimes are the main exogenous risk vectors. We outline hedging and procurement playbooks in the report to translate those inputs into near-term margin stabilization measures.
Operational dynamics shaping supplier strategy
-
Raw material pressure: Copper spot prices rose markedly year-over-year into early 2026, materially increasing production cost bases for Litz manufacturers and prompting many firms to re-price contracts or adopt index-linked clauses. Procurement teams must reassess hedging tenors and supplier payment terms.
-
Enamel and resin constraints: Lead times for high-performance polyimide enamels extended significantly, impacting new-product launches and turn-key coil suppliers. We provide tactics for alternative qualifying strategies, dual-sourcing templates, and risk-weighted inventory buffers that are practical for 2026 execution.
-
Trade and policy headwinds: Recent export control tightening on high-purity copper enabling components and selective tariff measures on certain imports are already reshaping sourcing footprints. Our regional sourcing playbook models the commercial impact of these measures and prescribes tactical responses to limit customer disruption.
Regulatory and standards environment
-
Material restrictions: Updated material directives are increasing scrutiny on halogen content in insulations effective in 2026. Product roadmaps and qualification timelines for new insulation chemistries must be accelerated to avoid non-compliance and market access delays.
-
Quality and aerospace/aeronautics benchmarks: AS and IATF certifications are differentiators in aerospace, automotive, and industrial segments. We map credentialing pathways and certification cost/lead-time trade-offs for manufacturers seeking to enter higher-value OEM supply chains.
Competitive landscape — what we found
The market is competitive but not winner-take-all. The three largest producers collectively hold a meaningful share, and the five largest firms further consolidate near-term supply control—conditions that favor strategic partnerships and selective M&A. Below is an executive view of key incumbents and their strategic postures (full profiles and capability matrices are in the report).
-
Elektrisola (Stolberg, Germany): A global leader in enameled and high-temperature Litz variants. Recent product launches include high-temp series for EV wireless charging coils—validated to automotive quality standards—positioning the firm for OEM wireless power opportunities.
-
MWS Wire Industries (Westlake, OH): Specializes in custom, ultra-fine strand configurations for RF and aerospace. Demonstrated technology leadership at trade shows with offerings aimed at next-generation telecom and antenna arrays.
-
New England Wire Technologies (Lisbon, NH): Focused on miniaturization and aerospace-grade product lines, with recent recertification achievements that reinforce its positioning in high-reliability applications.
-
Sam Dong (Gyeonggi-do): Active in the Asian automotive supply chain, with multi-year supply deals into EV battery and charging systems—signals a targeted play into high-volume automotive assembly lines.
-
Essex Furukawa and regional high-volume producers: Offer broad portfolio coverage into renewable energy and industrial transformer markets, often leveraging global operational footprints to serve large OEMs.
-
Ruiyuan Group and other high-volume manufacturers: Compete strongly on cost and scale for consumer electronics and power-supply segments, but face margin pressure from material inflation and trade tariffs.
-
Cooner Wire and niche specialists: Provide flexibility and speed-to-market for audio, medical, and specialized RF applications where customization and lead-time responsiveness matter more than unit-cost scale.
-
Fujikura : Focuses on telecom and high-frequency components with advanced manufacturing capabilities and integrated R&D, targeting high-growth telecom infrastructure projects.
Recent commercial signals to act on in 2026
-
Product innovation continues to be the primary route to premium pricing—new high-temperature and ultra-fine constructions that meet automotive and telecom specs are the fastest path to differentiated margins.
-
Certification achievements and multi-year OEM agreements materially shorten sales cycles in enterprise accounts; firms with validated quality systems capture the early commercial benefits of electrification programs.
-
Trade and policy events are compressing supplier choice for some buyers. Tactical near-term responses include longer contract tenors with price adjustment clauses, strategic safety stock, and selective on-shoring of critical processes.
What the PW Consulting report delivers (practical assets)
-
Robust forecasting model: Three scenarios with transparent assumptions, sensitivity levers tied to EV adoption, wireless power commercialization, and renewable inverter deployments.
-
Commercial due diligence toolkit: Supplier scorecards, contract clause templates, and pricing indexation models you can apply to vendor negotiations in 2026.
-
Technology and product roadmaps: Comparative performance matrices for round, rectangular, and shaped Litz constructions (technical trade-offs, expected cost deltas, and qualification timelines).
-
Supply-chain playbook: Risk maps, alternative raw-material strategies, and a supplier prioritization algorithm for single vs. dual sourcing under constrained enamel supply.
-
M&A and partnership screeners: Target profiles, accretion/dilution pre-checks, and integration checklists for bolt-on and scale plays—supported by a curated short-list of potential targets and scenario-based valuation ranges.
-
Regulatory impact assessment: A compliance matrix for new material standards and export controls, with recommended operational mitigations and labeling adjustments.
How leading teams are already responding
-
Commercial teams are negotiating index-linked pricing tied to copper and enamel indices rather than fixed-price multi-year contracts.
-
Procurement groups are qualifying secondary resin suppliers and implementing 12–16 week buffer policies for critical enamel inputs to stabilize production schedules.
-
Strategic investors and corporate development functions are using the current consolidation profile to evaluate tuck-in acquisitions that add technical strand expertise or certification-heavy product lines.
Next steps: using this intelligence to shape 2026 action
PW Consulting’s report is designed as an operational manual for executives—not just a market snapshot. For leadership teams preparing budgets, supplier strategies, or M&A pipelines in 2026, the report provides the quantitative foundations, tactical playbooks, and deal-ready documentation to move from strategy to execution.
To access the complete regional and application segmentation, full company profiles with capability heatmaps, and the model templates referenced here, please visit our report landing page. The executive briefing above intentionally omits those detailed splits to preserve the strategic value of the full deliverable and to ensure decision-makers engage with the underlying models during procurement, partnering, or transaction planning.
Contact PW Consulting to request the report, schedule a tailored walk-through of the forecast model, or commission a bespoke consulting engagement to apply these insights directly to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Litz Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Molten Salt Pumps Market Set to Grow at a 9.1% CAGR Through 2032
By PW Consulting, 2026-08-12
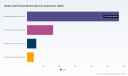
Worldwide Molten Salt Pumps Market: Strategic Intelligence for 2026 Decision-Makers
Executive snapshot
As the energy transition deepens and high-temperature fluid handling moves from pilot projects to industrial-scale deployments, molten salt pumps have emerged as a mission-critical equipment class across concentrated solar power (CSP), thermal energy storage (TES), emerging molten salt reactors (MSR), and high-temperature industrial processes. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — finds the global molten salt pumps market reached approximately USD 834.1 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 9.1% through 2032, reaching roughly USD 1,534.6 Million by the end of the forecast period. This research package is designed to convert that macro momentum into defensible 2026 decisions for OEMs, EPCs, equipment buyers, investors, and service providers.
Electrical Double Layer Capacitor Single Cell Market
Why this matters for 2026 planning
2026 is a strategic inflection point: utility-scale CSP projects are progressing from second- to third-generation designs, thermal storage architectures are being engineered for longer duration and higher temperatures, and first commercial-scale demonstrations of MSRs are moving from test loops to integrated prototypes. Those transitions convert design-level risks (materials, sealing, thermal distortion) into procurement and operational risks that directly affect project economics, lifetime maintenance costs, and financing feasibility.
Worldwide Absorbent Pad Market
Key takeaways for 2026 decision cycles:
Worldwide VP Latex Market
- Market momentum is strong and durable. The high-single-digit CAGR and near-term uplift in total market value indicate sustained procurement activity across multiple end-markets.
- Technology and materials choices made at the RFP/contracting stage will materially influence LCOE and asset availability over decades — particularly in applications operating above 600°C or with chloride salts.
- Supplier selection should weigh not only unit price but proven high-temperature metallurgy, coating systems, thermal mapping capabilities, and lifecycle service networks.
What the report delivers — practical, decision-grade content
PW Consulting’s Worldwide Molten Salt Pumps Market report is structured as an actionable toolkit, not just a dataset. Highlights include:
- Market sizing and trajectory: base-year calibration (2025) and a transparent forecast model for 2026–2032 that quantifies topline exposure for strategy and investment planning.
- Technology profiling: evaluation of vertical cantilever, vertical submerged and other high-temperature special pump families against use-case requirements (thermal limits, NPSH, bearing systems, maintenance access, seal strategies).
- Materials and coatings compendium: engineering-grade guidance on high-temperature alloys (e.g., Inconel 625) and advanced HVOF cermet coatings (e.g., NiWC-based systems) for chloride and nitrate salt chemistries.
- Supply-risk analytics: supplier concentration indicators, lead-time sensitivity, critical raw-material exposure, and geographic manufacturing bottlenecks mapped to likely procurement windows.
- Commercial playbooks: RFP templates, technical specifications checklists, acceptance-test protocols, and O&M service-contract frameworks calibrated for long-life molten-salt assets.
- Scenario stress-tests: bottom-up stress testing across three market scenarios (Base, Accelerated CSP adoption, Reactor-led diversification) to quantify capex, spare-parts inventories, and service revenue pools.
- Supplier scorecards and shortlists: comparative performance matrices (engineering robustness, project references, aftermarket capability, certification readiness) to shorten vendor selection timelines.
Competitive landscape: who matters and why
The market demonstrates moderate concentration, with the top three and top five suppliers capturing a meaningful share of global revenues — an important consideration when structuring multi-year supply agreements or contingency plans. The report’s competitive chapter synthesizes public disclosures, project awards, product architectures and recent field milestones to produce buyer-oriented insight.
- Sulzer (Winterthur, Switzerland)
Sulzer’s product suite for CSP (VEY and VNY vertical mixed-flow pumps) and recent contract wins for molten salt energy storage underline its strength in large-scale, engineered pump deliveries. Sulzer’s track record on both hot and cold molten salt pumps — and their manufacturing footprint for high-power motors — positions them as a primary partner for utility-scale CSP and storage projects seeking turnkey pump supply. - Flowserve (Irving, Texas, USA)
Flowserve’s molten-salt-specific vertical turbine wet-pit designs and emphasis on thermal mapping and 30-year lifecycle considerations make them a compelling choice where longevity and thermal distortion mitigation are procurement priorities, particularly for Gen3 CSP projects that are placing a premium on reliability. - Hayward Tyler
With capabilities targeting extreme temperatures (nominally >750°C) and a focus on nuclear- and solar-grade materials, Hayward Tyler is positioned for advanced CSP and MSR opportunities that require bespoke high-temperature engineering and compliance with nuclear-applicable QA regimes. - Rheinhütte Pumpen (ITT)
Longstanding experience with nitrate salts and corrosion-resistant pump designs provides Rheinhütte with a niche competence for chemical- and CSP-oriented projects that emphasize material longevity and wear resistance. - WEM Pumps, Auro Pumps, Zigong (ZGPV), Nagle, Jinan Warwick
These suppliers range from legacy specialists in molten-salt transfer systems to regional manufacturers offering competitive engineering and local content advantages. For projects seeking cost-differentiation or in-region sourcing, these vendors warrant inclusion in technical pre-qualification dialogues.
Recent industry developments reinforce the shifting risk landscape: independent test-loop validation of molten-salt pump operation (multi-year continuous run) and marquee contract awards for energy storage pumps highlight both technology maturation and growing project-level demand. Buyers should interpret these signals as both opportunity and caution — the technology base is being validated but scale-up risks remain.
Market dynamics shaping supplier and buyer strategies
- Materials and coatings dominate engineering trade-offs. Engineering decisions about alloy selection (e.g., Inconel 625 for chloride service), cermet components, and HVOF-applied coatings materially alter maintenance intervals and spare-parts strategies. Procurement teams must convert metallurgical roadmaps into supplier qualification criteria.
- Regulatory and programmatic drivers. Public programs (notably DOE CSP initiatives) are tightening performance expectations around reliability and longevity, increasing the value of suppliers who can demonstrate validated thermal-mapping, distortion mitigation, and nuclear-standard QA when applicable.
- Aftermarket and service economics. Given high capital intensity and criticality of pump uptime, service agreements and local spares provisioning often represent a substantial portion of a project’s lifecycle cost. Early negotiation of long-term service-level agreements (SLAs) can materially reduce project risk premiums.
- Concentration and supply-risk. The market shows notable share concentration among leading suppliers. Project teams should build dual-sourcing strategies or strategic inventory buffers to protect against single-supplier disruptions, especially for multi-project rollouts in the 2026–2028 window.
Strategic recommendations for 2026
- Procurement timing and lead-time management: Lock in critical long-lead items (impellers, high-alloy wetted components, bespoke motors) during 2026 RFP cycles; expect multi-month to multi-quarter lead times for high-spec components.
- Material-first supplier prequalification: Require metallurgical evidence (trial coupons, third-party analysis) and validated HVOF or equivalent coatings for chloride/nitrate service in commercial tender packages.
- Service and spare strategy: Include spare-parts pools and staged commissioning support in initial contracts. Favor suppliers that offer digital condition monitoring and thermal-mapping services as part of a bundled O&M offering.
- Partnerships and risk-sharing: For first-of-kind MSR or Gen3 CSP projects, structure risk-sharing mechanisms (performance bonds, milestone payments, staged acceptance) that align supplier incentives with operational availability metrics.
- M&A and co-investment scouting: For OEMs and service providers looking to scale, consider targeted acquisitions of niche pump manufacturers or coating specialists to secure proprietary capabilities and reduce supplier concentration risk.
How to use this report in 2026
Procurement directors should use the report’s supplier scorecards and RFP templates to accelerate pre-qualification. Project leads should apply the materials compendium and acceptance-test protocols to reduce commissioning risk. Investors and portfolio managers should leverage the scenario outputs to stress-test capital allocation decisions under different adoption pathways for CSP, TES and MSR technologies.
Call to action
PW Consulting’s Worldwide Molten Salt Pumps Market report arms executives with the intelligence to translate a market expanding at a 9.1% CAGR into executable 2026 strategies — from procurement timing and technical specifications to partner selection and risk mitigation. For detailed regional, application and type-level splits, and the supplier-by-metric scorecards that power our recommendations, please consult the full report on our website. The executive toolkit and raw model inputs are provided to licensees to accelerate procurement, engineering and investment decisions during the critical 2026 planning window.
For detailed analysis of this topic, please visit the official page: Worldwide Molten Salt Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide EMU Market at USD 642.7 Million in Base Year 2025, Poised to Grow at 6.22% CAGR to USD 979.23 Million by 2032 — North America (USD 261.98M) and EEG Hardware (USD 399.97M) Leading the Way
By PW Consulting, 2026-08-12
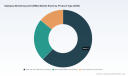
Worldwide Epilepsy Monitoring Unit (EMU) Market — Strategic Briefing for 2026 Decision‑Makers
Executive Summary
The global EMU market is entering a period of disciplined expansion driven by converging forces: rising epilepsy prevalence recognition, technology shifts toward wireless and remote telemetry, evolving accreditation rules that change how monitoring is delivered, and reimbursement dynamics that increasingly affect patient flow and facility economics. Our PW Consulting base‑year (2025) model pegs the total EMU market at approximately USD 643 million (revenue unit: Million). We forecast the market to expand to roughly USD 704 million in 2026 and to approach the high‑nines (around USD 980 million) by 2032, representing a compound annual growth rate (CAGR) of 6.22% across the 2026–2032 forecast window.
Worldwide Activated Alumina Sorbent Market
This briefing highlights the strategic implications of those macro trends for hospital systems, device and software vendors, investors and specialty centers. It is intended as a high‑value “trailer”: it demonstrates the depth of PW Consulting’s analysis and the practical, decision‑grade guidance the full report provides, while intentionally omitting granular segment tables and regional breakdowns to encourage access to the complete dataset and interactive model.
Educational Monocular Microscopes Market
Why the 2026 Inflection Matters
-
Policy and accreditation are reshaping delivery models. The 2026 NAEC accreditation updates explicitly permit 24/7 monitoring provision by qualified off‑site third parties, creating an immediate opportunity for vendors and service providers to extend monitoring services beyond the physical EMU.
Worldwide Vessel Management Software Market -
Technology is enabling decentralized care. Advances in wireless long‑term monitoring, cloud analytics and wearables mean EMU capabilities can be stretched across care settings, amplifying the addressable market but also intensifying competition and changing capital intensity.
-
Reimbursement friction is real. The treatment of EMU stays under Observation Status versus bundled inpatient DRGs can materially change patient out‑of‑pocket costs and hospital margins—an operational and commercial risk that must be managed in 2026 planning cycles.
-
Supply and staffing constraints persist. Continuous monitoring requires skilled EEG technologists and multidisciplinary clinical teams; centers that optimize staffing models through technology augmentation will gain both throughput and safety advantages.
What the PW Consulting Report Delivers (Practical, Actionable)
-
Transparent market model and reproducible forecasting engine (Excel) covering 2020–2032 with scenario toggles for accreditation, reimbursement and technology adoption rates.
-
Demand driver maps linking epidemiology, referral pathways and care‑setting migration to capex and opex implications for EMUs and hospital networks.
-
Regulatory and reimbursement playbook that decodes the 2026 NAEC accreditation change, Observation vs. Inpatient billing implications, and payer negotiation priorities for centers and vendors.
-
Operational benchmarks: staffing mixes, safety protocols, length‑of‑stay drivers, and throughput optimization levers validated against NAEC survey data and leading center case studies.
-
Commercial and technology go‑to‑market blueprints: channel strategies, outcomes‑based contracting frameworks, and software licensing models tuned for EMU use cases.
-
Competitive intelligence dossier: company profiles, capability matrices, partnership opportunities, and M&A screening criteria—presented to preserve confidentiality of our detailed segment revenue allocations.
-
Investment and capital allocation guidance: ROI models for new EMU facilities, retrofit vs. greenfield decisions, and capex phasing tied to reimbursement scenarios.
Market Structure and Competitive Dynamics
The EMU market displays moderate concentration: our concentration metrics indicate that the top 3 vendors control under half of total market revenues, while the top 5 vendors capture roughly three‑fifths. That structure leaves room for specialized players, vertically integrated incumbents, and new entrants with disruptive technology or service models.
Key industry participants include established neurodiagnostic suppliers, hospital‑facing monitoring platforms, neuromodulation and devices companies, and emerging wearable innovators. Each class of competitor brings distinct strategic intent and routes to market:
-
Natus Medical Incorporated — a leader in dedicated EMU hardware and wireless LTM amplifiers that prioritize patient mobility during extended video EEG monitoring. Their product focus makes them a natural partner for centers pursuing patient‑centric monitoring environments.
-
Cadwell Industries — known for high‑channel‑count EEG platforms and flexible in‑hospital systems that support both surface and intracranial workflows, appealing to centers with complex surgical‑evaluation pipelines.
-
Nihon Kohden — a broad monitoring portfolio with recent product advancements including a new Live View remote assessment panel, underscoring the company’s push into remote and distributed monitoring use cases.
-
Compumedics — leverages a diverse sleep and neurodiagnostics portfolio, providing EMU‑relevant equipment often bundled into larger neurology service contracts.
-
Medtronic — while primarily a therapeutic device firm, Medtronic’s neuromodulation and diagnostic capabilities position it within EMU workflows, particularly where long‑term evaluation informs implantable therapy decisions.
-
Philips — offers integrated patient monitoring systems and enterprise platforms that can be configured for EMU deployments at scale across hospital networks.
-
Empatica — an example of the new wave of wearable seizure detection firms whose physiological sensor data complement traditional video‑EEG, opening partnership options with EMU providers and remote monitoring services.
Recent sector events underscore these dynamics: new EMU facility openings have expanded capacity in both adult and pediatric segments; product upgrades were announced that increase remote assessment capabilities; and the NAEC accreditation clarification creates both opportunity and competitive pressure for off‑site monitoring services.
Strategic Implications and Recommended 2026 Actions
-
Recalibrate capital plans for hybrid delivery models. Buyers and hospital systems should evaluate a hybrid EMU architecture that combines on‑site capability with robust remote monitoring. This reduces peak capex and permits scaled utilization across multiple facilities.
-
Invest in software and analytics as a differentiator. With hardware increasingly commoditized, long‑term value will accrue to vendors and centers that capture and act on continuous physiologic datasets—analytics-enabled triage, anomaly detection, and outcome tracking will support higher‑value contracts.
-
Build third‑party monitoring partnerships and service offers. The NAEC change enables qualified off‑site monitoring; vendors and MSPs should develop certified remote monitoring services and compliance frameworks to be first movers in a newly legitimized channel.
-
Proactively manage payer and coding risk. Clinical and finance leaders must map EMU pathways against payer policies (Observation vs. Inpatient coding) and negotiate bundled pathways or carve‑outs to protect patient access while stabilizing margins.
-
Optimize workforce through role redesign and technology augmentation. Centers should pilot models where experienced technologists supervise multiple beds remotely, leveraging automated alarm‑triage to prioritize human intervention for complex events.
-
Pursue M&A and alliances with focused criteria. Buyers should prioritize targets that supply the missing piece in a hybrid care model: remote monitoring platforms, wearable data integrators, or analytics firms with validated seizure detection algorithms.
Strategic KPIs to Track in 2026
-
EMU utilization and bed turnover time.
-
Percent of monitoring hours covered by remote/third‑party services.
-
Time‑to‑event detection and alarm‑to‑response intervals.
-
Revenue mix by service type (monitoring services vs. capital equipment vs. analytics licensing).
-
Net margins adjusted for Observation vs. Inpatient billing outcomes.
Conclusion — Where PW Consulting Adds Immediate Value
For executives making 2026 investments—whether they lead hospital networks, build medical device roadmaps, or evaluate targets for acquisition—the EMU market represents a medium‑growth, structurally shifting opportunity. PW Consulting’s Worldwide EMU Market report combines time‑series market sizing, regulatory and reimbursement playbooks, operational benchmarks, and competitive intelligence into a single decisioning toolkit designed to accelerate capital allocation and commercial choices.
To preserve the strategic utility of this briefing, we have intentionally withheld granular regional, product and end‑user revenue splits from this public summary. The full report contains the complete segment matrices, downloadable interactive models, and the precise revenue allocations that underpin the recommendations summarized above.
Next Steps
-
Access the full PW Consulting Worldwide EMU Market report and interactive forecast model to run customized scenarios for your organization.
-
Schedule a workshop with our EMU practice team for a two‑day strategic session: financial modelling, go‑to‑market sequencing and M&A target short‑list generation.
-
Contact PW Consulting to commission a tailored due‑diligence or market entry study based on your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Epilepsy Monitoring Unit (EMU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rhus Verniciflua Peel Cera Market Poised to Grow at a 6.01% CAGR Through 2032
By PW Consulting, 2026-08-12
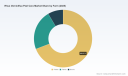
Worldwide Rhus Verniciflua Peel Cera Market — Strategic Imperatives for 2026
By PW Consulting — Senior Strategy & Industry Analysis
Rhus Verniciflua Peel Cera has emerged as a niche yet strategically important ingredient in contemporary personal care and cosmetic formulations. Our new market study — covering historical performance (2020–2025), a 2026 base, and a detailed forecast to 2032 — provides the commercial intelligence that ingredient buyers, product teams, and M&A strategists need to make confident decisions in 2026. The market is small in absolute terms but dynamic: from USD 13.96 Million in 2025 the global market is forecast to follow a compound annual growth rate (CAGR) of 6.01% through 2032, reaching approximately USD 21.0 Million in that year. This trajectory underscores both premium positioning and structural opportunities for value capture.
Surface Drilling Rigs Market
Executive summary — what matters right now
- Market growth is steady and predictable: the category has expanded through 2023–2025 and is projected to grow at a mid-single-digit CAGR through 2032, reflecting steady demand in targeted personal care niches.
- Supply-side concentration is meaningful: the top three suppliers account for a majority share of the market, and the top five approach three quarters of global supply — a fact with direct implications for procurement strategy and negotiating leverage.
- Functionality and formulation advantages — low melting point, emollience and a unique sensory profile — are driving adoption in anhydrous systems, sticks and targeted skin/lip applications.
- Regulatory and sourcing clarity reduces entry friction: the ingredient is listed on key inventories and is treated as a non-dangerous vegetable substance under relevant classifications, though traceability and supplier due diligence remain essential.
Why this report is a strategic asset for 2026 decision-makers
Small-format specialty ingredients like Rhus Verniciflua Peel Cera present a paradox for planning: unit volumes may be modest, but formulation impact and margin premiums can be disproportionately large. Between 2023 and 2025 the market showed measured expansion, and 2026 represents a pivotal year for scaling from niche experimentation to broader application. Our report consolidates primary supplier intelligence, validated market sizing (base year 2025), and forward-looking scenarios across the 2026–2032 forecast window. The quantified growth path — a 6.01% CAGR to roughly USD 21.0 Million by 2032 — provides a defensible financial baseline against which product roadmaps, sourcing commitments, and potential acquisition targets can be stress-tested.
Ball Tow Hook System Market
What the report contains — practical, actionable modules
- Market sizing and methodology: transparent approach linking historical sales (2020–2025) to 2026 base and scenario-driven forecasts to 2032.
- Supply chain and sourcing maps: primary origin pathways, processing steps (including extraction techniques), and freight/tariff considerations to support procurement planning.
- Supplier benchmarking: commercial profiles, product dossiers, capacity estimates and risk assessments for incumbent producers and distributors.
- Formulation intelligence: technical properties (e.g., melting behavior, emulsification potential, sensory attributes), recommended use cases, and integration best-practices for anhydrous and semi-solid systems.
- Go-to-market playbooks: tactical guidance for brand positioning, specification creation, and margin modelling when introducing Rhus-derived waxes into product lines.
- Regulatory & compliance compendium: inventory statuses, classification guidance and due diligence checklists tailored for EU, China and US markets.
- Commercial scenarios and M&A screening: valuation heuristics, integration risk matrices, and strategic options aligned to buyer objectives.
Competitive landscape — who matters and why
The competitive topology is dominated by a handful of established players and specialised distributors. Market concentration metrics indicate that the top three companies capture a majority share, and the top five consolidate a substantial proportion of global supply — a configuration that makes supplier relationships and certification status a key negotiating lever.
Worldwide Smart LED Indoor Signage Market
Notable participants include: Kahl GmbH & Co. KG (KahlWax), a European specialist that markets low-melting berry waxes with distinct sensory profiles for cosmetics; ROELMI HPC USA (via ABWAX), which promotes a low-melting Rhus berry wax adapted for anhydrous stick systems; traditional distributors such as Ulrich GmbH offering bulk supply solutions; Bay House Aromatics providing certified natural/vegan sources with traceability emphasis; and ingredient-to-finished-product players like Olive Tree People (Oliveda) that demonstrate finished goods use-cases. Recent supplier activity — including product documentation updates and product listing refreshes during 2025 — emphasizes ongoing product positioning and technical transparency across the supply base.
Supply chain, sourcing and regulatory considerations
Rhus Verniciflua Peel Cera is produced through extraction from the berry peels of the Rhus verniciflua tree, with processing workflows commonly involving boiling and phase separation. The primary sourcing origin is concentrated, and logistics strategic planning should account for seasonality, supplier concentration, and freight volatility. On the regulatory front, the ingredient is listed on key inventories (EU Cosmetics Regulation compliance, IECSC in China, TSCA in the US) and is treated as a non-dangerous vegetable substance under applicable classifications — factors that lower regulatory friction but do not eliminate the need for supplier audits, contaminant testing, and chain-of-custody documentation.
Additionally, commercial importers should be aware of the commodity’s tariff classification and related customs considerations. Our report provides a practical importer’s playbook — from tariff code mapping to packaging and labelling controls — to reduce clearance delays and duty surprises.
Strategic recommendations for 2026 (high impact, executable)
- Prioritise supplier diversification while securing first-mover formulation exclusivity. Negotiate volume options and technical collaboration clauses with two tiers of suppliers to balance cost and innovation access.
- Embed low-melting wax properties into product innovation roadmaps. For brands targeting premium texture and ‘natural’ credentials, pilot formulations in lip and stick formats where material advantages are most visible.
- Invest in specification standardisation and testing regimes. Implement third-party analytical verification for batch consistency and contamination thresholds to support regulatory claims and retailer approvals.
- Use procurement levers tied to certification and traceability. Value-add beyond price — e.g., supplier audits, sustainability certificates, and country-of-origin transparency — is a differentiator for retail and indie channels.
- Screen small-to-mid acquisition targets in the supply chain. Given the market’s concentration and modest absolute size, bolt-on acquisitions or strategic minority investments can secure capacity and proprietary sourcing without large capital outlays.
- Prepare pricing and cost-pass models. With raw-material-driven cost variability, pricing frameworks that incorporate indexed pass-through or tiered margins reduce margin erosion risk as volumes scale.
Scenario outlook to 2032
Our baseline (central) scenario follows the calculated CAGR of 6.01% across the forecast window, producing a market value near USD 21.0 Million by 2032. This baseline assumes steady demand growth in personal care niches, continued supplier capacity expansion, and stable regulatory conditions. Upside scenarios — driven by accelerated uptake across mass-premium beauty categories, new formulation breakthroughs that expand use-cases, or certification waves boosting natural/vegan appeal — could lift growth materially above the baseline. Conversely, downside scenarios are conceivable if supply constraints, raw-material price shocks, or substitution by alternative waxes occur. The report presents full scenario matrices with trigger points to support contingency planning.
How to apply this intelligence in 2026
Product development leads can use the formulation intelligence to accelerate prototype-to-market cycles. Procurement teams will find the supplier risk and tariff mapping immediately actionable for contracting and import planning. Corporate development functions can apply our M&A screening checklist to identify targets that deliver immediate commercial synergies. Importantly, the report couples market sizing with practical playbooks so teams can move from insight to execution within quarters, not years.
Accessing the full intelligence
In this preview we have intentionally highlighted strategic conclusions and synthesis to demonstrate the report’s depth. To preserve the value of granular commercial detail we have withheld certain segment-level data and granular regional/application splits from this release. The full report contains detailed breakdowns, primary-sourced supplier volumes, formulation case studies, and downloadable modelling tools — resources designed to convert strategic intent into measurable outcomes.
For organisations preparing 2026 plans — whether launching a product, securing supply, or scouting strategic investments — our Worldwide Rhus Verniciflua Peel Cera Market report is a compact operational guide and decision-support tool. Contact PW Consulting to request the full report and the accompanying data workbook to unlock the category-level granularity and supplier dossiers necessary for high-confidence action.
For detailed analysis of this topic, please visit the official page: Worldwide Rhus Verniciflua Peel Cera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide All‑Solid‑State RF Power Supply Market Poised for 9.48% CAGR (2026–2032) Driven by Rising Semiconductor Etching Demand
By PW Consulting, 2026-08-12
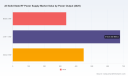
Worldwide All Solid State RF Power Supply Market: Strategic Insights for 2026 Decision-Making
PW Consulting today releases an executive briefing drawn from its forthcoming Worldwide All Solid State RF Power Supply Market report (base year 2025). The briefing synthesizes the report’s most consequential strategic takeaways for corporate leaders preparing capital allocation, R&D roadmaps, and go‑to‑market moves in 2026. Built on a quantitative foundation and practitioner-focused deliverables, this briefing signals where competitive advantage will be created — while reserving the full granularity (regional and application splits, segment tables and price curves) for the complete report.
Flat Linear Motor Market
Market Snapshot: Growth Profile and Why It Matters
The all solid state RF power supply market has entered a sustained growth phase. Our modelling shows the market expanding from roughly USD 912 million in 2020 to USD 1,465 million in 2025, and continuing toward a multi‑billion dollar opportunity by the end of the 2026–2032 forecast window. The baseline compound annual growth rate for the forecast period is 9.48% (USD, revenue unit: Million), underscoring structural demand driven by technology transition, energy efficiency mandates, and capital equipment refresh cycles in semiconductor and industrial applications.
Knee Positioning System Market
Why this macro trajectory is strategically important for 2026:
Worldwide Vineyard Equipment Market
- It justifies near‑term investments in product development and digital control capabilities to capture accelerating replacement demand.
- It elevates the value of aftersales and service models (remote diagnostics, predictive maintenance) as recurring revenue streams.
- It increases M&A optionality for incumbents and well‑funded challengers seeking scale in power output tiers or geographic reach.
What the Full Report Delivers (Practical, Actionable Content)
PW Consulting’s report is intentionally practical. Beyond headline market sizing and a seven‑year forecast, the deliverables are designed to be operational from day one for strategy teams, product managers, and corporate development:
- Transparent market model (historical trends 2020–2025; base year 2025; forecast 2026–2032) with sensitivity scenarios tied to capex cycles and semiconductor equipment demand.
- Segment‑level decision matrices for power‑output tiers, application families, and technology preferences — with commercial benchmarks and unit price ranges (note: full segment tables are available in the paid report).
- Competitive profiling with capability maps, product roadmaps, and partnership/ channel coverage assessments for the market’s leading and fast‑growing vendors.
- Supply‑chain risk analysis focused on core semiconductor building blocks (LDMOS, GaN, SiC), alternative sourcing strategies, and inventory playbooks for 12–18 month procurement cycles.
- Regulatory and compliance playbook for ISM band operations and emissions limits, including a checklist for OEM integrators and end users.
- Financial impact tools, including energy‑savings case calculators and total cost of ownership (TCO) templates to quantify migration benefits versus legacy tube/magnetron systems.
- Go‑to‑market and commercial diligence templates for partnerships, licensing, and M&A screening — tuned to the market’s concentration profile and channel dynamics.
Competitive Landscape: Who Matters and How They Compete
The market is meaningfully concentrated: the top three suppliers account for a majority share, and the top five firms control close to seven in ten dollars of revenue. That structure shapes both competitive conduct and acquisition opportunities in 2026. Key competitive archetypes we profile include:
- Precision control and semiconductor‑centric platforms — Advanced Energy and MKS Instruments lead here with product families that integrate RF generation and matching networks for wafer fab and vacuum processing OEMs. Their value lies in tight RF/pulse control, integration with process control systems, and proven reliability in high‑mix manufacturing.
- Industrial and heating specialists — TRUMPF Hüttinger and Ampegon bring deep industrial heating and accelerator expertise, combining high‑power solid‑state architectures with rugged packaging and service footprints for continuous heavy‑duty operation.
- Cost‑efficient, application‑specific suppliers — Coaxial Power Systems and others focus on tailored, competitively priced units and automatic matching networks for OEMs in coating, welding, and small‑batch industrial processes.
- High‑power, magnetron replacement innovators — Elite RF, Empower RF, Aethera, Crescend, and pinkRF are examples of suppliers pushing high‑power solid‑state alternatives to legacy magnetron and vacuum tube assets, especially in dielectric heating, plasma generation, and fusion research domains.
Recent vendor dynamics illuminate competitive momentum and product differentiation. Notably, a late‑2025 launch of a programmable 10 kW solid‑state generator targeted at ISM‑band industrial heating and plasma processing emphasizes reliability and magnetron replacement narratives. Other vendors continue to showcase full‑digital RF platforms at major trade events and regional shows — a sign that precision, programmability, and lifecycle cost advantage are central positioning levers.
Technology and Supply‑Side Dynamics
Three technical themes dominate near‑term strategy:
- Semiconductor device mix: LDMOS, GaN and SiC transistor technologies are the core enablers. Their availability, cost trajectory, and thermal management implications are the principal supply‑side constraints to monitor.
- Energy efficiency as a commercial argument: Contemporary solid‑state systems advertise efficiencies ranging broadly but reaching up to the mid‑90s under optimized conditions. For many continuous industrial processes, that translates into compelling TCO and carbon footprint benefits versus tube‑based incumbents.
- Digital control and integration: Vendors differentiating with advanced digital RF and pulse control, instrumented feedback loops, and software ecosystems (remote diagnostics, recipes) are winning OEM design‑wins and aftermarket contracts.
Regulation, Standards and Operational Constraints
Regulatory considerations are non‑trivial: operation within licensed and ISM bands (e.g., 13.56 MHz, 27.12 MHz and 2.45 GHz for industrial uses) means compliance and emissions management are table stakes for industrial and medical customers. Our report synthesizes the applicable requirements and offers a compliance checklist for product teams and integrators.
Strategic Imperatives for 2026
For boards and leadership teams finalizing 2026 priorities, the report distills five actionable imperatives:
- Prioritize efficiency and software‑enabled differentiation: Allocate R&D to digital control and energy‑optimization features that materially lower TCO for end users.
- Hedge component risk: Establish multi‑sourcing plans for LDMOS/GaN/SiC devices, consider long‑term supply agreements, and assess in‑house module assembly to reduce lead‑time exposure.
- Design aftermarket as a strategic asset: Build service offerings (remote health monitoring, spare module pools) that convert one‑time equipment sales into annuity streams.
- Execute focused M&A or partnership plays: Use the market’s concentration profile to target bolt‑on capabilities — higher power blocks, geographic service networks, or niche application expertise — rather than broad horizontal consolidation.
- Commercialize magnetron replacement narratives: Develop migration packages (performance data, retrofit kits, financing options) to accelerate conversions in dielectric heating, plasma processing and industrial heating segments.
How to Use the Report in 90 Days
We designed the report with busy executives in mind. In the first 90 days after purchase, the recommended actions are:
- Run the included TCO calculator against two representative customer profiles to create a short casebook for sales and OEM business development.
- Map supplier risk against your existing procurement contracts using the report’s supply‑chain heatmap and a 12‑month procurement checklist.
- Prioritize three product features for near‑term R&D sprints (digital controls, thermal management for higher power density, and modular power blocks) based on the feature‑value matrix we provide.
Conclusion and Next Steps
Solid‑state RF power supplies are transitioning from a promising niche to an industrially strategic technology with measurable operational and sustainability benefits. The PW Consulting market model quantifies that momentum, showing robust growth from 2020 through 2025 and a strong forecast trajectory through 2032 at a 9.48% CAGR for the forecast period. For decision makers planning 2026 spend, the choice is clear: invest selectively where you can establish durable, serviceable differentiation and de‑risk component supply while accelerating customer conversions away from legacy tube technologies.
For teams seeking the full dataset, detailed segment tables, regional and application splits, vendor scorecards, and the suite of practical templates described above, please access the complete report via PW Consulting’s report page. The full document is structured to convert insight into executable workstreams for product, procurement, commercial, and M&A teams.
About PW Consulting
PW Consulting delivers strategic market intelligence and pragmatic playbooks for industrial and semiconductor supply chains. Our worldwide all solid state RF power supply research blends quantitative forecasting, primary interviews with OEMs and vendors, and scenario planning to help clients translate market momentum into sustainable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide All Solid State RF Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Green Elevator Market to Rise from USD 52,380 Million in 2025 to USD 86,890.75 Million by 2032 at a 7.51% CAGR — Asia‑Pacific and Machine Room‑Less Elevators Lead, Top 5 Capture 58.3%
By PW Consulting, 2026-08-12
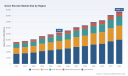
Worldwide Green Elevator Market — Strategic Imperatives for 2026
PW Consulting’s latest market research, the Worldwide Green Elevator Market report (base year 2025), frames a fast-maturing vertical-transportation landscape at the intersection of decarbonization, urban densification, and regulatory tightening. Our top-line model shows the global green elevator market reaching approximately USD 52,380.0 Million in 2025 and expanding at a compound annual growth rate (CAGR) of 7.51% across the 2026–2032 forecast window. By 2032 the market is projected to approach the high tens of billions of dollars, reflecting both replacement cycles in developed markets and greenfit demand in emerging urban regions.
Worldwide RF Probes Market
Why this matters for 2026 corporate decision-making
-
Procurement and CAPEX planning: With regulators in major jurisdictions increasing minimum energy performance standards and building-level obligations, elevator systems are shifting from a purely equipment CAPEX decision to a multi-decade operational and compliance choice. The timing of purchases, retrofit windows, and specification on regenerative technologies will materially affect lifecycle costs and compliance risk.
Ligament Restoration Fixator Market -
Supply-chain and input-price risk: Raw-material dynamics—most notably a marked increase in U.S. steel mill-product prices in 2025 (driven in part by tariff action) and elevated hot-rolled coil indices in early 2026—are compressing margins for OEMs and creating near-term cost pass-through decisions for contractors and asset owners. Procurement strategies that do not explicitly hedge or contract for material exposure risk higher realized cost of ownership.
Hydropower SCADA Systems Market -
Regulatory acceleration: New and revised energy directives in key markets (including heightened annual energy savings obligations and transposed building energy performance rules) will materially increase minimum performance expectations for vertical-transport systems—especially in non-residential building typologies. Early compliance planning will avoid stranded-asset risk for both new builds and major refurbishments.
-
Technology-driven differentiation: Energy-recovery systems, permanent magnet motors, destination-dispatch logic, and low-VOC materials are no longer niche features—they are becoming baseline requirements for projects targeting green certification and extended operational savings. The technology roadmap your teams adopt in 2026 will determine competitive positioning for the next decade.
What our report delivers (practical, decision-ready content)
-
Integrated market sizing and demand-model: A top-down / bottom-up model aligned to historical performance (2020–2025) and calibrated across multiple demand drivers for 2026–2032. The model supports scenario toggles for policy, material-cost shocks, and adoption curves.
-
Regulatory impact maps: Jurisdiction-level rule sets and the practical implications for specification, retrofits, and certification timelines; includes actionable compliance checklists for project teams and procurement departments.
-
Technology and TCO playbooks: Lifecycle cost frameworks that translate energy-efficiency improvements, regenerative yields, and maintenance differentials into standardized decision rules for CAPEX vs. OPEX budgeting.
-
Competitive supplier assessments: Vendor scorecards, go-to-market footprints, product-roadmap gaps and strengths, plus an acquisition target shortlist—designed to inform negotiations, partnerships, and potential roll-up strategies.
-
Risk and sensitivity analyses: Stress testing for raw material shocks, tariff scenarios, and accelerated retrofit mandates—presented in an interactive Excel model for direct use in board-level investment discussions.
Note: This release intentionally omits granular regional and application split tables to preserve the full commercial value of the underlying modeling. The report contains detailed sub-segment figures and datasets available via the official purchase page.
Competitive dynamics — what leading OEMs are doing
The market is dominated by established global OEMs that combine scale manufacturing with integrated service networks. These firms are converging on common strategies—regenerative drives, machine-room-less (MRL) architectures, high-efficiency motors, low-VOC materials, and digital services that extend asset life and improve energy management. Key strategic moves observed in our research include:
-
Otis Worldwide: Focusing on MRL platforms with regenerative drives and coated-steel belt designs to reduce energy use and maintenance needs. These solutions strongly target green building certification pathways and lifecycle cost reductions.
-
KONE: Investing in high-rise technologies and lightweight rope systems combined with low-energy MRL offerings; emphasizing gearless, low-energy systems and an explicit roadmap away from hydraulic models for sustainability reasons.
-
Schindler: Pushing power-factor optimized regenerative drives and stand-by ECO modes that can return energy to the building grid—paired with sustainable materials and retrofit-first service packages.
-
TK Elevator: Positioning digitally native elevators and destination-dispatch ecosystems to improve handling capacity and traffic efficiency, while bringing eco-efficient cabin materials to market through design partnerships.
-
Japan-based OEMs (Mitsubishi Electric, Hitachi, Fujitec) and regional leaders (Hyundai): Continuing to push energy-efficient hardware (permanent-magnet motor technologies, smart controls) and expand service offerings across fast-growing urban markets.
Recent industry showcases—such as a major trade event in Milan (late 2025) where innovative home-lift designs and eco-efficient platforms were presented, and regional expos highlighting sustainability-focused product launches—underscore the sector’s pivot to green credentials as a central competitive battlefield.
Scenarios for 2026 and recommended investment priorities
-
Baseline: Continued steady growth consistent with the report’s CAGR. Prioritize staged retrofits in higher-cost-of-energy buildings and embed energy-performance clauses in procurement documents.
-
Accelerated decarbonization: If policy enforcement outpaces expectations, asset owners will need to accelerate retrofit timetables—prioritize modular, upgradeable lift systems and flexible service agreements to avoid mid-life obsolescence.
-
Supply-chain shock: A sustained elevation in input prices or tariff-driven constraints will require early procurement contracting, negotiated pass-through terms, and material-substitution studies. Consider inventory prepositioning for long-lead components where economically justified.
Five strategic actions for decision-makers in 2026
-
Specify energy performance in procurement: Move beyond brand names—require quantifiable energy metrics, regenerative capability, and TCO scenarios as part of tender evaluations.
-
Prioritize retrofit pilots: Run targeted pilots of MRL/regenerative systems in representative asset classes to build internal procurement and maintenance playbooks before large-scale rollouts.
-
Hedge material risk: Use forward contracts, collaborative sourcing, or local-content strategies to reduce exposure to steel-price volatility and tariff disruptions.
-
Design for upgradability: Favor platforms allowing drive and control upgrades without full cabin replacement to reduce lifecycle embodied emissions and cost.
-
Embed digital services: Require data interfaces and open protocols in new equipment to enable ongoing energy optimization, predictive maintenance, and performance verification.
Why PW Consulting’s analysis matters
Our methodology marries primary interviews with OEMs, service providers, and building owners to a robust market model calibrated across 2020–2025 historicals and forecast 2026–2032 scenarios. The report combines quantitative market-sizing, regulatory impact overlays, vendor scorecards, and practical tools designed for procurement committees, product teams, and private-equity due diligence. Clients receive not only the market data but executable frameworks—TCO calculators, retrofit decision matrices, and an M&A target map—designed to translate insight into action.
We intentionally present a high-level summary here to demonstrate the rigor and relevance of our work while reserving the full sub-segment tables, vendor share matrices, and downloadable Excel models for report subscribers. For teams preparing 2026 budgets, tenders, or M&A roadmaps, those datasets are the actionable assets that materially shorten time-to-decision and reduce negotiation asymmetry.
Next steps and access
For procurement officers, asset managers, and C-suite teams developing 2026 strategies, immediate actions include requesting a bespoke briefing, licensing the full dataset for integration into financial models, or commissioning a short-form scenario workshop tailored to your portfolio. The full report contains the granular regional, technology and application splits, vendor shares, and pricing decks that underpin the high-level guidance summarized above.
Contact PW Consulting to schedule a tailored executive briefing and to obtain secure access to the Worldwide Green Elevator Market report and its supporting models. Our analysts will walk through the scenarios, vendor scorecards, and tailored TCO calculations that will drive strong, defensible 2026 decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Green Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Cryostation Optical Cryostat Market to Rise from USD 188.45M in 2025 to USD 386.83M by 2032 at a 10.82% CAGR — North America Leads with USD 73.85M
By PW Consulting, 2026-08-12
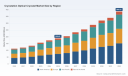
Worldwide Cryostation Optical Cryostat Market: Strategic Intelligence to Shape 2026 Decision-Making
Executive summary
PW Consulting’s newest market study on the Worldwide Cryostation Optical Cryostat Market provides an operationally focused intelligence package designed to inform strategic choices in 2026. The segment has moved from niche laboratory equipment into a core enabling technology for quantum science, advanced spectroscopy and precision materials research. Our analysis shows the market accelerating from an established 2025 base to nearly double size by the end of the forecast window, driven by persistent demand for low-vibration, cryogen-free platforms and integrated magneto-optical capability. The report blends a rigorous market model (historical 2020–2025, base year 2025) with scenario-driven forecasts (2026–2032) and an industry playbook for suppliers and institutional buyers.
Portable Dishwasher Market
Market snapshot and growth dynamics
Key macro takeaways from the research: the Cryostation optical cryostat market delivered sustained compound growth through the early 2020s and achieved a substantive market scale in 2025. Our forecast model, built on bottom-up product adoption curves and capital equipment procurement cycles, projects the market to expand at a compound annual growth rate of approximately 10.8% across the 2026–2032 horizon, reaching a materially larger addressable market by the end of the period.
Worldwide Application Development Life Cycle Management Market
Two structural trends underpin this expansion. First, the continued migration of research programs from liquid-cryogen systems to closed-cycle, low-vibration platforms has broadened the buyer base to include both national labs and high-throughput university facilities. Second, the rapid maturation of experiment suites—combining high-NA optical access, integrated magnetic fields and high-frequency wiring—has driven demand for configurable, automation-ready cryostats rather than off-the-shelf cabinets.
Worldwide RNA Sample Preparation Market
Why this matters for 2026 strategic planning
-
Product strategy and R&D prioritization: Vendors should prioritize modular architectures that enable rapid reconfiguration for quantum optics, magneto-optical experiments, and integrated spectroscopy. Our product decision framework assesses trade-offs between sample-space volume, vibration isolation and thermal performance, and maps those trade-offs to buyer personas (national lab instrumentation, quantum computing groups, advanced spectroscopy labs). For 2026 roadmaps, capitalizing on the premium segment for high-stability, automation-enabled systems offers outsized margin potential.
-
Go-to-market and commercial segmentation: The market is neither atomized nor monopolistic—leading vendors command a meaningful share while specialist builders capture premium niches. Suppliers should adopt hybrid GTM models combining direct engagement with reference lab programs and channel partnerships targeting instrument integrators. Our commercial playbook includes bid/no-bid thresholds, tender response templates and partner selection criteria to accelerate revenue capture in 2026.
-
M&A, partnerships and ecosystem plays: Strategic acquisitions and technology partnerships are effective levers to close capability gaps—examples include integrating high-performance nanopositioning, fiber management and cryogenic RF feedthrough expertise. The report identifies opportunity archetypes where inorganic moves can accelerate entry into magneto-optical or sub-4K mobile cryogenics markets with lower execution risk than greenfield development.
-
Supply chain resilience and manufacturing scale: Component-level constraints (pulse-tube and GM cryocoolers, precision windows, low-thermal-conductivity supports) will shape both lead times and margin. For 2026, scenario planning suggests that flexible supplier agreements and localized spares inventories materially reduce procurement friction for buyers and compress delivery timelines for suppliers targeting fast-turn installations in competitive research environments.
-
Procurement strategy for institutional buyers: Universities, national labs and corporate R&D groups should adopt a total-cost-of-ownership lens when evaluating platforms, emphasizing automation, uptime and integration costs rather than headline price. Our decision support tools include weighted evaluation matrices, suggested SLA language and commissioning checklists that buyers can deploy immediately.
Competitive landscape: positioning, recent moves and tactical implications
Our vendor analysis synthesizes public product specifications, trade-show activity, and primary interviews. The competitive field blends established laboratory-equipment manufacturers, specialist cryogenic OEMs and innovative subsystem suppliers. Market concentration is moderate—top-tier providers retain a meaningful combined share, while a second tier competes on customization and rapid delivery.
-
Montana Instruments (Bozeman, MT, USA): A recognized leader in cryogen-free, closed-cycle optical cryostats with emphasis on automation and low-vibration platforms. Their offerings—characterized by large sample spaces and high-stability control—position them well for quantum materials and precision optical experiments. Recent trade-show activity through 2025 and early 2026 underscores their continued focus on industry visibility and user engagement. Strategic takeaway: competitors should expect aggressive reference-account plays and a premium positioning around integrated automation and nanopositioning ecosystems.
-
Lake Shore Cryotronics (Westerville, OH, USA): Known for broad optical access solutions spanning UV to IR and flexible cryogen/cryogen-free options. Their portfolio appeals to Raman, FTIR and spectroscopy labs that demand versatile window configurations. Strategic takeaway: Lake Shore’s strength in application breadth means they are a logical partner for instrument integrators seeking adaptable optical interfaces.
-
attocube systems GmbH (Haar, Germany): Focused on compact, low-vibration closed-cycle systems with strong magneto-optical suitability. Their attoDRY and rack-compatible attoCMC lines target researchers requiring high magnetic field capability in constrained footprints. Strategic takeaway: attocube is a strong contender in mobility and lab-space-constrained deployments—watch for expanded portfolio moves into turnkey quantum testbeds.
-
Advanced Research Systems (ARS) (Macungie, PA, USA): Builds highly configurable laboratory cryostats, including ultra-low-drift models optimized for quantum optics. Their custom flow systems and probe stations give them an edge in tailored applications. Strategic takeaway: ARS is likely to maintain share in bespoke procurement where adaptability and rapid customization trump economies of scale.
-
Quantum Design (San Diego, CA, USA): Offers magneto-optical platforms with high-field options and was notable for launching a vector-magnet version of its OptiCool platform in early 2025. The company’s solution set is particularly compelling for magneto-optical experiments requiring integrated vector fields. Strategic takeaway: product innovations that marry vector magnets and optical access are differentiators that can reset buyer expectations around experimental capability.
-
Oxford Instruments / Andor (Abingdon, UK): Strong incumbent in spectroscopy and microscopy cryostats with a variety of Cryofree options and flexible loading configurations. Their ecosystem advantage—optics and detectors—creates cross-selling opportunities. Strategic takeaway: suppliers that can bundle optics, detectors and cryogenics will continue to extract premium value.
Recent market signals and what they imply for 2026
-
Product launches and vector-magnet integration reported in 2025 spotlight a trend toward higher-functionality platforms that reduce the number of discrete instruments required for complex experiments. For vendors, this raises the bar on systems engineering; for buyers, it increases the importance of multi-year integration roadmaps.
-
Elevated trade-show presence from multiple suppliers across 2025–2026 illustrates a renewed emphasis on direct scientific engagement and reference-lab conversions. Companies that invest in hands-on demos and in-situ trial programs will shorten sales cycles in 2026.
-
Procurement data points—such as sole-source awards for high-capacity, custom-integrated closed-cycle systems—suggest that large-scale projects continue to favor vendors capable of end-to-end engineering and systems integration. For vendors, developing a configurable platform strategy with repeatable customization kits is a priority.
What the PW Consulting report delivers (practical contents)
The study is structured to support immediate action in 2026. Key deliverables include:
- Market model and forecast engine: Transparent assumptions and sensitivity scenarios covering 2026–2032 to stress-test investment cases.
- Go-to-market playbooks: Commercial segmentation, recommended pricing architectures, tender templates and partner selection criteria.
- Product roadmap blueprints: Modular design patterns, prioritized capability stacks (vibration isolation, optical access, magnet integration), and R&D investment maps tied to ROI timelines.
- Supply-chain and manufacturing playbook: Critical-bill-of-materials risk assessment, sourcing strategies and spares inventory policies to de-risk lead-time volatility.
- Vendor scorecards and procurement templates: Comparative vendor evaluation frameworks, SLAs, and commissioning checklists for buyers.
- Primary research appendices: Executive interviews, lab-level use cases, and anonymized procurement benchmarks that illustrate contract structures and delivery expectations.
To preserve commercial sensitivity and to follow our “trailer” principle, the report intentionally withholds granular regional and application-level revenue splits in the public summary. Subscribers and report purchasers receive the full segmentation tables, granular TAM by application, and downloadable models for scenario customization.
How to use this intelligence in Q1–Q2 2026
- Vendors: Use the GTM playbook to prioritize pilot accounts and convert them into reference installations; accelerate modular productization to shorten lead times for custom orders.
- Buyers: Adopt the total-cost-of-ownership templates and evaluation matrices to secure better long-term SLAs and spare-part commitments in long-run procurements.
- Investors and corporate development: Use the M&A archetypes and vendor scorecards to identify bolt-on targets that accelerate entry into complementary subsystems (e.g., nanopositioners, cryogenic RF management).
Conclusion and next steps
The Cryostation optical cryostat market is entering a phase where product capability, delivery reliability and systems integration will trump simple unit-price competition. PW Consulting’s report equips executives with the quantitative model and the tactical playbooks necessary to convert market momentum into durable commercial advantage in 2026. For organizations that require the full granular segmentation, vendor-by-vendor financial benchmarking, and downloadable scenario models, please consult the full report on our website—this executive release intentionally omits the detailed breakdowns to protect third-party relationships and proprietary supplier data.
For direct inquiries, enterprise briefings, or bespoke modeling support tied to your 2026 strategic plan, PW Consulting’s industry team is available for confidential workshops and vendor-selection support.
For detailed analysis of this topic, please visit the official page: Worldwide Cryostation Optical Cryostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Coconut Oil Methyl Esters Market Hits USD 945.5 Million in 2025, Poised for 4.78% CAGR to USD 1,311.32 Million by 2032 as Asia‑Pacific Leads with USD 484.22 Million
By PW Consulting, 2026-08-12
Worldwide Coconut Oil Methyl Esters Market — Strategic Imperatives for 2026: A PW Consulting Preview
PW Consulting’s new market study on Worldwide Coconut Oil Methyl Esters (base year 2025; forecast 2026–2032) distills the competitive, regulatory, and raw-material forces that will determine winners and laggards in the next strategic cycle. The study blends granular commercial intelligence with forward-looking scenario analysis: the total market expanded from approximately USD 742 million in 2020 to roughly USD 945 million in 2025 and, at a compound annual growth rate (CAGR) of 4.78% across our forecast horizon, is projected to surpass USD 1.3 billion by 2032. This release note explains why executives should use the report as a decision-making toolkit for 2026 without disclosing the detailed sub-segment figures reserved for the full report.
Aircraft Drive Shaft And Couplings Market
Why this market matters in 2026
-
Strategic intersection of food, personal care, and biofuel policy: Coconut oil methyl esters (CME) are uniquely exposed to parallel demand drivers—cosmetics and surfactants, industrial intermediates, and biodiesel blending mandates. The confluence of these end-markets makes CME a strategic feedstock whose economics matter to producers, distributors, and downstream formulators alike.
Worldwide Web Portal Software Market -
Moderate, resilient growth: The market’s mid-single-digit CAGR to 2032 reflects robust structural demand and the commodity-linked volatility of feedstock prices. Growth is sufficient to justify investments that improve margins, enhance traceability, or secure feedstock, but insufficient to guarantee outsize scale economies for late entrants without differentiation.
Automatic Truck Bag Loader Market -
Concentration and opportunity: The market exhibits a moderate top-player concentration (CR3 ≈ 42.2%; CR5 ≈ 58.6%), indicating room for regional specialists, integrated players, and technical differentiators to capture value alongside global suppliers.
Key strategic questions for 2026
-
How exposed is your P&L to coconut oil price swings and what hedging options (contract terms, vertical integration, alternative feedstocks) are commercially available?
-
Which product and application adjacencies (e.g., specialty methyl esters, fractionation, emollients for personal care) deliver premium margins versus commodity CME volumes?
-
How will domestic biofuel policies, especially in major producing countries, shift demand composition — and what operational flexibility is needed to respond quickly?
-
Where should capex be deployed to protect margins: purification & distillation, certifications for personal care, logistics hubs, or supply-side partnerships?
Market dynamics you cannot ignore
-
Feedstock inflation: International coconut oil averaged in the USD 2,000–2,300/MT range in 2026 and has periodically exceeded that band in key origins due to weather impacts and competing demand. Elevated coconut oil prices create margin compression for downstream CME producers unless offset by higher-value product positioning, technical improvements, or contractual pass-through mechanisms.
-
Policy levers in producing countries: The Philippines continues to treat CME as a strategic industry. As of early 2026 the national biodiesel blend remains at 3%, with planned reviews for stepwise increases. Policy decisions—whether to sustain mandatory blends, adjust targets, or permit substitution with alternative methyl esters—have direct demand implications for domestic producers and global trade flows.
-
Supply-side sensitivity: Weather-driven harvest variability and concentrated production geographies mean short-term dislocations can translate quickly into price spikes. Companies with upstream integration or multi-origin procurement strategies are better positioned to maintain supply security and optimize margins.
-
Regulatory and reputational requirements: Personal care and cosmetic customers increasingly demand traceability, sustainability credentials, and low residuals in methyl esters—drivers that favor suppliers who can invest in certification, independent testing, and transparent supply chains.
Competitive landscape: profiles and strategic implications
-
Wilmar International Limited (Singapore) — Wilmar’s oleochemical footprint, capacity for fractionation and distillation, and portfolio of C8–C18 methyl esters make it a leading integrator across surfactants and industrial uses. For competitors, Wilmar exemplifies the advantage of scale combined with technical capability in product fractionation.
-
Tantuco Enterprises, Inc. (Philippines) — A vertically integrated producer with mill-to-ester continuity, Tantuco demonstrates how feedstock control supports commercial resilience. Companies assessing supply security in Southeast Asia should model vertically integrated procurement scenarios.
-
Stepan Company (United States) — Stepan’s branded methyl laurate and related series signal a route to value through product differentiation and application-specific formulations. Producers seeking margin uplift should consider branded, specification-driven product lines.
-
Oleon NV (Belgium) — Oleon’s focus on oleochemical specialties illustrates the European demand for high-quality, application-ready methyl esters for personal care and industrial emulsions. Localized technical service and regulatory alignment are competitive levers in mature markets.
-
Covalent Chemical (United States) — As a distributor of methyl cocoate, Covalent highlights the role of channel partners in connecting technical materials to formulation customers across cosmetics, textiles, and coatings.
-
Parchem Fine & Specialty Chemicals (United States) — Parchem’s specification-driven approach for multiple applications underlines the importance of meeting stringent quality metrics (e.g., FFA limits, color indexes) demanded by downstream industrial users.
Collectively, these players illustrate three repeatable strategies: upstream integration to control feedstock cost and continuity; product and service differentiation to capture specialty premiums; and channel/brand strategies to secure formulation and distribution relationships.
Recent developments shaping near-term choices
-
Policy stance in the Philippines (March 2026): The Philippine Coconut Authority publicly opposed full suspension of the mandatory CME blending program and advocated maintaining or modestly reducing the blend rather than allowing substitution with imported palm methyl ester. This stance preserves a meaningful domestic demand floor for local CME producers and raises the regulatory bar for any rapid policy reversal.
-
Raw-material tightness persists: Price data from early 2026 show origin prices remain elevated, reinforcing the need to stress-test business plans across price bands materially above pre-pandemic norms.
What PW Consulting’s report delivers (operationally usable outputs)
-
Demand-supply maps and short-run balancing models that quantify how biofuel mandate changes, cosmetic market growth, and industrial demand shifts affect spot vs contracted pricing dynamics.
-
Feedstock-sensitivity and margin waterfall tools that let CFOs simulate EBITDA under alternative coconut oil price paths and contract structures.
-
Go-to-market playbooks for incumbents and new entrants: differentiated approaches for commodity CME, fractionated specialty esters, and service-led distribution.
-
M&A and partnership checklists, valuation heuristics, and integration risk profiles tailored to oleochemical targets.
-
Regulatory scenario modules including country-level biofuel policy impact matrices and a prioritized watchlist of policy events likely to move demand.
-
Vendor scorecards and supplier due-diligence templates that capture production footprint, technical capability (e.g., distillation/fractionation), sustainability credentials, and counterparty risk.
How senior executives should use this preview to set 2026 priorities
-
For producers: Prioritize flexible product platforms and invest selectively in fractionation/distillation to migrate volumes into higher-margin specialty methyl esters where buyers will pay for lower impurities and consistent specs.
-
For traders and distributors: Strengthen contractual diversity (mix of spot, short-term, and indexed supply) and build technical advisory capabilities to move up the value chain into formulation support.
-
For investors: Focus on assets that combine feedstock security with selective technical differentiation; avoid undifferentiated capacity additions in regions with weak logistics or policy uncertainty.
-
For policy and procurement teams: Model fiscal exposure across alternative blend scenarios and prepare engagement strategies with national authorities where mandatory blending policy is a material demand determinant.
Why the full report is essential
This preview outlines the high-level trajectory and critical levers, but the actionable intelligence required to execute decisions—granular regional and application demand splits, supplier-level capabilities, contract benchmarking, and the proprietary scenario matrices—are consolidated in the full PW Consulting report. We intentionally withhold detailed sub-segment figures in this preview to protect the analytical integrity of the study and to ensure that purchasing organizations access the full suite of tools and datasets needed to implement the strategies described above.
Next steps
-
Download the report landing page to review the table of contents, sample exhibits, and advisory packages available for executive briefings and bespoke modelling support.
-
Book a strategy session with PW Consulting to run a tailored feedstock sensitivity test or a two-hour competitive positioning workshop that leverages our proprietary vendor scorecards and scenario modules.
Contact PW Consulting’s Industry Intelligence team to secure the full Worldwide Coconut Oil Methyl Esters Market report and receive a complimentary executive executive brief outlining three prioritized actions you can start in Q2 2026 to protect margins and capture growth.
For detailed analysis of this topic, please visit the official page: Worldwide Coconut Oil Methyl Esters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


