



Category: market research
PW Consulting: Worldwide Reconstituted Tobacco Leaf Market at USD 3,115.0 Million in 2025 — Forecast to Reach USD 4,330.78 Million by 2032 at a 4.82% CAGR, Led by Asia Pacific (USD 1,440.65M)
By PW Consulting, 2026-08-12
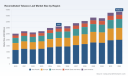
Worldwide Reconstituted Tobacco Leaf Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market intelligence on the Worldwide Reconstituted Tobacco Leaf (RTL) market synthesizes quantitative projection, competitive mapping, technology trajectory and regulatory headwinds into a single decision-grade briefing tailored for C-suite and trading-room use in 2026. The market reached an inflection point in 2024–2025 and, based on our base-year calibration (2025) and scenario modelling for 2026–2032, is expected to expand at a mid-single-digit compound annual growth rate (CAGR) of approximately 4.82%, culminating in a materially larger market by the end of the forecast horizon. This preview explains why the report matters to strategic choices in 2026 — and what executives should prioritize now — while reserving the granular segmentation matrices and transactional datasets for the full report.
Industrial Noise Control System Market
Why RTL matters in 2026: strategic implications at a glance
- RTL is no longer a marginal cost-optimization input. It underpins product formulation for both legacy cigarettes and next‑generation heated tobacco products (HTP), and it is becoming a lever for regulatory, cost and sustainability strategies.
- Market momentum is being driven by product substitution in HTP and by manufacturers’ need to optimize raw-tobacco utilization under constrained global supply and rising environmental scrutiny.
- Consolidation and technological differentiation are reshaping supplier power; the market concentration metrics indicate a sector where a handful of players control a meaningful share of supply, creating both counterparty risk and targeted M&A opportunities.
Key macro metrics that should shape 2026 planning
PW Consulting’s calibrated model uses 2025 as its base year and projects forward across a 2026–2032 forecast window. At the market level, the RTL sector is forecast to grow at roughly 4.82% CAGR through the period, reflecting steady demand uplift driven by HTP adoption, product reformulation needs, and increased integration of tobacco-processing by-products into production lines. From a competitive structure perspective, the top-three suppliers account for close to half of the market by revenue, while the top-five approach two-thirds, indicating a market with meaningful concentration effects for procurement and pricing strategy.
Worldwide Outdoor LED Street Lighting Market
Report content — what’s in the toolkit for executives
- Quantitative market model: a calibrated, bottom-up revenue model covering 2020–2025 history and a 2026–2032 forecast window. The model is sensitive to adoption scenarios for HTP, substitution elasticities between paper-based and slurry/powder RTL variants, and raw-material availability shocks.
- Competitive landscaping: strategic profiles, capability maps, and a supplier heatmap that highlight manufacturing footprints, process mixes (paper-making, slurry and emerging powder/airlaid techniques), and go-to-market strengths for leading suppliers.
- Technology and product playbook: a technical primer on slurry, paper-making, airlaid and ultrafine powder forming approaches, with readiness assessments for HTP core-material applications and guidance on CAPEX versus outsourced sourcing decisions.
- Supply‑chain risk & sustainability module: raw-material availability scenarios, extended producer responsibility (EPR) exposure analysis, and operational levers to reduce waste and regulatory risk while preserving product characteristics.
- M&A and partnership playbook: valuation comparables, integration checklists, and scenario-tested recommendations for horizontals (capacity buys) and verticals (blend-to-consumer integration), focused on 12–24 month execution windows.
- Actionable dashboards: procurement negotiation levers, cost-per-equivalent formulations, and sensitivity tools tailored for procurement, R&D and regulatory affairs teams.
Competitive dynamics: supplier moves to watch in 2026
The sector’s competitive field blends legacy European capacity, large-scale Chinese manufacturing, nimble Indonesian producers and emergent technology providers. Several themes emerge from the recent corporate activity and R&D landscape.
Robotic Wind Turbine Maintenance System Market
- Consolidation and integration: Recent acquisitions and portfolio integrations by established homogenized-tobacco suppliers have widened product suites and improved bargaining power with multinational tobacco manufacturers. Firms that have combined tipping paper, homogenized tobacco and RTL lines are positioning themselves as single-source partners for cigarette and HTP integrators, accelerating lock-ins in procurement cycles.
- Scale and process diversity: Major Asian manufacturers have invested in high-throughput papermaking lines alongside slurry and airlaid capabilities, targeting the dual demands of cost efficiency for mainstream cigarette blends and formulation flexibility for HTP. Scale brings cost advantage, but also requires nimble product customization to retain blue-chip customers.
- Technology differentiation: Technical advances — notably ultrafine powder-based RTL formulations and nanofiber recon techniques — are beginning to change the product-performance calculus for HTP cores. Players investing in or partnering around these technologies can capture higher margins if they demonstrate reproducible HTP performance and regulatory acceptability.
- Regional footprint & trade flows: Suppliers with multi-geography production can optimize tariff and logistics pathways and respond faster to regional regulatory shifts. However, trade exposure also introduces geopolitical and EPR-related risks that must be hedged.
Selected company implications
- Large homogenized-tobacco and multi-process firms: Their integrated product sets and combined manufacturing footprints make them natural strategic partners for tobacco multinationals seeking single‑vendor simplification. For such firms, 2026 is a year to choose between deeper vertical integration versus structured JV models to share the CAPEX risk of slurry and powder lines.
- Specialists and technology pioneers: Smaller, technology-led suppliers are attractive targets for strategic partnerships and bolt-on acquisitions. Buyers should prioritize IP clarity, reproducibility of HTP performance, and regulatory dossiers supporting non‑tobacco or herbal RTL alternatives.
- Regional exporters: Suppliers that serve global HTP supply chains from low-cost geographies will benefit from rising demand but must actively manage reputational and compliance risks tied to environmental and waste‑management regulations.
Regulatory and raw-material dynamics that will drive 2026 risk-adjusted choices
Two structural pressures will shape near-term strategic choices. First, global raw-tobacco supply has contracted materially over the past decade, reducing the pool of primary leaf available to manufacturers and increasing the attractiveness of RTL as a resource‑optimization mechanism. Second, environmental and policy pressures — including intensified calls for extended producer responsibility and stricter waste-management regimes — elevate the regulatory risk premium for operators that do not adopt circular‑economy practices.
For procurement and strategy teams, this means building sourcing scenarios that prioritize feedstock diversification (including validated non-tobacco alternatives where appropriate), supplier resilience evaluations, and traceability mechanics that align with incoming EPR regimes.
Actionable priorities for 2026 — a short strategic checklist
- Procurement: Re-scope supplier contracts to include performance guarantees for HTP applications, hold periodic technology trials with multiple providers, and embed supply continuity clauses tied to feedstock diversity.
- R&D and product: Fast-track trials for slurry- and powder-based RTL in HTP cores, and invest in analytical comparability studies to shorten regulatory acceptance timelines.
- M&A and partnerships: Target bolt-ons that offer differentiated process capability (ultrafine powder, nanofiber recon) or access to new geographies; prioritize deals that immediately improve margin or de-risk feedstock availability.
- Sustainability & compliance: Implement traceability and waste‑recovery pilots aligned with EPR principles; quantify potential cost pass-throughs and reputational impacts in board-level risk dashboards.
- Scenario planning: Maintain three procurement scenarios — base, constrained raw-material, and rapid HTP adoption — and stress-test product margins and working capital under each through 2032.
What PW Consulting’s full report provides (and why you’ll want it)
The full report contains the granular inputs, segmentation tables, regional and application shares, supplier-by-supplier revenue and capacity schedules, and our proprietary scenario model that underpins the headline CAGR and market-size trajectory referenced here. It also includes transaction comparables, due-diligence checklists, and a chronicle of recent sector events and patents that are critical to execution. To respect the “trailer” principle and preserve the competitive value of the granular datasets, PW Consulting is withholding full segmentation matrices and per-supplier revenue breakdowns from this public summary; these are available through the report package and our client portal.
Next steps for executives
For 2026 decision cycles, senior teams should use the PW Consulting model as the single source of truth for budgeting, M&A screening and supplier portfolio design. Begin by commissioning a rapid supplier stress test against the three scenarios we recommend, prioritize pilot investments in slurry/powder technology trials with selected partners, and schedule a management briefing to translate the market-level growth assumptions into SKU-level profitability redeployment plans.
PW Consulting’s Worldwide Reconstituted Tobacco Leaf Market report combines forward-looking quantitative models, supplier intelligence and operational playbooks to convert market signals into executable strategy. For access to the full dataset, regional and application splits, and downloadable modelling tools, please consult the PW Consulting report page — the complete intelligence package is structured to support board-level decisions and near-term procurement commitments in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Reconstituted Tobacco Leaf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide CTFE Market Poised to Grow at a 5.1% CAGR Through 2032
By PW Consulting, 2026-08-12
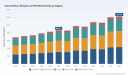
PW Consulting: Strategic Insights — Worldwide Chlorotrifluoroethylene (CTFE) Market Outlook to 2032
Executive preview for 2026 decision-makers
As corporations across fluorochemicals, semiconductors, pharmaceuticals and aerospace plan capital and sourcing decisions for 2026, understanding the evolving CTFE market is critical. PW Consulting’s latest Worldwide Chlorotrifluoroethylene (CTFE) Market report synthesizes multi-year market modeling, supply-chain mapping, regulatory risk matrices and competitive intelligence to give commercial, procurement and strategy teams the contextual foresight needed to act with confidence. The market reached approximately USD 866.5 million in our 2025 base year and—after a near-term rebalancing—our forecast shows a steady compound annual growth rate (CAGR) of 5.1% across 2026–2032, driving the market toward roughly USD 1.23 billion by 2032. This release highlights the strategic takeaways companies must weigh in 2026, while reserving the granular regional and application-level figures for the full report.
Intelligent Ultrasonic Bird Repellent Market
What’s in the full report (practical, transaction-ready content)
- Transparent methodology: reproducible market-sizing approach, data sources and sensitivity tests that explain how we derive the base and forecast figures.
- Supply-chain maps: feedstock sources, processing routes and bottleneck points, with supplier cross-references and tiered risk scoring for procurement teams.
- Regulatory and ESG matrix: jurisdictional compliance obligations, anticipated policy shifts, and implementation pathways for lower-impact production practices.
- Commercial analytics: price-volatility scenarios, margin pressure modeling for producers and converters, and procurement playbooks for buyers.
- Competitive profiles and M&A screening: vetted dossiers on leading producers, recent strategic moves, and acquisition targets prioritized by fit and integration risk.
- Scenario playbooks: three operational scenarios (constrained-supply, demand-shock, and sustainable-transition) with recommended actions and financial impacts tailored to suppliers, OEMs and distributors.
Market dynamics shaping the 2026 landscape
Several structural dynamics converge in the CTFE market to define 2026 as a decision-critical year. First, end-market demand is diversifying: CTFE’s high-barrier and cryogenic properties keep it in strategic applications—pharmaceutical blister packaging, advanced electronics and semiconductor processing, aerospace systems, and specialized chemical equipment. Secular growth in semiconductor fabrication and pharmaceutical packaging regulations is supporting demand resilience, even as individual end-markets experience cyclical pressures.
Worldwide Heat Spreaders Market
Second, supply-side realities are mixed. CTFE production is tied to specific feedstock routes and specialized catalysts, meaning incremental capacity additions are discrete and capital-intensive. The market demonstrates elevated concentration among a small set of producers, a fact that amplifies the impact of strategic investments or disruptions at any single site. Our concentration analysis indicates that the top three producers collectively control the overwhelming majority of global capacity, and the top five widen that dominance—an oligopolistic structure that shapes negotiation leverage, contract tenors and spot-market volatility.
Inventory Optimization ERP Software Market
Third, regulatory and sustainability forces are accelerating product and process change. TSCA export-notification requirements, REACH obligations in Europe, and evolving EPA guidance constrain both trade flows and allowable process chemistries. At the same time, downstream customers increasingly require traceability and lower-impact manufacturing footprints from monomer suppliers. These twin pressures elevate compliance capability and decarbonization planning from cost-center exercises to strategic imperatives.
Price and capacity signals (what to watch in 2026)
Prices and utilization rates are sensitive to new capacity coming online and to feedstock availability. Recent capacity investments and strategic partnerships announced by leading producers signal producer intent to capture higher-purity, value-added applications. Buyers should expect intermittent tightening and a two-speed market where access to certified high-purity streams commands a premium. Our report models multiple price trajectories under different capacity-addition schedules and provides hedging and contracting recommendations tailored to each scenario.
Competitive landscape — who matters and why
The CTFE value chain is populated by global chemical majors, specialized fluorochemical groups and regional players who have invested selectively in high-purity production and downstream polymerization capabilities. Key players profiled in the report include well-known integrated multinationals and specialized regional suppliers:
- Honeywell International Inc.: An established producer of high-purity CTFE monomer, with a strategic focus on supply to fluoropolymer makers and applications in electronics, aerospace and chemical processing. Recent capacity investment announcements underline Honeywell’s intent to secure market share where quality and reliability are decisive.
- Daikin Industries Ltd.: A global supplier that not only produces CTFE monomer but also polymerizes it into engineered PCTFE resin grades for high-barrier and cryogenic applications. Daikin’s recent strategic partnership with a major semiconductor manufacturer and acquisition of a specialized CTFE fluid manufacturer signal a deliberate move up the value chain into semiconductor-grade supply and integration with OEM processes.
- Jiangsu Bluestar Technology and other Chinese suppliers: Regional producers that are broadening offerings across fluorine intermediates, coatings and elastomers. Their presence strengthens regional supply options, but also intensifies competitive pressure on pricing and volume contracts.
- Specialist manufacturers (e.g., Changshu Hongjia Fluorochemical Technology, Yufeng Chemical): High-purity-focused suppliers that compete on niche capabilities and localized service models. These companies play important roles in regional supply security, especially for downstream converters and localized OEMs.
Collectively, market leaders’ recent actions—capacity expansions, targeted acquisitions and strategic off-take or partnership deals—are reshaping market access dynamics. For buyers focusing on semiconductor or pharmaceutical-grade inputs, securing long-term partnerships with producers who have validated high-purity supply chains will be a differentiator in 2026.
Strategic recommendations for 2026
- Prioritize supply resilience: For critical applications, negotiate long-term offtake agreements with quality and delivery SLAs, and include step-up clauses to hedge against concentration-driven tightness.
- Segment procurement by quality class: Differentiate contracting strategies for high-purity monomer versus technical-grade streams; align payment terms and quality auditing to protect conversion yields.
- Invest in compliance and traceability: Build internal regulatory-monitoring capabilities for TSCA/REACH-related developments and invest in supplier audits that verify both process controls and sustainability claims.
- Pursue selective partnerships: For OEMs in semiconductors and pharmaceuticals, consider joint development or co-investment to secure tailored CTFE grades and ensure upstream alignment with fabrication or packaging requirements.
- Model disruption scenarios: Run downside stress tests that assume episodic supply constraints or accelerated regulation—understand the P&L sensitivity and capex timing required to insulate operations.
- Prepare M&A and JV playbooks: With concentrated supply and fragmented specialty players, targeted acquisitions or joint ventures can rapidly close capability gaps, but require rapid commercial and technical due diligence to avoid integration missteps.
How PW Consulting’s analysis supports execution
Beyond forecasting, our report equips decision-makers with executable tools: supplier-risk heatmaps, contract negotiation templates, and a decision-tree framework linking strategic choices (e.g., vertical integration vs. long-term contracts) to expected returns under alternative regulatory paths. For private equity and corporate development teams, the report includes an M&A diligence checklist and valuation sensitivities keyed to purity grades and customer segmentation—elements that materially affect transaction pricing in this market.
Closing: why the timing matters
2026 is a pivotal year where demand trajectories, capacity additions and regulatory signals converge to create asymmetric opportunities and risks. Companies that act with forward-looking procurement strategies, that align with high-integrity suppliers, and that translate regulatory uncertainty into operational resilience will secure competitive advantage. PW Consulting’s Worldwide CTFE Market report provides the actionable intelligence to make those choices with clarity—while preserving the detailed regional and application breakdowns for subscribers and clients who require transaction-grade specificity.
To access the full dataset, granular segment breakdowns, supplier scorecards and scenario models that support strategic decision-making in 2026 and beyond, visit the PW Consulting report page or contact our industry advisory team for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Chlorotrifluor Ethylene (CTFE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Dry Electrostatic Precipitator Market Poised for 4.12% CAGR from 2026 to 2032
By PW Consulting, 2026-08-12
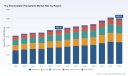
Worldwide Dry Electrostatic Precipitator Market 2026: Strategic Imperatives for Industrial Emissions Control
Executive summary
PW Consulting’s new market study on the Worldwide Dry Electrostatic Precipitator (ESP) market provides a decision-grade roadmap for executives, investors, and engineering managers planning capital and operational strategies in 2026. Anchored on a comprehensive historical review (2020–2025) and a granular forecast (2026–2032), the report synthesizes primary interviews, vendor benchmarking, regulatory intelligence, and component-level cost dynamics into actionable recommendations.
Worldwide PTFE Lined Pipes Market
The global dry ESP market reached approximately USD 3,803.9 Million in the base year (2025). Driven by regulatory tightening, retrofit demand, and selective greenfield activity, our modeling anticipates a compound annual growth rate (CAGR) of 4.12% over the 2026–2032 forecast window. Year-on-year projections indicate the market expands to roughly USD 4,000 Million in 2026 and crosses the USD 5 Billion threshold during the forecast period—highlighting both steady demand and pockets of accelerated spending tied to compliance and performance upgrades.
Ethylene Oxide Device Sterilization Market
Why this report matters for 2026 decision-makers
-
Timing of capital allocation: The blend of retrofit cycles and selective new build programs means that project windows in 2026 will be uneven across regions and end‑use sectors. Our scenarios show where timing advantage—early ordering, modular procurement, or staged installations—yields measurable CAPEX and commissioning benefits.
MTHFR Gene Detection Kit Market -
Supplier selection under evolving concentration dynamics: The market demonstrates moderate concentration; while several global incumbents retain leading positions, mid‑tier specialists continue to capture defined niches. Our vendor scorecards enable procurement teams to balance performance guarantees, delivery lead times, and lifecycle OPEX risks.
-
Regulatory-driven retrofit mandates: Stricter particulate and submicron control requirements in advanced regulatory regimes mean that plants facing near-term compliance deadlines will favor proven dry ESP solutions and integrated monitoring systems. The report maps compliance levers to practical upgrade pathways.
-
Supply-chain and component volatility: Steel, specialized high-voltage components and engineered electrodes remain critical inputs. Procurement strategies that incorporate hedging, multi-sourcing, and long‑lead vendor agreements materially reduce execution risk.
Market dynamics that will define 2026
Three forces converge to shape purchasing and deployment decisions for dry ESPs in 2026:
-
Regulatory tightening and enforcement: Jurisdictions that have revised industrial emissions rules are accelerating retrofit schedules and imposing more stringent performance expectations for particulate control, including capture of finer fractions that historically challenged dry ESP technology.
-
Operational efficiency and lifecycle economics: Operators are demanding solutions that lower net plant-level emissions while reducing pressure‑drop penalties and parasitic energy consumption. Equipment that pairs mechanical robustness with smarter control reduces total cost of ownership and shortens payback horizons.
-
Technology convergence: Advances in digital controls, AI‑based maintenance optimization, and hybrid configurations are shifting value from purely electrostatic capture to systems that optimize particle charging, rapping, and power supply dynamics in real time.
Practical contents of the PW Consulting report
This study is designed as a hands‑on toolkit for planners and procurement teams. Key deliverables include:
-
Top‑line and segmented forecasts (2026–2032) with scenario variants (baseline, accelerated retrofit, and subdued capex) to stress test capital plans.
-
Vendor benchmarking—independent scorecards covering technical performance, delivery reliability, aftermarket coverage, and integration readiness for plant controls.
-
Detailed technology deep dives: performance envelopes for single‑stage vs. multi‑stage dry ESPs, control philosophies, and retrofit versus replacement decision frameworks.
-
Procurement playbook: tender templates, risk allocation clauses, lead‑time mitigation strategies, and acceptance test protocols tailored to complex industrial sites.
-
Financial models: CapEx/Opex calculators, payback & sensitivity analyses under different fuel, throughput, and maintenance scenarios.
-
Supply chain assessment: critical components, concentration risks, and mitigation strategies for long‑lead transformers and engineered electrodes.
-
M&A and partnership heatmaps: opportunity matrices identifying tech owners, system integrators, and regional champions suitable for inorganic growth or joint development.
Competitive landscape—who matters and why
The market is served by a mix of long‑established multinational engineering houses and specialized equipment manufacturers. Our analysis highlights strategic positioning for several key players:
-
Babcock & Wilcox (USA) — known for modular designs and industrial experience across power and cement applications. Recent deliveries include a U.S. cement plant retrofit to meet upgraded PM compliance requirements, underscoring strength in turnkey project execution.
-
GE Power (General Electric, USA) — emphasizes systems designed for low pressure-drop and emissions compliance in utility and waste‑to‑energy contexts; appeals to customers prioritizing integrated plant control and long‑term service agreements.
-
Hitachi Zosen (Japan) — strong in heavy industry installations with hardware designed for durability in harsh environments; secured strategic orders at steel expansion projects demonstrating deep sector relationships.
-
Mitsubishi Heavy Industries (Japan) — brings high‑voltage transformer expertise and fine‑particle capture focus; well-suited for plants where high reliability and engineering depth are paramount.
-
Sumitomo Heavy Industries (Japan) — targets niche, energy‑sensitive applications with innovations in rapping systems and efficiency improvements for non‑ferrous smelters and glass manufacturing.
-
FLSmidth (Denmark) — a strong presence in cement and minerals, actively showcasing next‑generation solutions blending AI‑optimized maintenance with high‑temperature tolerant designs; visible at industry trade forums in 2025.
-
Dürr AG (Germany) — focuses on compact configurations and integrated controls for manufacturing lines where footprint and automation integration are key decision factors.
Overall market concentration remains meaningful but not prohibitive—top-tier vendors continue to command a significant share while regional specialists and engineering partners capture technical niches and aftermarket opportunities. This creates an environment where alliance strategies, service differentiation, and targeted product innovation can generate outsized returns.
Supply‑chain and component risk considerations
Procurement and project teams must evaluate three discrete risk layers:
-
Raw material supply and price volatility for specialized alloys and transformer grade steels—these inputs affect lead times and margin on system builds.
-
Critical component availability—high‑voltage power supplies, insulation systems, and engineered electrodes have historically fixed suppliers; contingency sourcing and early vendor engagement are practical mitigants.
-
Logistics and installation complexity—onsite integration and commissioning windows are sensitive to plant schedules and downtime costs; modularization and offsite testing can accelerate time to effective operation.
Regulatory and macro drivers shaping procurement
Two regulatory trends are particularly salient:
-
Stringent particulate emission limits—authorities in several large markets are closing the gap on fine and submicron particle control, effectively raising the bar for acceptable capture performance. This is accelerating retrofit cycles in coal and industrial plants that previously relied on older technologies.
-
Carbon neutrality programs and industrial emissions directives are nudging operators to view dry ESP upgrades not as compliance-only projects but as components of broader decarbonization and operational efficiency programs.
Strategic recommendations for 2026 execution
-
Adopt a two‑track procurement approach: secure long‑lead items and proven vendors for compliance‑critical units, while piloting advanced, AI‑enabled configurations on lower‑risk lines to capture future upside.
-
Prioritize lifecycle cost metrics over first‑cost competition—energy penalty, maintenance cadence, and spare parts availability materially affect total cost of ownership.
-
Lock in performance guarantees with verifiable acceptance tests focused on fine fraction capture and operational stability under representative load profiles.
-
Build flexibility into contracts to allow staged upgrades as sensor and control innovations mature—this reduces stranded‑asset risk while enabling continuous improvement.
How PW Consulting supports the decision journey
Our report is tailored to support boardrooms, plant managers, engineering procurement teams, and private equity sponsors assessing sector exposure. In addition to the strategic narrative, subscribers receive practical annexes: tender language, standard test procedures, vendor negotiation playbooks, and a prioritized project pipeline for regions and end uses (detailed tables available in the full report).
Because the most value‑add decisions depend on granular regional and end‑user splits, our release follows a “show‑and‑tease” approach: we surface the analytical backbone and strategic implications to build confidence, while detailed segment tables, contract templates, and primary‑data appendices are provided exclusively to report subscribers.
Next steps
Organizations preparing budgets, vendor shortlists, or M&A due diligence for 2026 should request our executive briefing. PW Consulting can deliver a tailored 90‑minute workshop that translates the study’s findings into a prioritized implementation plan aligned to your asset base and regulatory timeline.
For access to the full report—including the proprietary regional and end‑use breakdowns, vendor scorecards, and financial models—visit the PW Consulting research portal or contact our industry desk to schedule your briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dry Electrostatic Precipitator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Pet Ramp & Stair Market to Climb to USD 862.78 Million by 2032PW Consulting: Worldwide TFLN Modulator Market to Surge at 35.53% CAGR, Reach USD 2,196.72 Million by 2032
By PW Consulting, 2026-08-12
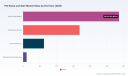
Worldwide Pet Ramp and Stair Market 2026 Outlook: Strategic Implications for Manufacturers, Retailers and Investors
Executive summary
PW Consulting’s latest market study on the Worldwide Pet Ramp and Stair Market delivers a forward-looking, decision-ready perspective for organizations planning 2026 strategies. After analyzing five years of historical performance (2020–2025) and running scenario-driven forecasts through 2032, our model shows the market expanding at a compound annual growth rate (CAGR) of 7.25%. The industry reached approximately USD 528.6 Million in 2025 and, under our base case, is projected to approach USD 863 Million by 2032. These headline dynamics reflect a mix of durable demographic tailwinds (aging companion animals), product innovation (lighter, modular designs), and shifting channel economics.
Ocean Temperature Difference Power Market
Why this matters for 2026 planning
-
The moderate, steady growth profile makes 2026 a pivotal year for choices that determine mid-term positioning: portfolio reshaping, manufacturing footprint decisions, and investment in direct-to-consumer capabilities.
Worldwide Microtube Storage Racks Market -
Macro supply shocks and trade policy actions introduced in 2024–2025 have created a narrower window in 2026 to lock in raw-material sourcing and pricing strategies before inflationary pressures pass through to finished goods.
Virtual Instant Credit Cards Market -
Market fragmentation persists. Our competitive mapping shows many specialized incumbents and multiple OEM/ODM suppliers—creating opportunity for scale players to capture share through distribution partnerships, value-added service bundles, and product-system thinking (integrated ramps + pet-health subscription services).
Market trajectory and core dynamics
Demand for pet access solutions is being driven by three structural forces: the humanization of pets (longer, health-focused lifecycles), the growth in multi-channel retailing (eCommerce plus experiential retail), and vehicle ownership patterns that sustain demand for vehicle-specific access products. These converge to support a steady market expansion at roughly 7.25% CAGR over the 2026–2032 forecast horizon.
However, headline growth masks critical heterogeneity beneath the surface—different materials, form factors and end-use contexts are evolving at different speeds. Manufacturers that understand where margin pools will concentrate (premium, engineered vehicle solutions vs. high-volume, low-cost foam steps) will be better positioned to allocate R&D and commercial resources in 2026.
Supply chain, materials and regulatory headwinds
-
Resin and polymer markets: Prices for common thermoplastics such as PE, PP and PS have trended lower into late 2025, improving cost outlooks for many injection-molded and rotationally-molded components. In contrast, PET prices rose modestly late in 2025 following new tariffs on PET/rPET imports—this has immediate implications for manufacturers using recycled/resin-based textiles or PET-blended materials.
-
Metal inputs: Reintroduced tariffs and duties on steel and aluminum in early 2025 increased costs for frames and mounting systems. For companies producing metal-reinforced ramps or aluminum loading solutions, 2026 procurement strategies must include hedging, material substitution validation and supplier diversification.
-
Regulatory visibility: Tariff policies remain a live risk. Businesses with cross-border production or significant imported inputs should model a 2–4% cost shock to finished-goods bills of materials in 2026 under a conservative scenario and plan margin protection measures accordingly.
Consumer and channel insights
End-user demand now reflects a blend of clinical need (mobility for senior dogs), lifestyle convenience (vehicle and furniture access), and aesthetic expectations (design-forward furniture-grade ramps). Retailers report that hybrid product formats—combinations of stairs and ramps, modular systems with interchangeable surfacing—resonate strongly among urban and suburban buyers seeking both function and style.
Direct-to-consumer channels continue to gain share, supported by enhanced product videos, fit-guides, and virtual measurement tools that reduce return friction. Brick-and-mortar players retain a role on trialable, tactile categories (wood and furniture-grade ramps) but will need to revamp store assortments to emphasize consultative selling for high-ticket vehicle and specialty solutions.
Competitive landscape: who to watch
The market remains fragmented with a broad mix of specialist brands, consumer-product incumbents and Asia-based OEM/ODM suppliers. Our qualitative and quantitative assessment highlights distinct competitive archetypes that matter for 2026 strategy.
-
Design-led portable ramp specialists: Companies that pioneered lightweight composite folding ramps and non-slip surfacing hold structural advantages in pool, vehicle and home categories. Their product IP, patent portfolios and channel relationships make them logical partners or acquisition targets for firms seeking a plug-and-play entry to premium portable ramps.
-
Heavy-duty vehicle step and stair specialists: Firms focused on ergonomics, lower ascent angles and heavy-load ratings are well positioned to command premium pricing in vehicle retrofit channels, fleets and boating markets. Emphasizing "made-in-country" manufacturing has been a successful differentiation strategy for North American suppliers in buyer segments where perceived durability and domestic supply matter.
-
Ultra-light and modular consumer offerings: Brands that offer ultra-light free-standing ramps and combination stairs appeal to a broad online consumer base and scale well through low-cost fulfillment models. These players benefit from high-volume SKU velocity but face margin pressure without brand or fabrication differentiation.
-
Furniture-grade hardwood specialists: Boutique manufacturers producing hardwood ramps for beds and sofas occupy a profitable niche. Their value proposition—craftsmanship and interior design fit—remains resilient, particularly in higher-income geographies.
-
OEM/ODM and international fabricators: China-based suppliers with BSCI/ISO certifications supply private-label and white-label programs at scale. Their cost efficiency is attractive for large retailers and wholesalers, but buyers should account for lead-time variability and tariff risk in supplier contracts.
Recent market activity underlines practical competitive shifts: editorial product guides updated in early 2026 reshuffled perceived best-in-class lists across foam, wood and combo products, while certain manufacturers have emphasized direct-from-factory distribution to capture retail margin and build closer customer relationships. These developments indicate increased emphasis on review-driven discovery and manufacturer-led commerce.
Strategic recommendations for 2026 decision-makers
PW Consulting’s work crystallizes a set of high-leverage moves leaders should consider for 2026. These are framed to be implementable in the near term while protecting optionality through 2032.
-
Hedge and diversify material sourcing: Given mixed pressure across polymers and metals, establish multi-sourcing contracts and consider forward-buy options for critical resins and alloys. Evaluate alternative materials (high-density foam blends, engineered composites) for cost-performance trade-offs.
-
Prioritize modular, serviceable designs: Product families that allow interchangeable surfacing, adjustable heights and retrofit kits unlock higher lifetime customer value and simplify SKUs across channels.
-
Invest in digital product validation tools: Virtual fit guides, AR visualization and robust how-to content reduce returns and accelerate online conversion—critical for higher-ticket ramps and vehicle-specific solutions.
-
Evaluate nearshoring for vehicle-centric products: For heavy-duty vehicle steps and metal-framed ramps, moving assembly closer to core markets mitigates tariff and logistics risk while supporting “made-local” positioning.
-
Develop channel-specific assortments: Tailor SKUs and service offers for big-box, specialty pet retailers and direct channels—don’t assume one SKU fits all. Bundling with veterinary partners and senior-pet care services can create defensible differentiation.
-
Screen M&A for complementary capabilities: Look for targets that bring either patented ergonomic designs, scalable OEM relationships, or proprietary supply of differentiated materials—these are the assets that can accelerate growth without extensive organic R&D cycles.
What PW Consulting’s report contains (high-level)
The full report is designed as a practical playbook for 2026 execution and includes:
-
A detailed forecast model (2026–2032) with scenario levers for raw-material costs, tariff shocks and channel mix changes;
-
Product and materials segmentation maps, with margin and volume sensitivity analyses;
-
Competitive landscape profiles and supplier benchmarking across design IP, manufacturing footprint and channel capabilities;
-
Go-to-market playbooks for manufacturers, retailers and private-label buyers, including sample pricing and cost-to-serve templates;
-
Primary interviews with manufacturers, retail buyers and supply-chain specialists, plus a curated list of KPIs to track through 2026.
Note: consistent with our "trailer" approach, we present strategic conclusions and the macro market trajectory here while reserving segment-level data, regional splits and detailed company revenue comparisons for the full report. That deeper intelligence is required to execute the tactical steps summarized above and is accessible through PW Consulting’s report portal.
Closing perspective
The pet access market is no longer a cottage industry; it is a maturing category with clear submarket winners and losers. 2026 offers a decisive window for companies to lock in supply flexibility, sharpen product differentiation and capture outsized share through targeted investments in design, channel and operational resilience. Organizations that treat this year as a strategic inflection—rather than a routine planning cycle—will be best positioned to benefit from the roughly 7.25% CAGR growth path into the next decade.
For organizations preparing board-level or investor-facing recommendations, PW Consulting’s full Worldwide Pet Ramp and Stair Market report provides the detailed segment analytics, supplier scorecards and scenario tools necessary to convert insight into action. Visit PW Consulting’s report page to access the complete dataset and supporting advisory services.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Ramp and Stair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Veterinary API Manufacturing Market to Grow from USD 7,200 Million in Base Year 2025 to USD 11,675.6 Million by 2032 at 7.15% CAGR — Antibiotics and Chemical Synthesis Lead While CR5 Remains Sub‑50% (48.65%)
By PW Consulting, 2026-08-12
Worldwide Veterinary API Manufacturing Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s newest market study, published with base year 2025 and a forward-looking horizon to 2032, reframes how animal-health executives, investors, and supply-chain leaders should approach the veterinary Active Pharmaceutical Ingredient (API) manufacturing landscape in 2026. The industry is on a sustained growth trajectory — our model projects a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast window, with global market size rising materially from the base-year level. This preview surfaces the strategic implications that matter most in 2026 while intentionally reserving granular segment-level tables and regional splits for the full report.
Atomic Energy Batteries Market
Why 2026 is a Strategic Inflection Point
Several converging dynamics turn 2026 into a year of strategic choices rather than incremental adjustments. First, market demand drivers remain robust across both livestock and companion-animal portfolios: intensifying livestock productivity goals, rising companion-animal healthcare spend, and the broadening use-cases for biologics are collectively sustaining higher API volumes and expanding therapeutic complexity. Second, regulatory and stewardship pressures — particularly around antimicrobials and drug residue limits — are reshaping product lifecycles and qualification requirements for suppliers. Third, the supply chain architecture that supported the industry during the previous decade is under fresh strain from geopolitical friction, tariff measures, and concentrated upstream supply of key inputs.
Electrical Busbar Tray Market
Taken together, these forces create a two-speed industry: integrated animal-health majors and vertically integrated players compete on scale and captive development capability, while specialized CDMOs and regional API manufacturers compete on agility, cost-efficiency, and niche technical expertise. Our analysis shows that this mix will continue to drive transactional activity (partnerships, minority investments, and targeted M&A) and a reallocation of capex toward regulatory-compliant, resilient manufacturing footprints.
High Power and Lightweight Wind Turbine Blade Market
Macro Snapshot (Selected headline metrics)
- CAGR (2026–2032): 7.15%.
- Base-year market scale: detailed figures and the full time-series are included in the report (summary headline: base-year market size and projected 2032 market level demonstrate a mid-single-digit-plus growth path to the end of the forecast period).
- Market concentration: the top three and top five groups account for a meaningful share of supply, indicating a market that is neither fully commoditized nor tightly consolidated — the result is persistent competitive intensity and opportunity for differentiated providers.
Supply-Chain Risk: From Vulnerability to Strategic Opportunity
The veterinary API supply chain remains exposed in specific ways that materially affect procurement and product availability decisions in 2026. Historical shortages in certain key APIs, ongoing logistical friction for overseas production, and the high share of upstream sourcing concentrated in particular manufacturing geographies create near-term risk for landed costs and continuity of supply. At the same time, these vulnerabilities are catalyzing constructive shifts: onshoring and nearshoring experiments, strategic inventory framing, and a stronger commercial rationale for dual-sourcing and qualified second-source programs.
For decision-makers, the core trade-offs are straightforward but consequential: balancing landed-cost pressure against the insurance value of diversified capacity; weighing near-term sourcing savings against longer-term regulatory and reputational risk; and evaluating whether to outsource capacity expansion to CDMOs or to invest in captive capability. Our report provides the decision framework and scenario models needed to quantify these trade-offs in financial and operational terms.
Technology and Manufacturing Evolution: Chemical Synthesis, Biotech, and Beyond
Manufacturing technology choices are a major determinant of competitive positioning. Traditional chemical synthesis remains the backbone of many veterinary APIs, but the proportionate role of biotech-derived APIs and advanced biologics is growing — both in absolute market size and in strategic importance due to higher value-per-dose therapeutics and vaccine adjuvants. Recent facility investments and technology partnerships underscore this trend: examples include commissioning of dedicated veterinary API production units that bring higher regulatory readiness and sustainability metrics, and strategic licensing or partnerships for synthetic biology platforms that enable faster route-to-market for novel products.
Key implications for 2026 strategy include accelerating investments in process intensification and continuous manufacturing where appropriate, evaluating biotech capabilities (including nucleic-acid based and recombinant technologies) as a hedge against future product mix shifts, and incorporating sustainability KPIs into manufacturing-site selection and supplier scorecards.
Competitive Landscape: Strategic Roles and Market Positioning
The market features a mix of global animal-health leaders with in-house API capabilities, regionally focused API specialists, and growing CDMOs that bridge both worlds. Large integrated players retain strategic advantages in end-to-end development, regulatory dossiers, and global marketing reach; specialized API manufacturers and CDMOs win on flexibility, cost competitiveness, and niche technical expertise. Recent industry moves — targeted site acquisitions, facility expansions, and technology partnerships — confirm an active competitive environment where vertical integration, strategic partnerships, and capability-led differentiation are central themes.
- Integrated animal-health companies continue to invest selectively in manufacturing capacity that supports strategic product lines and supply continuity. Their choices will influence downstream finished-dosage sourcing and partner selection across 2026 decisions.
- Specialized API manufacturers and CDMOs are consolidating positions through capacity expansion and by adding regulatory-ready facilities that serve export markets. These players are primary candidates for OEMs seeking rapid scale or regional diversification.
- Technology collaborations — for example, those that accelerate biologics or synthetic-biology approaches — are emerging as higher-conviction levers to shorten development timelines and capture premium product segments.
For executives evaluating partners or M&A targets, our competitive scorecards in the full report map capability gaps against commercial needs and regulatory exposure — enabling targeted, evidence-based deal sourcing.
Practical, Actionable Guidance for 2026
Below are prioritized moves our clients are adopting to convert insight into 12–24 month impact. Each recommendation is backed by scenario analytics, supplier-qualification matrices, and a regulatory roadmap included in the full report.
- Immediate: execute a supply-risk heat map for the top 10 APIs used in your portfolio, and deploy a prioritized supplier qualification program focused on regulatory readiness and traceability.
- Near-term: structure dual-source contracts or strategic reserves for high-risk inputs while negotiating cost-sharing for capacity expansions with key CDMO partners.
- Capex allocation: reweight short-term CAPEX toward process upgrades that lower OPEX and improve regulatory compliance, while preserving optionality for biotech-capability investments where product roadmaps justify.
- Partnerships and innovation: pursue targeted licensing or technology partnerships (e.g., nucleic-acid platforms, recombinant technologies) to accelerate access to biologics and higher-margin APIs.
- M&A and portfolio reshaping: evaluate tuck-ins that add regulatory-ready capacity in preferred geographies, or bolt-on capabilities that shorten time-to-market for prioritized products.
- Sustainability and stewardship: integrate antimicrobial stewardship and environmental-responsibility metrics into supplier scorecards and contractual clauses to mitigate regulatory and reputational risk.
Implementation Roadmap — What 2026 Looks Like
We recommend a staged implementation sequence for 2026 that aligns strategic goals with operational realities: Q1–Q2 should be devoted to diagnostics (supply-risk mapping, cost-of-failure modeling, supplier pre-qualification); Q2–Q3 to contracting and pilot dual-source arrangements or CDMO partnerships; and Q3–Q4 to targeted investments or M&A execution. This cadence allows organizations to move from risk identification to mitigation and then to capability ownership within a single fiscal year.
What the Full Report Provides (Practical Deliverables)
- Comprehensive time-series of market size (historical 2020–2025 and forecast 2026–2032) with scenario sensitivity.
- Supplier and CDMO benchmarking templates, including regulatory-readiness and sustainability scoring.
- Cost-of-goods (COGS) and margin models, with break-even and CAPEX amortization calculators tailored to chemical and biotech synthesis routes.
- Regulatory roadmap outlining dossiers, residue constraints, and antimicrobial stewardship implications across key jurisdictions.
- M&A screening lists and a short-list of capability-led targets based on strategic-fit criteria.
- Actionable playbooks for procurement teams, R&D heads, and corporate development groups to execute the recommendations above.
Call to Action
This preview highlights the strategic contours and decision levers that will matter most in 2026. For organizations that need executable roadmaps, supplier matrices, full segment-level data, and the granular financial models that underpin our recommendations, PW Consulting’s full Worldwide Veterinary API Manufacturing Market report provides the detailed intelligence and tools to act confidently. Reach out to our market team to obtain the full dataset, scenario models, and bespoke advisory support for turning 2026 choices into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary API Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Cooling Mattress Topper Market Poised to Grow at an 8.16% CAGR Through 2032
By PW Consulting, 2026-08-12
Worldwide Cooling Mattress Topper Market — Strategic Imperatives for 2026
Executive summary
The global market for cooling mattress toppers has matured from an emergent niche in 2020 into a robust growth category by 2025, with aggregate industry revenues approaching the mid‑single‑billion USD range. Our latest forecast projects sustained expansion through 2032 at a compound annual growth rate of approximately 8.16%, with the market more than doubling in size from the early 2020s to the end of the forecast window. The competitive landscape remains fragmented (CR3 ~19.5%; CR5 ~27.6%), creating an opportunity-rich environment for focused incumbents, agile challengers and strategic acquirers alike.
Worldwide Business Continuity Management Program Solutions Market
This PW Consulting report is designed as a decision‑grade tool for executives planning product, channel and M&A moves in 2026. In the paragraphs that follow we surface the report’s practical outputs, high‑impact implications and tactical recommendations — while intentionally withholding the granular regional, channel and product split tables that accompany the full dossier to preserve the report’s commercial value and direct interested parties to the full study.
Worldwide Automated Demand Response (ADR) Market
What the report delivers — practical, actionable intelligence
-
Close‑up market sizing and forecast model: baseline historicals (2020–2025), multiple forward scenarios (2026–2032) and sensitivity testing that isolates demand drivers, pricing trajectories and product substitution effects.
Worldwide Ultra Precision Lathe (UPL) Market -
Go‑to‑market playbooks: channel prioritization matrices, customer acquisition economics for direct‑to‑consumer (D2C) and retail partnerships, and shelf/assortment recommendations for specialty bedding and mass retail environments.
-
Product and technology roadmap: comparative assessment of gel‑infused foams, phase change materials (PCMs), active circulation systems and natural/breathable fiber constructions — including R&D investment case templates and time‑to‑market estimates.
-
Supply chain and sourcing playbook: supplier maps, raw‑material risk heatmaps (notably for gel and PCM inputs), cost pass‑through scenarios and recommendations for certification and quality control (e.g., CertiPUR‑US pathways).
-
Competitive benchmark and strategic options: role‑based profiles of leading players, capability gaps, IP hotspots, and a curated M&A/partnership shortlist with acquisition yardsticks and integration checklists.
-
Commercial models and KPI dashboards: price elasticity experiments, lifetime value calculators, aftermarket service options (e.g., trial, warranty, subscription temperature control), and metrics to operationalize performance monitoring.
-
Regulatory and sustainability guidance: compliance timelines, testing milestones for VOC and fire safety, and a roadmap to meet consumer demand for natural and certified products without compromising thermal performance.
Market drivers and dynamics executives must internalize
-
Demand is increasingly driven by consumer awareness of sleep quality and temperature regulation. “Hot sleeper” cohorts and health‑conscious purchasers value demonstrable science (thermal testing, certification) over commodity claims.
-
Technology bifurcation is underway: passive cooling (advanced foams, PCM treatments, breathable natural fibers) competes with active solutions (water circulation, dual‑zone thermal controls). Each pathway has distinct cost, margin and channel implications.
-
Certification and safety standards (e.g., CertiPUR‑US) are de‑facto trust signals for memory‑foam products. Achieving and communicating certification materially shortens sales cycles in higher‑value channels.
-
Channel evolution: digital commerce and D2C models continue to accelerate penetration and data capture, but specialty stores and select retail partners still command influence for premium buyers seeking tactile validation.
-
Raw material concentration for cooling technologies (notably gel and PCM chemistries) creates supply risk that should be managed through diversified sourcing, long‑term contracts and where sensible, backward integration.
Competitive landscape — positioning and strategic options
The market features a mix of legacy mattress brands, digitally native challengers, technology specialists and retail channels. Major players exhibit three distinct strategic archetypes:
-
Brand and materials incumbents (examples include established mattress manufacturers): rely on proprietary comfort materials, broad retail networks and premium branding. Defensive priorities include margin protection, SKU rationalization and certification as a trust builder.
-
Tech‑led specialists (examples include active cooling providers and app‑enabled systems): differentiate via temperature control hardware/software, subscription services and integration with smart‑home ecosystems. Their strategic levers are IP protection, service monetization and partnerships with mattress OEMs.
-
Value and niche innovators (examples include copper‑infused or organic options): compete on ingredient storytelling, sustainability credentials and targeted channel placement (e.g., eco retailers, boutique bedding stores).
Key company dynamics spotlighted in our analysis:
-
Established name brands preserve reach and trust but must accelerate product innovation cycles and reduce product development lead times to match challenger pace.
-
Active cooling players (water‑based or electrically controlled systems) are expanding product families and pursuing app ecosystems to convert one‑off buyers into repeat service revenue; integration with mattresses and toppers is a clear route to higher lifetime value.
-
Smaller innovators continue to claim niche attention through ingredient‑level differentiation (graphite, copper, organic fibers) and targeted clinical claims; these firms are frequently attractive bolt‑on targets for both incumbents and retailers.
-
Recent product launches (e.g., April 2026 innovations from new entrants) underline the speed of product refresh in cooling systems — incumbents must weigh build vs. buy decisions carefully.
What this means for 2026 strategy: five priority plays
-
Prioritize a two‑track product strategy: a near‑term SKU ladder focused on optimized passive cooling (lower CAPEX, faster channel rollout) plus a selective hedge into active systems where service revenue economics justify the investment.
-
Lock in supply and certification pathways now. Negotiate multi‑year agreements for PCM/gel inputs, invest in third‑party testing and secure CertiPUR‑US or equivalent marks to reduce time‑to‑shelf friction in premium channels.
-
Rebalance go‑to‑market spend toward high‑conversion digital acquisition while protecting in‑store touchpoints for premium lines. Operationalize A/B tests for pricing, bundling and trial periods to accelerate learnings.
-
Use M&A and partnerships strategically: target IP or active‑cooling technology providers to accelerate feature roadmaps, and consider distribution partnerships to scale quickly in under‑penetrated markets.
-
Institutionalize consumer thermal segmentation in product development and marketing. Create test cells for “hot‑sleeper” cohorts, hospitality pilots and clinical endorsements to prove efficacy and justify premium positions.
How C‑suite and boards should use this report in 2026
-
Frame a 90‑day action plan: prioritize supplier negotiations, certification milestones and two rapid product pilots (one passive, one active).
-
Refine capital allocation: allocate incremental R&D to the product track with the highest near‑term payback and reserve M&A capital for targeted technology tuck‑ins.
-
Establish measurable KPIs for adoption, returns and retention tied to new cooling features — track thermal performance claims through independent testing to reduce warranty and reputational risk.
-
Deploy a commercial experiment roadmap for channel and pricing permutations, with strict decision gates aligned to forecast milestones and the projected market growth trajectory.
Why act now
With the market on a clear growth path at roughly an 8.16% CAGR into the early 2030s and fragmentation leaving room for decisive consolidation, 2026 represents a strategic inflection point. Faster‑moving competitors are converting product innovation into distribution wins; supply constraints in key cooling materials introduce execution risk; and consumer expectations around certification and proven thermal performance are hardening. These combined forces mean that companies who delay will face higher cost structures and narrower strategic choices.
Next steps and how to access detailed intelligence
This article has summarized the high‑value, action‑oriented findings from PW Consulting’s Worldwide Cooling Mattress Topper Market report and outlined the immediate strategic choices facing executives in 2026. To operationalize the insights above, our full report provides the proprietary model, granular scenario tables, regional and channel splits, product‑level economics and company dossiers that underpin each recommendation.
-
Download the complete study to obtain: detailed regional and channel segmentation, product SKU economics, supplier scorecards, and a prioritized M&A target list with indicative valuation ranges.
-
Contact PW Consulting for a tailored executive briefing: we will align the market model to your portfolio, simulate strategic choices and co‑design a 12‑month execution roadmap.
Executives who convert these insights into decisive action in 2026 will capture disproportionate share of the category’s expansion, secure higher margin positions through product and service differentiation, and build the operational resilience required for long‑term leadership in a rapidly evolving thermal comfort market.
For detailed analysis of this topic, please visit the official page: Worldwide Cooling Mattress Topper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Managed Office Market to Expand at a Robust 13.44% CAGR, Reshaping Global Workspaces
By PW Consulting, 2026-08-12
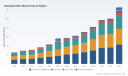
PW Consulting Releases Strategic Preview: Worldwide Managed Office Market Report — Guiding 2026 Decisions for Corporates, Operators, and Investors
Executive preview
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Managed Office Market report (base year 2025, forecast 2026–2032). The managed office sector is shifting from recovery to structurally higher demand as hybrid work models mature, energy and regulatory pressures reshape real estate economics, and enterprise customers seek plug‑and‑play occupational flexibility. Our proprietary market model shows the global managed office market expanding from an estimated USD 48.5 billion in 2025 to a projected USD 117.2 billion by 2032, reflecting a compound annual growth rate of 13.44% across the 2026–2032 forecast window. This preview outlines the strategic value of the full report for decision makers planning budgets, footprints, and M&A activity in 2026.
Electric Automatic Popcorn Machine Market
Why this matters for 2026 strategic planning
Three dynamics converge to make 2026 a pivotal planning year for occupiers, operators, and portfolio investors:
Worldwide Drywall Contractor Market
- Acceleration of hybrid adoption: With more than half of global firms operating permanent hybrid arrangements, demand is shifting to managed solutions that reduce fixed lease exposure while delivering consistent employee experience and corporate governance.
- Regulatory and cost pressures: Energy efficiency mandates and rising facilities labour costs are altering the total cost of occupancy and forcing a re‑thinking of capex vs. opex tradeoffs for both landlords and operators.
- Fragmented supply, concentrated opportunity: The market remains fragmented — the combined share of the three largest providers is modest — creating white space for regional roll‑ups, service specialization, and technology‑enabled scale plays.
Market trajectory — growth you can plan around
Our time‑series sizing traces a steady post‑pandemic rebound: from roughly USD 25.4 billion in 2020 to USD 48.5 billion in 2025, with an inflection into accelerated expansion from 2026 onward. The model projects USD 57.2 billion in 2026 and sustained expansion to USD 117.2 billion by 2032. For strategy teams, three practical takeaways emerge from the trajectory:
Worldwide Carborundum Wafer Market
- Portfolio planning must move from static headcount assumptions to dynamic occupancy scenarios that incorporate hybrid elasticity and seasonal peaks.
- Investment underwriting should reflect higher revenue growth potential but also rising operating cost baselines driven by labour and energy compliance.
- Operators can justify technology and service investments today on the basis of stronger, recurring revenue streams through 2032 — provided they can demonstrably control opex and deliver consistent workplace experience metrics.
Competitive landscape — who’s shaping the market
The managed office sector combines global network players, premium boutique specialists, and local operators pursuing scale. In our analysis we profile the strategic positioning and recent moves of the market’s most visible names to highlight competitive risks and partnership opportunities.
- IWG plc (Zug): A broad global footprint under multiple brands, balancing volume with standardized delivery. Recent full‑year results show revenue growth and continued openings — a playbook focused on reach and unit economics.
- WeWork (New York): Reorganized balance sheet following court‑approved restructuring to reduce leverage and stabilize operations, enabling selective growth where enterprise demand and yield align.
- Servcorp (Sydney): Premium, full‑service towers targeted at multinational and executive clientele — an approach that trades scale for higher per‑seat yields and elevated service standards.
- The Executive Centre (Hong Kong): Luxury executive spaces concentrated in major commercial nodes, with concierge and tech services optimized for APAC corporates and regional HQs.
- Industrious (New York): US‑centric premium flexible workspaces, expanding selectively in growth markets with a hospitality‑grade operator model.
- JLL Flex and CBRE FlexWork: Global integrators leveraging broker and real‑estate platforms to provide managed solutions to enterprise occupiers — competing on scale, data, and client relationships rather than only physical assets.
- Fora (New York): Focus on hospitality‑driven services for SMBs and scaled enterprise offerings in select urban centers.
These players illustrate three viable routes to scale: network expansion, enterprise partnership aggregation, and premium specialization. The market concentration metrics in our study underline a fragmented marketplace — meaning incumbents face both the threat of new entrants and attractive consolidation opportunities for disciplined acquirers.
Operational and regulatory headwinds
The report embeds several real‑world constraints that materially affect modelled returns and rollout plans. Key inputs include recent office vacancy dynamics, labour cost inflation in facilities support, energy efficiency regulatory deadlines, and supply‑chain impacts on workplace technology:
- Elevated vacancy rates in many global markets pressure providers to offer flexible lease terms and creative revenue models.
- Rising wages for facilities services and higher compliance costs increase opex; operators must offset these through productivity gains, automation, and demand management.
- Energy performance regulations require capex strategies for decarbonization and retrofits that will factor into long‑term occupancy cost and asset valuation.
- Export controls on IT hardware have increased the cost base for fitted‑out managed spaces in some markets, affecting time‑to‑market for tech‑heavy offerings.
What PW Consulting’s full report delivers — practical, actionable content
Designed for strategy teams, corporate real‑estate leaders, private equity and operating executives, the full report goes well beyond headline sizing. Highlights include:
- Scenario models calibrated to hybrid adoption rates, vacancy trajectories and regulatory cost curves — enabling stress‑tested forecasts for 2026–2032.
- Operator benchmarking dashboards with unit economics, margin levers and labour productivity metrics to inform buy vs. build decisions.
- Customer segmentation frameworks and RFP scorecards that translate corporate occupant priorities into service level commitments and pricing strategies.
- Site and network optimization tools — occupancy mix optimization, yield management playbooks, and location selection heuristics tuned to enterprise demand density.
- M&A target maps and partnership archetypes that identify sensible consolidation paths and owner‑operator JV structures across maturity stages.
- Compliance and retrofit playbooks aligned to upcoming energy performance requirements, with cost ranges and payback matrices for different asset vintages.
- Case studies and implementation timelines drawn from operator rollouts and landlord/operator collaborations to reduce execution risk.
Each deliverable includes practical templates — investment memoranda, RFP checklists, and an occupancy optimization calculator — enabling teams to move from insight to action within weeks.
Use cases — how executives should apply the report in 2026
Below are concrete ways different stakeholders can apply insights from the full study during the 2026 planning cycle:
- Corporate occupiers: Use the occupancy optimization tool to reallocate spend across traditional leases, managed offices, and remote allowances; derive a three‑year TCO for each scenario and build a phased transition roadmap.
- Operators and landlords: Recalibrate leasing and pricing frameworks to reflect rising opex, prioritize retrofit investments that unlock premium pricing, and test partnership models with brokerage integrators to secure enterprise pipelines.
- Investors and PE sponsors: Stress test target valuations with our scenario set, identify bolt‑on acquisition archetypes that improve unit economics, and map exit timing against macro demand inflection points.
Why the preview — and what’s intentionally withheld
Consistent with our “preview” principle, this release reveals high‑level market sizing, growth trajectory, and the strategic implications you need to prioritize in 2026. To preserve the commercial integrity of actionable segmentation and provider share tables, detailed regional/application splits, and downloadable data tables are available only in the full paid study. These granular datasets include the specific revenue breakdowns by geography, space type, and end‑user that corporate and investor clients use to build hyper‑localized rollout and acquisition plans.
Next steps and how to access the full study
For teams preparing budgets, RFPs, M&A pipelines, or retrofit strategies for 2026, the full PW Consulting Worldwide Managed Office Market report provides the validated data, scenario tools, and execution templates necessary to move from strategy to a near‑term action plan. To access the full report — including downloadable data tables, detailed segmentation, and the operational toolset — visit PW Consulting’s report page or contact our market team for a briefing with one of our senior analysts.
About PW Consulting
PW Consulting is a strategic advisory firm specializing in real estate, workplace strategy, and operational transformation. Our research combines primary operator interviews, proprietary modelling and scenario analysis to help clients make high‑confidence decisions in rapidly changing markets.
For detailed analysis of this topic, please visit the official page: Worldwide Managed Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Burrito Forming Machine Market to Surge from USD 421.68 Million in 2025 to USD 646.72 Million by 2032, Fueled by a 6.3% CAGR
By PW Consulting, 2026-08-12
Worldwide Burrito Forming Machine Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Burrito Forming Machine Market offers a forward-looking, operationally focused briefing aimed at manufacturers, foodservice groups, private equity investors, and equipment vendors preparing strategic moves in 2026. The market has demonstrated steady expansion through the early 2020s and is continuing on a multi-year growth trajectory. Our base-year analysis (2025) captures the evolution from 2020 through 2025 and projects performance across a 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 6.3%.
Pharmaceutical Robots Market
Why this report matters for 2026
-
Timing: 2026 is a pivotal year for operational modernization across food manufacturing. Labor cost pressures, post‑pandemic supply-chain normalization, and rising demand for consistent, high‑volume convenience foods create an inflection point for investment in burrito forming automation.
Worldwide Autogenous Grinding Mill Market -
Actionability: Rather than a high-level snapshot, the study is architected as a playbook—containing procurement frameworks, vendor scorecards, and total cost of ownership models—that procurement, operations, and strategy teams can put into motion immediately.
MESFET (Metal Semiconductor Field-Effect Transistor) Market -
Risk-aware forecasting: We pair quantitative projections with scenario-based sensitivities for raw-material inflation, labor-cost volatility, and regulatory shifts, enabling CFOs and COOs to stress-test capital allocations for 2026 and beyond.
Market trajectory and headline metrics
Between 2020 and 2025 the market expanded meaningfully as manufacturers transitioned parts of manual wrapping lines to mechanized solutions. Our base-year analysis shows the market size increasing from just over USD 300 million in 2020 to over USD 420 million in 2025. The market continues to scale into the forecast period, with predicted mid-single-digit annual growth (CAGR 6.3%) through 2032. By the end of the forecast horizon, the market is projected to exceed USD 640 million, reflecting the twin forces of productivity-driven replacement and new-capacity installation across frozen-food manufacturers, foodservice chains, and institutional catering operations.
Structural dynamics shaping 2026 decisions
-
Automation economics: Equipment capable of automating filling, folding, and rolling materially reduces labor intensity. Manufacturer disclosures and independent operator case studies in our report show labor savings of up to 70% when comparing manual wrapping to automated lines—an outcome that materially alters payback calculations and justifies higher upfront CapEx for many operators.
-
Material cost sensitivity: Stainless steel remains the food‑grade material of choice for hygienic equipment construction. The broader stainless-steel market and associated supply-chain dynamics (including lead times for food-grade finishes) are embedded into our procurement models; we flag stainless-steel index shocks as a primary cost risk for 2026 equipment budgets.
-
Regulatory and certification tailwinds: Leading suppliers publish compliance with international equipment standards (ISO9001, CE, UL) which simplifies cross-border deployments and reduces time-to-market for products intended for multinational food manufacturers and retailers.
-
Integration with upstream/downstream systems: Buyers increasingly prize machines that integrate with upstream wrapper/crepe production and downstream packaging automation. Systems that offer modular interfaces and servo-driven quick changeovers decrease line downtime and support SKU diversification strategies.
Operational implications for manufacturers and foodservice operators
-
CapEx vs. Opex: The right procurement decision in 2026 will hinge on a nuanced TCO analysis. Our report provides customizable models that quantify acquisition cost, installation, commissioning, energy consumption, maintenance, spare-part inventories, and expected labor savings over typical service lifecycles—allowing procurement teams to compare leasing, CAPEX, and hybrid financings.
-
Throughput and SKU strategy: Beyond headline throughput figures, machine selection must align with product mix (tortilla thickness, fillings, finished weight) and desired flexibility. Systems with adaptable folding mechanisms and rapid-tooling changeovers lower SKU-switching penalties and accelerate innovation cycles.
-
Aftermarket and service: Service footprint—spare parts availability, remote diagnostics, and local technical support—can be the deciding factor for accelerated rollouts. Our vendor scorecards in the full report evaluate service metrics and incident-response times across leading suppliers.
-
Sustainability and waste: Calibration of dispensing accuracy and folding consistency drives finished-product yield and reduces rework/waste. For operators with sustainability targets, this can transform machine choice into a measurable ESG win.
Competitive landscape — who matters (and why)
The competitive field is a blend of specialized equipment makers and broader packaging-automation suppliers. Market concentration is moderate: the top three vendors account for a meaningful share of installed capacity while the top five broaden that influence further—an environment that supports both established OEMs and niche innovators. Key profiles and strategic implications follow.
-
ANKO FOOD MACHINE CO., LTD. (Taiwan) — ANKO’s sensor-controlled burrito forming solutions are designed to automate the end-to-end process (filling, folding, rolling) and address variances such as thicker tortilla geometries. Patented mechanisms and a global footprint make ANKO a default partner for commercial food manufacturers looking to transition from manual to automated production. Recent announcements indicate ramped marketing and trade-show activity in 2026 as the company showcases its BR-1500 platform to global buyers—signaling both continued product marketing investment and an emphasis on international aftermarket expansion.
-
Solbern (United States) — Solbern’s portfolio of folding machines targets uniform output across burritos and related handheld formats (egg rolls, taquitos), positioning the company well for processors seeking multi-format lines. Their focus on folding precision and uniformity appeals to high-volume processors emphasizing product consistency.
-
Daiei Engineering Co., Ltd. (Japan) — Daiei’s high-throughput wrapping and integration capabilities (including linkage to wrapper/crepe ovens) make it attractive to firms where upstream wrapper production and synchronized line speeds are critical. Their higher-speed configurations are particularly relevant for frozen-burrito manufacturers prioritizing throughput and end-to-end automation.
-
Formost Fuji Corporation (United States) — As an established supplier of horizontal flow wrappers and automation systems, Formost Fuji’s strengths lie in high-performance packaging automation with rapid changeover technologies. For frozen-burrito system integrators, suppliers who can both form and package at required line rates simplify vendor management and accelerate deployment timelines.
In combination, these vendors exemplify two sourcing archetypes: single-vendor systems providing turnkey solutions (appealing to buyers who want a single point of accountability) and best-of-breed assemblies where integrators combine forming machines with separate packaging and upstream baking solutions. Our competitive matrices and win‑loss analyses in the full study help buyers choose the appropriate approach by product class and operational maturity.
Practical deliverables within the full report
-
Procurement playbook: RFP templates, technical checklists, and an evaluation rubric weighted for throughput, flexibility, certification, and serviceability.
-
TCO and ROI models: Excel-based calculators that allow finance and operations teams to simulate scenarios across different labor-cost regimes, material-price shocks, and financing structures.
-
Vendor scorecards and reference validation: Standardized assessments of lead times, spare-parts strategy, field-service coverage, and documented customer references.
-
Integration and line-design guidance: Best-practice line layouts showing how forming machines interface with crepe ovens, fillers, and horizontal flow wrappers to minimize footprint and maximize uptime.
-
Scenario planning: Sensitivity analyses for raw-material volatility, labor inflation, regulatory shifts, and demand surges tied to retail and QSR channel dynamics.
How procurement and strategy teams should use this intel in 2026
-
Prioritize pilots that quantify real-world labor savings and yield improvements. Use short-term pilot results to calibrate full-line ROI models.
-
Lock in critical long-lead items—especially food-grade stainless components—within 2026 capital budgets to mitigate supplier lead-time risk.
-
Negotiate outcome-based service contracts that align vendor incentives with uptime and yield targets rather than pure time-and-materials models.
-
Consider hybrid sourcing: combine a proven forming machine with local integrators for installation and maintenance to balance accountability and service reach.
What we hide (and why)
To preserve the strategic value of the underlying intelligence and encourage direct engagement with the full study, this preview intentionally omits granular regional splits, application-level revenue slices, and specific procurement pricing data. The full report provides those detailed segmentations, audited vendor revenue shares, and downloadable financial models—information that is essential for transaction-level decisions and is available exclusively through the PW Consulting report portal.
Next steps and contact
For executives preparing procurement RFPs, capital planning, or M&A evaluations in 2026, PW Consulting’s Worldwide Burrito Forming Machine Market report converts market-level signals into actionable operational plans. To access the complete dataset, vendor scorecards, and executable TCO tools, please visit the PW Consulting report landing page or contact our team to schedule a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Burrito Forming Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ultrasonic Probe Covers Market Set for a Robust 6.5% CAGR, New Report Reveals
By PW Consulting, 2026-08-12
Worldwide Ultrasonic Probe Covers Market — Strategic Outlook for 2026: A PW Consulting Intelligence Brief
As ultrasound remains a frontline imaging modality across hospitals, outpatient centers, and point-of-care environments, the market for disposable ultrasonic probe covers is entering a phase where incremental technology, regulatory clarity, and procurement discipline will determine winners and losers. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — finds the addressable market expanding meaningfully: from an assessed market size of USD 229.72 Million in 2025 to an expected USD 356.99 Million by 2032, representing a compound annual growth rate of roughly 6.5% over the forecast window. This briefing summarizes the report’s strategic value for executives making 2026 decisions, highlights the practical deliverables within the full study, and outlines the competitive, regulatory, and supply-side dynamics that will shape near-term outcomes.
Worldwide Specialty Practice Management Software Market
Market Snapshot — What the Macro Numbers Reveal
-
A steady recovery and expansion path: The sector has shown steady year-on-year growth through 2020–2025 and is forecast to sustain a mid-single-digit CAGR through 2032. That trajectory reflects an intersection of increased ultrasound utilization, heightened infection-control protocols, and material innovation (notably the shift to latex-free films).
Worldwide Back Office Automation Market -
Moderate market concentration: The competitive structure is characterized by a meaningful presence of specialist manufacturers and medical-supply players. Our concentration analysis indicates a market where leading firms capture a substantive share of revenue, yet there remains material room for mid-sized innovators and regional suppliers to gain share through differentiation and regulatory compliance.
Worldwide Tablet Friability Testers Market -
Timing matters: The pace of regulatory clearances (sterility claims, labeling, packaging standards) and the speed at which end-users adopt latex-free or gel-free alternatives will be determinative for both product adoption and pricing power in 2026.
What the PW Consulting Report Delivers (Practical Takeaways)
-
Integrated market model and scenarios: A transparent, reproducible market-sizing model covering historicals (2020–2025) and detailed forecast runs to 2032, including base, upside and downside scenarios driven by utilization, pricing, and sterilization-cost variables.
-
Commercial playbooks: Go-to-market guidance for OEMs, contract manufacturers and distributors — including product positioning (endocavity vs. general imaging), bundling strategies, and pricing levers.
-
Regulatory and packaging matrix: A practical roadmap for navigating device classification, 510(k) strategies for sterile products, and ISO-aligned requirements for packaging and sterilization validation.
-
Supplier and material assessment: Due-diligence templates, supplier scorecards, and total-cost-of-ownership calculators for key film substrates and sterilization pathways.
-
Competitive intelligence dossiers: Strategic profiles and capability matrices for leading market participants, with a focus on product breadth, regulatory status, distribution footprints and recent commercial moves.
-
Procurement and clinical adoption toolkit: Contract templates, clinical-evidence checklists, and infection-control alignment notes to support hospital buying teams in 2026.
Strategic Implications for 2026 Decision-Making
-
For manufacturers and OEMs: Prioritize modular investments in sterile-processing validation and ISO-compliant packaging early in 2026. Firms that can demonstrate robust sterilization validation (EO or radiation) and clear compatibility with major ultrasound platforms will preserve pricing and open enterprise contracts.
-
For product development teams: Accelerate adoption or improvement of latex-free materials and low-profile, gel-free designs. Imaging clarity and tactile feedback remain differentiators for clinical acceptance — invest in material-science partnerships and clinical usability studies to shorten adoption cycles.
-
For hospital procurement: Reassess contract scopes to reflect total cost (device plus labor and infection-control externalities). Because probe covers are commonly bundled into procedure codes rather than reimbursed separately, cost-avoidance strategies and supplier rationalization can yield immediate budgetary relief.
-
For investors and corporate development: The market profile favors strategic consolidation where scale accelerates sterilization, distribution and R&D economics. Look for tuck-in targets that offer differentiated materials, validated sterile processes, or superior channel access to ambulatory surgery centers.
Competitive Landscape — Profiles and Strategic Reads
-
CIVCO Medical Solutions (Coralville, IA, USA): A recognized provider of sterile and non-sterile disposable covers, CIVCO’s recent portfolio expansion showcased at major industry venues signals a continued push into sterile endocavity solutions. Expect them to leverage trade-show visibility into enterprise-level engagements.
-
Parker Laboratories (Fairfield, NJ, USA): Parker’s emphasis on gel-free, low-profile designs positions it well for infection-control-conscious clinical settings. Their differentiated product form-factors are designed to reduce preparation time and contamination risk — an important claim for procurement teams.
-
Kentec Medical (Bicester, UK): Kentec’s alignment with EU MDR and global distribution networks makes them a credible partner for customers seeking MDR-compliant sterile sheaths. Regulatory compliance is a strategic asset in markets with stringent device pathways.
-
Sunray Medical (Edison, NJ, USA): With FDA-cleared offerings and a range of clear-view and endovaginal covers, Sunray’s positioning is squarely in regulated markets that value documented clinical performance and clearance histories.
-
ImaX Medical (Montreal, QC, Canada): ImaX’s focus on high-clarity materials for TEE and ultrasound probes appeals to imaging-centric use-cases where optical performance cannot be compromised.
-
Strategic read: The market comprises well-established specialists and nimble innovators. Competitive advantage will accrue to players who combine regulatory rigor, materials know-how and channel depth. Expect M&A and partnership activity as companies pursuit scale and fill product gaps.
Regulatory, Reimbursement and Clinical Dynamics
-
Regulatory posture: Disposable probe covers occupy an interesting regulatory space. Non-sterile covers may be Class I exempt in certain jurisdictions, while sterile covers typically require a more rigorous pathway (e.g., 510(k) clearances in the U.S.). Sterile-packaging and sterilization validation (ISO 11607; ISO 11135/11137) are table stakes for sterile claims.
-
Reimbursement reality: There is no dedicated HCPCS code for probe covers; costs for probe covers are commonly bundled into ultrasound procedure reimbursements. This bundling compresses pricing flexibility and pushes suppliers to compete on total-cost and supply reliability rather than list price alone.
-
Clinical guidance: Major public-health authorities recommend disposable covers for endocavitary procedures to reduce healthcare-associated infections. Hospitals and ambulatory centers with strong infection-control governance will prioritize validated sterile products.
Supply Chain & Material Risk Considerations
-
Material evolution: The industry is moving toward latex-free polyurethane and polyethylene films to meet biocompatibility and clarity demands. These substrate choices have downstream impacts on production processes, sterilization compatibility, and unit economics.
-
Sterilization trade-offs: Ethylene oxide sterilization delivers broad compatibility but introduces lead times and regulatory oversight; radiation sterilization reduces cycle time for certain materials but requires capital access. Suppliers and buyers should stress-test scenarios against sterilization capacity constraints.
-
Mitigation levers: Dual-sourcing of medical-grade films, strategic supplier partnerships, and localized sterile-packaging cells can materially reduce supply disruption risk — tactics that PW Consulting’s procurement playbooks quantify for 2026 contracting cycles.
How PW Consulting Supports Execution
-
Custom strategy workshops to convert the market model into a 90–180 day action plan for product launches, regulatory filings and procurement renegotiations.
-
Commercial due diligence and M&A support, with granular unit-economics modeling and integration roadmaps tailored to probe-cover businesses.
-
Procurement and supplier-management programs that align clinical requirements, sterility validation and logistics to reduce TCO and stockouts.
-
Hands-on regulatory navigation to optimize 510(k) strategies, international registrations, and sterilization validation plans.
Every decision made in 2026 — from allocating R&D dollars to selecting sterilization partners and negotiating multi-year supply agreements — will compound over the forecast period. Firms that move quickly to lock in validated materials, compliance pathways, and channel commitments will capture disproportionate share of the upside in a market projected to grow at a steady mid-single-digit CAGR through 2032.
PW Consulting’s full Worldwide Ultrasonic Probe Covers Market report contains the complete dataset, including granular segmentation tables, regional dynamics, application-level analyses, price curves and company-level revenue estimates that underpin the strategic summaries above. For executives preparing budgets, M&A roadmaps or procurement strategies in 2026, the report provides the evidence base and tactical templates required to convert insight into measurable outcomes. Visit our website to request the full study and bespoke advisory options tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Probe Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Decision Intelligence Market to Grow at 18.25% CAGR, Surging from USD 18.45 Billion in 2025 to Nearly USD 59.65 Billion by 2032
By PW Consulting, 2026-08-12
Worldwide Decision Intelligence Market — Strategic Preview for 2026
As organizations enter 2026, decision intelligence (DI) has moved from experimental pilots to boardroom strategy. PW Consulting’s new Worldwide Decision Intelligence Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) provides a practical, enterprise-focused roadmap for leaders who must convert data, models, and governance into repeatable, auditable decisions. This release previews the report’s strategic value for 2026 planning cycles and explains how our findings should change the way CFOs, CIOs, heads of analytics, and risk officers prioritize investments.
Tank Gauge Systems for Fueling Stations Market
Market Momentum: the macro picture
The DI market has been expanding rapidly: from the early 2020 baseline to a materially larger ecosystem by 2025, and our projection shows continued acceleration across the forecast window driven by enterprise adoption, cloud-native architectures, and governance requirements. PW Consulting models a compound annual growth rate (CAGR) of 18.25% from 2026 through 2032 — a pace that signals the transition of decision intelligence from niche capability to core enterprise infrastructure. The market’s trajectory underscores three structural shifts that matter to executives in 2026: the industrialization of decision models, the normalization of decision systems of record, and the integration of DI into regulated workflows.
Disposable Blood Pressure Sensor Market
Why this matters for 2026 planning
- Investment timing — Organizations that budget in 2026 face a tradeoff between accelerating production deployments now versus investing in modular governance and observability that reduce downstream risk. The market growth rate implies vendors will continue to innovate rapidly; however, hastily deployed systems without lifecycle controls multiply legal, ethical, and operational risk.
- Vendor selection — Buyers will prioritize platforms that balance rapid decisioning with explainability, version control, and audit trails. Technology capability alone is insufficient; integration with existing process orchestration and people workflows is the decisive factor.
- Regulatory alignment — Standards and frameworks — from ISO/IEC 42001 to regional AI regulations and frameworks such as the EU AI Act and NIST’s AI RMF — make compliance a baseline requirement. 2026 is the year when compliance-related features stop being “nice to have” and become procurement filters.
What the PW Consulting report delivers (practical content)
This report is designed for decision-makers who need operational next steps rather than academic theory. Our deliverables include:
Worldwide Penetration Service Market
- Operational playbooks for three adoption archetypes: centralized centers of excellence, distributed decision hubs, and product-led embedded decisioning — each with governance matrices and implementation milestones.
- Decision lifecycle templates covering modeling, testing, deployment, monitoring, and feedback loops — built to align with auditor expectations and the emerging standards for AI management systems.
- Procurement and architecture checklists that map vendor capabilities to enterprise requirements (performance, explainability, SLAs, data lineage, and human-in-the-loop controls).
- Risk and compliance heat maps showing where decision intelligence amplifies regulatory exposure — and the mitigation designs most favored by regulators and auditors.
- Case studies and cost-to-value frameworks that allow comparative ROI estimates for supply chain, risk, customer engagement, and clinical decision-support pilots.
Note: this preview intentionally omits the granular subsegment revenue tables and region/application splits available in the full report. Those detailed breakdowns and vendor scorecards are available on our site for subscribers and enterprise clients.
Competitive landscape: how vendors are positioning in 2026
The DI vendor ecosystem remains fragmented (three-firm concentration is modest), with a mix of analytics incumbents, specialist DI platforms, rules engines, and newer AI-native entrants. Competitive dynamics in 2026 are shaped by horizontal capability (decision modeling, orchestration, monitoring) versus vertical go-to-market execution (industry workflows, regulatory knowledge, data integration). Below we summarize the strategic positioning of core vendors featured in the full report.
- FICO — Strength in analytic workflows and scoring-centric decisioning; favored in risk and compliance scenarios where deterministic models and model lifecycle controls are prioritized.
- SAS — A broad analytics and decisioning stack with embedded governance; recent industry recognition reinforces SAS’s strength in regulated verticals such as finance, healthcare, and manufacturing.
- Aera Technology — Positioned as a decision agent platform for real-time enterprise optimization, with supply chain and finance orchestration as primary use cases.
- Quantexa — Differentiates with entity resolution and knowledge-graph-based context-building, increasingly leveraged for complex risk and fraud decisioning.
- IBM — Integrates DI capabilities into a wider AI and hybrid-cloud portfolio, appealing to large enterprises seeking vendor consolidation and professional services.
- ACTICO — Focus on decision automation blending rules and ML, often chosen where explainability and deterministic rule governance are required.
- o9 Solutions — Targets cross-domain decision execution with strong ties to supply chain planning and enterprise planning systems.
- Cloverpop — Emphasizes structured human collaboration, decision records, and bias reduction in group decision-making contexts.
- Decisions — Focus on low-code/no-code process orchestration with decision modeling and simulation capabilities.
- InRule Technology — Offers business-rule centric automation, suitable for organizations seeking to empower non-developers to manage decision logic.
- Rulex — Combines explainable AI with no-code interfaces and what-if simulation, attractive for supply chain and life sciences teams.
- Sapiens — End-to-end decision platform targeted at insurance and financial workflows with strong policy and logic management features.
- Pegasystems (Pega) — Blends decision intelligence with process automation, useful where decisions must be orchestrated across complex customer journeys.
- Sparkling Logic — Cloud-native decision management with AI-assistant features for design, deployment, and monitoring.
- Taktile — Visual decision modeling and real-time decisioning oriented toward operational teams.
Recent market signals reinforce these vendor dynamics. In early 2026 a number of vendor and ecosystem developments shaped buyer expectations: a leading analytics vendor was recognized in Gartner’s inaugural Magic Quadrant for Decision Intelligence Platforms; specialist firms announced partnerships to enhance enterprise risk capabilities; and several organizations disclosed patents and product launches focused squarely on DI workflow automation and hybrid compute strategies. These events accelerate vendor specialization and raise the bar for enterprise-grade governance and explainability.
Regulatory and governance headwinds
Standards and regulation are no longer peripheral concerns. ISO/IEC 42001’s arrival as an international AI management systems standard, combined with regional frameworks such as the EU AI Act and national RMFs, is forcing architecture-level changes in DI deployments — from auditable versioning and fairness metrics to human oversight mandates. Gartner’s framing of decision intelligence as an engineering discipline — treating decisions as digitized assets with explicit lifecycle controls — is now evident in procurement language. PW Consulting’s report maps these requirements to concrete system and organizational controls so teams can move from compliance risk to competitive advantage.
Actionable recommendations for 2026
- Embed governance before scale: design decision logs, lineage capture, and explainability into the first production use case rather than retrofitting later.
- Adopt modular architectures: separate decision models, execution engines, and observability layers so upgrades and audits can be performed without wholesale rewrites.
- Prioritize human-in-the-loop designs for high-risk decisions: ensure role-aware interfaces, escalation rules, and decision records are in scope of the initial MVP.
- Use vendor scorecards tied to enterprise criteria: performance, explainability, SLAs, integration adapters, and industry-specific regulatory compliance should determine shortlists.
- Plan for continuous validation: stress-test decision models against fairness and robustness metrics and automate monitoring to detect concept drift and compliance regressions.
Why PW Consulting’s report is mission-critical for 2026
This report combines market sizing and vendor benchmarking with operational playbooks and compliance mappings — a rare blend designed to support immediate procurement and implementation decisions. Our forward-looking scenario analysis links the macro market growth and vendor innovation to tactical choices that influence 12–36 month outcomes. For decision-makers who must justify budgets, mitigate regulatory risk, and accelerate measurable business impact, our report provides the templates and vendor-context you need to move from POC to production safely and quickly.
Next steps
This preview is intended to equip executives with strategic direction for 2026. The full PW Consulting Worldwide Decision Intelligence Market report contains the granular market tables, proprietary vendor scoring, subsegment forecasts, and detailed implementation playbooks referenced here. To obtain the full report, subscribe via our website or contact our enterprise advisory team for a briefing tailored to your industry and use-case priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Decision Intelligence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


