



Category: market research
PW Consulting: Worldwide Paper Dry Strength Resin Market to Reach USD 1,333.1 Million by 2032 with 3.82% CAGR (2026–2032) — Asia Pacific Leads at USD 428.77M
By PW Consulting, 2026-08-05
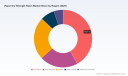
Worldwide Paper Dry Strength Resin Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s new Worldwide Paper Dry Strength Resin Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) delivers an actionable intelligence package designed to shape commercial and technical strategy in 2026 and beyond. Anchored in rigorous primary research and bottom‑up market modelling (all values in USD Million), the study quantifies a market that passed the USD 1.0 billion threshold in our base year and — under the base case — grows at a compound annual growth rate (CAGR) of 3.82% through 2032. That trajectory masks important short‑term dynamics and supplier opportunities that procurement, R&D and corporate development teams must address now.
Worldwide Paper Dry Strength Resin Market
Why this report matters for 2026
-
Decision clarity in a transitional market: 2026 will be the first full planning year in which many paper mills, chemical producers and converters execute on pandemic‑era investment and sustainability plans. Our report translates market-level growth into discrete strategic levers — pricing, formulation choice, procurement hedging and lab-to-line validation — that materially affect 2026 P&L and capital allocation.
Worldwide Paper Dry Strength Resin Market -
Integrates macro and micro: beyond headline sizing and a 3.82% CAGR, the analysis links raw material cost volatility, regulatory pressure and evolving mill operating practices to product mix, margin compression and adoption curves for bio‑based alternatives.
Worldwide Paper Dry Strength Resin Market -
Risk‑calibrated scenarios: the forecast includes stress tests for feedstock price shocks, tighter chemical regulation and accelerated substitution toward starch and other bio‑based chemistries — enabling boards to run ‘what‑if’ simulations for M&A, capacity investments or pricing moves in 2026.
Key data points you will use in 2026 planning
-
Market sizing and trendline: the market exceeded USD 1,000 million in our 2025 base year and the model shows a recovery and moderate growth path through 2032 under the base case. Short‑term year‑on‑year fluctuations reflect fibre economics, mill grade mix and energy‑driven production cost changes.
-
Concentration and competitive dynamics: the sector is moderately consolidated — top‑three and top‑five supplier groups account for a meaningful portion of market demand — which creates differentiated pricing power, but also room for regional and technology challengers to capture niche margins.
-
Input cost sensitivity: acrylamide monomer — a primary feedstock for many synthetic polyacrylamide resins — has exhibited notable price swings in recent years, driven by energy and supply‑chain volatility. Producers and buyers should assume ongoing volatility in 2026 and model procurement via a mix of hedging, strategic sourcing and formulation flexibility.
What the report contains — practical, deployable modules
-
Market sizing & methodology: transparent, bottom‑up estimates for 2020–2025 and point forecasts for 2026–2032, including sensitivity ranges and scenario outputs for low, base and high adoption paths.
-
Demand driver analysis: grade‑level demand drivers (packaging, tissue/towel, graphic and specialty papers), fiber economics, machine runnability considerations and lightweighting opportunities that directly translate into chemical usage per tonne.
-
Supplier benchmarking & scorecards: comparative diagnostics on technology portfolios, application support, dosing systems, sustainability credentials, geographic reach and price positioning for leading vendors.
-
Procurement playbook: tactical guidance on contracting structures, spot vs. term mix, supplier qualification, and a model to quantify savings from switching chemistries or adjusting dosing strategies.
-
R&D & go‑to‑market frameworks: practical roadmaps for piloting alternative chemistries (e.g., GPAM, amphoteric PAM, starch‑based blends), lab‑to‑mill validation templates and key performance indicators (KPI) to track quality, runnability and lifecycle environmental metrics.
-
M&A and strategic options: identification of capability gaps, bolt‑on acquisition targets and partnership archetypes that accelerate market entry or extend portfolios into value‑accretive adjacent segments.
Competitive landscape — how incumbents and challengers are positioning for 2026
The report’s supplier analysis synthesizes public disclosures, patent activity, customer interviews and lab trial data. The players profiled range from global chemical majors to regional specialists and include producers of polyacrylamide‑based resins, glyoxalated variants, modified polyamines and natural polymer solutions. Key strategic themes we observe:
-
Portfolio breadth and application insight as a differentiator: global specialty chemical companies that combine product breadth (e.g., amphoteric, cationic GPAM, engineered cellulose) with dosing and technical service enjoy stickier customer relationships and superior ASP (average selling price) protection.
-
Innovation focused on dose‑efficiency and life‑cycle benefits: vendors launching “pump‑and‑go” or low‑dosage, high‑effect products are capturing trials in tissue and packaging where lightweighting and fiber substitution are active. Recent new product activity in late 2025 underscores this trend.
-
Regional players and cost‑competitors remain important: manufacturers with local raw material sourcing or lower operating cost bases are aggressive on volume and can be ideal partners for regional mill clusters prioritizing cost control over premium functional add‑ons.
Examples from the market (summarized without proprietary trial data): leading specialty chemical firms have been updating portfolios and capturing sustainability milestones. One provider received recognition from a major mill for CO2 reduction after deploying a dry strength program that combined advanced polymer chemistries and performance additives. Another global supplier introduced a pump‑ready dry strength solution in late 2025 that promises single‑digit to mid‑double‑digit percentage strength improvements at controlled dosing — a commercial proposition aimed directly at tissue manufacturers looking to reduce refining and adjust basis weight.
Industry dynamics shaping supplier economics in 2026
-
Feedstock volatility: cost swings in acrylamide and energy reshape margins for synthetic resin producers and alter the arbitrage versus natural alternatives. Buyers should model supply disruptions and incorporate alternative sourcing or substitution levers into contracts.
-
Regulatory and sustainability pressure: end customers and brand owners increasingly require low‑impact chemistries and documented CO2 reductions. This accelerates development of bio‑based and starch‑complemented systems and affects lifecycle cost comparisons.
-
Operational priorities at mills: machine runnability, retention/drainage balance and dewatering remain primary criteria for adoption. Suppliers that demonstrate runnability improvements and provide integrated dosing systems secure faster commercial uptake.
Strategic actions for commercial, technical and procurement leaders in 2026
-
Prioritize formulation flexibility: invest in trials that allow rapid switching between synthetic and starch‑enhanced systems depending on feedstock price or regulatory constraints.
-
Hedge feedstock exposure: combine longer‑term supply agreements with indexed pricing clauses and strategic inventory buffers for critical monomers and reagents.
-
Close the mill‑to‑molecule loop: require suppliers to provide technical service bundling (dosing systems, lab support, KPI dashboards) as part of commercial proposals — this reduces risk during scale‑up and often justifies modest premium pricing.
-
Use procurement as a source of product innovation: invite suppliers to co‑fund trials that test low‑dose technologies on high‑value grades where the ROI is quickest (e.g., high‑yield tissue or specialty packaging).
-
Incorporate regulatory scenarios into capex planning: accelerated uptake of bio‑based chemistries would change processing energy and dryer load economics — factor alternate chemistry trials into mill modernization projects.
Scenario outlook and investment thesis
Under PW Consulting’s base case (3.82% CAGR through 2032), the market grows steadily as packaging and tissue demand, plus productivity initiatives at mills, support sustained use of dry strength resins. Upside occurs if new low‑dosage chemistries and accelerated substitution toward bio‑based systems materially increase effective application rates or open new end‑use windows; downside follows sustained acrylamide price spikes or abrupt regulatory constraints on specific chemistries.
For investors and corporate strategists, the most attractive plays in 2026 are those that (a) pair technology differentiation with application support (service + dosing), (b) control critical feedstock sourcing, and (c) can show rapid lifecycle benefits to brand owners through validated CO2 or waste reductions.
How to obtain the full intelligence suite
This release is a strategic preview. PW Consulting’s full report contains the complete set of segment‑level forecasts, company scorecards, country/capacity modelling, pricing curves and a procurement toolkit that you can deploy immediately in 2026 sourcing cycles. We deliberately withhold granular sub‑segment tables and proprietary trial matrices in this summary to prompt direct engagement — those datasets are included in the licensed report and in our advisory engagements.
Contact PW Consulting to schedule a walkthrough of the model, obtain executive summaries tailored to your business unit, or request a mill‑level pilot template that converts lab observations into 12‑month implementation plans.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Dry Strength Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Military Off‑Road Vehicles Market to Accelerate at a 5.12% CAGR Through 2032
By PW Consulting, 2026-08-05
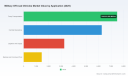
Worldwide Military Off‑road Vehicles Market: Strategic Imperatives for 2026
Executive snapshot
PW Consulting’s latest market study on Worldwide Military Off‑road Vehicles provides a decision‑grade lens for defense planners, OEM executives, investors, and procurement authorities preparing strategies for 2026 and beyond. The market has expanded from a mid‑teens billion USD base in the early 2020s to USD 18.45 billion in our 2025 base year, and PW projects steady expansion at a 5.12% CAGR through 2032, arriving at roughly USD 26.17 billion by the end of the forecast. Those headline numbers frame a durable market—large enough to justify multi‑year industrial investments and M&A activity, yet sufficiently fragmented to reward differentiated technology and supply‑chain strategies.
Worldwide Military Off-road Vehicles Market
Why this report matters to 2026 decision‑makers
- It translates market momentum into concrete procurement and investment options. We move beyond high‑level trends to outline the specific choices program managers must make when balancing mobility, protection, sustainability, and total cost of ownership (TCO).
- It aligns capability roadmaps with industrial realities. The report reconciles combat requirements with supplier capacity, materials risk and regulatory exceptions that materially affect platform design and sustainment.
- It de‑risks strategic bets. For leaders weighing autonomy, electrification, modular armor, or hybrid propulsion, the analysis provides scenario‑based outcomes tied to supplier capability, cost sensitivity, and operational constraints.
Market trajectory and structural context
Our modeling uses 2025 as the base year and captures historical performance from 2020–2025, with forecasts through 2026–2032. The market’s compound annual growth rate of 5.12% reflects a convergence of sustained defense spending, modernization programs, and an ongoing replacement cycle for legacy fleets. Growth is not uniformly distributed across capability classes or theatres—demand drivers include expeditionary operations, emphasis on protected mobility, and accelerating interest in unmanned and hybrid platforms.
Worldwide Military Off-road Vehicles Market
Concentration metrics point to a market that is competitive but consolidated at the top: the three largest suppliers collectively account for roughly 42% of market value, while the top five capture near 58%. This structure creates both competitive pressure for incumbents to protect program wins and room for specialized entrants to capture niche, higher‑margin segments.
Worldwide Military Off-road Vehicles Market
Recent dynamics that will shape 2026 decisions
- Autonomy and complex terrain navigation: DARPA’s final demonstrations of autonomous breaching and mobility platforms in early 2026 validate technical feasibility and accelerate integration timelines for Infantry Squad Vehicles. Program managers should expect prototype to fielding cycles to compress but must plan for incremental capability insertion and interoperability testing.
- Industry demonstrations and market signaling: OEM demonstrations—such as the light vehicle lineup shown by a leading U.S. contractor in late 2025 and JLTV showcases at major conferences—underscore the priority given to off‑road survivability and payload versatility. These events are as much about industrial positioning as they are about technical maturity.
- Procurement programs integrating autonomy: Recent selections to integrate autonomous mobility into squad vehicles demonstrate that prime contractors and software integrators are moving from R&D partnerships into prototype contracts. This reduces technical risk but raises program management and supplier coordination complexity.
- Regulatory and fuel realities: Military tactical off‑road trucks remain exempt from many civilian on‑road and off‑road emissions regulations. That exemption preserves operational flexibility—allowing use of fuels such as JP‑8 and enabling engine designs optimized for reliability and torque rather than civilian emissions compliance. Procurement planners must weigh this operational advantage against broader sustainability goals and potential future policy shifts.
- Supply‑chain fragility and commodity volatility: Fragility in supply of armor steel and power electronics, coupled with observed steel price volatility that increased armor production costs materially between 2022 and 2023, has created a need for hedging strategies, dual sourcing and longer lead inventories. Programs that ignore these realities risk schedule slippage and cost growth.
Competitive landscape—what leading companies bring to the table
Our competitive analysis profiles established primes and emergent players across capabilities, industrial footprint, and technology trajectories. Key strategic takeaways:
- Oshkosh Defense: A leading supplier in tactical wheeled mobility, with mature products emphasizing independent suspension systems and crew protection. Their JLTV family and MRAP lineage make them a reference design partner for mobility‑focused programs; expect them to continue leveraging proven architectures while incorporating modularity and digital upgrades.
- AM General: The maker of legacy light tactical platforms remains relevant through sustainment and modernization offerings. Their focus on high‑mobility, upgradeable tactical kits positions them as a pragmatic partner for nations managing large HUMVEE fleets or requiring cost‑effective transition paths to newer platforms.
- General Dynamics Land Systems: With experience across armored and wheeled platforms, they combine survivability engineering and systems integration, and are increasingly visible in demonstrators exploring hybrid‑electric drivetrains—an important strategic hedge against fuel logistics risk in expeditionary operations.
- BAE Systems and Rheinmetall AG: European primes bring modular armored architectures and heavy‑wheeled platforms with high off‑road capability. Their export reach and modular design philosophies make them preferred partners where rapid role conversion and protection scaling are required.
- GM Defense, Navistar, Mack Defense, Iveco, Arquus, Tata Motors, Hanwha Defense and others: These players span a spectrum from light tactical innovators to logistics truck specialists. Several are advancing hybrid‑electric demonstrators or forming software partnerships to accelerate autonomy integration.
Recent tactical events reinforce these dynamics: industry showcases and first‑of‑type demonstrations in 2025–2026 show an industry pivot toward rapid delivery pipelines, while multi‑vendor contracts for autonomy integration signal a coming wave of distributed systems work that will favor primes who can coordinate complex supplier ecosystems.
Practical content included in the PW Consulting study
The report is intentionally operational. Rather than generic forecasting, PW delivers tools and frameworks you can apply directly to 2026 decision cycles:
- Program investment checklists that translate capability priorities into procurement language and milestones.
- TCO and sustainment models that incorporate fuel, spares, and mean time between failures (MTBF) sensitivity—designed to stress test trade‑offs between upfront acquisition cost and lifecycle expense.
- Scenario playbooks for autonomy and electrification adoption, from incremental autonomy kits to platform‑level hybridization, with recommended verification steps and partner archetypes.
- Supplier benchmarking and sourcing heat maps that combine capability, production capacity, geographic risk and previous program performance to identify optimal prime‑sub partner configurations.
- Supply‑chain resilience prescriptions: dual‑sourcing strategies, inventory positioning, contractual levers (e.g., cost‑sharing mechanisms for commodity spikes), and a roadmap for near‑term materials substitution where feasible.
- M&A and JV playbook for entrants and incumbents aiming to scale quickly—covering valuation sensitivities, integration priorities and prioritized capabilities (autonomy stack, power electronics, modular armor systems).
- Executive dashboards and procurement decision templates tailored for program offices, industrial policy units, and defense investors.
Strategic recommendations for 2026 action
- Prioritize modular architectures. Design choices that isolate autonomy, protection, and propulsion subsystems reduce obsolescence risk and make mid‑life upgrades tractable.
- Hedge material risk now. Locking down armor steel and critical power‑electronics suppliers with multi‑year agreements or capacity‑sharing arrangements will materially reduce schedule risk.
- Plan autonomy in layers. Treat autonomy as iterative capability insertions—start with driver‑assist and supervised autonomy on deployed fleets before committing to fully autonomous mission profiles.
- Balance propulsion decisions with operational constraints. Use the existing regulatory exemptions strategically—but model migration paths toward lower operational footprints as logistics concepts of operation evolve.
- Leverage supplier ecosystems. Winning programs will be those that can orchestrate software integrators, component specialists and systems integrators under clear interoperability and verification standards.
How to use this report
For program managers, the study is a briefing book for initial procurement scoping, risk budgeting and supplier selection. For OEMs and tier‑one suppliers, it provides a competitive intelligence toolkit and M&A playbook. For investors, the report highlights addressable markets, concentration dynamics and the capability adjacencies likely to generate outsized returns.
Next steps
PW Consulting’s market study combines quantitative forecasting, supplier benchmarking, scenario planning and practical templates designed to be actionable in 2026. The executive summary here highlights the strategic contours; the full report contains the granular segmentation, supplier matrices, and model outputs that operational teams will need to implement the recommendations. To access the complete dataset, proprietary models and supplier scorecards, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Military Off-road Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Deicing Salt Market to Reach USD 3,446.75 Million by 2032, Growing at a 3.55% CAGR (2026–2032)
By PW Consulting, 2026-08-05
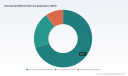
Worldwide Deicing Salt Market: Strategic Imperatives for 2026 — Executive Release
Why this report matters to 2026 decision-makers
As the 2025 base year closes and organizations across supply chains prepare 2026 budgets, PW Consulting’s Worldwide Deicing Salt Market study offers the decisive, action-oriented intelligence procurement, operations, and corporate development teams need. The deicing salt market has demonstrated steady expansion through the first half of the decade — rising from approximately USD 2,267.9 million in 2020 to USD 2,700.0 million in 2025 — and our forecast expects continued growth to roughly USD 3,446.8 million by 2032 at a compound annual growth rate (CAGR) of about 3.55%. These macro trajectories, layered with cost drivers, regulatory inflection points, and supplier-level moves, create a narrow window in 2026 for value-preserving investments and defensive planning.
Worldwide Deicing Salt Market
Top-line takeaways
- Market resilience, measured opportunity: The market’s steady CAGR signals reliable baseline demand tied to infrastructure maintenance and winter logistics, but growth is uneven, driven by shifts in treatment technologies, environmental constraints, and raw-material cost cycles.
- Costs and margins under pressure: Energy and underground mining cost increases, combined with packaging and logistics headwinds, are compressing supplier margins and will influence contract pricing and inventory strategies in 2026.
- Regulation reshapes product mixes: Accelerating environmental standards and public-sector procurement preferences are moving buyers toward treated salts and lower-chloride alternatives — creating opportunities for differentiated formulations and services.
- Consolidation isn’t yet mature: Market concentration remains modest; global leaders control material shares, but the sector’s fragmentation leaves room for bolt-on M&A and regional scale plays.
How PW Consulting’s insights translate into 2026 actions
Organizations that translate market data into tactical moves will fare better next winter. Below are pragmatic actions, each anchored to evidence and near-term levers:
Worldwide Deicing Salt Market
- Lock selective capacity now, hedge the rest: With mining energy costs and evaporation facility input prices elevated, we recommend a hybrid sourcing posture for 2026 — long-term contracts with tier-one producers for core volumes, complemented by shorter-term spot coverage to arbitrage seasonal price dips. Our model quantifies the relative payoff of various contract tenors under multiple energy-price scenarios (detailed in the report).
- Invest in low-corrosion treated blends where procurement rules allow: Regulatory guidance and public-works procurement are increasingly favoring chloride-reducing or corrosion-inhibited products. Buyers can justify premium pricing via total-cost-of-ownership (TCO) savings — lower infrastructure corrosion, reduced vehicle maintenance, and longer pavement life. Our scenario analysis demonstrates break-evens across typical municipal asset portfolios.
- Reassess packaging and logistics cost pools: Tariff actions and container steel-cost inflation have lifted packaging costs in recent cycles. Re-evaluate pack-size economics, inventory-location strategies, and cross-border sourcing to reduce landed cost in 2026 planning.
- Prioritize supplier sustainability credentials for public contracts: Sustainability certifications and operational ESG performance are increasingly procurement filters. Suppliers with updated environmental certifications or demonstrable low-emission evaporation operations win preferred access to infrastructure tenders.
- Plan contingent capacity expansions selectively: For producers considering growth capex, the calculus for 2026 should be guided by local energy-cost forecasts and long-term service agreements rather than short-term spot tightness. Our capital-allocation framework maps payback under varying demand and price trajectories.
Report content — practical, decision-ready modules
PW Consulting’s report is structured for immediate operationalization by executive teams. Highlights include:
Worldwide Deicing Salt Market
- Macro demand models that reconcile historical seasonality with infrastructure spending scenarios and climate-variability adjustments.
- Supplier cost stacks that disaggregate mining, evaporation, treatment, and packaging inputs — enabling margin and price-sensitivity analysis.
- Regulatory impact matrices that quantify the procurement and compliance implications of low-chloride directives and environmental thresholds.
- Commercial playbooks for buyers and sellers — contract templates, hedge approaches, and logistics optimization checklists to drive savings in 2026.
- Sector-focused M&A screening tools and valuation ranges for bolt-ons and capacity acquisitions, informed by recent strategic moves and available mining footprints.
To preserve the strategic value of this work, detailed segmentation matrices (by region, formulation, and application) and confidential company-by-company financial estimates are reserved for the full report and subscription clients.
Competitive landscape — what leaders are doing now
The deicing salt marketplace features several established multinationals alongside strong regional operators. Competitive dynamics are shaped by resource footprint, logistics reach, product treatment capabilities, and increasingly, environmental credentials.
- Cargill, Incorporated — A vertically integrated global presence with mines and evaporation facilities across multiple continents. Recent capacity expansions reflect a strategy to secure core volume supply and service key road- and airport-maintenance contracts.
- Morton Salt, Inc. — A North American stalwart with deep underground mining assets and a broad packaged and bulk offering. Their product portfolio and distribution network make them a primary counterparty for large municipal and state contracts.
- K+S Aktiengesellschaft — A European anchor supplier whose certification upgrades and export reach reinforce its position in continental tenders and cross-border logistics corridors.
- Compass Minerals International, Inc. — Operates large-capacity mines and has been active on product innovation, launching treated salts focused on corrosion inhibition to meet infrastructure buyer needs.
- CNSIC (China National Salt Industry Corporation) — A state-backed producer with massive coastal capacity that serves domestic demand and selectively exports to neighboring regions.
- Ineos Enterprises, Cheetham Salt, Sudsalz — Regional specialists that leverage geographic proximity to critical highways and port access to service localized demand and niche applications.
Recent public company moves underscore strategic themes: capacity expansions targeted at high-demand corridors, product launches that emphasize reduced environmental impact, and sustainability certification upgrades that unlock procurement opportunities.
Market dynamics and risk factors to watch in 2026
- Raw-material and energy cost volatility: Underground mining cost inflation and variable natural-gas prices for evaporation facilities alter cost curves quickly. Historical data show material upticks in mining operating costs; in 2026, dynamic energy scenarios must be run against long-term contracts.
- Environmental regulation and procurement shifts: Directives and agency recommendations favoring low-chloride options or magnesium chloride blends will change demand composition in sensitive watersheds and densely populated regions. Firms without product alternatives risk loss of municipal business.
- Trade and tariff noise: Packaging and shipping tariffs can materially change landed costs across borders, making supply-chain flexibility and nearshoring considerations strategic priorities.
- Public-sector budget cycles: Infrastructure spending and winter-maintenance allocations determine seasonality intensity; monitoring municipal procurement calendars provides early signals for demand spikes.
- Technological substitution risk: Adoption of alternative deicing approaches (e.g., brine pre-treatment, mechanical clearing enhancements) can dampen traditional bulk-salt volumes in targeted use cases.
Implications for buyers, producers, and investors
For buyers (municipalities, contractors, large facility operators): prioritize procurement mechanisms that lock price certainty for core volumes while preserving flexibility for treated or low-chloride products. For producers: accelerate product-treatment investments and sustainability certifications to capture premium tenders and defend margins. For private-equity and strategic investors: look for regional consolidation plays and asset-light service models that exploit distribution inefficiencies.
Why PW Consulting’s 2026 edition is different
Our 2025-base study combines granular cost-stack analysis with procurement-ready tools. We translate a predictable overall growth path — from the USD 2.27 billion range in 2020 to USD 2.70 billion in 2025, and a forecast reaching roughly USD 3.45 billion by 2032 at a 3.55% CAGR — into executable actions for 2026. We intentionally present high-confidence scenarios and reserve the sensitive segmentation tables and company-level financials for the full product so that subscribers obtain exclusive, monetizable insight.
Next steps and how to access the full intelligence
For procurement directors, supply-chain heads, and corporate strategists preparing 2026 plans, the full report provides the needed operating models, contract templates, and supplier scorecards. Visit the PW Consulting market page to download an executive summary, review subscription options, or engage with our advisory team for a tailored briefing that maps the report’s scenarios to your specific portfolio.
Closing perspective
2026 will be a year where operational discipline and nimble procurement determine winner and laggard outcomes in the deicing salt value chain. The core demand base is stable, but cost structures, regulatory preferences, and supplier moves will reallocate value. PW Consulting’s Worldwide Deicing Salt Market study equips decision-makers with the frameworks to protect margins, seize premium product opportunities, and time capacity or M&A plays — without exposing the contested segmentation intelligence that gives paying clients a competitive edge.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Alternate Light Sources Market to Rise from USD 470.83M in 2025 to USD 694.05M by 2032 at a 5.72% CAGR; LEDs, Forensic Applications and North America Drive Growth
By PW Consulting, 2026-08-05
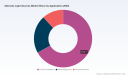
Worldwide Alternate Light Sources Market: Strategic Imperatives for Corporate Decision-Making in 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present an executive preview of our latest market research: the Worldwide Alternate Light Sources (ALS) Market report. This briefing synthesizes the strategic findings that matter most to procurement leaders, R&D heads, M&A teams, and public safety policymakers as they set priorities for 2026. The full report offers the granular data and decision-support toolkits professionals need; what follows is a high-value “trailer” — deep on insight, light on proprietary segmentation — designed to orient action and provoke the right questions for your 2026 planning cycle.
Worldwide Alternate Light Sources Market
Why ALS matters now: market momentum and strategic context
Alternate light sources have moved beyond a niche forensic tool to become a multi-domain enabling technology. In 2025 the ALS market reached a material scale (reported in USD Million terms in our base-year analysis), and the market is on a sustained growth trajectory with a compound annual growth rate (CAGR) of approximately 5.72% across the forecast horizon. This pace reflects a convergence of forces: modernization of forensic and clinical workflows, growing adoption of LED and laser technologies, and public-sector procurement driven by standardized equipment lists and evolving safety/regulatory expectations.
Worldwide Alternate Light Sources Market
For corporations, governments, and system integrators, the strategic implication is clear: ALS technology is now a recurring line-item in budgeting for crime labs, emergency response units, and inspection teams, and it should be treated as part of broader digital-physical infrastructure investments rather than a one-off forensic purchase.
Worldwide Alternate Light Sources Market
What the report delivers — practical chapters that influence 2026 choices
-
Market sizing & forecast framework: A transparent, audit-ready model covering historical performance (2020–2025) and forward-looking scenarios for 2026–2032. The model is built to be interactive so your team can stress-test assumptions on adoption curves, technology substitution, and procurement cycles.
-
Vendor landscape and competitive positioning: A repeatable framework for assessing vendors across product breadth, channel coverage, service capability, and compliance readiness — enabling vendor consolidation or diversification strategies with measurable KPIs.
-
Technology differentiation matrix: Comparative analysis of LED, xenon, and laser-based ALS platforms — focusing on operational characteristics (power, wavelength flexibility, battery life, ergonomics) and downstream impacts on evidence-processing throughput and lab safety regimes.
-
Procurement playbooks and TCO modelling: Decision trees and total-cost-of-ownership templates that capture acquisition, consumables, training, certification, and maintenance — tailored to public agencies and private-sector inspection services.
-
Regulatory and standards navigator: Practical guidance on meeting NIST definitions, using equipment listed on authorized equipment lists, and embedding SWGDE-aligned practices in SOPs to reduce litigation and compliance risk.
-
Scenario planning and investment cases: Three investment archetypes (Consolidator, Niche Innovator, and Service-Led Integrator) with quantified ROI windows and sensitivity analyses for 12–36 month horizons.
-
Supplier risk and resilience assessment: Supply chain heatmaps, key component scarcity indicators, and mitigation tactics for firms reliant on critical optical components and semiconductor LEDs.
Competitive landscape: what to watch among established and emerging suppliers
The ALS space is characterized by a moderate level of concentration, with leading vendors collectively commanding a material share of market revenue. This concentration creates both competitive stability and strategic tension — scale enables investments in R&D, certification, and global distribution, while niche players continue to capture specialized use cases through rapid iteration.
-
Foster + Freeman (United Kingdom): A technology leader that has successfully translated high-intensity LED and multi-spectral capability into products tailored for both field investigators and forensic laboratories. Its recent product initiatives emphasize multi-wavelength consolidation in single units, a strategic response to buyer demand for tool rationalization and lab throughput gains.
-
Labino AB (Vallentuna, Sweden): Known for rugged, waterproof LED kits optimized for crime scene deployment. Labino’s product-folder refresh and kit-level focus underscore a channel strategy aimed at law enforcement procurement pools and OEM partnerships for bundled offerings.
-
Sirchie (United States): Anchored in law enforcement channels, Sirchie’s portfolio targets hands-on tactical requirements, including shortwave UV options. Its positioning reflects strength in training, consumables, and bundled solution sales — important for agencies that require vendor-supported operational readiness.
-
HORIBA Scientific / SPEX Forensics (United States): Bringing laboratory-grade instrumentation and documentation-focused ALS platforms to market, this vendor’s value proposition aligns with labs that prioritize imaging fidelity and integration with analytical chains.
-
FoxFury (United States): Focused on rugged, cordless solutions, FoxFury targets forensic and emergency-response teams that prioritize mobility and durability. The company’s product families play well into rapid-response procurement and multi-environment deployments.
-
Lynn Peavey Company and UltraLite ALS (United States): These suppliers occupy critical distribution and portable-device niches, servicing agencies that prioritize cost-effective, deployable solutions, and deep channel relationships in North America.
These vendors exemplify the strategic options available to buyers: purchase from scale-oriented incumbents for lifecycle support and certification, or partner with specialized providers to capture narrow operational advantages. Our vendor scorecards — included in the full report — unpack the trade-offs in a procurement-ready format.
Regulatory and standards dynamics shaping procurement
Regulation and standardization are now active forces in ALS adoption. NIST’s definitional work, departmental equipment lists that identify ALS kits as authorized equipment for certain types of crime-scene operations, and procedural guidance from SWGDE collectively raise the bar for vendor compliance and buyer documentation. For procurement teams this means three immediate actions:
-
Require evidence of standards alignment (e.g., NIST and SWGDE best practices) in RFPs and technical specifications;
-
Embed safety and training deliverables into contracts to mitigate liability from hazardous-spectrum sources, such as shortwave UV; and
-
Prioritize vendors that provide traceable calibration and chain-of-custody support to reduce downstream forensic challenge risk.
Operational trends and implications for buyers
Several operational shifts dictate procurement strategy in 2026:
-
Consolidation of tools: Buyers are seeking multi-wavelength, multifunction devices to reduce kit complexity and training overhead.
-
Field-to-lab continuity: Demand for ALS platforms that integrate with digital evidence management and imaging workflows is rising, making API-enabled devices and standardized imaging outputs a competitive differentiator.
-
Service and lifecycle economics: Extended warranties, on-site calibration, and training-as-a-service are becoming determinants in buying decisions, not just price.
Strategic recommendations for 2026 planning
-
Adopt a portfolio approach to ALS procurement: balance high-grade lab instruments with rugged field kits and standardized consumables to optimize throughput and reduce rework.
-
Insist on standards and traceability: make SWGDE-compliant photography protocols and NIST-aligned definitions contractual deliverables.
-
Prioritize vendors with service ecosystems: choose partners that offer training, calibration, and lifecycle management to reduce total cost of ownership and forensic risk.
-
Use scenario-based budgeting: apply the report’s stress-tested forecast model to quantify the financial impact of faster-than-expected adoption or supply-side constraints on your capital plan for 2026.
How PW Consulting’s report converts insight into action
This report was developed to move beyond descriptive market commentary into prescriptive action. It contains ready-to-use procurement templates, vendor selection scorecards, and financial models that your team can deploy in RFPs and board-level investment memos. We also provide a configurable sensitivity model to help you evaluate the impact of alternative adoption rates and procurement consolidation scenarios on departmental budgets and fiscal-year planning.
We intentionally preserve certain core segmentation tables and product-level metrics for the full report — consistent with our “trailer” strategy of demonstrating analytical rigor while guiding readers to the source for the complete dataset and downloadable tools. Those who require the complete geographic and application-level splits, product-level pricing distributions, and vendor-level revenue estimates will find the granular intelligence in the full report package.
Next steps
For procurement leads, R&D managers, and public-sector program officers preparing budgets and tactical plans for 2026, the path forward is straightforward: integrate ALS strategy into your broader evidence-management and inspection procurement roadmap, require standards compliance in sourcing, and use lifecycle economics rather than headline prices to make durable decisions.
To access the full dataset, segmentation matrices, vendor scorecards, and customizable financial models, please visit the official report page. The full report provides the detailed, auditable inputs needed to execute supplier consolidation, launch pilot programs, or make acquisition decisions with confidence.
PW Consulting remains available for tailored briefings, scenario workshops, and procurement support to help organizations turn the ALS market’s growth into measurable operational and strategic advantage in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Electricity Trading Platform Market Set to Hit USD 3,181.25 Million by 2032, Expanding at a 13.12% CAGR
By PW Consulting, 2026-08-05
Worldwide Electricity Trading Platform Market — Strategic Preview for 2026 Decision-Makers
As energy systems accelerate toward higher renewables penetration, real‑time dispatch, and new large‑load behaviors (notably data centers), electricity trading platforms are evolving from niche execution venues into mission‑critical market infrastructure. PW Consulting’s forthcoming market study — anchored on a 2025 base year and a rich 2020–2025 historical dataset with forecasts through 2032 — synthesizes quantitative growth drivers and the practical playbooks executives need to act in 2026. The headline: the global electricity trading platform market is on a sustained double‑digit trajectory, with the study modeling a compound annual growth rate of 13.12% and the market more than doubling over the forecast horizon (values expressed in USD Million).
Worldwide Electricity Trading Platform Market
Market Snapshot: Momentum and What It Means for 2026
Our consolidated market model shows a clear inflection point between the historical period and the forecast: substantial year‑on‑year expansion through 2025 supports a confident projection into the 2026–2032 window. This growth is driven by: (1) regulatory reforms that accelerate short‑term market granularity and balancing products; (2) enterprise demand for sophisticated hedging and procurement — especially among hyperscale data centers and industrial large loads; and (3) technology shifts toward cloud‑native execution, real‑time analytics and distributed ledger experiments for peer‑to‑peer settlements.
Worldwide Electricity Trading Platform Market
For corporate strategy teams, the implication is straightforward: platform capability is no longer “nice to have.” By 2026, firms that lack integrated trading, dispatch coordination, and clearing‑grade risk controls will face materially higher procurement and operational exposure. The market sizing and trend analysis in our report quantify that exposure in financial terms and provide scenario models that connect market outcomes to business P&L sensitivities.
Worldwide Electricity Trading Platform Market
Why This Report Is Practically Valuable — What’s Inside
- Actionable Forecasting Engine: A calibrated, transparent forecasting model (base year 2025) that supports bespoke scenario runs — including high renewables, accelerated data‑center procurement, and slower regulatory harmonization.
- Vendor Strategy Playbook: A decision framework for build vs buy vs partner, mapped to procurement size, regulatory footprint, and operational maturity. Includes go‑to‑market pathways for incumbent exchanges, software vendors, and new P2P entrants.
- Implementation Roadmaps: Step‑by‑step migration roadmaps for platform modernization—covering integration with SCADA/EMS, back‑office settlement, margining changes, and cloud transition checkpoints.
- Risk & Compliance Toolkit: Practical templates for margining, collateral management, and compliance checks aligned to evolving rulesets (short‑term market units, imbalance settlement reforms, and capacity allocation approaches).
- Commercial Benchmarking: Pricing and contract archetypes for SaaS subscriptions, transaction fees, and custom implementation services; plus negotiation levers tailored by buyer archetype (exchanges, retailers, large loads, IPPs).
- Vendor Scorecards: Qualitative and operational assessments across technology, liquidity access, product breadth, and compliance readiness for the main global and regional players.
Competitive Landscape: Who Matters and How They’re Moving
The electricity trading platform space uniquely combines exchange operators, technology vendors, and new decentralized entrants. Our analysis profiles the key participants whose strategic moves will shape 2026 market dynamics:
- EEX Group and EPEX SPOT: European exchange operators remain focal points for institutional liquidity. Recent volume upticks and investments in margining systems reflect a push to industrialize short‑term and derivatives flows.
- ICE, CME Group, Nasdaq and Deutsche Börse / Euronext: Large capital market operators are expanding electricity product sets and analytics to capture institutional hedging demand and cross‑commodity integrations.
- Regional challengers (e.g., IEX, PXIL, Axpo): These players combine market access and local regulatory expertise to serve rapid-growth emerging markets and complex retail procurement segments.
- Technology vendors (OpenLink/ION, Trading Technologies, Trayport, Beacon, Wipro): These firms enable end‑to‑end trading and risk management systems, often serving both exchanges and corporate trading desks.
- Decentralized and P2P innovators (Power Ledger, Piclo, niche regional platforms): They are experimenting with bilateral settlement, local flexibility markets, and renewable PPA facilitation — forcing incumbents to respond on UX and settlement efficiency.
- Regional specialists (e.g., Plataforma Energía): Focused players are capitalizing on niche opportunities such as data center procurement, non‑regulated consumer-supplier matching and new commercial products.
From a competitive posture perspective, the market displays meaningful fragmentation at the vendor level while liquidity and clearing capabilities concentrate around a subset of established exchanges and large platform providers. That structural balance creates differentiated entry vectors: technology providers can scale globally; exchanges compete on liquidity and clearing; and P2P vendors fight for local DER and renewable PPA niches.
Regulatory and Market Dynamics Shaping 2026 Priorities
Executives must plan for a regulatory landscape that is actively reshaping short‑term markets and the cost of serving large loads. Notable shifts we embed into our scenarios:
- Market time‑unit reforms: The move to finer market time units and modified imbalance pricing in multiple jurisdictions changes intraday liquidity patterns and requires platform latency and order‑matching redesigns.
- Capacity and reliability frameworks: New procedures for allocating transmission and capacity upgrade costs to large co‑located loads (e.g., data centers) alter procurement economics and incentivize active hedging strategies.
- Price and availability shocks: Wholesale price spikes in certain data‑center hotspots have materially increased procurement costs and accelerated interest in direct procurement platforms and virtual PPAs.
We translate these dynamics into practical enterprise actions: re‑run supply‑cost curves under alternate market rule sets, stress test bilateral contracts for allocation risk, and build contingency timelines for tariff and network upgrade pass‑throughs.
Recent Developments: Signals You Can Act On Now
- Exchange liquidity is still expanding: A major European exchange reported a notable increase in power derivatives volumes in 2025 and is prioritizing new margining systems in 2026 — a sign that institutional activity is intensifying and that counterparty and clearing capabilities will be competitive differentiators.
- Market rule evolution is accelerating: Transition to more granular market time units and related imbalance reforms are already implemented in select markets, requiring platform upgrades and operational playbooks for intraday optimization.
- Data center procurement is strategic: Regional platforms are publicly outlining strategies to serve large, non‑regulated consumers (data centers), creating new bilateral matching and tariff design products that change demand profiles for trading venues.
Strategic Recommendations for 2026
- Prioritize interoperability and margining readiness: Ensure your chosen platform supports evolving margining and clearing models; where possible, phase integration to avoid single‑point upgrade risks.
- Adopt a modular procurement approach: Combine a core trading engine with specialist modules for renewables PPAs, P2P settlement, and market dispatch — this reduces time to market and preserves optionality.
- Define clear data‑center procurement strategies: For companies exposed to large co‑located loads, treat power procurement as a core operational risk and use market tools (capacity auctions, hedges, day‑ahead/intraday coordination) to mitigate price and allocation volatility.
- Use scenario stress tests tied to regulatory outcomes: Operational readiness should be validated against at least three regulatory scenarios (default, accelerated reform, and local protectionist treatments) to measure capital and operating impacts.
- Monitor boutique and decentralized entrants: They will continue to pilot P2P and blockchain settlement models that can be partnered with or white‑labeled for corporate procurement experiments.
How PW Consulting’s Report Helps You Execute
This study is designed to be a practical toolkit for 2026 execution: beyond headline market sizing (anchored to 2025 and projected through 2032), the deliverables include downloadable models, vendor negotiation playbooks, technical integration checklists, and regulatory impact simulations. We deliberately balance strategic narrative with executable artifacts so corporate and exchange leaders can move from insight to action within a quarter.
Note: this preview intentionally highlights the report’s depth and operational value while reserving certain proprietary segment‑level allocations and nuanced vendor scoring details for the full publication. Those core segment datasets and granular vendor benchmark tables are available through the official report page and are essential for transaction‑grade decision making.
Next Steps
- Executive teams: request a tailored briefing to map our models to your procurement portfolio and regulatory footprint.
- Platform vendors and exchanges: explore a comparative vendor assessment or join a focused workshop on margining and settlement modernization.
- Investors and M&A teams: commission a rapid diligence package that applies our forecast scenarios to target valuation and integration risk.
For the full dataset, downloadable forecast models, and the complete vendor scorecards that support transaction and procurement decisions, visit the PW Consulting report page to access the comprehensive Worldwide Electricity Trading Platform Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Electricity Trading Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Barrel Compressor Market Hits USD 5,420 Million in 2025, Poised to Grow at 4.69% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Barrel Compressor Market — 2026 Strategic Outlook
PW Consulting’s new market study on the Worldwide Barrel Compressor Market is released to support senior executives making capital, procurement, and technology decisions in 2026. The report synthesizes historical performance, near-term market dynamics, vendor strategy, and actionable execution playbooks into a single, decision-ready package. It is deliberately structured as a practical “operating manual” for teams that must commit project budgets, negotiate long-cycle equipment contracts, or pivot service strategies to capture growth in low-carbon and high-pressure process markets.
Worldwide Barrel Compressor Market
Market snapshot: growth, trajectory, and what it means for decisions in 2026
After a steady recovery in the first half of the decade, the barrel compressor market reached an estimated USD 5,420 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 4.69% over the 2026–2032 period. Under the baseline scenario in our study, global market revenues advance into the USD 7.4–7.5 billion range by 2032, reflecting sustained demand from high-pressure hydrocarbon processing, expanding carbon capture infrastructure, and emergent hydrogen handling projects.
Worldwide Barrel Compressor Market
For executives the headline matters because it reframes investment timing: the market is growing at a pace that rewards early positioning for large-scale decarbonization projects, but it is not hyper‑cyclical. That combination favors strategic partnerships, long-term service agreements, and staged CapEx deployment tied to firm project milestones rather than speculative fleet expansion.
Worldwide Barrel Compressor Market
Why 2026 is an inflection year
- Energy transition projects moving from FEED to execution. Several CCS and hydrogen initiatives are entering contract and procurement phases, creating immediate demand for high‑pressure, corrosion‑resistant barrel compressor skids.
- Regulatory and technical standard evolution. API 617 remains the primary guideline for centrifugal and barrel compressors; ongoing updates and the prospect of a Ninth Edition are influencing specification language in tenders and risk allocation clauses.
- Supply chain pressure points. Manufacturing is dependent on specialized steels and alloys. Price volatility and extended lead times for these inputs are already affecting delivery schedules and warranty negotiations.
- Vendor consolidation and capability expansion. Recent contract awards and strategic acquisitions highlight a movement toward vertically integrated service models where supply, aftermarket service, and digital lifecycle tools are bundled.
What our report delivers — practical, transaction‑ready content
This study is designed for immediate operational use. It goes beyond descriptive market commentary to provide tools that procurement, engineering, and corporate strategy teams can apply in 2026:
- Fast‑track procurement playbook: recommended contract structures (fixed price vs. reimbursable), preferred warranty language, lead‑time buffers tied to alloy procurement cycles, and a negotiation checklist for performance guarantees.
- CapEx / TCO modeling templates: configurable calculators that translate quoted equipment costs into lifecycle cost outcomes (CapEx, operating fuel/power implications, maintenance intervals, spare parts inventory and NPV of service agreements).
- Scenario-based demand models: three scenario runs (baseline, accelerated decarbonization, and delayed projects) that stress-test fleet requirements and spare‑parts inventory for 2026–2028 procurement windows.
- Vendor diligence pack: standardized vendor scorecards, RFP evaluation matrices, and sample FAT (Factory Acceptance Test) protocols tailored to barrel-type centrifugal compressors.
- Supply chain risk maps: line‑by‑line component risk assessments (casings, impellers, bearings, seals), alternate supplier lists, and suggested dual-sourcing approaches for critical alloys.
- Service and MRO playbook: recommended SLAs, remote monitoring KPIs, parts consignment strategies, and retrofit upgrade paths for efficiency and emissions monitoring.
- Regulatory compliance checklist: template clauses to capture API standard changes, CO2/hydrogen handling considerations, and documentation required for project financiers and insurers.
- Investment and M&A screens: shortlists and financial filters to identify attractive service players, rotating equipment specialists, and digital firms suitable for bolt-on acquisitions or JV partnerships.
Competitive landscape — who is shaping the next contract cycle
The barrel compressor market combines long‑cycle OEM engineering with an expanding aftermarket opportunity. Established turbomachinery manufacturers and specialist integrators remain the primary suppliers; the competitive set is characterized by strong engineering IP, global project execution footprints, and growing aftermarket/service capabilities.
- MAN Energy Solutions (Everllence) (Germany, https://www.man-es.com/) — deep experience with vertically split RB barrel compressors and an emphasis on modular packaged solutions and rebundling for offshore and CCS projects. Recent offshore CCS contract wins illustrate the OEM’s ability to convert engineering depth into project awards.
- Baker Hughes (United States, https://www.bakerhughes.com/) — known for BCL barrel designs and integrated compressor packages for high-pressure CO2 and corrosive services; active on FPSO and floating projects where modularity and integration with electrical systems matter.
- Siemens Energy (Germany, https://www.siemens-energy.com/) — single‑shaft vertically split designs with capability up to very high pressures; strong systems integration for process industries.
- Hitachi Industrial Products (Japan, https://www.hitachi-ip.com/) — high installed base across refinery and pipeline services; extensive global delivery experience.
- Mitsubishi Heavy Industries Compressor Corporation (MCO) (Japan, https://www.mhi.com/group/mco/) — broad centrifugal portfolio and a recent acquisition to strengthen maintenance and service capabilities.
- Kobelco / Kobe Steel Group , Atlas Copco Gas and Process , ShenGu Group , and Elliott Group — each brings regional strengths, niche technical capability, or scale in aftermarket parts and services that are meaningful to project developers and operators.
Recent market developments underscore these dynamics. For example, an RB barrel-type award for an offshore CCS project confirmed OEMs’ ability to address large, ocean‑located capture facilities; a strategic acquisition strengthened compressor maintenance capacity for an OEM seeking to lock-in aftermarket revenue; and major FPSO project wins demonstrate continued demand for integrated compressor solutions on complex offshore assets. These are not isolated events — they point to a broader trend toward service-lined, project-capable OEMs.
Execution risks and mitigation priorities
- Raw material and lead-time risk: specialized alloys drive delivery uncertainty. Mitigation: early material procurement, long‑lead purchase options, and indexed pricing clauses where justified.
- Specification drift and standards evolution: changing API language can lead to rework. Mitigation: lock technical baselines at FEED stage and include change‑order frameworks.
- Integration and testing complexity: barrel compressors are often integrated into larger process trains with stringent FAT requirements. Mitigation: staged FAT, independent third‑party witnessing, and local commissioning hubs.
- Aftermarket capacity constraints: installing new units is only part of lifecycle cost. Mitigation: secure long‑term service agreements with spares consignment and digital monitoring to pre‑empt outages.
Strategic implications for executives in 2026
For buyers, OEMs, and service providers, the following actions are recommended to convert market trends into defensible outcomes this year:
- Prioritize early supplier engagement for CCS/hydrogen projects: secure option‑to‑buy slots and negotiate material lead‑time protections.
- Adopt a staged procurement strategy: split major procurements into engineering‑deliverable milestones to reduce repricing risk from material volatility.
- Embed lifecycle KPIs into all supplier contracts: move cost conversations from CapEx to total cost of ownership (TCO) with clear measurement windows (3–7 years).
- Evaluate M&A and JV opportunities focused on aftermarket services and digital lifecycle tools to capture post‑installation revenue.
- Require supplier digital readiness: include minimum remote monitoring, anomaly detection, and spare parts analytics in technical specifications.
- Stress-test project schedules for standards changes: ensure FEED documentation anticipates forthcoming API revisions and that contractual change mechanisms are robust.
How PW Consulting supports 2026 decision cycles
PW Consulting’s full report delivers the datasets, interactive models, and vendor scorecards you need to move from strategy to execution. The report shares comprehensive historical time series, forecast models, supplier profiles, and a library of RFP and FAT templates. In line with our “trailer” approach, this public summary surfaces the strategic takeaways and tools that clarify risks and opportunities — while the full report contains the core region/application splits, company market shares, and downloadable spreadsheets that firms rely on for bid preparation and board-level decisions.
If you are preparing CapEx approvals, negotiating service arrangements, or evaluating acquisition targets in 2026, PW Consulting’s barrel compressor market package will save valuable calendar time and reduce execution risk. Visit PW Consulting’s research portal to access the full dataset, the interactive forecast model, and bespoke advisory engagements tailored to your operating footprint.
For detailed analysis of this topic, please visit the official page: Worldwide Barrel Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide DC Power Supplies & Electronic Power Loads Market at USD 3,845.5M in 2025, Poised for 6.42% CAGR to USD 5,944.5M by 2032 — Asia Pacific Leads (USD 1,677.6M), Programmable Supplies Top Segment (USD 1,909.3M)
By PW Consulting, 2026-08-05
Worldwide DC Power Supplies and Electronic Power Loads Market — Strategic Outlook for 2026
As companies navigate the accelerated electrification of industry and the rapid evolution of test-and-measurement needs, PW Consulting’s new market study on Worldwide DC Power Supplies and Electronic Power Loads offers a focused, decision-grade vantage point for 2026. Our analysis synthesizes market trajectory, competitive positioning, supply‑chain risk, and actionable playbooks — intentionally revealing strategic direction while preserving the granular segment tables and proprietary forecasts that drive high‑value transaction and product decisions. This release functions as a trailer: deep enough to inform boardroom choices, concise enough to motivate acquisition of the full dataset and tailored advisory engagement.
Worldwide DC Power Supplies and Electronic Power Loads Market
Macro snapshot: why 2026 is a pivotal planning year
Using 2025 as the base year, PW Consulting’s model shows the global market reaching approximately USD 3.85 billion (revenue unit: Million) in 2025 with a steady compound annual growth rate (CAGR) of 6.42% across our 2026–2032 forecast window. Under our central scenario, the industry expands toward roughly USD 5.94 billion by 2032. Those topline dynamics underscore three planning imperatives for 2026: (1) validate capacity investments against multi‑year demand curves, (2) align product roadmaps to emerging power‑electronics topologies, and (3) stress‑test procurement strategies against concentrated component risk.
Worldwide DC Power Supplies and Electronic Power Loads Market
Primary forces reshaping the market
-
End‑market acceleration and technical requirements: Electrification in transportation, higher power density demands in data centers, and stringent validation needs in semiconductor and ICT manufacturing are driving complexity in both DC power supplies and electronic loads. Customers increasingly demand not only power and precision but also higher efficiency, compactness, and bidirectional capabilities.
Worldwide DC Power Supplies and Electronic Power Loads Market -
Component and raw‑material volatility: Early‑2026 shocks — including notable price rises in tantalum capacitors and MLCCs and upstream price increases for power MOSFETs and IGBTs — are elevating BOM risk and lengthening lead times. These pressures make cost pass‑through, design flexibility, and multi‑sourcing essential elements of profitable roadmaps.
-
Geopolitical and regulatory friction: Export controls on critical materials and government actions addressing mineral import dependencies have injected new uncertainty into global supply chains. For equipment makers, this translates into strategic choices about geographic diversification, in‑region assembly, and deeper supplier integration.
-
Technology transitions: SiC and GaN adoption is changing design boundaries for converters and supplies, especially where efficiency and thermal density enable competitive advantage. Regenerative and bidirectional electronic loads are rising in importance as battery and EV testing demands proliferate.
Competitive landscape — structure, leaders, and strategic gaps
The market remains moderately consolidated: our concentration metrics show a three‑firm aggregate market share and a five‑firm aggregate share that indicate a mix of global leaders and specialized niche players. That structure produces distinct strategic implications: scale matters for high‑power and customized projects, while agility and technology leadership win in fast‑moving subsegments.
-
TDK‑Lambda (TDK Corporation) — Strong in both programmable and standard DC supplies across industrial and semiconductor sectors; advantages come from breadth of portfolio and high‑density power conversion capabilities.
-
Keysight Technologies — A precision test‑equipment leader, with deep credibility in R&D and production environments for power device testing, battery simulation, and validation tasks. Their systems‑level approach is a template for premium positioning.
-
Chroma ATE — Recognized for high‑performance electronic loads, including regenerative and bidirectional models; well aligned with EV, battery, and renewable test needs.
-
XP Power, Mean Well, Vicor, Delta, Murata — These suppliers illustrate divergent strategic plays: XP Power and Vicor focus on advanced topologies and high‑efficiency modules; Mean Well delivers cost‑effective, high‑volume designs; Delta and Murata emphasize broad industrial and telecom portfolios with strong manufacturing scale.
-
Specialists (EA Elektro‑Automatik, Advanced Energy, Magna‑Power, B&K Precision, Acopian) — These vendors occupy critical niches (high‑power programmable supplies, bench and rack systems, water‑cooled high‑current solutions, rapid‑ship industrial products) and are frequently targeted in procurement shortlists when performance or delivery guarantees matter.
Recent product launches across the industry — from high‑voltage 1U DC supplies to SOSA‑aligned DC/DC modules and new-generation programmable bench supplies — confirm that incumbents are investing to defend segments while smaller innovators pursue adjacency plays. For buyers and strategic investors, the differentiation axis is no longer price alone but the intersection of performance, modularity, and supply resilience.
What the PW Consulting report includes — practical, executable deliverables
Our full study is deliberately operational. It contains:
-
Topline market sizing and a seven-year forecast framework (2026–2032) with scenario variants and sensitivity to commodity and component price paths.
-
Competitive benchmarking across product classes and technology vectors, including supplier scorecards that evaluate manufacturing footprint, tech roadmap, and aftermarket revenue potential.
-
Supply‑chain heatmaps and a component‑risk matrix—identifying single‑source exposures, lead‑time dynamics, and regulatory pinch points to inform procurement hedges and dual‑sourcing strategies.
-
Technology adoption timelines for SiC, GaN, regenerative loads, and bidirectional architectures, linked to recommended R&D priorities and partner archetypes.
-
Go‑to‑market playbooks tailored to suppliers, OEMs, and test‑lab customers — covering pricing, modular product families, service monetization, and channel optimization.
-
M&A and investment screening tools — an initial shortlist of acquisition archetypes, valuation drivers, and integration risks suited to consolidation or capability buys.
-
Practical Excel models that allow users to stress test revenue and margin outcomes under alternate component‑cost and demand scenarios.
To honor the trailer principle, we do not publish core segment tables, regional allocation percentages, or product‑level revenue breakdowns in this release. Those detailed slices are contained within the paid report and are available to advisory clients under NDA.
Strategic recommendations for executives making decisions in 2026
-
Prioritize supply resilience: implement a component‑risk register, qualify secondary suppliers for long‑lead items (Si MOSFETs, IGBTs, MLCCs), and evaluate near‑shoring or regional assembly to mitigate trade‑policy shocks.
-
Accelerate technology migration where ROI is clear: invest in SiC/GaN design capability for segments where efficiency and thermal density materially reduce total system costs.
-
Design for modularity and service revenue: offer modular power blocks, firmware upgradability, and predictive maintenance contracts to increase lifecycle value and improve gross margins.
-
Target regenerative and bidirectional capabilities: these are becoming table stakes for battery and EV test systems and unlock new service revenues linked to energy recovery and sustainability metrics.
-
Adopt dynamic pricing and contract terms: incorporate commodity pass‑through clauses and lead‑time‑aware delivery pricing for bespoke and high‑power orders.
-
Pursue focused M&A to fill capability gaps: consider tuck‑ins that add high‑power digital controls, regenerative electronics, or regional manufacturing footprint rather than broad, unfocused consolidation.
How to use this research in practical decision-making
For Strategy teams: use our scenario models to test capex timing and to prioritize R&D investments that protect margin under adverse commodity scenarios.
For Procurement: deploy the component‑risk matrix to negotiate multi‑year supply agreements and to construct second‑source strategies for critical passive and active components.
For Product and Engineering: align roadmaps with the technology adoption timelines in the report to balance performance gains against qualification cycles and manufacturing transitions.
For Corporate Development and PE: our M&A screening tools and supplier scorecards accelerate target prioritization and de‑risk integration assumptions on capability buys.
Next steps — where to access the full intelligence
PW Consulting’s full Worldwide DC Power Supplies and Electronic Power Loads Market report contains the complete set of segmented forecasts, supplier scorecards, and downloadable models that underpin the strategic recommendations summarized here. Organizations seeking rapid capture of the 2026 opportunity can engage PW Consulting for: a) the full report and data package, b) bespoke scenario modeling tied to your product portfolio, or c) an executive workshop to convert market insights into a one‑year operating plan.
Contact our advisory team to request the complete dataset, NDAs for confidential benchmarking, or a customized brief that applies the report findings directly to your business objectives. The decisions you make in 2026 about sourcing, technology investment, and partnership will determine whether you capture rising demand and protect margin in a market growing at roughly a mid‑single‑digit CAGR through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Soft Shackle Market to Surge to USD 545.43 Million by 2032 on a 7.21% CAGR
By PW Consulting, 2026-08-05
Worldwide Soft Shackle Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s newest market research, based on a 2025 baseline and a 2026–2032 forecast horizon, provides decision-grade intelligence for companies shaping strategy in the fast-evolving soft shackle ecosystem. Our analysis shows the total market expanding from approximately USD 236.4 Million in 2020 to USD 335.3 Million in 2025, with a near-term inflection: the market is projected to exceed USD 380.6 Million in 2026 and reach roughly USD 545.4 Million by 2032. The forecast period carries a compound annual growth rate (CAGR) of 7.21% (USD Million). For corporate development, procurement, and R&D leaders preparing plans in 2026, the report frames clear, actionable options—while reserving the granular segment-level tables and proprietary datasets for subscribers.
Worldwide Soft Shackle Market
Why 2026 is a strategic inflection point
Soft shackles have migrated from niche outdoor and marine accessories into mainstream rigging, industrial lifting, and defense use cases. Three converging dynamics make 2026 pivotal:
Worldwide Soft Shackle Market
- Material-driven capability leaps: Ultra High Molecular Weight Polyethylene (UHMWPE) fibers—marketed under trade names such as Dyneema and Plasma—continue to deliver compelling strength-to-weight advantages versus steel, along with corrosion resistance and flotation. Innovations in protective jackets, coatings and machine stretching are increasing in-service durability and usability.
- Certification and procurement tailwinds: A subset of manufacturers now meet quality-management and public-procurement certifications (ISO 9001:2015, Berry Amendment, Buy American Act compliance) and military approvals, enabling entry into defense and regulated public-sector supply chains.
- Fragmented but consolidating supplier base: Market concentration remains low—CR3 ≈ 18.45% and CR5 ≈ 25.6%—which signals both the opportunity for strategic consolidation and the need for buyers to perform deep supplier diligence.
What PW Consulting’s report delivers — Operational, decision-ready content
This study is designed as a practical toolkit for 2026 strategic planning. The core deliverables include:
Worldwide Soft Shackle Market
- Executive synthesis with decision triggers tailored for three buyer types: OEMs, distributors, and institutional procurement teams.
- Macro market sizing and a year-by-year forecast (2026–2032) in USD Million, including base-year reconciliation and historical series (2020–2025).
- Scenario models (baseline, supply-constrained, accelerated-adoption) with sensitivity levers for raw material pricing, safety-standard adoption rates, and regulatory procurement shifts.
- Segment architecture (by region, by material/type, by application) with a user-controlled data table—note: granular split values are available in the full report to protect proprietary modelling and to encourage direct download.
- A competitive intelligence module: comparative capability matrix, product-differentiation maps, and public-filed warranty / test-statements for market-leading vendors.
- Commercial playbooks: sourcing & negotiation levers, supplier qualification checklists (traceability/serialization, factory testing, third-party validation), and an outsourced manufacturing vs. in-housing decision framework.
- Technology and product roadmaps: guidance on coatings, abrasion jackets, machine-stretching processes, and life-cycle testing protocols that translate to TCO improvements.
- M&A and partnership screening tool: valuation heuristics, integration risks, and a prioritized shortlist of target archetypes (technology owner, regional consolidator, OEM captive).
- Compliance and safety annex: recommended test standards (including approaches to establishing a 5:1 safety factor for overhead lifting), paperwork templates, and a regulatory heat map for defense and public procurement channels.
- Deliverables ready for the C-suite: an investor-grade slide pack and linked financial models (Excel) for rapid scenario comparison and board-level decisioning.
Competitive landscape — who matters and why
The soft shackle supplier ecosystem is heterogeneous, composed of specialist brands, vertical rope manufacturers, and industrial lifting incumbents. Key strategic signals for 2026:
- ASR Offroad (USA) — An early mover with ISO 9001:2015 production credentials and a focus on high-quality HMPE/Plasma soft shackles for off-road recovery. Strengths: established brand equity with the outdoor/off-road community, domestic production capabilities, and emphasis on process-certified traceability. Strategic implication: attractive partner for OEMs seeking domestic supply chains and rapid product iteration.
- Factor 55 (USA) — Focused on engineered recovery hardware with lab- and field-tested minimum breaking strengths and protective Fiber Lock coatings. Strengths: engineering rigor and trusted product validation. Strategic implication: premium-positioned supplier suitable for closed-system winching and safety-conscious fleets.
- Bubba Rope (USA) — Recognized for heavy-duty Plasma rope soft shackles across off-road, agriculture, mining and marine sectors. Strengths: emphasis on robustness, flotation and corrosion resistance. Strategic implication: preferred partner where durability and multi-environment use are procurement priorities.
- Safe‑Xtract (USA) — Military-approved soft shackles with serialized traceability, Berry Amendment and Buy American Act compliance; in-service with SOCOM. Strengths: certified defense pipeline access and advanced coatings. Strategic implication: incumbent for defense-related contracts and a high-barrier supplier for regulated buyers.
- Cortland Company (USA) — Developer of AeroLock-style synthetic connectors and rigorous fatigue testing regimes targeted at lifting/rigging. Strengths: engineering depth in industrial and lifting standards. Strategic implication: competitor to metal-shackle incumbents when buyers require certified lifting hardware.
- Erickson Manufacturing & Robship — Represent commercial marine and rigging specialists, the former emphasizing towing/load securement and the latter integrating in-house rope production for compact, strong solutions. Strategic implication: regional or vertical specialists that offer integrated supply and customization services.
- Wichard (France), Fulcrum Lifting, Dynamica Ropes — European and lifting-focused suppliers with expertise in sailing and industrial lifting applications. Strategic implication: critical partners for regional market entry and compliance with local marine standards.
Takeaway: product differentiation is now driven as much by process and certification (ISO, serialized traceability, military approvals) as by raw material choice. The current CR3/CR5 structure signals acquisition opportunities for strategic consolidators and gaps for new entrants that can combine certification, domestic manufacturing, and rigorous lab validation.
Strategic actions PW Consulting recommends for 2026
- For OEMs: Lock supplier contracts that include traceability clauses, minimum-breaking-strength guarantees, and conditional price protection tied to UHMWPE feedstock indices. Require factory audits to confirm ISO 9001 implementation and serialized product tracking.
- For Distributors and Channel Partners: Differentiate with service-based offerings—on-site re-certification, testing-as-a-service, and inventory programs for critical fleet operators. Prioritize suppliers with proven lab and field-testing histories.
- For Strategic Buyers / Procurement: Embed 5:1 safety-factor language and third-party fatigue testing requirements into supplier RFPs for overhead lifting applications; create a two-tier sourcing strategy separating defense-eligible suppliers from commercial suppliers.
- For Investors / M&A Teams: Target vertical integrators (rope-manufacturing plus finishing/coating capabilities) and defense-compliant manufacturers that offer immediate access to higher-margin channels.
- For R&D Leaders: Invest selectively in coatings and abrasion-jacket technology that demonstrably extend service life; document performance gains via standardized lab test protocols to justify price premiums.
Key uncertainties to monitor
- Raw material volatility: price or supply disruption of UHMWPE feedstock can materially impact margins and supplier selection.
- Regulatory shifts: changes in defense procurement requirements or lifting safety standards would rapidly re-rank certified suppliers.
- Safety incidents: product failures in lifting or public applications could accelerate standardization and raise total cost of compliance.
- Technology substitution: alternative high-performance synthetics or hybrid connectors could alter product roadmaps and reposition incumbents.
PW Consulting’s Worldwide Soft Shackle Market report blends macro forecasting (2026–2032), rigorous supplier benchmarking, and actionable commercial playbooks to inform boardroom decisions in 2026. The report is deliberately structured as a “trailer”: it reveals the analytical approach, the strategic implications, and headline macro figures while reserving the full set of proprietary segment splits, supplier scorecards, and downloadable financial models for the complete report package.
For immediate access to the full datasets, company scorecards, and the downloadable scenario models that underpin the figures cited above, please visit the PW Consulting report page and request the Worldwide Soft Shackle Market full report and executive slide deck.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Shackle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Meeting Minutes Software Market Poised to Expand at a 19.34% CAGR Through 2032
By PW Consulting, 2026-08-05
Worldwide Meeting Minutes Software Market: Strategic Intelligence for 2026 Decision-Making
Executive snapshot
PW Consulting's new Worldwide Meeting Minutes Software Market report arms C-suite leaders, procurement teams, and product strategists with an evidence-based narrative for 2026: a fast-growing, technology-driven category that is reshaping how organizations capture, govern, and extract value from meetings. The market—driven by AI, hybrid working models, and tighter compliance demands—has moved from niche automation to an enterprise-grade capability. Our analysis shows the market reached roughly USD 1.74 billion in 2025 and is forecast to expand at a compound annual growth rate of 19.34%, crossing the multi-billion-dollar threshold through the forecast horizon to 2032.
Worldwide Meeting Minutes Software Market
Why this matters for 2026
- Strategic timing: 2026 is the inflection year for many organizations transitioning pilot deployments to enterprise rollouts. The accelerating CAGR implies that decisions made this year will determine platform lock-in, operational efficiency gains, and data governance postures for the next five years.
- Value capture: Automation of meeting capture directly reduces administrative labor costs and increases the velocity of decision follow-up. Our cost-modeling shows that replacing manual minute-taking can pay back in months for high-meeting-volume teams.
- Risk management: Regulatory expectations—GDPR, HIPAA, and state-level recording consent laws—combined with buyer demand for SOC 2 and data residency options, turn vendor selection into a risk-management decision as much as a productivity choice.
What the report delivers — practical, executable intelligence
This is not a high-level overview: the PW Consulting report offers operational tools executives can use immediately. Key deliverables include:
Worldwide Meeting Minutes Software Market
- Proprietary market-sizing and a transparent forecasting model that quantifies adoption curves, showing how revenue pools shift as cloud-native AI features become table stakes.
- A vendor evaluation framework that scores providers across eight dimensions: transcription accuracy, summarization intelligence, integration depth (video platforms, CRMs, project tools), privacy and compliance controls, on-device/local processing options, enterprise management, customization, and total cost of ownership.
- Implementation playbooks for three buyer archetypes—enterprise IT, corporate governance (boards and committees), and high-volume knowledge teams—detailing procurement checklists, pilot designs, and success metrics tied to ROI and risk reduction.
- Regulatory and security annexes that map country- and sector-specific obligations (GDPR lawful bases, HIPAA BAA requirements, consent constraints under wiretapping statutes) to vendor feature sets and contractual clauses buyers should require.
- Scenario roadmaps that translate market trajectories into decision levers: when to pilot, when to standardize, and how to structure contractual terms for model training opt-outs and data residency.
Competitive landscape: who matters and why
The category includes pure-play AI notetakers, meeting intelligence platforms with conversation analytics, and governance-focused board solutions. Market concentration is moderate: the top five vendors account for roughly half the market, signaling both meaningful scale among leaders and room for differentiated challengers.
Worldwide Meeting Minutes Software Market
- Otter.ai (Mountain View) — market leader in real-time transcription and enterprise knowledge integration; evolving from single-meeting capture to enterprise knowledge bases and workflow hooks.
- Fireflies.ai (Miami) — strong in conversation intelligence and CRM integrations, with live-assist coaching features designed for sales and customer-facing teams.
- Fathom — focused on frictionless, free-tier capture that accelerates adoption; emphasizes lightweight integrations for Slack/Asana follow-up.
- MeetGeek — multi-language enterprise offering with workflow automation and analytics for HR, sales, and CS teams.
- tl;dv (Germany) — privacy-first positioning with unlimited core recordings and team collaboration features.
- Avoma, Sembly AI, Grain, Supernormal, Granola — each brings distinct specialization from sales enablement and coaching analytics to local-first processing and developer-friendly integrations.
- Diligent Boards and OnBoard — purpose-built for governance and board workflows; they combine minutes automation with compliance controls and agenda-driven minute generation.
Recent product moves underscore the competitive dynamics: Diligent released enhanced AI-generated minutes and governance controls in early 2026 to tighten board workflows across jurisdictions; Otter.ai launched an enterprise suite in late 2025 to marry meeting data with centralized knowledge systems; Granola achieved SOC 2 Type II in 2025, signaling how data controls are becoming a differentiator.
Market dynamics: drivers, bottlenecks, and regulatory realities
- AI capability acceleration. Improvements in real-time transcription, summarization and semantic search are converting meeting audio into repeatable knowledge assets, increasing the ROI of adoption.
- Hybrid work permanence. As organizations solidify hybrid meeting practices, demand increases for solutions that normalize capture across platforms (Zoom, Teams, Google Meet) and supports searchable repositories.
- Compliance and data sovereignty. Buyers increasingly require demonstrable GDPR and HIPAA compliance, SOC 2 attestations, and options for local-first or on-device processing to meet cross-border data controls.
- Procurement friction. Legal and infosec teams are introducing contract requirements—data processing addendums, limits on model training, and retention controls—that extend negotiation timelines and privilege vendors with mature compliance toolkits.
- Labor substitution economics. Manual minute-taking averages 45–90 minutes per meeting; for organizations running dozens of meetings monthly, the labor savings are material and a core part of the business case for automation.
Recommendations for 2026 strategic decisions
Based on our analysis, PW Consulting recommends a pragmatic, risk-aware adoption path that unlocks operational value while preserving future negotiating leverage and vendor optionality.
- Create a prioritized pilot portfolio. Begin with high-frequency, low-compliance teams (product, customer success) to validate integrations and measure time-to-action metrics, while simultaneously piloting compliant options (on-device/regionally hosted) with regulated units.
- Embed compliance into RFPs. Require BAAs for healthcare, GDPR lawful basis documentation for EU subjects, SOC 2 Type II, and explicit clauses prohibiting model training without consent or providing opt-out mechanisms.
- Negotiate platform interoperability. Insist on APIs, exportable transcripts, and open standards for knowledge export to avoid lock-in to a single vendor’s search layer or model stack.
- Procure with staged commercialization terms. Use short-term enterprise agreements with defined success gates (accuracy thresholds, integration SLAs, retention guarantees) before multi-year rollouts.
- Plan for governance of meeting data. Define retention policies, role-based access, and audit trails, and mandate that legal/information-security sign off on template-based minute generation for boards and committees.
Implementation playbook highlights (from the report)
- Pilot blueprint: 6–8 week cycle with technical validation, UX feedback, and ROI measurement tied to reduced follow-up time and increased decision-closure rates.
- Change management: templates for meeting owners, role definitions for minute reviewers, and a training curriculum that reduces adoption friction and creates repeatable operating rhythms.
- Integration checklist: prioritized integrations (calendar, video platform, CRM, project management) with sample API calls and fallback export strategies for legal hold scenarios.
- Negotiation levers: sample contract clauses for data residency, model training opt-outs, SLAs for transcription accuracy, and remediation paths for noncompliance.
What PW Consulting’s report does not disclose here (and why you should download it)
To preserve the report’s commercial utility for purchasers and to abide by our “trailer” principle, we intentionally do not publish detailed segment-level revenue splits, region-by-region allocations, or buyer-segment pricing matrices in this release. The report contains the full-model spreadsheets, scenario sensitivities, and vendor-scorecard data that procurement and strategy teams need to operationalize the insights summarized here.
How to use this intelligence
Senior leaders should treat this report as a decision accelerator in 2026. Use it to: prioritize pilots that deliver rapid ROI; retool procurement criteria to reflect regulatory and data-residency realities; and negotiate contracts that preserve future leverage while securing immediate productivity gains. For product and corporate development teams, the vendor benchmarking and feature roadmap are a concise guide for build vs. buy choices.
Next steps
- Download the full report for detailed vendor scorecards, downloadable forecasting models, and our procurement playbook.
- Book a briefing with PW Consulting to run a 90-minute executive workshop tailored to your organization’s risk posture and meeting volume profile.
- Request a tailored vendor shortlist and pilot design that aligns with your infra, compliance constraints, and integration requirements.
Contact PW Consulting to access the full Worldwide Meeting Minutes Software Market report and to schedule a personalized briefing. The choices you make in 2026—platform selection, contractual guardrails, and rollout sequencing—will set the productivity and compliance baseline for the next strategic cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Meeting Minutes Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft Load Control Solutions Market Poised to Grow at a 6.72% CAGR from 2026–2032
By PW Consulting, 2026-08-05
Worldwide Aircraft Load Control Solution Market — Strategic Briefing for 2026 Decision Makers
As airlines, ground handlers, and aviation service providers prepare investment and operational roadmaps for 2026, the aircraft load control solutions market is transitioning from niche operational tools to mission-critical digital infrastructure. PW Consulting’s latest market study — covering historical performance through 2025 and a detailed forecast to 2032 — quantifies this shift and translates it into an actionable playbook for executives. This briefing highlights the strategic value of the full report and previews the insights that should shape procurement, partnership, and transformation priorities next year.
Worldwide Aircraft Load Control Solution Market
Market in a Snapshot: Why 2026 Matters
-
The global market for aircraft load control solutions grew steadily through 2025 and is projected to continue expanding: our base-year analysis for 2025 values the market at approximately USD 174.5 Million (USD Million basis), with an anticipated uplift in 2026 to roughly USD 187.5 Million. Over the forecast window, the sector is expected to expand at a compound annual growth rate of 6.72%.
Worldwide Aircraft Load Control Solution Market -
By 2032 the market is projected to be materially larger than the mid‑decade base, reflecting durable demand for automation, regulatory compliance, and fuel-efficiency gains linked to optimized load control.
Worldwide Aircraft Load Control Solution Market -
Market structure is neither atomized nor monopolistic: the top-tier vendors command a meaningful share of revenue, indicating moderate consolidation and room for both specialist competitors and platform integrators to grow.
Why PW Consulting’s 2026 View Is Strategic
-
Timing and capital allocation: The 2026 investment cycle will be pivotal for decision-makers seeking to lock in efficiencies before broader fleet and network changes accelerate operating complexity. Our forecast quantifies the payback horizons and scenarios most sensitive to fuel-price and utilization shocks.
-
Vendor selection under uncertainty: With digital load control now a point of integration across flight planning, dispatch, EFBs, and ground services, procurement decisions have outsized downstream impacts. The report provides evaluation criteria and risk matrices tuned to integration depth, offline capability, and certification posture.
-
Regulatory alignment and certification risk: Evolving FAA, ICAO, and regional authority requirements, plus NextGen initiatives, make regulatory readiness a procurement and implementation risk factor. The study maps certification dependencies to vendor offerings and change programs.
What the Report Contains — Practical, Executable Deliverables
-
Market sizing and demand scenarios (2026–2032) with sensitivity analyses for fuel costs, traffic recovery, and centralization trends.
-
Vendor landscape and competitive heat maps, including CRx analysis and go-to-market archetypes for OEMs, pure‑play software vendors, and service operators.
-
Operational playbooks: step‑by‑step implementation guides for Centralized Load Control (CLC), decentralized station models, and hybrid approaches — including resource planning, training curriculums aligned to IATA standards, and cutover sequencing.
-
Integration frameworks and API checklists for flight planning systems, EFBs, and departure control systems to reduce integration timelines and avoid costly rework.
-
Regulatory and certification roadmap: assessment of compliance gaps vis‑à‑vis ICAO, FAA, EASA, and IATA guidance, with remediation plans and audit-readiness templates.
-
Commercial models and TCO/ROI templates tailored to airlines, ground handling firms, and centralized service providers — factoring in fuel-savings potential from optimized weight distribution and EZFW calculations.
-
Vendor due diligence kits: RFP templates, scoring matrices, cybersecurity baselines, and performance SLAs for both cloud and on-premise deployments.
-
Case studies and pilots: documented outcomes from early adopters and CLC operators, highlighting efficiency gains, safety outcomes, and integration pitfalls to avoid.
Competitive Landscape — Who Matters and Why
The market is characterized by a mix of established aviation IT players, specialist W&B vendors, and large-scale ground service providers offering centralized load control. Our coverage profiles firms across these categories and highlights differential advantages that buyers should weigh during 2026 procurement cycles.
-
Damarel Systems International Ltd.: Recognized for robust, airline-focused weight & balance applications that support both centralized control centers and station-level operations. Strengths include mature features for bulk and containerized loading and a track record in commercial narrow and wide‑body fleets.
-
Evionica: A differentiated value proposition around automation and autonomy, emphasizing high levels of automation in loadsheet generation, offline resilience, and tight integration with flight planning and EFB platforms — attractive to carriers pushing for “zero‑click” operational models.
-
Smart4Aviation Technologies B.V.: Focused on visual, exception-based workflows and broad systems integration, well-suited to carriers that prioritize operational transparency and monitoring across centralized and decentralized structures.
-
ABOMIS Innovations: A practical, optimization-led offering oriented to airlines, ground handlers, and flight crews — valuable for operators seeking immediate operational gains through real-time calculations and messaging capabilities.
-
AeroData and Jeppesen (Boeing): Platform integrators that bring weight & balance capabilities as part of broader flight operations suites — offering advantages where operators require deep dispatch and performance tool integration.
-
Service providers (e.g., Swissport, Global Load Control, Samsic Assistance Aviation): These firms combine software and high-volume operational expertise through CLC centers, offering scale economics and rapid deployment options for multi-station networks. Swissport’s 2025 disclosure of centralized centers supporting dozens of airlines and processing in excess of 170,000 load sheets annually illustrates how service-led models are commercializing scale.
-
Large airline IT players (Amadeus, Sabre): Integrate load control into broader airline ecosystems, providing one-stop operational stacks but requiring careful evaluation of modularity and vendor lock-in risks.
Collectively, the leading vendors control a significant share of the market, indicating moderate concentration that favors both strategic partnerships and selective M&A activity. Our full competitive analysis includes sourcing strategies and negotiation playbooks for each vendor archetype.
Regulatory and Operational Dynamics Shaping 2026 Choices
-
Regulatory pressure: ICAO and national authorities mandate precision in weight & balance processes. FAA NextGen modernization efforts further incentivize digital, interoperable solutions that reduce human error and speed turnaround times.
-
Standardization and training: IATA’s weight & balance guidance and training frameworks continue to influence certification and staffing models for load controllers; compliance is a baseline risk filter for vendors and integrators.
-
Centralization benefits: CLC models are proving measurable reductions in fuel burn through optimized load distribution and calculated EZFW gains. These operational benefits are a key lever in ROI models used for procurement decisions.
-
Certification requirements: EASA, FAA, and other authority certifications for related systems elevate technical due diligence — particularly for vendors offering simulation or training modules alongside operational software.
Strategic Imperatives for 2026
-
Prioritize integration-first procurement. Evaluate vendors for API maturity, data model alignment, and proven EFB/flight planning integrations to minimize post‑purchase integration cost.
-
Design for resilience. Ensure solutions offer offline capability and rapid synchronization to protect operations at low-connectivity airports and during systems outages.
-
Adopt a hybrid deployment playbook. Cloud-hosted platforms accelerate feature adoption and analytics, but on-premise or edge capabilities remain essential for regulatory compliance in some geographies.
-
Quantify fuel and safety upside. Use scenario-based TCO and pilot outcomes to make the business case, tying load control metrics to measurable KPIs like turnaround time, EZFW, and error rates.
-
Plan certification and training early. Embed regulatory readiness and IATA-aligned training into program timelines to avoid implementation slippage.
-
Prepare for partnership and consolidation. Given moderate market concentration, consider alliances, reseller agreements, or targeted acquisitions to accelerate capability acquisition.
How PW Consulting Can Support Your 2026 Agenda
-
Vendor selection and RFP design tailored to your integration and operational tolerance levels.
-
Implementation program management and cutover sequencing for CLC or hybrid rollouts, including staff certification and SLA design.
-
ROI and TCO modeling under multiple traffic and fuel-price scenarios to de‑risk board-level investment decisions.
-
Due diligence for partnerships or acquisitions, with a focus on tech stack, regulatory posture, and commercial defensibility.
PW Consulting’s full Worldwide Aircraft Load Control Solution Market report delivers the granular, operationally focused intelligence that senior aviation leaders need to act confidently in 2026. This briefing is intended as a strategic trailer: it surfaces the signals and implications but reserves the detailed segmentation, vendor scoring, and modelled financial scenarios for the comprehensive report.
To obtain the full study, implementation templates, and vendor due diligence kits that underpin the recommendations above, visit PW Consulting’s report portal or contact our aviation strategy practice directly. Equip your 2026 plans with the market intelligence that reduces execution risk and accelerates measurable operational value.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


