



Category: market research
PW Consulting Forecast: Worldwide Memory Packaging Market to Surge at 10.53% CAGR (2026–2032)
By PW Consulting, 2026-08-05
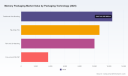
Worldwide Memory Packaging Market: Strategic Imperatives for 2026 — A PW Consulting Preview
PW Consulting today releases an executive preview of our forthcoming Worldwide Memory Packaging Market report. Grounded in a rigorous historical review (2020–2025) and a forward look to 2032, the study models the global memory packaging landscape through the lens of commercial decision-making in 2026. The market is both large and accelerating: our base-year assessment pegs 2025 global memory packaging revenue at USD 36,898.6 Million, with a modelled year‑over‑year increase to USD 42,140.5 Million in 2026 and a compound annual growth rate (CAGR) of 10.53% across the forecast window (2026–2032). By 2032, the market reaches roughly USD 74,380 Million under our central-case assumptions.
Worldwide Memory Packaging Market
Why this matters for 2026 decisions
-
Capacity and outsourcing choices made in 2026 will determine supply-positioning through the next wave of DRAM, NAND, and high-bandwidth memory cycles. The industry’s trajectory — strong mid‑teens to low‑double-digit growth on an aggregate basis — magnifies both upside and downside for capital allocation.
Worldwide Memory Packaging Market -
Pricing power and cost management are in flux. We observed manufacturer-led outsourcing ramps and provider price adjustments in late 2025/early 2026 that materially impact supplier margins and OEM total cost of ownership (TCO) models.
Worldwide Memory Packaging Market -
Geopolitical and regulatory risk has shifted from episodic to structural. New tariffs, export controls, and licensing regimes are reshaping where advanced packaging work can be conducted profitably and compliantly.
Practical, decision‑grade insights you can expect (teaser)
-
Scenario-aligned capacity maps that show where marginal MW/wafer‑level packaging capacity is likely to be available — and at what incremental lead times — under alternative demand ramps.
-
Supplier concentration analytics (our CR3 is 58.4% and CR5 is 72.15%) and an associated risk heat map that quantifies single‑point vulnerabilities across the OSAT ecosystem.
-
Cost‑sensitivity frameworks that translate raw-material and labor inflation into break‑even pricing for key packaging formats, enabling procurement to assess pass‑through versus margin‑absorption tradeoffs.
-
Regulatory-impact playbooks that convert tariff and export-control permutations into recommended operational responses — from dual‑sourcing and qualification playbooks to selective on‑shoring/near‑shoring options.
-
M&A and partnership scorecards that rank OSATs and strategic suppliers against a composite of capacity, technology readiness, customer exposure, and regulatory footprint.
Market dynamics reshaping 2026 strategy
-
Demand momentum and right-sizing: The broad market rebound we model for 2026 is being driven by both classic memory cycles (e.g., DDR generations) and structural shifts (e.g., higher penetration of stacked/advanced memory in AI and networking). That combination favors service providers with flexible, high-mix capacity.
-
Price and input‑cost volatility: Several memory packaging and test providers announced price increases of up to ~30% in early 2026 amid constrained capacity for DRAM and NAND packaging. Firms should bake elevated unit costs and shorter lead‑time premiums into procurement planning for at least the next 12–18 months.
-
Materials & critical inputs: Export controls and export‑licensing regimes on critical minerals (including gallium) and specialized process chemistries are creating upstream pinch points. Firms dependent on single-source supply for these inputs face an outsized operational risk.
-
Policy & geopolitical overlay: U.S. tariff measures and sustained export controls on advanced computing chips, HBM and certain DRAM technologies have heightened compliance complexity. Companies must treat trade policy as a core component of plant-location and partner-selection decisions.
Competitive landscape — what the OSAT map implies for strategic moves
The memory packaging space is concentrated among a few large OSAT leaders and a broader set of regional specialists. The competitive set includes global integrators, high-volume specialists, and locally focused vendors. Below we summarize strategic profiles and near-term implications for 2026 decision‑makers.
-
Advanced Semiconductor Engineering Inc. (ASE Inc.) — A leading OSAT with broad capability across DRAM, NAND and advanced formats (including HBM and SiP). For OEMs seeking scale and advanced technology roadmaps, ASE remains a primary partner for capacity scaling and co-development. Watch ASE for strategic capacity commitments and cross‑border footprint adjustments in response to policy changes.
-
Amkor Technology Inc. — Strong in memory and storage packaging with significant engineering depth. Amkor’s portfolio supports migration pathways for OEMs moving toward fan‑out and wafer‑level packaging. Strategic recommendation: prioritize Amkor for programs where engineering cadence and qualification throughput matter more than the absolute lowest per‑unit price.
-
Powertech Technology Inc. (PTI) — Focused memory packaging and test specialist with significant DRAM/NAND capacity. Recent price adjustments across PTI and peers reflect tight DRAM/NAND service markets; customers should model multi‑tier supplier networks and contingency pricing clauses into contracts.
-
ChipMOS Technologies, Hana Micron, Lingsen, FATC, Walton, and other regional players — These vendors provide targeted capacity, regional market access, and often closer OEM integration. They are natural partners for OEMs seeking capacity diversification or lower latency in local markets, but customers should validate technology parity and long‑run reliability before migrating high‑complexity products.
-
JCET, STATS ChipPAC and larger Chinese/Taiwan operators — These firms offer scale and mature high-volume NAND/DRAM packaging lines. However, regulatory restrictions and licensing requirements increase the complexity of deep technology transfer and long-term commitments. Companies should map licensing risk into any extended supply agreements.
Recent market developments to factor into 2026 planning
-
Applied Materials announced a long-term R&D partnership with SK hynix focused on materials engineering and advanced packaging for next‑generation DRAM and HBM — a signal that upstream materials and equipment innovation will be a key battleground.
-
Memory packaging firms announced price increases in early 2026 in response to tight DRAM and NAND packaging supply — immediate implications for 2026 P&L forecasting and negotiation posture.
-
Large memory OEMs have accelerated outsourcing for DDR5 and other product ramps, increasing the near‑term demand burden on OSATs and compressing qualification windows for alternative suppliers.
How to convert insight into action in 2026
-
Short term (next 6–12 months): Lock in critical capacity through multi‑year agreements with flexible volume clauses; secure alternative suppliers for qualified packaging formats; and run a rapid compliance assessment against tariffs and export-license exposures for each potential partner and facility.
-
Medium term (12–36 months): Invest selectively in co‑development with leading OSATs to qualify advanced packaging formats that confer product differentiation (e.g., HBM stacks, TSV/3D stacking). Use scenario models to test the ROI of near‑shoring versus multi‑regional sourcing under realistic tariff/licensing scenarios.
-
Strategic M&A and partnerships: Given the market concentration metrics, acquiring or partnering with an OSAT can be an efficient route to secure capacity and capture margin — but targets should be screened for regulatory footprint, technology parity, and customer concentration.
What’s in the full PW Consulting report (practical deliverables)
-
Full market model (2020–2032) with downloadable Excel: base-case, upside and downside demand scenarios; CAPEX and utilization sensitivity; and revenue forecasts by packaging technology and memory type (note: segment tables and datasets are provided in the full report).
-
Supplier scorecards and M&A playbook: due diligence checklists, integration risk assessments, and earn‑out structuring templates for OSAT transactions.
-
Regulatory-response playbooks: step‑by‑step guides to re‑routing production, qualifying alternate sites, and implementing compliant supply‑chain architectures under current U.S. export controls and tariff regimes.
-
Procurement & pricing playbooks: negotiation levers, escalation thresholds, and contract language templates to manage up to 30% short‑term price volatility observed in the market.
-
Operational readiness tools: qualification checklists for advanced packaging formats, sample timelines for ramping production, and vendor audit frameworks focused on materials traceability.
Final recommendations for executives
2026 will be a year where decisive, data‑driven action separates winners from laggards in the memory packaging ecosystem. Use the market’s strong growth trajectory — modelled at a 10.53% CAGR for 2026–2032 — to justify priority investments in supply security, but do so with calibrated hedges against policy and input‑supply risk. Prioritize partners that offer both technology leadership and a transparent regulatory footprint. Where scale and advanced-process capability are required, favor capacity commitments with leading OSATs; where agility matters, build a qualified multi‑supplier network.
PW Consulting’s full Worldwide Memory Packaging Market report contains the underlying datasets, scenario models, and executable playbooks referenced above. The executive preview you have just read is intentionally high‑level: the detailed segment numbers, regional splits and the full supplier scorecards are available only in the complete report and accompanying data pack. For procurement, corporate strategy, or M&A teams preparing 2026 budgets and roadmaps, accessing the full dataset is the next pragmatic step.
To request the full report or a tailored briefing for your executive team, please visit our official release page or contact PW Consulting’s semiconductor practice. Our analysts are available to run a bespoke workshop translating the report’s scenarios into specific capital, sourcing, and regulatory action plans.
For detailed analysis of this topic, please visit the official page: Worldwide Memory Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 11.2% CAGR for Worldwide 3D AOI in PCB Market Through 2026–2032
By PW Consulting, 2026-08-05
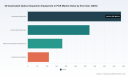
Worldwide 3D Automated Optical Inspection Equipment in PCB Market — Strategic Outlook for 2026
As global electronics complexity accelerates, 3D Automated Optical Inspection (AOI) has moved from a quality-assurance luxury to a strategic manufacturing vector. PW Consulting’s newest market study — Worldwide 3D Automated Optical Inspection Equipment in PCB Market (base year 2025, forecast 2026–2032) — frames the investment choices that will define supplier relationships, factory economics, and product reliability for the next investment cycle. The headline: the global market reached roughly USD 1.1 billion in 2025 and, under a set of conservative assumptions, is forecast to more than double by 2032, implying a compound annual growth rate of approximately 11.2% across the forecast window. This growth is concentrated among a handful of high-capability vendors (CR3 ~52.4%, CR5 ~68.2%), creating both opportunities and supplier risk for OEMs and EMS providers preparing capital plans in 2026.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Why this matters to 2026 strategic choices
-
Capital allocation and timing: With unit prices and optics inflation putting upward pressure on AOI equipment (sector analysis indicated an average price increase of about 8% YoY in 2025, with unit pricing commonly in a premium band), procurement teams must weigh earlier procurement to lock pricing vs. delaying to capture next-generation sensor capabilities.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market -
Production mix and yield economics: The transition to finer-pitch components and HDI boards has elevated the value of sub-2μm height measurement accuracy — a capability explicitly embedded in recent IPC standard updates. The report translates those measurement thresholds into practical ROI models for first-pass yield improvements and rework cost avoidance.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market -
Supply-chain fragility: Long lead times for high-resolution 3D camera modules (reported at 16–20 weeks in Q4 2025) and geopolitical controls affecting advanced imaging exports in 2025 materially change sourcing strategies. Our analysis quantifies the business impact of single-supplier dependency and proposes mitigations ranging from buffer stocking to sensor localization partnerships.
What the PW Consulting report delivers (practical, deployable content)
-
Decision-ready vendor benchmarking: a multi-dimensional scoring system combining sensor capability (height accuracy, resolution), inspection throughput, false-call rate, integration effort, service ecosystem, and TCO over a 7-year horizon. The framework is designed to be reused for RFP shortlisting.
-
CapEx prioritization matrix: trade-offs between retrofitting legacy lines with 3D AOI versus greenfield deployment on new SMT lines, with payback sensitivity to yield improvements, scrap reduction, and labor cost differentials.
-
Supply continuity and risk stress tests: scenario-driven models that simulate camera-module supply shocks, tariff shocks, and export-control scenarios. For each scenario we provide contingency plans and estimated P&L impact ranges for typical EMS and OEM production footprints.
-
Implementation playbook and KPIs: from pilot design through full-line roll-out, including sample-size recommendations for statistical acceptance, cycle-time budgeting, operator training modules, and continuous improvement loops to reduce false calls.
-
Compliance and standards mapping: an actionable interpretation of the IPC-9252B/IPC-2581 family and how updated accuracy mandates translate into procurement specifications and acceptance tests.
-
Commercial levers: negotiation playbooks for service contracts, spare parts agreements, and trade-in strategies that preserve equipment uptime during multi-year sensor supply disruptions.
Competitive landscape — who matters and why
The 3D AOI market for PCBs is concentrated around a small set of specialized vendors. PW Consulting’s qualitative and quantitative analysis focuses on product differentiation, installed base quality, and aftermarket/service economics rather than raw shipment tallies. Below are executive summaries of the key players we modeled in depth.
-
Koh Young Technology (Seoul, South Korea) — A market leader recognized for high-speed true-3D imaging in SMT inspection. Recent product cadence (e.g., a refreshed Zenith Alpha platform) emphasizes embedded AI for defect classification and higher throughput. Their installed base and software maturity give them an advantage in high-mix environments seeking throughput and low false-call rates. More: https://www.kohyoung.com
-
CyberOptics Corporation (Minneapolis, MN, USA) — Noted for multi-reflection suppression and precision models optimized for fine-pitch BGAs and QFNs. Recent platform upgrades target ultra-miniature components. Their approach blends optical innovation with ease of integration into existing MES workflows. More: https://www.cyberoptics.com
-
Viscom AG (Hannover, Germany) — Strong in high-volume assembly, with an emphasis on sensor resolution suitable for HDI boards. Their product demonstrations focus on throughput consistency and robustness for automotive and industrial applications. More: https://www.viscom.com
-
Test Research, Inc. (TRI) (Taipei, Taiwan) — Competes on AI-driven analytics and domain expertise for solder-paste and placement inspection. TRI’s software-led differentiation helps customers extract higher value from existing hardware stacks. More: https://www.tri.com.tw
-
SAKI Corporation (Tokyo, Japan) — Known for precise gimbal-less camera architectures that deliver tight height-measurement tolerances, especially in high-reliability markets. Compliance-focused offerings respond to recent IPC updates. More: https://www.saki.com
-
Mirtec Corporation (Oxford, CT, USA) — Emphasizes high-resolution imaging and laser profiling; their MV-series is frequently specified for post-reflow analysis in mixed-technology lines. More: https://www.mirtec.com
-
Nordson TEST & INSPECTION (Carlsbad, CA, USA) — Integrates AOI with AXI capabilities for complex inspection requirements in high-mix environments, positioning itself for customers who want a consolidated inspection platform. More: https://www.nordson.com
Recent vendor moves reflected in our analysis include product launches and model refreshes throughout 2025 that push the technology envelope (e.g., AI-enabled classifiers, support for 01005 components, and higher-resolution options for HDI). These are meaningful for procurement timing: a purchase committed today may be materially different in capability and price from the same spec cycle in 12 months.
Strategic implications and recommended actions for 2026
-
Adopt a phased procurement approach: prioritize pilot deployments on your highest-value SKUs to quantify yield uplift, then scale with a modular capex plan that protects budget flexibility as sensor availability and tariffs evolve.
-
Diversify sensor sources and contractually protect supply: build dual-sourcing clauses for critical optical modules, negotiate advance purchase commitments for high-resolution cameras, and include price-adjustment caps tied to optics-material indices.
-
Make standards compliance a procurement gate: require suppliers to demonstrate compliance with updated IPC accuracy mandates in acceptance tests rather than rely on vendor claims alone.
-
Leverage service and analytics as competitive advantages: structure long-term service agreements with performance SLAs (false-call thresholds, uptime), and insist on access to analytics APIs to integrate inspection data into your quality dashboards.
-
Stress-test your ROI: use the report’s scenario modules to run “what-if” simulations for tariff events, a 16–20 week camera delay, and 10–20% variation in installation productivity. This will reveal when to buy, lease, or partner for inspection-as-a-service.
-
Watch for consolidation and partnership opportunities: the CR3/CR5 concentration necessitates monitoring for M&A activity that could reshape pricing and aftermarket dynamics; be prepared to act on strategic supplier alliances that secure capacity.
Risk matrix and scenario highlights
Key near-term risks include sensor-module supply shocks, export-control escalation, and tariff inflation. For example, export controls that impacted shipments in 2025 materially increased lead-time and sourcing complexity for some buyers; similarly, new EU import tariffs instituted in 2025 raised landed costs for non-EU equipment. PW Consulting’s scenarios quantify these risks and map them to specific procurement and operational actions — from advance inventory strategies to regional sourcing hubs — enabling leadership teams to prioritize mitigations by expected P&L impact.
How to use this research in your 2026 planning cycle
-
For C-suite: integrate the high-level scenarios and vendor concentration implications into capital-allocation and supply-risk narratives supporting your 2026 budget ask.
-
For procurement: use the supplier scorecard and negotiation playbook to execute RFPs that extract performance guarantees and protect against sensor-price inflation and lead-time variability.
-
For operations: adopt the implementation playbook and KPI set to run pilots that produce defensible yield-improvement estimates for business cases.
Final note — what’s behind the paywall
This overview highlights the strategic themes and executable frameworks contained in PW Consulting’s full report. The full study contains granular regional, technology and end-user splits, detailed vendor scorecards, full RFP templates, and downloadable Excel models for scenario testing — deliberately omitted here to preserve the value of the primary research and to encourage direct access to the source materials. Organizations preparing procurement, production, or M&A decisions for 2026 will find the full package essential for converting inspection capability into predictable business outcomes.
To discuss how our findings map to your manufacturing footprint and to obtain the full dataset and interactive models, PW Consulting’s industry team is available for briefings and customized workshops focused on converting inspection modernization into concrete margin and quality improvements.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Low‑Power Solid‑State Microwave Generator Market to Grow from USD 684.83 Million in 2025 to USD 1,663.76 Million by 2032 at a 13.52% CAGR
By PW Consulting, 2026-08-05
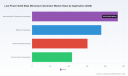
PW Consulting Strategic Preview — Worldwide Low-Power Solid State Microwave Generator Market: A 2026 Decision Playbook
As organisations plan capital allocation and product roadmaps for 2026, PW Consulting releases a targeted strategic preview of our full market study on the Worldwide Low-Power Solid State Microwave Generator market. Built on a 2025 base year with historical coverage from 2020–2025 and a forecast window through 2032, our analysis highlights a market expanding at a compound annual growth rate (CAGR) of 13.52%. In monetary terms, PW Consulting projects the market to grow from approximately USD 684.8 Million in 2025 to roughly USD 1,663.8 Million by 2032 — a scale-up that creates distinct opportunity windows for OEMs, suppliers, integrators and investors in 2026.
Worldwide Low-Power Solid State Microwave Generator Market
Why 2026 is a Pivot Year
Several structural inflection points converge in 2026 to make near-term strategic choices unusually consequential. First, semiconductor materials and packaging advances — led by gallium nitride (GaN) — are accelerating efficiency and form-factor gains for low-power solid-state microwave solutions. Second, regulatory and standardization dynamics (including tighter control of heating uniformity in food applications and the narrower frequency stability achievable with solid-state systems) are shifting buyer preferences toward frequency-agile, software-controllable generators. Third, industry momentum on decarbonization and zero-emission process technologies is elevating solid-state alternatives to legacy magnetron systems as a key investment theme.
Worldwide Low-Power Solid State Microwave Generator Market
Finally, market structure shows moderate concentration: the three largest firms capture a meaningful but not dominant share (CR3 ≈ 42.5%), while the five largest firms increase that footprint to a majority position (CR5 ≈ 58.8%). This profile indicates both incumbent strength and fertile territory for challengers with differentiated propositions.
Worldwide Low-Power Solid State Microwave Generator Market
What the Full PW Consulting Report Contains (Practical, Transaction-Ready)
- Executive Decision Brief: A two‑page C-suite summary with prioritized actions for 12–18 month horizons.
- Validated Market Sizing & Forecasts: Top-down and bottom-up estimates for 2020–2032, with sensitivity bands and scenario pathways that stress-test adoption under regulatory and supply‑chain shocks.
- Commercial Segmentation Framework: Structured segmentation by geography, technology platform (e.g., GaN, LDMOS, others) and application verticals (laboratory/R&D, medical/healthcare, industrial heating/plasma, communications/aerospace), accompanied by buyer persona templates — note: the public summary deliberately omits granular split metrics; full tables are available in the report.
- Supply-Chain & Sourcing Map: Bill-of-materials analysis, single‑point-of-failure identification for GaN and other critical inputs, and mitigation playbooks.
- Competitive Intelligence & Vendor Scorecards: Comparative profiles, product architectures, IP posture, channel models and aftermarket strategies for leading and emerging players.
- Technology Roadmaps: Performance trajectories, switching-cost assessment and investment timelines for modular, field‑repairable and liquid/air‑cooled architectures.
- Regulatory & Standards Impact Matrix: Country-level compliance implications, certification timeframes and recommended pre-emptive testing strategies for food and medical uses.
- M&A & Investment Heatmap: Transaction themes, valuation benchmarks, and integration risk checklists tailored for financial sponsors and strategics.
Actionable Strategic Imperatives for 2026
- Prioritise GaN Integration with Commercial Roadmaps: Firms that accelerate GaN-based modules — balanced against supply and quality risk — will capture efficiency- and size-sensitive applications. Evaluate co-investment or long-term purchase agreements with key GaN foundries to secure capacity.
- Design for Modularity and Field Serviceability: Customers value uptime. Modular, field-repairable architectures reduce total cost of ownership and open aftermarket revenue streams — a decisive differentiation in industrial and production environments.
- Embed Frequency Agility and Software Control: Narrow-band, software-tuned solutions unlock process repeatability (e.g., predictable heating patterns required by regulators) and allow premium pricing for deterministic performance.
- Develop Regulatory-Ready Food and Medical Pilots: Given tightened FDA and international requirements on heating uniformity and safety, early validated pilots with regulatory traceability accelerate procurement cycles for end-users in food and healthcare.
- Operationalise Aftermarket and Service Models: With rising installed bases, service contracts, consumables and field diagnostics provide high-margin, durable revenue — essential for mid-size vendors to offset price pressure on hardware.
- Target Strategic Partnerships over Price Wars: Systems integrators, plasma producers and process-tool OEMs are attractive partners for bundled offerings. Prioritise collaboration over pure cost competition, especially when targeting regulated verticals.
- Assess Consolidation Opportunities: With CR3/CR5 figures indicating partial concentration, 2026 is a window for acquisitive scale-ups — tuck-ins that add channel access, specialized IP or capacity may be accretive in the medium term.
Competitive Landscape — Who Matters and Why
PW Consulting’s competitive mapping identifies a mix of specialist innovators, diversified instrument companies and regional low‑cost producers. Key strategic profiles include:
- SAIREM (France / US office): Strength in precision low-to-medium power modules with patented auto‑tune capabilities, appealing to R&D and lab markets where process repeatability is non‑negotiable.
- Crescend Technologies (USA): A candidate for buyers seeking magnetron-to-solid-state transitions; positions its offerings around decarbonization and zero-emission process claims.
- Elite RF (USA): Rapid GaN adoption and field-serviceable, modular designs make it competitive for production environments that require uptime and easy maintenance.
- MKS Instruments (USA): Offers higher-power rack-mount, water-cooled units with strong process control pedigree — attractive to industrial and research institutions demanding precision.
- LEANFA / Muegge Group (Italy): Strong OEM module capability with robust distributed software architectures — suited to integrators building bespoke process tools.
- RFHIC (South Korea): Cost-efficient GaN low-power models with competitive efficiency figures, addressing price-sensitive industrial heating and plasma applications.
- Fricke & Mallah (Germany): Compact industrial units emphasising protection features and ruggedisation for manufacturing environments.
- Chengdu Wattsine, Qualwave, Alaris Kuhne: Regional and component specialists that offer breadth across ISM bands and volume-driven price competitiveness.
Recent ecosystem developments to monitor include LEANFA’s 2024 launch of a new 1000 W LDMOS module, Elite RF’s 2024 GaN product-line expansion, AmpliVisionS’s 2025 scaling across broad frequency ranges, and a 2026 scientific review that underscores measurable improvements in heating uniformity using solid-state generators — all signals of technology maturation and market readiness.
Top Risks and Blind Spots for 2026 Planning
- GaN Material & Capacity Risk: GaN availability and supplier concentration could create lead-time and pricing volatility. Hedging through long-term agreements or multi-sourcing is prudent.
- Regulatory Fragmentation: Food and medical applications face country-specific compliance requirements. A “one-size-fits-all” go-to-market risks costly rework.
- Low-Cost Imports and Margin Pressure: Price competition from large-volume regional suppliers may compress margins in commodity segments — focus on feature and service-based differentiation.
- Standards Adoption Pace: Advantages that rely on narrow-band frequency stability depend on broad customer and regulator acceptance; slower standards harmonisation delays premium adoption.
- Integration Risk with Process Tools: System-level performance is often more important than generator metrics alone; poor integration can negate technology advantages.
Methodology & Confidence
Our full study synthesises primary interviews with buyers, OEMs and foundries; product-level technical review of vendor datasheets and patents; secondary data from trade, regulatory sources and scientific literature; and quantitative triangulation via top‑down and bottom‑up modelling. The report’s base year is 2025, historical coverage spans 2020–2025, and forecasts run through 2032. The headline CAGR and market totals are presented here to contextualise scale; detailed segmentation tables, regional breakdowns and vendor scorecards are intentionally reserved for the full report to preserve client value and support actionable commercial engagements.
Next Steps — How to Use This Preview
- Buyers and integrators: request the process‑use appendices and test-protocols to accelerate regulatory compliance pilots.
- OEMs and suppliers: commission a supplier-readiness assessment and a two-quarter productisation sprint plan.
- Investors: request the M&A heatmap and vendor scorecards to identify accretive targets and valuation comparators.
PW Consulting’s complete Worldwide Low-Power Solid State Microwave Generator Market report contains the full data set, granular segmentation, supplier valuations, and implementation playbooks referenced here. This preview is designed to clarify the strategic stakes for 2026 while driving practitioners to the full report for transaction-ready detail. To obtain the comprehensive study and a tailored executive briefing, contact PW Consulting’s industry desk or visit our reports portal.
For detailed analysis of this topic, please visit the official page: Worldwide Low-Power Solid State Microwave Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Laundry RFID Tags Market to Soar at 12.48% CAGR During 2026–2032
By PW Consulting, 2026-08-05
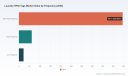
Worldwide Laundry RFID Tags Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive overview
As enterprises in hospitality, healthcare, industrial laundry and uniform rental re-evaluate supply chain resilience and operating cost structures for 2026, the laundry RFID tags market has moved from a niche automation play to a strategic enabler of operational continuity and asset intelligence. PW Consulting’s latest Worldwide Laundry RFID Tags Market report — grounded in a 2025 base year and a seven-year forecast window through 2032 — quantifies that transformation. The market reached USD 580.45 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 12.48%, passing the USD 1.3 Billion threshold within the forecast horizon. These headline metrics understate a more important truth for 2026: adoption is being driven as much by use-case economics and regulatory tailwinds as by unit-level technology improvements.
Worldwide Laundry RFID Tags Market
Why this matters for 2026 decision-makers
-
Operational efficiency is now a board-level KPI in asset-heavy service industries. RFID-enabled visibility directly attacks the twin profit drains of procurement inflation and inventory leakage. Our analysis shows device-level economics combine with systems-level process redesign to deliver measurable reductions in linen purchasing and loss — outcomes that make RFID a capital-efficient intervention versus incremental staffing or manual controls.
Worldwide Laundry RFID Tags Market -
Risk management has a new lever. Labels and tags that survive industrial sterilization and gamma irradiation are opening medical- and pharma-adjacent use cases that were previously out of scope. This widens addressable demand and accelerates procurement cycles where compliance is non-negotiable.
Worldwide Laundry RFID Tags Market -
Scale economics are real. The market is consolidating: the three largest suppliers control a meaningful share of industry shipments and the five largest approach majority share — an important consideration for procurement teams that want long-term warranties, re-use programs and interoperability commitments.
Market dynamics shaping 2026 strategies
-
Unit resilience and read performance have become differentiators. Recent product generations target survivability through hundreds of industrial cycles, compatibility with sterilization processes and reliable bulk-read distances in high-throughput washers and tunnels. For enterprises, this means planning replacement and amortization cycles with higher confidence and reducing lifecycle total cost of ownership.
-
Standards and certifications matter more than ever. Interoperability with global RFID standards and certifications for textile safety or medical conditionality are increasingly non-negotiable procurement criteria for multinational operators and hospital groups. Buyers that prioritize certified solutions reduce integration risk and accelerate time-to-value.
-
Automation at the line and laundry level is maturing. Innovations in print-ready roll formats and automated tag-on-label insertion enable item-level tagging to be embedded directly into textile production or finishing lines. This removes a major friction point for scale deployments and creates a stronger link between manufacturing and service lifecycles.
-
Software and systems integration now drive premium value. Tag performance is necessary but insufficient. The realized business outcomes depend on software workflows — inventory reconciliation, repair routing, lifetime analytics and integrations with ERP and linen management platforms. Expect competitive outcomes to hinge on ecosystems, not just tag physics.
Competitive landscape — who to watch
The sector exhibits a measured degree of concentration: the top three vendors capture a significant portion of the market, while the top five approach majority control. That structure produces a competitive environment where differentiation is achieved through product durability, scale deployments, certifications and service models.
-
Datamars Textile ID (Lamone, Switzerland) — A global incumbent with deep domain focus in industrial laundry. Their portfolio spans chips, readers, antennas and software, and their installed base is mature. Recent product activity includes tag and label automation as well as specialized solutions for gamma sterilization — a strategic move to deepen presence in medical textiles.
-
HID Global (United States) — Leverages broad enterprise security and identity capabilities into textile-safe offerings with certifications that matter in regulated settings. Their product designs focus on textile-friendly form factors and variants that address MRI-safe environments, making them a preferred supplier where safety certifications factor into RFPs.
-
Xerafy (Singapore) — Competes on read performance and industrial wash durability, and has invested in roll-format tags designed for print-on-demand workflows. Their product roadmap targets performance at scale — a critical consideration for laundries that require high throughput bulk reading.
-
JYL-Tech (Shanghai) — Focused on automation in manufacturing and high-volume insertion tooling. Their roll-format solutions are playing to demand from textile producers and large laundry chains seeking an integrated upstream tagging capability.
-
Regional and specialized players — European, North American and Canadian specialists bring differentiated competencies on materials engineering, custom tag forms, and tag reuse programs. These players are attractive to customers seeking tailored service levels, local support or cost-competitive sourcing.
Recent product signals (select highlights)
-
March 2026: a leading supplier introduced a UHF tag designed to survive extensive gamma sterilization cycles — a step-change for textile tracking in medical environments.
-
Early 2026: a manufacturer launched an automated tag-in-roll solution for linen production lines, bridging the factory-to-facility tagging gap and enabling item-level traceability from the first wash.
-
Mid-2025: print-ready roll-format tags incorporating next-generation RAIN RFID chips reached the market — a tangible productivity lever for large-scale laundries and label converters.
Report deliverables — what’s inside and how leaders should use it
PW Consulting’s report was built for 2026 strategic decisions. It combines quantitative forecasting, supplier benchmarking and tactical tools that procurement, operations and CIO teams can deploy quickly:
-
Actionable market sizing and scenario-driven forecasts to support investment cases and capital planning.
-
Supplier scorecards that evaluate durability, certification footprint, read-range performance, ecosystem integration and service models — enabling shortlist creation and RFP design.
-
Procurement playbooks covering total cost of ownership, tag reuse economics, warranty negotiation levers and volume pricing strategies tailored to multi-site programs.
-
Operational templates for pilot design, KPI selection (loss rates, turn cycles, read accuracy), and governance models to transition pilots into rollouts at scale.
-
Integration matrices for IT and OT teams that align RFID deployments with existing asset management, ERP and linen management systems to avoid costly retrofit work.
Strategic recommendations for 2026
-
Prioritize pilots that mirror scale: design proofs of concept that replicate production throughput and sterilization/regulatory requirements so that tag survivability and read-performance are validated under real operational stress.
-
Push vendors on long-term service economics, not only unit price. Reuse programs, repair/refurbishment pathways and guaranteed read performance over life materially change ROI.
-
Specify standards and certifications early in the RFP to avoid integration and compliance surprises. Certificates and conditional-use ratings should be mandatory pass/fail criteria for regulated deployments.
-
Plan for software-first deployments. Tag hardware does the sensing; software converts sensor data into decisions. Identify use cases where analytics can reduce linen inventory or automate routing and prioritize those as first waves for automation.
-
Monitor consolidation and supplier innovation closely. The market’s concentration profile means supplier roadmaps will alter competitive dynamics — strategic buyers should secure roadmap commitments and interoperability clauses to protect future optionality.
Methodology and confidence
Our forecast combines historical shipment and revenue data (2020–2025), primary interviews with suppliers and large end-users, and bottom-up modeling of unit economics and replacement cycles. We stress-tested scenarios against variations in wash-cycle survivability, regulatory acceptance in medical markets, and the pace of automation adoption in linen production. The resulting 12.48% CAGR reflects both steady organic adoption and discrete upside tied to clinical-textile use cases and automated tagging adoption in manufacturing.
Next steps — how executives should use this insight
-
For CFOs and procurement leaders: use the report to structure multi-year capex plans, supplier commitments and volume-based price schedules with performance-based SLAs.
-
For COOs: adopt our pilot templates to de-risk rollouts and set KPIs that translate RFID visibility into inventory and procurement savings.
-
For CIOs and integration leads: leverage the integration matrices to prioritize API and middleware investments that will unlock cross-system value.
Conclusion
In 2026, laundry RFID tags are transitioning from a specialized automation accessory to a foundational element of asset-centric operations. The combined forces of improved tag survivability, production-line automation, and ecosystem-aware software make this a decisive year for organizations that must balance cost containment with quality and compliance mandates. PW Consulting’s Worldwide Laundry RFID Tags Market report equips leaders with the forecast, supplier intelligence and operational playbooks to turn adoption into durable advantage. For readers seeking the detailed regional, application and supplier split data that underpin bespoke procurement decisions, the full report and accompanying datasets are available from PW Consulting.
For detailed analysis of this topic, please visit the official page: Worldwide Laundry RFID Tags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vorinostat Market to Reach USD 312.42 Million by 2032 at a 5.4% CAGR — North America Accounts for USD 106.47M in 2025
By PW Consulting, 2026-08-05
Worldwide Vorinostat Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s newest market study on the Worldwide Vorinostat Market (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the forward-looking intelligence required to make high-consequence decisions in 2026. Our model, denominated in USD Million, shows the market expanding from a mid‑hundreds million footprint in 2025 with a compound annual growth rate (CAGR) of 5.4% through 2032. By combining a proprietary market-sizing engine, scenario-driven forecasts and roll-up commercial playbooks, the report is built to move portfolio, manufacturing and M&A decisions from hypothesis to execution-ready.
Worldwide Vorinostat Market
Why this preview matters for 2026 decision cycles
- Budget cycles and manufacturing investments being set in 2026 require visibility into both steady-state demand and upside scenarios; our forecast horizon (2026–2032) is aligned to typical capital-planning windows.
- Vorinostat’s mixed lifecycle — an approved originator product alongside an active generic landscape — demands differentiated strategies for brand owners, generics manufacturers and private investors. The report translates competitive dynamics into actionable options.
- Regulatory, reimbursement and safety constraints (including entrenched label warnings requiring monitoring) materially affect prescribing patterns and payer coverage decisions; operational guidance in the report turns those constraints into commercial levers.
Market trajectory at a glance
From the baseline established in 2025, PW Consulting’s central forecast projects consistent, moderate growth through 2032 driven by continued use in established hematologic indications, steady research interest in additional indications and the maturation of generic supply chains. Our scenario engine quantifies the sensitivity of market value to variables that matter most to 2026 planners — unit price erosion, adoption in new research settings, and shifts in payer rules — enabling prioritization of interventions that preserve EBITDA under stress.
Worldwide Vorinostat Market
Core dynamics shaping the vorinostat landscape
- Regulatory heritage and guideline support: Vorinostat’s pathway to approval and subsequent guidance placements have anchored it as a clinical option for relapsed/refractory cutaneous T‑cell lymphoma (CTCL). That status supports baseline demand while defining the parameters of label‑driven use.
- Post‑patent competitive structure: The original composition‑of‑matter patent expiration opened the market to generic competition. Since then, multiple manufacturers have pursued regulatory approvals and commercial launches, creating pronounced pricing and access pressures in mature channels.
- Safety profile as a commercial constraint: Black‑box risks — including thromboembolic events and QT prolongation — mean that vorinostat is often deployed with ECG monitoring and DVT prophylaxis protocols. These safety requirements affect formulary negotiation, outpatient prescribing patterns and total cost of care calculations.
- Concentration and supplier power: Market share concentration is high among the leading manufacturers, a structural factor that both reduces price fragmentation in some channels and heightens single‑supplier risk for specific tenders and public procurement events. PW Consulting’s analysis shows a market where the top three and five players command dominant shares, intensifying competitive pricing dynamics and raising the strategic value of secure manufacturing alliances.
- Research pipeline and off‑label interest: Beyond approved indications, vorinostat remains an active compound in combination and translational research (including latency‑reversal approaches in virology). Research demand is a predictable, if smaller, contributor to overall volume and an important channel for lifecycle extension strategies.
Competitive landscape — positioning and implications
Our competitive analysis synthesizes incumbent originator strategy with generic manufacturers’ commercial playbooks to outline tactical options for market participants.
Worldwide Vorinostat Market
- Originator (developer): As the original developer, the originator’s residual brand value and historical safety dataset are strategic assets. Defending residual premium segments requires targeted stewardship — label optimization, focused RWE to support differentiated outcomes, and selective co‑development of combination regimens that leverage clinical familiarity.
- Large generics and specialty players: Several global generics manufacturers have pursued approvals and market entry, emphasizing cost‑competitive supply and broad geographic coverage. Their playbook typically includes aggressive tender participation, partnerships for local distribution, and cost leadership in emerging markets.
- Regional suppliers: Mid‑sized manufacturers leverage nimble regulatory strategies and local market knowledge to win formulary inclusion where pricing thresholds favor incumbents with local presence. For these players, the pathway to scale is through targeted tender wins and contract manufacturing partnerships.
- Recent tactical moves: Regulators and manufacturers continue to shape access. Notable recent developments — regulatory approvals that established AB‑rated generics in major markets and targeted product launches in regional markets — demonstrate how timing of regulatory clearance and first‑to‑market dynamics materially alter competitive positioning.
What’s inside the full PW Consulting report — practical, transaction‑ready deliverables
Our report is intentionally operational: it does not stop at descriptive analysis but provides tools executives can deploy immediately in 2026 planning cycles.
- Interactive market model (USD Million): Build‑your‑own scenario capability with inputs for price erosion pathways, uptake curves, and research demand. The model supports top‑down and bottom‑up views and exports to client financial systems.
- Price erosion and tender simulation engine: Quantifies revenue and margin trajectories under competing tender scenarios and formulary decisions to prioritize markets and optimize bidding strategy.
- Payer and reimbursement matrices: Granular playbooks for engagement, including dossier templates and value‑argument frameworks aligned to safety monitoring costs and real‑world outcomes.
- Supply‑chain and manufacturing heatmaps: Risk scoring for API suppliers, suggested redundancy strategies, and CAPEX templates for capacity expansion or contract manufacturing options.
- Clinical and regulatory roadmap: A navigable registry of ongoing trials, label‑change opportunities and jurisdictional approval pathways to guide lifecycle management and combination trials.
- M&A and partnership target shortlists: Scored dossiers of potential tuck‑ins and alliance partners, ranked by strategic fit, regulatory foothold and manufacturing capability.
- Commercial playbooks and KPI templates: Launch, post‑launch and pricing playbooks tailored to brand, generic and hybrid commercialization models, plus KPI dashboards for executive monitoring.
Strategic recommendations for 2026 — prioritized actions
- For originator players: Deploy targeted RWE investments to quantify safety‑management cost offsets and patient outcomes vs. generics; prioritize label clarity and negotiated reimbursement bundles that reflect monitoring requirements.
- For generic entrants: Focus initial capacity and tender efforts on markets where conversion windows are widest and logistics complexity is manageable; use AB‑rated approvals to accelerate formulary inclusion and generate scale economics quickly.
- For investors and PE: Prioritize assets that add manufacturing redundancy or differentiated formulation capabilities; value accretion will be driven by supply‑chain control and the ability to compete in tendered volumes.
- For contract manufacturers/CROs: Position offerings around end‑to‑end support — from regulatory filings to pharmacovigilance services — to capture adjacent revenue streams as safety monitoring needs remain front‑of‑mind.
- Cross‑cutting: Execute a two‑track scenario plan that protects downside (accelerated price erosion, payer pushback) while funding selective upside bets (combination trials, label expansion) that can materially lift mid‑cycle growth.
Use cases — how different stakeholders should leverage the report
- Commercial leadership: Use the tender simulator and payer matrix to set 2026 pricing floors and prioritize markets for salesforce allocation.
- Corporate development: Leverage the M&A shortlist and valuation sensitivity analyses to surface targets that de‑risk supply or add adjacencies.
- Manufacturing and operations: Apply supplier heatmaps and capacity templates to make 18–36 month investment decisions with quantified ROIC scenarios.
- Medical affairs & RWE teams: Align evidence generation with the identified clinical gaps and payer evidence requirements outlined in the report’s dossier templates.
Final note — a “trailer” built to convert interest into action
This preview aligns PW Consulting’s strategic lens with the practical needs of organizations planning for 2026. We have deliberately showcased methodology, high‑level market trajectory and competitive dynamics while reserving the detailed segmentation tables and transaction‑grade spreadsheets for the full report. For teams ready to translate insight into executable plans — whether to defend brand value, scale a generics franchise, or target high‑impact M&A — the full dataset and interactive models are available on the PW Consulting report page. Contact our team to schedule a walk‑through and to obtain the report package that will serve as the playbook for your 2026 vorinostat strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smartphone Panel Market to Expand at 5.19% CAGR, Reaching USD 64.91 Billion by 2032
By PW Consulting, 2026-08-05
PW Consulting Strategic Brief: Worldwide Smartphone Panel Market — A 2026 Decision Playbook
PW Consulting’s new Worldwide Smartphone Panel Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) offers a focused, actionable intelligence set for executives who must make capital, procurement and product decisions in 2026. Our model projects market revenue rising from USD 45,520 Million in 2025 to USD 64,910.12 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.19% over the forecast window. This brief synthesizes the report’s strategic implications without disclosing the granular segment tables and confidential supplier metrics reserved for the full report.
Worldwide Smartphone Panel Market
Why this report matters for 2026 decision cycles
-
Timing of investment. With steady mid-single-digit market growth through 2032, the window for prudent capacity investments and selective technology bets is open but narrowing. The report’s capex tracker and tranche-based investment triggers help align factory expansion or outsourcing decisions with realistic demand trajectories.
Worldwide Smartphone Panel Market -
Supplier selection under volatility. Supply-side concentration and raw-material geopolitics increase the cost of supplier missteps. Our supplier scorecards and scenario-tested sourcing playbooks enable procurement teams to balance price, tech roadmap and supply risk.
Worldwide Smartphone Panel Market -
Product roadmap prioritization. The migration dynamics toward emissive technologies and flexible form factors require product managers to re-weight R&D and BOM strategies. The report’s technology timelines and cost inflection curves quantify when AMOLED and flexible investments become nominally accretive.
-
Policy and contingency planning. Trade-policy risk and critical-mineral control are now first-order variables for enterprise risk management. The report’s trade-scenario stress tests and mitigation matrices provide practical contingency plans for 2026 implementation.
What the report delivers (practical, board-ready assets)
-
Transparent forecasting engine — a replicable demand model with sensitivity levers for unit volumes, display mix and ASP that executives can use to run bespoke scenarios.
-
Supplier scorecards — multi-factor assessments that combine capacity, technology readiness, quality performance, client concentration and geopolitical exposure into a procurement-ranked universe.
-
Capex and ramp tracker — line-by-line visibility on announced and industry-validated capacity changes, their likely ramp timing and the implied impact on global panel supply balances.
-
Technology migration timelines — when key cost and performance inflection points are expected for AMOLED variants, LTPO evolution, ultra-thin glass (UTG) usage and flexible substrates.
-
Supply-chain risk matrix — granular failure modes for critical inputs (e.g., ITO, indium, polyimide, UTG), node-level concentration mapping and mitigation options (dual-sourcing, strategic inventory, vertical integration scenarios).
-
Commercial playbooks — buyer negotiation strategies, make-vs-buy decision frameworks, launch-timing optimization and pricing levers for smartphone OEMs targeting premium, mid-range and entry segments.
-
Policy scenario analysis — discrete scenarios reflecting potential tariff regimes, export controls and critical-mineral interventions, each with quantified P&L and supply impacts.
Market dynamics that should shape 2026 plans
-
Gradual but clear growth trajectory. The market shows steady expansion from the mid-2020s baseline into the early 2030s. The structural growth is driven by device refresh cycles, penetration of new form factors and component upgrades; however, growth is uneven across technologies and geographies.
-
AMOLED acceleration. Independent industry forecasts point to accelerating unit adoption of emissive displays across price tiers. This is reshaping both BOM cost structures and supplier competitive dynamics, and it is a central input to our product roadmap counsel.
-
Flexible and foldable moving from halo to mainstream. Engineering improvements (substrates, UTG, crease mitigation) and supply-side investments are turning previously niche form factors into credible product lines for premium and adjacent segments.
-
Supply concentration and strategic suppliers. The market remains concentrated: a small group of global suppliers captures a dominant share of high-value panel sales, with several large-volume manufacturers competing for scale in mid-to-high tiers. This structure favors incumbents with integrated technology stacks, while creating opportunities for specialized entrants.
-
Raw-material and policy volatility. Control over processing of critical materials (e.g., indium, gallium) and the potential for trade measures tied to national-security reviews raise meaningful tail risks for supply chains. Procurement and legal teams must embed trade-policy triggers into sourcing contracts.
Competitive landscape — what leading suppliers are positioning for
-
Samsung Display (South Korea) — remains the technology leader for premium emissive and foldable displays, demonstrating advanced LTPO and foldable OLED capabilities and evaluating additional capacity targeted at flagship device programs.
-
LG Display (South Korea) — focusing on flexible AMOLED technologies for premium models and expanding strategic partnerships in the high-end device segment.
-
BOE Technology Group (China) — the largest-volume supplier with end-to-end capabilities across legacy LCD and increasingly competitive OLED lines; recent activations of higher-generation OLED capacity materially alter supply dynamics for mid-to-high-end panels.
-
TCL CSOT (China) — scaling AMOLED competence while leveraging partnerships to increase share in mid-range and selected flagship programs.
-
Other noteworthy players — a mix of focused OLED specialists, established LCD makers and emerging challengers from Taiwan, Japan and China are each pursuing differentiated strategies (niche premium supply, cost-led scale, or flexible OLED specialization).
Recent industry signals that change the odds in 2026
-
Capacity and ramp announcements from large suppliers are accelerating supply-side transitions and will influence pricing and availability in 2026.
-
Independent market trackers estimate global smartphone panel shipments at multi-billion unit levels in 2026 with continued growth in AMOLED share—an indicator that mid-range adoption is an important vector of demand.
-
Leading suppliers are actively showcasing advanced display innovations (privacy modes, slidable screens) and reviewing targeted investments for devices from marquee OEMs—signs that premium-product roadmaps remain an area of intense competition and customer-specific capacity allocation.
-
Raw-material and regulatory developments are injecting short-to-medium-term uncertainty. Firms should treat these as strategic variables rather than isolated procurement inconveniences.
Strategic recommendations for executives in 2026
-
Embed supply-risk metrics into every sourcing decision. Require supplier bids to include quantified exposure to critical-material constraints and policy scenarios; adjust contract terms to reflect those exposures.
-
Accelerate dual-sourcing for technology transitions. Where AMOLED or flexible panels are material to product differentiation, secure at least two qualified suppliers with staggered qualification timelines to reduce single-vendor risk.
-
De-risk through staged capex participation. For OEMs considering joint investments or captive lines, use tranche-based commitments tied to validated demand milestones from our forecast engine to avoid stranded capacity.
-
Prioritize product segmentation by value capture, not purely by feature. The report’s margin models show when display innovations drive sustainable ASP uplift versus transient price competition.
-
Operationalize trade-policy contingency plans. Build “go/no-go” triggers for inventory build, tariff pass-through clauses in supplier agreements and an escalation ladder for rapid re-sourcing.
-
Use M&A and partnership selectively. Acquire or partner with specialists in flexible substrates, UTG or advanced OLED process expertise when it accelerates go-to-market advantage inexpensively compared with organic development.
How PW Consulting’s report delivers defensible advantage
Our analysis combines a fact-based demand model, validated capacity tracker, supplier performance datasets and policy-scenario quantification to produce recommendations that are both executable and auditable. We deliberately withhold the granular segment and supplier share tables in this brief — those core datasets and detailed dashboards are reserved for the full report and client workshops. The result is a practical, board-level playbook tied to executable procurement, product and capital plans for 2026.
To operationalize these insights in the coming quarter, PW Consulting recommends convening a cross-functional “display risk and strategy” working group that uses our scenario engine to stress-test board-approved plans and to translate high-level strategy into supplier contracts, capex timetables and product launch priorities.
For access to the complete data tables, supplier scorecards, scenario models and the full fifty-plus page playbook that supports the 2026 decision calendar, please refer to the Worldwide Smartphone Panel Market report landing page. The public brief above illustrates the strategic direction and executive actions implied by our findings; the full report contains the detailed segmentation and proprietary metrics necessary to implement them.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rail Components Market to Reach USD 99.6 Billion by 2032 at a 4.65% CAGR, Asia Pacific Commanding 31.9% Share
By PW Consulting, 2026-08-05
Worldwide Rail Components Market: Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on Worldwide Rail Components delivers a focused intelligence package designed to convert macro trends into actionable decisions for 2026. Using a base year of 2025 and a forecast window through 2032, the report synthesizes historical performance (2020–2025), forward-looking demand scenarios, supplier economics, regulatory exposures and M&A opportunities. Our analysis shows the addressable market moving from an estimated USD 72.45 billion in 2025 to USD 99.6 billion by 2032, equivalent to a 4.65% compound annual growth rate over the forecast period—figures that frame investment thresholds, capacity plans and product roadmaps for next-year decision cycles.
Worldwide Rail Components Market
Market trajectory and what it means for 2026
The rail components market entered 2026 after a period of mixed momentum: solid recovery in rolling-stock procurement combined with variable freight cycles and episodic infrastructure spending. PW Consulting’s model captures these dynamics and projects a steady expansion through 2032 driven by electrification, automation, fleet renewals and modal shifts toward rail for decarbonization. Importantly, growth is not evenly distributed across product classes or geographies: our research highlights asymmetric pockets of demand where electrification programs, heavy-haul upgrades and urban rail projects are accelerating component replacement cycles.
Worldwide Rail Components Market
For 2026 planning, the headline numbers serve three practical purposes. First, they validate near-term demand visibility for suppliers sizing capacity and inventories. Second, they give capital allocators confidence in multi-year revenue baselines when evaluating factory upgrades, JV structures or bolt‑on acquisitions. Third, they provide operators and infrastructure managers a quantitative footing to prioritize refurbishment vs. replacement trade-offs under tightening budget envelopes and emissions constraints.
Worldwide Rail Components Market
Key macrodrivers shaping supplier strategy
- Electrification and automation: Accelerated deployment of electrified traction and driverless systems is shifting component content and software intensity per vehicle. Suppliers that can pair powertrain hardware with systems-level control and cybersecurity will capture higher value pools.
- Regulatory tightening: New interoperability and signaling mandates are forcing architecture upgrades in major markets; compliance timelines create near-term retrofit windows as well as long-term design lock‑ins that influence product roadmaps.
- Raw material and carbon economics: Steel and alloy price volatility—compounded by carbon border regimes—are driving procurement strategies that blend vertical integration, hedging and material substitution to protect margins.
- Consolidation and specialization: Market concentration data indicate that top-tier suppliers hold a disproportionate share of market influence, encouraging targeted partnerships for mid‑market players and opportunistic M&A by strategic buyers.
What the report delivers: operational intelligence, not just numbers
PW Consulting’s report is built as a decision toolset for executives who must translate market dynamics into 2026 choices. Key deliverables include:
- Forward demand scenarios (three-tier) with sensitivity to capex cycles, energy prices and modal demand shifts—enabling stress-testing of capacity and cash-flow plans.
- Win/loss playbooks for OEMs and Tier‑1 suppliers that map product portfolios to probable procurement frameworks and procurement KPIs used by major operators.
- Supplier economics and cost-to-serve models that quantify margin erosion risk under raw-material spikes and carbon tariff exposure.
- Regulatory impact matrix aligned to the latest interoperability and signaling mandates, translating compliance scenarios into engineering and certification timelines.
- M&A and partnership scouting list with valuation heuristics and integration risk scores to accelerate target screening and diligence workstreams.
- Commercial go-to-market blueprints by strategic theme—localization, digitalization, aftermarket services—designed to convert project pipelines into recurring revenue streams.
Competitive landscape: dynamics and positioning
The rail components market shows clear clustering of capabilities: traditional mechanical specialists, systems integrators, and emerging digital-platform players. Market concentration metrics—where the top three incumbents account for approximately 38.4% of market share and the top five for roughly 52.15%—underscore a mid-to-high consolidation level. This structure creates both barriers and niches: while leading players can dictate standards and win platform-level deals, mid-tier firms can profitably serve specialized or regionalized needs.
How leading firms are positioning for 2026:
- Alstom is reinforcing its bogie, braking and pantograph franchises through joint developments and local engineering agreements, focusing on indigenization strategies in large networks to reduce lead times and improve compliance with local content rules.
- Siemens Mobility has pivoted toward automation and electrification platforms; the roll-out of advanced GoA4 automation components signals intensifying competition for driverless and metro automation contracts.
- Wabtec is deepening its digital fleet-management and friction-products integration—an approach that converts single‑product engagements into lifecycle service relationships with Class I and regional operators.
- Knorr‑Bremse continues to expand through targeted acquisitions in compact braking calipers and metro subsystems—building a portfolio that spans heavy-haul to urban mass-transit regimes.
- voestalpine, Nippon Steel and ArcelorMittal maintain strategic positions upstream with rail steels and sections; certification gains and premium metallurgical grades are being used to secure long-term supply contracts with infrastructure owners.
- Thales, Hitachi Rail and Stadler are strengthening systems‑level competencies—signaling, traction and control architectures—that can lock in downstream component demand.
- CRRC and regional manufacturers are leveraging scale and cost competitiveness in rolling stock and core rotating components, especially in regions prioritizing rapid fleet expansion.
- Specialists such as Lucchini RS, Greenbrier, Trinity and Titagarh are doubling down on product differentiation—high-performance wheelsets, freight car assemblies and region-specific designs—to protect margins against price competition.
Recent industry moves—product launches in automation, targeted acquisitions in brake and caliper technologies, AREMA certifications, and large supply contracts for digital optimization—illustrate an active market where technology and regulatory compliance are driving transactional activity. For buyers and investors this means heightened diligence on integration risk and certification pipelines during 2026 dealmaking.
Regulation, raw materials and carbon: managing second-order risks
Three regulatory and input-cost realities deserve explicit attention in 2026 planning. First, interoperability mandates in major markets are creating compulsory retrofit and replacement windows that suppliers should model into production planning. Second, modern signaling mandates and positive train control upgrades are transforming the content of wayside and onboard equipment, creating a serviceable aftermarket opportunity. Third, steel and specialty alloy pricing—and the introduction of carbon border mechanisms—are reshaping landed costs and supplier selection criteria.
PW Consulting’s report includes a calibrated raw-material sensitivity engine that quantifies margin exposure under a range of steel-price and carbon-tariff outcomes, and prescribes procurement and sourcing responses (e.g., long-term offtakes, vertical partnerships, material substitution paths). For procurement teams, these tools convert headline risks into tactical levers for 2026 contracting rounds.
Decision roadmap for 2026: four priority moves
- Lock in certified supply lines and compliance roadmaps: Prioritize suppliers with certified metallurgy and signaling interoperability to avoid certification delays that can push projects out of 2026 windows.
- Translate electrification into product modularity: Re-architect offerings to combine traction hardware with software and service bundles—this increases wallet share per fleet and reduces commodity exposure.
- Hedge raw-material and carbon exposure: Use blended procurement techniques—multi-sourcing, hedging, and strategic inventory—to smooth cost curves and protect margins during peak volatility.
- Accelerate aftermarket and life‑cycle service models: Shift the revenue mix toward recurring maintenance and digital optimization services to stabilize revenues against capex cyclicality in 2026 and beyond.
Why PW Consulting’s study is uniquely actionable
Beyond headline forecasts, the report is scaffolded to support immediate execution: it provides procurement-ready scenario tables, an M&A screening matrix with integration checklists, and operator-grade retrofit roadmaps aligned to regulatory timetables. We intentionally withhold detailed segment-by-segment figures in this briefing to preserve the value of the full dataset—those granular splits underpin contract simulations, plant-utilization models and deal valuation work that many executives will want to run before committing capital in 2026.
In a market where certification timelines, carbon economics and digital transformation intersect, the right intelligence—packaged for use at the board, commercial and engineering levels—becomes a competitive weapon. PW Consulting’s Worldwide Rail Components Market report equips decision-makers with that weapon: rigorous, actionable and calibrated for the 2026 planning cycle.
Next steps
- Download the full report to access the detailed segmentation models, certified supplier database, and our interactive demand-sensitivity tools.
- Contact our rail practice to commission a tailored brief that applies the report’s scenarios to your product lines, plants or M&A targets for 2026 decision windows.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automatic Cosmetic Powder Pressing Machine Market to Rise from USD 172.5 Million in 2025 to USD 273.05 Million by 2032 at a 6.78% CAGR
By PW Consulting, 2026-08-05
Worldwide Automatic Cosmetic Powder Pressing Machine Market — Strategic Outlook for 2026
PW Consulting today publishes an executive market brief accompanying our full report: "Worldwide Automatic Cosmetic Powder Pressing Machine Market, 2026–2032." Drawing on a multi-source database and primary interviews across the value chain, this briefing highlights the strategic implications for senior executives planning capital allocation, supplier selection, and product-line roadmaps in 2026. The market reached USD 172.5 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of approximately 6.78% through the 2026–2032 period, reaching a projected market size by 2032 that signals meaningful opportunity for both equipment OEMs and end users.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
Why this report matters for 2026 decision-making
- Timing CapEx with market momentum: With sustained mid-single-digit CAGR projected for the next seven years, procurement teams face the classic trade-off between early adoption (securing technological advantage) and cost optimization (benefiting from subsequent product improvements). Our research translates forecast trajectories into investment thresholds that inform "buy, upgrade, or wait" decisions.
- Vendor selection under new compliance pressures: Regulatory changes globally—most notably the post-MoCRA compliance environment—are shifting buyers toward machines that deliver consistent compaction, traceable process controls, and GMP-aligned documentation. Procurement strategies that prioritize lifecycle service and software compatibility materially reduce regulatory friction.
- Operational resilience and automation ROI: Labor constraints and rising input costs are increasing the return on automation. The report supplies TCO frameworks and sensitivity analyses that quantify when automated servo and rotary systems outperform semi-automatic or manual solutions in different operating contexts.
Market dynamics shaping 2026 strategy
Three converging forces are driving momentum in the powder pressing equipment market. First, regulatory and quality requirements (e.g., GMP alignment and adverse‑event reporting enhancements) are elevating demand for machines capable of repeatable output and data capture. Second, macro‑cost dynamics—especially labor inflation and modest upward pressure on structural raw materials—are accelerating automation adoption, particularly among contract manufacturers and high‑volume brands. Third, technological diffusion (servo control, modular rotary platforms, Industry 4.0 interfaces) is enabling new operating models: smaller footprints with higher throughput, remote diagnostics, and predictive maintenance.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
These dynamics translate into concrete procurement implications: OEMs that offer modularity, robust software ecosystems, and field-proven compaction consistency capture a premium in procurement cycles; buyers that insist on validated process data and aftermarket support create barriers to supplier switching.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
What PW Consulting’s full report delivers (actionable contents)
- Proprietary market-sizing and a seven-year forecast model (2026–2032) with adjustable inputs—enabling scenario planning for conservative, base, and accelerated demand cases.
- Practical buyer tools: capital expenditure scorecards, total cost of ownership calculators, RFP templates, and a supplier evaluation matrix to short-list OEMs by technical fit, service footprint, and upgrade roadmap.
- Supply‑chain and input‑cost sensitivity analysis—covering steel and mechanical component pricing, spare‑parts lead times, and logistics disruption scenarios—plus mitigation playbooks.
- Comprehensive competitive landscape analysis that profiles technologies (servo vs hydraulic vs pneumatic), form factors (rotary, single‑color, multi‑color, lab and pilot presses), and lifecycle economics.
- Case studies and implementation guides: three anonymized buyer journeys detailing specification development, pilot testing, scale‑up, and quality assurance integration under GMP regimes.
Competitive landscape — what buyers and investors need to know
The competitive field blends established European engineering houses with agile Chinese OEMs that combine customization and cost flexibility. The market exhibits a moderate concentration: the top three global players account for roughly two‑fifths of market revenue, while the top five exceed the halfway mark—an important signal for M&A-minded strategists and procurement teams seeking diversified supply bases.
- GIENI (Shanghai GLENI Industry Co., Ltd.) — Shanghai: GIENI’s portfolio emphasizes full automation, PLC/servo integration, and modular designs targeted at high-volume compact production. Recent product enhancements unveiled in early 2026 emphasize user-friendly interfaces, servo-fed dosing, hydraulic compaction, and integrated powder extraction—features that directly address GMP and process‑consistency demands. GIENI’s active trade-show presence signals an intent to compete on both product breadth and global sales channels.
- Eugeng International Trade Co., Ltd. — Shanghai: Eugeng’s strategy centers on a wide range of fully automatic lines complemented by hydraulic lab and servo variants. Their consistent visibility at regional trade events underscores strength in channel relationships and rapid time‑to‑delivery for tailored configurations—a key advantage for contract manufacturers requiring short lead-time pilots.
- Guangzhou Jutao & Guangzhou Yeto — Guangzhou: These OEMs play to customization and lab/one‑mold solutions. Their portfolios matter to brands and R&D facilities seeking flexible proof‑of‑concept machines before committing to larger rotary platforms.
- Lorenzato S.r.l. — Italy: A long-standing engineering name, Lorenzato emphasizes precision rotary platforms and Industry 4.0 compatibility—appealing to European and global manufacturers prioritizing integration with automated production lines and digital quality systems.
- Bonals Technologies & Foshan Henwi — Spain/China: These suppliers provide a mix of eccentric/rotary presses and hydraulic machines suitable for a range of powder characteristics. Their technical depth supports specialized formulations (e.g., high‑pigment eyeshadows or humidified blends) where machine mechanics materially impact end-product stability.
Together, the competitive set indicates differentiated routes to market: high‑precision European platforms sell on integration and reliability, while several Chinese suppliers compete on configurability, speed of delivery, and aggressive aftermarket packages. Buyers must weigh these trade-offs against lifecycle costs and compliance requirements rather than headline CapEx alone.
Strategic implications and recommended actions for 2026
- Adopt a phased procurement strategy: Start with pilot installations using lab‑scale or single‑color platforms to de‑risk formulation transfers. Transition to modular rotary or multi‑color presses when yield and throughput targets are validated.
- Prioritize process data and service contracts: Machines that provide validated data capture, remote diagnostics, and robust spare‑parts availability reduce regulatory and operational risk. Locking favorable service-level agreements at purchase can materially shorten downtime exposure.
- Stress‑test suppliers for regulatory readiness: Require GMP evidence, change-control workflows, and adverse‑event reporting support during vendor selection—especially for exporters into tightly regulated markets.
- Model raw‑material and labor sensitivities: Use the report’s TCO and sensitivity tools to quantify how modest steel price shifts or incremental labor inflation affect payback periods for different machine classes.
- Consider consolidation and partnership plays: For OEMs and investors, the current concentration metrics and differentiated capabilities point to selective acquisition strategies—targeting lab‑scale specialists or service-centric providers to round out product portfolios and aftersales reach.
Scenario planning: three practical paths
- Conservative (preservation): Delay large capital outlays, standardize formulations to limit tooling changes, and prioritize service contracts. Useful for firms facing margin pressure in the near term.
- Base (capture steady growth): Invest selectively in automated single‑color/rotary machines where throughput gains and compliance benefits are clear; deploy pilots and scale driven by validated ROI thresholds from the report model.
- Aggressive (market capture): Fast‑track multi‑color and Industry 4.0‑capable platforms, pursue partnership deals with OEMs for co‑development, and expand contract manufacturing capacity to win volume business.
Final thought — positioning for the next growth wave
The 2026 procurement horizon is shaped as much by regulatory rigor and labor economics as by pure demand for cosmetics. For manufacturers and investors, the core decision is not merely which machine to buy, but how to align equipment strategy with compliance, digital integration, and lifecycle economics. PW Consulting’s full market study translates the headline CAGR and trajectory into practical, executable guidance—delivering the dataset, vendor scoring frameworks, and implementation blueprints necessary to operationalize capital decisions in 2026.
To access the complete dataset, regional and machine‑type breakdowns, vendor scorecards, and the full suite of buyer tools referenced in this briefing, please refer to the report landing page on PW Consulting’s website where the full report and executive package are available.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Cosmetic Powder Pressing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Solenoid Reversing Valve Market Valued at USD 962.46 Million in 2025, Poised to Reach USD 1.38 Billion by 2032 at a 5.24% CAGR
By PW Consulting, 2026-08-05
Worldwide Solenoid Reversing Valve Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting's latest market study on the Worldwide Solenoid Reversing Valve Market offers executives a focused, decision-ready view of a critical component ecosystem that sits at the intersection of HVAC decarbonization, industrial automation and refrigeration reliability. This preview highlights the report’s strategic value for boardroom and product roadmap decisions in 2026, outlines competitive dynamics, and explains how macro headwinds and technology shifts will shape supplier and OEM choices over the next business cycle.
Worldwide Solenoid Reversing Valve Market
Executive Snapshot: Size, Growth and Momentum
-
Market base year: 2025 (historical window 2020–2025; forecasting period 2026–2032).
Worldwide Solenoid Reversing Valve Market -
Compound annual growth rate (CAGR) for the forecast window (2026–2032): 5.24%.
Worldwide Solenoid Reversing Valve Market -
Observed trajectory: the market expanded steadily from a mid‑2020s base and reached approximately USD 962.5 Million in 2025. The PW forecast model anticipates ongoing growth through 2032 as the market responds to heat‑pump adoption, refrigerant transitions and greater demand for reliable reversing mechanisms in both residential and commercial systems.
These headline figures are included here to orient strategic planning. The full report supplies the granular build‑up behind each annual datum, including bottom‑up demand assumptions, OEM penetration rates, and component pricing models that produce our published time series and 2032 projection.
Why This Report Matters for 2026 Decisions
-
High leverage to long‑term energy transition trends: The accelerating adoption of heat pump systems and energy‑efficient HVAC architectures is increasing demand for robust four‑way reversing valves and other solenoid reversing solutions. For product and procurement leaders this creates both volume opportunities and heightened reliability expectations.
-
Material and supply‑chain sensitivity: Steel and component costs materially affect valve BOMs. PW’s field intelligence observed US hot‑rolled coil (HRC) spot prices stabilizing in a band in mid‑2025 and moving higher into early 2026 as mill pricing actions tightened availability — a dynamic that changes the unit economics of valve families and has prompted several vendors to reprice or requalify materials.
-
Regulatory and certification gating items: Reversing valves used in heat pumps and HVAC must meet industry recognition standards and pressure ratings (for example, UL recognition and compatibility with typical HFC operating pressures up to defined thresholds). These gating items affect time‑to‑market and upgrade cycles for OEMs targeting low‑GWP refrigerants.
-
Consolidation and concentration effects: Market concentration is high among the top vendors, producing differentiated bargaining power, channel relationships and aftermarket footprint considerations. Our competitive matrix translates concentration metrics into strategic implications for suppliers and buyers alike.
What the Full Report Contains (Practical, Actionable Deliverables)
-
Market sizing and forecast model with downloadable Excel workbooks that let you test alternative assumptions (refrigerant transition speed, heat pump penetration, unit replacement cycles).
-
Demand‑driver diagnostic: primary research‑backed analysis of end‑use velocity (residential, commercial, industrial) and technology adoption curves supporting product prioritization.
-
Regulatory and standards map: compliance pathways, certification timing estimates and the pressure/refrigerant compatibility matrix that shape engineering specs.
-
Supplier benchmarking and capability heat maps: product portfolios, manufacturing footprint, technology differentiation, and aftermarket service capabilities to guide sourcing and alliance strategies.
-
Component cost sensitivity models and scenario planning: evaluate the P&L impact of raw‑material price shifts, tariff scenarios, and legislative incentives for low‑GWP systems.
-
Go‑to‑market playbooks for OEMs and tier‑1 suppliers: recommended actions across R&D prioritization, quality assurance, distribution, and digital monitoring partnerships.
-
M&A and partnership screen: target profiles and valuation sensitivities for strategic buyers focused on consolidation, technology access or geographic expansion.
In line with the “trailer” approach we adopt for this release, we are intentionally summarizing the report’s scope and practical outputs here while withholding the granular sub‑segment allocations and proprietary scenario tables that appear in the paid study. Those datasets are designed as decision tools for corporate planners and investors and are available through the report portal.
Competitive Landscape — Who Matters and Why
-
Sanhua Holding Group (Hangzhou, China): Global leader in four‑way reversing valves for HVAC and heat pumps. Recent product activity includes the SHF‑G stainless steel series introduced in late 2025 — an example of suppliers moving toward materials and designs explicitly tuned to next‑generation refrigerants and cycling durability.
-
Danfoss (Nordborg, Denmark): Broad portfolio spanning solenoid valves and reversing solutions; strength in integrated system partnerships with major OEMs and a well‑established channel network.
-
Parker Hannifin and Bosch Rexroth: Both bring deep expertise in hydraulic and pneumatic directional control valves, with particular pull in industrial and mobile applications where robustness under harsh service conditions is a premium.
-
Robertshaw and Wilspec (US): Notable for heat‑pump centric reversing designs and field‑serviceability claims; Wilspec’s strength in geothermal applications highlights niche specialty playbooks that can command premium margins.
-
SMC, ASCO (Emerson), DunAn and Shandong Yikaide: Each occupies a part of the broader automation and refrigeration valve ecosystem—ranging from pneumatic actuation to electromagnetic four‑way units—contributing to supplier diversity and technology substitution risk.
Our competitive assessment combines product performance scoring, reliability baselining from field studies, go‑to‑market breadth and pricing power. The result: a ranked map of strategic options for incumbents and challengers, and a short list of capabilities that most strongly predict success over the next two investment cycles.
Recent Developments and Their Strategic Read‑through
-
Sanhua’s late‑2025 SHF‑G stainless steel series release and the company’s presence at major expos in early 2026 underscore the race to deliver corrosion‑resistant, refrigerant‑flexible reversing valves that reduce warranty exposure and extend service life.
-
On raw materials, PW’s supplier checks and secondary sources documented HRC price stabilization in mid‑2025 followed by upward pressure into early 2026. Procurement teams need to quantify the pass‑through and consider hedging or long‑term sourcing to maintain margin stability.
-
Regulatory attention on low‑GWP refrigerants means earlier product requalification cycles and potential redesigns for pressure and seal materials; engineering roadmaps must embed certification time and test cycles as deterministic inputs to launch calendars.
Strategic Recommendations — 12‑ to 24‑Month Priorities
-
Embed refrigerant agnosticism in new designs: prioritize valve architectures and seal/material selections that are compatible with both common HFC blends and lower‑GWP/natural refrigerants to avoid near‑term retrofit costs.
-
Lock supply for critical metals: consider strategic contracts or qualification of alternate vendors for stainless steel and processed components to mitigate price spikes and lead‑time volatility.
-
Fast‑track certification pipelines: allocate dedicated program resources for UL recognition and pressure‑rating validation to reduce time‑to‑market when launching new valve platforms.
-
Invest in serviceability and digital diagnostics: for OEMs and aftermarket providers, offering simpler swap‑outs, condition monitoring and warranty analytics reduces installed‑base churn and increases lifetime revenue.
-
Evaluate selective M&A or JV activity: given the high concentration at the top of the supplier stack, strategic buyers should assess bolt‑on targets that add material technology, niche end‑market reach or aftermarket service scale.
Scenario Sensitivities and Stress Tests
PW’s scenario framework evaluates outcomes across three primary vectors: refrigerant transition pace, heat‑pump adoption curves, and raw‑material cost scenarios. Each vector has non‑linear effects on supplier margins, SKU rationalization, and total addressable market timing. Our forecast model allows corporate users to run bespoke permutations; for example, a faster transition to natural refrigerants compresses product cycles but expands long‑term volumes, while sustained metal price inflation favors suppliers with vertically integrated or geographically diversified sourcing.
Conclusion — What to Do Next
For executives preparing 2026 operating plans or planning capital allocation into 2027 product launches, PW Consulting’s Worldwide Solenoid Reversing Valve Market report provides the granular forecasting, risk matrices and competitive playbooks required to make informed choices. This preview has surfaced the strategic themes—material risk, regulatory gating, concentration dynamics and technology migration—that should define board‑level discussion. The complete report contains the detailed segmental outputs, company scorecards and downloadable models necessary to execute on those discussions.
Access the full PW Consulting study to obtain the detailed regional and application splits, proprietary supplier scoring, and the interactive forecast workbook that underpin our conclusions and recommended action plans.
For detailed analysis of this topic, please visit the official page: Worldwide Solenoid Reversing Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fabric Flame Retardancy Testers Market to Reach USD 167.89 Million by 2032 on a 5.45% CAGR — Asia‑Pacific Captures Nearly 49.2% Share
By PW Consulting, 2026-08-05
Worldwide Fabric Flame Retardancy Testers Market — Strategic Imperatives for 2026
Executive snapshot
PW Consulting today releases a focused market briefing extracted from our forthcoming Worldwide Fabric Flame Retardancy Testers Market report, intended to equip executive teams with the strategic context they need to make high‑confidence decisions in 2026. This briefing demonstrates the depth and rigor of our analysis while intentionally withholding core segment-level tables and granular share data — the detail that our clients rely on for transaction and planning work is available through the full report.
Worldwide Fabric Flame Retardancy Testers Market
Market trajectory and what it means for 2026 planning
The fabric flame retardancy testers market has shown steady expansion across the past half decade, growing from an estimated USD 88.8 million in 2020 to roughly USD 115.8 million by our base year (2025). Our forecast indicates continuation of that expansion, with the market moving through an expected USD 122.9 million in 2026 and reaching approximately USD 167.9 million by 2032. The forecast period is characterized by a midpoint compound annual growth rate of 5.45% — a pace that supports disciplined investment but also rewards agility and differentiated product strategies.
Worldwide Fabric Flame Retardancy Testers Market
For leaders allocating CapEx in 2026, these topline trajectories signal two practical realities: first, demand growth is real and persistent, driven by regulatory scrutiny, evolving materials innovations and end‑market safety priorities; second, the incremental value will increasingly accrue to players who combine hardware reliability with services (calibration, software analytics, compliance assurance) and rapid standards alignment.
Worldwide Fabric Flame Retardancy Testers Market
Why 2026 is a strategic hinge year
- Regulatory inflection points: Rule updates and persistent enforcement activity are elevating lab workloads and equipment refresh cycles. Notably, U.S. authorities have updated the Standard for the Flammability of Clothing Textiles (16 CFR 1610), expanding permissible equipment categories while keeping flammability classes intact — a change that creates supply‑side and validation workstreams for test houses and OEMs aligning product portfolios to new procedural flexibilities.
- Standards persistence and specialization: Legacy and specialist methods such as ASTM D6413 (vertical flame resistance) and ISO 15025 (limited flame spread for protective clothing) remain core to customer buying criteria. Newer cross‑domain requirements (automotive, furniture, children's products) are adding test permutations and accessory demand, requiring manufacturers to broaden modularity and traceability in their platforms.
- Manufacturing cost signals: Steel and aluminum raw material cycles have shown meaningful movement into 2025–early 2026 — a backdrop that elevates procurement and margin pressure for instrument manufacturers. This increases the importance of supplier contracting strategies and product designs that optimize for lighter non‑ferrous components where technically feasible.
What the full report delivers (practical, actionable content)
We designed the report to be operationally useful to investment committees, product teams, compliance leads and test house operators. Highlights include:
- Top‑down market sizing and a transparent forecasting model (2020–2032) with scenario toggles for regulatory stringency and raw material price shocks.
- A demand‑driver map linking end‑market regulatory cycles, materials substitution trends and lab‑service growth to equipment replacement and aftermarket services.
- Supplier cost‑structure benchmarking, including BOM sensitivity to steel and aluminum price movements and recommended component substitution levers to protect gross margins.
- Practical go‑to‑market playbooks for OEMs and distributors: channel segmentation, tender readiness, and a checklist for certifying instruments against prevalent standards.
- Due diligence annexes for M&A and JV activity — valuation multiples observed in adjacent instrumentation markets, integration risks, and a value‑creation roadmap focused on services and software monetization.
- Operational diagnostic templates for labs to prioritize capital refreshes and build a five‑year calibration and recertification budget.
Competitive landscape — who matters and why
The market retains a mix of specialized domestic manufacturers, multi‑product global vendors and testing solution houses that bundle hardware with software and aftercare. Concentration is moderate: our concentration metrics show a top‑three aggregate and a top‑five aggregate that indicate opportunities for both scale players and fast‑moving niche entrants to gain position.
- DaRong (China): A comprehensive product suite addressing vertical, horizontal and 45‑degree test methods plus several specialized fixtures (e.g., for mattresses and protective footwear). Strengths lie in breadth of standards compliance (including domestic standards drafting participation), channel depth in regionally focused markets and a cost‑competitive manufacturing base.
- AVENO Technology (China): Offers a broad range of flame test apparatus oriented to textiles, automotive interiors and specialized requirements (curtains, upholstery). Aveno’s emphasis on automated and curtain propagation testers positions it well where throughput and repeatability are procurement priorities.
- GESTER (China): Known for robust single‑purpose systems (e.g., hanging fabric burn testers) with industrial design emphasis on corrosion resistance and operator ergonomics — attributes that matter for labs operating in harsh environments or with continuous testing programs.
- TESTEX (China): Brings multi‑purpose platforms with PLC control and optical scanning; an attractive option for test labs seeking consolidation of multiple test methods into a smaller equipment footprint and for OEMs looking to standardize across factories.
- FYI Tester (China): Focuses on classic UL and SPI method families, retaining appeal among garment and decorative textile manufacturers that need legacy method compatibility and straightforward automation options.
- SDL Atlas (USA, with regional operations): Represents the archetype global supplier with strong brand recognition in automotive, aerospace and high‑end lab segments; its platforms are often chosen where service SLAs, certification pathways and global spare parts support are decisive.
Together, these vendors illustrate two competitive vectors: (1) cost‑efficient, broad‑range suppliers who win on price and local service; (2) premium, service‑oriented vendors who win on lifecycle support and global standards alignment. The market concentration metrics underline that selective consolidation or strategic partnerships can quickly alter regional advantage.
Standards, testing protocols and product design implications
Compliance is not static. ISO 15025 and ASTM D6413 remain anchors for protective and vertical flame testing respectively, and specific jurisdictional methods (e.g., NFPA 701 for curtain materials, 16 CFR 1610 in the U.S.) continue to define test permutations that buyers demand. Recent regulatory updates have expanded acceptable equipment categories without changing core flammability classes, which creates two practical product design imperatives:
- Design modular instrumentation that can be recertified across a broader range of procedural interpretations to minimize replacement cycles.
- Invest in traceable software and data‑capture modules that support audit trails, reverse‑traceability and remote verification — features increasingly specified by procurement teams.
Supply chain and cost management signals
Raw material cycles in steel and aluminum have implications for instrument cost baselines. By mid‑2025, hot‑rolled coil steel prices stabilized at elevated levels with futures showing modest firmness into early 2026. Aluminum mill shapes exhibited significant year‑over‑year increases into early 2026. For manufacturers of test equipment, this translates into near‑term margin compression unless addressed through:
- Strategic forward purchasing and index‑linked supplier contracts.
- Design rationalization to reduce non‑critical steel content and leverage composite or lighter alloys where performance permits.
- Value capture through services (installation, calibration, subscription‑based software) to offset hardware margin declines.
Actionable strategies for 2026 decision‑makers
For executives preparing 2026 budgets and strategic roadmaps, the following priorities will materially influence outcomes:
- Prioritize modularity: Favor platforms that can be field‑upgraded to support multiple test methods and standards to extend equipment lifetime and address procurement cycles.
- Monetize services: Accelerate development of calibration and compliance assurance offerings — recurring revenue models significantly improve enterprise value multiples in this sector.
- Hedge procurement cost risk: Lock in key raw material suppliers or move to blended BOMs to lower sensitivity to metal price volatility.
- Prepare for regulatory shifts: Embed regulatory monitoring into product roadmaps so firmware, software and documentation updates can be shipped rapidly without requiring hardware replacement.
- Pursue focused M&A or partnerships: Consider tuck‑ins that add software telematics, calibration laboratories or regional service networks to accelerate global expansion with limited CapEx.
About the report and next steps
This briefing is a curated preview: it establishes the market contours and offers strategic guidance while intentionally omitting the detailed segment tables, region‑by‑region allocations and the granular vendor market shares that our clients purchase to inform tactical decisions and transaction due diligence. The full report contains the complete empirical model (2020–2032), scenario sensitivity files, supplier scorecards and a playbook tailored for OEMs, lab operators and private equity investors.
To access the complete dataset, vendor scorecards and the scenario model needed to finalize 2026 investment decisions, please visit PW Consulting’s Worldwide Fabric Flame Retardancy Testers Market report page or contact your PW Consulting account lead. Our team is available to run a bespoke briefing that applies the model to your product portfolio, procurement plans or M&A targets.
Analyst contact
PW Consulting — Industry Intelligence & Strategic Advisory. Report base year: 2025. Forecast period: 2026–2032.
For detailed analysis of this topic, please visit the official page: Worldwide Fabric Flame Retardancy Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


