



Category: market research
PW Consulting Forecasts Worldwide Microbial Fuel Cell Market to Expand at a Robust 11.25% CAGR Through 2032
By PW Consulting, 2026-08-05
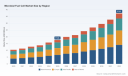
Worldwide Microbial Fuel Cell Market — Strategic Outlook for 2026 Decision-Making
Executive summary
PW Consulting’s new market study on the Worldwide Microbial Fuel Cell (MFC) market synthesizes five years of historical performance (2020–2025) with an actionable forecast spanning 2026–2032. The global market has expanded from approximately USD 10.45 Million in 2020 to USD 17.65 Million in 2025, and our modeling projects sustained growth at a compounded annual growth rate (CAGR) of 11.25% through 2032, when the market is expected to approach USD 37.23 Million. For executives evaluating capital allocation, technology partnerships, or pilot-to-scale roadmaps in 2026, the report provides the strategic analytics required to prioritize investments, structure pilots, and prepare for near-term commercialization inflection points.
Worldwide Microbial Fuel Cell Market
Why this report matters for 2026 strategy
-
Actionable horizon: The 2026–2032 forecast isolates the window when pilot learnings and incremental technology improvements converge to create measurable commercial opportunity. Our analysis identifies which business models are likely to move from project-based pilots to recurring revenue streams.
Worldwide Microbial Fuel Cell Market -
Decision-grade inputs: We translate market momentum into decision-support deliverables—scenario-modelled revenue impacts, capex/opex drivers, and sensitivity analyses that allow CFOs and R&D heads to stress-test investment cases under varying adoption rates and regulatory outcomes.
Worldwide Microbial Fuel Cell Market -
Competitive posture: With market concentration metrics showing a moderately consolidated landscape (CR3 ~38.5% and CR5 ~52.15%), the report helps mid-sized players and late-stage investors identify defensible niches and partnership strategies to outflank incumbent advantages.
Market trajectory and what the numbers say
Between 2020 and 2025 the MFC market more than recovered from its nascent-stage constraints, rising from USD 10.45 Million to USD 17.65 Million. Our base-year is 2025 and the forecast period covers 2026–2032. We project the market will grow to USD 19.93 Million in 2026 and continue on the path to USD 37.23 Million by 2032, reflecting an aggregate CAGR of 11.25% for the forecast period.
These topline figures capture a combination of organic adoption in wastewater treatment and biosensing, incremental commercial deployment for small-scale power generation, and steady improvement in system reliability and materials. We emphasize that while headline growth is attractive, the pace at which pilot-scale systems transition to sustained commercial deployments will be the decisive factor for revenue capture.
Technology dynamics: constraints and levers
-
Power density and reactor design: Recent field-validated reports indicate advanced MFC configurations can reach power densities up to 5 W/m³ in continuous-flow wastewater reactors. This performance envelope is sufficient to offset certain onsite energy demands, but only when reactor design and hydraulic management are optimized.
-
Materials economics: Carbon-based electrodes remain a primary cost driver; catalog pricing for carbon cloth electrodes currently sits in the range of USD 45–75 per m². Electrode lifecycle, fouling resilience, and replacement cadence therefore exert outsized influence on total cost of ownership for municipal and industrial buyers.
-
Regulatory tailwinds: Policy frameworks that prioritize energy-efficient secondary treatment—such as the EU Urban Waste Water Treatment Directive—create procurement levers that favour technologies delivering simultaneous wastewater treatment and energy recovery. Such mandates accelerate evaluation cycles within utilities and industrial wastewater operators.
-
Commercial limitation: Despite progress, many systems remain at pilot scale, with deployments often constrained to sub-kilowatt outputs due to electrode fouling and limited sustained power density. Overcoming these operational barriers is the single largest gating item for scaled rollouts.
Competitive landscape — positioning and strategic moves
The MFC vendor ecosystem includes focused innovators and systems integrators with differentiated value propositions. Our report offers in-depth company profiles, strategic assessments, and partnership roadmaps for leading players. Highlights:
-
Aquacycl Ltd. (Didcot, UK) — Focused on high-strength industrial wastewater, Aquacycl’s USABR™ bioelectrochemical reactors integrate energy recovery into processes where organic loading is significant. Their engineering-first approach targets industrial decarbonization use cases and positions them for partnerships with large wastewater generators seeking load-leveling benefits.
-
Plant-e B.V. (Wageningen, Netherlands) — Plant-e has commercialized plant-MFC concepts that capture electricity from the rhizosphere. Their strength lies in novel application design and environmental integration; this offers unique opportunities in distributed sensing and low-power microgrid augmentation rather than mainstream industrial energy replacement.
-
Microbenergy S.L. (Valladolid, Spain) — Producer of modular BEE-BOX® units, Microbenergy targets decentralized wastewater treatment with simultaneous electricity generation. Their modularity simplifies deployment logistics and appeals to off-grid or resource-constrained sites where combined treatment and power can displace diesel generators or reduce grid reliance.
-
Nijhuis Saur Industries (Doetinchem, Netherlands) — With BeeVe® membrane-free bioelectrochemical systems, Nijhuis Saur combines municipal-scale engineering capabilities with bioelectrochemical principles. Their market positioning as a systems integrator creates an opportunity to move MFC concepts from pilot to integrated treatment trains at utility scale.
Across these players, strategic differentiation falls into three vectors: technology ownership (materials and reactor design), systems integration capability (ability to embed MFCs into standard treatment trains), and route-to-market (direct utility sales, industrial partnerships, or OEM integrations). Our vendor matrix scores firms against these vectors and identifies likely partners for 2026 pilots.
What the report delivers — operationally focused contents
Beyond headline forecasts, the report is constructed as a playbook for operators, investors, and technology managers. Key deliverables include:
-
Commercial-grade TAM/SAM/SOM frameworks, with scenario modelling and sensitivity levers to evaluate upside under accelerated standards or slower technology maturation.
-
Technology assessment matrices that score reactor topologies, electrode materials, and operational protocols against reliability, scalability, and total cost of ownership.
-
Go-to-market frameworks tailored to three buyer archetypes: utilities, industrial wastewater operators, and distributed-power-use cases (e.g., remote sensing/ IoT charging).
-
Pilot-to-scale playbook: stepwise KPIs, sample test protocols, expected measurement windows, and a supplier selection checklist to reduce scale-up risk.
-
Capex/Opex modeling templates and procurement negotiation guidance focused on electrode sourcing, module warranties, and aftermarket service agreements.
-
Risk matrices that synthesize technology, regulatory, market, and supply-chain risks and propose mitigation tactics, including staged investments tied to performance milestones.
To preserve competitive value for subscribers and corporate clients, the report intentionally refrains from publishing granular subsegment revenue breakdowns in public summaries; those detailed segment tables and company-level revenue implications are available exclusively in the full report.
Investment and partnership thesis for 2026
-
Selective early-stage investments (R&D and field pilots) remain attractive where the target offers demonstrable gains on electrode longevity, fouling mitigation, or modularity that reduce parity time to payback.
-
Strategic partnerships between technology providers and large engineering firms (or utilities) accelerate adoption by embedding MFCs into the procurement and financing structures of established buyers.
-
Revenue models will favor-as-a-service and performance contracts in the near term; buyers are more likely to agree to models where payment is tied to verified treatment performance and energy offsets rather than upfront asset purchases.
Regulatory and procurement implications
Policy drivers that privilege energy-efficient secondary treatment create near-term projects with lower commercial friction. Procurement teams should build RFP language that includes lifecycle performance metrics and service-level agreements specific to bioelectrochemical modules. Given electrode costs and lifecycle impacts, centralized procurement and long-term supplier agreements can materially reduce unit cost and ensure technical support across pilot networks.
Frequently asked practical questions
-
Q: What is the realistic scale of current commercial deployments? A: Many MFC applications are still in pilot stages; public and private deployments have largely been constrained to sub-kilowatt installations due to electrode fouling and current power-density limitations. The next two years will be decisive as vendors demonstrate sustained operation at higher throughputs.
-
Q: Which inputs most affect the project economics? A: Electrode cost and replacement frequency, reactor hydraulic design (affecting power density), and integration complexity with existing treatment trains. Carbon-cloth electrodes remain a common cost line item.
-
Q: Where should we prioritize pilots in 2026? A: Sites with high organic loading and existing plans for energy-efficiency upgrades—such as food & beverage processing, agro-industrial facilities, and select municipal secondary treatment plants—offer the fastest path to meaningful measurable outcomes.
Next steps for executives
For companies evaluating entry or scale-up in 2026, we recommend three immediate actions: 1) run a short-list evaluation of internal wastewater sites against our KPI checklist; 2) define a two-stage pilot structure with performance gates tied to electrode life-cycle and power-density KPIs; and 3) engage prospective system integrators under a small-scale partnership agreement that includes technical support and data-sharing clauses.
Conclusion and how to access the full intelligence
Microbial fuel cells are transitioning from laboratory curiosity to a constrained but growing commercial market. Our topline forecast and concentration metrics show both opportunity and competitive clarity—while key vendors have carved out differentiated niches, the path to scale remains conditional on materials innovation, system integration, and regulatory alignment. PW Consulting’s full Worldwide Microbial Fuel Cell Market report contains the granular segment tables, vendor-level revenue scenarios, and operational templates needed to convert 2026 pilots into scalable revenue streams. Visit our report page to access the complete dataset and downloadable playbooks designed for immediate deployment.
For detailed analysis of this topic, please visit the official page: Worldwide Microbial Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Highly Pure Coconut Shell Activated Carbon Market Poised for 9.15% CAGR Through 2026–2032
By PW Consulting, 2026-08-05
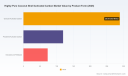
Worldwide Highly Pure Coconut Shell Activated Carbon Market — Strategic Outlook to 2032
PW Consulting’s new market research brief on the Worldwide Highly Pure Coconut Shell Activated Carbon market synthesizes five years of historical performance (2020–2025) and delivers a robust forecast framework for 2026–2032. Built around a 9.15% compound annual growth rate (CAGR) assumption across the forecast period, the study translates macro growth dynamics into practical decision tools for procurement, manufacturing, investment, and regulatory planning as firms prepare for 2026’s commercial inflection points.
Worldwide Highly Pure Coconut Shell Activated Carbon Market
Market trajectory in brief
Our base-year analysis registers sustained expansion from the beginning of the decade into 2025, with the market more than halving the gap between early-2020 and mid-decade demand levels. The report captures the market’s momentum into 2026 and models multiple recovery and stress-case pathways through 2032—culminating in a materially larger market at the end of the forecast window. These topline figures are embedded throughout the report and drive the scenario-based sensitivity testing that underpins our recommendations for near-term strategic planning.
Worldwide Highly Pure Coconut Shell Activated Carbon Market
Why 2026 is a strategic inflection point
- Raw material tightness and cost pressure: Coconut shell charcoal prices rose sharply across principal producing countries between late 2024 and mid-2025, creating supply-side pressure that feeds directly into production costs for high-purity activated carbon. Our report models persistent tightness into 2026 and quantifies the operating-margin impact across different manufacturing and processing configurations.
- Upstream capacity moves: Recent investments and capacity additions by tier-one producers change the timing and geography of supply availability. We translate plant-level capacity shifts into regional availability curves and flow-path maps to clarify where and when new supply will relieve pressure.
- Pricing and trade dynamics: Leading manufacturers implemented commercial price adjustments in 2025; meanwhile, changing tariff and trade policies are prompting buyers to reevaluate sourcing strategies and total landed cost models. Our analysis offers calibrated pass-through timelines and scenarios for varying tariff regimes.
- Regulatory tailwinds: Stricter standards for water and air treatment are sustaining baseline demand for high-purity, coconut-shell-based products—particularly where low-ash and robust mechanical strength are required. The report aligns regulatory milestones with demand resilience by end-use.
What the report contains — practice-ready modules
This study is built for executives who must convert market intelligence into executable plans in 2026. Highlights include:
Worldwide Highly Pure Coconut Shell Activated Carbon Market
- Topline market sizing and scenario models: Historical series, base-year validation, and probabilistic forecasts through 2032. Models include downside, base, and upside cases linked to raw material price trajectories and demand shocks.
- Supply chain stress tests: Multi-node mapping of feedstock sourcing, activation and finishing capacity, and port/transport chokepoints; stress scenarios quantify delivery risk and lead-time inflation under alternate disruption profiles.
- Pricing and margin playbooks: Time-to-pass-through matrices, indexation options, and hedging strategies for buyers and sellers seeking to stabilize margins in 2026.
- Supplier benchmarking and concentration analysis: A comparative framework covering technical capabilities, capacity, sustainability credentials, and commercial behavior. The report integrates market concentration metrics to highlight consolidation risks and competitive openness.
- Go-to-market and procurement templates: Tactical checklists for near-term supplier diversification, inventory buffers calibrated to lead-time scenarios, and recommended contractual language to manage input-cost volatility.
- Investment and M&A intelligence: Valuation multiples informed by scenario cash-flow models, capex prioritization guidance for new activation capacity, and due-diligence scorecards for potential targets and JV partners.
- Regulatory & compliance matrix: Cross-jurisdictional guidance for water and air treatment specifications, certification pathways, and product registration hurdles—mapped to practical timelines for 2026 launches.
Competitive landscape — how to interpret the map
The market exhibits a moderate degree of concentration among established global and regional players. Our concentration metrics provide a clear lens for strategic positioning: the upper tiers of the market control a meaningful share of capacity and global flows, while a long tail of regional producers supplies niche and standard grades.
Key strategic profiles captured and analyzed in the report include:
- Haycarb PLC (Sri Lanka): One of the world’s leading producers with a substantial share by volume and a sizeable annual activation capacity. The company’s emphasis on low-ash, high-hardness grades and sustainable feedstock sourcing is examined in the context of the firm’s automation investments and forward procurement strategy.
- Jacobi Carbons Group (Osaka Gas Chemicals): A major global manufacturer with broad geographic footprints and premium-grade offerings. We analyze the 2025 commercial price adjustment and its ripple effects on short-term supply balances and competitor margin strategies.
- Raj Carbon, Kalpaka Chemicals, and other Indian producers: Indian manufacturers remain a critical supply node. Our comparative assessment evaluates manufacturing scale, export-readiness, and port logistics efficiencies relevant to buyers seeking reliability in 2026.
- Chinese manufacturers (multiple bases): Firms with large annual output continue to provide high-iodine and drinking-water grade products. The report contrasts their cost structures and route-to-market with Western players offering regeneration and specialized services.
- North American and European suppliers: Producers and integrators focused on regional delivery, regeneration services, and bespoke filtration systems are profiled for buyers prioritizing near-shore sourcing and tighter regulatory alignment.
Beyond profiles, the report offers a practical supplier scorecard that quantifies capability across quality consistency, ESG performance, capacity flexibility, and commercial responsiveness—enabling procurement to rank shortlists for 2026 tenders quickly.
Implications and recommended actions for 2026
- Procurement & sourcing: Rebalance sourcing mixes toward a tiered strategy: secure short-term volume agreements with established tier-one producers while developing alternative suppliers to protect against concentrated feedstock shocks. Increase contractual use of forward-priced tranches and indexation clauses.
- Inventory & logistics: Reassess safety-stock levels and contractual lead times. Where possible, establish consignment or vendor-managed inventory programs at strategic distribution hubs to reduce delivery risk without inflating working capital unduly.
- Pricing strategy: Prepare transparent pass-through models for customers tied to feedstock indices; segment contracts by grade and end-use to facilitate differentiated commercial responses to cost inflation.
- Capex & capacity planning: Evaluate brownfield upgrades and small modular activation lines over large greenfield investments in the near term; the report provides NPV and payback analyses across several capex sizing options relative to our 2032 demand horizon.
- M&A and partnerships: Prioritize targets with complementary geographic reach or value-added services (e.g., regeneration, finished filtration systems). Use our valuation overlays to screen transaction economics under stressed commodity-price scenarios.
- Innovation & product strategy: Invest selectively in grade differentiation (e.g., ultra-low ash, specialty pore distributions) and in regeneration services that reduce dependency on feedstock availability.
Practical deliverables — what teams can use on day one
- Executive dashboards with scenario toggles for raw-material price, tariff levels, and demand elasticity.
- Supplier due-diligence checklist and on-site audit template for quality and sustainability verification.
- Procurement contract clause library with templates for indexation, volume flexibility, and force majeure tailored to activated carbon supply chains.
- Capex decision tool that models cash flow impacts under alternate price and demand trajectories through 2032.
- Regulatory compliance roadmap that aligns product specifications to required standards in key markets.
How to read the invisible lines — where the report stops and bespoke advisory begins
In line with our “trailer” approach, this public briefing demonstrates the analytic depth and practical outputs available in the full study while intentionally omitting granular regional and application-level splits in this release. Those discrete segment tables, mesh-size breakdowns, and full country-by-country revenue forecasts are preserved in the report to ensure clients receive strategic depth behind a paywall or in a tailored consulting engagement. For organizations that need an immediate tactical playbook—procurement RFP templates, supplier negotiation simulations, or an executable 90-day stabilization plan—PW Consulting offers expedited advisory workstreams that convert the report’s intelligence into operational decisions.
Next steps and how to engage
For corporate strategy teams, procurement heads, manufacturing leaders, and private-equity sponsors planning actions in 2026, this report functions as both an evidence-based market map and a playbook of executable responses. To obtain the full intelligence set—complete with granular segmentation, country-level forecasts, and downloadable financial models—visit the Worldwide Highly Pure Coconut Shell Activated Carbon Market report page on PW Consulting’s research portal or contact our industry specialists for a bespoke briefing and scenario run tailored to your portfolio.
PW Consulting — Senior Strategic Advisory and Industry Analysis. This briefing is intended to guide near-term commercial choices while preserving the detailed, actionable datasets that power contract-level decisions for our clients.
For detailed analysis of this topic, please visit the official page: Worldwide Highly Pure Coconut Shell Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High-capacity NFC Chip Market to Surge from USD 664.28 Million in 2025 to USD 1,534.92 Million by 2032 at a 12.71% CAGR
By PW Consulting, 2026-08-05
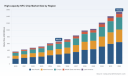
Worldwide High-capacity NFC Chip Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As enterprises plan product roadmaps, procurement strategies, and strategic investments for 2026, high-capacity NFC tag ICs have moved from niche enabler to boardroom-level consideration. PW Consulting’s latest market research — based on a 2025 base year with a 2026–2032 forecast window — quantifies a market that has more than doubled since 2020 and is set to continue a rapid expansion at a compound annual growth rate (CAGR) of 12.71% over the forecast period. Our topline modeling shows the market growing from roughly USD 365 million in 2020 to about USD 664 million in 2025, with a near-term projection of approximately USD 728 million in 2026 and an expectation to surpass USD 1.5 billion by 2032. For decision-makers, these macro dynamics signal both opportunity and urgency: demand is accelerating, product capabilities are diversifying, and supplier dynamics are tightening.
Worldwide High-capacity NFC Chip Market
Why this report matters for decisions made in 2026
-
Timing of design-ins and component qualification. With lead times and supplier programs shifting, design cycles that begin in early 2026 will determine who wins production slots in 2027–2028. Our report maps realistic windows for qualification, sample availability, and scale production for high-capacity variants.
Worldwide High-capacity NFC Chip Market -
Procurement and cost strategy. Rapid market growth is coinciding with upward pressure on average selling prices and component lead times. Businesses need a clear procurement playbook — including multi-sourcing, long‑lead buy decisions, and staged inventory buffers — to avoid margin erosion or product launch delays.
Worldwide High-capacity NFC Chip Market -
Technology and standards alignment. Next-generation onboarding and security standards (including emerging smart-home protocols) are changing the value proposition of high-capacity NFC chips. A 2026 product architecture that ignores these shifts risks early obsolescence.
-
M&A, partnerships and IP strategy. Concentration among a handful of leading suppliers creates attractive targets for partnerships and licensing. The report identifies where joint development or supply agreements can accelerate time-to-market while limiting supplier concentration risk.
-
Regulatory and supply-chain risk management. Export controls and region-specific trade measures are already affecting assembly footprints and component flows. Effective sourcing plans in 2026 must integrate regulatory scenario planning to maintain production continuity.
What the PW Consulting report delivers — practical, executable intelligence
-
Comprehensive demand forecasts with scenario variants: base, upside (fast-adoption), and downside (supply-shock) cases across 2026–2032 to help finance and product teams stress-test plans.
-
Technology roadmaps and buyer’s guide: mapping memory‑capacity tiers, key protocol features, cryptographic capabilities, and recommended integration points for mobile, IoT, authentication, and transit applications.
-
Supplier scorecards and commercial playbooks: independent assessments of capability, time-to-samples, roadmap alignment, AND typical contract levers for volume, lead time and support.
-
Go-to-market and cost-to-serve analysis: practical guidance for OEMs and brands on packaging, firmware integration, and service models that monetize high‑capacity capabilities (e.g., post-sale authentication, lifecycle services).
-
Risk and compliance module: export-control scenario analysis, alternative sourcing architectures, and recommended contractual clauses to mitigate component halt scenarios.
-
Case studies and procurement templates: real‑world examples showing how early qualification and multi-vendor strategies preserved launch dates while controlling cost.
Note: this press brief purposefully omits granular regional and end-use subsegment figures. The full report contains detailed splits by geography, memory-capacity tiers, and end-use verticals that are essential for program-level decisions; access instructions are provided at the end of this brief.
Competitive landscape — who matters and why
The high-capacity NFC chip market is meaningfully concentrated. Our concentration metrics indicate that the top three suppliers control a significant majority of market share, while the top five account for well over three-quarters of the market. That structural reality shapes bargaining power, technology diffusion, and the speed at which new features become industry norms.
-
NXP Semiconductors — NXP continues to lead with high-performance tag IC families engineered for fast read rates and enhanced RF handling. Recent product introductions add substantial user memory and features tailored to IoT and vicinity labeling use cases, strengthening its position in high-value applications.
-
STMicroelectronics — With a broad ST25 portfolio and a clear push into smart-home standards, ST is positioning itself as the go-to partner for secure, standards-compliant onboarding. Their recent secure NFC chip targeted at Matter 1.5 tap-to-pair onboarding is likely to accelerate adoption in battery-less commissioning scenarios.
-
Infineon Technologies — Infineon’s secure element and SOLID FLASH technology offerings make it a strong choice where contactless security and multi-protocol support are prerequisites (e.g., payments, identity, and industrial systems).
-
Broadcom — Broadcom’s connectivity-focused combo chips (integrating Bluetooth and NFC) remain important for mobile and consumer electronics OEMs that require integrated wireless stacks and low power.
-
Samsung Electronics — Samsung’s NFC ICs target mobile and lifestyle devices with embedded crypto and robust interface options, maintaining relevance where integration with handset ecosystems is required.
-
Sony Corporation (FeliCa) — Sony’s Type 3-compliant FeliCa ICs retain strength in payment and transit niches where the ecosystem and local acceptance remain decisive advantages.
Two product developments in 2025–2026 are illustrative of competitive dynamics:
-
In June 2025, NXP launched a high‑performance HF tag IC family offering substantially expanded user memory and faster read rates, together with RF optimization features and tamper detection options — explicitly aiming at IoT labeling and vicinity applications.
-
In November 2025, STMicroelectronics announced a secure NFC chip designed to support Matter 1.5 tap-to-pair onboarding, enabling battery-less commissioning through on-chip digital signatures and secure key storage; mass production was targeted for 2026, signaling a speed-to-market advantage for smart-home OEMs that adopt early.
Market dynamics to watch closely in 2026
-
Price increases and margin pressure. Several suppliers implemented price adjustments in 2026, driven by higher materials and energy costs. For procurement teams, this raises the importance of locked-price agreements and cost pass-through planning.
-
Extended lead times. Global semiconductor supply constraints have extended lead times for NFC tag ICs in many cases, creating real risk for single-sourced BOMs. Our field checks report lead-time stretches into multiple quarters for advanced, high-capacity parts — a core planning input for 2026 product launches.
-
Regulatory friction. Export control measures and trade actions are affecting assembly and component flows for firms with China‑based operations. Organizations with cross-border manufacturing must build regulatory scenario playbooks to preserve continuity.
-
Standards-driven adoption. The commoditization of basic NFC functionality is giving way to premium use cases enabled by higher memory, better RF performance, and on-chip security. Standards and reference implementations (notably in smart home and secure onboarding) are accelerating product differentiation.
Strategic recommendations for 2026
-
Start dual‑track qualification today. Qualify at least two suppliers per high-capacity part family to reduce single‑point risk and preserve negotiating leverage.
-
Secure sample and pilot allocations. Lock early-sample and pilot-volume commitments as part of development contracts to avoid downstream slot competition.
-
Embed standards compliance in R&D roadmaps. For products targeting smart-home, payment, or transit channels, prioritize chips that support the appropriate onboarding and cryptographic standards.
-
Negotiate flexible pricing formulae. Where possible, use indexed pricing, volume ramps, and partial hedges to mitigate short-term price shocks while preserving cost predictability.
-
Design for optionality. Architect products to accept alternate tag families with minimal firmware changes to shorten switch-over time if supply or pricing constricts.
-
Invest in lifecycle monetization. High-capacity tags enable post-sale services (authenticity checks, lifecycle updates). Capture value through software and service layers rather than competing solely on BOM cost.
-
Update contract clauses for regulatory risk. Include clear escalation paths, support commitments, and force‑majeure definitions tied to export controls in supplier agreements.
How to access the full report and next steps
This executive brief is intended as a strategic trailer: it highlights the forces shaping the high-capacity NFC chip market and the kinds of operational actions companies must take in 2026. The full PW Consulting Worldwide High‑capacity NFC Chip Market report contains the granular segmentation, regional and end‑use splits, supplier scorecards, pricing curves, and actionable templates that product, procurement and corporate development teams need to execute on these recommendations. We have intentionally withheld detailed subsegment tables from this public summary to ensure subscribers and clients obtain the comprehensive, verifiable datasets required for program-level decisions.
For access to the full dataset, supplier benchmarking tools, and a tailored briefing for your engineering and procurement teams, contact PW Consulting’s Market Intelligence desk. Early access clients receive a one‑hour private briefing and a bespoke risk‑scenario appendix tailored to their supply‑chain footprint.
About PW Consulting
PW Consulting is a global strategic advisory firm specializing in high-growth semiconductor-driven markets. Our industry teams combine primary sourcing interviews, supplier audits, and quantitative modeling to deliver practical intelligence that links market dynamics to executable corporate strategies.
For detailed analysis of this topic, please visit the official page: Worldwide High-capacity NFC Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Intelligent TCM Diagnosis System Market Poised for Rapid Expansion at a 14.48% CAGR, New Insight Reveals
By PW Consulting, 2026-08-05
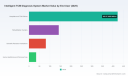
Worldwide Intelligent TCM Diagnosis System Market: Strategic Imperatives for 2026 Decision-Makers
Executive snapshot
The Worldwide Intelligent Traditional Chinese Medicine (TCM) Diagnosis System market is entering a decisive growth phase that will shape investment, product and clinical strategy through the latter half of this decade. Built on converging advances in sensors, artificial intelligence and clinical workflow integration, the market has demonstrated sustained expansion from the early 2020s and — according to our base-year-aligned forecast framework — is expected to expand at a compound annual growth rate (CAGR) of approximately 14.48% over the 2026–2032 forecast window. The result is a market that has more than doubled in size since 2020 and is projected to reach a significantly larger scale by the end of the forecast period, creating clear strategic inflection points for vendors, hospital groups, payers and regulators in 2026.
Worldwide Intelligent TCM Diagnosis System Market
Market trajectory: why 2026 matters
Between 2020 and 2025 the market moved from early-adopter revenue levels to a broadening commercial phase, driven by validated clinical pilots, improved sensor fidelity (for pulse, tongue and facial analysis), and growing institutional acceptance. With 2025 established as the base year for strategic planning, our forecast maps a continuation of that trajectory into 2026 and beyond — with the market accelerating materially on the back of technology maturation and policy drivers. For executives assessing allocation of R&D, sales capacity and regulatory investment in 2026, this profile signals a shift from exploratory projects to scalable commercial deployments.
Worldwide Intelligent TCM Diagnosis System Market
Two macro implications arise immediately: first, unit economics are approaching inflection — early high-cost hardware cycles are giving way to recurring software and service revenue models; second, buyer sophistication is rising, which will pressure vendors to demonstrate clinical validity, workflow compatibility and reimbursement alignment rather than just technical novelty.
Worldwide Intelligent TCM Diagnosis System Market
What our report delivers — practical, transaction-ready intelligence
PW Consulting’s Worldwide Intelligent TCM Diagnosis System Market report is deliberately operational. It goes beyond market sizing to deliver the types of artifacts that support boardroom decisions and transaction diligence in 2026:
- Validated market sizing and a clear forecast framework (base year 2025; forecast period 2026–2032), including scenario-based projections to stress-test strategy under different adoption curves.
- Actionable go-to-market playbooks for vendors (hospital tenders, rehabilitation channel strategies, and emerging home-healthcare pathways), with sample commercial constructs and margin models.
- Regulatory and reimbursement mapping specific to China and cross-border considerations, including how DRG-based payment reforms interact with TCM service lines and device utilization.
- Clinical adoption roadmaps and evidence-generation blueprints for hospitals and research institutions to support procurement and integration decisions.
- Due-diligence templates for corporate development teams assessing M&A and partnership targets, including operational KPIs and integration risks specific to AI-enabled diagnostics.
- Vendor benchmarking and technology scoring across hardware, algorithmic maturity, data interoperability and service models — presented to support shortlist creation without revealing proprietary vendor share data.
Competitive landscape: profiles and strategic positioning
The ecosystem is increasingly populated by specialist device manufacturers, AI-first software teams, established TCM service providers, and research institutions that act as technology incubators. Key industry participants — including multiple established Chinese device vendors and university-affiliated development centers — occupy differentiated niches across sensor hardware, algorithmic IP and clinical pathways. Notable strategic archetypes in the market include:
- AI-first diagnostic developers that emphasize algorithmic decision-support and cloud-enabled model updates. These players are positioning their platforms for rapid clinical validation and third-party integration.
- Hardware-integrated incumbents that bundle multi-modal sensing (pulse, tongue, and facial diagnostics) with on-premise software. Their value proposition is around turnkey clinical deployment and durability in high-volume hospital settings.
- Academic and research center spin-outs that translate validated clinical protocols into commercial-grade devices; these units often act as technology accelerators and credibility amplifiers for early clinical adoption.
Representative organisations in the field include Beijing Aizhenyun Health Technology, Yimai AI Medical Technology (Tianjin), Shanghai Baosongtang Biotechnology, Shanghai Zhiyun Medical Technology, Shanghai Zhenkang Medical Technology, KANGWAY MEDICAL, and others. These companies vary in their emphasis — some lead with hardware engineering and manufacturing scale, others with AI models and clinical workflow integration, and a subset with deep institutional ties that facilitate hospital pilots and evidence generation. A notable dynamic in 2026 is the increasing role of university research centers, such as the development teams at Shanghai University of Traditional Chinese Medicine, which have moved from lab validation into clinical deployments.
Regulatory and reimbursement dynamics shaping adoption
Policy and payment frameworks are central to the pace and pattern of diffusion. The nationwide push to implement a DRG-style payment mechanism across hospitals (including TCM institutions) has direct implications for device adoption. Where reimbursement frameworks reward shorter lengths of stay and standardized clinical pathways, intelligent diagnostic systems that can demonstrably support more efficient, evidence-driven TCM practice are advantaged. Additionally, concurrent policies that provide targeted subsidies for validated TCM techniques create a mixed incentive structure that healthcare providers will navigate tactically.
For decision-makers in 2026, the key takeaway is that regulatory and reimbursement forces are not monolithic — they create both headwinds and tailwinds at different points in the value chain. Vendors should prioritize clinical outcomes and cost-of-care evidence to align with DRG-focused procurement, while hospital executives should integrate device evaluation with internal case-mix and cost-accounting processes.
Recent signal: clinical deployment accelerates credibility
A prominent signal of market maturation occurred in March 2026, when a major university-affiliated team publicly reported deployment and clinical use of an AI-assisted Intelligent TCM Diagnostic Instrument for objective pulse, tongue and facial data collection. This deployment — highlighted in both institutional announcements and national press — crystallizes the pathway from research to clinical screening and routine hospital applications. For strategic planners, such deployments reduce translational risk and increase the pool of clinical evidence that payers and procurement committees will demand in 2026.
Strategic imperatives for 2026
To convert market potential into commercial success in 2026, stakeholders should focus on a small set of high-leverage actions:
- Prioritize evidence that aligns with payment levers. Develop prospective studies and health-economic models that speak directly to DRG-based metrics (length of stay, complication rates, standardized pathways).
- Design flexible commercial models. Move beyond a pure hardware sale: offer software subscriptions, outcome-based contracts and bundled service agreements to capture recurring value.
- Invest in interoperability and clinical workflow integration. Hospitals will prefer solutions that integrate with electronic medical records, support clinician decision-making and minimize disruption to established TCM practices.
- Stage market entry by use case and channel. Large hospitals, research institutions and rehabilitation centers will have differing evidence thresholds — tailor pilots and value propositions accordingly.
- Form strategic partnerships with academic and clinical centers. Collaborations with research institutions accelerate evidence generation and can materially reduce adoption friction within hospital systems.
- Prepare for consolidation. As adoption scales, expect transactional activity: both acquisitions (to fill technology or distribution gaps) and partnerships (to co-develop pathway-specific solutions).
Why this report is mission-critical for 2026 decisions
Executives and clinical leaders need an analytically rigorous yet operationally practical roadmap to navigate the rapidly evolving TCM intelligent diagnostics landscape. This report synthesizes market-size trajectories, regulatory context, technology benchmarking and go-to-market playbooks — enabling leaders to prioritize investments, structure deals and design clinical programs that align with near-term policy and reimbursement realities.
Importantly, the report follows a “trailer” philosophy: it presents robust, verifiable market and technology insight while intentionally reserving proprietary segmentation and detailed vendor share analytics for the full study. That design choices helps boards and deal teams confirm the strategic direction while prompting the targeted follow-up required for transaction-level commitments.
Next steps
For organizations preparing budgets, revising clinical strategies, or evaluating acquisition targets in 2026, we recommend downloading the full report and scheduling a tailored briefing with the PW Consulting team. Our briefings translate the market-level insights into quantified scenarios and executable 12–18 month roadmaps specific to product, clinical and commercial leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent TCM Diagnosis System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Memory Packaging Market to Surge at 10.53% CAGR (2026–2032)
By PW Consulting, 2026-08-05
Worldwide Memory Packaging Market: Strategic Imperatives for 2026 — A PW Consulting Preview
PW Consulting today releases an executive preview of our forthcoming Worldwide Memory Packaging Market report. Grounded in a rigorous historical review (2020–2025) and a forward look to 2032, the study models the global memory packaging landscape through the lens of commercial decision-making in 2026. The market is both large and accelerating: our base-year assessment pegs 2025 global memory packaging revenue at USD 36,898.6 Million, with a modelled year‑over‑year increase to USD 42,140.5 Million in 2026 and a compound annual growth rate (CAGR) of 10.53% across the forecast window (2026–2032). By 2032, the market reaches roughly USD 74,380 Million under our central-case assumptions.
Worldwide Memory Packaging Market
Why this matters for 2026 decisions
-
Capacity and outsourcing choices made in 2026 will determine supply-positioning through the next wave of DRAM, NAND, and high-bandwidth memory cycles. The industry’s trajectory — strong mid‑teens to low‑double-digit growth on an aggregate basis — magnifies both upside and downside for capital allocation.
Worldwide Memory Packaging Market -
Pricing power and cost management are in flux. We observed manufacturer-led outsourcing ramps and provider price adjustments in late 2025/early 2026 that materially impact supplier margins and OEM total cost of ownership (TCO) models.
Worldwide Memory Packaging Market -
Geopolitical and regulatory risk has shifted from episodic to structural. New tariffs, export controls, and licensing regimes are reshaping where advanced packaging work can be conducted profitably and compliantly.
Practical, decision‑grade insights you can expect (teaser)
-
Scenario-aligned capacity maps that show where marginal MW/wafer‑level packaging capacity is likely to be available — and at what incremental lead times — under alternative demand ramps.
-
Supplier concentration analytics (our CR3 is 58.4% and CR5 is 72.15%) and an associated risk heat map that quantifies single‑point vulnerabilities across the OSAT ecosystem.
-
Cost‑sensitivity frameworks that translate raw-material and labor inflation into break‑even pricing for key packaging formats, enabling procurement to assess pass‑through versus margin‑absorption tradeoffs.
-
Regulatory-impact playbooks that convert tariff and export-control permutations into recommended operational responses — from dual‑sourcing and qualification playbooks to selective on‑shoring/near‑shoring options.
-
M&A and partnership scorecards that rank OSATs and strategic suppliers against a composite of capacity, technology readiness, customer exposure, and regulatory footprint.
Market dynamics reshaping 2026 strategy
-
Demand momentum and right-sizing: The broad market rebound we model for 2026 is being driven by both classic memory cycles (e.g., DDR generations) and structural shifts (e.g., higher penetration of stacked/advanced memory in AI and networking). That combination favors service providers with flexible, high-mix capacity.
-
Price and input‑cost volatility: Several memory packaging and test providers announced price increases of up to ~30% in early 2026 amid constrained capacity for DRAM and NAND packaging. Firms should bake elevated unit costs and shorter lead‑time premiums into procurement planning for at least the next 12–18 months.
-
Materials & critical inputs: Export controls and export‑licensing regimes on critical minerals (including gallium) and specialized process chemistries are creating upstream pinch points. Firms dependent on single-source supply for these inputs face an outsized operational risk.
-
Policy & geopolitical overlay: U.S. tariff measures and sustained export controls on advanced computing chips, HBM and certain DRAM technologies have heightened compliance complexity. Companies must treat trade policy as a core component of plant-location and partner-selection decisions.
Competitive landscape — what the OSAT map implies for strategic moves
The memory packaging space is concentrated among a few large OSAT leaders and a broader set of regional specialists. The competitive set includes global integrators, high-volume specialists, and locally focused vendors. Below we summarize strategic profiles and near-term implications for 2026 decision‑makers.
-
Advanced Semiconductor Engineering Inc. (ASE Inc.) — A leading OSAT with broad capability across DRAM, NAND and advanced formats (including HBM and SiP). For OEMs seeking scale and advanced technology roadmaps, ASE remains a primary partner for capacity scaling and co-development. Watch ASE for strategic capacity commitments and cross‑border footprint adjustments in response to policy changes.
-
Amkor Technology Inc. — Strong in memory and storage packaging with significant engineering depth. Amkor’s portfolio supports migration pathways for OEMs moving toward fan‑out and wafer‑level packaging. Strategic recommendation: prioritize Amkor for programs where engineering cadence and qualification throughput matter more than the absolute lowest per‑unit price.
-
Powertech Technology Inc. (PTI) — Focused memory packaging and test specialist with significant DRAM/NAND capacity. Recent price adjustments across PTI and peers reflect tight DRAM/NAND service markets; customers should model multi‑tier supplier networks and contingency pricing clauses into contracts.
-
ChipMOS Technologies, Hana Micron, Lingsen, FATC, Walton, and other regional players — These vendors provide targeted capacity, regional market access, and often closer OEM integration. They are natural partners for OEMs seeking capacity diversification or lower latency in local markets, but customers should validate technology parity and long‑run reliability before migrating high‑complexity products.
-
JCET, STATS ChipPAC and larger Chinese/Taiwan operators — These firms offer scale and mature high-volume NAND/DRAM packaging lines. However, regulatory restrictions and licensing requirements increase the complexity of deep technology transfer and long-term commitments. Companies should map licensing risk into any extended supply agreements.
Recent market developments to factor into 2026 planning
-
Applied Materials announced a long-term R&D partnership with SK hynix focused on materials engineering and advanced packaging for next‑generation DRAM and HBM — a signal that upstream materials and equipment innovation will be a key battleground.
-
Memory packaging firms announced price increases in early 2026 in response to tight DRAM and NAND packaging supply — immediate implications for 2026 P&L forecasting and negotiation posture.
-
Large memory OEMs have accelerated outsourcing for DDR5 and other product ramps, increasing the near‑term demand burden on OSATs and compressing qualification windows for alternative suppliers.
How to convert insight into action in 2026
-
Short term (next 6–12 months): Lock in critical capacity through multi‑year agreements with flexible volume clauses; secure alternative suppliers for qualified packaging formats; and run a rapid compliance assessment against tariffs and export-license exposures for each potential partner and facility.
-
Medium term (12–36 months): Invest selectively in co‑development with leading OSATs to qualify advanced packaging formats that confer product differentiation (e.g., HBM stacks, TSV/3D stacking). Use scenario models to test the ROI of near‑shoring versus multi‑regional sourcing under realistic tariff/licensing scenarios.
-
Strategic M&A and partnerships: Given the market concentration metrics, acquiring or partnering with an OSAT can be an efficient route to secure capacity and capture margin — but targets should be screened for regulatory footprint, technology parity, and customer concentration.
What’s in the full PW Consulting report (practical deliverables)
-
Full market model (2020–2032) with downloadable Excel: base-case, upside and downside demand scenarios; CAPEX and utilization sensitivity; and revenue forecasts by packaging technology and memory type (note: segment tables and datasets are provided in the full report).
-
Supplier scorecards and M&A playbook: due diligence checklists, integration risk assessments, and earn‑out structuring templates for OSAT transactions.
-
Regulatory-response playbooks: step‑by‑step guides to re‑routing production, qualifying alternate sites, and implementing compliant supply‑chain architectures under current U.S. export controls and tariff regimes.
-
Procurement & pricing playbooks: negotiation levers, escalation thresholds, and contract language templates to manage up to 30% short‑term price volatility observed in the market.
-
Operational readiness tools: qualification checklists for advanced packaging formats, sample timelines for ramping production, and vendor audit frameworks focused on materials traceability.
Final recommendations for executives
2026 will be a year where decisive, data‑driven action separates winners from laggards in the memory packaging ecosystem. Use the market’s strong growth trajectory — modelled at a 10.53% CAGR for 2026–2032 — to justify priority investments in supply security, but do so with calibrated hedges against policy and input‑supply risk. Prioritize partners that offer both technology leadership and a transparent regulatory footprint. Where scale and advanced-process capability are required, favor capacity commitments with leading OSATs; where agility matters, build a qualified multi‑supplier network.
PW Consulting’s full Worldwide Memory Packaging Market report contains the underlying datasets, scenario models, and executable playbooks referenced above. The executive preview you have just read is intentionally high‑level: the detailed segment numbers, regional splits and the full supplier scorecards are available only in the complete report and accompanying data pack. For procurement, corporate strategy, or M&A teams preparing 2026 budgets and roadmaps, accessing the full dataset is the next pragmatic step.
To request the full report or a tailored briefing for your executive team, please visit our official release page or contact PW Consulting’s semiconductor practice. Our analysts are available to run a bespoke workshop translating the report’s scenarios into specific capital, sourcing, and regulatory action plans.
For detailed analysis of this topic, please visit the official page: Worldwide Memory Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 11.2% CAGR for Worldwide 3D AOI in PCB Market Through 2026–2032
By PW Consulting, 2026-08-05
Worldwide 3D Automated Optical Inspection Equipment in PCB Market — Strategic Outlook for 2026
As global electronics complexity accelerates, 3D Automated Optical Inspection (AOI) has moved from a quality-assurance luxury to a strategic manufacturing vector. PW Consulting’s newest market study — Worldwide 3D Automated Optical Inspection Equipment in PCB Market (base year 2025, forecast 2026–2032) — frames the investment choices that will define supplier relationships, factory economics, and product reliability for the next investment cycle. The headline: the global market reached roughly USD 1.1 billion in 2025 and, under a set of conservative assumptions, is forecast to more than double by 2032, implying a compound annual growth rate of approximately 11.2% across the forecast window. This growth is concentrated among a handful of high-capability vendors (CR3 ~52.4%, CR5 ~68.2%), creating both opportunities and supplier risk for OEMs and EMS providers preparing capital plans in 2026.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Why this matters to 2026 strategic choices
-
Capital allocation and timing: With unit prices and optics inflation putting upward pressure on AOI equipment (sector analysis indicated an average price increase of about 8% YoY in 2025, with unit pricing commonly in a premium band), procurement teams must weigh earlier procurement to lock pricing vs. delaying to capture next-generation sensor capabilities.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market -
Production mix and yield economics: The transition to finer-pitch components and HDI boards has elevated the value of sub-2μm height measurement accuracy — a capability explicitly embedded in recent IPC standard updates. The report translates those measurement thresholds into practical ROI models for first-pass yield improvements and rework cost avoidance.
Worldwide 3D Automated Optical Inspection Equipment in PCB Market -
Supply-chain fragility: Long lead times for high-resolution 3D camera modules (reported at 16–20 weeks in Q4 2025) and geopolitical controls affecting advanced imaging exports in 2025 materially change sourcing strategies. Our analysis quantifies the business impact of single-supplier dependency and proposes mitigations ranging from buffer stocking to sensor localization partnerships.
What the PW Consulting report delivers (practical, deployable content)
-
Decision-ready vendor benchmarking: a multi-dimensional scoring system combining sensor capability (height accuracy, resolution), inspection throughput, false-call rate, integration effort, service ecosystem, and TCO over a 7-year horizon. The framework is designed to be reused for RFP shortlisting.
-
CapEx prioritization matrix: trade-offs between retrofitting legacy lines with 3D AOI versus greenfield deployment on new SMT lines, with payback sensitivity to yield improvements, scrap reduction, and labor cost differentials.
-
Supply continuity and risk stress tests: scenario-driven models that simulate camera-module supply shocks, tariff shocks, and export-control scenarios. For each scenario we provide contingency plans and estimated P&L impact ranges for typical EMS and OEM production footprints.
-
Implementation playbook and KPIs: from pilot design through full-line roll-out, including sample-size recommendations for statistical acceptance, cycle-time budgeting, operator training modules, and continuous improvement loops to reduce false calls.
-
Compliance and standards mapping: an actionable interpretation of the IPC-9252B/IPC-2581 family and how updated accuracy mandates translate into procurement specifications and acceptance tests.
-
Commercial levers: negotiation playbooks for service contracts, spare parts agreements, and trade-in strategies that preserve equipment uptime during multi-year sensor supply disruptions.
Competitive landscape — who matters and why
The 3D AOI market for PCBs is concentrated around a small set of specialized vendors. PW Consulting’s qualitative and quantitative analysis focuses on product differentiation, installed base quality, and aftermarket/service economics rather than raw shipment tallies. Below are executive summaries of the key players we modeled in depth.
-
Koh Young Technology (Seoul, South Korea) — A market leader recognized for high-speed true-3D imaging in SMT inspection. Recent product cadence (e.g., a refreshed Zenith Alpha platform) emphasizes embedded AI for defect classification and higher throughput. Their installed base and software maturity give them an advantage in high-mix environments seeking throughput and low false-call rates. More: https://www.kohyoung.com
-
CyberOptics Corporation (Minneapolis, MN, USA) — Noted for multi-reflection suppression and precision models optimized for fine-pitch BGAs and QFNs. Recent platform upgrades target ultra-miniature components. Their approach blends optical innovation with ease of integration into existing MES workflows. More: https://www.cyberoptics.com
-
Viscom AG (Hannover, Germany) — Strong in high-volume assembly, with an emphasis on sensor resolution suitable for HDI boards. Their product demonstrations focus on throughput consistency and robustness for automotive and industrial applications. More: https://www.viscom.com
-
Test Research, Inc. (TRI) (Taipei, Taiwan) — Competes on AI-driven analytics and domain expertise for solder-paste and placement inspection. TRI’s software-led differentiation helps customers extract higher value from existing hardware stacks. More: https://www.tri.com.tw
-
SAKI Corporation (Tokyo, Japan) — Known for precise gimbal-less camera architectures that deliver tight height-measurement tolerances, especially in high-reliability markets. Compliance-focused offerings respond to recent IPC updates. More: https://www.saki.com
-
Mirtec Corporation (Oxford, CT, USA) — Emphasizes high-resolution imaging and laser profiling; their MV-series is frequently specified for post-reflow analysis in mixed-technology lines. More: https://www.mirtec.com
-
Nordson TEST & INSPECTION (Carlsbad, CA, USA) — Integrates AOI with AXI capabilities for complex inspection requirements in high-mix environments, positioning itself for customers who want a consolidated inspection platform. More: https://www.nordson.com
Recent vendor moves reflected in our analysis include product launches and model refreshes throughout 2025 that push the technology envelope (e.g., AI-enabled classifiers, support for 01005 components, and higher-resolution options for HDI). These are meaningful for procurement timing: a purchase committed today may be materially different in capability and price from the same spec cycle in 12 months.
Strategic implications and recommended actions for 2026
-
Adopt a phased procurement approach: prioritize pilot deployments on your highest-value SKUs to quantify yield uplift, then scale with a modular capex plan that protects budget flexibility as sensor availability and tariffs evolve.
-
Diversify sensor sources and contractually protect supply: build dual-sourcing clauses for critical optical modules, negotiate advance purchase commitments for high-resolution cameras, and include price-adjustment caps tied to optics-material indices.
-
Make standards compliance a procurement gate: require suppliers to demonstrate compliance with updated IPC accuracy mandates in acceptance tests rather than rely on vendor claims alone.
-
Leverage service and analytics as competitive advantages: structure long-term service agreements with performance SLAs (false-call thresholds, uptime), and insist on access to analytics APIs to integrate inspection data into your quality dashboards.
-
Stress-test your ROI: use the report’s scenario modules to run “what-if” simulations for tariff events, a 16–20 week camera delay, and 10–20% variation in installation productivity. This will reveal when to buy, lease, or partner for inspection-as-a-service.
-
Watch for consolidation and partnership opportunities: the CR3/CR5 concentration necessitates monitoring for M&A activity that could reshape pricing and aftermarket dynamics; be prepared to act on strategic supplier alliances that secure capacity.
Risk matrix and scenario highlights
Key near-term risks include sensor-module supply shocks, export-control escalation, and tariff inflation. For example, export controls that impacted shipments in 2025 materially increased lead-time and sourcing complexity for some buyers; similarly, new EU import tariffs instituted in 2025 raised landed costs for non-EU equipment. PW Consulting’s scenarios quantify these risks and map them to specific procurement and operational actions — from advance inventory strategies to regional sourcing hubs — enabling leadership teams to prioritize mitigations by expected P&L impact.
How to use this research in your 2026 planning cycle
-
For C-suite: integrate the high-level scenarios and vendor concentration implications into capital-allocation and supply-risk narratives supporting your 2026 budget ask.
-
For procurement: use the supplier scorecard and negotiation playbook to execute RFPs that extract performance guarantees and protect against sensor-price inflation and lead-time variability.
-
For operations: adopt the implementation playbook and KPI set to run pilots that produce defensible yield-improvement estimates for business cases.
Final note — what’s behind the paywall
This overview highlights the strategic themes and executable frameworks contained in PW Consulting’s full report. The full study contains granular regional, technology and end-user splits, detailed vendor scorecards, full RFP templates, and downloadable Excel models for scenario testing — deliberately omitted here to preserve the value of the primary research and to encourage direct access to the source materials. Organizations preparing procurement, production, or M&A decisions for 2026 will find the full package essential for converting inspection capability into predictable business outcomes.
To discuss how our findings map to your manufacturing footprint and to obtain the full dataset and interactive models, PW Consulting’s industry team is available for briefings and customized workshops focused on converting inspection modernization into concrete margin and quality improvements.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Automated Optical Inspection Equipment in PCB Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Low‑Power Solid‑State Microwave Generator Market to Grow from USD 684.83 Million in 2025 to USD 1,663.76 Million by 2032 at a 13.52% CAGR
By PW Consulting, 2026-08-05
PW Consulting Strategic Preview — Worldwide Low-Power Solid State Microwave Generator Market: A 2026 Decision Playbook
As organisations plan capital allocation and product roadmaps for 2026, PW Consulting releases a targeted strategic preview of our full market study on the Worldwide Low-Power Solid State Microwave Generator market. Built on a 2025 base year with historical coverage from 2020–2025 and a forecast window through 2032, our analysis highlights a market expanding at a compound annual growth rate (CAGR) of 13.52%. In monetary terms, PW Consulting projects the market to grow from approximately USD 684.8 Million in 2025 to roughly USD 1,663.8 Million by 2032 — a scale-up that creates distinct opportunity windows for OEMs, suppliers, integrators and investors in 2026.
Worldwide Low-Power Solid State Microwave Generator Market
Why 2026 is a Pivot Year
Several structural inflection points converge in 2026 to make near-term strategic choices unusually consequential. First, semiconductor materials and packaging advances — led by gallium nitride (GaN) — are accelerating efficiency and form-factor gains for low-power solid-state microwave solutions. Second, regulatory and standardization dynamics (including tighter control of heating uniformity in food applications and the narrower frequency stability achievable with solid-state systems) are shifting buyer preferences toward frequency-agile, software-controllable generators. Third, industry momentum on decarbonization and zero-emission process technologies is elevating solid-state alternatives to legacy magnetron systems as a key investment theme.
Worldwide Low-Power Solid State Microwave Generator Market
Finally, market structure shows moderate concentration: the three largest firms capture a meaningful but not dominant share (CR3 ≈ 42.5%), while the five largest firms increase that footprint to a majority position (CR5 ≈ 58.8%). This profile indicates both incumbent strength and fertile territory for challengers with differentiated propositions.
Worldwide Low-Power Solid State Microwave Generator Market
What the Full PW Consulting Report Contains (Practical, Transaction-Ready)
- Executive Decision Brief: A two‑page C-suite summary with prioritized actions for 12–18 month horizons.
- Validated Market Sizing & Forecasts: Top-down and bottom-up estimates for 2020–2032, with sensitivity bands and scenario pathways that stress-test adoption under regulatory and supply‑chain shocks.
- Commercial Segmentation Framework: Structured segmentation by geography, technology platform (e.g., GaN, LDMOS, others) and application verticals (laboratory/R&D, medical/healthcare, industrial heating/plasma, communications/aerospace), accompanied by buyer persona templates — note: the public summary deliberately omits granular split metrics; full tables are available in the report.
- Supply-Chain & Sourcing Map: Bill-of-materials analysis, single‑point-of-failure identification for GaN and other critical inputs, and mitigation playbooks.
- Competitive Intelligence & Vendor Scorecards: Comparative profiles, product architectures, IP posture, channel models and aftermarket strategies for leading and emerging players.
- Technology Roadmaps: Performance trajectories, switching-cost assessment and investment timelines for modular, field‑repairable and liquid/air‑cooled architectures.
- Regulatory & Standards Impact Matrix: Country-level compliance implications, certification timeframes and recommended pre-emptive testing strategies for food and medical uses.
- M&A & Investment Heatmap: Transaction themes, valuation benchmarks, and integration risk checklists tailored for financial sponsors and strategics.
Actionable Strategic Imperatives for 2026
- Prioritise GaN Integration with Commercial Roadmaps: Firms that accelerate GaN-based modules — balanced against supply and quality risk — will capture efficiency- and size-sensitive applications. Evaluate co-investment or long-term purchase agreements with key GaN foundries to secure capacity.
- Design for Modularity and Field Serviceability: Customers value uptime. Modular, field-repairable architectures reduce total cost of ownership and open aftermarket revenue streams — a decisive differentiation in industrial and production environments.
- Embed Frequency Agility and Software Control: Narrow-band, software-tuned solutions unlock process repeatability (e.g., predictable heating patterns required by regulators) and allow premium pricing for deterministic performance.
- Develop Regulatory-Ready Food and Medical Pilots: Given tightened FDA and international requirements on heating uniformity and safety, early validated pilots with regulatory traceability accelerate procurement cycles for end-users in food and healthcare.
- Operationalise Aftermarket and Service Models: With rising installed bases, service contracts, consumables and field diagnostics provide high-margin, durable revenue — essential for mid-size vendors to offset price pressure on hardware.
- Target Strategic Partnerships over Price Wars: Systems integrators, plasma producers and process-tool OEMs are attractive partners for bundled offerings. Prioritise collaboration over pure cost competition, especially when targeting regulated verticals.
- Assess Consolidation Opportunities: With CR3/CR5 figures indicating partial concentration, 2026 is a window for acquisitive scale-ups — tuck-ins that add channel access, specialized IP or capacity may be accretive in the medium term.
Competitive Landscape — Who Matters and Why
PW Consulting’s competitive mapping identifies a mix of specialist innovators, diversified instrument companies and regional low‑cost producers. Key strategic profiles include:
- SAIREM (France / US office): Strength in precision low-to-medium power modules with patented auto‑tune capabilities, appealing to R&D and lab markets where process repeatability is non‑negotiable.
- Crescend Technologies (USA): A candidate for buyers seeking magnetron-to-solid-state transitions; positions its offerings around decarbonization and zero-emission process claims.
- Elite RF (USA): Rapid GaN adoption and field-serviceable, modular designs make it competitive for production environments that require uptime and easy maintenance.
- MKS Instruments (USA): Offers higher-power rack-mount, water-cooled units with strong process control pedigree — attractive to industrial and research institutions demanding precision.
- LEANFA / Muegge Group (Italy): Strong OEM module capability with robust distributed software architectures — suited to integrators building bespoke process tools.
- RFHIC (South Korea): Cost-efficient GaN low-power models with competitive efficiency figures, addressing price-sensitive industrial heating and plasma applications.
- Fricke & Mallah (Germany): Compact industrial units emphasising protection features and ruggedisation for manufacturing environments.
- Chengdu Wattsine, Qualwave, Alaris Kuhne: Regional and component specialists that offer breadth across ISM bands and volume-driven price competitiveness.
Recent ecosystem developments to monitor include LEANFA’s 2024 launch of a new 1000 W LDMOS module, Elite RF’s 2024 GaN product-line expansion, AmpliVisionS’s 2025 scaling across broad frequency ranges, and a 2026 scientific review that underscores measurable improvements in heating uniformity using solid-state generators — all signals of technology maturation and market readiness.
Top Risks and Blind Spots for 2026 Planning
- GaN Material & Capacity Risk: GaN availability and supplier concentration could create lead-time and pricing volatility. Hedging through long-term agreements or multi-sourcing is prudent.
- Regulatory Fragmentation: Food and medical applications face country-specific compliance requirements. A “one-size-fits-all” go-to-market risks costly rework.
- Low-Cost Imports and Margin Pressure: Price competition from large-volume regional suppliers may compress margins in commodity segments — focus on feature and service-based differentiation.
- Standards Adoption Pace: Advantages that rely on narrow-band frequency stability depend on broad customer and regulator acceptance; slower standards harmonisation delays premium adoption.
- Integration Risk with Process Tools: System-level performance is often more important than generator metrics alone; poor integration can negate technology advantages.
Methodology & Confidence
Our full study synthesises primary interviews with buyers, OEMs and foundries; product-level technical review of vendor datasheets and patents; secondary data from trade, regulatory sources and scientific literature; and quantitative triangulation via top‑down and bottom‑up modelling. The report’s base year is 2025, historical coverage spans 2020–2025, and forecasts run through 2032. The headline CAGR and market totals are presented here to contextualise scale; detailed segmentation tables, regional breakdowns and vendor scorecards are intentionally reserved for the full report to preserve client value and support actionable commercial engagements.
Next Steps — How to Use This Preview
- Buyers and integrators: request the process‑use appendices and test-protocols to accelerate regulatory compliance pilots.
- OEMs and suppliers: commission a supplier-readiness assessment and a two-quarter productisation sprint plan.
- Investors: request the M&A heatmap and vendor scorecards to identify accretive targets and valuation comparators.
PW Consulting’s complete Worldwide Low-Power Solid State Microwave Generator Market report contains the full data set, granular segmentation, supplier valuations, and implementation playbooks referenced here. This preview is designed to clarify the strategic stakes for 2026 while driving practitioners to the full report for transaction-ready detail. To obtain the comprehensive study and a tailored executive briefing, contact PW Consulting’s industry desk or visit our reports portal.
For detailed analysis of this topic, please visit the official page: Worldwide Low-Power Solid State Microwave Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Laundry RFID Tags Market to Soar at 12.48% CAGR During 2026–2032
By PW Consulting, 2026-08-05
Worldwide Laundry RFID Tags Market: Strategic Imperatives for 2026 — PW Consulting Insight
Executive overview
As enterprises in hospitality, healthcare, industrial laundry and uniform rental re-evaluate supply chain resilience and operating cost structures for 2026, the laundry RFID tags market has moved from a niche automation play to a strategic enabler of operational continuity and asset intelligence. PW Consulting’s latest Worldwide Laundry RFID Tags Market report — grounded in a 2025 base year and a seven-year forecast window through 2032 — quantifies that transformation. The market reached USD 580.45 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 12.48%, passing the USD 1.3 Billion threshold within the forecast horizon. These headline metrics understate a more important truth for 2026: adoption is being driven as much by use-case economics and regulatory tailwinds as by unit-level technology improvements.
Worldwide Laundry RFID Tags Market
Why this matters for 2026 decision-makers
-
Operational efficiency is now a board-level KPI in asset-heavy service industries. RFID-enabled visibility directly attacks the twin profit drains of procurement inflation and inventory leakage. Our analysis shows device-level economics combine with systems-level process redesign to deliver measurable reductions in linen purchasing and loss — outcomes that make RFID a capital-efficient intervention versus incremental staffing or manual controls.
Worldwide Laundry RFID Tags Market -
Risk management has a new lever. Labels and tags that survive industrial sterilization and gamma irradiation are opening medical- and pharma-adjacent use cases that were previously out of scope. This widens addressable demand and accelerates procurement cycles where compliance is non-negotiable.
Worldwide Laundry RFID Tags Market -
Scale economics are real. The market is consolidating: the three largest suppliers control a meaningful share of industry shipments and the five largest approach majority share — an important consideration for procurement teams that want long-term warranties, re-use programs and interoperability commitments.
Market dynamics shaping 2026 strategies
-
Unit resilience and read performance have become differentiators. Recent product generations target survivability through hundreds of industrial cycles, compatibility with sterilization processes and reliable bulk-read distances in high-throughput washers and tunnels. For enterprises, this means planning replacement and amortization cycles with higher confidence and reducing lifecycle total cost of ownership.
-
Standards and certifications matter more than ever. Interoperability with global RFID standards and certifications for textile safety or medical conditionality are increasingly non-negotiable procurement criteria for multinational operators and hospital groups. Buyers that prioritize certified solutions reduce integration risk and accelerate time-to-value.
-
Automation at the line and laundry level is maturing. Innovations in print-ready roll formats and automated tag-on-label insertion enable item-level tagging to be embedded directly into textile production or finishing lines. This removes a major friction point for scale deployments and creates a stronger link between manufacturing and service lifecycles.
-
Software and systems integration now drive premium value. Tag performance is necessary but insufficient. The realized business outcomes depend on software workflows — inventory reconciliation, repair routing, lifetime analytics and integrations with ERP and linen management platforms. Expect competitive outcomes to hinge on ecosystems, not just tag physics.
Competitive landscape — who to watch
The sector exhibits a measured degree of concentration: the top three vendors capture a significant portion of the market, while the top five approach majority control. That structure produces a competitive environment where differentiation is achieved through product durability, scale deployments, certifications and service models.
-
Datamars Textile ID (Lamone, Switzerland) — A global incumbent with deep domain focus in industrial laundry. Their portfolio spans chips, readers, antennas and software, and their installed base is mature. Recent product activity includes tag and label automation as well as specialized solutions for gamma sterilization — a strategic move to deepen presence in medical textiles.
-
HID Global (United States) — Leverages broad enterprise security and identity capabilities into textile-safe offerings with certifications that matter in regulated settings. Their product designs focus on textile-friendly form factors and variants that address MRI-safe environments, making them a preferred supplier where safety certifications factor into RFPs.
-
Xerafy (Singapore) — Competes on read performance and industrial wash durability, and has invested in roll-format tags designed for print-on-demand workflows. Their product roadmap targets performance at scale — a critical consideration for laundries that require high throughput bulk reading.
-
JYL-Tech (Shanghai) — Focused on automation in manufacturing and high-volume insertion tooling. Their roll-format solutions are playing to demand from textile producers and large laundry chains seeking an integrated upstream tagging capability.
-
Regional and specialized players — European, North American and Canadian specialists bring differentiated competencies on materials engineering, custom tag forms, and tag reuse programs. These players are attractive to customers seeking tailored service levels, local support or cost-competitive sourcing.
Recent product signals (select highlights)
-
March 2026: a leading supplier introduced a UHF tag designed to survive extensive gamma sterilization cycles — a step-change for textile tracking in medical environments.
-
Early 2026: a manufacturer launched an automated tag-in-roll solution for linen production lines, bridging the factory-to-facility tagging gap and enabling item-level traceability from the first wash.
-
Mid-2025: print-ready roll-format tags incorporating next-generation RAIN RFID chips reached the market — a tangible productivity lever for large-scale laundries and label converters.
Report deliverables — what’s inside and how leaders should use it
PW Consulting’s report was built for 2026 strategic decisions. It combines quantitative forecasting, supplier benchmarking and tactical tools that procurement, operations and CIO teams can deploy quickly:
-
Actionable market sizing and scenario-driven forecasts to support investment cases and capital planning.
-
Supplier scorecards that evaluate durability, certification footprint, read-range performance, ecosystem integration and service models — enabling shortlist creation and RFP design.
-
Procurement playbooks covering total cost of ownership, tag reuse economics, warranty negotiation levers and volume pricing strategies tailored to multi-site programs.
-
Operational templates for pilot design, KPI selection (loss rates, turn cycles, read accuracy), and governance models to transition pilots into rollouts at scale.
-
Integration matrices for IT and OT teams that align RFID deployments with existing asset management, ERP and linen management systems to avoid costly retrofit work.
Strategic recommendations for 2026
-
Prioritize pilots that mirror scale: design proofs of concept that replicate production throughput and sterilization/regulatory requirements so that tag survivability and read-performance are validated under real operational stress.
-
Push vendors on long-term service economics, not only unit price. Reuse programs, repair/refurbishment pathways and guaranteed read performance over life materially change ROI.
-
Specify standards and certifications early in the RFP to avoid integration and compliance surprises. Certificates and conditional-use ratings should be mandatory pass/fail criteria for regulated deployments.
-
Plan for software-first deployments. Tag hardware does the sensing; software converts sensor data into decisions. Identify use cases where analytics can reduce linen inventory or automate routing and prioritize those as first waves for automation.
-
Monitor consolidation and supplier innovation closely. The market’s concentration profile means supplier roadmaps will alter competitive dynamics — strategic buyers should secure roadmap commitments and interoperability clauses to protect future optionality.
Methodology and confidence
Our forecast combines historical shipment and revenue data (2020–2025), primary interviews with suppliers and large end-users, and bottom-up modeling of unit economics and replacement cycles. We stress-tested scenarios against variations in wash-cycle survivability, regulatory acceptance in medical markets, and the pace of automation adoption in linen production. The resulting 12.48% CAGR reflects both steady organic adoption and discrete upside tied to clinical-textile use cases and automated tagging adoption in manufacturing.
Next steps — how executives should use this insight
-
For CFOs and procurement leaders: use the report to structure multi-year capex plans, supplier commitments and volume-based price schedules with performance-based SLAs.
-
For COOs: adopt our pilot templates to de-risk rollouts and set KPIs that translate RFID visibility into inventory and procurement savings.
-
For CIOs and integration leads: leverage the integration matrices to prioritize API and middleware investments that will unlock cross-system value.
Conclusion
In 2026, laundry RFID tags are transitioning from a specialized automation accessory to a foundational element of asset-centric operations. The combined forces of improved tag survivability, production-line automation, and ecosystem-aware software make this a decisive year for organizations that must balance cost containment with quality and compliance mandates. PW Consulting’s Worldwide Laundry RFID Tags Market report equips leaders with the forecast, supplier intelligence and operational playbooks to turn adoption into durable advantage. For readers seeking the detailed regional, application and supplier split data that underpin bespoke procurement decisions, the full report and accompanying datasets are available from PW Consulting.
For detailed analysis of this topic, please visit the official page: Worldwide Laundry RFID Tags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vorinostat Market to Reach USD 312.42 Million by 2032 at a 5.4% CAGR — North America Accounts for USD 106.47M in 2025
By PW Consulting, 2026-08-05
Worldwide Vorinostat Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s newest market study on the Worldwide Vorinostat Market (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the forward-looking intelligence required to make high-consequence decisions in 2026. Our model, denominated in USD Million, shows the market expanding from a mid‑hundreds million footprint in 2025 with a compound annual growth rate (CAGR) of 5.4% through 2032. By combining a proprietary market-sizing engine, scenario-driven forecasts and roll-up commercial playbooks, the report is built to move portfolio, manufacturing and M&A decisions from hypothesis to execution-ready.
Worldwide Vorinostat Market
Why this preview matters for 2026 decision cycles
- Budget cycles and manufacturing investments being set in 2026 require visibility into both steady-state demand and upside scenarios; our forecast horizon (2026–2032) is aligned to typical capital-planning windows.
- Vorinostat’s mixed lifecycle — an approved originator product alongside an active generic landscape — demands differentiated strategies for brand owners, generics manufacturers and private investors. The report translates competitive dynamics into actionable options.
- Regulatory, reimbursement and safety constraints (including entrenched label warnings requiring monitoring) materially affect prescribing patterns and payer coverage decisions; operational guidance in the report turns those constraints into commercial levers.
Market trajectory at a glance
From the baseline established in 2025, PW Consulting’s central forecast projects consistent, moderate growth through 2032 driven by continued use in established hematologic indications, steady research interest in additional indications and the maturation of generic supply chains. Our scenario engine quantifies the sensitivity of market value to variables that matter most to 2026 planners — unit price erosion, adoption in new research settings, and shifts in payer rules — enabling prioritization of interventions that preserve EBITDA under stress.
Worldwide Vorinostat Market
Core dynamics shaping the vorinostat landscape
- Regulatory heritage and guideline support: Vorinostat’s pathway to approval and subsequent guidance placements have anchored it as a clinical option for relapsed/refractory cutaneous T‑cell lymphoma (CTCL). That status supports baseline demand while defining the parameters of label‑driven use.
- Post‑patent competitive structure: The original composition‑of‑matter patent expiration opened the market to generic competition. Since then, multiple manufacturers have pursued regulatory approvals and commercial launches, creating pronounced pricing and access pressures in mature channels.
- Safety profile as a commercial constraint: Black‑box risks — including thromboembolic events and QT prolongation — mean that vorinostat is often deployed with ECG monitoring and DVT prophylaxis protocols. These safety requirements affect formulary negotiation, outpatient prescribing patterns and total cost of care calculations.
- Concentration and supplier power: Market share concentration is high among the leading manufacturers, a structural factor that both reduces price fragmentation in some channels and heightens single‑supplier risk for specific tenders and public procurement events. PW Consulting’s analysis shows a market where the top three and five players command dominant shares, intensifying competitive pricing dynamics and raising the strategic value of secure manufacturing alliances.
- Research pipeline and off‑label interest: Beyond approved indications, vorinostat remains an active compound in combination and translational research (including latency‑reversal approaches in virology). Research demand is a predictable, if smaller, contributor to overall volume and an important channel for lifecycle extension strategies.
Competitive landscape — positioning and implications
Our competitive analysis synthesizes incumbent originator strategy with generic manufacturers’ commercial playbooks to outline tactical options for market participants.
Worldwide Vorinostat Market
- Originator (developer): As the original developer, the originator’s residual brand value and historical safety dataset are strategic assets. Defending residual premium segments requires targeted stewardship — label optimization, focused RWE to support differentiated outcomes, and selective co‑development of combination regimens that leverage clinical familiarity.
- Large generics and specialty players: Several global generics manufacturers have pursued approvals and market entry, emphasizing cost‑competitive supply and broad geographic coverage. Their playbook typically includes aggressive tender participation, partnerships for local distribution, and cost leadership in emerging markets.
- Regional suppliers: Mid‑sized manufacturers leverage nimble regulatory strategies and local market knowledge to win formulary inclusion where pricing thresholds favor incumbents with local presence. For these players, the pathway to scale is through targeted tender wins and contract manufacturing partnerships.
- Recent tactical moves: Regulators and manufacturers continue to shape access. Notable recent developments — regulatory approvals that established AB‑rated generics in major markets and targeted product launches in regional markets — demonstrate how timing of regulatory clearance and first‑to‑market dynamics materially alter competitive positioning.
What’s inside the full PW Consulting report — practical, transaction‑ready deliverables
Our report is intentionally operational: it does not stop at descriptive analysis but provides tools executives can deploy immediately in 2026 planning cycles.
- Interactive market model (USD Million): Build‑your‑own scenario capability with inputs for price erosion pathways, uptake curves, and research demand. The model supports top‑down and bottom‑up views and exports to client financial systems.
- Price erosion and tender simulation engine: Quantifies revenue and margin trajectories under competing tender scenarios and formulary decisions to prioritize markets and optimize bidding strategy.
- Payer and reimbursement matrices: Granular playbooks for engagement, including dossier templates and value‑argument frameworks aligned to safety monitoring costs and real‑world outcomes.
- Supply‑chain and manufacturing heatmaps: Risk scoring for API suppliers, suggested redundancy strategies, and CAPEX templates for capacity expansion or contract manufacturing options.
- Clinical and regulatory roadmap: A navigable registry of ongoing trials, label‑change opportunities and jurisdictional approval pathways to guide lifecycle management and combination trials.
- M&A and partnership target shortlists: Scored dossiers of potential tuck‑ins and alliance partners, ranked by strategic fit, regulatory foothold and manufacturing capability.
- Commercial playbooks and KPI templates: Launch, post‑launch and pricing playbooks tailored to brand, generic and hybrid commercialization models, plus KPI dashboards for executive monitoring.
Strategic recommendations for 2026 — prioritized actions
- For originator players: Deploy targeted RWE investments to quantify safety‑management cost offsets and patient outcomes vs. generics; prioritize label clarity and negotiated reimbursement bundles that reflect monitoring requirements.
- For generic entrants: Focus initial capacity and tender efforts on markets where conversion windows are widest and logistics complexity is manageable; use AB‑rated approvals to accelerate formulary inclusion and generate scale economics quickly.
- For investors and PE: Prioritize assets that add manufacturing redundancy or differentiated formulation capabilities; value accretion will be driven by supply‑chain control and the ability to compete in tendered volumes.
- For contract manufacturers/CROs: Position offerings around end‑to‑end support — from regulatory filings to pharmacovigilance services — to capture adjacent revenue streams as safety monitoring needs remain front‑of‑mind.
- Cross‑cutting: Execute a two‑track scenario plan that protects downside (accelerated price erosion, payer pushback) while funding selective upside bets (combination trials, label expansion) that can materially lift mid‑cycle growth.
Use cases — how different stakeholders should leverage the report
- Commercial leadership: Use the tender simulator and payer matrix to set 2026 pricing floors and prioritize markets for salesforce allocation.
- Corporate development: Leverage the M&A shortlist and valuation sensitivity analyses to surface targets that de‑risk supply or add adjacencies.
- Manufacturing and operations: Apply supplier heatmaps and capacity templates to make 18–36 month investment decisions with quantified ROIC scenarios.
- Medical affairs & RWE teams: Align evidence generation with the identified clinical gaps and payer evidence requirements outlined in the report’s dossier templates.
Final note — a “trailer” built to convert interest into action
This preview aligns PW Consulting’s strategic lens with the practical needs of organizations planning for 2026. We have deliberately showcased methodology, high‑level market trajectory and competitive dynamics while reserving the detailed segmentation tables and transaction‑grade spreadsheets for the full report. For teams ready to translate insight into executable plans — whether to defend brand value, scale a generics franchise, or target high‑impact M&A — the full dataset and interactive models are available on the PW Consulting report page. Contact our team to schedule a walk‑through and to obtain the report package that will serve as the playbook for your 2026 vorinostat strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smartphone Panel Market to Expand at 5.19% CAGR, Reaching USD 64.91 Billion by 2032
By PW Consulting, 2026-08-05
PW Consulting Strategic Brief: Worldwide Smartphone Panel Market — A 2026 Decision Playbook
PW Consulting’s new Worldwide Smartphone Panel Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) offers a focused, actionable intelligence set for executives who must make capital, procurement and product decisions in 2026. Our model projects market revenue rising from USD 45,520 Million in 2025 to USD 64,910.12 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.19% over the forecast window. This brief synthesizes the report’s strategic implications without disclosing the granular segment tables and confidential supplier metrics reserved for the full report.
Worldwide Smartphone Panel Market
Why this report matters for 2026 decision cycles
-
Timing of investment. With steady mid-single-digit market growth through 2032, the window for prudent capacity investments and selective technology bets is open but narrowing. The report’s capex tracker and tranche-based investment triggers help align factory expansion or outsourcing decisions with realistic demand trajectories.
Worldwide Smartphone Panel Market -
Supplier selection under volatility. Supply-side concentration and raw-material geopolitics increase the cost of supplier missteps. Our supplier scorecards and scenario-tested sourcing playbooks enable procurement teams to balance price, tech roadmap and supply risk.
Worldwide Smartphone Panel Market -
Product roadmap prioritization. The migration dynamics toward emissive technologies and flexible form factors require product managers to re-weight R&D and BOM strategies. The report’s technology timelines and cost inflection curves quantify when AMOLED and flexible investments become nominally accretive.
-
Policy and contingency planning. Trade-policy risk and critical-mineral control are now first-order variables for enterprise risk management. The report’s trade-scenario stress tests and mitigation matrices provide practical contingency plans for 2026 implementation.
What the report delivers (practical, board-ready assets)
-
Transparent forecasting engine — a replicable demand model with sensitivity levers for unit volumes, display mix and ASP that executives can use to run bespoke scenarios.
-
Supplier scorecards — multi-factor assessments that combine capacity, technology readiness, quality performance, client concentration and geopolitical exposure into a procurement-ranked universe.
-
Capex and ramp tracker — line-by-line visibility on announced and industry-validated capacity changes, their likely ramp timing and the implied impact on global panel supply balances.
-
Technology migration timelines — when key cost and performance inflection points are expected for AMOLED variants, LTPO evolution, ultra-thin glass (UTG) usage and flexible substrates.
-
Supply-chain risk matrix — granular failure modes for critical inputs (e.g., ITO, indium, polyimide, UTG), node-level concentration mapping and mitigation options (dual-sourcing, strategic inventory, vertical integration scenarios).
-
Commercial playbooks — buyer negotiation strategies, make-vs-buy decision frameworks, launch-timing optimization and pricing levers for smartphone OEMs targeting premium, mid-range and entry segments.
-
Policy scenario analysis — discrete scenarios reflecting potential tariff regimes, export controls and critical-mineral interventions, each with quantified P&L and supply impacts.
Market dynamics that should shape 2026 plans
-
Gradual but clear growth trajectory. The market shows steady expansion from the mid-2020s baseline into the early 2030s. The structural growth is driven by device refresh cycles, penetration of new form factors and component upgrades; however, growth is uneven across technologies and geographies.
-
AMOLED acceleration. Independent industry forecasts point to accelerating unit adoption of emissive displays across price tiers. This is reshaping both BOM cost structures and supplier competitive dynamics, and it is a central input to our product roadmap counsel.
-
Flexible and foldable moving from halo to mainstream. Engineering improvements (substrates, UTG, crease mitigation) and supply-side investments are turning previously niche form factors into credible product lines for premium and adjacent segments.
-
Supply concentration and strategic suppliers. The market remains concentrated: a small group of global suppliers captures a dominant share of high-value panel sales, with several large-volume manufacturers competing for scale in mid-to-high tiers. This structure favors incumbents with integrated technology stacks, while creating opportunities for specialized entrants.
-
Raw-material and policy volatility. Control over processing of critical materials (e.g., indium, gallium) and the potential for trade measures tied to national-security reviews raise meaningful tail risks for supply chains. Procurement and legal teams must embed trade-policy triggers into sourcing contracts.
Competitive landscape — what leading suppliers are positioning for
-
Samsung Display (South Korea) — remains the technology leader for premium emissive and foldable displays, demonstrating advanced LTPO and foldable OLED capabilities and evaluating additional capacity targeted at flagship device programs.
-
LG Display (South Korea) — focusing on flexible AMOLED technologies for premium models and expanding strategic partnerships in the high-end device segment.
-
BOE Technology Group (China) — the largest-volume supplier with end-to-end capabilities across legacy LCD and increasingly competitive OLED lines; recent activations of higher-generation OLED capacity materially alter supply dynamics for mid-to-high-end panels.
-
TCL CSOT (China) — scaling AMOLED competence while leveraging partnerships to increase share in mid-range and selected flagship programs.
-
Other noteworthy players — a mix of focused OLED specialists, established LCD makers and emerging challengers from Taiwan, Japan and China are each pursuing differentiated strategies (niche premium supply, cost-led scale, or flexible OLED specialization).
Recent industry signals that change the odds in 2026
-
Capacity and ramp announcements from large suppliers are accelerating supply-side transitions and will influence pricing and availability in 2026.
-
Independent market trackers estimate global smartphone panel shipments at multi-billion unit levels in 2026 with continued growth in AMOLED share—an indicator that mid-range adoption is an important vector of demand.
-
Leading suppliers are actively showcasing advanced display innovations (privacy modes, slidable screens) and reviewing targeted investments for devices from marquee OEMs—signs that premium-product roadmaps remain an area of intense competition and customer-specific capacity allocation.
-
Raw-material and regulatory developments are injecting short-to-medium-term uncertainty. Firms should treat these as strategic variables rather than isolated procurement inconveniences.
Strategic recommendations for executives in 2026
-
Embed supply-risk metrics into every sourcing decision. Require supplier bids to include quantified exposure to critical-material constraints and policy scenarios; adjust contract terms to reflect those exposures.
-
Accelerate dual-sourcing for technology transitions. Where AMOLED or flexible panels are material to product differentiation, secure at least two qualified suppliers with staggered qualification timelines to reduce single-vendor risk.
-
De-risk through staged capex participation. For OEMs considering joint investments or captive lines, use tranche-based commitments tied to validated demand milestones from our forecast engine to avoid stranded capacity.
-
Prioritize product segmentation by value capture, not purely by feature. The report’s margin models show when display innovations drive sustainable ASP uplift versus transient price competition.
-
Operationalize trade-policy contingency plans. Build “go/no-go” triggers for inventory build, tariff pass-through clauses in supplier agreements and an escalation ladder for rapid re-sourcing.
-
Use M&A and partnership selectively. Acquire or partner with specialists in flexible substrates, UTG or advanced OLED process expertise when it accelerates go-to-market advantage inexpensively compared with organic development.
How PW Consulting’s report delivers defensible advantage
Our analysis combines a fact-based demand model, validated capacity tracker, supplier performance datasets and policy-scenario quantification to produce recommendations that are both executable and auditable. We deliberately withhold the granular segment and supplier share tables in this brief — those core datasets and detailed dashboards are reserved for the full report and client workshops. The result is a practical, board-level playbook tied to executable procurement, product and capital plans for 2026.
To operationalize these insights in the coming quarter, PW Consulting recommends convening a cross-functional “display risk and strategy” working group that uses our scenario engine to stress-test board-approved plans and to translate high-level strategy into supplier contracts, capex timetables and product launch priorities.
For access to the complete data tables, supplier scorecards, scenario models and the full fifty-plus page playbook that supports the 2026 decision calendar, please refer to the Worldwide Smartphone Panel Market report landing page. The public brief above illustrates the strategic direction and executive actions implied by our findings; the full report contains the detailed segmentation and proprietary metrics necessary to implement them.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


