



Category: market research
PW Consulting: Worldwide Non‑Thermal Food Processing Market Poised for 10% CAGR, Expected to Top USD 10.68 Billion by 2032
By PW Consulting, 2026-08-05
Worldwide Non-Thermal Food Processing Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Non-Thermal Food Processing provides an operationally focused intelligence package for executives steering technology investments, commercial expansion, or M&A in 2026. Anchored on a 2025 base year and a detailed forecast through 2032, the report quantifies a market that we project to nearly double over the forecast horizon — reflecting a compound annual growth rate (CAGR) of roughly 10% from 2026 to 2032. This headline trajectory underscores both accelerating commercial adoption and a widening set of use-cases where non-thermal technologies deliver shelf-life extension, sensory advantage and cleaner-label claims without the organoleptic penalties of traditional heat-based processing.
Worldwide Non-Thermal Food Processing Market
Why 2026 Is a Strategic Inflection Point
Manufacturers that move decisively in 2026 will capture disproportional value as non-thermal processing transitions from early-adopter niches into mainstream production lines. Several factors converge to make this year pivotal:
Worldwide Non-Thermal Food Processing Market
- Macro growth momentum. After recovery and post-pandemic reconfiguration, total market scale in our base year (2025) signals a maturing addressable market. Our forecast to 2032 indicates a steep growth arc, creating windows for scale-driven cost reduction and first-mover share gains.
- Regulatory clarity is improving. Agencies in major markets increasingly validate non-thermal approaches for food safety equivalency. This reduces technology adoption risk for regulated categories and shifts corporate focus from "proof" to "scale."
- Commercial proof points and supplier expansion. Vendors are launching higher-throughput platforms and regionally expanding manufacturing footprints, enabling processors to deploy these technologies with lower CapEx lead times and better service economics.
Operational Questions Executives Must Resolve in 2026
Deciding whether to invest, partner or defer requires clear answers to six operational questions. PW Consulting’s report equips leaders to answer them with data-driven frameworks and executable templates.
Worldwide Non-Thermal Food Processing Market
- Which non-thermal technology aligns to my product portfolio objectives (shelf life, taste, nutritional retention, label claims) and at what scale will it be economically accretive?
- What CapEx and Opex trade-offs should my finance team expect when comparing incremental throughput from new non-thermal lines versus conventional pasteurization upgrades?
- How do regional regulatory regimes and export rules affect the time-to-market and certification costs for processed SKUs?
- Where are supply chain pinch points — raw material cost volatility and labor intensity — most likely to erode project returns?
- What contracting and lifecycle service models with equipment suppliers minimize downtime and protect margin over a 7–10 year horizon?
- Which strategic partnership or M&A archetypes align to accelerate capability uptake (e.g., technology licensing, JV manufacturing, co-investment in line integration)?
What the Report Delivers — Practical, Actionable Intelligence
Beyond market sizing and trend narration, the PW Consulting study is deliberately operational. The report contains:
- Investment-grade market sizing and scenario modelling (base case, high-adoption upside, and downside sensitivity), with an explicit methodology so CFOs and corporate planners can reconcile internal forecasts to our results.
- Technology benchmarking matrices comparing throughput, energy intensity, product scope, and typical line integration challenges for the major non-thermal families.
- CapEx and Opex model templates calibrated to real-world installations — enabling rapid back-of-envelope ROI and payback analyses by product family and plant scale.
- Vendor shortlists and vendor-selection scorecards that map supplier capabilities to buyer priorities, including service network, spare-parts logistics, and retrofit competence.
- Regulatory and export compliance playbooks for primary markets — a practical matrix linking technology pathways to notifications, equivalency benchmarks and typical documentation required for cross-border trade.
- Case studies that distill operating lessons from commercial roll-outs — from line balancing and microbiological validation to packaging integration and supply chain redesign.
- M&A and collaboration opportunity frameworks that identify likely consolidation vectors and the value levers acquirers should prioritize in diligence.
Competitive Landscape: Who Matters and Why
The vendor ecosystem is maturing. A small set of technology-specialist OEMs and integrated systems providers collectively capture a meaningful share of commercial deployments, yet the market remains sufficiently fragmented to reward differentiated go-to-market plays.
- Hiperbaric (Burgos, Spain) — a recognized leader in high-pressure processing (HPP) equipment. Hiperbaric’s continued product innovation is lowering yield-impact and improving throughput on juice and meat lines, making conversion decisions more commercially palatable for brand owners focused on sensory fidelity.
- JBT FoodTech (Chaska, Minnesota, USA) — one of the large industrial integrators that offers end-to-end non-thermal processing lines. Recent expansion of regional manufacturing capabilities enhances their speed-to-deploy in growth geographies and reduces localized CapEx friction for large food companies.
- Multivac Group (Wolfertschwenden, Germany) — combines packaging expertise with HPP capabilities. This systems-integration approach reduces integration risk for processors seeking single-vendor responsibility for sterilization and packaging continuity.
- Elea Technology GmbH (Quakenbrück, Germany) and Pulsemaster (Ochten, Netherlands) — PEF specialists focused on cell-disruption use-cases such as extraction and texture modulation in fruits, vegetables and tuber processing. Their demonstrator work at trade shows is accelerating commercial interest in PEF for high-value ingredients.
- Steriflow (Thyssenkrupp) (Quimper, France) — a legacy pressure systems manufacturer extending capabilities into non-thermal applications, offering options for players evaluating multi-technology strategies within a single supplier relationship.
Recent vendor developments — product launches, trade-show demonstrations and regional facility openings — are not just PR. They materially shorten the time horizon to adoption, reduce project risk and change negotiation dynamics with purchasers. For instance, suppliers delivering higher yield retention and integrated packaging reduce the need for costly retrofit investments.
Regulatory and Input-Cost Dynamics Shaping 2026 Decisions
Regulation is a structural enabler. Authorities in key markets increasingly recognize certain non-thermal methods as meeting pasteurization or pathogen-reduction equivalency, removing a major adoption barrier. At the operational level, import/export rules and novel-food classifications will remain a gating factor for cross-border SKU rollouts — companies must bake regulatory timelines into their launch sequencing.
Input-cost volatility also matters. Fresh produce pricing swings and regional labor-cost differentials materially affect per-unit processing economics and, by extension, the relative attractiveness of automation-intensive non-thermal lines. These dynamics make sensitivity testing essential: modest shifts in procurement or wage assumptions can meaningfully alter project IRR for mid-scale plants.
Strategic Playbook for 2026
For executives preparing capital allocation plans next year, we recommend a prioritized playbook:
- Pilot-to-scale pathways: Start with tightly scoped pilots that validate product quality, line integration, and regulatory certification. Use pilot data to standardize CapEx templates and to de-risk full-scale rollouts.
- Vendor ecosystem strategy: Adopt a layered supplier model — a primary systems integrator for line responsibility and niche specialists for advanced unit operations. Negotiate mutual commitment clauses for spare parts and uptime SLAs.
- Regulatory-forward commercialization: Build cross-functional launch teams that combine regulatory, quality assurance, and commercial functions to compress time-to-market for export-dependent SKUs.
- Cost resiliency: Integrate raw-material hedging and contract labor-scope scenarios into project financial models. Consider vertically integrated procurement for high-volatility inputs where scale permits.
- M&A and partnership scouting: Identify targets that close capability gaps (e.g., packaging integration, regional service networks, or ingredient extraction) and prioritize bolt-on acquisitions that unlock immediate cross-selling opportunities.
Market Structure and Competitive Intensity
Market concentration metrics suggest a moderate level of consolidation: a small cohort of suppliers captures a meaningful portion of commercial deployments, yet there remains substantive opportunity for niche players that can deliver measurable process advantages or superior service economics. This structure favors both larger incumbents expanding functionality and specialized entrants pursuing focused technology leadership.
Concluding Perspective — The Strategic Payoff
Non-thermal food processing is no longer a laboratory curiosity; it is a deployable industrial strategy that can differentiate brands, extend margins and open new product propositions. PW Consulting’s report translates the market’s macro momentum into executable intelligence for 2026 decisions: capital prioritization, supplier selection, regulatory navigation and M&A origination.
In keeping with our “trailer” principle, this press release outlines the analytical thrust and executive takeaways without publishing the full set of granular segment-level tables and supplier scorecards. For access to the complete dataset, including detailed segment breakdowns, region-application matrices, and vendor scorecards, please consult the full report at our website or contact PW Consulting’s research desk for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Thermal Food Processing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Fuel Level Sensor Market Hits USD 950.0 Million in 2025 — Poised to Grow at 3.2% CAGR to ~USD 1.18 Billion by 2032 as Asia‑Pacific Leads with USD 413.1 Million
By PW Consulting, 2026-08-05
Worldwide Shape Memory Alloys for Civil Engineering Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting’s latest market study on Shape Memory Alloys (SMAs) in civil engineering is intended as an actionable briefing for executives, infrastructure planners, and investors setting strategy for 2026. The study synthesizes primary research, engineering validation, procurement analysis, and commercial due diligence into a single roadmap. This release previews the strategic implications and decision points that will matter most next year — while reserving the full segmentation tables, supplier scorecards and model outputs for subscribers and report purchasers.
Worldwide Shape Memory Alloys for Civil Engineering Market
Market snapshot: growth, scale and what it means for 2026 decisions
From a modest commercial base in 2020, the worldwide SMA market for civil engineering expanded steadily through 2025. Our base-year assessment (2025) anchors a forecast window spanning 2026–2032. The market’s compound annual growth rate over the modelled period is 8.5%, and our scenario suite produces a clear line of sight to materially larger addressable volumes by the early 2030s. In practical terms, this trajectory converts SMA technologies from niche specialty solutions into a distinct procurement category for major bridge, building retrofit and resilient-transportation programs.
Worldwide Shape Memory Alloys for Civil Engineering Market
Two observations from the numeric trend are critical for 2026 planning. First, growth is both sustained and accelerating as engineering prototypes move into demonstrator deployments and as standards and procurement practice mature. Second, there are identifiable inflection points driven by a mix of regulatory alignment, materials availability and successful pilot programs — all of which create windows of opportunity for early movers to capture specification leadership and supplier advantage.
Worldwide Shape Memory Alloys for Civil Engineering Market
Why 2026 is a pivot year
-
Standards and specification momentum: ASTM test methods and alloy standards (including guidance relevant to SMA actuators and structural applications) are beginning to be adopted by specification bodies and public agencies. That alignment shortens the path from research to procurement and reduces bid uncertainty for contractors and owners.
-
Demonstrations moving toward deployment: Recent academic and field demonstrations — including heat-activated iron-based strengthening methods for bridge decks and digitally fabricated structural applications — are lowering technical risk and validating installation workflows. These demonstrations underpin practical procurement templates described in our full report.
-
Supply-side differentiation and vertical integration: Some suppliers are vertically integrated from melting to components, while others focus on system integration and service delivery. The strategic choice between sourcing high-performance nickel-titanium (NiTi) alloys versus iron-based SMAs (Fe-SMA) will hinge on performance needs, unit economics and manufacturability at scale.
-
Raw material and geopolitical noise: Nickel and titanium price volatility and selective mining restrictions are increasing input-cost risk for NiTi solutions. By contrast, Fe-SMA routes offer advantages in conventional metallurgical processing, supporting larger-scale, lower-cost production — an important consideration for infrastructure owners planning mass deployments.
What the PW Consulting report delivers — practical, transaction-focused content
The report is engineered to support immediate 2026 decisions. Key deliverables include:
-
Actionable procurement playbooks: specification checklists, bid templates and acceptance test plans tailored to both new-build and retrofit contexts.
-
Investment and ROI models: Excel-ready templates with sensitivity cases for material cost fluctuation, installation labour, lifecycle maintenance and resilience value-adds.
-
Pilot-to-scale blueprints: step-by-step deployment pathways for pilots that minimize civil-disruption while capturing data required for full-scale rollouts.
-
Risk and mitigation matrices: encompassing supply-chain exposure, regulatory compliance, installation quality control and long-term monitoring strategies.
-
Supplier evaluation framework: scorecards and procurement negotiation playbooks that distil technical, operational and commercial differentiation — provided in the full report as downloadable templates.
-
Policy and standards mapping: an annotated guide to relevant standards and recommended clauses for public works contracts to accelerate acceptance.
To preserve the value of our primary research as a subscription asset, detailed tabulations by region, alloy type and end-application are intentionally summarized here; the full breakdowns and model inputs are accessible in the paid report.
Competitive landscape: strategic implications from leading players
The supplier ecosystem shows a mix of material specialists, vertically integrated producers and system integrators. Market concentration is moderate: our competitive analysis shows the top-three suppliers account for roughly one-third of visible commercial activity, while the top-five approach mid‑forties in percentage share — a structure that favours both focused innovation and strategic partnerships.
-
re-fer AG (Brunnen, Switzerland — https://www.re-fer.eu) : A leader in iron-based memory®-steel for structural strengthening and concrete/masonry repairs. Their patented approach to prestressing and retrofit has been field-proven in dozens of projects and used in digitally fabricated architectural elements. For owners planning rapid retrofits of aging assets, re-fer’s know-how offers a low-complexity path to deploy Fe‑SMA solutions at scale.
-
Ingpuls GmbH (Bochum, Germany — https://ingpuls.de) : Provides customizable alloy components and complete turn-key assemblies for building services and vibration control. Ingpuls’s capability to deliver from specification through assembly positions them as a preferred partner where integration, sensing and actuation are bundled with structural interventions.
-
SMA CORES Inc. (Champaign, Illinois, USA — https://sma-cores.com) : Specializes in SMA-based structural technologies that exploit thermal prestressing and superelasticity to reduce labour and schedule risk on repairs and upgrades. Their technology is particularly relevant where time-on-site is a critical constraint.
-
SAES Getters S.p.A. (Lainate, Italy — https://www.saesgetters.com) : A vertically integrated NiTi producer able to supply alloy from melt to component. For projects requiring high-performance actuation and predictable material supply, SAES’s vertical model can reduce vendor handoffs and quality risk.
-
Dynalloy Inc. (Irvine, California, USA — https://dynalloy.com) : Known for Flexinol® NiTi actuator wire, a component choice for retrofitted active controls and damping elements in buildings and long-span structures.
-
Memry Corporation (Bethel, Connecticut, USA) : A supplier of Nitinol forms and components, serving engineering customers who require standardized stock shapes and precision components for sensing and damping applications.
Recent developments to watch in 2026 include field demonstrations of heat-activated Fe‑SMA strengthening methods and scheduled industry convenings focused on infrastructure applications. These events accelerate the mutual learning loop between research, suppliers and owners, and will materially influence specification choices over the next 12–18 months.
Strategic playbook for 2026 — recommended actions by stakeholder
-
Public owners and agency planners: Commission small-scale demonstrator contracts with clear performance metrics tied to lifecycle maintenance and resilience outcomes. Incorporate ASTM-aligned acceptance criteria in procurement language to reduce technical disputes.
-
Engineering and construction firms: Build internal capability to assess NiTi versus Fe‑SMA trade-offs and pilot hybrid solutions that exploit each alloy’s strengths — high-actuation NiTi for control systems; Fe‑SMA for mass-produced strengthening elements.
-
Material and component suppliers: De-risk supply by securing strategic feedstock contracts or by assessing vertical integration options. Invest in certification and test-lab capacity to shorten the time between contract award and site delivery.
-
Investors and private capital: Prioritize platform plays that combine materials capability with system-level integration and installation services rather than pure-play commodity suppliers. Consider minority investments in firms offering turnkey pilot execution for public agencies.
-
R&D and standards bodies: Focus on durability data, NDT and embedded sensing methods that enable condition-based maintenance contracts — a critical commercial lever for SMA adoption.
How our report supports a 2026-ready strategy
PW Consulting’s market model and decision-support materials are designed to be used during contract scoping, CAPEX approvals and early vendor selection. The report contains peer-reviewed engineering appraisals, vendor scorecards, regionally-adjusted price curves and deployment-case financials — all linked to an integrated scenario engine so users can re-run sensitivities reflecting local labour, material and regulatory conditions.
Importantly, while this briefing outlines trends and strategic recommendations, it does not disclose the report’s detailed segment tables, supplier scoring metrics, or the full suite of model outputs. Those granular deliverables are the intellectual property of PW Consulting and are intentionally reserved for report subscribers to sustain the independent primary research that underpins our conclusions.
Takeaways
-
SMA technologies are moving from experimental to practical in civil engineering; the market exhibits sustained growth with an 8.5% CAGR across the 2026–2032 forecast window and materially higher realized demand in several adoption scenarios.
-
2026 is a decisive year for specification leadership: early pilots, standards adoption and supply-chain decisions will determine who captures the first wave of large infrastructure contracts.
-
Strategic choices will center on alloy selection (NiTi vs Fe‑SMA), supplier integration, and risk mitigation for raw material volatility — all of which are addressed in our decision-ready playbooks and financial models.
For procurement-ready templates, supplier scorecards, full regional/application breakdowns and the scenario models that power our recommendations, please visit PW Consulting’s report page or contact your account representative to request access to the full Worldwide Shape Memory Alloys for Civil Engineering Market report. Our team is available to brief executive committees and technical teams throughout the remainder of 2026 as agencies and owners translate demonstration success into procurement programs.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Conductive Fibers Market to Reach USD 2,073.81 Million by 2032 at a 7.5% CAGR
By PW Consulting, 2026-08-05
Worldwide Conductive Fibers Market — Strategic Imperatives for 2026: PW Consulting Report Highlights
PW Consulting’s new market study on the Worldwide Conductive Fibers Market provides an actionable intelligence suite tailored for executives, corporate strategists, procurement leaders, and investors preparing for 2026. The market reached approximately USD 1.25 billion in 2025 and is projected to expand at a 7.5% CAGR through the 2026–2032 forecast window, approaching just over USD 2.07 billion by 2032. These macro trajectories frame a near-term window of strategic opportunity: companies that translate technical performance into manufacturable, certifiable product lines will capture disproportionate value as end markets—wearables, EMI shielding, anti‑static/industrial safety and others—scale rapidly.
Worldwide Conductive Fibers Market
Why this report matters for 2026 decision-making
- Timing. The combination of rising end‑market demand and ongoing product innovation is compressing the commercialization cycle. Firms that finalize supplier contracts, validation programs, and pilot production in 2026 position themselves to lead by 2027–2029.
- Risk‑adjusted investment. Our analysis quantifies sector growth and concentration dynamics (the market remains moderately fragmented — CR3 ≈ 22.5%, CR5 ≈ 34.8%), clarifying whether to pursue organic scale, bolt‑on M&A, or strategic partnerships based on risk tolerance and capital access.
- Operational readiness. Technical performance alone no longer wins deals — washability, durability, and certifiable electrical behavior under real‑world stressors are table stakes for many OEMs. The report translates these technical requirements into procurement and validation checklists for immediate deployment.
Market trajectory and practical implications
Between 2020 and 2025 the market moved from an early‑stage specialty into a broader commercial phase—driven by smarter wearables, rising standards for EMI mitigation in compact electronics, and expanded industrial safety specifications. For 2026 decisions, this means three practical imperatives:
Worldwide Conductive Fibers Market
- Prioritize suppliers with validated scale and reproducible quality rather than novel lab innovations without production readiness.
- Embed end‑use certification criteria (washability cycles, conductivity retention, mechanical fatigue) into RFPs and pilot acceptance tests.
- Use hybrid sourcing strategies to manage raw‑material exposure (silver vs stainless steel vs carbon-based chemistries) and maintain margin resilience as commodity cycles fluctuate.
Supply‑side dynamics and materials economics
Raw material choice remains a central economic and technical tradeoff. Silver‑plated fibers continue to lead on absolute conductivity and antimicrobial benefits, while stainless steel and carbon‑based approaches offer meaningful cost, durability, and processing advantages in textile integration. Conductive polymers are closing performance gaps where flexibility and low weight trump ultimate conductivity. The report’s supplier cost model and manufacturing economics module allow procurement teams to run ‘make vs buy’ and ‘material substitution’ scenarios calibrated to client‑specific performance thresholds.
Worldwide Conductive Fibers Market
Competitive landscape — strategic profiles and implications
The industry’s competitive fabric is woven from global materials conglomerates, specialized metalizing firms, and nimble innovators. Our executive synopses — grounded in product roadmaps, public disclosures, and proprietary interviews — distill where each leading player is positioned and what that means for potential partners or acquirers.
- Toray Industries, Inc. (Tokyo, Japan). Strengths: deep polymer and textile expertise, vertically integrated R&D and manufacturing capabilities for high‑performance smart textile applications. Strategic implication: partners and OEMs seeking end‑to‑end material engineering should prioritize collaboration with Toray for scale pilots.
- Teijin Limited (Tokyo, Japan). Strengths: focus on medical and automotive segments with an emphasis on sustainability and integration. Strategic implication: Teijin is a strong co‑developer for regulated applications where lifecycle and biocompatibility matter.
- Bekaert (Zwevegem, Belgium). Strengths: metallurgical capability in stainless‑steel conductive fibers (Bekinox®) with durable performance for EMI and harsh environments. Strategic implication: attractive supplier for industrial and defense programs where longevity and mechanical robustness are prioritized.
- 3M Company (St. Paul, USA) & DuPont de Nemours, Inc. (Wilmington, USA). Strengths: portfolio breadth, distribution reach, and cross‑industry credibility. Strategic implication: these firms are preferred for rapid commercialization with existing customer relationships in electronics and industrial markets.
- Seiren, Shieldex, Swift Textile Metalizing, Kolon and others. Strengths: specialized metalizing techniques, silver‑plating expertise, and niche product portfolios for applications from antimicrobial textiles to aerospace EMI. Strategic implication: prime targets for OEMs needing specialized functional attributes, or for strategic investors seeking differentiated IP.
- Agile innovators (Syscom/Agsis, Eeonyx, Shakespeare Polymers & Filaments, Haining Taierxin). Strengths: focused product R&D, rapid iteration, and tailored yarn solutions for wearables and e‑textiles. Strategic implication: attractive for strategic partnerships, licensing, or M&A to access new sensor and integration capabilities.
Recent product and positioning moves underscore tactical directions in the market. For example, Haining Taierxin’s 2026 repositioning emphasized benchmark functional textiles and production scale in conductive filament yarns; earlier, DexMat’s 2025 launch of a high‑strength, low‑resistivity conductive yarn signaled material innovations targeting both weight‑sensitive and high‑strength use cases. These developments reflect a bifurcation: suppliers scaling commodity‑grade, cost‑sensitive fibers versus those pushing high‑performance, application‑specific materials.
Customer‑facing playbook: procurement and product teams
For procurement and product teams, the report translates market dynamics into discrete actions for 2026:
- Deploy a three‑stage supplier evaluation (Laboratory validation → Pilot integration → Production ramp), with pass/fail criteria tied to washability, conductivity retention, and failure modes under mechanical stress.
- Implement a materials decision matrix that weights conductivity, cost, mass, durability, and regulatory burden—enabling objective trade‑offs between silver, stainless steel, carbon and polymer approaches.
- Adopt dual‑sourcing or strategic hedging where single‑supplier dependencies could imperil launch timelines or where rare metals create supply‑chain volatility.
- Negotiate long‑lead sampling and co‑development clauses to secure capacity for second‑generation iterations and to preserve IP sharing controls.
Technology roadmap and regulatory context
Technical evolution is clustered around three themes: enhanced conductivity at lower mass, textile‑grade washability and durability, and integration of sensing functionality within yarn architectures. Regulatory and standards trajectories are accelerating: conductive fibers intended for wearables and medical interfaces must satisfy both electrical performance and textile safety standards. Our regulatory checklist and test protocol templates equip R&D teams to accelerate certification timelines while minimizing iterative rework.
M&A and investment thesis for 2026
With a 7.5% CAGR underpinning long‑term upside and only moderate top‑tier concentration, 2026 is a favorable year for strategic acquisitions that secure production capacity, IP around metalizing or carbon‑infusion processes, or unique integration expertise in e‑textiles. Buyers should prioritize targets with documented manufacturing reproducibility, customer pilots with recognizable OEMs, and defensible cost positions (e.g., stainless‑steel metallurgical advantage or proprietary polymer formulations). The report’s transaction playbook outlines valuation heuristics and integration checklists specific to conductive fiber assets.
What the full report contains (practical, deployable modules)
- Market sizing and method‑of‑forecast with sensitivity scenarios (base, upside, downside) — enabling board‑level stress‑testing of revenue plans.
- Supply chain maps and cost models for leading material families, including break‑even capacity and capex estimates for greenfield and brownfield expansion.
- Competitive profiles and strategic positioning analysis of incumbent and emerging players, with partnering and M&A implication matrices.
- Buyer‑focused toolkits: supplier scorecards, RFP templates, pilot acceptance criteria, and a regulatory testing checklist.
- Technology readiness matrix and innovation calendar, highlighting near‑term advances and disruptive pathways.
- Case studies and rapid‑deployment playbooks for three priority use cases: wearables, EMI shielding in electronics, and industrial anti‑static applications.
Note: while this executive briefing synthesizes the market’s strategic contours, granular segment level tables and region/application breakdowns are intentionally reserved for the full report to preserve analytical context and enable direct benchmarking. Interested executives and investors are encouraged to access the full dataset and interactive models on our report landing page.
Concluding guidance for 2026
Conductive fibers are transitioning from specialty material to a mainstream enabling platform across multiple industries. For organizations planning capital allocation, supply‑chain commitments, or strategic partnerships in 2026, the winning approach is pragmatic: prioritize suppliers with validated production readiness, embed robust acceptance testing in procurement flows, and build optionality against raw‑material risk. PW Consulting’s Worldwide Conductive Fibers Market report combines the forecasting rigor and tactical toolkits necessary to convert market growth into sustainable commercial advantage. To evaluate the detailed segmentation, company profiles, and downloadable decision tools, please consult the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Fleet Maintenance Service Market 2026: Strategic Imperatives for Decision‑Makers
PW Consulting’s new market study, Worldwide Fleet Maintenance Service Market (base year 2025), equips executives with the disciplined, forward‑looking analysis required to make high‑stakes maintenance, IT and operational decisions in 2026. The report synthesizes macro growth projections, competitive dynamics, regulatory shifts and operational levers into an actionable playbook—presented here as a strategic preview that demonstrates our depth while reserving the detailed segment tables and proprietor scoring models for the full report.
Worldwide Fleet Maintenance Service Market
Why 2026 Is a Pivotal Year
After a period of steady post‑pandemic recovery, the global fleet maintenance service market has escalated to a scale that demands deliberate strategy rather than ad hoc fixes. Our analysis indicates the market expanded through 2020–2025 and reached an estimated global size in 2025; from that base the market is set to grow at a compound annual growth rate (CAGR) of approximately 5.11% into the forecast window beginning 2026. This growth trajectory underscores two truths for leaders: the economics of uptime and lifecycle cost control are strengthening, and competition for the highest‑value maintenance proposition—one that blends automation, mobile service and predictive analytics—is intensifying.
Worldwide Fleet Maintenance Service Market
What the Report Delivers — Practical Value for 2026 Decisions
-
Decision frameworks for capital allocation: a prioritized set of investment avenues (telemetry, AI diagnostics, mobile maintenance, parts‑sourcing and training) with scenario‑based ROIs calibrated to the next 12–36 months.
Worldwide Fleet Maintenance Service Market -
Vendor selection and procurement playbook: vendor shortlists matched to fleet size, asset type and operational complexity; evaluation rubrics that weigh integration costs, data ownership and service level guarantees without defaulting to vendor hype.
-
Compliance and risk templates: ready‑to‑use operational checklists aligned to the latest regulatory changes (including 2026 federal and state shifts), cost impacts and mitigation pathways to contain downtime and inspection exposure.
-
Operational KPIs and change management plan: a blueprint to convert new capabilities into measurable outcomes—mean time to repair (MTTR), first‑time fix rate, technician utilization and predictive maintenance penetration—tied to incentive structures.
Market Structure and Competitive Implications
The market remains broadly fragmented—top providers do not dominate to the extent seen in other enterprise software or transportation verticals. Measured concentration ratios indicate significant space for regional specialists, white‑label service integrators and new digital entrants to win share by delivering localized, predictable value. For corporate buyers, this fragmentation creates negotiation leverage but also elevates integration risk: partners must be evaluated as ecosystems, not point solutions.
Key vendors shaping the competitive landscape exemplify distinct strategic approaches:
-
Fleetio (Birmingham, AL) focuses on cloud‑native maintenance tracking and recently opened an AI‑powered Service Advisor in beta (Mar 2026) to streamline repair approvals and cost control—representing the push toward decision automation at scale.
-
Geotab (Oakville, ON) offers an open telematics platform with advanced analytics and marketplace integrations, emphasizing extensibility for fleets that prefer modular stacks.
-
Verizon Connect (Atlanta, GA) and Samsara (San Francisco, CA) leverage network and sensor ecosystems respectively to deliver real‑time vehicle health, safety telematics and maintenance scheduling—two lenses on the same uptime problem.
-
Traditional fleet operators and full‑service providers such as Ryder, Penske and Wheels continue to compete on scale and integrated maintenance operations, offering on‑site and networked repair capacity that modern SaaS players increasingly partner with or white‑label.
-
Mobile and hybrid operators (Wrench, FleetNet America, Dickinson) are disrupting downtime economics by converging digital job orchestration with on‑site execution.
Collectively, these players highlight the multi‑vector competition of 2026: platform capabilities (data and AI), physical service reach (mobile/on‑site repair), and integrated compliance/workflow orchestration will decide winners.
Regulatory and Labor Dynamics — Practical Consequences
-
Regulatory realignments in 2026 materially affect inspection cadence and documentation requirements. For example, recent federal and state changes alter inspection regimes for certain classes of vehicles and reconfigure enforcement categories—making speed and completeness of pre‑trip documentation a direct driver of CSA outcomes. Organizations must assume increased inspection granularity in their maintenance workflows.
-
California’s ongoing programs continue to impose per‑asset compliance fees and retest overheads for emissions‑related maintenance; fleets operating in high‑regulation jurisdictions should budget for these recurring costs and design retrofitting and test‑readiness into their lifecycle plans.
-
Labor market constraints—persistent technician shortages and upward pressure on labor costs—are elevating the value of automation. Industry reporting indicates repair cost inflation driven in part by higher wages and turnover; as a result, effective 2026 strategies tilt toward productivity uplift (better diagnostics, remote assistance, higher first‑fix rates) and targeted workforce programs (apprenticeships, pay bands tied to diagnostic proficiency, remote expert networks).
Technology Themes That Matter in 2026
Our field work and vendor assessments underline four technology vectors where near‑term investments yield the largest operational delta:
-
Predictive analytics plus integrated parts forecasting—reduces stockouts and unplanned downtime by shifting to condition‑based consumption models.
-
AI‑assisted service orchestration—tools such as Fleetio’s AI Service Advisor and similar offerings reduce approval latency and standardize repair decisions across decentralized fleets.
-
Edge telematics and camera systems—recent launches of cloud AI dashcams and multi‑IQ camera solutions provide richer failure context, which shortens diagnostic cycles and supports remote triage.
-
Unified platforms that combine claims, repairs and maintenance data into a single operational fabric—exemplified by recent integrated platform launches—are accelerating where total cost of ownership (TCO) benefits outweigh transition costs.
Actionable 90‑180‑Day Agenda for 2026
-
90 days: Run a vendor interoperability stress test—evaluate three shortlisted systems on API maturity, parts‑catalog integration and speed of data ingestion from telematics devices. Prioritize pilots that demonstrate measurable MTTR reduction within 60 days.
-
180 days: Implement a ‘predictive pilot’ on a control cohort of high‑utilization assets to validate failure models, spare parts optimization and remote diagnostic workflows. Tie pilot KPIs to concrete cost targets (parts holding, shop labor hours, off‑route minutes).
-
12–18 months: Deploy workforce and change management programs—upskilling technicians on digital diagnostics, establishing remote expert escalation paths, and formalizing SLA‑driven partnerships with mobile repair networks.
M&A and Partnership Playbook
Given the market’s fragmentation and the strategic value of platform‑to‑service integration, we advise a balanced approach: bolt‑on acquisitions that add geographic service density or mobile repair capability for operations with significant on‑site needs; strategic partnerships with telematics and diagnostics providers for fleets seeking rapid data capture without full platform replatforming. In all cases, prioritize deals that secure data access and contractual rights to operational telemetry for continuous improvement loops.
Risks, Unknowns and Where to Find the Details
Material risks for 2026 include faster‑than‑expected labor inflation, sudden regulatory tightening in key urban jurisdictions, and supplier consolidation that could compress supplier diversity. The report’s sensitivity analyses quantify these downside scenarios and map the thresholds at which different investment profiles (conservative, balanced, aggressive) change recommended action.
PW Consulting’s release adheres to a “preview” principle: we disclose strategic insights and synthesized vendor intelligence to equip readers for 2026 planning while reserving granular segment tables, regional and application‑level breakouts, and the proprietary vendor scoring matrix for report subscribers. Those datasets contain the detailed revenue splits, regional exposure maps and per‑service economics that operational procurement teams require when finalizing budgets and contractual terms.
Conclusion — What Leaders Should Do Now
-
Treat 2026 as a year to convert platform trials into durable operational capability. The macro growth and the fragmented incumbent structure create acquisition and partnership windows that close once consolidation accelerates.
-
Invest in diagnostic velocity and remote support to blunt labor cost inflation and reduce shop dependence.
-
Make compliance and data governance non‑negotiable components of vendor selection; regulatory risk is now embedded in maintenance economics and cannot be outsourced without contractual safeguards.
For procurement leaders, operations heads and board members preparing 2026 budgets, our report provides the quantitative forecast, evaluation templates and program‑level roadmaps to translate market growth into defensible decisions. To access the full datasets, proprietary segmentation, and vendor scorecards that guide execution, please consult the PW Consulting report page for Worldwide Fleet Maintenance Service Market.
For detailed analysis of this topic, please visit the official page: Worldwide Fleet Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oyster Shell Calcium Market Set to Expand at a 6.02% CAGR Through 2032PW Consulting: Worldwide Tasigna Market Forecast to Shrink at -11.45% CAGR from 2026–2032, New Report Reveals
By PW Consulting, 2026-08-05
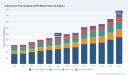
Worldwide Oyster Shell Calcium Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Oyster Shell Calcium Market delivers an evidence-based roadmap designed to inform high-stakes commercial and investment decisions in 2026. As regulatory scrutiny intensifies, global nutrition demand evolves, and sustainability considerations reshape upstream sourcing, executives need forward-looking clarity more than ever. This briefing synthesizes the report’s most consequential, decision-ready insights while preserving the proprietary segmentation detail that drives its tactical value — compelling executives to consult the full report for the granular inputs required to execute strategies with confidence.
Worldwide Oyster Shell Calcium Market
Executive snapshot
Using 2025 as the study’s base year, the oyster shell calcium market is estimated at approximately USD 513 million and is forecast to grow at a compound annual growth rate (CAGR) of roughly 6.0% across the 2026–2032 horizon, reaching an estimated market size approaching USD 773 million by 2032. This trajectory reflects a combination of sustained demand across nutritional, feed and functional ingredient channels, together with steadily improving processing capabilities that broaden end‑use opportunities.
Worldwide Oyster Shell Calcium Market
Why this matters for 2026 strategic planning
- Timing for capacity investments: The near‑term upcycle supports selective investments in processing and quality control to capture premium segments, while the multi‑year CAGR justifies capacity expansion programs tied to differentiated product tiers (e.g., high‑purity pharmaceutical grade vs. feed grade).
- Supply chain resilience: Oyster shell is a natural resource with regional sourcing constraints and variable quality. For 2026, procurement teams must prioritize traceability, supplier diversification, and inventory models that balance cost and continuity.
- Regulatory and product-compliance readiness: Markets for dietary supplements, pharmaceuticals and fortified foods are increasingly demanding documentation on source, heavy‑metal content, and microbial safety. Firms that embed compliance into product design will shorten time‑to‑market and reduce recall risk.
- Value capture through product segmentation: Differentiation by particle size, purity and certification (e.g., pharmaceutical, organic, non-GMO) will be a primary driver of margin expansion; price competition persists at undifferentiated commodity levels.
What’s in the full PW Consulting report (practical, execution-ready deliverables)
The report combines granular market modeling with operator-level playbooks. Key deliverables include:
Worldwide Oyster Shell Calcium Market
- Proprietary top‑down and bottom‑up market sizing and a validated forecast to 2032 (base year 2025), expressed in USD million, with scenario analysis showing variance under alternate demand and supply shocks.
- A practical segmentation framework (by region, form and application) that links demand characteristics to commercial levers and margin pools — presented with downloadable data tables and interactive charts for internal modeling.
- Supply‑chain mapping across raw material sourcing, processing technologies, and logistics constraints; vendor scorecards; and a supplier‑selection matrix tailored to quality and cost objectives.
- Regulatory heat maps and compliance checklists for major end markets, including recommended QA protocols and documentation templates to accelerate approvals for supplements and pharmaceutical ingredients.
- Go‑to‑market playbooks for incumbents and new entrants: pricing strategies, channel prioritization, product positioning, and step‑by‑step commercial rollouts for private label, branded and B2B supply agreements.
- M&A and partnership intelligence: target screening criteria, deal structuring options (JV, off‑take, tolling), and a valuation framework reflecting segment-specific margin differentials and integration synergies.
- Risk register and mitigation plans covering raw‑material variability, environmental restrictions on shell harvesting, and reputational risks tied to sustainability and traceability.
Market structure and concentration — what the metrics tell you
The market exhibits a measurable degree of concentration: our analysis indicates that the top three firms control a substantial single‑digit to low‑forties share of global revenue, while the top five firms combine for slightly more than half of the market. This mid‑level concentration profile creates room for regional champions and specialized players to coexist with larger scale operators — a dynamic that shapes M&A and partnership strategies.
Competitive landscape: focused profiles and strategic implications
Across the competitive set, three archetypes have emerged — high‑purity specialty suppliers, high‑volume commodity processors, and regionally integrated players that combine sourcing and local distribution. Below are strategic summaries of representative firms reviewed in the report:
-
Carich Biotechnology Co., Ltd. (Taichung, Taiwan) — A specialty producer known for high‑purity oyster shell calcium carbonate powders targeted at dietary supplement and pharmaceutical customers. Their technical emphasis on purity and consistent particle morphology positions them to capture premium, regulatory‑sensitive segments. Strategy implication: scaled investments in process control and documentation make Carich‑type businesses attractive partners for formulators seeking certified inputs.
-
Viet Delta Industrial Co., Ltd. (Ho Chi Minh City, Vietnam) — A high‑throughput producer focused on ground oyster shell powder for animal feed, agricultural uses and general nutrition applications. Cost‑efficient processing and export orientation make this model competitive on price and volume. Strategy implication: these operators are natural partners for food and feed integrators pursuing cost‑effective local sourcing, but they must augment traceability to access higher‑margin supplement channels.
-
Eiwa Chemical Industrial Co., Ltd. (Osaka, Japan) — Supplies processed oyster shell calcium for food supplements and functional materials, with expertise in processed forms and quality control. Their positioning underlines a middle path between commodity and high‑spec players. Strategy implication: investing in product innovation (e.g., functional ingredient blends, surface treatments) can yield premium pricing for Eiwa‑style manufacturers.
Overall, the competitive field rewards firms that either scale to reach cost leadership in bulk segments or specialize into certified, high‑purity niches. The middle ground demands continuous product innovation to avoid margin erosion.
Key market dynamics shaping 2026 opportunities and threats
- Demand drivers: Demographic aging, greater mineral supplementation adoption, and growth in fortified food categories underpin steady volume increases. Animal feed and agricultural applications sustain baseline demand tied to protein production and soil amendment activity.
- Quality and certification premium: Buyers are increasingly differentiating by source traceability and impurity profiles. Certifications and validated processes unlock up‑market customers in supplements and pharma.
- Sustainability and reputational risk: Harvesting practices and waste disposal attract scrutiny. Firms that can demonstrate circularity, low environmental impact and community engagement will have competitive advantage in procurement decisions by brand‑sensitive customers.
- Processing technology and product innovation: Advances in purification, micronization and surface modification expand applications into functional ingredients and specialized formulations, creating new revenue streams beyond bulk calcium supply.
- Price and margin pressure in commodity channels: Bulk feed‑grade segments remain price‑sensitive; players active here must optimize logistics, scale and cost control to maintain profitability.
Actionable recommendations for executives preparing 2026 initiatives
- Define a two‑track portfolio strategy: Segregate commodity feed supply from high‑margin, certified supplement/pharma offerings. Allocate R&D and capital selectively to each track and lock in contractualized off‑take for new capacity.
- Invest in provenance and quality systems now: Implement traceability and third‑party testing to qualify for premium channels; delay risks longer than necessary increase barrier to entry for competitors.
- Prioritize supply diversification: Build relationships across multiple sourcing geographies and consider tolling arrangements or strategic JVs to secure feedstock without fully committing capital.
- Use M&A tactically: Target bolt‑on acquisitions that add certifications, specialized processing capabilities or regional distribution — not just volume. The mid‑market concentration leaves room for accretive deals focused on capability rather than scale alone.
- Embed scenario planning into budgets: Model upside and downside cases around raw material disruptions, regulatory tightening and rapid product substitution to keep capital allocation nimble.
How PW Consulting’s report supports execution
Beyond diagnosis, the report supplies executable artifacts — validated financial models, supplier evaluation templates, regulatory checklists and playbooks for commercial launch — all calibrated to the 2026 decision cycle. For leadership teams, this removes the uncertainty from strategic choices and shortens the time from decision to measurable commercial outcomes.
Methodology and transparency
The market estimation uses a hybrid methodology combining historical shipment and production data (2020–2025), primary interviews with producers and end‑users, and a bottoms‑up demand synthesis by application. Forecasts to 2032 include sensitivity testing across demand elasticity and processing throughput; currency denominated in USD (revenue unit: Million). Our market concentration metrics were derived from company‑level revenue synthesis and triangulated with customs and trade datasets.
Next steps and where to access the full intelligence
This overview intentionally omits the proprietary granular splits and data tables that underpin our recommendations — those suppressed details are precisely what enable rapid, confident execution. For procurement directors, corporate development teams, and private equity investors preparing 2026 strategies, the full report contains the segment‑level revenues, regional trajectories, and supplier scorecards required to build binding contracts, sign term sheets, or commence integration planning.
Contact PW Consulting or visit our report page to download the executive package and learn how to access the full Worldwide Oyster Shell Calcium Market report, including the interactive data files and model licenses tailored for enterprise use. Our analysts are available to deliver bespoke briefings that map the report’s findings to your business case and investment criteria.
For detailed analysis of this topic, please visit the official page: Worldwide Oyster Shell Calcium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oil Hose Market to Grow at a 4.8% CAGR Through 2032, New Report Reveals
By PW Consulting, 2026-08-05
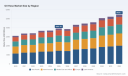
Worldwide Oil Hose Market Outlook 2026: Strategic Imperatives for Procurement, Product and M&A Leaders
As PW Consulting releases its latest Worldwide Oil Hose Market report, senior executives and strategic planners face a defining moment. The global oil hose market, which reached USD 3,925.76 Million in our 2025 base-year assessment, is entering a new phase of steady expansion. Our modeling projects a compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast horizon, guiding the market toward a materially larger ecosystem by 2032. For companies making capital-allocation, sourcing and go-to-market decisions in 2026, this report converts abstract momentum into operational priorities.
Worldwide Oil Hose Market
Why 2026 Is a Tactical Year
Three coincident forces make 2026 especially consequential. First, demand drivers tied to oil & gas exploration, marine bunkering and industrial fluid transfer remain persistent, sustaining baseline volumes and replacement cycles. Second, regulatory and standards enforcement—particularly in offshore and bunkering contexts—continues to elevate technical requirements for chemical resistance, abrasion tolerance and fire performance. Third, upstream cost volatility—most notably in elastomers and other polymer feedstocks—has shifted procurement from a transactive to a strategic activity.
Worldwide Oil Hose Market
For executive teams, 2026 is where long‑term strategic themes (material substitution, digital service layers, and selective consolidation) must be converted into actionable 12–24 month plans. The PW Consulting report is designed to be a playbook for that conversion.
Worldwide Oil Hose Market
What the Report Delivers — Practical, Executable Intelligence
- Market sizing and scenario maps: Robust triangulation of historical performance and forward scenarios to inform revenue forecasts, capex plans and working-capital needs across conservative, base and upside cases.
- Competitive landscaping: A qualitative and quantitative evaluation of leading OEMs and independent manufacturers, with implications for procurement bargaining power and partnership strategies.
- Supply‑chain risk matrix: Detailed pressures and mitigation levers tied to elastomer feedstocks, reinforcement materials and downstream processing capacity—presented as decision-ready actions for procurement and operations teams.
- Product and regulatory playbook: Engineering-to-market checklists mapping material choices and certification pathways (including common standards used in fuel and mineral oil applications) so product teams can accelerate approvals while managing cost-to-serve.
- Commercial strategies: Tender templates, service-installation bundling options, and aftermarket monetization levers designed to lift margins in a market where hardware alone is increasingly commoditized.
- M&A and partnership primer: Identification of capability adjacencies and integration risks—aligned to a fragmentation-sensitive roll-up strategy for players seeking scale.
Market Structure and Competitive Dynamics
The oil hose market exhibits meaningful fragmentation. The combined share of the top three and top five players remains modest relative to many industrial sectors, signaling room for both regional champions and specialized independents. This market structure produces two strategic realities: incumbents must protect margin through product differentiation and services, while mid-size and smaller manufacturers can capture niche value by focusing on technical specialization or customer intimacy.
Our competitive analysis synthesizes public profiles and product footprints of leading suppliers. Broadly:
- Global diversified industrial groups (companies with large hydraulics and fluid-power portfolios) leverage scale in R&D, distribution and aftermarket service to defend higher-margin segments, particularly where certifications and performance claims matter.
- Specialist hose manufacturers (including thermoplastic and reinforced hose specialists) compete on lead time, customization and applications engineering—an advantage in offshore, dockside and refinery environments that require bespoke solutions.
- Regional independents and niche builders play to service speed and local regulatory familiarity, often winning retrofit, maintenance and emergency-response contracts—areas where global suppliers struggle to match proximity and flexibility.
Several strategic patterns emerge from company-level positioning:
- Scale players are doubling down on certified, high‑end product platforms and expanding service contracts to lock in recurring revenue.
- Specialists focus on material science and manufacturing process enhancements (e.g., composite reinforcements, thermoplastic extrusion) to shorten product lifecycles and reduce cost-to-serve.
- Manufacturers of rubber-based hoses are balancing mature demand with R&D into alternative compounds and processing efficiencies to offset feedstock price pressure.
Supply-Chain and Raw-Material Realities
One of the most immediate inputs to pricing power and margin stability is polymer feedstock cost and availability. Recent market dynamics show sustained upward pressure in key elastomers, producing margin compression for firms that cannot rapidly translate cost increases through contractual pricing or productivity gains. In this environment, procurement leaders must convert spot-market exposure into strategic actions such as multi-sourcing, long-term offtakes with pass-through clauses, and selective vertical integration for critical compounds.
Equally important is compliance risk: oil hose products destined for bunkering, aviation refuelling or offshore service must meet tightening standards for chemical resistance, abrasion and fire propagation. Engineering teams that pre-emptively align materials and test protocols to recognized norms will shave months off certification timelines and gain pricing leverage in tenders.
Growth Pockets and Product Strategy (Trailer-Level Insights)
While the market for traditional rubber hoses remains substantial, the fastest-growing opportunities derive from applications requiring lighter-weight, higher-performance materials and integrated systems: composite-reinforced solutions for high-pressure transfer, thermoplastics for reduced weight and contamination risk, and engineered assemblies for bunkering and offshore suction/discharge. Our full report maps these opportunities with use-case level economics and go-to-market playbooks—without exposing the underlying segment-level shares here.
Commercial and Operational Recommendations for 2026
- Procurement resilience: Move from transactional buying to a portfolio approach—blend spot, fixed, and hedged volumes; prioritize long-term supplier relationships for critical elastomers; and explore backward integration or captive compounding where scale allows.
- Product and certification cadence: Prioritize materials and designs that reduce total cost of ownership for customers (durability, ease of installation, lower maintenance). Standardize certification kits and field-test protocols to accelerate approvals in regulated segments.
- Service-led differentiation: Bundle installation, inspection and predictive maintenance services with product sales. Use condition-monitoring technologies and digital records to win multi-year contracts and create recurring revenue streams.
- Selective M&A and partnerships: Target bolt-on acquisitions that add manufacturing flexibility, regional aftermarket footprints, or specialized compound capabilities. For global players, consider JV structures to access local certifications and supply chains efficiently.
- Price realization: Implement value-based pricing for high-spec products; maintain competitive per‑meter pricing on commoditized SKUs while protecting margin through efficiency programs.
- Sustainability and material innovation: Invest in lower-carbon elastomers, recycling programs and lighter-weight constructions that reduce life-cycle emissions—an increasingly important procurement criterion for industrial and maritime customers.
Decision Roadmap: What to Act on in Q1–Q2 2026
- Finalize a three-year supply strategy that quantifies exposure to volatile feedstocks and secures at least one alternative source for each critical polymer.
- Fast-track certification projects for any product variants targeting offshore, bunkering and aviation-related contracts—these win tenders with technical adjudication.
- Pilot a service bundle in one high-value geography to validate aftermarket pricing and field logistics before scaling globally.
- Initiate a disciplined M&A filter: target high-margin niche specialists or regionally dominant manufacturers with service networks that plug gaps in your footprint.
Why This Report Matters to Your 2026 Plan
PW Consulting’s analysis converts a mixed landscape—steady top-line growth, material cost volatility, and fragmented supply—into a set of prioritized actions that procurement, product and corporate development teams can implement within 6–18 months. The market’s 4.8% CAGR through 2032 signals predictable macro expansion, but the near-term competitive battleground will be decided by agility in sourcing, certification speed, and the ability to monetize services.
We deliberately present this briefing as a high-value trailer: it highlights the structural forces, supplier strategies and operational playbooks you need to evaluate, while reserving the granular segment-by-region and application-level datasets for the full report. Those datasets are the foundation for detailed revenue forecasts, customer-by-customer opportunity maps and M&A valuation models—content that senior teams routinely use to set budgets and approve transactions.
Next Steps and How to Use the Full Report
Leaders seeking to operationalize these insights should request the full PW Consulting Worldwide Oil Hose Market report. The full deliverable provides:
- Detailed segment-level sizing and growth drivers (by material, application and region) supporting investment cases;
- Company-level revenue and capability matrices to prioritize targets for partnerships or acquisitions;
- Scenario-modeled P&L and balance sheet impacts under alternative raw-material price paths;
- Templates for RFPs, certification roadmaps and aftermarket service SLAs.
Adopting the report’s recommendations in 2026 positions organizations not just to capture market share, but to lock in recurring, higher-margin revenue and to future-proof operations against feedstock and regulatory shocks. For executives planning capex, M&A or supplier strategies this year, the PW Consulting report is designed to shorten the path from insight to action.
Contact and Access
Access to the full dataset, customized scenario runs and advisory support is available through our report portal. For tailored briefings that map these insights to your company’s product portfolio, procurement exposure and M&A appetite, PW Consulting’s industry practice is prepared to facilitate executive workshops and integration playbooks.
For detailed analysis of this topic, please visit the official page: Worldwide Oil Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Buruli Ulcer Treatment Market to Rise from USD 78.45 Million in 2025 to USD 108.92 Million by 2032 at a 4.8% CAGR — Africa Accounts for 48.66% Share
By PW Consulting, 2026-08-05
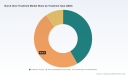
Worldwide Buruli Ulcer Treatment Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Buruli Ulcer Treatment Market delivers a concise, decision-focused synthesis designed to inform strategy and resource allocation in 2026. Built on a base year of 2025 and a forecast window running through 2032, the report combines time-series market sizing, competitive mapping, regulatory and supply-chain diagnostics, and executable playbooks for public-sector programs, pharmaceutical suppliers, and philanthropic funders.
Worldwide Buruli Ulcer Treatment Market
Why this matters for 2026
Buruli ulcer remains a niche but high-impact public health challenge in endemic settings. From a commercial perspective, the overall market is modest in absolute terms but demonstrates steady expansion driven by programmatic commitments, guideline-endorsed treatment protocols, and incremental improvements in case detection and wound care delivery. PW Consulting’s topline synthesis shows the market expanding from a base of USD 78.45 Million in 2025 to an expected USD 108.92 Million by 2032 — reflecting a compound annual growth rate of 4.8% across the 2026–2032 forecast period. These macro dynamics create a predictable planning environment for procurement cycles, capacity investments, and donor budgeting in 2026.
Worldwide Buruli Ulcer Treatment Market
How the report helps executives make 2026 decisions
-
Prioritize investments: We translate market growth and concentration indicators into clear recommendations for manufacturers and distributors on where limited commercial resources should be concentrated to maintain supply continuity while preserving margin integrity.
Worldwide Buruli Ulcer Treatment Market -
De-risk procurement: For program managers, our scenario analysis models the implications of single-source dependency for key antibiotics, providing procurement pathways that balance WHO prequalification requirements and supplier diversification.
-
Design catalytic interventions: For funders and NGOs, the report identifies the most leverageable interventions—such as strengthening surgical capacity or scaling community-based wound management—that amplify clinical outcomes without proportionate increases in per-patient spend.
What’s inside — practical, actionable content
The report is intentionally operational. Beyond headline market sizing and a forward-looking CAGR, PW Consulting provides a suite of implementation-ready tools aimed at shortening the time from insight to action:
-
Market sizing and demand scenarios: Rolling baseline and upside scenarios calibrated to WHO guideline adoption, case-finding efficacy, and program financing assumptions.
-
Procurement playbook: Practical evaluation criteria for WHO-prequalified products, contract structures suitable for low-volume essential medicines, and recommended contingency buffers for endemic-area stock planning.
-
Supply-chain diagnostics: A mapped assessment of API sourcing, manufacturing concentration risks, and cold-chain / logistics constraints specific to Buruli ulcer treatment packs and wound-care consumables.
-
Competitive benchmarking: Profiles, strategic intents, and capability matrices for leading suppliers and generic manufacturers that shape the procurement landscape in endemic programs.
-
Program impact levers: Evidence-based recommendations for integrating antibiotics treatment protocols with surgical referral networks, task-shifting in community care, and rehabilitation services to reduce long-term disability.
-
Investor and donor briefs: Short-form, board-ready summaries that translate epidemiologic trends into grant-design or limited commercial opportunities.
Competitive landscape — who matters and why
Market supply is dominated by a small set of producers and distributors capable of meeting WHO prequalification and donor procurement standards. Key players examined in the report include WHO-prequalified suppliers (illustrated by manufacturers such as Macleods Pharmaceuticals), multinational generics divisions (examples include Sandoz within a global pharmaceutical group), and established Indian generic producers (such as Cipla). Our supplier assessments focus on regulatory credentials, manufacturing scale, portfolio breadth for neglected tropical diseases, and historical responsiveness to WHO and national program procurement.
Recent developments highlighted in the report carry operational consequences for procurement and clinical practice. The WHO guideline update in October 2023 endorsing an 8-week daily regimen of rifampicin and clarithromycin (with surgical intervention for advanced lesions) crystallizes the standard of care and thus the composition of program procurement baskets. Complementing this, WHO prequalification of certain fixed-dose formulations has reduced technical entry barriers for supplier inclusion in donor-funded tenders but has not negated concentration risks intrinsic to a small supplier base.
From a concentration standpoint, the market exhibits moderate centralization: the top three suppliers account for a meaningful share of global supply, and the top five further consolidate market access. For decision-makers this means supplier diligence, dual-sourcing where feasible, and contractual mechanisms for continuity are high-priority risk mitigations.
Regulatory, reimbursement and supply-chain dynamics
-
Regulatory clarity: WHO’s endorsement of standardized antibiotic regimens simplifies clinical algorithms and aligns procurement specifications; programs that adopt these guidelines can expect greater predictability in product requirements.
-
Reimbursement and financing: In most endemic programs treatment is delivered free at point of care through WHO-supported national initiatives. This financing architecture influences supplier pricing expectations and compresses commercial incentives—hence reliance on low-cost generics.
-
Raw material exposure: The market’s economic characteristics make it dependent on generic API suppliers, with a concentration of manufacturers located in India. This introduces upstream concentration risk that can manifest as supply interruptions or price volatility if not proactively managed.
Strategic implications by stakeholder
-
Manufacturers and distributors: With market growth moderate but stable, the optimal commercial posture is not large-scale capacity expansion but rather securing quality certifications, participating in WHO prequalification processes, and offering flexible contract and packaging options suitable for low-volume tenders.
-
Procurement agencies and national programs: In 2026, prioritize supplier qualification and dual-source agreements for critical antibiotics and wound-care essentials. Use pooled procurement or multi-year framework agreements to stabilize supply and negotiate favorable terms.
-
Donors and philanthropic actors: Target catalytic investments in surveillance and early case detection to reduce downstream surgical burden. Investments in supply-chain visibility tools yield high returns by preventing stock-outs in peripheral clinics.
-
Clinical networks and NGOs: Standardizing treatment pathways in line with WHO guidance reduces variability in care and improves outcomes; invest in training programs that combine antibiotic management with pragmatic wound-care and rehabilitation protocols.
Risks and mitigation strategies
Key downside scenarios mapped in the report include supplier consolidation-driven shortages, delayed adoption of WHO recommendations in some national programs, and funding volatility among traditional donor constituencies. PW Consulting proposes a layered mitigation framework:
-
Operational: Maintain buffer stock policies at national and regional warehouses, and build contractual clauses for emergency allocations from diversified suppliers.
-
Clinical: Strengthen referral and surgical escalation pathways to reduce morbidity when antibiotic therapy is delayed or insufficient.
-
Financial: Encourage blended finance instruments that reduce single-donor exposure and enable multi-year purchasing commitments.
How to use this intelligence in 90 days
For leaders preparing 2026 plans, the report offers a short-action checklist to convert insight into impact within three months:
-
Conduct a rapid supplier risk audit and, where needed, initiate qualification conversations with WHO-prequalified manufacturers.
-
Align national formularies and procurement specs to the WHO-recommended antibiotic regimen to unlock donor financing and simplify tender evaluation.
-
Deploy a pilot community-based wound-care program in one high-burden district to validate integrated treatment pathways and collect programmatic cost data for scale-up decisions.
Limitations and where the full report adds value
This preview intentionally focuses on strategic implications and omits detailed segment-level figures and tables that underpin operational procurement and investment decisions. The full PW Consulting report provides the granular breakdowns—by treatment modality, by end-user channel, and by region—plus downloadable model files and supplier scorecards that are required to finalize budgets, design tenders, or negotiate supplier contracts. If your 2026 planning requires those inputs, the full dataset and model are available through our source page.
Concluding note
For 2026, Buruli ulcer treatment stakeholders face a landscape of steady market growth, clear clinical guidance, and supplier concentration that together create a manageable but non-trivial set of strategic choices. PW Consulting’s analysis converts those macro trends into operational roadmaps: secure quality suppliers, align procurement to WHO protocols, and invest in programmatic levers that reduce long-term morbidity. The market’s modest scale masks outsized public-health value: pragmatic, evidence-driven investments now can materially improve outcomes in endemic communities while stabilizing supply and cost structures.
To access the full market model, segmentation tables, supplier scorecards, and three executable procurement templates, please visit the PW Consulting report page referenced in our release.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automatic Weapons Market to Reach USD 14,853.48 Million by 2032
By PW Consulting, 2026-08-05
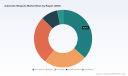
Worldwide Automatic Weapons Market 2026: Strategic Imperatives from PW Consulting’s New Forecast
PW Consulting’s latest market intelligence report — covering historical performance from 2020–2025 (base year 2025) and forward-looking projections for 2026–2032 — reframes how defense executives, procurement leaders, and industrial investors should approach the automatic weapons market in 2026. Anchored by a robust compound annual growth rate (CAGR) of 7.0% across the 2026–2032 forecast window, the market is projected to expand from approximately USD 9.25 billion (2025) to an estimated USD 14.85 billion (2032). This growth trajectory, combined with evolving regulatory, material-cost, and capability-driven dynamics, creates a distinct decision-making environment for suppliers, prime contractors, and buyers alike.
Worldwide Automatic Weapons Market
Why this report matters for 2026 decisions
-
Timing procurement and modernization cycles: With a clear upward revenue trajectory through 2032, defense planners can align multiyear procurements to benefit from scale economics while maintaining flexibility for technology insertion. Our forecast quantifies the window for first-mover advantage on emerging small‑arms technologies and highlights when production volumes are expected to ramp to deliverable scale.
Worldwide Automatic Weapons Market -
Capital allocation and M&A prioritization: A sector-level concentration analysis shows a market that is consolidated enough to reward scale yet open to targeted acquisitions. The top-three and top-five concentration metrics (CR3 ≈ 38.5%; CR5 ≈ 52.1%) imply meaningful room for consolidation plays, bolt-on acquisitions, and strategic partnerships that can rapidly improve market access and margin profiles.
Worldwide Automatic Weapons Market -
Supply-chain risk triage: Material price signals and control-list updates are creating asymmetric supply risks across components. This report equips sourcing teams with scenario-based sensitivity analysis to steel, composites, and high-value sensors so procurement can optimize hedging, inventory policy, and qualification strategies ahead of contract award windows.
-
Regulatory-compliance planning: Changes in export control frameworks and multilateral control lists require preemptive legal and program-management action. Our analysis maps likely friction points in licensing and outlines mitigations for cross-border production and sustainment plans.
What PW Consulting’s report contains — operationally useful deliverables
-
Market sizing and validated forecast model (2020–2032) with scenario variants and sensitivity to macro drivers (raw materials, geopolitical shocks, and procurement policy shifts).
-
Procurement playbooks tailored for national armed forces and law‑enforcement agencies, including decision trees for life‑cycle cost vs. capability trade-offs and contracting strategies (e.g., IP licensing, co-production, and performance-based logistics).
-
Supply‑chain stress tests and actionable mitigation plans covering critical inputs — from hot‑rolled steel to advanced ceramics and imaging subsystems — with recommended buffer policies and supplier-matrix templates.
-
Competitive landscaping with vendor scorecards, capability matrices, and innovation-readiness assessments that inform sourcing, partnership, and R&D investment decisions.
-
Regulatory tracker and impact matrix that synthesizes recent international control-list changes and national export-control shifts, coupled with a licensing risk heatmap for cross-border programs.
-
Commercial intelligence assets: contract-award trackers, tender calendars, and prioritized target lists for investors and BD teams seeking to engage with procurement cycles over the next 36 months.
Industry dynamics shaping 2026 strategy
-
Cost trajectory of primary inputs: Our report factors in material‑price developments such as hot‑rolled coil steel and other metallurgy inputs. Weak demand and overcapacity in global steel markets have kept short‑term prices depressed, but localized supply disruptions and alloy demand for next‑generation platforms can create abrupt input-cost spikes. Procurement and manufacturing executives should assume intermittent price volatility and implement flexible sourcing contracts and forward-buy strategies where feasible.
-
Export controls and multilateral commitments: The late‑2025 update to multilateral control lists has raised the administrative burden for several weapon-system inputs that have dual-use characteristics. Concurrently, national frameworks governing fully automatic weapons and components continue to evolve. Program managers must factor longer lead times for ITAR/EAR and multilateral licensing and prioritize early engagement with regulatory authorities.
-
Capability-driven procurement: Military modernization efforts — including next‑generation small-arms programs — are a core demand driver. Requirements are increasingly defined by range, lethality against advanced body‑armour, integration with soldier systems, and modularity. Suppliers that demonstrate clear pathways to integrate advanced ammunition types, suppressor systems, and electronic fire‑control capability will capture premium positions in upcoming competitions.
Competitive landscape: what the leaders are doing
The vendor field combines historic incumbents with agile innovators. Leading manufacturers are pursuing parallel strategies: product modernization, modularity and suppressor/munition alignment; certification and program wins with major defense customers; and regional partnerships to secure offset or sustainment footprints.
-
Legacy small‑arms specialists are doubling down on modular platforms and variants that support rapid caliber and accessory swaps. This product approach reduces platform lifecycle risk and addresses common procurement requirements for multi-role deployments.
-
Prime defense contractors with broader vehicle and naval portfolios are increasingly integrating automatic cannon and chain‑gun systems into turret and mounting suites, offering fully integrated solutions rather than stand‑alone weapons. This integration is a clear differentiator in vehicle and shipboard procurements.
-
Newer entrants and modernizers are leveraging digital design, additive manufacturing for low‑rate production, and targeted materials substitutions to shorten lead times and lower tooling costs — an attractive value proposition for smaller procurement programs and rapid fielding initiatives.
Recent industry events underscore these dynamics. Early 2026 saw the launch of a next‑generation modular rifle platform from a major manufacturer, emphasizing suppressor compatibility and modular upgrades — a clear signal that product refresh cycles will continue to accelerate. Meanwhile, a major U.S. supplier achieved program certification for a next‑generation squad weapon family in 2025, clearing the path for full production and broader fielding. These developments validate our thesis that capability-oriented procurement and certification milestones are primary short‑term demand drivers.
Strategic recommendations for 2026
-
Align R&D roadmaps to field‑integration pathways: Technical upgrades should prioritize interoperability with soldier systems, suppressor ecosystems, and ammunition evolution. Make modularity a default design principle to minimize obsolescence risk.
-
Hedge material exposure and qualify alternate alloys: Adopt a two‑track procurement strategy — secure long‑lead critical inputs under fixed or indexed contracts while qualifying secondary suppliers and near‑shoring where feasible to reduce geopolitical licensing friction.
-
Prepare for tougher export and dual‑use controls: Institutionalize early compliance reviews for product modifications that touch control-list items (e.g., advanced sensors, ceramics) and keep licensing contingency plans at program inception.
-
Targeted M&A and partnerships: Given the market concentration profile, selective acquisitions that add unique technical capability or regional sustainment capacity can materially increase addressable market. Prioritize targets that bring certification pipelines or critical IP for next‑generation systems.
-
Embed services into bids: Offer lifecycle sustainment, training, and performance-based logistics to differentiate on total-cost-of‑ownership rather than unit price alone.
How PW Consulting supports your 2026 agenda
For decision‑makers preparing 2026 budgets, procurement roadmaps, or investment theses, our report is structured to convert insight into executable action. We combine granular forecasting with procurement playbooks, supplier‑stress testing, and regulatory roadmaps to reduce execution risk and accelerate time to contract. Where necessary, our advisory teams can translate the report’s findings into custom workshops, sourcing strategies, or M&A diligence packages tailored to a client’s portfolio.
Next steps and access to the full intelligence
This release is a strategic preview intended to surface the market forces most relevant to 2026 planning. Detailed tables, segment-level forecasts, vendor scorecards, tender-tracking appendices, and the full methodological appendix (including our scenario assumptions and sensitivity matrices) are intentionally reserved for the full report. To obtain the complete dataset and client tools that support contract-level decisions and competitive bid preparation, visit the PW Consulting report landing page and request the full Worldwide Automatic Weapons Market report and supporting advisory services.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oilseed Extraction Equipment Market to Hit USD 7,446.57 Million by 2032 on 5.12% CAGR — Asia Pacific Leads with USD 2,148.75 Million
By PW Consulting, 2026-08-05
Worldwide Oilseed Extraction Equipment Market — Strategic Outlook for 2026
As senior strategic advisers at PW Consulting, we present an executive briefing built from our latest market study on the Worldwide Oilseed Extraction Equipment Market (base year 2025; forecast 2026–2032). This briefing is written as a strategic “trailer”: it surfaces the evidence-based themes and decision levers that will matter to management teams in 2026, while reserving detailed segment-level models and scenario tables for the full report.
Worldwide Oilseed Extraction Equipment Market
Headline Market Context
The global market for oilseed extraction equipment is recovering and expanding. By our accounting the market stood at roughly USD 5,250 million in 2025 and is projected to begin the forecast window with a rebound in 2026 before steady expansion at a compound annual growth rate (CAGR) of 5.12% through 2032 — reaching approximately USD 7,446 million by the end of the forecast period. This macro trajectory reflects a combination of demand-side resilience in oils & fats processing and supply-side pressures tied to raw-material and energy cost dynamics.
Worldwide Oilseed Extraction Equipment Market
Why this report matters to C-suite and M&A teams in 2026
- Timing for capacity decisions: After a period of uneven investment, 2026 is a pivotal year to decide whether to scale production, hedge capital equipment spend, or prioritize upgrading existing lines with automation and energy-saving retrofits.
- Technology differentiation: Equipment vendors and processors that can demonstrably improve yield, reduce energy intensity, and simplify regulatory compliance will capture outsized margin expansion.
- Supply chain cost pass-through: Fluctuations in stainless steel and energy prices mean procurement strategies (longer contracts, local sourcing, alloy substitution where allowable) will directly affect project economics.
- M&A and partnership clarity: With a market that is growing but not hyper-consolidated, disciplined bolt-on acquisitions and strategic alliances remain high-potential avenues to secure intellectual property, channel access, and turnkey capabilities.
Practical utility embedded in the full PW Consulting report
Our research is designed for operators, OEMs, investors, and policy teams who need actionable outputs rather than academic generalities. The full report includes:
Worldwide Oilseed Extraction Equipment Market
- Proprietary market sizing and revenue forecasts across the 2026–2032 horizon, with scenario variants reflecting energy and raw-material price stress events.
- Investment-return templates for common equipment upgrade packages (mechanical pressing upgrades, solvent extraction modernization, pre-treatment optimization).
- CapEx vs. OpEx sensitivity models that illustrate the break-even windows for automation and energy-recovery investments under multiple feedstock and electricity-price paths.
- Compliance and design checklists aligning line specifications to contemporary food-safety rules and common international standards — enabling rapid specification reviews during procurement.
- Commercial playbooks for vendors and processors: go-to-market segmentation, tendering best practices, and retrofit service monetization strategies.
- A curated, ranked database of suppliers and OEMs with capability matrices, references, and a deal-flow tracker for recent trade-show visibility and product launches.
Competitive landscape — what we see in 2026
The market’s competitive topology combines long-tenured OEMs with regional specialists that offer full-line solutions or focused technologies. In our vendor analysis we profile both global system integrators and highly specialized manufacturers; a few representative themes emerge:
- Heritage innovators with system depth: Companies that historically pioneered core technologies — such as continuous mechanical screw presses and industrial-scale solvent extractors — retain advantages in turnkey project delivery and engineering depth. These firms are preferred partners where end-to-end commissioning and performance guarantees are required.
- Regional champions and export specialists: Several manufacturers based in Asia and India have scaled export operations and compete aggressively on total project cost and localized service support. Their value proposition resonates where lower capital intensity and faster delivery matter most.
- Technology integrators: Firms with strong automation and control capabilities are differentiating on yield and energy efficiency. Integrators who can marry mechanical hardware with advanced process controls unlock near-term margin improvements for processors.
- Stable niche players: Manufacturers of high-reliability mechanical presses and pre-treatment equipment hold steady positions in specific seed-type and process segments, enabling focused partnerships for processors targeting particular feedstocks or product specifications.
In the full report we provide company-level capability maps, procurement checklists for OEM selection, and a comparative evaluation of recent strategic moves such as trade-show demonstrations, expanded service offerings, and turnkey plant deliveries. Recent market activity we track includes major OEM participation at global trade events through 2026, signalling both product refreshes and active business development across geographies.
Market dynamics that will shape 2026 decisions
Four operational dynamics deserve explicit attention when crafting strategy in 2026:
- Raw material volatility: Stainless steel — a foundational material for corrosion-resistant equipment in food processing — has shown regional price divergence and volatility in early 2026. Procurement teams must build contingency into BOMs and consider alloy alternatives or long-term purchase agreements to protect margins.
- Automation and digitization: Adoption of advanced control systems is accelerating, delivering measurable gains in throughput, energy use, and oil yield. Process control upgrades are often the highest-ROI interventions when the objective is near-term margin recovery without major capital investment.
- Regulatory and food-safety compliance: Line designs and facility layouts increasingly must demonstrate compliance with prescriptive food-safety requirements (including hygiene infrastructure). Equipment choices that simplify compliance, reduce rework, and shorten certification timelines materially lower time-to-market for new capacity.
- Energy and sustainability imperatives: Energy-saving technologies — smart temperature control, heat recovery, and high-efficiency transmissions — are no longer optional for processors targeting resilience. They are strategic levers that reduce exposure to electricity and thermal fuel price swings while improving lifecycle emissions profiles.
Strategic recommendations for 2026
For executive teams preparing 2026 capital allocation, procurement, or M&A moves, our prioritized recommendations are:
- Prioritize retrofit-first budgets: Where balance sheets are constrained, prioritize automation, heat-recovery, and transmission upgrades that shorten payback windows and enhance throughput without full-line replacement.
- Secure raw-material exposure: Negotiate supplier agreements or hedges for high-impact materials (notably corrosion-resistant alloys), and evaluate multiyear procurement to stabilize build costs for planned projects.
- Adopt a modular procurement approach: Break large turnkey projects into phased modules — pre-treatment, pressing, extraction, and refining — to de-risk delivery and allow technology substitution between phases as new innovations prove out.
- Benchmark vendor total-cost-of-ownership: Move beyond CAPEX-only tender evaluations; require vendors to provide lifecycle energy, maintenance, and yield models as part of bid submissions.
- Hunt for targeted partnerships: Consider strategic partnerships or minority acquisitions with regional suppliers who offer fast-market access or service networks that complement your footprint.
- Factor compliance early: Integrate regulatory and hygienic design checks into the RFP stage to avoid costly redesigns and delayed commissioning.
What the trailer omits — and why you should download the full report
This briefing intentionally highlights strategic themes, vendor archetypes, and decision levers without disclosing granular segment splits, region-by-region revenue breakdowns, or the detailed company-by-company revenue maps that underlie our models. Those specific figures and the full suite of sensitivity scenarios are central to procurement FID, M&A valuation, and board-level approval processes — and are included in the full PW Consulting report.
For teams planning capital allocation, vendor selection, or M&A activity in 2026, the complete dataset and executable tools in our full study will shorten evaluation cycles and reduce bid-to-contract execution risk. The full report contains the downloadable financial models, procurement scorecards, and a ranked supplier dossier you will want when negotiating tenders or conducting due diligence.
Next steps
- Contact PW Consulting for immediate access to the full Worldwide Oilseed Extraction Equipment Market report and the accompanying financial and procurement toolkits.
- Schedule a briefing with our industry specialists to walk through bespoke scenarios (e.g., varying energy-price shocks or feedstock mixes) and to map a 90–180 day action plan tailored to your capital and operational constraints.
Our analysis equips leadership teams to make informed, defensible choices in 2026 — whether that means accelerating automation, staging capacity investments, or pursuing targeted M&A. The near-term market is characterized by opportunity and complexity; disciplined decision frameworks and the right intelligence will determine who captures disproportionate value as the market expands toward 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Oilseed Extraction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Chinese Domestic Databases Market Hits USD 3,800M in 2025; Forecasted 18.5% CAGR to 2032PW Consulting: Worldwide Areca Nut Market to Grow at 3.88% CAGR Through 2032, Led by Asia Pacific Demand
By PW Consulting, 2026-08-05
PW Consulting Strategic Brief: Preview — Worldwide Chinese Domestic Databases Market (Official Release)
Executive Snapshot
Our latest market study — base year 2025, forecasting through 2032 — maps the rapidly evolving landscape of Chinese domestic database technologies and the ecosystems that surround them. The domestic databases market reached approximately USD 3.8 billion in 2025 and is set on a fast growth trajectory: applying our forecast assumptions produces a compound annual growth rate of 18.5% across the 2026–2032 horizon, with the market expanding severalfold by 2032. This preview synthesizes the strategic implications decision-makers must weigh in 2026 while reserving the report’s operationally sensitive segment-level intelligence for subscribers and authorized readers.
Worldwide Chinese Domestic Databases Market
Market Trajectory and Drivers
-
High-growth runway. Sustained double-digit expansion is driven by a convergence of policy-driven demand for localization, accelerated cloudification of enterprise workloads, and increasing adoption of AI-native database capabilities that unify transaction, search, vector and analytical workloads.
Worldwide Chinese Domestic Databases Market -
Transition dynamics. The market is undergoing a structural shift: legacy on-premise deployments remain material for regulated and latency-sensitive systems, while cloud-native distributed and NewSQL architectures are increasingly preferred for scale, elasticity and operational efficiency.
Worldwide Chinese Domestic Databases Market -
Policy and infrastructure tailwinds. Regulatory reinforcement of data sovereignty, an ongoing national program to replace foreign critical systems within public institutions and key industries, and continued expansion of national data center capacity (measured in millions of standard rack units) together create a persistent demand floor for domestic database offerings.
-
Emerging workload vectors. AI and hybrid search capabilities — including recent vendor releases and open-source initiatives — are reshaping requirements for latency, throughput, observability and lifecycle management of database estates.
Why This Matters for 2026 Decision-Making
-
Procurement and vendor selection will no longer be guided by performance alone. Compliance with evolving cybersecurity and data transfer rules, long-term maintainability, and integration with AI and observability toolchains are now equally decisive.
-
Migration planning must be evidence-based. CIOs need executable migration pathways that minimize business disruption, quantify hidden migration costs and define rollback/escape routes — particularly when replacing foreign vendors in regulated environments.
-
Platform strategy should be workload-aware. Transactional core systems, nearline analytical stores and AI feature stores demand distinct architectures; converged platforms reduce overhead but require disciplined governance to avoid performance and cost surprises.
-
Capital allocation must incorporate regulatory risk. The amended landscape for cross-border transfers and data sovereignty increases the value of domestic-stack investments and alters TCO comparisons between on-premise and cloud deployments.
Competitive Landscape — Who Matters and Why
The competitive map blends nationwide cloud incumbents, dedicated database vendors, open-source champions, and systems integrators. Market concentration is meaningful: the top three suppliers command roughly half of market revenues, and the top five approach well over two-thirds, creating a marketplace where scale confers ecosystem advantages but specialization creates niches.
-
Alibaba Cloud (OceanBase, PolarDB) — Strong engineering depth across distributed and cloud-native product lines. Recent achievements include top-tier benchmark results and product introductions focused on AI-native capabilities and operational observability.
-
Huawei Cloud (GaussDB) — Positioned for high-end applications in finance, telco and government, emphasizing hardened distributed architectures for mission-critical workloads.
-
Tencent Cloud (TDSQL / TencentDB) — Deep traction in enterprise, gaming and other high-concurrency segments, with differentiated operational support within the Tencent ecosystem.
-
PingCAP (TiDB) — Leading NewSQL open-source project with thousands of enterprise deployments; strong play for hybrid transactional and analytical processing across cloud and on-premise estates.
-
Other specialized players — including vendors focused on financial-grade distributed databases, government-localization stacks, analytical variants and AI-integrated offerings — continue to capture specific vertical pockets and compliance-driven contracts.
Recent vendor developments underscore two important dynamics: (1) aggressive feature innovation — especially around AI-native capabilities and observability — and (2) an expanding commercial footprint as vendors balance domestic regulatory needs with selective international expansion. We identify strategic moves, partnership patterns and technology bets in the full vendor scorecards contained in the report.
Regulation, Infrastructure and Cost Dynamics
-
Regulatory tightening in late 2025 and into 2026 materially raises the bar for cross-border transfers and data custody. Organizations must now factor security assessment timelines and new compliance gates into program schedules and procurement contracts.
-
“Xinchuang” and government-led localization initiatives continue to create project-level mandates that favor domestic solutions for government, state-owned enterprises and critical industries. These programs change procurement timelines and evaluation criteria.
-
Local incentives and infrastructure subsidies — from electricity bill offsets to data center colocations — partially mitigate the higher operational costs associated with some domestic hardware stacks, altering TCO calculus for site selection and deployment mode.
-
National data center capacity and regional compute strategies are enabling new architectural patterns (for example, geo-distributed processing and centralized governance) that enterprises can exploit to balance latency, compliance and cost.
What the Report Contains — Practical, Operative and Confidential
PW Consulting’s full study goes beyond high-level forecasts to provide operationally actionable assets for 2026 programs, including:
- Vendor scorecards that synthesize technology maturity, ecosystem integrations, roadmap signals and reference implementations (detailed metrics and scoring models retained in the report).
- Migration playbooks and phased templates for common replacement scenarios (e.g., legacy RDBMS to distributed cloud-native platforms; in-scope risk mitigations and rollback paths).
- Proprietary TCO models that compare on-premise, hybrid and cloud-native deployments across CAPEX/OPEX, compliance costs and transition overhead (spreadsheet models included in report appendix).
- Compliance mapping tied to the latest regulatory amendments and realistic program timelines for security assessments and cross-border authorization.
- Scenario-driven demand modeling and contingency plans covering technology disruption, vendor consolidation and policy shifts.
To respect commercial sensitivities and preserve negotiating leverage for our clients, the report’s granular segment tables and vendor pricing matrices are accessible only within the subscription package and through authorized client briefings.
Recommended Actions for CxOs and Program Leads in 2026
-
Initiate a compliance-first inventory. Map sensitive datasets to required controls, and fast-track security assessments where cross-border flows or third-party hosting are involved.
-
Pilot AI-native database capabilities on non-core workloads. Validate performance, observability and governance before committing to broader migrations.
-
Adopt a hybrid deployment stance. Preserve on-premise operational capability for regulated cores while expanding cloud-native platforms for scale and analytics.
-
Negotiate blended commercial terms that retain escape options. Given a concentrated vendor landscape, contract clauses for interoperability, data exit and third-party audits are essential.
-
Design procurement roadmaps to match policy timelines. Where localization mandates exist, early engagement with domestic vendors and integrators reduces execution risk.
-
Plan for supplier co-evolution. Many leading vendors are rapidly adding AI and hybrid search features; evaluate integration timelines and roadmap alignment before standardizing on a single stack.
How to Use This Briefing — and Where to Go Next
Consider this document a strategic primer. It highlights the directional forces shaping vendor viability, procurement risk and technology choice in 2026, but it deliberately omits the granular tables and segment-level numbers indispensable for execution. For teams preparing procurement, migration or investment decisions this year, the full PW Consulting report provides the calibrated analytics, scenario models and playbooks you will need to operationalize these recommendations.
Closing — Strategic Value for 2026
As regulators and customers impose new expectations on data custody and application availability, organizations must reframe database strategy as a cross-functional program: part regulatory compliance, part platform modernization and part AI-enablement. The market’s rapid compound growth rate and the concentration of supplier capability establish both opportunity and risk. Leaders who act in 2026 with a blend of compliance rigor, pragmatic pilot investments and contractual discipline will secure competitive advantage while avoiding common migration pitfalls.
To obtain the full report, subscription access and PW Consulting’s bespoke advisory engagements tailored to this market, please visit our official report page or contact our research team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


