



Category: market research
Commercial Dishwasher Market — Strategic Outlook for 2026 Decisions
As organizations finalize CapEx plans and channel strategies for 2026, the commercial dishwasher market is shifting from incremental upgrade cycles to a phase where regulation, efficiency mandates, and labor economics jointly reshape procurement priorities. PW Consulting’s new market study synthesizes the last half-decade of performance (2020–2025) and delivers actionable forward-looking intelligence across a 2026–2032 forecast horizon. The report combines rigorous market-sizing, competitive diagnostics, regulatory impact analysis, technology roadmaps, and practical decision frameworks tailored to manufacturers, distributors, foodservice operators, and private equity investors.
Commercial Dishwasher Market
Macro trajectory: a mature market with steady growth
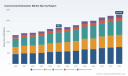
After recovering from pandemic-related distortions in the early 2020s, the global commercial dishwasher market recorded consistent expansion through 2025. Our market model shows the industry rising from roughly USD 1,329 Million in 2020 to USD 1,661 Million in the base year 2025. Looking forward, the market continues on a steady trajectory: an estimated USD 1,697 Million in 2026 and reaching approximately USD 2,276 Million by 2032 under a central scenario driven by a 4.6% compound annual growth rate across the forecast period.
Commercial Dishwasher Market
These headline numbers mask a more nuanced reality: growth is being reallocated across type, application, and regional pockets according to differential adoption of water/energy efficient systems, automation technologies, and regulatory compliance investments. The PW Consulting report decomposes that reallocation and quantifies the business cases for each stakeholder group without revealing proprietary segment-level tariffs in this preview.
Commercial Dishwasher Market
Why 2026 is an inflection year for buyers and sellers
- Regulatory tightening: New sanitation standards and materials specifications—exemplified by recent NSF/ANSI updates—are increasing compliance costs and shortening acceptable product lifecycles for non-compliant designs. This accelerates retrofit and replacement cycles in institutional buyers who must document traceable, certified surfaces and wash parameters.
- Energy and water efficiency pressures: Energy-labeled models (e.g., ENERGY STAR equivalent performance) are now demonstrably better in both operating cost and total cost of ownership. Buyers are increasingly evaluating equipment through lifecycle cost analysis rather than sticker price alone.
- Labor dynamics: Acute labor shortages across foodservice operations are pushing owners toward models that reduce manual handling and cleaning time—driving interest in higher-throughput conveyor systems, pot/pan wash solutions, and integrated automation that reduces headcount needs.
- Capital cycles: Many operators deferred equipment replacement earlier in the decade. With operating margins tightening and ESG metrics rising on corporate scorecards, 2026 is when deferred CapEx begins to flow back into the market—favoring vendors who can demonstrate quick payback and predictable uptime.
Competitive landscape and strategic positioning
The commercial dishwasher market remains moderately consolidated: the top three and top five players control a meaningful share of activity, but the CR metrics indicate room for regional and niche challengers. This structure has important implications for pricing power, go-to-market partnerships, and M&A strategies.
- Hobart (Troy, Ohio): A benchmark brand for high-volume operations, Hobart’s product focus—ranging from door-type to specialized prep-ware machines—centers on lifetime value. Recent product introductions emphasize reduced water, chemical use, and labor savings. Hobart’s scale and installed-base services remain competitive advantages when buyers prioritize long-term TCO and reliability.
- Jackson WWS (Gray, Kentucky): Notable for energy- and utility-saving architectures across undercounter and conveyor platforms, Jackson’s offerings are positioned squarely at buyers who evaluate operating cost optimization. Their product messaging emphasizes water conservation and utility savings—an increasingly salient procurement criterion.
- CMA Dishmachines (Perris, California): With a strong heritage in high-throughput conveyor and scullery solutions, CMA captures a disproportionate share of institutional and high-volume restaurant demand where throughput and sanitation traceability are non-negotiable.
- Champion Industries (Winston-Salem, North Carolina): As part of the Moyer Diebel group, Champion’s portfolio addresses mid-volume segments with an emphasis on serviceability and channel partnerships—attributes that matter for independent dealer networks.
- MEIKO (Offenburg, Germany) and Miele (Gütersloh, Germany): European vendors continue to lead in integrated systems, hygienic design, and automation controls—appealing to hospital, institutional, and hospitality buyers that prioritize certification and short cycle-times.
- Winterhalter (Meckenbeuren, Germany) and Electrolux Professional (Milan, Italy): These vendors combine compact-system expertise and global channel reach. Winterhalter’s digital services and Electrolux’s focus on selection guides and labor reduction tools are differentiators in competitive procurements.
Each competitor displays a different vector of strength—installed-base services, utility-efficiency claims, high-throughput engineering, or digital service ecosystems. Our report maps these vectors to buyer personas and procurement levers so manufacturers and distributors can target investments in R&D, service networks, and trade channels with greater precision.
Technology, product, and service themes that will decide market winners
- Integrated automation and UX: Reducing touchpoints and simplifying operator interaction is now central. Systems that automate pre-wash detection, cycle selection, dosing, and diagnostics reduce labor dependency and increase adoption in labor-constrained environments.
- Water and chemical optimization: Beyond basic recycling, next-generation dosing and filtration technologies materially lower operating costs. Vendors who can quantify savings against regional utility tariffs will win share among cost-conscious buyers.
- Digital services and uptime guarantees: Remote diagnostics, predictive maintenance, and telemetry-linked service SLAs move purchasing conversations from CapEx to hybrid CapEx+Opex models—especially attractive to multi-site operators.
- Hygiene and materials compliance: New sanitation standards have made hygienic design a purchase criterion. Material choices, finish specs, and validated cycle programs are now differentiators that reduce buyer risk in sensitive sectors (healthcare, education).
Risk vectors and scenario planning
Buyers and manufacturers must weigh several risks that could materially alter demand curves:
- Regulatory acceleration: Faster adoption of stricter surface and material standards could accelerate replacement cycles for non-compliant equipment or create retrofit demand.
- Energy policy changes: Incentive programs for water/energy-efficient equipment would compress payback periods and shift procurement to higher-efficiency tiers faster than baseline forecasts.
- Supply chain volatility: Component shortages or inflationary shocks could push lead-times, altering the balance between new purchases and repairs.
Our forecast contains tailored scenarios that stress-test portfolios against these variables and quantify implied impacts on revenue, margin, and installed-base profitability.
What PW Consulting’s report delivers (practical, action-oriented)
The full study is designed as an executive playbook for immediate use in 2026 planning cycles. Among the deliverables:
- Validated market sizing and trend decomposition across historical and forecast horizons, with methodology transparency and confidence intervals.
- Buy-side decision frameworks: cost-of-ownership calculators, payback templates, and procurement scorecards aligned to operator types (independent restaurants, chains, institutions, hotels).
- Technology adoption roadmaps and R&D priority matrices linking engineering investments to revenue uplift and margin expansion.
- Channel and distribution maps showing where OEMs should scale service footprints, distributor partnerships, and digital sales models.
- Competitive threat assessments and M&A target shortlists ranked by strategic fit and integration complexity.
- Scenario-model outputs that quantify the P&L impact of regulation shifts, incentive rollouts, and labor-market stressors.
Importantly, while this introduction highlights themes and headline market figures, the detailed segmented demand curves, regional/application splits, and price-band analyses are intentionally withheld here to preserve the commercial integrity of the dataset. These are included in the paid report and underpin the ROI tools and procurement templates.
How executives should use this research in 2026
- Manufacturers: Prioritize engineering and service investments where lifecycle economics create defensible premium positioning. Use our product-level ROI models to rebalance portfolios away from low-margin commoditized SKUs.
- Distributors and dealers: Recalibrate inventory and service staffing to capture retrofit opportunities and to support higher-value digital service contracts. Our channel maps identify underserved corridors.
- Operators (restaurants, hotels, institutions): Adopt a lifecycle procurement rubric—factoring in water and energy tariffs, labor scarcity, and regulatory certification—to replace equipment in a sequenced, cost-minimizing manner.
- Investors: Use the competitive heat maps and CR metric analysis to identify consolidation targets and bolt-on acquisition opportunities in value-add service companies.
Next steps and access to the full intelligence
For leadership teams planning 2026 strategies, this market and strategy briefing provides the right mix of macro sizing, competitive insight, and practical tools to prioritize investments. To execute with confidence, PW Consulting’s full report contains the segment-level models, regional growth corridors, and product-price matrices that operational teams use to draft CapEx requests and distributor plans. Access to the complete dataset and the interactive forecasting workbook is available through our report page—where subscribers can also request a tailored briefing and a 90-minute workshop to align the findings to their scenarios.
PW Consulting stands ready to partner on implementation: from rapid product portfolio stress-testing to go-to-market pilots that convert insight into near-term revenue and measurable operating-cost reductions. If 2026 is the year your organization redefines equipment strategy around efficiency, automation, and service economics, the time to act is now—and this study is the roadmap.
For detailed analysis of this topic, please visit the official page: Commercial Dishwasher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UPS Market 2026 Strategic Briefing — Navigating Resilience, Efficiency, and Supply‑Chain Fragility
Executive snapshot
Our consolidated market model — base year 2025 — shows the Uninterrupted Power Supply (UPS) market progressing from USD 163.15 Million in 2020 to USD 215.0 Million in 2025, and is forecast to reach USD 344.8 Million by 2032. That trajectory equates to a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. The expansion is neither linear nor uniform: technology refresh, AI-driven compute density, and rapid adoption of lithium‑ion batteries are compressing product lifecycles even as supply‑chain and raw‑materials pressures introduce new timing risks to procurement and operations.
Uninterrupted Power Supply (UPS) Market
Why this matters for 2026 decision‑makers
-
Capital allocation: Enterprises and data‑center operators must choose between CAPEX refreshes, hybrid replacement strategies, or third‑party power‑as‑a‑service models in an environment where equipment lifespans are shortening and upgrade cycles are accelerating.
Uninterrupted Power Supply (UPS) Market -
Risk management: Battery raw‑material volatility and policy interventions are shifting counterparty risk onto buyers. Supply security and end‑of‑life pathways must now be considered alongside price and performance.
Uninterrupted Power Supply (UPS) Market -
Operational performance: High‑density compute footprints (AI/ML workloads) are changing UPS sizing, cooling integration, and maintenance priorities; mis‑sizing a solution today can materially increase TCO and downtime exposure over the next five years.
-
Regulatory & ESG exposure: National critical‑materials strategies and end‑of‑life regulations are elevating the importance of traceability, recycling commitments, and embodied carbon in procurement decisions.
What the PW Consulting UPS Market Report delivers (practical, decision‑ready content)
-
Robust market sizing and forward scenarios — base year 2025 with historical context (2020–2025) and granular forecasts to 2032 — modeled under multiple demand, price, and supply assumptions.
-
Vendor scorecards and strategic positioning maps that assess product families, battery chemistries, modularity, service models, and appetite for software‑enabled operations.
-
Technology roadmaps covering online double‑conversion, modular architectures, silicon‑carbide (SiC) power electronics, and battery chemistry tradeoffs with lifecycle performance curves.
-
Supply‑chain heatmaps and procurement playbooks — including critical‑minerals exposure, second‑tier concentration risk, and mitigation options such as strategic stocks, alternative chemistries, and recycled materials sourcing.
-
Operational playbooks and TCO models for fleet rationalization, energy‑efficiency optimization, and as‑a‑service commercial constructs calibrated to 2026 contract markets.
-
Scenario analyses and stress tests — e.g., accelerated lithium price shocks, export controls, or rapid switchovers to lithium‑ion — with quantified impact bands on replacement cadence and operating cost.
-
Action templates — procurement RFP language, service‑level KPIs, battery‑recycling contractual terms, and an M&A shortlist for consolidation or partnership plays.
Competitive landscape — how leading vendors are positioning (strategic takeaways)
-
Schneider Electric (APC) — solidifying a premium, modular‑centric play for AI and hyperscale workloads. Recent launches emphasize high‑density modular systems and lithium‑ion options, reflecting a push to marry power continuity with compute rack economics.
-
Eaton — doubling down on distributed IT and edge resiliency with compact, high‑efficiency platforms. Their adoption of advanced SiC components in recent product iterations signals a focus on efficiency and footprint reduction.
-
Vertiv — plays to high‑density, mission‑critical applications; product families target data‑center consolidation and workloads that demand predictable, scalable power delivery.
-
ABB and Riello UPS — both emphasize high‑power, industrial‑grade systems that appeal to utilities, infrastructure owners, and industrial OEMs seeking hardened, long‑life platforms.
-
Delta Electronics, Toshiba, and Huawei — represent a mix of scale, cost optimization, and vertical integration, with strong product breadth across enterprise and hyperscale segments.
-
CyberPower, Xiamen Kehua, Sendon — provide competitive options for edge, rackmount, and mid‑market buyers where price/performance and channel reach are decisive.
-
S&C Electric Company — focuses on high‑voltage and power‑quality niches linked to utility and large industrial customers.
-
Market concentration is moderate: the leading vendors together control a meaningful portion of revenue, but there remains room for regional specialists and newer entrants to capture niche or vertically integrated opportunities.
Sector dynamics shaping vendor and buyer strategies in 2026
-
Raw‑material flows: Critical minerals (lithium, nickel, cobalt, graphite, copper) remain strategic inputs. Policy actions such as the U.S. Department of Energy funding for domestic processing and recycling, and multilateral ministerial efforts to secure supply, are already reshaping supplier selection criteria and encouraging investment in circularity.
-
Regulatory momentum: National critical‑materials assessments and export‑control dialogues create a dynamic compliance overlay — buyers must incorporate traceability and provenance into procurement specifications.
-
Technology adoption: Silicon‑carbide power stages and increasingly common lithium‑ion battery packs are improving density and efficiency but increase reliance on sensitive commodity chains. For many buyers the transition window requires careful risk‑reward assessments.
-
Demand vectors: Surging compute density from AI and edge proliferation continues to be the single largest structural demand driver, combined with sectoral reliability needs in healthcare, telecom, and financial services.
Actionable strategic plays for enterprises in 2026
-
Diversify procurement channels: Build a two‑tier sourcing strategy that mixes global OEMs with qualified regional suppliers and capacity from specialist integrators to reduce single‑point supply risk.
-
Adopt a battery‑lifecycle policy: Require supplier commitments on recyclability, take‑back, and refurbishment; evaluate total‑life carbon and cost, not just first‑cost.
-
Pilot high‑density vs. distributed deployments: Run controlled trials that compare modular, lithium‑ion systems against upgraded traditional platforms to quantify TCO and operational impacts over 5–7 years.
-
Embed flexibility in contracts: Negotiate upgrade clauses, spare parts pools, and swap‑out agreements to accelerate technology refresh without full replacement CAPEX.
-
Invest in predictive maintenance: Digital telemetry and AI analytics materially reduce mean‑time‑to‑repair and allow for capacity planning that avoids premature replacements.
-
Prepare for policy shifts: Map critical‑materials exposure across your UPS fleet and create contingency plans for sudden policy or trade changes affecting battery inputs.
-
Explore financing alternatives: Power‑as‑a‑service and managed availability contracts can shift obsolescence risk to suppliers while guaranteeing uptime commitments — analyze these offerings against internal cost of capital.
Research limitations & the “trailer” offer
The summary above highlights the report’s strategic findings and actionable frameworks. To preserve competitive value for subscribers, detailed regional and application splits, granular supplier market shares, and certain scenario‑level numerical tables are intentionally withheld in this briefing. PW Consulting’s full report contains those detailed segmentations, supplier scorecards with quantitative rankings, and downloadable models that will enable precise financial and operational planning for 2026 procurement cycles.
Next steps
If your team is making 2026 budgetary commitments, sizing edge vs. centralized capacity, or redesigning resilience playbooks, the PW Consulting UPS Market Report is designed to convert uncertainty into a prioritized set of actions. Access the full analysis and downloadable decision tools on our publication page or contact our advisory team for a tailored briefing and scenario run‑through tuned to your portfolio.
For detailed analysis of this topic, please visit the official page: Uninterrupted Power Supply (UPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MBR Market to Reach USD 8.18 Billion by 2032 at 8.57% CAGR (2026–2032)
By PW Consulting, 2026-08-02
Membrane Bioreactor (MBR) Market: Strategic Imperatives for 2026
Executive teaser
The global Membrane Bioreactor (MBR) market has moved from a niche advanced-treatment solution to a core technology class in modern wastewater strategy. After steady expansion across 2020–2025, the market size—measured in USD billion—accelerates into the forecast window 2026–2032 at a compound annual growth rate (CAGR) of 8.57%. This trajectory highlights both volume expansion and premiumisation: customers increasingly demand higher-performance membranes, integrated systems, and outcome-based contracts that reduce lifecycle risk. Our latest PW Consulting study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesises these forces into actionable guidance for boardrooms, technology officers, investors and infrastructure planners preparing decisions in 2026.
Membrane Bioreactor (MBR) Market
Why this report matters for 2026 decisions
- Capital allocation: Decide which MBR configurations, modules and vendors to prioritise when sanctioning projects or evaluating M&A targets.
- Technology selection: Differentiate between membrane chemistry, module formats and system-level integration choices that affect total cost of ownership and regulatory resilience.
- Regulatory and compliance planning: Translate emerging PFAS-related rules and national funding programs into procurement and retrofit roadmaps.
- Commercial strategy: Design pricing, service and outcome-based propositions to capture share in a market with high concentration among incumbent vendors.
- Risk management: Anticipate raw-material constraints and supply-chain disruptions that will influence lead times and margins in 2026.
Market context: growth profile and concentration
MBR demand has roughly doubled from the early 2020s to the mid-2020s, reflecting broader adoption across municipal and industrial applications. The market’s forecast to 2032 shows sustained, above-market growth driven by regulatory tightening, capital replacement cycles, and new high-demand use cases such as data-center cooling and industrial water reuse. Structurally, the market is concentrated: the top three players collectively represent a dominant share of vendor revenue, and the top five command an even larger portion—an important dynamic for competition, pricing and procurement strategies.
Membrane Bioreactor (MBR) Market
Drivers, accelerants and headwinds
- Regulatory acceleration: National and regional regulations on trace contaminants—and corresponding public funding—have moved MBR from optional to, in some cases, essential. For example, the U.S. PFAS drinking-water regulation and sizeable federal funding commitments for advanced treatment materially increase project pipelines that favour MBR-capable solutions.
- Materials and technology substitution: Growing scrutiny of certain fluorinated polymer membranes in multiple jurisdictions has prompted manufacturers to fast-track PVDF-free options and alternative chemistries. Market participants must now manage both technology transition risk and opportunity.
- New demand pockets: Non-traditional end users—data centres, resorts, industrial parks seeking zero-liquid discharge (ZLD), and circular-economy initiatives—are sourcing bespoke MBR + post-treatment systems, expanding addressable demand beyond municipal upgrades.
- Scale and service economics: Large incumbent suppliers with integrated engineering, aftermarket service networks, and validated performance records enjoy a structural advantage in bidding for complex, high-value contracts.
- Supply-chain and raw-material risk: Membrane feedstock and module production capacities remain concentrated; any rapid pivot away from restricted chemistries will create transient capacity tightness and re-shape supplier power.
Competitive landscape — strategic reads on core vendors
Our competitive analysis profiles vendors across technology stacks, geographic reach, and commercial models. Highlights:
Membrane Bioreactor (MBR) Market
- Kubota Corporation (Osaka, Japan): Offers both flat-sheet and hollow-fiber platforms and has signalled readiness with PVDF-free alternatives—positioning itself for regulatory shifts while maintaining a strong municipal systems footprint.
- Veolia Environnement SA (Paris, France): Leverages a large installed base and product families that emphasise high-performance biological membrane separation; its global project execution capability makes it a go-to partner for complex municipal and industrial retrofits.
- SUEZ Water Technologies & Solutions (Paris, France): Competes on integrated solutions, drawing value from combined process engineering and membrane technology, attractive to operators seeking single-vendor responsibility for performance guarantees.
- Xylem Inc. (Stamford, United States): Positions MBR as part of larger activated-sludge and treatment portfolios—appealing to customers that prioritise modularity and retrofit simplicity.
- Pentair Plc (London, United Kingdom): Offers tubular, flux-enhanced modules that target specific industrial needs where fouling control and solids handling matter.
- Toray Industries and Mitsubishi Chemical (Tokyo, Japan): Key membrane-material suppliers; their R&D choices and regulatory compliance posture materially influence the technology roadmap of OEMs and integrators.
- OriginWater, CITIC Envirotech, Aquatech, Memstar and other regional specialists: These firms are competitive in localized markets and project niches—particularly where bundled EPC+O&M models or local certification matter.
For buyers, the strategic takeaway is clear: vendor selection is both a technology and an ecosystem decision (spare parts, service SLAs, performance guarantees and regulatory compliance). Our full vendor scorecards and procurement playbooks quantify these trade-offs.
Recent market movements that matter for 2026
- Large-scale, purpose-built MBR projects (e.g., bespoke solutions for data-center cooling) demonstrate growing demand for high-capacity, reliable membrane trains and are creating new reference projects that accelerate adoption.
- Independent performance reports and certification outcomes increasingly drive procurement preferences; objective third-party validation is becoming a de facto requirement for large public tenders.
- Strategic partnerships and technology alliances continue to reshape supply chains—suppliers form coalitions to deliver integrated MBR+post-treatment packages for water reuse and desalination-preconditioning.
- Regulatory developments—both restrictions on certain membrane chemistries and dedicated funding for advanced treatment—are the near-term inflection points that will reallocate capex and redirect R&D efforts.
Scenario planning: what 2026 could look like (and how to act)
- Regulatory-Acceleration Scenario: If PFAS and related restrictions tighten rapidly and funding continues to flow, demand for compliant MBR systems will spike. Actions: accelerate supplier qualification for PVDF-free options; secure long-lead inventory; prioritise service contracts that guarantee contaminant removal performance.
- Technology-Transition Scenario: If alternative membrane chemistries and ceramic modules scale faster than expected, price parity pressures could benefit late-mover adopters. Actions: pilot hybrid membrane stacks; co-develop long-term supply agreements; re-evaluate product roadmaps to reduce exposure to constrained feedstocks.
- Consolidation Scenario: If leading global players continue to capture the largest projects, regional specialists will need carve-out strategies (niche specialization, local partnerships, aftermarket focus). Actions: pursue white-label manufacturing partnerships and focus on service-led differentiation.
Report deliverables — practical tools included
- Market-sizing model and forward curves with base-year calibration (2025) and scenario toggles for regulatory and supply-chain variables.
- Vendor benchmarking suite: technology profiles, installation reference cases, O&M cost comparators and risk-adjusted performance scores.
- Procurement playbook and contract templates for CapEx and outcome-based O&M agreements.
- CapEx/Opex modelling templates, unit economics and NPV sensitivity calculators tailored to municipal and industrial project profiles.
- Regulatory-impact dashboard that maps jurisdictional rules to technology and procurement choices.
- Deal origination and diligence checklist for investors and M&A teams focused on platform-scale acquisitions or bolt-on plays.
Note: This article intentionally omits granular regional, application and type-level splits to preserve the value of the underlying datasets. The full report contains the complete subsegment tables, competitor revenue breakdowns and downloadable models.
How executives should use this research in 2026
- CEOs & Boards: Use the scenario-constrained market sizing to validate strategic choices—build, buy or partner—over a 3–5 year horizon.
- CFOs: Integrate the report’s CapEx/Opex templates into business-case workflows and stress-test liquidity against potential supply-chain shocks and regulatory compliance costs.
- CTOs & Product Heads: Prioritise R&D and supplier certification workstreams to ensure membrane chemistries meet emergent regulatory standards and client performance expectations.
- Project Developers & EPCs: Apply vendor scorecards and procurement playbooks to compress delivery timelines and reduce lifecycle risk in bids.
- Policy Makers & Utilities: Leverage the regulatory-impact dashboard to understand how funding instruments can accelerate the deployment of advanced treatment while protecting supply resilience.
Conclusion — the strategic call to action
MBR is no longer a specialist add-on; it is a core lever for water resilience, regulatory compliance and circular-economy value capture. The market’s growth profile through 2032, combined with concentrated vendor economics and rapid regulatory change, creates both risk and opportunity for those making decisions in 2026. Our PW Consulting study provides the analytic backbone—scenario-ready market models, vendor benchmarks and procurement playbooks—to convert uncertainty into a defensible strategy. For decision-makers aiming to prioritise projects, structure partnerships, and safeguard margins in an era of regulatory transition, the full dataset and operational toolkits are indispensable.
Access the complete report and downloadable models to unlock the subsegment-level intelligence and bespoke recommendations required for 2026 execution.
For detailed analysis of this topic, please visit the official page: Membrane Bioreactor (MBR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCB & PCBA Market to grow at 5.5% CAGR to USD 279.77M by 2032PW Consulting: Mozzarella Market to Grow at 4.31% CAGR Through 2032
By PW Consulting, 2026-08-02
PW Consulting Industry Brief: Strategic Imperatives from the 2026 PCB & PCBA Market Outlook
Executive snapshot
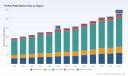
The global printed circuit board (PCB) and printed circuit board assembly (PCBA) market is entering 2026 from a position of steady expansion and heightened strategic complexity. Our latest research — anchored on a 2025 base year and projecting through 2032 — documents a clear growth trajectory: the market expanded meaningfully over 2020–2025 and, under our baseline, is set to grow at a compound annual growth rate (CAGR) of 5.5% across 2026–2032. In absolute terms, the market in 2025 stood at approximately USD 192.0 Million (revenue unit: Million), moving toward a materially larger opportunity by 2032. This trajectory reflects durable end-market demand from electrification, connectivity, and industrial automation, while simultaneously exposing manufacturers and OEMs to near-term cost and policy shocks that will shape strategic choices in 2026.
PCB & PCBA Market
Why this study matters for 2026 corporate decisions
-
Operational resilience is now strategic: Raw material volatility (notably copper-clad laminates, copper foil, and glass fiber) and periodic supplier price adjustments have moved from episodic to frequent. For 2026 planning cycles, CFOs and supply chain leaders must translate market forecasts into concrete hedging, contracting and capacity decisions. Our study provides the scenario-based cost sensitivities and negotiation playbooks required to translate a top-line CAGR into a resilient margin plan.
PCB & PCBA Market -
Capital allocation requires new rigor: With steady market growth but higher systemic risk (tariff uncertainty, feedstock-driven price inflation), capital deployed to capacity expansion, automation, or vertical integration must be stress-tested. The report offers investment KPIs and break-even models calibrated to the sector’s current cost environment and projected demand profile.
PCB & PCBA Market -
Technology choices determine competitive positioning: Adoption of HDI, rigid-flex, and embedded solutions is accelerating in prioritized end markets. For 2026 product roadmaps, our analysis connects technology migration rates to supplier capability requirements and margin differentials — enabling product teams to decide when to redesign for manufacturability versus when to select specialist partners.
-
M&A and partner selection need data-backed screening: Given moderate market concentration (CR3 ≈ 38% and CR5 ≈ 55%), there is room for consolidation and bolt-on acquisitions. The report’s competitive scorecards and due-diligence templates support rapid triage of targets and detailed synergies assessment tailored to strategic buyers and financial sponsors.
What the full report delivers (practical, transaction-ready content)
-
Multi-year market model (2020–2032) with scenario toggles: baseline, upside (faster technology adoption/reshoring), and downside (tariff/raw-material shock) views. Note: granular segmentation tables and interactive model files are reserved for the full report.
-
Price-inflation and margin sensitivity matrices that convert supplier price actions into P&L outcomes for board-level decision-making.
-
Supply chain heatmap and critical-path risk register, including single-source exposure, lead-time concentration, and inbound logistics vulnerabilities by supplier tier.
-
Commercial playbooks: long-term contract templates, price-collar mechanisms, and inventory-financing structures designed to protect margins while preserving supplier relationships.
-
Technology and capacity playbooks: investment sizing for selective automation (SMT, high-density assembly lines), capex scheduling, and tool qualification checklists linked to product roadmaps.
-
Competitive benchmark dossiers and M&A screening: profiles, margin diagnostics, and integration risk checklists for the sector’s strategic and financial players.
Competitive landscape — who matters and what they signal for 2026
The sector remains a mix of broad-scope EMS integrators, specialist PCB fabricators, and premium substrate producers. Each archetype implies different strategic responses for customers and investors.
-
Jabil Inc. — As a leading EMS provider with end-to-end PCBA capabilities, Jabil’s scale and systems integration expertise make it a preferred partner for OEMs seeking product-to-production continuity. For buyers, Jabil represents a low-risk route to accelerate time-to-market and absorb technology complexity, but its scale also means commercial leverage is tilted toward the supplier in tight capacity scenarios.
-
TTM Technologies — TTM’s focus on advanced fabrication (HDI, rigid-flex, RF/microwave, backplane) positions it as a strategic partner for high-performance and aerospace applications. Supply decisions favor TTM when technology complexity and thermal/mechanical tolerances are decisive procurement criteria.
-
Sanmina Corporation — Sanmina’s global footprint and full-spectrum services (from prototyping to high-volume) make it a go-to for companies seeking geographic diversification of production. Their presence underscores the strategic premium for multi-region supply options in 2026 planning.
-
Flex Ltd. — Flex sits at the intersection of EMS breadth and sector specialization (notably automotive and medical). For OEMs prioritizing lifecycle services and system integration, Flex’s model demonstrates why long-term partnerships and co-investment in capacity are increasingly common.
-
Plexus Corp. — With a reputation for high-reliability and regulated-market assemblies, Plexus is illustrative of the margin advantages available in medical and defense segments where certification and traceability are barriers to entry.
-
AT&S AG — As a premium substrate and HDI specialist, AT&S highlights the supplier-side differentiation that emerges from advanced material science and process control. Premium players can command price and capacity premiums in high-growth, high-complexity subsegments.
-
Compeq Manufacturing — A major fabricator with an emphasis on rigid, flexible and rigid-flex boards, Compeq demonstrates how scale plus vertical capabilities (fabrication + assembly) create attractive integrated propositions for consumer and infrastructure customers.
Together these players establish a market structure that is neither fully fragmented nor monopolistic. The measured concentration suggests both competitive tension and room for strategic consolidation — an important insight for investors or corporates seeking inorganic growth.
Supply-chain dynamics and regulatory noise to watch in 2026
Recent industry events crystallize the two-sided nature of near-term opportunity: healthy bookings and technology-driven demand on one hand; persistent raw-material inflation and policy uncertainty on the other. Key developments informing our 2026 playbook include:
-
Industry demand signals: Trade shows and IPC industry releases in early 2026 confirmed sustained booking and shipment momentum, reinforcing the demand assumptions embedded in the baseline 5.5% CAGR forecast.
-
Raw material inflation: Major laminate and prepreg suppliers implemented substantial price increases in late 2025–early 2026 to offset rising copper, fiberglass and logistics costs. These actions materially compress factory margins unless offset by price pass-through, design changes or supplier agreements.
-
Policy risk: Proposed tariff actions and regional tariff implementations have the potential to re-draw near-term sourcing economics for companies reliant on cross-border inputs. Procurement and tax teams must stress-test scenarios in the upcoming planning cycle.
Practical 90-day actions for leadership teams
-
Run a supplier stress test: Identify single-source materials and quantify the P&L impact of recent and potential future supplier price actions. Prioritize dual-sourcing or contract renegotiation where value at risk is greatest.
-
Lock in selective capacity: Where product roadmaps require HDI, rigid-flex or high-density assembly, secure committed capacity with clear performance SLAs and price collars.
-
Revisit product-design trade-offs: Use value-engineering sprints to identify components or board-layer reductions that preserve functionality while reducing exposure to high-cost laminates and complex processes.
-
Prepare an M&A screen: If inorganic growth is on the table, use the report’s benchmarking framework to evaluate targets quickly on capability fit, margin upside and integration risk.
Conclusion — what leaders should take away
2026 is a year for pragmatic, data-driven choices. The PCB & PCBA market is growing, but growth alone is no guarantee of margin or strategic advantage. Our study translates a clear macro trajectory (historical expansion into a baseline 5.5% CAGR through 2032) into operational choices — from negotiating laminate contracts to prioritizing HDI capacity and structuring acquisition targets. The full PW Consulting report contains the granular segmentation, interactive financial models, supplier scorecards and playbooks that operationalize these insights. For leaders building resilient, high-performing supply chains and product roadmaps in 2026, that level of granularity is essential — and available through the full analysis.
Next step
Access the full report to obtain the complete datasets, the interactive forecast model, and the supplier-by-supplier benchmarking that underpin the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: PCB & PCBA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GaAs Market to Reach USD 3,425.07M by 2032 at 6.35% CAGR - PW Consulting
By PW Consulting, 2026-08-02
Gallium Arsenide Market: Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As organizations prepare capital allocation, supply‑chain moves, and product roadmaps for 2026, a concise, analytically rigorous view of the global gallium arsenide (GaAs) market is an operational necessity. PW Consulting’s latest market research establishes the macro baseline: the global GaAs market reached approximately USD 2,226 Million in the base year (2025) after a sustained expansion from the pandemic era (USD ~1,472 Million in 2020). Our forecast shows continued momentum into the new decade — the market is projected to grow at a compound annual growth rate (CAGR) of 6.35% across the 2026–2032 forecast period, reaching roughly USD 3,425 Million by 2032.
Gallium Arsenide Market
What these headline numbers mean for corporate strategy
-
Validation of demand continuity: The near‑term uplift versus the early‑2020s baseline demonstrates that GaAs is not a passing niche. Buyers and investors should treat GaAs demand as a structural feature of semiconductor supply chains tied to wireless communications, optoelectronics, microwave systems and power RF devices.
Gallium Arsenide Market -
Capital intensity with predictable tailwinds: Mid single‑digit CAGR implies steady but capital‑intensive growth. This favors strategic investors and established players with access to fabrication, vertical integration, or long‑term offtake contracts over small entrants relying purely on spot sales.
Gallium Arsenide Market -
Timing matters: With measurable growth already priced into supply markets by 2025, decisions taken in 2026—whether to greenfield capacity, expand R&D, or enter JV structures—will determine whether players secure disproportionate share as the market scales into the early 2030s.
Market structure and competitive dynamics (teaser)
The GaAs market exhibits moderate fragmentation: concentration metrics indicate that the top three firms account for a minority share of global revenues, with the top five still capturing less than one third of the market. That structure creates simultaneous opportunities and risks: on one hand, nimble challengers can carve differentiated niches; on the other, customers face supplier diversification challenges and potential pricing leverage from larger integrated suppliers.
PW Consulting’s full report contains a granular competitive map — including capability matrices across wafer production, epitaxial services, device integration, and downstream OEM relationships — designed to inform M&A screening, partnership selection, and procurement negotiation strategies. (Core company and segment level revenue tables are intentionally withheld in this briefing to preserve the value of the full dataset.)
Drivers, headwinds and volatility vectors
-
Demand drivers: GaAs demand is being propelled by a convergence of technological trends — higher frequency 5G/6G infrastructure, photonics and optoelectronic device adoption, specialized RF power applications, and certain defense and aerospace systems that require the specific material properties of GaAs.
-
Competitive pressure from adjacent technologies: GaN (gallium nitride) and silicon carbide continue to encroach on some high‑power and RF segments. Strategy must therefore balance investments in GaAs capabilities with roadmap options for technology hybridization or migration where economics and performance dictate.
-
Supply‑chain sensitivity: Given the supply concentration of critical upstream inputs and regionalization trends in semiconductor manufacturing, companies should treat wafer access, epitaxy capacity, and logistics as strategic assets. Planning must account for tiered supply availability and lead‑time risk in 2026 procurement cycles.
-
Policy and geopolitical drivers: Export controls, domestic incentive programs for chipmaking, and defense procurement policies can materially change cost curves and addressable markets within short policy cycles. Scenario planning in the full report models plausible policy shifts and their commercial impacts.
How PW Consulting’s GaAs report supports 2026 decisions
Our research is structured to move beyond descriptive statistics to operational decision support. The report is a practical toolset for executive teams, corporate development, supply‑chain, and product leaders. Core deliverables include:
-
Robust base‑case and scenario financial model (2026–2032): A dynamic spreadsheet model that lets you test demand, pricing, and capacity scenarios and evaluate NPV, IRR and payback for capex options. The model is keyed to historical performance (2020–2025) and the PW baseline CAGR of 6.35%.
-
Demand heatmaps and opportunity scoring: Actionable maps of high‑priority application pockets (e.g., microwave RF modules, optoelectronic components, fiber‑optic subsystems, high‑power electronics) by strategic attractiveness and ease of entry. Note: the briefing here omits segment revenue tables; the full report provides the complete ranked scorecard.
-
Supply‑side anatomy and risk register: Capacity balances, critical supplier dependencies, and a prioritized mitigation playbook for procurement and operations teams to reduce lead‑time and input price risk.
-
Competitive benchmarking and M&A screen: Capability matrices, technology ownership indexes, and a short‑list methodology for inorganic growth targets. Detailed financials and seller profiles appear in the full deliverable to protect research integrity.
-
Regulatory & incentives tracker: An updatable module that quantifies the potential financial impact of jurisdictional incentive programs and export control scenarios on manufacturing economics and go‑to‑market decisions.
-
Commercial playbooks: Go‑to‑market archetypes for incumbents and new entrants, pricing strategies aligned to capacity utilization cycles, and sample long‑term offtake contract templates to anchor supplier relationships.
Concrete strategic moves for 2026
Below are the priority actions we recommend C‑suite teams and divisional heads adopt in 2026 to convert market momentum into durable advantage. These actions are calibrated to the growth path implied by the report’s macro baseline and the observed market structure.
-
Lock in secured supply with tiered contracts: Negotiate staged offtake agreements with options to scale. Prioritize suppliers that can provide a combination of capacity certainty and technical collaboration on epitaxy and device process integration.
-
Targeted capex sequencing: Rather than broad capacity expansion, favor modular investments that can be combined with contract manufacturing or foundry partnerships. Use the report’s scenario model to stress‑test utilization assumptions before committing to multi‑year buildouts.
-
Product segmentation and premiumization: Identify high‑margin application pockets—those dependent on GaAs unique properties—and align R&D and IP protection to those product lines. Consider platform strategies that enable rapid customization for telecom, aerospace, and photonics customers.
-
M&A and alliance playbook: Pursue tuck‑ins that fill capability gaps (e.g., epitaxial expertise, packaging, or test) rather than only volume plays. The market’s moderate concentration means well‑executed bolt‑ons can yield rapid synergy capture.
-
Operational resilience and localization: Map both geopolitical risk and customer proximity to set priorities for localized capacity or dual‑sourcing arrangements, especially for defense‑adjacent or national‑security‑sensitive programs.
-
R&D portfolio optimization: Balance near‑term product improvements with longer‑term bets on materials co‑design (e.g., GaAs/GaN integration paths). Use staged funding tied to technical milestones to preserve optionality.
Use cases: how different stakeholders extract value
-
Corporate development teams can use the report’s M&A screen and financial model to rank targets and structure earn‑outs tied to capacity ramp metrics.
-
Supply‑chain leads can deploy the risk register and offtake templates to reduce lead‑time volatility and negotiate better payment and inventory terms.
-
Product and R&D heads can prioritize development sprints against high‑value applications identified in the opportunity heatmaps while preserving portfolio flexibility where adjacent materials are encroaching.
-
Investor and strategy teams can stress‑test thesis scenarios—e.g., accelerating 5G infrastructure rollouts or policy shifts that favor domestic manufacturing—using the report’s scenario suite.
Why this matters now
2026 is a pivot year. The market has moved past post‑pandemic recovery and is entering a phase where incremental investments yield disproportionate strategic advantage. The 6.35% CAGR across 2026–2032 implies that early decisions to secure capacity, partnerships, and IP will compound into leadership positions as the market approaches the early‑2030s scale. Conversely, procrastination risks being locked into expensive spot markets or missing critical customer contracts in high‑value application areas.
Next steps — a recommended 90‑day action agenda
-
Commission a tailored scenario run: Have PW Consulting run your corporate assumptions through our financial model to quantify the impact of alternative demand, pricing, and capacity timelines.
-
Initiate supplier due diligence: Start bilateral conversations with two‑tier suppliers and at least one potential foundry partner; request capacity roadmaps and conditional offtake proposals.
-
Prioritize a 6‑month R&D sprint: Select one product family where GaAs provides unique value and fund a focused program to produce a manufacturable roadmap and TAP (technology acceptance plan).
-
Prepare an M&A shortlist: Use PW’s screening criteria to identify 3–5 targets for further diligence that fit your capability gaps or distribution objectives.
Closing note
PW Consulting’s GaAs market study blends rigorous macro sizing (2020–2025 historical series, a 2025 base year, and a 2026–2032 forecast at 6.35% CAGR) with operational playbooks designed for commercial and technical decision‑makers. This briefing surfaces the strategic imperatives and immediate actions for 2026; the full report contains the proprietary segment‑level datasets, company profiles, and transaction‑ready tools that convert insight into execution. For teams that must make capital, procurement, or portfolio decisions this year, that granular detail will be decisive.
To obtain the complete dataset, scenario models, and bespoke briefing for your executive team, please consult the full PW Consulting report or contact our GaAs practice lead.
For detailed analysis of this topic, please visit the official page: Gallium Arsenide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Servo Motors Market to Reach USD 20.63B by 2032 at 4.8% CAGR
By PW Consulting, 2026-08-02
Servo Motors Market 2026: Strategic Imperatives for Decision-Makers
As companies finalize 2026 plans, the servo motors market presents a mix of predictable expansion and accelerating complexity. Our PW Consulting market study — grounded in a 2025 base year, with historical observation across 2020–2025 and projections through 2026–2032 — frames that landscape with a rigorous, investment-grade lens. The global market is on a steady growth path (a 4.8% CAGR across the forecast window), moving from an assessed market size of approximately USD 14.86 Billion in 2025 to a projected USD 20.63 Billion by 2032. These headline numbers are not just comforting arithmetic: they encode the operational, regulatory and technology-led inflection points that will determine winners and losers in 2026 and beyond.
Servo Motors Market
Why this study matters to corporate leaders in 2026
-
Actionable horizon scanning: The market is mature enough to reward disciplined strategy and early movers, yet dynamic enough that missteps (e.g., ignoring efficiency standards or magnet supply risk) will be costly. Our analysis translates the aggregate growth trajectory into tactical guidance for procurement, product roadmaps, and M&A prioritization.
Servo Motors Market -
Risk-adjusted investment signals: A steady CAGR masks concentrated pockets of regulation-driven demand and raw-material-driven margin volatility. We quantify these forces and provide scenario outputs that support capital allocation decisions — from factory automation upgrades to long-term strategic sourcing contracts.
Servo Motors Market -
Competitive differentiation blueprints: With a diverse set of global vendors serving industrial automation, robotics, CNC, aerospace and other verticals, our study dissects capability clusters and go-to-market models. This helps OEMs and system integrators align product features and after-sales models with evolving buyer expectations.
-
Timing and sequencing for compliance: New and proposed efficiency regulations (domestic and international) are compressing retrofit and product development timelines. We provide a prioritized timeline that helps legal, engineering and commercial teams sequence compliance investments for minimal disruption and maximal upside.
Core dynamics shaping 2026 strategy
-
Regulatory tightening is now a baseline planning assumption. From national energy efficiency mandates to model regulation templates for emerging markets, authorities are raising the floor for allowable performance. The ripple effects are threefold: product redesigns to meet minimum thresholds, accelerated demand for higher-efficiency servo platforms, and a greater role for certification and compliance services within the value chain.
-
Raw material pressures — particularly on rare-earth permanent magnets — materially affect supplier cost curves. Procurement and product teams must translate price volatility into hedging, dual-sourcing and, where feasible, alternative-technology strategies (e.g., reduced-magnet topologies, redesigns that trade off magnet content for electronics complexity).
-
Customer expectations are shifting from component-only transactions to outcome-based relationships. Buyers increasingly value integrated motion solutions (hardware + drives + software + lifecycle services), which changes margin pools and favors suppliers who can bundle capabilities across disciplines.
-
Fragmentation and specialization: The market is neither monopolistic nor atomized. A cluster of established global brands competes with regional and niche players that offer differentiated value in price, lead times, local support, or domain-specific optimizations (e.g., aerospace, high-speed packaging, precision CNC). This creates targeted entry points for both incumbents and challengers.
What the PW Consulting report delivers (practical content for 2026 decision cycles)
-
Integrated market model: A calibrated topline model linking macro demand drivers to end-market consumption (historical 2020–2025 base plus yearly forecasts through 2032), with scenario toggles for regulation, raw-material shocks, and adoption curves for electric vs. magnetic architectures.
-
Strategic playbooks: Actionable templates for procurement (RFP design, total cost of ownership modeling), product development (modular design approaches, software-embedded differentiation), and commercial expansion (channel selection, service bundling).
-
Commercial diligence kits: Benchmarked supplier scorecards, technology risk matrices, and guided interview plans for validating claims around reliability, lead time, and service capability — structured for rapid use in M&A or large vendor selections.
-
Cost and margin analytics: Unit-level cost drivers, sensitivity tables for magnet price swings, and break-even analyses for aftermarket service offerings that can bolster gross margin in low-growth scenarios.
-
Regulatory navigator: A prioritized registry of active and prospective efficiency rules, their likely commercial impacts, and a compliance roadmap by product family and market entry sequence.
-
Interactive decision tools: Scenario dashboards that let management teams test investment choices — e.g., whether to accelerate a new high-efficiency motor program or to negotiate multi-year magnet supply deals — and observe bottom-line and NPV impacts.
Competitive landscape: how to read the supplier map in 2026
The vendor ecosystem is populated by global industrial champions and high-focus specialists. Established automation majors bring deep systems expertise and strong channel relationships; industrial-electronics specialists emphasize precision motion control and tight integration with drives and PLCs; component-focused firms deliver cost-competitive building blocks and niche innovations.
-
Systems integrators and industrial conglomerates (examples include firms headquartered in Switzerland, Germany, France, and Japan) continue to invest in verticalized offerings for factory automation and robotics, leaning on product families that integrate motion control, safety and digital services.
-
Specialist motion-control suppliers (including several based in Japan, the U.S. and Taiwan) maintain leadership in high-precision and high-performance niches, where latency, torque density and control algorithms determine value.
-
Regional and component-focused players, often with strong OEM relationships, provide critical price and lead-time advantages in price-sensitive segments or where local support differentiates procurement decisions.
Our competitive profiles in the report go beyond public marketing narratives: each includes product roadmaps, recent commercial moves, channel strategies, and a practical assessment of where each player is likely to compete aggressively in 2026. We deliberately withhold granular segment share tables in this overview to preserve the strategic value of the full report — those tables are included in the subscriber edition and underpin the diligence-ready scorecards referenced above.
Recent market signals you cannot ignore in 2026 planning
-
Trade-show and product-launch cadence in 2026 highlights two priorities: compact, high-performance motor form factors and embedded controller integration for reduced system complexity. Several companies used major industry events in 2026 to showcase compact servo modules and controller-embedded solutions that accelerate OEM time-to-market for motion applications.
-
Regulatory moves in major markets are accelerating adoption cycles. New federal proposals and international model guidelines are prompting earlier-than-expected upgrades in product families and testing protocols, which has direct implications for product roadmaps and certification budgets.
-
Supply-chain signals — notably sustained pressure on rare-earth magnet pricing — are prompting suppliers to publish alternative designs and for procurement teams to elevate strategic sourcing to the boardroom. The elasticity of margin to magnet cost is high for many architectures; our report quantifies that elasticity across product families.
How to use this study in board-level and operational decision-making in 2026
-
Short-term (6–12 months): Re-baseline procurement contracts with sensitivity clauses for magnet pricing and energy-regulation pass-throughs; prioritize certification investments for markets where new standards come into force imminently.
-
Medium-term (12–36 months): Decide whether to pursue horizontal scale (broaden product range) or vertical depth (integrated systems and services). Our scenario outputs show which path preserves margin under different regulatory and raw-material regimes.
-
Long-term (36+ months): Build optionality into product architectures (modular platforms, software-first upgrades) to insulate investments against both disruptive entrants and commodity cost shocks.
Concluding perspective — the strategic payoff in 2026
For leaders making allocation and go-to-market choices in 2026, the servo motors market is simultaneously an efficiency play and a strategic moat opportunity. The headline growth (4.8% CAGR and a clear upward path from the 2025 base) validates continued investment, but the distribution of returns will depend on the quality of execution: regulatory foresight, supply-chain resilience, and the ability to convert component competence into outcome-focused solutions. The PW Consulting report equips executives with the models, playbooks and diligence artifacts required to make those critical choices with conviction.
To access the full data tables, supplier scorecards, scenario dashboards, and tender-ready procurement templates that underpin the recommendations summarized here, please consult the complete Servo Motors Market study on our website. The executive overview you are reading is intended to inform and orient — the actionable intelligence that drives 2026 decisions is available in the subscriber edition.
For detailed analysis of this topic, please visit the official page: Servo Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mosquito Killer Market Poised for 6.2% CAGR Through 2032
By PW Consulting, 2026-08-02
Mosquito Killer Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
As vector control moves from seasonal nuisance management to a year‑round commercial category, PW Consulting’s Mosquito Killer Market study provides the practical intelligence required to align product roadmaps, regulatory strategies, and distribution plays for 2026. The global market has expanded steadily from an estimated USD 150.0 Million in 2020 to USD 215.0 Million in 2025, and our base‑case model projects a compound annual growth rate (CAGR) of 6.2% through a 2026–2032 forecast horizon, with the market approaching roughly USD 345.0 Million by 2032. These headline figures frame a market that is neither niche nor fully consolidated — an environment that rewards focused differentiation, regulatory foresight, and scalable go‑to‑market execution.
Mosquito Killer Market
Why this preview matters for 2026
- Investment timing: Mid‑decade buyers and product teams face a window where incremental technology improvements (smart controls, non‑chemical attractants, solarization) yield meaningful share gains without requiring step‑change R&D spend.
- Regulatory convergence: U.S. and international guidance is clarifying device vs. pesticide boundaries, increasing the importance of registration strategy and field‑trial design for any player making claims of killing or population suppression.
- Channel reconfiguration: New distribution arrangements and growing interest from specialty channels and online omnichannel strategies are reshaping how products reach both residential and commercial end users.
What the full study delivers — practical, executable outputs
This report is built for operators, investors, and corporate strategists who need more than descriptive analysis. Key deliverables include:
Mosquito Killer Market
- Market sizing and trend decomposition: historical 2020–2025 benchmarking and a transparent forecasting model for 2026–2032, including scenario runs and sensitivity to pricing, adoption, and regulatory lag.
- Go‑to‑market playbook: channel mapping, retail and professional distribution strategies, and launch templates for new SKUs targeted at indoor, outdoor, and hybrid use cases.
- Regulatory and field data roadmap: stepwise EPA/FIFRA registration planning, evidence packages (efficacy, safety), and realistic timelines and budgets for pre‑market field trials.
- Technology and product blueprint: comparative assessment of UV/electric, fan+glue, photocatalytic, solar and app‑controlled platforms; cost‑to‑manufacture estimates; IP and component sourcing risks.
- Competitive intelligence pack: qualitative positioning maps, capability profiles of leading vendors, and a playbook for defensive and offensive moves (pricing, bundling, service add‑ons).
- Investment and M&A diagnostics: target screening criteria, valuation ranges under multiple scenarios, and integration checklists for bolt‑on acquisitions.
- Operational risk matrix: supply chain pinch points, manufacturing cost drivers, and mitigation plans for scaling production into low‑resource settings.
Market structure and competitive dynamics (high level)
The market exhibits low‑to‑moderate concentration: the combined market share of the top three vendors sits below industry monopolies, while the top five also leave ample room for mid‑tier challengers. This fragmentation creates opportunities for faster‑moving brands to win by focusing on product experience, channel execution, or partnership models with public health and landscape management firms.
Mosquito Killer Market
Incumbents and notable players include traditional manufacturers of UV and electric devices, innovators of glue‑board and fan capture systems, specialized surveillance and attractant companies, and several entrants pushing app control, solar power, and photocatalyst approaches. Across these groups we observe two enduring plays:
- Incremental innovation on classic platforms: improved lamp chemistries, more efficient grids, and weather‑resilient housings that reduce warranty costs and increase lifetime value.
- Platformization: devices that integrate sensing, connectivity, and subscription services for proactive maintenance, refill logistics, and epidemiological reporting.
Competitive readouts — what leaders and challengers are doing
Product launches over the last 18 months highlight a bifurcated market response. Some vendors are doubling down on rugged, high‑throughput outdoor units for commercial customers, while others focus on compact, smart indoor devices for urban consumers:
- Smart outdoor innovation: a notable vendor introduced an app‑controlled, large‑area trap in late 2025, emphasizing configurable attractant profiles and remote monitoring for landscape and event management teams.
- Distribution moves: a major specialty distributor expanded its coverage of an attractant‑based trap across multiple U.S. locations in 2025, illustrating how integrated pest management channels are consolidating procurement for professional applicators.
- Convergent consumer devices: hybrids combining car‑freshener form factors with UV traps debuted in 2025, demonstrating an appetite for multi‑functionization in consumer touchpoints.
These examples signal a competitive environment where product differentiation increasingly rests on system features — connectivity, attractant algorithms, refills and consumables — rather than on raw trapping capacity alone.
Regulatory and field‑trial realities
Regulatory constraints are among the most consequential non‑market risks. In the U.S., devices that claim killing or reproductive interference are regulated under FIFRA; EPA registration requires substantive efficacy and safety data, and review times can range from months to years. Industry experience suggests that building a defensible dossier entails staged field trials and iterative validation; when combined with EPA expectations, total program timelines can extend materially if field complexity or data gaps emerge.
For companies planning to scale in 2026, the practical implication is clear: factor registration program costs and timelines into product launch roadmaps, invest early in trial partners and data collection infrastructure, and avoid market claims that trigger heavier regulatory pathways unless the company is prepared for the compliance investment.
Strategic priorities for 2026 — recommended plays
- Prioritize platform economics: design hardware that enables recurring revenues (attractant refills, data subscriptions, consumables). Even modest attachment rates materially change return profiles in a market growing at ~6% annually.
- Regulatory first design: embed regulatory planning into product development — label claims, trial design, and safety testing — to avoid rework and market delays. Consider partnership with third‑party registrants or contract research organizations that specialize in FIFRA dossiers.
- Channel segmentation: separate GTM efforts for residential e‑commerce, retail mass, and professional pest management. Invest in trade‑facing rebate and demo programs for professional buyers who influence bulk procurement cycles.
- Selective international expansion: use pilot markets to validate low‑cost manufacturing and service models before wide geographic rollouts; account for local public‑health procurement cycles and seasonal demand swings.
- M&A and partnership playbook: pursue bolt‑ons that add complementary capabilities — e.g., sensor analytics, attractant chemistry, or distribution footprints — rather than duplicative manufacturing capacity.
- Resilience in manufacturing: address cost pressure by redesigning for modularity and sourcing alternate suppliers for LEDs, fans, and battery subsystems to improve margins without compromising quality.
Risk calibration and go/no‑go gates
Key decision metrics for 2026 should include breakeven time under conservative adoption assumptions, regulatory lead‑time contingencies, and channel payback periods. Our report includes a set of investment gates — preclinical evidence thresholds, pilot performance metrics, and distribution KPIs — that executive teams can adopt as stop/go criteria to limit downside while preserving upside optionality.
Next steps — how to use this preview
This preview highlights the strategic value of a detailed, execution‑focused market study as companies plan 2026 investments. The full PW Consulting Mosquito Killer Market report includes the underlying market model, scenario outputs, regulatory checklist templates, and an expanded competitive intelligence dossier that disaggregates product‑level performance and go‑to‑market tactics (available for licensed download).
If your 2026 plan needs to address product portfolio prioritization, regulatory sequencing, channel rollouts, or a targeted M&A search in this sector, the complete report provides the data, templates, and actionable roadmaps to convert insight into decisions.
Contact and access
For access to the full dataset, model files, and the complete competitive appendix, please consult our distribution page or contact PW Consulting’s industry practice. The public preview above outlines the strategic contours — the full study arms you with the granular evidence required to execute confidently in 2026.
For detailed analysis of this topic, please visit the official page: Mosquito Killer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Colorants Market to Reach USD 2,516.7M by 2032 at 7.85% CAGR
By PW Consulting, 2026-08-02
Natural Colorants Market — 2026 Strategic Brief
As the global food, beverage, personal care and specialty ingredient landscapes pivot decisively toward “clean” and sustainable formulations, natural colorants have moved from niche to strategic necessity. PW Consulting’s latest market study—anchored on a 2025 base year—provides the forward-looking intelligence leaders need to make high-conviction decisions in 2026. The market is sizable and expanding: from mid-single billions in 2025 growth to a forecasted market that more than halves its size over the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 7.85%. This brief explains why the study matters for 2026 decision-making, what practical modules it contains, and how leading companies are positioning themselves in response to regulatory shifts, raw-material volatility and new biotechnologies.
Natural Colorants Market
Why this report matters for 2026 decisions
Three forces are converging in 2026 to make natural colorants a strategic priority rather than a tactical add-on: sustained demand for clean-label solutions, regulatory activity reshaping permissible uses and labeling language, and rapid innovation in production technologies such as precision extraction and microbial fermentation. Our forecast and scenario analysis quantify how these forces interact to shape near-term pricing, supply risk and addressable market expansion.
Natural Colorants Market
-
Growth context. The natural colorants market recorded material expansion through the early 2020s and reached a clear inflection by 2025; our models project continued robust growth through 2032 under the central scenario, driven by reformulation in key end-use industries and premiumization trends.
Natural Colorants Market -
Regulatory inflection points. In 2025–2026 several pivotal regulatory developments (notably a series of approvals and policy clarifications by the FDA and other authorities) materially affect what colors can be used, how products may be labeled, and the pace at which innovation can be commercialized. These changes have immediate implications for formulation roadmaps, marketing claims and global product launches.
-
Supply-side transformation. Seasonality and complex extraction economics continue to favor players that can secure raw inputs or deploy alternative production methods. Concurrently, biotechnology companies are demonstrating credible scale-up pathways that could alter cost curves and sourcing risk over the medium term.
What the report delivers — practical, decision-ready modules
-
Executive synthesis with actionable implications tailored to executive teams, R&D heads and procurement leaders.
-
Market sizing and forecast (2026–2032) with scenario modelling and sensitivity analyses to support investment cases and budget planning.
-
Regulatory &claims tracker that maps recent approvals, enforcement attitudes, and pending rule-making — updated to incorporate the most recent regulatory actions through early 2026.
-
Supply-chain stress tests including raw-material price elasticity, crop-seasonality scenarios, and contingency playbooks for shortages.
-
Competitive landscape and supplier diligence pack with strategic profiles, capability maps, and M&A/partnering opportunities (high-level summaries here; detailed supplier financials and client interviews included in the full study).
-
Technology & innovation assessment comparing extraction, formulation and fermentation routes — with commercialization timelines and cost curve estimates.
-
Go-to-market playbooks and commercial KPIs: product prioritization matrices, pricing levers, shelf-life and stability considerations, and labeling/marketing guidance.
-
Transaction support tools: valuation comparables, synergy frameworks and integration checklists for common tie-ups with biotech and ingredient houses.
Competitive landscape — who matters and why
The market is shaped by several archetypes: large ingredient multinationals with global formulation and sales networks; specialty extractors with deep upstream sourcing capability; and agile biotech players commercializing fermentation-based pigments. At an aggregate level the market shows meaningful concentration at the top tier, with a cluster of established players capturing a substantial share of industry revenues — enough to influence pricing and set technical performance standards.
-
Ingredient multinationals (scale + formulation): Companies with global R&D and customer channels leverage formulation know-how to embed natural colorants into complex matrices (e.g., beverages, confectionery, cosmetics). Their strategic edge is the ability to combine color with flavor and functional ingredients at scale, and to absorb upfront regulatory and compliance costs when launching new color solutions.
-
Specialist extractors (sourcing + quality): Firms that control raw-material sourcing and extraction processes are advantaged when crops are seasonal or when traceability and sustainability certifications command a premium. These players often win early contracts with premium brands seeking provenance-backed claims.
-
Biotech innovators (fermentation + novel pigments): Startups and specialist biotechs are moving from proof-of-concept to industrial-scale demonstrations. Collaborations between fermentation companies and established ingredient houses are increasingly common, enabling rapid route-to-market without requiring full internal scale-up.
Recent milestones underscore these dynamics: regulatory approvals in 2025–2026 expanded the palette of permitted natural additives, while milestone partnerships and development progress among fermentation specialists indicate accelerating commercialization pathways. At the same time, policy moves that affect labeling discretion introduce both risk and optionality for marketers — a dynamic that should be managed proactively rather than reactively.
Supply and raw-material dynamics — managing volatility
Natural colorants are inherently tied to agricultural and biological supply chains. Commodity seasonality, crop yield variability, and processing yields create recurring cost and supply volatility. Key mitigation levers include diversified sourcing, contracting with defined quality and delivery windows, forward procurement and investment in upstream agricultural partnerships or controlled-environment production.
-
Near-term pressure: expect episodic input-price spikes in response to poor harvests or logistic constraints; procurement teams should run scenario-based hedging and quantified stress tests.
-
Medium-term opportunities: microbial fermentation and precision bioprocessing can reduce dependency on seasonal crops and compress lead times — making them high-priority targets for R&D partnerships or minority investments.
-
Sustainability as a commercial lever: traceable, low-impact sourcing frameworks support premium pricing and are increasingly requested by brand customers and regulators.
Prioritized strategic actions for 2026
-
Reassess portfolio positioning vs. regulatory realities: Align product claims and label language with the latest enforcement trends and approvals; adjust launch plans where approvals materially change allowable claims or formulations.
-
Secure critical inputs: Create a tiered sourcing matrix (immediate bilateral contracts; medium-term supplier development; long-term vertical options or fermentation partnerships).
-
Invest selectively in formulation R&D that addresses stability, heat and pH sensitivity — these attributes remain the primary commercial differentiators.
-
Pursue strategic partnerships with biotechnology firms to accelerate time-to-market for fermentation-derived pigments without assuming full manufacturing capex risk.
-
Embed stress-tested pricing and margin models into commercial negotiations; use premium sustainability credentials selectively to protect margins.
-
Build a regulatory rapid-response cell to monitor approvals, labeling guidance and enforcement actions in real time; use the report’s regulatory tracker as the baseline for escalation paths.
-
Evaluate targeted M&A for capability gaps — particularly in extraction, fermentation or traceable sourcing — using the study’s valuation and integration playbooks.
How to use the full PW Consulting report
This brief is designed as a high-value preview: it highlights the strategic levers and near-term actions every senior executive should consider in 2026. The full report contains the granular detail that fuels transaction models and operational plans — regional and application-level segmentation, supplier-level profiles and scorecards, downloadable financial models, primary-interview-driven risk matrices, and confidential case studies that benchmark successful reformulations and partnership structures.
For teams that need to convert insight into action quickly, the complete deliverable also includes an editable scenario-based model, a procurement playbook with supplier negotiation scripts, and a short-list of high-priority partner targets aligned to specific corporate goals (innovation, cost reduction, sustainability). Accessing the full dataset will enable you to quantify revenue and margin outcomes across specific product strategies and to validate investment cases for 2026 expenditures.
PW Consulting’s Natural Colorants Market study is purpose-built to bridge the gap between marketing aspiration and operational reality — providing the forecasting rigor, regulatory foresight and commercial playbooks that good decisions in 2026 require.
To explore the granular insights, supplier dossiers, and the scenario model that underpin these recommendations, please refer to the full market research release and contact PW Consulting’s strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Natural Colorants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Collagen Hydrolysate Market — Strategic Briefing for 2026 Decision-Makers
As firms position for growth in the nutrition, personal care, and pharmaceutical ingredients space, Collagen Hydrolysate has evolved from a niche specialty ingredient into a strategic product family with meaningful revenue and margin implications. Our latest PW Consulting market study, based on a 2025 base year and a 2026–2032 forecast horizon, quantifies that evolution: the global market expanded from roughly USD 1.26 Billion in 2020 to USD 1.72 Billion in 2025 and is projected to approach USD 2.67 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.5% across the forecast period.
Collagen Hydrolysate Market
Why this study matters for 2026 decisions
-
Strategic timing: 2026 is a pivot year. Supply-side consolidation, new IP grants, and product innovations announced between 2024–2026 are reshaping competitive advantage. Decisions taken now on capacity, partnerships, and IP strategy will determine market share capture as demand accelerates through the late 2020s.
Collagen Hydrolysate Market -
Revenue clarity: The market’s steady mid-single-digit CAGR creates predictable upside—but not evenly across segments. Understanding where premiumization, clinical-backed claims, and formulation convenience converge is essential to picking winners.
Collagen Hydrolysate Market -
Concentration and competitive dynamics: The market exhibits high concentration at the top: a three‑player concentration (CR3) in the high‑60s percent and a CR5 approaching eight‑tenths of the market. This structure amplifies the importance of strategic partnerships and scale economies for challengers and buyers alike.
Top-line market trajectory (what the numbers mean)
The market’s progression from early‑stage niche product to broadly used functional ingredient is reflected in the growth path between 2020 and 2025 and the forecast to 2032. That progression is not simply a volume story: it is being driven by expanding application sets (from traditional supplements into beverages, foods, and beauty-from-within concepts), increased clinical substantiation, and ingredient innovation that supports dose reduction, solubility, and organoleptic performance. Firms that convert this macro growth into differentiated formulations and secure feedstock will capture outsized value.
Core industry dynamics to monitor
-
Demand drivers: Aging demographics, rising consumer interest in joint, skin, and metabolic health, and the mainstreaming of “beauty-from-within” concepts are sustaining steady demand growth. Sports nutrition and meal-replacement innovations are adding higher-frequency use cases, supporting recurring purchase economics.
-
Feedstock economics: Animal-source raw materials differ materially on cost and supply resilience. Bovine hide and bone–derived peptides currently offer cost competitiveness; marine-derived solutions command premiums tied to traceability and niche positioning. These fundamental cost differentials influence margin structures across product formulations.
-
IP and regulatory shifts: Recent patents and approvals—covering therapeutic claims, glycemic-response support, and peptide compositions—are raising the bar for product differentiation. Market entrants must now plan for IP freedom-to-operate and invest in clinical endpoints if they intend to compete in premium segments.
-
Supply consolidation and capacity moves: Announced JVs and facility expansions signal an industry preparing for volume growth and commercializing larger-scale, branded peptide platforms. Capacity moves will influence near-term pricing dynamics and create windows for contract renegotiation and stockpiling strategies.
-
Innovation and formulation complexity: Improvements in enzymatic hydrolysis, fractionation, and precision peptide design allow suppliers to tailor functional profiles (e.g., targeted bioactivity, solubility, taste masking). These technical differentials are increasingly decisive in customer selection and pricing power.
What the full report delivers (practical, actionable content)
-
Validated market sizing and a 2026–2032 forecast model with scenario outputs that let commercial teams stress-test demand against price and feedstock shocks.
-
Segment and application analyses that map growth corridors (consumer health, F&B, cosmetics, pharmaceuticals) and identify where premiumization and volume play out—presented with layered confidence intervals and sensitivity testing. Note: granular regional and application dollar splits are deliberately summarized here; full, downloadable tables and underlying model inputs are in the full report.
-
Supply chain and raw material diagnostics: origin risk scores, cost buckets, and supplier concentration analyses that feed procurement playbooks and hedging considerations.
-
IP and regulatory landscape: patent mapping, claim risk matrices, and jurisdiction-specific pathways for health claims and novel ingredient filings.
-
Competitive benchmarking and vendor playbooks: strategic profiles, capability heatmaps, and acquisition/partnership targets tailored to common buyer archetypes (brand-owner, co-manufacturer, ingredient house).
-
Go‑to‑market and product strategy templates: dose-to-label economics, route-to-market options by channel, and an innovation roadmap for product teams seeking to optimize consumer efficacy claims while managing cost-in-use.
-
Scenario planning and M&A playbooks: quantifying the commercial impact of capacity expansions, new patent protections, and entry of low-cost producers—plus prioritized M&A targets and JV structures aligned to different strategic objectives.
Competitive landscape — what’s happening and why it matters
The market’s competitive map is a mix of deep-technology ingredient specialists, large multinational food processors, and regional producers with strong cost positions. Several high-impact developments have crystallized competitive advantage in 2024–2026:
-
Strategic consolidation and capacity ambitions: A high-profile JV term sheet announced to combine collagen/gelatin businesses aims to create a significant global capacity platform. For buyers and competitors, this raises questions about future bilateral supply agreements, co‑branding opportunities, and pricing frameworks as large-scale capacity comes online.
-
IP-driven differentiation: Multiple patent grants on bioactive compositions and glycemic-support peptides have been awarded to leading ingredient players. Ownership of targeted clinical claims is translating directly into premium positioning in nutraceutical and functional F&B channels.
-
Product and route-to-market innovation: New beverage concepts and clinically validated formulations have been launched by major suppliers, demonstrating how branded ingredient platforms can migrate into B2C concepts and co-marketing relationships with finished-goods manufacturers.
-
Capacity expansions by major gelatin and peptide manufacturers in strategic geographies are increasing the supply-side flexibility, particularly for contract manufacturers and private-label converters.
Collectively, these moves mean that scale, IP, and clinical evidence are the three principal axes of competition. Firms that are strong on only one axis will find themselves margin-pressed; those that align two or all three can extract sustainable premium returns.
Practical recommendations for 2026
-
Secure feedstock flexibility: negotiate multi-sourced contracts and consider partial vertical integration or long-term offtakes to hedge against raw-material and capacity shocks.
-
Prioritize clinically backed claims where commercial payoff is greatest—invest selectively in trials that support clear, monetizable positioning (e.g., joint health, skin elasticity, post‑meal metabolic endpoints).
-
Build IP vigilance into product development: conduct freedom‑to‑operate reviews early and allocate budget for defensive patents where proprietary formulations will materially affect pricing.
-
Develop tiered product strategies: pair cost-efficient base peptides with premium, branded bioactive lines to cover both mass and premium channels without cannibalization.
-
Assess M&A and JV options as a fast follower to capacity consolidation—target acquisitions that add formulation expertise, clinical assets, or regional route-to-market capabilities.
-
Operationalize a scenario desk: translate the report’s model into quarterly monitoring triggers (e.g., patent grants, capacity ramp milestones, raw-material price bands) that guide tactical procurement and commercial pricing.
How to use this briefing
This article is a strategic “trailer”: it outlines the market trajectory, competitive inflection points, and the tactical moves executives must consider in 2026. For teams preparing board papers, pitch decks, or investment memoranda, the full PW Consulting report provides the granular tables, regional and application splits, and downloadable financial models that underpin the recommendations summarized here. We intentionally withhold core segmented figures in this briefing to preserve the analytical value of the full deliverable.
If your 2026 plan hinges on securing supply, validating a premium positioning, or evaluating acquisition targets in the Collagen Hydrolysate ecosystem, use this briefing as the orientation step—and consult the full report for the transactional-grade data and model outputs required to execute with confidence.
For detailed analysis of this topic, please visit the official page: Collagen Hydrolysate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PV Inverters Market Set to Grow at 7.2% CAGR Through 2032
By PW Consulting, 2026-08-02
PV Inverters Market — Strategic Outlook for 2026 Decision-Makers
As global power systems accelerate the transition to variable renewable generation, the PV inverters market sits at the intersection of electrification, digitalization, and grid resilience. PW Consulting’s latest market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance with forward-looking scenario analysis to equip commercial leaders, investors, and policy teams with actionable direction for 2026. Our headline findings are grounded in a market that has nearly doubled in size since 2020 and is expected to continue expanding at a steady mid-single-digit compound annual growth rate (CAGR of 7.2%). This briefing outlines the strategic value of that research while intentionally withholding the granular segment-level splits to encourage access to the full report for decision‑critical details.
PV Inverters Market
Why this research matters in 2026
-
Timing investments. With the market demonstrating robust growth from the 2020 base and clear momentum into the second half of the decade, 2026 is a pivotal year for capital allocation decisions. Our analysis identifies whether near-term opportunities favor scaling manufacturing capacity, accelerating R&D in grid-forming technologies, or prioritizing aftermarket services and digital platforms.
PV Inverters Market -
Technology roadmaps. The competitive frontier is shifting toward integrated inverter–storage architectures, grid-forming capability, and the incorporation of GaN semiconductors and AI for performance optimization. The report maps maturity curves and commercial readiness across these vectors to inform product roadmaps and partner selections.
PV Inverters Market -
Policy and market risk calibration. Recent regulatory moves—tariff extensions, evolving exclusions for procurement programs, and national grid codes—are reshaping supply chains and procurement economics. Our study translates these dynamics into risk-adjusted scenarios to support procurement windows and market entry timing.
-
Concentration and bargaining power. The industry exhibits a notable top-tier concentration (CR3 and CR5 metrics indicate material market share by leading vendors). That structure has implications for component supply, pricing pressure, and consolidation potential—insights crucial for procurement, alliance, and M&A strategies.
Market trajectory: a data-driven headline
From the report’s historical series and forecast, the market demonstrates a clear upward trajectory. After an accelerated recovery and growth period through 2024–2025, the sector continues to expand underpinned by capacity additions across residential, commercial, and utility-scale segments and by increasing functional complexity of inverter systems. PW Consulting’s forecast to 2032 embeds a median-case CAGR of 7.2%, reflecting sustained demand alongside gradual technology-driven cost declines and expanding serviceable addressable markets.
Key dynamics shaping competitive advantage
-
Grid-forming and ancillary services: System operators increasingly require inverters to provide grid-support functionalities (voltage/frequency ride-through, black start, inertia emulation). Vendors that can demonstrate validated grid-forming performance in both lab and live deployments will command premium positioning for large-scale and C&I contracts.
-
Integration with storage and management software: The value of inverters is shifting from power conversion to system orchestration. Seamless integration with battery management systems and cloud-based energy platforms—covering forecasting, optimization and warranty/monitoring services—drives lifecycle revenues and stickiness.
-
Power electronics innovation: New materials (e.g., GaN) and modular topologies reduce losses and enable higher-density, lighter systems. Rapid adopters of these innovations gain cost and performance advantages in both residential and commercial microinverter/string product lines.
-
Channel and after-sales networks: As warranty terms and service expectations tighten, service infrastructure becomes a differentiator. Localized distribution, extended warranty models, and digital proactive maintenance reduce lifetime costs for end-customers and create defensible revenue streams for vendors.
-
Supply chain geopolitics: Trade measures and funding exclusions in major markets complicate sourcing strategies. Manufacturers and buyers must reconcile cost-competitive sourcing with regulatory compliance and eligibility for public incentives.
Competitive landscape — who matters and why
The industry’s competitive set is composed of diversified global incumbents, specialized power-electronics companies, and agile modular innovators. The leading vendors combine scale, product breadth, and functional differentiation. Key strategic postures include:
-
Technology-led incumbents with integrated solutions: Companies that couple advanced inverter platforms with cloud software and system-level integration are positioning to capture both equipment and recurring software/service revenues. Their strengths lie in validated grid-forming features, large-scale deployments, and established warranty and service frameworks.
-
Modular and microinverter specialists: Firms focused on module-level power electronics and GaN-enabled microinverters push performance at the residential edge and in constrained rooftop scenarios. Their value is in higher module-level yields, simplified retrofit projects, and scalability for distributed energy resource aggregation.
-
Regionally focused distributors and OEMs: Strategic partnerships between manufacturers and regional distribution networks accelerate market access. Recent tie-ups and channel expansions underscore the importance of localized service and inventory models for faster installations and warranty execution.
Recent vendor activity illustrates these trends. Early 2026 product launches by major vendors introduced next-generation smart string and utility-grade platforms emphasizing grid-forming capability and integrated transformer‑station solutions. Parallel announcements expanded GaN-based microinverter availability and extended warranty or channel strategies—moves that reflect the transition from pure hardware competition to holistic system offers and go-to-market sophistication. Select strategic alliances and distributor expansions in 2026 indicate an active consolidation of route-to-market capabilities in growth regions.
Regulatory and policy frame — what to watch in 2026
-
Trade and procurement restrictions: Extensions of trade remedies and eligibility exclusions for funding programs are forcing buyers and manufacturers to revisit sourcing choices and to assess compliance pathways for major public tenders.
-
Incentive phaseouts and transition windows: Shifts in tax incentives and subsidy timelines create condensed demand windows; identifying those windows is essential for capacity planning and pricing strategies.
-
Grid code updates and simplified registration: Where grid codes evolve to simplify small-scale interconnections, uptake of small inverter products accelerates—opening consumer and prosumer segments but also demanding mass-scale aftermarket support.
Strategic imperatives for 2026
-
Adopt a dual-track product strategy: Prioritize investments that address both utility-scale grid-forming and distributed-energy optimized inverters. This hedge captures near-term large-project demand while securing long-term distributed revenues.
-
De-risk supply chains: Build multi-sourcing strategies and flexible manufacturing footprints to navigate trade restrictions and to preserve access to incentive-funded tenders.
-
Monetize software and services: Accelerate development of monitoring, predictive maintenance, and optimization offerings to capture recurring revenues and to differentiate on total lifecycle cost.
-
Pursue selective partnerships and channel expansion: Where local regulations or market dynamics favor regional distributors, pursue alliances or bolt-on acquisitions to accelerate market share gains and after-sales coverage.
-
Use warranty and financing as levers: Extended warranty models, bundled service contracts, and financing options can improve sell-through in residential and commercial channels while smoothing revenue recognition.
-
Prepare for consolidation: With a concentrated top-tier and continuing technology-driven churn, M&A will be an efficient route to acquire capability gaps—particularly in power electronics, software platforms, or regional networks.
What the full PW Consulting report delivers
For teams preparing 2026 strategies, the full study is an operational manual rather than a high-level overview. It includes:
-
Robust market sizing and a seven-year forecast grounded in scenario analysis, with sensitivity to policy and technology adoption rates.
-
Competitive benchmarking across product categories, with vendor capability matrices, route-to-market profiles, and recent M&A and partnership mapping.
-
Technology deep dives on grid-forming, GaN adoption, hybrid integration, and inverter-as-a-platform economics.
-
Supply chain and cost-driver analysis, including component bottlenecks, logistics risks, and inventory strategies.
-
Commercial playbooks for OEMs, EPCs, developers, and distributors—covering pricing, warranty design, and service models.
-
Policy impact scenarios translating trade, funding eligibility, and grid-code changes into quantified upside/downside cases for procurement planning.
To preserve competitive value for commissioning teams and executive sponsors, the report intentionally reserves detailed regional and application-level splits for subscribers and clients. These disaggregated insights are the data that inform contract-level decisions and asset-level modeling; they are available through PW Consulting’s subscription portal and bespoke advisory engagements.
Next steps for executives
2026 is the year to align capital, product, and channel decisions with a maturing PV inverter market. Use the headline macro trajectory and the strategic imperatives above to guide immediate choices: fast-track initiatives that enhance system-level differentiation, shore up procurement agility in response to regulatory shifts, and expand service propositions to capture recurring revenue.
For teams that require the granular segmentation, vendor scorecards, and contract-level modeling to execute these strategies, PW Consulting’s full PV Inverters Market study provides the evidence base and playbooks needed to move from strategy to implementation. Contact our advisory desk or visit the PW Consulting research portal to access the complete intelligence package and to commission tailored scenario work for 2026 decision cycles.
For detailed analysis of this topic, please visit the official page: PV Inverters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


