



Category: market research
PW Consulting: Shikimic Acid (CAS 138-59-0) Market Poised for 4.6% CAGR (2026-2032)
By PW Consulting, 2026-07-30
Shikimic Acid (CAS 138-59-0): Strategic Outlook for 2026 — A PW Consulting Preview
Shikimic acid has moved from a niche biochemical to a decision-critical commodity for companies operating across pharmaceuticals, personal care, and specialty chemicals. Our latest market study — anchored on a 2025 base year, covering historical performance from 2020–2025 and projecting through 2026–2032 — quantifies both the steady growth and the episodic shocks that will shape boardroom choices in 2026. The market’s compound annual growth rate of 4.6% and our topline model (USD Million basis) indicate a market expanding from roughly 37.3 Million in 2020 to an estimated 46.7 Million in 2025 and continuing toward approximately 64.0 Million by 2032. These macro trajectories create a strategic imperative: optimize supply architecture, accelerate product differentiation, and align regulatory risk management with commercial ambitions.
Shikimic Acid (CAS 138-59-0) Market
Why this study matters for 2026 decision cycles
-
Actionable foresight for procurement and production: With moderate market concentration (top 3 players ≈45%; top 5 ≈52%), incumbent suppliers retain pricing power, but new capacity and shifts in sourcing technology are reshaping bargaining dynamics. Procurement teams that enter 2026 armed with scenario-based supply models will capture margin and continuity advantages.
Shikimic Acid (CAS 138-59-0) Market -
Product and go-to-market alignment: Demand is no longer monocultural. Pharmaceutical-grade specifications, high-purity analytical forms, and cosmetic-grade ingredients are converging in the same supplier landscape. R&D and commercial teams must prioritize purity roadmaps and certification strategies to win in segmented end-markets.
Shikimic Acid (CAS 138-59-0) Market -
Regulatory and reputational risk mitigation: Recent regulatory headwinds and raw-material supply disruptions mean that compliance, traceability, and supplier auditing are not back-office items but core strategic filters for partnership decisions in 2026.
Market dynamics: growth underpinned by structural and episodic forces
The long-term growth trend is clear: a steady multi-year expansion illustrated by the market’s historical climb from the low- to mid-30s (USD Million) in 2020 to mid-40s by 2025, and a forecast path to the low 60s by the end of the 2032 horizon. That steady base growth, reflected in the 4.6% CAGR, co-exists with sudden supply-side episodes that materially affect short-term pricing and availability.
Two dynamics deserve special attention for strategic planning in 2026. First, the raw-material supply chain is prone to seasonality and acute shortages; industry data recorded a 17% uptick in raw shikimate biomass pricing during supply-constrained periods, and external reporting documented an extreme price spike—multiples within a single month—during a demand surge in 2026. Second, regulatory friction arising from species identification (notably the confusion risk between Illicium verum and the toxic Illicium anisatum) is prompting more stringent export controls and lab testing requirements in major buying jurisdictions. Combined, these forces elevate the value of traceable sourcing, certified supply channels, and flexible manufacturing.
Competitive landscape: profiles and strategic implications
The competitive field combines large, diversified chemical suppliers and specialized extractors and fermentative producers. A selective reading of key players exposes distinct strategic postures that buyers and potential investors must consider.
-
Sigma-Aldrich (St. Louis, USA) — A legacy supplier offering multiple grades (analytical standards, synthetic intermediates, ≥99% purity). Their breadth and reputation make them a preferred partner for research and regulated industrial use. Strategic implication: premium positioning and reliability; potential price premium but reduced sourcing risk for critical applications.
-
Cayman Chemical (Ann Arbor, USA) — Focused on biochemical grades (≥95% purity) for pharma and research. Their niche specialization indicates strong customer intimacy in R&D channels; strategic partnerships here can accelerate product validation cycles.
-
Carl Roth (Karlsruhe, Germany) — Laboratory- and analytical-focused supplier offering ≥98% grades. Their European footprint and compliance orientation are advantageous for clients prioritizing regional regulatory alignment and fast catalog access.
-
Sichuan Xieli Pharmaceutical (Pengzhou, Sichuan, China) — A producer combining plant extraction with a new microbial fermentation route; recent pilot fermentation runs achieved ~12.4 g/L production rates. Strategic implication: if scaled, this capability could lower unit costs and reduce reliance on botanical harvest cycles—creating a different competitive tier.
-
JIAHERB, Inc. (Pine Brook, USA; China-based manufacturing) — Positions as an NSF-GMP-registered herbal extract supplier with star anise-derived shikimic acid for nutraceutical and cosmetic uses. Their certification focus is a differentiator for buyers requiring documented GMP pathways.
-
Shanghai Pharmaceuticals Holding (Shanghai, China) — Expanded into cosmetic-grade shikimic acid and has reported supply to dozens of personal-care brands. Strategic implication: a vertically integrated path into consumer applications, potentially compressing margins for third-party ingredient suppliers.
-
Guangxi Wanshan Spice (Guangxi, China) — Specialist extractor of high-purity shikimic acid from star anise. Their upstream control of botanical feedstock remains a critical asset when botanical supply is the constraint.
The market therefore presents a bifurcated topology: on one axis, branded chemical distributors and lab suppliers dominate trust and certification; on the other, upstream extractors and emerging microbial fermentation players are contesting raw-cost and capacity. The winners in 2026 will be those that bridge these axes through offtake agreements, co-investment in scaling fermentation, or M&A that combines certification with upstream feedstock control.
What the full report delivers (practical toolkit)
Our full study translates this strategic context into operational tools for executives and functional leaders. Highlights include:
-
Forward-looking demand-supply model (2026–2032) with scenario toggles for fast/slow recovery, high-volatility, and fermentation adoption curves.
-
Price-sensitivity and margin-impact simulations that show how raw-material shocks and regulatory testing costs propagate through the value chain.
-
Supplier scorecards and diligence checklists covering capacity, certification, feedstock security, and technology roadmap (including pilot fermentation metrics and extractive yields).
-
Commercial playbooks: premiumization strategies for cosmetic-grade offerings, supply contracts templates for long-term offtake versus spot buying, and channel strategies for laboratory versus industrial buyers.
-
Regulatory heatmap and traceability matrix tailored to North American and European import controls, including mitigants for botanical species misidentification risks.
-
Transaction screening list for M&A and strategic partnerships — identifying capability gaps (e.g., fermentation scale-up expertise) that create the fastest path to cost leadership.
Note: this preview intentionally omits the granular regional and application split tables and the detailed segmented revenue figures. Those sub-segment quantities are core proprietary outputs of the full PW Consulting report and are available through the source link for clients seeking operational-level intelligence.
Recommended strategic moves for 2026
-
Dual-source with differentiated contracts: Combine long-term offtake for a portion of annual volume with a flexible spot allocation to capture upside during price dips. Include audit and traceability clauses addressing species verification to mitigate regulatory disruption.
-
Invest selectively in fermentation capabilities: Target partnerships or minority investments in fermentation players demonstrating pilot yields ≥10 g/L; even minority equity can secure preferential pricing and off-take without full-capex exposure.
-
Prioritize certification and shelf-ready formulations: For companies targeting personal care and nutraceutical segments, cosmetic-grade and NSF-GMP credentials unlock faster market access and higher realized prices.
-
Embed scenario planning into procurement cycles: Build internal dashboards that combine spot market indicators, raw biomass availability, and regulatory alerts so procurement can convert early signals into tactical hedges.
-
Pursue bolt-on acquisitions for supply security: Targets should be prioritized based on feedstock control (star anise upstream position), fermentation intellectual property, or complementary certification assets.
Final thought: using this preview
This analysis is designed as a strategic trailer: it presents the macro trends, competitive dynamics, and actionable implications that will shape decisive moves in 2026, while reserving the full, transaction-grade segmentation and supplier-level financials for the comprehensive report. For procurement heads, R&D leaders, private equity sponsors, and M&A teams, the next step is to convert this high-level orientation into targeted diligence: on-the-ground supplier audits, fermentation scale feasibility, and regulatory-compliance testing. PW Consulting’s full Shikimic Acid market study provides those operative datasets and scenario tools to convert strategic intent into measurable outcomes.
Contact PW Consulting to access the complete dataset, supplier scorecards, and bespoke scenario modeling templates that support executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Shikimic Acid (CAS 138-59-0) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ion Exchange Resins Market to Reach USD 311.27M by 2032 at 5.4% CAGR
By PW Consulting, 2026-07-30
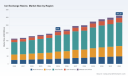
Ion Exchange Resins Market — Strategic Outlook for 2026: A PW Consulting Preview
As companies calibrate capital allocation, supply-chain risk mitigation, and product roadmaps for 2026, the ion exchange resins sector presents a distinct mix of steady growth, regulatory-driven demand, and pockets of technology-led disruption. PW Consulting’s latest market study offers decision-makers a practical compass: anchored in robust macro sizing and trend analysis, and oriented toward the tactical choices that will define winner/loser positions through the next strategic cycle.
Ion Exchange Resins Market
Why this research matters for 2026 decisions
-
Clarifies the near-term opportunity envelope: The ion exchange resins market, measured at an estimated USD 215.0 Million in the 2025 base year, is forecast to expand at a compound annual growth rate of 5.4% through the 2026–2032 horizon, reaching roughly USD 311.3 Million by 2032. That trajectory is neither hyper-growth nor stagnation — it is the kind of predictable expansion that rewards strategic focus, operational scale, and technology differentiation.
Ion Exchange Resins Market -
Converts regulation into revenue strategy: Accelerating regulatory pressure around potable-effluent standards and PFAS limits is creating near-term retrofit demand across municipal and industrial water systems. Firms that map compliance timelines against their sales and manufacturing plans will capture disproportionate share of replacement and retrofit spending.
Ion Exchange Resins Market -
Informs capital and capacity decisions: With select incumbents announcing capacity expansions and supply-side cost adjustments, the timing and scale of greenfield investments, surcharge pass-throughs, and inventory policies will be critical inputs to 2026 P&L and balance-sheet planning.
What the report delivers — practical modules for decision-makers
-
Macro sizing and validated forecasts: historical trend reconstruction (2020–2025) and consensus-aligned forecasts through 2032, with scenario variants that model regulatory shocks, tariff regimes, and large-capacity project ramps.
-
Demand-driver diagnostic: an anatomy of end-use needs (water purification, power generation, biopharma, specialty separations, and others), highlighting where premium technical features (e.g., PFAS affinity, ultrapure conductivity control, specialty agarose chemistries) command pricing and long-term contracts.
-
Supply-side heat map: manufacturing footprints, latent capacity, input-cost exposure, and supplier concentration metrics (CR3 and CR5). These metrics help quantify bargaining power and vulnerability to supply shocks.
-
Regulatory and trade overlay: mapped compliance deadlines, safety standards for food- and pharma-contact resins, and tariff impacts that materially affect cross-border sourcing economics.
-
Competitive playbooks: company profiles, capability matrices, recent strategic moves, and a tactical scorecard that identifies where to partner, where to compete, and where to differentiate via application-specific formulations or services.
-
Commercial execution templates: go-to-market recommendations by buyer type (municipal procurement, industrial OEMs, engineering firms, and OEM aftermarket), pricing frameworks for surcharges, and sample contractual clauses to mitigate raw-material inflation and regulatory liability.
-
Investment appraisal tools: discounted cash-flow templates, scenario stress-tests for capacity expansions, and sensitivity analyses keyed to regulatory timelines and OPEX/CapEx levers.
Market dynamics executives must internalize in 2026
-
Regulation is a demand multiplier. Tighter potable and effluent water standards, alongside binding PFAS MCLs in several jurisdictions, are converting latent need into capital projects and replacement cycles. Procurement teams should anticipate accelerated tendering and longer evaluation phases for new chemistries certified for regulatory compliance.
-
Tariffs and trade actions matter for sourcing strategy. Recent trade measures have materially changed landed-cost calculations for multiple manufacturers — a factor that favors diversified sourcing, nearshoring where economically justifiable, and renegotiation of long‑term supply agreements.
-
Productization of services. Buyers increasingly prize integrated offers — resin plus service agreements (monitoring, regeneration, replacement) — particularly for critical uses like semiconductor ultrapure water and power plant boiler feedwater. Vendors that can sell outcomes rather than kilograms of resin will capture higher lifetime value.
-
Consolidation at the top but fragmentation in niches. The market exhibits moderate concentration at the top, with the largest suppliers controlling a meaningful portion of global supply. At the same time, specialized niches (high-purity chromatography media, PFAS-selective adsorbents, and resource-recovery resins) remain accessible to innovative challengers.
Competitive landscape: strategic implications from company behavior
Our analysis synthesizes public disclosures and market behavior of incumbent and emerging suppliers to draw operational implications.
-
Large integrated chemical players (examples include manufacturers that provide legacy resin brands and broad water-treatment portfolios) are using scale to push into regulated and industrial segments where long-term service contracts and aftermarket parts support higher margin capture. Their recent moves — capacity investments and strategic partnerships in filtration ecosystems — signal a focus on secure supply and upstream-to-aftermarket integration.
-
Specialist resin companies and regional producers are doubling down on technical differentiation and application-specific formulations. They compete less on price and more on performance validation, localized service, and faster lead times, which is particularly valuable for municipal projects and industrial retrofit schedules.
-
Cross-sector entrants and materials companies are targeting adjacent opportunities: chromatography media for biopharma, resins for green hydrogen purification, and engineered adsorption resins for micropollutant removal. These entrants increase innovation velocity and shorten commercialization cycles for novel chemistries.
-
Recent corporate-level actions provide concrete signals: surcharge announcements, trade-show positioning focused on micropollutants, product launches in chromatographic media for oligonucleotide purification, and announced capacity expansions. Each move represents a playbook for either value-capture (price/volume leverage) or capability expansion (new chemistries and higher-purity grades).
Actionable 90–180 day priorities for executive teams
-
Revise procurement contracts to include inflation and tariff pass-through mechanisms; build optionality into sourcing (secondary suppliers, regional inventory buffers) to blunt supply disruptions.
-
Segment customers by regulatory urgency. Prioritize pipeline development and technical sales resources toward accounts facing imminent compliance deadlines — these buyers compress sales cycles and accept premium pricing for certified solutions.
-
Invest selectively in demonstrable differentiation: allocate R&D and pilot budgets toward chemistries that address PFAS, ultrapure semiconductor water, and biotech separations. Use third-party validation and pilot-case economics to accelerate adoption.
-
Design outcome contracts for high-value use cases. Move beyond unit pricing to subscriptions, service-level guarantees, and performance-based pricing tied to water quality metrics and system uptime.
-
Run an enterprise-level scenario drill. Model the financial and operational impact of three contingencies: aggressive regulatory enforcement, an extended tariff environment, and a competitor-driven price war. Convert the drill outputs into a prioritized investment and contingency roadmap.
Where the research intentionally withholds — and why
To preserve the value of the complete study for clients and subscribers, this preview demonstrates analytical depth while deliberately withholding granular segment-level revenue splits and per-region/application monetary figures. The full report contains those high-resolution data layers, interactive scenario models, and downloadable valuation templates that enable transaction-grade decision-making. PW Consulting’s approach is to provide enough insight to inform immediate strategic prioritization while inviting stakeholders to access the full dataset and tools to execute optimally.
How PW Consulting’s deliverables convert insight into execution
-
Interactive dashboards: customizable filters for scenario testing (regulatory speed, tariff shocks, capacity additions) and downloadable outputs for board-level presentations.
-
Supplier risk scoring: a pragmatic rubric that translates supply‑chain exposure, margin impact, and customer-criticality into an actionable risk heat map.
-
Commercial playbooks and RFP templates: ready-to-use contract language and procurement playbooks that incorporate surcharge clauses, lead-time SLAs, and technical acceptance criteria.
-
Investment memos and acquisition screening: deal-level worksheets for screening strategic buy-side targets in specialty resins and adsorption niches, with acquisition premium sensitivity and integration checklists.
Final strategic lens for 2026
For executives deciding how to allocate capital, prioritize markets, or defend margins in 2026, the choice is not binary. The market’s steady growth and regulatory tailwinds favor both scale players and focused innovators. The winners will be those who pair operational resilience (diversified sourcing, contractual protections) with technical differentiation (certified chemistries, outcome-based services) and the commercial agility to capture accelerated retrofit and compliance-driven demand.
PW Consulting’s full Ion Exchange Resins Market study provides the granular inputs, scenario models, and practical templates that executives need to turn these strategic imperatives into executable 2026 plans. For teams preparing budgets, negotiating supplier commitments, or evaluating M&A opportunities, the report is designed to reduce execution risk and accelerate value capture.
For detailed analysis of this topic, please visit the official page: Ion Exchange Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Winches Market to Grow at 4.9% CAGR (2026–2032)
By PW Consulting, 2026-07-30
Electric Winches Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
The electric winches market has moved from a niche industrial accessory to a strategic component across mobility, energy, marine, and heavy industry ecosystems. Our base-year analysis (2025) shows a clear expansion from the start of the decade, with total industry revenues growing materially between 2020 and 2025 and a forecast trajectory that takes the market well into the early 2030s. PW Consulting’s modeling projects a compound annual growth rate (CAGR) of 4.9% across the 2026–2032 forecast window, with the market approaching the USD 1.24 billion (Million, USD) range by 2032. For decision-makers planning 2026 investments, this report translates macro momentum into focused, executable options — from product architecture to supply-chain hedging, from aftermarket services to M&A prioritization.
Electric Winches Market
Why this matters for 2026 strategy
- Timing matters: Firms that align 2026 product roadmaps and procurement cycles with the forecast inflection points can avoid retrofit costs and capture first-mover premium in verticals that are set to accelerate spending.
- Regulation is already reshaping demand: New mandates — notably legislative moves that require electric winches on certain offshore projects and strengthened industrial safety standards — create non-discretionary demand pockets and raise minimum feature requirements.
- Input-cost volatility is non-trivial: Steel-market swings and tariff dynamics are creating margin pressure and supply-readiness differentials that will determine who can price competitively while investing in higher-spec safety and control features.
- Fragmentation creates options: Low-to-moderate market concentration leaves whitespace for focused product plays, regional specialists, and aftermarket service models that can scale quickly without contending with entrenched incumbents across every segment.
Market dynamics that will drive boardroom choices in 2026
Four converging forces should govern capital allocation and commercial strategy next year:
Electric Winches Market
- Regulatory push and standards harmonization: The EU’s 2025 regulation requiring electric winches on new offshore wind projects (effective in project procurement cycles beginning 2027) is the clearest near-term policy signal. Simultaneously, international safety standards (e.g., DIN EN 14492-1) increasingly mandate features such as load limiters and emergency stops, raising baseline engineering and testing requirements for industrial suppliers.
- Raw-material and tariff shocks: Steel-price volatility has re-opened the cost ledger for winch makers. Recent data show year-over-year steel appreciation and hot-rolled coil prices materially above historical averages in 2026 amid tightened tariff regimes — a dynamic that heightens the importance of input hedging, cost pass-through capability, and substitution/weight-optimization in product design.
- Electrification and system integration: OEMs and aftermarket suppliers are converging on higher-voltage platforms (including the emergence of 48V variants targeted at ATVs, light commercial, and industrial applications), integration with battery-management systems, and modular control electronics as differentiators.
- Service and lifecycle monetization: As winches embed into critical assets (construction cranes, marine slipways, recovery vehicles, wind farms), buyers shift preference toward suppliers who can demonstrate lifecycle reliability, fast spare-part fulfilment, and connected diagnostics — expanding opportunities for recurring revenue beyond discrete hardware sales.
What PW Consulting’s Electric Winches Market report delivers
We designed the report to be immediately actionable for commercial, product, and corporate finance teams. Highlights include:
Electric Winches Market
- Top-down market sizing and bottom-up model reconciliation for 2020–2025 (historical) and 2026–2032 (forecast), including scenario sensitivity to steel costs and regulatory adoption.
- Competitive benchmarking across product, pricing, channel, and service capabilities — with supplier scorecards that inform procurement and selection criteria.
- Go-to-market playbooks for three priority use cases (mobile recovery, industrial lifting, and marine/mining), including channel economics and recommended distributor partnerships.
- Cost-to-serve maps and a build-versus-buy decision matrix for critical subassemblies (motors, drums, braking systems, control electronics), plus a supplier-risk heatmap tied to lead time and concentration risk.
- Regulatory impact analysis modeling (e.g., EU offshore wind mandates and relevant safety standards) with compliance timelines and estimated investment requirements to meet certification for major markets.
- Commercial negotiating levers, price elasticity analysis, and an aftermarket service-play revenue model for 1–5 year horizons.
- Strategic M&A and partnership screening: target-critical capabilities, valuation multipliers observed in the sector, and integration risks we regularly encounter in diligence.
Competitive landscape — distilled intelligence on core players
The market is characterised by a blend of specialist manufacturers and diversified motion-control groups. Concentration metrics indicate a market that is not dominated by a single ecosystem — enabling tactical plays for agile entrants and strategic moves by established players. PW Consulting’s fieldwork and primary interviews surface distinct strategic postures among the leading names:
- Warn Industries (Clackamas, OR): Deep brand recognition in the towing and recovery space and a reputation for severe-duty designs. Their strength is channel penetration with aftermarket partners and strong OEM relationships in off-road and recovery markets.
- Mile Marker Industries (Pompano Beach, FL): Premium positioning and a history of approvals for demanding applications (including military-spec lines) give Mile Marker leverage in contracts that value reliability and certification over unit price.
- Columbus McKinnon Corporation (Charlotte, NC): Diversified industrial motion portfolio, leveraging Duff‑Norton and Pfaff‑Silberblau product lines for larger-scale lifting and motion-control integration — an advantage for customers seeking system-level suppliers.
- Carl Stahl Hebetechnik GmbH (Süßen, Germany): European engineering pedigree and expertise in wire-rope winch systems for construction and crane applications — a key contender for projects requiring strict adherence to continental standards.
- COMEUP INDUSTRIES INC. (China): Rapid product development cycles and cost-competitive manufacturing; notable for introducing 48V winch models in mid‑2025 that respond to light-vehicle electrification and ATV market demand.
- Dutton‑Lainson Company (Hastings, NE): Niche strength in portable and enclosed-cable designs, emphasizing safety upgrades in recent product iterations.
- Warrior Winches (Worcestershire, UK): Focus on heavy‑duty commercial and warehouse winches, with active trade-show presence to capture regional towing and recovery demand.
- Thern Inc. (USA): Known for heavy-duty industrial power winches for pulling and tensioning — competes on engineered solutions and customization.
- CP Winch Group / CP Machinery (Taiwan): Strong offering for marine, mining and slipway applications, with recent catalogue updates targeting those end-markets.
Recent company movements reinforce the themes above: product launches for higher-voltage/vehicle-tuned winches, catalogue refreshes aimed at marine and industrial buyers, and safety-driven product updates. These are not isolated product cycles but part of a broader shift toward electrified, connected, and standards-compliant solutions.
Practical playbook: four tactical priorities for 2026
- Lock in raw-material strategies: Adopt multi-sourcing for key steel components, pursue hedging where possible, and evaluate light-weighting or alternate materials for non-critical housings to protect margin against commodity swings.
- Certify early for regulatory tailwinds: If you serve energy and offshore sectors, accelerate compliance programs to capture mandated procurement windows tied to new regulations; early certification is a barrier to entry for late movers.
- Invest selectively in electrified platforms: Prioritize modular architectures that allow voltage-variant SKUs (e.g., 12V/24V/48V) without retooling whole lines. This reduces unit-cost risk while addressing diverse OEM requirements.
- Monetize lifecycle services: Design service contracts with predictive maintenance, rapid spare-part logistics, and remote diagnostics; even small attach rates materially improve installed-base economics.
How PW Consulting’s approach reduces execution risk
Our analysis synthesizes primary interviews, factory visits, proprietary cost build-ups, and scenario-driven demand models. We deliberately present high-level conclusions here to validate the strategic narrative and to protect the actionable granular datasets that drive procurement decisions, negotiation playbooks, and M&A diligence. For teams preparing 2026 capex, sourcing strategies, or product investments, the full report contains downloadable financial models, supplier-risk matrices, and interactive scenario tools that convert insight into measurable actions.
Next steps
For procurement leaders, product heads, corporate development teams, and private-equity sponsors, the question is no longer whether the market will grow — it is how to capture disproportionate value from that growth. PW Consulting’s Electric Winches Market report is structured to answer the “how” with operational-level recommendations, financial levers, and prioritized execution roadmaps. Contact the PW Consulting market team or visit our Electric Winches Market page to access the full dataset, model workbooks, and the practitioner’s playbook needed to make confident 2026 decisions.
For detailed analysis of this topic, please visit the official page: Electric Winches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mozzarella Cheese Market: Strategic Outlook for 2026 Decision-Making
Executive snapshot
As companies prepare capital plans and commercial strategies for 2026, the Mozzarella Cheese market sits at a clear inflection point. Our PW Consulting Mozzarella Market Study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes production, demand and competitive signals into an actionable decision framework. The global market, measured in USD (Million), reached approximately 215.0 in 2025 and is projected to expand at a compound annual growth rate (CAGR) of about 4.31% through the 2026–2032 forecast horizon, approaching an overall market size in excess of 340 by 2032 under the base scenario.
Mozzarella Cheese Market
Why this study matters for 2026 corporate decisions
- Timing of capacity investments: Several large-scale plant projects are transitioning from commissioning to ramp-up in 2026 — meaning new supply will enter the market precisely when many buyers are re-evaluating sourcing strategies. Corporates must decide whether to secure off-take from new facilities, invest in their own capacity, or take advantage of improved supplier economics.
- Channel and product segmentation choices: Demand drivers differ materially between industrial B2B processors, foodservice (HoReCa), and retail/household channels. Companies that align product specification (moisture, format, IQF vs. block, private-label) with channel economics will capture margin expansion.
- Risk-adjusted pricing and procurement: The projected mid-single-digit CAGR suggests steady growth rather than a boom. That environment rewards buyers and suppliers that deploy dynamic pricing strategies, hedged procurement, and volume-flex contracts tied to transparent cost indices.
- M&A and partnership windows: Fragmentation persists across geographies and formats, so 2026 represents an opportunistic period for bolt-on acquisitions and strategic partnerships — especially where scale unlocks distribution to foodservice or industrial processors.
Market dynamics and near-term catalysts
Two forces are shaping the immediate 2026 landscape: supply-side capacity inflection and demand-side product mix evolution. On the supply side, new and expanded facilities are moving into production, with several players reporting trials and staged ramp-ups. These investments are not simply volume-additive — they reflect process modernization (automation, IQF capabilities, standardized block/shred formats) that compresses unit labor costs and tightens quality consistency. On the demand side, growth continues to be anchored by the pizza and foodservice ecosystem, while retail and institutional programs (including authorized inclusion in certain school meal programs) provide stable, recurring volume.
Mozzarella Cheese Market
Operationally, recent industry data show a step-up in aggregate U.S. cheese production and a notably stronger response from mozzarella output in late 2025. Concurrently, the regulatory backdrop is relatively calm for mozzarella specifically — although broader shredded cheese recalls in late 2025 underscore the reputational and supply-chain risks associated with contamination events and traceability gaps.
Mozzarella Cheese Market
Competitive landscape — positioning and strategic moves
The market juxtaposes global-scale integrators with regional specialists. Players differ by specialization (industrial pizza cheese, IQF/snack formats, private-label conversion, artisan/independent pizzeria focus) and by their route-to-market capabilities. The most consequential recent developments for 2026 strategy include:
- Large-scale processors increasing throughput: One leading global producer is bringing a large new facility to capacity in 2026, designed to process multiple millions of pounds of milk daily and optimized for high-volume block and pizza cheese production. This move materially alters supplier capacity maps and domestic sourcing dynamics.
- Regional expansions targeted at foodservice and retail: Several established processors have completed or opened new processing sites through 2025–2026 to expand distribution reach, reduce logistics costs and accelerate private-label programs.
- Specialist players doubling down on format differentiation: Some mid-sized firms are leveraging IQF, string-cheese, and snack-format capabilities to win share in convenience-led channels and to differentiate from commodity-style pizza cheese offerings.
For executives evaluating partnerships, the choice is between the operational leverage and pricing power of large manufacturers and the niche product agility of regional converters. Both archetypes present distinct options for buyers: secure scale and consistency, or access to differentiated SKUs and closer commercial service.
Strategic priorities for 2026 — recommendations
Based on our integrated market model and scenario stress tests, PW Consulting recommends that leaders prioritize the following actions this year:
- Lock in medium-term volumes from preferred suppliers: Where new capacity is coming online, negotiate staged off-takes with performance SLAs tied to ramp metrics to capture favorable pricing before markets re-equilibrate.
- Invest selectively in product format R&D: Margins often favor formats that reduce waste in downstream kitchens (e.g., portion-controlled IQF or pre-shredded solutions tailored to foodservice). Small development investments can materially increase channel share.
- Develop an operations continuity playbook: Strengthen traceability, QA sampling frequency and rapid-recall protocols. The late-2025 shredded cheese events highlight the asymmetric damage from supply-chain disruptions.
- Adopt a blended sourcing strategy: Combine primary contracts with strategic spot windows to exploit short-term dips in commodity spreads and to maintain negotiation leverage as capacity ramps.
- Evaluate consolidation opportunities: Use M&A to fill format gaps (IQF, snack formats) or to add cold-chain distribution nodes that shorten lead-times into foodservice clusters.
What our competitive analysis reveals
We reviewed the strategic positioning of the sector’s leading participants and mapped capability sets to buyer use-cases. Highlights include:
- Scale integrators: The largest producers leverage high-throughput platforms and significant product breadth (pizza cheese, shredded, IQF, block formats) to serve national pizza chains, large foodservice operators and industrial users. Their investments in mechanization reduce labor intensity and raise consistency — a critical advantage for customers with strict specification needs.
- Premium and specialty suppliers: Competitors focusing on premium low-moisture, authentic Italian-style, smoked and retail-focused SKUs compete on product differentiation and brand equity, often serving independent pizzerias and foodservice operators that prioritize texture and melt characteristics.
- Converters and private-label providers: These firms sit close to retail and CPG customers, providing flexible co-packing, private-label execution and localized distribution. Their value proposition is speed-to-shelf and category management support.
- Regional multi-format players: Companies producing IQF sticks, string cheese and snack formats are exploiting the high-growth convenience category while maintaining industrial supply contracts — a diversification that cushions volatile pizza demand cycles.
Recent publicly reported developments — including facility expansions, new plant ramp-ups and industry summits attended by sector leaders — validate the directional thesis of increased capacity, technology-driven efficiency gains and persistent channel diversification. We profile the strategic implications of each of these moves in the full report.
What’s contained in the full PW Consulting report (practical, executable content)
The study contains operationally focused deliverables designed for strategy, procurement and operations teams. Key inclusions are:
- Proprietary market-sizing model (historical 2020–2025; forecast 2026–2032) with scenario toggles for demand shocks, commodity cost shocks, and accelerated capacity entry.
- Channel- and format-specific demand drivers and margin benchmarks, with playbooks for foodservice, industrial processors and retail/private-label strategies.
- Supplier scorecards and a prioritized list of M&A targets and JV candidates based on capability fit and integration complexity.
- CapEx prioritization tool and a unit-cost curve that helps identify where scale economics meaningfully improve EBITDA margins.
- Regulatory and recall readiness checklist, including recommended sampling cadences, traceability investments, and PR playbook templates.
- Commercial negotiation templates: sample off-take agreements, price-index clauses and contingency clauses for supply disruptions.
- Executive dashboards and slide-ready visuals that summarize key assumptions, risk matrices and go-to-market options for board-level decision-making.
Note: This article intentionally omits granular regional and application breakdowns, as well as the detailed segmentation tables. Those core subsegment datasets and the underlying Excel model are available exclusively in the full report and on our secure client portal.
Scenarios you should stress-test in 2026
- High-capacity ramp scenario: New plants achieve faster-than-expected throughput — downward pressure on commodity prices and a winner-take-most dynamic emerges in key industrial channels.
- Demand shift to convenience formats: Rapid household and retail preference for IQF/snack formats accelerates, penalizing commodity block/shred producers that lack format agility.
- Traceability shock: A contamination event in a major production cluster triggers temporary export restrictions and heightens buyer requirements for provenance data.
Each scenario carries distinct implications for inventory strategy, pricing architecture, capex timing and M&A posture. Our report models these outcomes and quantifies P&L and balance-sheet sensitivities under different strategic responses.
How PW Consulting can support your 2026 agenda
We combine sector expertise with commercial pragmatism: bespoke supplier due diligence, integration planning for acquisitions, negotiation support for long-term supply agreements, and implementation of digital traceability solutions tailored to dairy operations. If you are prioritizing capital deployment, channel expansion, or supply-chain resiliency for 2026, our team can deliver the market intelligence and transaction-ready workstreams required to move from insight to execution.
Next steps
To access the full dataset, scenario models, and the supplier scorecards referenced here, please consult the PW Consulting Mozzarella Cheese Market Study. The full report contains the granular regional and application breakdowns, SKU-level pricing trends and the downloadable Excel model that informed the projections summarized above.
For detailed analysis of this topic, please visit the official page: Mozzarella Cheese Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solar Back Sheet Market to Reach USD 3.43B by 2032 at 7.35% CAGR
By PW Consulting, 2026-07-30
Solar Back Sheet Market 2026: Strategic Compass for Decision-Makers
Executive preview
The Solar Back Sheet market is entering a strategic inflection point as the industry migrates from cost-driven commoditization toward differentiated performance, sustainability credentials, and trade-aware supply chains. Our PW Consulting market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) quantifies this transition: after a turbulent first half of the decade the market stabilizes and resumes growth, with a modeled compound annual growth rate (CAGR) of 7.35% across the 2026–2032 forecast window and a projected total market size rising from roughly USD 2.21 Billion in 2025 to around USD 3.43 Billion by 2032. These headline numbers set the frame for corporate planning in 2026—yet the strategic value of our work lies less in a single topline and more in the operational road map it delivers for procurement, product, and M&A teams.
Solar Back Sheet Market
Why this study matters for 2026 decisions
-
Timing: 2026 is a turning year. Regulatory updates, certification shifts, and trade enforcement actions have already changed module sourcing economics; companies that defer supply-chain restructuring will face higher rework and compliance costs.
Solar Back Sheet Market -
Profit leverage lies in the periphery: backsheets are not the largest line item on a PV module BOM, but they are a critical enabler of module lifetime, warranty performance, and new module formats (bifacial, transparent, high-voltage). Small changes in material selection or supplier qualification can materially affect total lifecycle economics.
Solar Back Sheet Market -
Strategic optionality: our scenario analyses show that choices made in 2026 on supplier diversification, material chemistry, and regional manufacturing footprints determine exposure to trade duties and certification backlogs through the remainder of the decade.
Market trajectory and what it implies
The market’s path from 2020 to 2025 reflects cyclical demand, capacity build-out in low-cost geographies, and the initial commoditization of standard PET-based products. Post-2025, we forecast a clear recovery and steady growth driven by three forces: accelerating module installations in key markets, adoption of higher-value backsheet formats for bifacial and advanced cell technologies, and selective premiumization where reliability and certification matter most.
For corporate planners this means recalibrating investments from volume-only plays toward segmented value plays—targeting applications and geographies where premium features or regulatory compliance command price differentiation and lower warranty risk.
Regulatory and trade dynamics—real operational risk
Compliance regimes and trade measures are no longer peripheral. Recent updates to international certification standards—such as the new IEC requirements—and active enforcement of anti-dumping/circumvention measures have created a two-track supply environment: suppliers who can demonstrate certified product lines and transparent origin/tracking enjoy preferential access to high-value tenders; others face cascading costs and lost access. The practical implication for 2026 procurement is straightforward: prioritize suppliers with demonstrable certification pipelines and on-the-ground capacity that match your market-entry timing.
Material and product trends
-
Material differentiation is front and center. Fluoropolymer-based and multi-layer laminates retain a strong niche where durability, UV resistance, and warranty extension are mission-critical. At the same time, fluorine-free alternatives and recycled-content offerings are gaining traction as buyers internalize Scope 3 and end-of-life considerations alongside procurement KPIs.
-
Form-factor innovation—transparent backsheets for bifacial modules, patterned and colored finishes for architectural integration—creates new specification layers that procurement and product teams must master. These formats carry higher unit prices but unlock premium module pricing and new market segments.
Competitive landscape—who to watch and why
The Solar Back Sheet market shows moderate concentration. The top three firms account for a majority share of industry shipments, and the top five increase that share further—indicating meaningful advantages for established producers with scale and validated quality. Yet the market is not closed: targeted capacity expansions, product launches, and regional plays are reshaping supplier competitiveness.
-
Jolywood (Suzhou) Sunwatt Co., Ltd. – A vertically oriented PV materials player offering a broad backsheet portfolio and substantial annual volumetric capacity. Their strategy blends scale with product line breadth, and recent product launches targeted at stringent sustainability markets indicate an intent to defend premium segments while serving high-volume demand.
-
Krempel GmbH – A European specialist in fluoropolymer-based, multi-layer laminates. Krempel’s AKASOL® series and repair solutions position it as a supplier of choice where material performance and post-installation serviceability are prioritized.
-
Coveme S.p.A. – An Italian laminator with a clear sustainability angle (recycled-content products) and a large lamination capacity. Coveme’s approach signals the commercial viability of recycled and monolayer solutions when coupled with robust manufacturing discipline.
-
Dunmore Corporation – A U.S.-based supplier focused on high-performance TPT/TPE offerings, appealing to North American module manufacturers seeking certified, high-durability options.
-
Emerging and regional specialists – Companies such as Vikram Solar, Vishakha Renewables, Taiflex, Toyo Aluminium and Endurans Solar illustrate an important dynamic: national champions and niche innovators are pursuing product differentiation (e.g., patterned backsheets, PVDF/PVF chemistries, transparent formats) and localized supply to reduce trade exposure and certification friction.
Recent industry signals that matter to 2026 strategy
-
Product launches of transparent and fluorine-free backsheets highlight two parallel value pools: performance-driven premium modules and sustainability/ESG-driven procurement mandates.
-
Capacity expansions in Asia by legacy chemical and materials companies suggest continued pressure on standard PET/TPT suppliers, but also a tactical shift: producers are investing in specialized lines to serve export-focused module assemblers.
-
Trade enforcement and evolving certification requirements add near-term transaction costs and long-term sourcing implications—favoring suppliers with transparent compliance processes and geographically diversified production.
What our report delivers (practical content for 2026 action)
PW Consulting’s Solar Back Sheet Market study is structured to support operational decision-making, not just to inform. Highlights include:
-
A detailed, model-driven demand forecast (2026–2032), including scenario variants for aggressive bifacial adoption and accelerated decarbonization policies.
-
Supply-side mapping with plant-by-plant capacity overlays, vintage, and certification status—enabling procurement teams to shortlist suppliers based on timing, capacity, and regulatory fit.
-
Unit-cost and margin benchmarking across major chemistry families and product formats—designed to inform price negotiation and make-or-buy analyses.
-
Supplier profiles and capability assessments for the leading manufacturers, including technology differentiators, recent developments, and strategic risks.
-
Regulatory and trade risk heat maps tied to procurement levers—giving buyers a playbook to mitigate AD/CVD exposure and to prioritize certified product introductions.
-
Commercial templates: RFP checklists, qualification testing matrices, and long‑term sourcing templates tailored to module OEMs, EPCs, and independent module assemblers.
-
M&A and investment watchlist: technology adjacencies and consolidation opportunities, with valuation sensibilities and integration risk flags for 2026 transactions.
How to use the report in your 2026 planning cycle
-
Procurement: adopt a dual-track sourcing strategy—secure volume via established low-cost suppliers while qualifying regional certified partners for high-value tenders and warranty-covered projects.
-
Product & R&D: prioritize development of fluorine-free and transparent backsheet options where lifecycle and ESG metrics will be decision levers for buyers and financiers.
-
Regulatory & Legal: embed certification timelines and trade-compliance checks into supplier onboarding; treat auditability of origin and certification documents as minimum qualifying criteria.
-
Corporate Development: use our market concentration and capacity overlays to identify acquisition targets that provide immediate access to certification, differentiated products, or regional manufacturing footprints.
Closing—what this preview leaves intentionally unsaid
To preserve the practical utility of our work for paying subscribers and to encourage direct engagement, this preview does not publish the granular regional and application-level splits, unit-price matrices, or confidential supplier-by-supplier shipment tables that underpin our recommendations. Those details are the core of the exercise: they convert strategic direction into executable procurement contracts, technology road maps, and M&A playbooks.
For executive teams preparing 2026 budgets and road maps, the full PW Consulting Solar Back Sheet Market report provides the granular analytics, scenario models, and commercial toolkits to act decisively. If your 2026 plan includes supply‑chain reconfiguration, technology adoption, or inorganic growth in the PV value chain, this study is designed to be your operationally actionable guide.
For detailed analysis of this topic, please visit the official page: Solar Back Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Grow Lights Market to Reach USD 5,596M by 2032 (16.7% CAGR)
By PW Consulting, 2026-07-30
LED Grow Lights Market: Strategic Preview for 2026 Decisions
Executive summary
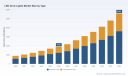
The LED grow lights market is transitioning from a high-growth, innovation-driven phase into a strategic consolidation window. After expanding from under USD 900 million in 2020 to roughly USD 1.91 billion in 2025, the sector is projected to sustain a compound annual growth rate (CAGR) of approximately 16.7% into the medium term, reaching well north of USD 5 billion by the early 2030s. That trajectory creates both runway and urgency: large addressable demand exists, but regulatory tightening, rising listed-product requirements, and buyer sophistication are shifting the battlefield from simple product differentiation to proven system-level value.
LED Grow Lights Market
Why this preview matters for 2026 corporate decisions
-
Timing of investments: The market’s annualized growth profile means that capex and commercial pilots initiated in 2026 will determine competitive positions for the subsequent five years. Delays compound as standards and purchaser expectations harden.
LED Grow Lights Market -
Risk shaping: Non-price risks—standards compliance, warranty engineering, supply-chain resilience, and channel credibility—now carry as much weight as efficiency metrics in procurement decisions.
LED Grow Lights Market -
M&A and partnership windows: As the industry consolidates, M&A and selective partnerships offer the fastest route to scale, distribution breadth, and standards-aligned portfolios.
Market trajectory and the macro drivers
The headline numbers are unambiguous: the market has more than doubled since 2020 and is on course for sustained, double-digit expansion. This growth is driven by the convergence of three forces: accelerating adoption of controlled-environment agriculture (CEA) across geographies, steady improvements in LED efficacy and fixture-level controls, and the rising economic case for electrified lighting solutions as labor and land cost pressures intensify.
Yet, beneath the top-line there is differentiation. Buyers are moving beyond raw efficacy figures toward lifecycle economics (total cost of ownership), validated crop outcomes, and integrated lighting controls. Procurement teams increasingly ask for traceable performance under standardized test protocols, on-site validation studies, and reassurance of long-term serviceability. Companies that can document end-to-end value—fixture, controls, data, and agronomy—are the ones winning specification-level placements.
Standards, listings, and a new compliance baseline
A pivotal dynamic for 2026 is the maturation of horticultural lighting standards. The DesignLights Consortium (DLC) has played a central role: its Horticultural Technical Requirements have just moved to V4.0, and the Horticultural Lighting Qualified Products List (QPL) has seen exponential growth—now comprising over a thousand listed products from well over a hundred manufacturers. This ecosystem impact is twofold:
-
Procurement gatekeeping: Being listed (and meeting V4.0 thresholds) is rapidly becoming a de facto entry requirement for institutional buyers, utilities, and rebate programs.
-
Performance transparency: The QPL’s expansion increases comparability and compresses buyer search costs—but it also intensifies competition on margin-differentiating services versus commodity LEDs.
For executives, the implication is clear: compliance is not optional. Firms that are not aligned with the new baseline risk being excluded from programs, incentives, and large-scale RFPs. For fast followers, obtaining listings aligned with V4.0—and communicating that achievement—is a pragmatic way to reduce commercial friction.
Competitive landscape: who matters and why
The market is moderately concentrated: the top three vendors account for a substantial portion of the market, and the top five increase that share meaningfully. That structure has created a two-tier dynamic—global incumbents and highly specialized challengers—each with distinct strategic advantages.
-
Valoya (Finland): Known for patent-protected full-spectrum fixtures and a strong presence in tissue culture and controlled chamber applications. Valoya’s R&D-led differentiation is aimed at growers who prioritize spectrum engineering and predictable crop outcomes.
-
Signify / Fluence (Netherlands): A high-profile player with award-winning fixtures and a broad portfolio across cannabis, greenhouse, and vertical farming. Signify’s scale and channel reach make it a frequent incumbent on large projects.
-
Philips GreenPower (Netherlands): Focused on horticulture-specific toplighting and supplemental fixtures, leveraging strong brand trust with greenhouse operators and integrators.
-
Illumitex (United States): A U.S.-centric competitor that targets cannabis and vertical farming, emphasizing fixture robustness and project-level services.
-
LumiGrow (United States): Positions itself on full-spectrum offerings for both commercial operators and high-end residential users, with an emphasis on control systems.
-
GE Current (Daintree) & P.L. Light Systems (United States): Both bring manufacturing or standards-listed fixture expertise with an appeal to buyers prioritizing domestic production and compliance with horticultural standards.
Collectively, these players illustrate two winning plays: scale + channel breadth (to capture large greenhouse and institutional projects), and deep agronomic differentiation (to command premium pricing in specialized applications). Niche specialists maintain attractive margins by coupling spectrum IP with agronomic services; larger players defend scale through distribution, rebates, and integrated building-lighting relationships.
Regulatory, incentive, and operational noise to watch
-
DLC adoption and rebates: Utility and government incentive programs are increasingly referencing DLC listings and efficacy thresholds. Manufacturers must align product roadmaps to these requirements to preserve incentive-driven demand.
-
Local incentive volatility: Rebate levels and program rules can change rapidly at state and municipal levels. Recent reductions in some residential incentives demonstrate fiscal tightening risk; firms should design go-to-market pathways that are not solely rebate-dependent.
-
Operational economics: LEDs are now a structural fixture in many commercial cannabis and controlled-environment operations. Studies indicate high adoption rates within certain regional operations; for suppliers, this underlines the importance of service contracts and retrofitting capabilities as replacement cycles accelerate.
Strategic implications and recommended actions for 2026
For executives preparing budgets and strategy cycles in 2026, the choices made this year around product certification, channel configuration, and portfolio architecture will be material. Below are pragmatic actions we recommend.
-
Certify early, build defensibility: Prioritize getting core SKUs onto the DLC QPL under V4.0 requirements. The process tightens bidding access and accelerates procurement approvals.
-
Productize outcomes, not components: Reframe offerings as “crop-lighting systems” that bundle spectrum-design, controls, analytics, and service-level guarantees. Commercial buyers increasingly value predictable yield uplift and reduced installation friction over marginal efficacy gains.
-
Channel architecture: For large players, double down on utility and integrator partnerships. For challengers, pursue vertical integrations with agtech partners and local contractors to accelerate adoption.
-
Supply chain resilience: Diversify key components and secure long-lead suppliers. Expect localized content and manufacturing to become a commercial lever for large-scale greenhouse projects.
-
M&A and partnerships: Target bolt-on acquisitions that add either agronomic IP (spectral recipes, trials data) or distribution reach (regional integrators, utility program managers).
-
Commercial pilots and evidence generation: Invest in tightly controlled, publishable trials across representative crops and geographies. Buyers increasingly cite third-party-validated performance as a procurement differentiator.
-
Scenario-based financial planning: Model three scenarios—baseline growth aligned with current trajectories, accelerated adoption tied to expanded rebates and large-scale vertical farms, and downside pressure from rebate contraction—and stress test cashflow and capex plans.
What PW Consulting’s full report delivers
This introductory note is a strategic preview. The full PW Consulting market study provides the operational intelligence necessary to convert these high-level implications into executable plans:
-
Detailed annualized market-sizing (historical 2020–2025 and forecast 2026–2032) with modeled demand drivers and sensitivity tables.
-
Competitive positioning maps and capability heatmaps for leading vendors (including product, channel, and agronomy-service capabilities), plus acquisition targets by strategic fit.
-
Regulatory and incentives playbook, mapping the DLC/QPL landscape and utility program trajectories, with practical timelines for achieving compliance under V4.0.
-
Commercial blueprints: go-to-market templates for selling into greenhouses, vertical farms, and specialized tissue-culture / growth-chamber applications—each with pricing levers, bundling suggestions, and service-contract archetypes.
-
Implementation roadmaps for product certification, pilot design and scaling, supply-chain hedging, and M&A diligence checklists.
Final perspective: positioning for durable advantage
The LED grow lights market presents a clear but nuanced growth opportunity. Rapid expansion under a 16.7% CAGR creates scale—but the path to durable returns requires more than shipping efficient diodes. In 2026, strategic winners will be the firms that convert product-level performance into verifiable crop outcomes, align with tightening standards, and construct channels that reduce buyer friction. Those that treat certification, data, and service as core capabilities—not add-ons—will transform growth into long-term value.
PW Consulting’s full study supplies the granular, actionable intelligence necessary to make those decisions with confidence. For practitioners looking to commit capital, plan M&A, or reshape product roadmaps in 2026, the detailed analyses and playbooks contained in the report are designed to accelerate decision quality and execution speed.
For detailed analysis of this topic, please visit the official page: LED Grow Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stevia Market to Reach USD 1,323 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-30
Stevia Market 2026: Strategic Implications for Leaders — A PW Consulting Preview
As companies position for growth in low- and zero-calorie sweeteners, the stevia market has moved from niche natural curiosity to a mainstream strategic frontier. PW Consulting’s latest Stevia Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies that transition and translates it into practical decision levers for 2026. The global stevia market grew from roughly USD 500 million in 2020 to about USD 750 million in 2025 and — at a compound annual growth rate (CAGR) of 8.5% — is forecast to exceed USD 1.3 billion by 2032. This trajectory is both opportunity and complexity: it rewards scale, formulation capability, and regulatory agility, while penalizing exposure to commodity-price swings and fragmented supply chains.
Stevia Market
Why this study matters to 2026 decision-makers
-
Strategic timing: 2026 is a hinge year. The market has demonstrated resilient end‑market demand (beverages, bakery, dairy, tabletop and others) and is entering a phase where premiumization, sugar-reduction programs, and clean-label product roadmaps accelerate purchasing decisions. Executives planning launches, capacity investments, or M&A in 2026 need forward-looking, risk‑weighted forecasts through 2032 to avoid stranded assets.
Stevia Market -
Risk calibration: Regulatory signals and high-purity innovations are reshaping product acceptability across geographies. Our study maps GRAS, EFSA and trade‑compliance vectors into scenario stress tests that quantify upside and downside for product portfolios and supply agreements.
Stevia Market -
Commercial playbooks: The category now demands capabilities beyond supply — taste modulation, formulation science, and co-manufacturing flexibility. The report turns macro growth into commercial tactics: which formulations to prioritize, how to structure off-take and tolling contracts, and where to price for margin recovery without sacrificing volume growth.
What the PW Consulting report delivers (practical, action-ready)
-
Market sizing and validated forecasts (2026–2032) built on proprietary demand models and a 2020–2025 historical baseline.
-
Regulatory risk matrix with scenario outcomes — including GRAS pathways, EFSA interpretations, import controls and their likely time-to-resolution for key markets.
-
Supply chain and cost map: supplier archetypes, raw‑material exposure, and a sensitivity model linking stevia raw material indices to finished‑good prices and margin erosion.
-
Commercial segmentation approach (by form, application and region) that prescribes go‑to‑market strategies for private label, co-manufacturers and ingredient innovators — note: granular regional/application splits are intentionally summarized in this preview to guide your next step to the full report.
-
Competitive playbooks and capability audits — what leaders have now and what gaps open up under three plausible demand/regulatory scenarios.
-
Investment and M&A frameworks: valuation anchors, due-diligence checklists for high-purity production, fermentation-based platforms, and vertically integrated leaf-to-sweetener operations.
-
Implementation toolkits: supplier contract templates, a product reformulation checklist, and a timeline for piloting taste trials and scaling manufacturing in 12–24 months consistent with our forecast window.
Market dynamics: what’s driving the 8.5% CAGR
-
End-market momentum. Sugar reduction initiatives across beverages, bakery, and dairy continue to push demand for intense natural sweeteners. Reformulation cycles in large consumer packaged goods (CPG) brands and new product introductions sustain a multi-year tailwind.
-
Product innovation. Two technical pathways dominate future differentiation: fermentation-derived steviol glycosides that promise cost and taste advantages, and high‑purity extracts from plant sourcing that emphasize traceability and “natural” claims. Both pathways are advancing rapidly but require different capex, regulatory and sourcing approaches.
-
Supply consolidation. Market concentration is meaningful: the top three players account for a substantial share of the market (CR3 ~45%), and the top five approach majority control (CR5 ~60%). That concentration affects negotiation dynamics, raw-material availability and barrier-to-entry economics for new entrants.
-
Regulatory complexity. The regulatory environment remains heterogenous and active. High‑purity steviol glycosides continue to be subject to GRAS/no‑objection pathways in some jurisdictions while EFSA has articulated permissive frameworks for specified additives under E 960. Separately, controls on crude leaf imports and certain unpurified extracts in key markets raise compliance and logistics issues for supply chains.
-
Raw-material volatility. Improvements in processing capacity have not eliminated price volatility. Buyers and procurement teams must plan for spikes and develop hedging or vertical‑integration strategies to protect margin.
Competitive landscape: how the leading players shape choices
The competitive profile in our study focuses on a mix of global agribusinesses, ingredient specialists, and vertically integrated producers. Each archetype implies distinct partnership or competitive decisions for buyer and investor clients.
-
Cargill, Incorporated (EverSweet®): Cargill’s fermentation-based platform and sustainability-focused sourcing program pair technological scalability with upstream control. The recent positive safety opinion from European authorities strengthens market access for fermentation-derived products and shifts some taste/price trade-offs in favor of biotech routes.
-
Ingredion Incorporated (PureCircle™): Positioning around clean-taste solutions and proprietary varietals, Ingredion is focused on formulation support for sugar reduction. For CPGs prioritizing sensory parity, collaborations with such ingredient specialists remain attractive.
-
GLG Life Tech Corporation : High‑purity extract production and complementary natural sweetener portfolios (e.g., monk fruit) create bundling opportunities for manufacturers seeking multi-sweetener reduction strategies.
-
SweeGen, Inc. (BESTEVIA®): Specialized high‑purity steviol glycosides with targeted taste profiles support rapid product development cycles for start-ups and private label players.
-
Archer-Daniels-Midland Company (ADM) (SweetRight®): The combination of global processing scale and formulation support helps food formulators accelerate time-to-market while mitigating supply risk.
-
Layn Natural Ingredients : Advances in highly soluble formulations (e.g., next‑generation Reb M variants) demonstrate how suppliers compete on technical functionality as much as on price.
-
Regional and vertical players (Stevia Corp., Sweet Green Fields, Sunwin): These firms emphasize seed-to-sweetener integration, traceability, and shorter lead times, which can be decisive for customers who prioritize origin, sustainability and supply security.
For buyers and investors, the practical implication is clear: partnership choice is a trade-off among scale, taste performance, regulatory coverage, and supply reliability. Our report overlays each supplier’s capabilities against eight practical decision criteria to produce prioritized sourcing and partnership roadmaps.
Regulatory and raw-material developments to watch in 2026
-
Regulatory approvals and opinions are moving elements in 2026: positive safety opinions for fermentation-derived products in major markets have accelerated some commercial launches, but residual restrictions on leaf and crude extracts in certain jurisdictions remain binding. Companies must maintain active regulatory engagement and contingency plans.
-
High‑purity variants continue to be evaluated under GRAS-type pathways in the U.S. and adjacent jurisdictions. Firms investing in novel glycoside purification should plan for staggered market access and integrate regulatory timelines into commercialization milestones.
-
Raw-material pricing remains an input risk. While processing capacity and breeding advances have moderated some pressure, procurement teams must build dual sourcing, longer contracts and price pass‑through mechanisms into commercial models to protect margins.
How PW Consulting converts insight into 2026 action
-
Prioritized portfolio decisions: a rapid assessment tool that tells product teams whether to pursue fermentation-derived solutions, high‑purity extracts, or blended approaches based on brand risk tolerance and margin targets.
-
Supply-contract negotiator: playbooks for off-take, capacity reservation and toggled pricing tied to raw-material indices to hedge volatility while retaining flexibility for product reformulation.
-
M&A and capex decision frameworks: a scorecard that translates strategic fit, regulatory status, plant footprint and customer overlap into transaction valuation adjustments and integration milestones.
-
Taste-and-go‑to-market roadmap: staging trials that balance sensory acceptance, shelf stability and cost-per-serving economics so pilots can be scaled with predictable margin outcomes.
Conclusion — the 2026 imperative
Stevia is no longer a simple ingredient bet: it is a complex, strategic lever that touches R&D, procurement, regulatory affairs and commercial strategy. With a market that expanded from about USD 500 million in 2020 to roughly USD 750 million in 2025 and is projected to grow at an 8.5% CAGR to exceed USD 1.3 billion by 2032, companies that move with disciplined scenarios, supplier options and regulatory playbooks will capture disproportionate value.
This preview surfaces the strategic choices and risks. The full PW Consulting Stevia Market report provides the granular segmentation, supplier-level scorecards, price-sensitivity models and executable templates that corporate leaders, investors and procurement teams need to translate the 2026 momentum into durable advantage. For access to the full data set, detailed regional and application splits, and our proprietary modeling workbook, visit the report page or contact PW Consulting’s industry desk.
For detailed analysis of this topic, please visit the official page: Stevia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Firestop Sealants Market to Reach USD 2,929.16M by 2032 (4.42% CAGR)
By PW Consulting, 2026-07-30
Firestop Sealants Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present this strategic preview of our latest Firestop Sealants Market study. The aim is to equip executives, portfolio managers, and product leaders with the precise intelligence they need to make high-stakes 2026 decisions — while preserving the full depth of our proprietary datasets for subscribers. Below you will find a concise, insight-driven synthesis of market dynamics, competitive posture, supply-chain stressors, and the tactical playbook that successful players are already adopting.
Firestop Sealants Market
Market trajectory at a glance
The firestop sealants market has undergone a notable structural shift over the past half decade. After contracting through the early 2020s, the industry reached a low point in our 2025 base year and is set to re-enter a growth phase. Our topline model shows a steady compound annual growth rate (CAGR) of 4.42% across the 2026–2032 forecast window, producing a meaningful expansion of market value by 2032. That trajectory reflects a combination of renewed construction activity, stricter building and fire codes, and technological refreshes in passive fire protection.
Firestop Sealants Market
Two observations are central for 2026 planning. First, the market is recovering, but the recovery is uneven and closely tied to regional construction cycles and retrofit waves. Second, margins and competitive advantage are increasingly shaped by supply‑chain moves—raw material inflation and trade measures are exerting direct pressure on formulations, pricing, and sourcing strategies.
Firestop Sealants Market
Why this study matters for 2026 choices
- Actionable timing: 2026 will be a pivot year for procurement contracts and product rollouts. The study’s forecast and scenario models convert macro trends into precise windows for contract renegotiation, inventory hedging, and launch sequencing.
- Margin protection: Our cost-sensitivity analysis quantifies how silicone and polyurethane raw‑material shocks filter through to product-level gross margins, enabling CFOs to design pass-through clauses, indexed contracts, or hedging programs.
- Commercial playbooks: We translate code evolutions and installer behavior into GTM tactics — from spec‑writer influence to contractor training — so sales leaders can prioritize the highest-return channels in 2026.
- M&A and portfolio moves: The study highlights capability gaps and attractive adjacencies (e.g., perimeter barriers, prefabricated devices, stone‑wool integrated systems) to inform acquisitions and JV decisions that accelerate time-to-market.
Market dynamics shaping 2026 strategy
Three interlocking forces will dominate outcomes in 2026:
- Regulatory tightening and code enforcement: Stronger fire-safety regulations and a growing emphasis on building-resilience programs are expanding demand for tested, certified firestop solutions — particularly in retrofit and high-rise segments.
- Raw-material volatility: Suppliers and formulators are navigating multiple cost pressures. Recent producer price actions for silicone feedstocks and MDI-based polyurethane intermediates have materially increased input costs. In parallel, supplier-side pricing initiatives for construction chemicals have introduced short-term margin compression unless mitigated by pricing strategies or sourcing shifts.
- Trade and sourcing complexity: Trade measures affecting certain origins of silicone raw materials remain in force, compelling manufacturers to revisit country sourcing, qualify alternate supplies, or accelerate local production to preserve competitiveness.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms capture a meaningful but not dominant share, and the top five expand that footprint slightly. This structure creates a dual pathway to scale — defend through product breadth and channel reach, or win pockets of higher margin via specialization and technical services.
Key competitive positions observed in our study:
- 3M Fire Protection Products: Global R&D and brand authority underpin broad portfolio depth — from intumescent latex formulations to advanced silicone systems and engineered inserts. Their investments in intumescent technologies and specification-grade devices make them a leading influence on architectural specifications and OEM partnerships.
- Hilti Corporation: Renowned for installation-focused innovation, Hilti’s recent rapid-deploy flexible sealant launch underscores their strategy: reduce on-site labor time and total installed cost. Their service-led sales model and installer loyalty are durable advantages.
- Specified Technologies Inc. (STI): Highly specialized in perimeter and curtain-wall solutions, STI’s SpecSeal systems capture demand where integration with the façade and system testing is critical. Their deep test-catalog expertise positions them strongly in high-spec commercial projects.
- Tremco Inc.: Tremco’s TREMstop range and recent expansion into acrylic sprays and intumescent wraps reflect a two‑pronged product and channel play: broaden SKU coverage while strengthening contractor-friendly formats.
- RectorSeal (Metacaulk), H.B. Fuller, Dow, Sika, Rockwool and Promat: These firms collectively cover supplier-to-system roles — from raw-material leadership and silicone formulations to stone‑wool integrated barriers and passive system assemblies. Dow’s dual role as raw-material supplier and sealant brand is particularly influential: upstream price moves and product launches ripple across the supply base.
Recent vendor activity reinforces a strategic theme: speed and specification certainty. Product launches and enhancements over the past 12–18 months have emphasized faster install times, broader substrate adhesion without priming, and integrated intumescent performance for mixed-geometry penetrations.
Operational and commercial implications
For executives mapping 2026 priorities, our analysis crystallizes six imperatives:
- Hedge or index raw-material exposure: Where possible, negotiate indexed supply agreements or implement pre-buy windows for silicone and MDI feedstocks. Absent hedges, prioritize pass-through mechanisms tied to transparent indices.
- Prioritize product formats that reduce installed cost: Faster-install systems win spec and contractor preference. Investment in cartridge, pumpable, and pre-formed devices increases share in retrofit and rapid-build projects.
- Localize critical supply chains: Tariff exposure and transport risk argue for closer regional sourcing or toll-manufacturing partnerships in key target markets.
- Convert technical differentiation into procurement value: Tie tested-system claims to total cost-of-ownership analyses; this helps justify premium pricing despite input-cost headwinds.
- Scale after-sales and certification services: Training, inspection support, and certification documentation become decisive for large-spec customers and institutional owners.
- Scan M&A selectively: Small bolt‑on acquisitions that add perimeter systems, wrap technologies, or upstream resin security can unlock rapid margin recovery and new specification pathways.
Report deliverables — what you will get
Our full PW Consulting study translates these strategic imperatives into operational levers and quant models. Deliverables include:
- A detailed market model covering historical performance and forward scenarios through 2032 with sensitivity testing to raw-material price shocks.
- Competitive scorecards and product-matrix benchmarking mapping sealant chemistries, system claims, tested assemblies, and installer workflows.
- Supply‑chain heat maps highlighting single‑sourcing risks, tariff exposure, and lead‑time variability by procurement node.
- Commercial playbooks for value-based pricing, specification capture, and contractor engagement tailored to targeted segments.
- M&A thesis and screening framework identifying accretive targets across product, capability, and geographic axes.
- Excel-ready dashboards and decision-support tools for CFOs and commercial leaders to run what-if scenarios on raw-material pass-through, price elasticity, and margin recovery timelines.
How to use this intelligence in 2026
Use our study as a decision amplifier. Procurement teams should calibrate Q1 renegotiations against our price‑sensitivity outputs; product and R&D functions should prioritize formulations that reduce dependency on the most volatile feedstocks; commercial leadership should rework distributor incentives toward system sales, not just SKU turnover. For investors, the study identifies which business models — scale + specification leadership vs. specialization + service — will most likely deliver resilient returns under continuing input-cost volatility.
Closing — the trailer
This preview demonstrates the strategic contours of the firestop sealants market in 2026: a recovering market, concentrated yet contestable, and acutely sensitive to raw-material and trade levers. PW Consulting’s full report contains the granular, executable datasets and the supplier- and SKU-level intelligence necessary to convert these insights into immediate actions. To preserve the exclusivity and commercial value of those datasets, we have purposely withheld the line‑by‑line segmentation and SKU economics from this preview.
For firms that must move from insight to execution in 2026, the complete PW Consulting package is designed as both a strategic roadmap and an operational toolkit. Contact our research desk to access the full report, scenario models, and advisory services that translate these market forces into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Firestop Sealants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Headrest Market Poised for 5.7% CAGR Through 2032
By PW Consulting, 2026-07-30
Automotive Headrest Market: Strategic Imperatives for 2026
PW Consulting’s latest Automotive Headrest Market briefing (base year 2025; forecast 2026–2032) distils the competitive, regulatory and product design forces that will define winners and laggards through the next technology cycle. The market we modelled has grown steadily from the low hundreds of USD million in 2020 to USD 186.4 Million in 2025, and at a compound annual growth rate of 5.7% our central forecast projects that market value will approach roughly USD 272.3 Million by 2032. Those headline numbers are a starting point: this note explains why that growth matters to strategic decision‑makers in 2026, what to prioritise, and how to convert surface-level data into defensible action plans.
Automotive Headrest Market
Why this study matters for 2026 decision-makers
-
Regulation has become an accelerant. Safety regulators and influential test bodies have tightened performance protocols for head restraints; recent programmatic activity from IIHS and NHTSA elevates whiplash prevention from a checklist item to a product-defining requirement. The full report maps the timing, technical triggers and compliance costs associated with these updates.
Automotive Headrest Market -
Product complexity is increasing while concentration remains low. The segment shows modest overall market concentration (CR3 ≈ 26.8%, CR5 ≈ 32.1%), indicating a fragmented supplier environment. That fragmentation creates room for technology-driven consolidation—but only for firms that can rapidly scale validated solutions that meet new safety protocols and OEM feature sets.
Automotive Headrest Market -
Value pools are shifting. Comfort, active safety integration, lightweighting and smart features (sensors, heating/cooling integration) are re‑shaping the headrest value chain. The ascent of EVs and premium comfort expectations creates higher ASP potential; the report translates those qualitative trends into demand velocity scenarios and margin implications.
-
Timing matters. With the market exhibiting steady growth through 2025 and a forecast CAGR of 5.7% into the 2030s, 2026 is a decisive year to lock in capability investments, supplier agreements and certification pathways that will amortize across the forecast period.
What the report delivers — practical, transaction‑grade intelligence
-
Transparent sizing and methodology: historical series (2020–2025) and a granular 2026–2032 forecast built from component-level drivers, OEM program roadmaps and scenario stress‑tests. The methodology appendix documents assumptions so teams can re-run scenarios with alternate cost, pricing or regulatory inputs.
-
Decision-ready playbooks: product roadmaps for passive vs active head restraint platforms, test and validation timelines aligned with IIHS/NHTSA updates, and a compliance cost estimator you can use to model program budgets.
-
Commercial intelligence pack: supplier scorecards, OEM sourcing behaviours, lead-time and capacity risk matrices, and negotiation levers for volume and technical guarantees.
-
Technology and cost deep dives: materials heatmaps, assembly labour and BOM benchmarks, scaling curves for active mechanisms (actuators, sensors), and trade-offs for lightweighting vs crash performance.
-
M&A and partner screening: a prioritized list of acquisition and JV targets based on capability gaps, integration risk and potential to capture incremental margin from safety-driven upgrades.
-
Full data annex: complete segment and region-level tables, pricing trajectories and sensitivity outputs (available in the full report; summary insights are synthesised in this briefing).
Competitive landscape — what incumbents and challengers are doing
The competitive topography is a mix of global seating giants, component specialists and niche innovators. Below are high-level strategic positions for the players we audited; the full report contains scorecards, program overlap matrices and supplier‑to‑OEM mapping for each firm.
-
Adient (Ireland) — As a full-systems seating supplier, Adient’s strength lies in integrated seat-and-headrest platforms and OEM relationships. Their ability to bundle adjustable and dynamic headrest mechanisms within broader seating contracts gives them a defensive edge where OEMs prioritise single-supplier systems for architecture simplification.
-
Lear Corporation (United States) — Lear’s emphasis on thermal comfort and smart headrest integration positions them well for EV and premium segments where occupant experience is a differentiator. Expect them to push sensor integration and comfort electronics as part of value-add packages.
-
Toyota Boshoku Corporation (Japan) — OEM-aligned capabilities and deep Toyota program experience make Toyota Boshoku a strong supplier for high-volume systems with tight quality controls. Their strategic advantage is early access to OEM design requirements and long product life-cycle support.
-
Windsor Machine Group (Canada) — A specialist in custom and power headrests, Windsor is an attractive partner for OEMs seeking differentiated comfort features or for Tier 1s wanting to outsource complex actuator subassemblies.
-
Polydesign Systems (United States) — Focused on wrapped headrests and covers, Polydesign plays the cost, fit-and-finish game. Their margin profile depends on fabric/leather sourcing and assembly efficiency; they are a strategic target for suppliers aiming to control interior trim bundles.
-
Innotec Group (United States) — As a supplier of patented metal headrest stays, Innotec exemplifies the value of component IP. Their tube-forming technology can be a choke point or a bargaining chip in supplier negotiations where mechanical reliability is paramount.
-
Tachi-S Co., Ltd. (Japan) — A full-seat supplier offering headrest mechanisms and covers, Tachi-S combines global manufacturing scale with localized engineering support—particularly relevant for program launches in Asia and Japan.
-
FORVIA SE (France) — With a stated focus on sustainable and smart mobility, FORVIA’s route-to-market emphasises sensor integration and material sustainability. Expect them to lead in programs where OEMs have explicit carbon and recyclability targets.
-
Honasco Kunststofftechnik GmbH (Germany) — Specialising in headrest guides and components for premium applications, Honasco is relevant where fit, finish and tight tolerances are non-negotiable—luxury OEMs and high-volume German marques.
Each profile in the full report includes HQ, web reference and a succinct assessment of strategic intent—useful for supplier selection, competitive positioning or carve‑out diligence.
Regulatory shockwaves and roadmap consequences
-
IIHS and NHTSA activity has immediate product consequences. The IIHS whiplash prevention test (recently updated and relaunched in early 2026) and NHTSA’s notice on dynamic head restraint performance (ANPRM published in 2024 and actively reviewed) accelerate the need for validated forward-moving or energy-absorbing head restraint designs. Our compliance modelling quantifies development timelines and incremental certification costs under alternate regulatory trajectories.
-
Design trade-offs are now formal program drivers: achieving improved rear-impact neck protection typically requires changes to headrest geometry, energy management materials, and mechanisms that permit controlled forward motion in rear impacts. These changes interact with weight, packaging and interface constraints, and will materially affect BOM and assembly processes.
-
Independent testing and early simulation become non-negotiable. Firms that front-load CAE validation and IIHS/NHTSA lab engagement halve certification risk and reduce time-to-production compared to those relying on post-design validation cycles.
Priority actions for 2026 — convert insight into outcomes
-
Compliance-first product development: rebase your 2026 R&D roadmap on the most conservative regulatory scenario; test early in accredited labs and secure IIHS/NHTSA pre-clearance where possible.
-
Modular platform economics: invest in modular actuator and trim architectures that can be configured across multiple seat platforms to drive scale and amortize development costs.
-
Partner selectively: pursue technology JV for active mechanisms or sensor integration rather than full in-house builds unless you have sufficient volume to justify capitalisation.
-
Build pricing playbooks: incorporate certification, warranty and remote diagnostics costs into total cost of ownership models; lock price escalators with suppliers for key commodity inputs.
-
Explore targeted M&A: use the market’s fragmentation to acquire complementary capability—component IP, actuator specialists or premium trim providers—to accelerate compliance and feature parity.
-
Operationalise intelligence: deploy a supplier risk dashboard (lead times, capacity, geographic risk) and a product release calendar aligned to regulatory milestones—this is included as a template in the report.
Conclusion — the strategic value of timely intelligence
2026 is a hinge year for the automotive headrest market. Rising regulatory scrutiny, shifting OEM feature priorities and steady market expansion (historical gains through 2025 and a projected CAGR of 5.7% into the 2030s) mean that decisions taken this year about technology selection, partner arrangements and certification strategy will have multi‑year consequences. PW Consulting’s full Automotive Headrest Market report provides the data tables, supplier mapping and executable playbooks you need to make those decisions with confidence. For the complete dataset, segment-level breakdowns and downloadable tools referenced in this briefing, consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Automotive Headrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Linear Alkylbenzene Sulfonic Acid (LABSA) Market Outlook: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior strategy team releases its latest LABSA market research, this briefing outlines the strategic value of the study for corporate decision-making in 2026. The aim here is to demonstrate the analytical depth and practical orientation of the full report while preserving the proprietary, segment-level intelligence that underpins our recommendations. Consider this a high-fidelity trailer: it maps the terrain, reveals the directional trends and risks you cannot ignore, and highlights the decision levers that will matter next year — but it intentionally withholds the granular tables and segment dashboards you’ll want at the negotiating table.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Market snapshot: scale, momentum and near‑term trajectory
LABSA has moved from a mid‑single‑digit niche into a structurally important surfactant market in the past half decade. The global market expanded materially from the early 2020s and reached a base year size of approximately USD 5.53 billion in 2025. Our forecast framework — underpinned by bottom‑up demand drivers, feedstock availability scenarios and regulatory trajectories — projects a steady expansion through the forecast window, consistent with a compound annual growth rate in the mid‑single digits. That pace reflects a mix of continuing detergent demand, substitution dynamics that favor biodegradable anionic surfactants, and rising premiumisation of formulated products where LABSA remains competitive on performance and cost.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Dynamics reshaping the value chain (what keeps CFOs and procurement awake at night)
-
Feedstock concentration and disruption risk: n‑paraffin and related petrochemical intermediates remain the dominant cost and availability drivers. Recent disruptions in Middle East supply routes and export restrictions have tightened availability to Asian producers, generating price spikes and intermittent force majeure declarations. These events illustrate how geopolitics and logistics can transmit quickly into feedstock‑driven margin volatility for both producers and formulators.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market -
Price volatility and margin compression: sudden feedstock price moves can flip competitive advantage between integrated players and merchant producers. 2024–2025 episodes demonstrated how short‑run shocks can force plant curtailments among smaller makers and create short windows for larger integrated manufacturers to reprice contracts.
-
Regulatory and sustainability pull: biodegradability requirements in major markets continue to favour LABSA over certain alternatives. At the same time, carbon accounting and product‑level Environmental Product Declarations (EPDs) are becoming commercial differentiators — both at the buyer level (retailers and formulators) and in procurement mandates. Low‑carbon LAB offerings and EPD‑certified supply will command a premium in tender processes.
-
Industrial structure: the market is neither a pure commodity oligopoly nor a fragmented cottage industry. A handful of global and regional integrators control meaningful integrated upstream and sulfonation capacity, while numerous regional players service local demand. This mixed structure creates opportunity for strategic aggregation, capacity rationalisation and differentiated service propositions.
Competitive landscape — who matters and why
The LABSA competitive set includes global specialty chemical leaders, petrochemical majors with integrated value chains, and nimble regional producers. Market concentration metrics indicate a mid‑level concentration: a small cluster of firms accounts for a material share of global capacity, but a long tail of local manufacturers remains commercially significant. The practical implication is twofold: large buyers and traders can rely on several global counterparties for scale and risk mitigation, while local producers retain leverage in spot and short‑term markets.
Key strategic archetypes in the landscape
- Integrated petrochemical players with LAB and downstream sulfonation capability — advantaged on feedstock integration and scale economies.
- Specialty chemical manufacturers with global merchant networks — strong in formulation support and customer service for detergent and personal care customers.
- Regional, cost‑focused producers — flexible on pricing and local presence but vulnerable to feedstock shocks and regulatory compliance costs.
Recent corporate moves illustrate strategic themes you should monitor closely: launches of low‑carbon LAB/LABSA streams and EPD‑backed product declarations have already altered procurement evaluation criteria; and episodes of severe domestic price spikes have caused temporary capacity loss among small formulators in price‑sensitive markets. These dynamics are signals for procurement, R&D and M&A teams planning 2026 actions.
What the PW Consulting LABSA report delivers (practical, board‑ready outputs)
Our full report translates market complexity into executable intelligence across commercial, operational and strategic functions. Deliverables include:
- Demand and supply mapping with granular end‑use overlays and forward scenarios — modelled for three plausible feedstock and regulatory pathways.
- Price‑path scenario models and sensitivity analyses (feedstock, freight, FX) that feed directly into working capital and margin stress tests.
- Supplier scorecards and a procurement playbook — total‑cost benchmarking, operational resilience scores, sustainability credentials and contract templates (incl. force majeure & pass‑through clauses).
- Capex and capacity planning guidance — shortlists of brownfield expansion opportunities vs. greenfield timing, with estimated payback banding under base and stress cases.
- M&A and JV target universe with screening filters and integration risk checklists for acquirers seeking scale, geographical coverage or low‑carbon credentials.
- A regulatory and EPD roadmap that quantifies premium capture for low‑carbon, certified streams and recommends traceability checkpoints for downstream claims.
- Interactive dashboards and downloadable models (price curve, demand-by-end-use, supplier risk matrix) for scenario testing in board and commercial reviews.
Actionable strategic priorities for 2026
For executives preparing budgets, negotiating multi‑year contracts, or sizing capital deployments in 2026, we recommend prioritising the following actions based on the report’s integrated analysis:
-
Lock in supply diversity. Build multi‑sourced feedstock strategies combining long‑term offtake from integrated producers, regional contracts to mitigate logistics risk, and financial hedges where practical. Relying on a single supply corridor is a direct route to margin volatility.
-
Formalise a carbon‑and‑compliance premium play. Require supplier EPDs in tenders and model the willingness to pay for certified low‑carbon LABSA across your customer base; early movers capture procurement share with sustainability‑focused retail and institutional buyers.
-
Adopt contract structures that are stress‑tested for 2026 shock scenarios. Include clearer feedstock pass‑through clauses, inventory commitments, and shorter re‑opener windows tied to objective indices for feedstock and freight.
-
Evaluate backward integration or strategic alliances. For medium‑to‑large buyers, partial vertical integration or exclusive JV offtakes with integrated producers secures margin predictability and reduces exposed volume to spot shocks.
-
Prioritise capex for process flexibility and higher‑purity grades where product mix permits differentiation. Producers able to move up the value chain into certified, higher‑value LABSA streams will sustain margins as baseline volumes commoditise.
-
Keep M&A pipelines active but disciplined. Distressed or consolidation opportunities may appear following regional price shocks; valuations will favour buyers with clear integration plans for feedstock, logistics and regulatory compliance.
-
Operationalise an early‑warning system. Combine real‑time feedstock tracking, carrier and port congestion analytics, and supplier financial health scoring to trigger pre‑approved mitigation actions.
How boards and commercial teams should use this research in 2026 planning cycles
Translate the report outputs into three concrete deliverables for 2026 planning:
- Procurement playbook and KPI set (quarterly feedstock exposure limits; supplier resilience score; percentage of EPD‑certified purchases).
- Capex prioritisation heatmap (short‑term reliability upgrades vs. mid‑term integration projects) linked to payback thresholds under stress scenarios.
- M&A watchlist and engagement plan (targets grouped by strategic fit: feedstock integration, regional footprint, sustainability credentials).
These deliverables are most valuable when the board aligns on risk tolerance bands and when the commercial team can stress‑test price pass‑through across customer cohorts. Our report supplies the models and the scenario narratives to accelerate that alignment.
Closing: why this research matters for 2026
LABSA sits at the intersection of commodity feedstock exposure, regulatory tailwinds for biodegradability and emergent premiums for verified low‑carbon supply. The combination of geopolitical risk, episodic price volatility and evolving procurement criteria means 2026 will be a year where strategic choices have outsized impact on earnings and market positioning. This PW Consulting study is designed to convert market complexity into concrete decisions: who to source from, what levels of integration to pursue, where to place capital, and how to price for risk and sustainability.
If you are preparing commercial agreements, negotiating capex or scoping M&A for 2026, the full report contains the segment tables, supplier‑by‑region matrices, and downloadable price models you will need to execute. Our team is ready to walk your executive committee through the scenarios, tailor the supplier scorecards to your procurement constraints, and model the specific margin impacts of alternative sourcing strategies.
For detailed analysis of this topic, please visit the official page: Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


