



Category: market research
PW Consulting: Gear Cutting Machines Market to Reach USD 344.8M by 2032 (6.98% CAGR)PW Consulting: Electric Fencing Market to Expand at 7.9% CAGR to 2032
By PW Consulting, 2026-07-30
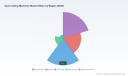
Gear Cutting Machines Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry primer designed to orient C-suite leaders, corporate development teams, and plant-level decision-makers as they set capital allocation and competitive strategies for 2026. This briefing distills the market dynamics, technology inflection points, regulatory pressures, and competitive moves shaping the gear cutting machines market — and explains how our full market study converts those dynamics into executable decisions. Consider this a high-value preview: rigorous in insight, selective in detail, and deliberately withholding granular splits so you’ll consult the full report for transaction-grade intelligence.
Gear Cutting Machines Market
Executive snapshot: a market re-accelerating on modernization
The global gear cutting machines market recovered steadily through the early 2020s and is entering a medium-term expansion phase. By our base year (2025) the industry’s installed-equipment and replacement market is estimated at approximately USD 215 million. From 2026 onward the market is forecast to grow at a compound annual growth rate (CAGR) of about 7.0% through 2032, reaching roughly USD 345 million by the end of the forecast window. This rate reflects a convergence of demand drivers: automotive electrification and powertrain diversification, rising complexity in aerospace and precision industrial gears, and a wave of capex tied to energy-efficiency and automation retrofits in manufacturing plants.
Gear Cutting Machines Market
Why this research matters for 2026 strategic choices
- Capital allocation and timing: Equipment procurement cycles in gear production are long and lumpy. Our modeling translates macro growth into timing recommendations for greenfield investments, targeted replacements, and flexible-capacity buys to minimize idle capital and maximize throughput gains.
- M&A and partnership screening: The market remains meaningfully fragmented — the leading vendors collectively control only a minority share of industry revenue — creating highly asymmetric opportunities for bolt-on acquisitions, distribution partnerships, and platform plays. Our deal pipeline framework prioritizes targets by technology fit, service footprint, and aftermarket potential.
- Operations and retrofit ROI: Energy constitutes a material share of operating costs in metalworking. The report provides plant-level TCO and payback templates that quantify savings from dry-cutting platforms, power-optimized drives, and integrated tool-life monitoring — enabling CFOs to build capital requests with defensible IRRs.
- Product and channel strategy: For OEMs and system integrators, the study translates buyer preferences into product design priorities and channel segmentation strategies that lift order-intake conversion in 2026.
Market trajectories and plausible scenarios
Our scenario set centers on three trajectories: baseline (policy continuity and steady electrification), upside (accelerated EV penetration and industrial reshoring), and downside (macroeconomic slowdown and extended inventory destocking). The baseline aligns with the 7.0% CAGR path described above. The upside scenario lifts demand materially for high-precision, energy-efficient solutions and for configurations that support dry cutting and reduced coolant usage. The downside compresses upgrade cycles and shifts buyer focus to refurbishment and aftermarket services — an area we highlight as a defensive play for suppliers.
Gear Cutting Machines Market
Two structural features moderate risk across scenarios. First, gear manufacturing is capital-intensive and tied to long industrial supply chains, creating predictability in replacement cycles. Second, the technology differential between new and legacy machines is widening: advanced hobbing, skiving, and integrated finishing solutions offer clear unit-cost and quality advantages that are increasingly captured by firms willing to invest.
Technology and operational dynamics to watch
- Dry cutting and tooling systems: Manufacturers are accelerating adoption of complete dry cutting platforms. These systems reduce coolant handling costs and environmental footprint but require rethinking tool metallurgy, coating, and chip evacuation. High-performance PM high-speed steels with modern PVD coatings are now standard for hobs and form tools in premium installations.
- Integrated finishing and automation: Buyers increasingly prefer end-to-end cell solutions — hobbing plus shaping or skiving plus finishing — with inline quality feedback. This trend favors suppliers with modular automation and digitalization stacks that can be deployed around existing lines.
- Energy optimization: Energy efficiency standards and building-performance regulations in leading jurisdictions are elevating the importance of machine-level power management. Because energy can represent a material share of operating expense, even incremental drive and cooling improvements materially influence lifecycle economics.
- Digital services and aftermarket: Predictive maintenance, tool-life analytics, and subscription-based spare parts are no longer “nice-to-have.” They are core margins drivers that can offset commoditization in new-equipment sales.
Competitive landscape — who is strategically positioned?
The vendor set combines established machine-tool groups with specialized gear-focused manufacturers. The market concentration metrics indicate a relatively open field: the top three vendors control roughly a quarter of revenue, and the top five only slightly more. That fragmentation creates an advantage for buyers but also opportunity for disciplined consolidation.
- EMAG (Germany): Broad product range across hobbing, shaping, skiving, and shaving. EMAG’s strength lies in integrated gear production cells and strong engineering services that support complex customer retrofit projects.
- Bourn & Koch (United States): Niche high-precision hobbing up to large diameters, favored in segments requiring high AGMA classes. Their vertical focus and U.S. manufacturing footprint support near-market responsiveness for North American integrators.
- Liebherr (Germany): Deep presence in automotive and wind-turbine gear technologies. Liebherr combines heavy-duty machine engineering with global service networks, making it a go-to for large-scale industrial and renewable-energy gears.
- Nidec Machine Tool (Japan): Offers GE and HS series with a strong push for dry cutting and high-throughput systems. Nidec’s exhibition activity in Asia underlines their focus on export-led growth and technology demonstrations.
- Gleason (United States): Long-standing in precision gear cutting and shaping, Gleason’s strength is in legacy brand equity and specialized finishing systems that remain essential in precision-demanding segments.
- Reishauer (Switzerland): A leader in gear grinding and finishing, Reishauer is the supplier of choice when precision and surface integrity are paramount.
- Klingelnberg (Germany): Specializes in bevel gear cutting and remains visible through targeted conferences and product showcases focused on bevel gear technologies.
- FFG Werke (Germany): Portfolio breadth across machine tools positions them as a systems supplier for integrated shops pursuing multi-technology deployments.
Recent market activity through trade shows, conferences, and demonstration events has followed a predictable pattern: vendors are using high-profile exhibitions to show dry-cutting capabilities, integrated automation cells, and digital-service demonstrations. These venues are the primary channels for technology diffusion and partnership formation in the coming 12–24 months.
Regulatory and input-cost levers shaping adoption
- Energy and building-performance standards: Regulatory frameworks in key manufacturing jurisdictions are making energy performance not just an environmental checkbox but a capital-planning criterion. Compliance requirements and potential energy-account savings are accelerating retirements of inefficient platforms.
- Tooling supply chain: Advances in cutting-tool metallurgy and coatings (the move toward modern PM HSS grades with PVD treatments) are enablers for dry cutting and higher feed rates. Buyers must consider tooling total-cost alongside machine CAPEX when assessing new installs.
What the full PW Consulting study provides (practical, decision-ready modules)
- Scenario-based demand modeling and a prioritization matrix that converts macro forecasts into order-of-magnitude CAPEX needs by customer archetype.
- Supplier benchmarking with strategic position maps, product roadmaps, and an acquisition-target shortlist scored on integration risk and aftermarket leverage.
- Plant-level TCO and ROI tools that compare retrofit vs. greenfield choices under varying energy-price and utilization assumptions.
- Contracting and pricing playbooks for OEMs and distributors, including channel-margin diagnostics and competitive-response templates.
- Commercial due-diligence templates for M&A and JV evaluation: technology validation checklists, service-network gap analysis, and synergy-estimation worksheets.
- Actionable go-to-market recommendations for 2026, layering short-term tactical plays (trade-show sequencing, demo fleet deployment) onto multi-year strategic moves (partnerships, service platform rollouts).
How to use this intelligence in 2026 — three immediate actions
- Run an equipment TCO sprint: Use our TCO templates to identify 2–3 machines in your fleet whose replacement would unlock the largest energy and quality gains. Prioritize investments with sub-24 month paybacks under conservative utilization assumptions.
- Frame an aftermarket play: If you sell machines or components, accelerate development of subscription spare-part packages and remote-monitoring services. Our monetization frameworks show how small service attach rates boost overall enterprise value.
- Screen acquisition targets: Shortlist candidates by capability (dry-cutting, finishing), regional service footprint, and aftermarket attach rates. Our deal filters help you balance price expectations against integration complexity.
Final note — what you gain by accessing the full report
This briefing maps the strategic terrain. The full PW Consulting Gear Cutting Machines Market study converts that map into GPS-grade directions: localized demand curves, OEM- and model-level competitive intelligence, contract and pricing matrices, and downloadable financial models you can plug into board-level investment memoranda. If your 2026 capital, M&A, or manufacturing strategy involves gears — whether for automotive, aerospace, renewables, or industrial machinery — our full analysis will materially shorten your path from insight to decision.
To explore the complete dataset, supplier scorecards, and the operational playbooks referenced here, visit our market research portal and request the comprehensive brief tailored to your role — executive, investor, or operations leader.
For detailed analysis of this topic, please visit the official page: Gear Cutting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engine Nacelle Market Poised to Reach USD 844.28M by 2032
By PW Consulting, 2026-07-30
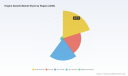
Engine Nacelle Market — 2026 Strategic Outlook and Decision-Grade Insights
As global air travel and fleet renewal strategies continue to evolve, the engine nacelle market has returned to a path of steady expansion. Our latest baseline assessment (base year 2025) values the market at USD 600 Million (revenue unit: Million, USD) and projects a compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast horizon, reaching roughly USD 844 Million by 2032. These topline dynamics frame a market that is big enough to attract strategic capital yet sufficiently concentrated that a relatively small number of incumbent players continue to shape technology, certification and aftermarket economics.
Engine Nacelle Market
Why this research matters for 2026 decisions
For executives making capital allocation, procurement, and product strategy decisions in 2026, the nacelle market occupies a unique position: it sits at the intersection of aerospace OEM programmes, materials and manufacturing supply chains, regulatory certification cycles, and aftermarket service economics. The market’s steady 5% CAGR signals predictable topline expansion, but beneath that steady headline growth lie structural inflection points — titanium availability, composite adoption, noise regulation and certification timetables — that will determine who captures the margin pool.
Engine Nacelle Market
Market trajectory and what it implies
- Resilience with pockets of volatility: Our historical series shows a recovery profile in the early-2020s followed by stabilization into 2025. That pattern points to continued demand from new aircraft programmes and a growing aftermarket share driven by fleet utilization and MRO cycles.
- Aftermarket as a growth lever: With OEM deliveries on a multi-year cadence, aftermarket services (repair, overhaul, upgrades, and life-extension packages) will be a reliable recurring revenue source. Companies that invest in long-term service agreements and on-wing support stand to increase lifetime margin capture.
- Technology and certification timing matter: Noise reduction technologies, thrust-reverser innovations and nacelle-integrated systems will be differentiated by how quickly suppliers can validate designs against regulatory frameworks and secure program-level integration with engine OEMs.
Key structural dynamics shaping the market
- Material supply fragility: A notable risk driver is raw material availability. The disruption to titanium supply chains has already increased procurement complexity and cost pressure for metallic nacelle components. Strategic buyers and suppliers must evaluate alternatives (material substitution, increased recycling, redesign for composites) while quantifying certification and lifecycle impacts.
- Regulation is a gating factor: Certification rules such as FAA 14 CFR Part 33 remain a decisive determinant of time-to-market and program economics. Suppliers that embed certification strategy early in design cycles — and maintain transparent regulatory engagement plans — reduce program timeline and cost risk.
- Moderate market concentration: Market concentration metrics indicate that a few large suppliers control the majority of program awards. That dynamic creates both barriers and opportunities: incumbents can leverage scale and certification pedigrees, while nimble challengers can win niche work through innovation or cost advantage.
- Manufacturing and materials shift: Adoption of advanced composites and manufacturing techniques (including automated layup and selective use of additive manufacturing) is accelerating. These methods reduce weight and can improve fuel efficiency but require upfront investment, supply chain retooling and new qualification pathways.
Competitive landscape — strategic takeaways
The competitive field is composed of long-established system integrators, tier-1 aero-structure groups, and specialized niche suppliers. Below are distilled strategic positions and implications for 2026 planning. (Full company dossiers, procurement profiles and partnership matrices are available in the main report.)
Engine Nacelle Market
- Safran Nacelles (France): A systems integrator with deep program partnerships and a proven track record on major engine programs. Their capability to deliver end-to-end nacelle systems and program-level support makes them a natural partner for OEM-led, long-cycle platforms. Strategic implication: competing suppliers must differentiate through cost, certification speed or aftermarket services to win program awards against Safran.
- Collins Aerospace (RTX, United States): Decades of heritage, broad program certifications and focused R&D in noise reduction and lean manufacturing make Collins a formidable incumbent. For customers, Collins offers scale and certification certainty; for competitors, the path to displacement typically requires demonstrable performance or supply-cost improvements.
- Spirit AeroSystems and other aero-structure majors: Strong in component volume production for high-rate platforms. Their focus on manufacturing efficiency and programme readiness means they often compete on cost and integration ease, particularly for OEM-driven content.
- Nexcelle, GKN, FACC, Aernnova and equivalent specialists: These firms combine nimble engineering with targeted manufacturing capabilities (composites, inlets, fan cowls, thrust reversers). They can win work by offering modular architectures or by taking program risk-sharing positions with OEMs.
- Service and systems suppliers (Nordam, Woodward, Liebherr, Magellan, Triumph, Barnes, Ducommun): These players are critical for actuation, thrust reverser systems and MRO capability. Their aftermarket footprint and reaction time for repairs make them indispensable partners for airlines and MRO providers.
- Innovation signals: Industry showcases (e.g., recent 2026 product demonstrations) underscore an accelerated pace of component-level innovation. Suppliers that convert these demonstrations into certified, program-ready products will expand addressable share.
Report deliverables — practical tools inside
This research is designed to be operationally actionable for supply chain, strategy and product teams. Highlights of what you will find in the full report include:
- Proprietary market sizing and a 2026–2032 forecast model (base year 2025), with scenario and sensitivity modules so teams can stress-test upside and downside cases.
- Supply-chain mapping and risk heatmaps identifying single-source dependencies, material pinch points (including titanium exposure) and near-term mitigation strategies.
- Regulatory and certification playbook detailing critical milestones under prevailing airworthiness standards and the downstream implications for program timelines.
- Technology adoption timelines for composites, additive techniques, and noise-reduction systems, linked to cost curves and certification effort estimates.
- Company profiles and competitive positioning matrices, including capability assessments, programme footprints and probable strategic moves for leaders and challengers.
- MRO and aftermarket opportunity assessment, with playbooks for service contract design, spare parts optimization and on-wing support models.
- A buyer’s toolkit for procurement and contract design tailored to 2026 priorities: dual-sourcing strategies, inventory hedging, and supplier KPI frameworks.
Strategic imperatives for 2026 decision-makers
- Secure and diversify critical materials: Immediate action is required to hedge titanium exposure. Options include strategic stockpiles, long-term off-take agreements, material substitution programs and accelerated testing of composite alternatives.
- Prioritize certifiable innovation: Invest in development pathways that align innovation with certification timelines. Proof-of-concept is necessary but insufficient — align R&D milestones with regulator engagement and test programs to avoid delayed product introductions.
- Expand aftermarket and service offerings: With steady fleet utilization driving MRO demand, suppliers that build service capability — predictive maintenance, rapid-turn repairs, integrated support contracts — will capture disproportionate lifetime value.
- Adopt modular, upgradable architectures: Design nacelle systems for in-service upgrades (noise attenuation kits, lightweight panels, digital sensors) to extend program revenue ramps and offer customers lower-life-cycle costs.
- Forge strategic partnerships: Consider JV structures, capability partnerships, or program-level risk-sharing to gain access to certification pedigrees and programme slots controlled by incumbents.
- Operationalize digital and lean manufacturing: Scale automation, digital twins and lean processes to compress manufacturing cycle times and reduce unit cost while ensuring traceability for certification bodies.
- Monitor regulatory and geopolitical signals: Maintain a cross-functional war-room to track certification updates (e.g., FAA rule changes) and geopolitical developments that affect raw material flows and labor availability.
Concluding perspective — how to use this intelligence
The nacelle market is neither a high-velocity disruptor nor a static commodity industry. Instead, it is an ecosystem shaped by program-level commitments, certification discipline, materials availability and aftermarket economics. The 5% CAGR from 2026 to 2032 reflects reliable growth, but the winners in this market will be defined by their ability to manage supply-chain risk, accelerate certifiable innovation, and monetize aftermarket service capabilities.
Our full Engine Nacelle Market report contains the granular segmentation tables, supplier scoring models, program-level forecasts and appendices required to convert these insights into executable plans. Because the market’s fine-grained intelligence (regional and application splits, segment-level revenues and detailed supplier contract exposure) is commercially sensitive, those datasets are deliberately hosted on the source page to support secure access and tailored briefings.
To translate the market trajectory into 2026 action, prioritize material supply strategies, certification-aligned development, and aftermarket expansion — and contact PW Consulting for a briefing on the proprietary models and bespoke scenario work that will underpin executable capital and procurement plans.
For detailed analysis of this topic, please visit the official page: Engine Nacelle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Offshore AUV Market to Hit USD 5,207.46M by 2032 at a 10.8% CAGR — PW Consulting
By PW Consulting, 2026-07-30
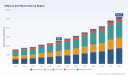
Offshore AUV Market — 2026 Strategic Briefing
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our comprehensive Offshore AUV Market study (base year 2025, forecast 2026–2032). This briefing synthesizes the macro trajectory—including a 2025 market base of USD 2,550 Million and a 10.8% compound annual growth rate through the forecast window—into the practical implications that matter to executives, investors, and program managers preparing strategic moves in 2026. Consider this a “trailer”: robust frameworks, critical signals, and prescriptive guidance are here; the full, granular datasets and vendor-level splits are reserved for the full report and interactive dashboards.
Offshore AUV Market
Why 2026 Is a Strategic Inflection Point
-
Momentum and scale: The Offshore AUV market has accelerated through 2020–2025 and, at a near-double-digit CAGR, is on track to roughly double in size by the end of the forecast period. That pace transforms AUVs from niche tools into mission-critical assets for offshore inspection, surveying, and intervention.
Offshore AUV Market -
Confluence of demand drivers: Aging subsea infrastructure, rapid build-out of offshore renewables, and renewed defense procurement are converging to create simultaneous demand pockets. Operational pressures—cost reduction, personnel safety, and rapid data turnarounds—are pushing operators to substitute or complement ships and ROVs with autonomous platforms.
Offshore AUV Market -
Operationalizing autonomy: 2026 will be the year many organizations shift from pilots to fleet rollouts. Expect procurement questions to move beyond “can it do the job?” to “how do we run, maintain, and monetize a permanent AUV capability?”
Key Market Dynamics That Should Shape Your 2026 Bets
-
Service-first commercial models: Beyond vehicle sales, recurring revenue from inspection-as-a-service, data analytics subscriptions, and managed operations will be a decisive source of differentiation. Buyers should model both CapEx and multi-year OpEx impacts when assessing suppliers.
-
Hybrid and dual-mode systems: Hybrid AUV/ROV platforms and extended-endurance architectures are moving from demonstrations to operational deployments, enabling more complex missions (e.g., light intervention, 360-degree asset inspection) and expanding addressable use cases.
-
Data and autonomy stack convergence: Sensor fusion, onboard processing, and cloud-native post-processing workflows will determine practical value. OEMs that pair vehicle performance with robust data operations and turnkey analytics will command premium positioning.
-
Supply-chain and production scale: Strategic manufacturing agreements and partnerships are already reshaping capability roadmaps. Expect contract wins and production pacts (including defense and industrial-scale procurements) to accelerate lead times for larger programs.
-
Regulatory and defense tailwinds: Naval procurement and national security programs are catalyzing design-for-certification pathways and dual-use platforms, shortening adoption cycles for technology that satisfies military-grade reliability and interoperability requirements.
-
Fragmentation and partnership economics: The market remains fragmented—top vendors collectively hold a modest share—creating room for new entrants, tiered suppliers, and white-label service providers. Strategic partnerships and M&A will be the fastest route to scale for many players.
Competitive Landscape — Strategic Positions to Watch
The Offshore AUV landscape is populated by specialized platform OEMs, systems integrators, and robotics-focused innovators. Several vendors have demonstrated differentiated propositions through platform endurance, dual-use capability, and integration of high-value sensor stacks. Leading players include long-standing maritime technology houses, diversified subsea service providers, and nimble robotics startups that excel in specific niches.
-
Kongsberg Maritime — A mature portfolio emphasizing long-endurance deep-water AUVs optimized for detailed mapping and infrastructure monitoring. Recent deliveries underscore a sustained push into defense and commercial survey contracts.
-
Oceaneering International — Positioned as a systems and service provider, leveraging multi-mission AUVs for inspection and light intervention. Notable contract awards demonstrate traction in both defense and high-value offshore service delivery.
-
Teledyne Marine — Offers versatile mid-size vehicles with strong seabed mapping and cable/asset inspection capabilities; benefits from broad sensor and subsea systems integration expertise.
-
Exail Technologies — Strong in converting defense-grade autonomy into commercial offerings, with emphasis on robust mission repeatability and industrial inspection standards.
-
ISE Ltd, Cellula Robotics, Kraken, Bluefin Robotics — Innovators delivering compact to large-class platforms for targeted survey and inspection missions; their agility and modern architectures make them attractive partners for specialized programs.
-
Saab Seaeye, ECA Group — Hybrid and dual-mode systems highlight their strength in flexible mission profiles and integration with defense procurement cycles.
Recent confirmed developments illustrate these dynamics: multi-million dollar defense and industrial contracts are moving into production and deployment; strategic orders from fleet operators are expanding AUV deployments; and production agreements are accelerating OEM output capacity. These events are accelerating maturity curves and compressing adoption risk for large-scale customers.
What Our Full Report Delivers (Actionable, Not Academic)
PW Consulting’s Offshore AUV Market report is designed as a decision-enabler for 2026 initiatives. Our deliverables are structured to be directly usable in boardrooms, procurement RFIs, and M&A diligence:
-
Top-down and bottom-up market sizing (2020–2025 historical; 2026–2032 forecast) with sensitivity and scenario runs—supporting conservative, base, and aggressive adoption trajectories.
-
Technology readiness and differentiation matrix—vehicle endurance classes, autonomy level, sensor payload compatibility, and integration complexity.
-
Commercial playbook—pricing archetypes, contract structures (CAPEX sale vs. managed services), and negotiation levers for each buyer persona.
-
Operational readiness templates—fleet deployment planning, maintenance cycles, crew training requirements, and onshore remote operations center (ROC) design considerations.
-
Vendor benchmarking—capability heatmaps, strategic fit assessments for potential partners, and M&A target scoring (technology, scale, go-to-market reach).
-
Investment and cash-flow models—TCO calculators that incorporate vehicle lifecycles, mission throughput, and data services margins for 5–10 year horizons.
-
Risk register and mitigation playbooks—supply-chain fragility, certification timelines, cybersecurity for autonomy stacks, and regulatory pathways for military adoption.
-
Executive-ready deliverables—concise one-page investment cases, board briefings, and procurement RFP templates complete with evaluation criteria.
How to Use This Intelligence When Making 2026 Decisions
-
For offshore operators (energy and renewables): prioritize modular procurement that preserves upgrade paths for sensors and autonomy software; model managed-service partnerships to accelerate capability while limiting upfront capital outlay.
-
For OEMs and systems integrators: double down on software-enabled services, invest in remote-operations tooling, and seek strategic partnerships that complement scale gaps—defense contracts are a credible route to sustained production demand.
-
For investors and corporate development teams: focus diligence on margin economics of recurring services and the quality of data pipelines; valuation multiples will increasingly reflect service annuities, not just hardware sales.
-
For defense acquisition planners: use dual-use platforms to accelerate procurement, but incorporate lifecycle-support contracts and interoperable data standards to maximize long-term value.
Signals to Monitor Closely in 2026
-
Defense contract awards and production agreements—these create capacity commitments and often de-risk supply chains for commercial uptake.
-
Fleet expansion orders by major operators—orders that move beyond pilot fleets into multi-unit deployments are the clearest indicators of structural demand.
-
Partnership announcements between vehicle OEMs and analytics or cloud providers—these often precede packaged as-a-service offerings that reshape buyer economics.
-
Regulatory or standards activity around autonomy, data formats, and certification—these can lower operational friction for adopters or create new compliance costs.
Final Note — The Trailer Ends Here; the Full Feature Awaits
This briefing outlines the strategic framing you need to act in 2026: a rapidly expanding market (with 2025 as the analytical base), double-digit CAGR through the forecast window, and a competitive environment where both incumbents and innovators will jockey for differentiated service positions. PW Consulting’s full Offshore AUV Market study contains the detailed regional and application splits, vendor-level revenue estimates, unit-price curves, and downloadable scenario models referenced here. Those granular datasets are intentionally withheld from this preview to preserve the utility of the full deliverable and the interactive tools we provide with it.
To convert insight into action—whether executing a multi-unit fleet roll-out, pursuing an acquisition, or drafting a multi-year defense procurement—access the complete report and interactive dashboards on our site. PW Consulting’s consultants stand ready to convert the report’s findings into bespoke strategic plans, procurement documents, and implementation roadmaps tailored to your organization’s risk profile and objectives.
For detailed analysis of this topic, please visit the official page: Offshore AUV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Protocatechuic Acid Market to Expand at 6.5% CAGR Through 2032
By PW Consulting, 2026-07-30
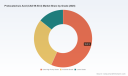
Protocatechuic Acid (CAS 99-50-3): Strategic Market Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive orientation to our full Protocatechuic Acid (PCA) market study (base year 2025). This briefing synthesizes the high-impact signals—demand drivers, quality and regulatory dynamics, supply-side architecture, and competitive posture—that will matter most to corporate decision-makers when shaping strategy in 2026. It is intentionally analytical but selective: we surface directional, data-driven conclusions while withholding granular splits to direct stakeholders to the full report for transactional-level intelligence.
Protocatechuic Acid (CAS 99-50-3) Market
Market trajectory and what it means for 2026 strategy
PCA has transitioned from a niche reagent to a strategic specialty chemical across pharmaceuticals, nutraceuticals, cosmetics and chemical intermediates. Our market model (historical 2020–2025; forecast 2026–2032) shows steady expansion driven by application diversification and upgraded purity requirements. Measured in USD Million, the global market expanded from an estimated ~83.5 in 2020 to roughly 115.0 in 2025, and under our central forecast it continues to grow at a compound annual growth rate (CAGR) of 6.5% through 2032, reaching an estimated ~179.3 by the end of the forecast window.
Protocatechuic Acid (CAS 99-50-3) Market
For 2026 corporate planning, three implications follow directly from that trajectory:
Protocatechuic Acid (CAS 99-50-3) Market
- Volume-led opportunities will co-exist with quality-led premiumization. Firms that can pair scale with validated ultra-high-purity capability will capture outsized margins.
- Supply-chain resilience is a commercial differentiator: buyers in regulated end-markets will pay a premium for consistent, audited sourcing that supports pharma/nutra filings.
- Product innovation (specialty grades, application-specific formats) unlocks value beyond commodity pricing—new grades targeted to adjacent categories (e.g., UV protection, bio-actives) already command higher willingness-to-pay.
Regulatory and quality landscape — constraints and enablers
PCA’s regulatory positioning is favorable but demanding. It is listed under FDA food substances (EAFUS) and is registered under REACH with no new broad environmental restrictions identified in our review. That baseline permits commercial applications across foods, flavors and nutraceuticals. However, the pharmaceutical pathway imposes a different calculus: both FDA and EMA require reproducible ultra-high-purity production and comprehensive quality systems for API or excipient use.
For 2026 action plans this implies two urgent priorities: (1) invest in validated quality systems and documentation (GMP, change controls, stability data) if pursuing pharma/nutra customers; and (2) codify regulatory readiness as a commercial asset—publishable quality certificates, audit trails, and regulatory dossiers materially shorten procurement cycles in regulated buys.
Supply-side archetypes and strategic choices
PCA production is bifurcating along technological and commercial lines: traditional organic synthesis manufacturers and emerging bioprocess/renewable producers. The former emphasize scale and synthetic route optimization; the latter emphasize traceable, renewable feedstocks and increasingly competitive yields. Both approaches co-exist in the market—and each creates distinct strategic options for buyers and investors.
- Organic synthesis players deliver predictable API-grade streams but face feedstock price volatility and synthetic step complexity.
- Bioprocess producers reduce carbon intensity and improve brand positioning for sustainability-conscious buyers, but require capex to scale and validated downstream purification to reach ultra-high-purity specifications.
2026 recommendations: industrial players should evaluate a dual approach—retain core synthetic routes for baseline supply while piloting bioprocess-derived PCA for premium, green-labeled product lines. Investors should prioritize platforms demonstrating scalable yield improvements or purification breakthroughs that close the quality gap with synthetic routes.
Competitive landscape: profiles and strategic readouts
The market is specialist-driven rather than consolidated. Leading suppliers range from long-established chemical houses to niche biotech-driven manufacturers and laboratory catalog suppliers. Key competitor archetypes we model include:
- Established regional manufacturers with deep synthesis experience and pharma-facing packaging/logistics capabilities—these firms excel at supplying intermediates and have entrenched customer relationships in traditional chemical applications.
- High-purity phytochemical specialists and GMP-capable providers—positioned to serve nutraceutical and API markets where documentation and traceability matter.
- Bioprocess innovators leveraging modified strains and plant-sourced feedstocks—their differentiator is sustainability and novel grade development for high-value applications in cosmetics and specialty nutraceuticals.
- Laboratory and custom synthesis suppliers—focused on small-batch, high-mix customers and custom derivatives for research and development pipelines.
Representative examples from our benchmark set illustrate these archetypes: a Zhejiang-based manufacturer with decades of production experience and packaging systems optimized for intermediates; GMP-capable phytochemical suppliers focused on high-purity nutraceutical ingredients; a Japanese bioprocess firm commercializing a proprietary, renewable route and recently launching an application-specific grade for UV protection; and global catalog leaders who protect market access via breadth of grades and trusted supply to research markets.
For 2026 competitive plays, three tactical moves stand out: (1) incumbents should double-down on quality credentials and customer audits to defend pharma/nutra channels; (2) growth-focused suppliers should diversify product lines to include application-optimized grades (e.g., cosmetic actives); and (3) new entrants and PE sponsors should target bolt-on buys that close a technology or regulatory gap rather than chase volume alone.
Commercial risks and mitigation
Our scenario analysis identifies four primary risks for 2026 planning:
- Quality disruption: batch-to-batch variability can shut out pharma/nutra demand. Mitigation: invest in analytical labs, robust QC, and third-party validations.
- Feedstock and energy price volatility: impacts synthetic-route economics. Mitigation: diversify feedstock contracts, explore hedging and partial vertical integration.
- Regulatory surprises in target geographies: localized rules on ingredients can delay commercialization. Mitigation: establish regulatory intelligence and dossier-ready assets.
- Competitive premium compression as more players pursue specialty grades. Mitigation: differentiate by certified sustainability claims, co-development services, and application-specific formulations.
What our full report delivers (practical, transaction-ready chapters)
The published study was designed as a playbook. Highlights of the practical deliverables include:
- Market sizing (historical 2020–2025; base year 2025) and a transparent forecast model (2026–2032) with scenario toggles for yield, price and demand elasticity.
- Regulatory matrix across FDA/EMA/REACH and flavor/food listings, complete with dossier checklists and audit-ready documentation templates.
- Supply chain and value-chain mapping: supplier tiering, logistics bottleneck analysis, and a raw-material purchasing scorecard.
- Competitive benchmarking and vendor scorecards covering manufacturing route, quality credentials, capacity posture, and go-to-market channels.
- Commercial playbooks: price negotiation levers, contract structures for long-term offtake, and product launch templates for specialty grades.
- M&A and partnership screens: financial thresholds, technological gap maps, and integration risk checklists customized for strategic and financial buyers.
Action plan for 2026 — prioritized and time-bound
Below is a short, prioritized roadmap we recommend for stakeholders preparing plans in 2026:
- 0–6 months: Conduct an audit of quality systems and obtain or update GMP-equivalent documentation if targeting pharma/nutra channels; secure at least two alternative supply lines and contractually protect price/volume exposure.
- 6–18 months: Fast-track a pilot for bioprocess-derived PCA or a differentiated specialty grade (coselect for sustainability certification); implement enhanced QC analytics and accelerated stability programs.
- 18–36 months: Execute capability-enhancing M&A or strategic JV to close identified production or regulatory gaps; scale premium grade commercialization and develop co-marketing arrangements with downstream formulators.
How PW Consulting can accelerate your 2026 outcomes
Our full PCA market study furnishes the numerical granularity and transaction tools that executives need to act with confidence: downloadable financial models, supplier due-diligence templates, regulatory dossier checklists and a ranked M&A target list. We pair the report with bespoke advisory services—supply-contract negotiation, techno-economic modeling for bioprocess scale-up, and integration support for acquisitions.
Note on market structure: the PCA marketplace remains specialist-driven and relatively fragmented compared with large commodity chemical categories—leading suppliers collectively account for under one-third of global volumes—so consolidation and bolt-on strategies remain valid routes to rapid scale if executed with quality and regulatory discipline.
Closing — why this matters in 2026
By 2026, PCA will no longer be a mere catalog item for many buyers; it will be a strategic input whose origin story, purity profile and supply reliability materially affect downstream product performance and regulatory acceptability. The combination of stable demand growth (our central forecast at a 6.5% CAGR) and accelerating premiumization creates a narrow window where capability upgrades and targeted partnerships produce asymmetric returns.
For executives evaluating investment, partnership, or acquisition opportunities in 2026, the decisive questions are simple but exacting: can you guarantee reproducible high purity at a competitive cost, and can you document it in a way that reduces buyer adoption friction? If the answer is no, the path forward is opportunistic partnership or targeted M&A; if yes, prioritize capacity and product differentiation to capture the margin spread between commodity and specialty segments.
For full segment-level data, supplier scorecards, and downloadable forecast models that underpin these strategic recommendations, please consult the complete PW Consulting Protocatechuic Acid market report. The granular intelligence there will move you from directional insight to executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Protocatechuic Acid (CAS 99-50-3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Ostomy Bags Market to Reach USD 306.83 Million by 2032 (5.4% CAGR)
By PW Consulting, 2026-07-30
Disposable Ostomy Bags Market 2026: Strategic Outlook for Corporate Decision‑Makers
As healthcare systems recalibrate after a period of accelerated change, disposable ostomy bags remain a mission‑critical category for manufacturers, payers and providers. PW Consulting’s new market research — anchored on a 2025 base year, five years of historical tracking (2020–2025) and a 2026–2032 forecast horizon — provides a pragmatic, executable framework for decisions in 2026. The global market reached approximately USD 215.0 Million in 2025 and, under our central forecast, expands at a 5.4% CAGR through 2032 to approach the low‑hundreds of millions of USD. This briefing summarizes the strategic value of the study and highlights the priorities executives must act on this year. (Note: detailed segment tables and granular competitive shares are reserved for the full report.)
Disposable Ostomy Bags Market
Why this study matters for 2026 decision cycles
-
Investment prioritization: Capital and R&D allocation in 2026 will hinge on near‑term growth, unit economics and regulatory risk. Our study converts market growth projections into actionable demand curves and break‑even timelines for product launches and manufacturing investments.
Disposable Ostomy Bags Market -
M&A and partnership targeting: The market shows meaningful concentration among a small number of established players, creating predictable consolidation dynamics. We map acquisition targets, likely synergies and valuation anchors to inform deal pipelines.
Disposable Ostomy Bags Market -
Reimbursement and bidding readiness: Recent changes to reimbursement and competitive bidding frameworks materially affect volume, pricing and channel choice. The report translates policy shifts into cash‑flow scenarios and go‑to‑market priorities.
-
Supply‑chain and regulatory risk mitigation: New sterilization and material requirements are already influencing supplier qualification and plant design decisions. The research outlines compliance pathways and alternative sterilization economics.
What the report delivers — practical, transaction‑grade outputs
-
Comprehensive market sizing and trend models (historical 2020–2025; forecast 2026–2032) with sensitivity runs and upside/downside scenarios.
-
Segment playbooks covering product types, clinical indications and distribution channels, each with decision trees for product prioritization.
-
Competitive landscape dossiers: strategic positioning, product portfolios, distribution reach and where each incumbent is vulnerable or defendable.
-
Regulatory and reimbursement impact assessment, including modelling of near‑term policy shocks and multi‑year outcomes for price & volume.
-
Commercial strategies: pricing optimization, bidding playbooks, tender strategies, and patient support program blueprints.
-
Supply‑chain and manufacturing playbook: sourcing of medical‑grade materials, ISO 13485 compliance checklists, sterilization options and cost comparisons.
-
M&A screening tools and valuation frameworks, including synergies for platform consolidation and bolt‑on models.
Data‑driven macro picture — what the numbers tell us
Our historified dataset shows steady expansion from 2020 through 2025, and the base case forecast anticipates continued, mid‑single‑digit annual growth through 2032. That growth is sufficient to sustain new product investment while also encouraging incumbents to compete on differentiation beyond basic functionality — for example, comfort, skin protection, and integrated care services.
The market exhibits a moderate to high level of concentration at the top: the leading three firms account for a substantial portion of global revenue, and the top five capture a clear supermajority. This concentration creates structural advantages for market leaders (scale in procurement, distribution contracts, and clinical trust), while creating opportunities for focused challengers to attack niche indications, low‑cost geographies or service enhancements.
Competitive landscape — what we examined
We profiled the principal global participants and numerous regional players to analyze where each competitor is positioned along the spectrum of product innovation, commercial reach and operational resilience. Among the notable firms covered are manufacturers with well‑established branded lines and global distribution footprints, providers of both one‑piece and two‑piece systems, and several regional specialists with strong clinician relationships. Our competitive assessment highlights:
-
Product differentiation vectors (e.g., adhesive technology, drainable vs closed systems, accessory ecosystems).
-
Distribution models (direct to clinic, distributor networks, retail and home‑delivery channels).
-
Clinical and brand equity factors that influence switching costs for patients and providers.
-
Potential white‑space areas—where incumbents underinvest or where regulatory change opens a window for newcomers.
Regulatory and reimbursement dynamics that will reframe 2026 tactics
Several developments are converging to impose new operational constraints and commercial opportunities:
-
Sterilization compliance: New occupational exposure limits and engineering control expectations for ethylene oxide sterilization mean manufacturers and contract sterilizers must invest in monitoring, containment and potentially alternative sterilization modalities. These changes affect unit costs, lead times and site selection for sterilization services.
-
Reimbursement policy updates: Recent Medicare and contractor guidance — including updated FAQs on ostomy supply coverage and the inclusion of ostomy supplies in bidding programs — require providers and suppliers to reassess pricing strategies and procurement participation. Short‑term coverage has remained intact, but competitive bidding adds pressure on margin and distribution models.
-
Quality and materials standards: Continued emphasis on ISO 13485 certified materials and manufacturing processes keeps the bar high for entrants and forces incumbent suppliers to maintain or upgrade certification regimes.
Strategic implications — recommended priorities for 2026
PW Consulting recommends executives prioritize the following actions this year:
-
Reassess sterilization strategy. Model the total cost of ownership for ethylene oxide vs validated alternatives (e‑beam, gamma, vaporized hydrogen peroxide) and define a staged transition plan to reduce exposure and regulatory risk.
-
Secure supplier redundancy for ISO‑certified raw materials. Build two‑tier supply relationships and qualify regional sources to shorten lead times and reduce single‑point vulnerabilities.
-
Prepare for competitive bidding. Run scenario analysis on net pricing, volume shifts and channel mix under both conservative and aggressive bidding outcomes; reconfigure contracts to protect margins where possible.
-
Invest in differentiated value propositions. Where product features converge, service elements (patient education, home delivery, adherence programs) and clinical outcomes data become decisive purchase drivers.
-
Target bolt‑on acquisitions that close supply chain, technical or distribution gaps. Use our M&A screen to prioritize targets with immediate synergies and manageable integration risk.
-
Align pricing and reimbursement teams with market access: proactively engage payers to document medical necessity and secure favorable quantities and coverage rules under local determinations.
-
Design commercial pilots in underpenetrated channels, using digital patient engagement to lower acquisition costs and improve adherence metrics.
How PW Consulting translates insight into execution
Clients engaging PW receive not only the market models and competitive intelligence but also hands‑on program support: bespoke financial models, regulatory readiness roadmaps, supplier due‑diligence packages, and implementation support for participation in bidding processes. Our team can rapidly deploy cross‑functional squads to deliver executable one‑page strategies for board review, detailed integration playbooks for M&A, and KPI dashboards to monitor market share and margin in real time.
Closing — a strategic “trailer”
Our research demonstrates a clear, actionable growth path for the disposable ostomy bags category: steady market expansion, concentrated leadership, and intensifying regulatory and reimbursement pressures that will reallocate advantage to operators who move decisively in 2026. This briefing intentionally highlights the strategic contours while withholding the detailed segment tables, regional breakouts and company share matrices that are most useful for transaction planning and tactical rollout. Those proprietary datasets—along with downloadable models, granular scenario outputs and competitor scorecards—are available via the full report.
Next steps
-
Request the full report to access segment‑level forecasts, pricing curves, regional demand matrices and detailed competitor market shares.
-
Commission a focused executive workshop (half‑day) to translate the findings into a 90‑day action plan covering commercial, operations and regulatory agendas.
For leadership teams deciding where to deploy capital, whom to partner with, or how to protect margin under evolving regulation, the 2026 window closes quickly. PW Consulting’s disposable ostomy bags study equips decision‑makers to act with clarity and speed — contact us to move from insight to impact.
For detailed analysis of this topic, please visit the official page: Disposable Ostomy Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ionomer Market — 2026 Strategic Outlook (Executive Introduction)
Why this briefing matters for 2026 enterprise decision-making
As companies reset priorities in 2026, ionomers are re-emerging from niche specialty polymers to strategic inputs across packaging, consumer goods, and emerging electrochemical technologies. Our latest PW Consulting study — anchored on a 2025 base year and a historical baseline from 2020–2025 — shows the global ionomer market has expanded from roughly USD 450 million in 2020 to about USD 580 million by 2025, and is forecast to continue growing at a compound annual growth rate of approximately 6.5% through 2032 (reaching roughly USD 890 million by the end of the forecast window). These headline metrics matter because they quantify scale, signal predictable demand corridors, and enable CFOs and strategy teams to stress-test capex, procurement and M&A scenarios against realistic market momentum.
Ionomer Market
How to read this briefing (the “trailer” approach)
-
We provide evidence-based directional insight and executable strategy framings that equip senior leaders to prioritize investments in 2026.
Ionomer Market -
To preserve actionable differentiation for subscribing clients, this introduction highlights structural drivers, competitive posture and decision levers — while withholding granular segment-level splits and proprietary tables that are available in the full study.
Ionomer Market -
Think of this document as a strategic compass: it shows the destination and the terrain; the full report provides the map, compass and downloadable waypoints.
Market momentum and what’s driving growth
-
Steady end-market expansion. The ionomer market’s mid-single-digit CAGR reflects a blend of mature demand in consumer packaging and selective, higher-growth adoption in performance applications (e.g., specialized industrial sealing, certain medical packaging formats, and performance sports goods). This combination produces a predictable base demand with episodic uplift from technology-driven pockets.
-
Product substitution and formulation advances. Incremental performance improvements in ionomer chemistries are enabling displacement of lower-value polymers in applications where toughness, clarity and barrier balance matter. Manufacturers that invest in tailored grades and concentrated go-to-market efforts are capturing value beyond commodity pricing.
-
Procurement and channel consolidation. Buyers are increasingly favoring suppliers with reliable supply chains, multiregional capacity and documented regulatory compliance. This dynamic amplifies the advantage of incumbents with integrated operations or secure distribution agreements.
Supply-side realities and regulatory context
-
Feedstock and cost volatility. Feedstock price swings and periodic disruptions in petrochemical feedstocks continue to compress margins for downstream processors. Procurement teams should assume elevated cost volatility and model scenarios where raw-material-driven input costs spike for extended periods.
-
Trade and tariff pressures. Recent trade policy shifts and tariff actions have altered the net landed cost calculus for resin imports and exports. Companies with agile sourcing — including alternate routing, nearshoring or tariff-mitigating contractual clauses — will defend margin and service levels more effectively.
-
Regulatory compliance as a differentiator. Stricter chemical registration regimes and environmental compliance requirements are raising the bar for new capacity and for suppliers that operate across multiple regulatory regimes. Suppliers that demonstrate early and robust compliance protocols gain preferential access to compliance-conscious buyers.
Competitive landscape — structure and implications
The market presents a moderately concentrated supplier base: the top three and top five players together account for a meaningful share of supply, creating a landscape where leading incumbents exert pricing and innovation influence while a long tail of regional players competes on specialization and service.
-
Incumbent manufacturers — Dow Inc., E.I. du Pont de Nemours, Honeywell, ExxonMobil, Solvay and others — retain advantages in scale, long-term offtake relationships and R&D depth. These firms are positioned to defend technical segments while pursuing incremental improvements in cost-to-serve.
-
Regional and specialty suppliers — including several Asia-based producers and niche formulators — are important sources of flexibility and local service. They play a critical role in regional supply balancing and can be acquisition targets for global players seeking market penetration.
-
Distributors and channel partners extend reach. Specialist distributors and formulators add value by bundling logistics and small-batch formulation services, a capability that matters to mid-sized converters and OEMs.
Company-level strategic postures (high-level)
-
Scale players (e.g., Dow, DuPont, ExxonMobil): prioritizing portfolio optimization, selective capex to support strategic grades and tighter integration with high-value customers. Expect them to lean on supply-security offers and co-development agreements.
-
Technology- and specialty-focused firms (e.g., Solvay, Asahi Kasei, Kuraray): emphasizing differentiated grades, niche applications and regulatory compliance credentials. Their playbook centers on premiumization and technical partnerships.
-
Regional challengers and distributors: leveraging agility, competitive cost structures and proximity to local converters. They are potential consolidation targets for global players pursuing faster market entry.
-
Market implications: buyers will need to balance the security and innovation of tier-one suppliers with the cost and proximity advantages offered by regional producers and distributors.
What the full PW Consulting report delivers (practical contents)
-
Validated market sizing and forecasts (2020–2032), with scenario breakouts that stress-test demand under different macroeconomic and feedstock scenarios.
-
Comprehensive segmentation analyses by region, product type and application — available in interactive charts and downloadable datasets for client modelling (note: detailed segmental tables are included in the full report access).
-
Supply-chain and cost-to-serve mapping, including a supplier capability matrix, logistics risk heatmaps and second-tier supplier visibility.
-
Regulatory and policy matrix summarizing compliance obligations across major jurisdictions, plus a compliance-readiness checklist for manufacturers and importers.
-
Commercial playbooks: pricing strategy frameworks, procurement hedging options, and go-to-market tactics for suppliers and converters.
-
M&A and partnership screening: prioritized targets, valuation benchmarks, and integration risk considerations tailored to different strategic objectives (scale, technology access, regional entry).
-
Case studies and supplier scorecards that illuminate winning commercial and R&D initiatives from market leaders and fast followers.
Actionable 2026 recommendations for decision-makers
-
Finance & Planning: Rebase medium-term plans to the market growth envelope — use the study’s base-case CAGR and scenario models to size capex and inventory buffers. Prioritize flexible investments that retain upside optionality.
-
Procurement: Implement multi-scenario sourcing playbooks that hedge against feedstock-driven cost inflation and trade-policy shocks. Secure contractual language for supply continuity and indexed pricing where appropriate.
-
Commercial & Product: Fast-track application development in higher-value niches and validate premium formulations with co-development partners. Where possible, move from raw-material purchasing to value-based contracting.
-
Regulatory & Compliance: Invest in registration and compliance programs in jurisdictions where your supply chain is exposed. Early compliance is a barrier to entry and a commercial differentiator.
-
M&A & Partnerships: Scan for regional producers or specialty formulators that complement existing portfolios. Focus on bolt-on acquisitions that deliver immediate route-to-market or technical capability.
Decision-support deliverables and next steps
For leadership teams, this study functions as both a market intelligence tool and an execution playbook. In addition to the narrative and analytic chapters summarized above, subscribing clients receive: downloadable datasets, financial benchmarks and a customizable slide pack for board-level briefings. We also provide optional scenario workshops and supplier negotiation simulations to translate insights into measurable actions for 2026.
How PW Consulting’s analysis differs
-
Integrated forward-looking scenarios: we combine macro demand trajectories with supply-side shock modeling so leaders can see not just the most likely path, but plausible stress cases that affect margin, availability and customer service.
-
Action-orientation: beyond market maps, the report prescribes concrete tactical moves — from procurement clauses to M&A prioritization — with impact estimates tailored to client archetypes.
-
Supplier-level intelligence: our firm-level benchmarking and scorecards illuminate which suppliers lead on innovation, service, compliance and cost — enabling sharper shortlist decisions.
Closing summary
The ionomer market in 2026 is a market of measured growth: sufficient scale and predictable expansion to justify strategic investment, but also subject to episodic volatility from feedstocks, trade policy and regulatory developments. Firms that combine disciplined scenario planning, supplier strategy and targeted product innovation will capture disproportionate value as the market passes through its next phase of industrialization.
Call to action
To access the full datasets, interactive segment dashboards and the vendor scorecards referenced above, please visit the PW Consulting report page for the Ionomer Market 2026 Strategic Outlook. The full study contains the detailed segment tables, regional splits and downloadable financial models that executives and deal teams require to translate strategic intent into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Ionomer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Duty Free Retailing to Hit USD 83.91B by 2032 at 6.2% CAGR
By PW Consulting, 2026-07-30
Duty Free Retailing Market — Strategic Outlook for 2026 Decision-Making
As global travel re-enters a phase of structural normalization and experiential retail regains its premium appeal, the duty free retailing sector is once again at an inflection point. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical performance and a forward-looking forecast to 2032, providing commercial leaders with the decision-ready intelligence they need for 2026 and beyond. At a macro level, the market expanded materially through 2020–2025 (rising from roughly USD 41.6 billion in 2020 to USD 55.0 billion in 2025) and is projected to continue growing at a steady compound annual growth rate of 6.2% in our 2026–2032 forecast, reaching an elevated market scale by 2032. This report is designed as a practical playbook: deep enough to validate strategy, selective enough to preserve competitive advantage — and intentionally structured to send readers to our full intelligence platform for the granular datasets and proprietary segmentation tables.
Duty Free Retailing Market
Why 2026 Is a Strategic Pivot Year
Several converging dynamics make 2026 a critical year to revisit positioning and investment plans. First, passenger volumes and spend-per-passenger are decoupling across corridors and customer cohorts — meaning the old “one-size-fits-all” concession model is increasingly suboptimal. Second, the balancing act between experiential real estate (gate-side, boutique concepts) and efficiency-led formats (cashwrap consolidation, automated kiosks) is sharpening capital allocation decisions. Third, regulatory and partnership changes — evidenced by high-profile terminal partnerships and new long-term contracts awarded across major hubs — are altering bargaining power between landlords, operators, and brands. Finally, a rising concentration among leading operators signals both scale advantages and pockets of opportunity for differentiated entrants.
Duty Free Retailing Market
Key Market Signals from the Report
-
Stable, mid-single-digit growth trajectory: The sector’s 2026–2032 CAGR of 6.2% positions duty free as a durable, inflation-hedged retail category, attractive to strategic investors focused on travel-linked retail exposure.
Duty Free Retailing Market -
Moderate market concentration: The top three and five players command a substantial share of global concessions (our report documents CR3 and CR5 metrics), which creates both entry barriers and predictable consolidation patterns for M&A and bid strategies.
-
Format and channel evolution: Gate-side convenience stores, curated luxury boutiques, lounge-integrated concepts, and omnichannel pickups are becoming table stakes in premium hubs; meanwhile, secondary hubs are optimizing footprint versus revenue density.
-
Regulatory and contract cadence: Recent contract awards and public-private partnerships are shifting value capture — long-term concession wins are now driving strategic investments in store experience and digital enablement.
What the Report Delivers (Practical Contents)
The study is intentionally action-oriented. Leaders who implement its findings will find tools and templates that translate market intelligence into executable plans. Key deliverables include:
-
Top-down market sizing and scenario forecasts (2026–2032), with alternate demand scenarios tied to passenger recovery curves and pricing environments.
-
Concession economics models for multi-format portfolios (capex, opex, revenue-per-square-meter stencils, breakeven matrices).
-
Operator benchmarking: qualitative and quantitative scorecards covering brand curation, loyalty integration, supply chain resilience, and digital maturity.
-
Negotiation playbooks for airports and landlords: concession term design, performance KPIs, revenue-share modeling, and incentive structures for customer-experience investments.
-
Retailer playbook: assortment optimization frameworks, dynamic pricing triggers, and omnichannel tactics to capture spend pre-trip, in-airport, and post-trip.
-
Investment and M&A compendium: valuation multiples, typical earn-out structures, and risk-adjusted return scenarios for buy-side and sell-side stakeholders.
-
Regulatory and tax-impact matrix that ties changing duty rules, customs processes, and travel policies to revenue sensitivity across models.
Competitive Landscape — Themes and Strategic Moves
The competitive map is dominated by operators with scale, deep airport relationships, and differentiated service offerings. Our analysis covers the major global players, their strategic archetypes, and the recent tactical moves that will shape competition in 2026:
-
Avolta AG — expansion through long-term airport contracts and experiential offers. Recent multi-year contract wins and store openings in major international hubs signal aggressive network growth and a willingness to invest in F&B-integrated retail experiences.
-
DFS Group and China Duty Free Group — luxury-led proposition and travel-hub dominance. These firms continue to set benchmarks for premium brand partnerships and curated in-store experiences tailored to high-spend travelers.
-
Gebr. Heinemann and Lagardère Travel Retail — platform operators that balance concession breadth with concept innovation. The launch of new retail concepts and strategic contract awards demonstrates a dual focus on footprint quality and creativity.
-
Lotte Duty Free, The Shilla, King Power — regional champions with cross-border ambitions. Their strength in home markets and outbound traveler flows remains a key differentiator for brand suppliers seeking scale in specific source markets.
-
Dubai Duty Free, Aer Rianta, Duty Free Americas, DFI, and regionally focused operators — niche leadership at high-volume hubs and borders. These operators leverage iconic locations and operational excellence to sustain premium sales density.
-
OSPR EE — an example of rapid local-market innovation: targeted campaigns and lounge-integrated concepts in India show how operators can extract incremental revenue by aligning with local passenger behavior and premium travel segments.
Recent public developments reported in the market — new contracts at major U.S. terminals, gate-side store rollouts, and strategic concept launches in Europe and Latin America — underscore two realities: contract wins today are the seedbeds of revenue growth through the 2030s, and operators that pair network scale with local curation will capture the highest value per passenger.
Strategic Implications by Stakeholder
-
Operators: Prioritize a two-speed approach — invest selectively in experiential flagship stores at premium hubs while optimizing micro-format economics in secondary locations. Use concession analytics to negotiate downside protection and capex milestones with landlords.
-
Airport landlords: Redesign concession packages to incentivize digital revenue capture and brand exclusivity while safeguarding base rent. Long-term contracts should embed experience and data-sharing KPIs.
-
Luxury and consumer brands: Treat duty free as a high-ROI brand-staging channel; invest in travel-exclusive SKUs and seamless omnichannel customer journeys that link pre-trip touchpoints to in-terminal conversion.
-
Investors and PE: Focus on operators with proven concession renewal pipelines and digital monetization levers; the market’s moderate concentration favors platform roll-up strategies in underpenetrated regions.
Risk Scenarios and Operational Priorities
Our scenario analysis highlights variables that will materially alter outcomes for 2026 strategy:
-
Downside travel shocks (geo-political events, health disruptions) could compress spend-per-passenger and shift mix toward essentials; resilient operators will rely on flexible lease terms and rapid assortment rebalancing.
-
Regulatory shifts in duty and customs processing can create both upside and downside; operators should model sensitivity to tax changes and pursue multi-jurisdiction pricing strategies.
-
Technology disruption (biometrics, frictionless checkout, data-driven personalization) will separate leaders from laggards; prioritize scalable tech pilots and brand-partner integrations.
-
Sustainability and social licensing are emerging procurement filters for major brands and airports — embedding circularity and transparency into supply chains reduces reputational and regulatory friction.
How Companies Should Use This Report in 2026
Concrete use-cases for 2026 planning include:
-
Bid and concession strategy — use our concession economics templates to stress-test offers and structure performance-linked renewal clauses.
-
Portfolio optimization — identify which formats to scale, where to co-locate F&B, and where to introduce gate-side concepts to capitalize on dwell time.
-
Go-to-market for brands — map premium activation budgets to hubs that deliver target KPIs (frequency of high spenders, dwell time, purchase intent) rather than relying solely on historical allocations.
-
M&A diligence — apply our valuation and synergy frameworks when evaluating platform acquisitions, particularly in regions with fast passenger rebound and favourable concession cycles.
Closing — The Strategic Value Proposition
Duty free retailing in 2026 is less about reclaiming pre-pandemic status and more about reimagining the travel retail proposition for a segmented traveler base. Our study provides the forecasting rigor, commercial tools, and competitive diagnostics required to make informed, high-confidence choices about footprint, partnerships, and capital allocation. The analysis you see here is a strategic trailer: it outlines the map and the high-ROI trails. The full report contains the proprietary segmentation tables, regional and application-level modeling, and vendor scorecards that will enable detailed financial modeling and concession-level decisioning. For the full dataset, scenario files, and bespoke advisory engagement options, please refer to PW Consulting’s Duty Free Retailing Market research portal.
For detailed analysis of this topic, please visit the official page: Duty Free Retailing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pentaerythritol Market to Reach USD 304.6 Million by 2032
By PW Consulting, 2026-07-30
Pentaerythritol (CAS 115-77-5) Market — 2026 Strategic Preview
Executive summary
As companies set budgets and capital plans for 2026, a precise understanding of the pentaerythritol market is becoming a commercial imperative. PW Consulting’s latest market study positions the industry at a clear inflection point: after expanding from an estimated market value of USD 163.15 Million in 2020 to USD 215.0 Million in our base year 2025, the sector is forecast to grow to approximately USD 304.6 Million by 2032 under a 5.15% compound annual growth rate for the 2026–2032 horizon. That trajectory masks important near‑term volatility driven by raw material pricing, discrete capacity additions, and a tightening regulatory and trade landscape — dynamics that will materially influence supplier selection, contract terms, and investment timing in 2026.
Pentaerythritol (CAS 115-77-5) Market
Why this study matters for 2026 decision-makers
-
Timing of capacity: Several large capacity projects commissioned in 2024–2025 have already begun to reshape regional supply balances. Buyers and investors who wait for longer-term trendlines without a tactical response risk margin compression or missed volume opportunities.
Pentaerythritol (CAS 115-77-5) Market -
Cost structure sensitivity: Formaldehyde remains the dominant cost input in pentaerythritol production. Our analysis shows formaldehyde can account for roughly 58–68% of operating costs — a structural exposure that makes feedstock strategy (integration, hedging, or long‑term contracting) one of the strongest levers for 2026 performance.
Pentaerythritol (CAS 115-77-5) Market -
Regulatory and trade noise: Recent tariffs and duties introduced in specific markets, along with classification under established HTS codes, are already altering trade flows and landed cost calculations. Such developments require immediate incorporation into pricing and sourcing models.
Market dynamics and demand drivers
Pentaerythritol’s industrial role continues to be anchored by mature downstream segments such as coatings, lubricants, and plasticizers, with additional pockets of demand coming from explosives precursors and select agricultural chemistries. Demand growth through the next planning horizon is modest but structurally resilient, driven by end‑market paint and coatings recovery, incremental lubricant formulation upgrades, and diversification into higher‑value specialty applications (including renewable certified grades).
Price dynamics are already reflecting this mixture of steady underlying demand and episodic supply changes. For example, market reporting in late 2025 registered a near‑term price correction in the U.S. — an 8% month‑over‑month decline in November 2025 while still showing meaningful year‑over‑year gains. Those moves illustrate how new capacity, regional demand shifts, and feedstock cost pass‑through manifest quickly in trading lanes.
Supply‑side shifts and competitive landscape
The producer base is moderately concentrated: the top three players account for a majority share, and the top five capture a substantial portion of global output. That concentration profile creates both opportunities and risks for corporate buyers and strategists. On one hand, it enables negotiating leverage with a limited set of suppliers; on the other, it amplifies the impact of individual capital projects or policy changes on global availability.
Recent, material supplier movements are illustrative. A leading European specialty producer commissioned a 40,000 MT/year plant in India in 2024 that is aimed at both standard pentaerythritol and an ISCC Plus certified renewable grade, signalling clear supplier intent to win formulated coatings and sustainability‑driven business. Parallel expansions and new lines — including small‑to‑midscale launches targeted at coatings and pharmaceutical grades, and announced capacity additions in China with integrated feedstock strategies — tighten regional supply in the near term and shift competitive dynamics toward cost and sustainability differentiation.
Key producers active in this cycle include legacy specialty chemical companies and regional manufacturers across Europe, Asia, and the Middle East. Companies have varied strategic postures: some are pursuing green‑grade certification and geographic diversification; others are focused on incremental capacity and feedstock integration to lower cash costs. For procurement and strategy teams, mapping supplier intent (capacity, feedstock, product grades, sustainability credentialing) is now table stakes for effective sourcing negotiations in 2026.
Cost, trade and regulatory headwinds
Operational economics for pentaerythritol are highly sensitive to formaldehyde feedstock pricing. Spot and contract formaldehyde prices — for example, reported FOB levels in major chemical production regions — should be an input to every forecast and hedging model. As an example of volatility transmission, even modest moves in feedstock pricing translate directly into margin swings for merchant producers and influence the competitiveness of integrated producers.
Trade measures are also shifting competitive advantages. Certain jurisdictions have introduced additional import duties or administrative measures in recent years; classification under established HTS headings means general duty schedules apply in important markets but these can be amended or compounded by country‑level measures. Procurement teams must therefore treat landed cost as a dynamic variable, not a static input.
Pricing and scenario playbook for 2026
Our market model stresses three plausible scenarios for 2026, each with distinct commercial implications:
-
Base case — steady demand with full absorption of recent capacity: Moderate price compression relative to peak levels but sustainable margins for integrated and specialty producers. Tactical recommendation: favor flexible annual contracts with volume bands and indexation to formaldehyde.
-
Downside — overhang from quicker‑than‑expected capacity ramp-up or demand softness: Spot prices face notable pressure; merchant sellers are forced into aggressive commercial terms. Tactical recommendation: secure offtake or capacity reservation agreements and accelerate downstream product migration to differentiated grades.
-
Upside — sustained end‑market strength and feedstock tightness: Improved pricing power returns to sellers, rewarding producers with feedstock integration and premium product portfolios. Tactical recommendation: selectively release volumes to spot and renegotiate long‑term contracts with step‑up pricing clauses.
What the PW Consulting report delivers (practical content)
-
Forward-looking demand model calibrated to historical 2020–2025 performance and detailed to 2032, with scenario toggles for feedstock price, regional demand elasticity, and capacity ramp timing.
-
Price deck and margin sensitivity tables that explicitly model formaldehyde pass‑through and the effect of regional duties and freight on landed costs.
-
Supplier benchmarking and strategic profiles, including production footprint, recent capex, sustainability credentials and commercial posture — enabling rapid short‑lists for sourcing or partnership.
-
Regulatory and trade impact analysis that operationalizes HTS classifications, recent country measures, and likely near‑term policy risk.
-
Commercial playbooks for procurement, sales and M&A: recommended contracting structures, integration pathways, and a prioritized list of tactical moves for 12–24 month horizons.
-
Risk heatmaps, capex stress tests, and investor due diligence templates for buyers and financiers evaluating capacity investments or strategic acquisitions.
Strategic recommendations for 2026
-
Prioritize feedstock security: given formaldehyde’s outsized share of production cost, evaluate vertical integration, long‑dated supply contracts, or formaldehyde price hedges as core defensive moves.
-
Diversify against regional trade risk: incorporate duty and landed‑cost scenarios into supplier selection; maintain at least two non‑coincident supply sources for critical volumes.
-
Lock in differentiated product supply: align procurement and R&D to secure access to ISCC‑certified and other higher‑margin grades that are being rolled out by major suppliers.
-
Adopt flexible contracting: move away from rigid fixed‑price, fixed‑volume contracts where possible; use indexed pricing, step‑clauses, and volume bands to share risk with suppliers.
-
Prepare for opportunistic M&A and JV activity: capacity and technology acquisitions can be executed at attractive prices in downside scenarios — have a 90‑day action plan and a short list of targets.
-
Institutionalize scenario planning: embed a rolling 18‑month scenario review into commercial planning cycles to react to feedstock, capacity and trade shocks in near real time.
Conclusion — the decision horizon for 2026
For executives and commercial teams making 2026 decisions, the choice is between passive exposure to market volatility and an active strategy that uses feedstock management, selective contracting, and supplier intelligence to lock in margin and volume. PW Consulting’s study provides the analytical scaffolding to make those choices defensible: a calibrated market model, supplier and regulatory mapping, and executable commercial playbooks designed for immediate use.
This preview highlights the strategic contours you need to consider now. For the complete dataset, segmented demand and supply matrices, and downloadable contract templates that operationalize the recommendations above, consult the full PW Consulting Pentaerythritol Market report — it contains the granular inputs and proprietary segment breakouts necessary to convert 2026 uncertainty into advantage.
For detailed analysis of this topic, please visit the official page: Pentaerythritol (CAS 115-77-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Artificial Grass Turf Set to Grow to USD 12.4B by 2032, 8.3% CAGR
By PW Consulting, 2026-07-30
Artificial Grass Turf Market — Strategic Outlook for 2026 Decision-Makers
Executive teaser
PW Consulting’s 2026 Artificial Grass Turf Market brief synthesizes a decade of observable shifts into a practical strategic playbook for executives, investors, and procurement leads. The global market has expanded steadily from an estimated USD 5.2 Billion in 2020 to USD 7.3 Billion in the base year 2025, and our forecast projects continued expansion through 2032 (reaching roughly USD 12.4 Billion) at a compound annual growth rate (CAGR) of 8.3% over the 2026–2032 horizon. These headline figures frame a market that is large enough to support global incumbents and specialized challengers alike, while remaining fragmented (CR3 ~35%, CR5 ~38%)—a structural feature that shapes competitive and transactional opportunities in 2026.
Artificial Grass Turf Market
Why this research matters for 2026 decisions
-
Capital allocation: prioritize investments between product innovation (infill-free systems, bio-based fibers), retrofit pipelines for sports venues, and geography-specific go-to-market deployments.
Artificial Grass Turf Market -
Regulatory readiness: quantify the near‑term commercial impact of hard deadlines and evolving chemical evaluations so R&D and compliance teams can sequence filings and certifications.
Artificial Grass Turf Market -
Supply chain resilience: model scenarios that incorporate raw-material constraints, tariff reclassifications, and recycling feedstock availability to protect margins and delivery commitments.
-
M&A and partnership scouting: identify segments where consolidation or vertical integration delivers outsized value—manufacturing, infill innovation, and professional installation services are primary levers.
-
Commercial execution: tune pricing, warranty, and service bundles to reflect lifecycle economics that buyers increasingly demand (installation, maintenance, end‑of‑life management).
Data‑driven trends shaping the market
Several convergent forces make 2026 a tactical inflection point rather than a routine planning year. Urban densification, water‑conservation mandates, and municipal investments in sports and recreation are sustaining demand; meanwhile product innovation is expanding addressable use cases beyond traditional stadium and landscaping applications. The market’s mid‑single‑digit-to-high‑single‑digit growth trajectory is underpinned by continued replacement cycles and rising adoption in residential and commercial retrofit projects.
At the same time, external constraints are reconfiguring the economics of incumbent systems: regulatory action on microplastics and chemical exposures, evolving end‑of‑life expectations (recycling and circular‑feedstock loops), and tariff/legal reclassifications are compressing the runway for “business as usual” product portfolios. For suppliers, the strategic imperative in 2026 is to translate these macro realities into defensible product roadmaps and resilient supply chains.
Regulatory and raw‑material dynamics to watch now
-
European regulatory pressure—illustrated by a ban on granular turf infill enacted in 2023 with a sales prohibition timeline—creates a multi‑year compliance cliff. Companies that rely on conventional granular infill must accelerate alternative infill development, certification, or managed exit strategies for EU markets.
-
North American risk/reassurance signals are mixed: California’s DTSC background work (2024) elevated chemical screening and disclosure expectations, while a March 2026 OEHHA study produced findings that reduce immediate health‑risk uncertainty for certain crumb‑rubber systems. Together these developments create a patchwork of obligation and opportunity—companies that can demonstrate robust exposure analyses and transparent materials sourcing will enjoy competitive advantage.
-
Crumb rubber has been a major recycled feedstock for infill systems; substitution economics and circular‑supply opportunities will be decisive. Expect manufacturers and recyclers to compete over large tire‑derived streams and alternative bio‑based infill options in 2026–2027.
-
Trade and classification shifts (notably a CBP ruling effective mid‑2024) affect landed cost calculations for importers and should trigger an immediate review of supplier contracts and pricing models.
Competitive landscape — positioning and implications
The market structure—large installed players plus many regional specialists—rewards distinct strategic postures. Below we summarize the competitive DNA and likely near‑term plays of primary firms covered in our full analysis.
-
FieldTurf (Montreal, Canada — https://fieldturf.com/en/) : Historically the pioneer of infilled synthetic turf for sports, with very large global installed base. Strengths include brand equity in elite sports venues, proven field‑performance data, and installation expertise. In 2026 their strategic choices will center on accelerating low‑microplastic and infill‑replacement offerings while leveraging service contracts to stabilize aftermarket revenue.
-
Tarkett (Paris, France — https://www.tarkett.com/) : As a global flooring group manufacturing FieldTurf products, Tarkett’s multi‑category scale enables cross‑selling into institutional channels. Their advantage lies in systems integration and global distribution; risk centers on aligning legacy production footprints with new EU regulatory timelines and sustainability disclosures.
-
SYNLawn (United States — https://www.synlawn.com/) : Distinguished by plant‑based artificial grass solutions geared to residential, playground, and commercial clients. Their value proposition is differentiated‑materiality (bio‑based content) and direct‑to‑consumer channels—an attractive model for premium residential retrofit demand where homeowners prize aesthetics and low maintenance.
-
TenCate Grass (Netherlands — https://www.tencategrass.com/) : A leading materials and fiber producer, with notable technology in infill‑free systems. TenCate’s strategic leverage is upstream control over fiber innovation and performance testing; they are well placed to supply OEMs looking to pivot away from granular infill.
-
Smart Turf (Santa Fe Springs, CA — https://smartturf.com/) : A North American wholesale manufacturer known for high‑quality product breadth. Their playbook in 2026 will emphasize cost competitiveness, rapid fulfillment for installers, and private‑label partnerships—critical for channel expansion.
-
Sprinturf (United States — https://www.sprinturf.com/) : Integrated polyethylene turf manufacturer concentrating on athletic fields. Sprinturf’s core asset is manufacture‑to‑spec capability and turnkey delivery for performance sport segments; strategic focus should include durability enhancements and lifecycle service offerings to lock in stadium and institutional contracts.
-
Southern Turf Co. (Austin, Texas — https://www.southernturfco.com/) : Regional specialist with strong local installer relationships for sports and landscaping. Their agility in project execution and local authority approvals is a commercial moat—an attractive acquisition target for vertically integrated players seeking field service scale.
-
GeoSurfaces (St. Gabriel, Louisiana — https://geosurfaces.com/) : Designer and installer of high‑performance sports surfaces including artificial turf. GeoSurfaces’ value proposition is design and performance optimization for competitive venues; they are a natural collaborator for material innovators seeking pilot venues and performance validation.
Strategic implications by corporate archetype
-
Large OEMs and conglomerates: protect installed‑base economics with warranty and service tiers, invest in certification and regulatory lobbying, and accelerate low‑microplastic product lines.
-
Material innovators and fiber suppliers: push toward infill‑free, recyclable fibers and collaborate with certification bodies to shorten time‑to‑market.
-
Regional installers and wholesalers: capture retrofit demand through bundled design‑to‑maintenance contracts and cultivate municipal relationships where replacement cycles accelerate.
-
Private equity / investors: pursue roll‑up strategies in regional installation platforms and aim to integrate upstream fiber or infill capabilities to improve margin capture.
What the full PW Consulting report delivers (select operational assets)
-
Dynamic market model (2020–2032) with scenario toggles for regulatory trajectories, material‑price shocks, and substitution adoption curves.
-
Competitor benchmarking toolkit: product specs, performance matrices, and go‑to‑market scoring for the primary players and 50+ regional providers.
-
Regulatory impact calculator that simulates revenue sensitivity to major policy moves (EU infill ban timelines, state chemical restrictions, tariff reclassifications).
-
Procurement and installation playbooks: sample RFPs, contract clauses for end‑of‑life handling, and lifecycle cost calculators for buyers and sellers.
-
Technical annexes: LCA templates, field‑test protocols, and certification roadmaps to support fast‑tracked product approvals.
-
M&A shortlist and diligence checklists tailored to buyer archetypes, including integration risk matrices and synergies checklist.
Decisioning framework for 2026 — recommended next moves
For executives making portfolio decisions this year, PW Consulting recommends a three‑pronged approach:
-
Immediate (0–12 months): complete regulatory gap analyses for your product lines; accelerate certification efforts where OEHHA or equivalent studies reduce liability uncertainty; and lock down critical recycled feedstock or substitute infill supply contracts to avoid mid‑cycle shocks.
-
Near term (12–24 months): pilot infill‑free and bio‑based offerings in priority markets, bundle maintenance/monitoring services to create recurring revenue, and pursue targeted bolt‑on acquisitions in installation capabilities.
-
Medium term (24–48 months): scale circular‑economy operations (recovery and recycling), reconfigure manufacturing footprints to optimize tariff exposure, and deploy product lines aligned with the most restrictive regulatory scenarios.
Closing — why read beyond this trailer
The Artificial Grass Turf sector in 2026 is simultaneously expanding and fragmenting—growth opportunities coexist with regulatory and supply‑chain inflection points that require nuanced, operationally specific responses. PW Consulting’s full study converts headline growth (CAGR 8.3%, projected market expansion through 2032) into executable choices: what to invest in, which partners to court, where to avoid stranded assets, and how to capture aftermarket value. For teams tasked with prioritizing 2026 capital, product, and M&A workstreams, the full report provides the models, benchmarks, and playbooks to act with conviction. Access the complete dataset and proprietary segmentation to translate these strategic directions into measurable plans.
For detailed analysis of this topic, please visit the official page: Artificial Grass Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mobile Photo Printer Market to Reach USD 652M by 2032 at 7.6% CAGR
By PW Consulting, 2026-07-30
Mobile Photo Printer Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The mobile photo printer market is re-entering a structural growth phase after a short-term contraction, driven by renewed consumer interest in physical mementos, expanding use-cases in experiential marketing, and steady improvements in portable printing technology. Our base-year analysis (2025) shows the market at roughly USD 390 million. Under the core forecast assumptions, the market is expected to expand at a compound annual growth rate (CAGR) of 7.6% through 2032, reaching approximately USD 652 million. Market concentration remains meaningful (CR3 ~62.5%; CR5 ~78.0%), which shapes competitive behavior, pricing power, and the strategic calculus for challengers and incumbents alike.
Mobile Photo Printer Market
Why this research matters for 2026 decision cycles
-
Timing for product and channel investments: 2026 is the inflection year when many firms will decide whether to double down on portable hardware, pivot toward software-enabled ecosystems, or pursue asset-light models (licensing, branded consumables). Our forecast horizon (2026–2032) provides the basis for NPV-driven capital allocation under three plausible macro scenarios.
Mobile Photo Printer Market -
Supply-chain resilience and sourcing choices: the 2025 downturn amplified supplier risk (paper, inks, components). Procurement strategies formulated in 2026 will determine manufacturers' unit economics for the remainder of the decade.
Mobile Photo Printer Market -
M&A and partnership windows: given the concentrated vendor landscape and rising value of embedded software and consumables, 2026 will offer unique opportunities to acquire capabilities or lock distribution channels before mid-decade consolidation accelerates.
Market trajectory and structural drivers
High-level dynamics are simple but consequential. After recent volatility that produced a lower base in 2025, the sector regains momentum as product innovation (smaller, faster, app-centric printers), materials advances (water-based inks, recyclable media), and service-led models (print-as-a-service for events, subscription consumables) converge. The projected 7.6% CAGR to 2032 reflects a combination of modest unit growth, improving ASPs for feature-rich devices, and recurring consumable revenues.
Three demand vectors underpin the forecast:
-
Consumer personalization: Despite digital-first lifestyles, physical prints retain emotional and gifting value. Manufacturers that embed creative apps, AR filters, and social integrations unlock higher attach rates.
-
Commercial experiential use: Retail, hospitality, and events increasingly use mobile printing for customer engagement — a pathway to larger average order values and recurring B2B contracts.
-
Cost and sustainability pressures: Regulation and raw-material constraints are shifting supplier economics, creating winners among firms that optimize for recyclable media and low-waste thermal technologies.
Competitive landscape — what we see and what it means
The market is led by a mix of legacy imaging brands and more agile, often China-based specialists. Key competitive attributes are brand equity, media/consumables ecosystems, technology choice (ZINK vs dye-sublimation vs thermal), app experience, and channel reach.
-
Fujifilm Holdings (Japan) — With the instax mini Link family, Fujifilm couples strong brand recognition with hardware and app co-design. The January 2026 launch of the instax mini Link+ shows a continued play on differentiated user experiences (augmented app features and tighter device-app integration). For incumbents, Fujifilm’s roadmap highlights the importance of combining tactile product appeal with a compelling mobile UX to sustain premium pricing.
-
Canon Inc. (Japan) — Canon’s SELPHY and IVY series illustrate the advantage of leveraging optical and printing expertise into compact, dye-sublimation solutions. Canon’s channel depth in photo-retail and office channels is a strategic asset; competitors should consider partnerships that replicate similar channel intimacy.
-
HP Inc. (United States) — HP’s Sprocket line demonstrates the viability of pocket-form printers paired with strong software ecosystems. HP’s scale enables promotional bundling and consumable distribution that smaller players find difficult to match.
-
Kodak (United States) — Kodak’s STEP and Mini offerings blend heritage branding with multiple print technologies. Kodak’s approach underscores that legacy IP can be repositioned successfully for mobile-first consumers if supported by a compelling value prop and reliable media supply.
-
Polaroid (United States) — Polaroid has focused on premium, nostalgia-driven experiences (e.g., Hi-Print). The brand’s strategy shows that emotional positioning and distinctive design can sustain margins even when device specs converge.
-
Seiko Epson (Japan) — Epson’s portable printers indicate a continued role for OEMs with strong print-head and ink expertise. Epson’s emphasis on connectivity and reliability highlights the importance of robust firmware and long-term serviceability.
-
Phomemo (China) — As a representative of nimble entrants, Phomemo competes on price-performance and rapid iteration (M02 PRO, Q02). These players pressure incumbents on cost while also expanding addressable markets through low-tier affordability.
Collectively, these profiles reveal two strategic polarities: (1) premium, vertically integrated players that monetize both devices and consumables; and (2) low-cost, high-volume entrants that capture first-time buyers and drive market penetration. Effective strategies in 2026 will likely be hybrids: protecting premium segments while cultivating volume via platform partnerships.
Regulatory, materials, and geopolitical headwinds
Industry dynamics are increasingly shaped by non-market forces. Stricter rules on photo chemicals in North America and Europe are pushing vendors toward water-based inks and recyclable materials. ISO standards for small electronics and batteries add compliance overhead that particularly impacts small/mid-sized manufacturers. Paper and specialty media costs are under upward pressure due to supply constraints, and tariffs on certain electronic components have distorted sourcing economics in some regions.
These pressures compress margins for device manufacturers but simultaneously raise the bar for competitors that can certify sustainability claims and secure resilient supply chains. In practice, 2026 procurement strategies must include multi-source agreements, nearshoring options, and sustainable-material roadmaps.
What our full report delivers (operational highlights)
-
Validated market sizing and historical analysis (2020–2025) with bottom-up checking and sensitivity ranges for 2026–2032 forecasts.
-
Segment-level modeling (by region, device type, and application) with demand drivers, elasticities, and unit economics — presented with downloadable data tables and scenario toggles.
-
Detailed competitor scorecards including product portfolios, go-to-market models, consumables strategies, and patent/IP mapping.
-
Supply-chain heatmaps and sourcing playbooks (including component-level tariffs and compliance risk matrices).
-
Commercial playbooks for B2B and B2C—pricing ladders, channel incentives, bundling strategies, subscription models, and digital engagement tactics to improve attach and retention rates.
-
Investment memo templates for M&A, JV, or minority investments, complete with synergy checklists and integration risks.
-
Executive-ready scenarios (base, upside, downside) with trigger events and recommended guardrails for capital allocation.
Strategic recommendations for 2026 (actionable priorities)
-
Prioritize software-first product enhancements — camera integrations, editing filters, AR layers, and community features — to increase device utility and consumable attachment.
-
Lock supply of critical media through long-term agreements and strategic investments in recycling-capable substrates to mitigate input-price volatility and meet emerging regulations.
-
Pursue selective bundling and subscription models for consumables in B2C while offering SLA-backed managed-print services for B2B experiential customers (events, retail activations).
-
Use the 2026 window to explore tuck-in M&A for software or distribution assets that complement hardware portfolios, focusing on deals that accelerate recurring revenue streams.
-
Differentiate along sustainability and serviceability: certified recyclable media, low-energy operation, and modular designs that extend device life will command premium positioning.
-
Establish clear geo-prioritization using multi-criteria scoring (market readiness, supply-chain cost, regulatory risk) rather than volume-only heuristics.
Closing — the value of the complete intelligence
This preview highlights the strategic contours that will matter in 2026: a market rebounding from a lower base, meaningful concentration among a few large brands, and an evolving competitive field where software, consumables, and sustainability increasingly determine winners. The full PW Consulting Mobile Photo Printer Market report provides the granular segment data, regional splits, company profiles, and financial models required to convert these insights into executable plans. For CFOs planning capex, CMOs designing channel strategies, and corporate development teams seeking targets, the underlying datasets and scenario analyses are essential to reduce execution risk.
Access the complete report for the confidential segment tables, downloadable models, and proprietary recommendation decks that we intentionally omit from this preview to protect analytical value and to ensure optimal use in strategic decision-making.
For detailed analysis of this topic, please visit the official page: Mobile Photo Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


