



Category: market research
PW Consulting: Ear Plugs Market to Reach USD 2,142.8M by 2032, Growing at 5.9% CAGR
By PW Consulting, 2026-07-30
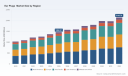
Ear Plugs Market — 2026 Strategic Preview
As organizations reset priorities for 2026 — balancing worker safety, regulatory compliance, product differentiation and cost control — a clear, actionable view of the global ear plugs market becomes a strategic necessity. This preview, prepared by PW Consulting’s senior strategy and industry analysis team, synthesizes the market’s macro trajectory, regulatory inflection points, competitive structure and commercial playbooks that will matter to CEOs, business unit leaders, product heads and M&A teams in the year ahead.
Ear Plugs Market
Why this study matters for 2026 decisions
- Market momentum: The ear plugs market, measured on a USD Million basis with 2025 as the base year, sits at approximately USD 1.47 billion and is projected to expand at a compound annual growth rate (CAGR) of roughly 5.9% across the 2026–2032 forecast window. By 2032 the market trajectory points towards a materially larger addressable pool.
- Timing: Growth is concentrated where regulatory enforcement, occupational safety programs and consumer demand for higher-fidelity, reusable solutions intersect — making 2026 a pivotal year for investment and repositioning decisions.
- Strategic leverage: Firms that translate macro growth into defensible, profitable segments — through product architecture, channel strategy and compliance-first engineering — will capture outsized returns as the market moves into mid-cycle expansion.
What the full PW Consulting report delivers (practical, executable outputs)
- Actionable market sizing and forecast models (TAM/SAM/SOM) with driver-level sensitivity analysis — editable Excel models with scenario toggles so teams can stress-test pricing, channel mix and regulation impacts.
- Regulatory & standards playbook — decision trees that translate NIOSH, OSHA and FDA rules into product development and labeling checklists, import/export considerations and clinical-reconciliation flows for manufacturers and distributors.
- Go-to-market blueprints — segment-specific channel maps (industrial procurement, healthcare, consumer retail, travel/entertainment), pricing ladders, and distributor negotiation playbooks for three archetypal company sizes.
- Competitive assessment and capability matrix — comparative scoring across R&D, manufacturing, channel reach and regulatory readiness for the leading incumbents and high-potential challengers.
- M&A & partnership heatmap — prioritized target profiles, valuation heuristics, and integration checklists focused on consolidating distribution, acquiring high-fidelity tech or expanding custom-molded services.
- Operational levers & margin roadmaps — manufacturing sourcing strategies (economies of scale vs. localized production), warranty/returns frameworks for reusable products, and SKU rationalization templates.
Market dynamics shaping 2026 strategy
Four structural forces are combining to reshape competitive advantage:
Ear Plugs Market
- Regulatory tightening and clarity. Practical compliance obligations are rising: regulators and guidance bodies have reinforced derating practices for noise reduction ratings, tightened premarket pathways for hearing protectors, and aligned medical device quality standards with ISO frameworks. These developments increase time-to-market for certain product classes but also raise barriers to entry for low-compliance competitors.
- Employer-driven purchasing. Occupational requirements that mandate employers provide hearing protection at no cost to eligible workers create stable institutional demand and concentrate negotiating power in the hands of large procurement organizations and safety distributors.
- Product innovation and segmentation. The value equation between low-cost disposable units and higher-priced reusable or custom solutions is increasingly framed as a total-cost-of-ownership discussion; custom-molded and high-fidelity products promise longer service life and improved end-user adoption in premium applications (entertainment, professional audio, and clinical settings).
- Sustainability and consumer expectations. Sustainability credentials — reusability, lower lifecycle waste and circular packaging — are becoming differentiators in consumer and corporate procurement, presenting opportunities for premium pricing and subscription models.
Commercial channels and operational implications
Successful go-to-market strategies in 2026 will tailor offerings by channel economics and customer procurement behavior:
Ear Plugs Market
- Industrial & occupational channel: Emphasize compliance documentation, bulk procurement solutions, employee training add-ons, and bundled PPE offerings. Procurement cycles are longer but unit volumes and contract values are significant.
- Consumer & retail channel: Focus on branding, design-led differentiation (comfort and aesthetics), DTC and marketplace distribution, and subscription-replenishment to lock in recurring revenue.
- Service-enabled models: Custom-molded solutions create opportunities for service revenue (fitting, scanning, remote support) and margin extension; they also demand investments in logistics and point-of-care capabilities.
- Pricing & lifecycle management: Product strategies must balance low-priced disposables for mass segments with premium reusable lines marketed on lifecycle cost savings and acoustic fidelity.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three players control a meaningful share of market revenue, and the top five bring the cumulative share to roughly half of the market. This structure creates both incumbent advantages and openings for specialty entrants and regional leaders.
- 3M Company — large-scale R&D and distribution advantages, broad PPE portfolio and visibility at major industry tradeshows; well-positioned to bundle hearing protection into comprehensive safety programs and to accelerate adoption through enterprise channels.
- Honeywell International Inc. — enterprise sales strength and integrated safety offerings for industrial clients; a natural partner for bundled procurement and global rollouts across multi-site organizations.
- Moldex-Metric, Inc. — specialized voice in hearing protection; product-focused innovation and strong relationships with safety distributors give it a competitive edge in occupational segments.
- Loop BV — design- and sustainability-led consumer propositions that appeal to lifestyle and travel segments; the brand strategy is a template for premium reusable positioning.
- Alpine Hearing Protection Inc. — a European-centered specialist with focused hearing protection product lines and strong regional reseller networks.
- E.A.R. Inc. and Etymotic Research — legacy and audiophile/digital-audio adjacent capabilities respectively; Etymotic’s high-fidelity competencies are relevant where acoustic transparency is a value driver.
- UVEX SAFETY GROUP and Hellberg Safety AB — safety-focused brands with regional strength and trade-show visibility; active engagement at major events signals continued investment in industrial channels.
- Elvex Corporation — US-focused safety player with distribution relationships across industrial and construction verticals.
Recent industry events — for example, major trade fair participation by 3M in late 2025 and uvex in mid-2026 — show incumbents continuing to invest in visibility and partner engagement to win institutional contracts.
Decision frameworks and recommended 2026 plays
We recommend leaders evaluate and prioritize choices across three strategic dimensions: product architecture, go-to-market route, and compliance/cost posture. For each, PW Consulting provides executable frameworks:
- Product architecture: Use a three-tier offering model (entry disposable, mid-tier reusable, premium custom/high-fidelity) and map each tier to channel economics, margin targets and CAPEX requirements.
- Go-to-market: Select a primary channel focus (industrial procurement, consumer e-commerce or professional audio) and a secondary growth channel to diversify risk; align marketing, distributor incentives and CRM to the selected focus.
- Compliance-first engineering: Prioritize regulatory-ready design for products intended for occupational and medical-adjacent uses to reduce regulatory risk and protect margins.
- M&A & partnerships: Pursue tuck-ins that consolidate regional distribution, acquire high-fidelity intellectual property, or add fitting/service capabilities to accelerate market entry into premium segments.
Scenario planning — what to watch and trigger points for action
Our forecast baseline assumes a steady CAGR of circa 5.9%, but tactical choices must be guided by scenario triggers:
- Regulatory tightening scenario: Fast action on 510(k) readiness and ISO-aligned QMS reduces time-to-market risk and prevents margin erosion from recalls or rework.
- Technology-led disruption: Rapid adoption of high-fidelity or digital-enabled ear plugs (sensors, connectivity) would favor R&D-centric players and require accelerated IP or partnership strategies.
- Macro slowdown: A cost-focused fallback plan emphasizing low-cost manufacturing, SKU rationalization and channel consolidation preserves cash and protects margin share.
For each scenario the full report provides KPI thresholds (procurement velocity, R&D time-to-certify, SKU profitability) that will indicate when to scale up investment or pivot.
How PW Consulting accelerates execution
The full market research package goes beyond insight — it includes the tools business leaders need to execute:
- Editable financial models and scenario toggles calibrated to the 2020–2025 historical series and the 2026–2032 forecast window;
- Regulatory checklists mapped to product classes with recommended timelines for 510(k) and QMS alignment;
- Channel rollout playbooks, distributor scorecards and negotiation templates;
- Detailed competitor benchmarking and an M&A target short-list with high-conviction rationale.
Note: this preview intentionally omits the granular segmentation tables, regional and application-level split datapoints and proprietary company-level revenue estimates that appear in the full report. Those detailed inputs — including the unit economics by product type, channel-level margins, and the supplier scorecard — are provided exclusively within the complete PW Consulting deliverable and the living model workbook.
Final strategic takeaway
Entering 2026, the ear plugs market offers predictable expansion but with sharper stakes around compliance, product positioning and channel orchestration. Firms that act now to harden their regulatory posture, selectively invest in premium and service-enabled offerings, and optimize channel economics will convert the market’s steady CAGR into durable competitive advantage. PW Consulting’s full report provides the forensic detail and implementation tooling to turn these strategic options into prioritized actions and measurable outcomes.
To unlock the complete segmentation breakouts, company-level assessments and executable workstreams, access the full PW Consulting Ear Plugs Market report and the accompanying models.
For detailed analysis of this topic, please visit the official page: Ear Plugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Audio Market to climb from USD 29B (2025) to USD 47.99B by 2032 (7.5% CAGR)
By PW Consulting, 2026-07-30
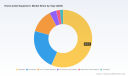
Home Audio Equipment Market — Strategic Briefing for 2026 Decision-Making
Executive overview
Our latest PW Consulting market study for Home Audio Equipment (base year 2025) arrives at a pivotal moment for manufacturers, channels, and investors. After a sustained recovery through the early 2020s, the global market reached approximately USD 29.0 Billion in 2025 and is projected to expand with a compound annual growth rate (CAGR) of 7.5% across the 2026–2032 forecast window, reaching roughly USD 48.0 Billion by 2032 under our central scenario. That trajectory reflects a combination of continued consumer upgrade cycles, the mainstreaming of immersive audio formats, and an accelerating shift to wireless and smart-home-integrated systems.
Home Audio Equipment Market
Why this matters for 2026 strategy
2026 will be the year in which strategy translates to durable advantage. The market's steady expansion creates attractive options for organic growth, targeted M&A, and strategic partnerships — but several structural forces mean that execution matters more than ever:
Home Audio Equipment Market
- Market fragmentation versus premium concentration: with the top three players representing roughly a quarter of global revenues and the top five around thirty percent, the field remains relatively unconsolidated. That dynamic sustains margin and brand premium opportunities for niche and regional specialists, while leaving scope for meaningful consolidation plays for firms seeking scale.
- Technology and ecosystem lock-in: consumers are increasingly valuing whole-home experiences — connectivity, voice and app ecosystems, calibration software, and cross-device audio coherence are becoming purchase drivers as much as raw acoustic performance.
- Supply-chain and regulatory inflection points: new international e-waste controls and tightened attention to critical minerals elevate both compliance cost and strategic risk. Procurement strategies and product design choices will determine which OEMs can meet demand without margin erosion.
What the report delivers — practical, decision-ready intelligence
This study is designed as an operational strategic tool for boardrooms and commercial teams. Key deliverables include:
Home Audio Equipment Market
- A validated historical baseline (2020–2025) and transparent forecasting framework for 2026–2032 (base year 2025; revenue unit USD Billion), showing demand drivers and downside/upside scenarios tied to macroeconomic and component-supply variables.
- Go-to-market playbooks for consumer, premium-AV, and trade-install channels — including channel margin models, promotional elasticity testing, and trade-partner segmentation to prioritize distribution investments.
- Supply-chain stress tests for critical components (magnets, silicon ICs, copper-intensive assemblies), plus mitigations: dual-sourcing roadmaps, nearshoring models, and design-for-recycling directives that reduce exposure to mineral concentration risk.
- Scenario-based M&A and JV heatmaps: mapped against market fragmentation, technology adjacencies, and aftermarket service opportunities to identify high-ROI inorganic targets and partnership structures.
- Commercial tools: pricing ladders, feature-value regressions, and consumer willingness-to-pay matrices calibrated to recent product launches and channel performance.
- Competitive benchmarking and product-feature parity matrices that cover hardware acoustics, software ecosystems, and post-sale services without disclosing proprietary market shares at the segment level (to preserve the value of full-data access).
Competitive landscape — who to watch and why
The home audio field combines legacy audio engineering houses, smart-audio specialists, and consumer-electronics incumbents. Our report profiles each major competitor and assesses strategic posture, route-to-market, and capability gaps.
- Bose Corporation — an established premium brand with deep heritage in acoustic R&D and a strong presence across premium wireless speakers, soundbars, headphones, and integrated theater systems. Bose's investments in advanced noise-cancellation and premium wireless experiences keep it competitive in both direct-to-consumer and installer channels.
- Sonos Inc. — a leading whole-home wireless specialist whose portfolio spans multi-room smart speakers, high-end soundbars, and modular subwoofers. Recent product introductions have emphasized spatial processing and software management, positioning Sonos as a platform play where ecosystem services and subscription revenue warrant close attention.
- Harman / JBL — with roots in pro audio and broad consumer reach, this group leverages Pro sound legacy into high-power Bluetooth speakers, soundbars, and subwoofers. Their strength lies in brand recognition and global distribution, especially in mid-to-high-volume product tiers.
- Klipsch — competing on the premium acoustic experience, Klipsch's horn-loaded drivers and high-efficiency designs target audiophile and lifestyle buyers. Recent product collaborations and outdoor soundbar concepts suggest a dual strategy of heritage-product upgrades and category extension.
- Onkyo — focused on AV receivers, amplifiers, and preamp/processors, Onkyo is central to the home theater and high-channel immersive segments. Their refreshed product roadmaps signal renewed commitment to high-end signal processing and multi-channel power solutions.
Recent events that shape 2026 choices
We monitor product, warranty, and ecosystem updates because they materially affect purchase cycles and aftermarket economics:
- Product refresh cycles: 2025–2026 saw multiple high-profile launches and refreshes across soundbars, powered speakers, and AV receivers — moves that reset consumer expectations for software-enabled features, spatial processing, and format support.
- Warranty and service economics: notable warranty extensions by premium players indicate a trend toward longer service liabilities that can be leveraged as a competitor differentiator but which also raise reserve and logistics requirements for manufacturers and retailers.
- Channel innovation: new hybrid amplifier and environment speaker launches for home theater installers reflect demand for professional-grade, installation-friendly hardware that sits between consumer convenience and pro-audio performance.
Regulatory and raw-material dynamics — risk and opportunity
Two cross-cutting supply-side themes will be particularly influential for 2026 decisions:
- International e-waste controls — revised Basel Convention terms implemented beginning 2025 now require prior written consent for cross-border shipments of electronic waste and scrap. For manufacturers and refurbishers this raises compliance cost, redefines end-of-life logistics, and increases the commercial value of in-region recycling and takeback programs.
- Critical minerals and component concentration — major jurisdictions have formalized lists of critical minerals (including rare-earth elements used in permanent magnets and widely used inputs such as silicon and copper). These regulatory and geopolitical shifts increase the probability of supply interruptions and price volatility for magnet and copper-intensive assemblies, making design-for-substitution, recycling and long-term offtake agreements essential elements of risk mitigation.
Strategic implications and recommended actions for 2026
To convert market momentum into sustainable advantage, we recommend a focused set of actions that combine portfolio, go-to-market, and supply-chain levers.
- Prioritize ecosystem differentiation over one-off hardware upgrades. Invest in calibration software, seamless multi-device handoff, and post-sale services. Small increases in lifetime revenue per user materially improve unit economics when scaled across a growing installed base.
- Operationalize mineral and e-waste risk assessment into product roadmaps. Require critical-mineral exposure disclosures for major BOMs and execute pilot recycling and component-recovery programs in key markets to shorten the circularity loop.
- Targeted M&A and alliance plays. Use the relatively fragmented market structure to acquire technology adjacencies (voice/user-experience, wireless protocol licensing, immersive DSP) or regional scale in underpenetrated channels, with playbooks for integrating software stacks and go-to-market teams.
- Revisit channel economics and installation-focused SKUs. Professional-install segments and trade partners are primed for higher-margin AV and multi-room systems; prioritize installer-friendly features and trade promotions that reduce installation friction.
- Embed extended-warranty and subscription strategies selectively. Warranty extensions can drive differentiation but must be underpinned by service-cost models and spare-parts logistics that preserve margins.
How PW Consulting can accelerate your 2026 plan
Our full report includes the proprietary datasets, retailer checks, and supplier interviews that underpin these conclusions. It provides the granular segmentation tables, regional demand models, and SKU-level pricing analyses that senior leaders need to finalize budgets and M&A targets — elements we intentionally withhold in this briefing to preserve the strategic value of the full dataset.
If your team is preparing product roadmaps, procurement contracts, or a transaction thesis in 2026, PW Consulting can deliver tailored modules from the study: a 90-day supply-chain remediation program, a pricing-and-featureing workshop, or a market-entry playbook calibrated to your balance sheet and channel strategy.
Closing note
The home audio market is expanding and maturing simultaneously. Growth is large enough to support multiple strategic approaches — premium engineering, platform plays, or scale-driven consolidation — but the winners will be those who align product, supply chain, and service economics with evolving regulatory realities and consumer expectations. Our study is crafted to make those trade-offs explicit and operational: to convert foresight into a practical, funded roadmap for 2026 execution.
For detailed analysis of this topic, please visit the official page: Home Audio Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Earbuds Market 2026: Strategic Priorities for Decision‑Makers
As PW Consulting’s lead industry analyst, I prepared this forward‑looking briefing to explain why our Earbuds Market research is a must‑read for executives planning their 2026 strategies. The earbuds industry is no longer a simple accessory market: it has become a consequential battleground for platform control, supply‑chain differentiation, and audio experiences that influence consumer lock‑in. Our study synthesizes historical performance, near‑term inflection points and seven‑year forecasts to translate market dynamics into executable choices for product, channel and corporate development leaders.
Earbuds Market
Why this research matters for 2026 decisions
-
Proven growth trajectory: The category has shifted from niche accessory to mainstream primary audio device. Between 2020 and 2025 the market scaled rapidly, and our base‑year analysis (2025) frames a multi‑year expansion path that continues through the 2026‑2032 forecast window at a compound annual growth rate of roughly 9.45%.
Earbuds Market -
Decision timing: 2026 is a strategic hinge year — new wireless standards, regulatory changes in major markets, and product cycles among leading OEMs create windows of advantage that will be decisive for share gains.
Earbuds Market -
Cross‑functional impact: Choices made in product engineering, procurement, channel strategy and partnerships in 2026 will determine cost structure, margin recovery and ecosystem access for at least the next three product cycles.
Key market forces shaping strategy
-
Platform interoperability and ecosystem control. Device makers with deep OS integration continue to extract premium pricing and retention value through features such as seamless pairing and spatial audio. Regulatory moves in 2024–2026 (notably actions in the EU targeting charging harmonization and platform openness) are altering the economics of exclusivity and creating new routes for third‑party differentiation.
-
Technology inflection points. Bluetooth 6.0, lossless codecs, Auracast audio broadcasting and on‑device AI are moving from R&D into mainstream portfolios. Fast adopters are using these as both feature and supply levers—differentiating on latency, battery, and codec stacks.
-
Product diversity and use‑case segmentation. Consumer expectations now span premium noise cancellation for commuting, open‑ear situational awareness for urban fitness, and ruggedized, low‑latency models for gaming and enterprise. Each use case demands different component choices and go‑to‑market tactics.
-
Supply‑chain specialization. Component suppliers—especially premium driver and MEMS/ANC specialists—are gatekeepers of sound quality and form factor. Partnerships and exclusive supply agreements are becoming an accelerant for brand‑level differentiation.
Competitive landscape — strategic takeaways
The market is broadly competitive with clear tiers: global platform incumbents, premium audio maisons, consumer electronics giants, and agile challengers. Our report offers deep profiles of the principal players, but the strategic highlights below indicate where each type of incumbent can win or is vulnerable.
-
Platform incumbents (ecosystem owners) : Companies that tightly integrate earbuds into an OS enjoy superior user experience economics and higher average selling prices. Their strategic advantage in device pairing, spatial audio features, and cross‑device continuity is substantial — but regulatory measures around platform access in key jurisdictions are reducing friction for third parties. For non‑platform players, pursuing standards‑level compatibility (e.g., Auracast, lossless codec support) is mandatory to remain competitive.
-
Premium audio specialists : Brands with heritage in acoustics continue to command respect for fidelity and ANC performance. Their playbook is to maintain technology leadership in sound and ANC while selectively partnering to broaden distribution. This is where component partnerships (balanced armature drivers, custom tuning) offer defensive moats.
-
Mass market and value challengers : These players compete on feature parity at aggressive price points and rapidly iterate on form factor and battery improvements. Their speed‑to‑market and flexible supply bases enable share gains in emerging segments, particularly when they bundle features like multi‑device pairing, app customization, or extended warranties.
-
Specialists and niche innovators : Open‑ear, bone‑conduction and sports‑focused brands are carving defensible niches. These categories benefit from differentiated IP and distinct use‑case positioning, reducing direct head‑to‑head with mainstream ANC models.
Recent moves that matter (illustrative examples)
-
Several firms launched new products in early‑2026 that crystalize two trends: (1) open‑ear solutions incorporating active noise reduction to balance awareness with clarity, and (2) compact ANC entries aimed at underserved fit‑and‑form segments. These launches underscore how innovation is shifting toward blending situational awareness with performance.
-
Leading component suppliers expanded partner lists, supplying balanced armature drivers and other high‑value components to a broad set of OEMs. This reinforces the importance of supplier relationships for differentiation and cost control.
-
Manufacturers are adopting Bluetooth 6.0 and Auracast capability in mid‑price tiers, accelerating industry‑wide feature parity and forcing premium competitors to redefine their value propositions beyond headline specs.
Regulatory and macro developments—practical implications
-
Charging harmonization and battery rules in major markets change after‑sales support and repair economics. Businesses should reassess packaging, accessory strategies and EPR (extended producer responsibility) obligations in light of evolving EU guidance.
-
Proposals clarifying removability for wearable batteries and exemptions for wet‑environment devices have direct design and BOM implications—particularly for swim‑proof and sports models.
-
Platform openness requirements (e.g., DMA‑era remedies) can unlock pairing and proximity features for third parties, creating an opportunity for brands that can rapidly certify compatibility and translate it into a superior first‑time setup experience.
-
Trade policy adjustments and provisional tariff agreements affecting electronics imports require scenario planning across sourcing geographies and price architectures to preserve margins.
What the PW Consulting report delivers (actionable content)
Our full report is built as a practitioner’s toolkit for 2026. Highlights include:
-
Executive summary with 90‑day and 12‑month playbooks for product, channel and procurement teams.
-
Scenario models that quantify revenue and margin outcomes under alternative regulatory and technology adoption paths — enabling CFOs to test sensitivity to tariffs, component shortages and OS access changes.
-
Go‑to‑market frameworks that map feature bundles to channel economics (direct‑to‑consumer, retail partner, carrier bundles) and recommend optimal pricing ladders by archetype.
-
Component and supplier heatmaps that identify strategic suppliers for drivers, ANC ICs, MEMS mics and battery modules, together with negotiation playbooks and potential single‑sourcing risks.
-
Competitive profiles and watchlists that identify likely disruptors, partnership targets and acquisition candidates — including suggested diligence checkpoints for each target type.
-
IP and standards readiness checklist covering Bluetooth versions, Auracast, codec licensing and enterprise provisioning features.
How leaders should act in 2026
-
Prioritize near‑term wins that protect margins: finalize supplier contracts for high‑value components, lock in pricing tiers for the next two product generations, and accelerate certification for new wireless standards.
-
Defend and broaden ecosystem advantages: if you’re a platform owner, prepare to meet regulatory obligations while converting technical openness into user retention features. If you’re a non‑platform player, invest in seamless onboarding flows and standards compliance to neutralize first‑mover pairing advantages.
-
Segment with conviction: differentiate by primary use‑case (commute/ANC, fitness/open‑ear, enterprise/secure comms) and align R&D, marketing and channel incentives to those priorities rather than pursuing a “one size fits all” portfolio.
-
Prepare for consolidation and partnership plays: with mid‑tier innovation heating up, M&A and supplier partnerships are the most efficient routes to scale and differentiation. Use our acquisition/due‑diligence playbook to expedite integration planning.
Why readers should consult the full report
This briefing is designed to surface the strategic contours and near‑term choices that will shape competitive outcomes in 2026. The full PW Consulting Earbuds Market report contains the granular models, competitor scorecards, procurement levers and executable roadmaps needed to convert these insights into measurable results. We deliberately present high‑value strategic direction here while preserving the detailed segmentation and numerical annexes for our report subscribers — those datasets provide the tactical specificity required to finalize pricing, channel splits and SKU economics.
For executive teams preparing budgets, product roadmaps or M&A screens for 2026, our study translates the market’s strong growth trajectory and the changing regulatory/technology landscape into an operational checklist you can act on immediately. Contact PW Consulting to access the full dataset, scenario models and the 90‑day tactical playbook.
For detailed analysis of this topic, please visit the official page: Earbuds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
XRF Analysers Market to Reach USD 300.2 Million by 2032; 7.2% CAGR Forecast (PW Consulting)
By PW Consulting, 2026-07-30
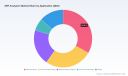
XRF Analysers Market — 2026 Strategic Briefing for Corporate Decision‑Makers
Executive trailer: why PW Consulting’s new XRF market research matters this year
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present a focused preview of our comprehensive XRF Analysers Market research — designed to convert complex instrumentation dynamics into executable 2026 actions. This briefing surfaces the high‑impact trends and competitive signals that will determine where capital, procurement effort, and product development should flow over the next strategic planning cycle. It demonstrates the depth of our analysis while intentionally withholding the granular segmentation tables and raw numeric breakdowns to guide you to the full study for purchase and boardroom use.
XRF Analysers Market
Market trajectory: the headline numbers you need to plan around
The XRF analysers market has moved from a resilient recovery phase into a steady growth trajectory. Measured on a USD‑denominated revenue basis (Million), market size expanded from the low‑hundreds in 2020 to an estimated USD 186.5 Million in the 2025 base year used in our study. Our forecast for the 2026–2032 period projects continued expansion at a compound annual growth rate (CAGR) of approximately 7.2%, reaching an anticipated market size above USD 300 Million by 2032. That pace reflects sustained demand across regulated labs, on‑site materials testing, and industrial quality control — and frames the opportunity size for new entrants, aftermarket services, and software‑enabled analytics.
XRF Analysers Market
Why 2026 is a decision inflection point
- Regulatory tightening and public procurement are accelerating demand for validated, rapid, non‑destructive elemental screening solutions. Recent government sourcing activity and standards adoption are forcing stricter technical requirements into procurement specifications.
- Vendor innovation is bifurcating the market: improvements in handheld ergonomics, connectivity and alloy identification are shifting some use cases away from traditional benchtop systems, while advanced optics and micro‑XRF continue to push the performance envelope for laboratory and medical device testing.
- Commercial concentration is modest: market share is distributed among several global OEMs and regional specialists, creating opportunities for differentiation through vertical specialization, service models, and regulatory expertise rather than pure scale alone.
Primary demand drivers and implications for corporate strategy
Four dynamics dominate the near‑term landscape and should inform 2026 planning:
XRF Analysers Market
- Regulatory procurement and certification: Agencies are increasingly specifying tight detection limits and application‑specific test protocols for heavy metals and regulated commodities. Companies that align product roadmaps and compliance documentation with these tender specifications will gain a competitive edge in public and private contracts.
- Shift to portable and hybrid workflows: Field screening and rapid on‑site verification are displacing some lab throughput. Organizations must evaluate tradeoffs between portability, detection limits, and sample preparation when setting procurement priorities.
- Lifecycle economics and aftermarket services: With capital outlays for high‑precision analyzers remaining material, buyers are prioritizing predictable total cost of ownership — instrument uptime guarantees, calibration services, and software updates are now critical value levers.
- Industry convergence on data and connectivity: Operators expect integrated analytics, cloud reporting and digital chain‑of‑custody. Vendors that can deliver validated software stacks and secure data pipelines will command premium positioning.
Competitive landscape — who matters and why
The market is anchored by several global instrumentation leaders and a cohort of fast‑moving specialists. Our report provides vendor profiles, comparative performance matrices, and go‑to‑market playbooks tailored to each supplier archetype. Key companies featured in the study include:
- Malvern Panalytical (UK) — strengths in benchtop and high‑precision spectrometers; broad channel reach into regulated sectors.
- Evident (US) — strong traction in handheld analyzers optimized for rapid alloy and material screening.
- Horiba Instruments (Japan) — offers micro‑XRF and EDXRF systems with relevance for pharmaceutical and clinical impurity screening.
- Bruker Corporation (US) — established handheld portfolio with recent new product launches targeting advanced elemental workflows.
- Thermo Fisher Scientific (US) — leverages brand and distribution reach to serve laboratory and field use cases in regulated industries.
- SPECTRO Analytical Instruments (Germany) — emphasises high‑precision EDXRF for tightly regulated materials testing.
- Rigaku Corporation (Japan) — focused on coating, thin‑film and specialized quality control applications.
For each vendor we map product strengths to specific procurement profiles (e.g., field‑first buyers, lab‑first buyers, contract laboratories) and highlight likely partnership or M&A targets for companies seeking rapid capability acquisition.
Recent industry events and their strategic read
Our intelligence collection through mid‑2026 highlights several actionable signals:
- Public procurement activity: A regulatory body recently issued an RFI seeking commercially available benchtop XRF solutions for rapid, non‑destructive heavy‑metal detection in regulated commodities. Such solicitations accelerate adoption cycles for validated instruments and shift procurement preferences toward vendors who can demonstrate compliance and rapid delivery.
- New product introductions: Multiple vendors unveiled next‑generation handheld systems with improved ergonomics, connectivity and alloy identification functionality. These launches signal heightened competition on user experience and software capability rather than hardware alone.
- Technical standards and operator certification: National authorities are updating operator certification frameworks and referencing ISO guidance as the basis for training programs. Companies that invest in certified operator training and documentation reduce buyer friction for higher‑spec equipment.
- Historical safety and recall precedent: Past device recalls for software safety underscore the operational risk associated with instrument lifecycle management and reinforce the importance of robust software validation and post‑market surveillance practices.
What PW Consulting’s full report contains — practical modules for 2026 action
Our publication is structured to be directly usable by strategy teams, procurement leads, R&D and regulatory affairs. Highlights include:
- Granular market sizing and forecast model (2026–2032) with downloadable scenario flexibility for conservative, base and accelerated adoption cases.
- Vendor benchmarking matrix with performance against technical KPIs, regulatory readiness, service footprint and TCO metrics.
- Buyer personas and procurement playbooks tailored for contract laboratories, medical device manufacturers, environmental testing agencies, and mining operations.
- Regulatory and standards matrix mapping active tenders, certification requirements, and compliance documentation templates.
- Go‑to‑market blueprints for new entrants and incumbents, including channel strategies, pricing levers, and value‑added services that increase stickiness.
- Operational tools: ROI calculators, tender readiness checklists, specifications templates aligned to government RFI expectations, and an after‑sales service playbook.
- Risk and resilience assessment: supply‑chain concentration points, component obsolescence timelines, and recommended mitigation steps for sustained instrument availability.
Actionable recommendations for C‑suite and procurement leaders in 2026
- Prioritize compliance‑aligned sourcing: Build instrument requirements around the most demanding expected tenders (public and private) rather than average specifications — this reduces rework when responding to government contracts.
- Differentiate via services: If you are a vendor, convert calibration and reporting into subscription products. If you are a buyer, negotiate multi‑year service level agreements and bundled analytics to stabilize lifecycle costs.
- Invest selectively in connectivity: Modernize data capture and audit trails now; retrofitting later is more expensive and increases validation risk in regulated environments.
- Balance capital and operational budgets: For organizations with mixed workflows, adopt a hybrid procurement strategy that pairs portable field units for rapid screening with benchtop instruments for regulated confirmation testing.
- Prepare for tender responsiveness: Maintain pre‑validated compliance packs, operator competency records, and sample testing protocols to reduce lead times when government RFIs or contracts are announced.
Research signal: where the debate will be in your boardroom
Expect three persistent debates across leadership teams in 2026: how aggressively to migrate testing capacity to fieldable platforms; how much to invest in software and data services versus hardware; and whether consolidation via M&A is more efficient than organic capability builds. Our report equips boards to run scenario workshops with the financial, operational, and regulatory implications already modeled.
Conclusion — the strategic value of the full study
PW Consulting’s XRF Analysers Market research synthesizes technical, commercial and regulatory intelligence into a playbook that corporate decision‑makers can operationalize in 2026. The market’s steady growth trajectory (CAGR ~7.2% over the forecast window) and the mix of regulatory procurement and vendor innovation create clear timing windows to outperform peers — if you align product, procurement and service strategies to the signals we outline.
Next step — where to obtain the full intelligence
This preview demonstrates the analytic depth and actionable orientation of our study while intentionally omitting the detailed regional, type and application splits, vendor scorecards and downloadable models. To access the full dataset, segmentation breakouts, bespoke vendor matrices, and procurement templates for immediate deployment, visit the PW Consulting report page. Purchasing the full report provides the granular numbers and decision tools required for contract bids, capital allocation, and R&D prioritization in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: XRF Analysers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IPDA market reaches USD 838.46M in 2025 with 3.2% CAGR to 2032
By PW Consulting, 2026-07-30
Isophorone Diamine (IPDA) Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a forward-looking strategic preview of the Isophorone Diamine (IPDA) market designed to inform executive decisions in 2026. This piece synthesizes macro trends, competitive moves, supply-chain dynamics and regulatory pressures that will determine value creation opportunities across the IPDA value chain. It intentionally demonstrates analytical depth while withholding granular segment tables and proprietary forecasts — a curated “trailer” that clarifies why our full report is essential for transaction, sourcing and production planning in 2026.
Isophorone Diamine (IPDA) Market
Market at a Glance — Scale, Momentum and the Near-Term Forecast
Using 2025 as the base year, the global IPDA market has evolved into a moderate-growth specialty chemical market characterized by steady expansion and episodic volatility. Our topline model places the 2025 market near USD 840 million (USD Million basis), with a compound annual growth rate (CAGR) of approximately 3.2% through the 2026–2032 forecast window. The early forecast years show a bump as post‑pandemic demand normalization and restocking cycles intersect with capacity adjustments; over the full horizon, the growth path remains balanced rather than exponential, reflecting the material’s status as a niche, high‑value curing agent and intermediate.
Isophorone Diamine (IPDA) Market
For strategists, two simple implications follow: first, IPDA is sufficiently large and concentrated to matter strategically for players in epoxy, polyamide and specialty polyurethane value chains; second, the market’s modest CAGR implies that margin expansion and competitive advantage will be driven more by differentiation (e.g., renewable grades, logistics optimization, customer intimacy) than by raw top‑line volume growth alone.
Isophorone Diamine (IPDA) Market
Where the Real Competitive Value Lies
Several structural characteristics are determinative for 2026 strategy:
- High concentration among leading suppliers. Market concentration metrics indicate that incumbent groups capture the lion’s share of global supply, making supplier relationships and capacity moves critical bargaining levers for offtakers and new entrants alike.
- Feedstock and regional production footprints matter. Because IPDA production economics are sensitive to feedstock cost swings and regional regulatory regimes, producers with integrated or geographically diversified sourcing are materially advantaged.
- Product differentiation is shifting from price to sustainability. Clients increasingly reward renewable‑based grades and lower‑emission production footprints — a dynamic that creates premium pockets even within a modestly growing market.
Competitive Landscape — Who’s Doing What (and Why It Matters)
A focused competitive review highlights a small group of strategic players whose actions will re-shape supply dynamics in 2026:
- BASF SE (Ludwigshafen, Germany) — As an integrated chemicals house with Verbund production capabilities, BASF’s IPDA offering is positioned as a reliable, large‑scale supply option for global epoxy systems. Their presence signals continuity of supply for industrial offtakers who prioritize quality, regulatory compliance and after‑sales technical support.
- Evonik Industries AG (Essen, Germany) — Evonik is moving the market toward sustainability with renewable isophorone‑based grades. Its product launches that leverage bio‑sourced acetone derivatives are strategically important for end‑users seeking LCA improvements and compliance with tightening EU standards.
- Wanhua Chemical Group (Shandong, China) — Wanhua’s aggressive capacity expansion plans are a pivotal supply‑side development. Their scale ambitions, coupled with a historically competitive feedstock cost base, make them a candidate to exert meaningful price and logistics influence — particularly across Asia and export flows.
- Achilles Chemical (United States) — Representing a premium specialty supplier, Achilles competes on product quality, certification and service. Their role matters for customers in applications where technical performance and reliable certification traceability trump commodity pricing.
Recent company moves are illustrative of strategic priorities in 2025–2026. For example, Wanhua’s disclosed environmental impact assessment and capacity plan indicate a long‑term buildout that could reshape global availability metrics. Evonik’s launch of renewable IPDA grades reflects a deliberate pivot to capture sustainability‑driven premiums. For buyers, these developments mean greater choice — and more complexity — in negotiating supply terms and in evaluating total cost of ownership beyond unit price.
Supply‑Side Dynamics and Risk Vectors
Three supply‑side dynamics require executive attention:
- Feedstock volatility: Annualized feedstock swings exceeding typical specialty‑chemical ranges can materially alter production economics. Procurement teams should stress‑test supplier offers for feedstock pass‑through clauses and build scenarios where feedstock shocks compress margins.
- Regulatory pressure in production hubs: Stricter emission and compliance standards — particularly in the EU — are already increasing operational costs and reducing short‑term flexibility. Producers exposed to high‑cost regulatory regimes may optimize by shifting production or investing in abatement, which influences lead times and regional price differentials.
- Concentration and capacity cycles: With a few suppliers capturing a dominant share of supply, capacity expansions or outages have disproportionate market impact. Executives should monitor announced project pipelines and EHS permitting progress as leading indicators of near‑term supply tightness.
Demand Dynamics — Application and Buyer Behavior
End‑market dynamics for IPDA remain diverse. Traditional demand from high‑performance epoxy curing systems and specialty polyamides continues to underpin volume, while emerging sustainability requirements are lifting demand for renewable‑based grades. Buyers face three pragmatic choices in 2026:
- Compete on total cost and logistics: prioritize suppliers with integrated supply chains and regional warehousing to reduce lead‑time risk.
- Pay for differentiation: shift share to suppliers offering certified lower‑carbon or renewable‑feedstock grades when end‑customers require documented LCA improvements.
- Diversify risk: maintain multi‑sourcing strategies with contractual protections for force majeure, minimum supply guarantees and price collars.
What Our Full PW Consulting Report Delivers (Practical, Actionable Components)
The full report translates market intelligence into executable guidance for 2026. Highlights of the operational and strategic tools included are:
- Scenario-driven demand and supply models covering 2026–2032 with sensitivity to feedstock price, regulation, and capacity announcements.
- Commercial playbooks for buyers and producers: negotiating clauses, inventory optimization tactics, and pricing indexation strategies that lock in margin or protect volume.
- Investment decision frameworks: NPV and payback analyses for greenfield capacity, debottlenecking, and retrofits to meet emission regulations.
- Detailed competitor profiles and capability maps, including production footprints, strategic priorities and public commitments to sustainability.
- Regulatory impact assessment outlining compliance costs and adaptive measures by region to quantify operational risk and timing implications.
- Risk matrix and early‑warning indicators: permit timelines, feedstock price bands, and supplier concentration triggers that should prompt immediate contract or sourcing changes.
Note: while this preview summarizes the tactical contents and strategic implications, the granular segmentation tables, region‑by‑application revenue splits, and proprietary scenario outputs are reserved for the full report. Those elements are the linchpins for deal structuring, procurement hedging and asset investment analysis.
Recommendations for Executives in 2026
Based on our integrated analysis, PW Consulting recommends a prioritized set of actions for corporates, investors and procurement teams:
- Embed sustainability premiums into procurement strategy where end‑market customers demand LCA improvements; identify which product specifications justify a meaningful premium and which do not.
- Accelerate supplier diversification and long‑term contracts with flexible indexation to mitigate feedstock volatility and regional regulatory shocks.
- For producers, prioritize capital allocation toward incremental debottlenecks and emissions reduction investments that unlock premium positioning while preserving unit economics.
- Monitor leading indicators — announced capacity projects, EIA progress, and renewable‑grade product launches — and be ready to act quickly as these signals presage supply shifts.
- For investors and M&A teams, target assets or partnerships that provide access to either differentiated renewable IPDA technology or advantaged feedstock integration; these attributes are the most likely paths to durable value.
Why This Matters Now
By 2026, the IPDA market will be defined less by raw volume growth and more by how industry players navigate feedstock volatility, regulatory tightening and the demand for sustainable chemistries. The market’s overall size and its projected steady CAGR provide a stable backdrop — but the most meaningful value creation will accrue to organizations that translate foresight into commercial and operational moves: locking in flexible supply, investing selectively in green technology, and structuring customer offers that capture a premium for sustainability and reliability.
PW Consulting’s comprehensive IPDA market study operationalizes these insights. The full report contains the detailed numerical segmentation, supplier scorecards, scenario outputs and model access that procurement chiefs, corporate strategists and investment committees require to act decisively in 2026. Consider this preview a strategic orientation — the full intelligence pack is the playbook.
Next Steps
- Contact PW Consulting for the full IPDA market report to access proprietary tables, regional and application splits, and executable scenario models.
- Schedule a tailored briefing if your priorities include supplier negotiations, capex evaluation or sustainability road‑mapping — we will calibrate our models to your feedstock exposure and customer commitments.
For detailed analysis of this topic, please visit the official page: Isophorone Diamine (IPDA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solketal Market to Hit USD 107M by 2032, Growing at 3.5% CAGR — PW Consulting
By PW Consulting, 2026-07-30
Solketal (CAS 100-79-8) Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused, executive-level introduction to our comprehensive Solketal market study. This briefing distills the critical macro dynamics and strategic implications that will shape boardroom decisions in 2026, while intentionally withholding granular segmentation data reserved for the full report.
Solketal (CAS 100-79-8) Market
Why Solketal Matters Now
Solketal has transitioned from a niche glycerol derivative into a multipurpose specialty solvent and intermediate with cross-sector relevance—from pharmaceutical synthesis to personal care and emerging biofuel formulations. The chemical’s profile as a bioderived, low-toxicity solvent positions it favorably within sustainability-driven purchasing mandates and regulatory scrutiny that is tightening across major markets. For executives evaluating portfolio allocations, supply-chain resilience, or M&A targets in 2026, our research frames Solketal as both a growth lever and a strategic hedging instrument against fossil-solvent exposure.
Solketal (CAS 100-79-8) Market
Market Trajectory at a Glance
-
Historical momentum: PW Consulting’s base-year assessment (2025) records the Solketal market at USD 83.7 Million (revenue in Million USD), up from USD 70.5 Million in 2020—reflecting steady adoption through reformulation, regulatory substitution, and niche industrial uses.
Solketal (CAS 100-79-8) Market -
Near-term outlook: Our forecast period (2026–2032) projects the market to expand to approximately USD 107.0 Million by 2032. The modeled compound annual growth rate for the forecast interval is 3.5%, reflecting tempered but durable demand driven by sustainable sourcing, incremental application penetration, and selective price normalization.
-
2026 inflection: The market is expected to reach roughly USD 87.9 Million in 2026, setting the stage for mid-decade strategic moves—procurement contracts, feedstock lock-ins, and capacity optimizations.
What Is Driving Value—and Risk
-
Feedstock and sustainability premium: The availability and cost of glycerol, particularly renewable glycerol sourced as a biodiesel byproduct, materially influence unit economics. Manufacturers leveraging renewable glycerin as feedstock report not only ESG advantages but also differentiated supplier narratives that matter to brand-conscious formulators.
-
Regulatory clarity and compliance: Recent regulatory developments and product classifications have begun to crystallize market access conditions. Selected Solketal offerings have been updated under EU classification and labelling regimes, and several product dossiers indicate active alignment with REACH/CLP frameworks. For commercial teams, early regulatory compliance is an entry barrier and a pricing differentiator.
-
Concentration and competitive density: The market exhibits meaningful concentration—our competitive concentration metrics indicate that the top three suppliers control approximately 72% of the market, while the top five reach about 85%. This structure favors established suppliers on scale, regulatory dossiers, and quality certifications, but leaves space for focused entrants with specialty propositions.
Competitive Landscape—Who to Watch
Our competitive map highlights incumbent specialty-chemical players and vertically integrated niche producers. Two illustrative profiles illuminate strategic positioning in 2026:
-
Solvay SA —A European-based chemicals leader that has articulated bio-based solvent offerings under product lines designed for surface care, coatings, and leather. Their product framing emphasizes multi-application usability and regulatory alignment, which supports premium customer relationships where compliance and supply reliability are paramount.
-
GLACONCHEMIE GmbH —A Germany-headquartered specialist producing a Solketal offering sourced exclusively from renewable plant-based glycerin (a biodiesel byproduct). This upstream feedstock strategy is commercially salient for customers prioritizing renewable content and traceability in their procurement specifications.
These profiles underscore two repeatable strategic archetypes: scale-focused incumbents competing on dossier completeness and global reach, and smaller, feedstock-integrated specialists competing on sustainability and traceability. Both archetypes will be active acquisition targets and procurement partners in 2026.
Practical, Board-Ready Takeaways for 2026
-
Secure differentiated feedstock pathways: Prioritize sourcing arrangements that guarantee renewable glycerol supply or consider backward integration via offtake agreements with biodiesel producers. Firms locking in traceable glycerin inputs will be able to command formulation premiums and reduce exposure to commodity glycerol volatility.
-
Leverage regulatory compliance as market access: Given evolving classification and labelling expectations, ensure product dossiers and CLP/REACH alignment are in place before scaling. Early alignment avoids market delays and enables premium positioning for customers prioritizing regulatory certainty.
-
Targeted M&A and partnerships: With a concentrated supplier landscape, acquisitive strategies should focus on small-to-midscale specialty producers that offer either feedstock exclusivity, unique application know-how (e.g., pharmaceutical intermediates), or established customer relationships in high-value end uses.
-
Commercial playbooks for formulators: For companies in cosmetics, personal care and pharma formulation, build a two-track go-to-market—(1) pilot programs emphasizing regulatory and sustainability credentials, and (2) scale pilots where cost-in-use and performance parity can be demonstrated.
-
Risk-mitigating procurement: Negotiate flexible pricing bands tied to glycerol indices and include volume-flex clauses to manage inventories across cyclical demand in adjacent end markets.
Report Contents—What the Full Study Delivers
The full Solketal market report is designed for commercial leaders, corporate development teams, and procurement heads. It contains:
-
Detailed market sizing and historic growth analysis (2020–2025 base, with forecast to 2032) expressed in Million USD, including scenario-based projections and sensitivity to feedstock pricing.
-
Top-down and bottom-up methodology documentation that explains model assumptions, CAGR derivation, and margin impact analyses for manufacturers and formulators.
-
Segmentation by region, application, and end-use with an interactive map and time-series data (note: granular split tables and company-level share sheets are gated in the full report).
-
Supply-chain maps highlighting feedstock sources, route-to-market channels, logistics chokepoints, and supplier scorecards.
-
Regulatory tracker and compliance heatmap covering CLP/REACH developments and country-level labelling impacts pertinent to 2026 commercial launches.
-
Competitive benchmarking with strategic profiles of incumbent suppliers, innovation playbooks, and acquisition target screening criteria.
-
Commercial scenarios and go-to-market roadmaps tailored to three buyer archetypes: formulators, industrial consumers, and specialty distributors.
-
Actionable annexes: contract templates, procurement negotiation points tied to feedstock indices, and a checklist for technical due diligence on renewable glycerol sourcing.
How to Use This Intelligence in 2026
-
Board strategy: Use the forecast and concentration metrics to set M&A targets and defensible scales for in-house production versus outsourcing.
-
Commercial planning: Integrate regulatory timelines into product launch sequencing; for instance, prioritize markets where dossier readiness reduces time-to-revenue.
-
Procurement and supply chain: Implement staged offtake agreements with renewal clauses tied to feedstock indices and ESG verification milestones.
-
R&D prioritization: Allocate development budgets toward formulations that exploit Solketal’s solvent properties while highlighting renewable content—an increasingly important buyer filter.
Final Note—A Strategic “Trailer”
This briefing is designed as a high-fidelity preview: evidence-based and actionable at a strategic level, but deliberately omitting the granular region- and application-level split sheets that constitute the core commercial intelligence. Those gated details—critical for precise revenue targeting, competitive share analysis, and transaction planning—are included in the full PW Consulting Solketal market study.
For teams planning capital deployment, supplier consolidation, or product replatforming in 2026, the combination of measured growth (CAGR 3.5% across the forecast horizon), a clear movement toward renewable feedstocks, and a concentrated supplier market creates both opportunity and urgency. Accessing the complete dataset and tactical annexes will materially shorten your path from strategy to execution.
To commission the full report or arrange a bespoke briefing for your leadership team, please contact PW Consulting’s Industry Insights desk. Our work is designed to convert market intelligence into defensible, executable decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Solketal (CAS 100-79-8) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microcatheter Market 2026: Strategic Imperative for Medical Device Leaders
Executive snapshot
By 2025 the global microcatheter market had matured into a mid-market medical device segment, with PW Consulting’s base-year estimate placing total industry revenue at approximately USD 1,763 Million. Our forward-looking model — calibrated on historical performance (2020–2025), primary interviews, and supply-chain intelligence — projects a continued structural expansion through 2032 at a compound annual growth rate (CAGR) of 7.1%, culminating in a market size approaching USD 2.83 Billion by 2032. The market structure today is neither atomized nor monopolistic: the top three firms capture a meaningful but not dominant share, and the top five account for slightly more than half of total value—conditions that reward both focused scale plays and smart niche innovation.
Microcatheter Market
Why this matters for 2026 decision-makers
-
Strategic timing: 2026 is the inflection point when recent regulatory clearances and commercial launches convert into meaningful clinical adoption. Firms that align product availability with go-to-market readiness in the first half of 2026 will disproportionately capture the near‑term growth opportunity.
Microcatheter Market -
Capital allocation: a steady, mid‑single‑digit CAGR over the forecast period supports both organic investment and M&A activity. But returns will not be uniform — success depends on segment focus, clinical evidence generation, and supply resilience.
Microcatheter Market -
Business model choice: reimbursement within bundled payment frameworks (e.g., MS‑DRGs) compresses per‑case device economics. Companies that can demonstrate procedure-level value or secure differentiated contracting will preserve margin and pricing flexibility.
Market trajectory: what the headline numbers tell us
The market’s growth profile is consistent with a technology-led upgrade cycle across multiple interventional specialties. After recovering from pandemic-era procedural volatility, total revenue expanded from about USD 1.26 Billion in 2020 to roughly USD 1.76 Billion in 2025. Growth drivers include expanded procedural volumes, broader clinical indications, and a wave of incremental device innovations (steerability, lower-profile delivery systems, and aspiration performance). Our scenario work shows that the market’s baseline path — a 7.1% CAGR — is sensitive to three levers: rate of adoption for steerable platforms, speed of reimbursement recognition for novel workflows, and short‑term raw material cost pressures that affect gross margins.
Competitive landscape: dynamics you must model
The competitive field blends global incumbents with agile innovators. Legacy device manufacturers retain strong clinician relationships and distribution reach, while smaller technology-first entrants are driving differentiation with steerable constructs and integrated delivery solutions. Recent regulatory and commercial milestones are already re‑shaping GTM calculus:
-
Bendit’s clearance of a sub‑miniature steerable microcatheter introduces a new class of navigational capability that shortens procedure time in complex anatomies and can alter product preference in neurovascular suites.
-
Merit’s steerable device clearance strengthens the steerable segment’s credibility for peripheral and coronary use, accelerating hospital procurement committees’ willingness to adopt steerable platforms.
-
Commercial launches from Vantis, Penumbra, and ASAHI INTECC in 2025 demonstrate how integrated delivery systems and clinically focused messaging (e.g., coil compatibility, delivery stability) can open share quickly when coupled with targeted clinical champions.
For corporate strategy teams this implies three tactical priorities: (1) map clinical preference pathways by specialty (cardiac, neuro, oncology), (2) rehearse evidence packages that speak to both outcomes and cost-per-case, and (3) evaluate partnership or tuck‑in acquisition opportunities to accelerate access to steerability or low‑profile delivery technologies.
Market dynamics and operational resilience
Two non‑clinical factors will disproportionately influence 2026 outcomes: raw materials and reimbursement design. PTFE and other high‑performance polymer availability has been volatile. Shortages in 2024 prompted several manufacturers to insource extrusion capability and re‑architect supply contracts. That operational response creates a new set of competitive advantages for firms with verticalized supply — shorter lead times, improved quality control, and narrower margin volatility.
On reimbursement, most microcatheter usage is embedded in bundled inpatient or cath‑lab DRGs. That reality favors devices that either reduce total procedure cost (e.g., shorter OR time, fewer adjunct devices) or enable revenue uplift through differentiated billing codes. Successful vendors in 2026 will deploy real‑world evidence showing procedure efficiency gains and will engage payers and IDNs with contracting models that recognize total cost of care.
Report deliverables: what this PW Consulting study contains (practical, actionable)
-
Market sizing and growth scenarios — a transparent, bottom‑up model calibrated to 2020–2025 history and stress‑tested across three adoption curves for 2026–2032.
-
Segmentation framework and clinical use matrices — product form, design architecture, and application-led demand drivers mapped to physician workflows (note: this public overview intentionally omits granular regional and product split figures; full segmentation tables are available in the paid report).
-
Competitive playbooks — company profiles, capability maps, and a timeline of near‑term regulatory/commercial catalysts with implication analysis for direct competitors, distributors, and OEM partners.
-
Supply chain heat‑map — critical materials exposure, recommended insourcing thresholds, and supplier diversification strategies to mitigate PTFE and polymer risk.
-
Reimbursement and pricing playbook — mapping of bundled payment dynamics, evidence thresholds for incremental pricing, and contracting templates for hospital systems and integrated delivery networks.
-
M&A and partnership screening tool — targets prioritized by capability gap, integration risk, and value creation runway aligned to a 24‑month execution horizon.
-
Clinical adoption & KOL engagement plan — segmented clinician archetypes, proof‑point sequencing, and an ROI model for clinical trial vs. real‑world data investment.
Prioritized actions for 0–36 months (practical roadmap for 2026)
-
0–6 months: Execute supply resilience triage — secure critical polymer contracts, evaluate insourcing extrusion, and perform SKU rationalization to protect margin while demand normalizes.
-
6–18 months: Product and evidence acceleration — invest selectively in clinical studies that quantify procedure time savings and complication reductions for steerable and delivery platforms; launch targeted hospital pilots tied to KOLs.
-
18–36 months: Scale or consolidate — depending on performance, pursue tuck‑ins to acquire complementary delivery technologies or, conversely, pursue geographic expansion using the strengthened supply base and evidence dossier.
What we advise corporate development teams to model now
Given the current market concentration profile — where the leading firms control meaningful share but not a decisive monopoly — there is room for disciplined M&A to create scale without encountering prohibitive integration complexity. Model scenarios that assume (a) continued organic CAGR at 7.1% as baseline, (b) an accelerated adoption case tied to wider steerable device uptake, and (c) a downside case driven by protracted raw-material inflation. Use these scenarios to stress-test multiples and to prioritize assets that deliver either manufacturing resilience or faster clinical adoption curves.
Our methodological DNA — why PW Consulting’s outlook is decision-grade
We combine a bottom‑up revenue model, primary clinician and procurement interviews, device-level performance benchmarking, and supplier network audits. Regulatory intelligence, including the 2025–2026 wave of 510(k) clearances and product launches, is integrated into adoption curves rather than treated as binary events. Finally, we overlay reimbursement and hospital contracting dynamics to translate clinical adoption into net price realizations — the variable that ultimately determines ROIC for new product introductions.
Final note — the trailer purpose
This overview exposes the strategic contours that senior leaders must internalize in 2026: a predictable mid‑single‑digit CAGR, a market shaped by targeted innovation and supply resilience, and a competitive field where both incumbents and nimble entrants can win. To preserve commercial advantage, firms must act on supply-chain positioning, evidence generation, and differentiated contracting now.
PW Consulting’s full Microcatheter Market research contains the detailed segmentation tables, regional and application splits, pricing sensitivity analyses, and downloadable models that operational teams need to execute. We intentionally withhold the granular split numbers in this public summary to protect the report’s commercial integrity — access the full dataset and the interactive model via our report portal to convert these strategic implications into executable plans for 2026.
For detailed analysis of this topic, please visit the official page: Microcatheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Interlinings & Linings Market to Hit USD 4,491 Million by 2032 (4.5% CAGR)
By PW Consulting, 2026-07-30
Interlinings & Linings Market — Strategic Outlook for 2026 Decision-Makers
As apparel value chains enter a new phase of cost pressure, sustainability scrutiny, and design-led differentiation, interlinings and linings sit at the intersection of technical performance and commercial margin. PW Consulting’s latest Interlinings & Linings Market study (base year 2025, historic 2020–2025, forecast 2026–2032) synthesizes market-scale modelling, supplier benchmarking, and scenario-based stress tests to inform capital allocation, sourcing strategy, and product innovation choices that will be decided in 2026.
Interlinings & Linings Market
Market snapshot: size, trajectory and concentration
-
Scale and growth. The global interlinings & linings market reached approximately USD 3,324 Million in 2025 after steady growth from 2020. Under our central forecast (2026–2032), the market expands at a compound annual growth rate (CAGR) of roughly 4.5%, reaching about USD 4,491 Million by 2032. This pace reflects a balance of modest apparel demand growth, product premiumization, and the steady penetration of sustainable content.
Interlinings & Linings Market -
Industry structure. The market displays moderate concentration—our analysis shows the top three companies capture a material share of global revenues while the top five further consolidate market control. This creates a competitive landscape where scale advantages coexist with regional and niche players that compete on specification and service.
Interlinings & Linings Market
What the report delivers — practical modules for 2026 decision cycles
-
Actionable market model. A granular, auditable supply-demand model spanning 2020–2032, enabling sensitivity testing against raw material cost shocks and demand scenarios. The model is delivered in workbook form so procurement and finance teams can run bespoke “what-if” simulations.
-
Commercial playbooks. Go-to-market templates for apparel brands and converters, including commercial clauses for long-term supply agreements, specification change management, and margin pass-through frameworks that protect product economics amid input price volatility.
-
Supplier benchmarking. A vendor scorecard that combines capacity footprint, technical portfolio (woven/non-woven/knit), sustainability credentials, lead-time reliability, and recent investment activity—designed to support SRM (Supplier Relationship Management) and dual‑sourcing decisions.
-
Product and innovation roadmaps. Scenario-based recommendations on where to prioritize R&D (adhesive chemistry for biodegradability, recycled-content laminates, low-temperature fusible technologies) to capture premium segments without sacrificing manufacturability.
-
Regulatory & compliance checklist. Practical guidance on certifications, customs classification, and labelling that affect sourcing, with a compliance calendar for predictable audit readiness in major export markets.
-
Investment and M&A playbook. Valuation comparables, capex sizing for greenfield and brownfield expansions, and an M&A screening matrix tailored to strategic objectives—capacity build, upstream integration, or technology acquisition.
Dynamics shaping 2026 decisions
-
Raw-material volatility. Polyester feedstock volatility remains a live risk: regional polyester DTY prices in Northeast Asia rose to approximately USD 1.56/kg in May 2026 — a sharp move over recent months driven by upstream feedstock constraints. PTA levels moved materially in early 2026 as well, reinforcing the need for dynamic procurement tools and hedging strategies for large converters and manufacturers.
-
Certified sustainability isn’t optional. OEKO-TEX Standard 100 remains the primary compliance baseline for polyester interlinings, and recycled polyester represented a meaningful minority share of polyester fiber output in 2024. Buyers and suppliers will increasingly compete on verified recycled content and end‑of‑life credentials; product claims without traceable evidence will attract commercial and regulatory scrutiny.
-
Trade and tariffs: stability, for now. Interlinings are classified under HS Code 590390 and, at the time of this study, no significant tariff adjustments targeting the segment have been announced for 2025–2026. That said, policy volatility in adjacent upstream petrochemical inputs can still transmit to finished‑goods cost bases.
-
Moderate consolidation. With the three largest players controlling a substantial share and five players further extending control, competition is focused on service differentiation, local footprint expansion, and sustainability credentials rather than pure price wars. This creates opportunities for mid‑tier firms to win through specialization or regional partnership strategies.
Competitive landscape — profiles and recent moves
-
Freudenberg Performance Materials (Global; Germany): A global leader, noted for a broad portfolio across fusible, sewn‑in, and recycled‑content interlinings. The company’s product strategy strongly emphasizes high recycled polyester content and biodegradable adhesive developments. Recent capacity additions and regional investments illustrate a push to secure local supply chains in key apparel manufacturing hubs.
-
Freudenberg & Vilene International Ltd (Hong Kong): Operating across woven, knitted, and non‑woven interlinings, this business emphasizes garment stability and structural solutions. Its product breadth and technical collaboration with garment manufacturers position it as a preferred partner for tailored shirt and outer garment solutions.
-
Chargeurs Interlining (HK) Ltd / Chargeurs PCC (France): These related businesses combine brand-led distributor reach with manufacturing know‑how across knitted, woven, and non‑woven technologies. Recent executive appointments and organizational strengthening signal an intensification of global go‑to‑market efforts and operational expansion in high-growth corridors.
-
Wendler Interlining H.K. Limited (Hong Kong): A specialist in shirt interlinings with a reputation for focused, high-quality woven, knitted, and non‑woven options—an example of a niche player that maintains relevance through product depth and technical service.
-
Recent strategic moves. Several leading players expanded capacity in India during 2025–2026, reflecting a strategic response to demand localization and the need to shorten lead times. Executive-level hires aimed at strengthening regional leadership also indicate a shift toward tighter commercial management in EMEA and APAC markets.
Strategic implications for 2026 — five recommended moves
-
1) Institutionalize dynamic procurement. Convert spot exposure into a layered procurement approach: strategic contracts for core volumes, indexed shorter-term purchases tied to feedstock movements, and selective forward buys. Integrate the report’s price-sensitivity model into procurement KPIs.
-
2) Prioritize supplier segmentation and dual-sourcing. Use our vendor scorecard to create A/B-class suppliers across regions to manage capacity shocks and ensure specification continuity. For technically critical SKUs, lock in capacity with minimum purchase commitments tied to performance metrics.
-
3) Invest selectively in sustainability technologies. Target R&D or minority investments in adhesive chemistries and recycled-content process technologies that can be industrialized at reasonable capex. Certification and traceability technologies that reduce audit friction will deliver outsized commercial returns.
-
4) Reassess nearshore and onshore strategies. Where lead time and responsiveness trump pure cost, consider reshoring or nearshoring small series production to accelerate design-to-market cycles. The report’s regional scenario analyses quantify the trade-offs between landed cost and speed-to-retail.
-
5) Evaluate M&A and partnership windows. Moderate market concentration creates opportunities to acquire capability in niche technologies or to consolidate fragmented regional players. Use the provided M&A playbook to align valuation expectations with strategic targets.
How to use this study in your 2026 planning
-
Board & investment committees: Use the study’s scenario outputs to stress-test CAPEX proposals and to justify contingency budgets for raw-material spikes.
-
Procurement teams: Deploy the report’s price-sensitivity dashboards and supplier scorecards to renegotiate contracts and to set dynamic inventory policies.
-
R&D and product development: Leverage the technology roadmaps and certification checklists to prioritize projects that deliver measurable commercial uplift and reduce audit risk.
-
Corporate development: Apply the M&A screening tools to identify bolt-on targets that complement capacity, geography, or sustainable technology. The study’s market model helps set realistic growth multiples tied to volume and margin synergies.
Where we intentionally withhold (and why)
To prompt the informed executive action that this study targets, we expose methodology, modelling assumptions, and scenario mechanics—but we deliberately reserve the full segment-level numeric breakout (regional and application-specific revenue splits) for the complete report. This “trailer” approach demonstrates analytical depth while ensuring that stakeholders who need the granular inputs and validated line-item tables access the full dossier through PW Consulting. Those segment breakouts are essential for detailed procurement tenders, SKU-level costing, and exacting investment models, and they are available in the complete package.
Final note — timing matters
Market inflection points are rarely announced in real time. In the interlinings & linings segment, near-term triggers — raw-material repricing, certification-driven demand shifts, and strategic capacity additions — mean that procurement cycles and investment approvals initiated in 2026 will determine competitive positioning through the remainder of this forecast window. PW Consulting’s Interlinings & Linings Market study is designed to be both a strategic compass and a hands-on toolkit for those 2026 decisions.
For executives preparing budgets, negotiating multi-year purchase agreements, or scoping M&A targets this year, the study delivers the models, playbooks, and intelligence needed to convert uncertainty into differentiated, executable strategy.
For detailed analysis of this topic, please visit the official page: Interlinings & Linings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gears Market to Grow at 5.77% CAGR, Hitting USD 328.95M by 2032
By PW Consulting, 2026-07-30
Gears Market 2026: Strategic Insights for Decision-Makers
As firms move from recovery to growth planning in 2026, the gears market presents a distinctive blend of steady demand, technological disruption, and structural fragmentation. PW Consulting’s Gears Market report synthesizes multi-year historical performance, a detailed seven-year forecast, and forward-looking scenario analysis to arm executives with the near-term playbook they need to convert market momentum into sustainable advantage. This article highlights the report’s strategic value for 2026 decision cycles—showing the analytical depth at a high level while reserving the granular tables and supplier-level intelligence for the full report.
Gears Market
Market snapshot: trajectory and what it means for 2026
The gears market expanded consistently through the pandemic recovery years and into 2025, with overall market value rising meaningfully from the 2020 base and reaching a clearly stronger position in the 2025 base year. PW Consulting’s modeling projects continued expansion across the 2026–2032 forecast window, driven by a blend of automotive electrification, industrial automation, and growing replacement markets. On a compound basis, the market is expected to grow at a mid-single-digit CAGR (5.77%) through 2032, reaching a markedly larger market size by the end of the forecast period.
Gears Market
For 2026 planning, three implications are immediate: (1) steady market growth validates expansion and modernization investments, (2) mid-cycle cyclical factors—especially raw-material and labor dynamics—require defensive operational tactics, and (3) a fragmented competitive landscape keeps M&A, vertical integration, and targeted partnerships on the table as viable routes to scale and margin improvement.
Gears Market
Why this report matters to 2026 strategy
- Actionable sizing and pacing: The report uses a consistent base year (2025) and reconciles historicals (2020–2025) to produce realistic demand curves for 2026–2032. That alignment is critical for capital budgeting, pricing strategies, and product roadmap prioritization.
- Risk-weighted scenarios: We provide sensitivity analyses that connect raw-material shocks, labor constraints, and regulatory shifts to revenue and margin outcomes—giving procurement and finance teams concrete hedging and contingency plans.
- Go-to-market and portfolio playbooks: The study translates market-level trends into runnable initiatives—e.g., productization of noise‑reduction features for premium segments, modular platform strategies for shorter lead times, and channel tactics for OEM vs. aftermarket sales.
- Benchmarking for M&A and capex decisions: Comparative performance metrics, concentration analysis, and growth forecasts enable acquirers and investors to quickly screen targets and size required post-merger investments.
Competitive landscape—who matters and why
The gears industry remains relatively fragmented, with the top three and top five manufacturers accounting for a modest share of total market value (CR3 ~26.2%; CR5 ~28.1%). For 2026 strategies, that fragmentation creates both opportunity and complexity: scale players can move fast on platform investments, while specialized vendors retain strong technical moats in niches like noise reduction, high‑torque right‑angle drives, and marine/defense systems.
- Philadelphia Gear (King of Prussia, PA): Known for precision marine and industrial gears and major reduction systems for naval applications, Philadelphia Gear’s strength in high-performance drives positions it well for defense and heavy-industrial aftermarket work.
- IMS Gear GmbH (Germany): A specialist in high-precision metal and plastic gears, IMS’s emphasis on noise-reduction technologies speaks directly to premium industrial and robotics segments where acoustic performance is a differentiator.
- Brelie Gear (Waukesha, WI): Focused on precision industrial and commercial power-transmission solutions, Brelie remains relevant for legacy OEMs seeking reliable aftermarket supply and custom engineering services.
- Cone Drive (Traverse City, MI): Their portfolio of high-torque right-angle worm and cycloidal drives addresses applications requiring compact, high-efficiency torque conversion—relevant to renewables, heavy machinery, and material-handling equipment.
- KHK Gears (Japan): As a major source of stock and standardized components across spur, helical, and worm designs, KHK’s scale in stocked catalog parts supports fast-turn OEM supply chains and prototyping cycles.
- Nabtesco Precision Europe GmbH (Europe): Specializing in precision gearboxes and cycloidal gears for robotics and automation, Nabtesco is well-placed to capture ongoing spends tied to factory automation and collaborative robotics.
- Gear Motions (USA) & Bharat Gears Ltd (India): Both firms emphasize custom precision gear capabilities for industrial and automotive applications—opportunities exist to capture regional aftermarket demand and localized content mandates.
- GKN, Robert Bosch, American Axle & Manufacturing, Curtiss-Wright: These diversified engineering groups bring scale and system-level integration capabilities; their strategies often set the bar for OEM partnerships and platform-level sourcing.
Across these players, competitive differentiation is increasingly technical (noise, efficiency, materials), operational (supply-chain agility, lead time), and relational (OEM partnerships, service networks). Our full competitive matrices dissect these dimensions and map them to near-term opportunity windows.
Industry dynamics shaping 2026 choices
- Raw-material volatility: Recent tariff-driven disruptions and pricing premiums on steel and aluminum have raised input cost baselines and complicated long-term procurement. Manufacturers must evaluate hedging strategies, alternative materials, and design-for-material-efficiency to protect margins.
- Regulatory and standards influence: Recognition of technical standards—such as recent developments around high-speed helical gear specifications—creates both a compliance floor and a performance benchmark; firms that align product roadmaps with evolving standards can capture specification-driven demand.
- Labor market constraints: Slower hiring in manufacturing sectors is prompting firms to accelerate automation, upskill existing workforces, and re-evaluate distributed vs. consolidated manufacturing footprints.
- Market consolidation and trade bodies: Institutional consolidation in trade associations and collaborative standards bodies points to accelerating industry coordination—useful signals for companies planning collective advocacy or co-investments in R&D infrastructure.
Recent signals and what they imply
- Trade shows and product expansions from key vendors underscore continued investment in automation and robotics channels—momentum that 2026 commercial strategies should exploit via demo fleets and application pilots.
- Industry awards and specification contributions signal which firms are influencing next‑generation performance criteria; aligning development work with these leaders reduces technical risk and shortens validation cycles.
- Events reflecting organizational consolidation in trade bodies indicate a more coordinated sector response to supply-chain stressors—expect more standardized reporting, certification, and collective lobbying in the near term.
Recommended 2026 playbook for executives
- Prioritize modular platforms: Invest in modular gear platforms that enable fast customization and reduce inventory complexity across global SKUs.
- Hedge raw-material exposure: Combine financial hedging, multi-sourcing, and substitution engineering to reduce cost volatility impact on margins.
- Pursue bolt-on M&A where scale gaps exist: Given the market’s fragmentation, targeted acquisitions can deliver immediate market share, engineering talent, and access to high-value aftermarket channels.
- Monetize technical differentiation: Convert noise-reduction and high-efficiency designs into premium product tiers with warranty and performance guarantees.
- Operationalize workforce modernization: Pair automation investments with retraining programs and performance-based incentives to accelerate productivity without sacrificing capability depth.
- Align product development with standards: Proactively engage in standards committees and align R&D to forthcoming specifications to shorten qualification cycles for critical OEMs.
- Build strategic OEM partnerships: Lock in longer-term agreements for EV driveline, robotics, and defense supply opportunities where predictable volumes enable capex recovery.
What the full Gears Market report delivers
PW Consulting’s full Gears Market research report provides the granular intelligence that underpins the strategic recommendations above. Deliverables include:
- Reconciled historical market sizing (2020–2025) and a transparent forecast model (2026–2032) with scenario toggles;
- Segmented demand models by region, gear type, and application with underlying assumptions and sensitivity tables;
- A complete competitive benchmarking suite including technology positioning, capability heatmaps, and M&A target screening tools;
- Supplier and cost-model templates, price curve analytics, and procurement playbooks to operationalize raw-material and logistics risk mitigation;
- Actionable go-to-market frameworks, investment case templates, and 90–180–360 day implementation roadmaps for executives and business units;
- Primary-interview-based insights from manufacturers, OEMs, and trade bodies to validate near-term adoption barriers and demand levers.
To preserve the strategic value of the research and ensure vendors and competitors cannot reverse-engineer opportunity maps from a short preview, this article offers the directional narrative and strategic implications while withholding detailed segment-level tables, supplier-level financials, and the complete dataset. Those proprietary elements are included in the full report and dataset package.
Next steps
For executives planning capital allocations, product launches, or M&A activity in 2026, the path from insight to execution must be rapid and defensible. PW Consulting’s Gears Market report is built to bridge that gap: it couples validated market-sizing, scenario-tested forecasts, and executable playbooks. Contact our research team to arrange a briefing and to access the detailed datasets and competitive scorecards that will allow you to operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Gears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Healthcare & Medical System Integrators to Reach USD 2,403M by 2032 (CAGR 11.02%)
By PW Consulting, 2026-07-30
Healthcare and Medical System Integrators Market — Strategic Brief for 2026 Decision‑Makers
As healthcare providers, payers, technology vendors, and investors plan capital and operating moves in 2026, the Healthcare and Medical System Integrators market has become a systemic lever for clinical transformation. Our latest PW Consulting market study — base year 2025 — quantifies a market that expanded materially through the early 2020s (rising from roughly USD 700 million in 2020 to about USD 1,160 million in 2025) and is projected to continue growing at an annualized rate of approximately 11.02% through 2032 (with a 2032 projection near USD 2.4 billion). This brief explains why those macro trends matter for your strategy, what practical intelligence the full report delivers, and how to convert the findings into executable choices in 2026.
Healthcare and Medical System Integrators Market
Why this research matters right now
-
Capital allocation under uncertainty — The market’s sustained double‑digit growth trajectory demonstrates both expanding opportunity and intensifying competition. Boards and investment committees need a defensible view of structural demand drivers (interoperability projects, device and IoT integration, clinical‑IT convergence) to prioritize bets and sizing assumptions for the next three to five years.
Healthcare and Medical System Integrators Market -
De‑risking M&A and partnerships — Integrator assets are increasingly differentiated by their technology IP, regulatory certifications, and domain verticals. Our study gives acquirers the diagnostic framework to value recurring services, capture synergies, and surface integration risks before closing.
Healthcare and Medical System Integrators Market -
Vendor selection and contracting — Health systems seeking enterprise‑wide integration must balance pragmatic, incremental projects with platform bets. The research provides supplier archetypes, sourcing playbooks, and contracting templates to shift commercial negotiations from hour‑by‑hour scoping to outcomes‑based engagements.
-
Regulatory and compliance preparedness — Data privacy and interoperability regimes in the US and EU are tightening. The report highlights compliance vectors that materially affect delivery timelines and cost structures for both buyers and vendors.
-
Operational readiness for AI and device convergence — The early commercialization of AI‑native EHR functionality and certified AI medical software is already reshaping integration requirements. Executives must align platform roadmaps and talent models to exploit these transitions.
What the full PW Consulting report delivers (operationally focused)
-
Market sizing and methodology — Transparent, reconciled top‑down and bottom‑up estimates (base year 2025) and scenario forecasts through 2032; sensitivity models that let you test alternative growth drivers and adoption curves.
-
Demand‑side intelligence — Buyer personas, procurement cycles, typical project economics, and a prioritized list of use cases driving incremental spend (interoperability, clinical device integration, telehealth enablement, facility AV and collaboration integration, etc.).
-
Vendor landscaping and scorecards — A comparative framework assessing go‑to‑market motion, IP assets, implementation delivery capability, compliance posture, and scalability for the leading providers in the space.
-
Go‑to‑market playbooks — Segment‑specific sales motions, pricing architectures (including managed services and outcome contracts), and sample contracting terms to accelerate capture while protecting margins.
-
M&A and partnership playbook — Identification of archetypal bolt‑on targets, valuation heuristics, integration checklists, and a shortlist of mid‑market targets for strategic players and private equity sponsors.
-
Regulatory and implementation checklist — Actionable steps to align projects with US and EU privacy regimes, medical device regulation pathways, and procurement compliance to reduce time‑to‑value.
-
Executive dashboards — A set of KPIs and a sample data room that boards and sellers can use to benchmark performance and model earn‑outs or milestone payments.
Competitive landscape: what the market is signaling
-
iNTERFACEWARE Inc (Toronto) — Specialization in the Iguana integration engine and deep EHR interoperability expertise positions the firm as a go‑to for complex, message‑level integrations and device data normalization. Recent industry activity — visible presence at HIMSS 2026 and an active user conference in 2026 — underscores a strategy of community‑led adoption and product‑led services. Notably, Iguana’s market reputation for interoperability performance has been externally validated by strong KLAS scores, which matters for procurement teams seeking low‑risk integration platforms.
-
Burwood Group, Inc (United States) — A services and consulting specialist whose integration capabilities have been strengthened by recent strategic alignment with a larger professional services firm. This move reflects a broader trend of consultancies acquiring or embedding integration capabilities to deliver end‑to‑end digital transformation for health systems and value‑based care models.
-
FORTÉ (formerly AVI Systems) — The rebrand and expanded focus reflect a deliberate pivot toward converged collaboration, AV, and clinical facility integration at scale. Operating across many countries, the company demonstrates the operational rigor and delivery footprint required for large capital projects in multi‑facility health systems.
-
InterSystems Corporation (Boston) — A platform leader with deep legacy presence in health information systems; the company’s early commercialization of AI‑native EHR capabilities and recent regulatory certification activity (notably EU medical device pathways) indicate a strategic thrust to embed intelligent capabilities at the core of care workflows.
-
Veradigm LLC (Chicago) — Focused on connected care and EHR integrations, Veradigm highlights the convergence of population health, analytics, and integration services. Its public positioning around privacy and interoperability requirements signals the centrality of regulatory compliance to purchasing decisions.
Together, these players illustrate two durable market archetypes: platform‑centric vendors that build for scale and reuse (often with certified IP and product‑led adoption), and advisory/integration firms that deliver customized, high‑touch implementations. Buyers should expect continued consolidation and a more pronounced divide between generalized integrators and specialized, domain‑specific providers.
Market dynamics you cannot ignore
-
Regulation is a growth filter — Compliance timelines for data privacy and medical device regulation materially change procurement sequencing and total cost of ownership. Planning must bake regulatory milestones into roadmaps.
-
Talent and labor economics — Skilled integration engineers and clinical informaticists remain scarce; labor cost inflation and retention risk are primary determinants of implementation margins and lead times.
-
Platformization and AI — Early wins from AI‑native EHRs and certified AI modules will accelerate demand for integration services that can operationalize AI outputs into clinical workflows.
-
Delivery footprint matters — Global facility integrators and regional specialists coexist; multi‑facility health systems increasingly prefer partners that combine local delivery depth with enterprise governance and security standards.
Actionable strategic implications by stakeholder
-
For CIOs and digital leads — Prioritize an interoperability architecture that is vendor‑agnostic and supports both immediate interoperability projects and a staged migration to AI‑enabled workflows; insist on supplier SLAs that include regulatory compliance attestations and measurable clinical outcomes.
-
For vendor executives — Distinguish your offering through certified IP, domain templates (e.g., device families, specialty workflows), and outcome‑based pricing. Investing in developer communities and productized connectors reduces bid costs and increases stickiness.
-
For private equity and corporate development teams — Target bolt‑on acquisitions that deliver capabilities in regulated clinical domains or proprietary connector libraries; value creation will come from standardized delivery playbooks and cross‑sell into installed customer bases.
-
For procurement and compliance — Treat regulatory readiness and data governance as pre‑bid gating criteria; procurement should require proof points on privacy, MDR/CE pathways, and operational security as part of vendor shortlisting.
Six tactical moves to implement in 2026
-
Adopt an interoperability first roadmap — sequence projects by clinical impact and regulatory exposure, not by ease of implementation.
-
Create a vendor scorecard that incorporates compliance, product roadmap, and integration reuse metrics — use it to rationalize the list of approved integrators.
-
Pursue small, rapid bolt‑on acquisitions to obtain vertical expertise and connector libraries rather than large platform buyouts that take years to integrate.
-
Negotiate outcome‑linked service contracts with clear clinical and operational KPIs, and structure payments to de‑risk the buyer while preserving vendor margins.
-
Operationalize regulatory checkpoints into every project plan — incorporate privacy impact assessments, MDR/CE mapping, and documentation sprints into delivery milestones.
-
Invest in talent pipelines — build partnerships with clinical informatics programs and create internal certification programs for integration engineers.
How to use the full PW Consulting study
The full report provides the granular, transaction‑ready detail that executives need to act: interactive financial models, regional and application breakouts, vendor market‑share matrices, detailed vendor scorecards, sample contracts and implementation checklists, and scenario forecasts that quantify upside and downside outcomes. It is deliberately structured to move organizations from strategic intent to operational execution.
If you are evaluating expansion plans, M&A targets, vendor selection, or regulatory preparedness in 2026, the intelligence in this report will materially shorten decision cycles and reduce execution risk. For access to the full dataset, vendor benchmarking tables, and our bespoke scenario models, please consult PW Consulting’s Healthcare and Medical System Integrators Market research page and contact our advisory team for a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Healthcare and Medical System Integrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


