



Category: market research
PW Consulting: Worldwide Chain Door Guard Market to Expand at 4.51% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Chain Door Guard Market: Strategic Insights for Corporate Decision‑Making in 2026
Executive preview
As organizations plan capital allocation, product strategy, and route‑to‑market moves for 2026, the worldwide chain door guard market presents a quietly resilient opportunity. PW Consulting’s latest market study—anchored on a 2025 base year, examining historical performance from 2020–2025 and projecting through 2032—synthesizes financial trajectories, regulatory inflection points, material cost dynamics, and competitor playbooks into an action‑oriented roadmap. The headline: the market expanded from roughly USD 390 million in 2020 to about USD 487 million in 2025 and is forecast to grow to an estimated USD 663 million by 2032, reflecting a compounded annual growth rate (CAGR) of 4.51% over the 2026–2032 forecast window. This release distills the strategic implications for procurement, product development, channel partners, and M&A teams while deliberately reserving detailed segmentation numbers for subscribers to the full report.
Worldwide Chain Door Guard Market
Market snapshot: steady expansion within a fragmented industry
The chain door guard segment has shown steady, if unglamorous, growth through macro cycles. After a modest dip and rebound in the early 2020s, total market revenue reached just below half a billion USD in 2025. Our forecast anticipates continued expansion, driven by urban residential upgrades, strengthening security standards in multifamily housing, and incremental demand from commercial retrofit projects. Importantly, market concentration metrics indicate a fragmented landscape—the top three and top five manufacturers account for a relatively small share of global revenue—leaving meaningful runway for both regional champions and international consolidators.
Worldwide Chain Door Guard Market
Why this matters for 2026 decision cycles
- Procurement and sourcing: Volatility in metal prices and shifting supplier footprints mean that sourcing strategies executed in 2026 will materially influence COGS over the next three fiscal years. Tactical hedging, dual‑sourcing from diversified geographies, and renegotiating payment terms are immediate levers to protect margins.
- Product and compliance roadmaps: Evolving standards—particularly in markets adopting enhanced mechanical testing protocols—require manufacturers and OEM partners to accelerate product certification plans. Failure to align product roadmaps with these standards will create aftermarket and channel frictions as regulators and specification writers favor compliant designs.
- Channel and distribution decisions: Fragmentation creates space for distributors and ecommerce platforms to aggregate brands; manufacturers must decide whether to double down on direct channels, deepen trade partnerships, or lean into private label and OEM/ODM models to defend share.
- M&A and partnership timing: With modest but consistent market growth and low top‑player concentration, 2026 is an attractive year for strategic acquisitions—especially bolt‑ons that provide capability gaps (e.g., compliance labs, design IP, regional manufacturing footprints).
Competitive landscape—what incumbent playbooks tell us
Our competitive analysis profiles established international vendors and regional specialists to extract repeatable strategic moves. Key players we examined include sector specialists with OEM capabilities, global security brands with diversified portfolios, and hardware distributors focused on trade channels. Across these profiles we see several common strategic themes:
Worldwide Chain Door Guard Market
- Product breadth vs. specialization: Global security brands leverage brand trust and cross‑sell into broader lock and access control portfolios, while manufacturers specializing in door guards compete on product engineering (e.g., high‑security chain designs, magnetic retention, low‑profile aesthetics) and manufacturing flexibility for OEM/ODM customers.
- Channel sophistication: U.S. and European players tend to invest in multi‑channel availability (builders’ merchants, ecommerce, hardware chains), whereas some Asian manufacturers emphasize B2B relationships with door makers and project contractors, using OEM to secure large, steady volumes.
- Regulatory and standards positioning: Firms that prioritize testing and certification—both voluntary industry marks and mandatory standards—gain faster access to institutional channels (developers, social housing, and specification‑driven commercial projects).
- Design and material mix: A spectrum of material choices (stainless steel, zinc alloys, brass variants) creates product ladders from cost‑efficient to premium. Manufacturers are balancing cost pressures with demand for “visible security” products that also deliver improved user experience (smooth operation, corrosion resistance, discreet aesthetics).
We avoid naming specific market share breakdowns in this release, yet the full report provides granular competitor revenue trajectories, product SKU benchmarking, and channel share matrices that underpin these strategic takeaways.
Regulation, standards, and the operational consequences
2025–2026 marks an inflection where mechanical security standards are increasingly embedded into procurement specifications. For example, in some mature markets door chain and limiter products are being evaluated against rigorous test regimes that simulate repeated impacts and measure allowable opening thresholds—benchmarks that change product design and installation requirements. Beyond compliance, approvals such as recognized security schemes provide a commercial premium in certain public and institutional tenders. For manufacturers and specifiers, the operational impacts are clear: re‑engineer mounting systems, invest in third‑party testing, and document performance to remain eligible for high‑value contracts.
Raw material dynamics: a margin risk and product design lever
Fluctuating metal prices for stainless steel, zinc, brass and related alloys have been a cross‑cutting theme in our interviews and supplier surveys. These fluctuations are not merely cost nuisances; they shape choices across the value chain—material substitutions, plating processes, and even packaging decisions. Leading manufacturers are adopting scenario‑based costing models and locking partial volumes under short to medium‑term contracts, while others are redesigning components to achieve equal perceived quality with lower material intensity. For 2026 budgeting, CFOs and procurement leads should stress‑test P&Ls against a range of commodity scenarios and quantify the impact of common mitigation measures (substitution, standardization of finishes, and component consolidation).
Recent product innovation signal: what to watch
Product innovation continues to be incremental but strategically meaningful. A July 2025 launch of a slim, magnetic hold chain product from a UK‑based specialist illustrates two important trends: a push for better user experience (preventing swing and inadvertent opening) and alignment to tougher test standards for heavy duty doors. Such launches show that product differentiation—whether through small mechanical improvements or new finishes—can materially shift specification outcomes and retailer assortments.
What the PW Consulting report delivers—practical contents for 2026 action
Our report is built to be executable. Key deliverables include:
- Validated market sizing and seven‑year forecasting models (USD, Revenue) with scenario variants that stress commodity and regulatory outcomes.
- Competitive profiles and benchmarking, including SKU‑level feature matrices, channel strategies, and product positioning narratives.
- Regulatory compliance matrix mapping test standards to product design changes and procurement eligibility across major markets.
- Supply chain heatmap with supplier concentration indicators, lead time analysis, and risk mitigation playbooks (dual‑sourcing, near‑shoring, inventory strategies).
- Commercial growth playbooks for manufacturers and distributors covering premiumization, value engineering, private label strategies, and retail/channel optimization.
- Target list for strategic M&A and partnerships, prioritized by capability gaps and regional expansion potential.
Each module is accompanied by templates, checklists, and a set of financial sensitivity models so teams can translate insight into executable plans within a single quarter.
Recommendations—six pragmatic moves for 2026
- Embed standards compliance into product roadmaps: allocate budget in H1 2026 for testing and certification where target markets are tightening requirements.
- Reassess material specifications: pilot low‑intensity designs and standardized finishes to protect margins while preserving perceived quality.
- Pursue selective consolidation: evaluate bolt‑on targets that supply regional distribution networks or complementary installation hardware.
- Strengthen OEM/ODM contracts: lock longer‑term supply for key customers while introducing flexible pricing clauses to share commodity risk.
- Digitize channel analytics: centralize sell‑through and SKU performance data to optimize assortments across retail and trade partners.
- Build scenario finance: run at least three commodity and regulatory scenarios into 2027 capex and working capital plans to ensure resilience.
Next steps and how to get the full intelligence
This article offers a strategic overview and highlights the operational levers that will matter in 2026. For decision‑makers seeking procurement line‑items, SKU‑level cost impacts, regional demand models, or an M&A target shortlist, the full PW Consulting report contains the datasets and appendices necessary to make those decisions with confidence. Our comprehensive annexes include supplier scorecards, SKU benchmarking tables, and a regulatory readiness checklist designed to be integrated into product development and procurement workflows within 30 days.
PW Consulting continues to advise manufacturers, distributors, investors, and public sector buyers on turning market signals into measurable outcomes. To request an executive briefing or obtain the full report and supporting models, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Chain Door Guard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Paper Dry Strength Resin Market Poised to Reach USD 1,333.1 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Paper Dry Strength Resin Market: Strategic Insights for 2026 Decision‑Makers
Executive snapshot
PW Consulting's new market study on the Worldwide Paper Dry Strength Resin Market (base year 2025, historical coverage 2020–2025, forecast 2026–2032) equips senior executives and operational leaders with an actionable roadmap for 2026. The sector is returning to growth after a near‑term correction: the industry-wide revenue base held around USD 1.03 billion in 2025 and, under our central scenario (CAGR 3.82% for the forecast window), is modelled to reach approximately USD 1.33 billion by 2032. These macro trajectories capture the combined effects of raw material volatility, sustainability-driven product shifts, and evolving papermaking economics — and form the quantitative spine of the strategic guidance in the report.
Worldwide Paper Dry Strength Resin Market
Why this matters for 2026 decisions
-
Procurement and pricing: volatile acrylamide feedstock markets and supply chain dislocations require firms to move from ad hoc buying to structured hedging and supplier-partner models in 2026.
Worldwide Paper Dry Strength Resin Market -
Product portfolio prioritization: customers will increasingly demand dry strength solutions that enable lightweighting, recycled-fiber compatibility, and demonstrable sustainability benefits — translating into R&D and commercialization choices with five- to seven‑quarter payback horizons.
Worldwide Paper Dry Strength Resin Market -
M&A and partnership timing: moderate market concentration (CR3 ~32.4%; CR5 ~48.8%) creates windows for bolt-on acquisitions and commercial alliances that can move the needle on distribution, formulation IP, and regional manufacturing footprint.
Market dynamics — what is driving value and risk
The report synthesizes primary interviews, plant-level surveys, and a proprietary demand model to unpack three parallel dynamics shaping 2026 strategy:
-
Feedstock and cost pressure: acrylamide monomer pricing has swung materially (historical band observed between USD 1,200 and USD 1,800/MT) as energy, feedstock integration, and logistics costs reverberate through supplier margins. Organizations that lock in multi-period supply agreements or co-invest in upstream integration gain durable cost advantage.
-
Sustainability and regulation: regulatory attention and buyer preference are catalyzing investment in bio-based and hybrid solutions. Cationic starch remains a resilient natural complement in many paper systems; however, synthetic polyacrylamide chemistries will continue to be required where performance or fiber furnish constraints are binding. The transition to lower-carbon chemistries is a technical and commercial programme, not a single switch.
-
Operational optimization at the mill: dry strength additives are now evaluated not only on tensile/burst improvement but as levers for machine runnability, drainage, retention, and energy savings. Suppliers that bundle dosing hardware, performance analytics, and mill-level trials convert capability into sticky commercial outcomes.
What our full report contains — practical, transaction‑ready intelligence
This study is structured to be directly usable in 2026 strategy sprints and commercial planning cycles. Highlights include:
-
Proprietary market model with monthly demand phasing, upside/downside scenarios, and sensitivity to acrylamide and pulp pricing.
-
Supplier scorecards and capability mapping (technical performance, geographic footprint, regulatory readiness, and service/installation strength).
-
Buy‑side playbook for procurement teams: contracting models, price indexation templates, and politically‑sensitive sourcing pathways.
-
Product and R&D matrix: decision criteria for choosing synthetic vs. starch‑based vs. hybrid chemistries by mill objective (lightweighting, recycled furnish, tissue softness vs. strength).
-
Operational pilots and validation protocols: step‑by‑step trial design, KPIs to track, and statistical thresholds for scale‑up.
-
Commercial commercialization guide: value‑based pricing calculators, conversion-case arguments for OEMs and converters, and routes to capture share in packaging and tissue segments.
-
Transaction annex: M&A screening criteria, valuation checkpoints, and post‑merger integration risks specific to polymer-based chemistry businesses.
Competitive landscape — capabilities that will determine winners in 2026
The study benchmarks leading suppliers across technology, route‑to‑market, and service. Several themes emerge:
-
Full‑spectrum additives houses (Solenis, Kemira) combine extensive R&D pipelines with mill services and dosing systems — enabling client outcomes that span strength, retention, and sustainability claims.
-
Regional specialists and chemical groups (Buckman, SNF Group, BASF, Harima, Ecolab/Nalco Water) bring formulation depth and enterprise contracts; their advantage is rapid deployment across multinational mill networks.
-
Emerging and local producers (select Chinese and Indian manufacturers, plus nimble specialty players) compete on cost and customization; their place in a buyer's supplier matrix depends on qualification barriers and regulatory tolerances.
-
Smaller innovators (Derypol, Aurora Specialty Chemistries, Thermax, Aries, Seiko PMC) are sources of formulation niches and sustainability‑oriented chemistries that larger suppliers may seek to acquire or partner with.
Recent industry signals underline these patterns: in 2025 Kemira launched a pump‑and‑go dry strength solution designed to deliver 20–30% strength improvements for tissue manufacturers, and Solenis-supported mill initiatives were recognized for CO2 reductions tied to dry strength additive programs. These developments highlight the commercialization premium attached to turnkey, demonstrable sustainability outcomes.
Recommended 2026 playbook — prioritized actions for market participants
To translate the report's insights into measurable outcomes in 2026, PW Consulting recommends a five‑pillar playbook:
-
Secure strategic feedstock arrangements: move from spot exposure to layered contracts (short/medium/long) with price‑index components and optionality to mitigate acrylamide swings.
-
Invest in blended chemistries: accelerate pilot programmes that blend starch and synthetic polymers to balance cost, performance, and ESG credentials where acceptable.
-
Operationalize supplier partnerships: require proof‑of‑value pilots tied to contractual clauses that convert performance gains (e.g., basis weight reduction, energy saved) into shared savings.
-
Prioritize quick‑win M&A and licensing targets: seek bolt‑ons that fill capability gaps (formulation IP, regional manufacturing, dosing hardware) and avoid transformational deals until the post‑2026 demand path clarifies.
-
Embed sustainability into product economics: create internal carbon and water cost functions to evaluate next‑generation formulations — aligning commercial claims with verifiable mill performance and third‑party validation.
How PW Consulting helps clients execute in 2026
Our advisory support aligns to the lifecycle of a strategic decision:
-
Pre‑deal diligence: rapid target screens, technical due diligence on polymer IP, and write‑downs of integration risk.
-
Procurement transformation: template contracts, supplier scorecards, and negotiation playbooks for multi‑year supply frameworks.
-
Operational deployment: turnkey trial design, KPI dashboards, and training modules for mill operators and chemists.
-
Commercialization support: go‑to‑market launch plans, value‑capture mechanisms, and distributor channel optimization.
Clients commissioning bespoke projects in advance of 2026 receive tailored scenario runs from our market model, a prioritized action matrix, and access to mill‑level benchmark data that supports rapid decision‑making.
Next steps — where to get the full dossier
This press overview is intentionally selective: it lays out the strategic implications and tools but stops short of disclosing the granular subsegment tables, regionally segmented forecasts, and supplier‑level revenue breakdowns contained in the full report. The complete study includes the segmentation matrices, detailed supplier financials, and downloadable procurement templates that procurement directors and corporate strategists need to act in 2026.
To obtain the full report and supporting datasets, visit PW Consulting’s Worldwide Paper Dry Strength Resin Market report page or contact our market advisory team for a briefing and demonstration of the model.
Closing perspective
2026 will be a year of selective advantage in the dry strength resin market: those who move from hypothesis to validated pilots, secure resilient raw material pathways, and convert sustainability investments into verifiable mill economics will capture disproportionate value. PW Consulting’s report is designed to be the operational playbook and strategic scoreboard that decision‑makers can use to align short‑term actions with medium‑term value creation.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Dry Strength Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide PEI Films Market Poised for Rapid Growth at a 7.12% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Polyetherimide (PEI) Films Market — 2026 Strategic Briefing
PW Consulting’s latest market research report on Worldwide Polyetherimide (PEI) Films delivers an actionable intelligence package tailored for executives preparing strategic moves in 2026. Built on a comprehensive historical review (2020–2025) and a forward-looking forecast horizon (2026–2032), this briefing synthesizes the macro trajectories, supply-side pressures, regulatory inflections, and competitive dynamics that will determine winners and laggards in the global PEI films arena.
Worldwide Polyetherimide (PEI) Films Market
Executive snapshot
By the report’s base year (2025) the global PEI films market had consolidated into a mature yet expanding industrial niche, with total reported revenues of approximately USD 521.5 Million. Our forecast points to steady, above-market growth through the 2026–2032 window, tracking at a midpoint compound annual growth rate (CAGR) of roughly 7.12%. Under the central scenario, the market reaches the high hundreds of millions by the end of the forecast period, reflecting sustained demand from high-value applications such as advanced electronics, aerospace, medical, and selected industrial uses.
Worldwide Polyetherimide (PEI) Films Market
Why this matters for 2026 decision-makers
- Procurement and cost modeling: With raw material volatility increasingly transmitted to film makers, procurement teams must move beyond spot-buy thinking. Tactical hedging, multi-sourcing of upstream monomers, and supplier scorecards that incorporate feedstock exposure are now essential.
- Product and process roadmaps: Material scientists and product managers face a bifurcating market: standard grades will compete on cost and supply consistency, while specialty grades (high-temperature, acoustic and bespoke compounds) will command premium margins if paired with targeted certification strategies.
- Regulatory and certification strategy: Compliance with aerospace fire-safety standards and food-contact regulations can be a decisive go/no-go for product placement. Firms that embed certification early into development timelines will shorten commercialization lead times.
- M&A and portfolio moves: The market exhibits meaningful concentration among top-tier suppliers, creating opportunities for bolt-on acquisitions by mid-sized compounders seeking scale or by large polymer players looking to extend value chain capture.
- Go-to-market timing: Capital allocation decisions should be phased in sync with expected volume inflection and certification milestones rather than headline growth rates alone.
Key market dynamics
- Feedstock pressure and cost pass-through: A notable upstream development for 2024 was a material spike in the price of m-Phenylene diamine (MPDA), a key monomer used in PEI synthesis. Industry reporting documented a double-digit YoY increase in select Asian markets during Q3 2024, evidence that feedstock tightness can transmit quickly into film producers’ cost bases. For 2026 planning, scenario work must include sustained elevated feedstock cases and their margin impact under different contract structures.
- Regulatory and performance thresholds: PEI films are uniquely positioned when high heat resistance and flame retardance are required. Certain PEI films are tested to meet UL 94 V-0 ratings at thin gauges, and compliance with aerospace fire-safety standards has been achieved at thicknesses as low as approximately 0.075 mm. Separately, some grades meet stringent chemical-migration restrictions used in EU food-contact regulations, broadening addressable applications when supported by documented compliance.
- Application tempo and durable demand: Demand drivers remain centered on electronics and semiconductors, aerospace and defense, automotive electrification, and medical/industrial segments. While end-market cyclicality creates short-term demand swings, secular trends — miniaturization in electronics, higher thermal budgets in EV powertrains, and stricter medical sterilization regimes — underpin longer-term growth.
- Concentration and bargaining power: Supply-side dynamics show a market where leaders control a sizeable share of global revenues. Concentration at the top creates a dual pressure: it supports premium pricing for certified, high-performance films, but it also elevates strategic exposure when a limited number of suppliers experience upstream constraints or capacity disruptions.
Competitive landscape — who to watch
Our competitive benchmarking examines the strategies, positionings, and capabilities of incumbent film producers and compounders. Three firm profiles illustrate the spectrum of competitive approaches:
Worldwide Polyetherimide (PEI) Films Market
- SABIC (Riyadh, Saudi Arabia) — A global industrial powerhouse and the leading name associated with ULTEM™ PEI films. SABIC’s strengths lie in thin-gauge product lines engineered for highest-temperature performance and regulatory certification, making it a preferred supplier for aerospace and high-end electronics OEMs. Their value proposition combines material pedigree with global logistics and a strong documentation suite for regulated applications.
- Ensinger GmbH (Nufringen, Germany) — A specialist in technical films and sheets, positioning itself through custom thickness ranges and engineering support for automotive and medical customers. Ensinger competes on technical service and the ability to integrate film specifications into component-level designs within European supply chains.
- RTP Company (Winona, Minnesota, USA) — A differentiated player focusing on custom compounding and application-specific PEI formulations, including flexible circuitry and specialized electrical insulation. RTP’s advantage is its close collaboration model with customers to produce grade-tailored solutions and rapid prototype-to-production pathways.
Overall, market concentration metrics show a significant share held by the top-three and top-five providers, validating both the advantage of scale in certification-heavy markets and the tactical opening for focused challengers to capture niche high-margin segments.
What the full PW Consulting report provides (practical contents)
Our published research is structured to be directly operational for strategy teams. It includes:
- Transparent market-sizing methodology and reproducible assumptions for 2020–2032;
- Scenario-based forecasts with upside/downside cases that stress-test feedstock shocks, regulatory accelerants, and substitution risks;
- Supply-chain mapping from monomer sourcing through film extrusion and finishing, including cost-driver models;
- Certification and regulatory matrices that crosswalk grades against aerospace, automotive, medical, and food-contact standards;
- Competitive benchmarking with supplier scorecards, capability heat maps, and likely strategic intents;
- Commercial playbooks for customers and entrants—pricing templates, sample contractual clauses for raw material pass-throughs, go-to-market sequencing, and IP protection checklists;
- Three executable investment cases covering bolt-on M&A, greenfield capacity, and a joint-development model with OEMs.
To preserve the utility of this briefing as a gateway, the report intentionally reserves certain detailed segmentation tables, granular regional and application revenue breakdowns, and downloadable financial models for subscribers and licensed purchasers.
Strategic recommendations for 2026
- Embed certification timelines into R&D budgets: For firms targeting aerospace, medical or food-contact applications, build certification milestones into project financing and product roadmaps to avoid last-minute cost overruns.
- Adopt a dual-sourcing procurement strategy: Protect critical programs from single-supplier exposure by qualifying alternative suppliers and evaluating toll-manufacture or contract-compounding options.
- Prioritize high-value niches: Where possible, shift commercial focus from undifferentiated standard grades to specialty formulations that command higher margins and create stronger defensibility.
- Model feedstock scenarios in investment appraisals: Use stress-testing to understand sensitivity of EBITDA to monomer-price spikes and to design contractual protections or vertical partnerships.
- Consider strategic alliances and small-scale M&A: Given the high concentration at the top, smaller players can accelerate scale and capabilities through targeted acquisitions or joint ventures focused on certifications and regional access.
- Leverage sustainability and compliance as a competitive wedge: Documented compliance with REACH and other migration restrictions, plus transparent lifecycle analytics, will increasingly influence buyer choices in regulated markets.
How to use this intelligence in 90 days
- Week 1–4: Run a cross-functional risk assessment (procurement, product, regulatory, finance) using the report’s feedstock and certification scenarios.
- Week 5–8: Prioritize one or two tactical initiatives (dual-sourcing qualification or a certification-focused product sprint). Use our supplier scorecards as evaluation templates.
- Week 9–12: Finalize commercial terms and pilot contracts; prepare board-level briefing with investment cases drawn from the report.
PW Consulting’s Worldwide PEI Films Market report is designed to be a decision-useful asset: deep enough to underwrite investment, but framed to enable rapid executive action. For access to the full dataset, granular segmentation tables, downloadable financial models, and vendor-level analytics — including the confidential appendices that map regional demand curves and application breakouts — please visit our report page and request a subscription or an executive briefing.
Contact PW Consulting to schedule a tailored workshop that integrates these insights into your 2026 operating plan and capital-allocation roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Digital Cultural Tourism Market Poised for 17.6% CAGR in 2026–2032, Signaling Rapid Global Expansion
By PW Consulting, 2026-07-15
Worldwide Digital Cultural Tourism Market: Strategic Briefing for 2026 Decisions
PW Consulting’s latest market research—Worldwide Digital Cultural Tourism Market (base year 2025; forecast period 2026–2032)—arrives at a pivotal moment for public institutions, experience-led travel brands, technology vendors, and investors. The sector has transitioned from exploratory pilots to commercially meaningful deployments: global market size expanded markedly through 2020–2025 and is forecast to accelerate across 2026–2032 at a compound annual growth rate (CAGR) of 17.6%, with total market revenues projected to multiply meaningfully over the forecast window. For executives shaping 2026 budgets and three‑ to five‑year strategies, this briefing distills the research’s strategic value and the operational levers that will determine winners and losers.
Worldwide Digital Cultural Tourism Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the inflection point when digital cultural tourism moves from niche value-adds to core visitor experience and revenue channels. Public policy, funding streams, and large-scale platform projects launched in early 2026 materially change investment calculus for governments and operators.
Worldwide Digital Cultural Tourism Market -
Scale: Our modeled market trajectory shows both robust near-term demand and long-term expansion potential. The headline growth metrics demonstrate that organizations that commit resources intelligently in 2026 can capture disproportionate share and create durable business models.
Worldwide Digital Cultural Tourism Market -
Decision relevance: The report converts macro growth into decision-ready guidance—vendor selection criteria, capability roadmaps, procurement templates, KPIs, and six strategic playbooks—so leadership teams can translate opportunity into executable 18–36 month programs.
What the full report delivers (practical, vendor-agnostic)
-
Actionable market sizing and scenario models calibrated for 2026 budget cycles and investment committee reviews, with sensitivity analyses for access, monetization, and deployment speed.
-
Six strategic playbooks—Platform Partnerships, Immersive Experience Rollout, Public‑Private Pilots, Content Monetization, Data Governance & Interoperability, and Sustainability & Community Engagement—each with milestone maps, cost buckets, and KPIs.
-
Vendor evaluation framework and procurement checklist to compare solution providers on technical fit, scaleability, data ownership, localization support, and total cost of ownership.
-
Case studies that translate technology choices into measurable outcomes (visitor conversion, new revenue lines, inclusion metrics, and preservation impact), plus templated contractual language for IP and data reuse.
-
Risk registers and mitigation playbooks addressing regulatory, privacy, cultural sensitivity, and digital preservation concerns—aimed at legal, curatorial, and IT sponsors.
-
Executive one‑page roadmaps and investment prioritization matrices that align with FY2026 planning cycles.
Market dynamics shaping 2026 strategy
-
Policy and public‑sector endorsement: Early‑2026 agreements between global institutions and the creation of competence centers have elevated digital cultural tourism from experiment to strategic public good. These shifts unlock multilateral funding, influence procurement requirements, and prioritize interoperability and sustainability in funded projects.
-
Technology convergence: High-resolution 3D scanning, cloud-based digital twins, and generative AI for content creation are converging to lower production cost and accelerate time-to-experience. Organizations capable of combining these capabilities will shorten pilot cycles and scale monetization faster.
-
Infrastructure and standards: New competence centers and collaborative platforms are beginning to codify standards for 3D data reuse, metadata, and rights management. Early adopters that implement standards-compliant architectures will enjoy lower integration costs and wider distribution partnerships.
-
Fragmentation and consolidation opportunity: Market concentration remains low relative to mature digital industries, indicating a fragmented supplier landscape and room for consolidation. Strategic M&A and partnership plays are likely over the next 24–36 months as buyers seek turnkey capabilities.
-
Commercial model evolution: Monetization is shifting from single‑ticket analog equivalents to subscription access, tiered digital experiences, licensing of digital assets, and hybrid physical-digital bundles. Successful pilots in 2025–26 are proving the economics of these models at scale.
Competitive landscape — who matters and why
The competitive field combines global platform leaders, specialist immersive vendors, public-interest preservation non‑profits, and regional innovators. Each archetype brings distinct strategic implications for partnerships and procurement.
-
Google Arts & Culture — With unparalleled distribution reach and established institutional partnerships, platform incumbents shape audience expectations and discovery flows. For institutional buyers, Google-style collaboration can provide scale and visibility; the tradeoff is negotiating data and IP terms that protect long‑term curatorial control.
-
YouVisit — Specialists in 360° interactive tours and layered media, such vendors are valuable for organizations seeking rapid, immersive experiences without heavy in‑house production overhead. They excel at visitor engagement metrics and cross-device delivery, making them attractive for marketing-led pilots.
-
Matterport — Leading edge in 3D spatial scanning and digital twins, players like Matterport convert physical assets into persistent digital property. Their value proposition is infrastructure: a repeatable pipeline for scanning, hosting, and integrating spatial data into commerce and interpretation systems.
-
Global Mofy AI Limited — Regional innovators combining generative AI and 3D asset pipelines are proving that local content specialization (ecological, heritage, themed experiences) can be monetized through both domestic tourism platforms and exportable immersive products. Their activities illustrate how localized IP creation is becoming a competitive differentiation.
-
ARCTUR / 3D-4CH — Projects that create competence centers and training ecosystems are shifting the supply-side dynamics by standardizing capabilities and enabling reuse across networks of cultural institutions. Institutions that plug into these competence centers gain accelerated access to skills, tools, and compliant data flows.
-
CyArk — As a preservation-first organization, CyArk demonstrates how mission-driven providers can combine rigorous documentation with public-interest access. Their work highlights the reputational and risk-mitigation value of partnering with recognized conservation bodies for at-risk or sensitive assets.
Strategic implications and recommended 2026 moves
-
Prioritize interoperability and data governance in procurement: Require open formats, clear IP and licensing terms, and exportable metadata pipelines. In 2026, compatibility with emerging competence centers and standards will determine long‑term distribution and reuse value.
-
Adopt a phased “pilot-to-platform” roadmap: Run rapid, measurable pilots that validate user experience and monetization hypotheses, then bundle successful components into a platform operating model with recurring revenue streams and cross-sell potential.
-
Invest selectively in core capabilities: Build or procure robust 3D capture pipelines and AI-assisted content generation, but outsource distribution scale to platform partners where appropriate. This hybrid approach balances speed with ownership of strategic assets.
-
Use public‑private partnership (PPP) models for risk-sharing: Leverage new multilateral and national funding programs created or accelerated in early 2026 to underwrite digitization costs, while structuring commercial rights to secure downstream monetization.
-
Prepare for consolidation: Establish M&A-ready KPIs and integration playbooks. Buyers with clear product roadmaps and data governance will be attractive targets, while institutional buyers should consider acquisition as a rapid capability build route.
-
Embed ethics, inclusion, and sustainability: Success in cultural contexts depends on community engagement, culturally sensitive interpretation, and demonstrable environmental stewardship of on-site digitization programs. These elements are increasingly part of funding and regulatory criteria.
Risks, scenarios, and mitigation
-
Regulatory shifts: International commitments made in 2026 place greater emphasis on preservation, digital access, and responsible tourism. Organizations should monitor funding conditions and compliance requirements to avoid stranded investments.
-
Data sovereignty and privacy: Cross-border hosting and distribution of cultural assets can trigger legal constraints. Mitigate via modular architectures that allow localized storage and controlled sharing.
-
Technology obsolescence: Rapid advances in capture and AI can make early systems outdated. Reduce risk with modular, standards-based components and vendor clauses for upgrades and data portability.
-
Monetization gaps: Not all digitized assets will immediately monetize. Use multi-sided models (public funding, B2B licensing, direct consumer subscriptions, and hybrid bundles tied to physical visitation) to diversify revenue.
Conclusion — what leaders should do now
For boards and C‑suite teams finalizing 2026 strategy, the central question is not whether to engage, but how fast and with whom. The market’s compound momentum and the policy shifts in early 2026 create a narrow window to establish platform leadership, secure valuable digital IP, and lock in distribution partnerships. PW Consulting’s report translates the sector’s macro growth into executable actions—stepwise pilots, procurement templates, vendor comparisons, and governance frameworks—that enable measurable value capture while preserving cultural stewardship.
We intentionally present the strategic architecture and decision playbooks here while withholding the granular regional, segment-level splits, and detailed vendor scorecards that underpin our commercial forecasting. Those detailed analytics—including scenario models, regional rollout sequencing, and proprietary vendor performance matrices—are available in the full Worldwide Digital Cultural Tourism Market report and the accompanying data toolkit on the PW Consulting research portal.
Contact PW Consulting to schedule a private briefing or to license the full report, model files, and procurement templates to inform your FY2026 investments and three‑year execution roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Cultural Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 13.12% CAGR for Worldwide Electricity Trading Platform Market as SaaS Platforms Drive a New Growth Wave
By PW Consulting, 2026-07-15
Worldwide Electricity Trading Platform Market — Strategic Preview for 2026 Decision-Makers
Executive summary
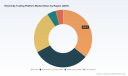
PW Consulting’s new market research brief previews the Worldwide Electricity Trading Platform market as enterprises prepare strategy for 2026 and beyond. The market, measured on a USD million revenue basis, reached an estimated USD 1,342.22 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 13.12% through our 2026–2032 forecast horizon, reaching approximately USD 3,181.25 Million by 2032. This rapid growth is driven by accelerated digitization of power markets, the proliferation of short-term trading products, rising participation from non-traditional large loads (notably hyperscale data centers), and a structural shift toward cloud-native trading architectures.
Worldwide Electricity Trading Platform Market
This preview follows the “trailer” principle: it surfaces the analysis, frameworks, and decision levers that matter to boardrooms and trading desks, while reserving the granular sub-segment tables and vendor scorecards for the full report. The aim is to enable senior leaders to prioritize investments, procurement timelines, and regulatory engagement through 2026 without disclosing the proprietary segment-level datapoints that underpin our models.
Worldwide Electricity Trading Platform Market
Why this report matters to 2026 strategic planning
-
Timing: 2026 is a hinge year. Market structures in several regions are undergoing rule changes (e.g., shorter market time units), while exchanges and platform providers roll out next-generation margining and clearing systems. These developments materially alter liquidity patterns and counterparty exposure in short-term power markets.
Worldwide Electricity Trading Platform Market -
Risk and revenue: Elevated wholesale price volatility and new obligations for large, co-located loads have changed the economics of self-procurement vs. market participation. Our modeling demonstrates how trading platform selection, margining approach, and settlement cadence influence both P&L volatility and working capital needs.
-
Technology shift: The market is transitioning rapidly toward SaaS-native deployments, API-first integration, and real-time analytics. The report synthesizes TCO breakouts, migration trajectories, and latency-cost trade-offs to guide 3–5 year procurement roadmaps.
-
Concentration and competitive positioning: Market concentration metrics indicate a market where a small set of incumbents retains substantial share, yet opportunity exists for specialized platforms and decentralised models to capture vertical niches and local regulatory arbitrage.
What the PW Consulting report delivers (practical, operational content)
-
Executive playbooks: Prioritized strategic actions for energy companies, exchanges, utilities, large consumers (including data centers), and fintech entrants. Each playbook includes timing, investment thresholds, and KPIs tied to liquidity, margin exposure, and settlement risk.
-
Vendor decision framework: A repeatable scoring matrix for platform selection that balances functional coverage, latency, integration risk, regulatory compliance, and total cost of ownership. The framework is designed to be applied to both greenfield procurement and vendor consolidation scenarios.
-
Integration blueprints: Detailed architectures for hybrid deployments (SaaS + on-premise gateways), API contracts for meter-to-market flows, and recommended security and governance controls for multi-party settlement workflows.
-
Scenario-based financial models: Stress-tested ROI and working-capital models under alternative market structures and volatility regimes; including sensitivity to shorter market time units and margining reforms.
-
Regulatory watch & impact maps: Mapping of recent and anticipated regulatory moves across major jurisdictions, with implications for market access, clearing, and cost allocation for large loads.
-
Buy-side tools: Decision checklists, procurement RFP templates, and a configurable ROI calculator to quantify platform payback under different liquidity and price environments.
Market dynamics shaping vendor and buyer strategies
Several concurrent dynamics are re-writing competitive advantage in electricity trading platforms:
-
Market design evolution: The transition to shorter market time units in European day-ahead and intraday markets, along with related imbalance pricing reforms, materially increases the value of low-latency matching, real-time dispatch optimization, and automated reconciliation.
-
Data center-driven demand: Large hyperscale and colocation customers are reshaping procurement and transmission cost allocation frameworks. Regulatory actions in North America to incorporate these loads into special procurement and auction mechanisms introduce new sources of concentrated demand and allocation risk.
-
Price volatility and localized scarcity: Wholesale electricity costs in key data center hotspots have risen sharply over recent years, increasing both the urgency and the stakes for robust trading and hedging capability among large consumers and their suppliers.
-
Clearing and margining upgrades: Leading exchanges are implementing new margining systems that affect liquidity, collateral needs and clearing relationships—changes that alter counterparty credit dynamics and the viability of certain trading strategies.
Competitive landscape: who matters and why
The supplier ecosystem comprises several archetypes—exchange incumbents, multinational financial market operators, software platform specialists, peer-to-peer innovators, and systems integrators. Our report profiles and benchmarks the key players, assessing where each is likely to invest and expand in 2026:
-
Exchange and marketplace incumbents (examples include major European and U.S. exchanges): These players control significant pools of liquidity and are investing in margining/clearing modernization. Their strategic moves in product design and market microstructure will be determinants of where institutional liquidity concentrates.
-
Financial marketplace operators (global derivatives exchanges): They bring deep clearing capabilities and a track record of scaling futures and options liquidity into new asset classes, making them natural partners for scale-seeking electricity trading businesses.
-
Platform and software specialists (trading engines, risk-management vendors): These firms provide enterprise-grade trading front-ends, algorithmic execution tools, and ETRM capabilities. Their strength is adaptability and integration depth with corporate treasury and risk operations.
-
Peer-to-peer and blockchain innovators: Startups in the P2P space are experimenting with distributed settlement, local flexibility markets, and direct renewable procurement—offering differentiated value propositions for local balancing and corporate buyers looking for traceable renewable energy certificates.
-
System integrators and regional specialists: Firms with deep local-market expertise are bridging regulatory complexity and implementing bespoke solutions for clients in nascent or uniquely structured power markets.
Market concentration metrics underline a competitive market where the top three providers hold a meaningful share (CR3 ≈ 34.65%) and the top five accumulate a majority position (CR5 ≈ 51.18%). That mix signals both the defensibility of incumbent liquidity pools and the opportunity for specialist vendors to win by serving vertical or geographically specific needs.
Recent developments and what they imply
-
Exchange volume growth and focus on margining: Significant year-on-year increases in power derivatives volumes have pushed exchanges to refresh margining and risk collateral practices. For buyers, this creates both cost pressures and an opportunity to negotiate bilateral arrangements or cleared derivatives to optimize collateral use.
-
Market rule changes for time granularity: Adoption of 15-minute market time units and related imbalance pricing reforms elevates the premium on real-time orchestration and intraday optimization tools.
-
Regional procurement innovations: Initiatives to integrate large-load forecasting and allocate network upgrade costs to specific customers change the calculus of where and how large buyers participate in spot and capacity markets.
How executives should use this report in 2026
-
Prioritize platform capability gaps: Use the vendor decision framework to identify whether to buy, build, or partner for low-latency matching, advanced hedging, or PPA execution capabilities.
-
Stress-test procurement strategies: Apply the scenario models to determine hedging intensity, collateral budgeting, and operational readiness for alternative market designs (e.g., shorter dispatch intervals).
-
Design a regulatory engagement plan: Map the firm’s exposure to regional rule changes—particularly where large customers may be subject to new allocation rules or emergency procurement mechanisms—and align advocacy accordingly.
-
Re-assess vendor consolidation timelines: With consolidation pressure and platform modernization happening in 2026, consider accelerated integration or phased migrations to avoid legacy lock-in costs.
Next steps and where to access full intelligence
This preview highlights the strategic choices and near-term inflection points that matter for 2026. PW Consulting’s full Worldwide Electricity Trading Platform Market report contains the proprietary segment models, regional forecasts, vendor scorecards, and downloadable decision tools referenced above. For procurement teams, trading heads, and C-suite decision-makers who need the full dataset and executable templates, the full report and accompanying toolkits are accessible at our report page.
PW Consulting stands ready to support bespoke scenario workshops, vendor selection sprints, and integration planning sessions that translate the research into a three-step operational roadmap: assess, select, and deploy. Reach out to our industry practice leads to schedule a briefing tailored to your organization’s exposure and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Electricity Trading Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.61% CAGR for Worldwide Sauna Steam Generator Market Through 2032
By PW Consulting, 2026-07-15
Worldwide Sauna Steam Generator Market — Strategic Imperatives for 2026 (PW Consulting)
Executive snapshot
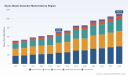
PW Consulting’s latest Worldwide Sauna Steam Generator Market report (base year 2025, forecast period 2026–2032) synthesizes quantitative forecasting with hands-on strategic guidance tailored for executives making high-stakes 2026 decisions. The market has expanded from roughly USD 512.5 million in 2020 to USD 707.1 million in 2025 and is projected to continue rising — our base-case model yields a compound annual growth rate (CAGR) of 6.61% through 2032, when the market is modeled to exceed USD 1.1 billion. These aggregate trends conceal important inflection points for product engineering, channel strategy, and M&A — the core purpose of this report is to translate macro momentum into concrete corporate moves while preserving the granular proprietary datasets for subscribers.
Worldwide Sauna Steam Generator Market
Why this report matters for 2026 decision makers
As headwinds from raw material price volatility and tightening energy-efficiency regulation collide with accelerating commercial demand driven by wellness tourism, 2026 will be the year when product roadmaps and go‑to‑market choices determine market leaders. The report is structured around decision-ready outputs: scenario-based forecasts that reflect regulatory thresholds and cost shocks; supplier and BOM sensitivity models that quantify margin risk; and playbooks that convert engineering trade-offs (efficiency vs. first-cost vs. connectivity) into prioritized product backlogs—without overwhelming leaders with raw tables in initial briefings.
Worldwide Sauna Steam Generator Market
Market dynamics shaping 2026
-
Input-cost pressure and procurement strategy — Stainless steel prices have moved materially higher amid global supply constraints, creating immediate margin pressure for boiler-heavy steam units. Our cost-build models show that a sustained steel-price step-change requires a combination of material substitution strategies, long-term purchase agreements, and design-for-cost resets to preserve margin without compromising durability.
Worldwide Sauna Steam Generator Market -
Regulatory re-rating of product specs — The regulatory landscape is being redefined by tightened efficiency and safety standards. For example, European mandates now expect commercial steam systems to meet elevated efficiency thresholds by 2026. Product development timelines, certification plans, and test protocols must be adjusted now to avoid delayed market access or costly retrofits.
-
Demand-side acceleration from wellness and hospitality — Wellness tourism growth is driving higher CAPEX and retrofit activity in spas, resorts, and boutique hotels. This commercial pull is raising both average deal sizes and expectations for service, reliability, and integrated wellness experiences (steam plus controls, aroma systems, and IoT-enabled hygiene features).
-
Labor and installation economics — Certified installation capacity remains constrained in key markets; in North America, for instance, installation labor rates reflect a scarcity premium that must be factored into total ownership cost and aftermarket service design. Closing the certified-technician gap through training programs and simplified-install designs is a fast ROI lever.
-
Safety and certification as market access gates — Standards such as UL 1778 continue to be hard gates for commercial deployment in certain regions. Achieving and communicating compliance is no longer a checkbox but a market-entry strategy that reduces buyer friction.
Competitive landscape — what matters to buyers and investors
The market is competitive but not opaque: several seasoned OEMs dominate product innovation, channel influence, and brand recognition. Our qualitative assessment profiles vendors across product breadth, connectivity, compliance posture, and commercial-service competence. Key strategic signals include:
-
Product and connectivity differentiation — Companies that combine hardware reliability with modern control experiences are setting new buyer expectations. Recent launches from established vendors underscore this shift toward app-enabled and Bluetooth‑linked controls in both residential and commercial segments.
-
Portfolio breadth versus specialization — Firms offering both residential and heavy-commercial capacities retain corridor advantages with multi-site hospitality chains, while niche suppliers that deliver stainless‑steel, custom-boiler solutions capture higher margin retrofit work.
-
Regional execution capability — Global brands that maintain localized compliance and service footprints gain procurement preference with major installers and hotel groups. Strategic investments in regional spare-parts hubs and certified training networks are differentiators that shorten sales cycles.
Notable market participants profiled in the report include established OEMs with complementary strengths in consumer-facing luxury systems, commercial boiler engineering, and integrated sauna systems. Recent vendor activity — such as product launches with enhanced Bluetooth control, trade-show rollouts of new series, and refreshed export-focused catalogues — confirms a market pivot toward connectivity and energy efficiency. Market concentration metrics point to meaningful room for consolidation and scale plays: the top 3 and top 5 vendors control a material portion of the market, creating strategic acquisition opportunities for mid-sized engineering-focused players.
What’s inside the PW Consulting report (practical, actionable content)
Our aim is operational: readers should be able to convert insight into projects, budgets, and board-level asks within 30–90 days. The proprietary deliverables include:
- Transparent market-sizing methodology and the underlying demand model (2020–2032) with scenario toggles for regulatory and input-cost shocks.
- Cost-build models and a BOM sensitivity tool that quantify margin exposure to steel and labor price moves.
- Regulatory compliance matrix per region with certification timelines, test protocols, and recommended engineering responses.
- Competitor benchmarking dashboards — product portfolios, channel reach, patent trends, and service coverage.
- Go-to-market playbooks for residential OEMs, commercial integrators, and hospitality chains (sales motions, ARR levers, and pilot templates).
- M&A and partnership fit maps with integration checklists and synergies scoring.
- Operational playbooks for installation optimization, from installer certification programs to plug‑and‑play electrical and plumbing interface designs.
To preserve strategic exclusivity for report subscribers, detailed regional and application-level tables, vendor scorecards, and downloadable model files are available through the report portal.
Strategic recommendations for 2026 execution
-
Fast-track energy-efficiency upgrades — Make 95%+ thermal efficiency a core product requirement for any new commercial model and budget for third-party testing early in the development cycle to align with evolving EU and similar standards.
-
Invest in connectivity and service monetization — Embed remote diagnostics, predictive maintenance, and user-experience controls to convert traditional hardware sales into recurring-service relationships that mitigate installation-cost exposure.
-
De-risk raw-material exposure — Hedge critical stainless-steel purchases through layered procurement (spot, futures, and strategic supplier agreements), and accelerate evaluation of alternative alloys and protective coatings that preserve lifecycle performance.
-
Optimize installation economics — Redesign mechanical interfaces to reduce certified-install hours; deploy certification-as-a-service programs and co-funded training with channel partners to expand licensed installer capacity.
-
Pursue pragmatic consolidation — Evaluate bolt-on acquisitions that bring service networks, spare-parts warehouses, or regional approvals rather than only product SKU count to realize faster integration synergies.
-
Target wellness-tourism ecosystems — Structure commercial offers for resort groups and wellness operators with bundled uptime SLAs, on-site spare kits, and financing terms that align with renovation cycles.
How PW Consulting supports your 2026 agenda
We combine market intelligence, engineering economics, and commercial strategy in a modular engagement model: standalone playbooks for product teams, diligence packages for M&A, supplier negotiation support, and implementation sprints (supply-chain redesign, certification fast-tracks, and channel pilot rollouts). Our workbench and modelling assets are designed to plug into client ERP and product-roadmap processes to accelerate decision-to-execution timelines.
Next steps (how to access the full report)
This brief provides the strategic contours and execution priorities PW Consulting has identified for 2026. For the detailed regional breakdowns, end‑use segmentation, vendor scorecards, and downloadable financial models that underpin our recommendations, visit the official report page. The full dataset and downloadable forecasting model are available to subscribers, and PW Consulting offers a 60‑minute briefing package to walk executives through the parts of the model that matter most to their strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Sauna Steam Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report forecasts Worldwide Robotic Scope Holder market to climb from USD 310.0 Million in 2025 to USD 514.3 Million by 2032 at a 7.5% CAGR
By PW Consulting, 2026-07-15
Worldwide Robotic Scope Holder Market — Strategic Insights for 2026 Decision-Makers
Executive summary
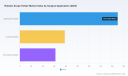
As hospitals and surgical centers confront rising procedure volumes, staff shortages, and the accelerating integration of robotics into the operating room, robotic scope holders have moved from niche adjuncts to strategic platform components. PW Consulting’s new market research report, published with base year 2025, synthesizes five years of historical performance (2020–2025) and provides a granular, scenario-based forecast for 2026–2032. The global market expanded steadily through 2025 and is expected to sustain a mid-single-digit compound annual growth rate (CAGR) of 7.5% through 2032, crossing the half‑billion‑dollar threshold by the end of the forecast period. This release highlights the report’s strategic value for procurement leads, product teams, corporate development groups, and health systems planning capital expenditures in 2026.
Worldwide Robotic Scope Holder Market
Market trajectory at a glance
Between 2020 and 2025 the total worldwide market for robotic scope holders experienced consistent expansion driven by improvements in ease-of-use, regulatory progress, and broader adoption of minimally invasive procedures. Our base-year assessment (2025) captures the market at a mature inflection point—large enough to attract scale players yet fragmented enough to sustain innovation-led entrants. Under our central scenario, the market grows at a 7.5% CAGR from 2026 through 2032, reflecting continued penetration into existing laparoscopic procedures, incremental adoption in adjacent surgical specialties, and growing attachment rates to multi‑purpose surgical robots and hybrid systems.
Worldwide Robotic Scope Holder Market
Why this matters for 2026 strategic decisions
- Capital allocation and procurement: Hospitals scheduling FY2026 capital plans need defensible projections for adoption curves and total cost of ownership. Our forecast and sensitivity analyses enable CFOs and procurement teams to size CAPEX commitments and operating budgets with scenario-bound risk adjustments.
- Product roadmap prioritization: Vendors planning next-generation controllers, AI-assisted positioning, or sterilization-optimized form factors can use our technological roadmaps and buyer persona work to prioritize feature sets that materially influence purchasing decisions in the next 18–36 months.
- M&A and partnership screening: With notable consolidation underway among platform incumbents and targeted startups, acquirers can employ our fragmentation and concentration metrics to identify attractive targets or defensive investments.
- Reimbursement and regulatory readiness: As payers and coding bodies evolve their guidance for computer‑assisted navigation and robotic adjuncts, health systems and vendors will require an integrated regulatory‑reimbursement playbook to support commercialization in 2026.
What’s in the report — practical, actionable content
The report is deliberately operational. Rather than a high-level narrative, it contains specific tools and deliverables designed for decision-makers who must act in 2026:
Worldwide Robotic Scope Holder Market
- Detailed, auditable market model (historical 2020–2025 and forecast 2026–2032) with scenario toggles for adoption rates, procedure mix, and pricing sensitivity.
- Buyer decision frameworks and procurement checklists that translate clinical value into measurable KPIs for procurement committees.
- Regulatory and reimbursement playbook that maps IEC and FDA touchpoints to coding and payer strategies (including guidance on relevant CPT pathways).
- Technology roadmap and feature-pricing elasticity analysis to inform R&D prioritization and commercial positioning.
- Supplier scorecards and “go-to-partner” matrices that evaluate vendors on technical fit, distribution reach, regulatory status, and integration readiness.
- Deal playbooks for M&A and commercial partnerships, including valuation sensitivities and integration risks.
Note: the report provides full segmentation by region, product type, and surgical application with accompanying assumptions; however, headline segment-level splits are intentionally summarized here to encourage direct engagement with the full dataset and model.
Competitive landscape: who to watch and why
The market demonstrates a notable degree of concentration among leading incumbents while leaving strategic whitespace for specialized entrants. Our concentration analysis indicates that the top three vendors control a meaningful majority of market value, with the top five exerting even greater footprint—conditions that both raise entry barriers and create attractive targets for bolt-on M&A.
Key players profiled in the report include:
- Mitaka Kohki (Tokyo): Recognized for field-proven mechanical designs and recent firmware/AI positioning enhancements. Their focus on multi-axis manipulators and workflows that integrate with leading surgical robots positions them well in higher-acuity operating suites where interoperability is a purchase determinant.
- FreeHand Surgical (London): A nimble innovator with voice-activated control systems and widespread clinical demonstrations. Their emphasis on ease-of-use and low-touch clinician interfaces makes them attractive in community hospitals and early-adopter centers focused on workflow efficiencies.
- EndoControl (now part of Medtronic): Backed by a large distribution and regulatory engine, the ViKY legacy platform benefits from expanded clearances and global support. For buyers prioritizing comprehensive service networks and long-term device lifecycle management, this type of scale incumbent is likely to win competitive tenders.
- Olympus (Tokyo): Leveraging end-to-end endoscope ecosystems, their positioning is strongest where device and imaging platform integration matter. Olympus’ approach appeals to integrated hospital groups seeking single-vendor consistency across imaging, scope, and holding systems.
Collectively, these companies illustrate three strategic archetypes: platform incumbents focused on ecosystem integration, specialist innovators targeting ease-of-use and clinical workflow, and scale players leveraging distribution and regulatory depth. Recent product updates, trade-show demonstrations, and regulatory milestones reinforce these trajectories—signals that buyers and investors should interpret as both competitive threat and partnership opportunity.
Market dynamics and operational constraints
- Regulatory baseline: Compliance with established electrical and medical-device standards (e.g., IEC 60601-1) is a de‑facto requirement for OR deployment. Devices typically follow Class II regulatory pathways with 510(k) submissions where applicable.
- Reimbursement context: Existing CPT frameworks provide routes for coverage of computer-assisted surgical navigation and positioning adjuncts, but payer acceptance varies by market and clinical evidence strength. Effective reimbursement strategies in 2026 will require bundled evidence dossiers that tie device usage to OR efficiency and clinical outcomes.
- Materials and sterilization: Device design decisions—choice of medical-grade stainless steel, titanium alloys, and autoclave-compatible components—drive lifecycle costs and OR throughput constraints. Sterilization time and durability remain practical gating factors for high-turnover surgical environments.
- Clinical safety history: To date, major models have no widespread recall history post‑2020; this low incident rate reduces adoption friction but does not obviate the need for robust field service and training programs.
Strategic recommendations for 2026
Based on our analysis, PW Consulting recommends the following priority actions for stakeholders planning around 2026:
- Embed interoperability requirements into procurement RFPs—specify API-level integrations and validation test cases for popular surgical robots and imaging platforms.
- Invest in clinical evidence generation focused on workflow efficiency and OR throughput gains rather than only clinical non-inferiority—payers and hospital CFOs respond most to demonstrable cost/time savings.
- Pursue partnership-first commercialization in geographies with complex regulatory pathways—partnering with established distributors or platform incumbents de‑risks market entry.
- Implement flexible pricing and service models (e.g., subscription for holders + consumables) to lower procurement hurdles and smooth adoption curves.
- For investors and M&A teams: prioritize targets that close technology gaps (e.g., AI-assisted positioning or sterilization breakthroughs) and those that bring complementary distribution channels.
- Operational teams should pilot devices in high-turnover laparoscopic suites where time savings compound quickly; use these pilots as reference cases for broader rollouts.
Next steps and how PW Consulting can help
The full report includes the complete, auditable market model, downloadable supplier scorecards, negotiation playbooks, and a prioritized 18‑month implementation roadmap for providers and vendors. For decision-makers preparing FY2026 plans, the report functions as both an evidence base and an operational toolkit—supporting capital allocation choices, R&D prioritization, and M&A screening.
To access the full dataset, interactive model, and tailored advisory services, please visit our report page. PW Consulting also offers bespoke briefings and workshop sessions to translate the research directly into procurement specs, product roadmaps, or investment memoranda.
In an operating-room landscape that is increasingly defined by automation, connectivity, and evidence-based purchasing, the choices made in 2026 will shape competitive positions for the rest of this decade. PW Consulting’s Worldwide Robotic Scope Holder Market report provides the market sizing, competitive framing, and operational playbooks necessary to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Face & Voice Biometric Market to Expand at 14% CAGR, Reaching USD 18.72 Billion by 2032
By PW Consulting, 2026-07-15
Worldwide Face-Voice Biometric Market: Strategic Preview for 2026 Decision‑Makers
Executive snapshot
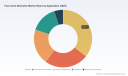
PW Consulting's latest market study on face-voice biometrics delivers a strategic briefing for executives preparing technology, compliance, and procurement decisions in 2026. The market has moved from an early commercial phase into a scale-up cycle: total industry revenues expanded rapidly over the first half of the decade and, with a compounded annual growth rate of roughly 14% from our 2025 base year, are projected to more than double through the 2026–2032 forecast window. This growth trajectory signals expanding commercial opportunity, but also higher expectations on interoperability, privacy compliance, and operational resilience.
Worldwide Face Voice Biometric Market
Why this report matters for 2026 planning
-
Actionable risk management: The report translates evolving regulatory pressure and technical standards into concrete operational mandates — helping legal, privacy, and security teams design compliant deployment roadmaps.
Worldwide Face Voice Biometric Market -
Vendor selection clarity: We provide a structured framework to evaluate vendors not just on accuracy claims but on certification status, multi‑modal integration capability, delivery model (edge vs cloud), and post‑deployment support.
Worldwide Face Voice Biometric Market -
Investment prioritization: Our scenario-based modeling highlights which technology bets and organizational investments are likely to unlock differentiated ROI in 12–36 month horizons.
Market trajectory — a disciplined view
From a market sizing perspective, the face‑voice biometric market has moved from early adopter revenue bands in 2020 into a substantial industry by 2025, and is forecast to continue robust expansion through 2032. That expansion is driven by accelerating enterprise demand for multi‑modal authentication, payments and fraud prevention in financial services, contact center transformation, and public sector identity programs. The 14% CAGR forecast is meaningful: it reflects both increased deployments and rising average contract values as vendors bundle software, hardware acceleration, and managed services.
What the full report contains (practical, hands‑on deliverables)
-
Market and technology outlook: Forward curves under three adoption scenarios, sensitivity testing for regulatory headwinds, and stress testing for latency and compute constraints.
-
Vendor evaluation playbook: A repeatable vendor scorecard that weights accuracy, PAD (presentation attack detection) certification, integration APIs, edge‑compute readiness, and support footprint.
-
Procurement templates: RFP language, SLA examples, and red‑flag clauses that protect customers from algorithmic drift and undisclosed model updates.
-
Implementation blueprints: Reference architectures for cloud, hybrid, and fully‑edge deployments including recommended NPU/processor families for sub‑100ms matching where required.
-
Regulatory mapping and consent playbook: Practical guidance to operationalize GDPR and high‑risk AI conformity requirements into consent flows, DPIAs (data protection impact assessments), and audit trails.
Competitive landscape: who to watch and why
The ecosystem is populated by specialist biometrics firms, platform incumbents, and systems integrators. Market concentration is moderate: the three largest vendors account for roughly one‑third of the market, while the top five approach half. That structure creates choice for buyers — an ability to source best‑of‑breed capabilities — but also means integration and long‑term support are decisive selection criteria.
-
NEC Corporation (Tokyo) — NEC continues to lean into high‑throughput surveillance and enterprise security with upgraded NeoFace offerings that increasingly bundle voice modules for real‑time multi‑modal surveillance. Their product launches underline a strategy focused on large, mission‑critical deployments.
-
Aware Inc. (Bedford, MA) — Aware’s SDK approach emphasizes mobile and embedded authentication. Notably, their integration pathway into Android’s authentication framework expands addressable use cases for device‑native biometric sign‑in and reduces friction for mobile-first deployments.
-
ID R&D / Neurotechnology (Cambridge, MA) — Specialization in liveness detection pays off when buyers demand robust PAD. Third‑party certifications for voice and face liveness materially de‑risk vendor evaluation for contact centers and remote onboarding.
-
Daon Inc. (Reston, VA) — Daon’s IdentityX position targets identity proofing and fintech KYC, with growing traction via targeted pilots in regulated banking environments. Their platform approach speaks to customers who prioritize end‑to‑end KYC workflows.
-
Voice Biometrics Group (Redmond, WA) — A niche specialist that couples voice strengths with facial adjuncts; they remain relevant for organizations with large contact center footprints focused on fraud prevention.
-
Thales Group (Paris) and HID Global (Austin) — These incumbents bring systems integration scale and experience with border control, digital identity, and enterprise access — an advantage where procurement favors vendors with high assurance and lifecycle management capabilities.
-
Verint Systems (Melville, NY) — Verint’s strength is in embedding biometrics into customer engagement platforms, offering practical wins in contact center authentication and workforce optimization.
Recent vendor movements that change the decision calculus
-
Product launches that combine face and voice in surveillance or endpoint devices increase the value proposition for security operations, but raise additional privacy and legal scrutiny.
-
SDK and platform integrations with major OS providers materially lower integration cost and speed time‑to‑market for mobile authentication use cases.
-
Independent certification of PAD capabilities (e.g., iBeta) is becoming a practical procurement filter — buyers should require proof of third‑party PAD validation in RFPs.
-
Pilot successes in regulated sectors (notably banking) are maturing into referenceable case studies; procurement teams should ask for sandbox access and measurable KPIs from pilot programs.
Dynamics shaping enterprise risk and opportunity
Regulatory, standards, and technical dynamics are converging in ways that will define winners and laggards in 2026:
-
Regulation: The EU AI Act’s classification of facial and voice biometrics as high‑risk requires conformity assessments for many deployments. Parallelly, data protection regimes such as the GDPR continue to constrain lawful bases for biometric processing — requiring explicit consent or a tightly defined legal basis.
-
Standards and testing: ISO/IEC protocols for presentation attack detection, and national benchmarking efforts (e.g., NIST enhancements that now include voice‑face integration tests), are creating hard evaluation criteria buyers can use to validate vendor claims.
-
Hardware and latency: Real‑time multi‑modal matching with strict latency targets demands edge AI processors with dedicated NPUs. Procurement decisions must account for hardware lifecycle, thermal envelope, and model update paths.
-
Ethics and trust: Transparency about training data, bias testing, and redress mechanisms is no longer optional. Buyers must demand auditability and explainability to mitigate reputational risk.
Operational implications — from POC to production
Successful enterprise programs move beyond accuracy proofs into durable operational models. Important considerations covered in the report include:
-
Data strategy: Minimize raw biometric retention through templateization and homomorphic or tokenized approaches; define retention and deletion policies aligned to legal requirements.
-
System architecture: Adopt hybrid architectures that allow sensitive matching to occur on device or a controlled edge node while leveraging cloud orchestration for model updates and analytics.
-
Continuous validation: Deploy periodic bias and performance testing against representative populations and environmental scenarios; require vendors to support reproducible test harnesses.
-
Vendor management: Structure contracts with clear change control for model updates, and include service credits for SLA breaches tied to false accept/reject thresholds.
Five immediate actions for leaders in 2026
-
Run a regulatory impact workshop mapping product use cases to compliance tests required by regional authorities and high‑risk AI frameworks.
-
Shortlist vendors using a two‑stage process: technical sandbox validation, followed by a commercial pilot with contractual guardrails on data handling and model governance.
-
Budget for edge compute and lifecycle management — latency and model update costs are material drivers of total cost of ownership.
-
Institutionalize an ethics and audit function to own bias testing, consent management, and audit logging.
-
Design KPIs focused on business outcomes (fraud reduction, onboarding time, authentication success rates) rather than raw accuracy metrics alone.
About this release and next steps
This release is a strategic preview designed to inform 2026 investment and procurement decisions. The full PW Consulting Worldwide Face‑Voice Biometric Market report contains the detailed methodologies, vendor scorecards, procurement templates, and scenario models referenced above. It also includes proprietary forecasts and granular, regionally contextualized guidance for organizations planning pilots and rollouts throughout the forecast horizon.
For enterprise leaders ready to move from strategy to execution, the full report provides the templates and test harnesses you will need to accelerate secure, compliant, and high‑value deployments — and to avoid common procurement and integration pitfalls that slow time‑to‑value.
For detailed analysis of this topic, please visit the official page: Worldwide Face Voice Biometric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide LAG3 Antibody Market to Surge at 26.8% CAGR Through 2032, Revolutionizing Cancer Therapy Opportunities
By PW Consulting, 2026-07-15
Worldwide LAG‑3 Antibody Market — Strategic Outlook for 2026: Why This Report Will Shape Your Next Move
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive preview of our newest market study: Worldwide Lymphocyte Activating 3 (LAG‑3) Antibody Market, base year 2025, with a 2026–2032 forecast. This sector is evolving from niche scientific curiosity into a high‑stakes competitive arena. Our analysis shows the market has already moved from single‑digit millions in 2020 to a vibrant, multi‑billion‑dollar opportunity by the end of the forecast period — underpinned by a 2026–2032 compound annual growth rate (CAGR) of 26.79%. For corporate leaders, investors, and R&D strategists planning actions in 2026, this report delivers the strategic framing and the operational tools needed to translate clinical signals into commercial value.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Why 2026 Is a Pivotal Inflection Point
The LAG‑3 landscape today is defined by three concurrent dynamics: the maturation of an approved agent into routine clinical use, a broad and diversified clinical pipeline that tests both classical monoclonal approaches and bispecific architectures, and rapid market expansion driven by checkpoint‑combination strategies. Our market-level modeling captures this transition: total market revenue has grown steeply from 2020 and reached a material commercialization scale by 2025, with projections that continue to accelerate through 2032. Those macro trajectories change how executives must prioritize capital allocation, clinical program sequencing, manufacturing scale‑up, and payer engagement in 2026.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
What This Report Gives You — Practical, Decision‑Grade Intelligence
- Strategic market sizing and growth scenarios calibrated to real commercial milestones and clinical outcomes — including sensitivity runs that show how trial results, label expansions, or reimbursement setbacks would tilt the market pathway.
- Competitive positioning and capability maps for the leading programs and developers, oriented to commercial readiness (approval status, trial readouts, partnership structures, and manufacturing footprints).
- Actionable go‑to‑market playbooks that cover pricing strategy, bundling with existing checkpoint inhibitors, tender and reimbursement tactics, and market access sequencing for major payer systems.
- Clinical development prioritization frameworks that help sponsors choose between indication depth (e.g., front‑line expansion) versus breadth (e.g., multiple tumor types), aligned to competitive windows in 2026 and beyond.
- Operational risk matrices for biologics manufacturing, cold‑chain logistics, and supply continuity — focused on minimizing time‑to‑revenue and avoiding launch disruptions.
- M&A and partnership scenario analysis, with valuation sensitivities driven by likelihood of approval, market exclusivity periods, and integration complexity.
We designed the report to be operational: each chapter concludes with clearly defined, time‑bound recommendations and a one‑page “board briefing” slide that senior leadership can use to accelerate investor, partner, or internal approvals.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Market Dynamics — Drivers, Risks, and Near‑Term Catalysts
- Regulatory and clinical momentum: The approval and commercialization of a LAG‑3 blocking antibody combination has proven clinical and payer pathways exist for this class. That regulatory precedent materially de‑risks first‑to‑market considerations, while catalyzing comparative trials and label expansion programs across developers.
- Pipeline diversity: Sponsors are pursuing multiple mechanistic approaches — from conventional monoclonal antagonists to bispecific modalities and non‑blocking fusion proteins. This architectural diversity increases both the probability of differentiated clinical benefit and the complexity of head‑to‑head positioning.
- Concentration and competitive intensity: The market exhibits very high concentration among a handful of established players, creating both opportunity for late entrants with superior differentiation and a barrier for small developers lacking commercialization infrastructure.
- Clinical readouts as inflection events: Adjuvant or neoadjuvant trial results, combination checkpoint trials, and biomarker‑linked studies will be primary drivers of market share shifts in 2026–2028. Sponsors must plan launch sequencing and payer evidence generation with those milestone dates as anchors.
- Payer and pricing environment: As an oncology biologic class, pricing and reimbursement will follow established checkpoint inhibitor precedents. Payer negotiations will hinge on incremental benefit over existing regimens, real‑world safety tolerability, and budget‑impact modeling rather than novelty alone.
Competitive Landscape — Who Moves the Needle
Our competitor analysis focuses on the companies currently shaping clinical and commercial expectations in the LAG‑3 field. We provide succinct program assessments and strategic implications for each:
- Bristol Myers Squibb (BMS): The commercial provider of the only approved LAG‑3 blocking antibody in a fixed‑dose combination has converted clinical proof‑of‑concept into real world use. BMS’s experience with launch sequencing, label framing, and payer negotiations sets a pragmatic benchmark for others. Recent adjuvant trial results that did not meet the primary endpoint alter how the company — and competitors — will prioritize indications and evidence generation.
- Regeneron (with Sanofi partnership): A late‑stage anti‑LAG‑3 monoclonal program in combination with an established PD‑1 agent positions this team as the most credible near‑term challenger in the metastatic and potentially earlier‑line settings. Their strategic partnership structure and access to commercial infrastructure are material competitive advantages.
- Merck, Roche, Novartis, and other large pharma: These firms bring scale, development experience, and global commercialization reach. Their programs — including both monoclonal and bispecific candidates — increase launch competition and create the potential for rapid label fragmentation if multiple agents achieve approvals.
- Biotech innovators (MacroGenics, Xencor, Immutep, Incyte, F‑star): These smaller and mid‑cap companies are the source of technological differentiation — bispecific scaffolds, fusion proteins, and alternative mechanisms that could win niche positions or become attractive acquisition targets for larger partners.
For each company profiled in the full report, we include program timelines, trial comparator landscapes, likely launch geographies, and an actionable risk/opportunity scorecard that links science to commercial outcomes.
Recent Developments That Matter for 2026 Plans
- Regulatory precedent: The initial approval of a LAG‑3 inhibitor combination validated the class and created an immediate reference product in major markets. This is a structural driver for faster uptake of competing regimens that can demonstrate incremental benefit.
- Signal ambiguity in adjuvant setting: A high‑profile adjuvant trial did not meet its primary endpoint. That readout demands recalibration of expectations for early‑disease indications and will likely reallocate sponsor resources toward metastatic and combination studies in the near term.
- Pipeline concentration: Despite the breadth of investigational assets, the commercial market is top‑heavy. A small number of programs and sponsors will determine pricing dynamics and channel access strategies in 2026 and beyond.
Implications for Corporate Decision‑Making in 2026
Our analysis produces several clear imperatives for executives preparing budgets and strategic roadmaps for 2026:
- Prioritize clinical evidence that directly answers payer questions. Incremental overall survival, quality‑of‑life improvements, and toxicity reductions relative to the reference combination will be decisive in contracting discussions.
- Design launch sequences around differentiated label niches rather than lowest‑common‑denominator indications; early wins in specific populations can create durable positions against entrenched incumbents.
- Mitigate manufacturing and supply risks proactively. Given the biologic nature of these molecules, manufacturing scale‑up and redundant capacity planning must be part of any commercialization timeline.
- Consider partnering or M&A to close capability gaps. Market concentration and the capital intensity of global launches mean strategic alliances will remain a dominant route to commercialization for many developers.
- Invest in biomarker and real‑world evidence programs early. Payer negotiations will rely on real‑world comparative effectiveness as much as on randomized data, especially in crowded indication spaces.
About Our Methodology and Why You Can Rely on It
PW Consulting’s study uses a base year of 2025 and a historical window covering 2020–2025, with forecasts extending through 2032. All revenue figures are reported in USD (Million) and our core 2026–2032 CAGR is modeled at 26.79% under a central scenario. We synthesize regulatory filings, clinical registry data, proprietary primary interviews with payers and KOLs, and manufacturing/HTA inputs. Importantly, we triangulate company disclosures against independent uptake models to produce robust, scenario‑based market paths rather than single‑point estimates.
What We Deliberately Hold Back — And Why
In keeping with our “preview” approach, this release highlights the strategic insights and operational tools included in the full study while deliberately withholding granular segmentation tables and downloadable financial schedules that form the core of our subscriber offering. Detailed regional and application splits, unit‑volume forecasts, and revenue waterfalls by company are available only in the full report and the associated interactive model. This is to ensure decision‑makers access validated, context‑rich datasets together with our advisory team’s interpretation — a prerequisite for deal‑grade action in 2026.
Next Steps
If your 2026 strategy depends on winning position, executing a competitive launch, or structuring M&A in the LAG‑3 space, PW Consulting’s full Worldwide LAG‑3 Antibody Market report is built to be the operational backbone of that work. Contact our market intelligence team to arrange a briefing, licensing of the interactive forecast model, or a bespoke advisory engagement that maps the report’s insights into a board‑level action plan.
In fast‑evolving therapeutic classes, the difference between a calibrated, timely decision and a missed window is measured in quarters. The 2026 planning cycle will determine who captures sustained value from the LAG‑3 wave — and this report is designed to help you lead that race.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mini‑Program Short Drama Market to Reach USD 10.85B in 2025 — Asia‑Pacific Leads with USD 8.12B as 13.9% CAGR Drives Growth to USD 27.03B by 2032
By PW Consulting, 2026-07-15
Worldwide Mini Program Short Drama Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Mini Program Short Drama Market positions this format as one of the fastest-evolving intersections of mobile UX, serialized storytelling, and direct monetization. From a nascent sub‑industry in 2020 to a multi‑billion dollar ecosystem by 2025, the space has matured rapidly and will remain a strategic battleground for platforms, studios, IP owners, and global distribution partners through 2032. The report synthesizes quantitative trajectory, competitive moves, regulatory headwinds, and pragmatic playbooks that senior executives and product leaders must use to make confident 2026 investments.
Worldwide Mini Program Short Drama Market
Why this market matters in 2026
Two macro facts frame the urgency for corporate decision-making in 2026. First, the market’s compound annual growth rate (CAGR) across our forecast window is an elevated 13.93%, reflecting sustained consumer appetite and expanding monetization formats. Second, the total market—measured in USD millions—has expanded dramatically over five years and continues to project strong increases through 2032. These dynamics create a rare window where late‑stage platform effects, content scalability, and international expansion can be captured without the hyper‑dilution of returns that follows in fully saturated markets.
Worldwide Mini Program Short Drama Market
Trajectory highlights (what the numbers tell you)
- Rapid scale: The market moved from single‑hundred millions to multi‑billions within five years—an arc that denotes both technological standardization (mini program runtimes, vertical video formats) and rapid audience habituation.
- Sustained growth: A nearly 14% CAGR to 2032 signals durable revenue pools driven by diversified monetization rather than a single channel dependency.
- Moderate concentration: Industry concentration metrics indicate a market that is neither winner‑takes‑all nor fully fragmented—top groups command meaningful share but room remains for specialized entrants and regional consolidators.
Competitive landscape — who matters and why
The competitive map is a hybrid of mega‑platforms with integrated ecosystems and nimble specialty studios pushing format and distribution innovation. Understanding this split is essential to crafting partnerships and capex plans.
Worldwide Mini Program Short Drama Market
- Tencent / WeChat ecosystem: Leveraging WeChat Mini Programs, Tencent integrates payments, social distribution, and first‑party data to enable deeply monetized short drama consumption. Expect continued strategic use of cross‑platform promotional levers and exclusive windows.
- ByteDance (Douyin, international arms): ByteDance pairs aggressive product experimentation with international rollouts. Recent moves show focus on region‑specific platforms and free‑model experimentation to build scale, then layer monetization.
- Kuaishou: Historical involvement followed by strategic realignment demonstrates the industry’s sensitivity to regulatory and content quality pressures—platforms are reducing low‑quality inventory and prioritizing compliance and creator incentives.
- Incumbent streaming studios (iQIYI, Youku, Bilibili, Mango TV, WeTV): These players are adopting mini‑program distribution as an adjunct to traditional streaming, building dedicated short drama studios, creator tools, and analytics to monetize serialized micro‑episodes for younger cohorts.
- IP & content suppliers (China Literature, etc.): Owners of readable IP have become pivotal upstream partners, supplying serializable narratives that shorten production cycles and improve conversion rates.
- Global & niche producers (Mega Matrix, Snail, ReelShort, DramaBox): Specialist producers and regional platforms are accelerating international distribution, embedding AI personalization, and testing immersive/interactive elements to differentiate offerings outside major platform ecosystems.
Recent strategic moves underscore these dynamics: cross‑border production agreements integrating AI personalization, platform partnerships with major international studios for exclusive windows, and product launches that put creator monetization and analytics at the center of distribution strategies.
Regulation, quality control, and content dynamics
Regulatory frameworks introduced in recent periods have materially changed operational imperatives. Filings, production cost disclosures, and systematic takedowns of non‑compliant micro‑dramas have elevated compliance from a back‑office cost into a front‑line strategic capability. Simultaneously, consumer behavior has consolidated—hundreds of millions of regular viewers now treat micro‑dramas as a daily habit—so content quality and platform trust are increasingly determinant of monetization velocity.
Monetization and product vectors (what to prioritize)
Platform monetization is no longer binary. Revenue mixes now include episode paywalls and in‑app microtransactions, subscriptions, and advertising formats configured for ultra‑short episodes and vertical consumption patterns. For 2026 strategies, prioritize designs that:
- Maximize lifetime value by combining transactional and relational models (micro‑payments layered with community and social hooks).
- Use first‑party data and social graph mechanics to boost conversion and reduce acquisition costs.
- Design modular content units that can be re‑packaged across windows and territories to extract additional monetization without linear production cost increases.
What the PW Consulting report delivers (practical contents)
Our full study goes beyond high‑level forecasts to equip commercial teams, content strategists, and platform operators with operational tools. Key deliverables include:
- Go‑to‑market playbooks for platform launches and creator acquisition tailored to mini program constraints.
- Production optimization templates—episode runtimes, budget allocation frameworks, and rapid‑cycle editorial QA checklists for serialized short drama production.
- Monetization experimentation roadmaps and pricing sensitivity matrices suitable for A/B testing across markets and cohorts.
- Partner evaluation and M&A screening tools to assess studio or IP targets against platform distribution synergies.
- Regulatory compliance playbooks and content governance frameworks that translate filing requirements into production cycles and audit trails.
- Customizable forecasting models and scenario planners calibrated to the market’s CAGR and concentration dynamics, enabling finance teams to stress‑test investments through 2032.
Strategic implications for 2026 decision-making
For executive teams preparing budgets and roadmaps in 2026, the interplay of scale, regulation, and platform differentiation produces clear priority choices:
- Invest early in compliance and metadata capabilities. Platforms that can demonstrate auditable content origins, cost allocations, and rapid takedown responsiveness will preserve monetization and reduce regulatory risk.
- Lock in IP pipelines and creator economics. Securing serialized IP and creator loyalty prevents margin erosion as competition for high‑quality micro‑content intensifies.
- Design hybrid monetization experiments. A disciplined program of small‑batch experiments across micro‑payments, subscriptions, and ad formats will reveal the fastest path to positive unit economics.
- Globalize with localization infrastructure, not mere distribution. Leading players are deploying localized product variants and partnering with regional producers to accelerate overseas adoption.
- Use partnerships to de‑risk expansion. Strategic MOUs and co‑production deals with seasoned local players can compress time‑to‑market while enabling scale economies.
Case signals and near‑term catalysts
Watch for several inflection signals in 2026 that will inform allocation shifts: strategic international launches by major platforms, studio partnerships that create exclusive windows, and platform enforcement cycles that prune low‑quality inventory. Additionally, breakthrough uses of AI for personalized episode sequencing and interactive story branches will differentiate winners from followers.
How to use this briefing with your 2026 playbook
Use this briefing to set investment guardrails. We recommend a three‑step approach for 2026:
- Fast audit (0–3 months): Benchmark current IP, platform, and creator exposures against compliance and monetization KPIs described in our report.
- Pilot and learn (3–12 months): Launch two constrained experiments—one focused on transactional micro‑payment UX, another on ad‑supported scale—to test consumer elasticity and retention.
- Scale or pivot (12+ months): Based on pilot outcomes and the evolving regulatory landscape, scale proven channels, or redeploy capital into partnerships and tech that preserve margins.
Why PW Consulting’s report is unique
Our study combines forward‑looking financial trajectories (anchored to a 13.93% CAGR through the forecast window) with hands‑on operational toolkits and partner‑level competitive analysis. We intentionally balance public market signals with proprietary frameworks that translate growth rates and concentration metrics into board‑level decisions—without disclosing sensitive segmentation detail in this briefing. This “trailer” approach gives leaders enough insight to prioritize, while reserving the granular segmentation, regional breakouts, and model inputs for clients accessing the full report.
Next steps and how to access the full intelligence
For executives preparing budgets, partnership strategies, or content pipelines for 2026, the full PW Consulting Worldwide Mini Program Short Drama Market report provides the granular segmentation, scenario models, and step‑by‑step playbooks necessary to operationalize the recommendations summarized here. To obtain the complete dataset, proprietary segmentation tables, and downloadable templates, access the report package through PW Consulting’s research portal or contact our industry practice lead to arrange a briefing and model walk‑through.
PW Consulting — Senior Strategy & Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Worldwide Mini Program Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


