



Category: market research
PW Consulting: Worldwide Consumer and Enterprise Hearables Market to Expand at 12.35% CAGR, Hitting USD 155,014.22 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Consumer and Enterprise Hearables Market — Strategic Outlook for 2026
Executive preview
As hearables evolve from a consumer audio accessory into a multi-domain platform for communication, health, and enterprise workflows, 2026 will be a year of decisive strategic moves. PW Consulting’s new Worldwide Consumer and Enterprise Hearables Market report (base year 2025, forecast 2026–2032) captures this inflection: the total market exceeded USD 68.6 billion in 2025 and is projected to grow at a sustained CAGR of approximately 12.35% through the forecast window. That growth is driven by converging forces — faster silicon and sensor innovation, expanding software value stacks (AI-based audio and health features), and enterprise adoption for collaboration, safety and assistive applications.
Worldwide Consumer and Enterprise Hearables Market
Why this report matters for 2026 decision-making
-
Actionable foresight for investment timing: The report translates macro growth into decision-ready intelligence — which product bets to accelerate, when to reallocate R&D, and the realistic horizons for monetizing advanced features such as AI hearing health, multi‑device enterprise integrations, and immersive audio for professional applications.
Worldwide Consumer and Enterprise Hearables Market -
Risk-aware supply chain playbooks: With component volatility and trade policy uncertainty intensifying, procurement and operations teams need concrete mitigation strategies. Our research combines upstream supplier mapping, scenario stress tests and cost‑sensitivity analysis to inform near‑term sourcing and regionalization choices.
Worldwide Consumer and Enterprise Hearables Market -
Commercial roadmaps for enterprise adoption: The report offers practical go‑to‑market and procurement playbooks for selling hearables into unified communications, healthcare, field services and industrial safety, including pilot KPIs, TCO models and integration checklists for enterprise IT and telephony platforms.
What’s in the report — deeply practical deliverables
-
Robust market sizing and forecasting methodology: Transparent models (TAM/SAM/SOM), base‑case and alternative scenarios, and sensitivity analyses that let commercial leaders stress test outcomes under different adoption curves and component-cost regimes.
-
Competitive capability matrix: Positioning of the leading OEMs and specialist players across product, software, enterprise features, channel strength and margin profiles — designed to identify partnership and M&A targets without disclosing proprietary segment tables here.
-
Supplier and component risk mapping: Multi-layer supplier maps, single‑source exposure heatmaps, and mitigation options for MEMS microphones, battery chemistries, semiconductors and proprietary ASICs. Includes event-driven scenarios (tariffs, raw‑material shocks, extreme weather) and response playbooks.
-
Feature ROI & pricing simulators: Quantitative frameworks to evaluate the incremental revenue and margin impact of features such as active noise cancellation, health monitoring, AI-based scene tuning and multi‑platform security — enabling pricing experiments for both consumer and enterprise SKUs.
-
Enterprise go‑to‑market toolset: Buyer personas, procurement negotiation templates, deployment & support cost models, and pilot-to-scale adoption templates for verticals (healthcare, field services, contact centers, education).
-
M&A and partnership playbooks: Screening criteria, valuation sensitivities, integration checklists, and deal case studies to help corporate development teams prioritize strategic acquisitions and licensing opportunities.
-
Regulatory and compliance map: Jurisdictional assessment of hearing‑health regulations, data privacy and telecom certifications, with remediation checklists for product teams and legal counsels.
-
Executive dashboards and KPIs: Ready‑to‑use dashboards covering unit economics, channel performance, warranty/return drivers, and real‑world feature usage metrics to feed monthly executive reviews.
Competitive landscape — who to watch in 2026
The hearables market sits at the intersection of consumer electronics giants, premium audio specialists, and domain-focused hearing‑health incumbents. Global household names continue to shape platform expectations through tight ecosystem integrations and scale; premium and professional brands compete on acoustic fidelity and enterprise features; and hearing‑aid leaders are accelerating into hybrid clinical/consumer offerings. A handful of large vendors command a meaningful portion of market revenue, while an active long tail of regional brands and OEMs competes aggressively on price and niche functionality.
-
Platform incumbents (ecosystem advantage): Vendors with trusted device ecosystems are leveraging tight hardware–software integration to migrate consumer users into emerging health and enterprise use cases. Expect steady investment in AI‑enabled health monitoring and firmware upgrades that lock in platform value.
-
Premium audio brands: Companies with a legacy in high‑fidelity audio and noise cancellation continue to push technical differentiation important to enterprise customers who prioritize speech intelligibility and immersive audio for professional content creation.
-
Hearing‑health specialists: Clinical players are accelerating R&D to bridge clinical-grade hearing assistance with everyday hearables, creating new opportunities in tele‑audiology, occupational health and insurance‑backed procurement.
-
Enterprise‑focused vendors: Providers specializing in unified communications and call‑quality optimization are deepening integrations with collaboration platforms and expanding into managed services — a valuable model for large corporate buyers seeking low friction deployment.
Industry dynamics and near‑term risks to model
Three operational realities should be front and center when constructing 2026 plans:
-
Supply‑chain & raw‑material volatility — Recent events have underscored single‑source risks for components such as MEMS microphones and certain quartz/silicon inputs. Episodic events can extend lead times and inflate costs; our report includes supplier concentration scores and mitigation pathways.
-
Trade and regulatory pressure — Tariff shifts and jurisdictional certification requirements are already prompting manufacturers to explore regional manufacturing hubs and dual‑sourcing strategies. Procurement and finance teams must build tariff sensitivity into price and margin models.
-
Component and sensor innovation — New sensor designs and smart accelerometers tailored for voice and activity detection are accelerating feature roadmaps. Device differentiation increasingly depends on software and services layered over commodity hardware — a dynamic our feature ROI tools quantify.
Priority strategic moves for 2026
To convert the forecasted market momentum into sustained competitive advantage, companies should act on three, high‑impact priorities in 2026:
-
Harden the supply chain now. Establish regional second‑source agreements for critical components, secure strategic inventory positions for long‑lead items, and run at least two stress scenarios (tariff spike and supplier outage) using the report’s supplier risk matrix.
-
Productize software & services. Reframe hearables as subscription‑enabled platforms — health monitoring, enterprise device management, advanced call processing and analytics deliver recurring revenue and stickiness much faster than hardware alone.
-
Double down on enterprise integration. Build certified integrations with major unified‑communications and device‑management software, and offer white‑glove procurement and lifecycle services (deployment, security hardening, warranty management) to capture enterprise wallet share.
Tactical checklist for C‑suite and product leaders
-
By Q2 2026, complete a supplier exposure audit and negotiate alternate sources for at least two critical components.
-
Launch one enterprise pilot that bundles hardware, device management and analytics as a managed service — measure TCO, deployment time and user adoption over six months.
-
Prioritize firmware/AI features that can be delivered via OTA updates to unlock near‑term monetization without retooling hardware.
-
Review M&A targets against a clear capability matrix (software IP, sensor ASICs, enterprise channels) and de‑risk integration via pre‑defined playbooks.
How PW Consulting supports your 2026 agenda
Our report is designed as a decision‑grade toolkit, not a static PDF. Subscribers gain access to interactive forecast models, supplier heatmaps, scenario simulators and a prioritized list of partnership and acquisition targets tailored to your strategic profile. We also offer facilitated workshops to translate findings into actionable quarterly roadmaps and procurement scorecards.
Next steps
Markets that grow as quickly as hearables do require more than intuition — they demand structured, scenario‑based planning. PW Consulting’s Worldwide Consumer and Enterprise Hearables Market report equips leadership teams to make 2026 investment, procurement and commercial decisions with confidence. For executives planning product bets, supply‑chain redesigns, or enterprise rollouts next year, the full report contains the granular segmentation, vendor benchmarking and financial models needed to operationalize strategy — details we intentionally omit here to drive direct access to the source intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer and Enterprise Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Deicing Salt Market to Grow at 3.55% CAGR, Rising from USD 2,700 Million in 2025 to USD 3,446.8 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Deicing Salt Market — Strategic Insights for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on the Worldwide Deicing Salt Market (base year 2025) provides senior executives and procurement leaders with the forward-looking intelligence they need to make high-stakes decisions in 2026. The global market reached approximately USD 2.7 billion in 2025 and, under our central-case forecasts, will expand at a compound annual growth rate (CAGR) of 3.55% across the 2026–2032 horizon to approach roughly USD 3.45 billion by 2032. This report synthesizes five years of recent historical trends (2020–2025) with seven-year scenario modelling (2026–2032) to translate market movement into actionable strategy.
Worldwide Deicing Salt Market
Why this report matters now
Deicing salt is a deceptively simple input with outsized operational, environmental and fiscal consequences for public agencies, highway contractors, airports and major industrial sites. Changes in energy costs, regulatory pressure on chloride discharges, shifts in packaging and trade tariffs, and product innovation (treated salts, blends and brines) are converging to reshape supplier economics and buyer sourcing decisions in time for the 2026 procurement cycle.
Worldwide Deicing Salt Market
- Cost pressure from energy-intensive underground mining and evaporation processes has altered supply economics — recent industry data shows notable increases in mining operating costs and volatility in natural gas inputs that feed evaporation facilities.
- Regulatory scrutiny on environmental impacts is accelerating product substitution in sensitive watersheds: low-chloride alternatives and corrosion-inhibited formulations are increasingly referenced in official guidance.
- Commercial factors — including packaging cost inflation tied to trade measures and new product launches that reduce infrastructure corrosion risk — are changing buyer evaluation criteria beyond price-per-ton.
What PW Consulting delivers — practical, decision-ready outputs
Our objective was to construct a hands-on toolkit for managers preparing budgets, sourcing strategies and capex plans for 2026. Instead of a purely descriptive report, PW Consulting delivers a sequence of pragmatic modules that connect market intelligence to executable choices:
Worldwide Deicing Salt Market
- Proprietary market sizing and topline forecasts for 2020–2032, with scenario branches to model slow-, base- and fast-growth outcomes.
- Supplier mapping and scorecards that rank upstream producers across production footprint, logistics access, product portfolio (including treated salts and blends), sustainability credentials and operational resilience.
- Procurement playbooks: request-for-proposal (RFP) templates, index-linked contracting clauses, seasonal purchase hedging strategies and unit-cost normalization tools that account for treated-product premiums.
- Investment decision frameworks: NPV-driven models for greenfield capacity, mine reactivation or terminal investments, with sensitivity analyses for energy prices, labor and regulatory constraints.
- Environmental compliance and transition roadmap: regulatory gap-analysis, low-chloride pilot design, infrastructure corrosion-cost model and stakeholder engagement templates for regulators and communities.
- Operations toolkit: inventory optimization for seasonality, logistics bundling strategies for port and rail utilization, and contingency playbooks for supply disruptions.
- M&A and partnership screening: criteria and scorecards to evaluate targets and joint ventures in both upstream production and downstream distribution.
Strategic takeaways for 2026 planning cycles
We translate the report’s insights into a set of prioritized actions that should be considered by C-suite teams, procurement heads and public sector buyers as they prepare 2026 budgets and contracts.
- Recalibrate supplier scorecards to emphasize product attributes and lifecycle costs. Buyers who continue to evaluate exclusively on delivered price risk hidden costs from corrosion, environmental remediation and warranty claims.
- Diversify supply and logistics footprints. The market is not monopolistic — concentration metrics indicate space for regional suppliers and displacing entrants — but localized disruptions (energy, labor, regulatory) can cascade quickly during peak season.
- Incorporate regulatory scenario planning into procurement cycles. With environmental directives and agency recommendations increasingly favoring lower-chloride solutions in sensitive areas, contractual flexibility for product substitution and pilot trials should be standard in 2026 agreements.
- Model packaging and trade exposures. Recent tariff-driven increases in packaging costs have raised the delivered cost of packaged product; strategic use of bulk distribution, shared terminals and contract indexation can mitigate this risk.
- Prioritize treated and blended products where lifecycle benefits exceed upfront premiums. New formulations that reduce corrosion or improve melting efficiency can produce net cost savings when infrastructure damage and operational downtime are considered.
- Embed seasonality-adjusted inventory strategies. Optimized stocking that leverages forward purchases when markets permit and tactical spot buying during mild winters will be key to managing working capital without sacrificing readiness.
Competitive landscape — leading players, tactical moves and what they imply for buyers
The deicing salt market is characterized by a mix of global miners, regional incumbents and vertically integrated suppliers. Market concentration is moderate: the top three producers account for a meaningful but not dominant share of industry volumes, and the top five increase that share further — a structure that encourages both strategic partnerships and localized competition.
- Cargill — a global heavyweight with integrated mining and evaporation assets — recently announced capacity expansion in North America to address demand spikes. Such expansions can ease seasonal tightness but also signal intense competition for long-term offtake agreements.
- Compass Minerals — focused on higher-value treated products — launched a corrosion-inhibited deicing solution late in 2024, illustrating how product innovation is being used to command price premiums and open infrastructure-focused value propositions.
- K+S and other European producers are leaning heavily into sustainability certification and compliance upgrades. Updated environmental credentials can be decisive for buyers subject to EU directives or corporate ESG mandates.
- Large state-owned and regional producers remain critical source partners in several markets, providing scale and export capacity that buyers should consider when constructing multi-supplier strategies.
For 2026, executives should monitor announcements on capacity, certification and new formulations closely — these tactical moves frequently presage shifts in contract terms, premium pricing and availability windows.
Methodology and data confidence
The analysis is built on a multi-source, triangulated approach combining company filings, primary interviews with procurement and operations leaders, miner output data, national energy price indices, regulatory texts and proprietary logistics-cost modelling. Forecasts use a base-case econometric model augmented by qualitative scenario narratives that capture tail-risk events such as extreme winters, sudden tariff changes or energy price spikes. Sensitivity testing is provided for energy, labor and regulatory input variables so users can stress-test capex and sourcing strategies under plausible 2026 shocks.
How to use the report in your 2026 planning
PW Consulting’s report is designed to be directly usable in boardrooms and tender committees. Typical applications we see from clients preparing for 2026 include:
- Aligning annual procurement calendars to modelled seasonal tightness and pre-buy windows.
- Rewriting supply contracts to include product-substitution clauses, corrosion-cost-sharing and indexation to energy or packaging indices.
- Running pilot programs with treated or blended products in infrastructure-critical corridors to generate local performance data for wider adoption.
- Screening potential capacity partners and acquisition targets using our M&A scorecards and scenario-adjusted valuations.
What the executive reader should do next
In an environment where modest percentage-point differences in product performance or a single winter’s infrastructure costs can dwarf short-term procurement savings, decision-makers need a tightly-integrated view of supply, cost, regulation and product innovation. PW Consulting’s Worldwide Deicing Salt Market report equips teams to turn that view into defensible 2026 decisions — from contract design and inventory strategy to capex allocation and M&A screening.
For executives who require the full dataset, detailed regional and application-level segmentation, supplier scorecards and scenario-ready financial models, the report includes downloadable tools and a decision-support appendix. To access the complete intelligence package and companion modelling templates, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide D‑Ring Blood Pressure Cuffs Market Poised for Robust 7.0% CAGR Through 2032, New Report Finds
By PW Consulting, 2026-07-15
Worldwide D-Ring Blood Pressure Cuffs Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide D-Ring Blood Pressure Cuffs Market (base year 2025; historical 2020–2025; forecast 2026–2032) crystallizes a clear strategic narrative for medical-device executives, procurement leads, and private-equity sponsors preparing for 2026 and beyond. The market expanded from USD 385.42 Million in 2020 to USD 539.36 Million in 2025 and is projected to grow at a steady 7.0% CAGR across the 2026–2032 forecast window, reaching an estimated USD 866.10 Million by 2032. This trajectory creates a multi-dimensional agenda for product development, go-to-market investment, supply-chain resilience, and regulatory positioning.
Worldwide D-Ring Blood Pressure Cuffs Market
Why this market matters to 2026 strategy
-
Durable growth with commercial optionality: A mid-single-digit-to-low double-digit CAGR combined with clear pockets of clinical and homecare demand makes D-ring cuffs a defensible add-on for monitoring systems and consumables portfolios. Strategic bets now can deliver meaningful recurring-revenue streams by 2028–2030.
Worldwide D-Ring Blood Pressure Cuffs Market -
Moderate concentration, high opportunity for differentiation: The top three vendors capture a significant share of the market (CR3 ≈ 42.5%) while the top five rise to nearly 59% (CR5 ≈ 58.8%). This structure leaves room for adjacent entrants to carve specialty niches—materials innovation, single-patient disposables, and integration with proprietary monitor ecosystems.
Worldwide D-Ring Blood Pressure Cuffs Market -
Regulatory and reimbursement clarity reduces execution risk: International standards such as ISO 81060-1:2019 set accuracy expectations and clinical-validation requirements, while reimbursement codes (e.g., HCPCS A4574 in the U.S.) create visible unit economics for reusable cuffs. Understanding these rules is table stakes for 2026 product launches and hospital contracting.
Headline market dynamics
-
End-user shifts. Growth in homecare monitoring, outpatient settings, and long-term care underpins demand for robust yet user-friendly D-ring designs. This is a structural trend rather than a pandemic-era spike.
-
Product segmentation. Reusable versus single-patient-use models continue to coexist; the former is favored by institutional purchasers for cost efficiency and reimbursement, while the latter addresses infection-control protocols and bundled-service propositions.
-
Material and manufacturing levers. Key materials—medical-grade nylon, polyester, and non-woven fabrics—remain the primary cost and differentiation levers. Our sector scan indicates raw-material input costs (e.g., medical-grade nylon and PVC bladders) are a determinative factor in unit economics and sourcing strategy.
-
Regulatory hygiene. Compliance with device accuracy standards and increasing expectations for latex-free materials (driven by major hospital accreditation bodies) are non-negotiable design constraints for 2026 market entry.
Competitive landscape: what leading players are betting on
The competitive map is dominated by global device OEMs and specialized cuff manufacturers. Our dossier profiles manufacturers that set the feature and channel benchmarks—product compatibility, size breadth, materials, and connectivity. Representative strategic moves observed in the market include:
-
Integration and compatibility as a defensive moat. Large monitor OEMs emphasize cuff compatibility across their lines to lock in consumables demand. Product examples include D-ring offerings compatible with major monitors and proprietary connectors that simplify supply agreements.
-
Feature-driven differentiation. Competitors are layering attributes—antimicrobial treatments, segmented bladders for more accurate fit, flexible porting systems, and bariatric sizing—to address either hospital procurement specifications or consumer ease-of-use in home settings.
-
Regulatory and certification milestones accelerate adoption. Recent real-world events illustrate this: a major OEM obtained FDA 510(k) clearance for an antimicrobial-enhanced D-ring cuff in late 2024, and another supplier expanded its bariatric and single-patient portfolio mid-2024—moves that influence tender outcomes and distributor listings.
We assess several representative competitors (profiles summarized from primary and public sources):
-
Welch Allyn (Hillrom): Strong presence with FlexiPort D-ring cuffs in both reusable and disposable formats; focus on cross-monitor compatibility and live trade-show demonstrations of one-tube connectivity.
-
Omron Healthcare: A blend of home and professional D-ring styles, with an emphasis on wide-range sizing and consumer trust that supports captive channel strength in retail and direct-to-consumer models.
-
GE Healthcare: DINAMAP D-ring variants spanning single-patient and reusable lines; recent regulatory clearance for antimicrobial features is a notable credential for institutional buyers.
-
Philips: Latex-free D-ring cuffs positioned for IntelliVue and SureSigns systems; global OEM reach and hospital integration capabilities are core advantages.
-
SunTech Medical: Product innovation around segmented bladders and an expanded line that caters to bariatric sizing—an explicit play for clinical accuracy and high-acuity segments.
-
A&D Medical and ADC: Durable, cost-effective offerings that appeal to value-focused buyers and point-of-care channels; emphasis on nylon construction and clinical compatibility.
Implications for strategic choices in 2026
-
Product roadmap prioritization. Firms should prioritize a short list of feature additions that materially change procurement decisions—antimicrobial materials, verified latex-free constructions, and validated compatibility with leading monitors. These are faster to commercialize than full platform integrations but have high procurement impact.
-
Channel and commercial model. Expect differentiated strategies for hospitals (tender and GPO playbooks), homecare (retail and OEM-bundling), and ASC/outpatient clinics (service contracts). Reimbursement visibility for reusable cuffs improves institutional buying cases, while single-patient products carry pricing power in infection-control contracts.
-
Supply-chain hedging. Given the sensitivity of unit costs to fabric and bladder inputs, buyers and manufacturers should execute dual-sourcing strategies, strategic inventory buffers for key components, and explore near-shore options for repeatable supply assurance.
-
M&A and partnership criteria. Targets that bolster differentiated materials technology, proprietary cuff-to-monitor connectors, or distribution footprints in rapidly expanding homecare channels merit premium attention. The market concentration metrics suggest that acquisitive moves can materially shift share balances.
What the PW Consulting report delivers (practical, decision-ready outputs)
Our full study is designed as an executable playbook for 2026 planning cycles. Key deliverables include:
-
Market model and forecast (historical 2020–2025; forecast 2026–2032) with scenario sensitivity to material-cost swings and reimbursement changes.
-
Competitive benchmarking with feature-by-feature scorecards, channel footprints, and recent product certification timelines.
-
Procurement negotiation toolkit: unit-cost breakdowns, supplier scorecards, and negotiating levers (warranty, service, exclusivity, volume tiers).
-
Regulatory matrix and clinical-validation checklist aligned to ISO 81060-1:2019 and major jurisdictional requirements, plus a practical roadmap for FDA 510(k) submission considerations.
-
Material-cost and manufacturing sensitivity analyses that tie raw-input price movements to margin and pricing strategy; includes modeled ranges for nylon and PVC bladder inputs.
-
Go-to-market playbooks tailored to hospital tenders, homecare retail rollouts, and high-acuity ambulatory centers; each playbook includes KPIs and 12–18 month tactical plans.
-
M&A screening framework and shortlist methodology for bolt-on and platform opportunities—balanced for scale, differentiation, and channel access.
-
Primary research appendices: structured interviews with procurement leads, clinical engineers, and device OEMs; plus anonymized tender outcomes demonstrating price bands and feature priorities.
Where to focus resources in 2026
-
Short-term (0–12 months): Certify latex-free/antimicrobial variants, secure HCPCS-relevant procurement paths, and ensure demonstrable ISO 81060-1 clinical validation to shorten hospital adoption cycles.
-
Medium-term (12–24 months): Expand material choices for comfort and disposability trade-offs, finalize connector standards for monitor compatibility, and pilot D2C or telehealth channel partnerships for homecare adoption.
-
Longer-term (24–48 months): Evaluate M&A targets that add specialty sizing or manufacturing scale, and invest in digital-tagging or inventory services that convert consumables into recurring-revenue contracts.
Limits, risks and watch-list
-
Input-cost volatility: Raw-material price inflation materially compresses margins for low-differentiation producers; hedging and supplier partnerships are critical mitigants.
-
Regulatory tightening: Any changes to clinical-validation thresholds or changes in procurement hygiene requirements may accelerate single-patient adoption and disrupt reusable unit economics.
-
Channel disintermediation: Monitor OEMs and large distributors seeking to bundle cuffs as part of device-service contracts may marginalize standalone suppliers without broader integration capability.
Final note — the intelligence you’ll need to act
This preview highlights the directional findings and strategic implications we see heading into 2026, supported by a robust market model (USD Million basis), concentration analysis, and primary-source company profiling. To preserve competitive value for subscribers and to enable tactical planning, detailed segmentation by region, material and end‑use (the full quantitative splits, pricing tables, and supplier contract exemplars) are provided exclusively in the full report and online data portal.
For procurement teams, product leads, and M&A sponsors, the PW Consulting report converts market momentum—7.0% CAGR and a market poised to approach USD 866.10 Million by 2032—into prioritized, executable options. Visit the report page to access the complete models, granular segment tables, and our proprietary supplier scorecards required to finalize a 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide D-Ring Blood Pressure Cuffs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Student Microscopes Market Set to Grow at a 5.1% CAGR, New Report Finds
By PW Consulting, 2026-07-15
Worldwide Student Microscopes Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
PW Consulting’s latest market study on the Worldwide Student Microscopes Market synthesizes a multi‑year historical view (2020–2025), a robust base year analysis (2025), and a forward forecast window (2026–2032) to translate observable trends into near‑term, executable strategies for 2026. The market reached an estimated USD 751.5 Million in 2025 and, under our base‑case assumptions, grows at a compound annual growth rate of 5.1% through the forecast period — putting the market on a trajectory to exceed one billion dollars before the end of the decade. This report is purpose‑built for executives who must make procurement, product, channel, and M&A decisions in 2026 with confidence and speed.
Worldwide Student Microscopes Market
Why this report matters for 2026
- Budget cycles and procurement timing: Education institutions and distributors are locking multi‑year capital and operational budgets in 2026; vendors that align product refreshes and promotions with those cycles capture disproportionate share.
- Technology inflection point: The rapid integration of digital imaging, USB/Wi‑Fi connectivity and software‑enabled learning tools is shifting value from optics alone to holistic classroom solutions. Companies that can package hardware + imaging + learning content will see elevated ASPs and retention.
- Supply‑chain clarity matters: Margins are sensitive to commodity and assembly cost swings. Line‑level visibility into lens blanks, PCB sourcing and regional assembly can be a make‑or‑break capability in 2026.
- Regulatory & compliance risk: Adherence to standards such as ISO 10993 (biocompatibility for optical components) and CE marking for EU electronic safety are non‑negotiable and affect time‑to‑market and tender eligibility.
- Consolidation signals: The market is moderately concentrated — our analysis shows the top three vendors control a meaningful portion of revenue, with the top five approaching half the market — creating both competitive pressure and acquisition opportunity.
What the report delivers — practical, transaction‑ready intelligence
This is an operational playbook as much as a market study. Clients will find:
Worldwide Student Microscopes Market
- Proprietary total market sizing and a demand model calibrated to historical 2020–2025 trends, with base‑year granularity for 2025 and forecasts through 2032.
- Scenario modelling (base, upside, downside) tied to adoption curves for digital imaging, K‑12 curriculum investments, and home‑education channels.
- Channel and go‑to‑market diagnostics: tender behavior, distributor margins, direct vs. institutional sales tradeoffs, and reseller incentive frameworks.
- Commercial due diligence templates for M&A and JV activity, including an acquisition target scoring matrix and sensitivity analysis for synergies.
- Supply‑chain heatmap: key upstream inputs, typical cost buckets (e.g., borosilicate lens blanks and assembly labor), supplier consolidation risk, and recommended mitigation levers.
- Regulatory checklist and time‑to‑compliance playbook for major markets, plus an IP exposure primer for digital imaging firmware and educational content licensing.
- Pricing and margin optimisation tools including elasticities by product architecture (optical vs. digital), service bundle economics, and five tactical pricing experiments for near‑term uplift.
Key market dynamics and strategic implications
The market’s steady 5.1% CAGR masks a set of structural shifts that will determine winners and losers in 2026:
Worldwide Student Microscopes Market
- Digitalization and software leverage: USB, Wi‑Fi and integrated cameras are migrating value into software and cloud‑enabled services. Companies that remain optics‑centric risk commoditization; those that offer imaging workflows and classroom integration capture longer customer lifetime value.
- Education policy and procurement patterns: Renewed investments in STEM at multiple administrative levels are driving purchasing waves, but budget windows are discrete. Vendors must time product launches and certification milestones to these procurement calendars.
- Cost pressure on components and assembly: Typical glass lens blanks for student microscopes are subject to material and supply constraints — our industry checks indicate unit lens blank costs in the low tens of dollars and high‑volume assembly labor in the low single‑digit dollars per unit in certain production geographies. These line items materially impact gross margins.
- Regulatory and certification gatekeeping: Compliance with standards such as ISO 10993 and CE marking not only reduces legal risk but is a commercial differentiator in institutional tenders.
- Consolidation and channel concentration: With a market where the top vendors account for a meaningful share, mid‑market players should evaluate defensive partnerships, distribution exclusives, or carve‑outs to sustain growth trajectories.
Competitive landscape — who to watch in 2026
The competitive set features a mix of specialist educational vendors, diversified optics manufacturers and global scientific brands. PW Consulting’s competitive profiles include capability maps, product roadmaps and distribution footprints for each of the principal companies listed below:
- AmScope — Irvine, CA, USA ( https://amscope.com). Well‑established in K‑12 and home education with robust compound and stereo offerings; recent product refreshes continue to emphasize classroom durability and LED illumination.
- OMAX Microscopes — Irvine, CA, USA ( https://omaxmicroscopes.com). Competitive pricing and an expanding digital portfolio (including Wi‑Fi enabled models) position OMAX as a fast follower for labs and educational institutions.
- Celestron — Torrance, CA, USA ( https://celestron.com). Known for accessible entry‑level models and portable designs that appeal to blended learning environments.
- Swift Microscopes — San Jose, CA, USA ( https://swiftmicroscopes.com). Focused on classroom‑grade durability and serviceability; active in education trade shows and channel partnerships.
- National Optical & Scientific Instruments (NOVA) — Skokie, IL, USA ( https://www.nationalmicroscope.com). Offers beginner models targeted at institutional buyers seeking standardized kits.
- Meiji Techno — Saitama, Japan ( https://meijitechno.com). Longstanding optics expertise combined with entry‑level models for biology education.
- Euromex — Arnhem, Netherlands ( https://www.euromex.com). European education specialist with compliance pedigree for school systems.
- Motic — Xiamen, China ( https://motic.com). Early mover in educational digital microscopes with integrated imaging options for labs and classrooms.
- Leica Microsystems — Wetzlar, Germany ( https://www.leica-microsystems.com). Premium educational models with modularity, strong service infrastructure and brand recognition in institutional procurement cycles.
- Olympus (Evident Scientific) — Tokyo, Japan ( https://evidentscientific.com). Ergonomically designed entry models that benefit from global service and reseller networks.
Recent signal events include product launches and catalog updates that show vendors accelerating digital and illumination improvements — examples include AmScope’s LED‑improved model releases, OMAX’s Wi‑Fi digital catalog enhancements, Swift’s trade‑show product showcases, and portable battery updates from Celestron. These actions indicate a 2026 product landscape that will reward software integration, ease of use, and serviceability.
Strategic playbook for 2026
Based on our analysis, the following moves are urgent for organizations planning 2026 strategy:
- Product packaging: Shift from hardware‑only SKUs to bundles that include imaging, classroom software licensing and teacher training. Price bundling can raise realized ASPs while locking in renewals.
- Localized assembly and risk mitigation: Diversify assembly footprints and qualify second‑tier suppliers for critical inputs such as borosilicate lens blanks to blunt raw material volatility.
- Certification roadmap: Prioritise ISO 10993 testing and CE marking timelines for product families you intend to sell into institutional tenders in 2026–2027.
- Channel incentives: Recalibrate distributor economics toward recurring revenue (consumables, service contracts) rather than one‑off hardware discounts.
- M&A and partnerships: Target bolt‑on acquisitions that add digital imaging IP, curriculum content, or local distribution in high‑growth education markets.
- Operational KPIs: Monitor lens unit costs, assembly labor per unit, time‑to‑certification, and software activation rates as leading indicators of commercial performance.
Scenario planning and investment implications
Use the 5.1% CAGR base case as your operational planning baseline for 2026. We recommend running two additional scenarios before committing capital:
- Upside: Faster adoption of integrated imaging and classroom software drives higher ASPs and penetration into non‑traditional channels (home education, maker spaces), compressing payback periods on product development spend.
- Downside: Material cost inflation, delayed certifications, or tender deferrals compress margins and extend inventory holding times — in this scenario, short‑cycle SKUs and flexible pricing become critical.
For investors and M&A teams, 2026 should be evaluated as a window to acquire software capabilities and distribution reach before these command premium multiples. For manufacturers, incremental investment in modular electronics and firmware testing will yield outsized returns relative to purely optical enhancements.
How PW Consulting can accelerate your 2026 agenda
PW Consulting provides executive workshops, practical diligence packages, and implementation sprints tailored to the student microscope value chain. Our services include commercially actionable growth plans, cost‑to‑serve optimization, RFP readiness for education tenders, and a M&A playbook that maps potential targets to quantified synergy scenarios.
For teams preparing strategic decisions in 2026 — whether you are a manufacturer seeking higher margins, a distributor optimizing channel mix, an education buyer formalizing procurement, or a private equity sponsor evaluating an add‑on — our report and tailored advisory engagements translate market intelligence into executable actions. Access to the full data tables, demand model, and competitive scorecards is available through PW Consulting’s report portal.
Closing observation
The Worldwide Student Microscopes Market is not merely growing; it is being reshaped. The transition from optics alone to integrated learning solutions, combined with pragmatic supply‑chain and certification constraints, creates a distinct set of winners. Firms that move in 2026 with a clear plan to monetize software, secure critical components, and accelerate certification will be best positioned to capture the upside of the projected growth trajectory.
For detailed analysis of this topic, please visit the official page: Worldwide Student Microscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Amino Acid Metabolism Disease Market Set to Grow at a 7.2% CAGR Through 2032, New Report Finds
By PW Consulting, 2026-07-15
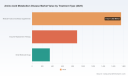
Worldwide Amino Acid Metabolism Disease Market — Strategic Insights for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest market research, with base year 2025 and a historical window covering 2020–2025 and forecasts through 2026–2032, delivers the strategic line of sight executives need to act confidently in 2026. The market we track — global commercial activity addressing inherited and acquired amino acid metabolism disorders — expanded from approximately USD 2,150.4 Million in 2020 to USD 2,990.8 Million in 2025. Under our central forecast the market continues to grow at a compound annual growth rate (CAGR) of 7.2%, reaching an expected USD 4,865.4 Million by 2032. These macro dynamics create a structural growth story for specialized therapeutics, medical foods, and next‑generation modalities while reshaping competitive and access landscapes that will determine winners and losers over the next planning cycle.
Worldwide Amino Acid Metabolism Disease Market
Why this report matters to corporate leaders in 2026
For biopharma strategy, corporate development, and commercial teams, 2026 is a pivot year. The market’s steady mid‑single‑digit real expansion masks accelerating pockets of opportunity driven by label expansions, self‑administration capabilities, late‑stage clinical programs, and the early commercial preparation for gene and enzyme therapies. At the same time, predictable headwinds — patent expirations on key biologics, supply chain dependencies for critical APIs, and nuanced payer rules for specialty products — require preemptive strategic moves.
Worldwide Amino Acid Metabolism Disease Market
PW Consulting’s report translates those macro dynamics into decision‑grade inputs: actionable go‑to‑market playbooks, investment prioritization matrices, payer evidence roadmaps, and M&A candidate shortlists calibrated to realistic success odds. The analysis is designed to reduce uncertainty where it matters most — product development prioritization, commercial launch sequencing, licensing negotiations, and manufacturing risk mitigation — without substituting for company-specific due diligence.
Worldwide Amino Acid Metabolism Disease Market
What the report contains — practical, execution‑oriented deliverables
- Proprietary demand model and scenario suite (base, upside, downside) covering 2026–2032 with sensitivity to price, reimbursement, and clinical readouts.
- Decision frameworks for portfolio prioritization: an investment checklist that ranks assets by clinical differentiation, payer risk, manufacturing complexity, and strategic fit.
- Commercial playbooks for rare‑disease launches: channel segmentation, patient‑centred adherence programs, and self‑administration enablement strategies designed to accelerate uptake while controlling cost‑to‑serve.
- Regulatory and reimbursement matrices mapping orphan exclusivities, likely HTA considerations, and payer levers across major markets to inform dossier design and real‑world evidence plans.
- Supply chain and manufacturing risk register: API concentration analysis, vendor qualification roadmaps, and options for vertical integration or secure long‑term supply agreements.
- Competitive and pipeline intelligence: structured profiles of incumbent and emergent players, trial readouts, and licensing/partnership opportunities.
- M&A and partnership playbook: valuation yardsticks, integration risk checklists, and prioritized target archetypes to accelerate inorganic growth.
- Investor‑grade slide decks and board briefing notes tailored to CFOs and CDOs — ready for 2026 budgeting and capital allocation cycles.
Competitive landscape — who matters and why
The market is moderately concentrated: the top three companies collectively represent a significant minority of global revenues, while the top five control a majority share. This concentration creates both barriers to entry and clear targets for strategic partnering or bolt‑on acquisitions.
- BioMarin Pharmaceutical Inc. — With established enzyme replacement and novel biologic programs, BioMarin remains a commercial and clinical bellwether. Recent regulatory progress expanding self‑administration options materially alters channel economics and patient convenience, lowering the barrier to broader ambulatory management and reducing infusion‑center dependency. Strategically, competitors should plan for accelerated patient uptake where self‑administration is both clinically appropriate and reimbursed.
- Travere Therapeutics, Inc. — Although focused historically on related rare renal and metabolic indications, Travere’s late‑stage readouts highlight the cross‑disciplinary value of shared modality expertise (e.g., small molecules impacting stone‑forming and amino acid aggregation pathways). Successes in adjacent rare disease trials signal potential platform applicability and make Travere an attractive partner for specialized formulations or formulation lifecycle assets.
- Chiesi Farmaceutici S.p.A. — As the steward of nitisinone in tyrosinemia, Chiesi’s control over established manufacturing routes and pediatric formulations (including oral suspension approvals) underscores the importance of formulation know‑how in pediatric rare disease markets. Their supply chain position also speaks to potential sourcing risks for competitors dependent on similar APIs.
- Recordati Rare Diseases — Speciality small molecules addressing metabolic crises and acute care settings remain commercially durable. Recordati’s portfolio illustrates the value of tight integration between hospital‑based formularies, emergency medicine protocols, and specialty pharmacy supply chains.
- Dimension/Takeda and LogicBio/AstraZeneca — Acquisitions and in‑licensing of gene therapy platforms have rapidly reshaped the long‑term competitive set. These larger players bring development scale, global commercial reach, and balance‑sheet capacity to shepherd first‑in‑class genetic interventions through commercialization once regulatory and reimbursement pathways mature.
- PTC Therapeutics — Late‑stage clinical activity in transporter and cofactor replacement strategies highlights the expanding modality mix in amino acid disorders: not only enzyme replacement and medical nutrition, but also small molecules that modulate intracellular pathways. Monitoring PTC’s Phase 3 trajectory is essential for competitive forecasting.
Recent developments and regulatory context — implications for 2026 planning
- Label expansions and administration flexibility are changing commercial math — recent approvals enabling self‑administration materially reduce the service cost for some biologics and can speed market penetration when combined with patient support programs.
- Orphan designations and exclusivities remain powerful de‑risking mechanisms: sponsors with granted designations should factor exclusivity windows into pricing and partnership strategies while preparing for post‑exclusivity competition several years ahead.
- API and formulation patents create practical entry hurdles. Where synthesis routes or process IP are concentrated with incumbent manufacturers, strategic buyers should prioritize supply security (e.g., CMOs, backward integration, or exclusive supply agreements) as part of valuation and integration planning.
- Gene therapies show high strategic promise but — as of the start of 2026 — remain constrained to clinical trial use in several indications. Commercial readiness plans should therefore include extended development cost scenarios and payer evidence generation roadmaps to bridge clinical validation and reimbursement acceptance.
- Payer behavior remains heterogeneous: certain branded therapies are covered under public programs with utilization controls. Market access teams must be prepared to demonstrate clinical and economic benefit to secure predictable uptake in both public and private payer systems.
Strategic implications — what to do in 2026
- Adopt a two‑track portfolio strategy: accelerate differentiated biologics and advanced modalities that can command premium access, while maintaining selective exposure to durable, lower‑risk franchises (e.g., acute care small molecules or medical nutrition) to stabilize revenue streams.
- Secure supply chains now: where APIs or critical formulation know‑how are concentrated, negotiate multi‑year agreements, diversify to qualified alternate manufacturers, or evaluate acquisition of upstream capabilities to prevent launch disruptions and margin erosion.
- Design evidence generation to payers’ expectations: invest in pragmatic trials and real‑world evidence programs that address head‑to‑head effectiveness, health‑economic outcomes, and adherence in ambulatory self‑administration models.
- Price strategically around exclusivity cliffs: align commercial launches and lifecycle investments with patent timelines and orphan‑exclusivity windows to maximize value capture while planning for post‑exclusivity competitive scenarios.
- Pursue creative partnerships: for mid‑sized companies, partnering with large multispecialty players or forming cross‑asset alliances can accelerate market access and global reach while sharing development risk for next‑generation gene therapies.
- Use scenario planning for capital allocation: with a mid‑cycle CAGR near 7.2% and meaningful upside from successful late‑stage programs, capital deployment should balance near‑term commercialization support with optionality to scale manufacturing and evidence generation for transformative modalities.
Final outlook and how to use this report
The amino acid metabolism disease market presents a classic rare‑disease growth narrative: steady baseline expansion amplified by a handful of high‑impact clinical and regulatory inflection points. For 2026 planning cycles, the priority for executives is clear — convert market tailwinds into durable competitive advantage by securing supply, aligning evidence generation with payer needs, and selectively investing in modalities that change the standard of care.
PW Consulting’s Worldwide Amino Acid Metabolism Disease Market report is built to be operational: it pairs a rigorous quantitative forecast (USD figures in Millions, base year 2025) and a suite of decision tools with granular competitive and regulatory intelligence. To preserve the strategic value of the underlying segment and company models for clients, detailed segmentation outputs and proprietary company valuations are reserved for the full report and advisory engagements.
Contact PW Consulting to request the full report, bespoke scenario runs, or an executive briefing tailored to your company’s portfolio and growth objectives for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Metabolism Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide AI Learning Machine Market Set to Reach USD 8.9 Billion in 2025 on a 21.08% CAGR — Asia Pacific Leads with $4.11B
By PW Consulting, 2026-07-15
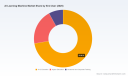
Worldwide AI Learning Machine Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide AI Learning Machine market is designed as a strategic compass for corporate leaders, product strategists, and public-sector planners anticipating rapid change in 2026. Our analysis combines rigorous historical tracking (2020–2025), forward-looking forecasting (2026–2032), and actionable scenario planning to translate technology trends into boardroom decisions. This briefing highlights the report’s strategic value, core competitive dynamics, and the operational levers enterprises should prioritize next year — while reserving detailed segmentation tables and proprietary forecasts for the full report.
Worldwide AI Learning Machine Market
What the headline numbers mean for strategy
The market for AI learning machines has matured from niche experimentation into a scale sector. By our accounting, the worldwide market reached USD 8,900 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 21.08% over the 2026–2032 period, reaching a multi‑billion‑dollar watershed by 2032. That pace is not merely growth; it is market formation. For 2026, the implied acceleration signals a tipping point where product portfolios, channel models, content strategies, and regulatory alignment materially influence winners and losers.
Worldwide AI Learning Machine Market
Why 2026 is a decision inflection point
- Commercial velocity: High-teens to low‑twenties CAGR implies revenue pools large enough to warrant dedicated go‑to‑market teams, differentiated hardware roadmaps, and bespoke content partnerships rather than one-off pilots.
- Product convergence: Hardware, embedded large models, and curriculum-aligned content are converging. Vendors that unify learning science, model safety, and compelling UX will capture disproportionate share.
- Regulatory crystallization: Emerging standards and education ministry directives are converting regulatory risk into commercial constraints and, simultaneously, barriers to entry for latecomers.
Strategic implications for enterprise decision-makers
Executives considering entry, expansion, or partnership in 2026 must treat the AI learning machine opportunity as a systems play — not a single-product bet. The market dynamics favor organizations that can orchestrate four interdependent capabilities:
Worldwide AI Learning Machine Market
- Model & content governance: Compliance with machine‑learning security standards and content safety rules is table stakes. Embed governance into product development lifecycles to avoid reactive remediations that erode trust and margins.
- Hardware-software integration: Because AI learning experiences depend on low-latency inference, effective thermal and compute design choices impact cost, battery life, and classroom usability. Strategic sourcing and long‑term silicon partnerships matter more than ever.
- Distribution & channel strategies: Channel economics are shifting — from retail and school procurement to subscription-enabled direct-to-home models and content bundles. Optimize pricing, service tiers, and after-sales education services to maximize lifetime value.
- Localized content partnerships: Exclusive content and curriculum alignment are competitive moats. Rights-managed content can accelerate adoption in education markets where cultural fit and syllabus congruence influence buying decisions.
Competitive landscape — what the leaders are signaling
Market concentration metrics indicate a moderately fragmented field, with the top three players accounting for roughly 39% of the market and the top five capturing just over half. That structure supports both incumbent dominance in core segments and rapid disruption through specialized plays.
Key strategic behaviors observed among frontrunners:
- End-to-end platform control: Several large education incumbents are integrating proprietary large models, hardware form factors, and curriculum‑level content to create sticky ecosystems that combine tutoring, diagnostics, and parental analytics.
- Content exclusivity and co‑development: Strategic content licensing and co‑creation are being used to differentiate product offerings and justify premium pricing tiers.
- Service and subscription layering: Companies are moving beyond device sales into subscription content, assessment-as-a-service, and teacher-assist tools that increase recurring revenue.
Profiles and implications — selected competitors (strategic takeaways)
- iFLYTEK (Hefei, China) — Strategy: Deep vertical integration of cognitive models with domain-optimized tutoring. Tactics: Rapid content partnerships to enhance language exposure and differentiated UX. Implication: Their combination of proprietary models and exclusive content highlights how alliances can be converted into conversion funnels — a playbook for firms seeking scale through content lock-in.
- Yuanfudao (Xiaoyuan, Beijing) — Strategy: Device-plus-robotic-base ergonomics to enhance interactivity and diagnostics. Tactics: Emphasis on emotional interaction and homework scanning that creates habitual usage. Implication: Products that blend hardware movement and multimodal sensing can command higher engagement, a proxy for upsell into services.
- Zuoyebang (Beijing) — Strategy: Strong focus on homework assistance and companionship features. Implication: Emotional and behavioral design can be a differentiator in K‑12 segments where parental acceptance matters as much as pedagogical efficacy.
- TAL Education Group (Xueda/Xueersi, Beijing) — Strategy: Leverage brand recognition and classroom content to extend into hardware with adaptive learning models. Implication: Established education brands can rapidly monetize trust by bundling devices with existing curricula.
- BBK (China) — Strategy: Consumer hardware expertise applied to education devices, emphasizing screen ergonomics and curriculum synchronization. Implication: Consumer OEMs can undercut on cost while still achieving differentiated ergonomics demanded by parents and schools.
- Readboy & Xiaodu (Baidu) — Strategy: Mix of traditional hardware suppliers upgrading to AI and platform players integrating voice and search capabilities. Implication: Expect continuing convergence between classic edtech form factors and smart assistant capabilities.
Regulatory, supply, and policy dynamics that will shape outcomes in 2026
- Standards & safety: New national standards for algorithmic security and generative AI safety are moving from policy into procurement checklists. Vendors without documented compliance frameworks will suffer elongated sales cycles or exclusion from institutional contracts.
- Curriculum policy shifts: Government directives to embed AI literacy in school curricula create both a demand multiplier and a quality filter: educational policy will favor devices and content that demonstrably align with mandated learning outcomes.
- Trade and hardware constraints: Export controls on advanced semiconductors create uneven access to the highest-performance inferencing stacks. This will accelerate architectural diversification — hybrid on-device / cloud inference models — and premium pricing for devices that can claim superior offline capabilities.
- Behavioral policy impacts: Measures that limit certain forms of offline tutoring have already redirected demand to compliant at-home learning devices, reshaping the pricing and packaging calculus for vendors and education providers.
What PW Consulting’s full report contains (practical utility)
The full report is an operational toolkit for 2026 planning, including:
- Comprehensive market model with historical performance and scenario-based forecasts through 2032;
- Stakeholder maps for channels, content licensors, and procurement authorities that illuminate negotiation levers and partnership economics;
- Go‑to‑market playbooks for hardware OEMs, content owners, and platform operators, with pricing experiments and subscription bundling options;
- Regulatory compliance checklists and a risk mitigation matrix tied to emerging standards and education ministry directives;
- Product and technology decision frameworks comparing on-device, cloud-hybrid, and edge-accelerated architectures against cost, latency, and data-governance tradeoffs;
- Case studies of successful launches and failed pilots with root-cause analyses and recovery prescriptions;
- Interactive scenario workbooks that allow executives to stress-test entry timing, capex needs, and channel investments under multiple regulatory and supply constraints.
Note: The report intentionally reserves detailed regional and application-level breakdowns for subscribers. These granular tables — including proprietary share estimates across regions, product types, and end-user categories — are pivotal to tactical entry and pricing decisions and are accessible via the full report.
How to use this intelligence in 2026
- Board briefings: Use the executive scenarios to set investment gates and decide whether to lead with hardware, content, or platform plays.
- R&D prioritization: Reallocate engineering effort to model governance, offline inference efficiency, and UX flows that reduce teacher friction.
- Partnership sequencing: Prioritize content deals that provide curriculum alignment over one-off entertainment licenses; evaluate exclusivity only where it materially accelerates adoption.
- Regulatory readiness: Establish a compliance roadmap and evidence repository that can be handed to procurement teams to shorten institutional sales cycles.
Conclusion — the operational choice ahead
2026 will separate incumbents with disciplined, system-level strategies from fast followers that rely on product novelty alone. The market’s growth trajectory creates large addressable opportunities, but realizing them requires integrating governance, content, distribution, and hardware strategy. PW Consulting’s Worldwide AI Learning Machine Market report provides the tactical scaffolding and decision-ready analytics necessary to convert 2026’s momentum into enduring competitive advantage.
For access to the full dataset, granular segment tables, and subscription options for ongoing scenario updates, visit the report landing page. PW Consulting will continue to publish monthly tracker notes through 2026 to help clients navigate this rapidly evolving landscape.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Estate Agent Fees to Reach USD 331.58 Billion in 2025, Growing at 4.5% CAGR to USD 451.24 Billion by 2032
By PW Consulting, 2026-07-15
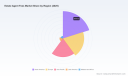
Worldwide Estate Agent Fees Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting today publishes its Worldwide Estate Agent Fees Market report, an actionable intelligence product designed to inform executive decision-making as organisations enter 2026. Built on a 2025 base and a disciplined historical series (2020–2025), the study presents a global market sizing and forward projection that places the market at USD 331.58 Billion in 2025, growing to an estimated USD 451.24 Billion by 2032 on a 4.5% compound annual growth rate (CAGR). The trajectory reflects a mature but evolving marketplace where structural forces — regulation, digitisation and labour economics — are re-shaping how fees are set, disclosed and captured across channels.
Worldwide Estate Agent Fees Market
Why 2026 is a pivotal year
Two dynamics make 2026 a watershed for fee strategy. First, regulatory reform enacted in major jurisdictions during 2023–2024 has redefined how commissions are negotiated and disclosed, upending incumbent fee arrangements and accelerating experimentation with decoupled, bilateral buyer-seller agreements. Second, technology-enabled platforms and new agent compensation models are compressing traditional margins while expanding addressable services (leasing, property management, ancillary transaction services). Together these trends create both downside risk for legacy commission models and upside for firms that rapidly reconfigure pricing and go-to-market models.
Worldwide Estate Agent Fees Market
Executives must therefore treat 2026 as a transition year: where the pace of regulatory enforcement and consumer expectations will determine which business models scale and which are relegated to niche roles. Our report quantifies the market-wide implications of these shifts and translates them into decision-ready options for boards, corporate development teams and operating executives.
Worldwide Estate Agent Fees Market
What PW Consulting’s report delivers — practical, executable intelligence
- Robust market sizing and validated forecasts (2026–2032), including sensitivity runs tied to regulatory and macro-economic scenarios.
- A modular benchmarking toolkit that enables quick comparison of fee structures, channel economics and service-margin ladders against best-practice peers.
- Segment-level playbooks (residential, commercial, industrial, leasing and property management) focused on revenue migration, bundling and upsell tactics — presented as executable pilots rather than academic recommendations.
- Regulatory risk heatmaps that map jurisdictional enforcement probability to near-term P&L impact, enabling prioritised compliance and lobbying strategies.
- Agent economics models that reconcile pay mix, attrition drivers and productivity levers, with implementation-ready compensation templates.
- Technology ROI frameworks that quantify breakeven points for marketplace, CRM and transaction platforms under multiple adoption curves.
- An M&A and partnership playbook with target archetypes (scale consolidators, vertical specialists, tech enablers) and diligence checklists calibrated to fee-runway risk.
- Proprietary scenario workbooks in Excel for boardroom “what-if” analysis and investor briefings.
Competitive landscape — how incumbents and disruptors are likely to respond
The market’s competitive structure remains fragmented, with the top few players collectively holding a modest share of global fee pools. This fragmentation underpins opportunity for both consolidation and differentiation.
- RE/MAX International (Denver) — A long-established global franchise network that leverages local brand recognition and a distributed agent base. Their strategic play will likely emphasise tightening franchise standards and technology-enabled lead-conversion tools to defend margins as retail fee expectations shift. ( https://global.remax.com/)
- Century 21 Real Estate (Madison, NJ) — An extensive international brand operating through local offices; its advantage lies in cross-border brand equity and standardised operating playbooks. Expect continued focus on hybrid franchising and selective service-bundling to protect residential fee pools. ( https://www.century21.com/)
- Keller Williams Realty (Austin) — The agent-centric ownership model provides a built-in alignment lever for redesigning commission splits and experimenting with subscription or cap-based remuneration. Their response is likely to prioritise recruitment and retention through attractive agent economics tied to tech-enabled productivity gains. ( https://kw.com/)
- Coldwell Banker (Madison, NJ) — Positioned in the upper tiers of the market, Coldwell Banker will place emphasis on premium listing services, concierge offerings and integrated marketing for high-value transactions to protect average fee realisation. ( https://www.coldwellbanker.com/)
- eXp Realty (Bellingham) — A cloud-native brokerage that uses virtual operating models to lower fixed costs and experiment with low-transaction-fee structures; its scale-enabled economics make it a natural aggressor on price and commission innovation. ( https://exprealty.com/)
- Savills (London) — An international services firm leveraging advisory breadth to cross-sell fee-based services such as valuation and advisory, thereby diversifying revenue away from transaction-only models. ( https://www.savills.com/)
- Knight Frank (London) — A consultancy-led approach focused on high-value residential and commercial mandates; strategic levers will include exclusivity packaging and bespoke value-added services to justify premium fee bands. ( https://www.knightfrank.com/)
- Berkshire Hathaway HomeServices (Omaha) — A premium residential network that will likely emphasise reputation and referral economics while selectively piloting alternative fee structures in competitive markets. ( https://www.berkshirehathawayhs.com/)
Collectively, these firms illustrate the range of strategic responses available: defend via premiumisation, disrupt via low-cost/virtual models, or diversify via advisory and ancillary service bundling. Our report maps which response archetypes have the best probability of success by market context and regulatory environment.
Regulatory and consumer dynamics to watch closely
- High-impact regulatory actions in 2024–2025 have altered transaction norms in core markets and will continue to cascade internationally. Firms must operationalise new disclosure and agreement workflows immediately to avoid transactional friction and penalties.
- Consumer cost-sensitivity is increasing in select mature markets; transparency and channel choice (sole vs. multi-agency, fixed-fee vs. percentage) are becoming decision drivers. Pricing experiments must therefore be coupled with value communication frameworks.
- Labour economics — specifically agent remuneration levels and employment dynamics — are a structural cost lever. Employers who redesign agent contracts toward productivity incentives, training and platform-enabled leads will capture disproportionate share of listings.
Strategic playbook for 2026 (recommended priorities)
- Immediate: Audit fee disclosure and buyer-broker agreement processes; implement standardised written agreements where legally required and recommended elsewhere to reduce transactional risk.
- Near-term (0–12 months): Launch controlled pricing experiments in representative markets — fixed-fee pilots, tiered service bundles and subscription-based offerings — with rigorous A/B measurement and cohort tracking.
- Medium-term (12–36 months): Invest in agent enablement technology (lead scoring, virtual showings, automated contracts) and redesign commission frameworks to reward conversion and retention, not just listing placement.
- Capital strategy: Prioritise acquisitions that add margin-accretive services (property management, valuation platforms, mortgage distribution) and partnerships with fintech players to capture downstream revenue.
- Communications: Reframe consumer messaging around outcomes and certainty rather than headline commission numbers; transparency must be a competitive advantage, not a liability.
- Scenario planning: Build three stress-test scenarios (baseline, regulatory shock, rapid virtual adoption) and align liquidity plans to each; the report provides ready-to-use financial templates for this purpose.
Market structure insight
Despite the presence of several recognisable global brands, global fee pools exhibit low to moderate concentration — a fact that underlies both competitive pressure and M&A opportunity. Fragmentation means scale still matters (for brand, distribution and tech investment), but local incumbency and service differentiation remain powerful defences against commoditisation.
How this report should be used by executives
Use this report as a decision accelerator: for corporate strategy refreshes, M&A screening, commercial model re-writes, and regulatory preparedness. It converts market-level growth and risk into board-ready options with quantified payoffs and implementation roadmaps. For consulting engagements, the report’s scenario workbooks and the competitive playbook provide immediate foundations for rapid pilots and investment memos.
Next steps — obtain the full intelligence
This press briefing is intended to highlight the strategic imperatives and the value of the underlying analysis. The full Worldwide Estate Agent Fees Market report contains the granular regional, property-type and service-type splits, detailed competitive benchmarking, and downloadable financial models that underpin the recommendations summarised here. PW Consulting offers tailored briefing sessions and implementation workshops for leadership teams that require interactive walkthroughs of the scenarios and playbooks.
To access the complete report and arrange a strategic briefing with PW Consulting’s real estate practice, please visit our website or contact our industry team. For 2026, moving from analysis to structured pilots will determine which organisations protect margin and which cede price leadership to more agile competitors.
For detailed analysis of this topic, please visit the official page: Worldwide Estate Agent Fees Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Materials Recovery Facility Market Poised for 6.61% CAGR Through 2032
By PW Consulting, 2026-07-15
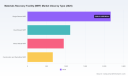
Worldwide MRF Market 2026: Strategic Preview for Executives — What to Know Before You Commit Capital
PW Consulting’s latest market intelligence on Worldwide Materials Recovery Facilities (MRFs) is designed as a strategic primer for boards, corporate strategy teams, infrastructure investors, and public-sector planners preparing decisions in 2026. Our analysis synthesizes historical performance (2020–2025), a forward-looking forecast (2026–2032) and an actionable playbook distilled from site-level economics, technology trajectories, policy shifts, and supplier capabilities. Key macro takeaways: the global MRF market is on a sustained expansion path with a compound annual growth rate (CAGR) of 6.61%, rising from roughly USD 4.9 billion in 2025 to an expected USD 7.65 billion by 2032. This preview highlights the strategic imperatives and tactical questions the full report answers; it intentionally omits detailed segment-level allocations to encourage review of the complete dataset and modelling assumptions available on our report portal.
Worldwide Materials Recovery Facility (MRF) Market
Why this report matters for 2026 decision cycles
-
Capital allocation timing: The market’s mid-single-digit CAGR translates into windows where early movers capture outsized capacity, technology, and offtake advantages. Our modelling identifies where near-term investments yield differentiated returns under multiple policy and commodity scenarios.
Worldwide Materials Recovery Facility (MRF) Market -
Policy-driven demand: Recent regulatory shifts—especially tighter enforcement of separate-collection mandates in major economic blocs and stricter rules on transboundary waste flows—have materially altered the pipeline for MRF upgrades and greenfield projects. The report quantifies the implied capacity needs and procurement timing without exposing sensitive project-level data here.
Worldwide Materials Recovery Facility (MRF) Market -
Technology transition: Sensor-based sorting, AI-driven robotics, and modular plant design are moving from pilot to scale. Understanding deployment trade-offs (throughput, purity, lifecycle economics) is essential for procurement strategies; we provide vendor scorecards and integration templates to de-risk rollouts.
Market trajectory and macro drivers
From 2020 through 2025 the market experienced steady expansion with episodic uplifts tied to policy acts and commodity cycles. Looking into 2026–2032, growth is driven by three overlapping forces: regulatory compliance and collection mandates, capital replacement and modernization of aging infrastructure in established markets, and rising domestic MRF investments in markets formerly reliant on exports. Those dynamics are amplified by cost pressures: raw-material price volatility and rising labor costs have compressed feedstock economics and increased the premium on automation and process optimization.
Our forecast scenario set projects the global market rising to approximately USD 7.65 billion by 2032, reflecting the compounding effects of mandated collection schemes and steady replacement demand. Importantly, market concentration remains relatively low — our CR3 and CR5 measures indicate a fragmented competitive landscape where regional integrators and equipment specialists coexist with global systems suppliers. That fragmentation shapes contracting strategies: owners often balance turnkey relationships with modular procurement to preserve optionality.
What the full report contains — practical, investible deliverables
-
Decision-ready dashboards: Executive scorecards that translate technical performance (throughput, recovery rates, sort purity) into financial outcomes (IRR, payback under multiple commodity price and labor-cost scenarios).
-
Tender and procurement blueprints: Standardized RFP templates and vendor-evaluation matrices aligned to plant typologies—single-stream, dual-stream, mixed-waste and construction‑&‑demolition—so owners can accelerate procurement without re-inventing specifications.
-
CapEx and OpEx benchmarking: Site-level baseline models calibrated to recent deployments and vendor equipment families to stress-test automation levels and labor-content trade-offs.
-
Technology adoption roadmaps: A staged deployment playbook for sensor sorting, AI robotics, ballistic separators, and modular conveyors including integration checklists and common failure modes learned from recent commissioning projects.
-
Regulatory impact matrix: A map of policy levers (collection mandates, import/export rules, extended producer responsibility) and their quantified effect on MRF throughput and commodity mix across our forecast horizon.
-
Risk and mitigation toolkit: Scenario-based risk registers covering feedstock price shocks, permit delays, and supply-chain constraints, plus contracting templates that shift specific risks to suppliers or insurers.
Competitive landscape — what suppliers are doing and why it matters
The supplier field combines specialist equipment manufacturers and end-to-end integrators. Rather than present exhaustive scorecards here, we surface strategic posture and recent moves that should inform procurement and partnership strategies:
-
CP Group continues to scale turnkey capacity with new high-throughput single-stream installations in North America, signaling confidence in demand for large, integrated plants and offering opportunities for owners seeking single-vendor accountability.
-
Tomra is accelerating sensor-based innovation with its next-generation optical sorter, which promises step-change gains in plastic recovery — a tech path that reduces downstream manual sort labour and increases commodity quality premiums.
-
Bulk Handling Systems (BHS) is pushing AI-driven robotics and securing certifications that ease adoption risk in high-throughput environments, a factor that shortlists them for operators prioritizing robotic automation.
-
Metso and STADLER are competing with modular, adaptable plant architectures that enable staged investment; vendors like these appeal to fiscally constrained municipalities or private owners seeking predictable upgrade paths.
-
Regional specialists such as Machinex, Van Dyk, and Eggersmann maintain strong local service footprints, which sustains their relevance for projects where uptime and spare-part responsiveness are critical.
Collectively, recent vendor developments (new product launches, capacity additions, certifications and contract awards) point to two concurrent trends: (1) differentiation through advanced sorting and automation, and (2) a market that rewards integrated delivery capability and local after-sales support. Our full vendor matrix provides comparative metrics on throughput, automation level, energy intensity and parts‑availability lead times to support supplier selection decisions.
Strategic implications for 2026 decision-makers
-
Prioritise modularity in procurement. Given policy uncertainty and technology change, structuring projects as modular investments reduces sunk capital risk and allows staged technology insertion as new sorting systems prove out.
-
Value automation where labour cost inflation and feedstock contamination constrain margins. Use our CapEx/OpEx models to calculate the marginal return of robotics and sensor layers versus labour retention in high-volume lines.
-
Layer policy hedges into off-take and financing. Where collection mandates increase feedstock volumes but price volatility persists, contract structures that index payments or include take-or-pay features reduce owner exposure.
-
Invest in supplier integration capabilities. Owners who can manage systems integration, commissioning and continuous improvement programs will extract higher recovery rates and operational resilience from the same hardware base.
-
Plan for circularity beyond the MRF gate. Capturing higher-value streams requires downstream partnerships (reclaimers, compounders) and product design engagement with brand owners under extended producer responsibility models.
How to use this intelligence in 90 days
-
Phase 1 (0–30 days): Run the decision-ready dashboard on candidate projects to compare IRR under low, base, and high commodity scenarios; identify projects that justify immediate procurement activity.
-
Phase 2 (30–60 days): Issue targeted RFPs using our procurement templates to a short list of vendors; include performance-based acceptance criteria tied to recovery and purity outcomes.
-
Phase 3 (60–90 days): Finalize contracts with staged payment structures, import spare‑parts commitments, and agreed performance improvement roadmaps; align financing to the project’s staged CAPEX profile.
What the preview omits — and why you should read the full report
This release intentionally previews strategic conclusions and high-level modelling results while omitting the detailed region- and application-level splits, project-level unit economics and proprietary segment share tables that underpin our procurement templates and vendor scoring. Those detailed tables — essential for procurement negotiations, investor due diligence, and bid evaluation — are available in the full PW Consulting report and the interactive data workbook accessible via our report portal.
Closing perspective
For executives making capacity, technology, or M&A choices in 2026, accurate timing and an evidence-based vendor strategy are the primary determinants of success. The MRF market offers growth and upside, but it is also characterized by fragmentation, technology evolution, and policy-driven inflection points. PW Consulting’s Worldwide MRF Market report is structured to transform those complexities into executable plans — from RFP to commissioning, and from plant economics to circular‑value capture. To move from insight to action, access the full report and the interactive modelling toolkit on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Materials Recovery Facility (MRF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Livestock Diagnostics Kits Market to Rise from USD 1,845.5 Million in 2025 to USD 3,162.9 Million by 2032 at an 8.0% CAGR
By PW Consulting, 2026-07-15
Worldwide Livestock Diagnostics Kits Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s new market study on Worldwide Livestock Diagnostics Kits (base year 2025, historical 2020–2025; forecast 2026–2032) reframes how executives should interpret investment risk and commercial opportunity in animal health diagnostics. The market reached approximately USD 1,845.5 Million in 2025 and, under our central scenario, is projected to expand at a compound annual growth rate (CAGR) of roughly 8.0% through 2032 — approaching a USD 3.16 billion run‑rate by the end of the forecast window. Market concentration is meaningful but not prohibitive: the top three and top five vendors account for a plurality of supply (CR3 ≈ 48.2%; CR5 ≈ 59.4%), leaving space for specialist entrants and regional champions.
Worldwide Livestock Diagnostics Kits Market
This communiqué follows a “trailer” logic: it surfaces the strategic insights and operational frameworks that matter for 2026 decisions while intentionally withholding granular sub‑segment tables and region/application breakdowns—those are available in the full report. Below, we translate the sizeable macro trend into pragmatic choices boardrooms need to make this year.
Worldwide Livestock Diagnostics Kits Market
Why this report matters to executives in 2026
- Investment clarity: quantifies a durable, mid‑single‑digit to high‑single‑digit growth runway that supports capex on platform development and scaled manufacturing.
- Portfolio prioritization: tells R&D leaders whether to double down on molecular multiplexing, point‑of‑care lateral flow, or integrated serology platforms.
- Commercial timing: helps sales and distribution leaders decide when to accelerate rollouts of cartridge/cartridge‑like systems versus low‑cost rapid tests.
- Regulatory risk management: maps compliance levers and export constraints that materially affect cross‑border revenues.
Market dynamics shaping 2026 strategy
Three structural forces are defining winners and losers in livestock diagnostics:
Worldwide Livestock Diagnostics Kits Market
- Technology convergence: multiplex PCR panels and advanced lateral flow assays are narrowing the trade‑off between accuracy, speed, and cost. Industry data indicate on‑farm tests are routinely approaching high‑90s accuracy and delivering results in under 15 minutes for many use cases—transforming everyday biosecurity and herd management decisions.
- Regulatory harmonization and trade conditioning: international bodies are standardizing validation pathways. The World Organisation for Animal Health (WOAH) now maintains a register with a standardized validation procedure for infectious disease tests; meanwhile, updated guidance from USDA APHIS sets clearer expectations for production and expiration‑dating of immunodiagnostic kits. These developments reduce technical uncertainty but raise the bar for dossier completeness—meaning R&D and regulatory teams must plan longer lead times and higher documentation quality for market access.
- Commercialization of point‑of‑care platforms: cartridgeized, AI‑assisted hematology and diagnostic analyzers have reached commercial maturity, shifting value from single‑use reagent sales to recurring cartridge and service revenue models.
Competitive landscape — strategic positioning of core vendors
The supplier landscape blends global platform incumbents, diagnostic specialists, and vertically integrated animal‑health companies. The leading players profiled in our study illustrate three repeatable strategic archetypes:
- Platform integrators (e.g., Thermo Fisher Scientific, Bio‑Rad): competing on breadth of molecular and serological capability, deep lab channels, and regulated‑market credibility. Their strength is end‑to‑end validation and large‑scale manufacturing capacity.
- Veterinary native champions (e.g., IDEXX Laboratories, Zoetis, Neogen): leveraging strong field networks, practitioner trust, and an ability to commercialize point‑of‑care and rapid immunoassays directly into farms and clinics.
- Specialists and regional innovators (e.g., Indical Bioscience, IDvet, Eurofins Technologies): focused on high‑value niches—zoonotic surveillance, specific pathogen panels, or laboratory services that complement reagent sales.
Recent product moves underscore near‑term competitive pressure. Zoetis’ introduction of a cartridge‑based, AI‑enhanced hematology analyzer signals aggressive pursuit of recurring consumables and device integration; IDEXX’s recent diagnostic panel launches highlight a strategy of leveraging existing customer trust to expand into adjacent disease monitoring segments. For incumbents and challengers alike, the key questions are: can you secure recurring revenue via consumables and platform subscriptions, and how quickly can you scale regulatory dossiers for export markets?
Strategic implications for R&D, manufacturing, and commercial leaders
- R&D: Prioritize modular platforms that allow rapid swapping of assay panels. Multiplexing and assay‑agnostic cartridges reduce time‑to‑market for novel pathogen coverage.
- Manufacturing & supply chain: De‑risk critical raw materials and reagent suppliers—single‑source constraints will bottleneck scale. Consider dual sourcing or co‑located fill/finish facilities in export hubs to shorten lead times and satisfy importing country validation requirements.
- Commercial: Move from one‑off instrument sales to bundled service models (device + cartridges + analytics). Training and after‑sales service are difference‑makers for adoption among large producers and veterinary networks.
- Regulatory & trade: Invest in dossier quality aligned to WOAH and USDA APHIS expectations now, not later. Exportability is often a function of preemptive compliance with international validation protocols.
What PW Consulting’s full report contains (practical deliverables)
Our market study is structured to be immediately actionable for 2026 planning cycles. Highlights include:
- Scenario‑based revenue models and sensitivity testing calibrated to a base 8.0% CAGR (2026–2032).
- Competitive benchmarks and product matrices for the 15+ suppliers we profiled—covering technology mix, route‑to‑market, and regulatory posture.
- Commercial playbooks: go‑to‑market options for platform launches, price‑stack templates, and channel partnership models for labs, integrators, and large farms.
- Regulatory roadmap templates aligned to WOAH and USDA standards and a checklist for export readiness.
- M&A and partnership screening tool: target archetypes where acquisition adds meaningful differentiation or accelerates market entry without eroding margin structure.
How to convert insight into 2026 decisions — five tactical moves
- Lock in consumable economics: model multiple pricing tiers for cartridges and reagents; stress‑test profitability against variable adoption rates among large producers.
- Accelerate validation pipelines: allocate budget to prepare WOAH‑compatible validation studies in parallel with domestic submissions.
- Pilot integrated POC solutions with anchor customers: prioritize one or two large herd clients for real‑world performance validation and case studies that shorten sales cycles.
- Hedge supply risk with strategic sourcing: identify critical reagent and plastic consumable suppliers and qualify alternatives within a 9–12 month timeframe.
- Use analytics as a moat: embed basic AI/analytics into instruments (as seen in recent product launches) to capture farm‑level usage data and justify recurring fees.
Methodology and confidence
Our estimates combine bottom‑up revenue modeling from manufacturer disclosures and market activity, primary interviews with industry stakeholders, and validation against public institutional inputs (WOAH registers, USDA APHIS memoranda, and major veterinary diagnostic laboratory guidance). We report historical performance for 2020–2025 and provide a transparent forecast through 2032 with scenario and sensitivity layers. Certain granular sub‑segment tables (region by technology by animal type) are intentionally withheld from this summary to preserve the design of this précis as an executive teaser—the full dataset and interactive model are provided to report purchasers.
Final perspective — how to read the 2026 opportunity
The livestock diagnostics kits market in 2026 is both mature and nascent: mature in that proven molecular and serological platforms dominate lab workflows; nascent in the rapid growth and monetization of on‑farm, cartridgeized diagnostics and analytics. The 8.0% CAGR we model reflects a market where technological improvement, regulatory alignment, and rising biosecurity investment converge to expand addressable demand. For market participants, the decision levers are clear — control consumable economics, accelerate validation for exportability, and convert instrument sales into recurring revenue streams through integrated services and analytics.
Next steps
For procurement, R&D, and strategy teams preparing 2026 budgets, the full PW Consulting report provides the granular splits, downloadable model, and competitive scorecards necessary to make defensible investment decisions. To access the complete intelligence — including regional, technology and animal‑type breakouts, full company profiles, and the interactive forecast model — please visit the PW Consulting report page linked from our corporate site.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Livestock Diagnostics Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Stearyl Methacrylate Market to Rise from USD 163.1 Million in 2025 to USD 236.94 Million by 2032, Backed by a 5.48% CAGR
By PW Consulting, 2026-07-15
Worldwide Stearyl Methacrylate (SMA) Market — Strategic Outlook for 2026 Decisions
Executive teaser
PW Consulting’s new market intelligence brief on the Worldwide Stearyl Methacrylate (SMA) market delivers a focused, actionable view intended to inform executive decisions in 2026. Built on a base year of 2025, our model shows SMA growing from an estimated USD 163.1 Million in 2025 at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 forecast window, reaching a projected market size of approximately USD 236.94 Million by 2032. Historical context in the report traces the market from 2020’s baseline through 2025, demonstrating steady expansion driven by industrial lubricant formulations, personal care applications, and specialty coatings demand.
Worldwide Stearyl Methacrylate (SMA) Market
Why this matters for 2026 strategic planning
- Procurement and supply-chain teams need validated near-term demand assumptions to renegotiate long-term feedstock contracts and manage inventory risk.
- Product and R&D leaders must prioritize development bets between standard-purity and high-purity SMA variants, and decide where to invest in sustainable feedstock substitutions.
- Business development and corporate strategy functions require a clear view of competitive concentration and potential M&A or JV targets to secure feedstock, technology, or regional access.
- Commercial teams must refine channel strategies to capture incremental value in lubricant additive formulations and personal care, where margin profiles differ materially.
What the PW Consulting report delivers (practical contents)
- Proprietary market model: annual market sizing (2020–2025), scenario-based forecasts (2026–2032) and sensitivity runs tied to raw-material price shocks and end-use demand scenarios.
- Price and cost build-up: methodology to translate fatty-alcohol and methacrylic acid feedstock movements into expected SMA pricing bands under different procurement strategies.
- Supply-chain heatmaps: upstream feedstock origins (natural oils vs petrochemical routes), conversion points, and logistics risk nodes—paired with recommended mitigation levers.
- Competitive intelligence: concise strategic profiles for incumbent suppliers, playbook-style moves they are likely to make, and an acquisition target shortlist by strategic need.
- Regulatory and sustainability lens: implications of chemical regulations, eco-labeling expectations, and lifecycle considerations for renewable-based SMA variants.
- Commercial and technical go-to-market frameworks: account segmentation, value-proposition templates, and sample commercial KPIs for 12–24 month execution plans.
Key market dynamics shaping SMA into 2026
The SMA market is maturing from a specialty-chemical niche into a recognized strategic input across several adjacent value chains. Demand drivers include industrial lubricants (where SMA-derived derivatives function as pour-point depressants and viscosity modifiers), personal care formulations seeking emollient performance, and specialty adhesives and coatings that prize hydrophobic functional performance. These applications respond differently to macroeconomic cycles, but collectively underpin a steady mid-single-digit CAGR for the market.
Worldwide Stearyl Methacrylate (SMA) Market
Upstream feedstock dynamics are a central determinant of near-term pricing and margin variability. SMA is manufactured via esterification of methacrylic acid with stearyl alcohol (octadecan-1-ol). Stearyl alcohol itself is sourced either from natural oils (oleochemical route) or petrochemical feedstocks. The choice and availability of feedstock, regional oleochemical capacity, and logistics constraints drive cost pass-through and availability risk. Our financial scenarios demonstrate that even modest shifts in fatty-alcohol supply or pricing materially change supplier economics and favor different commercial responses.
Worldwide Stearyl Methacrylate (SMA) Market
On market structure, SMA exhibits moderate-to-high concentration: the top three suppliers account for a material majority of market supply while the top five consolidate well over three-quarters of capacity. This concentration creates a market where strategic supplier relationships, co-development agreements, or targeted acquisitions can quickly alter competitive dynamics.
Competitive positioning — high-level view of incumbent suppliers
- BASF SE (Ludwigshafen, Germany) — A global chemicals leader offering long-chain mono-functional monomers such as SMA 1618 and SMA 1618 F. Strengths include broad application know-how in coatings and lubricants, deep R&D capability, and global distribution reach. For customers, BASF is a strategic supplier when scale, formulation expertise, and integrated technical support are required.
- Mitsubishi Gas Chemical Company, Inc. (Tokyo, Japan) — A supplier with strong regional relationships and positioning in fiber treatment agents, coatings and adhesives. Mitsubishi’s value lies in tailored applications engineering and established supply into Asian specialty markets.
- Jamorin International (Luxembourg / Global) — A focused supplier that targets oil-additive applications, positioning SMA variants as viscosity index improvers and pour-point depressants for paraffinic oils. Their niche specialization appeals to formulators seeking performance optimization for lubricant basestocks.
- NOF Corporation (Tokyo, Japan) — Part of a broader portfolio of functional monomers and oleo-specialty chemicals, NOF offers strategic value in markets that require integrated oleochemical expertise and customized monomer supply.
These firms occupy differentiated positions — global scale and application breadth on one side, and niche technical specialization on the other. This opens multiple strategic spaces for entrants and incumbents alike: collaborative supply agreements, toll-manufacturing partnerships, private-label production, and targeted bolt-on acquisitions.
Strategic recommendations for corporate decision-makers in 2026
- Procurement strategy: Move from spot-dominated sourcing to a hybrid approach combining multi-year indexed contracts with retained spot exposure; evaluate partial vertical integration into fatty-alcohol supply where scale and capital economics justify it.
- Portfolio focus and R&D investment: Prioritize development of differentiated, higher-value SMA derivatives aimed at lubricant and personal care formulators; accelerate projects targeting renewable feedstock parity and low-carbon production footprints.
- Commercial go-to-market: Recalibrate segmentation to sell to formulators not only on price but on total system performance (e.g., pour-point plus oxidative stability), and deploy technical application labs in priority regions to reduce customer switching costs.
- M&A and partnership playbook: Screen for regional tollers with excess capacity, fatty-alcohol producers, and specialty additives houses that can immediately boost distribution and application know-how. Prioritize deals that offer rapid margin accretion and de-risked integration paths.
- Risk management: Implement near-term inventory hedging rules, map single-source exposure, and build a quantified scenario register for feedstock shocks, regulatory changes, and demand shifts across end-use segments.
- Sustainability and regulatory readiness: Invest in feedstock traceability and LCA capabilities now to preempt supplier exclusion in regulated markets and to access premium channels that reward lower-carbon chemistries.
How PW Consulting accelerates your 2026 roadmap
PW Consulting supports clients across the strategic decision stack for SMA with modular services:
- Customized market models and forecast scenarios linked to client-specific demand assumptions;
- Supplier due diligence and commercial negotiation playbooks tailored to feedstock risk profiles;
- M&A target screening, valuation templates, and integration roadmaps for bolt-on acquisitions;
- Operational playbooks for capex decisions around tolling vs. greenfield investments;
- Technical-commercial launch programs to convert formula-level innovation into premium pricing.
Next steps — using this insight
This briefing is a strategic preview designed to surface the decisive levers and risk vectors for steering SMA-related investments in 2026. It intentionally refrains from publishing full segment-by-segment tables and granular regional splits in order to focus executive attention on the high-impact decisions. For clients and prospects seeking the complete dataset — including the detailed segmentation, region- and application-level forecasts, company-level market share estimates, and our full suite of appendices (pricing ladders, supplier scorecards, and scenario worksheets) — PW Consulting offers access to the full Worldwide Stearyl Methacrylate Market report and bespoke advisory engagements.
Contact PW Consulting to schedule a confidential briefing of the full report, obtain a tailored forecast for your product lines, or commission a transaction-ready diligence package. Our models are built to convert market intelligence into executable 12–36 month plans that align procurement, R&D, commercial, and corporate development teams around a prioritized set of actions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Stearyl Methacrylate (SMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


