



Category: market research
PW Consulting: Suspension Bridge Apparatus Market to Rise from USD 49.5M in 2025 to USD 74.44M by 2032 at a 6.01% CAGR
By PW Consulting, 2026-07-15
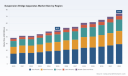
Worldwide Suspension Bridge Apparatus Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting today releases an executive preview of its Worldwide Suspension Bridge Apparatus Market report (base year: 2025; forecast period: 2026–2032). The market has shown steady expansion through the first half of the decade and, backed by our proprietary modelling, is projected to continue growing at a compound annual growth rate of approximately 6.01% through 2032. From a market level perspective, instrument and educational apparatus demand rose consistently from the early 2020s and is forecast to approach three‑quarters of a hundred million USD in revenue by the end of the forecast horizon — a trajectory that has clear implications for manufacturers, lab operators, investors and policy makers planning capital and R&D allocation in 2026.
Worldwide Suspension Bridge Apparatus Market
Why this report matters in 2026
-
Actionable timing: 2026 is the inflection point for many institutional procurement cycles in engineering education and applied research. Universities, vocational institutes and industrial research centres are upgrading curricula and lab estates; understanding market momentum and supplier capabilities is essential to align procurement, training and product roadmaps.
Worldwide Suspension Bridge Apparatus Market -
Risk & regulation: New industry guidance on risk‑based inspection for cable systems has elevated the importance of realistic test rigs and data acquisition in teaching and calibration. Manufacturers and training providers must align product specifications and service offerings to evolving inspection standards to preserve relevance.
Worldwide Suspension Bridge Apparatus Market -
Supply chain exposure: High‑carbon steel wire rod is the core raw material for cable components. Volatility in this upstream market — and the broader steel wire rope sector — materially affects cost structures and sourcing strategies for apparatus vendors and therefore procurement pricing and total cost of ownership for buyers.
-
Market concentration and competition: Top suppliers account for a material share of the market, producing a landscape where mid‑size specialists can exert influence through feature differentiation, service models and regional partnerships. This creates both consolidation opportunities and niches for new entrants.
What the report delivers — practical, decision‑ready content
-
Market sizing and growth scenarios: a validated market model that reconciles historical trends (2020–2025) with three forward scenarios to support capital budgeting and procurement timing.
-
Buyer’s decision framework: a checklist and scoring matrix to select apparatus according to technical fidelity, data acquisition capability, total cost of ownership, training requirements and maintainability.
-
Vendor scorecards and comparative feature mapping: a structured evaluation of incumbent and emerging suppliers across engineering features, software integration, aftermarket services and compliance posture (presented at a strategic level in this preview; detailed scorecards contained in the full report).
-
Technical deployment playbook: lab footprint and infrastructure requirements, installation and calibration workflows, data capture and reporting templates, and maintenance schedules tuned for university and industrial environments.
-
Commercial playbook: go‑to‑market options for suppliers including bundling strategies (hardware + DAQ + software + curriculum), financing offers for educational institutions, and aftermarket service models that convert one‑time sales into recurring revenue.
-
Supply chain risk matrix and mitigation options: supplier mapping, raw material exposure analysis and procurement hedging strategies with practical checklists for 2026 contracting cycles.
-
Scenario planning and sensitivity analyses: stress tests for price, demand and input cost shifts to inform R&D prioritisation, inventory policy and potential M&A targets for firms seeking scale or capability gaps.
Competitive landscape — strategic read on core players
The competitive field blends established engineering educational manufacturers and regional specialists. The leading firms offer combinations of robust mechanical design, curriculum alignment and increasing levels of digital instrumentation. Our qualitative analysis identifies distinct positioning and strategic opportunities for each group.
-
TecQuipment (Nottingham, UK) — A strong brand in education‑grade structures kits. Strengths include modular platforms and optional data acquisition/software layers that lower the barrier to digital lab transformation. Strategy consideration: pivoting further into software subscription models and campus‑level licensing could monetise their installed base.
-
P A Hilton (UK) — Known for visually intuitive apparatus that emphasise direct observation of structural behaviour. Strengths in hands‑on pedagogical design; potential downside is lower digital integration. Strategy consideration: retrofit DAQ options and partner integration can extend product lifetime and drive aftermarket revenue.
-
Edibon (Madrid, Spain) — Focused on strength and mechanics labs with emphasis on realistic stress and force simulation. Opportunity lies in co‑developing validated curricula or accreditation offerings with universities to increase adoption.
-
Infinit Technologies (Saudi Arabia) — Regional supplier with product features tailored to local lab environments. Growth leverage: regional infrastructure investment programs and industry training contracts.
-
Edutek Instrumentation, Shambhavi Impex, Swarg Systems, Ambros India and Elshaddai Engineering Equipments (India and regional providers) — A set of manufacturers focused on cost‑efficient lab models and accessible service support. These vendors are well‑placed to serve expanding vocational and undergraduate lab demand in price‑sensitive segments; differentiation through software, certification and bundled services would raise margins.
Market concentration metrics show that the top tier of suppliers controls a meaningful share of the market, though a diverse mid‑tail creates fertile ground for targeted partnerships, OEM supply arrangements and regional distributors. For established vendors, the strategic imperative is to convert product sales into recurring service and software revenue; for challengers, focus on niche technical features, competitive cost structures and fast local service will win transitions.
Key market dynamics for 2026 to monitor
-
Upstream materials: The steel wire rope ecosystem — underpinned by high‑carbon steel wire rod — remains the primary cost driver for cable components. Movements in that market have outsized effects on pricing and supplier margin. Buyers should structure procurement contracts with indexed clauses and multiple sourcing paths.
-
Standards and inspection regimes: Latest guidance on risk‑based inspection for main cable systems elevates the need for apparatus that can replicate inspection scenarios and capture high‑fidelity data. Vendors who co‑develop curriculum with standards bodies will secure preferential adoption.
-
Digital adoption: Demand is moving from purely mechanical demonstration rigs to integrated systems with data acquisition, cloud‑ready analytics and learning management integration. This shift opens a strategic playbook for hardware vendors to bundle software and analytics services.
-
Infrastructure investment: Renewed global infrastructure spending and university capital plans are lengthening procurement pipelines but increasing total addressable market. Alignment with regional funding cycles will be critical to hit sales targets.
Strategic recommendations for executives planning 2026 moves
-
Prioritise digital enablement: If you are a manufacturer, accelerate development of plug‑and‑play DAQ modules and software that can be sold as a subscription. If you are a buyer, require open APIs and data export capability to future‑proof lab investments.
-
Design for serviceability: Equip apparatus with modular replaceable components and remote diagnostic features to support tiered maintenance contracts — a key lever for predictable revenue and tighter customer relationships.
-
Hedge raw material exposure: Adopt procurement contracts with indexation, maintain safety inventories for critical cable components, and consider forward purchase agreements with primary wire rope suppliers to stabilise margins.
-
Build accreditation partnerships: For vendors, co‑author lab exercises and certification programs with academic partners and standards bodies to institutionalise product adoption. For buyers, demand supplier support for curriculum alignment.
-
Pursue selective alliances and M&A: Consider transactions that add software capabilities, regional distribution or certification expertise rather than broad manufacturing consolidation; the mid‑tail offers multiple bolt‑on opportunities.
-
Segment offering by buyer economics: Create distinct SKUs and commercial models for vocational training centres, university civil‑engineering labs and industrial research centres — each segment exhibits different upgrade cycles and value thresholds.
How PW Consulting’s report supports 2026 decision cycles
This report is built to be a strategic instrument: it combines a transparent top‑down market model with primary interviews, detailed supplier evaluations and executable commercial playbooks. It is structured to support investment committees, procurement teams and product leaders through the typical 6–18 month decision window that governs lab procurement and capital upgrades.
For senior leaders, the immediate value is in: (a) using scenario outputs to align 2026 budget asks with realistic procurement timing, (b) applying our vendor scorecard to shorten vendor selection timelines, and (c) adopting our supply chain mitigations to protect margins against raw material swings. For product and R&D leaders, the detailed feature matrices and customer use cases guide roadmap prioritisation for DAQ integration, modularity, and lifecycle services.
Next steps
This preview highlights the report’s strategic contours while respecting the “preview” principle: core segment tables, granular regional and application breakdowns, and full vendor scorecards are reserved for the full report. Organisations evaluating market entry, product investment, procurement or M&A activity in 2026 should consult the comprehensive dataset and executable annexes in PW Consulting’s full study.
To request the complete report and supporting datasets, contact PW Consulting through our report landing page or speak with your usual PW Consulting advisor. For decision‑makers aiming to translate the market trajectory into profitable action in 2026, this report is designed to be the operating manual and investment guide.
For detailed analysis of this topic, please visit the official page: Worldwide Suspension Bridge Apparatus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Centrifugal Lorry Washing Pump Market to Rise from USD 442.5 Million in 2025 to USD 626.82 Million by 2032 at a 5.14% CAGR
By PW Consulting, 2026-07-15
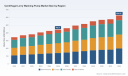
Worldwide Centrifugal Lorry Washing Pump Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market intelligence brief on the Worldwide Centrifugal Lorry Washing Pump Market delivers a focused playbook for executives preparing critical 2026 decisions. Grounded in a multi-year historical review and a seven‑year forecast horizon, the study crystallizes where value will accrue, what capabilities will win, and which operational trade-offs merit immediate action. At the macro level the market is mature but expanding: our base‑year assessment (2025) pegs global revenue at approximately USD 442.5 Million, with a steady compound annual growth rate of 5.14% through the 2026–2032 forecast window, culminating in a materially larger market by the end of the period.
Worldwide Centrifugal Lorry Washing Pump Market
Why this study matters for 2026 strategic planning
-
Timing: 2026 is a hinge year. Buyers and specifiers of commercial vehicle wash systems are consolidating procurement specifications around energy, water reuse, and automation attributes — decisions that will lock in vendor relationships for multiple equipment lifecycles.
Worldwide Centrifugal Lorry Washing Pump Market -
Risk management: Regulatory pressure on water discharge and municipal reuse standards is accelerating capital spending on integrated treatment and reclaim systems. Pump selection is no longer a commodity choice — it is a compliance and total-cost-of-ownership decision.
Worldwide Centrifugal Lorry Washing Pump Market -
Profit optimization: Energy mandates and labor constraints make pump efficiency, control sophistication (e.g., VFD-enabled platforms), and aftermarket service economics central to margin improvement for OEMs, integrators, and fleet customers.
Data-driven narrative — what the numbers reveal (high level)
The market trajectory over the past half decade shows consistent expansion, reflecting growth in commercial vehicle fleets, increasing adoption of automated wash systems, and retrofit cycles driven by environmental and efficiency imperatives. By combining historical performance with forward-looking scenario modeling, the report quantifies upside under multiple adoption pathways — from a conservative base case tied to modest fleet growth and retrofit replacement, to an accelerated electrification/automation case where water-recycling mandates and energy-efficiency incentives materially advance pump modernization.
Market structure and concentration — implications for competitors and buyers
The centrifugal lorry washing pump market exhibits moderate concentration. The leading three suppliers command a meaningful share of industry revenue, while the top five collectively represent a majority position — a dynamic that creates both barriers and opportunities. For established global pump OEMs, scale and integrated system capabilities (pump + controls + water treatment) confer a competitive edge in large commercial projects. For specialists and regional players, differentiation via materials expertise (e.g., thermoplastics vs stainless steel), rapid delivery, and niche application know‑how remains a viable route to sustainable margins.
-
Strategic takeaway for suppliers: focus on platform modularity, aftermarket service economics, and channel partnerships with wash-system integrators to capture recurring revenue streams.
-
Strategic takeaway for buyers: leverage concentration to negotiate bundled pricing and service-level agreements, while maintaining competitive tension by qualifying specialist suppliers for niche use cases.
Competitive landscape — who matters and why
The report’s company benchmarking section profiles the market’s most consequential vendors and evaluates them against a consistent scorecard of technical breadth, channel reach, aftermarket capability, and innovation trajectory. Among the noteworthy companies:
-
Cat Pumps — recognized for industrial-duty, high‑pressure pump solutions tailored to truck wash contexts. Their emphasis on high-pressure cleaning, wide flow ranges, and VFD compatibility positions them strongly where energy efficiency and cleaning performance are prioritized.
-
MP Pumps — offers centrifugal and self‑priming platforms with materials choices for corrosion resistance, making them a practical choice in environments with aggressive fluids or heavy-duty operational cycles.
-
Pacer Pumps — known for thermoplastic centrifugal designs that balance corrosion resistance and cost, appealing to operators prioritizing chemical compatibility and reduced capital intensity.
-
Ampco Pumps — brings robust series engineered for wastewater and gray water handling, aligning with stations that integrate reclaim and treatment systems.
-
Xylem (Goulds Water Technology) and Grundfos — represent global incumbents with broad single‑stage and multistage offerings, strong brand recognition, and extensive service networks that ease adoption for large-scale wash installations.
-
Kärcher — while primarily recognized as a systems integrator for vehicle wash solutions, its integrated approach (pumps + water treatment + gantry systems) illustrates the competitive pressure from equipment providers who sell complete, water‑efficient packages.
Recent product and marketing activity underscores a pattern: established pump OEMs are beefing up presence at industry events, launching series tailored for high‑capacity cleaning, and promoting VFD‑capable solutions. This momentum reflects two structural facts explored in the report: an increased emphasis on operational efficiency and the premium placed on integrated water management.
Key market dynamics and operational drivers
-
Materials and durability: Stainless steels (e.g., 304/316) and engineered thermoplastics are core choices. Materials selection drives lifecycle costs, particularly where road salts, detergents, and reclaimed water are common.
-
Water reclamation and treatment: Advanced filtration systems enable substantial water savings — in some configurations delivering up to high double‑digit recovery rates. Pump selection must account for solids handling, variable suction conditions, and intermittent duty cycles tied to recycling operations.
-
Energy efficiency and controls: VFD integration is emerging as standard practice in higher‑spec installations, with payback windows that can be compelling (often sub‑12 months in high‑use contexts). The report models energy savings under representative duty cycles to quantify ROI sensitivity to electricity price scenarios.
-
Labor and automation: Automated gantry and touch‑free wash systems reduce labor exposure and shift value to system uptime and remote diagnostics — areas where pumps with integrated monitoring and predictive maintenance features create differentiation.
What the report contains — operational assets for executives
PW Consulting’s full report is designed as an operational toolkit, not just an academic forecast. Key deliverables include:
-
Proprietary demand model and sensitivity analysis that can be re‑run under client assumptions to test procurement and pricing strategies.
-
Supplier scorecards and a product matrix that map pump families to washing system archetypes, duty cycles, and water treatment requirements.
-
Scenario-based ROI calculators for VFD retrofits, water-reuse projects, and aftermarket service contracts.
-
Regulatory heatmaps and compliance pathways by jurisdiction to prioritize investment and planning for plant and wash‑station operators.
-
M&A and partnership playbook identifying value creation levers in bolt‑on acquisitions, technology licensing, and channel expansion.
-
Case studies and implementation checklists drawn from recent projects and trade‑show disclosures across the vendor landscape.
2026 strategic imperatives — recommended actions
-
For OEMs and pump manufacturers: accelerate modular VFD‑ready platforms, build clear aftermarket subscription propositions, and formalize integration partnerships with water‑treatment and wash‑system integrators.
-
For systems integrators: prioritize validated pump families with documented reclaimed‑water performance and incorporate digital monitoring into service contracts to capture recurring revenue.
-
For fleet operators and wash‑station owners: commission pilot VFD retrofits and water‑recovery trials now to secure fast payback and defer larger capital projects with evidence‑based results.
-
For investors and M&A teams: target assets that combine product differentiation with serviceable aftermarket potential — companies with installed base data and remote monitoring capabilities deliver superior multiples.
Risks and downside scenarios
The report outlines contingency scenarios where growth is constrained by raw material inflation, slower fleet expansion, or delayed regulatory enforcement. Supply‑chain disruptions for stainless steel and specialty polymers could compress margins and extend lead times. Conversely, accelerated regulatory tightening or incentive programs for water conservation would materially tilt the market toward higher‑spec pumps and integrated systems, increasing average selling prices.
How to use this report in your 2026 playbook
Executives will find immediate, actionable outputs for procurement cycles, product roadmaps, and P&L planning. The forecasts provide a defensible baseline for budgeting; the scenario tools enable stress‑testing of capital investments; and the supplier benchmarking shortlists candidates for qualification rounds. Critically, the report is purpose‑built to support near‑term RFQ cycles — with templated specification language and retrofit comparators that reduce procurement friction and speed vendor selection.
Want the full intelligence?
This release is a strategic synopsis designed to demonstrate the depth and practical orientation of PW Consulting’s analysis. We deliberately omit the detailed segmentation tables and granular regional/application revenue splits in this preview to preserve the full, actionable datasets for subscribers. The complete report includes all underlying data, interactive models, and supplier scorecards required to execute on the 2026 strategies outlined above.
Contact PW Consulting to access the full Worldwide Centrifugal Lorry Washing Pump Market report and obtain the data extracts, model files, and implementation workshops that will convert insight into realized outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Centrifugal Lorry Washing Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Military Protective Gear Market to Reach USD 16,850.5 Million in 2025, Poised for 4.5% CAGR (2026–2032)
By PW Consulting, 2026-07-15
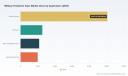
Worldwide Military Protective Gear Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence release on the Worldwide Military Protective Gear Market provides a tactical playbook for defence and security procurement leaders, product strategists, and corporate development teams preparing plans in 2026. The market—estimated at USD 16,850.5 Million in 2025—is on a steady growth path, with a near-term market value projected at USD 17,877.52 Million in 2026 and a compound annual growth rate (CAGR) of 4.5% through our 2026–2032 forecast horizon. By 2032, the market is expected to approach USD 22,931.18 Million under our baseline scenario.
Worldwide Military Protective Gear Market
Our analysis blends hard market sizing with scenario-driven strategy, supplier and materials intelligence, procurement pipeline mapping, and risk-adjusted recommendations designed to be directly actionable for calendar-year 2026 decisions. This press release outlines the strategic value of the report and highlights the kinds of insights we provide—while intentionally withholding core sub-segment detail to direct practitioners to the full report for transaction- and bid-level intelligence.
Worldwide Military Protective Gear Market
Why 2026 is a strategic inflection point
-
Defense budget trajectories and procurement cycles are synchronizing with multi-year capability programs in 2026: several NATO members and allied countries are shifting to more localized sourcing and accelerated modernization of dismounted soldier systems. That alignment translates into predictable demand for body protection, helmets, CBRN solutions, and integrated systems.
Worldwide Military Protective Gear Market -
Material-technology inflection: ongoing advances in aramid and UHMWPE composites, plus rising adoption of integrated electronic and augmented-reality (AR) features, create both premium-product opportunities and supply-chain complexity for manufacturers and prime contractors.
-
Procurement complexity is increasing: export controls, testing regimes, certification requirements and offset policies are reshaping how OEMs and Tier‑1 suppliers participate in cross-border programs.
Market dynamics that will determine winners and losers in 2026
The market exhibits a moderate concentration profile — top firms capture a material portion of revenue, but there remains room for nimble technology-focused entrants and regional champions. This structure favors companies that can simultaneously deliver certified ballistic performance, lightweight materials, systems integration (communications and AR), and secureized production-ready supply chains.
Key demand drivers we analyze in the report include: the modernization of dismounted systems, procurement of multi-threat protective kits, lifecycle sustainment and replacement of legacy ballistic plates and helmets, and increased CBRN readiness programs in select geographies. On the supply side, premium raw materials (advanced aramid fibers and UHMWPE) and composite manufacturing capacity remain bottlenecks that create both margin pressure and strategic sourcing opportunities.
Competitive landscape — strategic positioning of industry participants
Our company-by-company competitive assessment synthesizes public disclosures, contract activity, product roadmaps, and technology advantages to produce action-oriented profiles. Select strategic observations include:
-
3M Company — Strength lies in advanced ballistic composites and integrated personal protection systems. 3M’s R&D depth in lightweight multi-threat solutions positions it well for broad military and allied procurement programs that prioritize lifecycle performance and ergonomics.
-
BAE Systems — As an integrated systems prime, BAE leverages modular design and advanced materials across soldier systems. Their strength is in program-level integration and scale, making them a preferred partner for multi-domain procurements.
-
Gentex Corporation — Leading in helmet systems and communications-integrated head protection, Gentex’s recent contract extensions on Advanced Combat Helmet programs underscore its importance in U.S.-led procurement streams and continuity opportunities through 2026.
-
Point Blank Enterprises, Safariland, ArmorSource, Revision Military — These firms compete across tactical vests, carriers, helmets and modular systems; their agility and deep relationships with government buyers enable them to win niche and follow‑on contracts, especially when coupled with rapid manufacturing lead-times.
-
DuPont and Honeywell — As critical materials suppliers, they enable many OEMs’ ballistic performance claims. Control over high-performance fibers and composite technologies continues to be a strategic moat for producers that can lock preferential supply or co-development agreements.
-
Avon Protection and MKU Limited — Specialists in CBRN and regionally-scaled production respectively, they illustrate two viable routes to growth: high-technology specialization and export-focused local manufacturing.
-
Ningbo Chowey — Representative of growing OEM capacity in Asia, companies like Ningbo demonstrate how international standards-compliant production can compete on price and scale where export rules permit.
Recent transactions we track are signaling continued consolidation at the product-adjacent level and sustained program follow‑ons: Gentex secured a contract extension under a major helmet program (Nov 2025), a U.S. Army delivery order for lightweight ballistic plates was awarded in Sept 2025, and an acquisitive move by a U.S. manufacturer of ballistic components occurred in early 2025. Each event has implications for supply availability, pricing dynamics, and competitive positioning in 2026.
Regulation, materials and geopolitics — the non-negotiable constraints
-
Material cost and availability: Advanced ballistic fibers and UHMWPE composites carry premium costs driven by R&D, complex manufacturing, and limited upstream capacity. Buyers and manufacturers must plan multi-year procurement and hedging strategies to avoid margin erosion or program delays.
-
Standards and certifications: Stringent international ballistic testing and certification regimes require ongoing third‑party validation. Programs that underestimate time and cost for certification risk missed delivery milestones.
-
Export controls and ITAR: Certain ballistic technologies remain controlled under international arms regulations, constraining transferability and commercial scale in cross-border joint programs. We model these impacts across procurement scenarios in the full report.
-
Geopolitical procurement preferences: Rising defense-spending commitments among allied states, and increasing emphasis on localized sourcing, reallocate program opportunities toward regional suppliers that can meet certification and industrial participation requirements.
What the PW Consulting report delivers — actionable, practice-ready content
The report was designed as a strategy toolset for 2026 implementation. Highlights include:
-
Proprietary market sizing and spend forecasts (2020–2032) with scenario variants for accelerated modernization and stress scenarios.
-
Supplier risk heatmap and Tiered dependency model for raw materials and subassembly suppliers.
-
Competitive intelligence dossiers for the leading OEMs and materials suppliers, including capability matrices, likely contract pipelines, partnership fit, and M&A targets.
-
Procurement playbooks for primes and OEMs: bid/no-bid decision frameworks, local offset strategies, and compliance checklists for export controls and certification timelines.
-
Commercial models and go-to-market strategies for entrants and scale-ups: price-to-win benchmarks, channel selection, and integration approaches for communications and AR subsystems.
-
Scenario-based risk-adjusted ROI models tailored to program sizes and procurement rhythms typical in 2026 defense budgets.
How leaders should use this intelligence in 2026
We recommend three immediate actions for corporate and procurement leaders:
-
Recalibrate supplier agreements to secure advanced-material capacity. Convert ad-hoc relationships into medium-term contracts with performance and delivery SLAs tied to certification milestones.
-
Prioritize modularity and systems integration in proposals. Buyers increasingly favor modular solutions that reduce platform obsolescence and ease sustainment—capability that commands price premiums and long-term contract attachment.
-
Build a regulatory-first program timeline for cross-border projects. Incorporate export-control gates and third-party testing into program baselines to avoid late-stage disqualifications.
Risk outlook and contingency planning
Our stress-testing indicates three risk scenarios that should inform 2026 planning: supply-constrained inflation in high-performance fibers, certification delays from increasingly rigorous testing standards, and geopolitical-driven procurement shifts that favor localized producers. The full report provides contingency playbooks—supplier diversification maps, alternative-material assessments, and procurement clause templates—to operationalize mitigation plans.
Conclusion — the strategic value of this report
For decision-makers navigating 2026 program windows, the report acts as both a market map and an execution toolkit. It translates macro trends—steady CAGR of 4.5% and an expanding market base from USD 16,850.5 Million in 2025 toward USD 22,931.18 Million in 2032—into prioritized actions, commercial tactics, and risk controls that materially improve win rates and program resilience.
To preserve the commercial integrity of program-level and regional split data that buyers and sellers rely on during negotiations, this release outlines the analytical frame and the decisions it supports while reserving the granular sub-segment matrices and transaction-level tables for subscribers. PW Consulting clients receive the full set of models, vendor scorecards, and procurement playbooks designed for immediate use in 2026 bid cycles.
Next steps
-
Executive briefings: Book a 60-minute strategic briefing with our analyst team to map the findings to your 2026 priorities.
-
Download the full report: For program-ready data, segmented forecasts, and supplier-level insights, access the complete Worldwide Military Protective Gear Market report on PW Consulting’s website.
-
Custom engagement: Engage our M&A or sourcing specialists for tailored due diligence, supplier negotiations support, or tender response optimization ahead of key 2026 procurement windows.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Occlusion Spray Market Poised to Reach USD 165.72 Million by 2032 on a 5.28% CAGR
By PW Consulting, 2026-07-15
Worldwide Occlusion Spray Market 2026 Outlook: Tactical Intelligence for Strategic Decision-Making
Executive Summary
PW Consulting’s latest market intelligence release — the Worldwide Occlusion Spray Market report (base year 2025, historical 2020–2025, forecast 2026–2032) — delivers a decision-grade perspective for manufacturers, distributors, dental laboratory groups, dental service organizations, and private equity investors planning actions in 2026. Built on a rigorous market model and primary interviews across the value chain, the study quantifies recent momentum and projects forward with scenario-based clarity. The market reached USD 115.45 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 5.28% through the forecast window, reaching USD 121.57 Million in 2026 and continuing toward USD 165.72 Million by 2032. These macro trajectories reflect a stable, innovation-friendly segment embedded in both traditional dental workflows and emerging digital scanning applications.
Worldwide Occlusion Spray Market
Why this report matters for 2026 decisions
-
Timing of investment and capacity planning: With predictable mid-single-digit growth and clearly defined market concentration dynamics (CR3 ~48.5%; CR5 ~62.25%), companies can calibrate manufacturing scale-ups, SKU rationalization, and inventory commitments to avoid overcapacity while preserving service levels across channels.
Worldwide Occlusion Spray Market -
Portfolio and product strategy: The report surfaces which product attributes—colour fidelity, removability, intraoral safety, water solubility, and scan-compatibility—drive clinician preference. This allows R&D prioritization and faster go-to-market decisions that will matter in contractual negotiations and tender cycles in 2026.
Worldwide Occlusion Spray Market -
Channel and pricing optimization: We map the cost-to-serve and margin profile across direct sales, dental distributors, and e-commerce; companies preparing commercial reorganization for 2026 can use these benchmarks to reweight investments in higher-margin channels.
-
M&A and alliance screening: Concentration metrics and company profiles in the report help identify consolidation targets and strategic partnerships that could alter competitive dynamics within a 12- to 24-month window.
Market dynamics shaping 2026
-
Cross‑workflow convergence: Occlusion sprays remain essential in analog prosthetic workflows (crowns, bridges, dentures) while a growing subset of formulations double as digital scan sprays. This dual utility is shifting purchasing criteria toward multi‑functional products that lower per-procedure handling time and SKU complexity.
-
Regulatory and safety drivers: Regulatory clarity is improving. Several occlusion sprays are permitted for intraoral use under applicable FDA guidance for dental articulating materials, and leading European products comply with medical device directives. Manufacturers that proactively document intraoral safety and environmental profiles of propellants will gain preference among institutional buyers and procurement committees in 2026.
-
Preference for physiologically safe and environmentally neutral propellants: Market feedback indicates buyers increasingly consider sustainability and patient-safety claims in procurement—factors that will affect specification language in supplier contracts next year.
-
Standardization of formats and color options: Industry catalogs commonly show aerosol formats (typical sizes include 75 ml, with some offerings in smaller and larger variants) and multiple color choices to suit visibility needs across different sub‑procedures. This creates a baseline expectation for any new market entrant in 2026.
Competitive landscape — what incumbents and challengers are doing
The market is characterized by a mix of specialized dental-supply incumbents and regional players that differentiate on formulation, regulatory compliance, and channel reach. Our competitive analysis synthesizes product-level nuances and commercial strategy insights for core vendors.
-
Pascal International, Inc. (Bellevue, WA, USA) — Pascal’s Occlude aerosol (approved for intraoral use) is positioned as a clinically focused offering for precise occlusal contact marking in wet or dry fields. Its intraoral clearance is a strategic asset for clinical channel penetration; companies evaluating clinical adoption should benchmark against Pascal’s claims and documentation processes.
-
Bausch (Dr. Jean Bausch GmbH & Co. KG, Cologne, Germany) — With a multi-color suite and an established medical-device compliance posture, Bausch’s Arti‑Spray represents a classically broad-spectrum approach targeted at both dental laboratories and clinicians. Their emphasis on a thin removable film and adherence to European device rules signals an approach that balances safety and usability.
-
Renfert GmbH (Hilzingen, Germany) — Renfert’s Occlutec line focuses on clarity of marking for high-spot detection on model castings and restorations. Companies seeking to compete on performance will need lab-validated data that demonstrate comparable resolution and removal characteristics.
-
YETI Dentalprodukte GmbH (Engen, Germany) — YETI emphasizes intense color recognition and water-soluble formulations, aligning with laboratories that prioritize easy cleanup and minimal interference with downstream processes.
-
DFS Diamon GmbH (Riedenburg, Germany) — DFS positions its product as resistant to water and alcohol and non-discoloring on plaster models. This variant appeals to specific prosthetics workflows where solvent resistance is a requirement.
-
Vacalon (USA) — Vacalon’s Quickcheck doubles as a digital scan spray in certain formulations, exemplifying the convergence of analog and digital use cases and highlighting the attractiveness of scan‑compatible offerings for future market share gains.
-
Indenco Dental Products (USA) — A diversified supplier offering multiple colors and container sizes; their strategy reflects the importance of channel breadth and portfolio depth for addressing heterogeneous buyer needs.
Collectively, the top three vendors account for a substantial portion of market revenue but leave meaningful share for regional specialists and innovators. That balance creates fertile ground for targeted product innovation and regional expansion plays in 2026.
Opportunities and risks for 2026
-
Opportunity — Scan compatibility and digital workflow integration: Products that demonstrably improve scan fidelity while preserving occlusal marking quality will command price premiums and faster adoption in digital-first dental labs.
-
Opportunity — Differentiated safety claims: Suppliers that secure and publicize intraoral approvals, or that document physiologically safe and environment-friendly propellants, can accelerate adoption within institutional procurement cycles.
-
Risk — Commoditization pressure: Where suppliers compete purely on price and standardization, margin erosion is likely. Strategic players must balance value-added services (training, scanning protocols, bulk logistics) with competitive pricing.
-
Risk — Regulatory tightening: Any tightening of medical device classifications or new inhalation/environmental controls could increase compliance costs. Scenario planning and compliance investment should be part of 2026 budgets.
-
Risk — Supply-chain concentration: Reliance on specific propellant or solvent suppliers creates vulnerability. Diversifying raw-material sourcing and qualifying alternative formulations will mitigate disruption risk.
What the full report delivers (practical, actionable contents)
PW Consulting’s report is structured to move stakeholders from insight to action. Key deliverables include:
-
A validated market model with historical trends and forward-looking forecasts (2026–2032) by revenue, plus sensitivity scenarios tailored to penetration of digital workflows and regulatory shifts.
-
Commercial playbooks for product managers and sales leaders: SKU optimization, pricing ladders, channel economics, and a content plan to accelerate adoption among labs and clinics.
-
Go-to-market and M&A screening matrices: target characteristics, valuation multipliers observed in the category, and integration checklists to expedite post‑transaction value capture.
-
Operational checklists: manufacturing throughput templates, packaging and SKU sizing considerations (reflecting common industry formats), and distribution playbooks to lower lead times and reduce SKU obsolescence.
-
Regulatory and safety dossier templates: best-practice language and testing protocols that helped market leaders document intraoral compatibility and environmental compliance.
-
Channel-level pricing and margin benchmarks, route-to-market decision trees, and a prioritized list of commercial experiments to run in 2026.
How to use these insights in 2026 planning
-
Short‑term (0–6 months): Prioritize rapid wins—SKU rationalization, targeted clinician pilots for scan‑compatible formulations, and tightening distributor agreements to protect margin.
-
Medium‑term (6–18 months): Invest in regulatory dossiers and third-party validation studies to unlock institutional tenders and expand into clinical channels that require intraoral clearances.
-
Long‑term (18+ months): Consider M&A or strategic partnerships to acquire formulation IP, expand geographic footprint, or capture digital-scan integration technology that bridges occlusion marking and CAD workflows.
Closing note — the “trailer” approach
This release intentionally highlights the strategic contours and practical utility of PW Consulting’s analysis while preserving the detailed sub‑segment datasets and proprietary scoring models that form the core of our full report. If your 2026 plan depends on confident allocation of R&D dollars, manufacturing capacity, or M&A capital, the full report contains the granular segmentation, price and volume matrices, and vendor-by-vendor scorecards you’ll need to act with conviction.
Contact PW Consulting to request the comprehensive report and bespoke executive briefing that aligns our modeling outputs to your specific scenario planning and decision deadlines for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Diaphragm Pump Market Set to Expand at 5.15% CAGR During 2026–2032
By PW Consulting, 2026-07-15
Worldwide Industrial Diaphragm Pump Market — Strategic Preview for 2026 Decisions
Executive synopsis
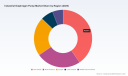
As corporations and investors set budgets and capital priorities for 2026, diaphragm pump supply chains, product portfolios, and regulatory compliance pathways have become high-stakes areas of industrial strategy. PW Consulting’s new market study provides a disciplined, decision-focused view of the worldwide industrial diaphragm pump market that traces performance from 2020–2025 and projects through 2026–2032. At the macro level, the market expanded materially during the historical window and is projected to grow at a compound annual growth rate (CAGR) of 5.15% across the forecast horizon. The analysis projects continued expansion toward the latter part of the decade as infrastructure upgrades, stricter effluent and emissions standards, and electrification initiatives accelerate replacement and retrofit cycles.
Worldwide Industrial Diaphragm Pump Market
Why this report matters for 2026 corporate strategy
-
Actionable foresight for capital allocation — The study quantifies market momentum and presents scenario-weighted forecasts that help management teams prioritize CAPEX for manufacturing scale, R&D, or aftermarket expansion in 2026.
Worldwide Industrial Diaphragm Pump Market -
Regulation-first investment planning — With rising wastewater discharge standards and fugitive-emissions limits influencing procurement specifications, our report maps regulatory corridors and identifies which pump architectures and material choices will reduce compliance cost and time-to-certification.
Worldwide Industrial Diaphragm Pump Market -
Risk-adjusted supplier decisions — Volatility in core raw-materials and concentrated supplier footprints require procurement strategies grounded in the report’s supply-chain stress tests and mitigation playbooks.
-
Product and service roadmap alignment — The analysis highlights where electrification, digital sensing, and sealless designs unlock new value pools for OEMs and aftermarket providers. These insights are designed to be translated directly into 12–24 month product and service roadmaps.
Market trajectory and structural context
Our top-line market sizing shows steady expansion from the start of the decade through 2025, followed by disciplined growth across the 2026–2032 forecast window. The quantified view enables executive teams to stress-test plans against moderate and aggressive adoption scenarios. Additionally, concentration metrics indicate a market that is neither a monopoly nor highly fragmented; the three largest firms account for a meaningful but not dominant share, and the cumulative share of the top five firms underscores an environment where scale and niche specialization both offer pathways to profitable growth.
Key dynamics shaping 2026 decisions
-
Regulatory acceleration — New limits on wastewater effluent and fugitive emissions, coupled with regional standards for explosion-proof equipment (e.g., ATEX-type regimes), are steering buyers toward sealless pumps and PTFE-lined wetted paths. Procurement teams should assume more stringent spec-checking in tender processes and longer validation cycles for new installations.
-
Material and input cost pressure — Stainless steels, aluminum, and high-grade elastomers have experienced price volatility since 2024. These swings affect landed manufacturing costs and ASP dynamics; firms that secure diversified sourcing or apply design-for-cost initiatives will preserve margins.
-
Electrification and energy efficiency — Advances in electric diaphragm technology have produced step-change reductions in energy use for certain applications. Efficiency gains can translate into lower total cost of ownership and can be decisive in capital planning where energy costs or emissions reporting matter.
-
Digitization and smart products — Pumps with integrated sensing (flow, pressure, vacuum) and basic telemetry are increasingly prized for predictive maintenance programs. Early adopters of sensor-enabled platforms can reduce downtime and establish service revenue streams.
Competitive landscape — capabilities, moves and implications
We profile incumbent OEMs and emergent challengers across product design, channel reach, and aftermarket service capabilities. The market contains traditional industrial pump houses with broad portfolios, specialized diaphragm players with patented actuation systems, and agile manufacturers delivering high-flow electric models and digital-enabled dosing pumps. Notable firms examined in the report include global pump leaders and specialized diaphragm-focused companies; our company-by-company matrices assess technology differentiation, proprietary materials expertise, manufacturing footprint resilience, aftermarket capability, and channel strategy.
-
Xylem Inc. — Strong positioning in water and wastewater applications; leverages its positive-displacement expertise and systems-level capabilities to win integrated projects with utilities and industrial water managers.
-
Wanner Engineering (Hydra-Cell) — High-pressure, seal-less diaphragm solutions suited to heavy industrial fluid handling where leakage risk and maintenance intervals are critical decision factors.
-
Graco Inc. — A dual-path strategy of air-operated and electric diaphragm offerings, including energy-efficient electric models that materially reduce operational power consumption for many use cases.
-
Dover Corporation (PSG brands) — Broad AODD and positive-displacement heritage with extensive channel partnerships tailored to chemical and sanitary markets.
-
IDEX (Warren Rupp / Sandpiper), Ingersoll Rand (ARO), Grundfos, Flowserve and other established pump OEMs — Each brings distinct strengths in specific end markets, materials expertise, or digital dosing platforms; the report maps those strengths against buyer procurement criteria.
Recent product activity illustrates how competition is playing out around electrification and sensing. For example, firms launched new sensor-integrated diaphragm units and higher-flow plastic air-operated pumps during 2025–2026, confirming an industry push toward both smarter and higher-throughput products. These moves signal that incumbents and challengers alike expect the next two to three years to reward investments in energy efficiency, corrosion-resistant materials, and modular serviceability.
Supply chain and raw-material considerations
PTFE remains a strategically important material for chemically resistant diaphragms — and demand for PTFE across industrial applications is substantial. At the same time, metals and elastomer price swings have intermittently compressed margins and lengthened lead times. Our supply-chain module provides scenario playbooks: hedging strategies, dual-sourcing templates, geographic reshoring impact analyses, and bill-of-material redesign options that reduce exposure without compromising compliance or performance.
Practical, actionable contents in the full report
PW Consulting’s report is built for implementers. Highlights of the practical content include:
-
Transparent market-sizing methodology, including base-year calibration and sensitivity bounds for the forecast period.
-
Scenario models (base/moderate/accelerated) that translate macro demand assumptions into unit and spend estimates for investment planning.
-
Competitive playbooks that map product features to buyer pain points and recommend go-to-market tactics by customer segment.
-
Supply-chain resilience templates: supplier scorecards, alternative-material matrices, and short- to medium-term procurement actions that materially reduce risk.
-
Regulatory impact maps that link expected standards to equipment specifications and time-to-market requirements for certification.
-
Aftermarket and service monetization frameworks, including spare-parts forecasting, predictive-maintenance ROI models, and subscription-based service packages.
-
Investment and M&A screening tools that highlight targets for bolt-on acquisitions, technology licensing, or co-development partnerships.
How executives should use this preview in 2026 planning cycles
-
Procurement and operations leaders: Use the supply-chain playbooks to build six- and twelve-month procurement plans that reduce input-cost exposure and shorten lead-time buffers.
-
R&D and product teams: Rebase product roadmaps to prioritize energy-efficient electrified models, PTFE-compatible materials engineering, and sensor integration for predictive maintenance.
-
Corporate development teams: Apply the M&A screening matrix to identify acquisition candidates that add missing capabilities (e.g., high-pressure sealing, digital dosing) or expand accessible distribution channels.
-
Service and commercial teams: Pilot service-subscription models in select verticals where uptime premiums and regulatory compliance create willingness to pay.
What we are not disclosing here — and why
In keeping with our “trailer” principle, this release presents strategic insight and high-level quantitative direction while withholding granular segment and regional share details that form the core of the full study. The complete report contains detailed split-level data, region-by-region scenarios, and downloadable tables that organizations rely on to build year-by-year P&L and investment plans. Those detailed datasets are available through the official PW Consulting distribution channel.
Next steps and how to access the full analysis
For executive teams preparing 2026 budgets, PW Consulting’s full Worldwide Industrial Diaphragm Pump Market report offers the data, models, and practical playbooks required to move from insight to execution. The publication includes the full segmentation matrices, company scorecards, and downloadable scenario tools. Contact PW Consulting’s research desk to obtain the complete report and tailored advisory support to turn the study’s findings into a prioritized action plan for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Zero-Gravity Bed Market Set to Reach USD 3,975.76 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Smart Zero Gravity Bed Market: Strategic Insight Briefing — PW Consulting
Executive summary
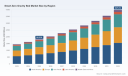
PW Consulting’s latest market study, anchored on a 2025 base year and spanning historical performance (2020–2025) and forward-looking forecasts (2026–2032), finds the Worldwide Smart Zero Gravity Bed market on a sustained double-digit growth path. At an aggregate compound annual growth rate (CAGR) of 11.85% through the forecast window, the industry is evolving from a niche therapeutic product to a mainstream adjustable-sleep solution that intersects consumer wellness, post-acute care, and hospitality-grade comfort.
Worldwide Smart Zero Gravity Bed Market
This briefing highlights the strategic value of the full report for 2026 enterprise planning: it synthesizes market scale and trajectory, competitive dynamics, regulatory and reimbursement headwinds/opportunities, and pragmatic market-entry and growth playbooks. True to PW Consulting’s “trailer” approach, we present the actionable implications and strategic direction you need now — while reserving detailed segmented tables and proprietary scenario outputs for the full report.
Worldwide Smart Zero Gravity Bed Market
Market trajectory and what the numbers mean for 2026 planning
Measured in USD million, the global market shows clear momentum, accelerating from recent historical levels into a materially larger market by the mid-point of the forecast. The 11.85% CAGR is not an abstract projection: it reflects converging demand vectors — an ageing population with rising long-term care needs, increasing consumer willingness to pay for sleep-health functionality, and rising penetration of smart-home and IoT-enabled devices into bedrooms and care settings.
Worldwide Smart Zero Gravity Bed Market
- For corporate planners, this implies that 2026 is the year to shift from pilot investments to scaled commercialization if your product or partnership can be differentiated on clinical outcomes, connectivity, or channel reach.
- For investors and M&A teams, the growth runway supports strategic bolt-ons (manufacturing scale, sensor analytics, distribution partnerships) to accelerate time-to-profitability.
- For suppliers and OEMs, the projection underscores the necessity of supply-chain resilience and capacity planning to avoid missed revenue opportunities as volumes ramp.
Demand drivers and structural dynamics
The report integrates demand-side drivers into a layered framework that informs strategic choices:
- Clinical utility and outcomes: Zero gravity positioning reduces pressure points and improves circulation, which sustains demand across elderly care and post-operative patient segments.
- Consumer wellness adoption: Premium sleep systems are migrating features once exclusive to clinical products (positioning presets, massage, integrated sleep tracking) into mainstream channels, expanding addressable markets.
- Channel expansion: Direct-to-consumer digital channels, omnichannel retail partnerships, and medical device distributor networks are each playing a role in faster adoption curves.
- Regulation and reimbursement: Coverage rules and medical necessity criteria will continue to shape the portion of the market that routes through healthcare payers versus private consumers.
Competitive landscape — who wins and why
The market is characterized by a mix of large established adjustable-bed manufacturers, premium sleep-system brands, and regional medical-equipment producers. Competitive advantage is driven by an intersection of product engineering, channel access, and ecosystem services (analytics, servicing, warranty).
- Ergomotion — As a high-volume, global supplier of adjustable bases, Ergomotion’s scale, retail partnerships, and design leadership create a durable advantage in consumer and retail channels. Their recent 20th-anniversary investments in brand experience and showroom design (October 2025) signal continued commitment to retail and channel-driven growth.
- Leggett & Platt (adjustable beds division) — With deep manufacturing footprint and a legacy of supplying large retailers and OEMs, their strength lies in cost-efficient platform scale and proven mechanical designs that meet both consumer and medical requirements.
- Tempur-Pedic — A premium brand leveraging differentiated materials, sleep-tracking integration, and consumer loyalty. Their smart bases, combined with software features, make them a formidable competitor in the high-margin premium segment.
- SonderCare — Positioned at the intersection of home-hospital care and premium consumer solutions, with a focus on therapeutic positioning and long-term care applications. Their positioning is relevant for partnerships with home-health providers and insurers.
- Regional hospital-bed manufacturers (e.g., Hebei Chibang, Zero-G Beds India) — These players maintain competitive edges where price-performance and proximity to local healthcare systems matter. Their product portfolios often include medically certified features tailored to local reimbursement and procurement processes.
Across the competitive set, market leadership is a function of three capabilities: (1) platform breadth and manufacturability, (2) channel depth across retail and medical distribution, and (3) software/sensor ecosystems that create recurring value beyond one-time device sales. The market is neither fully fragmented nor monopolistic — a mid-range concentration profile that leaves space for both incumbents and well-capitalized challengers to scale.
Regulation, reimbursement and their operational impact
Two regulatory realities require board-level attention:
- Reimbursement policy for hospital beds and accessories continues to shape pathway-to-purchase for medically indicated users. Durable medical equipment rules and HCPCS coding practices determine whether a unit sells through a clinical route (payer supported) or through retail. For companies targeting the medical channel, navigating code coverage, documentation workflows, and clinician-facing ordering processes is essential.
- Medical necessity criteria and face-to-face practitioner examination requirements remain a gating factor for coverage. Firms pursuing the healthcare payer channel must invest in clinician education, evidence generation, and order-processing workflows to minimize friction.
Strategically, this bifurcates the market into payer-influenced demand (where clinical evidence, compliance, and service are essential) and consumer-driven demand (where brand, convenience, and integrated wellness features dominate). Each path has a different margin profile and sales cycle — an important consideration for 2026 investment prioritization.
Strategic playbook for 2026 decision-makers
Based on scenario analyses and sensitivity testing in the full report, PW Consulting recommends a triage of strategic moves for executives preparing 2026 budgets:
- Prioritize product platforms that enable multi-channel positioning: design modular bases that can be configured for clinical and consumer channels with limited rework to accelerate market entry.
- Invest in evidence generation for clinical outcomes if pursuing payer pathways — randomized or real-world evidence that links zero-gravity positioning to measurable reductions in pressure ulcer risk, sleep quality, or post-operative outcomes will unlock reimbursement volumes.
- Build software-as-a-service (SaaS) revenue mechanics around sleep analytics, remote monitoring, and preventive maintenance to capture recurring revenue and justify higher upfront pricing.
- Secure strategic distribution partnerships early in 2026 — OEM arrangements with mattress brands, retail rollouts, and partnerships with home-health providers materially shorten the sales cycle.
- Hedge supply chains by qualifying alternate component suppliers and expanding manufacturing flexibility to cope with ramp-up scenarios modeled in the forecast.
Practical contents of the PW Consulting report (what you get)
The full report delivers hands-on intelligence for commercial, product, and corporate strategy teams. Highlights include:
- A transparent market-sizing model (historical and forecasted) with adjustable assumptions you can run to test alternative growth scenarios;
- Competitive benchmarking across product features, channel presence, and unit economics for the leading suppliers;
- Go-to-market playbooks segmented by channel (retail, medical, hospitality) with recommended partnerships and sample commercial KPIs;
- Regulatory and reimbursement playbooks detailing clinical evidence thresholds, coding mechanisms, and operational workflows required for payer engagement;
- Supply-chain and cost-sensitivity analysis, identifying critical component risks and mitigation strategies;
- M&A and partnership screening criteria with modeled valuation sensitivities for tuck-in versus scale deals;
- Executive-ready slide decks and implementation checklists to accelerate stakeholder alignment in Q1–Q2 of 2026.
Implications for investors and M&A teams
For investors, the market’s projected growth and pathway-to-recurring revenue models create attractive entry points across several value chains — component suppliers, software platforms, and service providers. The full report’s valuation framework outputs acquisition price ranges under multiple synergies assumptions and identifies priority targets that could deliver 12–36 month integration payback when paired with distribution-rich partners.
Next steps — how to use this intelligence
If you are calibrating a 2026 strategy, begin with three immediate actions:
- Run the PW Consulting scenario model for your product roadmap to quantify break-even timelines under different channel mixes;
- Map your clinical evidence gaps versus payer requirements and prioritize investment areas that convert clinicians and payers into stable referral sources;
- Engage target channel partners (retailers, mattress brands, home-health providers) now to lock preferred terms and shelf space for 2026 rollouts.
Conclusion — why this matters for 2026
The smart zero gravity bed market is shifting from early adoption to scaled opportunity. With an 11.85% projected CAGR across the forecast horizon, 2026 represents an inflection year where tactical choices — around product modularity, payer engagement, and channel partnerships — will determine which firms capture disproportionate share of the expanding market. PW Consulting’s full report equips executives with the market-sizing models, competitive diagnostics, and executable roadmaps to make those choices with confidence.
To access the complete dataset, segmented forecasts, company scorecards, and downloadable scenario tools referenced in this briefing, please visit the PW Consulting report page or contact our industry practice leads. The detailed segment-level tables and proprietary model inputs are available exclusively in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cold Ramming Paste (CRP) Market Set to Expand at 4.0% CAGR During 2026–2032, New Report Shows
By PW Consulting, 2026-07-15
Worldwide Cold Ramming Paste (CRP) Market Outlook 2026: Strategic Imperatives for Decision‑Makers
PW Consulting’s latest market study on the Worldwide Cold Ramming Paste (CRP) market positions 2026 as an inflection point for downstream manufacturers, smelters, and materials suppliers. With the industry transitioning from legacy binder chemistries toward low‑emission formulations, and with raw‑material supply dynamics tightening in key anthracite and graphite corridors, executives must adopt holistic strategies rooted in both materials science and commercial foresight. Our report—built on a 2020–2025 historical base and projecting through 2026–2032—delivers the evidence base required for board‑level decisions in 2026.
Worldwide Cold Ramming Paste (CRP) Market
Macroeconomic Snapshot: Measured, Durable Growth
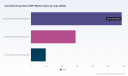
The CRP market demonstrated resilience through recent cyclical headwinds. Using 2025 as the analytical base year, the global market stood at approximately USD 487.04 Million (revenue units in Million USD) and is forecast to expand at a compound annual growth rate (CAGR) of about 4.0% over the 2026–2032 period. Our baseline projection anticipates a steady climb to roughly USD 640.9 Million by 2032 under a continuation of current technological adoption and regulatory trajectories.
Worldwide Cold Ramming Paste (CRP) Market
These headline figures mask important inflection points: short‑term volatility stemming from raw‑material price swings and region‑specific smelter investment cycles, coupled with medium‑term upside from regulatory‑driven substitution toward low‑PAH and zero‑PAH formulations. For 2026 planning cycles, management teams should treat the projected CAGR as a floor scenario and stress‑test operations for accelerated adoption of eco‑compliant products.
Worldwide Cold Ramming Paste (CRP) Market
Why This Report Matters to 2026 Decision‑Making
- Actionable Demand Forecasts: Forward curves by product architecture and application enable procurement and production planning to align with anticipated shifts in smelter maintenance and retrofit cycles.
- Regulatory Readiness: Detailed analysis of binder alternatives and compliance pathways helps innovators and buyers prioritize R&D and capex to meet tightening occupational and environmental standards.
- Supplier Risk and Sourcing Playbooks: The study maps supplier footprints, capacity constraints, and logistics vulnerabilities—critical inputs for 2026 supplier negotiations and buffer inventory policies.
- M&A and Partnership Targets: Proprietary screening criteria highlight acquisition candidates and strategic alliances suited for companies seeking to accelerate entry into eco‑friendly CRP formulations or to secure feedstock access.
What the Report Contains (Practical, Workable Deliverables)
- Integrated market model: a bottom‑up demand model that reconciles metallurgical production trends with CRP consumption norms and maintenance cycles.
- Scenario analysis: conservative, base, and accelerated adoption scenarios for eco‑compliant binders—each mapped to financial impact on suppliers and end users.
- Supplier benchmarking: operational scorecards covering technical capabilities, geographic footprints, product portfolios, and regulatory credentials for leading CRP players.
- Raw‑material sensitivity module: elasticities for anthracite, artificial graphite, and binder costs; stress tests showing margin compression points and pass‑through thresholds.
- Regulatory risk matrix: jurisdictional readiness indicators for occupational exposure limits and PAH restrictions, with mitigation playbooks for manufacturers and smelters.
- Technical annex: comparative performance metrics (e.g., density, thermomechanical stability, electrical resistivity targets), and recommended test protocols for qualification.
Note: The report provides granular segmentation by region, type, and application—available in full in the source publication. The present executive summary intentionally omits those segment‑level disclosures to preserve the value of the full dataset.
Market Dynamics and Technology Trends Shaping 2026
- Feedstock constraints and input cost pressure: CRP formulations remain principally derived from calcined anthracite, artificial graphite, and traditional coal tar pitch binders. Price dynamics for these inputs are increasingly influenced by mining capacity, logistics bottlenecks, and competition from adjacent carbon product markets.
- Binder evolution: Concerns over polycyclic aromatic hydrocarbons (PAHs) associated with coal tar pitch are accelerating adoption of alternative binders—furan resins, lignin‑based systems, and treated pitches—that deliver reduced or zero PAH emissions without materially sacrificing thermal stability.
- Performance conformance: Industry practice targets finished CRP electrical resistivity in low ranges appropriate for cathode and furnace sealing functions; suppliers are optimizing particle size distribution and additive mixes to balance density, adhesion, and thermal cycling resistance.
- Regulatory tightening: Several large aluminum producers and furnace operators are actively trialing eco‑friendly pastes, and jurisdictions are increasingly scrutinizing PAH emissions and volatile organic compound (VOC) liberation—creating both compliance obligations and first‑mover commercial advantages.
Competitive Landscape — Who Matters
The CRP supply base blends multinational incumbents and regional specialists. Market concentration is modestly elevated at the top: the three largest suppliers account for around 45.5% of reported market volume, while the top five reach about 62.3%. That structure creates room for niche innovation and for regional scale plays.
- Elkem ASA (Oslo, Norway): A leading technology and materials provider, Elkem’s ELSEAL® cathode ramming paste variants—paired with Brazilian production capacity—underscore a strategy of integrated product branding and localized supply for aluminum electrolysis customers.
- Maruti Electro Carbon (Korba, India): Known for robust thermal‑stability formulations, Maruti competes on cost‑effective engineering and proximity to growing aluminum capacity in South Asia.
- Henan Rongxing Carbon (Rongxing Group, China): With decades in carbon metallurgy, Rongxing’s portfolio includes eco‑variants and furnacing products—appealing to regional smelters seeking compliant, locally sourced CRP.
- Bawtry Carbon (UK) and Carbone Savoie (France): European suppliers are differentiating on reduced‑PAH products and validated industrial trials; Carbone Savoie explicitly markets 100% eco‑friendly CRP with reduced or zero PAH content, an important reference point for purchasers targeting sustainability KPIs.
- Chinese players (multiple): A cluster of manufacturers—Ningxia Hongyuan Huida, Luoyang Longxin, Shandong Robert New Material, Wuhai Cowin Carbon, Ningxia Coalician—provide scale and cost competitiveness, often coupled with product lines aimed at both new lining projects and repair cycles.
For 2026, the strategic tension is clear: incumbent, high‑quality suppliers emphasize validated low‑PAH formulations and industrial trial data; regional players leverage proximity and price. The optimal commercial playtable for buyers will blend technical validation with secure supply arrangements.
Strategic Imperatives for 2026
- Prioritize binder qualification now: Procurement and technical teams should accelerate qualification programs for low‑PAH binders in Q1–Q2 2026 to avoid reactive sourcing later in the year when adoption scales and lead times extend.
- Secure diversified feedstock routes: Hedging strategies for anthracite and artificial graphite—through multi‑sourcing, toll‑processing agreements, or vertical partnerships—will materially reduce margin volatility.
- Adopt a phased price‑pass‑through framework: Contractual mechanisms that reflect raw‑material indexes while protecting end‑users from sudden spikes ensure commercial stability across the value chain.
- R&D and co‑development partnerships: Smelters and paste makers should co‑fund field trials to accelerate scale‑up of eco‑compliant mixes; sharing test data reduces qualification timelines and diffusion risk.
- Prepare for accelerated capex on retrofits: OEMs and smelters that plan furnace or cell relining should incorporate low‑emission paste specifications into procurement tenders to capture future cost of compliance.
- Scan for bolt‑on M&A: For participants seeking to expand technology breadth, target companies that offer validated low‑PAH chemistries or control strategic feedstock access—these will command premiums in 2026.
Getting the Full Picture
PW Consulting’s full report provides the operational worksheets, supplier scorecards, and the complete segmentation matrices necessary to execute the recommendations above. It also includes a technical appendix detailing typical formulations—where binders historically represent a significant portion of CRP composition—and the test protocols used to measure electrical resistivity and thermomechanical performance.
In short: 2026 is the year to move from observation to implementation. Companies that align sourcing, product development, and regulatory strategy now will convert a measured market expansion—forecast at a 4.0% CAGR through 2032—into lasting competitive advantage. For the comprehensive dataset, granular segment forecasts, and bespoke advisory support, access the full Worldwide Cold Ramming Paste Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dispute Advisory & International Arbitration Market Set to Expand at 6.35% CAGR Through 2032, Report Finds
By PW Consulting, 2026-07-15
Worldwide Dispute Advisory and International Arbitration Market — 2026 Strategic Brief
Executive summary
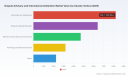
As companies confront a more litigious and geopolitically fragmented commercial environment in 2026, dispute advisory and international arbitration have shifted from episodic cost centers to strategic levers for portfolio protection, regulatory compliance, and cross-border deal certainty. PW Consulting’s new market study — covering historical performance (2020–2025) and forward projections through 2032 — combines quantitative market architecture with practical playbooks designed for C-suite, in-house counsel, and advisory leaders. The global market for dispute advisory and international arbitration services expanded materially in the 2020–2025 period and, with a compound annual growth rate of 6.35% embedded in our forecasts, is positioned for continued mid-single-digit growth through 2032. The 2025 market baseline documented in the study provides a robust starting point for scenario planning in 2026.
Worldwide Dispute Advisory and International Arbitration Market
Why this report matters for 2026 decision-makers
- Strategic timing: The confluence of renewed commercial activity, tariff- and sanction-driven disputes, and accelerated digital evidence flows has increased both the frequency and complexity of international arbitrations. Our study converts these macro dynamics into actionable decision criteria for boardrooms and legal operations teams.
- Investment prioritization: With service delivery increasingly hybrid — blending counsel, expert networks, and technology platforms — leaders must choose where to allocate capital for optimal dispute readiness. The report frames trade-offs between insourcing, panel counsel, and specialist boutiques.
- Risk-weighted planning: We translate market momentum and institutional case volumes into scenario-based financial and operational stress tests that counsel and CFOs can use when sizing reserves, insurance, and third-party funding needs.
Market trajectory and macro drivers
The market expanded from its 2020 baseline through 2025, reflecting resilient demand across commercial, investor-state, and post-transaction disputes. Our projection pathway to 2032 incorporates a 6.35% CAGR and quantifies how shifts in cross-border trade, ESG-linked disputes, and the adoption of AI for document review and analytics will influence demand for differentiated advisory capabilities.
Worldwide Dispute Advisory and International Arbitration Market
Beyond volume growth, market structure matters. While a healthy set of global firms and specialist boutiques compete for high-value mandates, concentration metrics show the sector remains fundamentally fragmented — top-tier players hold meaningful but not dominant shares, creating room for regional specialists and service innovation. Recent institutional data documenting high internationality of casework and the continued significance of major arbitral centres further reinforce that organisational reach and multi-jurisdictional coordination are decisive selection criteria for claimants and respondents alike.
Worldwide Dispute Advisory and International Arbitration Market
Practical content you can deploy immediately — what the report includes
A defining objective of this study is operational utility. We intentionally balance market-level intelligence with step-by-step tools and templates to accelerate capability development inside legal, commercial, and risk functions. Highlights from the report’s practical toolkit include:
- Scenario playbooks: Three alternative macro scenarios (baseline, accelerated globalization, and fragmentation) with corresponding dispute volumes, cost-impact curves, and recommended resourcing mixes for small, mid-market, and large enterprises.
- Tactical templates: Draft RFPs for appointing lead counsel and experts; a modular arbitration project plan covering intake, case budget phasing, evidence management, and enforcement strategy; and a sample governance charter for multi-jurisdictional arbitration portfolios.
- Forensic and quantum checklists: Practical procedures for forensic accounting, damage quantification, and chain-of-custody for digital evidence aligned with contemporary data protection expectations.
- Data privacy & e-evidence playbook: Compliance checklists mapped to GDPR Article 32 and best-practice guidance from the ICCA-IBA Joint Task Force — designed to reduce disclosure risk while preserving evidentiary value.
- AI governance framework: Controls and procurement criteria for integrating AI tools into review, analytics and expert support, incorporating model validation, audit trails, and defensibility constructs for tribunal scrutiny.
- Vendor selection and operating model comparator: Criteria-based scorecard to assess forensic, technical, and counsel providers, supported by a qualitative matrix of service delivery models and outsourcing thresholds.
- Enforcement and funding playbooks: Decision trees that align enforcement jurisdictions’ practicalities with third-party funding, insurance recoverability, and corporate risk appetites.
The full report contains additional field-level benchmarks, case studies and contract clause recommendations — including granular regional and service-line splits and pricing matrices reserved for subscribers and report purchasers.
Competitive landscape — who matters and why
The dispute advisory and international arbitration market blends global full-service firms, elite arbitration boutiques, and the major professional services networks. Our competitive review evaluates capability across four dimensions: advocacy strength, integrated advisory services (forensics, valuation, technical), geographic reach, and innovation in case management (including tech adoption).
- Global 1–2 firms: Long-established full-service firms bring breadth and institutional client relationships across litigation, transactional work, and public international law. Their value proposition is integrated end-to-end handling of complex, cross-border matters.
- Elite boutiques: Specialist arbitration practices deliver focused advocacy, deep tribunal relationships, and often strong outcomes in high-stakes mandates where reputational capital and specialist knowledge of arbitration institutions are decisive.
- Advisory networks: Professional services firms and accountancy-led practices provide forensic accounting, quantum, and expert services that increasingly sit at the centre of settlement dynamics and tribunal decision-making.
Profiles in our analysis include leading global law firms and specialist practices known for arbitration excellence, as well as the major professional services networks. We assess these organisations along actionable axes: where to choose a global integrated team versus a boutique lead counsel plus specialist advisory split; how to structure fee arrangements; and when to mobilise in-house dispute units to reduce long-term spend and preserve institutional knowledge.
Recent industry signals that shape 2026 priorities
Institutional and market developments point to a recalibration of priorities:
- ICC releases and other institutional statistics demonstrate sustained internationality and significant pending case values, reinforcing the need for enforceability-first strategies and forum selection diligence.
- Rankings updates and awards continue to concentrate reputation and referral flows among recognized market leaders, but the sector’s fragmentation gives specialist entrants and regional champions clear pathways to growth.
- Regulatory and technical trends — including GDPR-aligned evidence handling and the ICCA-IBA guidance on data protection — require firms and corporates to harmonise disclosure practices with operational security and tactical advantage.
- AI and digital evidence trends introduce both efficiency gains and governance obligations; adopting tools without robust validation and auditability risks procedural exposure in tribunal proceedings.
Strategic recommendations for 2026
- Align dispute strategy with broader commercial objectives: Treat arbitration choice (forum, seat, rules) as a strategic variable in contract negotiation and deal structuring, not merely a post-dispute response.
- Invest in modular in-house capability: Build a core team for intake, triage, and coordination, supplemented by panel relationships with boutiques and forensic experts for spikes in demand.
- Embed data governance in dispute readiness: Map data flows, define defensible e-disclosure strategies, and adopt the AI governance checklist recommended in the report before procurement of automated review tools.
- Use scenario-based budgeting: Apply the report’s scenario playbooks to stress-test reserves, insurance cover, and third-party funding triggers across plausible macro paths through 2032.
- Prioritise enforceability and remedies planning early: Evaluate enforcement corridors, sovereign exposure, and recovery mechanics as part of case intake rather than an afterthought.
Methodology and data integrity
The study synthesises proprietary PW Consulting modelling, public institutional statistics, firm-level disclosures, and primary interviews with in-house counsel, arbitration practitioners, and expert witnesses. Historical coverage spans 2020–2025 with a base year of 2025; forecasts run to 2032 and embed a 6.35% compound annual growth assumption balanced across volumetric and value drivers. Concentration indicators and institutional casework inputs have been cross-validated against market publications and arbitration registry releases to ensure conservative, defensible projections.
Next steps — where to get the full intelligence
This briefing is designed to demonstrate the strategic value of the full PW Consulting market study for 2026 operational and investment decisions. The report contains proprietary segmentation tables, region- and service-line level benchmarks, transaction- and case-level vignettes, and downloadable operational templates. For counsel and leaders seeking to convert the study’s insights into an executable dispute readiness programme, PW Consulting provides bespoke advisory workshops, implementation roadmaps, and live scenario modelling sessions.
Contact PW Consulting to request the complete report, arrange a briefing, or commission a tailored arbitration readiness assessment aligned to your firm’s portfolio and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Multi-Point Ground Flares Market to Expand at 6.52% CAGR During 2026–2032
By PW Consulting, 2026-07-15
Worldwide Multi-Point Ground Flares (MPGF) Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on Worldwide Multi-Point Ground Flares (MPGF) synthesizes technical, regulatory, and commercial intelligence into a compact playbook for executives facing investment, procurement, and compliance choices in 2026. Anchored on a 2025 base year and a seven-year forecasting horizon (2026–2032), the report models a steady market expansion at a compound annual growth rate (CAGR) of 6.52%. Our baseline scenario places the market at approximately 346.5 USD Million in 2025, rising to roughly 369.1 USD Million in 2026 and projecting toward 539.1 USD Million by 2032 (USD Million). This growth backdrop creates both clear opportunities and discrete risks for players across oil & gas, petrochemical, and LNG value chains.
Worldwide Multi-Point Ground Flares (MPGF) Market
Why this briefing matters for 2026 strategy
-
Timing: 2026 is a hinge year for many capital programs initiated in the post‑pandemic recovery; supply chain normalization and regulatory scrutiny are converging to change procurement levers and project economics.
Worldwide Multi-Point Ground Flares (MPGF) Market -
Risk and compliance: Recent regulatory precedents—such as EPA-sanctioned Alternative Means of Emission Limitation (AMEL) approvals for pressure-assisted MPGFs and the ongoing reliance on standards including ISO 23251/API 521 and 40 CFR 60.18—mean that design decisions now will have multi-year compliance implications.
Worldwide Multi-Point Ground Flares (MPGF) Market -
Market concentration: The MPGF market shows meaningful concentration at the top (CR3 ~58.4%; CR5 ~72.15%), implying that vendor selection, long‑lead components, and aftermarket agreements should be treated strategically rather than transactionally.
What the full PW Consulting report delivers (high level)
We designed the report as a practitioner’s resource that translates market intelligence into executable actions. Key deliverables include:
-
Market model and demand scenarios (2026–2032) with sensitivity to energy prices, upstream activity, and regulatory tightening — enabling risk-adjusted CAPEX planning.
-
Procurement and vendor evaluation matrices that weight technical performance (smokeless capacity, turndown range, destruction efficiency), lifecycle cost (CAPEX + predictable O&M), and compliance track record.
-
Technical decision framework outlining when to choose enclosed array vs. open MPGF, assist‑gas strategies (air/steam/pressure assist), staging philosophies, and monitoring/ignition redundancy approaches.
-
O&M playbook covering inspection schedules, spare parts criticality mapping, and remote monitoring requirements (including camera/SCADA integrations) to meet both operational and permitting obligations.
-
ESG and emissions reporting templates aligned with key regulatory expectations and investor disclosure practices, helping asset owners demonstrate Best Available Control Technology (BACT) considerations when required.
-
Competitive landscaping and supplier scorecards, including technology differentiators, aftermarket footprint, and typical contract structures (turnkey, EPC, equipment supply + services).
Data-driven directional insights (what the numbers imply)
The market’s mid-single-digit CAGR reflects a dual reality: stable, structural demand stemming from ongoing hydrocarbon processing volumes, and technology-driven replacement and upgrade cycles as operators prioritize smokeless, low-radiation solutions in environmentally sensitive locations. The year-on-year growth from 2025 into 2026 indicates capital allocation windows that will be meaningful but selective — favoring projects that combine emissions performance with predictable lifecycle economics.
Given the elevated share of the market controlled by a small set of suppliers, buyers should assume that lead times and negotiation leverage will vary across tiers. Early engagement on long‑lead items, modularization to mitigate site constraints, and service-level commitments for ignition and assist gas systems will materially affect both uptime and regulatory compliance.
Competitive landscape — who matters and why
The MPGF vendor ecosystem combines global combustion specialists and niche manufacturers who differentiate on smokeless performance, staging/turndown capability, and turnkey delivery. PW Consulting’s analysis highlights several strategic archetypes:
-
Zeeco, Inc. (United States, https://www.zeeco.com) — Positioned as a provider of MPGF systems engineered for highly variable waste gas volumes. Zeeco emphasizes safe, smokeless, and low-visibility flaring with a focus on pressure, flow, radiant heat, noise, and flame visibility control in sensitive areas. Suitability: operators prioritizing site‑specific customization and integrated emissions control.
-
John Zink Hamworthy Combustion (United States, Oklahoma, https://www.johnzink.com) — Offers LRGO™ MPGFs marketed on reliability, lifespan, high destruction efficiency (>99.5%), and wide turndown through staging systems. Often referenced where turnkey supply and established standards compliance (API 537 among others) are deciding factors. Suitability: larger projects requiring proven operational track records and extended performance warranties.
-
Aereon (part of Cimarron, United States, https://aereon.com) — Known for designs handling very large flows in array-enclosed configurations with multi-stage operation and assist gas/air/steam strategies for smokeless performance. Suitability: high‑throughput facilities and projects where staged operation and low-regime performance are critical.
-
Honeywell UOP Callidus (United States, https://uop.honeywell.com) — Supplies MPGF systems with a focus on high smokeless capacity and staged high-pressure burners for automatic matching to waste gas flow, targeting reduced radiation and versatility across onshore/offshore gas and petrochemical applications. Suitability: integrated process environments with complex control and automation expectations.
-
Encore Combustion (United States, https://encorecombustion.com) — Offers enclosed combustion MPGF (CrossFire series) that emphasize reliable ignition and proprietary burner designs for large-volume waste gas combustion. Suitability: operators seeking compact ground-footprint solutions with robust ignition architectures.
The report includes vendor scorecards that go beyond marketing claims to assess field performance, aftermarket presence, and contract risk — essential for procurement teams that must translate supplier selection into measurable uptime and compliance outcomes.
Regulatory and operational dynamics to watch in 2026
-
Regulatory precedent: EPA AMEL approvals for pressure-assisted MPGFs have set templates for monitoring and performance verification. Expect permitting authorities to require clearer monitoring plans and to favor systems with demonstrable low-visibility, low-smoke operation.
-
Standards convergence: Compliance with standards such as ISO 23251/API 521 and 40 CFR 60.18 — along with product-level API/ISO attestations — will increasingly be part of bid evaluation criteria.
-
Site monitoring expectations: Operators are installing additional camera and instrumentation coverage as a matter of routine (a step already observed in recent projects), and such monitoring investments often weigh favorably in permitting reviews.
Practical decision checklist for 2026 (executive summary)
-
Prioritize requirements: Define must-have vs. nice-to-have performance metrics — e.g., guaranteed destruction efficiency, turndown range, and smokeless performance at low regimes — before engaging suppliers.
-
Model lifecycle costs: Incorporate realistic O&M, assist gas consumption, spare parts, and monitoring/permit compliance costs into financial models rather than relying on headline CAPEX offers.
-
Lock supply chain early: Given market concentration and specialized components, secure long‑lead items and service agreements during early procurement stages to avoid schedule slippage.
-
Mitigate regulatory risk: Prepare AMEL-aligned monitoring and reporting plans where pressure-assisted MPGFs are proposed, and verify supplier experience with EPA/agency approvals.
-
Validate through pilot or phased deployment: Where feasible, adopt staged implementation to validate assist gas strategies and control logic before large-scale rollout.
-
Include aftermarket commitments: Insist on performance guarantees, spare parts lead-time clauses, and training packages for local O&M teams as components of contracts.
How PW Consulting supports your 2026 program
Our full MPGF market report and advisory services convert the above into actionable deliverables: vendor selection matrices, procurement templates, risk-adjusted NPV models, regulatory compliance checklists, and tailored supplier negotiations support. For boards and C-suite leaders, we also provide scenario briefings that translate technical options into shareholder-impact metrics (e.g., project IRR sensitivity, emissions disclosures, and compliance timelines).
We have intentionally withheld granular regional and application-level segmentation statistics from this briefing to preserve the “trailer” effect and to invite a direct consultation where we can share the full datasets and tailored implications for your asset portfolio. The comprehensive dataset in the report includes historical 2020–2025 trends, regional and application splits, and supplier-level market share detail — information that materially changes procurement and investment tactics when applied to a specific operating footprint.
Next steps
-
Schedule a tailored briefing with our MPGF practice to map the report’s scenarios against your project pipeline and compliance calendar.
-
Request the vendor scorecards and procurement templates if you are preparing an RFP in 2026; early access materially improves negotiation outcomes.
-
Engage PW Consulting for on-site due diligence and commissioning support to translate vendor guarantees into measurable performance during the warranty period.
PW Consulting’s Worldwide MPGF Market study is designed to be both a strategic compass and an operational manual for 2026. If your organization is evaluating MPGF investments, upgrading legacy flares, or reassessing compliance programs, the choices you make this year will determine cost, uptime, and regulatory exposure for the decade ahead. Contact our MPGF advisory team to access the full report and receive the datasets and templates that turn market intelligence into decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Point Ground Flares (MPGF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Agricultural Nanotechnology Market to Expand at 14.03% CAGR, Reaching USD 816.02 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Agricultural Nanotechnology Market 2026 Preview: Strategic Playbook for Executives
Why this report matters for 2026 decision-makers
The agricultural nanotechnology sector is transitioning from a technology-curiosity phase to a commercially actionable industry. PW Consulting’s latest market study captures that shift: the global market more than doubled in five years to reach an established mid‑market scale by 2025, and our forecast models point to sustained double‑digit expansion through 2032 at a compound annual growth rate (CAGR) of approximately 14.03%. By 2026, executives across agribusiness, specialty chemicals, and agtech must translate this trajectory into concrete choices about R&D priorities, go‑to‑market sequencing, M&A, and regulatory engagement. This press release summarizes the strategic takeaways and the ways PW Consulting’s full report is designed to support high‑stakes decisions—while deliberately leaving granular segment numbers for the report itself to preserve the “teaser” orientation that drives direct engagement with the source material.
Worldwide Agricultural Nanotechnology Market
Market momentum at a glance (macro signals)
- Strong historical growth: The sector exhibited rapid expansion in the early 2020s as lab innovations moved into field proofs and early commercial rollouts. The market more than doubled from the beginning of the decade to our 2025 base year.
- Accelerating commercialization: Our forecast shows market scale accelerating through the late 2020s and into the early 2030s, reflecting deeper adoption across fertilizer, pesticide, sensor and soil amendment use cases.
- Moderate concentration: Market concentration metrics indicate a moderate incumbent presence—top‑3 players account for roughly 31% of the market, and the top‑5 players just under 43%—leaving meaningful scope for disruptive entrants and local champions.
What corporate leaders need to wrestle with in 2026
Four decision vectors will disproportionately determine winners and losers in 2026:
Worldwide Agricultural Nanotechnology Market
- Product positioning vs. farmer economics: Nano‑enabled inputs often command a premium pricing structure given higher production complexity. The near‑term commercial question is whether crop‑level yield/quality improvements and total cost‑of‑use savings (application frequency, logistics, environmental compliance) convincingly offset higher unit costs for end users.
- Regulatory and environmental risk management: Concerns around nanoparticle fate, soil ecosystem interactions and long‑term environmental impact are real and will shape market access. Firms whose development pipelines are paired with transparent environmental data and third‑party validation will secure faster adoption.
- Integration with digital and precision agriculture: Nanotechnology is becoming most valuable when coupled with data streams from precision ag platforms and nano‑sensors. Strategies that align formulations with sensing, analytics and variable‑rate deployment will unlock superior ROI for growers.
- Supply chain and raw material strategies: Securing low‑cost, sustainable feedstocks—such as nanomaterials derived from agricultural waste biomass—will reduce unit economics and improve ESG narratives.
What PW Consulting’s report delivers (practical, actionable content)
Our full study is structured to convert market insight into implementation. Key deliverables include:
Worldwide Agricultural Nanotechnology Market
- Decision frameworks for prioritizing R&D investments (including go/no‑go criteria based on efficacy thresholds, toxicity testing requirements and farmer payback horizons).
- Commercial playbooks for channel strategies: pathways for direct farmer adoption, partnerships with distributors, and licensing models for co‑development with incumbents.
- M&A and partnership diagnostics: heat maps highlighting which sub‑segments and geographies are most likely to deliver strategic scale or de‑risked entry for corporate buyers.
- Regulatory navigation toolkit: a practical checklist for trial design, environmental monitoring, and stakeholder engagement to accelerate approvals and reduce litigation risk.
- Operational uplift recommendations: sourcing options for nanomaterial feedstocks (including biomass‑derived routes), scale‑up capex estimates, and manufacturing quality control protocols to preserve functional performance at scale.
Competitive landscape—profiles and strategic implications
The sector comprises a mix of specialized start‑ups, regional champions, and global agrochemical majors. Our qualitative and competitive analysis focuses on capabilities, go‑to‑market models, and strategic intent rather than headline revenue splits—allowing readers to identify partners, targets and rivals at the level required for 2026 planning.
- Aqua‑Yield Operations, LLC (Nano‑Yield) (United States) — A commercialization first mover in nano‑fertilizer and nutrient delivery systems. Their strength lies in agronomic field validation and rapid adoption among early‑adopter growers. Strategic implication: attractive partner for route‑to‑market pilots and localized scale‑ups.
- Indogulf BioAg LLC (US/India operations) — Focused on practical nano‑fertilizer SKUs and a cross‑border operational footprint. Strategic implication: represents a model for hybrid regional scaling and product localization in large, price‑sensitive markets.
- Migrow Agro Products, Annadata Organic, Ray Nano Science & Research Center, Coromandel International (regional innovators) — These firms illustrate the importance of localized formulation expertise, regulatory familiarity and farmer trust in emerging markets.
- BASF SE and Syngenta AG (global incumbents) — Both have stepped up nano‑enabled product development and portfolio integration, signaling that large agrochemical players are prepared to industrialize nanotech offerings. Strategic implication: agile start‑ups should expect fast follower behavior and consider licensing or selective partnerships to scale without provoking direct competition.
- Nanoshel, Zyvex Labs, Nanoco Group (materials and engineering specialists) — Provide upstream nanomaterials and platform technologies that can be embedded across fertilizers, pesticides and sensors. Strategic implication: vertical integration or long‑term supply agreements with materials providers will be critical to secure consistent performance and mitigate quality risk.
Recent industry moves and what they signal
- BASF accelerated development of nano‑enabled crop protection (Mar 2026), underscoring incumbents’ ability to deploy R&D firepower toward lower‑impact delivery systems.
- Syngenta expanded nano‑formulations into seed treatment and precision agriculture (Feb 2026), signaling end‑to‑end product integration as a priority.
- Nano‑Yield’s rapid growth recognition (Inc. 5000, Aug 2025) highlights the commercial viability of focused nano‑fertilizer propositions in permissive markets.
- Independent validation emphasis—exemplified by SGS field trials (Aug 2025)—points to the rising importance of third‑party evidence for efficacy and safety claims.
Regulatory, ESG and technical headwinds
Stakeholders should anticipate a bifurcated pathway to scale. On one hand, environmental and sustainability narratives (lower GHG through waste‑derived nanomaterials, reduced over‑application) support broader adoption. On the other hand, peer‑reviewed work and regulatory scrutiny raise legitimate questions about nanoparticle toxicity, persistence, and soil‑food chain interactions. Firms must prepare rigorous, transparent environmental monitoring data and proactively engage with regulators and civil society to avoid costly market delays in 2026.
Actionable strategic moves for 2026 (recommended priorities)
- Establish proof‑point partnerships now: Run co‑funded field trials with credible third parties and prepare data packages that answer regulator and buyer questions simultaneously.
- Prioritize sensor/formulation integration: Teams that align nano‑sensors with formulation economics will create differentiated value propositions for precision‑minded growers.
- Secure feedstock and materials agreements: Locking supply from low‑cost, sustainable sources (including biomass‑derived nanomaterials) will be a durable competitive advantage.
- Design staged go‑to‑market plays: Start in regions with clear regulatory pathways and receptive distribution channels, then scale through licensing or contract manufacturing rather than heavy capex when possible.
- Plan contingent M&A and alliance plays: Use the period of 2026–2028 to acquire capability (field validation, regulatory dossiers, regional distribution) rather than just product lines.
Methodology and how PW Consulting’s report supports execution
The report synthesizes historical market data (2020–2025 baseline), forward projections (2026–2032 forecasting), primary interviews with industry leaders, third‑party laboratory validation summaries, and a proprietary scenario model that stress‑tests adoption curves under alternative regulatory and price trajectories. The analysis provides both topline market sizing and the operational decision tools described above; however, granular segmentation tables and specific regional/application dollar splits are reserved for the full report—intentionally excluded from this preview to preserve commercial exclusivity for report purchasers.
Where this leaves executives in 2026
By the middle of 2026, leaders must treat agricultural nanotechnology as a strategic front rather than an R&D curiosity. The available data show a market with meaningful scale and attractive growth potential, paired with real technical and regulatory complexity. Executives who pair disciplined field validation, supply chain foresight, and regulatory transparency with pragmatic commercial models will capture disproportionate value as the market consolidates over the coming years.
Next steps
PW Consulting’s full Worldwide Agricultural Nanotechnology Market report is built to be a practical, board‑ready input for strategy and execution teams. For decision makers preparing 2026 budgets, M&A pipelines and product roadmaps, the report serves as both a diagnostic and a playbook. Detailed segmentation, scenario outputs, and executable checklists are available in the complete report—access it to move from strategic intent to operational execution.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Nanotechnology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


