



Category: market research
PW Consulting Forecast: Worldwide Facial Rejuvenation Market to Rise from USD 32,500 Million in 2025 to About USD 57,530 Million by 2032 at an 8.5% CAGR
By PW Consulting, 2026-07-15
PW Consulting: Worldwide Facial Rejuvenation Market — A 2026 Strategic Playbook for Executive Decision‑Making
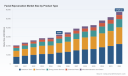
PW Consulting today publishes the executive overview for our Worldwide Facial Rejuvenation Market report (base year 2025), a practical intelligence product designed to inform boardroom decisions, commercial planning, and M&A prioritization throughout 2026. The global market—which grew strongly through the first half of the decade and reached an estimated USD 32,500 Million in 2025—is projected to expand at a compound annual growth rate (CAGR) of approximately 8.5% over the 2026–2032 forecast window, delivering robust upside potential for companies that align product, regulatory and go‑to‑market (GTM) strategies to emerging patient and provider behaviors.
Worldwide Facial Rejuvenation Market
Why 2026 is a Pivotal Year for Facial Rejuvenation Strategy
- Regulatory inflection points: New and intensified regulatory activity—ranging from cosmetic product modernization to device safety advisories—has raised the bar for market entry and post‑market surveillance. Firms that invest early in compliance and risk mitigation will avoid costly interruptions and will be favored by institutional buyers and clinic networks.
- Clinical and product innovation cadence: Clinical data and indication expansions (notably in injectables and energy‑based technologies) continue to reshape the clinical use cases for facial rejuvenation, creating both incumbent defense and new‑entrant opportunities.
- Consolidation and capability plays: The market shows concentrated leadership at the top tier alongside a vibrant middle market of specialized device makers and regional injectables companies. Expect M&A to remain an active lever for scale, distribution and portfolio diversification.
- Consumer and provider dynamics: An ongoing shift toward minimally invasive procedures, combined with a demand for outcome transparency and safety, is favoring integrated solutions that combine product efficacy with robust provider training and post‑care pathways.
What the Report Delivers — Pragmatic, Transaction‑Ready Insights
Our report is structured as a decision tool rather than a purely academic exercise. Key components include:
Worldwide Facial Rejuvenation Market
- Top‑down market sizing and seven‑year forecasts through 2032, with scenario outputs to stress test growth under alternative regulatory and reimbursement assumptions.
- Demand‑side analysis: patient demographics, clinical indications, treatment adoption curves, and reimbursement touchpoints that materially affect commercial uptake.
- Provider economics and channel models for dermatology clinics, medical spas and hospital‑based services — focused on throughput, average treatment value, and service mix optimization.
- Competitive profiles and strategic positioning for the leading pharmaceutical and device players in facial rejuvenation, including capability maps, R&D pipelines, commercial footprint, and likely M&A vectors.
- Regulatory and HTA landscape—practical compliance checklists, certification timelines and risk registers for devices, injectables and regenerative products.
- Commercial playbooks: pricing levers, distributorship models, clinical education programs, digital engagement and patient retention tactics that have demonstrated ROI in global pilots.
- A proprietary deal‑origination matrix and target list for acquirers and private equity investors, plus an integration playbook that minimizes clinic and clinician churn post‑transaction.
- Primary research appendices and a transparent methodology including our mix of expert interviews, payer assessments, and anonymized practice‑level data samples for reproducibility.
Competitive Landscape — Who Moves the Market
The sector’s leadership combines large pharmaceutical firms with deep injectables portfolios and specialist energy‑device manufacturers. Market concentration metrics indicate a meaningful share held by the top tier of competitors, which creates both barriers and opportunities depending on your entry strategy.
Worldwide Facial Rejuvenation Market
- Pharmaceutical incumbents: Global injectables leaders have fortified positions through product breadth, training networks and clinician loyalty programs. Recent activity demonstrates continued investment in training infrastructure and label expansions to broaden clinical use cases.
- Device specialists: Laser and energy‑based platform vendors sustain durable relationships with high‑volume clinics and hospital systems. Their success is increasingly tied to differentiating on safety, ease‑of‑use and outcomes measurement rather than raw energy specifications alone.
- Strategic transactions and new entrants: The past 24 months have seen trophy acquisitions that combine neuromodulator or filler platforms with adjacent skin health portfolios. New product launches from non‑traditional entrants (e.g., consumer skincare brands moving into cleared devices) are raising competitive intensity at the lower end of the market.
Representative companies covered in the report include well‑known global players across injectables and energy devices, along with a selection of innovative mid‑market vendors. For each we provide an assessment of strategic strengths, gaps to close, and near‑term catalysts to watch.
Recent Developments to Watch (Implications for Strategy)
- Major injectables players are expanding clinician training capacity—an explicit recognition that education is now a strategic asset linking product adoption, safety outcomes and recurring revenue.
- Regulatory approvals extending indications for volume restoration and regenerative stimulators have immediate GTM implications: companies that rapidly operationalize new indications into bundled clinical pathways capture premium positioning.
- Device safety communications and national consultations on non‑surgical cosmetic regulation are increasing compliance costs and creating an operational premium for firms that can certify product safety and training standards at scale.
Five Strategic Priorities for 2026
- Operationalize regulatory readiness: Embed regulatory and safety expertise into product development and commercialization with an explicit compliance timeline and a product‑specific risk registry. Prioritize audit‑ready documentation and surgeon/clinician certification programs.
- Invest in provider enablement: Scale hands‑on training, digital education platforms and accredited mentorship programs. Training centers and high‑quality clinical education are now a competitive moat for leading injectables businesses.
- Design portfolio resilience: Balance high‑growth minimally invasive offerings with durable, repeatable revenue sources (e.g., maintenance protocols, consumables and clinic service subscriptions) to reduce sensitivity to episodic demand shifts.
- Pursue pragmatic M&A and partnerships: Target deals that either extend access to high‑value clinical channels (multi‑clinic groups, hospital outpatient networks) or add differentiated technology that accelerates patient outcomes measurement and retention.
- Differentiate through outcomes and digital experiences: Deploy objective outcome metrics and patient‑facing digital journeys that reduce perceived risk, improve adherence to aftercare protocols, and support premium positioning in competitive markets.
How Different Stakeholders Should Use This Intelligence
- CEOs and corporate development teams: Use our scenario models to prioritize acquisition targets, size integration investments and model synergies based on treatment economics rather than headline revenue multiples.
- Commercial leaders: Leverage the clinic and provider economics playbooks to design incentive models, training curricula and distribution partnerships that drive recurring utilization.
- Investors: Apply the report’s risk‑adjusted forecasts and deal origination matrix to refine valuation assumptions and to identify actionable roll‑up strategies in fragmented local markets.
- Policy and compliance teams: Adopt the regulatory checklists and device safety playbooks as a foundation for global harmonization efforts and to prepare for jurisdictional licensing changes under discussion in several markets.
Accessing the Full Intelligence — Why You’ll Want the Data Room
This release is a strategic preview. Our full report and interactive data models include proprietary segmentation by product, region and end‑user, scenario‑based P&L impacts, and downloadable clinic‑level assumptions. These granular datasets power transaction models, GTM roadmaps and regulatory compliance timelines that clients use to accelerate execution in the first 90–180 days after acquisition or market entry.
PW Consulting’s methodology combines primary interviews with clinicians and procurement leads, anonymized practice economics, regulatory timeline mapping and a bottoms‑up supply/demand synthesis. The result is an operational forecast you can action — not a high‑level chartbook.
Final Word — From Insight to Impact in 2026
Facial rejuvenation is in a phase where scientific innovation, increased regulatory scrutiny and evolving patient expectations are converging into actionable commercial opportunities. With a strong baseline market size and a healthy CAGR, the prize remains substantial—but it is contingent on disciplined execution across regulatory, clinical and commercial dimensions. PW Consulting’s Worldwide Facial Rejuvenation Market report is designed to be the single source of truth for leaders who must make defensible bets in 2026: choosing the right M&A targets, structuring provider partnerships, and building product portfolios that withstand regulatory and market shocks.
To access the full report, interactive models and confidential deal‑origination lists, contact PW Consulting’s research team or visit our report page for purchase and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Facial Rejuvenation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.02% CAGR for Worldwide Oyster Shell Calcium Market Through 2032
By PW Consulting, 2026-07-15
Worldwide Oyster Shell Calcium Market — Strategic Imperatives for 2026
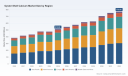
PW Consulting today publishes an executive briefing drawing on our new Worldwide Oyster Shell Calcium Market report (Base Year: 2025; Historical: 2020–2025; Forecast: 2026–2032). The market has demonstrated resilient expansion — rising from a market size in 2020 to a materially larger industry by 2025 — and our baseline forecast projects continued growth through 2032 at a compound annual growth rate (CAGR) of approximately 6.02%. With an evaluated trajectory into the early 2030s, oyster shell calcium is transitioning from a niche raw material into a strategic building block for nutritional, feed, food & beverage, pharmaceutical, and specialty industrial value chains.
Worldwide Oyster Shell Calcium Market
Why this briefing matters for 2026 corporate strategy
- Timing a structural growth phase: After a multi-year period of expansion, the market is entering a phase in which demand broadens across established and emerging applications. Organizations that translate that momentum into procurement, R&D, and channel playbooks in early 2026 will capture disproportionate share.
- Margin and supply balance risk: Raw material sourcing, processing yields, and quality specifications are primary determinants of margin in oyster shell calcium. Small variances in ash, carbonate purity and particle-size distribution materially affect downstream formulation cost and product claims.
- Regulatory and traceability pressures: Health-and-supplement regulations, feed-grade approvals, and clean-label expectations are converging to make provenance and documentation a competitive differentiator.
- Consolidation window opening: Market concentration metrics indicate a mid-level aggregation of supply. This is a market where targeted M&A and strategic alliances can rapidly re-shape regional access and product portfolios.
Data-driven context (selected headline metrics)
Using 2025 as the base year, our top-line model captures historical performance from 2020–2025 and projects forward through 2032. The model embeds a 6.02% CAGR across the forecast period, reflecting a blend of volume growth in core applications and incremental price/mix uplift from higher-value processed forms and specialty grades. The market concentration measured at the top end — with three- and five-firm concentration ratios — suggests a competitive environment that is neither highly fragmented nor dominated by a single actor (CR3 ~38.5%; CR5 ~54.1%).
Worldwide Oyster Shell Calcium Market
These headline statistics are the foundation for scenario planning: conservative, base, and accelerated adoption cases in our report quantify sensitivity to feedstock availability, regulatory shifts, and value-added product development.
Worldwide Oyster Shell Calcium Market
What the full report delivers — practical, decision-grade intelligence
- Transparent methodology: Detailed explanation of data sources, forecasting assumptions, and scenario parameterization so executives can audit the model and re-run sensitivity tests against internal KPIs.
- Demand maps and end-use economics: Application-level demand drivers, unit economics, and margin waterfalls for dietary supplements, animal feed, food & beverage, and pharmaceutical applications (note: this briefing intentionally omits segment line-item numbers; full splits are available in the full report).
- Supply-chain diagnostic: Sourcing profiles, seasonal yield variability, processing throughput benchmarks, and logistics cost models tailored to powdered vs. granular production formats.
- Regulatory & quality framework: Comparative compliance checklists across priority markets, certification pathways, and a traceability playbook for ingredient-to-pack documentation.
- Competitive and M&A playbooks: Company scorecards, capacity overlays, and a prioritized shortlist of M&A targets and JV candidates based on strategic fit and integration risk.
- Commercial tactics: Go-to-market strategies for premiumization, co-branding with supplement manufacturers, route-to-market options for animal feed converters, and sample launch templates for food ingredient customers.
- Risk register & contingency planning: Tailored mitigation options for feedstock shocks, regulatory tightening, and rapid demand shifts in adjacent ingredient markets.
Competitive landscape — positioning three market exemplars
- Carich Biotechnology Co., Ltd. (Taichung, Taiwan)
Strengths: High-purity calcium carbonate powder engineered for dietary supplements and pharmaceutical uses. Strategic focus on quality control, traceability, and high-value segments. Value proposition centers on consistent purity specs and GMP-oriented processes.
Implication: Companies targeting premium supplement and pharmaceutical customers should evaluate supply agreements or co-development partnerships to secure high-spec feedstock and accelerate time-to-market for clinically oriented formulations.
- Viet Delta Industrial Co., Ltd. (Ho Chi Minh City, Vietnam)
Strengths: Cost-competitive ground oyster shell powder for animal feed, agriculture and broader nutritional applications. Competitive advantage derives from sourcing access and scale in commodity-grade processing.
Implication: For players prioritizing volume-driven feed or agricultural channels, partnering with or benchmarking against cost structures from this supplier archetype is a necessary first step in building a resilient, low-cost supply chain.
- Eiwa Chemical Industrial Co., Ltd. (Osaka, Japan)
Strengths: Processed oyster shell calcium tailored to food supplements and functional ingredient markets with a reputation for product consistency and technical support for formulators.
Implication: Companies seeking application development support and market-ready formulations should consider technical alliances or toll-processing arrangements to shorten product qualification cycles.
Collectively, these profiles illustrate the coexistence of premium, technical-grade suppliers and high-volume, cost-focused processors — a dynamic that both creates arbitrage opportunities and raises barriers for new entrants that lack specialty capabilities or sourcing control.
Strategic action road map for 2026
- Immediate (0–6 months): Conduct a supplier and contract audit using our supplier scorecard; initiate a pilot qualification with a technical-grade supplier for at least one high-margin SKU; benchmark landed cost by geography.
- Near term (6–18 months): Secure dual-sourcing for feedstock with complementary risk profiles; invest in particle-size and surface-modification capabilities to capture premium formulation premiums; deploy traceability and documentation systems aligned to regulatory expectations.
- Medium term (18–36 months): Consider M&A or JV to secure raw-material access or expand into adjacent processing capacity; launch value-added product lines (e.g., standardized supplement grade blends) with co-marketing agreements to accelerate pull-through.
Use cases — how executives should apply the report in 2026 decisions
- Procurement leaders: Use the cost-models and supply-risk scenarios to renegotiate long-term contracts and set indexation clauses tied to validated purity/particle metrics rather than crude commodity indices.
- R&D and product teams: Leverage the formulation benchmarks and processing profiles to reduce qualification cycles and move toward proprietary blends that command higher margins.
- M&A teams: Apply the company scorecards and valuation playbooks to prioritize targets that close gaps in geography, capacity, or technical capability — accelerating time-to-scale at lower integration risk.
- Regulatory & quality leads: Implement the compliance matrix to preempt market-specific labeling and safety audits, reducing time-to-market delays and protecting brand reputation.
Why PW Consulting’s report is unique
- We combine granular technical understanding of calcium carbonate processing with commercial forecasting that links to real-world procurement and formulation decisions.
- Our scenario-driven model is audit-ready and re-runnable against client-supplied assumptions, enabling bespoke strategy stress-tests for price, supply disruption, or regulatory change.
- We deliver practical playbooks — not just charts — so teams can act immediately on sourcing, product development, and M&A opportunities.
Next steps and how to access the full intelligence
This briefing selectively highlights the strategic implications and headline market metrics to inform high-level planning. To preserve the commercial integrity of our work and to ensure clients can perform transaction-grade diligence, detailed segment-level figures, regional splits, application-specific numbers, and full company valuation appendices are available only in the full report.
For procurement teams, product leaders, and corporate development executives preparing 2026 budgets and road maps, the full report provides the numerical granularity, scenario matrices, supplier scorecards, and M&A shortlists needed to make executable decisions. Contact PW Consulting or visit our report landing page to request the full report, sample exhibits, or a tailored brief specific to your corporate use case.
PW Consulting — translating market signals into executable strategy for the oyster shell calcium value chain in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Oyster Shell Calcium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Wearable Injectors Market Poised to Grow at 13.5% CAGR
By PW Consulting, 2026-07-15
Worldwide Wearable Injectors Market: Strategic Imperatives for 2026 — A PW Consulting Preview
PW Consulting’s latest market intelligence on the Worldwide Wearable Injectors market synthesizes verified market sizing, supplier dynamics, regulatory and reimbursement shifts, and actionable go-to-market frameworks to inform executive decisions in 2026. This briefing highlights the report’s strategic value, outlines the major forces reshaping the market, and previews the competitive landscape — while preserving the report’s proprietary, granular segment tables and playbooks for subscribers.
Worldwide Wearable Injectors Market
Why this report matters for 2026 planning
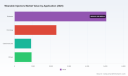
The wearable injectors sector is maturing from a niche delivery innovation into a strategic channel for high-value biologics and chronic care therapies. After strong expansion through the early 2020s, global adoption accelerated; by our base year the market has reached a multibillion-dollar scale and is forecast to sustain double-digit growth through the early 2030s at a 13.5% compound annual growth rate. For commercial leaders, R&D heads, and corporate strategy teams, this trajectory signals a time-sensitive window to secure partnerships, adapt device-development roadmaps, and optimize reimbursement strategies before the technology becomes entrenched across therapy classes.
Worldwide Wearable Injectors Market
What you get from PW Consulting’s Worldwide Wearable Injectors Market report
- Validated market sizing and trend analysis covering historical performance (2020–2025) and long-range forecasts (2026–2032), with scenario stress-tests tied to regulatory and reimbursement inflection points.
- Competitive intelligence dossiers on the leading platform providers, contract manufacturers, and strategic partners — including technology profiles, capability maps, and commercialization readiness scoring.
- Operational playbooks for device-to-drug co-development: preferred development timelines, human factors priorities, regulatory routes, and pivotal clinical endpoints that payers and regulators scrutinize.
- Commercialization blueprints: reimbursement pathway templates, pricing sensitivity models, formulary negotiation checklists, and patient-adherence impact simulations.
- Supplier and materials benchmarking: cost drivers, sourcing risk matrices, and cost-reduction levers rooted in component- and polymer-level analysis.
- Customizable slide decks and board-ready one-pagers for investor, partner, or internal stakeholder engagement.
Market dynamics shaping 2026 decisions
Several converging forces make 2026 a decisive year for stakeholders in wearable injectors:
Worldwide Wearable Injectors Market
- Regulatory harmonization and device safety expectations: International device standards — notably ISO 11608-01 for needle-based injection systems and IEC 60601-1 for electrical safety — remain foundational for product design and premarket submissions. Compliance timelines are non-negotiable for market access and liability management.
- Reimbursement momentum in major markets: Reimbursement pathways are maturing; in the United States the Centers for Medicare & Medicaid Services (CMS) recognizes wearable injector supplies under HCPCS coding that supports Medicare Part B reimbursement for subcutaneous delivery devices. This institutional recognition materially de-risks commercial uptake for hospital-administered and outpatient biologics.
- Cost pressure and supply-chain sensitivity: Device bill-of-materials are sensitive to polymer resin costs and specialty components. For example, medical-grade housing resins are a persistent cost input that device makers must manage through supplier diversification and design-for-cost strategies.
- Therapeutic migration: Wearable injectors are transitioning from diabetes-focused solutions to broader applicability in oncology, immunology, and long-acting cardiovascular biologics, altering value propositions across channel partners and payers.
Competitive landscape — who to watch
The market has consolidated around a set of platform specialists, CDMOs, and distribution partners. Market concentration is meaningful: the top three suppliers command a majority share while the top five approach three-quarters of the industry’s commercial footprint, underscoring the importance of strategic alliances or distinctive differentiation for challengers.
- Ypsomed (Switzerland) — A leading on-body injector provider with a portfolio geared toward high-volume subcutaneous biologics. Recent product iterations emphasize improved connectivity and real-time dose telemetry, which align with pharma sponsors’ demand for adherence data and remote monitoring capabilities.
- West Pharmaceutical Services (USA) — Active in large-volume wearable platforms through its SmartDose offering and commercial supply agreements. West’s strengths lie in scale manufacturing, integrated drug-device supply chains, and deep OEM partnerships that accelerate commercialization for pharma customers.
- Enable Injections (USA) — Notable for an FDA-cleared enFuse platform and a track record of partnering on commercial launches. Regulatory clearances and early commercial deployments position Enable as a fast follower for new biologic indications.
- Stevanda (India) — Focused on cost-competitive wearable auto-injectors aimed at emerging markets, offering a potential low-cost alternative for price-sensitive therapy segments.
- Medipim (Belgium) — Developer of multi-day delivery systems for chronic conditions, targeting differentiated use cases such as extended subcutaneous infusion from a single wear duration.
- Nexus Pharmaceuticals (USA) — A commercialization partner that leverages distribution and specialty pharmacy channels for on-body devices, particularly in oncology and rare disease niches.
Recent sector moves illustrate the dynamic nature of platform competition: product launches with enhanced connectivity (Ypsomed, Oct 2025), regulatory milestones enabling 10mL-class devices for additional indications (Enable, Jun 2025), and commercial supply deals that accelerate pharma adoption (West Pharma, Mar 2025). These developments validate a shift toward electronically controlled, data-enabled devices that integrate with patient-support ecosystems.
Strategic implications for industry players
For executives setting 2026 priorities, the PW Consulting report frames five strategic imperatives:
- Prioritize platform fit early in the molecule lifecycle. Clinical and commercial development plans should evaluate delivery modality trade-offs (self-administered wearable vs. clinic-administered vial/pen) by modeling adherence benefits, patient-experience uplifts, and payer willingness-to-pay across launch geographies.
- Embed digital and data strategies into commercial value propositions. Connectivity and real-world adherence data are becoming differentiators in payer negotiations and specialty pharmacy models.
- Secure manufacturing and materials flexibility. Design-for-manufacture and multi-sourcing are necessary to mitigate resin and component cost volatility; contractual volume guarantees and strategic inventory can blunt short-term raw-material price swings.
- Map regulatory pathways and pre-specify human-factors evidence. Conformance to ISO and IEC standards, plus robust human factors validation, shortens time to market and reduces post-market remediation risks.
- Design reimbursement-first launch strategies. Early engagement with payers and demonstration pilots that quantify administration cost offsets and adherence-driven outcomes enable more favorable coverage decisions.
What the report reveals — and what it withholds
PW Consulting’s report offers detailed market models, scenario analyses, company scorecards, supplier maps, and go-to-market templates designed for immediate operational use. To preserve the investigative value of the publication and to encourage direct engagement with our analysts, the summary above intentionally omits the granular regional and application-level tables and proprietary unit-cost spreadsheets — these are available only through the full report package and custom client briefings.
How leading firms will use this insight in 2026
- Biopharma sponsors will use the report to decide whether to adopt an on-body wearable strategy at Phase II vs. reserve for later lines, basing those decisions on payer-sensitivity scenarios and partner readiness matrices.
- Device manufacturers and CDMOs will prioritize investments in connected electronics and supply-chain resiliency, guided by the supplier benchmarking and BOM cost models included in the full study.
- Commercial teams will employ the reimbursement templates and pilot-design playbooks to secure coverage pathways and to design evidence generation studies that payers consider material.
Next steps
PW Consulting is releasing a limited series of executive briefings and custom workshops in Q3–Q4 2026 to operationalize these findings for clients pursuing collaborations, licensing agreements, or go-to-market launches. For companies evaluating product strategies, the full Worldwide Wearable Injectors Market report includes raw-model access, interactive scenario tools, and analyst hours to tailor findings to your portfolio.
To obtain the full dataset, proprietary segmentation tables, and our bespoke commercialization toolkit, please visit PW Consulting’s report page or contact our industry specialists for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Buruli Ulcer Treatment Market to Grow at 4.8% CAGR, Hitting USD 108.92 Million by 2032
By PW Consulting, 2026-07-15
Worldwide Buruli Ulcer Treatment Market: Strategic Preview for 2026 Decision-Makers
PW Consulting is pleased to release a strategic preview of our forthcoming Worldwide Buruli Ulcer Treatment Market report — a practitioner-focused dossier designed to orient commercial, procurement and public-health leaders as they make critical 2026 investment and operational decisions. This executive narrative synthesizes the report’s top-line market trajectory, competitive dynamics, and actionable playbooks, while intentionally withholding granular segment-level tables and price curves to encourage review of the full report for procurement-sensitive intelligence.
Worldwide Buruli Ulcer Treatment Market
Market trajectory at a glance
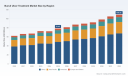
After steady growth during 2020–2025, the Buruli ulcer treatment market exhibits a resilient expansion profile. In absolute terms, PW Consulting’s market sizing places global annual revenues at approximately USD 62.15 million in 2020, rising to USD 78.45 million in our 2025 base-year. Under a range of demand and policy scenarios we modelled, the market is projected to continue expanding through the forecast horizon, reaching approximately USD 108.92 million by 2032. The central forecast implies a compound annual growth rate (CAGR) of 4.8% over the 2026–2032 period.
Worldwide Buruli Ulcer Treatment Market
These headline numbers reflect more than arithmetic growth: they capture the interplay of guideline-driven treatment protocols, donor and programmatic procurement patterns, and constrained commercial economics that characterise markets for neglected tropical diseases (NTDs). The headline growth is therefore meaningful for strategy: it signals a stable, predictable demand pool where execution — not market size volatility — differentiates winners.
Worldwide Buruli Ulcer Treatment Market
Why 2026 is a strategic inflection point
- Guideline consolidation: The World Health Organization’s 2023 update endorsing an 8-week daily rifampicin-plus-clarithromycin regimen crystallised demand profiles for fixed-dose and generic antibiotic packs. That standardisation reduces clinical uncertainty and simplifies procurement specifications — enabling scale-driven cost improvements for established suppliers.
- Procurement structures and pricing pressure: Treatment delivery remains largely funded through WHO-supported national programs and donor channels in endemic geographies. This procurement model prioritises cost-effectiveness and supply reliability over premium positioning, compressing margins but rewarding scale, WHO-prequalification, and tender agility.
- Supply-side fragility: The economics of Buruli ulcer treatment provide limited incentives for diversified API investment; supply chains remain heavily reliant on generic manufacturers and a small set of API sources. Firms that de-risk upstream supply via partnerships, backward integration, or long-term offtake agreements will materially improve their tender competitiveness into 2026.
What the PW Consulting report delivers (practical content)
Clients purchasing the full report receive a playbook tailored to 2026 operational choices. Our deliverables include:
- Transparent market-sizing and demand-forecast methodology (bottom-up and top-down reconciliation) anchored to treatment guidelines and country-level program data;
- Scenario-based price modelling and unit-cost curves calibrated to procurement modalities (tender cycles, buffer stocks, emergency procurements);
- Actionable supplier scorecards and procurement negotiation levers — including WHO prequalification implications, lead-time sensitivities, quality risk adjustments, and tender-weighting options;
- Supply-chain risk matrix and mitigation blueprints: API concentration mapping, dual-sourcing templates, and contract structures to safeguard continuity of supply;
- Commercial playbooks for non-profit and commercial entrants: go-to-market options by channel (tendering, program partnership, local manufacturing collaborations), pricing strategies, and partnership architectures;
- Regulatory & reimbursement pathway maps for priority geographies, and a prioritized list of program tenders and funding windows for the next 18 months;
- Company strategy diagnostics and M&A target shortlist for buyers seeking scale or capability augmentation within the niche NTD antibiotic space.
We designed these sections to be immediately operational: procurement directors can extract negotiation-ready language; commercial teams can run down prioritized partner targets; investors can identify de-risked acquisition candidates. To preserve competitive sensitivity, the public summary deliberately omits granular region-by-region and treatment-type splits — these are available in full to report subscribers and advisory clients.
Competitive landscape — who matters and why
The market structure is moderately concentrated, and PW Consulting’s concentration metrics indicate a top-tier grouping of established suppliers that capture a meaningful share of program tenders. The three largest suppliers together command a substantial portion of procurement volume, while the top five increase that concentration further — a dynamic that creates both barriers and opportunities for new entrants depending on their route to market.
Key incumbents we profile in depth include:
- WHO prequalified suppliers (exemplified by Macleods Pharmaceuticals): Firms holding WHO prequalification for relevant fixed-dose combinations benefit from preferential access to program procurement lists and long-term frameworks. Macleods’ prequalification for combination regimens strengthens its eligibility across many tenders and reduces evaluation friction in procurement cycles.
- Sandoz (Novartis Division): As a major generics player, Sandoz brings scale manufacturing and established global supply chains to antibiotic supply. Its distribution reach and compliance credentials make it a credible partner for program-level procurement, particularly when tender specifications value supplier reliability and QA history.
- Cipla: Cipla’s experience producing generics for various NTDs and its cost-competitive manufacturing platform make it a natural supplier to program-driven markets. Its ability to integrate global tenders with regionally adapted supply solutions is a differentiator.
Our competitive diagnostic highlights how WHO prequalification, tender responsiveness, supply continuity (backed by API security), and local-market access form the highest-weighted criteria used by national procurement bodies. Recent developments — notably the WHO guidance reaffirmation and prequalification actions — have immediate procurement implications: buyers can simplify technical evaluations but will also demand watertight supply guarantees from shortlisted suppliers.
Regulatory, reimbursement and programmatic drivers
- Clinical standardisation: The WHO’s endorsement of the 8-week rifampicin-clarithromycin regimen reduces regimen variability and shapes pack-sizing and SKU rationalisation for manufacturers and procurers alike.
- Program-funded reimbursement: In most endemic settings, treatment is provided through WHO-supported national programs at no direct cost to patients. This public funding model centralises purchasing and privileges low-cost, WHO-prequalified suppliers in tender reviews.
- No vaccine pathway: With no preventive vaccine currently available, program spend remains concentrated on diagnostics, antibiotics and wound care — supporting predictable baseline demand for therapeutic products.
Risks, friction points and opportunity windows
Important strategic considerations for 2026 decisions include:
- API concentration risk: Heavy reliance on a narrow set of generic suppliers for core antibiotics exposes procurers and producers to upstream shocks. Firms that secure API supply via long-term contracts or regional API investments can differentiate on reliability.
- Commercial incentives are limited: Because treatments are provided free in program settings, margin pressures are persistent. New entrants must identify non-traditional value levers — such as local manufacturing partnerships, integrated diagnostics-plus-treatment offers, or service-level contracts with program implementers.
- Tender timing & donor alignment: Visibility into donor funding cycles and national procurement windows offers tactical advantage. Our full report includes a prioritized tender calendar and donor-engagement playbook to maximise 2026 capture rates.
What PW Consulting recommends for decision-makers in 2026
- For suppliers: Prioritise WHO prequalification where feasible, secure API offtake agreements, and structure tender responses emphasizing delivery guarantees, buffer-stock proposals, and total-cost-of-supply metrics rather than headline price alone.
- For procurers and donors: Use multi-year framework agreements with performance-linked incentives to stabilise supply and reduce transaction costs. Invest selectively in local capacity-building to shorten lead times and reduce logistics risks.
- For investors and M&A teams: Target companies with WHO prequalification, demonstrated tender success, and API security. Asset-light entrants should partner with incumbents to access program lists while deploying capital into API or secondary packaging capabilities.
Next steps — access to the full intelligence
This executive preview highlights the strategic levers and decision pathways that matter in 2026, but it intentionally omits procurement-sensitive segment tables and granular regional/treatment splits. PW Consulting’s full Worldwide Buruli Ulcer Treatment Market report provides those line-item tables, supplier scoring matrices, price-by-SKU curves, and a prioritized tender map — all essential for executing on the strategies described above.
Clients seeking rapid, tailored advice for 2026 planning can commission a PW Consulting briefing or a short advisory engagement. Our team will map the report’s intelligence to your organisation’s objectives, producing a concise action plan (tender targeting, supplier negotiation script, or M&A shortlist) ready for immediate execution.
For procurement and health program leaders, 2026 will reward those who pair guideline-aligned product offerings with ironclad supply continuity and nuanced donor engagement. PW Consulting’s analysis equips decision-makers to convert the market’s steady growth (projected at a 4.8% CAGR through 2032) into predictable, de-risked operations and targeted investments — while the full report supplies the precise segmentation and price intelligence necessary for execution.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.48% CAGR to Drive Worldwide Thoracic Drainage Devices Market Growth Through 2032
By PW Consulting, 2026-07-15
Worldwide Thoracic Drainage Devices Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to present an executive preview of our new market intelligence: the Worldwide Thoracic Drainage Devices Market report. Designed expressly to inform boardroom decisions in 2026, this study translates clinical trends, regulatory shifts, supplier moves and purchaser economics into concrete strategic choices. At a macro level, the global market reached approximately USD 940 million in 2025 and is poised to resume accelerated expansion in our forecast window, reflecting a compound annual growth rate (CAGR) of roughly 6.48% across the 2026–2032 horizon. That growth trajectory — and the competitive dynamics behind it — will shape product roadmaps, M&A pipelines, and procurement strategies over the next 24 months.
Worldwide Thoracic Drainage Devices Market
Why this report matters for 2026 decision-making
- It converts epidemiology, procedure volumes and device adoption curves into revenue and margin scenarios that matter to executive teams planning R&D and go-to-market budgets for FY26.
- It aligns regulatory context (notably the predominance of Class II 510(k) pathways in the United States) with tactical product development checklists and pre-market evidence packages required to accelerate approvals.
- It frames reimbursement realities — for example, the coding environment surrounding thoracic tube procedures — so product pricing and health-economic arguments map to actual hospital payment flows.
- It anticipates disruption vectors (digital drainage systems, sensor-enabled monitoring, and service-based consumables models) and quantifies their potential to alter revenue mix and aftermarket economics.
Report composition — practical, actionable content (high level)
The report is structured to be immediately actionable rather than purely descriptive. Highlights include:
Worldwide Thoracic Drainage Devices Market
- Comprehensive market sizing and forecast (historical baseline 2020–2025; forward view 2026–2032) with scenario sensitivity to surgical volume recovery, outpatient migration and device substitution rates.
- Regulatory and reimbursement playbooks: step-by-step 510(k) checklists, recommended clinical endpoints for pivotal studies, and guidance on CPT/APC/DRG positioning to improve hospital adoption rates.
- Commercial execution modules: value-selling decks tailored to cardiothoracic surgery, thoracic/pulmonology services, and trauma/emergency procurement; tender and GPO negotiation tactics; and distributor-vs-direct channel decision frameworks.
- Technology roadmaps and IP strategy: evaluation of digital drainage systems, automated clog-clearance technologies and remote monitoring capabilities, together with recommended R&D investment sequencing.
- M&A and partnership playbooks: target profiles, integration risk checklists, and three-year synergy realization templates for both strategic acquirers and private-equity sponsors.
- Supply-chain and manufacturing guidance: SKU rationalization, cost-to-serve analysis, and contingency planning driven by recent device discontinuations and recall events.
- Hospital operational guidance: best-practice care pathways, staff training programs and clinical protocols to reduce length-of-stay and device-related complications.
Market dynamics and growth drivers
Between 2020 and 2025 the market demonstrated resilience, recovering from procedural slowdowns and moving to an enlarged base as elective services normalized — a trend reflected in our historical market measurements. Looking forward, several converging forces underpin the roughly 6.48% CAGR we model for 2026–2032:
Worldwide Thoracic Drainage Devices Market
- Procedure volume expansion in cardiothoracic surgery, thoracic surgery and trauma care as demographic trends and access to care improve in many healthcare systems.
- Gradual substitution of traditional water-seal devices with dry and digital systems that deliver faster mobility, objective air-leak monitoring, and potential reductions in hospital length-of-stay.
- Increasing hospital focus on bundled-care economics — creating demand for devices that can demonstrate measurable improvements in throughput or reductions in complication rates.
- Regulatory stability in major markets via established Class II/510(k) frameworks, which lowers time-to-market for incremental innovation while still requiring focused evidence generation for digital functionalities and electrical safety compliance.
Competitive landscape — what leaders and challengers mean for 2026 strategy
The market exhibits a moderate degree of consolidation: a meaningful share of revenue is generated by a limited set of established device manufacturers, yet there remains ample runway for differentiated entrants — particularly those offering digital monitoring, enhanced patient mobility, or consumable-led business models. Our concentration analysis indicates that the top tier of incumbent vendors captures a substantial portion of market revenue, creating both barriers and opportunities:
- Incumbent global medtech companies bring scale, distribution breadth and buying relationships that favor bundled hospital procurement. They also have the balance-sheet capacity to invest in clinical evidence and to absorb short-term recall or remediation costs.
- Specialist innovators (including digital drainage system providers and automated monitoring platforms) are introducing clear product-level differentiation. These technologies can disrupt traditional chest-drain economics by shifting value from disposables to data-driven care pathways.
- Regional manufacturers and low-cost producers maintain competitive pressure on commoditized catheter and basic drainage-unit segments, which underscores the importance of after-sales service and health-economic differentiation for premium price realization.
Notable recent market developments underscore how quickly the competitive landscape can change and why active portfolio management is essential. A major supplier announced commercial withdrawal of certain chest drainage units in a key market during 2025 and subsequently experienced a Class II recall event early in 2026. Those moves reshuffle procurement decisions and open short-term demand pockets for alternative suppliers — but also raise caution on product reliability and post-market quality management. Simultaneously, regulatory clearances for novel drainage-monitoring devices and continued trade-show activity by innovative manufacturers demonstrate that both incremental and step-change innovations are being actively commercialized.
Strategic implications and 2026 priorities — recommended actions
For executive teams planning 2026 priorities, our report translates market signals into a sequenced action plan you can execute within the next 12 months. Key recommendations:
- Prioritize digital evidence generation: Invest in well-designed clinical studies that quantify reductions in length-of-stay, air-leak detection accuracy and staff time savings. These metrics will materially influence hospital adoption and justify premium pricing.
- Revisit product portfolios through a profitability lens: Rationalize SKUs where commoditization pressure is highest and reallocate commercial resources to high-margin consumables and monitoring subscriptions.
- Strengthen regulatory and quality preparedness: Ensure all electrical and performance standards are validated for digital systems and prepare 510(k) dossiers in markets where class II pathways predominate.
- Deploy agile go-to-market models: Combine direct clinical partnerships with targeted distributor agreements and value-based contracting pilots in large hospital systems.
- Scenario-plan for supplier disruption: Build dual-sourcing strategies and short-latency fulfillment channels to capture displacement demand created by competitor discontinuations or recalls.
- Assess M&A and partnership windows: For incumbents, pursue tuck-in acquisitions that add digital analytics or automated clog-clearance; for investors, identify regionally differentiated OEMs with strong consumables penetration and stable regulatory records.
- Educate purchasers on coding and reimbursement leverage: Work with clinical champions to align device utilization with CPT/DRG payment drivers so hospitals understand the downstream financial impact of device selection.
What you’ll find in the full report (and what we intentionally withhold here)
In keeping with the “preview” intent of this release, we present strategic context and actionable recommendations while deliberately omitting granular sub-segment figures and region-specific share details that are available exclusively in the full report. The complete study includes:
- A fully modeled forecast with downloadable scenario tools that let you stress-test growth assumptions against procedure volumes, digital adoption rates and price erosion.
- Detailed segmentation by product type, clinical application and region, with vendor-by-vendor revenue benchmarking and product-level margin assumptions.
- Vendor scorecards and a documented playbook for managing product discontinuations and recalls — including supplier transition checklists and clinical continuity plans.
- Procurement negotiation templates and sample value-based contracting terms aligned to hospital reimbursement mechanics.
If your team is preparing strategy, capital allocation, or M&A activity in 2026, access to those granular analytics will materially reduce execution risk and compress time-to-decision.
Final perspective
The thoracic drainage device market in 2026 presents a mix of steady baseline growth and pockets of strategic disruption. A moderate market concentration among established players coexists with accelerating technological differentiation driven by digital systems and monitoring intelligence. For executives, the imperative is clear: pair disciplined product-portfolio management with focused investments in clinical evidence and regulatory readiness. Those who move fastest to bundle device performance with measurable hospital outcomes will capture outsized share as the market scales at an expected CAGR of about 6.48% through the early 2030s.
To obtain the full dataset, vendor benchmarking, and the scenario model that underpins these recommendations, please consult the PW Consulting Worldwide Thoracic Drainage Devices Market report available through our research portal. The complete analysis will equip your leadership team to convert market growth into sustainable, defensible revenue and margin gains in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Antibody Fragments Market Poised for 9.6% CAGR Through 2032, Driven by Surging Therapeutics Demand
By PW Consulting, 2026-07-15
Worldwide Antibody Fragments Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest market intelligence on the Worldwide Antibody Fragments Market delivers a forward-leaning, decision-ready synthesis designed to inform C-suite strategy, R&D prioritization, and commercial planning for 2026 and beyond. Built on a rigorous historical baseline (2020–2025) and a detailed forecast window (2026–2032), the analysis shows the market expanding at a compound annual growth rate (CAGR) of 9.6%—a trajectory that translates into a material reweighting of portfolios and capabilities across biopharma and specialized CDMOs.
Worldwide Antibody Fragments Market
Why this briefing matters for 2026
From a buy-side, build-versus-buy, and regulatory preparedness perspective, antibody fragments now occupy a strategic sweet spot: they combine differentiated tissue penetration, modular engineering opportunities (e.g., bispecifics, half-life extension tags), and lower development cycles for some formats, while simultaneously presenting manufacturing, purification, and reimbursement complexities that materially affect unit economics. With the total market nearly doubling from the early 2020s and entering a phase of sustained expansion—our model puts the market at roughly USD 12.0 billion in 2025 and projects it to approach USD 22.8 billion by 2032—boards and strategy teams must decide where to allocate scarce capital, talent, and partnership bandwidth.
Worldwide Antibody Fragments Market
What the full PW Consulting report delivers (practical, actionable contents)
- Transparent market sizing and scenario-based forecasting: a base-year audit (2025) with alternate growth trajectories and sensitivity analyses keyed to reimbursement, clinical success rates, and manufacturing cost evolution.
- Proprietary cost-model for COGS and gross margins: granular inputs for expression systems, purification complexity, and half-life extension approaches—enabling commercial teams to stress-test pricing in target indications.
- Regulatory pathway mapping: stage-gated checklists for preclinical, clinical, and post-market evidence that recognize fragment-specific nuances and global regulator expectations.
- Supply-chain and CDMO scorecard: capability maps and RFP templates for outsourcing scFv, Fab, and single-domain (VHH/nanobody) production across microbial and mammalian platforms.
- Competitive benchmarking and M&A playbook: profiles, strategic positioning, and divestiture/partnership scenarios for leading incumbents and specialist suppliers.
- Commercial go-to-market playbooks: reimbursement risk matrices, pricing levers (including value-based contracting), and launch sequencing frameworks by indication complexity.
- Innovation & technology radar: assessment of platform advantages (nanobodies, PEGylation, albumin-binding tags, Fc fusions), IP landscapes, and platform transferability for biologics portfolios.
Key market dynamics and implications
Several structural forces are shaping 2026 choices:
Worldwide Antibody Fragments Market
- Growth momentum and addressable market size. The market has shown robust compound growth from 2020 through 2025 and is forecast to maintain near-double-digit CAGR through 2032—creating substantial runway for late-stage pipelines, platform licensing, and CDMO capacity expansion.
- Manufacturing complexity vs. yield trade-offs. Antibody fragments without an Fc domain cannot leverage Protein A affinity capture, necessitating multi-step purification strategies (ion exchange, hydrophobic interaction chromatography and others) that can increase manufacturing costs significantly versus full monoclonal antibodies. Conversely, microbial expression systems (for scFv and VHH formats) can offer cost and yield advantages under optimized processes; commercial teams must therefore balance expression system choice against downstream purification and regulatory expectations.
- Half-life engineering economics. Techniques to extend systemic exposure—PEGylation, albumin binders, or Fc fusion—carry proven pharmacokinetic benefits but materially increase cost of goods sold (COGS). Payers and pricing teams must build these incremental costs into value demonstration and contracting discussions early.
- Regulatory and reimbursement pressure points. Although antibody fragments follow the biologics regulatory pathway, fragment-specific considerations (immunogenicity profiling, novel excipient justification, and comparator selection) require tailored evidence plans. Reimbursement sensitivity in price-constrained specialties will influence indication targeting and launch sequencing.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms capture a meaningful share of commercial activity, and the top five extend that concentration further—evidence that both global pharmas and specialist platform companies are shaping commercial dynamics. Strategic leaders combine clinical pipelines with platform IP, manufacturing scale, or unique discovery partnerships.
- F. Hoffmann-La Roche AG / Genentech. A landmark commercial presence with validated Fab fragment therapeutics in ophthalmology provides not only revenue precedent but also a playbook for regulatory and commercial pathways for fragment-based therapies.
- Sanofi (Ablynx). The NANOBODY® platform and commercialized single-domain product case history represent a differentiated route to tissue-penetrant, manufacturable formats—a model many competitors are attempting to emulate or partner around.
- UCB. Demonstrates the commercial viability of PEGylated Fab fragments in chronic autoimmune indications and highlights payer negotiation templates for high-cost fragment therapies.
- Large biopharma (Novartis, AbbVie, Amgen, Pfizer, J&J/Janssen, Bristol-Myers Squibb, Eli Lilly). These players are integrating fragment technologies into broader biologics pipelines, selectively investing in platform capabilities, and using licensing to expand modality sets.
- Specialists and CDMOs (Sino Biological, evitria, and others). These firms are critical execution partners for rapid scale-up, custom expression strategies, and novel stabilization techniques—making them high-value targets for strategic alliances or supplier diversification.
Recent industry developments underline these trends: Sanofi’s continued promotion of its NANOBODY® platform in 2025 signals platform-focused commercialization plans; partnership activity from discovery engine companies reflects expanding preclinical pipelines; and literature syntheses of VHH industrialization indicate maturing manufacturing knowledge that de-risks some scale-up paths.
Strategic recommendations for 2026 decision cycles
- Prioritize platform choices to match indication economics. For indications where tissue penetration or rapid onset matters, consider single-domain platforms; for systemic, chronic indications, prioritize half-life extension strategies but model payer thresholds early.
- Adopt a manufacturing "bimodal" approach. Maintain in-house capabilities for early-stage proof-of-concept and partner with specialist CDMOs for scale. Use our COGS model to quantify break-even points for internalization vs. outsourcing.
- Embed regulatory and reimbursement pathways into portfolio gates. Allocate budgets for comparator and immunogenicity studies tailored to fragment-specific risks, and design health-economic dossiers for high-value launches from day one.
- Structure partnership and M&A criteria around three vectors: platform differentiation, manufacturability (process yields and purification complexity), and commercial fit (payer-acceptable therapeutic value). Our M&A playbook includes valuation multipliers adjusted for manufacturing risk and platform defensibility.
- Invest in manufacturing innovation but be pragmatic on timing. Technologies that reduce purification steps or enable robust microbial expression for complex formats can be decisive—yet must clear regulatory and CMC risk thresholds before heavy capital allocation.
What PW Consulting's clients are already doing
Early-adopter clients are using our report to redefine capex phasing, select preferred CDMO partners, and build reimbursable value propositions for pipeline assets. Examples include staged investments into nanobody discovery nodes, renegotiated supply agreements with specialist manufacturers to lock in advanced process know-how, and scenario-based repricing for fragmented portfolios ahead of phase III readouts.
Next steps — how to use this intelligence
- Download the full market model and interactive dashboards to run custom scenarios for your asset classes and geographies.
- Engage our advisory team for an accelerated, bespoke workshop: align R&D, manufacturing, and commercial functions around a 24-month execution plan informed by our cost and regulatory matrices.
- Request the confidential competitor compendium for board-level benchmarking and M&A candidate screening.
PW Consulting’s Worldwide Antibody Fragments Market report is intentionally crafted as a strategic "trailer": it reveals the market direction, structural risks, and practical playbooks you need to act in 2026, while preserving the granular segment-level models and detailed company benchmarks for subscribers. To unlock the full datasets, scenario tools, and company benchmarking modules—necessary for transaction diligence or portfolio reallocation—visit PW Consulting’s report landing page or contact our advisory desk to schedule a briefing tailored to your organization’s priority decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Optoelectronics Market to Grow from USD 6.25 Billion in 2025 to USD 15.5 Billion by 2032, Driven by a 13.85% CAGR
By PW Consulting, 2026-07-15
Worldwide Automotive Optoelectronic Market — Strategic Insights for 2026 Decision-Making
PW Consulting’s new market study on the Worldwide Automotive Optoelectronic Market delivers a decision-grade view tailored for executives, corporate strategists, and investment committees preparing for 2026. The study synthesizes hard market math, technology roadmaps, supplier capability mapping, regulatory and supply‑chain stress tests, and financially actionable scenarios—enough detail to change program priorities and M&A pacing, while reserving the report’s full segmentation and proprietary tables for subscribers.
Worldwide Automotive Optoelectronic Market
Executive summary: scale, growth and concentration
Automotive optoelectronics is no longer a peripheral spend category; it has become a core system-level investment for OEMs and tier suppliers. Our market model shows a progression from roughly USD 3.45 billion in 2020 to USD 6.25 billion in 2025, with an accelerating trajectory through the forecast window. Under PW Consulting’s baseline forecast the market grows at a compound annual growth rate (CAGR) of approximately 13.85% in the 2026–2032 period, moving industry revenue into the mid‑double‑digit billions by the end of the decade.
Worldwide Automotive Optoelectronic Market
Market concentration has implications for supplier strategy: the top three suppliers capture a meaningful share of the market, and the top five together account for over half of global revenues—an environment that favors scale players for high-volume lighting and imaging modules, while still leaving niches for focused innovators.
Worldwide Automotive Optoelectronic Market
Why this report matters for 2026 planning
- Align R&D and product roadmaps to a high-growth envelope. With a double‑digit CAGR expected through 2032, optoelectronic investments will materially affect IVI, ADAS and lighting architectures.
- De‑risk procurement and production. Geopolitical incentives and episodic supply shocks force reassessment of sourcing, vertical integration, and dual‑sourcing policies.
- Prioritize systems-level value capture. The winner-takes-most dynamics on certain components mean OEMs and tier suppliers must choose where to internalize IP versus partner for speed to market.
What you get in the full PW Consulting deliverable
The report is designed to be immediately operational for leadership teams working on product, sourcing and M&A decisions in 2026. Key contents include:
- Market sizing and methodology: a reproducible market model, historicals (2020–2025), and scenario-driven forecasts (2026–2032) with sensitivity levers for adoption, price erosion and component substitution.
- Technology roadmaps: maturity curves for LEDs, laser diodes, VCSELs, CMOS image sensors, time‑of‑flight and infrared components; anticipated cost curves and performance inflection points.
- Supplier capability matrix: comparative analysis across device performance, automotive qualification readiness (including ASIL pathways), manufacturing footprint and vertical integration.
- Use‑case economics: ROI frameworks for ADAS sensor suites, LiDAR subsystems, adaptive matrix headlights and next‑generation cockpit displays, with break‑even and TCO models.
- Supply‑chain stress tests: scenarios that model the impact of fab outages, tariff regimes and policy-driven onshoring on lead times, margins and inventory strategy.
- Regulatory and standards impact analysis: implications of camera mandates, functional safety standards and emerging test protocols on design cycles and supplier selection.
- Commercial playbook: procurement checklists, supplier negotiation levers, co‑engineering templates, and an M&A screening rubric focused on strategic fit and integration risk.
Competitive landscape — how to read the vendor map
The market blends a handful of large, vertically integrated incumbents with fast‑moving specialists. Strategic positioning differs by technology cluster:
- High‑power lighting and laser optics: Established lighting specialists lead on optics, thermal management and system integration for forward lighting. These players are consolidating product portfolios toward matrix and pixel‑level control to meet OEM demands for adaptive, software‑driven lighting.
- Image sensors and vision stacks: Global sensor houses and specialist CMOS providers dominate imaging performance curves at scale. Their strategic advantage comes from process node maturity, automotive qualification pipelines and longstanding partnerships with Tier‑1 camera integrators.
- Component suppliers and systems houses: Companies providing drivers, connectors and sensor fusion interfaces are evolving from components vendors to systems partners, offering differentiated software and calibration services along with hardware.
Key companies covered in the competitive chapter include leading LED and laser manufacturers, major semiconductor groups delivering automotive‑grade image sensors and VCSEL drivers, and interconnect and connector specialists. For each firm the report provides an assessment of strategic intent, R&D posture, manufacturing footprint, and near‑term product milestones—plus a ranking on readiness for automotive qualification and mass production ramp risks.
Recent industry moves that matter for 2026
- Next‑generation matrix light engines and pixelated laser sources demonstrated by lighting incumbents are rapidly shifting the feature set of premium lighting modules—implications include higher content per car and new calibration/service needs.
- Multiple suppliers launched automotive-qualified global shutter and high-dynamic-range image sensors, narrowing the performance delta between competing sensor stacks and increasing the importance of downstream software and sensor fusion.
- Geopolitical and policy levers—such as semiconductor incentives in major markets—and discrete supply interruptions have accelerated diversification of wafer sources and capacity expansion plans among both device makers and foundries.
Regulatory and supply risks — practical takeaways
Several external forces will materially influence supplier selection and system architecture decisions in 2026:
- Regulatory mandates for camera-based safety systems increase baseline content and drive stringent automotive qualification timelines across imaging suppliers.
- Functional safety standards require repeatable ASIL-compliant processes for optoelectronic devices used in safety-critical functions; programs that miss early qualification gates face costly redesigns.
- Public incentives to onshore semiconductor production alter cost and lead‑time calculus; programs that assume the status quo on sourcing will find themselves underpriced or delayed.
- Supply events—ranging from regional natural disasters to capacity constraints for GaN and compound wafers—require playbooks for dual sourcing, strategic inventory and prioritized allocation clauses.
Priority recommendations for 2026 executive action
PW Consulting’s strategic advisory emphasizes a set of high‑impact moves that company leadership teams should consider executing in 2026:
- Embed scenario planning based on a robust baseline CAGR and two alternative demand scenarios. Use these scenarios to size R&D budgets, capital commitments and supplier earn‑ins.
- Move from single‑source to prioritized‑source relationships on critical die and epiwafers; establish second-source qualification pipelines early in the program lifecycle.
- Design modular optics and sensor platforms that enable product differentiation through software and incremental hardware updates—reduce the cost of change orders and speed feature rollouts.
- Accelerate regulatory and safety compliance investments (test labs, ASIL processes, calibration ecosystems) because late certification is frequently the primary cause of launch delays.
- Prioritize bolt‑on M&A and strategic partnerships that add either manufacturing margin control (epis/packaging) or proprietary system IP (sensor fusion and calibration), evaluated through the report’s M&A rubric.
How to use this research in boardroom and program reviews
Boards and program owners should treat the report as a playbook for three decisions: where to compete for content, which suppliers to accelerate or decouple, and where to deploy balance‑sheet capital to secure manufacturing and IP. The report’s ready‑to‑use dashboards allow rapid "what‑if" interrogation of tradeoffs—e.g., content value versus risk exposure—so teams can generate defensible roadmaps for 2026 investment cycles.
Next steps — access and engagement
PW Consulting has prepared this study as both a strategic briefing and an operational toolkit. The public summary demonstrates the rigor of our approach; the full report contains the complete dataset, regional and application-level forecasts, vendor market shares, and downloadable financial models. For teams who require tailored scenarios, bespoke supplier due diligence or an executive workshop using your internal assumptions, PW Consulting offers engagement packages that convert insights into executable plans.
Contact PW Consulting to obtain the full Worldwide Automotive Optoelectronic Market report and to schedule a strategy workshop designed to convert the 2026 horizon into a prioritized action plan. The full dataset and vendor-level tables are available through our client portal—book a briefing to see the numbers that matter for your programs.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Optoelectronic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Automatic Weapons Market to Grow at 7.0% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Automatic Weapons Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the Worldwide Automatic Weapons Market synthesizes five years of historical data and a seven‑year forecast to deliver a practical, decision‑grade view for 2026. At a macro level, the market reached roughly USD 9.25 billion in 2025 and is on track to approach USD 10.0 billion in 2026. Under our baseline scenario, the sector is expected to grow at a compound annual growth rate (CAGR) of about 7.0% through 2032, reaching approximately USD 14.85 billion by the end of the forecast window.
Worldwide Automatic Weapons Market
This briefing explains why those headline figures matter for program managers, procurement chiefs, corporate strategy teams, and investors in 2026 — and how the full report converts the numbers into executable choices. In short: the market is substantial, expanding, and structurally changing. The remainder of this document outlines actionable implications while intentionally withholding granular segment-by-segment figures to encourage direct access to the full PW Consulting report for tactical planning.
Worldwide Automatic Weapons Market
Why 2026 is a pivot year
-
Program transitions and fielding schedules are compressing: Major modernization programs and next‑generation infantry initiatives are moving from prototype and test to procurement and fielding, creating concentrated windows of opportunity for suppliers who can meet scale, compliance, and sustainment requirements.
Worldwide Automatic Weapons Market -
Supply‑chain pressure points are crystallizing: Even modest volatility in key inputs such as hot‑rolled coil steel — which traded near USD 900 per short ton in mid‑2025 — alters supplier economics for receivers, barrels and structural components. Buyers and OEMs must proactively manage cost pass‑through and substitution risk.
-
Regulatory regimes are tightening and aligning: Multilateral updates to conventional arms control lists and continuing revisions to national export controls are raising the bar for licensing and technology transfer. Compliance is now a competitive differentiator, not just a cost center.
What the numbers imply for strategy (high level)
The market’s ~7% CAGR signals robust demand but not runaway expansion. Growth is sufficient to support both incumbents and disciplined new entrants, yet the competitive landscape remains concentrated: the three largest firms collectively capture a material share of the market, and the top five firms consolidate more than half of total sales. For 2026 this translates into three strategic imperatives:
-
Focus on differentiated product programs that solve modern mission problems — modularity, suppressor and sensor integration, and armor‑defeat performance — because volume alone will not displace established incumbents quickly.
-
Lock in supply resilience for long‑lead inputs and components. Dual‑sourcing, qualified secondary suppliers, and forward pricing agreements will materially reduce program risk across the production ramp phases in 2026–2028.
-
Invest in compliance and export control capabilities now. The administrative lead time for ITAR/EAR licensing and new multilateral control list implementations makes earlier legal and operational alignment indispensable for international tenders and offsets.
Practical, decision‑ready content in the PW Consulting report
The full report was designed to be operationally useful to purchasing, engineering and corporate development teams. Highlights include:
-
Normalized market sizing and demand‑curve models across 2020–2032, with scenario variants (base, accelerated procurement, and constrained funding) so executives can stress‑test their revenue and production plans.
-
Procurement playbooks and RFx checklists that map requirements to compliance checkpoints and supplier evaluation criteria — reducing evaluation cycles and improving award defensibility.
-
Supplier risk heatmaps and mitigation templates that incorporate raw material exposure, geographic concentration, and technology dependencies.
-
M&A and partnership screening tools: target heuristics, valuation multiples observed in adjacent defense subsectors, and integration checklists for rapid post‑deal value capture.
-
Technology adoption frameworks for modular weapons, suppressor ecosystems, and electro‑optical/aiming integrations — prioritizing investments that deliver fielded capability within typical procurement windows.
-
A regulatory tracker and licensing playbook tailored to jurisdictions that matter for multinational procurement and sustainment networks.
Competitive landscape — who to watch in 2026
The market is served by a mix of established global primes and specialized manufacturers. Our analysis profiles leading OEMs, their strategic positioning, and where they are likely to compete for share in 2026 tenders. Representative companies covered in depth include:
-
FN Herstal SA (FN America) — long‑standing platform supplier with global small arms pedigree and recent modular upgrade activity aimed at suppressor and multi‑caliber integration.
-
Heckler & Koch GmbH — renowned for battlefield‑proven platforms and an active pipeline in special forces and NATO support markets.
-
SIG Sauer Inc. — positioned to capitalize on next‑generation squad weapon transitions following major U.S. program certifications.
-
Rheinmetall AG — integrating automatic cannon solutions with vehicle and turret systems; draws strength from systems engineering capabilities.
-
General Dynamics and Northrop Grumman — system integrators whose automatic weapon offerings are often bundled into aircraft, naval, and vehicle platforms.
-
BAE Systems, Colt, IWI, Kalashnikov Concern, Beretta, Denel, and ST Engineering — each with specific strengths in platform lineage, regional relationships, or niche systems.
For 2026 tactical planning we map these players against two axes: platform lineage and program capture agility. The result is a playbook that helps suppliers and buyers evaluate partner fit, predict bid behavior, and identify niche entry points that avoid head‑on competition with tier‑one incumbents.
Recent developments that reframe 2026 decisions
-
Product momentum: In January 2026 FN America announced a next‑generation modular SCAR upgrade package emphasizing suppressor compatibility and user‑configurable options. That upgrade signals a broader market move toward platform modularity and integrated signature‑reduction accessories.
-
Program milestones: SIG Sauer received U.S. Army type classification for its XM7/XM250 family under the Next Generation Squad Weapon program in 2025, clearing the path for production and fielding. This milestone changes procurement dynamics in allied programs, as adoption and interoperability considerations accelerate supply and logistics commitments.
-
Regulatory developments: The Wassenaar Arrangement updates in December 2025 and continuing adjustments to ITAR/EAR have increased compliance complexity for multi‑jurisdictional supply chains, affecting lead times for export licenses and technology transfers.
-
Input‑cost signals: Steel market overcapacity and soft HRC prices in 2025‑26 reduce raw material input costs in the near term but create margin pressure for suppliers who cannot diversify into higher‑value components.
Actionable recommendations for 2026
-
Procurement executives: Recalibrate RfP schedules to include compliance windows and supplier qualification pilots. Require supplier roadmaps for modular upgrades and sustainment.
-
OEM product leaders: Prioritize modularity, suppressor integration, and rapid upgrade kits that allow retrofit into legacy platforms — these accelerate adoption in constrained budget environments.
-
CFOs and corporate development: Use PW Consulting’s scenario models to stress‑test EBITDA sensitivities under different procurement pacing assumptions; explore bolt‑on acquisitions that add non‑metallic materials, optics or thermal‑imaging capabilities to capture system‑level value.
-
Sourcing teams: Implement dual‑sourcing for critical forgings and barrels; negotiate multi‑year forward pricing for HRC input where possible; and qualify secondary suppliers in lower‑risk jurisdictions before award announcements.
-
Compliance and legal: Institute a regulatory change‑management squad to handle Wassenaar and export control updates, reduce approval cycle times, and advise on technology‑transfer structures that preserve competitive positioning.
Why PW Consulting’s report is uniquely useful for 2026
Our work bridges market forecasting and executable roadmaps. We do not stop at topline projections: the report translates forecast scenarios into procurement and product decisions with templated RFx language, supplier vetting checklists, and M&A screening criteria specifically adapted for the automatic weapons ecosystem.
Importantly, to preserve the tactical integrity of program‑level planning we intentionally keep granular split‑level data reserved for subscribers and clients. The high‑level figures and strategic frameworks included here are designed to inform first‑order decisions; the full dataset and supporting annexes provide the segment‑level sizing, regional demand curves, and supplier scorecards needed for bid construction, internal business planning, and transaction due diligence.
Next steps
For procurement officers, OEM product leads, and investors preparing decisions in 2026, the critical next step is to convert the market’s growth trajectory into a prioritized actions list for the fiscal year. PW Consulting’s full report contains the operational templates and raw datasets required to execute those tasks. Contact PW Consulting or visit our report page to request the executive dataset, client‑only annexes, and a briefing with our lead analysts.
PW Consulting will continue to monitor inputs — from raw material markets to regulatory updates and program milestones — and publish quarterly briefings that translate new developments into immediate tactical implications for suppliers and buyers. In an industry where timing, compliance and incremental innovation determine program success, 2026 will reward organizations that pair disciplined commercial execution with early regulatory and supply‑chain planning.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Used & Refurbished Telehandler Market to Reach USD 4.73 Billion by 2032, Expanding at a 5.81% CAGR
By PW Consulting, 2026-07-15
Worldwide Used and Refurbished Telehandler Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Used and Refurbished Telehandler Market offers a focused, decision-oriented briefing designed for executives, investors and fleet managers preparing strategic moves in 2026. The used/refurbished telehandler sector has emerged as a resilient layer of the construction and agriculture equipment ecosystem: from a global market value of USD 2,405.6 Million in 2020 it expanded to USD 3,185.5 Million by 2025 and is forecast to grow at a Compound Annual Growth Rate (CAGR) of 5.81% through 2032, reaching an estimated USD 4,730.04 Million. This preview outlines the report’s strategic value, high-level takeaways and recommended actions — while intentionally reserving granular subsegment tables and proprietary channel modelling for report subscribers.
Worldwide Used and Refurbished Telehandler Market
Why this report matters for 2026 decision cycles
-
Timing: As capital-constrained contractors, rental houses and dealers recalibrate capex vs opex, used and refurbished telehandlers are a fast-growing alternative that preserves utilization while lowering up-front spend. The report quantifies demand momentum and models sensitivity to equipment cycle lengths — critical to 2026 procurement and fleet planning.
Worldwide Used and Refurbished Telehandler Market -
Supply-side leverage: OEM-certified refurbishment programs and dealer-certified used channels are maturing into strategic profit centers. Our analysis shows where margin capture shifts from new-vehicle sales into aftermarket services and certified resale — a decisive factor for OEMs and independent refurbishers reevaluating go-to-market models.
Worldwide Used and Refurbished Telehandler Market -
Regulatory and input-cost stress testing: Recent policy and cost events materially change refurbishment economics and lifecycle TCO. Our scenarios integrate tariff shifts, evolving operator certification rules, and raw-material dynamics to inform pricing, hedging and localization strategies.
-
Competitive posture: With market concentration that reflects a handful of strong incumbent OEMs alongside active regional players, the report surfaces realistic pathways for strategic alliances, selective M&A and distribution optimization.
Key market dynamics shaping strategy in 2026
-
Steady demand growth: The overall market trajectory points to a multi-year expansion that supports investment in certified refurbishment infrastructure and digital inspection tools. Growth is not homogeneous — our model identifies faster-adopting buyer cohorts and slower segments where price sensitivity remains dominant.
-
Input-cost and trade policy pressure: Steel and components pricing and trade-policy adjustments have increased cost uncertainty for refurbishment operations that rely on imported parts. Notably, elevated steel tariffs implemented mid‑2025 materially affect sourcing decisions and total refurbishment bill-of-materials costs, prompting many suppliers to revisit local sourcing and inventory strategies.
-
Compliance and operator credentialing: Regulatory updates emphasizing documented operator certification and digital records have accelerated demand for refurbished units delivered with verified compliance packages — an opportunity for dealers and refurbishers to differentiate through bundled services.
-
Rental and subscription expansion: Rental houses and rental-as-a-service models are actively increasing rotation and refurbishment cycles. Contractors prefer converting capex to opex while preserving access to fit-for-purpose telehandlers; this is reshaping resale timing and refurbishment throughput requirements.
-
Product innovation and lifecycle extension: Recent industry showcases signaled incremental but material innovations — smarter controls, improved stability systems and efficiency features — that extend the useful life of earlier vintages via retrofit pathways rather than outright replacement.
What the PW Consulting report contains (practical deliverables)
-
Independent market sizing and seven-year forecast broken down by type, application and distribution channel, with sensitivity testing across three macro scenarios.
-
Refurbishment economics and margin waterfalls for OEM-certified, dealer-certified and independent refurbishers, including parts cost structures, labor models and warranty provisioning templates.
-
Distribution and channel map: auctions, rental fleets, dealer trade-ins and direct OEM outlets — with practical channel playbooks for scaling certified programs.
-
Procurement decision tools: a TCO calculator prototype, optimal trade-in timing guidelines and replacement thresholds tuned for differential jobsite utilization rates.
-
Regulatory impact analysis: operational checklists to align refurbishment processes with updated credentialing and inspection requirements.
-
Competitive landscaping: vendor profiles and differentiated go-to-market strategies for leading OEMs and refurbishers (high-level summaries included in this preview).
-
Actionable M&A and partnership scorecards highlighting targets where scale, parts access and remarketing reach unlock outsized value.
-
Proprietary dealer and rental operator survey insights that illuminate demand drivers, refurbishment cycle metrics and preferred certification features.
Competitive landscape — practical implications
The used and refurbished telehandler market sits at the intersection of traditional OEM power and aftermarket fragmentation. Leading manufacturers maintain strong influence through certified used programs, authorized dealer networks and rental partnerships. Key industry participants include JCB; Caterpillar; Manitou Group; JLG (Oshkosh Corporation); Merlo; Dieci; Terex/Genie; Bobcat (Doosan); Liebherr; CNH Industrial (New Holland); Wacker Neuson; Haulotte; and Claas. Each player pursues distinct routes into the used and refurbished value chain: some emphasize OEM-certified refurb with warranty bundles, others leverage rental fleets for high-turn rotation, and specialists focus on vertical applications such as high-reach or rotating telehandlers.
Aggregate concentration metrics indicate a market with meaningful leaders but substantial room for agile players: the top three competitors control a material share of market volume while the top five expand that presence further, leaving mid‑market and regional specialists numerous opportunities to capture niche premium margins through service differentiation and localized inventory strategies.
Recent trade-show activity — notably ConExpo 2026 — highlighted incremental product advances (smarter controls, enhanced stability systems and retrofit-ready efficiency upgrades) that materially affect refurbishment priorities. For executives, the strategic questions are which retrofit kits to stock, which certification credentials to offer, and how to price retrofit vs replacement.
Actionable recommendations for 2026
-
Establish a certified-refurbishment center of excellence: Standardize inspection, parts sourcing and digital recordkeeping to reduce turnaround times and guarantee compliance packages that command price premiums.
-
Integrate rental partners into feedstock pipelines: Negotiate rotating inventory contracts and refurbish-for-rent agreements to stabilize throughput and reduce acquisition costs for high-utilization units.
-
Hedge input-cost exposure: Reassess supplier contracts and near-shore critical components to mitigate tariff-driven margin erosion and supply-chain disruptions.
-
Invest in digital inspection and lifecycle analytics: Use telematics and condition‑based indicators to raise refurbishment yield and accurately forecast resale timing.
-
Productize compliance: Bundle documented operator certification and inspection records with sale/refurb for differentiated market positioning and lower buyer friction.
-
Test retrofit bundles at scale: Pilot retrofit packages that deliver control upgrades and stability enhancements — measure acceptance rates and incremental resale value before wider rollouts.
-
Prepare targeted M&A plays: Prioritize acquisitions that provide parts scale, dealer reach or access to specialized models that are underserved by OEM certified programs.
How PW Consulting’s report supports implementation
Beyond high-level guidance, the full report supplies the operational artefacts required to act: refurbishment labor models, parts-cost benchmarks, auction-to-dealer flow maps, diligence checklists for acquisition candidates and scenario-ready forecasts that feed into capital allocation decisions. Importantly, it includes reproducible templates for RFPs, refurbishment SLAs and resale pricing ladders so that teams can move from strategy to execution within months — not quarters.
Note on transparency: this preview deliberately omits detailed subsegment tables, regional market shares and channel-level price grids to respect proprietary modelling and client confidentiality. Subscribers to the full report receive the comprehensive datasets, interactive models and vendor scorecards needed to validate hypotheses and run bespoke simulations.
Next steps
-
Download the full report for access to the detailed breakdowns, downloadable Excel models and vendor shortlists that underpin the forecasts and recommendations summarized here.
-
Request a tailored briefing with PW Consulting’s telehandler practice to translate findings into a 90‑day implementation roadmap for procurement, refurb operations or M&A screening.
For executives preparing 2026 strategies, the used and refurbished telehandler market presents actionable revenue and margin opportunities — but only where refurbishment quality, channel control and regulatory compliance are managed as strategically as new-equipment sales. PW Consulting’s comprehensive study is designed to convert market momentum into executable plans that protect margins, accelerate asset turns and de‑risk fleet investments.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Water Tube Industrial Boilers Market to Reach USD 9,450.5 Million in 2025, Forecasted to Grow at 4.51% CAGR to 2032 as Asia‑Pacific Leads with USD 3,988.4M
By PW Consulting, 2026-07-15
Worldwide Water Tube Industrial Boilers Market — Strategic Imperatives for 2026
PW Consulting’s latest market brief, released alongside our comprehensive Worldwide Water Tube Industrial Boilers Market report (base year 2025, forecast period 2026–2032), translates sector-level evidence into a concise playbook for executives who must make capex, sourcing, and technology choices this year. The global market reached approximately USD 9.45 billion in 2025 and is projected to cross the USD 10.06 billion threshold in 2026, growing at a compound annual growth rate (CAGR) of 4.51% through 2032 to reach roughly USD 12.87 billion. These headline figures capture a market that is expanding steadily while being reshaped by decarbonization mandates, raw-material inflation, and supplier consolidation dynamics.
Worldwide Water Tube Industrial Boilers Market
Market snapshot: structure, concentration and momentum
The water tube industrial boiler market remains moderately fragmented. Our market concentration analysis shows that the top three suppliers account for roughly one-third of global revenue, and the top five approach half the market, leaving meaningful shares distributed among regional specialists and niche providers. Historical performance from 2020–2025 shows resilient demand through cyclical headwinds, while the 2026–2032 forecast reflects an industry transitioning from replacement-driven activity to a mix of retrofits, fuel conversions and new-builds aligned with low-carbon objectives.
Worldwide Water Tube Industrial Boilers Market
Why this matters to C-suite and project leaders in 2026
- Technology lock-in risk: Decisions made in 2026—whether to specify oxy-combustion-ready designs, hydrogen-capable burners, or biomass co-firing—will determine retrofit feasibility and stranded-asset risk over multi-decade plant lifecycles.
- Capex and supply-chain pressure: Elevated hot-rolled coil prices and procurement lead times are compressing project economics. Our modelling shows that material cost swings materially alter payback timelines and vendor selection calculus.
- Aftermarket as strategic margin: With capital deployments under scrutiny, long-term service agreements, spare-parts provisioning and remote-monitoring offerings are increasingly important for both OEMs and asset owners seeking predictable O&M costs.
- Regulatory arbitrage and incentive capture: Emerging grant programs and decarbonization mandates are redirecting investments (for example, toward biomass conversions and demonstration projects for CO2 capture), creating windows for firms that can move quickly to align project scope with available incentives.
- M&A and partnership opportunities: Moderate market concentration indicates room for targeted acquisitions of complementary engineering capability, geographic footprint, or aftersales platforms that can boost total addressable market quickly.
What the PW Consulting report delivers — practical, operational, decision-ready analysis
Beyond headline sizing and a multi-scenario forecast (base, accelerated decarbonization, and delayed-recovery cases), our report is designed to be actionable for procurement, engineering, and investment teams. Key toolkit elements include:
Worldwide Water Tube Industrial Boilers Market
- Validated market sizing and trend diagnostics (2020–2025 historical, 2026–2032 forecast) to underpin five‑year and ten‑year capex planning.
- Scenario-based financial models that stress-test project IRR and payback under alternative steel price, fuel price and carbon-cost paths.
- Technology-readiness maps and retrofit feasibility checklists (oxy-combustion, hydrogen-readiness, biomass conversions) to support early specification decisions.
- Vendor scorecards covering engineering depth, global service footprint, inventory strategy, and product modularity — formatted for direct use in RFP shortlists.
- Procurement playbooks and RFQ templates aimed at reducing lead time risk and securing favorable warranty and spare-parts terms.
- Regulatory tracking and incentive-mapping for major markets, enabling project teams to align scope and timelines with funding windows.
- Supply‑chain sensitivity analyses and mitigation options — including hedging strategies, alternative sourcing, and phased procurement approaches.
To preserve the strategic value of these tools for subscribers and clients, the report intentionally refrains from public disclosure of detailed segment-level shares and proprietary vendor scores; these are available in full to report purchasers and retained-advisory clients.
Competitive landscape: capability patterns and tactical implications
Our competitive assessment synthesizes product portfolios, manufacturing footprint, recent moves and go-to-market models across established OEMs and regional specialists. Several clear patterns emerge:
- Modular, high-efficiency players: Manufacturers emphasizing fast-deploy modular designs and low-NOx performance are winning demand from industrial sites prioritizing operational flexibility and emissions compliance. These firms are differentiating through compact footprints, rapid commissioning and lower operating emissions.
- Full-system providers: Long-established global OEMs that offer packaged boilers as part of broader steam and energy systems continue to capture large industrial and utility projects where integration risk matters most. Their advantage derives from engineering depth and service network scale.
- Inventory and speed-focused suppliers: Companies maintaining large inventories or modular manufacturing capacity are able to address short-notice replacement and peak demand more effectively — an increasingly valuable capability where uptime risk is high.
- Regional champions and low-cost manufacturers: Cost-competitive suppliers with local manufacturing are reshaping procurement choices in price-sensitive markets, especially for standard packaged units.
- Service- and data-driven strategies: Leaders are packaging digital monitoring, predictive maintenance and performance guarantees as a differentiation lever for aftermarket revenue growth and customer retention.
Notable recent industry developments underscore these dynamics. Equipment showcases by regional manufacturers at international trade events highlight commercial momentum for lower-emission designs. Demonstration projects for oxy-combustion and hydrogen-fuel conversions — both now moving from pilots into commissioned units — signal that decarbonization pathways are increasingly technically viable and entering the commercial decision horizon. Select biomass-fired project awards illustrate how policy incentives can accelerate fuel-switch strategies in process industries.
Strategic playbook: prioritized actions for three stakeholder groups
- For plant owners and operators: Prioritize hybrid procurement strategies that mix immediate replacement capacity with hydrogen-ready and oxy-combustion-capable assets where retrofit options are likely. Lock in long-term service agreements and spare-part kits to mitigate lead-time exposure.
- For OEMs and suppliers: Accelerate modularization, certify hydrogen-compatibility where feasible, and expand outcome-based service offers. Consider bolt-on acquisitions to fill capability gaps (digital services, emission-control systems, regional assembly centers).
- For investors and financial sponsors: Target assets with predictable aftermarket revenue streams and technology optionality. De-risk deals via staged payments linked to performance milestones and by structuring seller warranties to cover emissions and efficiency guarantees.
Risk map and timing — what to act on in 2026
Our sensitivity work shows three near-term risk vectors that should inform budgets and contracting approaches this year:
- Raw-material inflation: Sustained higher steel prices have immediate pass-through into equipment costs. Early procurement and strategic hedging can protect project economics.
- Regulatory timing: The sequencing of regional decarbonization measures and grants creates windows of opportunity; missing application deadlines or deployment windows can push projects into a less favorable economic environment.
- Technology convergence: As hydrogen and CO2-capture demonstrations move to early commercial stages, procuring non-upgradable designs risks future stranded-value. Adopt phased technology deployment where possible.
How PW Consulting supports implementation
PW Consulting couples market intelligence with implementation support: from vendor due diligence and bid evaluation to pilot-specification oversight and financial modelling for board-level approval. Our advisory engagements typically include customized scenario modelling, an executable procurement timetable, and a vendor negotiation playbook calibrated to each client’s operating profile and regulatory exposure.
Executives planning capital commitments in 2026 should view this market as one of measured growth and strategic inflection. With the global market expected to exceed USD 10 billion in 2026 and to grow at a steady mid-single-digit CAGR through 2032, the next 12–24 months are decisive for specifying technology pathways, locking in supply-chain resilience, and securing access to incentive programs that offset transition costs.
For procurement teams, engineering directors, and investors, the full PW Consulting report provides the granular scenario outputs, supplier benchmarks, and implementation templates required to move from strategy to contract. Visit our report landing page to access the complete dataset, supplier scorecards, and the downloadable executable models that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Water Tube Industrial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


