



Category: market research
PW Consulting: Worldwide Oilseed Extraction Equipment Market Poised for 5.12% CAGR in 2026–2032
By PW Consulting, 2026-07-15
Worldwide Oilseed Extraction Equipment Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Oilseed Extraction Equipment (base year 2025; forecast 2026–2032) synthesizes industry dynamics that will shape capital allocation, sourcing strategy, and plant-level investments in 2026. The market reached an estimated USD 5,250.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.12% over the forecast window, arriving at roughly USD 7,446.6 Million by 2032 under the central scenario. This briefing highlights the report’s strategic value for executives and procurement leads who must make near-term, high-consequence commitments without revealing the granular segmentation tables reserved for subscribers.
Worldwide Oilseed Extraction Equipment Market
Why this report matters for 2026 planning
-
Capital allocation clarity: The report translates top-line growth assumptions into practical guidance for brownfield upgrades and greenfield capacity decisions, converting macro growth trajectories into plant-level capacity scenarios and payback ranges.
Worldwide Oilseed Extraction Equipment Market -
Procurement timing and price risk: With raw material and component cost pressures front of mind, the analysis maps supplier lead times, price drivers, and a recommended procurement calendar that reduces exposure to stainless-steel and energy-price volatility.
Worldwide Oilseed Extraction Equipment Market -
Technology and efficiency ROI: We benchmark the operational benefit of automation, heat-recovery, and high-efficiency transmission technologies—showing where incremental CAPEX can be recovered via energy and yield improvements within typical contract horizons.
-
Regulatory and operational preparedness: The study identifies hygiene and food-safety compliance vectors that materially change equipment specification and plant layouts, ensuring capex is not wasted on non-compliant installations.
-
Competitive positioning and partnership opportunities: Using supplier scorecards and concentration metrics, the study helps buyers and potential entrants calibrate negotiation strategies, outsourcing choices, and M&A screening criteria.
Practical deliverables in the full study (operational, not academic)
-
Investment playbooks — step-by-step templates for evaluating new presses, extraction lines, and pre-treatment modules, including CAPEX/OPEX backtests under three energy-price and raw-material scenarios.
-
Total Cost of Ownership (TCO) models — configurable spreadsheets that account for spare parts, energy consumption, throughput variability, and labor differentials.
-
Procurement and contracting levers — standard contractual clauses, warranty negotiation checklists, uptime KPIs, and spare-parts stocking guidance to de-risk long lead times.
-
Turnkey and retrofit decision matrices — vendor-agnostic criteria to decide when to buy a turnkey plant, retrofit existing lines, or hybridize procurement across local and global suppliers.
-
Scenario-based capacity planning — near-term (2026–2028) demand scenarios tied to feedstock availability and mechanization adoption rates that help prioritize projects across a regional portfolio.
-
Aftermarket and service strategies — playbooks for building local service networks, spare-parts ROIs, and digital monitoring roadmaps to convert equipment into recurring revenue channels.
Market structure and what it means for buyers and investors
The market shows a mixed structure: there are well-established global OEMs with broad portfolios and regional specialists that serve niche needs or cost-sensitive segments. Measured concentration indicates a marketplace where a small group of suppliers capture a meaningful but not overwhelming share of revenue — a structure that supports both scale providers and new entrants who can differentiate on price, speed to install, or specialized capabilities.
For 2026 decision-making, this implies three pragmatics:
-
Leverage supplier competition: Use staged awards and parallel RFPs to preserve leverage when awarding major extraction and pretreatment contracts.
-
Pursue hybrid sourcing: Combine a tier-1 global OEM for core extraction systems with local fabricators for balance-of-plant and civil integration to shorten timelines and control costs.
-
De-risk through aftermarket contracts: Shift portions of performance risk into service agreements that align incentives for uptime and yield improvements.
Competitive landscape — what to watch among headline suppliers
Our proprietary vendor analyses distill each company’s strategic strengths and likely 2026 playbook. Highlights include:
-
Anderson International Corp — Recognized for inventing the continuous mechanical screw press, Anderson’s strength is in end-to-end mechanical pressing systems and global commissioning experience. Expect continued emphasis on automation retrofits and services that monetize lifetime plant performance.
-
French Oil Mill Machinery Company — A specialist in custom screw presses and roller mills, the company uses deep technical customization as a differentiator. Recent exhibitions at industry forums signal a push to capture processors planning upgrades or expansions.
-
CPM (including Crown Iron Works) — With advanced solvent extraction technologies and a strong events calendar presence, CPM is positioning for projects that prioritize high throughput and proven solvent extraction reliability.
-
Myande Group — A turnkey supplier with significant delivered capacity in Asia, Myande is a natural partner for large integrated crushing and refining projects where single-supplier accountability is valuable.
-
GOYUM, Bühler, RoseDowns, Henan Huatai, Muez Hest — These vendors span low-cost equipment providers, established European technology houses, and China/India-based turnkey specialists. Their competitive positions hinge on local market access, aftermarket networks, and the ability to meet hygiene and energy-efficiency specifications.
Recent trade-show activity — French Oil at the AOCS Annual Meeting & Expo, CPM’s planned participation in BioInnovAsia and other 2026 events, and the 19th International Grain and Oil Exhibition in China — is an important signal: suppliers are actively cultivating leads and demonstrating new service-based offerings. For buyers, trade shows are concentrated opportunities to expedite RFP cycles and validate supplier claims in person.
Operational dynamics and external cost pressures
Two external cost variables will materially affect deal economics in 2026:
-
Raw materials: Stainless steel remains a primary cost driver for corrosion-resistant components. Market-size and pricing dynamics in 2026 reflect upstream inputs such as nickel and chromium, and regional price spreads can be notable—factors that should feed directly into LCC (life-cycle cost) and hedging strategies.
-
Energy and process efficiency: Energy-saving technologies—smart temperature control, heat-recovery systems, and high-efficiency transmissions—are increasingly embedded in new equipment. Our benchmarking suggests that selective investments in energy recovery and automation can shorten payback in many operating contexts.
Operational controls such as modern automation systems not only improve throughput and yield but also reduce operator dependency and variability—an increasingly important attribute as processors pursue consistent product quality across multi-site footprints. Meanwhile, food-safety regulations will continue to affect equipment specifications; even seemingly granular requirements (for example, specified water-temperature ranges for handwashing stations in production areas) have knock-on effects for facility plumbing design, energy budgets, and CAPEX timing.
Actionable recommendations for executives in 2026
-
Run a 24–36 month procurement roadmap that aligns equipment orders with projected steel-price cycles and supply-chain lead times.
-
Adopt a hybrid sourcing model for major lines: combine a global supplier for core extraction technology with regional fabricators for civil works and installation.
-
Include energy-efficiency and automation KPIs in RFPs and price them explicitly in CAPEX/OPEX models to avoid scope-creep during commissioning.
-
Structure aftermarket agreements to convert fixed-cost risks into performance-based payments tied to uptime, yield, and energy consumption.
-
Embed regulatory compliance checks early in engineering procurement to eliminate retrofit risk driven by hygiene and food-safety codes.
Where this briefing leaves you and how to obtain the full intelligence
This press release is designed as a strategic trailer: it surfaces the report’s main implications for 2026 decision-making while preserving the granular regional, application, and seed-type splits that subscribers rely on for transactional decisions. PW Consulting’s full report contains the detailed segmentation tables, interactive scenario models, vendor scorecards with comparative metrics, and downloadable TCO tools that translate market-level forecasts into project-level commitments.
For procurement teams, plant managers, and investors preparing 2026 budgets and project pipelines, the full deliverables provide the missing mile-markers: exact segment-level forecasts, supplier-specific pricing sensitivity, and turnkey vs. retrofit break-evens. Access details and subscription options are available on the PW Consulting website.
In a market characterized by steady growth, selective consolidation, and accelerating technology adoption, the right intelligence in 2026 will determine whether capital is deployed defensively or used to capture disproportionate advantage. PW Consulting’s Worldwide Oilseed Extraction Equipment Market study is designed to make that choice auditable, repeatable, and defensible.
For detailed analysis of this topic, please visit the official page: Worldwide Oilseed Extraction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Self‑Checkout in Retail Market to Reach USD 13,730.8 Million by 2032, Growing at a 13.01% CAGR
By PW Consulting, 2026-07-15
Worldwide Self-Checkout in Retail Market: Strategic Imperatives for 2026
As retailers enter 2026, self-checkout is no longer a fringe convenience feature — it is a strategic lever shaping labor economics, customer experience, and loss-prevention strategies. PW Consulting’s new market study, Worldwide Self-Checkout in Retail Market (base year: 2025; forecast: 2026–2032), synthesizes longitudinal market dynamics and practical deployment intelligence to equip executive teams with decision-grade insight. The report models a market that expanded from about USD 3.12 billion in 2020 to roughly USD 5.84 billion in 2025 and is forecast to grow to approximately USD 13.73 billion by 2032, with a projected compound annual growth rate (CAGR) of 13.01% across the 2026–2032 forecast window. These macro trends underline the urgency for retailers and vendors to translate momentum into sustainable value.
Worldwide Self-Checkout in Retail Market
What the Report Delivers — Actionable, Not Academic
- Proven forecasting frameworks and transparent methodology anchored to a 2020–2025 historical baseline and a 2026–2032 scenario suite.
- Executive playbooks for capital allocation, pilot design, and phased rollouts that link technology choices to measurable KPIs (labor substitution, throughput, shrinkage delta, and NPS impact).
- Vendor evaluation matrices and procurement checklists that emphasize modularity, cloud readiness, AI/vision capability, and privacy/compliance posture.
- Operational implementation guides covering hybrid checkout models, store footprint optimization, and integration steps with POS, loss-prevention, and loyalty systems.
- Commercial models — including TCO and ROI templates — stress-tested under three macro scenarios (accelerated automation, privacy-constrained deployment, and labor-cost shock).
- Risk registers and a regulatory compliance checklist tailored to recent changes in privacy and labor law environments.
Why This Matters for 2026 Decisions
Decision-makers must balance three converging forces in 2026: persistent labor cost pressure and shortages; rapid maturation of AI and vision-based checkout tech; and an increasingly complex privacy and regulatory landscape. Our findings show that retailers face a strategic inflection point where investments in self-checkout can either lock in long-term cost advantage or introduce operational and compliance vulnerabilities if executed piecemeal.
Worldwide Self-Checkout in Retail Market
- Labor economics: Recent labor-cost and overtime-rule changes have materially altered store-level operating models. Self-checkout deployments are being re-evaluated not just for headcount reduction but for scheduling efficiencies and margin preservation.
- Technology maturity: AI-enabled item recognition and cloud-native architectures are shifting the vendor selection calculus from hardware-centric to platform-centric decisions. Expect faster feature rollouts, reduced on-site maintenance, and more continuous improvement cycles.
- Security & privacy: With multiple U.S. state privacy laws effective from 2025 and privacy maturity in retail lagging global averages, systems that capture vision or biometric data require tightened governance. The cost of breaches — averaging nearly USD 3.91 million per incident in cross-industry benchmarks — raises the stakes for secure implementations.
Market Structure & Competitive Dynamics
The market remains oligopolistic: the top three vendors account for a large majority share (CR3 ~74.2%), and the top five consolidate an even larger portion (CR5 ~86.5%). This concentration creates a dual reality for buyers — predictable roadmaps from established suppliers alongside opportunities to leverage niche innovators for specialized capabilities.
Worldwide Self-Checkout in Retail Market
- NCR Voyix Corporation: Positioned as a platform leader with cloud-first architecture and modular hardware. Recent product updates emphasize real-time software update pathways and adaptable checkout footprints, signaling a bet on continuous delivery as a differentiator.
- Diebold Nixdorf: Focused on AI-driven shrink reduction and non-barcode recognition capabilities. Vynamic Smart Vision and similar enhancements target two of retailers’ highest-needs areas: theft mitigation and speed of transaction for complex items.
- Toshiba Global Commerce Solutions: Plays to adaptability, offering configurable kiosks and hybrid checkout models suited to varied retail formats — an attractive option for multi-format chains seeking operational commonality.
- Fujitsu: Investing in RFID and computer-vision integrations to accelerate contactless and queue-free experiences in high-throughput environments such as supermarkets and hypermarkets.
- Specialists and component suppliers (e.g., Zebra, Honeywell, Datalogic): Continue to underpin the ecosystem with ruggedized scanning, sensing, and data-capture technologies critical to reliability at scale.
- Emerging innovators (e.g., Mashgin, Partner Tech, Slabb): Offer AI-native, cashierless experiences and compact kiosks that appeal to high-density convenience formats and QSRs where footprint and speed are paramount.
Recent vendor moves — from cloud-focused launches to collaborative hackathons — indicate competitive trajectories: incumbents are consolidating platform capabilities while startups push specialized computer-vision and AI differentiation. For buyers, this translates into a risk/reward calculus around single-vendor simplicity versus best-of-breed agility.
Strategic Playbook: Where to Invest in 2026
Our advisory framework recommends a portfolio approach across five strategic buckets — each with practical actions for 2026:
- Core Platform Modernization: Prioritize cloud-native software and modular hardware that enable incremental feature rollouts and reduce refresh cycles. Require APIs and standardized integration points in procurement RFPs.
- Shrink & Loss Prevention: Combine AI-driven vision analytics with tactical store policies. Deploy targeted pilot programs in higher-risk formats and measure shrink delta over 90–180 day windows.
- Privacy & Data Governance: Implement privacy-by-design for camera and sensor data, including clear retention policies, anonymization, and local-edge processing where regulation or stakeholder sensitivity is high.
- Pilot-to-Scale Pathways: Use small, representative pilots to validate business case assumptions and interoperability, then adopt a two-speed rollout plan that separates pilot innovation from enterprise-scale standardization.
- Vendor Risk Management: Require SOC2/ISO attestations, source-code escrow options for critical integrations, and contractual SLAs tied to transaction throughput and fraud-mitigation outcomes.
Regulatory & Operational Risks to Manage in 2026
- Privacy Regulation: Recent state-level privacy laws in the U.S. increased compliance complexity for systems that capture camera or sensor data. Retailers must map data flows and apply strategic controls to avoid regulatory and reputational risk.
- Labor Policy Shifts: Adjustments to overtime thresholds and wage rules have a direct bearing on the ROI timing for automation investments. Modeling should incorporate labor-scheduling elasticity and alternative redeployment strategies.
- Shrink and Merchandising Fit: Some formats have reduced self-checkout footprints where shrink is intractable. Our scenario testing shows that targeted deployment by format and merchandising strategy produces materially different payback curves.
- Cyber & Privacy Incident Costs: With average breach costs nearing USD 3.91 million in benchmark datasets, cybersecurity controls and breach response planning should be non-negotiable elements of any rollout.
How C-Suites Should Use This Report in 2026
For CEOs and COOs: use the market sizing and scenario analyses to set multi-year capital allocation and store-format strategies. For CIOs and CTOs: adopt the vendor matrices and TCO templates to reset integration standards and lifecycle planning. For CMOs: leverage insights on customer experience trade-offs between speed and human interaction to refine loyalty and channel strategies. For CFOs: apply the ROI templates under the three stress scenarios provided to stress-test budgets and funding timelines.
Next Steps & Where to Find the Full Intelligence
PW Consulting’s study offers the data-driven, operationally-focused playbooks that senior teams need to make confident self-checkout investments in 2026. This brief intentionally highlights strategic directions and macro metrics while reserving full segment-level tables, regional splits, vendor scorecards, and downloadable financial models for the complete report package. For procurement teams, our vendor comparison grid and executable RFP clauses in the full report will accelerate sourcing timelines. For implementation teams, our store-level pilot protocols and shrink-measurement templates provide ready-to-use tools.
To access the complete segmented intelligence, vendor matrices, and downloadable ROI models, please visit the PW Consulting report page — the only source for the full dataset and practical templates required to operationalize your 2026 self-checkout roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Self-Checkout in Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fish & Shrimp Feed Additives Market to Top USD 3,552.16 Million by 2032, Driven by a 5.45% CAGR
By PW Consulting, 2026-07-15
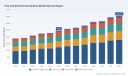
Worldwide Fish and Shrimp Feed Additive Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global market for fish and shrimp feed additives has moved from a niche support market into a strategic battleground. Our new PW Consulting report, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, models an industry growing at a mid-single-digit compound annual growth rate (CAGR) of 5.45% as it transitions to USD-scale maturity. Measured in the base year 2025, the market sits squarely in the multi-billion-dollar range and is projected to continue expanding through 2032. For executives planning investments, partnerships, or operational pivots in 2026, this report translates macro momentum into practical decision levers while intentionally reserving granular subsegment tables to drive direct engagement with our web-based data hub.
Worldwide Fish and Shrimp Feed Additive Market
Why this market matters in 2026
-
Feed additives are no longer ancillary inputs; they sit at the intersection of productivity, disease management, sustainability and cost control. As feed formulation shifts away from traditional marine ingredients, additives determine whether new protein mixes can deliver the same or better biological and economic performance.
Worldwide Fish and Shrimp Feed Additive Market -
Regulatory and compliance trends are elevating additive strategy to board-level attention. Our compilation of regulatory impacts includes a quantified model of compliance costs for developed markets and scenario tests showing how changes in approval timelines, residue limits, and label claims can materially affect product portfolio economics.
Worldwide Fish and Shrimp Feed Additive Market -
The supplier landscape is consolidating unevenly: while global integrators and ingredient specialists scale capability and distribution, a diverse cohort of regional and specialty vendors continues to innovate at the formulation layer. The market exhibits moderate concentration—enough that M&A and strategic alliances are a viable path to gain scale quickly in targeted geographies or technologies.
Industry dynamics shaping 2026 strategy
-
Raw material volatility remains the primary cost shock. Synthetic amino acids and key oil/fat inputs exhibit sensitivity to feedstock energy prices and regulatory shifts in major producing countries. Our scenario models quantify pass-through effects on feed additive margins under multiple commodity paths.
-
Sustainability-driven protein substitution is accelerating. Alternative proteins—most notably insect-derived meals—are crossing from pilot to commercial adoption in shrimp and finfish diets. We map commercial readiness across species and identify where additives (e.g., digestibility enhancers, mycotoxin binders, and microbiome modulators) will be required to bridge performance gaps.
-
Regulatory headwinds and opportunities. Recent regulatory approvals and evolving regional frameworks create both risks and openings. Our report integrates recent milestones—such as the first generic florfenicol approval for freshwater feed use—and models the compliance cost baseline for aquaculture operators in major markets, allowing firms to estimate the net present value (NPV) impact of regulatory change on product launches and reformulations.
-
Product functionality is diversifying. Demand for additives that combine health, performance and sustainability attributes (e.g., functional probiotics, targeted amino acid blends, pigment systems, and natural antioxidants) is rising. We provide a functionality map that links additive classes to the most likely near-term commercial use-cases and margin profiles.
What the PW Consulting report delivers (practical content)
-
Actionable market-sizing and forecast models: comprehensive topline trajectories and demand drivers for 2026–2032 with sensitivity analyses across commodity, regulatory and adoption scenarios.
-
Decision-ready playbooks: go-to-market frameworks for ingredient suppliers, feed integrators and aquaculture producers covering pricing, channel strategy, and co-development partnerships. Each playbook includes tactical checklists and a phased 12–24 month implementation roadmap.
-
Portfolio optimization tools: cost-benefit matrices and a “reformulation stress-test” that models the P&L impact of substituting fishmeal/fishoil and incorporating alternative proteins while maintaining biological performance targets.
-
Regulatory intelligence dashboard: a regionalized tracker of approval pathways, residue limits and compliance cost estimates, plus templates for regulatory dossier preparation to accelerate time-to-market.
-
Supplier and ingredient heatmaps: verified capability profiles, manufacturing footprints, and risk scores for strategic sourcing. (Note: granular regional share tables are intentionally reserved for the online dataset to preserve the report’s role as a strategic trailer.)
-
M&A and partnership pipeline: a curated list of technologists, specialty additives SMBs and manufacturing assets assessed for strategic fit across four archetypal buyer profiles, complete with valuation sensitivity ranges and integration checklists.
-
KPIs and measurement templates: trial designs, statistical thresholds and monitoring protocols for on-farm and hatchery validation of additive performance—designed for rapid in-market evidence generation.
Competitive landscape—who matters and why
The competitive field combines multinational ingredient giants, specialized additive innovators and large vertically integrated feed manufacturers. Leading players include Cargill, Nutreco (Skretting), BioMar, Alltech, ADM, dsm-firmenich, Evonik, BASF, Adisseo, Kemin, and a set of large regional feed producers in Asia-Pacific such as Guangdong HAID, Tongwei and CP Foods. Each brings distinct strategic assets:
-
Cargill and ADM: breadth in global distribution and ingredient integration—competitive advantage for scale formulations and rapid route-to-market.
-
Nutreco (Skretting) and BioMar: premium R&D capability and species-specific nutrition programs—well-positioned to commercialize microbiome and functional nutrition innovations.
-
Alltech, Kemin and Adisseo: specialty natural solutions and gut-health portfolios—key partners for producers aiming to reduce antimicrobial reliance.
-
Evonik and BASF: specialty amino acids, vitamins and performance chemicals—critical for margin optimisation in low-fishmeal diets.
-
Regional integrators (e.g., Tongwei, CP Foods, Guangdong HAID): control of local feed channels and strong procurement leverage—important for scaled trials and rapid adoption.
Market concentration is meaningful but not prohibitive for new entrants: the top-tier players control a notable share, yet structural and technological niches exist for focused innovators. Recent industry moves—such as BioMar’s commercialization of insect meal partnerships and certification milestones—illustrate how sustainability-linked propositions can accelerate commercial uptake when combined with feed manufacturer alliances.
Implications for 2026 corporate strategy
-
Supply chain resilience must move from procurement to product design. Firms should model dual-sourcing for critical inputs (particularly synthetic amino acids and essential lipid fractions), maintain strategic inventory buffers for high-volatility components, and invest in co-development contracts that hedge feedstock exposure.
-
Prioritize modular additive platforms over single-purpose products. The most investable solutions in 2026 will be those that can be rapidly tuned to different protein bases or species and that provide measurable on-farm ROI.
-
Make sustainability a commercial advantage, not just compliance. Certification, traceability and alternative protein integration (e.g., black soldier fly meal) should be tied to value-capture mechanisms—premium pricing, preferred supplier status, or co-branded product lines with feed integrators.
-
Prepare for regulatory flux. Regulatory intelligence is now a core strategic capability: companies should allocate dedicated resources to dossier strategy, residue science, and proactive engagement with authorities to accelerate approvals.
-
Use M&A selectively to fill capability gaps. With market concentration at a level that rewards scale for distribution and R&D depth for technology, targeted acquisitions of specialty additive SMEs or toll-manufacturing capacity can deliver rapid capability lift.
-
Measure commercial experiments like investments. Deploy short-cycle on-farm pilots with predefined endpoints and economic triggers for scale-up to minimize time-to-decision and financial exposure.
How PW Consulting’s report supports your 2026 choices
This market briefing is purpose-built to be decision-centric. The full report contains downloadable financial models, regulatory dossiers templates, supplier scorecards, and field-trial protocols. It translates the broader market trajectory—anchored by a 2020–2025 historical analysis and a 2026–2032 forecast at a 5.45% CAGR—into templates and playbooks executives can operationalize in the coming 12–18 months.
Next steps—where to get the full dataset
To preserve the integrity of strategic analysis while enabling privileged access to the granular tables, segmentation breakdowns, and model inputs that underpin this synopsis, the report reserves detailed subsegment data for our online portal and licensed deliverables. PW Consulting invites procurement teams, strategy groups, and R&D leaders to contact our client services team to arrange access to the full dataset, bespoke scenario runs, and a strategy workshop tailored to 2026 operational calendars.
Closing note
As 2026 approaches, the fish and shrimp feed additive market will be defined by the companies that can align ingredient science, regulatory agility and commercial execution. Our report is designed to help decision-makers convert market visibility into competitive advantage—without surrendering the proprietary analyses that create that advantage. Visit our website to unlock the full intelligence pack and begin implementing the 12–24 month moves that will define market leadership through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Fish and Shrimp Feed Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Portable Device Charging Kiosks Market — Strategic Imperatives for 2026
PW Consulting today publishes a forward-looking executive brief drawn from our new Worldwide Portable Device Charging Kiosks Market report (base year 2025). The market has expanded rapidly over the most recent five-year cycle, rising from roughly USD 348 million in 2020 to an estimated USD 570 million in 2025. Our analysis projects continued momentum through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 11.02%, reaching approximately USD 1.18 billion by 2032. For executive teams planning 2026 investments, this report crystallizes the commercial and operational choices that will separate winners from laggards in a market that remains consolidating but far from mature.
Worldwide Portable Device Charging Kiosks Market
Why this matters for 2026 decision-making
- Accelerating demand, but nuanced adoption paths. The overall market trajectory is robust: double-digit CAGR into the next decade signals strong demand across venues and use cases. Yet commercial success in 2026 will hinge on selecting the right business model (owned, rented, ad-supported, or hybrid) and tailoring offers to operator economics rather than assuming one-size-fits-all deployments.
- Capital and operating cost trade-offs are strategic, not just tactical. Operators and venue partners must evaluate both upfront installation and recurring maintenance. Industry data suggest Level‑2 infrastructure and associated electrical work can push installation costs into a higher bracket, and maintenance labor can approach several hundred dollars per unit annually—variables that materially affect payback periods and pricing strategies.
- Regulation alters commercial math. Evolving frameworks around kWh-based pricing and tax treatment—particularly in the United States—create localized regulatory risk and opportunity. Rules that exclude charging operators from public utility definitions in many states enable flexible pricing experiments, while certain state-level taxes on kWh for higher-capacity stations introduce a fiscal premium that needs to be modeled into 2026 rollouts.
- Market concentration leaves room for differentiated plays. The market is partially concentrated: the top three players control roughly one-third of the market, while the top five approach half. That structure rewards differentiated productization (security, solar, UV‑C disinfecting, cloud management), service models (rental vs. sale), and integrated media/advertising bundles for site owners.
What the PW Consulting report delivers (operationally focused)
This study is intentionally practical—built for decision-makers who need executable plans rather than vanity metrics. Key deliverables include:
Worldwide Portable Device Charging Kiosks Market
- A validated market-size and growth model with transparent assumptions and sensitivity scenarios for 2026–2032, enabling CFOs to stress-test deployment and monetization strategies under multiple demand, price, and cost paths.
- Vendor benchmarking and a procurement scorecard that evaluates suppliers on manufacturing provenance, software/platform capability, security, warranty and SLAs, customization, and after‑sales service.
- Hands‑on playbooks: site-selection matrix, location economics templates, go‑to‑market sequencing for pilots and rollouts, and KPI frameworks for customer experience and uptime.
- TCO and ROI models pre-populated with industry-validated inputs (installation, recurring labor, consumables, insurance, tax considerations) that buyers and operators can adapt to their portfolios.
- Commercial model templates (free, pay-per-use, subscription, ad-supported), sample contracts, and negotiation checklists designed to accelerate vendor and venue partnerships while protecting margin.
- Regulatory and compliance annexes that map relevant U.S. state-level rules and broader global considerations that affect revenue recognition, taxation, and municipal permitting.
Competitive landscape — what to watch in 2026
The market’s competitive field is diverse: established product manufacturers, event‑specialist rental providers, software-enabled operators, and a growing number of manufacturers serving OEM and white-label channels. Key strategic positions we observed include:
Worldwide Portable Device Charging Kiosks Market
- goCharge Networks (USA) — Strengths: scalable power-bank dispensing units and large-slot kiosks for events and venues; recent product pricing updates and solar options improve total cost of ownership for outdoor and temporary deployments.
- InCharged (New Jersey, USA) — Strengths: award-winning designs, fast wireless multi-device support, deep quality testing, and a vertically integrated U.S. manufacturing footprint that appeals to customers prioritizing domestic production and tight QA controls.
- Veloxity (USA) — Strengths: event technology specialist with flexible rental and purchase models, useful for organizations seeking temporary capacity without capital commitments.
- ChargeBar (USA) — Strengths: long track record since 2009, product breadth including solar units and extended warranty offerings; content and customer education have been recent focal points to build loyalty.
- Chargetech (USA) — Strengths: secure charging lockers and specialized products for government and healthcare clients, including disinfecting carts—an advantage where security and infection control are procurement priorities.
- ChargerGoGo (USA) — Strengths: operator/provider hybrid with a broad deployed base of shared power bank stations and advanced cloud/QR rental workflows; recent regional network expansion in early 2026 shows momentum in scaling operations.
- chargeFUZE, Winnsen, HonestWaves, The Power Stop (VendPart) — Each contributes specific capabilities: remote network management and data tracking (chargeFUZE), high-security CE/FCC-certified manufacturing (Winnsen), solar and rental flexibility (HonestWaves), and advertising-integrated hardware (The Power Stop).
For buyers, the essential diligence questions are consistent: What is the supplier’s software upgrade cadence and roadmap? How is spare-parts and field-support organized (domestic vs offshore)? What SLA has been contractually defined for uptime, and how are digital revenue streams (ads, data) shared?
Operational, fiscal and regulatory headwinds to model now
- Maintenance and labor. Annual upkeep—including technician visits, parts, and service labor—moves from being a line-item to a strategic lever. In several industry analyses maintenance costs can approach several hundred dollars per unit annually; procurement teams should insist on detailed, scenario-based maintenance pricing from vendors.
- Installation and hardware inputs. Advanced charging deployments, particularly those requiring electrical upgrades, bring significant one‑time costs that can materially extend payback timelines. Level‑2 infrastructure projects often require transformers and civil/ electrical works that should be budgeted into pilot economics.
- Regulatory nuance. While many U.S. jurisdictions have enabled flexible pricing models for charging infrastructure, select states impose kWh-based taxes or fees for higher-capacity installations—local tax and permitting regimes must be factored into any multi-state roll‑out.
Five strategic moves for leaders deploying in 2026
- Adopt modular commercial offers: combine short-term rentals for events with long-term ad-supported or subscription placements in high-footfall fixed locations.
- Insist on plug-and-play analytics: require cloud telemetry and remote management to reduce mean time to repair and to monetize site-level impressions and dwell-time data.
- Negotiate maintenance SLAs tied to performance metrics and include spare‑parts inventory commitments to reduce downtime risk during critical seasons.
- Build regulatory scenarios into financial models: run sensitivity analyses incorporating local kWh taxes and potential permitting delays in prioritized roll-out geographies.
- Remain open to partner-based scale: pursue co-located media/ad partners and F&B or retail anchors to accelerate user adoption while sharing capex and OPEX burdens.
How to use the PW Consulting report
This release is a strategic “trailer”: it highlights market direction, competitive dynamics, regulatory drivers, and practical playbooks that will be material to capital allocation and operational plans in 2026. The full report includes the complete segment-level detail, vendor scorecards, downloadable TCO/ROI models, and sample contracting language that procurement and strategy teams need to act. For organizations preparing budgets, pilot programs, or M&A screens in 2026, the report provides the templates and scenario tools to make defensible choices and to accelerate time-to-revenue.
To access the full report and the embedded operational tools that support immediate decision-making, please visit PW Consulting’s report page for ordering and licensing options.
Contact PW Consulting for an executive briefing or a tailored workshop to calibrate the report’s models to your portfolio and to map a prioritized 90‑day pilot and a 24‑month roll‑out roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Device Charging Kiosks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Metal Cutting Gas Market to Grow at a 5.4% CAGR from 2026 to 2032
By PW Consulting, 2026-07-15
Worldwide Metal Cutting Gas Market — Strategic Outlook to 2032
PW Consulting's new market study, Worldwide Metal Cutting Gas Market (base year 2025, forecast 2026–2032), equips industrial leaders with the intelligence required to make defensible commercial and investment decisions in 2026 and beyond. Our analysis shows the market at approximately USD 4,850 Million in 2025 and projecting to roughly USD 7,009 Million by 2032, reflecting a compound annual growth rate of 5.4% across the forecast period. This report is written for procurement chiefs, operations leaders, strategy teams and investors who must reconcile short-run volatility with multi-year planning.
Worldwide Metal Cutting Gas Market
Why 2026 Is a Strategic Inflection Point
Several structural and cyclical forces are converging as companies write their 2026 playbooks. Global fabrication volumes are stabilizing after pandemic-era dislocations, while technology adoption (plasma, laser, hybrid oxy-fuel processes) is shifting the composition of gas demand toward higher-value blends and specialty formulations. At the same time, raw-material and regulatory dynamics are becoming more consequential for cost and compliance:
Worldwide Metal Cutting Gas Market
- Feedstock-driven price volatility: acetylene cost dynamics continue to ripple through cutting-gas economics—Analysts’ reporting in April 2026 highlighted widening regional price differentials linked to calcium carbide feedstock costs. These moves materially affect marginal cutting costs and supplier margins across regions.
- Regulatory tightening and logistics oversight: U.S. emission standards for integrated iron and steel operations and ongoing hazardous-materials transport-rule workstreams (PHMSA) are increasing both compliance costs and operational risk for producers and large fabricators.
- Trade policy shifts: the April 2026 restructuring of Section 232 measures alters the effective cost of certain metal-containing imports, indirectly changing domestic fabrication economics and, therefore, gas demand profiles for some manufacturers.
For executives building 2026 capital plans, these forces mean that decisions on supplier commitments, inventory strategies and technology conversion (for example, moving capacity toward laser or plasma cutting) must be informed by forward-looking price and regulatory scenarios—not just historical averages.
Worldwide Metal Cutting Gas Market
What the Report Delivers — Operationally Actionable Content
PW Consulting designed this study to be a hands-on toolset. Key, practical components include:
- Macro market sizing and medium‑term forecast (2026–2032) with sensitivity bands calibrated to alternative economic and steel-demand pathways.
- Demand-driver diagnostics that map industrial end‑use trends to gas-type and technology adoption curves, enabling prioritized interventions by segment and manufacturing archetype.
- Supply‑chain anatomy and supplier scorecards—covering upstream feedstock exposure, production flexibility, logistics risk, and service bundling—which procurement teams can use to qualify and rank counterparties.
- Price‑and-cost models that link key inputs (calcium carbide, LPG, natural gas) to delivered gas cost under multiple transportation and storage assumptions, with downloadable model templates for internal use.
- Regulatory-impact assessments and compliance playbooks focused on emissions rules, hazardous-materials transport standards and trade-policy scenarios likely to impact 2026 procurement and compliance budgets.
- Scenario planning modules and a risk register identifying high‑probability, high‑impact events (feedstock shocks, port closures, tariff re-pricing) and recommended contingency actions.
- An M&A and partnership screen identifying where scale, specialty blends, or geographic reach produce defensible returns—useful for corporate development and PE teams scoping targets.
- Executive briefings and supplier negotiation frameworks suitable for board-level discussion and immediate use in supplier renewal cycles.
To maintain the utility of this document as a decision tool, the report provides full disclosures of underlying assumptions and the primary data series used to construct our forecast models.
Competitive Landscape: Who Matters and Why
The supply-side of the market remains commercially significant but not hyper‑concentrated—our concentration analysis indicates notable room for regional and niche players even as a handful of global suppliers exert scale advantages. This structure creates differentiated strategic choices for buyers and investors alike.
- Linde plc — A global industrial‑gas leader with broad product depth and integrated solutions for oxy‑fuel, plasma and laser environments. Linde’s value proposition centers on scale, global logistics and packaged service models that combine gas supply with equipment and technical support.
- Air Liquide S.A. — Strong in innovative gas blends and high‑service offerings, Air Liquide pairs product R&D with industrial-services contracts, making it a go‑to partner for large fabricators seeking uptime guarantees and efficiency improvements.
- Air Products and Chemicals, Inc. — Notable for its portfolio of cutting gases and total-solution approach, including proprietary formulations and on-site gas systems. The company’s emphasis on integrated service reduces friction for multinational customers.
- Messer SE & Co. KGaA — A focused industrial gas specialist with strong European roots and growing presence in Americas and Asia. Messer competes on regional agility and customized supply arrangements.
- TotalEnergies SE — An energy-company supplier of fuel gases and specialized formulations, leveraging downstream distribution strengths to reach industrial and contractor markets.
- Regional and national players (examples include Indian Oil Corporation, Bharat Petroleum, Brothers Gas, NISSAN TANAKA CORPORATION and ESAB) — These firms play decisive roles in their home markets via price competitiveness, localization, and tailored service bundles; they are often the preferred partners for regional fabricators and contractors.
Our CR metrics show meaningful scale among the top players while leaving ample room for niche competitors and service innovators to win through differentiation. For buyers, this competitive mix creates leverage—but only for procurement programs that bring structured scorecards and a clear view of total cost of ownership.
Priority Actions for 2026 Decision-Makers
Based on the analysis, PW Consulting recommends the following prioritized actions for companies that need to translate foresight into 2026 execution:
- Embed price-curve scenarios into contracting: move beyond fixed‑price vs. spot dichotomies and use indexed contracts with caps/floors tied to transparent feedstock indices. This reduces volatility risk while preserving upside participation in favorable markets.
- Score suppliers on total service, not just price: include delivery reliability, emergency response time, on-site support capability, blended‑gas R&D and compliance capability in supplier selection matrices.
- Accelerate conversion pilots where ROI is clear: target plasma/laser retrofits in high‑precision, high‑throughput lines where gas cost exposure and product-value uplifts are quantifiable within typical capital‑payback windows.
- Harden logistics and storage: renew site-level inventories, review cylinder vs. bulk trade-offs, and stress-test transport routes under tariff and regulatory scenarios—especially where hazardous-materials transport rules are changing.
- Monitor and model regulatory developments: compliance costs (air emissions, transport) should be scenario-tested into product‑line profitability and capex plans for 2026–2028.
- Use M&A and partnership screens opportunistically: prioritize assets that fill geographic gaps, add specialty blend capabilities or enhance last‑mile service models.
How to Use the Forecast and Scenario Tools
The report’s forecast is not a single-line prediction; it is a toolkit with three internally consistent scenarios—baseline, upside and downside—each underpinned by alternative assumptions on macro activity, technology adoption and feedstock pricing. We provide downloadable worksheets so teams can:
- Stress-test capital approvals against demand shock and price shock scenarios;
- Model the P&L impact of converting a production line from oxy‑fuel to plasma or laser, including gas cost, equipment amortization and yield changes;
- Quantify supplier consolidation or dual‑source strategies’ impact on service levels and inventory requirements;
- Build a conditional M&A valuation overlay that adjusts target valuations for regulatory and feedstock risk.
Signals to Watch in 2026
PW Consulting highlights a short list of near-term signals that should trigger tactical or strategic responses:
- Feedstock price trajectories and spreads (especially calcium carbide and LPG) that change delivered-cost parity between proprietary blends and commodity gases;
- Regulatory announcements on emissions or hazardous-materials transport that recalibrate site‑level compliance costs;
- Major capital investments by global suppliers—new capacity or on‑site service rollouts—that could compress margins and change contract dynamics;
- Policy shifts affecting the effective cost of imported metal-containing goods, which can materially alter fabricator throughput and gas demand.
Conclusion — The Strategic Value for 2026
In a market that is growing at mid-single-digit CAGR and where supplier scale coexists with valuable regional specialists, the difference between cost control and margin erosion will be the quality of foresight and the robustness of execution. PW Consulting’s Worldwide Metal Cutting Gas Market study translates raw data into commercial levers: it helps procurement teams negotiate with clarity, supports operations in selecting productive technology conversions, guides investors in target screening, and enables corporate strategists to prepare for regulatory and trade‑policy swings.
Our analysis surfaces both the levers companies can pull immediately and the indicators to monitor as the year unfolds. For teams that need the complete set of segment tables, supplier scorecards, and the downloadable scenario models that support 2026 decisions, the full report and data appendices are available on the PW Consulting report page.
Contact PW Consulting to request the report, arrange an executive briefing, or license the underlying data models for internal planning and supplier‑negotiation processes.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Narrow‑Body Aircraft MRO Market to Reach USD 80.89 Billion by 2032 on a 5.6% CAGR — Asia‑Pacific Leads with USD 17.71B in 2025
By PW Consulting, 2026-07-15
Worldwide Narrow Body Aircraft MRO Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s latest market study, Worldwide Narrow Body Aircraft MRO Market (base year 2025, forecast period 2026–2032), delivers a decision‑grade analysis designed to inform capital allocation, network planning, and partnership strategies for 2026 and beyond. The global narrow‑body MRO market reached roughly USD 55.2 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 5.6% across the 2026–2032 horizon. Our study synthesizes fleet scenarios, cost drivers, and competitive positioning into a practical playbook for executives weighing capacity investments, capability upgrades, and contract negotiations over the next 18 months.
Worldwide Narrow Body Aircraft MRO Market
Why this matters for 2026 planning
-
Timing of capacity investments: With healthy medium‑term growth and accelerating shop‑visit demand for both legacy and newer narrow‑body engines, 2026 is a pivotal year to decide on hangar expansion, specialized tooling, and licensing partnerships. Delays to commitments now materially compress optionality later in the decade.
Worldwide Narrow Body Aircraft MRO Market -
Capability mix is strategic, not tactical: The MRO economics for narrow‑bodies are being reshaped by the co‑existence of mature platforms and next‑generation types. Providers and airlines must prioritize which capabilities to in‑house, which to outsource, and where to seek certified Premier licenses for high‑value engine families.
Worldwide Narrow Body Aircraft MRO Market -
Labor and materials will drive margins: Wage inflation and elevated material costs remain a dominant margin pressure. Operational improvements that reduce turnaround time and inventory exposure will produce outsized returns relative to traditional cost cuts.
Market trajectory and the strategic inflection
Our forecast shows steady expansion through 2032, underpinned by robust flight activity recovery in short‑haul markets and a growing installed base of next‑generation narrow‑body variants requiring specialized maintenance workflows. This growth is not linear: expect episodic surges in demand tied to fleet renewal cycles, regulatory directives, and concentrated shop‑visit waves for specific engine types. For strategic planners, the implication is clear — build flexibility into capacity plans and prioritize modular investments that can pivot between airframe, engine, and component work mix.
Cost dynamics: labor, materials and supply chains
Two structural cost vectors dominate the MRO P&L in 2026: certified labor and parts/materials. Skilled mechanic shortages are persistent, with wage inflation materially above historical norms. At the same time, parts availability continues to be cyclical, extending turnaround times and necessitating higher spare inventory or more complex vendor financing arrangements. Our modelling in the report assesses breakeven points for different facility utilization scenarios under varying labor and material inflation paths, enabling CFOs to stress‑test capital proposals against realistic supply‑chain disruption scenarios.
Engine MRO as a strategic battleground
The narrow‑body engine landscape—particularly the mixed fleet environment of legacy and LEAP‑family engines—has become a central competitive arena. Premier licensing for newer engines is a gatekeeper for high‑margin shop visits. Recent provider announcements and facility openings indicate a deliberate industry pivot to secure certified capabilities for LEAP engines alongside continued service for mature engine types. For airline operators and independent MROs, the choice between investing in licensed capability or securing long‑term outsource arrangements will materially affect lifecycle cost and resilience.
Network optimization: where to invest and why
Geographic network choices should be guided by a combination of demand clustering, access to certified talent, and supply‑chain proximity. The report reframes classic hub‑and‑spoke thinking into a three‑dimensional optimization problem that balances:
-
Capacity scaling (short‑term surge handling vs. steady base load)
-
Capability concentration (engine‑centric vs. airframe/component balanced facilities)
-
Regulatory and licensing constraints (e.g., Premier engine certifications)
We provide a decision matrix and scenario models that allow executives to rank potential sites and investment phasing according to return on capital, time‑to‑certification, and labor availability.
Competitive landscape: positioning the leading players
The market displays moderate concentration with a cluster of full‑service providers, airline‑affiliated shops, and large independents. The top tier of providers leverages scale, licensed engine capabilities, and multi‑region footprints to capture a disproportionate share of complex shop visits. Key strategic observations from our corporate benchmarking:
-
Lufthansa Technik remains a model of integrated capability development, combining comprehensive base and line MRO with engine overhaul offerings and facility specialization that supports narrow‑body fleets at scale. Their multi‑site approach shows how base capacity and geographic redundancy deliver commercial resilience.
-
ST Engineering has differentiated through massive man‑hour scale in airframe MRO and recent capacity expansion in engine maintenance. Their strategy of balanced capability across regions—backed by a sizable workforce—positions them well for both volume work and larger contract wins.
-
AAR Corp. and dedicated independents continue to capture North American demand with focused investments in landing gear, component repair, and airframe heavy maintenance—areas where turn‑key capability and regional proximity to airline customers matter most.
-
Airline‑affiliated MROs such as Delta TechOps and TAP blend guaranteed internal demand with selective third‑party services. Notably, Delta TechOps’ expansion of full licensed overhaul capability for key LEAP engines alters the supplier map in North America and raises the bar for regional competition.
-
Specialists like SR Technics and HAECO extract value through concentrated expertise—engine heavy shop visits and targeted line support respectively—often winning multi‑year contracts with large operators due to reliability and bespoke service models.
These profiles are examined in our competitive scorecards, which assess capability breadth, certification depth, facility throughput, and strategic partnerships. Full provider benchmarking, including contract case studies and facility capability maps, is available in the complete report.
Regulatory and certification friction
Regulatory complexity—particularly around engine manufacturer licensing—remains a gating factor for many MRO strategies. The LEAP engine family requires specific certifications and shop infrastructure, forcing operators and MROs to make early strategic choices about whether to pursue licensed capability, partner with certified providers, or secure long‑term MRO contracts. Our analysis quantifies the time and capital required to achieve certification and models the revenue uplift necessary to justify those investments.
What’s inside the full PW Consulting report (practical deliverables)
-
Holistic 2026–2032 financial forecast scenarios (base, upside, downside) with sensitivity to labor and parts inflation.
-
Operational playbook: step‑by‑step guidance for capacity expansion, certification roadmaps, and cost‑to‑serve optimization for airframe, engine and component workstreams.
-
Provider scorecards and heatmaps that rank MROs on capability depth, turnaround efficiency, and strategic fit for airline outsourcing strategies.
-
Deal‑making toolkit: negotiation levers for long‑term material services, shop‑visit pooling arrangements, and joint‑venture structuring for capacity sharing.
-
Scenario modelling tools and executive dashboards to run bespoke fleet and regional planning exercises for 2026 board decisions.
Because this release is a strategic preview, the full report reserves the granular regional and activity‑level splits, exact revenue buckets, and proprietary serviceable market calculations for subscribers and license holders. Those datasets are the core of our commercial models and are provided via secure download to enable precise contract or capital planning.
Recent market moves that change the calculus for 2026
-
Capacity expansions and facility openings by major independents and engineering groups are shortening the timeline to certified LEAP engine capacity in key markets—this compresses the window for first‑mover advantage.
-
Multi‑year service agreements and material management MoUs between operators and OEM‑aligned providers are reshaping inventory and parts financing practices, reducing short‑term exposure for airlines but shifting working capital to service providers.
-
Contract awards for legacy engine shop visits demonstrate that mature platforms will continue to support a significant base of high‑utilization maintenance work, even as next‑generation types proliferate.
Actionable recommendations for executives
-
Prioritize modular, phased investments in tooling and certification to retain optionality between engine and airframe workstreams.
-
Lock in strategic supply partnerships or long‑term material service agreements to reduce working capital volatility and shorten turnaround time variability.
-
Use capacity‑sharing mechanisms (JV, reciprocal support networks) to absorb surge demand without overcapitalizing fixed assets.
-
Leverage our scenario tools to stress‑test capital proposals against at least three labor/material inflation paths; require break‑even analysis under each scenario before committing.
Next steps — where to get the full intelligence
This release highlights the strategic themes and operational levers PW Consulting believes will determine winners in the narrow‑body MRO market in 2026 and beyond. To access the full dataset, regional and activity‑level splits, provider benchmarking matrices, and the downloadable scenario tools, please visit our report page. The complete report is intended for C‑suite, strategy, and MRO operations teams seeking executable plans—not just high‑level insight.
PW Consulting stands ready to support tailored advisory engagements, including site selection, M&A diligence, and contract negotiation support based on the report’s proprietary models. Contact our team to schedule a briefing and receive the curated dataset that will permit precise, defensible decisions for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Digital Dermatoscope Market to Reach USD 2,155.38 Million by 2032, Growing at a 9.2% CAGR
By PW Consulting, 2026-07-15
Worldwide Digital Dermatoscope Market — Strategic Imperatives for 2026: A PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the Worldwide Digital Dermatoscope Market maps a fast-maturing medical-imaging niche that is transitioning from hardware-led differentiation to software- and data-driven value propositions. The market expanded from USD 752.4 Million in 2020 to USD 1,164.04 Million in 2025 and, under our base forecast, is projected to continue on a robust growth trajectory — reaching USD 2,155.38 Million by 2032. The forecast period (2026–2032) reflects an anticipated compound annual growth rate (CAGR) of 9.2% driven by AI-enabled diagnostic workflows, teledermatology adoption, and increasing clinical acceptance of digital lesion monitoring.
Worldwide Digital Dermatoscope Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a strategic inflection point — early adopters of integrated AI and telemedicine workflows will begin to capture outsized clinical and commercial share.
Worldwide Digital Dermatoscope Market -
Commercial model shift: The product-to-platform transition (hardware plus recurring software/service revenues) will determine margin expansion and valuation multiples.
Worldwide Digital Dermatoscope Market -
Regulatory and reimbursement alignment: Firms that achieve early conformity to updated safety standards and secure billing pathways for digital dermoscopy will unlock faster adoption in outpatient and hospital settings.
Market trajectory and primary growth drivers
Our analysis identifies three mutually reinforcing drivers underpinning the projected 9.2% CAGR through 2032: (1) clinical validation and regulatory maturity of AI-assisted lesion analysis, (2) integration of dermoscopy into teledermatology and longitudinal care pathways (total-body mapping, monitoring), and (3) steady improvement of affordability and form-factor (handheld, wireless) that expands use beyond specialist clinics. While the installed base is concentrated among established device vendors and imaging platforms, the competitive field is broad enough to allow disruptive entrants with superior software or integration capabilities.
Competitive landscape — what leaders are doing
The market shows a clear separation between vendors that compete primarily on optics and form-factor versus those leveraging software ecosystems as the primary differentiation. The top vendors we profile in this preview illustrate distinct strategic postures:
-
Heine Optotechnik (Germany) — Premium optical engineering and device reliability. Recent CE updates on advanced digital models strengthen Heine’s positioning among clinicians prioritizing image fidelity and device safety. Their DELTA series retains a strong reputation for clinical-grade imaging with AI-enabled workflows being layered on legacy strengths.
-
DermLite (Caliber I.D., USA) — Portability and clinician workflow integration. DermLite’s DL series focuses on polarized/non-polarized imaging and practical connectivity (USB, app integration), aimed at point-of-care and teledermatology use. Visibility at major clinical forums underscores their commercial push to be the “everyday” dermatoscope for primary and specialist care.
-
FotoFinder Systems (Germany) — Software-led total-body and AI excellence. FotoFinder’s Moleanalyzer suite and recent v5.0 release demonstrate how strong AI analytics and total-body mapping create sticky SaaS-like revenue opportunities and clinical preference for longitudinal monitoring.
-
Canfield Scientific (USA) — Integrated imaging platforms and clinic workflow solutions. Their focus on integrated studio systems and clinical tracking software targets large dermatology practices and hospital departments that require ecosystem integration.
-
Dinolite and AnMo Electronics (USA/Taiwan) — Cost-competitive, portable USB and wireless models. These vendors occupy a value-performance niche, accelerating adoption in emerging telehealth and non-specialist settings where affordability and USB connectivity matter most.
Recent vendor activity — product launches, certifications, and trade-show rollouts — indicate an industry accelerating along two axes: device refinement (optics, illumination, durability) and software/cloud services (AI lesion scoring, mapping, EHR integration). The competitive map is therefore evolving into a layered ecosystem where partnerships, certification, and data access are as decisive as hardware specs.
Regulatory, reimbursement and cost structure considerations
-
Regulatory: Compliance with medical electrical safety standards such as IEC 60601-1 remains non-negotiable for market access in regulated geographies. Certification updates materially influence procurement cycles within hospitals and multi-site dermatology practices.
-
Reimbursement: CPT and local billing codes (e.g., coverage guidance that cites dermoscopy procedures) materially affect device economics. Capturing reimbursement pathways accelerates enterprise purchasing and service uptake.
-
Cost structure: Medical-grade optics and LED illumination components represent a substantial portion of manufacturing costs (our sector analysis estimates 40–50%). This concentration exposes vendors to supply-chain and input-cost volatility, making design-for-cost and supplier consolidation critical operational levers.
What the full report delivers (practical, action-oriented content)
PW Consulting’s full report is designed as an operational playbook for executive teams evaluating entry, expansion, or M&A in the digital dermatoscope space. Highlights include:
-
Market sizing and forecast models (2020–2032) with scenario analysis tailored to regulatory and reimbursement outcomes.
-
Segmentation analysis by product architecture, clinical end-user, and region — with demand drivers, pricing dynamics, and adoption timelines for each segment.
-
Vendor benchmarking: comparative scorecards across product, software, commercialization, regulatory status, and service capabilities for the market’s leading suppliers.
-
Go-to-market playbooks for manufacturers and software developers: channel strategies, pricing archetypes, bundled hardware+software offers, and pilot-to-scale rollouts in clinics and hospitals.
-
Operational diagnostics: component-cost sensitivity (optics/LEDs), supplier risk mapping, and recommended margin-protection techniques.
-
M&A and partnership screening frameworks including target prioritization, valuation heuristics, and integration checklists for combining device and AI capabilities.
-
Clinical and regulatory roadmap templates to accelerate CE/FDA readiness and reimbursement capture.
Strategic recommendations for leaders in 2026
For 2026 planning cycles, we advise stakeholders to treat the market as a platform opportunity rather than a simple device sale. Tactical priorities differ by company type:
-
Incumbent premium-device vendors: Fast-track software/sensor partnerships and convert customers to subscription revenue for analytics and longitudinal monitoring. Leverage reputation in optics to justify premium tiers while introducing lower-cost companion devices for broader clinical coverage.
-
Software/AI specialists: Prioritize clinical validation and regulatory pathways. Without device-agnostic clinical evidence and clearance, AI algorithms will face adoption headwinds. Seek alliances with device OEMs to fast-track data collection and clinical pilots.
-
New entrants and low-cost hardware players: Focus on niche use-cases (telehealth, primary care screening) and flexible integration (mobile, cloud). Build reference customers quickly via pilot programs and target geographies with supportive reimbursement policies.
-
Private equity and strategics considering M&A: Target bolt-on acquisitions that either (a) add validated AI models and clinical datasets, or (b) close gaps in software/cloud capabilities for existing device portfolios. Pay attention to concentration metrics — while leadership is meaningful, there remains room for consolidation-driven scale.
Risk map and mitigation levers
-
Supply-chain risk: Reduce single-supplier exposure for optics/LEDs; design modular platforms allowing component substitution.
-
Regulatory uncertainty: Invest early in compliance resources and clinical evidence-generation to avoid elongated go-to-market timelines.
-
Reimbursement variability: Build health-economic dossiers that quantify downstream savings (reduced biopsies, earlier detection) to support payer conversations.
-
Data privacy and interoperability: Prioritize standards-based APIs and robust security to ease integration with EHRs and telemedicine suites.
How we built this analysis
The report combines bottom-up device shipment and pricing intelligence with top-down adoption modeling, validated through primary interviews across OEM product management, hospital procurement, dermatology opinion leaders, and payers. We synthesize public filings, regulatory databases, clinical literature, and proprietary supply-chain audits to create scenario-ready forecasts. Our competitive assessments incorporate vendor announcements, product certifications, and recent launches to reflect the market as of late 2024.
Closing — what to read in the preview vs. get in the full report
This preview outlines the macro trajectory, competitive dynamics, regulatory context, and strategic playbooks that will determine winners and losers in the 2026 commercial window. To maintain the value of the report as a decision tool, detailed segment-level datapoints, region-by-region forecasts, vendor market shares, and the granular financial model that power strategic recommendations are available exclusively in the full report.
Next steps
Organizations preparing 2026 budgets or evaluating strategic moves should prioritize three immediate actions: (1) commission a short strategic audit (4–6 weeks) to map product gaps vs. platform expectations; (2) initiate clinical validation pilots with prospective payer and provider partners to build reimbursement cases; and (3) run a supply-chain stress-test focused on optics and LED sourcing. PW Consulting can support each of these actions with tailored workstreams drawing on the full dataset and playbooks contained in our complete Worldwide Digital Dermatoscope Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dal Mill Machine Market to Rise from USD 520.0 Million in 2025 to USD 788.22 Million by 2032 at a 6.12% CAGR — Asia Pacific Leads with USD 280.8M
By PW Consulting, 2026-07-15
Worldwide Dal Mill Machine Market — Strategic Outlook for 2026
PW Consulting’s latest market study on the Worldwide Dal Mill Machine Market (base year 2025; historical 2020–2025; forecast 2026–2032) delivers a pragmatic, decision-ready picture for executives planning capital allocation, product strategy, and M&A activity in 2026. The report combines 360° commercial intelligence — market sizing, competitive mapping, regulatory and input-cost stress tests, and financial playbooks — to translate market dynamics into concrete strategic choices. Our topline: the industry is on a steady expansion path, with total market value rising from USD 386.4 Million in 2020 to USD 520.0 Million in 2025 and projected to reach USD 788.22 Million by 2032 at a 6.12% CAGR.
Worldwide Dal Mill Machine Market
Why this report matters for 2026 decision-makers
-
Timing and scale: 2026 is the year when automation investments, export policy shifts, and input-cost pressures converge. Our analysis quantifies the ROI horizon for automated plants versus incremental upgrades for existing processors, enabling CFOs and plant managers to prioritize projects that de-risk cash flow while capturing premium yield.
Worldwide Dal Mill Machine Market -
Regulatory inflection: With HACCP compliance mandated for dal processing equipment from January 2025, equipment specifications and vendor selection now directly impact market access and buyer confidence. The report translates compliance requirements into engineering and OPEX checklists that procurement teams can action immediately.
Worldwide Dal Mill Machine Market -
Consolidation playbook: Market concentration remains low (CR3: 21.4%; CR5: 31.8%), indicating a fragmented vendor landscape. This fragmentation presents roll-up opportunities for strategic acquirers and OEMs seeking scale economics through geographic reach, product modularity, and after-sales service networks.
Market trajectory and what the numbers mean
Demand for dal mill machinery has expanded consistently through 2020–2025, driven by rising pulse production and a push toward mechanization across processing nodes. The total market value increased from USD 386.4 Million in 2020 to USD 520.0 Million in 2025. Under base-case assumptions — incorporating production growth, gradual automation adoption, and modest price inflation — we project a compound annual growth rate of 6.12% from 2026 through 2032, with the market reaching USD 788.22 Million by 2032.
For strategy teams, these topline dynamics translate into three immediate planning imperatives: (1) align CapEx cycles to capture mid-decade volume growth, (2) prioritize retrofit and modular automation that shortens payback periods, and (3) incorporate regulatory and input-cost stress-testing into procurement contracts and capital approvals.
Key demand and supply dynamics
-
Feedstock and end-market momentum: India's pulse output (26.1 million tons in 2024–25) is a primary structural driver for global dal milling equipment demand. Larger, consistent crops support higher utilization rates for modern plants and create downstream incentives for higher-value processing (polishing, sorting, grading).
-
Input-cost pressure: Fabrication costs are under pressure — hot-rolled coil steel prices rose by around 8% to approximately USD 650/ton in late 2025 — impacting stainless and structural components. This trend forces OEMs to re-evaluate bill-of-materials choices and to pass on or absorb costs depending on competitive positioning.
-
Labor economics: Skilled labor costs in the food-processing sector rose materially (reported wage increases in 2025), narrowing the differential benefit of labor-intensive configurations and increasing the attractiveness of semi- to fully-automated solutions where operators complement rather than replace automated lines.
-
Trade and policy shocks: Export measures such as the 20% duty on unprocessed pulses implemented to support domestic milling change raw-material flows and increase incentive for domestic processing capacity — a structural tailwind for local equipment demand and aftermarket services.
Competitive landscape — structure, players and recent moves
The market is characterized by a mix of specialized regional OEMs, engineering houses that supply integrated lines, and a growing set of technology-focused incumbents introducing automation and sorting innovations. The CR3 (21.4%) and CR5 (31.8%) metrics underscore a low level of concentration: leadership exists, but no single supplier dominates across regions or capacity segments.
-
Milltec Machinery Pvt. Ltd. (Bengaluru) — A recognized leader in fully automated dal mill plants, Milltec has recently showcased a next-generation automatic plant with AI-driven sorting at AgriTech India 2025. Their strengths are turnkey integration and high-yield splitting and polishing lines suitable for large processors and exporters.
-
Pramick Engineering (Hyderabad) — Specializes in mini and semi-automatic machines optimized for micro and small processors. Pramick’s February 2025 launch of a compact, energy-efficient 500 kg/hr machine underscores a market for lower-footprint, lower-capex solutions that shorten payback.
-
GBS Engineering Enterprises (Hyderabad) — Known for complete processing lines with emery roll polishers and gravity selectors, GBS reported a major delivery of a 10-ton plant to an exporter in late 2024, highlighting demand from scale-focused traders and processors targeting export-grade product.
-
Jay Khodiyar, Narnoli Engineering, Bharat Agritech, Masoor Industries, United Oil Mill Machinery — These firms collectively cover compact mills, polishers, graders, and PLC-integrated systems. Their strengths vary across price points, service networks, and specialized lines (e.g., masoor-specific splitters or oil-coated polishers), creating a rich supplier set for buyers to optimize for cost, yield, and aftermarket support.
What the report contains — practical tools and datasets
PW Consulting’s research is structured to be operationally useful for procurement, engineering, and corporate strategy teams. Core deliverables include:
-
Market sizing and forecast models (historical 2020–2025; forecast 2026–2032) with scenario toggles for input-cost shocks and export-policy permutations.
-
Competitive profiles and capability maps for primary OEMs and engineering houses, with supplier scorecards on technology, service footprint, and typical lead times.
-
CapEx and OPEX benchmarking templates (plant-level) and payback calculators that let you model semi-automatic vs. fully automatic adoption under custom utilization assumptions.
-
Regulatory compliance playbook mapping HACCP requirements onto equipment specifications, process flows, and audit-readiness checklists.
-
Supply chain risk matrix that includes steel-price pass-through scenarios, logistic-disruption stress tests, and single-supplier exposure maps.
-
M&A and partnership screen: target criteria, valuation heuristics, and integration templates tailored to strategic acquirers and financial sponsors.
Importantly, while we summarize high-level segmentation and drivers publicly, the full dataset includes granular splits by product type, capacity band, and regional demand drivers. Those subsegment tables and transaction-level comparables are intentionally withheld here to drive direct report engagement and ensure clients receive the complete, auditable dataset needed for investment-grade decisions.
Strategic implications and recommended plays for 2026
-
OEMs (manufacturers): Prioritize modular, PLC-enabled platforms and a service-first commercial model. Investments in AI-enabled sorting and condition-monitoring reduce total cost of ownership and can be monetized via premium warranties and consumables.
-
Processors (mills & exporters): Use our CapEx/Opex templates to compare full-plant automation vs. targeted retrofits. For corporations facing labor-cost inflation and stricter export standards, upgrading polishing and sorting lines yields faster margin capture than capacity-only investments.
-
Private equity and strategic acquirers: The fragmented vendor base is ripe for roll-ups. Target assets with strong service networks and repeatable retrofit revenues; apply standardized integration playbooks to accelerate cross-selling and spare-parts margins.
-
Equipment distributors and service providers: Build HACCP-compliance advisory bundles and remote-monitoring subscription services — these are high-margin, low-capex services that drive customer stickiness.
Next steps — where to get the full intelligence
This announcement is a concise strategic brief designed to position 2026 decisions. PW Consulting’s full Worldwide Dal Mill Machine Market report contains the underlying Excel models, scenario-based forecasts, granular segmentation tables, and vendor scorecards that are essential for executable decisions. For procurement teams, M&A desks, and plant operators requiring auditable inputs or bespoke consulting workshops, please visit our research download page or contact your PW Consulting account lead to request the full report and supporting data package.
Prepared by: PW Consulting — Senior Strategy & Industry Analysis Team. Our methodology combines primary interviews with OEMs and processors, manufacturer shipment data, and bottom-up equipment costing to deliver a defensible, actionable market view.
For detailed analysis of this topic, please visit the official page: Worldwide Dal Mill Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Bitterness Suppressor & Flavor Carrier Market Poised to Reach USD 964.54 Million by 2032 on a 5.8% CAGR (2026–2032)
By PW Consulting, 2026-07-15
PW Consulting Releases Strategic Preview: Worldwide Bitterness Suppressor and Flavor Carrier Market — What Leaders Must Know for 2026
Executive summary
As companies prepare their 2026 product roadmaps and sourcing strategies, understanding the trajectory of the bitterness suppressor and flavor carrier market is becoming mission-critical. PW Consulting’s new market study — base year 2025, historical window 2020–2025, forecasting through 2032 — shows a resilient growth story. The market expanded from roughly USD 485 million in 2020 to about USD 650 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.8% during the 2026–2032 forecast period, reaching an estimated USD 965 million by 2032. That steady expansion masks a complex set of commercial pressures: raw-material volatility, evolving regulatory regimes, tariff frictions, and an intensifying competitive race around clean-label and encapsulation technologies.
Worldwide Bitterness Suppressor and Flavor Carrier Market
Why this report matters for 2026 decision-makers
-
Product strategy: Formulation teams must reconcile sensory objectives (masking bitterness, preserving aroma, enabling reduced-sugar profiles) with rising demand for natural, label-friendly ingredients. The balance between performance and compliance will determine product acceptability across regulated segments in 2026 and beyond.
Worldwide Bitterness Suppressor and Flavor Carrier Market -
Procurement and supply chain: Raw material inflation and trade policy shocks are already altering cost curves. Procurement organizations need a clear supplier-risk playbook and financially defensible hedging strategies to protect margins without sacrificing innovation cadence.
Worldwide Bitterness Suppressor and Flavor Carrier Market -
Commercial positioning: Marketing and sales teams must translate technical superiority (e.g., better encapsulation efficiency, controlled release) into quantifiable consumer benefit and willingness-to-pay — particularly for beverage, nutraceutical and pharmaceutical customers where sensory acceptance is central.
-
M&A and partnership timing: With industry concentration moderate (top 3 players account for roughly one-third of the market and top 5 approaching half), there is a narrow window for bolt-on acquisitions and strategic alliances to secure technology or channel advantages before multiples re-rate.
What the report delivers — practical, implementable content
This study is designed as a decision-support toolkit rather than an academic exercise. Key deliverables include:
-
Transparent market model (2020–2032) with scenario variants for price shocks, regulatory constraints, and adoption curves for natural vs. synthetic suppressors.
-
Supplier risk heatmaps and contingency plans that rank suppliers by technical capability, geographic exposure, raw-material dependency, and compliance risk.
-
Technology adoption matrix: encapsulation approaches, cyclodextrin applications, modified-starch carriers, and “other” platforms assessed by cost-to-performance and scale-up risk.
-
Regulatory-impact simulations (including modeled outcomes reflecting recent EU and US developments) to quantify reformulation costs and time-to-market under alternative compliance scenarios.
-
Commercial playbooks for go-to-market segmentation, value-selling templates for food and beverage customers, and KPI dashboards for R&D and procurement leaders.
-
Execution checklists: short-term (6–12 months) and medium-term (12–36 months) priorities to secure supply, accelerate reformulation, and capture premium pricing for clean-label credentials.
Competitive landscape: shaping winners and losers in 2026
The market combines specialized flavor houses with major ingredient suppliers. Leading firms are shifting from product-centric supply to solution-centric partnerships — bundling taste modification, encapsulation, and regulatory guidance. PW Consulting’s analysis highlights strategic posture and near-term moves of core players:
-
Givaudan (Switzerland) — A leader in aroma and masking technologies. Recent launches emphasize EU-compliant, clean-label emulsions and carrier systems. Strengths lie in global application know-how and strong relationships with large F&B customers. Risk vectors include exposure to commodity cost swings and the need to demonstrate clear cost-benefit for premium formulations.
-
International Flavors & Fragrances (IFF, USA) — Strong in proprietary bitterness suppressors and encapsulation systems, reinforced by quality certifications that support “next-gen” clean-label positioning. IFF’s scale aids rapid commercial rollouts, but they must continue driving efficacy narratives to justify price differentials in commoditizing segments.
-
DSM-Firmenich (Switzerland) — Investing in specialized carriers for plant-based and dairy-alternative beverages. Recent product launches signal a deliberate strategy to front-run plant-protein bitterness challenges. Their integrated R&D-to-manufacturing setup reduces scale-up risk for customers.
-
Kerry Group (Ireland) — Focused on emulsion-based carriers and sensory tuning platforms. Kerry’s advantage is application depth in savory and sweet systems and a consultative sales approach that aligns reformulation with consumer trends.
-
Sensient Technologies (USA) — Offers encapsulated flavors and inhibitors across beverage, confectionery, and pharma, with strong formulation support. Their mid-market positioning is well-suited for customers seeking performance at controlled cost.
-
Symrise (Germany) — Emphasizes encapsulation and functional masking (SymMask, SymGlobe) for functional foods and nutraceuticals. Symrise’s playbook is product-centric with growing emphasis on co-development with brand owners.
Collectively, the top three firms account for roughly 34–35% of the market, while the top five approach nearly half — a structure that favors scale players able to invest in certification, global supply chains, and broad application testing. Yet pockets of opportunity remain for nimble specialists, particularly those delivering validated natural solutions or lower-cost carriers under new tariff regimes.
Market dynamics to watch in 2026
Our fieldwork and primary-source monitoring identified four cross-cutting dynamics that should drive board-level attention in 2026:
-
Raw-material volatility: Cyclodextrin and starch-derived carrier costs remain sensitive to upstream agricultural supply. A documented price uptick tied to regional corn-starch constraints highlights the need for multi-sourcing and formula flexibility.
-
Regulatory tightening and segmentation: Recent EU measures restricting certain synthetic suppressors in infant nutrition and other sensitive segments are accelerating reformulation toward natural alternatives. Expect compliance timelines to compress product launch windows and raise reformulation costs.
-
Trade and tariff friction: New tariffs on imported encapsulation agents have materially changed landed costs for some users, prompting on-shore sourcing and nearshoring conversations for critical applications.
-
Environmental and labeling constraints: Jurisdictional rules (for example, state-level labeling thresholds) are influencing ingredient choice and risk tolerance for certain synthetic carriers — a consideration increasingly factored into product design and market entry strategies.
Strategic imperatives for 2026
Based on scenario modeling and client engagements, PW Consulting recommends five priority actions for executive teams:
-
Develop a dual-track formulation roadmap that balances short-term cost control with parallel investment in natural, regulatory-ready solutions.
-
Build contingent supplier ecosystems: qualify secondary suppliers, establish toll-manufacturing options, and consider backward integration for high-risk feedstocks.
-
Quantify sensory benefit in commercial terms: create standardized taste-acceptance metrics and translate them into value-based pricing models for customers.
-
Prioritize regulatory intelligence and fast-track certification paths for strategic applications (infant nutrition, pharmaceuticals, and certain nutraceutical formats).
-
Use targeted M&A or JV activity to acquire missing capabilities — particularly in encapsulation scale-up, natural bitterness suppressors, or regional manufacturing footprints affected by tariffs.
How PW Consulting can help
PW Consulting offers a tiered advisory suite aligned to 2026 planning cycles: a rapid 8-week “market-entry and supplier-readiness” package, a full-spectrum strategic review that includes our proprietary market model and scenario simulations, and hands-on implementation workshops for R&D and procurement teams. Each engagement includes a live decision-support model, a reforms impact roadmap, and an actionable commercial playbook.
Next steps and how to access the full report
This preview highlights the near-term imperatives and the practical analytics packed into our full study. To evaluate specific implications for your product portfolio, supply base, or M&A pipeline, we invite you to request the full Worldwide Bitterness Suppressor and Flavor Carrier Market report, which contains the complete segmentation analysis, detailed supplier benchmarking, pricing curves, and downloadable modeling tools. Visit our report page to download the executive dataset and schedule a briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Bitterness Suppressor and Flavor Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Umbilical Cable Market to Reach USD 6,768.18 Million by 2032, Expanding at a 7.1% CAGR (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Umbilical Cable Market: Strategic Imperatives for 2026
As the offshore energy landscape recalibrates for the next phase of exploration, production and energy transition projects, umbilical cable systems have shifted from a niche engineering input to a strategic asset that shapes project economics, supply-chain resilience and long-term operating risk. PW Consulting’s new Worldwide Umbilical Cable Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—provides the forward-looking intelligence decision-makers will need in 2026. The global market was valued at roughly USD 4.19 billion in 2025 and is modelled to expand at a compound annual growth rate of 7.1% over the forecast period, reaching an upper market boundary by 2032 that underscores material strategic demand for higher-specification umbilicals.
Worldwide Umbilical Cable Market
Why this report matters for 2026 decisions
- Capital budgeting and procurement timing: Umbilicals are long‑lead, high-cost components. Our demand curves and scenario variants let project owners and EPCs align procurement windows to pricing and capacity cycles, reducing exposure to sudden price escalations or delivery bottlenecks.
- Supply‑chain and sourcing strategy: The report highlights where manufacturing capacity tightness and raw‑material dependencies (notably high‑spec stainless and super‑duplex tubing) create single points of failure and suggests hedging and localisation approaches.
- Technology and product strategy: For OEMs and integrators, the intelligence supports portfolio prioritisation—deciding when to scale thermoplastic, steel‑tube or hybrid solutions and where to push R&D to capture premium applications in deep and ultra‑deep waters.
- M&A and partnership screening: Market concentration metrics, competitor profiles and contract pipelines provide acquirers and JV partners with a short list of strategically aligned targets and the commercial rationale for consolidation or strategic alliances.
- Aftermarket and service revenue capture: Operators and suppliers can quantify the size and timing of lifecycle services—testing, inspection, repair and retrofit—that account for a growing share of long‑term project economics.
Data‑driven signals: what the headline numbers reveal
The historical series (2020–2025) shows volatility followed by recovery and accelerating demand into 2026, reflecting both project restarts and new investments in deeper and longer‑tieback developments. The 7.1% CAGR in our central forecast is consistent with a market reorientation: more technically demanding projects, increasing adoption of longer, higher‑pressure umbilicals, and the nascent but growing role of umbilical-like systems in offshore renewable export and array cabling.
Worldwide Umbilical Cable Market
Two structural signals deserve attention. First, market concentration remains material—three global incumbents control a large share of high‑end project awards, with a broader top‑five dominated by diversified SURF and cable houses. That concentration creates both competitive pressure and supplier risk: operators negotiating large CAPEX programmes should anticipate limited competitive levers on highly customised or urgent orders. Second, raw‑material dynamics—especially demand for stainless and super‑duplex tubing—translate quickly into capacity constraints and price risk; recent tube award activity in early 2026 signals continued demand for these inputs.
Worldwide Umbilical Cable Market
Competitive landscape: reading capability, reach and strategic intent
The umbilicals market combines specialised subsea engineering, advanced materials, controlled manufacturing processes and integrated testing/installation capabilities. Our analysis distils competitors along three dimensions: product breadth and technical differentiation; manufacturing footprint and installation capability; and lifecycle services and aftermarket positioning.
- TechnipFMC — A global leader with vertically integrated design and manufacturing capabilities across steel‑tube, thermoplastic and hybrid systems. Strengths include programmable engineering suites and manufacturing scale that serve large, geographically diverse projects.
- Oceaneering — Strong in deepwater and harsh‑environment solutions, with an emphasis on integrated IWOCS portfolios and diversification into renewable array/export cable work. Known for robust project execution and installation services.
- OneSubsea (SLB) — Offers patented designs and systems tailored for ultra‑deepwater performance and integrated production umbilicals; benefits from SLB’s broader reservoir and subsea services footprint.
- Prysmian Group — Long heritage in SURF and subsea cabling, focused on high‑pressure, high‑temperature and long tie‑back projects for major oil & gas players.
- JDR Cable Systems — Specialist in subsea power and hybrid systems with strong testing and lifecycle support capability; active in Middle East and complex project testing contracts.
- Smaller specialists (Fibron BX, Umbilicals International, APAR, Tratos/MFX, Ningbo Orient, ZTT, Tubacex) — These firms provide critical niche capabilities: bespoke static/dynamic systems, high‑spec tubes, local manufacturing and competitive alternatives for specific applications or regional projects.
For buyers, the strategic question is not simply “who can make an umbilical” but “who can deliver the specific performance envelope, timetable and lifecycle support my project requires.” Our report maps that question to supplier scorecards, tender behaviour and recent contract activity to identify realistic shortlists by project archetype.
Operational playbook: seven tactical moves for 2026
- Lock in long‑lead supply early: Prioritise early procurement of tubing and extrusion lines where contract flexibility is low and delivery bottlenecks are likely.
- Diversify specification options: Where possible, develop dual‑qualified BOMs (e.g., alternative alloys or hybrid architectures) to expand competitive sourcing without sacrificing performance.
- Invest in modular testing capability: Bring pre‑deployment testing and performance monitoring in‑house or contract with strong third‑party testers to reduce installation risk and expedite commissioning.
- Negotiate lifecycle service clauses: Embed aftermarket and performance guarantees into supply contracts to convert one‑off capex into predictable service relationships.
- Pursue local manufacturing partnerships: For large regional programmes, joint ventures with regional cable houses or tubing suppliers shorten logistics and de‑risk customs and geopolitical exposure.
- Prioritise R&D on heat & flow assurance: Thermal management and flow assurance features are differentiators in ultra‑deepwater projects; budget innovation there to command premiums.
- Scenario‑test under commodity and regulatory shocks: Build scenario playbooks that quantify the P&L impact of raw‑material uplifts, delivery delays and stricter safety standards.
Regulatory, material and execution risks
Umbilical systems operate in some of the most hostile subsea environments; regulators and operators demand stringent design, testing and safety compliance. Non‑compliance or marginal testing regimes increase the risk of costly rework and environmental exposure. Raw‑material concentration in certain alloy grades creates strategic supply risk—an issue exacerbated where single vendors dominate seamless tubing supplies. Finally, installation complexity, particularly for ultra‑deep or long‑tieback deployments, amplifies schedule risk and can cascade into broader project delays.
What the PW Consulting report contains (practical, executable intelligence)
Our Worldwide Umbilical Cable Market report is designed as a decision support toolkit, not an academic exercise. Key deliverables include:
- Market sizing and demand modelling (2020–2025 historical; 2026–2032 forecast) with scenario sensitivity for commodity, CAPEX cycle and energy transition uptake;
- Supplier scorecards and capability maps that translate technical specification requirements into shortlists tailored to project archetypes;
- Contract and tender pipeline analysis, with an events calendar identifying near‑term award windows and likely procurement pressures;
- End‑to‑end supply‑chain heatmaps, highlighting lead‑time hotspots, raw‑material dependencies and strategic localisation opportunities;
- Technology deep dives on steel‑tube vs thermoplastic vs hybrid systems, and the emerging role of umbilical architectures in renewables export/array applications;
- Practical procurement playbooks, negotiation checklists and model contractual clauses for lifecycle services and performance guarantees;
- Strategic M&A and partnership opportunities framed by market concentration, regional capacity and technical gaps.
To follow the “trailer” principle: while this press piece highlights core themes, the granular regional, type and application splits—together with detailed company-by-company financial overlays, tender trackers and license‑by‑license analytics—are reserved for the full report and interactive dashboard.
How executives should act in Q1–Q2 2026
- Project owners and EPCs: validate umbilical specifications against alternative architectures and secure supplier commitments in parallel to FEED to avoid late‑stage value leakage.
- Supply‑side players: prioritise capacity investments in tubing and cable extrusion that align with the report’s mid‑cycle demand peaks; accelerate testing and aftermarket services to capture annuity streams.
- Investors and strategics: use the market concentration and contract pipeline intelligence to prioritise targets with demonstrated execution track records and defensible technical IP.
In short, 2026 is a year to move from tactical procurement to strategic asset management for umbilicals. Those who align procurement timing, secure critical materials and invest in testing/aftermarket capability will capture both the immediate uptick in project activity and the longer‑term service economics that underpin sustainable returns.
Next steps
PW Consulting’s Worldwide Umbilical Cable Market report equips senior executives with the models, supplier intelligence and operational playbooks required to translate market forecasts into executable strategies. For access to the full dataset, regional/application/type breakdowns and the interactive supplier shortlists, please visit our report page to download the complete study and accompanying decision toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Umbilical Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


