



Category: market research
PW Consulting: Worldwide Automotive Linear Position Sensors Market to Reach USD 6,660.21 Million by 2032 at a 6.45% CAGR
By PW Consulting, 2026-07-15
Worldwide Automotive Linear Position Sensors Market — Strategic Briefing for 2026
Executive snapshot
PW Consulting’s latest market study on Worldwide Automotive Linear Position Sensors positions this segment as a durable growth engine for automotive suppliers and OEMs as they navigate the twin imperatives of electrification and regulatory compliance. The market expanded robustly through the early 2020s — rising from roughly USD 3.1 billion in 2020 to an estimated USD 4.3 billion in 2025 — and is forecast to continue growing at a compound annual growth rate of 6.45% through our 2026–2032 horizon, reaching approximately USD 6.66 billion by 2032. That trajectory underscores sustained demand across powertrain, steering, braking, suspension and body-control functions, amplified by increased sensing requirements in electrified and automated vehicle architectures.
Worldwide Automotive Linear Positions Sensors Market
Why this report matters for 2026 decisions
- Actionable timing: 2026 is a pivotal year for product-platform choices, supplier contracts and capital allocation. The report translates long-run forecasts into near-term breakpoints for technology bets, capacity investments and strategic partnerships.
- Risk-aware growth: By combining historical performance (2020–2025) with scenario-based forecasts (2026–2032), the study helps executives stress-test product roadmaps against macro and regulatory shocks.
- Competitive context: With market concentration skewed toward a handful of established suppliers (top three firms account for roughly 38% of the market; the top five for about 53%), the report identifies where scale matters and where niche differentiation can win share.
- Commercial leverage: The intelligence is tailored to inform OEM sourcing decisions, tier‑1 component strategies, and private-equity evaluation of sensing assets ahead of the next consolidation wave.
What’s inside — practical deliverables
The study was built to be operationally useful for commercial, R&D and M&A teams. It includes:
Worldwide Automotive Linear Positions Sensors Market
- Aggregated market sizing and validated time series from 2020–2025, with a detailed forecast through 2032, including base-case and alternate scenarios that reflect variations in EV penetration, ADAS adoption and regulatory tightening.
- Technology pathway maps that compare Hall-effect, inductive, potentiometric, magnetostrictive and hybrid approaches across key attributes (cost, robustness, resolution, EMC immunity, packaging footprint and qualification timelines).
- Use-case analysis: mapping sensor requirements against application classes — powertrain/transmission, chassis and suspension, braking and steering, body and comfort — with design-to-cost levers and qualification milestones required by vehicle OEMs.
- Value-chain and cost-stack insights: bill-of-material drivers, commodity exposure, and supplier margin benchmarks to support sourcing negotiations and make-vs-buy choices.
- Competitive benchmarking: product feature matrices, go-to-market models, and strategic profiles for leading incumbents and emerging challengers to guide partner selection or acquisition targets.
- Regulatory and validation playbook: test matrices and timeline implications for sensors used in emissions-critical and safety-critical systems, plus recommended compliance checkpoints for global markets.
- Scenario planning templates and a prioritization framework for capital deployment, enabling teams to convert market intelligence into a 12–36 month operational plan.
Market dynamics shaping 2026 strategy
Several structural forces converge to shape supplier and OEM choices in 2026:
Worldwide Automotive Linear Positions Sensors Market
- Electrification and software-defined controls — EVs and hybrid powertrains increase the density and functional requirements of sensors in control loops, particularly where linear displacement inputs feed electronic actuators.
- Safety and emissions regulations — sensors that underpin throttle control, transmission actuation and exhaust systems remain central to both safety and compliance objectives; these regulatory pressures continue to raise qualification bar and favor proven, robust sensor technologies.
- Technology trade-offs — Hall-effect and magnetic IC-based approaches score highly on non-contact robustness and long life; inductive solutions offer cost and tolerance advantages in metallic and misaligned environments; potentiometric sensors remain relevant where ultra-low cost and simplicity dominate system requirements.
- Materials and manufacturing resilience — designs that minimize rare-earth magnet exposure or provide alternative sensing topologies will be advantaged by volatile raw-material markets and long lead times for certain magnetic materials.
- Aftermarket and commercial vehicle segment dynamics — rising fleet telematics and efficiency mandates in commercial vehicles create a parallel demand corridor for sensors tailored to automated manual transmissions and heavy-duty actuation systems.
Notable industry moves and technical innovations
Product and supplier activity in early 2026 shows continued investment into higher-resolution, longer-stroke Hall-effect devices and industrialized inductive solutions optimized for automotive tolerance. A recent example: in March 2026, Vishay Intertechnology launched a 40 mm-stroke Hall-effect linear position sensor characterized by high linearity and micrometer-level resolution — a clear signal that suppliers are racing to deliver both performance and automotive-grade robustness for motion-control applications.
Competitive landscape — positioning for scale and differentiation
The sector is populated by a mix of large multi-domain suppliers and focused specialists. The field’s structure — moderate concentration among the top players with room for specialist entrants — produces distinct strategic pathways:
- Broad-system leaders (e.g., Bosch, Continental) leverage systems integration and OEM relationships to embed sensors across powertrain, chassis and safety systems. Their scale offers advantages in qualification throughput, global manufacturing footprint and platform supply agreements.
- Component-centric global suppliers (e.g., Honeywell, TE Connectivity, Sensata, Allegro, Infineon) compete on IP, IC-level innovation, and cross-domain reuse of sensor sub-systems. These firms commonly provide both sensing elements and the supporting electronics that reduce OEM integration burden.
- Specialists and niche players (e.g., CTS, Piher, Novotechnik, Phinia, Littelfuse) win business through customized form factors, targeted performance tradeoffs, and rapid engineering support for specific actuator or transmission interfaces — especially in commercial vehicles and industrialized platforms.
- Start-ups and semiconductor-focused entrants are compressing the cost/performance curve for magnetic sensing ICs, raising the bar on resolution and integration into higher-level vehicle domain controllers.
Our competitive matrices assess not only product attributes but also non-price factors that drive OEM selection: validation velocity, failure-mode evidence, supply-chain redundancy and software/tooling compatibility. Given the market’s CR3 and CR5 positions, scale and platform access are strategic moats, but there remains room for suppliers that can solve narrowly defined technical problems or deliver superior total-cost-of-ownership.
Strategic playbook — five priorities for 2026
Executives should translate the market outlook into concrete moves in the coming 12–24 months. PW Consulting recommends five priority actions:
- Refine product segmentation by value: invest selectively in sensor variants that address high-value control loops (safety and emissions-critical) while rationalizing SKUs for low-cost body and comfort applications where commoditization is accelerating.
- Accelerate electronics integration: move up the stack with sensor + IC + diagnostic firmware bundles to lock in higher-margin system sales and shorten OEM validation cycles.
- De-risk raw-material exposure: qualify alternative magnet and coil suppliers and develop design variants that reduce dependence on scarce materials, particularly for inductive and magnet-based architectures.
- Pursue targeted M&A and partnerships: prioritize acquisitions that add specific capabilities (high-resolution magnetic ICs, rugged inductive designs, or validation/test houses) rather than broad diversification that dilutes execution focus.
- Operationalize qualification excellence: invest in shared validation assets and accelerated test protocols to reduce time-to-platform approval by OEMs — a decisive advantage in winning new program slots in 2026 procurement cycles.
How to use the full report
This briefing highlights strategic implications and directional market sizing. The full PW Consulting report provides the granular tools necessary to act now: downloadable scenario models, supplier scorecards, product-feature comparison matrices, and a commercialization checklist mapped to 2026 procurement calendars. Importantly, we intentionally withhold detailed regional and application split figures in this summary to preserve the competitive value of the full dataset; the complete intelligence package contains all segmentation breakdowns and program-level revenue streams required for budgeting, sourcing negotiations and M&A diligence.
Next steps
- For OEMs: request the validation-playbook module to align sensor selection with your 2026 platform launches and safety cases.
- For tier‑1 suppliers and component makers: use the scenario templates to stress-test your 2026 capacity and R&D portfolio against raw-material and regulatory upside/downside cases.
- For investors: consult the provider scorecards and consolidation scenarios to identify targets with defensible margins and scalable qualification capabilities.
PW Consulting stands ready to brief executive teams on the report’s implications and to run customized workshops that translate market scenarios into board‑level decisions. Access the full Worldwide Automotive Linear Position Sensors Market report through our insights portal to obtain the detailed segmentation, program-level sizing and interactive models that underpin the strategic recommendations above.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Linear Positions Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Network Telemetry Market Poised to Expand at a Robust 28.45% CAGR
By PW Consulting, 2026-07-15
Worldwide Network Telemetry Market: Strategic Imperatives for 2026
As enterprises move from reactive troubleshooting to proactive, AI-driven operations, network telemetry has shifted from a niche capability to a board-level concern. PW Consulting’s latest market study — covering historical dynamics (2020–2025), a 2026 base, and forecasts through 2032 — quantifies that transition and converts it into decision-grade guidance for CIOs, CTOs, and infrastructure investors planning for 2026 and beyond.
Worldwide Network Telemetry Market
Macro picture: scale, speed and strategic timing
The market for network telemetry has expanded rapidly over the past half-decade, rising from an emerging technology spend to a mainstream investment line in networking and observability stacks. Our analysis places the 2025 global market at approximately USD 1.05 billion (base year 2025) and projects a sustained compound annual growth rate of roughly 28.45% through the forecast period. By 2032 the market is modeled to be a multi-billion-dollar opportunity — underscoring both the technology’s increasing pervasiveness and the expanding addressable use cases across cloud, enterprise, telco and security domains.
Worldwide Network Telemetry Market
For enterprise decision-makers, two simple implications follow: first, network telemetry is no longer an experimental add-on; it is a core capability that materially affects SLA delivery, security posture, and AI/automation ROI. Second, the window to architect telemetry as a strategic asset — rather than a bolt-on monitoring cost — is immediate. Early adopters who define standards, ingestion and storage patterns, and governance in 2026 will realize disproportionate returns as vendors and service partners consolidate around those choices.
Worldwide Network Telemetry Market
What this report delivers (practical, operational, and procurement-ready)
- Executive playbooks that translate market growth into procurement timelines and budget phasing for 2026–2028.
- Deployment blueprints detailing ingest pipelines (streaming vs. batch), storage tiering, and cost-efficient telemetry retention strategies optimized for mixed cloud / on-prem environments.
- Vendor shortlists and comparative frameworks built around interoperability, protocol support, silicon-level telemetry, and operational maturity — designed to speed vendor selection without compromising due diligence.
- ROI and TCO models calibrated to real-world data center energy and processing costs, enabling scenario-based business cases for telemetry expansion projects.
- Compliance and privacy checklists (GDPR-safe telemetry patterns, data minimization controls) and operational guardrails for regulated industries.
- Use-case driven reference architectures for AI/ML use (anomaly detection, root-cause correlation, predictive maintenance) and for security telemetry fusion with SIEM/XDR systems.
The report deliberately balances strategic narrative with deployable artifacts. Readers will find both board-level positioning and step-by-step technical checklists intended to remove ambiguity during vendor RFPs and integration pilots.
Competitive landscape: what vendors bring to the table in 2026
The vendor ecosystem is diverse, spanning systems integrators, network OEMs, ASIC vendors, cloud-native analytics players, and security platform vendors. Our qualitative benchmarking highlights complementary strengths and typical adoption modes for the providers most frequently encountered by enterprise buyers.
- Cisco Systems (San Jose, CA) — Cisco continues to lead with model-driven telemetry innovations embedded across IOS XR, NX-OS and Catalyst platforms, leveraging gRPC-based streaming and dial-out modes that align closely with large service providers and enterprise campus deployments focused on real-time analytics.
- Juniper Networks (Sunnyvale, CA) — Juniper’s Junos Telemetry Interface and support for gNMI and IPFIX make it a preferred choice for customers emphasizing high-frequency operational state exports and integration with modern analytics stacks.
- Arista Networks (Santa Clara, CA) — Arista’s EOS telemetry primitives and CloudVision orchestration appeal strongly to cloud-scale data center operators and hyperscalers that demand programmatic state access with developer-friendly tooling.
- Nokia (Espoo, Finland) — With telemetry in SR OS and service provider-class routers, Nokia addresses telco service assurance and high-throughput carrier networks where deterministic telemetry is required.
- Broadcom (San Jose, CA) — As a major merchant-silicon supplier, Broadcom’s telemetry export features in modern ASICs influence how telemetry is implemented at the switch fabric level, affecting downstream collector architectures.
- Huawei (Shenzhen, China) — Huawei’s integrated telemetry across router portfolios and its management platforms enable end-to-end observability in markets where its portfolio remains available, though geopolitical controls shape procurement decisions in some regions.
- Extreme Networks (Morrisville, NC) — Extreme’s approach emphasizes converged wired/wireless telemetry and zero-touch provisioning workflows that speed deployments in enterprise campuses and distributed sites.
- Palo Alto Networks (Santa Clara, CA) — Security-focused telemetry streaming from PAN-OS is increasingly stitched into observability pipelines for threat detection and network-security correlation use cases.
- F5 Networks (Seattle, WA) — F5’s BIG-IP Telemetry Streaming integrates application delivery metrics into network observability, useful for app teams and SREs aligning application and network telemetry signals.
- Kentik (San Francisco, CA) — As a cloud-native analytics and observability platform, Kentik provides fast ingestion and query capabilities for flow and telemetry data at scale, attractive to organizations prioritizing SaaS-based analysis.
Recent vendor developments underscore rapid productization: operating system releases and tooling updates from major OEMs have accelerated gRPC/gNMI support and introduced developer toolkits for custom telemetry pipelines. For enterprises, the implication is clear — the interoperability baseline is rising, and migration risk from today’s proprietary exporters is declining.
Regulation, standards, and operating constraints shaping adoption
Telemetry adoption does not occur in a vacuum. Regulatory choices and standards evolution materially influence architecture and vendor selection:
- Net neutrality rulings in key markets are reducing the risk of telemetry traffic being deprioritized or blocked, simplifying architectural assumptions for remote collectors deployed across ISP networks.
- GDPR-driven data minimization and privacy-by-design principles require telemetry streams to be scoped and pseudonymized where appropriate, pushing organizations to standardize filtering and schema enforcement at source.
- Standards consolidation — notably around model-driven telemetry and gNMI — is lowering integration costs and accelerating cross-vendor toolchains, but it also raises the bar for legacy deployments that need migration paths.
- Geopolitical export controls in hardware supply chains influence vendor eligibility in global procurement, making diversified supplier strategies and secondary sourcing critical for risk-conscious buyers.
- Operational cost inputs such as data center energy prices are non-trivial: telemetry at scale is compute- and storage-intensive. Our TCO models explicitly link telemetry retention policies to realistic energy and processing cost assumptions.
Strategic recommendations for 2026 planning cycles
- Adopt a “telemetry-first” architecture design for any network refresh in 2026 — treat telemetry as a first-class interface, not an afterthought. Define schema and retention policies at project inception.
- Prioritize vendor capabilities that align with your automation roadmap (gNMI/gRPC support, native exporters, and programmatic configuration) to avoid rip-and-replace migrations later.
- Build a phased ingestion plan: start with high-value telemetry sources for rapid wins (SLA-critical paths, security chokepoints), then expand to full-fabric coverage as analytics ROI materializes.
- Institutionalize privacy and compliance checks into telemetry pipelines to ensure data minimization and traceability; this will reduce audit overhead and operational risk.
- Evaluate hybrid analytics models: leverage cloud-native analytics where scale and agility matter, and retain hot-path correlation capabilities on-prem for low-latency operational control.
- Incorporate supplier risk assessments tied to geopolitical exposure, silicon-level capabilities, and integration roadmaps — diversify where single-supplier risk is unacceptable.
Why PW Consulting’s report is strategic for 2026 decisions
This study translates a multi-fold market expansion into executable guidance. It combines quantitative market sizing and trajectory (with a robust forecast through 2032) with the operational artifacts that engineering, procurement, and compliance teams need to execute in 2026. The report’s unique value is its bridge between market dynamics and deployable playbooks: vendors and standards evolve quickly, but strategic procurement windows and architectural choices made in 2026 will determine who captures the benefits of telemetry-enabled automation in the next contract cycle.
To preserve the tactical edge for enterprise buyers and vendors, this public briefing intentionally highlights strategic takeaways without reproducing detailed segment-level tables and vendor scoring matrices. PW Consulting’s full report contains the complete breakdowns, vendor scorecards, deployable templates, and interactive models required for RFPs and capital planning.
Next steps
Enterprises planning large-scale network transformations, security initiatives that depend on richer telemetry, or analytics teams aiming to operationalize AI/ML should treat the findings of this study as a decision accelerant. For procurement-ready assessments, custom TCO scenarios, or a briefing of the vendor scorecards tailored to your environment, access the full Worldwide Network Telemetry Market report and supporting toolkits on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Network Telemetry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Chinese Domestic Databases Market Poised for Rapid Expansion — 18.5% CAGR Projected (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Chinese Domestic Databases Market — Strategic Outlook for 2026
Executive teaser
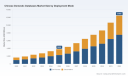
PW Consulting’s new market study on the Worldwide Chinese Domestic Databases market (base year 2025) synthesizes regulation, infrastructure incentives, vendor evolution and technology trajectories into an actionable strategic narrative for enterprise decision‑makers in 2026. The market reached approximately USD 3,800 Million in 2025 and is poised to grow at a compound annual growth rate (CAGR) of 18.5% over our 2026–2032 forecast window, moving the market into a materially larger scale by the end of the period. This release is a preview: it demonstrates the depth of analysis and operational playbooks in the full report while intentionally withholding fine‑grained segment tables to guide readers to the source for complete datasets and downloadable tools.
Worldwide Chinese Domestic Databases Market
Why this market will shape 2026 enterprise decisions
-
Regulatory tightening raises the stakes for procurement strategy. Amendments to China’s Cybersecurity Law that took effect on January 1, 2026, alongside the existing Data Security Law and Personal Information Protection Law, materially increase compliance burdens for cross‑border transfers and elevate the importance of data sovereignty. Procurement teams will need compliance assurance, traceable data flows and hardened security controls as ballot items in supplier selection.
Worldwide Chinese Domestic Databases Market -
Policy programs and incentives change economics. The xinchuang (IT application innovation) initiative continues to prioritize replacement of foreign database infrastructure across government, state‑owned and critical sectors, creating a structural demand channel for domestic vendors. Local fiscal incentives — including electric‑bill subsidies for data centers that deploy approved domestic chips — reshape operating cost models and make certain domestic cloud and on‑prem configurations more financially attractive.
Worldwide Chinese Domestic Databases Market -
Infrastructure capacity enables scale migrations. National data‑center deployments exceeded 4.2 million standard rack units by end‑2025, supporting strategy programs such as 'East Data, West Computing'. This physical capacity, combined with evolving national procurement patterns, accelerates migration plans for large database workloads in 2026.
-
Concentration and competitive dynamics demand sharper partner strategies. The vendor landscape exhibits a mid‑to‑high level of concentration among a handful of domestically strong providers, creating both dependency risks and negotiating leverage depending on the vertical and workload. CIOs must balance strategic single‑vendor optimizations against diversification to manage resilience and future regulatory shifts.
What PW Consulting’s report equips you to do
Our report converts market foresight into practical decision support for CIOs, procurement leads, platform architects and investors. Key operational outputs include:
-
Procurement playbooks and scorecards that translate regulatory and technical criteria into vendor evaluation fields (compliance posture, integration risk, SLA constructs, upgrade and exit costs).
-
TCO and scenario modeling templates that incorporate local incentives, electricity subsidy effects and migration costs under alternative architectures (cloud‑first, cloud‑augmented on‑prem, and hybrid patterns).
-
Migration blueprints and phased runbooks — including observability and O&M priorities — tailored for core banking, public sector, telecom and large energy deployments (practical checklists for cutover, rollback and regulatory evidence collection).
-
Security and compliance checklists aligned with the latest Cybersecurity Law updates and cross‑border assessment requirements, designed for use as audit inputs during vendor due diligence.
-
Benchmark synthesis and feature maps that help architects evaluate tradeoffs between relational, NewSQL/distributed, NoSQL and AI‑native approaches — presented as non‑binary decision matrices keyed to workload archetypes.
-
Commercial negotiation frameworks and contract clauses for cloud‑native, managed and on‑prem deployments that reflect market concentration dynamics and SLAs observed in recent enterprise procurements.
Competitive landscape — who matters and why
The market’s competitive architecture blends large cloud incumbents with specialist database vendors and systems integrators. Below are concise, decision‑relevant profiles and implications for partners and buyers; the full report contains extended vendor scorecards, strengths/weaknesses matrices and migration references.
-
Alibaba Cloud (OceanBase, PolarDB) — A dual track of self‑developed distributed and cloud‑native offerings positions Alibaba Cloud to serve both high‑transaction core systems and cloud‑scale services. Recent milestones include a top TPC‑C benchmark position (PolarDB) and the open‑sourcing of an AI‑native, hybrid search database (seekdb). These developments accelerate evaluation for organizations aiming to consolidate transactional scale with emerging vector/text workloads.
-
Huawei Cloud (GaussDB) — Strong adoption in banking and sectors with high compliance expectations marks GaussDB as a go‑to for enterprises seeking closely controlled deployments. Huawei’s focus on telecommunications, finance, energy and governmental use cases creates a compelling proposition where vertical optimizations and long‑term vendor support are decisive.
-
Tencent Cloud (TDSQL / TencentDB) — Tencent’s database portfolio targets enterprise transactional and gaming workloads with mature managed services and deep domestic market penetration. Organizations prioritizing rapid managed deployments and integration with wider cloud service ecosystems will find Tencent’s offerings attractive.
-
PingCAP (TiDB) — An open‑source NewSQL leader, TiDB’s appeal is grounded in hybrid transactional/analytical processing and a strong enterprise deployment base. For teams exploring open‑source licensing strategies and vendor flexibility, PingCAP represents a strategic option that reduces lock‑in risk while enabling scale.
-
Specialists and system vendors — Companies such as SequoiaDB (financial‑grade transaction systems), Baidu Cloud (AI‑integrated databases), GBase, KingbaseES, Wuhan Dameng and leading system integrators like Inspur fill differentiated roles across localization, compliance and analytics. Their collective presence supports the xinchuang ecosystem and offers alternatives for regulated workloads that require domestic solution stacks.
Recent vendor signals to watch in 2026
-
Product innovation is accelerating around AI‑native database capabilities and observability. OceanBase’s open‑sourcing of an AI‑native search database and subsequent product releases focused on operational enhancements signal a shift: vendors are integrating vector, text and structured search into core DB feature sets.
-
Benchmark and regional expansion moves persist as vendors pursue credibility and international presence. Competitive benchmark leadership and geographic product launches are being used to bolster enterprise trust and to support cross‑border cloud offerings, even as regulation complicates data flows.
Policy and infrastructure — the non‑technical multipliers
The conjunction of stricter data regulations, xinchuang procurement mandates and targeted infrastructure subsidies creates a multi‑vector driver set for 2026. Practically, this means:
-
Procurement cycles will likely lengthen as compliance validation, security assessments and localization requirements become standard gating items.
-
Cost curves for domestic chip‑based data centers may improve where local subsidies apply, changing the calculus for on‑prem vs. cloud deployment.
-
Enterprise architecture roadmaps must include scenarios for segmented data footprints (localized core data vs. less sensitive workloads) and explicit cross‑border assessment procedures.
Practical strategic recommendations for 2026
-
Begin with data classification and regulatory mapping. Treat regulatory changes as design constraints and revalidate existing cross‑border data transfer mechanisms to avoid exposure.
-
Adopt a hybrid vendor stance. Maintain a primary supplier for core scale and a secondary, open‑source or specialist option to preserve bargaining power and operational escape hatches.
-
Invest in observability and O&M automation. The fastest path to predictable TCO is reducing failover, recovery and operational toil — capabilities vendors are actively improving in 2025–26 releases.
-
Pilot AI‑native and vector search capabilities in low‑risk domains. Early experimentation will reveal integration costs and business value without jeopardizing compliance posture.
-
Use scenario‑based TCO models that incorporate subsidies, energy differentials and multi‑year licensing impacts to surface the real cost of vendor lock‑in versus migration.
Closing — next steps
For executives preparing 2026 budgets, technology roadmaps and vendor strategies, PW Consulting’s full report delivers the evidence, models and playbooks required to make defensible decisions in a rapidly evolving domestic database market. This preview outlines the strategic context, vendor direction and regulatory inflection points you must factor into near‑term planning. To unlock detailed segment tables, vendor scorecards, downloadable TCO templates and operational runbooks, please consult the full report on our website — the data‑rich annexes and decision tools are purposefully gated to ensure clients receive complete, auditable datasets and repeatable methodologies for immediate adoption.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Molding Compound Market Poised to Grow at a 4.85% CAGR, Says New Report
By PW Consulting, 2026-07-15
Worldwide Phenolic Molding Compound Market — Strategic Outlook for 2026 Decision Makers
PW Consulting today publishes a forward-looking industry briefing tied to our full Worldwide Phenolic Molding Compound (PMC) Market report (base year 2025, forecast 2026–2032). The global market has shown steady recovery and expansion through the early 2020s — rising from approximately USD 1,810.45 Million in 2020 to USD 2,245.50 Million in 2025 — and our baseline forecast points to continued growth toward roughly USD 3,128.18 Million by 2032, implying a compound annual growth rate (CAGR) of 4.85% over the 2026–2032 horizon. For 2026 strategy cycles, that trajectory reframes capital allocation, procurement hedging and portfolio prioritization decisions across resin producers, compounders, molders and OEMs.
Worldwide Phenolic Molding Compound Market
Why this briefing matters in 2026
-
Market momentum is no longer uniform. While aggregate growth is steady, regional price and feedstock dynamics, certification requirements for electrical applications, and pockets of demand in automotive and industrial segments are creating asymmetrical opportunities and risks.
Worldwide Phenolic Molding Compound Market -
Supply-side players face margin pressure and sourcing volatility driven by phenol and cumene feedstock swings. Our report translates price moves into margin scenarios and identifies hedging levers and vertical-integration trade-offs.
Worldwide Phenolic Molding Compound Market -
Moderate market concentration (CR3 ~24.15%; CR5 ~38.60%) leaves room for both regional scale plays and bolt-on consolidation — a critical consideration for private equity and corporate development teams mapping M&A targets.
What the full report delivers — practical, transaction-ready intelligence
PW Consulting’s full study is designed as an operational toolkit for 2026 decision-making rather than a purely academic exercise. Key deliverables include:
-
Proven market-sizing & forecasting model: time series (2020–2025) and scenario-based forecasts (2026–2032) with upside/downside demand corridors tied to macro and end-market drivers.
-
Segment playbooks: actionable guidance for owners of novolac and resol formulations, molders, and OEM spec teams — each playbook aligns product attributes to prioritized applications and go-to-market approaches.
-
Pricing & cost models: build-your-own spreadsheets that map phenol and additive cost moves to compound margin outcomes under alternative sourcing strategies.
-
Supply-chain risk maps: supplier concentration, logistics chokepoints, lead-time sensitivity, and mitigation levers (dual-sourcing, vertical integration, strategic inventory).
-
Competitive scorecards & capability benchmarking: operational footprints, product portfolios, certification status and strategic posture for key incumbents and challengers.
-
M&A & partnership playbook: heatmaps of attractive subsegments, valuation multiples observed in adjacent transactions, and integration checklists tuned to phenolic businesses.
-
Regulatory and compliance checklist: certifications and material standards that matter for electrical, automotive and industrial specifications (including UL-related requirements common in PMCs).
-
Executive decision dashboards: a concise set of KPIs and triggers to support quarterly review cycles and capex approvals.
Note: this article intentionally refrains from reproducing the report’s proprietary subsegment tables and regional/application-level volumes; those detailed datasets and interactive models are available in the paid report package.
Competitive landscape: what incumbents and challengers are signaling
The PMC industry is characterized by a mix of multinational resin specialists, regional compounders and niche formulators. Our analysis highlights strategic differences across the competitive set that will shape deal flow and partnership opportunities in 2026.
-
Sumitomo Bakelite Co., Ltd. — With a broad range of glass-fiber reinforced and filler-modified PMCs and an established global footprint, Sumitomo is both a technology leader and capacity player. Recent activity includes a 2024 capacity expansion in Nantong and a 2026 new-product launch for high-adhesion phenolic resins. For corporate strategists, Sumitomo’s moves underscore the value of combining formulation innovation with targeted greenfield/ brownfield capacity to lock in OEM qualification cycles.
-
PLENCO (Plastics Engineering Company) — A specialty compounder producing novolac and resol systems with an emphasis on dimensional stability and electrical insulation. PLENCO’s model illustrates the resilience of niche, application-focused compounders that serve industrial molding processes (compression, transfer, injection).
-
Bakelite Synthetics — A global thermoset supplier with a legacy brand position in high-quality molding compounds. Larger, diversified players such as Bakelite offer scale advantages in raw-material procurement and distribution reach.
-
Chang Chun Plastics (Longlite) — A formulary-driven producer focusing on customer-specific PMCs for electrical and automotive uses. Its approach demonstrates the commercial value of co-development agreements with OEMs.
-
Resinoid Engineering — A U.S.-based custom compounder with high-temperature products (continuous use above 400°F) for aftermarket and industrial niches. Firms like Resinoid highlight an attractive strategy: specialized product attributes command higher margins and defensible niches.
-
Shengquan Group — One of the largest phenolic resin manufacturers with integrated resin-to-compound capability; the company’s scale in feedstock production creates a competitive edge when raw material prices spike.
-
Kaihua Ruida Plastic-Tech — Producer of UL-approved PMCs and Bakelite powders with emphasis on appliances and construction applications; demonstrates the commercial importance of third-party certification for market access.
Strategic implication: the spectrum from large integrated resin houses to agile niche compounders creates multiple strategic options — from vertical integration and capex-led scale to bolt-on M&A focusing on product differentiation and certification-led market access.
Segment dynamics & supply-chain signals you must watch in 2026
Raw-material cost trends and certification requirements are now primary determinants of near-term margin and sourcing decisions.
-
Phenol pricing: regional price divergence continues to shape sourcing arbitrage. In Q1 2026, phenol quotes showed notable movement: Northeast Asia recorded an uptick relative to late 2025 driven by firm resin demand and cumene feedstock pressures, while Europe and North America experienced varying degrees of softness influenced by local demand and import competition. These moves are directly modeled in the report’s margin and breakeven scenarios.
-
Certifications: UL listings remain a gating factor for many electrical and appliance specifications; PMCs supplied as pellets commonly carry flame-class, HWI/HAI and RTI ratings. The report maps certification workflows and timeline impacts on product launches and customer qualification.
-
Operational cadence: OEM cycles (automotive, consumer electronics) require multi-year qualification windows. Capacity decisions made in 2026 should align with the timing of these qualification pipelines to secure high-margin OEM supply contracts.
How buyers and executives should apply the report in 2026
-
Procurement: use the report’s cost models to stress-test supplier contracts against phenol-price scenarios and design hedging strategies or tolling arrangements that preserve margin during raw-material spikes.
-
Manufacturing & CapEx: let the forecasted demand corridors and certification timelines drive plant sizing and location (proximity to resin supply vs. proximity to end-markets), and employ the report’s sensitivity tests before approving greenfield projects.
-
R&D and product strategy: prioritize formulations (e.g., high-adhesion phenolics, high-temperature variants) that shorten qualification timelines and open higher value applications.
-
M&A & partnerships: target regional compounders with UL-approved product lines or resin producers with excess capacity; the report’s M&A heatmap helps rank targets by strategic fit and integration complexity.
-
Commercial: align sales incentives and technical service investments to OEM qualification cycles; use the report’s account-level segmentation to defend price and accelerate adoption in prioritized verticals.
Access and next steps
The executive briefing above is a strategic preview. The paid report package contains the full time-series datasets, application- and region-level scenario tables, interactive Excel models, full company profiles and a prioritized action plan that PW Consulting can adapt into a 90-day implementation roadmap for clients.
For leadership teams preparing 2026 budgets, procurement negotiations or a strategic growth agenda, the report converts market direction into executable initiatives – from hedging and sourcing strategies to capex prioritization and M&A target lists. To obtain the full report, data files and bespoke advisory workshops, visit PW Consulting’s market research portal or contact our industry team directly for an access briefing.
PW Consulting — translating market intelligence into strategic action for the phenolic molding compound value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Smart Ticketing Market to Expand at a Robust 12.35% CAGR Through 2032
By PW Consulting, 2026-07-15
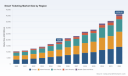
Worldwide Smart Ticketing Market: Strategic Preview for 2026 Decision‑Makers
As transport, events and mobility operators prepare capital and procurement plans for 2026, PW Consulting’s latest market intelligence provides a focused, action‑oriented lens on the smart ticketing ecosystem. The global market reached an estimated USD 18,250 Million in 2025 and is on a steep growth trajectory—projected to expand to roughly USD 21,304 Million in 2026 and to exceed USD 41,235 Million by 2032, reflecting a compound annual growth rate of 12.35% across the 2026–2032 forecast horizon. This briefing outlines the report’s strategic value for senior leaders while preserving the core segmentation data and proprietary models that are available in the full report.
Worldwide Smart Ticketing Market
Why this update matters for 2026 planning
-
Timing: Major regulatory, technology and product inflection points converge in 2025–2026. Several jurisdictions are implementing open‑standards mandates and enhanced payment security rules that materially affect procurement cycles and vendor selection.
Worldwide Smart Ticketing Market -
Scale opportunity: The market more than doubled from 2020 to 2025, and the coming six years offer a second leg of market expansion driven by mobile ticketing, account‑based systems and contactless payments integration.
Worldwide Smart Ticketing Market -
Practical focus: Beyond trend narratives, the report provides procurement checklists, deployment cost models, and vendor selection frameworks that translate growth forecasts into executable programs for 2026 budgets.
Key macro takeaways (for boardrooms and investment committees)
-
Rapid, sustained expansion: From approximately USD 10,450 Million in 2020 to USD 18,250 Million in 2025, the market has experienced structurally higher adoption rates. Our projection through 2032 highlights continued acceleration rather than a plateau—creating runway for new entrants, scale buys and strategic partnerships.
-
Moderate concentration but open spaces: A relatively small group of global suppliers anchor many major public transport installations, while specialist vendors and regionally strong integrators capture niche opportunities. This structure creates realistic M&A and partnership playbooks for mid‑sized vendors seeking scale.
-
CapEx to OpEx transition: Account‑based and cloud platform models are shifting cost profiles—capital investment in fare gates and readers persists, but software and services are moving to subscription models, changing how finance teams should evaluate total cost of ownership.
Regulatory, standards and infrastructure forces shaping 2026 choices
-
Interoperability mandates: New public policy frameworks in key markets are moving toward mandated open standards for ticket interoperability by 2026. Operators that delay standard alignment risk costly retrofits and interoperability gaps with neighboring systems.
-
Payments and data compliance: PCI DSS v4.0 and related payment‑security requirements are now fundamental procurement filters for any solution handling cardholder data—enforced not only by payment networks but increasingly by transit authorities.
-
Standards convergence: Contactless card standards governed by ISO/IEC 14443 remain central to many legacy networks, even as mobile and tokenized payment rails proliferate. Systems that can bridge both worlds are commercially advantaged.
-
Cost drivers in hardware rollouts: Urban NFC reader deployments continue to be a nontrivial line item for rollout budgets. Operators should expect meaningful per‑unit hardware costs and plan phased rollouts that prioritize high‑yield corridors and multimodal integration.
Technology and application dynamics—what to prioritize
-
Hybrid adoption is the near‑term reality: Smart cards are still foundational in many cities, while mobile applications and NFC/QR experiences are accelerating user adoption and driving innovative modality bundling (transit plus events, micro‑mobility, etc.).
-
Account‑based ticketing (ABT) moves from pilot to standard: ABT platforms reduce friction for riders and simplify fare reconciliation across modes. Investment in ABT capability (or partnering with ABT‑enabled vendors) should be front‑of‑mind for 2026 tender specifications.
-
Multimodal UX wins loyalty: Operators that unify transit, shared mobility and event ticketing flows into a single credential or wallet experience see higher retention and ancillary revenue opportunities.
Competitive landscape—what to watch from the major players
The market is characterized by a mix of platform specialists, semiconductor suppliers, system integrators and transportation incumbents. PW Consulting’s competitive profiles combine capability mapping, go‑to‑market posture and recent strategic moves to identify who is best positioned for the next wave of deployments.
-
Masabi (London, UK — https://masabi.com) : A leader in mobile‑first ticketing platforms, Masabi’s Justride continues to gain momentum with transit agencies focused on contactless mobile journeys. Recent integration with Apple Wallet (October 2025) to enable express transit on iPhone materially expands its channel reach and reduces friction for commuter uptake.
-
Moovit (Tel Aviv, Israel — https://moovit.com) : Combining trip planning and MaaS (Mobility as a Service) with ticketing, Moovit’s pivot deeper into account‑based ticketing and new European city expansions (announced June 2025) reflect a strategy to embed ticketing as a platform capability within multimodal consumer apps.
-
HID Global (Austin, TX, USA — https://www.hidglobal.com) : With a strong heritage in secure credentials and NFC solutions, HID remains a preferred supplier where credential security and enterprise identity integration are essential—particularly in complex, multi‑stakeholder deployments.
-
NXP Semiconductors (Eindhoven, Netherlands — https://www.nxp.com) : As a core supplier of contactless smart card ICs, NXP’s MIFARE technology continues to underpin many legacy and new smart card rollouts. Its role in the hardware layer makes it strategically important to any operator balancing legacy card stock with migration plans.
-
Thales Group (Paris, France — https://www.thalesgroup.com) : Thales combines systems integration with contactless EMV solutions and continues to deploy bank‑card acceptance models in rail and metro networks. Their March 2025 deployment in a major Asian metro underlines their capability to deliver large‑scale, contactless EMV projects.
-
Cubic Transportation Systems (San Diego, CA, USA — https://www.cubic.com/transportation) : Cubic’s account‑based Umo Mobility platform remains a benchmark for city‑scale deployments. The 2024 launch of Umo Mobility 2.0, with enhanced QR and NFC multimodal functionality, reinforces their product roadmap focused on openness and extensibility.
-
Scheidt & Bachmann (Ratingen, Germany — https://www.scheidt-bachmann.de) : Specializing in fare collection modules and turnkey systems, Scheidt & Bachmann is positioned for regional contracts and airport transit integrations where proven operational reliability matters.
-
Vix Technology (Adelaide, Australia — https://www.vixtechnology.com) : Vix’s experience with contactless solutions in complex national and city networks makes it a strong contender for cross‑jurisdictional, multimodal rollouts that require deep operational support.
Recent strategic moves revealing market direction
-
Platform‑to‑wallet integration is accelerating: Masabi’s Apple Wallet integration (Oct 2025) is emblematic of vendor efforts to remove app friction and leverage native wallet flows for tap‑to‑ride.
-
ABT expansion is now a competitive baseline: Moovit’s extended ABT deployments across Europe (June 2025) confirm that municipalities are moving beyond pilots to production ABT solutions.
-
Contactless EMV deployments scale: Thales’ March 2025 EMV project and ongoing bank card acceptance rollouts show that both closed and open payment models will coexist, requiring vendors to support hybrid payment architectures.
-
Vendor product evolution: Cubic’s Umo 2.0 (Nov 2024) illustrates vendor focus on multimodal QR/NFC parity and integration with third‑party mobility services.
What PW Consulting’s report delivers for 2026 execution (high‑value assets)
-
Actionable playbooks—procurement and deployment templates tailored for capital committees, including phased rollout scenarios, financing structures (CapEx vs OpEx tradeoffs), and interoperability checklists linked to current standards.
-
Vendor decision matrices—comparative capability maps, risk factors and scorecards that align vendor strengths to operator priorities (scale, security, UX, TCO).
-
Cost and budget models—detailed unit cost build‑ups and scenario simulations for hardware, software and O&M across urban, regional and multimodal deployments.
-
Regulatory compliance guidance—practical steps to meet open‑standards mandates and payment security requirements without disrupting service continuity.
-
Case studies and proof points—deployed program summaries profiling time‑to‑value, rider adoption strategies and integration pitfalls with lessons learned.
-
Proprietary forecasts and sensitivity analyses—base, upside and downside scenarios under alternative technology adoption, regulatory and macroeconomic assumptions.
Concrete recommendations for 2026 decision cycles
-
Prioritize modular procurement that preserves interoperability. Specify open APIs and ABT‑friendly architectures to avoid vendor lock‑in and costly rewrites.
-
Budget for hybrid payment acceptance—design fare systems to accept contactless EMV and tokenized mobile credentials alongside legacy smart card systems during transition phases.
-
Embed compliance into vendor evaluation—require demonstrable PCI DSS v4.0 readiness, and ISO/IEC 14443 compatibility where card legacy systems are in play.
-
Use phased hardware rollouts—deploy readers and gates where ridership density justifies per‑unit spend, using cloud‑first ticketing to unlock rapid feature releases.
-
Assess partnership models—incumbents and platform vendors increasingly partner with wallet providers, banks and MaaS aggregators; evaluate strategic alliances as a speed‑to‑market lever.
How to access the full intelligence
This preview highlights strategic themes and the operational playbooks we see as critical for 2026. The full PW Consulting Worldwide Smart Ticketing Market report includes the granular segmentation, regional and application revenue breakdowns, vendor financial benchmarking, and the proprietary forecast tables that inform the models summarized here. For procurement teams, investors and civic technology leaders who require the underlying data and downloadable models to execute 2026 plans, the full report and supporting datasets are available at PW Consulting’s report page.
Contact PW Consulting to arrange a briefing with our lead analysts and to obtain the complete dataset, implementation templates and vendor assessment tools that translate this market growth into a concrete, fundable program for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Ticketing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mobile Unified Communications & Collaboration Market Set to Expand at 17.52% CAGR During 2026–2032
By PW Consulting, 2026-07-15
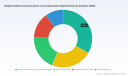
PW Consulting: Strategic Briefing — Worldwide Mobile Unified Communications and Collaboration Market (2026 Outlook)
PW Consulting’s latest market study — the Worldwide Mobile Unified Communications and Collaboration Market — is released with a clear mandate: equip enterprise leaders, CIOs, network planners, and commercial strategists with the actionable intelligence they need to make high‑stakes 2026 decisions. Anchored on a 2025 base year, a five‑year historical window (2020–2025) and a forward forecast to 2032, the report quantifies a market advancing at a compound annual growth rate (CAGR) of 17.52%. Our models show the ecosystem accelerating from roughly USD 27.8 billion in 2025 to a multi‑decade inflection by the end of the forecast horizon — a trajectory that transforms supplier economics, procurement tactics, and network investment priorities.
Worldwide Mobile Unified Communications and Collaboration Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a transition year. AI‑augmented collaboration capabilities, new spectrum initiatives, and hybrid workplace modalities converge, making tactical vendor choices and architectural decisions material to operating cost and competitive agility.
Worldwide Mobile Unified Communications and Collaboration Market -
Risk and reward are concentrated: while the market remains commercially attractive, the supplier landscape shows moderate concentration — the top three and top five players represent distinct shares of market control — underscoring the importance of negotiating leverage, integration risk assessment, and multi‑vendor resilience planning.
Worldwide Mobile Unified Communications and Collaboration Market -
Operational impact: decisions made in 2026 will affect capital allocation and service delivery through 2032. Network upgrades, cloud migration strategies, and AI adoption timelines should be aligned to expected market growth and changing buyer expectations.
What’s in the report — practical, execution‑focused deliverables
-
Market sizing and growth scenarios. We provide calibrated baseline, upside, and downside forecasts across the 2026–2032 horizon, driven by demand elasticity, technology adoption curves, and macro assumptions. (Core regional and segment spreadsheets are available on the report portal.)
-
Buyer’s playbook. Procurement templates, SOW checklists, and migration blueprints for cloud, hybrid and on‑prem deployments targeted at reducing integration time and minimizing disruption to end users.
-
Technology decision frameworks. Comparative matrices for mobile video, voice, unified messaging, contact center integration, and presence/mobility features—scored by latency sensitivity, bandwidth footprint, security posture, and AI readiness.
-
Total cost of ownership (TCO) models and scenario planners. Multi‑year TCO calculators that incorporate license economics, network upgrade costs, device lifecycle, and productivity delta estimates tied to use‑case archetypes.
-
Security, privacy and sovereignty assessment tools. A risk matrix aligning regulatory regimes, data residency needs, and technology controls against supplier capabilities to accelerate compliance planning.
-
Vendor scorecards and deal archetypes. A pragmatic vendor evaluation methodology covering technical fit, roadmap coherence, commercial flexibility, channel strategy, and integration risk—designed to be operationalized by procurement and architecture teams.
-
Use cases and vertical playbooks. Prescriptive guidance for IT & telecom, financial services, healthcare, government, retail/manufacturing and education—each with recommended deployment patterns, SLAs, and performance benchmarks.
-
Partner and ecosystem maps. Identification of systems integrators, managed service providers, and technology partners best suited to accelerate rollouts and mitigate operational risk.
Market dynamics shaping vendor strategy and buyer choices
-
AI as a functional multiplier. Generative and agentic voice AI are shifting from pilot to production in 2026; vendors that embed AI within voice/video workflows and contact center automation will capture outsized value. Buyers must define measurable productivity targets tied to AI features to avoid wasted spend.
-
Network readiness is non‑negotiable. Advances in last‑mile and access technologies — including cable operator spectrum expansion, DOCSIS 4.0, and distributed access architectures — materially improve multi‑gig capabilities for unified communications but introduce variability across enterprise footprints. Network assessments should be prioritized ahead of large‑scale UC rollouts.
-
Regulatory and sovereignty constraints. Regulatory shifts — from spectrum allocation efforts to changes in reporting obligations and the development of sovereign infrastructure in certain regions — are elevating compliance costs and influencing architectural choices (cloud vs. sovereign cloud vs. on‑premise hybrid designs).
-
Concentration and consolidation. Market concentration metrics indicate a competitive set where a handful of vendors command meaningful share but room exists for niche players with vertical specialization or differentiated integrations. This dynamic favors strategic multi‑vendor deployments combined with standardized interoperability specifications.
Competitive landscape — strategic profiles and implications
-
Microsoft: Embedded within a broader productivity suite, Microsoft’s mobile collaboration footprint emphasizes seamless integration across content, identity, and workflow. Enterprises prioritizing consolidated vendor stacks gain simplified identity, compliance and lifecycle benefits, but should quantify lock‑in implications.
-
Cisco: Strengths in secure, hybrid deployments and hardware‑software integration make Cisco a natural fit for organizations with complex networking and on‑premise requirements. Recent asset additions to the contact center stack extend its enterprise reach.
-
Zoom: Zoom’s simplicity of mobile experience and continued expansion into phone and workplace services position it well for rapid end‑user adoption. Enterprises should validate enterprise‑grade security and carrier interconnects for scale deployments.
-
RingCentral & 8x8: Cloud‑first UCaaS vendors are leading with operational simplicity and rapid feature rollouts, including AI enhancements. Their value is strongest where speed‑to‑market and operational expense models are prioritized over deep systems integration.
-
Avaya, Mitel, Alcatel‑Lucent Enterprise, NEC, Nextiva: These suppliers cover a spectrum from legacy telephony strongholds to modern hybrid UC platforms. Their roadmaps emphasize continuity and control for customers requiring gradual migration paths.
-
Verizon & Google: Telco and hyperscaler plays offer differentiated value—carrier integration and global connectivity from telcos; platform scale and developer ecosystems from hyperscalers. Both archetypes matter for enterprises seeking scale and third‑party ecosystem access.
-
Implication: Select vendor archetypes based on strategic priorities—consolidation, control, agility, or scale—and apply our vendor scorecards to translate those priorities into procurement metrics.
Notable 2026 developments and what they signal
-
Agentic voice AI rollouts by UCaaS vendors signal a step‑change in contact center automation and conversational capabilities; buyers should pilot with clear KPIs tied to handle time, NPS and containment rates.
-
Platform upgrades and targeted acquisitions (document capture, e‑signature, contact center extensions) highlight vendor moves to deepen workflow ownership—evaluate the integration path and data governance impacts before committing.
-
Carrier‑vendor partnerships and network capacity investments underscore the need to align application roadmaps with connectivity upgrades to unlock low‑latency, high‑quality mobile UCC experiences.
Practical guidance — five actions for 2026
-
Run a network readiness audit now. Prioritize firmware, QoS, and last‑mile capacity validations in locations designated for early AI or video‑intensive use cases.
-
Define a two‑tier procurement strategy. Use a core platform for mission‑critical collaboration and a complementary set of niche vendors for specialized capabilities (e.g., vertical workflows, advanced contact center AI).
-
Embed measurable KPIs for AI. Require vendors to commit to pilot outcomes and include rollback clauses if targets are not met within agreed time windows.
-
Protect data sovereignty. Map data flows and apply our sovereignty decision tree to select deployment topology that meets regulatory and business constraints.
-
Negotiate for interoperability. Require open APIs, documented integration roadmaps, and testable SLAs to limit vendor lock‑in and accelerate future migrations.
How to extract the full value
This briefing offers the strategic context and practical checklists executives need to navigate 2026. For teams that require the empirical backbone to operationalize decisions, the full PW Consulting report provides the complete set of market tables, interactive dashboards, vendor scorecards, downloadable procurement templates, and step‑by‑step migration blueprints. Given the pace of change in 2026, those granular assets — including our regional and segment forecasts, supplier market shares, and scenario‑based TCO outputs — are intentionally gated to ensure readers access the latest validated datasets.
To download the full market dataset, interactive tools, and vendor assessment packs — and to see the granular segmentation that informs our models — please visit the PW Consulting Worldwide Mobile Unified Communications and Collaboration Market report page.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.45% CAGR for Worldwide Precision Resistors Market in 2026–2032
By PW Consulting, 2026-07-15
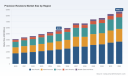
Worldwide Precision Resistors Market — Strategic Outlook for 2026: PW Consulting Releases In-Depth Intelligence to Guide Executive Decisions
PW Consulting today publishes the authoritative market intelligence briefing that global electronics OEMs, component distributors, and strategic investors will rely on as they set priorities for 2026. Our Worldwide Precision Resistors Market report (base year 2025) synthesizes five-year historical performance, near‑term supply dynamics and a seven‑year forecast horizon (2026–2032) into a single, action‑orientated resource. The analysis is grounded in proprietary demand-models and primary interviews across design, procurement and fabrication nodes, and is delivered in USD Million with a clear view of market scale and growth momentum.
Worldwide Precision Resistors Market
Headline Market View
Key macro takeaways provide an unambiguous backdrop for corporate planning. The precision resistors market expanded from USD 4,120.5 Million in 2020 to USD 5,610.0 Million in 2025 (base year), and is projected to continue expanding at a compound annual growth rate (CAGR) of 6.45% through the 2026–2032 forecast period. Under our central scenario the market reaches roughly USD 8.7 billion by 2032, reflecting sustained demand across automotive electrification, industrial instrumentation, telecommunications and high‑reliability medical and aerospace applications. Market concentration metrics show a moderately consolidated supplier base (CR3 ≈ 38.45%; CR5 ≈ 52.12%), implying meaningful market share for established players while leaving space for niche specialists and new entrants.
Worldwide Precision Resistors Market
Why this report matters for 2026 strategic decisions
- Translate market momentum into concrete investment decisions: With a clear CAGR and modeled demand curves, CFOs and strategy teams can calibrate capex phasing for capacity expansion, automation and vertical integration.
- Mitigate supply‑side risk: Our supply‑chain diagnostics quantify exposure to raw‑material shocks, lead‑time volatility and trade policy; procurement teams get scenario plays to preserve continuity while optimizing cost.
- Prioritize product roadmaps: Engineering leaders receive forward‑looking signal lines on tolerance, TCR and form‑factor traction to inform design‑win pursuits for 2026 product launches.
- Shape M&A and partnership agendas: The concentration profile and competitive mapping identify target classes—technology specialists, regional manufacturers, and asset plays—that can accelerate market access or secure IP.
What the report contains — practical, executable intelligence
PW Consulting structures the report to be immediately usable by cross‑functional teams. Key deliverables include:
Worldwide Precision Resistors Market
- Top‑line market-sizing and validated historical series (2020–2025) plus modeled forecasts to 2032 in USD Million, enabling scenario-based financial planning.
- Driver decomposition and elasticities that quantify how volume and ASP respond to automotive electrification rates, telecom infrastructure rollouts, and industrial CapEx cycles.
- Supplier risk heatmaps and a lead‑time tracker that capture Q4 2025 extensions and supplier concentration points—tools that procurement can operationalize within 30 days.
- Regulatory impact analysis covering RoHS updates and export control regimes, with compliance checklists and time‑phased actions for product qualification and market access.
- Procurement playbooks and cost‑pass‑through models that translate raw‑material fluctuations into negotiated contract language and hedge options.
- M&A playbook and valuation comparables calibrated to CR3/CR5 dynamics and technology premium drivers (precision tolerance, TCR, power rating).
- Template dashboards for KPI monitoring (order fill rate, design‑win velocity, supplier on‑time performance) that tie market indicators to executive scorecards.
Competitive landscape: who matters and why
The precision resistors ecosystem blends global incumbents with specialized regional players. PW Consulting’s competitive analysis profiles leading OEMs and highlights capability differentiators that matter for 2026 planning:
- Vishay Intertechnology (Malvern, PA, USA) — a leader in thin‑film and foil precision parts with ultra‑tight tolerances and low TCR offerings tailored to automotive and aerospace test equipment. Recent product introductions reinforce its emphasis on e‑mobility and industrial reliability.
- TE Connectivity (Schaffhausen, Switzerland) — strong in wirewound and high‑stability thin‑film lines, with product families designed for military and high‑reliability industrial markets.
- Yageo Corporation (New Taipei City, Taiwan) — a major chip‑resistor supplier whose compact, consumer‑grade precision arrays address space‑constrained telecom and IoT designs.
- KOA Speer Electronics (Bradford, PA, USA) — focused on thick‑film and metal‑film chip resistors with recent qualifications enhancing its position in automotive current‑sense applications.
- Susumu International (Tokyo, Japan) — niche specialist in ultra‑tight tolerance thin‑film resistors for RF and high‑frequency use cases.
- Isabellenhütte (Selb, Germany); Ohmite Manufacturing (Arlington Heights, IL, USA); TT Electronics (Newbury, UK); Walsin Technology and Viking Technology — each bringing unique IP and geographic reach that create differentiated routes to market.
We document recent, actionable developments—product launches, AEC‑Q qualifications and platform introductions through 2025—that materially affect competitive positioning and near‑term supply capacity. These micro‑events are synthesized into strategic implications for sales coverage, inventory posture and R&D prioritization.
Supply chain and regulatory headwinds to account for in 2026
- Raw materials: Nickel‑chromium alloy foil price pressure (notably a ~15% uplift observed in 2025) is compressing margins for precision foil and current‑sense resistors. The report models pass‑through timelines and suggests hedging and forward contracting options.
- Lead times: Precision thin‑film lead times extended materially (20–24 weeks in late 2025). We map contingency sourcing and parallel qualification strategies that can shorten effective customer lead times.
- Trade and compliance: New trade restrictions and export controls since late 2024, together with EU RoHS updates requiring halogen‑free materials, create both cost and time‑to‑market implications. The report includes compliance pathways and a remediation roadmap for affected product lines.
- Tariffs: US Section 301 duties continue to impact procurement economics on certain bilateral shipments; our scenario engine quantifies margin impacts across sourcing mixes to inform near‑term supplier negotiations.
Demand signals and product trends shaping 2026
Design wins will increasingly favor components that deliver lower TCR, tighter tolerance, and integrated current‑sense functionality. Automotive and e‑mobility rollouts remain a primary volume driver, while higher‑value niches—5G infrastructure, advanced medical instrumentation and aerospace systems—sustain margin expansion for specialized offerings. The report highlights the shift toward thin‑film and low‑TCR metal foil solutions in high‑reliability segments, and the continuing role of wirewound and thick‑film parts in power and thermal‑stress environments.
How to use this intelligence in the boardroom
- Board-level scenario planning: Overlay the forecast cases with corporate revenue and EBITDA sensitivity to determine acceptable investment thresholds for capacity or acquisition through 2026.
- Procurement strategy reset: Move from spot buying to multi‑year frameworks with clear escalation clauses tied to raw‑material indices; use our templates to fast‑track contract renegotiations.
- R&D and product roadmap: Reallocate development budget toward low‑TCR and current‑sense calibration offerings that capture premium ASPs in industrial and automotive markets.
- M&A screening and integration plan: Use our consolidation heatmap and valuation comparables to shortlist targets offering immediate capacity or complementary IP.
- Compliance and commercial readiness: Adopt our time‑phased RoHS compliance checklist and export‑control mitigation playbook to avoid market access delays.
Conclusion — actionable foresight without the noise
PW Consulting’s Worldwide Precision Resistors Market report provides the rigorous, executable intelligence that decision‑makers need to convert 2026 market dynamics into competitive advantage. We deliver validated market sizing (USD Million), a clear CAGR trajectory, supplier concentration context and operational playbooks that procurement, engineering, finance and corporate development teams can apply immediately.
For executives seeking the granular segmentation tables, downloadable datasets, supplier‑level dashboards and the full scenario workbooks that underlie these conclusions, please visit PW Consulting’s report page to access the complete document and request bespoke briefings. Our analysts are available for client workshops to translate these insights into a 90‑day tactical plan tailored to your organization’s role in the precision resistors value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Precision Resistors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Atmospheric Water Generator Market Set to Expand at a Robust 17.15% CAGR, New Report Finds
By PW Consulting, 2026-07-15
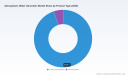
Worldwide Atmospheric Water Generator Market: Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide Atmospheric Water Generator (AWG) market informs executive decision-making for 2026 and beyond. The global market, which we peg at approximately USD 3,461.5 million in our 2025 base year, is poised for rapid expansion — rising to an expected USD 4,181.8 million in 2026 and continuing toward a multi‑billion dollar opportunity by the end of the forecast window (our top‑line projection for 2032 is USD 10,482.33 million). This trajectory reflects a compound annual growth rate of 17.15% across the 2026–2032 forecast period and underpins why AWG should sit on the strategic agenda of industrial water users, infrastructure investors, and climate‑resilient technology integrators in 2026.
Worldwide Atmospheric Water Generator Market
Why this matters for 2026 corporate strategy
-
Acceleration of demand: High growth rates mean near‑term volume and scale opportunities, but also intensifying competition for positioning and channel access.
Worldwide Atmospheric Water Generator Market -
Technology inflection: Rapid improvements in condensation efficiency, hybrid solar integration, IoT monitoring and smart mineralization are changing product economics and the set of credible use cases.
Worldwide Atmospheric Water Generator Market -
Policy and procurement levers: Targeted incentives and procurement programs — for example, recent subsidy initiatives in large emerging markets — are lowering adoption barriers and reshaping where it is commercially viable to deploy AWG systems at scale.
What the PW Consulting report delivers (practical assets)
Our report is designed for executives who must translate a fast‑moving technology market into concrete 2026 actions. It includes:
-
Verified market sizing and a seven‑year forecast model (2026–2032) with sensitivity scenarios to stress‑test CAPEX/OPEX assumptions under different climate and energy price trajectories.
-
Segmental frameworks covering regional, product‑type (condensation vs. desiccant/solar hydropanel approaches) and application pathways (residential, commercial, industrial) — presented to guide sizing, but with core granular splits reserved for report subscribers.
-
Competitive mapping and an acquisition target matrix that overlays technology readiness, certification status, manufacturing footprint and channel access to highlight near‑term inorganic options.
-
Go‑to‑market playbooks for three archetypal buyers (municipal procurement, industrial water buyer, energy‑offgrid integrator), including procurement checklists, nomination criteria, and contracting templates for performance‑based supply.
-
Regulatory and standards tracker that catalogs potable water certification requirements by jurisdiction and the common testing regimes purchasers should require as part of acceptance testing.
-
Capex/Opex modeling templates and a total cost of ownership (TCO) comparator to evaluate AWG alternatives against conventional water supply options and decentralized hybrid solutions.
Competitive landscape — what to watch in 2026
The AWG industry is maturing but remains fragmented; market concentration is meaningful at the top end (the top three firms account for a material share, and the top five extend control over roughly half of market value). That structure creates both opportunity and risk: established players can secure premium margins on certifiable, turnkey solutions, while agile entrants can win share through niche technical differentiation or novel commercial models.
-
Watergen Ltd. (Israel, https://www.watergen.com/) — A technology incumbent with a history of integration across residential, commercial, military and vehicle platforms. Watergen’s installed partnerships and OEM integrations (notably recent vehicle integrations announced in prior years) make it a strategic partner for firms seeking rapid in‑market credibility and a route into mobility and defense procurement pipelines.
-
GENAQ Technologies S.L. (Spain, https://genaq.com/) — Focused on industrial and commercial systems using HVAC‑derived engineering. GENAQ’s emphasis on certified, high‑efficiency systems positions it as a target for industrial buyers where performance guarantees and integration with existing HVAC estates matter.
-
Regional specialists and product innovators — Companies such as Akvo (India), EcoloBlue (US), SOURCE Global (solar hydropanel specialist), ACCAIR (China), Aeronero (Series 2.0 scalable platforms) and Quench Innovations each bring differentiated value: cost‑competitive condensation units, solar‑hybrid low‑maintenance hydropanels, IoT‑enabled scalable modules, or point‑of‑use integrations. These players are often the fastest to pilot new commercial models and localize manufacturing for specific markets.
-
New entrants and adjacent plays — The entrance of firms offering solar‑integrated AWG, and partnerships pairing AWG with electric vehicle platforms or energy storage, is increasing cross‑sector competitive pressure. Expect consolidation around firms that can combine certified water output, predictable maintenance regimes, and vertically integrated supply chains.
Recent developments shaping 2026 choices
-
Policy action in large emerging markets introduced purchase incentives and tax benefits for decentralized AWG installations — a near‑term catalyst for project pipelines in water‑stressed rural and peri‑urban areas.
-
Product launches in 2024–2025 have moved the technology envelope: compact consumer devices debuted at major trade shows while industrial‑scale Series solutions with IoT and thermodynamic improvements expanded capacity up to several thousand liters per day.
-
Academic and institutional pilots (including installations for research on infrastructure resilience) are generating third‑party performance data that will accelerate public procurement and standards alignment.
-
Cross‑sector partnerships (for instance, integration of AWG into electric vehicles and renewable energy projects) are creating new commercial channels and bundling opportunities that can materially improve unit economics.
Strategic imperatives and recommended actions for 2026
Below are priority moves we recommend for corporate leadership teams considering AWG exposure or adoption in 2026. Each is actionable within a 12–18 month horizon.
-
Define a clear use‑case and value metric — Separate customers into three commercialization buckets (capex buyers who own plant, O&M buyers who demand uptime SLAs, and service buyers who prefer subscription/leasing). For each bucket, define the acceptable TCO delta versus incumbent water supply and set target payback windows before procurement.
-
Product and R&D roadmap alignment — Prioritize improvements that unlock the widest commercial value: efficiency gains in low‑humidity operations, integration with renewable energy, automated mineralization and remote diagnostic capability. For manufacturers, modular designs that scale from point‑of‑use to industrial capacity reduce channel complexity and accelerate deployments.
-
Partnership and channel plays — Evaluate OEM partnerships (e.g., mobility and off‑grid energy integrators), energy‑water co‑location strategies (solar + battery + AWG), and local manufacturing alliances to capture incentive programs. Closed‑loop pilot programs with municipal utilities or industrial anchor customers are high‑value proof points.
-
Manufacturing and supply chain hedging — Local assembly and diversified supplier bases reduce exposure to freight and component shortages and improve access to market subsidies and procurement preferences.
-
Clinical procurement and compliance regime — Require potable water certification evidence, third‑party performance testing, and defined acceptance testing criteria tied to payment milestones. This mitigates operational risk and improves lifecycle economics for end customers.
-
M&A and investment posture — With meaningful concentration at the top of the market, strategic buyers should pursue tuck‑ins that add distribution, certification, or complementary product technology (solar panels, IoT stacks, or advanced filtration). Financial buyers can deploy roll‑up strategies focused on standardizing O&M.
-
Commercial models to accelerate adoption — Consider performance contracting, water‑as‑a‑service, and hybrid leasing that align provider and buyer incentives for uptime, water quality, and efficiency. These models are particularly effective for large commercial and industrial customers who lack CAPEX flexibility.
Risks and mitigation
Key risks for 2026 decision‑makers include variability in real‑world yield (particularly in arid, low‑humidity settings), evolving certification requirements across jurisdictions, and potential commoditization of basic condensation units. Mitigations include insisting on site validation pilots, multi‑jurisdictional certification roadmaps, and contracting structures that price performance and availability rather than unit delivery alone.
How PW Consulting supports your 2026 agenda
PW Consulting offers a tailored set of services to convert the market opportunity into executable programs: custom due‑diligence on target acquisitions, pilot design and supplier selection, TCO modelling tuned to your operating geographies, and implementation support for regulatory approvals and acceptance testing. Our full report contains the detailed segmentation tables, regional and application splits, supplier scorecards and the downloadable financial model that underpin this preview.
To obtain the complete dataset, granular segmentation, company scorecards and the interactive forecast model that empower transaction‑level decisions in 2026, access the PW Consulting Worldwide Atmospheric Water Generator Market report and supporting advisory services through our market release channels.
For detailed analysis of this topic, please visit the official page: Worldwide Atmospheric Water Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Solar Laser Drilling Market to Rise from USD 692.47 Million (Base Year 2025) to USD 1,696.53 Million by 2032 at a 13.66% CAGR — Asia Pacific Leads with USD 498.01 Million
By PW Consulting, 2026-07-15
Worldwide Solar Laser Drilling Market: Strategic Imperatives for Corporate Decision-Making in 2026
PW Consulting today releases an executive briefing based on our forthcoming market research report, Worldwide Solar Laser Drilling Market (Base year: 2025; Forecast period: 2026–2032). This briefing synthesizes the report’s core strategic insights and explains why organisations across the solar value chain should incorporate laser drilling market dynamics into capital planning, supplier strategies, and technology roadmaps as they finalise budgets and investment priorities for 2026.
Worldwide Solar Laser Drilling Market
High-level market trajectory: growth that demands strategic attention
The solar laser drilling market has transitioned from niche capability to a near‑core enabler for high-efficiency photovoltaic manufacturing. Our topline model shows a clear expansion: the market more than doubled through the early 2020s and continues to accelerate. From the mid‑2020s baseline, PW Consulting projects a sustained compound annual growth rate of 13.66% across the 2026–2032 forecast window. By 2026 the market is poised to move into the next inflection phase, with continued expansion through 2032 driven by higher-efficiency cell architectures, module form‑factor innovations and growth in double‑glass module formats.
Worldwide Solar Laser Drilling Market
For executives evaluating 2026 deployments of capital equipment, these aggregate growth dynamics translate into two practical implications: first, timing matters — under‑investing in laser capability risks a competitive yield and throughput gap; second, flexibility matters — equipment choices made now will interact with near‑term technology shifts (e.g., advanced cell coatings and glass handling requirements) and must therefore be evaluated under multiple scenarios.
Worldwide Solar Laser Drilling Market
What the report delivers — practical, decision‑grade intelligence
- Market sizing and forward scenario modelling (historical window 2020–2025, outlook 2026–2032) with sensitivity bands calibrated to policy, commodity and technology adoption scenarios.
- Technology deep dives that benchmark nanosecond, picosecond and femtosecond laser approaches for drilling, ablation and dicing — including process tradeoffs for throughput, thermal impact and downstream yield.
- Operational playbooks: equipment selection matrices, integration checklists for retrofit vs greenfield lines, and total cost of ownership (TCO) models tailored to cell and module architectures.
- Vendor landscape and competitive scorecards combining quantitative metrics with qualitative assessments of R&D pipelines, manufacturing footprint, systems integration capability and service networks.
- Supply chain mapping and risk heatmaps covering optical components, beam delivery subsystems, and specialized consumables — with mitigation strategies for procurement and inventory planning.
- Investment and M&A guidance, including valuations of vertical integration opportunities and criteria to identify high‑value targets or partnerships.
- Primary research insights — executive interviews, plant‑level case studies and equipment trial data — to ground forecasts in practical manufacturing outcomes.
Competitive dynamics: who matters and why
The vendor ecosystem comprises global industrial laser incumbents, specialised process integrators and nimble laser‑system start‑ups. Market concentration is material: the top three suppliers control a significant share of systems demand, while the top five represent an even larger portion of the market. This concentration creates both risk and opportunity for buyers.
Key vendor archetypes we profile include:
- High‑throughput systems specialists — companies delivering dedicated micromachining platforms for functions such as laser contact opening (LCO) and thermal laser separation (TLS) that are optimized for classical high‑efficiency PERC processes.
- Industrial laser OEMs — large laser manufacturers offering broad product portfolios (from fiber lasers to ultrafast sources) that provide scale advantages, global service networks, and component-level innovation.
- Beam delivery and motion control specialists — firms focused on scan systems, optics and beam shaping that are often the differentiators for process repeatability and cycle time.
- Application‑specific innovators — vendors targeting niche but rapidly growing needs such as precision drilling of thin photovoltaic back glass and laser processes adapted for new cell architectures (including perovskite integrations).
Representative vendors evaluated in the report include European micromachining system providers with strong LCO and TLS product families, large industrial laser groups with extensive global footprints, and North American and Asian firms focusing on fiber lasers, beam delivery and laser ablation for thin films. Each vendor assessment highlights product maturity, field deployment references, after‑sales support, and roadmap fit with next‑generation PV processes.
Recent market signals and what they imply for 2026
- Investment caution has surfaced in parts of the market: public disclosures from equipment vendors indicate order postponements tied to macro policy uncertainties, including tariff discussions and regional subsidy shifts. For purchasers, this creates short windows of negotiation leverage but also heightens timeline risk for equipment delivery.
- Technological progress in glass drilling is accelerating: recent demonstrations show dramatic reductions in cycle time for precision drilled back glass — improvements that materially lower per‑module cost for double‑glass architectures and influence the competitiveness of module formats in utility and BIPV applications.
- Material and process transitions, especially experimentation with perovskite coatings and tandem stacks, are creating temporary demand moderation in some legacy process lines while opening long‑term opportunity vectors for laser processing specialists who can adapt to new material chemistries.
These signals underpin a core strategic tension in 2026: should firms accelerate adoption to capture efficiency and form‑factor advantages, or pause to observe which cell and module standards emerge from pilot lines? Our scenario analysis equips decision‑makers to answer this with a structured approach rather than intuition alone.
Practical recommendations for corporate leaders preparing 2026 strategies
- Adopt a staged procurement cadence. Use pilot projects and modular equipment purchases to validate process changes (e.g., glass drilling parameters or ultrafast laser integration) before committing to full‑line capital expenditures.
- Prioritise suppliers offering modularity and software openness. Systems that support rapid retuning and remote updates reduce risk when cell chemistries or module formats evolve.
- Integrate laser process selection into product roadmaps. Equipment choice should be made in tandem with cell architecture decisions; misalignment drives rework costs and yield erosion.
- Hedge supply chain exposure. Given concentration dynamics and specialized optical component constraints, maintain a multi‑sourcing strategy for critical subsystems and consider strategic inventory buffers for lead items.
- Target collaboration over acquisition in the short term. Co‑development partnerships with laser OEMs or integrators can accelerate application‑specific optimisations with lower capital outlay than outright buyouts, while preserving optionality should consolidation opportunities arise.
- Design CAPEX scenarios with policy sensitivity. Model tariff, subsidy and incentive paths to understand the impact on breakeven timelines for new equipment investments.
How the report helps you act — not just predict
PW Consulting’s Worldwide Solar Laser Drilling Market report is explicitly structured to convert market intelligence into executable plans. Beyond forecasting, the report includes hands‑on deliverables such as an equipment selection matrix, ROI calculators for retrofits versus new lines, a vendor negotiation checklist and recommended KPI dashboards for production trials. These tools are designed for procurement leads, operations managers and corporate strategy teams seeking to align technology investments with 2026 business targets.
Why this matters now
2026 is a decision year for many solar manufacturers. Material innovations, module format shifts and policy uncertainty are converging to create asymmetric outcomes for firms that act decisively versus those that delay. Laser drilling is not a peripheral process — it directly affects cell efficiency, module form factor economics and manufacturing yield. The market’s projected growth and supplier concentration mean that smart timing and supplier selection will materially influence unit economics and competitive positioning as the industry transitions through the late 2020s.
Next steps and how to access the full intelligence
This briefing intentionally highlights the strategic signal and operational implications of the laser drilling market while withholding full segmentary tables and company scorecards. The complete report contains the granular segmentation, country‑level forecasts, detailed vendor scorecards, process‑level performance data and the primary datasets that underpin our models — information that is essential for executable 2026 plans.
To obtain the full report, interactive data dashboards and subscription access to ongoing updates, please visit the PW Consulting report page or contact our industry research desk. For tailored advisory engagements — including scenario modelling, vendor selection RFP design, and pilot program management — PW Consulting offers bespoke strategic support to translate the report’s findings into action.
PW Consulting remains committed to helping industry leaders turn market insight into competitive advantage in the rapidly evolving solar manufacturing landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Glycopeptide Antibiotics Market Reaches USD 1,984 Million in 2025
By PW Consulting, 2026-07-15
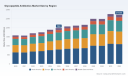
Worldwide Glycopeptide Antibiotics Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market study on glycopeptide antibiotics delivers a concise, actionable intelligence brief designed to sharpen executive decisions as companies enter 2026. The global glycopeptide market—anchored by legacy agents such as vancomycin and newer lipoglycopeptides—remains a steady-growth specialty market. Our base‑year assessment (2025) values the market at approximately USD 1,984 Million, and our forecast models project a compound annual growth rate (CAGR) of 4.6% across the 2026–2032 window, culminating in a materially larger market by 2032. This briefing outlines why and how that growth will matter to corporate strategy while deliberately reserving detailed regional, product-application and fine-grain split data for the full report.
Worldwide Glycopeptide Antibiotics Market
Why this market matters in 2026
-
Enduring clinical relevance: Glycopeptides remain first‑line or critical‑line options for serious Gram‑positive infections, including MRSA and select enterococcal infections. Regulatory positions for core products (notably vancomycin) remain stable, supporting predictable demand for hospital and critical-care channels.
Worldwide Glycopeptide Antibiotics Market -
Portfolio leverage and differentiation: Newer lipoglycopeptides such as dalbavancin and oritavancin provide differentiated dosing and outpatient administration models that are reshaping care pathways (e.g., ABSSSI and increasingly hospital‑outpatient transitions). Reimbursement alignment for certain agents already favours outpatient administration, creating commercial windows for firms that can execute on channel shift strategies.
Worldwide Glycopeptide Antibiotics Market -
Supply‑chain & cost dynamics: Our analysis confirms meaningful input‑cost pressure—API and manufacturing costs for antibiotic production rose materially between 2022–2025—forcing manufacturers to revisit sourcing, contract structures and price strategies. China’s dominant role in antibiotic API supply remains a systemic dependency for many markets, with implications for risk mitigation and vertical integration strategies.
Headline implications for corporate strategy
-
Secure and diversify API supply: With raw material and energy inflation driving API cost increases, and with concentrated sourcing risk evident, procurement strategies must shift from spot pricing to multi‑tiered, long‑term contracting and strategic inventories. For manufacturers and large buyers, near‑sourcing or co‑investment in API capacity should be modeled as a core option.
-
Prioritise product‑format innovation: The successful market introduction of ready‑to‑infuse vancomycin formulations and long‑acting lipoglycopeptides changes inpatient workflows and outpatient feasibility. Firms should prioritize development or licensing of formulations that reduce infusion time, lower nursing burden, and enable outpatient care—each of which can unlock differentiated reimbursement and hospital formulary placements.
-
Reimbursement‑aligned commercialization: Reimbursement codes and payer pathways already favour certain outpatient uses (e.g., dalbavancin in ABSSSI). Commercial teams must align evidence generation and HEOR activities to support these settings—short, targeted studies demonstrating total cost of care reductions will be high‑return investments.
-
Consolidation and scale plays: Market concentration metrics demonstrate material share held by a handful of firms. For mid‑sized players, M&A or niche specialization (e.g., sterile injectables for critical care, API supply) are viable routes to defend margins and extend market access.
-
Stewardship and diagnostics integration: Regulatory updates to antimicrobial susceptibility testing (AST) breakpoints have immediate clinical and commercial consequences. Companies should invest in diagnostic partnerships and educational programmes that align product positioning with the evolving AST landscape to preserve appropriate use and market access.
Competitive landscape: what 2026 entrants and incumbents need to know
The competitive architecture of the glycopeptide market blends large multinational innovators, specialty API suppliers and diversified injectables manufacturers. Key strategic positions include:
-
Pfizer Inc.: A major multinational with a commercial lipoglycopeptide offering (dalbavancin/Dalvance/Xydalba). Pfizer’s position illustrates how global scale and branded product strategy can accelerate outpatient adoption through channel penetration and payer engagement.
-
Hikma Pharmaceuticals PLC: Demonstrated commercial leverage via formulation innovation—the 2025 FDA clearance for a room‑temperature, ready‑to‑infuse vancomycin injection marks a significant workflow and logistics advantage in hospital and infusion settings. This approval underscores how formulation and supply‑chain innovations can create compelling differentiation even in mature classes.
-
ANI Pharmaceuticals / Aurobindo / Xellia / Fresenius / Viatris (Mylan): These firms underscore the critical role of generic and contract supply in the market. Their portfolios—centered on vancomycin injectables, APIs and finished dosage forms—are pivotal to hospital supply continuity and price competition dynamics.
-
Zhejiang Hisun and other large API suppliers: For many global players, API sourcing decisions (including relationships with Chinese manufacturers) are strategic gatekeepers of cost and continuity. Vertical integration or long‑term strategic sourcing agreements are therefore central competitive levers.
Together, the competitive set and regulatory developments paint a picture of a market where innovation is less about novel molecular classes and more about formulation, supply‑chain resilience, and delivery models that shift care out of the inpatient setting.
Regulatory, reimbursement and supply‑side pressures to monitor
-
AST and breakpoint updates: Recent FDA‑cleared updates to AST systems and breakpoints for agents such as telavancin and daptomycin alter susceptibility profiles and prescribing behaviour, particularly for enterococcal infections. Manufacturers should coordinate label strategies, lab‑based education, and real‑world evidence collection to respond swiftly.
-
API cost inflation: Industry sources document a substantial rise in antibiotic API production costs from 2022–2025 driven by energy, chemical inputs, and labor—this directly compresses margins for both innovators and generics unless mitigated by pricing, efficiency, or forward procurement.
-
Concentrated sourcing exposures: A large share of antibiotic API volume imported into major markets originates from a small number of countries, creating geopolitical and operational risk for supply continuity. Companies must quantify this exposure and develop contingency plans.
-
Reimbursement levers: Codes and payer policies that recognise the health‑economic benefits of single‑dose or outpatient regimens (for selected indications) materially affect product economics and adoption curves; proactive payer engagement is high priority.
What’s in the PW Consulting report (practical deliverables)
Designed for commercial leaders, corporate development teams, R&D heads and procurement officers, the full report includes:
-
Robust market-sizing and forecast models (2026–2032) with scenario analysis reflecting supply shocks, pricing pressure, and accelerated outpatient adoption.
-
Actionable go‑to‑market playbooks customised for branded launches, generic competition defense, and API suppliers—including payer engagement templates and formulary access roadmaps.
-
Supply‑chain risk assessments and sourcing optimization blueprints—covering dual‑sourcing, captive manufacturing thresholds, and contract management algorithms.
-
Competitive intelligence dossiers on leading players with strategic options analyses (M&A targets, licensing partners, and white‑space opportunities).
-
Regulatory impact matrices integrating AST updates and label strategies, plus an implemented HEOR framework to quantify total cost of care advantages for outpatient regimens.
-
Financial models and valuation sensitivity analyses for portfolio decisions, including IRR and payback timelines for manufacturing investments and acquisition scenarios.
How to use this preview in boardroom decisioning for 2026
-
Prioritise investment in formulation and logistics: Use capital allocation to support product formats that enable outpatient and rapid‑turnaround use—these have the highest near‑term ROI given payer receptivity and provider workflow benefits.
-
Model supply disruption scenarios: Run stress tests on your 2026 P&L assuming staggered API availability and a 25–30% input‑cost shock, and prepare risk mitigation budgets accordingly.
-
Deploy a payer evidence programme: Fast‑track small, well‑designed health‑economic studies to secure outpatient reimbursement pathways where possible.
-
Assess M&A and partnership options: For mid‑market players, pursue bolt‑on deals that fill formulation, sterile manufacturing or API gaps—scale matters for margin preservation in an inflationary cost environment.
What this preview intentionally omits (and why)
In keeping with the “trailer” principle of this press brief, we have deliberately withheld detailed regional and application‑level splits, line‑by‑line revenue waterfalls, and segment‑level prices. These granular datasets and downloadable models are included within the full PW Consulting report, which also contains configurable spreadsheets and confidential scenario analyses that clients can use to run bespoke simulations.
Next steps and how to engage
For teams preparing budgets and strategic roadmaps in 2026, this market represents a manageable growth profile with identifiable risk vectors and clear levers for differentiation. If your 2026 priorities include supply‑chain resilience, outpatient commercialisation, M&A or targeted formulation innovation, PW Consulting’s full report will provide the proprietary, model‑ready inputs necessary to move from strategy to execution.
To access the complete dataset, scenario models, and executable playbooks—along with client‑only advisory sessions on how to apply findings to your portfolio—please consult PW Consulting’s market report page or contact our global life‑sciences practice for a briefing and demo of the report toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Glycopeptide Antibiotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


