



Category: market research
PW Consulting: Worldwide High Purity Lignin Market to Grow at 7.21% CAGR, Reaching USD 69.18 Million by 2032
By PW Consulting, 2026-07-15
Worldwide High Purity Lignin Market: A Strategic Roadmap for 2026 Corporate Decision‑Making
PW Consulting today publishes an executive companion to our full Worldwide High Purity Lignin Market report — a focused briefing that translates market-scale dynamics into actionable choices for executives planning investments, partnerships, and product roadmaps in 2026. Drawing on five years of historical tracking (2020–2025) and a seven-year forecast (2026–2032), this briefing distills the strategic implications of a market that is maturing rapidly yet remains opportunity‑rich for companies that move with clarity and speed.
Worldwide High Purity Lignin Market
Executive snapshot: market momentum you cannot ignore
High purity lignin has transitioned from an experimental feedstock to a commercially relevant industrial material. Our market model values the global market at USD 42.5 Million in 2025 and projects steady expansion at a compound annual growth rate (CAGR) of 7.21% across the 2026–2032 forecast window. Under central scenarios, the market continues to scale through a combination of product innovation, policy incentives that favor low‑carbon materials, and downstream adoption in resins, carbon materials, and emerging bio‑polymers.
Worldwide High Purity Lignin Market
These headline figures understate a more important truth for strategists: the growth is uneven across use cases and lifecycle stages. Some segments are near commercial maturity and are witnessing volume uptake, while others are still proving techno‑economic parity against incumbents. The consequence is a multi‑speed landscape where timing, partnership design, and technical anchoring determine winners more than raw R&D spend.
Worldwide High Purity Lignin Market
Why 2026 is a decision inflection point
- Policy convergence: Strengthening carbon regulations and circular‑economy procurement in key jurisdictions are shifting corporate sourcing priorities. Buyers are increasingly prepared to pay for demonstrable lifecycle benefits, which shortens payback windows for lignin‑based formulations in selected applications.
- Feedstock economics: The pulp and biorefining sector is now a visible source of high‑quality lignin. For example, global kraft‑pulp infrastructure supports large upstream availability; industry reporting indicates kraft lignin capacity has reached industrial scale. This reduces one of the early barriers — feedstock scarcity — while raising questions about cost competitiveness and logistics optimization.
- Value chain ripening: Parallel developments in processing (e.g., LignoBoost and organosolv routes), formulation know‑how, and pilot‑to‑commercial movements demonstrate that several players have crossed the “proof of scale” threshold. 2026 will be the year where companies either lock in commercialization pathways or cede early mover advantages.
Competitive landscape — consolidation with room for differentiation
The market is moderately concentrated. The top three suppliers account for a plurality of market power and the top five strengthen that position further. This structure produces both stability and strategic friction: incumbent producers provide reliable supply and technical support, while smaller, focused challengers introduce differentiated chemistries and business models.
Key industry participants shaping the competitive frontier include long‑standing pulp‑derived producers and agile new entrants developing proprietary conversion platforms. Established players bring scale, feedstock integration, and broad customer relationships; specialist firms bring high‑purity chemistries, targeted product families, and flexible engagement models for material trials. Recent corporate actions illustrate this duality — partnerships that blend an incumbent’s manufacturing scale with a start‑up’s product innovation are becoming a repeatable template.
- Breadth and legacy capability: Veteran producers with decades in lignin and lignosulfonate businesses continue to push product families optimized for industrial adhesives and dispersants, leveraging deep process expertise to meet industrial specifications.
- Vertical innovation leaders: Kraft‑integrated players and biorefinery arms are commercializing LignoBoost‑derived grades and organosolv variants for higher‑value applications such as carbon precursors and engineered polymers.
- Specialist challengers: A cadre of technology‑intensive companies is focused on producing ultra‑high‑purity native lignin and on transforming lignin into thermoplastic platforms, attracting venture and project funding to scale niche markets.
Representative corporate moves over the last 18 months underline realignment across the value chain: several demo‑to‑early commercial shipments have been reported, product launches for concrete and battery anode precursors have been announced, and funding rounds have accelerated capacity and commercialization plans. Together these actions are converting technical proofs into addressable market opportunities.
Practical implications for corporate strategy
- Market entry and timing: Firms considering entry should align investments to the maturation curve of target applications. For segments already approaching commercial acceptance, de‑risk through offtake contracts, co‑development agreements, or licensing of proven conversion technology. For nascent applications, prioritize pilots that generate comparable performance metrics against incumbents and quantify lifecycle advantages.
- Supply integration vs. tolling: Evaluate whether to secure lignin via vertical integration (co‑located with pulp mills or biorefineries) or via tolling/contract manufacturing. Integration favours cost control and supply security; tolling offers speed and capital efficiency. Our scenario analysis models both approaches under fluctuating feedstock and energy prices to show breakpoint economics for each strategy.
- Partnership and ecosystem playbooks: Early commercial wins are frequently realized through pragmatic collaborations — formulators, system houses, and OEMs are effective partners for demonstrating performance at scale. Structuring agreements to share risk and IP while preserving upside is a recurring best practice documented in the report.
- Regulatory and procurement alignment: Firms that embed third‑party lifecycle assessment and comply with emerging disclosure rules unlock procurement pipelines in regulated markets. Our compliance matrix helps prioritize certifications and reporting that materially affect commercial acceptance.
Operational priorities: technology, quality, and cost control
Success in high purity lignin requires engineering across three domains: consistent feedstock pretreatment, reproducible purification yielding defined molecular distributions, and formulation expertise to integrate lignin into end‑use products without compromising performance. Our techno‑economic chapters map where capex should be deployed to improve yield, lower impurity removal costs, and enhance product uniformity — the levers that most directly influence commercial margins.
We also benchmarked conversion routes and documented where process choices create product differentiation. For instance, certain technologies produce lignin with functional groups that are particularly suitable for carbon fiber precursors, while others produce powders optimized for polymer blending. These distinctions matter when negotiating offtake or selecting co‑development partners.
What the PW Consulting report delivers
The full report is structured to serve deal teams, product managers, and corporate strategists preparing decisions in 2026. Key deliverables include:
- Market sizing and forecast model (2020–2032) with scenario variants to stress test price, feedstock, and policy shocks;
- Commercial roadmaps for four priority end‑use tracks with go‑to‑market playbooks and buyer decision matrices;
- Supplier due diligence dossiers and a competitive positioning framework for incumbent and challenger firms;
- Capex and operating cost benchmarking across major conversion technologies, including sensitivity analyses for energy and chemical inputs;
- Risk register and mitigation strategies covering feedstock availability, regulatory shifts, and substitution threats;
- Dealflow intelligence: a curated list of recent scale‑up milestones, funding events, and strategic partnerships with assessment of strategic intent;
- Appendices with primary interview transcripts, methodology notes, and proprietary data tables (regional and application splits are available exclusively in the full dataset).
How to use this intelligence in 90 days
Executives can convert insights into action quickly. We recommend a three‑month playbook:
- Month 1 — Strategy validation: use our scenario model to stress‑test internal forecasts and identify prioritized target applications;
- Month 2 — Partnership mapping: initiate technical trials with shortlisted suppliers and negotiate pilot commercial terms that share risk;
- Month 3 — Investment decision: finalize capital allocation or offtake commitments using our techno‑economic breakpoints and procurement checklist.
Final perspective: play where the market window is open
High purity lignin is no longer an academic exercise — it is a commercial frontier with defined pockets of immediate opportunity and broader markets that will open with incremental technical and policy progress. For 2026, the strategic choice for firms is not whether to consider lignin, but how fast and in which shape they will enter. The difference between an early strategic foothold and a catch‑up strategy will be determined by alignment across technical, commercial, and regulatory tracks — precisely the integrated view our full report supplies.
PW Consulting’s full Worldwide High Purity Lignin Market report contains the detailed regional and application breakdowns, proprietary vendor benchmarking, and downloadable model used to generate the forecasts summarized here. To access the complete analysis, proprietary data tables, and subscription options for ongoing market monitoring, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide TRIS Buffer Market Poised for 6.32% CAGR in 2026–2032, Signaling Strong Growth Outlook
By PW Consulting, 2026-07-15
Worldwide TRIS Buffer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting today releases an executive briefing summary of our new Worldwide TRIS Buffer Market report, delivering an actionable line of sight for corporate leaders, procurement teams, and investors shaping plans for 2026 and beyond. The global TRIS buffer market reached approximately USD 324.5 million in our 2025 base year and is forecast to expand at a compound annual growth rate (CAGR) of 6.32% through the 2026–2032 horizon, lifting total market value materially by the end of the projection window. This briefing synthesizes the report’s strategic implications while preserving the proprietary, granular segment intelligence available in the full study.
Worldwide TRIS Buffer Market
Why this report is essential for 2026 strategy
TRIS (tris(hydroxymethyl)aminomethane) and TRIS-HCl are foundational reagents across life-science research, diagnostics, and bioprocessing. Small shifts in supply, quality standards, or trade policy have outsized effects on product continuity, regulatory compliance, and margin capture in downstream applications. Our study combines demand-side modelling, supply-chain due diligence, and scenario analysis to produce guidance that is immediately usable in 2026 planning cycles.
Worldwide TRIS Buffer Market
- Macro traction: After a period of steady expansion from 2020–2025, the market enters a mid-single-digit growth phase driven by bioprocessing build-out, diagnostic throughput, and renewed investment in academic and industrial R&D.
- Concentration and negotiation leverage: Market concentration is meaningful—our analysis shows a top-three/top-five concentration profile that creates supplier-side leverage for firms that understand supplier economics and capacity footprints.
- Supply tightness and buffer economics: Global production capacity and consumption metrics indicate available headroom in aggregate but localized stress points and quality-tier mismatches that can create price and availability volatility at the point of use.
Market dynamics that will shape 2026 outcomes
Three structural dynamics stand out for executives planning 2026 budgets and capex:
Worldwide TRIS Buffer Market
- Trade and regulatory risk: Recent trade actions and petitions have elevated the probability of tariffs, quota changes, and protracted anti-dumping procedures. Firms must assume shorter planning horizons for import-dependent supply chains and build contingency routes and cost scenarios into procurement models.
- Raw-material and input-cost volatility: A meaningful share of TRIS producers identify raw-material cost swings as a production-limiting factor. This implies that pricing models should incorporate volatility bands and that procurement should consider indexed contracts or hedging mechanisms where feasible.
- Quality segmentation and premiumisation: Demand is bifurcating between research-grade, bioprocess-grade, and regulated cGMP supply. Players able to assure multicompendial and ISO-aligned quality at scale capture premium win rates in biopharma and diagnostics, creating margin differentials that justify targeted investments.
Competitive landscape — who moves the market
The TRIS buffer ecosystem is a mix of global life-science distributors, specialized chemical manufacturers, and regional commodity producers. Our company-level analysis evaluates manufacturing footprint, quality credentials, channel strength, and strategic initiatives. Highlights from the competitive review include:
- Integrated manufacturers with dual-site or multi-tier production: Companies that own upstream synthesis and downstream buffer preparation position themselves to manage quality, lead times, and regulatory documentation more effectively. Recent capacity expansions and new product introductions from integrated players have increased resilience for customers who prioritize single-sourced quality assurance.
- Specialist regional producers: Several Asia-based producers supply high-volume, competitive-cost TRIS grades into global distribution networks. Their role in base-material supply underpins cost-effective channels, but their commercial impact will depend on evolving trade measures and quality-certification investments.
- Global distributors and brand leaders: Large life-science distributors and reagent brands continue to dominate end-user channels, offering convenience, regulatory documentation, and bundled solutions—capabilities that are especially valued by clinical, diagnostic, and academic buyers.
Notable recent market moves we analyze in depth (and the strategic implications for 2026) include:
- Capacity and capability expansions at U.S. and European production sites by leading integrated firms, strengthening regional supply security for research- and life-science-grade buffers.
- Distribution agreements that re-shape North American channel dynamics and reduce friction for laboratory and bioprocessing customers seeking validated suppliers.
- Trade petitions filed in early 2026 that could result in tariffs or countervailing measures—these have immediate procurement and sourcing implications for companies reliant on certain import routes.
What the PW Consulting report contains — practical, executable content
This study is designed as a hands-on decision tool for 2026 planning. The report’s components include:
- Transparent market sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) with revenue denominated in Million USD and scenario-based outputs for conservative, base, and upside pathways.
- Supply-chain mapping and capacity audit that highlights active production nodes, documented quality certifications, and single points of failure at the supplier and logistics levels.
- Company scorecards for the leading global suppliers, assessing manufacturing redundancy, product-grade breadth (research → cGMP), distribution networks, and strategic initiatives such as capacity build-outs and exclusive channel agreements.
- Price and margin sensitivity matrices, alongside procurement playbooks (contract templates, quality acceptance checklists, and vendor-monitoring KPIs) tailored to labs, CDMOs, and in-house bioprocess teams.
- Regulatory and trade scenarios, including modeled P&L impacts of tariff introductions, import restrictions, or sudden raw-material cost shocks.
- M&A and partnership screening criteria and an investment thesis framework for corporates evaluating vertical integration, bolt-on acquisitions, or captive supply arrangements.
Strategic recommendations for executives acting in 2026
Applying the report’s findings, PW Consulting recommends a set of prioritized actions that are both pragmatic and defensible under multiple market scenarios:
- Short-term (0–12 months): Secure multi-sourced supply agreements with at least one quality-certified, geographically diversified supplier; negotiate year-over-year price collars; and validate incoming lots against a standardized QC protocol to reduce operational disruption risk.
- Medium-term (12–24 months): Invest in supplier development programs (quality upgrades, audit support) or exclusive distribution partnerships to lock preferential access to high-purity grades required by biopharma customers.
- Policy and advocacy: Proactively monitor trade petitions and engage with trade advisors—companies with significant import exposure should model tariff scenarios and consider import re-routing or localized buffer preparation as mitigants.
- Portfolio and product strategy: Differentiate on quality documentation, traceability, and customized buffer formulations for therapeutic and diagnostic applications—premiumization is a defensible route to higher margins where regulatory requirements are strict.
- Capital allocation: For manufacturers, prioritize investments in dual-site redundancy and analytical testing capacity; for distributors and CDMOs, allocate capex for localized buffer preparation (WFI/compliance-grade lines) to capture near-term demand shifts.
Using the full PW Consulting report
The full report is engineered to be a working tool for sourcing managers, corporate strategists, and M&A teams. Clients gain access to interactive models, supplier scorecards, and a regulatory-impact simulator that allows rapid evaluation of tariff outcomes and raw-material price shocks. Our "what-if" dashboards let users run bespoke scenarios and export procurement- and P&L-ready outputs to support board-level decisions in 2026.
Final perspective — why act now
The TRIS buffer market sits at the intersection of chemical commodity dynamics and stringent life-science quality expectations. The market’s steady base-year size and the mid-single-digit CAGR through the forecast period signal robust, sustained demand—but the near-term environment is being reshaped by policy interventions, cost volatility, and selective capacity additions. Companies that enter 2026 with a disciplined supplier playbook, clarity on quality-tier economics, and pre-defined contingency scenarios will convert market uncertainty into competitive advantage.
PW Consulting’s Worldwide TRIS Buffer Market report delivers the empirically grounded, decision-ready analysis required to do just that. For the detailed segment tables, supplier-by-supplier financial and capacity profiles, and the interactive forecasting model referenced in this briefing, please consult the full report available through our publications portal.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Semiconductor Magnetic Sensor Market Set to Expand at a 9.0% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Semiconductor Magnetic Sensor Market — Strategic Primer for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Semiconductor Magnetic Sensor Market (base year 2025) equips executives with the strategic intelligence needed to make high-stakes product, supply-chain, and M&A decisions in 2026. The market is on a multi-year expansion trajectory — growing from roughly USD 2.15 billion in 2020 to an estimated USD 3.28 billion in 2025, and projected to reach approximately USD 6.0 billion by 2032 at a 9.0% CAGR across the 2026–2032 forecast window. This research brief highlights the practical implications of those macro trends, the competitive dynamics shaping supplier choices, and the operational playbooks that leaders should adopt this year.
Worldwide Semiconductor Magnetic Sensor Market
Why this study matters for 2026
-
Acceleration and bifurcation: The market’s near-term growth is being driven by accelerating demand in electrified mobility, industrial automation, and next-generation consumer sensing, while advanced applications are concentrating value in higher-performance technologies. Executives who understand where value is consolidating will avoid costly technology bets.
Worldwide Semiconductor Magnetic Sensor Market -
Supply-chain fragility: New trade and export controls, concentrated processing of critical magnet materials, and tariff shifts have created acute sourcing risk for sensor manufacturers and OEMs. Procurement and sourcing strategies that ignore these structural constraints will face lead-time spikes and margin erosion.
Worldwide Semiconductor Magnetic Sensor Market -
Consolidation opportunities: Market concentration metrics indicate meaningful share for the top vendors, creating both competitive pressure and M&A potential. Well-timed partnerships or bolt-on acquisitions can secure capability gaps and accelerate time-to-market.
What the report delivers — operational, decision-ready intelligence
-
Market sizing and scenario forecasts to 2032: a baseline plus upside and downside scenarios that stress supply shocks, tariff regimes, and demand slowdowns so teams can build contingency budgets and product launch timelines.
-
Technology trade-off matrices: actionable guidance on Hall-effect vs. various magnetoresistive technologies (including performance, cost, manufacturability, and qualification timelines) to inform BOM decisions and roadmap sequencing.
-
Supply-chain risk mapping: granular supplier topology, single-point-of-failure diagnostics, and an input-material exposure index for rare-earth and specialty material dependencies — designed for procurement to execute mitigation tactics in 90–180 day windows.
-
Regulatory impact dashboard: step-by-step playbooks for compliance and market access under recent measures — including assessments of export controls, tariffs, and foreign-direct-product-style licensing — tailored to North American, European, and Asia-Pacific operating models.
-
Commercial and go-to-market playbooks: pricing sensitivity models, channel optimization strategies, and buyer persona analysis for automotive OEMs, industrial suppliers, and high-volume consumer platforms.
-
M&A and partnership shortlist: vetted target profiles and integration risk scoring, focused on technology fills (high-sensitivity TMR/GMR capability), wafer-level integration, and material-sourcing control.
-
Procurement toolkit: contract clauses, hedging strategies for magnet and rare-earth price volatility, and supplier qualification templates designed to be executed within Q1–Q3 2026 procurement cycles.
Competitive landscape — who matters and why
The market is oligopolistic enough that moves by leading suppliers reshape product and supply dynamics. PW Consulting’s analysis profiles the incumbent and emerging specialists that matter to buyers and investors in 2026.
-
Allegro MicroSystems, Inc. — Strengths: deep automotive-qualified portfolio across Hall and TMR, and a fast-follow product cadence (notably a high-bandwidth TMR current sensor introduced in late 2025). Strategic implication: ideal partner for OEMs requiring automotive-grade current sensing and for firms seeking immediate access to TMR IP post-acquisition integrations.
-
Infineon Technologies AG — Strengths: broad portfolio under a unified sensor platform approach and a strong automotive systems play. Strategic implication: a go-to supplier for integrated system-level qualification and long-lifecycle automotive programs.
-
NXP Semiconductors — Strengths: automotive-focused MR and low-power Hall solutions coupled with strong ECU ecosystem ties. Strategic implication: preferred for energy-constrained vehicle and IoT applications where software and MCU integration matters.
-
Asahi Kasei Microdevices (AKM) — Strengths: tri-axis and consumer-grade TMR/Hall devices optimized for compact, high-integration consumer and industrial products. Strategic implication: high fit for consumer platform suppliers seeking miniaturized multi-axis sensing.
-
TDK Corporation — Strengths: material and sensor integration—recently introduced a TMR angle sensor optimized for safety-critical automotive and industrial systems. Strategic implication: valuable for customers needing supplier-level materials expertise tied to sensor performance.
-
Melexis — Strengths: integrated 3D magnetic position sensors with strong automotive and industrial traction. Strategic implication: high-quality option for position sensing needs with established qualification processes.
-
STMicroelectronics — Strengths: multi-sensor reference designs and ultra-low-power 3-axis magnetic sensors, supporting cross-sensor fusion strategies. Strategic implication: choice partner for multi-sensor architectures and system integration at scale.
-
Honeywell International — Strengths: legacy aerospace/industrial pedigree and reliable Hall-effect offerings. Strategic implication: incumbent in safety and certified sectors where heritage qualification is required.
-
Texas Instruments — Strengths: widely adopted Hall-effect ICs and strong industrial channel presence. Strategic implication: pragmatic choice for high-volume, cost-sensitive industrial programs.
-
ABLIC Inc. — Strengths: compact Hall switch/latch ICs tailored for general-use and automotive switch applications. Strategic implication: tactical supplier for cost-optimized switching functions.
-
Tower Semiconductor — Strengths: foundry services enabling integration of high-temperature Hall sensors and TMR elements with CMOS for specialized high-sensitivity markets. Strategic implication: critical partner when wafer-level integration or specialty process control is required.
Recent product and market developments to watch in 2026
-
Several leading vendors have refreshed their product stacks in 2024–2025 with TMR and ultra-low-power multi-axis designs, and new high-bandwidth TMR current sensors emerged in late 2025 — indicating a technology migration toward higher-performance magnetoresistive solutions in demanding applications.
-
Concurrently, regulatory and trade moves (including export controls and tariffs implemented in 2025–2026) are reshaping procurement math and favoring suppliers with diversified, non-exclusive upstream sources or localized manufacturing footprints.
-
Raw material dynamics — particularly concentrated rare-earth processing capacity and export licensing for heavy rare earths — remain structural negatives for any strategy that assumes frictionless magnet supply. Battery pack price declines in 2024 have eased some cost pressure in electrified systems, but magnet and rare-earth exposure is still a distinct vector of volatility.
Strategic recommendations for corporate leaders in 2026
-
Adopt a two-track technology strategy: defend current product roadmaps where qualification cycles are long (e.g., automotive), while selectively piloting higher-performance magnetoresistive solutions (TMR/GMR) in adjacent fast-follower platforms to capture premium value.
-
Prioritize supply resilience: execute dual-sourcing for critical magnet and wafer inputs, negotiate longer-term agreements with indexed pricing, and evaluate nearshoring or licensed local assembly to mitigate tariff and export risks.
-
Use scenario planning to price for volatility: incorporate regulatory-triggered cost adders and lead-time buffers into commercial bids; preserve margin by structuring tiered pricing linked to material-cost pass-through mechanisms.
-
Targeted M&A and partnerships: prioritize acquisitions that deliver scarce capabilities (high-sensitivity TMR IP, wafer integration) or reduce upstream exposure (magnet processing, specialty materials). For non-strategic businesses, consider divestiture to free capital for capability plays.
-
Accelerate systems-level competence: OEMs and Tier-1s should insist on supplier co-engineering and system reference designs to reduce integration cycles and lower qualification risk—vendor co-development is now a competitive advantage.
-
Operationalize regulatory intelligence: create a rapid-response compliance cell to translate export control and tariff updates into procurement and product deployment decisions on a weekly cadence.
How PW Consulting’s report helps you act in 2026
This market study is designed as an executable toolkit — not an academic exercise. For leadership teams the report provides the forecast foundation, the supplier playbook, and the procurement and M&A decision templates needed to convert the projected 9.0% CAGR through 2032 into profitable growth. Because the highest-value, deal-closing details (including precise segment-by-segment shares, regional splits, and company-level revenue triangulation) are maintained as premium deliverables, PW Consulting’s full report includes downloadable models, supplier heatmaps, and executable contract language to implement the recommendations rapidly.
Next steps
-
Download the full report and the accompanying Excel model from PW Consulting to access the detailed segmentation, supplier scorecards, and scenario-based financial models required to build your 2026 plans.
-
Contact our advisory team for a tailored briefing: we provide board-level presentations, hands-on procurement workshops, and integration roadmaps that convert insight into action within 60–120 days.
PW Consulting’s Worldwide Semiconductor Magnetic Sensor Market study gives executives the forecasting clarity, risk-adjusted supplier playbooks, and M&A roadmaps necessary to navigate 2026’s fast-evolving landscape. The macro trajectory is clear — significant growth and rebalancing lie ahead — but success will be determined by those who pair market insight with rapid operational and procurement execution.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Baggage Packaging Service Market to Reach USD 1,453.93 Million by 2032 at a 6.51% CAGR, Asia‑Pacific Leading with USD 322.25M
By PW Consulting, 2026-07-15
Worldwide Baggage Packaging Service Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s new market study—anchored on a 2025 base year and forecasting through 2032—provides a focused, decision‑ready view of the worldwide baggage packaging service market at a moment of structural change. Between 2020 and 2025 the market expanded materially, and our modelling projects sustained expansion through the forecast horizon at a compounded annual growth rate of 6.51%, reaching a market size in the mid‑hundreds of millions in 2025 and continuing to grow toward the low billions by 2032. For executives planning capital allocation, procurement strategy, M&A, or operational transformation in 2026, the report translates those headline dynamics into concrete choices and quantified scenarios—without losing sight of the tactical actions that deliver results within 12–36 months.
Worldwide Baggage Packaging Service Market
Why 2026 is a Pivotal Year
Three converging forces make 2026 a strategic inflection point for baggage packaging services: recovering and reconfiguring travel demand, accelerating sustainability and regulatory pressures, and technology upgrades at the point of service.
Worldwide Baggage Packaging Service Market
- Demand normalization with segmentation opportunities: Passenger volumes and international travel continue to recover post‑pandemic, but growth is uneven by route and service offering—creating pockets of premium demand (value‑added protection and tracking) alongside cost‑sensitive segments.
- Regulatory and sustainability inflection: Extended Producer Responsibility (EPR) regimes (notably in several U.S. states and multiple international jurisdictions) are shifting lifecycle costs onto producers and providers. Many operators are committing to biodegradable or fully recyclable films as part of their 2025–2027 sustainability roadmaps.
- Technology meets efficiency: Automation, machine upgrades and digital add‑ons (e.g., NFC tracking) are now productive levers to reduce materials consumption and unlock ancillary revenue streams.
For leadership teams, the practical implication is this: firms that treat 2026 as a year for targeted investment (efficiency + sustainability + digital) will capture disproportionate margin expansion and pricing power as travel demand stabilizes.
Worldwide Baggage Packaging Service Market
What the PW Consulting Report Delivers
This study is designed as a hands‑on toolkit for corporate strategists, procurement heads, investors, and airport operators. Key deliverables include:
- Proprietary market sizing and a transparent forecasting model (2026–2032) that maps demand drivers to revenue outcomes under multiple scenarios.
- Cost‑and‑margin archetypes for service operators (from compact single‑terminal kiosks to large franchise networks), including a deployable CapEx/Opex calculator for wrapping equipment.
- Regulatory impact assessment, synthesising global EPR trajectories and practical compliance pathways for packaging providers and airports.
- Commercial playbooks: contract negotiation checklists, bundling and pricing strategies, loyalty‑program integrations, and retail merchandising templates for terminal footprints.
- Vendor and technology evaluation frameworks—covering wrapping machines, film types (LDPE/LLDPE and biodegradable options), digital tracking hardware and software, and lifecycle assessment tools.
- An actionable M&A and partnership guide: due diligence templates, valuation sensitivities, and integration roadmaps for targets across the value chain (service operators, film suppliers, and equipment OEMs).
The analysis balances macro fidelity with operational relevance: readers will find both the headline market trajectory and the tactical steps needed to convert that trajectory into financial performance.
Competitive Landscape — Who Matters and Why
The market features a mix of global incumbents, regional specialists and local operators. Our competitive analysis synthesises primary research, operator interviews, and on‑site assessments. Representative company profiles included in the report:
- Safe Bag S.p.A. (TraWell) — An established global leader in airport baggage protection and tracing services. Recent product innovation (launched early 2025) introduced an automatic wrapping platform integrating NFC tracking and a significant material‑use improvement—key indicators of how incumbents are protecting margins through technology and sustainability claims.
- Secure Wrap — U.S. based operator offering TSA‑authorized services and customer‑friendly policies (e.g., complimentary rewraps after inspection). Their model highlights the value of compliance and customer trust in premium retail positioning.
- BagWrap — UK/European player focused on durable protection across airports and rail stations, with emphasis on ultra‑resistant films that also address weather and hygiene considerations.
- Wrap N’ Fly & TrueStar Group (Wrap and Fly) — Operators known for terminal throughput and franchise scalability. They exemplify two commercial models: high‑velocity terminal operations and franchised network expansion.
- Seal & Go — Notable for rapid sustainability moves, having rolled out biodegradable film services across UK airport locations in 2025; an example of first‑mover green positioning within established geographies.
- Encalm Enwrap — Indian operator offering biodegradable film options, underscoring the regional innovation response to local sustainability and regulatory pressures.
- Excess Baggage Company — Operator with a hygiene and security focus, leveraging ultra‑resistant films at major UK airports and selected overseas locations.
Collectively, top incumbents demonstrate three consistent strategic priorities: tighter operational efficiency through automation, public‑facing sustainability commitments, and incremental revenue development via digital services and insurance/bundling partnerships.
Segment and Supply Dynamics to Watch
At the segment level, the industry remains materially driven by film type and equipment productivity. Baggage wrapping primarily uses stretch films based on LDPE or LLDPE; shifts toward biodegradable or 100% recyclable films are accelerating, driven by airport procurement criteria and consumer expectations. Separately, raw material cycles matter: plastics packaging film pricing is volatile—illustrated by the US Producer Price Index for Plastics Packaging Film and Sheet Manufacturing, which reached 185.768 in March 2026—creating immediate cost‑pass‑through and hedging considerations for service providers.
Risk and Opportunity Matrix
- Risks: accelerating regulatory costs via EPR regimes; film price volatility; terminal access and concession fee pressure; reputational risk if sustainability promises are not backed by lifecycle evidence.
- Opportunities: premiumization through verified sustainable offers; ancillary revenue from digital tracking and claims management; cost savings from newer automatic wrapping platforms that materially reduce film consumption; consolidation plays where disciplined operators can scale fixed costs across more terminals.
Our report quantifies these levers: it models how a mid‑sized operator can improve unit margins through a single combination of machine upgrades, film substitution and revised pricing—while also modelling downside scenarios tied to sustained plastics price elevation or escalated EPR fees.
Recommended 2026 Playbook — Practical Next Steps
- Immediate (0–6 months): conduct a contract and cost audit focused on film procurement and concession economics; pilot biodegradable film with clear lifecycle disclosure and customer communication; run a proof‑of‑concept for NFC‑based tracking on high‑value routes.
- Near term (6–18 months): prioritize capital retrofit of wrapping fleets where ROI < 24 months (using our CapEx/Opex calculator); renegotiate supplier agreements with indexed pricing clauses tied to polymer indices; implement a customer upsell funnel (protection + tracking + insurance).
- Medium term (18–36 months): explore consolidation or strategic partnerships to secure film supply or equipment financing; integrate sustainability certification into procurement tenders; develop a modular software stack for claims and tracking that can be white‑labeled to airport partners.
Why This Report Matters to Executives in 2026
Our study is built to shorten the path from insight to implementation. It combines granular operational testing (equipment throughput, film consumption measurements), proprietary demand modelling through 2032, legal/regulatory scenario planning for EPR regimes, and commercial playbooks that have been road‑tested with airport partners and service operators. The result is not just a market forecast but a step‑by‑step guide you can use to prioritize investments, negotiate contracts, and evaluate M&A targets in 2026.
For readers seeking the complete dataset—detailed segmentation, regional and application breakdowns, modeled P&L impacts at operator level, and a downloadable interactive financial model—please consult the full PW Consulting report. The public brief above demonstrates the depth and practical orientation of our work; the full report contains the granular tabulations and appendices required for transaction‑level decision making.
PW Consulting remains available to run bespoke scenario workshops, underwriting exercises, or procurement negotiations informed by the report’s models and field findings. In a market where small changes in film usage, machine efficiency, or regulatory cost allocation can swing returns, a disciplined, data‑driven approach in 2026 will separate winners from laggards.
For detailed analysis of this topic, please visit the official page: Worldwide Baggage Packaging Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Single Point Anchor Reservoir Market to Rise from USD 1,420.5 Million in 2025 to USD 2,059.5 Million by 2032 at a 5.45% CAGR (2026–2032)
By PW Consulting, 2026-07-15
Worldwide Single Point Anchor Reservoir Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Single Point Anchor Reservoir (SPAR) market frames an industry at an inflection point. Our analysis shows the market expanded from USD 1,089.45 Million in 2020 to USD 1,420.50 Million in 2025 (base year), and is projected to grow to USD 2,059.53 Million by 2032. Across the 2026–2032 forecast window our models point to a compounded annual growth rate (CAGR) of 5.45%. These topline dynamics reflect the combined influence of extended deepwater hydrocarbons activity, the maturation of floating offshore renewables, and a reconfiguration of supply chains and manufacturing footprints.
Worldwide Single Point Anchor Reservoir Market
This press brief is designed as a strategic “trailer”: it demonstrates the depth and operational rigor of the full PW Consulting report while intentionally withholding granular segment-level disclosures to preserve the value of the complete analysis. Senior executives, strategy teams, and investment committees will find the perspectives below immediately actionable as they prepare capital allocation and partnership decisions in 2026.
Worldwide Single Point Anchor Reservoir Market
Why 2026 is a pivotal year for SPAR stakeholders
- Capex and project timing convergence: Several large-scale offshore projects initiated in the mid-2020s enter procurement and FEED phases in 2026–2027, compressing demand for long-lead equipment and specialist fabricators. Alignment (or misalignment) with these cycles will materially affect supplier bargaining power and project economics.
- Technology and design bifurcation: Truss, classic and cell SPAR architectures are each being optimized for different risk profiles—weight, fabrication complexity and lifecycle OPEX. Strategic product choices now determine competitiveness over the asset life, not just at handover.
- Energy transition impact: The growing role of floating offshore wind introduces new addressable demand and requires adaptations in anchoring strategies, interface standards and service models. Companies that treat renewables as a complementary market rather than a footnote will gain strategic optionality.
- Concentration and consolidation pressures: The market exhibits a meaningful degree of concentration (CR3 ~42.5%, CR5 ~61.25%), indicating scale advantages for incumbent leaders, while leaving space for consolidation plays, specialist entrants and vertically integrated challengers.
Key implications for executive decision-making
- Portfolio prioritization: Firms must re-evaluate product portfolios to balance near-term revenue capture against long-term service and retrofit opportunities. Prioritize designs and contracts that optimize total lifecycle returns rather than headline CAPEX reductions.
- Procurement and supplier strategies: With supply chain friction expected to persist in 2026, secure long-lead items through strategic volume agreements, co-investment partnerships, and capacity reservation clauses. Supplier scorecards and financial stress-testing are now essential bargaining tools.
- Manufacturing footprint and localization: Time-sensitive projects favor modular fabrication and localized assembly hubs. Assess trade-offs between centralized economies of scale and regional speed-to-install advantages in contract adjudication.
- R&D and materials innovation: Materials science (advanced steels and composites) and novel joining/welding techniques can alter weight and cost trade-offs. Invest selectively in demonstrable technology readiness levels that shorten schedule and reduce lifecycle costs.
- Service-led monetization: The installed base creates annuity streams—inspection, maintenance, retrofits and digital monitoring. Firms should productize lifecycle services and integrate them into bid economics rather than treating them as afterthoughts.
- M&A and alliance playbooks: Given market concentration, opportunistic M&A, bolt-on acquisitions and strategic JVs can accelerate capability access. Focus deal diligence on manufacturing know-how, long-term contracts, and addressable serviceable markets.
What PW Consulting’s full report delivers (practical, ready-to-use content)
- Robust top-line market sizing (historical 2020–2025, base year 2025) and granular forecasting for 2026–2032, including sensitivity to oil & gas pricing scenarios and renewables uptake.
- Scenario-based demand modeling with three distinct market paths (conservative, central, accelerated) and corresponding procurement timelines to help procurement and planning teams stress-test capacity needs.
- Commercial decision-support tools: downloadable CAPEX/OPEX models, break-even analyses, and bid-versus-build calculators aligned to standard project contracting mechanics.
- Supplier benchmarking templates and a procurement playbook that operational teams can use to evaluate fit-for-purpose fabrication partners, including financial resilience and delivery on-time metrics.
- Risk matrices and mitigation checklists covering geopolitical exposures, export controls, raw material inflation, and regulatory shifts related to offshore operations and decommissioning standards.
- A playable M&A diligence module: target screening criteria, valuation adjustment guides, integration scorecards, and synergy capture templates tuned to the SPAR market.
- Case studies and build-to-operate roadmaps from recent projects (anonymized) that distill lessons on schedule compression, interface management and cost overruns.
- Executive dashboards and an interactive data pack for board briefings—plug-and-play charts and scenario tables to support capex committees, investment memos and lender presentations.
Competitive landscape — what concentration means and how to act
The market’s measured concentration (CR3 ~42.5%; CR5 ~61.25%) signals that scale confers meaningful advantages—manufacturing leverage, integrated project delivery, and stronger negotiating positions with operators and EPC contractors. However, concentration also creates strategic openings:
Worldwide Single Point Anchor Reservoir Market
- Specialists can win on niche value: Firms that specialize in retrofit solutions, rapid-delivery kits, or bespoke interfaces for renewables projects can secure premium margins even without top-tier scale.
- Partnerships overcome scale gaps: Non-integrated players can pursue alliances with yard capacity owners, logistics providers and financing houses to offer turnkey propositions that mirror incumbent strengths.
- Vertical integration for margin control: Leading players will continue to pursue upstream and downstream integration—fabrication, mooring systems, long-term service contracts—to protect margins and stabilize revenue.
Operational priorities for teams executing 2026 strategies
- Fast-track validation of supply pipelines for key long-lead items and secure conditional allocations in 2026 contracts.
- Standardize interfaces and modularize sub-assemblies to reduce on-site schedule risk and enable parallel manufacturing streams.
- Embed digital twins and condition monitoring into new projects to create serviceable data estates and justify premium servicing contracts.
- Conduct systematic workforce planning: welding, composite assembly, offshore hook-up crews and digital engineering skills are decisive constraints.
- Adopt a staged investment approach where prototype builds de-risk full-scale tooling and allow early commercial references for buyers and lenders.
- Use procurement clauses to transfer specific inflation and schedule risks back to suppliers where feasible, while balancing contractor appetite to win work.
How to use this report in boardrooms and investment committees
Leaders can deploy the PW Consulting report to inform three critical processes for 2026:
- Scenario-led capital allocation: Integrate the report’s demand scenarios into capital planning cycles and use the downloadable models to quantify NPV impacts across alternative project timing assumptions.
- Negotiation and procurement strategies: Leverage supplier benchmarking outputs and procurement playbooks when negotiating conditional awards and capacity reservations.
- M&A and partnership diligence: Use the M&A module to establish target screens and to quantify synergy capture timelines—this reduces transaction execution risk and speeds post-deal integration.
Next steps — accessing the complete intelligence
This preview highlights the strategic choices that will define winners and laggards in the SPAR market as companies set course for 2026. The full PW Consulting report contains the proprietary models, playbooks and client-ready templates referenced above—materials designed to be operationalized immediately by strategy, commercial and operations teams.
To obtain the complete report, interactive data pack and to arrange a tailored executive briefing, visit the PW Consulting website or contact your account lead. For clients seeking hands-on support, PW Consulting offers customized workshops that translate the report’s outputs into board-level decision memos, procurement RFP templates and integration roadmaps.
PW Consulting’s outlook is clear: the SPAR market presents a mix of continuity and disruption. Companies that combine disciplined portfolio choices, supply-chain foresight, and pragmatic technology adoption will convert the projected growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Single Point Anchor Reservoir Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide HEA, HEMA, HPA & HPMA Market to Expand at a 5.28% CAGR Through 2032
By PW Consulting, 2026-07-15
Global HEA, HPA, HEMA & HPMA Market: Strategic Imperatives for 2026
Executive summary
The global market for hydroxy-functional acrylates and methacrylates—HEA, HPA, HEMA and HPMA—has entered a phase of steady, structurally-driven expansion. PW Consulting’s latest Worldwide HEA, HPA, HEMA, & HPMA Market study (base year 2025; historical run 2020–2025; forecast 2026–2032) shows the market at USD 1,530 Million in 2025 and projects growth to approximately USD 2,193 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.28% across the forecast window. Concentration metrics indicate a market where the top three and top five suppliers exert meaningful pricing and capacity influence (CR3 ~45.5%; CR5 ~62.3%), but a diverse cohort of regional and specialty producers continues to shape innovation and niche supply dynamics.
Worldwide HEA, HPA, HEMA, & HPMA Market
Why this report matters for 2026 decision-making
- Procurement and price risk management: Feedstock and upstream monomer dynamics are creating asymmetric cost pressures that materially affect margins across formulations and value chains. Procurement strategies built on static assumptions will underperform in 2026.
- Capacity and investment timing: New and expanded capacities—both from large incumbents and ambitious regional players—are altering utilization rates and near-term pricing. Timing capex or brownfield expansions requires scenario-tested forecasts and supplier-stability analysis.
- Regulatory compliance and product stewardship: Changes to emissions control regulations and renewed scrutiny of biomaterials used in medical applications mandate proactive compliance programs and material-risk mapping.
- M&A and partnership plays: With meaningful consolidation among leaders and fast-growing regional competitors, targeted acquisitions or strategic alliances can accelerate access to specialty grades, geographic markets, and downstream formulations.
Macro signals shaping 2026 strategy
The market profile in 2025–2026 is the result of intersecting macro forces. Raw material feedstocks that drive acrylate and methacrylate pricing have shown volatility: acrylic acid experienced sharp month-over-month swings in 2025 even as year-over-year trajectories moderated, and methacrylic acid saw regional quarter-to-quarter softening in late 2025 tied to export flows. Simultaneously, new global capacities and propylene feedstock trends introduced downward pressure on bulk monomer prices in H2 2025.
Worldwide HEA, HPA, HEMA, & HPMA Market
Regulatory shifts such as the US EPA’s HON emissions-control measures—now operating with temporary relief mechanisms for certain stationary sources—are reshaping permit timelines, capital expenditure planning, and emissions-reporting requirements for chemical manufacturing sites. In the medical-device domain, ongoing biocompatibility reviews of pHEMA and related materials underscore the need for rigorous material-data dossiers and proactive engagement with regulators and OEM customers.
Worldwide HEA, HPA, HEMA, & HPMA Market
Competitive landscape — how leading players are positioning
The market is anchored by global chemical majors and several specialized regional producers. Incumbents maintain advantages in scale, integrated feedstock access, and global distribution; specialty suppliers compete on high-purity grades, low-sensitization chemistries, and close technical support to formulators.
- Dow Inc. (Midland, Michigan) remains a cornerstone supplier with broad portfolio coverage across HEA/HPA/HEMA/HPMA and deep integration into coatings, adhesives, and resin value chains. Its scale and technical service capability are primary differentiators for multinational formulators.
- BASF SE (Ludwigshafen) continues to leverage technology-led offerings and has used price adjustments to manage margin erosion from energy and feedstock pressure—an indicator of how majors will balance commercial discipline with market share protection.
- Mitsubishi Chemical Group and Nippon Shokubai (Japan) have differentiated through high-purity, application-specific grades—especially for electronics, photoresists and medical uses—where regulatory and performance barriers raise switching costs.
- Evonik and Röhm (Germany) prioritize specialty methacrylate lines and branded resin systems, targeting formulators that require reactive diluents and tailored reactive-monomer blends.
- Wanhua Chemical (China) and other Chinese producers have rapidly scaled capacity and are actively pursuing both domestic and export opportunities; Wanhua’s announced capacity expansion for methacrylate grades in 2025 is an example of how regional scale-up is pressuring global utilization and pricing.
- Smaller and specialty producers—ranging from Dechem to Polysciences and regional Chinese manufacturers—are increasingly important for niche grades, research-focused supplies, and shorter lead-time service models.
Recent developments worth noting
- Capacity expansions from large regional players are shifting the supply balance and creating localized price deflationary pockets in H2 2025–2026.
- Price management actions by major producers reflect efforts to offset elevated energy and feedstock costs; these measures influence contract cycles and force buyers to reassess indexation clauses.
- Upstream feedstock volatility and regulatory updates continue to generate near-term commercial shocks; companies with flexible sourcing and robust hedging frameworks are positioned to outperform peers.
What PW Consulting’s report delivers (operational, decision-ready content)
Our study is designed for commercial and technical executives who must convert market intelligence into operational decisions in 2026. Core deliverables include:
- Proprietary, reconciled market size and long-run forecast models (USD Million basis), with base- and scenario-based outputs for 2026–2032 that stress-test demand under alternative GDP, construction, electronics and medical-device growth pathways.
- Supply-side mapping and a supplier heatmap that ranks manufacturers by scale, specialty capability, technical service, lead-time performance and regulatory standing—presented in an actionable supplier-score format for sourcing teams.
- Price-sensitivity and margin-stress tools that model the pass-through of acrylic- and methacrylic-acid cost shocks into finished goods under multiple contractual indexation schemes.
- Regulatory impact playbook covering emissions-control requirements, permitting timelines, and material-specific medical-device scrutiny—designed to prioritize compliance investments and documentation efforts.
- M&A and partnership screening: proprietary signals highlighting acquisition targets and JV candidates, including estimated strategic fit, integration risks and value-creation levers.
- Commercial playbooks for coatings, adhesives and medical-device OEMs: go-to-market tactics, formulation migration roadmaps to specialty grades, and customer-contract clauses to mitigate pass-through risk.
- CapEx decision toolkit: ROI calculators, utilization-sensitivity analyses and phased investment roadmaps that help finance and operations teams sequence capacity commitments.
Note: consistent with our “trailer” approach to this release, we present comprehensive, decision-ready insight in the full report. Detailed regional and application splits, supplier-specific volumes, and granular price decks are intentionally omitted from this public summary to preserve the actionable value of the primary deliverable.
Strategic plays for executives in 2026
- Refine procurement strategy: Move beyond single-index contracts. Implement multi-factor indexation, shorter reset periods for spot-exposed purchases and strategic forward-booking for specialty grades.
- Prioritize specialty portfolios: Allocate R&D and commercial resources toward low-sensitization and medical-grade chemistries where switching costs and regulatory barriers protect margins.
- Leverage supplier scorecards: Use performance-weighted scorecards to rebalance sourcing across global majors and nimble regional suppliers to optimize cost, service and regulatory risk.
- Stress-test capex decisions: Use scenario-based utilization and price models to phase expansions, retaining optionality against feedstock and demand cycles.
- Prepare for regulatory headwinds: Fast-track emissions-compliance timelines and strengthen materials data dossiers for medical applications to reduce approval and audit risk.
- Pursue targeted M&A: Acquire capability (high-purity grades, niche formulations) rather than scale alone; tuck-ins that provide technical service and customer intimacy can offer rapid payback.
How to use the full PW Consulting report
This press summary highlights the structural drivers, competitive dynamics and pragmatic plays that will define winners and laggards in 2026. PW Consulting’s full report provides the calibrated inputs and executable tools that procurement, commercial, regulatory and corporate development teams need to operationalize these plays—complete with downloadable spreadsheets, supplier matrices, contract templates and scenario models.
For teams preparing budgets, capex proposals, or M&A diligence in 2026, the report converts market-scale forecasts and concentration metrics into immediate, executable activities. If your decisions hinge on feedstock exposure, supplier resilience, regulatory timelines or specialty-grade adoption curves, the full report contains the granular intelligence and modelled outcomes required to justify and defend those choices to boards and investors.
Closing
As the HEA/HPA/HEMA/HPMA complex moves into a growth phase characterized by selective specialization and regional capacity shifts, executives who pair rigorous supply-side analysis with scenario-tested pricing and regulatory playbooks will capture disproportionate value. PW Consulting’s Worldwide HEA, HPA, HEMA, & HPMA Market report translates market-scale dynamics and concentration metrics into practical, accountable actions for 2026. To access detailed segmentation, supplier-level metrics, and the decision-ready tools referenced above, please refer to the full report and supporting data package.
For detailed analysis of this topic, please visit the official page: Worldwide HEA, HPA, HEMA, & HPMA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Paper Cup Sleeve Market Worth USD 642.5 Million in 2025, Set to Reach USD 916.2 Million by 2032 at a 5.19% CAGR — Corrugated Paper and North America Lead
By PW Consulting, 2026-07-15
Worldwide Paper Cup Sleeve Market: Strategic Insights for 2026 Decision-Makers
As companies finalize budgets and product roadmaps for 2026, the paper cup sleeve market presents a clear but nuanced opportunity: steady growth driven by foodservice expansion, sustainability mandates and material-cost dynamics that will reward proactive commercial and operational strategies. PW Consulting’s latest Worldwide Paper Cup Sleeve Market report (base year 2025, forecast period 2026–2032) quantifies that trajectory — the market expanded materially from the start of the decade and is projected to continue compounding at a mid-single-digit CAGR (5.19%) through 2032, reaching roughly USD 916 million by the end of the forecast. What follows is an executive distillation of the report’s strategic value to corporate decision-makers in 2026 — purposefully deep on implications, deliberately light on proprietary segment tables to encourage readers to access the full study for transaction‑grade detail.
Worldwide Paper Cup Sleeve Market
Why this market matters for 2026
-
Convergence of sustainability and regulation — Packaging rules in key jurisdictions and buyer expectations are compressing product lifecycles and redirecting purchasing criteria from price‑only to lifecycle cost and compliance readiness.
Worldwide Paper Cup Sleeve Market -
Predictable, investable growth — With a projected CAGR in the mid‑single digits across 2026–2032, cup sleeves remain an attractive incremental revenue stream for paper‑packaging players, branded coffee chains, and specialty converters that can scale without heavy capex.
Worldwide Paper Cup Sleeve Market -
Fragmented supply base — Market concentration is low compared with many other packaging categories (CR3 and CR5 measures indicate the sector remains decentralized). That fragmentation creates room for nimble suppliers to gain share via customization, sustainability credentials, and logistic excellence.
-
Price and input risk — Raw material volatility is real and uneven across regions (evidence from Q1 2026 kraft-paper price observations shows a material spread between major markets). This creates opportunities for cost arbitrage, blended sourcing strategies, and pass‑through pricing mechanisms.
What the report delivers — practical tools for 2026 action
Our research was designed for operators deciding where to allocate resources this calendar year. The report is not an academic exercise; it is a playbook. Highlights include:
-
Robust market-sizing and scenario modelling: baseline and three downside/upside scenarios for volume, price, and regulatory shock. These scenarios include sensitivity matrices so procurement, pricing and finance teams can stress‑test P&L impact under different pass‑through and adoption assumptions.
-
Regulatory impact modelling: bespoke modules that map the EU Packaging and Packaging Waste Regulation (effective from August 2026), multi‑state U.S. EPR regimes and California SB 54 trajectories into unit economics. The models quantify how modulated EPR fees and compostability mandates change landed cost and margin by product architecture.
-
Raw material and cost playbook: granular cost‑build templates that incorporate regional kraft and corrugated price inputs, energy, labor and freight. Users can input proprietary supplier quotes to produce supplier‑level margins and breakeven buy‑back points.
-
Product redesign ROI: engineering‑to‑commercial templates that evaluate alternative constructions (e.g., corrugated vs. kraft vs. embossing finishes; plant‑based linings versus conventional PE) based on recyclability, thermal performance and total landed cost.
-
Commercial and procurement toolkits: RFP templates, supplier scorecards focusing on sustainability credentials (FSC, compostable certifications), capacity mapping, minimum order economics and recommended contracting clauses for price‑indexation and EPR fee allocation.
-
M&A and partnership screening: a prioritized list of target profiles and a valuation overlay for tuck‑ins and regional converters that would help global players attain scale quickly in resilient segments.
Competitive landscape — who to watch and why
The market is served by a mix of global packaging majors, regional converters and specialist branding vendors. Leading firms demonstrate three strategic postures worth emulating or countering:
-
Integrated sustainability innovators — Companies that tie product launches to credible sustainability claims and systems (e.g., compostable linings or recycled content) are capturing premium placements with café chains and multinational quick‑service operators. Recent product introductions in 2025 underlined this trend and show how new material architectures can become a launch pad for cross‑category upsell.
-
Channel specialists and customizers — Several U.S. and China‑based players focus on rapid, brand‑centric customization (printed sleeves, promotional runs) and maintain differentiated value through responsiveness, digital print capacity and low minimums. These suppliers are attractive partners for retailers seeking co‑branding and local inventory flexibility.
-
Scale converters with integrated foodservice portfolios — Large packaging incumbents leverage distribution to major foodservice accounts, bundling sleeves with cups and lids to drive procurement consolidation. Strategic partnerships with national coffee chains or distributor networks materially de‑risk volume volatility.
Notable recent developments underscore these strategic postures: a major European supplier released fully compostable cup solutions in 2025, complementing insulated sleeve lines; a leading U.S. manufacturer announced a strategic partnership with a national coffee retailer to co‑develop insulated, recyclable cup systems; and an industry initiative launched in 2025 to pilot closed‑loop recycling programs in select municipalities. These moves highlight the acceleration of product‑level sustainability and collaboration between manufacturers, retailers and local stakeholders.
Market dynamics that will determine winners in 2026
-
Regulatory alignment: firms that can demonstrate product designs compatible with EPR scorecards and modulated fee regimes will preserve margin and retain access to priority tenders in regulated markets.
-
Cost engineering and sourcing: given the observed regional spread in kraft paper costs, organizations that implement blended sourcing, local converting and material substitution will protect margins and improve lead times.
-
Brand and co‑marketing capability: the sleeve is increasingly a branding surface. Suppliers offering integrated artwork, limited‑edition print runs and fast turnaround create stickiness with coffee chains and promotional calendars.
-
Operational resilience: low market concentration means opportunities for scale capture exist, but only for suppliers that can balance quality certifications, capacity and traceable supply chains.
Recommended 90‑day agenda for 2026
-
Procurement: implement the report’s supplier scorecard and RFP templates to run a renegotiation or dual‑sourcing exercise focused on EPR‑compliant alternatives and indexed pricing clauses linked to kraft benchmarks.
-
Product development: run a rapid three‑option piloting program (baseline, compostable‑lined, corrugated‑insulated) with at least two retail partners to gather thermals, recyclability validation and consumer feedback.
-
Commercial: pilot a premium “sustainability sleeve” SKU with branded co‑marketing; test price elasticity and measure take‑rate to inform roll‑out and margin models.
-
M&A/opportunities: screen regional converters that offer complementary design or print capabilities as bolt‑on candidates for volume capture in targeted markets.
Closing — the strategic value of full visibility
For 2026 corporate strategy and operating plans, the paper cup sleeve market is a classic example of a modestly growing, structurally changing category where timely, data‑driven moves create outsized returns. Our report synthesizes the quantitative forecasts, regulatory mappings, cost‑builds and supplier diagnostic tools that will answer the key business questions: How should we design product lines to meet upcoming regulatory thresholds? Where can we defensibly optimize cost without sacrificing compliance? Which partners best accelerate go‑to‑market at scale?
This article has surfaced the critical signals and the practical implications. To access the full segment tables, regional and application breakdowns, company financial snapshots, and the downloadable modelling templates referenced here, visit the PW Consulting report page. The full report contains the detailed, transaction‑grade intelligence that executives, procurement leaders and product teams will use to finalize 2026 commitments with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Cup Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laboratory Glass Container Market Set to Reach USD 6,157.6 Million by 2032, Expanding at a 5.42% CAGR
By PW Consulting, 2026-07-15
Worldwide Laboratory Glass Container Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market briefing on the Worldwide Laboratory Glass Container Market synthesizes five years of historical performance (2020–2025) and delivers a forward-looking view across the 2026–2032 forecast window. The market has demonstrated resilient expansion through the pandemic recovery, climbing from a mid‑single billion base in 2020 to a substantially larger ecosystem by the 2025 base year, and our top‑line forecast projects continued growth to reach over USD 6.1 billion by 2032 at a compound annual growth rate (CAGR) of 5.42% across the forecast period. For executives planning capital, sourcing, or M&A moves in 2026, the intelligence in this report converts market momentum into concrete strategic options.
Worldwide Laboratory Glass Container Market
Why this report matters for 2026 strategy
- Actionable market sizing with scenario-ready models. The briefing provides a validated top‑down market trajectory and scenario variants that stress-test growth against raw‑material price shocks, demand shocks in end‑markets, and accelerated substitution by engineered plastics. This enables CFOs and corporate development teams to quantify downside risk before deploying capital.
- Supply‑chain and input‑cost diagnostics. Borosilicate remains the dominant technical grade for laboratory containers due to its superior thermal shock and chemical resistance. Our study includes a detailed materials map — from boron inputs through soda ash and lime — and a sensitivity model that demonstrates how rising boron costs can pressure margins across manufacturing footprints.
- Competitive and concentration insights. The sector shows a moderate-to-high level of concentration: the three largest players control a material portion of the market and the top five capture more than half. That structure creates distinct opportunities for challengers to capture niches or for mid‑tier players to pursue consolidation strategies.
- Commercial playbooks that work. For product and commercial leaders, we translate market dynamics into go‑to‑market tactics: premiumization of borosilicate offers, bundled sterile-ready solutions, value-based pricing for specialty volumetric ware, and distributor partnership models to accelerate access to target labs and pharma customers.
Report contents — what you will find
- Proven market-sizing methodology and reconciled historicals (2020–2025), with an auditable forecast run to 2032.
- Demand-driver analysis across pharmaceuticals, diagnostics, academic research, and industrial labs, with scenario overlays for pandemic and macro downturn stress-tests.
- Supply‑chain heatmap and supplier risk matrix, including concentration of critical inputs and logistics chokepoints that influence lead times and working capital.
- Competitive benchmarking and capability mapping for leading manufacturers and significant regional suppliers, highlighting product portfolios, R&D positions, and route-to-market strengths.
- Commercial levers and procurement playbook: tactical sourcing options, contract structures, and price-protection strategies tailored to laboratory consumables.
- M&A and partnership playbook: screening criteria for targets, valuation sensitivities, and integration risk checklists, based on observed deal activity and gap analysis.
- Regulatory and compliance checklist linked to regional pharmacopeia and diagnostic standards that affect container qualification and time-to-market.
- Executive dashboards and Excel-ready models for NPV, break‑even, and cost-to-serve calculations, including a vendor scorecard template for supplier selection.
Competitive landscape: who matters and why
The market structure is populated by global incumbents, European tradition brands, and agile regional manufacturers. Global leaders are differentiated by scale, brand trust, and technical pedigree in borosilicate production. Niche players excel in custom apparatus, rapid prototyping or specialized cell culture systems, and often compete on lead time and service. Key strategic profiles covered in detail include:
Worldwide Laboratory Glass Container Market
- Global technology and brand leaders — companies with long heritage brands and deep technical IP in laboratory glassware that serve multinational pharmaceutical and industrial customers.
- European precision specialists — firms that focus on volumetric accuracy, high‑precision borosilicate ware, and pharmaceutical container-grade products. Their core strengths are product reliability and regulatory alignment for drug packaging.
- Regional champions and low-cost manufacturers — suppliers that combine broad catalogues with localized service models to serve educational institutions and regional lab markets at competitive price points.
- Custom and engineered glasshouses — smaller manufacturers and engineering shops that produce bespoke apparatus and serve high-value R&D and industrial clients.
Recent market moves illustrate strategic intent: a notable Indian manufacturer has expanded beyond commodity glassware into analytical vials, filtration products and pharma primary packaging through targeted acquisitions, signaling a deliberate pivot up the value chain. Separately, expansion of distribution agreements between instrumentation groups and major scientific distributors in the United States underscores the continued importance of channel strategies to reach end users rapidly.
Worldwide Laboratory Glass Container Market
Structural themes shaping decisions in 2026
- Premiumization vs. commoditization. Demand for high‑performance borosilicate for critical lab and pharmaceutical uses supports a two‑tier market: premium quality and cost-competitive commodity segments. Product positioning and Value‑Added Services (VAS) will determine margin trajectories.
- Input cost volatility. Boron feedstock and related inputs have placed upward pressure on production costs relative to soda‑lime alternatives. Procurement strategies, hedging options, and supplier partnerships will be decisive for margin protection.
- Single‑use plastics competition. Engineered plastics and single‑use systems continue to encroach on some laboratory workflows. Glass producers competing in these adjacent spaces are investing in value propositions around reusability, lifecycle cost and purity advantages.
- Regulatory and quality demands. Escalating regulatory scrutiny — especially for pharmaceutical primary containers — raises barriers to entry and increases qualification timelines, favoring established, compliant suppliers.
- Servitization and digitalization. Traceability, serialized vials, and integrated inventory solutions are becoming differentiators for customers seeking compliance and supply predictability.
Strategic playbook — priority moves for 2026
- Run scenario‑based capital allocation. Use the report’s sensitivity models to size CAPEX under different boron‑price and demand scenarios before committing to new furnace investments or greenfield capacity.
- Secure critical input channels. Establish dual‑sourced boron supply agreements, consider long‑term purchase contracts, and evaluate backward integration opportunistically if it materially improves margin resiliency.
- Differentiate through services. Bundle pre‑sterilized products, fast‑track qualification kits for pharma clients, and introduce traceability services to create switching costs and premium pricing opportunities.
- Pursue targeted M&A and partnerships. Prioritize acquisitions that add analytical vial capabilities, sterile packaging, or filtration competencies rather than chasing scale alone; integration playbooks in this report reduce execution risk.
- Optimize manufacturing footprint. Rebalance near‑market production for quick delivery to high‑value customers while leveraging cost‑efficient sites for commodity lines.
- Invest selectively in R&D. Focus on coatings, thermal‑shock resistant formulations, and closure compatibility to protect premium segments from plastic substitution.
How to use this intelligence
Executives should treat this briefing as the operational bridge between macro strategy and 2026 execution. Procurement teams can use the input‑cost models to renegotiate supplier terms; product leaders can apply the segmentation logic to prioritize SKUs for premiumization or cost‑reduction; M&A teams can use the valuation frameworks and vendor scorecards to accelerate due diligence while minimizing integration surprises.
For teams preparing board materials, the report’s executive dashboards offer ready visuals and stress scenarios for capital planning rounds. For commercial leaders, the companion go‑to‑market playbook contains channel scorecards and tactical pricing levers proven to increase penetration with diagnostic and pharma buyers.
Next steps and where to find the details
This article provides a strategic preview of the full Worldwide Laboratory Glass Container Market report. PW Consulting’s full study contains the granular segment tables, regional demand breakdowns, vendor scorecards, and downloadable financial models that underpin the recommendations above. To access the detailed intelligence required for transaction execution, sourcing negotiations, or product roadmap finalization, consult the full report and our tailored advisory engagements.
Our analysts and senior advisors are available to walk through bespoke scenario runs, supplier stress‑tests, or M&A target screens that align with your strategic priorities for 2026. Contact PW Consulting to schedule a briefing and translate these insights into a prioritized, executable plan.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Education Computing Devices Market Poised to Expand at a Robust 14.5% CAGR — Digital Classrooms Drive Demand Through 2032
By PW Consulting, 2026-07-15
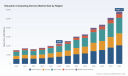
Worldwide Education Computing Devices Market — Strategic Preview for 2026 Decision‑Makers
As education systems worldwide enter a new procurement cycle in 2026, PW Consulting’s latest market study provides a timely, actionable intelligence package for executives who must align device strategy to learning outcomes, budget cycles and emerging technology risks. Our research shows the global education computing devices market accelerating from a 2025 base toward sustained expansion through 2032, underpinned by a projected compound annual growth rate (CAGR) of 14.5% over the 2026–2032 forecast window. The momentum reflected in our topline sizing — with the market crossing the USD 22.45 billion threshold in 2025 and continuing to expand rapidly thereafter — creates both opportunity and strategic complexity for vendors, school systems and investors alike.
Worldwide Education Computing Devices Market
Why this report matters for 2026
-
Timing of procurement cycles: 2026 will be a pivotal year for many districts and higher education institutions renewing 1:1 and shared device programs. Our study connects macro growth trends to practical procurement calendars, helping buyers synchronize RFPs, pilot programs and refresh schedules with expected supplier roadmaps and component availability.
Worldwide Education Computing Devices Market -
AI and connectivity convergence: Devices are no longer merely endpoints — they are gateways to cloud AI services and managed classroom ecosystems. The report explains how AI-enabled device features, OS-level integrations and classroom management tools are reshaping total cost of ownership and support models.
Worldwide Education Computing Devices Market -
Regulatory and infrastructure uncertainty: Recent judicial and policy shifts are altering the connectivity landscape. Our analysis interprets those shifts and quantifies strategic exposure so leaders can make defensible choices on zero‑rating, mobile data strategies and public‑private partnerships.
Report scope and practical deliverables
PW Consulting’s Worldwide Education Computing Devices Market report combines robust market sizing and scenario forecasting with highly practical tools for procurement and operations teams. Key deliverables included in the publication:
-
Market sizing and seven‑year forecasts (2026–2032) built from bottom‑up shipment and ASP models, reconciled to top‑down macro drivers and validated by vendor interviews.
-
Scenario frameworks that test demand under alternate assumptions for connectivity policy, device-as-a-service adoption, and classroom AI uptake.
-
TCO and lifecycle models that translate device specs, warranty choices and management platforms into multi-year budget scenarios tailored for K‑12 and higher education procurement cycles.
-
Vendor scorecards and go‑to‑market playbooks highlighting capability gaps, service propositions and supply chain resiliencies for major OEMs and ecosystem partners.
-
Playbooks for closing the digital divide: procurement templates, carrier engagement checklists, and operational models for large‑scale LTE/5G deployments and device staging.
-
Regulatory impact assessment and mitigation strategies: tailored guidance on zero‑rating programs, state‑level broadband regulation and energy‑related grid upgrades that affect deployment costs.
-
Case studies and pilot templates covering real implementations, change management plans for teacher adoption, and metrics to measure learning ROI.
Competitive landscape — what to watch in 2026
The market shows a moderate degree of vendor concentration: the top three vendors account for a meaningful plurality of supply, while the top five vendors represent a commanding share of the addressable market. This creates a two‑tier competitive dynamic where global OEMs set baseline platform capabilities and scale advantages, while tier‑two vendors and specialists compete on differentiation such as ruggedization, accessibility for special educational needs (SEND), or AI-enabled classroom services.
Our vendor intelligence examines product positioning and go‑to‑market strengths across the competitive set. Highlights include:
-
Long‑established OEMs that have built education‑specific SKUs focused on durability, manageability and serviceability — these players continue to win large institutional contracts where scale and lifecycle support are decisive.
-
Manufacturers emphasizing affordability and classroom‑centric features — they remain attractive to cost‑constrained districts and frequently lead in Chromebook and value laptop segments.
-
Platform owners and OS providers that shape the ecosystem through management consoles and AI services, influencing procurement decisions beyond hardware specifications.
Recent industry movements that will influence 2026 decisions are highlighted in the report. Examples include January 2026 product introductions by major OEMs that bring Wi‑Fi 7, AI‑enhanced devices and SEND‑focused designs to market; and large municipal deployments that demonstrate new connectivity-first procurement approaches. These real‑world events inform our vendor risk assessments and partnership recommendations.
Connectivity, regulation and infrastructure — risk factors that matter
Two regulatory developments and one major industry commitment dramatically change the risk calculus for device programs:
-
A notable judicial decision altered federal broadband classification in the United States, shifting enforcement dynamics and increasing the role of states and legislatures. For education buyers this raises uncertainty about future pricing and the permissibility of zero‑rating or prioritization programs intended to protect digital learning traffic.
-
Public interest exceptions in some jurisdictions preserve the ability to prioritize educational content — a pathway for school systems to secure usable bandwidth for learners. The report examines legal contours and policy levers that procurement teams should monitor before committing to long‑term carrier agreements.
-
Major cloud and technology companies have publicly committed to underwriting new power generation and grid upgrades for data center expansion. While this reduces some upward pressure on residential rates, it also signals an industry shift where energy‑related infrastructure costs are increasingly material to total deployment economics for cloud‑backed education services.
Combined, these elements change how institutions should evaluate carrier partnerships, device selection and content delivery strategies. Our models quantify the sensitivity of device TCO to connectivity cost escalations and to different regulatory outcomes, enabling procurement teams to stress‑test budgets and contract clauses.
Strategic implications and actionable recommendations for 2026
-
Adopt scenario‑based procurement. Do not base multi‑year contracts on a single forecast. Use scenario outputs to specify flexible renewal windows, connectivity fallbacks and price indexing tied to proven cost drivers.
-
Design device portfolios for manageability and teacher workflows. Prioritize platforms that minimize IT overhead through zero‑touch enrollment, standardized management tooling, and predictable warranty/service chains.
-
Build carrier relationships early. With connectivity an explicit part of many device programs (including large municipal LTE/5G rollouts), negotiate pilot‑to‑scale pathways and carve‑outs for zero‑rating where legally permissible.
-
Factor AI and accessibility into adoption roadmaps. Devices with on‑device AI acceleration or curated cloud integrations change software procurement and professional development needs — include teacher upskilling and content licensing in total program budgeting.
-
Prioritize lifecycle sustainability. The combination of supply chain pressures and energy‑related infrastructure costs favors longer refresh cycles, refurbishment programs and as‑a‑service models that can transfer risk and reduce upfront capital requirements.
-
Insist on data‑driven vendor scorecards. Require prospective suppliers to disclose deployable metrics — mean time to repair, zero‑touch enrollment rates, carrier interoperability test results — and benchmark those in contract SLAs.
What the full report unlocks
This preview outlines the strategic themes that will dominate education device decisions in 2026: accelerating market scale, AI and connectivity convergence, regulatory uncertainty and a competitive field shaped by a handful of large OEMs and an active ecosystem of specialists. PW Consulting’s full report delivers the operational detail to act on these themes, including downloadable procurement templates, editable TCO models, a proprietary vendor scoring matrix, and region‑level implementation playbooks. Critical granular intelligence — regional demand mixes, device‑type share curves and the full vendor scorecard data — are intentionally withheld in this summary to protect commercial sensitivity and to direct decision‑makers to the source documentation where they can access validated, auditable tables and models.
Next steps for leaders
Leaders preparing 2026 budgets and procurement strategies should prioritize scenario planning, accelerate carrier and vendor pilots, and align IT, curriculum and finance stakeholders behind a multi‑year deployment framework. PW Consulting is offering tailored briefings and workshop sessions to translate our market forecasts and tools into organization‑specific action plans. For organizations that require immediate tactical support — from RFP language and supplier evaluation to pilot design and SLA negotiation — our advisory teams are standing by to deliver rapid, evidence‑based assistance.
Access the full Worldwide Education Computing Devices Market report for the complete datasets, vendor scorecards and executable playbooks that will enable confident, defensible decisions in 2026 and beyond. Detailed regional splits, device‑type scenarios and the full quantitative appendices are available exclusively in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Outdoor Sound Barriers Market Set to Grow at a 5.06% CAGR Through 2032
By PW Consulting, 2026-07-15
Worldwide Outdoor Sound Barriers Market — 2026 Strategic Preview
PW Consulting today releases an executive preview of its forthcoming Worldwide Outdoor Sound Barriers Market report, delivering forward-leaning analysis designed to shape corporate and public-sector decisions in 2026. This preview outlines the market’s macro trajectory, emergent risks and opportunities, and the practical intelligence executives will need to convert acoustic strategy into measurable project outcomes. It intentionally showcases the depth and applicability of the study while reserving the segmented data and full benchmarking tools for the full report.
Worldwide Outdoor Sound Barriers Market
Why this report matters for 2026 decisions
-
Actionable timing: The outdoor sound barriers market enters 2026 from a position of steady expansion — PW Consulting’s base-year assessment pegs global market revenue at approximately USD 6.45 billion in 2025, with a multi-year compound annual growth rate (CAGR) of roughly 5.06% through our forecast horizon. This trajectory creates immediate windows for procurement, retrofit programs and product innovation that decision-makers should not miss.
Worldwide Outdoor Sound Barriers Market -
Regulatory inflection: Recent updates to outdoor noise measurement standards and EU-level regulations have accelerated demand for verifiable attenuation performance and transparent reporting. Buyers and suppliers who can demonstrate compliance and auditable performance will capture outsized share in tender processes.
Worldwide Outdoor Sound Barriers Market -
Cost and supply-chain sensitivity: Volatility in core raw materials — notably steel — is reshaping vendor economics and favoring design strategies that emphasize modularity, alternative materials and lifecycle cost optimization.
Snapshot of the market trajectory
After recovering from pandemic-era disruptions, the market reached a near-term milestone in 2025. PW Consulting’s modeling shows the market expanding further through the 2026–2032 forecast window, supported by infrastructure renewal programs, urban densification, industrial decarbonization projects and increasing expectations for acoustic comfort in residential and mixed-use developments. While growth is steady rather than exponential, the market's profile favors firms that can combine engineering rigor with procurement-friendly commercial models such as hire/purchase, modular supply and outcomes-based contracting.
Key macro drivers and their strategic implications
-
Standards and compliance: The 2024–2025 cycle saw important updates to outdoor noise engineering practices (notably ISO 9613-2 revisions) and implementation of new reporting requirements across EU member states. Companies must translate these technical changes into project-level risk matrices and updated specification templates. Clients should require accredited modeling and measurement evidence as part of tender documentation to reduce post-installation liability.
-
Raw material dynamics: Engineering News-Record data and industry price forecasts indicate a meaningful rise in steel costs through 2025, with price stabilization at mid-2025 levels. Procurement teams should adopt hedging strategies, multi-sourcing and design-for-material-substitution to mitigate input-cost exposure. Suppliers that present transparent commodity pass-through clauses and lifecycle cost analyses will win longer-term contracts.
-
Product innovation and materials mix: Demand is shifting toward solutions that balance performance, aesthetics and durability — from high-performance absorptive walls to lightweight composite and transparent systems. Manufacturers able to certify acoustic performance while reducing embodied carbon or installation time will be advantaged in public and private tenders.
-
Temporary and rental models: The rise of portable acoustic barriers for construction and event applications introduces recurring-revenue opportunities and alters procurement dynamics for short-term works. Rental providers with robust logistics and rapid-deploy systems create alternative channels to traditional capital procurement.
Competitive landscape — what to expect
The market exhibits a low-to-moderate level of concentration: the top three and top five players together account for a minority share, underscoring a fragmented competitive environment and significant regional incumbency effects. For strategic buyers and investors, this fragmentation creates multiple pathways: consolidate through M&A, partner via white-label agreements, or specialize in niche high-performance segments.
Our company-level analysis in the full report profiles established incumbents and fast-moving specialists, mapping capabilities, service models and recent strategic moves. Highlights from our corporate review include:
-
Sound Fighter Systems (United States) — Longstanding expertise in fully absorptive, high-performance outdoor walls. Their emphasis on demonstrable dB reductions for highways and industrial projects positions them well for infrastructure contracts that prioritize acoustic performance.
-
AIL Sound Walls (Canada) — A turn-key provider that blends absorptive and reflective solutions, serving municipal and residential categories where ease of integration and compliance are as important as attenuation.
-
Echo Barrier (United Kingdom) — A leader in portable and temporary acoustic barriers with hire and purchase models; their business model exemplifies the recurring-revenue opportunity in short-duration applications such as construction, events and demolition.
-
Kinetics Noise Control, IAC Acoustics, Noise Barriers and ArtUSA — Each brings differentiated product portfolios and regional strengths, from lightweight panel systems to Noishield and QuietLine product families tailored to exterior environments and industrial applications.
-
Acoustiblok, Acoustic Sciences Corporation and Sound Seal — Specialists in retrofit systems, fence-integrated absorptive inserts and fabric/assembly-based solutions that cater to residential, commercial and small industrial deployments.
Recent corporate moves — product launches, trade-show demonstrations and content updates — signal a marketplace intent on proving performance, diversifying delivery models and addressing procurement friction points. PW Consulting’s report translates these developments into vendor scorecards and strategic engagement playbooks so buyers can shortlist suppliers against measurable RFP criteria.
Practical intelligence and tools included in the full report
PW Consulting’s full study is built for decision activation. Among the operational tools and deliverables that underpin the report’s utility are:
-
Robust market-sizing and demand scenarios using multiple adoption curves—enabling capital planners to stress-test budgets under conservative, base-case and accelerated deployment assumptions.
-
Procurement playbooks and specification templates aligned to the latest measurement standards and regulatory frameworks—designed for infrastructure owners, municipal buyers and private developers.
-
Lifecycle cost models and TCO calculators that compare material classes, erection methods and maintenance regimes—helping buyers quantify operating expense trade-offs and carbon-intensity considerations.
-
Vendor performance scorecards, M&A maps and an integration roadmap for acquirers looking to consolidate capabilities across materials, installation and measurement services.
-
Implementation checklists and risk matrices for temporary barrier deployments, retrofits, and large linear infrastructure projects (e.g., highways, rail corridors, plant perimeters).
Strategic recommendations for 2026
-
Procurement modernization: Adopt outcomes-based contracting where feasible. Require pre- and post-installation acoustic verification aligned to updated ISO and EU measurement regimes to reduce warranty claims and to create performance benchmarks.
-
Material and supplier diversification: Lock in options across metal, composite and transparent systems while building relationships with rental specialists for short-term needs. Design specifications should allow substitution without compromising measured performance.
-
Invest in modularization and logistics: For large linear projects, modular panel systems that reduce on-site labor and installation time materially decrease schedule risk and enable faster noise mitigation delivery.
-
Pursue targeted M&A and partnerships: Given the market’s fragmentation, complementary acquisitions (e.g., a high-performance panel maker plus a logistics-enabled rental operator) can accelerate growth and entry into adjacent geographies.
-
Design for resilience and sustainability: Embed maintenance pathways and recyclability into product specifications. Procurement teams should value lifecycle carbon metrics and serviceability as part of total cost evaluation.
Risks and contingencies
-
Commodity shocks: Sudden moves in steel and polymer pricing can compress margins or prompt specification swaps — include contractual mechanisms for material-cost pass-throughs or fixed-price hedging for long-term frameworks.
-
Regulatory misalignment: Differing national implementations of measurement standards create project-level compliance complexity; require vendors to demonstrate local accreditation and provide harmonized modeling inputs.
-
Performance verification: Without robust third-party measurement programs, buyers risk accepting sub-optimal installations. Insist on independent acoustic testing clauses in contracts and royalties for performance warranties.
What the full report delivers (and how it supports execution)
PW Consulting’s complete Worldwide Outdoor Sound Barriers Market report goes beyond descriptive forecasting; it equips practitioners with the tools needed to act. The full package contains the detailed segmented market analysis, proprietary vendor benchmarking, regional deployment scenarios, procurement templates, and downloadable financial models that underpin the executive recommendations summarized here. For investors, the report outlines priority investment themes and potential consolidation targets informed by our supply-side due diligence. For public owners and contractors, the report provides specification libraries and installation cost indices tied to current commodity dynamics.
To preserve the integrity of vendor-sensitive benchmarks and client-grade model outputs, this preview deliberately omits granular regional and application splits — these are fully documented and interactive in the complete report, which also includes downloadable spreadsheets and scenario workbooks.
Next steps
Organizations evaluating noise mitigation portfolios, drafting procurement documents for infrastructure projects, or sizing investment programs for acoustic product lines should use this preview as the strategic starting point for 2026 planning. PW Consulting’s analysis translates market momentum, regulatory change and supplier dynamics into operational actions and deal-ready intelligence.
For access to the complete dataset, vendor scorecards, and the procurement toolset, please visit the PW Consulting report landing page and download the full Worldwide Outdoor Sound Barriers Market study. The full report contains the segmented data, company benchmarking, and executable templates that will convert insight into outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


