



Category: market research
PW Consulting: Laser Line Dielectric Mirror Market Set to Expand at a 6.25% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Laser Line Dielectric Mirror Market 2026: Strategic Imperatives for Executives — PW Consulting Release
As laser systems continue to proliferate across industrial, medical, scientific and defense platforms, the market for laser line dielectric mirrors is entering a phase of sustained, structurally driven growth. PW Consulting’s new market study — covering 2020–2025 history with a 2026–2032 forecast — shows the global market expanding from approximately USD 326.1 Million in 2020 to USD 441.6 Million in 2025, and projected to reach USD 675.1 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of 6.25% across the forecast window. For senior executives and strategic planners, the takeaway is clear: positioning in this market during 2026 will determine competitive advantage for the remainder of the decade.
Laser Line Dielectric Mirror Market
Why this report matters for 2026 corporate decision-making
-
Actionable foresight: The market is no longer a boutique optics niche. Measured growth—supported by increasing industrial laser deployments, expanded medical diagnostics, and programmatic defense spending—means companies must move from ad-hoc sourcing and product development to disciplined commercial strategies.
Laser Line Dielectric Mirror Market -
Operating model choices: Procurement, qualification cycles, and capacity planning for coatings and substrates are becoming strategic levers. Lead-time variability and material constraints now influence product roadmaps and customer commitments.
Laser Line Dielectric Mirror Market -
Capital allocation and M&A timing: With mid-single-digit CAGR and pockets of higher-margin custom work, 2026 is the inflection year to decide whether to invest in in-house coating capabilities, enter supply partnerships, or pursue tuck-in acquisitions to secure critical IP and capacity.
What PW Consulting’s study delivers (practical, executable content)
-
Executive summary with thematic scenarios — three go-to-market pathways mapped to different demand and regulatory outcomes.
-
Commercial playbooks — supplier qualification checklists, time-to-qualification matrices, and procurement negotiation frameworks tailored for dielectric mirror specifications (coating technology, LIDT, GDD, substrate selection).
-
Technology & product roadmaps — comparative analysis of coating approaches (e-beam, IBS, sputtered thin films), design trade-offs for ultrafast vs. high-energy mirrors, and recommended R&D priorities to reduce Total Cost of Ownership (TCO).
-
Supply-chain resilience toolkit — supplier tiering, lead-time stress tests under export-control scenarios, alternate material sourcing playbooks, and a quantifiable inventory buffer model by risk profile.
-
Competitive scorecards — capability maps, upstream partnerships, and go-to-market strengths for the leading OEMs and specialist coaters, enabling rapid benchmarking and partner selection without wading through raw datasheets.
-
Scenario-based financial models — topline and margin sensitivities under price pressure, material-supply shocks, and accelerated adoption in adjacent applications (e.g., ultrafast scientific lasers, high-power material processing).
-
Regulatory & compliance impact assessment — jurisdictional risk heatmaps and pragmatic mitigation steps for export-control and raw-material constraint scenarios.
Competitive landscape — who matters and why
The market blends large, diversified optics suppliers with nimble specialist coaters. PW Consulting’s analysis profiles a cross-section of strategic players to illuminate realistic partnership, supplier, and M&A options:
-
Thorlabs (Newton, NJ, USA) — Strength lies in broad catalog offerings and strong channel presence for laboratory and industrial customers. Their product set includes variants tuned for specific laser lines with practical emphasis on reliability and field support.
-
Newport Corporation / MKS Instruments (Irvine, CA, USA) — Known for narrowband, high-reflectance solutions and strong engineering services around integration into OEM systems; attractive as a systems-level supplier partner.
-
Edmund Optics (Barrington, NJ, USA) — Breadth across source types (Nd:YAG, Ti:sapphire, Yb:YAG) and ultrafast-compatible variants position them well where low group delay dispersion matters.
-
European precision coaters (Layertec, OPTOMAN, Alien Photonics, EKSMA Optics) — High-precision coatings, IBS expertise and capability to supply large reference mirrors and ultrafast designs make them preferred partners where performance trumps unit cost.
-
China-based manufacturers (Hangzhou Shalom EO, Shanghai Optics) — Offer competitive pricing and customization speed for narrowband and UVFS options; strategic for firms seeking cost-effective sources but requiring robust qualification programs.
-
Specialist high-power and high-LIDT vendors (LASER COMPONENTS, Perkins Precision, Alien Photonics) — Focused on high-energy mirrors and advanced thin-film stacks, attractive where laser-induced damage threshold (LIDT) and long-term reliability are core purchase drivers.
Collectively, these players create a market where top suppliers account for a meaningful share of sales but do not completely dominate — leaving room for specialized entrants and integrators. This dynamic supports multiple viable strategic plays: partner for scale, niche for margin, or consolidate capacity through targeted acquisitions.
Recent product and supplier moves — implications
-
New product introductions and catalog refreshes (examples: large reference mirrors and coatings engineered for higher LIDT or ultrafast performance) signal suppliers are betting on premium, application-specific demand.
-
Supplier awards and trade show activity indicate shortened qualification cycles for high-performing vendors and growing buyer emphasis on lead time and quality consistency.
-
These developments increase the commercial value of supplier scorecards and qualification playbooks — things we include in the full report.
Supply-chain and regulatory realities to factor into 2026 plans
Geopolitical shifts and export control regimes have moved from background risk to boardroom priority. Recent export restrictions and new controls on critical materials have tightened access to certain coating materials and processing equipment, creating price volatility and elongated lead times. Meanwhile, common substrates such as fused silica and Zerodur remain essential inputs; their availability and the dependency on a limited set of upstream suppliers should be modeled into procurement and inventory policies.
Implication: firms that execute dual-sourcing strategies, pre-qualify alternate material stacks, and invest in strategic safety stock can convert supply-side risk into a competitive advantage. The report supplies a practical stress-test framework you can run against your supplier base in Q1–Q2 2026.
Technology & product trends shaping buying decisions
-
High-LIDT coatings and IBS processes are becoming baseline requirements for high-energy material-processing systems.
-
Ultrafast-compatible mirrors with low GDD are driving differentiation in scientific and medical instruments.
-
Multi-wavelength and broadband solutions reduce SKUs for OEMs but increase coating complexity and qualification burden.
-
Custom assemblies (pre-aligned modules and large reference mirrors) are an expanding margin pool for suppliers that can meet tight tolerances.
How executives should use this study in 2026 — five pragmatic recommendations
-
Run a 90-day supplier concentration audit: identify single-source exposures and create a prioritized dual-source plan with qualification timelines.
-
Calibrate R&D spend to performance vectors that the market rewards — prioritize LIDT improvements, ultrafast performance, or cost-to-qualification depending on your end markets.
-
Design procurement contracts with indexed clauses for material-price pass-throughs and lead-time SLAs to mitigate raw-material-driven margin compression.
-
Evaluate targeted M&A for capability gaps — particularly in high-precision coating, IBS processes, or large-scale mirror manufacturing — where integration accelerates time-to-market.
-
Implement a regulatory-watch function to monitor export-control developments and regional sourcing constraints; incorporate trigger-based playbooks for immediate execution.
About the full PW Consulting report and next steps
This press summary highlights the strategic contours of a market that is both maturing and being reshaped by materials, coatings technology, and geopolitical dynamics. PW Consulting’s complete study provides the granular intelligence corporate leaders need to act in 2026: detailed revenue and volume forecasts by market slice, supplier lead-time and performance matrices, company scorecards with capability assessments, and downloadable financial models to test strategic choices.
For procurement directors, product leaders, and corporate development teams preparing their 2026 roadmaps, the report is intended as a tactical instrument — not merely a descriptive study. It is structured to accelerate decision cycles, lower execution risk, and identify where to invest for defensible, high-return positions across the laser line dielectric mirror ecosystem.
Access to the full dataset, methodology, and downloadable tools is available via PW Consulting’s report page; the public summary is designed to demonstrate the rigor of our work while preserving the detailed segmentation that clients rely on for competitive advantage.
For detailed analysis of this topic, please visit the official page: Laser Line Dielectric Mirror Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Naloxone Market Climbs to USD 920 Million in 2025 — Strong Growth Outlook Ahead
By PW Consulting, 2026-07-13
Naloxone Market 2026: Strategic Imperatives from PW Consulting’s Market Research
Executive summary
PW Consulting’s latest Naloxone Market report synthesizes epidemiology, regulation, procurement, product innovation and supply-chain risk into an actionable strategic playbook for commercial and public-sector decision-makers planning for 2026. The market has moved from a crisis-driven emergency response product to a professionally managed public-health commodity with meaningful commercial dynamics; our analysis quantifies that transition and translates it into decisions that will determine winners and losers over the coming planning cycle.
Naloxone Market
Market snapshot — what the headline numbers tell you
Underpinned by rising demand and shifting distribution models, the naloxone market has shown sustained expansion over the 2020–2025 historical period and enters the 2026–2032 forecast window with robust momentum. On a base-year (2025) of USD 920 Million, the market is projected to continue growing at a compound annual growth rate (CAGR) of approximately 8.2% through our forecast horizon, reaching a materially larger market size by the end of 2032.
Naloxone Market
These headline metrics reflect a confluence of factors: the continuing public-health burden of opioid overdoses, expanded regulatory access (including OTC pathways), active public procurement and evolving reimbursement rules. For strategic planners, the headline takeaway is simple — demand is both enlarging and structurally changing; companies that treat naloxone as a static legacy product will cede share to organizations that re-design products, channels and contracts to the new reality.
Naloxone Market
What’s inside the PW Consulting report (practical, transaction-ready deliverables)
- Market sizing and demand modelling that reconciles epidemiological scenarios with procurement and retail adoption curves.
- Scenario-based forecasts (conservative, base, accelerated) with sensitivity to OTC adoption, public-stockpile replenishment and major regulatory shifts.
- Competitive benchmarking: product positioning, manufacturing footprint, route-to-market capabilities and financial exposure for the leading suppliers.
- Go-to-market playbooks for manufacturers, distributors and public-health agencies covering OTC retail, institutional tenders, community distribution and OEM partnerships.
- Supply-chain resilience analysis: critical raw-material nodes, single-source risks, and tactical mitigation actions (dual-sourcing, fill-finish flex capacity, contract buffers).
- Commercial models: pricing architecture for institutional vs retail channels, reimbursement sensitivity analysis, and payer engagement frameworks.
- M&A and partnership scouting: prioritized target profiles, valuation ranges under different integration synergies and post-merger integration risk matrices.
- Operational checklists and procurement templates for 2026 tenders and national stockpile negotiations.
Competitive landscape — who matters and why
The naloxone market today is characterized by a mix of branded innovators, large generics players and specialized injectables suppliers. Our competitive review profiles the major players, their strategic strengths and the near-term moves that will shape share dynamics in 2026:
- Emergent BioSolutions (Gaithersburg, MD) — market-leading Narcan nasal spray franchise with a strong OTC push and significant brand recognition in many public-health programs.
- Amphastar Pharmaceuticals (Santa Ana, CA) — entrenched in injectable naloxone supply for emergency medical services and hospital use, with manufacturing depth but exposed to lot-specific quality and recall risk events.
- Teva Pharmaceutical Industries (Petah Tikva, Israel) — global generics scale that allows rapid price-response and broad distribution of nasal and injectable formats.
- Viatris Inc. (Canonsburg, PA) — leverages generics and device partnerships to compete across retail and institutional channels.
- Hikma Pharmaceuticals (London, UK) — hospital/EMS supply specialist with significant reach in multiple regulatory jurisdictions.
- Pfizer Inc. (New York, NY) — institutional incumbent via Hospira portfolio, notable for hospital procurement relationships and global logistics capability.
- Sandoz International GmbH (Basel, Switzerland) — European generics competitor with strong regulatory depth and device formulation experience.
Market concentration metrics indicate a moderate level of concentration among the top competitors, which creates both opportunities for entrenched players to leverage scale and windows for nimble entrants (innovative devices, differentiated OTC packaging, or integrated services) to capture incremental share.
Recent regulatory, procurement and supply dynamics
Regulatory and public-health developments have materially altered the operating environment:
- Regulatory access: FDA’s authorization of OTC naloxone nasal spray has shifted demand from prescription-limited channels to retail and community distribution models, accelerating consumer-facing adoption.
- Procurement: major public procurements and national stockpile purchases over the last 18–24 months have materially impacted short-term demand timing and created exigent supply pressure for manufacturers.
- Innovation and competition: market entry by generic nasal-spray equivalents and new OTC pack formats has broadened choice while intensifying price pressure in certain channels.
- Clinical and social drivers: provisional mortality data continue to show a high absolute burden of opioid-involved overdose deaths, driving policy and funding continuity in many markets.
- Supply-side fragility: intermittent shortages of injectable naloxone and isolated quality recalls underscore the continued vulnerability of supply chains where capacity and quality controls are uneven.
Strategic playbook for 2026 corporate decisions
For executives preparing 2026 operating plans, the PW Consulting report translates market intelligence into prioritized actions:
- Revisit portfolio strategy. Classify products by channel (OTC retail, institutional, community programs) and assign investment priorities. Prioritize formats and pack configurations that align with payer coverage and retail shelf economics.
- Secure manufacturing resilience. For companies that rely on single plants or single suppliers for critical inputs, accelerate dual-sourcing, contract manufacturing options and fill–finish contingency agreements to avoid near-term shortages.
- Channel-specific pricing and commercial models. Move beyond a one-price-fits-all approach: institutional tenders, retail OTC, and community distribution programs have distinct price elasticity and procurement rules—tailor contracts and rebates accordingly.
- Engage payers and procurement authorities proactively. Demonstrate value through real-world evidence (RWE), cost-offset modeling and distribution logistics to secure favorable formulary placement and procurement awards.
- Design OTC go-to-market execution. OTC success requires packaging, consumer education, retail placement and pharmacist engagement—plan cross-functional launches that integrate marketing, regulatory and trade strategies.
- Explore alliances and vertical partnerships. Consider licensing device innovations, co-marketing with harm-reduction organizations, or distribution partnerships to accelerate uptake in community programs.
- Prioritize quality governance. Strengthen lot-release testing, supplier audits and recall-readiness plans—investing here protects revenue and reputation in the event of quality incidents.
- Use M&A selectively. Target deals that bring scale in fill–finish, differentiated device IP, or preferred access to public procurement channels; use integration playbooks that secure supply and preserve channel relationships.
How to apply the report in practical 2026 workflows
Decision-makers will find specific modules in the PW Consulting report that map directly to typical 2026 planning cycles:
- Finance teams: use the scenario forecasts and sensitivity tables to stress-test return-on-investment cases for capacity expansion or new product launches.
- Commercial teams: deploy the channel playbooks and competitor reaction matrices to shape tender strategies and retail launch plans.
- Procurement and operations: implement the supplier risk heatmaps and mitigation templates to shorten time-to-reline for critical inputs.
- Regulatory and legal: leverage our country-by-country policy tracker to calibrate registration timelines and OTC conversion strategies.
- Corporate development: use our prioritized M&A target list and valuation frameworks for disciplined deal sourcing and diligence.
Why this report matters for 2026 — the strategic value condensed
2026 will be a year when access policy, brand positioning and supply resilience intersect to determine market outcomes. Our market sizing and scenario analysis provide revenue and volume envelopes; our competitive and procurement intelligence show where contracts and access will be decided; our operational playbooks reduce execution risk. For executives, the report reduces uncertainty in three critical dimensions: demand timing, price pressure, and supply reliability — enabling sharper capital allocation, smarter contract bids and faster go-to-market execution.
Next steps and how to access full intelligence
This article is a strategic preview. The full PW Consulting Naloxone Market report contains proprietary, granular segmentation tables, regional and channel forecasts, unit-level pricing scenarios, and downloadable operational templates that are intentionally omitted from this summary. To obtain the complete report or to request a bespoke executive briefing tailored to your organization’s exposure and ambitions, please contact PW Consulting via our official channels. We also offer focused 1:1 workshops to translate the report’s findings into a 90–180 day execution plan.
Closing
As naloxone transitions from an emergency-only product to an embedded part of public-health architecture, 2026 will reward organizations that invest in the right combination of supply integrity, channel differentiation and payer engagement. PW Consulting’s report equips leaders with the market context, competitor intelligence and tactical playbooks needed to make those investments with confidence.
For detailed analysis of this topic, please visit the official page: Naloxone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
M Cresol Market 2026 Strategy Brief: Navigating Feedstock Volatility, Regulatory Pressure and Concentration Risks
PW Consulting’s new M Cresol Market report (base year 2025; forecast window 2026–2032) equips C-suite executives, procurement heads and investors with a pragmatic, scenario-driven playbook for 2026 decision-making. Anchored in a comprehensive dataset and primary supply‑side interviews, the analysis shows an industry that has expanded from a mid‑hundred million USD base in 2020 to an estimated USD 541.1 Million in 2025, and is projected to grow at a compounded annual growth rate (CAGR) of 3.9% through 2032 (reaching roughly USD 707.2 Million by 2032). These headline metrics underscore steady expansion but mask substantive near‑term structural risks that will determine winners and losers in 2026.
M Cresol Market
Executive summary — what matters for 2026
-
Moderate, steady market growth: The market’s mid-single‑digit CAGR reflects resilient downstream demand across specialty chemicals, agrochemicals and formulation markets; however, growth is uneven and sensitive to feedstock and regulatory shocks.
M Cresol Market -
Supply concentration and bargaining power: Market concentration is meaningful at the top end — the three largest players control a dominant share of capacity, with the top five exerting even stronger influence. This creates pricing and availability dynamics that buyers must manage proactively.
M Cresol Market -
Feedstock and energy economics drive margins: M‑cresol manufacturing remains tightly coupled to petroleum derivatives (notably toluene and benzene streams). Feedstock price swings and regional energy cost variations materially change production economics and capex recovery timelines.
-
Policy and trade risk are real and present: Recent trade measures and environmental compliance costs materially alter global sourcing economics—import levies and tightening environmental rules increase the total landed cost and capital expenditure requirements.
-
Short‑term pricing signals are mixed: Industry reporting in late 2025 noted cost relief in specific regions driven by lower naphtha and related feedstock prices, even as pockets experienced heightened toluene costs in Q4 2025—creating divergent regional competitiveness.
What the PW Consulting report delivers (practical, transaction‑ready content)
-
Transparent market sizing and demand scenarios — including upside/downside cases and sensitivity to feedstock and energy assumptions.
-
Supply‑side cost‑curve modelling showing cash‑costs, break‑even ranges by technology route, and the impact of tariffs and environmental compliance on unit economics.
-
Granular supplier and asset mapping (asset vintage, technology route, feedstock flexibility, and export orientation) coupled with an M&A watchlist and valuation comparables.
-
Regulatory impact assessment that quantifies the near‑term capex and opex burden from pollution control, waste‑management requirements and trade measures.
-
Procurement playbook for 2026: contracting templates, hedging strategies, dual‑sourcing blueprints and tariff‑mitigation options.
-
Commercial strategy templates tailored to producers and downstream formulators (product‑grade strategies, premiumisation paths, and route‑to‑market options).
-
Interactive dashboards and annexes: raw‑material price histories, scenario calculators, and primary interview transcripts to test management assumptions.
Industry dynamics that will shape 2026 decisions
The technical and commercial characteristics of the m‑cresol value chain create real options—and constraints—for firms planning 2026 moves. Key dynamics include:
-
Feedstock exposure: Toluene and benzene derivatives remain the dominant feedstocks. Where to source and how to hedge these inputs will determine cost competitiveness.
-
Trade intervention and tariffs: Phenolic compounds under longstanding tariff regimes have seen additional levies on certain origins—this magnifies landed cost dispersion and encourages onshore processing or tariff engineering strategies.
-
Regulatory compliance: Phenolics carry environmental safety obligations that necessitate investment in pollution control and waste management; compliance is non‑negotiable but can be a differentiator for premium buyers.
-
Regional cost divergence: A late‑2025 easing in naphtha-driven costs in some regions contrasted with toluene cost spikes in others—creating windows for opportunistic arbitrage, but also transient supply tightness.
Competitive landscape — positioning and strategic readiness
The market structure is dominated by a mix of global chemical majors, regional integrated producers and specialty niche players. Top players collectively shape pricing and capacity deployment; smaller specialists compete on quality, service and proximity.
-
LANXESS AG (Cologne, Germany) — A leading specialty chemical producer, positioned for high‑purity applications. Strengths: technical quality, global customer base and formulations know‑how. Strategic risks: margin sensitivity to feedstock spikes and the capital intensity of meeting environmental standards in Europe.
-
Sasol Limited (Johannesburg, South Africa) — Uses coal‑tar and synthetic routes with feedstock flexibility. Strengths: route diversification and established global distribution. Risks: exposure to regional energy pricing and the need to modernize older assets to meet tightening environmental norms.
-
Mitsui Chemicals, Inc. (Tokyo, Japan) — Focused on high‑quality intermediates. Strengths: technology and product consistency for resins and antioxidants. Opportunities: premium formulations and partnerships in electronics and pharma supply chains.
-
Atul Ltd & VDH Chem Tech (India) — Cost‑competitive producers serving regional and export markets. Strengths: cost base and local integration with agrochemical and pharmaceutical supply chains. Risks: trade barriers and the need to scale compliance investments to access regulated markets.
-
Chinese manufacturers (e.g., Anhui Haihua, Nanjing Datang) — Large capacity and export orientation. Strengths: scale and low unit cost. Constraints: higher effective duties on some exports and increasing regulatory scrutiny, which compresses arbitrage advantages.
-
Konan Chemical, Dakota Gasification, SABIC — Konan: niche high‑purity supplier for fine chemicals and electronics; Dakota: byproduct supplier leveraging coal‑gasification linkages; SABIC: integrated major with downstream integration advantages. Each has a distinct strategic play—specialization, feedstock integration, or scale.
Collectively, the market exhibits significant top‑end concentration (the top three and top five firms together control a material share of capacity and influence). For buyers, this implies potential supply tightness during feedstock stress and the need for contractual resilience. For investors, the concentration highlights candidate targets for bolt‑on acquisitions and consolidation playbooks in select geographies.
Actionable recommendations for 2026 (prioritized)
-
Run three scenario models for your supply chain: Base (current trajectory), Stress (sustained feedstock inflation and tariff escalation), and Disruption (regional shut‑ins or rapid regulatory closures). Use these to set contract hedges and inventory policy.
-
Negotiate flexible supply contracts with indexed pricing and defined pass‑through clauses for feedstock and compliance costs. Where feasible, secure short‑term optional volumes from diversified geographies.
-
Pursue technical partnerships or JV structures with specialty producers to secure high‑purity grades without carrying full build‑out capex. This is especially relevant for formulators moving into higher‑margin downstream niches.
-
Embed tariff and rule‑of‑origin analysis into sourcing decisions. With additional levies effective in 2025, re‑routing, onshore processing or tariff mitigation (e.g., reclassification, tariff engineering) can materially improve economics.
-
Accelerate environmental and safety capex planning. Compliance investments are now a commercial requirement in many end‑markets; early movers can win premium contracts and reduce long‑term risk.
-
Monitor M&A selectively: look for bolt‑ons that add feedstock optionality, localized inventory hubs, or specialty grades that raise overall portfolio margins.
Why PW Consulting’s report is strategic for 2026
This report is designed as a decision‑ready tool for management teams and investors. It combines robust market sizing, cost‑curve engineering, tariff and regulatory quantification, supplier due‑diligence and a tactical procurement playbook — all supported by primary interviews and scenario modelling. The aim is to convert market intelligence into executable options for 2026: where to buy, when to invest, and how to structure supply‑side resilience.
We intentionally omit detailed segment tables and proprietary company share allocations in this release to preserve the report’s value as an actionable intelligence product. PW Consulting’s full M Cresol Market report contains the complete segment‑level breakdowns, supplier scorecards and downloadable modelling tools that decision‑makers require.
How to get the full analysis
For access to the full report, interactive dashboards and a tailored executive briefing for your leadership team, please visit PW Consulting’s research portal or contact our industry practice to schedule a 60‑minute walk‑through. The 2026 planning window is narrow; firms that translate these insights into procurement, investment and compliance actions in Q1–Q2 2026 will materially improve their risk‑adjusted returns over the forecast period.
For detailed analysis of this topic, please visit the official page: M Cresol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Tool Change Spindle Market Poised to Reach USD 1,130.82 Million by 2032, Backed by a 5.31% CAGR
By PW Consulting, 2026-07-13
Automatic Tool Change Spindle Market — Strategic Outlook for 2026 Decision‑Making
Executive snapshot
PW Consulting’s latest market study on Automatic Tool Change (ATC) spindles positions the segment as a steady-growth industrial niche with clear implications for procurement, R&D and M&A decisions in 2026. Using a 2025 base year, our model shows the global ATC spindle market at roughly USD 787.8 million, and our 2026–2032 forecast projects a compound annual growth rate (CAGR) of approximately 5.31%, taking the market toward the billion‑dollar threshold by the end of the period. Historical momentum (2020–2025) combined with structural drivers — automation in machining, lights‑out manufacturing and material-specific throughput requirements — create predictable expansion patterns that can be acted upon this year.
Automatic Tool Change Spindle Market
Why this report matters for 2026 strategic planning
- Capital allocation clarity: Our growth scenarios turn market momentum into timing signals for CAPEX and capacity investments — helping OEMs and contract manufacturers avoid both over-commitment and missed windows.
- Product and R&D prioritization: Technology choices (motorized, belt‑driven, gear‑driven, air/air‑bearing solutions) are not one‑size‑fits‑all; our framework ranks these choices by application sensitivity, integration cost and aftermarket economics.
- Supply‑chain resilience: The report translates raw material and component risk (notably bearings and precision electro-mechanical parts) into hedging and supplier‑diversification playbooks.
- M&A and partnership playbook: We identify where bolt‑on acquisitions — from niche spindle makers to ATC integrators — can accelerate route‑to‑market or fill capability gaps with defensible economics.
Key market dynamics to factor into 2026 decisions
- Automation and labor pressure: Continued skilled labor shortages in CNC machining are accelerating ATC spindle adoption in both greenfield automation projects and retrofit programs intended to enable lights‑out operations.
- Raw‑material and component cost volatility: Precision bearings and related high‑tolerance components remain a key cost driver; recent periods have seen notable price pressure and margin impact, disproportionately affecting smaller manufacturers. Our sensitivity scenarios quantify profitability erosion under varied raw‑material cost paths.
- Technology bifurcation: A clear split is emerging between very high‑speed, low‑torque air/air‑bearing solutions tailored to composites and finishing, and higher‑torque motorized electro‑spindles aimed at heavier milling and robotic cell integration. Each trajectory has unique service, tooling and value‑chain implications.
- Aftermarket economics: Service, repair and retrofit mounting solutions are evolving into high‑margin revenue streams; suppliers that build robust aftermarket channels can materially improve customer lifetime value.
- Regulatory and input‑cost headwinds: Recent increases in component costs have raised production costs materially for many suppliers; our scenario analysis models the pass‑through and demand elasticity implications for OEMs and distributors.
Competitive landscape — profiles and strategic takeaways
The market shows moderate concentration at the top‑end: top‑three vendors account for a meaningful share of supply, and the top five widen that share further. This concentration level creates both barriers and opportunities for new entrants, depending on specialization and go‑to‑market agility.
Automatic Tool Change Spindle Market
- GMN USA (subsidiary of GMN Germany) — High‑speed CNC spindles with ATC systems; product guidance updates in early 2026 underscore a continuing focus on speed, serviceability and maintenance guidance. Strategy implication: strong aftersales and documentation programs raise switching costs for customers.
- Celera Motion (Novanta) — Specialist in precision air‑bearing spindles reaching very high speeds; plays to composites and precision finishing use cases. Strategy implication: premium niche positioning with engineering sales is effective in high‑value verticals.
- Teknomotor — European electrospindle maker oriented to wood and aluminum machining with quick‑change tooling systems; focus on regional wood/aluminum clusters suggests targeted distribution strategies work.
- Jingjiangcity Jianken — Chinese supplier of pneumatic ATC spindle motors; price and local supply advantages make this segment a strong retrofit and local OEM play in certain markets.
- CNC Depot, SPINOGY, Air Turbine Tools, PwnCNC, RapidChange ATC — A mix of regional manufactured offerings, modular high‑frequency designs and affordable ATC systems that feed both pro‑hobbyist and industrial retrofit markets. Strategic implication: these players are sources of rapid adoption signals and may be attractive targets for roll‑up strategies.
Report contents — what you will find inside
This study is designed as a practical decision tool, not only a market narrative. Key deliverables include:
Automatic Tool Change Spindle Market
- Market sizing and validated demand model (base year 2025; historical analysis 2020–2025; forecast 2026–2032 with scenario bands).
- Technology and application mapping (motorized, belt, gear, air/air‑bearing) with decision matrices for OEMs, system integrators and contract manufacturers.
- Supply‑chain risk maps and supplier scorecards, including raw‑material sensitivity and recommended mitigation actions for 2026 procurement cycles.
- Competitive benchmarking and vendor capability matrices, plus a curated list of acquisition targets and partnership candidates tailored by strategic objective (scale, technology, channel).
- Buyer playbooks: TCO calculators, procurement RFx templates, retrofit integration blueprints and sample service contracts to accelerate commercial deployment.
- Scenario and stress testing: pricing shocks, bearing‑cost escalation, labor‑availability scenarios and their quantitative impact on unit economics and payback periods.
- Technical appendix with test protocols, performance validation checklists and maintenance best practices — designed to shorten vendor qualification cycles.
How executives should use this report in 2026
- Manufacturers (OEMs & Tier‑1s): Use the demand model to time product launches and prioritize platform investments where margin expansion is most defensible (e.g., integrated ATC + servo control suites, aftermarket spares programs).
- Spindle manufacturers: Reassess supplier contracts for high‑tolerance bearings and invest selectively in service networks; consider modular designs to broaden addressable markets without proportional inventory expansion.
- Systems integrators and contract manufacturers: Pilot hybrid adoption strategies — retrofit ATC kits where lead times or CAPEX constraints exist, and deploy fully integrated cells for greenfield automation projects.
- Distributors and OEM service providers: Build certified maintenance programs; maximize recurring revenue through preventative maintenance contracts and rapid spares fulfilment.
- Investors and M&A teams: Target assets that combine engineering IP with aftersales channels, and be ready to refinance or consolidate smaller regional players that lack diversified supply chains.
Near‑term signals to monitor
- Public statements and product guidance from leading suppliers — recent updates from GMN USA (Jan 2026) and ecosystem releases from suppliers such as Sienci Labs (Dec 2025) are early indicators of product positioning and channel focus.
- Bearing and precision component price trajectories and lead times — spikes will compress margins for smaller suppliers and accelerate consolidation.
- Order patterns from key end markets (automotive, aerospace, die & mold, consumer electronics) — an uptick signals broader adoption and justifies capacity expansion.
- Regulatory or tariff actions affecting component imports — these can rapidly re‑shape sourcing strategies and regional competitiveness.
Strategic next steps and call to action
For 2026 planning cycles, the recommended immediate actions are:
- Acquire the full PW Consulting ATC Spindle report to access the granular demand tables, vendor scorecards and customizable TCO models needed for procurement and capital‑planning committees.
- Run a six‑month supplier‑risk audit focused on precision bearing exposure and lead‑time concentration; institute contingency sourcing where necessary.
- Launch one pilot automation project that prioritizes retrofit compatibility to validate ROI assumptions before committing to large greenfield investments.
- Consider strategic partnerships or bolt‑on acquisitions that add local aftermarket capability or specialized high‑speed technologies.
PW Consulting’s study is structured to move executives from hypothesis to action: clearly defined scenarios, vendor intelligence and implementation playbooks that translate the 5.31% CAGR and underlying market momentum into executable 2026 plans. For decision makers preparing budgets, negotiating supplier contracts, or evaluating targets, the report provides the empirical, operationally focused insight necessary to make confident, time‑sensitive choices. Access the full report for the complete data tables, detailed segmentation and tailored advisory options to support your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Automatic Tool Change Spindle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 5.12% CAGR for Machine Tool Protection Bellows Market, Driven by Asia‑Pacific Demand
By PW Consulting, 2026-07-13
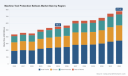
Machine Tool Protection Bellows Market — Strategic Insights for 2026 Decisions (PW Consulting)
Executive teaser
Our new PW Consulting market study on the Machine Tool Protection Bellows market (base year: 2025; forecast period: 2026–2032) synthesizes quantitative market sizing and forward-looking strategic analysis to support executive decision-making in 2026. The market reached approximately USD 548.2 Million in 2025 and, under our central scenario, is projected to expand at a 5.12% CAGR through 2032, reaching roughly USD 777.6 Million by the end of the forecast horizon. This briefing highlights the report’s strategic value — what it enables C-suite teams, product leaders, procurement heads, and corporate development groups to do — while intentionally withholding the detailed subsegment-level figures to invite deeper engagement with the full report.
Machine Tool Protection Bellows Market
Market trajectory and macro context
The bellows market for machine tool protection has moved from stability into a phase of measured growth driven by renewed machine tool investments, incremental automation, and material innovations. After a period of volatility during the early-2020s, the market regained momentum in 2023–2025 and is forecast to sustain mid-single-digit annual growth through 2032 underpinned by three macro dynamics:
Machine Tool Protection Bellows Market
- Automation-led machine tool investment: global manufacturing automation drove a notable uptick in machine tool procurement in 2025, reinforcing demand for protective components.
- Material and input-cost pressure: heavy-duty components and polymer-coated bellows are sensitive to raw-material movements. In 2025 supply-side constraints elevated steel plate prices and polyurethane resin costs, exerting margin pressure on commodity-dependent producers and prompting price pass-through negotiations.
- Regulatory and trade shifts: evolving safety standards and trade/tariff regimes (including EU measures on steel imports effective 2026) are reshaping cost structures and sourcing strategies for producers and OEMs in Europe and beyond.
What the PW Consulting report delivers — practical, decision-ready content
This study is designed as an operational playbook as well as a market forecast. Key deliverables included in the full report are:
Machine Tool Protection Bellows Market
- Top-down and bottom-up market sizing (validated across demand and supply channels) with scenario-based forecasts through 2032.
- Segmentation by product type (folded, circular, stitched and other constructions), by application (CNC, grinding, laser cutting, lathes/mills and specialty segments), and by region — each supported by demand drivers, adoption curves and price tension analysis. The public summary intentionally omits subsegment revenue calls to preserve the strategic value of the full dataset.
- Supplier mapping and capability scorecards, including manufacturing footprint, material competence, cleanroom and high-speed offerings, and aftermarket/service capabilities.
- Supply-chain stress testing: raw-material exposure matrix, tariff and compliance scenarios (including ISO safety standard impacts), and recommended mitigation levers such as strategic hedging, nearshoring, or supplier diversification.
- Commercial playbooks: go-to-market strategies and pricing frameworks for OEM supply vs aftermarket channels, bundled service/maintenance offerings, and warranty risk models.
- M&A and partnership intelligence: prioritized target lists, accretion/dilution modeling, and integration risk checklists tailored to roll-up, capability-buy, and geographic-extension strategies.
- Case studies and practical tools: procurement RFP templates, supplier evaluation matrices, product roadmaps for materials innovation, and an executive dashboard that ties market scenarios to P&L and CapEx planning.
Competitive landscape — who matters and why
The market shows moderate concentration (CR3 ~32.5%; CR5 ~46.8%), indicating that a small set of established specialists capture a meaningful share while leaving scope for differentiated entrants and regional players. The competitive set profiled in this study includes established global fabricators, niche composite innovators and precision specialty firms. Highlights and strategic implications:
- Dynatect Manufacturing, Inc. (Rockford, IL, USA; https://www.dynatect.com/) — Strengths: deep capability in custom and heavy-duty solutions, broad aftermarket channel and form-fit replacements for ball screws and linear guides. Recent product activities showcased at trade events underline a clear push into low-profile, high-speed machining segments. Strategic implication: well-positioned to defend OEM relationships; a potential partner for scale-focused roll-ups or for OEMs seeking design-for-manufacture collaboration.
- A&A Manufacturing Co., Inc. (Los Angeles, CA, USA; https://www.aamfg.com/) — Strengths: cost-competitive accordion-style bellows across fabric, rubber and plastics. Strategic implication: plays to volume aftermarket and replacement parts; pricing agility is a lever, but limited materials differentiation elevates vulnerability to input-cost swings.
- Gortec Bellows B.V. (Barneveld, Netherlands; https://www.gortec.nl/) — Strengths: polyurethane/steel hybrid constructions tailored to high-speed and cleanroom applications. Recent launches and EMO Hannover exposure spotlight a cleanroom-focused growth path. Strategic implication: attractive acquisition or alliance partner for OEMs targeting semiconductor/precision manufacturing customers.
- Tecnovel S.r.l. (Modena, Italy; https://www.tecnovel.com/) — Strengths: cleanroom-capable products, European precision-engineering credentials. Strategic implication: suitable partner for premium OEMs with strict cleanliness or certification requirements.
- Advanced Composites, Inc. (Salt Lake City, UT, USA; https://aci-usa.com/) — Strengths: composite material expertise for high-temp/chemical-resistant applications. Strategic implication: materials differentiation that supports margin expansion and entry into higher-performance niches.
- Hohmann Platten GmbH (Bad Berleburg, Germany) and Fa. Willich Präzisionswerkzeuge GmbH (Velbert, Germany) — Strengths: heavy-duty steel plate bellows and precision telescopic covers for larger metalworking machines. Strategic implication: critical suppliers for heavy industry and bespoke OEMs; subject to steel price dynamics and trade measures.
Segment dynamics, input risks and regulatory constraints
Three practical supply-side pressures require immediate executive attention in 2026:
- Raw-material volatility — heavy steel and polymerized coatings remain primary cost levers. Steel plate supply tightness during 2025 materially increased input prices in heavy-duty segments, and polymer resin inflation pushed coating costs higher; manufacturers must model margin compression and consider hedging, long-term contracts or material substitution strategies.
- Regulatory compliance — machine guards and bellows are governed by safety standards such as ISO 14120:2015. Compliance affects design cycles, testing requirements and aftermarket documentation; non-compliance risk elevates warranty and liability exposure.
- Trade policy impact — new tariff and carbon-adjustment measures (notably affecting EU-imported steel) shift sourcing math for European producers and their customers. Nearshoring and localized production become economically compelling for certain segments where freight and tariffs offset labor differentials.
Practical strategic moves for 2026 (executive checklist)
- Prioritize a dual-track sourcing strategy: secure long-term contracts with key raw-material suppliers while qualifying alternative polymers and composite suppliers to reduce single-source exposure.
- Accelerate product differentiation through material innovation (composites, coated polymers) to move away from commodity competition and protect margin.
- Recalibrate pricing models to incorporate input-cost pass-through clauses and modular pricing for OEM vs aftermarket channels.
- Evaluate bolt-on acquisitions that add cleanroom, high-speed or composite capabilities to accelerate access to premium segments.
- Align R&D and regulatory teams to ensure new designs meet ISO and industry-specific safety/cleanroom certifications from concept stage to reduce time-to-market risk.
- Deploy an aftermarket-first growth program: service contracts, spares availability, and field-installation teams to capture recurring revenue and strengthen OEM lock-in.
How PW Consulting’s deliverables convert insight into decisions
Beyond forecasting, our report equips teams with decision-ready tools that map directly to 2026 planning cycles:
- Scenario-linked financial model: P&L and cash-flow sensitivity to input-cost, tariff and demand shocks.
- Supplier assessment and RFP templates to accelerate sourcing reviews and supplier rationalization.
- Acquisition shortlist and accretion/dilution playbook with integration-risk ratings for inorganic growth.
- Commercial playbooks tailored to OEM negotiation, aftermarket monetization and bundled-service pricing.
- Operational checklists to align quality, compliance and production ramp-up when introducing new materials or moving production footprints.
Concluding note — where this briefing leaves you
This briefing demonstrates the strategic contours of the Machine Tool Protection Bellows market entering 2026: steady expansion, concentrated but contestable supply, and a set of near-term risks tied to materials, standards and trade. The full PW Consulting report contains the granular segmentation, regional flows, price curves, and supplier-level revenue tables necessary to build detailed 2026 CapEx, procurement and M&A plans. In line with the “trailer” approach, we have presented the actionable implications and executive playbook while withholding core subsegment figures — those are available in the complete report.
Next step
For the full dataset, supplier scorecards, downloadable financial model and a tailored briefing for your leadership team, please contact PW Consulting or visit our report page to request access and licensing options. Our analysts are available to run a customized 90-minute workshop to translate the findings into a prioritized 12-month strategic roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Machine Tool Protection Bellows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inertia Base Market Reaches USD 364.5M in 2025, Poised to Hit USD 530.2M by 2032 on a 5.5% CAGR
By PW Consulting, 2026-07-13
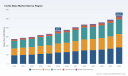
Inertia Base Market Research 2026: Strategic Imperatives for Companies Planning Growth, Risk Mitigation, and Procurement
PW Consulting / Inertia Base Market Research — Executive preview (base year 2025)
Our new Inertia Base Market Research (base year 2025; historical 2020–2025; forecast 2026–2032) shows a resilient, technically driven market expanding at a mid-single-digit pace. The global market reached USD 364.5 Million in 2025 and is forecast to grow at a 5.5% CAGR over the 2026–2032 period, approaching roughly USD 530 Million by 2032. This briefing highlights the strategic implications for executives who must decide on supply-chain investments, product positioning, and risk management through 2026 and beyond. To preserve competitive advantage, this release demonstrates the analytical depth of our study while withholding detailed segment-level metrics; full datasets and proprietary splits are available in the report.
Inertia Base Market Research
Why this market matters for 2026 decision-making
-
Transitional CapEx window: Many asset-intensive industries (HVAC, pumps, data centers, medical facilities) plan replacements and new-builds in 2026 that lock in vibration-control architectures for a decade or more. Decisions on inertia base types and procurement strategies made in 2026 will shape maintenance, warranty, and retrofit costs well into the 2030s.
Inertia Base Market Research -
Regulatory inflection: Evolving seismic and building-code requirements are increasing the technical bar for inertia base design and isolator pairings. Organizations that proactively align procurement and installation practices with these requirements will reduce retrofit risk and lifecycle cost.
Inertia Base Market Research -
Labor and manufacturing economics: Pre-fabrication, modular frames, and site-ready pouring forms are eroding onsite labor intensity — a key consideration for projects facing skilled labor scarcity and rising installation wages.
Market trajectory — what the numbers signify
The market’s trajectory is both steady and structural. After recovering from pandemic-era disruption through 2023–2025, overall system demand is now being driven by steady infrastructure investment, continued data-center expansion, and replacement cycles in industrial and institutional HVAC fleets. A 5.5% CAGR from 2026 through 2032 signals a market that is neither hyper-growth nor stagnant; rather, it is mature with targeted pockets of premiumization (seismic-rated systems, high-mass composite solutions) and labor-saving product innovations (pre-welded frames, modular systems).
For strategy teams this means: prioritize initiatives that capture value beyond commoditized mass — engineering services, seismic certification, integrated isolator + base solutions, and aftermarket maintenance contracts all score higher in return-on-capital terms than competing on price alone.
Drivers and dynamics shaping supplier and buyer strategies
-
Technical standards and seismic compliance — Standards such as ASHRAE recommendations for inertia-base selection and IBC seismic requirements are increasingly influential. Buyers must validate that combined base + isolator solutions meet local seismic design forces and manufacturer warranty conditions.
-
System-level warranty linkage — OEMs and equipment manufacturers increasingly require specific inertia-base and isolator pairings to preserve equipment warranties. This is driving closer OEM–inertia-base supplier collaboration and creates opportunities for certified bundle offerings.
-
Raw-material and design realities — Structural steel channels and I-beams filled with concrete (common fill thicknesses ranging across standard engineering options) remain the dominant engineering approach. Suppliers that optimize material use for mass, manufacturability, and transportability gain cost and schedule advantages.
-
Labor-to-productivity trade-offs — Pre-welded, ready-for-pour frames reduce onsite labor and schedule risk. For large projects and markets with high labor costs, these designs shorten critical-path operations and decrease installation variability.
Segmentation and opportunity pockets (high-level)
The market is logically segmented by region, by base type (steel frames with concrete infill, poured concrete bases, composites and elastomeric systems), and by application (HVAC systems, industrial pumps/compressors, data centers, medical and laboratory equipment, among others). Our analysis identifies differentiated growth and margin profiles across these segments but preserves the full segmentation tables for the report.
Key opportunity themes we highlight for 2026:
-
Premiumization in seismic and mission-critical applications — Projects in seismically active regions and mission-critical facilities prioritize certified systems and integration services.
-
Aftermarket and lifecycle services — Long-term vibration monitoring, retrofit design, and warranty-extension services represent higher-margin, recurring revenue opportunities.
-
Modularization and logistics-led value — Manufacturers that offer lighter, modular units that minimize on-site labor and meet international shipping constraints will win larger projects and global accounts.
Competitive landscape — positioning and strategic moves
The supplier base combines established vibration-control specialists, regional fabricators, and a growing set of value-engineered propositions. The market exhibits moderate concentration: leading specialized providers control a meaningful share of institutional and large-commercial business, while many regional and niche manufacturers serve local HVAC and industrial contractors.
Representative company profiles and strategic implications (select):
-
Kinetics Noise Control (USA) — Known for concrete-filled inertia base frames in multiple configurations and a strong focus on engineered solutions to reduce vibration and control amplitude. Strength lies in broad configuration breadth and technical product documentation; strategic buyers should evaluate Kinetics for large institutional and retrofit projects where detailed specifications matter. ( https://kineticsnoise.com)
-
VMC Group (USA) — Offers poured-form inertia bases with seismic and non-seismic variants, plus stocked structural channel frames. VMC’s positioning is compelling for customers needing code-compliant, seismically rated solutions and shorter lead times. ( https://www.thevmcgroup.com)
-
Novia Corporation (USA) — Emphasizes OEM-aligned inertia bases designed to preserve equipment warranties and partner with isolation mounts. Novia’s strength is in equipment-vendor collaboration and warranty-driven adoption, a key consideration for chiller and pump manufacturers. ( https://noviacorp.com)
-
Acrefine (USA) and Vibrasystems (Canada) — Both emphasize pre-welded frames and labor-saving designs, offering competitive advantage where on-site labor is scarce or costly. These approaches reduce schedule risk and are highly attractive to EPCs and contractors. ( https://acrefine.com, https://vibrasystems.com)
-
Isotech Industries, ISAT, Vibro-Acoustics, Farrat, and Diamond Walraven — Each occupies niche strengths from neoprene-sprung solutions and seismic-focused frames to composite bases and international market reach. Strategic buyers should map supplier capabilities to project-specific constraints (seismic, footprint, start-up torque, and service access). ( https://isotechindustries.com, https://isatts.com, https://virs.vibro-acoustics.com, https://farrat.com, https://hirawalraven.com)
Across these vendors, differentiators include: engineering depth, pre-assembly and logistics readiness, seismic certification capability, and aftermarket service models. Competitive moves to watch for 2026 include deeper OEM partnerships, bundled base + isolator warranties, and expanded modular product lines to reduce installation labor.
Actionable implications for executives (priorities for 2026)
-
Procurement: Require supplier certification for seismic compliance and include lifecycle performance guarantees; shift RFPs to evaluate integrated base+isolator solutions rather than component-only bids.
-
Product strategy: Invest in pre-fabricated and modular base offerings to reduce installation risk; bundle engineering design services and commissioning to capture higher margins.
-
OEM partnerships: Negotiate warranty-aligned supply agreements that lock in certified base solutions to protect equipment warranties and reduce field disputes.
-
Risk management: Model retrofit costs under evolving code scenarios; prioritize solutions that minimize future scope creep when seismic or ASHRAE-driven retrofits occur.
-
Aftermarket growth: Create service packages (vibration monitoring, scheduled inspections, retrofit design) to develop recurring revenue and strengthen customer stickiness.
-
Geographic strategy: Align manufacturing and distribution footprints to project pipelines and labor cost realities; lean on pre-welded frames for high-wage regions.
What’s in the full PW Consulting Inertia Base Market Research report
-
Proprietary market sizing and seven-year forecasts (2026–2032) with scenario modeling and sensitivity to raw-material and regulatory shocks.
-
Granular segmentation by region, product type, and application with historical series (2020–2025) and drivers for each segment — provided in downloadable datasets and interactive dashboards.
-
Supplier benchmarking with capability matrices, product-configuration maps, and go-to-market profiles for leading manufacturers and regional players.
-
Procurement playbooks and contracting templates for integrated base + isolator purchases, including sample warranty language and seismic-compliance checklists.
-
Deal pipeline and M&A outlook identifying consolidation vectors, target profiles, and valuation heuristics for investors and strategics.
Closing — positioning for 2026
As organizations set budgets and award contracts in 2026, inertia-base choices will cascade into maintenance profiles, warranty exposure, and retrofit risk for years. The market is steady, technically nuanced, and increasingly driven by code compliance and labor-economics. PW Consulting’s Inertia Base Market Research equips executives with the market-size context, supplier maps, and operational playbooks needed to convert technical choices into strategic advantage. For the full data tables, segmented forecasts, and downloadable procurement tools, access the Inertia Base Market Research report on PW Consulting’s Inertia Base market page — detailed insights and datasets are available only in the full report.
For detailed analysis of this topic, please visit the official page: Inertia Base Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Servo Electric Press Brake Market to Reach USD 1,436.54 Million by 2032, Expanding at an 8.52% CAGR (2026–2032)
By PW Consulting, 2026-07-13
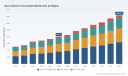
Servo Electric Press Brake Market — Strategic Outlook for 2026: A PW Consulting Intelligence Brief
Executive summary
The servo electric press brake market is entering a decisive phase for capital investment and technology adoption. Our latest market model shows the sector expanded from roughly USD 510 million in 2020 to about USD 810 million in 2025, and we forecast continued expansion through 2032 at a compound annual growth rate (CAGR) of approximately 8.52% for the 2026–2032 window, reaching an overall market size in excess of USD 1.4 billion by 2032. These macro trends reflect accelerating replacement of hydraulic systems, stronger demand for automated bending cells, and rising regulatory pressure for energy- and oil-free systems.
Servo Electric Press Brake Market
This brief highlights the report’s strategic value to executives making 2026 decisions — procurement timing, factory automation roadmaps, product investments, M&A screening, and go-to-market prioritization — while deliberately omitting the detailed regional and application splits contained in the full report to encourage readers to consult the original publication for granular intelligence.
Servo Electric Press Brake Market
Why this report matters for 2026 decision-makers
- Capital allocation and timing: With market momentum clear and an 8.52% CAGR underpinning the 2026–2032 forecast, the window for cost-effective replacement and capacity expansion is now. Early movers secure supply slots and preferential pricing.
- Technology selection: The transition from hydraulic to servo-electric solutions is shifting buying criteria from raw tonnage to metrics such as cycle-energy-per-bend, integration capability, and TCO over 5–7 years. Procurement teams need comparative models, not just price quotes.
- Automation and workforce planning: Automation-led bending cells reduce operator dependency and cycle time variability. Manufacturers should align training, OEE targets, and change management plans with expected automation rollouts in 2026.
- Supply chain and supplier risk: Component concentration in high-strength steel frames and precision servo motors creates strategic supplier dependencies that should be managed via multi-sourcing, inventory buffers, and strategic partnerships.
Key market dynamics to factor into 2026 strategies
- Energy and sustainability: Servo-electric systems consume substantially less energy than hydraulic alternatives — industry data indicate up to ~50% lower operational energy usage by virtue of power-on-demand motor operation. This translates directly into operating-cost reduction and improved ESG performance metrics.
- Regulatory tailwinds: Tighter environmental and safety directives — particularly across Europe — favor non-hydraulic solutions that eliminate oil-handling risks. Compliance-driven fleet renewal will continue to be a material demand driver.
- Industry 4.0 integration: Modern servo-electric presses increasingly ship with CNC controllers supporting OPC-UA and other factory protocols. Interoperability with laser-cutting, robotic handling, and MES systems makes these units strategic enablers for smart factories.
- Component and raw-material constraints: Frames, precision guideways, and servo motors remain the core cost and lead-time drivers. Manufacturers that vertically integrate or secure long-term supplier agreements for these components will realize both margin and delivery advantages.
- Labor and productivity: The ability of servo-electric technology and integrated automation to lower operator dependence is reshaping workforce requirements — prioritizing multi-skilled technicians and digitally literate maintenance staff.
Competitive landscape — what leading vendors are doing (high-level analysis)
The market exhibits moderate concentration, with the top three vendors holding a meaningful but not dominant share and the top five commanding just over half the market. This structure creates a competitive environment in which technology differentiation, after-sales capability, and automation partnerships matter at least as much as price.
Servo Electric Press Brake Market
- Amada (Isehara, Japan) — Known for the EGB and HG series, Amada competes on precision, adaptive bending algorithms, and deep automation integration for sheet-metal fabrication. Strategic implication: strong for OEMs and tier-1 buyers seeking proven adaptive bending workflows and global service networks. ( https://www.amada.com)
- TRUMPF (Ditzingen, Germany) — TruBend solutions emphasize energy efficiency, smart-factory connectivity and advanced measurement systems. Strategic implication: attractive for manufacturers prioritizing factory-level interoperability and measurement-driven quality control. ( https://www.trumpf.com)
- Bystronic (Niederönz, Switzerland) — Xpert Electric lines focus on high-speed, high-precision bending and integration with laser cutting and automation. Strategic implication: compelling for mixed high-mix/high-volume environments where cycle speed and integration reduce total lead time. ( https://www.bystronic.com)
- SafanDarley (Lochem, Netherlands) — Founder of broad E-Brake ranges (35–300 tons), prioritizing low energy consumption and accuracy. Strategic implication: strong contender for diversified product portfolios and energy-conscious buyers. Recent catalog expansions further strengthen market coverage. ( https://safandarley.com)
- LVD (Gullegem, Belgium) — Offers adaptive laser bending tech and broad ranges; well-suited for precision sheet metal work. Strategic implication: an option for manufacturers seeking advanced bending accuracy coupled with adaptive tooling. ( https://www.lvdgroup.com)
- Salvagnini (Sarego, Italy) — B3 Kinetic lines emphasize flexible automation for mixed and high-volume production; suited to integrated line solutions where bending is part of a larger automated flow. ( https://www.salvagnini.com)
- Prima Power (Collegno, Italy) — Integrates servo-electric press brakes into robotic bending cells and smart factory solutions; active in trade shows with automation highlights, signaling its continued focus on robotics-enabled offering. ( https://www.primapower.com)
- Accurpress (Rapid City, USA) — Known for heavy-duty, reliable servo-electric brakes in North America; a consolidation play for customers prioritizing ruggedness and local support. ( https://www.accurpress.com)
- Durma (Bursa, Turkey) — Targets SMEs with affordable, compact servo-electric solutions that deliver acceptable precision and footprint advantages. ( https://www.durmazlar.com.tr)
- JialiPress (China) — Focuses on intelligent, cost-effective servo solutions, increasingly relevant to cost-sensitive high-volume producers and regional OEMs seeking localized supply. ( https://www.jialipress.com)
Recent vendor moves in late 2024–2026 (product showcases, catalog expansions, and trade show debuts) reinforce a theme: suppliers are competing on automation integration, energy credentials, and modularity rather than on pure tonnage metrics. Suppliers that demonstrate clear TCO advantages and easy integration into automated cells are gaining share.
What the PW Consulting report contains (practical, actionable modules)
- Methodology and market model with historicals (2020–2025) and granular forecast (2026–2032) — including sensitivity scenarios tied to energy costs and automation adoption rates.
- Vendor scorecards and capability matrices covering precision, connectivity, automation readiness, typical lead times, and service footprint.
- Total cost of ownership (TCO) calculators and break-even analyses comparing hydraulic vs servo-electric across typical use cases and run rates.
- Technology and component supply maps highlighting critical motor, controller, and frame suppliers and potential bottlenecks.
- Deal archetypes and guidance for procurement: lease vs buy, retrofit pathways, and financing structures optimized for 2026 budgets.
- Commercial playbook for OEMs and distributors: channel strategies, aftermarket revenue models, and service KPIs to sustain margins.
- M&A and partnership radar: high-probability targets and integration checklists for buyers seeking scale or capability lift.
Top-line recommendations for 2026
- Prioritize investments in servo-electric units that are proven in integrated automation cells and support OPC-UA/CNC interoperability — this reduces integration risk and shortens commissioning time.
- Use TCO models rather than CAPEX-only comparisons; include energy-per-bend and maintenance intervals in procurement scorecards.
- Negotiate multi-year supplier agreements for key components (servo motors, precision guides) to protect timelines and pricing amid component tightness.
- Deploy pilot robotic-bending cells in brownfield sites to validate throughput and quality assumptions before full-scale roll-outs.
- Build aftermarket service capabilities (remote diagnostics, predictive maintenance) as a margin-enhancing priority — service monetization becomes differentiating as product parity increases.
- Monitor regulatory developments and incorporate oil-free, low-emission machines into ESG reporting frameworks to capture incentives and reduce compliance risk.
How to use this brief and where to go next
This article is a strategic preview of PW Consulting’s full market study. The full report contains the discrete regional and application breakdowns, vendor market shares, price trajectory tables, and downloadable TCO templates that procurement teams, strategy groups, and investors will need to execute 2026 plans. We intentionally withheld those detailed tables here to preserve the report’s role as the primary source of transactional-grade intelligence.
For procurement leaders, OEM strategists, private equity teams, and production managers preparing 2026 budgets, the full report provides the operational tools and vendor benchmarking required to convert the macro growth story into defensible, measurable actions.
About PW Consulting
PW Consulting combines strategic advisory and industry analytics to help industrial clients convert market intelligence into executable plans. Our servo electric press brake market study synthesizes primary vendor interviews, factory-level benchmarking, and a proprietary demand model to deliver recommendations calibrated for 2026 decision cycles.
For detailed analysis of this topic, please visit the official page: Servo Electric Press Brake Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Endosseous Implant Market Poised for 6.55% CAGR, Signaling Robust Growth for Implant Makers
By PW Consulting, 2026-07-13
Endosseous Implant Market — 2026 Strategic Preview: Opportunity Maps, Competitive Plays, and Decision-Ready Intelligence
Introduction
PW Consulting’s latest Endosseous Implant Market report (base year 2025; forecast period 2026–2032) delivers a concise, actionable intelligence package designed to inform near-term corporate strategy and 2026 planning cycles. Built on a five-year historical base (2020–2025) and forward-looking scenario modelling, the study projects a compound annual growth rate (CAGR) of 6.55% across the forecast horizon. At the macro level, the market trajectory shows consistent expansion from the mid-2020s into the early 2030s, underscoring a sustained demand environment for implant manufacturers, device developers, distributors, and clinical service providers.
Endosseous Implant Market
Why this report matters for 2026 decisions
- Translate market momentum into prioritized investment: Understand where product innovations (material science, surface technology, implant geometry) will most rapidly convert into share gains.
- De-risk regulatory and reimbursement pathways: We map practical entry strategies around FDA 510(k) expectations, EU MDR timing, and payer coding realities that materially affect product launch sequencing.
- Drive commercialization with clinical evidence that matters: The report links real-world outcomes and 3–5 year clinical endpoints to go-to-market sequencing, pricing tolerance, and KOL engagement plans.
- Convert competitive moves into countermoves: We synthesize competitor playbooks and recent tactical developments into response options that are executable within a 12–18 month horizon.
- Supply-chain and sterilization resilience: Operational checklists address sterility assurance (including common gamma irradiation targets), materials compliance (ISO references), and outsourced manufacturing risk.
Macro snapshot (strategic context, not a substitute for the full dataset)
Key macro takeaways to frame 2026 planning:
Endosseous Implant Market
- The market is growing on a mid-single-digit CAGR (6.55%) through 2032—supportive for both incremental innovation and measured capacity investments.
- Historical momentum across 2020–2025 establishes a reliable baseline for 2026 planning, with expected continuity in procedure volumes and a steady shift toward immediate-loading and tapered designs favored in contemporary clinical practice.
- Market concentration is meaningful: the top three manufacturers account for a substantial share of market value, and the top five control a clear majority—implications include pricing discipline, channel leverage, and premium positioning opportunities for differentiated entrants.
Competitive landscape — what matters for strategy
Our competitive analysis coaches decision-makers to read intent in product moves, regulatory filings, and clinical publications rather than merely chasing market share. Highlights and strategic implications for key players include:
Endosseous Implant Market
- Straumann Group (Basel, Switzerland) — continues to invest in materials and platform extensions (e.g., Roxolid alloys, SLActive surfaces, and BLX platform expansion). The strategic imperative here is vertical integration of material science with global distribution muscle to defend premium segments.
- Nobel Biocare Services AG (Zurich, Switzerland) — remains a design and treatment-concept innovator (All-on-4, TiUnite surfaces), with regulatory clearances reinforcing lifecycle management of core platforms. Competitors should anticipate Nobel leveraging treatment protocols to entrench full-arch workflows.
- Dentsply Sirona (Charlotte, NC) and Zimmer Biomet Dental (Warsaw, IN) — both emphasize clinically validated tapered geometries and robust long-term survival data; Zimmer’s recent long-term survival publication exemplifies how clinical evidence can be converted into market advantage for premium systems.
- Osstem, Megagen and regional champions — increasingly sophisticated on product engineering (SLA/Hydroplasma surfaces, knife-thread geometries) while pursuing distribution partnerships to scale in priority markets. These firms create competitive pressure at price-sensitive nodes while incrementally moving upmarket through evidence generation.
- Other specialized firms (BEGO, Thommen, BioHorizons, Implant Direct, Alpha-Bio, Neodent) — offer niche differentiation through thread geometry, surface chemistry, connector design, or cost-competitive systems. Tactical collaborations, OEM deals, and channel partnerships are common competitive responses.
Recent tactical events flagged in our monitoring (product expansions, regulatory clearances, long-term clinical results, and distribution agreements) illustrate a market where platform enhancements and regional scaling are the dominant levers companies use to influence short-term demand and long-term positioning.
Regulatory, standards and payer dynamics — practical implications
- Regulatory pathing: Endosseous implants remain regulated with clear premarket requirements (e.g., FDA 510(k) for many device modifications and Notified Body requirements under EU MDR). Tactical recommendation: integrate regulatory strategy with clinical protocol design from day one to compress time-to-market.
- Materials & manufacturing standards: Titanium Grade standards and sterilization norms (including typical gamma irradiation doses used to achieve standard sterility assurance) should be embedded in supplier contracts and quality agreements to avoid downstream compliance failures.
- Reimbursement and coding: Dental surgical codes and payer constructs materially affect uptake in private and institutional settings. Early payer engagement and clinical-economic dossiers will accelerate acceptance for higher-priced technologies.
Strategic plays for 2026 (by stakeholder)
- Manufacturers: Prioritize platform modularity—invest in connector systems and prosthetic libraries that shorten chair time and reduce SKU proliferation. Pursue one or two high-value clinical publications within 18 months to support premium pricing.
- New entrants: Target narrow, defensible niches (e.g., soft-bone geometries, immediate-loading platforms, or zirconia esthetic lines) and use distributor partnerships to conserve capital while proving the model in priority geographies.
- Distributors and service providers: Forge integrated offerings combining consumables, training, and digital workflow services. Value-based bundles that reduce clinical friction will be powerful in the mid-market clinics segment.
- Private equity / M&A: Use concentration metrics and capability maps from the report to identify bolt-on targets—commercial access, localized manufacturing, or clinical registry assets—that accelerate scale without diluting core technology.
- Clinics & hospitals: Consider device rationalization that prioritizes systems with consolidated prosthetic libraries and evidence-aligned survival data to optimize inventory and reduce chair-side complexity.
What’s inside the full PW Consulting report (practical deliverables)
The published study is structured to be used as a playbook by commercial, clinical, regulatory, and M&A teams. Core components include:
- Market sizing & forecasting model (2026–2032) with scenario simulations and sensitivity analysis to test price, volume, and reimbursement shocks.
- Segment analysis by region, material (titanium vs. ceramic), and end-user channel—each with traction indicators and go-to-market checklists. (Note: detailed segment-level figures and regional splits are exclusively available in the full report.)
- Company scorecards and capability matrices for the leading manufacturers, with strategic recommendations tailored to each competitive archetype.
- Regulatory & reimbursement playbooks that translate FDA and EU MDR requirements into milestone-driven launch plans.
- Clinical evidence prioritization guides linking study design to reimbursement and commercial impact, plus sample protocols for 12–36 month registries.
- Supply-chain risk heatmap covering material standards (ISO references), sterilization requirements, and contract manufacturing contingencies.
- Go-to-market templates: pricing elasticity worksheets, channel incentive structures, and training/education roadmaps for KOL networks.
How to use this intelligence in Q1–Q2 2026
- Executive planning: Use our scenario outputs to set capital allocation between R&D, regulatory spend, and commercial rollout—aligning investment to the areas of highest probabilistic return.
- Product roadmap: Sequence features and regulatory submissions so that incremental launches purposefully defend against competitors’ platform extensions.
- M&A screening: Apply the concentration and capability matrices to prioritize targets that either fill a capability gap or extend regional reach with minimal integration risk.
- Commercial pilots: Launch focused pilots that validate clinical workflow improvements and gather economic endpoints needed for payer conversations in under 12 months.
Conclusion & next steps
For executives planning their 2026 playbook, PW Consulting’s Endosseous Implant Market report converts market momentum into executable strategy. The mid-single-digit CAGR and steady expansion over the forecast window create an environment where disciplined investments in clinical evidence, regulatory preparedness, and channel optimization will yield outsized returns. Our competitive and operational frameworks are designed to be directly operationalized—yet the granular regional and segment-level data that informs precise market-entry or pricing decisions is reserved for the full report.
To download the complete report, obtain company scorecards, and access the interactive forecasting model (including regional and material splits and full scenario outputs), please visit our report page or contact PW Consulting’s industry desk.
For detailed analysis of this topic, please visit the official page: Endosseous Implant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low Refractive Index Resin Market Poised to Reach USD 836.95 Million by 2032
By PW Consulting, 2026-07-13
Low Refractive Index Resin Market: Strategic Outlook and Decision Framework for 2026
Executive summary
PW Consulting's new market intelligence brief on the Low Refractive Index (Low‑RI) Resin market translates technical material science trends into actionable strategic guidance for 2026 decision‑makers. The market—anchored in fiber optics, AR/VR optics, anti‑reflective coatings and advanced photonics—has demonstrated steady expansion through the 2020–2025 historical window and is modeled to continue growing through the 2026–2032 forecast period at an 8.1% compound annual growth rate (CAGR). Using 2025 as the study base year, our topline projections show a material increase in absolute market value by 2032, reflecting both broad adoption of Low‑RI solutions and technology-driven premiumization across optical subsystems.
Low Refractive Index Resin Market
Why this report matters for 2026 planning
For manufacturers, component integrators, materials suppliers and strategic investors, 2026 is a pivot year: product roadmaps and procurement cycles initiated now will shape revenue and supply‑chain exposure through the next technology wave of co‑packaged optics, AR/VR headsets, and compact photonic modules. PW Consulting’s report is designed as a decision support toolkit rather than a purely descriptive study. It surfaces near‑term market trajectories and risk vectors while deliberately withholding proprietary, deal‑level segmentation to preserve competitive value—aligning with the “trailer” principle: we show the shape and forces of the market, and direct qualified readers to the source for the full dataset and supplier‑level intelligence.
Low Refractive Index Resin Market
What’s in the report — practical deliverables
- Market sizing and scenarios: base‑year benchmarking (2025), and three forward scenarios through 2032 under differentiated demand, pricing and regulatory outcomes.
- Commercial playbooks: go‑to‑market and pricing strategies tailored to resin suppliers, converter partners and optical OEMs, including channel design and specification gating.
- Supplier diligence framework: a scorecard for technical, regulatory and supply‑chain resilience, with sample RFx templates and lab validation protocols.
- Technology roadmaps: comparative assessment of fluorinated, siloxane and acrylate chemistries—strengths, limitations, and near‑term R&D inflection points.
- Regulatory and sourcing risk matrix: PFAS‑related compliance scenarios, precursor price‑shock stress tests and mitigation playbooks.
- M&A and partnership target filters: criteria and red flags for bolt‑on acquisitions and strategic JV opportunities.
High‑level market dynamics
Our historical analysis (2020–2025) captures a period of accelerating adoption as optical systems demand ever‑tighter control over refractive indices and interface losses. In quantitative terms, the market base year (2025) reflects meaningful scale, and under our central scenario the sector continues to expand through 2032 at an 8.1% CAGR—driven by: higher fiber counts and new fiber types in telecommunications; miniaturized optics in AR/VR and co‑packaged optics; increased deployment of anti‑reflective and waveguide coatings in consumer and industrial devices; and specialty LED and photonic packaging applications.
Low Refractive Index Resin Market
Growth is not uniform: technology adoption curves and procurement cycles vary by end‑market. Chemical formulation innovation (e.g., PFOA/PFOS‑free fluorinated grades, ultra‑low RI siloxanes, UV‑curable systems with near‑zero shrinkage) is enabling new form factors and assembly techniques, but these advances also increase the technical bar for material qualification and supplier selection.
Segmentation themes and technology tradeoffs
Market participants are choosing chemistry families based on a tradeoff between optical performance, thermal and environmental stability, process compatibility and regulatory exposure. Fluorinated chemistries remain the workhorse where the lowest achievable refractive index and low surface energy are required; siloxane‑based systems deliver exceptional low‑index windows and flexibility for coatings; acrylate systems offer cure speed and adhesion advantages for certain assembly processes. Each family has distinct cost structures and qualification timelines.
Regulatory pressure—especially scrutiny of fluorinated chemistries in several jurisdictions—adds a parallel constraint to technology selection. While some regulatory submissions have sought essential‑use exemptions or characterized certain fluoropolymers as lower environmental concern under specific conditions, procurement and compliance teams must now quantify testing obligations and potential market access restrictions as part of supplier onboarding.
Competitive landscape: who is shaping the market
The Low‑RI resin market exhibits moderate concentration: our market concentration metrics indicate that the top three players command a material share, and the top five consolidate majority market presence. This structure produces a competitive dynamic where specialized technology leaders coexist with vertically integrated resin and chemical suppliers.
- Luvantix ADM Co., Ltd. — A technology leader with deep IP in UV‑curable low‑RI chemistries and a track record of supplying photonics OEMs. Their product portfolio spans ultra‑low RI grades and thermally robust resins; recent product introductions include ultra‑thin GRIN lens arrays for co‑packaged optics and epoxy systems with zero cure shrinkage. Luvantix’s patent estate and marquee customers make them a strategic supplier for high‑precision photonic assemblies.
- Fospia — Specializes in fluorinated acrylate formulations targeted at specialty fiber and laser recoating applications. Their focus on PFOA‑free grades and silane surface‑compatibility addresses both performance and regulatory concerns, positioning them well for fiber‑centric use cases.
- Inkron (Nagase Group) — Known for siloxane‑based low‑RI coatings, Inkron plays strongly in anti‑reflective, waveguide and AR/XR adhesive layers where ultralow index and optical clarity are priorities.
- MY Polymers — A polymer specialist active across photonics and display markets. Their product line and global engagement at major optics conferences indicate a pragmatic supply strategy for manufacturers seeking qualified, application‑focused resin partners.
- NTT‑AT and DIC Corporation — Both provide technically configurable resin systems with emphasis on precision RI control and transparency, supporting optical recording, display and optical energy assemblies. Product discontinuations and lifecycle management from legacy SKUs are also catalysts for customer migration and re‑qualification projects.
Recent signals worth watching
- Product innovation continues at pace: ultra‑thin GRIN lens arrays and zero‑shrinkage epoxies demonstrate that materials advances are enabling new optical architectures and packaging densities.
- Market visibility is increasing: suppliers are ramping presence at photonics and AR/VR shows, signaling acceleration of prototype‑to‑production transitions for next‑gen optics.
- Regulatory and commercial lifecycle events—such as planned discontinuations of legacy acrylate grades—are driving re‑qualification cycles and supplier switching opportunities for buyers and partners.
Risk profile — supply, regulatory and pricing volatility
Three risk themes should be prioritized in 2026 planning:
- Raw material volatility: specialty monomers and fluorinated precursors have shown episodes of sharp price movement—industry sources indicate swings that have exceeded 25% year‑over‑year in recent cycles—making cost pass‑through and hedging essential components of commercial strategy.
- Regulatory complexity: PFAS‑related testing and regional restrictions require proactive engagement with regulators and robust substance data reporting to preserve market access for fluorinated offerings.
- Qualification friction: optical OEMs’ extended qualification timelines mean that supplier shifts (whether driven by performance needs or regulatory pressures) carry multi‑year revenue and schedule implications.
Actionable recommendations for executives in 2026
- Build a two‑track sourcing strategy: secure dual‑supply or validated alternative chemistries for critical product lines, pairing incumbent suppliers with qualified niche specialists to reduce single‑source exposure.
- Invest in shortened validation loops: co‑fund accelerated qualification programs and shared test protocols with key customers to shorten time‑to‑production and capture premium design‑win share.
- Implement a regulatory surveillance function: map chemical portfolios against evolving PFAS and polymer policies; obtain necessary testing and consider strategic reformulation roadmaps where exposure is material.
- Prioritize materials R&D aligned to manufacturability: focus on low‑shrink UV‑curable systems, thermally robust grades and process‑compatible adhesion chemistries that reduce assembly rework and test failures.
- Stress‑test commercial models under price‑shock scenarios: run portfolio P&L sensitivity to precursor cost swings and embed contractual mechanisms (indexation, cap floors) where feasible.
- Pursue selective partnerships: technology co‑development with photonics OEMs or strategic JVs can accelerate adoption and de‑risk large qualification investments.
How PW Consulting’s report supports your 2026 decisions
This study combines a rigorous market model with practitioner tools that translate forecasts into executable plans: scenario‑driven demand curves, supplier scorecards, RFx templates, lab acceptance criteria and a regulatory impact matrix calibrated to regional enforcement trends. We intentionally present high‑level market sizing and forces in this release while preserving the report’s granular segmentation, supplier shortlists and model inputs behind our client portal—ensuring that the intelligence retains commercial exclusivity and maximizes decision advantage for subscribers.
To convert 2026 uncertainty into tactical advantage: use our report to prioritize supplier engagements, align R&D and qualification timelines with expected demand inflections, and design contractual protections against raw material and regulatory shocks. The market is expanding, but value will accrue to organizations that can marry materials innovation with disciplined sourcing and regulatory foresight.
Next steps
PW Consulting invites materials manufacturers, optics integrators and strategic investors to access the full Low Refractive Index Resin Market report for the proprietary datasets, supplier analysis and executable templates referenced here. The full package contains the confidential segmentation tables, supplier shortlists and scenario model files required to implement the strategies outlined in this briefing.
For detailed analysis of this topic, please visit the official page: Low Refractive Index Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cost Estimating Software Market Poised for Rapid Expansion — 8.5% CAGR Forecast Through 2032
By PW Consulting, 2026-07-13
Cost Estimating Software Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
As organizations prepare budgets and technology roadmaps for 2026, PW Consulting’s forthcoming market research on Cost Estimating Software provides an indispensable, action-oriented lens. The global cost estimating software market — measured on a USD million revenue basis and modeled across a 2026–2032 forecast horizon with historical coverage from 2020–2025 — shows robust momentum. After steady expansion in the early 2020s, the market reached approximately USD 1,880.5 million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of 8.5% through 2032, approaching just over USD 3.3 billion by the end of the forecast period. This preview summarizes the report’s strategic value for executive decision-making while deliberately holding back granular segment tables to encourage review of the full report.
Cost Estimating Software Market
Why this matters for 2026 decisions
Procurement cycles, capital planning, and digital transformation initiatives slated for 2026 must account for both the accelerating adoption of cloud-native cost-estimating platforms and the changing competition among enterprise vendors. Our market sizing and trajectory modeling indicate that the sector is in a growth phase driven by SaaS transitions, AI-enabled automation of takeoffs and predictions, and tighter integration with BIM and enterprise project systems. For CFOs, CIOs, and heads of construction and engineering, the implications are concrete:
Cost Estimating Software Market
- Investment timing: Delaying a move from legacy on-premise solutions to modern cloud-enabled platforms risks missing productivity gains tied to AI-assisted takeoff and predictive analytics.
- Vendor negotiation: A market with moderate concentration among leading players creates leverage for enterprise buyers but also requires careful vendor selection to avoid lock-in.
- Risk management: Regulatory and data-protection requirements, together with evolving cloud hosting cost structures, make total cost of ownership (TCO) and contractual SLAs central to procurement evaluations in 2026.
Market structure and concentration — what senior leaders should know
Our competitive concentration analysis shows a market where the top three vendors account for a meaningful share of industry revenue, while the top five consolidate further industry influence. This dynamic produces a mix of scale advantages (broader integration, capital for R&D) and opportunities for niche innovators that provide specialized workflows or regional strengths. The full report explains how concentration influences pricing, partner ecosystems, and acquisition likelihoods over the next 24 months.
Cost Estimating Software Market
Key dynamics shaping vendor and buyer strategies
The report synthesizes multiple forces that will determine which vendors and buyers capture the most value through 2032:
- AI and automation: Advances in AI-assisted quantity takeoffs and predictive cost modeling materially reduce manual estimator workload and dampen bid variability. Early adopters report faster cycle times for preconstruction and fewer cost overruns at tender stage.
- Cloud economics and subscription models: Migration to cloud-hosted offerings shifts vendor revenue toward recurring models and changes buyer budgeting from CAPEX to OPEX. Cloud hosting remains a primary operational cost for providers, influencing pricing and feature packaging.
- Labor and skills constraints: The sector still relies on specialized estimator expertise for data validation and custom assemblies. Software that embeds intelligent validation and lowers the skill barrier creates competitive differentiation in regions with estimator shortages.
- Regulation and data security: GDPR-style privacy regimes and emerging state-level laws in the U.S. increase the compliance burden on cloud platforms handling sensitive bid and cost data. Buyers must insist on demonstrable security posture, contractual data ownership clauses, and clear incident response commitments.
Competitive landscape — who to watch
The market features established construction-technology incumbents, enterprise software providers, and specialized niche vendors. Key companies profiled in our research include major cloud-first construction platforms, CAD/BIM incumbents expanding into cost, and focused takeoff/estimating specialists. Highlights from our corporate review:
- Procore Technologies — A cloud-first construction-management platform with integrated estimating capabilities; strong appeal to general contractors seeking a unified project environment.
- Autodesk — Through its construction cloud and acquired estimating capabilities, Autodesk combines BIM and cost workflows for tighter design-to-cost traceability.
- Trimble — Integrates estimating into a broader construction-technology portfolio, leveraging its field-to-office connectivity and surveying/BIM assets.
- STACK and other takeoff specialists — Deliver rapid, cloud-native takeoff and preconstruction workflows; recent AI-enabled feature updates accelerate symbol recognition and counting across large plan sets.
- Sage, HCSS, and enterprise niche players — Offer deep cost databases, heavy civil estimating capabilities, and industry-specific templates that appeal to specialized buyer segments.
- International and engineering-focused vendors (e.g., Cleopatra Enterprise, Nomitech/CostOS, RIB, Glodon) — Provide capabilities tailored to process industries, 2D/3D/BIM/GIS takeoffs, and multi-discipline estimating requirements.
Notable recent product developments underscore how quickly capability barriers are shifting: one major incumbent updated its estimating suite for cloud deployment and introduced AI-enabled takeoffs and enhanced bid analytics in early 2026, while a prominent takeoff vendor rolled out automated symbol recognition and rapid counting enhancements in late 2025. These feature moves are representative of vendor strategies to embed AI and improve preconstruction velocity.
What the PW Consulting report delivers — practical, decision-ready content
Designed for executives and procurement teams, the full report combines quantitative market modeling with qualitative, executable guidance. Key deliverables include:
- Validated market size and forecast model (2026–2032) with scenario sensitivity analysis that links macro drivers to revenue outcomes.
- Vendor scorecards that evaluate product capability across takeoff, estimating, BIM integration, reporting, API/connectivity, security/compliance, and go-to-market strength — enabling shortlists for RFPs.
- TCO and ROI templates that help finance and technology leaders compare subscription vs. on-prem deployments, factoring in hosting, training, maintenance, and data migration costs.
- Integration playbooks for IT and PMO teams detailing common pitfalls and success factors when connecting estimating platforms to ERP, project controls, and digital twin environments.
- Procurement negotiation levers and recommended contract clauses covering data governance, portability, performance metrics, and exit provisions.
- Roadmaps for change management and skills uplift — practical next steps to bridge estimator capability gaps and accelerate adoption of AI-assisted workflows.
To preserve commercial value for subscribers, the report intentionally withholds granular regional and application-level tables in this public summary. Those detailed splits and downloadable financial models are available in the full report package.
Actionable recommendations for 2026
Based on scenario modeling and vendor assessments, PW Consulting recommends a prioritized set of moves for organizations planning for 2026:
- Start with a one-year “sprint” to assess quick wins: pilot AI-assisted takeoff on a representative project cohort to measure accuracy gains and labor productivity improvements within three to six months.
- Recast procurement criteria to emphasize interoperability and data portability: require open APIs, exportable cost libraries, and documented migration paths as core evaluation filters.
- Build security and compliance into TCO: include cloud hosting costs, encryption-at-rest and in-transit, and contractual breach/response obligations when modeling vendor offers.
- Negotiate staged commitments: tie pricing and rollout to performance milestones and integration deliverables to reduce risk while enabling rapid value capture.
- Invest in estimator training and governance: pair software rollout with a recorded knowledge-transfer plan and a small, centralized data-curation team to maintain databases and templates.
How PW Consulting’s research supports board-level decisions
Boards and executive committees are asking three questions when evaluating cost estimating technology in 2026: (1) Will this materially reduce bid-to-contract leakage and improve margin predictability? (2) Does the vendor roadmap align with our BIM/digital-twin and ERP investments? (3) What are the compliance and exit-risk exposures? Our report maps three plausible adoption scenarios to financial and operational outcomes, providing the evidence base required for capital approval, M&A consideration, or strategic partnership decisions.
Next steps and access
This preview is intended to demonstrate the report’s strategic utility for 2026 planning while reserving the full analytical depth — including regional, type, and application segmentation tables and downloadable models — for report subscribers. To obtain the complete PW Consulting Cost Estimating Software Market report with full datasets, vendor scorecards, and TCO templates, visit PW Consulting’s report landing page or contact our research team for corporate subscription options and bespoke advisory engagements.
For senior executives, CIOs, and procurement leads preparing 2026 technology plans: the time to evaluate cloud migration strategies, vendor roadmaps, and estimator upskilling initiatives is now. The choices made this year will determine who captures the productivity, margin, and risk-management gains as the market scales through 2032.
For detailed analysis of this topic, please visit the official page: Cost Estimating Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


