



Category: market research
Agarose Market 2032: Why the 6.98% CAGR Trajectory Signals Strategic Shifts in Life Sciences
By PW Consulting, 2026-09-21
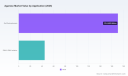
Strategic Trends and Commercial Opportunities in the Agarose Market
Market Overview and Core Challenges
The global agarose market has demonstrated consistent expansion over the past half-decade, establishing itself as a critical component within the broader life sciences and bioprocessing supply chain. Starting from a valuation of approximately 153.44 million USD in 2020, the market has grown steadily to reach an estimated 215.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.98 percent, with projections indicating continued expansion through 2032. By the end of the forecast period, the market is expected to surpass 344 million USD, signaling sustained demand across research and industrial applications.
This growth is not merely a function of population or academic output increases; it represents a structural shift in how biological materials are processed and analyzed. The market has moved from a niche consumable model toward a more integrated industrial supply dynamic. However, this expansion faces headwinds that strategic planners must account for. The period from 2025 to 2032 will not be defined solely by volume growth but by how players navigate supply chain fragility and regulatory divergence.
Three critical challenges define the current inflection point for industry stakeholders. First, raw material security remains a persistent vulnerability. Agarose is primarily derived from seaweed, linking market stability directly to marine agriculture and geopolitical trade flows. Recent data indicates that geopolitical tensions between major seaweed-producing nations and key import markets like the European Union and the United States have triggered higher import/export tariffs. These barriers have increased operational costs for producers, squeezing margins on standard grades while complicating long-term capacity planning.
Second, regulatory uncertainty in key regions is altering demand patterns. In 2024, China introduced classification rules for bio-stimulant products such as seaweed extracts that created inspection delays and price fluctuations. While this specifically impacts biostimulants, it signals a broader trend of tighter oversight on seaweed-derived materials that can spill over into industrial and laboratory-grade agarose supply chains. Additionally, the new French national roadmap launched in March 2025 aims to triple domestic seaweed production by 2027. While this enhances sector resilience in Europe, it also shifts regional supply dynamics and may alter competitive advantages for producers reliant on specific geographic sources.
Third, the market is experiencing a bifurcation in demand quality. Standard agarose continues to drive volume, but high-performance variants such as low melting point agarose are gaining strategic importance in specialized applications. This divergence forces manufacturers to choose between competing on cost efficiency in commoditized segments or investing in differentiation for high-value niches. Companies that fail to align their product portfolios with this shift risk exposure to margin compression as standard-grade pricing comes under pressure from rising input costs.
For executives and investors, these challenges underscore the need to look beyond top-line growth figures. The market size trajectory is positive, but the underlying economics are tightening. Success in the next cycle will depend on supply chain agility, regulatory foresight, and the ability to capture value in differentiated segments rather than competing solely on volume.
Gracilaria Agarose and Gelidium Agarose Market
Key Growth Drivers
Understanding the forces propelling the agarose market requires examining the intersection of technological advancement, regulatory evolution, demand-side shifts, and cost structures. Each driver influences not only the pace of growth but also where value is created within the market ecosystem.
Technological Innovation and Performance Breakthroughs
Innovation in agarose chemistry and manufacturing processes is reshaping application boundaries. Advances in purification and gel characterization have enabled products that deliver higher resolution and reproducibility for nucleic acid analysis. More importantly, the development of specialized resins for bioprocessing has opened new commercial pathways. Manufacturers are increasingly engineering agarose-based matrices tailored for affinity purification and monoclonal antibody processing, where performance consistency directly impacts downstream therapeutic production.
Recent market activity illustrates this trajectory. In February 2024, Purolite, part of Ecolab, commercially launched Praesto CH1, a 70-micron agarose-based affinity resin developed in partnership with Repligen for specialized monoclonal antibody purification. This launch highlights how agarose is moving beyond traditional laboratory electrophoresis into high-value bioprocessing workflows. Such developments expand the addressable market and create pricing power for suppliers capable of meeting stringent performance and regulatory standards for biological drug manufacturing.
Policy and Regulatory Environment
Regulatory frameworks are acting as both constraints and catalysts. On one hand, trade policies and tariffs are raising input costs and complicating cross-border sourcing. On the other, government initiatives aimed at strengthening domestic production capacity are creating new opportunities. The French national roadmap to triple seaweed production by 2027 exemplifies this dual dynamic. By supporting local cultivation, the policy reduces dependency on imported raw materials and enhances supply chain resilience for European processors.
At the same time, regulatory clarity around product classification remains uneven. The 2024 Chinese regulatory adjustments for seaweed-derived biostimulants caused temporary market disruptions, demonstrating how policy ambiguity can ripple through related supply chains. For agarose producers, this signals the importance of monitoring regulatory developments in bothsource and destination markets. Proactive engagement with policy trends can help companies anticipate sourcing shifts and position their product lines to comply with evolving standards for laboratory and industrial-grade materials.
Demand-Side Shifts in Research and Biomanufacturing
End-user behavior is evolving as laboratory workflows become more automated and throughput requirements increase. In academic and clinical research settings, the demand for reliable DNA and RNA isolation and gel electrophoresis remains foundational. However, the scale and standardization expectations are rising. Laboratories are increasingly seeking precast solutions and certified powders that reduce variability and preparation time. This shift favors suppliers who can offer consistent quality and integrated product systems rather than bulk commodity powders alone.
Simultaneously, the biopharmaceutical sector's expansion is driving demand for agarose-based chromatography media. As monoclonal antibody therapies and advanced biologics continue to scale, manufacturers require purification resins that can handle larger volumes while maintaining binding capacity and flow properties. This demand is less price-sensitive than routine research applications and more focused on performance validation and supply reliability. Companies that can demonstrate batch-to-batch consistency and offer technical support for process integration are capturing a growing share of this higher-value demand segment.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping competitive positioning across the value chain. Rising fuel prices and trade barriers since 2024 have increased the cost of seaweed extract biostimulants and related upstream resources used in agarose production. These input cost increases affect both raw material procurement and logistics. Producers with diversified sourcing strategies or localized supply networks are better positioned to absorb these shocks compared to those relying on single-source or long-distance procurement models.
At the same time, the cost structure is encouraging consolidation and specialization. Smaller players may struggle to invest in the capacity expansions or quality systems required to meet bioscience-grade standards, while larger entities can leverage scale and integration to maintain margins. This dynamic is pushing the market toward a structure where competitive advantage is increasingly tied to supply chain robustness, technical service capabilities, and the ability to offer graded product portfolios that match distinct end-user requirements.
Competitive Landscape and Leading Strategies
The agarose market is characterized by a mix of specialized manufacturers and broader life sciences companies, each pursuing distinct strategic positions. Market concentration data shows that the top three companies hold approximately 35 percent of the market, while the top five account for around 48 percent. This moderate concentration suggests a landscape where established leaders maintain meaningful share but room remains for niche players and regional specialists to compete on differentiation.
Thermo Fisher Scientific and Bio-Rad Laboratories represent the large-cap life sciences segment, offering certified agarose powders and precast gel systems optimized for routine and high-throughput nucleic acid analysis. Thermo Fisher's UltraPure powders and E-Gel precast systems cater to laboratories seeking consistency and workflow efficiency, while Bio-Rad's certified molecular biology powders and precast gels serve similar demand with a strong reputation in research and teaching environments. Their strategic advantage lies in brand trust, distribution scale, and integrated product ecosystems that reduce user variability.
Lonza occupies a specialized position with products such as SeaKem and NuSieve grades tailored for nucleic acid gel electrophoresis. Its focus on high-clarity and specialized gel formulations addresses applications where resolution and reproducibility are paramount. By maintaining a dedicated product architecture for electrophoresis, Lonza competes on technical performance rather than volume pricing, appealing to users with demanding analytical requirements.
Agarose Bead Technologies (ABT) and Purolite represent the bioprocessing-oriented flank of the market. ABT, based in Spain, specializes in high-performance custom agarose resins for bioprocessing applications including monoclonal antibody purification and advanced therapies. Its strategy emphasizes customization and capacity investment. In October 2024, ABT completed a 1,000 square meter addition to its Burgos facility, increasing agarose resin production capacity to 100,000 liters annually. This expansion signals a commitment to scaling supply for bioprocessing demand. ABT's participation in Analytica 2026 in Munich further underscores its focus on showcasing agarose-based resins and custom chromatography solutions to a global bioprocessing audience.
Purolite, operating across the UK and US under Ecolab, leverages patented jetting technology for agarose-based chromatography resins used in bioprocessing and affinity purification. Its partnership-driven approach, exemplified by the Praesto CH1 launch in collaboration with Repligen, illustrates how resin suppliers are building ecosystems around specific therapeutic manufacturing needs. This model allows Purolite to align product development with customer process requirements and capture value in the antibody purification workflow.
Worldwide Agar Resin Market
The competitive landscape is evolving along two axes: integration and specialization. Larger life sciences companies are expanding their agarose offerings through brand extension and precast system integration, competing on workflow convenience and global reach. Specialized manufacturers are deepening their technical focus on custom resins, high-performance grades, and bioprocessing applications, competing on performance, customization, and supply reliability for advanced therapies. New entrants are most likely to succeed by targeting underserved niches, such as regional supply optimization, tailored resin specifications, or cost-efficient production of standard grades with consistent quality. Mergers and partnerships may increase as companies seek to combine upstream raw material access with downstream application expertise.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the 2026 to 2032 period, several trends are likely to shape market direction and create distinct commercial opportunities. These trends are grounded in current data trajectories and recent industry developments, offering a basis for strategic planning.
Trend 1: Premiumization and Workflow-Integrated Solutions
The market is likely to see continued growth in high-performance and low melting point agarose variants as laboratories and bioprocessors prioritize reproducibility, speed, and integration. Demand for precast gels, certified powders, and resins with validated performance characteristics will expand as users seek to reduce preparation variability and accelerate throughput. This trend favors suppliers that can offer complete workflow solutions, technical documentation, and application support. Commercial opportunities lie in bundling products with service offerings, developing application-specific grades, and building partnerships with equipment and automation providers to embed agarose solutions into standardized workflows.
Trend 2: Regional Supply Restructuring and Sourcing Diversification
Policy initiatives such as France's push to triple domestic seaweed production and ongoing trade tensions affecting import/export tariffs will encourage regional supply chain restructuring. Producers and buyers alike will increasingly value diversified sourcing strategies and localized processing capabilities to mitigate tariff risks and input cost volatility. Over the next few years, expect more investment in regional cultivation partnerships, alternative sourcing routes, and capacity located closer to key demand centers. Companies that secure resilient raw material access and can offer transparent sourcing will gain a competitive edge, particularly in Europe and North America where supply security is becoming a strategic priority.
Trend 3: Convergence of Research and Bioprocessing Demand
As biomanufacturing scales and research workflows become more standardized, the boundary between laboratory-grade and bioprocessing-grade agarose applications may continue to blur in certain segments. Advanced therapies and biologics production require high-purity, consistent resins, while research labs increasingly adopt precast and certified products that mirror industrial quality expectations. This convergence creates opportunities for suppliers that can span both domains with appropriate quality tiers and regulatory documentation. It also raises the bar for quality systems, traceability, and technical support, rewarding companies that can bridge research and production requirements without compromising cost efficiency.
Potential risks and uncertainties accompany these trends. Regulatory ambiguity in key seaweed-producing and consuming markets could resurface, causing supply disruptions or reclassification of products that affect demand. Geopolitical tensions and fuel price volatility may continue to pressure input costs, particularly if trade barriers persist or intensify. Additionally, oversaturation in standard-grade segments could intensify price competition, eroding margins unless companies successfully differentiate through quality, service, or application-specific value. Strategic planners should stress-test their assumptions around sourcing stability, regulatory clarity, and pricing power in commoditized segments.
Actionable Insights for Decision Makers
For manufacturers, the priority is to align product portfolios with the shift toward differentiation and workflow integration. Investing in high-performance grades, precast systems, and custom resin capabilities can protect margins and capture higher-value demand. At the same time, strengthening supply chain resilience through diversified sourcing, regional partnerships, or localized processing can reduce exposure to tariffs and input cost volatility. Manufacturers should also evaluate whether capacity expansion aligns with demand concentration in bioprocessing or whether a regional strategy better serves market needs. Technical service capabilities and application support should be treated as core competitive assets rather than ancillary functions, as end-users increasingly value validation, consistency, and process integration.
For investors, the market offers attractive structural growth supported by a steady CAGR and expanding demand across research and bioprocessing. However, due diligence should focus on supply chain robustness, regulatory exposure, and product mix. Companies with diversified sourcing, clear quality systems, and a balanced portfolio of standard and premium products are better positioned to navigate input cost pressures and regulatory uncertainty. Interest in specialized bioprocessing resins and custom chromatography solutions is likely to remain a value-creation driver, particularly as monoclonal antibody and advanced therapy production scales. Evaluating capacity expansion plans against realistic demand trajectories and regional policy developments can help identify companies with sustainable competitive positioning.
For procurement and supply chain leaders, securing reliable supply while managing cost volatility requires proactive supplier engagement and sourcing diversification. Qualifying multiple suppliers across regions, establishing clear quality and documentation requirements, and exploring partnerships with manufacturers that offer transparent sourcing and capacity visibility can reduce risk. Buyers should also assess the total cost of ownership beyond unit price, considering workflow efficiency, reproducibility, and technical support, especially for critical applications where variability can impact results or production timelines. Monitoring regulatory developments in source and destination markets enables earlier adjustments to sourcing strategies and reduces the likelihood of disruption from classification changes or trade policy shifts.
Accessing detailed segmentation data, regional demand patterns, and customized strategic recommendations can sharpen decision-making in this evolving landscape. Comprehensive market intelligence that breaks down growth trajectories by application, product type, and region, along with scenario analysis for regulatory and supply chain variables, provides the granularity needed to turn high-level trends into actionable plans. For organizations seeking to optimize sourcing, prioritize product development, or evaluate investment and partnership opportunities, a deeper data-backed view of the agarose market is an essential input to strategic planning.
For detailed analysis of this topic, please visit the official page: Agarose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lab Glassware Market 2026: The 4.7% CAGR Trajectory and What It Reveals
By PW Consulting, 2026-09-21
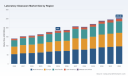
Navigating the Laboratory Glassware Market: Strategic Trends and Commercial Imperatives
The laboratory glassware market is entering a phase of structural transformation, driven by technological refinement, evolving regulatory expectations, and shifting procurement behaviors across end-user segments. Valued at approximately USD 185.0 million in 2025, the market has expanded from USD 140.5 million in 2020, reflecting steady compounding growth over the post-pandemic period. Forward projections indicate a trajectory toward USD 253.28 million by 2032, with a compound annual growth rate of 4.7 percent across the forecast horizon. This expansion is not merely incremental; it reflects a market responding to heightened precision requirements, supply chain recalibration, and the integration of traceability and standardization into routine laboratory operations. For executives, investors, and procurement leaders, the window to align product portfolios, capital allocation, and sourcing strategies with these underlying shifts is opening now.
Market Snapshot: Growth Trajectory and Structural Realities
The market’s historical performance from 2020 through 2025 demonstrates a consistent upward curve, with annual revenue crossing the USD 160 million threshold in 2022 and accelerating into the USD 170–185 million range by mid-decade. The forecast period from 2026 to 2032 projects continued expansion, though the growth path is not uniform. The transition from USD 185.0 million in 2025 to the projected USD 253.28 million in 2032 implies that demand generation will increasingly depend on application-specific precision, regulatory compliance, and regional capacity dynamics rather than broad volume expansion alone.
At the structural level, the market operates with moderate concentration. The top three participants collectively command roughly 45 percent of total revenue, while the top five extend that share to approximately 60 percent. This concentration pattern indicates that established manufacturers retain meaningful pricing power and distribution leverage, yet the remaining 40 percent of the market remains fragmented across regional players, specialty suppliers, and cost-focused producers. Such a landscape creates both defensive moats for incumbents and entry points for well-positioned challengers, particularly where customization, compliance documentation, or supply chain reliability becomes a differentiating factor rather than a baseline expectation.
The market is also characterized by a clear hierarchy of product and application relevance. Volumetric measurement tools and general containment vessels continue to anchor demand, while pipettes and precision dispensing instruments represent a growing precision segment. In application terms, pharmaceutical and biotechnology workflows consume the largest share of glassware volumes, followed by academic and research environments, clinical diagnostic settings, and ancillary use cases. This distribution indicates that demand is increasingly tied to regulated, high-throughput, or quality-sensitive environments where measurement accuracy, material consistency, and documentation traceability carry direct operational and compliance implications.
Defining Challenges and Inflection Points
Despite the favorable growth baseline, the industry faces several interconnected challenges that will shape competitive outcomes over the next three to five years.
Precision Standards and Calibration Expectations
The laboratory glassware sector is moving toward tighter standardization for measurement-critical items, particularly in one-mark volumetric instruments. Updated international requirements are reinforcing calibration consistency, marking accuracy, and manufacturing repeatability. For producers, this translates into higher compliance costs, more rigorous quality control protocols, and the need to align product specifications with evolving normative references. Laboratories and procurement teams, in turn, are placing greater weight on certification documentation and conformance assurance, raising the barrier for sellers that cannot demonstrate consistent specification integrity across batches.
Material Consistency and Thermal Performance Requirements
Borosilicate glass remains the dominant material foundation because of its thermal shock resistance and chemical durability. While this dominance provides stability, it also constrains rapid material substitution and heightens sensitivity to raw material quality, melting consistency, and forming precision. Variability in feedstock composition or furnace control can affect wall thickness uniformity, dimensional tolerance, and long-term reliability in temperature-cycling applications. Manufacturers that treat material consistency as a core process capability rather than a commodity input will be better positioned to capture demand from environments where thermal stress and chemical exposure are routine.
Traceability, Documentation, and Procurement Digitalization
A quiet but consequential shift is underway in how laboratories track, verify, and manage glassware inventory. The introduction of QR-coded product items, enhanced batch traceability, and digital catalog integration reflects growing demand for item-level identification and audit-ready documentation. This trend is especially relevant in regulated environments where lot traceability, usage history, and replacement scheduling influence both operational efficiency and compliance reviews. Suppliers that enable faster verification, clearer product identification, and smoother integration with laboratory inventory systems can reduce friction in the procurement cycle while strengthening supplier-of-choice positioning.
Core Drivers Reshaping the Market
Regulatory Alignment and Standardization Momentum
The push toward harmonized international standards is one of the most consequential forces in the market. Updated normative references for one-mark volumetric flasks are establishing clearer expectations for dimensional accuracy, marking, and conformity testing. Rather than treating standards as static compliance checkboxes, leading manufacturers are using them as product development anchors, aligning tooling, inspection routines, and documentation with anticipated certification expectations. For buyers, the practical implication is that specification sheets and conformity evidence are becoming more comparable across suppliers, which can compress differentiation based solely on branding and shift attention toward reliability, lead-time consistency, and technical support.
Innovation in Safety and Durability Features
Product-level innovation is increasingly focused on reducing breakage risk, improving handling safety, and extending service life in demanding workflows. Coated laboratory bottles with enhanced shatter protection illustrate this direction, addressing both workplace safety and total cost of ownership concerns. In settings where glassware is handled frequently, moved across benches, or used in environments with vibration, temperature variation, or incidental impact, safety-oriented design features can differentiate a product line and influence purchasing decisions beyond base price comparisons. Innovation is also extending to interchangeability, filtration-compatible configurations, and specialized vessel geometries that reduce workflow adaptation time.
Demand-Side Shifts in Regulated and Research Workflows
End-user behavior is evolving as laboratory workflows become more standardized, auditable, and throughput-sensitive. Pharmaceutical and biotechnology environments continue to absorb the largest share of demand because measurement precision, contamination control, and reproducibility carry direct implications for development timelines and quality outcomes. Academic and research institutions remain a substantial demand base, but their procurement patterns are increasingly influenced by budget cycles, shared instrumentation models, and the need for broad compatibility across teaching and research labs. Clinical diagnostic settings add another layer of complexity, where glassware usage is tied to laboratory service delivery and reimbursement frameworks that do not always map cleanly onto individual product codes. This fragmentation in reimbursement and procurement pathways means that suppliers must navigate both technical specifications and institutional purchasing logic.
Supply Chain and Cost Structure Pressures
Cost dynamics in the market are influenced by raw material availability, energy intensity in glass melting and forming, and logistics complexity across regions. Borosilicate glass production requires controlled high-temperature processing, which makes energy pricing and furnace utilization relevant to cost structure. At the same time, regional demand patterns are reshaping sourcing strategies. North American and European markets maintain substantial demand bases, while Asia Pacific represents a growing volume center supported by expanding research infrastructure, manufacturing capacity, and domestic consumption. The result is a supply environment in which regional presence, export capability, and inventory positioning increasingly matter for competitive responsiveness. Companies that can combine consistent production output with dependable distribution and clear compliance documentation are gaining an advantage in tenders and recurring procurement programs.
Competitive Landscape and Strategic Positioning
The competitive environment blends incumbent scale, regional manufacturing strength, and niche specialization. Companies with established brand portfolios and broad product ranges are using brand trust, specification consistency, and application coverage to defend share. At the same time, regional manufacturers are gaining relevance by offering competitive cost profiles, adaptable production runs, and growing conformity to local certification expectations. This dual dynamic creates a market where scale and reputation matter, but they no longer guarantee automatic preference if a competitor can match specifications and improve traceability, lead time, or safety features.
Differentiation Patterns Among Leading Players
Several strategic positioning patterns are evident across the competitive set.
-
Brand-led premium positioning: Multi-brand manufacturers leverage well-known product lines and long-standing laboratory recognition to anchor trust in precision measurement and material quality. Their differentiation often rests on specification consistency, broad application coverage, and established distribution relationships.
-
Customization and specialty systems: Some suppliers emphasize custom configurations, reaction systems, and application-specific geometries. This approach is particularly relevant for research environments that require non-standard vessel dimensions, specialized port configurations, or integrated handling solutions.
-
Standards-aligned volume manufacturing: Regional producers focus on USP, ASTM, and local certification alignment, offering general laboratory glassware and consumables at competitive cost points. Their relevance grows where procurement teams prioritize specification compliance, batch consistency, and pricing predictability.
Glassware Market -
Traceability and catalog modernization: Suppliers introducing QR-coded items, updated catalogs, and improved identification systems are reducing friction in inventory verification and lot tracking. This is becoming a practical value-add, especially for repeat purchasers managing large SKU counts or regulated usage environments.
-
Safety-enhanced product extensions: Manufacturers introducing shatter-protection coatings, coated bottles, and handling-safety features are targeting total cost of ownership and workplace risk reduction. This positioning resonates in environments where breakage-related disruptions, cleanup, and replacement frequency influence operating costs.
PW Consulting
Evolution of the Competitive Structure
The market is unlikely to consolidate into a single dominant configuration over the near term. Instead, the structure appears to be evolving through selective integration, regional capacity expansion, and specialization by workflow. Incumbents are defending core positions by strengthening product reliability, demonstration value at major industry events, and application-aligned product launches. Regional producers are expanding relevance by combining cost efficiency with growing conformity to certification and standards expectations. At the same time, new entrants and expanders can gain traction by addressing unmet needs in traceability, safety, specialized geometries, or regional service responsiveness. The practical outcome is a landscape where competitive advantage is increasingly defined by the intersection of specification integrity, documentation readiness, and operational convenience rather than by brand alone.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Standards-Driven Harmonization of Precision Glassware
Over the next several years, the emphasis on harmonized requirements for measurement-critical items is likely to intensify. One-mark volumetric instruments will continue to serve as a focal point for calibration discipline, and suppliers that proactively align manufacturing controls, inspection protocols, and documentation with evolving normative expectations will face fewer friction points in regulated procurement. The commercial implication is that quality documentation and specification consistency will become more central to supplier selection, and companies that treat conformance as a design and process priority rather than an after-the-fact certification activity will be better positioned for repeat business in quality-sensitive environments.
Trend 2: Safety, Durability, and Total-Cost-of-Ownership Framing
Demand for safety-enhanced and durability-oriented products is expected to grow as laboratories and procurement teams evaluate glassware not only by unit price but by handling risk, breakage frequency, replacement cycles, and workflow interruption. Coated bottles, protective designs, and improved handling characteristics can shift purchasing conversations toward operational outcomes. This trend creates opportunity for manufacturers that can demonstrate measurable benefits in safety and lifecycle performance, especially where laboratory staffing constraints, training variability, or high-throughput handling increase exposure to breakage and handling errors.
Trend 3: Digital Traceability and Procurement System Integration
QR-enabled identification, updated product catalogs, and improved traceability are early indicators of a broader move toward inventory digitization and audit-readiness. As laboratories seek faster verification, clearer lot history, and easier integration with procurement and inventory systems, suppliers that provide machine-readable identification and well-structured product data will reduce administrative burden and improve buyer confidence. This trend is particularly relevant for recurring procurement programs, multi-site institutions, and regulated settings where documentation continuity matters. The opportunity lies not only in labeling, but in supporting buyers with data consistency, clear product hierarchy, and compatibility with modern procurement workflows.
Risks and Uncertainties to Monitor
Several risks could temper or redirect these trends. Regulatory and standards implementation can vary by region and by procurement cycle, creating uneven adoption timelines. Raw material and energy cost volatility may pressure margins, particularly for producers with limited pricing flexibility or high exposure to energy-intensive forming processes. Reimbursement and procurement structures in diagnostic and clinical service settings remain complex, which can obscure demand signals and slow purchasing decisions. In addition, the fragmented portion of the market can intensify price competition, especially where differentiation is limited to specification parity and brand recognition. Companies that fail to strengthen traceability, documentation, and safety value propositions may find themselves competing primarily on price in an increasingly demanding specifications environment.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Owners
Strengthen the link between product design and compliance readiness. Where measurement-critical items are concerned, investment in process control, inspection discipline, and conformity documentation can reduce friction in regulated procurement and improve repeat-order reliability. Equally important is the differentiation path beyond base specifications: safety coatings, handling improvements, traceability features, and application-specific geometries can shift purchasing conversations toward operational value. Manufacturers should also evaluate regional certification expectations and determine where local compliance, service responsiveness, or cost-positioning can open access to growing demand centers. Participation in major industry exhibitions and consistent product demonstration can reinforce visibility, but the durable advantage will come from repeatable conformance, clear documentation, and the ability to reduce buyer risk across the ordering and use cycle.
For Investors and Strategic Allocators
Evaluate exposure through the lens of specification integrity, regional capacity, and value-added differentiation rather than aggregate volume alone. Segments tied to precision measurement, safety-enhanced products, and traceability-enabled catalog systems are likely to see stronger demand resilience because they address compliance, handling risk, and procurement efficiency. It is also important to assess the regional balance of demand and production capacity, since energy intensity, raw material access, and logistics can shape margin durability. Companies that combine stable production quality with clear documentation and differentiated product features may offer more defensible positioning than those reliant on undifferentiated commodity supply. In addition, investors should monitor how reimbursement and procurement structures evolve in diagnostic-linked settings, since those frameworks influence demand timing even when the product itself is not directly coded.
For Procurement Leaders and Laboratory Operators
Expand evaluation criteria beyond unit price to include specification conformance, documentation completeness, handling safety, and traceability support. In precision-sensitive workflows, the cost of measurement uncertainty, replacement delays, and compliance friction can outweigh small differences in list price. Suppliers that provide clearer product identification, reliable conformity evidence, and efficient replenishment processes can reduce administrative burden and improve continuity. Procurement teams should also consider total cost of ownership when breakage, handling risk, and replacement frequency are material, since safety-enhanced options may lower downstream disruptions even if upfront pricing differs. Where multi-site or regulated environments are involved, standardized product data and traceable lot management can simplify audit preparation and inventory control.
From Insight to Execution
The laboratory glassware market is moving from a period of steady expansion to one where differentiation is increasingly determined by precision discipline, safety enhancement, traceability readiness, and regional execution. The baseline growth trajectory remains constructive, but the more valuable question for decision-makers is not whether the market will continue to grow, but which capabilities will earn preference as specifications tighten and procurement becomes more documentation-driven. Manufacturers that align product development with standards expectations, reinforce material and process consistency, and reduce operational friction for buyers can convert market-wide growth into share gains. Investors and procurement leaders, meanwhile, can use these signals to prioritize exposure, negotiate with clearer evaluation criteria, and reduce hidden cost risks in precision-sensitive workflows.
Worldwide Laboratory Glass Container Market
For organizations that need a granular view of regional demand splits, product-type dynamics, application-level consumption patterns, and company-specific competitive positioning, a more detailed research view can help translate these high-level trends into segment-specific strategy. Access to the full breakdown supports scenario planning, sourcing decisions, and portfolio prioritization with finer granularity than is possible in a market overview alone.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LPO Market at 22.91% CAGR: What’s Really Driving the $125.85B Surge to 2032
By PW Consulting, 2026-09-21
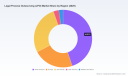
The Legal Process Outsourcing Market: Strategic Shifts and Growth Horizons (2025–2032)
The legal process outsourcing (LPO) sector has transitioned from a cost-arbitrage experiment into a core operational function for corporations, law firms, and compliance teams worldwide. Over the past five years, the market has demonstrated consistent expansion, with revenues climbing from approximately 11.0 billion USD in 2020 to nearly 30 billion USD by 2025. The trajectory continues upward, with annual growth momentum expected to push the sector past 125 billion USD by 2032. At a compound annual growth rate of roughly 22.9 percent across the 2026–2032 forecast window, LPO is outpacing many adjacent professional services categories, reflecting a structural recalibration of how legal work is sourced, managed, and delivered.
This growth is not merely a function of volume expansion. It reflects a deeper transformation in how organizations approach legal capacity, regulatory complexity, and technology integration. For executives, investors, and procurement leaders, the LPO landscape now offers a mix of established scale players, specialized capability providers, and emerging technology-driven models. Navigating this environment requires a clear understanding of where value is being created, where operational friction persists, and which strategic moves are separating consistent performers from the rest of the field.
Healthcare BPO Market
Market Realities and Core Challenges
The LPO market has reached a scale where traditional outsourcing playbooks no longer apply uniformly. Organizations today are leveraging external legal operations for everything from high-volume document review to regulatory monitoring, contract lifecycle management, and specialized intellectual property support. The breadth of services has expanded significantly, and the revenue base now spans multiple service categories with varying maturity levels. Litigation support and e-discovery workflows remain a substantial portion of the service mix, while contract management, regulatory and compliance services, and legal research functions have grown in strategic importance as internal legal teams face increasing workloads and tighter budgets.
Despite the strong growth profile, the industry faces several structural challenges that will shape its next phase of development.
- Quality and consistency at scale. As volumes increase and service delivery crosses multiple jurisdictions, maintaining consistent quality standards becomes more difficult. Legal work is inherently high-stakes, and errors in contract review, compliance monitoring, or discovery processes can carry significant financial and reputational consequences. Vendors must balance speed and cost efficiency with rigorous quality controls, which often requires layered review processes, specialized training, and robust performance metrics.
- Data security, privacy, and cross-jurisdictional compliance. Legal outsourcing frequently involves transferring sensitive information across borders, which introduces regulatory complexity. Data protection requirements, industry-specific confidentiality obligations, and evolving cross-border data transfer rules create operational hurdles for providers and clients alike. Delivery models must be designed with security architecture, access controls, and compliance monitoring built in from the start rather than treated as add-ons.
- Talent availability and capability gaps. The LPO sector depends on a blend of legal knowledge, process discipline, and increasingly technical skills. Demand for professionals who can operate across legal workflows, data analytics, and AI-assisted tools is rising, but supply remains uneven across regions. Provider organizations that can develop, retain, and continuously upskill talent gain a meaningful advantage, while those relying on purely labor-cost arbitrage face growing pressure as automation absorbs more routine tasks.
These challenges are not static barriers; they are becoming strategic differentiators. Providers that design their operating models around quality assurance, secure data handling, and talent development are better positioned to capture higher-value work, while those that compete primarily on price are likely to face margin compression and client churn as buyers become more sophisticated.
Core Drivers Reshaping the Market
The expansion of the LPO sector is being driven by a combination of technological, regulatory, demand-side, and cost-structure forces. These drivers interact with one another, creating feedback loops that accelerate adoption in certain segments while reshaping competitive expectations across the broader market.
Technology Innovation as a Core Enabler
Artificial intelligence and automation are no longer peripheral tools in legal operations; they are increasingly embedded in how work is scoped, executed, and reviewed. Machine-assisted document review, contract analysis, legal research, and compliance monitoring are reducing turnaround times and allowing provider teams to focus on higher-judgment tasks. The shift is not simply about replacing manual effort. It is about re-architecting workflows so that technology handles the repetitive, high-volume components while human expertise is applied where nuance, interpretation, and client-specific context matter most.
Recent industry activity illustrates how seriously providers are investing in this direction. Several leading firms have moved to strengthen their AI-enabled service lines and data capabilities, integrating legal operations support with more advanced analytics, contract management platforms, and compliance workflows. In parallel, partnerships aimed at deploying end-to-end platforms with stronger security and compliance controls are becoming more common, particularly where cross-border data handling is involved. These moves signal that technology is now a competitive baseline rather than a differentiator reserved for a few early adopters.
Regulatory Complexity and Monitoring Demands
The regulatory environment for large corporations and regulated industries continues to become more demanding. Environmental, social, and governance expectations, data privacy regimes, sector-specific compliance obligations, and cross-border operational requirements have all increased the volume and urgency of legal and compliance work. This is pushing organizations to seek external support not only for episodic litigation or transaction work, but also for ongoing monitoring, reporting, and risk management.
A notable example is the introduction of managed services focused on ESG compliance, including real-time regulatory monitoring and reporting. Such offerings reflect a broader trend: clients increasingly want continuous, structured support rather than ad hoc project-based assistance. As regulatory expectations become more dynamic, providers that can combine legal knowledge with operational monitoring and reporting capabilities are well placed to capture recurring revenue streams.
Demand-Side Shifts in Legal Capacity and Procurement
Internal legal departments are under growing pressure to manage expanding workloads with constrained headcount and budgets. At the same time, corporate procurement and legal operations teams are becoming more deliberate about how they source external support. The conversation has evolved from simple cost reduction to total value, including speed, quality, predictability, security, and the ability to scale up or down as needs change. This has encouraged a shift toward managed services and longer-term partnerships rather than one-off engagements.
The result is a more diverse buyer profile. Some organizations are building hybrid models in which internal teams oversee strategy and high-judgment work while external providers handle volume-driven processes. Others are using LPO providers to fill capability gaps in specialized areas, such as multilingual litigation support, intellectual property analytics, or jurisdiction-specific compliance. In both cases, the common theme is flexibility: buyers want providers who can adapt to changing caseloads, regulatory demands, and internal priorities without sacrificing control or consistency.
Cost Structure and Delivery Model Evolution
Cost remains a foundational driver, but the way cost advantage is achieved is changing. Pure labor-cost arbitrage is increasingly insufficient in segments where quality, turnaround speed, and technology integration matter most. Providers are restructuring delivery around a blend of onshore, nearshore, and offshore locations, with secure facilities and specialized centers supporting specific legal domains or jurisdictional requirements. This geographic diversification helps manage cost while also addressing data residency, language, and legal system familiarity.
At the same time, operational efficiency is being improved through process standardization, workflow automation, and better portfolio management. Organizations that treat legal outsourcing as a managed operation—complete with governance, performance tracking, and continuous improvement—are more likely to realize durable savings and service reliability than those that rely on transactional, project-by-project purchasing.
Competitive Landscape and Leading Strategies
The LPO market remains moderately fragmented, with the top three providers accounting for a combined share in the high twenties and the top five reaching just over a third of total market revenue. This structure implies that while scale players have meaningful presence, there is still substantial room for specialization, regional strength, and capability-based differentiation. The competitive dynamic is less about a single dominant model and more about how providers combine scale, technology, domain expertise, and delivery footprint.
Strategic Positioning Among Key Players
Several established providers illustrate different pathways to competitive advantage.
- Integreon Managed Solutions has focused on AI-powered legal operations support spanning contract management, document review, legal research, and compliance services. Its recent strategic collaboration with PwC for legal managed services in the EMEA region, along with the opening of a new secure delivery center in Cape Town to support offshore outsourcing with an emphasis on English common law jurisdictions, reflects a strategy centered on both geographic expansion and partnership-driven scale.
- Elevate Services has positioned itself around AI-powered legal services that include litigation support, contract management, legal operations consulting, and managed services. Its acquisition of a specialist in Chinese, Japanese, and Korean language support for litigation, together with a legal data and AI consulting company, demonstrates a push to deepen multilingual capability and data/AI advisory strength in a single move.
- QuisLex has built its offering on managed services for document review, contract management, compliance, litigation support, and legal spend optimization. Its launch of a managed service focused on ESG compliance with real-time regulatory monitoring and reporting shows an effort to move beyond traditional litigation-support work into recurring, compliance-driven engagements.
- Epiq Global continues to emphasize technology-enabled legal and compliance services, including e-discovery, class actions, bankruptcy, and outsourcing for law firms and corporations. Its profile reflects the importance of scale infrastructure and specialized case-type expertise in high-volume, process-intensive work.
- Axiom Law has carved out a position around on-demand legal talent, secondments, and AI-enabled services supporting in-house legal teams and complex projects. This model highlights the value of flexible talent deployment and close integration with internal legal functions, especially for organizations that want external support without fully handing off operational control.
- UnitedLex has focused on data-driven legal and litigation support services, including e-discovery, patent analytics, and case management. Its strategic partnership with a major cloud provider to deploy an advanced end-to-end e-discovery platform with enhanced data security and cross-border compliance capabilities underscores the increasing importance of secure technology infrastructure in competitive positioning.
How the Landscape Is Evolving
Three patterns are evident in the current competitive environment.
- Capability-driven consolidation. M&A and strategic partnerships are being used to add multilingual capacity, data and AI consulting, and broader managed-service portfolios. This suggests a market in which buyers increasingly want integrated solutions rather than narrow point services.
- Geographic and jurisdictional specialization. Providers are expanding or refining delivery centers to align with common law frameworks, language requirements, and regional compliance expectations. This reflects a recognition that legal outsourcing is not a uniform global service; jurisdictional familiarity and data handling rules shape where and how work can be performed.
- Platform and security as competitive foundations. Partnerships and platform investments focused on secure, end-to-end processing are becoming more prominent, particularly for e-discovery and other data-sensitive workflows. In a market where information security and regulatory compliance are central concerns, technology infrastructure is increasingly part of the value proposition rather than a back-office utility.
For new entrants, the bar is rising. Pure cost-based entry is harder to sustain as automation reduces the advantage of low-cost labor alone, and buyers are more capable of evaluating quality, security, and service design. New players that can bring specialized domain expertise, strong technology integration, or a clear regional and jurisdictional fit have a more credible path than those offering only generalized volume services.
Forward Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape how the LPO market develops and where commercial opportunities emerge.
AI-Embedded Legal Operations Become Standard Configuration
The integration of AI and automation into legal workflows is expected to deepen, moving from selected use cases to broader operational baselines. Document review, contract abstraction, legal research, compliance monitoring, and matter management are all candidates for increased automation, with human reviewers focusing on exception handling, strategic judgment, and client-specific interpretation. For providers, this trend creates opportunities to redesign service offerings around technology-assisted efficiency, predictable turnaround times, and measurable quality outcomes. For buyers, it opens the possibility of scaling legal support without proportionally increasing headcount, provided vendor selection emphasizes workflow design and governance rather than tool presence alone.
Compliance and ESG-Linked Services Grow as Recurring Revenue Engines
As regulatory expectations continue to expand, managed services tied to regulatory monitoring, compliance reporting, and ESG-related obligations are likely to become more prominent. Unlike episodic litigation or transaction support, these engagements can create more predictable, recurring demand. Providers that can combine real-time monitoring, structured reporting, and cross-functional coordination with legal and compliance teams are well positioned to capture this demand. For enterprises, the opportunity lies in moving from reactive compliance support to continuous operational oversight, reducing the risk of late responses to regulatory changes and improving internal accountability.
Regional Rebalancing and Jurisdiction-Focused Delivery Models
The geographic distribution of LPO activity is expected to remain dynamic. While some regions already account for a substantial share of market activity, others are positioned for faster growth during the forecast period as legal demand, regulatory complexity, and delivery infrastructure evolve. Western Europe, for example, is widely expected to emerge as one of the fastest-growing regions during the forecast window, reflecting expanding compliance needs and increasing adoption of external legal operations support. At the same time, Asia Pacific continues to hold a leading share, underscoring the region’s established role in global legal service delivery. For providers, this environment favors deliberate investment in regional capabilities, language coverage, and jurisdiction-specific expertise. For buyers, it creates options for aligning delivery location with legal framework familiarity, data residency requirements, and cost considerations.
Legal Practice Management Software Market
Risks and Uncertainties to Monitor
Despite the strong growth outlook, several uncertainties could affect the pace and shape of market development. Regulatory changes around data transfer, privacy, and cross-border operations may increase compliance costs and slow certain delivery models if requirements become more restrictive. Security incidents or quality failures in high-stakes legal work could also shift buyer caution and raise due-diligence requirements. In addition, rapid automation could compress margins for providers that have not reinvested in workflow redesign, talent development, or higher-value service capabilities. Finally, macroeconomic fluctuations may influence how aggressively organizations expand external legal support, even if the underlying structural drivers remain intact.
Implications for Decision-Makers
The current LPO environment rewards deliberate strategy over reactive purchasing. Executives, investors, and procurement leaders each face a distinct set of priorities, but all benefit from a clearer view of where the market is heading and how to position accordingly.
For Corporations and Legal Operations Leaders
- Move from project-based buying to managed service design. Where possible, structure engagements around governance, service-level expectations, quality metrics, and continuous improvement. This reduces variability and makes it easier to scale support as workload fluctuates.
- Define security and compliance requirements before sourcing. Data handling, jurisdiction, access controls, and reporting expectations should be part of the initial scoping process, not negotiated after the fact. Providers with built-in secure infrastructure and cross-border compliance capabilities will be easier to integrate into sensitive workflows.
- Use external support to build capability, not just capacity. The most valuable engagements often combine volume handling with knowledge transfer, process improvement, and access to specialized expertise. This helps internal teams evolve while maintaining strategic control over high-judgment work.
For Investors and Strategic Allocators
- Focus on models with durable differentiation. Sustainable advantage is increasingly tied to technology integration, quality systems, multilingual and jurisdiction-specific capability, and recurring compliance-oriented services rather than labor-cost advantage alone.
- Watch consolidation and partnership activity as signals. Acquisitions and collaborations that add language coverage, data and AI advisory strength, or platform security capabilities often indicate where the market is heading and which capability gaps are being closed.
- Evaluate exposure to regulatory-driven demand. Segments tied to ongoing compliance monitoring, ESG reporting, and data-sensitive discovery workflows may offer more predictable demand profiles, though they also carry higher expectations for security, accuracy, and operational discipline.
For Procurement and Sourcing Professionals
- Evaluate total value, not just unit cost. Speed, quality, security, scalability, and the ability to manage changing requirements can matter as much as price, especially in complex or high-volume legal work.
- Build vendor portfolios by capability, not by brand alone. Different providers are stronger in different areas, such as litigation support, contract management, IP analytics, or compliance monitoring. A diversified sourcing approach can match work types to the most suitable providers.
- Embed performance management into ongoing relationships. Regular review of quality, turnaround, cost predictability, and security compliance helps maintain alignment and reduces the risk of service drift over time.
Conclusion
The legal process outsourcing market is entering a phase defined by greater technological integration, more demanding compliance expectations, and a growing preference for managed, scalable service models. Growth momentum remains strong, but the competitive edge is shifting toward providers that can combine secure infrastructure, quality assurance, jurisdictional awareness, and AI-enabled workflows with the ability to support recurring legal and compliance needs. For organizations seeking to use LPO strategically, the priority is no longer simply finding lower-cost support. It is selecting partners and service designs that improve speed, control, and resilience while allowing internal teams to focus on the work that most requires judgment and accountability.
PW Consulting
For decision-makers needing a more detailed view of service-line dynamics, regional trajectories, competitive positioning, and custom sourcing implications, the full research report provides a deeper breakdown of market segments, company-level developments, and forward scenarios. It is designed to support more granular planning, from service portfolio design and vendor evaluation to investment prioritization and risk assessment.
For detailed analysis of this topic, please visit the official page: Legal Process Outsourcing (LPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fresh Meat Packaging Market: How 5.12% CAGR and Plastic Dominance Are Redefining the $5.79B Landscape
By PW Consulting, 2026-09-21
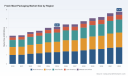
The Fresh Meat Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Defining Challenges
The global fresh meat packaging market has evolved from a commoditized segment into a strategically contested arena where material science, regulatory compliance, and supply chain resilience intersect. Historical trajectory from 2020 through 2025 demonstrates consistent expansion, anchored by steady volume growth in developed retail channels and accelerating modernization in emerging distribution networks. The baseline year value reached approximately 4.09 billion USD, representing a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast horizon. This trajectory projects revenue climbing toward 5.79 billion USD by 2032, signaling a market that is expanding at a measured but structurally significant pace.
Several structural headwinds define the current inflection point. First, the gap between conventional plastic-dependent formats and rapidly evolving recyclability mandates creates a compliance-cost squeeze. Processors and converters must balance shelf-life performance with design-for-recyclability requirements that increasingly dictate fee structures and market access. Second, raw material volatility has shifted from a cyclical nuisance to a persistent margin pressure. Limited availability of key polymer resins has elevated input costs for trays and films, pushing converters and brand owners to evaluate alternative material pathways that can maintain barrier properties while improving end-of-life outcomes. Third, retail and foodservice procurement models are fragmenting. Case-ready and centralized packaging specifications vary significantly across geographies and retailer tiers, forcing suppliers to navigate a maze of performance, sustainability, and footprint requirements simultaneously.
Vacuum Skin Packaging Market
These challenges are not isolated. They interact to reshape cost structures, dictate formulation and tooling investments, and influence where competitive advantage can be sustained. Companies that treat packaging as a performance and compliance layer rather than a disposable cost center are better positioned to navigate the transition ahead.
Core Drivers Reshaping the Market
Material and design innovation remains the primary engine of differentiation. Mono-material architectures and recyclable polymer structures are advancing rapidly, driven by the need to maintain oxygen and moisture barriers while simplifying downstream sorting and recycling streams. Vacuum skin packaging continues to evolve with tighter film tolerances and integrated equipment logic, enabling retailers to standardize display readiness while extending case life. The shift toward paper-based and fiber-reinforced formats is gaining commercial traction where fresh meat applications demand reduced plastic load and clearer recyclability claims. Innovations in heat-sealable membranes, die-cut lids, and preformed trays are narrowing the historical performance gap between conventional and sustainable formats, creating more options for processors seeking to balance cost, protection, and compliance.
Regulatory momentum is accelerating the pace of change. Extended producer responsibility frameworks are expanding across multiple jurisdictions, with several U.S. states now embedding recycled content and recyclability-based fee schedules that directly affect packaging economics. In parallel, European requirements are reinforcing design-for-recyclability expectations and minimum recycled content thresholds for plastic packaging. These mandates are not static footnotes; they alter the total cost of ownership for packaging portfolios and create financial incentives for early adopters of compliant materials and designs. Producer fees tied to recyclability performance are increasingly influencing sourcing decisions, particularly for high-volume formats such as trays and films used in beef, poultry, and seafood categories.
Pet Food Packaging Market
Demand-side behavior is reinforcing the material transition. Consumers continue to prioritize freshness visibility, portion clarity, and label legibility, while retailers are under growing pressure to demonstrate shelf-level sustainability credentials without compromising product integrity. Processors are responding by standardizing case-ready formats that reduce handling and improve throughput, while also aligning packaging specifications with retailer sustainability scorecards. The result is a more demanding specification environment where protection, presentation, and post-consumer outcomes must be optimized together rather than in sequence.
Cost and supply chain dynamics are reshaping sourcing strategies. Resin availability constraints have elevated film and tray costs, accelerating evaluation of recycled content and alternative materials. At the same time, processing-side efficiency opportunities are attracting attention; adjustments to slaughter line speeds and throughput logistics can unlock meaningful cost savings for meat operations over multi-year horizons, indirectly influencing the packaging specification conversation by altering the cost context in which packaging decisions are made. Companies are increasingly weighing packaging investments against broader operational levers, recognizing that packaging performance and processing efficiency are linked in total landed cost and service reliability.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leaders differentiating through material portfolios, equipment integration, and regional manufacturing footprints. Amcor has built a position around responsible and recyclable flexible and rigid solutions, emphasizing mono-material films and trays tailored to fresh meat applications. Sealed Air maintains a strong presence through specialized vacuum skin packaging, preformed trays, and integrated automation that supports case-ready workflows for beef, pork, lamb, and poultry. Berry Global pursues next-generation vacuum skin and sustainable flexible solutions, focusing on shelf-life extension and improved recyclability profiles.
Regional and fiber-oriented players are expanding the strategic options available to buyers. Pactiv Evergreen continues to serve processors and retailers with foam trays, films, and case-ready solutions that prioritize display readiness and throughput. Huhtamaki emphasizes sustainable fiber-based and flexible packaging, aligning fresh meat applications with evolving recyclability expectations. Mondi has moved aggressively in paper-based mono-material and pulp solutions, pairing tray and film innovations with targeted partnerships and acquisitions that expand production capacity in key regions. Winpak rounds out the flexible segment with heat-sealable membranes, die-cut lids, and processing-focused flexible formats. Sonoco contributes paperboard trays, tubes, and composite packaging, while Coveris has expanded its portfolio across paper-based and flexible sustainable solutions, including dedicated fresh meat ranges and new vacuum skin packaging capacity. Edelmann rounds out the landscape with high-performance packaging solutions and facilities oriented toward fresh meat products.
Recent moves highlight how incumbents are translating strategy into capability. Mondi partnered with Scan Sverige to advance recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to compliance and performance. In parallel, Mondi completed the acquisition of a pulp mill in Alberta to strengthen sustainable paper-based packaging capacity for North America, illustrating how vertical capacity can be used to secure supply and regional relevance. Coveris introduced a fully recyclable paper-based flexible packaging range for fresh meat and expanded a vacuum skin packaging facility in the UK, reflecting coordinated investment in both material innovation and manufacturing scale. These actions suggest a market where differentiation is increasingly built on material architecture, regional capacity, and the ability to deliver compliant solutions without sacrificing barrier or presentation performance.
The landscape is evolving through both consolidation and specialization. Large converters are broadening portfolios to capture cross-category volume and compliance advantages, while focused players are carving out niches around fiber-based solutions, advanced vacuum skin systems, and regional case-ready formats. New entrants are likely to appear where material innovation intersects with recycling infrastructure readiness, but scale, tooling, and qualification timelines continue to favor established players with proven supply reliability and retail relationships. Concentration among the top firms remains notable, yet the diversity of material pathways and regional demand patterns creates room for differentiated positioning rather than pure price competition.
Forward-looking Trends to 2030 and Beyond
The first trend is the broadening commercial viability of mono-material and recyclable structures for fresh meat. As design-for-recyclability expectations become embedded in procurement and compliance frameworks, formats that simplify sorting and improve recovery outcomes will gain preference in high-volume channels. This favors suppliers that can deliver barrier performance in mono-material architectures, supported by film and tray designs that meet both protection and circularity criteria. The commercial opportunity lies in standardizing these formats across retail ready lines and processor specifications, reducing complexity while improving compliance economics.
A second trend is the growing role of fiber-based and paper-forward solutions in select applications where plastic reduction and recyclability communication provide commercial value. These formats are advancing in areas where presentation, protection, and end-of-life messaging align with retailer and consumer expectations. The opportunity is not universal replacement; it is targeted deployment where fiber-based trays, films, and flexible ranges can meet performance thresholds and simplify sustainability narratives without compromising shelf life or handling efficiency. Success will depend on matching format to application, ensuring that barrier and structural requirements are met while leveraging recyclability positioning where it truly matters.
A third trend is the tightening linkage between packaging strategy and regional compliance economics. Producer responsibility fees, recycled content mandates, and recyclability rules are increasingly shaping total cost profiles and market access. Companies that anticipate these shifts and align material choices with local regulatory trajectories can reduce future rework, avoid fee exposure, and secure preferential positioning with sustainability-conscious buyers. The risk is regulatory fragmentation, where differing requirements across regions complicate portfolio standardization and increase qualification overhead. Firms that manage this tension through modular material platforms and region-specific compliance mapping will navigate the transition more efficiently.
PW Consulting
Potential uncertainties include raw material availability, which can shift the economics of polymer-based versus alternative formats faster than expected, and processing-side changes that alter the cost context of packaging decisions. If resin constraints persist or intensify, the pace of migration toward paper and recycled content could accelerate, while in a more benign supply environment the transition may unfold more gradually. Retail specification volatility and regional recycling infrastructure readiness also remain variables, meaning that the timing and scale of adoption will differ by market and application.
Implications and Action Points for Decision Makers
For packaging manufacturers and converters, the priority is to build material and format flexibility that can absorb regulatory and cost shifts without disrupting supply. Invest in mono-material and recyclable film and tray architectures that maintain barrier performance, and develop modular designs that can be tuned to regional recyclability rules and retailer specifications. Strengthen regional production or sourcing options where compliance economics and resin availability are likely to diverge, and align equipment and lines with formats that reduce qualification friction for case-ready and retail-ready workflows. Validate performance claims with rigorous shelf-life, sealing, and handling data so that sustainability positioning is credible and defensible.
For investors and corporate strategists, the market rewards exposure to companies with clear material-transition roadmaps, credible compliance positioning, and the capacity to execute across regions. Assess portfolios for diversification across plastic, paper-based, and flexible formats, and evaluate the quality of recent partnerships and capacity investments that secure supply and regional relevance. Weigh concentration dynamics against the opportunity set created by material innovation and regional compliance divergence. Focus on players that demonstrate both technical performance and the operational discipline to scale compliant formats without sacrificing service reliability.
For procurement leaders and retail or foodservice buyers, the strategic task is to align specifications with total cost, compliance exposure, and shelf impact rather than unit price alone. Standardize where possible to reduce complexity, but maintain application-specific flexibility for formats where protection and presentation requirements differ. Incorporate recyclability and recycled content expectations into sourcing criteria early, and map those expectations to supplier capability and regional infrastructure readiness. Communicate specifications clearly to reduce rework and qualification delays, and coordinate with suppliers on pilot programs that validate performance and compliance before broad rollout.
The trajectory of the fresh meat packaging market will be shaped by how effectively companies integrate material innovation, compliance strategy, and supply chain resilience. Detailed segmentation, regional dynamics, and scenario-level cost modeling can sharpen these decisions further, and the full PW Consulting research report provides the granular data and tailored analysis needed to translate these trends into concrete plans for specific business contexts.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Denim Jeans Market 2026: 5.8% CAGR and Strategic Shifts Reshaping Global Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Denim Jeans Market: A 2025–2032 Outlook
The global denim jeans market continues to demonstrate measured resilience, growing from 131.0 million USD in 2020 to an estimated 170.0 million USD in 2025. Over the historical period from 2020 to 2025, the category navigated pandemic-era disruptions, inventory corrections, and shifting consumer preferences, ultimately stabilizing at a pace that reflects both the durability of denim as a wardrobe staple and the structural adjustments taking place across sourcing and manufacturing. Looking toward the 2026–2032 forecast window, the market is projected to expand at a CAGR of 5.8 percent, reaching 252.0 million USD by 2032. This trajectory is not merely a function of population growth or rising disposable incomes; it reflects deeper changes in how denim is designed, produced, regulated, and valued by end users. For executives and investors, the central question is no longer whether denim will grow, but where value will crystallize in a market that is increasingly shaped by raw material volatility, regulatory scrutiny, and divergent consumer expectations across regions.
Market Snapshot and Core Challenges
The current market size reflects a category that has moved past the acute volatility of the early 2020s and is now operating in a more normalized but still complex environment. Revenue growth has been underpinned by steady end-use demand in casual wear, where denim remains a default choice for consumers seeking versatility, durability, and relative affordability. At the same time, the segment has seen gradual expansion in more structured applications and specialized fits, indicating that denim is no longer confined to a single occasion or silhouette. The 2025 baseline of 170.0 million USD sets the stage for a forecast period in which growth will increasingly depend on the ability of companies to manage cost pressures, navigate trade policy shifts, and respond to sustainability expectations without eroding margin or brand equity.
Three challenges stand out as particularly consequential for commercial planning. First, raw material dynamics are introducing renewed cost uncertainty. Each kilogram of cotton is projected to cost up to 1.75 USD in 2026, a 2.9 percent increase from prior forecasts, against a backdrop of a global cotton production contraction of up to 2 percent during the 2025–2026 season. This tightening supply environment pressures both fabric suppliers and finished-goods manufacturers, particularly those with thin pricing flexibility or limited access to alternative fibers. Second, trade policy and enforcement are reshaping sourcing calculus. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, creating a landscape where incremental cost adjustments can quickly alter the economics of established supply chains. Third, compliance risk is becoming a material commercial factor rather than a back-office concern. U.S. Customs and Border Protection issued a Withhold Release Order against Firemount Group Ltd. in November 2025, directing detention of denim jeans and apparel produced in Mauritius due to indicators of forced labor. This action, along with broader enforcement trends, signals that sourcing visibility and documented labor practices are now integral to market access, especially for companies selling into high-value Western markets.
Denim Market
Key Drivers Reshaping the Category
Technical innovation and product differentiation
Product-level innovation is moving from a peripheral creative exercise to a core commercial lever. The introduction of heavier, selvedge-inspired denim and customizable fits reflects a broader shift toward premiumization, where consumers are willing to pay for construction quality, longevity, and a more deliberate sense of style. In November 2025, Levi Strauss & Co. expanded availability of its Blue Tab premium line, featuring Japanese selvedge-inspired heavier denim jeans, to more stores for fall 2026. This move illustrates how established brands are using product architecture to protect margin and reinforce brand distinctiveness in a category that can easily slip into commodity competition. Alongside signature fits and heavier constructions, innovation is also occurring in fabric technology, where stretch formulations, regenerative inputs, and lower-impact processing are becoming differentiated selling points rather than niche add-ons.
At the fabric and materials level, circularity and regenerative approaches are increasingly embedded in commercially available offerings. Candiani Denim has built its positioning around high-end denim fabrics and jeans with a focus on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while maintaining supply chain relationships for fashion brands. In September 2025, Alberto Candiani x Velasca launched a new made-in-Italy denim capsule collection with customizable Millesimo fits, showing how premium Italian fabric competence can be paired with consumer-facing customization. Meanwhile, MUD Jeans specializes in premium circular denim jeans produced from post-consumer recycled jeans and emphasizes lower-impact production for men and women. These examples suggest that sustainability in denim is no longer a single message but a set of product and process choices that can be tailored to different price points, regions, and brand identities.
Regulatory and policy environment
Policy dynamics are exerting a direct influence on sourcing decisions, cost structures, and market access. The Withhold Release Order against Firemount Group Ltd. demonstrates how enforcement actions can alter the viability of specific suppliers and geographies in a short period. For vertically integrated manufacturers and importers alike, the implication is that documented supply chain transparency is becoming a commercial prerequisite, not just a reputational preference. This is reinforced by the broader regulatory environment around import duties. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, meaning that sourcing diversification and tariff-aware inventory planning are now central to operational resilience.
These regulatory pressures are interacting with the structural reality that many leading players already operate distributed, contract-based manufacturing models. Gap Inc. sources and offers denim jeans under Gap and Old Navy brands while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. H&M Group operates as an outsourced manufacturer of denim jeans for H&M and other brands, maintaining quarterly-updated supplier lists across 969 tier-1 factories primarily in Asia. In this context, regulatory exposure is not uniform across the industry; it varies by geography, tier of supplier, and the level of visibility a company has into its upstream operations. The practical effect is that policy risk is increasingly a selection criterion, influencing which partners are viable over a multi-year horizon.
Demand-side behavior and category evolution
Consumer demand in denim is bifurcating along two overlapping axes: value-driven volume and premiumized differentiation. Casual wear remains the dominant application, absorbing a large share of category revenue and providing a stable base for everyday fits, durable construction, and accessible pricing. Yet demand is also expanding in more formal and specialized applications, where denim is being repositioned for smarter occasions, structured silhouettes, and premium finishes. This is visible in the growth of formal wear applications and the increasing relevance of tailored denim within broader menswear and womenswear assortments. The commercial takeaway is that denim is no longer a monolithic segment; it is a set of sub-categories with different frequency patterns, margin profiles, and innovation requirements.
A second demand-side dynamic is the growing importance of transparency as a purchasing heuristic. Consumers and retail partners are increasingly attentive to where and how denim is made, particularly as sustainability claims become more scrutinized and as regulatory enforcement raises the stakes of opaque sourcing. This is not simply a matter of marketing language; it affects product design, material selection, factory relationships, and even the cadence of supplier disclosure. Companies that can credibly connect product attributes to process choices are better positioned to command price integrity and reduce the risk of reputational friction.
Supply chain and cost structure shifts
The cost environment is being reshaped by the combination of raw material projections, tariff exposure, and labor-related enforcement. With cotton projected to reach up to 1.75 USD per kilogram in 2026 amid a contraction in global production, fabric procurement will likely place upward pressure on input costs unless offset by efficiency gains, blend strategies, or alternative fiber adoption. At the same time, tariff conditions on key sourcing countries create a need for dynamic scenario planning. A 46 percent baseline scenario for Vietnamese imports and a 10 percent scenario for Turkish imports are not trivial adjustments; they can reallocate cost competitiveness across regions and alter the relative attractiveness of nearshore, offshore, and multi-country sourcing models.
Supply chain structure itself is also a strategic variable. Vertically integrated manufacturers such as Firemount Group Ltd. have historically offered the advantage of integrated control over production and logistics, with documented supply chain details supporting operational coordination. However, vertical integration does not insulate a company from enforcement actions or policy risk, as the November 2025 Withhold Release Order against Firemount Group Ltd. illustrates. For importers and distributors such as Denim and Beyond LLC, which handles U.S. distribution and import logistics for lines including Levi Strauss and Banana Republic, the challenge is to manage flow, visibility, and compliance without over-concentrating exposure in any single geography or supplier. The broader trend is toward more deliberate sourcing architectures, where redundancy, documentation, and trade-aware planning are treated as value drivers rather than overhead.
Competitive Landscape and Leading Strategies
The competitive structure of the denim jeans market remains relatively fragmented at the top, with no single company dominating total category revenue. The CR3 and CR5 concentration levels indicate that while large global players are influential, the market still accommodates a wide range of models, from premium brands and fabric specialists to vertically integrated manufacturers and circular denim specialists. This fragmentation is important because it suggests that leadership will be defined less by scale alone and more by the ability to combine product differentiation, supply chain resilience, and credible sustainability positioning.
Levi Strauss & Co. exemplifies a brand-led strategy built around design, marketing, and global sourcing, with contract manufacturers operating across more than 32 countries and supply chain transparency supported by an interactive supplier map. Its recent move to expand the Blue Tab premium line for fall 2026 underscores a strategy of using signature product tiers to reinforce brand equity and price integrity. Gap Inc. competes through brand portfolio breadth, using Gap and Old Navy to address a wide consumer base while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. This diversification is strategically meaningful because it provides flexibility in cost and geography, though it also requires disciplined supplier oversight. H&M Group operates at scale through outsourced manufacturing, maintaining quarterly-updated supplier lists across a large base of tier-1 factories primarily in Asia, which allows agility in assortment and production but also places a premium on continuous compliance monitoring.
Denim Fabric Market
A different set of strategies is emerging among specialists. MUD Jeans focuses on premium circular denim jeans produced from post-consumer recycled jeans, emphasizing lower-impact production for men and women. Candiani Denim has positioned itself at the fabric and premium jeans level, with emphasis on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while supplying fashion brands through its fabric capability. Firemount Group Ltd. has pursued a vertically integrated model with production in Mauritius and documented supply chain details, a structure that can support coordination and quality control but also concentrates regulatory exposure. Denim and Beyond LLC operates on the distribution and import side, handling U.S. logistics for established denim lines, which makes it sensitive to tariff and enforcement dynamics but less directly exposed to production-level sourcing decisions.
PW Consulting
These profiles point to a market that is simultaneously consolidating around scale and brand power while also fragmenting around specialization. New and specialist entrants can compete by owning a clear point of differentiation, whether that is circularity, premium fabric quality, customizable fits, or specific regional production advantages. At the same time, larger players are using product architecture, supplier diversification, and transparency tools to defend share and manage cost and policy risk. The most consequential evolution is not a single wave of consolidation, but a broadening of what “competitive advantage” means in denim: product credibility, sourcing visibility, tariff-aware cost design, and the ability to translate sustainability into tangible product attributes.
A practical illustration of the innovation ecosystem is the Denim Show, which returned to Pragati Maidan in New Delhi, India, offering a platform for denim brands to launch new products and explore innovation trends. Events of this kind matter because they concentrate fabric innovation, product launches, and supplier connections in one place, accelerating the spread of new fits, finishes, and process ideas across a globally connected supply base. For companies seeking to stay ahead of product cycles, these nodes of industry interaction are increasingly important complements to internal R&D and supplier development.
Outlook for the Next Three to Five Years
The first major trend is continued premiumization paired with fit and construction specialization. Heavier denim, customizable fits, and signature construction details are likely to become more important as brands search for ways to differentiate beyond price. This trend favors companies that can control quality, manage longer production runs of specialty items, and communicate product value in a way that resonates with consumers who view denim as an investment garment rather than a disposable commodity. The commercial opportunity lies in building product hierarchies that protect entry-level volume while creating higher-margin tiers with fewer direct comparability points.
The second trend is the institutionalization of circularity and lower-impact production as commercial norms rather than niche initiatives. As post-consumer recycled denim, regenerative cotton, and biodegradable stretch options become more available through suppliers such as Candiani Denim and MUD Jeans, brands will have more options to align product claims with demonstrable process choices. The opportunity here is twofold: brands can use material and process transparency to support price integrity, and fabric and mill specialists can become preferred partners for brands seeking credible differentiation. The risk is that consumer skepticism and regulatory scrutiny will increase alongside the number of sustainability claims, making verification, traceability, and consistent disclosure essential rather than optional.
The third trend is a more complex sourcing and compliance environment driven by tariff uncertainty and enforcement actions. Import duty dynamics affecting Vietnam and Turkey, together with enforcement measures such as the Withhold Release Order against Firemount Group Ltd., suggest that companies will need to treat trade and compliance planning as a continuous operational discipline. Over the next three to five years, sourcing portfolios that balance cost, geography, and documentation are likely to outperform those optimized primarily for unit cost. The associated opportunity is for suppliers and service providers that can help brands manage multi-country sourcing, audit readiness, and import logistics with greater predictability. The primary risk is that rapid policy shifts or enforcement actions can disrupt established supply paths faster than a company can replan, especially if visibility into tier-1 and upstream suppliers is incomplete.
A broader uncertainty to monitor is raw material supply. With cotton projected at up to 1.75 USD per kilogram in 2026 and global production contraction of up to 2 percent during the 2025–2026 season, the denim market could face periodic cost pressure that tests margin discipline and accelerates the adoption of blends, recycled content, or alternative sourcing strategies. The direction of this pressure will depend on weather, harvest outcomes, and broader commodity dynamics, but the prudent planning assumption is that input volatility will remain a recurring factor rather than a one-time event.
Actionable Priorities for Decision-Makers
For manufacturers and fabric producers, the immediate priority is to strengthen the link between product innovation and cost resilience. This means investing in specialty fits, premium constructions, and lower-impact material options while also building flexibility into sourcing and production planning. Companies that can offer regenerative cotton, recycled denim, or biodegradable stretch options with verifiable documentation will be better positioned to serve brands under pressure to demonstrate credible sustainability. Equally important is scenario planning for cotton costs and tariff exposure, so that pricing and capacity decisions are not made on the assumption of a stable input environment.
For investors, the opportunity is to evaluate denim businesses on the basis of differentiation quality, sourcing resilience, and compliance readiness rather than revenue scale alone. Brands and manufacturers with clear premium product tiers, documented supplier visibility, and diversified sourcing footprints are better equipped to navigate enforcement actions and tariff volatility. Specialist players with defensible circular or regenerative positioning can also offer attractive exposure to the growing demand for lower-impact denim, provided their claims are operationalized through product, process, and disclosure. The risk to watch is over-concentration in any single geography or supplier model without the documentation and contingency planning needed to respond to enforcement or trade changes.
For procurement and sourcing leaders, the priority is to treat transparency and geographic diversification as value-protecting disciplines. Tariff scenarios affecting Vietnam and Turkey, along with enforcement actions such as the Withhold Release Order against Firemount Group Ltd., make it prudent to map exposure, strengthen supplier documentation, and maintain alternatives across regions. Procurement teams should also align fabric and product decisions with consumer-facing claims, because the commercial value of sustainability positioning will increasingly depend on the credibility of the underlying process and supply chain evidence. In practical terms, this means more disciplined supplier audits, clearer traceability, and closer coordination between merchandising, compliance, and logistics functions.
For organizations seeking a deeper operational view, the full research report provides additional segmentation detail, company-level sourcing profiles, and scenario analysis that can support more precise planning. The market trajectory is clear enough to justify strategic action now, but the value of that action will depend on how well it is calibrated to product strategy, sourcing architecture, and regulatory exposure. Denim is entering a phase in which durable growth will belong to companies that can combine product credibility, resilient sourcing, and verifiable sustainability with disciplined cost management.
For detailed analysis of this topic, please visit the official page: Denim Jeans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Global Polymer Substrates Market
Market Landscape and Core Challenges
The worldwide polymer substrates market has demonstrated robust expansion over the past half-decade, evolving from a steady growth trajectory into a dynamic sector shaped by technological convergence and shifting industrial priorities. Valued at approximately $12.25 billion in 2020, the market reached an estimated $16.45 billion by 2025, reflecting a compound annual growth rate of 6.42 percent through the forecast period extending to 2032. This expansion is not merely a function of volume but reflects deepening penetration across high-value electronics, energy infrastructure, and security applications. The market structure remains moderately fragmented, with the top three participants capturing just over 32 percent of total revenue and the top five firms approaching 48 percent. Such concentration levels indicate a landscape where scale advantages exist but are not insurmountable, leaving room for specialized players to compete on performance, regional proximity, or application-specific engineering.
Despite the positive trajectory, the industry stands at a critical inflection point defined by three interlocking challenges. First, raw material volatility has transitioned from a periodic disruption to a structural stressor. Feedstocks such as ethylene, propylene, and purified terephthalic acid form the backbone of mainstream polymer films, yet their pricing can swing by as much as 25 percent within a single year. This unpredictability compresses margins for manufacturers who operate on fixed-price contracts or lack the agility to pass costs downstream. Second, regulatory tightening is reshaping compliance economics. Recent restrictions on methylene chloride as a bonding agent for acrylic and polycarbonate substrates, alongside the phase-out of hexavalent chromium in plastic plating, have elevated compliance expenditures by roughly 18 to 25 percent for treatment facilities. These rules do not merely add administrative burden; they force retooling, process redesign, and verification protocols that disproportionately affect mid-tier producers. Third, the rapid proliferation of advanced display architectures and flexible circuit designs is raising performance thresholds. Suppliers must now balance thermal stability, optical clarity, dielectric consistency, and mechanical durability within thinner form factors, creating a technical barrier that favors companies with integrated R&D and application-specific formulation capabilities.
For executives evaluating market entry, expansion, or procurement strategies, these dynamics signal a shift from volume-driven competition to value-driven differentiation. The organizations that navigate this phase successfully will be those that treat feedstock risk, regulatory adaptation, and performance specification as interconnected strategic variables rather than isolated operational concerns.
Key Drivers Reshaping the Market
Technological innovation remains the primary engine of market evolution. The transition from rigid to flexible electronic architectures has elevated polymer substrates from passive carriers to active enablers of device performance. Polyimide and polyester films, for instance, are no longer evaluated solely on mechanical flexibility; they are scrutinized for thermal endurance, coefficient of thermal expansion matching, and compatibility with lamination and etching processes. Meanwhile, newer thiol-based optical polymer films and engineered adhesives are addressing long-standing trade-offs between transparency, adhesion, and reworkability in display manufacturing. These material advances are not incremental; they are unlocking form factors that were previously uneconomical or technically unfeasible, particularly in ultra-thin wearable devices and foldable display panels.
Policy and regulatory frameworks are acting as a second, equally powerful driver. Environmental mandates are accelerating the redesign of both materials and processing pathways. Restrictions on certain solvents and heavy-metal plating compounds are pushing manufacturers toward water-based adhesives, low-volatile organic compound formulations, and alternative surface treatments. While compliance costs have risen, these regulations are also creating a structural advantage for firms that have already invested in cleaner process architectures. In regions where electronics waste directives and chemical safety standards are tightening, suppliers with verified environmental compliance are finding preferential access to premium contracts, particularly with multinational OEMs that face their own downstream reporting obligations.
Demand-side behavior is undergoing a parallel transformation. Consumer electronics manufacturers are racing to reduce device weight and thickness while maintaining durability, a push that directly increases the share of flexible printed circuits and OLED display applications within the substrate mix. Simultaneously, the expansion of photovoltaic installations and the electrification of automotive systems are driving requirements for substrates that can withstand UV exposure, moisture ingress, and thermal cycling over extended service lives. Medical device designers are adopting polymer films for imaging substrates, diagnostic patches, and sterilization-compatible housings, valuing their biocompatibility and dimensional stability. These application shifts are not isolated; they are converging on a common requirement set that favors materials with tunable mechanical properties, predictable dielectric behavior, and reliable supply continuity.
Supply chain and cost structure dynamics complete the driver set. Regional production footprints are being recalibrated as companies respond to freight volatility, tariff uncertainty, and the desire for shorter lead times. Price adjustments on engineered materials and polymer dispersions have become more frequent, reflecting both upstream feedstock conditions and the costs of maintaining compliance-ready facilities. In this environment, procurement strategies that once prioritized unit price are increasingly incorporating total cost of ownership metrics, including yield loss, rework rates, logistics resilience, and regulatory risk. Suppliers that can offer consistent lot-to-lot quality, transparent sourcing, and application engineering support are capturing disproportionate value, even when their headline pricing is higher.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global materials giants, regional specialists, and application-focused innovators. DuPont continues to leverage its polyimide heritage, particularly its Kapton legacy, to serve flexible electronics, display, and high-temperature automotive applications. Its positioning emphasizes long-standing process knowledge, broad qualification history with major OEMs, and the ability to supply substrates that meet stringent thermal and mechanical specifications. 3M complements this profile with a focus on optical clarity, durability, and precision film engineering, targeting display and printed electronics applications where surface quality and dimensional consistency are decisive. Toray and Teijin, together with Sumitomo Chemical and Mitsubishi Chemical, form a strong Asian manufacturing core that combines polyester and polyimide expertise with deep integration into regional electronics and display supply chains. Their advantage lies in scale, proximity to panel and circuit manufacturers, and the ability to tailor film grades to specific lamination and etching workflows.
Beyond mainstream electronics, a distinct competitive cluster has emerged around security and currency substrates. Companies such as CCL Secure, De La Rue, Landqart, and Giesecke+Devrient have built specialized capabilities that combine biaxially oriented polymer films with integrated security features, authentication layers, and printing compatibility. De La Rue, for example, operates an integrated model that couples substrate production with security feature embedding and print readiness, reducing coordination friction for central bank issuance programs. The recent adoption of Q&T Hi-Tech Polymer's domestic PolySecure substrate in Vietnamese currency illustrates how regional producers can capture sovereign issuance cycles by offering localized supply, cost competitiveness, and alignment with national printing infrastructure. This segment demonstrates that polymer substrates are not a monolithic market; competitive advantage often comes from mastering a specific application's certification, security, and logistics requirements rather than competing purely on film thickness or polymer grade.
The market's evolution is being shaped by simultaneous consolidation and specialization. Larger materials groups are acquiring or partnering to secure feedstock access, expand high-performance film portfolios, and broaden regional coverage. At the same time, new entrants are carving out positions through targeted innovations such as thiol-based optical films, RF and microwave-grade substrates, and next-generation display-compatible architectures. Recent pricing actions by major producers highlight the tension in the current environment: several global manufacturers announced material price increases effective in early 2026, citing raw material and production costs. These adjustments are not merely tactical; they reflect a structural recalibration as firms protect margins amid feedstock volatility and compliance investment. Buyers are responding by diversifying supplier bases, locking in longer-term agreements with performance guarantees, and shifting certain certifications in-house to reduce dependency on single-source qualification cycles.
For strategists, the clearest signal is that differentiation is increasingly earned at the intersection of material science, regulatory readiness, and application engineering. Companies that can demonstrate measurable improvements in yield, thermal reliability, or processing speed are winning premium placements, while those competing solely on commodity pricing are facing progressive margin erosion.
Future Trends and Commercial Implications
Several trajectories are likely to define the next three to five years. The first is the continued migration of polymer substrates into higher-complexity electronic architectures. As foldable displays, wearable sensors, and advanced flexible circuits move from premium niches toward broader adoption, substrates will need to satisfy tighter tolerances for dimensional stability, dielectric uniformity, and long-term fatigue resistance. This trend will create opportunities for suppliers that offer co-engineered film systems, including adhesives, cover layers, and surface treatments optimized for specific assembly processes. Manufacturers that provide application engineering support and process validation will capture more value than those selling bare film alone.
Ceramic Substrate Market
A second trend is the deepening influence of regulatory and sustainability mandates on material selection. Chemical restrictions and emissions expectations are unlikely to plateau; they will expand in scope and enforcement intensity. This will favor substrates and processing routes that reduce solvent use, lower heavy-metal dependency, and improve recyclability or end-of-life handling. Companies that proactively redesign offerings around compliance-forward chemistries will gain preferential access to OEMs facing their own procurement standards and public reporting requirements. In parallel, procurement teams will increasingly evaluate suppliers on environmental documentation, traceability, and audit readiness, making these capabilities a commercial differentiator rather than a back-office function.
Worldwide Polished Substrates Market
A third trend is the regional reconfiguration of supply networks. Freight instability, lead-time sensitivity, and currency exposure are prompting buyers to diversify across geographies and to favor suppliers with local or near-local production capacity. This shift creates openings for regional specialists that can deliver reliable volume, faster response cycles, and lower logistics risk, even if they lack the global footprint of multinational incumbents. The resulting landscape will reward agility, transparent communication, and the ability to manage qualification and certification efficiently across multiple jurisdictions.
These trends carry both opportunity and uncertainty. Demand growth is likely to remain positive, but the distribution of value will tilt toward firms that can absorb feedstock and compliance risk without sacrificing performance consistency. Buyers who treat substrates as strategic components rather than commoditized inputs will be better positioned to manage cost volatility and technology transitions.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize application-specific film development and process integration over broad commodity expansion. Investing in co-engineered substrate systems, qualification support, and consistent lot quality will strengthen customer retention and protect margins against price competition. Where feedstock exposure is significant, long-term sourcing agreements, hedging strategies, and alternative polymer pathways should be evaluated to reduce vulnerability to annual volatility swings.
Investors should focus on companies with defensible technical moats, regulatory readiness, and diversified application exposure across electronics, energy, security, and medical uses. Business models that combine material capability with service layers such as engineering support, certification assistance, and regional supply resilience are better positioned to sustain pricing power. Caution is warranted where growth depends primarily on volume throughput without corresponding differentiation in performance or compliance.
PW Consulting
Procurement and sourcing leaders should expand evaluation criteria beyond unit cost to include total cost of ownership, yield impact, lead-time reliability, and regulatory documentation. Multi-supplier strategies, paired with clear performance specifications and shared qualification data, can reduce single-point failures while maintaining competitive tension. Early engagement with suppliers on upcoming material or regulatory changes will also shorten adaptation cycles and lower the risk of production disruption.
For organizations seeking deeper segmentation data, company-level positioning detail, and customized scenario planning across regions and application verticals, the full research report provides expanded datasets and tailored analysis. The complete study maps growth trajectories by material type, application, and region, alongside competitive profiling and procurement risk frameworks, offering a practical reference for strategy development and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Polymer Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Military Protective Eyewear Market’s 6.78% CAGR Reshapes Procurement Strategy
By PW Consulting, 2026-09-18
The Global Military Protective Eyewear Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide military protective eyewear market has demonstrated sustained momentum, evolving from a niche procurement category into a strategically significant segment of defense logistics and soldier modernization. Between 2020 and 2025, market revenue expanded steadily, reflecting consistent procurement cycles, incremental capability upgrades, and the widespread institutionalization of eye protection as a baseline combat requirement. This upward trajectory is projected to persist through the 2026–2032 forecast horizon, supported by a compound annual growth rate that underscores the segment's resilience and strategic relevance. The market's scale now positions protective eyewear as an integral component of force readiness rather than an ancillary accessory, with procurement volumes increasingly tied to fleet-wide modernization initiatives and coalition interoperability standards.
Despite this favorable backdrop, industry participants navigate a complex operating environment defined by several structural tensions. First, the dual mandate of meeting rigorous ballistic performance thresholds while maintaining ergonomic comfort, optical clarity, and environmental adaptability creates a persistent engineering balancing act. Specifications such as MIL-PRF-32432 and MIL-PRF-31013 establish demanding impact-resistance criteria, requiring products to withstand high-velocity fragments without compromising field usability. At the same time, the Authorized Protective Eyewear List framework introduces a procurement dynamic where approval status, logistical compatibility, and mission-specific suitability directly influence adoption rates. Manufacturers must therefore align technical performance with procurement workflows and user acceptance patterns, a challenge that intensifies as operational environments grow more varied.
Worldwide Military Protective Gear Market
Second, supply chain and cost structures introduce volatility that reverberates across the value chain. The market's concentration profile, with a notable share held by a relatively small group of established players, highlights both the barriers to entry and the operational scale required to compete effectively. Splitting production across specialized component sourcing, optical coating, frame manufacturing, and stringent quality assurance means that raw material fluctuations, logistics disruptions, or certification delays can quickly translate into margin compression. For buyers, this translates into procurement cycles that must account for lead-time management and qualification timelines; for manufacturers, it underscores the importance of resilient sourcing strategies and modular design architectures that can accommodate supply variability without sacrificing compliance.
Third, the market sits at a transition point driven by evolving threat profiles and changing procurement philosophies. Modern combat scenarios increasingly involve asymmetric threats, urban engagements, and multi-domain operations where fragmentation, laser-based systems, and environmental hazards coexist. This shifts the priority from baseline protection toward integrated capability sets that can adapt across missions. At the same time, budget cycles and multinational procurement programs favor standardization, interoperability, and lifecycle cost considerations. Companies that can demonstrate not only compliance but also operational value—reduced injury incidence, improved situational awareness, clearer optics under varied lighting, and streamlined maintenance—are better positioned to secure sustained demand in an environment where procurement decisions increasingly weigh total value rather than unit price alone.
Key Drivers Reshaping the Market
Several interrelated forces are shaping the direction of the military protective eyewear market, each reinforcing the others and creating distinct implications for product strategy, procurement planning, and competitive positioning.
Technological innovation continues to redefine what protective eyewear can deliver in the field. The dominant product category remains ballistic spectacles, reflecting the enduring requirement for high-velocity impact and fragment protection in operational settings. Yet the performance envelope is expanding well beyond baseline impact resistance. Photochromic and polarized lens technologies, for example, address real-world visibility challenges by adapting to changing light conditions and reducing glare without sacrificing ballistic integrity. Anti-fog coatings, moisture-management frame designs, and prescription-compatible configurations further bridge the gap between protection and sustained operational usability. These enhancements are not cosmetic; they respond directly to the practical demands of extended deployments, fast-paced engagements, and environments where visual performance influences both safety and mission effectiveness. As a result, differentiation increasingly emerges from the integration of multiple functional capabilities rather than from a single standout feature.
Worldwide Military Wearable Market
Policy and regulatory frameworks act as both gatekeepers and accelerators. In the U.S. context, the requirement to meet MIL-PRF standards ensures a high floor for performance, while the Authorized Protective Eyewear List provides a procurement mechanism that shapes which products gain field traction. The existence of a formal approval pathway creates predictability for suppliers that invest in compliance, but it also raises the stakes for entry, since qualification is a prerequisite for large-scale adoption in many programs. Outside the U.S., comparable standards and multinational procurement expectations are increasingly influencing product development priorities. ANSI/ISEA Z87.1 remains a widely recognized baseline, but military applications often exceed that threshold through additional ballistic, optical, and environmental performance requirements. This layered standards environment rewards manufacturers that can navigate both commercial safety benchmarks and defense-specific certification regimes, while also aligning product roadmaps with anticipated specification updates.
On the demand side, shifting procurement behavior and user expectations are altering the value proposition. Rising global defense expenditures and soldier modernization programs continue to drive demand for advanced military protective eyewear across major NATO and allied forces. This is not merely a volume story; it reflects a broader modernization philosophy in which individual equipment is evaluated as part of an integrated soldier system. Procurement teams increasingly look for solutions that support interoperability, reduce logistical complexity, and perform reliably across training and combat conditions. End-user preferences also play a growing role, as operators favor gear that is comfortable, lightweight, and adaptable without compromising protection. When products are perceived to enhance mission readiness—through better optics, fewer field adjustments, or seamless compatibility with helmets and other tactical equipment—adoption momentum strengthens accordingly.
Supply chain and cost dynamics form the fourth major driver. The market's structure favors organizations that can manage complexity at scale, balancing component sourcing, manufacturing precision, and qualification rigor. Recent activity illustrates how companies are responding to these pressures through contract wins, certification milestones, and new product introductions. Several manufacturers have secured framework agreements and specialized program awards that underscore the importance of reliable supply and proven compliance. At the same time, the launch of newer eyewear systems at major industry events signals continued investment in capability upgrades and platform compatibility. These developments point to a competitive environment in which operational reliability, certification readiness, and program execution are becoming as important as product features alone. Cost management is therefore not just a procurement concern but a strategic capability: companies that can maintain performance and compliance while controlling total cost of ownership are better equipped to win multi-year programs and defend margins in a market that rewards consistency.
Competitive Landscape and Leading Strategies
The competitive environment in military protective eyewear is defined by a small group of entrenched manufacturers that combine technical capability, program experience, and established relationships with procurement authorities. Market concentration reflects the realities of certification, scale, and long-cycle defense procurement, but it also leaves room for differentiation through product architecture, mission-specific configuration, and execution reliability. Several companies have built leading positions by aligning their offerings with the dual demands of ballistic performance and field usability, while also pursuing strategic moves that extend their reach across programs and operating environments.
Revision Military has maintained a strong profile as a specialist in ballistic and performance eyewear for military and tactical users. Its portfolio spans multiple systems designed to meet rigorous standards and serve diverse operator requirements, and recent developments highlight a dual focus on contract execution and product qualification. The company's activities in 2025, including supplying special forces with established eyewear systems and securing national stock number recognition for a goggle kit for U.S. military use, illustrate how qualification milestones and targeted program wins can reinforce market presence. An earlier framework contract with the NATO Support and Procurement Agency points to a longer-term strategy centered on multinational relevance and supply chains that can support coalition requirements. This combination of product breadth, certification progress, and institutional engagement positions the company to compete where interoperability and proven compliance matter.
Gentex Corporation occupies a distinct position through its emphasis on advanced eyewear and optics for both ground forces and aircrew. Its product portfolio includes ballistic eyewear systems and laser eye protection solutions, and recent program activity demonstrates the company's ability to engage with specialized requirements. The launch of an updated ballistic eyewear system at a major industry showcase signaled continued investment in platform-compatible design and field-oriented performance. Equally notable was the award of a U.S. Air Force aircrew laser eye protection program, which reflects demand for mission-specific optical solutions that address distinct threat environments. This blend of ground and aircrew focus suggests a strategy oriented around capability breadth and program specialization, where value is created not only through protection but also through optical performance tailored to specific operational roles.
Other established players contribute to a competitive field shaped by different strengths. ESS Eye Pro emphasizes high-performance impact protection for military, law enforcement, and tactical use, with a product set built around ballistic goggles, sunglasses, and eyeshields that meet recognized safety standards. Oakley Standard Issue leverages brand recognition and optical engineering to supply ballistic sunglasses and tactical eyewear designed for helmet compatibility and clarity, with products aligned to military procurement specifications. Wiley X focuses on tactical and ballistic-rated eyewear featuring high-velocity impact protection and interchangeable lens systems, an approach that supports adaptability across environments. Bolle Safety and uvex bring European manufacturing heritage and defense-adjacent safety expertise, with product lines and industry affiliations that reinforce their relevance in multinational and special-forces contexts. American Optical draws on a long supply history with the U.S. military and a specification-driven approach to military eyewear, reinforcing a positioning rooted in proven pedigree and compliance orientation.
What distinguishes these leaders is not only product performance but strategic positioning. Leading manufacturers tend to pursue a combination of certification readiness, program execution, and mission-specific configuration. They invest in meeting or exceeding military specifications, while also developing product architectures that simplify field use, maintenance, and compatibility with other equipment. The result is a market in which success increasingly depends on the ability to deliver consistent compliance, reliable supply, and practical operability rather than on a single breakthrough feature. At the same time, the landscape appears to be evolving along multiple axes. Consolidation pressure exists where scale, qualification expertise, and program relationships create advantages for larger or well-connected players. At the same time, differentiation remains possible through specialized solutions, such as laser protection for aircrew, advanced lens technologies for varied lighting conditions, or configurations optimized for special operations. New entrants face meaningful hurdles, but niche positioning around particular mission needs, coalition procurement pathways, or complementary technologies can create viable avenues for growth.
Forward Outlook: Trends and Commercial Implications
Looking ahead across the 2026–2032 period, several trends are likely to shape the market's direction and create distinct commercial implications. The first is the continued shift from baseline protection to integrated capability. As operational environments become more complex, demand will increasingly favor eyewear that combines ballistic resilience with optical versatility, environmental durability, and compatibility with broader soldier systems. Products that can reduce the number of separate accessories operators must carry, or that support rapid adaptation across training and combat conditions, are well placed to capture attention in modernization programs. Commercial opportunity here lies in modular designs, advanced lens technologies, and configurations that simplify logistics while preserving performance across mission profiles.
A second trend is the growing importance of specialized protection segments within the broader market. Laser eye protection for aircrew and other specialized roles illustrates how threat-specific requirements can create focused demand streams that reward targeted development and program specialization. These segments may not dominate total volume, but they often carry higher value intensity and stronger differentiation potential because they address distinct operational needs. Manufacturers that cultivate capability depth in these areas can build defensible positions, particularly where certification pathways and program relationships reinforce repeat engagement. The commercial implication is that companies should evaluate not only overall market growth but also the relative attractiveness of sub-segments where technical complexity and mission specificity support stronger positioning.
A third trend concerns procurement architecture and multinational alignment. Rising defense expenditures and soldier modernization programs across major allied forces are likely to sustain demand, but procurement decisions will increasingly emphasize standardization, interoperability, and lifecycle performance. Framework agreements, stock number recognition, and approval-list dynamics will continue to shape how products move from qualification to field adoption. For suppliers, this means that commercial success may depend as much on navigating procurement processes and demonstrating total value as on product innovation alone. For buyers, the implication is that supplier selection should account for qualification status, supply reliability, and support for multi-year logistics needs, not just unit specifications.
These trends carry inherent uncertainty. Budget cycles can shift procurement timing; standards may evolve in ways that change qualification requirements; and supply chain disruptions can affect delivery confidence. In addition, the balance between performance enhancement and cost control will remain a persistent pressure point. Companies and buyers alike should therefore treat the market's direction as promising but contingent, with success depending on adaptability, program execution, and the ability to translate technical advantage into procurement-relevant value.
PW Consulting
Strategic Actions for Decision Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning their strategies with the forces most relevant to their positions.
-
For manufacturers, the priority is to strengthen the link between compliance, operability, and program execution. This means treating certification readiness as a strategic asset, investing in product architectures that support modularity and field adaptability, and building supply-chain resilience that protects delivery confidence. Differentiation is increasingly gained through the ability to meet military specifications reliably while also reducing logistical friction and enhancing mission usability. Companies should also evaluate where specialized capabilities—such as laser protection, advanced lens systems, or coalition-friendly configurations—can create stronger positioning than broad commodity competition.
-
For investors, the relevant question is not simply whether the market is expanding, but where value is being created and sustained. Market growth is supported by modernization programs and rising defense expenditures, but profitability and competitive durability depend on execution capability, certification access, and differentiation in higher-intensity segments. Attention should focus on organizations that demonstrate consistent program wins, credible qualification pathways, and product strategies that align with evolving procurement priorities. At the same time, risk awareness is essential, particularly around standards evolution, supply variability, and the concentration dynamics that shape entry barriers and competitive intensity.
-
For procurement and program leaders, the actionable insight is to evaluate protective eyewear not only as a compliance item but as a readiness enabler with total-cost implications. Selection criteria should account for approval status, supply reliability, optical performance in realistic conditions, compatibility with helmets and other equipment, and support for lifecycle management. Where programs span multiple forces or coalition environments, interoperability and standardization should carry additional weight. A disciplined evaluation framework that balances protection, usability, and logistical reliability can improve both field outcomes and procurement resilience.
The commercial stakes in this market are rising alongside its strategic importance. Decision makers looking to navigate segmentation detail, procurement pathways, competitive positioning, and forward scenario implications will find value in more granular research that ties market structure to actionable planning parameters. Further analysis of segment-specific dynamics, company-level capability assessments, and procurement-aligned forecasts can help translate these high-level trends into decisions that hold up under program scrutiny.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Eyewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Computer on Wheels Market: Why 14.5% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Computer on Wheels Market
Market Landscape and Core Challenges
The global computer on wheels (COW) market has demonstrated robust expansion over the past half-decade, transitioning from a niche healthcare mobility segment to a mainstream component of clinical infrastructure. Market valuation placed the sector at approximately USD 1,577.16 million in 2025, reflecting consistent year-over-year growth from a base of USD 801.4 million in 2020. Forward-looking projections indicate a compound annual growth rate of 14.5 percent through 2032, with revenue anticipated to surpass USD 4 billion by the end of the forecast horizon. This trajectory underscores a structural shift rather than cyclical fluctuation, as healthcare delivery models increasingly prioritize bedside documentation, mobile diagnostics, and real-time electronic medical record access. Regional and product-type dynamics reveal a mature but still evolving demand pattern, with powered systems commanding the largest share of revenue while non-powered alternatives maintain relevance in cost-sensitive or space-constrained environments.
Despite the favorable growth trajectory, the industry faces several structural headwinds that will shape competitive positioning over the next decade. First, regulatory scrutiny around medical device compliance continues to tighten across multiple jurisdictions. Electrical safety, electromagnetic compatibility, and infection control standards now function as baseline requirements rather than differentiators, forcing manufacturers to embed compliance into design cycles rather than retrofitting existing platforms. Second, the integration of advanced battery and power management systems has introduced both an operational imperative and a supply chain vulnerability. Lithium iron phosphate packs with hot-swap capabilities have become the de facto infrastructure for sustained clinical operation, yet sourcing, lifecycle management, and replacement logistics remain fragmented across the vendor ecosystem. Third, labor cost pressures and nursing workflow inefficiencies are driving demand for mobility solutions, but procurement cycles in healthcare systems remain lengthy and highly sensitive to total cost of ownership calculations. Organizations must navigate the tension between immediate workflow gains and long-term capital justification, which can delay adoption in budget-constrained settings.
The market is also approaching a consolidation inflection point. Revenue concentration among the top three and top five participants indicates a moderately fragmented landscape with clear leadership clusters, but the presence of specialized regional suppliers and custom-configuration providers suggests that differentiation will increasingly hinge on integration depth, service networks, and lifecycle support rather than pure hardware specifications. Companies that treat COW deployments as static equipment purchases risk losing ground to competitors who position these systems as configurable, service-enabled platforms aligned with clinical workflow evolution.
Medical Computer Cart Market
Key Drivers Shaping Market Evolution
Several interdependent forces are accelerating demand and reshaping product requirements across the COW sector. At the technology frontier, the convergence of low-profile computing architectures, ruggedized enclosures, and modular battery ecosystems has redefined what mobile workstations can deliver at the point of care. Patented fast-swap battery technologies and lithium iron phosphate systems with hot-swap capabilities now enable continuous operation without downtime, which is critical for hospitals running extended clinical shifts. Manufacturers have responded by designing carts that accommodate third-party computing modules or integrate all-in-one medical-grade displays, allowing facilities to standardize on a mobility platform while retaining flexibility in processor selection, operating system configuration, and peripheral attachment. This modularity reduces replacement friction and extends asset longevity, aligning hardware refresh cycles with clinical IT roadmaps rather than forcing simultaneous upgrades across every deployment.
Policy and regulatory environments are acting as both a constraint and a catalyst. Healthcare computer on wheels systems must comply with medical device standards for electrical safety, electromagnetic compatibility, and infection control in hospital environments. Rather than treating these requirements as purely defensive, leading manufacturers are using compliance as a trust signal and a design anchor. Standardized certification pathways reduce procurement friction for health systems, while infection-control features such as seamless surfaces, antimicrobial coatings, and easily disinfected contact points are increasingly specified in tender documents. In parallel, broader digital health policies that encourage electronic medical record adoption and bedside data capture indirectly expand the addressable base for mobile workstations, since facilities investing in digital workflows require reliable, mobile access points that move with clinicians rather than anchor them to fixed terminals.
On the demand side, the most pronounced shift is the operational response to labor cost pressures and workflow inefficiency. Mobile computer on wheels reduce time spent by nurses walking to stationary terminals, supporting workflow efficiency in point-of-care documentation. This logistical benefit translates into measurable time savings during documentation, medication administration, and bedside rounding, which in turn influences purchasing decisions among nursing leadership and clinical operations teams. Beyond time savings, the expectation for real-time data access has raised the stakes for device reliability. Clinicians increasingly view mobile workstations as extensions of the clinical team rather than peripheral equipment, which elevates expectations for uptime, ergonomic design, and seamless docking or charging behavior. Facilities that have deployed sit-to-stand configurations or customizable workstation heights are reporting improved clinician acceptance, suggesting that ergonomics and usability have become as important as raw computing capability.
Supply chain and cost structure changes are also reshaping competitive dynamics. The shift toward battery-centric infrastructure has introduced a recurring component management dimension to what was historically a one-time capital purchase. Hot-swap battery packs and modular power systems create opportunities for repower services, warranty extensions, and lifecycle support contracts, converting some hardware revenue into longer-duration service relationships. At the same time, ISO-certified manufacturers with established export experience are expanding their footprint into global healthcare markets, increasing price and specification competition in regions where procurement teams balance clinical-grade requirements against budget constraints. This dynamic is encouraging both incumbents and new entrants to clarify their value propositions: whether they compete on integration depth, regional service coverage, cost efficiency, or specialized workflow configurations.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by a group of U.S.-based manufacturers that have built recognizable positions around customization, battery innovation, and workflow alignment. Scott-Clark Medical has carved a niche around customizable healthcare computer on wheels and mobile computer carts, with powered systems featuring patented FMCPT battery technology optimized for point-of-care use in hospitals. This battery-led differentiation gives the company a tangible engineering narrative in procurement discussions where uptime and battery reliability are primary concerns. Altus Inc. competes across both powered and non-powered medical carts, offering battery-powered computer on wheels workstations designed for hospital EMR and patient care workflows. Its broader product span allows flexibility across budget tiers and deployment contexts, which is useful for health systems standardizing across multiple units or campuses. DTG Power emphasizes battery-powered workstation on wheels solutions and LFP battery systems, and notably positions repower services for existing carts from various manufacturers. This service-oriented angle extends the company's relevance beyond new equipment sales and into lifecycle support, an increasingly important consideration for facilities managing mixed-fleet environments.
Ergotron and Capsa Healthcare illustrate complementary strategic angles within the same ecosystem. Ergotron manufactures mobile computer carts and workstations on wheels for healthcare environments, frequently integrated with third-party battery and computing solutions, which positions the brand as a flexible platform partner rather than a closed-system vendor. Capsa Healthcare produces medical carts including computer on wheels and medication workstations designed for hospital point-of-care documentation and mobile computing, aligning product design directly with documentation and medication workflows. Cybernet and Teguar approach the market from the computing-hardware side, supplying all-in-one medical computers and rugged medical computers respectively, with configurations suitable for integration into computer on wheels carts in healthcare settings. Their strength lies in hardware durability, certification readiness, and compatibility with mobile cart ecosystems, making them relevant to buyers who prioritize compute reliability and environmental resilience. DataCart adds a further dimension with customizable workstations on wheels featuring sit-to-stand capabilities, targeting healthcare mobility and point-of-care applications where ergonomics and clinician posture are decision factors.
International participants are expanding the scope of competition. All Modul GmbH develops various models of computer on wheels from budget to high-end configurations, with customization options for European healthcare markets, which allows it to address both price-sensitive and specification-driven buyers in its region. ZHAOFA Technology operates as an ISO-certified manufacturer of hospital-grade computer on wheels and mobile workstations for global healthcare markets, and its continued offering of custom hospital-grade COW and WOW systems reflects a sustained focus on export-oriented, specification-adaptable production. Convergint Innovative Medical supplies workstations on wheels and computer on wheels solutions tailored for nursing workflows and simulation labs in healthcare, underscoring a workflow-and-training orientation that resonates with academic medical centers and simulation-based training environments.
The recent dynamics across these players point to a market that is simultaneously consolidating around a few recognizable leaders and fragmenting around specialized use cases. ZHAOFA's ongoing catalog emphasis on custom hospital-grade COW and WOW systems, supported by a decade of manufacturing experience, signals that configurable production remains a viable entry and growth path for established OEMs serving international buyers. Indurock's updated analysis of COW terminology, hospital applications, and future trends in mobile computer workstations for healthcare and logistics indicates that the category itself is being refined and communicated more precisely, which benefits buyers but also raises the bar for vendors to articulate clear use-case fit. Convergint's continued promotion of WOW/COW benefits for nurses and ongoing supply for healthcare simulation and clinical use highlights how workflow advocacy and training environments are becoming explicit demand channels, not just end-point deployments.
Strategically, the most successful players are those that convert hardware into a platform story. Battery technology, repower services, ergonomic configuration, infection-control design, and simulation-ready deployment all function as differentiators when they are tied to measurable clinical outcomes or operational savings. The market is therefore moving away from generic cart specifications toward solution-level competition, where vendors are evaluated on how well their mobile workstations fit nursing workflows, EMR integration expectations, and lifecycle management requirements. New entrants that bring clear workflow alignment, regional service capacity, or cost-efficient ISO-certified manufacturing can still gain traction, but they must do so by targeting a defined segment rather than competing broadly on price alone.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to define how the COW market evolves and where commercial opportunities concentrate. First, battery and power management will become the central lifecycle differentiator rather than a secondary feature. As lithium iron phosphate packs with hot-swap capabilities become standard expectations in clinical settings, competitive advantage will shift toward battery reliability metrics, replacement logistics, and repower or refresh services. Manufacturers and service providers that can standardize battery health monitoring, hot-swap training, and predictable replacement cycles will be better positioned to retain customers and expand into service-based revenue. The commercial implication is clear: mobility hardware will increasingly be evaluated as part of a managed power ecosystem, and procurement decisions will weigh total uptime and service coverage alongside initial unit economics.
PW Consulting
Second, workflow-integrated configurations will gain prominence over generic mobile carts. The push to reduce nursing walking time and improve point-of-care documentation is driving demand for sit-to-stand features, ergonomic adjustability, medication-specific workstation layouts, and simulation-ready setups. This trend favors vendors that can demonstrate how a specific cart configuration supports a documented clinical pathway, whether for bedside rounding, medication administration, or training environments. Companies that invest in workflow research, clinician feedback loops, and configurable options are likely to secure stronger preference in tenders, particularly in health systems that have moved beyond pilot deployments and are standardizing across multiple units. The opportunity here lies in packaging configuration flexibility with clear guidance on which layouts fit which workflows, reducing the decision burden for procurement teams and clinical leaders.
Third, the market will see continued pressure toward regional specialization and certified manufacturing footprints. ISO-certified manufacturers with global export experience are expanding reach into international healthcare markets, while regional customizers are refining offerings for local compliance expectations and procurement norms. This creates a dual dynamic: global scale players compete on integration breadth and service networks, while regional and cost-efficient manufacturers compete on specification adaptability and price-to-performance ratios. For commercial strategy, this means that buyers will increasingly choose between standardized global platforms and locally tailored configurations depending on their compliance environment, service expectations, and budget posture. The risk for vendors is that undifferentiated hardware becomes commoditized quickly, while the risk for buyers is that over-customization complicates maintenance and standardization across sites.
Computer On Module (COM) Market
A persistent uncertainty across these trends is the pace of health system capital cycles. Even when workflow benefits are well documented, procurement timelines can stretch, especially in environments where total cost of ownership justification must compete with other clinical priorities. Supply chain stability for battery components and the consistency of infection-control compliance across product lines will also influence adoption speed. Organizations that can align their value proposition with both clinical workflow gains and predictable lifecycle economics are best positioned to navigate these uncertainties.
Actionable Recommendations for Decision Makers
For manufacturers and solution providers, the priority is to move beyond product specifications and build a defensible workflow-and-lifecycle narrative. Differentiate around battery reliability, repower or refresh services, ergonomic configurations, and infection-control design, and make those claims traceable to documented clinical or operational benefits. Tailor go-to-market messaging to specific use cases rather than broad category language, since procurement teams increasingly evaluate mobile workstations against defined workflows and service expectations. Companies that can combine configurable hardware with predictable service coverage will be better positioned to protect margin and extend customer relationships over the asset lifecycle.
For investors evaluating exposure to this segment, focus on the durability of competitive advantages rather than headline growth alone.Assess whether a target company has genuine differentiation in battery technology, service infrastructure, workflow-aligned design, or regional manufacturing scale. Examine the balance between one-time hardware sales and longer-duration service potential, since lifecycle support and repower capabilities can materially affect recurring revenue quality. Also pay attention to compliance readiness and certification positioning, as these factors influence procurement speed and customer retention in regulated clinical environments. Companies whose growth depends primarily on price competition without workflow or service differentiation carry higher exposure to margin compression as the category matures.
For healthcare procurement teams and clinical operations leaders, the most effective approach is to evaluate mobile workstations as configurable platforms integrated into documented workflows, not as interchangeable equipment purchases. Standardize on core requirements for electrical safety, electromagnetic compatibility, infection control, and battery uptime, then use configuration flexibility to address department-specific needs such as sit-to-stand ergonomics, medication workstation layouts, or simulation lab use. Where possible, prioritize vendors that can support mixed-fleet environments, provide clear battery lifecycle management, and offer training or workflow guidance for clinicians. This reduces operational friction and helps ensure that mobility investments translate into measurable time savings and documentation efficiency rather than unused capacity.
Given the speed at which battery standards, compliance expectations, and workflow preferences are evolving, detailed segment-level data and customized scenario planning remain valuable for precise decision making. Organizations preparing capital plans, product roadmaps, or procurement strategies can benefit from a fuller breakdown of regional demand patterns, product-type economics, end-user dynamics, and company-level benchmarking to ensure that commitments are aligned with the most current market structure.
For detailed analysis of this topic, please visit the official page: Worldwide Computer on Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Enclosed Track Conveyors Market: How 5.85% CAGR Drives 2032 Expansion Beyond Scale
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Enclosed Track Conveyors Market
Market Overview: Current Landscape and Core Challenges
The global enclosed track conveyor industry enters the late 2020s as a mature yet steadily expanding segment within material handling and industrial automation. Valued at approximately USD 784.5 million in 2025, the market has demonstrated consistent growth from its 2020 baseline, with projections indicating a trajectory toward USD 1.17 billion by 2032. This expansion reflects a compound annual growth rate of 5.85 percent across the forecast horizon, signaling durable demand rather than cyclical volatility. The sector's resilience stems from its foundational role in overhead material transport, where enclosed track systems offer a compelling balance of load capacity, spatial efficiency, and operational safety compared to open I-beam alternatives.
However, growth trajectories are not without friction. Three structural challenges currently shape the industry's evolution. First, supply chain volatility in specialized steel profiles and precision chain components continues to influence lead times and system pricing. Enclosed track conveyors depend on engineered track geometries and hardened chain links that require controlled metallurgical processes, making upstream material availability a persistent operational variable. Second, the regulatory environment is tightening around safety and dust exposure, with updated standards introducing new compliance requirements for design, inspection, and maintenance protocols. Manufacturers and end-users must now navigate more rigorous documentation and installation verification, which raises upfront engineering costs but also creates a barrier that favors established players with mature quality systems. Third, the market faces a integration paradox: as facilities pursue smarter, data-driven operations, legacy enclosed track installations often lack native connectivity, forcing operators to weigh retrofit investments against full system replacements. This tension between operational continuity and digital upgrade paths defines much of the current procurement discourse.
Geographically, the market exhibits a clear concentration pattern, with the Asia Pacific and North America regions accounting for the largest revenue shares, followed by Europe. This distribution reflects differing industrial maturation levels, automotive and electronics manufacturing footprints, and logistics infrastructure investment cycles. Application demand remains anchored in automotive assembly and industrial finishing, while e-commerce fulfillment and food processing continue to gain incremental share as hygiene standards and flexible layout requirements intensify. The competitive structure remains moderately fragmented, with the top three suppliers capturing roughly one-third of total revenue and the top five approaching half, leaving substantial room for regional specialists and technology-differentiated entrants.
Key Demand Drivers and Structural Shifts
Technological Innovation and Modular System Design
The most visible driver of market expansion lies in the ongoing refinement of modular, enclosed track architectures that prioritize installation flexibility and maintenance efficiency. Traditional overhead conveyor deployments often required extensive structural modification and long commissioning windows. Newer system designs emphasize standardized trolley interfaces, quick-swap chain segments, and pre-engineered bend radii that reduce on-site fabrication. This modularity aligns directly with the operational reality of modern manufacturing floors and distribution centers, where production lines must be reconfigured for product mix changes, seasonal volume swings, or footprint optimization. Companies that have showcased integrated demonstrations combining enclosed track conveyors with robotic handling and automated order fulfillment illustrate how mechanical material transport is increasingly treated as a component within broader automation ecosystems rather than a standalone utility. The commercial implication is clear: system value is shifting from pure load-moving capability toward integration readiness, serviceability, and layout adaptability.
Policy, Safety Standards, and Compliance Dynamics
Regulatory and standards activity is reshaping procurement criteria across the sector. Updated safety frameworks for conveyors and related equipment now extend more explicitly to enclosed track designs, introducing provisions that address dust hazards, inspection frequency, and operational verification. These requirements do not merely add bureaucratic steps; they alter the total cost of ownership calculus. Facilities operating in finishing, powder coating, food processing, and light industrial environments must account for contamination control, surface protection, and worker exposure in ways that favor enclosed configurations over exposed alternatives. At the same time, compliance pressure rewards suppliers with documented quality management, traceable component sourcing, and field service networks capable of supporting recurring inspection cycles. The trend effectively raises the floor for market participation while creating a differentiation axis for vendors that can package safety compliance, documentation, and lifecycle support into a single procurement proposition.
Demand-Side Shifts in Manufacturing and Logistics
End-user behavior is evolving under the combined influence of labor availability pressures, throughput expectations, and facility design priorities. In automotive and heavy assembly environments, enclosed track systems continue to serve as reliable work-in-process transporters that keep floor space clear and reduce manual handling risk. In finishing and coating applications, the enclosed nature of the track helps contain overspray, protect moving components, and support cleaner_process environments. Meanwhile, e-commerce and logistics operations increasingly evaluate overhead conveyance not only for bulk movement but also for sequenced order picking, sorting integration, and ergonomically optimized workstations. This broadening application base reduces dependence on any single vertical and creates cross-sector demand for systems that can be scaled in span, speed, and load rating without major redesign. The practical outcome is a more diversified demand profile, where flexibility and hygiene considerations often compete with pure cost-per-foot arguments.
Supply Chain and Cost Structure Considerations
Cost dynamics are being reshaped by the interplay of raw material sourcing, component specialization, and service expectations. Enclosed track systems rely on engineered steel tracks, precision chains, trolleys, and drive units, meaning that fluctuations in metal pricing, motor availability, and machining capacity reverberate through project quoting and delivery schedules. At the same time, customers are increasingly sensitive to installed cost, downtime during changeovers, and long-term maintenance burden. This environment favors suppliers that can offer standardized component libraries, regional inventory positioning, and predictive maintenance guidance. It also encourages end-users to evaluate lifecycle economics more rigorously, weighing initial capital expenditure against spare parts availability, technician training, and the ability to expand or reconfigure the system without replacing the entire track infrastructure. In effect, cost competition is moving from unit price to reliability, lead time, and upgrade-option value.
Competitive Landscape and Strategic Positioning
The competitive field combines long-established North American manufacturers with international component suppliers and regional specialists. This mix creates a layered environment where incumbents compete on system breadth, engineering support, and installed-base service, while newer or regional players compete on price, niche load ratings, and localized deployment agility.
PW Consulting
Among the established names, companies with long track records in enclosed track monorail systems emphasize durability, modular installation, and application breadth. Profiles from firms originating in the mid-twentieth century often highlight standardized configurations that simplify specification for auto-body shops, manufacturing floors, and receiving areas. Their differentiation rests on proven uptime narratives, extensive field references, and the ability to offer power-only, power-and-free, and towline variations within a common design language. This breadth allows them to address a wide range of load profiles and throughput requirements while maintaining consistent spare-parts logistics.
Other leading players focus on capacity tiers and integration readiness. Some offer medium-capacity solutions tailored for tight spaces, while others provide heavy-duty variants or over-under configurations designed for large-volume production at a favorable cost position versus traditional I-beam systems. A distinct subset of competitors centers on component-level strength, supplying chains, trolleys, and specialty hardware to system builders and end-users alike. This component-focused model is strategically important because it embeds the supplier within multiple system architectures, creating recurring demand even when full-system projects fluctuate.
Recent activity underscores how competition is shifting toward integration and application-specific demonstrations. Public showcases combining enclosed track conveyors with robotic handling for carton movement and order fulfillment point to a market where mechanical transport is increasingly validated within end-to-end automation scenarios. At the same time, catalog and product updates emphasizing standard components with free-running trolleys for lower-cost overhead applications indicate continued segmentation between value-oriented installations and engineered, higher-capacity systems. The competitive signal is that suppliers are pursuing both ends of the spectrum: premium integration for complex workflows and standardized affordability for simpler overhead transport needs.
Worldwide Enclosed Torque Motor Market
Future Outlook: Trends Shaping the Next Three to Five Years
Several interdependent trends are likely to define market direction through the early 2030s. First, integration depth will increase as facilities seek overhead conveyance that communicates with broader control architectures. This does not necessarily mean every installation becomes highly automated, but it does suggest that compatibility with sensors, programmable logic, and data collection layers will become a more frequent selection criterion. Systems that can be instrumented for throughput monitoring, fault detection, and maintenance scheduling will hold a growing advantage in environments where downtime is costly and changeover frequency is high.
Second, hygiene and contamination control will continue to pull demand toward enclosed configurations in finishing, food-adjacent processing, and clean manufacturing contexts. As environmental and operational standards tighten, the enclosed track's ability to shield chains and trolleys from particulates, overspray, and incidental contamination will be valued not only for equipment longevity but also for process consistency. This trend favors suppliers that can articulate cleaning protocols, material compatibility, and service practices aligned with regulated or high-purity environments.
Third, regional capacity and supplier diversification will likely expand, particularly as end-users seek shorter lead times, localized service, and reduced exposure to single-region supply disruptions. Asia Pacific's substantial revenue presence and the presence of component manufacturers in Taiwan and India indicate an ecosystem capable of supporting both full-system projects and component-level supply. The opportunity for new entrants and expanding incumbents lies in pairing regional manufacturing responsiveness with reliable engineering specifications and compatible interface standards.
Potential risks remain. Steel and motor cost volatility can compress margins and delay projects, especially for engineered systems with long quote-to-delivery cycles. Regulatory updates may raise compliance costs in the near term, particularly for operators retrofitting older installations. In addition, if automation budgets soften in key verticals, procurement may shift toward incremental upgrades rather than full replacement, pressuring suppliers to offer flexible expansion paths and retrofit-compatible components.
Strategic Actions for Decision-Makers
For manufacturers and automation engineers, the priority should be to evaluate enclosed track systems not only on load capacity and footprint, but also on integration readiness, service access, and reconfiguration flexibility. Favor designs that allow span adjustments, trolley interchangeability, and straightforward inspection access, and align component selection with the facility's anticipated product-mix volatility.
For investors and corporate development teams, the opportunity lies in identifying suppliers that combine application breadth with credible service networks and component-level repeatability. Companies that can support multiple verticals while maintaining standardized interfaces and documented compliance practices are better positioned to capture demand as facilities modernize incrementally rather than replacing systems wholesale.
Enclosed Belt Conveyor Market
For procurement and operations leaders, total cost of ownership should be assessed across lead time, spare-parts compatibility, maintenance burden, and upgrade options rather than initial installed price alone. Where hygiene, dust control, or turnover frequency are material, enclosed track configurations warrant explicit comparison against open alternatives, with due attention to compliance documentation and service-response capability. Given the pace of standards updates, integration expectations, and regional supply shifts, more granular segmentation data and tailored scenario analysis can help decision-makers narrow specification choices and time investments more effectively. Readers seeking deeper breakdowns by application profile, regional deployment patterns, and company-level positioning can review the full PW Consulting market report for detailed segmentation metrics and actionable recommendations aligned to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Enclosed Track Conveyors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Egg Packing Machinery Market: Why Automatic Systems and 5.43% CAGR Redefine Supply Chains
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Egg Packing Machinery Market
1. Market Overview and Core Challenges
The global market for egg packing machinery has demonstrated consistent expansion over the past half-decade, with revenue estimates indicating a trajectory from approximately $572.25 million in 2020 to a projected $1.079 billion by 2032. Driven by a compound annual growth rate of 5.43 percent during the 2026-2032 forecast period, the sector reflects a maturation phase where efficiency, hygiene, and scalability dictate procurement decisions rather than mere capacity expansion. The current market size of roughly $745.5 million in 2025 underscores a robust foundation, yet the path forward is not without structural friction. Industry participants must navigate a landscape where volume growth increasingly depends on operational excellence rather than simple market penetration.
One of the most pressing challenges facing the sector is the persistent tension between labor availability and automation requirements. Agricultural and egg processing facilities across multiple regions are grappling with workforce constraints, which directly impact manual grading and packing lines. This labor shortage is not merely a temporary cyclical issue; it represents a structural shift that forces producers to reconsider their reliance on manual processes. The imperative to reduce manual handling and operational costs is accelerating the transition toward automated solutions, yet the capital expenditure required for such transitions can be a barrier for smaller operators who lack the cash flow to invest in high-throughput systems without clear ROI timelines.
Tray Sealing Machines Market
Regulatory pressures form a second critical pivot point. Stringent food safety mandates, particularly those focused on hygiene, Salmonella control, and pasteurization protocols during egg handling, are reshaping equipment specifications. Compliance is no longer optional, and machinery that lacks enhanced sanitary design faces obsolescence risk. Manufacturers and end-users alike must account for these regulatory demands in their capital planning, as retrofitting older lines or investing in new systems with compliant materials—such as stainless steel components for egg contact areas—adds complexity to procurement cycles and total cost of ownership calculations.
A third challenge lies in balancing throughput demands with product integrity. The macro trend of increasing global demand for eggs and processed egg products is pushing facilities to adopt machines capable of handling 10,000 to 60,000 eggs per hour. However, higher speeds must not compromise gentle handling, a requirement that remains paramount for table eggs and breeding stock. Equipment that can deliver both velocity and care is in high demand, but engineering such dual-capability systems requires sophisticated modular designs and precise control systems. Companies that fail to align their product offerings with this balance risk losing ground to competitors who can demonstrate verifiable gentle handling at scale.
2. Key Drivers of Market Growth and Transformation
Technological innovation stands as the primary catalyst reshaping the competitive dynamics of egg packing machinery. Advances in sensor technology, vision systems, and automated sorting algorithms are enabling machines to achieve higher accuracy in grading while minimizing breakage rates. Modular designs have become a hallmark of modern equipment, allowing producers to scale their operations incrementally rather than committing to monolithic line replacements. This flexibility is particularly valuable in an environment where farm sizes and processing volumes can fluctuate due to market conditions, avian influenza outbreaks, or shifting consumer preferences. The ability to integrate fixed or variable speed options, mobile units, and adaptable packing configurations means that machinery can evolve alongside the business, reducing the risk of stranded assets.
The policy and regulatory environment is exerting a profound influence on equipment selection and deployment. Beyond the baseline hygiene and food safety requirements, there is an increasing expectation for traceability and data capture within packing lines. Automated systems that log grading decisions, track egg batches, and integrate with broader farm management software are gaining traction as producers seek to demonstrate compliance and optimize operational insights. Regulations that mandate specific sanitation protocols for wash and packing lines also drive demand for materials and designs that facilitate rapid cleaning and reduce contamination risks. Equipment manufacturers that proactively align their R&D with these regulatory trajectories position themselves as partners in compliance rather than mere vendors of hardware.
On the demand side, consumer and enterprise behavior is shifting in ways that favor processed and value-added egg products alongside traditional table eggs. This diversification requires packing and grading equipment that can handle multiple formats, from standard trays to specialized packaging for liquid egg or further processing. Medium and large farms, as well as dedicated egg processing plants, are increasingly looking for integrated solutions that bridge grading, washing, printing, and packing into a cohesive workflow. The pursuit of throughput efficiency is not solely about volume; it is about consistency, reduced waste, and the ability to meet fluctuating order profiles without sacrificing quality. Enterprises that can demonstrate reliable performance across varied product streams are capturing a larger share of capital expenditure budgets.
PW Consulting
Supply chain and cost structure dynamics also play a pivotal role. The reliance on stainless steel for components in contact with eggs ensures hygiene and durability, but material costs and availability can influence pricing and lead times. Furthermore, the concentration of manufacturing capabilities in certain geographic clusters means that logistics, customs, and local support networks become critical considerations for buyers. Companies that can offer localized service, spare parts availability, and rapid response to downtime minimize the operational risks associated with global procurement. At the same time, cost pressures are driving a search for machines that deliver higher throughput per unit of labor and energy, reinforcing the value proposition of automation even in contexts where labor is available but expensive.
Recent industry activities illustrate how these drivers converge in practice. Participation in major trade exhibitions such as IPPE 2026, which featured extensive exhibits on poultry and egg processing equipment with record attendance and floor space, signals the sector's vitality and the intensity of innovation dissemination. Similarly, manufacturers showcasing their latest grading and packing machines at regional events like CAHE 2026 in Chengdu highlight the growing importance of Asian markets and the desire to demonstrate capabilities directly to a diverse audience of producers and integrators. These events serve as barometers for where technology, demand, and regional growth intersect, offering tangible evidence of the market's directional shifts.
3. Competitive Landscape and Leading Strategies
The competitive environment in egg packing machinery is characterized by a mix of established multinational players and specialized regional manufacturers, with a concentration ratio that suggests a moderately consolidated structure. Leading firms differentiate themselves through a combination of product breadth, technological sophistication, and service ecosystems. Companies that offer automated systems spanning from small farm applications to full-scale production lines with gentle egg handling and modular designs are well-positioned to capture value across diverse customer segments. The ability to provide high-capacity automated packing lines and integrated solutions allows leaders to address the throughput demands of large operations while maintaining the flexibility to adapt to varying egg types and packaging formats.
Strategic positioning among top competitors often hinges on the balance between automation level and operational practicality. Some manufacturers specialize in compact, versatile automatic packing machines that emphasize modularity, mobility, and fixed or variable speed options, catering to facilities that require reliable performance without excessive footprint or complexity. Others focus on gentle egg handling and packing for table eggs in trays, offering both semi-automatic and automated packers suited for layers and breeders. This segmentation of strengths means that buyers must evaluate not only technical specifications but also the alignment of a supplier's core competencies with their own operational profile, growth plans, and regulatory obligations.
Regional diversity among manufacturers adds another layer to the competitive dynamics. Firms based in Europe and North America often emphasize advanced automation, integration with broader poultry systems, and compliance with stringent food safety frameworks, while manufacturers from Asia and other emerging regions frequently compete on cost efficiency, rapid deployment, and complete automated processing and packing lines that cover grading, washing, printing, and separation. This divergence creates opportunities for cross-regional learning and partnership, as well as potential friction in terms of perceived quality, support infrastructure, and long-term reliability. Buyers increasingly weigh total cost of ownership, including service availability and spare parts logistics, against upfront pricing, which can shift the competitive advantage toward suppliers with strong local presence and responsive after-sales networks.
The market is also witnessing evolutionary trends in consolidation and new entry. Larger players with integrated poultry and egg production system portfolios, including egg handling and packing solutions, are well-placed to offer end-to-end value propositions that reduce integration risk for customers. At the same time, specialized firms focusing on egg processing equipment with capabilities supporting packing and sorting lines for food industry applications are carving niches around specific processing needs, such as pasteurization readiness or specialized tray configurations. New entrants and expanding regional players continue to challenge incumbents by targeting underserved segments, leveraging cost structures, and adopting proven technologies to accelerate time-to-market. In this environment, the ability to demonstrate consistent performance, gentle handling, and regulatory compliance becomes a key differentiator, as does the capacity to provide modular, scalable solutions that grow with the customer's business.
The competitive landscape is further shaped by the emphasis on hygiene and material standards. Equipment that prioritizes stainless steel components for egg contact areas not only meets sanitary design expectations but also signals durability and lower long-term maintenance burdens. Suppliers that embed these material choices into their core engineering philosophy, and that can articulate the operational and compliance benefits clearly, build trust with procurement teams that must justify capital investments against both financial and risk-management criteria. The interplay of these factors suggests a market where differentiation is increasingly derived from integrated technology, service reliability, and the ability to navigate the intersection of throughput, hygiene, and flexibility.
4. Future Trends and Strategic Outlook (2026-2032)
One of the most significant trends likely to define the next three to five years is the deepening integration of automation with data-driven management. As labor constraints persist and regulatory scrutiny intensifies, packing lines will increasingly function as nodes within broader digital ecosystems. Grading and packing equipment will be expected to capture granular operational data, support traceability requirements, and interface with farm and processing management platforms. This shift creates commercial opportunities for manufacturers and integrators who can offer seamless connectivity, analytics dashboards, and predictive maintenance capabilities, while also posing a risk for those whose products remain isolated hardware solutions without clear pathways to data integration.
A second trend is the continued push toward higher throughput combined with uncompromising gentle handling. Demand for eggs and processed egg products is expected to remain robust, and facilities will seek machines that can process 10,000 to 60,000 eggs per hour without elevating breakage or compromising hygiene. Innovation in conveyance, cushioning, and speed control will differentiate suppliers, and end-users will reward systems that balance speed with product protection. The opportunity here lies in engineering and marketing solutions that provide verifiable performance metrics, enabling buyers to model ROI based on reduced waste and higher quality output. A risk to monitor is the potential for over-optimization on speed at the expense of handling quality, which can erode trust and lead to costly retrofits or replacements.
Third, regional demand dynamics will continue to reshape where growth is most pronounced and where competitive pressure intensifies. Markets with expanding medium and large farm operations, as well as dedicated processing plants, will drive demand for integrated, high-capacity lines, while smaller or more cost-sensitive regions may favor semi-automatic or modular solutions that allow incremental upgrades. This divergence creates opportunities for tailored go-to-market strategies, localized support models, and product configurations that match regional regulatory and operational contexts. A key uncertainty is the pace of regulatory evolution and the extent to which hygiene and safety mandates accelerate automation adoption across all segments, which could compress the window for semi-automatic solutions in certain markets.
5. Strategic Considerations for Decision-Makers
For manufacturers, the priority is to sustain investment in modular, sanitary, and data-ready designs that can serve a spectrum of farm sizes and processing formats. Aligning R&D with the dual imperatives of throughput and gentle handling, while ensuring compliance with evolving hygiene standards, will strengthen competitive positioning. Building robust service and parts networks, along with clear communication of material choices such as stainless steel for critical components, can differentiate offerings in a market where total cost of ownership matters as much as initial price.
High Speed Packaging Machine Market
For investors, the landscape suggests selective opportunities in companies that demonstrate scalable technology platforms, strong regional presence, and the ability to integrate packing solutions with broader poultry system portfolios. Concentration dynamics indicate that consolidation and partnership activity may continue, and due diligence should weigh service capabilities, regulatory alignment, and the flexibility of product lines to adapt to shifting demand patterns. Tracking exhibition activity and product launches at major industry events can provide early signals of innovation direction and regional focus.
For purchasers and procurement teams, the decision matrix should extend beyond headline throughput figures. Evaluating gentle handling performance, hygiene design, modularity, and the supplier's ability to support compliance and data integration will reduce long-term operational risk. Engaging with suppliers that can demonstrate reliable performance across varied product streams, and that offer clear pathways for incremental capacity expansion, helps balance immediate needs with future growth. For those seeking granular segmentation data and tailored strategic recommendations, the full research report provides detailed breakdowns across regions, types, and applications, along with scenario analysis to support capital planning and competitive positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Egg Packing Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


