



Category: market research
PW Consulting Report: Bone Cement for Spine Market Tops USD 895 Million in 2025
By PW Consulting, 2026-07-13
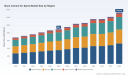
Bone Cement for Spine Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s latest market study on bone cement for spine (base year 2025) delivers a compact, decision-ready roadmap for executives planning 2026 actions. At a global level the market sits at roughly USD 895 million in 2025 and — under our base-case assumptions — is forecast to grow to more than USD 1.3 billion by 2032, representing a mid-single-digit compound annual growth rate (CAGR). That trajectory is notable for supply-chain sensitivity, technology-led product differentiation (viscosity profiles, antibiotic-loaded formulations, delivery systems), and a reimbursement environment that favors standardized augmentation procedures. This release highlights the strategic takeaways from the full report while intentionally withholding certain granular segment-level figures to preserve the report’s role as a commercial intelligence product.
Bone Cement for Spine Market
Market dynamics shaping 2026 decisions
-
Clinical demand and procedure mix — The clinical drivers behind vertebral augmentation remain robust: an aging population, sustained incidence of osteoporotic and pathological vertebral compression fractures, and a continued preference among interventional spine specialists for minimally invasive stabilization techniques. Device adoption is being influenced as much by operator workflow and injection control as by material properties.
Bone Cement for Spine Market -
Product innovation — Two technical threads dominate supplier investment: controllable viscosity (including ultra-high-viscosity formulations optimized for anterior column support) and adjunct functionality (e.g., antibiotic-loaded PMMA for combined infection risk mitigation). Radio-opacity and working/injection windows are increasingly marketed as clinical differentiators.
Bone Cement for Spine Market -
Regulatory & reimbursement context — PMMA bone cements used in vertebral augmentation remain regulated under established Class II pathways in major jurisdictions, with special controls and sterilization expectations shaping dossier requirements. In the US, common percutaneous vertebral augmentation procedures are covered under established CPT codes that include cavity creation and cement injection with imaging guidance — a practical advantage for adoption but one that still requires payer-level diligence for new product introductions.
-
Quality, sterilization and materials risk — Manufacturers face rigorous sterilization validation expectations (e.g., documented methods, sterility assurance levels, pyrogenicity testing). On the materials front, standard PMMA formulations continue to exceed ISO mechanical baselines, but raw material sourcing and monomer handling present latency risks that must be managed in supplier contracts and manufacturing operations.
What the full PW Consulting report delivers (practical contents)
-
Proprietary market model with transparent assumptions — multi-scenario forecasts covering 2026–2032 and sensitivity testing for key inputs (procedure volumes, pricing erosion, market entry timing).
-
Regulatory playbook — classification mapping, recommended 510(k)/equivalent strategies, essential documentation checklists (including sterility and pyrogenicity pathways) and timings to market in major regions.
-
Reimbursement and coding guide — payer levers, procedural code implications, and hospital-level bundle impacts for percutaneous vertebral augmentation.
-
Clinical evidence compendium — outcome metrics, comparator data for high- vs low-viscosity formulations, and guidance on randomized vs registry-driven evidence programs to support product claims.
-
Commercial playbooks — go-to-market options by tier (incumbent OEM, challenger, start-up), distributor selection criteria, tender playbooks and pricing negotiation frameworks.
-
Supplier & manufacturing checklist — material qualification criteria, sterilization vendor shortlist templates, and inventory resilience strategies for monomer and radiopaque additives.
-
M&A and partnership scanner — prioritized target profiles, valuation sensitivities, and integration risks for bolt-on acquisitions versus co-development alliances.
Competitive landscape — practical implications for 2026
The market is characterized by a mix of large medtech incumbents and specialized suppliers. Global orthopedics and spine players maintain scale advantages through integrated portfolios and distribution networks, while smaller specialists compete on niche innovations and faster regulatory cycles. Key competitive themes we emphasize:
-
Stryker — leverages a spine-focused product suite with high-viscosity and clinically positioned cements; strength lies in integrated sales channels and long-standing trust with interventional spine clinicians.
-
Medtronic — combines legacy vertebral augmentation platforms with established PMMA offerings; regulatory experience and global reach support rapid rollouts of incremental product improvements.
-
Zimmer Biomet — increasingly targeting differentiated clinical niches (e.g., antibiotic-loaded cements) and leveraging orthopedic scale to cross-sell into spine.
-
DePuy Synthes (J&J) — consistent PMMA portfolio compatibility with spine workflows; pricing and procurement relationships with hospitals are core strengths.
-
Heraeus & Tecres — European-origin suppliers that compete on formulation specificity (high-viscosity, radiopacity) and regulatory craft for EU and broader markets.
-
Merit, IZI Medical, Xelite Biomed and others — smaller, nimble players focusing on differentiated delivery systems, RF-modulated cement systems, or recently cleared products to penetrate the US market.
Recent regulatory and product developments underline near-term shifts in competitive positioning: several entrants obtained US clearances in late 2024–2025 and new antibiotic PMMA launches in 2025 signal pockets of rapid product refresh. These moves increase clinical choice and can compress pricing unless matched by demonstrable outcome advantages.
Strategic recommendations for 2026
-
Prioritize clinical differentiation backed by evidence — invest in prospective registries or limited randomized studies that show procedure-time savings, leak reduction, or infection mitigation; these datapoints materially improve contracting outcomes with hospital systems.
-
Pursue regulatory efficiency with sterilization-first design — embed validated sterilization pathways early (including SAL documentation and pyrogen testing) to avoid late-stage delays and to reduce time-to-market risk.
-
Design resilient supply chains — secure secondary suppliers for critical monomers and radiopaque additives and include inventory buffering in commercial contracts to mitigate spikes in demand for vertebral augmentation seasons.
-
Segment go-to-market by hospital archetype — academic centers value clinical data and novel delivery systems; community hospitals prioritize cost, packaging and ease-of-use; tailor pricing and service bundles accordingly.
-
Explore adjacent value propositions — antibiotic-loaded PMMA, combined scaffold/adhesive approaches, or bundled augmentation systems (implant + cement) can unlock premium positioning if supported by clinical benefit.
-
Prepare for consolidation plays — use 2026 to identify bolt-on targets that provide formulation IP, regulatory dossiers, or regional distribution as part of defensible share gain strategies.
90–120 day tactical plan for executive teams
-
Complete a portfolio stress test: map each SKU against regulatory readiness, sterilization validation, and reimbursement exposure.
-
Kick off a focused registry protocol with 6–12 month interim endpoints to build hospital adoption cases.
-
Negotiate conditional supply agreements with secondary monomer suppliers and establish safety stock triggers.
-
Run pricing simulations by hospital archetype and prepare targeted contracting pilots for high-volume systems.
-
Scan for acquisition or partnership targets that close capability or geographic gaps and pre-draft integration playbooks.
Why this PW Consulting report is essential for 2026 planning
Leadership decisions in 2026 will be made at the intersection of clinical value, regulatory readiness and supply resilience. PW Consulting’s report combines a transparent, model-driven forecast with concrete operational tools — regulatory checklists, reimbursement playbooks, supplier templates, and M&A screening frameworks — to accelerate executive decision cycles and reduce execution risk. We surface not only where growth is likely to occur, but which commercial and technical levers move the needle on share and margin.
Next steps and how to access the intelligence
This briefing intentionally highlights the strategic framing, practical levers and competitive moves that will matter in 2026 without reproducing the report’s detailed segment-level tables and targetable numeric splits. For board-ready slides, market model access, or a tailored advisory workshop that maps these insights to your portfolio and risk appetite, contact PW Consulting for the full market study and executive-briefing package.
For detailed analysis of this topic, please visit the official page: Bone Cement for Spine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 3.8% CAGR for TDI 80/20 Market (2026–2032) in New Market Insights Report
By PW Consulting, 2026-07-13
TDI 80/20 Market — TDI 80/20: Strategic Imperatives for 2026 Decision‑Makers (TDI 80/20 Market — TDI 80/20 Market Report, TDI 80/20 Market — TDI 80/20 Market Research)
Executive summary
PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report (base year 2025; historical window 2020–2025; forecast period 2026–2032) delivers a focused, decision‑grade playbook for corporate strategy, capital allocation, and procurement optimization in the global TDI 80/20 value chain. The market is valued at approximately USD 2,850 million in 2025 and, under our central scenario, grows at a compound annual growth rate (CAGR) of 3.8% to reach roughly USD 3,700 million by 2032. The near‑term profile includes a modest post‑2025 rebalancing before recovery into the late 2020s driven by capacity additions, energy and feedstock volatility, and regulatory pressure.
TDI 80/20 Market
Why this report matters for 2026 planning
-
Actionable timing: Our cross‑check of recent capacity moves, modernization programs and trade policy shifts identifies specific windows in 2026 when sourcing, hedging and investment decisions will capture outsized value — particularly for foam converters, CASE formulators and upstream feedstock integrators.
TDI 80/20 Market -
Risk triage: We quantify seven operational and market risks (feedstock cost shocks, localized trade barriers, safety/regulatory compliance, concentrated supply, energy transition exposure, technology obsolescence, and logistics bottlenecks) and prioritize mitigation measures that fit typical corporate risk appetites.
TDI 80/20 Market -
Competitive signals: The report synthesizes primary and secondary research on incumbent producers, revealing how recent capacity and efficiency actions reshape regional sourcing dynamics and margin pools in 2026–2028.
Market trajectory — what the headline numbers hide
The headline CAGR of 3.8% to 2032 masks a two‑phase trajectory that should directly influence 2026 decisions. After a near‑term inventory and price adjustment, driven by feedstock volatility and selective capacity startups, the market re‑accelerates as demand for flexible polyurethane foam and other polyurethane segments regain momentum. Importantly, the market concentration is material: the top three producers account for a majority share of capacity, and the top five approach four‑fifths of supply — a structural factor that amplifies the impact of individual producer investments and outages on global availability and pricing.
Primary demand and cost drivers (what matters in 2026)
-
Feedstock price dynamics: Toluene price pressure is a direct, measurable input to TDI 80/20 manufacturing economics. Recent northeast Asia price moves—sharp appreciation in the referenced period—translate into single‑digit to double‑digit percentage shifts in cash‑cost curves for exposed producers. Procurement teams must build scenario hedges and supplier scorecards that account for at least three realistic toluene paths over 12–24 months.
-
Energy and decarbonization initiatives: Plant modernizations that capture reaction energy for steam generation materially change unit economics and CO2 intensity. Facilities that lower energy and emissions profiles will enjoy regulatory and off‑taker advantages in markets where downstream purchasers are imposing carbon criteria.
-
Regulatory and occupational safety: TDI remains tightly regulated globally as a respiratory sensitizer. Occupational exposure limits from agencies such as OSHA and guideline values like those from ACGIH create compliance cost floors. Companies must treat occupational safety and REACH‑style chemical management as strategic investments — not just compliance items — because they affect licensing, insurance, and customer acceptance.
-
Trade policy and protectionism: Antidumping and other trade measures can create sudden regional dislocations in supply and pricing. Ongoing duties in major markets are already influencing sourcing decisions and will remain a lever for domestic policy makers through 2026.
Competitive landscape — what recent moves tell us
The competitive map is being redrawn by two simultaneous dynamics: (1) large, integrated capacity additions from resource‑rich incumbents and (2) targeted efficiency investments in legacy plants. Our firm view, based on primary interviews and plant‑level disclosures, is that these moves produce asymmetric advantages for both global exporters and regionally focused suppliers.
-
Large Chinese integrated producers: Recent capacity startups significantly expand global outbound availability from certain Chinese producers. These investments are purpose‑built to serve both domestic foam chains and export markets. For buyers and investors, this means short to medium‑term pricing pressure in exposed corridors but an eventual leveling as trade barriers and freight dynamics reassert themselves.
-
European energy/efficiency upgrades: Select European players have completed modernization projects that reduce energy intensity and emissions per tonne. These projects change competitive positioning by lowering variable cost and improving access to customers with sustainability procurement mandates.
-
Regional producers and market protection: Local producers in major consumption markets retain strategic advantages through proximity, regulatory familiarity and, in several cases, targeted trade defense policies that sustain higher local realizations.
Spotlight: tactical developments to watch in 2026
-
Capacity startups that came online in late 2025 will be the proximate trigger for a short‑term supply cadence reset; monitoring ramp rates is essential for procurement timing.
-
Plant modernizations that recycle reaction heat into steam and other utilities materially reduce energy exposure and CO2 output; these projects are the differentiator for long‑term cost leadership.
-
Trade remedies enacted through 2026 will continue to reallocate supplier‑buyer relationships and may force relocation or reshoring discussions among exposed downstream players.
Implications for 2026 corporate decision‑making
-
Procurement: Move from transactional spot buying to layered coverage: short‑term tactical pools, medium‑term indexed contracts tied to energy/feedstock benchmarks, and strategic supply agreements with performance and service metrics. Include clauses for force majeure, trade duty pass‑throughs, and sustainability attributes.
-
Operations & CAPEX: Prioritize retrofit opportunities that deliver rapid energy and emission paybacks. Greenfield or brownfield investments should be timed to capture windows when incumbent ramp‑ups temporarily depress input prices and labor availability.
-
M&A and JV strategy: Target bolt‑on positions in logistics hubs and feedstock integration rather than only seeking new polymer capacity. Minority stakes with offtake rights in modernized facilities yield outsized optionality while limiting capital exposure.
-
Regulatory & safety governance: Strengthen chemical safety programs and product stewardship capabilities. Compliance excellence is now a commercial differentiator in tender processes where purchasers insist on supplier safety records and low‑emission footprints.
What the PW Consulting TDI 80/20 Market report contains (practical deliverables)
-
Quantitative market model (2020–2032) with base case, upside and downside scenarios, sensitivity runs for feedstock and energy, and a policy shock module designed for CFO stress testing.
-
Supplier scorecards and mapped value chains for strategic sourcing, including plant‑level capability, retrofit potential and logistics latency analysis.
-
Commercial playbooks for buyers, manufacturers and investors — containing contract language templates, risk allocation recommendations and a prioritized list of mitigations for the top seven risks identified.
-
Competitive profiles of the major producers with operational summaries and strategic intent indicators based on announced capacity, modernization projects, and public filings.
-
Regulatory and occupational safety annexes that summarize relevant limits, compliance costs and engagement templates for global regulators and trade authorities.
How PW Consulting’s insight is different
We combine plant‑level engineering economics with procurement scenario planning and regulatory foresight. Rather than merely publishing descriptive segmentation, our report offers executable guidance: when to hedge, when to invest, and which supplier strategies will preserve margin through feedstock and policy cycles. To preserve commercial sensitivity and to encourage a calibration with real operational parameters, detailed region/application split tables and producer‑specific financials are available exclusively in the full report download and interactive dashboard.
Next steps for executives and investors
-
Review the scenario appendix and run the policy‑shock module against your current procurement book to identify exposure timing in 2026.
-
Engage with a short advisory to model a retrofit vs. new‑build decision under the energy and emissions sensitivities set out in the report.
-
Use supplier scorecards to re‑negotiate 12–24 month contracts with clauses for trade remedy pass‑through and sustainability credits.
Accessing the full intelligence
This release frames the strategic implications from PW Consulting’s TDI 80/20 Market — TDI 80/20 Market Report. The full report contains the complete segmentation tables, plant‑level data, producer‑specific metrics and the downloadable market model that drive the recommendations summarized here. For licensing, enterprise access and bespoke advisory services to operationalize these findings in 2026, please visit the TDI 80/20 Market report page or contact our industry desk for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: TDI 80/20 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Castor Oil Modified Polyol Market Poised to Expand at 7.02% CAGR, Reaching USD 492.7 Million by 2032
By PW Consulting, 2026-07-13
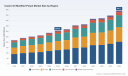
Castor Oil Modified Polyol Market — Strategic Outlook for 2026: An Executive Preview
Executive summary
PW Consulting’s latest Castor Oil Modified Polyol Market study frames a fast-evolving value chain that is shifting from niche bio-based experimentation toward industrial-scale adoption. The global market, which PW Consulting tracks on a USD Million revenue basis, expanded from an estimated USD 218.4M in 2020 to USD 306.4M in our 2025 base year and is forecast to continue rising through the 2026–2032 horizon, reaching an estimated USD 492.7M by 2032. This trajectory implies a compound annual growth rate of approximately 7.02% over the forecast period — a growth profile that is large enough to justify strategic resource allocation but still concentrated enough to reward targeted moves on technology and supply chain.
Castor Oil Modified Polyol Market
Why this preview matters for 2026 decision‑makers
-
Investment timing — The mid-single-digit-to-high-single-digit CAGR underlines a window in which first-mover or fast-scaler advantages translate into long-term commercial relationships with formulator OEMs, particularly in coatings, adhesives and polyurethane systems.
Castor Oil Modified Polyol Market -
Raw material risk management — Castor seed and oil remain the systemically critical feedstock. Global castor oil market volumes were approximately 965–978 KMT in 2025, with India continuing as the dominant supplier. Buyers and producers must bake in volatility: our prices and procurement scenarios show material quarter-to-quarter swings that affect gross margins and competitive positioning.
Castor Oil Modified Polyol Market -
Regulatory arbitrage — Stricter VOC/VOC‑adjacent policies in the EU and progressive procurement preferences (bio-preferred incentives) are creating demand pull for certified bio-content chemistries. At the same time, policy changes such as China’s April 1, 2026 cancellation of the VAT export rebate for polyether polyols will alter relative cost differentials and could re-shape trade flows and import parity economics through 2026–2027.
-
Consolidation and supplier concentration — The market exhibits moderate concentration: the three largest suppliers account for a meaningful share of the market, with the top five approaching half of reported revenues. Strategic buyers should therefore map dependency and optionality across the supply base now.
-
Technology and go‑to‑market choices — Differentiation is increasingly achieved via low‑viscosity, high bio-content grades, waterborne variants, and grades engineered for specific CASE and foam formulations. Product stewardship (certifications, documentation, formulation support) is becoming as important as price in commercial win rates.
Market dynamics and implications
The market’s growth is driven by three overlapping forces: demand-side policy and procurement preferences that favor renewable inputs; formulation-led substitution in established polyurethane and CASE supply chains; and industrial players moving to secure castor-based capacity as feedstock economics become better understood. Environmental regulation — from EU REACH and the Green Deal to US TSCA/EPA guidance and procurement standards — is accelerating adoption among formulators that must meet VOC limits and demonstrate bio-based credentials.
Supply-side dynamics remain anchored in agricultural cycles and geopolitics. India’s dominant position in castor seed supply creates both opportunity and vulnerability: when yields or harvest acreage change, FOB price indices and regional trading spreads react quickly. Our scenario workbench models show that average castor oil price swings materially affect margins for both modified polyol producers and downstream formulators, and they amplify incentives for vertical integration or long‑term offtake agreements.
Competitive landscape — strategic takeaways
Market participants fall broadly into three strategic archetypes: global chemical majors with portfolio breadth and certification capabilities; regional castor-specialist producers with proximity to feedstock and cost advantages; and nimble formulators supplying tailored grades and services. Key companies to watch:
-
Alberdingk Boley GmbH (Krefeld, Germany) — Their ALBODUR® portfolio and the July 2025 technology documentation update signal a play focused on high-solid, solvent-free systems and downstream formulation support. The emphasis on certified biobased content and application guidelines is a template for premium positioning in corrosion protection and industrial floor coatings.
-
Jayant Agro‑Organics / Vithal Castor Polyols (Jhagadia, India JV) — Recent capacity announcements (site opening in November 2025) reinforce the strategic value of feedstock proximity. Their vertically integrated model is a core risk-mitigation and cost-leadership enabler for downstream customers looking for stable supply.
-
BASF SE — As a global major, BASF’s natural-oil polyols and branded solutions (e.g., SOVERMOL®, Lupranol Balance series) combine performance claims with global commercial reach and technical service. Their playbook underscores the importance of combining product performance with compliance certification.
-
Stepan Company — Focused grades and reactivity control (STEPANPOL® family) position them to win in controlled production environments and reactive polyurethane systems where processing consistency matters.
-
Regional and specialist players (Eagle Specialty Products, Gokul Overseas, Emirachem, Modi Oil Mill) — These suppliers compete on specialized grade ranges, custom blending, and agility. Their value is highest for customers requiring tailored low-volume formulations, local logistics advantages, or specific sustainability narratives.
What the PW Consulting report delivers (practical modules)
This study is designed as a directly actionable briefing for commercial leaders, product managers, procurement teams, and corporate development groups preparing decisions in 2026. Core modules include:
-
Market sizing and proven methodology — full historical reconciliation 2020–2025 and top‑down/bottom‑up triangulation for the 2026–2032 forecast.
-
Supply chain and cost build-up — feedstock-to-finished-good cost models, sensitivity analyses to castor oil price scenarios, and suggested hedging/contract structures.
-
Regulatory and certification matrix — mapping of REACH/TSCA/Green Deal implications, bio-preferred certification pathways, and compliance timelines.
-
Competitive benchmarking — vendor scorecards, capability heatmaps, recent developments and capacity tracker (including the July 2025 & November 2025 updates), and tactical playbooks for supplier negotiations.
-
Commercial playbooks — go-to-market templates for premium bio-content grades, waterborne strategies, and CASE/foam-focused application roadmaps.
-
M&A and partnership scouting — target criteria, valuation sensitivities, and a short‑list of mid-market acquisition and JV opportunities aligned to scale and feedstock integration.
-
Client-ready slide packs and data extracts — configurable datasets for board-level briefings and investment committees.
How to use this preview in 2026 planning
-
Procurement managers should re-run supplier stress-tests using the report’s price‑sensitivity templates and model the impact of China’s April 2026 VAT rebate cancellation on regional import parity and landed costs.
-
R&D and product leadership must prioritize two tracks: (1) enhancing formulation work to convert existing polyurethane systems to high‑bio-content castor polyols without performance trade‑offs, and (2) developing lower‑VOC, waterborne offerings supported by technical documentation and lifecycle claims.
-
Corporate development teams should evaluate smaller regional producers for bolt‑on capacities that improve feedstock optionality, or for access to application-specific formulations and customer book advantages.
-
Regulatory/compliance teams need to fast-track certification dossiers where required — procurement preferences and tender processes increasingly include bio-content proof points.
What we are intentionally withholding here — and why
In this executive preview we present market trajectory, strategic implications, and company-level signals; however, granular regional and application split tables, price-by-region series, and detailed segment-level revenue figures have been reserved for the full report and interactive datasets. This “preview” approach preserves the strategic value of the primary research while providing enough insight to inform near-term planning. For teams that require the complete tables, downloadable models, and bespoke regional breakdowns, PW Consulting provides a dedicated data pack and client workshop options.
Next steps
For 2026 planning cycles, a concentrated effort in Q1 will capture the highest value: update procurement contracts to incorporate hedging triggers, prioritize a two-phase R&D roadmap (fast followers for immediate wins; platform investments for 2028+), and accelerate supplier audits against bio-content and traceability criteria. PW Consulting is available to run a focused 48–72 hour rapid workshop to translate the report’s scenarios into an operational action plan tailored to your company’s footprint and risk tolerance.
To access the full dataset, proprietary segmentation, and the interactive cost models referenced in this preview, please visit our report page or contact your PW Consulting account lead to arrange a briefing and data license.
For detailed analysis of this topic, please visit the official page: Castor Oil Modified Polyol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Light Therapy Device Market to Reach USD 616.32 Million by 2032, Growing at a 7.15% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Infrared Light Therapy Device Market — Strategic Outlook for 2026
PW Consulting’s new market brief on Infrared Light Therapy Devices equips executives with the evidence and tactical playbook needed to make high-conviction decisions in 2026. Built on a 2025 base year and a seven-year forecast window (2026–2032), the study projects continued expansion at a compounded annual growth rate (CAGR) of 7.15%. After a strong recovery through 2020–2025 (market value reached approximately USD 380 Million in 2025), the market is expected to expand materially through the forecast period, passing the USD 400 Million threshold in 2026 and approaching the mid‑hundreds of millions by 2032. This brief summarizes the report’s strategic value while deliberately reserving granular splits and financials to the full report—intentionally designed to prompt direct engagement with PW Consulting for the complete dataset, models, and vendor scorecards.
Infrared Light Therapy Device Market
Why this analysis matters for 2026 corporate strategy
- Timing of market entry: The sub‑segment growth dynamics and macro trajectory show that 2026 is a decisive year for product launches and regulatory initiatives. Firms that move from prototype to clinical validation now can capture disproportionate share as clinics and health systems scale adoption.
- Regulatory differentiation: FDA 510(k) requirements for Class II devices and the growing emphasis on clear therapeutic indications create barriers that favor players with clinical programs and regulatory experience.
- Reimbursement levers: Existing billing codes and therapy session allowances create a commercialization path for clinic-focused offerings; savvy payor strategies materially improve unit economics.
- Supply‑chain risk and cost structure: High‑power near‑infrared LEDs (especially ~850nm units) are a material portion of device BOM — our sector analysis shows these components can drive 20–30% of BOM — making supplier strategy and cost management a priority.
- Fragmented competitive landscape: Market concentration remains modest, indicating fertile ground for consolidation, partnerships, and white‑label opportunities for medical OEMs and clinical players.
What’s in the PW Consulting report (practical, decision-ready content)
- Executive summary with investment thesis and go/no‑go decision checkpoints for 2026.
- Market sizing and forecast model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario and sensitivity analysis.
- Segment methodology and assumptions (type, application, and regional frameworks) with downloadable model worksheets—note: detailed segment tables and revenue splits are available only in the full report.
- Commercialization playbooks for direct‑to‑consumer, clinic, and hospital channels including pricing models and reimbursement capture strategies.
- Vendor benchmarking and go‑to‑partner scorecards based on product capability, clinical evidence, regulatory status, distribution strength, and manufacturing readiness.
- Regulatory and reimbursement mapping: 510(k) pathways, applicable CPT codes, and payer engagement templates.
- Supply‑chain risk matrix and supplier negotiation playbook focused on high‑power LED sourcing, BOM optimization, and inventory strategies.
- M&A target shortlist, value‑creation levers, and integration risk checklists for roll‑up strategies in a fragmented market.
- Appendices: clinical evidence compendium, IP landscape snapshot, and raw data export for custom modeling.
Competitive landscape — who’s shaping the market
The market is currently driven by a mix of consumer wellness brands, clinical device manufacturers, and specialty medical laser companies. No single player dominates; the three‑ and five‑firm concentration ratios indicate a market that remains open to entrants with clinical credibility or differentiated go‑to‑market approaches.
Infrared Light Therapy Device Market
- Infraredi (USA) — Focused on portable panels for pain relief and recovery with devices covering the 660–850nm range. Competitive strengths: portability and targeted pain solutions for athlete recovery.
- Mito Red Light (USA) — Consumer and clinical panels with recent product upgrades. Strategic note: launched the MitoPRO+ series (Oct 2025), enhancing near‑infrared output to improve depth of penetration—an important move for clinic‑grade positioning.
- Joovv (USA) — Modular full‑body systems with near‑infrared capability. Strategic note: received FDA Class II clearance for a portable device in June 2025, adding an important regulatory credential for OTC pain indications.
- PlatinumLED Therapy Lights (USA) — High‑power BIOMAX panels combining red and near‑infrared LEDs; credible in both wellness and therapeutic use cases.
- Novaa Lab (USA) — Wearable devices like iTorus aimed at joint and targeted relief; represents the miniaturized/wearable axis of product strategy.
- Celluma (USA) — Clinic‑focused, FDA‑cleared LED devices with an evidence base for acne, aging, and pain; published data (March 2025) showing significant efficacy in arthritis pain reduction is a marketable clinical asset.
- NovoTHOR (UK) — Whole‑body bed systems for clinical recovery; notable for strategic distribution deals with hospital chains (e.g., November 2024), illustrating a hospital‑partnership route to scale.
- THOR Photomedicine (UK) — Portable and clinical near‑infrared lasers targeting wound healing and neurological indications; strengths include clinical depth and laser expertise.
- Multi Radiance Medical (USA) — Combines super‑pulsed laser with infrared LEDs for non‑invasive pain therapy; notable for device hybridization strategies.
- Erchonia (USA) — FDA‑cleared low‑level laser therapy devices with infrared wavelengths; strong clinical positioning in musculoskeletal therapy.
Key market dynamics and tactical implications
- Regulation is a gating factor: Non‑invasive infrared therapy devices are typically Class II and often require 510(k) clearance for pain indications. Firms that design clinical studies aligned to FDA expectations shorten time‑to‑market and reduce recall risk.
- Reimbursement unlocks clinical demand: Existing CPT codes and Medicare/physical‑therapy allowances create a repeatable revenue stream for clinic‑deployed systems; capture requires documented outcomes and clear billing pathways.
- Clinical evidence is becoming table stakes: High‑quality trials and peer‑reviewed results accelerate adoption among clinicians and payors. Recent positive outcomes (e.g., arthritis pain reductions) materially de‑risk hospital conversations.
- Component economics matter: Medical‑grade, high‑power LEDs (notably those near 850nm) are a key cost driver. Locking preferred pricing and secondary suppliers is essential to protect margins and avoid passthrough price shocks.
- Fragmentation = opportunity: With relatively low top‑tier concentration, incumbents and new entrants can grow via differentiation (wearables, whole‑body beds, hybrid laser/LED solutions) or consolidation.
Practical 2026 playbook — five recommended actions for executives
- Finalize your regulatory roadmap now: Decide between OTC, clinic, or hospital‑grade positioning and initiate the 510(k) and documentary programs aligned to that pathway.
- Invest in targeted clinical programs: Prioritize one high‑value indication (e.g., musculoskeletal pain or wound healing) to build a repeatable clinical case and payer argument.
- Secure LED supply and BOM resilience: Negotiate long‑term contracts with LED suppliers, validate secondary sources, and model BOM sensitivity in pricing scenarios.
- Design hybrid go‑to‑market channels: Combine DTC for consumer wellness with clinician partnerships for reimbursement capture; pilot hospital deployments with KOLs to accelerate adoption.
- Prepare for consolidation: Use the relatively low CR3/CR5 concentration to proactively screen acquisition targets—wearables, clinical bed makers, or companies with FDA clearances—to accelerate capability build‑out.
Why purchase the full PW Consulting report
This brief demonstrates the kind of actionable insight embedded in PW Consulting’s full report: robust scenarios, downloadable financial models, granular segmentation (by region, type, and application), vendor financial and product scorecards, go‑to‑market templates, and an M&A shortlist. To preserve the strategic value of our proprietary analysis, we have withheld the detailed numerical splits, regional revenue tables, and vendor revenue breakdowns from this summary. The full report includes those items plus Excel‑ready models you can drop into your planning cycle.
Infrared Light Therapy Device Market
For product teams, regulatory leads, corporate development groups, and investors planning activity in 2026, the full PW Consulting Infrared Light Therapy Device Market report is designed to reduce execution risk, sharpen strategic choices, and shorten time to market. Contact PW Consulting to obtain the complete dataset, vendor dossiers, and our 90‑day implementation roadmap.
For detailed analysis of this topic, please visit the official page: Infrared Light Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Di-tert-Butyl Peroxide (DTBP) Market Poised to Expand at a 5.1% CAGR Through 2032PW Consulting Predicts LCP Antenna Market to Surge at 17.98% CAGR Through 2032
By PW Consulting, 2026-07-13
Di‑tert‑Butyl Peroxide (DTBP) Market — Strategic Outlook for 2026: Insights from PW Consulting
Executive summary
The global Di‑tert‑Butyl Peroxide (DTBP) market has demonstrated steady expansion through the mid‑2020s and remains on a positive growth trajectory into the early 2030s. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies this momentum and converts it into practical, decision‑grade intelligence for executives planning capital allocation, sourcing strategies, regulatory compliance, and commercial positioning in 2026.
Di-tert-Butyl Peroxide (DTBP) Market
Key macro takeaways: between 2020 and 2025 the market grew meaningfully, passing the mid‑500 million USD threshold in 2025, and our baseline forecast points to sustained growth at a compound annual growth rate (CAGR) of 5.1% during the 2026–2032 forecast window, culminating in a market north of three‑quarters of a billion USD by 2032. Market concentration metrics show meaningful incumbent scale (CR3 ~42.5%; CR5 ~61.8%), indicating a market that is neither a pure commodity nor tightly oligopolistic — a space where operational excellence, regulatory standing, and customer intimacy create durable advantages.
Di-tert-Butyl Peroxide (DTBP) Market
Market trajectory and primary drivers
DTBP’s growth is driven by a combination of end‑market demand patterns and structural supply‑side dynamics. Growth in polymerization and crosslinking applications remains the dominant commercial engine, while incremental pockets of demand — such as specific specialty monomer and additive uses — contribute to an expanding addressable base. On the supply side, feedstock availability and production concentration shape pricing volatility and access risk. Our model captures both cyclical and secular components, with sensitivity scenarios that stress raw material dislocations, regulatory actions, and capacity additions.
Di-tert-Butyl Peroxide (DTBP) Market
-
Growth profile: A mid‑single‑digit CAGR over the forecast window reflects resilient industrial demand and gradual penetration of higher‑purity grades and specialty uses.
-
Concentration & competitive dynamics: The market’s CR3/CR5 profile suggests that while a few global players set the tone on capacity and quality standards, sizable regional and domestic producers remain relevant for transactional supply and price flexibility.
-
Volatility levers: Feedstock price swings, regulatory restrictions on peroxide handling and use, and logistics/safety incidents are the primary near‑term risk vectors our scenarios examine.
What the PW Consulting report delivers — operational, actionable content
Our report is purposely structured to convert market measurement into operational choices. It blends detailed market sizing, scenario analysis and tactical playbooks intended for procurement, operations, R&D, and corporate development teams. Highlights include:
-
Proprietary demand model with historical calibration (2020–2025) and a transparent bottom‑up forecast engine for 2026–2032, together with alternative scenarios stress‑testing raw material, regulatory and demand shocks.
-
Commercial playbooks for buyers and sellers: contract design (term vs. spot), inventory optimization under classification‑specific transport constraints, and sample procurement tender templates tailored to peroxide handling requirements.
-
Regulatory compliance and safety checklist summarizing transport, storage and process safety obligations that materially affect plant siting, capex phasing, and insurance costs.
-
Price and margin analytics derived from blended feedstock and conversion cost curves, plus a routed cost estimate for new manufacturing capacity under multiple feedstock assumptions.
-
Supplier risk matrix and preferred‑partner screening that ranks counterparties on quality, capacity, regulatory track record, geographic proximity and logistics resilience — accompanied by recommended contracting terms by risk tier.
-
M&A and JV scanner that identifies strategic entry points, typical multiples observed in adjacent specialty peroxide transactions, and integration playbooks focused on safety, regulatory harmonization, and portfolio fit.
Note: the public summary intentionally omits granular sub‑segment breakdowns and regional/application level shares — these are provided in full within the paid report to preserve the commercial lift and ensure our clients retain exclusive access to the most actionable micro‑insights.
Competitive landscape — how incumbents and challengers are shaping the market
Our competitive analysis synthesizes company capabilities, asset footprints, strategic priorities and commercial behavior. The DTBP supplier set is a mix of global specialty chemical majors, regional integrated peroxide producers, and independent commodity producers. Representative players profiled in the report include:
-
Nouryon (Netherlands) — A global specialty chemicals firm offering Trigonox B; notable for positioning DTBP as a higher‑temperature initiator for LDPE and crosslinking applications, reinforced by a global logistics and manufacturing footprint including Asia operations.
-
United Initiators GmbH (Germany) — Focused on peroxides for polymers, coatings and specialty applications; strong technical support and local production capacity in key markets underpin its commercial model.
-
Arkema (France) — A diversified producer of organic peroxides with integrated operations in multiple geographies; leverages global scale and formulation capabilities to serve higher‑value polymer grades.
-
Pergan GmbH and NOF Corporation — Niche contributors with deep technical expertise for polymer and rubber end uses; they represent the class of suppliers that compete on formulation services and localized customer programs.
-
Asian producers (select China and India manufacturers) — Several regional manufacturers offer significant volumes at competitive cost points; they are increasingly important for short‑lead, price‑sensitive supply and export growth.
-
European specialty distributors (e.g., Vesta Chemicals) — Play a critical role in REACH‑compliant distribution and regional warehousing, enabling fast supply to formulators across Europe.
Strategic implications from our supplier analysis: differentiation is achieved through a combination of production reliability, REACH/OSHA compliance credentials, and technical service for polymerization and crosslinking processes. For buyers, supplier selection should be a matrix decision balancing price, delivery lead time, regulatory footprint and technical co‑development capability.
Regulatory, feedstock and logistics dynamics affecting 2026 decisions
Two structural supply‑side themes will shape 2026 execution decisions.
-
Upstream feedstock and process routes: DTBP is predominantly manufactured from tert‑butyl alcohol (TBA) and hydrogen peroxide via acid catalysis; alternative routes such as isobutane peroxidation over MoO3 catalysts are being explored. The choice of feedstock and route materially affects plant CAPEX, unit economics and feedstock exposure.
-
Transport and process safety: DTBP is classified under UN3107 (Organic Peroxide Type E, Liquid, Class 5.2) and is subject to OSHA Process Safety Management requirements (notably threshold quantities that trigger additional controls). Compliance influences plant design, inventory buffers and insurance arrangements. In the EU, REACH restrictions impose additional use‑level constraints that require careful legal and product stewardship review.
Additionally, our market monitoring shows stabilization in related tert‑butyl feedstock pricing since 2025, which moderates short‑term margin stress but does not eliminate supply risk from capacity outages or logistics disruptions. These factors are modeled in the report’s price outlook scenarios.
Actionable strategic recommendations for 2026
PW Consulting recommends that companies translate the market view into a prioritized set of actions during 2026. Short to medium term priorities we advise include:
-
Lock conditional capacity through multi‑year offtakes with tiered pricing and force majeure clauses adjusted for peroxide‑specific hazards. Include audit and compliance covenants that preserve supply continuity.
-
Reassess inventory and safety stock policies in light of transport classification and border inspection variability; model working capital trade‑offs under 30, 60 and 90‑day disruption scenarios.
-
Accelerate regulatory and process safety investments where threshold quantities are approached; pre‑emptive compliance reduces project delays and insurance cost volatility.
-
Pursue supply diversification: balance global majors for technical support with regional producers for price flexibility; where appropriate, structure dual‑sourcing to hedge geo‑political or logistics risk.
-
Evaluate adjacent product or feedstock integration opportunities if your corporate strategy favors verticalization — our cost models outline the CAPEX breakeven and payback bands for backward integration into TBA hydrogenation or peroxide synthesis lines.
-
Invest in application development with end customers to move up the value chain (higher‑purity grades, tailored initiation profiles), where margin expansion is realized through co‑development and specification lock‑in.
How to use this report in 2026 planning
Executives should use PW Consulting’s report as a decision support tool across three planning horizons:
-
Short term (0–12 months): refine procurement contracts, update safety/inventory policies and stress‑test counterparty exposure.
-
Medium term (12–36 months): prioritize capital allocation for product development, potential upstream integration or regional warehousing investments; use our scenario outputs to size required CAPEX under different demand outcomes.
-
Long term (36+ months): evaluate strategic M&A or JV opportunities and embed safety/regulatory roadmaps into business case assumptions.
The public summary above is designed as a strategic “trailer”: it highlights the analytical rigor and practical orientation of the PW Consulting study while preserving the full sub‑segment detail, supplier rankings and model outputs for report subscribers. These granular datasets and downloadable tools (interactive model, supplier scorecard, contract templates) are included in the full report and are essential for implementing the tactical recommendations described here.
Next steps
For immediate access to the full DTBP market model, supplier scorecards and bespoke scenario runs for your portfolio, visit our report page or contact PW Consulting to schedule a briefing. Our team can provide tailored extracts — for example, a two‑day rapid assessment focused on procurement optimization or a three‑week M&A diligence package — to accelerate your 2026 decision cycle.
For detailed analysis of this topic, please visit the official page: Di-tert-Butyl Peroxide (DTBP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Party Costumes Market Surges to USD 5,650 Million in 2025, Signaling Strong Growth Ahead
By PW Consulting, 2026-07-13
Party Costumes Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
PW Consulting’s latest Party Costumes Market research—anchored on 2025 as the base year and projecting through 2032—arrives at a clear, executive-grade conclusion: this category is expanding and evolving. The global party costumes market was valued at USD 5,650 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.2% over the 2026–2032 forecast period, pushing total industry revenues into the multi‑billion-dollar range by the end of the decade. Those headline numbers mask dynamic structural shifts that will dictate winners and losers in 2026, and our report translates those macro trends into boardroom-ready actions.
Party Costumes Market
Why this report matters for 2026 decision-making
-
Seasonality meets strategic complexity: Costume demand remains highly seasonal and IP-driven, but the drivers behind seasonal spikes are changing—licensing windows, theatrical releases, and social commerce accelerants now reshape timing and elasticity.
Party Costumes Market -
Supply-side vulnerability is material: Production concentration in select Asian manufacturing hubs and recent tariff volatility create a tangible pricing and availability risk for global buyers and retailers.
Party Costumes Market -
Channel economics have bifurcated: Fast-growing direct and marketplace channels amplify SKU velocity but also compress margins; brick-and-mortar and pop-up specialists retain a tactical edge around immediacy and experiential merchandising.
-
Fragmentation creates opportunity: Market concentration levels show a fragmented supplier base, giving thoughtful acquirers and brand builders room to consolidate, acquire capability, or enter white-space segments with differentiated propositions.
What’s inside the report — practical, actionable deliverables
PW Consulting designed this brief as a hands-on toolkit for commercial leaders, buyers, and investors. Key deliverables include:
-
Forward-looking demand models and scenario forecasts across short (2026 seasonal cycles) and medium term (through 2032), enabling rapid stress-testing of merchandising and inventory plans.
-
Tariff and freight sensitivity analysis with breakpoint pricing models—showing how input-cost shifts feed through to wholesale and retail price points and margin impact for common SKU archetypes.
-
SKU rationalization playbook: an evidence-based approach to prune low-margin, low-turn products and to prioritize high-velocity SKUs by channel and license type.
-
Go-to-market frameworks for four archetypal players (IP licensors, licensed manufacturers, omnichannel retailers, and low-cost OEMs), each with specific 90‑ and 180‑day action plans.
-
Channel optimization matrices and promotional calendars that integrate pop-up retail, ecommerce marketplaces, and wholesale timelines to maximize seasonality capture while minimizing inventory risk.
-
Supplier scorecards and sourcing-path simulations designed to help procurement teams diversify capacity, shorten lead times, and quantify the value of nearshoring versus Asian sourcing.
-
Investor-focused dashboards: consolidated competitor profiles, M&A targets by capability, and return scenarios for platform-style roll-ups and niche consolidation plays.
Market dynamics and strategic implications
The market’s 6.2% CAGR through 2032 reflects steady consumer appetite for events, themed entertainment, and social media-driven costume moments. However, beneath that headline growth lie several practical levers companies must command in 2026:
-
Cost inflation and policy risk: Recent import tariff actions pushed wholesale costume prices materially higher in 2025 and altered cost structures for many assortments. Retailers that postpone sourcing strategy adjustments risk margin compression and forced markdowns during seasonality peaks.
-
Consumer spend concentration: A significant portion of occasion-related spend continues to center on a small set of high-impact events. Smart assortments and targeted adult/children/pet positioning—depending on brand and channel—will outcompete broad, undifferentiated catalogs.
-
IP and licensing economics: Licensed character costumes continue to command disproportionate attention and margin. Yet licensing cycles are shortening; licensors and licensees that synchronize launch calendars with entertainment release windows capture premium pricing and organic demand lift.
-
Channel differentiation: Online retail is essential for reach, but pop-up and specialty channels remain highly effective at capturing last‑minute spend. Integrated promotional strategies that convert popup footfall into digital lifetime customers will be a key performance differentiator.
Competitive landscape — strategic positioning of key players
PW Consulting’s company-by-company analysis in the report synthesizes operating models, supply chains, IP portfolios, and go-to-market strengths. High-level takeaways for the principal player types are below.
-
Large licensed manufacturers and distributors: Industry leaders with deep IP relationships and broad distribution networks have scale advantages—enabling rapid licensing rollouts, diversified sourcing, and promotional muscle. Their challenge: protecting margin amid tariff pressure and sustaining innovation beyond headline licenses.
-
Seasonal and experiential retailers: Pop-up specialists and seasonal operators excel at urgency merchandising and converting event-driven foot traffic. To extend value, these operators must invest in digital acquisition and year-round community engagement to stabilize cash flow outside peak windows.
-
Specialty and fashion-driven brands: Players focused on adult and fashion-forward designs rely on product differentiation and social-driven marketing. They can capture higher ASPs but must manage inventory risk by aligning limited-run collections with influencer cycles.
-
Large-scale OEMs and Asian manufacturers: Cost-leaders enable competitive private‑label and wholesale programs with low minimums and fast replication. Strategic buyers should balance cost advantages with concentration risk and compliance transparency.
-
Rental and theatrical providers: Organizations with large archives and rental capabilities serve institutional events and productions; they offer high-margin, low-volume opportunities and are attractive targets for consolidation by firms seeking to add service-based revenue streams.
Recent industry activity—trade shows in Las Vegas and St. Louis and a wave of movie-themed and inflatable product innovations—reinforces two tactical trends: IP synchronization (timely product introductions tied to media releases) and experiential differentiation (novel product formats that drive social shareability). For market participants, these trade events are as much product labs as they are distribution forums.
2026 playbook — what leaders should do now
Based on our modeling and competitive diagnostics, PW Consulting recommends a concise set of priority actions for CXOs, merchandising leads, and investors planning for the 2026 season:
-
Pursue targeted sourcing diversification in Q1–Q2 2026. Move from single-source exposure to a multi-node supply base, and create pre‑negotiated contingency capacity to limit last-minute freight shocks.
-
Implement dynamic pricing and promotion ladders. Use a tiered launch strategy for licensed SKUs to protect early-season margins and then deploy elastic promotions for late-season fulfillment.
-
Rationalize SKUs now. Cut slow movers and reallocate working capital to high-turn, IP-aligned assortments that perform across both ecommerce and temporary retail footprints.
-
Double down on licensing agility. Build closer ties with entertainment partners to secure shorter, higher-impact windows and co-marketing support that reduces customer acquisition cost.
-
Invest in micro‑fulfillment and returns optimization to mitigate cost leakage from high sell-through reversals typical of costume seasonality.
-
Explore M&A and JV opportunities that add complementary capabilities—sourcing, distribution, or experiential retail—to accelerate omnichannel scale.
How PW Consulting’s report delivers competitive advantage
This study is structured to move beyond descriptive market statistics; it supplies executable decisions. Clients receive not only our proprietary forecast models but also scenario tools, supplier scorecards, and step-by-step implementation guides tailored to each player archetype. The report balances strategic clarity with operational specificity—enabling procurement teams to renegotiate terms, merchandisers to rework assortments, and corporate development teams to prioritize targets.
Next steps — where to get the full intelligence
The analysis above intentionally omits granular regional and subsegment figures to preserve the strategic value of the complete dataset. PW Consulting’s full report includes the detailed breakdowns (by region, end‑user, and distribution channel), company financial profiles, and downloadable scenario models that underpin our recommendations. For executives preparing 2026 budgets and seasonal plans, accessing the full dataset is the fastest route from insight to impact.
Contact PW Consulting to request the complete Party Costumes Market report, our executive briefing, and the interactive forecasting tools that will power your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Party Costumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low & Medium Capacity Gas Generator Market Tops USD 3,100.0 Million in 2025, Poised for 6.82% CAGR Through 2026–2032
By PW Consulting, 2026-07-13
Low and Medium Capacity Gas Generator Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new market study on Low and Medium Capacity Gas Generators (base year 2025; historical period 2020–2025; forecast 2026–2032) provides a rigorous, practitioner-focused foundation for corporate strategy in 2026. The report synthesizes proprietary modelling and primary interviews to quantify market trajectories, stress-test near-term scenarios and translate opportunities into executable actions. Headline findings: the market expanded materially through the early 2020s (moving from a low‑single‑billion USD base in 2020 to approximately USD 3.10 billion in 2025) and our forecast shows sustained growth through 2032 with a compound annual growth rate (CAGR) of 6.82% across the 2026–2032 horizon, taking the market toward roughly USD 4.9 billion by 2032. These macro figures set the stage for high‑stakes decisions in procurement, R&D prioritization, M&A, and regulatory engagement in 2026.
Low And Medium Capacity Gas Generator Market
Why this report matters in 2026
-
Timing investments under volatility: 2026 will be a pivot year for allocating capital across backup and prime power portfolios. With persistent energy price swings and evolving incentive regimes, firms need precise, market‑calibrated timing to avoid stranded capacity or overpaying for fuel consumption and emissions compliance.
Low And Medium Capacity Gas Generator Market -
Aligning product roadmaps to buyer economics: Buyers increasingly evaluate TCO across lifecycle emissions, fuel flexibility and digital services. The report translates market growth and efficiency trends into concrete product features that win in low and medium capacity segments.
Low And Medium Capacity Gas Generator Market -
M&A and partnership signals: The market shows room for consolidation and strategic alliances. Our analysis identifies the types of targets that create defensible scale quickly—service networks, controls/software providers, and regional manufacturing footprints—informing a 90‑day M&A hit list for 2026.
-
Regulatory and incentive optimization: The interplay between federal funding, tax credit reform and emissions reporting will materially affect project economics. The study models alternative policy scenarios so commercial, financial and regulatory teams can prioritize near‑term actions.
What the report contains — practical, decision‑ready deliverables
-
Bottom‑up market sizing and multi‑scenario forecasts (2026–2032) with sensitivity testing against fuel price and policy shocks.
-
Actionable competitor benchmarking and vendor scorecards that assess product depth, service footprint, channel strategy and technology roadmaps.
-
Go‑to‑market playbooks tailored for OEMs, distributors and large end‑users, including margin maps, contractual structures, and service‑monetization levers.
-
CapEx vs. OpEx decision templates and lifecycle cost models to evaluate new builds, retrofits and hybrids under multiple fuel and carbon pricing regimes.
-
Regulatory impact analyses and a policy tracker that quantifies how recent and pending measures alter project IRRs and incentive capture strategies.
-
Supply‑chain heatmaps, supplier risk assessments, and parts‑availability forecasts designed to support procurement timing and inventory policies.
-
M&A and alliance playbooks including valuation multiplicands used in our model, integration checklists, and example term sheets.
-
Primary interview summaries and several real‑world case studies showing how operators reduced downtime, improved fuel cost management, and monetized ancillary services.
Note: this press briefing intentionally omits detailed segmentation tables and proprietary split‑level data (by region, capacity band and end‑user). Those granular datasets and model files are available in the full report on our site and are provided to clients under license.
Competitive landscape — who to watch and strategic implications
The low and medium capacity gas generator market sits in a moderately concentrated competitive structure (CR3 ~34.2%; CR5 ~47.6%), meaning the top players exert meaningful influence yet mid‑market and regional specialists can still capture growth through focused plays. Our report profiles incumbent OEMs, their strategic orientations and the plausible moves they may make in 2026:
-
Caterpillar Inc. (Irving, Texas; https://www.cat.com) — Strong installed base and dealer network for both backup and continuous applications. Recent product activity (e.g., the October 2025 introduction of the G3512 and expansions in the G3500‑H series) signals renewed focus on continuous and high‑uptime segments. Expect Caterpillar to lean into integrated service contracts and fuel‑efficiency upgrades.
-
Cummins Inc. (Columbus, Indiana; https://www.cummins.com) — A leader in integrated power systems and bi‑fuel capability. Their emphasis on systems optimization positions them well for commercial and industrial buyers seeking turnkey solutions and emissions flexibility.
-
Generac Power Systems (Waukesha, Wisconsin; https://www.generac.com) — Deep penetration in residential and light commercial channels with scalable solutions. Generac’s channel strength and brand recognition make it the vendor of choice where dealer reach and rapid deployment matter.
-
Kohler Co. (Kohler, Wisconsin; https://www.kohler.com) — Known for innovation and reliability in standby and commercial applications; continues to win where operational continuity is prioritized.
-
MTU Onsite Energy (Rolls‑Royce Power Systems) (Friedrichshafen, Germany; https://www.mtu-solutions.com) — Differentiates via sustainability features and engineered medium‑capacity systems for mission‑critical use cases. Their offering is attractive for buyers prioritizing emissions pathways and long‑life performance.
-
Atlas Copco AB (Stockholm, Sweden; https://www.atlascopco.com) — Offers both portable and stationary solutions, with a strong presence in construction and temporary power where mobility and rapid deployment are differentiators.
-
Mitsubishi Heavy Industries Ltd. (Tokyo, Japan; https://www.mhi.com) — Offers a broad technology stack including turbine‑based systems for medium capacity applications; suited to utility‑grade and heavy‑industry buyers.
Strategic implication: incumbents will continue to compete on service, fuel flexibility and digital offerings. Niche specialists that can demonstrate cost‑of‑ownership improvements, smaller footprints, or emissions‑reduction pathways will be acquisition targets or partnership candidates.
Market dynamics, policy and fuel‑price noise — what keeps CFOs awake
Three convergent dynamics should shape 2026 strategy:
-
Fuel price volatility: Henry Hub natural gas prices have shown notable variability. Projections for 2026 settled at a mid‑range level, but monthly swings in early 2026 saw spikes well above the annual average. This creates asymmetric downside risk for fuel‑intensive operating models and changes payback calculations for new deployments.
-
Incentives and regulation: Recent policy actions—federal funding for high‑efficiency generator technologies, the broad impacts of tax‑credit reform implemented in mid‑2025, and potential changes to greenhouse gas reporting—are recalibrating project economics and compliance obligations. These shifts create opening windows for capex acceleration, but also raise documentation and audit requirements that must be built into procurement and financing structures.
-
Service and parts availability: As systems become more software‑enabled, aftermarket service and remote diagnostics are emerging as the primary value capture channel. Firms that invest in service networks and spare‑parts resilience will reduce churn and protect margins.
Practical recommendations for 2026
-
Run at least three funded scenarios for each major project: base case, high‑fuel‑price, and accelerated‑incentives. Model the full lifecycle (including likely reporting and tax compliance costs).
-
Prioritize fuel‑flexible platforms and efficiency upgrades for projects with operating horizons beyond five years. In many cases, the incremental cost for dual‑fuel capability is accretive to portfolio resilience.
-
Use short, targeted M&A to acquire service networks or control‑software specialists rather than pursuing largescale horizontal consolidation in 2026—this drives faster ROI and reduces integration risk.
-
Establish an internal “policy war‑room” to capture incentives (federal/state tax credits, grants) and to respond to evolving reporting requirements. Early engagement materially improves effective returns and audit readiness.
-
Lock in conditional supply agreements for critical spares and key components to mitigate parts shortages and price spikes—consider consignment models for high‑value spares.
-
Monetize services and digital diagnostics through subscription models that reduce end‑user TCO and create recurring revenue streams.
How PW Consulting supports your 2026 agenda
We translate the study’s insights into execution: bespoke scenario models, due‑diligence support for transactions, go‑to‑market accelerators and procurement playbooks. Clients can license our forecast models, request tailored sensitivity runs, or engage our advisory teams for rapid deployment planning and M&A execution. For teams preparing 2026 budgets and strategic plans, we offer expedited workshops that convert the report’s scenarios into prioritized initiatives and 90‑180 day action plans.
This release is a précis designed to orient decision‑makers. Detailed segmentation by region, capacity band and end‑use, the full set of model files and vendor scorecards are available in the complete PW Consulting report on the Low and Medium Capacity Gas Generator Market. Contact us or visit our report page to access the full intelligence and the underlying datasets that will guide robust, defensible decisions in 2026.
For detailed analysis of this topic, please visit the official page: Low And Medium Capacity Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Glass Fiber Composites Market — Strategic Outlook for 2026: Executive Preview
PW Consulting’s latest Glass Fiber Composites Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) equips executives with the forward-looking intelligence required to set priorities in 2026. The global market reached approximately USD 66,450 Million in 2025 and, on our base-case trajectory (CAGR 5.24% over the forecast window), is modeled to approach roughly USD 95,008 Million by 2032. This preview outlines the strategic implications of that trajectory, highlights structural supply‑side shifts and regulatory headwinds, and sketches the decision frameworks we advise firms to adopt as they enter 2026. For full segment-level tables, regional and application breakdowns, and downloadable datasets, please consult the full report on our website.
Glass Fiber Composites Market
Why this matters for 2026 decision-making
- Market momentum: steady mid‑single-digit CAGR implies that 2026 will be a pivotal year to convert runway into scale — not simply to defend volume, but to capture premium value pools that form around specialization and integration.
- Margin pressure vectors: upstream feedstock cost volatility and trade measures are compressing downstream margins in selected supply chains, changing the calculus for pricing, hedging and contract structures.
- Consolidation and concentration: market concentration metrics indicate a market where a relatively small group of global players hold meaningful share — creating both barriers and opportunities for challengers through targeted differentiation.
- Regulatory and sustainability inflection: procurement teams and OEMs increasingly require EPDs and regulatory compliance as purchase qualifiers, so product portfolio and certification strategies will drive commercial access in key accounts.
What the full report delivers (practical, executable content)
- Proprietary market sizing and validated demand models (2020–2032) with scenario toggles that let you stress-test revenue, margin and utilization outcomes against alternate macro and sectoral assumptions.
- Segment playbooks: go‑to‑market blueprints for resin‑type strategies, application prioritization, and regional supply footprint design — with clear path-to-value for premium vs. volume plays (note: segmented numerical tables are available only in the full report).
- Supply chain heat maps: plant networks, lead‑time overlays and import/tariff exposure matrices that highlight single‑point risks in critical corridors and suggest mitigation levers (dual sourcing, forward stocking, contract manufacturing).
- Price and input sensitivity analyses: scenario-linked margin impacts from raw material and freight moves, plus practical hedging and procurement tactics calibrated for 2026 procurement cycles.
- Competitive intelligence dossiers: detailed profiles and capability assessments of the industry’s largest manufacturers, including capacity moves, product portfolios, technical differentiators and likely strategic intents.
- M&A and partnership frameworks: target screening filters, valuation heuristics for specialty vs. commodity assets, and integration playbooks tailored to composite material businesses.
- Regulatory tracker and sustainability roadmap: implications of tariffs, anti‑dumping measures, and certification requirements (e.g., EPD timelines) — and the minimum compliance steps firms must take to avoid commercial exclusion.
Key market themes shaping 2026
- Demand diversification: demand remains anchored by long-cycle industrial applications, but accelerating electrification, renewed wind‑energy capex in selected markets, and infrastructure modernization are shifting the mix toward higher‑value and higher‑specification glass fiber products.
- Upstream reinvestment and capacity rebalancing: the supply base is adding capacity in both commodity E‑glass and specialty fibers. These expansions will relieve some near‑term tightness but will also intensify competition in mid‑cycle volumes unless accompanied by product differentiation.
- Cost and trade volatility: raw material cost upticks and persistent trade measures in important markets are creating regional price differentials and forcing re‑routing and inventory strategies — buyers and suppliers must treat logistics and tariff exposure as strategic rather than tactical issues.
- Premiumization and technical differentiation: specialty glass types and engineered reinforcements (high‑strength fibers, electronic‑grade variants, tailored prepregs) are becoming gatekeepers to premium margins, especially in electronics, aerospace and high‑performance industrial segments.
- Consolidation pressure: concentration metrics show that leading groups control a meaningful share of market flows; this dynamic favors integrated players and strengthens the hand of scale players in long‑term OEM negotiations.
Competitive landscape — strategic observations
- Scale incumbents (examples): large global producers maintain advantaged cost positions and customer access thanks to broad product portfolios and regional plant networks. Their strategic play is to defend volume contracts while selectively moving up the value chain via specialty grades and service offerings.
- Capacity leaders: manufacturers investing in electronic‑grade and high‑performance lines signal an industry bifurcation — commodity E‑glass remains volume-focused, while electronic and specialty fibers are strategic differentiators for margin expansion.
- Specialty and performance players: a subset of firms pursues S‑glass and higher‑specification reinforcements for aerospace, defense and electronics; these firms are prime targets for OEM partnerships and premium pricing, but scale can be a constraint without strategic alliances.
- Pultruders and downstream integrators: companies that convert raw reinforcements into structural profiles and systems are capturing incremental value by offering engineered end‑use solutions; this vertical move is a viable route to insulation from raw material price swings.
- Recent corporate actions: capacity expansions among major producers and investments into electronic‑grade and microfiberglass lines indicate where firms expect growth and margin expansion — signaling competitive intent and future supply availability in those niches.
- Concentration data: the three‑ and five‑firm concentration ratios indicate a market where leading players significantly influence pricing dynamics; nimble challengers can carve profitable niches by focusing on specialty grades, service and technical collaboration with OEMs.
Operational and commercial moves we recommend for 2026
- Prioritize product differentiation: allocate R&D and small‑scale production capacity to develop certified specialty fibers and value‑added reinforcements that meet OEM performance and sustainability specs. This is the most direct route to improving price realization.
- Reshape supply contracts: move from spot purchases toward hybrid contracting (index‑linked with caps/floors and volume collars) and prepay/option structures to stabilize cost of goods sold amid raw material swings.
- Regionalize inventory strategy: create short‑cycle buffers in tariff‑sensitive corridors and align regional assortments to local regulatory and procurement requirements to reduce friction and lead‑time penalties.
- Form industrial partnerships: pursue co‑development agreements with OEMs in high‑growth applications (e.g., electrified transport components, wind‑energy blades, electronic packaging) to lock in long‑term offtake and co‑fund certification cycles.
- Accelerate sustainability certification: secure environmental product declarations and lifecycle data early — procurement teams increasingly use these as exclusionary filters, not just differentiators.
- Identify M&A targets pragmatically: prioritize bolt‑on specialty producers, regional converters with customer ties, or technology platforms that accelerate certification and application engineering.
- Invest in digital OEE: targeted automation and process analytics in glass‑fiber production yield immediate improvements in quality and cost per tonne — pursue rapid pilots across plants early in 2026.
Scenarios and decision triggers (practical lenses for 2026 planning)
- Base case (CAGR ~5.2%): steady demand growth allows staged capacity additions focused on specialty grades. Trigger: sustained utilization above historical norms and stable input cost trendline — accelerate specialty capex.
- Upside case (faster decarbonization & electrification): strong demand pull for higher‑spec fibers. Trigger: multi‑quarter order momentum from OEMs and declared national capex programs — shift quickly from volume to premium playbooks and prioritize long‑term supply agreements.
- Downside case (trade shocks / raw‑material spike): near‑term margin pressure and regional dislocation. Trigger: tariff escalations or sustained feedstock price spikes — implement contingency protocols (price pass‑through, stockpiling, temporary volume rationalization) and expedite contract re‑negotiations.
How PW Consulting supports executive teams
- Rapid diagnostics: 8–12 week supply‑chain stress tests, including tariff exposure and inventory optimization roadmaps.
- Deal advisory: target screening and valuation for specialty glass fiber assets, plus integration playbooks to preserve technical capability and OEM relationships.
- Commercial transformation: pricing, contract design and OEM engagement strategies that shift value capture toward higher‑margin product lines.
- Operational improvement: plant‑level OEE programs and digital pilots tailored to composite reinforcements manufacturing.
Our full Glass Fiber Composites Market report contains the complete datasets, granular segment forecasts, company dashboards and downloadable model files that underpin the insights summarized above. This executive preview intentionally omits detailed segment tables and per‑region/application numeric breakdowns to encourage review of the full analytical package and interactive models on our portal. Visit PW Consulting’s report page to access the complete study, request a briefing, or commission a bespoke scenario run aligned to your 2026 strategic planning calendar.
Glass Fiber Composites Market
For detailed analysis of this topic, please visit the official page: Glass Fiber Composites Market
Glass Fiber Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Hirschsprung Disease Drug Market to Grow at a 5.01% CAGR from 2026–2032
By PW Consulting, 2026-07-13
Hirschsprung Disease Drug Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive preview
PW Consulting’s latest Hirschsprung Disease Drug Market report delivers an evidence-based, action-oriented roadmap for biopharma leaders, investors, and health-system strategists preparing for the next phase of innovation in a market on the cusp of therapeutic transformation. Our analysis shows that after steady growth through the early 2020s, the market base sits in 2025 and is projected to expand at a multi-year compound annual growth rate of approximately 5.01% across the 2026–2032 forecast window. By 2032 the market reaches a materially higher run rate compared with the mid-2020s baseline — underscoring a sustained opportunity for entrants and incumbents that align clinical, regulatory, and commercial playbooks now.
Hirschsprung Disease Drug Market
Why this matters for 2026 decision-makers
2026 will be a pivotal year for corporate strategy in this segment. The therapeutic landscape for Hirschsprung disease remains dominated by supportive and complication-focused pharmacologic management, while no approved disease-modifying drug exists. That structural gap creates a high-value prize for successful novel therapeutics; and with regulatory pathways increasingly favorable for rare pediatric indications, companies that time clinical development and market access activities correctly can secure outsized returns relative to market scale.
Hirschsprung Disease Drug Market
-
Capital allocation: A predictable mid-single-digit CAGR combined with orphan incentives alters risk-adjusted return thresholds. Portfolio managers should re-evaluate capital deployment for late preclinical/early clinical assets in 2026, balancing high development leverage against modest absolute market size.
Hirschsprung Disease Drug Market -
Clinical strategy: Sponsors advancing first-in-class candidates must synchronize IND-enabling activities, pediatric study plans, and early engagement with regulators and HTA bodies to compress time-to-reimbursable label post-approval.
-
Commercial readiness: Given the rarity and specialist delivery requirements of many potential therapies, commercial models that emphasize center-of-excellence partnerships, hub-and-spoke patient support, and specialty pharmacy integration will outperform traditional mass-market approaches.
Market dynamics and unmet needs
Current standard-of-care focuses on acute management of Hirschsprung-associated enterocolitis (HAEC) and chronic bowel dysfunction following surgical correction. Clinical practice continues to rely on antibiotics, rectal irrigations, laxatives, and, in select cases, botulinum toxin for symptomatic control. These supportive approaches address complications rather than the underlying enteric nervous system deficit — a gap that emerging biologic and regenerative strategies aim to fill.
Regulatory signals through 2025 — including orphan and rare pediatric designations for promising candidates — emphasize the sector’s strategic inflection. Such designations accelerate development timelines, create pricing dynamics tied to small patient populations, and often open pathways to expedited review. For organizations charting 2026 strategies, these realities make early regulatory and payer engagement an operational imperative.
Competitive landscape: spotlight on innovation
Our report includes detailed profiles of emerging and established players shaping the pipeline. A notable case study is Neurenati Therapeutics Inc., which is developing NEU-001 — a novel intrarectal combination therapy leveraging a neurotrophic growth factor aimed at regenerating the enteric nervous system. NEU-001 received both FDA Orphan Drug and Rare Pediatric Disease designations in March 2025, and EMA orphan designation in October 2025. With preclinical completion and human trials projected to start in 2026, NEU-001 exemplifies the class of first-in-class, potentially disease-modifying candidates that could redefine long-term management paradigms for Hirschsprung disease.
Importantly, market concentration remains moderate: the top three and top five firms together do not fully dominate the space, leaving strategic room for novel entrants to establish meaningful commercial positions provided they execute clinical and reimbursement strategies effectively.
What our report delivers (practical, actionable content)
PW Consulting’s study is structured to move clients from insight to action. Key deliverables include:
-
Robust market-sizing and forecast model (2026–2032): transparent assumptions, sensitivity scenarios, and downloadable model templates to test alternative adoption curves and pricing outcomes.
-
Pipeline and clinical-development intelligence: a clinical matrix that maps candidates by mechanism, development stage, regulatory milestones, and expected commercialization timing.
-
Regulatory and HTA playbooks: jurisdiction-specific pathways for orphan and pediatric designations, key submission considerations, and real-world evidence (RWE) strategies that accelerate reimbursement discussions.
-
Commercial readiness toolkit: go-to-market archetypes for rare pediatric therapeutics, channel prioritization checklists, hub services cost models, and clinician engagement frameworks tailored for pediatric surgeons, gastroenterologists, and specialty nurses.
-
M&A and partnership framework: acquisition target scoring, milestone valuation guidance, and integration risk matrices designed for strategic corporate development teams evaluating bolt-on or transformational opportunities.
-
Risk and mitigation mapping: regulatory, clinical, manufacturing, and payer risks with prioritized mitigation plans that executives can operationalize in 90–180 day planning cycles.
-
Primary research: interviews with clinicians, payers, and KOLs, plus validation workshops with leading pediatric surgery centers — all synthesized into decision-ready recommendations.
Strategic recommendations for 2026 (executive checklist)
-
Prioritize regulatory engagement now: submit pre-IND briefing packages, request protocol assistance where available, and build pediatric study plans aligned with global regulators to preserve accelerated pathways.
-
Start payer and HTA dialogue in parallel with early clinical development: define plausible value propositions and initial evidence packages required for reimbursement in major jurisdictions.
-
Design clinical programs for real-world utility: include patient-reported outcomes and health-economic endpoints early to shorten the gap between approval and coverage.
-
Invest in rare-disease commercialization capabilities: specialized distribution, patient services, and clinician training are non-linear costs that determine uptake in small patient communities.
-
Use scenario planning for capacity and supply: rare pediatric therapies can face episodic demand and manufacturing bottlenecks; model multiple demand trajectories and secure flexible capacity options.
-
Evaluate M&A selectively: targets with clinical assets plus established specialty distribution footprints can accelerate market entry and dilute development risk.
Why PW Consulting’s analysis is distinct
Our approach combines quantitative rigor with field-level validation. The report’s forecasting leverages an audited base year (2025), extrapolated through 2032 using a 5.01% CAGR scenario that reflects conservative adoption assumptions plus sensitivity bands for higher uptake in the event of disease-modifying approvals. We complement modeling with qualitative insight from clinicians and payer interviews to ensure recommendations translate to executable plans rather than theoretical outcomes.
Critically, this press release deliberately omits granular subsegment figures — the regional and product-channel splits and their precise revenue values are presented in full in the purchased report. That level of granularity is essential for detailed commercial planning and valuation, and it is available in the report’s interactive models and appendices.
Use cases — how clients are already applying these insights
-
Biotech C-suite: rerouting R&D budgets to prioritize indications with orphan incentives and developing an early-launch access strategy for 2026–2028 candidates.
-
Private equity: using our valuation scenarios to price add-on acquisitions and to model exit IRRs under different regulatory and reimbursement outcomes.
-
Pharma corporate development: screening partnership targets with complementary manufacturing or pediatric specialist networks to shorten commercialization timelines.
-
Health systems: designing centers of excellence and referral networks to improve patient identification and support adoption of novel therapies when available.
Next steps and how to obtain the full report
PW Consulting’s Hirschsprung Disease Drug Market report provides the granular segmentation, primary data tables, and executable templates required to operationalize the strategic recommendations summarized here. For teams that need to turn insight into a 90–180 day plan for 2026, the full report includes downloadable models, regulatory milestone calendars, and a prioritized action matrix.
To access the complete report, licensed modeling tools, and bespoke advisory support, please visit PW Consulting’s Hirschsprung Disease report page or contact our client services team. We also offer tailored briefings and scenario workshops for executive teams preparing board-level decisions in 2026.
Final note
The Hirschsprung disease landscape is entering a rare but high-impact window: emerging clinical candidates, favorable regulatory designations, and a consistent demand base for supportive therapies create a strategic environment where careful, early action can yield outsized competitive advantage. PW Consulting’s report equips decision-makers with the data, strategic frameworks, and operational checklists needed to capture that advantage — while preserving the detailed subsegment intelligence for report subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Hirschsprung Disease Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Focus Ring Market Set to Expand at 8.22% CAGR Through 2032, Driving Revenues to USD 4,259.12 Million
By PW Consulting, 2026-07-13
Semiconductor Focus Ring Market: A Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our new Semiconductor Focus Ring Market research — a practical briefing designed to orient executive decision-making in 2026. The focus ring segment of the semiconductor consumables market is no longer a niche line-item for fab planners: it is a strategic lever affecting yield, tool uptime, supply resiliency and, increasingly, geopolitical risk exposure. Our study uses 2025 as the base year and models the market across 2026–2032. At the macro level, the market is on a sustained growth trajectory (CAGR 8.22% through the forecast), moving from the mid‑2020s base into materially larger absolute scale by the early 2030s. Market concentration remains meaningful (CR3 ≈ 54.2%; CR5 ≈ 68.45%), underlining the importance of supplier selection and qualification strategies.
Semiconductor Focus Ring Market
Why this market matters to corporate strategy in 2026
-
Process scaling and device complexity are elevating the strategic importance of focus rings. As etch chemistries and multilayer stacks multiply, small incremental changes in edge-ring performance translate into measurable wafer-level yield gains or losses. Procurement decisions that were once transactional now carry product roadmap and cost-of-goods implications.
Semiconductor Focus Ring Market -
Supply-chain fragility and raw-material pressures (notably for high‑purity SiC and specialty ceramics) make single‑sourced or just‑in‑time supply models riskier. Longer lead times for specialty ceramics — and the potential for export controls or mineral restrictions — require procurement and operations to build alternative qualification pipelines and buffer strategies.
Semiconductor Focus Ring Market -
Concentration among a relatively small set of technical suppliers means commercial leverage is asymmetric. Strategic sourcing, co-development agreements and multi-year qualification roadmaps are effective levers to secure supply while embedding product differentiation.
Key market signals executives must act on in 2026
-
Adopt qualification windows that align with tool OEM cadence and device development cycles. Our research shows that qualification lead-times remain a critical gating factor; compressing those windows through early technical collaboration yields outsized returns in time-to-production.
-
Build a material‑risk heat map. Focus ring performance is sensitive to material choice (e.g., silicon, CVD/solid SiC, quartz and engineered ceramics). Given rising cost and availability volatility for high‑purity SiC and specialty ceramics, manufacturers should maintain at least one validated alternate material path for each critical etch process.
-
Prioritize suppliers that offer integrated lifecycle services — design-for-etch support, on-tool tuning, failure analytics and predictable spares pipelines. Vendors that combine materials science with field service and analytical feedback reduce time-to-yield and total cost of ownership.
-
Embed export-control and trade policy scenarios into sourcing decisions. Recent measures across allied jurisdictions have demonstrated how regulation can disrupt parts supply. Scenario planning and regional dual-sourcing help avoid single-point failures in the supplier base.
Market dynamics and operational impacts
Our study synthesizes primary interviews, supplier capability audits and process‑level testing data to map the dominant forces shaping the market. Key dynamics include material migration (toward more durable SiC in high-stress etch regimes), the rising tactical importance of nitride-free designs in select nodes, and a bifurcation between high-performance/low-volume specialty rings and commoditized mass‑production variants. These drivers interact with macro inputs — raw material pricing, geopolitical tensions and tighter export controls — to increase the value of proactive supplier management.
Operationally, fabs will face three concrete impacts:
-
Qualification calendars will lengthen unless mitigated by joint-development agreements and standardized test protocols agreed with suppliers.
-
Inventory strategies will need rebalancing — a move away from pure just‑in‑time toward controlled onshore buffer stocks for critical geometries and materials.
-
R&D teams must incorporate consumable packaging and ring‑tool interactions earlier in device and process design to avoid late-stage yield cliffs.
Competitive landscape: who matters and why
The competitive map combines established global materials specialists, CVD SiC pioneers and regional high-volume producers. Suppliers differ not only by material capability (CVD SiC, solid SiC, single‑crystal silicon, engineered ceramics, quartz) but also by scale, vertical integration and service model. The market’s top tier controls a majority share, but regional and niche players are gaining relevance through product innovation and local partnerships.
-
CoorsTek (United States) — Strengths: high‑purity ceramics, deep materials science and engineered solutions for extreme etch environments. Best suited for fabs requiring bespoke, high‑reliability ceramic rings and integrated service models. URL: https://www.coorstek.com
-
Morgan Technical Ceramics (United Kingdom) — Strengths: CVD SiC and high‑purity alumina offerings, long history in high‑temperature and plasma‑resistant components. Strong R&D partnership potential for European and global OEMs. URL: https://www.morgantechnicalceramics.com
-
Tokai Carbon Co., Ltd. (Japan) — Strengths: pioneer status in solid SiC focus rings via proprietary CVD processes; recognized for durability in high-performance etch applications. High technical credibility for advanced nodes. URL: https://www.tokaicarbon.co.jp
-
BC&C (South Korea) — Strengths: mass production capability for polycrystalline silicon rings and recent commercial traction with nitride‑free poly‑Si designs; demonstrates how process innovation can unlock cost and yield advantages at scale. Recent development: order and qualification success with a North American chipmaker (product entering mass supply in early 2025), reinforcing the commercial viability of non-SiC alternatives in targeted use-cases.
-
China-based suppliers (e.g., Semicorex, Semicera, DSTC) — Strengths: rapid scale-up, competitive pricing and an expanding portfolio of CVD SiC and coated graphite solutions. These firms are increasingly relevant for regional fab projects and for buyers seeking alternative sources.
-
Other notable players (Ferrotec, Kyocera, Worldex, Kallex, Daewon, Greene Tweed, etc.) — Each brings differentiated capabilities across ceramic chemistry, silicon processing, quartz fabrications and aftermarket services; selection should be driven by process fit and long‑term supply resilience.
Report deliverables: what executives will find inside
The full research package is purpose‑built for commercial, operations and R&D leaders. It delivers:
-
Proprietary market-sizing and a validated CAGR forecast (8.22% through the 2026–2032 horizon) with scenario analyses that stress-test export control, raw‑material shock and regional capacity build-outs.
-
Supplier capability heat maps and a buyer’s playbook that ranks vendors by technical fit, qualification complexity, and supply‑risk exposure.
-
Actionable procurement frameworks: qualification timelines, test protocols, contractual clauses for supply assurance, and suggested inventory posture by process risk tier.
-
Hands‑on engineering guidance for ring‑tool interaction optimization, on-wafer performance diagnostics, and recommendations for co‑development agreements to accelerate qualification.
-
Supply‑chain risk matrices including material sourcing vulnerability analyses (notably for high‑purity SiC and specialty ceramics) and mitigation levers such as dual-sourcing, onshoring, and inventory hedging.
-
Executive decision templates: CapEx vs. OpEx tradeoffs for in‑house machining vs. outsourced supply, and a procurement scorecard aligned to TTM, yield impact and regulatory exposure.
Practical recommendations for 2026 planning cycles
-
Initiate prioritized supplier qualifications now for every critical etch family. Even when a current supplier is performing, the cost of switching later is high; parallel qualification preserves optionality.
-
Negotiate technical collaboration clauses into key supplier contracts to accelerate shared root‑cause analysis and on‑tool tuning, reducing TTM for node transitions.
-
Establish a materials contingency plan: identify at least one validated alternate material and one alternate geographic source for critical ring types within 12–18 months.
-
Make supply‑resilience a board-level KPI for fabs with advanced node exposure. Track supplier concentration, lead‑time volatility and regulatory risk as part of quarterly risk reviews.
Conclusion and next steps
The focus ring market is maturing from a technical commodity into a strategic component class that links materials science, supply-chain resilience and device economics. For 2026 planning cycles, the essential moves are clear: diversify validated sources, embed supplier partnerships early in process development, and optimize inventory and contractual structures to absorb material and regulatory shocks. Our full report contains the granular segment tables, supplier scorecards and quantitative scenario outputs that will enable executable roadmaps; this preview is intended to surface the critical strategic choices you need to make now to avoid costly delays later.
To access the complete dataset, segment-level breakdowns, supplier profiles and procurement templates, please visit the PW Consulting report page for the Semiconductor Focus Ring Market. The full study is tailored for procurement leads, process R&D managers and corporate strategy teams preparing their 2026–2028 action plans.
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


