



Category: market research
PW Consulting: Gas Humidity Sensors Market to Reach $2.43B by 2032 at 7.51% CAGR
By PW Consulting, 2026-07-13
Gas Humidity Sensors Market 2026 — Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive preview of our newest market study on Gas Humidity Sensors. This briefing distills the research’s strategic value for corporate leaders planning actions in 2026, highlights the market trajectory, and identifies the operational levers that will determine winners over the next planning cycle. The goal: demonstrate the depth of our analysis while reserving the granular segment-level datapoints for the full report.
Gas Humidity Sensors Market
Market at a Glance — The Macro Frame
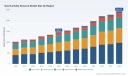
The gas humidity sensors market is on a multi-year expansion path. After a steady recovery across the early 2020s, the market base in our 2025 reference year stands near the mid‑single‑billion dollar mark (USD, revenue unit: Million). Under our central forecast — grounded in historical 2020–2025 performance and validated demand drivers — the market grows at a compound annual growth rate of approximately 7.51% through our 2026–2032 forecast horizon, with the 2032 market approaching roughly USD 2.43 billion. Market concentration is moderate: the top three firms account for about 32.4% of industry revenues, and the top five about 48.2%, indicating meaningful room for both scale-driven incumbents and specialized challengers.
Gas Humidity Sensors Market
Why This Matters for 2026 Strategic Planning
- Revenue predictability with tactical inflection points: The underlying CAGR provides a baseline for budget planning, but 2026 is characterized by discrete catalysts — product upgrades to meet safety standards, OEM design-wins in automotive sensing, and integrated multi-sensor modules for IoT — that can materially accelerate adoption in targeted verticals.
- Margin and procurement pressure: Supply-chain frictions remain a structural risk. Our research flags a notable increase in lead times for certain specialty electronic materials used in sensing modules; clients should expect procurement volatility unless they actively diversify suppliers or secure strategic inventory positions.
- Regulatory and safety-driven demand: Functional-safety certification requirements (e.g., ASIL-level readiness in automotive perception and LiDAR systems) are creating premium segments within the market where suppliers can command differentiation and pricing power.
What the Full Report Delivers — Actionable, Practically Oriented Content
This study is designed to be operationally prescriptive for executives and commercial teams. Key deliverables include:
Gas Humidity Sensors Market
- Forward-looking market sizing and scenario models (base, upside, downside) that you can plug directly into corporate planning tools. Models are parameterized for demand shocks, technology adoption, and regulatory shifts.
- Commercial playbooks for OEM engagement: prioritized verticals, value-proposition templates, and recommended channel strategies for capturing design wins in automotive, HVAC, industrial controls, and healthcare applications.
- Supply-chain resilience toolkit: supplier segmentation, dual-sourcing constructs, recommended inventory buffers, and cost-to-serve analysis to mitigate lead-time and rare-material exposure.
- Technology roadmap and R&D scorecards: comparative assessment of MEMS, digital sensor integration, and hybrid sensing approaches with time-to-market and IP risk indicators.
- M&A and partnership map: target archetypes for bolt-on acquisitions, JV models for co-development with automotive Tier 1s, and licensing opportunities with complementary semiconductor partners.
- Regulatory impact matrix: compliance timelines, certification cost estimates, and go/no-go decision thresholds for adopting ASIL and other region-specific standards.
Competitive Landscape — Who to Watch and Why
The industry mixes established sensor specialists, diversified industrial conglomerates, and semiconductor players. The competitive dynamics are nuanced: incumbents with high-precision heritage enjoy credibility in industrial and life-sciences segments, while semiconductor and electronics OEMs are leveraging integration and scale to acquire share in consumer and automotive adjacencies.
- Sensirion AG (Stäfa, Switzerland) — Maintains a technology leadership posture in high-precision digital humidity sensors and has recently highlighted safety-rated (ASIL) product developments and several automotive design-wins. Sensirion’s moves underscore the strategic premium available for suppliers that certify sensors for functional-safety environments.
- Honeywell International — Leverages its building technologies portfolio to sustain strong placements in HVAC and building automation, where integrated environmental sensing is a staple of retrofit and new-build projects.
- Texas Instruments — Brings semiconductor scale and power-efficiency credentials to digital humidity sensing, forcing a commercial playbook that bundles sensors with broader embedded-system solutions.
- Bosch Sensortec — Focused on MEMS-enabled combo sensors for consumer, wearable and IoT platforms; their strategy highlights the value of sensor fusion in constrained form factors.
- Amphenol, TE Connectivity, Vaisala, and E+E Elektronik — These firms represent a mix of robust industrial offerings, aerospace/defense channel access, and high-accuracy instrumentation, making them attractive partners for customers that require environmental-grade performance, long-term support, or sector-specific certifications.
Recent corporate actions accelerate these themes: product launches integrating humidity elements into broader environmental sensors, distribution agreements to reach aerospace and defense OEMs, and investor presentations calling out ASIL-rated sensor roadmaps are all signs the competitive bar is rising in 2025–2026.
Key Dynamics Shaping Competitive Advantage
- Integration wins: The market increasingly rewards vendors that can deliver combined temperature, humidity, pressure, and gas sensing in compact, calibrated modules suitable for IoT and automotive platforms.
- Safety and lifetime support: Designers and procurement teams in regulated industries now factor multi‑year support and safety certification into supplier selection. Products promising extended legacy support windows command strategic value.
- Supply chain friction: Geopolitical tariff actions and rare-material bottlenecks have increased procurement complexity; firms that secure upstream continuity via multi-region sourcing or backward integration will realize a pricing and reliability edge.
Strategic Imperatives for 2026 — What Executives Should Do Now
- Prioritize ASIL and certification roadmaps: If you supply or depend on sensors for automotive or safety-critical systems, accelerate certification planning. Early movers will capture design wins and create switching costs.
- Hedge supply risk with tactical inventory and dual-sourcing: Our supply-chain analysis quantifies lead-time volatility for critical components; firms should combine limited strategic stockpiles with validated alternate suppliers to avoid production stoppages.
- Adopt a product differentiation playbook: Invest in sensor fusion, calibration services, and edge-compute software to move from component supplier to systems partner — this expands TAM per device and deepens customer stickiness.
- Embed commercial flexibility: Offer tiered SLAs and long-term support contracts for enterprise and industrial customers, monetizing durability and lifetime assurance as a premium service.
- Explore focused inorganic moves: Use M&A selectively to acquire niche IP (e.g., MEMS or coating technologies), channel access, or certifications — faster than building in-house capability.
How to Use This Research in Your 2026 Planning Cycle
Integrate our forecast and scenario outputs into three core planning processes this quarter:
- Capital allocation: benchmark R&D and manufacturing investments against the market growth envelope and allocate to initiatives with >2x return under our central case.
- Commercial strategy: use the OEM engagement frameworks to prioritize design-win opportunities where certification and integration create outsized value.
- Risk management: apply the supply-chain toolkit to stress-test your sourcing and develop contingency playbooks tied to specific supplier disruption probabilities.
Final Observations — The Strategic Horizon
By 2026, the gas humidity sensor market will still be shaped by technological integration, regulatory pressure, and supply-chain realignment. Firms that combine certification readiness, supply resilience, and product differentiation will capture disproportionate value as the market scales toward the early-2030s. The market’s mid-term CAGR and concentration metrics suggest enough growth to reward both incumbent scale and focused innovators — but execution risk remains high for those that wait to react.
For executives preparing 2026 budgets and go-to-market plans, our full PW Consulting report provides the granular segmentation, regional demand maps, supplier scorecards, and downloadable financial models required to convert insight into action. This preview reveals the strategic contours; the complete study contains the detailed tables, heat maps, and scenario workbooks you will need to operationalize these recommendations.
Next Steps
- Contact PW Consulting to access the full report and downloadable scenario models.
- Request a tailored briefing with our sensor-market specialists to align our findings to your product roadmap, procurement strategy, or M&A pipeline.
PW Consulting’s Gas Humidity Sensors Market study is engineered to be a direct input into 2026 decision-making — pragmatic, defensible, and calibrated to the execution challenges that separate strategic plans from realized outcomes.
For detailed analysis of this topic, please visit the official page: Gas Humidity Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polymer Gel Market to Reach USD 33.94 Billion by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-13
Polymer Gel Market — Strategic Outlook for 2026 Decisions
Executive snapshot
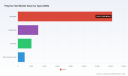
By 2025 the global polymer gel market had matured into a multi‑billion dollar industry, and our base‑year assessment places total market revenue at just over USD 20.4 billion. PW Consulting’s modelling projects a sustained mid‑single‑digit expansion at a compound annual growth rate of 7.5% across the 2026–2032 forecast window, lifting the market toward roughly USD 34.0 billion by 2032. That momentum is neither uniform nor accidental: it is driven by converging forces in healthcare, hygiene, agriculture, personal care, and industrial applications that reward both scale and technical differentiation.
Polymer Gel Market
Why this research matters for 2026 decision-making
- Capital allocation: Clear demand trajectories and scenario outputs enable CFOs and corporate development teams to prioritise brownfield expansions, pilot plants, or strategic M&A with higher conviction.
- Supply‑chain risk management: Volatility in key upstream feedstocks and shifting trade policies require procurement strategies calibrated to 18–36 month planning horizons rather than purely spot decisions.
- Product portfolio strategy: The market rewards companies that can segment offerings into commoditised SAP volumes and higher‑margin, formulated specialty gels for clinical, cosmetic and advanced industrial use cases.
- Regulatory preparedness: New restrictions on microplastics and PFAS are material to formulation roadmaps; being first‑mover on compliant formulations is a commercial advantage.
- Commercial go‑to‑market: Channel selection, contract lengths and co‑innovation partnerships differ by end‑use; our analysis translates that into actionable sales playbooks.
Data‑driven lens: what the numbers tell us (high level)
The headline growth profile (CAGR 7.5% for 2026–2032) reflects two linked realities: persistent end‑market expansion in hygiene and healthcare, and accelerating adoption in non‑traditional segments such as thermal management and specialty agriculture. Historical trends from 2020–2025 show steady recovery and re‑rating after pandemic disruptions, while our scenario work identifies asymmetric outcomes under alternate macroeconomic and raw‑material price paths.
Polymer Gel Market
Market concentration is meaningful but not prohibitive: the three largest players control a material share of demand, and the top five approaches a near‑majority position. This structure creates both opportunity and tension — incumbents can leverage scale economics, but mid‑tier and specialist firms can carve defensible niches through formulation IP and application‑specific service models.
Polymer Gel Market
Critical market dynamics and near‑term risks
- Feedstock volatility: Acrylic‑acid based supplies remain the principal upstream input. Recent price cycles have shown double‑digit percentage swings in regional markets over 12 months; procurement teams must model both price and availability scenarios into product margin analyses.
- Regulatory headwinds: EU measures targeting intentionally added microplastics and proposed PFAS restrictions are already influencing formulation choices and supplier disclosure requirements. Companies that delay reformulation run reputational and commercial risk in major end‑market jurisdictions.
- Trade and tariff exposure: New tariff regimes introduced in 2025 applied to polymer and chemical imports at non‑trivial ad‑valorem rates, compressing optionality for cross‑border sourcing and increasing the value of local production footprints.
- Technology substitution and premiumisation: Advances in antimicrobial hydrogels, aerogel‑enhanced thermal products, and engineered organogels are creating differentiated premium segments that command higher ASPs and demand closer collaboration between R&D and sales.
Competitive landscape — what the market leaders are doing
The market topology blends global chemical majors, specialty polymer houses, regional champions and application‑driven players. Several strategic behaviors stand out and should inform competitor response plans:
- BASF SE (Ludwigshafen) — leveraging scale in SAP and polymer gel production, BASF has recently completed a targeted efficiency and sustainability upgrade at a key North American site. That move is consistent with a strategy to improve unit economics while shrinking the carbon footprint of high‑volume grades.
- Evonik Industries AG (Essen) — focusing on higher‑performance gel formulations, Evonik’s recent launch of an antimicrobial super‑absorbent product for wound care exemplifies a playbook centred on clinical differentiation and premiumisation.
- Nippon Shokubai and Sumitomo Seika (Osaka) — both Japanese incumbents are expanding capacity and accelerating pilot programs in Asia, reflecting a bet on regional demand growth in hygiene and incontinence products and a desire to shorten lead times for regional customers.
- LG Chem and Dow Inc. — these players are integrating polymer gel offerings with adjacent material platforms (e.g., acrylic systems, specialty additives) to present bundled solutions for OEMs in consumer and industrial markets.
- Specialists such as Ashland , SNF , and Cabot — compete on niche application expertise (personal care, water treatment, aerogel thermal solutions). Their agility in product development and customer intimacy makes them attractive partners or targets for larger strategic investors.
- Regional suppliers (e.g., Chemtex, Saudi Arabian Amiantit) — play to local market needs with tailored formulations and distribution networks; they are often the front line for agriculture and construction applications.
Recent strategic moves worth noting
- BASF completed a capacity and efficiency upgrade in Texas aimed at better polymer performance and a lower carbon footprint — a signal that incumbents are willing to invest to defend share in mature volumes while improving sustainability metrics.
- Evonik’s product launch for antimicrobial wound‑care gels highlights the margin opportunity in medical specialties and the value of early clinical validation.
- Sumitomo Seika’s twin actions — regional hydrogel expansion and a new SAP pilot plant — underscore a two‑track strategy: meet near‑term demand growth while de‑risking next‑generation formulations prior to large‑scale rollout.
Strategic implications and recommended 2026 moves
- Prioritise “supply assurance + price flexibility” in procurement. Hedging programmes, multi‑sourcing and selective upstream integration for acrylic‑acid derivatives will materially protect gross margins under volatile feedstock scenarios.
- Differentiate via formulation IP rather than competing on commodity volumes alone. Invest in R&D to translate regulatory constraints into product advantages (e.g., microplastics‑free, PFAS‑free, bio‑based polymers).
- Map capacity expansion to real, contractable demand. Use our scenario outputs to size brownfield expansions vs greenfield projects; shorter lead‑time brownfield projects often dominate ROI in the 2026 investment window.
- Pursue bolt‑on M&A to fill capability gaps — targets that offer clinical validation, application engineering teams, or regional distribution can accelerate market access with lower execution risk than greenfield growth.
- Revisit pricing and commercial terms in light of tariffs and regionalisation. Longer‑dated contracts with indexation clauses and flexible volume bands will mitigate margin leakage.
- Embed regulatory roadmaps into product development lifecycles. Cross‑functional teams comprising regulatory, R&D and commercial should be mandated to certify first‑to‑market compliant formulations for high‑value end uses.
What the full PW Consulting report delivers (practical, board‑ready assets)
- Dynamic market model with historicals (2020–2025) and probabilistic forecasts (2026–2032), including sensitivity tables and scenario comparators you can plug into investment cases.
- Financial impact toolkit: margin modelling templates that combine feedstock price curves, tariff scenarios and product mix to quantify EBITDA exposure.
- Supplier scorecards and heat maps (capability, cost, capacity, compliance readiness), with acquisition attractiveness indices for M&A screening.
- Technology and product roadmap: maturity matrices for hydrogels, organogels, aerogels and emergent hybrids, showing time‑to‑market and IP risk profiles.
- Regulatory impact matrix linking specific measures (e.g., EU microplastics rules, proposed PFAS restrictions) to product classes, reformulation lead times and certification costs.
- Commercial playbooks: go‑to‑market strategies for premium medical gels, scaled SAP volumes, and new industrial applications (thermal, battery, water treatment), including recommended channel structures and contract framing.
- M&A and partnership shortlist with deal rationales, high‑level valuation comparators and integration risk checklists.
- Implementation roadmap and 100‑day action plans tailored for CEOs, Heads of Strategy, and Procurement leads to convert insight into deliverable initiatives during 2026.
Using this research in the boardroom
- Convert the market scenarios into capital allocation choices: use the PW model to stress test NPV outcomes of expansion, refurbishment or acquisition alternatives.
- Brief procurement and commercial teams with a condensed playbook from the report to renegotiate supplier contracts and update pricing mechanisms.
- Rapidly prioritise R&D projects that both mitigate regulatory risk and open access to higher‑margin specialty segments.
- Use the M&A screening outputs as a pre‑qualified pipeline for corporate development — enabling quicker, lower‑risk deal execution when market windows appear.
Concluding note — an actionable preview
PW Consulting’s Polymer Gel Market research is intentionally engineered as a decision‑support tool for 2026. It combines macro forecasts (base‑year 2025, CAGR 7.5% to 2032), scenario stress testing, supplier due diligence and regulatory impact mapping into a single, operationally oriented suite. This article is a strategic preview: it surfaces the critical trends, competitive moves and high‑impact choices you need to consider now, while preserving the full segmentation granularity, interactive models and targetable datasets for subscribers of the complete report.
For boards, investors and commercial leaders preparing budget cycles or M&A roadmaps in 2026, the right next step is access to the complete dataset and the downloadable model — these contain the detailed segment breakdowns, regional demand curves and company‑level volumes that turn strategy into executable plans.
For detailed analysis of this topic, please visit the official page: Polymer Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Carpal Tunnel Syndrome Treatment Market: Strategic Insights for 2026 Decision‑Making
As PW Consulting’s senior industry analyst, I present an evidence‑based briefing designed to orient executive teams to the strategic inflection points shaping the Carpal Tunnel Syndrome (CTS) treatment market in 2026. This briefing synthesizes historical performance, near‑term trajectory, regulatory and reimbursement inflections, technology vectors, and competitive behaviors that should be central to boardroom discussions. It intentionally signals the report’s depth while reserving granular segment tables for subscribers — a deliberate “teaser” to catalyze informed engagement with our full market study.
Carpal Tunnel Syndrome Treatment Market
Executive summary
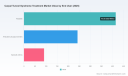
The CTS treatment market has moved from a niche procedural arena to a diversified, innovation‑driven specialty market. Between 2020 and 2025, the market expanded noticeably — reflecting both clinical adoption of minimally invasive techniques and improvements in diagnostic workflows. Our base‑year analysis shows steady growth culminating in 2025, and our forecast projects continued expansion through 2032 at a compound annual growth rate (CAGR) of 6.12% (USD, revenue unit: Million). Market concentration metrics indicate a moderately consolidated landscape (CR3 ≈ 34.3%, CR5 ≈ 51.1%), which creates both competitive barriers and entry opportunities for focused innovators.
Carpal Tunnel Syndrome Treatment Market
Market trajectory and what it means for 2026 strategy
Macro trajectory matters because it determines the scale of commercial investment and the timing of returns. The market’s steady CAGR of ~6.1% through the forecast window aligns with broader orthopedic and ambulatory surgery growth trends, but it is the composition of that growth — driven by device innovation, procedural shifts, and reimbursement change — that dictates differentiated strategy.
Carpal Tunnel Syndrome Treatment Market
-
Clinically, there is a clear shift toward less invasive and image‑guided procedures that shorten recovery time and enable ambulatory settings. This trend supports device suppliers that can demonstrate safety, reproducibility, and scalable training models.
-
Economically, payor and coding changes in 2026 materially alter the reimbursement calculus for percutaneous and endoscopic approaches. Reimbursement clarity will be a gating factor for adoption in outpatient environments.
-
Regulatory dynamics and evidence generation will disproportionately favor entrants that can rapidly convert approvals into peer‑reviewed outcomes and payer‑facing value dossiers.
Recent regulatory and reimbursement inflections
-
New procedural coding: Effective January 1, 2026, a Category I CPT code was established for percutaneous carpal tunnel decompression (CPT 64728). Its zero‑day global period and valuation methodology (day‑of‑service focus with separate reporting of post‑procedure visits) change the economics for office‑based procedures and ambulatory surgical centers. Manufacturers and providers must align procedural documentation and billing workflows to capture appropriate revenue.
-
Endoscopy reimbursement: Some endoscopic systems have associa ted reimbursement under existing endoscopy codes; device makers that can map clinical workflows to established coding pathways will accelerate adoption in Medicare populations.
-
Regulatory signal: Recent 510(k) clearances for ultrasound‑guided and endoscopic release systems, together with supportive independent publications, are lowering the clinical adoption friction for image‑guided approaches — but regulatory scrutiny persists, as demonstrated by an FDA warning to an unapproved device vendor in 2025. Robust labeling, claims substantiation, and post‑market surveillance programs are non‑negotiable.
Technology vectors to watch in 2026
-
Ultrasound‑guided release: Real‑time visualization is becoming a differentiator. Systems that tightly integrate imaging, ergonomics, and single‑use safety features are positioned to displace blind techniques in select practice settings.
-
Miniaturized endoscopy and percutaneous platforms: Lower‑trauma options with reduced recovery time align with payer and patient preferences for fast return to function. The market is rewarding devices that reduce procedure time and post‑op resource use.
-
Diagnostic AI and point‑of‑care tools: Handheld ultrasound with neural nets that automate median nerve metrics is shifting diagnostic throughput from referral centers to primary care and specialty clinics, creating earlier intervention opportunities.
-
Consumables and single‑use ecosystems: Commercial models that bundle capital light entry with recurring consumables can accelerate footprint expansion into ambulatory centers and specialty clinics.
Competitive landscape: who’s shaping adoption and why it matters
The competitive set spans global orthopedic OEMs, niche device innovators, and diagnostics vendors. Established medtech firms bring scale, distribution and clinician relationships; smaller players contribute focused innovations that can rapidly change practice patterns.
-
Large OEMs: Companies with broad orthopedic or minimally invasive surgery portfolios leverage installed salesforces and integrated systems to push endoscopic and instrument‑based solutions into hospitals and ambulatory surgical centers. Their strengths lie in reimbursement navigation, multi‑channel distribution, and bundled clinical training.
-
Specialty innovators: Firms focused on ultrasound‑guided or percutaneous technologies are converting clinical interest into regulatory clearances and peer‑reviewed evidence. These entrants excel in niche technical performance and lower upfront capital requirements, making them attractive to ambulatory settings.
-
Diagnostics and AI players: Vendors offering handheld ultrasound with median nerve analytics are not just diagnostic suppliers; they are demand creators — enabling earlier detection and referral pathways that expand addressable procedure counts.
Notable recent milestones to incorporate into 2026 planning:
-
Regulatory clearances in 2025–2026 for image‑guided release systems and median nerve AI tools, which reduce clinical adoption friction for ultrasound‑based pathways.
-
Independent publication activity validating ultrasound‑guided release through the 2026 literature, providing payers and clinicians with outcome data needed for broader uptake.
-
Regulatory enforcement actions against vendors making unapproved therapeutic claims, reminding market participants that compliant claims and robust evidence frameworks are critical to sustainable commercialization.
Strategic implications and recommended actions for 2026
Executives should prioritize a focused set of actions that translate market trajectory and regulatory signals into competitive advantage.
-
Build a reimbursement playbook: Map product claims to CPT and ICD codes, simulate payer coverage scenarios, and prepare procedural documentation templates that capture day‑of‑service value. For percutaneous approaches, ensure billing workflows reflect the 0‑day global period and separate post‑op visit reporting.
-
Invest in clinical evidence and publication strategy: Rapidly generate peer‑reviewed outcomes and health economics analyses. Independent registry data demonstrating real‑world recovery, complication rates, and resource utilization will be decisive in 2026–2027.
-
Prioritize training and scale: Devices that reduce procedural variability through modular training — simulator, proctoring, and digital content — will shorten the sales cycle, especially with ambulatory surgical centers and specialty clinics.
-
Explore partnerships and distribution flex: Small innovators should consider alliances with established OEMs for market access, while incumbent players should scout acquisition or licensing opportunities to fill capability gaps in image guidance and AI diagnostics.
-
Operationalize ambulatory and office‑based models: Commercial strategies, pricing, and clinical support must be tailored for lower‑cost settings where procedural volumes and throughput economics differ from inpatient hospitals.
-
Mitigate regulatory downside: Maintain conservative claims, rigorously document indications, and set up proactive post‑market surveillance to avoid enforcement that can quickly erode market trust.
What the PW Consulting report delivers (high‑practicality checklist)
-
Five‑year and extended‑forecast scenarios incorporating reimbursement sensitivity and adoption curves for image‑guided/percutaneous technologies.
-
Competitive intelligence dossiers on leading OEMs and niche innovators, including capability maps, go‑to‑market strengths, and M&A watch points.
-
Revenue and unit forecasts (historical 2020–2025 baseline and 2026–2032 outlook) with scenario toggles for coding, reimbursement, and adoption speed.
-
Commercial playbooks: coding alignment templates, payer value scripts, clinician training program outlines, and pricing frameworks for hospital vs. ambulatory settings.
-
Risk register and regulatory watchlist: probable enforcement vectors, evidence gaps by claim type, and clinical endpoints most persuasive to payers.
Why this analysis matters to decision‑makers in 2026
2026 is a transition year: new procedure coding, multiple recent device clearances, and the emergence of diagnostic AI converge to change who performs CTS procedures and where they take place. Strategic choices made in 2026 — on evidence generation, reimbursement positioning, and channel strategy — will disproportionately determine market share and return on investment over the remainder of the planning horizon.
With market concentration levels indicating room for focused competitors to capture meaningful share, the winners will be those that convert clinical innovation into payer‑aligned value propositions and scalable go‑to‑market models.
Next steps (how to use our intelligence)
-
Use the PW forecast scenarios to stress‑test your product roadmap and capital allocation plans under multiple coding and adoption assumptions.
-
Deploy the reimbursement templates in pilot markets to validate coding capture and revenue realization for percutaneous and endoscopic workflows.
-
Engage PW Consulting for a tailored competitive intercept study or a rapid evidence gap assessment to prioritize pivotal clinical investments.
Final note — what we intentionally withheld
This briefing intentionally omits granular regional and treatment‑type breakouts and specific segment revenue tables. Those detailed segmentations, granular competitive shares and modelled pricing assumptions are included in the full PW Consulting Carpal Tunnel Syndrome Treatment Market report and interactive dashboards. Access to that intelligence provides the precise inputs your commercial, regulatory, and clinical development teams need to operationalize the strategies outlined here.
To translate these strategic insights into an executable plan for 2026, contact PW Consulting to obtain the full market dataset, scenario models, and bespoke advisory support.
For detailed analysis of this topic, please visit the official page: Carpal Tunnel Syndrome Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mp System On A Chip (SoC) Market — Strategic Outlook for 2026 Decision‑Makers
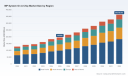
As companies recalibrate product roadmaps, capital allocation, and supply‑chain strategies for 2026, the Mp System On A Chip (SoC) market is a linchpin that will determine competitive advantage across consumer electronics, telecommunications, automotive and industrial systems. PW Consulting’s latest market study synthesizes seven years of historical data and a seven‑year forward forecast to give executives a precise, actionable view of where investment and strategic effort will produce the highest returns. The market has expanded materially in recent years — rising from approximately USD 128,110 million in 2020 to roughly USD 195,500 million in 2025 — and our base‑case projection places the market above USD 215,000 million in 2026 with a compound annual growth rate of 9.25% through 2032, reaching an expected USD 363,159 million at the end of the forecast window. These headline dynamics create both opportunity and complexity for strategic decision‑makers in 2026.
Mp System On A Chip Market
Why this study matters for 2026 decisions
-
Timing of technology inflection points: 2026 is the first year many leading foundries and designers will roll out 2nm‑class products at scale. This will reshape performance, power and integration economics for flagship SoCs and high‑end edge devices.
Mp System On A Chip Market -
Strategic policy tailwinds and headwinds: public funding programs and export control regimes are simultaneously accelerating domestic capacity in some markets while constraining cross‑border technology flows. Firms must navigate incentives, compliance risk and the new economics of localized supply chains.
Mp System On A Chip Market -
Consolidation pressure vs. fragmentation opportunity: the market exhibits moderate concentration among global leaders, but technology specialization (imaging, automotive-grade safety, mixed‑signal integration) leaves room for targeted entrants and M&A plays.
-
Packaging and integration shifts: advanced packaging and standardized chiplet interconnects are changing the value chain — companies that adopt heterogeneous integration early will shorten time‑to‑market for differentiated performance.
What the report delivers — practical, decision‑grade insight
-
Robust market sizing and scenario models: transparent methodology that reconciles historical revenues (2020–2025) with three forecast scenarios (base, upside, downside) across 2026–2032, enabling stress‑tested volume and revenue planning.
-
Go‑to‑market playbooks: prioritized GTM options for semiconductor vendors, OEMs and system integrators by technology stack and buyer persona, including product positioning, channel choices and pricing levers.
-
Supply‑chain and manufacturing roadmaps: evaluation of node transition timelines, advanced packaging adoption curves, and high‑margin assembly strategies, with a focus on risk mitigation under export control regimes.
-
Technology and IP strategy: assessment of chiplet adoption, UCIe standardization impacts, and how to structure partnerships with foundries and packaging specialists to capture performance cost improvements.
-
Commercial due diligence toolkit: vendor scorecards, M&A screening criteria, and integration checklists to accelerate target selection and post‑acquisition value capture.
-
Regulatory and compliance matrix: practical guidance for export control exposure analysis, navigating incentives (including national chip funding programs), and building a defensible compliance posture.
-
Risk and contingency planning: scenario‑based operational playbooks for yield shocks, geo‑political supply interruptions and sudden demand shifts in automotive or telecommunications segments.
Competitive landscape — what the leaders are doing and why it matters
The competitive field spans vertically integrated platform owners, fabless specialists, diversified semiconductor giants and niche systems vendors. The market’s top three players collectively command a meaningful portion of aggregate revenue, while the top five account for a dominant slice of industry revenue — a structure that supports both scale advantages and differentiated niche strategies. Key strategic positioning to watch in 2026:
-
Qualcomm Technologies, Inc.: Continues to leverage modem and connectivity IP alongside high‑performance application processors to defend its mobile and expanding automotive footprint. Its integrated approach to connectivity and heterogeneous compute remains a commercial advantage for OEM partnerships.
-
Apple Inc.: Vertical integration of SoC design and system architecture drives substantial per‑device differentiation. Its control of silicon and software stacks makes it a benchmark for performance per watt and user experience optimization.
-
MediaTek Inc.: A proven operator in cost‑performance tradeoffs for mainstream mobile and consumer segments; its recent tape‑out on advanced process technology signals an intent to close the gap on flagship performance while preserving aggressive cost structures for high‑volume markets.
-
Samsung Electronics: Dual role as designer and foundry provides flexibility in aligning SoC design to manufacturing advances and memory integration including HBM, valuable for both mobile and high‑performance segments.
-
AMD and Intel: Both are converting traditional CPU franchises into broader SoC strategies for data center, edge and PC markets, with implications for platform consolidation and software ecosystem lock‑in.
-
NVIDIA: Focused on GPU‑centric SoCs for automotive and edge AI; its strengths in deep learning acceleration make it a go‑to for workloads that prioritize parallel compute and model inference at the edge.
-
Broadcom, NXP, STMicroelectronics, Texas Instruments: Each occupies differentiated niches in networking, automotive, industrial and analog/mixed‑signal SoCs. Their breadth of product portfolios delivers resilience against single‑market downturns.
-
OMNIVISION and Socionext: Examples of specialized IP and systems expertise — from imaging sensor SoCs to custom automotive solutions — that enable targeted wins where domain knowledge and integration matter most.
Industry dynamics shaping strategic choices in 2026
-
Node adoption and packaging: The industry’s march toward 2nm‑class process nodes and wider deployment of advanced packaging (including large‑reticle interposers supporting HBM) will change the performance/cost frontier. Decision‑makers should assess where node upgrades materially improve product value versus where multi‑die integration yields better TCO.
-
Standardization and modularization: The emergence of chiplet standards is lowering barriers to heterogeneous integration but increasing the importance of IP orchestration and ecosystem partnerships.
-
Policy and supply‑chain realignment: Export control regimes and national incentives are reconfiguring supply footprints. Firms must develop localized manufacturing options or secure strategic supply agreements to avoid market access constraints.
-
Domain‑specific acceleration: Automotive L2–L4, edge AI, and telecommunications (5G/6G evolution) are driving differentiated SoC requirements — from functional safety certification to determinism and long‑term availability commitments.
Strategic imperatives for 2026 — recommended action checklist
-
Prioritize investment where node and packaging advances unlock clear product differentiation; defer blanket node upgrades where chiplet or packaging alternatives deliver similar performance at lower capital spend.
-
Harden regulatory playbooks: map export control exposure to product roadmaps, and align R&D footprints to incentive programs and compliant manufacturing partners.
-
Forge ecosystem partnerships: early adoption of chiplet standards and joint engineering agreements with foundries and packaging houses will accelerate time‑to‑market for heterogeneous SoCs.
-
De‑risk supply: diversify high‑risk suppliers, secure long‑lead materials, and design for multi‑sourcing of critical IP blocks where possible.
-
Targeted M&A: prioritize tuck‑ins for missing capabilities (imaging ISPs, automotive safety IP, mixed‑signal expertise) over large horizontal purchases that dilute focus.
-
Commercial readiness: establish price‑performance tiers aligned to buyer personas and produce modular product families that simplify platform migration for OEM customers.
How PW Consulting’s study helps operationalize these imperatives
This research is designed as a decision‑support engine: detailed financial models, LCOE style cost curves for node and packaging options, vendor scorecards, and stepwise GTM templates are included so that product and corporate strategy teams can convert insight into executable plans within quarters, not years. Importantly, this introduction intentionally omits granular regional and application splits and the vendor‑level financial tables — those sensitive, high‑value datasets are available in the full report and the accompanying interactive dashboard for subscribers.
For executives preparing 2026 budgets, negotiating supplier agreements, or screening M&A targets, the combination of a 9.25% CAGR base case, our scenario stress tests, and the technology‑policy overlay provided in the full study will materially improve the quality and defensibility of strategic choices.
Next steps
-
Download the full report and interactive models to access regional and application breakouts, vendor financials, and a prioritized list of acquisition targets and partnership candidates.
-
Engage PW Consulting for a tailored workshop: scenario planning, capex optimization, and regulatory risk quantification specific to your product portfolio.
PW Consulting’s Mp System On A Chip Market study is structured to convert complexity into executable strategy for 2026 — providing a roadmap that balances technological ambition, regulatory realism and commercial discipline. For access to the granular intelligence and tools that support concrete investment and partnership decisions, please consult the full report.
For detailed analysis of this topic, please visit the official page: Mp System On A Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Recycling & Reuse Market to Reach USD 47,349.62M by 2032 (11.25% CAGR)
By PW Consulting, 2026-07-13
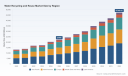
Water Recycling and Reuse Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-grade preview of our full Water Recycling and Reuse Market study — designed to fast-track C-suite and corporate strategy teams in 2026. This piece demonstrates the depth of our analysis and the concrete strategic implications emerging today, while preserving proprietary segment-level intelligence to encourage direct access to the full report and interactive tools.
Water Recycling And Reuse Market
Market Snapshot: Scale, Trajectory, and the Investment Imperative
The global water recycling and reuse market has transitioned from a niche sustainability play to a major infrastructure and industrial investment theme. Our base-year assessment shows the market reached approximately USD 22.45 billion in 2025. Under a central-case projection, the market expands at a compound annual growth rate (CAGR) of 11.25% across our 2026–2032 forecast horizon, nearly doubling to an estimated USD 47.35 billion by 2032. This trajectory reflects the combined effect of policy acceleration, industrial demand for closed-loop water systems, urban-scale recycling programs, and growing commercial viability of advanced treatment technologies.
Water Recycling And Reuse Market
Strategic Drivers That Will Shape Corporate Decisions in 2026
- Regulatory acceleration and mandate-driven demand. New policy frameworks and standards are proliferating. Notable examples include the US EPA’s Water Reuse Action Plan 2.0, which explicitly targets industry verticals such as data centers and energy; state-level mandates increasing reuse of produced water in oil & gas; and adoption of testing/qualification standards for onsite reuse systems. These create predictable demand corridors for firms able to meet compliance thresholds and demonstrate validated treatment performance.
- Large-scale municipal and industrial projects as market pull. Major programmes — from municipal purified-recycled-water initiatives to industrial reuse facilities built under long-term O&M contracts — are crystallizing the market into investable, bankable assets. Project milestones in 2025–2026 have converted theoretical demand into executable pipelines.
- Technology maturation and cost dynamics. Membrane-based systems, modular MBRs, and multi-barrier tertiary treatment are now proven at scale. Capital-intensity remains a consideration: industry benchmarks continue to quote capital cost ranges for membrane bioreactor systems and advanced tertiary treatment in per-gallon terms, which materially affect project-level IRR and procurement choice between centralized and decentralized architectures.
- Commercial models shifting to services and outcomes. The value pool is moving from equipment sales toward integrated offerings — performance guarantees, long-term service contracts, and digital-enabled lifecycle optimization. Acquirers and platform investors are seeking recurring-revenue streams tied to O&M and analytics.
- Fragmented supplier base with rising consolidation pressure. Market concentration metrics show meaningful room for consolidation: leading vendors account for a material but not dominant share, leaving strategic space for M&A, roll-up plays, and strategic partnerships between technology specialists and global operators.
What the PW Consulting Report Delivers — Actionable, Not Academic
Our full report is structured to convert market intelligence into executable initiatives. Highlights include:
Water Recycling And Reuse Market
- Proprietary market sizing and three scenario-based forecasts (conservative, central, disruption) with sensitivity analysis to policy and capital-cost variables.
- Demand-driver mapping by use-case (municipal programs, industrial reuse, produced water, onsite greywater), translating regulatory signals and capital cycles into addressable opportunity curves.
- Technology assessment framework that ranks treatment pathways by total cost of ownership, regulatory fit, footprint, and time-to-deploy — with deployment playbooks for centralized vs. decentralized models.
- Supplier and competitive intelligence, including strategic profiles and capability heatmaps for global and regional challengers. (Profiles of core companies included in the public synopsis; full comparative matrices are in the report.)
- Investment and procurement toolkits: project-level financial models, contractor RFP templates, O&M contracting options, risk allocation matrices, and a regulatory tracker for major markets.
- Ten detailed case studies that distill lessons from recent project wins, large-scale municipal programs, and industrial ZLD implementations — each with implementation timelines and supplier ecosystem maps.
Competitive Landscape — Who Matters and Why
The market is competitive and strategically diverse: global operators with integrated water-management capabilities are competing alongside specialized membrane and modular-system vendors. Key players we profile in depth include Veolia, Xylem Inc., SUEZ Water Technologies & Solutions, Ecolab (Nalco Water), DuPont Water Solutions, Pentair, Aquatech, Kubota, ALFA LAVAL, Hitachi, Siemens, Fluence, Kurita, Culligan, and Consolidated Water. Our report evaluates each firm across three strategic vectors: technology stack and IP, go-to-market model (project EPC vs. recurring O&M vs. product sales), and corporate capability to scale across geographies and verticals.
- Veolia continues to leverage its project-development and long-term O&M expertise to secure consortium-scale industrial reuse contracts, exemplified by large industrial plant agreements signed in 2025.
- Xylem’s platform expansion via acquisition is a defining move — combining fluid-handling, membranes, and analytics shifts the value proposition toward integrated lifecycle services and data-driven performance guarantees.
- SUEZ and Ecolab remain strong in modular solutions and customized industrial programs; their strength lies in multi-barrier approaches and chemical/biological process integration.
- Specialists — from membrane manufacturers to ZLD system integrators and modular decentralized providers — are the most likely acquisition targets or partners for larger engineering and services firms seeking rapid capability scaling.
Recent, tangible developments underscore these dynamics: a major acquisition completed in early 2026 that enlarged a membranes-and-analytics platform; milestone project agreements and contract awards for large-scale industrial and municipal plants in 2025–2026; and municipal programs advancing environmental approvals — all of which convert stated strategies into near-term addressable revenue.
Strategic Playbook for Executives in 2026
- Prioritize use cases with policy-backed demand. Immediate priorities should be projects and contracts anchored to regulatory mandates or long-term municipal programmes. These are the highest-confidence revenue streams for capex deployment and investor pitches.
- Design offerings around lifecycle economics, not just capex. Given the capital intensity of advanced treatment, winning in 2026 requires service-centric pricing, performance guarantees, and ability to reduce total cost of ownership through predictive maintenance and process optimization.
- Pursue targeted M&A and partnerships. Buyers should acquire modular-treatment specialists, membrane IP, or analytics providers to create bundled solutions. Sellers should seek strategic buyers that can deliver large-scale O&M contracts to convert product revenues into recurring streams.
- Use pilots to derisk and prove commercial models. Structure limited pilots with clear KPIs and scale-up triggers tied to financing milestones; consider shared-risk, incentive-aligned contracts to accelerate customer adoption.
- Embed digital to monetize performance data. Invest in remote monitoring and analytics to enable outcome-based contracts and to protect margins as hardware becomes commoditized.
- Monitor cost benchmarks and procurement timing. Capex-per-unit benchmarks for membrane bioreactors and tertiary treatment remain central inputs to bid strategy and ROI calculations — incorporate these ranges into tender pricing and lifecycle models.
- Engage regulators early and shape standards. Proactive engagement on standards and testing protocols will accelerate approvals and give first-mover advantages in nascent reuse categories (e.g., industrial reuse for data centers, produced water mandates).
Why PW Consulting’s Report is Valuable for 2026 Decisions
This study is not an academic compendium; it is a hands-on, transaction-oriented playbook. It gives corporate strategists and investment committees the forecasts, vendor scorecards, and risk-adjusted financial models needed to: prioritize capital allocation, design deals that convert projects into annuity-like income, position organizations for consolidation waves, and operationalize regulatory change. We surface where policy and project execution intersect to create bankable opportunities — and where capability gaps will determine winners and losers.
For decision-makers preparing budgets, negotiating partnerships, or evaluating M&A opportunities in 2026, the choice is twofold: rely on high-level public narratives — or equip your team with the granular scenarios, commercial templates, and supplier assessments that materially improve project selection, pricing discipline, and negotiation outcomes. Our report delivers the latter.
Next Steps
Access to the full PW Consulting Water Recycling and Reuse Market report provides the detailed, segment-level models, vendor matrices, and interactive ROI tools referenced above. For executives ready to convert the 2026 market dynamics into a clear growth agenda — whether through organic investment, partnership, or acquisition — the report is the operational map and the decision support system you need.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Selective Soldering Market to Hit USD 922.6M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-13
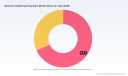
Selective Soldering Equipment Market: Strategic Intelligence for Executive Decisions in 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an incisive preview of our latest Selective Soldering Equipment Market study — a practical briefing designed to inform capital allocation, product strategy, supply-chain prioritization, and M&A decision-making throughout 2026. This article emphasizes the strategic value of the research while deliberately withholding the granular sub-segment figures that reside in the full report to preserve the incentive to engage with our complete analysis.
Selective Soldering Equipment Market
Executive snapshot: why this matters to 2026 decision-makers
Selective soldering is no longer a niche workshop capability; it is a foundational technology for high-reliability, mixed-technology PCB assembly across automotive electrification, advanced industrial controls, telecom infrastructure and increasingly demanding consumer electronics. Our base-year view (2025) positions the global selective soldering equipment market at approximately USD 582.1 Million, with a projected 2026 market step-up to roughly USD 663.2 Million and a compound annual growth rate (CAGR) of 6.8% through our 2026–2032 forecast window. Those topline numbers quantify a recovery and acceleration trajectory that corporate leaders must internalize when planning CAPEX cycles, equipment refresh programs, and factory modernization roadmaps in 2026.
Selective Soldering Equipment Market
Market trajectory and the mechanics behind the growth
-
Recovery and momentum: The market exhibited pandemic-era volatility during 2020–2022, followed by stabilization and renewed investment through 2023–2025. The forecast to 2032 anticipates steady expansion driven by miniaturization, lead-free requirements, and rising complexity in mixed-technology assemblies.
Selective Soldering Equipment Market -
Consolidation and concentration: Market concentration is non-trivial: the leading three suppliers control close to half the market, while the top five approach two-thirds of market share. This balance of scale and specialized engineering capacity shapes pricing, service coverage and innovation cycles for buyers and investors.
-
Structural demand drivers: Adoption is being propelled by three structural shifts — miniaturized components that require focused heat control, regulatory and lead-free soldering mandates, and the growth of electric vehicle (EV) and ADAS electronics which demand selective accuracy and low-void solder joints.
Why 2026 is a pivot year for equipment and operations strategy
For OEMs, EMS providers, and equipment vendors, 2026 represents a decision inflection: deferment of equipment investment risks falling behind in throughput and process yield versus competitors; premature replacement risks under-utilized assets and eroded returns. Our study frames that tradeoff through three executable decision lenses:
-
Capital allocation: Use forward-looking demand curves and scenario stress-tests to time major inline selective soldering investments. Short-cycle production needs can still be met with modular or standalone platforms, while strategic high-volume lines justify integrated, multi-station in-line systems.
-
Operational efficiency: Selective soldering’s cost profile (notably lower flux and solder consumption and reduced nitrogen use) can materially alter TCO compared with conventional wave soldering — a critical lever when margins are under pressure.
-
Quality & compliance: The technology supports compliance with IPC-level industry standards and can achieve void and reliability targets necessary for aerospace, medical and automotive electronics, making selective soldering a risk-management investment as much as a throughput play.
Practical, actionable content inside the full report
Our Selective Soldering Equipment Market study was assembled specifically for operational leaders and strategic investors. Key pragmatic deliverables include:
-
Decision-ready financial models — TCO calculators that contrast CAPEX, OPEX, consumables, and service across equipment classes and production profiles.
-
Vendor scorecards — engineering, aftermarket support, global service footprint, and retrofit compatibility metrics to accelerate shortlisting and procurement.
-
Technology roadmaps — comparative analysis of inline multi-station architectures versus standalone/batch systems, including modular upgrade paths and automation integration considerations.
-
Scenario playbooks — three to five demand and supply scenarios with sensitivity analysis for raw-material price swings, labor constraints, and regulatory tightening.
-
M&A and partnership lenses — playbooks for strategic and financial buyers highlighting integration risks, service-synergy opportunities, and quickly accretive bolt-ons.
-
Service & spares optimization — inventory policies and aftermarket strategies to reduce downtime and guarantee process repeatability across multi-site rollouts.
Competitive landscape: who matters and why
The competitive field blends long-established OEMs with focused niche specialists. Our study contains detailed vendor profiles, but the strategic highlights follow.
-
Kurtz Ersa GmbH (Germany) — A market leader with modular VERSAFLOW and ECOSELECT platforms. Strengths: broad platform range from entry-level to high-volume, electromagnetic pump technology and multi-nozzle adaptability that supports throughput scaling.
-
Nordson SELECT (United States) — Offers a complete spectrum (standalone, inline, multi-station) with a deep global service network. Competitive edge: turnkey solutions and aftermarket coverage for high-volume electronics manufacturers.
-
SEHO Systems GmbH (Germany) — Strong in integrated fluxing, preheating and soldering zones aimed at productivity and yield. Notable for platform-level engineering to support higher first-pass yields.
-
Pillarhouse International Ltd (UK) — Pioneer of selective soldering with a high-patent count; competitive in high-engineering-standard, reliability-focused segments.
-
JUKI Corporation & Apollo Seiko (Japan) — Provide batch and inline platforms, respectively, with particular relevance to through-hole legacy transitions and dual-pot innovations for precision soldering.
-
US and regional specialists (DDM Novastar, RPS Automation, TM Soldering Solutions, Hentec, VennTek-SASinno, INERTEC) — Offer cost-effective, niche and retrofit solutions that improve access to selective soldering across small and medium-sized EMS providers.
Recent vendor movements underscore competitive dynamics: multiple product launches and trade show showcases in late 2025 and early 2026 signal accelerating feature competition and an emphasis on throughput and modularity. Our full profiles catalog disclosed product launches, service expansions and regional go-to-market tactics in granular detail.
Key operational and regulatory context
-
Raw materials: The solder flux market — a critical consumable for selective processes — was estimated at roughly USD 3.12 billion in 2025 and is itself a growth market. Understanding flux segmentation and supply-chain concentration is essential for reliable OEE planning.
-
Process efficiency: Empirical process studies and vendor claims point to substantial reductions in solder usage and nitrogen consumption for selective soldering versus wave approaches. These efficiencies directly influence operating margins and environmental footprint.
-
Standards & reliability: Selective soldering is a practical enabler of compliance with IPC-level requirements and lower void percentages demanded by aerospace, medical and automotive assemblies — translating into lower warranty risk and higher product reliability.
Risk factors and scenario planning
While demand fundamentals remain constructive, 2026 strategies must include contingency playbooks addressing:
-
Raw-material volatility and supply chain disruptions for fluxes and specialty alloys.
-
Geopolitical shifts affecting capital-equipment sourcing and service footprints.
-
Rapid technology substitution or unexpected shifts in production architectures — for instance, a faster-than-anticipated move to fully automated inline cells that renders some legacy standalone investments sub-optimal.
Actionable strategic recommendations for 2026
-
For OEMs and Tier-1 manufacturers: Prioritize selective soldering investments on product lines where reliability premiums or regulatory compliance deliver quantifiable margin uplift. Use staged adoption: start with pilot inline cells on critical SKUs before committing to full-line conversions.
-
For EMS providers: Build a flexible equipment portfolio that mixes compact standalone systems for short runs and modular inline stations for predictable, high-volume customers. Strengthen service contracts and spare-parts availability to turn uptime into a competitive differentiator.
-
For equipment vendors: Invest in service orchestration, remote diagnostics, and modular upgradeability. Product differentiation will hinge on throughput scaling, ease-of-retrofit, and lifecycle service economics.
-
For investors & M&A teams: Seek targets that offer either niche technological IP (e.g., unique pump or nozzle technologies) or service-reach that can be rapidly integrated into a global aftermarket network; focus on assets that improve gross margin predictability in rolling 12–24 month horizons.
What the full PW Consulting report unlocks
The complete study contains the operational models, supplier scorecards, and scenario analytics required to convert these strategic signals into executable plans. To respect proprietary value and maintain the “selective” nature of this preview, we have withheld the granular regional and application splits from this article — those tables and the interactive modeling tools are available within the full report package and on our data portal.
Next steps
If you are responsible for CAPEX planning, factory modernization, procurement of selective soldering systems, or evaluating investment targets in 2026, the PW Consulting Selective Soldering Equipment Market study provides the operational blueprints and financial models you need. Contact our team or visit the report landing page to obtain the full dataset, vendor scorecards, and the TCO calculator.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Logistics Software Market to Reach USD 58,052.5M by 2032 (14.5% CAGR)
By PW Consulting, 2026-07-13
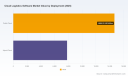
Cloud Logistics Software Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
Executive snapshot
As organizations reset supply‑chain priorities for the post‑pandemic, AI‑enabled decade, cloud logistics software has moved from “nice to have” to a board‑level imperative. PW Consulting’s latest study—anchored on a 2025 base year and a six‑year historical run (2020–2025) with a forward forecast covering 2026–2032—documents a market that has more than doubled in momentum over the past half‑decade and is set to expand at a sustained compound annual growth rate of approximately 14.5% through the forecast horizon. This research synthesizes macro sizing, competitive dynamics, regulatory forces, and operational playbooks into a single, execution‑focused reference for CIOs, supply‑chain chiefs, and procurement leaders planning for 2026.
Cloud Logistics Software Market
Why this research matters for decisions in 2026
-
Investment timing and ROI: With rapid growth and rising vendor sophistication, enterprise buyers must align procurement windows, pilot cadences, and migration budgets to capture both short‑term efficiency and medium‑term strategic advantage.
Cloud Logistics Software Market -
Risk management: Escalating cloud hosting cost pressure and evolving regulatory requirements (data transfer documentation, AI transparency mandates, and heightened vendor risk expectations) are reshaping total cost of ownership and contractual terms.
Cloud Logistics Software Market -
Vendor selection and ecosystem planning: The market is large and growing fast, but remains only moderately concentrated—creating choices between integrated platform plays, best‑of‑breed specialists, and new entrants focused on AI or last‑mile orchestration.
Market trajectory and macro dynamics
Our topline sizing places the cloud logistics software market firmly in a high‑growth category as we enter 2026. After a period of accelerated adoption across transport management, warehousing, freight forwarding, and visibility services, the market’s baseline in 2025 provides the springboard for robust expansion through 2032—driven by rising e‑commerce volumes, omnichannel fulfillment complexity, and the application of AI/advanced analytics to network optimization.
Two external forces deserve special emphasis because they will materially affect vendor economics and enterprise deployment decisions in 2026:
-
Cloud hosting and infrastructure cost pressure: Major cloud and hardware suppliers signaled notable price adjustments in late‑stage 2025 and into 2026. Enterprises evaluating SaaS offers must treat host‑cost volatility as a line‑item risk when modelling multi‑year TCO and when negotiating pass‑throughs or fixed‑price elements in vendor agreements.
-
Regulatory and compliance tightening: GDPR enforcement continuity around cross‑border transfers, plus the operational demands of the EU AI Act for systems that process personal data, mean that buyers and vendors must now bake transfer impact assessments, SCC documentation, and model‑level transparency into contracts and implementation plans.
What the full report delivers (practical, operational, and boardroom ready)
PW Consulting designed this study to do more than describe trends; it is built to be applied. The full deliverable includes:
-
Topline market sizing and validated demand model (historical 2020–2025, forecast 2026–2032) with scenario stress‑testing for macroeconomic and cost‑inflation paths.
-
A market concentration and competitive landscape assessment enabling go‑to‑market targeting and M&A diligence, including CR3/CR5 concentration context to frame consolidation risk and white‑space opportunities.
-
Vendor scorecards and capability matrices mapping functional depth (TMS, WMS, freight forwarding, visibility), cloud‑native maturity, data fabric architectures, and partner ecosystems—useful for shortlisting and RFP design.
-
Implementation playbooks and migration roadmaps tailored to enterprise archetypes (global manufacturers, retailers, 3PLs, and asset‑light freight forwarders), including phased KPIs, integration patterns, and change‑management checklists.
-
Procurement templates: contract clauses for cloud cost pass‑throughs, service credits tied to delivery and event metrics, data governance and AI transparency obligations, and vendor exit/portability provisions.
-
Financial models and TCO templates (capex/opex tradeoffs, incremental margin impact, and sensitivity to hosting price inflation) that can be dropped into internal capital asks.
-
Security and compliance controls: zero‑trust architecture recommendations, third‑party risk assessment checklists, and operational controls aligned with current regulatory expectations.
Competitive landscape: how to read vendor differentiation
The vendor ecosystem in cloud logistics can be viewed through three pragmatic lenses: integrated ERP clouds, best‑of‑breed logistics suites, and specialist freight/forwarding platforms. Each category follows distinct commercial and technical tradeoffs buyers must weigh against their operating model.
-
Integrated ERP clouds (examples among incumbents): These providers leverage broad installed bases and offer end‑to‑end enterprise process continuity—from order to cash through logistics execution. Their strengths are in unified data models and single‑vendor support; tradeoffs include potential slower innovation cycles on logistics‑specific features and higher switching costs.
-
Best‑of‑breed logistics suites: Vendors focused on warehouse, transportation, and optimization bring deeper operational functionality and faster release cadences for logistics innovation. Their differentiation often lies in domain expertise, flexible deployment, and partner ecosystems for execution (carrier integrations, TMS/TM). However, integration effort and cross‑functional coordination are procurement considerations.
-
Freight‑forwarding and niche specialists: Platforms optimized for forwarding, customs, and cross‑border documentation deliver workflow efficiency and compliance strength for international trade flows. They can be attractive to freight forwarders and 3PLs but may require more extensive ERP interfaces for global shippers.
Notable competitive cues from recent market activity and our vendor review:
-
Longstanding logistics software vendors continue to defend enterprise footprints through integrated suites and ecosystem play—pushing customers toward bundled cloud‑managed offerings.
-
Cloud‑native, AI‑first entrants are accelerating capabilities for last‑mile orchestration and dynamic routing, intensifying competition in urban delivery and final‑mile SLAs.
-
Recognition and award activity among niche vendors underscores the continuing market appetite for specialized solutions that deliver rapid time‑to‑value in focused use cases such as freight forwarding and trade compliance.
-
Overall concentration metrics indicate meaningful market share for leading players, but enough fragmentation remains to permit strategic partnerships, regional champions, and acquisition opportunities.
Recent signals: product launches, recognition, and what they imply
Our monitoring of industry developments through early 2026 highlighted two signals worth noting for strategy teams:
-
A prominent last‑mile platform unveiled a unified AI‑driven logistics system that consolidates execution, analytics, and automation in a single cloud‑native stack—an explicit bet on bringing orchestration and optimisation closer to the delivery edge.
-
Specialist forwarding platforms continue to receive industry recognition for product maturity and customer satisfaction, emphasizing that vertical depth and executional fit still win deals, particularly for complex cross‑border flows.
Procurement and implementation counsel for 2026
Enterprises preparing to select or renew cloud logistics solutions in 2026 should institutionalize six practices immediately:
-
Treat hosting cost volatility as procurement risk—require transparent pass‑through mechanisms, caps, or multi‑year fixed elements where possible, and simulate cost shocks in TCO models.
-
Demand AI model documentation and risk assessments as part of RFP responses—this anticipates regulatory expectations and reduces downstream remediation costs.
-
Define composable integration boundaries—standardize on APIs and data models to avoid lock‑in and to enable best‑of‑breed composition.
-
Adopt zero‑trust and continuous monitoring requirements in security annexes, and make third‑party audit evidence a contractual prerequisite.
-
Prioritize early wins with focused pilots (e.g., route optimization, dock scheduling, customs automation) that generate measurable ROI within 6–9 months.
-
Preserve exit optionality—require structured data exports, runbook transfer support, and interoperability guarantees to safeguard future strategic pivots.
Strategic scenarios and recommended next steps
Based on our scenario modeling, enterprises should align vendor choices to one of three strategic paths:
-
Defensive consolidation: For firms seeking single‑vendor simplicity and deep ERP alignment, prioritize integrated clouds with defined roadmaps for logistics capability growth.
-
Operational differentiation: For companies competing on fulfillment speed and cost, adopt best‑of‑breed logistics suites and invest in API‑first integration and data fabrics.
-
Edge innovation: For urban delivery and last‑mile leaders, pilot AI‑driven orchestration platforms and develop carrier/partner networks that can be orchestrated through a single control tower.
Conclusion and how to use this briefing
This introduction provides the strategic framing enterprise leaders need to prioritize cloud logistics investments for 2026. The full PW Consulting report expands each of these themes with granular models, vendor scorecards, contractual language, and implementation templates that operational teams can use immediately. If your goal is to accelerate time‑to‑value while controlling cost and regulatory risk, the complete research package and downloadable tools will provide the practitioner‑level detail you need to act in 2026—without the need to reinvent frameworks or rebuild financial models from scratch.
To access the full dataset, segmentation models, and actionable playbooks referenced here, please consult the PW Consulting report portal for the Cloud Logistics Software Market 2026 edition.
For detailed analysis of this topic, please visit the official page: Cloud Logistics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity Tungsten Market to 2032 — USD 1,001.64M, 6.5% CAGR
By PW Consulting, 2026-07-13
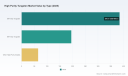
High Purity Tungsten Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest High Purity Tungsten Market study is designed as a decision‑grade intelligence package for corporate strategists, procurement leaders, and investors gearing up for the 2026 planning cycle. Built on a full historical series (2020–2025) and a forward forecast (2026–2032), the analysis combines a robust demand model, supply‑side mapping, and scenario stress‑tests to translate commodity dynamics into executable business options.
High Purity Tungsten Market
Why this study matters in 2026
-
Strategic inflection. The high purity tungsten market is transitioning from a niche industrial material into a strategic raw material for advanced electronics, semiconductor sputtering targets, and select aerospace/medical applications. That transition creates both volatility and structurally higher long‑term value—requiring distinct strategic choices for suppliers, consumers, and financiers.
High Purity Tungsten Market -
Policy and trade shocks. Recent policy moves—tariff increases and export controls—have altered supply economics and rendered previously robust sourcing strategies fragile. Procurement teams and corporate strategists must reconcile short‑term price volatility with longer term supply security objectives.
High Purity Tungsten Market -
Capital allocation decisions. With the market on a growth trajectory and increasing interest in upstream project development, 2026 is a pivotal year to decide on greenfield investments, offtake agreements, and M&A plays that will determine access to high‑purity feedstocks for the decade ahead.
Market snapshot — the macro view
Our macro model tracks the high purity tungsten market from roughly USD 462 million in 2020 to approximately USD 645 million in 2025, driven by stronger electronics demand and constrained feedstock flows. We project the market to expand at a compound annual growth rate (CAGR) of about 6.5% over the 2026–2032 forecast window, reaching roughly USD 1.0 billion by 2032 under the baseline scenario. These headline numbers mask significant structural shifts beneath the surface—changes in buyer concentration, grade mix, feedstock sourcing, and the role of geopolitical policy—that materially affect margin pools across the value chain.
Key market dynamics reshaping strategy
-
Feedstock tightness and price volatility. Ammonium paratungstate (APT), the primary intermediate for high purity production, experienced acute price moves driven by supply controls and trade measures—creating immediate margin pressure for processors and downstream buyers. Rotterdam and domestic price indicators tracked sharp increases through 2025–2026, underscoring the need for explicit raw‑material risk management in contracts and forecasting.
-
Regulatory and trade interventions. Major jurisdictional actions—most notably increased tariffs on imports from China in the U.S., and Chinese export controls on selected tungsten intermediates—have elevated the cost basis for cross‑border flows and accelerated regionalization of processing capacity. These interventions change commercial calculus for sourcing and capital projects and require continuous monitoring in supplier selection frameworks.
-
Supply response and new project pipeline. The supply side is responding: new mining production and advanced project developments in multiple jurisdictions, together with targeted public funding for domestic capacity in several markets, will change availability over the medium term. However, upstream lead times and metallurgy constraints mean that supply elasticity will remain limited in the near term.
-
Consolidation and concentration. The market exhibits moderate concentration: incumbent manufacturers and integrated material houses retain dominant shares of high‑purity manufacturing capabilities. This concentration supports pricing discipline but also raises counterparty risk for large raw‑material consumers.
What the PW Consulting report delivers (practical, operational modules)
-
Interactive demand model — build your own scenarios by application, purity grade, and procurement horizon (baseline, upside, downside).
-
Supply chain map — from concentrate to ultra‑high purity metal and finished components, identifying single points of failure and alternative routing options.
-
Price and feedstock sensitivity matrices — quantify margin exposure across realistic APT price trajectories and tariff permutations.
-
Regulatory watchlist and export‑control matrix — jurisdictional rules and likely policy pathways that impact trade flows and permitting timelines.
-
Company profiles and capability heatmap — strengths, technological differentiators, capacity footprints, and counterparty risk indicators (detailed supplier dossiers included for leading market participants).
-
Project evaluation templates — capex/opex heuristics, payback thresholds, and blended cost of supply models tailored for greenfield and brownfield investments.
-
Commercial playbooks — procurement levers, hedging blueprints, offtake negotiation frameworks, and M&A screening criteria focused on 2026 execution.
Competitive landscape — strategic reads on core participants
-
Elmet Technologies LLC (Lewiston, ME, USA) — Fully integrated U.S. manufacturer with reduction‑based powder making and downstream mill products. Elmet’s integration gives it defensible margin control and fast response times to North American demand surges. Strategic implication: attractive partner for short‑term offtake and for firms seeking to shorten supply lines, but scale limitations may constrain large program commitments without capacity expansion.
-
Buffalo Tungsten Inc. (Depew, NY, USA) — Independent specialist focused on ultra‑high purity powders and tungsten carbide powders. Buffalo’s product purity and niche customer relationships make it a preferred supplier for high‑value electronics work; however, independents remain exposed to feedstock cost shocks and freight disruptions.
-
Global Tungsten & Powders (GTP) — Plansee Group affiliate — A major integrated materials house with broad downstream capabilities, positioned to capture value across the chain (powder, chemicals, components). GTP’s global footprint and downstream product mix reduce single‑point exposure, making it a logical counterparty for OEMs seeking supply continuity and technical partnerships.
-
H.C. Starck / Plansee Group / A.L.M.T. / JX Nippon / Xiamen / Chongyi Zhangyuan / Masan High‑Tech — A mix of European, Japanese, Chinese and Southeast Asian manufacturers covering a range of technological capabilities—from specialty powders and wires to large‑scale powder production. The competitive set presents a spectrum of tradeoffs between cost, quality, speed, and geopolitical exposure. Strategic buyers must weigh price against security and qualification lead times for critical applications.
Recent developments that change the game
-
Project momentum in exploration and development has picked up—new staking and land expansions in North America and project approvals in Europe create optionality for future feedstock supply lines.
-
Trade and regulatory measures enacted since late 2024 and into 2025 have meaningfully tightened cross‑border flows of key intermediates and prompted buyers to re‑evaluate sourcing and inventory policies.
-
Public funding and strategic programs in mine jurisdictions are reducing some sovereign risk, but not eliminating short‑term price spikes driven by immediate constraints in processing and transport.
Actionable plays for corporate leaders in 2026
-
Adopt a two‑tier procurement strategy: secure a core of qualified, long‑term suppliers (to cover critical needs) and maintain a flexible margin of opportunistic purchasing to exploit spot dislocations.
-
Hedge selectively using contract structures that share raw‑material risk—indexation clauses, blended pricing corridors, and multi‑year offtake with escape provisions for extreme policy moves.
-
Prioritize qualification pipelines: accelerate qualification of alternative suppliers and regional sources (even at a premium) for mission‑critical components to shorten response time in supply shocks.
-
Assess vertical integration selectively: for manufacturers with scale, upstream processing or strategic equity stakes in concentrate projects can be accretive—model conservatively and stress‑test on delayed ramp scenarios.
-
Target bolt‑on M&A where it reduces counterparty risk or speeds time‑to‑market for higher‑purity grades; for investors, look for platform assets with repeatable processing technology and locked‑in offtake.
-
Invest in materials R&D that substitutes high‑cost grades or improves recovery—small improvements in yield or downstream processing can materially change unit economics over multi‑year production runs.
Why PW Consulting’s study is different
Beyond conventional market sizing, our study ties macro dynamics to micro decisions through an integrated demand/supply/risk model and an actionable toolkit for 2026. We combine granular supplier intelligence, a dynamic pricing sensitivity engine, and regulatory scenario mapping so that commercial, procurement, and corporate development teams can run "what‑if" strategies and produce investment‑grade outputs suitable for Board review.
Note: this briefing emphasizes strategic takeaways and constrained disclosure by design. Core subsegment tables, granular regional shares, and application‑level revenue splits are intentionally withheld from this public overview to preserve the report’s commercial integrity. Full access to the segmentation, supplier dossiers, and interactive models is available through the PW Consulting report portal.
Immediate next steps for readers
-
Procurement & Supply Chain leads — request the report’s procurement playbook and the supplier risk heatmap to incorporate into 2026 sourcing cycles.
-
Corporate Strategy & M&A teams — schedule a scenario workshop to test acquisition and investment hypotheses against our baseline and downside cases.
-
Investors & Project Developers — use the project evaluation templates and offtake framework to fast‑screen opportunities in the new supply pipeline.
For organizations that need to convert market signals into executable plans in 2026, this study provides the models, vendor intelligence, and tactical playbooks to act with conviction. Access to the full study, including the underlying segmentation tables, supplier dossiers, and the interactive forecast model, is available via PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recovered Carbon Black (RCB) Market to Grow at 11.5% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Recovered carbon black (rCB) has moved rapidly from niche sustainability pilots into a commercially material segment of the carbon black industry. Our PW Consulting Recovered Carbon Black Rcb Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—documents a clear, investment-grade growth trajectory: the rCB market expanded materially between 2020 and 2025 and is projected to compound at a double-digit clip (11.5% CAGR) into the early 2030s. By 2025 the market reached a level that demands serious strategic attention from tire makers, masterbatch formulators, coatings companies and raw-material traders; by 2032 the market is expected to be more than double the size it was in 2020.
Recovered Carbon Black Rcb Market
Why this matters for 2026 corporate strategy
-
Supply security & cost resilience: rCB introduces a new upstream vector that can reduce exposure to fossil-derived feedstock pricing cycles. For companies deciding 2026 procurement strategies, rCB supply agreements and feedstock partnerships can be structured to complement traditional carbon black sourcing while de‑risking long-term cost volatility.
Recovered Carbon Black Rcb Market -
Regulatory arbitrage and market access: policy moves—most notably European recognition of tire pyrolysis as a recovery process and the emergence of ISCC PLUS for circular carbon—create a compliance and commercial pathway for rCB to be treated as a non‑waste, tradeable input. Firms adjusting product specifications or sustainability claims in 2026 will need to embed certification prerequisites into procurement contracts.
Recovered Carbon Black Rcb Market -
Product strategy and margin management: rCB’s current material properties (purity levels that are lower than top‑grade virgin carbon black) create both opportunity and constraint. 2026 decisions will hinge on pragmatic product segmentation—where to deploy rCB blends without compromising performance, and where to retain virgin carbon black for high‑stress applications.
-
M&A and capex prioritization: the rCB value chain is consolidating but far from mature (market concentration shows leading groups do not yet dominate the sector). For corporates evaluating inorganic growth or greenfield investments in 2026, the market offers attractive bolt‑on and joint‑venture prospects, particularly for firms that can marry feedstock access to downstream integration.
Market trajectory — what the headline data says
Our modeling, which synthesizes historical data and primary interviews across the value chain, shows robust expansion from the early 2020s into the 2030s. After a multi‑year ramp from 2020 to 2025, the market’s compound annual growth rate during the forecast window points to sustained demand pull and accelerating commercialization. This macro momentum is driven by three structural forces: increasing tire and rubber recycling rates, industrial adoption for lower‑risk elastomer and non‑tire applications, and policy frameworks that reward circular inputs.
Competitive landscape — who to watch (and why)
The rCB competitive set is populated by technology‑led specialists and strategic initiatives from incumbent tyre and chemical players. Key profiles include:
-
Pyrolyx AG (Germany) — A commercial pyrolysis producer that has moved from demonstration to industrial production. Pyrolyx’s early plant commercialization provides practical evidence that scaled rCB supply can meet industrial reinforcement specifications, supporting integration strategies for downstream users.
-
Black Bear Carbon (Netherlands) / Michelin partnership — Backed by a major tire manufacturer, this operation is emblematic of the “buyer‑backed” approach to feedstock security and quality control. Strategic partnerships of this sort materially shorten commercialization timelines and reduce technical adoption risk for tyre makers.
-
Enviro AB (Sweden) — Focused on certification and compliance, Enviro’s attainment of circularity credentials demonstrates the importance of verified sustainability chains for market acceptance, especially in Europe.
-
Hi‑Green Carbon (India) — A lower‑cost regional producer whose ISCC‑certified production lines and proximity to feedstock pools illustrate the geographic arbitrage and trade flows that will shape regional supply dynamics.
Market concentration remains moderate: the top three and top five suppliers do not yet command an overwhelming share of the market, leaving room for new entrants and consolidation. That balance favors strategic buyers who can secure preferential supply or form joint ventures without paying monopoly premia.
Regulatory and technical dynamics impacting 2026 decisions
-
Regulatory recognition and certification: The EU Waste Framework’s treatment of pyrolysis outputs and the adoption of ISCC PLUS establish a compliance framework that allows rCB to be commercially used and marketed as circular. Companies planning 2026 product claims must lock in certified supply and ensure mass‑balance bookkeeping.
-
Purity and application scope: rCB purity presently sits below the highest‑performance virgin grades. This technical constraint will dictate a phased adoption: early wins will be in non‑critical rubber goods, some plastics/masterbatch formulations and selected coatings/inks, with gradual penetration into higher‑performance tire compounds as R&D advances.
-
Trade and tariffs: Regional fiscal treatments (including import duties in certain jurisdictions) will influence global sourcing strategies. These are tangible near‑term considerations for companies designing 2026 cross‑border procurement programs.
What our report delivers — practical outputs for 2026 action
The PW Consulting Rcb Market report is intentionally built for decision makers who need executable recommendations, not just high‑level commentary. Key deliverables include:
-
Global market model with scenario and sensitivity analysis—enabling buyers and investors to stress‑test demand, feedstock availability and price pathways without exposing proprietary segment splits in this preview.
-
Supplier due‑diligence and scorecard toolkit—covering technology maturity, certification status, feedstock security, and commercial reliability to accelerate vendor selection.
-
Procurement playbook—templates for offtake agreements, quality acceptance criteria, and contract provisions that incorporate certification and traceability clauses.
-
Commercial adoption roadmap—segment‑by‑segment go‑to‑market sequencing, pilot design checklists, and KPI frameworks to measure performance during 2026 rollouts.
-
CapEx and investment decision matrix—an interactive framework for evaluating greenfield vs. JV vs. supplier partnerships, with trigger thresholds for investment readiness calibrated to market growth and concentration dynamics.
-
Regulatory and certification checklist—practical steps to achieve ISCC compliance, engage with authorities and ensure claims are auditable across multiple jurisdictions.
Case actions for 2026 (recommended)
-
Secure short‑to‑mid term offtake: Negotiate staggered offtake volumes with certified suppliers to de‑risk supply while preserving optionality as product acceptance evolves.
-
Embed certification requirements: Make ISCC (or equivalent) certification a contractual condition for sustainability claims and corporate reporting.
-
Run targeted formulation pilots: Prioritize non‑critical rubber and plastics applications where rCB performance parity is closest, then scale into higher‑risk tire applications only after validated performance data and lifecycle assessments.
-
Design a blended sourcing strategy: Combine regional low‑cost producers with strategic local partners to balance price, logistics and regulatory exposure.
-
Allocate a small strategic M&A war chest: Use it to secure minority stakes in technology‑proven producers or recycling networks that provide privileged access to feedstock.
Where the uncertainty lies—and how the report helps
-
Feedstock price volatility and competition for scrap tires: Increased recycling demand can drive feedstock costs. Our forecast scenarios quantify impacts on margin and recommend hedging and vertical integration strategies.
-
Technical parity with virgin carbon black: Current purity gaps limit some tyre tread applications. The report includes an R&D prioritization guide and blending decision matrix to minimize performance tradeoffs.
-
Policy tailwinds and trade friction: Divergent regional treatments create both arbitrage and compliance complexity; our regulatory matrix maps actions by jurisdiction to keep 2026 strategies compliant and efficient.
Final thoughts — the 2026 strategic inflection
Recovered carbon black is no longer a speculative sustainability experiment; it is a maturing industrial commodity with clear pathways to scale and meaningful implications for cost structures, product positioning and sustainability claims. The macro indicators point to rapid expansion through the remainder of the decade, but the commercial story will be written in 2026 by firms that move from assessment to disciplined operational execution—locking in certified supply, proving formulations in prioritized applications, and using structured procurement and investment frameworks to capture upside while managing purity and regulatory constraints.
Next step
This briefing is a curated preview designed to help senior leaders frame 2026 choices. Our full PW Consulting Recovered Carbon Black Rcb Market report contains the granular forecasting, supplier performance benchmarking, contractual templates and scenario models you will need to operationalize the recommendations above. Visit the report page to access the complete dataset, downloadable toolkits and supplier matrices that support immediate execution.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micro System Analyzer Market to Hit USD 431.2M by 2032 at 8.36% CAGR
By PW Consulting, 2026-07-13
Micro System Analyzer Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
The Micro System Analyzer (MSA) market sits at an inflection point. After a steady recovery and expansion through the early 2020s, the global market escalated from a modest base in 2020 to a substantially larger industry by 2025, and our forecast shows continued acceleration through 2032. PW Consulting’s baseline model projects a compound annual growth rate (CAGR) of 8.36% across the 2026–2032 forecast horizon, reflecting rising demand for non‑contact optical characterization, tighter product qualification cycles, and broader adoption across high‑value end markets. In absolute terms, the market nearly doubles over the next several years under our central scenario, driven by technology maturation, higher test-throughput requirements at wafer and device level, and expanding applications that demand precise dynamic and topographic measurement.
Micro System Analyzer Market
Why this research matters for 2026 corporate decisions
-
Timing for capital allocation: An 8%+ structural growth trajectory means executives must decide whether to accelerate capital deployment in test equipment, or to pursue capacity-light options (contract test services, partnerships) to capture growth without over-investment.
Micro System Analyzer Market -
R&D and product roadmap prioritization: As measurement capabilities move from single-point probing to integrated, non-contact optical workstations, product teams must weigh embedding measurement-friendly features (test hooks, design-for-measurement) against system cost and manufacturability tradeoffs.
Micro System Analyzer Market -
M&A and partnership strategies: A market with noticeable concentration at the top creates premium for bolt-on capabilities—companies can buy optics competency, software analytics, or expand into wafer-level quality assurance through targeted acquisitions or co-development agreements.
-
Regulatory and reimbursement posture for medical applications: Non-contact dynamic characterization is gaining acceptance in medical device development workflows. Decision makers in med‑tech need to integrate validated measurement protocols early to shorten clinical and regulatory cycles.
What PW Consulting’s Micro System Analyzer Market report delivers
Our study is designed as a practical playbook for leaders making investment, product, and market entry decisions in 2026. The report combines proprietary market sizing and scenario-driven forecasts with market structure diagnostics and tactical tools for execution. Highlights include:
-
A transparent market model—historical time series (2020–2025) and forward-looking scenarios for 2026–2032—allowing financial planners to stress test capital plans against upside/downside demand trajectories.
-
Technology deep dives that decode performance envelopes (frequency, spatial resolution, throughput) and map product families to typical use cases (R&D, wafer‑level inspection, reliability testing).
-
Action-oriented go‑to‑market modules—buyer personas, procurement decision trees, and commercial playbooks for OEMs, test houses, and academic labs.
-
Competitive benchmarking and capability matrices that identify where incumbents dominate and where white‑space exists for new entrants or adjacent players.
-
Investment and M&A scoring tools that rank targets against integration risk, time‑to‑market contribution, and margin accretion potential.
-
Risk registers and mitigation roadmaps covering supply chain fragility, software validation, and evolving regulatory scrutiny—especially for biomedical applications.
To preserve the value of the dataset for our subscribers, this public overview purposely omits granular regional and application segment figures. The full report includes those breakdowns alongside downloadable financial models and primary‑research transcripts.
Competitive landscape: focus on Polytec and market structure
Market structure matters for strategy. Our concentration analysis indicates the market is neither highly fragmented nor monopolized—top vendors capture a meaningful share of demand, creating advantages in scale, installed base, and aftermarket services. That balance produces both stability for incumbent margins and windows of opportunity for innovative entrants.
Polytec GmbH emerges as the most visible incumbent in the MSA category. The company’s MSA series—positioned as all‑in‑one, optical, non‑contact workstations—serves static and dynamic three‑dimensional characterization needs across MEMS and microsystems development. Key strategic implications from Polytec’s footprint:
-
Product breadth and depth: Polytec’s lineup spans instruments optimized for high‑frequency vibration analysis through to comprehensive surface topography mapping. For buyers, this creates a compelling single‑vendor option for multi‑stage workflows (R&D → wafer test → reliability).
-
Clinical and biomedical relevancy: Polytec explicitly supports non‑contact characterization of biomedical samples and medical MEMS devices. For med‑tech firms, the ability to validate dynamic behavior without mass loading is a material advantage for device verification and regulatory filing strategies.
-
Channel and service moat: Mature instrumentation vendors like Polytec typically benefit from installed‑base lock‑in via calibration, software updates, and training—elements that increase switching costs for key R&D and production customers.
-
Competitive posture: New entrants should plan to undercut incumbents on either cost or data‑centric features (analytics, integration with PLM/ALM systems). Incumbents will likely respond by deepening software ecosystems and expanding test services.
Key market dynamics and risks to model into 2026 planning
-
Adoption versus commoditization: As optical and data‑processing components scale, certain measurement functions may commoditize, compressing hardware margins but raising value of software and services.
-
Regulatory tailwinds and constraints: Non‑contact measurement supports medical device validation without introducing measurement artifacts—a strategic benefit—but it also introduces scrutiny over traceability and validation protocols. Companies must prepare for tighter documentation and auditability in clinical pathways.
-
Supply chain concentration: Specialized opto‑electronic components and high‑precision mechanics remain concentrated among a handful of suppliers. Procurement strategies should include multi‑sourcing or long‑lead contracting for critical parts.
-
Consolidation dynamics: Given meaningful share captured by leading vendors, strategic acquisition activity is likely around software analytics, automated inspection integration, and wafer‑level throughput improvements.
2026 playbook: recommended actions for executives
-
Integrate measurement strategy into product design cycles. Treat non‑contact characterization capabilities as first‑class design requirements to reduce iteration and accelerate qualification.
-
Prioritize pilot deployments with clear KPIs. Run small, cross‑functional pilots that pair MSA vendors with manufacturing test engineers to validate throughput, yield impact, and process integration before scaling procurement.
-
Hedge hardware risk by buying modularity. Specify instruments with modular optics and upgradeable software so you can extend useful life and protect against early obsolescence.
-
Evaluate M&A or partnership for rapid capability acquisition. For those seeking near‑term entry into wafer‑level testing, acquiring analytics or service capabilities offers faster path to market than in‑house development.
-
Lock in regulatory certainty early. For medical device programs, mandate validated measurement protocols and traceable calibration practices during preclinical stages to de‑risk later submission delays.
How to use this report in Q1 2026
Leadership teams should treat the report as an execution tool rather than a theoretical brief. Immediate uses include: model-driven capital budgeting that ties equipment buys to revenue scenarios; configuration checklists for procurement that articulate must‑have technical specs; target lists for M&A screening; and regulatory playbooks for medical device qualification. Each deliverable in the report is paired with templates—RFP language, ROI calculators, and pilot test plans—to move from decision to deployment within a single fiscal quarter.
Conclusion and next steps
The Micro System Analyzer market offers disciplined growth and strategic leverage for organizations that decide early and design measurement strategy into their product and production lifecycles. PW Consulting’s research synthesizes market sizing, technology assessment, competitive insight, and executable playbooks to shorten the path from insight to impact in 2026.
Note: this overview highlights our core findings while intentionally withholding the granular regional and application split data and downloadable financial models that subscribers receive. To access the full dataset, vendor matrices, and the scenario financial model that powers our CAGR and forecast, please visit the report landing page or contact PW Consulting’s industry practice for a demo and sample worksheets.
For detailed analysis of this topic, please visit the official page: Micro System Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


