



Category: market research
PW Consulting: Animal Feed Ingredients to hit USD 52.9B by 2032 at a 3.6% CAGR
By PW Consulting, 2026-07-12
Animal Feed Ingredients Market 2026: Strategic Briefing for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing designed to equip C-suite and business-unit leaders with the strategic context they need to make high-confidence decisions in 2026. Our full Animal Feed Ingredients Market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — synthesizes hard market sizing, competitive dynamics, regulatory shifts, and raw-material risk to convert market intelligence into executable options. The market we track expanded from roughly USD 29.7 billion in 2020 to about USD 41.3 billion in the 2025 base year, and it is forecast to grow at a compound annual growth rate of 3.6% toward the 2032 horizon (reaching an estimated USD 52.9 billion). This macro trajectory frames the near-term choices executives must confront in 2026.
Animal Feed Ingredients Market
Why this briefing matters for 2026 decisions
-
Timing and resource allocation: With the market in a mid-cycle growth phase, managers face trade-offs between volume-led expansion and margin-protection investments (e.g., precision additives, quality assurance, logistics). Our study clarifies the return profiles of those alternatives under multiple price and regulation scenarios.
Animal Feed Ingredients Market -
Innovation window: Recent regulatory acceleration in several jurisdictions has shortened approval timelines for microbiome- and emissions-related additives, compressing the window for first-mover advantage. Companies that strategically align R&D, regulatory affairs, and commercialization will capture disproportionate value from premium additives and differentiated formulations.
Animal Feed Ingredients Market -
Supply-chain choreography: Volatility in grains and oilseed markets, coupled with evolving trade policy in priority export markets, means procurement strategy is now a competitive lever rather than a back-office function. Executives must decide whether to double down on vertical integration, secure offtakes, or diversify supplier bases in 2026.
Topline market dynamics
The animal feed ingredients market shows resilient, steady growth: from roughly USD 29.7 billion in 2020 to USD 41.3 billion in our 2025 base year and continuing upward to an estimated USD 52.9 billion by 2032 under our central-case projection (CAGR ~3.6%). This is not a hyper-growth theme, but it is large, strategic, and increasingly sophisticated — where incremental improvements in feed conversion, animal health, and regulatory compliance translate directly into meat, dairy, and aquaculture producers’ margins.
Three structural forces shape outcomes in 2026:
-
Cost pass-through pressure and raw-material cycles: Grain and oilseed price dynamics remain the primary determinant of short-run margin swings for conventional ingredient classes. Commodity prices moderated in 2025, and 2026 projections show continued stability in certain grains — an opportunity for processors and integrated suppliers to optimize mix and capture margin.
-
Shift from commodity to specialty: Growth in value-added feed additives, enzymes, amino acids, and targeted premixes is outpacing commodity volumes in many channels as producers seek productivity and sustainability gains. Regulatory facilitation of microbiome-focused solutions further accelerates adoption.
-
Regional policy inflections: Trade and fiscal policy moves in key import and export markets are re-shaping logistics economics — creating new export corridors while compressing margins in previously protected niches.
Regulation and raw-material signals you cannot ignore in 2026
-
Shortened approval timelines for gut- and emissions-focused inputs: A recent regulatory initiative has materially reduced time-to-market for products that meaningfully alter the gut microbiome or reduce enteric emissions. For strategy teams, this changes pipeline prioritization — invest in categories with accelerated approval and first-to-market potential.
-
Grain and oilseed pricing context: Stable-to-moderate grain prices observed in 2025 and similar 2026 projections create a favorable backdrop for demand recovery in sensitive livestock segments. However, soybean meal price volatility remains a persistent input risk; hedging and diversified sourcing should be part of any procurement playbook.
-
Trade policy shifts: Fiscal and tariff policy changes in selective emerging markets are opening up export opportunities and altering landed cost calculations. Firms with nimble commercial teams can exploit these short-term arbitrage windows to secure new customers and long-term contracts.
What the full report delivers (practical, executable content)
PW Consulting’s comprehensive report is designed to be immediately operational for strategy, commercial, and procurement teams. Highlights include:
-
Top-down and bottoms-up market sizing with historical validation and scenario-based forecasts to 2032 — enabling capital planning and revenue targets aligned to market trajectories.
-
Product and channel playbooks that translate technical ingredient trends (from commodity to specialty) into commercial tactics for pricing, bundling, and field support.
-
Regulatory impact matrix and go/no-go decision trees for product registration and market entry, reflecting shortened approval timelines for microbiome and emissions innovations.
-
Raw-material sensitivity models and procurement options analysis (hedging, vertical integration, strategic offtake), calibrated to recent grain and oilseed price paths.
-
Competitive heatmaps, capability benchmarking, and M&A candidate screens to inform inorganic growth strategies and partnership prioritization.
-
Client-ready slide decks and an executive dashboard for ongoing monitoring of price, policy, and demand indicators.
Competitive landscape — what to watch in 2026
The market displays moderate concentration: the top three players account for a little over half of global revenue, while the top five capture roughly two-thirds. This structure creates a balance — large incumbents retain scale economics and distribution reach, while mid-sized and specialty players lead on innovation and niche solutions. For 2026, the following competitive moves merit attention:
-
Scale players (global traders and processors): Firms with upstream origination and processing capabilities continue to leverage logistics and distribution networks to secure volume contracts and stabilize supply. Investments in regional production assets remain a key defensive and offensive lever.
-
Specialty ingredient and additive firms: Companies focused on enzymes, amino acids, probiotics, and mycotoxin solutions are the primary innovation engines. Their agility in registrational pathways and formulation expertise positions them to capture premium value as producers shift toward productivity-enhancing inputs.
-
Integrated animal nutrition divisions: Vertically integrated feed companies and divisions of larger agri-business players are experimenting with bundled offers (ingredients + premixes + advisory services), seeking to lock in lifetime customer value.
Notable corporate developments in the recent 12–18 months illustrate these dynamics. Strategic acquisitions in specialty additives have consolidated capabilities in gut health and mycotoxin mitigation, while partnerships and capital infusions into animal nutrition businesses reinforce the focus on scale plus innovation. Investments in regional manufacturing assets — exemplified by new, high-capacity feed plants — demonstrate that global players continue to optimize local supply footprints to serve fast-growing consumption corridors.
Operational and M&A implications for 2026
-
Prioritize capability fills over broadscale M&A: In a market where regulation accelerates category adoption, acquiring specific formulation, regulatory, or application expertise is often higher-return than chasing topline expansion via commodity bets.
-
Optimize go-to-market by livestock segment: Different livestock classes react to price and productivity levers in distinct ways. Tailored commercial models — from performance-based contracts to bundled advisory services — will prove decisive.
-
Secure supply: Use a mix of long-term contracts, strategic stocks, and selective integration to manage commodity cycles. For 2026, locking favorable offtakes in regions where fiscal changes remove import frictions presents an immediate arbitrage opportunity.
-
Pivot R&D roadmaps: Re-allocate a portion of R&D budgets toward microbiome and emissions-reducing solutions that now face shortened regulatory pathways. Fast-follower strategies can work where first-mover clinical data is scarce but registration is expedited.
Three actionable recommendations for 2026
-
Implement a short-cycle product commercialization track: Create a fast-track path that coordinates regulatory, manufacturing scale-up, and field trial teams to exploit accelerated approval windows for targeted additives.
-
Undertake a targeted supplier diversification program: Identify two to three strategic suppliers per major input category and negotiate mixed hedging/profiled contracts to reduce P&L volatility without sacrificing flexibility.
-
Build partnership and bolt-on acquisition pipelines: Focus on specialty players with differentiated science and registrational momentum; these assets are both defensive (protecting margin) and offensive (driving premium product sales).
Conclusion — how to use this intelligence in 2026
The animal feed ingredients market in 2026 is a large, steady-growth arena where marginal improvements in product performance, regulatory agility, and supply resilience compound into sizable commercial advantage. Executives who combine disciplined procurement, targeted innovation investment, and selective inorganic moves will secure outsized returns. PW Consulting’s full report provides the granular, proprietary segmentation, supplier profiles, and scenario tools necessary to operationalize the strategies summarized here — including the region- and ingredient-level detail and financial models that we intentionally reserve for the full product.
For teams preparing budgets, evaluating acquisition targets, or refreshing product roadmaps this year, the report is designed to be a decision-ready playbook: not just what’s happening, but what to do next. Visit our report page to access the complete dataset, interactive dashboards, and bespoke advisory options that will convert insight into 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Animal Feed Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Native Starches Market Reaches USD 24.71 Billion in 2025
By PW Consulting, 2026-07-12
Native Starches Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare strategy roadmaps for 2026, native starches sit at the intersection of food innovation, industrial reformulation, and sustainability-driven supply chain transformation. PW Consulting’s forthcoming Native Starches Market study (base year 2025; forecast 2026–2032) synthesizes market dynamics, competitor moves, and risk vectors into an actionable framework for C-suite and corporate development teams. This preview outlines the strategic value of the full study, highlights the high-level market trajectory, and summarizes competitive and operational flashpoints that will determine winners in the next planning cycle — while preserving the granular segment intelligence available in the full report.
Native Starches Market
Why this study matters for 2026 decision-making
-
Clear market momentum: Between the historical window and the forecast horizon, the native starches market exhibits steady expansion underpinned by demand in food and adjacent industrial applications. The study’s baseline shows multi-year growth culminating in a robust outlook through 2032, driven by product reformulation, label-friendly ingredient demand, and selective industrial uptake.
Native Starches Market -
Actionable foresight for capital allocation: With a compounded annual growth rate of approximately 5.05% across the forecast window, the market is neither commodity-tame nor hyper-volatile — a profile that favors disciplined capacity investments, targeted R&D, and partnership-led expansion over indiscriminate greenfield buildouts.
Native Starches Market -
Competitive and regulatory inflection points: Fragmented market structures, certification trends, and raw-material cost variability create pockets of premium opportunity (e.g., label-friendly, non-GMO, sustainably certified starches) and downside risk (emissions, compliance, input-price shocks). The report prioritizes these themes for 2026 planning cycles.
Market trajectory at a glance
PW Consulting’s consolidated market model charts a recovery-and-growth arc. The market expanded through the early 2020s, accelerating toward the 2025 baseline. From that base, our forecast anticipates steady growth through 2032, driven by incremental gains across food, industrial, and specialty use-cases. The model is built from bottom-up demand drivers, price and volume scenarios, and supply-side capacity adjustments — producing a mid-case consistent with the ~5% CAGR noted above. Readers should treat this preview as directional; the full report contains the underlying sensitivity analyses and scenario permutations used to derive the headline projection.
What’s in the full report — practical content for executives
-
Executive dashboard: concise KPIs, market sizing and growth drivers, and three investment-case archetypes for roll-up decisions in 2026 (capacity-led, specialty-led, or channel-led).
-
Methodology and data appendix: transparent sourcing, modeling assumptions, and reconciliation of global trade versus domestic consumption flows for robust valuation work.
-
Segment playbooks: go-to-market playbooks for core product types and end-use clusters, with recommended pricing strategies, technical dossier checklists, and customer segmentation matrices.
-
Supply chain deep dives: supplier maps, procurement levers and hedging templates, cold-chain and processing bottleneck analysis, and a procurement playbook tailored to agricultural-commodity input risk.
-
Regulatory & sustainability toolkit: certification pathways (including renewable-carbon and mass-balance schemes), emissions compliance checklists, and cost-benefit analysis for sustainability investments.
-
Competitive intelligence: company profiles, recent developments, an M&A radar, and a 12–24 month action calendar you can apply directly to business development and investor outreach.
-
Scenario & sensitivity analyses: upside and downside market scenarios tied to raw-material price shocks, substitution trends, and rapid adoption of label-friendly alternatives.
Competitive landscape — what incumbents and challengers are doing
The native starch arena is characterized by a mix of global ingredient houses, regionally strong cooperatives, and specialized processors. Overall market concentration remains modest; leading groups do not fully dominate the space, leaving room for agile competitors and niche specialists to capture premium segments. The CR3 and CR5 metrics we track underscore a marketplace where scale matters for raw-material access and cost-efficiency, but where differentiation and technical capabilities deliver outsized margins.
-
Cargill, Incorporated — A large-scale integrator with broad native-starch capabilities across multiple botanical sources. Cargill’s strength lies in its upstream raw-material footprint and its ability to integrate starch offerings into broader food-ingredient platforms for texturizing and thickening.
-
Roquette Frères — A major product innovator with a wide native starch portfolio and a strategic tilt toward label-friendly and plant-based credentials. Recent product introductions and certification achievements evidence Roquette’s push into differentiated native starch formats tailored to confectionery and coating applications.
-
AGRANA Beteiligungs AG — A producer focused on potato, corn, and wheat pathways, recently active on capacity expansion through partnership models. AGRANA’s joint-venture approach illustrates how mid-sized processors can scale selectively to serve European and export markets.
-
Emsland Group, Royal Avebe, KMC Ingredients, and MGP Ingredients — Collectively, these companies represent the cooperative and specialist cohort, leveraging botanical expertise and regional supply chains to serve both food and industrial needs with focused portfolios.
These profiles demonstrate three broad competitor archetypes: integrated multinationals that prioritize scale and cross-product bundling; specialty processors that win on botanical or process expertise; and cooperative models that secure raw-material reliability. Each archetype implies distinct strategic levers for 2026 — from vertical integration and long-term supply contracts to premium product development and co-investment with growers.
Recent developments that shape 2026 tactics
-
Product innovation is accelerating. A notable example is the launch of thermally soluble, label-friendly starches designed for confectionery and coatings — a category that opens reformulation opportunities for FMCG manufacturers seeking cleaner labels without sacrificing functionality.
-
Certification and sustainability credentials are becoming table stakes. Leading producers are securing renewable-carbon and mass-balance certifications to access sustainability-driven procurement programs and to mitigate buyer-level ESG risk.
-
Capacity expansion via partnerships: joint ventures and capacity-sharing agreements indicate a preference for capital-light scaling when demand is uncertain. Such structures are efficient ways to increase throughput while preserving financial flexibility.
-
Compliance and legacy environmental liabilities remain an operational risk. Historical regulatory actions in related processing segments serve as reminders that emissions and permitting exposures can carry balance-sheet and reputational costs if not proactively managed.
Operational levers for 2026 — what we recommend
-
Prioritize product differentiation over scale-first plays. Invest in label-friendly formulations and specialty botanical formats where margin expansion is demonstrable.
-
Lock in raw-material security with hybrid sourcing: combine long-term contracts, local cooperative partnerships, and strategic inventory buffers to reduce exposure to agricultural volatility.
-
Make certification a commercial enabler. ISCC-style and similar certifications are increasingly embedded in buyer specs; the incremental cost of certification often pays back through access to higher-margin customers.
-
Evaluate partnerships for capacity flexibility. JVs and tolling arrangements offer a lower-risk path to expand capacity into new geographies or product formats.
-
Embed emissions and compliance due diligence into M&A and capex approvals to avoid legacy liabilities that erode ROI.
-
Run a price–volume sensitivity analysis for product portfolios to understand margin resilience under input-price spikes — and design pass-through mechanisms for key customers.
How PW Consulting supports execution
Our full Native Starches Market study is designed as an execution tool, not just an analytical document. Clients receive modular deliverables that can be deployed directly into investment committees, procurement negotiations, or R&D prioritization workshops. Deliverables include a one-page investment memo, a 12-month commercialization sprint plan, supplier scorecards, and a tailored risk-heatmap aligned with corporate risk tolerances.
This preview intentionally omits the granular regional and application-level split tables, price-by-origin matrices, and the full company-level financial comparatives that our subscribers rely on for transaction and operational work. Those elements are available within the full report package to preserve the commercial value of proprietary modeling.
Next steps — using the preview to inform 2026 plans
-
Use the headline CAGR and trajectory to update medium-term demand assumptions in your strategic planning cycle, replacing ad-hoc estimates with a scenario-based approach.
-
Leverage competitor archetypes to stress-test your capability gaps: where do you compete on scale, where do you compete on specialty, and where should you consider partnerships?
-
Institute a short-term tactical plan (90–180 days) to shore up raw-material sourcing and to scope certification projects that can be operational by late 2026.
-
Contact PW Consulting for an executive briefing and a customized extraction of the report’s playbooks — including the confidential segmentation tables and price-sensitivity models that will be decisive for M&A and capex decisions.
In sectors where small formulation benefits compound across thousands of SKUs, having the right market intelligence is the difference between margin recovery and margin erosion. PW Consulting’s Native Starches Market study gives you that intelligence packaged for decision-making in 2026 — rigorous, operational, and calibrated to the realities of agricultural sourcing and ingredient innovation.
For detailed analysis of this topic, please visit the official page: Native Starches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AWG Market to Reach USD 300 Million by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-12
Arrayed Waveguide Grating (AWG) Market: Strategic Outlook for 2026 Decision‑Makers
As AWG-enabled photonics moves from niche telecom applications into mainstream data‑center interconnects, coherent optics, and integrated photonic platforms, 2026 will be a pivotal year for corporate strategy. This briefing — drawn from PW Consulting’s latest AWG Market research (base year 2025; historical 2020–2025; forecast 2026–2032) — synthesizes the practical intelligence executives need to convert technical signals into commercial advantage.
Arrayed Waveguide Grating (AWG) Market
Data‑driven snapshot you can act on
-
Measured in USD (Million), the AWG market expanded materially through the early 2020s, growing from the low‑hundreds of millions to a base‑year size of USD 170 Million in 2025.
Arrayed Waveguide Grating (AWG) Market -
Our forecast horizon (2026–2032) assumes a compound annual growth rate (CAGR) of 8.5%, with the market tracking toward an approximate USD 300 Million size by 2032 under the base scenario.
Arrayed Waveguide Grating (AWG) Market -
Market concentration remains moderate: the top three suppliers account for roughly 30% of global share, while the top five reach about 45% — a structure that favors nimble specialists and opportunistic consolidation alike.
These headline metrics are intended to inform capital allocation, product roadmaps, and M&A screening in 2026. The full report contains the granular segmentation, pricing bands, and channel economics required to convert these directional numbers into executable plans.
Why this research matters for 2026 decisions
-
Standards and regulation are converging on AWG performance thresholds. Recent standards work (e.g., channel grids and spacing) and operator specifications for insertion loss and crosstalk are establishing pass/fail gates that will determine which modules scale in hyperscale deployments.
-
Thermal management is a commercial battleground. Athermal AWG solutions remove active temperature control from the bill of materials and operations, creating a durable OPEX advantage for outdoor and uncontrolled environments. The implications span product engineering, procurement, and field operations.
-
Manufacturing complexity and labor intensity remain high. Wafer‑scale AWG fabrication requires cleanroom capacity, specialized photonic engineers, and strict process control — a barrier that constrains rapid commoditization and shapes supplier selection.
-
Growth is uneven across end‑use drivers. Internet backbone upgrades, data center interconnects, and enterprise optical fabric programs are each on different adoption curves. Strategic planners must align product features (e.g., channel spacing, athermal behavior, uniformity) with the precise requirements of target use cases.
Key dynamics shaping 2026–2032
-
Standards alignment: ITU‑T grids and Ethernet developments (e.g., large‑bandwidth datacenter optics) are driving demand for specified channel spacings and filter performance. Suppliers that pre‑qualify products to these standards shorten buying cycles and reduce qualification risk.
-
Regulatory and procurement requirements: Data center interconnect specifications increasingly mandate low insertion‑loss uniformity and stringent crosstalk limits for cascaded AWG chains. These technical barometers are now commercial gates for hyperscalers and telecom operators.
-
Technology tradeoffs: Substrate choice (silica, PLC, polymer, silicon photonics) defines the trade space: cost, thermal behavior, channel density, and integration potential. Different substrates appeal to different buyers — and companies that can span more than one technology stack have new cross‑selling opportunities.
-
Manufacturing and supply risk: High precision fabrication concentrates value around foundries with appropriate tooling and skills. Outsourcing strategies, IP protection, and dual‑sourcing are critical levers for manufacturing‑heavy players.
Competitive landscape — what to watch in 2026
The AWG supplier ecosystem is composed of distinct archetypes: silicon‑photonics integrators, PLC and silica module specialists, polymer/SoS athermal vendors, and niche optics houses. Below we summarize strategic postures for key players featured in our global coverage.
-
Aloe Semiconductor (Middletown, NJ, USA) — Focused on silicon photonic integrated circuits that embed AWG functions alongside active components. Strengths: integration density, roadmap alignment with coherent optics and transceiver OEMs. Strategic risks: foundry dependences and thermal sensitivity at scale.
-
Bright Photonics (Eindhoven, Netherlands) — IP and prototyping specialist offering AWG cores and modules for custom foundry runs. Strengths: rapid prototyping, access to European photonic ecosystems, and IP flexibility. Strategic play: act as an innovation bridge between universities/foundries and systems OEMs.
-
Agilechip Photonics (Zhongshan, China) — Manufactures PLC‑based AWGs, including athermal variants for DWDM, CWDM, and data‑center optics. Strengths: manufacturing scale and cost competitiveness in high‑volume segments. Watch: globalization efforts and customer qualification timelines outside local markets.
-
SENKO Advanced Components (Japan) — Producer of polymer and SoS athermal AWG modules with a focus on DWDM mux/demux uniformity. Strengths: field‑proven athermal designs and strong OEM relationships in Asia. Opportunity: lead in outdoor/uncontrolled deployments where OPEX matters most.
-
AC Photonics (United States) — Silica‑on‑silicon athermal AWG specialist targeting 100/150 GHz DWDM coherent markets. Strengths: high channel uniformity and alignment to coherent telecom requirements. Strategic runway: move up the value chain into subsystem integration for coherent transceivers.
-
engionic Fiber Optics (Germany) — Niche high‑performance photonic component specialist. Strengths: deep engineering capabilities and tailored solutions for demanding optical subsystems. Strategic fit: attractive partner for customized, high‑margin applications.
Collectively, these players demonstrate the sector’s heterogeneity: technology specialization, geography, and business model diversity. For buyers and investors in 2026, supplier selection will hinge on technology fit, qualification velocity, and the supplier’s ability to manage manufacturing and supply risk.
What PW Consulting’s full report contains (practical deliverables)
-
Market sizing and forward forecasts (2026–2032) with scenario sensitivity analyses that stress test CAGR assumptions against supply disruptions, standard shifts, and hyperscaler adoption — enabling realistic upside/downside planning.
-
Segmented demand drivers by use case, with a procurement playbook for qualifying AWG modules against operational KPIs (including insertion loss uniformity and crosstalk thresholds mandated by data center specifications).
-
Technology maps that compare substrate tradeoffs (silicon photonics, silica, PLC, polymer/SoS), product roadmaps, and cost drivers to inform product‑level decisions and make/buy debates.
-
Supplier scorecards, benchmarking, and a prioritized M&A target list — with commercial due diligence templates and red‑flag indicators for intellectual property, foundry access, and qualification backlog.
-
Operational guidance: sample RFP language, test‑plan checklists tethered to IEEE/ITU‑T norms, and capex/OPEX models that quantify the lifetime savings of athermal modules in uncontrolled environments.
-
Scenario playbooks for 2026 procurement cycles: supplier negotiation levers, dual‑sourcing roadmaps, and pilot program designs to de‑risk deployment at scale.
Actionable recommendations for 2026
-
For OEMs and subsystem integrators: prioritize athermal solutions where the lifetime energy and thermal management cost outweigh incremental BOM savings. Pre‑qualify at least two substrate technologies to avoid single‑technology risk.
-
For hyperscalers and carriers: insist on supplier compliance to industry performance gates and include staged acceptance tied to field metrics (insertion loss, crosstalk) to accelerate vendor accountability.
-
For investors and private equity: target consolidation candidates that own differentiated IP or exclusive foundry access. The market’s CR3/CR5 profile indicates room for bolt‑on value creation without competing on low‑margin commoditized products.
-
For foundries and contract manufacturers: invest in wafer‑scale process control and workforce development — these are persistent supply constraints that will command premium contracting terms with OEMs.
Intentional withholding — why you should read the full study
In keeping with our “trailer” approach, this article deliberately highlights strategy, dynamics, and actionable themes while withholding granular subsegment tables, regional breakdowns, and unit‑price banding that are essential for procurement negotiation and precise financial modeling. The full PW Consulting AWG Market report supplies those confidential line items, detailed supplier cost models, and buyer‑specific scenario outputs to convert strategic intent into executable plans.
Next steps
-
Use the high‑level intelligence here to set internal priorities for 2026 (standards alignment, athermal pilots, supplier due diligence).
-
Engage PW Consulting for a tailored briefing that maps the report’s granular data to your product roadmap, procurement calendar, and M&A thesis.
AWG technology is no longer a peripheral component — it is a gating factor for future optical architectures. In 2026, the right combination of standards readiness, manufacturing resilience, and product differentiation will separate leaders from followers. PW Consulting’s full study provides the segmented facts and decision tools you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Arrayed Waveguide Grating (AWG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vehicle-to-Grid (V2G) Market 2026: Strategic Imperatives for Corporates — A PW Consulting Preview
As the energy transition accelerates, Vehicle-to-Grid (V2G) has moved from niche pilots to the threshold of commercial scale. Our PW Consulting Vehicle-to-Grid Market study (base year 2025) synthesizes quantitative forecasting, policy overlays, commercial pilots and supplier due diligence into a decision-grade guide for corporate leaders planning capital allocation, product roadmaps, and market entry in 2026. This preview explains why V2G should be on every energy, mobility and asset-management executive’s 2026 agenda — and how our full study equips organizations to act with confidence.
Vehicle-to-Grid (V2G) Market
Why 2026 is the Inflection Year
Two converging forces create a unique window for V2G value capture in 2026: regulatory standardization and improving economics. Binding technical requirements that mandate bidirectional communication in new/renovated charging infrastructure are scheduled to take effect across major jurisdictions, effectively turning “nice to have” bidirectionality into a compliance and market-access requirement. Separately, recent policy moves — for example the removal of double grid fees in key markets — materially improve the commercial case for exporting vehicle-stored energy back to the network.
Vehicle-to-Grid (V2G) Market
Price signals are supportive. Global residential electricity rates and wholesale futures in 2026 have produced realistic revenue pathways for aggregate V2G fleets to monetize arbitrage and ancillary services. These conditions convert theoretical V2G value into executable business cases for utilities, aggregators, OEMs and large fleet owners.
Vehicle-to-Grid (V2G) Market
Market Momentum — The Macro Picture
Our bottom-up model traces the V2G market from early commercial traction in 2020 through the 2025 base year, and projects forward across a 2026–2032 forecast horizon. The market expanded from the low hundreds of millions (USD, revenue unit: Million) in 2020 to roughly USD 215.0 Million by the 2025 base year; projected growth accelerates thereafter, reaching an estimated USD 344.8 Million by 2032. The forecast is driven by a compound annual growth rate (CAGR) of approximately 6.98% over the modeled forecast period — a pace signaling steady, platform-enabled adoption rather than exponential consumer-led uptake.
Two implications follow: first, V2G is not a rapid, consumer-driven gold rush; it is a multi-stakeholder systems play that rewards strategic positioning and partnerships. Second, early movers who secure grid access, aggregation capacity, and regulatory alignment will capture durable, higher-margin revenue streams as the market matures.
Competitive Landscape — Who Matters and Why
The V2G ecosystem today is characterized by meaningful technical differentiation and a fragmented supplier base. Market concentration metrics confirm a low consolidation state: the top-three and top-five providers hold modest combined shares, reflecting room for partnership, consolidation and regional champions. For corporates this means the competitive battlefield will be defined less by price alone and more by integration capability, regulatory footprint, and data/aggregation competence.
- Technology providers and aggregators: Players such as Nuvve (GIVe platform) and Virta emphasize fleet aggregation, bidirectional control stacks and virtual power plant services — capabilities essential for monetizing grid services. Recent organizational moves (e.g., Nuvve’s deployments and local leadership appointments in Japan in 2026) underscore a push into critical new geographies.
- Hardware and industrial integrators: ABB and The Mobility House specialize in bidirectional charging hardware and integrated systems — from chargers to V2G control software — enabling scale deployments for commercial, industrial and fleet customers. Standalone hardware competence without software and aggregation partnerships will limit addressable value.
- OEMs and ecosystem partners: Vehicle manufacturers and utilities (e.g., Nissan launching affordable bidirectional charging solutions, and energy groups such as E.ON and Enel) are closing the loop between vehicles, tariffs and customer propositions. Examples in early 2026 show OEMs and energy companies bringing market-ready bundles to residential and commercial customers.
- Retail energy innovators: New tariff and platform experiments by energy retailers (e.g., Octopus Energy’s Powerloop) illustrate the consumer-facing business model evolution: V2G as a differentiated retail product combining hardware incentives, smart tariffs and customer engagement.
These firms are all active in the field through product launches, deployments and commercial pilots — but none alone dominates the space today. That presents an opening for thoughtful strategic engagement, whether through JV models, white-label partnerships, or targeted M&A focused on aggregation, software IP and market access.
What the PW Consulting Report Contains — Practical Deliverables
Our full study is designed as an executable toolkit for 2026 decision-making. Highlights include:
- Forecast model with scenario branches (baseline, accelerated policy adoption, and slow consumer uptake) and sensitivity levers for energy prices, vehicle-to-charger adoption rates, and tariff structures.
- End-to-end value chain analysis mapping revenue pools by use case (e.g., residential arbitrage, ancillary services, demand-side management), supplier roles, and margin profiles.
- Commercial playbooks: go-to-market options for OEMs, utilities, fleet operators and retailers including pricing templates, partner scorecards, pilot-to-scale transition checklists, and B2B contract clauses for aggregation and energy settlement.
- Regulatory and compliance matrix tied to product design — including implementation pathways for ISO 15118-20 and jurisdictional fee structures — to accelerate product certification and tariff approval processes.
- Technology assessment and interoperability map: charger and vehicle compatibility matrices, cyber-security best practices, and data governance frameworks required for grid services participation.
- Vendor diligence annex: comparative profiles, recent developments, patent and IP snapshots, and M&A heatmaps identifying likely consolidation targets.
- Financial tools: TCO calculators for fleet and residential deployments, capital expenditure planning templates, and investment cases capturing bidirectional hardware costs, software-as-a-service revenue, and O&M assumptions.
The full report contains granular regional and application splits, vendor scorecards and downloadable models. In this preview we intentionally withhold those segmented figures to preserve the value of the detailed datasets and proprietary scoring methods included in the subscription edition.
Practical Strategic Recommendations for 2026 Decision-Makers
- Utilities and system operators: Prioritize partnership pilots with aggregators that can demonstrate real-time dispatch and settlement capability. Use 2026 commercial pilots to validate revenue stacking (ancillary + arbitrage + capacity) and to influence tariff design that supports bidirectional participation.
- OEMs: Embed V2G capability into product roadmaps where it aligns to customer value and regional regulation. Consider white-label charging partnerships and enable flexible warranty/maintenance models for bidirectional hardware to lower customer adoption friction.
- Fleet operators and large energy buyers: Test aggregation contracts that offer predictable revenue streams; use short-term procurement to build operational experience and refine fleet management practices before committing to large-scale capital expenditure.
- Charge-point operators and hardware vendors: Invest in software layers and open APIs for marketplace participation. Hardware-only strategies are increasingly fragile: the monetizable economics of V2G come from orchestration, settlement and QoS guarantees.
- Investors and corporate development: Focus M&A on companies that combine aggregation software with documented grid revenue performance and regulatory footprints in priority markets. Early-stage investments should prioritize IP around bidirectional control algorithms, cyber-resilient communications, and settlement engines.
Risk & Mitigation — What to Watch in 2026
- Regulatory timing and implementation risk: Mandates and technical standards are evolving; companies should build flexible architectures that can adapt to ISO 15118-20 implementations and AFIR timelines without costly hardware retrofits.
- Revenue stacking dependence on price signals: V2G returns are sensitive to electricity price volatility and ancillary market design. Mitigation: secure pre-commercial agreements with grid operators and explore revenue guarantee structures during pilot stages.
- Interoperability and cybersecurity: As multiple vendors and vehicle platforms interact, interoperability failures or breaches could stall deployments. Recommended mitigation includes vendor certification requirements, layered security designs, and third-party interoperability testing.
- Customer acceptance and behavioral risk: Residential adoption depends on perceived battery degradation risk and simplicity of proposition. Transparent warranty terms and intuitive tariffing are essential.
Signals from the Field — 2026 Developments Worth Noting
- OEM-led consumer product launches (e.g., Nissan’s affordable bidirectional chargers in early 2026) are shifting V2G from research labs into retail channels.
- Energy-utility collaborations (e.g., BMW/E.ON residential V2G commercial offers launched in Germany) demonstrate how tariff innovation can accelerate customer take-up when paired with OEM hardware commitments.
- Localized deployments (for example, bidirectional charger installations using Quasar 2 technology) show real-world interoperability tests between hardware vendors and vehicle models — useful early lessons for scale rollouts.
- Corporate moves into key markets (e.g., Nuvve’s organizational expansion in Japan) reveal where operator confidence in local market structures is rising.
Conclusion — What PW Consulting Recommends for 2026
V2G in 2026 is a strategic opportunity best pursued with a systems view. The macro trajectory — reflected in our forecasted growth to the end of the decade and a near-7% CAGR — favors orchestrators who can align vehicle OEMs, charge-point vendors, energy retailers, and grid operators. For executives deciding budgets and partnerships this year, PW Consulting recommends a three-track approach: (1) secure pilot-level technical and commercial proof points in priority markets; (2) build or partner for aggregation and settlement capabilities; and (3) embed regulatory foresight into product design to avoid costly rework when standards take effect.
Our full report provides the actionable segmentation, vendor scorecards, and financial models necessary to translate these strategic imperatives into procurement decisions and investment theses. For teams preparing 2026 capital plans, the report functions as both roadmap and risk register — designed to shorten time-to-value while preserving optionality as the market consolidates.
Next Steps
Contact PW Consulting to access the complete V2G Market study, including the downloadable forecast model, regional and application splits, detailed vendor profiles and custom advisory options tailored for executives preparing 2026 strategies. The market is at an inflection point — firms that prepare now will be best positioned to convert nascent grid services into recurring, defensible revenue streams.
For detailed analysis of this topic, please visit the official page: Vehicle-to-Grid (V2G) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Scrap Lifting Magnets Market to Reach USD 290.5 Million by 2032 (5.7% CAGR)
By PW Consulting, 2026-07-12
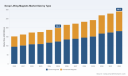
Scrap Lifting Magnets Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present an executive preview of our new market research on the global scrap lifting magnets sector. This essay highlights the report’s strategic value for corporate leaders making capital-allocation, product, and M&A decisions in 2026. It is written as a professional trailer: we reveal the analytical framework, market trajectory, competitive dynamics, and the pragmatic tools executives need — while preserving the granular, transaction-ready data inside the full report.
Scrap Lifting Magnets Market
Why this study matters in 2026
- Base and scope: Our study uses 2025 as the base year, captures historical trends from 2020–2025, and models multiple scenarios through a 2026–2032 forecast horizon.
- Market momentum: The market has shown steady growth through the historical period and is forecast to continue expanding at a compound annual growth rate (CAGR) of 5.7% over the forecast window.
- Decision contexts covered: procurement optimization, product roadmap prioritization, capacity planning, aftermarket and service expansion, channel strategy, and transaction screening for strategic or financial buyers.
For procurement teams and asset managers, timing of equipment replacement and the selection of technology (electro-permanent vs. electromagnetic vs. permanent systems) is increasingly value-critical. For corporate development and private equity, the sector’s growth profile, pockets of consolidation, and technology-driven differentiation create specific M&A and partnership opportunities that require precise demand and margin modeling — which our report provides.
Scrap Lifting Magnets Market
Market trajectory at a glance
Readers will find in the full report a rigorous time series that traces market value through the pandemic and recovery years, demonstrating how demand normalized and then accelerated under new regulatory and operational dynamics. To orient strategic thinking: the global market moved from the low hundreds of millions (USD) at the start of the decade to a larger base by 2025, and is projected to grow meaningfully by the early 2030s under our base-case assumptions. The 5.7% CAGR reflects a mix of steady replacement cycles, expanding recycling and scrap-handling activity, and technology-driven conversions in mobile and stationary applications.
Scrap Lifting Magnets Market
Key demand and supply dynamics shaping 2026 choices
- Regulatory pressure and circular-economy mandates. Governments across multiple regions are tightening waste-management and recycling targets, pushing industrial operators to invest in higher-throughput and safer scrap-handling systems.
- Commodity price volatility. Steel scrap pricing has migrated into the mid-hundreds per ton range in recent years, increasing the economic incentive to recover more metal per lift and shorten handling cycles — both of which favor investment in advanced lifting magnets and automation.
- Labor and operating-cost pressures. Rising labor and service costs are accelerating the shift to systems that reduce manual load handling time and deliver higher uptime through modular, battery-assisted, or electro-permanent technologies.
- Energy and operational efficiency. Battery-powered and electro-permanent solutions are gaining share because they combine operational flexibility with lower downtime versus some legacy electrically powered alternatives, influencing total cost of ownership (TCO) calculations.
- Safety and OEM-driven standards. Large end-users — notably automotive and heavy industry OEMs — increasingly specify lifting equipment to meet stringent quality, traceability, and risk-management standards, reinforcing the value of established suppliers with certification and long-term service footprints.
Technology and product trends to prioritize
Technology trends in the sector have clear strategic implications for product development and procurement: modular electromagnets with remote switching, electro-permanent units that maintain magnetic holding without continuous power, battery-operated mobile systems that enable longer operating windows, and sensorized units for predictive maintenance. Each approach carries different CapEx vs. OpEx trade-offs, and the optimal choice depends on rhythm-of-use, maintenance infrastructure, and safety requirements — all modeled in the full report’s TCO and sensitivity tools.
Competitive landscape — what structure means for strategy
The market exhibits moderate concentration: the largest players together account for a substantial share, but meaningful pockets of niche specialist activity remain. That structure has three strategic takeaways:
- Incumbent advantage: Established manufacturers with broad product lines and global service networks can capture premium margins on safety-certified, high-duty-cycle systems and aftermarket service contracts.
- White-space for specialists: Companies that focus on a narrow application (e.g., shovel-mounted units, skid-steer systems, or compact battery-powered lifters) can build defensible niches that remain attractive to consolidators.
- Channel and partnership play: Local service partners, OEM integrators, and distributors continue to be key growth levers for firms seeking to scale penetration in industrial end markets with complex service demands.
Selected companies profiled in our competitive analysis include manufacturers and OEMs that illustrate these strategic archetypes:
- Walker Magnetics (Boyne City, Michigan) — recognized for product breadth across lighter and heavier scrap-handling families designed for steel mills and recycling applications.
- SGM Magnetics (Manerbio, Italy) — an engineering-driven player known for proprietary electro lifting magnet designs that reduce side magnetic attraction and improve handling safety.
- Sinfonia Technology (Japan) — focused on shovel-mounted and integrated systems prioritizing secure load transfer and operational efficiency.
- Gensco Equipment (Canada) — offers hydraulic and skid-steer solutions with strong appeal to demolition and site-level recycling operations.
- DIMET (United States) — producers of a portfolio of electromagnets for scrap and turnings with global sales reach and presence at regional trade shows.
- HVR MAG (China), Bunting Magnetics (United States), and Magnetool, Inc. (United States) — each illustrating different strategic bets: electro-permanent technologies, separation and lifting integration, and mobile battery-powered lifting systems, respectively.
Activity signals in the market reinforce an active product and trade-show calendar, highlighting continued investment in visibility and new-product rollout: recent exhibitor participation and demonstrations by manufacturers in major industry expos underscore the speed of iterative product development and the centrality of field demonstrations to sales cycles.
What the PW Consulting report delivers — practical, actionable outputs
We designed this study to be immediately operational for executives and deal teams. Key deliverables include:
- Robust market sizing and baseline demand curves (2020–2025), plus scenario-based forecasts to 2032 using alternative macroeconomic and commodity assumptions.
- Vendor and product mapping with a decision matrix that links operating profile (lift cycles per hour, duty class, mobility requirement) to recommended technologies and supplier archetypes.
- TCO and sensitivity models that estimate CapEx, energy use, maintenance, and downtime impacts across electrified, electro-permanent, and battery systems.
- Go-to-market playbooks for market entrants and incumbents — channel strategies, pricing frameworks, and aftermarket service bundles that maximize lifetime value.
- M&A screening tools: scorecards, valuation sensitivities, and integration risk checklists customized for both strategic acquirers and financial sponsors.
- Risk matrix and regulatory mapping that align compliance requirements across major jurisdictions with procurement timelines and certification roadmaps.
- Primary interview summaries, expert-opinion synthesis, and a methodology appendix that documents data sources, assumptions, and modeling approaches.
To respect the “trailer” principle, we present the analytical structure and outcomes here, while detailed segment-level splits, regional roll-ups, and the downloadable datasets that underpin our forecasts are available only in the full report package.
How executives should use this intelligence in 2026
- CapEx & procurement: Use the report’s TCO modules to decide between retrofit, replacement, or reconfiguration of fleets — prioritizing projects that shorten payback under plausible scrap-price scenarios.
- Product roadmap and R&D: Prioritize battery management, sensor integration, and modular serviceability where the model shows the highest incremental value per dollar spent.
- Channel strategy: Evaluate partnerships with regional maintenance providers and OEMs to secure long-term service revenue and compliance credentials.
- M&A & JV screening: Identify consolidation targets that offer complementary product capabilities or service footprints; use our M&A scorecards to size integration upside and downside risks.
- Pilot programs: Run targeted field pilots for electro-permanent and battery-assisted platforms to validate productivity uplift and serviceability metrics before full-scale rollouts.
Conclusion — where this report fits in your 2026 playbook
As scrap flows increase and industrial operators pursue higher throughput with lower operating costs, the scrap lifting magnets market sits at the intersection of regulatory demand, energy-efficiency priorities, and technology-driven differentiation. The sector’s steady CAGR and forecasted market expansion create a compelling environment for both incremental investment and selective consolidation. PW Consulting’s full study converts those dynamics into operational guidance — from tactical procurement checklists to strategic M&A screens and validated TCO models.
For teams preparing 2026 budgets, product launch roadmaps, or transactional diligence, the full report provides the granular segmentation, regional demand profiles, and downloadable financial models you will need. Access the complete research package on our site to unlock the datasets and the tactical annexes that make these strategic recommendations executable.
For detailed analysis of this topic, please visit the official page: Scrap Lifting Magnets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UGC Software Market to Hit USD 10.99B by 2032 with 10.6% CAGR — PW Consulting
By PW Consulting, 2026-07-12
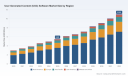
User Generated Content (UGC) Software Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Industry Analyst, I present an executive preview of our new market research on the User Generated Content (UGC) Software market. This briefing is designed as a strategic “trailer”: it surfaces the essential macro trends, competitive positions, and actionable levers that should inform enterprise decisions in 2026, while intentionally withholding certain proprietary segment tables and vendor scorecards reserved for the full report.
User Generated Content (UGC) Software Market
Why this research matters for 2026
UGC software is no longer a niche marketing tool — it has become a foundational layer of contemporary commerce, customer experience, and brand trust architecture. Organizations making platform, vendor, and data governance decisions in 2026 must reconcile three concurrent shifts: accelerating AI-driven content collection and personalization, increasing regulatory scrutiny on AI/curated content, and the rising commercial value of shoppable, permissioned visual media.
User Generated Content (UGC) Software Market
Our modeled market trajectory captures these dynamics. From a clearly observable expansion across 2020–2025, the market reached a material inflection point in 2025 (base year) and is forecast to grow at a 10.6% compound annual growth rate over the 2026–2032 horizon. The outcome is a near-doubling of market scale through the forecast period, underscoring both intensifying vendor activity and expanding buyer demand for integrated UGC capabilities.
User Generated Content (UGC) Software Market
High-level market picture (what leaders need to know)
- Growth profile: The market has expanded steadily through 2020–2025 and transitions into a mature acceleration phase in 2026, driven by enterprise adoption of UGC as a conversion and retention tool.
- Concentration: Market concentration is meaningful but not prohibitive — three vendors account collectively for a majority share of commercial activity, with the top five increasing that footprint. This creates a dual environment of stable incumbency and targeted opportunity for challengers with differentiated capabilities.
- Value drivers: The principal ROI levers for buyers are content authenticity and rights management, shoppable integrations that shorten commerce funnels, and AI-assisted moderation and tagging that reduce operational cost.
Dynamics shaping vendor selection and implementation
- AI as paradox: AI both unlocks scale (automated tagging, sentiment, visual recognition) and introduces new risks (hallucinations, synthetic content). Buyers must evaluate vendor approaches to provenance, explainability, and human-in-the-loop workflows.
- Regulatory noise and compliance priorities: Recent regulatory moves — for example, new rules requiring rapid removal of demonstrably harmful AI-generated content and explicit labeling of AI-curated media in some jurisdictions — elevate compliance from checklist to core capability. Vendors’ content governance, audit trails, and localization support will be decisive.
- Integration tax: UGC value accrues only when tightly integrated with commerce stacks, CDPs, and CX platforms. Procurement assessments should weight API quality, latency SLAs, and headless/rendering options equally with feature lists.
- Rights & moderation economics: Clear, auditable rights acquisition and automated moderation workflows materially affect total cost of ownership and legal exposure—features that have moved from “nice-to-have” to “must-have.”
Competitive landscape — strategic snapshots
The competitive set is diverse: from legacy e-commerce review platforms to AI-first personalization vendors and visual-content specialists. Below are targeted assessments of the primary vendors covered in our study. These snapshots synthesize public positioning, product focus, and strategic implications for enterprise buyers.
- Bazaarvoice (Austin, Texas) — Bazaarvoice is positioned as a robust e-commerce UGC collection and syndication platform. Its strengths are mature review workflows, retailer integrations, and an extensive syndication network. Strategic fit: organizations prioritizing scale of review distribution and cross-retailer consistency. Considerations: evaluate roadmap for AI curation and visual UGC expansion.
- Yotpo (New York, New York) — Yotpo presents an AI-augmented UGC stack covering reviews, social, and visual commerce. Strengths include tight e-commerce UX integrations and marketing automation. Strategic fit: DTC brands seeking embedded loyalty and conversion optimization. Considerations: probe for provenance controls and moderation latency under peak loads.
- Taggbox (Covina, California) — Taggbox emphasizes social feed widgets, reviews, and shoppable content aggregation across platforms. Strengths are flexibility in display formats and channel-agnostic aggregation. Strategic fit: event-driven, campaign-centric use cases and experiential marketing. Considerations: assess enterprise-grade governance and platform SLAs for high-traffic deployments.
- Emplifi (Columbus, Ohio) — Emplifi integrates UGC with social analytics, commerce, and broader CX capabilities. Strengths include an analytics-centric approach and cross-channel orchestration. Strategic fit: enterprises that require UGC insight to feed loyalty, CX, and service functions. Considerations: clarify data ownership models and cross-module interoperability.
- Nosto (Helsinki, Finland) — Nosto is recognized for AI-powered commerce experience and visual UGC personalization. Strengths include recommendation engines and visual merchandising tied to UGC. Strategic fit: retailers investing heavily in personalization at scale. Considerations: request transparency on model training data and regional regulatory compliance readiness.
- PowerReviews (Chicago, Illinois) — PowerReviews focuses on ratings and reviews with conversion optimization and syndication capabilities. Strengths lie in review authenticity features and conversion analytics. Strategic fit: brands focused on review-led conversion strategies with large SKU catalogs. Considerations: understand how visual UGC and influencer-driven content are supported.
- Crowdriff (Toronto, Ontario) — Crowdriff specializes in visual content discovery, management, and publishing, with particular traction in travel, hospitality, and retail. Strengths include visual search and rights-cleared publishing. Strategic fit: destination marketing and retail brands that rely on aspirational imagery. Considerations: evaluate commerce linkage maturity for direct shoppability.
Recent events and regulatory signals to watch in 2026
- Platform innovation: New entrants and product launches continue to change the competitive calculus. For example, early-2026 product introductions aimed at capturing text-based experience data are expanding the types of consumer narratives that can be monetized or moderated.
- Regulatory accelerants: Jurisdictions are moving quickly to impose obligations around AI-generated content — including removal timeframes for harmful content and mandatory labeling of AI-curated media. These measures shift vendor evaluations toward demonstrable auditability and localization features.
- Operational implications: The combined effect of product innovation and regulation increases the premium on vendors that can demonstrate low-latency moderation, strong provenance, and clear rights management across country boundaries.
What the full report delivers (practical, actionable components)
Our full market study is built for practitioners and C-suite decision-makers who need to turn insight into execution in 2026. Deliverables include:
- Comprehensive market sizing and forecast (2020–2032) with sensitivity scenarios and CAGR decomposition by driver.
- Competitive landscaping that pairs vendor capabilities with use-case fit, implementation complexity, and buying signals.
- Go-to-market and procurement playbooks: RFP templates, vendor scorecards, and negotiation levers tailored to enterprise priorities.
- Technical integration blueprints and API evaluation checklists for commerce, CDP, CMS, and moderation pipelines.
- Actionable ROI and TCO models with benchmarked assumptions for content moderation, rights clearance, and shoppable conversion uplift.
- Regulatory compliance annex with jurisdictional heatmaps, sample contractual clauses, and audit trail templates aligned to 2026 regulations.
- Deployment roadmaps and pilot designs to validate value quickly while managing legal and operational risk.
- Curated executive briefs and one-page decision frameworks for board and procurement committees.
How to use this briefing to act in 2026
- Prioritize a rights-first evaluation: Require vendors to demonstrate rights acquisition, verifiable provenance, and chain-of-custody for visual assets as a gating criterion.
- Make AI governance concrete: Insist on explainability, human-in-the-loop review thresholds, and remediation SLAs tied to regulatory timeframes in your contracts.
- Prize integration over point features: Choose vendors that reduce integration lift and offer clear pathways into your commerce and CX ecosystems.
- Pilot for legal and commercial outcomes: Structure initial engagements as limited-scope pilots with measurable conversion and compliance KPIs before rolling out wholesale.
Closing — a strategic prompt
The UGC software market in 2026 sits at an inflection of opportunity and obligation. Growth is robust — reflecting sustained enterprise investment — but the competitive and regulatory environments are evolving rapidly. This briefing surfaces the strategic signposts leaders must use to select vendors, design pilots, and scale responsibly.
For the complete segmentation tables, provider scorecards, and the proprietary appendices that translate these insights into executable procurement and integration artifacts, access the full PW Consulting report. Our research includes the granular data and templates required to turn the market’s projected 10.6% CAGR and the full 2020–2032 sizing into a concrete 12–18 month action plan for your organization.
For detailed analysis of this topic, please visit the official page: User Generated Content (UGC) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SMS Medical Nonwoven Market at USD 402.46M in 2025 — 5.75% CAGR Ahead
By PW Consulting, 2026-07-12
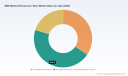
SMS Medical Nonwoven Fabric Market — Strategic Outlook and Decision Playbook for 2026
Executive preview
As healthcare systems, PPE manufacturers, and hospital procurement teams recalibrate for a post‑pandemic steady state, the SMS (spunbond–meltblown–spunbond) medical nonwoven fabric market is entering a phase defined by steady growth, concentrated supply, and a new set of regulatory and sustainability pressures. Our PW Consulting market study — based on a 2025 base year with historical tracking from 2020–2025 and forward projections through 2032 — shows a resilient market trajectory underpinned by a compound annual growth rate (CAGR) of roughly 5.75% over the forecast horizon. Global revenue has expanded meaningfully over the past five years and is expected to continue its upward climb through 2032.
SMS Medical Nonwoven Fabric Market
Why this research matters for 2026 decisions
- Timing: 2026 is the inflection year when incremental demand drivers (elective procedures rebound, routine PPE procurement normalization, and renewed focus on biodegradables) meet the cyclical effects of capacity additions announced in 2024–2025. The study translates those interactions into decision-ready scenarios.
- Capital allocation: Companies considering greenfield lines, capacity upgrades, or converting existing meltblown assets to SMS lines need forward‑looking demand curves and utilization sensitivity models — not just historical size figures. Our model provides scenario-based utilization thresholds tied to price and raw‑material volatility.
- Regulatory readiness: With recent FDA clarifications and 510(k) clearances relevant to SMS constructions, 2026 procurement and compliance strategies must change. The report maps regulatory pathways and the risk/reward of pursuing classification changes or exemptions.
Market trajectory and macro drivers
From a macro standpoint, the SMS medical nonwoven segment has moved from emergency-driven spikes to predictable, healthcare-driven growth. The study quantifies that transition: after the rapid demand shocks of the early 2020s, annual market revenues have expanded and are projected to continue growing at mid-single-digit rates through the end of the decade. This is driven by a confluence of forces:
SMS Medical Nonwoven Fabric Market
- Structural healthcare demand — routine surgeries, outpatient care growth, and expanding access in developing markets.
- Product innovation — manufacturers are introducing SMS variants that balance barrier performance with breathability and comfort, widening the addressable applications beyond traditional gowns and drapes.
- Sustainability and circularity — biodegradable blends and recyclable constructions are becoming procurement differentiators, influencing both OEM selection and premium pricing potential.
- Regulatory de‑risking — clearer FDA guidance on exemptions for certain nonwoven medical devices and recent 510(k) clearances reduce time‑to‑market uncertainty for modification of SMS constructions.
Competitive landscape — what the market structure means for strategy
The market exhibits moderate concentration with the top three players controlling a substantial share and the top five an even larger portion. That structure produces distinct competitive dynamics:
SMS Medical Nonwoven Fabric Market
- Scale advantages: Large global producers have the balance-sheet capacity to invest in multi‑regional capacities and sustainability R&D, enabling them to capture enterprise OEM contracts and hospital system frameworks.
- Regional specialist plays: Mid‑sized and local producers compete by offering customization, faster lead times, or lower cost bases in localized markets.
- Collaborative innovation: The trend toward co‑development partnerships and cross‑licensing (notable between multinational material suppliers and performance‑fabric specialists) is accelerating differentiated product launches.
Key players profiled in the study include established global integrators and regional specialists. The report assesses each on dimensions that matter for strategic counterpart selection and competitive response: manufacturing footprint, product portfolio breadth (including SMMS and reinforced laminates), sustainability roadmap, regulatory clearances, and customer segmentation focus.
Recent industry moves and regulatory context — implications for 2026
- Strategic partnerships and product launches: Several strategic collaborations and new product introductions in 2024–2025 signal a shift from capacity‑race tactics to capability‑led competition. Notably, collaborations targeting sustainable SMS formulations and high‑performance barrier fabrics suggest that technical differentiation — not purely price — will drive premium procurement decisions.
- Capacity expansions: Announcements of manufacturing expansions by leading firms point to upcoming capacity additions that will moderate raw‑material inflation pass‑throughs but will also pressure utilization for smaller producers unless demand growth accelerates as forecasted.
- Regulatory clarity: Recent FDA notices and 510(k) activities have reduced some approval risk for specific SMS constructions, while regional certifications (e.g., CE conformity of blood/biological sample collection materials) open adjacent market opportunities for material suppliers. Commercial teams need to align product claims, testing packages, and submission strategies to exploit these windows.
Strategic playbook for 2026
For executives planning actions in 2026, the study translates macro forecasts and competitive intelligence into a set of prioritized strategic moves. Examples include:
- Capacity and footprint decisions: Use our utilization-trigger matrix to decide between incremental capacity (module expansion), asset retrofits (converting meltblown to SMS lines), or contract manufacturing partnerships. The matrix highlights breakpoints where internal capacity becomes accretive versus outsourcing.
- Product portfolio and differentiation: Prioritize investment in SMS variants that offer validated barrier-breathability trade-offs and in biodegradable/polyolefin blends that meet hospital sustainability procurement criteria. The study includes concept-to-commercial timelines and cost implication models.
- Partnerships and M&A targets: Identify targets that fill capability gaps — whether raw‑material resilience (regional polymer supplies), specialty meltblown technology, or validated regulatory dossiers — and use our valuation overlay to size accretive deals under multiple demand scenarios.
- Regulatory and quality readiness: Align R&D and regulatory teams to the simplified entry pathways for select SMS device classes; prepare 510(k) or equivalent dossiers for high‑value product extensions to minimize launch delays.
- Procurement and supply resilience: Rebalance supplier mix and contract tenors to mitigate polymer feedstock volatility; consider vertical integration or strategic long‑term offtakes for meltblown intermediates where scale advantages justify CAPEX.
What’s in the full report (practical, executable content)
The full PW Consulting report is structured to support immediate decision-making and phased strategy execution. Highlights include:
- Bottom‑up market sizing and validated growth scenarios through 2032, including sensitivity to adoption rates for biodegradable and reinforced SMS constructions.
- Utilization and capacity maps incorporating announced expansions and plausible new builds, with breakeven and payback analyses for different capex pathways.
- Competitive benchmarking across manufacturing footprint, product capabilities, regulatory clearances, and sustainability credentials — enabling prioritization of partners and competitors.
- Segment playbooks (go‑to‑market, pricing, and procurement strategies) for hospital systems, OEMs, and national health agencies — presented as executable 90‑, 180‑, and 360‑day plans.
- M&A screening tool: a short list of target archetypes and valuation ranges tied to synergy and integration complexity.
- Regulatory navigators: step‑by‑step guidance for leveraging recent FDA clarifications and CE conformity precedents to accelerate market entry.
Note: To preserve strategic advantage and respect commercial sensitivity, our public executive summary intentionally omits detailed sub‑segment revenue splits, regional share tables, and explicit pricing ladders. These are included in the full dataset and interactive dashboards available on our report portal.
How to use these insights in boardroom conversations
- Frame capital requests with scenario‑tested utilization outcomes: present conservative, central, and aggressive demand cases derived from the study.
- Use competitive profiles to justify partnership versus build decisions: show how capability gaps will impact time‑to‑contract for large health systems.
- Prioritize regulatory investment: align 510(k) and certification timelines to product launch windows where margin recovery is highest.
- Embed sustainability metrics into procurement negotiation: leverage hospital ESG mandates to capture premium pricing for certified biodegradable or recyclable SMS options.
Closing — a call to action for 2026
The SMS medical nonwoven fabric market is no longer a pure-volume play — it has evolved into a multi‑dimensional battleground where technology, sustainability, regulatory positioning, and regional footprint determine who captures value. Our analysis shows a clear path for companies that can synchronize capacity deployment with differentiated product offerings and regulatory readiness. For executives preparing 2026 plans, the immediate priority is to convert market visibility into executable roadmaps: align capex, partner selection, and compliance investments to the demand scenarios that best fit your risk appetite.
For full access to the detailed breakdowns, sub‑segment forecasts, regional demand analytics, and our interactive scenario tools, request the complete PW Consulting SMS Medical Nonwoven Fabric Market report and dataset.
For detailed analysis of this topic, please visit the official page: SMS Medical Nonwoven Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
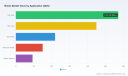
Biotin Market 2026 Strategic Preview — PW Consulting
As companies set strategy for 2026 and beyond, biotin is no longer a niche ingredient story: it is a strategic supply-and-demand battleground with implications across nutrition, pharmaceutical, personal care, and animal-feed value chains. Our PW Consulting Biotin Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes five years of observed dynamics with a seven-year projection to 2032 to give commercial leaders the decision-grade intelligence needed for sourcing, product development, M&A, and regulatory positioning.
Biotin Market
Market trajectory at a glance
The biotin market has expanded rapidly over the past half-decade, growing from approximately USD 1,000 Million in 2020 to USD 1,482 Million in 2025. Our scenario-based forecast anticipates continued momentum: by 2032 the market is projected to reach roughly USD 2,637 Million under the central scenario, reflecting a compound annual growth rate (CAGR) of 8.6% across the 2026–2032 forecast window. That scale and pace make biotin a strategic priority for ingredient buyers, formulators, and investors: demand growth is robust, while supply-side stressors create differentiated margin and risk profiles across product forms and end-markets.
Biotin Market
Why this report matters for your 2026 decisions
-
Supply concentration is a strategic risk. Control of D-biotin production capacity is highly concentrated, with a single geographic region accounting for the lion’s share of global output for this critical stereo-specific intermediate. The resulting single-source exposure raises sourcing risk, pricing volatility, and geopolitical sensitivity — issues that need to be addressed explicitly in supplier strategy and contingency planning.
Biotin Market -
Value is shifting toward traceability and specialty formats. Premium buyers are increasingly willing to pay for traceable, pharma-grade and application-optimized biotin. European and specialty suppliers are moving up the value chain with verified traceability, higher-bioavailability formulations, and documented quality systems — creating commercial opportunities that go beyond raw-volume supply.
-
Regulatory and IP signals affect market access and differentiation. Patent disputes, local IP enforcement, and tightened label and claim rules in major markets are reshaping competitive positioning. Recent patent outcomes and regulatory rulings have real commercial impact on manufacturing routes, product claims, and the ability of new entrants to scale internationally.
-
Market concentration is material but not monopolistic. Market concentration metrics indicate a mid-to-high consolidation level among the largest producers, leaving room for nimble mid-tier suppliers and specialty players to capture share through differentiation, vertical integration, or regional partnerships.
What PW Consulting’s report delivers (practical, transaction-ready content)
-
High-fidelity market sizing and methodology. Transparent, auditable sizing from 2020–2025 and an adaptable forecasting model covering 2026–2032. The model includes demand-driver elasticities, scenario switches (supply-shock, premium-adoption, and regulatory tightening), and an interactive input sheet that lets commercial teams stress-test assumptions against price and supply scenarios.
-
Supply-chain mapping and supplier risk heatmap. A mapped universe of active producers and intermediate suppliers, with a supply-risk score combining capacity concentration, quality certification, export compliance, and financial strength. The heatmap highlights single points of failure and recommended hedging strategies for contract and inventory design.
-
Commercial playbooks for buyers and brand owners. Negotiation scorecards, RFP templates tailored to traceability and quality specifications, techniques for securing long-term capacity, and sample contract clauses to mitigate force majeure, price pass-through, and IP exposure.
-
Product and formulation playbooks for R&D and marketing. Guidance on form selection (capsules, gummies, powders, etc.), stability and bioavailability considerations, co-formulation constraints, and claim-substantiation frameworks aligned to major regulatory regimes.
-
Due diligence and M&A toolkits. Commercial and technical red flags for target assessment, integration checklists, unit economics sensitivity analysis, and a shortlist methodology for identifying high-fit acquisition targets — especially useful where supply consolidation or backward-integration is a strategic objective.
-
Regulatory & IP intelligence. A compendium of relevant regulatory thresholds and labeling requirements in key markets, patent landscape mapping, and an assessment of how recent rulings affect freedom-to-operate and process selection.
-
Appendices with raw datasets and interactive files. For subscribers we provide the underlying time-series data, supplier master file, and an adaptable Excel model so internal teams can rerun forecasts using company-specific assumptions.
Competitive landscape — who matters and why
The competitive map in biotin is differentiated by strategic intent. A set of global specialty chemical and ingredient houses compete on quality, traceability, and regulatory reach; a large group of manufacturers in concentrated geographies compete on volume, cost, and scale. Key players profiled in the report include established European ingredient houses that emphasize pharma-grade, traceable products and Chinese manufacturers that offer high-volume synthetic biotin and integrated supply capability.
-
DSM-Firmenich (Kaiseraugst, Switzerland) — Global specialty player with an emphasis on pharmaceutical-grade and traceable branded solutions. Recent activity includes a traceable branded biotin line aimed at clean-label supplement demand, demonstrating how traceability and data-backed quality are being commercialized.
-
BASF SE (Ludwigshafen, Germany) — Supplies biotin ingredients across food, beverage, pharmaceutical and nutrition markets; management commentary shows a resilient business backing continuing investment in bioavailability and regulatory compliance capabilities.
-
Merck KGaA (Darmstadt, Germany) — Offers fine-chemical and diagnostic-grade biotin inputs; strengths lie in application-specific formulations and strict quality systems serving regulated end-markets.
-
Evonik Industries AG (Essen, Germany) — Focuses on specialty derivatives and custom formulations, enabling product differentiation for food and pharma customers.
-
Leading Chinese producers (multiple headquarters) — A cohort of major producers supplies the bulk of synthetic biotin volumes globally. These firms benefit from large-scale integrated production, strong cost positions, and export reach. IP and capacity dynamics among these producers are central to price and availability outcomes.
The report’s company profiles extend beyond public summaries to include capacity estimates, quality certification matrices, export footprint, and a commercial posture assessment (e.g., premium vs. volume play). Where competitive developments have direct market impact — such as new traceable product lines, patent decisions, and public earnings commentary — we flag implications for supplier selection and pricing strategy.
Industry signals you cannot ignore in 2026
-
Geographic concentration of critical production steps raises the probability of supply shocks and trade friction translating to abrupt cost increases or allocation events.
-
Patent and IP developments have real commercial consequences: process patents and stereoselective synthesis rulings affect who can scale and where they can sell.
-
Price volatility and sourcing spreads continue to influence gross margins for downstream manufacturers and private-label brands — necessitating dynamic procurement approaches rather than static spot purchasing.
-
Regulatory scrutiny on labeling and structure/function claims means marketing and claims teams must align early with regulatory counsel and product development to avoid rework or market access loss.
Recommended strategic actions for 2026
-
Stress-test your supply base. Run scenario exercises using the provided model to quantify the P&L impact of allocation events, price spikes, and lead-time elongation. Translate results into prioritized mitigation measures (dual-sourcing, safety-stock policies, strategic inventory hubs).
-
Pursue premiumization where regulatory and traceability demand supports higher ASPs. Invest in branded or co-branded traceability propositions for customers in personal care and high-trust supplement segments.
-
Lock in strategic capacity through blended contracts. Mix long-term offtake for core volumes with indexed short-term arrangements for flexibility; use contract design to balance cost and supply security.
-
Monitor IP and patent developments closely. Legal outcomes can change the attractiveness of certain synthesis routes or acquisition targets; build IP clauses into any acquisition or joint-development deal.
-
Position R&D and regulatory teams early. If your product mix relies on label claims or structure/function messaging, a preemptive regulatory plan reduces launch risk and speeds time to market.
How to use this preview and next steps
This preview surfaces the high-impact signals and recommended actions that corporate leaders must consider in 2026. For procurement leaders, R&D heads, corporate development teams, and private-equity investors, the full PW Consulting Biotin Market report includes the granular, transaction-ready datasets, supplier master files, segment-level forecasts, and commercial templates required to execute. To preserve the strategic value of that intelligence, segment-level market shares and company revenue estimates are provided only within the full report and interactive models.
If your 2026 plan involves supply diversification, product premiumization, M&A in the ingredient space, or stronger regulatory alignment for biotin-containing products, this study is designed to be the operating manual for action. PW Consulting’s diagnostic frameworks and deliverables convert market insight into executable roadmaps — minimizing downside from concentrated supply and maximizing upside from premium offerings.
For access to the full dataset, supplier shortlists, scenario models, and a tailored briefing for your executive team, request the full PW Consulting Biotin Market study.
For detailed analysis of this topic, please visit the official page: Biotin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Coated Abrasive Market Poised for 5.97% CAGR Through 2032
By PW Consulting, 2026-07-12
Coated Abrasive Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations prepare 2026 budgets and strategic roadmaps, the coated abrasive market presents a mix of steady expansion, tectonic shifts in product expectations, and pockets of consolidation that demand targeted responses. Our benchmarking shows the global market expanded from roughly USD 8.1 Billion in 2020 to approximately USD 10.93 Billion in 2025, and is projected to continue expanding to about USD 16.44 Billion by 2032 — an underlying compound annual growth rate of 5.97% across the 2026–2032 forecast window. Market concentration is meaningful but not prohibitive: the top three suppliers account for around 38.5% of the market, and the top five for roughly 50.2% — a structure that rewards scale while leaving room for focused innovators and regional challengers.
Coated Abrasive Market
Why this matters for 2026 planning
-
Investment prioritization. Predictable mid-single-digit CAGR supports continued investment in capacity, but success will hinge on capital allocation toward product innovation, sustainability adaptation, and digital customer channels rather than undifferentiated volume expansion.
Coated Abrasive Market -
Supply-chain resilience becomes strategic. Recent and ongoing disruptions to key bonding chemicals and specialty inputs have shortened planning horizons and elevated the value of alternative sourcing, upstream partnerships, and on-shore buffer strategies.
Coated Abrasive Market -
Regulatory and procurement risk. Sustainability mandates and tightening product-compliance requirements are accelerating adoption of bio-based and certifiable product options. Firms that can combine performance with verifiable environmental credentials will unlock premium segments and preferred-supplier status with OEMs.
-
Automation-led demand shifts. Labor shortages and expanded robotic finishing lines are changing product specifications (durability under robotic cycles, dust control, integration with automated tooling). Suppliers who co-develop solutions with systems integrators capture higher-margin, recurring-revenue streams.
Market dynamics — from raw materials to end-use
The coated abrasive value chain is being reconfigured along several vectors simultaneously. On the supply side, intermittent shortages in specialty chemicals and adhesives have increased lead-time volatility and input-cost pass-through complexity. On the demand side, adoption patterns are diverging by end-use: traditional industrial metalworking continues to provide a volume foundation, while newer growth pockets are driven by automation, precision finishing in electronics and semiconductors, and sustainability-led replacement cycles in aftermarket and construction segments.
Regulation and certification are no longer peripheral considerations. Product launches in 2025 that emphasize biodegradability and life-cycle performance reflect an emerging baseline expectation among institutional buyers. Meanwhile, digital procurement and traceability features — exemplified by recent platform rollouts — are migrating from nice-to-have to procurement criteria tied to compliance and supplier rationalization programs.
Competitive landscape — what leading firms are doing
-
Saint‑Gobain Abrasives / Norton brand — A broad portfolio and recent inorganic expansion have reinforced global coverage, particularly in growth geographies. Their strategy appears focused on marrying range breadth with local manufacturing to protect margins against freight and input shocks. For incumbents, the lesson is clear: combine product depth with distribution proximity to remain relevant to industrial OEMs and large distributors.
-
3M — The company has sharpened its sustainability messaging with product innovation (e.g., biodegradable coated abrasives launched in August 2025). 3M’s playbook is to translate material science into brand-differentiated products, then leverage broad channel reach to scale adoption. Competitive response should evaluate where material innovation can create defensible features rather than commodity parity.
-
Norton Abrasives — While Norton remains a major brand within larger groups, recent investments in digital customer experience (new platform launched October 2025) demonstrate a shift to procurement-led value capture. The platform also aligns supplier capabilities with ISO-compliance requirements — a blueprint for suppliers seeking deeper integration into customer procurement workflows.
-
Klingspor — High-quality, application-focused product lines and strong woodworking-industrial finishing credentials make Klingspor a resilient player in premium niches. Their model underlines the commercial advantage of tightly aligned product-development with specific industrial workflows.
-
Mirka — A recognized leader in precision surface finishing, Mirka’s emphasis on systems (abrasives + tools + consumables) highlights how bundling raises switching costs and creates stickier customer relationships — particularly in OEM and high-precision subcontractor segments.
-
sia Abrasives — High output capacity and strong automotive and building-sector focus enable sia to compete on scale for contract manufacturing and large-scale projects. Their capability profile is instructive for firms evaluating contract manufacturing vs. in-house production decisions.
-
Carborundum Universal Limited (CUMI) — A leading regional player with a broad product catalog and strong presence in construction and industrial channels. Recent catalog updates and product portfolio refreshes keep the brand relevant for distribution-led growth in emerging markets.
Recent corporate moves with strategic implications
-
Product launches emphasizing biodegradability and sustainability (notably from a major global player in 2025) signal that product life-cycle attributes will be a point of competitive differentiation in procurement dialogues during 2026.
-
Acquisition activity in Asia by a leading European incumbent underscores the importance of strategic M&A to secure local capacity and reduce exposure to freight and input-price inflation.
-
Digital platform rollouts that embed compliance and procurement workflows are becoming a competitive moat. Expect an acceleration of supplier digitization projects as buyers demand traceability and easier re-ordering.
Strategic playbook for 2026
-
Prioritize product portfolios into three buckets: (1) high-performance systems for automation and precision finishing, (2) sustainability-certified offerings for regulated channels and green procurement, and (3) cost-optimized ranges for high-volume industrial applications. Allocate R&D and capex according to downstream margin potential, not historical volume alone.
-
Invest in supplier diversification and chemical-substitute R&D. A dual approach — securing alternative suppliers for key inputs while developing formulations that reduce dependency on constrained chemistries — materially reduces service-risk in 12–18 month planning horizons.
-
Embed digital procurement and compliance features into customer-facing platforms. Platforms that simplify ISO certification, batch traceability, and automated re-ordering convert technical product advantages into commercial stickiness.
-
Assess M&A and JV targets with an “access-to-technology” and “access-to-market” lens. Regional producers with strong channel relationships or unique material know-how offer faster paths to capability expansion than greenfield investments.
-
Develop partnerships with systems integrators and robotic suppliers. Co-engineering abrasive consumables for robotic finishing lines will be a significant value driver as automation adoption grows.
What the full PW Consulting report delivers (practical, actionable)
-
Transparent market-sizing and growth scenarios with sensitivity analysis that connects macro trends to unit economics and margin outcomes — enabling finance teams to stress-test 2026 capex proposals.
-
Commercial playbooks for supply chain resilience, including a prioritized list of alternative suppliers, suggested inventory buffers by risk-profile, and supplier scorecards tailored to abrasive-specific inputs.
-
Competitive benchmarking across product, price, channel, and service dimensions with go-to-market tactics for defending share or entering adjacent segments.
-
Innovation radar and R&D roadmaps that map material science advances to potential premium features and regulatory-ready product variants.
-
M&A heatmaps that prioritize targets by strategic fit (technology, geography, channel) and modeled synergy ranges to support deal conversations in 2026.
-
Operational playbooks for digitizing the customer interface, including procurement integrations, traceability workflows, and KPIs to measure commercial impact.
How to use this intelligence in boardrooms and procurement meetings
For CEOs and CFOs: use the market trajectory and scenario outputs to stress-test capital allocation between capacity, R&D, and digital transformation. For commercial leaders: adopt the segment-specific playbooks to prioritize sales coverage and channel investments in 2026. For procurement and operations: implement the supply-chain resilience checklist immediately to mitigate near-term input risks and ensure continuity for high-value contracts.
Closing — the strategic choice in 2026
The coated abrasive market offers a predictable growth backdrop combined with disruptive inflection points around sustainability, automation, and digital procurement. Success in 2026 will not be decided by scale alone; it will hinge on the ability to convert material science and digital capabilities into procured value — measurable through reduced total cost of ownership and improved compliance footprints for buyers. PW Consulting’s full Coated Abrasive Market report delivers the granular segmentation, country-level analytics, and downloadable models required to operationalize the strategies outlined here.
For the complete dataset, in-depth segment economics, and executable playbooks referenced in this preview — including the withheld granular splits and customer-level insights — visit our report page to access the full intelligence suite and downloadable decision-support tools.
For detailed analysis of this topic, please visit the official page: Coated Abrasive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LDPE Extrusion Coating to hit USD 344.8M by 2032 at 5.2% CAGR
By PW Consulting, 2026-07-12
LDPE Extrusion Coating Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our new market study on LDPE extrusion coating — a practical intelligence asset designed to inform senior executives, commercial leaders, and investment committees as they set strategy for 2026 and beyond. This briefing summarizes the study’s strategic value, synthesizes the most consequential market forces, and outlines the competitive implications for incumbents and challengers alike. It deliberately signals depth while reserving the granular tables and segmented figures for the full report — the information you will need to operationalize moves in 2026.
LDPE Extrusion Coating Market
Market snapshot — clear, calibrated, and forward-looking
Our work is grounded in a rigorously constructed time series and forecast model with a 2025 base year. The LDPE extrusion coating market demonstrates steady, mid-single-digit growth: the report applies an underpinning compound annual growth rate of 5.2% across the 2026–2032 forecast window. This trajectory reflects continued demand from core packaging end-markets, gradual product premiumization, and selective capacity additions globally. The base-year sizing and the projected terminal values are integrated throughout the report’s commercial scenarios and sensitivity runs to ensure decisions are tested against realistic volumetric and revenue outcomes.
LDPE Extrusion Coating Market
Why this study matters for 2026 strategic choices
- Timing of capacity and contract decisions: 2026 will be a year when several capacity moves and contract roll-offs intersect. Our forecast and scenario engine lets you evaluate the commercial impact of executing or deferring capex, entering long-term off-take agreements, or pursuing tactical spot exposure.
- Risk-aware commercial planning: Feedstock and film price volatility remain the fastest route to margin swings. The study overlays price scenarios and hedging playbooks onto customer and channel segmentation so sales and trading teams can set defensible floor/ceiling pricing.
- Regulatory posture and market access: Recent standards updates and quality control amendments in major markets are reframing acceptance criteria for LDPE extrusion coating grades. Our regulatory consequence matrix helps procurement and regulatory affairs teams prioritize compliance investments and certification timelines.
- M&A and partnership screening: With moderate market concentration among the largest players, there is strategic optionality for bolt-on transactions and JV models. The report provides a prioritized target list and valuation stress-tests consistent with 2026 capital constraints.
Key demand and supply dynamics shaping 2026
- End-market momentum and product mix: Packaging demand, especially in liquid and flexible sectors, continues to underpin LDPE extrusion coating volumes. The report traces substitution risk (incl. barrier films and mono-material formats), customer-spec upgrades, and the commercial premium attached to higher-performance extrusion grades.
- Feedstock and pricing volatility: Raw-material swings remain a dominant short-term earnings driver. Seasonal and regional feedstock dislocations — combined with the introduction of new converting capacity in Southeast Asia and occasional rebounds in major supply hubs — produce a patchwork pricing environment. The full study models these dynamics through probabilistic price paths informed by recent industry observations.
- Regulatory and standard-setting shifts: Policy updates in large consuming countries have tightened quality and testing requirements for extrusion-coating resins. These changes increase the compliance burden for suppliers lacking formal certification pathways and accelerate demand for traceable, quality-assured grades.
- Capacity additions and regional re-balancing: New LDPE and film capacity in select regions has temporarily depressed pricing in those markets, while localized feedstock advantages continue to support higher utilization elsewhere. Our supply-side module maps announced and probable greenfield/expansion projects and assesses their commercial impact under multiple demand scenarios.
Competitive landscape — what differentiates winners
The LDPE extrusion coating market is served by a mix of large integrated petrochemical majors, regional champions, and specialty producers. Market concentration is moderate: the top three players account for roughly one-third of reported market activity, while a broader top-five group expands that share further. This topology produces both scale advantages and niches for targeted differentiation.
LDPE Extrusion Coating Market
- Global integrated majors (e.g., Dow, LyondellBasell, ExxonMobil Chemical): These players leverage feedstock integration, broad product portfolios, and global sales networks. Their advantages are most evident in multi-region supply agreements, custom grade development, and risk management at scale. Expect them to defend share through technology licensing, customer co-development, and bundled commercial offers.
- Regional and national champions (e.g., Sinopec Beijing Yanshan, Braskem, Westlake): Local production footprint and access to favourable feedstock or logistics cost structures enable competitive local pricing and rapid response to domestic regulatory shifts. They often play a crucial role in regional pricing and service benchmarks.
- Specialty and flexible producers (e.g., LG Chem, SABIC, Chevron Phillips, INEOS): These companies compete on product differentiation — higher performance grades, tailored resin properties for extrusion coating, and sustainability credentials. Their commercial playbook emphasizes technical service and conversion support for brand owners seeking premiumized packaging formats.
- Strategic takeaways: For buyers — diversify homologous supply sources across integrated and specialty partners; for suppliers — invest in certification, application support, and selective local capacity to blunt commoditization pressures.
Recent market signals to watch
- Commercial offers from major feedstock producers have recently influenced delivered pricing into key export hubs; these offers have the potential to shift regional competitive dynamics when combined with new converting capacity.
- Regional film prices have shown episodic weakness where capacity additions outpaced demand growth, while other markets have experienced cyclical rebounds after short-term declines — underscoring the need for dynamic pricing playbooks.
- Regulatory updates in sizeable consuming economies have tightened quality-control standards for LDPE extrusion uses. Compliance timelines and audit-readiness will be a differentiator for suppliers seeking to retain or expand market access.
- Public commentary from major integrated producers suggests an expectation of continued supply disruptions in the near term — a signal for buyers and sellers to stress-test 2026 plans against upside and downside supply scenarios.
What PW Consulting’s full report delivers — practical outputs for 2026
The study is designed as an operational toolkit, not an academic exercise. Key deliverables include:
- Granular market sizing and a probabilistic demand-forecast model (2026–2032) with scenario toggles for volume, price, and feedstock pathways.
- Competitive scorecards and capability maps for every major supplier, including product line-up, regional capacity, quality certifications, and go-to-market strength.
- Price-sensitivity and margin impact calculators that tie feedstock trajectories to finished-product margins under multiple contracting assumptions.
- A regulatory impact matrix that translates recent and pending standards into certification costs and market-access timing by jurisdiction.
- Commercial playbooks for buyers and sellers — including recommended contract terms, hedging strategies, and supplier consolidation tactics appropriate to different company profiles.
- Capital projects tracker and M&A screening framework that ranks opportunities by strategic fit, integration complexity, and likely valuation bands under conservative and optimistic market cases.
- Excel-based models and dashboards to run bespoke corporate scenarios and to stress-test strategic choices ahead of board decisions.
Actionable strategic recommendations for 2026
- Lock selective long-term supply while preserving optionality: Negotiate blended contracts that combine a fixed baseline with indexed volumes to protect against short-term price spikes without surrendering upside in favorable price environments.
- Prioritise certification and quality-traceability investments: For suppliers, early compliance to tightened standards will create a barrier to entry for less-prepared rivals and support premium positioning with multinational brand owners.
- Use regional arbitrage for tactical margin capture: For trading desks and commercial teams, opportunistic sourcing from regions where new capacity has depressed pricing can be profitable, provided logistics and quality risks are managed.
- Accelerate product differentiation efforts: Invest in application-specific grades and conversion support to anchor higher-margin relationships with converters and consumer-packaging firms moving toward mono-material and recyclable designs.
- Screen M&A for strategic rather than purely volumetric gains: Targets that bring technical differentiation, downstream channels, or regulatory-certification advantages will deliver superior returns in a moderately concentrated market.
Conclusion — how to use this intelligence in 2026
Decisions in 2026 will be made under the influence of intertwined supply, pricing, and regulatory forces. The PW Consulting LDPE Extrusion Coating study equips decision-makers with the forecast fidelity, scenario tooling, and commercial playbooks required to mobilize capital, renew contracts, and outmaneuver rivals. We have structured the deliverables to be immediately actionable at the board and commercial desk levels — with downloadable models and step-by-step implementation templates in the full report.
For access to the complete dataset, segmented tables, supplier scorecards, and the scenario-enabled Excel model, please consult the full report on our website — the only place where the granular segment splits and price ladders are disclosed in their entirety.
For detailed analysis of this topic, please visit the official page: LDPE Extrusion Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


