



Category: market research
PW Consulting: Shower Trays Market to Reach USD 5,939.25M by 2032 at 5% CAGR
By PW Consulting, 2026-07-08
Shower Trays Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, practice-oriented preview of our new Shower Trays Market study — a timely intelligence product designed to shape capital allocation, product strategy, and M&A activity in 2026. This preview surfaces the market’s structural trajectory, competitive dynamics, cost pressures and opportunity corridors while deliberately withholding the granular segmentation tables and proprietary splits that form the core of our paid research. That selective opacity is intentional: this note is a trailer that demonstrates the depth of our analysis and explains how the full study will materially improve your 2026 planning and risk management.
Shower Trays Market
Big Picture: Where the Market Is and Where It’s Headed
Our consolidated market model shows the global shower trays market expanded materially in the first half of the decade, rising from approximately USD 3,263.02 million in 2020 to USD 4,164.53 million in 2025 (base year). The market is forecast to keep growing through the 2026–2032 outlook window at a compound annual growth rate of roughly 5.0%. By the end of the forecast horizon, the total market size is modeled to reach approximately USD 5,939.25 million. While the overall trajectory is upward, the path is not uniform — our scenario analysis highlights episodic demand shifts and product-cycle inflections that matter when scheduling launches, procurement, or capacity expansion.
Shower Trays Market
Why This Study Matters for 2026 Decisions
- Immediate cost pressures are compressing margins across categories. Our raw-material index shows input costs for acrylic, resin compounds, steel and ceramic rose by roughly 28% across recent production cycles — a structural headwind to incumbents and new entrants alike.
- Installation economics are a strategic lever. Professional shower pan installation labor typically ranges between US$350 and US$570 per job; this range drives the commercial viability of prefabricated vs. site-built solutions and affects channel incentives across contractors, distributors, and OEMs.
- Product and regulatory convergence intensify go-to-market coordination. Safety and product standards (for example, requirements around tempered safety glass in regulated markets) are raising compliance costs and shortening windows for product iteration.
- Design trends are re-ordering product roadmaps. Ultra-thin tray designs — favored in contemporary bathroom aesthetics — accounted for nearly 22% of recent product introductions, signaling a durable design premium that alters BOM composition and pricing power.
What the Report Delivers: Actionable Modules
- Verified market-size model (historical 2020–2025, base year 2025) and a differentiated forecast through 2032, with multiple scenarios (base, downside, upside) that stress-test elasticity, input-cost pass-through and project-scheduling risk.
- Segment-level playbooks covering material strategies, product families, and application roadmaps. Note: this preview intentionally omits the detailed segment splits; those are provided exclusively in the full report to protect our proprietary intelligence model.
- Competitive benchmarking for leading players and challenger brands: product portfolios, R&D posture, sustainability claims, channel strategy and IP posture.
- Supply-chain diagnostics and cost-transformation levers, including sourcing alternatives, design-to-cost interventions and nearshoring feasibility assessments.
- Commercial deployment toolkits — pricing elasticities, installer economics, specification capture tactics for architects and developers, and pilot templates for B2B and B2C rollouts.
- M&A/partnership heatmaps and a prioritized list of strategic moves (bolt-on, capability buy, or greenfield) informed by concentration metrics and portfolio fit.
Competitive Landscape — How Leading Vendors Are Positioning
Market concentration at the headline level is moderate: our CR3 sits at approximately 45% and CR5 at about 55%. This configuration creates defensive advantages for established players while leaving room for specialist challengers and vertical integrators. Below are concise strategic reads on the core incumbents we analyze in depth.
Shower Trays Market
- Kaldewei (Germany) — A legacy player focused on steel-enamel systems. Their product strategy couples a broad series range (including flat floor-level options) with sustainability narratives built around high recycled content. Strengths: material durability and brand recognition in premium segments. Strategic implication: incumbency in hard-surface trays can be defended via sustainability investments and lifecycle cost messaging.
- Roca (Spain) — Positioned around ceramic and composite trays with anti-slip and extraslim designs plus mineral-resin composites. Strengths: breadth of finishes and distributor reach. Strategic implication: product differentiation via surface engineering and finish options will continue to win specification share in renovations.
- Duravit (Germany) — Ceramic bases and an expanding recyclable product family (e.g., DuroCast Nature). Strengths: strong designer cachet and premium channel presence. Strategic implication: sustainability-certified offerings can command price premiums in high-growth urban refurbishment markets.
- Schluter (Germany) — A systems player focused on prefabricated sloped trays paired with integrated waterproofing kits for tiled showers. Strengths: channel stickiness with tile contractors and installers. Strategic implication: systems integration routes are a durable moat, particularly in commercial and multi-family renovation segments.
- Noken (Spain) — Offers mineral stone and ceramic trays with sustainability variants. Strengths: design flexibility and finish choices for spec-driven projects. Strategic implication: bespoke aesthetics plus ESG labeling can open premium renovation pockets.
- Acquabella (Spain) — Specialist in custom and modular trays with slate and stone-effect finishes. Recent move: March 2026 launch of Livo Slate and Acqua Zero lines emphasizing material innovation and contemporary aesthetics. Strengths: design-led positioning and modularity. Strategic implication: niche-first innovation can act as a wedge for geographic expansion or channel partnerships.
Supply-Chain, Cost and Regulatory Dynamics — What to Watch in 2026
- Raw-material volatility. A near-30% rise in key inputs elevates the importance of hedging strategies, long-term supplier agreements and the evaluation of alternative substrates. Manufacturers with flexible BOMs or captive supply stand to protect gross margins.
- Installation economics as product differentiator. Given the meaningful per-job labor component, design choices that reduce on-site labor (prefab kits, single-piece bases, integrated waterproofing) materially affect total project cost and adoption curves.
- Regulatory friction. Compliance around safety glazing and other standards in major markets increases time-to-market for novel composites; regulatory-readiness should be embedded into new-product development timelines.
- Design premium. The shift to ultra-thin profiles is not just aesthetic — it changes material usage and manufacturing techniques, creates opportunities for premium pricing, and increases supplier concentration risks for specialized components.
Where the Revenue Opportunities Concentrate (Strategic Themes)
From our scenario work, the strongest near-term opportunities for 2026 execution fall into four strategic themes:
- Design-led premiumization: capitalize on ultra-thin and bespoke finishes to capture higher ASPs in urban retrofit projects.
- Systems and installer enablement: offer integrated waterproofing and prefabricated kits to reduce on-site labor cost and accelerate specification by contractors.
- Material & supply reshaping: de-risk input exposure through alternative materials, strategic sourcing, or partial vertical integration.
- Service and aftermarket: monetize installation, maintenance and refurb services as a margin-rich complement to product sales.
How PW Consulting Translates This Intelligence into 2026 Wins
Clients engage us when they need rapid, executable insight rather than academic overviews. Our deliverables span short-term execution and medium-term strategic repositioning:
- Rapid cost-pass-through playbooks (4–8 weeks) to protect margins against raw-material shocks.
- Product portfolio rationalization and SKU optimisation, informed by price-elasticity and installer-economics modeling.
- Commercial pilots for direct-to-contractor models and prefabricated-systems distribution strategies.
- Targeted M&A due diligence and integration planning aligned with our concentration analysis and capability maps.
Next Steps
This preview is intended to demonstrate the strategic value embedded in our full Shower Trays Market study: validated market-sizing, proprietary segmentation matrices, a multi-scenario forecast and company-level scorecards that feed directly into 2026 capital and commercial decisions. The complete report contains the detailed segmentation breakdowns, regional demand heatmaps, and company-level revenue estimates that we have purposefully excluded here to preserve the exclusivity of our proprietary dataset.
To commission the full study, schedule a briefing, or request a bespoke workshop that translates these insights into a 90-day action plan for your organization, contact PW Consulting’s industry team via our website or speak directly with your account partner. In complex markets defined by rising input costs, tightening regulation and rapid design shifts, timely and actionable intelligence is the difference between defending margin and realizing growth — we stand ready to make that outcome more certain.
For detailed analysis of this topic, please visit the official page: Shower Trays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Audible & Visual Signaling Devices Market to reach USD 42.88M by 2032 at 4.36% CAGR
By PW Consulting, 2026-07-08
Audible & Visual Signaling Devices Market: Strategic Intelligence for 2026 Decision‑Making
As PW Consulting’s lead industry analyst, I present a concise yet high‑impact orientation to the Audible & Visual Signaling Devices market that will guide executive decisions in 2026. This briefing synthesizes the market’s macro trajectory, competitive dynamics, material and regulatory headwinds, and the practical types of intelligence our full study delivers — without revealing the granular subsegment tables and proprietary splits reserved for the full report. Think of this as the trailer: enough depth to shape questions, priorities, and near‑term moves; intentionally withheld specifics to direct you to the full dataset and interactive models available in our published research.
Audible & Visual Signaling Devices Market
Market snapshot: the macro trajectory that frames 2026 choices
The market has displayed steady recovery and structural expansion through the base period (2020–2025) and enters the forecast window (2026–2032) from a position of renewed momentum. PW Consulting’s model — built from vendor releases, procurement tenders, and equipment replacement cycles — shows a clear compound annual growth rate of 4.36% across the forecast horizon. After a modest dip and subsequent correction during the mid‑cycle years, the industry baseline in 2025 positions incumbents and new entrants for measurable growth beginning in 2026.
Audible & Visual Signaling Devices Market
Why this matters: a mid‑single digit CAGR combined with predictable regulatory refresh cycles shifts the competitive calculus from short‑term price competition toward engineered differentiation, services monetization, and modularity that reduces lifecycle cost for end users. In short, 2026 is the year buyers move from spec‑based purchasing to value‑based procurement — and vendors who can quantify total cost of ownership and compliance assurances will win the next wave of contracts.
Audible & Visual Signaling Devices Market
Why this briefing is strategic for 2026 decisions
- Product roadmaps: The growth profile rewards investment in LED, IoT‑enabled notification, and integrated audible‑visual combinations that reduce installation and commissioning time.
- M&A and partnership timing: Moderate market concentration creates opportunistic windows for bolt‑on acquisitions that add certification scopes, regional channels, or software capabilities.
- Procurement & sourcing: Material and semiconductor price volatility necessitates diversified sourcing, hedging strategies, and supplier scorecards tied to service levels and lead times.
- Compliance & risk management: Stricter enforcement of fire, life‑safety, and occupational standards elevates certified product portfolios and testing labs as strategic assets.
- Commercial execution: Sales organizations must transition from product feature pitches to outcome selling — quantifying downtime reduction, compliance uplift, and lifecycle cost savings.
What the full PW Consulting report delivers — practical, executable intelligence
Our study is structured around the needs of executives who must translate market signals into executable plans in 90–180 days. The core deliverables include:
- Proprietary market model (historical and forecasted market sizes with scenario toggles) that powers sensitivity testing across price, input‑cost, and regulatory shock scenarios.
- Decision‑grade playbooks: go‑to‑market templates for product OEMs, distributors, and systems integrators, including channel economics and bundling strategies for service contracts.
- Supplier benchmarking and scorecards covering certification breadth, manufacturing footprint, delivery reliability, and after‑sales service KPIs.
- Regulatory compendium and compliance gap analysis that maps common certification roadblocks to timelines and cost estimates for remediation.
- TCO and CAPEX/OPEX calculators for buyer conversations and internal prioritization of R&D investments.
- M&A trigger list and valuation sensitivities based on revenue growth, margin expansion potential, and technology/IP uniqueness.
- Practical annexes: procurement templates, technical acceptance checklists, and an installer/commissioning guide tailored for industrial and harsh‑environment deployments.
These assets are designed for immediate operational use by product, commercial, and corporate development teams — again, the full numeric matrices and vendor‑level splits are available in the report to paying subscribers and clients.
Competitive landscape: what incumbent and specialist strategies reveal
The market exhibits moderate concentration: the top three players account for a meaningful portion of global revenues, with the top five extending that reach further. That structure produces a competitive environment where global systems integrators and diversified industrial groups compete with highly specialized manufacturers focused on hazardous areas, modular signal towers, or IoT‑integrated devices.
- R. STAHL (Germany): A recognized player in hazardous‑area combined audible/visual devices; strength lies in certification and robust product portfolios for explosive atmospheres.
- WERMA Signaltechnik (Germany): Known for modular signal towers and configurable optical‑audible combinations that appeal to manufacturers seeking standardized, scalable lineside signaling.
- E2S Warning Signals (UK) & Pfannenberg (Germany): Both emphasize high‑performance alarms and safety‑system integration; Pfannenberg’s focus on safety integrity and recent product showcases underscore investment in premium, compliance‑focused segments.
- Edwards Signaling, Federal Signal, Auer Signal, Patlite: These firms cover breadth from factory automation alerts to global stack light leadership; Patlite’s push into compact audible devices and IoT capabilities highlights innovation at the intersection of edge connectivity and signaling hardware.
- Major systems suppliers (Schneider Electric, Honeywell, Siemens, Eaton, Rockwell Automation): Leverage ecosystem integration and cross‑sell opportunities — their signaling products are often bundled with building automation, fire detection, and industrial control systems.
- China‑based and niche manufacturers: Offer cost‑competitive, specialized features (for example motion‑activated voice alarms) and can win with aggressive pricing and regional scale.
Recent vendor activity in early 2026 — new audible alarm launches and trade‑show showcases — confirms vendor strategies are bifurcating: one track focused on certification and premium safety solutions, another on compact, connected devices and installation efficiency. Executives should read this as a cue to match product investments with channel capabilities and target end‑user willingness to pay for compliance vs. convenience.
Supply chain & regulation: the operational levers that will determine winners
Raw materials and components matter. Design decisions about enclosures and housings — from polycarbonate for environmental toughness to aluminum for fire‑protection and recyclability, and industrial ABS for shock resistance — materially affect product lifecycle cost, recyclability claims, and approval paths in regulated markets. Semiconductor availability and price swings remain the single largest near‑term margin pressure point; manufacturers and buyers must bake lead‑time premiums and alternate‑supplier clauses into contracts.
Regulatory enforcement is tightening across key standards for alarm and signaling equipment. Stronger alignment with regulatory timelines and third‑party testing accelerates time‑to‑spec for buyers and reduces the risk of product delistings in public tenders. The result: certified portfolios and lab access provide durable competitive advantage and should be prioritized in capital allocation and M&A screening.
Immediate actions for 2026 — a concise executive checklist
- Run a 90‑day product portfolio triage: quantify margins by certification level and eliminate or partner on low‑margin SKUs that require disproportionate compliance spend.
- Secure multi‑tiered supply agreements for critical electronic components and establish rotational sourcing to mitigate single‑supplier risk.
- Prioritize sales enablement to sell outcomes: equip field teams with TCO calculators and compliance benefit narratives for industrial buyers.
- Target one bolt‑on acquisition that fills a certification or software gap; use our M&A trigger list to screen targets based on realistic integration paybacks.
- Invest in a service offering for lifecycle compliance management — recurring revenue from annual testing, firmware updates, and recertification is under‑penetrated.
Each of these actions is supported by templates, models, and scenario outputs in the full PW Consulting study, enabling you to move from strategic intent to operational execution with measurable KPIs.
Next step
This brief outlines the strategic implications and actionable lines of inquiry you should adopt in 2026. For board‑grade appendices, interactive market models, vendor scorecards, and the withheld subsegment detail that informs acquisition valuation and pricing strategy, consult the full Audible & Visual Signaling Devices Market report from PW Consulting. The report is the only source that combines our proprietary market model with executable playbooks and vendor‑level diagnostics tailored for rapid implementation.
For detailed analysis of this topic, please visit the official page: Audible & Visual Signaling Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Urokinase Market to Reach USD 263.5M by 2032 at 5.9% CAGR
By PW Consulting, 2026-07-08
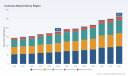
Urokinase Market 2026: Strategic Preview for Executives — A PW Consulting Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet incisive preview of our Urokinase Market research — designed to orient executive decision-making in 2026. This briefing synthesizes the market’s recent trajectory, near-term regulatory inflection points, competitive dynamics, and the commercial levers that will determine winners and laggards over the next investment cycle. We show the analytic depth behind our conclusions while intentionally reserving detailed segmentation tables and unit-level forecasts for the full report.
Urokinase Market
Market snapshot: what the numbers tell us
Measured on a global basis, the urokinase market matured from roughly USD 144 million in 2020 to about USD 178.6 million in 2025. Momentum persists into the forecast window: our base-case model projects continued expansion at a mid-single-digit compound annual growth rate (CAGR) of about 5.9% through the 2026–2032 horizon, with the market reaching roughly USD 263.5 million by 2032 under the central scenario.
Urokinase Market
Two takeaways are immediate for 2026 planning. First, this is a market large enough to sustain differentiated, margin-accretive plays (novel formulations, branded reintroductions, and specialty clinical pathways), yet small and fragmented enough that focused tactical moves can materially shift competitive positions. Second, steady headline growth masks critical chokepoints — regulatory timing, manufacturing readiness, and distribution friction — which will determine whether the growth is captured by incumbents, newcomers, or both.
Urokinase Market
Why 2026 is a strategic pivot
- Regulatory inflection: Legacy assets and reformulated biologics are entering regulatory cycles that will change commercial access. In particular, planned sBLA pathways and manufacturing modernization programs for established urokinase products create a narrow window in which regulatory progress will translate directly to revenue re-entry.
- Manufacturing and supply-chain reconfiguration: Recent CDMO partnerships and production modernization efforts point to an industry re-alignment where capacity ownership and contract-manufacturing relationships will confer first-mover advantage in the most commercially attractive indications.
- Commercial pressure from generic supply: A global set of manufacturers, particularly firms focused on sterile injectables and export markets, is sustaining price competition and broad availability across clinical settings. Organizations that rely solely on price competitiveness risk margin erosion without a clear scale plan.
What our report delivers — practical, transaction-ready intelligence
The full PW Consulting study goes beyond headline forecasts to provide a toolkit you can use in 2026 to make decisions today. Key modules include:
- Comprehensive market-sizing methodology and a dynamic financial model with scenario and sensitivity levers (policy, adoption, pricing, and supply shocks).
- Regulatory blueprints and timelines for re-authorization and supplemental filings, including stepwise decision trees for sBLA-style pathways.
- Supply-chain and CDMO evaluation frameworks: supplier risk scoring, on-time-to-scale modeling, and capital vs. contract capacity tradeoffs.
- Competitive benchmarking that combines capability maps, route-to-market analysis, and M&A archetypes to identify attractive consolidation targets and partnership fits.
- Commercial playbooks for segmentation by clinical pathway (acute thrombolysis, catheter clearance, hospital pharmacy), tendering matrices, and reimbursement negotiation tactics.
- Investment and M&A diligence checklists: valuation sensitivities tied to regulatory milestones, clinical uptake, and margin assumptions.
Competitive landscape — who matters and why
The market is notably fragmented; top-tier concentration is modest, reflecting a landscape where regional manufacturers and specialist players coexist with legacy branded assets. That fragmentation creates strategic space for consolidation, differentiated product strategies, and targeted clinical positioning.
Microbix Biosystems stands out as a strategic focal point. As the steward of a globally approved low-molecular-weight urokinase, the company has pursued re-commercialization through CDMO partnerships and regulatory relaunch strategies focused on catheter clearance and other acute-use scenarios. Their recent manufacturing partnerships and production modernization initiatives are material: they reduce technical risk ahead of planned regulatory filings and de-risk supply for potential U.S. re-entry. For potential partners, acquirers, and distributors, the Microbix trajectory illustrates the commercial upside of combining regulatory stewardship with scalable contract manufacturing.
At the same time, a cohort of established injectables manufacturers — including several India-based producers and global sterile-injectable suppliers — maintain broad supply footprints and price-competitive offerings. Their strength is operational: scalable sterile facilities, export-oriented distribution, and product portfolios that serve hospital and emerging-market channels. These firms reinforce pricing discipline in the market, particularly in non-premium segments.
Strategic implications by stakeholder
- Pharma/biotech holders of urokinase assets: Prioritize regulatory timelines and CDMO secures. A clearly articulated sBLA pathway (or equivalent) combined with validated contract manufacturing will enable timely market re-entry and value capture. Consider phased launches that pair catheter clearance rollouts with targeted evidence generation to accelerate hospital adoption.
- CDMOs and contract manufacturers: Invest selectively in sterile-fill capabilities and regulatory support services. Offer integrated packages (process modernization + regulatory dossier support) to be the preferred partner for re-launches; build commercial SLAs that align incentives with successful approvals and on-time delivery.
- Distributors and hospital systems: Differentiate procurement by total cost of care rather than unit price. Suppliers who can substantiate reduced administration costs, simplified logistics (e.g., powder formats that cut cold-chain dependency), or superior clinical support will win formulary share.
- Private equity and strategic buyers: Look for bolt-on targets where regulatory clarity or CDMO relationships unlock disproportionate value. Fragmentation means synergies are achievable through consolidation of distribution, regulatory dossiers, and manufacturing capacity.
High-conviction plays for 2026
- Secure or strengthen CDMO partnerships early. Manufacturing readiness is the gating factor for any regulatory relaunch and the principal lever for time-to-revenue.
- Differentiate with formulation strategy. Powdered formats that reduce cold-chain costs and extend shelf life have discrete commercial advantages in certain markets and care settings.
- Target niche clinical pathways where payers and clinicians accept premium positioning (for example, catheter-related indications) while simultaneously defending broad-volume channels through competitive pricing and service.
- Prepare for multi-speed regional strategies. The same product will require different commercial and regulatory playbooks across major regions; aligning these in 2026 will accelerate scale after approval milestones.
- Build an evidence-generation roadmap that pairs early post-market surveillance with value-based contracting pilots, especially for higher-acuity indications where economic arguments matter.
Decision tools included with the full study
To move from insight to action, PW Consulting’s full report includes:
- Interactive financial models (base, upside, downside) tied to regulatory milestones and adoption curves.
- CDMO selection scorecards and negotiation playbooks.
- Go-to-market roadmaps with resource and timing overlays for phased launches.
- M&A screening matrices calibrated to regulatory, manufacturing, and distribution vectors.
- Risk heatmaps and mitigation plans for supply disruptions, pricing shocks, and rapid generics entry.
Closing perspective — what to prioritize this quarter
If you are evaluating exposure to the urokinase market in 2026, your near-term checklist should be short and executable: validate your manufacturing pathway (internal or CDMO), map regulatory milestones against your go-to-market timeline, and stress-test pricing and tender scenarios against a fragmented supplier base. The macro backdrop — mid-single-digit CAGR and a market size that has materially expanded since 2020 — means there is growth to capture; but timing and execution will determine who captures the premium versus who competes primarily on price.
PW Consulting’s full Urokinase Market report contains the granular segmentation, model inputs, and tactical annexes required to underwrite investment cases and commercial launches this year. For decision-makers seeking to convert insight into action, the detailed breakdowns and scenario-ready tools in the report are the operational next step.
For detailed analysis of this topic, please visit the official page: Urokinase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Balancing Valves Market Poised for 5.8% CAGR Through 2032
By PW Consulting, 2026-07-08
Balancing Valves Market — Strategic Outlook for 2026 Decision‑Makers
Executive teaser
As organizations recalibrate capital allocation and product roadmaps for 2026, the Balancing Valves market is emerging as a pragmatic lever to capture durable efficiency gains across HVAC and hydronic systems. PW Consulting’s forthcoming market brief synthesizes seven years of historical data (2020–2025) and a seven‑year forecast window (2026–2032) to translate market momentum into decision‑grade insights. The market expanded from USD 355.5 Million in 2020 to USD 471.27 Million in our base year (2025) and, under a 5.8% CAGR through the forecast horizon, is projected to approach USD 699.3 Million by 2032. This introduction outlines why that trajectory matters for strategic moves in 2026 — and what our full report provides to guide them.
Balancing Valves Market
Market snapshot: momentum and structural drivers
-
Growth trajectory: Between 2020 and 2025 the market grew significantly (USD 355.5M → USD 471.27M). Our forecast starts at USD 489.64 Million in 2026 and, at a compound annual growth rate of 5.8% for 2026–2032, reaches USD 699.31 Million by 2032. These figures reflect both retrofit demand and new construction adoption driven by energy code tightening and operational cost optimization.
Balancing Valves Market -
Regulatory tailwinds and standards: The field is being reshaped by formal standardization — most notably ISO 16484‑4:2025, which for the first time defines dynamic balancing systems and performance classes for hydronic networks. Parallel policy signals (including documented increases in the share of retrofits and code‑driven uptake in new office designs) are accelerating baseline demand for balancing solutions that can demonstrably reduce energy use and improve occupant comfort.
Balancing Valves Market -
Input cost and supply risk: Raw material volatility remains a live risk. For example, steel market metrics show upward pressure (notably mid‑2026 pricing spikes), reinforcing the need for procurement playbooks that buffer margin erosion through hedging, supplier diversification, or design material substitutions where feasible.
Why this matters for 2026 corporate strategy
-
Prioritize product‑market fit under new standards: With ISO 16484‑4 now in the market lexicon, product portfolios must be audited against performance classes (A/B/C). Packages that combine dynamic balancing hardware with commissioning and measurement protocols will command premium positioning in commercial retrofits and code‑compliant new builds.
-
Capture retrofit economics: A notable share of efficiency upgrades now include balancing valves as a cost‑effective measure to realize measured savings. For equipment manufacturers and distributors, this shifts sales tactics from component selling to system outcomes — e.g., guaranteed delta kWh or normalized energy performance contracts linked to valve deployment.
-
M&A and consolidation scouting: The market concentration metrics (CR3 ~41%, CR5 ~48%) indicate a moderately consolidated field with space for bolt‑on acquisitions to build geographic or capability scale. Strategic buyers in 2026 should prioritize targets that provide certified dynamic balancing technology, digital commissioning capabilities, or channel access to large HVAC service providers.
-
Service and lifecycle monetization: The migration from manual to dynamic balancing approaches creates recurring revenue pathways — commissioning, digital monitoring subscriptions, warranty extensions, and performance remediation services. Recent commercial signalling — extended warranties and showrooming at major trade events — suggests warranty and service packaging will become a competitive battleground.
What PW Consulting’s full report delivers (select actionable modules)
-
Market sizing and validated forecasts: Annualized market figures from 2020–2025, with bottom‑up scenario modeling for 2026–2032 under multiple adoption and policy scenarios.
-
Commercial segmentation playbook: A pragmatic segmentation framework that maps product types, applications, and sales channels to profitable go‑to‑market motions — including bundle strategies for retrofits versus OEM new builds. (Note: granular regional and application splits are included in the full report and intentionally withheld from this preview.)
-
Procurement and cost management toolkit: Supplier scorecards, raw material sensitivity analyses, and hedging case studies tailored to valve manufacturers and distributors.
-
Standards and compliance matrix: Interpretation of ISO 16484‑4 performance classes and a practical implementation checklist for R&D, testing labs, and product managers.
-
M&A screening model: Deal‑sizing heuristics, integration risk templates, and five candidate archetypes (technology, channel, geographic, service, and vertical OEM) to evaluate return on investment for 2026 transactions.
-
Commercial war‑game and pricing simulations: Scenario playbooks for warranty offers, bundled service contracts, and tiered product launches that protect margin while accelerating share.
Competitive landscape: who’s shaping the field and how
The market blends legacy valve specialists with pump and control integrators. Legacy and specialist manufacturers retain technical leadership in hydronic balancing, while broader systems players leverage channel reach and integrated system offerings. Key industry participants include established U.S. manufacturers known for HVAC and commercial building solutions, European firms with deep hydronics and dynamic balancing portfolios, and pump OEMs offering combined pump‑valve solutions. Recent market signals include a notable acquisition and standardization moves that will reframe competitive dynamics.
-
Specialist valve firms (examples): Several North American firms are highly focused on HVAC balancing valves for commercial and industrial use, prioritizing robustness and retrofit fit. Their go‑to strengths are installer familiarity, broad distributor networks, and competitive service offerings.
-
European hydronics leaders: Manufacturers from Europe lead in dynamic balancing technology and standards compliance. Their portfolios tend to emphasize measurement accuracy, integration with building automation systems, and product families mapped to ISO performance classes.
-
System integrators and pump OEMs: Entities that supply pumps alongside valves can sell whole‑system efficiency narratives to engineering‑procurement construction (EPC) firms, which is a growing advantage in large commercial and district heating projects.
Strategic developments to watch (recent highlights):
-
Standards momentum: The formalization of ISO 16484‑4:2025 elevates dynamic balancing performance as a procurement criterion — favoring vendors that can certify performance and offer standardized commissioning regimes.
-
Corporate moves: Consolidation activity (including the acquisition of a dynamic‑valve specialist by a larger valve group) signals buyers’ appetite for capability consolidation and geographic scale.
-
Commercial innovation: Warranty extensions and expanded trade show engagement point to more aggressive commercial plays around assurance and installer education. These tactics can shift procurement toward bundled offerings that lock in service revenues.
Strategic playbook: recommended 90‑ to 360‑day actions for 2026
-
90 days — Portfolio triage: Audit existing valve and control SKUs for compliance with ISO 16484‑4 classes; fast‑track lab testing or third‑party certification for top sellers; adjust pricing to reflect new compliance value.
-
180 days — Channel and service pilots: Launch two geographically targeted retrofit pilots that bundle dynamic balancing hardware with digital commissioning and a warranty uplift. Use measured outcomes to build a repeatable sales case for EPCs and property managers.
-
360 days — Strategic growth moves: Evaluate bolt‑on acquisitions that (a) supply certified dynamic balancing tech, (b) provide local commissioning capabilities, or (c) open a priority channel. Parallelly, implement a procurement strategy to mitigate raw material exposure — including multi‑sourcing and indexed supply contracts tied to steel price movements.
Data, methodology and where to go next
Our analysis is anchored on base year 2025, historical tracking for 2020–2025, and a forecast period of 2026–2032. It combines primary interviews with OEMs, distributors and commissioning firms, structural modeling of construction and retrofit cycles, and sensitivity testing against commodity and regulatory scenarios. The full PW Consulting report contains the granular regional, type, and application splits, supplier scorecards, detailed M&A target archetypes, and downloadable modeling templates — data intentionally withheld in this preview to preserve the report’s transactional value.
Final note — the strategic value proposition
For 2026 decision‑makers the Balancing Valves market is not merely a hardware segment; it is a measurable lever to improve system efficiency, reduce operating expenses, and generate recurring service revenues. The convergence of new standards, retrofit spending, and commercial warranty innovation creates a narrow window for companies to reposition: those that certify performance, reinforce channel execution, and de‑risk supply will translate market growth (from USD 471.27M in 2025 toward USD 699.31M by 2032 at a 5.8% CAGR) into sustained competitive advantage. PW Consulting’s full report equips leaders with the playbooks, models, and due‑diligence tools to act decisively in 2026.
To access the complete dataset, granular segmentation, and executable annexes, please visit the PW Consulting report page or contact our Balancing Valves market desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Balancing Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Human Milk Oligosaccharides (HMO) Market — Strategic Preview for 2026 Decision-Making
As lead analysts at PW Consulting, we present a concise, high-fidelity preview of our forthcoming Human Milk Oligosaccharides (HMO) market study. This executive preview surfaces the actionable intelligence that will matter most to senior executives and investors planning capital allocation, M&A, commercial launches and supply‑chain buildouts in 2026. The global HMO market has moved from a niche research arena into a fast-scaling commercial market: measured at USD 172.5 Million in 2020, it reached USD 281.31 Million in our base year (2025) and is forecast to accelerate to USD 758.23 Million by 2032. Our forecast envelope (2026–2032) assumes a compound annual growth rate (CAGR) of 13.85%—a pace that forces strategic choices on capacity, partnerships and regulatory sequencing.
Human Milk Oligosaccharides (HMO) Market
Why this study matters for 2026
-
Timing is strategic. The market is at a juncture where regulatory clearances, manufacturing scale‑up and payer recognition are converging. In 2026, executives must decide whether to invest in own‑site fermentation capacity, secure long‑term supply agreements, or pursue bolt‑on acquisitions to access established IP and approvals.
Human Milk Oligosaccharides (HMO) Market -
Fast structural growth creates winner‑takes‑most dynamics. Market concentration metrics indicate a concentrated supply base (CR3 ~62%, CR5 ~72.5%), meaning leading incumbents are consolidating commercial access and regulatory covers. Late movers face higher entry costs and negotiating from weaker positions unless they secure differentiating capabilities.
Human Milk Oligosaccharides (HMO) Market -
Policy and approvals are reshaping addressable demand. Recent regulatory decisions—most notably explicit approvals in key Asian markets in 2025–2026 and a widening list of jurisdictions that permit HMO use in infant nutrition—have expanded the commercial runway and altered market access strategies.
What the full report delivers (operationally focused)
-
High‑granularity market sizing and seven‑year forecasting (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario modelling for regulatory, pricing and capacity shocks.
-
Segment playbooks: product‑level economics, approval timelines, route‑to‑market templates and a prioritized list of commercial applications with ROI and break‑even analysis per strategy. (Note: detailed segment splits are contained in the full study to preserve proprietary granularity.)
-
Manufacturing and capex benchmarking: precision‑fermentation plant sizing, expected throughput profiles, OPEX drivers and a build vs contract‑manufacture decision framework including payback curves.
-
Regulatory & reimbursement matrix across priority jurisdictions, including approval status, dossier expectations and typical transition timelines from GRAS/novel food to infant‑formula acceptance and reimbursement drivers.
-
Commercial diligence tools: competitor capability heat maps, pricing tolerance analysis, a supplier‑risk register and a ready‑to‑use M&A playbook for targets and valuation multiples appropriate to HMO assets.
Market dynamics and near‑term catalysts
-
Regulatory expansion: 2025–2026 saw several pivotal approvals that materially increase market addressability. Notably, national authorities in major markets have cleared additional HMO structures for infant formulas and related applications—reshaping formulation roadmaps and procurement strategies.
-
Precision fermentation scale‑up: advances in fermentation platforms have lowered marginal production costs and shortened time‑to‑volume. This is the dominant production pathway for multi‑gram‑scale commercial HMO supply and is central to any capex planning exercise.
-
Reimbursement and early‑life nutrition policies: in several priority markets, HMO‑fortified formulas are now part of reimbursed nutrition programs, which accelerates adoption by creating a payor pathway and stabilizing premium pricing bands for approved formulations.
-
Supply architecture complexity: commercial fermentation requires biotech infrastructure with multi‑thousand‑litre capacity, specialized downstream purification, and quality systems aligned to infant nutrition regulations—factors that extend lead times and favor incumbents that have already invested.
Competitive landscape — who matters and what they bring
The competitive set is a mix of large ingredient conglomerates, fermentation specialists and specialized oligosaccharide suppliers. The following incumbents are shaping the market through complementary strengths in scale, approval portfolios and partner networks:
-
dsm‑firmenich (Netherlands): A fully integrated fermentation platform with a dedicated HMO production site and a broad regulatory playbook enabling multi‑structure commercial supply to infant nutrition manufacturers globally.
-
Chr. Hansen (Denmark): Fermentation‑based capabilities with scale and an expanded product portfolio following selective asset acquisitions; strong go‑to‑market capability in functional nutrition and infant formula channels.
-
Kyowa Hakko Bio (Japan): Proven fermentation technology with regulatory approvals in several Asian markets and established regional manufacturing footprints—an attractive partner for market entry into APAC jurisdictions.
-
BENEO (Belgium) with WACKER partnership: Commercialization route that pairs ingredient marketing and precision‑fermentation production in Europe—illustrative of the strategic partnerships that can accelerate market access without sole big‑ticket capex.
-
Inbiose, Elicityl, Dextra, Carbosynth and other specialized suppliers: These players provide proprietary platforms, custom manufacturing and specialty back‑up supply for clinical and high‑value applications, and are frequently acquisition or partner targets for larger players seeking niche capabilities.
Recent corporate actions highlight momentum: regulatory approvals for additional HMO structures in early 2026, product launches in 2025 by strategic partners, and targeted capacity expansions in adjacent ingredient plants demonstrate that both organic scale‑up and collaborative models are active in parallel.
Strategic imperatives for executives in 2026
-
Decide on a supply strategy now. The choice is effectively between (a) build‑own‑operate for long‑term control and margin capture, (b) long‑term tolling or supply agreements to preserve balance sheet, or (c) acqui‑hire of niche producers to buy approvals and IP. Our capex models show materially different payback profiles—selecting a path early reduces exposure to tightening supply as demand ramps.
-
Prioritize regulatory sequencing. Not all HMO structures and territories move at the same pace. Successful players align product development to likely approval windows and channel access, and use staggered launches to manage inventory and pricing dynamics.
-
Negotiate anchoring agreements. Given the sector’s concentration, incumbents will favor multi‑year off‑take contracts. New entrants should design flexible offtake terms tied to price corridors and volume options to reduce downside risk.
-
Embed reimbursement and public health narratives into commercial planning. Where early‑life nutrition reimbursement exists, formulators can secure volume predictability and favorable shelf pricing; these payor pathways materially improve NPV for premium formulations.
-
Use M&A to close capability gaps. Targets that deliver regulatory dossiers, small‑scale GMP production and bespoke HMO structures command premiums but can accelerate market entry and reduce time‑to‑revenue.
How PW Consulting’s study will help you act
-
We provide the decision tools you need in 2026: integrated financial models, plant‑sizing calculators, regulatory roadmap templates and a prioritized partner shortlist. These are built to be operational—ready to be handed to business development, supply chain and regulatory teams for execution.
-
We flag the critical inflection points: the volumes at which building makes economic sense, the number of jurisdictional approvals required to support a premium price point, and the contingencies to mitigate supply and regulatory risk.
-
We preserve the detailed segment tables and competitive share matrices for the full report so you can model bespoke strategies against the precise splits by region, type and application that underpin our headline forecasts.
Closing note — a pragmatic call to action
The HMO market is no longer a speculative vector; it is a commercial ecosystem moving from experimentation to standardization. With a base year of 2025 and a clear, high‑growth trajectory over 2026–2032 (CAGR 13.85%), 2026 is the year to convert strategic intent into executable programs. Our full PW Consulting HMO Market study contains the source tables, segment allocations, regulatory trackers and executable playbooks required to make those decisions with conviction. Access to the complete dataset and operational templates is available through our release portal—download the full report to translate this strategic preview into a 2026 action plan.
For detailed analysis of this topic, please visit the official page: Human Milk Oligosaccharides (HMO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MDI Market to Reach USD 27.25 Billion by 2032 at 5.2% CAGR
By PW Consulting, 2026-07-08
MDI Market Strategic Outlook 2026: Navigating Supply Disruption, Policy Shock, and Durable Demand — PW Consulting
Executive preview
As we enter 2026, Methylene Diphenyl Di-isocyanate (MDI) stands at a strategic inflection point. After a robust recovery through 2020–2025 that grew the global market from the low teens to an estimated USD 19.1 Billion in 2025, PW Consulting projects continued expansion through our 2026–2032 forecast (compound annual growth rate: 5.2%), taking the market toward the high‑20s by 2032. For executives planning capital allocation, procurement strategy, or competitive moves in 2026, the decisions you make now will determine whether you capture upside from structural foam demand and new supply, or bear the cost of misallocated capacity and regulatory friction.
Methylene Diphenyl Di-isocyanate (MDI) Market
Why this research matters for 2026 decision cycles
-
MDI’s role as a foundational feedstock for insulation, automotive systems, coatings and specialty elastomers makes its price, supply and regulatory profile highly levered to broader capital and decarbonization cycles. Our report converts macro trajectories into executable actions: which facilities to prioritize, how to stress‑test procurement contracts, and where to position new product launches.
Methylene Diphenyl Di-isocyanate (MDI) Market -
2026 is the year when several large capacity initiatives and trade enforcement measures simultaneously alter availability and regional flows. That convergence creates both tactical disruption and strategic opportunity — our analysis quantifies the direction and tempo of these shifts, isolating transitory versus structural effects.
Methylene Diphenyl Di-isocyanate (MDI) Market -
We synthesize market sizing, demand elasticity, margin sensitivity to feedstock swings, and regulatory risk into decision tools executives can actually use in boardrooms, not just in powerpoint decks.
Market trajectory: growth, resilience and what the headline numbers conceal
The headline is straightforward: the global MDI market expanded materially over 2020–2025 and is expected to sustain mid‑single digit annual growth through 2032 (CAGR 5.2% for 2026–2032). That growth is underpinned by steady demand for energy‑efficient building materials and automotive lightweighting, while specialty applications — from adhesives to engineered elastomers — provide margin diversification.
But beneath the aggregate curve lie three layered dynamics that will dictate near‑term profitability and strategic positioning in 2026:
-
Supply additions and re‑routing of trade flows as major producers commission new capacity and as policy actions re‑shape cross‑border trade.
-
Raw‑material and feedstock volatility — particularly aniline/benzene pathways — that transmit quickly into MDI pricing and margin swings.
-
Customer segmentation: segments with long product cycles and insulation retrofit demand show lower price elasticity compared with higher‑volume flexible foam uses.
Supply dynamics & recent corporate movements (what matters in 2026)
2025–2026 activity by leading producers is reshaping regional access and bargaining power. Key developments we monitor include capacity projects nearing start‑up, targeted quality innovations, and commercial responses to trade rulings. Notable movements include:
-
BASF’s North American expansion with the Geismar, Louisiana project entering its final phase and scheduled for commercial start‑up in 2026. This materially changes regional availability and gives BASF additional leverage on volume contracts in NAFTA markets.
-
Covestro’s active pricing posture in North America in early 2026, reflecting tighter local supply and margin preservation strategies that downstream purchasers must respond to.
-
Wanhua’s aggressive capacity roadmap in China and planned large project approvals — a strategic pivot that signals intent to secure global scale across multiple hubs.
-
Kumho Mitsui and other regional producers continuing phased capacity increases focused on reliability and grade diversification (including low‑free‑monomer grades).
These moves matter because they change not only nominal tonnage but also the quality mix available to customers (e.g., low‑VOC elastomer grades or specialty polymeric blends), which has direct implications for product positioning and premium pricing.
Regulatory and trade risk: the immediate and strategic impact
Two concurrent policy developments demand immediate attention from 2026 planners. First, antidumping enforcement and trade investigations have introduced high precautionary tariffs and procedural constraints that are already affecting import availability and commercial negotiations. Second, Section 337 trade action outcomes have the potential to restrict certain imports, creating short‑term scarcity in affected corridors. For procurement and legal teams this means:
-
Urgent need for scenario plans that consider constrained import availability and higher landed cost assumptions for affected sources.
-
Review of supply contracts for force majeure, diversion rights and renegotiation triggers tied to trade rulings.
-
Increased value for locally‑sourced or contractually guaranteed tonnage, pushing buyers to rethink inventory policy and hedging.
Feedstock sensitivity and margin risk
Aniline (and upstream benzene dynamics) remains the primary transmission mechanism for raw‑material driven margin swings. Our report quantifies elasticities and provides a short list of pragmatic hedging approaches — from index‑linked contracts to multi‑sourced feedstock strategies — that procurement teams can implement in 2026 to stabilize margins while preserving optionality.
Competitive landscape: concentrated players amid a fragmented market
Though a number of major chemical companies anchor the market, measured concentration (CR3 and CR5 metrics) points to room for regional competition and tactical consolidation. Key players we analyze in depth include:
-
BASF SE — scaling North American capacity and integrating downstream feedstock and logistics to lock in market share.
-
Covestro AG — focusing on commercial price discipline and customer segmentation in NAFTA markets.
-
Wanhua Chemical — pursuing large‑scale projects and a multi‑hub strategy that could shift global flows if fully realized.
-
Huntsman, Dow, Tosoh, Kumho Mitsui, Karoon Petrochemical and Hindustan Organic — each playing differentiated regional and product‑grade strategies, from low‑monomer specialties to integrated production footprints.
Our competitive maps do more than name names: they model capacity timing, likely commercial responses to supply shocks, and M&A playing fields that could accelerate consolidation if price cycles tighten.
What PW Consulting’s report delivers (practical, transaction‑ready outputs)
-
Demand and price modeling calibrated to historical 2020–2025 performance and stress‑tested across multiple 2026 scenarios (trade shock, feedstock spike, demand slowdown).
-
Supply‑side timeline and impact assessment that maps announced expansions and start‑up risks to regional availability and freight patterns.
-
Procurement playbooks with contract templates, indexing recommendations and inventory sizing rules calibrated for different buyer archetypes.
-
Investment decision frameworks for CAPEX and M&A — including hurdle rate adjustments, break‑even utilization schedules, and integration checklists tailored for chemical assets.
-
Regulatory risk matrix and litigation scenario analysis tied to ongoing trade investigations and international compliance obligations.
Importantly, while this article highlights the types of intelligence included, the report intentionally withholds proprietary segment‑level tables and granular regional/application splits in public excerpts — these are delivered in the subscription package to preserve client value and competitive edge.
How corporate leaders should act in 2026
-
Procurement: Adopt multi‑axis hedging. Combine short‑term indexed procurement with selective long‑term take‑or‑pay capacity to insulate against abrupt supply squeeze and tariff‑driven cost jumps.
-
Commercial teams: Differentiate pricing by grade and application elasticity. Preserve margins where customers have low elasticity and offer value‑added services where competition intensifies.
-
Investment & M&A: Prioritize assets that provide logistical resilience or feedstock integration. Given market concentration metrics, bolt‑on acquisitions can be accretive if acquisition timing aligns with mid‑cycle supply scarcity.
-
Risk & compliance: Accelerate legal reviews of contracts to reflect trade investigation outcomes and build alternative sourcing playbooks for impacted corridors.
Final note — why PW Consulting’s MDI study is a must‑have for 2026
We designed this study to convert complexity into clarity: a compact set of decision tools, scenario calculators and transaction checklists that senior leaders can deploy immediately. The market’s headline growth hides distributional shifts in supply, evolving regulatory posture and feedstock exposure that will determine relative winners. This article previews our approach and key directional insights; the full report contains the models, granular sensitivity tables and supplier scorecards that teams need to operationalize strategy in 2026.
Next steps
PW Consulting can provide executive briefings, bespoke scenario workshops, and transaction support tailored to your role in the value chain — whether you are a purchaser grappling with landed cost volatility, an investor assessing a greenfield MDI asset, or a producer planning a grade differentiation strategy. Access to the full report and our proprietary segmentation datasets is available through our research subscription portal and consulting engagement packages.
Note: This article intentionally omits detailed regional and application breakdowns from the public synopsis. Subscribers receive the full segmentation matrix, granular demand drivers by end‑use, and the time‑series models that underlie our 2026 recommendations.
For detailed analysis of this topic, please visit the official page: Methylene Diphenyl Di-isocyanate (MDI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Garage Door Openers Market Poised for 6.15% CAGR Through 2032 — PW Consulting
By PW Consulting, 2026-07-08
Garage Door Openers Market 2026: Strategic Imperatives from PW Consulting
As companies prepare strategy for 2026 and beyond, the Garage Door Openers market is transitioning from a mature mechanical product category into a digitally enabled, service-oriented ecosystem. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—provides the strategic blueprint executives need to convert disruption into competitive advantage. The market expanded from roughly USD 158 million in 2020 to an estimated USD 210 million in 2025, and our base forecast sees that trajectory continuing to roughly USD 319 million by 2032 at a compounded annual growth rate of about 6.15%. These macro dynamics are the springboard for four pragmatic decision levers covered in depth in our report: product-platform strategy, channel & commercial models, supply-chain resilience, and adjacent services monetization.
Garage Door Openers Market
Why this study matters for 2026 planning
For leadership teams allocating capital in 2026, three realities define the opportunity and the risk landscape:
Garage Door Openers Market
- Steady, above-inflation market growth. The mid-single-digit CAGR underpins predictable topline expansion but hides shifting margin pools as devices integrate sensors, cameras, and cloud services.
- Concentration and competitive intensity. The category exhibits moderate concentration — the top three and top five firms account for nearly half and three-fifths of the market respectively — creating both advantages for incumbents and entry points for nimble challengers.
- Structural shifts in productization. Hardware alone is no longer the primary value driver. Smart features, retrofitability, installation economics, and recurring service or subscription models are redefining customer lifetime value.
Understanding these forces at a granular yet actionable level is essential to prioritize R&D spend, shape go-to-market investments, and design M&A or partnership strategies that will produce measurable ROI in 2026.
Garage Door Openers Market
Key market dynamics shaping 2026 decisions
Several interlocking dynamics will determine winners and losers in the coming 18–36 months. Our report synthesizes quantitative forecasting with qualitative channel checks to identify which dynamics are transient and which are structural.
- Smart home convergence. Increasing household adoption of integrated home ecosystems is driving demand for openers that natively support video, voice, and secure cloud access. Recent product introductions from leading players signal a race to establish platform-level advantages (device + video + app + services).
- Retrofit and spatial innovation. A meaningful share of demand is now driven by retrofitable and space-optimized solutions—side-mount and compact-drive units are moving from niche to mainstream in constrained installations.
- Regulatory and safety continuity. Existing U.S. safety standards (e.g., the federal safety standard for residential automatic garage door operators) remain in force, setting a stable compliance baseline. Manufacturers can therefore focus R&D resources on feature differentiation rather than sudden compliance redesigns.
- Raw material and cost pressure. Input cost trajectories — exemplified by rising hot-rolled coil steel prices — are squeezing gross margins and prompting a closer look at material substitution, localized sourcing, and hedging strategies across the value chain.
- Channel economics and installation labor. The installer network remains a crucial differentiator. Speed of installation, compatibility with existing door systems, and installer-friendly digital tools will directly influence adoption curves and warranty costs.
Competitive landscape: what incumbents and challengers are doing
The competitive map is nuanced. Legacy manufacturers continue to leverage brand and distribution, while specialized innovators attack specific white spaces such as ultra-compact drives, high-duty industrial operators, and integrated video-enabled units. Our competitive benchmarking in the report profiles over a dozen firms, highlighting strategic posture, product roadmaps, and go-to-market footprints.
- Established global players (e.g., major U.S. and European manufacturers) are doubling down on platformization—integrating cameras, cloud services, and subscription models into premium lines while retaining traditional channels for volume products.
- Smaller, focused firms are commercializing modular and space-saving architectures that lower installation time and expand the addressable retrofit market.
- Recent product launches and trade show reveals through late 2025 and early 2026 underscore acceleration in smart and high-duty segments: several companies introduced next-gen video-enabled units, compact side-mount designs, and heavy-duty operator lines—moves that sharpen product differentiation and increase aftermarket service opportunities.
PW Consulting’s company dossiers objectively assess strategic positioning across the competitive set, including legacy advantages (brand, distribution), engineering differentiators (drive type, integration capability), and service potential (warranties, connected services). These dossiers also map ideal partnership and M&A targets for companies seeking to accelerate capability-building without building in-house from scratch.
What the full report contains (practical deliverables)
This study goes beyond high-level market narrative. It is structured to be immediately actionable for executive teams preparing 2026 plans:
- Quantified market size and forecast (2020–2032) with scenario analysis and sensitivity testing; clear implications for volume, revenue mix, and margin pools under alternative technology adoption curves.
- Go-to-market playbooks for OEMs, distributors, and installer networks—covering pricing strategies, bundling options (hardware + service), and channel-specific customer journeys.
- Technology and product roadmaps that prioritize features with the highest NPV uplift, including integration pathways for video, telematics, and over-the-air updates.
- Supply-chain and procurement playbooks addressing raw-material volatility, contract design, and inventory strategies to mitigate hot-rolled coil and component cost pressure.
- Competitive benchmarking and M&A screening: deep profiles of leading firms, capability heatmaps, and a short-list of tuck-in and scale-up targets by strategic intent.
- Installer economics and after-sales optimization: field data on installation times, warranty cost drivers, and service monetization levers.
- Regulatory and safety compliance matrix aligned to current standards—allowing product managers and compliance officers to prioritize design trade-offs without surprises.
To respect the "trailer" principle, we highlight that the report contains granular segmentation and regional breakouts, but those detailed splits are intentionally reserved for subscribers and purchasers of the full analysis.
Strategic actions for 2026 (executive checklist)
Based on our integrated analysis, here are prioritized, time-bound actions for leadership teams entering 2026 planning cycles:
- Define a platform thesis by Q2 2026. Determine whether to compete on integrated video/cloud platforms, retrofit-first compact hardware, or cost-leading fleet operators. Each thesis implies different capex, talent, and channel strategies.
- Accelerate installer enablement. Invest in digital installation tools, pre-configured kits, and training partnerships to reduce field labor costs and improve first-time-fix rates—key levers that boost installer preference and lower warranty exposure.
- Hedge material exposure. Implement a two-pronged procurement approach: negotiate multi-year agreements for critical steel inputs while qualifying alternative suppliers and material formulations to retain design flexibility.
- Pilot subscription services in 2026. Test video-storage, premium diagnostics, and extended-warranty bundles in selected markets to validate ARPU uplift and identify the right revenue share with dealer networks.
- Prioritize cybersecurity and data governance. As openers become connected endpoints, adopt secure-by-design principles and clear user-consent models—these will be non-negotiable for channel partners and large-scale customers.
- Use M&A selectively to buy time and capability. Target assets that accelerate time-to-market for digital features or provide strategic access to high-value installation channels.
Implications by stakeholder
Executives should interpret the market through their organization’s core mandate:
- For product teams: emphasize modularity—design common control platforms that can serve consumer, commercial, and industrial variants with minimal rework.
- For commercial leaders: reconfigure incentives for distributors and installers to prioritize high-margin, service-attach solutions rather than one-off hardware sales.
- For finance and corporate development: use the 6.15% CAGR and scenario outputs to stress-test valuations and prioritize investments with shorter payback windows.
- For supply-chain managers: treat raw-material price forecasts as a core input into contractual and inventory strategy; consider onshore sourcing or vertical integration options where defensible.
Final note: where this report adds unique value
PW Consulting’s Garage Door Openers study blends market forecasting, competitor intelligence, and operational playbooks into a single deliverable designed for immediate use in boardrooms and strategy offsites. The research balances the quantitative rigor executives require—highlighted by our detailed top-line trajectory and concentration metrics—with practical, field-tested recommendations for product and channel execution.
We intentionally withhold the full segmented tables and the most granular regional and application-level data in this overview to preserve the investigative depth available in the full report. If your team is evaluating product roadmaps, channel strategies, or acquisition targets for 2026, this study is structured to convert market insight into executable plans.
Contact PW Consulting to access the comprehensive dataset, scenario models, and company dossiers that will allow your team to operationalize these insights and set a winning course through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Garage Door Openers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stem Cell Media to Reach USD 856M by 2032, 8.97% CAGR (2026-2032)
By PW Consulting, 2026-07-08
Stem Cell Media Market — Strategic Preview for 2026 Decision-Makers
As cell- and gene-based therapeutics move from promise to practice, the stem cell media market has consolidated into a mission-critical supply layer that determines both clinical credibility and commercial scalability. Our PW Consulting Stem Cell Media Market study (base year 2025; forecast 2026–2032) shows a market expanding at a compound annual growth rate of 8.97% — rising from roughly USD 478 million in 2025 to an estimated USD 856 million by 2032. This trajectory is not a passive trend: it reflects convergent forces — regulatory stringency, product standardization, industrial-scale manufacturing, and new clinical and industrial use cases — that will shape commercial strategy through 2026 and beyond.
Stem Cell Media Market
Why this review matters to C-suite and product leaders in 2026
-
Investment prioritization: With near-term market growth accelerating, leaders must decide whether to expand in-house media capabilities, secure preferred supply agreements, or pursue M&A to gain vertical control. The margin and time-to-market impact of those decisions is amplified by the market’s steady upward slope and clear regulatory direction.
Stem Cell Media Market -
Regulatory readiness equals commercial access: cGMP compliance and full traceability of raw materials are now prerequisites for submissions supporting advanced therapies. Companies that neglect validated media supply chains will face delayed approvals and constrained reimbursement conversations.
Stem Cell Media Market -
Operational leverage: Automation and process engineering are shifting cost structures. Our analysis highlights production workflows where automation can reduce labor costs by up to 70%, creating new unit-cost thresholds and enabling economically viable scale-up for clinical and industrial-grade media.
-
Partner and supplier selection: The market concentration and vendor capabilities observed in the report define bargaining power and partnership opportunity windows; choosing the right supplier archetype (platform provider vs. specialist innovator) is a strategic lever for both biotechs and CMOs.
What PW Consulting’s report gives you — practical, decision-ready content
-
Transparent macro sizing and a seven-year forecast model (2026–2032) that you can stress-test against your product roadmap and capital plan.
-
Scenario-led commercial playbooks that map actions to three industry trajectories (accelerated adoption, regulatory delay, and supply-constrained outcomes), with clear triggers for pivoting strategy.
-
Regulatory and reimbursement toolkit — pragmatic checklists and documentation templates that shorten time-to-compliance for cGMP and traceability expectations.
-
Supplier architecture and risk assessment — vendor scorecards, testimony-weighted reference checks, and contractual terms you should insist on for security of supply.
-
Go-to-market playbooks for research-grade vs. industrial-grade segments, including recommended pricing levers, channel models, and account penetration strategies.
-
M&A and partnership candidate shortlists built from capability maps, market share dynamics, and integration risk assessments.
-
Operational benchmarks: cost-per-liter ranges, automation impact models, and quality-control KPIs for manufacturing scale-up.
Market dynamics and structural drivers driving value in 2026
-
Regulatory and quality escalation: Regulators increasingly expect media used in clinical and commercial stem cell products to be cGMP-compliant with complete raw-material traceability. This changes procurement from a cost exercise into a compliance and risk-mitigation exercise.
-
Ethical and reproducibility norms: Chemically defined and animal-origin-free formulations are fast becoming the default design point, both for ethical reasons and to reduce batch-to-batch variability. This favors suppliers who have invested in defined formulations and validated supply chains.
-
Automation as a margin lever: Advances in production automation are not just productivity wins. They recast the economics of scale, lowering labor-driven variability and creating predictable cost curves that enable aggressive pricing in industrial applications.
-
Reimbursement conditionality: Payers and national health systems increasingly request evidence of validated manufacturing inputs (including media) before agreeing coverage. Early alignment on media validation can shorten reimbursement timelines for therapy developers.
-
Infrastructure and reproducibility: Xeno-free and chemically defined products address the reproducibility gap that has historically slowed technology transfer from the bench to GMP lines. Firms that standardize on such media reduce time-to-clinic and post-approval manufacturing risk.
Competitive landscape — how to interpret supply-side signals
The market exhibits moderate concentration: the combined market share of the top three suppliers sits comfortably above majority control, with the top five consolidating a clear dominant position. That structure creates both stability and strategic pressure: incumbents control distribution channels and regulatory credibility, while challengers compete on specialization, cost, and co-development agility.
-
Platform leaders (Thermo Fisher Scientific, Merck KGaA, Lonza Group AG): These players pair broad distribution, regulatory credentials, and integrated reagent portfolios. Their strategic advantage is the ability to supply validated, GMP-compatible media alongside platform services (analytics, QC, scale-up), making them default partners for large biopharma and CMOs.
-
Specialist innovators (STEMCELL Technologies, Miltenyi Biotec, FUJIFILM Biosciences): Focused product lines, rapid protocol development, and close ties to research communities allow specialists to capture early-adopter customers and niche clinical programs. Recent initiatives — including new protocols for cell enrichment and educational partnerships around standards — demonstrate how these firms convert technical leadership into commercial momentum.
-
Enablers and format specialists (Sartorius AG, Corning Incorporated, PromoCell GmbH): These firms compete on xeno-free formulations, GMP-grade supplements, and culture systems optimized for specific workflows (e.g., 3D culture). Their role in the value chain is often as trusted co-developers to therapy manufacturers.
Strategic implications: Large platform providers are best partners for program portfolios requiring global regulatory reach and supply redundancy. Specialist providers are ideal for early-stage or highly differentiated programs where formulation performance and protocol sophistication are differentiators. An optimal supplier strategy in 2026 will often be hybrid: primary supply agreements with a platform vendor plus strategic technical partnerships with specialists.
Commercial and regulatory playbook for 2026
-
Prioritize cGMP-ready suppliers early in program development. Lock in traceability and quality terms as pre-conditions for clinical transfers.
-
Design experiments and production runs with chemically defined, xeno-free media to minimize downstream validation scope and reduce variability risk during tech transfer.
-
Invest selectively in automation where unit economics matter most — i.e., clinical-scale and industrial production lines. Use automation ROI thresholds from our report to prioritize capital allocations.
-
Embed reimbursement evidence into media validation strategies: require suppliers to provide validation packages and stability data aligned with payer expectations.
-
Use vendor scorecards and staged qualification (pilot → bridged lots → full qualification) to manage supply risk while preserving negotiation leverage.
-
Consider bolt-on acquisitions to secure niche formulation IP or to bring specialized manufacturing capabilities in-house when strategic dependence on a supplier threatens program timelines.
Scenarios, leading indicators, and KPIs to monitor into 2026
-
Leading indicators: rate of adoption of chemically defined media in IND submissions; number and scale of cGMP-compliant production facilities commissioned; automation adoption rate in media manufacturing; supplier consolidation activity.
-
KPIs to track monthly/quarterly: validated lot release lead time, supplier qualification cycle time, cost per liter at scale, supplier concentration metrics for your supply chain, and time-to-tech-transfer for clinical production.
-
Scenario planning: model three baselines — rapid clinical adoption (highest growth, favorable pricing), measured adoption with reimbursement delays (moderate growth), and supply-constrained outcomes (slower growth, premium pricing). Each implies different inventory, contract, and investment choices.
Closing perspective — how to use our analysis in 2026
For executives and investment committees, the takeaway is straightforward: the stem cell media market is evolving from a fragmented, research-focused ecosystem into a regulated, industrial supply market with predictable growth and rising technical barriers to entry. Success in 2026 will favor companies that align procurement, regulatory, and product strategies to the new industrialized reality — securing validated supplier partnerships, adopting defined formulations, and selectively investing in automation and scale.
PW Consulting’s full study provides the granular segmentation, vendor scorecards, scenario models, and operational benchmarks that underpin the high-level guidance summarized here. To access the detailed data tables, sensitivity runs, and supplier dossiers referenced in this preview, please visit the PW Consulting report page for the Stem Cell Media Market and download the full research package.
For detailed analysis of this topic, please visit the official page: Stem Cell Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Motorcycle Market to Reach USD 170.8B by 2032 at 18% CAGR — PW Consulting Insight
By PW Consulting, 2026-07-08
Electric Motorcycle Market — Strategic Briefing for 2026 Decisions
Executive summary
The electric motorcycle market is entering a decisive phase. After strong historical expansion from 2020 through 2025, the market is positioned for accelerated scale as incumbents and new entrants convert prototype momentum into series products. Our analysis uses a 2025 base year and projects the global market to grow at an 18% compound annual growth rate across the 2026–2032 forecast horizon, producing a multi-fold increase in industry revenue by the end of the period. For 2026 decision-makers, this is a growth window defined by rapid product launches, tightening safety regulation, cost curve improvements in battery packs, and a competitive landscape that is concentrated enough to enable strategic consolidation yet fragmented enough to reward focused specialization.
Electric Motorcycle Market
Why this matters for 2026 strategy
- Scale meets bifurcation: As overall market volumes expand materially in 2026, firms will face diverging fortunes depending on their ability to industrialize product lines, secure battery supply, and meet evolving certification requirements.
- Timing is strategic: 2026 is not only the start of a multi-year growth leg — it is the pivot year when prototype-stage programs from traditional OEMs move into production and when regulatory gating (safety, certification and vehicle classification) becomes binding for market access.
- Value capture shifts forward in the stack: Battery systems, power electronics, and platform software are increasingly decisive in value allocation; manufacturers that lock in integrated capabilities will command premium pricing and margin expansion.
Market trajectory and what the numbers tell us
Historical growth through 2025 demonstrates clear consumer and fleet-level uptake. With a 2025 base and an 18% CAGR through the 2026–2032 forecast window, the industry is set to more than treble in scale over the decade that follows. That pace of growth creates distinct horizons for investment: 1) capacity and tooling investments required to hit near-term production targets; 2) mid-term investments in charging and service networks to sustain adoption; and 3) longer-term strategic moves such as software monetization, subscription services, and cross-border expansion.
Electric Motorcycle Market
For executives planning capital allocation in 2026, the key takeaway is straightforward: commitments made this year — on supply agreements, certification programs, and channel partnerships — will determine whether a company participates meaningfully in the larger market or competes for a shrinking niche.
Electric Motorcycle Market
Drivers, constraints and operational dynamics
- Battery cost and chemistry: Battery pack cost improvements continue to be a primary driver of unit profitability and achievable range. Recent data shows a meaningful reduction in lithium-ion pack prices in 2025, which is already lowering entry barriers for higher-range models and opening new product segments.
- Regulation as a market-shaper: 2025–2026 regulatory updates (notably enhanced safety testing and certification requirements) are creating new compliance baselines. These standards raise the bar for new models but also create durable market advantages for manufacturers that certify early and build compliance into their design processes.
- Channel and service ecosystems: Real-world ownership economics hinge on charging availability, aftersales service, and parts distribution. OEMs and distributors that secure service footprints and certification for battery swapping or DC fast charging will accelerate fleet and consumer adoption.
- Product segmentation shifting: While legacy low-speed electrics remain relevant in certain use-cases, mid- and high-performance segments are expanding as OEMs introduce street, trail, and dual-sport electric models with broader appeal to mainstream riders.
Competitive landscape — implications for incumbents and entrants
The competitive field in 2026 reflects a mix of established electric-native brands, traditional motorcycle OEMs transitioning to electrics, and new mobility players. Market concentration is moderate: the top three players account for roughly one-third of industry revenue and the top five do not exceed half of the market. This structure supports both scale advantages for larger players and meaningful opportunities for focused challengers.
- Electric-native specialists: Firms that started as electric-only manufacturers have advantages in platform modularity, battery integration, and brand positioning among early adopters. Their challenge is industrial scale — turning boutique performance models into high-volume, margin-stable product lines.
- Traditional OEMs going electric: The entry of legacy manufacturers into full-size electric motorcycles represents a strategic inflection. These incumbents bring dealer networks, manufacturing scale, and channel trust, but must accelerate learning curves in software, battery management, and fast-paced product cycles.
- New product launches and timing: Several high-profile product introductions scheduled for 2026 — including full-size and dual-sport electric models from both legacy OEMs and newer brands — will force a re-evaluation of pricing architectures and market segmentation across urban, touring and off-road categories.
- Certification and regional compliance as moat: Early certification in major markets creates effective barriers to late entrants and forms a defensible commercial advantage for those who invest first in compliance testing and homologation.
Key players — strategic read of recent moves
- Specialists that balance performance with industrialization: Brands known for high-performance electric motorcycles have proven R&D and product credibility; their near-term challenge is improving manufacturing throughput while broadening their model portfolios to address mass-market requirements.
- Legacy OEMs broadening portfolios: Established manufacturers entering the electric space in 2026 bring scale and channel advantages and will push price pressure on performance segments. Their presence will accelerate consumer familiarity with electric motorcycles and expand addressable demand.
- Global OEMs with regulatory and distribution strengths: Players offering globally compliant products and capable of navigating diverse homologation regimes will win rapid distribution deals, particularly where safety standards have been newly codified.
- Cross-regional suppliers and low-cost volume players: Firms that successfully offer certified, cost-competitive platforms will capture fleet and last-mile demand; however, their long-term margin trajectory depends on product differentiation beyond cost alone.
Supply chain, cost and regulatory risk matrix
- Raw materials: Downward pressure on battery-pack prices in 2025 provides a tailwind but also signals intense supplier competition. Procurement teams must balance short-term cost savings with multi-year supply security and technology lock-ins.
- Certification requirements: New mandatory standards for rechargeable energy storage systems and vehicle-level safety testing require earlier and deeper investment in validation. Firms that defer compliance risk delayed market entry and higher retrofit costs.
- Vehicle classification and operating rules: Changes in vehicle code definitions for off-highway and street-legal classifications affect product positioning, distribution, and aftersales obligations. Early legal and regulatory strategy will reduce go-to-market friction.
Strategic playbook for 2026 — prioritized actions
To translate market opportunity into durable advantage in 2026, firms should prioritize decisive, time-bound moves across five dimensions:
- Secure battery and subsystem supply with staged commitments. Negotiate layered contracts that provide near-term cost certainty while preserving flexibility to adopt next-generation chemistries.
- Invest in certification and homologation early. Allocate budget and technical resources to meet new safety and overcurrent testing regimes; certifications secured in 2026 will function as commercial permits to scale in 2027–2028.
- Define a clear product-to-channel alignment. Decide which segments to lead (performance, commuter, dual-sport) and map each to the most realistic distribution model — direct retail, dealer network, or fleet tenders.
- Build service and digital ownership experiences. Establish warranty structures, predictive maintenance programs, and connected services that increase residual value and create recurring revenue opportunities.
- Prioritize M&A and partnerships strategically. Consider acquiring niche battery system integrators, regional distributors with service networks, or software providers to accelerate time-to-market and close capability gaps.
What the full PW Consulting report delivers
The full Electric Motorcycle Market report provides actionable modules designed for executive decision-making:
- Comprehensive market sizing (historical 2020–2025 and detailed forecasts to 2032) and scenario modeling tailored to different regulatory and cost paths;
- End-to-end commercial playbooks for OEMs, suppliers, and mobility operators (go-to-market, channel economics, and service strategies);
- Detailed competitive benchmarking and acquisition targets mapped to strategic objectives (including capability heatmaps and integration considerations);
- Supply chain risk matrices and procurement templates for battery sourcing, powertrain components, and critical electronics;
- Regulatory impact analysis with compliance roadmaps for major jurisdictions and certification timelines;
- Executive dashboards and implementation checklists that convert insights into 90/180/360 day action plans.
Note: This briefing deliberately omits the granular regional and application-level splits and other detailed segmentation tables reserved for the full report. Those granular schedules are a critical part of scenario-based decisioning and are available in the source report.
Practical next steps for leadership teams
- Convene a cross-functional 60-day task force (product, supply chain, regulatory, sales) to convert these strategic priorities into decision points with specific owners and budget requests.
- Use the 2026 window to pilot certification-first engineering programs for at least one platform to reduce time-to-market risk for subsequent variants.
- Reassess pricing strategy in light of battery cost improvements and competitive product launches — aim for a test-and-learn approach with selective market-entry discounts tied to service commitments.
Conclusion — why PW Consulting’s insight is decision-critical in 2026
The market dynamic entering 2026 rewards decisiveness: the combination of accelerating demand, rapid product introductions from both electric-native and legacy OEMs, and tightening safety and certification regimes creates a high-reward window for first movers who are operationally prepared. Our analysis provides the strategic framework and operational toolkits needed to convert market growth into sustained competitive advantage. For teams preparing budgets, channel strategies, or M&A plans in 2026, the choices made now will have outsized impact on market share and profitability across the forecast period.
To access the full datasets, regional and application segmentation, and the implementation templates referenced above, consult the complete PW Consulting Electric Motorcycle Market report available on our website.
For detailed analysis of this topic, please visit the official page: Electric Motorcycle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sorghum Seed Market 2026: Strategic Imperatives for Growth and Resilience
Executive snapshot — why this matters for 2026 decision cycles
As agribusinesses and seed investors finalize budgets and strategic plans for 2026, the sorghum seed domain is moving from a niche defensive play into a mainstream portfolio consideration. Our PW Consulting analysis (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) shows the global sorghum seed market expanding at a compound annual growth rate (CAGR) of 5.5% through the forecast period. Measured in USD (Million), the market has grown from a baseline of 1,000 in 2020 to 1,250 in 2025 and is projected to reach approximately 1,817 by 2032 under the central case.
Sorghum Seed Market
These headline dynamics — steady growth, resilience to systemic shocks, and strong pockets of demand — are sufficient cause for corporate strategy teams to treat sorghum not as a one-off tactical play but as a component of medium-term product, channel and M&A plans. However, meaningful decisions require more than topline CAGR; they require line-of-sight to trait economics, channel economics, regional demand elasticity and competitive positioning. That depth is what our full report is designed to deliver.
Sorghum Seed Market
Market dynamics shaping 2026 strategies
-
Demand-side momentum: The market’s growth is anchored in diverse end-uses — animal feed, human food applications and industrial uses (including biofuel). Shifts in dietary protein demand and downstream processing economics are re‑allocating value across these uses, creating differentiated margin pools for seed suppliers with tailored varietal portfolios.
Sorghum Seed Market -
Supply-side innovation: Seed companies that combine hybrid vigor with trait packages (drought tolerance, herbicide resistance, stay‑green phenotypes and improved threshability) are commanding faster adoption curves. Recent product launches leveraging advanced genomics indicate an acceleration of breeding cycle efficiency and a steeper diffusion curve for premium hybrids.
-
Trade and policy tailwinds: Recent USDA program updates and variety listings are changing the economics of exportable grain and the incentives for certain varieties in subsidy-linked programs. Simultaneously, export opportunity forecasts to major importers are materially supporting grower interest in high-performing sorghum, altering planting decisions in producing regions.
-
Price and risk volatility: Cash price movements at key elevators and regional differentials continue to influence seed uptake timing and varietal mix. Effective risk management — from pricing contracts to logistical hedging — is now a core competence for seed distributors and upstream suppliers.
Competitive landscape — what the leading players signal
The market exhibits moderate concentration: the top three firms account for a meaningful but not dominant share, and the top five increase that concentration materially. This structure creates both room for differentiated positioning and a clear path for consolidation or strategic alliance formation.
-
Corteva Agriscience (Indianapolis, USA) — an established player leveraging legacy brands and trait pipelines. Recent launches of drought‑tolerant hybrids underscore their strategy to protect acreage in water‑stressed geographies and to capture premium seed premiums through genetics and trait licensing.
-
KWS SAAT SE & Co. KGaA (Einbeck, Germany) — focuses on early‑maturity and stability traits attractive to European and certain international producers. Their breeding emphasis on adaptation and yield stability complements regional cropping systems where risk‑adjusted yield is the primary purchasing driver.
-
Advanta Seeds (Dubai/US operations) — a global hybrid supplier with broad geographic reach. Their commercial footprint across diverse agroecologies positions them well to arbitrage regional price and margin differentials and to scale fast‑growing hybrids through licensed networks.
-
Bayer CropScience (Monheim, Germany) — brings integrated seed and crop protection capabilities to sorghum, emphasizing agronomic traits that reduce downstream handling costs (standability, threshability, stay‑green) — features that translate into farm‑gate value and adoption levers.
-
S&W Seed Company (Longmont, USA) — a specialist hybrid player concentrating on proprietary traits including herbicide resistance and portfolios aimed at animal protein and healthier consumer diets. Their recent strategic review and portfolio refocus signal an intent to sharpen core competencies rather than pursue broad diversification.
Collectively, these players illustrate two strategic archetypes that matter for 2026 planning: (1) integrated multinationals that leverage R&D scale and channel breadth to commercialize premium trait stacks, and (2) focused specialists that extract margin through proprietary traits and targeted market niches. Both archetypes will pursue different partnership, licensing and M&A playbooks as the market expands.
Recent developments with structural implications
-
S&W Seed Company initiated a strategic alternatives review in early 2025, refocusing on core U.S. sorghum and high‑margin trait portfolios — a move that could create short‑term transactional noise but longer‑term concentration opportunities for premium assets.
-
Corteva launched a drought‑tolerant hybrid in 2025 using advanced genomics; this elevates the technology baseline for market entrants and changes the minimum competitive offering for water‑limited regions.
-
USDA and the United Sorghum Checkoff Program updated variety listings and eligibility for program support in 2026, affecting program participation and the attractiveness of certain varieties under loan and deficiency programs.
-
Macro indicators such as rising export prospects to key markets have been reported alongside persistent price dispersion at local elevators — factors that together increase arbitrage opportunities but also amplify execution risk for exporters and seed distributors.
Key strategic implications for 2026 planning
-
Product and portfolio strategy: Prioritize breeding and licensing investments in traits that address water stress, harvest efficiency and market‑specific quality attributes. Portfolio pruning is likely to create value for firms that redeploy capital into high‑conviction hybrids.
-
Channel and go‑to‑market: Strengthen distributor economics in regions where price volatility drives short planting windows. Digital advisory and seed placement services can increase effective market share without equivalent increases in physical footprint.
-
M&A and alliances: Expect continued interest in bolt‑on acquisitions of breeding assets and trait licenses. For buyers, disciplined payoffs must be tied to demonstrable uplift in germplasm value and route‑to‑market synergies.
-
Risk management: Incorporate price‑scenario planning and targeted hedging into commercial programs. Regulatory and program changes (e.g., variety eligibility for support programs) must be tracked proactively as part of commercial contracts.
What PW Consulting’s full report delivers — practical, executable intelligence
Our Sorghum Seed Market study is structured to convert insight into action. The full deliverable includes:
-
Transparent market sizing and methodology (historical 2020–2025 benchmarking; base year 2025; forecast 2026–2032) with sensitivity scenarios reflecting commodity price and policy shifts.
-
Competitive benchmarking with capability heatmaps covering R&D pipelines, trait portfolios, channel reach and financial posture for primary market participants.
-
Commercial playbooks for four archetypal players (incumbent multinationals, regional leaders, focused specialists and new entrants), including suggested go‑to‑market moves, pricing strategies and potential alliance partners.
-
Scenario‑based M&A and investment roadmaps, complete with target profiles, valuation heuristics and integration risk checklists tailored to 2026 market realities.
-
Operational diagnostics and a set of KPI dashboards to monitor adoption curves, channel performance and trait premium realization on a rolling quarterly cadence.
To preserve the strategic advantage for subscribing clients, the report intentionally withholds the granular sub‑segment tables and regional application splits from public summaries. Those data are available in the full report appendices and the interactive dashboards on our client portal.
Recommended near‑term moves for executives
-
Run a 90‑day portfolio stress test: Identify underperforming varieties, reallocate seed‑pipeline spend toward high‑probability trait programs, and establish stop‑loss criteria for low‑velocity SKUs.
-
Lock strategic partnerships: Negotiate conditional licensing deals that align trait payments with realized farm‑level premiums to reduce upfront R&D exposure.
-
Operationalize market intelligence: Deploy the report’s KPI dashboards to monitor export demand signals, elevator‑level price deviations and variety eligibility announcements that affect planting incentives.
-
Prepare M&A playbooks: Identify 2–3 bolt‑on targets and establish valuation ranges tied to royalty flows and trait capture models prior to market re‑rating events.
Closing — why access to the full study matters now
The sorghum seed market presents an atypical blend of steady aggregate growth and highly local execution risk. The headline CAGR of 5.5% masks important heterogeneity across traits, channels and geographies that will determine winners and losers through 2032. PW Consulting’s full Sorghum Seed Market report translates the top‑line trajectory into the specific levers that corporate leaders must pull in 2026 — from R&D prioritization and licensing strategies to channel economics and M&A timing.
For strategy teams, the difference between opportunistic and disciplined capture is access to the granular adoption curves, price‑elasticity tables and competitor capability matrices that we reserve for report subscribers. To request the full report, interactive dashboards and a tailored executive briefing for your leadership team, please follow the link on our publication page.
For detailed analysis of this topic, please visit the official page: Sorghum Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


