



Category: market research
PEKK Market 2026: A Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a high-level, actionable preview of our forthcoming Poly (Ether-ketone-ketone) (PEKK) Market study. This piece is designed as a strategic “trailer”: it demonstrates the report’s analytical depth, frames the critical choices facing leadership in 2026, and highlights why immediate access to the full study is mission-critical — while intentionally withholding granular segment-level figures to preserve premium value for subscribers.
Poly (Ether-ketone-ketone) (PEKK) Market
Why PEKK matters in 2026
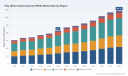
PEKK has moved from a niche engineering polymer to an industrial lever in high-value sectors — notably aerospace, advanced electronics, and electrified powertrains. Between 2020 and our base year (2025), the PEKK market expanded materially, and our modeling projects robust, steady growth through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 6.98%. Measured in USD (Million), cumulative market momentum across 2020–2025 establishes a clear inflection point entering 2026: the market that was modest in scale at the start of the decade is now large enough to influence supplier strategies, capital allocation, and product roadmaps.
Poly (Ether-ketone-ketone) (PEKK) Market
Two macro dynamics drive this transition. First, performance requirements in target applications (high-temperature stability, dielectric performance, chemical resistance, and suitability for additive manufacturing) are increasingly non-negotiable. Second, supply-side shifts — new grades, capacity additions, and targeted product launches — are lowering barriers to industrial adoption. Collectively, these forces create a strategic window in 2026: companies that act with calibrated speed can capture preferential positioning as specifications harden and qualification cycles compress.
Poly (Ether-ketone-ketone) (PEKK) Market
What 2026 decisions must solve
- Supply security vs cost optimization: PEKK’s supply base remains technologically concentrated but commercially fragmented. Market concentration metrics indicate a low-to-moderate level of dominance by the largest suppliers (CR3 and CR5 remain in the mid-20s percent range), which means buyers must balance multi-sourcing for resilience against the price and logistics trade-offs of diversifying vendors.
- Qualification cadence and commercialization risk: Lead times for materials qualification in aerospace and semiconductor segments remain long. Firms must decide in 2026 whether to accelerate co-development with suppliers (bearing near-term R&D or qualification costs) or to wait for broader market adoption and potentially face higher entry barriers.
- Technology pathway selection: Additive manufacturing (AM) compatibility, high-voltage insulation grades for EVs, and thin-film processability are three divergent development tracks. Allocating investment across these requires reframing product roadmaps into scenario-based portfolios that capture upside without over-committing scarce CAPEX.
- Regulatory and trade exposure: New EU regulations on pellet loss and active trade measures (notably tariffs applied to PEEK/PAEK imports in certain markets) meaningfully alter total landed cost and compliance overheads. Firms must integrate regulatory risk into procurement and site-selection decisions immediately.
Industry dynamics shaping 2026 strategy
- Product innovation and targeted launches: Through 2025, several suppliers introduced application-specific PEKK grades — from aerospace collaborations that focus on lightweighting to formulations optimized for additive manufacturing and high-voltage EV insulation. Expect the pace of niche grade introductions to accelerate in 2026 as suppliers compete on differentiated performance rather than bulk pricing.
- Capacity response: Primary producers have reacted to demand signals with selective capacity expansions. These moves reduce the probability of acute shortages but create a transitional price dynamic: near-term upward pressure from feedstock and labor cost increases can coexist with medium-term price moderation as new volumes ramp up.
- Regulatory pressure and compliance cost: The EU’s Regulation (EU) 2025/2365 on plastic pellet loss raises operational compliance costs for polymer processors and suppliers. The regulation’s requirements — containment, incident tracking, formal training and documented pellet management — will shift cost structures and favor players with advanced containment and traceability systems.
- Trade friction and tariffs: Elevated tariffs applied to certain PAEK/PEEK imports into North America alter supply-chain calculus and favor regionalized sourcing or nearshoring strategies. For companies selling into tariff-exposed markets, tariff mitigation must be a discrete line item in sourcing models for 2026 decisions.
- Input cost environment: Announcements from leading polymer producers of price adjustments reflect an environment where labor, energy, and feedstock volatility are real constraints. Buyers should assume higher base costs in 2026 than in recent historical norms and model sensitivity scenarios accordingly.
Competitive landscape — how leading firms are positioning
The competitive set combines incumbent chemical majors, specialty polymer houses, and application-focused manufacturers. Each archetype brings different advantages for customers and partners; understanding these different operating models is essential for effective partner selection and M&A screening.
- Arkema S.A. (France): Arkema’s strategy emphasizes advanced resin formulations and integrated customer support for high-performance applications. Their R&D-led approach targets collaboration with OEMs that require customized resin properties and processability guidance. For buyers, Arkema represents a partner capable of co-development at scale and with rigorous quality systems.
- Evonik Industries AG (Germany): Evonik is leveraging its materials science platform to expand PEKK offerings, including grades aimed at additive manufacturing and specialty engineering uses. Recent catalog updates and price adjustments indicate a dual strategy: capture premium AM and electrification segments while recalibrating pricing to reflect increased input costs. Evonik’s global footprint and application engineering capabilities make them a preferred collaborator for process-intensive conversions.
- Solvay S.A. (Belgium): Solvay combines polymer expertise with deep application knowledge in aerospace and automotive. Their differentiation is in systems-level thinking — packaging resin properties with processing recommendations and long-term qualification support. For strategic buyers, Solvay is attractive where integrated material-performance validation is needed.
- Victrex plc (United Kingdom): Victrex is a specialty PAEK player with a heritage in high-performance thermoplastics. Their strength lies in established supply relationships with critical industries and a proven track record for qualifying materials in regulated environments. Victrex’s role is often as a preferred supplier for customers prioritizing qualification history and long-term lifecycle support.
- Oxford Performance Materials, Inc. (United States): Oxford brings a strong focus on application platforms where PEKK’s performance unlocks system-level advantages — particularly in additive manufacturing for medical and aerospace applications. Their vertical orientation on specific use cases makes them a strategic partner for OEMs seeking rapid application development and end-to-end validation.
Recent market moves amplify these strategic choices: BASF’s partnership with an aerospace manufacturer (Sept 2025) signals increased OEM engagement; Evonik’s product catalog expansion (Aug 2025) shows a push into AM; SABIC’s capacity additions (July 2025) reflect supplier willingness to scale; and new grades optimized for 800V EV battery insulation suggest representational demand from electrification programs. Together, these developments compress the window for decisive action in 2026.
What our report delivers — practical and executable
The full PW Consulting PEKK Market study is built for enterprise decision-making. It combines quantitative rigor with deployment-level guidance across procurement, product, and corporate strategy. Key deliverables include:
- Market sizing and validated demand curves (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario-based outlooks under different adoption and regulatory assumptions.
- Supply-chain heatmaps and a supplier scorecard that benchmarks technical capability, geographic footprint, qualification track-record, and commercial flexibility.
- Competitive intelligence dossiers on incumbent and emergent suppliers, including capability gap analysis and partnership suitability matrices.
- Price and cost-stack models that incorporate feedstock, labor, regulatory compliance, and tariff impacts — enabling total landed cost modeling for 2026 procurement strategies.
- Technology roadmaps and go-to-market playbooks for three priority tracks: additive manufacturing, high-voltage EV insulation, and aerospace-grade structural components.
- M&A and JV target screening with financial stress-testing under alternate tariff and regulatory scenarios.
- Operational checklists for compliance with pellet-loss and containment regulations, including training and incident-tracking templates.
- Actionable near-term recommendations for CAPEX allocation, supplier lock-in timing, and co-development contracting terms that preserve optionality.
How leaders should act in 2026 — a short playbook
- Immediate (0–6 months): Run a rapid supplier resilience audit, stress-testing current agreements against tariff exposure and the new EU containment requirements. Fast-track one co-development pilot for a high-priority application where lead-time arbitrage will create market advantage.
- Medium-term (6–18 months): Invest selectively in qualification programs (shared-risk contracts) for PEKK grades that map to strategic product lines. Lock in partial supply through capacity reservation clauses while preserving flexibility via formula-based pricing mechanisms that account for validated feedstock indices.
- Strategic (18–36 months): Evaluate targeted M&A or JVs to secure upstream integration or unique grade access, especially where supplier R&D capabilities provide differentiation. Reassess global footprint choices to mitigate tariff and logistics drag.
Closing — why the full report is indispensable
Our analysis shows the PEKK market entering a phase where technical differentiation, supply security, and regulatory compliance define winners and losers. The headline metrics — market sizing from 2020 through 2025, the base-year calibration at 2025, and our forecast through 2032 at a 6.98% CAGR — frame an opportunity set that is large enough to require strategic choices in 2026. Yet the tactical levers (which suppliers to prioritize, which grades to co-develop, and how to structure commercial terms) demand granular, validated inputs that we have assembled in the full study.
For executives preparing budgets, procurement leaders recalibrating supplier panels, and technology heads prioritizing R&D spend, the full PW Consulting PEKK Market report delivers the practical intelligence you need to convert market momentum into competitive advantage. Contact PW Consulting to access the complete report, supplier scorecards, and proprietary models that translate these insights into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Poly (Ether-ketone-ketone) (PEKK) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slot Machines Market to Hit USD 320.75M by 2032 at 8.28% CAGR
By PW Consulting, 2026-07-08
Slot Machines Market 2026: A Strategic Preview for Decision Makers
Introduction — why this briefing matters for 2026
As operators, OEMs, investors and regulators enter 2026, the slot machines market sits at a crossroads of technology adoption, regulatory tightening, and concentrated supplier power. This preview distills the strategic value of PW Consulting’s full Slot Machines Market research: it shows where revenue pools are expanding, where supply-chain and regulatory risk are compressing margins, and where competitive moves will determine who captures the upside through 2032. Consider this a high-fidelity trailer — we reveal directional truths, diagnostic frameworks, and tactical implications while reserving proprietary segment-level detail for the full report.
Slot Machines Market
Market snapshot: growth trajectory and what it implies
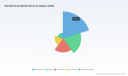
Using 2025 as the analytical base year, our market model confirms the slot machines market is on a robust expansion path. The market reached an established scale in 2025 (reported in USD Million) and is projected to continue growing through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 8.28%. By the end of the forecast horizon the market is materially larger than in 2025, reflecting both product refresh cycles and rising demand for digitally enabled cabinets and experiences.
Slot Machines Market
What that growth means strategically: steady, above‑average expansion validates capital investment in new cabinets and digital platforms — but it also sharpens the need for disciplined capital allocation. When a market grows at this pace, the first-mover advantage accrues to firms that can simultaneously scale manufacturing, secure inputs, and commercialize differentiated content and cabinets.
Slot Machines Market
Structural dynamics shaping 2026 decisions
- Demand composition and product evolution: Player preferences continue to migrate toward digitally enabled experiences and video-driven cabinets. The pace of digital replacement versus legacy mechanical refresh will be a key determinant of OEM sales cycles, aftermarket revenues and operator lifetime value.
- Supply‑side constraints and cost pressure: Semiconductor shortages have lengthened lead times for critical cabinet control boards, compressing gross margins for manufacturers in North America. Steel price volatility across 2024–2025 has further strained margins on cabinet production, increasing the importance of hedging strategies and diversified supplier networks.
- Regulatory tightening and compliance cost: Recent regulatory updates — including newly adopted device manufacturing and approval rules in major gaming jurisdictions — change the timing and cost of bringing products to market. Local licensing fees and approval processes are now a material consideration in go-to-market planning for suppliers.
- Market concentration: The industry exhibits high concentration at the top: the three largest competitors account for a dominant share of sales, and the top five control a sizable majority. This concentration amplifies the strategic advantages of scale, IP libraries, and distribution relationships, but it also opens white-space for nimble specialists and regional challengers.
Competitive landscape: strategic moves to watch
The competitive map is a mix of large, diversified OEMs, regional specialists, and technology-focused entrants. Leading names maintain scale advantages through global distribution networks, expansive content libraries, and integrated hardware-software offerings. Several tactical themes emerge as decisive for 2026:
- Manufacturing footprint optimization: Recent facility investments — for example, new manufacturing capacity openings in core gaming hubs — signal that supply chain locality and vertical control are prioritized. Firms that secure flexible, near‑market manufacturing reduce lead-time risk and can respond faster to operator demand.
- Product differentiation via cabinet and lighting innovation: Manufacturers are investing in synchronized lighting systems, modular cabinet designs, and immersive audio-visual features to increase per-unit revenue and dwell time on casino floors. These features are a competitive lever harder to replicate than baseline hardware.
- M&A and partnership strategies: Consolidation remains a pragmatic route to scale, IP acquisition, and regulatory access. Expect continued deal activity as larger players shore up content libraries and regional distribution through bolt-ons and strategic partnerships.
- Aftermarket and services monetization: Software-as-a-service models, remote content updates, and performance analytics are growing contributors to lifetime revenue per cabinet — shifting the business model from one‑time sales to recurring revenue streams.
Notable players and strategic posture (select)
- Large global OEMs: Several incumbents headquartered in established gaming markets continue to anchor the market with broad product portfolios and deep operator relationships. Their strategies emphasize content breadth, regulatory compliance pathways, and global distribution.
- Regional specialists and challengers: Firms from market-leading jurisdictions are leveraging tailored product sets and local service models to win operator share. Their agility to local regulation and fast product iteration remains an advantage.
- Technology-forward entrants: Newer vendors focus on digital-first cabinets, API-enabled gaming platforms, and data monetization. Their success depends on securing approvals and proving floor performance against established IP-rich competitors.
Recent developments illustrate these dynamics: a significant new manufacturing facility opened in a major gaming hub in April 2026 following a strategic acquisition; and product launches in 2025 introduced synchronized lighting systems and new cabinet concepts that elevate in-cabinet player engagement. Such moves alter cost structures, speed to market, and differentiation vectors for the coming five years.
Report contents — what the full PW Consulting study delivers
The full Slot Machines Market report is designed as a pragmatic decision-support kit for 2026 budgeting and strategy cycles. Key deliverables include:
- Proprietary market sizing and growth model (historical 2020–2025 base and forecast 2026–2032) with scenario toggles for demand shocks, regulatory change, and supply constraints.
- Consolidation and competitive analysis with CR3/CR5 benchmarking and market position maps to quantify share mobility under multiple scenarios.
- Go-to-market playbooks for OEMs and operators covering product launches, floor layout optimization, and monetization of digital content and services.
- Supply‑chain stress-test matrix highlighting semiconductor, metal and labour exposures, mitigation levers, and contract negotiation templates.
- Regulatory tracker and compliance roadmaps for key jurisdictions, including recent updates to device manufacturing and approval rules and local licensing impacts.
- M&A heatmap and valuation comps to support inorganic growth or defensive acquisition planning.
- Vendor profiles and capability audits, including technology stacks, IP libraries, and manufacturing footprints.
- Executive dashboards and an accompanying financial model (Excel) for sensitivity analysis and capex planning.
How executives should use this research in 2026
- Capital expenditure and product roadmaps: Use the model’s scenarios to set bounded capex plans that account for component lead-time risk and regulatory approval timing. Prioritize investments that accelerate digital monetization to capture recurring revenues.
- Procurement and supply‑chain resilience: Rebalance sourcing to reduce exposure to singular suppliers for semiconductors and cabinet components; negotiate multi-year agreements and explore nearshoring to shorten lead times.
- Regulatory strategy and market access: Build compliance and approval timelines into product launch calendars early — licensing and testing lead times are now a determinative factor in commercial rollouts.
- M&A and alliance scouting: Target acquisitions that either extend content IP, add local manufacturing capacity, or provide immediate regulatory approvals in priority jurisdictions.
- Commercial tactics for operators: Optimize floor mixes to accelerate replacement of underperforming mechanical units with digital cabinets that drive higher engagement and ancillary spend; insist on data-sharing agreements to measure true lifetime value.
Final takeaways — risk, reward and the path ahead
The slot machines market presents a clear growth runway through 2032, underpinned by technology-driven player experiences and rising operator demand for differentiated cabinets and services. Yet, growth is not uniform: supply chain volatility, commodity cost swings, and a tightening regulatory environment mean that strategic execution and operational resilience will separate winners from laggards. High market concentration magnifies the advantage of firms that combine broad content libraries, manufacturing scale, and regulatory fluency — but it also leaves space for nimble entrants that can exploit regional niches or innovate business models.
For boards and executive teams preparing decisions in 2026, the choice is between reactive cost management and proactive reconfiguration: those who treat 2026 as a year to shore up supply lines, accelerate digital roadmaps, and align regulatory timelines to product calendars will capture disproportionate share as the market expands. PW Consulting’s full report provides the calibrated models, competitive intelligence and playbooks to make those decisions with confidence.
Next step
This preview highlights the strategic contours. For the detailed segment-level forecasts, regulatory appendices, vendor scorecards and executable playbooks referenced here, please consult the full Slot Machines Market report available through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Slot Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Styrene-Maleic Anhydride Copolymer Market Set to Reach USD 1,772M by 2032
By PW Consulting, 2026-07-08
Styrene‑Maleic Anhydride Copolymer Market — Strategic Outlook and Decision Playbook for 2026
Market snapshot: what the numbers tell you (but not the full map)
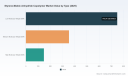
Between 2020 and 2025, the global Styrene‑Maleic Anhydride (SMA) copolymer market expanded from roughly USD 800 million to about USD 1,250 million (USD Million basis, base year 2025). Our baseline outlook projects continued expansion through the forecast window (2026–2032), taking total market value to roughly USD 1,772 million by 2032 under a central scenario. That trajectory implies a compound annual growth rate (CAGR) of approximately 5.2% over the forecast period.
Styrene-Maleic Anhydride Copolymer Market
Those headline numbers are directional: they validate a market that is sizeable, resilient to cyclical swings, and capable of delivering steady returns to well‑positioned suppliers and integrators. But for 2026 corporate decision‑makers the real question is not whether the market grows, but where margins, risk and optionality concentrate — the granular answers to which are reserved for the full PW Consulting report.
Styrene-Maleic Anhydride Copolymer Market
Why this study matters for 2026 strategic choices
-
Prioritizing investment: Capital allocation in specialty polymers now competes with other high‑return opportunities across chemicals and materials. Our study translates top‑line growth into actionable capital plans, enabling executives to size investment needed to maintain or gain share in segments that generate the highest margin density.
Styrene-Maleic Anhydride Copolymer Market -
Securing feedstock resilience: Styrene and maleic anhydride feedstocks drive a large portion of production cost. We quantify exposure to feedstock price swings and offer hedging and sourcing strategies that are realistic for 2026 supply markets.
-
Assessing regulatory risk and opportunity: With recent entries on the FDA Inventory of Effective Food Contact Substances for certain sodium salt forms of SMA and rising sustainability certification activity, compliance decisions now intersect with product development and route‑to‑market timing. The study provides a compliance impact matrix that converts regulation into go/no‑go guidance for product launches.
-
Shaping sustainability-driven premiumization: Buyers in automotive, electronics and specialty coatings increasingly price sustainability attributes. Our work maps where sustainability credentials (e.g., ISCC PLUS, recycled feedstocks) can unlock premium pricing or are table stakes, and which investments have the fastest payback.
Key market dynamics that will decide winners in 2026
-
Raw material volatility: Styrene monomer and maleic anhydride remain the primary cost drivers. Small shifts in either feedstock cause disproportionate margin compression for commodity grades and create arbitrage for differentiated chemistries. The report includes stress tests and break‑even curves that quantify this sensitivity for different product formulations.
-
Regulatory and food‑contact considerations: Inclusion of certain SMA sodium salts in official food‑contact inventories reduces regulatory friction for some end‑use routes. However, registration timelines and regional differences create windows of opportunity — and risk — that demand coordinated regulatory and commercial planning.
-
Labor and manufacturing complexity: Higher‑performance SMA grades used in automotive and electronics require specialized compounding and processing labor. Labor intensity increases working capital needs and constrains rapid scaling; manufacturers must therefore optimize tech transfer and workforce training as part of capacity expansion plans.
-
Sustainability certification as market leverage: Recent ISCC PLUS certifications in the sector demonstrate how traceability and verified feedstock pathways are becoming commercial levers. Firms that combine sustainable feedstock conversion with validated certifications can command improved buyer attention and earlier entry into circular value chains.
Competitive landscape — concentration, capabilities and recent moves
The SMA market remains moderately concentrated: the top three suppliers account for a meaningful share of the market, and the top five approach roughly half of global volumes. That degree of concentration creates both risks and opportunities for mid‑tier players — from pricing power to niche specialization.
-
Polyscope Polymers B.V. (Geleen, Netherlands): A recognized leader in SMA R&D and a primary supplier of branded XIRAN® grades and derivatives for engineering plastics and specialty applications. Their capabilities in specialty compounds make them a bellwether for high‑performance demand.
-
Cray Valley (TotalEnergies) (Saint‑Avold, France): A specialty producer with an emphasis on coatings, adhesives and polymer modification. Recent operational upgrades and the Carling facility’s ISCC PLUS certification indicate strategic emphasis on sustainable supply chains and brand assurance.
-
INEOS Styrolution (Frankfurt, Germany): A major producer of Lustran® SMA grades. Their entry into mechanically recycled polystyrene commercialization signals how large producers intend to bridge circular feedstocks with existing product portfolios.
-
Kraton, Denka, Eastman, LG Chem and Nippon Steel & Sumikin Chemical : These firms bring complementary strengths — from regional manufacturing scale to formularies tailored for automotive and electrical applications. Each player’s balance between commodity scale and specialty differentiation is a primary axis of competition in 2026.
Recent company developments illustrate the strategic paths in the sector: certification and safety milestones are being used to secure premium routes to market and to derisk industrial buyers; meanwhile, progress on recycled styrenic feedstocks is reshaping supplier value propositions. The full report profiles each major player’s asset footprint, capability clusters and strategic options without revealing proprietary customer or contract values.
What the PW Consulting report contains — practical intelligence, not just charts
-
Time‑series market model (2020–2032): An accessible, scenario‑driven model that translates macro assumptions (feedstock pricing, end‑use demand shifts, regulatory trajectories) into revenue and volume outcomes. Users can run sensitivity analyses to see how different market shocks alter required capital and inventory strategies.
-
Supply chain and procurement playbook: Detailed guidance on feedstock sourcing strategies, vendor diversification, tolling vs. captive production economics and a supplier scorecard to prioritize strategic partnerships.
-
Product and pricing frameworks: Segmentation‑aware approaches to portfolio rationalization, price‑to‑value mapping, and trade‑off matrices for introducing sustainable or higher‑performance grades.
-
M&A and partnership screening: A practical checklist and valuation templates tailored to SMA assets, including integration risk flags specific to compounding, regulatory exposure, and labor‑intensive production sites.
-
Regulatory impact matrix and go‑to‑market timing: Actionable timelines aligned with food‑contact approvals, certification processes (e.g., ISCC), and major regional regulatory milestones, enabling tactical product rollouts.
-
Commercial playbook for OEMs and converters: Concrete procurement and co‑development strategies for automotive, electronics and coatings customers seeking to secure differentiated SMA formulations.
How leaders should use this study in 2026 — six immediate actions
-
Convert headline CAGR into resource allocation: Use the segmented models in the report to determine how much capital is needed to defend or grow your position in target application clusters.
-
Hedge feedstock exposure strategically: Combine short‑term hedges with medium‑term supplier partnerships and on‑site inventories to protect key formulations against styrene and maleic anhydride price swings.
-
Prioritize certification where it unlocks margin: Target ISCC PLUS and equivalent certifications only in product lines where the report shows a quantifiable willingness‑to‑pay from buyers.
-
Design capex for flexibility: Invest in modular compounding lines and tolling options that allow rapid switching between standard and high‑performance grades as demand signals change.
-
Use competitor playbooks to inform M&A targeting: Screen potential targets against our proprietary integration and value leakage matrices before advancing to bids.
-
Embed regulatory intelligence into product roadmaps: Align R&D timelines with approval and notification windows to avoid commercial launch delays and to capture first‑mover advantage where applicable.
What we intentionally withhold here — and why
This preview demonstrates the analytical depth and the practical outputs that PW Consulting delivers. It intentionally omits granular region‑by‑region and application‑by‑application revenue breakdowns, as well as proprietary customer contracts and price trajectories: these are core assets in the full report. The reason is deliberate — the most valuable, decision‑enabling slices of the data are delivered in the report package and the interactive model, which are designed to be used directly in internal planning and board deliberations.
Next step for executives
If you are preparing capital plans, negotiating long‑term feedstock contracts, or evaluating M&A targets in 2026, the full PW Consulting Styrene‑Maleic Anhydride Copolymer Market report converts market growth statistics (and the 5.2% CAGR foundation) into a step‑by‑step decision playbook. The report includes the downloadable model, supplier scorecards, regulatory timelines and an executive briefing pack tailored for board presentation.
Contact PW Consulting to access the full study and the interactive forecast model — and equip your 2026 strategy with the market intelligence that turns headline growth into executable advantage.
For detailed analysis of this topic, please visit the official page: Styrene-Maleic Anhydride Copolymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aluminum Plates Market to Hit USD 39.95B by 2032 at 5.5% CAGR — PW Consulting
By PW Consulting, 2026-07-08
Aluminum Plates Market — Strategic Outlook for 2026 Decision-Making
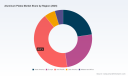
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the aluminum plates market as firms enter the pivotal 2026 planning cycle. Our full market study uses a 2025 base year and traces the 2020–2025 historical arc before projecting out to 2032. In headline terms, the global aluminum plates market expanded from roughly USD 21 billion in 2020 to USD 27.5 billion in 2025, and PW Consulting’s scenario work supports a mid-single-digit compound annual growth rate—5.5%—through the 2026–2032 forecast window, with the market approaching the USD 40 billion range by the end of the period. These macro dynamics frame every near-term commercial decision: procurement, capacity, product strategy, and corporate development.
Aluminum Plates Market
Why this study matters for 2026
-
Precision in a constrained environment: Executives are making capital and sourcing commitments against a backdrop of supply-chain reconfiguration and evolving trade policy. The difference between a 12-month and a 36-month view materially changes the ROI calculus on rolling lines, casting upgrades, and alloy-specific capacity.
Aluminum Plates Market -
From cost management to value capture: Low-carbon premiums, alloy differentiation, and downstream integration are shifting margin pools. Buyers and sellers who align commercial terms with lifecycle cost and sustainability profiles will capture outsized value.
Aluminum Plates Market -
Deal flow and valuation: M&A and joint-venture opportunities are concentrated around specialty alloy capabilities, low-carbon footprint assets, and regionalized finishing capacity. Our research isolates where strategic acquisitions create defensible higher-margin positions.
Key market dynamics shaping 2026 choices
-
Demand composition and secular trends. Aerospace, automotive (including EV body-in-white and structural applications), construction and high-performance industrial applications remain the core volume drivers. Demand growth is heterogeneous across applications: structural and high-strength alloys are growing faster than commodity sheet in many markets, creating material mix shifts that matter for pricing and throughput planning.
-
Supply-side reconfiguration. A mix of integrated producers (smelting-to-rolling), specialty plate makers, and distributors shapes availability. Recent capacity investments and restarts in primary metal and casting/rolling facilities are moderating tightness in certain product lines, but lead times for high-strength plate and specialty temper grades remain lengthy.
-
Input-cost and feedstock evolution. Raw-material cycles—bauxite, alumina and energy—continue to create episodic volatility. Price softening and regional surpluses emerged through 2025, but the structural balance remains sensitive to restart timings, logistical bottlenecks and environmental constraints in alumina refining.
-
Trade policy and industrial strategy. Recent policy moves aimed at strengthening domestic production have altered cross-border economics. Tariff, subsidy and security-of-supply considerations are forcing producers and OEMs to re-evaluate long-term sourcing footprints, regional hedging strategies and local value creation commitments.
-
Decarbonization and product innovation. Low-carbon primary aluminum, electrified smelting, hydro-power integrated production, and improvements in casting/rolling technology are creating differentiation opportunities. Buyers increasingly reward demonstrable lifecycle emission reductions; producers with credible low-carbon credentials command pricing optionality.
Competitive landscape — what matters in 2026
The aluminum plates market sits at a medium concentration level: the top three global participants control a meaningful but not overwhelming share of the market, and the top five collectively approach a plurality position. That concentration profile creates both cooperation and competition dynamics—large integrated suppliers can exert pricing influence and service scale, while nimble specialists capture premium end-markets.
-
Integrated global leaders: Firms with scale in rolling and downstream finishing, established supply relationships with OEMs, and geographic reach are positioned to supply high-volume needs and to influence benchmark pricing.
-
Specialty alloy and defense-focused suppliers: Companies concentrating on 2000-, 6000- and 7000-series alloys and military/aerospace specifications derive stronger margins per ton and benefit from longer qualification cycles that raise barriers to entry.
-
Low-carbon and regional champions: Producers leveraging low-emission power inputs or localized supply chains capture both sustainability-linked premiums and buyer preference in regulated markets.
Relevant market participants covered in our competitive analysis include leading integrated roll-to-cast players, specialty plate makers, regional integrated groups, and major distributors and service centers. Each profile in the full report includes operational footprint mapping, alloy capability matrices, investment pipelines, and an M&A posture assessment—an indispensable input for sourcing and strategic-investor teams.
Recent industry signals you must interpret in 2026
-
Targeted capacity investments and defense-backed programs are redirecting capital toward domestic casting and finishing capability; these projects are changing the availability profile of cast-to-roll plate volumes and qualification windows for aerospace-grade alloys.
-
Commercial product expansions in prepainted and value-added flat products indicate distributor and coil-coating segments are seeking higher-margin offerings and faster time-to-market for architectural and industrial customers.
-
Market noise around feedstock and alumina supply has created short-term price swings and excess availability in certain regions; buyers that build dynamic purchasing protocols and sprint-response logistics can convert volatility into a competitive advantage.
Scenario implications for 2026 decision-makers
-
Base Case (Mid-single-digit growth, continued re-shoring): Expect steady demand growth in core applications and gradual easing of some supply constraints. Recommendation: prioritize flexible capacity upgrades that reduce time-to-qualification for high-strength alloys, and secure staged offtake agreements with variable-price collars.
-
Protectionist/Regionalization Upside: If trade barriers and strategic procurement intensify, regional players with local casting/rolling capacity and secure feedstock access will outcompete distant suppliers. Recommendation: accelerate local partnerships, shorter supply chains and inventory decentralization.
-
Rapid Demand & Premiumization: In a technology- or policy-driven spike in demand for low-carbon or high-strength plates, capacity will be the constraining factor. Recommendation: pursue bolt-on acquisitions in specialty plate makers, enter into capacity reservation agreements, and prioritize premium alloy R&D.
Actionable playbook — priority moves for 2026
-
Establish a tariff- and subsidy-aware sourcing playbook. Reprice long-term contracts to reflect regional policy shifts and maintain alternative sources for critical alloy grades.
-
Lock in alloy-specific supply through qualification-focused partnerships. Invest in jointly-funded qualification lines to cut time-to-approval for aerospace and defense OEMs.
-
Layer sustainability into procurement and commercial terms. Include lifecycle emission metrics in supplier selection and develop a premium pricing strategy for low-carbon plate variants.
-
Pursue selective M&A to secure specialty alloy capabilities and local finishing capacity. Target assets that shorten qualification cycles and raise entry barriers for competitors.
-
Optimize inventory and hedging for input cyclicality. Use blended hedges and dynamic safety stocks for alumina-based risk while maintaining responsiveness to product-specific lead times.
-
Embed technical differentiation through R&D partnerships. Co-develop higher-strength, manufacturable tempers and coatings that reduce total system cost for OEMs.
What PW Consulting’s full report delivers (teaser)
-
Granular, scenario-based demand model to 2032 with application-by-alloy trajectories (note: specific segment-level tables are available in the full report).
-
Supplier and capacity atlas with operable footprints, grade capabilities, expansion pipelines and regional service-network maps.
-
Tariff and policy impact simulator that models landed-cost outcomes across alternative sourcing routes and duty scenarios.
-
Cost curve and margin pool analysis for commodity vs. specialty plates, including sensitivity to energy and alumina cost paths.
-
Competitive profiles and strategic playbooks for leading players, including capacity and investment signals to watch for.
-
M&A screening list and valuation templates tailored to strategic and financial buyers, plus a prioritized due-diligence checklist.
-
Buy-side and sell-side negotiation tools, procurement templates, and a recommended governance framework for long-term supply agreements.
Concluding guidance
For executives setting 2026 budgets and strategic roadmaps, the aluminum plates market presents a classic combination of structural growth and tactical uncertainty. The mid-single-digit CAGR to 2032 underlines a sizable commercial opportunity, yet value capture will be concentrated in alloy differentiation, low-carbon credentials and regional supply-security plays. Our report is designed to accelerate the required strategic choices—what to build, buy, or reserve—and to translate market dynamics into executable commercial and M&A actions.
PW Consulting’s full study provides the confidential, data-rich foundation for those decisions. The public primer you are reading purposefully omits the core, segment-level datasets and price curves that are essential to transaction- and procurement-grade work. Contact PW Consulting for the complete dataset, bespoke scenario workshops, or a focused executive briefing to convert the 2026 planning horizon into a defensible and value-accretive strategy.
For detailed analysis of this topic, please visit the official page: Aluminum Plates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-paper Display (EPD) Market to grow at 6.98% CAGR through 2032
By PW Consulting, 2026-07-08
E-paper Display (EPD) Market — Strategic Outlook for 2026 Decision-Makers
This briefing introduces PW Consulting’s flagship E-paper Display (EPD) Market study and explains why its insights are mission-critical for corporate strategy in 2026. Built on a 2025 base year and a detailed historical series (2020–2025), our forecast extends through 2032. The market is projected to grow from an estimated USD 215.0 Million in 2025 to roughly USD 344.8 Million by 2032, representing a compound annual growth rate (CAGR) of 6.98% over the forecast period. This note is written as a ‘trailer’: it surfaces the strategic implications and the kinds of operational decisions the study supports, while reserving the granular segmentation tables and proprietary metrics for the full report.
E-paper Display (EPD) Market
Why this study matters for your 2026 planning
- Timing and scale of investment: The mid‑2020s are a window in which capacity expansions, color EPD commercialization and new module technologies converge. Our growth trajectory signals when to accelerate capex and when to pilot low‑risk product variants.
- Supply‑chain resilience and sourcing: Volatility in raw materials, changes in tariff regimes, and uneven regional manufacturing dynamics make supplier mapping and contractual design essential to protect margin and delivery commitments.
- Product and go‑to‑market strategy: Market adoption will be driven by color and large‑format EPDs, energy‑optimized modules for IoT, and integrated solutions (drivers + NFC + touch). Strategic licensing, vertical partnerships and modular offerings will determine winners.
- Regulatory and sectoral readiness: Regulatory fragmentation across end markets — from medical device certification to automotive qualification — requires differentiated compliance roadmaps for any commercialization schedule.
What the report delivers (actionable components)
- Top‑line market sizing and scenario forecasts (base year 2025; detailed 2026–2032 outlook with sensitivity testing around macro and commodity shocks).
- Technology roadmaps comparing electrophoretic, color digital‑ink variants and emerging substrates, with impact analysis on bill‑of‑materials and manufacturing yield.
- Competitive landscaping and supplier scorecards, including capability matrices (materials, modules, integration services) and likely strategic moves by incumbents and challengers.
- Go‑to‑market playbooks for OEMs, module integrators and system architects: pricing ladders, bundling strategies (hardware + firmware + services), and channel acceleration templates.
- Supply‑chain stress tests and mitigation templates covering tariffs, input price shocks, labor shifts and capacity ramp timelines.
- Commercial case studies and procurement checklists for pilots, volume rollouts and aftermarket support commitments.
- Financial modeling tools and investment memos that translate market scenarios into IRR, payback and valuation sensitivities for boardrooms.
Market dynamics shaping strategy in 2026
Several convergent forces in 2025–2026 are creating both opportunity and complexity for market participants:
E-paper Display (EPD) Market
- Macroeconomic and trade pressures: Elevated tariffs on specific imports and shifting trade policy raise landed cost uncertainty for display frames, metals and peripheral components. These dynamics increase the value of near‑sourcing and multi‑country sourcing strategies.
- Raw material volatility: Instability in key producing regions is producing pronounced swings in input costs. Manufacturers that can lock supply, hedge exposures or redesign assemblies for commodity resilience will secure margin advantage.
- Regulatory fragmentation: End markets such as healthcare and automotive demand differentiated certification pipelines. Firms planning to sell into regulated verticals must invest in early qualification programmes to avoid multi‑quarter delays.
- Capacity and scale shifts: Strategic manufacturing collaborations and JV activity are accelerating large‑format and high‑volume capacity. Notable production alliances and planned capacity investments in 2025–2026 indicate that industry scale economics will shift for large signage and ESL players.
- Product evolution: Commercial launches of color and bio‑material‑housed E‑paper models, alongside faster refresh and NFC‑enabled driver solutions, are expanding addressable use cases beyond e‑readers into retail, public signage and battery‑free IoT.
Recent strategic moves — highlights
- Major joint ventures have been announced to accelerate large‑format EPD production capability and to align module supply with downstream signage demand — signaling a deliberate move toward capacity consolidation in large sizes.
- Global consumer and enterprise vendors have launched color EPD products and introduced sustainable materials into housing and panel design, underlining the commercialization of new material science approaches.
- A wave of module and driver board introductions focusing on faster refresh, multi‑color capability and NFC/battery‑free operation is lowering the technical entry barriers for novel end‑device form factors.
- Material and labor investments by leading manufacturers underscore an industry pivot to both scale and regional diversification; this is an area where vendor selection will materially affect time‑to‑market.
Competitive landscape — who to watch and why
The report profiles established leaders, specialized module houses and emergent system suppliers. Here are the strategic positions of the most consequential players we track:
E-paper Display (EPD) Market
- E Ink Holdings Inc. (Hsinchu, Taiwan) — A global leader in electrophoretic EPD technology and a vertically integrated supplier of core materials, modules and production lines. Strengths: IP portfolio, large‑format module capability and scale. Strategic considerations: leveraging production partnerships and cross‑border capacity to meet signage and ESL demand.
- Pervasive Displays Inc. (Tainan, Taiwan) — Focused on industrial IoT and ultra‑low power embedded modules. Strengths: specialized low‑power designs and embedded solutions for ESL and connected devices. Strategic considerations: opportunities in volume IoT deployments and long‑lifecycle industrial applications.
- SEEKINK (China) — A one‑stop provider for high‑resolution, ultra‑thin modules and optical bonding services aimed at commercial and creative uses. Strengths: integration services and thin‑module expertise. Strategic considerations: expansion into value‑added integration and regional distribution partnerships.
- Samsung Electronics Co., Ltd. (Suwon, South Korea) — Rapidly moving color EPD into commercial channels with large‑format models and sustainability‑focused housing innovations. Strengths: scale, brand, and access to retail deployment channels. Strategic considerations: incumbency in signage and public display segments, and potential acceleration into enterprise retrofits.
- GooDisplay (China) — Agile producer of customizable driver boards, NFC‑enabled solutions and multi‑color panels across a broad size range. Strengths: modular driver ecosystems and fast refresh product introductions. Strategic considerations: viability as a systems partner for OEMs seeking rapid prototyping and feature integration.
Together, these players illustrate a market where technical differentiation, manufacturing scale and software/hardware integration determine competitive advantage. Although consolidation is occurring in select segments (notably large‑format capacity agreements), a meaningful portion of value remains distributed across specialist module makers and service providers.
Strategic playbook for 2026 decision‑makers
- Define your target horizon using our market growth cadence: With a mid‑single digit CAGR through 2032, prioritize initiatives that balance near‑term revenue capture (pilots, signage pilots, ESL rollouts) with medium‑term bets (color, large‑format, certified automotive/medical products).
- Lock flexible supply to mitigate tariff and commodity risk: Build dual‑sourcing, regional buffer stocks and supplier KPIs tied to price‑pass mechanisms to protect margin while maintaining agility.
- Invest in certification early: For medical and automotive targeting, front‑load compliance investments to avoid multi‑quarter commercialization delays and to capture premium pricing.
- Pursue partnership plays not just acquisition: JVs for capacity, technology licensing for color stacks, and module integration partnerships accelerate market entry while keeping capital requirements manageable.
- Differentiate beyond the panel: Offer bundled solutions (hardware, drivers, cloud management, installation services) to create recurring revenue and higher switching costs for customers.
- Prepare operationally for scale: Align manufacturing ramp plans with projected demand curves and use scenario models (included in the full study) to time investments and minimize underutilized capacity.
How to use the full PW Consulting EPD report
This summary outlines the strategic pressure points and actionable playbooks that the full study expands into operational templates, detailed region/type/application forecasts, supplier scorecards, and transaction playbooks. If your 2026 agenda includes capital deployment, product launches, supply‑chain redesign or M&A in the EPD ecosystem, the comprehensive datasets, sensitivity models and vendor comparisons in our full report will provide the precise inputs your board and investment committees require.
For teams preparing investment memos, procurement RFPs, or market entry roadmaps, PW Consulting’s EPD study turns the headline growth rates and public developments into executable plans — and delivers the guarded segmentation and financial models you’ll need to validate next‑step commitments.
Contact PW Consulting to access the full report, the downloadable financial model and bespoke advisory packages tailored to manufacturing partners, OEMs and strategic investors operating in the E-paper Display value chain.
For detailed analysis of this topic, please visit the official page: E-paper Display (EPD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LCP Films & Laminates Market to reach USD 246.8 Million by 2032 (5.24% CAGR)
By PW Consulting, 2026-07-08
Liquid Crystal Polymer (LCP) Films and Laminates Market: Strategic Implications for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic primer on the Liquid Crystal Polymer (LCP) films and laminates market — a sector that is transitioning from a niche high‑performance polymer family to a broadly deployed enabling material across high‑frequency electronics, advanced packaging and select medical and industrial applications. This briefing distills the research foundations, the near‑term market trajectory, competitive dynamics, and the concrete strategic choices executives should be making in 2026. The narrative is intentionally high‑signal: it demonstrates the depth of our analysis while reserving detailed subsegment metrics for the full report.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Executive snapshot
LCP markets have shown steady expansion through the early 2020s and enter 2026 with positive momentum. Our base year analysis (2025) indicates a mature but still-growing market that has expanded materially since 2020 and is projected to continue expanding through the 2026–2032 forecast window at a mid‑single‑digit compound annual growth rate (CAGR). Market concentration remains moderate: the combined revenue share of the top three and top five suppliers confirms a fragmented supplier base with leading specialists and many regional players — a structure that creates M&A and partnership opportunities for scale seekers.
Liquid Crystal Polymer (LCP) Films and Laminates Market
- Clear growth pathway: a predictable CAGR across the forecast horizon provides a reliable demand foundation for capex decisions and product portfolio prioritization.
- Fragmented supply side: the CR3 and CR5 metrics indicate room for consolidation and for fast followers to build scale through selective vertical integration.
- Technology differentiation: recent product launches and patents are reshaping the value proposition from simple film supply to integrated high‑frequency substrate solutions.
Market trajectory — what the numbers tell us
From 2020 through 2025 the LCP films and laminates market moved from early recovery into steady adoption, driven by high‑frequency telecom applications, PCB innovations and semiconductor packaging needs. Our base‑year assessment captures that momentum and projects a continued expansion across the next six years under a set of practical assumptions: sustained roll‑out of 5G and next‑wave RF front‑end architectures, persistent demand for thinner and higher‑reliability substrates in advanced packaging, and growing, selective adoption in medical and flexible electronics niches.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Two numeric anchors define the investment context for 2026 planners: a clear multi‑year growth rate that validates multi‑year capital programs, and a forecast path that highlights cyclical inflection points where demand, capacity and pricing will intersect. Executives should treat these anchors as directional guides for inventory policy, capacity timing and strategic partnerships rather than precise targets to be hit in isolation.
Report contents — practical, transaction‑ready analysis
The underlying study is built for decision implementation. For executives considering investments, procurement shifts or technology roadmaps, the report provides:
- Demand modelling with scenario overlays: baseline, upside (accelerated telecom and packaging adoption), and downside (feedstock or energy shocks), enabling stress‑tested capacity planning.
- Cost‑to‑serve diagnostics: energy sensitivity, feedstock exposure, and processing cost differentials that inform location, automation and supplier selection choices.
- Commercial playbooks: go‑to‑market pathways for product extensions (films → adhesive‑free FCCLs → integrated substrates), recommended partner archetypes, and early customer engagement templates.
- M&A and partnering scorecards: valuation multipliers, capability gaps, and integration risk checklists calibrated to both strategic and financial acquirers.
- Regulatory and circularity pathways: compliance impacts and near‑term forward plans for end‑of‑life management and recycling trials suitable for European and global contexts.
Note: this briefing deliberately omits granular subsegment tables and precise regional/application splits; the full dataset and model are available through the complete report package.
Competitive landscape — who matters and why
The competitive topology is a mix of global polymer manufacturers, specialized substrate firms, and regional laminate producers. The most active players combine materials science, manufacturing scale and application‑level system relationships.
- Material incumbents with resin and film expertise (examples include firms producing LCP resins and grades): they remain advantaged where upstream monomer control and formulation IP create performance and margin differentiation. These players also accelerate commercialization when they expand into films and laminates.
- Integrated electronics suppliers and substrate specialists: companies that can pair LCP film capabilities with multilayer laminate production and advanced inner‑cavity or adhesiveless constructions are redefining the product set for RF and high‑frequency markets.
- Regional challengers: a number of Asia‑based manufacturers are focused on cost‑competitive film and laminate supply, often coupled with close proximity to key electronics manufacturing clusters.
Recent corporate actions signal the strategic priorities driving competitive moves:
- Product innovation and market timing: a major producer announced the mass production of an inner‑cavity LCP flexible substrate for ultra‑low‑loss high‑frequency applications late in 2025 — a development that moves LCPs from material to system‑level enabler for certain telecom and radar use cases.
- Capability pooling via M&A: an acquisition in early 2025 by a leading chemical firm expanded its neat resin franchise, reinforcing follow‑through into ICT and mobility end markets.
- Channel and portfolio reinforcement: distribution partnerships renewed in 2025 improved market access for global LCP families and accelerated adoption by contract manufacturers and PCB fabs.
- IP fencing and defensive positioning: patent grants for multilayer compositions underscore the R&D race to own differentiated laminate stacks tailored to RF and high‑speed applications.
Dynamics and headwinds that will shape 2026 decisions
Four structural dynamics merit executive attention when setting 2026 priorities:
- Feedstock concentration risk: specialty monomer supply chains remain concentrated with single‑source exposure in certain geographies. Procurement teams should model multi‑sourcing strategies and strategic inventory coverage to blunt potential interruptions.
- Energy and processing cost pressure: in some regions LCP processing consumes substantially more electricity than alternate high‑performance polymers, creating location‑specific cost disadvantages as tariffs rise. Energy intensity should therefore be a core input to any new capacity siting analysis.
- Geopolitical disruption to hydrocarbon logistics: recent regional conflicts have demonstrated how shifts in naphtha/LPG flows and LNG rerouting can propagate into feedstock and utility price volatility. Scenario planning that combines supply interruptions with price shocks is now standard practice for resilient capex and contract strategies.
- Regulatory and circularity requirements: EU circular‑economy initiatives and institute‑led recycling investigations are increasing the cost of non‑compliance while opening the door to early‑mover differentiation through end‑of‑life solutions and recycled content offerings.
Concrete strategic moves for 2026
Based on the combination of market growth, technology shifts and supply‑side dynamics, we recommend a focused set of actions for corporate leaders:
- Prioritize dual‑track capacity planning: pursue modular, debottleneckable investments that can be accelerated if high‑frequency substrate demand materializes faster than the baseline scenario.
- Lock in feedstock resilience: establish layered contracts (short‑term indexed + strategic long‑term) with geographic diversity and optionality clauses; consider upstream partnerships or minority stakes in monomer suppliers where technically and financially viable.
- Invest in high‑value differentiation: move beyond commodity films toward integrated substrates (inner‑cavity, adhesiveless FCCLs) and validated laminate stacks for RF and semiconductor packaging where margins and customer stickiness are higher.
- Embed energy strategy into location decisions: select sites based on a blended metric of energy cost, grid reliability, and access to low‑carbon electricity to avoid utility‑driven margin erosion.
- Lead on recyclability and compliance: develop pilot programs for LCP end‑of‑life processing and recycled feedstock trials to preempt regulatory headwinds and capture sustainability premiums with blue‑chip customers.
- Use M&A and partnerships smartly: target bolt‑on buys to fill capability gaps (e.g., laminates, FCCL manufacturing, IP portfolios) rather than chasing scale in low‑margin commodity film production.
Why this briefing matters for 2026 decisions
By 2026, commercial outcomes in the LCP space will be determined less by raw market growth and more by the timing of technology transitions, the resilience of feedstock chains, and the ability of firms to offer system‑level solutions that reduce customer integration risk. The market’s mid‑single‑digit growth profile provides a steady revenue backdrop, but strategy will be won by those who combine supply‑chain foresight, targeted product differentiation, and regulatory alignment.
Accessing the full intelligence
This article showcases the analytical orientation and strategic framing contained in PW Consulting’s full LCP films and laminates study. To preserve the report’s commercial integrity and to follow the “preview” principle, we have withheld detailed subsegment tables, regional/applications splits, and the full financial model in this primer. Executives and project teams who need the transaction‑ready datasets, supplier scorecards and the scenario models should consult the complete report package.
Contact PW Consulting to obtain the full dataset and a tailored briefing that maps this sector analysis to your portfolio, supply chain and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Liquid Crystal Polymer (LCP) Films and Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Programmable Logic Controller (PLC) Market 2026: Strategic Imperatives for Decision‑Makers
PW Consulting’s latest PLC market study (base year 2025; forecast 2026–2032) is designed as an operational playbook for executives making capital, product and portfolio decisions in 2026. The study synthesizes a calibrated market model — the PLC market expanded steadily through the first half of the decade and, guided by a 5.6% compound annual growth rate, is forecast to continue that trajectory over the 2026–2032 horizon. That momentum underpins a multi‑year window for strategic moves across procurement, R&D investments, M&A and service transformation.
Programmable Logic Controller (PLC) Market
Why this research matters for 2026 decision cycles
-
Timing investment: Capital planning for automation projects requires an accurate view of market momentum and product lifecycle inflection points. Our model translates macro growth into actionable timing signals for equipment refresh, software licensing and service launches.
Programmable Logic Controller (PLC) Market -
Supplier strategy: With a market structure that shows moderate concentration among top vendors, procurement teams must reconcile supplier dependency risks with the benefits of deep platform partnerships.
Programmable Logic Controller (PLC) Market -
Product roadmap alignment: The transition toward software‑defined control (vPLC), edge AI and modular architectures forces OEMs and integrators to reweight R&D spend. The report maps where capability investments earn the highest marginal returns.
-
Cybersecurity and compliance: Recent advisories and standards updates change the threat and compliance landscape for PLC owners. The study translates regulatory signals into concrete mitigation and sourcing recommendations.
-
M&A and partnerships: Growth with constrained component supply and accelerating software monetization creates distinct arbitrage opportunities for strategic buyers and financial sponsors.
What’s inside: practical deliverables for enterprise teams
-
Transparent market model: a reconciled historical series and a forward projection across 2026–2032 with downloadable assumptions, sensitivity levers and scenario outputs.
-
Go‑to‑market playbooks: playbooks for OEMs, system integrators and aftermarket service providers that include pricing archetypes, channel incentives and contract structures aligned to current market dynamics.
-
Buyer‑persona and procurement timelines: decision‑making maps for end users (process vs. discrete industries), procurement trigger points and recommended contractual clauses for risk allocation.
-
Vendor scorecards and supplier due‑diligence templates: comparative frameworks that go beyond marketing claims — assessing software ecosystems, upgrade policies, cybersecurity posture and long‑term service economics.
-
Technology roadmaps and use case ROI: prioritized pilots for vPLC, AI‑assisted engineering, edge analytics and predictive maintenance with expected payback ranges and implementation risk matrices.
-
Supply‑chain diagnostics: component‑level vulnerability mapping, tariff exposure analysis and mitigation options for semiconductor sourcing constraints.
-
Regulatory & cybersecurity playbook: synthesis of the latest advisories and standards with step‑by‑step remediation and compliance planning templates.
-
Scenario analyses and M&A shortlist: upside/downside scenarios, valuation sensitivities and a curated list of strategic targets and investment‑grade acquisition candidates (with rationale).
Market dynamics shaping 2026 strategy
The PLC market is at an inflection point where incremental technology shifts aggregate into system‑level change. Three dynamics dominate:
-
Platformization: Leading vendors are expanding from discrete PLC hardware to integrated automation platforms that bundle controllers, I/O, software and cloud services. The resulting focus on lifecycle revenue is changing OEM economics, raising the value of software compatibility and long‑term service agreements.
-
Edge intelligence & virtualization: Demonstrations of virtual PLCs (vPLC), AI‑assisted engineering and PC‑based control illustrate an industry push toward modular, software‑defined control stacks. These advances lower marginal deployment cost for complex control logic but raise questions about certification, latency and safety cases.
-
Supply‑chain and security constraints: Semiconductors and specialized components remain a strategic choke point; trade measures and tariffs continue to shape suppliers’ sourcing choices. Simultaneously, nation‑state and affiliated threat actors are increasingly weaponizing PLC vulnerabilities — a reality reinforced by recent advisories calling out active exploitation patterns and vendor‑specific guidance. Heightened IEC 62443 guidance and vendor remediation programs are now operational priorities for buyers.
Competitive landscape: leaders, challengers and strategic posture
The vendor field combines legacy industrial giants with specialist players pushing new architectures. Key firms covered in the study include:
-
Rockwell Automation Inc. — Milwaukee, Wisconsin, United States — https://www.rockwellautomation.com — portfolio depth in Allen‑Bradley controllers and automation platforms.
-
Siemens AG — Munich, Germany — https://www.siemens.com — strong positioning around SIMATIC lines and Industry 4.0 integration.
-
Schneider Electric SE — Rueil‑Malmaison, France — https://www.se.com — Modicon and process‑centric automation solutions.
-
ABB Ltd. — Zurich, Switzerland — https://www.abb.com — broad automation and infrastructure offerings.
-
Mitsubishi Electric Corporation — Tokyo, Japan — https://www.mitsubishielectric.com — MELSEC series for industrial automation.
-
Omron Corporation — Kyoto, Japan — https://www.omron.com — PLCs for robotics and machine control.
-
Beckhoff Automation GmbH & Co. KG — Verl, Germany — https://www.beckhoff.com — PC‑based control and TwinCAT platforms pushing open architectures and AI integration.
-
Bosch Rexroth AG, Emerson Electric Co., Eaton Corporation plc, IDEC Corporation and Delta Electronics — each bringing distinct strengths across motion control, process automation, industrial controls and compact PLCs.
Market concentration metrics indicate that the top three and top five groups hold material shares of vendor revenue — a structure that favors incumbents on platform lock‑in but leaves room for specialist challengers around software, open control paradigms and aftermarket services.
Signals from the field: product and market validation
Recent trade‑show demonstrations and vendor announcements validate several trends flagged in our model. Examples include next‑generation PC‑based control and AI integration showcased at major industrial fairs, and platform refreshes from incumbents emphasizing virtualization and expanded I/O architectures. Meanwhile, corporate disclosures and public advisories underscore the operational realities: volume volatility at specialist suppliers, persistent component constraints, and active cybersecurity threats targeting controllers.
Strategic playbook for 2026 (prioritized)
-
Immediate (0–12 months): patch and harden. Implement prioritized cybersecurity remediations; require supplier attestations aligned to IEC 62443; execute short‑list supplier diversification for critical components.
-
Near term (12–24 months): pilot platform transitions. Run two to three vPLC/edge AI pilots aligned to high‑value use cases; codify upgrade paths to minimize integration risk; create a services‑led offering to capture aftermarket upside.
-
Medium term (24–36 months): rationalize portfolio and accelerate software monetization. Rebalance product roadmaps toward modular, software‑centric architectures; bundle predictable service revenue and lifecycle contracts.
-
Strategic (36–60 months): pursue targeted M&A and strategic alliances. Seek bolt‑on acquisitions that close capability gaps (AI analytics, cybersecurity tool sets, regional service networks) and negotiate preferred supply agreements for semiconductors.
How buyers and investors should use this study
For procurement and operations leaders, the study is a source of negotiation leverage — benchmark TCO models, supplier scorecards and procurement timelines translate directly into RFP requirements and SLA design. For R&D and product leaders, the technology roadmaps and ROI analyses prioritize feature investments against realistic adoption curves. For corporate development teams and investors, the scenario analyses and M&A shortlist provide a defensible basis for valuation and target selection.
A note on the teaser format
This article highlights the study’s strategic value and key thematic insights while intentionally withholding granular segment matrices and certain proprietary data outputs — the detailed regional/application splits, the vendor revenue ladders by product type and the full downloadable financial model are available inside the full report. That detailed data is where operational teams will find the exact inputs required to execute procurement clauses, validate capex plans and identify specific acquisition targets.
Next steps
PW Consulting offers briefing workshops and custom scenario runs for leadership teams ready to convert insight into action. If your 2026 plan requires a defensible, executable automation strategy — from supplier rationalization to cybersecurity remediation and M&A prioritization — the report and its supporting tools provide a turnkey starting point.
Contact your PW Consulting representative to schedule a targeted briefing and obtain the complete dataset, vendor scorecards and executable playbooks that drive decisive action.
For detailed analysis of this topic, please visit the official page: Programmable Logic Controller (PLC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Spandex Fiber Market — 2026 Strategic Primer
PW Consulting presents a concise strategic primer to accompany our full Spandex Fiber Market research. This briefing distills the macro forces, competitive posture, and near-term tactical imperatives that will determine winners and laggards in 2026 — while intentionally withholding segmented datapoints reserved for the full study. Use this as a decision-focused preview: it demonstrates the depth of analysis and line of sight our clients can expect, and it identifies the critical trade-offs that executive teams must resolve during 2026 planning cycles.
Spandex Fiber Market
Macro picture: why 2026 is a pivotal planning horizon
The spandex fiber market remains on a structurally positive trajectory. After recovering firmly through the early 2020s, overall market revenue expands from a mid‑single billion USD base in 2020 to a roughly USD 9 billion market in the 2025 base year. Our modeling projects continued expansion through the forecast window, with the market moving towards the mid‑to‑high single‑digit billion range by the early 2030s under a compound annual growth rate (CAGR) of approximately 7.1% for the 2026–2032 period. These topline dynamics reflect steady demand growth across apparel and technical applications, combined with product premiumization and an increase in sustainable/biobased offerings that command differentiated pricing.
Spandex Fiber Market
What the full report delivers (practical modules)
- Market sizing & forecast engine — Proprietary bottom‑up model calibrated to 2020–2025 historicals and flexible scenario drivers for 2026–2032.
- Demand driver matrices — Elasticities and adoption curves for apparel, medical and industrial end‑uses; trend maps for athleisure, performance wear and functional textiles.
- Raw material & cost pass‑through analysis — Detailed PTMEG/BDO/THF cost models, sensitivity tables and supplier concentration mapping that quantify margin exposure at various feedstock price points.
- Regulatory & sustainability impact framework — Assessment of REACH and major climate disclosure regimes plus a pragmatic ROI model for bio‑derived and recycled spandex investments.
- Competitive benchmarking & supplier heatmap — Capability, brand, technology and geographic overlays for established players and emerging challengers.
- Scenario playbooks — Three operational playbooks (Base, Accelerated Bio, Demand Shock) that translate market outcomes into required inventory, offtake, and capex actions.
- M&A & partnership scorecard — Acquisition targets ranked by strategic fit, integration complexity and near‑term synergies (cost, revenue, sustainability).
- Procurement playbook & risk register — Tactical supplier contracting templates, hedging approaches and contingency triggers for abrupt input price moves or capacity shifts.
Dynamics shaping strategic choices in 2026
Four dynamics will most influence corporate choices this year:
Spandex Fiber Market
- Feedstock volatility — PTMEG led cost inputs showed a gradual uptick through early 2025; THF remains a structural lever in the PTMEG cost chain and any supply tightness or feedstock dislocation rapidly changes margin calculus for producers and converters.
- Supply evolution — New capacity announcements and phased expansions are concentrated among a handful of integrated and large regional producers. The net effect is episodic pressure on spot availability and pricing, but also opportunities for consolidation and differentiation by technology or sustainability credentials.
- Regulatory & buyer pressure — Tighter chemical and disclosure rules in major markets are already accelerating procurement of bio‑derived and recycled elastane grades. Early‑commercial contracts for biobased solutions trade at a premium, and brand procurement functions increasingly incorporate lifecycle compliance as a gating criterion for supplier selection.
- Consolidation of value capture — The industry displays a mid‑level concentration: the top three players do not dominate the market outright, and the top five together command a meaningful minority of supply. That structure enables both scale advantages for incumbents and strategic entry points for capable challengers focused on cost, service or sustainability differentiation.
Competitive implications — how incumbents and challengers are positioning
The competitive landscape is multi‑dimensional: brand strength, vertical integration, IP in polymer chemistry, cost base and sustainability positioning all matter. Our report profiles the leading producers and synthesizes implications for suppliers, converters and brand customers.
- Hyosung Corporation (South Korea) — A global leader with vertically integrated capabilities and an early mover in bio‑based spandex product lines. Their strategy centers on integrated feedstock-to‑fiber control and brandable bio offerings that target premium apparel customers.
- INVISTA (United States) — Leverages strong brand equity and a broad product portfolio to secure offtake with large apparel and technical customers. The company is actively transitioning select grades to lower‑carbon feedstocks.
- DuPont (United States) — Maintains a global footprint and technology depth; strategic priorities include protecting premium elastane brand positions while enabling sustainable variants for regulated markets.
- Asahi Kasei (Japan) — Focused on premium, high‑performance spandex and early adoption of recycled inputs; product differentiation is their primary defense against cost competition.
- Major Chinese manufacturers and regional players — Several large Asian producers compete on scale and cost efficiency; they are also the most active in capacity expansion cycles and in serving a highly price‑sensitive portion of demand.
- Integrated chemical players and specialty suppliers — Some chemical conglomerates and regional specialists are selectively moving up the value chain to capture margin via direct fiber supply or strategic partnerships with converters.
Recent market signals reinforce these strategic orientations. Suppliers implemented price increases in early 2026 reflecting tighter spot dynamics. Leading incumbents advanced bio and recycled product lines late in 2025 and into 2026, and a number of capacity projects have progressed to first‑phase production — creating near‑term supply and price implications that buyers must explicitly model into sourcing and inventory plans.
Actions for executives planning 2026 budgets
Our clients should prioritize three tactical moves this planning cycle:
- Lock strategic raw material exposure — Blend short‑term tactical hedges with selective long‑dated offtake agreements tied to sustainability milestones. Given the sensitivity of margins to PTMEG/THF movements, procurement strategies must be actively linked to product pricing and contract terms.
- Differentiate through sustainability where it matters — Invest in bio‑derived or recycled grades only where downstream buyers reward the attribute with measurable pricing or shelf‑access benefits. Where regulatory regimes (e.g., REACH revisions, emerging climate disclosure laws) impose compliance or reporting costs, early movers can capture both margin and preferred supplier status.
- De‑risk capacity and serveability — Before committing to greenfield capacity, stress‑test demand scenarios and consider joint ventures or tolling arrangements to preserve flexibility. When capacity is available from regional players, secure performance guarantees and quality audits as part of contracts.
What you will not find in this primer (and why)
This preview purposefully omits granular segment tables, region‑by‑region revenue splits and per‑application volumes. Those detailed segmentations and micro‑price curves are included in the full report and the supporting data pack; they are essential for transaction work, procurement negotiations and detailed operating budgets. Think of this article as the executive trailer: it exposes the strategic narrative and the actionable implications while reserving the underlying segment math — the working capital, capex and contract levers — for clients who engage with the full deliverable.
Next steps — how to convert insight into action
- Request the full dataset and scenario model to run customized sensitivity analysis against your product and feedstock mix.
- Commission a 4‑week supplier due diligence or target screening to identify partnership and M&A opportunities aligned with your strategic gap (capacity, tech, sustainability).
- Deploy the procurement playbook with targeted contract templates and a two‑quarter implementation timetable to lock favorable supply terms before seasonal volatility reappears.
PW Consulting’s full Spandex Fiber Market report (base year 2025; forecast 2026–2032) contains the quantitative foundations and hands‑on tools required to operationalize these recommendations. If your 2026 plan includes any combination of capacity planning, premium product launches, sustainability commitments, or M&A activity, the analysis we provide will materially reduce execution risk and surface the most attractive timing and partner options. Contact us to access the full study, the interactive model, and a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Spandex Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roughness & Contour Measuring Machines to Reach USD 344.8M by 2032 (CAGR 6.98%)
By PW Consulting, 2026-07-08
Roughness and Contour Measuring Machine Market — Strategic Preview for 2026 Decision‑Makers
As capital allocation committees and engineering leadership set priorities for 2026, the choices they make about metrology platforms will have multi‑year implications for product quality, throughput and cost of ownership. PW Consulting’s new market study provides a decision‑grade lens on the Roughness and Contour Measuring Machine market using a 2025 base year and a 2026–2032 forecast horizon. The global market — measured in USD Million — recovered steadily through the early 2020s and is projected to expand at a compound annual growth rate (CAGR) of 6.98% over the forecast period, reflecting accelerating demand across high‑precision manufacturing segments. Our briefing below highlights the strategic value of the full report for 2026 planning while deliberately withholding granular regional and application splits so readers must consult the source for complete proprietary tables and models.
Roughness and Contour Measuring Machine Market
Why this study matters to leaders in 2026
-
Timing of investment: With market momentum established by 2025, selecting the right measurement technology in 2026 impacts line yield and product qualification cycles for several years. The study quantifies capital intensity and payback timing under multiple adoption scenarios so CXOs can prioritize upgrades vs. incremental replacements.
Roughness and Contour Measuring Machine Market -
Technology roadmap alignment: The market is being shaped by a proliferation of tactile, optical and hybrid systems. Strategic sourcing decisions — whether to standardize on stylus‑based profilometers, deploy focus‑variation optical systems, or pursue hybrid platforms — require an independent assessment of accuracy tradeoffs, cycle times and shop‑floor robustness. Our analysis benchmarks incumbent and emerging approaches against specific manufacturing needs.
Roughness and Contour Measuring Machine Market -
M&A and partnership screening: 2026 will remain an active year for tuck‑ins and distribution partnerships. The report provides a vendor scorecard tied to revenue resilience, channel reach and IP depth to help corporate development teams screen targets and craft integration assumptions.
-
Regulatory and compliance planning: New or updated quality standards influence acceptance criteria and supplier contracts. The full report maps how DIN and ISO measurement standards interplay with qualification protocols and service obligations — essential context for quality and procurement teams drafting 2026 contracts.
Macro trajectory and what it implies
From the pandemic recovery through 2025 the market showed consistent expansion in measured revenues (reported in USD Million). The growth outlook into 2032 is robust — the implied CAGR of 6.98% reflects structural drivers rather than a short cyclical uptick. For planning purposes, procurement officers should assume a multi‑year technology refresh cycle influenced by: tighter surface specification tolerances from advanced componentry, rising automation of inspection tasks, and the need to integrate metrology data into manufacturing execution and quality IT stacks. These pressures create both capex demand for measurement hardware and recurring revenue opportunities for service and software vendors.
Demand drivers, constraints and near‑term uncertainties
-
End‑market intensity: High‑precision sectors — notably semiconductor wafer processing, advanced packaging and certain precision components — are the primary engines of demand. These applications increase requirements for sub‑micron repeatability and combined roughness/contour analysis, favoring suppliers that can demonstrate validated performance across temperature and vibration regimes.
-
Technology substitution and hybridization: Optical focus‑variation systems offer non‑contact, fast 3D surface mapping while stylus‑based devices retain advantages in traceability and tactile verification under established standards. Hybrid offerings that combine both families are gaining traction where throughput and traceable metrology are simultaneously required.
-
Raw material and input cost pressures: Manufacturing cost structures are influenced by upstream commodity moves. For example, the U.S. steel mill products producer price index rose materially from 2025 into 2026, adding cost pressure on frame and fixture manufacturing as well as service part inventories. Vendors and buyers must factor these cost trends into total cost of ownership (TCO) models.
-
Standards and traceability: Instruments in the market comply with established measurement standards (notably DIN EN ISO 21920 and DIN EN ISO 25178, which align with ISO 25178 and related surface descriptors). These standards drive acceptance criteria, supplier selection and calibration workflows — a non‑negotiable factor for regulated industries.
Competitive landscape: positioning of leading vendors
The competitive map is characterized by specialist metrology firms and diversified measurement corporations. Market concentration remains modest — no single vendor commands a dominant share — which sustains healthy competition on technology differentiation, service propositions and software integration. Below we summarize strategic positions of notable vendors covered in the full research.
-
Mahr GmbH (Göttingen, Germany) — Mahr’s MarSurf LD series (LD 280 and LD 140) exemplifies a mature stylus‑based approach optimized for simultaneous roughness and contour measurement. The company has extended both manual and motorized options, and a 2026 launch expanded automated station capabilities for integrated roughness, contour and waviness inspection. Mahr’s strengths lie in traceable tactile metrology, established calibration ecosystems and deep standards alignment.
-
Alicona Imaging GmbH (Raaba, Austria) — Alicona’s InfiniteFocus G6 and SL systems are representative of optical focus‑variation 3D measurement platforms that combine shape, surface roughness and contour assessment in one optical workflow. Alicona’s value proposition centers on non‑contact scanning for delicate surfaces and rapid 3D data capture suitable for inline or near‑line inspection strategies.
-
Taylor Hobson (Leicester, UK) — Taylor Hobson’s product span — from Surtronic handheld roughness testers to the Intra PRO portable profiler — targets shop‑floor flexibility. Their portable instruments position them as a practical choice for manufacturers prioritizing field diagnostics, rapid troubleshooting and reduced inspection footprint.
-
Mitutoyo Corporation (Kawasaki, Japan) — Mitutoyo’s FORMTRACER Avant series sits within a hybrid systems strategy, offering simultaneous contour and surface roughness measurement with an emphasis on automated workflows and integration into coordinate metrology environments. Mitutoyo’s global service network supports large installed bases.
-
HOMMEL ETAMIC (Jenoptik Industrial Metrology Germany GmbH) — HOMMEL ETAMIC’s Waveline and Formline families cover portable and stationary tactile measurement needs. The company used Control 2025 to preview the Formline F900, a tactile device that broadens combined shape, position, roughness and twist measurement capabilities — illustrating a product roadmap that balances shop‑floor usability with expanded functional scope.
Collectively, these vendors illustrate three strategic playbooks: (1) deep tactile specialization with traceability and calibration services; (2) optical and non‑contact innovation focused on speed and surface mapping; and (3) hybrid or modular platforms designed to capture both markets. The full report contains a vendor benchmarking framework that evaluates offerings across 12 parameters including accuracy, throughput, integration readiness, lifecycle cost and services coverage.
What the full PW Consulting report contains (practical deliverables)
-
Market sizing and forecasting model (2020–2032) with scenario analysis and sensitivity to capex and commodity inputs.
-
Methodology appendix detailing data sources, triangulation approach and model assumptions (useful for internal audit and board review).
-
Vendor profiles and competitive scorecards with feature comparisons, go‑to‑market maps and suggested partner/competitor watch lists.
-
Technology adoption playbooks showing when to standardize, when to pilot hybrids, and how to phase integration with MES/automation stacks.
-
Procurement‑grade RFP checklist and installation acceptance test (IAT) templates tailored to tactile, optical and hybrid systems.
-
Service and spare parts TCO models, including calibration frequency sensitivity and recommended service‑level agreements.
-
Regulatory alignment matrix illustrating how DIN/ISO standards translate to inspection protocols and supplier contractual clauses.
-
Risk heatmap covering commodity cost exposure, single‑source risks, and supplier concentration scenarios, plus contingency options.
Actionable recommendations for 2026
-
Run a three‑year pilot of hybrid measurement platforms where product complexity justifies the premium — this hedges between optical speed and tactile traceability and accelerates time‑to‑qualification for complex surfaces.
-
Revise procurement TCO models to account for rising input costs and potential calibration cycle increases; include spare‑parts indexation clauses to mitigate margin erosion from commodity swings.
-
Mandate standards compliance (DIN/ISO family) as a contractual precondition for capital purchases and calibration services to preserve auditability across regulated product lines.
-
Prioritize vendors that provide open API and data integration capabilities to avoid siloed inspection data — metrology must feed into your quality analytics and digital twin initiatives.
-
For potential acquirers, focus diligence on recurring service revenue and software‑enabled analytics rather than hardware resale alone; these elements drive higher multiples and durable margins.
How to use this preview
This article is a strategic preview that highlights the decision‑relevant findings and vendor landscape that PW Consulting uncovered. It is designed to help senior executives and functional leaders orient their 2026 plans without divulging the proprietary segment tables, regional breakouts and application shares that underpin our models. Those detailed splits — and an interactive model you can adapt to your company’s specific volumes and cost structure — are only available in the complete study.
Contact PW Consulting to request the full Roughness and Contour Measuring Machine Market report and the editable forecast model if you are evaluating capex commitments, scouting M&A targets, or updating inspection strategies for 2026. Our team can also deliver an executive workshop to translate the insights into a one‑page go‑forward plan aligned with your product roadmap and financial targets.
For detailed analysis of this topic, please visit the official page: Roughness and Contour Measuring Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Background Music Market USD 2,050M in 2025; 6.35% CAGR to USD 3,135M by 2032
By PW Consulting, 2026-07-08
Background Music Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As PW Consulting’s Head of Industry Analysis, I present a concise, decision‑focused briefing on the Background Music Market to frame 2026 strategic choices. Our study uses 2025 as the base year and traces the market trajectory from 2020 through a multi‑year forecast to 2032. At a macro level, the market expanded from roughly USD 1.5 billion in 2020 to about USD 2.05 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 6.35% through the 2026–2032 horizon, approaching the low‑mid USD 3 billion range by the end of the forecast period. These headline figures underline a market that is neither hyper‑speculative nor stagnant — it is steadily enlarging as business owners, platforms and creators converge on new models of music delivery, licensing and experience design.
Background Music Market
Why this study matters for 2026 decisions
-
Strategic timing: The mid‑single‑digit CAGR signals an open window for both incumbent vendors and new entrants to scale commercial models without facing the extreme volatility of a hype cycle. For corporate buyers and investors, this translates into predictable runway for pilots, integrations and payback models.
Background Music Market -
Platformization and AI acceleration: 2025–2026 has seen a rapid shift from pure catalogue licensing to platform services that combine discovery, adaptation and integration. The introduction of production‑grade AI toolkits and studio features is reshaping supplier value propositions and procurement evaluation criteria.
Background Music Market -
Regulatory complexity as an operational risk: Licensing for public performance—especially in large markets—remains a non‑trivial operational exposure. Recent regulatory and billing updates reinforce the need to incorporate licensing risk into contracting, commercial models and cost forecasts.
-
Margin pressure and value capture: As product offerings expand beyond raw tracks (analytics, curation, branded playlists, adaptive music), buyers must distinguish between true value‑added services and commoditized catalogue access when negotiating price and service levels.
What the PW Consulting report delivers
-
Robust market sizing and trend analysis: a reproducible top‑down and bottom‑up approach covering 2020–2025 historicals and scenario‑based projections through 2032.
-
Actionable segmentation frameworks: delivery modes, licensing models, and application use cases with pragmatic buyer decision matrices (note: detailed regional and application‑level tables are included in the full report).
-
Vendor benchmarking and integration playbook: qualitative and quantitative vendor profiles, API/integration maturity assessment, and an RFP template tailored for enterprise procurement.
-
Licensing & compliance checklist: operational procedures to mitigate public‑performance exposure, PRO navigation (including US Performing Rights Organizations), and contract clauses to align pricing with usage intensity.
-
Technology and monetization playbooks: AI adoption framework, rights‑management architecture, and pricing experiments with sample contract language for pilots and rollouts.
-
M&A and partnership screening: diligence scorecards for IP vs. rights‑managed assets, and valuation sensitivities reflecting market concentration and content ownership models.
Key strategic takeaways for 2026
-
Make licensing risk an early gating item. For buyers operating across the US, Europe or multi‑territory networks, the structure and cadence of PRO billing (and recent changes to billing minimums) materially affect TCO. Incorporate a licensing sensitivity in any three‑year TCO model.
-
Differentiate between content ownership and distribution control. Companies that own IP or secure exclusive rights (even partial) will command better margins and negotiating leverage as platform capabilities commoditize catalogue access.
-
Pilot AI where it reduces friction, not where it replaces trust. New AI‑driven search/adapt tools dramatically speedup music selection and localization, but buyer acceptance will hinge on traceable rights and human oversight for brand safety.
-
Design modular sourcing contracts. Opt for modular buys (catalogue access + curation + adaptive layer + reporting) so you can scale services independently as user behavior and business use cases evolve.
-
Prioritize integration over lowest price. Suppliers that expose robust APIs and embed into content workflows (video editors, POS systems, digital signage, in‑venue audio) deliver asymmetric value versus pure library vendors.
-
Use the growth window to build proprietary data. The market’s steady expansion gives buyers time to instrument audience response and convert music selection into measurable customer‑experience KPIs.
Competitive landscape: what recent moves reveal
The market remains moderately fragmented: the top three and top five vendors together account for a meaningful but not dominant share of commercial activity, leaving room for niche specialists and technology challengers. Recent corporate actions illustrate two converging themes — platform consolidation and AI‑enabled differentiation.
-
Epidemic Sound (Stockholm) : Recently accelerated platform expansion with an AI‑enabled Studio, an AI assistant for search/adaptation, and strategic integrations following acquisitions. This signals a pivot toward being a one‑stop creative audio platform — bundling discovery, rights and production workflows. For enterprises, Epidemic’s moves suggest increasing value in platform‑level integrations and a higher bar for vendor SLAs and content adaptation features.
-
Artlist (Netherlands) : By shipping an AI toolkit and an image model as part of a broader video production roadmap, Artlist is demonstrating a multi‑modal creative strategy. Expect competition to shift toward creative toolchains that pair audio with visual generation and editing, making integrated licensing and cross‑asset rights management a buying criterion.
-
Soundstripe (US) : Strategic library partnerships expanding premium content availability indicate a hybrid approach — combining curated premium catalogs with subscription simplicity. Buyers should evaluate the elasticity of premium pricing and the value of exclusive collections for brand differentiation.
-
Magnific, West One Music, Musicbed, AudioJungle, AKM, SoundMachine, TakeTones and Free‑Stock‑Music: These firms represent a spectrum from marketplace and catalogue specialists to AI‑oriented and clearance‑focused providers. The long tail of suppliers supports differentiated use cases (premium bespoke licensing, low‑cost Creative Commons options, or fully cleared turnkey libraries). Procurement strategies must therefore map vendor type to use case and compliance posture.
Regulation and reimbursement: operational implications
-
Public performance rights remain central. In key markets, streaming or playing recorded music in public spaces requires permission from copyright owners or their representatives. That regulatory baseline affects contract drafting, liability allocation and the feasibility of cost‑sharing models with landlords and franchisees.
-
In the US, licensing frameworks and billing practices differ across Performing Rights Organizations (PROs). Variations in billing cadence and fee floors create operational complexity for multi‑site operators — a factor that should be conservatively modeled in pilot to rollout transitions.
-
Joint licensing options can simplify compliance but may not eliminate cost variability across portfolio locations. Our report includes a guide to aligning contract clauses with licensing exposures to reduce unexpected fees.
How executives should use this research in 90/180/360 day plans
-
90 days — Run a focused vendor shortlist and pilot. Use our RFP template and licensing checklist to validate API maturity, sample SLAs and compliance posture.
-
180 days — Instrument and measure. Implement A/B testing of music strategies across a representative site set and start capturing direct KPIs (dwell time, transaction value, satisfaction metrics) tied to audio experiences.
-
360 days — Scale with contractual modularity. Move to multi‑year agreements with options to add adaptive/AI layers, integrate reporting and secure broader rights as your measurement framework demonstrates ROI.
Closing: why the full report is essential
This brief delivers the high‑level strategic framing required for immediate decision‑making in 2026, but the commercial details that drive contract terms, regional rollout sequencing and M&A valuation are deliberately held back to preserve the value of the full report. PW Consulting’s complete Background Music Market study includes granular segmentation tables, regional and application‑level demand curves, vendor scorecards, pricing benchmarks and downloadable RFP artifacts — all crafted to convert strategic intent into executable plans.
If your organization is evaluating platform selection, planning a corporate rollout, or assessing investment opportunities in music‑driven customer experience, use this briefing to align leadership and prioritize next steps — then consult the full report for the data and templates that convert strategy into procurement and execution.
For detailed analysis of this topic, please visit the official page: Background Music Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


