



Category: market research
PW Consulting Predicts Solid State Cooling Market to Reach USD 2,019.32 Million by 2032, Growing at a 12.48% CAGR
By PW Consulting, 2026-07-02

Solid State Cooling Market: Strategic Preview for 2026 Decision-Makers
As organizations plan product road maps, capital allocation and partnership strategies for 2026, PW Consulting’s latest Solid State Cooling Market report delivers the strategic intelligence required to make confident, timely decisions. This advisory brief previews the report’s high‑value insights: a macro view of market growth through 2032, the competitive landscape and technology inflection points, operational levers for rapid commercialization, and the practical frameworks we provide to translate opportunity into executable programs. Consider this a trailer — deep enough to inform priorities, intentionally withholding granular segment tables so stakeholders visit the full report for the complete playbook.
Solid State Cooling Market
Market snapshot: a fast‑maturing market with sustained double‑digit growth
Our analysis establishes solid‑state cooling as a growth market transitioning from niche, specialty deployments into broader commercial and industrial adoption. Using 2025 as the base year, the market is approaching a near‑billion dollar scale (USD, revenue in Million), and under our central forecast grows at a compound annual growth rate (CAGR) of 12.48% through the 2026–2032 horizon. The trajectory is non‑linear — the technology is already accelerating into adjacent applications as efficiency gains, regulatory pressure on traditional refrigerants, and system‑level integration reduce historic barriers.
Solid State Cooling Market
Key market structure signals worth noting for 2026 planning: the market demonstrates modest concentration with the top three firms representing a meaningful but not dominant share of global revenue (our CR3 and CR5 measures indicate a market that is competitive but consolidating). This dynamics profile favors both incumbent manufacturers focused on volume and reliability, and agile entrants that can capture premium niches with differentiated materials or integration expertise.
Solid State Cooling Market
Why this matters for 2026 strategy
- Prioritization: Firms must choose between scaling established thermoelectric product lines for near‑term revenue and investing in next‑generation materials and system architectures for longer‑term upside.
- Timing: With a steep growth curve expected in the latter half of the decade, 2026 is a pivot year — investments made now in supply chain resilience, prototype validation and standards alignment will compound advantage as adoption widens.
- Risk calibration: The market offers asymmetric upside but requires active mitigation of material supply constraints and realistic timelines for efficiency improvements to reach parity with vapor compression at larger scales.
Technology inflection: efficiency breakthroughs and their strategic implications
One of the most consequential developments we track is a 2025 breakthrough in nano‑engineered thin‑film thermoelectric materials, validated in laboratory refrigeration testing and recognized in industry awards. The technology promises substantial efficiency improvements versus incumbent bismuth‑telluride‑based modules, effectively compressing time‑to‑market for systems that can compete at larger cooling capacities.
Our scenario analysis models two outcomes: a conservative pathway where incremental material improvements steadily improve module performance, and a disruptive pathway where thin‑film solutions materially boost system‑level COP within three to five years. For executives, the implications are clear — treat advanced materials as both an opportunity and a hedge. Active R&D partnerships, selective licensing or minority investments in material innovators can be decisive in capturing the premium value pool if the disruptive pathway materializes.
Competitive landscape — positioning and strategic playbooks
The competitive field contains legacy thermal specialists, diversified electronics and power providers, and focused solid‑state system integrators. The market structure allows multiple strategic postures: scale‑oriented manufacturers, system integrators targeting high‑value use cases (cold chain, data center, medical), and nimble component specialists aiming to sell IP or kits for OEM integration.
- Established thermoelectric manufacturers : Companies with long histories in module production benefit from manufacturing scale, quality control, and established OEM relationships. Their near‑term playbook focuses on cost reduction, incremental efficiency improvements, and expanding into adjacent systems (e.g., integrated thermal subsystems for electronics and medical devices).
- Systems integrators and refrigeration challengers : Newer entrants focused on complete refrigeration and liquid‑cooling systems are commercializing on differentiated system architectures and control algorithms. Their advantage is speed of systems engineering and the ability to sell turnkey solutions into verticals emphasizing reliability and servicing.
- Diversified electronics and power companies : These players can bundle solid‑state cooling with power and thermal management offerings, enabling OEMs to adopt integrated modules rather than discrete components, which simplifies procurement and shortens time‑to‑market for customers.
- Material and component innovators : Emerging thin‑film and nano‑engineered material developers represent optionality for incumbents; strategic partnerships or supply agreements will likely determine who captures the first‑mover benefit from improved module efficiency.
Across all profiles, winners will be those that align product roadmaps with verified system KPIs, secure critical material supply, and build go‑to‑market models tailored to the dynamics of their target verticals.
Practical contents of the PW Consulting report — what executives will use on day one
The full report is built as a decision support kit rather than an academic compendium. It includes:
- Executive playbook: prioritized action items for R&D, supply chain, sales and M&A over 12–36 months.
- Technology roadmaps: a comparative assessment of thermoelectric, magnetocaloric, electrocaloric and emerging thin‑film approaches, with timelines to commercial readiness under alternative R&D scenarios.
- Supply chain heat map: raw material sensitivity modeling (notably reliance on bismuth telluride), supplier concentration analysis, and suggested mitigation strategies including sourcing diversification and inventory policies.
- Commercialization blueprints: go‑to‑market templates for OEM partnerships, channel development for medical and data‑center customers, and service economics for maintenance and warranty models.
- Scenario‑based financial models: revenue and margin projections under multiple adoption curves, with configurable inputs so CFOs can stress‑test CapEx, payback and IRR across strategic choices.
- Regulatory and standards matrix: practical guidance on aligning product design with prevailing data‑center, laboratory and industrial safety and performance standards.
Each section pairs executive summaries with downloadable templates, ready‑to‑use checklists and decision trees to accelerate planning cycles in 2026.
Regulation, standards and material realities — constraints and accelerants
Market dynamics are shaped not only by technical performance but by regulatory and standards frameworks. Heightened regulatory scrutiny of HFC refrigerants and global commitments to reduce greenhouse gas emissions increase the attractiveness of refrigerant‑free, solid‑state approaches for certain applications. At the same time, compliance with laboratory and industrial safety standards remains a gating factor for adoption in regulated sectors.
From a materials standpoint, conventional devices have relied heavily on bismuth telluride. That creates both a supplier risk and an R&D opportunity. Firms that lock in diversified material sources or that invest in next‑generation materials stand to reduce cost volatility and improve competitiveness. Our report includes pragmatic steps to classify supplier risk, design supplier scorecards, and implement alternate supply pathways.
Commercialization levers and go‑to‑market timing
Successful commercialization will require a calibrated combination of product, channel and service innovations:
- Focus on differentiated verticals where solid‑state cooling’s unique attributes (compactness, lack of moving parts, refrigerant‑free operation, precise temperature control) translate into higher willingness‑to‑pay — examples include medical devices, cold‑chain micro‑refrigeration, and high‑density electronics cooling.
- Pair hardware platforms with value‑added control software and predictive maintenance to convert one‑time hardware sales into recurring revenue streams.
- Design pilot programs and validation protocols that de‑risk adoption for conservative buyers (standards testing, field reliability data, clear failover strategies to traditional systems).
Timing matters: firms ready to scale production and channel partnerships by 2026–2027 will be well positioned for the accelerating demand in the late‑2020s captured by our forecast scenarios.
What to expect in the competitive battle for the market
Our competitive analysis identifies several operational differentiators that will determine market share shifts: manufacturing cost per Watt of cooling, system‑level COP in field conditions, integration capability with power and control architectures, and after‑sales service networks. Companies that can tangibly demonstrate superior lifecycle costs and total cost of ownership (TCO) in target verticals will convert pilots into scaled programs.
We also see a strong role for partnerships: incumbents with deep module know‑how and OEM access, vertically integrated electronics firms, and pure‑play system integrators will form alliances or pursue M&A to assemble complementary capabilities rapidly. PW Consulting’s deal screening framework in the full report helps executives identify the most synergistic targets and construct defensible valuation assumptions.
Next steps — how to use the report for 2026 planning
For 2026 board cycles and annual planning, treat this report as both a horizon scanner and an implementation toolkit. Use the scenario financial models to stress‑test capital allocation choices. Deploy the supplier heat map to triage procurement actions. And adopt the commercialization playbooks to prioritize pilots that will deliver measurable, investable KPIs within 12–18 months.
PW Consulting’s Solid State Cooling Market report is intentionally structured to move teams from insight to action. The summary above highlights the strategic contours and decision levers; the full report contains the granular segment intelligence, market sizing by sub‑segment, and downloadable models that leaders need to finalize budgets and execution plans.
For executives preparing 2026 strategies — whether you are scaling production, scouting technology partners, or evaluating M&A — this report provides the disciplined, market‑tested guidance required to convert emerging opportunity into realized competitive advantage.
For detailed analysis of this topic, please visit the official page: Solid State Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbes Protein Hydrolysates Market to Climb from USD 465.5 Million in 2025 to USD 721.0 Million by 2032, Expanding at a 6.45% CAGR
By PW Consulting, 2026-07-02
PW Consulting Releases Strategic Brief: Microbial Protein Hydrolysates Market — A Decision-Maker’s Guide for 2026
Executive Summary
PW Consulting today publishes an executive-level market briefing derived from our forthcoming Microbial Protein Hydrolysates Market report. This briefing synthesizes the macro trajectory, competitive dynamics, technology and feedstock trends, and regulatory inflection points that will shape commercial choices in 2026. Our analysis shows a resilient addressable market that expanded materially in the early 2020s and is forecast to continue growing at a compound annual growth rate (CAGR) of 6.45% during the 2026–2032 forecast window. With the global market exceeding USD 460 million by 2025 and a projection toward a substantially larger market by 2032, corporate strategies formed in 2026 will determine which players capture scalable share in the next growth cycle.
Microbes Protein Hydrolysates Market
Why 2026 Is a Strategic Pivot Year
-
Commercialization momentum is accelerating: Multiple pilot-to-scale transitions that began earlier in the decade are moving into sustained production and regulatory commercialization. 2026 is the year when several scale-up decisions, capacity allocations, and offtake arrangements will crystallize into durable competitive advantage.
Microbes Protein Hydrolysates Market -
Cost and feedstock debates shift from theory to practice: Producers are now choosing between gas-fermentation routes (methane/natural gas), autotrophic CO2‑and‑hydrogen systems, and traditional yeast fermentation tied to sugar feedstocks. Each pathway implies distinct cost curves, geographic capital intensity and environmental narratives—factors that buyers and investors will prioritize in 2026.
Microbes Protein Hydrolysates Market -
Regulation and market acceptance reach tipping points: Regulatory approvals for microbial single-cell proteins and related hydrolysates in feed and food sectors have already occurred in targeted jurisdictions. 2026 will reveal whether regulatory windows widen or remain patchwork—directly influencing go-to-market sequencing and risk allocation for new entrants.
Macro Snapshot: Trajectory and Scale
Our historical tracking shows the market expanding steadily through 2020–2025. By the base year (2025) the market scale surpassed the mid‑hundreds of millions (USD), reflecting both rising demand in feed/food and widening applications in pharma and bio‑stimulants. Under our central forecast, the market grows at a 6.45% CAGR for 2026–2032, reflecting the combined effect of industrial scale-up, broader regulatory approvals, and incremental application adoption across animal feed, food ingredients, and biotechnology uses.
What Our Report Delivers — Practical, Actionable Outputs
PW Consulting’s full market research report is structured to be directly operational for corporate strategy teams, investment committees and commercial leaders. Key deliverables include:
-
Strategic scenarios and 18–36 month decision playbooks: tailored for producers, ingredient buyers and feed formulators to prioritize markets, pick partners and schedule capital deployment.
-
Technology readiness and economics matrix: comparative techno‑economic analysis of methanotroph gas fermentation, autotrophic CO2/hydrogen routes, and yeast fermentation, showing capital intensity, operating cost drivers, and sensitivities to feedstock price swings.
-
Regulatory roadmap and risk register: jurisdictional summaries, approval pathways for feed and food, and recommended evidence packages to accelerate dossier acceptance and commercial clearance.
-
Supply chain stress tests and sourcing playbook: scenarios for feedstock shortages, logistics disruptions and long‑lead equipment, plus mitigation strategies including co‑location, feedstock hedging and contract structures.
-
Commercialization blueprints: go‑to‑market templates for B2B and B2B2C routes, licensing vs manufacturing make/buy decision trees, and price positioning models based on formulation economics.
-
M&A and partnership radar: a prioritized shortlist of strategic targets and partnership archetypes aligned to five distinct corporate strategies (vertical integrator, niche specialist, ingredient aggregator, licensing platform, and sustainability-first challenger).
Segmentation and Concentration (What We Reveal — and What We Privately Model)
The market is segmented by region, source organism (yeast, bacterial, fungal and single‑cell proteins), and application (animal feed & pet food, food & beverage, pharmaceuticals & biotech, agriculture & bio‑stimulants). Publicly, we provide high‑level directional splits and growth vectors; within the full report we offer granular volume and revenue splits, price curves by application, and sensitivity runs. Market concentration is moderate: our CR3 and CR5 metrics indicate that top-tier specialists and industrial fermentation incumbents jointly command a meaningful portion of the market, leaving substantial room for differentiated challengers.
Competitive Landscape — Players to Watch
We profile established ingredient suppliers, fermentation innovators and vertically integrated feed players. Selected company dynamics observed in the last 18 months illustrate strategic patterns:
-
Unibio (Denmark) — A gas‑fermentation pioneer focused on methanotrophic single‑cell protein for aquaculture. Regulatory approvals for targeted uses and initial commercial shipments position Unibio as a practical case study for market entry via feed segments with clear safety endpoints.
-
Calysta Inc. (United States) — Developer of FeedKind via methane fermentation; the company’s operational shift toward concentrated manufacturing footprints (notably in joint ventures) illustrates a common industry tradeoff between distributed R&D presence and centralized commercial output.
-
Solar Foods (Finland) — Advances in autotrophic protein production (CO2 + hydrogen + electricity) underscore the growing role of electro‑driven bioproduction. Solar Foods’ product showcases for food applications highlight a dual pathway: premium food ingredients vs. scaled feed markets.
-
Angel Yeast, Kerry Group, DSM‑Firmenich, Corbion, Lallemand, and Alltech — These incumbents bring manufacturing scale, route‑to‑market breadth, and established formulations expertise. Their activities range from supplying yeast hydrolysates for cell culture to integrating fermentation‑derived ingredients into nutrition portfolios.
Recent Movements: Signals and Tactical Lessons
-
Product showcases and formulation demos (e.g., Solar Foods’ consumer‑oriented protein beverages) demonstrate that microbial proteins are transitioning from technical proof to consumer propositions; companies should plan for both ingredient specifications and consumer communication strategies.
-
Operational consolidations (e.g., Calysta reallocating resources toward joint‑venture manufacturing) show that capital discipline and production scale are prioritized over distributed R&D footprints once commercial validation is achieved.
-
Research breakthroughs in functionality (e.g., Angel Yeast’s yeast peptide synergies with mineral nutrition) highlight the innovation runway in value‑added hydrolysates beyond crude protein metrics — these functional claims can command premium pricing when supported by clinical or field data.
-
Regulatory approvals for specific feed uses (e.g., Unibio approvals for aquaculture) are practical enablers that materially reduce adoption friction; companies should coordinate regulatory strategy with early adopter customers to accelerate pathways to revenue.
Implications for Corporate Strategy in 2026
-
Prioritize feedstock and energy security: Given divergent process chemistries, secure access to low‑cost methane, renewable electricity, or sugar substrates early. Our scenarios show feedstock cost exposure dominates margin outcomes for many producers.
-
Design staged scaling with contractual de‑risking: Move from pilots to committed capacity using offtake-backed financing, modular plants, or JV structures to share capex risk while locking in demand from anchor customers.
-
Differentiate on function, not just protein: Investing in hydrolysis processes that yield defined peptide profiles or functional bioactivity creates defensible product tiers and reduces commoditization risk.
-
Adopt a regulatory-first commercialization calendar: Align product launches to jurisdictions with clear approval pathways and early adopter channels, particularly in feed segments that can accept novel ingredients more rapidly than human food.
-
Plan M&A and partnerships proactively: Larger ingredient players and fermentation specialists will be selective buyers; 2026 is an opportune window for mid‑sized innovators to seek partnership capital or strategic exits as markets consolidate.
How PW Consulting’s Report Supports 2026 Decisions
This briefing is a doorway to a comprehensive toolkit in the full PW Consulting report: downloadable data models, proprietary price and cost curves, ready‑to‑use commercial slide decks, regulatory dossier templates, and a prioritized partnership/M&A list. For strategy teams, the immediate value is threefold: accelerate due diligence with validated assumptions; reduce execution risk with proven scaling playbooks; and sharpen portfolio choices by marrying techno‑economic realities with market demand pathways.
Methodology and Confidence
Our analysis combines a bottom‑up build of supply capacity, expert interviews across producers and buyers, proprietary survey data, and a curated regulatory and patent landscape review. We apply conservative adoption curves for human food use and more aggressive trajectories for feed and industrial applications where regulatory pathways are comparatively established. Confidence bands are provided in the full report so decision‑makers can stress‑test outcomes under alternative feedstock, energy price, and regulatory timelines.
Next Steps — Access and Engagement
PW Consulting’s Microbial Protein Hydrolysates Market report is designed as an active decision support tool for teams making capital allocation, partnership and portfolio choices in 2026. This briefing intentionally highlights strategic lines of sight while reserving the granular segment tables, regional and application splits, and deal‑level company models for the full report. To obtain the complete dataset, scenario models and industry playbooks, please visit our report page or contact PW Consulting’s industry desk to schedule a deep‑dive workshop tailored to your organization’s strategic questions.
For detailed analysis of this topic, please visit the official page: Microbes Protein Hydrolysates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Smart Card Readers Market 2026: Strategic Imperatives for Procurement, Security, and Scale
PW Consulting today releases a forward-looking briefing distilled from our forthcoming Smart Card Readers Market report (base year 2025). As enterprises and public-sector leaders prepare capital and operating plans for 2026, the market’s macro trajectory, evolving standards, and supplier dynamics collectively create a narrow window of strategic decisions that will determine deployment success for the next technology cycle.
Smart Card Readers Market
Why the 2026 inflection matters
Our market model shows a robust compound annual growth rate (CAGR) of 10.45% over the forecast period, reflecting accelerating adoption of contactless and hybrid authentication technologies across identity, payment, and access-control use cases. The global market—measured in USD millions—has expanded markedly from the early 2020s baseline and continues into 2026 with a clear uptrend. That expansion is driven not only by volume replacement of legacy readers but also by incremental feature adoption (FIDO, PKI, NFC enhancements) and regulatory-driven refresh cycles in government and financial services.
Smart Card Readers Market
For decision makers, three implications are immediate: timing matters for procurement and certification, investment in interoperability reduces total cost of ownership, and supplier selection must balance innovation leadership with proven compliance and supply resilience.
Smart Card Readers Market
What the report delivers — operationally actionable intelligence
PW Consulting’s report is designed as a strategic playbook for vendors, system integrators, and enterprise buyers who must translate market signals into procurement and deployment choices in 2026. The deliverables include:
- Market sizing and scenario modeling: a top-down macro view plus three demand scenarios tied to policy, payment modernization, and enterprise security refresh cycles.
- Regulatory and standards matrix: mapping FIPS 201, ISO/IEC 7816, ISO/IEC 14443, FIDO and PKI requirements to procurement specifications across major verticals.
- Vendor diligence templates: a checklist and scorecard for RFPs covering cryptographic modules, certification footprints, lifecycle support, and supply-chain risk.
- Deployment playbooks: migration pathways from legacy contact systems to hybrid contact/contactless architectures, including infrastructure needs (e.g., cabling, RS-485 vs TCP/IP, edge-to-cloud integration).
- Commercial frameworks: licensing and maintenance models, cost-to-serve benchmarks, and contracting language to protect buyers against long lead times and support discontinuities.
- M&A and partnership lenses: indicators for strategic investments and potential consolidation targets based on market concentration and technological gaps.
We intentionally present these practical tools without disclosing the granular segmentation tables in this preview; the full dataset—broken down by region, interface type, and end-use—is reserved for subscribers to preserve competitive advantage for readers who elect to access the full report.
Competitive landscape: balancing innovation and compliance
The supplier field includes global incumbents with deep compliance pedigrees and regional players that compete on cost and integration flexibility. High-level concentration metrics tell a story of moderate consolidation: the three-largest firms capture a meaningful share of the market, and the five-largest materially extend that concentration. This structure creates both opportunities and risks for buyers. On one hand, established vendors reduce certification friction for government and regulated financial deployments; on the other, concentrated supply creates exposure to capacity constraints and pricing pressure during periods of rapid demand.
Representative suppliers in the competitive set include:
- Advanced Card Systems Ltd. (ACS) — a Hong Kong–based supplier with a broad portfolio spanning PC-linked, contact, contactless and mobile readers, and a strong presence in e-government and identity solutions. Recent activity: ACS showcased FIDO and NFC innovations and secured domestic certification pathways in key markets during early 2026.
- Identiv Inc. — U.S.-based provider of the uTrust reader family used for PIV/FIPS 201 and enterprise logical access control, with multiple USB and contactless models focused on identity ecosystems.
- HID Global Corporation — a major U.S. player offering OMNIKEY readers that integrate PKI, FIDO and access control capabilities for large enterprise and government programs.
- Thales Group and IDEMIA — European suppliers with an emphasis on high-assurance cryptographic implementations and strong ties to national eID and payment programs.
- Regional and specialist vendors — including secure payment terminal manufacturers and component specialists from Asia and North America who compete on embedded integration, cost, and route-to-market partnerships.
Recent vendor developments highlight two important dynamics. First, certification and standards alignment remain a gating factor for public-sector contracts—ACS’s 2026 test certifications and trade-show activity underscore how suppliers leverage compliance endorsements to accelerate adoption. Second, standards evolution continues to expand capability: the NFC Forum’s 2025 certification update (CR15) extended practical contactless read range, enabling richer use cases in convenience payment and mobile-onboarding scenarios. Buyers should treat standards updates as trigger points for procurement reviews rather than marginal upgrades.
Regulatory and standards considerations that should shape 2026 buys
- Government procurement often requires FIPS 201 or equivalent credentials; approved-product lists materially shorten procurement cycles but narrow supplier choice.
- ISO/IEC 7816 and ISO/IEC 14443 remain the interoperability bedrock for contact and contactless readers; any RFP absent explicit compliance statements will generate risk in cross-vendor deployments.
- Market access rules—such as BIS certification for specific geographies—must be embedded in sourcing timelines to avoid deployment delays.
These constraints mean procurement teams should front-load certification verification and request up-to-date compliance artifacts during the RFP stage. In many projects, the time-to-market delta caused by certification gaps exceeds hardware lead times.
Three strategic playbooks for 2026
From our advisory practice, three pragmatic strategies emerge for organizations planning deployments in 2026:
- Risk-aware innovation: pursue pilot programs with vendors that combine FIDO and PKI support but require contractual clauses for firmware updates, escrowed cryptographic modules, and interoperability testing across your incumbent systems.
- Phased migration with infrastructure alignment: adopt a staged replacement approach that synchronizes reader rollouts with network upgrades—especially when moving from legacy proprietary wiring to TCP/IP or RS-485 backbones. Include a migration lane for dual-interface (contact + contactless) readers to protect backward compatibility.
- Supplier ecosystem hedging: maintain at least two validated vendors per deployment region to mitigate supply-chain shocks. For high-assurance government or financial implementations, prioritize vendors with documented presence on government approved-product lists and an on-the-ground support footprint.
Procurement checklist — what to require in your RFP
- Explicit statement of standards compliance (ISO/IEC 7816, ISO/IEC 14443, FIPS 201 where applicable).
- Cryptography and lifecycle management details (supported algorithms, firmware signing, key escrow options).
- Interoperability test results and references for similar deployments in your vertical.
- Warranty, spare-parts lead times, and field-service SLAs calibrated to your risk tolerance.
- Roadmap alignment: vendor commitments on upcoming standards (e.g., FIDO evolution, NFC read-range improvements) and a plan for fielding critical updates.
Risks and red flags
Key risks we identify for 2026 decision makers include:
- Supplier concentration risk — a small set of firms account for a disproportionate share of installed bases and certification expertise, elevating the cost of switching.
- Standards drift — rapid updates to NFC and FIDO specifications can produce partial interoperability unless managed as part of procurement governance.
- Regulatory friction — jurisdictional certification requirements or approved-product lists can force last-minute vendor changes if not anticipated early in the procurement cycle.
How PW Consulting’s report helps you act
The full Smart Card Readers Market report translates the macro trajectory and supplier dynamics into blueprint-level guidance for 2026. Subscribers will receive:
- Complete market sizing and segmentation datasets (regional, interface, and end-use) with scenario-based projections through 2032.
- Vendor capability matrices and comparative profiles with direct links to certification records and recent product developments.
- Actionable deployment templates and contractual language to accelerate procurement while protecting against certification and supply risk.
In this preview we have deliberately withheld granular segmentation figures to preserve the strategic advantage available in the full dataset. Organizations seeking to align 2026 capital and operating plans with market realities should review the complete report for the methodological appendices, supplier scorecards, and downloadable RFP templates.
Next steps for leaders
If your 2026 plan includes identity modernization, point-of-sale refresh, or large-scale access-control replacement, start by: (1) mapping your certification requirements to target vendors, (2) initiating supplier pre-qualification to validate compliance artifacts, and (3) scheduling standards-impact reviews aligned to your procurement calendar. Early alignment with these steps will convert market momentum into operational advantage and reduce execution risk.
PW Consulting stands ready to brief executive teams and procurement committees with tailored insights from the report. For access to the full market dataset and customized advisory engagements, please contact our industry team or visit our report subscription page.
For detailed analysis of this topic, please visit the official page: Smart Card Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soldier Combat System Market Poised for 6.45% CAGR in 2026–2032 Forecast
By PW Consulting, 2026-07-02
Soldier Combat System Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive summary
PW Consulting today releases a strategic briefing based on our full Soldier Combat System Market research report (base year 2025, forecast 2026–2032). The market has moved from a post‑pandemic recovery phase into a sustained modernization cycle—driven by digitization of small units, proliferation of multispectral sensors, and renewed procurement programs across advanced militaries. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 6.45% through 2032, reflecting accelerating investment in networked C4I, soldier lethality and protection, and power/data management solutions.
Soldier Combat System Market
Market trajectory: the macro picture
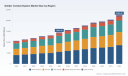
Between 2020 and 2025 the Soldier Combat System market demonstrated steady expansion as programs evolved from prototype to initial fielding. Our topline data shows the global market grew from roughly USD 10.7 billion in 2020 to about USD 14.5 billion in 2025. Under our base forecast, that trajectory continues—reaching an estimated market size in the mid‑tens of billions by 2026 and rising toward the low‑tens of billions by 2032 as persistent modernization, capability refreshes, and new program starts aggregate.
Soldier Combat System Market
Market concentration is moderate: the three largest providers account for close to two‑fifths of market revenues, while the five largest approach just over half. This structure indicates meaningful incumbent strength but ample opportunity for well‑targeted entrants, specialists and integrators.
Soldier Combat System Market
What is driving growth — and what constrains it
- Drivers
- Operational digitization: Nations are funding full‑system digitization for small units—integrated C4I, sensor fusion, and sensor‑to‑shooter chains are now programmatic priorities.
- Sensor and multi‑modal awareness: Multispectral day/night sensors, heads‑up displays and battlefield positioning are being integrated into head‑borne and dismounted architectures.
- Protection and survivability: Advances in lightweight armour, camouflage materials and biomonitoring are converging with electronic solutions to create differentiated, layered protection packages.
- Power & data management: The need to supply and manage multiple high‑draw devices on a soldier is creating demand for centralized power hubs, smart textiles and energy‑efficient subsystems.
- Constraints and risk factors
- Integration complexity and soldier burden: More capability does not automatically translate into operational advantage—power, weight, ergonomics and human‑machine interfaces remain primary risk vectors.
- Export and regulatory controls: Systems that include munitions‑listed items, night vision, or advanced comms face export controls and licensing regimes that materially affect route‑to‑market strategies.
- Programme timing and budget uncertainty: Large framework awards skew supplier landscapes; procurement timing creates waves of demand that require precise capacity planning.
- Supply chain and materials: E‑textiles, advanced optics and bespoke electronics expose suppliers to component lead times and sourcing vulnerabilities.
Competitive landscape — reading the field
The market exhibits a mix of prime systems integrators, platform specialists and component innovators. Leading primes leverage system‑of‑systems capabilities—integrating C4I, sensors and protection—while niche players drive material and component innovation. Recent program activity underscores these dynamics.
- Systems integrators and primes — Companies with existing footprint in vehicle and force digitization have translated that expertise into soldier system programmes. Their value proposition is end‑to‑end integration: sensor suites, communications, mission management and vehicle connectivity that reduce fielding risk for procurement authorities.
- Sensor, optronics and comms specialists — Firms focusing on imaging, night vision and soldier‑worn comms provide high‑margin modules that repeatedly appear across integrator solutions. The competitive battleground is increasingly about SWaP (size, weight, and power) and multispectral performance.
- Protection and apparel innovators — Lightweight armour, multispectral camouflage and smart textiles are now integral to system effectiveness. Partners who can marry protection with sensor/data conduits gain a procurement edge.
Prominent firms exemplify these roles: prime integrators with modular, open‑architecture platforms; sensor and optronics providers delivering next‑generation situational awareness; and protection specialists offering materials innovation and production scale. High‑visibility programme awards and showcases during 2024–2026 confirm that incumbents remain influential, but teaming, consortia and OEM partnerships are the primary channels for market entry and scale-up.
Recent programme signals (selected)
- Major European digitization programmes have moved into framework contracting and initial regeneration rounds, underscoring opportunities for suppliers that can support long‑term sustainment and iterative capability upgrades.
- U.S. acquisition authorities are funding head‑borne mission command and multispectral sensor integrations through competitive rapid‑prototype vehicles—creating a near‑term ramp for qualified vendors able to meet military‑grade certification.
- Cross‑industry teaming arrangements—combining armour manufacturers with data and apparel specialists—have emerged as a dominant route to winning national procurement lots and international competitions.
What’s inside PW Consulting’s full report (practical deliverables)
- Actionable market models: topline historicals and a 2026–2032 forecast by capability area, platform and procurement cycle that enable revenue planning and scenario analysis (detailed subsegment tables and downloadable data included in the subscriber package).
- Buyer and programme mapping: a prioritized view of active and near‑term national programmes, procurement milestones and procurement modalities to enable capture planning.
- Competitive playbooks: supplier profiles, capability matrices and capability‑to‑procurement fit—designed for commercial teams to identify prime‑teaming partners and measuring sticks for RFP responses.
- Technology deep dives: assessments of power/data management, multispectral sensors, heads‑up interfaces and biomeasurement/e‑textile readiness for integration, together with TRL recommendations and test regime checklists.
- Regulatory and export advisory: practical guidance on export control exposure, ITAR implications and mitigation strategies for multinational supply chains.
- Investment and M&A signals: valuation and capability gaps that create acquisition targets, licensing opportunities and co‑development options.
Strategic implications for 2026 corporate decision‑makers
For executives and strategy teams preparing 2026 planning cycles, the report emphasizes five immediate priorities:
- Prioritize modularity and open architecture — Procurement authorities are favoring systems that enable incremental upgrades and multi‑vendor ecosystems. Companies should productize modular interfaces and compliant data/power standards to lower integration friction and increase survivability as a supplier.
- Invest in power and human‑centred integration — Marginal gains in sensor performance are insufficient if battery life and ergonomics degrade mission performance. Allocate R&D resources to power hubs, e‑textile integration, and rigorous field ergonomics testing.
- Adopt a programme capture playbook — Large framework awards create long windows of demand but require sustained engagement. Firms should combine targeted teaming agreements, regional compliance plans and a backbone of sustainment capability to win and keep programmes.
- Mitigate export/regulatory exposure — Build export control expertise into business development; factor ITAR and national licensing regimes into partner selection and contractual frameworks early.
- Pursue selective partnerships and bolt‑ons — Given the market concentration and the modular nature of programmes, sensible M&A and JV activity—focused on sensor fusion, power systems or protective materials—accelerates market access without incurring full systems integration risk.
How to use this research in 2026 planning
Procurement teams, product strategy groups and investors will use this report differently—but with a common objective: reduce uncertainty around programme timing, technical risk and go‑to‑market pathways. Examples of immediate actions we recommend:
- Run a 12‑month capture sprint for one prioritized programme with a validated teaming partner and a compliant export plan.
- Accelerate lab‑to‑field validation of power and e‑textile subsystems to secure inclusion in next‑generation integration contracts.
- Map existing product roadmaps to C4I and sensor standards to identify three product design changes that eliminate integration blockers for prime partners.
- Use the market model to stress‑test capacity and cash‑flow across scenario cases—programme wins, delayed awards, and accelerated multinational buys.
Final note — why this matters
By 2032 the soldier combat system landscape will be defined less by individual capability advances and more by how disparate technologies are stitched together under doctrine, sustainment and export constraints. The next 18 months are pivotal: programmes in procurement and prototype today will set the rhythm for supply chains and capability refreshes for a decade. PW Consulting’s report provides the modelling, programme mapping and playbooks your team needs to make decisive, risk‑calibrated moves in 2026.
Accessing the full intelligence
This release is a strategic preview. The full PW Consulting Soldier Combat System Market report contains the detailed subsegment analytics, programme calendars, supplier scorecards and downloadable datasets that senior leaders use for bid/no‑bid decisions, M&A screening and product investment roadmaps. Visit our report page to view the executive dashboard and to request the full data package and client workshop.
For detailed analysis of this topic, please visit the official page: Soldier Combat System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Desktop Ultrasonic Equipment Market Poised to Reach USD 10.39 Billion by 2032, Expanding at a 6.0% CAGR
By PW Consulting, 2026-07-02
Medical Desktop Ultrasonic Equipment Market: Strategic Implications for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s new market study on Medical Desktop Ultrasonic Equipment frames 2026 as a pivotal year for capital deployment, portfolio rebalancing, and go-to-market repositioning. Built on a 2020–2025 historical base with 2025 as the reference year, the study quantifies the desktop ultrasonic market at approximately USD 6,911.9 Million in 2025 and traces growth from USD 5,120.45 Million in 2020. Our forecast horizon (2026–2032) points to steady expansion at a 6.0% CAGR, with the market projected to approach USD 10,392.94 Million by 2032. Those macro trajectories underscore durable demand driven by hospital departmental upgrades, point-of-care diffusion, and a multi-year replacement cycle among imaging capital stock.
Medical Desktop Ultrasonic Equipment Market
Why 2026 matters to executives
-
CapEx windows are opening. Fiscal and tax policy shifts in 2025—most notably the expansion of Section 179 deduction limits under the One Big Beautiful Bill Act (OBBBA)—create a near-term incentive to accelerate purchases of qualifying medical equipment, including desktop ultrasound systems. For CFOs and heads of procurement, this changes the calculus on timing versus financing of upgrades and fleet renewals.
Medical Desktop Ultrasonic Equipment Market -
Aftermarket and service are strategic value pools. Labor market projections and the evolving repair ecosystem (employment for medical equipment repairers is forecast to grow significantly through 2034) make service contracts, spare-parts logistics, and remote diagnostic capabilities critical levers for margin protection and customer retention.
Medical Desktop Ultrasonic Equipment Market -
Reimbursement and cost-allocation dynamics remain a constraint and an opportunity. Macro-level evidence from workers' compensation and health-plan analyses shows that durable medical equipment occupies a modest but meaningful share of medical spend—making cost-of-ownership narratives (throughput improvements, downtime reduction, and reimbursement optimization) persuasive with hospital CFOs.
-
Technology and product roadmaps are accelerating. AI-enabled image enhancement, compact beamformer architectures, and PC-based scanning platforms are reshaping product tiering between desktop and handheld systems. This creates strategic choices for OEMs: compete on features, integrate vertically into software platforms, or specialize in niche clinical workflows.
What the PW Consulting report delivers (practical, decision-ready content)
-
Proprietary market sizing and forecast: A transparent model covering 2020–2032 with scenario runs calibrated to demand, procurement cycles, and regulatory shocks (base year 2025; forecast CAGR 6.0% for 2026–2032).
-
Demand-driver heat maps and buyer personas: Hospital departments, outpatient clinics, ambulatory surgical centers, and veterinary clinics profiled by purchase drivers, procurement timelines, and service expectations.
-
Supply-side diagnostic: Component dependencies, critical supplier concentration, and lead-time sensitivities for transducers, beamformers, and display subsystems—with mitigation playbooks for sourcing risk and dual-sourcing scenarios.
-
Go-to-market playbooks and commercial pilots: Channel strategies for direct sales, distributors, and OEM partnerships; pricing frameworks; and trial-to-adoption conversion templates tailored to desktop-form factor use-cases.
-
Aftermarket and service economics: Modular contract templates, tiered service offerings, spare-parts inventory models, and revenue-smoothing approaches for subscription & SaaS-enabled imaging features.
-
M&A and portfolio prioritization toolkit: Deal-screening scorecards, payback models, and integration checklists aimed at identifying bolt-on opportunities and defensive investments given observable market concentration metrics.
-
Regulatory readiness checklist and reimbursement mapping: Practical steps to prepare for 510(k) pathways, clinical validation plans, and payer engagement blueprints—critical for companies planning U.S. market entry or platform upgrades.
Competitive landscape — concentrated yet dynamic
Market concentration is material: the top three firms account for nearly half of current revenue share (CR3 ~48.5%), and the top five exceed roughly two-thirds of the market (CR5 ~64.2%). That structure produces a bimodal competitive environment where scale incumbents defend broad clinical footprints while focused specialists and new entrants pursue niche workflows and cost-efficient desktop alternatives.
-
GE Healthcare (Chicago, Illinois, USA) — A broad clinical portfolio and deep channel relationships make GE a natural anchor for hospital-grade desktop upgrades and enterprise imaging suites. Expect continued emphasis on integration with enterprise imaging and service-led solutions (www.gehealthcare.com).
-
Philips Healthcare (Amsterdam, Netherlands) — Philips balances premium desktop offerings with workflow-centric features and enterprise software integrations. Its strength lies in cross-modality purchasing influence and lifecycle service contracts (www.philips.com/healthcare).
-
Mindray Medical International (Shenzhen, China) — Cost-competitive desktop and tabletop systems, combined with aggressive global distribution, position Mindray to capture share in emerging and mid-market hospital segments (www.mindray.com).
-
Esaote (Genoa, Italy) — Specialist desktop and tabletop platforms focused on musculoskeletal and cardiovascular niches; differentiation through clinical specificity and tailored probes (www.esaote.com).
-
Telemed (Vilnius, Lithuania) — PC-based beamforming and OEM-friendly platforms offer flexibility for partners seeking desktop ultrasound integrations and low-cost customization (www.pcultrasound.com).
-
MEDA Co., Ltd. (Tianjin, China) — Focused on platform-style devices for ophthalmic and general diagnostic use; potential consolidation target for product-line expansion (www.meda.com.cn).
-
Keeler (part of Halma plc; Broomall, Pennsylvania, USA / Windsor, UK) — Ophthalmic desktop systems with high clinical trust; attractive for specialty practice penetration (www.keelerusa.com).
-
Contec Medical Systems (Qinhuangdao, China) — Volume-oriented desktop B-ultrasound offerings targeted at price-sensitive buyers and emerging markets (www.contecmed.com).
-
BMV Medtech Group (Shenzhen, China) — Compact desktop solutions with a focus on automatic modes and color Doppler functionality for mixed human and veterinary markets (www.bmvmed.com).
-
Edan Instruments (Shenzhen, China) — Recent regulatory momentum: Edan secured U.S. FDA 510(k) clearance in December 2025 for its Nano series (Nano C5/C5 EXP and Nano L12/L12 EXP), expanding its addressable desktop-compatible opportunity set (U.S. FDA K251268; www.edan.com).
Recent regulatory and technology signals to watch
-
FDA clearance activity continues to open U.S. adoption pathways for portable and desktop-capable platforms. Notable 2025 clearances (for example, Edan and other portable systems) shorten time-to-market for devices designed to play in desktop workflows.
-
New device approvals combining imaging with AI-assisted guidance (e.g., AI-driven navigation for spinal procedures) are beginning to tilt buyer preferences toward integrated software-and-hardware bundles; Accuro’s regulatory clearance in 2025 for SpineNav-AI–enabled devices exemplifies this trend.
-
Component and manufacturing risk management is a live boardroom issue; our supply-side chapters model lead-time shocks and provide mitigation scorecards.
-
Macro imaging market context remains supportive: broader ultrasound imaging markets continue expanding on technological upgrades and broader clinical uses (historical external market analyses project a multi-year rise from a baseline in 2021 toward materially higher valuations by 2030), which validates long-term desktop demand in our scenarios.
A 2026 playbook — practical recommendations for decision-makers
-
Prioritize high-conviction CapEx that leverages tax benefits. Use accelerated Section 179 allowances where eligible to shorten payback periods on fleet refreshes.
-
Tie R&D to modularity. Develop common beamformer and software stacks to enable both desktop and portable SKUs without duplicative development cost.
-
Monetize service. Create tiered service bundles and remote-diagnostics subscriptions to capture recurring revenue and increase lifetime customer value.
-
Screen M&A targets with concentration in mind. Tactical acquisitions should either increase scale in underpenetrated clinical segments or add differentiated clinical functionality not easily replicated by incumbents.
-
Negotiate channel exclusivity and demo fleets. For market entry teams, securing in-hospital pilot sites with clear KPIs accelerates diffusion and supports reimbursement conversations.
-
Operationalize regulatory readiness. Prepare 510(k) strategies in parallel with clinical studies and establish payer engagement teams to map reimbursement trajectories early.
How to use the full PW Consulting report
This market brief highlights the strategic contours you need to plan for 2026, but our full report contains the granular segmentation, proprietary forecasting tables, buyer-level pricing elasticities, and downloadable financial models necessary to execute. PW Consulting clients will find plug-and-play ROI calculators, M&A scorecards, and a supplier-risk dashboard to support immediate board-level decisions. To access the complete intelligence package, including the full breakdown by product form, application clusters, and regional go-to-market matrices, please consult the PW Consulting report webpage and client portal.
Closing note
In a market forecast to expand from a mid-single digit billion-dollar base toward double-digit-billion territory over the next decade, desktop ultrasound represents both a defensive core for incumbent portfolios and an entry point for nimble challengers. The 2026 decision window—shaped by tax incentives, regulatory clearances, and accelerating service economics—requires integrated strategy across product, commercialization, and aftermarket functions. PW Consulting’s report equips leaders with the analytics and playbooks to translate that strategic intent into executable plans.
For detailed analysis of this topic, please visit the official page: Medical Desktop Ultrasonic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Endocrine Disease Treatment Market Forecast to Grow from USD 16,450 Million in 2025 to USD 29,592 Million by 2032 (8.75% CAGR) — North America Leads (USD 7,651.9M), Somatostatin Analogs Top Therapy; Top 3 Firms Hold 42.15%
By PW Consulting, 2026-07-02
Rare Endocrine Disease Treatment Market 2026: Strategic Imperatives from PW Consulting
Executive preview
PW Consulting’s latest market research — Rare Endocrine Disease Treatment Market — equips biopharma executives, investors, and health-system strategists with the evidence and decision frameworks required to set winning priorities in 2026. Built on a transparent modeling framework spanning 2020–2025 (historical) and a detailed forecast from 2026–2032, the study shows a resilient, innovation-driven market that grew from approximately USD 10,850.5 Million in 2020 to USD 16,450 Million in 2025, and is projected to reach roughly USD 29,591.76 Million by 2032 at a compound annual growth rate (CAGR) of 8.75% through the forecast window.
Rare Endocrine Disease Treatment Market
Why this report matters for 2026 corporate decision-making
-
Momentum and timing: The market’s high-single-digit CAGR reflects a unique intersection of regulatory incentives, meaningful clinical breakthroughs, and growing payer willingness to fund high-value rare-disease therapies. 2026 will be a pivotal year for translating clinical wins into durable commercial advantage.
Rare Endocrine Disease Treatment Market -
Prioritization under constraint: R&D budgets and M&A war chests are finite. Our deliverables translate macro growth into specific go/no‑go thresholds and launch sequencing recommendations that preserve optionality while accelerating high-impact programs.
Rare Endocrine Disease Treatment Market -
Risk management: With several first-in-class and label-expansion approvals materializing in 2024–2026, strategic choices around manufacturing scale-up, payer contracting, and evidence generation will determine who captures the fastest-growing share of the expanding headline market.
What the PW Consulting report delivers (operationally focused)
-
Actionable market sizing & forecasting — a transparent global model with downloadable worksheets (USD, revenue unit: Million), historical reconciliation (2020–2025), and scenario alternatives (base, upside, downside) for 2026–2032.
-
Segmentation roadmaps — disease, therapy modality, and regional opportunity maps that prioritize subsegments by commercial attractiveness, but intentionally withhold granular public splits to protect proprietary insight and drive full report engagement.
-
Launch playbooks — step‑by‑step execution plans (pricing, contracting, field force sizing, KOL engagement, and digital patient support) for first-in-class agents and late-stage label expansions.
-
Commercial and payer modelling — HTA and reimbursement pathways, value-dossier templates, and outcome-based contracting frameworks tailored for orphan‑disease dynamics.
-
Portfolio optimization and M&A screen — scoring engine that integrates scientific differentiation, addressable population, regulatory risk, manufacturing readiness, and likely reimbursement to rank assets for buy/sell/license decisions.
-
Clinical and RWE playbook — pragmatic designs for confirmatory studies, surrogate endpoints acceptable to regulators and payers, and RWE generation plans that maximize post-launch value capture.
-
Supply chain & manufacturing readiness assessment — capacity, cold-chain, and tech-transfer checklists that reduce launch latency and allocation risk.
Methodology highlights (so you can interrogate the model)
-
Base and historical years: The model uses 2025 as the base year and incorporates historical market activity from 2020–2025 to validate growth drivers.
-
Forecast horizon: 2026–2032 with an explicit CAGR of 8.75% in the base-case projection; scenario analysis varies underlying epidemiology, uptake curves, and pricing assumptions.
-
Currency and units: All financials are presented in USD (revenue unit: Million) and include transparent assumptions for price erosion, patient access timelines, and market exclusivity impacts.
-
Sensitivity testing: User-accessible drivers include time-to-peak uptake, label breadth, reimbursement coverage rate, and competitor entry timing.
Competitive landscape: who’s shaping the market and what to watch
The market is neither a pure commodity nor a closed oligopoly: the top three firms account for a meaningful, but not dominant, share (CR3 ≈ 42.15%), and the top five account for a majority positioning (CR5 ≈ 58.6%). That structure favors both disciplined incumbents and focused new entrants with differentiated assets.
-
Ascendis Pharma (Copenhagen) — a leader in pro‑drug and sustained‑release TransCon technologies with late-stage programs across growth hormone and hypoparathyroidism. Their platform approach reduces dosing burden, a competitive axis that materially affects adherence and payer value conversations.
-
Novo Nordisk (Bagsværd) — leveraging strong commercial reach to expand once-weekly growth hormone indications. Recent regulatory momentum around pediatric label expansions underscores how rapid label breadth can convert platform reach into market share.
-
Recordati Rare Diseases (Milan) — a focused portfolio player in pituitary and adrenal dysfunctions; its specialized channel experience makes it an attractive partner or acquirer for orphan programs needing dedicated field expertise.
-
Neurocrine Biosciences (San Diego) — with the approval of the first non‑steroidal adjunct therapy for classic congenital adrenal hyperplasia, the company demonstrates how mechanism novelty can unlock new clinical practice patterns and payer conversations.
-
Ipsen, Pfizer, and AstraZeneca (Alexion) — these established players bring deep specialty-commercial capabilities and global reimbursement relationships that matter most in launch execution and contracting.
-
Spruce Biosciences and MBX Biosciences — smaller, nimble firms that represent the upstream innovation pool; their success will often hinge on partnering or well‑timed exits.
Recent industry inflections and regulatory tailwinds
-
Novel approvals and label expansions are remapping addressable populations. Notable regulatory events in 2024–2026 have validated new mechanisms and dosing paradigms (e.g., oral somatostatin receptor ligands and expanded weekly growth-hormone indications), accelerating payer discussions about long-term cost-effectiveness.
-
Orphan drug incentives, Fast Track and priority designations continue to lower development risk and extend exclusivity advantages, shaping transaction timing and competitive entry calculus.
-
Approval of breakthrough modalities that reduce treatment burden (oral vs. injectable, less frequent dosing) creates two-tier markets within the same therapeutic class: high-value premium segments and legacy lower-price segments. Capturing premium positioning requires coordinated clinical, commercial, and HEOR strategies.
Priority strategic plays for 2026
-
Optimize launch sequencing: Use a dynamic threshold approach to prioritize indications and geographies where price realization and access are highest in year 1–3 post-launch.
-
Evidence-first contracting: Build integrated pre-launch HEOR packages with commitment to post‑launch RWE that underpin outcomes-based contracts favored by specialty payers.
-
Partnerships over binary bets: Smaller innovators should pursue staged licensing deals that align milestone payments with regulatory and payer de‑risking events to maximize valuation while preserving upside.
-
Manufacturing and distribution hedges: Early investment in secondary manufacturing capacity and cold-chain resilience reduces launch disruption risk for differentiated biologics and extended-release formats.
-
Defend with label and service: Incumbents should combine label expansion, patient-support services, and digital adherence tools to blunt disruptive entrants offering improved convenience.
-
M&A screening cadence: Target assets should demonstrate either immediate revenue synergy potential or clear pathway to payer-acceptable outcomes within a 24–36 month window post-acquisition.
How PW Consulting helps you act in 2026
Clients commissioning our full report receive the complete model, competitor dashboards, bespoke scenario workshops, and an executive decision pack that converts market insight into board-ready recommendations. Practical outputs include launch scorecards, M&A candidate prioritization matrices, payer engagement scripts, and a customizable financial workbook to stress-test internal planning at multiple price and uptake points.
Closing (the trailer)
The Rare Endocrine Disease Treatment Market is entering a phase where clinical innovation, regulatory incentives, and payer sophistication converge to create outsized opportunities for companies able to align evidence generation with commercial execution. PW Consulting’s report distills the complexity into the strategic choices that will define market leadership in 2026 and beyond.
To access the full dataset, interactive models, and the detailed segmentation maps that inform our recommendations, please visit our report landing page — the granular figures and regional/disease-level splits are available exclusively with the full report.
For detailed analysis of this topic, please visit the official page: Rare Endocrine Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Government & Military SATCOM Market Hits USD 10.9 Billion in 2025, Poised for 7% CAGR Through 2032
By PW Consulting, 2026-07-02
Government And Military Satellite Communications Market: Strategic Imperatives for 2026 Decision‑Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Government And Military Satellite Communications Market
Executive summary
The Government and Military Satellite Communications (Gov/Mil SATCOM) market is transitioning from platform-centric procurement to outcome-driven, multi-orbit communications architectures. PW Consulting’s new market report — calibrated to a 2025 base year and projecting through 2032 — quantifies this transition and translates it into practical decision frameworks for defense and government program managers, prime contractors, and commercial SATCOM providers planning 2026 investments.
Government And Military Satellite Communications Market
Key macro facts that shape the 2026 decision window: the addressable Gov/Mil SATCOM market exhibited steady expansion in the early 2020s, achieving a clear inflection by the 2025 base year, and our modelling points to a sustained compound annual growth rate (CAGR) of approximately 7.0% across the 2026–2032 forecast horizon. That trajectory underpins an industry that is simultaneously growing in absolute scale and evolving structurally as multi‑orbit, resilient, and allied‑centric capabilities gain procurement priority.
Government And Military Satellite Communications Market
Why this matters for 2026 strategy
-
Budget timing & program alignment: Growing market scale means more commercial capacity and a larger pool of suppliers competing for government contracts — but procurement windows are tightening. Governments are accelerating programs that favor proliferated and protected SATCOM, changing the cadence of awards and sustainment decisions.
-
Technology risk vs procurement agility: Investments in protected payloads, resilient terminals, and cross‑linking demand careful tradeoffs between immediate capability and long‑lived platform commitments. The right strategic posture in 2026 preserves operational options without over‑committing to a single orbit or vendor.
-
Allied interoperability & export controls: Recent export‑control reforms and allied licensing adjustments materially affect partnership strategies. Firms and government buyers must balance sovereign assurance with the operational benefits of allied supply chains and international commercial capacity.
Market trajectory and what the numbers imply
Our time‑series synthesis shows sustained growth from the historical window into the forecast period. This is not a commodity market expansion: growth is being driven by demand for resilience, anti‑jamming capability, low latency tactical links, and managed services that blur the line between commercial and defense SATCOM offerings. The CAGR of roughly 7% over 2026–2032 reflects the combined effect of modernization programs, commercial LEO service adoption for tactical use, and increasing sustainment spend on protected terminals and ground systems.
For decision‑makers, the implication is twofold: first, procurement strategies framed for 2026 must be modular and optioned to accept alternative capacity paths (GEO, MEO, LEO), and second, suppliers must present interoperable, coalition‑ready solutions rather than single‑vendor stacks to remain competitive.
Strategic themes that define winners and losers
-
Resilience as the organizing principle — Multi‑layered architectures that combine protected GEO payloads with proliferated LEO/MEO constellations are becoming the baseline requirement for high‑value missions. Programs emphasizing mobility, anti‑jamming, and assured communications will capture disproportionate budget attention.
-
Services over hardware — A shift toward managed SATCOM services and networked mission support is reshaping procurement economics. Buyers increasingly favor predictable, service‑level driven contracting that bundles capacity, ground systems, and sustainment.
-
New entrants and incumbents co‑exist — LEO native players and small GEO specialists accelerate innovation cycles, while legacy primes convert systems engineering depth into integrated architectures for national programs. Strategic collaboration models (alliances, JV, subcontracting) will determine access to major contracts.
-
Policy levers matter — Export control adjustments and dedicated government initiatives that underwrite commercial participation (e.g., proliferated GEO programs) materially change opportunity sizing for suppliers; staying ahead of these policy inflections is a source of competitive advantage.
What the report contains — actionable intelligence for 2026
This report was written to be a tactical tool for executives and program managers. Readers will find:
-
Proprietary market sizing and multi‑scenario forecasts (base year 2025, forecast 2026–2032) with sensitivity analyses calibrated to policy and technology inflection points.
-
Decision frameworks for procurement: modular contracting templates, commercial‑services integration blueprints, and a vendor short‑listing methodology that converts strategic priorities into RFP evaluation criteria.
-
Capability roadmaps: comparative assessments of GEO, MEO, and LEO access strategies, protected payload options, and terminal modernization pathways indexed against mission types.
-
Supplier playbooks: vendor risk and opportunity matrices, alliance candidate lists, and negotiation levers informed by procurement practices in the U.S. and allied nations.
-
Operational impact studies and war‑gaming scenarios: performance tradeoffs under contested environments, sustainment and logistics modelling, and rapid‑fielding templates for tactical units.
-
Regulatory and policy tracker: a concise digest of export control shifts, procurement office behaviors, and program funding signals that quantifies impact on supplier market access.
Competitive landscape — what the major players are doing
The Gov/Mil SATCOM ecosystem in 2026 is a mosaic of large defense primes, satellite operators, terminal specialists, and disruptive LEO entrants. Market concentration is meaningful but not monopolistic: the top three firms together account for a notable portion of spend, and the top five extend that influence further — a pattern that favors integrated proposals for national scale programs while leaving room for specialized suppliers to excel in terminals, managed services, and tactical payloads.
-
Defense primes (Lockheed Martin, Northrop Grumman, Boeing): These firms convert systems integration depth into program wins for programmatic efforts that demand secure, resilient architectures. Their strengths lie in heritage MILSATCOM payloads, complex ground systems, and program management for high‑assurance missions.
-
Network and systems integrators (L3Harris, RTX): Focused on terminal modernization and sustainment, these companies are critical in translating protected payload capabilities into fielded tactical connectivity, with large sustainment programs providing steady revenue backbones.
-
Commercial operators (SES, Intelsat, Iridium): Offering multi‑orbit and managed capacity, these operators are increasingly competing for government business through hybrid commercial‑defense contracts and service agreements that emphasize flexibility and rapid capacity provisioning.
-
New orbit and platform entrants (SpaceX, Astranis, AST SpaceMobile): LEO constellations and small GEO specialists are forcing incumbents to reconsider architectural assumptions. Their offers — low latency, global reach, and rapid refresh cycles — are compelling for tactical and beyond‑line‑of‑sight use cases.
-
Terminal and antenna specialists (Cobham, Gilat, Viasat): Ruggedized, multi‑band terminals and field‑deployable antenna systems are the interface layer that ultimately determines mission effectiveness. Competitive differentiation is increasingly about software, waveform agility, and supply chain robustness.
Recent contract signals and policy moves to watch in 2026
-
Large program awards and IDIQ ceilings for protected tactical SATCOM concepts are reshaping supplier pipelines and investment priorities. Program design contracts for anti‑jam GEO solutions have drawn both primes and emergent small‑sat vendors into collaborative bid strategies.
-
Government procurement behavior shows a pronounced tilt toward commercial purchasing channels for SATCOM capacity, which intensifies competition among commercial operators to meet defense SLAs and security requirements.
-
Targeted export‑control reforms and allied licensing realignments reduce friction for coalition supply chains, increasing the attractiveness of multinational industrial architectures — but also introduce new compliance and IP governance questions that require early legal and programmatic alignment.
Guidance — what to do next (for buyers and suppliers)
-
Buyers: adopt modular contracting with option windows for alternative orbit capacity; require coalition and cross‑vendor interoperability in RFPs; insist on measurable resilience KPIs, not just bandwidth metrics.
-
Primes & operators: structure proposals as outcome packages (capacity + terminal + sustainment + cyber hardening) to meet evolving procurement preferences; accelerate partnerships with LEO providers and terminal specialists.
-
SMEs and terminal vendors: prioritize waveform agility, anti‑spoofing features, and ruggedization while validating sustainment and logistic readiness to compete for prime-led procurements.
-
Investors: look for companies that can deliver integrated service propositions, demonstrate government procurement wins, and show roadmap alignment with protected payload programs and multi‑orbit service offerings.
Access the full intelligence
This article highlights the strategic takeaways from PW Consulting’s Government And Military Satellite Communications Market report. The full report — incorporating granular segment modelling, company scorecards, procurement templates, and downloadable scenario models — provides the operational data and decision‑support tools necessary to execute on 2026 strategies.
To retain competitive advantage in a market that is both expanding and reconfiguring its core economics, program managers and commercial leaders must pair technical choices with procurement design and alliance strategy. The full PW Consulting report supplies that integrated playbook — enabling confident 2026 decisions while preserving flexibility for the unpredictable operational environment ahead.
For detailed analysis of this topic, please visit the official page: Government And Military Satellite Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Clinical Disorder Treatment Market to Expand at a 6.18% CAGR During 2026–2032, New Report Finds
By PW Consulting, 2026-07-02
Clinical Disorder Treatment Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our newly published Clinical Disorder Treatment Market report. This briefing is designed to demonstrate the strategic value of the full report for executives, investors, payers and product teams planning actions in 2026, while reserving the proprietary granular tables and segment-level line items for the complete publication.
Clinical Disorder Treatment Market
Market trajectory at a glance
The global clinical disorder treatment market is on a structurally positive trajectory. Using 2025 as our base year, PW Consulting’s top-line model projects the market expanding from an estimated USD 585,500 Million in 2025 to approximately USD 892,100 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.18% across the 2026–2032 forecast window. The 2026 near-term inflection is notable: our model anticipates acceleration relative to the early-2020s recovery curve as regulatory shifts, reimbursement dynamics, and care-delivery innovations combine to enlarge addressable patient flows and therapeutic adoption.
Clinical Disorder Treatment Market
While this preview highlights macro directionality and strategic ramifications, the complete report contains full historical series (2020–2025), monthly and annualized revenue scenarios, and proprietary sensitivity runs. To preserve the report’s role as the single source of detailed segmentation intelligence, we are intentionally omitting the granular regional and sub-segment tables here.
Clinical Disorder Treatment Market
Why the 2026 planning cycle should prioritize this market
- Durable demand fundamentals — Rising prevalence of mental health conditions and expanding insurance coverage are lifting baseline demand across settings and disorder types.
- Regulatory re‑rating — Accelerated FDA pathways and priority mechanisms for novel modalities (notably psychedelic-assisted and other experimental agents) are compressing time-to-market for a new class of therapeutics, creating first-mover advantages for sponsors who can execute robust clinical and commercial plans.
- Commercial churn — Imminent patent expirations and ongoing generic pressure will reshape product portfolios and pricing power, increasing the value of differentiation through delivery models, adjunctive indications and label expansions.
- Service model transformation — Telehealth, hybrid care and expanded outpatient capacity are shifting revenue between inpatient and community-based settings, requiring providers and payers to rethink contracts and capacity investments.
Competitive landscape — implications for 2026 positioning
The sector is characterized by a mix of large multinational originators, specialty psychiatric providers, and major generics players. Market concentration remains relatively low: the top-three players account for under a fifth of market revenue (CR3 ~18.45%) and the top-five account for roughly one-quarter (CR5 ~25.12%). That structure creates both opportunity and risk — scale matters for R&D and supply resilience, but nimble entrants can capture meaningful niche value.
Key strategic profiles and near-term implications:
- Johnson & Johnson (Janssen): With Spravato (esketamine) and an extended neuroscience franchise, J&J continues to be a bellwether for how complex, clinic-administered therapies scale commercially. Their acquisition-driven expansion into novel CNS assets suggests an aggressive play for label breadth and treatment sequence positioning — important for competitors to anticipate when modeling adoption curves.
- Eli Lilly and Company: As a long-standing innovator in antidepressant development, Lilly’s pipeline and commercialization muscle make it a natural contender in both new-molecule launches and label-extension strategies; agile payer engagement will be essential to defend premium pricing.
- Pfizer and GlaxoSmithKline (GSK): These incumbents supply broad portfolios that serve as backbone therapies; their global reach and partnership capacity allow rapid lifecycle management and geographic prioritization following regulatory events.
- AstraZeneca and Otsuka: Heavyweights in antipsychotics and bipolar treatments, they will be closely affected by patent cliffs and need to accelerate diversification into adjunctive and novel modalities.
- Specialty behavioral health operators (e.g., Acadia Healthcare, Universal Health Services): Providers are reconfiguring care networks to capture demand shifts to outpatient and residential models — their contract negotiations, capacity investments and payer partnerships will materially influence local pricing and access dynamics.
- Teva and other generics manufacturers: Intensifying generic competition following key patent expirations will compress branded margins while expanding volume-driven access; originators should prepare for rapid erosion in unit price across vulnerable molecules.
Regulatory and policy catalysts shaping 2026
2026 is already proving to be a watershed year for regulatory dynamics in psychiatric therapeutics. The US FDA’s recent acceleration mechanisms — including national priority designations for psychedelic-based therapies and allowances for early-phase work on previously constrained compounds — materially change the risk/reward calculus for sponsors. These shifts dovetail with a broader policy environment: a presidential focus on serious mental illness, heightened attention to domestic manufacturing of APIs and finished products, and evolving reimbursement pathways for clinic-administered and digital hybrid therapies.
Concurrently, patent expirations on several high-revenue molecules later in 2026 will unlock generics competition and necessitate strategic responses such as lifecycle extensions, combination product strategies, and differentiated service offerings linked to proprietary delivery platforms.
Operational and supply-chain considerations
- API and finished-dose manufacturing risk: Current analyses show significant reliance on non-domestic production for both patented APIs and finished products; executives should run stress tests and secure dual-sourcing strategies as part of 2026 contingency planning.
- Capacity rebalancing across care settings: As outpatient and hybrid models scale, capital allocation should prioritize ambulatory infrastructure and digital integration to capture shifting revenue pools.
- Payer contracting and value demonstration: With new modalities and psychedelic-assisted programs entering regulatory pathways, rigorous real-world evidence (RWE) plans and economics-of-care models will be decisive in securing favorable coverage.
What PW Consulting’s report delivers — practical, executable intelligence
Our full Clinical Disorder Treatment Market report is structured to support immediate 90/180/360-day decision cycles and longer-term strategic investments. Core deliverables include:
- Top‑line and scenario-based forecasts (2026–2032) with sensitivity to adoption curves, pricing erosion and reimbursement shifts.
- Regulatory pathway maps and approval-timing impact assessments, including implications of accelerated programs for psychedelic and novel agents.
- Patent-expiry impact models and generics-entry timing, calibrated to company portfolios and therapeutic classes.
- Care-delivery market maps that tie patient flows to provider economics across inpatient, outpatient, residential and emergency settings.
- Commercial playbooks: launch sequencing, payer evidence dossiers, and salesforce deployment optimization for clinic-administered therapies.
- M&A and portfolio optimization frameworks: valuation sensitivities, integration risk matrices and divestiture candidates.
- Supply chain resilience frameworks: API sourcing heatmaps, dual-sourcing strategies and manufacturing investment prioritization.
Each section pairs quantitative models with executable checklists and templated board-ready slides so teams can move from insight to investment or operational decision in weeks, not months.
Practical strategic actions for 2026
- For R&D and portfolio teams: Prioritize accelerated programs with clear payer-endpoints; build RWE protocols early to shorten commercialization timelines under priority regulatory mechanisms.
- For commercial and market-access leaders: Prepare for rapid formulary negotiations tied to new specialty-administered products; invest in outcomes-based contracting pilots where data collection infrastructure exists.
- For providers and health systems: Rebalance bed and outpatient capacity with an emphasis on multidisciplinary, hybrid-care models that can capture higher outpatient throughput and lower cost per episode.
- For finance and corporate development: Model downside scenarios tied to patent expirations and upsides from psychedelic-class approvals; maintain optionality via staged M&A contingent on regulatory milestones.
- For operations: Initiate API sourcing stress-tests and short-list alternative contract manufacturers to mitigate concentrated supplier risk.
Final note — why PW Consulting’s analysis matters for 2026
Decisions made in 2026 will determine which organizations capture the majority of value created over the next decade. Our macro forecast (CAGR 6.18% through 2032 with a materially larger market by the end of the forecast period) indicates both growth potential and disruption risk. The combination of regulatory acceleration, patent-driven commoditization, evolving care models and supply-chain exposures means leaders must translate insight into concrete operational moves this year.
To maintain our role as a strategic enabler, PW Consulting intentionally positions this preview as a directional briefing. The full report contains the segment-level revenue tables, regional splits, disorder-type and service-setting forecasts, and the proprietary scenario matrices necessary for valuation, commercial planning and operational redesign. Access to those granular datasets and bespoke advisory engagement options is available through PW Consulting’s market research portal.
For executive teams preparing 2026 budgets, M&A roadmaps or regulatory strategies, our report is built to accelerate decision cycles and reduce execution risk. Contact PW Consulting to obtain the full report and schedule a tailored executive briefing that translates these insights into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Clinical Disorder Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Oil & Gas Reciprocating Compressor Market to Grow at a 3.52% CAGR, Reaching USD 5,250.46 Million by 2032
By PW Consulting, 2026-07-02
Reciprocating Compressor For Oil & Gas Market: Strategic Imperatives for 2026
PW Consulting's new market intelligence brief on Reciprocating Compressors for the oil & gas sector synthesizes operationally focused analysis with forward-looking strategy to inform capital allocation and product decisions in 2026. The global market reached approximately USD 4.12 billion in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 3.52% over the 2026–2032 forecast window, reaching roughly USD 5.25 billion by 2032. Market concentration is meaningful but far from monopolistic: the top three suppliers account for about one-third of industry revenue while the top five represent just under half — a structure that rewards scale, specialization, and aftermarket reach.
Reciprocating Compressor For Oil Gas Market
Why this report matters for 2026 decision-makers
Operators, OEMs, and service providers face intersecting pressures in 2026: tightening emissions regulation, volatile raw-material costs, evolving fuel mixes (hydrogen, CO2, low‑emission gas), and increasing demand for uptime and lifecycle cost predictability. Decision cycles for compressor procurement, retrofit programs, and aftermarket contracting now hinge on integrated assessments that combine engineering constraints, supply‑chain exposure, and regulatory compliance rather than on CAPEX line-item comparisons alone.
Reciprocating Compressor For Oil Gas Market
- Procurement teams need validated total cost of ownership (TCO) and scenario-driven sensitivity analysis to justify multi-year contracts.
- Engineering groups need frameworks to prioritize hydrogen- and CO2-capable designs while managing current gas service obligations.
- Service and aftermarket leaders must define differentiated offerings (digital monitoring, retrofits, spare parts pooling) to capture a growing share of lifecycle value.
What the PW Consulting report delivers — practical, actionable outputs
- Executive dashboard with historical baseline (2020–2025) and finance-grade forecasts for 2026–2032, enabling board-level scenario planning.
- Cost-build models that decompose a compressor package (materials, fabrication, assembly, testing, logistics) and simulate the P&L impact of steel-price and freight volatility.
- Regulatory impact maps that translate standards (ISO 13707, API practices) and regional emissions rules (including EPA OOOOb implications for rod packing monitoring and replacement intervals) into compliance pathways and CAPEX/OPEX impact estimates.
- Technology and retrofit playbook that ranks opportunities by ROI: valve upgrades, electronic clearance control, hydrogen-ready sealing technologies, modular frames and controls integration.
- Commercial and go-to-market templates for OEMs and service players — pricing guardrails, aftermarket contract structures, channel-partner frameworks and local service network models.
- Vendor benchmarking and diligence materials built to accelerate M&A or supplier-selection processes, including a proprietary supplier risk heatmap.
Competitive landscape — how to read the major players
The competitive map remains a blend of global OEM leaders, specialized engineering houses, and regional service champions. Our qualitative and capability-led assessment highlights strategic positioning rather than disclosing granular segment shares (full segmentation is available in the report). Key takeaways:
Reciprocating Compressor For Oil Gas Market
- Ariel Corporation — Known as a leading manufacturer of separable reciprocating gas compressors, Ariel combines breadth in high- and medium‑speed offerings with deep aftermarket penetration in gathering, processing, transport and distribution services. Their recent showcase of advanced compressor controls and hydrogen mobility concepts signals accelerated product road‑mapping toward decarbonization use‑cases.
- Baker Hughes — Brings modular API 618 designs and heavy‑duty engineering that targets full‑stream oil & gas installations. Their emphasis on reduced vibration, low pulsation and serviceability positions them well for demanding high‑pressure applications and long‑life warranties.
- Burckhardt Compression AG — A specialist in highly engineered, customizable reciprocating systems, with a growing focus on hydrogen, CO2 and LNG value‑chain compression. Their trade show presence and targeted marketing demonstrate a clear push into energy‑transition applications.
- Siemens Energy (Dresser‑Rand) — Leverages advanced valve and capacity control technologies and significant plant capabilities to serve process and oil & gas clients requiring integrated solutions and high reliability.
- Ingersoll Rand, Atlas Copco, Howden, MAN Energy Solutions, Neuman & Esser, Borsig — Each contributes differentiated strengths: high‑pressure models, oil‑free technology, retrofit and upgrade expertise, integrated offshore/onshore portfolios, and highly customized engineering solutions. Collectively these firms define the competitive arms race between scale, specialization and aftermarket services.
Recent industry activity underscores these dynamics: new service centers and partnership appointments are expanding aftermarket reach (Cook Compression’s 2025 service center opening and Scandinavian service partnership), while product showcases at events (Ariel at TPS 2025; Burckhardt’s planned presence at Gastech 2026) reveal priority investment areas — digital monitoring, hydrogen mobility, and electronic clearance control. These tactical moves are signals that long‑term aftermarket capture and hydrogen/CO2 readiness are central competitive vectors.
Market dynamics that will determine winners and losers in 2026
- Raw‑material exposure: steel price normalization in mid‑2025 (stabilized in the low–mid $800s per short ton) reduces near‑term capex uncertainty, but supply and alloy differentials remain a source of margin and timing risk for fabrication and pressure‑containing components.
- Regulatory compliance as a business driver: EPA OOOOb and international standards compel specific mechanical and monitoring requirements that impact design choices, maintenance cycles, and service offerings.
- Energy transition: demand for compressors able to handle hydrogen blends, pure hydrogen and CO2 is a strategic inflection point; this creates premium segments for firms that design for compatibility today.
- Aftermarket economics: service, retrofit and spare parts are higher-margin, recurring revenue pools; the ability to convert installed base into reliable service revenue streams will have outsized impact on medium‑term valuations.
Strategic playbook: four priority actions
- Design to future fuels: accelerate hydrogen/CO2 compatibility workstreams and create retrofit kits for existing fleets — prioritize valve materials, sealing systems, and electronic clearances.
- Operationalize emission compliance: adopt monitoring programs matching regulatory cycles (rod packing inspection/replacement cadences), and include compliance thresholds in service SLAs.
- De‑risk supply and cost: lock key steel and alloy purchases with multi‑year agreements, diversify fabrication centers regionally, and quantify freight and inbound logistics in project bids.
- Monetize aftermarket: bundle predictive maintenance, digital monitoring, and spare‑parts subscriptions into multi‑year revenue contracts; use data to validate TCO improvements for customers and justify premium pricing.
Why PW Consulting’s report is unique
Our deliverable is engineered for decision readiness. It combines a verified historical baseline (2020–2025), finance‑grade 2026–2032 forecasts, primary interviews with OEM and operator supply chains, plant‑level CAPEX reverse engineering, and regulatory overlay. Proprietary models translate macro trends into discrete implications for design, procurement, and aftermarket monetization. This is not academic: it is a hands‑on toolkit for commercial teams, engineering leaders, and corporate strategy groups aiming to make defensible 2026 commitments.
To respect the “trailer” principle and preserve the value of proprietary segmentation, this release highlights the strategic insights and top‑line market trajectory while withholding granular regional, type and application splits. The full report contains the complete dataset and drill‑downs you need to run procurement tenders, model acquisition targets, and stress‑test product roadmaps under alternative regulatory and raw‑material scenarios.
Next steps
- If you are evaluating new compressor acquisitions or retrofit programs in 2026, use our cost‑build and compliance modules to run three stress scenarios (baseline, high‑steel, accelerated‑decarbonization).
- OEMs and service providers should request our competitive capability matrix and aftermarket monetization playbook to identify most attractive pockets for investment or partnerships.
- For M&A and strategic sourcing, our supplier risk heatmap and vendor diligence templates compress months of commercial due diligence into an actionable checklist aligned with board‑level decision timing.
PW Consulting’s Reciprocating Compressor For Oil & Gas Market report is designed to inform those pivotal 2026 choices with rigor, operational detail and scenario clarity. For access to the full dataset, segmentation, and downloadable financial models, visit the report page to request the complete brief and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Reciprocating Compressor For Oil Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Secondary Medical Diagnosis & Treatment Microscope Market Poised to Grow at an 8.15% CAGR, Unlocking Major Opportunities
By PW Consulting, 2026-07-02
Secondary Medical Diagnosis and Treatment Microscope Market: Strategic Preview for 2026 Decisions
PW Consulting is pleased to release a strategic preview of our forthcoming market research report, Secondary Medical Diagnosis And Treatment Microscope Market (base year 2025). This briefing distills the high‑confidence insights executives and investors will need to set winning strategies in 2026 — from capital allocation to product roadmaps, regulatory timing and M&A prioritization — while reserving the granular, model‑driven segment outputs for the full report.
Secondary Medical Diagnosis And Treatment Microscope Market
Executive snapshot: a growing, technology‑led capital equipment market
The secondary surgical and diagnostic microscope market has transitioned from optical‑dominated equipment to a hybrid ecosystem where digital visualization, heads‑up displays, and AR fluorescence are now standard differentiators. Our market model shows the total market expanded from approximately USD 621.8 Million in 2020 to USD 920.0 Million in 2025, and is forecast to continue at an 8.15% compound annual growth rate through 2032 — reaching roughly USD 1,592 Million by the end of the forecast horizon. This trajectory reflects a mix of replacement dynamics in mature hospitals, new adoption in high‑volume specialty suites, and incremental revenue from digital modules, software, and services.
Secondary Medical Diagnosis And Treatment Microscope Market
Why this matters for 2026 strategic choices
- Capital investment planning: Procurement cycles for capital equipment are lengthening, and the growing attachment of software and visualization modules changes lifetime value calculations. Organizations that assume a purely hardware depreciation model risk underestimating recurring service and upgrade revenue potential.
- Product development prioritization: Buyers are valuing interoperability, ergonomics and team‑centric visualization features (3D/4K, heads‑up, AR fluorescence). Roadmaps that convert optical excellence into digitally enabled workflows capture disproportionate share during upgrade cycles.
- M&A and partnership playbooks: The market shows moderate concentration among established OEMs while leaving niches for focused innovators. Strategic bolt‑ons that add AI‑assisted visualization, fluorescence capability, or OR integration platforms will accelerate time‑to‑value for acquirers.
Market structure and concentration — what incumbents and challengers should know
The competitive landscape remains a blend of long‑standing optical specialists and aggressive digital entrants. Market concentration is meaningful: the top three players control a substantial portion of industry revenue, and the top five entities account for a clear majority. For market entrants, this implies that commercial strategies must be surgical — either targeting underserved clinical workflows and geographies or offering compelling platform interoperability that obviates incumbent switching costs.
Secondary Medical Diagnosis And Treatment Microscope Market
Technology trends shaping buyer behaviour
- Digital visualization is table stakes. Heads‑up displays, 3D/4K exoscopes, and hybrid optical/digital systems are no longer optional for high‑volume neurosurgery and ophthalmology suites. These features materially improve ergonomics, teaching and team alignment in the OR.
- Augmented fluorescence and task‑specific imaging are moving from experimental to procedural standard. Fluorescent visualization for tumor margins and intraoperative tissue characterization is gaining regulatory and clinical traction, changing feature roadmaps for microscope manufacturers.
- Service and software monetization. After‑sales software features (workflow integration, OR video management, analytics) are increasingly the lever for margin expansion and customer retention.
Regulatory and reimbursement context — near‑term considerations
Regulatory activity in early 2026 reinforces the move toward digital adjuncts. Notably, U.S. regulatory clearances enabling intraoperative fluorescence visualization have expanded options for neuro‑oncology workflows. In parallel, the U.S. FDA’s reclassification of certain optical diagnostic devices signals that agencies are focusing on balancing access with device controls — a dynamic companies must track when launching imaging adjuncts or diagnostic analytics.
On reimbursement, surgical microscopes continue to be supported indirectly through existing DRG and CPT pathways tied to procedures (neurosurgery, ophthalmology, ENT), rather than via discrete hardware codes. That structural fact shapes sales cycles: hospital capital committees evaluate microscopes as part of procedural productivity and clinical outcome investments rather than standalone revenue generators.
Competitive landscape: capabilities, differentiators and strategic playbooks
The market’s profile mixes global optical leaders and fast‑moving digital innovators. Across the competitive set, three recurring strategic archetypes have emerged:
- Platform incumbents that leverage optical heritage while iterating digitally. These firms compete on imaging quality, brand trust and integrated workflow solutions for multispecialty ORs.
- Focused ophthalmic specialists that optimize red reflex, coaxial illumination and ergonomics for eye surgery. Their play emphasizes clinical outcomes and high procedural throughput.
- Digital disruptors and exoscope developers that prioritize remote visualization, deep integration with surgical navigation, and minimally invasive workflows. These players often pursue partnerships with software and AI companies to extend capability rapidly.
Recent corporate actions underscore these dynamics. Manufacturers have secured regulatory approvals and expanded product families with heads‑up 3D modules, 4K digital microscopes and AR‑enabled devices, accelerating conversion of traditional optical buy cycles into digital upgrade cycles. For acquirers and OEMs preparing 2026 launches, the lesson is clear: new products must justify premium pricing through measurable improvements in OR throughput, ergonomics and intraoperative insight.
What PW Consulting’s full report delivers (practical, executable outputs)
Our full report is built for strategy teams, corporate development and product leaders who must act in 2026. It includes:
- A closed‑form market model and base case/alternative scenarios calibrated to clinical adoption rates, hospital procurement cycles and module attach‑rates — enabling rapid stress‑testing of revenue outcomes under differing rollout speeds.
- A vendor matrix that maps product portfolios against capability vectors (optical quality, digital visualization, fluorescence, OR integration, service models), plus qualitative scoring to identify attack and defense priorities.
- Commercial playbooks for market entry and expansion, including channel strategies, tender vs. direct mixes, and value‑based selling approaches tailored to neurosurgery, ophthalmology and ENT buyers.
- Regulatory and reimbursement trackers with timeline scenarios and impact assessments for fluorescence adjuncts and diagnostic reclassifications.
- Transaction and partnership pipeline guidance that prioritizes targets based on capability gaps, cultural fit and expected synergies by the year‑end 2026 value creation horizon.
- An ROI stress tester to model upgrade vs. replace decisions in hospital fleets, incorporating capital depreciation, service contracts and software monetization assumptions.
Strategic recommendations for 2026 (actionable and prioritized)
- Prioritize modular digital architectures: Roadmaps should enable field upgrades from optical to hybrid/digital modes to protect installed bases and accelerate attach‑rate for software services.
- Build fluorescence and task‑specific imaging capability early: Regulatory windows and adoption by specialty societies create first‑mover advantage in tumour and retinal applications.
- Design selling motions around clinical and operational outcomes: Procurement teams react to measured throughput and training benefits more than to technical specifications alone.
- Use M&A selectively to acquire interoperability and analytics capabilities rather than optics alone: software and visualization platforms are the primary drivers of sustained margin expansion.
- Invest in education and OR integration services: Demonstrable improvements in ergonomics and team performance accelerate hospital‑level adoption of premium systems.
How PW Consulting’s intelligence supports boardroom decisions
Boards and executive teams face tradeoffs between organic R&D, bolt‑on acquisitions, and commercial partnerships. PW Consulting’s integrated model and strategic playbooks compress the time to insight by connecting clinical trends, regulatory pathways and procurement economics. The result is an evidence‑based roadmap that translates technical differentiation into 24‑ to 36‑month commercial KPIs.
Next steps — where to get the full intelligence
This preview surfaces the critical strategic signals you will need for 2026 planning. The full Secondary Medical Diagnosis And Treatment Microscope Market report contains the complete market model, scenario outputs, executable go‑to‑market plans and detailed vendor assessments. To access the full report, company‑level briefings, or a customized strategy workshop, please visit PW Consulting’s research portal or contact our advisory team directly. Note: to preserve competitive integrity, the full report contains the granular segmentation and vendor share tables omitted here.
PW Consulting remains committed to equipping healthcare technology leaders with actionable, defensible strategies that align clinical impact with commercial performance. In a market where optical craft meets digital acceleration, the right play in 2026 will determine who leads the next wave of OR transformation.
For detailed analysis of this topic, please visit the official page: Secondary Medical Diagnosis And Treatment Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


