



Category: market research
PW Consulting: Global Freight Forwarding Market to Hit $200M in 2025, Grow at 4.55% CAGR to 2032
By PW Consulting, 2026-09-17
Navigating the Global Freight Forwarding Landscape: Strategic Intelligence for 2026 and Beyond
The international freight forwarding industry stands at a critical inflection point. As supply chains adapt to geopolitical shifts, regulatory pressures, and rapid technological transformation, organizations require more than surface-level market data to navigate the coming years with confidence. This comprehensive market research study delivers a rigorous, data-driven analysis of the Worldwide International Freight Forwarding Services Market, offering executives and strategy teams the actionable intelligence needed to make informed decisions across 2026 and the forecast horizon through 2032.
Drawing on historical performance data from 2020 through 2025 and projecting forward across a seven-year forecast period, this report captures both the cyclical volatility and the structural growth trajectories that define modern logistics ecosystems. The base year analysis establishes a clear foundation, while forward-looking projections equip decision-makers with the planning parameters necessary for capacity allocation, partnership strategies, and technology investment roadmaps.
Market Size Evolution and Growth Trajectory
The global freight forwarding market has demonstrated remarkable resilience despite confronting unprecedented disruptions over the past half-decade. Historical revenue figures reveal a market that weathered pronounced fluctuations before stabilizing and returning to a sustainable growth path. After reaching a valuation exceeding 174,000 million USD in 2020, the sector experienced a pronounced surge through 2022, driven by pandemic-era demand restructuring and inventory restocking cycles. The subsequent correction in 2023 and 2024 reflected normalization patterns as freight rates adjusted and consumer spending patterns shifted, yet the underlying demand fundamentals remained intact.
By the 2025 base year, the market had recovered to approximately 200,000 million USD, establishing a solid platform for forward expansion. The forecast period from 2026 through 2032 charts a steady upward trajectory, with projected revenues expanding from roughly 203,300 million USD in 2026 to over 273,000 million USD by 2032. This growth reflects a compound annual growth rate of 4.55 percent, a figure that underscores the sector's capacity to generate consistent value even amid fluctuating macroeconomic conditions. For enterprise planners, this growth rate provides a reliable benchmark for modeling revenue expectations, evaluating market entry opportunities, and calibrating long-term investment commitments.
Structural Segmentation: Where Value Is Created
Understanding the multidimensional structure of the freight forwarding market is essential for targeting the right opportunities and mitigating concentration risks. This report dissects the market across three critical analytical dimensions: geographic regions, transport modes, and end-use industries. Rather than presenting opaque aggregates, the analysis isolates the revenue contributions and growth characteristics of each segment, enabling stakeholders to identify high-potential corridors and service lines.
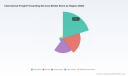
The geographic breakdown reveals distinct regional dynamics shaped by trade policy, infrastructure readiness, and industrial composition. Asia Pacific commands the largest revenue share, driven by manufacturing exports, intra-regional trade intensification, and expanding port infrastructure. Europe maintains a substantial position, supported by integrated multimodal networks and stringent regulatory frameworks that drive demand for compliance-forward logistics solutions. North America represents a mature but evolving market where e-commerce acceleration and nearshoring trends are reshaping forwarding volumes. Latin America and the Middle East and Africa, while smaller in absolute terms, present high-growth opportunities tied to emerging market industrialization, resource-sector logistics, and corridor development initiatives.
On the service mode front, the analysis differentiates between ocean freight, air freight, road and rail transport, and specialized other services. Ocean freight remains the dominant revenue contributor, reflecting the continued centrality of maritime shipping to global trade. Air freight sustains a significant share, buoyed by time-critical shipments, high-value goods, and resilience-driven routing decisions. Road and rail transport segments demonstrate steady demand, particularly in intra-continental corridors where multimodal integration offers cost and efficiency advantages. Complementary service lines, including customs brokerage, warehousing integration, and value-added logistics, represent differentiated niches where forwarders can capture margin premium.
End-use industry segmentation further clarifies where forwarding demand originates. Manufacturing remains the largest consumer of freight forwarding services, reflecting complex global sourcing networks and just-in-time production requirements. Retail and e-commerce continue to expand their logistics footprint, driven by consumer expectations for faster delivery and the proliferation of cross-border online commerce. Consumer goods, healthcare, and automotive and energy sectors each present distinct forwarding requirements shaped by regulatory standards, temperature control needs, hazardous materials handling, and project logistics complexity. By mapping forwarding demand to these end-use verticals, the report provides a practical lens for aligning service portfolios with sector-specific growth cycles.
Competitive Landscape and Market Concentration
The freight forwarding industry operates within a fragmented yet consolidating competitive environment. The analysis indicates a moderate level of market concentration, with the top three players collectively accounting for approximately 12.4 percent of total market revenue and the top five firms representing roughly 18.25 percent. This concentration profile suggests ample room for both established incumbents and specialized challengers to compete on service differentiation, digital capabilities, and regional expertise.
Several globally recognized enterprises define the competitive frontier, each pursuing distinct strategic positions. Kuehne + Nagel has reinforced its position as a leader across sea, air, and road forwarding by integrating digital platforms such as myKN to deliver end-to-end visibility and streamlined transaction workflows. DSV has expanded its comprehensive forwarding capabilities across all major transport modes while building distinctive strength in project logistics, culminating in a landmark acquisition of DB Schenker in September 2025 that created the world's largest freight forwarder by revenue. DB Schenker itself has built a strong reputation for ocean, air, and land forwarding with particular emphasis on automotive and healthcare verticals.
DHL Global Forwarding continues to lead in time-critical air freight and ocean forwarding, leveraging resilience capabilities such as resilience360 to provide supply chain visibility and risk mitigation. Expeditors International has differentiated itself through technology-driven operations, proprietary EDI systems, and a focus on air, ocean, and ground services that emphasize operational precision and client responsiveness. CEVA Logistics offers full-service forwarding integrated with contract logistics, targeting automotive and consumer sectors with coordinated supply chain solutions. UPS Supply Chain Solutions and FedEx Trade Networks bring the advantage of integrated global networks, with UPS emphasizing Quantum View tracking and FedEx specializing in customs brokerage alongside its air and ocean forwarding capabilities.
Regional and specialized players further enrich the competitive landscape. Nippon Express anchors strong Asia-Pacific trade lane expertise across air, sea, and rail services. Sinotrans provides integrated sea, air, and rail forwarding from a Chinese base with global reach. C.H. Robinson has scaled a digital freight forwarding platform through Navisphere, enabling ocean, air, and truck services with a technology-first operating model. Hellmann Worldwide Logistics, as a family-owned forwarder, combines air, sea, and contract logistics with cloud-based track and trace functionality. Geodis delivers multi-modal forwarding with notable strength in e-commerce and healthcare supply chains. Bolloré Logistics focuses on Africa and energy sector logistics via air and sea networks, while Agility Global Integrated Logistics targets emerging markets and provides integrated warehousing and forwarding services through its GWC operations.
Industry Dynamics Shaping Strategic Decisions
Market size and participant profiles alone do not capture the forces that will determine competitive outcomes in 2026 and beyond. A suite of operational, regulatory, and geopolitical dynamics exerts direct influence on forwarding costs, service reliability, and routing strategies. Understanding these forces is indispensable for scenario planning and risk management.
Fuel cost volatility remains a persistent pressure point. Ocean freight bunker fuel prices averaged approximately 650 USD per metric ton in the fourth quarter of 2025, representing a year-over-year increase of 15 percent driven in part by compliance costs associated with IMO 2020 sulfur regulations. For forwarding providers and their clients, fuel cost fluctuations translate directly into freight rate variability and require proactive hedging and pricing strategies.
Regulatory developments are adding new layers of compliance complexity and cost. The European Union Emissions Trading System was extended to shipping in 2025, imposing carbon-related costs on a portion of emissions for intra-EU voyages. This regulatory shift incentivizes carbon-efficient routing, modal optimization, and investment in greener equipment, while simultaneously affecting cost structures for European-facing trade lanes. Labor cost escalation represents another structural headwind. Global logistics labor costs rose by approximately 8 percent in 2025, propelled by port worker shortages across the United States and Europe. This tightening labor market pressures throughput capacity at key nodes and elevates the value of automation and workforce productivity initiatives.
Worldwide Freight Forwarding Service Provider Services Market
Trade policy and geopolitical events continue to reshape freight flows in ways that forwarding strategies must accommodate. Tariff actions, including the imposition of 25 percent tariffs on Chinese steel imports by the United States effective March 2025, have influenced forwarding volumes and routing decisions by altering the economics of specific trade corridors. Geopolitical disruptions have similarly forced adaptive responses. Red Sea disruptions rerouted a significant share of Asia-Europe container traffic via the Cape of Good Hope in early 2025, increasing transit times and fuel consumption while testing the resilience of forwarding networks. These events highlight the importance of diversified routing options, scenario-aware contingency planning, and real-time visibility capabilities that enable rapid response to unfolding disruptions.
Worldwide International Freight Forwarding Services Market
What This Research Delivers for Strategic Decision-Makers
This market research study is designed to translate complex market data into clear strategic guidance. The full report provides an extensive toolkit for executives, business development leaders, investors, and operations strategists. Key deliverables include:
- Detailed historical market sizing and forward projections segmented by region, transport mode, and end-use industry, enabling precise demand forecasting and market opportunity quantification.
- Competitive benchmarking across leading global forwarders, with analysis of strategic positioning, service portfolios, digital capabilities, and recent corporate developments such as acquisitions, platform launches, partnership initiatives, and major client engagements.
- Assessment of market concentration trends and their implications for pricing power, partnership dynamics, and competitive strategy.
- Analysis of the operational and regulatory forces affecting cost structures, route viability, and service reliability, including fuel cost patterns, emissions regulations, labor market conditions, tariff impacts, and geopolitical disruption scenarios.
- Strategic recommendations for aligning service offerings, technology investments, and regional expansion plans with the most promising growth vectors identified in the data.
By integrating quantitative market sizing with qualitative assessments of competitive and operational dynamics, the report equips organizations to move beyond reactive adjustments and toward proactive, evidence-based strategy formulation.
Why This Research Matters for 2026 Planning
The freight forwarding market of 2026 will be defined by organizations that can balance growth ambition with operational adaptability. The 4.55 percent compound annual growth rate projected through 2032 signals a market that continues to expand, but the path of that expansion will be uneven across regions, modes, and industries. Companies that understand where demand is concentrating, which competitors are capturing share, and how regulatory and cost pressures are evolving will be best positioned to allocate resources efficiently and capture disproportionate value.
Digital transformation remains a decisive competitive differentiator. Recent moves by leading forwarders, including AI-driven rate management platform updates, partnerships focused on supply chain resilience, and proprietary technology systems that enhance tracking and transaction efficiency, demonstrate that technology investment is no longer optional. Similarly, corporate consolidation events underscore the importance of scale, network reach, and integrated service capabilities in a market where clients increasingly demand end-to-end solutions.
For enterprises evaluating market entry, service expansion, partnership formation, or investment targeting, the granular insights contained in this report reduce uncertainty and sharpen strategic focus. The segmentation data clarifies which corridors and verticals offer the most attractive risk-adjusted returns. The competitive analysis identifies where incumbents are strengthening their positions and where gaps may exist for differentiated service models. The dynamics assessment provides the context needed to design cost structures, pricing frameworks, and contingency plans that withstand volatility.
Next Steps for Intelligence-Driven Strategy
Accessing the complete dataset, segmentation breakdowns, and competitive profiles allows decision-makers to move from high-level awareness to specific, actionable planning. The full version of this market research includes detailed revenue projections, mode-level and region-level performance analysis, end-use industry demand drivers, company-specific strategic profiles, and a comprehensive overview of the industry events and regulatory developments shaping near-term market behavior.
For organizations seeking to strengthen their positioning in the global freight forwarding market, this research provides the evidence base required to make confident strategic choices in 2026 and beyond. Explore the complete market intelligence to uncover the segmentation insights, competitive benchmarks, and forward projections that will inform your next round of strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide International Freight Forwarding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Power CW Laser Market Surges to $3.4B in 2025, Projected to $6.02B by 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the High-Power CW Laser Era: Why 2026 Demands Precision Market Intelligence
The industrial landscape of 2026 is defined by an uncompromising demand for precision, throughput, and energy efficiency. At the heart of this transformation lies the continuous-wave (CW) high-power laser sector—a market that has evolved from a niche manufacturing enabler into a critical infrastructure component for global production ecosystems. As automation accelerates and material processing requirements grow increasingly complex, decision-makers across industrial manufacturing, semiconductor packaging, and emerging technology sectors face a critical imperative: move beyond superficial trend tracking and ground capital allocation, R&D roadmaps, and supply chain strategies in rigorously validated market intelligence.
Our recently published Worldwide High Power CW Laser Market research delivers exactly that foundation. Spanning a comprehensive historical baseline from 2020 through 2025 and extending a structured forecast horizon to 2032, this study transforms fragmented industry signals into a cohesive strategic narrative. For executives, investors, and engineering leaders navigating the 2026 operating environment, the report serves not as a static reference document, but as a dynamic decision-support framework calibrated to the velocity of technological adoption and competitive realignment.
The Macro Trajectory: Sustained Expansion Anchored in Industrial Realities
Market momentum in the high-power CW laser space is no longer speculative; it is quantifiable, structural, and increasingly non-linear. Drawing on validated historical revenue tracking and forward-looking econometric modeling, the research documents a clear trajectory of expansion. Starting from an established base in 2020, the market has consistently advanced through 2025, crossing significant descriptive milestones that reflect both capacity expansion and deepening application penetration. Looking ahead, the forecast window through 2032 projects a sustained compound annual growth rate of 8.5 percent, measured in USD millions. This growth rate is not an artifact of optimistic modeling; it is anchored in observable adoption curves across metal fabrication, battery manufacturing, additive processes, and precision industrial marking.
For strategic planners, the implication is straightforward: the high-power CW laser market is entering a phase where scale advantages, technological differentiation, and regional supply chain positioning will dictate competitive outcomes. The forecast horizon to 2032 provides a multi-year lens that aligns with typical capital equipment procurement cycles, facility expansion timelines, and technology refresh schedules. Executives who integrate this trajectory into their 2026 planning will be better positioned to time capacity investments, negotiate long-term supply agreements, and anticipate shifts in customer demand before they become visible in quarterly order books.
Worldwide High Power CW Laser Market
Navigating Market Concentration and Competitive Realignment
Scale alone does not guarantee strategic advantage in a market characterized by concentrated leadership and rapidly evolving technological boundaries. The research captures a highly structured competitive environment, with the top three participants commanding a combined share of approximately 56.4 percent and the top five collectively representing over 72 percent of total market revenue. This concentration signals mature competitive dynamics, where incumbents leverage manufacturing scale, application engineering depth, and system-level integration to defend positioning, while challengers and regional specialists pursue targeted differentiation in cost structure, beam quality, or application-specific optimization.
Understanding these dynamics requires more than a leaderboard view. The report dissects how established players balance diversified product portfolios with focused high-margin offerings, how regional manufacturing footprints influence cost competitiveness and logistics resilience, and how strategic partnerships, channel relationships, and vertical integration shape go-to-market effectiveness. For 2026 decision-making, this competitive intelligence translates directly into actionable planning: it informs benchmarking exercises, identifies potential partnership or acquisition targets, highlights whitespace opportunities in underserved application segments, and clarifies where pricing pressure is likely to intensify versus where technology premium positioning remains defensible.
CW DFB Laser Diode Market
Structural Partitioning: Technology, Application, and Regional Interplay
A market of this scale cannot be understood through aggregate figures alone. The research maps the underlying structural partitions that drive demand creation, pricing behavior, and technology roadmapping. Across the laser technology spectrum, the study differentiates performance trajectories, cost curves, and adoption velocity among fiber-based architectures, CO2 platforms, solid-state and disk configurations, and direct diode solutions. Each architecture carries distinct implications for beam delivery, thermal management, maintenance complexity, and end-use suitability, and the report translates these technical attributes into commercial relevance for procurement teams, systems integrators, and technology planners.
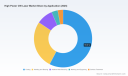
On the application side, the analysis isolates the demand drivers that are reshaping purchasing priorities. Cutting processes continue to anchor a substantial portion of high-power CW laser deployment, reflecting their centrality to metal fabrication, sheet processing, and high-volume manufacturing. Welding and brazing applications represent a parallel growth axis, increasingly influenced by battery assembly requirements, automotive lightweighting initiatives, and aerospace structural joining demands. Additive manufacturing, marking and engraving, and surface treatment applications each contribute distinct volumes and margin profiles, and the report delineates how these segments interact with regional industrial policies, automation investment cycles, and quality-certification requirements.
Regional demand distribution further complicates the strategic picture. The research examines how manufacturing capacity, local automation adoption rates, industrial policy incentives, and supply chain regionalization influence market pull across major geographic corridors. Rather than presenting static share tables, the report contextualizes regional behavior within broader macroeconomic and industrial transformation trends, enabling readers to assess where localized production strategies, export-oriented supply positioning, or regional partnership models will yield the strongest return on commercial engagement in 2026 and beyond.
Tactical Intelligence for 2026 Decision-Making
High-level trajectory and structural analysis are necessary, but rarely sufficient for operational planning. The report is engineered to bridge strategic overview and tactical execution. It provides procurement and engineering leaders with framework-level insights into technology selection criteria, including guidance on when fiber-based solutions dominate, where diode or solid-state alternatives offer compelling tradeoffs, and how beam quality, power stability, and back-reflection resilience influence application suitability for reflective or thermally sensitive materials.
For supply chain and operations executives, the study addresses material dependency considerations and production scalability constraints. It traces how specialized semiconductor and optical raw material dynamics, including regional supply concentration and spot price volatility observed in recent periods, intersect with manufacturing continuity planning. The report also incorporates regulatory and safety compliance requirements that shape design, qualification, and maintenance processes for high-power systems, emphasizing that thermal management complexity and non-linear optical effects demand specialized engineering expertise and rigorous process controls. These factors directly influence total cost of ownership, service network requirements, and vendor evaluation criteria.
Commercial and go-to-market teams will find actionable frameworks for positioning, segmentation, and partnership strategy. The research outlines how application-specific value propositions differ across cutting, welding, additive, and surface treatment contexts, and how system-level integration, service availability, and performance guarantees influence buyer decision-making. By aligning market structure with commercial execution pathways, the report equips teams to refine pricing architectures, prioritize addressable segments, and design channel strategies that match the realities of regional demand and competitive intensity.
Recent Developments Reshaping the Competitive Frontier
The 2026 operating environment is being actively reshaped by product launches, sampling programs, and recognition events that signal where technology leadership is concentrating. Recent industry activity underscores this momentum. In early 2026, leading fiber laser developers showcased compact high-power single-mode sources with tightly controlled beam quality metrics, earning industry recognition for packaging efficiency and industrial usability. These exhibitions and awards are not merely ceremonial; they signal commercial readiness, validate performance claims, and often precede accelerated adoption in precision cutting and welding workflows where beam consistency directly impacts process yield.
Simultaneously, adjacent high-power CW developments are expanding the addressable context beyond traditional industrial processing. Sampling programs for high-power CW sources targeting AI datacenter and co-packaged optics applications indicate a broadening demand ecosystem, where optical power requirements, linewidth control, and fabrication scalability on advanced substrate lines are becoming commercially relevant. Early-stage production timelines and initial revenue expectations tied to these initiatives illustrate how high-power laser technology is feeding into next-generation infrastructure and photonics architectures, creating cross-sector demand linkages that traditional industrial laser markets did not previously capture.
Additional recent introductions in high-efficiency CW sources with stringent linewidth and wall-plug efficiency targets further reflect the industry-wide push toward energy optimization and integration compatibility. Together, these developments demonstrate that the high-power CW laser market is not a closed industrial loop; it is a convergent technology platform where manufacturing, photonics, and infrastructure demands increasingly interact. The report synthesizes these signals into a coherent view of where near-term commercial activity is likely to concentrate and which performance benchmarks are becoming table stakes for competitive participation.
Why This Research Matters for 2026 Strategy
The strategic value of this market research lies in its integration of macro trajectory, structural partitioning, competitive positioning, and near-term industry signals into a single, decision-ready framework. For 2026, that integration matters because the cost of misreading market direction is rising. Capital deployed into misaligned technology platforms, capacity added without clear regional demand justification, or supply agreements negotiated without visibility into concentration dynamics and raw material risk can quickly erode competitive positioning. Conversely, organizations that anchor their planning in validated market structure, realistic growth trajectories, and application-specific demand drivers can time investments more effectively, negotiate from a position of informed confidence, and identify differentiation pathways before competitors lock them in.
The report is designed to support precisely that informed confidence. It equips leadership teams with the context needed to evaluate technology roadmaps against realistic adoption curves, to assess competitive vulnerability and opportunity across regions and applications, and to align procurement, manufacturing, and commercial strategies with the structural realities of a high-growth, technically demanding market. It also provides the analytical discipline required to separate transient market noise from durable demand shifts, a distinction that becomes increasingly critical as automation, electric vehicle manufacturing, aerospace additive requirements, and emerging photonics applications collectively reshape purchasing priorities.
Direction for Deeper Engagement
This overview establishes the analytical foundation and strategic relevance of the study, but the full market intelligence required for definitive 2026 planning resides in the complete research deliverable. The underlying segmentation detail, regional demand mapping, application-specific volume and revenue context, technology performance comparisons, and company-level profiling are structured to support granular scenario modeling, vendor evaluation, and investment prioritization. Accessing the complete report enables decision-makers to move from directional understanding to precise, actionable intelligence tailored to their operational footprint, technology roadmap, and commercial objectives.
For executives and strategy teams seeking to align 2026 capital allocation, product positioning, and supply chain planning with the trajectory of the worldwide high-power CW laser market, the full research offers the depth, structure, and forward visibility required to act with confidence. The market is expanding, concentrating, and converging across industrial and infrastructure applications; the organizations that navigate this environment successfully will be those that replace assumption with evidence, and direction with detail.
For detailed analysis of this topic, please visit the official page: Worldwide High Power CW Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Solar Urban Equipment Market Hits $1.14B in 2025, 15.02% CAGR to 2032
By PW Consulting, 2026-09-17
The Urban Energy Transformation: Strategic Insights into the Worldwide Smart Solar Urban Equipment Market (2026-2032)
The global urban landscape is undergoing a profound metamorphosis, driven by the urgent need for sustainable infrastructure and the integration of intelligent technologies into public spaces. At the forefront of this transformation is the smart solar urban equipment sector, a niche yet rapidly expanding market that merges renewable energy generation with IoT-enabled urban furniture. As municipalities and commercial developers seek to reduce carbon footprints while enhancing citizen engagement, the demand for autonomous, connected solar solutions is reshaping procurement strategies and urban planning paradigms. This article serves as a strategic primer to our latest comprehensive study, the Worldwide Smart Solar Urban Equipment Market Research, designed to equip industry leaders with the critical intelligence needed to navigate the opportunities and complexities of the 2026-2032 forecast period.
Executive Market Overview: Trajectory of Exponential Growth
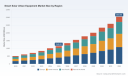
The market for smart solar urban equipment has demonstrated robust momentum over the past half-decade, evolving from a novelty into a staple of modern smart city initiatives. Our analysis captures a market that has steadily accelerated, reflecting the compounding effects of policy support, technological maturity, and the economic imperative for off-grid resilience. In the base year of 2025, the global revenue associated with this sector reached approximately $1,142.83 million. This figure represents a substantial escalation from the $510.45 million recorded in 2020, underscoring a consistent double-digit expansion trajectory that has outpaced many broader infrastructure segments.
Looking ahead to the forecast window ending in 2032, the market is projected to surge past the $3 billion mark, reaching an estimated $3,043.66 million in revenue. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 15.02 percent. Such a rate signals not merely incremental adoption but a structural shift in how urban assets are powered and managed. The period from 2026 through 2032 is poised to be defined by scaling infrastructure projects, increased investment in public-private partnerships, and the maturation of the product ecosystem. For decision-makers, understanding this velocity is paramount; it indicates a window of opportunity where early movers can secure market share and establish technological standards before the market reaches saturation.
The Role of Data-Driven Insights in 2026 Decision-Making
In an environment characterized by rapid technological iteration and shifting regulatory frameworks, decisions based on intuition or outdated benchmarks carry significant risk. The strategic value of a dedicated market research report lies in its ability to distill complex macroeconomic signals into actionable intelligence. For 2026, stakeholders face a unique inflection point. Costs for core components, such as photovoltaic modules, have seen volatility and downward pressure in global spot markets, yet regulatory dynamics, including trade duties on specific cell types and modules, introduce new variables into supply chain planning. Furthermore, incentive structures at the state and municipal levels are evolving, creating pockets of high ROI that require precise identification.
Our research report goes beyond top-line projections to unpack the drivers and restraints influencing these numbers. It provides a granular examination of how cost structures, installation efficiencies, and capacity-weighted averages impact total cost of ownership for urban deployments. By analyzing the interplay between raw material pricing trends and equipment performance metrics, the report enables procurement managers and strategic planners to model sensitivity scenarios. Whether evaluating the financial viability of a fleet of smart solar benches for a public park or assessing the long-term maintenance costs of solar street lighting in municipal infrastructure, access to accurate, forward-looking data is the difference between a speculative venture and a calculated investment.
Product and Application Landscape: Where Value is Being Created
The market is not monolithic; it is a mosaic of distinct product categories and application verticals, each with its own adoption curve and value proposition. The research delves deeply into the segmentation of the market, revealing which equipment types are capturing the lion's share of revenue and why. The analysis covers a spectrum of solutions, including smart solar benches that serve as community hubs with integrated connectivity and charging, solar smart waste bins that optimize municipal collection routes through sensor data, solar street lighting that eliminates trenching and grid reliance, and solar kiosks and signage that provide interactive information in off-grid locations.
Each of these categories addresses specific pain points for urban operators. For instance, smart benches and kiosks are increasingly viewed as assets for public engagement and digital inclusion, while solar waste bins offer tangible operational cost savings through compaction and fill-level monitoring. The report provides a comparative assessment of these segments, highlighting the relative market valuation of each and the growth drivers specific to their use cases. Readers will gain clarity on which product types are resonating most strongly with current procurement trends and where the innovation pipeline is likely to disrupt existing categories.
Worldwide Smart Solar Urban Equipment Market
Similarly, the application landscape is dissected to reveal the end-use environments driving demand. Public parks and plazas represent a significant focal point for smart urban furniture, leveraging solar solutions to create sustainable, functional gathering spaces without the burden of extensive grid infrastructure. Municipal infrastructure projects are deploying these technologies to modernize street lighting and waste management, often driven by sustainability mandates and budget constraints. Commercial real estate developers are integrating solar equipment to enhance property amenities and meet green building certifications, while transportation hubs are utilizing these assets to support transit users with lighting and connectivity. The report quantifies the revenue allocation across these applications and identifies the key performance indicators that influence purchasing decisions in each vertical.
Geographic Dynamics and Market Concentration
Regional variations play a critical role in the deployment and adoption of smart solar urban equipment. The research provides a detailed breakdown of market performance by region, highlighting the distinct characteristics and growth trajectories of key geographies. Europe continues to demonstrate strong leadership, underpinned by aggressive sustainability targets, supportive regulatory environments, and a mature ecosystem of smart city initiatives. North America remains a potent market, fueled by substantial public infrastructure spending, a focus on energy independence, and the rapid adoption of off-grid solutions in diverse climates. Asia Pacific is characterized by rapid urbanization and large-scale smart city projects, offering immense volume potential, while the Rest of the World segment is emerging with niche opportunities driven by specific regional needs and development programs.
Beyond regional splits, the report examines the competitive structure of the market. Analysis of market concentration reveals that the sector is relatively fragmented, with the top three companies commanding a combined market share of 21.4 percent and the top five holding 32.65 percent. This level of concentration suggests a market that is still open to new entrants and consolidation, where competitive advantages are derived not just from scale but from technological differentiation, service models, and regional expertise. Understanding this landscape is essential for companies evaluating partnership opportunities, acquisition targets, or positioning strategies.
Competitive Intelligence: Navigating a Dynamic Player Ecosystem
The smart solar urban equipment space is populated by a diverse array of companies, ranging from specialized hardware manufacturers to integrated solution providers. Our research includes comprehensive profiles of key market participants, offering insights into their product portfolios, strategic focus, and recent activities. These profiles are designed to provide a 360-degree view of the competitive landscape, enabling clients to benchmark their offerings and identify potential collaborators or rivals.
EnGoPlanet Energy Solutions LLC, based in New York, exemplifies the trend toward multi-functional urban assets. Their portfolio encompasses smart solar street lights with IoT connectivity, Wi-Fi hotspots, security cameras, and environmental sensors, alongside smart solar benches and a subscription-based solar lighting-as-a-service model. This service-oriented approach addresses the budget constraints of municipalities by shifting capex to opex, a strategy that is gaining traction. EnGoPlanet has also been active in high-visibility projects, with developments noted in early 2024 regarding major installations in Texas, and ongoing thought leadership on solar integration in urban contexts.
SOLTECH LLC, headquartered in Emeryville, California, focuses on high-efficacy commercial solar LED lighting systems. Their offerings include street lights, pathway lights, bollards, flood lights, and mobile solar light towers, with an emphasis on off-grid reliability capable of sustaining illumination for extended periods. Recently, SOLTECH has highlighted performance capabilities suitable for demanding applications, including Olympic-grade standards, and promoted fast-deploy solutions that avoid the need for trenching or wiring, a significant advantage for event infrastructure and rapid urbanization projects.
Archasol operates as a global supplier of solar-powered urban furniture, providing smart benches with phone charging and lighting, solar charging stations, pathway lighting, and sign lighting. Their value proposition centers on delivering functional public space enhancements without the requirement for mains power connections, making them relevant for parks, pedestrian zones, and areas where grid extension is cost-prohibitive.
SEEDiA, based in Poland, develops smart solar benches equipped with USB and inductive charging, LED lighting, and sensors, managed through the InCity.io platform. Their ecosystem extends to solar bus shelters, info kiosks, and e-scooter chargers, positioning them as a comprehensive provider for smart urban mobility and public interaction nodes. The integration of remote management platforms is a recurring theme among leading players, emphasizing the shift from passive hardware to actively managed data-generating assets.
Sunna Design, a pioneer with operations in France and North America, specializes in autonomous solar street lighting and energy management systems. Their connected, off-grid solutions are tailored for both urban and rural smart city applications, leveraging robust lighting control algorithms to optimize energy usage. Strawberry Energy, based in Serbia, offers highly customizable smart solar benches with WiFi, charging, LED lighting, and IoT features, allowing municipalities to tailor solutions to specific aesthetic and functional requirements. Finbin, from Finland, addresses the waste management dimension with CitySolar smart solar-powered compacting waste bins that utilize sensors to improve collection efficiency. These profiles, and others detailed in the report, illustrate the breadth of innovation and the varying approaches competitors are taking to capture market value.
Industry Dynamics, Trends, and Strategic Implications
The market does not operate in a vacuum; it is influenced by a complex web of industry dynamics, including raw material pricing, regulatory changes, and incentive structures. Our report synthesizes these external factors to provide a holistic view of the operating environment. For example, the analysis incorporates data on global PV module spot prices and installed costs of utility-scale PV systems, providing context for the cost structures of smaller urban-scale deployments. While utility-scale metrics differ from urban equipment economics, they signal broader trends in the solar supply chain that affect component availability and pricing power.
Regulatory developments are another critical focus. The report addresses relevant trade policies, such as additional duties on solar cells and modules imposed in key markets, which can impact procurement costs and supply chain strategies. Simultaneously, the research highlights positive regulatory tailwinds, such as local solar access funds and grant programs that provide financial support for community solar projects. These incentives can significantly alter the project economics for municipalities and developers, and the report identifies where and how such mechanisms can be leveraged. Furthermore, the broader context of global solar PV additions and the dominance of certain regions in manufacturing and deployment sets the stage for understanding supply-demand balances and innovation flows.
Why This Report is Essential for 2026 Planning
As we enter 2026, the stakes for strategic decision-making in the smart solar urban equipment market have never been higher. The convergence of sustainability mandates, technological advancements, and economic pressures is creating a fertile ground for growth, but also a landscape filled with potential pitfalls. Companies that rely on fragmented data or lagging indicators risk misallocating resources, entering the wrong segments, or failing to capitalize on emerging trends.
Our Worldwide Smart Solar Urban Equipment Market Report is designed to be the definitive resource for navigating this landscape. It offers a depth of analysis that goes beyond surface-level summaries, providing the granular insights necessary to formulate robust strategies. Whether you are a manufacturer looking to expand your product line, a distributor seeking high-growth regions, a municipality planning a smart city initiative, or an investor evaluating opportunities, this report delivers the intelligence you need. It combines quantitative rigor with qualitative context, offering a clear view of the market's past performance and future potential.
The market is on a trajectory to triple in size over the forecast period, driven by a CAGR of over 15 percent. The competitive landscape is evolving, with players differentiating through technology, service models, and regional focus. The product and application segments are maturing, revealing clear winners and value drivers. The industry dynamics are shifting, demanding agile responses to pricing, regulation, and incentives. To make sense of it all and to position your organization for success, you need the comprehensive, authoritative analysis that only this report provides.
Secure your copy of the Worldwide Smart Solar Urban Equipment Market Research today and gain the strategic edge required to lead in the urban energy transformation. Access the full dataset, detailed segmentation analysis, competitive profiles, and forward-looking insights that will empower your 2026 and beyond decision-making.
Solar Mobile Light Tower Market
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reusable Food Wrap Market Hits $245M in 2025, Projects 7.15% CAGR to 2032
By PW Consulting, 2026-09-17
The Reusable Food Wrap Revolution: Strategic Insights for Navigating Market Growth Through 2032
A PW Consulting Executive Preview
The global transition away from single-use plastics has moved from a niche consumer preference to a mainstream operational imperative. For businesses operating in the food storage, packaging, and sustainable goods sectors, the reusable food wrap market represents one of the most dynamic growth vectors of the decade. Our latest comprehensive study, Worldwide Reusable Food Wrap Market, offers a granular, data-driven roadmap for navigating this evolving landscape. This article serves as a strategic preview, outlining the macro-trajectory, the competitive architecture, and the regulatory catalysts that will define market winners between 2026 and 2032.
The Macro Trajectory: From Recovery to Accelerating Expansion
Over the past half-decade, the worldwide reusable food wrap market has demonstrated a robust recovery and expansion phase. Historical revenue data from 2020 through 2025 illustrates a clear upward trajectory, with the market size climbing from 173.46 million USD to a projected 245.0 million USD. This growth reflects not only the post-pandemic normalization of supply chains but also a structural shift in consumer purchasing behavior. As households and commercial kitchens increasingly prioritize waste reduction, demand for breathable, plastic-free alternatives has cemented itself as a recurring revenue stream rather than a transient trend.
Looking forward to the forecast period spanning 2026 to 2032, the market is positioned for sustained expansion. The projected compound annual growth rate of 7.15 percent signals that the sector will outperform many traditional consumer goods categories. By 2032, the overall market revenue is expected to reach 397.3 million USD. For corporate strategists, this CAGR implies a compounding opportunity: early movers who establish distribution networks, brand loyalty, and regulatory compliance frameworks today will capture disproportionate market share as the total addressable market expands. The forecast also highlights year-over-year inflection points, such as the jump toward 315.56 million USD in 2028, suggesting that regulatory deadlines and commercial adoption curves will likely accelerate demand velocity in the latter half of the forecast window.
It is crucial for decision-makers to understand that these macro figures represent the aggregate of distinct regional performances, product typologies, and end-use applications. Our full report unpacks these layers systematically, providing the precise volume and value breakdowns required for regional go-to-market planning, product portfolio optimization, and capacity allocation. However, the headline trend is unambiguous: the market is scaling, and the pace of scaling is tightening around a consistent mid-single-digit growth rate that rewards strategic foresight over reactive positioning.
Decoding the Competitive Architecture
The reusable food wrap sector is characterized by a moderately fragmented but strategically consolidating competitive landscape. Market concentration metrics indicate that the top three players command approximately 28.5 percent of total revenue, while the top five hold around 36.2 percent. This distribution suggests that while no single entity dominates the global stage, established brands with strong product differentiation, ethical sourcing narratives, and supply chain resilience are capturing meaningful pockets of influence. The remaining market share is distributed among a vibrant ecosystem of specialized manufacturers, regional producers, and emerging direct-to-consumer brands, creating a highly dynamic environment for both competition and partnership.
Key incumbents exemplify the strategic pillars driving success in this space. Bee's Wrap, LLC, headquartered in Vermont, has positioned itself as a pioneering brand by offering reusable beeswax food wraps crafted from GOTS-certified organic cotton, ethically sourced beeswax, jojoba oil, and tree resin. Their emphasis on breathable, plastic-free alternatives across various sizes and patterns demonstrates how product variety and material transparency can build enduring consumer trust. Similarly, Abeego Designs Inc. from Canada has capitalized on the original beeswax food storage wrap concept, designing products that allow food to breathe while protecting it. Their focus on extending the freshness of produce, cheese, and bread aligns tightly with the narrative of reducing household food waste, a powerful purchase driver.
Reusable Water Bottle Market
The competitive field also includes Etee, another Canadian player providing organic reusable food wraps and zero-waste products that serve as sustainable alternatives to single-use plastics. LilyBee Wrap targets eco-conscious consumers with organic cotton beeswax wrappers featuring diverse designs, highlighting the importance of aesthetic differentiation alongside functional sustainability. The Beeswax Wrap Company Ltd operates as a manufacturer and supplier focused on reusable, biodegradable options for household food preservation, illustrating the role of dedicated B2B and wholesale channels in scaling distribution. Keep Leaf integrates reusable food wraps into a broader sustainable kitchen product line, emphasizing eco-friendly materials that resonate with lifestyle-focused retail assortments.
Further down the value chain, U-KONSERVE offers reusable food storage solutions including wraps that prioritize durable, sustainable alternatives to disposable plastics. Khala & Company provides beeswax wraps and related eco-products with an emphasis on natural and ethical sourcing, reinforcing how supply chain integrity has become a competitive differentiator. SuperBee supplies beeswax wraps and eco-friendly products compliant with various dietary and manufacturing standards, targeting sustainable food storage with a framework that appeals to regulated and quality-conscious markets. Honeywrap and Apiwraps both offer beeswax-based reusable food wraps for everyday kitchen use, representing the steady demand from brands that focus on everyday utility and repeatable purchase cycles.
On the manufacturing and export frontier, Henan Green Wrap Products Co., Ltd in China operates as a large-scale manufacturer of beeswax wraps, vegan wraps, and related products compliant with LFGB, REACH, and FDA standards, while offering OEM/ODM services. This profile underscores the strategic importance of regulatory compliance and flexible manufacturing partnerships for brands seeking to scale internationally or launch private-label offerings. Green Wrap, also based in China, positions itself as an experienced manufacturer of reusable beeswax food wraps and bags, emphasizing stable quality and efficient production. Together, these manufacturers illustrate how production capacity, certification portfolios, and service models are reshaping the competitive dynamics beyond consumer-facing brands.
For executives, the central insight is that competition in this market is multidimensional. It is not merely a price war; it is a contest over material credibility, product performance, regulatory readiness, and supply chain agility. Our full report provides detailed comparative assessments that help brands identify white-space opportunities, benchmark against incumbents, and evaluate potential acquisition or partnership targets within this ecosystem.
Regulatory Catalysts and Raw Material Realities Shaping the Demand Curve
Market growth in the reusable food wrap sector cannot be understood in isolation from the regulatory environment. Policy interventions across multiple jurisdictions are actively reshaping end-user demand and creating compliance-driven purchasing behavior. In the United States, California's SB 54 mandates that 100 percent of single-use packaging and food service ware sold in the state must be recyclable or compostable by 2032. This legislative trajectory is a powerful demand catalyst for reusable alternatives, as food service operators and packaging suppliers seek compliant, scalable solutions that can meet both environmental targets and operational practicality. The regulation effectively expands the commercial addressable market by forcing a structural shift in procurement priorities.
Beyond California, a cascade of state-level actions is tightening the regulatory perimeter around single-use plastics. New Jersey's law prohibits food service businesses from providing single-use utensils and condiments under certain conditions, effective August 1, 2026. Georgia has implemented a ban on single-use plastic food packaging and foodware for food service establishments, effective July 1, 2026. These measures, documented by CalRecycle and the New Jersey Department of Environmental Protection, among other sources, signal a clear policy direction: single-use disposables are increasingly constrained, and reusable, durable alternatives are moving from optional sustainability enhancements to baseline compliance requirements. For commercial end-users and the brands that supply them, this regulatory cadence creates both urgency and a multi-year window to align product portfolios with evolving mandates.
At the same time, raw material dynamics introduce both opportunity and risk. Beeswax, a foundational input for many reusable wrap products, has experienced notable price volatility. In late 2025, visible trade data indicated that US beeswax transaction prices reached approximately 18.29 USD per kilogram. Meanwhile, the global average beeswax export price in 2024 was recorded at 6,311 USD per ton. These figures highlight the importance of input cost monitoring, supplier diversification, and formulation strategies that can buffer margin pressure. Brands that rely heavily on beeswax must navigate geographic sourcing variations, certification requirements, and seasonal supply fluctuations, while manufacturers of vegan or alternative-material wraps must track the cost and performance trajectories of their own material substitutes. Our research integrates these raw material realities into the broader demand forecast, enabling clients to model sensitivity scenarios and make informed sourcing decisions.
Inside the Report: Practical Intelligence for Strategic Execution
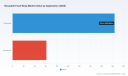
The Worldwide Reusable Food Wrap Market study is designed as an operational decision-support tool, not merely a high-level overview. It provides a structured exploration of the market's foundational drivers, restraints, and enabling factors, connecting macro forces to actionable business implications. Readers gain access to a detailed segmentation analysis that dissects the market by region, by product type, and by application, allowing stakeholders to pinpoint where growth is concentrating and where competitive intensity is rising. This multi-dimensional segmentation is essential for companies evaluating market entry, expansion, or portfolio rebalancing, as it reveals the relative weight of household versus commercial demand and clarifies how product categories perform across different economic and regulatory contexts.
The report also includes comprehensive profiles of the key companies shaping the competitive landscape. Each profile examines brand positioning, material and sourcing strategies, product range breadth, compliance frameworks, and distribution approaches. By mapping these profiles against market share and concentration metrics, the study helps clients identify competitive gaps, evaluate benchmarking targets, and anticipate likely strategic moves from both established players and agile challengers. For investors and corporate development teams, this company-level intelligence supports due diligence, partnership screening, and market positioning exercises with a clear view of who is leading in which segment and why.
Worldwide Reusable Food Wrap Market
Beyond segmentation and company analysis, the study embeds the regulatory and raw material context directly into the market narrative. This integration ensures that forecasts are not developed in a vacuum; instead, they reflect the combined influence of legislation, material pricing, consumer behavior shifts, and supply chain capacity. The forecast period through 2032 is treated as a sequence of decision-relevant milestones, allowing clients to align product launches, capacity investments, and geographic prioritization with the most probable market inflection points. The result is a research asset that supports scenario planning, pricing strategy, channel mix optimization, and risk assessment within a single coherent framework.
Translating Insight into 2026 Decision-Making
As organizations move into 2026, the strategic imperative is to convert market awareness into structured action. The reusable food wrap market is large enough to reward focused investment, yet dynamic enough to penalize delayed or uninformed decisions. Companies that act early can secure distribution relationships, align product specifications with emerging regulatory expectations, and build brand equity around material transparency and performance reliability. Those that wait risk entering a market where compliance costs are higher, consumer expectations are more entrenched, and competitive positions are already defended by brands with multi-year head starts.
For consumer brands, the priority is to determine which product types and application segments offer the most defensible growth profile, then to calibrate pricing, packaging, and marketing around the value propositions that resonate with target buyers. For manufacturers and suppliers, the focus should be on certification readiness, production efficiency, and the ability to support OEM/ODM demand from brands seeking to scale quickly while maintaining quality and compliance. For investors and corporate strategists, the opportunity lies in identifying which companies possess the combination of material expertise, regulatory agility, and market reach needed to compound value as the forecast period unfolds.
The macro figures point to a market moving from 245.0 million USD in 2025 toward 397.3 million USD in 2032, with a CAGR of 7.15 percent anchoring a credible growth narrative. Yet the real strategic advantage comes from understanding the distribution of that growth: which regions are expanding fastest, which product types are gaining share, which applications are shifting from early adoption to mainstream procurement, and how regulatory timelines will compress decision windows. Those details are the difference between a general sense of optimism and a precise execution plan.
Access the Full Intelligence
This preview has outlined the structural forces, competitive architecture, and regulatory momentum defining the reusable food wrap market through 2032. To move from directional confidence to decision-ready precision, stakeholders need the complete dataset, segmentation matrices, company benchmarking, and forecast sensitivities contained in the full study. The detailed breakdown of regional performance, product-type dynamics, household versus commercial application splits, and raw material scenario modeling is available in the comprehensive Worldwide Reusable Food Wrap Market report. We invite executives, strategists, and investment teams to access the full research asset and equip their 2026 planning with the depth required to act decisively in a market that is scaling quickly and rewarding informed positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Zero-Point Clamping Market Hits $633.19M in 2025, To Hit $987.21M by 2032
By PW Consulting, 2026-09-17
Unlocking Precision and Speed: Strategic Insights into the Global Zero-Point Clamping System Market 2026–2032
In the high-stakes environment of modern manufacturing, the margin between profitability and obsolescence often comes down to seconds. Every minute spent on machine setup is a minute of lost capacity. As we move deeper into 2026, the imperative for high-mix, low-volume production environments has never been more critical. The global Zero-point Clamping System market stands at the forefront of this operational shift, offering the technological backbone required for rapid changeovers, lights-out production, and uncompromising precision. Our latest Worldwide Zero-point Clamping System Market study is not merely a collection of statistics; it is a strategic compass designed to navigate the complex interplay of technological innovation, regional dynamics, and competitive intensity that defines this sector through 2032.
The Macro Economic Trajectory: A Decade of Sustained Growth
Understanding the broader market trajectory is the first step in strategic planning. The data reveals a robust growth story that extends well beyond temporary fluctuations. In our base year of 2025, the global market for zero-point clamping systems established a significant revenue baseline. Looking forward, the forecast period from 2026 to 2032 projects a steady and compelling compound annual growth rate (CAGR). This growth is not accidental; it is the direct result of manufacturing industries prioritizing efficiency metrics that were previously secondary to raw output.
Historical analysis covering the period from 2020 to 2025 shows a consistent upward trend in revenue valuation, measured in millions of USD. This historical resilience sets the stage for the future. The market size is expected to expand significantly by the end of the forecast period in 2032. For enterprise strategists, this indicates a healthy ecosystem where investment in clamping technology is viewed as a capital expenditure with demonstrable returns in operational throughput. The shift from manual intervention to automated, repeatable clamping solutions is becoming a standard rather than a luxury. However, the aggregate numbers only tell part of the story. The true value for decision-makers lies in understanding the velocity of adoption across different actuation technologies, the specific demands of key application verticals, and the uneven distribution of market revenue across global regions. These nuanced layers of data are essential for identifying where the next pockets of growth will emerge.
Industry Dynamics: The Drivers of Change in 2026
Several macro trends are converging to accelerate the adoption of zero-point clamping technology. The primary driver remains the urgent need to reduce setup times. In high-mix production environments, traditional workholding methods often create bottlenecks. Industry leaders highlight that implementing zero-point systems can reduce setup times by up to 90%. This efficiency gain directly translates to increased machine capacity, allowing manufacturers to run more batches or dedicate more time to actual cutting operations.
Furthermore, the integration of these systems into the broader Industry 4.0 framework is a critical dynamic. Zero-point clamping systems provide standardized, repeatable interfaces that are essential for CNC and robotic handling. This standardization enables lights-out production scenarios where machines operate autonomously overnight or during weekends. For corporations aiming to reduce labor dependency and mitigate supply chain volatility, the ability to run unmanned shifts is a strategic advantage that hinges on reliable workholding technology.
Precision and repeatability are also key factors capping the ceiling of market growth. Modern systems are engineered to compensate for thermal expansion with symmetrical fixed zero points and clearance-free fits. Achievement of repeat accuracy below 2.5 micrometers allows for tighter tolerances in finished parts, which is particularly vital in sectors where component failure is not an option. Additionally, the materials used in these systems are critical. High-strength hardened alloy steel components, often treated to approximately 57 HRC, ensure durability and precision under heavy loads. This material specification underscores the engineering rigor required to maintain system integrity over thousands of clamping cycles.
Report Scope and Operational Content
Our comprehensive study is structured to provide actionable intelligence rather than abstract theory. The report delves into the segmentation of the market by actuation type, covering pneumatic, hydraulic, and manual mechanical clamping solutions. Each actuation type offers distinct advantages regarding speed, force, and integration complexity. The analysis extends to the application landscape, dissecting demand across automotive manufacturing, aerospace and defense, medical device manufacturing, and general machinery and tooling. Each vertical presents unique challenges regarding vibration resistance, clamping force requirements, and cycle times.
Regional analysis is another cornerstone of this research. We examine the market concentration across Europe, Asia Pacific, North America, and the Rest of World. Understanding the regional distribution of revenue is vital for supply chain planning and market entry strategies. The report also scrutinizes the competitive landscape, analyzing market concentration metrics to understand the balance between dominant incumbents and emerging challengers. This includes an assessment of the top players who command significant market share, providing insight into pricing power and consolidation trends.
- Segmentation Analysis: Deep dives into actuation types and application verticals to identify high-growth niches.
- Regional Breakdown: Country and region-specific revenue trends to support geographic expansion or sourcing decisions.
- Competitive Intelligence: Profiles of key industry players, including their strategic moves, product launches, and exhibition activities.
- Investment Viability: Identification of high-value segments where capital deployment yields the highest return on investment.
Key Enterprise Profiles and Strategic Moves
The competitive arena is populated by specialized manufacturers who have anchored their reputations on precision and reliability. STARK Spannsysteme GmbH, part of the ROEMHELD Group, continues to pioneer zero-point clamping technology. Their solutions focus on fast, precise workpiece and fixture clamping in CNC machining, optimizing setup time across milling, turning, and automation. Similarly, LANG Technik GmbH offers the Quick•Point® system, known for modular 52 mm and 96 mm grids that emphasize versatility and retrofitting capabilities on various CNC machines.
The Zimmer Group provides modular systems suitable for milling, turning, EDM, and grinding, emphasizing error reduction. HAINBUCH GmbH offers the DockLock system for stationary applications, enabling quick change-over of clamping devices in under two minutes with form-fit clamping. SMW-AUTOBLOK supplies systems including APS series modules with turbo functions for enhanced pull-down force and sealed designs. EROWA AG specializes in systems optimized for automated CNC manufacturing and lights-out production, integrating loading units with platforms for EDM, milling, and measurement.
In the Americas, Jergens Inc. supplies a Zero Point System that combines fixing, positioning, and clamping in one step, reducing setup times by up to 90%. SCHUNK GmbH & Co. KG provides Vero-S and other solutions widely referenced for precision workholding. NIKKEN Kosakusho Works Ltd., operating in Japan and the USA, develops integrated technology directly into rotary tables to maintain machine rigidity without additional stack height.
Recent activity indicates a vibrant pipeline of innovation. Gressel AG released new plate modules for their gre4doc system in early 2025. The ROEMHELD Group and Gressel both showcased their technologies at EMO Hannover 2025. NIKKEN highlighted integrated zero-point clamping in their 5AX-201 rotary table in March 2025. AMF Andreas Maier GmbH & Co. KG published a comprehensive catalog covering mechanical, hydraulic, and pneumatic modules. These developments signal that the industry is not static; product lifecycles are active, and competition is fierce.
Competitive Landscape and Market Concentration
The market structure is characterized by a concentration of revenue among a core group of established players. Analysis of market concentration reveals that a significant portion of the total revenue is held by the top companies. This concentration suggests strong brand loyalty, high barriers to entry regarding precision engineering certifications, and the importance of existing customer relationships in CNC machining networks. However, the presence of specialized manufacturers, such as ZeroClamp GmbH and Suzhou SET Industrial Equipment System Co., Ltd., indicates niche opportunities where specific value propositions like extreme repeat accuracy or custom high-precision solutions can carve out market share.
Worldwide Zero-point Clamping System Market
Strategic decisions for 2026 must account for this landscape. Whether a company is looking to source clamping technology to improve internal operations or considering market entry, understanding the capabilities of competitors like STARK, LANG, and EROWA is essential. These companies are not just selling hardware; they are selling uptime and precision. Their recent trade show exhibitions and catalog releases demonstrate a commitment to continuous improvement and adaptation to new machining requirements, such as additive manufacturing compatibility seen in recent presentations by companies like LEHMANN.
Magnetic Clamping Technology Market
Strategic Recommendations for 2026 Decision Makers
As we navigate 2026, the integration of zero-point clamping systems should be viewed through the lens of total cost of ownership rather than just initial procurement cost. The reduction in setup time allows for quicker changeovers, which is critical for the demand for customization in automotive and medical sectors. In aerospace and defense, the emphasis on error reduction and material durability aligns with the stringent quality standards required.
For manufacturers, the first step is evaluating current bottlenecks. If setup times are consuming significant machine availability, the ROI on zero-point systems is likely clear. For investors and analysts, the growth trajectory suggests that companies enabling high-mix, low-volume production will continue to see favorable conditions. The technology supports the macro trend of reducing labor intensity while increasing output quality. Supply chain managers should also note the importance of material specifications, such as the hardness of steel components, which impacts longevity and maintenance schedules.
The data presented in this overview serves as a foundation. The specific percentages of regional revenue splits, the exact valuation of each actuation segment, and the detailed share percentages of the top five competitors require a deeper dive into the full analysis. These granular details are necessary for precise budgeting and strategic targeting. For example, while the broad strokes show strong growth, the specific disparity between pneumatic and hydraulic adoption rates in specific regions can dictate sourcing strategies.
Conclusion: Accessing the Full Intelligence
The Worldwide Zero-point Clamping System Market is evolving from a niche component supply chain to a critical enabler of modern manufacturing efficiency. The projected growth through 2032 reflects a structural shift in how workpieces are held, positioned, and changed. The competitive landscape is dynamic, with established German and Swiss engineering prowess coexisting with innovative solutions from Japan and emerging players in China. Recent product launches and trade show demonstrations confirm that innovation is accelerating, particularly in areas related to automation integration and thermal management.
While this article provides a strategic overview of market dynamics, segmentation drivers, and competitive profiles, it is designed as a preview of the comprehensive intelligence available in our full study. The aggregate figures and qualitative trends serve to establish context, but the detailed breakdown of market sizes, regional revenue splits, and compound growth rates for each sub-segment holds the specific data required for immediate tactical execution. To access the complete dataset, including the precise market valuation for each region and application, and to leverage the full competitive benchmarking, we invite you to explore the full Worldwide Zero-point Clamping System Market report. This resource is designed to equip stakeholders with the granular intelligence necessary to secure a competitive advantage in the precision engineering sector.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-point Clamping System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pregnant Mosquito Repellent Water Market Hits $275M in 2025, 7.5% CAGR to $456M by 2032
By PW Consulting, 2026-09-17
Strategic Imperatives in the Global Mosquito Repellent Water Market: Navigating Pregnancy Safety Standards Through 2032
The intersection of maternal health security and vector-borne disease prevention has created one of the most nuanced and high-stakes segments in the personal care and consumer goods landscape. Our latest comprehensive analysis, the Worldwide Mosquito Repellent Water For Pregnant Women Market report, dissects a sector undergoing rapid structural transformation. As regulatory frameworks tighten, consumer preferences pivot toward dermatologically compatible formulations, and global climate patterns expand the geographic footprint of disease-carrying mosquitoes, industry leaders must recalibrate their strategies. This intelligence briefing extracts the strategic architecture of the full study, offering decision-makers a clear view of the forces shaping the 2026–2032 horizon while preserving the granular, actionable intelligence required for precise market entry, portfolio optimization, and competitive positioning.
Macro Trajectory: A Sustained Expansion Cycle Anchored in Safety-Driven Demand
The global market for mosquito repellent water formulated specifically for pregnant women has demonstrated remarkable resilience and consistent upward momentum. Tracking historical performance from 2020 through 2025, the sector has evolved from a baseline of approximately 190.5 million USD to a mature valuation exceeding 275.0 million USD in 2025. This trajectory reflects more than cyclical growth; it signals a fundamental shift in consumer behavior, where expectant mothers and healthcare providers actively seek EPA-registered, dermatologically validated protection that balances efficacy with fetal safety.
Looking forward, our forecasting models project a compound annual growth rate of 7.5% across the 2026–2032 evaluation window. The market is positioned to surpass 303.56 million USD in 2026, accelerating steadily through the decade and approaching 456.24 million USD by 2032. This growth is not merely a function of population dynamics; it is driven by an expanding awareness of vector-borne threats, heightened recommendations from maternal health authorities, and a surge in product innovation that aligns repellent formulations with the physiological sensitivities of pregnancy.
For strategic planners, the implications are clear. The 7.5% CAGR represents a sustained expansion cycle that rewards early-mover positioning, robust distribution partnerships, and transparent safety communication. Companies that treat this segment as a peripheral niche will find themselves outpaced by competitors who recognize its structural growth drivers and invest accordingly in R&D, regulatory compliance, and targeted market penetration.
Regulatory Consensus and Formulation Innovation: Redefining the Product Landscape
The competitive playing field in this sector is heavily influenced by a convergence of public health guidance and formulation science. As of the 2025–2026 period, major health authorities including the CDC and ACOG have reinforced their position that EPA-registered repellents containing active ingredients such as DEET at concentrations up to 30%, picaridin, IR3535, oil of lemon eucalyptus/PMD, or 2-undecanone are considered safe and effective for pregnant women when used according to label directions. This regulatory clarity has done two things: it has legitimized synthetic actives as the preferred standard for disease prevention, and it has spurred formulators to address the aesthetic and dermatological concerns that historically limited adoption among expectant users.
Contemporary product development increasingly blends synthetic active ingredients with hydrating and soothing agents like sodium hyaluronic acid, creating water-based formulations that minimize skin irritation while maintaining prolonged protection windows. DEET concentrations between 25% and 30% continue to deliver six to twelve hours of efficacy, backed by extensive safety data demonstrating no increased risk of adverse fetal outcomes when applied as directed. Simultaneously, plant-based variants maintain a substantial share of consumer interest, particularly in regions where clean-label preferences intersect with traditional wellness paradigms.
Our research maps these formulation trends against regional regulatory environments, consumer risk tolerance, and supply chain constraints. The resulting intelligence reveals clear pathways for product differentiation, whether through advanced delivery mechanisms, concentration optimization, or hybrid ingredient architectures that satisfy both efficacy mandates and maternal comfort expectations.
Mosquito Repellants Market
Competitive Dynamics: Leaders, Regional Contenders, and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively capturing approximately 32.4% of global revenue and the top five holding 48.6%. This distribution suggests ample room for specialized entrants and regional specialists to carve out defensible positions through targeted messaging, localized distribution, and formulation differentiation. Several core companies define the current competitive architecture.
PARA'KITO has established a strong presence by offering spray and roll-on formats designed for the entire family, with explicit attention to the risk-benefit calculus required for pregnant users. Their approach emphasizes user-friendly application and transparent safety framing, which resonates with healthcare-endorsed consumption patterns. In the United States, Sawyer Products has positioned its picaridin-based and premium DEET formulations as clinically trusted options, explicitly highlighting their safety profiles for expectant mothers. This clinical trust positioning has become a powerful differentiator in a market where credibility directly influences purchase decisions.
SC Johnson, through its OFF! brand, continues to leverage the widespread recognition of its Deep Woods line and EPA-registered DEET variants. By maintaining concentration ranges that align with recommended safety thresholds, the brand balances mass-market accessibility with regulatory compliance. Repel, operating under Spectrum Brands, similarly reinforces its 100 DEET offering within pregnancy safety guidance frameworks, appealing to consumers who prioritize maximum efficacy against disease-carrying mosquitoes. Meanwhile, MURO, a South Korean manufacturer, has introduced bugs zero spray formulations that combine icaridin with hydrating sodium hyaluronic acid, explicitly marketing the product as suitable for pregnant women and infants over six months. This hybrid approach illustrates how Asian manufacturers are leveraging ingredient synergy and sensitive-skin positioning to compete in a global arena.
Strategic analysis within the report goes beyond corporate profiles. It examines distribution leverage, regulatory navigation capabilities, safety communication strategies, and regional adaptation tactics. Companies that invest in clear, evidence-based messaging and align their product architecture with maternal health guidelines are better positioned to capture share as the market matures.
Distribution Channels and Consumer Behavior: Rewiring the Path to Purchase
Where expectant mothers and healthcare-recommended consumers acquire mosquito repellent water has undergone significant recalibration. Pharmacies and drugstores remain a dominant channel, leveraging their trusted health-adjacent environment and the ability to provide pharmacist guidance on safe usage during pregnancy. Online retail has expanded rapidly, driven by convenience, subscription models, and the growing reliance on digital health information sources. Supermarkets and specialty stores continue to serve as accessible touchpoints, particularly in regions where immediate availability and household purchasing patterns favor mass retail formats.
Worldwide Mosquito Repellent Water For Pregnant Women Market
Consumer habits in this segment are increasingly shaped by a preference for EPA-registered products over unregistered natural alternatives like citronella, which may lack proven efficacy against disease vectors. Pregnant women are advised to prioritize scientifically validated formulations, and this guidance directly influences channel selection, brand loyalty, and repeat purchase behavior. As digital health content proliferates, retailers and brands that provide transparent ingredient disclosures, clear application instructions, and authoritative safety references will capture higher conversion rates and stronger customer retention.
Our study maps channel performance, regional access dynamics, and the interplay between digital discovery and offline purchase. Understanding where safety-conscious consumers complete their transactions, how they evaluate product credibility, and which retail environments foster trust is critical for optimizing go-to-market strategies and inventory placement.
Regional Architecture: High-Growth Corridors and Strategic Market Entry
The global market reflects pronounced regional variation in maturity, consumer awareness, and regulatory enforcement. Asia Pacific represents the largest revenue concentration, reflecting dense population centers, growing maternal health awareness, and expanding retail infrastructure. North America follows as a highly regulated, trust-driven market where clinical endorsements and EPA compliance heavily influence purchase decisions. Europe maintains a stable demand base shaped by stringent cosmetic and biocidal regulations, with consumers increasingly favoring dermatologically tested, low-irritation formulations. Latin America and the Middle East and Africa, while smaller in absolute terms, represent emerging corridors where vector-borne disease exposure, rising urbanization, and expanding distribution networks are accelerating adoption.
Rather than treating geography as a static variable, our analysis examines how regional regulatory climates, healthcare recommendation networks, retail maturity, and climate-driven mosquito seasonality interact to shape localized demand. This regional lens is essential for companies evaluating expansion pathways, localization requirements, and partnership models, whether they are scaling existing formulations or introducing new active ingredient platforms.
Strategic Takeaways for 2026 Decision-Making
As corporate leaders prepare for the 2026 planning cycle, the Worldwide Mosquito Repellent Water For Pregnant Women Market research delivers a structured foundation for evidence-based strategy. The report synthesizes historical performance, forward-looking forecasts, competitive intelligence, regulatory context, formulation trends, and channel dynamics into a unified decision-support framework. Key strategic imperatives emerging from this analysis include:
- Align product development with EPA-registered safety standards and maternal dermatological compatibility to capture trust-driven demand.
- Leverage the 7.5% projected CAGR by investing in distribution partnerships, digital commerce optimization, and clear safety communication.
- Monitor formulation innovation that combines proven synthetic actives with skin-soothing agents to differentiate in a moderately concentrated market.
- Assess regional entry opportunities by mapping regulatory environments, retail maturity, and healthcare recommendation ecosystems rather than relying on generic volume projections.
- Anticipate shifts in consumer preference toward scientifically validated protection over unregistered natural alternatives, adjusting portfolio messaging and channel focus accordingly.
This intelligence is designed for teams that require more than headline figures. It provides the operational granularity needed to evaluate segment-specific growth vectors, benchmark competitive positioning, and calibrate investment timing. The full study delivers detailed segmentation analysis, regional breakdowns, distribution channel performance metrics, competitive benchmarking, and actionable scenario planning tables that enable precise resource allocation.
Accessing the Complete Intelligence Ecosystem
For organizations seeking to convert market dynamics into executable strategy, the complete report offers a comprehensive toolkit. Beyond the macro trajectory and competitive landscape summarized here, the full publication contains deep-dive segmentation data, ingredient-level demand mapping, regional market sizing, distribution channel evolution, regulatory timeline analysis, and company-specific strategic assessments. Decision-makers in product development, market expansion, procurement, and executive planning will find targeted frameworks to reduce uncertainty, prioritize initiatives, and align cross-functional teams around a shared market view.
The 2026–2032 outlook favors organizations that combine scientific credibility, formulation agility, and channel precision. Accessing the complete research package equips leadership with the granular intelligence necessary to navigate this evolving landscape, identify high-probability growth corridors, and execute with confidence in a market where safety, efficacy, and consumer trust converge.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Negative Ion Cyclotron Market Hits $425.5M in 2025, 6.15% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Intelligence in the Global Negative Ion Cyclotron Market: Navigating the 2026–2032 Expansion
The worldwide negative ion cyclotron market stands at a critical inflection point. As diagnostic imaging demand strengthens and therapeutic radioisotope production accelerates, the equipment landscape is evolving from a niche manufacturing segment into a strategically vital healthcare infrastructure market. This article introduces PW Consulting’s latest Worldwide Negative Ion Cyclotron Market research, a comprehensive analysis designed to equip executives, procurement leaders, and investment committees with the decision-grade intelligence required for 2026 planning and beyond.
Built on a rigorous quantitative foundation and filtered through operational, regulatory, and competitive lenses, this study does more than project top-line figures. It maps the structural shifts reshaping procurement cycles, technology adoption, supply chain dependencies, and competitive positioning. The following overview outlines the analytical architecture of the report, demonstrates how the data translates into strategic action, and clarifies why this research has become an essential reference for organizations operating at the intersection of medical technology, radiopharmaceutical manufacturing, and capital equipment investment.
Market Trajectory and Structural Growth Dynamics
The historical record from 2020 through 2025 reflects a market that has consistently absorbed institutional demand, capacity upgrades, and geographic expansion. Revenue has climbed steadily from 312.45 million USD in 2020 to 425.5 million USD in 2025, demonstrating resilience across product cycles and regional procurement patterns. Looking forward, the forecast period from 2026 to 2032 projects sustained momentum, with the market expected to reach 454.05 million USD in 2026 and advance to 646.16 million USD by 2032. This trajectory corresponds to a compound annual growth rate of 6.15 percent, a rate that signals more than incremental expansion; it reflects a structural realignment in how healthcare systems and research organizations approach isotope production, beamline infrastructure, and on-site radiopharmacy capabilities.
Worldwide Negative Ion Cyclotron Market
Several underlying forces are reinforcing this trajectory. The expansion of positron emission tomography networks continues to drive demand for reliable, centrally located or decentralized isotope production. At the same time, the growing clinical adoption of theranostic approaches is pushing buyers to evaluate equipment flexibility, beam performance, and multi-isotope compatibility with greater scrutiny. Organizations that understand not just the size of the opportunity but the timing, sequencing, and risk profile of adoption will be best positioned to allocate capital efficiently and secure competitive advantage in procurement, installation planning, and service partnerships.
This research does not simply chart a growth curve. It decomposes the drivers behind the curve, evaluates the durability of demand signals, and identifies where market participants are likely to encounter capacity constraints, validation delays, or competitive recompetition. The result is a planning framework that supports scenario-based budgeting, site readiness assessment, and long-range capacity strategy.
Energy-Level Segmentation and the Strategic Meaning of Beam Architecture
Negative ion cyclotrons are not interchangeable assets. The market divides into three energy-level categories, each serving distinct operational requirements and buyer priorities. Low energy systems below 20 MeV account for the largest revenue share among the three categories, reflecting their broad applicability in routine diagnostic radioisotope production and their alignment with the installation requirements of many hospital-based and regional radiopharmacy sites. Medium energy systems in the 20 to 70 MeV range represent a substantial and strategically important segment, typically selected where facilities require broader isotope portfolios, higher throughput, or preparation for advanced therapeutic workflows. High energy systems above 70 MeV form the most specialized tier, with revenue concentration in applications that demand the highest acceleration performance for theranostic isotope production and complex research programs.
From a strategic standpoint, these energy tiers are not merely technical specifications; they are proxy indicators for buyer maturity, facility readiness, regulatory exposure, and commercialization ambition. Lower-energy deployments often align with faster installation timelines and narrower operational scopes, while higher-energy systems typically entail more demanding infrastructure, stricter export and licensing scrutiny, and longer validation pathways. Decision-makers evaluating capital allocation, site selection, or technology roadmaps must therefore treat energy level as a strategic variable, not just a procurement parameter.
The report examines how these energy categories interact with buyer behavior, installation economics, and long-term service requirements. It explores where demand is most responsive to capacity expansion, where competitors are likely to defend share through product specialization, and how infrastructure requirements shape total cost of ownership. By isolating these dynamics, the analysis enables organizations to align product strategy with realistic adoption curves rather than aspirational forecasts.
Regional Demand Patterns and Deployment Geography
Demand for negative ion cyclotrons is distributed across geographies with distinct maturity profiles, procurement rhythms, and infrastructure prerequisites. North America remains a leading market in absolute terms, reflecting established diagnostic imaging networks, substantial research footprints, and a relatively mature ecosystem for radioisotope supply and clinical adoption. Europe represents a similarly significant demand base, characterized by strong institutional procurement frameworks, rigorous device and safety standards, and an active pipeline of facility upgrades and new installations. Asia Pacific contributes a substantial share of market activity, supported by expanding imaging capacity, growing regional radiopharmaceutical capabilities, and increasing investment in medical infrastructure. Latin America and the Middle East and Africa together form a smaller but strategically relevant demand footprint, often shaped by selective flagship installations, phased capacity building, and partnerships that bridge technology access with local operational readiness.
Regional analysis in this study goes beyond share comparisons. It evaluates procurement timing, the influence of local regulatory and safety frameworks, the role of distribution and service networks, and the practical implications of deploying complex beamline equipment in environments with varying levels of technical support maturity. For organizations considering market entry, partnership development, or site-specific installation strategy, these regional dynamics determine not only where demand exists, but where it can be converted into executable projects with acceptable risk and timeline certainty.
The report also addresses how export controls and dual-use considerations shape the flow of high-energy systems across borders. In certain cases, systems above specific energy thresholds are subject to licensing requirements that affect sales cycles, dealer networks, and cross-border project execution. This is a critical variable for any organization planning international expansion or multi-country procurement programs, and it is analyzed here with the operational specificity required for realistic planning.
Application Mix and the Shifting Value of Isotope Production
Negative ion cyclotron revenue is anchored by a clear hierarchy of applications. Diagnostic radioisotope production remains the dominant demand driver, reflecting the continued centrality of PET and related imaging workflows in clinical practice and the corresponding need for dependable, on-site or regionally distributed isotope supply. Radiation and proton therapy applications represent a significant secondary tier, tied to facilities where beam infrastructure supports therapeutic programs and where equipment selection must accommodate both production and clinical delivery requirements. Industrial and scientific research constitutes a smaller but meaningful application pool, often linked to specialized isotope needs, materials analysis, and institutional research programs that value beam stability and multi-purpose capability.
Application mix is strategically important because it influences equipment configuration, validation requirements, service intensity, and long-term revenue durability. A facility optimized for diagnostic isotope output may prioritize different performance characteristics than one preparing for therapeutic workflows or research diversification. Buyers increasingly assess not only immediate production needs but also the optionality of the installed base, especially as radiopharmaceutical pipelines evolve and clinical programs expand.
This research evaluates how application demand interacts with product design, procurement decision-making, and competitive positioning. It identifies where application-driven purchasing is most concentrated, where expansion is likely to be incremental versus step-change, and how manufacturers and operators can align product portfolios with the most resilient demand pools. The objective is to help organizations move from generic market sizing to application-aware investment strategy.
Competitive Landscape: Differentiated Positioning Among Leading Suppliers
The market is shaped by a concentrated group of established manufacturers, each pursuing distinct product strategies, geographic reach, and application focus. Ion Beam Applications SA (IBA), headquartered in Louvain-la-Neuve, Belgium, provides the Cyclone series of negative ion cyclotrons, including models such as Cyclone 18+, Cyclone 30, Cyclone KIUBE, and Cyclone 70. These systems support H- ion acceleration up to 70 MeV and are positioned across PET and therapeutic radioisotope production. Recent activity underscores IBA’s continued footprint in both regional deployment and higher-energy theranostic programs, including the delivery of a Cyclone KIUBE system to a hospital facility in Australia and a major contract for a Cyclone 70 high-energy negative ion cyclotron for theranostic isotope production in the United States.
Advanced Cyclotron Systems Inc. (ACSI), based in Richmond, British Columbia, Canada, manufactures the TR series, including TR-19, TR-24, and TR-30, which accelerate H- ions for multi-isotope production in PET imaging. ACSI’s recent installation activity, including the delivery of a TR-24 system to a new PET facility in Poland, highlights the ongoing relevance of mid-tier systems in expanding imaging networks and regional radiopharmacy development.
GE Healthcare, headquartered in Chicago, Illinois, offers the PETtrace 800 and 880 negative ion cyclotrons designed for on-site production of PET isotopes through H- acceleration. Its presence reflects the intersection of molecular imaging strategy and isotope supply reliability, particularly for health systems seeking integrated diagnostic workflows.
Sumitomo Heavy Industries, Ltd., based in Shinagawa, Tokyo, supplies HM-18 and HM-30 negative ion cyclotrons for clinical PET radionuclide production. Its product focus aligns with clinical isotope manufacturing requirements and supports buyers seeking established hardware platforms with defined operating envelopes.
TeamBest Global Companies, Inc., located in Sugar Land, Texas, produces Best Cyclotron models such as the 18p and 14p, using negative hydrogen ion acceleration for radioisotope manufacturing. This offering reinforces the competitive breadth of the market and the continued relevance of specialized configurations tailored to specific production goals.
The research does not treat these players as a static roster. It evaluates how product differentiation, service capability, installation track record, and regulatory readiness influence competitive outcomes. It also examines concentration dynamics, including the extent to which leading firms command disproportionate share and how that concentration affects pricing, vendor selection, and the bargaining position of buyers. Understanding this landscape is essential for organizations planning procurement, partnership, or market-entry strategies in a market where trust, compliance, and long-term support often matter as much as headline specifications.
Regulatory, Infrastructure, and Operational Constraints as Strategic Variables
Capital equipment in this sector does not succeed on performance claims alone. It must operate within a framework of safety standards, device classification requirements, infrastructure limitations, and export controls that collectively shape project feasibility. Medical cyclotrons must comply with IAEA Safety Standards Series No. SSG-49 for radiation protection and facility design, creating a baseline expectation for site planning, shielding, and operational governance. In parallel, cyclotrons used for isotope production are classified as Class IIb medical devices under the EU Medical Device Regulation 2017/745, which requires ISO 13485 certification and introduces quality-management discipline into product development, manufacturing, and post-market support.
On the technical side, negative H- ion sources in commercial cyclotrons are generally limited to beam currents of 1 to 5 mA because of space charge effects and extraction challenges. This constraint matters because it influences throughput expectations, isotope production planning, and the practical boundaries of system performance. In addition, cyclotron facilities require RF power systems in the range of 100 to 200 kW and ultra-high vacuum conditions below 10^-8 mbar to maintain stable negative ion acceleration. These requirements have direct implications for site design, utilities, maintenance planning, and total cost of ownership.
The study integrates these constraints into market analysis rather than treating them as background notes. It evaluates how regulatory compliance timelines affect procurement cycles, how infrastructure readiness influences installation sequencing, and how technical limits shape competitive differentiation. For executives, this means the report provides not only market size and growth estimates, but also an operational reality check on what it takes to convert demand into installed capacity.
Report Scope: What Decision-Makers Will Find Inside
This research is structured to support practical decision-making across strategy, procurement, investment, and operational planning. It combines macro-level market sizing with segmentation analysis, competitive profiling, and contextual assessment of the regulatory and infrastructure environment that governs deployment. Rather than functioning as a static data table, the report is designed as an actionable intelligence package that helps organizations answer questions such as:
Medical Cyclotron Market
- Where is demand most likely to convert into installed capacity over the forecast horizon, and under what conditions
- How do energy-level requirements shape buyer selection, site preparation, and service expectations
- Which application pools provide the most durable revenue opportunities for manufacturers and the most strategic value for operators
- How do regional procurement patterns differ in timing, risk, and support requirements
- What competitive advantages are emerging from product specialization, installation track record, and compliance readiness
- How do export controls, safety standards, and device regulation influence market access and project execution
The report also provides context for evaluating total cost of ownership, including the implications of RF power requirements, vacuum system performance, beam current limitations, and post-installation support. By linking market structure to operational reality, the analysis enables more disciplined capital planning and more credible go-to-market or procurement strategies.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle is not simply another forecast update. It is the point at which organizations must reconcile rising demand signals with practical limits on installation capacity, regulatory readiness, service scalability, and competitive recompetition. In that environment, decision-makers need intelligence that connects market growth to implementation risk, product differentiation to buyer priorities, and regional opportunity to operational feasibility.
PW Consulting’s Worldwide Negative Ion Cyclotron Market research is built for that purpose. It provides the analytical depth required to support scenario planning, capacity strategy, vendor evaluation, and investment prioritization. It also intentionally preserves the granularity of segmentation detail, regional deployment logic, and competitive benchmarking within the full study, so that organizations can access the specific figures and comparative frameworks needed for internal modeling and executive review.
The strategic message is straightforward: the market is expanding at a measured but meaningful pace, the demand core is anchored in diagnostic isotope production, competitive differentiation is increasingly tied to compliance, installation capability, and service reliability, and the practical constraints of beam performance and infrastructure are shaping what can realistically be deployed and when. Organizations that understand these dynamics early will be better positioned to secure supply partnerships, plan site readiness, and align product or procurement strategy with durable demand rather than short-term momentum.
Next Steps for Stakeholders
For executives, procurement leaders, investors, and technology strategists evaluating the negative ion cyclotron sector, this research offers a structured pathway from high-level market context to decision-ready insight. The complete study delivers the detailed segmentation data, competitive comparisons, regional deployment analysis, and operational constraint mapping required to translate strategic intent into executable plans.
Readers seeking the full range of figures, segmentation breakdowns, and company-specific strategic assessments are encouraged to access the complete report through PW Consulting’s official market research portal. There, the full intelligence architecture is available to support internal validation, procurement benchmarking, and long-range planning with the precision required for high-stakes capital and capacity decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Livestock Diagnostics Kits Market Hits $1.85B in 2025, 8.0% CAGR Predicted
By PW Consulting, 2026-09-17
Strategic Intelligence for 2026: Navigating the Global Livestock Diagnostics Kits Market
The global livestock diagnostics kits market is undergoing a period of structural transformation, driven by tightening biosecurity mandates, accelerating adoption of point-of-care testing, and a shifting competitive landscape where diagnostic precision directly influences trade eligibility and herd health outcomes. For executives, investors, and procurement leaders operating in animal health, agricultural inputs, or veterinary services, the ability to read this market with clarity in 2026 is no longer optional. It is a strategic prerequisite.
Our newly released Worldwide Livestock Diagnostics Kits Market study is designed to convert that complexity into actionable intelligence. Built on a rigorous historical baseline spanning 2020 through 2025 and extended through a forward-looking forecast window to 2032, the research equips decision-makers with a credible framework for capacity planning, portfolio prioritization, partnership evaluation, and scenario modeling. What follows is a strategic preview of the market logic, competitive forces, and regulatory currents shaping the sector, along with what the full study delivers beyond the surface narrative.
A Market on a Deliberate Growth Trajectory
The sector has demonstrated sustained expansion over the past half-decade, supported by rising disease surveillance intensity, increased investment in herd-level prevention, and broader consolidation of diagnostic workflows across commercial farms and veterinary networks. Historical revenue progression from 2020 to 2025 reflects a market that has consistently scaled despite supply chain volatility, shifting input costs, and periodic regulatory recalibrations. That momentum carries into the forecast period, where the study projects a compound annual growth rate of 8.0 percent, underscoring a durable expansion path rather than a short-lived spike.
This trajectory is not merely a function of volume. It reflects a deeper structural shift: diagnostics are moving from periodic laboratory confirmation toward continuous, on-farm decision support. As producers seek faster containment of infectious threats, reduce unnecessary treatments, and maintain compliance with trade-related health documentation, demand is broadening across technologies and use cases. The forecast window to 2032 allows leadership teams to evaluate not only where the market is heading, but how growth might compound across different operational assumptions, adoption curves, and regional readiness levels.
Importantly, the study frames this growth as contingent on real-world dynamics rather than abstract projections. Input availability, validation standards, cold-chain logistics, and the pace at which producers integrate diagnostic data into daily management all influence how the projected path materializes. That is why the analysis is built to connect top-line direction with the operational factors that determine execution risk.
Why 2026 Is a Decision Point
For organizations making capital, R&D, or commercial allocation decisions in 2026, the strategic value of this research lies in timing. Several forces are converging to make this year particularly consequential. First, international trade linkages are increasing the cost of diagnostic ambiguity. Health certification, pathogen detection, and standardized testing protocols are increasingly tied to market access, which elevates the strategic importance of validated kits and reliable service networks. Second, the diagnostic toolkit itself is becoming more diversified, with faster turnaround formats and multiplex capabilities reshaping what producers expect from a testing program. Third, competitive intensity is rising as incumbents expand their platforms and new entrants target specific animal segments or regional niches.
In this environment, strategy cannot rely on static assumptions. A credible planning process needs to account for where the market is absorbing capacity, which diagnostic formats are gaining or losing relative relevance, how regulation may alter the competitive playing field, and what indicators signal a shift in adoption speed. The study is structured to answer those questions with a research architecture that moves from market-wide signals to segment-level logic, enabling users to test assumptions rather than simply consume a single number.
That is the core of the "trailer" value proposition: the published narrative provides enough analytical depth to establish credibility and reveal the framework, while reserving the full segment detail, scenario sensitivities, and commercial mapping for the complete study. In other words, the research is designed to demonstrate rigor while motivating the next step: accessing the complete intelligence package for decision-grade granularity.
Competitive Landscape: Scale, Specialization, and Platform Expansion
The competitive field is defined by a blend of broad-scale animal health companies, specialized diagnostic manufacturers, and technology providers extending their platforms into livestock applications. Market concentration reflects the presence of established players with strong distribution reach, regulatory familiarity, and increasingly integrated diagnostic ecosystems. At the same time, the breadth of participants suggests a market where differentiation often comes from format, speed, animal-specific coverage, and service model rather than volume alone.
IDEXX Laboratories, Inc. continues to operate as a central reference point in the space, offering comprehensive livestock diagnostic solutions that span ELISA, PCR, and rapid test formats for ruminants, swine, and poultry. Its positioning around both on-farm and laboratory-based kits illustrates how leading providers are extending diagnostic utility across points of care. Zoetis Inc. reinforces a similar breadth through immunodiagnostic kits and point-of-care platforms, with product activity in 2025 highlighting continued investment in cartridge-based, AI-enhanced hematology analysis for veterinary and livestock settings. These moves matter strategically because point-of-care expansion changes the economics of testing: faster results can compress decision cycles and broaden the occasions where diagnostics influence day-to-day management.
Thermo Fisher Scientific Inc. contributes a different form of leverage, with molecular and serological diagnostic kits that support pathogen surveillance and USDA-licensed solutions for farm animal disease monitoring. Its presence underscores the strategic importance of laboratory-grade rigor in a market that increasingly values both accuracy and traceability. Neogen Corporation maintains a focus on rapid and immunoassay-based solutions, reflecting a commercial logic centered on usability and field-ready deployment. bioMérieux S.A. and Virbac add European and global coverage in veterinary diagnostic kits, while Bio-Rad Laboratories, Inc. supplies immunoassay and molecular tools that support a range of veterinary and livestock applications.
Livestock Genetic Engineering Vaccines Market
The field also includes specialized contributors with strong regional or technology-focused positions. Indical Bioscience GmbH, part of the Vimian Group, specializes in molecular and immunodiagnostic solutions including ELISA and PCR kits. Agrolabo S.p.A. manufactures high-technology diagnostic kits for infectious diseases in livestock and companion animals. Innovative Diagnostics SAS, known as IDvet, develops ELISA and PCR kits aimed at monitoring infectious and zoonotic diseases. Eurofins Technologies provides diagnostic kits and services for animal health, GD Animal Health focuses on testing services and kits for livestock health monitoring, and Randox Laboratories Ltd. supplies veterinary diagnostic reagents and kits. Heska Corporation extends point-of-care diagnostic platforms with relevance to livestock settings, while FUJIFILM Holdings Corporation brings veterinary diagnostic solutions spanning imaging and test kits for animal health.
What matters for strategic planning is not simply who occupies the field, but how these players are shaping expectations around speed, standardization, and service. The recent product activity in 2025, including point-of-care analyzer introductions and diagnostic panel expansions, signals that the market is moving toward higher-resolution testing and broader integration across veterinary workflows. These developments do not just change product menus; they alter the basis of competition by elevating the importance of workflow compatibility, turnaround time, and credible validation.
Worldwide Livestock Diagnostics Kits Market
Regulatory and Operational Dynamics That Redefine Value
No assessment of this market is complete without addressing the regulatory and operational environment that governs product acceptability and commercial execution. Diagnostic kits are not evaluated only on performance claims; they are evaluated within frameworks that influence trade, surveillance, and legal compliance. The World Organisation for Animal Health maintains a Register of diagnostic kits with standardized validation procedures for tests detecting infectious animal diseases. This kind of harmonization supports transparency and helps Members align on test credibility, which in turn affects cross-border confidence in livestock shipments and disease reporting.
In parallel, national frameworks continue to refine expectations around validation, production outlines, and expiration dating. Guidance from USDA APHIS on immunodiagnostic test kits reflects the growing insistence that antibody- or antigen-detecting kits meet defined production and performance standards. For exporters and domestic producers alike, diagnostic compliance is increasingly linked to the ability to demonstrate test integrity under recognized protocols. Veterinary diagnostic test kits intended for livestock export must also align with importing country requirements, which are often tied to WOAH-aligned standards. These requirements do not merely constrain the market; they shape it by rewarding participants who can prove consistency, documentation quality, and regulatory readiness.
Operational reality is equally important. The industry is seeing diagnostic kits increasingly incorporate multiplex PCR panels and lateral flow assays, with reported accuracy improvements and faster on-farm results becoming meaningful differentiators. When a diagnostic format can deliver results quickly under field conditions, it changes adoption economics: fewer delays, quicker containment decisions, and a stronger case for integrating testing into routine production workflows. At the same time, some products remain subject to use restrictions that limit distribution to approved laboratories, illustrating that regulatory design can segment the market by purpose, setting, and risk profile.
For strategists, the implication is clear: in 2026 and beyond, value is created not only by launching a kit, but by building a defensible position around validation, compliance, speed, and compatibility with the decision environments in which producers and veterinarians actually operate.
What the Full Study Delivers
This preview is intentionally framed to show the analytical shape of the research while preserving the deeper segment architecture for the complete study. The full Worldwide Livestock Diagnostics Kits Market report extends well beyond the macro narrative introduced here. It connects historical performance with a detailed forecast structure, enabling users to examine growth logic across a multi-year window and evaluate how different adoption, regulatory, and competitive assumptions alter the outlook.
The study is built for practical use. It maps the market across technology categories, animal-type segments, and regional frameworks, allowing commercial leaders to identify where demand concentration is forming and where differentiation opportunities may emerge. It examines the competitive field with enough granularity to support partnership screening, benchmark positioning, and threat assessment. It also integrates the regulatory and operational forces that influence product acceptability, trade readiness, and deployment feasibility, so that strategy is grounded in real-world execution conditions rather than idealized demand.
Crucially, the full report is designed to help organizations answer forward-looking questions that a top-line summary cannot. Which diagnostic format dynamics are most likely to influence procurement choices over the forecast period? Where do validation and standardization requirements create barriers or advantages? How do regional preparedness and trade-linked testing expectations shape market access? What indicators should leadership teams monitor to anticipate shifts in adoption speed or competitive pressure? These are the kinds of questions the complete study is built to address with structured intelligence rather than speculation.
Entering 2026 With a Clearer Strategic Frame
The livestock diagnostics kits market is expanding within a context that rewards precision, speed, and regulatory credibility. For organizations making decisions in 2026, the strategic task is not simply to track growth, but to understand the underlying drivers that will determine which participants capture value as the market matures. The convergence of trade-linked compliance, point-of-care adoption, multiplex and rapid-format innovation, and a competitive field that spans global platforms and specialized specialists makes this a market where insight has direct commercial consequences.
This study provides the framework to navigate that landscape with discipline. It combines historical clarity, forecast orientation, competitive mapping, and regulatory context into a single decision-support architecture. The published overview establishes the logic and the rigor; the complete report delivers the segment-level detail, scenario sensitivity, and commercial intelligence needed to convert strategy into action. For leaders who need to plan with confidence in a fast-moving animal health environment, that distinction matters.
For detailed analysis of this topic, please visit the official page: Worldwide Livestock Diagnostics Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global MRI Compatible IV Infusion Pumps Market to Hit $828M by 2032, 8.6% CAGR
By PW Consulting, 2026-09-17
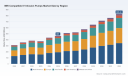
Navigating the Magnetic Frontier: Strategic Imperatives in the Worldwide MRI Compatible IV Infusion Pumps Market
The intersection of high-resolution diagnostic imaging and critical care infusion therapy represents one of the most technically demanding and commercially significant niches in modern medical device markets. As healthcare systems worldwide consolidate imaging capabilities into centralized suites and hybrid operating environments, the requirement for infusion pumps that can operate safely within the intense magnetic fields of Magnetic Resonance Imaging scanners has evolved from a specialized want to a clinical necessity. Our latest Worldwide MRI Compatible IV Infusion Pumps Market research study provides a comprehensive, data-backed examination of this evolving ecosystem, offering executives, procurement directors, and R&D strategists a clear roadmap for navigating an 8.6% compound annual growth trajectory through the 2032 forecast horizon.
This market intelligence report is engineered not merely as a statistical archive, but as an operational decision-support framework. Drawing on historical performance from 2020 through 2025 and extending our analytical models across 2026 to 2032, the study maps revenue expansion, competitive positioning, regulatory friction points, and procurement mechanics. For enterprise leaders evaluating capital allocation, supply chain resilience, and clinical workflow integration, the research delivers the contextual precision required to move from reactive participation to proactive market shaping. Below, we outline the strategic architecture of the study, illuminate the core dynamics driving adoption, and demonstrate why timing and technical differentiation will define market leadership in the coming cycle.
Market Architecture and Growth Vectors
The global market for MRI compatible IV infusion pumps has demonstrated consistent structural expansion, with overall valuation scaling from approximately 312 million USD in the 2020 baseline through to a projected 828 million USD by the 2032 forecast terminus. The trajectory reflects a compound annual growth rate of 8.6 percent, a pace that outpaces general infusion pump market averages and underscores the accelerating convergence of advanced imaging volumes and complex infusion protocols. The 2025 base year valuation of 465 million USD establishes a mature but still expanding commercial landscape, driven by recurring replacement cycles, hospital infrastructure modernization, and the clinical imperative to maintain continuous medication delivery during prolonged MRI procedures.
Historical data reveals a resilient growth pattern, with performance holding steady despite broader macroeconomic volatility in healthcare capital equipment procurement. The 2023 dip to 376 million USD, followed by a robust rebound to 435 million USD in 2024, illustrates how procurement hesitation during economic recalibration quickly yields to renewed procurement urgency once clinical workflows recognize the operational risks of non-compatible infusion alternatives. Looking forward, the forecast period projects sustained expansion across all major revenue streams, with 2026 positioning at 512 million USD and the late-decade corridor accelerating toward the 700 to 800 million USD range. This growth is not merely volume-driven; it reflects structural upgrades in technology portfolios, regulatory pathway maturation, and institutional procurement frameworks that increasingly recognize the unique safety and performance requirements of magnetic environment operations.
Core Segmentation and Clinical Adoption Logic
The market is stratified across pump design architectures, clinical deployment environments, and geographic procurement clusters, each reflecting distinct workflow demands and capital planning rhythms. By pump architecture, the landscape splits between syringe-driven and volumetric delivery systems, with syringe-based configurations commanding a leading share of installed revenue. These systems are particularly favored in neuroimaging, contrast administration, and pediatric protocols where precise low-volume delivery and compact form factors are prioritized. Volumetric platforms, meanwhile, serve high-volume fluid administration, large-volume medication reservoirs, and extended-duration infusion workflows common in interventional radiology suites and hybrid procedural environments. Both segments benefit from continuous engineering refinement, yet their adoption curves diverge based on institutional procurement priorities, staff training familiarity, and the specific imaging modalities most frequently utilized within a given health system.
Clinically, hospital environments dominate deployment volume, anchoring the majority of procurement activity across acute care networks, integrated delivery systems, and academic medical centers. Diagnostic imaging centers constitute the second major adoption pillar, reflecting specialized outpatient workflows where MRI procedure throughput is high and infusion compatibility requirements are non-negotiable for safe contrast and sedation delivery. Ambulatory surgical centers, while representing a smaller volume footprint, are emerging as strategic growth nodes as facility consolidation and outpatient migration policies shift complex imaging-infusion protocols toward lower-acuity settings with stringent equipment standardization requirements. Procurement decisions across these settings increasingly balance upfront capital expenditure against total lifecycle cost, staff safety metrics, interoperability with existing medication management networks, and the regulatory liabilities associated with equipment failure or magnetic interference in high-stakes imaging environments.
Competitive Landscape and R&D Differentiation
The competitive architecture of this market is characterized by high concentration, with leading manufacturers accounting for a substantial portion of consolidated industry revenue. This concentration does not indicate market stagnation; rather, it reflects the rigorous engineering, regulatory validation, and clinical workflow integration barriers that protect established players while simultaneously raising the competitive bar for new entrants. The marketplace is populated by a mix of specialized innovators and broad-spectrum infusion therapy leaders, each pursuing distinct value propositions around magnetic shielding, non-magnetic motor technology, wireless remote control capability, drug library integration, and interoperability with hospital information systems.
IRadimed Corporation has institutionalized its leadership through a focused engineering philosophy that prioritizes non-magnetic construction for operation inside MRI environments up to 10,000 gauss. Its MRidium 3860+ platform, along with the newly cleared MRidium 3870 system, exemplifies the industry trajectory toward ultrasonic motor technology, touchscreen interfaces, and updated drug libraries that streamline workflow while preserving strict magnetic compatibility. B. Braun Melsungen AG approaches the market through the SpaceStation MRI system, a shielded configuration that enables up to four Space infusion pumps, including large-volume and syringe variants, to operate safely during MRI examinations across adult, pediatric, and neonatal patient populations. Baxter International Inc., Fresenius Kabi AG, and Becton, Dickinson and Company (BD) embed MRI-compatible considerations within broader infusion therapy portfolios, emphasizing hospital-scale deployment, reliability, and integration with existing medication management ecosystems. ICU Medical, Inc., including its Smiths Medical legacy portfolio, and Arcomed AG extend the competitive field with precision IV pump architectures and MRI-compatible options designed for diverse clinical environments. Moog Medical (Curlin) contributes ambulatory and multi-therapy infusion pump capabilities that support specialized settings where portability, durability, and protocol flexibility intersect.
Regulatory, Procurement, and Lifecycle Dynamics
The commercial viability of MRI compatible infusion pumps is tightly coupled to regulatory clearance pathways, procurement justification frameworks, and capital equipment lifecycle planning. Recent regulatory milestones underscore how clinical safety protocols, engineering validation, and classification pathways intersect to shape market entry velocity. In May 2025, IRadimed Corporation received FDA 510(k) clearance for the MRidium 3870 MRI Infusion Pump System, with the clearance specifying a Class II device classification for the delivery of IV fluids and medications in MRI environments. This regulatory milestone reflects the broader FDA expectation framework for infusion pump total product lifecycle management, which emphasizes additional pre-market clinical and human factors data for new or modified pump submissions. The clearance architecture not only validates device safety for magnetic environment use but also signals to health systems and procurement officers that the technology has cleared structured equivalence and performance benchmarks.
Worldwide MRI Compatible IV Infusion Pumps Market
Procurement mechanics represent an equally critical dynamic. Institutional buyers increasingly rely on sole source justification frameworks for highly specialized non-magnetic MRI compatible infusion pumps, recognizing that unique safety requirements in magnetic resonance environments constrain competitive bidding parameters. The U.S. Department of Veterans Affairs procurement process, for example, has formally acknowledged this dynamic, issuing a notice of intent for a sole source award for MRidium 3870 MRI IV pump units, accessories, software licenses, and training based on the device's status as a non-magnetic MRI compatible infusion pump. Such procurement approaches reduce competitive friction in highly technical categories while reinforcing the value proposition of devices engineered specifically for magnetic safety compliance.
Capital equipment lifecycle planning further shapes purchase timing and replacement forecasting. Institutional depreciation schedules and capital planning benchmarks frequently reference useful life standards for infusion pumps that directly influence procurement cadence, budgeting horizons, and technology refresh cycles. As installed bases age and clinical workflows demand more sophisticated interfaces, drug library capabilities, and interoperability features, replacement cycles accelerate and create recurring revenue opportunities for manufacturers that can demonstrate clear clinical workflow improvements and safety enhancements over legacy configurations. The interplay between aging equipment infrastructure, regulatory updates, and evolving clinical protocols creates a continuous refresh dynamic that sustains market momentum across the forecast period.
Why This Research Is a 2026 Decision-Making Asset
For executives and strategic planners, market intelligence must do more than summarize historical performance. It must translate data into trade-off analysis, competitive positioning guidance, procurement strategy recommendations, and technology investment roadmaps. This Worldwide MRI Compatible IV Infusion Pumps Market research study is structured to deliver precisely that operational utility. The report provides granular coverage of segment dynamics across pump architectures, clinical application settings, and geographic procurement clusters, mapping revenue distribution patterns and adoption drivers without forcing decision-makers to reassemble fragmented competitor intelligence. Instead, the study consolidates competitive profiles, recent regulatory and procurement developments, and structural market concentration metrics into a single strategic reference framework.
Elastomeric Infusion Pumps Market
Readers will find detailed profiling of the market's leading participants, including engineering differentiators, portfolio positioning, and recent clearance or procurement milestones that signal near-term market movement. The study contextualizes these developments within broader industry dynamics, including regulatory expectations for infusion pump lifecycle management, procurement justification mechanics for specialized non-magnetic devices, capital equipment useful life benchmarks, and the operational consequences of legacy equipment replacement cycles. By aligning historical data with forward-looking analytical models, the research supports scenario planning for capital allocation, supply chain and aftermarket service strategy, product portfolio investment, and competitive response planning.
Importantly, the report is designed to surface the institutional and clinical logic behind procurement behavior, not just the surface-level numbers. Decision-makers in hospital administration, imaging center operations, ambulatory facility planning, and device R&D can use the analysis to anticipate shift patterns in procurement criteria, evaluate the strategic implications of sole source dynamics in specialized safety categories, and assess the relative durability of technology moats built around non-magnetic motor architectures, wireless remote control integration, and drug library sophistication. The study bridges the gap between regulatory and procurement reality and commercial strategy, equipping leadership teams with the insights needed to align product development, pricing architecture, and market access planning with the structural realities of this niche.
Strategic Positioning for the Next Growth Cycle
As the Worldwide MRI Compatible IV Infusion Pumps Market advances along its projected growth corridor, the institutional pressures shaping procurement will intensify rather than recede. Hybrid imaging environments, outpatient migration, neonate and pediatric protocol expansion, and the clinical premium on uninterrupted infusion delivery during high-stakes imaging procedures will continue to elevate the strategic importance of magnetic-compatible infusion technology. Simultaneously, competitive intensity will reward manufacturers that can synchronize engineering innovation with regulatory fluency, procurement-ready documentation, and interoperability features that align with hospital medication management networks and capital planning realities.
The firms best positioned to capture disproportionate value across the 2026 to 2032 horizon will be those that treat MRI compatibility not as an accessory feature but as a core engineering discipline integrated into pump architecture, user interface design, drug library management, serviceability, and procurement enablement. Executive teams that understand the lifecycle economics, procurement justification mechanics, and segment-specific workflow priorities will be better equipped to optimize market entry timing, pricing strategies, and channel partnerships. They will also be more capable of anticipating replacement cycle accelerations as aging installed bases confront the growing incompatibility gap between legacy equipment and modern imaging environments.
This research delivers the analytical foundation to make those strategic calls with confidence. By consolidating market size trajectories, competitive profiling, regulatory and procurement dynamics, and segmentation logic into a single actionable framework, the study supports precise decision-making for the 2026 operating cycle and beyond. For organizations seeking to sharpen their competitive positioning, optimize capital deployment, or validate R&D investment priorities in the MRI compatible infusion pump space, the full report provides the detailed intelligence needed to move beyond assumptions and into structured, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVDF Coatings Market to Reach $2.41B by 2032 with 6.02% CAGR
By PW Consulting, 2026-09-17
Decoding the Global PVDF Fluorocarbon Coatings Landscape: Strategic Imperatives for 2026 and Beyond
The global coatings industry stands at a critical inflection point. As infrastructure modernization accelerates across emerging economies and sustainability regulations tighten in mature markets, fluorocarbon coatings have cemented their position as the standard for high-durability, weather-resistant protective finishes. At the center of this evolution is the polyvinylidene fluoride (PVDF) fluorocarbon coatings market, a specialized segment that bridges advanced polymer chemistry with large-scale architectural, industrial, and infrastructure applications.
PW Consulting's latest Worldwide PVDF Fluorocarbon Coatings Market report delivers a comprehensive strategic intelligence package designed explicitly for executive decision-makers, procurement leaders, and competitive intelligence teams navigating the 2026-2032 forecast cycle. Rather than offering a static snapshot of market boundaries, this research builds a dynamic framework that connects pricing trajectories, regional demand shifts, formulation transitions, and regulatory pressures to actionable commercial strategies.
Market Trajectory: From Consolidation to Sustained Growth
The historical record establishes a clear growth narrative. Between 2020 and 2025, the worldwide PVDF fluorocarbon coatings market expanded from approximately 1,180.5 million USD to 1,600.68 million USD, reflecting sustained investment in premium protective coatings for metal substrates across construction, industrial equipment, and automotive applications. This upward trajectory has carried momentum into 2026, with baseline revenue projected at 1,615.17 million USD, and the forecast horizon extending through 2032 forecasts a market value of 2,410.01 million USD.
The compound annual growth rate (CAGR) of 6.02 percent across the 2026-2032 forecast window signals more than incremental expansion. It reflects structural demand drivers that are reshaping procurement strategies and production planning across the value chain. Companies that treat PVDF coatings as a commodity input risk missing the strategic implications embedded in this growth curve: regional capacity reallocation, formulation chemistry transitions, raw material volatility management, and intensifying competitive positioning among global resin producers and formulated coating suppliers.
This report contextualizes the macro trajectory within the operational realities that executives face on the ground. Rather than presenting growth as a uniform trend, the analysis maps how different demand centers and application verticals contribute to the overall expansion, enabling leadership teams to prioritize investments where margin resilience and volume growth intersect.
Forecast Architecture: 2026-2032 Strategic Planning Window
The 2026-2032 forecast period is structured to support multi-year capital allocation and product portfolio decisions. The baseline year of 2025 anchors the analysis in recent market conditions, while the forward projections account for the interplay between raw material cost dynamics, capacity expansion timelines, and evolving end-use specifications. By 2027, the market approaches 1,795.94 million USD, and by 2030 it reaches 2,021.2 million USD, before accelerating toward the 2032 endpoint.
This growth path is not a straight line. The forecast architecture incorporates year-by-year variations that reflect the timing of production capacity additions, the pace of regulatory implementation across key jurisdictions, and the lag between raw material price shocks and downstream formulation adjustments. Decision-makers using this research can model sensitivity scenarios around these inflection points rather than relying on blunt average growth assumptions.
The report's forecast methodology is built to answer a specific set of executive questions: Where will incremental volume materialize over the next seven years? Which formulation categories are positioned to capture share as environmental standards evolve? How should organizations sequence capacity, inventory, and supplier diversification strategies against projected demand? These questions are addressed through segment-level analysis that preserves analytical precision without sacrificing strategic clarity.
Competitive Intelligence: The Arena's Principal Architects
The PVDF fluorocarbon coatings market is defined by a concentrated yet highly specialized competitive landscape. Leading resin producers and formulated coating manufacturers each occupy distinct strategic positions, balancing raw material control, application expertise, and regional distribution strength. Understanding these positions is essential for benchmarking, partnership evaluation, and threat assessment.
Worldwide PVDF Fluorocarbon Coatings Market
Arkema, headquartered in France, anchors its offering through Kynar PVDF resins and Kynar 500 for high-performance fluorocarbon coatings in architectural and industrial applications, with emphasis on weatherability, durability, and PFAS surfactant-free grades. Notably, Arkema announced a 20 percent expansion of Kynar PVDF production capacity at its Changshu site in China, with startup planned for 2028 to support demand in coatings and other applications. This capacity move signals a deliberate alignment with Asia-Pacific demand growth and underscores the strategic importance of resin supply availability in the coming years. Earlier, in June 2025, Arkema highlighted Kynar Aquatec waterborne low-VOC protective coatings for architectural applications, offering extended durability and reflectivity compared to traditional systems, illustrating the formulation innovation trajectory toward lower-emission architectures.
Solvay, based in Belgium, supplies Hylar PVDF resins used by licensed formulators for premium 70 percent PVDF fluorocarbon coatings focused on long-term color retention and architectural metal protection. Its resin-centric model highlights the partnership dynamics that shape the formulated coatings tier, where resin availability, grade consistency, and technical support directly influence downstream product performance and brand reputation.
PPG Industries and Sherwin-Williams, both headquartered in the United States, operate at the formulated coating end of the value chain. PPG formulates and supplies PVDF-based fluorocarbon coatings for architectural and industrial uses, leveraging high-durability resin systems for metal substrates. Sherwin-Williams markets Fluropon and other 70 percent PVDF fluorocarbon coatings for coil and extrusion on architectural metal, delivering superior color retention and longevity. Their market presence reflects the premiumization trend in architectural metal finishing, where performance claims around color stability, gloss retention, and substrate protection differentiate brands in specification-driven procurement environments.
AkzoNobel, headquartered in the Netherlands, produces PVDF fluorocarbon coatings for architectural applications, offering weather-resistant solutions for metal cladding and building exteriors. Daikin Industries and Kureha Corporation, both Japan-based manufacturers, produce PVDF resins suitable for fluorocarbon coatings and broader fluoropolymer applications, with emphasis on chemical resistance and durability. Together, these companies form a competitive ecosystem in which resin supply, formulation capability, and regional service networks interact to determine market positioning.
The report's competitive analysis goes beyond corporate profiling. It evaluates how recent capacity decisions, product advancements, and formulation shifts alter relative positioning across regions and end-use segments. Executives gain a structured view of where competitive intensity is rising, where proprietary technology or supply relationships create defensibility, and where market entry or partnership opportunities may emerge as incumbents reallocate resources.
Formulation Evolution and Regulatory Pressures
Formulation strategy has become a decisive competitive variable. The market spans solvent-borne, powder-based, and water-borne formulations, each responding differently to performance requirements, application conditions, and environmental regulation. The report analyzes how these formulation categories are evolving as manufacturers balance durability benchmarks against emissions constraints and processing economics.
Regulatory pressure is reshaping formulation priorities across key markets. Tightening VOC emission standards and PFAS-related scrutiny in North America and Europe influence the formulation of PVDF fluorocarbon coatings toward low-VOC and surfactant-free options. These dynamics are not abstract compliance issues; they affect product specifications, qualification cycles, and customer adoption timelines. Formulators that anticipate regulatory direction and align their portfolios accordingly gain a faster path to specification inclusion and repeat procurement.
At the same time, raw material conditions continue to inject cost volatility into the supply chain. In Northeast Asia, PVDF price stood at 15.36 USD per kilogram in April 2026, reflecting a 2.7 percent increase. Environmental clampdowns in Jiangsu and Shandong provinces in China led to 10-12 percent cost spikes for PVDF production, and vinylidene fluoride monomer raw material costs for PVDF increased significantly, contributing to overall production cost pressures. These cost dynamics interact with formulation choices, regional sourcing strategies, and pricing negotiation leverage. The report translates these pressures into strategic recommendations for cost pass-through management, inventory timing, and supplier diversification.
Application Demand and Regional Expansion Patterns
End-use demand provides the structural foundation for market growth. Architectural construction represents the dominant application category, driven by sustained demand for weather-resistant metal cladding, building exteriors, and long-life coil and extrusion coatings. Industrial equipment applications contribute a substantial secondary demand stream, where corrosion resistance and chemical durability justify premium coating solutions. Automotive, electrical and electronics, and other end-use segments add diversified demand that supports overall market resilience and expands the addressable base for specialized formulations.
Regional dynamics reveal a market with clear geographic hierarchy and shifting momentum. Asia Pacific stands as the largest revenue region, reflecting the concentration of construction activity, industrial manufacturing, and infrastructure investment. North America and Europe follow as mature but still strategically significant markets, where premium specifications, replacement cycles, and regulatory-driven formulation upgrades sustain demand. The Middle East and Africa, along with Latin America, contribute additional growth vectors tied to urbanization, industrial development, and coatings adoption in emerging applications.
The report examines how regional demand patterns interact with capacity location, pricing differentials, and specification influence. For multinational coating suppliers, understanding the relative weight of each region is not enough; it is equally important to grasp how local regulatory environments, construction cycles, and industrial procurement practices shape volume timing and margin profiles. This regional granularity supports market entry assessment, channel strategy refinement, and localized product positioning decisions.
Polyvinylidene Difluoride (PVDF) Market
Concentration Dynamics and Sourcing Strategy Implications
Market concentration remains a defining feature of the PVDF fluorocarbon coatings landscape. The combined share of the top three competitors reaches 42.15 percent, while the top five account for 58.6 percent. This level of concentration indicates that a relatively small group of established players exercises substantial influence over resin supply, formulation standards, and specification capture in premium applications.
For downstream formulators and end-user procurement teams, concentration carries both risk and opportunity. On the risk side, reliance on a narrow set of resin suppliers or coating manufacturers can expose procurement to capacity constraints, price adjustments, and qualification bottlenecks. On the opportunity side, the concentrated structure rewards strategic supplier relationships, long-term contracting, and technical collaboration that can secure consistent supply and preferential access to advanced grades. The report evaluates these concentration dynamics in the context of recent capacity expansion announcements and monomer cost pressures, helping organizations design sourcing strategies that balance resilience with cost efficiency.
What the Report Delivers for 2026 Decision-Making
This research is built as an operational intelligence platform rather than a high-level market summary. It provides the analytical scaffolding needed to connect market structure to commercial execution. The report includes detailed segmentation analysis across formulation types and end-use applications, regional market sizing that captures local demand intensity, and competitive profiling that compares strategic positioning, product architecture, and recent corporate moves.
Readers gain access to year-by-year market sizing through 2032, segment-level revenue breakdowns, and concentration metrics that quantify competitive structure. The report integrates recent industry developments, including capacity expansion timelines, product advancement milestones, raw material price movements, and regulatory change trajectories, into a unified analytical framework. This integration allows decision-makers to see how individual events fit into broader market dynamics rather than evaluating them in isolation.
The output is designed to support practical decisions: how to prioritize formulation investments in response to VOC and PFAS-related shifts; where to focus sales and specification efforts as regional demand patterns evolve; how to structure procurement and inventory strategies around raw material volatility; and how to benchmark competitive positioning against capacity and portfolio moves by leading players. Each section is written to feed directly into strategy workshops, procurement reviews, and competitive planning cycles.
Accessing the Complete Intelligence Package
The intersection of sustained market growth, formulation transition, raw material volatility, and regulatory evolution makes the PVDF fluorocarbon coatings market a strategic priority for organizations operating across construction, industrial equipment, automotive, and electrical applications. Navigating this environment requires more than headline market size and growth rates; it demands segment-level visibility, competitive context, and forward-looking scenarios that connect external market dynamics to internal planning assumptions.
PW Consulting's Worldwide PVDF Fluorocarbon Coatings Market report provides that depth. It is structured to serve as a reference point for executive teams seeking to align product strategy, sourcing strategy, and market expansion plans with a rigorous view of where the market is heading through 2032.
To access the complete dataset, regional and segment breakdowns, full competitive profiles, and the detailed forecast model supporting this analysis, visit the source report page. The full report delivers the granularity required to convert market intelligence into precise, defensible strategic action for the 2026-2032 planning horizon.
For detailed analysis of this topic, please visit the official page: Worldwide PVDF Fluorocarbon Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


