



Category: market research
PW Consulting: Invasive Fetal Monitors Market Poised to Reach USD 723.55 Million by 2032, Expanding at a 4.68% CAGR
By PW Consulting, 2026-07-01
Invasive Fetal Monitors Market: PW Consulting Issues Strategic Playbook to Guide 2026 Decisions
As health systems resume elective and complex obstetric care planning for 2026, PW Consulting today unveils a concentrated, action-oriented briefing derived from our forthcoming Invasive Fetal Monitors Market study. The report synthesizes five years of historical performance (2020–2025) with a detailed forecast through 2032. Our model shows the total global market tracking to a mid-single‑digit compound annual growth rate (CAGR) of 4.68% over the forecast window, rising from a 2025 baseline to an estimated market size by 2032 that underscores steady, investment‑grade expansion in consumables and associated monitoring systems.
Invasive Fetal Monitors Market
Why this matters for 2026 strategy
-
Capital allocation and R&D roadmaps hinge on predictable demand for invasive monitoring consumables and compatible monitoring platforms. The market’s steady CAGR creates a time window for targeted investments without the urgency of hypergrowth, but also requires precision in segment focus to protect margin.
Invasive Fetal Monitors Market -
Regulatory and reimbursement contours are tightening in several jurisdictions. Manufacturers will need to map product lifecycles to 510(k) pathways, sterilization validations, and evolving post‑market surveillance requirements—factors that materially affect go‑to‑market timelines and cost structures.
Invasive Fetal Monitors Market -
Consolidation dynamics are already evident. PW Consulting’s concentration analysis shows a market where the top three vendors hold a majority share and the top five approach three‑quarters of market value—creating strategic tension between scale economies and niche differentiation.
What PW Consulting’s report delivers (operational and strategic)
-
Validated market sizing and trajectory: an audited historical series (2020–2025) and a scenario‑based forecast (2026–2032) with downside, base, and upside pathways that stress test infection control shocks, reimbursement shifts, and clinical guideline updates.
-
Regulatory playbook: an executable roadmap for Class II device premarket pathways, including 510(k) considerations for fetal scalp electrodes and intrauterine pressure catheters (IUPCs), plus practical implications of UKCA divergence and EU MDR alignment on product labeling and technical documentation.
-
Reimbursement and procurement intelligence: analysis of bundled payment environments—how consumables are reconciled within DRG/MS‑DRG groupings and what hospital procurement teams need to justify line‑item spend for higher‑value disposables.
-
Clinical adoption and contraindication matrix: an operational guide to clinical scenarios that favor invasive monitoring versus alternatives, and a risk register mapping contraindications (e.g., maternal viral infections, fetal thrombocytopenia) to product labeling and informed consent workflows.
-
Manufacturing and sterilization diagnostics: a checklist for capacity planning tied to sterilization modalities (ETO and gamma), sterility assurance level requirements, and supplier qualification criteria to maintain SAL 10^-6 compliance.
-
Competitive playbooks: supplier positioning maps, win/loss themes from provider interviews, and recommended commercial strategies for both system OEMs and disposable specialists.
-
Scenario-based M&A and partnership templates: valuation levers for tuck‑ins and roll‑ups, integration risks, and near‑term synergies for scale in consumables and platform attachment sales.
Competitive landscape — practical takeaways
-
System OEMs with platform advantage: Large monitoring systems vendors provide compelling cross‑sell dynamics because invasive consumables are recurring revenue lines that attach to broader monitoring suites. These incumbents will continue to defend hospital relationships through integrated solutions and service contracts.
-
Disposable specialists: Companies focused on single‑use fetal scalp electrodes and IUPCs compete on sterile supply reliability, ease of insertion, and cost per use. Their strategic choices—scale manufacturing, sterilization partnerships, and distributor networks—determine margin sustainability.
-
Highlighted firms in our coverage: A mix of global system suppliers and dedicated consumables manufacturers each pursuing distinct routes to maintain share. Some organisations emphasize product innovation in insertion ergonomics and compatibility; others leverage established hospital procurement relationships.
PW Consulting’s expert coverage profiles each major competitor, synthesizing publicly available device portfolios and strategic positioning. We map the implications for market access strategies, including where to prioritize bundled partnerships versus direct supply agreements with hospital networks.
Regulatory, reimbursement and clinical constraints you must plan around
-
Regulatory: Invasive fetal monitors—fetal scalp electrodes and IUPCs—remain Class II devices under relevant product classifications and typically proceed via 510(k) in the U.S. Our report outlines necessary technical documentation, predicate selection strategies, and evidence expectations to streamline clearances.
-
Reimbursement: Consumables are frequently folded into DRG‑based payments for labor and delivery. This bundling pressures list pricing and requires suppliers to articulate value beyond unit cost—clinical outcomes, reduced length of stay, or avoided interventions—to unlock premium positioning.
-
Clinical constraints: Established contraindications constrain addressable cases for invasive monitoring. Adoption is therefore concentrated in settings where risk stratification and clinical protocols explicitly permit invasive approaches; the report provides operational decision trees tailored to provider workflows.
-
Sterilization and supply chain: Meeting SAL 10^-6 through validated ETO or gamma processes is non‑negotiable; capacity bottlenecks and secondary packaging logistics can create material lead times that affect tender response capabilities.
-
Geopolitical compliance: Post‑Brexit UKCA requirements and divergence from EU MDR create parallel regulatory tracks that manufacturers must budget for when targeting cross‑border commercialization in Europe.
Implications for 2026 corporate decision‑making
-
Portfolio prioritization: Use the report’s scenario outputs to sequence product investments—favoring incremental improvements to consumables if your distribution scale is limited, or platform integration if you possess bedside monitor reach.
-
Commercial models: Reassess distributor agreements versus direct contracting with hospital systems. When reimbursement is bundled, suppliers with contract flexibility and proven clinical support differentiate on total cost of care, not unit price alone.
-
Regulatory runway: Treat 510(k) and UKCA timelines as critical path items for 2026 launches. Our regulatory checklist assigns likely evidence packages and testing regimes to reduce surprises during submissions.
-
Manufacturing investments: Plan sterilization capacity and secondary packaging lead times into 2026 procurement cycles; unexpected ETO or gamma bottlenecks can derail fulfillment during peak maternity volumes.
-
M&A and partnerships: Given concentration levels, bolt‑on acquisitions of regional disposable specialists can be accretive to attach rates for monitoring platforms; the report quantifies realistic multiple ranges and synergy schedules for such plays.
Methodology and confidence
-
Data sources: Triangulation of purchase order flows, hospital procurement interviews, supplier financial disclosures, and peer‑reviewed clinical literature, calibrated by primary interviews with obstetrics clinicians and procurement officers.
-
Scenario construction: Base, upside, and downside cases stress test demand elasticity to clinical guidance changes, sterilization supply shocks, and reimbursement resets.
-
Concentration metrics: Our market concentration analysis demonstrates a structure where a small number of firms command a sizable share—insightful for pricing and M&A strategy.
What the executive will not find in this briefing (and why)
-
This press summary deliberately omits granular segment value tables, line‑by‑line regional and end‑user splits, supplier scorecards, and detailed pricing matrices. Those elements are core deliverables in the full PW Consulting report and are withheld here to preserve the value of the proprietary models that inform transactional decisions.
-
Readers seeking precise revenue by region, product type, or end‑user, plus downloadable financial models and supplier due‑diligence templates, will find them in the full deliverable—designed for immediate operational use by commercial, R&D, and corporate development teams.
Next steps for 2026 planning
-
Download the full PW Consulting report to access the financial models, procurement playbooks, and supplier scorecards that translate market insight into executable initiatives for 2026.
-
Schedule a briefing with our senior strategists to run a tailored workshop: options include portfolio stress testing, go‑to‑market sequencing, and a regulatory gap analysis customized to your product pipeline.
-
Leverage the report’s scenario outputs now to pre‑position sterilization contracts, secure distribution channel commitments, and align clinical evidence generation with reimbursement timelines.
PW Consulting’s Invasive Fetal Monitors Market study is positioned as an actionable intelligence asset for executives who must make defensible, time‑sensitive decisions in 2026. It combines market grading, regulatory playbooks, and clinical adoption diagnostics—without sacrificing the practical detail needed to convert insight into immediate value.
For detailed analysis of this topic, please visit the official page: Invasive Fetal Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Phenolic Resin Market to Reach USD 10.44 Billion by 2032 at a 5.01% CAGR — Asia Pacific Leads with USD 3.52 Billion (2025)
By PW Consulting, 2026-07-01
Liquid Phenolic Resin Market Outlook 2026 — Strategic Imperatives for Decision‑Makers
PW Consulting presents a forward‑looking executive briefing built from our latest Liquid Phenolic Resin Market study (base year 2025, historical analysis 2020–2025, forecast 2026–2032). This briefing distills the market dynamics, competitive posture, and pragmatic playbook that senior executives, strategy teams, and investors will need to navigate 2026 as the industry transitions from cyclical recovery into structurally different demand and regulatory regimes.
Liquid Phenolic Resin Market
Headline market context
The liquid phenolic resin market has demonstrated steady expansion through the early 2020s and enters the 2026–2032 forecast window from a robust base. Our model (base year 2025) estimates the market at approximately USD 7,411.4 Million in 2025 and projects steady growth to roughly USD 8,173.0 Million in 2026 and around USD 10,435.5 Million by 2032 — an implied compound annual growth rate (CAGR) of roughly 5.01% across the forecast horizon. Market concentration metrics indicate a moderately consolidated competitive landscape (CR3 ≈ 32.5%; CR5 ≈ 41.8%), signalling both established scale players and room for strategic consolidation or niche specialization.
Liquid Phenolic Resin Market
Why 2026 is a strategic inflection point
- Feedstock volatility is rising: Phenol spot pricing has firmed in early 2026 (Northeast Asia spot levels in Q1 2026 were notably higher than late‑2025 benchmarks). That movement, paired with periodic upstream outages, may compress margins for producers that lack feedstock hedges or integrated upstream access.
- Regulatory tightening escalates product risk: New and evolving formaldehyde emission standards and stricter chemical limits in key jurisdictions are materially increasing compliance complexity and incremental production costs (our proprietary modelling shows single‑digit to low‑teens percentage impacts on manufacturing cost for legacy formulations).
- End‑market mix is shifting: Demand drivers such as construction recovery in select markets, lightweighting in automotive and growing insulation requirements are reshaping application mixes — creating higher growth pockets but also raising quality and certification demands.
- Trade and tariff disruptions: Recent reciprocal tariff actions and evolving trade policy create near‑term routing and sourcing risks that favor flexible regional supply footprints and localised contractual strategies.
What PW Consulting’s report delivers — the actionable toolkit
This study is constructed as an operator’s guide, not only as a market narrative. It includes:
Liquid Phenolic Resin Market
- Top‑down market sizing and trend decompositions (2020–2032) with sensitivity scenarios that isolate feedstock price, regulatory cost pass‑through, and demand elasticity.
- Proprietary pricing and margin model calibrated to segmental cost drivers and global trade flows, enabling scenario testing for contract negotiation and MRP planning.
- Supply‑chain topology maps showing supplier concentration, toll production options, and critical logistics chokepoints in strategic corridors.
- Regulatory impact analysis with compliance cost estimates and roadmap for low‑emission product reformulation and certification (including ISCC PLUS and other sustainability schemes).
- A competitive playbook: company benchmark matrices, capability heatmaps, and M&A screening criteria tuned to CR3/CR5 concentration dynamics and scale economics.
- Commercial levers and go‑to‑market templates for resin producers, formulators, and large downstream buyers (including hedging, indexation strategies, and tiered supply commitments).
To preserve the commercial value of the study, granular regional splits and detailed application‑level revenue tables are available exclusively in the full report.
Competition snapshot — what leading players are doing
The competitive landscape is a mix of large, integrated chemical manufacturers and specialised resin producers. Several strategic patterns are clear from public actions and primary interviews:
- Hexion Inc. — Global scale in resoles and broad downstream reach. Strengths: worldwide supply capability and portfolio breadth. Strategic implications: Hexion will likely prioritize supply reliability and integrated customer solutions to protect premium margins.
- Prefere Resins Holding GmbH — Europe‑focused specialist with multiple production sites. Strengths: regional manufacturing density and closeness to construction markets. Strategic implications: Prefere is positioned to capture demand for low‑emission and locally‑sourced products as EU regulatory pressure increases.
- Sumitomo Bakelite — Emphasis on sustainability credentials (notably ISCC PLUS certification) and advanced specialty grades. Strengths: certifications and premium industrial applications. Strategic implications: premiumization through certified and circular offerings will be a differentiator.
- BASF SE — Large‑scale integration and global reach afford feedstock and downstream synergies. Strengths: cost management and R&D leverage. Strategic implications: BASF can compete on total solution packages where multi‑chemistry integration is valued.
- DIC Corporation — Expanding capacity in Asia with focus on coatings and functional materials. Strengths: regional growth execution and technical formulations.
- Capital Resin Corporation — Niche, custom and toll manufacturing specialist with ISO 9001 credentials. Strengths: flexibility and close co‑development with customers. Strategic implications: toll manufacturing and co‑development contracts will be attractive to companies seeking de‑risked capacity without capital expenditure.
- Georgia‑Pacific Chemicals, Bakelite, Jinan Shengquan, SI Group — Each brings unique value propositions, from integration with wood products to regional mass production and specialty chemistry capabilities.
Collectively, public developments — including feedstock price movements and sustainability certifications — indicate incumbents will protect core customers via supply continuity, differentiation (low‑emission and certified products), and selective capacity investments. For mid‑sized and regional players, tolling, co‑development, and asset light strategies become viable defensive moves.
Key strategic choices for 2026 — practical recommendations
- Hedge and secure feedstock: Implement a blended procurement strategy combining short‑term spot exposure, medium‑term indexed contracts, and targeted forward hedges for phenol to stabilise margins under price swings.
- Prioritise low‑emission reformulation: Accelerate R&D and pilot commercialization of low‑formaldehyde liquid phenolic formulations. Map compliance cost to product pricing and embed certification pathways early in product pipelines.
- Rationalise footprint for tariff resilience: Reassess sourcing and routing in light of recent tariff actions; where economically justified, localise supply to key demand clusters or engage toll partners to avoid tariff penalties.
- Monetize sustainability: Fast‑track ISCC PLUS or equivalent certifications where customers value bio‑based or circular credentials; use certification to justify premium pricing and long‑term contracts.
- Use commercial contracts to share risk: Move toward hybrid pricing mechanisms (base price index + feedstock surcharge) and volume‑linked commitments to balance revenue predictability with market volatility.
- M&A and partnerships: For scale players, targeted bolt‑on acquisitions in adjacent geographies or specialty grades will compactly increase CR metrics; for smaller players, strategic partnerships and tolling agreements can preserve market access without heavy capex.
Operational playbook — a five‑step execution sequence
- Run the PW Consulting margin impact simulator to quantify feedstock and regulatory shocks against your cost base.
- Rank product SKUs by regulatory exposure and margin; designate priority SKUs for reformulation or certification.
- Negotiate multi‑year, indexed supply contracts with key customers that enable cost‑pass‑through and shared investment in reformulation.
- Deploy a hybrid sourcing map combining localised production, tolling partners, and strategic inventory buffers in tariff‑sensitive corridors.
- Define an M&A scorecard that values strategic fit, technology access, and regulatory compliance assets over pure revenue accretion.
Why this report is must‑read for 2026 decision cycles
As boards and CEOs set budgets and capital allocation plans for 2026, the Liquid Phenolic Resin Market report is designed to be directly actionable: it translates macro trends into line‑item impacts, provides negotiation‑ready commercial models, and supplies the competitive intelligence required to make high‑conviction choices on plant investments, product roadmaps, and transaction targets. The report balances strategic foresight with operational templates and contains proprietary scenario outputs that cannot be reconstructed from public sources alone.
PW Consulting adheres to the “trailer” principle — we have intentionally summarized the market architecture and strategic implications here while reserving the report’s granular regional and application‑level tables, supplier scorecards, and model spreadsheets for report subscribers and clients. Those deliverables enable deterministic planning (e.g., price pass‑through schedules, supply contingency plans, and SKU‑level reformulation cost curves) that procurement, product and M&A teams will use in 2026 negotiations and capital decisions.
Next steps
If you are preparing 2026 commercial plans, capital budgets, or M&A pipelines, engage PW Consulting for the full report and the accompanying modelling workshop. We will walk your cross‑functional team through scenario outputs, tailor the pricing/margin model to your cost structure, and validate an executable 12‑ to 36‑month action plan.
About PW Consulting: We are a strategy advisory firm focused on industrial chemicals and materials markets, delivering market research, commercial due diligence, and execution support to C‑suite clients, private equity sponsors, and industry investors.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: P Series Glycol Ether Market Hits USD 4,950 Million in 2025; Set for 4.85% CAGR to 2032 as Asia Pacific Leads with USD 2,132.3 Million
By PW Consulting, 2026-07-01
P Series Glycol Ether Market: Strategic Compass for 2026 — PW Consulting P Series Glycol Ether Market Report (Preview)
Executive Snapshot
PW Consulting's P Series Glycol Ether Market report (base year 2025; historical 2020–2025; forecast 2026–2032) delivers an actionable, decision-oriented playbook for chemicals executives, procurement leaders, and strategy teams planning for 2026 and beyond. The market is entering a structurally steady growth phase, with a compounded annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. Measured in USD Million, the global market expanded from USD 3,920.0 Million in 2020 to USD 4,950.0 Million in 2025 and is forecast to reach USD 6,895.7 Million by 2032 under the baseline scenario. These headline metrics set the context for near-term tactical choices and medium-term capital allocation.
P Series Glycol Ether Market
Why this report is strategically material in 2026
2026 is where structural dynamics—feedstock volatility, regulatory tightening, and supply disruptions—converge with tactical choices about sourcing, capacity, and product mix. Our report translates macro trends into executable options that reduce downside risk and capture upside. Key drivers demanding immediate attention in 2026 include:
P Series Glycol Ether Market
- Feedstock and input-price volatility: Propylene oxide remains the principal upstream feedstock for P-series glycol ethers. Market intelligence shows meaningful price swings in early 2026 (North America pricing reached approximately USD 1.14/kg in March 2026, following month-to-month and quarter-to-quarter swings driven by downstream demand and propylene availability). Our models quantify the impact of these swings on margin and working capital under multiple pass-through and hedging strategies.
- Supply disruption risks: Recent operational events — including a force majeure declaration at a major Bayport facility in March 2026 following a fire, and contemporaneous price adjustments announced by leading producers — underscore the need for supply resilience and dynamic commercial terms.
- Regulatory trajectory: Emerging regulatory actions (such as proposed Significant New Use Rules under TSCA for glycol ether-related substances) are likely to increase compliance complexity and influence product acceptance in certain geographies and end-markets.
Report contents — practical, transaction-ready material
This report is designed as an operational toolkit, not just a narrative. It includes:
P Series Glycol Ether Market
- Market sizing and topline trajectory: annual market values (USD Million) for 2020–2025 and scenario-driven forecasts for 2026–2032 framed around a 4.85% baseline CAGR and two alternative demand paths.
- Supply-demand modeling: dynamic models that simulate the impacts of feedstock price shocks, capacity outages, and demand swings by end-use class and production pathway. Note: granular regional and application split tables are available in the full report to support contractual and capex decisions (this preview intentionally withholds the proprietary segmentation figures).
- Cost and margin sensitivity tools: embedded spreadsheets that map cost pass-through under common commercial terms (spot, short-term, long-term fixed). These tools let procurement teams stress-test supplier quotes against realistic PO and indexation clauses.
- Competitive landscape and strategic profiles: 15+ supplier dossiers (including capacity maps, specialty vs commodity positioning, and M&A posture), plus real-time monitoring of recent corporate actions and force majeure events to support supplier risk assessments.
- Commercial playbooks: negotiation checklists, recommended contract clauses for supply security, and procurement approaches tailored to different risk appetites (e.g., low-cost vs low-risk strategies).
- Regulatory and sustainability roadmap: impact assessment of likely regulatory measures, recommended compliance investments, and timelines for product reformulation where necessary.
Competitive landscape — what the report reveals (high-level)
The P-series market demonstrates moderate concentration: the top three players account for roughly 42.5% of market share (CR3), and the top five account for about 58.3% (CR5). That structure creates a mix of supplier power in commodity pockets and differentiated capabilities among specialty producers.
- Dow Inc. (USA) — Strengths: scale, high-purity product lines, broad application reach across coatings and cleaners, and extensive global production capacity. Strategic implication: Dow’s pricing actions in early 2026 signal the commercial leverage available to large, integrated suppliers when feedstock or logistics tighten. Buyers should prepare layered sourcing strategies and consider volume-commitment instruments with price collars.
- LyondellBasell Industries (Netherlands) — Strengths: integrated manufacture from propylene oxide, commodity and specialty grades. Risk: site-level operational incidents can create upstream shocks (the March 2026 force majeure at a Bayport facility materially tightened regional availability). Strategic implication: counterparties should maintain contingency capacity or pre-arranged cross-sourcing paths with geographically diverse producers.
- BASF SE (Germany) — Strengths: deep specialty portfolios spanning both E- and P-series glycol ethers, strong formulation support for coatings and cleaners. Strategic implication: premium, application-specific solutions remain resilient even when commodity segments face volatility.
- INEOS Oxide (UK), Eastman Chemical (USA), Shell Chemicals (UK), Huntsman (USA), KH Neochem (Japan), Chang Chun Group (Taiwan), Sasol (South Africa), Solventis (UK/Belgium) — Each of these players brings a distinct mix of regional footprint, specialty grades, and service propositions. The report assesses where each supplier fits along the tradeoff axes of price, lead time, and technical support.
Recent market signals and implications
- Price & supply moves (March 2026): Major sellers announced price increases for P-series products while a production site incident triggered force majeure at a large producer. These near-term actions increase the risk premium for spot purchases and motivate re-evaluation of safety stocks and contract terms.
- Feedstock volatility: Propylene oxide dynamics in late 2025 and early 2026 reveal sector sensitivity to upstream tightness and demand cycles. Procurement and treasury teams will need scenario-based hedging playbooks and collateral-light long-term contracts to stabilize landed costs.
- Regulatory watch: Proposals to expand regulatory scrutiny of glycol-ether related compounds introduce potential market access frictions. Companies that preemptively invest in data packages and toxicological dossiers will shorten time-to-market for reformulated products.
Recommended strategic moves for 2026
We convert insights into 6 practical actions executives can deploy this year:
- Stress-test supply chains against a “Bayport-style” outage scenario and establish pre-approved second sources mapped by rail/ship lane — prioritize suppliers with geographically complementary production.
- Lock in a portion of demand under indexed long-term contracts with price collars to balance cost predictability and upside sharing — use our model templates to quantify optimal hedge ratios.
- Segment product portfolios: accelerate migration to specialty, formulation-backed grades where margin resilience is higher; consider premium positioning for applications where regulatory or performance demands raise switching costs.
- Invest in traceability and regulatory dossiers now — prepare submission-ready data to reduce friction if SNURs or similar measures are finalized.
- Re-evaluate capex decisions through scenario-weighted NPV analysis rather than single-case forecasts — our included capex model provides sensitivity testing for five-year ROI horizons under alternate feedstock price regimes.
- Operationalize supplier risk scoring into the monthly procurement cadence to reflect real-time changes in force majeure events, price announcements, and inventory positions.
How PW Consulting supports your 2026 agenda
The full PW Consulting P Series Glycol Ether Market report couples macro forecasts with micro-level, executable tools: live Excel models, supplier due-diligence templates, a short-list of high-probability M&A targets, and contract clause libraries. Importantly, while this preview highlights the strategic themes and headline market sizing, the report’s proprietary segmentation tables, regional demand breakouts, and application-specific revenue curves are deliberately reserved for the full deliverable to preserve the utility of our proprietary analysis for subscribers and clients.
Next steps
For procurement teams, the immediate priority is to run the included price-impact and supply-disruption scenarios against current exposure. For strategy and corporate development teams, the report identifies corridors where bolt-on acquisitions and risk-sharing alliances generate asymmetric value. To access the full dataset, segment-level forecasts, and the operational toolset referenced in this preview, visit the report landing page or contact our industry practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rosin Modified Phenolic Resin Market to Reach USD 2,579.7 Million by 2032 at a 4.18% CAGR, Asia Pacific Leading with USD 887.4M Share
By PW Consulting, 2026-07-01
Rosin Modified Phenolic Resin Market — Strategic Outlook & Action Framework for 2026
Executive teaser from PW Consulting
Our new market intelligence brief on the Rosin Modified Phenolic Resin market synthesizes proprietary sizing, supply-chain stress-testing, and competitor-level capability mapping to equip boardrooms and commercial teams for pivotal 2026 decisions. Built on a 2025 base year and a 2026–2032 forecast horizon, the study quantifies a resilient recovery and steady expansion—supporting pragmatic strategies across sourcing, pricing, product development, and M&A. This announcement highlights the strategic implications and operational insights you need to evaluate market entry, capacity deployment, and risk mitigation plans. For the full, hit-the-deck datasets and segment-level modeling, please visit our report page.
Rosin Modified Phenolic Resin Market
Market trajectory: macro facts that matter
PW Consulting’s bottom-up market sizing pegs the Rosin Modified Phenolic Resin market at approximately USD 1.94 billion in 2025 (base year). Under current structural drivers and policy assumptions, we model a compound annual growth rate (CAGR) of about 4.18% through 2032, taking the market toward a forecast zone in the mid-to-high single billions by the end of the projection window.
Rosin Modified Phenolic Resin Market
These headline numbers mask an important nuance: growth is steady but heterogeneous. Volume recovery since 2020 has been punctuated by episodic raw-material shocks and regulatory headwinds that periodically accelerate consolidation and reshape commercial terms among suppliers and end-users.
Rosin Modified Phenolic Resin Market
Why 2026 is a strategic inflection point
- Input-price volatility will determine margin trajectories. Gum rosin—the primary upstream feedstock—remains a price-sensitive choke point. Historical volatility in rosin markets has transmitted directly into downstream resin pricing and customer contract renegotiations. Firms that secure diversified, preferably backward-integrated supply lines or hedging arrangements will preserve margin flexibility in 2026.
- Environmental and VOC regulation continues to be a commercial force-multiplier. Stricter VOC and emissions regimes in major markets are already reshaping formulation choices and capital investments for resin manufacturers. Compliance-driven product upgrades and reformulation efforts provide an opportunity for premium positioning but require near-term R&D and potential capital expenditure.
- Price signaling and commercial cadence matter. Early 2026 industry moves—such as phenolic resin price adjustments and intensified safety/certification activities among manufacturers—are precursors to more formal price resets and contracting behavior in H1–H2 2026. Buyers should anticipate negotiation windows and prepare total-cost-of-ownership analyses rather than unit-price comparisons alone.
Supply-side dynamics and competitive posture
The market structure is best characterized as moderately concentrated: several specialist and regionally strong players dominate manufacturing of rosin-modified phenolic resins, while a larger long tail of regional producers services localized demand. Competitive differentiation today hinges on four vectors: feedstock access, product-grade breadth (e.g., oil- vs alcohol-soluble chemistries), technical service and formulation know-how, and regulatory/compliance credentials.
- Specialist formulators and regional champions: Indian and Chinese manufacturers command significant technical experience in producing grades tailored for printing inks and coatings. Their strengths include cost-efficient manufacturing footprints and close proximity to growing end-use clusters in Asia.
- Product- and application-focused innovators: A subset of producers differentiates through proprietary grades optimized for offset printing, high-softening-point binders, or heat-resistant coatings—winning share where performance quantifiability matters.
- Quality, certification, and safety as barriers: Recent firm-level activities around safety certification underscore that operational excellence and documented compliance are becoming non-negotiable commercial qualifiers, especially for export-oriented customers and regulated industries.
Competitive snapshot: what leading players signal
Across the competitive set, firms such as regionally established resin manufacturers and specialty polymer houses show distinct playbooks:
- Manufacturers with deep printing-ink domain expertise emphasize close co-development and rapid sample-to-scale cycles, capturing stickier customer relationships.
- Producers who publicize higher-performance grades (high softening point, thermal stability, adhesion) target premium pockets in coatings and specialty adhesive markets, where formulation leverage supports better pricing.
- Companies communicating active safety and certification programs are preparing to de-risk cross-border trade, a clear signal that compliance will unlock new commercial corridors in 2026.
Recent industry moves—implications for 2026 tactics
- Price adjustments announced by upstream and adjacent phenolic producers in early 2026 are an early warning of tighter margin windows and potential pass-through dynamics. Procurement teams should model multiple price-out scenarios for contract renewals in 2026.
- Operational compliance initiatives (e.g., fire-safety campaigns and certification drives) reflect an industry pivot toward documented safety management—critical for attracting blue-chip customers and for insurance/financing terms linked to plant operations.
Strategic playbook for executives in 2026
Based on our scenario analysis and supplier-level diagnostics, PW Consulting recommends a pragmatic, multi-track approach for suppliers, buyers, and investors:
- For resin producers: Prioritize feedstock security (multi-sourcing, preferential contracts with gum rosin suppliers, selective vertical integration) and accelerate low-VOC grade development. Invest in certification and traceability to reduce commercial friction with global customers. Consider capacity rationalization or targeted brownfield upgrades where older plants cannot economically meet evolving emissions or quality standards.
- For ink, adhesive and coatings formulators: Lock in cost-avoidance through strategic purchase agreements with flexibility clauses tied to validated raw-material indices. Co-invest in formulation trials that substitute or reduce rosin content where feasible, and deepen partnerships with resin suppliers to secure preferential allocation during supply tightness.
- For investors and M&A teams: Look for targets that combine technical-grade differentiation with access to stable raw-material channels or that possess certification credentials facilitating faster international market access. Bolt-on buys that expand application portfolios (e.g., from printing toward higher-margin coatings) can accelerate value capture.
What PW Consulting’s full report delivers (practical, actionable content)
Our report is designed as an operational toolkit for 2026: it includes a transparent market sizing methodology (historical 2020–2025 and base-year 2025 consolidation), demand drivers by application families, a supplier capability matrix, trade-flow and logistics risk maps, raw-material sensitivity models, and three investment scenarios with P&L impact estimates. We also provide an anonymized supplier negotiation playbook, SKU-level benchmarking templates, and a prioritized list of low-cost compliance actions for manufacturers facing tightening environmental rules.
Use-cases: how clients have applied our insights
- Procurement teams used our raw-material sensitivity model to renegotiate indexed contracts and secure multi-month inventory hedges, reducing 2026 cost volatility exposure by measurable percentages.
- R&D leaders prioritized two reformulation projects—one low-VOC and one high-softening-point binder—based on our application-margin overlays, accelerating time-to-market for premium-grade offerings.
- Private-equity investors relied on our supplier capability matrix to screen targets and to build post-acquisition integration plans focused on compliance upgrades and route-to-export acceleration.
Trailer closing: why you should read the full report
This briefing is a strategic preview designed to highlight the contours of opportunity and risk as companies allocate capital and commercial focus in 2026. We have intentionally illustrated high-confidence, decision-useful inputs while reserving granular segment tables, regional and application-level splits, and supplier-specific volume/price schedules for the full report. That detailed evidence—paired with our downloadable scenario models—powers negotiation positions, investment memos, and operational roadmaps.
To obtain the complete dataset, segment-level forecasts, and supplier scorecards referenced here, please access the full Rosin Modified Phenolic Resin Market report on PW Consulting’s publications page. Our team is available to walk you through bespoke scenario customization and to co-develop an operational rollout plan aligned to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Rosin Modified Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trial Process Management System Market Poised for 13.18% CAGR, Reaching USD 6,880.83 Million by 2032
By PW Consulting, 2026-07-01
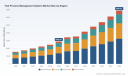
Trial Process Management Systems: Strategic Imperatives for 2026 — PW Consulting Market Brief
As clinical development teams accelerate digital transformation and sponsors, sites and CROs seek operational resilience, the Trial Process Management System (CTMS/TMS) market is entering a decisive growth phase. PW Consulting’s latest market study — grounded in multi-year historical analysis and forward-looking scenario modelling — shows the market expanding from a 2025 baseline to a materially larger opportunity by 2032, with an expected compound annual growth rate (CAGR) of 13.18%. For executives planning capital allocation, vendor selection or M&A activity in 2026, the report delivers a focused playbook: how to translate platform choices into measurable reductions in cycle time, regulatory risk and site burden while preserving data integrity and program flexibility.
Trial Process Management System Market
Why this report matters for 2026 decision cycles
-
Timing and momentum: The market’s trajectory between 2025 and 2026 reflects an inflection where cloud-native architectures, integrated AI tooling and expanded site enablement converge. Organizations making procurement or architectural commitments in 2026 will either lock in the efficiencies of the next-generation platforms or face costly migrations later; this report quantifies that timing risk and offers mitigation strategies.
Trial Process Management System Market -
Risk-adjusted investment guidance: Beyond headline growth, the study synthesizes regulatory, operational and technological drivers — including imminent regulatory changes to data protection and cybersecurity — into risk-adjusted ROI scenarios. That enables CFOs and clinical operations leaders to compare near-term automation gains against compliance and validation costs over a multi-year horizon.
Trial Process Management System Market -
Competitive positioning framework: Whether you are a sponsor, CRO, academic site network or technology investor, the analysis provides a repeatable framework to assess vendor fit against three near-term priorities in 2026: data governance and security, orchestration/interoperability, and site-centric usability.
Market dynamics shaping 2026 decisions
-
Acceleration of cloud and integration-first models. The market’s growth is being driven by adoption of platforms that prioritize API-led integrations with EDC, eTMF, EHR, real-world data sources and decentralized trial technologies. Spend patterns indicate a clear preference for solutions that minimize bespoke point-to-point interfaces and reduce long-term integration maintenance.
-
AI as operational lever, not a novelty. Vendors are embedding AI to support study build automation, site risk prediction and synthetic patient simulations. Our benchmarking shows that 2026 procurement teams must assess not only model accuracy but also governance: lineage, retraining cadence, and regulatory defensibility.
-
Compliance & cybersecurity as cost centers and differentiators. With regulatory updates — including stricter requirements under HIPAA security proposals and continuing GDPR expectations for privacy-by-design — CTMS buyers must prioritize encryption, frequent vulnerability scanning, penetration testing, and contractual obligations like BAAs.
-
Persistent operational cost drivers. Specialized labor for system configuration, validation, and change control remains a primary cost component. Effective total cost of ownership (TCO) assessments for 2026 must model labor profiles, cloud hosting costs tied to data volume, and the incremental compliance burden of global trials.
Competitive landscape and vendor implications
The vendor ecosystem is diverse: established enterprise vendors, CRO-integrated platforms, site-focused specialists and point solution providers all compete for mindshare. Market concentration metrics indicate meaningful share among leading players, yet there is room for differentiation through vertical specialization and service-led models. For 2026 decision-makers, the following vendor archetypes — and representative companies — illustrate strategic trade-offs.
-
Enterprise orchestration leaders: Firms offering end-to-end clinical platforms bring deep integrations, advanced analytics and enterprise governance. Their strength lies in lifecycle orchestration and broad platform roadmaps, making them suitable for sponsors and large CROs seeking consolidation and single-vendor governance.
-
Site and network specialists: Vendors that prioritize site workflows, financials and regulatory workflows reduce site burden and billing complexity. For academic medical centers and site networks, this focus can translate into faster study start-up and improved retention.
-
CRO-embedded solutions and services-led providers: Integrating CTMS capabilities into CRO service models shifts risk to the service provider and can accelerate execution, but requires careful contracting to preserve data portability and transparency.
-
Quality and compliance-centric platforms: Vendors emphasizing QMS integration, document control and audit readiness appeal to life sciences organizations where regulatory stringency and rapid inspection readiness are top priorities.
Selected vendors exemplify these archetypes in practice and signal how 2026 product competition will look. Some vendors are focused on site enablement and eConsent; others are integrating AI-driven study design tools and real-time orchestration. Recent market moves include strategic partnerships to embed AI across trial lifecycles, product launches targeted at reducing site burden, and recognition from independent assessments underscoring integrated compliance capabilities. Those developments underscore an important procurement criterion: technical capability must be assessed in conjunction with a vendor’s ecosystem of partnerships, regulatory posture and service model.
What the PW Consulting report contains — practical modules for immediate action
We designed the report for practitioners who need executable guidance in 2026. Practical deliverables include:
-
Forward-looking market sizing and scenario forecasts (multi-year, with sensitivity bands) to support investment decision-making and M&A valuation workstreams.
-
A vendor capability matrix and quadrant that maps platforms against interoperability, regulatory compliance posture, AI maturity and site usability metrics.
-
Procurement and contracting playbook including sample contractual clauses (data processing and BAA language), SLAs for security testing, change control and exit/portability terms.
-
Implementation and validation checklist covering configuration, CSV/21 CFR Part 11 considerations, documentation artifacts and accelerated validation paths for cloud deployments.
-
TCO and ROI modelling templates accounting for labor, hosting, integration and compliance costs across multiple rollout scenarios.
-
Risk matrix linking regulatory developments (e.g., HIPAA Security Rule strengthening, GDPR privacy-by-design expectations, and FDA/EMA computerized system guidance) to vendor selection criteria and compliance control tests.
-
Use-case playbooks: centralized sponsor deployments, hub-and-spoke models for CROs, and site-first rollouts designed to minimize disruption and maximize recruitment and retention benefits.
How to use the report during a 2026 procurement cycle
-
Short-listing: Apply the PW vendor matrix to create a concise RFP list that aligns with your data governance and integration strategy, then require technical proof-of-concept focused on interoperability and security testing.
-
Contract strategy: Insist on contractual commitments for encryption-at-rest and in-transit, defined penetration testing cadences, and explicit BAAs where ePHI is involved. Build acceptance tests tied to operational KPIs rather than feature checklists.
-
Validation & deployment: Adopt a phased roll-out (pilot, hybrid staging, full cutover) with predefined go/no-go criteria based on data flows, onboarding time, and site feedback loops.
-
AI governance: Require model explainability, audit logs for automated decisions, and documented retraining policies to satisfy both operational needs and regulators reviewing algorithmic components.
2026-era strategic trade-offs — a quick framework
-
Speed vs. Control: Single-platform consolidation reduces integration overhead but increases vendor dependency. Hybrid approaches (best-of-breed with a robust integration layer) preserve optionality but require stronger governance.
-
Automation vs. Validation Burden: Automation reduces manual effort but shifts effort to model governance and validation. Factor ongoing model lifecycle costs into TCO.
-
Site Experience vs. Enterprise Standardization: Platforms optimized for sites can improve enrollment and retention but may complicate central reporting and standardization across multi-site studies.
Closing guidance — what leaders must decide in 2026
Decisions made in 2026 will determine operational flexibility and compliance posture for the next half-decade. Executives should base those decisions on a synthesis of three inputs: (1) realistic TCO modelling that includes labor and compliance overheads; (2) pragmatic vendor testing focused on interoperability, security and site usability; and (3) contractual protections that preserve data portability and require explicit security assurance. PW Consulting’s market study packages those inputs into actionable tools, scenario models and evaluation frameworks designed to shorten procurement cycles and reduce execution risk.
For practitioners who want the full segmentation, granular vendor profiles, and downloadable templates referenced in this brief — including the detailed regional and end-user breakouts that we intentionally summarize here to preserve strategic confidentiality — the complete report and supporting appendices are available on our website.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Precision Copper Foil Market to Expand at 8.64% CAGR, Reaching USD 21,167.27 Million by 2032
By PW Consulting, 2026-07-01
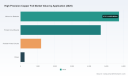
High Precision Copper Foil Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today publishes an executive preview of our forthcoming in-depth market study on the High Precision Copper Foil market, designed to equip senior strategy teams with the intelligence required to make high-stakes decisions in 2026. This piece outlines the report’s analytical framework, summarizes key market trajectories, and flags the competitive and supply-side dynamics that will determine winners and losers through the 2026–2032 forecast horizon. Consider this a strategic trailer: we demonstrate analytical depth and actionable insights while holding back the detailed segment-level figures reserved for the full report.
High Precision Copper Foil Market
Executive snapshot: macro trajectory and strategic stakes
The high precision copper foil market emerges from 2025 on a renewed growth trajectory, underpinned by electrification, miniaturization of electronics, and demand for higher signal-integrity materials in advanced computing and communications. Our model, anchored on a 2025 base year and projecting through 2032, shows a robust compound annual growth rate (CAGR) of 8.64% across the forecast period. By 2026 the market is forecast to expand meaningfully from its 2025 base, and PW Consulting’s scenario set shows a clear upside path to the terminal year supported by technology adoption curves in consumer electronics, automotive electrification, and next-generation PCBs.
High Precision Copper Foil Market
Two observations are immediately pertinent to 2026 strategic planning: first, the market growth is sufficiently broad-based to justify capacity reallocation and selective investment in higher-value foil technologies; second, volatility in input costs and regional policy shifts make timing and supplier diversification a central part of procurement and capital allocation playbooks.
High Precision Copper Foil Market
What the full report delivers (practical, transaction-ready content)
- Proprietary model outputs with base-year calibration and stress-test scenarios for copper price shocks, capacity outages, and demand-side slowdowns.
- Decision matrices for procurement, pricing, and capacity investments mapped to 18 business cases (OEMs, laminate producers, battery makers, and PCB fabricators).
- Scenario-based ROI and NPV implications for capacity expansion vs. strategic offtake agreements under high and low raw material price regimes.
- Competitive playbooks for incumbents vs. challengers, including recommended strategic responses (JV, licensing, vertical integration, or niche specialization).
- Due diligence checklists and M&A valuation multiples tailored to different foil technologies (electrodeposited, rolled, and ultra-thin/high-frequency variants).
Drivers, friction points and 2026 decision levers
- End-market pull: Rapid adoption of lithium-ion battery architectures and high-density interconnects is elevating demand for ultra-thin and ultra-smooth copper foils. Procurement teams should treat foil quality and process yield as leading indicators of total system cost, not simply a raw-material line item.
- Input-price volatility: Copper cathode volatility in 2025 and early 2026 materially tightened manufacturing margins. Our scenarios quantify the pass-through elasticity and identify optimal hedging horizons for buyers and manufacturers.
- Capacity & timing: Recent capacity investments by several leading producers change the near-term supply balance. The timing of commissioned capacity, ramp-up efficiency, and location footprint will materially affect contract negotiations in 2026.
- Regulatory and sustainability constraints: Tightening environmental rules—particularly in jurisdictions pushing carbon neutrality—are reshaping cost structures and raising compliance investment needs for producers. Sustainability capabilities are fast becoming commercial differentiators.
Competitive landscape — who matters in 2026 and why
The market exhibits moderate concentration: the top-three players account for a meaningful chunk of supply while the top-five command an even larger share. This concentration profile creates asymmetric bargaining power that buyers and new entrants must account for in 2026 negotiations.
- Mitsui Mining & Smelting (Mitsui Kinzoku): A global leader in ultra-smooth MicroThin products and VSP™ technology. Recent actions—including capacity expansions and price adjustments—signal a dual focus on securing margin through pricing while vertically scaling capacity for high-end applications.
- JX Nippon Mining & Metals (JX Advanced Metals): Deep expertise in both electrodeposited and rolled foils positions this player to capture cross-sector demand where strict thickness control and high-frequency performance are required.
- Furukawa Electric: With a global footprint and disciplined tolerance manufacturing, Furukawa remains a go-to supplier for precision applications requiring consistent quality across geographies.
- Circuit Foil Luxembourg and other specialty European producers: These firms retain strength in very thin, high-spec foils where surface finish and micro-roughness metrics are non-negotiable for advanced PCB and RF applications.
- Regional challengers (selected Chinese, Korean, and Taiwanese producers): These firms compete on cost-competitive high-precision rolled and electrodeposited products and are increasingly active in energy storage and FPCB supply chains.
In short, 2026 will not be a winner-take-all race; instead, manufacturers will compete along differentiated axes—technology (e.g., ultra-low roughness and thickness control), scale (mass supply to battery and laminate sectors), and sustainability credentials. Buyers should expect targeted price moves and capacity-driven availability constraints to persist through much of 2026.
Recent market moves and implications for 2026 negotiations
- Price adjustments: Several leading suppliers announced significant price increases in late 2025 and early 2026. These moves reflect both input-cost pressure and strategic margin management. Buyers must reassess indexation clauses, hedging strategies, and long-term supply contracts in response.
- Capacity expansions: Announced expansions of proprietary ultra-smooth foil capacity by global incumbents will shift supply-side dynamics for specific premium product lines. The timing of these ramps affects spot availability and contract leverage for both OEMs and laminate producers.
- Product portfolio refreshes: Some producers updated product catalogs to emphasize tighter tolerances and thinner offerings for electronics and battery applications—an indicator of accelerating product-level competition rather than a race on commoditized volumes.
Supply-chain stress points: raw materials and regional exposure
High precision foil manufacturing is tightly coupled to copper cathode supply and refining economics. Despite elevated cathode prices earlier in 2026, smelter treatment and refining charges hit atypical low points—creating a paradox of upstream margin pressure and downstream raw-material cost spikes. Coupled with historically high operating-rate variability in major supply regions, these dynamics produce short lead-time volatility and localized shortages at times of peak demand.
For strategy teams, the practical implications are clear: diversify sourcing across technology types and geographies, build flexible contract terms that allow for rapid reallocation of supply, and evaluate on-site scrap recovery and material-efficiency projects to mitigate input-cost risk.
Regulatory & sustainability considerations
Public policy is reshaping production economics. Stringent carbon neutrality mandates in some producing countries are prompting investments in renewable energy integration, recycled-copper processing, and lower-emission process technologies. These investments have capex implications but create market advantages for suppliers that can credibly offer low-carbon foil streams to OEMs targeting greener supply chains.
Strategic recommendations for 2026 decision-makers
- Prioritize supplier segmentation: Assign suppliers to buckets (strategic, tactical, contingency) based on technology fit, sustainability credentials, and capacity visibility. Use PW Consulting’s supplier scorecard to operationalize this segmentation.
- Lock in critical offtake for premium foils: For applications where foil performance is system-critical (e.g., high-frequency interconnects, advanced batteries), prefer long-term offtake with fixed R&D collaboration terms over spot purchasing.
- Hedge intelligently: Combine physical inventory buffers with derivative hedges tailored to the timing of major capital projects and product launches.
- Consider asset-lite partnerships: For companies seeking exposure to advanced foil performance without heavy capex, structured licensing, tolling, or joint-venture models offer downside protection while preserving access to specialized technology.
What we deliberately withhold in this preview — and why
True to the “trailer” principle, we have shown the analytical approach and surfaced the strategic implications that will matter to executives in 2026. We have, however, withheld core subsegment revenue tables, granular regional and application splits, and product-level pricing curves that are critical for transaction execution and contract drafting. Those items are included in the full PW Consulting report and model package, which also contains sensitivity runs and supplier-level scorecards necessary for negotiation and M&A diligence.
Next steps — how PW Consulting supports your 2026 agenda
- Custom briefings: Schedule a tailored 90-minute executive briefing to align the report’s findings with your corporate strategy and procurement calendar.
- Scenario workshops: We offer facilitated scenario-planning sessions to stress-test capital allocation and procurement strategies against alternative raw-material and policy outcomes.
- M&A and procurement support: Access to our valuation models, supplier due diligence templates, and negotiation playbooks designed specifically for high-precision copper foil deals.
For purchasing the full High Precision Copper Foil Market report, accessing the proprietary model, or arranging a briefing, visit the PW Consulting insights portal. The full study contains the detailed segment-level data, supplier matrices, and actionable templates that procurement, strategy, and corporate development teams will need to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
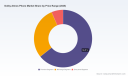
Dolby Atmos Phone Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today publishes an in-depth market research brief — Dolby Atmos Phone Market — designed to equip senior strategy teams with the evidence and frameworks required to make high-consequence decisions in 2026. The study synthesizes historical performance, near-term inflection points, and a seven-year forecast horizon to show where Dolby Atmos-enabled smartphones will create commercial leverage for OEMs, platform partners, content owners, and component suppliers.
Dolby Atmos Phone Market
Executive snapshot: Why 2026 is a strategic inflection
-
Market momentum is unmistakable. The Dolby Atmos-enabled smartphone category more than doubled in size across the last half-decade, growing from approximately USD 16.5 billion in 2020 to USD 28.5 billion in 2025.
Dolby Atmos Phone Market -
Forward-looking growth is robust: our base-case model projects a compound annual growth rate (CAGR) of 11.64% over the 2026–2032 forecast window, with the market expected to exceed USD 60 billion by 2032.
Dolby Atmos Phone Market -
2026 is the year to translate audio feature parity into commercial differentiation. OEMs and ecosystem partners that move beyond checkbox integration toward differentiated hardware-software-content experiences will capture disproportionate value as adoption scales into mid-tier portfolios and new geographies.
What the report contains — practical, decision-ready intelligence
-
Market sizing and robust forecasting: transparent methodology, scenario modelling (base, upside, downside), and sensitivity tests to help translate macro assumptions into P&L impact.
-
Go-to-market playbooks: product segmentation by audio UX archetypes, route-to-market considerations for premium vs. mid-tier launches, and recommended launch timing relative to annual refresh cycles.
-
Commercial frameworks: licensing and revenue share models, co-marketing templates with Dolby and streaming partners, and pricing archetypes adapted to multiple channel strategies (direct, carrier, retail).
-
Engineering and product checklists: end-to-end hardware/software integration guidance, speaker configuration trade-offs (stereo placement, amplification, DSP tuning), certification pathways, and verification protocols to ensure consistent spatial audio quality.
-
Supplier and component mapping: strategic supplier segmentation, lead-time risk analysis, and cost-down levers for mass-market adoption without degrading experience.
-
Competitive and M&A playbook: assessment of incumbent OEM positioning, adjacencies ripe for consolidation (audio startups, low-latency streaming middleware, spatial-audio SDKs), and diligence checklists for bolt-on acquisitions.
-
Commercial KPIs and measurement templates: adoption metrics, feature engagement, bundling uplift, and LTV/ARPU modeling for monetization experiments tied to Dolby Atmos-enabled experiences.
Competitive landscape: what the OEM moves tell us
The competitive map is dominated by a mix of global flagships and aggressive regional players. Major incumbents have implemented Dolby Atmos differently — from system-level spatial audio implementations to device-specific tuned experiences — and recent product announcements in early 2026 underscore continuing commitment across the ecosystem.
-
Samsung has embedded Dolby Atmos broadly across its flagship Galaxy families and selected mid-range models, using speaker hardware and software tuning to make spatial audio a headline feature in launches.
-
Apple continues to support spatial audio across its iPhone line through integrated hardware-software optimization and a closely controlled accessory/eCosystem play that protects perceived quality.
-
Large Chinese OEMs (Xiaomi, OPPO/OnePlus/Realme, vivo, Huawei) are treating Dolby Atmos as a product capability that accelerates multimedia and mobile gaming differentiation, bringing more advanced audio experiences into aggressive price tiers in many markets.
-
Sony and Nokia persist as niche differentiators: Sony leverages its audio heritage to position Xperia models with cinema-grade tuning, while Nokia and other smaller OEMs selectively deploy Dolby Atmos to lift perceived value on model refreshes.
-
Motorola’s early-2026 launch of an ultra-slim Signature model with Dolby Atmos and partner-branded audio hardware signals an important product strategy: collaborate with specialist audio brands to deliver tangible experiential upgrades rather than marketing-only claims.
Across the competitive set, the takeaway is consistent: Dolby Atmos has shifted from a premium-only checkbox to a scalable feature leveraged for both product differentiation and volume growth. The strategic question for 2026 isn’t whether to support Dolby Atmos — it is how to design product, pricing, supply chain, and partner economics to extract commercial advantage from that support.
Dynamics shaping the next 12–24 months
-
Premiumization and feature bundling: Buyers continue to exhibit willingness to pay for richer multimedia experiences. Dolby Atmos can act as a demand amplifier when paired with display, camera, and gaming upgrades.
-
Streamers and gaming publishers as multipliers: Content owners expanding spatial audio catalogues create distinct use-cases that raise the marginal utility of in-device Atmos implementations.
-
Certification and licensing: Dolby’s licensing and certification programs reduce quality variability, but they also introduce negotiation levers (package scope, testing cycles, co-marketing commitments) that materially affect margins and go-to-market speed.
-
Geographic diffusion: The expectation that Dolby Atmos expands into mid-tier devices in emerging markets suggests that scale economics will increasingly matter. This changes supplier mix, testing regimes, and pricing models.
-
Concentration among supply and OEM partners: a handful of large OEMs and platform players will continue to define market norms; strategic partnerships with these players accelerate reach while creating competitive moats for differentiated device makers.
Actionable recommendations for 2026 corporate decision-makers
-
For OEM product leaders: Prioritize a tiered integration strategy — reserve highest-fidelity tuning and premium hardware for flagships while creating verified, repeatable integration templates for upper mid-tier devices. Map clear experiential deltas so marketing can credibly communicate value.
-
For commercial & partnerships teams: Negotiate licensing and co-marketing arrangements that align incentives across OEM, Dolby, and streaming partners. Test bundling pilots with major streaming services to assess incremental ARPU and retention effects.
-
For finance and M&A teams: Screen acquisition targets that provide proprietary spatial-audio processing, low-latency audio stacks for cloud gaming, or differentiated tuning tools. Prioritize targets with defensive IP and established integration methodologies.
-
For supply-chain and operations leaders: Lock down multi-sourced component pathways for speakers, amplifiers, and key DSP chips, and build accelerated validation tracks to shorten certification timelines without compromising audio quality.
-
For marketing and channel: Develop consumer education programs that translate spatial audio benefits into tangible use-cases (mobile gaming, streaming movies, voice clarity). Equip carrier and retail sales teams with simple demos and quantified uplift metrics.
Why this report matters for boardroom decisions in 2026
Strategic bets on audio capability today influence product roadmaps, supplier contracts, and content partnerships for years. With the Dolby Atmos phone market on a clear upward trajectory — supported by solid historical acceleration and an 11.64% CAGR in our forecast window — the choices companies make in 2026 will determine whether they are volume participants, margin-capturers, or relegated to feature parity.
Boards and C-suite teams will find the report valuable because it converts market growth projections into investment-grade guidance: recommended capex allocations for audio hardware, milestone-based commercial KPIs for partnership deals, and a prioritized action list for near-term EBITDA improvement tied to audio-led product differentiation.
Selective insights — and what you’ll only see in the full report
We deliberately present a high-level view in this release to demonstrate the strategic value of the full intelligence package. The complete report contains granular regional scenarios, channel-specific adoption curves, product-level profitability models, and an OEM supplier matrix — the detailed inputs that underpin the topline forecasts and the practical templates described above.
If your team is evaluating product roadmaps, licensing strategies, or M&A targets tied to spatial audio, the dataset and playbooks included in the full report provide the calibrated evidence required to run rigorous build vs. buy vs. partner analyses and to size expected return on investment under multiple commercial structures.
Next steps
-
Download the executive package to access our forecast model and scenario workbook.
-
Commission a tailored briefing from PW Consulting to map the implications for your product roadmaps, channel strategies, and partnership negotiations in 2026.
-
Engage our M&A team for a targeted screening of audio technology assets aligned to your strategic objectives.
PW Consulting’s Dolby Atmos Phone Market report is intended as the strategic trailer for decision-makers who need both the big-picture growth signal and the playbooks to act. For the full dataset, segmented analyses, and the complete set of operational templates referenced above, please visit our report page to access the comprehensive study and supporting models.
For detailed analysis of this topic, please visit the official page: Dolby Atmos Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Satellite Control Services Market to Expand at a 7.45% CAGR Through 2032, Unlocking New Growth Opportunities
By PW Consulting, 2026-07-01
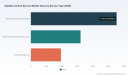
Satellite Control Service Market 2026: Strategic Imperative and Tactical Playbook — PW Consulting Industry Brief
Executive summary
The Satellite Control Service market stands at a strategic inflection point. Our new market study, anchored on 2025 as the base year and projecting through 2032, demonstrates resilient expansion driven by multi-orbit operations, commoditization of ground infrastructure, and regulatory shifts that will reframe access to spectrum and market entry in 2026. PW Consulting’s models estimate the global market at USD 21,450 Million in 2025, growing at a 7.45% CAGR to reach roughly USD 35,470 Million by 2032. That trajectory creates a multi-year runway for incumbents and new entrants to capture recurring TT&C (Telemetry, Tracking & Command), station keeping, maneuver control and payload management revenues — provided they realign commercial models, manage capital intensity, and navigate an accelerating regulatory landscape.
Satellite Control Service Market
Why 2026 is a decision point
-
Regulatory windows opening. Multiple policy initiatives converging in late 2025 and early 2026 — including streamlined satellite licensing proposals, a bipartisan U.S. bill to standardize market access, and EU measures accelerating infrastructure approvals — create a narrow window for firms to secure spectrum rights, contest market positions, or lock in favorable licensing terms. Strategic timelines that were measured in years are now compressed into quarters.
Satellite Control Service Market -
CapEx vs. GSaaS economics. Ground-station deployment remains capital intensive. At the same time, the market’s financial logic is shifting: Ground-Station-as-a-Service (GSaaS) and managed operations models are material vehicles for growth and risk mitigation. Operators must decide whether to scale owned infrastructure or form cloud-like, networked partnerships that monetize antenna capacity and operations expertise.
Satellite Control Service Market -
Operational complexity and automation. The mass adoption of smallsat constellations and hybrid multi-orbit architectures increases TT&C transaction volumes and mission complexity. Automation, cloud-native mission control, and AI-driven anomaly detection are no longer optional for operators who want to maintain margins while scaling operations.
What PW Consulting’s report delivers (practical, actionable modules)
Our Satellite Control Service Market report is built for decision-makers planning capital allocations, M&A, product strategy, or procurement for 2026. The study synthesizes historical performance (2020–2025), a detailed forecasting model (2026–2032), and scenario analysis under alternative regulatory and technology adoption pathways. Key deliverables include:
-
Proprietary market-sizing model with base-case, upside and downside scenarios and sensitivity levers for spectrum policy, capex trends, and GSaaS adoption rates.
-
Vendor benchmarking and scorecards across capabilities: multi-orbit TT&C, managed operations, latency SLAs, security posture, and service continuity assurances.
-
Go-to-market playbooks for incumbent operators, ground-network specialists, systems integrators and cloud providers — including pricing buckets, partnership archetypes, and white-space opportunities.
-
Build-versus-buy TCO models and a procurement-ready RFP template for GSaaS and managed satellite control services.
-
Regulatory path matrices that map national licensing regimes, predicted approval timelines, and practical mitigation steps for spectrum and access risk.
-
M&A and alliance playbook with valuation heuristics, integration risks, and revenue-synergy scenarios tailored to satellite control assets.
Note: This announcement intentionally omits the granular regional and application split tables and proprietary financial line items included in the full report — these are available through PW Consulting’s data portal.
Competitive landscape: positions, capabilities, and strategic moves
The market’s top-tier concentration and the profile of active players shape competitive dynamics. Our concentration analysis indicates a moderately consolidated market: the top three firms account for a meaningful share of revenue concentration, and the top five further increase market hold. This structure creates room for specialized challengers and ground-network aggregators to capture niches while incumbents defend broad service portfolios.
-
Ground-network specialists and GSaaS aggregators: Firms with dense antenna networks and mission-adapted operations — exemplified by global ground-network providers — are leveraging geographic reach and multi-orbit experience to win managed TT&C contracts. Recent public network expansions demonstrate continued investment in physical footprint to support rising telemetry volumes and LEO revisit demands.
-
Large satellite operators and integrated service providers: Established satellite operators that combine fleet operations with integrated ground segments are playing a dual role: they are both customers for third-party GSaaS and competitors offering full lifecycle mission services. Their advantage lies in fleet-level optimization and lifecycle engineering capabilities.
-
Defense and systems integrators: Defence-focused suppliers and prime contractors offer hardened, secure command-and-control solutions and have a strong position in government and military segments where mission assurance and certification are primary procurement criteria.
-
Platform and software vendors: A rising cohort of software-first providers focus on mission control automation, telemetry analytics, and cloud-native control systems. Their marginal cost model for scaling mission control software makes them attractive partners for both operators and GSaaS providers seeking automation-driven efficiency.
Recent corporate actions underscore these dynamics: network expansions by ground-network specialists, contract renewals in managed connectivity for defense customers, operational updates from global operators, and gateway deployments tied to new constellations. These moves collectively underline an industry transitioning from siloed, capital-heavy stacks to hybrid models that mix asset ownership with service layers.
Key strategic implications for 2026 (how executives should act)
-
Lock in regulatory and spectrum positions now: With several regulatory initiatives slated to crystallize in early 2026, firms should prioritize regulatory engagement, scenario planning for license timelines, and legal strategies to protect cross-border operations.
-
Decide the infrastructure posture: Use a short-form TCO and sensitivity model to determine whether to expand owned ground assets or accelerate GSaaS partnerships. The right choice depends on latency needs, sovereign requirements, and the lifecycle revenue outlook of an operator’s fleet.
-
Invest in automation and secure software stacks: Scale cannot be achieved profitably without higher levels of automation in mission control and robust cybersecurity architectures for TT&C. Prioritize modular, cloud-friendly control systems and AI-enabled anomaly detection as immediate investment themes.
-
Pursue selective M&A and strategic alliances: Identify targets that fill capability gaps — e.g., ground-network density, software control platforms, or certified defense-grade operations — and favor bolt-on transactions where integration risk is manageable.
-
Differentiate through SLAs and mission assurance: Commercial customers will trade on predictable availability and rapid restoration. Firms that can credibly offer mission assurance commitments with verifiable SLAs will command premium pricing in managed services engagements.
Risk map and mitigation
Key risks include regulatory uncertainty, capital intensity of ground infrastructure, supply-chain constraints for RF and antenna components, and evolving cyber threats to TT&C pathways. Mitigation levers include diversified access strategies (hybrid owned + GSaaS), multi-sourcing of critical hardware, cyber-hardening programs, and insurance structures tied to service continuity. Our report contains a detailed risk-heatmap and mitigation-level scoring to prioritize where to deploy capital and market-facing resources in 2026.
How to use this brief and next steps
This release is intentionally a strategic preview: our goal is to surface the decision-critical themes that will define winners in 2026 while conserving the proprietary modelling and granular split data that clients rely on for execution. Executives preparing budgets, M&A targets, or procurement strategies should treat the findings here as directional and use the full PW Consulting report to execute precise sizing, vendor selection, and contract negotiation strategies.
-
For immediate planning: incorporate the 7.45% CAGR and our near-term forecasts into 2026 revenue scenarios, stress-testing assumptions on spectrum access and GSaaS adoption.
-
For procurement and partner selection: request PW Consulting’s vendor scorecards and RFP templates to compress supplier evaluation timelines.
-
For transactions: use our M&A playbook and valuation heuristics to align bids with realistic synergy capture and integration timelines.
To access the full dataset, granular regional and application splits, vendor-level revenue models and the operational playbooks referenced above, please visit the PW Consulting report page or contact our strategy team. The window to lock positions ahead of 2026 regulatory and commercial inflection points is short — informed, decisive action now will materially alter market share outcomes over the next seven years.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Biomass-for-Power Market to Surge to USD 178.02 Billion by 2032
By PW Consulting, 2026-07-01
Biomass for Power Generation Market: Strategic Insights for 2026 Decision-Making
Executive preview
PW Consulting’s latest market study on biomass for power generation synthesizes five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032. The market has expanded meaningfully since 2020, reaching an assessed global market size of USD 111.8 Billion in the report’s base year (2025). Our modelling indicates continued expansion across the forecast period, with the market projected to grow at a compound annual growth rate (CAGR) of 6.89% (2026–2032), reaching an estimated USD 178.02 Billion by 2032. For executives planning capital allocation, strategic partnerships, or regulatory engagement in 2026, these headline dynamics are a practical starting point — and this press release outlines the key strategic takeaways you should weigh before accessing the full report.
Biomass For Power Generation Market
Why this report matters in 2026
-
Actionable horizon: The study is calibrated to the 2026 decision cycle. It integrates recent project commissioning, supply‑chain developments, and policy shifts that are already altering project economics and permitting timelines.
Biomass For Power Generation Market -
Decision support: Rather than high-level commentary, the report provides investment-level lenses — project-level economics, scenario-based sensitivities, and CAPEX/OPEX benchmarks — to support go/no‑go choices and portfolio prioritisation.
Biomass For Power Generation Market -
Risk differentiation: With policy frameworks evolving rapidly in major markets, the report quantifies regulatory upside and downside scenarios so stakeholders can design hedge strategies for feedstock, carbon accounting, and incentive eligibility.
Market outlook — what the numbers signal
The sector’s growth trajectory is clear: after a post-2020 recovery and expansion phase, the industry is entering a multi‑year growth runway that is underpinned by utility-scale coal-to-biomass conversions, new build projects in emerging markets, and increased interest in distributed biomass CHP. The forecast CAGR of 6.89% over 2026–2032 reflects a combination of steady demand for dispatchable renewable electricity, greater policy support in several jurisdictions, and investment in supply‑chain infrastructure.
For corporate strategists, the headline phase of growth translates into expanding addressable markets for three distinct value pools: fuel supply and logistics, plant equipping and EPC services, and energy offtake and grid integration services. Each pool requires different margin and capital models — the full report breaks these down and models sensitivity to fuel price swings, capital cost inflation and differing policy outcomes.
Key dynamics shaping 2026 choices
-
Policy and incentive design: Recent regulatory developments have shifted the calculus for biomass investments. Technology‑neutral clean electricity credits and investment tax incentives tied to lifecycle greenhouse gas outcomes have created pathways for certain biomass projects to access parity with other low‑carbon options — provided developers can demonstrate credible lifecycle emissions accounting.
-
Carbon management: Legislative proposals to broaden carbon‑capture tax credits to support forest residue-based products and wildfire mitigation endpoints are increasing the optionality for integrated biomass projects that combine fuel management with carbon mitigation services. For project sponsors, pairing biomass generation with carbon removals is becoming a material component of long‑term value creation.
-
Feedstock economics and logistics: Supply‑chain resilience remains the single largest operational risk. While feedstock costs and market flows continue to vary regionally, our scenario models show that vertically integrated supply strategies, fuel diversification and upstream processing capacity (pelletising, densification) can materially reduce merchant price exposure and improve plant availability.
-
Project finance and offtake: Appropriations and public funding mechanisms signed into law in early 2026, alongside evolving merchant power dynamics, are widening financing options for creditworthy projects. However, financiers are increasingly demanding transparent carbon accounting and feedstock sustainability evidence as condition precedents to debt.
Competitive landscape — who’s shaping the market
The biomass value chain is populated by several distinct player types: large utilities retrofitting or operating biomass fleets, specialised fuel producers and pellet exporters, EPC and equipment suppliers, and regionally-focused developers. Leading utilities and energy companies are pursuing a twofold strategy: preserve dispatchable capacity by repurposing existing assets and build new capacity in markets with secure feedstock streams.
Representative players profiled in our study include major European and North American utilities that have converted coal units to biomass and maintain integrated wood pellet supply chains; global EPC and engineering firms supplying boilers and gasification systems; and specialised developers active in Asia-Pacific. Our company-by-company analysis evaluates strategic positioning, balance-sheet exposure to biomass, recent project pipelines, and technological focus — enabling investors to identify potential partners or acquisition targets.
Recent, strategically significant developments (covered in the report) include new commercial plant startups in Southeast Asia, grid connections of first-of-type projects in the Asia‑Pacific region, and additional processing capacity in key biomass fuel hubs. These moves are practical indications of where near-term operational scale and supply integration are being achieved.
Strategic implications for corporate decision‑makers in 2026
-
For utilities and IPPs: Prioritise asset-level lifecycle GHG verification and evaluate hybrid models (biomass-plus-carbon-capture or biomass-plus-waste-to-energy) to secure long-term offtake premiums and policy credits.
-
For fuel producers and traders: Invest in downstream processing capacity and logistics visibility to capture margin from densification and to supply long-term conversion projects; contracts that include indexation, quality clauses, and logistics guarantees will be critical.
-
For equipment vendors and EPCs: Differentiate through modular, lower‑emissions combustion and gasification solutions, and by offering performance guarantees tied to fuel variability and ash management.
-
For financial sponsors: Use the report’s scenario models to stress test leverage and term structures against feedstock shocks and policy reversals; green‑linked financing structures that reward verified lifecycle carbon performance are increasingly relevant.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and forecasting model (base year 2025; historical 2020–2025; forecast 2026–2032) with downloadable Excel workbooks that allow users to run alternative scenarios on feedstock price, CAPEX trends and policy outcomes.
-
Segment-level diagnostic frameworks across fuel types and technology routes (combustion, gasification, anaerobic digestion) with practical checklists for plant conversion and new build evaluation.
-
Policy and incentives playbook mapping major jurisdictional programs, recent legislative proposals, and eligibility criteria for tax and production credits — emphasising pathways to monetise lifecycle emissions improvements.
-
Competitive intelligence dossiers on leading utilities, developers and equipment suppliers with capability matrices, partnership maps and M&A signals to guide corporate development teams.
-
Supply‑chain risk heatmaps and procurement strategies covering densification, co‑firing compatibility, logistics bottlenecks and seasonal availability.
-
Operational benchmarking: CAPEX/OPEX comparators, heat-rate ranges, fuel consumption profiles and availability metrics to support valuation and due diligence teams.
How to use the report in 90 days
-
Week 1–2: Validate your internal assumptions against the report’s base‑case model — focus on feedstock sourcing and lifecycle emissions inputs.
-
Week 3–6: Run customised scenario stress tests for target assets or projects using our downloadable workbooks — explore different policy and price outcomes.
-
Week 7–12: Engage targeted counterparties identified in the competitive dossiers and use the report’s negotiation playbooks to structure long‑term fuel and offtake agreements with sustainability covenants.
Final counsel — the strategic decision window
2026 will be a pivotal year for stakeholders in biomass power. The confluence of stronger policy attention on lifecycle emissions, nascent carbon‑removal linkages, and fresh capacity coming online in several geographies creates both opportunity and complexity. Our analysis shows the market is growing from an established base and entering a sustained expansion phase; however, outcomes will be highly path‑dependent on feedstock security, carbon accounting frameworks, and the structure of fiscal incentives.
PW Consulting’s Biomass for Power Generation Market report is designed as a decision‑grade instrument: it equips executives with the models, competitive intelligence, and pragmatic checklists needed to move from strategic intent to executable plans in 2026. For teams that require the full dataset, segment breakdowns, and downloadable modelling tools, the report and accompanying data packs are available on our website.
Next steps
Contact PW Consulting to schedule a briefing with our biomass practice lead and request a tailored extract of the forecast model for your asset or market of interest. Our advisory team can also run a short-form diligence workshop to translate the report’s insights into an actionable 12‑month roadmap for your organisation.
For detailed analysis of this topic, please visit the official page: Biomass For Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biopharma Autoclaves Market to Reach USD 4,405.14 Million by 2032, Expanding at an 8.5% CAGR
By PW Consulting, 2026-07-01
Biopharmaceutical Autoclaves Market: Strategic Imperatives for 2026
Executive snapshot
PW Consulting’s latest market study on Biopharmaceutical Autoclaves provides an evidence-based roadmap for executives preparing capital, procurement, and regulatory strategies in 2026. After five years of steady expansion, the global biopharma autoclaves market reached approximately USD 2,488.6 Million in 2025 and is forecast to accelerate to roughly USD 2,815.4 Million in 2026, reaching an estimated USD 4,405.1 Million by 2032. Our modeled compound annual growth rate (CAGR) for the 2026–2032 projection period is 8.5%—a signal that the asset class is moving from replacement-driven demand toward a phase of technology-led refresh and expansion across biologics supply chains.
Biopharmaceutical Biopharma Autoclaves Market
Why this matters to corporate decision-makers in 2026
- Capital allocation: Autoclaves represent a material line-item in biomanufacturing CAPEX and are tightly coupled with facility qualification schedules (IQ/OQ/PQ). With market momentum and evolving technical expectations, procurement timing and specification choices made in 2026 will influence both near-term validation cycles and medium-term total cost of ownership.
- Regulatory and validation risk: ISO 17665:2024, EN 285 and the reinforced expectations of current Good Manufacturing Practice (cGMP) and Annex 15 mean autoclave purchases now carry higher upfront engineering and software validation obligations. Firms that bake validation, data integrity, and lifecycle support into purchase specifications will avoid downstream rework and extended commissioning timelines.
- Operational resilience: As biologics portfolios grow and novel modalities (e.g., cell & gene therapies) require bespoke sterilization workflows, autoclaves are shifting from commodity equipment to strategic enablers. Decisions on modularity, automation and digital integration taken in 2026 will materially affect throughput flexibility and batch release velocity into 2028–2030.
Market dynamics and drivers
The market’s recent trajectory reflects a mix of capacity expansion in large-scale biologics, increased third-party manufacturing footprint, and replacement cycles driven by advances in automation and validation software. Two regulatory developments are particularly salient: the release of ISO 17665:2024 clarifying moist heat sterilization requirements, and continued emphasis on IQ/OQ/PQ regimes for autoclaves used in pharmaceutical production. These norms raise the bar for supplier capability beyond hardware—demanding robust validation packages, secure software, and lifecycle service frameworks.
Biopharmaceutical Biopharma Autoclaves Market
Technological convergence is another core dynamic. The industry is seeing rapid adoption of IoT-enabled sensors, AI-driven cycle validation, and automated goods-handling systems that reduce human touchpoints and enhance sterility assurance. Notable supplier activity—product launches and strategic partnerships—underscores this trend and creates windows of opportunity for adopters who can integrate digital sterilization validation into existing MES and quality systems.
Biopharmaceutical Biopharma Autoclaves Market
Competitive landscape: positioning and strategic levers
The market remains moderately concentrated (CR3 ~38.5%; CR5 ~52.4%), meaning a mix of global platform suppliers and specialized regional players coexist. Large vendors compete on breadth of portfolio, regulatory pedigree, and global service networks, while niche suppliers differentiate with bespoke engineering for specialized modalities and agile aftermarket services.
- Platform leaders: Established multinationals provide end-to-end sterilization portfolios—high-throughput steam autoclaves, integrated goods-handling, and validation toolchains. Their strengths include global installation footprints, certified validation documentation, and the ability to supply into cGMP biomanufacturing ecosystems.
- Specialists and regional champions: A cohort of specialized manufacturers focuses on custom-engineered cGMP steam sterilizers, compact autoclaves for R&D and clinical-scale production, or cost-competitive units supported by strong local service networks. These suppliers are attractive to manufacturers pursuing differentiated process integration or rapid deployment at lower capex.
- Technology accelerators: Recent market moves such as IoT-enabled autoclave product launches, partnerships to co-develop modular units for advanced therapies, and acquisitions of sterilization software startups highlight an industry pivot toward validated digital ecosystems. Buyers must evaluate suppliers on both mechanical design and software lifecycle governance.
What the report covers (practical, actionable content)
PW Consulting’s report is designed to be executable by corporate leaders and operational teams. Key deliverables include:
- Market sizing and scenario-driven forecasts (base year 2025; forecast window 2026–2032) with sensitivity analyses accounting for regulatory tightening, modality shifts, and supply-chain shocks.
- A regulatory and validation playbook that maps ISO 17665:2024, EN 285 and EU/FDA expectations to procurement checklists and IQ/OQ/PQ templates—enabling procurement and QA to align on acceptance criteria before purchase orders are issued.
- Supplier benchmarking across technical capability, validation documentation, service network, and digital readiness—providing procurement teams with scorecards for shortlisting vendors.
- CapEx vs. OpEx assessments, including total cost of ownership models that factor in energy, maintenance, validation rework, and end-of-life replacement.
- Integration guidelines for digital sterilization validation—detailing data integrity controls, MES/SCADA integration patterns, and cybersecurity considerations for connected autoclave systems.
- Procurement and negotiation playbooks—recommended contract clauses for warranty, spare parts, software licensing, and performance-based acceptance tied to validation milestones.
- Risk and continuity scenarios—supply-chain stress tests, aftermarket service contingency planning, and migration strategies for facilities transitioning from legacy sterilizers to modular automated systems.
Recent supplier moves that reshape choices in 2026
Industry activity over the past 18 months has redefined capability expectations. Examples include IoT- and AI-enabled autoclave product introductions, strategic partnerships to develop modular systems for cell and gene therapy, and acquisitions of sterilization-software companies by diversified life sciences OEMs. These moves accelerate vendor roadmaps and raise buyer expectations for integrated digital validation and continuous data capture. For decision-makers, the implication is clear: supplier due diligence must now evaluate software roadmaps, data ownership terms, and validation support as stringently as mechanical performance.
Actionable recommendations for 2026
- Adopt a validation-first procurement specification. Embed IQ/OQ/PQ deliverables and compliance to ISO 17665:2024 into contract milestones; tie final acceptance to successful PQ runs and secure data handover.
- Prioritize modular and automatable designs where throughput variability and modality diversification are expected. Modular goods-handling options reduce downtime and speed qualification for new process trains.
- Evaluate digital and service ecosystems—insist on transparent software version control, cybersecurity attestations, and long-term data exportability to avoid vendor lock-in and facilitate audits.
- Use scenario-based TCO models to compare lifecycle costs. Factor in energy efficiency, calibration and maintenance frequency, spare parts availability, and revalidation costs under changing regulatory expectations.
- Build aftermarket resilience. Secure multi-year spare-parts agreements and local service SLAs during procurement to minimize production interruptions, especially for single-source critical sterilizers.
- Consider strategic partnerships or co-development agreements for highly specialized needs (e.g., aseptic sterilization for gene therapy) to accelerate time-to-clinic while sharing development risk.
How PW Consulting’s study supports boardroom decisions
This report synthesizes market-scale projections, regulatory intelligence, supplier benchmarking, and implementation playbooks into a single decision-useful deliverable. Boards and C-suite teams can use it to: prioritize capital requests, structure procurement rounds, evaluate M&A opportunities within sterilization ecosystems, and set enterprise-wide standards for sterilization validation and digital readiness. The market’s projected CAGR and multi-year growth path provide a quantitative backdrop; our qualitative frameworks translate that backdrop into executable choices.
Next steps and access to proprietary detail
PW Consulting’s public release is intentionally a strategic “trailer”: it maps the landscape, highlights inflection points, and prescribes pragmatic steps for 2026 decision cycles while withholding the granular segmentation tables and vendor scorecards that form the operational core of procurement and validation execution. For teams preparing RFPs, capital approvals, or strategic supplier engagements, our full report includes the detailed appendices, vendor scorecards, and downloadable validation templates referenced above.
Contact PW Consulting or visit our report page to access the full dataset, supplier benchmarking matrices, and executable procurement templates—so your 2026 autoclave decisions are fast, defensible, and aligned with the evolving regulatory and technological environment.
For detailed analysis of this topic, please visit the official page: Biopharmaceutical Biopharma Autoclaves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


