



Category: market research
PW Consulting: DOTP Market Hits $2.15B in 2025, Projects 5.55% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Dioctyl Terephthalate (DOTP) Market: Strategic Foresight for 2026 and Beyond
The global chemicals landscape is undergoing a structural shift, driven by tightening regulatory frameworks, evolving downstream performance requirements, and a recalibration of supply chain geographies. At the center of this transformation sits Dioctyl Terephthalate (DOTP), a high-performance, non-phthalate plasticizer that has steadily gained traction as a critical enabler for flexible PVC applications across multiple end-use sectors. For procurement leaders, R&D directors, and strategic planners, the 2026 operating environment demands more than incremental forecasting. It requires a precise, forward-looking intelligence architecture that connects macroeconomic trajectories, regulatory inflection points, and competitive positioning into actionable strategy.
Our newly released Dioctyl Terephthalate (DOTP) Market research report is engineered to serve as that architecture. Spanning a rigorous historical baseline from 2020 through 2025 and extending into a forward-looking forecast window from 2026 to 2032, this study translates complex market signals into a coherent decision-making framework. The analysis is anchored in verified revenue trajectories, measured in USD millions, and calibrated to a long-term growth profile that reflects both near-term momentum and structural maturation. As we move deeper into the forecast period, the market is projected to expand to approximately 2.35 billion USD in 2026, continuing its upward trajectory toward a 2032 valuation that underscores sustained industrial demand. This growth is underpinned by a compound annual growth rate of 5.55 percent, a figure that captures the balance between volume expansion, pricing dynamics, and the gradual substitution of legacy phthalate-based additives.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a unique convergence of challenges and opportunities. On one side, manufacturers are navigating raw material procurement volatility, where the stoichiometric relationship between terephthalic acid and 2-ethylhexanol must be carefully optimized to balance cost efficiency with yield stability. On the other side, regulatory scrutiny has intensified, particularly in key import markets where trade remedy investigations have reshaped duty landscapes and altered competitive accessibility. Companies that treat these dynamics as isolated operational issues risk strategic misalignment. Those that integrate them into a unified market intelligence model can anticipate margin pressure points, identify compliant sourcing pathways, and align capacity investments with genuine end-use demand shifts.
This report is structured to bypass superficial trend commentary and deliver operational precision. It examines how material specifications, compliance certifications, and supply chain logistics intersect with regional demand patterns and application-specific performance thresholds. By mapping the interplay between production scalability, product grade differentiation, and regulatory validation, the study equips stakeholders with a clear lens through which to evaluate partnerships, sourcing strategies, and market entry or expansion scenarios. The narrative deliberately avoids granular percentage breakdowns or isolated regional revenue figures, focusing instead on the structural forces that will define competitive advantage throughout the forecast horizon.
Report Architecture: From Macro Trajectory to Operational Execution
The research is organized into a multi-layered framework designed for cross-functional utility. At the top level, the historical and projected revenue arc provides a validated baseline for scenario modeling. This is not a static curve; it is contextualized by capacity evolution, grade positioning, and the shifting economics of non-phthalate plasticizer adoption. The analysis tracks how market participants have navigated the transition from volume-driven growth to value-driven differentiation, particularly as downstream sectors demand materials that balance flexibility, thermal stability, and regulatory compliance.
A core component of the report delves into supply chain architecture and material dynamics. The production pathway for DOTP relies on precise feedstock integration, where the theoretical mass ratio of terephthalic acid and 2-ethylhexanol determines output yield per ton of processed material. Understanding this stoichiometric foundation is essential for evaluating cost structures, feedstock sensitivity, and the operational leverage available to integrated producers versus specialty formulators. The report examines how variations in feedstock procurement, synthesis guidance, and bulk supply arrangements influence competitive positioning, particularly for manufacturers that offer technical-grade formulations tailored to film, sheet, gaskets, molding, automotive interiors, floor coverings, cable insulation, and protective coatings.
Regulatory and compliance mapping forms another critical pillar. The study traces how food-contact migration limits, medical device standards, and children's article restrictions have become baseline expectations rather than niche differentiators. Products that meet established FDA indirect food additive migration thresholds and EU REACH requirements are no longer optional; they are table stakes for markets that demand versatility across packaging, synthetic leather, and consumer-facing applications. The report analyzes how compliance validation intersects with product launch cadence, capacity expansion milestones, and long-term supply reliability, ensuring that strategic planners can assess risk exposure with precision rather than speculation.
Competitive Positioning and Market Concentration Dynamics
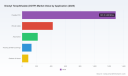
The competitive landscape reveals a market characterized by moderate concentration, with the top three participants collectively representing a substantial share of total revenue, while the top five extend that footprint into a broader but still consolidated structure. This concentration pattern reflects the capital intensity of dedicated production assets, the importance of feedstock control, and the value of established regulatory clearances. The report profiles the strategic posture of leading market participants, examining how each has carved out operational advantages through product differentiation, geographic reach, and application-specific technical support.
Among the profiled organizations, several illustrate the diverse pathways to competitive relevance. A U.S.-based specialist emphasizes technical-grade formulations designed as non-phthalate PVC plasticizer alternatives, distributed across drums, totes, and bulk channels to serve film and sheet manufacturing, gasket production, molding operations, automotive components, floor coverings, cable systems, and coating applications. A China-based manufacturer focuses on high-temperature-resistant DOTP grades tailored for cable applications, automotive interiors, food packaging, and synthetic leather, complemented by synthesis guidance and scalable bulk supply capabilities. Another China-based producer positions its DOTP plasticizer around PVC flexibility and durability, targeting automotive, construction, consumer goods, and medical applications while maintaining compliance with REACH and FDA standards. A Poland-headquartered producer operates as the largest EU-based manufacturer, leveraging a dedicated plant that utilizes proprietary 2-ethylhexanol feedstock to deliver a flagship non-phthalate plasticizer for PVC cables, automotive segments, flooring, and flexible packaging, with product validation extending to food-contact materials, children's articles, and medical devices.
Beyond static profiling, the report integrates recent market developments that signal how competitive dynamics are evolving. A major European producer marked the anniversary of its flagship DOTP launch, highlighting a decade of production stability and quality consistency alongside a capacity increase initiated in 2018 that underscores long-term commitment to non-phthalate plasticizer expansion. Separately, an Italian specialty manufacturer developed and introduced a high-performance grade engineered for flexible PVC packaging, emphasizing low volatility, enhanced flexibility, and environmental compliance. These developments are not isolated announcements; they reflect strategic responses to shifting downstream requirements, regulatory expectations, and the growing premium on application-specific performance attributes. The study synthesizes these activities into a forward-looking competitive assessment, enabling readers to gauge which operational models are scaling effectively and where market share reallocation is likely to occur.
Regulatory Inflection Points and Trade Dynamics
No strategic assessment of the DOTP market is complete without a rigorous examination of the regulatory and trade environment that shapes market access, cost structures, and competitive parity. The report provides a detailed timeline of trade remedy actions, mapping the progression from initial investigations through determinations of material injury and the subsequent issuance of antidumping duty orders. These developments have direct implications for import pricing, supply diversification strategies, and the relative competitiveness of domestically produced versus imported material.
The analysis traces how U.S. trade authorities evaluated imports originating from multiple jurisdictions, determining that material injury had occurred from shipments sold at less than fair value. This determination triggered antidumping duty orders that have reshaped the commercial calculus for both suppliers and buyers. The report contextualizes these actions within a broader regulatory enforcement pattern, noting that investigations were initiated by the U.S. Department of Commerce in mid-2024 and culminated in formal determinations by early 2025. For strategic planners, the critical insight lies not merely in the existence of duties but in how they interact with feedstock dynamics, capacity geography, and downstream compliance requirements. The study examines how market participants are adapting sourcing strategies, evaluating alternative supply corridors, and aligning product positioning with regulatory realities to preserve margin integrity and supply continuity.
Dimethyl Terephthalate (DMT) Market
Simultaneously, the report emphasizes that regulatory compliance is not solely a defensive function. Products validated under established food-contact migration limits and REACH frameworks are increasingly leveraged as competitive differentiators, particularly in applications where indirect food contact, medical device integration, or consumer safety standards dictate material selection. The study maps how compliance validation supports premium positioning, enables access to restricted downstream segments, and reduces qualification friction for new product introductions. By connecting regulatory milestones to commercial outcomes, the report provides a practical lens for assessing which product grades and supply partnerships are best positioned to capture value in a compliance-driven market environment.
Strategic Takeaways for Forward-Looking Planning
As organizations prepare their 2026 strategies, the DOTP market presents a clear mandate: success will belong to those who align operational execution with structural market intelligence. The convergence of sustained demand growth, moderate market concentration, evolving trade remedy frameworks, and rising compliance expectations creates a landscape where generic sourcing strategies and reactive procurement models are insufficient. Companies must evaluate feedstock integration, grade differentiation, capacity scalability, and regulatory validation as interconnected variables rather than isolated operational concerns.
Dioctyl Terephthalate (DOTP) Market
This report is designed to serve as a strategic compass. It translates historical performance data into forward-looking scenarios, contextualizes recent product launches and capacity expansions within competitive dynamics, and maps regulatory developments onto commercial implications. By focusing on the forces that will shape pricing, availability, and market access throughout the forecast window, the study enables stakeholders to make informed decisions about supplier partnerships, capacity investments, market entry timing, and product positioning. The narrative deliberately withhold granular segment-level breakdowns and isolated regional revenue figures, reserving those details for the full intelligence package that subscribers and purchasers can access directly through the source portal.
For executives, analysts, and strategic planners who require more than surface-level trend commentary, this research delivers the depth, structure, and operational relevance necessary to navigate the next phase of market evolution. The full study extends beyond the macro trajectory and competitive snapshots presented here, offering detailed segmentation analysis, application-specific demand mapping, regulatory compliance pathways, and scenario-based forecasting models calibrated to the 2026 through 2032 horizon. Readers seeking complete quantitative breakdowns, proprietary competitive benchmarking, and integrated strategic recommendations are encouraged to access the full report through the official research portal, where the complete intelligence architecture is available to support rigorous, data-driven decision-making.
For detailed analysis of this topic, please visit the official page: Dioctyl Terephthalate (DOTP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Loyalty Management Market to Hit $10.25 Billion in 2025, Surging to $23.21 Billion by 2032
By PW Consulting, 2026-09-16
Global Loyalty Management Market Intelligence: Strategic Imperatives for 2026 and Beyond
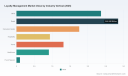
As organizations navigate an increasingly complex customer retention landscape, the global loyalty management market stands at a critical inflection point. Having been carefully tracked from 2020 through 2025 and projected forward across a 2026-2032 forecast horizon, this sector demonstrates a sustained growth trajectory that underscores shifting consumer expectations, technological maturation, and intensifying competitive dynamics. The most recent comprehensive analysis from PW Consulting reveals a market that expanded from approximately 5.4 billion U.S. dollars in 2020 to an estimated 10.25 billion in 2025, with forward calculations projecting continued acceleration toward 11.47 billion in 2026 and extending to a projected 23.21 billion by 2032. This represents a compound annual growth rate of 12.4 percent across the forecast window, positioning loyalty management as one of the more resilient and strategically vital technology domains in the broader customer experience ecosystem.
The Convergence of Scale and Strategic Necessity
What makes these aggregate figures particularly instructive for enterprise decision-makers is not merely the magnitude of expansion but the structural forces driving it. Historical data from 2020 through 2025 reflects a market that weathered macroeconomic volatility while maintaining steady adoption curves across industries. The transition from isolated point solutions to integrated loyalty ecosystems has fundamentally altered how organizations allocate budget, design program architecture, and measure return on customer retention investments. As we look toward 2026, the compounding effect of AI-enabled personalization, omnichannel orchestration, and heightened regulatory scrutiny on data practices creates a decision environment where tactical program adjustments are insufficient. Leadership teams require structural intelligence that maps technology pathways against consumer behavior shifts, competitive benchmarks, and compliance calendars.
Regulatory Realignment and Consumer Value Expectations
The 2026 operating environment introduces regulatory and behavioral pressures that directly reshape loyalty program design. Effective January 1, 2026, California Consumer Privacy Act regulations classify loyalty programs offering points, rewards, or other financial incentives as triggers for mandatory consumer disclosures. Businesses must now provide clear notices detailing material program terms, categories of implicated personal information, and the perceived data value exchanged before consumers opt into data collection. This regulatory layer compounds existing GDPR obligations around transparency in data processing and mandates Data Protection Impact Assessments for higher-risk loyalty activities.
Simultaneously, consumer motivation patterns are recalibrating around immediate economic benefit. Industry studies published in early 2026 indicate that approximately 85 percent of Quick-Service Restaurant loyalty participants prioritize cost-saving benefits as their primary engagement driver in an inflationary environment. This behavior signals a broader market shift where value-focused program structures, transparent reward economics, and frictionless redemption paths are becoming baseline expectations rather than competitive differentiators. Organizations that fail to align program architecture with these dual forces of regulatory clarity and consumer value sensitivity risk elevated opt-out rates, diminished lifetime value capture, and reputational exposure around data practices.
Competitive Landscape Architecture
The loyalty management vendor ecosystem now spans established enterprise platforms, cloud-native engagement suites, and specialized retail or sector-focused solutions, each occupying distinct positioning along orchestration depth, integration complexity, and deployment modality. Salesforce delivers cloud-based loyalty management capabilities that emphasize real-time insights and integrated customer profile analytics within broader marketing technology workflows. Oracle embeds loyalty functions within CRM and ERP architectures to support personalized retention strategies at enterprise scale, while SAP focuses on large-scale customer engagement programs driven by structured data and enterprise-grade reward management. Adobe contributes creative and data-driven platform capabilities with emphasis on journey orchestration and personalization for retention outcomes.
Loyalty Management Market
In the specialized and mid-market segments, several vendors have carved differentiated positions. Capillary Technologies concentrates on enterprise-focused, AI-powered omnichannel programs spanning retail, travel, and automotive verticals with an increasingly explicit posture toward privacy-first loyalty design. LoyaltyLion targets e-commerce and retail organizations with streamlined program setup and analytics-focused tooling. Yotpo integrates loyalty mechanics with reviews, referrals, and user-generated content to deepen engagement loops. Annex Cloud and Ignite Retail Technology both emphasize omnichannel engagement and scalable analytics, with Ignite notably extending its unified platform footprint through recent retail and convenience-channel deployments. Zinrelo and Open Loyalty differentiate through multi-channel program flexibility, gamification mechanics, and API-first or headless design philosophies that support bespoke program construction. TrueLoyal positions around combined rewards and fan club mechanisms to drive retention and brand advocacy across channels. GROWERS applies AI-enhanced loyalty architecture to agriculture retail, enabling customized rewards and predictive insights for retailers and producers.
This competitive spread reflects a market in which no single solution archetype dominates all use cases. Rather, enterprises face a segmentation challenge in matching organizational maturity, data infrastructure readiness, channel complexity, and compliance posture to appropriate platform classes. PW Consulting's market study maps these vendor archetypes against deployment patterns, solution types, and organizational sizing to support more defensible selection and investment reasoning. The analysis also highlights market concentration dynamics that indicate meaningful share distribution among leading providers while leaving substantial openness for specialized and emerging entrants in targeted verticals.
Operational Intelligence Within the Full Research Scope
The complete PW Consulting loyalty management market research extends well beyond headline sizing and growth rates. Executive and strategy readers can expect a structured examination of solution architecture classifications, deployment preference evolution, organization-size adoption curves, and industry vertical demand patterns that together reveal where investment momentum is concentrating and where white-space opportunities are forming. By solution orientation, the study distinguishes platform-based, API-based, and services-led delivery models and examines how each maps to enterprise integration requirements, speed-to-program timelines, and ongoing management burdens. Deployment analysis compares on-premise and cloud-anchored adoption trajectories, including the operational and governance implications of each path under evolving data-handling expectations.
Retail Bank Loyalty Program Market
The research also breaks down organization-size dynamics to differentiate large enterprise program strategies from small and mid-sized enterprise adoption constraints and acceleration paths. Vertical-level viewing captures demand intensity across BFSI, retail, consumer goods, hospitality, travel, healthcare, IT and telecom, and adjacent sectors, illustrating where loyalty programs are evolving from promotional vehicles into core retention and data-strategy assets. Importantly, the study intentionally withholds granular percentage splits and dollar-level breakdowns of these segments within this preview to preserve analytical exclusivity; full segment matrices, cross-tabulations, and forward demand allocations are reserved for the complete report and accompanying data appendices.
Recent Market Movements and Their Strategic Signals
Several recent developments provide early indicators of how vendor capabilities and enterprise adoption are co-evolving. In late 2025, Ignite Retail Technology announced a platform partnership through which a major convenience retailer transitioned loyalty operations to its unified platform for enhanced analytics and multi-channel engagement, signaling growing enterprise appetite for consolidated loyalty-and-analytics architectures rather than fragmented point tools. Earlier in the year, GROWERS launched AI-driven enhancements to its agriculture-focused loyalty offering, enabling predictive insights for retailers and farmers and demonstrating how sector-specific loyalty technology is moving toward forward-looking decision support rather than retrospective reward tracking. Mid-2025 saw Capillary Technologies publicly emphasize privacy-first loyalty strategies amid evolving regulations, reinforcing the market-wide recognition that compliance-aware design is now a core capability rather than a peripheral legal consideration. In early 2026, Alchemer released a Quick-Service Restaurant study reinforcing the consumer cost-sensitivity trend, further validating the strategic importance of value-aligned loyalty economics.
Strategic Decision Framework for 2026 Planning
For leadership teams constructing 2026 technology roadmaps, loyalty management now demands evaluation across three interlocking lenses. First, architecture and integration readiness determine whether loyalty data can feed broader customer profiles, personalization engines, and enterprise analytics with sufficient latency and fidelity. Second, compliance and data-value transparency must be designed into program mechanics from inception, particularly as incentive-linked data collection triggers expanded disclosure duties in key jurisdictions and as cross-border privacy expectations continue to harden. Third, program economics and consumer motivation alignment require explicit testing of reward structures, redemption friction, and perceived value against current inflationary behavior patterns, especially in high-frequency verticals where immediate savings increasingly outweigh abstract points accumulation.
The most effective 2026 strategies will treat loyalty platforms not as standalone promotional utilities but as structural components of customer data infrastructure, lifetime value optimization, and regulatory resilience planning. That shift requires decision-makers to evaluate vendors and deployment pathways against operational outcomes rather than feature checklists, and to incorporate segment-specific demand signals rather than relying on generic adoption narratives.
Accessing Complete Market Intelligence
A disciplined approach to loyalty investment in 2026 begins with access to the full dataset, competitive benchmarking, vertical demand mapping, and solution-deployment cross analysis that only the complete PW Consulting research provides. The detailed report delivers precise segment allocations, forward demand projections by organization size and industry vertical, solution-type growth reasoning, deployment trajectory commentary, and vendor positioning frameworks that together support procurement, product strategy, and board-level investment rationale.
The full study, accompanying executive summaries, and segment-level intelligence are available through the source research portal. Readers seeking complete quantitative matrices, competitive profiles, regulatory-impact scenario mapping, and actionable planning templates are encouraged to access the full report directly to obtain the granular intelligence necessary for high-stakes strategic decisions.
Conclusion: From Tactical Loyalty to Structural Retention Advantage
The loyalty management market's sustained double-digit growth trajectory through 2032 reflects a durable transition in how enterprises conceive retention: from transactional reward distribution toward integrated, data-rich, compliance-aware engagement infrastructure. For 2026 decision-makers, the strategic opportunity lies in selecting platforms, program architectures, and governance practices that convert regulatory complexity and consumer value sensitivity into differentiated retention advantage. PW Consulting's market research provides the foundational intelligence needed to make those choices with confidence, while the complete report preserves the segment-level detail and competitive depth that executive planning demands.
For detailed analysis of this topic, please visit the official page: Loyalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Auto Hand Dryer Market to Reach $372.52M by 2032, Growing at 8.2% CAGR
By PW Consulting, 2026-09-16
The Automatic Hand Dryers Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: Why Timing Matters
The automatic hand dryer industry stands at a critical inflection point. As commercial facilities, healthcare networks, and hospitality operators recalibrate their capital expenditure priorities for 2026 and beyond, the choice of hygiene infrastructure has evolved from a routine procurement decision to a strategic lever with implications for sustainability targets, regulatory compliance, and occupant experience. Our latest comprehensive research on the Automatic Hand Dryers Market is designed specifically to equip executives, procurement leaders, and industry analysts with the granular intelligence required to navigate this shifting terrain.
The market registered an estimated valuation of USD 215.0 Million in the 2025 base year, reflecting sustained momentum from the post-pandemic acceleration in facility modernization. Looking forward, the forecast period spanning 2026 through 2032 projects a compound annual growth rate of 8.2% , culminating in a market valuation of approximately USD 372.52 Million by the end of the horizon. These figures are not merely retrospective acknowledgments of growth; they represent a structural recalibration of how commercial environments approach hygiene, energy consumption, and operational efficiency. For organizations making procurement bets in 2026, this report provides the evidentiary framework necessary to align tactical purchasing with long-term strategic positioning.
Market Trajectory: Mapping the Growth Arc from 2020 to 2032
Over the historical window from 2020 through 2025, the automatic hand dryer sector demonstrated resilience that outpaced many adjacent facility management categories. Revenue expanded from USD 163.15 Million in 2020 to the aforementioned 2025 baseline, navigating supply chain friction, shifting public awareness of surface-contact transmission, and evolving building code expectations. The progression from year to year reveals a market that has matured beyond its initial pandemic-driven surge into a phase of sustained, utility-driven adoption.
The forward-looking trajectory through 2032 indicates continued expansion, with year-by-year forecasts suggesting incremental gains that compound meaningfully over the forecast horizon. The 2026 opening estimate of approximately USD 225.93 Million sets a foundation for steady growth through subsequent years, reaching the terminal valuation previously noted. This growth arc is underpinned by several structural forces: the replacement cycle of legacy drying equipment, municipal and corporate sustainability mandates that favor high-efficiency electro-mechanical solutions over single-use paper alternatives, and heightened institutional focus on touchless interaction in high-traffic environments. Decision-makers evaluating capital plans for the 2026-2032 window will find our time-series analysis and scenario modeling particularly valuable for aligning budget cycles with anticipated demand shifts.
Segmentation Dynamics: Navigating Category and Application Divergence
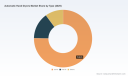
Our research dissects the market across multiple segmentation axes that matter most to product planners and commercial sales teams. At the product-category level, the Jet Air segment commands a distinctly larger share of total revenue compared to Hot Air units and Others categories, reflecting the industry's pivot toward high-velocity, low-cycle-time drying experiences that reduce queue congestion in busy facilities. Hot air variants continue to serve specific retrofit and cost-sensitive applications, while specialized equipment segments maintain relevance in niche institutional contexts.
Application-wise, the Hospitality sector emerges as the most significant demand driver, a finding that aligns with the segment's dual imperatives of guest experience enhancement and operational cost containment. Healthcare facilities represent a strategically important, regulation-intensive application environment where hygiene certification, rapid drying performance, and infection-control protocols converge to shape procurement decisions. The Others application cohort—encompassing educational institutions, corporate offices, and municipal buildings—contributes meaningful volume and serves as a bellwether for broader commercial adoption trends.
Geography further stratifies demand patterns. North America and Asia Pacific collectively anchor the largest revenue pools, while Europe , Latin America , and the Middle East and Africa regions each present distinct regulatory, climate, and procurement dynamics. Our report does not simply partition the market into static regional silos; it contextualizes regional behavior within the frameworks of local building codes, labor cost structures, energy pricing, and institutional procurement cycles. Readers seeking regional-specific procurement insights will find the detailed territorial breakdowns essential for tailoring market entry and expansion strategies.
Regulatory and Operational Dynamics: Compliance as Competitive Moats
The commercial hand dryer landscape is governed by a dense matrix of standards and protocols that directly influence product design, testing, certification, and go-to-market strategy. In the United States, ADA Accessibility Standards require that all commercial automatic hand dryers comply with accessibility and safety requirements, ensuring that deployed units accommodate a broad spectrum of user needs without creating barriers. Simultaneously, the UL 499 Standard for Safety – Electric Heating Appliances governs the construction and operational parameters of heating-element-based devices, establishing baseline electrical and fire-safety expectations that manufacturers must satisfy.
Automatic Hand Dryers Market
International considerations add further complexity. The NSF International Protocol P335 for Hygienic Commercial Hand Dryers is increasingly referenced in safety and hygiene certification frameworks, reflecting the sector's heightened scrutiny around microbial exposure and aerosolization dynamics. In European markets, Directive 2011/65/EU (RoHS 2) restricts the use of specified hazardous substances in electrical and electronic equipment, including hand dryers, compelling manufacturers to adapt material selections, component sourcing, and manufacturing processes accordingly.
These regulatory threads are not peripheral compliance checkboxes. They shape bill of materials decisions, influence total cost of ownership calculations, and determine which products can realistically compete in regulated procurement tenders. Our report maps the regulatory environment with precision, identifying which standards carry the greatest weight in specific application and regional contexts so that product strategists can anticipate certification pathways and commercial barriers before committing R&D or manufacturing resources.
Competitive Landscape: Differentiated Portfolios and Convergent Priorities
The automatic hand dryer market exhibits moderate concentration, with the top three firms collectively representing approximately 24.6% of total market share and the top five firms accounting for roughly 26.2% . This competitive structure indicates a field in which several established players maintain defensible niches while broader adoption creates room for challengers with differentiated value propositions. The profiles of leading participants illustrate how product engineering, compliance positioning, and production capacity decisions collectively define competitive advantage.
Excel Dryer Inc. , headquartered in East Longmeadow, Massachusetts, has continued to invest aggressively in capacity. The company's July 2025 expansion of its manufacturing facility in Massachusetts was explicitly aimed at increasing production capacity for automatic hand dryers, a move that signals both demand confidence and the strategic importance of supply responsiveness. Excel's portfolio centers on the XLERATOR high-speed automatic sensor-activated jet hand dryer, distinguished by HEPA filtration integration, ADA compliance, and eco-variants such as the XLERATOReco . These features reflect a coherent strategy that pairs performance credentials with sustainability and accessibility positioning.
World Dryer Corporation , based in West Bend, Wisconsin, competes with the SMARTdri Plus series, an automatic high-speed hand dryer lineup emphasizing low energy use and optional HEPA filtration. The emphasis on energy efficiency resonates strongly with facility operators managing long-term operating costs and sustainability reporting requirements.
American Dryer, Inc. , operating from Bensenville, Illinois, offers touchless high-speed automatic hand dryers including the Extreme Air and a Global value series tailored for commercial and institutional applications. This dual-track approach addresses both premium performance segments and cost-conscious procurement environments, broadening the addressable market across institution types.
Danish Design A/S , located in Denmark, brings a distinct aesthetic and hygiene-driven identity through its automatic touchless LOKI and BJØRK series. The brand's Danish design heritage is paired with hygiene features that appeal to markets where appearance, ergonomics, and cleanliness narrative converge in procurement criteria.
American Specialties, Inc. , based in the United States, fields the TURBO ADA and Roval series automatic high-speed hand dryers offered in stainless steel and matte black finishes. The emphasis on ADA-compliant touchless designs and finish options positions the company for hospitality and commercial environments where design integration and accessibility both matter.
Beyond these core firms, broader industry activity underscores the directional priorities of the sector. In 2026, the electric Handdryer Initiative highlighted the industry's trajectory during its week at InterClean 2026 in Amsterdam , emphasizing growing demand for touchless and green high-speed hand drying solutions. The initiative's May 2026 activities for World Hand Hygiene Day further reinforced advocacy for high-speed HEPA-filtered automatic hand drying technology. Meanwhile, Dyson Ltd. 's August 2025 launch of a latest hand dryer model featuring advanced HEPA filtration technology illustrated how premium engineering outfits continue to push hygiene and performance benchmarks, exerting downstream pressure on the entire category. Collectively, these developments demonstrate that the competitive field rewards firms that simultaneously deliver touchless operability, energy efficiency, filtration credibility, and installation elegance.
Hair Dryer Market
What Our Research Delivers: A Practical Toolkit for 2026 Decisions
The Automatic Hand Dryers Market research report is structured to translate macro-level intelligence into actionable decision support. Readers will find a rigorous quantitative foundation paired with qualitative analysis that connects data to commercial reality. The report's architecture is designed around several pillars.
- Historical Reconstruction and Forward Modeling: A detailed time-series analysis covering 2020-2025 provides the empirical backbone for understanding how the market behaved through distinct cycles. The 2026-2032 forecast framework extends this foundation with scenario-based projections that account for demand elasticity, replacement cycles, and adoption pacing across application types.
- Segmentation Detail at Category, Application, and Regional Levels: Our segmentation analysis goes beyond aggregate splits to reveal how product categories perform across different end-use environments and geographies. This enables readers to assess where growth concentrates, which segments exhibit resilience during economic variability, and how regional procurement cultures shape product preferences.
- Competitive Intelligence on Major Players: The report profiles leading manufacturers, examines their product strategies, evaluates recent corporate and facility developments, and contextualizes competitive positioning within the moderation of overall market concentration. This section supports benchmarking, partnership evaluation, and competitive response planning.
- Regulatory Mapping and Compliance Roadmaps: A dedicated treatment of relevant standards—including ADA accessibility, UL 499, NSF Protocol P335, and EU RoHS 2—helps product teams, procurement officers, and legal/compliance stakeholders anticipate certification requirements and identify potential barriers to market entry or expansion.
- Demand Drivers, Restraints, and Industry Event Context: The report synthesizes macro drivers such as hygiene awareness, sustainability mandates, and touchless interaction trends alongside constraints including cost sensitivity, installation complexity, and regulatory fragmentation. Recent industry events and association activities from 2025 and 2026 are integrated to ground analysis in current market sentiment and directional signals.
- Executive Decision Frameworks: Beyond raw data, the report provides interpretive guidance on how to prioritize investments, time procurement cycles, evaluate supplier alternatives, and align product selection with corporate sustainability and hygiene objectives for the 2026-2032 horizon.
Conclusion: Turning Market Intelligence into Strategic Advantage
The automatic hand dryer market is no longer a commoditized fixture category. It has become a strategically significant segment where hygiene performance, energy efficiency, regulatory adherence, and design sensibility converge to influence procurement outcomes and long-term operational economics. The 8.2% CAGR projected over the 2026-2032 period, anchored by a market that has grown from 163.15 million USD in 2020 to an estimated 372.52 million USD by 2032, reflects an environment in which informed decision-making can materially affect competitive positioning and total cost of ownership.
For executives, procurement leaders, and product strategists preparing for 2026 and the subsequent years, the detailed intelligence within our full report is purpose-built to reduce uncertainty and sharpen execution. Regional breakdowns, granular segmentation figures, company-level strategic profiles, regulatory pathway analyses, and forward scenario modeling are available in the complete publication. We invite you to access the full report to obtain the precise data and interpretive frameworks required to make confident, evidence-based decisions for the automatic hand dryer market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Automatic Hand Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Practice Management Software Market Hits $2.68B in 2025, 11.5% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for Legal Decision-Makers: Navigating the Practice Management Software Market in 2026
The legal technology landscape has reached an inflection point. What was once a fragmented market of niche tools has matured into a consolidated ecosystem where operational efficiency, AI integration, and regulatory compliance converge. For enterprise buyers, law firm managing partners, and institutional investors, understanding the trajectory of legal practice management software is no longer optional. It is a core component of operational strategy.
PW Consulting is pleased to introduce our latest market intelligence study, a comprehensive analysis designed to equip leadership teams with the actionable insights required to navigate the 2026 landscape and beyond. This report does not merely recount historical trends. It constructs a forward-looking framework that aligns technology procurement, competitive positioning, and capital allocation with the structural shifts reshaping legal service delivery.
Market Trajectory and the Case for Strategic Foresight
The legal practice management software sector has demonstrated consistent, above-average growth across the historical analysis window. Revenue expansion has outpaced many adjacent enterprise software categories, driven by a compounding set of operational pressures: rising labor costs, stringent client expectations around transparency, and the accelerating digitization of court and compliance workflows. The market has moved decisively from early-adopter experimentation to mainstream operational dependency.
This maturation is not accidental. It reflects a structural recalibration within legal operations. Firms of all sizes are confronting margin compression and talent scarcity, forcing a shift from manual, paper-heavy processes toward integrated platforms that centralize matter management, financial operations, and client engagement. Cloud-based architectures have become the default deployment model, supported by an increasingly robust security and compliance infrastructure that addresses the sector's unique trust accounting and data privacy requirements.
The forecast horizon captured in our analysis points to continued robust expansion through the end of the decade. However, aggregate growth rates only tell part of the story. The true strategic value of this research lies in its ability to segment that growth into actionable intelligence: where adoption is concentrating, which deployment models are winning, how revenue is shifting across user categories, and what competitive dynamics will determine market leadership over the next several years. These are the questions that separate reactive procurement from proactive strategy.
Inside the Analysis: What the Report Delivers
Our research methodology combines quantitative modeling with on-the-ground industry validation. The resulting publication is structured to serve multiple executive functions simultaneously: situational awareness, vendor evaluation, investment scenario planning, and operational roadmap development.
Readers will find detailed examinations across the dimensions that matter most to decision-makers:
- Market sizing and trajectory modeling spanning historical performance and a forward-looking forecast window, enabling scenario-based planning rather than single-point estimates.
- Deployment architecture analysis comparing cloud-native and on-premises environments, with emphasis on security postures, integration pathways, and total cost of ownership implications.
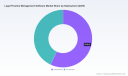
- Application-level segmentation distinguishing demand patterns across law firms and attorneys, court systems, and other institutional users, revealing where procurement momentum is strongest.
- Regional landscape mapping that contextualizes adoption maturity, regulatory environments, and purchasing dynamics across key geographic markets.
- Competitive benchmarking of leading platform providers, evaluating product roadmaps, AI integration depth, pricing architectures, and ecosystem partnerships.
- Operational dynamics assessment covering labor cost pressures, compliance frameworks, reimbursement cycle acceleration, and the evolving ethical boundaries around AI-driven case analysis and document review.
Each section is designed to produce a clear decision artifact. Rather than leaving readers with abstract market commentary, the report translates data into procurement criteria, vendor shortlisting guidance, and implementation sequencing recommendations.
The AI Inflection and Competitive Reconfiguration
No variable has reshaped this market more rapidly than artificial intelligence. Over the past year, AI usage among legal professionals has expanded meaningfully, with practice management platforms absorbing automation capabilities that were previously isolated in point solutions. Document generation, time capture, matter triage, and financial reconciliation are increasingly handled through embedded intelligence rather than manual workflow. This shift is altering vendor value propositions across the board.
The competitive landscape reflects this transformation. Market concentration remains moderate, with leading firms commanding a combined share that underscores both established presence and ongoing consolidation potential. The roster of influential players spans full-suite cloud platforms, specialized matter management systems, and AI-forward tools targeting specific practice verticals.
Analysis of the current vendor ecosystem reveals several distinct strategic postures. Cloud-native leaders such as Clio and MyCase continue to expand their functional breadth, embedding client intake, billing, trust accounting, and compliance tooling within unified workflows. Clio's strategic moves illustrate the scale-up dynamic: the acquisition of vLex in mid-2025 represents the largest legal tech M&A transaction in recent memory, merging AI-powered global legal research directly into practice management infrastructure. Shortly thereafter, the launch of a large-firm platform signaled a deliberate push into more complex case and process management environments.
Medical Practice Management Software Market
Other providers are executing differentiated plays. Rocket Matter and Filevine have emphasized reimagined platforms with stronger analytics and AI-powered case handling, while Smokeball and PracticePanther have doubled down on automated time capture, document automation, and trust accounting for firms seeking operational simplification. Centerbase's partnership to embed accounts payable automation directly into its midsize firm platform highlights a parallel trend: integration with back-office financial ecosystems as a competitive differentiator. Supio's specialization in personal injury and mass tort workflows demonstrates how vertical-specific AI can command premium positioning. Lexzur and Caseflow extend the field with AI-assisted matter management and client communication features, while LeanLaw's focus on QuickBooks-integrated revenue operations points to a growing appetite for financial tooling built around familiar accounting backbones.
These vendor movements matter because they redefine buyer expectations. A practice management decision in 2026 is simultaneously a decision about AI strategy, data residency, financial reconciliation speed, and vendor longevity. The report's competitive analysis maps these trade-offs explicitly, helping organizations match platform capabilities against their operating model rather than adopting a one-size-fits-all framing.
Industry Dynamics Driving Procurement and Adoption
Market growth is not simply a function of technology availability. It is being propelled by a set of interlocking operational and regulatory forces that raise the cost of inaction. Our research distills these dynamics into practical considerations for both buyers and vendors.
Cloud adoption has become the baseline expectation. Recent industry survey data indicates that a substantial majority of law firms now rely on cloud-based legal tools, with practice management and document management software posting the highest utilization rates. This shift is not cosmetic. It reflects reduced on-premises maintenance burdens, improved remote collaboration, and the ability to push updates and security patches without disrupting firm operations. For decision-makers, the question has moved from whether to adopt cloud architecture to how to select platforms that meet rigorous compliance and performance standards.
Security and regulatory compliance have accordingly become central procurement criteria. Cloud-based platforms increasingly emphasize SOC 2 alignment and data privacy standards to support trust accounting integrity and client data protection. These requirements are not uniform across jurisdictions, and the report examines how compliance posture varies by platform and what that means for multi-jurisdiction firms.
Financial workflow acceleration is another powerful driver. Automated billing, trust accounting, and integrated payment capabilities are shortening client payment cycles and reducing administrative overhead. For firms operating on tight margins, faster cash conversion is a direct operational benefit, not merely a feature checkbox. The analysis quantifies how these capabilities influence vendor selection and what performance indicators buyers should track post-implementation.
At the same time, AI integration introduces a new compliance layer. As automation expands into case analysis and document review, firms must navigate evolving professional ethics guidance on the use of AI in legal work. Regulatory bodies are actively updating expectations around supervision, accuracy, and client confidentiality. The report evaluates how leading platforms are addressing these requirements and what risk management frameworks should accompany AI adoption.
Legal Practice Management Software Market
Why This Research Matters for 2026 Decision-Making
The strategic stakes for 2026 are unusually high. Organizations that treat practice management software as a routine IT purchase risk underinvesting in capabilities that directly affect profitability, risk exposure, and client retention. Conversely, organizations that approach the market with structured intelligence can sequence implementations, negotiate from a position of clarity, and avoid vendor lock-in to platforms that lack the roadmap depth required for future growth.
This report is built for that decision environment. It provides the macro context needed to validate market timing, the segmentation detail needed to prioritize investment, and the competitive analysis needed to assess vendor durability. For law firm leadership, it supports operational transformation planning and resource allocation. For technology buyers and institutional stakeholders, it clarifies where durable demand is forming and which platform categories are likely to consolidate further.
Because the full value of this analysis depends on the underlying segmentation models, regional breakdowns, deployment comparisons, and company-level benchmarking, the complete dataset and executive findings are available through our comprehensive market study. The page-length overview presented here is intended as a strategic preview: a demonstration of the analytical rigor and decision-focus that define the full publication.
Next Steps for Strategic Alignment
Market leadership in legal technology is being redefined in real time. Firms that align their practice management strategy with the realities of AI adoption, compliance evolution, and financial workflow acceleration will be best positioned to convert operational software into durable competitive advantage. Those that delay structured evaluation risk entering a more consolidated market with fewer negotiating advantages and higher switching costs.
The complete market research extends well beyond this overview. It delivers the segmented data, vendor assessments, and forward-looking projections required to support confident 2026 decision-making across procurement, investment, and operational transformation initiatives. Readers seeking the full intelligence package, including detailed segmentation splits and competitive benchmarking, are encouraged to access the complete report at the source page, where the full dataset and executive insights are available for direct review.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Paper Pallet Market: Strategic Intelligence for 2026 Decision-Makers
As global supply chains recalibrate around sustainability mandates and regulatory pressures, the packaging sector stands at a pivotal inflection point. The paper pallet market, once a niche alternative to traditional wooden and plastic logistics solutions, has matured into a strategic imperative for enterprises managing high-volume freight across international borders. PW Consulting's latest comprehensive study on the Paper Pallet Market delivers actionable intelligence designed to inform capital allocation, supplier partnerships, and regional expansion strategies throughout the 2026–2032 horizon.
This introduction outlines the strategic architecture of our research, demonstrates how macroeconomic indicators translate into operational foresight, and illustrates why forward-looking organizations are treating paper-based palletization as a core component of their supply chain resilience playbook.
The Macro Trajectory: Growth Signals and Structural Shifts
Between 2020 and 2025, the global paper pallet market demonstrated consistent revenue expansion, reflecting a steady migration away from conventional wood-based packaging. Initial valuation benchmarks in the early 2020s established a foundation that subsequent years reinforced through accelerated adoption across logistics-intensive sectors. The market's progression through 2024 and 2025 reflects an ecosystem that has moved beyond early-adopter experimentation into mainstream procurement considerations.
Our forecast model projects continued revenue growth across the 2026–2032 period, with compound annual growth rates indicating a durable expansion path. This trajectory is not merely a reflection of volume displacement; it captures fundamental shifts in how multinational corporations evaluate total cost of ownership, customs compliance, and environmental reporting. Decision-makers who understand the drivers behind this upward curve position themselves to capture margin advantages before commoditization erodes early-mover benefits.
The scale of the opportunity underscores why organizations cannot rely on fragmented industry anecdotes. A structured, data-anchored view of revenue pathways, demand elasticity, and competitive intensity allows procurement leaders and supply chain executives to evaluate whether paper pallet integration belongs in their near-term roadmap or longer-term sustainability pipeline.
Regulatory Tailwinds and the ISPM-15 Advantage
One of the most consequential dynamics shaping the market involves international phytosanitary regulations. Wooden packaging materials entering cross-border trade corridors must comply with ISPM-15 treatment requirements, which mandate heat treatment or fumigation protocols to mitigate pest transmission risks. Paper pallets, by contrast, fall outside these treatment mandates, eliminating a layer of compliance complexity that has historically slowed freight movement and increased administrative overhead.
This regulatory distinction creates measurable operational advantages for shippers managing high-frequency transatlantic, transpacific, and intra-Asia logistics flows. Paper alternatives reduce dwell time at inspection points, lower the risk of shipment rejection, and simplify documentation workflows. As customs enforcement protocols become more stringent in 2026 and beyond, organizations that standardize paper pallet utilization across export lanes can expect smoother clearance cycles and reduced contingency costs.
Wood Pallet Market
The regulatory environment also intersects with corporate sustainability commitments. Enterprises tracking Scope 3 emissions and packaging circularity targets find that paper-based solutions offer clearer end-of-life pathways when paired with recycling infrastructure, reinforcing the business case beyond mere compliance convenience.
Competitive Architecture: Who Shapes the Market and How
Market leadership in the paper pallet sector is defined not by raw production capacity alone but by proprietary engineering, material science capabilities, and the ability to integrate pallet solutions into broader transit and storage ecosystems. Several organizations have emerged as influential players, each pursuing distinct value propositions that appeal to specific supply chain profiles.
Smurfit Kappa Group, headquartered in Dublin, has built a recognizable presence through engineered paper pallet offerings such as PaPillOn strong paper pallet and TOPPSafe™ pallet top systems. Their approach emphasizes load-bearing performance combined with compatibility into existing corrugated supply networks. DS Smith Plc, based in London, advances a complementary yet differentiated position with its patented fibre-based pallet technology, targeting organizations that prioritize structural consistency and manufacturability at scale.
International Paper Company brings extensive raw material and converting infrastructure to the market, offering corrugated and molded paper pallet formats that leverage decades of industrial packaging expertise. Sonoco Products Company, operating from Hartsville, South Carolina, focuses on integrated paper pallet systems designed for specialized transit requirements and operational durability. PALLITE Limited, headquartered in the United Kingdom, has carved a distinct niche through honeycomb paper pallet designs and PIX® storage solutions that appeal to organizations seeking lightweight yet structurally reliable storage and transport alternatives.
Signode, based in Illinois, has positioned itself around paper pallet options designed for transit environments with ISPM-15 compliance considerations, aligning its portfolio with cross-border shippers seeking regulatory simplicity. ATTA Pallet, located in Hungary, emphasizes production and assembly capabilities tailored to paper pallet manufacturing workflows, while EcoDuro Inc., operating in Canada, contributes molded pulp and paper-based pallet options that broaden the material palette available to sustainability-focused procurement teams.
The competitive field reflects a mosaic of engineering priorities, regional strengths, and integration strategies. Understanding which players are expanding capacity, which are locking in proprietary formulations, and which are building partnerships with logistics integrators is essential for organizations evaluating supplier resilience and pricing stability over multi-year contracting cycles.
Recent Developments Reshaping Product Expectations
The pace of product-level innovation has accelerated markedly in recent months, signaling that incumbents are actively responding to shifting procurement criteria. In September 2025, Smurfit Westrock introduced a recyclable paper pallet wrap engineered as a direct replacement for single-use plastic pallet wraps in shipment applications. This launch reflects a growing emphasis on eliminating plastic wrapping without compromising load containment, a concern that has become increasingly prominent among shippers tracking packaging waste reduction targets.
Earlier, in March 2024, Seaman Paper expanded the functional scope of paper-based transit solutions with the launch of SeaStretch™, a patented lightweight paper alternative designed for shipping and storage loads. This development reinforced the viability of paper as a performance-competitive material in contexts where plastic film had previously dominated, particularly when weight reduction and recyclability are weighted heavily in procurement evaluation frameworks.
These launches matter because they illustrate a market trend moving beyond pallet boards alone. The broader product ecosystem now includes wrapping solutions, load stabilization approaches, and storage geometries that collectively influence total logistics cost. Buyers evaluating paper pallet adoption must consider how compatible wrapping, cushioning, and handling practices affect throughput, damage rates, and downstream recycling feasibility.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
PW Consulting's Paper Pallet Market research is structured to support decision-making at multiple organizational levels. Rather than presenting a static snapshot, the study maps revenue evolution, segment dynamics, and competitive interventions across historical and forecast periods, enabling readers to test assumptions against evidence-based scenarios.
The report examines the structural composition of market demand, identifying how different product types and application categories contribute to overall revenue behavior. It explores regional demand patterns without reducing complexity to oversimplified ratios, offering instead a nuanced view of where adoption momentum is strongest and what local regulatory or logistics conditions amplify or constrain growth.
Detailed company profiles analyze strategic positioning, product differentiation, and recent developmental activity across key participants. This competitive mapping is paired with an assessment of concentration dynamics, helping stakeholders gauge pricing influence, supplier dependency risk, and the likelihood of consolidation pressure in the years ahead.
Operational considerations are addressed through analysis of material developments, product launches, and regulatory alignments that affect procurement planning. Readers gain insight into how transit compliance frameworks, sustainability reporting expectations, and packaging innovation cycles intersect with supplier selection and contract structuring. The research also contextualizes supply chain decision points such as total cost comparisons, damage-risk trade-offs, customs efficiency, and recyclability infrastructure readiness.
Because the study spans a defined historical baseline and extends across a multi-year forecast window, it supports scenario-based evaluation. Organizations can assess how shifts in freight volume, regulatory enforcement intensity, or material cost dynamics may alter adoption timing and budget allocation. This forward-looking structure is particularly valuable for teams planning capital-intensive logistics improvements or evaluating multi-year supplier partnerships.
Why 2026 Is a Defining Year for Strategic Action
The convergence of regulatory clarity, product innovation, and expanding adoption creates a window in which strategic choices carry disproportionate long-term effects. Organizations that delay evaluation risk entering supplier negotiations after pricing structures adjust to heightened demand visibility, while those that assess options prematurely may overlook rapid product improvements that reshape performance comparisons.
In 2026, procurement and supply chain leaders must determine whether paper pallet integration belongs within tactical cost-reduction programs or within broader transformation initiatives tied to compliance, sustainability reporting, and international freight efficiency. Answering that question requires a granular understanding of market direction, competitive behavior, and application-specific demand behavior, all of which our research is designed to clarify.
Firms operating across multiple regions face additional complexity. Regional demand intensity varies, and local regulatory expectations, recycling infrastructure availability, and logistics partner capabilities influence whether paper pallet adoption generates the anticipated benefits. A market-level view must therefore be paired with operational realism about implementation readiness, supplier reliability, and internal change management requirements.
The report enables this level of discernment by connecting macro growth signals with actionable procurement implications. Readers can evaluate whether current supplier options align with their technical specifications, whether product innovation timelines match their implementation horizons, and whether market concentration trends suggest a need for diversification or long-term contracting.
From Insight to Execution
Deep market intelligence becomes valuable only when it informs concrete decisions. PW Consulting's Paper Pallet Market study is built to support that translation. It equips strategy teams with evidence-based context, helps procurement groups benchmark supplier claims against market-wide patterns, and gives executive stakeholders the framing needed to prioritize packaging logistics investments alongside other transformation initiatives.
For organizations preparing for the 2026 decision cycle, the critical task is not simply recognizing that the market is expanding. The strategic value lies in understanding which forces are structural rather than cyclical, which supplier capabilities are likely to endure, and where adoption timing will most strongly affect cost and operational outcomes. Our research is designed to illuminate those distinctions without leaving decision-makers to infer them from partial data.
Paper Pallet Market
The complete analysis provides the depth, segmentation clarity, competitive mapping, and scenario-aware forecasting required to move from awareness to action. For teams tasked with evaluating paper pallet integration as part of broader supply chain strategy, the full report offers the intelligence foundation necessary to make informed, timely, and defensible decisions.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Structural Steel Pipe Market to Hit $489.1M by 2032, 3.45% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Structural Steel Pipe Market: Navigating the 2026-2032 Cycle
The structural steel pipe industry stands at a critical juncture as it moves through the 2026 fiscal year. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design and capital allocation. Our latest market research delivers a comprehensive examination of the forces shaping demand, pricing, and competitive positioning across the global structural steel pipe landscape. This introduction outlines the strategic value embedded in the full report, highlights the macro trends that demand attention, and explains how data-driven foresight can convert market volatility into competitive advantage.
The Macro Trajectory: Recovery, Expansion, and Measured Growth
Historical data reveals a market that has steadily climbed out of the pandemic-era disruptions and into a phase of structured expansion. Between 2020 and 2025, total market revenue moved from approximately 298.45 million USD to 386.5 million USD, reflecting a compound annual growth rate that underscores the sector's underlying resilience. The upward momentum carries into the forecast window: 2026 opens at an estimated 399.37 million USD, and the trajectory advances toward 489.1 million USD by 2032, supported by a projected CAGR of 3.45 percent.
While these aggregate figures establish the baseline, the real strategic insight lies in understanding why growth is unfolding at this pace and where the inflection points will emerge. The forecast period through 2032 does not imply a straight line. Year-over-year movement shows nuanced fluctuations that reward stakeholders who look beyond headline numbers. Readers who engage with the full report will find a detailed quarter-by-quarter and year-by-year narrative that connects macroeconomic signals—such as interest rate environments, infrastructure appropriations, and industrial construction cycles—to the demand patterns driving pipe procurement across multiple downstream sectors.
Diversified Demand Centers and the Changing Application Mix
Structural steel pipe is no longer a single-purpose commodity. Its deployment spans oil and gas infrastructure, commercial and civil construction, water and wastewater systems, and an expanding set of industrial applications that rely on high-integrity tubular products. The market's breadth means that shifts in any one vertical can materially alter procurement strategies, inventory planning, and pricing negotiations.
Our research dissects the application landscape without reducing it to simplistic rankings. The full report maps how project pipelines, regulatory mandates, and regional infrastructure spending are redistributing demand across use cases. It also examines the degree to which certain applications are becoming more cyclical while others exhibit steadier, policy-driven consumption. For executives planning multi-year supply agreements or evaluating capacity investments, this granularity matters. It allows organizations to anticipate which segments will tighten during downturns and which will remain robust, enabling more precise hedging of procurement exposure.
Equally important is the interplay between application demand and product type. Seamless pipes, welded pipes, and spiral welded variants each serve distinct performance and cost profiles. The report analyzes how engineering requirements, cost pressures, and manufacturing capabilities are shaping the adoption mix across these categories. Decision-makers who understand these dynamics can better align sourcing strategies with technical specifications, avoiding over-specification in cost-sensitive programs or under-specification in high-stress applications.
Geographies in Motion: Regional Dynamics That Reshape Sourcing
No market analysis is complete without a rigorous view of regional performance. The structural steel pipe market reflects divergent economic conditions, trade policies, and construction cycles across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each geography carries its own set of demand drivers, supply constraints, and policy risks that directly influence landed costs and availability.
In the full report, we avoid surface-level regional snapshots. Instead, we provide an integrated assessment of how cross-border trade flows, local production capacity, and infrastructure investment programs interact to create pricing divergence and availability gaps. This regional lens is especially valuable for multinational operators and distributors who must coordinate procurement across multiple markets. The analysis identifies where local supply is tightening, where import dependency creates exposure, and where domestic production is gaining strategic importance. Readers will see how these regional conditions translate into actionable sourcing recommendations rather than abstract market commentary.
Competitive Landscape: Vertically Integrated Leaders and the Battleground for Share
The competitive structure of the structural steel pipe market is defined by a mix of large, globally integrated steelmakers and specialized domestic producers with strong regional footprints. Market concentration remains moderate, with the top three firms holding approximately 25.8 percent of revenue and the top five reaching 32.4 percent. This structure suggests that while scale confers advantages, there is meaningful space for regional specialists to compete on service, lead times, and product specificity.
Nucor, headquartered in Charlotte, North Carolina, exemplifies the vertically integrated approach. As an electric arc furnace producer of domestic hollow structural sections and tested steel pipe—covering ASTM A500, A135/A795, and A53 specifications—Nucor has positioned itself around low-embodied carbon certification and domestic supply reliability. That positioning has translated into conspicuous pricing activity: in October 2025, the company announced a 50 USD per ton increase across tube steel, HSS, mechanical, and piping products, followed by a further 60 USD per ton increase implemented in February 2026. These moves signal not only cost pass-through but also a deliberate effort to protect margin in an environment where input costs and demand are both elevated.
ArcelorMittal, based in Luxembourg City, remains a global force in tubular products, producing high-strength structural steel pipe and welded pipes for infrastructure and energy applications. Its recent product development activity highlights the innovation dimension of competition: by May 2026, ArcelorMittal Nippon Steel India had commenced commercial production of EQ70 grade high-strength welded steel pipes with a 690 MPa yield at its Hazira mill, enabling weight savings in structural applications. Such advances illustrate how competitors are using grade differentiation and performance improvements to capture premium segments, rather than competing solely on volume.
Structural Steel Pipe Market
United States Steel Corporation, headquartered in Pittsburgh, continues to supply welded and structural steel pipe and tubing critical to construction and infrastructure programs. Meanwhile, California Steel Industries, based in Fontana, serves the western United States with ERW structural steel pipe and tubing for load-bearing and low-pressure applications. These regional specialists matter because they shape localized availability and lead time dynamics. In February 2026, structural tubing mills broadly extended lead times to 6–8 weeks amid rising pricing and demand—an industry-wide signal that procurement planning horizons must lengthen and inventory buffers may need recalibration.
The full report goes deeper into how these players—and the broader field—compete on pricing, product certification, lead time reliability, and sustainability credentials. It evaluates where vertical integration provides genuine insulation from input volatility and where it may create rigidity. It also examines how low-embodied carbon positioning is becoming a differentiator in bids where procurement teams are weighing total cost of ownership against decarbonization commitments.
Forces Reshaping Cost Structures and Pricing Power
Pricing in the structural steel pipe market is being influenced by a convergence of cost pressures, trade policy, and demand timing. Raw material and labor dynamics remain central. In the first quarter of 2026, steel scrap prices stayed firm to upward, with China pricing at 347.20 USD per metric ton and India at 397.20 USD per metric ton. These levels were supported by tight supply and higher freight costs, reinforcing the upward bias in producer input costs and constraining the ability of mills to absorb cost shocks without passing them downstream.
Trade policy has added another layer of complexity. Section 232 tariffs on steel imports were raised to 50 percent in June 2025 and affirmed in April 2026, applying directly to steel pipe and structural products. In parallel, Section 301 tariffs on steel pipe, tube, and structural shapes from excess-capacity countries continued to impact import costs as of May 2026. Together, these measures have altered the relative attractiveness of imported versus domestic supply, tightened available sourcing channels, and strengthened the pricing hand of domestic producers in certain markets.
The price environment has responded accordingly. Steel pipe and tube prices rose 12.5 percent year-over-year in spring 2026, with the producer price index for metals reaching 354.9 in March 2026. These movements matter for budgeting, bidding, and contract structuring. For buyers, they raise the stakes of contract timing, escalation clauses, and inventory strategy. For producers and distributors, they create opportunities to defend margins but also increase the reputational and operational risks associated with lead time reliability and service continuity.
The report provides a structured framework for interpreting these dynamics. It connects raw material indices, tariff timelines, and demand seasonality to practical forecasting tools that help organizations model price scenarios, evaluate make-versus-buy trade-offs, and design procurement contracts that share risk more intelligently. Rather than simply documenting that prices have risen, it explains the mechanisms behind the increases and the conditions under which they may ease or intensify.
What the Full Report Delivers: Operational Intelligence for 2026 and Beyond
This introduction provides the strategic framing; the complete report delivers the operational intelligence required to act on it. Designed for executives, category managers, supply chain planners, and investors, the study translates market data into decision-ready formats. Key content includes a detailed historical reconstruction from 2020 through 2025, a forward-looking forecast spanning 2026 to 2032, and scenario analyses that stress-test assumptions around input costs, tariffs, and demand cycles.
Readers will find a robust segmentation evaluation covering product types and application verticals, along with a regional assessment that connects local supply conditions to cross-border trade realities. The competitive section profiles major players and analyzes recent moves—including price actions, grade launches, and lead time shifts—that signal where market power is being exercised and where vulnerabilities are emerging. The regulatory and cost environment is examined not as background noise but as an integral input to procurement and investment decisions.
Structural Steel Market
Equally important, the report emphasizes practical application. It outlines how to interpret lead time extensions, how to evaluate the implications of tariff structures on total landed cost, and how to incorporate sustainability credentials into sourcing criteria without losing sight of cost and performance. It also provides the analytical scaffolding needed to anticipate where the market is likely to tighten or loosen over the forecast horizon, giving stakeholders a basis for proactive rather than reactive planning.
Why This Research Matters Now
The structural steel pipe market in 2026 is defined by strong but uneven growth, elevated input costs, shifting trade policy, and a competitive field in which both global scale and regional agility matter. Organizations that treat these conditions as isolated events risk mispricing risk and misaligning supply strategies. Those that integrate them into a coherent, data-backed view can make better decisions on contracting, inventory, capacity, and market entry.
The complete report is built to support that integration. It combines the macro trajectory—moving from 386.5 million USD in 2025 toward 489.1 million USD by 2032 at a 3.45 percent CAGR—with the granular, decision-level detail that turns numbers into strategy. For teams responsible for procurement, planning, or investment in structural steel pipe, the difference between reacting to price spikes and anticipating them can be material.
To access the full segmentation analysis, regional assessments, competitive profiles, and scenario-based forecasts, request the complete market research. The methodology, data tables, and actionable recommendations are structured to give your organization a clear line of sight from market intelligence to executive decision-making in 2026 and across the forecast period to 2032.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Unlocking Growth Trajectories in the Diethanol Isopropanolamine Market: A Strategic Imperative for 2026
The global chemical landscape is undergoing a quiet but decisive transformation, and at the center of this shift lies Diethanol Isopropanolamine, commonly known as DEIPA. Once confined to niche industrial applications, DEIPA has evolved into a critical enabler across construction chemistry, advanced materials, and precision manufacturing. As organizations navigate an era defined by supply chain recalibration, regulatory tightening, and demand concentration in high-value sectors, understanding the DEIPA market is no longer optional. It is a strategic necessity. Our latest comprehensive market study delivers exactly that clarity, providing enterprise leaders with the analytical rigor required to make informed capital allocation, sourcing, and expansion decisions throughout the forecast window.
The narrative arc of this market is compelling. Drawing from historical data spanning 2020 through 2025, the industry has demonstrated consistent expansion, culminating in a robust baseline valuation that sets the stage for an accelerated growth trajectory. The report projects a compound annual growth rate of 6.98 percent across the 2026 to 2032 period, pushing the market toward a multi-hundred-million-dollar valuation by the end of the forecast horizon. These macro indicators are not merely statistical artifacts. They reflect underlying structural shifts in how industrial chemicals are sourced, formulated, and deployed across increasingly specialized end-use environments. For corporate strategists, procurement directors, and market entry teams, this growth vector signals both opportunity and complexity. The challenge lies in translating broad market momentum into actionable, segmented intelligence that aligns with organizational capability and risk tolerance.
This is precisely where executive decision-makers encounter friction. Aggregate market size and headline growth rates offer direction, but they rarely provide the granularity required to model capacity expansion, pricing strategy, or regional prioritization. Our research framework is designed to bridge that gap. By dissecting demand drivers, supply chain dynamics, regulatory pressure points, and competitive positioning, the study equips stakeholders with a multidimensional view of where value is being created, where bottlenecks are emerging, and how incumbents and newcomers are positioning themselves for the next cycle. The objective is not to overwhelm with volume, but to deliver precision. Every analytical layer serves a practical purpose: reducing uncertainty, sharpening scenario planning, and enabling faster, more confident execution.
Diethanol Isopropanolamine (DEIPA) Market
Decoding the Structural Architecture of DEIPA Demand
DEIPA's growth story is fundamentally tied to its functional versatility. As a specialized chemical intermediate and performance additive, it serves applications where consistency, purity, and formulation compatibility are non-negotiable. The market's demand architecture reflects this reality, with certain application verticals commanding disproportionate share due to their sensitivity to chemical performance and their growth momentum in high-tech and infrastructure sectors. Understanding which verticals are expanding, which are consolidating, and how feedstock volatility influences pricing behavior is essential for any organization operating in or adjacent to this space.
From a supply-side perspective, the DEIPA ecosystem is characterized by a concentrated but strategically active manufacturing base. The report examines how leading producers are navigating raw material fluctuations, particularly around isopropanolamine and diethanolamine, whose pricing can swing sharply in response to global market instability. These input cost dynamics are not abstract concerns. They directly impact margin structures, inventory strategies, and long-term contract positioning. Organizations that integrate feedstock risk modeling into their procurement and production planning gain a measurable advantage, especially when competing in price-sensitive or specification-driven segments.
Equally critical is the role of product differentiation. Within the DEIPA market, performance tiers and purity specifications increasingly dictate commercial outcomes. The study maps how different product configurations align with specific industrial requirements, revealing where premium positioning can sustain pricing power and where volume-driven strategies may be necessary to capture scale. This segmentation lens allows companies to avoid the common trap of treating DEIPA as a homogeneous commodity, and instead approach it as a portfolio of distinct value propositions with varying margin profiles, customer retention characteristics, and entry barriers.
Navigating Regulatory Friction and Cost Dynamics
Growth in the DEIPA market does not occur in a vacuum. Environmental and compliance frameworks are reshaping production economics, particularly in mature markets where regulatory scrutiny has intensified. The research highlights a clear pattern: stringent environmental requirements in North America and Europe are elevating production costs for DEIPA manufacturers, forcing a strategic recalibration of operating models. Compliance is no longer a peripheral consideration. It is a core determinant of competitive positioning, capacity utilization, and regional sourcing strategy.
The operational reality on the ground is stark. A significant portion of global producers are encountering environmental compliance hurdles that affect throughput, capital planning, and time-to-market for new formulations. Nearly half of surveyed manufacturers report restrictions related to volatile organic compounds as a meaningful restraint, while more than half cite broader compliance challenges as direct pressure points on their operational footprint. These figures underscore a market where regulatory agility is becoming a differentiator. Companies that proactively invest in emission control, process optimization, and documentation readiness are better positioned to sustain production continuity, while those that treat compliance as reactive overhead risk margin erosion and supply disruption.
Worldwide N-Methyl Diethanolamine (MDEA) Market
Raw material volatility further compounds this environment. Because DEIPA production depends on precursor chemicals that are exposed to global pricing instability, manufacturers must balance cost pass-through mechanisms with customer retention strategies. The report explores how leading firms are structuring hedging approaches, renegotiating supply agreements, and adjusting formulation strategies to preserve competitiveness without sacrificing compliance standards. For procurement and commercial teams, these insights are vital. They reveal where pricing negotiations are likely to face resistance, where long-term contracts can create structural advantage, and where regional regulatory divergence may open arbitrage opportunities for organizations with multilateral sourcing capabilities.
Competitive Positioning and the Landscape of Strategic Operators
The DEIPA market is not dominated by a single monolithic player. Instead, it features a coalition of specialized producers, regional manufacturers, and distribution networks that collectively shape supply availability, technical service expectations, and market access. The research profiles a set of core companies whose operational footprint and strategic focus provide a clear window into how the market is being contested. These include established producers such as Nanjing Hongbaoli Group Co., Ltd. and Shandong Inniolamine New Material, which anchor significant production capacity around high-purity DEIPA grades for cement grinding aids and concrete admixtures. Their positioning reflects a broader trend in Asian manufacturing ecosystems, where scale, export orientation, and specification refinement are converging to support both domestic infrastructure demand and international supply channels.
India's chemical manufacturing base also features prominently, with organizations like Viswaat Chemicals Limited and Amines & Plasticizers Limited operating as influential contributors to the DEIPA supply chain. Their focus on construction chemicals and cement applications aligns with the region's ongoing infrastructure expansion and the increasing adoption of chemical admixtures to improve performance efficiency. Meanwhile, distribution and trading specialists such as Bisley International LLC play a critical intermediary role, ensuring that industrial and construction end-users can access DEIPA with reduced friction across geographies and specification requirements. This diversified competitive architecture means that market access is rarely about securing a single supplier relationship. It is about understanding how manufacturers, formulators, and distributors interact to create reliability, technical support, and pricing stability.
The report also examines market concentration as a structural indicator of competitive intensity. With a CR3 near 24.6 percent and CR5 at approximately 26.2 percent, the market displays a moderately fragmented profile. This concentration pattern suggests that while leading players hold meaningful influence, there remains substantial room for regional specialists, product-focused innovators, and service-oriented distributors to capture share through differentiation rather than scale alone. For companies evaluating partnerships, acquisitions, or greenfield capacity, this landscape offers multiple entry and expansion pathways, each with distinct risk-reward profiles depending on target segment, geographic exposure, and technical capability requirements.
Translating Market Intelligence into 2026 Execution
What separates useful market research from strategically actionable intelligence is relevance to decision cycles. Our DEIPA study is built around that principle. Rather than stopping at descriptive analysis, the report integrates practical frameworks that help organizations align market signals with internal planning processes. This includes scenario-based forecasting approaches that account for feedstock volatility, regulatory escalation, and demand concentration shifts. It also encompasses supplier evaluation criteria, regional cost-structure comparisons, and application-level demand sensitivity mapping that supports more precise commercial targeting.
For product and R&D teams, the research provides a structured view of specification trends and performance expectations across end-use environments. This enables formulation teams to anticipate where purity thresholds, compatibility requirements, or additive performance benchmarks are moving, reducing the lag between market demand and product readiness. For manufacturing and operations leaders, the study highlights where process efficiency, compliance readiness, and feedstock procurement strategy intersect, offering a basis for capital prioritization and capacity optimization. For commercial and go-to-market teams, the segmentation and competitive analyses clarify where pricing stability is most achievable, where technical service differentiation can protect share, and where geographic expansion may yield disproportionate returns.
The report's design reflects a commitment to operational utility. It organizes complex market dynamics into decision-ready components, allowing executive teams to extract relevant insights without navigating irrelevant detail. Whether the objective is to reassess sourcing strategy, evaluate expansion into adjacent application areas, benchmark competitive positioning, or stress-test margin assumptions under regulatory and raw material pressure, the study provides a coherent foundation for those conversations. In a market where misreading a single variable can compound into inventory imbalance, pricing misalignment, or missed entry windows, that coherence has direct financial and strategic value.
The Strategic Edge in an Accelerating Market
DEIPA is no longer a peripheral chemical story. It is a market where demand growth, regulatory pressure, raw material dynamics, and competitive differentiation intersect in ways that reward informed, anticipatory decision-making. The projected growth trajectory through 2032 signals that the window for strategic positioning is open, but it will not remain frictionless. Companies that treat DEIPA as a static procurement line item risk falling behind organizations that approach it as a strategic capability area, integrating market intelligence into sourcing, product development, compliance planning, and commercial execution.
Our full market study goes deeper into every dimension that matters for 2026 planning and beyond. It unpacks regional demand architectures, application-level growth drivers, competitive movement patterns, and regulatory impact pathways with the level of detail required for credible strategic action. The executive summary provided here is intended to demonstrate analytical depth and establish confidence in the methodology, while preserving the precise segmentation data, detailed company assessments, and scenario modeling frameworks for the complete report. For decision-makers who need more than directional insight, accessing the full study is the logical next step. The market is moving, and the organizations that move with it most effectively will be those that invest in intelligence before they invest in execution.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive EPS Market to Hit $397M by 2032, 5.57% CAGR Forecasted
By PW Consulting, 2026-09-16
Navigating the Torque Shift: Strategic Imperatives in the Global Automotive Electronic Power Steering Market Through 2032
The automotive industry is currently undergoing one of the most significant paradigm shifts in steering technology since the invention of the rack-and-pinion system. The transition from hydraulic power steering (HPS) to Electronic Power Steering (EPS) is no longer merely an incremental improvement in energy efficiency; it is the foundational enabler for modern Advanced Driver Assistance Systems (ADAS), autonomous driving capabilities, and rigorous emissions compliance. For original equipment manufacturers (OEMs) and tier-one suppliers alike, understanding the trajectory of the EPS market is not optional—it is a prerequisite for strategic resilience.
PW Consulting's latest comprehensive market research report offers a granular examination of the Automotive Electronic Power Steering sector, providing stakeholders with the intelligence necessary to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview of the market landscape, highlighting the macro-economic trends, regulatory pressures, and competitive dynamics that define this critical automotive subsystem.
Market Trajectory and Macroeconomic Environment
The global demand for electronic power steering systems has demonstrated robust growth over the past half-decade, driven by consumer preference for lighter steering feel, improved fuel economy, and the increasing electronic content in vehicles. Historical data from 2020 through 2025 indicates a consistent upward trend in revenue, reflecting the widespread adoption of EPS across various vehicle segments. As the industry moves into the forecast period, the market is projected to sustain a healthy compound annual growth rate, signaling continued investment opportunities in manufacturing capacity and R&D.
By the base year 2025, the aggregate market revenue had reached substantial levels in millions of USD, establishing a strong platform for the forecast years. The projected figures for 2026 and beyond suggest that while the pace of electrification may fluctuate based on regional economic conditions, the underlying demand for steering assist technology remains inelastic. This stability is underpinned by the fact that EPS is now the standard for nearly all new passenger vehicle platforms, displacing legacy hydraulic systems that carry parasitic energy losses.
It is crucial for decision-makers to recognize that the market size expansion is not uniform across all years. Forecasts indicate a gradual acceleration as newer vehicle architectures mature and as regulatory mandates fully take effect in key markets. Understanding the specific revenue projections for each forecast horizon is essential for capacity planning and supply chain optimization, details of which are extensively mapped out in the full report.
Regulatory Catalysts and Technology Dynamics
Regulatory frameworks are acting as potent accelerants for the adoption of EPS technologies. In Europe, the Union's commitment to reducing carbon emissions has directly impacted steering system specifications. With the Euro 7 regulation applicable to new type approvals from 2025, hydraulic power steering has effectively been eliminated from new passenger car specifications due to the parasitic CO2 penalty calculations associated with engine-driven pumps. This regulatory hard line forces manufacturers to prioritize electric solutions that decouple steering power from engine load.
Furthermore, safety standards are evolving to require active intervention rather than passive assistance. The Euro NCAP 2026 protocol now requires lane-keeping assistance as a rated safety feature. This mandate necessitates EPS torque overlay capability across all new passenger vehicle platforms seeking five-star ratings. Consequently, the EPS system is no longer just a comfort feature; it is a critical safety component that must integrate seamlessly with camera and radar inputs to execute corrective steering maneuvers.
Parallel to regulatory pressure, technological innovations are reshaping the competitive landscape. The development of solid-state and sensor-based EPS technologies is improving reliability while reducing system complexity. Modern EPS gearboxes are being engineered with high-strength materials and precision manufacturing techniques that not only improve durability but also reduce noise, vibration, and harshness (NVH)—a key differentiator in premium vehicle segments. Additionally, the shift toward steer-by-wire systems represents the next frontier, removing the mechanical connection between the steering wheel and the wheels entirely, offering unparalleled flexibility in vehicle packaging and human-machine interface design.
Competitive Landscape and Key Player Strategies
The market structure is characterized by high concentration, with a few dominant players holding significant sway over pricing, technology standards, and supply chain dynamics. The top three companies command a substantial share of the market revenue, while the top five entities collectively control an even larger portion of the industry output. This oligopolistic structure suggests that collaboration, strategic partnerships, and first-mover advantages in new technology segments are critical for maintaining market position.
Several key manufacturers are driving these trends through targeted product launches and strategic expansions:
-
Nexteer Automotive , based in Auburn Hills, Michigan, continues to diversify its portfolio beyond traditional column and pinion assist systems. Recently, they initiated series production of a steer-by-wire system as part of a full drive-by-wire chassis program for a leading Chinese New Energy Vehicle (NEV) manufacturer. This move signifies a strategic pivot toward next-generation architectures where steering is fully integrated into the software-defined vehicle ecosystem.
-
China Automotive Systems, Inc. has been aggressively expanding its geographic footprint. Following the award of its first South American C-EPS contract for a new vehicle platform from a leading local manufacturer, the company began volume shipments of EPS systems to a global automaker's European division for two new vehicle models. This demonstrates the increasing competitiveness of Chinese suppliers in established Western markets.
-
JTEKT Corporation confirmed the installation of next-generation steer-by-wire backup power and components in the Lexus RZ production BEV. This validation by a premium brand underscores the reliability challenges inherent in steer-by-wire technology and highlights the importance of redundancy systems in ensuring consumer trust.
-
Other major players such as Robert Bosch GmbH , ZF Friedrichshafen AG , N SK Ltd. , and Denso Corporation continue to refine integrated EPS solutions, focusing on energy-efficient designs and ADAS integration capabilities. Meanwhile, regional champions like Mando Corporation and Hyundai Mobis Co., Ltd. are leveraging their positions within Korean conglomerates to supply premium and volume vehicle platforms with rack-type and column-type systems.
The interplay between these companies involves a complex mix of patent licensing, joint development agreements, and vertical integration strategies. Understanding the specific supply relationships and technology ownership claims among these entities is vital for assessing supply chain risk.
Strategic Segmentation and Application Insights
While the overall market figures provide a top-down view, the true value lies in understanding the dynamics of specific segments. The market is broadly categorized by type, region, and application, each with unique growth drivers and constraints.
In terms of technology type, the market includes Column Assist EPS, Pinion Assist EPS, and Rack Assist EPS systems. Each configuration offers distinct advantages regarding packaging space, steering feel, and cost profile. Rack Assist systems often dominate in terms of revenue volume due to their prevalence in larger vehicles and trucks where higher torque assistance is required. However, Column Assist systems remain prevalent in smaller, cost-sensitive passenger cars. The choice of technology often depends on the vehicle class and the required integration with ADAS features.
Geographically, the market is diversified with significant contributions from North America, Europe, and Asia Pacific. Asia Pacific typically leads in volume due to the high production rates of passenger cars and commercial vehicles in the region. Europe remains a critical market driven by stringent emissions regulations and a strong presence of premium OEMs demanding high-performance steering solutions. North America continues to be a hub for innovation, particularly in steer-by-wire development. Latin America and the Middle East & Africa represent emerging growth areas, often driven by cost-effective manufacturing hubs and increasing vehicle ownership rates.
By application, the market is primarily split between Passenger Cars and Commercial Vehicles. Passenger cars account for the majority of the revenue share, reflecting the sheer volume of production and the mandatory nature of EPS in modern sedans, SUVs, and hatchbacks. Commercial vehicles, including heavy-duty trucks and buses, represent a high-growth niche. As fleet operators seek to reduce operational costs and comply with urban emissions zones, the electrification of steering systems in commercial vehicles is gaining momentum. The specific revenue splits and volume distributions between these applications are detailed in the full dataset, providing precise guidance for segment-specific targeting.
Automotive Electronic Power Steering Market
Implications for 2026 and Beyond
As we move deeper into the forecast period, several strategic implications stand out for industry participants. First, the integration of EPS with vehicle-wide electronic architectures will become a key differentiator. Suppliers who can offer scalable steering solutions that integrate seamlessly with autonomous driving stacks will capture greater value than those offering standalone components.
Second, supply chain resilience is paramount. The reliance on specific electronic components, sensors, and high-strength materials means that disruptions in semiconductor or raw material markets can have outsized impacts on EPS production. Companies must evaluate their supplier diversification strategies and consider localized manufacturing to mitigate geopolitical risks.
Worldwide Automotive Power Steering Market
Third, the rise of Chinese suppliers in European and South American markets suggests that cost competitiveness will remain a primary battleground. Western manufacturers must innovate not just in performance but also in manufacturing efficiency to maintain margins amidst intensifying competition.
Finally, the transition toward steer-by-wire technology, while still in its early stages relative to traditional EPS, will likely accelerate as regulatory approvals streamline and consumer acceptance grows. Early movers in this space have the opportunity to define the standards and interfaces that will govern steering systems for the next decade.
Unlocking the Full Intelligence
This overview provides a high-level synthesis of the Automotive Electronic Power Steering market dynamics, highlighting the critical intersection of regulation, technology, and competition. However, for executives and analysts who need to make precise investment decisions, allocate marketing budgets, or formulate sourcing strategies, a higher resolution of data is required.
PW Consulting's full market research report contains detailed quantitative forecasts, end-user consumption analysis, and granular segmentation data that remain essential for tactical planning. The complete report delves into specific revenue projections for each year through 2032, breaks down market share estimates by region and type with precision, and provides in-depth company profiles that include financial health assessments and product pipeline analyses.
To access the comprehensive intelligence needed to navigate the complexities of the EPS market, stakeholders are encouraged to refer to the full publication. Understanding the exact magnitude of growth, the competitive intensity in specific niches, and the timing of regulatory impacts will be the difference between leading the market and reacting to it.
The road ahead for automotive steering is electric, integrated, and increasingly autonomous. Armed with the right data, industry leaders can steer their organizations toward sustainable growth and technological leadership in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Automotive Electronic Power Steering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Zener Diodes Market to Hit $1,063.11M by 2032, 4.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Voltage Landscape: Strategic Imperatives in the Global Zener Diodes Market Through 2032
Executive Summary
In the complex ecosystem of modern electronics, few components are as fundamentally critical yet often overlooked as the Zener diode. Serving as the guardian of voltage stability, this discrete device underpins the reliability of everything from automotive control units to high-performance computing infrastructure. As we move further into the decade, the Zener Diodes Market presents a nuanced narrative of steady growth tempered by intense competitive dynamics and supply chain volatility. PW Consulting's latest comprehensive study offers a definitive roadmap for stakeholders aiming to capitalize on these shifts between 2026 and 2032.
The global market for Zener diodes is projected to demonstrate resilient growth, driven by the expanding electrification of transport, the ubiquitous nature of consumer electronics, and the increasing sophistication of industrial automation. Our analysis indicates that the market valuation is on a consistent upward trajectory, building upon the foundations laid in the post-pandemic recovery period. With the base year established at 2025 and forecast extending through 2032, this research provides a granular look at revenue streams measured in USD Million. The compound annual growth rate (CAGR) clocking in at 4.2 percent signals a mature but expanding sector where incremental gains are tied directly to technological innovation and geographic market penetration.
For strategic planners and procurement leaders, understanding the magnitude of this growth is only the first step. The real value lies in dissecting the drivers behind the numbers. The transition from historical analysis covering 2020 to 2025 into the forecast period allows organizations to benchmark their performance against market rhythms. The historical data reveals a steady climb from earlier valuation points, reflecting renewed demand cycles and the normalization of supply chains. As we look toward the 2032 horizon, the revenue projections suggest a market that is not only growing in size but also evolving in complexity, requiring a more sophisticated approach to market entry and expansion.
Zener Diodes Market
The Voltage of Competition: Key Players and Strategic Moves
The competitive landscape of the Zener Diodes Market is characterized by a mix of established semiconductor giants and specialized manufacturers. Market concentration metrics indicate that while the top players hold significant sway, there remains ample room for differentiation through technology and packaging innovation. The CR3 and CR5 values suggest a moderately consolidated environment where strategic partnerships and product portfolio breadth are key differentiators.
Texas Instruments continues to reinforce its position through aggressive portfolio expansion. In a recent move during January 2026, the company introduced Zener diodes as part of its growing protection devices portfolio, specifically targeting voltage regulation and overvoltage protection needs. This release coincides with updated data sheets for their BZX84Cx and BZX884Cx series, transitioning these devices from advanced status to full production. Such moves highlight a focus on stabilizing supply for high-yield production environments, where process control and capability analysis are paramount.
Diodes Incorporated remains a critical player focused on precision and package technology. Their recent catalog updates in December 2025 showcased surface-mount and leadless Zener diodes with voltage tolerances as tight as plus or minus 2.0 percent. This level of precision is crucial for applications requiring stringent voltage stability. However, the company also navigates the turbulent waters of supply chain dynamics, having experienced significant lead time expansions due to broader component demand shifts. This dual reality of high-precision offering and supply chain pressure underscores the volatility inherent in the sector.
Toshiba Electronic Devices & Storage Corporation has tailored its offerings toward robust protection in power lines and semiconductor devices. The launch of the CMZBxxA series in November 2025 introduced a new planar structure designed to protect against switching surges and overvoltage pulses close to DC. With AEC-Q101 qualification and PPAP capability, Toshiba is positioning its Zener diodes to meet the stringent reliability standards required in automotive applications. This regulatory alignment is a critical barrier to entry for competitors and a key trust signal for automotive OEM procurement teams.
Vishay Intertechnology, Inc. is pushing the boundaries of miniaturization and power handling. Their expansion in October 2025 included new leadless sidewall plated DFN1006-2A packages, enabling next-generation designs where space is at a premium. By offering automotive-qualified and PPAP capable parts alongside standard SMD options, Vishay addresses the dual needs of high-volume consumer manufacturing and specialized automotive supply chains. The use of silicon planar technology across their lineup ensures consistent performance across power ratings ranging from less than 350 mW to over 500 mW.
Nexperia Holding B.V. focuses on reducing noise and enhancing reliability for industrial and automotive designs. Their portfolio enhancements include new 50 microampere series and A-selection series with plus or minus 1 percent tolerance. These enhancements are designed to eliminate overswing and reduce noise, catering to sensitive electronic environments. Meanwhile, Microchip Technology Inc. and onsemi continue to broaden the availability of Zener diodes for general-purpose voltage regulation and transient overvoltage protection respectively, ensuring that the market remains well-supplied across diverse application verticals.
Segmentation Dynamics: Technology and Application Vectors
Understanding where value is generated within the market requires a look at the segmentation splits without losing sight of the overarching trends. The market is broadly divided by technology type and application sector, each presenting unique growth vectors and challenges.
Technology segmentation reveals a preference for specific packaging and mounting solutions that align with modern design constraints. Surface Mount Technology continues to hold a significant share of the market revenue, reflecting the industry wide shift toward miniaturized and automated assembly processes. Through Hole Technology maintains a substantial presence, particularly in applications where mechanical robustness and higher power handling are prioritized. The balance between these two technology types is shifting gradually as design architectures evolve toward denser integration, yet the legacy needs of industrial and heavy-duty sectors keep Through Hole technology relevant.
On the application front, the demand landscape is diverse. Consumer Electronics remains a dominant force, driven by the sheer volume of devices requiring voltage protection and regulation. Communications infrastructure also represents a substantial portion of the market, reflecting the need for reliable power management in network equipment and telecommunications hardware. The Automotive sector is experiencing a transformation, with Zener diodes playing a critical role in the increasing number of electronic control units and power management circuits within modern vehicles. Computer and Computer Peripherals constitute another vital segment, where stability and protection are non-negotiable for data integrity. Other applications collectively contribute to the market volume, encompassing specialized industrial and aerospace needs.
It is within these segments that the strategic opportunities lie. While the aggregate numbers show growth, the rate of adoption varies significantly across regions and sectors. Organizations must identify which segment aligns best with their technological capabilities and supply chain resilience. The interaction between technology type and application requirements often dictates the specific product specifications needed, such as voltage tolerance, power rating, and package size.
Market Dynamics and Operational Realities
The operational environment for Zener diodes is influenced by a confluence of supply chain, regulatory, and production factors. Recent industry intelligence highlights specific dynamics that cannot be ignored when formulating strategy for the 2026 to 2032 period.
Rectifier Diode Market
Supply chain stability remains a primary concern. There have been instances where lead times for Zener diodes and related components expanded significantly, moving from standard weeks to extended periods due to demand surges in adjacent sectors such as AI server motherboards. Price increases across product lines have also been observed, reflecting the inflationary pressure and component scarcity that can ripple through the discrete semiconductor market. Understanding these lead time fluctuations and their correlation with demand spikes in high-growth sectors is essential for inventory management and cost forecasting.
Regulatory compliance is another pillar of market dynamics. With the automotive sector demanding higher reliability, qualifications such as AEC-Q101 and capabilities like PPAP are becoming standard expectations rather than optional differentiators. Manufacturers that can demonstrate compliance with these stringent standards gain a competitive advantage in securing long-term contracts with automotive suppliers. This regulatory layer adds complexity to production but also serves as a moat for established players who have invested in quality assurance infrastructure.
Production processes are evolving to meet the needs of next-generation designs. The adoption of advanced wafer processes and leadless package technologies enables manufacturers to offer components that are smaller, more efficient, and more reliable. Miniaturization continues to be a key driver, as electronic devices become more compact. Providers that can maintain high yield production through rigorous process control while shrinking form factors are well-positioned to capture market share. The ability to verify capability analysis metrics during new product qualification ensures that volume production meets quality expectations from the outset.
Material technology also plays a role in defining product boundaries. The use of silicon planar technology allows for a wide range of power ratings, accommodating diverse application needs from low-power signal protection to higher-power regulation. New package innovations, such as leadless DFN structures, enable integration into designs where space constraints previously limited component choices. These material and packaging advancements are not merely technical specs but strategic assets that enable customers to innovate in their own product development cycles.
Strategic Recommendations for 2026 and Beyond
Based on the comprehensive data and qualitative insights gathered in this study, several strategic imperatives emerge for stakeholders operating in the Zener Diodes Market.
First, supply chain resilience must be prioritized. Given the observed volatility in lead times and pricing, organizations should diversify their supplier base and maintain strategic safety stocks for critical voltage regulation components. Engaging with suppliers who demonstrate robust process control and production capability can mitigate the risk of disruption.
Second, product portfolio alignment is crucial. As automotive and industrial applications demand higher reliability and tighter tolerances, manufacturers should focus on expanding offerings that meet AEC-Q101 standards and offer precision voltage regulation. The shift toward leadless and surface-mount packages suggests that investing in packaging technology innovation will yield competitive returns as designs become more constrained.
Third, geographic and application-specific targeting should guide expansion efforts. While the total market size offers a broad opportunity, growth is not uniformly distributed. Understanding which regions and application segments are driving the specific growth vectors allows for more efficient resource allocation. Companies should tailor their messaging and technical support to the specific pain points of each segment, whether it is noise reduction for industrial users or surge protection for automotive engineers.
Fourth, monitoring competitive developments is essential. The recent product launches and catalog updates by key players indicate a rapidly evolving landscape. Keeping abreast of new series introductions, package innovations, and qualification achievements allows organizations to anticipate market shifts and adjust their strategies proactively.
Finally, long-term planning should account for the forecasted trajectory through 2032. The consistent growth rate suggests a stable demand environment, but the competitive intensity means that margin protection and value-added services will become increasingly important. Partnerships, co-development opportunities, and deep integration with customer design cycles can create sticky relationships that withstand price competition.
Conclusion
The Zener Diodes Market stands at a pivotal juncture where steady demand growth intersects with rapid technological evolution and supply chain complexity. For decision-makers in 2026, the ability to navigate these dynamics will define success in the coming years. This market research provides the foundational intelligence required to make informed strategic choices, from product development to market entry. However, the full depth of segmentation data, regional analysis, and competitive benchmarking is detailed in the complete report. We invite you to access the full study to unlock the specific insights necessary to drive your organizational strategy forward in this critical component market.
For detailed analysis of this topic, please visit the official page: Zener Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermoplastic Edgeband Market Hits $2.96B in 2025, Forecast 7.2% CAGR to $4.82B by 2032
By PW Consulting, 2026-09-16
Navigating the Thermoplastic Edgeband Market: Strategic Intelligence for 2026 and Beyond
The global furniture and interior design industries are undergoing a material transformation, driven by aesthetics, durability requirements, and increasingly complex regulatory environments. At the heart of this shift lies the thermoplastic edgeband sector, a critical component in cabinetry and surface finishing that bridges the gap between raw substrates and premium visual appeal. As we move through 2026, understanding the trajectory of this market is no longer optional for stakeholders; it is a fundamental necessity for securing competitive advantage. PW Consulting's latest comprehensive market research report offers an unprecedented deep dive into the thermoplastic edgeband landscape, providing the quantitative rigor and qualitative analysis needed to navigate the coming years with confidence.
This report is not merely a collection of statistics; it is a strategic roadmap designed to inform capital allocation, supply chain optimization, and product development strategies. By synthesizing historical performance with forward-looking projections, we equip decision-makers with the clarity required to mitigate risk and capitalize on emerging opportunities. The following analysis outlines the key themes, growth drivers, and competitive dynamics explored in detail within our full study.
Market Trajectory and Growth Projections
The thermoplastic edgeband market has demonstrated robust resilience and steady expansion over the past half-decade. Our analysis tracks historical performance from 2020 through 2025, establishing a solid baseline for future forecasting. The market has evolved from a valuation of approximately 2100 Million USD in 2020 to an estimated 2955 Million USD by 2025. This historical growth underscores the consistent demand for high-quality finishing solutions across residential and commercial sectors.
Thermoplastic Edgeband Market
Looking ahead, our forecast period spans 2026 to 2032, projecting a continued upward trajectory. We anticipate the market revenue will surpass the 3100 Million USD mark in 2026, growing to reach nearly 4817 Million USD by the end of the forecast window. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 7.2 percent. Such growth rates indicate a healthy, maturing market that is expanding in line with broader construction and furniture manufacturing trends, yet still possesses significant headroom for innovation-led gains.
However, raw top-line numbers only tell part of the story. The true value of this research lies in dissecting the variables that influence this growth. Fluctuations in raw material costs, shifting regulatory landscapes, and geopolitical tensions all play pivotal roles in shaping the net profitability and operational stability of industry players. Our report contextualizes these macroeconomic factors against market volume to provide a nuanced view of potential returns on investment.
Strategic Drivers Influencing Market Dynamics
Several critical dynamics are currently reshaping the supply and demand equilibrium within the thermoplastic edgeband industry. Understanding these forces is essential for any strategic planning exercise in 2026.
One of the most pressing challenges identified in our sector analysis is the volatility of raw material pricing. For instance, polypropylene, a primary feedstock for many thermoplastic solutions, saw price increases of over 19 percent between 2021 and 2023. This surge significantly impacted production costs, squeezing margins for manufacturers who lacked hedging strategies or vertical integration. Furthermore, nearly 42 percent of manufacturers report ongoing challenges due to the combination of fluctuating raw material prices and tightening environmental regulations, particularly concerning PVC usage.
Regulatory pressure is driving a material shift in preferences across certain geographies. In Europe, ABS edgebands are increasingly favored as a chlorine-free alternative to PVC, especially given their incinerability in authorized facilities. This regulatory divergence creates distinct market realities that require localized strategies. Meanwhile, trade policies continue to introduce friction. Recent U.S. tariffs, including new 25 percent duties on goods from Mexico and Canada and 10 percent on Chinese imports, have directly raised the costs of imported edge banding materials, forcing companies to reconsider their sourcing maps.
Geopolitical instability further complicates the supply chain. The fallout from the Russia-Ukraine conflict has disrupted European polymer production through sanctions on Russian oil and gas, leading to increased ethylene costs which are a key feedstock for PVC. These intersecting pressures highlight the need for robust risk management frameworks, a core component of our analytical methodology.
Regional Growth Patterns and Demand Centers
The global market is not a monolith; it is a collection of distinct regional ecosystems with unique growth drivers. Our report provides a granular view of how demand is distributed across key geographies, based on the latest historical data from 2025.
Thermoplastic Composites Market
North America remains a dominant force in the market, reflecting a strong domestic furniture manufacturing base and significant consumption in interior design projects. Asia Pacific also represents a massive volume center, driven by rapid urbanization and a booming middle class in key economies. Europe continues to hold a substantial share, supported by its strong tradition of cabinetry and a regulatory environment that pushes for specific material standards. Meanwhile, emerging regions such as Latin America and the Middle East and Africa, while currently smaller in absolute volume, offer high-growth potential as infrastructure projects and consumer markets develop.
Strategic decision-makers must understand not just the size of these regions, but the velocity of their growth and the specific barriers to entry present in each. Our full report details the specific volume contributions of each region to help clients prioritize market entry or expansion strategies.
Application and Type Segmentation Insights
Demand is not evenly distributed across applications or material types. Our segmentation analysis reveals where the highest value concentrations lie. Furniture manufacturing remains the primary application driver, consuming the lion's share of market volume as manufacturers seek durable, aesthetically pleasing edges for cabinetry and casegoods. Interior design follows as a significant secondary application, where aesthetic versatility is paramount. Construction applications, while smaller in relative volume, offer steady demand driven by commercial fit-outs and modular building solutions.
On the material side, PVC continues to hold a significant position due to its cost-effectiveness and versatility. However, ABS is gaining traction, particularly in markets sensitive to environmental regulations or where specific processing advantages are required. PP and PMMA segments serve niche but important roles, offering specific performance characteristics such as flexibility or high-gloss finishes. Understanding the trade-offs between these materials regarding cost, processing technology, and end-of-life characteristics is vital for product portfolio management.
Competitive Landscape and Corporate Strategy
The market is characterized by a moderate level of concentration, with the top three companies capturing approximately 58 percent of the market share, and the top five holding around 68 percent. This structure suggests that while large incumbents hold significant sway, there is still room for specialized players and regional champions to thrive by focusing on niche technologies or superior service levels.
Leading the pack is SURTECO, headquartered in Buttenwiesen, Germany. With over 50 years of extrusion experience, SURTECO is a leading manufacturer of thermoplastic edgebands, offering PVC, ABS, and circular or sustainable designs. Their extensive international distribution network makes them a critical benchmark for global reach. Similarly, REHAU Group, based in Reinbek, Germany, stands as a powerhouse in the sector. They produce a wide array of thermoplastic edgebands including PVC, ABS, PP, PMMA, and specialty variants like FlexEdge and 3D variants. REHAU's unmatched color-matching technology and laser-edge capabilities position them at the forefront of innovation.
MKT, also based in Germany, specializes in premium ABS and PP thermoplastic edgebands. Their ALPHA-TAPE® line, featuring woodgrains, mirror gloss, and anti-fingerprint finishes, along with zero-joint technology solutions, targets high-end applications where finish quality is non-negotiable. In Turkey, ROMA PLASTIK has established itself as a major producer and leading export manufacturer. Headquartered in Gebze, they offer extensive decor catalogs covering PVC, ABS, and PMMA, leveraging their logistical advantages to serve both regional and export markets. Finally, Döllken-Kunststoffverarbeitung GmbH in Gladbeck, Germany, provides a comprehensive range of PVC, ABS, PP, and PMMA edgebands. Their focus on low static charge, high processing suitability, and Greenguard certification options appeals to clients with strict environmental and quality standards.
Recent Corporate Moves and Capacity Shifts
The competitive landscape is dynamic, with recent corporate activities signaling where investment is flowing. In May 2026, Wilsonart LLC announced a targeted expansion at its Temple, Texas facility specifically for ABS edge band production. This move is designed to serve the U.S. healthcare furniture market, indicating a strategic pivot towards specialized verticals with stringent hygiene and durability requirements.
Also in May 2026, REHAU Group expanded its digital decor printing capacity at its Viechtach plant. The addition of two high-resolution inkjet printing lines focuses on 3D-texture edge bands with haptic finishes, reinforcing their commitment to aesthetic innovation and customization. In a move to strengthen market presence in Central Asia, SURTECO participated in MebelExpo 2025 in Tashkent, Uzbekistan, showcasing their thermoplastic edgeband systems and highlighting the growing importance of emerging markets in product distribution strategies.
Capacity expansion is also occurring in Asia. E3 Edge Band inaugurated a new production plant in Andhra Pradesh, India, in May 2025 to expand PVC edge banding capacity, responding to local demand growth and potentially serving as an export hub. Furthermore, Roma Plastik invested in a new logistics centre in Gebze with a €23 million investment in May 2025 to support expanded edgeband production and distribution, underscoring the importance of supply chain efficiency in maintaining competitiveness.
The Strategic Value of Comprehensive Intelligence
In an environment defined by raw material volatility, regulatory fragmentation, and aggressive competitive maneuvering, intuition is insufficient. Success in the thermoplastic edgeband market requires data-driven precision. PW Consulting's report goes beyond surface-level trends to provide actionable intelligence. We analyze the interplay between feedstock costs and final pricing, the impact of trade tariffs on landed costs, and the technological differentiators that command premium pricing.
The report details the specific capacity expansions, product launches, and strategic partnerships that are reshaping the competitive field. It offers a critical assessment of market concentration metrics and identifies the vulnerabilities and strengths of key players. By understanding the specific dynamics of regions such as North America, Europe, and Asia Pacific, clients can tailor their go-to-market strategies to local realities rather than relying on global averages.
Conclusion: Making Informed Decisions for 2026
The thermoplastic edgeband market presents significant opportunities for growth, but realizing them requires a sophisticated understanding of the underlying forces at play. From the 7.2 percent CAGR driving overall expansion to the specific challenges posed by PVC regulations and raw material inflation, the landscape is complex. The strategic moves by key players like REHAU, SURTECO, and Wilsonart demonstrate where the industry is heading in terms of technology and capacity.
To access the complete dataset, including detailed segmentation splits, regional volume breakdowns, and deep-dive company profiles, stakeholders are invited to consult the full PW Consulting market research report. This document is designed to be a central reference for strategic planning, procurement, and investment decisions throughout 2026 and the forecast period to 2032. Equip your organization with the depth of insight necessary to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Thermoplastic Edgeband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


