



Category: market research
Navigating the Expansion: Strategic Insights for the Global Bike Racks Market (2026-2032)
The transportation and infrastructure sectors are witnessing a pivotal transformation as sustainable mobility solutions gain mainstream traction. Within this landscape, the bike racks market stands out as a critical enabler, bridging the gap between individual cycling habits and broader vehicular logistics or public infrastructure. As we move into 2026, understanding the nuanced dynamics of this sector is no longer optional for stakeholders involved in automotive accessories, urban planning, or retail operations. PW Consulting's latest comprehensive market research offers a definitive look into the trajectory of this industry, providing the data necessary to navigate the coming years with confidence.
Micro Rain Radar Market
This article serves as a strategic preview of our full report, highlighting the macro-economic shifts, competitive pressures, and regulatory environments that will define the market through 2032. While we outline the broader landscape here, the specific segmentation data and granular financial forecasts detailed in the full study are essential for precise internal planning. Our goal is to equip decision-makers with the context needed to recognize the value of deeper intelligence before committing to capital allocation or product development strategies.
Cloud Compute Services Market
Macro-Economic Trajectory and Value Chain Analysis
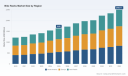
The fundamental story of the bike racks market over the last half-decade has been one of steady, resilient growth. Our analysis of historical data from 2020 through 2025 reveals a consistent upward trend in market valuation. In 2020, the market was valued at approximately 1214.01 Million USD. By the end of the historical review period in 2025, this figure had climbed to 1640.0 Million USD. This progression underscores a market that has successfully absorbed supply chain disruptions and shifting consumer preferences without losing momentum.
Weighing Granule Filling Machine Market
Looking forward, the forecast period from 2026 to 2032 suggests continued expansion. The market is projected to reach 1720.23 Million USD in 2026, growing to approximately 2498.71 Million USD by the end of the forecast window. This trajectory implies a Compound Annual Growth Rate (CAGR) of 6.2 percent during the forecast period. For strategic planners, this rate indicates a healthy, above-average growth environment compared to many mature industrial sectors. It suggests that demand drivers are not merely cyclical but structural, rooted in changing commuting patterns and increased investment in cycling infrastructure globally.
However, aggregate numbers only tell part of the story. The distribution of this value across different dimensions of the market reveals where the intensity of competition and opportunity lies. The full report dissects these layers to show exactly where margins are being won or lost. For instance, while the overall market expands, certain product types and application areas are outpacing others due to ergonomic improvements, material costs, and vehicle compatibility shifts. Understanding which segments are driving the majority of this 6.2 percent growth is crucial for companies deciding where to focus their R&D budgets. Similarly, regional disparities play a significant role in potential ROI. While the global number is impressive, the concentration of value varies significantly by geography, influenced by local regulations, cycling culture, and automotive ownership rates. Our detailed analysis maps these regional variances, providing a roadmap for market entry or expansion strategies that generic industry reports often overlook.
Competitive Landscape and Enterprise Positioning
The market is characterized by a mix of specialized innovators and established automotive accessory giants. Our research identifies twelve key companies that are currently shaping the competitive environment. These entities range from manufacturers focused on commercial facility infrastructure to those dominating the consumer vehicle transport segment. Understanding the specific strategic positioning of these players is vital for any organization looking to gain market share.
In the vehicle transport sector, companies like Thule, based in Sweden, maintain a strong presence with a diverse portfolio including hitch, roof, and trunk-mounted solutions such as the T2 Pro XTR and Verse series. Their recent activity highlights the pace of innovation; in November 2025, Thule provided a sneak peek of new Spring 2026 products, including the Thule Vero bike rack, signaling a continuous commitment to product refresh cycles despite market volatility. Similarly, RockyMounts in Colorado and Yakima in the USA focus heavily on hitch-mounted swing-away and monorail systems, alongside trunk and roof options like the StageTwo and FullBack models. These companies compete on durability and ease of use, catering to the outdoor enthusiasts who form a core demographic for transport racks.
Parallel to the consumer transport market is the commercial infrastructure segment, which is equally dynamic. Madrax, headquartered in Waunakee, Wisconsin, focuses on commercial bike parking racks, including the Orion series and post/ring styles for urban and facility use. Dero, another US-based entity, specializes in custom indoor and outdoor bike parking racks, featuring models like the Decker lift-assist 2-tier. Wagner Companies and Huntco further bolster this segment with steel commercial bike racks for industrial use and covered bike racks respectively. These companies are critical suppliers for municipal projects and corporate campuses, linking the market growth to urban development budgets and sustainability mandates.
Innovators in the hitch-mounted space such as Kuat and Saris are also notable. Kuat focuses on hitch-mounted piston and transfer bike racks, while Saris designs hitch, trunk, and roof bike racks with a strong emphasis on reliability. Hollywood Racks rounds out this group with their Destination E series, targeting specific vehicle compatibility needs. Meanwhile, North Shore Racks in Vancouver offers unique lightweight vertical mountain bike racks for hitch mounting, addressing a niche but high-value segment of mountain bikers. On the storage side, SteadyRack from Australia provides pivoting wall-mounted bike storage and gear racks, illustrating the global nature of innovation in this space.
Market concentration remains moderate, with the top three companies holding approximately 30.0 percent of the market and the top five holding around 35.0 percent. This fragmentation suggests that there is still room for new entrants or specialized players to capture niche value, provided they can differentiate effectively against these established brands. The full report provides a deep dive into the financial health, market share trends, and strategic moves of each of these key players, offering a comparative framework that is essential for competitive benchmarking.
Regulatory Environment and Quality Assurance Dynamics
One of the most critical aspects of operating in the bike racks market is navigating the regulatory landscape. Safety recalls and certification standards are not just operational hurdles; they are strategic risk factors that can impact brand reputation and liability. Our research integrates recent regulatory events to highlight the importance of compliance in product design and manufacturing processes.
Recent history has shown that even established manufacturers face scrutiny. For example, Kuat Innovations LLC was issued NHTSA Recall No. 24E-044 for their Transfer v2 bicycle hitch racks due to a pivot cam disengagement risk, affecting production from 2020 to May 2024. Similarly, Hyperax e-bike carriers faced NHTSA Campaign 25E-092 recall for latch mechanism wear, involving models including the 2023 Volt RV and 2024 Volt 2 produced from 2022 onward. Hollywood Racks also required service for their Destination E model due to a recall affecting units shipped from May 2022. These incidents underscore the necessity for rigorous testing and quality control protocols.
Beyond recalls, certification standards set the baseline for market entry. Bicycle racks must comply with EN ISO 11243 for vertical dynamic fatigue strength testing. This standard is not merely a technical checkbox but a barrier to entry that ensures product longevity and safety under stress. Companies that invest in exceeding these standards often capture premium market segments, while those that treat compliance as a minimum requirement risk higher failure rates and consumer trust erosion. Our report details how these regulations influence manufacturing costs and time-to-market, providing a risk assessment framework for product managers.
Market Drivers and Infrastructure Investment
The growth of the bike racks market is inextricably linked to broader trends in transportation and urban planning. Government initiatives play a significant role in stimulating demand, particularly in the commercial parking segment. A notable example occurred in January 2026, when the Massachusetts Department of Transportation awarded recipients for the 2025-2026 Safe Routes to School Bike Rack Grant Program. Such grant programs directly inject capital into the market, creating immediate demand for commercial parking solutions from suppliers like Dero, Madrax, and Huntco.
These initiatives reflect a wider policy shift toward promoting cycling as a viable mode of transport for education and commuting. As more municipalities and institutions seek to comply with sustainability goals or improve safety for students, the procurement of high-quality bike racks becomes a line item in public budgets. This trend reduces the reliance on consumer discretionary spending alone and diversifies the revenue streams available to manufacturers. However, leveraging these opportunities requires understanding the procurement cycles and specification requirements of public sector buyers, which often differ from the private retail channel.
Furthermore, the rise of e-bikes and specialized cargo cycles is changing the physical requirements for both transport and parking racks. Standard racks may not accommodate the weight or dimensions of newer electric models, creating an opening for specialized products. The interplay between vehicle type availability and rack compatibility is a key dynamic explored in our full analysis. As the fleet of bikes evolves, the infrastructure supporting them must evolve in tandem, creating a continuous cycle of replacement and upgrade demand.
Strategic Imperatives for 2026 and Beyond
For businesses operating in or entering this market, the data points to several strategic imperatives. First, diversification between consumer transport and commercial infrastructure offers a hedge against fluctuations in either sector. The resilience shown by the market between 2020 and 2025 suggests that a balanced portfolio can withstand economic headwinds better than a single-segment focus. Companies like Wagner Companies and Thule illustrate how different ends of the spectrum operate, and there may be value in understanding the supply chain synergies between them.
Second, compliance and safety must be treated as strategic assets rather than operational expenses. Given the recent recall events affecting multiple key players, a reputation for robust safety engineering can become a key differentiator. Marketing materials that highlight compliance with EN ISO 11243 and other relevant standards can reassure risk-averse consumers and commercial buyers. This is particularly important in the hitch-mounted segment, where failure risks are higher due to vehicle dynamics.
Third, geographic strategy should be informed by regional growth potentials. While global numbers are positive, the density of opportunity varies. North America, Europe, and Asia Pacific all present distinct regulatory and cultural environments. The full report provides a breakdown of regional market sizes and growth rates, allowing firms to prioritize markets where their specific product strengths align with local demand. For instance, markets with strong cycling infrastructure investment may favor commercial parking solutions, while regions with high vehicle ownership rates may drive demand for hitch-mounted transport racks.
Conclusion: The Value of Granular Intelligence
The bike racks market is poised for significant expansion over the next six years, driven by a combination of cultural shifts, infrastructure investment, and product innovation. The projected growth from 1720.23 Million USD in 2026 to nearly 2500 Million USD by 2032 represents a substantial opportunity for well-positioned companies. However, realizing this opportunity requires more than just awareness of the top-line figures. It demands a deep understanding of segmentation, competitive moves, regulatory risks, and regional nuances.
This article has outlined the broad strokes of the market landscape, but the decisive advantages lie in the details. Where exactly is the growth occurring within product types? Which application areas are seeing the fastest adoption rates? What are the specific market shares of competitors in each region? These are the questions that determine successful product launches and investment decisions. The full PW Consulting Bike Racks Market Research report answers these questions with precision, providing the actionable intelligence needed to navigate the 2026-2032 forecast period effectively.
We invite stakeholders to access the full study for a comprehensive view of the data, including detailed segmentation splits, competitor profiling, and risk assessments. In a market defined by 6.2 percent CAGR and evolving regulatory standards, having the complete picture is the best strategy for sustainable growth.
For detailed analysis of this topic, please visit the official page: Bike Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ribbon Fiber Optic Cable Market to Hit $4.74 Billion by 2032, 8.9% CAGR
By PW Consulting, 2026-09-07
Navigating the Ribbon Fiber Optic Cable Market: Strategic Intelligence for 2026 and Beyond
The global telecommunications infrastructure landscape is undergoing a structural shift. As demand for bandwidth intensifies across hyperscale data centers, enterprise networks, and fiber-to-the-x (FTTx) deployments, the ribbon fiber optic cable segment has emerged as a critical enabler of high-density, high-capacity connectivity. For strategic planners, procurement leaders, and industry executives, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, vendor selection, and long-term network architecture decisions.
Business Immigration Service Market
PW Consulting's latest Ribbon Fiber Optic Cable Market research report delivers a comprehensive, data-driven examination of this rapidly evolving sector. Spanning historical analysis from 2020 through 2025 and a forward-looking forecast window extending to 2032, this study equips decision-makers with the granular intelligence required to navigate supply chain complexities, competitive pressures, and technology adoption curves. What follows is an overview of the report's strategic architecture and the core insights it surfaces for the 2026 business environment.
Tilox Black (Ti4O7) Market
The Macro Trajectory: Sustained Growth Anchored by Infrastructure Expansion
The ribbon fiber optic cable market has demonstrated consistent upward momentum over the past half-decade, reflecting the broader acceleration of fiber deployment initiatives worldwide. Historical revenue figures from 2020 to 2025 illustrate a steady climb, with the market expanding from approximately 0.96 billion USD in 2020 to 2.58 billion USD by 2025. This trajectory underscores the compounding effect of sustained capital investment in fiber networks, driven by both public-sector digital inclusion mandates and private-sector hyperscale capacity requirements.
Worldwide Electroplated Diamond Wire for Monocrystalline Silicon Market
Looking ahead, the forecast period from 2026 to 2032 projects continued expansion, with the market expected to reach 4.74 billion USD by the close of the forecast window. This growth path is underpinned by a compound annual growth rate (CAGR) of 8.9 percent, signaling that ribbon fiber solutions are transitioning from niche high-density applications to mainstream infrastructure components. The 2026 baseline of 2.74 billion USD serves as a critical inflection point, offering a reference frame for evaluating near-term procurement strategies and long-range capacity planning.
It is important to note that these aggregate figures represent the top-line market universe. The full report decomposes this total across multiple analytical dimensions—type, application, and regional distribution—providing a layered view of where growth is concentrating and which sub-segments are outperforming. Readers seeking the complete breakdown of these directional splits will find the detailed segmentation tables and cross-referenced analysis within the full publication.
Competitive Architecture: Incumbents, Innovators, and the Density Arms Race
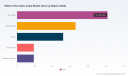
The ribbon fiber optic cable market is characterized by a moderately concentrated competitive landscape. Industry concentration metrics indicate that the top three players account for approximately 30 percent of market revenue, while the top five collectively represent around 45 percent. This structure suggests a market where scale advantages matter, yet sufficient fragmentation remains to allow specialized entrants and regional players to carve out defensible positions through technological differentiation and localized service capabilities.
Several established corporations anchor the competitive framework, each pursuing distinct approaches to maximizing fiber density, minimizing installation complexity, and adapting ribbon architectures to diverse deployment environments.
Corning Incorporated
Headquartered in Corning, New York, Corning has long been a reference point for optical fiber innovation. Its ribbon cable portfolio—including the RocketRibbon® product line—targets high-density data center and outside plant (OSP) applications with gel-free designs capable of accommodating up to 6,912 fibers. By reducing cable outer diameter by up to 60 percent and cutting installation time by roughly 30 percent, Corning's offerings address two persistent pain points in dense deployment scenarios: spatial constraints and labor efficiency.
Prysmian Group
Based in Milan, Italy, Prysmian Group has introduced FlexRibbon® Technology, which leverages intermittently bonded ribbon (IBR) architectures. This approach enables rollable and foldable cable handling while supporting microduct, flat cable, and flame-rated configurations. The emphasis on handling flexibility positions Prysmian's solutions for environments where traditional rigid ribbon cables face installation or routing limitations.
Furukawa Electric Co., Ltd.
Tokyo-based Furukawa Electric focuses on rollable ribbon high-density optical fiber cables that achieve substantial core counts—up to 6,912 fibers—within compact form factors. These designs are optimized for underground and high-capacity applications, prioritizing the smallest achievable diameter and the highest core density to maximize conduit utilization.
Fujikura Ltd.
Also headquartered in Tokyo, Fujikura has pushed the density envelope further with its 13824-fiber SWR™/WTC™ cable, which utilizes Spider Web Ribbon™ (12-fiber intermittently bonded ribbon) and Wrapping Tube Cable™ construction. Designed for hyperscale data center environments, the cable employs non-metallic construction to meet stringent fire and safety requirements. In January 2026, this product was recognized with the Grand Prize at the 2025 Nikkei Excellent Products and Services Awards, highlighting the industry's acknowledgment of extreme-density ribbon architectures as a viable hyperscale solution.
Sterlite Technologies Limited
Mumbai-based Sterlite Technologies offers the Celesta™ Ribbon Cable alongside high-count ribbon options tailored for duct installations. The company's solutions claim up to 4.5x fiber density improvements and approximately 80 percent installation time savings in FTTH and enterprise network contexts, emphasizing the operational efficiency gains that ribbon adoption can deliver.
YOFC (Yangtze Optical Fibre and Cable Co., Ltd.)
Wuhan-based YOFC provides high-density ribbon and multi-fiber cables serving data centers, metro networks, and FTTH deployments. Its product offerings incorporate G.652 and G.657 fiber types, including bend-insensitive options, reflecting the need to accommodate diverse routing environments where tight bends and space constraints are common.
Nexans S.A.
Paris-based Nexans focuses on high-density ribbon fiber optic patch cords and cables engineered for data-center applications. The company's emphasis on enabling higher capacity within compact formats aligns with the ongoing compression of data center footprints and the corresponding need for denser interconnect solutions.
CommScope Holding Company
Headquartered in Hickory, North Carolina, CommScope supplies ribbon and high-count optical cables across enterprise, data center, and broadband network segments. Its diversified portfolio addresses the overlapping demands of commercial IT infrastructure and wide-area network deployment.
Optical Cable Corporation
Based in Roanoke, Virginia, Optical Cable Corporation delivers high-performance fiber optic cables, including ribbon configurations designed for commercial enterprise, tactical, and military ground applications. This diversification into specialized and ruggedized use cases illustrates how ribbon architectures are extending beyond conventional telecom and data center contexts.
Belden Inc.
St. Louis-based Belden offers optical fiber cables and connectivity solutions that incorporate ribbon fiber for industrial, enterprise, and data communication networks. The company's integration of ribbon technology into broader connectivity portfolios reflects the convergence of physical layer infrastructure and higher-level network architecture planning.
The full report provides a deeper competitive benchmarking framework, examining product portfolio breadth, geographic reach, pricing orientations, and partnership ecosystems. Rather than presenting a static leaderboard, the analysis maps how these firms are positioning themselves across the type, application, and regional dimensions that will define competitive outcomes through 2032.
Segmentation Dynamics: Where Value Is Concentrating
The ribbon fiber optic cable market is not a monolith. Growth is distributed unevenly across cable types, end-use applications, and geographic regions, and understanding these distributional patterns is essential for targeted investment and procurement. The research report decomposes the market along three primary axes:
- By Type: The market is divided between multi-mode and single-mode ribbon cable architectures, each serving distinct performance profiles and deployment contexts. Multi-mode solutions address shorter-reach, high-bandwidth scenarios where cost-per-fiber economics and ease of termination are prioritized, while single-mode variants support longer-reach and higher-capacity applications where attenuation and dispersion characteristics drive selection.
- By Application: Demand is anchored across FTTx deployments, data center interconnects, and a range of other applications including enterprise networking, metro backbones, and specialized use cases. FTTx represents a substantial demand driver as broadband infrastructure programs accelerate globally, while data center interconnects reflect the explosive growth in intra- and inter-data center bandwidth requirements.
- By Region: Regional demand patterns reflect divergent infrastructure maturity, regulatory frameworks, and capital investment cycles. Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa each present distinct growth narratives shaped by local broadband policies, data center construction pipelines, and supply chain configurations.
The report's segmentation analysis goes beyond descriptive breakdowns to examine the interaction effects between type, application, and region. For instance, the relative preference for multi-mode versus single-mode ribbon cables in data center versus FTTx contexts varies meaningfully by geography, and these variations have direct implications for product roadmap planning and inventory strategy. Full segmentation tables, including year-by-year projections and share trajectories, are provided in the complete publication.
Market Dynamics and External Pressures Shaping 2026 Decision-Making
Strategic planning in the ribbon fiber optic cable market cannot be isolated from the broader industrial and regulatory environment. Several intersecting dynamics are reshaping cost structures, procurement pathways, and technology adoption timelines.
Input Cost Volatility and Fiber Pricing Pressures
Raw material and labor cost dynamics are exerting upward pressure on component pricing. As of early 2026, G.657A2 bend-insensitive fiber prices reached approximately 35 USD per kilometer, representing a roughly 90 percent increase from mid-2025 levels. This escalation has been driven by sustained demand and supplier warnings of further increases, creating a direct line item impact on cable manufacturing costs and, ultimately, end-user pricing. For procurement teams, this environment underscores the importance of forward contracting, supplier diversification, and design-stage optimization to mitigate exposure to volatile input markets.
Regulatory Alignment and Domestic Manufacturing Incentives
Policy support for digital inclusion and data-sovereignty requirements is converging across regions to favor domestic fiber optic cable production and procurement. In parallel, US tariffs on certain fiber optic products, including cables, have seen minimal disruption to deployment timelines as major providers shifted assembly and manufacturing to comply with Build America, Buy America Act requirements. These regulatory currents are reshaping supplier selection criteria, localization expectations, and the cost-benefit calculus of import-dependent supply chains. The report examines how these policy shifts are influencing regional market structures and what they signal for multinational procurement strategies.
Ecosystem Collaboration and Interoperability Initiatives
Product compatibility programs are emerging as a meaningful force in streamlining deployment workflows. In May 2025, PLP and Lightera announced a compatibility program pairing PLP's drop closures with Lightera's rollable ribbon fiber optic cable, aimed at simplifying FTTx network design and deployment. Showcased at Fiber Connect 2025, this initiative illustrates a broader trend toward ecosystem-level interoperability that reduces integration friction and accelerates time-to-service. Such collaborations are particularly relevant for operators seeking to standardize on compatible component sets and reduce field installation complexity.
What the Report Delivers: Operational Intelligence for Execution
Beyond macro trends and competitive positioning, the Ribbon Fiber Optic Cable Market report is structured to provide actionable, execution-ready intelligence. The following components form the analytical core of the publication:
- Historical Reconstruction and Baseline Calibration: A detailed reconstruction of market revenue from 2020 through 2025, enabling readers to validate internal forecasts against external benchmarks and identify inflection points that may have been missed in prior planning cycles.
- Forward Forecast with Scenario Sensitivity: Year-by-year projections from 2026 through 2032, presented with methodological transparency around growth drivers, adoption curves, and macroeconomic assumptions. The forecast framework is designed to support sensitivity testing, allowing users to adjust variables such as deployment pace, input cost trajectories, and regulatory timelines.
- Segment-Level Decomposition: Breakdowns by type, application, and region that reveal where growth is concentrating and which sub-segments are exhibiting above-average momentum. These decompositions are cross-referenced to highlight compound effects—for example, how a specific cable type performs across multiple applications within a given region.
- Competitive Profiling and Strategic Grouping: Detailed profiles of key market participants, including product offerings, technological differentiators, geographic footprints, and recent developments. The report groups competitors along strategically relevant dimensions rather than relying on simplistic revenue rankings, enabling readers to identify peer sets aligned with their own positioning goals.
- Recent Developments and Signal Monitoring: A curated overview of notable product launches, awards, partnership announcements, and compatibility initiatives that serve as leading indicators of technological direction and ecosystem alignment.
- Dynamics Analysis: An integrated examination of cost pressures, regulatory shifts, supply chain configurations, and policy trends that influence market behavior. This section connects external signals to internal planning implications, helping readers translate macro developments into procurement, sourcing, and investment decisions.
Throughout the report, data is presented with methodological clarity and source attribution, allowing readers to assess the robustness of each finding and adapt conclusions to their specific organizational context.
Why This Research Matters for 2026 Strategy
The 2026 business environment demands a more nuanced understanding of infrastructure markets than passive trend extrapolation can provide. Several factors make the Ribbon Fiber Optic Cable Market report particularly relevant for current decision-making:
- Capital Allocation Under Uncertainty: With input costs rising and regulatory frameworks shifting, the cost-benefit calculus for ribbon versus alternative cable architectures is in flux. The report's segment-level analysis helps identify where ribbon solutions deliver unambiguous density or installation-time advantages that justify premium pricing, and where alternative approaches may remain more economical.
- Supplier Selection in a Concentrated-but-Fragmented Market: The moderate concentration of the market means that scale players offer procurement leverage, while smaller specialists may provide superior performance in niche applications. The competitive profiling framework enables side-by-side evaluation of supplier capabilities against specific deployment requirements.
- Regional Strategy Alignment: Divergent regional growth trajectories and policy environments require tailored sourcing and deployment strategies. The regional decomposition in the report supports decisions about where to prioritize domestic procurement, where to leverage import supply chains, and where localized manufacturing investments may be warranted.
- Technology Roadmap Planning: The rapid evolution of ribbon cable architectures—from gel-free designs to intermittently bonded ribbons to extreme-density spider web configurations—means that product selection decisions made today will affect network performance for years. The report's technology snapshot and recent developments section provide context for evaluating which architectures are likely to become mainstream versus remain specialized.
- Risk Management and Scenario Preparedness: The forecast framework's sensitivity orientation allows organizations to stress-test their plans against alternative assumptions about demand pace, cost trajectories, and regulatory outcomes, reducing the risk of strategic surprise.
Accessing the Full Intelligence Package
The overview presented here captures the structural logic and strategic orientation of the Ribbon Fiber Optic Cable Market report, but it deliberately omits the granular segmentation data, detailed regional splits, application-level revenue figures, and comprehensive competitor benchmarking tables that form the backbone of the analysis. These details are essential for translating macro insights into operational plans, and they are available in full within the complete publication.
For organizations navigating infrastructure investment decisions, supplier negotiations, product roadmap development, or regional market entry strategies, the full report provides the depth required to move from directional confidence to precise execution. The 2026 to 2032 forecast window, combined with the historical reconstruction and dynamics analysis, creates a decision-support framework that can be adapted to a range of planning horizons and organizational contexts.
We invite strategic leaders, procurement executives, network architects, and industry analysts to engage with the complete research package. The full report is accessible through our research portal, where readers will find downloadable segmentation tables, competitor profiles, methodology notes, and scenario modeling templates designed to integrate directly into corporate planning workflows.
The ribbon fiber optic cable market is entering a phase of sustained expansion, but the distribution of that growth—and the competitive and regulatory forces shaping it—will reward those who plan with precision. PW Consulting's research is built to provide that precision.
For detailed analysis of this topic, please visit the official page: Ribbon Fiber Optic Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sports RTLS Market Hits $9.59M in 2025, Set to $49.44M by 2032 at 26.4% CAGR
By PW Consulting, 2026-09-07
Navigating the Real-Time Location Systems in Sports Market: Strategic Insights for 2026 Decision-Makers
The intersection of athletic performance, spectator experience, and operational efficiency is undergoing a radical transformation. At the heart of this shift lies Real Time Location Systems (RTLS), a technology stack that has evolved from niche industrial tracking into a cornerstone of modern sports infrastructure. As we move through 2026, the deployment of RTLS in sports venues, training facilities, and broadcasting ecosystems is no longer a question of technological feasibility but of strategic prioritization. PW Consulting's latest market research on the Real Time Location Systems in Sports Market provides a comprehensive intelligence framework designed to guide executive decisions, investment allocations, and technology adoption roadmaps for the remainder of the decade.
Worldwide Multifunctional Fiber Optic Interferometer Market
This analysis serves as a strategic preview of our full report. It outlines the macro trajectory, competitive architecture, and operational use cases that define the sector, while deliberately withholding the granular segmentation data, pricing models, and proprietary forecast matrices that constitute the core intelligence of the complete publication. For organizations seeking to capitalize on the RTLS expansion, understanding the structural forces at play is the first step toward capturing market advantage.
Mobile Stone Crushing Plant Market
The Macro Trajectory: Scale, Pace, and Strategic Implications
The RTLS in sports sector has transitioned from an emergent concept to a high-velocity growth market over the past half-decade. Historical tracking from 2020 through 2025 reveals a consistent upward curve, driven by converging demands for athlete load management, fan engagement optimization, and venue operational digitization. The market revenue base expanded from approximately $2.97 million in 2020 to $9.59 million by 2025, reflecting a period of rapid adoption across professional leagues, academic athletic programs, and large-scale event organizers.
Baby Playhouse Market
Looking forward, the forecast period spanning 2026 through 2032 projects an acceleration in monetization and deployment density. The market is positioned to reach $12.15 million in 2026, with growth compounding annually at a CAGR of 26.4 percent. By the close of the forecast window in 2032, the sector is expected to surpass $49.44 million in revenue. This trajectory signals more than incremental adoption; it indicates a structural integration of location intelligence into the fundamental operations of sports organizations worldwide.
For strategic planners, the implications of this growth curve are threefold. First, the compounding rate suggests that early adopters are securing architectural lock-in advantages, establishing data pipelines and integration standards that will become industry norms. Second, the rapid expansion creates a widening window for late entrants to leverage mature technology stacks while competing on venue-specific customization and service model innovation. Third, the sheer velocity of revenue generation underscores that RTLS is transitioning from a capital expenditure project to an operational revenue enabler, with applications ranging from ticketed fan experiences to predictive equipment maintenance.
Our full report dissects the temporal dynamics in greater detail, mapping historical inflection points against forward-looking scenario models. The complete publication includes sensitivity analyses that account for technology adoption lags, regulatory shifts in data privacy, and the impact of macroeconomic fluctuations on sports capital spending. These layers of analysis are essential for risk-adjusted planning, yet they require the full dataset to model accurately.
The Competitive Architecture: Differentiation, Alliances, and Innovation Velocity
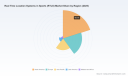
The RTLS in sports landscape is characterized by a concentrated yet dynamic competitive field. Market concentration metrics indicate that the top three players command approximately 48.0 percent of the market, while the top five collectively hold around 68.0 percent. This structure suggests a market where established incumbents maintain significant positioning strength, but where mid-tier and emerging players continue to challenge through technological novelty, geographic expansion, and vertical-specific solution design.
Several key enterprises define the current competitive equilibrium. Catapult Sports , headquartered in Australia, has established a formidable presence through its Vector and Vector Pro athlete monitoring systems. By integrating GPS and Local Positioning System (LPS) capabilities, Catapult delivers real-time indoor and outdoor player tracking paired with advanced performance analytics. Its solutions serve both professional and amateur sports organizations, creating a broadInstalled base that reinforces its data ecosystem advantages.
In the high-precision positioning segment, Quuppa Oy of Finland has emerged as a notable innovator. The company's Intelligent Locating System leverages Bluetooth Angle of Arrival (AoA) technology to deliver sub-meter accuracy for tracking athletes, staff, and assets across venues, events, and stadiums. Quuppa's recent strategic moves underscore its commitment to expanding the addressable market through ecosystem alliances. In March 2026, the company announced compatibility between the InPlay IN100 NanoBeacon and its Intelligent Locating System, a development that enables cost-efficient, high-volume IoT applications within sports environments. Shortly thereafter, Quuppa introduced the Precision Label Tag class through a collaboration with InPlay and MokoSmart, with rollout at LogiMAT targeting enterprise RTLS deployments that include sports venue applications. These moves illustrate a broader industry trend: the convergence of high-precision positioning with low-cost, scalable beacon infrastructure is lowering the barrier to entry for venue-wide tracking deployments.
Blueiot , based in China, represents a distinct competitive vector by focusing on Bluetooth AoA RTLS solutions that deliver sub-meter accuracy for stadium navigation, crowd management, staff coordination, and visitor tracking. Blueiot's emphasis on operational flow and spectator experience differentiates its positioning from purely performance-oriented tracking platforms, highlighting how RTLS value propositions are bifurcating between athlete optimization and venue operations.
Eliko , also headquartered in Finland, supplies UWB-based RTLS platforms that emphasize high-precision performance monitoring for athlete and equipment tracking within indoor sports facilities. UWB's inherent accuracy advantages in multipath-prone environments make Eliko's solutions particularly relevant for indoor arenas, training centers, and specialized sports complexes where precise spatial data is critical.
On the North American side, WISER delivers UWB RTLS tailored for sports analytics, player tracking, and stadium operations. The company's deployment at venues such as Minute Maid Park demonstrates the practical application of UWB infrastructure for guide services, crowd management, and operational efficiency. Sewio Networks , a Denmark-based provider, offers a multi-radio approach encompassing UWB, BLE, and GPS RTLS solutions. Originally rooted in industrial and venue asset and employee tracking, Sewio's technology stack is increasingly applicable to sports facilities seeking to enhance safety, operational efficiency, and asset utilization. Litum , headquartered in the United States, provides hybrid UWB/BLE LoRaWAN RTLS platforms designed for comprehensive venue and stadium tracking of athletes, equipment, and personnel. Litum's hybrid architecture reflects a broader industry recognition that no single radio technology optimally addresses all tracking requirements, and that interoperable, multi-protocol solutions are becoming the de facto standard for complex sports environments.
The competitive dynamics within this group are not static. Alliances, technology integrations, and product launches continually reshape market positioning. Quuppa's recent beacon compatibility announcements, for example, illustrate how established RTLS providers are expanding their addressable markets by aligning with semiconductor and IoT ecosystem players. Such moves reduce total cost of ownership for end users while extending the reach of high-precision locating systems into broader operational use cases. Our full report maps these competitive interactions in detail, including partnership networks, product roadmaps, and regional go-to-market strategies that determine which players are likely to capture share in specific verticals and geographies.
Operational Value Creation: Applications That Drive Demand
The adoption of RTLS in sports is not driven by technology ambition alone; it is anchored in concrete operational and commercial value creation. Across the market, three primary application categories dominate demand generation, each addressing distinct stakeholder priorities and revenue opportunities.
Player and Athlete Tracking
Performance tracking remains a foundational driver of RTLS investment. Player training tracking applications focus on load management, movement pattern analysis, injury risk mitigation, and tactical evaluation during practice and conditioning sessions. These systems provide coaching staffs with granular spatial and temporal data that inform training periodization, recovery protocols, and individualized performance targets. The value proposition extends beyond immediate athletic outcomes; organizations leverage this data to enhance scouting, draft decisions, and contract negotiations, creating a downstream monetization layer that justifies capital deployment.
In-game player tracking addresses the real-time demands of competitive match play. During live events, location data supports officiating assistance, broadcast enhancement, and tactical adjustment. The integration of RTLS data into broadcast pipelines has become a significant differentiator for leagues and media partners, as fans increasingly expect data-rich visualizations and augmented viewing experiences. The operational complexity of in-game tracking requires robust latency management, redundancy, and integration with existing venue and league data architectures, making it a higher-barrier but higher-value application segment.
Asset and Venue Management
Beyond athlete performance, RTLS platforms deliver substantial value through asset tracking and venue operations optimization. Sports facilities house extensive inventories of equipment, medical supplies, broadcasting hardware, and logistical assets. Real-time visibility into asset location, utilization rates, and movement patterns reduces loss, optimizes allocation, and streamlines maintenance workflows. For large venues, RTLS-driven asset intelligence supports just-in-time provisioning, reducing carrying costs and improving service responsiveness during events.
Venue operations also benefit from RTLS-enabled crowd management, staff coordination, and navigation systems. High-precision locating infrastructure allows organizers to monitor density patterns, route flow, and congestion points in real time, enhancing safety and spectator experience. Staff coordination applications improve response times for security, medical, and logistical teams by providing accurate location context during incident management. These operational use cases often represent the fastest path to ROI for venue operators, as they address immediate efficiency and safety priorities while building the infrastructure foundation for more advanced applications.
Strategic Integration and Data Architecture
The most successful RTLS deployments are those that integrate location data into broader organizational data architectures. Standalone tracking systems provide point solutions, but platforms that feed location intelligence into performance management software, fan engagement platforms, and operational dashboards generate compounding value. This integration imperative is shaping procurement criteria, as sports organizations increasingly prioritize interoperability, API accessibility, and data governance frameworks when evaluating RTLS vendors. The market is responding with platforms that emphasize open architectures and modular deployment models, allowing organizations to scale from pilot applications to enterprise-wide rollouts without architectural fragmentation.
Our complete market research provides a detailed mapping of application-level adoption patterns, procurement cycles, and integration requirements. It includes analysis of how organizations structure RTLS investments across performance, operations, and fan experience budgets, along with the decision criteria that differentiate adoption in professional leagues versus amateur and educational sports organizations. These insights are critical for vendors crafting go-to-market strategies and for buyers benchmarking their investment plans against industry norms.
Technology Divergence: UWB, Bluetooth AoA, and Hybrid Architectures
The RTLS technology landscape in sports is defined by a divergence of radio technologies, each offering distinct trade-offs in accuracy, cost, infrastructure requirements, and environmental robustness. Ultra-Wideband (UWB) remains the gold standard for high-precision applications, particularly in environments where multipath interference and occlusion challenge other technologies. UWB-based platforms excel in indoor sports facilities, arenas, and training centers where sub-meter or even centimeter-level accuracy is required for performance analysis and equipment tracking. The technology's inherent ranging accuracy and resistance to non-line-of-sight degradation make it particularly valuable for applications where spatial precision directly impacts decision quality.
Bluetooth Angle of Arrival (AoA) positioning has emerged as a compelling alternative for applications where cost efficiency and scalability are prioritized alongside sufficient accuracy. AoA systems leverage the directional properties of Bluetooth signals to estimate position, offering a favorable balance between precision and infrastructure expenditure. Recent developments, such as the integration of NanoBeacon technologies with established locating systems, are further enhancing the viability of Bluetooth-based RTLS for high-volume sports venue deployments. These advancements are expanding the addressable market for location intelligence by enabling organizations to deploy comprehensive tracking coverage without the capital intensity associated with higher-end positioning technologies.
GPS and hybrid architectures complete the technology spectrum. GPS remains relevant for outdoor tracking applications, particularly in large training grounds, open-field events, and scenarios where satellite-based positioning aligns with existing infrastructure. Hybrid solutions that combine UWB, BLE, and other radios are increasingly favored for complex venues that require seamless coverage across indoor and outdoor zones, varying density conditions, and multiple stakeholder use cases. The trend toward hybrid platforms reflects a pragmatic recognition that sports environments are heterogeneous, and that single-technology solutions often fail to address the full range of operational requirements.
Technology selection is rarely a purely technical decision; it is shaped by vendor ecosystems, existing infrastructure investments, data integration requirements, and total cost of ownership models. Our full report provides a comparative analysis of technology footprints, deployment cost structures, and accuracy-performance trade-offs across the major RTLS modalities. It also examines the implications of emerging standards, interoperability frameworks, and semiconductor advancements that are likely to influence technology adoption patterns over the forecast period.
Strategic Imperatives for 2026 and Beyond
As the RTLS in sports market accelerates toward its 2032 trajectory, organizational decision-makers face a series of strategic imperatives that will determine their ability to capture value from location intelligence investments. First, organizations must define clear use case priorities that align RTLS deployment with measurable operational or commercial outcomes. Pilots that lack defined success criteria or integration pathways risk becoming isolated technology experiments rather than value-generating assets. Second, procurement strategies should evaluate vendors not only on immediate technical specifications but on ecosystem compatibility, data governance capabilities, and long-term roadmap alignment. The concentration of market share among leading players underscores the importance of selecting partners with sustained innovation capacity and supportive service infrastructures.
Third, organizations should consider the sequencing of technology adoption. High-precision UWB deployments may be appropriate for performance-critical environments, while Bluetooth AoA or hybrid solutions may offer more scalable pathways for venue-wide operational tracking. A phased approach that matches technology choice to application requirements can optimize capital allocation while building organizational competency in location data management. Fourth, data architecture planning must precede or accompany RTLS deployment. Location data gains value through integration, and organizations that invest in data pipelines, analytics capabilities, and cross-functional data access early are better positioned to extract compounding returns as their RTLS ecosystems mature.
Finally, the rapid pace of market growth and technological evolution demands continuous intelligence refresh. Market share dynamics, vendor strategies, technology breakthroughs, and application-level adoption patterns are shifting in real time. Static evaluations quickly become outdated in a market expanding at a 26.4 percent CAGR. Organizations that institutionalize ongoing market monitoring and scenario planning are better equipped to adjust investment timing, renegotiate vendor terms, and identify emerging opportunities before they become mainstream.
Accessing the Full Intelligence Framework
This preview has outlined the structural forces, competitive architecture, application drivers, and strategic considerations that define the Real Time Location Systems in Sports Market as of 2026. The macro growth trajectory, the concentrated yet dynamic competitive landscape, and the diversified application demand all point to a market in which informed decision-making can yield significant competitive advantage. Yet the dimensions of this advantage are best understood through the detailed segmentation, pricing intelligence, regional deployment patterns, vendor-by-vendor strategic profiles, and scenario-based forecast models contained in the complete PW Consulting market research publication.
The full report provides the granular intelligence necessary to translate strategic awareness into actionable plans. It includes detailed segmentation analysis across regions, technology types, and application categories, along with the proprietary data matrices that enable precise market sizing, share modeling, and forward-looking scenario evaluation. For vendors, the report offers go-to-market guidance, competitive benchmarking, and technology trend analysis. For buyers and sports organizations, it provides investment benchmarking, vendor evaluation frameworks, and adoption pathway insights. For investors and financial analysts, it delivers the market structure clarity and growth driver decomposition required for informed capital allocation decisions.
To access the complete dataset, detailed segmentation breakdowns, competitive profiles, and forward-looking forecast models, visit the PW Consulting report page for the Real Time Location Systems in Sports (RTLS) Market. The full publication is designed to serve as a strategic reference for executive planning, procurement strategy, technology roadmap development, and investment analysis throughout the 2026 to 2032 forecast period.
The RTLS in sports market is not merely expanding; it is maturing into a foundational layer of sports operational and performance infrastructure. Organizations that approach this transformation with rigorous intelligence, clear strategic priorities, and a disciplined investment framework will be best positioned to capture the value that location intelligence creates. PW Consulting's comprehensive market research provides the intelligence foundation required to navigate this transformation with confidence.
For detailed analysis of this topic, please visit the official page: Real Time Location Systems in Sports (RTLS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Epoxidized Soybean Oil Market to Hit $825.27 Million by 2032, Growing at 7.58% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the Epoxidized Soybean Oil Market: Navigating Volatility and Opportunity Through 2032 The global chemical landscape is undergoing a profound transformation, driven by shifting regulatory frameworks, supply chain realignment, and an accelerating demand for bio-based alternatives across industrial applications. Within this complex matrix, epoxidized soybean oil has emerged as a critical enabler, functioning simultaneously as a versatile plasticizer, a stabilizing agent, and a renewable feedstock component. For executives, procurement leaders, and strategic planners, the question is no longer whether to integrate this material into long-term planning, but how to navigate its evolving value chain with precision. Our latest comprehensive market research delivers the analytical rigor required to turn ambiguity into actionable strategy.
Market Trajectory and the Macro Growth Blueprint
The epoxidized soybean oil market has demonstrated resilient expansion over the past half-decade, evolving from a mature specialty chemical segment into a strategically pivotal category. Historical valuation data from 2020 through 2025 reveals a consistent upward trajectory, with the base-year market size reaching approximately 496.5 million USD. This growth reflects both steady industrial consumption and the compounding effect of substitution trends favoring non-phthalate plasticizers in sensitive applications. Looking ahead, our forecast model projects sustained momentum through the 2026 to 2032 horizon. The market is expected to surpass 534.71 million USD in 2026, accelerating further as downstream adoption intensifies and production capabilities mature. By 2032, the aggregate valuation is projected to approach 825.27 million USD, representing a compound annual growth rate of 7.58 percent. This rate of expansion signals more than incremental demand growth; it reflects a structural shift where epoxidized soybean oil is increasingly embedded into formulation strategies across multiple industrial verticals. For corporate decision-makers, this trajectory carries several strategic implications. First, capacity planning must anticipate multi-year demand escalation rather than short-cycle fluctuations. Second, procurement strategies should account for the commoditized nature of upstream soybean oil, which constitutes approximately 58.6 percent of the raw material input in epoxidized soybean oil production. Third, pricing models must be calibrated against broader agricultural market dynamics, including the USDA forecast that places season-average soybean oil prices at 0.59 USD per pound for the 2025/26 marketing year, alongside record crush demand of 2.75 billion bushels driven in part by biomass-based diesel feedstock utilization. These intersecting forces create both margin pressure and cost-optimization opportunities, depending on how organizations structure their sourcing and hedging frameworks.
The Architecture of Our Research: Beyond Surface-Level Forecasts
Effective market intelligence must bridge the gap between high-level projections and granular, operational realities. Our report is constructed to serve as a working document for strategy teams rather than a static summary of industry trends. The analytical framework spans historical performance mapping, forward-looking scenario modeling, and competitive positioning assessments, all calibrated to the 2026 operational context. The study examines consumption patterns across major application categories, including plasticizer formulations, fuel additive integration, pigment dispersion functions, and diversified industrial uses. Rather than presenting isolated demand figures, the analysis connects application-level usage to formulation requirements, regulatory constraints, and performance thresholds. This approach enables readers to understand not just where demand is growing, but why specific grades and purity specifications are gaining preference in particular production environments. Equally critical is the end-use industry mapping. The report dissects consumption dynamics across food and beverage manufacturing, adhesives and sealants production, automotive component manufacturing, and supplementary industrial segments. By examining how epoxidized soybean oil functions within each vertical—from compliance-driven substitution in food-contact materials to performance stabilization in polymer matrices—the analysis provides a functional map of demand drivers that procurement and R&D teams can directly apply. The geographic dimension of the research follows a similar principle of depth over breadth. Regional consumption profiles are evaluated through the lens of manufacturing capacity, import dependency, regulatory timelines, and logistical cost structures. This allows executives to assess market entry feasibility, supply chain risk, and localization opportunities without relying on superficial regional rankings. The full breakdown of regional and application-level market splits, along with precise valuation allocations, is reserved for the complete report, ensuring that strategic teams can access unredacted intelligence when making capital allocation or market expansion decisions.
Competitive Landscape and the Strategic Positioning of Key Players
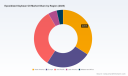
The epoxidized soybean oil sector is characterized by a moderately concentrated competitive environment, with the top three firms commanding approximately 55 percent of market share and the top five collectively holding around 65 percent. This structure indicates that while established players maintain significant influence, the market retains enough fragmentation to allow agile entrants and specialized distributors to capture niche demand, particularly in technical-grade supply and regional distribution networks. Leading companies have pursued distinct strategic pathways to strengthen their positioning. Cargill Incorporated has leveraged large-scale capacity expansion and modernization initiatives, including the completion of a major facility upgrade in Sidney, Ohio, to scale epoxidized oil production. Their product portfolio emphasizes Vikoflex and Vikoflex High IV grades, which serve as primary plasticizers and co-stabilizers for flexible and semi-rigid PVC formulations. This capacity-driven strategy aligns with their broader agricultural supply chain integration, allowing them to manage feedstock variability with structural advantages. Valtris Specialty Chemicals has focused on certification-backed differentiation, with Plas-Chek and Lankroflex grades positioned as secondary heat stabilizers and plasticizers for both flexible and rigid PVC. Their December 2024 product promotion highlighted food-safe, renewable, and Kosher-certified attributes, directly targeting compliance-sensitive segments where specification assurance carries premium value. Galata Chemicals LLC has pursued performance innovation, unveiling an advanced ESBO plasticizer in early 2024 engineered for superior heat stability in high-performance PVC applications. This product launch underscores a broader industry shift toward formulation-grade reliability, where thermal and mechanical consistency can determine contract retention in demanding manufacturing environments. CHS Inc. operates from a vertically integrated production model, utilizing soybean crushing operations to deliver cost-effective supply to PVC and polymer markets. This back-to-basics operational structure reduces intermediary exposure and enhances margin resilience when raw material pricing fluctuates. ADEKA Corporation continues to serve as a global supplier of epoxidized soybean oil additives and plasticizers, emphasizing PVC stabilization and plasticization across international customer bases. Acme-Hardesty maintains a focused product identity through Jenkinol 680, while ChemCeed and Interstate Chemical Company address distribution and technical-grade supply needs, with Interstate’s Interflex ESO line supporting general PVC and plastics formulations. Complementing these established players, J-Oil Mills entered the competitive conversation in March 2025 with an enhanced liquid epoxidized soybean oil variant designed for improved compatibility with PVC stabilizers, illustrating how targeted formulation improvements can rapidly alter competitive dynamics even in a mature category. Our report evaluates each of these players not merely through corporate descriptions, but through strategic lenses: capacity scalability, feedstock control, certification portfolios, product-grade differentiation, and regional distribution leverage. The full competitive matrix, including strategic vulnerabilities and partnership opportunities, is detailed in the complete study.
Regulatory Friction, Trade Policy, and the New Compliance Calculus
Regulatory and trade developments have become central drivers of market behavior, reshaping sourcing strategies and altering the risk profile of cross-border supply chains. In September 2024, Mexico initiated an antidumping investigation into ESBO imports from Brazil and China, focusing on materials with 85 to 99 percent purity content. This action illustrates how purity specifications, once viewed primarily as technical parameters, are now intertwined with trade defense mechanisms and localized production incentives. For importers and formulators, such investigations can trigger sudden shifts in landed cost, availability, and supplier qualification requirements. Simultaneously, the broader raw material environment continues to evolve. The USDA’s projection of record soybean crush demand, partly driven by biomass-based diesel feedstock utilization, introduces a competing demand channel for soybean oil. When agricultural commodities are pulled into multiple high-volume applications, the resulting price and availability dynamics can cascade into specialty chemical production. Organizations that treat epoxidized soybean oil sourcing as an isolated procurement function risk missing these upstream interdependencies. Regulatory compliance in food-contact and industrial applications further complicates the landscape. Certifications such as Kosher, food-safe approvals, and regional additive regulations increasingly influence purchasing decisions, particularly in segments where end-product labeling and consumer expectations demand verifiable material provenance. Companies that proactively map regulatory timelines and certification requirements gain a structural advantage in contract negotiations and market access planning. Our report integrates these regulatory and trade factors into a cohesive risk-and-opportunity framework, enabling teams to stress-test sourcing strategies against plausible policy shifts.
Demand Drivers Across End-Use Industries and Application Niches
The consumption profile of epoxidized soybean oil is shaped by a convergence of performance requirements, regulatory substitution trends, and formulation economics. In plasticizer applications, the material continues to serve as a preferred alternative in formulations where phthalate reduction is a strategic or compliance priority. This substitution dynamic is not uniform; it varies by region, by end-product category, and by the technical thresholds of the polymer matrix in question. In fuel additive contexts, epoxidized soybean oil contributes to combustion and stability functions that align with broader bio-based fuel integration trends. Pigment dispersion applications benefit from the material’s ability to support formulation consistency, particularly where dispersion stability and compatibility with carrier systems are critical. The diversified application segment captures additional industrial use cases, reflecting the material’s flexibility across non-standardized production environments. End-use industry analysis reveals equally nuanced demand patterns. Food and beverage manufacturing represents a substantial consumption channel, driven by the need for compliant, bio-based processing inputs and stabilization components that meet stringent contact regulations. Adhesives and sealants formulation leverages epoxidized soybean oil for performance consistency and compatibility with resin systems. Automotive applications, while more specialized, increasingly intersect with lightweight polymer strategies and interior component requirements where thermal stability and volatility reduction matter. The supplementary industrial segment captures cross-sector usage where customization and technical-grade availability determine adoption. Rather than treating these verticals as isolated demand pools, our report maps the interaction between application requirements, end-use constraints, and supply-side capability. This interconnected view allows strategy teams to identify where margin profiles are strongest, where specification upgrades command price premiums, and where volume growth is most likely to materialize over the forecast period. The detailed segmentation allocations, including precise market splits by region, application, and end-use industry, are reserved for the full report to preserve the analytical integrity of our proprietary breakdowns.
Strategic Imperatives for 2026 Decision-Making
As the market moves through its 2026 inflection point, several strategic imperatives come into focus. First, organizations must treat feedstock exposure as a strategic variable rather than a background cost. With soybean oil comprising the majority of raw material input and agricultural markets influenced by crush demand, biodiesel feedstock competition, and seasonal pricing forecasts, procurement functions need integrated monitoring that links crop reports, trade flows, and chemical production schedules. Second, capacity and supply reliability should be evaluated against regional trade actions and certification requirements. The antidumping probe in Mexico, combined with ongoing certification expectations in food-contact and specialty industrial applications, means that supplier qualification cannot be reduced to price comparison alone. Technical documentation, compliance traceability, and production consistency are becoming decisive factors in supplier retention. Third, product-grade strategy matters more than ever. As demonstrated by recent launches emphasizing heat stability, improved PVC compatibility, and food-safe certification, differentiation in epoxidized soybean oil is increasingly grade-specific. Companies that align their product portfolios with the performance thresholds of target applications are better positioned to protect margins and secure long-term contracts. Fourth, competitive positioning requires a clear understanding of concentration dynamics. With a significant share held by a handful of major producers, market entry, distribution partnerships, and capacity investments must be calibrated to realistic share-gain pathways. For distributors and technical suppliers, the opportunity often lies in service depth, logistical flexibility, and specification support rather than in direct production scale. Finally, forecasting accuracy depends on integrating multiple data layers. Historical consumption trends provide a baseline, but forward strategy must incorporate regulatory calendars, agricultural supply forecasts, trade policy signals, and application-level formulation shifts. Our report is designed to supply that multi-layered view, giving executives a structured foundation for scenario planning, investment prioritization, and risk mitigation.
Conclusion: The Case for Deep Intelligence in a Shifting Market
The epoxidized soybean oil market is not simply expanding; it is reconfiguring around feedstock competition, regulatory differentiation, grade-specific performance demands, and concentrated yet still accessible competitive dynamics. For organizations operating in PVC formulation, polymer stabilization, food-contact manufacturing, adhesives, automotive components, and related industrial segments, the strategic stakes are rising. The difference between reactive procurement and proactive market positioning will increasingly depend on access to precise, unredacted intelligence that connects macro projections with operational realities. Our comprehensive study delivers that intelligence. It maps the 2026 to 2032 growth path, dissects application and end-use demand drivers, evaluates the strategic posture of leading producers and distributors, and embeds regulatory and raw-material dynamics into a practical decision framework. The core segmentation data, regional valuations, and detailed competitive assessments are intentionally reserved for the full report, ensuring that strategic teams receive complete, protected insight rather than diluted summaries. For executives preparing 2026 planning cycles, the next step is clear: align sourcing strategy, compliance readiness, and product-grade positioning with a market view that accounts for both momentum and friction. The full report provides the depth required to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Worldwide Zero Gravity Seat Market
PMMA-coated Separator Market
Worldwide Electric Kettle for Coffee Brewing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plating Equipment Market to Hit $279.35M by 2032, Growing at 6.5% CAGR
By PW Consulting, 2026-09-07
Strategic Imperative: Why the Plating Equipment Market Demands Your Attention in 2026
In the landscape of modern manufacturing, surface finishing is no longer merely a post-processing step; it is a critical determinant of product longevity, conductivity, and aesthetic value. As industries pivot towards miniaturization, sustainability, and high-performance materials, the machinery responsible for these finishes—the plating equipment market—is undergoing a significant transformation. For C-suite executives and strategic planners, understanding the trajectory of this sector is not optional; it is a prerequisite for resilient supply chain management and capital allocation.
Worldwide Whole House Instantaneous Water Heater Market
PW Consulting's latest comprehensive study on the Plating Equipment Market offers a definitive roadmap for navigating the complexities of the upcoming forecast period. This research is designed to move beyond superficial trends, providing the granular intelligence necessary to make informed decisions in 2026 and beyond. The following insights outline the strategic value embedded within this report, highlighting why immediate engagement with this data is vital for your organization.
Worldwide Ceramic Coated Polypropylene Separator Market
Market Trajectory and Macro Economic Signals
The historical data presents a clear narrative of steady expansion, setting the stage for a robust forecast period. From a base valuation of 182.0 million USD in 2025, the market is projected to climb significantly, reaching an estimated 279.35 million USD by 2032. This growth trajectory reflects a Compound Annual Growth Rate of 6.5 percent over the forecast horizon. Such consistent expansion indicates that demand drivers are structural rather than cyclical, rooted in long-term industrial shifts rather than temporary spikes.
Hose & Tubing for Inks, Paints and Solvents Market
This upward momentum is not uniform across the board; it is propelled by specific technological adoptions and regional industrializations. Understanding where this capital is flowing is essential for identifying high-opportunity zones. The report dissects this growth velocity, offering a nuanced view of how the 2026 market size of 198.01 million USD serves as a launchpad for future valuations. Stakeholders who interpret these macro signals correctly can align their inventory, manufacturing capacity, and investment strategies to match the market's organic growth rhythm.
Segmentation Dynamics: Where Value Is Created
One of the most critical insights provided by this study lies in the segmentation analysis. The market is not a monolith; it is fractured by technology type, application vertical, and geographic presence. In terms of equipment type, the landscape is dominated by specific methodologies that cater to different throughput and precision requirements. The data reveals distinct market valuations for Rack Plating Equipment, Barrel Plating Equipment, Continuous Plating Equipment, and Other specialized systems. Each segment responds differently to labor costs, automation trends, and raw material fluctuations.
Similarly, the application landscape dictates the nature of the demand. High-volume sectors such as Automotive and Electrical and Electronics are primary contributors, but niche yet high-value segments like Aerospace and Defense, and Jewelry, offer specialized opportunities. The report details the revenue contribution of these verticals, allowing clients to benchmark their own portfolio exposure. For instance, understanding the specific market size dedicated to functional plating versus decorative plating can reshape a vendor's product development roadmap.
Geographically, the distribution of revenue highlights the global nature of the supply chain. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa all present unique regulatory and economic environments. The Asia Pacific region, for example, reflects massive industrial capacity, while North America and Europe are driven by stringent regulatory compliance and high-tech manufacturing. The report provides the specific revenue valuations for each region, enabling precise geographic targeting for sales teams and investors without relying on generalized assumptions.
Competitive Landscape and Strategic Positioning
The intensity of competition in the plating equipment sector is moderate but increasingly defined by technological integration and sustainability credentials. The market concentration, indicated by a CR3 of 28.5 percent and a CR5 of 37.8 percent, suggests a fragmented yet competitive environment where scale and specialization both play roles. Leading players are not just selling hardware; they are offering integrated solutions that encompass chemistry, automation, and waste management.
Atotech, headquartered in Berlin, Germany, stands as a leading provider of integrated plating chemicals and turnkey equipment. Their recent activities underscore a focus on high-tech integration. In June 2026, Atotech highlighted integrated PCB and advanced packaging solutions alongside laser systems at JPCA 2026. Furthermore, at SUR/FIN 2026, they presented sustainable surface finishing solutions for automotive and power distribution. These moves signal a strategic pivot towards industries that require both precision and environmental compliance.
In the United States, Technic Inc., based in Cranston, Rhode Island, remains a global leader in specialty chemistry and selective electroplating equipment. Their focus on brush plating systems positions them well for repair and enhancement applications. Similarly, SIFCO ASC, located in Cleveland, Ohio, specializes in selective brush plating equipment for on-site repairs. This specialization highlights a market niche where mobility and precision outweigh mass throughput.
Automation is another key battleground. KOCH Finishing Systems, based in Chicago, Illinois, recently launched innovative Hex Barrels in July 2025 for enhanced plating performance. This product launch indicates a drive towards improving efficiency in barrel plating, a segment crucial for small components. Meanwhile, companies like Allied Plating Supplies and A Brite Company continue to provide essential hardware and process equipment, ensuring the foundational layers of the market remain robust. Becker Industries Corp. and International Plating Technology (IPT LLC) also contribute to the diversity of the supply base, offering solutions ranging from jewelry-specific kits to automated plating lines.
For businesses evaluating partnerships or acquisitions, understanding the specific capabilities and recent developments of these key companies is crucial. The report profiles these entities in depth, analyzing their market share trajectories and potential strategic moves.
Regulatory and Environmental Pressures Reshaping Demand
No strategic analysis of the plating equipment market is complete without addressing the regulatory environment. Sustainability is transitioning from a corporate social responsibility initiative to a hard operational constraint. In March 2025, Atotech announced a new eco-friendly electroplating line featuring low waste chemistry. This development is indicative of a broader industry shift where equipment must now accommodate stricter chemical usage and waste disposal standards.
Furthermore, regulatory bodies are tightening the screws on effluent management. The US Environmental Protection Agency updated effluent limitations for electroplating industry wastewater treatment requirements effective 2025. Compliance with these standards requires capital investment in advanced filtration and treatment systems integrated directly into plating lines. Equipment vendors that can offer compliance-ready solutions hold a distinct competitive advantage.
Supply chain resilience is also under scrutiny. The US Department of Commerce reported that China's 2025 rare earth export controls are impacting global supply chains for plating equipment components. This geopolitical factor introduces volatility in sourcing critical materials, necessitating a diversified supplier strategy. Additionally, industrial market data reports copper anode prices at record highs in 2026 due to EV battery demand. This raw material inflation directly affects the cost of operations for plating facilities, influencing the type of equipment purchased—favoring systems that maximize material utilization and reduce waste.
Technological Drivers and Labor Market Realities
The labor market is exerting a profound influence on equipment selection. Sector analysis indicates that automation labor shortages are driving demand for robotic integration in plating systems. As skilled technicians become scarcer, manufacturers are increasingly willing to invest in automated lines that reduce manual intervention. This trend accelerates the adoption of continuous and rack plating systems that are equipped with smart monitoring and robotic handling.
The intersection of labor scarcity and regulatory pressure creates a compelling case for next-generation equipment. Systems that offer closed-loop water recycling, automated chemical dosing, and remote diagnostics are becoming the standard rather than the exception. The report delves into how these technological requirements are altering the purchasing criteria for procurement managers in 2026. It is no longer just about deposition quality; it is about total cost of ownership, operator safety, and environmental footprint.
For investors, this shift suggests that companies specializing in automation components, sensor technology, and software integration for surface finishing are poised for growth. The detailed segmentation within the report helps identify which sub-segments of the equipment market are most sensitive to these labor and technology drivers.
The Strategic Value of Deep-Dive Intelligence
Access to macroeconomic data is common, but actionable intelligence derived from deep segmentation and competitive profiling is rare. This market research report is structured to provide immediate utility. It goes beyond stating that the market is growing; it explains the mechanics of that growth. By providing specific revenue valuations for equipment types, application verticals, and geographic regions, the report allows stakeholders to model their own growth scenarios accurately.
For example, a manufacturer focusing on the Aerospace sector can cross-reference the specific market size for Aerospace and Defense applications against the regional demand in North America or Europe. A chemical supplier can assess the size of the Rack Plating Equipment segment to estimate potential co-marketing opportunities. The granularity provided ensures that strategic decisions are based on verified data rather than estimation.
Moreover, the inclusion of recent developments such as product launches and trade show participations provides a pulse on the competitive tempo. Knowing that KOCH Finishing Systems launched new barrels in 2025 or that Atotech is pushing sustainable solutions at 2026 trade shows helps businesses anticipate market reactions and competitor responses. This timeliness is critical in a market where technology cycles are accelerating.
Conclusion: Navigating the 2026 Landscape
The plating equipment market stands at a confluence of regulatory pressure, technological innovation, and steady economic growth. With a forecast CAGR of 6.5 percent and a market size expected to nearly double from 2025 levels by 2032, the opportunities are substantial. However, capturing this value requires precise navigation. The distinctions between segment sizes, the nuances of regional regulations, and the specific moves of key players like Atotech and Technic Inc. form the complexity of the decision-making environment.
PW Consulting's full study provides the comprehensive data architecture needed to succeed. It transforms raw data into strategic narratives, offering clarity on where to invest, who to partner with, and how to comply with the evolving regulatory landscape. For organizations aiming to secure a competitive edge in surface finishing technology, this research serves as an essential tool.
To leverage these insights for your specific operational context, we invite you to access the complete report. The detailed segmentation data, full competitive profiles, and extensive regional analysis contained within the source document will enable you to build a robust strategy for the 2026-2032 forecast period. Engaging with this level of detail is the first step towards turning market dynamics into measurable business growth.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Floor Underlayment Hits $1.94B in 2025, Growing at 4.8% CAGR Through 2032
By PW Consulting, 2026-09-07
Navigating the Next Wave of Growth in the Flooring Underlayment Market
The global construction and renovation ecosystem is undergoing a structural shift, and nowhere is this more evident than in the materials that sit beneath our floors. For manufacturers, distributors, and investors, the flooring underlayments market represents a critical intersection of acoustic performance, moisture management, raw material volatility, and evolving warranty standards. As of the 2025 base year, the market has demonstrated a clear upward trajectory, with historical revenue growing from 2020 through 2025 and a forward-looking forecast period extending through 2032. Analysts at PW Consulting have just published a comprehensive research study designed to equip enterprise stakeholders with the strategic clarity required to navigate this evolving landscape in 2026 and beyond. This article serves as a preview of that research, highlighting the macro-level indicators, competitive dynamics, and operational complexities that will define decision-making in the years ahead. To access the full dataset, granular segmentation matrices, and proprietary scenario models, stakeholders are encouraged to consult the complete market intelligence report.
Worldwide Bio Poly(Tetramethylene Ether) Glycol Market
Historical Performance and the 2026 Inflection Point
Over the past half-decade, the flooring underlayment sector has compounded revenue at a steady pace, reflecting sustained demand across residential renovation, commercial fit-outs, and industrial flooring upgrades. Revenue progression from the early 2020s to the 2025 base year illustrates a market that has not only recovered from pandemic-era supply chain friction but has also capitalized on a broader shift toward performance-driven flooring installations. The historical period reveals a consistent pattern of expansion, with revenue closing the base year at a level that positions the industry for a measured yet meaningful acceleration.
Worldwide Lid Air Fryer Market
The forward-looking forecast period, spanning 2026 through 2032, projects a compound annual growth rate of approximately 4.8 percent. This trajectory signals that the market is not merely reiterating past growth patterns but is entering a phase where technological differentiation, acoustic and moisture performance mandates, and material substitution strategies will begin to shape margin structures and competitive positioning. For executive teams planning capacity allocation, product roadmaps, and channel strategies in 2026, understanding the pace and shape of this growth is essential. The research report builds on these macro indicators to provide a structured view of how the base year transitions into the forecast horizon, and where the most consequential inflection points are likely to emerge.
Worldwide Renewable Microfibrillated Cellulose Market
Competitive Landscape and Strategic Differentiation
The industry is characterized by a moderate concentration of established players, with the top three firms holding a combined market share that reflects the presence of well-entrenched manufacturers and the ongoing entry of specialized producers. The top five competitors collectively account for a majority share, underscoring the importance of brand recognition, distribution reach, and performance certification in securing long-term contracts with flooring manufacturers, building specifiers, and regional distributors. Yet the landscape remains dynamic enough that differentiated product claims, material sourcing strategies, and installer-facing innovations can shift positioning within specific sub-segments.
Among the core participants shaping the market are several U.S.-based manufacturers with strong footholds in acoustic fiber, foam, and rubber underlayments. One Norfolk-based producer has built a recognizable presence around noise reduction and moisture protection for hardwood, laminate, and vinyl installations, with a product line gaining traction through recycled material emphasis. Another large U.S. manufacturer remains a dominant force in carpet cushion and hard surface underlayment, offering foam, rubber, and other formulations tailored for laminate, vinyl, and engineered wood applications. A third North American private-label specialist is widely recognized for supplying floating wood and laminate underlayment with customizable IIC, STC, and Delta performance ratings, giving distributors and installers a flexible toolkit for meeting project-specific acoustic and stability requirements.
Regional diversification is increasingly visible, with producers in Vietnam and China expanding capacity and showcasing high-density IXPE and XPE foam solutions aimed at luxury vinyl plank, laminate, and wood flooring. These manufacturers are leveraging cost-efficient production and targeted performance claims around soundproofing and moisture resistance, which resonate with distributors seeking reliable supply for high-volume LVP segments. Additional U.S. manufacturers and acoustic underlayment specialists contribute further nuance to the competitive field, reinforcing that the market rewards companies that can balance raw material strategy, warranty compliance, and installer convenience. The report examines these competitive dynamics in greater detail, mapping product positioning, regional footprints, and strategic responses to material and regulatory pressure points.
2026 Market Dynamics: Materials, Standards, and Cost Structures
For decision-makers operating in 2026, the most consequential market dynamics revolve around raw material volatility, warranty-driven technical constraints, and the cost impact of trade and transport surcharges. Polyethylene foam remains the primary feedstock for the dominant foam-based underlayment category, meaning that price movements in this segment are closely tied to crude oil price swings and refinery capacity constraints. This linkage introduces a rolling cost variable that can compress margins on standard-grade products unless manufacturers have secured forward contracts, diversified sourcing, or engineered alternative formulations.
At the same time, warranty requirements from resilient flooring manufacturers exert a direct influence on product design and installation practice. Underlayment specifications must meet manufacturer warranty conditions for resilient flooring, which often impose strict limits on total thickness, with maximum thresholds around 3mm to avoid placing stress on locking joints and voiding warranties. This technical constraint creates a ceiling for certain product upgrades and pushes differentiation toward acoustic performance, moisture protection, and installer ease rather than material thickness alone. In practical terms, it means that product innovation is increasingly evaluated through the lens of compatibility with the flooring system above, not just the underlayment’s standalone performance.
Trade policy and transport surcharges are adding another layer of cost complexity, particularly for imported foam materials, rubber components, and cork. These input categories have faced rising tariff impacts that affect landed cost and, in some cases, lead times. For manufacturers relying on cross-border sourcing, the pressure is twofold: maintain competitive pricing while preserving margin integrity, and accelerate qualification of alternative materials or regional supply paths. Supply chain normalization following the disruptions of 2022 and 2023 has enabled several producers to invest in capacity expansion, particularly where recycled rubber and natural cork formulations can be scaled without violating performance or warranty constraints. The research report isolates these dynamics into actionable risk and opportunity frameworks, helping leadership teams assess where cost pass-through is viable and where product engineering can offset input pressure.
Segmentation Signals: Type, Application, and Regional Variation
The market’s composition by type reflects the enduring dominance of foam-based solutions while highlighting meaningful contributions from cork, rubber, polyethylene, and plywood alternatives. Foam-based underlayment continues to command a leading share of revenue, consistent with its balance of cost, acoustic dampening, and moisture management attributes. Cork and rubber variants represent specialized value propositions, often associated with premium acoustic comfort or recycled content narratives. Polyethylene and plywood categories round out the portfolio, serving applications where specific installation requirements, stability needs, or substrate preferences drive material choice. The report examines these type-based dynamics in depth, including how performance claims and material availability shape demand patterns across different flooring formats.
By application, residential installations remain a substantial portion of total revenue, reflecting the scale of remodeling, housing turnover, and the consumer emphasis on quieter, more comfortable interior environments. Commercial applications form a significant secondary pillar, where project specifications, acoustic ratings, and warranty compatibility influence product selection at the building level. Industrial applications, while smaller in absolute scale, offer targeted opportunities in facilities where durability, moisture resistance, and underfoot comfort contribute to operational outcomes. The research does not stop at aggregate splits; it connects each application environment to the installer workflows, labor requirements, and moisture mitigation systems that affect total installed cost and margin realization.
Regional variation further complicates the strategic picture. North America, Europe, and Asia Pacific each present distinct growth drivers, from residential renovation cycles and multi-family construction in one geography to commercial retrofitting and sourcing strategies in another. Latin America and the Middle East and Africa represent smaller but increasingly relevant demand pools, often shaped by specific supply chain considerations and distributor networks. The report maps these regional characteristics without reducing them to simple share totals, instead focusing on the operational implications of local warranty norms, installer practices, and material sourcing realities. Stakeholders seeking a complete view of regional revenue breakouts and application-specific growth rates will find those details in the full dataset accompanying the publication.
Installer Economics, Labor Considerations, and Moisture Mitigation
A recurring theme in 2026 industry data is the importance of installer-facing innovation. Moisture mitigation systems and installer-focused product design are influencing labor requirements for floor prep and underlayment installation, particularly in the U.S. market. Where underlayment products simplify layout, reduce seams, or improve compatibility with adhesive and floating installation methods, they can meaningfully affect job-site efficiency and total project economics. Conversely, products that demand additional prep or create compatibility issues can increase labor exposure and the risk of warranty disputes.
This installer lens is often overlooked in top-line market sizing, yet it is central to practical adoption. The research report integrates labor and installation considerations into its segmentation analysis, linking product attributes to field performance and total cost of ownership. For channel partners and flooring manufacturers, this means that underlayment selection is not merely a material decision but a workflow decision, with consequences for scheduling, rework, and post-installation satisfaction. The report’s operational perspective is designed to help buyers evaluate how a product’s specifications will perform once it leaves the box and enters real installation conditions.
Recent Supplier Activity and Innovation Signals
Several recent developments illustrate the pace of innovation and promotional activity shaping the market. In early 2026, Cyg Tefa showcased advanced IXPE and XPE foam underlayment solutions at a major building materials event, emphasizing strong soundproofing, moisture resistance, and suitability for LVP, laminate, and wood flooring. The positive interest from manufacturers and distributors underscored the continued relevance of high-density foam formulations in segments where acoustic and moisture performance are prioritized. Around the same time, MP Global Products promoted its range of eco-friendly acoustic underlayments, highlighting recycled material usage and performance for noise reduction and moisture control across residential and commercial flooring applications. These activities reflect a broader industry emphasis on sustainability narratives paired with practical performance claims.
More recently, a newly introduced premium acoustic solution has entered the conversation with claims of improved floor stability, enhanced acoustic comfort, and added moisture protection for modern flooring systems. Such product launches indicate that differentiation is increasingly tied to multi-attribute benefits rather than a single performance metric. The report compiles and contextualizes these developments, separating marketing narratives from technically defensible product attributes and assessing where innovation is likely to influence purchasing criteria over the forecast period. By tracking the sequence of launches, showcases, and promotions, the research provides a timeline-based view of competitive momentum that is useful for planning product introductions, inventory positioning, and channel communication.
Strategic Use Cases for the 2026 Decision-Maker
For executives evaluating the flooring underlayment market in 2026, the research offers multiple practical use cases. Product planners can use the type- and application-based analysis to prioritize development efforts around acoustic performance, moisture protection, and warranty-compatible thickness profiles. Sourcing and procurement teams can leverage the raw material and trade dynamics to stress-test cost assumptions, evaluate alternate feedstocks, and identify where forward commitments or regional diversification may improve resilience. Commercial and channel leaders can draw on installer workflow insights to refine specifications, support training, and reduce on-site friction that affects total project economics.
Investors and corporate strategy teams can also use the concentration metrics and competitive profiles to assess where scale advantages matter most, where niche positioning can command price premiums, and where supplier entry or exit might alter local availability. The forecast horizon through 2032 provides a long enough window to evaluate capital decisions, capacity additions, and go-to-market investments without relying on short-term snapshots. Importantly, the report is structured to translate macro growth into operational questions: which product attributes matter in which application, what constraints shape acceptable thickness and compatibility, and how cost pressures flow through to final pricing.
What the Full Report Delivers
The complete PW Consulting study expands on every dimension introduced here. It provides a full historical-to-forecast revenue view with all macro indicators and growth trajectories, along with detailed segmentation analysis across type, application, and region. The report includes competitive profiles that assess product positioning, material strategies, and regional strengths, plus a structured examination of market dynamics such as raw material volatility, warranty-driven technical limits, transport and tariff surcharges, and labor-driven installation considerations. Recent supplier developments are mapped to market impact, helping readers understand not only what has launched but how those launches fit into broader performance and sourcing trends.
To keep this preview aligned with the teaser principle, the article intentionally avoids quoting specific regional or application percentages, type-level revenue amounts, or per-segment dollar figures. Those details are available in the full report, where they are presented within the analytical frameworks needed to interpret them correctly. Stakeholders who require granular breakouts, scenario modeling, and segment-level growth paths will find the complete dataset essential for planning in 2026 and for stress-testing assumptions through 2032.
Closing Perspective
The flooring underlayment market is entering a phase in which steady top-line growth is increasingly shaped by product performance, material cost discipline, and installer compatibility. Historical expansion has created a solid base, and the forecast period points to continued progress, but the strategic winners will be those who can align product attributes with warranty constraints, manage feedstock volatility, and respond to regional and application-specific demand patterns. This research is designed to give decision-makers the context they need to move from broad market awareness to targeted action. For a complete view of the numbers, segmentation detail, and competitive intelligence, readers are invited to access the full market research publication and explore the data that supports the analysis presented here.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting’s Waste Paper Recycling Report: Market Hits $53B in 2025, 5.0% CAGR to $74.3B by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for Smarter Capital Allocation in Waste Paper Recycling
2026 Market Research Preview
Executive Synopsis
The waste paper recycling industry is entering a phase of disciplined expansion. After navigating a period of volatile commodity pricing and shifting downstream demand, the sector has established a robust operational baseline and is now projected to compound at a steady rate through the end of the decade. This report serves as a strategic decision tool for executives weighing capacity investments, technology upgrades, geographic expansion, and supply chain restructuring. By synthesizing historical performance with forward-looking scenario modeling, it provides a structured framework for capital allocation in a market where profitability is increasingly tied to process efficiency, feedstock security, and regulatory readiness.
Worldwide Organic Button Battery Market
Our analysis places the base year at 2025 and extends a three-stage forecast trajectory from 2026 to 2032. The overall market reached approximately 53,000 million USD in 2025, following a consistent upward climb from 41,500 million USD in 2020. That trajectory reflects not only cyclical price recovery but also structural adoption of higher-yield recovery systems, improved sorting technologies, and long-term procurement commitments from industrial buyers seeking a stable recycled-fiber supply. The market is projected to surpass 56,491 million USD in 2026 and continue expanding toward 74,300 million USD by 2032. Achieving these outcomes will require operators to navigate tightening feedstock availability, energy intensity concerns, and evolving compliance expectations without sacrificing throughput or margin integrity.
Worldwide Buildings Decarbonization Solutions Market
This research is designed to help leadership teams interpret those dynamics with commercial precision. Rather than presenting broad directional commentary, the study isolates the operational and competitive levers that will determine which organizations capture disproportionate share over the forecast period. It examines where capacity is being added, which fiber categories are attracting the strongest demand, and how regional ecosystems differ in their logistics cost structures, policy environments, and reinvestment cycles. By framing these elements within a single decision-making template, the report enables executives to align business strategy with the market’s most durable growth vectors.
American Style Chandelier Market
Market Context and Operating Dynamics
The rehabilitation of waste paper as a core industrial input has shifted the market from a commoditized recovery model to a more strategically managed fiber ecosystem. In practical terms, this means that pricing, volume, and procurement behavior are increasingly influenced by long-term capacity planning rather than short-term spot activity alone. One of the most instructive examples of this shift appeared in March 2026, when recovered paper prices for OCC increased as stronger demand for recycled fiber intersected with tightening supply. That movement underscores a broader structural reality: as downstream manufacturers integrate recycled content targets into procurement policy, feedstock competition intensifies across both regional and application-specific channels.
From an operational perspective, market dynamics are now shaped by the interaction of three forces. First, demand growth is being driven by sectors that depend heavily on recycled board, liner, and pulp inputs, forcing recyclers to maintain consistent yield quality and inventory reliability. Second, processing efficiency has become a decisive margin differentiator, especially where energy costs, downtime, and contamination management can materially erode profitability. Third, regulatory and policy signals are reshaping the economics of collection, sorting, and downstream acceptance, particularly in markets where waste diversion mandates and extended producer responsibility frameworks influence feedstock availability.
These dynamics are not uniform across the value chain. Operations that prioritize high-contaminant tolerance, advanced cleaning, and flexible output configuration are better positioned to adapt when feedstock composition changes. Facilities built around high-throughput baling, compaction, and material handling can reduce logistics friction and labor intensity, improving the unit economics of collection and distribution centers. Meanwhile, complete recycling lines that integrate pulping, cleaning, screening, and deinking offer end-to-end control over fiber recovery, enabling producers to match output quality with specific buyer specifications. The strategic implication is clear: competitive advantage now derives from system design choices, not simply from volume processing.
Forecasting Scope and Strategic Utility for 2026
Effective 2026 planning requires a forecast framework that links near-term market behavior to longer-term structural shifts. This report integrates historical performance from 2020 through 2025 with a forward forecast covering 2026 to 2032, allowing executives to interpret growth as a sequence of transitional phases rather than a single trend line. The compound annual growth rate assessed across the forecast horizon provides a useful benchmark for evaluating incremental investment scenarios, expansion pacing, and capacity replacement cycles. More importantly, the forecast is framed around operational variables that influence real-world outcomes, including feedstock consistency, capital intensity of processing equipment, project commissioning timelines, and downstream absorption capacity.
For strategic planners, the value of the forecast lies in its ability to support staged decision-making. Near-term planning can focus on maintaining throughput stability, securing reliable feedstock contracts, and optimizing material handling workflows. Mid-term planning can incorporate technology selection, line configuration, and capacity additions that respond to evolving demand patterns. Long-term planning can address geographic positioning, regulatory readiness, and the potential need to diversify processing capabilities as fiber specifications become more demanding. By mapping these horizons against market trajectory, the report helps organizations avoid over-committing to static assumptions in a market defined by continuous adjustment.
The forecast also supports risk-weighted scenario evaluation. Because the market is influenced by both supply-side constraints and downstream demand variability, a rigid growth assumption can lead to mis-timed capacity expansion or underinvestment in process flexibility. This study instead structures the outlook in a way that helps leaders test assumptions about feedstock security, processing bottlenecks, and end-use demand resilience. That approach is particularly relevant for 2026, when procurement teams and plant operators must balance immediate cost pressures with the need to build durable competitive positioning.
Report Scope and Practical Applications
This market research is built around operational clarity. The full report examines the waste paper recycling market through a multi-dimensional lens that connects macro market behavior with actionable commercial intelligence. It outlines the structural composition of the market, evaluates the technologies and process configurations most relevant to current operations, and assesses how different segments of the industry interact with end-use demand. The objective is to give decision-makers a working understanding of where value is created, where inefficiencies persist, and where competitive exposure is most likely to intensify.
Within the analysis, the report breaks down the market across multiple classification dimensions, including material types, application destinations, and regional operating environments. Importantly, rather than relying on surface-level segmentation, the study contextualizes each dimension through its supply-chain implications, processing requirements, and commercial relevance. Readers gain insight into how fiber categories differ in contamination sensitivity, how end-use sectors drive specification requirements, and how regional ecosystems shape collection logistics, processing throughput, and reinvestment dynamics. This design ensures that segmentation is treated as a strategic tool rather than a static summary.
The report also includes practical guidance for evaluating equipment and process strategies. It examines the kinds of technologies that matter most for different operational priorities, from shredding and pre-processing to baling, pulping, and integrated recovery systems. These assessments are tied directly to operational outcomes such as volume reduction, labor efficiency, energy consumption, and downstream product suitability. For procurement teams, engineering managers, and expansion planners, that linkage is essential because it converts market data into actionable selection criteria.
Beyond technology and segmentation, the study addresses the competitive environment, recent industry activity, and policy-driven risk factors that affect long-term planning. It integrates relevant developments in the equipment and machinery space to show how vendor capabilities are evolving alongside market demand. It also evaluates market concentration to help leaders understand the balance between established operators and emerging entrants, and what that balance implies for pricing behavior, partnership opportunities, and market entry strategies. Collectively, these sections are designed to help organizations translate market intelligence into investment priorities, sourcing decisions, and operational roadmaps.
Competitive Landscape and Strategic Positioning
The competitive field in waste paper recycling equipment and process solutions reflects a mix of specialized machinery manufacturers and integrated solution providers. Rather than competing solely on price, leading companies are differentiating through application-specific configuration, throughput scalability, and compatibility with downstream fiber requirements. Understanding these differentiators is critical for organizations evaluating capital expenditure, vendor partnerships, and process upgrades.
Among the companies profiled in the study, WEIMA stands out for its focus on single-shaft shredders engineered for paper, cardboard, and OCC processing. Models such as the WLK 15 and WLK 18 Jumbo are designed to convert material into flakes or pulp with customizable configurations suited to recycling lines. For operators seeking consistent size reduction and reliable integration into broader recovery workflows, this type of equipment can influence downstream yield, handling efficiency, and line stability.
Parason Engineering offers a different strategic value proposition. Its emphasis is on complete turnkey recycled-fiber lines, including pulpers, cleaners, screens, and deinking systems for OCC and mixed waste. These lines are structured to produce board, liner, newsprint, and tissue at capacities ranging from 8 to 1030 TPD. For organizations that prioritize end-to-end process control and flexibility across output grades, a turnkey approach can shorten integration risk and provide a more cohesive path from feedstock intake to finished recycled fiber.
Material handling and compaction remain equally important to operational economics. American Baler Company provides horizontal and two-ram balers built for OCC, paper, and cardboard bales. These systems are oriented toward reducing volume and labor in recycling and distribution centers, which can directly affect transportation efficiency and storage utilization. Maren Engineering Corporation follows a similar operational logic with horizontal auto-tie, two-ram, and closed-door balers designed specifically for OCC and cardboard recycling. By flattening material for storage and transport, these solutions help address one of the recurring cost pressures in waste paper operations: the logistical burden of moving low-density feedstock.
Shredding and pre/post-shredding equipment are also central to effective recycling workflows. BHS-Sonthofen contributes to this segment with equipment designed for paper, cardboard, and OCC in recycling applications. Meanwhile, SOYU focuses on OCC dry pulping and recycling lines that convert waste paper into recycled pulp through energy-efficient dry processing. For operators looking to reduce thermal or moisture-related processing burdens while maintaining fiber recovery, dry processing configurations can represent an important efficiency lever. Rexon Hydraulics rounds out the competitive picture with automatic horizontal paper balers and recycling machines for cardboard and OCC, reinforcing the broader trend toward automation in material handling and baling workflows.
Industry activity continues to validate the relevance of these equipment ecosystems. Recent developments in the sector, including ReBAT’s confirmed participation as an exhibitor at the World of Recycling Expo 2026 in India, reflect ongoing investment in material recycling machinery and waste paper solutions. Events of this kind serve as practical indicators of where manufacturers, buyers, and integrators are directing their attention, and they often signal emerging priorities in throughput, automation, and regional expansion.
Market Concentration and Strategic Implications for Expansion
Market structure matters because it shapes pricing behavior, supplier dependency, and the realism of market-entry strategies. In this industry, the concentration profile suggests a moderately consolidated environment in which established players hold meaningful share, but room remains for capable regional and application-focused operators to expand through differentiated service, technology configuration, or localized feedstock advantages. This balance influences how organizations should think about partnerships, procurement strategy, and expansion pacing.
For buyers of recycling equipment and processed fiber, moderate concentration can be both an advantage and a risk. On one hand, established manufacturers and integrators often provide more mature engineering support, broader reference bases, and more reliable after-sales infrastructure. On the other hand, concentration can create dependency if a limited set of suppliers dominates critical process steps. Strategic planners therefore need to evaluate not only technical fit but also supply resilience, customization flexibility, and the risk of bottlenecking around key equipment or process capabilities.
For operators considering capacity additions or geographic expansion, the competitive structure implies that success will depend less on generic capacity deployment and more on targeted positioning. Facilities that align their technology mix with local feedstock characteristics, downstream specification demands, and logistics constraints are better equipped to defend margins and maintain uptime. Likewise, organizations entering new markets benefit from understanding how regional operating environments differ in terms of collection density, processing cost, regulatory expectations, and buyer requirements. These variables often determine whether expansion creates sustainable advantage or merely adds exposure to under-optimized operations.
Conclusion and Research Access
The waste paper recycling market is no longer defined solely by volume recovery. It is being reshaped by feedstock competition, processing efficiency, downstream specification demands, and the strategic choices organizations make about equipment, configuration, and capacity deployment. In that environment, the difference between reactive planning and durable competitiveness comes down to the quality of intelligence behind each decision. This report is designed to provide that intelligence in a form that supports capital allocation, technology evaluation, and market strategy in 2026 and beyond.
The full study goes beyond the directional overview presented here by delivering detailed segmentation interpretations, competitive profiles, operational benchmarks, and scenario-based planning guidance. It is structured to help executives move from market awareness to concrete action, whether that means selecting processing technology, prioritizing feedstock strategy, evaluating regional expansion, or interpreting the competitive dynamics that will shape procurement and partnership decisions. Readers who require the complete dataset, segment-level analysis, and operational detail needed for internal planning can access the full research through the source page, where the complete market outlook, company evaluations, and decision frameworks are available in full.
For detailed analysis of this topic, please visit the official page: Waste Paper Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steel Powder Market Revenue Hit $291M in 2025, Projected 6.4% CAGR to Reach $455M by 2032
By PW Consulting, 2026-09-07
The Steel Powder Market in 2026: Navigating Growth, Supply Chain Shifts, and Competitive Realignment
The global steel powder market is entering a definitive growth phase, driven by structural demand across advanced manufacturing, automotive light-weighting, and high-performance industrial applications. As organizations map out capital allocation and sourcing strategies for 2026 and beyond, accurate market intelligence has become a decisive competitive advantage. Our latest Steel Powder Market research study provides a comprehensive, data-driven assessment of the industry landscape, translating historical performance, forward-looking projections, and competitive dynamics into actionable decision frameworks for procurement leaders, product strategists, and market planners.
Expedited Auto Transport Market
This analysis is structured to serve as a strategic preview. It outlines the core themes, analytical depth, and practical utility embedded in the full report, while preserving the granular segmentation and proprietary benchmarking that define the complete publication. Readers seeking precise regional valuations, application-level revenue splits, and detailed supply-demand matrices will find those elements fully unpacked in the source report, available for immediate access.
Automotive Full Head Smart Helmet Market
Macro Trajectory and the Strategic Relevance of 2026
Market expansion across the forecast horizon reflects a sustained acceleration from the post-pandemic recovery cycle into a more mature, demand-driven growth environment. Historical revenue patterns from 2020 through 2025 show a market that has moved beyond initial volatility and established a clearer upward trajectory. By 2025, the global steel powder market reached an estimated 291.0 million USD, and the forward path indicates continued expansion through the end of the forecast period in 2032, with revenue projected to climb toward 455.0 million USD.
Worldwide Tahini Machine Market
The compound annual growth rate of 6.4 percent across the 2026–2032 forecast window signals more than simple top-line expansion. It reflects an ecosystem in which steel powders are increasingly integrated into engineering decisions rather than treated as commoditized inputs. For 2026 planning, this inflection point matters because it coincides with shifting regulatory regimes, evolving feedstock dynamics, and targeted capacity investments by leading producers. Companies that align sourcing, inventory, and product development strategies with this growth curve will be better positioned to manage price volatility, secure allocation, and capture emerging application upside.
The full report isolates the growth drivers behind this trajectory and separates structural demand from cyclical fluctuations. It also maps where growth is likely to be concentrated by end-use and product type, though the precise segmentation figures are reserved for the complete publication so that subscribers can benchmark their own portfolios against fully detailed market splits.
Industry Context and the Forces Shaping Market Dynamics
Several overlapping forces are reshaping how steel powder is produced, traded, and specified in 2026. Regulatory changes, feedstock availability, and regional demand oscillations are no longer peripheral concerns; they are now central variables in capacity planning and cost modeling.
- Trade and export policy shifts. Starting in early 2026, China introduced an export licensing system for certain steel products, including powders. This policy change introduces new layers of administrative oversight and potential supply routing adjustments for buyers that rely on Asian feedstock or finished powder imports. The full report examines how such licensing mechanisms can affect lead times, pricing dispersion, and regional availability without isolating single-market percentages in the executive summary.
- Carbon cost mechanisms in Europe. The EU CBAM implementation in 2026 adds a certificate-purchasing framework that influences the landed cost structure for steel and aluminum imports. For steel powder buyers with European exposure, this mechanism changes the relative economics of sourcing origins and can reshape supplier preference logic, particularly where production routes differ in carbon intensity.
- Broader tariff environment. Tariffs on select Chinese tungsten products implemented in 2024, with further increases anticipated in 2025, illustrate how trade measures can cascade into specialty alloy and powder markets. Even when not directly targeting steel powders, such measures can alter input costs, redirect material flows, and influence supplier risk assessments.
- Feedstock and sustainability links. Steel powder production frequently relies on recycled scrap as a primary feedstock. In practice, this connects powder economics to the availability, quality, and price of scrap streams, as well as to the broader sustainability narratives shaping procurement decisions. The study explores how feedstock integration can create advantages for producers with closed-loop material flows and how that positioning influences downstream buyer confidence.
- Regional demand oscillations. Recent industry updates have pointed to shipment variability in key regions, including a noted decline in North American iron and steel powder shipments in 2024 amid softness in powder metallurgy and additive manufacturing segments. Rather than treating such movements as isolated anecdotes, the report embeds them in a broader demand-cycle framework, helping readers distinguish temporary pauses from structural demand transitions.
These dynamics do not operate in isolation. The strategic value of the full report lies in its integrated treatment of regulation, raw material flows, and demand behavior as mutually reinforcing forces. Instead of offering broad generalizations, the publication provides decision-ready context for scenario planning, contract negotiation, and supply base diversification.
Segment Architecture: Product Types, Applications, and Strategic Implications
A central strength of the study is its structured segmentation framework. Steel powder demand does not grow uniformly; different product families and application sectors follow distinct adoption curves, specification requirements, and pricing dynamics. The report breaks the market into multiple product-type categories and application verticals, then evaluates the strategic significance of each without over-simplifying the nuances that matter to practitioners.
Product-Type Perspectives
Within the product landscape, several steel powder families occupy different strategic positions. Stainless steel powder remains closely associated with corrosion resistance, precision parts, and high-value manufacturing pathways. Alloy steel powder serves segments that require tailored mechanical properties and specialized processing behavior. Carbon steel powder continues to support high-volume industrial and component applications where cost-performance balance is critical. Tool steel powder addresses demanding wear, hardness, and performance thresholds, often in applications where part reliability is non-negotiable.
The report explores how these categories differ not only in end-use fit but also in production complexity, feedstock sensitivity, and competitive positioning. It discusses why certain product families may exhibit stronger linkages to additive manufacturing and high-performance industries, while others remain anchored in established powder metallurgy and industrial component ecosystems. This product-level framing helps buyers and developers match material selection to performance requirements and total cost considerations, while also providing suppliers with a clearer map of where differentiation is achievable.
Application-Side Demand Patterns
On the demand side, the study examines how steel powders flow into diverse verticals, each with distinct adoption drivers. Automotive applications continue to represent a significant demand pool, reflecting ongoing interest in component optimization, material efficiency, and manufacturing flexibility. Aerospace and defense demand is shaped by stricter performance requirements and the push toward advanced production methods for high-value parts. Construction and infrastructure applications contribute a more structural demand base, while industrial machinery supports recurring consumption across equipment manufacturing and maintenance. Electronics and medical/healthcare applications represent specialized pockets where material purity, consistency, and certification become especially important.
Rather than presenting a flat list of sectors, the report connects each application area to the specific purchasing logic that drives it. For example, some verticals prioritize volume and cost stability, while others value specification control, traceability, and supplier technical support. This distinction is critical for 2026 strategy because it determines where pricing power resides, which relationships are worth deepening, and where new entrants can most effectively challenge incumbents.
Detailed application-level revenue allocations and regional breakdowns are included in the full report for buyers who need that granularity for internal forecasting and competitive benchmarking.
Competitive Landscape and Strategic Positioning
The steel powder market is characterized by a concentrated core of established producers alongside specialized players that compete on product performance, process expertise, and application-specific capability. The study profiles the leading companies shaping this landscape and evaluates how their strategies influence supply availability, innovation pace, and buyer choice.
Höganäs remains a globally recognized leader in iron, steel, and stainless steel powders for powder metallurgy, additive manufacturing, and automotive applications. Its scale and breadth of offering make it a central reference point for buyers seeking broad coverage and established production pipelines. Outokumpu has strengthened its position in high-quality, customizable stainless steel and nickel-based alloy powders produced from recycled scrap, with relevance across powder metallurgy and 3D printing. This recycled feedstock orientation gives its offering a distinct sustainability and supply-chain narrative that can resonate with buyers under increasing environmental and procurement scrutiny.
Carpenter Technology Corporation focuses on premium stainless steels, alloy steels, and tool steel powders for additive manufacturing, powder forging, metal injection molding, and hot isostatic pressing. Its emphasis on advanced material families aligns with sectors that demand higher-performance characteristics and precise processing behavior. Sandvik contributes through its Osprey series of tool and stainless steel powders for additive manufacturing and powder metallurgy, with recent product introductions expanding the functional bridge between maraging steels and tool steels. Such product-level innovation matters because it affects how manufacturing teams think about material substitution, performance ceilings, and process optimization.
Kobe Steel and Laiwu Iron & Steel Group Powder Metallurgy Co., Ltd. both maintain steel powder offerings tied to powder metallurgy applications, reflecting the importance of regional production bases and specialized metallurgical know-how. Rio Tinto has entered the conversation through steel powders developed for additive manufacturing at its RTFT facility, signaling how large resource-oriented organizations can extend into high-value powder streams. Kymera International supports the broader ecosystem with metal powders including stainless steel variants, while Pometon SpA provides stainless steel powders for powder metallurgy, reinforcing the role of focused European producers in the supply mix.
Recent Strategic Moves and What They Signal
Recent company-level developments provide useful indicators of where the market is heading. In mid-2025, Höganäs announced an expansion of gas atomization capacity at its Swedish production facility, aiming to increase output of high-purity stainless steel and nickel-based powders for aerospace and medical applications. That move underscores the strategic premium on high-purity material streams and the willingness of leading producers to invest where performance requirements and margin profiles justify capacity additions.
Around the same period, Outokumpu expanded its metal powder business into aerospace and aviation, delivering its first batch of a new stainless steel powder grade for specialized 3D printing. This development illustrates how established stainless steel producers can extend into highly specified additive markets by leveraging existing metallurgical expertise and feedstock relationships. In parallel, Sandvik introduced Osprey MAR 55, a versatile tool steel powder bridging maraging steels and tool steels, highlighting how product portfolios are being refined to meet nuanced engineering requirements and broaden application fit.
These moves are not merely product news; they are competitive signals. The full report interprets such developments within a broader framework of capacity strategy, application targeting, and differentiation logic. It also assesses market concentration dynamics, including the extent to which a relatively small group of leading firms accounts for a substantial share of market revenue, shaping pricing behavior, negotiation leverage, and entry barriers for new competitors.
What the Full Study Delivers: A Practical Toolkit for 2026 Decision-Making
While this overview establishes the strategic context, the complete Steel Powder Market report is designed as a working document for commercial, operational, and investment decisions. It combines market sizing, segmentation, competitive intelligence, and regulatory context into a structured analytical toolkit.
Core Content and Operational Utility
- Market sizing and forecast structure. The study presents a coherent historical baseline and forward projection framework, enabling readers to test assumptions against an externally validated trajectory. Rather than relying on a single point estimate, the report frames growth in a way that supports sensitivity analysis and scenario planning for procurement budgets, capacity decisions, and revenue forecasts.
- Segmentation depth. Product-type and application-level breakdowns help identify where demand is strongest, which categories are likely to see more intense competition, and how different buyer groups evaluate material options. This level of detail supports product planning, inventory strategy, and sales targeting.
- Competitive profiling. Company-level assessments provide context on production orientation, application focus, and recent strategic activity. These profiles help buyers compare supplier alternatives and help suppliers understand where they sit relative to broader market positioning.
- Regulatory and trade context. The report integrates policy-driven variables into the market narrative, allowing users to anticipate cost and availability implications instead of reacting after the fact. This is especially relevant for organizations with cross-border sourcing or multi-region production footprints.
- Dynamics and risk framing. Supply-side considerations, feedstock linkages, regional shipment trends, and demand-cycle behavior are synthesized into a practical risk map. This helps teams distinguish between short-term fluctuations and durable shifts in market structure.
The intent of the publication is not simply to describe the market, but to make it analyzable. Subscribers can use the full segmentation data, company benchmarking, and forecast architecture to build internal models, compare sourcing alternatives, and evaluate the strategic fit of different product pathways.
How to Use This Research for 2026 Strategy
For 2026 planning, the most valuable use of this research is as a decision scaffold. The market is large enough and diverse enough that generic assumptions can lead to misallocated budgets, inappropriate supplier selection, or missed application opportunities. A structured view of size, growth, segmentation, and competitive behavior helps teams ask better questions: which product families align with our performance needs, which applications are expanding fastest in our target regions, where does concentration affect negotiation leverage, and how do regulatory changes alter the relative attractiveness of different sourcing routes?
The report is equally useful for supplier-side strategy. Producers and distributors can use the segmentation framework to identify underserved niches, calibrate capacity investments, and position product launches against real demand patterns rather than broad market generalizations. Recent capacity expansions and product introductions by leading firms illustrate the value of aligning innovation with application-specific requirements, and the full study provides a comparative environment in which to interpret those moves.
Conclusion: From Market Intelligence to Actionable Advantage
The steel powder market in 2026 is defined by more than headline growth. It is shaped by the interplay of advanced manufacturing demand, feedstock and sustainability considerations, regulatory adjustments, and targeted competitive investments. Organizations that treat these factors as connected variables rather than isolated news items will make better sourcing decisions, develop more resilient supply strategies, and identify higher-value applications with greater precision.
Our Steel Powder Market research study was built to provide that level of clarity. It combines a solid historical and forecast foundation with detailed segmentation, competitive profiling, and practical market-dynamics analysis. The executive overview presented here captures the strategic direction and analytical philosophy of the report; the complete publication contains the full segmentation detail, regional and application-level figures, and company benchmarking required for precise internal planning.
For decision-makers who need the complete dataset and the full analytical architecture behind it, the full report is available now. It offers the depth, structure, and decision-ready context necessary to turn steel powder market intelligence into a concrete advantage in 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Steel Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Biobanking Market Hits $73.5B in 2025, Projected 6.6% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperative in Biobanking: Navigating the 2026 Market Landscape
The global biobanking ecosystem is undergoing a structural transformation that demands more than passive observation from industry stakeholders. As we move through 2026, the convergence of precision medicine, advanced automation, and evolving regulatory frameworks has created a market environment where strategic foresight directly correlates with competitive resilience. Our latest market intelligence study on the biobanking sector provides a comprehensive decision-support framework designed for executives, investors, and operational leaders who must navigate this complex terrain with precision. This article outlines the methodological rigor, analytical scope, and strategic value embedded in our full report, while demonstrating why comprehensive market intelligence is no longer optional but essential for sustainable growth.
Personalized Therapy Biosimulation Platform Market
Macroeconomic Trajectory and the 2026 Decision Window
The biobanking market has demonstrated remarkable resilience and steady expansion over the past half-decade. Our analysis tracks revenue progression from a baseline of approximately 55.3 billion USD in 2020 through to 73.5 billion USD in 2025, reflecting a compound annual growth trajectory of 6.6 percent across the historical observation window. This expansion is not merely a function of incremental demand but rather the result of structural shifts in how biological samples are collected, stored, analyzed, and commercialized across healthcare and research ecosystems.
Worldwide Pilot Fermenter Market
Looking forward, our forecast model projects continued upward momentum through the 2026 to 2032 period. The market is expected to surpass the 75 billion USD threshold in 2026, with progressive acceleration culminating in valuations exceeding 114 billion USD by 2032. This growth arc is underpinned by several interconnected drivers, including the increasing reliance on high-quality biospecimens for drug development pipelines, the expansion of personalized medicine initiatives, and the institutionalization of biobanking infrastructure within both academic and commercial settings.
Worldwide Portable Insulin Refrigerator Market
For decision-makers operating in 2026, these figures represent more than macroeconomic indicators. They signal a market that is maturing but still possesses significant room for strategic differentiation. Organizations that understand the timing, scale, and regional nuances of this expansion will be better positioned to allocate capital, invest in infrastructure, and forge partnerships that yield compounding returns. However, realizing this potential requires moving beyond surface-level market sizing to dissect the underlying dynamics that shape competitive positioning, operational feasibility, and regulatory compliance. Our report is engineered specifically to bridge this gap between high-level market awareness and actionable strategic intelligence.
Report Architecture: An Integrated Intelligence Framework
The full market research publication is structured to serve as both a strategic reference and an operational planning tool. Rather than presenting isolated data points, the study constructs a multidimensional view of the biobanking ecosystem by integrating quantitative forecasting with qualitative assessment of industry dynamics. The analytical framework is divided into several core modules, each designed to address distinct decision-making requirements.
The foundational section establishes the overall market architecture, providing a granular breakdown of revenue streams, growth vectors, and historical performance patterns. This segment enables stakeholders to contextualize their own market position within broader industry trends and to identify whitespace opportunities that may not be apparent from aggregate figures alone. The segmentation analysis then disaggregates the market across multiple dimensions, offering a nuanced understanding of how demand distributes across different operational models and end-use applications. By examining the interplay between physical infrastructure, virtual networks, and hybrid configurations, the report illuminates the strategic trade-offs that organizations face when selecting deployment models.
Beyond structural analysis, the study dedicates substantial attention to the competitive landscape. Our research team has conducted detailed profiling of leading market participants, evaluating their technological capabilities, geographic reach, service portfolios, and strategic positioning. This competitive intelligence is not merely descriptive; it is designed to help readers benchmark their own capabilities, anticipate competitor moves, and identify potential collaboration or acquisition targets. The profiles encompass a diverse range of organizations, from global life sciences conglomerates to specialized niche providers, reflecting the heterogeneous nature of the biobanking supply chain.
A critical component of the report involves the examination of market concentration and competitive dynamics. The analysis reveals that the top three players command a combined market share of approximately 40.5 percent, while the leading five organizations collectively account for roughly 55.2 percent of total industry revenue. These concentration metrics provide insight into the degree of market fragmentation, the bargaining power of incumbent suppliers, and the barriers that new entrants must overcome to achieve meaningful scale. For strategic planners, these figures inform decisions regarding market entry timing, partnership strategies, and the potential for consolidation-driven competitive shifts.
Competitive Landscape: Strategic Profiles and Positioning Analysis
The biobanking equipment and services market features a constellation of established players and emerging specialists, each pursuing distinct value propositions and target segments. Our report provides comprehensive profiling of key organizations that shape the industry's competitive architecture, including Thermo Fisher Scientific Inc., Becton Dickinson and Company, PHC Holdings Corporation, Hamilton Company, Azenta Life Sciences, Cryoport Inc., Tecan Trading AG, Lonza Group Ltd., Taylor-Wharton, Charles River Laboratories, Stemcell Technologies Inc., Promocell GmbH, and Brooks Life Sciences.
Thermo Fisher Scientific Inc., headquartered in Waltham, Massachusetts, maintains a prominent position through its specialization in automated storage systems, temperature-controlled equipment, and laboratory information management systems tailored for biobanking sample management. The company's integrated approach to hardware and software solutions positions it as a comprehensive partner for large-scale biobanking operations that require seamless data integration and operational efficiency.
Becton, Dickinson and Company, based in Franklin Lakes, New Jersey, contributes to the market through its portfolio of biobanking equipment, including cryogenic systems and sample collection and storage solutions. The organization's established reputation in medical technology and specimen management provides a strong foundation for continued market penetration, particularly in clinical and research settings that demand reliable, standardized infrastructure.
PHC Holdings Corporation, operating from Tokyo, Japan, offers automated biobanking equipment with emphasis on cryopreservation and storage systems. The company's engineering expertise in precision temperature control and long-term sample integrity addresses critical requirements for biobanks handling sensitive biological materials. Meanwhile, Hamilton Company, located in Reno, Nevada, delivers robotic automation systems and liquid handling technologies designed to streamline biobanking workflows. Its focus on laboratory automation aligns with the broader industry trend toward reducing manual intervention and improving reproducibility in sample processing.
Azenta Life Sciences, headquartered in Chelmsford, Massachusetts, develops automated storage and retrieval systems specifically engineered for biobanking and cryogenic sample management. The company's specialized focus on high-throughput retrieval and inventory tracking addresses the operational challenges faced by large-scale biobanking facilities managing extensive specimen collections. Cryoport, Inc., based in Santa Ana, California, brings a distinct capability to the market through its specialization in cryogenic logistics and storage solutions, enabling secure transport and preservation of temperature-sensitive biological materials across distributed networks.
Tecan Trading AG, operating from Männedorf, Switzerland, provides laboratory automation and robotics solutions that support biobanking sample processing workflows. The organization's automation platforms contribute to throughput efficiency and standardization, which are increasingly critical as biobanks scale their operations to meet growing research and clinical demands. Lonza Group Ltd., headquartered in Basel, Switzerland, offers biobanking services and equipment focused on cell and tissue storage, positioning itself at the intersection of biomanufacturing and sample preservation for advanced therapeutic applications.
Taylor-Wharton, based in Asheville, North Carolina, manufactures cryogenic freezers and storage systems that form the backbone of physical biobanking infrastructure. Charles River Laboratories, located in Wilmington, Massachusetts, supplies biobanking equipment and services for research sample management, supporting the drug discovery and preclinical research ecosystems. Stemcell Technologies Inc., headquartered in Vancouver, Canada, provides specialized equipment and consumables designed specifically for stem cell biobanking, addressing the unique preservation requirements of these valuable and sensitive cell populations.
Promocell GmbH, operating from Heidelberg, Germany, offers biobanking storage and processing solutions tailored to cellular samples, while Brooks Life Sciences, based in Chelmsford, Massachusetts, delivers automated sample management and storage systems that enhance inventory control and operational efficiency. The presence of these diverse players reflects the specialization and segmentation that characterize the modern biobanking market, where organizations must carefully evaluate which partners align with their specific technical requirements, scale expectations, and long-term strategic objectives.
Industry Dynamics: Regulatory Pressures, Infrastructure Constraints, and Strategic Responses
The biobanking sector operates within a complex regulatory and operational environment that shapes both market growth and competitive strategy. Our 2026 analysis identifies several critical dynamics that decision-makers must incorporate into their planning processes. Regulatory standardization efforts have intensified, with the ISO 20387:2018 standard continuing to define requirements for competence, impartiality, and consistent operation across biobanking facilities. This standard, which addresses quality control for biological materials and data collections, serves as a benchmark for operational credibility and facilitates alignment across international research collaborations.
European Accreditation advanced the formalization of biobanking standards in 2025 through the launch of a Multilateral Agreement for biobanking, with further extensions scheduled for 2026. These accreditation initiatives reflect a broader push toward harmonization and quality assurance that raises the bar for operational excellence while simultaneously creating compliance burdens for smaller or less-resourced repositories. The regulatory landscape is further complicated by heterogeneous international requirements, including GDPR, HIPAA, and 21 CFR Part 11, which introduce operational complexity and financial overhead, particularly for smaller repositories that lack the administrative infrastructure to manage multi-jurisdictional compliance demands.
On the infrastructure side, the adoption of automated storage systems and robotic repositories presents both opportunity and constraint. These technologies offer significant improvements in throughput, accuracy, and sample security, but they require substantial capital expenditure and ongoing energy consumption to maintain ultra-low temperature preservation environments. This financial and operational threshold limits adoption among smaller facilities, creating a bifurcation in the market between well-capitalized institutional biobanks and smaller independent operations that must rely on manual or semi-automated processes. Understanding where an organization falls within this spectrum is essential for realistic capacity planning and technology investment decisions.
Recent developments from BBMRI-ERIC underscore the strategic importance of coordinated infrastructure planning. In April 2026, the organization launched a comprehensive 10-Year Roadmap for biobanking development extending through 2035, emphasizing One Health integration and infrastructure alignment across European networks. The roadmap outlines strategic objectives to secure infrastructural scalability, sustainability, and service excellence, providing a forward-looking framework that aligns with broader efforts to strengthen biobanking as a foundational component of health research and public health preparedness. Concurrently, BBMRI-ERIC announced the selection of eight biobanks for dedicated funding under the EvolveBBMRI project, aimed at integrating these facilities into the BBMRI-ERIC Federated Platform. These initiatives illustrate the growing recognition that networked, interoperable biobanking infrastructure will be critical for maximizing the scientific and clinical value of biological sample collections.
Strategic Applications and Segmentation Insights
The distribution of demand across application domains provides valuable insight into where market growth is likely to concentrate and where organizations should orient their investment and product development strategies. Drug discovery and clinical research represent the largest application segment, accounting for approximately 38.8 percent of total market demand. This dominance reflects the foundational role that high-quality biospecimens play in target validation, biomarker identification, and therapeutic development pipelines. As pharmaceutical and biotechnology companies continue to pursue increasingly complex molecular targets and personalized therapeutic approaches, the demand for well-characterized, properly stored, and readily accessible samples will remain a critical bottleneck and opportunity.
Personalized medicine constitutes the second major application pillar, representing roughly 20.45 percent of market activity. The growth of this segment is driven by the expanding use of genomic, proteomic, and metabolomic analyses in clinical decision-making, which in turn requires robust biobanking infrastructure to support longitudinal sample collection, standardized processing, and secure data linkage. Organizations that can demonstrate superior sample quality, comprehensive annotation, and interoperability with clinical data systems will be particularly well-positioned to capture value in this rapidly evolving segment.
Additional application areas, encompassing diverse research, diagnostic, and commercial uses, account for approximately 14.25 percent of market demand. While individually smaller, these segments collectively represent meaningful growth opportunities, particularly for organizations that can develop modular, adaptable solutions capable of serving multiple end-use scenarios. The segmentation by operational model further illuminates strategic considerations. Physical biobanking infrastructure commands the largest share at approximately 52.45 percent, reflecting the enduring necessity of tangible storage facilities and cryogenic equipment for sample preservation. Virtual biobanking networks account for roughly 15.1 percent, illustrating the growing importance of data-centric, distributed models that enable sample discovery and request management without requiring physical centralization. Other operational configurations contribute approximately 5.95 percent, pointing to emerging hybrid and specialized models that blend physical custody with digital coordination.
Regional demand patterns reveal additional strategic considerations. North America represents the largest regional market at approximately 30.69 percent of total demand, supported by well-established research infrastructure, significant biotech investment, and mature regulatory frameworks. Europe follows with roughly 26.65 percent, reflecting the influence of coordinated initiatives such as BBMRI-ERIC and strong public-sector research funding. Asia Pacific accounts for approximately 12.14 percent, with growth trajectories influenced by expanding research capacity, increasing healthcare expenditure, and growing participation in international clinical research networks. Latin America and the Middle East and Africa collectively represent smaller but potentially high-growth regions, accounting for approximately 2.51 percent and 1.51 percent respectively, where strategic investments in foundational infrastructure could yield disproportionate long-term returns as local research and healthcare capabilities mature.
Why Comprehensive Market Intelligence Matters in 2026
The biobanking market in 2026 presents a landscape where strategic advantage is derived not from passive market participation but from informed, anticipatory decision-making. Organizations that rely solely on publicly available summary figures or fragmented industry reports risk missing the subtle shifts in competitive dynamics, regulatory expectations, and technology adoption patterns that define the current environment. Our comprehensive study is designed to eliminate this informational asymmetry by providing a rigorous, data-driven, and strategically oriented analysis that equips decision-makers with the context and clarity needed to act confidently.
The value of this research extends across multiple organizational functions. For executives and board members, the report provides the macroeconomic context and competitive benchmarking necessary to validate strategic direction, assess market opportunity, and communicate growth narratives to stakeholders. For operational leaders, the segmentation analysis, technology assessment, and infrastructure discussion offer practical guidance for capacity planning, technology selection, and workflow optimization. For investors and financial analysts, the market sizing, growth trajectory, and concentration metrics support valuation models, risk assessments, and portfolio allocation decisions. For commercial teams, the competitive profiles and application segmentation inform go-to-market strategies, partnership identification, and customer segmentation.
Central to the report's utility is its commitment to balancing depth with clarity. While the full publication contains extensive quantitative datasets, scenario analyses, and detailed organizational profiles, this introductory overview has deliberately highlighted broader trends and structural insights rather than exhaustive numerical breakdowns. This approach reflects our conviction that meaningful strategic understanding requires more than isolated statistics; it requires a coherent narrative that connects market size, growth drivers, competitive forces, regulatory constraints, and application dynamics into an integrated decision-support framework. Readers who engage with the complete report will gain access to the full spectrum of data, analysis, and strategic recommendations necessary for detailed planning and execution.
Accessing the Full Strategic Intelligence
The insights summarized in this overview represent only a fraction of the analytical depth available in our complete Biobanking Market research publication. The full report contains detailed quantitative models, comprehensive segmentation data, in-depth competitive profiling, scenario-based forecasting, and actionable strategic recommendations that extend well beyond the high-level themes presented here. For organizations serious about capturing value in the evolving biobanking landscape, access to this level of intelligence is not merely advantageous; it is foundational to sound strategy formulation.
We invite executives, analysts, investors, and operational leaders to explore the complete study for a thorough understanding of market trajectories, competitive positioning, and strategic opportunities. The full report delivers the granular data, rigorous analysis, and forward-looking perspective required to make informed decisions in a market characterized by rapid technological change, regulatory evolution, and shifting demand patterns. By engaging with the complete research, stakeholders can move from general awareness to precise, evidence-based planning, ensuring that their strategies are grounded in the most comprehensive and current market intelligence available.
For detailed analysis of this topic, please visit the official page: Biobanking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hemodialysis Concentrates Market Hits $2,350M in 2025, Projects 6.2% CAGR to $3,560M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence Briefing: The Hemodialysis Concentrates Market 2026 Outlook
The global hemodialysis sector stands at a critical inflection point. As the prevalence of chronic kidney disease continues to rise across aging populations, the demand for precise, safe, and efficient dialysis fluids has never been more pronounced. For stakeholders navigating this complex landscape, understanding the trajectory of hemodialysis concentrates is not merely an academic exercise—it is a fundamental requirement for strategic planning. This report provides a comprehensive examination of the hemodialysis concentrates market, offering the granular intelligence necessary to drive decision-making throughout the forecast period and beyond.
Diversified Protein Degradation Platform Market
Our analysis positions the market at a total revenue of approximately 2350.0 Million USD in the base year of 2025. Looking ahead, the sector is projected to expand significantly, reaching an estimated 3560.0 Million USD by 2032. This growth trajectory underscores a compound annual growth rate of 6.2 percent over the forecast horizon. Such figures represent more than simple expansion; they indicate a shifting paradigm in how dialysis care is delivered, manufactured, and regulated globally. For executives and investors, these macro indicators serve as the foundational baseline for evaluating market entry opportunities, expansion strategies, and portfolio allocations.
O-Tolidine Diisocyanate (TODI) Market
Market Trajectory and Growth Drivers
The historical data from 2020 through 2025 reveals a consistent upward trend, despite global supply chain challenges and economic volatility. The market size grew from 1800.0 Million USD in 2020 to 2350.0 Million USD in 2025. This resilience suggests that hemodialysis concentrates are viewed as essential medical commodities rather than discretionary healthcare spending. As we move into the forecast period from 2026 to 2032, the momentum is expected to accelerate. The projected valuation of 2411.84 Million USD in 2026 marks the beginning of a period where innovation in formulation and delivery systems will likely outperform traditional volume-based growth models.
Worldwide Bike Phone Holder Market
Several underlying forces are propelling this demand. The transition from in-center dialysis to home-based care models is reshaping consumption patterns. While dialysis centers remain the dominant application segment, the home care sector is gaining traction due to patient preference for autonomy and reduced hospital exposure. Furthermore, the aging demographic in major economies is increasing the incidence of end-stage renal disease, directly correlating with higher consumption of acid and bicarbonate concentrates. Manufacturers who can align their production capacities with these shifting care delivery models will be best positioned to capture value in the coming years.
Product Segmentation and Technical Dynamics
The market is fundamentally divided into two primary product types: Acid Concentrates and Bicarbonate Concentrates. These components are critical for preparing the dialysate solution used during treatment. Acid concentrates typically contain electrolytes and buffers dissolved in water, while bicarbonate concentrates are used to balance the pH levels in the final dialysate mixture. The interplay between these two types dictates the efficacy of the dialysis procedure and the safety profile for the patient.
Material costs remain a pivotal consideration for both manufacturers and healthcare providers. The production of medical-grade concentrates relies on purified water and specific electrolytes and acids. Fluctuations in the supply chain infrastructure for these raw materials can impact pricing stability. Our research delves into how manufacturers are mitigating these risks through vertical integration and localized sourcing strategies. Additionally, the technical specification of concentrates—whether liquid or dry forms—plays a significant role in logistics and storage costs. Dry concentrates, for instance, offer advantages in shipping weight but require specific mixing infrastructure at the point of care. Understanding the trade-offs between these formats is essential for supply chain optimization.
Regional Landscape and Distribution Networks
Geographically, the market exhibits a mature yet evolving distribution network. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa regions each present unique regulatory environments and reimbursement structures. In major markets, reimbursement for hemodialysis concentrates varies by jurisdiction, often relying on standard CPT codes that cover dialysis fluid preparation. This regulatory framework influences pricing power and market accessibility for new entrants.
While established markets in North America and Europe continue to drive significant revenue, emerging regions are showing potential for accelerated adoption. The Asia Pacific region, for example, represents a substantial portion of the global demand, driven by increasing healthcare infrastructure investment and rising disease prevalence. Latin America and the Mideast and Africa also contribute to the global footprint, though at different scales of maturity. Our analysis provides a detailed breakdown of these regional dynamics without relying solely on historical revenue splits, focusing instead on the growth potential and barrier-to-entry analysis specific to each territory. This approach allows strategists to identify where capital deployment might yield the highest returns in the 2026-2032 window.
Competitive Landscape and Strategic Positioning
The industry is characterized by a concentrated competitive environment. High barriers to entry, driven by stringent quality control requirements and established distribution channels, protect incumbent players. Our market concentration analysis indicates that the top three companies hold a significant share of the market, while the top five firms command an even larger portion. This consolidation suggests that partnerships, acquisitions, and strategic collaborations will be key levers for growth rather than organic expansion alone.
Several key companies are defining the current competitive landscape. Fresenius Medical Care, headquartered in Bad Homburg, Germany, remains a pivotal player, manufacturing Citrasate and related liquid and dry acid/bicarbonate hemodialysis concentrates for both clinic and home dialysis settings. Their influence extends beyond product manufacturing into integrated care solutions. Similarly, B. Braun Melsungen, based in Melsungen, Germany, produces Dialog-plus and premixed dialysis concentrates that are integrated into their full dialysis systems portfolio, offering a bundled value proposition to healthcare providers.
Nipro Corporation, operating out of Osaka, Japan, manufactures MedicaPure liquid acid and MedicaLyte bicarbonate concentrates specifically designed for hemodialysis machines. Their focus on equipment compatibility highlights the importance of technical integration in this sector. Rockwell Medical, based in Wixom, Michigan, USA, produces a diverse range of products including CitraPure, Dri-Sate, RenalPure, and SteriLyte liquid and dry acid/bicarbonate concentrates. Their strategy often involves expanding product lines to cover various delivery mechanisms. Renacon Pharma Limited, based in Karachi, Pakistan, has been manufacturing RENACIT citrate hemodialysis concentrates and related products since 1996, demonstrating the role of long-standing regional manufacturers in the global supply chain.
Additionally, Farmasol, located in Kayseri, Turkey, produces acid and bicarbonate concentrates as part of the Pollet Medical Group dialysis portfolio. Pollet Medical Group, operating out of Belgium, acts as both an operator and producer of concentrate production systems and acid concentrate solutions. The interconnectivity between these entities illustrates the complex web of partnerships and subsidiary relationships that define the modern market structure. Our report provides detailed profiles on each of these entities, analyzing their strengths, weaknesses, and strategic moves to help clients understand where they fit within the value chain.
Recent Industry Developments and M&A Activity
The period leading into 2026 has seen significant activity among key market participants. In January 2025, Farmasol became part of Pollet Medical Group, a strategic move expanding in-house production of hemodialysis acid concentrates. This acquisition signals a trend toward consolidation to secure supply chain stability and reduce dependency on external suppliers. By integrating production capabilities, the combined entity can better control quality and cost structures.
Product innovation remains equally vigorous. In February 2025, Rockwell Medical added single-use bicarbonate cartridges to their hemodialysis concentrates portfolio. This launch addresses the growing demand for convenience and safety in home dialysis settings, where single-use options reduce the burden of preparation and storage for patients. Later in the year, in July 2025, Fresenius Medical Care launched the kinexus unified digital platform supporting hemodialysis concentrates integration. This move highlights the industry's shift toward digitalization, where data management and solution tracking become as critical as the chemical composition of the concentrates themselves.
Furthermore, Rockwell Medical exhibited their hemodialysis concentrates portfolio at ASN Kidney Week 2025 in October. Such trade show appearances are vital for maintaining visibility among clinicians and procurement officers, reinforcing brand presence in a crowded market. These developments collectively indicate that competition is shifting from purely price-based mechanisms to value-based offerings that include digital support, ease of use, and supply chain reliability.
Regulatory Environment and Risk Management
Navigating the regulatory landscape is a paramount challenge for manufacturers and distributors. In 2025, the FDA issued a Class 2 Device Recall for Premixed Dialysate for Hemodialysis on May 28, due to potential perimeter seal issues. This event underscores the critical importance of packaging integrity in preserving the sterility and efficacy of liquid concentrates. Later, on December 23, 2025, the FDA issued another Class 2 Device Recall for Diasol Liquid Concentrate, related to the safety and efficacy of dialysis acid concentrates. These incidents serve as stark reminders of the quality assurance burdens placed on manufacturers.
It is also important to note the historical context of regulatory oversight. A previous FDA Class 2 Device Recall for Dialysate Concentrate for Hemodialysis (Liquid/Powder) was terminated on July 11, 2024, with ongoing quality monitoring. This pattern of recalls and subsequent monitoring suggests that regulatory bodies are maintaining a heightened level of scrutiny. For companies operating in this space, compliance is not a one-time achievement but a continuous operational requirement. Our report analyzes the implications of these regulatory actions on market entry strategies and risk mitigation frameworks. Companies that can demonstrate robust quality management systems will likely find it easier to secure contracts and maintain market share during periods of regulatory volatility.
Cost Structures and Reimbursement Models
Understanding the economic underpinnings of the market is essential for financial planning. Reimbursement for hemodialysis concentrates varies by jurisdiction, with standard CPT codes covering dialysis fluid preparation in major markets. This coding structure dictates how providers are compensated and, by extension, influences the pricing pressure exerted on concentrate manufacturers. In regions where reimbursement rates are tightly controlled, manufacturers may need to focus on cost efficiency and volume scalability. In markets with more flexible reimbursement models, premium products with enhanced safety features or digital integration capabilities may command higher margins.
On the production side, medical-grade material costs for concentrates include purified water, electrolytes, and acids. Fluctuations in these input costs are often driven by supply chain infrastructure in manufacturing. Energy costs, logistics, and raw material availability all contribute to the final cost of goods sold. Our analysis examines how different companies are structuring their cost bases to remain competitive. Some are leveraging scale to absorb material cost fluctuations, while others are investing in technology to reduce waste and improve yield. For clients evaluating potential partners or competitors, understanding who holds the advantage in cost structure is key to predicting long-term viability.
Strategic Value for 2026 Decision Making
This market research report is designed to be a actionable tool for strategic planning. It goes beyond high-level statistics to provide the depth required for nuanced decision-making. Whether you are considering a merger, launching a new product line, or entering a new geographic region, the data presented here offers the evidence base needed to justify investment. The forecast period from 2026 to 2032 presents a window of opportunity where early movers can establish significant market presence.
We provide detailed segmentation analysis that allows you to pinpoint specific growth pockets within the broader market. By understanding the interplay between acid and bicarbonate concentrates, regional regulatory demands, and the competitive maneuvers of key players like Fresenius Medical Care, B. Braun, and Rockwell Medical, you can formulate strategies that are resilient to market shocks. The report also covers the implications of recent acquisitions and product launches, helping you anticipate competitor moves before they impact your market share.
In an industry where patient safety and regulatory compliance are non-negotiable, having access to verified intelligence is a competitive advantage. The insights contained in this study are curated to support board-level discussions, investment committee reviews, and operational planning sessions. We invite you to explore the full scope of our findings to ensure your organization is equipped with the most accurate and timely intelligence available for navigating the hemodialysis concentrates market in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


