



Category: market research
Wellington Boots Market to Hit $1.84B by 2032, Growing at 4.8% CAGR: PW Consulting
By PW Consulting, 2026-09-07
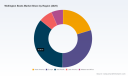
The Wellington Boots Market in 2026: Strategic Imperatives for a Reshaping Industry
The global Wellington boots market is entering a decisive phase of its evolution. After a decade of steady expansion, the sector is no longer defined by simple utility or seasonal sales cycles. Today, it sits at the intersection of supply chain realignment, material innovation, regulatory shifts, and changing end-user expectations across agriculture, industrial manufacturing, household use, and outdoor recreation. For executive teams, procurement leaders, and brand strategists, the 2026 landscape demands a more granular understanding of where value is being created, where margins are being tested, and how competitive positions are being reconfigured.
Worldwide Precision Fluid Dispensing Systems Market
Our latest Wellington Boots Market research study is designed to cut through the noise and provide a structured, data-informed view of the market from 2020 through 2032. The analysis is anchored in a clear historical trajectory and a forward-looking forecast period that maps the growth path from a 2025 revenue base of approximately 1,330.0 million USD to an estimated 1,842.67 million USD by 2032. This trajectory reflects a compound annual growth rate of 4.8 percent across the forecast horizon, signaling durable demand but also underscoring the importance of execution quality as competition intensifies and input costs remain volatile. The years from 2020 to 2025 already demonstrated how resilient the category can be, with revenue progressing from 1,087.15 million USD to 1,330.0 million USD. Yet the next phase will be less forgiving for players that rely on undifferentiated product portfolios or rigid sourcing models.
Productivity Tool Market
This article serves as a strategic preview of the full report. It highlights the market structure, competitive dynamics, and operational pressures that executives should be tracking right now. At the same time, it intentionally leaves the most granular segmentations, regional comparisons, and application-level revenue splits for the complete study. Those detailed breakdowns are essential for precise portfolio planning, pricing strategy, and geographic prioritization, and they are available in the full Wellington Boots Market research release.
PVC Footwear Market
Macro Momentum: Why the Wellington Boots Market Still Has Strategic Relevance
The Wellington boots category has moved beyond its traditional image as a narrow seasonal accessory. It now functions as a cross-sector footwear segment that supports professional work environments, agricultural operations, facility management, and leisure activities. That breadth gives the market a structural advantage: demand is diversified, and downturns in one application can be offset by stability or growth in another. At the same time, the category is exposed to macroeconomic forces that are difficult to ignore, including raw material pricing, freight volatility, labor costs, and evolving tariff regimes.
The historical record supports a constructive view, but not an automatic one. From 2020 to 2025, the market expanded from 1,087.15 million USD to 1,330.0 million USD. That progression reflects consistent end-user demand, broadened product positioning, and sustained relevance across both professional and consumer settings. The forecast period from 2026 to 2032 extends that momentum, projecting revenue movement from 1,352.27 million USD in 2026 to 1,842.67 million USD in 2032. The interim years show a market that is not simply growing linearly but steadily building scale: 1,508.07 million USD in 2027, 1,564.37 million USD in 2028, 1,575.3 million USD in 2029, 1,712.65 million USD in 2030, and 1,736.61 million USD in 2031.
For strategy teams, the key insight is that a 4.8 percent CAGR is meaningful but not exceptional in a vacuum. Its real value lies in what it implies about the prioritization of investments. In a market expanding at this pace, competitive advantage is increasingly determined by product differentiation, sourcing agility, channel execution, and the ability to manage cost inflation without eroding brand equity. Companies that treat Wellington boots as a commodity line will face pressure, while those that build defensible positions around durability, weather resistance, professional-grade performance, or style-led consumer appeal can capture disproportionate value.
What the 2026 Research Delivers: A Practical Toolkit for Decision-Makers
The full Wellington Boots Market study is built for applied decision-making rather than abstract observation. It combines historical market sizing, forecast modeling, segmentation analysis, competitive profiling, and industry context into a single integrated reference. The objective is to help leadership teams answer operational and strategic questions with greater confidence, especially in an environment where cost structures and regulatory conditions are changing quickly.
The report includes the following core components:
- Market sizing and forecast for the overall Wellington boots category, with a detailed historical series and forward outlook through 2032.
- Analysis of the materials landscape, including the relative importance of rubber, polyurethane, EVA, PVC, and other constructions in shaping product performance, cost profiles, and consumer perception.
- A structured view of application demand across agriculture, household, industrial manufacturing, outdoor recreation, and other end-use segments, helping teams understand where volume and value are concentrated.
- Regional market context that situates demand, supply exposure, and channel dynamics across major geographic markets without reducing the discussion to simplistic one-dimensional rankings.
- Competitive analysis of key companies and their strategic positioning, with an emphasis on product philosophy, brand character, target users, and recent commercial moves.
- Industry context covering regulation, import duties, raw material and freight pressures, product innovation trends, and pricing behavior that directly influence margin planning and sourcing decisions.
Equally important, the study is intended to support practical outputs: product roadmap prioritization, sourcing scenario planning, pricing architecture, channel strategy, and market-entry or expansion assessment. Because the Wellington boots market is fragmented across use cases and materials, high-level totals alone are insufficient. Decision-makers need the ability to see how demand patterns differ by application, how material choices affect both performance and cost, and how competitive intensity varies by segment. Those insights are developed in depth in the full report.
Competitive Landscape: Differing Philosophies in a Consolidated-but-Fragmented Market
The Wellington boots market presents an interesting competitive paradox. On one hand, the top players collectively hold a meaningful share of total industry revenue, with the top three accounted for by approximately 28.4 percent and the top five reaching about 37.2 percent. On the other hand, the market remains diverse enough that specialized brands, regional players, and multi-material manufacturers can all compete effectively by serving distinct customer groups. That balance creates both opportunity and risk: scale matters, but positioning matters just as much.
The competitive set covers a wide spectrum of product philosophies. Le Chameau, based in Normandy, France, emphasizes iconic handcrafted rubber Wellington boots, using a Chamolux rubber upper and dual-material construction designed for durability and weather resistance. Its approach reflects a premium, heritage-oriented positioning that appeals to customers willing to pay for craftsmanship and long-term product reliability. By contrast, Grundéns, headquartered in Canada, focuses on professional-grade rubber and neoprene fishing and work boots, including the Crewman model built for commercial durability. Its market identity is rooted in performance under demanding conditions rather than lifestyle appeal.
Xtratuf, operating in the United States, delivers durable waterproof rubber work and fishing boots under Rocky Brands ownership, bringing a more industrial-commercial orientation to the category. Rubbermaid, based in Atlanta, Georgia, contributes a commercial-grade perspective with rubber boots and protective footwear intended for industrial and facility use. Bogs Footwear, from Portland, Oregon, offers waterproof rubber and seamless Wellington-style boots for farm, work, and outdoor use, combining utility with comfort-oriented design. Blundstone, headquartered in Hobart, Australia, extends the category further by integrating rugged rubber and leather Wellington boots for both work and casual use, broadening the appeal of the style beyond purely functional settings.
Aigle, from France, adds a unisex outdoor and adventure orientation with rubber Wellington boots featuring lugged soles and dual-material uppers. Dunlop Boots, in the United Kingdom, reinforces the professional side of the category with industrial and rubber boots that include chemical-resistant features. Rockland, in the United States, leans toward more accessible pricing for general consumer and work applications, while Tingley Rubber serves safety and industrial needs with durable rubber overshoes and Wellington-style footwear. Together, these companies illustrate that Wellington boots are not a single product category so much as a family of related offerings with different performance expectations, styling priorities, and price points.
Recent company-level activity reinforces how actively this landscape is being shaped. In February 2025, Grundéns launched the Crewman boot after nine months of testing across Alaska, the Canadian Maritimes, Maine, and Europe for professional fishing and work use, signaling a clear investment in field-validated product development. In March 2025, Le Chameau previewed and began stocking new Fairfax collaboration Wellington boots at major retailers, showing how brand partnerships can extend reach and refresh consumer-facing offerings. These moves matter because they demonstrate two different routes to growth: one through specialized professional performance, the other through retail presence and collaborative design.
Industry Dynamics: Regulation, Cost Pressure, and Material Innovation
The Wellington boots market in 2026 cannot be understood without accounting for the external forces reshaping costs, sourcing options, and product development priorities. Several converging dynamics are worth close attention.
First, tariff and customs actions have introduced new uncertainty into footwear supply chains. In February 2026, U.S. Customs and Border Protection applied a 37.5 percent ad valorem duty under HTS 6401.99 for waterproof rubber boots originating from China under Executive Order 14389. This kind of measure directly affects landed cost calculations and can alter the economics of sourcing strategies that previously relied on specific export markets. The broader picture is equally important: in April 2025, the U.S. imposed new tariffs on imported footwear, raising duties for Vietnamese boots by 46 percent and Indonesian boots by 32 percent, with up to 145 percent on certain Chinese imports. These changes have direct implications for Wellington boots supply chains, especially for manufacturers and retailers that must rebalance sourcing footprints, renegotiation timelines, and inventory planning.
Second, import duty structures in other major markets also shape competitive conditions. As of 2026 HTS revisions, HS Code 6401.99.00 for rubber Wellington boots carries EU import duties of 16 percent and UK duties of 16 percent. For global suppliers and multinational distribution plans, these duty levels become part of the baseline cost architecture and can influence where products are positioned, how they are priced, and which markets are most attractive for expansion or consolidation.
Third, cost pressure has become a defining operational reality. Industry-wide pressure from rising raw material and freight costs in 2025 has led manufacturers to increase Wellington boot prices by 20 percent or more in order to maintain margins. This is not an isolated pricing event; it reflects a structural squeeze that requires careful management. Companies that pass on costs without a corresponding value narrative risk volume erosion, while those that fail to adjust pricing may damage profitability. The strategic response involves more than setting a higher sticker price. It requires clarity on which product tiers can absorb cost changes, how to communicate durability or performance benefits, and where sourcing or design improvements can offset input inflation.
Fourth, material and sustainability trends are influencing product roadmaps. Eco-friendly materials have featured in approximately 50 percent of new product launches for Wellington boots since 2023, driving consumer demand in Europe and North America. At the same time, broader footwear trend data indicates that Wellington boots dominate material demand with a 32 percent share in consumer footwear, ahead of rubber at 30 percent. This suggests that the Wellington boot style itself has become a meaningful fashion-and-function platform, not merely a utility item. For brands, the implication is clear: sustainability credentials, material innovation, and styling relevance are increasingly intertwined. A boot that performs well but fails to align with evolving consumer preferences may lose ground to competitors that integrate eco-conscious construction with strong design language.
Taken together, these dynamics create a market environment where strategic agility matters more than ever. Regulatory shifts can change the attractiveness of specific sourcing corridors. Cost inflation can compress margins if product architecture is not carefully managed. Sustainability-linked innovation can open new demand angles while raising expectations for transparency and performance. Companies that monitor these forces only at a high level risk being caught off guard; those that integrate them into sourcing, pricing, and product decisions will be better positioned to protect margins and grow share.
Where the Real Strategic Value Lies in 2026
For executives, the Wellington boots market presents a set of questions that are best answered with detailed segmentation, not broad averages. The overall growth story is encouraging, but the business implications differ sharply depending on which material categories matter most to a company's portfolio, which applications drive its volume, and which regions represent the best balance of opportunity and risk. The same market can look very different to a professional work-boot supplier, a consumer lifestyle brand, an agricultural distributor, or an industrial procurement organization.
Several strategic themes recur across the full analysis and should shape planning in 2026:
- Portfolio alignment: Companies need to determine where they compete in the material and application spectrum. Rubber remains central to the category, but polyurethane, EVA, PVC, and other constructions each carry distinct performance and cost characteristics. The right mix depends on target users, durability expectations, and price positioning.
- Sourcing and tariff strategy: With duties and trade measures affecting multiple export sources, companies must evaluate not just unit cost but total landed cost, lead-time reliability, and exposure to policy changes. Sourcing flexibility is likely to be a competitive advantage.
- Margin defense and value communication: In an environment where manufacturers have raised prices by 20 percent or more, the challenge is to justify price increases through product credibility, material quality, and clear use-case benefits rather than relying on category inflation alone.
- Retail and channel execution: Partnerships, seasonal placement, and retailer relationships can accelerate adoption for consumer-oriented Wellington boots, while professional and industrial channels may prioritize durability documentation, safety attributes, and supply consistency.
- Innovation and sustainability: With eco-friendly materials appearing in roughly half of new launches since 2023, brands need to decide how seriously to integrate sustainability into product design, messaging, and sourcing, especially in Europe and North America where consumer sensitivity is strongest.
These themes are not abstract. They directly affect product development timing, inventory strategy, pricing architecture, and long-term brand positioning. The full report provides the underlying market detail needed to translate these themes into concrete actions, including the segmentation depth that helps identify where demand is strongest and where competitive intensity is most pronounced.
Why the Full Report Matters Now
Market intelligence is most valuable when it reduces uncertainty at the point of decision. The Wellington boots category is large enough to offer real growth opportunities and fragmented enough to reward focused strategies. The combination of a 4.8 percent CAGR, a revenue trajectory moving from 1,352.27 million USD in 2026 toward 1,842.67 million USD in 2032, and a competitive field that spans premium heritage brands, professional-grade manufacturers, and value-oriented suppliers creates a landscape where precision matters.
The full Wellington Boots Market research study goes further than the summary figures and trend overview presented here. It offers a detailed breakdown of market size across the historical period and forecast horizon, a structured view of material and application segmentation, competitive profiles that connect product philosophy to commercial strategy, and an integrated account of the regulatory, cost, and innovation forces that will shape profitability. The deeper segmentation data, regional context, and application-level revenue splits are especially important for teams that need to evaluate where to invest, where to defend, and where to reposition.
For organizations preparing 2026 plans, the study is intended to serve as a practical foundation: not just a description of where the market has been, but a framework for deciding where it is heading and how to participate with confidence.
Access the Full Wellington Boots Market Research
This article provides a strategic preview of the market environment and the analytical approach behind our latest study. To explore the complete segmentation, competitive detail, regional insights, and forward forecast supporting 2026 decision-making, access the full Wellington Boots Market research report. The full edition contains the deeper data and structured analysis needed to turn market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Wellington Boots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: School Furniture Market to Hit $4.8B in 2025, 7.2% CAGR Through 2032
By PW Consulting, 2026-09-07
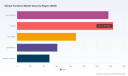
Navigating the Next Wave: Strategic Intelligence for the Global School Furniture Market 2026
The educational landscape is currently undergoing a significant transformation, driven by evolving pedagogical models, heightened health and safety standards, and a renewed focus on student well-being. For stakeholders in the school furniture sector, these shifts represent more than just operational adjustments; they signal a fundamental restructuring of demand dynamics. As we move into 2026, understanding the trajectory of this market is critical for procurement officers, manufacturers, and investors alike. This article serves as a strategic overview of the current environment, drawing upon comprehensive market intelligence to highlight the key forces shaping the industry and the imperative for data-driven decision-making.
PCBN Composite Sheet Market
For senior leadership, the question is no longer whether to invest in updating or expanding educational furnishings, but how to align those investments with the long-term trends that will define the next decade. The following analysis outlines the macro-economic backdrop, the evolving competitive landscape, and the regulatory currents that must be navigated to secure a sustainable position in the market.
Short-video Content Parsing Software Market
Market Trajectory and Growth Vectors
The global school furniture market has demonstrated remarkable resilience and expansion over the past several years. Following a period of stabilization post-2020, the sector has entered a robust growth phase. Trajectory data indicates a consistent upward trend in revenue, reflecting increased capital expenditure in educational infrastructure and the replacement of aging inventories with modern, functional solutions. The market momentum is expected to sustain this pace, with projections extending through the end of the decade.
Worldwide PA Filament Market
Strategic forecasts suggest that the industry will continue to expand at a compound annual growth rate (CAGR) of 7.2 percent during the forecast period. This growth is not merely a reflection of inflation or population increases; it represents a structural shift toward higher-quality educational environments that support collaborative learning, ergonomic health, and technological integration. For enterprises operating in this space, maintaining a market share requires not only capturing current demand but anticipating the volume spikes associated with this growth trajectory.
Revenue projections through 2032 indicate a substantial increase in total market value, suggesting that the peak opportunities for strategic entry or expansion lie within the immediate future. Companies that establish strong partnerships with educational institutions and government bodies now are well-positioned to benefit from the sustained capital inflow into school facilities. However, capturing this growth requires a nuanced understanding of where the value is concentrated within the broader ecosystem.
Competitive Landscape and Stakeholder Dynamics
The market structure is characterized by a moderately concentrated environment where established players hold significant influence. Industry analysis reveals that a small group of leading manufacturers controls a majority of the market share. This concentration implies that while there is room for niche players and specialized providers, the dominant strategies for market leadership involve scale, comprehensive product portfolios, and strong distribution networks. Understanding the positioning of these key players is essential for any entity seeking to benchmark its performance or identify acquisition targets.
Several core organizations define the competitive baseline. Smith System, based in Grand Haven, Michigan, has carved a distinct niche by specializing in wholesale ergonomic and flexible furniture designed for K-12 classrooms. Their focus on collaborative systems for elementary through high school levels illustrates a market preference for adaptability in younger educational settings. Similarly, Haworth, located in Holland, Michigan, provides broader institutional solutions that bridge the gap between higher education and K-12 environments, offering modular systems and seating that cater to diverse learning spaces.
International perspectives are also vital. VS Furniture, headquartered in Germany, offers school and office furniture with a strong emphasis on ergonomic systems and modular solutions. Their presence highlights the global nature of standards and design philosophies that are crossing borders. In the United States, manufacturers like Krueger International (KI) from Green Bay, Wisconsin, and Virco from Placentia, California, continue to be pivotal. KI's adherence to BIFMA standards for institutional furniture underscores the importance of compliance in building trust with institutional buyers, while Virco's focus on durable desks and modular seating solutions speaks to the longevity requirements of public sector procurement.
Smaller but significant players also contribute to the ecosystem. Insalco provides contract furniture including storage and seating systems, while Robert H. Lord offers specialized school furniture adhering to educational seating standards. PSI-New England Storage Products supplies essential storage and seating solutions as part of institutional contracts. The interplay between these large conglomerates and specialized providers creates a dynamic where differentiation is often achieved through specific product features, regional service capabilities, or adherence to emerging sustainability criteria.
Regulatory Frameworks and Industry Standards
One of the most critical aspects of operating in the school furniture market is navigating the complex web of industry standards and regulatory guidelines. Compliance is not merely a legal checkbox; it is a competitive differentiator that signals quality and safety to risk-averse educational administrators. Recent developments from the Business and Institutional Furniture Manufacturers Association (BIFMA) have reinforced the importance of staying updated with the latest protocols.
In February 2026, BIFMA published the updated Furniture Surfaces Guideline (BIFMA G8.1-2026). This document details protocols for furniture surface performance against cleaning, sanitizing, and disinfecting products. For manufacturers, this means that surface durability and resistance are no longer optional features but baseline expectations. Schools and universities are increasingly concerned with hygiene infrastructure, and furniture that can withstand rigorous cleaning regimes without degrading offers a distinct value proposition.
Furthermore, the BIFMA 360 Conference held in February 2026 featured sessions on industry leadership and standards development for institutional furniture, including education applications. These gatherings often serve as barometers for future regulatory directions. Alongside the conference, BIFMA released the Outdoor Furniture Whitepaper (OF-2025), which covers performance and sustainability criteria applicable to educational outdoor spaces. This white paper is particularly relevant as schools look to expand learning environments beyond the traditional four walls, focusing on ventilation and outdoor connectivity.
Existing standards remain foundational. The BIFMA X6.1-2018 standard for educational seating evaluates student seating in pre-school through adult education environments. Together with ANSI/BIFMA X5.1, these standards cover general-purpose seating performance and specific educational seating durability. Additionally, the BIFMA LEVEL certification program evaluates environmentally and socially responsible products for institutional and education facilities. For companies, aligning product development with these standards is a strategic necessity to access public procurement channels and satisfy the requirements of conscious institutional buyers.
Segmentation and Application Trends
While the overall market numbers tell a compelling story of growth, the strategic opportunities lie in understanding the segmentation drivers without getting lost in the aggregate. The market is divided across various dimensions, each presenting unique challenges and opportunities for product development and sales strategies.
In terms of product type, the demand is diverse. Seating remains the dominant category, reflecting the core need for student ergonomics and comfort during prolonged learning hours. However, storage furniture and lab furniture also represent significant value pools. The demand for lab furniture is particularly sensitive to STEM education initiatives and the integration of technology in science classrooms, requiring specialized durability and utility. Storage solutions are critical as schools manage increasing amounts of digital and physical learning assets, driving demand for modular and secure storage systems.
Application-wise, the classroom remains the primary locus of spending, but it is evolving. The traditional row-based seating is giving way to flexible configurations that support group work and project-based learning. However, substantial opportunities also exist in library and labs, as well as other specialized applications. Libraries are transforming into media centers, requiring furniture that accommodates technology and collaborative study. The "others" category encompasses administrative offices, cafeterias, and common areas, each with distinct aesthetic and functional requirements.
Regional dynamics also play a role in shaping demand, though specific quantitative breakdowns are proprietary to detailed market studies. Different regions face varying challenges regarding infrastructure age, funding models, and educational priorities. For instance, some regions may prioritize replacement cycles due to aging stock, while others may be focused on expansion to accommodate population growth. Understanding these regional nuances requires granular data that goes beyond the headline figures.
Strategic Implications for 2026 Decision-Makers
For executives and strategists, the data points to several actionable implications. First, the growth rate implies that the market is large enough to support new entrants and innovators, but the concentration of market share among top players suggests that differentiation is key. Competing solely on price in a commodity segment is increasingly risky. Instead, value creation through ergonomics, compliance with the latest BIFMA guidelines, and modular flexibility offers a stronger path to margin retention.
Second, the regulatory updates from early 2026 should be viewed as immediate project parameters. Any procurement cycle initiated in 2026 must account for the new surface performance guidelines and the sustainability criteria highlighted in recent white papers. Suppliers who can certify their products against these standards will reduce friction in the sales cycle and build credibility with facility managers.
Third, the distinction between K-12 and higher education needs, while sometimes overlapping, requires tailored approaches. K-12 furniture must withstand high usage rates and accommodate growing students, favoring durability and adjustability. Higher education environments may prioritize aesthetics and flexibility for adult learners. Product lines that can address these specific needs without compromising on core standards will outperform generic offerings.
Finally, the long-term forecast extending to 2032 suggests that investments made today will have a multi-year payoff. Supply chain stability, manufacturing capacity, and service networks need to be scaled in anticipation of this sustained demand. Delays in capacity expansion or supply chain resilience could result in missed opportunities as competitors secure long-term contracts with educational districts during this growth window.
Conclusion: The Value of Deep Market Intelligence
The school furniture market is at an inflection point where growth, regulation, and changing educational pedagogies converge. For organizations looking to capitalize on this environment, surface-level knowledge is insufficient. Success depends on a granular understanding of market size, segmentation splits, competitive positioning, and the specific regulatory frameworks that govern procurement.
While this overview highlights the broader trends and key players shaping the industry, the full strategic picture requires accessing detailed intelligence. Comprehensive analysis of regional revenue splits, exact segmentation values, and deep-dive competitor profiling provides the precision needed to refine go-to-market strategies. The data suggests a robust opportunity, but seizing it requires navigating the specifics with confidence.
We invite industry leaders to explore our complete market research report to unlock the full depth of these insights. By leveraging the detailed dataset and strategic analysis contained within, your organization can align its 2026 roadmap with the realities of the market, ensuring that your investments are backed by the most accurate intelligence available. The future of school furniture is being built now, and informed strategy is the blueprint for success.
For detailed analysis of this topic, please visit the official page: School Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sunglasses Market to Reach $310M by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-07
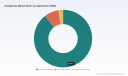
The 2026 Sunglasses Market: Strategic Imperatives in a Consolidating Landscape
The global sunglasses market stands at a critical inflection point. Over the past half-decade, revenue has expanded from 120.0 million in 2020 to an estimated 190.0 million in 2025, reflecting a compound trajectory that underscores both resilient consumer demand and a structural shift in how eyewear is designed, distributed, and differentiated. Our newly published Sunglasses Market study isolates the forces shaping the 2026-2032 forecast window, delivering a decision-ready framework for brand leaders, retail strategists, and supply chain executives who must navigate rising concentration, evolving material economics, and intensifying product specialization.
Helicopter Aerial Photography Services Market
This article provides a strategic preview of the report's architecture and the analytical rigor behind it. It is designed to surface the dimensions that matter most for 2026 planning while reserving the granular segmentation, regional revenue splits, and company-level market share calculations for the full intelligence suite. For executives who require precise quantification to support capex allocation, inventory planning, and competitive positioning, the complete dataset is available through the official report portal.
Metal Powder Gas Atomizer Market
Macro Trajectory and the 2026 Baseline
The sunglasses category has proven remarkably durable through a period of volatile input costs, shifting consumer spending patterns, and accelerated channel reconfiguration. Historical performance from 2020 through 2025 reveals a consistent upward arc, with revenue climbing from 120.0 million to 190.0 million. That expansion sets a robust platform for the forecast period, during which the market is projected to advance from 208.13 million in 2026 toward 310.0 million by 2032, sustaining a compound annual growth rate of 6.5 percent.
Roto-Molded Spray Box Market
This growth profile is not merely a function of baseline consumer demand. It reflects a convergence of product innovation, category blending, and strategic consolidation that is reshaping the competitive field. The 2026 snapshot of 208.13 million serves as a pivotal reference point for scenario modeling: it captures post-tariff cost realignment, early-cycle adoption of sustainable material platforms, and the initial market response to newly announced brand portfolio expansions. Decision-makers who anchor their planning to this baseline, rather than to historical averages alone, will be better positioned to calibrate production schedules, channel commitments, and promotional calendars.
The forecast arc from 2027 onward—progressing through 214.71 million, 244.01 million, 253.97 million, and ultimately 263.27 million in 2030 before reaching 297.96 million in 2031 and 310.0 million in 2032—signals an acceleration profile that rewards early-mover advantage in product architecture and supply chain resilience. Organizations that treat the 6.5 percent CAGR as a directional signal rather than a mechanical extrapolation will uncover specific pockets of outperformance that the full report quantifies in detail.
Structural Shifts Defining the 2026 Competitive Arena
Behind the aggregate numbers lies a market that is consolidating around a small set of dominant players while simultaneously fragmenting in product nuance. The concentration profile is pronounced: the top three firms command approximately 65.0 percent of market revenue, and the top five extend that control to roughly 80.0 percent. This dual characteristic—high concentration at the top, diverse specialization below it—creates a strategic environment where scale advantages in manufacturing, brand licensing, and distribution coexist with acute pressure to differentiate on lens technology, material provenance, and lifestyle alignment.
For 2026 planning, this structure has three practical implications. First, premium and lifestyle-driven segments are increasingly anchored by a limited number of multi-brand platforms, which means licensing strategy, co-brand architecture, and retail partnerships carry outsized weight. Second, mid-tier and performance-oriented players are competing on functional specificity rather than broad brand recognition, elevating the importance of lens engineering, fit ergonomics, and use-case marketing. Third, channel dynamics are being reshaped by cost pressures that originate upstream in raw material inputs and trade policy, requiring executives to model margin sensitivity across both domestic and cross-border sourcing routes.
The report dissects these dynamics through a structured lens that connects product architecture, application orientation, and geographic distribution to operational decision points. Rather than presenting static snapshots, the analysis maps how each structural layer interacts with pricing strategy, inventory turnover, and brand portfolio mix, enabling readers to identify where concentration confers advantage and where it creates vulnerability.
Product and Application Architecture: Where Value Is Created
The sunglasses category is no longer a single product class. It is a portfolio of specialized sub-segments, each with distinct engineering requirements, consumer expectations, and margin structures. The report organizes this complexity into type-level and application-level frameworks, revealing how polarized optics, mirrored aesthetics, and photochromic adaptability compete for consumer attention and retailer shelf priority.
Polarized lenses anchor the largest value pool within the type segmentation, driven by their dual appeal in both lifestyle and performance contexts. Their dominance reflects a broad consumer familiarity with glare reduction and visual comfort, as well as a growing emphasis on outdoor activity and travel-oriented apparel coordination. Mirrored sunglasses occupy a smaller but strategically significant position, leveraging fashion-forward reflectivity and brand-adjacent styling to capture attention in premium and trend-sensitive channels. Photochromic sunglasses represent a more specialized niche, appealing to consumers who value adaptive lens behavior across changing light conditions and who prioritize convenience in transitional environments.
On the application side, the market's value distribution is heavily weighted toward fashion and lifestyle use cases, which reflect the category's enduring role as both a functional accessory and a style expression. Sports and outdoor applications form a smaller but highly engaged segment, where product specifications such as impact resistance, comfort during extended wear, and lens clarity directly shape purchase decisions. Professional and safety-oriented use cases, while comparatively limited in revenue contribution, carry distinct regulatory and procurement requirements that reward reliability, certification compliance, and institutional purchasing relationships.
The full report quantifies each of these segments with precise revenue estimates and growth trajectories, allowing readers to assess where their product portfolios align with category momentum and where reallocation may be warranted. For 2026 decision-making, this segmentation is especially valuable because it connects directly to inventory planning, promotional targeting, and channel mix. Executives who understand which application domains are expanding fastest, and which lens types are gaining retail placement velocity, can prioritize SKU development and markdown strategy with far greater confidence.
Geographic Dispersion and the Regional Playbook
Geographic distribution is another layer where the report provides decision-grade clarity. The market's revenue is spread across a set of regional pools, each with its own consumer behavior patterns, channel maturity, and sensitivity to trade and materials dynamics. North America, Europe, and Asia Pacific collectively represent the largest revenue bases, while Latin America and the Middle East and Africa contribute smaller but strategically meaningful volumes.
Rather than treating geography as a static map, the analysis frames each region as a distinct operating environment with specific implications for assortment planning, pricing architecture, and distribution strategy. In mature markets, growth is increasingly tied to premiumization, brand storytelling, and retail experience quality. In emerging or mid-maturity markets, volume expansion is often supported by broader accessory adoption, growing outdoor recreation participation, and expanding retail footprints. The interplay between these regional profiles and the global concentration structure means that multinational producers and licensing platforms must carefully calibrate which brands, lens technologies, and price tiers are prioritized in each market.
The report's regional decomposition is designed to support this kind of market-by-market calibration. It isolates the revenue contributions and directional trends that help executives answer practical questions: which regions merit deeper brand investment, where distribution partnerships should be strengthened, and how assortment breadth should be adjusted to match local demand signals. The detailed regional figures and growth rates are reserved for the full publication, where they can be cross-referenced with channel data, brand-level performance, and tariff-impact scenarios.
Material Economics, Trade Policy, and Cost Architecture
One of the most immediate pressures shaping 2026 strategy is the evolving cost environment around raw materials and trade policy. Industry reporting indicates that additional duties on Chinese-origin materials, effective in February and March 2025, have disrupted eyewear production costs and supply chains. At the same time, tariffs on goods from Mexico and Canada at 25 percent, also effective in March 2025, are expected to increase production costs and require supply chain adjustments for optical products. Further pressure comes from steel and aluminum duties at 25 percent, effective March 12, 2025, which affect material inputs for eyewear manufacturing.
These policy shifts do more than raise input prices. They alter the relative attractiveness of different sourcing routes, influence the economics of frame construction and lens assembly, and change the cost-benefit calculus for nearshoring versus offshore production. For category participants, the practical challenge is to incorporate these cost dynamics into margin planning, pricing strategy, and inventory timing without losing responsiveness to consumer demand signals.
Sustainability is intersecting with this cost architecture in ways that are becoming commercially meaningful. One notable example involves the rollout of eco-frame collections using over 60 percent recycled inputs, which has driven a 12 percent unit mix shift toward sustainable SKUs in EMEA retailers during peak seasons. This is not merely a branding exercise; it reflects a measurable change in what retailers and consumers are selecting within the assortment, and it signals that material provenance is increasingly part of the purchasing decision. The report examines these developments within the broader context of production economics, showing how sustainability commitments can align with cost management, retailer engagement, and product differentiation when they are executed with operational precision.
Competitive Landscape: Scale, Specialization, and Portfolio Choreography
The competitive field in sunglasses is defined by a small group of large-scale platforms and a set of specialized players that compete on product performance, brand identity, and use-case authority. Understanding how these companies position themselves is essential for 2026 planning, because their strategies shape retail assortments, consumer expectations, and the pace of innovation across lens technology and frame design.
EssilorLuxottica operates as a dominant force through premium brands including Ray-Ban, Oakley, Costa, and Oliver Peoples, with extensive global production of polarized and photochromic lenses. Its scale allows it to influence category standards in lens engineering, distribution reach, and brand licensing. Kering Eyewear offers sunglasses under Maui Jim, Gucci, and other luxury brands, emphasizing polarized lenses and adventure-oriented collections. Its strategy blends heritage luxury positioning with performance-oriented lens technology, creating a bridge between style-driven and activity-driven consumer segments.
Safilo Group produces and distributes sun and optical frames with a strong emphasis on lifestyle, sport, and performance sunglasses. Its portfolio orientation makes it a significant player in the middle and upper tiers of the market, where brand relevance and product versatility are key. De Rigo Vision specializes in eco-friendly and high-performance sunglasses, including frames with recycled inputs and lifestyle collections, positioning sustainability as a core differentiator rather than an adjunct attribute. Marcolin manufactures sunglasses for licensed brands including Tom Ford, Adidas, and Timberland, focusing on fashion and performance, and thereby operates at the intersection of brand licensing and product execution.
Beyond the large platforms, several specialized companies illustrate the value of use-case authority. Maui Jim provides polarized sunglasses for fishing, outdoor sports, and adventure, with proprietary lens technology that reinforces its credibility in performance contexts. goodr produces affordable, fun, and polarized active sunglasses designed for no-slip and no-bounce performance, targeting a more value-conscious but activity-focused consumer. Bajio Sunglasses focuses on premium polarized sunglasses for fishing and water sports, emphasizing adventure and outdoor use, and demonstrating how a narrow application focus can support a distinct brand identity and loyal customer base.
Recent Strategic Moves and What They Signal for 2026
The competitive landscape is not static. Recent developments provide a live readout of how major participants are positioning for the forecast period. In February 2025, Maui Jim unveiled the Color You Can Feel 2 global advertising campaign for its Ekolu spring-summer collection, highlighting adventure and connection themes. This move underscores the continued importance of narrative-driven marketing in outdoor and lifestyle sunglasses, where emotional association and activity context amplify product relevance.
In May 2026, Safilo Group signed a binding agreement to acquire Spy+ and Serengeti, expanding its sunglasses portfolio. This acquisition signals a deliberate push to broaden brand coverage and strengthen the company's foothold across lifestyle and performance niches. Also in May 2026, EssilorLuxottica showcased future-ready eyewear solutions at Vision Expo 2026, reinforcing its focus on product innovation and forward-looking category leadership. Together, these moves highlight a market where portfolio expansion, brand acquisition, and technology showcasing are being used to lock in share and shape consumer perception ahead of the forecast window.
For decision-makers, the strategic takeaway is clear: consolidation and brand-building are accelerating, and the companies that define the category's next phase will be those that can combine scale with credible specialization. The report's competitive analysis goes beyond event tracking to assess how these moves alter channel leverage, assortment diversity, and the bargaining position of retailers and licensees. The full study provides the company-level context needed to evaluate where competitive pressure is intensifying and where strategic whitespace remains.
What the Full Study Delivers for 2026 Planning
This preview is built to establish the analytical frame behind our Sunglasses Market research. The complete report extends this foundation into a detailed, decision-oriented instrument that connects market sizing, segmentation, competitive profiling, and industry dynamics to executable strategy. It is designed for teams that need to move from high-level understanding to specific action in product planning, channel strategy, sourcing, and brand positioning.
Readers who engage with the full study will gain access to precise segmentation values across type, application, and region; company-level context that maps strategic positioning and recent developments; and structured analysis of how trade policy, raw material costs, and sustainability adoption are reshaping production economics. The report also integrates historical performance from 2020 through 2025 with the 2026-2032 forecast, enabling scenario comparison and sensitivity testing around growth assumptions, cost pressure, and portfolio mix.
For executives preparing 2026 plans, the strategic value lies in the report's ability to translate market structure into operational choices. That means understanding not only how large the market is, but where the value is concentrated, which product and application segments are gaining momentum, how regional demand signals differ, and how the competitive field is being reconfigured through acquisitions, brand campaigns, and technology showcases. The complete intelligence suite is available through the official report page, where the full dataset, segmentation detail, and competitive analysis can be reviewed in context.
Closing Perspective
The sunglasses market in 2026 is defined by resilient demand, high concentration, and a growing premium on specialization. Growth from 190.0 million in 2025 to a forecast of 208.13 million in 2026, and ultimately toward 310.0 million by 2032 at a 6.5 percent CAGR, creates opportunity for organizations that can act with precision. But opportunity in a concentrated, cost-sensitive, and brand-driven market rewards those who can see beyond headline numbers and understand the structural forces shaping product, channel, and competitive outcomes.
Our Sunglasses Market study is built to provide that structural clarity. It is designed to help leaders make informed decisions about where to invest, what to emphasize in assortment and messaging, how to respond to material and tariff pressures, and how to position against a competitive set that is both consolidated and rapidly evolving. For teams that need the full segmentation detail, regional revenue figures, and company-level intelligence to support 2026 commitments, the complete report is available through the source page, where the full depth of the analysis can be accessed and applied directly to strategic planning.
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gantry/Cartesian Robots Market to Grow at 9.4% CAGR, Reaching $5.9B by 2032
By PW Consulting, 2026-09-07
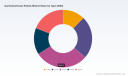
Strategic Horizon: Navigating the Gantry and Cartesian Robots Market Through 2032
The industrial automation landscape is undergoing a structural transformation, driven by the need for precision, scalability, and cost-efficiency in manufacturing environments. At the forefront of this shift is the Gantry and Cartesian Robots Market, a sector witnessing robust expansion as industries seek to optimize material handling, assembly, and processing workflows. PW Consulting's latest comprehensive study provides a critical roadmap for stakeholders aiming to capitalize on this growth trajectory. With a forecast period extending through 2032, this research moves beyond superficial market sizing to offer actionable intelligence on competitive dynamics, technological shifts, and regional deployment nuances.
Worldwide Medium Voltage Submarine Cable Market
For enterprise decision-makers, the value of this report lies not merely in historical validation but in its predictive capacity. The market has demonstrated resilience and consistent upward momentum, evolving from a niche automation solution to a cornerstone of modern factory architecture. By analyzing the interplay between raw material fluctuations, regulatory frameworks, and technological innovation, this study equips leaders with the insights necessary to mitigate risk and identify high-value opportunities in a crowded competitive field.
Worldwide Dry Type Cylinder Liner Market
Market Trajectory and Growth Vectors
The historical performance of the Gantry and Cartesian Robots Market underscores a clear trend of accelerating adoption. Between 2020 and 2025, the market revenue climbed steadily, reflecting a compound annual growth rate that signals sustained investor confidence and industrial demand. This growth is not accidental; it is the result of converging factors including labor shortages in key manufacturing hubs, the push for higher throughput in logistics, and the increasing complexity of production lines requiring precise multi-axis movement.
Mobile Application Testing Tools Market
Looking forward, the forecast period from 2026 to 2032 projects a continued expansion at a significant CAGR. This trajectory suggests that the market will more than double its value over the forecast horizon, driven by underlying demand across diverse application segments. The report details how specific use cases are fueling this demand, highlighting the dominance of material handling and palletizing operations while noting the rising interest in specialized welding and assembly applications. However, the true strategic value for your organization lies in understanding the velocity of this growth across different robotic configurations. Whether evaluating one-axis solutions for simple tasks or multi-axis gantry systems for complex payloads, the research delineates where capital allocation will yield the highest return on investment.
It is crucial for stakeholders to recognize that this growth is not uniform. Regional disparities play a significant role in shaping market access strategies. The report provides a granular breakdown of revenue contributions across major geopolitical zones, allowing companies to tailor their go-to-market strategies based on local industrial maturity and automation readiness. While some regions exhibit mature, saturated markets requiring differentiation strategies, emerging economies present greenfield opportunities where automation adoption is just beginning to accelerate. Understanding these regional nuances is essential for supply chain planning and sales force deployment.
Competitive Landscape and Strategic Positioning
The competitive environment within the Gantry and Cartesian Robots Market is characterized by a mix of specialized niche players and established industrial giants. Market concentration metrics indicate a moderately fragmented landscape, suggesting that while major players hold significant sway, there is ample room for specialized solution providers to capture value through innovation and targeted application expertise. PW Consulting's analysis profiles key entities that are defining the pace of this market, offering insights into their strategic focus and capacity for innovation.
Germany remains a powerhouse for engineering excellence in this sector, with firms like igus leading the charge in maintenance-free plastic linear robots. Their focus on cost-effective pick-and-place and palletizing solutions addresses a critical pain point for operations seeking to reduce lifecycle costs. Similarly, Festo continues to strengthen its position with ready-to-install Cartesian robots and 3D gantries based on linear and slide drives, emphasizing ease of integration for system integrators. Another German entity, Dunkermotoren, is carving out a niche with gantry systems utilizing ServoTube linear motors, specifically targeting high-speed packaging and electronics assembly where precision and speed are paramount.
In Japan, the competitive landscape is defined by robust factory automation capabilities. Yamaha Motor Co., Ltd. offers the XY-X series Cartesian robots, catering to high-performance factory automation needs with both moving arm and gantry types. IAI Automation complements this with compact 2- to 6-axis Cartesian robots featuring linear drives and parallel kinematics, appealing to applications where footprint size and flexibility are critical. Janome Industrial Equipment rounds out the Japanese contingent with standard Cartesian robots focused on cost-effective industrial handling, ensuring a broad entry point for manufacturers with budget constraints but high volume requirements.
Switzerland contributes high-precision heavy-load capabilities through Güdel Group AG, whose FP-5 and gantryRobot series are designed for handling loads up to several tonnes with high precision. This positions Güdel uniquely in sectors requiring substantial payload capacity without sacrificing accuracy. Across the Atlantic, the United States hosts a diverse set of competitors. Physik Instrumente (PI) USA specializes in precision modular XY/Z and XYZ gantries with air bearings and linear motors, targeting high-value sectors like semiconductor manufacturing and 3D printing. Nordson EFD focuses on 3-axis Cartesian systems for adhesive dispensing and material handling, addressing specific process requirements in assembly and packaging. Promation offers tabletop Cartesian robots for soldering and electronics assembly, catering to the nuanced needs of the electronics production ecosystem.
Recent strategic developments among these key players highlight the dynamic nature of the market. In late 2025, Yamaha Motor Co., Ltd. established TY ROBOTICS Co., Ltd. through a joint venture with Taiwanese partner TOYO Automation. This move aims to transfer single-axis and Cartesian robot production starting in early 2026, intended to expand lineups and reduce lead times. Such vertical integration and partnership strategies are critical indicators of where supply chain bottlenecks may be alleviated and where pricing power might shift. Furthermore, in early 2026, Festo introduced a GripperAI AI-based gripper solution compatible with Cartesian systems. This innovation enables mixed-product handling and faster deployment without brand lock-in, signaling a broader industry trend toward modularity and software-defined hardware capabilities. Meanwhile, the International Federation of Robotics featured Güdel's FP-5 gantry robot in a 3D concrete printing application, demonstrating real-world heavy-load precision in the construction industry, thereby validating the technology's expansion beyond traditional manufacturing into infrastructure.
Industry Dynamics and Operational Realities
Navigating the Gantry and Cartesian Robots Market requires a clear understanding of the headwinds and tailwinds shaping operational feasibility. The report delves deep into the macro-environmental factors that influence procurement, deployment, and long-term reliability. One of the most pressing issues analyzed is the volatility in raw material costs. Since 2022, prices for steel and rare-earth magnets have fluctuated significantly year-on-year. This volatility exerts direct margin pressure on manufacturers of linear guides and ball screws, which are core components of gantry systems. The research quantifies how these variations have compressed gross margins in standard-grade segments, providing a basis for more robust negotiation strategies with suppliers and more accurate cost forecasting for internal budgets.
Regulatory compliance represents another critical dimension of market dynamics. Strict regulatory standards and safety requirements, particularly in North America, impose significant restraints on the deployment of heavy industrial robots, including gantry systems. The report outlines how these constraints affect implementation timelines and total cost of ownership. Updated standards from 2025, including ISO and ANSI requirements, now necessitate comprehensive risk assessments for collaborative applications involving gantry robot cells. For compliance officers and plant managers, understanding these evolving mandates is not optional; it is a prerequisite for avoiding costly retrofits or operational shutdowns. The study provides a framework for interpreting these regulations in the context of Cartesian systems, helping organizations stay ahead of compliance curves.
Conversely, energy efficiency is emerging as a powerful driver for adoption. Manufacturers are increasingly integrating energy-efficient designs into robotic systems to minimize power consumption during intensive operations like heavy material handling. As energy costs rise and sustainability mandates tighten, the Total Cost of Ownership (TCO) calculation for automation equipment is shifting. Systems that offer lower energy consumption per cycle are gaining preference over those that prioritize speed alone. The report analyzes how leading vendors are responding to this demand through design innovations, allowing buyers to factor energy efficiency into their ROI calculations alongside acquisition costs.
Segmentation and Application Depth
A core strength of this market research is its detailed segmentation analysis, which goes beyond surface-level categories to explore the specific drivers within each segment. The market is categorized by type, application, and region, providing a multi-dimensional view of demand. In terms of robotic configuration, the demand varies significantly based on the complexity of the task. From single-axis systems used for simple linear transfers to complex multi-axis gantries capable of intricate manipulation, the report maps the revenue contribution and growth potential of each configuration. This allows engineering teams to align their technology roadmaps with market realities, ensuring that internal R&D efforts are directed toward configurations with the highest commercial viability.
Application-wise, the market is driven largely by material handling and palletizing, which account for a substantial portion of revenue. However, the report also highlights the growing sophistication in welding and other specialized applications. For instance, the use of Cartesian systems in adhesive dispensing and electronics assembly is creating new revenue streams for vendors who can offer specialized end-effectors and control systems. The analysis covers how different industries are adopting these technologies at varying rates. Logistics and warehousing continue to be strong adopters due to the need for speed and accuracy in order fulfillment, while heavy industry sectors are leveraging gantry systems for tasks that require significant payload capacity and repeatability. By understanding which application segments are most resilient to economic downturns and which are most sensitive to technological disruption, companies can diversify their portfolio risks effectively.
Strategic Implications for 2026 and Beyond
The insights provided in this report are designed to inform critical decisions in 2026 and the subsequent forecast period. For procurement leaders, the data on raw material trends and margin pressures offers a basis for strategic sourcing and inventory management. understanding the cost structures of key competitors can empower negotiation teams to secure better terms and lock in pricing stability amidst volatile markets. For product managers and R&D directors, the analysis of recent product launches and joint ventures provides a benchmark for innovation. The shift toward AI-enabled grippers and modular systems suggests that future competitiveness will depend on software integration and flexibility as much as on mechanical hardware.
Sales and marketing teams will find significant value in the regional segmentation and application breakdowns. Knowing where demand is concentrated allows for targeted campaign spending and distributor partnership selection. For example, recognizing the stringent safety regulations in North America helps sales teams prepare compliant solution packages that address customer concerns proactively, shortening the sales cycle. Conversely, identifying emerging regions with growing automation needs allows companies to establish a foothold before the market becomes saturated.
Furthermore, the report serves as a vital tool for investment strategy. Whether considering M&A opportunities, partnerships, or capacity expansion, the market concentration data and growth forecasts provide the necessary context to evaluate potential returns. The identification of key players and their recent strategic moves, such as production transfers via joint ventures or the launch of AI-compatible hardware, signals where industry consolidation or capability upgrades may occur. Investors and corporate strategists can use this intelligence to anticipate market shifts and position their assets accordingly.
Conclusion: The Intelligence Advantage
In a market growing at a robust pace with significant complexity in technology and regulation, information asymmetry is a competitive disadvantage. PW Consulting's Gantry/Cartesian Robots Market research eliminates this disadvantage by providing a unified, data-driven view of the landscape. From the macroeconomic drivers influencing overall market size to the micro-level details of competitor product offerings and regulatory constraints, this study covers the full spectrum of factors that define success in this sector.
The forecast to 2032 indicates that the growth story is far from over. As industries continue to digitize and automate, the demand for precise, reliable, and efficient linear motion solutions will only intensify. However, capturing this growth requires more than just participation; it requires strategic clarity. This report offers that clarity, enabling leaders to distinguish between transient trends and structural shifts.
We invite you to explore the full depth of this analysis. The insights summarized here are drawn from a comprehensive dataset that includes detailed segmentation splits, regional revenue breakdowns, and extensive competitor profiling. To access the complete intelligence required for your specific strategic planning, including granular data on market concentration and detailed case studies of recent industry developments, please visit the full report page. Secure your organization's competitive edge with the precise data needed to navigate the future of industrial automation.
For detailed analysis of this topic, please visit the official page: Gantry/Cartesian Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
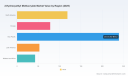
Strategic Horizons: Navigating the 2-Hydroxyethyl Methacrylate Market in 2026 and Beyond
The global specialty chemicals landscape is entering a decisive inflection point, where material science innovation intersects with evolving regulatory frameworks and shifting end-user demands. At the center of this transformation sits 2-Hydroxyethyl Methacrylate, a versatile monomeric building block whose applications span from high-performance automotive coatings to advanced biomedical hydrogels. As industry leaders prepare their capital allocation and product roadmaps for 2026, understanding the structural forces shaping this market has moved from optional intelligence to operational necessity.
Vacuum Bagging Breather Fabric Market
This executive briefing introduces the latest PW Consulting market research on the 2-Hydroxyethyl Methacrylate sector, crafted specifically to equip decision-makers with a forward-looking, data-anchored perspective. The following analysis outlines the macro trajectory, competitive architecture, and regulatory-material dynamics that will define strategic choices over the coming planning cycle, while preserving the granular segmentation intelligence that only the full report delivers.
Worldwide Steel Radiator Market
A Market in Measured Expansion: Framing Growth for the 2026 Planning Cycle
Over the historical review window from 2020 through 2025, the 2-Hydroxyethyl Methacrylate market has demonstrated consistent, compound-driven expansion. Revenue progression over this period reflects a sector that has absorbed raw material volatility, supply chain disruptions, and regional demand rebalancing while maintaining a fundamentally upward trajectory. By the close of the base year, total market revenue had climbed to a level that underscores the material's entrenched role across multiple industrial value chains.
Intra-city Logistics Market
Looking forward, the forecast horizon running from 2026 through 2032 signals a continuation of this momentum. The market is projected to reach approximately 550.99 million USD in 2026, building on a 2025 base of 531.0 million USD. This represents a notable step-up in absolute terms and sets the stage for sustained growth through the end of the decade. By 2032, the sector is anticipated to approach the 700 million USD threshold, reflecting the cumulative effect of capacity investments, application diversification, and the gradual penetration of higher-purity grades in quality-sensitive verticals.
Underlying this trajectory is a compound annual growth rate of 4.2% across the forecast period. For strategic planners, this figure is more than a historical abstraction—it is a baseline for scenario modeling. It informs decisions around production scaling, inventory positioning, pricing architecture, and partnership structures. A growth rate in this band suggests a market that is neither stagnant nor hyper-heated, but rather one where disciplined execution, grade specialization, and regional demand alignment will separate high-performing operators from those locked into commoditized competition.
The full report unpacks this trajectory with detailed year-by-year revenue modeling, allowing readers to stress-test their internal forecasts against our multi-scenario projections. What remains critical at this stage is recognizing that the headline growth figure masks a layered reality: different purity tiers, application segments, and geographies are expanding at divergent speeds, and the strategic implication of that divergence is precisely what our deeper analysis illuminates.
The Structural Anatomy of Demand: Purity Tiers, Application Verticals, and Regional Weighting
One of the most operationally significant dimensions of the 2-Hydroxyethyl Methacrylate market lies in how demand fractures across purity specifications. Not all end-use environments tolerate the same molecular consistency, and the price-quality trade-off is a decisive lever in formulation engineering. Our research tracks three principal purity bands, each serving a distinct set of performance requirements and cost constraints.
Mid-tier and high-tier purity grades continue to anchor a broad swath of industrial consumption. Applications where clarity, reproducibility, and regulatory compliance are less stringent can operate effectively with specifications that balance cost efficiency against acceptable performance envelopes. At the other end of the spectrum, ultra-high-purity variants are becoming an increasingly strategic differentiator, particularly in segments where optical clarity, biocompatibility, or long-term stability dictate formulation architecture. The emergence of grades pushing toward and beyond 99% purity signals that downstream formulators are willing to absorb premium pricing when the material directly enables product performance or regulatory passage.
On the application side, demand fragmentation tells a story of both concentration and diversification. Coatings represent the largest single consumption channel, reflecting the monomer's foundational role in film formation, adhesion promotion, and surface engineering. Reactive resin systems occupy the second tier of consumption, where the monomer's chemistry enables cross-linking architectures critical to three-dimensional printing, casting applications, and advanced composite fabrication. Adhesives form another substantial pillar, leveraging the material's bonding characteristics across industrial assembly, medical device construction, and specialty packaging. Beyond these core verticals, a residual category captures specialty and emerging uses that collectively contribute meaningful incremental demand.
Regionally, the market exhibits a decidedly global footprint, but one where Asia Pacific carries disproportionate weight in absolute consumption. This concentration aligns with the region's expansive manufacturing base, growing formulation capacity, and accelerating adoption of high-performance materials across electronics, medical, and industrial segments. North America and Europe each command meaningful shares, driven by mature industrial ecosystems, stringent quality expectations, and sustained investment in specialty coatings and biomedical applications. Latin America and the Middle East and Africa regions, while smaller in absolute terms, present growth pockets where industrial modernization and localized formulation capacity are steadily expanding the addressable user base.
Crucially, our report does not treat these segmentation layers as static snapshots. It maps how purity preferences migrate across regions and applications over time, how regulatory pressure reshapes grade selection, and where substitution risk or premium-grade migration is most likely to alter share balances. The strategic implication is clear: companies that position themselves solely on a global average view of the market will miss the localized grade shifts and application re-rating events that actually drive margin outcomes.
Voice of the Market: Competitive Posture and Company-Level Strategic Moves
The competitive landscape for 2-Hydroxyethyl Methacrylate is shaped by a mix of regional suppliers, specialized chemical manufacturers, and downstream-oriented formulators that influence grade standards and application specifications. Market concentration metrics indicate a moderately consolidated environment, with three major players accounting for a substantial share of total revenue and the top five firms extending that control further. This structure creates a market where scale, grade capability, and customer intimacy all matter, but where focused players can compete effectively by owning specific purity niches or application alliances.
Several companies stand out for their active positioning in the 2-Hydroxyethyl Methacrylate value chain. Shakti Chemicals, headquartered in Mumbai, operates as a trader and supplier supporting polymer chemistry applications across Asia, providing a commercial bridge between production capacity and regional formulation demand. In China, Qingdao RENAS Polymer Material Co., Ltd. has established itself as a manufacturer and supplier focused on polymer materials and specialty chemicals, aligning its product line with the country's expanding materials ecosystem. Nantong Chem-land Co., Ltd. similarly functions as an active trader and supplier, offering high-purity grades tailored for industrial and specialty use. Yancheng Green Chemicals Co., Ltd. rounds out this group as a manufacturer supplying polymer synthesis and advanced chemical applications, reflecting the breadth of production-oriented entrants in the region.
Beyond these core suppliers, the broader competitive narrative is increasingly defined by product innovation and application co-development among larger multinational and specialty chemical players. Recent industry activity underscores how grade engineering and end-use collaboration are becoming central to competitive differentiation rather than raw volume expansion alone.
Recent Developments as Strategic Signals
A notable product introduction occurred in mid-2025, when Chemical United launched HEMA HISS, an ultra-pure grade reaching 99.5% specification. The formulation was optimized for high-clarity applications in soft contact lenses, three-dimensional printing resins, medical hydrogels, and high-gloss coatings. This launch illustrates a market trend in which purity advancement is directly tied to performance claims that matter in regulated and quality-sensitive verticals. Delivering a grade with that level of specification is not merely a technical achievement—it is a commercial signal that the demand ceiling for premium HEMA is extending into biomedical and optical applications where tolerance for impurities is minimal.
In late 2024, Dow pursued an application development collaboration with an automotive manufacturer centered on a new HEMA-based coating for electric vehicle batteries. The project focused on enhancing thermal management and extending battery life, linking the monomer's surface and film-forming properties to a high-priority automotive engineering challenge. This type of collaborative development is telling: it shows that 2-Hydroxyethyl Methacrylate is being evaluated not just as a commodity component, but as an enabling element in advanced mobility solutions where thermal resilience and coating durability directly affect product performance.
Earlier in 2024, Evonik introduced VISIOMER HEMA-P 100, a phosphate methacrylate monomer derived from 2-Hydroxyethyl Methacrylate. The offering targeted improved flame retardancy, adhesion, and corrosion resistance in coatings and composites, expanding the functional utility of HEMA-derived chemistry into performance-enhanced material systems. By extending the monomer's value chain into derivative formulations, Evonik demonstrated how innovation can create premium downstream markets even as base monomer demand follows its own growth rhythm.
These developments collectively reinforce a central insight: competitive advantage in this market is increasingly derived from specification leadership, application co-engineering, and derivative innovation rather than pure production volume. The full report provides a structured examination of how each profiled company positions itself across these dimensions, including capability mapping, commercial orientation, and the likely strategic implications of their respective market postures.
Regulation, Raw Materials, and Environmental Boundaries as Strategic Variables
No strategic assessment of the 2-Hydroxyethyl Methacrylate market would be complete without accounting for the regulatory and operational constraints that shape the playing field. These factors do not merely set compliance baselines; they influence grade architecture, market access, formulation substitution, and the relative attractiveness of different application verticals.
Raw material dependency remains a foundational variable. HEMA production relies on ethylene glycol as a key upstream feedstock, and the price behavior of that input is closely tied to crude oil and natural gas cycles. This linkage means that margin planning cannot be isolated from energy market volatility. Suppliers and buyers alike must contend with cost fluctuations that ripple through procurement contracts, pricing strategies, and inventory timing. In a market where growth is steady but not explosive, raw material cost management can be as decisive as volume growth in determining profitability.
Regulatory divergence across regions introduces additional complexity. In the European Union, the Cosmetics Regulation has placed specific constraints on 2-Hydroxyethyl Methacrylate in nail cosmetics, limiting its use to professional applications only. The framework mandates specific labeling requirements and bars non-compliant products from market entry, a rule that has been actively enforced since September 2021. This regulatory posture narrows the accessible consumer-facing segment in Europe and shifts opportunity toward professional channels and alternative chemistries where appropriate. Meanwhile, the United States maintains a more permissive stance for certain medical and dental applications, allowing use in dental adhesives, medical tapes, and wound dressings without equivalent professional-use restrictions. This contrast creates an uneven regulatory terrain in which product positioning and market entry strategies must be tailored by jurisdiction rather than assumed globally uniform.
Environmental considerations further shape operational planning. HEMA is subject to hydrolysis into methacrylic acid and ethylene glycol, and producers are required to monitor and treat effluent to limit release to approximately 0.02 tonnes per year per plant. While this parameter originates from long-standing chemical assessment reporting, it remains relevant as a benchmark for environmental management and as a reminder that production compliance is tied to continuous effluent control. In an era where sustainability reporting and chemical stewardship are increasingly scrutinized, environmental management is not just a regulatory obligation but a reputational and operational consideration.
For high-purity applications, technical standards add another layer of discipline. ISO requirements for grades at or above 99% purity are in place for biomedical and pharmaceutical applications, mandating rigorous distillation and testing protocols. This means that accessing premium biomedical demand requires demonstrable process control and quality assurance capability, which in turn influences which suppliers can credibly compete in that segment.
Together, these dynamics create a market environment where strategic planning must incorporate regulatory monitoring, raw material risk hedging, and quality infrastructure investment. The full report integrates each of these factors into the broader market outlook, allowing readers to evaluate how they may affect regional demand, grade selection, and competitive accessibility over the forecast horizon.
What the Full Research Delivers for 2026 Decision-Making
This market study is designed to serve as a working intelligence asset rather than a static reference document. For executives, commercial leaders, and strategy teams preparing 2026 plans, the report provides the analytical scaffolding needed to translate macro trends into actionable positioning. The following elements represent the core operational value of the full research:
- A complete revenue trajectory spanning the historical review period and the full 2026 through 2032 forecast window, enabling year-by-year benchmarking against internal projections and investment cases.
- Detailed segmentation mapping across purity grades, application verticals, and regional markets, giving readers the ability to identify where growth is most concentrated and where competitive exposure is most acute.
- A structured competitive landscape assessment covering key suppliers and specialty players, including company positioning, commercial focus, and the strategic meaning of recent product and application developments.
- An integrated analysis of raw material dependencies, regulatory distinctions, and environmental constraints, framed specifically in terms of their impact on pricing dynamics, market access, and grade strategy.
- Scenario-ready context for capacity planning, partnership evaluation, and product roadmap decisions, helping teams connect market signals to concrete strategic options.
The intent of this briefing has been to demonstrate the analytical rigor and strategic relevance of the study while preserving the detailed segmentation and company-level intelligence that constitute the full value of the report. Headline figures and structural themes provide a necessary orientation, but the decisions that matter most—grade portfolio choices, regional entry or expansion plans, supply chain risk mitigation, and application-focused innovation—are best informed by the deeper, segmented evidence base contained in the complete publication.
Conclusion: Positioning for a Market Defined by Precision and Adaptation
The 2-Hydroxyethyl Methacrylate market is entering 2026 with a clear growth baseline, a maturing competitive architecture, and an expanding set of performance-driven applications. The combination of steady compound growth, increasing emphasis on higher-purity grades, and active innovation in both end-use formulations and derivative chemistries points to a sector where precision, compliance capability, and application partnership will increasingly determine commercial success. Raw material volatility and regulatory divergence will continue to test operational discipline, rewarding companies that treat these variables as strategic inputs rather than external noise.
For organizations seeking to align their 2026 decisions with the market's actual contours rather than broad generalizations, the full PW Consulting research offers the depth required to move from awareness to action. By translating macro trends into segmented evidence and competitive context, the report supports more confident planning across supply strategy, commercial positioning, and product development. The complete analysis is available in our latest market research release, where the full set of figures, segmentation breakdowns, and company evaluations can be reviewed in detail.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Concrete Fibers Market Hits $215M in 2025, Projects 6.5% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-07

Strategic Imperatives in the Synthetic Concrete Fibers Market: A 2026 Outlook
As global infrastructure priorities pivot toward accelerated construction timelines, reduced reliance on primary steel reinforcement, and enhanced durability standards, the synthetic concrete fibers market has emerged as a critical nexus for construction materials strategy. At PW Consulting, we have compiled a comprehensive market intelligence report that examines the structural shifts, competitive dynamics, and forward-looking revenue trajectories shaping this sector. This article provides a strategic preview of the research, emphasizing the analytical dimensions that decision-makers will need to navigate the 2026–2032 period with confidence.
Worldwide Sun Tube Market
While the broader construction chemicals and fiber reinforcement landscape has historically been characterized by fragmented regional activity and application-specific substitution patterns, recent developments indicate a convergence of demand drivers, raw material volatility, and product innovation that warrants a more coordinated commercial approach. Our study is designed not merely as a retrospective data exercise, but as a decision-support instrument that maps probable market pathways, competitive positioning, and procurement sensitivity to macroeconomic and feedstock fluctuations. Readers seeking the full set of quantitative segmentation, regional breakdowns, and proprietary strategic assessments will find the complete report at our source platform, where the entire intelligence framework is available for institutional review.
Round-Type Drop Optical Fibre Cable Market
The market sizing embedded in our analysis reflects a sustained expansion trajectory. Drawing on historical baselines that track installed volume and value realization across multiple end-use environments, the market has demonstrated steady accumulation, moving from a base reflecting the 2020 period to a substantially larger revenue position by 2025. The forward projection extends through the 2032 horizon, capturing the anticipated compound annual growth implied by infrastructure modernization programs, industrial flooring upgrades, and recurring substitution of steel mesh and rebar in slab and precast applications. This growth cadence is neither linear nor uniform across segments; rather, it reflects a layered set of adoption curves where certain applications and geographies accelerate ahead of others, creating both first-mover advantages and supply-demand mismatches that require careful operational planning.
Overhead Bins Market
A defining feature of the current market era is the intersection of supportive end-use demand with persistent feedstock price variability. Synthetic fiber economics are closely linked to the cost and availability of polymer inputs, particularly polypropylene, which serves as the backbone for a majority of macro and micro synthetic reinforcement products. Recent market intelligence indicates that polymer price levels have experienced notable volatility, with regional benchmarks showing meaningful divergence across Northeast Asia, North America, and Europe. For fiber manufacturers, converters, and downstream concrete producers, these price movements influence not only input cost structures but also the timing of procurement contracts, inventory strategies, and pricing architecture for finished reinforcement solutions. Our report examines how this raw material sensitivity propagates through the value chain and what operational responses are emerging among leading participants.
At the same time, the competitive field is consolidating practices even as it retains a broad set of international and regional players. Market concentration metrics indicate that a limited group of firms accounts for a meaningful share of total revenue, yet the sector still accommodates a diverse ecosystem of specialty manufacturers, technology-driven entrants, and application-focused suppliers. This structure creates a competitive environment where differentiation is increasingly determined by technical service, product consistency, performance certification, and the capacity to support large-scale infrastructure and commercial projects with reliable supply. The companies that are gaining strategic visibility are doing so not solely through volume expansion, but by aligning product portfolios with specific substitution scenarios, such as replacing welded wire mesh, enhancing crack control, and improving impact resistance in demanding floor regimes.
Within this competitive landscape, several established participants illustrate the strategic directions that are shaping the broader market. Sika AG continues to reinforce its position through macro and micro synthetic fiber offerings designed to substitute steel reinforcement in slabs, industrial flooring, and precast applications, while simultaneously expanding production capacity in the United States to address growing demand from industrial flooring, mining-related construction, and sustainable building requirements. That capacity expansion signals an important strategic posture: aligning manufacturing footprint with regional demand centers and project pipelines. Mapefibre by MAPEI S.p.A. represents a parallel emphasis on crack control and steel replacement through macro and micro synthetic fibers, with blended resin formulations developed to optimize performance in concrete dosage and structural behavior. Euclid Chemical Company has advanced the narrative of application-anchored growth through technology that targets replacement of welded wire mesh and steel in floors and industrial applications, reinforced by recent supply partnerships tied to new manufacturing construction projects. FORTA Corporation has built recognition around virgin copolymer macro synthetic fibers intended for crack control, impact resistance, and steel replacement across slabs and infrastructure, while also extending its portfolio into micro and monofilament solutions for shrinkage crack control and micro-reinforcement. GCP Applied Technologies Inc. has focused on post-crack protection functionality and digital enablement, notably through updated mobile-based tools that improve analysis, cost evaluation, and submittal workflows for synthetic macrofibers.
Beyond these principal actors, the competitive set reaches into specialized and regionally embedded providers. BarChip Inc. emphasizes engineered high-performance macro and micro synthetic fibers with structural reinforcement credentials and project-level deployment in global infrastructure. Fabpro Polymers contributes specialized high-performance synthetic fibers for reinforced concrete, with application coverage spanning macro and micro types. Polyfibers maintains a broad product line of micro and macro synthetic fibers with technical support oriented toward global concrete reinforcement. Mighty Shield Sdn Bhd positions its macro and micro synthetic fibers around crack bridging, flexural resistance, and diversified use cases in shotcrete, precast, and pavement environments. Adfil has developed a portfolio spanning floors, precast, pattern-imprinted concrete, and tunneling applications, reflecting the breadth of end-use contexts in which synthetic fibers are being specified. Belgian Fibers likewise participates across macro and micro reinforcement scenarios, adding further depth to a market that is increasingly defined by application specialization rather than commodity substitution alone.
Recent developments provide a practical lens on how strategy is being enacted on the ground. In mid-2025, Euclid Chemical Company moved forward with a partnership to supply macro synthetic fiber for concrete reinforcement at a new automotive manufacturing and vehicle assembly plant, demonstrating how product placement is increasingly tied to landmark construction projects that serve as reference cases for specification and adoption. In parallel, Sika AG announced an increase in synthetic macro-fiber production capacity at its Tennessee facility, targeting industrial flooring, mining applications, and sustainable construction outcomes. These actions illustrate two complementary approaches: securing strategic project wins that expand reference coverage, and investing in regional capacity to reduce supply-chain friction and improve responsiveness. A third illustrative move occurred when GCP Applied Technologies Inc. introduced an updated version of its synthetic macrofiber mobile application solution, enhancing analytical speed, cost analysis features, and PDF-format submittal packages. This type of digital tooling is not merely a convenience layer; it reduces specification friction, accelerates engineering reviews, and strengthens the commercial case for fiber-based reinforcement by improving transparency around performance and cost trade-offs.
These developments must be read against the backdrop of raw material dynamics that have introduced new complexity into procurement and pricing. Polypropylene-linked costs have experienced significant movement, with year-to-date increases recorded in early 2026 and regional benchmarks that reflect disparity across major markets. Price levels observed in Northeast Asia, North America, and Europe have at various points diverged enough to influence sourcing logic, margin planning, and regional competitiveness. More recent observations also point to intermittent downward adjustments over short horizons, even as longer-term comparisons remain elevated relative to prior-year baselines. For market participants, this environment underscores the importance of hedging strategies, contract structuring, formulation efficiency, and value-engineering engagement with concrete producers who must balance performance requirements against total installed cost. Our research framework addresses these sensitivity points by mapping the interplay of input price behavior, regional manufacturing economics, and application-level demand intensity.
From a commercial standpoint, the synthetic concrete fibers market is shaped by three reinforcing themes. First, substitution momentum remains the central growth engine: the drive to reduce steel dependency in slabs, precast elements, and industrial flooring continues to expand the addressable space for both macro and micro synthetic fibers. Second, specification quality is becoming a differentiator: technical documentation, performance reliability, certification credibility, and digital support tools increasingly influence procurement decisions alongside unit price. Third, regional execution capability matters more than ever, because large-scale projects and infrastructure programs reward suppliers who can deliver consistent quality, project-level technical support, and supply continuity across geographies. These themes do not simply describe the market; they define the conditions under which competitive advantage is created and sustained.
Against that backdrop, our report provides a multi-layered examination of the market structure, demand architecture, competitive positioning, and forward trajectory. The analysis begins with historical market evolution, using a documented value progression across the 2020 to 2025 interval to establish a credible baseline for forward-looking modeling. It then examines the projected period from 2026 through 2032, where growth assumptions are anchored in continued infrastructure spend, industrial flooring modernization, and ongoing steel-replacement adoption. To support strategic interpretation, the research disaggregates the market by type, application, and region, enabling clients to isolate the segments that matter most to their commercial objectives. Instead of presenting segmentation as a static list of shares, the report evaluates the structural logic behind volume distribution, the relative attractiveness of each demand pool, and the operational implications of serving them at scale.
The study also examines the competitive environment in detail, including the role of market concentration in shaping pricing behavior, supplier bargaining power, and the strategic room available to mid-tier and specialty players. Rather than merely identifying top participants, the report interprets how their product strategies, project targeting, capacity decisions, and digital-service initiatives contribute to differential positioning. Recent company-level developments are integrated into this analysis to show how strategic moves are translating into market presence and supply chain advantage. In doing so, the research provides a practical template for assessing where competitive intensity is rising, where differentiation opportunities are expanding, and where risk concentrations may warrant strategic mitigation.
Equally important is the report’s treatment of raw material and cost-side dynamics. Because synthetic fiber offerings are closely tied to polymer feedstock economics, understanding the trajectory of input costs and regional price dispersion is essential for forecasting margins, shaping procurement policy, and evaluating supplier resilience. Our analysis connects observable price behavior with broader implications for formulation strategy, contract timing, regional sourcing decisions, and downstream pricing adaptability. This dimension is especially relevant for organizations that must respond to project specifications while maintaining cost competitiveness in an environment where feedstock benchmarks can shift materially over relatively short intervals.
The report further includes actionable strategic frameworks designed for corporate planning teams, product managers, procurement leaders, and investment analysts. These frameworks address questions such as which applications offer the strongest near-term adoption potential, how regional demand patterns differ in their growth drivers and specification maturity, what capacity and partnership strategies are most effective under current competitive conditions, and how firms can navigate feedstock volatility without compromising technical credibility or service quality. By tying market data to operational decision logic, the research is intended to support both strategic planning and near-term execution, rather than functioning purely as a high-level market overview.
There is also a clear emphasis on sustainability and performance rationale. The move toward synthetic fibers is not solely a cost-driven substitution story; it is increasingly aligned with broader construction objectives related to durability, crack mitigation, reduced steel consumption, and application flexibility across precast, floor, shotcrete, and tunneling environments. Suppliers that can articulate and validate these performance benefits with credible technical support and repeatable product quality are better positioned to capture specification share, especially in projects where long-term performance and lifecycle considerations weigh heavily in material selection. Our analysis evaluates how these value propositions are being communicated, where they are gaining traction, and what evidence standards are becoming expected by engineering and procurement teams.
Ultimately, the intent of this research is to provide a precise and usable understanding of how the synthetic concrete fibers market is likely to evolve, where competitive value will accrue, and what operational choices will determine commercial success through the late 2020s and into the early 2030s. The study presents a structured synthesis of market size progression, segmentation logic, competitive positioning, and raw material sensitivity, while leaving room for tailored interpretation based on each organization’s product focus, geographic exposure, and customer base. For decision-makers who require the full complement of segmented figures, regional trajectories, concentration analysis, and company-level strategic detail, the complete report is available through our research portal, where the entire dataset and accompanying strategic commentary can be reviewed in depth.
In a market where growth is real but uneven, and where raw material behavior, regional manufacturing footprints, and project-based specification patterns all influence outcomes, the organizations best positioned to succeed will be those that combine demand insight with disciplined execution. This report is designed to support that combination: giving leadership teams a credible view of market direction, competitive pressure points, and actionable priorities, while preserving the depth of segmentation and company-level analysis needed for precise strategic planning. For the full intelligence package, including complete segmentation data and proprietary strategic assessments, please access the full report on our source platform.
For detailed analysis of this topic, please visit the official page: Synthetic Concrete Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Recovery Market Exceeds $118M in 2025, Growing at 2.51% CAGR Through 2032
By PW Consulting, 2026-09-07
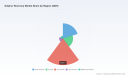
Strategic Imperatives in the Sulphur Recovery Market: A 2026 Outlook
The global energy landscape is undergoing a structural transformation, driven by the dual forces of tightening environmental regulations and the continued expansion of hydrocarbon processing capacity. At the center of this shift lies the sulphur recovery market, a critical infrastructure segment that converts hazardous acid gas streams into elemental sulphur while enabling refineries and gas processing facilities to meet stringent emission standards. As enterprises navigate the 2026 planning cycle, understanding the trajectory, competitive pressures, and regulatory catalysts shaping this market has moved from an operational afterthought to a boardroom priority. Our newly released Sulphur Recovery Market research provides a rigorous, data-grounded framework for strategic decision-making across engineering procurement, technology licensing, capacity expansion, and regulatory compliance.
Worldwide AEM Rubber Market
Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, this analysis distills macro-level market behavior into actionable intelligence. The overall market, measured in USD millions, expanded from approximately 103.53 in 2020 to 169.73 in 2024, reflecting sustained investment in desulfurization infrastructure, refinery modernization programs, and gas processing capacity additions across emerging and mature economies alike. The baseline year of 2025 records a revenue figure of 118.0, a moderation that aligns with cyclical project deferrals and the completion of several major capacity installations. From this base, the forecast period projects a compound annual growth rate of 2.51 percent, with market size anticipated to reach 117.45 in 2026, climb to 125.61 in 2027, and continue its upward trajectory toward 140.41 by 2032. These figures are not merely statistical projections; they represent the commercial footprint of capital allocation decisions, technology adoption curves, and the pace at which environmental compliance mandates translate into equipment and licensing demand.
Ultra Lightweight Bulletproof Helmet Market
Market Trajectory and Structural Drivers
The sulphur recovery market is defined by its capital intensity, technology specificity, and deep integration with upstream processing economics. Acid gas streams generated during crude oil refining and natural gas sweetening carry hydrogen sulfide concentrations that, depending on the processing configuration, can range from 5 to 30 percent, a feedstock variability that directly influences reactor sizing, catalyst selection, and tail gas treatment requirements. The dominant technological pathway remains the Claus process, which accounts for the vast majority of installed capacity globally and continues to serve as the baseline architecture against which advanced modifications and hybrid configurations are evaluated. Complementary tail gas treatment units have gained prominence as regulatory bodies and corporate sustainability frameworks demand near-complete sulfur removal, pushing operators to pair conventional thermal and catalytic stages with catalytic reduction, oxidation, or low-temperature oxidation processes that close the emission loop.
Worldwide Controllable Heating Mantle Market
Forecast models indicate that growth through 2032 will be shaped by three interlocking dynamics. First, the ongoing modernization of mature refining complexes in North America, Europe, and the Middle East is driving replacement and efficiency upgrades of existing units, often with a focus on reducing auxiliary energy consumption and improving catalyst longevity. Second, gas processing capacity expansions in Asia Pacific and Latin America are creating new sulphur recovery installations that must be engineered to handle variable sour gas compositions while maintaining operational flexibility. Third, the globalization of marine fuel sulfur restrictions and the expansion of emission control areas are indirectly reinforcing demand for high-efficiency recovery trains, particularly at facilities that supply intermediate streams to logistics corridors where compliance margins are narrow. These drivers do not operate in isolation; they interact with logistics costs, localized permitting timelines, and the availability of specialized engineering talent, all of which our research maps in granular detail.
Regulatory Catalysts and Compliance Implications
Regulatory frameworks are no longer peripheral constraints; they are primary architects of market behavior. In the United States, federal emission standards at 40 CFR establish specific sulfur dioxide emission limits for sulfuric acid manufacturing and sulphur recovery operations, creating a compliance baseline that informs equipment specification, monitoring instrumentation, and maintenance scheduling. Parallel permitting regimes, including those administered by state commissions, govern the authorization pathway for new and modified sulphur recovery units under ambient air quality standards, adding project timeline variability that must be factored into investment underwrite models. In Europe and adjacent maritime corridors, the Mediterranean Sea Emission Control Area mandates a marine fuel sulfur limit of 0.10 percent, effective from mid-2025, tightening the operational envelope for bunkering supply chains and reinforcing the value of low-sulfur output streams. On a global scale, the implementation of IMO 2020 fuel sulfur restrictions and the continued expansion of emission control areas have accelerated demand for advanced sulphur recovery tail gas treating solutions, particularly in regions where refineries and gas plants support marine fuel blending operations.
For corporate planners, the regulatory layer translates into three practical imperatives. First, technology selection must be evaluated against the most stringent likely future limit, not merely the current permitted threshold, to avoid stranded asset risk. Second, tail gas treatment capacity should be modeled as an integral component of overall recovery train economics rather than a downstream add-on, given that underinvestment in polishing steps can erode the compliance value of otherwise robust primary recovery units. Third, permitting and operational reporting workflows should be integrated into the early stages of front-end engineering to de-risk schedule exposure, particularly in jurisdictions where air quality standards trigger incremental review cycles. Our report quantifies these compliance-driven decision points and maps them against regional project pipelines, enabling clients to prioritize investments that align with both current mandates and emerging regulatory trajectories.
Competitive Landscape and Technology Positioning
The global sulphur recovery market exhibits a high degree of concentration among established technology licensors, engineering firms, and specialized service providers. The top three participants collectively command a 65 percent share of the market, while the top five hold an 85 percent concentration, signaling a landscape where incumbency, proprietary process licensing, and long-term service relationships create meaningful barriers to entry. This structure does not imply a static competitive environment; rather, it reflects a market where differentiation is achieved through process efficiency, integration capability, and the ability to deliver modular or brownfield solutions that minimize operational downtime.
Shell Catalysts & Technologies, headquartered in the Netherlands, offers a broad portfolio encompassing Claus, SCOT, sulphur degassing, and THIOPAQ oil and gas sulphur recovery technologies for refineries and gas processing facilities. This breadth allows the company to position itself across primary recovery, tail gas polishing, and sulfur handling, making it a preferred partner in integrated modernization programs. Worley, based in Australia, provides Comprimo sulphur recovery units and advanced tail gas treatment units engineered for high-efficiency recovery, with recent project activity underscoring its growing footprint in the Middle East gas processing segment. In December 2024, Worley secured a front-end engineering and design contract from ADNOC Gas for the Bab Gas Cap project, which includes dedicated sulphur recovery units, an award that highlights the value of integrated FEED capability in large-scale gas expansion programs.
Linde AG, headquartered in Germany, supplies LO-CAT sulphur recovery units built around low-temperature oxidation processes, a configuration that is particularly attractive in applications where operational simplicity, reduced thermal stress, and lower emissions footprints are prioritized. Fluor Corporation, based in the United States, delivers EconoClaus sulphur recovery units integrated with refinery operations, emphasizing footprint efficiency and retrofit compatibility for sites seeking to upgrade recovery performance without major front-end redesign. Technip Energies, operating from France, licenses SmartSulf and sulphur recovery processes for the oil and gas industries, leveraging its engineering scale to bundle recovery technology with broader front-end and detailed design services. Chiyoda Corporation, based in Japan, provides Superclaus and sulphur recovery unit technology under exclusive contracts for advanced sulphur recovery, a positioning that reinforces its role in high-specification projects where proprietary process guarantees are critical.
Sulfur Recovery Engineering, headquartered in Canada, specializes in optimization, maintenance, and services for sulphur recovery units, tail gas treatment units, and sour water stripping units, offering a service-centric model that extends asset life and improves availability in operating facilities. Air Liquide Engineering & Construction, also based in France, licenses the Lurgi Claus process for sulphur recovery from acid gas streams, combining process licensing with execution capability in projects that require gas treatment integration. KT-Kinetics Technology SpA, an Italy-based supplier, offers low-temperature oxidation and sulphur recovery units, providing an alternative pathway for applications that prioritize reduced thermal load and simplified gas cleaning. GTC Technology US, operating from the United States, delivers advanced Claus process and tail gas treating solutions, with a focus on engineered configurations that align with refinery and gas plant operating envelopes. Heurtey Petrochem, based in France, provides sulphur recovery units integrated with petrochemical refining, supporting sites where recovery infrastructure must interface with downstream conversion units. McDermott, headquartered in the United States, engages in sulphur recovery unit design and engineering for gas processing facilities, contributing execution depth in brownfield and greenfield gas infrastructure programs. Sunway Petrochemical Engineering, based in Malaysia, delivers modular sulphur recovery units for regional refineries, a model that is particularly relevant for markets seeking faster deployment timelines and reduced field construction exposure.
Recent project activity illustrates how these players are translating capability into market share. In April 2025, a major engineering and technology provider secured a contract from Saudi Aramco for the modernization of the Haradh and Hawiyah Gas Plants, upgrading sulphur recovery efficiency to 99.9 percent, a benchmark that reflects the industry’s movement toward near-complete sulfur capture in large-scale gas processing complexes. In December 2025, OMV Petrom completed a 45 million euro investment in a new sulphur recovery unit at the Petrobrazi refinery, signaling sustained capital commitment to recovery infrastructure in European refining assets. These developments are not isolated milestones; they represent the types of execution arcs that our research analyzes across technology families, geography, and project scale, enabling clients to benchmark their portfolios against comparable programs and anticipate supplier and licensor behavior.
Segmentation Context and Regional Demand Patterns
The sulphur recovery market is segmented by type, application, and region, each dimension carrying distinct implications for technology selection, supply chain design, and investment prioritization. In terms of type, the market is dominated by the Claus process, which remains the foundational architecture for the majority of installed and planned capacity. Complementary tail gas treatment represents a significant and growing share, reflecting the industry’s shift toward higher capture efficiency and the operational need to handle marginal streams that would otherwise escape primary recovery stages. Application segmentation underscores the market’s anchor in petroleum and coke processing, where desulfurization requirements are structurally embedded in crude throughput and product specification economics, alongside a substantial natural gas segment driven by sour gas processing and gas plant modernization. Additional applications contribute a smaller but strategically important portion, often tied to specialty gas streams and niche processing configurations that require customized engineering responses.
Regionally, demand patterns reflect the geography of refining capacity, gas processing growth, and regulatory intensity. The Asia Pacific segment accounts for the largest portion of market value, consistent with the concentration of refining and gas processing capacity in the region and the ongoing program of capacity additions and efficiency upgrades. North America follows as a significant segment, shaped by mature refining infrastructure, active modernization cycles, and a regulatory environment that maintains continuous pressure on sulfur emission performance. Europe, Latin America, and the Middle East and Africa collectively represent important but comparatively smaller segments in absolute terms, each characterized by distinct project rhythms, feedstock profiles, and compliance timelines. Our research examines these regional dynamics through the lens of project pipelines, technology mix, and supplier presence, but deliberately avoids presenting sub-regional or sub-application percentage breakdowns or discrete monetary figures, ensuring that the strategic narrative remains focused on decision architecture rather than point-in-time snapshots that can quickly become outdated.
What the Report Delivers for 2026 Decision-Makers
This market research is designed as an operational tool for strategy, procurement, engineering, and corporate development teams. It integrates historical market sizing from 2020 through 2025 with a forecast spanning 2026 to 2032, expressed in USD millions, and contextualized within the technological, regulatory, and competitive realities that shape capital deployment. The report provides a structured examination of the primary recovery and tail gas treatment technology families, their integration pathways, and the performance trade-offs that influence licensor selection and engineering scope. It profiles the leading companies by headquarters, technology portfolio, and recent contract and project activity, enabling readers to map supplier capabilities to specific project requirements and risk tolerances. It also details the regulatory environment across key jurisdictions, translating emission limits, permitting rules, and maritime fuel sulfur mandates into practical planning considerations for new installations and existing asset optimization.
Beyond macro and competitive description, the research delivers actionable content for near-term planning. It examines how feedstock variability, particularly hydrogen sulfide concentration ranges typical of gas processing plants, influences unit configuration and tail gas treatment necessity. It assesses the implications of industry-wide pushes toward higher recovery efficiency, including the operational and economic consequences of approaching 99.9 percent capture in large-scale gas plant modernization programs. It evaluates the strategic significance of modular delivery models, brownfield retrofit compatibility, and service-oriented optimization offerings, all of which affect timeline, cost structure, and availability outcomes. The report also provides a framework for evaluating concentration risk within the supplier base, helping procurement and engineering leaders balance incumbency advantages against the need for competitive tension in technology and execution sourcing.
How to Use This Intelligence in the 2026 Planning Cycle
For enterprises preparing investment decisions, capacity plans, or technology roadmaps for 2026 and beyond, the value of this research lies in its ability to connect market-wide behavior to firm-level action. The forecasted growth path and baseline historical trajectory provide a reference for sizing demand expectations and aligning internal capacity or procurement assumptions with market reality. The competitive and technology profiles support supplier evaluation, licensing negotiations, and partnership screening, particularly in contexts where multiple process options are technically feasible but differ in integration complexity, service support, and performance guarantees. The regulatory analysis informs risk-adjusted scheduling, compliance cost modeling, and the prioritization of tail gas treatment investments that may determine whether a facility remains comfortably within permitted limits or faces future retrofitting exposure.
Strategically, the report is intended to be used as a baseline for scenario planning rather than a single-point forecast. Teams can anchor capital allocation models to the central market trajectory while stress-testing assumptions around regional project pacing, regulatory tightening, and supplier capacity constraints. Engineering and procurement leaders can use the company and technology content to refine request-for-proposal scopes, evaluation criteria, and risk registers for upcoming front-end engineering and design phases. Corporate development and investor relations teams can draw on the market concentration and segment structure to frame discussions around competitive positioning, partnership opportunity, and exposure to high-growth demand corridors without relying on discrete sub-segment figures that may shift as project pipelines evolve.
Next Steps
The sulphur recovery market is entering a period in which the intersection of compliance pressure, technology maturity, and regional capacity growth will reward organizations that plan with precision and act with discipline. A compound annual growth rate of 2.51 percent across the forecast window, supported by historical expansion from 2020 through 2025 and a forecast trajectory extending to 2032, provides a credible baseline for strategic modeling, but the real decisions will hinge on technology fit, supplier alignment, regulatory anticipation, and project execution quality. This research is built to support those decisions at the level of detail that matters for 2026 and beyond.
For a complete view of the market structure, including the full segmentation analysis, detailed regional and technology dynamics, supplier capability mapping, and the comprehensive historical and forecast tables, we invite you to access the full report on our website. The complete intelligence package is designed to serve as the foundation for investment committees, engineering strategy reviews, procurement planning, and corporate development assessments, ensuring that your team enters the 2026 planning cycle with a clear, evidence-based understanding of where the sulphur recovery market is headed and how to position accordingly.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Newborn Screening Instruments Market to Reach $1.46B by 2032 with 8.5% CAGR
By PW Consulting, 2026-09-07
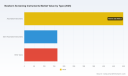
Strategic Intelligence for a Transforming Landscape: The Newborn Screening Instruments Market 2026-2032
The global newborn screening instruments market enters a decisive growth phase, driven by an expanding panel of detectable conditions, sustained public health investment, and accelerating shifts in laboratory automation. As we move into 2026, the industry is no longer defined by incremental equipment upgrades alone. Instead, it is being reshaped by evolving regulatory mandates, clinical workload pressures, reimbursement architectures, and the strategic choices manufacturers are making to control throughput, accuracy, and total cost of ownership. Our newly released research framework translates this complexity into a decision-ready intelligence set designed specifically for executive planning, portfolio alignment, and market positioning over the forecast horizon through 2032.
Unmanned Aerial Vehicle Interception Equipment Market
This market is moving from a mature, regionally uneven landscape toward a more standardized, throughput-oriented, and analytically expansive ecosystem. Historical momentum reflects steady expansion across instrumentation adoption, consumables integration, and software-enabled workflow control. The market registered approximately 832.11 million USD in 2025, with 2026 projected at 892.68 million USD. Over the full forecast window, the trajectory culminates at 1463.69 million USD by 2032, underpinned by a CAGR of 8.5 percent. These figures are not simply a record of growth; they describe the scale at which capital allocation, installation planning, consumables bundling, and service coverage must be managed to remain competitive.
Scenario-Based Healing Marketing Solution Market
For senior leaders, the core strategic question is not whether demand will continue to rise, but how to capture it efficiently. Automation is becoming a defining purchase criterion, particularly where laboratory staffing constraints and high sample throughput intersect. At the same time, the widening clinical panel demands instruments and analytical systems that can deliver consistent performance across more complex screening workflows. Manufacturers and laboratory operators alike must navigate a space where instrument capability, reagent compatibility, data management, and post-sale service now carry equal weight in procurement decisions.
Worldwide PC Terminal Payment Processing Software Market
Our study is built to help decision-makers read the market with precision. It is designed to convert broad macro momentum into operational insight, so that commercial teams, procurement leaders, and strategy functions can act with clarity rather than rely on directional assumptions. The report does not merely describe where the market has been. It structures the drivers, constraints, and competitive behaviors that shape where value will be created between 2026 and 2032.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle calls for a narrower, more actionable understanding of the newborn screening instruments market than most organizations currently possess. Procurement cycles are lengthening in some regions while accelerating in others. Public health programs are adding new target conditions to screening panels, which changes the required analytical scope for laboratories, install base planning for manufacturers, and long-term consumables forecasting. In that environment, market intelligence must be tied directly to commercial consequences: which capabilities matter most to end users, where installation wardrobes are likely to expand, and how reimbursement and regulation influence adoption timing.
This research supports those decisions by mapping the market in a way that links instrument type, application scope, and regional dynamics to real planning variables. Rather than presenting the market as a single growth story, it exposes the operational logic behind different demand streams and competitive postures. That distinction matters for any executive team trying to determine whether to prioritize high-throughput automation, modular flexibility, consumables-led revenue, or region-specific entry strategies.
The study also serves as a reference point for risk-adjusted planning. Forecast confidence, adoption speed, and competitive intensity vary across segments, and treating the market as uniform leads to overinvestment in weak demand pockets or underinvestment in fast-moving ones. By separating the determinants of demand from the broader headline numbers, the report enables more disciplined scenario planning, especially around capital deployment, manufacturing capacity, service infrastructure, and sales coverage.
For 2026 specifically, the strategic value lies in translation. Leaders need to understand not only that the market is expanding, but what that expansion means for product roadmaps, pricing architecture, channel partnerships, and customer engagement. Our research is organized to answer those practical questions directly.
Report Scope: What the Study Covers in Practice
This report is structured to support internal planning across commercial, operational, and strategic functions. It moves beyond a high-level market description and provides a working framework for interpreting demand, competitive pressure, and investment timing. The objective is to give teams a consistent basis for evaluating opportunities without needing to construct their own market model from scattered sources.
At the core of the study is a comprehensive market assessment covering the base year, a historical record, and the full forecast period through 2032. The analysis traces how demand has evolved and how future growth is expected to distribute across major instrument and application categories, while also identifying the operational and regulatory forces shaping adoption. The forecast is presented as a decision basis rather than a single projection line, with emphasis on the underlying drivers that determine how quickly different customer groups convert interest into procurement.
A significant portion of the research is devoted to practical segmentation intelligence. Customer needs are examined through the lens of instrument configuration, screening application breadth, and workflow integration. This allows readers to study how different laboratory environments, screening programs, and diagnostic priorities generate distinct purchasing behaviors. The segmentation review supports more precise product positioning and helps identify where performance requirements, service expectations, and consumables economics diverge.
The report also includes a detailed examination of competitive positioning. Rather than limiting the analysis to product descriptions, it assesses how leading participants differentiate themselves through system architecture, assay compatibility, workflow software, and end-to-end offering design. This competitive framing helps readers understand not just who is active in the market, but how value is being contested across instrument reliability, throughput, consumable bundling, and post-installation support.
Operational and transactional factors are analyzed alongside technology and competition. The study integrates market dynamics that influence purchasing timelines, facility-level adoption challenges, and the financial structures that shape demand. These sections are intended to help readers anticipate where procurement may accelerate, where capital constraints may slow it, and where reimbursement or regulatory clarity can alter adoption trajectories.
In addition, the research addresses the broader context that market participants must manage: laboratory capacity, consumables supply, training and service expectations, and the shifting requirements created by expanding screening panels. By placing these factors within a single analytical framework, the study supports internal discussions about installation strategy, service network design, and long-term customer retention.
Throughout the report, the emphasis remains on applicability. The analysis is built to help executives link market structure to commercial choices: where to concentrate selling effort, how to shape product messaging, which customer segments warrant dedicated capacity planning, and how to interpret new entrants or competitor launches within the broader demand cycle.
Competitive Landscape: Where Winning Is Being Defined
The newborn screening instruments market is not only shaped by demand growth. It is also shaped by how a small group of capable participants compete around workflow integrity, analytical reliability, and the breadth of their commercial offering. Market structure remains concentrated, with a significant share of activity held by a limited number of leading players. That concentration creates both barriers and opportunities: established participants defend installed bases and relationships, while new or expanding entrants must differentiate through measurable performance, workflow compatibility, and service credibility.
Within this landscape, several companies illustrate the strategic paths currently being pursued. One major player focuses on complete newborn screening systems that include instruments, kits, consumables, and software. This integrated approach reflects a broader industry shift toward offering coordinated workflows rather than isolated instrumentation. Systems of this type can reduce integration friction for laboratories, but they also raise expectations for performance consistency, consumables availability, and ongoing technical support.
Another competitive thread is centered on analytical specialization. Certain firms emphasize mass spectrometry-based analyzers and assays designed for quantitative amino acids and acylcarnitines derived from dried blood spots. In this space, differentiation comes from analytical precision, assay breadth, and the ability to support simultaneous determination of multiple analytes in routine newborn screening workflows. Updates in this area indicate how quickly instrument and assay portfolios can evolve when clinical screening panels expand and laboratories seek consolidated testing options.
A third competitive orientation revolves around automation, reagent integration, and data management. Some participants build around automated machines, reagents, and software designed to streamline the newborn screening workflow from sample handling through data output. This model addresses laboratory operational pressures directly by reducing manual variability and supporting standardized processing. It also positions the vendor closer to the daily operational needs of the laboratory, where reliability and throughput are often more influential than feature lists alone.
These competing orientations matter because they signal how the market is being contested. Some participants win through system breadth and end-to-end coordination. Others win through analytical depth or workflow automation. For commercial teams, the strategic implication is that purchase decisions are increasingly multi-dimensional. A buyer may value the convenience of an integrated kit-and-instrument package, the precision of a specialized assay pipeline, or the operating efficiency of a highly automated workflow. Vendors must therefore articulate not only what their product does, but what kind of laboratory problem it solves best.
Recent industry activity reinforces the intensity of this competition. Expanding screening panels, assay platform updates, and regulatory actions are reshaping what laboratories expect from their instruments and consumables. For example, the extension of certain assay panels to support simultaneous determination of a broader range of analytes illustrates how quickly analytical capability can become a competitive differentiator. Similarly, programmatic additions to screening panels change downstream demand for instrumentation and consumables, giving manufacturers another lever to align product development with clinical priorities.
In this environment, competitive intelligence is not about counting product launches. It is about understanding who is aligning their offering with the most consequential customer pain points and where future share shifts are most likely to occur. The report provides that perspective, helping readers anticipate where incumbents may defend share, where challengers may gain traction, and where the definition of “complete solution” continues to expand.
Market Dynamics: Policy, Payment, and Operating Reality
The commercial trajectory of the newborn screening instruments market depends on more than technology preference. It is strongly influenced by policy direction, reimbursement architecture, capital availability, and the practical constraints that laboratories face when scaling screening operations. These dynamics shape not only how fast demand grows, but also how purchasing decisions are timed and justified.
Regulatory direction is one of the most important levers. When screening panels are updated or when guidance clarifies expectations for test systems, laboratories and health authorities must reassess their analytical requirements. Such changes can increase demand for instruments capable of supporting broader panels, and they can also affect the pace at which existing equipment is replaced or supplemented. In this sense, regulatory evolution often acts as a trigger for procurement reconsideration, especially where public health programs seek to align instrumentation with newly recommended conditions.
Payment structures and reimbursement mechanisms similarly influence adoption. Where facilities can bill for collection kits, processing, and specified laboratory tests, the financial logic of screening programs becomes more workable, and equipment decisions are easier to justify within a broader service model. At the same time, reimbursement clarity affects which institutions are willing to invest in expanded workflow capability, since the economic sustainability of screening activity depends on how costs are recovered. These financial dynamics can either accelerate or constrain demand depending on local administrative conditions.
Capital availability is another practical factor shaping market behavior. Instrument replacement and acquisition programs demonstrate that public and institutional funding can directly support equipment refreshes and new installations. Where dedicated funding exists, procurement cycles may move faster and modernization may become more practical for facilities that would otherwise delay investment. For vendors and strategists, this means that capital programs can create localized acceleration points within an otherwise broad adoption curve.
Laboratory operating reality also plays a central role. Staff availability, sample volume, quality control demands, and the need for consistent throughput all influence whether a laboratory prioritizes automation, modular systems, or specialized assay platforms. As screening panels grow, the operational burden on laboratories increases, which in turn strengthens the appeal of instruments and workflows that reduce variability and simplify handling. This is a strategic pressure point because it links clinical goals directly to purchasing logic.
Taken together, these dynamics reveal a market where adoption is not purely a function of technological appeal. It is also a function of administrative feasibility, reimbursement stability, capital access, and operational resilience. Any market plan that overlooks these forces risks overestimating demand in constrained environments or underestimating it where policy and funding alignment improves. The report's dynamics section is designed to keep these factors visible throughout the analysis so that planning remains grounded in operating reality.
How to Use This Research for Strategic Advantage
This study is intended to be used as a working tool rather than a static reference document. For product and portfolio teams, it offers a structured way to assess which capabilities are most likely to matter as screening panels expand and lab workflows become more automated. For commercial leaders, it provides a basis for prioritizing customer segments, sale motions, and service investment. For strategists and finance groups, it supports more disciplined capital planning by linking forecast direction to the underlying forces that will actually shape procurement behavior.
Effective use of the report begins with segmentation discipline. The broadest market figures are useful for context, but the more valuable insights emerge when demand is interpreted through instrument type, application scope, and regional operating conditions. By separating those layers, teams can identify where growth is concentrated, where installation cycles may be faster, and where consumables or service revenue may be more durable.
Competitive planning benefits from the same approach. Rather than treating the market as if all players compete on the same terms, this research helps organizations see where differentiation is being built around integration, analytical scope, automation, or workflow support. That perspective makes it easier to anticipate competitor moves and to position products in a way that reflects the actual basis of buyer choice.
Finally, the report supports scenario readiness. Market growth is strongest when demand drivers, regulatory momentum, and operational feasibility align. It is weakest when one of those elements is disrupted. By keeping those dependencies explicit, the study helps organizations prepare for multiple outcomes and avoid overreliance on a single forecast narrative.
The complete analysis, including detailed segmentation evaluation, competitive assessment, forecast structure, and market dynamics, is available through our full market research report. That document provides the supported data and interpretive framework needed to translate these strategic themes into precise internal action plans.
For detailed analysis of this topic, please visit the official page: Newborn Screening Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Bus Market Reaches $20.47M in 2025, 14.2% CAGR to 2032
By PW Consulting, 2026-09-07
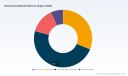
Strategic Intelligence for the Electric Bus Transition: Navigating the 2026 Market Landscape
The global electric bus market stands at a critical inflection point in 2026. After years of policy experimentation, pilot deployments, and gradual technology maturation, the sector has crossed into a phase of sustained commercial scaling. For transit authorities, mobility operators, investors, and supply-chain participants, the decisions made this year will define competitive positioning for the remainder of the decade. Our latest Electric Bus Market research is designed to translate macroeconomic momentum, regulatory shifts, and competitive dynamics into actionable intelligence for enterprise decision-making.
Worldwide Seedling Transplanter Market
This market study is built on a rigorous historical foundation spanning 2020 through 2025, with forward-looking analysis projecting through 2032. The overarching trajectory is unambiguous: total market revenue has advanced from approximately 11.54 million USD in 2020 to an estimated 20.47 million USD by 2025, and the forecast pathway points toward 23.7 million USD in 2026, accelerating to 51.21 million USD by 2032. This expansion translates into a compound annual growth rate of 14.2 percent across the full forecast horizon. Such figures are more than aggregate indicators; they signal a structural reallocation of transit capital, fleet procurement priorities, and infrastructure investment toward zero-emission mobility.
High-Precision Map for Self-Driving Cars Market
For enterprise strategists, the strategic value of this research lies not in the headline numbers alone, but in what those numbers reveal about timing, segmentation intensity, regional deployment patterns, and the evolving economics of electrification. The report is structured to give procurement leaders, product planners, and investment committees a credible basis for scenario planning, capacity decisions, partnership strategy, and risk mitigation. It is also deliberately designed as a strategic preview: the full study contains the granular segmentation breakdowns, regional share distributions, application-level adoption ratios, and detailed competitor benchmarking that operational teams require. This article demonstrates the analytical framework and contextual depth of the research while preserving the proprietary detail that makes the complete report an essential decision-support asset.
Smart Electronic Musical Instrument Market
The Commercial Logic Behind the Growth Trajectory
The projected expansion of the electric bus market reflects a convergence of cost dynamics, regulatory catalysts, and operational maturity. Lithium-ion battery pack pricing has declined substantially over recent years, with industry data indicating a roughly twenty percent reduction from 2023 to a record-low level near 115 USD per kilowatt-hour by late 2024. Lower energy-storage costs improve total cost of ownership calculations, reduce upfront procurement friction, and strengthen the economic case for fleet conversion, especially where vehicle utilization rates and mileage accumulation are high.
At the same time, regulatory frameworks are tightening the timeline for emissions reduction in public transport. The European Union's Fit for 55 package, adopted in May 2025, aims to cut greenhouse gas emissions by at least fifty-five percent by 2030 and includes incentives that directly support electric bus adoption. In parallel, the International Energy Agency reports that the average range of available battery-electric bus models reached 360 kilometers in 2025, addressing one of the early operational concerns that had limited broader deployment. Improved range capability, combined with evolving charging architectures and drivetrain modularity, is expanding the addressable use cases beyond short urban loops to longer regional and intercity services.
Public funding mechanisms are further reinforcing demand. In the United States, the Environmental Protection Agency's Clean School Bus Program allocated nearly one billion USD in rebates through 2024, with the vast majority directed toward electric school buses. More recently, the New Jersey Department of Environmental Protection awarded almost 32 million USD in grants in March 2026 to support 53 electric school buses and associated charging infrastructure. These reimbursement and incentive structures do more than subsidize purchases; they reshape procurement calendars, influence vehicle specification choices, and create staggered demand waves that manufacturers and service providers must anticipate.
Against this backdrop, the market's forecast path from 23.7 million USD in 2026 to 51.21 million USD in 2032 implies more than linear growth. It indicates broadening vehicle categories, increasing order backlog visibility, expanding service and charging ecosystems, and intensifying competition among manufacturers seeking regional scale. The report unpacks these layers systematically so that readers can distinguish between cyclical procurement spikes and durable structural growth.
What the Research Delivers: Operational Content for Decision-Makers
The study is developed for professionals who need more than trend commentary. It is organized to support concrete actions in fleet planning, vendor selection, investment allocation, and market-entry strategy. The report's substantive content covers the following operational dimensions:
- Market sizing and trajectory mapping across the historical window of 2020-2025 and the forecast period of 2026-2032, with revenue expressed in million USD and growth rates contextualized against deployment realities.
- Structural segmentation across vehicle type, application category, and regional demand geography, enabling readers to understand where growth is concentrated and how adoption drivers differ by market.
- Competitive landscape profiling that examines the strategic positioning, product families, manufacturing footprint, and recent activity of leading manufacturers and technology suppliers.
- Regulatory and funding analysis that tracks emission-reduction mandates, incentive programs, and reimbursement mechanisms influencing procurement behavior.
- Technology and cost dynamics, including battery pricing trends, range evolution, drivetrain innovations, and the implications for total cost of ownership and service planning.
- Order-book signals and recent corporate developments that provide forward visibility into production capacity, delivery infrastructure, and market momentum.
- Strategic implications for operators, OEMs, component suppliers, and financial stakeholders, with scenario-oriented guidance rather than generic market description.
Throughout the report, quantitative framing is paired with qualitative interpretation. The goal is to help readers evaluate not only how large the market is becoming, but also where the most consequential opportunities and vulnerabilities lie. For example, the research examines how procurement models differ between municipal transit systems, regional operators, and school-bus fleets, and how each segment responds to incentive timing, charging constraints, and vehicle-range requirements. It also evaluates how manufacturing capacity, local production presence, and delivery logistics shape competitive advantage in markets where lead times and service reliability matter as much as sticker specifications.
Readers seeking the complete segmentation architecture—including detailed regional share patterns, application-level adoption ratios, and type-level market decomposition—will find those breakdowns integrated into the full study. That level of detail is essential for market-entry screening, revenue forecasting, and competitive response planning, and it is precisely the kind of information that cannot be responsibly summarized without compromising analytical integrity.
Competitive Landscape: Scale, Specialization, and Regional Footprints
The electric bus market is characterized by a mix of broad-line global manufacturers, regional specialists, and technology-focused entrants. Competitive intensity is high, and leadership is increasingly defined not only by vehicle volume but also by battery integration capabilities, charging ecosystem partnerships, service networks, and ability to navigate differing regulatory environments. The report profiles the companies that are shaping this landscape, including BYD Company Limited, Volvo Buses, Daimler Truck Holding AG, Solaris Bus & Coach, New Flyer Industries, Yutong Group, Zhongtong Bus, Proterra Inc., Gillig LLC, and Blue Bird Corporation.
BYD Company Limited, headquartered in Shenzhen, Guangdong, China, remains a global leader in electric bus production with an extensive lineup of battery-electric city and intercity buses sold worldwide. Its scale and product breadth make it a reference point for commercial deployment across multiple regions. Volvo Buses, based in Gothenburg, Sweden, specializes in zero-emission electric buses with advanced battery systems and high-range models designed for both urban and intercity applications, emphasizing durability and operational flexibility. Daimler Truck Holding AG, through its Mercedes-Benz branded offerings, provides electric buses including the eCitaro series for city and regional transport, leveraging established urban-transit credibility and modular vehicle architectures. Solaris Bus & Coach, headquartered in Bochnia, Poland, develops and manufactures electric and hybrid buses, including the widely adopted Urbino electric models, and continues to strengthen its position in European procurement pipelines.
In North America, New Flyer Industries, based in Winnipeg, Manitoba, Canada, produces battery-electric Xcelsior series transit buses and maintains regional manufacturing capacity that supports localized supply and delivery. Gillig LLC, headquartered in Emeryville, California, offers battery-electric and hybrid buses for North American transit fleets, while Blue Bird Corporation, based in Fort Valley, Georgia, produces electric school buses and city transit buses in the United States, reflecting the importance of the school-transport segment in American electrification efforts. In China, Yutong Group and Zhongtong Bus both maintain strong manufacturing and export footprints. Yutong provides advanced battery-electric buses with long-life components and digital fleet integration for global markets, while Zhongtong focuses on battery-electric buses for urban and intercity applications with a strong presence in China and growing export activity. Proterra Inc., headquartered in Golden, Colorado, specializes in electric transit and school buses with proprietary battery and charging solutions, positioning around technology differentiation and fleet integration.
Recent corporate activity illustrates how competition is translating into concrete market momentum. In early 2026, multiple developments signaled both capacity expansion and demand solidification. Solaris secured contracts for 50 electric buses with an operator in Aarhus, Denmark, and received additional contracts totaling 103 electric buses from Nobina in April 2026. New Flyer opened a new customer acceptance and delivery facility in Winnipeg during the same month, reinforcing regional service capability and throughput. Yutong showcased its latest battery-electric buses and long-life EV technologies at the Next Mobility Exhibition in Milan in February 2026, highlighting continued product iteration and international visibility. ZF Friedrichshafen AG unveiled modular electric bus drivetrains at Mobility Move 2026 in Berlin, pointing to broader supplier-side innovation that affects vehicle architecture and integration flexibility. Alexander Dennis Limited unveiled its first Enviro100AEV autonomous electric bus in January 2026, indicating that autonomy and electrification are beginning to converge in product roadmaps.
These moves matter because they reveal where manufacturers are investing in throughput, service readiness, product differentiation, and long-term positioning. For fleet operators and investors, understanding which companies are expanding acceptance and delivery infrastructure, which are winning visible public contracts, and which are advancing modular powertrain technologies helps clarify future supply reliability and competitive pressure. The full research report provides a more complete competitive assessment, including an evaluation of market concentration dynamics. Current data indicates a consolidated landscape, with the top three competitors accounting for approximately 62.7 percent of market revenue and the top five holding the same approximate share, underscoring the importance of strategic positioning for both incumbents and new entrants.
Market Dynamics and Strategic Timing
Electrification of bus fleets is no longer a single-technology substitution story. It is a multi-vector transformation involving vehicle specification, charging strategy, garage infrastructure, grid interaction, maintenance retraining, and financing models. The strategic significance of the 2026 landscape comes from the fact that many of these vectors are maturing simultaneously, which compresses decision windows and raises the cost of delay.
Range improvement is a central enabler. With average available battery-electric bus range reaching 360 kilometers in 2025, operators have greater confidence in deploying electric buses across longer routes and higher-utilization schedules. This does not eliminate the need for route-specific planning or charging-zone strategy, but it reduces the probability that electric platforms will be restricted to a narrow subset of short-hop services. As a result, the addressable market expands beyond dense urban cores to include regional connectors and intercity applications where operational profiles are more demanding.
Battery cost trajectories further support adoption economics. The decline in lithium-ion pack pricing to near-record levels improves the financial case for electric buses when evaluated over a full asset lifecycle. For operators with high annual mileage and predictable duty cycles, the combination of lower energy costs, reduced maintenance complexity, and public incentives can produce compelling total cost of ownership outcomes. For manufacturers, lower battery input costs also influence vehicle pricing strategy, margin structure, and the ability to compete in price-sensitive public procurement.
Policy and reimbursement mechanisms add another layer of timing complexity. The Fit for 55 framework in Europe, the Clean School Bus Program in the United States, and state-level grant activity such as New Jersey's recent funding round demonstrate that public capital is actively shaping demand calendars. These programs can accelerate early adoption, but they can also create lumpy procurement patterns if funding cycles, application windows, and delivery timelines are misaligned. Strategic procurement teams therefore need to anticipate not only what vehicles to buy, but when to commit, how to structure down payments and delivery slots, and how to coordinate charging infrastructure with vehicle arrival.
The report provides a structured lens for interpreting these dynamics. Instead of treating regulation, cost, and technology as separate topics, it examines their interaction: how policy incentives alter payback periods, how battery and drivetrain innovation expands route applicability, and how order-book signals from leading manufacturers indicate where capacity is being directed. This integrated view is particularly valuable for organizations planning multi-year fleet transitions, capital expenditure programs, or market-entry initiatives.
How to Use This Research in 2026 Decision-Making
The strategic value of the study is greatest when it is used as an input to concrete planning processes rather than as passive market reading. For transit operators and mobility providers, the research supports fleet-mix decisions, route-by-route electrification sequencing, and charging-infrastructure prioritization. For manufacturers and suppliers, it aids production planning, regional sales focus, and partnership strategy around batteries, chargers, and service networks. For investors and financial analysts, it provides a market framework for assessing revenue growth potential, competitive concentration, and the timing of demand realization across applications and geographies.
Several practical use cases illustrate the report's intended function:
- Evaluating whether near-term growth is being driven by truly diversified demand or by concentrated activity in a limited set of segments or regions.
- Assessing competitive exposure by understanding which manufacturers are strengthening delivery infrastructure, securing visible contracts, or advancing modular powertrain and battery integration capabilities.
- Informing procurement timing by aligning vehicle orders with incentive windows, delivery-facility capacity, and charging-installation lead times.
- Benchmarking total cost of ownership assumptions against evolving battery pricing, vehicle range, and operational utilization patterns.
- Identifying where market concentration may affect pricing power, supply reliability, and the bargaining position of buyers and suppliers.
In each case, the report is designed to reduce uncertainty in the early stages of strategy formulation. It does not replace internal operational modeling, but it strengthens the assumptions on which those models depend. By combining historical performance, forward projections, competitive intelligence, and regulatory context, it gives decision-makers a more stable foundation for commitments that will affect operations and finances well beyond 2026.
Accessing the Complete Strategic Intelligence
This article provides the analytical orientation and contextual scope of the Electric Bus Market research, but the full study contains the detailed segmentation data, regional and application-level patterns, and proprietary competitive evaluation that enterprise teams need for execution. The complete report preserves the depth required for market-screening, revenue planning, vendor selection, and risk assessment, while remaining aligned with the strategic priorities of organizations active in transit electrification.
For decision-makers evaluating where to allocate capital, how to structure procurement, and which competitive signals to monitor, the full research offers the precision that a preview cannot. The macro trajectory is clear: the market is expanding from a 2025 baseline of approximately 20.47 million USD toward a 2032 outlook of 51.21 million USD, supported by a 14.2 percent CAGR and reinforced by technological progress, policy momentum, and public funding. What remains essential is understanding the segmentation logic beneath that trajectory, the regional dynamics shaping deployment pace, and the competitive maneuvers that will determine who captures value as the market scales.
The Electric Bus Market report is built to answer those questions with discipline and specificity. It is intended for leaders who need to move from awareness to action, and it is structured to support decisions that are both strategically ambitious and operationally realistic. For a complete view of the segmentation architecture, competitive profiles, and forward-looking market intelligence, access the full study to obtain the detailed data and analysis that underpin the 2026 strategic outlook.
For detailed analysis of this topic, please visit the official page: Electric Bus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railcar Leasing Market Hits $187.5M in 2025, 5.5% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Railcar Leasing Market: Navigating Growth and Regulation Through 2032
Executive Summary: The Value of Informed Decision-Making
As the global logistics landscape shifts towards greater supply chain resilience and multimodal efficiency, the railcar leasing sector stands at a critical inflection point. For stakeholders operating within the transportation and infrastructure sectors, understanding the trajectory of railcar leasing is no longer optional—it is a fundamental component of capital allocation and risk management strategy. PW Consulting has recently released a comprehensive market research study designed to equip enterprise leaders with the actionable intelligence required to navigate the complexities of the 2026 to 2032 forecast period.
Copper Pyrophosphate Market
This analysis serves as a strategic overview of the forthcoming report, highlighting the macroeconomic trends, competitive maneuvers, and regulatory frameworks that will define the industry. While this article outlines the broader market narrative and structural dynamics, the complete dataset and granular segmentation analysis are reserved for subscribers of the full study. By integrating historical performance data with forward-looking projections, this research provides a blueprint for identifying opportunities amidst a backdrop of evolving compliance requirements and shifting geopolitical supply chains.
Worldwide Solar Float Glass Market
Market Trajectory and Growth Projections
The railcar leasing market has demonstrated remarkable resilience over the past five years, recovering from initial pandemic-era disruptions to establish a robust growth trajectory. Historical data from 2020 through 2025 indicates a steady consolidation of market value, setting a solid foundation for the upcoming forecast period. The market, valued in the hundreds of millions of USD, has shown consistent upward momentum despite volatile economic conditions.
Guitar String Sets Market
Looking ahead, the industry is projected to expand significantly. The forecast period from 2026 to 2032 anticipates a compound annual growth rate (CAGR) that underscores the sector's vitality. This growth is not merely a function of inflationary adjustments but reflects genuine increases in freight volume, infrastructure investment, and the strategic necessity of owning versus leasing assets in a capital-intensive industry. The progression from the current baseline toward the end of the decade suggests a maturing market where early movers in fleet acquisition and technological integration will capture disproportionate value.
Understanding the timing of this growth is crucial for procurement and finance teams. The shift from historical stability to accelerated expansion implies that lease rates, availability, and asset valuations will move differently than in previous cycles. Our report details these inflection points, allowing clients to time their acquisitions and lease agreements to optimize cost structures and fleet availability.
Competitive Landscape and Key Industry Players
The market is characterized by a mix of dominant multinational lessors and specialized regional providers. Concentration remains moderate, with top players holding significant but not monopolistic shares, allowing room for strategic partnerships and niche expansion. The competitive environment is dynamic, with firms constantly adjusting their portfolios to meet demand in specific geographies and commodity segments.
North American Dominance and Expansion
In North America, the presence of major industry players is substantial. GATX Corporation, headquartered in Chicago, remains a premier railcar leasing company, offering diverse tank and freight railcar fleets. Their full-service maintenance and customer support model set a high bar for operational excellence in the region. Similarly, TrinityRail, based in Dallas, operates as a leading integrated railcar leasing provider. With a fleet exceeding 140,000 leased railcars, TrinityRail supports a wide range of equipment including tank cars, covered hoppers, and intermodal equipment, backed by their own manufacturing and logistics services.
European Ecosystem and Specialized Providers
The European market features distinct competitors focused on integrated logistics and multimodal solutions. VTG Aktiengesellschaft, headquartered in Hamburg, stands as Europe's largest private freight wagon leasing operator. They offer tank cars, standard freight wagons, and modular superstructures, complemented by multimodal logistics and digital solutions. In the United Kingdom, Beacon Rail Leasing provides a full-service leasing platform covering locomotives, passenger vehicles, and freight wagons across 18 European countries, emphasizing tailored operating packages.
Further strengthening the European footprint is RAILPOOL GmbH in Munich, a full-service leasing operator of electric locomotives and rail vehicles across 19 European countries with flexible contracts. In Poland, EUROWAGON Sp. z o.o. operates as a pan-European independent railcar lessor specializing in modern freight wagons and intermodal solutions, focusing on full maintenance and fleet management.
Strategic Movements and M&A Activity
Recent developments highlight the intensity of competitive consolidation. In June 2026, a significant strategic partnership and stake acquisition occurred involving TrinityRail Global Inc, Touax Group, and Texmaco Rail & Engineering Ltd. TrinityRail Global acquired a 32% stake in Touax Texmaco Railcar Leasing Pvt Ltd. This move was designed to form India's first global railcar leasing platform, integrating manufacturing, leasing, financing, and lifecycle management. This signals a strong strategic push toward emerging markets and integrated service models.
Earlier in the year, in January 2026, GATX Corporation and Brookfield Infrastructure Partners completed a railcar fleet acquisition. GATX acquired the Wells Fargo rail operating lease portfolio, comprising approximately 101,000 railcars. This transaction nearly doubled GATX's North American lease fleet, illustrating how capital partners are aggregating assets to achieve scale efficiencies and strengthen market positioning.
Regulatory Dynamics and Compliance Risks
A critical component of strategic planning in this sector is navigating the evolving regulatory environment. Compliance is no longer just about operational safety; it now encompasses supply chain origin and market transparency, directly impacting procurement and fleet composition strategies.
United States: Content Restrictions and Infrastructure Acts
Under the Freight Car Safety Standards implementing the Infrastructure Investment and Jobs Act, specific restrictions have been placed on freight car manufacturing and operation. A railroad freight car wholly manufactured on or after December 19, 2025, may only operate on the U.S. general railroad system if not more than 20 percent of its content originates from a country of concern or a state-owned enterprise. Furthermore, this limit is scheduled to tighten to 15 percent beginning December 19, 2028.
Railcar manufacturers must ensure compliance with these 15 percent content limitation requirements for freight cars manufactured after December 19, 2025, excluding sensitive technology components. For leasing companies, this creates a complex procurement landscape. Assets acquired or leased must adhere to these origin rules, potentially affecting lead times, supplier selection, and the valuation of existing fleets that do not meet future standards. Strategic planning must account for the tightening window between the initial 20 percent threshold and the stricter 15 percent requirement.
United Kingdom: Market Transparency Orders
In the UK, the Office of Rail and Road has reviewed the rolling stock leasing market competition remedies. Their conclusion indicates that the Transparency Order continues to be appropriate and proportionate, though recommended updates to terms are necessary following legislative changes. The Transparency Order requires ongoing monitoring and updates to remain fit for purpose amid rail reform. For lessors operating in this jurisdiction, maintaining compliance with these transparency requirements is essential to avoid regulatory friction and ensure market access.
Drivers of Market Demand
The demand for railcar leasing is driven by several interconnected factors. The need for flexible logistics solutions allows shippers to scale capacity without the heavy capital expenditure associated with purchasing assets. As supply chains become more volatile, the ability to access fleet capacity on demand provides a strategic advantage over fixed asset ownership.
Furthermore, the push towards decarbonization and efficiency in freight transport is influencing fleet compositions. Rail transport is increasingly viewed as a lower-emission alternative to trucking for long-haul freight, driving demand for modern, efficient railcars. However, the specific utilization of these assets varies across sectors. Agricultural transport, industrial and energy sectors, and bulk commodity movements all present distinct requirements for railcar specifications and lease durations. Understanding the relative weight of these drivers in specific regions and applications is key to forecasting demand accurately.
Lease Duration and Application Nuances
Market participants must also consider the structure of lease agreements. The market sees significant activity in both short-term and long-term leasing arrangements. Short-term leases, typically ranging from one to two years, offer flexibility for seasonal spikes or temporary capacity gaps. Long-term leases, extending three years or more, provide stability for operators with predictable freight volumes and allow lessors to secure steady revenue streams.
The allocation of assets across different applications is equally critical. Whether moving agricultural products, supporting industrial and energy projects, or transporting bulk commodities, each segment imposes different wear-and-tear profiles and regulatory requirements on the equipment. Our detailed analysis breaks down the prevalence of these applications without exposing the specific regional sensitivities that our clients need to protect in their strategic planning.
Why Subscribe to the Full Report?
While this overview establishes the macroscopic context, the true strategic value lies in the granular data contained within the full PW Consulting Railcar Leasing Market report. Decision-makers need precise figures to model ROI, assess risk, and benchmark against competitors. The proprietary intelligence within the study offers several distinct advantages:
- Granular Segmentation Data: Access detailed breakdowns of market size and share by specific regions and application types, enabling targeted market entry or expansion strategies. The full report provides the specific revenue contributions and growth rates for each segment, allowing for precise resource allocation.
- Forecast Accuracy: Utilize our expert-validated forecast models for 2026 through 2032 to align capital budgeting with market realities. The report provides year-by-year revenue projections that help in planning fleet acquisitions and retirement schedules.
- Company Profiles and Competitive Intelligence: Dive deeper into the operational metrics and strategic positioning of key players like GATX, TrinityRail, VTG, and others. Understanding their specific fleet compositions and recent financial moves can reveal gaps in the market or potential partnership opportunities.
- Regulatory Impact Analysis: Go beyond the headline regulations to understand the operational implications of US content restrictions and UK transparency orders on cost structures and compliance timelines. The report details how these regulations might affect specific asset classes and lease terms.
In an environment defined by rapid consolidation, regulatory tightening, and shifting trade flows, generic industry knowledge is insufficient. Leaders require data that is specific, timely, and actionable. The complete report ensures that your strategy is built on verified intelligence rather than assumptions.
Conclusion: Building Resilience in a Changing Market
The railcar leasing market is poised for sustained growth through 2032, driven by fundamental logistics needs and significant infrastructure investments. However, the path to capturing this value is fraught with complexity. From navigating the tightening US content restrictions to capitalizing on strategic partnerships in emerging markets like India, the required knowledge base is extensive.
PW Consulting's market research is designed to be the definitive resource for this journey. By combining macroeconomic trends with deep dives into competitive moves and regulatory impacts, we provide the clarity needed to make high-stakes decisions. We invite industry stakeholders to access the full study to unlock the detailed charts, regional splits, and application-specific data that will turn uncertainty into strategic advantage.
The future of rail logistics belongs to those who prepare today with the best available intelligence. Ensure your organization is equipped with the full spectrum of market data to lead rather than follow in the coming years.
For detailed analysis of this topic, please visit the official page: Railcar Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


