



Category: market research
PW Consulting: Sandals Market Hits $36.29B in 2025, Eyes 4.52% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons: Unlocking Value in the Global Sandals Market Through 2032
The global footwear industry is undergoing a subtle but significant transformation. While athletic sneakers and formal footwear often dominate headlines, the sandals market has emerged as a resilient and growing segment, driven by shifting consumer lifestyles, comfort-centric design trends, and evolving industrial safety requirements. As organizations plan their product portfolios, supply chain strategies, and market entry initiatives for 2026 and beyond, access to precise, forward-looking market intelligence is no longer optional. It is a strategic imperative.
Emulsified Oil for Powered Support Market
This introduction outlines the scope, methodology, and strategic value of our newly released comprehensive market study on the global sandals sector. The research covers historical performance from 2020 through 2025 and provides a detailed forecast horizon extending to 2032. By synthesizing macroeconomic indicators, regional supply-demand dynamics, product category evolution, and competitive positioning, the report equips executives, product developers, and investment planners with the analytical foundation needed to navigate an increasingly fragmented and opportunity-rich landscape.
Worldwide Cathodic Protection Service Market
Our analysis is anchored in rigorous data modeling and validated industry tracking. The global sandals market generated approximately USD 36.29 billion in revenue during 2025, reflecting a compound annual growth rate of 4.52 percent across the forecast period through 2032. This trajectory signals sustained expansion, with projected revenues surpassing the 49 billion USD threshold by the close of the decade. Such figures are not merely historical artifacts; they represent a structural shift in how consumers and industrial buyers approach casual, recreational, and safety-oriented footwear. Understanding the drivers behind this growth, the segments that will outperform, and the competitive pressures that will intensify is essential for any organization seeking to capture meaningful market share.
Real-Time Tire Monitoring System Market
The 2026 Decision Imperative: Why Timing Matters
Market timing in the footwear sector is rarely about sudden disruptions. More often, it is about recognizing inflection points before they become consensus. In early 2026, independent retail tracking confirmed that sandals posted measurable growth in both dollar value and unit volume during the first quarter, with specific silhouettes leading the expansion. This momentum is not isolated to a single geography or demographic. It reflects broader macro trends: warmer-weather travel rebound cycles, hybrid work environments that prioritize comfort without sacrificing style, and industrial buyers seeking compliant yet ergonomic safety footwear for automotive and workshop environments.
For corporate strategists, the implication is clear. Product development cycles that begin in late 2026 will face the 2028 to 2030 market reality. Supply chain investments finalized today will determine cost competitiveness in 2027 and beyond. Brand positioning decisions made now will either capitalize on emerging consumer preferences or lag behind them. Our study is structured to reduce the latency between market signal and strategic action. It translates high-level growth trajectories into actionable frameworks, enabling leadership teams to allocate capital, prioritize SKUs, and refine regional go-to-market plans with confidence.
The forecast period covered in this research extends through 2032, allowing decision-makers to model multiple scenarios. Whether an organization is evaluating a new product line, assessing distributor partnerships, or planning capacity expansion, the multi-year outlook provides the temporal granularity required to align short-term execution with long-term market architecture.
Decoding the Forecast Architecture: Regions, Categories, and Demand Patterns
A durable growth trajectory is rarely uniform across all dimensions. The sandals market exhibits distinct regional strengths, category-specific momentum, and demographic concentration patterns that collectively shape investment prioritization. Our analysis maps these dimensions without overwhelming stakeholders with fragmented percentages or isolated revenue figures. Instead, the report presents integrated demand narratives that connect geographic markets, product types, and end-user profiles into coherent strategic pathways.
Geographically, the market reflects a balanced but differentiated distribution of value. North America and Europe continue to serve as mature, high-volume demand centers, characterized by established retail channels, strong brand loyalty, and seasonal purchase cycles. The Asia Pacific region represents a structurally significant share of global revenue, supported by expanding middle-class consumption, localized manufacturing ecosystems, and growing domestic retail penetration. Latin America and the Middle East and Africa markets, while smaller in absolute terms, offer meaningful growth velocity and partnership opportunities for organizations seeking geographic diversification. The report details the commercial implications of these regional profiles, including channel maturity, import-export dynamics, and consumer preference gradients, without reducing complex markets to simplistic share percentages.
By product type, the landscape is anchored by three primary categories: flip flops, slides, and slippers. Each category carries distinct usage contexts, price architecture, and seasonal elasticity. Flip flops remain deeply associated with recreational, beach, and warm-weather casual wear, while slides have expanded their footprint into post-athletic recovery, casual office-adjacent settings, and home comfort. Slippers, often positioned around indoor comfort and certain occupational or hospitality applications, contribute a specialized but stable revenue stream. The study examines how these categories interact with broader style cycles, material innovation, and cross-category substitution patterns. It also incorporates recent consumer tracking that highlights additional silhouettes, such as mules, clogs, and ballerinas, contributing positively to category momentum. Recognizing these adjacent style influences is critical for brands aiming to capture share at the edges of the traditional sandals definition.
Gender and age segmentation further clarifies demand concentration. Women represent a substantial revenue share, reflecting both casual lifestyle adoption and fashion-forward design expectations. Men constitute a significant portion of the market, driven by comfort-oriented casual wear, athletic-adjacent slides, and, in certain industrial contexts, safety-compliant sandal formats. Children’s footwear forms a more specialized segment, often tied to family purchasing cycles and school-holiday seasonality. The report maps these demographic flows to procurement behavior, average transaction values, and repeat-purchase intervals, enabling product planners to tailor assortments and marketing architectures with precision.
Throughout these analyses, the study maintains a disciplined focus on strategic relevance. Rather than presenting raw segmentation numbers in isolation, it translates structural patterns into questions every leadership team must answer: Which categories align with our manufacturing capabilities? Which regions offer the best risk-adjusted return for our channel strategy? Where do adjacent style trends create expansion opportunities without diluting core brand equity?
Competitive Dynamics and the Anatomy of Market Leadership
Market growth does not automatically translate into shared prosperity. Competitive intensity, brand differentiation, and operational efficiency determine which organizations convert macro expansion into durable profitability. The sandals sector currently exhibits a moderately concentrated competitive structure, with the top three players collectively accounting for roughly 24.6 percent of market revenue and the top five reaching approximately 26.2 percent. This concentration pattern suggests a landscape where established players hold meaningful share, yet a substantial portion of value remains distributed across regional specialists, private-label operations, and emerging direct-to-consumer brands.
Our competitive assessment profiles the organizations shaping current supply and demand dynamics, with particular attention to firms operating at the intersection of casual footwear and specialized safety applications. WorkWay Safety, based in China, offers safety sandals and steel-toe sandals engineered for automotive work environments. Hillson Safety Shoes, also headquartered in China, provides safety footwear that includes sandals designed for automotive manufacturing and workshop conditions. These profiles are not included merely as company summaries. They serve as illustrative anchors for a broader competitive analysis that examines how manufacturers differentiate through compliance standards, ergonomic design, material durability, and channel specialization.
The study also integrates recent industry developments that signal the direction of market momentum. In May 2026, Circana released a market report confirming that sandals posted growth in both dollars and units during the first quarter, led by slides and flip flops. This external validation reinforces the internal forecast architecture and provides a timely reference point for organizations calibrating their 2026 production and inventory strategies. By connecting third-party retail signals with proprietary modeling, the report helps stakeholders distinguish between temporary seasonal uplift and sustained category reinforcement.
Competitive analysis in this research extends beyond corporate profiles. It evaluates distribution leverage, brand positioning, pricing architecture, and the strategic role of private-label and wholesale partnerships. For organizations considering market entry or expansion, the study identifies where competitive density is highest, where whitespace may exist, and what operational capabilities are required to compete effectively. For incumbents, it offers a structured lens to assess whether current portfolio mix, regional exposure, and innovation pacing are aligned with the market’s forward trajectory.
Inside the Report: Operational Content for Execution Teams
A market study is only as valuable as its applicability. Our sandals market research is designed for direct integration into planning workflows, not as a passive reference document. The report combines macro-level forecasting with granular, operationally oriented content that supports product, sales, supply chain, and investment decision-making.
Key components include a comprehensive market size and forecast model spanning 2020 through 2032, with year-by-year revenue trajectories that enable trend analysis and scenario planning. The segmentation framework examines regional demand structures, product type performance, and demographic consumption patterns in a format built for cross-functional discussion. Rather than overwhelming readers with exhaustive sub-segment tables, the report prioritizes interpretive clarity: what each segment means, how it behaves across cycles, and where strategic leverage can be applied.
The competitive landscape section delivers structured company profiling, market concentration analysis, and qualitative assessment of strategic positioning. It identifies how leading players differentiate, where specialization creates defensibility, and what operational capabilities matter most in the current environment. Recent industry developments are woven into the analysis to ensure that insights reflect both modeled projections and real-time commercial signals.
In addition to quantitative modeling and competitive assessment, the report addresses practical planning dimensions that often determine execution success. These include demand timing patterns, category substitution dynamics, material and design trend relevance, channel maturity considerations, and the strategic implications of adjacent style growth such as mules, clogs, and ballerinas. By connecting these factors to the broader forecast architecture, the study helps teams anticipate not only how large the market will become, but also how its composition will shift.
The document is organized to support multiple internal use cases. Executive teams can use the high-level trajectory and concentration data for capital allocation and long-range planning. Product and merchandising teams can draw on category dynamics and demographic patterns to refine assortment strategy. Sales and market development teams can leverage regional demand narratives to prioritize territories, channel partners, and entry modes. Supply chain and operations leaders can use the multi-year forecast to align capacity planning with projected volume evolution.
Translating Intelligence into Strategy: The 2026 Playbook
Understanding market direction is the first step. Converting that understanding into a coherent strategy is where competitive advantage is created. Our research is structured to support that translation by highlighting the decision points that matter most in the current cycle.
First, portfolio alignment requires clarity on category momentum. Slides and flip flops have demonstrated recent strength, and organizations should evaluate whether their current design pipelines, material sourcing, and seasonal launch calendars reflect this reality. At the same time, the positive contribution of adjacent silhouettes suggests that brands should monitor style diffusion carefully, distinguishing between fleeting trend activity and structural adoption that justifies dedicated SKU investment.
Second, regional strategy should be calibrated to market maturity and growth velocity. Mature markets demand differentiation through brand equity, channel execution, and product refinement. Higher-growth regions may offer volume expansion and partnership opportunities, but they also require localized insight into retail structures, consumer price sensitivity, and distribution logistics. The report provides the strategic context needed to match ambition with execution realism.
Third, competitive positioning should be assessed against concentration dynamics and specialization pathways. In a market where the top five players hold a modest share, there is room for focused differentiation. Organizations can compete on comfort innovation, safety compliance, aesthetic direction, channel access, or cost efficiency. The study helps identify which pathways are most viable given an organization’s capabilities and target segments.
Fourth, planning horizons must be extended. A forecast extending to 2032 is not a luxury; it is a practical tool for aligning product development, capacity investment, and brand-building efforts with the market’s medium-term architecture. Decisions made in 2026 will influence cost structures, channel relationships, and portfolio relevance in 2028 and beyond. The research is designed to reduce uncertainty across that timeline.
Conclusion: Access the Full Intelligence Architecture
The global sandals market is positioned for sustained expansion, supported by a 4.52 percent CAGR across the forecast period and a revenue trajectory that moves steadily toward the 49 billion USD range by 2032. Yet size alone does not create strategy. The real value lies in understanding where growth is concentrated, how competitive dynamics are evolving, which categories and regions offer the strongest alignment with organizational capabilities, and how recent consumer signals should shape near-term execution.
This introduction provides a structured overview of the strategic landscape and the decision context facing footwear leaders in 2026. It is designed to demonstrate the depth and practical relevance of our research while preserving the detailed segmentation, proprietary modeling, and complete competitive profiles for the full report. For organizations that require precise regional breakdowns, category-level revenue architecture, demographic share structures, and comprehensive company assessments, the complete study delivers the operational intelligence necessary to move from insight to execution.
The market will continue to evolve through shifts in consumer habits, industrial safety requirements, style diffusion, and channel development. Organizations that equip themselves with rigorous, forward-looking research will be better positioned to allocate resources wisely, enter or expand in the right segments, and build durable competitive advantage. We invite strategic leaders to access the full report and integrate its complete intelligence architecture into their 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Sandals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prothioconazole Market Hits $1.19B in 2025, Projected 6.4% CAGR to 2032
By PW Consulting, 2026-09-07
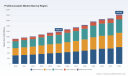
Navigating the Prothioconazole Market: Strategic Imperatives for 2026 and Beyond
As global agricultural systems face intensifying pressure from climate volatility, evolving pathogen resistance, and tightening regulatory frameworks, crop protection chemistries must deliver both reliability and adaptability. Prothioconazole has emerged as one of the most strategically important active ingredients in modern fungicide portfolios, particularly for cereal disease management and high-value broadleaf crop protection. Our latest market intelligence publication examines the structural trajectories, competitive repositioning, and regulatory inflection points that will define decision-making across the 2026-2032 horizon.
Worldwide Media Mist Collector Market
The purpose of this overview is to outline why a disciplined, data-grounded approach to prothioconazole market strategy matters for commercial, procurement, and R&D leadership in the current operating environment. Rather than offering static snapshots, the report is designed as an actionable planning instrument that maps revenue pathways, supply chain vulnerabilities, formulation shifts, and regulatory risk into a single decision framework.
Worldwide Car Mobile Phone Charger Market
Macro Trajectory and Structural Signals
Historical demand patterns for prothioconazole reflect a sector that has moved past early adoption curves and entered a phase of institutionalized usage across major cropping systems. Over the 2020-2025 evaluation window, the market expanded from approximately 927 million USD to just under 1.2 billion USD, demonstrating consistent year-over-year reinforcement even as input cost cycles and weather-driven planting variability created intermittent demand shocks. That trajectory underscores the ingredient's entrenched position in resistance management programs, particularly where Fusarium head blight, rust complex, and foliar disease pressure require dependable demethylation inhibitor performance.
Dog Shower Head Market
Looking forward, our forecast modeling projects steady expansion through the end of the decade, with the market expected to cross the 1.27 billion USD threshold in 2026 and continue compounding toward the higher ranges by 2032. The implied compound annual growth rate during the 2026-2032 forecast period is approximately 6.4 percent, a pace that reflects a blend of volume growth, registration-driven use case expansion, formulation upgrades, and substitution dynamics as growers rotate away from compromised efficacy profiles in certain disease complexes.
It is important to interpret that growth rate within the correct strategic context. A mid-single-digit CAGR in a mature crop protection category is not merely a demand story; it is a signal of portfolio reshuffling, geographic rebalancing, and active ingredient lifecycle management. Companies that treat the forecast as a simple planning multiplier risk missing the structural drivers underneath. The report therefore separates headline expansion from the operational forces that determine which participants capture disproportionate value: technical supply reliability, formulation differentiation, multi-crop registration progress, and speed to market in regions where regulatory pathways are opening or closing.
Concentration dynamics further clarify the competitive environment. The market remains moderately consolidated, with a meaningful share held by a limited set of technical suppliers and integrated crop protection developers. That concentration has strategic implications for procurement timing, contract structuring, and downstream formulation strategy. In a landscape where technical-grade availability can shift with manufacturing capacity, regulatory approvals, and partnership realignments, visibility into supply-side behavior becomes a critical planning input rather than a background concern.
Regulatory and Registration Dynamics Reshaping Demand Pathways
Regulatory developments have moved to the center of prothioconazole market strategy in recent quarters. Over the past year, evaluation activity across major agricultural jurisdictions has produced a series of technical assessments and modification requests that directly influence which crops, regions, and application systems can incorporate the active ingredient into standard programs.
In May 2025, the European Food Safety Authority published an opinion on the peer review of the pesticide risk assessment for prothioconazole as an active substance, setting the stage for subsequent regulatory discussion. That evaluation fed into a series of more targeted actions later in the year. In August 2025, Sipcam Oxon SpA submitted an application to the Greek evaluating member state under Article 6 of Regulation (EC) No 396/2005 to raise existing maximum residue levels for prothioconazole in pome fruits, apricots, cherries, plums, cucurbits, and rice. The intent of that filing was to accommodate new intended uses and broaden the practical deployment envelope for the molecule.
The regulatory conversation did not stop at the member state level. In January 2026, the EU peer review committee discussed the toxicological profile of prothioconazole and its metabolites during the Pesticides Peer Review Experts' TC 22 meeting. Shortly thereafter, in January 2026, EFSA adopted a proposal to raise MRLs for prothioconazole in apples, quinces, loquats, pears, apricots, cherries, plums, cucurbits, and rice following evaluation of the Sipcam Oxon SpA application. These processes matter strategically because MRL adjustments are often the difference between a technically viable fungicide and a commercially scalable one. They determine whether formulators can build multi-crop portfolios, whether distributors can commit to broad registration coverage, and whether growers can integrate the chemistry into high-value fruit and specialty crop programs without compliance friction.
For commercial leaders, the practical implication is that registration momentum is not uniform across crops or geographies. Some pathways are opening, others remain under active toxicological review, and the timing of finalization can reshuffle competitive positioning quickly. The report treats regulatory trajectory as a forward-looking variable, mapping the likely consequences of current EFSA and member-state processes rather than simply cataloguing them.
Competitive Landscape and Strategic Positioning
The prothioconazole ecosystem is defined by a mix of integrated crop protection developers, technical concentrate producers, formulators, and regional supply partners. Understanding how these participants compete requires more than a list of company names; it requires attention to role specialization, formulation strategy, supply footprint, and partnership behavior.
Bayer CropScience remains a foundational reference point in the market. As a core developer and global producer of technical-grade prothioconazole, Bayer markets the molecule under established brands such as Proline and Prosaro, positioning it as a foundational DMI fungicide for Fusarium head blight control in cereals and for Asian soybean rust management in soybeans. Its influence extends beyond volume; it shapes technical standards, use patterns, and the disease-control narrative that many downstream partners align with.
ADAMA Agricultural Solutions occupies a distinctly operational position. As a major technical producer and formulator, ADAMA maintains multi-purpose manufacturing plants, including a Brazil facility designed to support in-house active ingredient supply for the global crop protection pipeline. That manufacturing architecture has strategic relevance for regional responsiveness, supply buffer capacity, and the ability to align technical output with local formulation demand. In markets where logistics cost and supply continuity are decisive, such footprint choices can translate directly into commercial resilience.
Albaugh LLC participates in the market with a clear formulation-focused identity. It is an active provider of Prothioconazole 4L Select formulations, marketed as a premium DMI fungicide for turfgrass and ornamental disease control, emphasizing low use rates and a 4 lb/gal active ingredient concentration. This positioning illustrates how the same active ingredient can be adapted to distinct end-use segments with different value propositions, pack size economics, and application systems.
Sipcam Oxon SpA operates as a supplier of prothioconazole technical material and 400 g/L formulations for systemic control of diseases in cereals, pome fruits, and cucurbits. Its recent regulatory activity, including the EU MRL modification applications described above, reflects a strategy that combines technical supply with proactive registration expansion. Companies that pursue MRL adjustments for additional crops are effectively trying to widen the addressable market while managing compliance risk in parallel.
Corteva Agriscience also plays an active role as a producer of prothioconazole technical concentrate used in crop protection formulations for global markets. Its participation reinforces the importance of technical-grade supply capacity in shaping downstream formulation options and partnership structures.
Beyond the incumbents, a cluster of strategic collaborations and supply arrangements announced in 2025 signals that the market is entering a phase of deeper coordination across the value chain. In June 2025, Sumitomo Chemical announced a strategic partnership with BASF to co-develop and commercialize a new range of prothioconazole-based fungicides across Asia-Pacific. That move highlights how regional expansion can be accelerated through joint development and shared commercialization capacity rather than unilateral entry.
Also in June 2025, Syngenta signed a long-term supply agreement with FMC Corporation to secure stable supply of prothioconazole technical concentrate for global markets. This type of arrangement is strategically telling because it pairs one of the largest formulation and commercialization platforms with a deliberate supply assurance mechanism. In a category where technical availability can constrain downstream portfolio plans, long-term supply commitments become a competitive hedge as well as an operational enabler.
Taken together, these competitive dynamics suggest a market where technology ownership, manufacturing footprint, registration strategy, and supply agreements all interact. The report analyzes these interactions not as isolated company profiles, but as mutually reinforcing strategic levers that determine who can scale, who can differentiate, and who is exposed to supply or regulatory bottlenecks.
Where Growth Is Being Created: Application Realities and Segment Logic
Prothioconazole demand is not evenly distributed across crops or use systems. The practical value of the molecule lies in its fit with specific disease complexes and application contexts, which means growth is increasingly a function of where those use cases are expanding, intensifying, or being formally recognized through regulatory and commercial channels.
In cereals, the strategic role of prothioconazole is well established. Its performance in head blight and broader foliar disease programs has made it a recurring tool for growers who need dependable protection windows and resistance-conscious rotation options. As a result, cereal-linked demand often functions as a ballast for the broader market, especially in regions where wheat and barley production systems face recurring pressure from humidity-driven disease cycles.
Beyond cereals, significant demand signals are associated with broadleaf cropping systems, including soybeans and canola, where rust, foliar complexes, and yield-protection thresholds create recurring fungicide needs. The molecule's utility in these systems depends on timing, tank-mix compatibility, and the broader disease management strategy being deployed by growers and advisors. The report examines these application realities through a demand-structuring lens rather than a simple product description, focusing on how crop calendars, resistance pressure, and advisor recommendation patterns shape recurring procurement behavior.
There is also meaningful activity in specialty and higher-value applications. Regulatory efforts to expand MRL coverage in pome fruits, stone fruits, cucurbits, and rice indicate an attempted shift toward broader crop coverage. If such expansion is finalized and commercialized successfully, it can alter the demand composition of the market by adding higher-margin use cases and new customer segments. At the same time, these pathways remain contingent on regulatory conclusion, residue monitoring expectations, and the willingness of formulators and distributors to build crop-specific programs around them.
From a strategic planning perspective, this mix matters because it implies that growth will come from multiple, unevenly paced sources. Some expansion will be cyclical and weather-dependent; some will be registration-driven; some will be formulation-led. The report separates these channels so that readers can anticipate which levers are within their control and which depend on external regulatory or environmental conditions.
What the Report Delivers for 2026 Decision-Making
The full research publication is built around operational usability. It is intended to support market entry evaluations, portfolio prioritization, procurement strategy, technical supply planning, and competitive positioning assessments. Rather than presenting a single aggregate number, the analysis unpacks the market into a structured set of planning inputs.
At the core of the report is a multi-year market trajectory framework that connects historical demand behavior to the 2026-2032 forecast period. The historical record is used not as a nostalgia exercise but as a baseline for understanding how the market responded to pricing cycles, weather variation, disease pressure, and registration milestones. The forward projection then translates those lessons into a planning range that leadership teams can use for budgeting, scenario design, and resource allocation.
The publication also includes a detailed segmentation architecture covering product type, application context, and regional demand logic. This structure is used to identify where demand is most durable, where it is most responsive to regulatory or technical changes, and where competition is likely to intensify. Importantly, the report presents these segments as strategic categories with distinct risk-return profiles rather than as static breakdowns.
On the competitive side, the report maps the strategic roles of the principal participants, including their manufacturing footprints, formulation emphasis, technical supply posture, and recent partnership behavior. That mapping is paired with an assessment of concentration dynamics and supply-side dependency, helping readers evaluate where negotiation leverage lies, where supply continuity risk is concentrated, and where new collaboration models are reshaping competitive access.
A significant portion of the report is devoted to regulatory and registration monitoring. The analysis incorporates recent EFSA assessments, member-state MRL modification activity, and the broader peer review process to clarify which use-case expansions are advancing, which remain under evaluation, and what that implies for near-term commercial planning. The goal is to give decision-makers a clearer view of the compliance and access environment so that they can align product development, distribution commitments, and market entry timing accordingly.
The report also addresses practical commercial questions: how formulation strategy affects price realization, how technical supply agreements influence downstream flexibility, how regional manufacturing presence alters logistics risk, and how pairing registration activity with supply readiness can determine whether an opportunity is captured or ceded to competitors. These are not abstract themes; they are the operational variables that determine whether growth forecasts can be converted into actual revenue.
How to Use This Intelligence in Practice
For organizations operating in or entering the prothioconazole market, the central question is not whether the category is expanding, but whether their strategy is aligned with the forces actually generating that expansion. The report is structured to help leaders translate market context into concrete actions.
Procurement and supply chain teams can use the analysis to evaluate technical supply risk, partnership options, and inventory planning horizons in light of concentration patterns and recent supply agreements. Commercial teams can use the segmentation and application logic to prioritize territories, crop programs, and formulation mixes where demand durability and pricing potential are most favorable. Regulatory and registration teams can use the EFSA and member-state developments to sequence crop coverage strategies and anticipate compliance dependencies.
For developers and formulators, the report provides a basis for deciding where to commit formulation resources, which crop systems merit registration investment, and how to position products against incumbent usage patterns. For investors and corporate strategy functions, the analysis offers a way to assess where value creation is likely to concentrate, which partnership models are gaining traction, and which regulatory trajectories could alter competitive access over the forecast period.
The overarching premise is that the prothioconazole market is not moving as a single block. It is being reshaped by asynchronous regulatory processes, uneven regional adoption, differentiated formulation strategies, and selective supply-chain coordination. Organizations that rely on a single aggregate growth assumption will likely misread both risk and opportunity. Organizations that use a structured, multi-variable view will be better positioned to time investments, negotiate from a stronger position, and capture share where the market is genuinely opening.
Closing Perspective
The prothioconazole market in 2026 sits at the intersection of established agronomic utility and active strategic reconfiguration. Demand is being reinforced by disease-management needs in core cereals and broadleaf systems, while the potential for broader crop coverage depends on the outcome of ongoing regulatory processes and the speed with which participants can align technical supply, formulation readiness, and commercialization capacity. At the same time, concentration in technical supply and a recent wave of partnerships and supply agreements are changing how competitive advantage is built and defended.
This introduction is intended to signal the scope and intent of the full research publication. The complete report develops these themes with the analytical depth required for execution-level planning, linking market size evolution, segmentation logic, competitive behavior, regulatory developments, and supply-chain structure into a single strategic framework. For organizations that need to convert market momentum into actionable decisions, the detailed intelligence inside the report is designed to reduce uncertainty and sharpen prioritization.
The next step is to examine the full dataset, segment breakdowns, competitive mapping, and scenario-based interpretations that underpin the conclusions summarized here. Access to the complete publication provides the operational detail necessary to move from directional understanding to concrete planning, whether the objective is portfolio expansion, supply assurance, regulatory readiness, or competitive positioning in a market that is growing, but growing unevenly.
For detailed analysis of this topic, please visit the official page: Prothioconazole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Office Storage Market Hits $3.15B in 2025, Projects 7.9% CAGR to $5.34B by 2032
By PW Consulting, 2026-09-07
2026 Office Storage & Organization Market Outlook: Strategic Intelligence for Workplace Infrastructure Decisions
The office storage and organization market is entering a phase of structural realignment, driven by hybrid work permanence, rising density requirements in commercial real estate, and a renewed focus on workplace functionality. As organizations recalibrate their physical environments to support collaboration, compliance, and employee experience, the demand for intelligent storage solutions is evolving from a commodity procurement category into a strategic workplace investment. PW Consulting’s latest Office Storage & Organization Market research offers a comprehensive, decision-grade view of this transformation, equipping executives, procurement leaders, and facility planners with the analytical foundation needed to navigate 2026 and the years ahead.
Manure Agitators Market
This market research is designed as a strategic briefing rather than a static data dump. It maps the trajectory of an industry that has already demonstrated consistent expansion across the 2020–2025 period and is projected to continue its upward momentum through the 2026–2032 forecast window. The purpose of this article is to preview the depth, methodology, and strategic applicability of the full report while illustrating how its insights can be operationalized for high-impact business decisions. The complete dataset, segmentation breakdowns, competitive benchmarking matrices, and region-specific deployment scenarios are reserved for the published report, where they are presented with the granularity required for actionable planning.
Worldwide Drawer Air Fryer Market
Market Trajectory and the Strategic Implications of Sustained Growth
Over the past half-decade, the office storage and organization sector has moved through a period of measurable expansion, with revenue climbing steadily from 2020 through 2025. This trajectory reflects more than a post-pandemic recovery; it signals a broader rethinking of how physical workspace assets are designed, allocated, and utilized. As organizations consolidated remote work policies and adjusted office footprints, storage and organization products transitioned from peripheral furnishings to integral components of space management strategy. The trend has continued into 2026, where the market’s valuation reflects a maturing demand environment shaped by both commercial real estate optimization and the formalization of home-office infrastructure.
Artificial Grass Adhesive Market
Looking forward, the forecast period through 2032 indicates a continued expansion path supported by a robust compound annual growth rate. This growth is not incidental. It is anchored in several operational realities: the need to maximize usable square footage in high-cost urban markets, increasing requirements for secure and compliant document and equipment storage, and the aesthetic-functional pressure to integrate storage seamlessly into modern workplace design. For decision-makers, the implication is clear. Storage and organization spending is no longer a line item to be minimized; it is a variable that interacts with talent retention, space efficiency, regulatory compliance, and overall workplace productivity.
What makes this trajectory strategically significant is the way growth is distributed across product philosophies and deployment contexts. Rather than a uniform increase, the market is being shaped by divergent use cases that require different procurement logic, investment horizons, and evaluation criteria. Some organizations are prioritizing fixed storage architectures that anchor permanent headquarters, while others are investing in mobile and reconfigurable systems that support agile space allocation. Still others are scaling home-office and distributed-workplace setups, where storage decisions influence both functional output and employee satisfaction. Each of these pathways carries distinct cost structures, vendor ecosystems, and implementation risks, which is precisely why high-level market sizing is only the starting point for meaningful strategy.
The full research unpacks these dynamics with forward-looking projections that extend beyond aggregate revenue figures. It isolates the structural drivers that will determine which solution categories gain share, how procurement cycles are shifting, and where regional demand intensity is likely to concentrate. Decision-makers who rely solely on broad market headlines risk misallocating capital or underestimating the timing of transitions in supplier capacity, pricing behavior, and specification requirements. By contrast, the complete PW Consulting analysis is built to support scenario-based planning, allowing organizations to align procurement strategy with their own operational tempo and real estate roadmap.
Key Forces Reshaping the Competitive Landscape
The office storage and organization market is characterized by a mix of specialized manufacturers, broad-line furniture providers, and retail-oriented solution platforms. This diversity matters because it creates a competitive field in which value propositions differ substantially across customer segments. Some companies compete on modularity, speed of deployment, and catalog breadth, while others emphasize engineering durability, high-density capacity, or design-forward aesthetics. A few operators occupy niche positions that blend retail accessibility with workplace utility, broadening the range of options available to small and mid-sized enterprises as well as corporate procurement teams.
Several of the most active participants operate from distinct geographic and operational bases, which influences their supply chains, product development priorities, and market access strategies. On the North American side, firms with established showroom networks, online catalogs, and workplace-integrated system portfolios have continued to refine their storage and organization offerings to align with hybrid office needs. Meanwhile, manufacturers based in Asia have expanded their footprint by emphasizing modern cabinet design, plastic and composite container systems, and modular organizer lines that appeal to both office and home-office buyers. Large global retailers also play a role, particularly where affordability, accessibility, and branded modular systems influence purchasing decisions for smaller workplaces and remote setups.
A defining feature of the competitive landscape is the relatively fragmented concentration profile. The market does not rely on a small number of dominant incumbents to the exclusion of all others; instead, it supports a broad field of players that compete across dimensions such as price, customization, product durability, distribution reach, and specialty functionality. This fragmentation creates both opportunity and complexity. Buyers benefit from multiple sourcing pathways, but they also face the challenge of comparing solutions that may appear similar on the surface while differing sharply in load-bearing performance, mobility features, aesthetic finish, and long-term maintenance requirements.
Recent activity from several leading participants illustrates how competitive positioning is being sharpened through catalog updates, product showcases, and targeted launches. Throughout the 2025–2026 period, multiple companies have released updated product catalogs or showcased new storage and organization lines at major trade events. These moves are not merely promotional; they reflect an industry-wide effort to communicate updated design philosophies, material choices, and functional configurations that align with evolving workplace expectations. For procurement teams, such releases provide early signals about where suppliers are directing innovation investment and how product roadmaps may influence future purchasing decisions.
At the same time, competitive dynamics cannot be understood without accounting for the operational pressures affecting the supply side. Raw material cost volatility for steel, wood composites, and engineered plastics has introduced margin constraints that shape vendor pricing strategies and product mix decisions. In parallel, regulatory expectations around load-bearing performance and fire resistance are raising the baseline for what qualifies as a compliant storage solution in commercial environments. These forces interact with labor cost trends and producer price movements in the broader office furniture sector, creating a more complex decision environment for buyers who must balance specification quality, total cost of ownership, and delivery reliability.
The full report examines these competitive pressures in greater depth, mapping how major participants position themselves relative to one another and where differentiation is becoming increasingly important. It also evaluates how market concentration patterns influence negotiation leverage, supplier diversification strategy, and risk exposure for enterprise buyers. By situating company-level activity within the broader structural context, the research enables decision-makers to interpret market movements with greater precision rather than relying on surface-level brand recognition.
Strategic Dimensions for 2026 Decision-Makers
For executives planning workplace investments in 2026, the office storage and organization market presents several strategic questions that extend well beyond immediate purchasing needs. One central issue is the alignment between storage procurement and wider real estate strategy. As organizations optimize space utilization, storage systems increasingly need to support multiple functions: enabling efficient retrieval, reducing clutter that undermines productivity, facilitating secure storage for sensitive materials, and contributing to the overall visual coherence of the workplace. The right solution in one context may be inappropriate in another, which makes segmentation-aware planning essential.
Another strategic dimension involves the growing relevance of financing and investment pathways for office infrastructure. In certain markets, long-term financing mechanisms for small business infrastructure investment can influence the timing and scale of storage upgrades. When coupled with the need to manage material and labor-related cost pressures, procurement leaders must evaluate not only the sticker price of storage systems but also the financing structure, deployment timeline, and expected service life of the assets they acquire. This broadens the scope of decision-making from transactional purchasing to asset strategy.
Operational resilience is also becoming more prominent in procurement thinking. Organizations are increasingly attentive to vendor consistency, product availability, and the ability to scale orders without sacrificing specification quality. At the same time, compliance considerations remain central in commercial settings, where storage units must satisfy safety and performance standards relevant to the environment in which they are deployed. These requirements create a strong incentive to evaluate suppliers not only on aesthetics or price but also on documented performance, certification alignment, and post-sale support capacity.
The distributed workplace continues to add complexity. As remote and home office setups become a more permanent part of the work ecosystem, storage decisions must account for smaller-scale deployments, ease of assembly, aesthetic compatibility with residential environments, and the practical need to maintain organization without dedicated facilities support. This segment has distinct purchasing behaviors and specification preferences compared with large corporate headquarters, and it requires its own evaluation framework.
Taken together, these factors point to a market in which strategic value comes from matching the right solution architecture to the right operational context. That is precisely where the full PW Consulting research is intended to support executive judgment. It does so by organizing market intelligence in a way that connects demand drivers, product categories, application settings, and competitive realities to concrete planning decisions.
What the Full Report Delivers
The complete Office Storage & Organization Market research is structured to provide a practical, decision-oriented toolkit rather than a narrow statistical summary. It opens with a consolidated market overview that establishes baseline sizing and forward projections, then moves into the segmentation and demand-side analysis needed to interpret where growth is coming from and how it is likely to evolve. The report examines how different solution types are positioned across office environments, including fixed storage architectures and mobile or high-density systems that address space-constrained layouts. It also distinguishes between major deployment contexts, such as centralized corporate headquarters, remote and home office settings, and other organizational use cases, so that readers can calibrate expectations by environment rather than treating the market as a single homogeneous demand pool.
A substantial portion of the research is devoted to regional demand patterns and the operational factors that shape them. Rather than simply presenting geographic splits in isolation, the report situates regional variation within the broader context of workplace norms, procurement practices, regulatory expectations, and distribution dynamics. This allows decision-makers to understand not just where demand is occurring, but why it is occurring there and what that implies for market entry, sourcing strategy, and localization of product specifications.
The competitive section moves beyond basic company identification to analyze how leading participants differentiate themselves across product philosophy, distribution channels, and target customer profiles. It incorporates recent product catalog releases, showcase activity, and other visible indicators of strategic focus, using them to illuminate where innovation attention is being directed. By connecting company-level movement to broader market structure, the report provides a more useful competitive map than a simple roster of names and headquarters locations.
The research also integrates the operational and regulatory pressures that influence both supply and demand. Material cost volatility, producer price trends in related furniture categories, safety and compliance requirements, and financing mechanisms that affect investment timing are all addressed as part of the market environment. These elements are not treated as background noise; they are framed as decision-relevant variables that shape pricing behavior, specification choices, and procurement risk. For organizations planning multi-year workplace investments, this context is essential for building realistic cost assumptions and contingency plans.
Finally, the report is designed with an emphasis on usability. It supports read-through analysis for senior leadership while also providing the level of structural detail required by procurement, facilities, and strategic planning teams. The aim is to make the intelligence actionable: to help readers identify where to focus sourcing efforts, how to evaluate alternative solution types, which competitive signals deserve attention, and how macro-level growth translates into organization-specific opportunities.
Conclusion: Why This Research Matters Now
The office storage and organization market is not simply expanding; it is being redefined by changes in work patterns, space economics, compliance expectations, and supplier innovation. In that environment, high-level awareness of growth trends is necessary but insufficient. Decision-makers need a structured view of how demand is segmented, how competitive players are positioning themselves, and which external pressures are likely to influence cost, availability, and specification standards over the forecast period.
PW Consulting’s Office Storage & Organization Market research is built to meet that need. It translates macro growth into strategic context, connects market structure to practical procurement and workplace planning decisions, and provides the analytical depth required to move from observation to action. The full report contains the detailed segmentation data, regional intensity patterns, company-level competitive profiles, and forward-looking scenario content that executives and operational leaders need to make informed choices throughout 2026 and beyond.
For organizations seeking to align workplace storage investments with broader strategic objectives, the complete market intelligence offers a timely and practical foundation. The insights previewed here are intended to demonstrate the report’s scope and relevance; the full analysis is where the detailed numbers, segmentation logic, and competitive benchmarks are presented in the depth required for implementation-grade decision-making.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Stem Cell Therapy Market Hits $232.5M in 2025, 7.05% CAGR to $375.1M by 2032
By PW Consulting, 2026-09-07
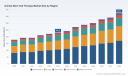
Strategic Intelligence for the Next Frontier: Inside the Animal Stem Cell Therapy Market 2026–2032
The animal health sector is undergoing a paradigm shift. For decades, veterinary medicine relied heavily on pharmacological interventions and surgical procedures to manage chronic conditions, degenerative diseases, and complex injuries in companion and livestock animals. Today, a new therapeutic class is redefining the standard of care: stem cell therapy. What was once confined to experimental research laboratories and elite specialty clinics has matured into a structured commercial landscape, driven by advances in regenerative biology, evolving regulatory frameworks, and an expanding willingness among pet owners and producers to invest in long-term animal health outcomes.
Hot Water Heating Cable Market
PW Consulting’s latest market research report on the Animal Stem Cell Therapy Market captures this inflection point with precision. Designed for executive leadership, R&D directors, commercial strategists, and investment committees, this study maps the trajectory of a market that has moved from nascent curiosity to measurable revenue momentum. The following analysis previews the strategic lens, structural insights, and decision-making utility embedded in the full report, while preserving the granular intelligence that will be delivered in the complete publication.
Shooting Earmuff Market
A Market That Has Crossed the Proof-of-Concept Threshold
Regenerative therapies for animals are no longer a speculative storyline. The data tells a clear story of consolidation and acceleration. Between 2020 and 2025, the market expanded from a modest baseline to a multi-hundred-million-dollar revenue pool, reflecting sustained adoption across veterinary practices, specialty clinics, and emerging commercial partnerships. The trajectory has not been linear, but it has been durable. Fluctuation in early years gave way to steadier growth as clinical applications broadened, practitioner awareness deepened, and supply-side capabilities improved.
Worldwide Pipe Grouting Service Market
Looking forward, the forecast window through 2032 indicates continued expansion at a compound annual growth rate that underscores the sector’s structural momentum. This is not a bubble built on hype; it is a commercial pathway shaped by tangible therapeutic demand, incremental regulatory clarity, and a growing number of players transitioning from investigational products toward commercialized offerings. For decision-makers evaluating market entry, partnership structures, or portfolio reallocation, the growth curve offers both opportunity and timing risk. The window for strategic positioning is open, but it is narrowing as more competitors validate the commercial viability of stem cell–based veterinary solutions.
The report situates these figures within a broader narrative of adoption maturity. It examines how early clinical enthusiasm has been tempered by operational realities, how pricing models are stabilizing around practitioner workflows, and how the balance between autologous procedures and off-the-shelf allogeneic products is reshaping the economics of veterinary regenerative medicine. Readers will find that the headline growth numbers are only the starting point; the strategic value lies in understanding the forces that will determine which business models scale and which remain confined to niche applications.
Segmentation as a Strategic Compass
Understanding where demand is concentrated, and why, is essential for resource allocation. The report dissects the market across multiple axes without reducing it to static percentage tables. Instead, it examines the structural logic behind each segmentation dimension so that executives can align their go-to-market strategy with the underlying drivers of adoption.
At the application level, the therapy landscape is anchored by orthopedic and degenerative conditions, with osteoarthritis representing the dominant clinical use case. Tendon and joint disorders, wound healing, bone repair, and inflammatory conditions each contribute distinct demand profiles, while emerging applications in oncology and complex systemic diseases illustrate the long-tail potential that will shape later-stage commercialization. The report analyzes how clinical evidence maturity, practitioner familiarity, and reimbursement or out-of-pocket willingness vary across these indications, and how those variables influence volume, margin, and cycle time for therapy developers.
Animal type segmentation reveals a market that is currently anchored by companion animals but with meaningful structural relevance from livestock applications. Companion animal segments benefit from higher owner spending capacity, emotional decision-making dynamics, and direct-to-consumer awareness channels. Livestock applications, while smaller in current revenue contribution, carry different economic logic: herd-level outcomes, production efficiency, and veterinary economics that reward scalable, cost-effective regenerative interventions. The report examines how these two segments diverge in purchasing behavior, clinical workflow requirements, and commercial scaling strategies, enabling readers to identify where their capabilities best align with end-market economics.
Geographic segmentation further illuminates the commercial map. North America currently represents the largest revenue concentration, supported by established veterinary specialty networks, advanced laboratory infrastructure, and early regulatory engagement. Europe follows with its own distinct demand patterns shaped by regional practice structures and differing attitudes toward regenerative modalities. Asia Pacific reflects an emerging but accelerating footprint, driven by expanding pet ownership, growing veterinary specialization, and increasing investment in animal health innovation. Latin America and the Middle East and Africa represent additional zones of potential expansion, each with unique access, pricing, and distribution dynamics. Rather than presenting raw regional splits, the report translates these patterns into actionable intelligence about where infrastructure, partnerships, and regulatory readiness create viable entry points, and where caution is warranted.
The Competitive Arena: Differentiated Strategies in a Contested Space
The animal stem cell therapy market is not a winner-take-all environment, but it is increasingly defined by differentiated positioning. Companies are competing along multiple dimensions: product format, regulatory status, clinical indication focus, delivery logistics, and veterinarian engagement models. The report provides a structured competitive landscape analysis that goes beyond company descriptions to examine how each player’s strategic choices shape their commercial prospects.
Gallant has emerged as a notable example of a company pursuing allogeneic, ready-to-use therapies for companion animals. Its focus on refractory feline chronic gingivostomatitis and osteoarthritis reflects a strategy centered on unmet clinical need and regulatory ambition, including advancement toward FDA conditional approval. In early 2026, Gallant announced a first-of-its-kind partnership with MWI Animal Health to establish ultra-low temperature cold chain logistics for delivery of ready-to-use stem cell therapies into veterinary clinics. This move highlights a critical commercial challenge: the requirement for reliable storage and distribution at very low temperatures can become a barrier to adoption if not solved at scale. By investing in cold chain infrastructure, the company is addressing a bottleneck that affects not only its own product pathway but also signals broader operational expectations for off-the-shelf regenerative therapies in veterinary medicine.
VetStem, Inc. represents a different strategic posture, with deep experience in autologous stem cell therapies derived primarily from adipose tissue for canine osteoarthritis, equine joint disorders, and chronic pain management. At the same time, the company is expanding toward allogeneic off-the-shelf products, including precise regenerative solutions and orthopedics-focused pipelines. Additional funding secured in early 2025 is being directed toward advancing StemStat Ortho toward FDA conditional approval, signaling a dual-track strategy that pairs established practitioner relationships with next-generation product development. The report examines how VetStem’s positioning illustrates the broader industry tension between customization and standardization, and how companies are attempting to capture value across both paradigms.
Ardent Animal Health operates with a strong in-clinic autologous regenerative therapy model, offering stromal vascular fraction–based treatments and platelet-rich plasma solutions for dogs and cats with orthopedic conditions. Its approach reflects the commercial reality that many veterinary practices prefer point-of-care procedures that integrate directly into existing clinic workflows. VETherapy, with development operations spanning San Francisco and Coimbra, Portugal, emphasizes cost-effective and time-efficient regenerative solutions for complex pet diseases, underscoring the importance of operational efficiency in a market where adoption depends heavily on practitioner convenience and case throughput.
Magellan Stem Cells, based in Australia, contributes a regional perspective by supplying autologous and donor-derived mesenchymal stem cells for osteoarthritis treatment in companion animals, with clinical trial planning underway. Its presence illustrates how market activity is distributed across geographies and how companies in emerging hubs are building capabilities that may eventually intersect with larger global commercialization pathways.
The competitive analysis in the report does not treat these players as isolated profiles. It evaluates them within the context of market concentration, showing that the sector remains moderately consolidated, with a meaningful share held by a relatively small group of active commercial and development-stage companies. This concentration pattern matters for M&A strategy, partnership targeting, and barrier-to-entry assessment. It also signals that the field is still open enough for new entrants with differentiated technology or business models, but increasingly crowded enough that undifferentiated plays will face pressure on pricing, clinical differentiation, and practitioner loyalty.
Regulatory Realities and Industry Dynamics
No assessment of this market is complete without confronting the regulatory environment, which remains one of the most important variables shaping commercial timelines, risk exposure, and strategic planning. The report dedicates substantial attention to the current state of oversight, the practical implications for product developers, and the signals that indicate where the regulatory trajectory is heading.
As of early 2025, no FDA-approved animal cells, tissues, and cell- and tissue-based products were available for veterinary use in the United States. This absence is not a marginal detail; it defines the current commercial landscape. Companies are navigating a space where therapeutic promise and investigator interest are substantial, but formal approval pathways remain incomplete. That reality creates both urgency and caution. For developers, it means clinical data generation, quality systems, and regulatory engagement must be advanced with precision. For veterinary practices and distributors, it means procurement, communication, and compliance strategies must account for the distinction between approved therapeutics and investigational or unregulated offerings.
Regulatory pressure has already begun to manifest in enforcement activity. In 2025, the FDA issued warning letters to companies including Ardent Animal Health, LLC and Safari Stem Cell, LLC for marketing unapproved stem cell and regenerative products. These actions signal a more active oversight posture and highlight the compliance risks facing organizations that move faster than regulatory frameworks can accommodate. The report examines what these enforcement patterns imply for market discipline, how they may influence practitioner confidence, and why companies with robust regulatory strategies may gain competitive advantage as the field matures.
At the same time, there are signs of constructive progress. Regulatory engagement is not uniformly obstructive. For example, the FDA Center for Veterinary Medicine completed the Reasonable Expectation of Effectiveness technical section letter for Gallant’s lead feline chronic gingivostomatitis stem cell therapy candidate in September 2025, a milestone that reflects a pathway toward conditional approval and a more structured interface between innovators and regulators. VetStem’s additional funding and advancement of StemStat Ortho toward FDA conditional approval further illustrate how companies are converting regulatory engagement into forward momentum. These developments are not guarantees of success, but they provide a realistic basis for scenario planning.
Beyond regulation, the report analyzes other industry dynamics that influence commercial execution. Supply chain architecture is one critical area. The cold chain requirements for certain stem cell products, including ultra-low temperature storage and transport, create logistical complexity that affects cost, reach, and clinic-level feasibility. The recent move by Gallant to establish the first ultra-low temperature cold chain in veterinary medicine for therapies requiring -80°C storage is a tangible example of how operational innovation can become a strategic differentiator. Distribution partnerships, storage equipment availability, training requirements, and clinic workflow integration all become variables that determine whether a product is theoretically promising or practically adoptable.
The report also explores practitioner adoption patterns, clinic economics, and the role of education and professional advocacy in accelerating uptake. Stem cell therapies do not sell themselves through traditional pharmaceutical channels alone; they require engagement with veterinarians who must understand indications, collection or delivery procedures, patient selection, expected outcomes, and realistic limitations. Companies that invest in veterinary education, clinical support, and evidence dissemination are better positioned to build durable demand than those that rely solely on product availability.
What the Report Delivers for Decision-Makers
This study is designed as an operational intelligence asset rather than a high-level overview. It translates market trajectory into concrete strategic inputs across multiple functional areas. The full report includes detailed analysis and structured content intended to support planning, prioritization, and risk assessment.
- A comprehensive market sizing and forecast framework that connects historical performance with the 2026–2032 outlook, enabling readers to benchmark internal projections and test growth assumptions against sector-wide trends.
- Application-level analysis that maps demand concentration, clinical maturity, and commercial implication across major therapeutic areas, helping R&D and commercial teams align pipeline focus with adoption readiness.
- Segmentation insights across animal type and geography, presented with strategic interpretation rather than raw splits alone, so that executives can evaluate where to invest, partner, or stage market entry.
- Competitive landscape profiling that examines company strategies, product formats, regulatory posture, and operational models, providing context for partnership screening, benchmarking, and positioning decisions.
- Regulatory and compliance analysis that addresses the current absence of FDA-approved veterinary cell- and tissue-based products, recent enforcement actions, and the implications of conditional approval pathways for product planning and market timing.
- Supply chain and distribution considerations, including cold chain requirements, clinic-level logistics, and the operational prerequisites for scaling off-the-shelf regenerative therapies.
- Strategic scenario inputs that support M&A evaluation, investment prioritization, and market-entry planning by identifying where concentration, differentiation, and execution risk converge.
By integrating these elements, the report enables readers to move from general market awareness to specific decision support. It is structured to help leadership answer practical questions: Which indications and animal segments offer the strongest commercial logic for a given capability set? How should a company respond to a regulatory environment that is simultaneously restrictive and progressively clarifying? What operational capabilities must be built or sourced before a therapy can be reliably delivered at scale? Where does market concentration create both partnership opportunity and competitive vulnerability? The full publication provides the structured evidence and interpretive framework needed to address these questions with confidence.
Why 2026 Is a Strategic Inflection Point
The years ahead will reward organizations that act on informed timing rather than reactive adaptation. In 2026, the market is positioned at a point where early adoption patterns are becoming clearer, regulatory engagement is intensifying, and operational infrastructure for regenerative veterinary therapies is beginning to take shape. Companies that treat these shifts as background noise risk being outpaced by competitors who are already aligning product strategy, compliance planning, and distribution design with the market’s emerging structure.
For therapy developers, the strategic priority is to connect clinical ambition with regulatory realism and commercial feasibility. For veterinary service providers and distributors, the priority is to understand which therapies are approaching credible regulatory and operational readiness, and how to integrate them into practice workflows without overcommitting to unproven or non-compliant offerings. For investors and corporate strategists, the priority is to distinguish sustainable differentiation from short-term promotional momentum, and to assess the operational and regulatory moats that will determine long-term value creation.
PW Consulting’s Animal Stem Cell Therapy Market research is built to support these decisions with depth, discipline, and a clear line of sight from market data to strategic action. The macro trajectory, segmentation logic, competitive dynamics, and regulatory context are all essential inputs, but the real value lies in how they are synthesized into an actionable view of where the market is going and what it will take to compete successfully within it.
The full report expands on every dimension previewed here, offering the detailed segmentation intelligence, competitive benchmarking, regulatory framing, and scenario-based strategic recommendations that enterprise decision-makers require. To access the complete analysis and the proprietary data that underpin it, readers are invited to visit the source page and retrieve the full market research package. In a market defined by rapid evolution and contested positioning, comprehensive intelligence is not a luxury; it is a prerequisite for confident strategy.
For detailed analysis of this topic, please visit the official page: Animal Stem Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glucagon Market to Reach $505M by 2032, Growing at 5.25% CAGR
By PW Consulting, 2026-09-07
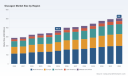
The Glucagon Market at an Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global glucagon market stands at a critical juncture where decades of steady therapeutic reliance are colliding with structural shifts in manufacturing capacity, regulatory clarity, and next-generation delivery formats. For pharmaceutical executives, investors, and healthcare strategists, the numbers alone tell only a fraction of the story. What matters now is the operational architecture behind those numbers: how concentrated supply chains are adapting, how dose-ready innovations are reshaping emergency care, and how macro policy signals are re-tuning metabolic supply networks that indirectly support glucagon diagnostics and rescue use. Our newly released Glucagon Market research report was designed to translate these layered dynamics into actionable intelligence for 2026 planning cycles and beyond.
Transparent PI Hard Coating Film Market
From a top-line perspective, the market has demonstrated resilient growth through the second half of the decade, with base-year valuation at USD 368.5 million in 2025 and a projected trajectory climbing toward USD 400.49 million in 2026. Over the historical window from 2020 to 2025, the segment moved from USD 288.5 million through a series of incremental expansions, reflecting both steady diabetes prevalence and gradual adoption of emergency hypoglycemia management tools. Looking forward, the forecast period from 2026 through 2032 maps a compound annual growth rate of 5.25 percent, with endpoint valuation approaching USD 505.0 million. These figures are not merely a backward-looking summary; they serve as the scaffold for a more granular examination of where value is being created, which product architectures are gaining share, and how regional demand curves are diverging under regulatory and reimbursement pressure. The full segmentation architecture, pricing sensitivity ranges, and regional volume splits are detailed within the report, because surface-level totals cannot reveal the operational logic decision-makers need.
Tunnel Jet Fans Market
What makes this edition distinct is its focus on decision readiness. Rather than simply charting historical trajectories, the research converts market momentum into a structured toolkit for capacity planning, portfolio prioritization, partnership evaluation, and risk calibration. Below is a preview of the analytical depth and operational content embedded in the full study.
Worldwide Silver Coated FEP Film Market
Competitive Architecture and the reshaped Supplier Landscape
The glucagon sector remains moderately concentrated, with the top three competitors accounting for roughly 55 percent of revenue and the top five capturing closer to 78 percent. That concentration is not a static relic; it reflects deliberate investments in manufacturing scale, differentiated formulation strategies, and territory-specific commercialization strengths. The report profiles the core participants shaping this environment, mapping their technical positioning, supply footprints, and recent strategic moves so that readers can assess not only who holds share today but which entities are structurally positioned to capture the next wave of demand.
Eli Lilly and Company, headquartered in Indianapolis, continues to anchor part of the emergency rescue segment through its recombinant rDNA-origin glucagon for injection, positioned both for severe hypoglycemia treatment and as a diagnostic aid to inhibit gastrointestinal motility. Its operational posture has recently been reinforced by a USD 3 billion commitment to U.S. injectable-drug manufacturing capacity for metabolic treatments, including glucagon signaling products, signaling a long-term view of domestic supply resilience and broader metabolic portfolio integration. Novo Nordisk A/S, based in Bagsværd, maintains its established position with GlucaGen rDNA glucagon injection for severe hypoglycemia in diabetes patients and diagnostic applications. The company's May 2026 announcement of a USD 4.1 billion expansion of its North Carolina manufacturing facility to boost injectable production lines, including glucagon, underscores a capacity build that extends well beyond incremental volume gains and into structural supply assurance.
Amphastar Pharmaceuticals, Inc., operating from Rancho Cucamonga, remains an active producer of generic glucagon for injection that is bioequivalent to established branded products, packaged within emergency kits for severe hypoglycemia treatment. This generic presence is strategically important because it defines the price-accessibility floor of the market and influences how branded players defend differentiation through convenience, stability, and device experience. Fresenius Kabi USA, LLC, based in Lake Zurich, continues as an active supplier of synthetic glucagon for injection for severe hypoglycemia treatment across pediatric and adult diabetes populations, reinforcing the hospital and clinical channels where reliability and compatibility with institutional procurement systems matter as much as product architecture.
The competitive frontier is increasingly defined by formulation and device innovation. Xeris Biopharma Holdings, Inc., from Austin, has built its identity around Gvoke, a ready-to-use stable liquid glucagon, alongside the Gvoke HypoPen autoinjector for severe hypoglycemia rescue in patients aged two and older. Its March 2025 FDA approval of a supplemental New Drug Application for Gvoke VialDx, expanding use as a diagnostic aid for glucagon, broadens the commercial and clinical footprint beyond rescue alone. More recently, the company's exclusive partnership with Beta Bionics to co-develop pump-ready liquid glucagon for dual-hormone artificial pancreas systems points toward an ecosystem where glucagon is no longer only an emergency fallback but an integrated component of automated metabolic management. Zealand Pharma A/S, headquartered in Copenhagen, advances the differentiated analog path with dasiglucagon under the ZEGALOGUE injection brand for severe hypoglycemia in diabetes patients. Its regulatory journey also illustrates the complexity that persistent innovation can encounter, including a second Complete Response Letter in October 2024 for pediatric congenital hyperinsulinism dosing, with data resubmission expectations by the end of 2025 for continued approval progress.
The strategic implication is that competitive advantage is migrating from pure volume toward delivery reliability, formulation stability, device usability, and ecosystem integration. The report's competitive section goes beyond biographical summaries to evaluate how these profiles interact with supply constraints, procurement cycles, and regulator-facing milestones. Readers who need to assess partnership opportunities, competitive response scenarios, or territory entry feasibility will find the comparative framework built for that purpose.
Market Dynamics: Supply Realities, Regulatory Signals, and the Stabilization Effect
A robust market view requires more than competitor mapping; it requires an honest accounting of the forces that can accelerate or disrupt the trajectory. One of the most consequential dynamics in the recent period has been the persistence of API and fill-finish supply constraints for synthetic glucagon products, driven in part by limited pre-filled syringe capacity and broader manufacturing capacity bottlenecks. These constraints are not abstract; they affect time-to-market, batch reliability, hospital stocking patterns, and the economics of emergency kit distribution. The report translates these constraints into commercial implications, distinguishing between temporary friction and structural capacity gaps, and identifies which product formats and supplier configurations are most exposed.
Regulatory stabilization in adjacent metabolic categories has also begun to re-tune the operating environment. The FDA's determination that the shortage of semaglutide injection products was resolved as of February 2025, followed by the resolution of tirzepatide injection shortages as of October 2024, has helped stabilize related metabolic supply chains. While these are GLP-1 receptor agonist products rather than glucagon therapies, the stabilization matters because it indirectly supports the broader diabetes management infrastructure within which glucagon diagnostics and emergency use operate. When surrounding supply networks are less volatile, procurement teams, distributors, and clinical protocols can plan with greater confidence, and that confidence tends to flow into more consistent demand realization for rescue and diagnostic glucagon applications.
At the same time, regulatory pathways for newer formulations remain iterative. The experience of dasiglucagon development demonstrates how promising innovation can still face gatekeeping milestones that alter commercialization timing, especially in pediatric and specialty indications. Conversely, the expansion of Gvoke VialDx into diagnostic use reflects how existing platforms can unlock additional use cases without requiring an entirely new product architecture. The dynamics section of the report traces these regulatory interactions carefully, not to predict every outcome, but to equip strategists with scenario-aware planning frameworks. In an environment where one Complete Response Letter or one supplemental approval can reshape a product's addressable market, organizations need more than a headline; they need a structured read on probability, timing, and downstream commercial impact.
Report Contents: What Decision-Makers Will Find Inside
The Glucagon Market research report is organized to support multiple workstreams simultaneously. It is not a single-view dashboard but a modular intelligence package that can be deployed for portfolio review, supply chain strategy, competitive benchmarking, investment screening, and market-entry evaluation. The following elements are developed in depth throughout the document.
- Historical performance reconstruction from 2020 through 2025, with base-year grounding and a clear explanation of the demand and supply factors that shaped year-over-year movement across the segment.
- A ten-year forecast window spanning 2026 to 2032, built around a CAGR of 5.25 percent and endpoint valuation near USD 505.0 million, with scenario sensitivity that accounts for formulation adoption, supply normalization, and regulatory pacing.
- Segment-level analysis by region, product type, and application, presented in a way that highlights structural drivers instead of isolated percentages. The full regional and format splits, including volume and value architecture, are provided in the report so teams can identify where relative opportunity is concentrating without relying on second-order estimates.
- A competitive landscape review that connects company profiles to recent operational events, including manufacturing expansions and partnership announcements, so readers can assess not only current share but forward capacity and ecosystem positioning.
- Market concentration metrics that show how the top three and top five competitors frame the pricing, supply, and innovation environment, with interpretation of what that concentration means for entry barriers, negotiation leverage, and differentiation requirements.
- Industry dynamics covering API and fill-finish constraints, pre-filled syringe capacity limitations, regulatory stabilization in adjacent metabolic supply chains, and the educational and clinical infrastructure trends that influence emergency hypoglycemia management.
- Regulatory and development milestone tracking, including diagnostic-use expansions, pediatric indication complexity, and the implications of approval timing on commercial readiness.
- Practical recommendations for capacity planning, portfolio sequencing, partnership targeting, and risk monitoring, tailored for teams that must convert market signal into operational decisions during 2026.
The report is built with an explicit understanding that different stakeholders consume intelligence differently. Commercial leaders may prioritize segment momentum and differentiation pathways; operations teams may focus on capacity constraints and supply normalization timing; investors may want the concentration structure and forward CAGR mapped against milestone risk; and market-access teams may need the regulatory and application context that shapes hospital and payer adoption. The content architecture accommodates those needs without forcing every reader into a single narrative.
Why This Research Matters for 2026 Decisions
The 2026 planning environment is defined by a tension that is familiar but unusually acute in this sector: demand fundamentals are strengthening, yet supply and regulatory complexity are preventing straightforward extrapolation. A 5.25 percent CAGR over the forecast period is meaningful, but the strategic value lies in understanding what drives that growth, which formats capture disproportionate value, how regional demand diverges under local reimbursement and clinical practice patterns, and which competitors are converting capital expenditure into durable supply advantage. Organizations that treat the forecast as a flat line will miss the operational inflection points that determine margin, reliability, and market access.
Three decision themes stand out. First, capacity is becoming a competitive variable, not just a cost variable. The recent manufacturing commitments from leading players reflect an understanding that injectable supply security, fill-finish throughput, and syringe/vial availability can determine who can reliably serve emergency and diagnostic demand. Second, formulation and device experience are increasingly the battleground for differentiation, especially where generic options establish a price floor and branded players must justify convenience, stability, and usability. Third, the regulatory environment is stabilizing in adjacent metabolic categories while remaining iterative for novel glucagon applications, creating a dual dynamic where some operational uncertainty is receding even as product-level approval pathways continue to require careful scenario planning.
For companies evaluating market entry, portfolio extension, or partnership strategy, the report's segmentation and competitive sections provide the necessary scaffold to test assumptions before committing resources. For incumbent players, the same material supports defensive planning: where concentration is high, where supply bottlenecks are most likely to affect service levels, and where adjacent use cases such as diagnostic aids can extend platform value. For investors, the research frames the market not as a single growth curve but as a set of overlapping trajectories with distinct risk and reward profiles tied to formulation maturity, regulatory status, and manufacturing scale.
How to Use the Intelligence: From Signal to Action
The most valuable market research does not simply describe what is happening; it helps teams decide what to do next. In practice, that means connecting market-wide trends to specific operational questions. For example, if a manufacturer is considering an expansion of emergency kit distribution, the report's segmentation logic helps identify which application and format dynamics are most relevant without relying on blunt aggregate figures. If a strategist is evaluating partnership opportunities around automated delivery or dual-hormone systems, the competitive and development event sections provide context on who is moving toward ecosystem integration and what recent partnerships suggest about the direction of travel. If a supply chain leader is mapping exposure to fill-finish constraints, the dynamics section helps distinguish intermittent friction from longer-term structural limits and highlights why pre-filled syringe capacity is a meaningful variable in product availability and commercialization pacing.
The report also supports more disciplined scenario planning. Because macro figures such as the 2025 base valuation, the 2026 projected size, and the 2032 endpoint are presented as part of a broader analytical framework, readers can stress-test their own assumptions against the underlying drivers rather than treating the forecast as a fixed outcome. That discipline matters in a market where regulatory milestones, manufacturing expansions, and formulation adoption can shift the timing and composition of growth even when the overall trajectory remains constructive.
Closing Perspective
The glucagon market is entering a period in which strategic advantage will be defined less by broad visibility and more by precise, actionable understanding. The top-line numbers establish that demand is expanding and that the segment is moving toward a mid-half-billion-dollar valuation by the end of the forecast window. But the operational story is richer: concentration is reshaping bargaining dynamics, manufacturing investments are altering supply assurance, formulation and device innovation are widening the definition of value, and regulatory signals in adjacent metabolic categories are stabilizing the broader infrastructure within which glucagon emergency and diagnostic use operates. Our Glucagon Market research report captures that full complexity in a form designed for 2026 decision-making. It offers the depth required to build confidence and the structure needed to convert insight into planning. For teams that need the regional splits, application and type architecture, concentration interpretation, and company-specific strategic context in detail, the complete report provides the comprehensive intelligence necessary to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Glucagon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Fountain Machines Market Hits $215M in 2025, Projects 33% Growth by 2032
By PW Consulting, 2026-09-07
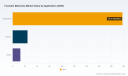
Navigating the Future of Beverage Dispensing: Strategic Insights from the 2026 Fountain Machines Market Report
A Critical Intelligence Brief for Decision-Makers in Foodservice and Equipment Manufacturing
The global beverage landscape is undergoing a subtle but profound transformation. For executives in the foodservice sector, equipment manufacturing, and supply chain management, understanding the trajectory of fountain machines is no longer optional—it is a strategic imperative. As we move through 2026, the inflection points in market volume, technological integration, and regulatory pressure are reshaping how convenience and customization intersect in commercial venues.
O-Tolidine Diisocyanate (TODI) Market
PW Consulting has completed an exhaustive analysis of the Fountain Machines Market, synthesizing historical performance from 2020 through 2025 with a detailed forecast extending to 2032. This introduction serves as a strategic primer, outlining the macro-economic realities and competitive pressures that define this sector. While we offer a high-level view of the landscape here, the granular data required to build precise business cases resides within the full report.
Worldwide Outdoor Camping Cookware Market
The objective of this briefing is to contextualize why immediate engagement with this data is vital for 2026 planning. The market is not merely growing; it is evolving in complexity. Leaders who rely on outdated assumptions about dispensing hardware risk capital misallocation and competitive obsolescence.
Worldwide Distributed Direct Acting Solenoid Valve Market
Macro Market Trajectory: Resilient Growth Amidst Economic Flux
The fountain machines market has demonstrated remarkable resilience over the past half-decade. Historical data indicates a steady climb in global revenue, reflecting the enduring demand for efficient beverage service solutions. From a baseline of approximately 163.15 Million USD in 2020, the market expanded consistently to reach an estimated 215.0 Million USD in 2025. This progression underscores a fundamental truth: despite supply chain disruptions and inflationary pressures during the early 2020s, the underlying demand for commercial dispensing infrastructure remained robust.
Looking forward, the forecast period from 2026 to 2032 suggests a continuation of this upward trend, albeit at a measured pace. The market is projected to reach approximately 237.44 Million USD in 2026, signaling a healthy start to the forecast window. By 2032, valuations are anticipated to approach 344.8 Million USD. This trajectory reflects a Compound Annual Growth Rate (CAGR) of roughly 2.6 percent over the forecast period.
While a 2.6 percent CAGR might appear moderate compared to high-growth technology sectors, it is significant within the context of mature hardware markets. It suggests steady replacement cycles, incremental upgrades, and adoption in emerging foodservice categories. For strategic planners, this stability offers a predictable environment for CAPEX planning, provided that regional and segment-specific nuances are accounted for. It is crucial to note that aggregate figures mask significant variations across geography and application, which are detailed fully in the proprietary sections of our analysis. However, the overarching message is clear: the total addressable market is expanding, creating opportunities for those positioned to capture value across the value chain.
Competitive Landscape: Innovation as the Primary Divisor
The fountain machines market is characterized by a blend of global beverage giants and specialized equipment manufacturers. Market concentration metrics indicate a moderately fragmented environment, with the top three players holding a combined share of approximately 24.6 percent and the top five reaching 26.2 percent. This structure implies that while major brands exert significant influence, there is ample room for specialized innovators to differentiate through technology and service models.
Several key companies are defining the trajectory of this sector. The Coca-Cola Company, headquartered in Atlanta, continues to leverage its Coca-Cola Freestyle platform, offering post-mix dispensing systems with extensive flavor combinations. Their recent moves highlight a shift toward connected innovations and data-driven service. Similarly, PepsiCo, based in Purchase, NY, maintains a strong presence with self-serve and manned dispensers tailored for QSR operators under their core brands.
On the manufacturing side, Lancer Worldwide in San Antonio, TX, remains a pivotal player with their Lancer CED and high-performance tower systems. Metro Fountain Service in Houston, TX, focuses on premium frozen and ice-based systems for institutional applications, while Cornelius Company supplies countertop IDC Pro dispensers with advanced touchscreen and carbonation features. In the Asia Pacific region, Tianwan (Shanghai) Intelligent Equipment Co., Ltd. is manufacturing soda fountain machines and ice-beverage combos for global brands, indicating the growing importance of cross-border equipment supply chains.
Coke Solutions (Coca-Cola Equipment) rounds out the landscape by providing a variety of counter electric, drop-in, and combo systems. The interplay between these entities creates a dynamic where hardware capability is increasingly tied to software integration and service reliability. Companies that fail to integrate with broader POS ecosystems or lack robust maintenance networks risk losing ground to more agile competitors.
Technology and Innovation: The Shift Toward Intelligence and Efficiency
The traditional view of fountain machines as static hardware is obsolete. The 2026 landscape is defined by intelligence, connectivity, and user experience. Recent developments underscore this shift. In May 2026, The Coca-Cola Company unveiled next-generation Freestyle dispensing equipment, including the Freestyle Equinox with a new user interface and the Freestyle Mini designed for compact venues. These launches emphasize real-time pour data, enabling custom drink creation and faster deployment cycles—sometimes as few as 90 days. Such innovations were showcased at the National Restaurant Show in Chicago, providing attendees with hands-on experience of the evolving interface between consumer and machine.
Beyond brand-specific launches, the industry is seeing a broader trend toward automation and integration. As of January 2026, various manufacturers introduced automated models with POS integration capable of handling cup, ice, and drink dispensing simultaneously. This convergence reduces labor friction and enhances throughput, addressing one of the critical pain points for high-volume venues.
Operational efficiency is another driving force. Technical service visits for soda fountain machines typically range from 150 to 300 USD per visit, making annual maintenance a critical factor for peak efficiency and cost control. Organizations that invest in systems with predictive maintenance capabilities or superior durability can significantly reduce total cost of ownership over the lifecycle of the equipment.
Regulatory and Environmental Dynamics
Compliance and sustainability are no longer peripheral concerns; they are central to market access and consumer perception. Regulatory frameworks are tightening around food safety and electrical standards. For instance, NSF and UL certifications are required for commercial fountain dispensers to meet these mandates. Manufacturers must ensure their equipment aligns with these standards to operate in regulated markets, adding a layer of complexity to product development and sourcing.
Hygiene protocols remain paramount. Regular nozzle and diffuser sanitization is mandated to comply with food safety standards, a practice that has been active since standards were established years ago and remains enforced today. Non-compliance can result in operational shutdowns or reputational damage, making equipment design that facilitates easy cleaning a competitive advantage.
Environmental efficiency is also reshaping procurement strategies. New environmental efficiency standards are driving adoption of energy-efficient dispensing systems, particularly in North America. This regulatory pressure aligns with broader corporate sustainability goals, pushing buyers toward solutions that minimize energy consumption without sacrificing performance. Furthermore, the use of syrup concentrates in fountain machines offers ancillary benefits, reducing single-use packaging waste and lowering beverage costs by up to 50 percent compared to pre-packaged alternatives.
Segmentation Nuances and Strategic Implications
While the macro growth figures provide a reliable baseline, the true strategic value of market intelligence lies in understanding the segmentation splits. The market is divided across distinct regions, types, and applications, each with unique growth drivers and barriers.
In terms of equipment type, tower fountain machines represent a significant portion of the market, reflecting their prevalence in large-scale foodservice operations where volume and visibility are key. Drop-in fountain machines constitute another substantial segment, often favored for their integration flexibility in existing countertops. Other types, including specialized countertop units, round out the mix. Understanding the specific demand elasticity for each type is crucial for manufacturers planning product line extensions and for buyers evaluating CAPEX portfolios.
Application-wise, restaurants dominate the consumption landscape, driven by the need for consistent, high-quality beverage service in high-traffic environments. Cinemas represent another key application, where fountain systems are integral to concession revenue models. Other applications, including institutional and corporate settings, offer niche but growing opportunities.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents distinct challenges regarding supply chain logistics, regulatory environments, and consumer preferences. For example, while North America sees push for energy efficiency, Asia Pacific may offer faster volume growth linked to expanding QSR chains. Detailed regional revenue breakdowns and growth rates are essential for determining where to allocate sales resources or manufacturing capacity, but these specifics require access to the full segmentation data to avoid strategic missteps.
Why the 2026 Report is Indispensable for Decision-Makers
In an environment where margin pressure is high and technology cycles are accelerating, generic market summaries are insufficient. The PW Consulting Fountain Machines Market Report provides the depth required to execute with confidence. The report goes beyond high-level valuations to offer operational content that directly informs business strategy.
Stakeholders will find detailed profiles of key companies, analyzing their product portfolios, strategic moves, and market positions. This includes analysis of recent developments such as product launches and trade show presence, allowing readers to anticipate competitor moves. For instance, understanding the timing of new UI launches or compact venue equipment can inform procurement timing or competitive positioning.
The report also integrates industry context noise—critical operational facts that impact profitability. Insights on labor costs associated with service visits, the cost benefits of syrup concentrates, and the specifics of NSF/UL certification requirements are woven into the analysis. This ensures that financial models built from the report data reflect real-world operational constraints rather than idealistic assumptions.
Furthermore, the forecast methodology accounts for historical volatility and future drivers, providing a range of scenarios rather than a single static number. This is vital for risk management. Whether you are a manufacturer planning capacity, a distributor evaluating inventory, or a foodservice operator budgeting for 2027 renovations, the granularity of this data supports more accurate financial modeling.
Connecting Macro Trends to Micro Actions
The convergence of stable market growth, technological innovation, and regulatory pressure creates a unique window for strategic action in 2026. Firms that act now can secure advantages in supply chain positioning, technology adoption, and market share retention.
For equipment manufacturers, the emphasis on POS integration and energy efficiency suggests a roadmap for R&D investment. Aligning product development with these trends can open doors to customers seeking compliance and operational efficiency. For distributors and service providers, understanding the maintenance costs and certification requirements allows for more competitive service contracts and value-added offerings. For end-users in restaurants and cinemas, selecting the right type of fountain machine—whether tower, drop-in, or countertop—based on specific application needs can optimize both customer experience and backend costs.
However, executing these strategies requires precise data. Knowing the overall market size is helpful, but knowing which region offers the highest ROI for a new product launch, or which application segment is most sensitive to labor cost savings, requires the detailed segmentation splits and regional analysis contained in the full study. The differences between market segments can determine the success or failure of a specific initiative.
Conclusion: Accessing the Full Intelligence Picture
The Fountain Machines Market is on a steady growth path, supported by enduring demand in foodservice and a shift toward smarter, more efficient dispensing solutions. The projected revenue growth from 237.44 Million USD in 2026 to nearly 344.8 Million USD by 2032 offers a compelling backdrop for investment and strategy. Yet, the aggregate numbers only tell part of the story.
The true competitive edge lies in the details: the specific regional dynamics, the precise application splits, the granular company profiles, and the operational cost factors that influence net profitability. The macro trends highlighted here—resilience in revenue, the rise of connected equipment, and the tightening of regulatory standards—signal a market that rewards informed, data-driven decision-making.
PW Consulting's full market research report delivers this depth. It transforms broad industry observations into actionable intelligence, enabling leaders to navigate the complexities of the fountain machines ecosystem with precision. We invite you to explore the complete analysis to unlock the specific data points, forecasts, and strategic recommendations necessary to optimize your position in this evolving market. Detailed segmentation values, regional revenue specifics, and comprehensive competitor benchmarking are available within the full report to support your 2026 and beyond planning.
For detailed analysis of this topic, please visit the official page: Fountain Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wheat Germ Oil Market Hits $649M in 2025, Poised for 5.81% CAGR Growth Through 2032
By PW Consulting, 2026-09-07
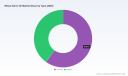
Strategic Horizons in the Global Wheat Germ Oil Market: A 2026 Leadership Brief
The global wheat germ oil market stands at a critical inflection point in 2026. What began as a niche ingredient confined largely to dietary supplements and traditional cosmetics has evolved into a multi-dimensional commodity intersecting pharmaceuticals, functional foods, premium personal care, and specialized animal nutrition. As supply chains recalibrate following years of input volatility, regulatory recalibration, and shifting consumer preferences, corporate leadership requires more than surface-level forecasts. They need a structured, granular understanding of where value is being created, which segments are expanding fastest, which manufacturers are building durable competitive moats, and how external forces such as raw material pricing and trade logistics will reshape margin profiles over the next strategic cycle.
Orange Peel Scrap Grapples Market
This market study was constructed to answer those questions with precision. Drawing on comprehensive historical tracking, forward-looking modeling, and primary-level industry intelligence, the analysis maps the trajectory of wheat germ oil from 2020 through the end of the forecast horizon in 2032. The resulting dataset is engineered not merely to describe where the market has been, but to equip executives, R&D leads, procurement directors, and strategy teams with the decision architecture needed to allocate capital, refine product portfolios, negotiate supply agreements, and anticipate regulatory shifts before they become market-wide constraints.
Worldwide Silicone Pressure Sensitive Adhesives Market
The Strategic Imperative of 2026 Market Intelligence
Corporate planning in 2026 demands a clear distinction between historical momentum and forward-looking inflection. The wheat germ oil sector has already absorbed significant volatility across its value chain, from fluctuating feedstock pricing to evolving pharmaceutical and cosmetic regulatory standards. Yet the underlying demand architecture remains resilient and structurally expanding. The broader market has demonstrated consistent upward progression, with measured scale moving from approximately $562.0 million in 2020 to a projected $665.85 million in 2026. This progression is not accidental. It reflects sustained adoption across health and wellness channels, growing integration into premium cosmetic formulations, and increasing recognition of wheat germ oil’s functional profile in specialized nutrition applications.
Worldwide Organic Preservatives Market
The forward trajectory outlined in the study projects continued expansion beyond 2026, with the market size anticipated to reach $714.04 million in 2027, $787.05 million in 2028, and $824.77 million in 2029, before advancing toward $862.83 million in 2030 and $928.68 million in 2031. By 2032, the modeled market size reaches $957.0 million. These projections are derived through a composite methodology that balances historical pattern recognition with structural demand drivers, competitive capacity shifts, and adoption curves across core usage categories. Importantly, the study does not treat these figures as static endpoints. Instead, it embeds them within scenario-aware planning frameworks that allow leadership teams to assess growth sensitivity, margin exposure, and segment reallocation under changing conditions.
The implied compound annual growth rate across the forecast period is approximately 5.81%, a pace that positions wheat germ oil as a steady, structurally supported category rather than a speculative one. For strategic planners, this level of growth carries specific implications. It suggests sustained demand pull across multiple downstream industries, but it also reinforces the necessity of supply-side discipline, ingredient traceability, and formulation differentiation. Growth at this scale does not automatically translate into margin expansion unless companies understand the underlying segmentation dynamics, regional demand intensity, and competitive density that shape pricing power and customer retention.
What This Study Reveals: Operational Intelligence Across the Value Chain
A credible market study must move beyond aggregate sizing and deliver actionable intelligence that can be operationalized within product development, procurement, sales strategy, and investor communication. This research is structured to serve each of those functions. At its foundation, the report establishes a rigorous baseline for market sizing, historical performance review, and forward modeling, but its differentiation lies in the depth of its applied analysis.
Readers will find a detailed breakdown of how the market is organized across product configurations and end-use channels. The report examines liquid oil formats alongside softgel-ready variants, mapping the distinct manufacturing requirements, formulation considerations, and downstream demand profiles associated with each. It further explores how wheat germ oil is deployed across dietary supplements, cosmetics and personal care, food and beverages, and animal feed, identifying the specific value drivers, adoption barriers, and formulation sensitivities that define each channel. Because each application area carries its own regulatory expectations, consumer perception dynamics, and purchasing behavior, the study isolates where integration is most mature and where emerging demand signals suggest opportunity for expanded penetration.
Equally important is the report’s treatment of regional demand architecture. The analysis maps how demand is distributed across major geographic corridors, highlighting where consumption intensity, manufacturing presence, import-export patterns, and formulation preferences diverge. Rather than presenting oversimplified regional snapshots, the research provides the structural logic behind regional performance, enabling companies to evaluate distribution partnerships, capacity placement, market entry sequencing, and cross-border sourcing strategies with greater confidence. This is particularly relevant in an environment where trade flows, export constraints in major wheat-producing countries, and logistics bottlenecks can materially affect ingredient availability and cost structures.
Competitive Landscape and Strategic Positioning
The wheat germ oil market is shaped by a concentration of established producers and specialized manufacturers, each pursuing distinct positioning strategies across pharmaceutical, nutraceutical, cosmetic, and functional food channels. The report provides a structured competitive assessment that examines how leading companies are aligning product grade, extraction methodology, capacity, and distribution strategy to capture share in a market where differentiation is becoming increasingly important.
Among the companies analyzed, Viobin operates as a producer of cold-processed wheat germ oil sourced from North American wheat, supplied in bulk formats and prepared for softgel integration in supplements and personal care. Connoils LLC functions as a bulk supplier and manufacturer of wheat germ oil and powders for supplement and nutraceutical applications, emphasizing scale and ingredient versatility. In Europe, Gustav Heess GmbH supplies pharmaceutical-grade wheat germ oil with specifications oriented toward purity and cross-application use in food, cosmetics, and nutraceuticals. NOW Foods manufactures cold-pressed wheat germ oil in both liquid and softgel formats, positioned around allergen-conscious consumer expectations. Henry Lamotte Oils GmbH produces high-purity wheat germ oil for pharmaceutical and cosmetic applications and has pursued recent capacity expansions to support growing demand. Th. Geyer GmbH focuses on gentle extraction processes aimed at clean-label food ingredients and organic quality options, reinforcing the importance of process transparency in premium segments. Hebei Jiafeng Plant Oils Co., Ltd. operates as a refined and odorless wheat germ oil producer serving functional foods and export markets, with a product emphasis suited to industrial formulation requirements.
The competitive structure of the market reflects meaningful concentration. The study notes that the top three firms collectively account for approximately 52.0% of market share, while the top five firms extend that concentration to roughly 65.0%. This level of concentration signals a market where scale, quality certification, and supply reliability can serve as durable advantages, but it also indicates that innovation, specification differentiation, and channel specialization remain essential for challengers seeking to expand share without engaging directly in low-margin commodity competition.
Recent Developments Reshaping Market Dynamics
Market dynamics in 2026 are being actively reshaped by operational moves, product launches, regulatory signals, and supply-side constraints. These developments are not peripheral noise; they are indicators of where strategic value is migrating. The report integrates these events into a forward-looking interpretation of market trajectory, rather than treating them as isolated headlines.
One of the most telling capacity signals comes from Henry Lamotte Oils GmbH, which expanded production capacity by 30% in September 2024 to meet growing European demand for pharmaceutical-grade wheat germ oil. This expansion underscores the premiumization trend within the sector and illustrates how quality-graded supply is becoming a strategic bottleneck for manufacturers targeting pharmaceutical and high-end cosmetic applications. In parallel, Hebei Jiafeng Plant Oils Co., Ltd. launched a refined, odorless wheat germ oil tailored for food manufacturers in November 2024, with particular relevance to Asia’s expanding functional food sector. The move highlights how formulation refinement and odor management are becoming critical enablers for broader food and beverage adoption.
Innovation in extraction technology is also reshaping competitiveness. In January 2025, Herbal Biosolutions unveiled a patented extraction technology designed to significantly improve the yield and purity of wheat germ oil for use in Ayurvedic medicine. Such technological advances can alter cost structures and specification boundaries, especially where traditional medicine and nutraceutical formulation intersect. At the same time, regulatory and quality events continue to influence market confidence. In February 2025, the USA FDA posted a voluntary nationwide recall by Brassica Pharma involving ophthalmic ointments containing wheat germ oil, including Equate Stye Lubricant Eye Ointment and CVS Health Lubricant Eye Ointment. Incidents of this nature reinforce the importance of supply chain integrity, specification control, and compliance documentation, particularly for companies operating across pharmaceutical-adjacent categories.
Beyond individual company actions, broader market dynamics are being shaped by raw material pricing, regulatory notices, and trade disruptions. In 2024, wheat germ oil export and import prices ranged from approximately $5.70 to $17.84 per kg, reflecting significant variability tied to grade, origin, and supply conditions. Meanwhile, the USDA projected the 2025/26 USA all-wheat season-average farm price at USD 4.90 per bushel, down from USD 5.52 per bushel in 2024/25, a shift with implications for feedstock cost expectations and upstream pricing leverage. Regulatory attention is also intensifying in select regions; for example, India’s CDSCO issued a public notice in February 2025 related to a soft gelatin capsule formulation containing refined wheat-germ oil BP 10 mg. More broadly, major wheat-producing countries such as India, Russia, and Ukraine continue to face export restrictions and logistical bottlenecks that affect wheat germ supply availability. These forces collectively shape procurement strategies, inventory planning, and price negotiation timelines across the value chain.
Why This Research Matters for Decision-Makers in 2026
For executives and strategy teams, the central challenge is not simply whether the market is growing, but how growth is distributed, where competitive risk is concentrated, and which operational decisions will determine margin resilience in the years ahead. This study is designed to support that decision-making process at multiple levels.
First, it provides a validated baseline for strategic forecasting. Rather than relying on heuristic assumptions or fragmented secondary indicators, the report grounds projections in a continuous historical series and a forward framework that accounts for adoption dynamics, capacity shifts, and regulatory evolution. This allows companies to benchmark internal plans against a defensible market trajectory and adjust investment timing accordingly.
Second, the report enables segment-level strategic prioritization. Because growth is not uniform across applications or product formats, companies need clarity on where specification requirements, consumer expectations, and volume potential align most favorably with their capabilities. The analysis helps identify which channels are likely to reward premium positioning, which formats are gaining manufacturing traction, and where formulation or packaging innovation may unlock additional demand.
Third, the competitive assessment supports realistic positioning strategy. In a market where top players already hold meaningful share and where capacity expansion, grade certification, and extraction quality influence customer selection, new entrants and incumbent competitors alike must define their value proposition with precision. The report helps organizations understand how peer companies are competing on purity, format readiness, organic positioning, and regional specialization, enabling more informed decisions about partnership, acquisition, capacity investment, and channel focus.
Finally, the study integrates supply-side and regulatory signals into a practical risk lens. With raw material pricing variability, evolving regulatory notices, and trade logistics constraints all capable of affecting ingredient availability and cost, procurement and supply chain leaders require early-warning context rather than retrospective data. This research surfaces those factors in a structured way so that companies can stress-test sourcing plans, assess alternative supply routes, and align product claims with compliance realities.
How to Use This Report for Planning and Execution
The research is organized to support multiple internal workflows. Product and formulation teams can use the segmentation and application analysis to evaluate where wheat germ oil can be integrated more effectively into existing portfolios or where new variants may address unmet specification needs. Procurement and supply chain teams can leverage the pricing context, regional demand patterns, and competitive capacity developments to refine sourcing strategies and anticipate timing constraints. Commercial leaders can use the competitive landscape and demand distribution analysis to sharpen positioning, prioritize geographic or channel expansion, and align marketing claims with category expectations. Executive teams can rely on the consolidated market sizing, growth trajectory, and concentration analysis to inform capital allocation, scenario planning, and investor communication.
Because the study balances breadth with depth, it can serve both high-level strategic review and more detailed operational planning. It is structured to help organizations distinguish between near-term tactical issues and longer-term structural shifts, ensuring that decisions are anchored in evidence rather than short-term market noise.
Closing Perspective: The Path Ahead
The wheat germ oil market in 2026 is not defined by a single driver, but by the interaction of demand expansion, competitive specialization, regulatory evolution, and supply-side variability. That complexity is precisely why leadership teams require a comprehensive, structured, and forward-looking research foundation. The market’s progression from a measured 2020 base toward a projected 2032 scale reflects durable interest in wheat germ oil’s functional and formulation value, but capturing the full strategic benefit of that growth will depend on how well companies understand the segment dynamics, competitive relationships, and external pressures that shape commercial outcomes.
This study offers that understanding in a form designed for action. It provides the market architecture, competitive intelligence, and contextual analysis needed to make informed decisions across product, supply, commercial, and governance functions. For organizations seeking to move beyond general market awareness into precise strategic planning, the full report delivers the deeper segmentation data, regional breakdowns, application-level analysis, and competitive benchmarking required to build a confident path forward. The complete dataset and detailed strategic assessment can be accessed through the full market research page, where the full scope of the analysis, underlying structure, and actionable detail is presented for review and planning use.
For detailed analysis of this topic, please visit the official page: Wheat Germ Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railway Equipment Market Set for 6.45% CAGR, Reaching $535.08 Million by 2032
By PW Consulting, 2026-09-07
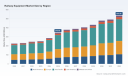
Railway Equipment Market Outlook 2026: Strategic Intelligence for Executive Decision-Making
The global railway equipment market stands at a critical inflection point in 2026. As infrastructure spending accelerates across continents and digital transformation reshapes operational paradigms, industry leaders require more than superficial trend analysis—they need precise, actionable intelligence to navigate capital allocation, regulatory compliance, and competitive positioning. This comprehensive market research publication delivers the depth required to make informed strategic decisions throughout the forecast period extending to 2032.
Worldwide Housekeeping Trolley Market
The railway sector has demonstrated remarkable resilience and growth momentum over the past half-decade. From a base of 225.0 million USD in 2020, the market has progressed through consistent expansion to reach an estimated 345.46 million USD by 2025. This trajectory reflects sustained investment in modernization programs, passenger transport demand recovery, and freight logistics optimization initiatives worldwide. Looking ahead, the market is projected to climb to 378.25 million USD in 2026, continuing its ascent toward 535.08 million USD by 2032. These figures represent more than incremental growth—they signal a structural transformation in how rail infrastructure and equipment are designed, manufactured, and integrated into broader transportation ecosystems.
Elevating Parking Robot Market
Understanding the compound annual growth rate of 6.45 percent across the forecast horizon is essential for executives evaluating long-term investment theses. This growth rate places railway equipment in a favorable position relative to broader industrial equipment categories, driven by unique tailwinds including decarbonization mandates, urbanization pressures, and government stimulus programs targeting sustainable mobility. However, capturing value in this expanding market requires nuanced understanding of segment dynamics, regional variations, and the competitive strategies employed by leading equipment manufacturers.
Worldwide Manual Tool Changer Market
Market Structure and Segment Dynamics
The railway equipment landscape encompasses multiple interconnected segments, each presenting distinct opportunities and challenges for equipment suppliers, operators, and investors. Rolling stock dominates the equipment mix, reflecting the capital-intensive nature of train manufacturing and fleet renewal programs globally. The track infrastructure segment follows, driven by network expansion, maintenance rehabilitation cycles, and safety enhancement projects. Signaling systems, while representing a smaller portion of the overall equipment expenditure, carry disproportionate strategic importance due to their role in capacity optimization, safety certification, and digital rail transformation initiatives.
Application-wise, the market divides between passenger transport and freight transport, both representing substantial and roughly comparable demand centers. This balance underscores the dual importance of commuter and intercity rail modernization alongside freight logistics efficiency improvements. Operators in both domains face common pressures: aging asset bases requiring replacement or upgrade, workforce transitions as experienced personnel retire, and the imperative to integrate digital solutions that improve asset utilization and maintenance predictability.
Regional dynamics vary considerably, with mature markets in Europe and North America focusing on replacement cycles and performance upgrades, while Asia Pacific markets exhibit stronger expansion characteristics driven by new network construction and high-speed rail deployment. Latin America and the Middle East and Africa regions present emerging opportunities tied to development finance initiatives and infrastructure modernization programs. Each regional context carries specific regulatory frameworks, procurement practices, and competitive conditions that demand localized understanding rather than generalized assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The railway equipment market exhibits significant concentration, with the top three firms commanding approximately 65 percent of market share and the top five collectively representing 82.5 percent. This oligopolistic structure reflects the high barriers to entry inherent in railway equipment manufacturing: stringent certification requirements, long qualification cycles, complex supply chain integration, and the need for sustained service and maintenance relationships spanning decades. For new entrants, partnership strategies and niche specialization represent more viable pathways than broad-based market entry attempts.
Several organizations define the competitive frontier through their product portfolios, geographic reach, and strategic moves. Wabtec Corporation, headquartered in Pittsburgh, Pennsylvania, operates as a leading global supplier spanning pantographs, electronic braking systems, couplers, and digital solutions for both freight and passenger rail applications. The company has pursued an aggressive strategic agenda in early 2026, including the completed acquisition of Dellner Couplers, a Sweden-based specialist in safety-critical train connection systems for passenger rolling stock. This acquisition strengthens Wabtec's coupling technology portfolio and expands its European manufacturing footprint. Simultaneously, the company secured multiple contracts to supply over 680 pantographs for six major commuter rail and metro projects in India, demonstrating execution capability in high-volume emerging market deployments. In a significant development for freight interoperability, Wabtec collaborated with more than twenty industry partners including Siemens, Alstom, and ÖBB on joint testing of Digital Automatic Coupler technologies, validating interoperable communication protocols. The company also signed a 670 million USD deal with CSX for 100 new Evolution Series locomotives, 50 modernized units, and integrated digital solutions, reinforcing its freight locomotive market position.
Alstom SA, based in Paris, France, stands as a major provider of signaling systems, rolling stock equipment, and integrated railway solutions serving global rail operators. The company's strategic focus in 2026 includes accelerating digital rail transformation in Queensland, Australia, where its first mainline ETCS contract supports the broader "The Wave" program aligned with Brisbane 2032 Olympics infrastructure preparation. Additionally, Alstom's TGV-M high-speed train received marketing authorization from the European Union Agency for Railways, advancing the product toward passenger service deployment. These developments illustrate the company's dual emphasis on signaling technology leadership and rolling stock innovation for premium high-speed corridors.
Hitachi Rail, headquartered in Tokyo, Japan, supplies signaling, rolling stock, and smart rail solutions including ETCS systems and high-speed train components. The organization combines engineering heritage with digital capability, positioning itself across both traditional equipment categories and next-generation connected rail solutions. Siemens Mobility, based in Munich, Germany, maintains a key position in railway signaling, train control, and high-speed rail equipment, notably advancing ETCS Level 2 systems and Velaro family trains. The company's June 2026 strategic partnership with VinSpeed for comprehensive high-speed rail development in Vietnam, encompassing Velaro Novo train supply, ETCS Level 2 signaling, and electrification systems, signals continued expansion of European technology standards into Southeast Asian markets.
CRRC Corporation Limited, headquartered in Beijing, China, operates as a global manufacturer of locomotives, rolling stock, and railway equipment with particular focus on high-speed and mainline systems. The company benefits from China's extensive domestic rail construction program while pursuing international project participation. Progress Rail, based in Albertville, Alabama, provides signaling systems, locomotives, and rail infrastructure equipment tailored to North American freight and passenger operators, representing a strong regional presence with specific market knowledge. CAF, Construcciones y Auxiliar de Ferrocarriles, headquartered in Beasain, Spain, manufactures rolling stock and railway equipment including trains and maintenance systems, maintaining a strong European manufacturing base with international project execution capability.
Regulatory Dynamics and Technical Standards Evolution
The regulatory environment for railway equipment is undergoing significant updates that will influence product design, certification timelines, and competitive positioning throughout the forecast period. EN 50155:2026, which became valid on 18 May 2026, defines updated requirements for the design, manufacturing, documentation, testing, and integration of all electronic equipment installed on-board rolling stock. This standard applies comprehensively to control, regulation, protection, diagnostic, and energy supply systems, representing a substantial revision from the preceding EN 50155:2021 edition.
The updated standard covers environmental and electrical operating conditions for railway electronic equipment, with specific requirements encompassing temperature tolerance, humidity resistance, shock and vibration resilience, operating voltage parameters, and electromagnetic compatibility testing. Critically, EN 50155:2026 applies to any electronic equipment for rolling stock subsystems, including external doors and wheel slide protection mechanisms. For equipment manufacturers and system integrators, this means that product development cycles must account for revised testing protocols and documentation requirements. Suppliers who proactively adapt their engineering processes and quality management systems will secure competitive advantages in qualification speed, while those with legacy designs may face extended re-certification timelines and potential market access delays.
Beyond product-level standards, the broader regulatory landscape continues to evolve around safety certification, interoperability mandates, and environmental compliance. Operators and equipment procurement teams must navigate these requirements while balancing cost constraints and delivery schedules. The interplay between national regulatory bodies, European standardization organizations like CENELEC, and industry consortiums creates a complex compliance environment that demands specialized expertise. Market participants who invest in regulatory intelligence and maintain active engagement with standards development processes will be better positioned to anticipate changes and manage transition risks.
Strategic Implications for 2026 Decision-Makers
The convergence of market growth, competitive concentration, technological transformation, and regulatory evolution creates a decision environment where informed strategic choices carry significant long-term consequences. For equipment manufacturers, the question is not merely whether to participate in a growing market, but how to position product portfolios, geographic presence, and partnership architectures to capture disproportionate value. Key considerations include:
- Portfolio alignment with high-growth segments: Understanding which equipment categories and application domains are expanding most rapidly enables targeted R&D investment and manufacturing capacity allocation decisions.
- Geographic strategy calibration: Regional market characteristics vary substantially, requiring nuanced approaches to pricing, localization, after-sales service, and partnership models rather than uniform global strategies.
- Certification and standards readiness: Proactive adaptation to evolving technical standards like EN 50155:2026 protects market access and creates differentiation against competitors who react more slowly to regulatory change.
- M&A and partnership evaluation: The acquisition activity visible in early 2026, particularly in specialized components and digital technology domains, signals ongoing industry consolidation. Organizations must continually assess whether organic development or external acquisition offers faster path to strategic objectives.
- Digital integration capability: As signaling, train control, and operational data systems become increasingly integral to equipment value propositions, manufacturers need to demonstrate integration expertise alongside traditional hardware competencies.
For rail operators, infrastructure owners, and public sector procurement entities, the strategic calculus centers on total cost of ownership, reliability, interoperability, and alignment with long-term network plans. Equipment selection decisions made in 2026 will influence operational performance, maintenance burdens, and upgrade pathways for decades. Access to comprehensive market intelligence that illuminates supplier capabilities, technology trajectories, and pricing dynamics supports more effective procurement and partnership strategies.
For investors and financial stakeholders, understanding market concentration patterns, growth segmentation, and competitive moats informs valuation frameworks and risk assessments. The high market concentration levels suggest that established players possess durable competitive advantages, but targeted analysis of segment-level dynamics, regional exposure, and technology transition risks remains essential for accurate investment judgment.
What This Market Research Publication Delivers
This comprehensive Railway Equipment Market research report provides the analytical depth and practical content required to support confident strategic decisions through 2032 and beyond. The publication encompasses detailed segment analysis across equipment types, application domains, and geographic regions, with quantitative projections that enable scenario planning and resource allocation modeling. Readers will find:
- Historical market performance analysis covering the 2020 to 2025 period, establishing baseline trajectories and identifying inflection points that inform forward-looking assumptions.
- Forecast projections through 2032 with granular segment-level data that supports detailed business planning, capacity investment analysis, and competitive benchmarking.
- Comprehensive competitive profiling of leading market participants, including organizational capabilities, strategic positioning, recent developments, and competitive strengths and vulnerabilities.
- Regulatory and standards landscape assessment, translating technical requirements into business implications for product development, certification, and market access strategies.
- Industry dynamics analysis identifying key drivers, restraints, opportunities, and challenges that shape market evolution and create differential outcomes across participants.
- Strategic recommendation frameworks that translate analytical findings into actionable guidance for various stakeholder types, from equipment manufacturers to operators to investors.
The report draws on rigorous research methodologies, primary source analysis, and expert interpretation to deliver insights that go beyond readily available summary statistics. While public information may provide headline market size figures or broad trend descriptions, the complete publication offers the structured detail, segment breakdowns, company-level intelligence, and forward-looking analysis that executives need to move from awareness to action.
Access the Complete Strategic Intelligence
The railway equipment market presents substantial opportunity for organizations positioned to navigate its complexities effectively. Realizing this opportunity requires more than general market awareness—it demands detailed segment intelligence, competitive benchmarks, regulatory foresight, and strategic frameworks tailored to specific decision contexts. This research publication is designed to provide that comprehensive foundation.
Readers seeking the full depth of analysis, complete segment data, detailed company profiles, and actionable strategic recommendations are encouraged to access the complete report through our official publication channel. The full version delivers the quantitative detail, methodological transparency, and interpretive depth necessary to support confident decision-making across the 2026 to 2032 forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Railway Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Dichromate Market to Reach $2,176 Million by 2032 at 5.2% CAGR
By PW Consulting, 2026-09-07
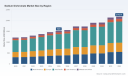
Strategic Intelligence in a Regulated Chromium Market: Navigating the Sodium Dichromate Landscape Through 2032
The global sodium dichromate market stands at a critical inflection point where industrial demand, supply chain reconfiguration, and intensifying regulatory scrutiny intersect. For senior executives, procurement leaders, and strategic planners, understanding the trajectory of this specialty chemical is no longer optional—it is a prerequisite for capital allocation, sourcing strategy, and long-term risk mitigation. PW Consulting’s latest market research delivers a structured, forward-looking assessment designed to translate complex market signals into actionable corporate strategy.
Fiber Glass PLY Yarn Market
This report is built for decision-makers who need more than historical snapshots. It maps the evolution of a market that has demonstrated consistent expansion while simultaneously confronting structural pressures from environmental legislation, feedstock volatility, and geopolitical supply chain shifts. By aligning quantitative forecasting with qualitative competitive and regulatory analysis, the study provides a comprehensive framework for evaluating market entry, capacity planning, vendor qualification, and compliance readiness through the end of the decade.
Worldwide Natural Piperonal Market
Market Trajectory and Structural Growth Dynamics
The sodium dichromate sector has followed a measured but uninterrupted growth path over the past half-decade, reflecting its entrenched role in metal treatment, surface finishing, pigment manufacturing, and specialized industrial processes. Historical revenue progression from 2020 through 2025 illustrates a steady upward curve, with market valuation expanding from approximately 1,217.0 million USD to 1,524.0 million USD. This five-year progression underscores the compound’s continued relevance despite mounting regulatory attention and the broader industry push toward alternative chemistries.
Casual Sneakers Market
Looking ahead, the forecast window extends through 2032 and captures a market environment shaped by both incremental demand expansion and periodic supply-side recalibration. The projected compound annual growth rate of 5.2 percent frames a landscape where volume growth is moderated by compliance costs, regional regulatory divergence, and shifting application priorities. Forecasts indicate the market will cross the 1,562.75 million USD threshold in 2026, followed by continued expansion toward the 1,730.26 million USD range by 2027 and further upward movement in subsequent years. The trajectory is not uniformly linear; it reflects the interplay of capacity adjustments, regional demand redistribution, and the gradual impact of authorization requirements on legacy usage patterns.
Importantly, the growth narrative is not simply a function of end-user consumption. It is increasingly influenced by feedstock availability, manufacturing efficiency, logistics constraints, and the strategic response of producers to regulatory timelines. Chromite ore remains the foundational input for sodium dichromate production, and any disruption in mining output, export policy, or processing capacity reverberates through pricing, availability, and regional supply balance. This linkage between raw material markets and downstream chemical demand is a central theme woven throughout the analysis.
Regulatory Pressures and the Changing Compliance Landscape
One of the most consequential forces reshaping the sodium dichromate market is the evolving regulatory framework around hexavalent chromium substances. The European Chemicals Agency has signaled its intent to propose restrictions under REACH targeting hexavalent chromium compounds, including sodium dichromate. This development, announced in April 2025, introduces a new layer of strategic uncertainty for manufacturers and downstream users operating in or supplying European markets.
Beyond the proposed restriction, sodium dichromate is already subject to authorization requirements under REACH Annex XIV, and it appears on the EU candidate list of substances of very high concern. These designations do not automatically eliminate usage, but they impose authorization burdens, supply-chain documentation requirements, and strategic planning obligations that affect procurement cycles, product design, and regional market access. For companies with European exposure, the compliance timeline becomes a strategic variable rather than a distant administrative concern.
Simultaneously, the broader Chromium VI restriction proposal continues to shape industry expectations. The practical effect is a market in which regulatory divergence between regions creates uneven competitive conditions. Markets with stricter authorization frameworks may experience slower volume growth or accelerated substitution, while regions with more permissive regulatory environments may see continued reliance on established chromium-based processes. Understanding where and how these regulatory pressures will concentrate is essential for formulating sourcing strategies, evaluating alternative chemistries, and anticipating shifts in regional demand patterns.
Competitive Landscape and Strategic Positioning
The sodium dichromate market is characterized by a moderately concentrated supplier base, with a limited number of established producers commanding meaningful share. The report’s competitive analysis highlights a group of companies whose manufacturing footprints, product specifications, and distribution strategies shape the overall market architecture. Market concentration metrics indicate that the top three players account for approximately 33.0 percent of revenue, while the top five represent roughly 35.2 percent. This level of concentration suggests a market in which scale, technical capability, and regulatory compliance infrastructure provide meaningful competitive advantages, yet it also leaves room for regional specialists and integrated producers to compete on efficiency, purity standards, and supply reliability.
Vishnu Chemicals Limited, headquartered in Hyderabad, India, operates as a primary manufacturer of sodium dichromate with a strong emphasis on high-purity grades and versatile application support. Its product portfolio spans metal passivation, pigments, electroplating, wood preservation, and organic synthesis, with packaging configurations designed to serve both standard industrial buyers and larger volume users. The company’s expansion of production capacity reflects a broader trend among key suppliers to reinforce supply resilience and strengthen global availability.
Nippon Chemical Industrial Co., Ltd., based in Japan, represents the high-purity, quality-assurance segment of the market. Its focus on metal treatment, aerospace applications, and specialized chemical uses positions it within supply chains where specification reliability and consistent quality are critical. The company’s Asian distribution network further illustrates how regional reach and technical reputation interplay in competitive positioning.
In China, Hubei Zhenhua Chemical Co., Ltd. and Yinhe Group operate as active participants in the regional supply landscape. Hubei Zhenhua’s profile reflects a supplier emphasis on chromium compounds with competitive positioning in Asian markets, while Yinhe Group approaches sodium dichromate as a core chromium product within a broader industrial chemistry framework. Both entities underscore the importance of modern production technology, export-oriented supply strategies, and regional cost dynamics in shaping competitive outcomes.
Soda Sanayii A.S., located in Turkey, adds another dimension to the competitive map by emphasizing production efficiency and product purity for domestic and regional markets. Its presence highlights how geographically positioned manufacturers can serve as important supply nodes for nearby industrial demand centers, particularly where logistics and regional trade flows influence procurement decisions.
Together, these companies exemplify the strategic diversity within the market: integrated producers, purity-focused specialists, regional supply providers, and capacity-expanding manufacturers. The report evaluates these competitive dynamics not merely as a roster of players, but as a system of interdependencies, capacity constraints, and differentiation levers that influence pricing behavior, supply security, and long-term market structure.
Application Demand and Regional Demand Architecture
Sodium dichromate demand is distributed across a range of industrial applications, each with distinct growth drivers, regulatory exposure, and substitution risk. Metal finishing remains a substantial demand center, supported by continued need for corrosion resistance, surface treatment, and passivation processes across manufacturing sectors. Pigments represent another significant application segment, where the compound’s chemical properties continue to support specific coloration and industrial coating requirements. Wood preservation and leather tanning also contribute to base demand, though these segments are increasingly influenced by environmental standards, consumer-facing product requirements, and regional regulatory posture.
Beyond these established uses, a broader set of industrial applications sustains additional demand. The cumulative effect is a demand structure that is diversified enough to provide resilience, yet sensitive enough to regulatory and substitution dynamics that no single application can be treated in isolation. The analysis frames these application segments as interdependent components of a demand ecosystem, where changes in one area—whether from compliance deadlines, process redesign, or material substitution—can influence overall procurement patterns and supplier planning.
On the regional side, the market exhibits a clear geographic hierarchy in which Asia Pacific carries substantial demand weight, North America and Europe represent mature, regulation-intensive markets, and Latin America and the Middle East and Africa function as smaller but strategically relevant demand centers. This regional distribution matters because it shapes where regulatory momentum will have the greatest impact, where capacity expansion is most likely to be absorbed, and where supply chain diversification strategies will yield the highest strategic value. The report examines these regional dynamics as part of a wider framework that connects demand geography with supplier location, logistics feasibility, and compliance exposure.
Strategic Value of the Report for 2026 Decision-Making
The 2026 decision environment demands more than retrospective market data. It requires a forward-looking synthesis that connects market size, growth trajectory, competitive structure, regulatory timelines, and application demand into a coherent strategic narrative. PW Consulting’s Sodium Dichromate Market research is designed to serve that need by offering a structured, evidence-based foundation for planning across multiple corporate functions.
For procurement and supply chain leaders, the report provides context for evaluating supplier reliability, regional sourcing trade-offs, and the implications of regulatory divergence on contract structuring and inventory strategy. For manufacturing and operations executives, it offers insight into demand stability, capacity trends, and the potential impact of compliance obligations on input availability and cost planning. For strategy and corporate development teams, it frames the market in terms of competitive positioning, regional opportunity, and the strategic implications of a moderately concentrated supplier base.
The research also supports scenario-aware planning. Because the forecast period spans 2026 through 2032, it allows decision-makers to assess not only near-term conditions but also the medium-term evolution of market size, demand redistribution, and regulatory pressure. This temporal breadth is particularly valuable in a market where authorization requirements, restriction proposals, and feedstock dynamics can alter the operating environment over multiple planning cycles.
Beyond macro-level insight, the report translates analysis into operational relevance. It details the components needed to evaluate market participation, supplier qualification, application-level demand behavior, and regulatory exposure in a manner that can be integrated into internal strategy workflows. The objective is not simply to describe the market, but to equip organizations with the analytical structure required to make informed decisions under uncertainty.
Why This Research Matters Now
The sodium dichromate market is entering a phase in which growth, regulation, and competition will interact more intensely than in previous years. The expansion trajectory projected through 2032 suggests continued commercial relevance, but it also coincides with an environment in which regulatory scrutiny on hexavalent chromium substances is becoming more structured and more consequential. In such a setting, strategic advantage will belong to organizations that can anticipate change, interpret its implications, and adjust sourcing, production, and planning accordingly.
This report is intended to serve as a practical intelligence asset for that purpose. It consolidates market sizing, growth expectations, competitive dynamics, regulatory context, and demand architecture into a single analytical framework. By doing so, it helps decision-makers move from generalized awareness to targeted action—whether that means reassessing supplier portfolios, preparing for compliance timelines, evaluating regional demand shifts, or refining long-range capital and capacity strategies.
The complete study provides the depth, segmentation context, and structured analysis required for detailed planning. It is designed for leaders who need to understand not only where the market is going, but how to respond with discipline and strategic clarity. For organizations navigating a market defined by both opportunity and regulatory complexity, this research offers the foundation needed to make better-informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AIM Market to Grow at 5.7% CAGR to USD 4.13 Billion by 2032
By PW Consulting, 2026-09-07
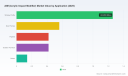
Strategic Intelligence for 2026: Navigating the Acrylic Impact Modifier Market
The global materials landscape is entering a decisive phase for polymer additives, and nowhere is this more evident than in the Acrylic Impact Modifier (AIM) sector. As downstream manufacturers face mounting pressure to balance performance, cost, and regulatory compliance, the ability to anticipate market shifts before they materialize has become a critical competitive advantage. Our latest market research initiative, the AIM (Acrylic Impact Modifier) Market intelligence report, is designed specifically to equip strategic decision-makers with the forward-looking visibility required to navigate the 2026 horizon and the years beyond. This preview outlines the analytical rigor, structural insights, and actionable frameworks embedded in the full study, while underscoring why proprietary depth matters when capital allocation and product strategy are on the line.
Worldwide Wall Mounted Hand Dryer Market
Why 2026 Demands a Reset in AIM Strategy
For much of the past half-decade, the AIM market operated within a relatively predictable trajectory, supported by steady demand from rigid PVC applications and consistent expansion in core manufacturing geographies. Historical records trace a clear upward path from 2020 through 2025, reflecting a sector that has steadily embedded itself into architectural profiles, piping systems, and exterior-grade polymer compounds. Looking forward, the forecast window captures an inflection point rather than a mere continuation of past trends. The projected growth path through 2032 signals a market that continues to expand, yet the pace and composition of that expansion will be shaped by new product introductions, capacity realignments, raw material volatility, and evolving regulatory expectations.
Worldwide Industrial Fiberscope Market
Strategic planners in 2026 cannot rely on static growth assumptions. The transition from historical momentum to forecast behavior reveals periods where growth rates may reconfigure as capacity additions, product substitutions, and regional demand shifts interact. In such an environment, decision-makers need more than headline trajectories; they require a granular understanding of where value is concentrating, which product architectures are gaining traction, and how external cost signals could compress or expand margins. This is precisely the space our research intends to illuminate.
Worldwide Corporate Media Production Services Market
The Macro Picture: Resilience Tempered by Structural Realignment
The overall market size trajectory tells a story of enduring demand backed by broad-based industrial usage. From the 2020 baseline through the most recent historical year, the sector advanced in measured steps, reflecting the ongoing integration of acrylic impact modifiers into high-volume PVC value chains. Entering the forecast period, the market is positioned to sustain growth, with the scale expected to rise meaningfully by the close of the decade. The implied compound annual growth rate across the full forecast horizon reinforces a market that remains structurally attractive, even as individual years may exhibit uneven momentum depending on capacity cycles and application mix.
What makes this trajectory strategically significant is not just the direction of growth, but the underlying concentration of activity. A market of this scale cannot be treated as monolithic. Demand is distributed across multiple end-use domains, each with distinct performance requirements, cost sensitivities, and regulatory exposure. Likewise, regional consumption patterns reflect divergent construction cycles, infrastructure investment priorities, and local manufacturing capabilities. Recognizing this dispersion is essential for any enterprise attempting to align production planning, distribution strategy, and product development with the most rewarding opportunities. The complete report unpacks these layers without reducing them to simplistic rankings, instead mapping where volume, value, and growth velocity intersect.
Segmentation That Matters: Type, Application, and Regional Nuance
A central strength of this analysis lies in its segmentation architecture. Rather than presenting broad aggregates, the report examines how the market divides across product types, downstream applications, and geographies, allowing readers to isolate the segments most relevant to their commercial objectives. On the product side, the market spans ordinary acrylic impact modifiers alongside low-temperature resistance variants engineered for more demanding service conditions. This distinction is not cosmetic; it reflects real differences in formulation strategy, performance thresholds, and end-user expectations, particularly where PVC components must withstand thermal cycling or mechanical stress in exterior environments.
The application perspective adds an equally important dimension. Window profiles, door frames, pipelines, outdoor furniture, and assorted specialty uses each draw on the AIM supply base with different intensity and different specification requirements. Architectural and infrastructure segments, for instance, typically prioritize durability, UV stability, and long-term weatherability, while consumer-facing applications may place greater weight on processing ease and final aesthetic quality. By analyzing these application streams in context, the report helps users understand where performance differentiation creates pricing resilience and where commoditization pressures are more likely to emerge.
Regional segmentation further sharpens the strategic picture. Consumption is not evenly dispersed; it concentrates in markets with established PVC processing ecosystems as well as in regions where construction activity and industrial development continue to expand. Each geography carries its own logistics footprint, feedstock access, competitive density, and regulatory backdrop. The full study maps these regional dynamics in detail, enabling businesses to evaluate where to anchor sales efforts, where to monitor import competition, and where local content expectations or trade dynamics may alter market access.
Competitive Landscape: A Concentrated Arena with Differentiated Playbooks
The AIM market is characterized by a meaningful degree of concentration, with leading participants holding substantial share and exercising significant influence over pricing norms, product standards, and innovation cadence. Yet concentration does not imply uniformity. The competitive field includes multinational specialty chemical players, regional manufacturers with strong domestic positioning, and focused producers that compete through niche formulations or cost-optimized manufacturing. Understanding how these actors differ is vital for any company evaluating supplier relationships, partnership opportunities, or market entry pathways.
A review of the principal companies active in this space highlights a diverse array of strategic approaches. Some participants emphasize broad product portfolios that span multiple polymer applications, using established technical service networks and global reach as differentiators. Others concentrate on specific grades or performance attributes, such as enhanced fusion, UV resistance, core-shell architecture, or tailored formulations for rigid PVC processing. Several producers have built their identity around specialized impact modifier families designed for profiles, pipes, sheets, conduits, and engineered plastics, while others have expanded into synergistic combinations that pair acrylic chemistry with complementary additives to improve processing efficiency and final property profiles.
Geographic origin also shapes competitive posture. Manufacturers based in major industrial regions often benefit from proximity to downstream converters and integrated supply chains, while global-scale players leverage research capabilities, brand equity, and multi-region distribution to sustain presence across varied market conditions. The report profiles these companies with an emphasis on their specific offering logic, giving readers a clearer sense of who competes on performance breadth, who competes on application specificity, and who competes on cost and availability. Such distinctions matter when selecting suppliers, benchmarking alternatives, or assessing the credibility of potential collaborators.
Beyond the static roster of competitors, recent activity shows that the market is by no means static. Product launches, certification updates, capacity expansions, and grade enhancements have all been documented during the recent period, each carrying implications for supply reliability, performance standards, and competitive positioning. A new acrylic impact modifier introduced for engineering plastics, for example, can open adjacent opportunities beyond traditional PVC uses. Capacity expansion in a key production location may alter regional supply balances and shift sourcing calculations for converters. Updated compliance certifications can reduce friction for customers navigating regulatory requirements, effectively improving a product's market viability. Enhanced core-shell grades targeting PVC profiles demonstrate how formulation refinement can reinforce a manufacturer's standing in high-value architectural applications. The report tracks these developments and interprets them not as isolated headlines, but as signals of where capability and momentum are accumulating.
Operating Conditions: Raw Materials, Regulation, and the Cost Equation
No strategy for the AIM market can be built in isolation from the cost and compliance environment. Raw material trends are a persistent force shaping producer economics and, by extension, the price expectations of downstream buyers. During recent periods, feedstock dynamics have displayed notable variability across regions. In Asia, certain key input prices have trended soft to stable, reflecting a combination of demand conditions and supply balance. In parallel, other essential feedstocks have moved lower in global assessments, with consistent declines recorded in CFR China benchmarks and downward movement observed in European pricing through the latter part of the year. These patterns matter because they influence production cost structures, margin flexibility, and the relative competitiveness of different manufacturing bases.
Equally important are the regulatory currents reshaping demand behavior. In Europe, ongoing debate around restrictions on certain stabilizers used in PVC introduces potential disruption risk for related additive demand, including impact modifiers that are part of broader formulation systems. At the same time, policy frameworks in multiple jurisdictions are increasingly incentivizing bio-based and recyclable solutions, encouraging investment in sustainable polymer technologies. This dual pressure creates a strategic paradox: some conventional demand pathways may face headwinds, while new opportunities emerge for additives that align with sustainability agendas and evolving compliance expectations. Companies that track these dynamics early can adapt formulation roadmaps, supplier selection, and customer messaging before shifts become consensus.
The interaction between raw material flexibility and regulatory direction also affects segmentation dynamics. In a softer input cost environment, producers may have more room to compete on price or to fund product improvement without immediate margin erosion. Under stricter regulatory scrutiny, customers may prioritize grades with documented compliance, predictable performance, and reduced reliance on restricted substances. The full report integrates these factors into its market dynamics assessment so that readers can gauge how external conditions may influence competitive outcomes over the forecast window.
What the Full Report Delivers: Operational Intelligence, Not Just Data
This market research is structured to support practical decision-making rather than passive observation. It is built around a set of actionable modules that translate market structure into strategic insight. Readers can expect detailed coverage of scope and methodology, historical performance tracking, and forecast construction that clarifies the assumptions behind forward estimates. Segmentation is presented in a way that supports segment-level evaluation of demand drivers, competitive intensity, and growth potential, while preserving the analytical discipline needed to avoid overgeneralization.
The competitive analysis extends beyond company identification. It connects product offerings, manufacturing footprints, and recent corporate actions to a broader assessment of how the market is likely to evolve. By examining who is expanding, who is refining grades, and who is responding to regulatory or sustainability pressures, the report helps clients anticipate shifts in supply reliability, differentiation opportunities, and potential partnership targets. Recent developments are woven into this narrative to show how near-term actions influence longer-term positioning.
Cost and dynamics analysis deserves particular emphasis. Because AIM purchasing decisions often hinge on the balance between performance gains and total formulation cost, the report incorporates feedstock trends, regional price posture, and regulatory risk into a coherent operating context. This allows users to evaluate margin exposure, sourcing strategy, and inventory planning with a clearer view of the forces that will shape price formation and availability through the forecast period.
In addition, the study is designed to support scenario thinking. Markets of this kind rarely move in straight lines, and effective strategy requires understanding how different combinations of demand growth, capacity response, raw material movement, and regulatory change could alter outcomes. The report provides the analytical scaffolding for that kind of assessment, helping organizations test assumptions and prepare for multiple plausible paths rather than a single baseline.
How to Use This Research for 2026 Decision-Making
For executive teams, procurement leaders, product developers, and commercial strategists, the practical value of this research lies in its ability to connect macro signals to operational choices. A supplier evaluating capacity allocation can use the segmentation and regional analysis to prioritize the most resilient demand pools. A converter assessing additive sourcing can benchmark competitors and recent product launches to understand where performance differentiation may justify premium positioning or where cost competition is intensifying. A strategist monitoring regulatory exposure can align formulation direction with compliance trajectories before customer requirements harden into mandates.
The report also serves as a reference point for investor and partnership conversations. In a market with measurable concentration and active corporate development, stakeholders need credible structure to evaluate where value is generated and how defensible particular positions may be. By providing a disciplined overview of shares, concentration, product families, application breadth, and recent momentum, the study gives decision-makers a stronger basis for negotiation, investment appraisal, and strategic planning.
Next Steps: Accessing the Full Intelligence Package
This preview has outlined the analytical framework and strategic intent behind the AIM (Acrylic Impact Modifier) Market research, but it cannot replicate the granularity, comparability, and segment-level insight contained in the full report. The complete study goes further into historical trends, forecast construction, segmentation behavior, competitive positioning, and the operating dynamics that influence cost and demand. Those details are essential for organizations that need to convert market awareness into procurement strategy, product planning, regional expansion decisions, or supplier evaluation.
For leaders preparing for 2026 and the forecast window beyond, the most effective next step is to engage with the full dataset and analysis directly. The complete report is available through our official research portal, where clients can access the comprehensive market model, company profiles, segmentation breakdowns, and the supporting context needed to operationalize the findings. In a market shaped by concentration, formulation innovation, raw material variability, and regulatory evolution, deeper intelligence is not a luxury; it is a prerequisite for confident action.
For detailed analysis of this topic, please visit the official page: AIM (Acrylic Impact Modifier) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


