



Category: market research
PW Consulting Reports Global Sintered NdFeB Magnet Market Expected to Reach USD 22,504 Million by 2032 Growing at 8.82 Percent CAGR with Asia Pacific Leading at USD 9,398.66 Million and New Energy Vehicles Dominating Segments
By PW Consulting, 2026-09-02
Strategic Imperatives in the High-Performance Sintered NdFeB Magnet Market: Navigating Growth and Geopolitical Complexity Through 2032
The global landscape for high-performance sintered NdFeB magnets is undergoing a profound transformation, driven by the inexorable rise of electrified transportation, the expansion of renewable energy infrastructure, and the deepening integration of advanced robotics in industrial manufacturing. For executives and strategy leaders operating in this sector, understanding the trajectory of this market is no longer optional—it is a fundamental prerequisite for capital allocation, supply chain resilience, and competitive positioning. This analysis draws upon the comprehensive insights contained in the Worldwide High-performance sintered NdFeB Magnet Market report, offering a strategic preview of the dynamics that will define the industry from 2026 through 2032.
Worldwide High-performance sintered NdFeB Magnet Market
The sintered neodymium-iron-boron magnet remains the cornerstone of modern high-efficiency electric motors and generators. Its unparalleled magnetic energy product enables the miniaturization and power density required by next-generation technologies. However, the market is not merely growing; it is evolving under the weight of technological innovation, raw material volatility, and increasingly complex geopolitical trade barriers. The following overview outlines the macro-environment, competitive forces, and structural shifts that decision-makers must internalize to secure advantage in this high-stakes arena.
Worldwide High-performance sintered NdFeB Magnet Market
Market Trajectory and Historical Context
The sector has demonstrated robust expansion over the past half-decade, recovering from pandemic-induced disruptions and accelerating through the early 2020s as demand for electric vehicles and clean energy solutions surged. Historical data from 2020 to 2025 reflects a steady climb in global revenue, moving from approximately 8,250 million USD at the start of the period to a base year valuation of 12,450 million USD in 2025. This growth underscores the successful commercialization of high-performance grades and the widespread adoption of permanent magnet technologies across diverse end-use sectors.
Worldwide High-performance sintered NdFeB Magnet Market
Looking forward, the forecast period from 2026 to 2032 projects continued momentum, with the market expected to reach over 22,500 million USD by the close of the forecast window. This trajectory implies a compound annual growth rate of 8.82 percent, signaling sustained investment and consumption. Such growth is not uniform; it is concentrated in specific technological grades and application verticals that are most sensitive to efficiency mandates and decarbonization goals. For strategic planners, this CAGR represents both an opportunity for revenue expansion and a challenge in scaling production capacity without compromising quality or margin integrity.
The revenue progression year-by-year illustrates a pattern of acceleration that tapers slightly in the outer forecast years, suggesting a market maturation effect as penetration rates in mature economies stabilize. However, the absolute value additions remain substantial, indicating that even incremental share gains can translate into significant financial impact. Companies that can align their production roadmaps with these growth curves will be best positioned to capture value as the market expands.
Segmentation Dynamics and Application Leaders
The market structure is defined by distinct segmentation dimensions that reveal where value is being created and consumed. By end-use application, the landscape is dominated by sectors that demand high torque, efficiency, and reliability. New energy vehicles constitute the largest application segment, reflecting the massive scale of the global electric vehicle transition. The motors in these vehicles rely heavily on high-performance sintered magnets to achieve range and performance targets that compete with internal combustion engines.
Industrial automation and robotics represent the second major pillar of demand. As manufacturing facilities worldwide adopt automated systems to address labor shortages and improve precision, the requirement for compact, powerful motors in robotic actuators and conveyor systems drives magnet consumption. Wind power generation forms another critical application area, where direct-drive turbine generators utilize high-grade magnets to eliminate gearboxes and enhance reliability in harsh operational environments. Consumer electronics and energy-saving appliances complete the application mix, though their growth rates and volume contributions differ significantly from the heavy industrial and automotive segments.
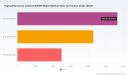
From a product grade perspective, the market is stratified by magnetic performance levels. The SH and UH series grades command a significant share of the market, driven by their ability to operate at higher temperatures and maintain magnetic stability under demanding conditions. These grades are essential for automotive traction motors and wind turbine generators where thermal management is critical. The N, M, and H series grades serve a broad range of industrial and automotive applications, offering a balance of performance and cost. The EH and AH series, representing the highest performance tiers, cater to niche but high-value applications where extreme coercivity is required, often in conjunction with heavy rare earth diffusion technologies.
Regional dynamics further complicate the segmentation picture. Asia Pacific remains the dominant region in terms of market revenue, reflecting both the concentration of manufacturing capacity and the immense demand from Chinese, Japanese, and Korean automotive and industrial sectors. Europe and North America represent significant markets, driven by their own decarbonization policies and defense and aerospace requirements, though their share of total revenue is smaller relative to Asia. The rest of the world segment, while smaller in aggregate, is growing as emerging economies adopt electrification technologies.
Strategic note: Detailed breakdowns of regional shares and application-specific revenue percentages are proprietary elements of the full report. Accessing the complete segmentation analysis is essential for modeling local market entry strategies and supply chain optimization.
Competitive Landscape and Strategic Positioning
The competitive environment in the high-performance sintered NdFeB magnet market is characterized by a mix of established global specialists and large-scale regional manufacturers. Market concentration metrics indicate a moderately consolidated industry, where the top three players hold a notable share of total revenue, and the top five firms account for a majority of market output. This concentration suggests that scale, technological proprietary, and supply chain control are critical differentiators.
Shin-Etsu Chemical Co., Ltd., headquartered in Tokyo, stands as the world's largest producer under its NEOMAX brand. The company's capability to offer grades up to 52 MGOe, combined with heavy rare earth diffusion techniques, positions it as a leader in supplying motors for electric vehicles and wind turbines. Shin-Etsu's recent launch of the NEOMAX H-grade sintered NdFeB with enhanced coercivity for high-temperature EV applications in mid-2025 demonstrates its continued focus on pushing performance boundaries to meet the evolving demands of automotive OEMs.
Proterial, Ltd., formerly known as Hitachi Metals, is another key Japanese player supplying high-coercivity sintered NdFeB magnets. The company's emphasis on grain boundary diffusion technology supports its automotive and industrial customer base. Proterial's achievement of IATF 16949 certification for a new production line in Vietnam in early 2025 highlights the industry's trend toward geographic diversification of manufacturing footprint to mitigate risk and serve regional markets more closely.
TDK Corporation contributes to the competitive fabric with its focus on sintered NdFeB magnets for automotive electric power steering, sensors, and actuators. TDK's emphasis on high-temperature grades aligns with the need for reliability in automotive environments where thermal cycling is frequent.
On the China side, several firms have emerged as significant forces due to their scale and vertical integration. JL MAG Rare-Earth Co., Ltd., based in Zhejiang, is a leading Chinese manufacturer specializing in high-performance sintered NdFeB magnets for EV traction motors, with an annual capacity exceeding 20,000 tons. The company's announcement in late 2025 of a 5,000-ton annual capacity increase targeting the EV market signals its ambition to capture growing demand from domestic and export markets. Beijing Zhong Ke San Huan Hi-Tech Co., Ltd. specializes in high-grade magnets for wind power generators and electric vehicles, leveraging its technical expertise to serve renewable energy and mobility sectors.
Ningbo Permanent Precision Technology Co., Ltd. and China National Nonferrous Metals (Group) Co., Ltd. further illustrate the breadth of Chinese manufacturing capability, covering consumer electronics, automotive uses, and industrial motors through subsidiaries and specialized production lines. These companies benefit from localized supply chains and government support, though they also face scrutiny regarding trade policies and export controls.
In the Western manufacturing landscape, Arnold Magnetic Technologies, based in Rochester, New York, offers custom high-performance sintered NdFeB magnets tailored for aerospace, defense, and medical devices. Electron Energy Corporation, located in Landisville, Pennsylvania, manufactures ITAR-compliant magnets for defense and space sectors, catering to applications where supply chain security and regulatory compliance are paramount. Vacuumschmelze GmbH & Co. KG, based in Hanau, Germany, provides high-remanence magnets with low weight loss for automotive and renewable energy applications, serving the European market's stringent quality and sustainability requirements.
Strategic note: Full competitor profiling, including market share estimates, pricing strategies, and detailed capacity analysis, is available in the complete report. Understanding the relative positioning of these players is vital for partnership, merger, or competitive response decisions.
Industry Dynamics and Risk Factors
The market operates within a complex web of raw material constraints, regulatory shifts, and trade policy changes that can materially impact profitability and supply security. Raw material prices are a primary cost driver for sintered NdFeB magnets. The spot price for Praseodymium-Neodymium oxide averaged 58 USD per kilogram in the fourth quarter of 2025, representing a 15 percent year-over-year increase due to supply tightness. This upward pressure on rare earth oxides directly affects the cost structure of magnet producers and can squeeze margins if not managed through hedging, long-term contracts, or product mix optimization.
The situation is even more acute for heavy rare earth elements. Dysprosium oxide prices reached 250 USD per kilogram in late 2025 amid production cuts, reflecting the scarcity and strategic importance of this element used to enhance coercivity in high-temperature grades. The volatility in heavy rare earth pricing underscores the need for technologies that reduce dysprosium usage, such as grain boundary diffusion, or for securing reliable sources of supply through vertical integration or long-term agreements.
Regulatory and trade measures add another layer of complexity. China's export licensing for NdFeB magnets tightened under 2024 rare earth measures, requiring dual-use approvals for certain shipments. This policy shift has cascading effects on global supply chains, prompting buyers outside China to reassess sourcing strategies and consider alternative suppliers or stockpiling strategies. Simultaneously, US Section 301 tariffs on sintered NdFeB magnets from China were raised to 25 percent effective in 2024, increasing the cost of imported magnets and incentivizing the development of non-Chinese supply sources or local manufacturing capabilities.
In Europe, EU REACH restrictions limit certain NdFeB grades for consumer goods unless recycled content exceeds 10 percent. This regulation pushes the industry toward circular economy practices and may influence product design and material sourcing decisions for manufacturers serving the European market. Compliance with such environmental regulations requires proactive engagement with recycling infrastructure and material traceability systems.
Additionally, the Chinese Ministry of Industry and Information Technology issued 2025 production quotas allocating 238,000 tons for sintered NdFeB production among six major firms in late 2024. Such quota systems control the pace of capacity expansion in China and can influence global supply availability and pricing dynamics. Companies operating in or purchasing from China must monitor these quota allocations as indicators of supply tightness or relaxation.
Strategic note: The full report provides an in-depth analysis of how these dynamics interact, including scenario modeling for raw material price fluctuations and the impact of trade policies on regional cost structures. Decision-makers should utilize these insights to build resilient procurement and pricing strategies.
Strategic Value of the Comprehensive Report
For enterprises navigating the high-performance sintered NdFeB magnet market, access to granular, forward-looking intelligence is a strategic asset. The report offers a multi-dimensional view of the market that goes beyond high-level trends to provide actionable data for planning and execution. Key components of the analysis include detailed segmentation breakdowns that allow companies to quantify opportunity in specific grades, applications, and regions, enabling targeted investment and marketing efforts.
The competitive landscape section provides deep profiles of key companies, including their technological capabilities, recent developments, and strategic moves. By understanding the strengths and weaknesses of competitors, organizations can identify whitespace opportunities, potential partnership targets, or areas where they can differentiate through innovation or service. The inclusion of recent developments, such as capacity expansions, new product launches, and certification achievements, offers a real-time view of the competitive race and helps anticipate shifts in market share.
Market dynamics analysis connects macroeconomic factors, raw material trends, and regulatory changes to the specific context of the sintered NdFeB magnet industry. This holistic view supports risk assessment and scenario planning, allowing companies to prepare for various outcomes, such as raw material price spikes, trade barrier escalations, or rapid demand shifts in key applications like electric vehicles or wind power.
Furthermore, the report's forecast model, built on historical data and informed by industry drivers, provides a credible baseline for revenue projections and capacity planning. The CAGR and size estimates serve as anchor points for financial modeling and strategic forecasting. However, the true value lies in the nuances of the segmentation and the qualitative insights that explain the why behind the numbers, enabling leaders to make informed judgments rather than relying on opaque assumptions.
To fully leverage these insights, stakeholders are encouraged to engage with the complete dataset and analysis. The report is designed to support diverse user needs, from supply chain managers assessing sourcing options to product strategists evaluating grade selection, and from financial analysts modeling growth to executives setting long-term direction. The depth of information ensures that decisions are grounded in evidence rather than conjecture.
Conclusion: Preparing for the Next Phase of Growth
The Worldwide High-performance sintered NdFeB Magnet Market is entering a phase where growth is coupled with complexity. The projected expansion to over 22,500 million USD by 2032 at an 8.82 percent CAGR presents significant opportunities for companies that can deliver high-quality magnets efficiently and reliably. However, realizing this potential requires navigating raw material volatility, adapting to trade and regulatory environments, and competing effectively in a market where technological leadership and scale matter.
The dominant application segments, particularly new energy vehicles and industrial automation, will continue to drive demand, but the composition of that demand will shift as technologies evolve and regional policies shape market access. Product grade preferences will be influenced by the trade-off between performance requirements and cost, with higher grades gaining share in applications where efficiency and temperature resistance are non-negotiable. Regional dynamics will remain shaped by the concentration of manufacturing in Asia Pacific and the efforts of other regions to build or secure supply chains for strategic materials.
The competitive field includes global leaders with deep technical pedigrees and large-scale regional players with significant capacity and market access. Success will depend on a company's ability to combine technological innovation, such as diffusion technologies and high-coercivity grades, with robust supply chain management and customer intimacy. Recent developments from key players highlight the intensity of this competition and the importance of staying ahead in capacity, certification, and product development.
Ultimately, strategic decisions in this market require a clear-eyed view of both the opportunities and the risks. The full report provides the comprehensive intelligence necessary to make those decisions with confidence. By exploring the detailed segmentation, competitor analysis, and dynamic scenario modeling, readers can uncover the specific insights that align with their organizational goals and operational context. We invite you to access the full study to equip your organization with the knowledge needed to thrive in the evolving landscape of high-performance sintered NdFeB magnets.
For detailed analysis of this topic, please visit the official page: Worldwide High-performance sintered NdFeB Magnet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Waterproof Servo Motor Market to Reach 774.79 Million USD by 2032 Driven by 6.99 Percent CAGR and Asia Pacific Leadership
By PW Consulting, 2026-09-02
Global Waterproof Servo Motor Market 2026–2032: Strategic Intelligence for Industrial Automation Leaders
Executive Overview: Navigating Reliability in Harsh Environments
The industrial automation landscape is undergoing a profound transformation, driven by an unyielding demand for motion control systems that can withstand moisture, chemical exposure, high-pressure washdowns, and extreme temperatures. Waterproof servo motors have emerged as a critical enabler across sectors ranging from hygienic food processing and pharmaceutical manufacturing to marine engineering, energy exploration, and outdoor robotics. As operational environments grow more hostile and automation penetration deepens, the ability to source, validate, and deploy sealed motion solutions is no longer a niche consideration—it is a core strategic imperative.
Worldwide Waterproof Servo Motor Market
PW Consulting's latest Worldwide Waterproof Servo Motor Market study delivers a comprehensive, data-rich view of this evolving ecosystem. Covering historical performance from 2020 through 2025 and extending forecasts to 2032, the report is designed to equip executives, procurement leaders, R&D directors, and investors with the contextual intelligence needed to navigate a market defined by concentrated competition, shifting raw material economics, tightening regulatory standards, and rapid technological convergence. This preview outlines the scope, analytical architecture, and decision-focused utility of the full study, while guiding readers toward complete segmentation data, competitive profiling, and scenario modeling available in the source publication.
Worldwide Waterproof Servo Motor Market
Market Trajectory and Structural Growth Dynamics
The global market for waterproof servo motors has demonstrated consistent expansion over the past half-decade, reflecting both cyclical industrial recovery and underlying structural shifts toward sealed, maintenance-resistant motion architectures. From a baseline of approximately 345.1 million USD in 2020, the market progressed through a period of steady acceleration, reaching 482.5 million USD by 2025. Forecasts indicate that this trajectory will continue, with the market projected to arrive at roughly 521.88 million USD in 2026 and expand further to an estimated 774.79 million USD by 2032.
Worldwide Waterproof Servo Motor Market
This growth path translates into a compound annual growth rate of approximately 6.99 percent across the 2026–2032 forecast horizon—a pace that signals durable demand rather than a transient surge. Several interlocking drivers underpin this momentum. First, industries operating in wet, corrosive, or sanitary environments increasingly view IP-rated servo systems as essential infrastructure rather than optional upgrades. High-pressure sterilization cycles in food and pharmaceutical facilities, subsea actuation requirements in offshore operations, and outdoor exposure in heavy industrial robotics all reward motor designs that can perform reliably without supplemental enclosures or frequent maintenance interventions.
Second, the broader automation wave is expanding the addressable footprint of servo technology. Manufacturers seeking to increase throughput, reduce changeover times, and improve precision are deploying servo-driven axes and end-effectors in environments previously considered unsuitable for conventional components. Third, energy efficiency mandates and the adoption of higher-efficiency motor classes are pushing designers toward permanent magnet solutions that pair well with advanced sealing and thermal management techniques. These dynamics together create a market where reliability, compliance, and efficiency are becoming mutually reinforcing purchase criteria.
Segmentation Architecture: Types, Applications, and Regional Distribution
The full report dissects the waterproof servo motor market across three analytical dimensions: protection rating tiers, end-use applications, and regional deployment patterns. Rather than presenting static share figures, the study evaluates how each segment's value contribution aligns with operational realities, compliance requirements, and technology adoption curves. The segmentation is constructed to reveal where demand concentration creates pricing power, where entry opportunities may exist, and where technical differentiation can shift competitive positioning.
Protection rating segmentation distinguishes among IP65/IP66 rated motors, IP67/IP68 rated motors, and IP69K rated motors. Each tier addresses a distinct set of environmental challenges. IP65/IP66 configurations offer robust protection against water jets and airborne particulates, making them suitable for many standard industrial and outdoor scenarios. IP67/IP68 designs extend capabilities for temporary or continuous immersion, serving applications from robotic cleaning systems to subsea components. IP69K ratings, by contrast, are engineered for stringent hygienic washdown regimes, enabling high-pressure, high-temperature cleaning without degrading internal electronics or mechanical integrity. This tier has become particularly consequential in food, beverage, and pharmaceutical production where sanitation protocols are non-negotiable and downtime for cleaning or reassembly carries significant cost.
Application segmentation captures a diversified demand base. Food and beverage processing represents a substantial share of the market's value, reflecting the scale of global food manufacturing and the regulatory emphasis on washdown-compatible equipment. Pharmaceutical and medical applications contribute a meaningful portion, driven by sterile processing needs and precision fluid handling. Marine and subsea operations add a specialized but expanding segment where pressure tolerance and corrosion resistance are paramount. Energy and oil & gas applications, while smaller in relative value compared with some processing sectors, involve highly demanding operating conditions that reward robust sealing and long service life. Outdoor and heavy industrial robotics round out the application landscape, combining exposure risk with growing investment in automated material handling, welding, and inspection systems.
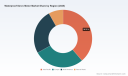
Regional distribution of market value reflects the geography of industrial production, automation investment, and export-oriented manufacturing. Asia Pacific accounts for the largest regional value base, consistent with the concentration of electronics, automation component production, and growing domestic automation deployment. Europe follows with a significant share, underpinned by strong food and pharma sectors, stringent hygiene standards, and mature automotive and industrial supply chains. North America holds a substantial position, supported by diversified manufacturing, energy operations, and robotics adoption. The Rest of World category encompasses additional demand pools that are gradually expanding as regional automation ecosystems mature. The complete analysis provides granular comparison frameworks, growth rates, and regional demand drivers without reducing the picture to static percentages—allowing decision-makers to weigh relative opportunity against operational context.
Competitive Landscape: Incumbents, Specialists, and Rapidly Evolving Players
The waterproof servo motor market exhibits a competitive structure in which a relatively concentrated group of established suppliers competes with specialized manufacturers and nimble entrants targeting distinct protection tiers, application niches, or geographic markets. Industry concentration metrics indicate that a core group of suppliers holds a meaningful share of total market value, while the remainder is distributed across firms with differentiated technical portfolios, regional strengths, or application-specific expertise. This structure matters because it shapes pricing behavior, supply reliability, and the pace at which new sealing technologies, protocol integrations, and safety features reach the market.
Several companies illustrate the breadth of competitive strategies currently in play. Kollmorgen, based in Radford, Virginia, offers the AKMH series of stainless steel hygienic servo motors with IP69K rating, emphasizing FDA-approved materials and 316L stainless steel construction for washdown environments in food, pharmaceutical, and harsh industrial applications. The brand's positioning reflects a focus on compliance-driven design and long-cycle hygiene requirements. JVL Industri Elektronik A/S, headquartered in Birkerød, Denmark, specializes in integrated servo motors, including the MAC400 IP66 waterproof version with stainless steel flange and shaft, Rulon Teflon sealing, and support for various industrial protocols. Its portfolio targets chemical, medical, and food processing environments where protocol compatibility and corrosion resistance must coexist. ROBOTIS, located in Seoul, South Korea, provides DYNAMIXEL XW series smart servo actuators such as the XW540-T140-R and XW540-T260-R with IP68 waterproof rating, designed for underwater and wet environment robotic applications—an example of how servo technology is expanding into autonomous and semi-autonomous systems operating in challenging media.
In China, Kpower, based in Dongguan, Guangdong, manufactures compact motion units including IP67 waterproof servos for industrial automation, robotics, and precision applications with modular drive technology, highlighting the growing role of integrated, cost-competitive solutions in high-volume automation. Savox, with headquarters in Taiwan and US distribution, supplies a range of waterproof digital and brushless servos, including SW series options for RC, automotive, and industrial uses with high torque and metal gear options—illustrating a crossover between hobbyist-grade performance expectations and industrial deployment needs. DSpower (Guangdong De Sheng Intelligent Technology Co., Ltd.), also in Dongguan, produces waterproof servos including IP67 models with CAN bus protocol for robotics, sweeping robots, and industrial motion control, underscoring the importance of communication integration alongside sealing performance. Flash Hobby, China-based, offers high-torque waterproof servos such as IP67 models in multiple torque classes targeted at RC and hobby/industrial applications, reflecting a market segment where performance density and sealing coexist. GDW Servo, China-based, manufactures digital servos with IP-rated sealing, including IPX8 for underwater use, using steel and titanium gears and aluminum casings for harsh environments—an indication of how material selection and sealing ratings are being tuned to application-specific risk profiles.
Recent corporate activity reinforces the strategic nature of this competition. In November 2025, Kollmorgen released an updated AKMH Stainless Steel Washdown Motor Catalog highlighting IP69K certification, FDA-approved materials, and hygienic design for washdown applications. Around the same period, JVL Industri Elektronik A/S issued participation details for the SPS fair, showcasing integrated servo motors including waterproof models, a move that signals active engagement with European industrial buyers and system integrators. In 2025, DSpower participated in the AWE Exhibition and the Low Altitude Economic Exhibition, demonstrating waterproof servo solutions for micro transmission and unmanned systems, a reminder that waterproof servo technology is increasingly linked to emerging mobility and aerial/ground robotics use cases. These events, among others, reflect a market in which product launches, exhibition presence, and specification clarity are being used to influence buyer perception, qualify new applications, and reinforce technical credibility.
Regulatory, Material, and Technology Forces Shaping Demand
Market growth is not simply a function of end-user demand; it is also shaped by regulatory expectations, raw material economics, and the integration of safety and communication features that alter value propositions. IP69K certification remains a key standard for hygienic waterproof servo motors in food and pharmaceutical applications, enabling high-pressure, high-temperature washdowns without additional covers. For buyers in these sectors, certification is not a vanity metric—it directly affects validation timelines, cleaning cycle design, and operational risk. As a result, motors that can demonstrably meet such standards carry a compelling commercial advantage in environments where compliance and downtime avoidance are closely linked.
Simultaneously, functional safety features compliant with IEC 61800-5-2, including safe torque off functionality, are increasingly integrated in servo systems for industrial automation safety standards. This trend reflects a broader shift toward motion systems that contribute to machine-level safety architectures rather than serving merely as power sources. In high-risk or high-availability environments, safety-integrated waterproof servos can simplify system design and reduce the burden on external safety controls.
Material economics add a separate layer of strategic complexity. Neodymium prices reached approximately 995,000 CNY per ton in early April 2026, up roughly 77 percent year-over-year, driven by demand in permanent magnet servo motors. NdPr oxide prices surged in 2025–2026 with forecasts of 700,000–900,000 RMB per ton in 2026 due to electric vehicle demand, robotics expansion, and supply constraints impacting servo motor production costs. These input cost dynamics are relevant not only for manufacturers but also for buyers who depend on predictable cost structures and supply continuity. While the full report does not reduce the discussion to narrow commodity forecasts, it incorporates these pressures into segmentation and competitive analysis, helping readers assess where cost insulation, design substitution, or supplier diversification may be necessary.
A further macro trend is the rising adoption of energy-efficient IE4/IE5 class motors and automation in harsh environments, which drives demand for waterproof servo motors with permanent magnet designs. The intersection of efficiency mandates and environmental resilience is sharpening buyer priorities: the most attractive products are increasingly those that combine sealing performance with improved electrical efficiency, thermal stability, and compact integration. In this context, waterproofing becomes part of a broader performance equation rather than an isolated feature.
What the Full Report Delivers: Operational Content for Decision-Makers
The complete PW Consulting study is structured to move beyond high-level narrative and into actionable market intelligence. It provides a consolidated view of historical market size and forecast trajectories, with data presented in a way that supports planning, budgeting, and scenario comparison. It includes segmentation analysis that maps protection tier, application, and regional value distribution to operational use cases, enabling readers to identify where demand is most concentrated, where growth rates are strongest, and where segments may be more vulnerable to input cost volatility or competitive entry.
The report also profiles key companies with attention to headquarters, product characteristics, sealing ratings, material choices, protocol support, and recent activity. Rather than cataloguing every manufacturer indiscriminately, the analysis filters for suppliers whose portfolios are directly relevant to waterproof servo applications and whose strategic moves are likely to influence pricing, availability, or specification expectations. Corporate developments such as catalog releases, exhibition participation, and product launches are contextualized to show how suppliers are signaling their positioning and where buyer attention is likely to be drawn.
In addition, the study integrates regulatory and standards considerations, including the role of IP69K in hygienic processes and the growing relevance of IEC 61800-5-2 functional safety compliance. It addresses raw material pressures through the lens of permanent magnet servo motor production, connecting neodymium and NdPr price movements to downstream cost and supply planning. Macro trends such as IE4/IE5 efficiency adoption and automation in harsh environments are woven into the analysis to show how broader industry shifts influence waterproof servo demand trajectories. The cumulative aim is to give readers a framework for evaluating suppliers, sizing opportunities, anticipating cost risks, and aligning product selection with both environmental and regulatory realities.
Strategic Implications for 2026 Decision-Making
For executives planning 2026 investments, procurement strategies, or product roadmaps, the waterproof servo motor market raises several strategic questions. Which protection tier best matches the operating conditions of target applications, and does the buyer's specification set include enough detail to differentiate between water-jet resistance, temporary immersion, continuous immersion, and high-temperature washdown? In which end-use segments does compliance, certification, or functional safety create a stronger purchasing preference, and how should sourcing strategies reflect that preference? How sensitive is the chosen supplier base to rare earth input cost movements, and what degree of supplier diversification or design flexibility is prudent given current price trajectories?
The answers are not uniform across regions or applications. Value concentration in certain segments implies that suppliers with strong compliance credentials and proven sealing performance may command pricing resilience. At the same time, expanding robotics adoption and unmanned system development are opening new application pathways where IP67/IP68 designs and integrated communication protocols can unlock demand outside traditional processing sectors. Energy and oil & gas, marine and subsea operations, and outdoor heavy industrial robotics each present distinct risk and reward profiles, and the report offers comparative context to support segment prioritization without reducing the analysis to simplistic rankings.
Ultimately, the strategic value of this study lies in its ability to connect macro market data with the operational realities that determine purchase decisions. For R&D teams, it clarifies where sealing, material, and protocol integration are becoming table stakes versus differentiators. For procurement and supply chain leaders, it highlights where concentration, certification, and raw material exposure may shape sourcing strategy. For investors and corporate development teams, it frames the competitive structure in terms of specialization, regional strength, and the extent to which recent developments are likely to shift market share dynamics over the 2026–2032 horizon.
Access the Full Worldwide Waterproof Servo Motor Market Study
This preview is designed to demonstrate the analytical depth, segmentation rigor, and decision-oriented framing available in the full PW Consulting report. It intentionally presents the macro trajectory, segmentation structure, competitive themes, and external forces shaping the market without disclosing the complete regional, application, and type-level breakdowns that form the backbone of detailed planning. To access the full dataset, company profiles, segmentation comparisons, and scenario-ready forecasts, readers are encouraged to visit the source page for the Worldwide Waterproof Servo Motor Market study. The complete publication provides the level of specificity needed to translate market intelligence into sourcing decisions, product specifications, and investment judgments with greater confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Waterproof Servo Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Smart Fitness Belt Market to Hit USD 1.16 Billion by 2032 with 13.21 Percent CAGR
By PW Consulting, 2026-09-02
Navigating the Next Wave: Strategic Intelligence for the Worldwide Smart Fitness Belt Market (2026–2032)
The global connected wellness sector has entered a decisive inflection point. As consumer preferences shift from passive tracking to active intervention, smart fitness belts have emerged as a critical hardware category bridging rehabilitation, athletic performance, and everyday posture management. For executives, product leaders, and investment committees evaluating physical connectivity and wearable health in 2026, timing and positioning have never carried higher stakes. The Worldwide Smart Fitness Belt Market research study released by PW Consulting provides a structured, data-backed foundation for navigating this transition. Rather than offering generic market commentary, this report distills macro trajectories, competitive signaling, regulatory friction points, and distribution mechanics into an executive-ready intelligence package designed to inform capacity planning, partnership selection, and portfolio prioritization through 2032.
Worldwide Smart Fitness Belt Market
What makes this market particularly compelling for strategic decision-makers in 2026 is the convergence of hardware maturation, software integration, and evolving regulatory classification. Smart fitness belts are no longer confined to niche fitness communities. They span electrical muscle stimulation (EMS) platforms targeting core activation, sensor-driven activity and heart rate monitoring wearables, and posture-correction systems engineered for sustained ergonomic support. Each subsegment carries distinct manufacturing footprints, buyer profiles, and channel economics. Understanding how these layers interact—and where margin concentration, innovation bottlenecks, and compliance hurdles emerge—is precisely the mandate this research addresses.
Worldwide Smart Fitness Belt Market
Macro Trajectory: What the Numbers Reveal for 2026 Planning
The market's recent historical arc demonstrates consistent expansion across the 2020–2025 review window, supported by broader adoption of remote health monitoring, home-based training routines, and consumer demand for multi-functional wearables. Current revenue baselines have climbed into the upper hundreds of millions in USD, positioning the category as a mid-tier but high-velocity hardware segment within the wider wearable ecosystem. The forecast horizon extending through 2032 indicates sustained momentum, anchored by a compound annual growth rate of 13.21 percent over the projection period.
Worldwide Smart Fitness Belt Market
For corporate strategists, that growth profile is not simply a headline figure. It is a planning parameter. A sustained double-digit CAGR implies compounding demand pressures on supply chains, component sourcing, firmware development, and go-to-market bandwidth. Executives evaluating whether to enter the category, scale existing lines, or divest non-core wearable SKUs must reconcile this growth velocity against execution constraints. The research translates the trajectory into decision-relevant context: where absolute revenue expansion concentrates over the forecast years, how the base evolves from the 2025 starting point, and which structural drivers reinforce the growth path versus those that could create volatility if left unaddressed. Importantly, the study preserves analytical integrity by keeping regional breakdowns, application splits, and channel-level valuations inside the full dataset—accessible only through the complete report—so that decision-makers treat the headline trajectory as a directional compass, not a substitute for granular allocation modeling.
Beyond the Headline: Operational Content Designed for Executable Strategy
A market study earns its value through usability. The PW Consulting smart fitness belt research is built around the practical questions that tend to stall cross-functional alignment: which product architecture is gaining traction, how buyers discover and purchase these devices, what component dependencies shape margin profiles, and where compliance frameworks are shifting the boundary between consumer wellness and regulated device pathways.
Core Report Anatomy
- Historical reconstruction from 2020 through the 2025 base year, mapping revenue progression, adoption inflection points, and category normalization after early-stage volatility.
- Forward modeling across the 2026–2032 forecast window, structured to support scenario planning for capacity investments, inventory strategy, and partnership pipelines.
- Product-type evaluation covering EMS muscle stimulation belts, heart rate and activity monitoring belts, and smart posture and support belts—each assessed for functional differentiation, user case viability, and engineering requirements.
- Distribution-channel analysis examining how online retail, specialty fitness stores, and supermarket/hypermarket formats compare in reach, conversion dynamics, and merchandising implications.
- Regional mapping of demand geography to help multinational teams prioritize launch sequencing, localization effort, and competitive exposure across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive monitoring and profiling of key participants, including company positioning, product emphasis, and geographic footprint, to support benchmarking and entry-risk assessment.
- Regulatory and standards context, incorporating recent FDA import alerts and De Novo classification activity that clarify how certain wearable smart belts are interpreted under U.S. device frameworks.
- Component and materials context, addressing electrode technologies such as hydrogel pads and silicone-based interfaces, including durability expectations relevant to product design and replacement-cycle economics.
- FAQ-aligned guidance on reimbursement considerations for wearables classified under medical indications, highlighting the distinction between consumer fitness devices and Class II-aligned pathways.
This structure is deliberately cross-functional. Product teams can use the product-type and component sections to pressure-test feature roadmaps. Sales and channel leaders can use the distribution analysis to refine channel mix and retailer partnership criteria. Regulatory and legal stakeholders can use the compliance material to anticipate classification risk, particularly for hybrid devices that straddle fitness and health-use claims. The full granularity—exact regional values, application-level splits, and channel-specific valuations—is reserved for the complete report so that teams are guided toward the full dataset when allocation decisions require precision.
Competitive Landscape: Positioning, Differentiation, and Strategic Posture
The smart fitness belt category is being shaped by a mix of established EMS hardware specialists, digital health entrants, and regional manufacturers that compete on engineering specificity, cost structure, and user-experience refinement. Competitive intelligence in the report focuses on the strategic posture of each profiled player, not just their brand visibility, because in this category differentiation is often driven by electrode design, app ecosystem integration, claims framing, and channel access.
MTG Co., Ltd., headquartered in Nagoya, Japan, has built recognition around SIXPAD EMS training devices, including abdominal and body fitness belts that leverage electrical muscle stimulation for home-based core training. Its market relevance lies in the translation of stimulation technology into consumer-accessible hardware, with positioning that bridges wellness marketing and tangible training routines. For competitors evaluating EMS entry or differentiation, MTG's product language and channel approach offer a reference point for how stimulation-based belts are communicated to end users.
PowerDot, based in the United States, contributes a different strategic angle: smart muscle stimulator devices and associated wearable EMS technology adapted for fitness applications, including targeted abdominal and core muscle activation. PowerDot's relevance in the competitive landscape comes from the integration of stimulation hardware with digital control and personalization layers, signaling a direction in which EMS belts may compete not only on hardware ergonomics but also on software-driven workout customization.
Shenzhen Roundwhale Technology Co., Ltd. operates as a manufacturer focused on electrode belts and EMS fitness belts specifically for abdominal muscle training. Its profile underscores the role of component-level andOEM/ODM-adjacent production capacity in the category's supply chain. For buyers and competitors monitoring manufacturing concentration, cost sensitivity, and speed-to-market, firms of this type represent the industrial backbone that shapes pricing dynamics and scaling options.
Lumo Bodytech, also U.S.-based, concentrates on posture and movement tracking smart belts with fitness and core engagement monitoring capabilities. Its differentiation is less about stimulation and more about motion intelligence, sensor interpretation, and behavioral feedback. This matters strategically because it illustrates a parallel category track in which value is created through analytics and guidance rather than direct muscle activation, broadening the competitive field beyond EMS-only positioning.
WELT, based in South Korea, produces smart belts focused on activity tracking, posture, and fitness metrics. Its inclusion reflects the growing influence of regional innovators that combine wearable sensing with everyday health-oriented use cases. In the competitive landscape, such players highlight how posture and activity monitoring can anchor a product narrative that appeals to both wellness consumers and users seeking ergonomic support.
Together, these companies demonstrate that the category's competitive frontier is multi-dimensional. EMS-based players compete on stimulation credibility and training claims. Sensor-led players compete on movement interpretation and posture feedback. Manufacturers compete on cost, component quality, and production flexibility. The full report deepens this analysis with company-level benchmarking and market concentration context, including the consolidated share held by leading participants, so that strategy teams can gauge how much room exists for new entrants versus how defended the core positions have become.
Regulatory and Material Context: Where Strategy Meets Compliance
Smart fitness belts do not operate in a vacuum. Their design choices, claims language, and intended use cases increasingly intersect with regulatory interpretation, particularly in the United States. The research incorporates recent FDA developments that matter for 2026 planning. One relevant signal is the FDA's maintenance of Import Alert 89-01 for detention without physical examination of certain misbranded and/or adulterated powered muscle stimulators, explicitly including devices such as the Abtronic X2 Dual Channel Fitness Belt. For manufacturers and importers, this is a pragmatic reminder that stimulation-based wearables can attract heightened scrutiny when labeling, safety, or marketing claims fall outside expected boundaries.
At the same time, another regulatory thread shows how smart belts can be interpreted through a medical device lens. The FDA's De Novo classification for the Tango Belt, a wearable fall injury prevention device, classified under Class II per 21 CFR 890.3780, illustrates how a wearable belt form factor can be aligned with injury mitigation rather than general fitness. This matters strategically because it highlights a classification pathway for devices intended for specific protective or clinical-adjacent indications, and it reinforces the importance of defining intended use early in product development. The distinction between a consumer fitness belt and a device positioned for fall injury mitigation is not cosmetic; it shapes registration strategy, documentation requirements, and market access expectations.
Beyond regulation, the research also addresses component-level realities. EMS models in particular rely on electrode components such as hydrogel pads or silicone electrodes. Available product specifications indicate that consumer-grade reusable hydrogel pads are often rated for multiple uses, which introduces design trade-offs around durability, replacement behavior, user hygiene, and recurring consumption economics. For product leaders, these considerations affect packaging strategy, lifecycle messaging, customer support burden, and total cost of ownership communication. The report keeps these material and compliance discussions tightly connected to commercial implications, ensuring they inform rather than merely inform.
Demand Dynamics and Channel Economics
The growth trajectory of smart fitness belts is underpinned by several reinforcing dynamics. Consumers continue to look for wearable devices that deliver more than step counting or basic heart-rate logging; they want devices that can support training routines, posture awareness, and targeted muscle engagement with minimal friction. At the same time, home-based fitness habits formed in earlier years have not fully reverted to gym-centric patterns across all demographics, sustaining demand for compact, at-home hardware that integrates into daily routines. These preferences create a favorable environment for belts that combine intuitive wearability with functional claims users can experience directly.
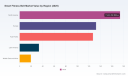
Channel economics add another layer of strategic importance. Online retail remains a dominant commercial conduit for this category, reflecting the convenience-driven purchase behavior of connected device buyers and the ability of digital storefronts to support product education, review aggregation, and direct-to-consumer experimentation. Specialty fitness stores contribute a complementary role by offering tactile evaluation, staff guidance, and brand credibility in contexts where buyers value hands-on exposure. Supermarkets and hypermarkets, while typically representing a smaller share of the category's flow, can matter for reach, visibility, and impulse-driven discovery in select markets. The report examines how these channels compare in function and strategic fit, and it preserves channel-level detail for buyers who need to model mix, margin, and inventory placement precisely.
Demand is also being shaped by the variety of use cases that smart belts serve. EMS-oriented belts appeal to consumers seeking assisted muscle activation and core-training support. Heart rate and activity monitoring belts address users who want integrated biometrics within a belt form factor rather than a chest strap or wrist device. Posture and support belts target ergonomic comfort and movement awareness, often extending the category's appeal beyond strict fitness into daily wellness and workplace habits. Each use case carries its own purchase motivation, retention logic, and upgrade cycle. The full report maps these use cases in greater depth, allowing teams to align product messaging and distribution plans with the behavioral drivers that matter most in each segment.
What This Means for Corporate Decision-Making in 2026
For organizations making tangible choices this year, the strategic value of the study lies in its ability to convert market signals into action frameworks. The headline growth rate and multi-year revenue path provide a macro anchor for budgeting, hiring, and investment sequencing. The product-type and channel structure helps teams avoid the mistake of treating smart fitness belts as a single homogeneous category, encouraging instead a segmented view that separates stimulation hardware from monitoring and posture devices, each with its own engineering roadmap and buyer journey. The competitive profiles give benchmarking context for assessing whether a new product should attempt to out-engineer incumbents, find a positioning gap, or compete on price and distribution efficiency. The regulatory and materials content reduces the risk of launching with misaligned claims or underestimating component lifecycle implications.
In practice, this translates into several decision domains:
- Portfolio strategy: determine whether to expand within EMS, monitoring, or posture belts, or to pursue hybrid designs that combine multiple value propositions while managing compliance exposure.
- Supply and component planning: assess electrode technology choices, durability expectations, and replacement economics against cost targets and user-experience goals.
- Go-to-market design: choose channel emphasis based on the product's educational needs, demonstration requirements, and target buyer profile rather than defaulting to a single route.
- Competitive response: evaluate whether to challenge established EMS players on stimulation efficacy and brand trust, or to differentiate through sensor-driven posture and activity insights that expand the addressable use case.
- Regulatory readiness: align intended-use language, labeling, and claims with current FDA expectations and classification signals, especially where a belt design might be interpreted as more than a general fitness device.
Each of these domains benefits from the full report's segmentation, regional evaluation, and concentration data, which collectively support allocation decisions that cannot be made responsibly on headline numbers alone.
Reading the Report as a Strategic Tool
This research is intended to function as a decision-support instrument rather than a static market summary. Executives can use it to pressure-test growth assumptions, channel teams can use it to refine sales infrastructure, product leaders can use it to prioritize features and material choices, and compliance stakeholders can use it to anticipate classification friction before it becomes a launch bottleneck. The study's value increases when it is paired with internal data on manufacturing capacity, regional sales history, and product-roadmap constraints, because the market context then becomes a calibration point rather than a standalone narrative.
To preserve analytical rigor, the publication intentionally presents the strategic framework, competitive context, and macro trajectory here while holding the detailed segmentation values, regional figures, and channel-level amounts for the complete Worldwide Smart Fitness Belt Market study. That design reflects a practical reality: effective strategy requires both directional insight and precise numbers, but the precision should be accessed when teams are ready to model specific scenarios, not diluted into general commentary.
Next Steps for Teams Ready to Act
Organizations that treat the smart fitness belt category as a fast-moving hardware-and-software intersection will have an advantage in 2026. The decision set is no longer limited to whether the category is growing; it now centers on where to place bets, how to position claims, which channels to build relationships with, and how to manage the regulatory and component realities that distinguish durable products from short-lived ones. PW Consulting's Worldwide Smart Fitness Belt Market research is structured to help leadership teams answer those questions with evidence rather than intuition.
For executives and strategy teams seeking the full segmentation, regional breakdowns, channel valuations, and concentration detail needed for allocation and entry decisions, the complete report is available through the source page. There, the macro narrative presented here is extended into the operational depth required for planning, forecasting, and competitive response through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Fitness Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Forecasts Global Chocolate Machines Market to Reach USD 7,440.61 Million by 2032 at 5.12% CAGR with Europe Leading
By PW Consulting, 2026-09-02
Strategic Horizons for the Worldwide Chocolate Machines Market: A 2026 Decision-Maker’s Preview
The global chocolate processing landscape has entered a phase of structural recalibration. Over the past half-decade, manufacturers, equipment vendors, and procurement teams have navigated raw material volatility, shifting regulatory expectations, and accelerating automation adoption. As capital expenditure decisions for the 2026–2032 horizon come into focus, understanding where the worldwide chocolate machines market stands today, and where it is headed, is no longer a discretionary exercise. It is a core input to capacity planning, supplier selection, and regional expansion strategy. This overview introduces our latest market research study, highlighting the strategic questions it answers and the analytical frameworks it applies, while deliberately reserving the most granular forecasts and segmentation breakdowns for the full report.
Worldwide Chocolate Machines Market
Since 2020, the market has demonstrated measured but consistent growth, with revenue scaling from approximately 4.12 billion USD to an estimated 5.25 billion USD by the 2025 base year. The forward trajectory indicates a continuation of this momentum, with a projected compound annual growth rate of 5.12 percent across the 2026–2032 forecast window. Such a figure, standing alone, is useful for high-level budgeting. Yet the true strategic value lies in unpacking what drives that growth, where it concentrates, and which operational variables will separate resilient operators from those merely reacting to market conditions. Our research is designed precisely for that purpose.
Worldwide Chocolate Machines Market
Why This Study Matters for 2026 Decision-Making
Entering 2026, executives face a convergence of pressures that make equipment investment decisions more consequential than ever. On the input side, cocoa prices have exhibited sharp swings, with futures contracting sharply from their 2024 peaks and touching lower thresholds in early 2026 before stabilizing in the mid-3,000 USD per tonne range by mid-March. At the same time, regional spot prices for cocoa butter have shown considerable divergence, with the United States, Germany, and India recording markedly different levels during the first quarter. For chocolate manufacturers and equipment buyers, the implication is clear: procurement and processing economics are being reshaped by lags between futures markets, physical inventory costs, and retail pricing stickiness. Equipment that can accommodate variable throughput, improve yield consistency, and reduce energy consumption is therefore gaining strategic relevance beyond simple capacity expansion.
Worldwide Chocolate Machines Market
On the demand side, premiumization continues to reshape product portfolios, while automation is becoming a baseline expectation rather than a differentiator. Rising per capita chocolate intake in parts of Asia-Pacific and selected African markets is reinforcing long-term volume potential, but realising that potential depends on machinery that can meet evolving food safety standards and efficiency mandates. Regulatory heterogeneity across major markets further complicates equipment design and procurement, requiring vendors and buyers to think in terms of compliance-ready architectures rather than one-size-fits-all configurations. In this environment, a market study that merely reports aggregate size is insufficient. Decision-makers need context around concentration, technology segmentation, application-level demand patterns, and the competitive dynamics that shape pricing and availability.
What the Worldwide Chocolate Machines Market Study Delivers
Our research is built around executable intelligence rather than descriptive summary. The report maps the market from a 2020 historical baseline through the 2025 evaluation year and extends a detailed forecast to 2032. It integrates demand-side segmentation, supply-side competitive analysis, and forward-looking market dynamics in a single structured reference. The objective is to equip strategy, operations, and procurement teams with a defensible foundation for capital allocation, vendor negotiations, and regional planning.
The study opens with a market overview that traces the evolution of revenue from 2020 through the forecast period, situating the observed growth path within broader industry dynamics. Rather than simply stating numbers, it interprets the trajectory in light of equipment modernization cycles, production rationalization trends, and the gradual shift toward higher-throughput, integrated processing lines. It then moves into a focused examination of market structure, including concentration indicators that help readers gauge competitive intensity and pricing power. This is particularly valuable for companies assessing supplier diversification strategies, evaluating entry barriers in specific geographies, or determining whether to invest in proprietary equipment capabilities versus relying on established OEMs.
A central strength of the report is its operational segmentation. The analysis breaks the market into equipment categories that matter on the factory floor, covering molding machines, tempering machines, enrobing and decorating lines, refining and grinding machines, and other auxiliary equipment. Rather than treating these categories as isolated product groups, the study frames them around the production realities they address: tempering precision, coating consistency, cooling efficiency, particle size control, and the integration of auxiliary systems into cohesive lines. This framing is essential for buyers comparing total cost of ownership, maintenance footprints, and line compatibility, as well as for vendors mapping their product roadmaps against the highest-value demand pools.
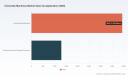
Equally important is the application-side perspective. The market is examined through the lens of the end users it serves, including large-scale industrial manufacturers and artisanal or semi-industrial producers. These two demand segments operate with fundamentally different priorities. Industrial manufacturers typically emphasize throughput, repeatability, hygiene compliance, and integration with upstream and downstream processes. Artisanal and semi-industrial operations, by contrast, often prioritize flexibility, footprint, startup reliability, and the ability to produce smaller batches of premium or specialty products without excessive complexity. By separating these demand profiles, the report helps readers calibrate investment logic to their own operating model and growth ambition, whether they are scaling a flagship facility or evaluating equipment for a regional craft-focused expansion.
Geographic Realities and Regional Demand Patterns
Geography remains a defining variable in chocolate machinery demand, but the relevant insight is not simply which region is larger. It is how regional industrial structures, ingredient sourcing patterns, regulatory environments, and consumer taste shifts interact to create distinct equipment demand profiles. The study maps the market across Europe, North America, Asia Pacific, Latin America, and the Middle East and Africa, treating each as a distinct strategic zone rather than a uniform revenue bucket. This regional lens is critical for companies planning cross-border rollouts, evaluating localization requirements, or assessing where capacity investments are most likely to generate durable returns.
In Europe, longstanding confectionery traditions, mature processing infrastructure, and a strong base of engineering-led equipment manufacturers create a market shaped by both high standards and continuous modernization. North America reflects a different mix of scale, regulatory focus, and retail-driven premiumization, with equipment procurement often tied to broader supply chain efficiency goals. Asia Pacific stands out for its growth trajectory and expanding domestic manufacturing base, where rising chocolate consumption and local production ambitions are gradually pulling demand toward more advanced processing lines. Latin America and the Middle East and Africa represent markets where infrastructure, import dynamics, and emerging producer ecosystems create opportunities that are real but uneven, requiring careful segmentation rather than blanket assumptions. The full report details how these regional environments translate into equipment demand intensity, procurement preferences, and competitive exposure, without reducing them to oversimplified rankings.
Competitive Landscape: A World of Specialists and Integrated Players
The chocolate machines market is not dominated by a single archetype of supplier. It is a competitive arena in which European engineering houses, specialized mid-sized producers, and increasingly capable Asian manufacturers coexist, each with distinct positioning. The report profiles a wide set of companies that collectively shape procurement options, technology diffusion, and pricing behavior across the market. These include established players with deep roots in tempering, molding, enrobing, and cooling systems, as well as firms that emphasize complete bean-to-bar and industrial processing lines.
Companies such as Selmi Group, Aasted ApS, SOLLICH KG, and ChocoMa illustrate the strong tradition of European and Danish expertise in tempering, molding, enrobing, and cooling equipment, often serving a range from artisanal to high-volume production. Bühler Group and Royal Duyvis Wiener represent the broader industrial processing side, with capabilities spanning grinding, refining, conching, and integrated production architectures. Hacos NV and Loynds reflect the continued importance of flexible, modular approaches, including solutions tailored to small and mid-sized operators. On the other side of the map, Chinese manufacturers such as G&D Machinery, MK Food Machinery, and Apex Machinery Corporation are expanding their international footprint with complete chocolate making and packaging lines, increasingly emphasizing CNC linear modular molding technology and full-production integrations. India-based Vec Chocolate Machines and Russia-based Kadzama add further dimensions, with offerings that span semi-automatic and artisanal-to-semi-industrial equipment. ProXES and Gondor Machinery round out a landscape in which product breadth, application focus, and regional manufacturing capability all matter.
This competitive diversity matters because procurement teams rarely choose machinery in a vacuum. They compare not only machine specifications, but also service networks, parts availability, integration support, local compliance readiness, and the stability of supply chains across plant upgrades and line expansions. The market study uses these profiles to build a competitive context in which buyers can interpret vendor claims, anticipate negotiation dynamics, and identify where differentiation is most likely to emerge in the next forecast cycle. It also provides the basis for understanding how concentration structures influence market behavior, without overstating the dominance of any single supplier group.
Recent Momentum: Trade Shows, Product Expansions, and the Signal They Send
Recent industry activity offers useful signals about where equipment innovation and commercial emphasis are heading. In early 2026, several developments highlighted a continued focus on line versatility, energy efficiency, and modular flexibility. At ISM 2026, NJ Machinery showcased chocolate molding and processing equipment developments aimed at both artisans and manufacturers, reinforcing the ongoing importance of trade exhibitions as arenas for technology demonstration and buyer engagement. Around the same time, an unnamed top chocolate equipment manufacturer expanded a production line with a new Chocolate Coating Machine series, emphasizing versatility and energy efficiency gains for chocolate production. Meanwhile, LST Machine used Canton Fair 2025 to present high-tech chocolate forming machines with a visible emphasis on efficiency improvements.
These events may appear episodic, but collectively they point to a market in which equipment suppliers are actively repositioning around operational practicality. Energy efficiency is increasingly part of the product narrative, not only as a sustainability message but as a cost and compliance consideration. Versatility and modularity matter because producers are seeking equipment that can adapt to SKU proliferation, batch-size variation, and changing packaging or finishing requirements without forcing full line replacement. For analysts and strategists, such developments are inputs to a broader hypothesis: the market’s next phase of growth will be supported not just by volume expansion, but by incremental capability upgrades that improve yield, reduce downtime, and enable faster changeovers. The report places these developments in context, connecting them to longer-term demand patterns and regional adoption signals rather than treating them as isolated news items.
Market Dynamics: Pricing, Premiumization, Automation, and Regulatory Friction
No equipment strategy is complete without addressing the dynamics that shape demand over time. Cocoa markets have become a focal point for manufacturers because input cost volatility influences everything from margin planning to equipment justification. Futures activity in early 2026 reflected a sharp pullback from prior highs, with prices falling below 4,000 USD per metric tonne before rebounding toward the mid-3,000 USD range by mid-March. Yet retail chocolate prices have remained elevated in many markets because of lagged inventory effects and the time it takes for cost relief to pass through complex supply chains. In that environment, processing efficiency is not merely a productivity goal; it becomes a buffer against volatility and an enabler of better cost control.
Parallel to input cost dynamics, the demand environment is being reshaped by premiumization and automation. As product portfolios move toward higher-value offerings, manufacturers need equipment that can maintain quality under more demanding processing conditions while supporting tighter consistency and traceability. Automation is increasingly tied to labor economics, quality assurance, and integration with downstream packaging and logistics. At the same time, regulatory heterogeneity continues to influence equipment design and procurement. Different food safety expectations, efficiency requirements, and documentation standards across major markets mean that equipment selection is increasingly a compliance-aware decision. The study treats these dynamics as structural forces rather than temporary disruptions, using them to inform the forecast logic and the interpretation of segment-level demand.
Using the Report for Strategic Execution in 2026
The value of this research is highest when it is translated into specific kinds of decisions. For capital planning teams, the forecast framework provides a reference for sizing investments against expected market growth and demand concentration, helping avoid both underinvestment and overcommitment in segments with weaker structural support. For procurement and engineering leaders, the equipment segmentation and competitive profiles support more disciplined evaluation of machine categories, integration requirements, and supplier options, especially when comparing total cost of ownership across different operating models. For executives assessing geographic expansion or localization, the regional analysis offers context for where demand signals are strongest and where regulatory and supply-chain variables warrant deeper due diligence.
Importantly, the report is designed to support comparative reasoning rather than simple target selection. A company evaluating a move from semi-industrial to fully integrated production can use the segmentation logic to understand which equipment categories become more critical at each stage. A supplier assessing market entry or product-line extension can use the competitive landscape and concentration structure to gauge where differentiation is feasible and where positioning risks being crowded. A strategist tracking the impact of cocoa volatility can use the market dynamics discussion to frame equipment investments as risk-mitigation tools, not just capacity additions. These are the kinds of applications that turn research into action.
Where the Full Intelligence lies
This preview has outlined the structure, logic, and strategic intent behind the Worldwide Chocolate Machines Market study. It has touched on the market’s historical growth path, its forward CAGR, the equipment categories and application segments that structure demand, the regional environments that shape procurement, and the competitive and dynamic context that influences decision-making. Yet the report goes further. It contains the detailed segmentation values, region-level and application-level breakdowns, equipment-category revenue distributions, concentration analysis, and forward forecasts that permit precise comparison and scenario planning. Those figures are intentionally reserved for the complete study because their value is highest when read alongside the full methodological context, the supporting demand interpretation, and the competitive and dynamic analysis that ties them together.
For leaders preparing 2026 investment decisions, the core question is not whether the chocolate machines market is expanding. The data already point to continued growth through 2032. The more important question is where growth will be most actionable, which equipment categories will carry the greatest strategic weight for a given operating model, how regional conditions will alter the investment case, and which competitive dynamics will shape supplier selection. Our study is built to answer those questions with the level of specificity that planning teams need, while keeping the narrative focused on execution rather than abstraction.
The full report is available through our market research portal, where readers can access the complete segmentation tables, regional and application-level revenue distributions, competitive profiling, recent industry developments, and the full forecast series from 2026 through 2032. We encourage strategy, operations, and procurement leaders to use the study as a reference point for capacity planning, supplier evaluation, regional prioritization, and risk-aware investment design. In a market shaped by volatility, premiumization, automation, and regulatory complexity, the organizations that act with the best-informed view of equipment demand will be the ones best positioned to convert market growth into durable operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Chocolate Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Intelligent Obstacle Avoidance Sonar Market to Reach USD 3,744.74 Million by 2032 with 8.5 CAGR
By PW Consulting, 2026-09-02
Navigating the Depths: Strategic Intelligence for the 2026 Global Intelligent Obstacle Avoidance Sonar Market
As autonomous systems transition from experimental prototypes to operational necessities, the ability to perceive and navigate complex underwater environments has become a critical bottleneck for technological adoption. The Worldwide Intelligent Obstacle Avoidance Sonar Market stands at the forefront of this transformation, enabling vessels ranging from commercial unmanned surface vehicles (USVs) to deep-sea autonomous underwater vehicles (AUVs) to operate safely without direct human intervention. At PW Consulting, we have synthesized years of historical performance data with forward-looking projections to deliver a comprehensive market study designed specifically to inform high-stakes corporate strategy in 2026 and beyond.
Worldwide Intelligent Obstacle Avoidance Sonar Market
This market research is not merely a retrospective on past sales figures; it is a strategic roadmap for navigating the technological and regulatory currents that will define the industry over the next decade. Our analysis covers the period from 2020 through 2032, grounding our forecasts in a five-year historical baseline while projecting growth trajectories that account for emerging technological paradigms and shifting defense priorities. The market has demonstrated consistent expansion, with overall revenue growing from approximately 1.4 billion USD in 2020 to an estimated 2.1 billion USD by 2025. Looking forward, we project the total market size to reach nearly 3.7 billion USD by 2032, reflecting a compound annual growth rate of approximately 8.5 percent over the forecast period.
Worldwide Intelligent Obstacle Avoidance Sonar Market
Such growth is not abstract; it is underpinned by tangible shifts in how underwater navigation is managed. This report provides actionable intelligence for executives, investors, and strategic planners who need to understand where value is being created, which technologies are gaining traction, and how competitive pressures are reshaping the landscape.
Worldwide Intelligent Obstacle Avoidance Sonar Market
Market Evolution and Growth Drivers
The trajectory of the intelligent obstacle avoidance sonar market reflects a broader industry trend toward increased autonomy and enhanced situational awareness. Over the historical period from 2020 to 2025, the market has experienced steady year-over-year expansion, driven by increasing investments in unmanned maritime systems and the growing sophistication of sonar sensor technology. The transition from 2024 to 2025 saw a particularly notable acceleration, with revenue figures surpassing 2 billion USD as early adopters in defense and commercial sectors began deploying next-generation imaging capabilities in operational settings.
Several structural forces are expected to sustain this momentum through 2032. First, the proliferation of uncrewed platforms across both defense and commercial applications creates a fundamental demand for reliable obstacle detection systems that can operate without constant human supervision. Second, advances in signal processing and machine learning are enabling sonars to provide richer real-time data, transforming these sensors from simple detection tools into intelligent navigation aids. Third, the normalization of autonomous navigation in challenging environments is raising the baseline requirement for obstacle avoidance capabilities across a wide spectrum of vessel types and operational profiles.
Our research examines how these drivers interact with market segmentation to create distinct growth pockets. While the overall market expands, different technology types and application areas are experiencing varied rates of adoption based on their specific performance characteristics, integration requirements, and cost structures. Understanding these nuances is essential for companies seeking to position their products effectively or allocate R&D resources toward the most promising opportunities.
Technology Segmentation and Deployment Patterns
The intelligent obstacle avoidance sonar market encompasses several distinct technology families, each serving different operational requirements. Our analysis identifies three primary categories that dominate the current landscape: forward-looking sonar systems, side-scan sonar technologies, and multibeam sonar solutions. Each technology offers unique advantages in terms of range, resolution, field of view, and integration complexity, making them suited to different deployment scenarios.
Forward-looking sonar systems represent a substantial portion of current market activity, particularly in applications where real-time obstacle detection ahead of a vessel is critical. These systems have evolved significantly in recent years, with newer models capable of generating three-dimensional imaging data that allows for comprehensive situational awareness. The ability to provide real-time true 3D images with operational ranges extending from 350 meters to over 1000 meters, while detecting obstacles from the sea surface down to depths of approximately 85 meters, has made these systems particularly valuable for autonomous navigation. Side-scan sonar technologies continue to serve important roles in mapping and detailed imaging applications, often complementing forward-looking systems in comprehensive navigation suites. Multibeam sonar solutions provide high-resolution volumetric data that supports both obstacle avoidance and detailed seabed characterization, making them attractive for survey-grade applications where precision is paramount.
From an application perspective, the market spans several key sectors that are adopting these technologies at different rates and for different purposes. Underwater vehicles, including both AUVs and ROVs, represent a significant application area where obstacle avoidance sonar is becoming increasingly integral to safe operation. These unmanned systems are being deployed for missions that range from scientific research and environmental assessment to commercial inspection and defense-related tasks, all of which require reliable obstacle detection capabilities. The automotive and transportation sector is also emerging as a notable application area, as surface vessel autonomy expands and the need for collision avoidance systems grows across commercial maritime operations.
Defense and security applications continue to play a central role in market development, with military programs driving requirements for high-performance systems that can operate in challenging conditions while maintaining low operator workload. Industrial robotics applications, while smaller in absolute terms, represent a growing niche where precision obstacle detection supports automated underwater operations in industrial environments such as offshore infrastructure inspection and underwater construction support. Our report provides detailed analysis of how each of these application segments contributes to overall market dynamics and what specific requirements are shaping technology development within each area.
Competitive Landscape and Strategic Positioning
The competitive environment in the intelligent obstacle avoidance sonar market is characterized by a mix of established players with deep technological heritage and specialized firms focusing on niche innovations. Our research identifies a competitive concentration that suggests a moderately consolidated landscape, with the top three firms accounting for approximately 38.5 percent of total market revenue and the top five firms representing roughly 52.15 percent. This concentration indicates a market where scale and technological capability provide meaningful advantages, yet where specialized innovation can still create distinct value propositions.
Several key companies are shaping the competitive dynamics through continuous product development and strategic partnerships. Exail, headquartered in France, offers the SeapiX-FLS series of 3D multi-beam forward-looking sonars specifically designed for mine and obstacle avoidance, navigation safety, real-time seabed mapping, and rapid environmental assessment in marine applications. Sonardyne, based in the United Kingdom, commercializes the Vigilant forward-looking sonar developed in collaboration with Wavefront Systems, targeting obstacle avoidance, confident maritime navigation, and situational awareness across both surface and subsurface platforms.
FarSounder, operating from the United States, develops and manufactures the Argos series of 3D forward-looking sonars that provide real-time 3D imaging for underwater obstacle detection, hazard avoidance, seafloor mapping, and navigation on vessels including USVs, with integration support for systems such as DARPA NOMARS. Wavefront Systems, also United Kingdom-based, designs the Vigilant family of forward-looking sonars for navigation and obstacle avoidance, delivering real-time 3D imagery of the seabed and water column with ranges up to 1500 meters for both uncrewed and crewed surface and sub-surface vessels. Kongsberg Gruppen, commonly known as Kongsberg Maritime, based in Norway, provides advanced sonar systems with autonomous navigation and obstacle avoidance capabilities tailored for marine and maritime applications.
Teledyne Technologies, through its Teledyne Marine division in the United States, supplies a range of sonar solutions including those supporting obstacle avoidance and underwater detection for marine robotics, AUVs, and ROVs. Impact Subsea, headquartered in the United Kingdom, offers the ISS360HD imaging sonar that demonstrates high performance in signal-to-noise ratio for obstacle avoidance and detection at extended ranges in underwater environments. NORBIT Subsea, also Norway-based, supplies multibeam echosounder sensors and integrated platforms that include obstacle avoidance sonar capabilities for survey and underwater applications. Tritech International, operating from the United Kingdom, provides sensors and tools including sonar systems for ROV and AUV markets with applications in obstacle detection and underwater navigation. Additionally, Echologger, also known as EofE Ultrasonics and based in South Korea, develops scanning sonar systems used for real-time detection and visualization of underwater obstacles to support avoidance in ROV and diver operations.
The strategic positioning of these firms reflects different approaches to market development. Some companies emphasize integration with broader navigation and autonomy systems, while others focus on raw sensor performance and imaging quality. Our report analyzes these positioning strategies and provides detailed profiles that help readers understand the strengths, target markets, and technological differentiation of each major competitor.
Recent Industry Developments and Innovation Timeline
The pace of technological advancement in the obstacle avoidance sonar market has been particularly rapid in recent months, with several significant developments underscoring the momentum in this sector. In February 2025, Wavefront Systems completed the first batch shipment of its compact Vigilant FLS 600 navigation and obstacle avoidance sonar, a product designed for surface, subsurface, crewed, and uncrewed platforms. This shipment marked an important milestone in making advanced obstacle avoidance capabilities more accessible across a broader range of vessel types.
By December 2025, FarSounder achieved a notable integration achievement, with its Argos 3D Forward Looking Sonar being integrated to deliver real-time seafloor and obstacle detection to users of the SYNAPSIS navigation system. This integration highlights the industry trend toward seamless interoperability between sonar sensors and comprehensive navigation platforms, enhancing the overall utility of obstacle avoidance capabilities for end users. In October 2024, Impact Subsea conducted a product demonstration of its ISS360HD sonar, showcasing superior signal-to-noise ratio and performance for obstacle detection at longer ranges. Such demonstrations reinforce the ongoing emphasis on improving detection range and image quality as key competitive differentiators.
These developments are part of a broader pattern of innovation that our report tracks in detail. We examine how companies are responding to evolving customer requirements, how new product introductions are reshaping competitive dynamics, and what these trends suggest about the future direction of technology development. By providing a structured analysis of recent milestones, we enable readers to identify patterns that may inform their own product development and market entry timing decisions.
Regulatory, Standardization, and Technology Context
The market for intelligent obstacle avoidance sonar operates within a complex environment of technical standards and regulatory considerations that shape both product development and deployment. One important standardization aspect relates to the design of forward-looking sonars for obstacle avoidance in AUVs and ROVs, which commonly incorporate suppressed side-lobe beam patterns to support ranging up to 100 meters with components for forward bottom tracking and surfacing clearance. These technical specifications help ensure consistent performance and reliability across different operating conditions.
From a regulatory perspective, notable developments include the US Special Operations Command FY2026 plans, which include continued development of machine learning enhancements on the obstacle avoidance sonar and technologies to reduce operator load. Such initiatives signal an increasing emphasis on intelligent processing capabilities that can automate hazard detection and classification, thereby reducing the cognitive burden on human operators. This trend toward machine learning integration aligns with broader industry movements toward AI-enabled situational awareness and automated hazard classification for autonomous vessel systems.
The integration of sonar systems with autonomous vessel platforms, including AI for hazard classification and real-time situational awareness, is becoming a defining feature of next-generation solutions. As these technologies mature, they are likely to raise the performance expectations for obstacle avoidance systems and create new opportunities for companies that can deliver integrated solutions combining advanced sensing with intelligent processing. Our report explores these regulatory and standardization dynamics in detail, providing context for understanding how external factors may influence market development and competitive strategies over the forecast period.
Strategic Value for 2026 Decision Making
For executives and strategic planners operating in 2026, the intelligent obstacle avoidance sonar market presents both significant opportunities and complex challenges. The combination of steady market growth, evolving technology requirements, and a competitive landscape that rewards both innovation and execution excellence creates an environment where informed decision-making can yield substantial strategic advantages.
Our market research is designed to support decision-making across multiple dimensions. For companies evaluating market entry or expansion, the report provides detailed analysis of segmentation dynamics, including the relative size and growth potential of different technology types and application areas. Understanding which segments are growing fastest and why can help organizations prioritize resources and tailor their go-to-market strategies. For companies already active in the market, the competitive analysis offers insights into positioning strategies, product development trends, and the relative strengths of key competitors, enabling more effective competitive responses.
For investors and financial analysts, the report offers a comprehensive view of market size, growth rates, and concentration dynamics that support valuation and due diligence activities. The historical data spanning 2020 through 2025, combined with the detailed forecast period extending to 2032, provides a robust foundation for assessing market trajectory and identifying inflection points. For technology developers and R&D leaders, the analysis of recent developments, technical specifications, and regulatory trends provides context for aligning innovation efforts with market demands and emerging requirements.
Comprehensive Report Contents and Methodological Approach
This Worldwide Intelligent Obstacle Avoidance Sonar Market research goes beyond aggregated market size figures to provide a granular, actionable analysis of the factors shaping this dynamic industry. The report is structured to deliver both high-level strategic context and detailed operational insights that can be directly applied to business planning.
Within the report, readers will find detailed segmentation analysis that breaks down market performance across technology types and application sectors, revealing the specific contributions and growth trajectories of each segment. The competitive landscape section provides in-depth company profiles for all major players, including assessments of their product portfolios, strategic positioning, recent developments, and likely future trajectories. This competitive intelligence is supplemented by an analysis of industry concentration metrics and market share dynamics that illuminate the structure and competitive intensity of the market.
The report also includes comprehensive coverage of market dynamics, examining the key drivers, restraints, opportunities, and challenges that will influence market evolution over the forecast period. This includes analysis of technological trends, regulatory developments, standardization efforts, and broader industry context that shapes demand patterns. Additionally, the research provides detailed geographic market analysis that identifies regional growth patterns and the specific factors driving performance in each major market area.
We employ a rigorous methodology that combines historical data analysis with forward-looking assessment based on expert evaluation of industry trends, technological developments, and market indicators. The forecast period from 2026 through 2032 is constructed using a structured approach that accounts for both baseline growth trends and scenario variations that may arise from changes in technology adoption rates, regulatory environments, or competitive dynamics.
Moving Forward with Confidence
The intelligent obstacle avoidance sonar market is entering a period of sustained growth and technological evolution that will create both winners and losers among companies competing for market share. As autonomous maritime systems become more prevalent and operational requirements grow more demanding, the ability to deliver reliable, high-performance obstacle avoidance capabilities will increasingly differentiate successful enterprises from those left behind.
This market research from PW Consulting is designed to equip decision-makers with the intelligence needed to navigate this complex landscape with confidence. By providing a comprehensive view of market size, growth trajectories, segmentation dynamics, competitive positioning, and key industry developments, we aim to support strategic planning that is grounded in rigorous analysis and oriented toward actionable outcomes.
For organizations seeking to understand the full depth of market opportunities, assess competitive threats, and make informed decisions about product development, market entry, investment, or partnership strategies, we invite you to access the complete study. The report delivers the detailed data, nuanced analysis, and forward-looking insights that executive teams need to position themselves effectively in the intelligent obstacle avoidance sonar market through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent Obstacle Avoidance Sonar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Worldwide Milling Machine Market to Reach $22.1 Billion by 2032 with 5.25% CAGR
By PW Consulting, 2026-09-02
Navigating Precision: Strategic Horizons in the Global Milling Machine Market 2026–2032
The global manufacturing landscape is undergoing a fundamental recalibration, driven by the relentless convergence of digitalization, supply chain restructuring, and precision engineering demands. At the center of this transformation lies the milling machine market—a foundational segment of industrial capital equipment that continues to dictate the pace of production across aerospace, automotive, electronics, and heavy machinery sectors. As enterprises brace for the 2026–2032 horizon, the ability to interpret macro trends, anticipate competitive shifts, and align capital expenditures with emerging technological paradigms has become a non-negotiable imperative. This article serves as a strategic preview of our newly published Worldwide Milling Machine Market research, offering decision-makers a structured lens through which to evaluate investment pathways, operational upgrades, and long-term capacity planning. While the complete dataset, granular segmentation breakdowns, and proprietary forecasting models reside exclusively in the full report, the following analysis establishes the analytical architecture, contextual drivers, and competitive intelligence framework that will shape strategic deliberations throughout 2026.
Worldwide Milling Machine Market
Macroeconomic Trajectory: Size, Growth, and the Forward Curve
The milling machine market has demonstrated consistent expansion over the past half-decade, moving from a global revenue base anchored in the early 2020s to a more complex, technology-integrated ecosystem today. Historical tracking from 2020 through 2025 reveals a clear upward trajectory, with cumulative market valuation progressing steadily as industrial output recovered, automation accelerated, and precision machining requirements intensified across end-use verticals. Entering 2026, the baseline market size establishes a new reference point for capital budgeting, while the forward forecast window through 2032 outlines a compounding growth path that underscores the sector's structural resilience.
Worldwide Milling Machine Market
The projected compound annual growth rate across the forecast period reflects a measured but persistent expansion signal, suggesting that milling machine demand will continue to outpace inflationary pressures while remaining sensitive to regional manufacturing cycles, raw material cost fluctuations, and technology adoption curves. This growth narrative is not merely a function of volume replacement; it is increasingly shaped by capability upgrades, multi-axis integration, and the migration toward smart, connected machining environments. Decision-makers evaluating 2026 capex timelines must recognize that market expansion is uneven across product architectures, application verticals, and geographic corridors. The full research report decomposes these movements into actionable segment-level projections, enabling procurement leaders, plant managers, and corporate strategists to distinguish between cyclical demand spikes and durable structural shifts.
Worldwide Milling Machine Market
Market Architecture: Segmentation Vectors That Shape Capital Allocation
Understanding where milling machine revenue concentrates—and why—is essential for aligning fleet investments, service readiness, and technology roadmaps. The market decomposes along three primary axes: machine architecture, end-use application, and regional deployment. Each axis carries distinct operational implications, pricing dynamics, and technology adoption timelines that influence how manufacturers configure production capabilities and respond to competitive pressure.
Machine Architecture Dynamics
The product landscape spans vertical, horizontal, and universal milling configurations, each addressing distinct manufacturing philosophies. Vertical systems remain deeply embedded in high-throughput machining environments, particularly where chip evacuation, tooling flexibility, and operator accessibility are prioritized. Horizontal architectures continue to serve heavy-duty volumetric removal and large-part fabrication, often in integrated production cells. Universal platforms provide operational versatility for job-shop environments and prototyping workflows where configuration agility outweighs pure throughput optimization. The strategic relevance of each architecture type depends on a manufacturer's part complexity, batch size profile, and automation maturity. Our report quantifies how these architectural preferences evolve through the forecast window, highlighting where capacity shifts, retrofitting demand, and next-generation platform launches are expected to alter competitive positioning.
Application-Driven Demand Patterns
Demand for milling machines is increasingly filtered through the operational requirements of specific end-use sectors. Automotive manufacturing continues to exert substantial pull on machining capacity, fueled by powertrain transitions, structural lightweighting, and high-volume precision component production. Aerospace and defense applications impose stricter tolerances, advanced material compatibility, and certification-aligned process controls, reinforcing demand for high-accuracy multi-axis platforms. General machinery, electronics, and specialized niche applications contribute additional layers of demand, each with unique throughput, rigidity, and surface-finish expectations. The full report maps how application-level priorities intersect with machine type selection, regional sourcing behavior, and technology premium adoption, allowing strategists to anticipate where demand intensity will concentrate and where substitution risk may emerge.
Geographic Distribution and Regional Manufacturing Rhythms
Regional deployment patterns reflect differences in industrial policy, labor economics, supply chain integration, and capital equipment accessibility. Mature industrial corridors maintain disproportionate shares of installed capacity, while emerging manufacturing hubs expand their reliance on milling solutions as localized production strategies deepen. Regional analysis in this market is not simply a matter of absolute size; it is equally about growth velocity, technology penetration rates, and the interplay between domestic manufacturing incentives and import-dependent equipment supply. The complete market study isolates regional momentum factors that are critical for capacity planning, localization assessments, and partnership sequencing. These insights are intentionally reserved for the full report to preserve analytical differentiation and support targeted go-to-market and procurement strategies.
Competitive Landscape: Corporation Profiles and Strategic Postures
The milling machine market is characterized by a moderately concentrated supplier base in which global incumbents, regional specialists, and technology-focused innovators compete across overlapping but distinct value propositions. Concentration metrics indicate that a limited set of leading manufacturers commands a meaningful share of global revenue, while a broader field of mid-tier and application-specialized players compete on agility, niche precision, service responsiveness, and total cost of ownership. Understanding how these companies position themselves requires more than headline market share figures; it demands an assessment of product strategy, geographic reach, technological differentiation, and recent moves that signal competitive intent.
Global Incumbents and Technology Leadership
Several Japanese manufacturers anchor the premium precision segment, with product portfolios that emphasize multi-axis integration, high-speed spindle architectures, and advanced control ecosystems. DMG Mori has reinforced its position through the continued expansion of its 5-axis machining families, including the DMU series, which targets aerospace and automotive applications demanding tight tolerance control and complex surface generation. Recent exhibition activity underscores a sustained emphasis on digital twin integration and process connectivity, signaling a broader industry shift toward simulation-driven machining workflows. Yamazaki Mazak similarly emphasizes multi-tasking flexibility, with 5-axis platforms designed to reduce setup complexity and consolidate machining steps for highly configured components. Okuma continues to pursue high-speed precision through integrated spindle and control strategies, while Makino maintains a strong orientation toward mold and die manufacturing, often pairing milling capability with complementary sinker EDM integration. Collectively, these firms compete not only on machine kinematics but also on software ecosystems, service depth, and lifecycle support models that increasingly define total value.
Value-Engineered and Application-Focused Players
On the broader accessibility end of the spectrum, manufacturers such as Haas Automation have built substantial presence through practical, high-utilization platforms that serve job shops, prototyping environments, and cost-sensitive production settings. The ongoing refinement of faster-spindle variants and intuitive probing integration highlights a competitive emphasis on reducing cycle times while maintaining operational simplicity. Hurco continues to emphasize control usability and batch-production efficiency, catering to environments where programming flexibility and operator training overhead are critical considerations. Doosan Machine Tools has expanded its footprint with heavy-duty vertical and production-oriented platforms, extending into large-capacity milling applications that align with high-volume industrial manufacturing requirements. Hardinge, Datron Dynamics, and Laguna Tools further illustrate the breadth of the competitive field, addressing toolroom-scale precision, high-speed aluminum and plastics machining, and light-duty CNC milling for specialized material workflows.
Specialized Precision and Large-Component Specialists
At the opposite end of the capability spectrum, firms such as GF Machining Solutions and Fives Group target precision-critical and large-structural markets. GF Machining Solutions maintains a strong orientation toward high-precision components for medical, optical, and advanced manufacturing applications, underscored by certifications and process-controlled machine architectures that align with regulated industries. Fives Cincinnati develops large gantry milling solutions for aerospace structural part fabrication, where envelope size, rigidity, and heavy-material removal capacity determine competitive relevance. These companies demonstrate that milling machine competition is not monolithic; it fractures across precision tiers, envelope requirements, material compatibility, and regulatory alignment. The full research report evaluates how these competitive postures translate into regional presence, technology roadmaps, and likely supply chain behavior through 2032.
Industry Dynamics and Emerging Pressures: Raw Materials, Regulation, Automation, and Trade
Market growth trajectories do not unfold in isolation. The operating environment for milling machine procurement and deployment is shaped by a matrix of cost pressures, compliance requirements, labor economics, and trade policy dynamics. Each of these forces influences not only end-user demand but also manufacturer pricing strategies, lead-time volatility, and service expectations.
Input Cost Volatility and Supply Chain Sensitivity
Structural cost changes in core raw materials exert direct pressure on equipment manufacturing economics. Elevated steel pricing for machine frames and structural components has increased input exposure for OEMs, prompting adjustments in sourcing strategies, product configuration decisions, and delivery timelines. In parallel, trade policy measures affecting steel imports have introduced additional cost layers for supply chains that depend on cross-border material flows. For buyers, this environment reinforces the need to evaluate total cost of ownership beyond sticker pricing, including lead-time reliability, service availability, and local inventory support.
Regulatory Standards and Process Assurance
Machine performance credibility remains anchored in standardized test procedures and accuracy verification protocols. Compliance with established CNC accuracy and repeatability standards provides a baseline for comparing machine capabilities across vendors and application environments. For procurement teams, adherence to recognized testing frameworks reduces evaluation ambiguity and supports more defensible capital approval processes. As precision requirements intensify, certification and standard alignment increasingly function as differentiators in competitive bids and engineered procurement packages.
Automation Drivers and Skills economics
Rising labor costs in key manufacturing regions continue to reinforce automation adoption across machining operations. As skilled machinist wage levels climb, manufacturers face stronger incentives to offset labor dependency through higher-throughput equipment, improved process reliability, and integrated automation-compatible machine designs. This dynamic is particularly relevant for repetitive high-volume machining and environments where operator availability constrains throughput scalability. Demand for smart CNC platforms with IoT connectivity is expanding in response to broader Industry 4.0 adoption, accelerating interest in data-linked machining environments that support predictive maintenance, process optimization, and remote diagnostics.
Recent Product and Strategic Developments as Signal Indicators
Recent corporate activity provides a valuable window into where competitive investment is flowing. Product launches showcasing faster spindles, enhanced probing, and wireless integration reflect a sustained focus on cycle-time reduction and operator efficiency. Exhibition showcases emphasizing 5-axis capability and digital twin integration highlight the growing importance of simulation, virtual commissioning, and connectivity in advanced machining workflows. Deliveries of large-capacity vertical platforms to industrial customers indicate continued demand for throughput-oriented equipment in high-volume contexts, while certification updates for high-speed milling platforms reinforce the relevance of quality assurance and process conformity in precision-oriented segments. Together, these developments illustrate that competition is increasingly defined by integrated capability rather than isolated mechanical performance.
How This Research Informs 2026 Decision-Making
Strategic clarity in 2026 depends on the ability to convert market signals into operational choices. Our Worldwide Milling Machine Market study is structured to support that translation across multiple decision layers. For capital expenditure planners, the report provides forward-looking sizing context that distinguishes baseline replacement demand from capability-driven expansion. For procurement and sourcing leaders, it frames the competitive field in terms of product positioning, regional availability, and technology premium structures. For manufacturing strategists, it maps application-level demand drivers and automation trends that influence fleet mix, retrofit timing, and integration roadmaps.
The research is designed to be operational rather than descriptive. It examines how machine types are likely to be adopted across different manufacturing contexts, which application sectors are expected to sustain the strongest demand intensity, and how regional manufacturing conditions shape procurement behavior and supply continuity. It also contextualizes competitive dynamics through company profiles, recent product and certification activity, and the broader forces that affect equipment economics, including raw material pricing, labor cost trajectories, and trade-related cost exposure. By maintaining a structured forecast view through 2032, the report enables scenario comparisons that support multi-year planning rather than single-cycle purchasing decisions.
Crucially, the full report contains the segmentation-level market sizing, growth decomposition, regional revenue distribution, and application-specific forecasting detail required for precise budgeting and competitive benchmarking. Macro-level figures establish the scale and momentum of the market, but the decision-grade intelligence that underpins procurement strategy, capacity investment, and vendor selection resides in the complete dataset. Readers seeking to quantify specific segment trajectories, compare regional deployment shares, or evaluate application-level growth differentials will find the full study structured to support that depth of analysis.
Conclusion: From Signal Recognition to Strategic Action
The milling machine market entering 2026 is defined by steady structural expansion, intensifying technology integration, and an increasingly diversified competitive landscape. Market growth is not uniform; it is distributed across machine architectures, application requirements, and regional manufacturing conditions that each demand distinct strategic interpretations. In this environment, organizations that treat capital equipment decisions as purely transactional risk missing the broader shifts in precision requirements, automation incentives, and supplier positioning that will shape operating economics over the next several years.
This research preview establishes the analytical foundation for evaluating those shifts. It identifies the growth architecture, competitive contours, and environmental pressures that matter most to 2026 planning cycles. The complete Worldwide Milling Machine Market report expands this foundation into full decision-ready intelligence, enabling a more granular assessment of where demand will concentrate, how competitive offerings are likely to evolve, and which strategic levers will deliver the strongest return on manufacturing investment. For organizations seeking to move beyond broad market awareness and into precise, data-supported planning, the full study provides the segmentation detail, company-level intelligence, and forecast structure necessary to convert industry signals into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Morcellator Market Valued at 165.5 Million in 2025 to Reach 221.46 Million by 2032 at 4.25 Percent CAGR With Gynaecology Surgery Dominating Applications
By PW Consulting, 2026-09-02
Global Morcellator Market Outlook 2026: Strategic Intelligence for Surgical Device Decision-Makers
The global morcellator market stands at a pivotal inflection point as it moves through the 2026 to 2032 forecast period. Following a measured recovery and stabilization cycle between 2020 and 2025, the sector now exhibits a clear growth trajectory anchored in evolving minimally invasive surgical practices, regulatory maturation, and continuous product innovation. Our newly released Worldwide Morcellator Market study translates this complex landscape into an actionable strategic framework, equipping executives, product leaders, and commercial planners with the intelligence required to navigate the next seven years with confidence.
Worldwide Morcellator Market
Stakeholders evaluating market entry, portfolio expansion, or capital allocation will find that morcellator adoption is no longer driven solely by procedural volume. Instead, growth is increasingly shaped by containment system integration, single-use conversion trends, reimbursement coding pathways, and the strategic positioning of incumbent manufacturers alongside emerging regional players. This report is designed to surface those layered dynamics and translate them into executable market intelligence.
Worldwide Morcellator Market
Market Architecture and Growth Trajectory
The worldwide morcellator market has transitioned from a period of volatility into a structurally stable expansion phase. Historical performance from 2020 through 2025 reflects the broader surgical device environment: initial contraction and recalibration, followed by gradual recovery as clinical protocols adapted and regulatory clarity improved. By 2025, the market had settled into a baseline that positions it for sustained advancement through the end of the decade.
Worldwide Morcellator Market
Our forecast modeling projects the global market to advance from its 2025 baseline to a materially larger revenue base by 2032, supported by an estimated compound annual growth rate of 4.25 percent. This trajectory reflects a combination of procedural demand growth, technology refresh cycles, and expanding indications across gynecologic and urologic applications. Importantly, the growth profile is not uniform. Revenue expansion is expected to be shaped by product format shifts, regional procurement dynamics, and the degree to which manufacturers align their offerings with containment-compatible standards and outpatient surgical preferences.
For decision-makers, the core implication is that aggregate growth will mask meaningful variation across product categories and end-use settings. The report unpacks these layers without relying on superficial top-line narratives, providing a structured view of where volume, value, and strategic opportunity are likely to concentrate.
Segmentation Dynamics: Type, Application, and Regional Deployment
Morcellator portfolios are typically evaluated across three primary lenses: device type, surgical application, and geographic deployment. Each dimension carries distinct commercial implications, and the interplay among them defines competitive positioning in this market.
- Device type divergence. The market encompasses electrical and electromechanical platforms, manual instruments, and disposable or single-use systems. While power-driven morcellators continue to anchor a substantial share of procedure volume, the disposable segment is gaining momentum as operating rooms prioritize turnaround efficiency, cross-contamination risk reduction, and workflow simplicity. Manual devices retain relevance in specific procedural contexts, but their strategic role is increasingly defined by cost structure and niche indications rather than broad procedural dominance.
- Application-driven demand. Gynecologic surgery remains the largest procedural anchor for morcellator utilization, reflecting its central role in tissue extraction during laparoscopic and hysteroscopic interventions. Urology surgery represents a significant second demand pool, with product designs increasingly tailored to endoscopic tissue removal requirements. General surgery applications contribute a smaller but strategically relevant share, often tied to specialized laparoscopic workflows. Each application pathway shapes sourcing decisions differently, from instrument compatibility to containment integration and clinical training requirements.
- Regional deployment patterns. North America continues to represent a dominant commercial base, supported by well-established minimally invasive surgical infrastructure, procurement systems, and reimbursement pathways. Europe maintains a substantial secondary market characterized by diverse national procurement models and a strong emphasis on clinical standardization. Asia Pacific reflects a growing demand environment driven by expanding surgical capacity and device adoption, while Latin America and the Middle East and Africa constitute smaller but progressively evolving markets with distinct access and reimbursement considerations.
Rather than presenting these dimensions as isolated snapshots, the report analyzes how type, application, and region interact to influence commercial outcomes. This integrated view helps clients anticipate where demand may accelerate, which product formats may outperform, and how regional procurement environments could alter adoption speed.
Regulatory and Reimbursement Context Shaping Commercial Strategy
No strategic assessment of the morcellator market is complete without engaging the regulatory and reimbursement environment that governs product design, market access, and clinical adoption. Over recent years, this landscape has become more defined, with clear expectations around tissue containment, performance documentation, and coding classification.
- Containment system expectations. Clinical guidance has reinforced the use of FDA-cleared tissue containment systems during laparoscopic power morcellation in gynecologic procedures to mitigate the risk of tissue dissemination. This has elevated containment compatibility from a technical feature to a commercial prerequisite for many health systems and procurement teams. Manufacturers are increasingly evaluated not only on morcellator performance, but also on how effectively their platforms integrate with contained tissue extraction workflows.
- Performance assessment guidance. Regulatory expectations have also advanced around non-clinical performance assessment for tissue containment systems used during power morcellation procedures. The emphasis on robust performance data for 510(k) submissions signals a more structured pathway for product clearance and reinforces the importance of testing, documentation, and compatibility validation in product development strategy.
- Reimbursement coding relevance. Coding frameworks such as HCPCS code C1782, which designates morcellators under assorted devices, implants, and systems for hospital outpatient prospective payment purposes, remain relevant to commercial planning. Reimbursement classification affects hospital budgeting, outsourcing decisions, and the relative attractiveness of reusable versus single-use solutions in specific payment environments.
- Clinical risk legacy. Historical concerns related to uncontained laparoscopic power morcellation and the potential dissemination of occult uterine malignancy continue to influence procurement caution, clinical training emphasis, and product design priorities. While the market has matured, this legacy still shapes institutional decision-making and reinforces demand for contained, well-documented systems.
These forces do not simply constrain the market; they actively structure it. The report examines how regulatory and reimbursement conditions influence product strategy, procurement behavior, and competitive differentiation, enabling clients to anticipate access requirements rather than react to them after deployment.
Competitive Landscape and Strategic Positioning
The morcellator market features a mix of established multinational manufacturers, specialized surgical instrument providers, and increasingly active regional players. Competitive advantage in this environment is rarely defined by a single parameter. It emerges from the combination of product reliability, procedural compatibility, regulatory readiness, containment integration, and the ability to serve both high-volume institutional buyers and specialized clinical centers.
Incumbent Manufacturers and Platform Breadth
Several long-standing companies anchor the market through broad laparoscopic and hysteroscopic portfolios, established clinical relationships, and multi-product instrument ecosystems.
- Karl Storz SE & Co. KG maintains a recognized presence through electromechanical morcellator options such as ROTOCUT, with emphasis on high-precision tissue removal and reusable and reposable configurations for laparoscopic gynecologic procedures. Its competitive posture reflects integration within a wider endoscopic instrument ecosystem.
- Olympus Corporation offers morcellator platforms including the PK Morcellator and related laparoscopic power morcellators, with increasing attention to contained tissue extraction systems such as PneumoLiner for gynecologic use. This containment-linked positioning aligns with prevailing procurement expectations and procedural safety priorities.
- Medtronic plc is known for the TruClear hysteroscopic morcellator system, addressing mechanical uterine tissue removal in gynecological procedures. Its inclusion within a broader therapeutic and surgical portfolio gives it cross-market visibility and institutional reach.
- Richard Wolf GmbH supplies morcellator systems such as Morce Power Plus for laparoscopic applications, contributing to a competitive field where procedural compatibility and instrument reliability remain central.
- LiNA Medical specializes in powered morcellators such as XCISE, with a focus on disposable and minimally invasive gynecologic tissue morcellation. Its emphasis on single-use solutions reflects a growing segment interest in workflow efficiency and contamination control.
Specialized and Emerging Players
Alongside incumbents, a set of specialized and regional manufacturers is expanding the competitive field through targeted product development, certification activity, and regulatory clearance initiatives.
- Nouvag AG manufactures morcellator systems for laparoscopic and gynecological procedures, supporting the broader European instrument supply environment.
- RUDOLF Medical GmbH offers laparoscopic morcellators within its gynecological instrumentation portfolio, reinforcing the role of specialized instrument makers in sustaining competitive variety.
- Hangzhou Kangji Medical Instruments produces morcellators with ISO 13485 and CE certifications, positioning itself for international laparoscopic markets through compliance-oriented product development.
- A.M.I. Agency for Medical Innovations GmbH developed the i-Cut single-use laparoscopic power morcellator, which received FDA 510(k) clearance in April 2025 for gynecologic procedures. This clearance highlights the continued entry of single-use concepts into the regulated U.S. market.
- Hangzhou Hawk Optical Electronic Instruments Co., Ltd. received FDA 510(k) clearance in January 2026 for its Medical Shaver System for endoscopic tissue morcellation, including removal of dissected benign prostatic hyperplasia tissue. This development underscores the expanding procedural relevance of morcellator-adjacent systems in urologic applications.
- Blue endo supplies laparoscopic morcellators for gynecological applications, adding further optionality in a market where procurement teams increasingly evaluate multiple vendor qualifications before standardization.
This mix of established and emerging players creates a landscape where differentiation is increasingly tied to clearance timing, containment compatibility, single-use positioning, and procedural specificity. Broad product presence is valuable, but the most consequential competitive advantages often arise from how well a company aligns its platform with institutional demands for safety, documentation, workflow efficiency, and vendor reliability.
Recent Developments Reshaping Market Momentum
Several recent events illustrate how regulatory actions, product launches, and catalog continuity are actively influencing market direction. These developments are not isolated news items; they signal structural shifts that affect sourcing strategies and competitive expectations.
- Regulatory clearance activity in single-use and endoscopic systems. The FDA 510(k) clearance of the i-Cut single-use laparoscopic power morcellator in April 2025 and the clearance of an endoscopic medical shaver system for benign prostatic hyperplasia tissue removal in January 2026 demonstrate continued regulatory openness to new morcellator and morcellation-adjacent devices. These milestones expand the field of commercially available options and signal that innovation remains active in both gynecologic and urologic pathways.
- Catalog continuity among major manufacturers. Through late 2025, multiple manufacturers including Karl Storz, Olympus, and Richard Wolf maintained active morcellator offerings within current laparoscopic and hysteroscopic instrument catalogs. This continuity is commercially meaningful because procurement teams often prioritize vendors with stable, supported product lines and predictable service ecosystems.
Together, these developments suggest a market that is neither stagnant nor chaotic. It is evolving through defined regulatory channels, with new entrants and established players alike adjusting their portfolios to meet containment expectations, procedural needs, and single-use workflow preferences.
What the Worldwide Morcellator Market Report Delivers
The Worldwide Morcellator Market study is built to move beyond descriptive overviews and provide a usable decision-making foundation. It is structured for executives who need to align market intelligence with product strategy, commercial planning, and risk assessment. The report integrates market sizing, segmentation analysis, competitive profiling, and industry dynamics into a single coherent framework.
Key components of the report include:
- Historical and forecast market sizing. A detailed revenue trajectory from 2020 through 2032 that supports planning around demand cycles, growth timing, and investment horizons.
- Segmentation analysis across type, application, and region. A structured breakdown that helps identify where commercial opportunity is concentrated and how product format and procedural context shape adoption patterns.
- Competitive profiling of key manufacturers. Company-level perspectives covering product focus, procedural emphasis, and market positioning, enabling benchmarking and strategic comparison.
- Regulatory, reimbursement, and clinical context. An integrated review of containment expectations, performance assessment guidance, coding relevance, and historical safety considerations that influence procurement and product development.
- Recent market developments and their implications. A focused look at regulatory clearances, product catalog continuity, and emerging product activity that can affect competitive balance and sourcing decisions.
- Strategic synthesis for 2026 decision-making. Interpretive analysis designed to help leadership teams assess entry points, portfolio gaps, competitive exposure, and demand directionality.
Crucially, the report connects these elements rather than presenting them in isolation. A market forecast is most useful when read alongside segmentation behavior. A competitor profile becomes more actionable when evaluated against regulatory and procurement context. The study is designed to replicate that integrated reasoning for the reader.
Strategic Implications for 2026 and Beyond
For organizations operating in or evaluating the morcellator market, the 2026 decision environment calls for disciplined strategic positioning. The growth outlook is positive, but realized performance will depend on how well companies align product design, regulatory readiness, and commercial execution with the practical priorities of hospitals, surgical centers, and procurement teams.
Several strategic implications stand out:
- Containment compatibility is now a commercial baseline. Products that cannot demonstrate credible integration with tissue containment systems may face growing friction in gynecologic procurement decisions. This does not eliminate conventional morcellator value, but it raises the bar for what constitutes a competitive offering.
- Single-use migration will remain a strategic question. Disposable and single-use devices are not automatically superior in every setting, but their traction reflects genuine operational priorities around turnaround, cleaning logistics, and consistency. Companies should assess where single-use economics align with customer preferences and where reusable systems still hold advantage.
- Clearance timing and documentation quality matter. Recent 510(k) clearances show that the regulatory pathway remains active and competitive. Speed, completeness, and compatibility evidence can influence market access and buyer confidence, especially in procurement environments that prioritize well-supported product lines.
- Regional strategy requires segmentation discipline. Because procurement systems, reimbursement conditions, and surgical capacity differ materially by geography, a uniform go-to-market approach is unlikely to perform optimally. Regional plans should reflect local demand drivers, purchasing structures, and competitive density.
- Competitive advantage will be portfolio-wide. In a market with both incumbents and targeted entrants, success often depends on more than a single instrument. Service support, training, catalog stability, and procedural breadth can be as important as product specifications.
Why This Research Matters Now
The morcellator market is entering a phase where informed strategic positioning can create durable advantage. Demand is expanding, regulatory expectations are clearer, and competitive activity is intensifying across both established and emerging manufacturers. In this environment, decisions made in 2026 will shape portfolio relevance, market access, and commercial performance through the end of the forecast period.
This Worldwide Morcellator Market report is intended to give leadership teams a structured, evidence-based view of that environment. It combines market sizing, segmentation logic, competitive profiling, and industry dynamics into a single strategic resource. The objective is not simply to describe the market, but to help organizations interpret it with enough precision to act confidently.
For executives seeking a fuller view of segmentation splits, regional dynamics, application-level demand behavior, and company-level benchmarking, the complete Worldwide Morcellator Market study provides the detailed intelligence necessary to support planning, investment, and competitive strategy throughout the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Worldwide Morcellator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Temperature-Controlled RF Ablation Technology Market to Reach USD 2841.33 Million by 2032 with 11.52 Percent CAGR
By PW Consulting, 2026-09-02
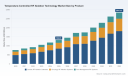
Strategic Intelligence for Navigating the Temperature-Controlled RF Ablation Landscape
Executive Overview
The global landscape for temperature-controlled radiofrequency ablation technology is undergoing a profound transformation, driven by an urgent need for precision in tissue destruction, improved patient outcomes, and the increasing adoption of minimally invasive procedures across multiple therapeutic areas. As we move further into 2026, enterprise decision-makers require more than just historical performance data; they need a forward-looking roadmap that integrates regulatory trajectories, technological differentiators, and competitive maneuvers. This analysis serves as a precursor to our comprehensive Worldwide Temperature-Controlled RF Ablation Technology Market study, designed to equip stakeholders with the acuteness required to navigate this high-growth sector.
Worldwide Temperature-Controlled RF Ablation Technology Market
The sector has demonstrated remarkable resilience and expansion momentum. Historical analysis from 2020 through 2025 reveals a consistent upward trajectory, with the market valuation rising from approximately 768.45 million USD to 1324.5 million USD. This growth underscores the clinical shift toward thermal ablation methods that offer controlled, predictable lesion formation compared to non-temperature-regulated alternatives. Looking forward, the forecast period from 2026 to 2032 projects the market to reach 2841.33 million USD. This expansion reflects a compound annual growth rate of 11.52 percent, signaling a robust environment for investment, product development, and strategic market entry.
Worldwide Temperature-Controlled RF Ablation Technology Market
For healthcare providers, medical device manufacturers, and investment firms, understanding the nuances of this growth is paramount. The transition from basic RF applications to sophisticated temperature-controlled systems represents a critical value inflection point. Our research delves into the mechanisms driving this shift, examining how real-time thermal monitoring, impedance-based feedback, and advanced generator technologies are reshaping clinical standards. The following insights highlight the strategic imperatives derived from our latest market intelligence, providing a high-level view of the opportunities and challenges defining the 2026 landscape.
Worldwide Temperature-Controlled RF Ablation Technology Market
Macroeconomic Trajectories and Revenue Drivers
The financial architecture of the temperature-controlled RF ablation market is characterized by steady accumulation and accelerating adoption rates in key therapeutic segments. The revenue progression from 2020 to 2025 established a strong baseline, with the market surpassing the 1 billion USD threshold in 2023 and continuing to climb. By 2026, the market is positioned to hit 1451.21 million USD, marking a significant step up in total addressable revenue. This growth is not merely linear; it is fueled by the integration of ablation technologies into broader treatment protocols for cardiac arrhythmias, oncology, pain management, and vascular conditions.
Projecting forward, the forecast data indicates sustained momentum. Between 2026 and 2032, the market is expected to almost double in size, reaching 2841.33 million USD. This trajectory suggests that temperature-controlled RF ablation is moving beyond niche applications to become a cornerstone of interventional procedures. The 11.52 percent CAGR reflects a confluence of factors, including an aging population requiring chronic disease management, the expansion of ambulatory surgical centers capable of performing these procedures, and continuous innovation in catheter and generator design. However, capturing this value requires a granular understanding of where growth is concentrated and which technological features are commanding premium pricing.
Our research dissects these revenue streams without losing sight of the broader economic context. The shift toward systems that offer precise temperature regulation addresses longstanding clinical challenges such as char formation, inconsistent lesion depth, and collateral tissue damage. As reimbursement policies evolve and hospitals seek to optimize procedural efficiency, the adoption of generators and catheters that provide real-time feedback and controlled energy delivery is accelerating. Decision-makers must recognize that the value proposition of these systems extends beyond clinical efficacy to include operational efficiency and reduced complication rates, which collectively drive procurement decisions.
Market Segmentation Dynamics and Application Focus
The temperature-controlled RF ablation ecosystem is diversified across product categories, geographic regions, and end-user settings, each contributing to the overall market expansion. In terms of product architecture, the market is anchored by cardiac RF ablation catheters, which represent the largest share of revenue due to the high prevalence of atrial fibrillation and other arrhythmias requiring precise thermal lesion formation. Oncology RF ablation systems constitute a significant and growing segment, driven by the demand for minimally invasive tumor destruction in liver, bone, and soft tissue applications. Pain management RF systems also hold a meaningful position, leveraging temperature-controlled technology to achieve consistent nerve ablation for chronic pain relief.
Geographic distribution reveals distinct patterns of adoption and growth potential. North America remains a dominant force in the market, supported by advanced healthcare infrastructure, high procedural volumes, and early adoption of innovative ablation technologies. Europe follows as a substantial revenue contributor, with growing utilization of temperature-controlled systems in both hospital and ambulatory settings. Asia Pacific represents a region of increasing interest, where expanding healthcare access and rising awareness of minimally invasive treatments are creating new opportunities. Latin America and the Middle East and Africa, while currently smaller in absolute terms, are emerging markets where strategic partnerships and localized regulatory navigation can yield long-term gains.
End-user segmentation further clarifies the market structure. Hospitals continue to be the primary setting for temperature-controlled RF ablation procedures, reflecting their role as centers for complex cardiac and oncological interventions. Ambulatory surgical centers are gaining traction as efficient venues for pain management and select vascular procedures, driven by cost pressures and the shift toward outpatient care. Specialty clinics also play a role, particularly in focused applications where targeted ablation services are offered. Understanding the interplay between these segments is essential for companies aiming to tailor their sales strategies, regulatory submissions, and clinical support programs to the specific needs of each customer group.
While the macro-level segmentation paints a clear picture of market breadth, the strategic nuances lie in the detailed breakdown of sub-segments, procedural volumes, and pricing dynamics. Our full report provides a granular dissection of these splits, revealing where competitive intensity is highest and which sub-markets offer the most favorable risk-reward profiles for expansion.
Competitive Intelligence and Strategic Positioning
The competitive environment in temperature-controlled RF ablation is defined by a mix of established multinational medtech giants and specialized innovators, each pursuing distinct strategies to capture market share. Leading players have built portfolios that span cardiac, oncology, pain management, and vascular applications, leveraging temperature control as a key differentiator. Medtronic, headquartered in Dublin, Ireland, exemplifies this multi-application approach with its DiamondTemp temperature-controlled irrigated RF ablation catheter for cardiac ablation in atrial fibrillation, which utilizes industrial diamonds for real-time tissue surface temperature measurement and control. The company also offers the OsteoCool cooled RF ablation system for bone tumors and the Accurian RF ablation platform with temperature-regulated lesion formation for pain management, demonstrating a broad footprint across critical indications.
Johnson & Johnson MedTech, through its Biosense Webster division based in Irvine, CA, USA, competes with high-precision cardiac solutions such as the QDOT MICRO Catheter with QMODE plus temperature control module. This system enables high-power short-duration RF ablation in cardiac electrophysiology and integrates with CARTO 3 mapping for precise real-time temperature monitoring via embedded thermocouples, highlighting the industry's emphasis on mapping integration and thermal accuracy. Abbott Laboratories, located in Abbott Park, IL, USA, focuses on chronic pain management with the IonicRF Generator, which features real-time temperature monitoring, the ProCharge algorithm for efficient temperature ramping, and multi-channel independent control, while also offering ablation technologies with temperature control features across its portfolio.
In the pain management and lesion ablation space, Boston Scientific Corporation, based in Marlborough, MA, USA, supplies the G4 RF Generator and GX1 RF Generator for nerve tissue and lesion ablation. These systems utilize temperature and impedance-based power control to ensure consistent lesion formation, supporting temperature-controlled procedures in pain management and other applications. BD, headquartered in Franklin Lakes, NJ, USA, brings a vascular focus with the Venclose RF Ablation System and Venclose Catheter, designed for endovenous treatment of superficial vein reflux by delivering controlled and uniform heat transfer at consistent temperature via a dual heating length coil.
Beyond the large incumbents, a cohort of specialized and emerging companies is pushing the boundaries of temperature-controlled ablation. STARmed Co., Ltd., based in Goyang-si, South Korea, specializes in FDA-cleared RFA machines and thermal ablation devices for soft tissue conditions including thyroid, biliary, and other applications, with systems supporting temperature-controlled radiofrequency ablation. Thermedical, located in Waltham, MA, USA, develops the saline-enhanced RF thermal ablation system designed for larger tissue volume ablation through advanced heat transfer and temperature management in soft tissue applications. Cambridge Interventional, based in the USA, offers the Cambridge CRF System for precision radiofrequency ablation across thyroid, liver, kidney, bone, and other soft tissue applications with temperature-controlled thermal ablation capabilities. RF Medical Co., Ltd., also from South Korea, develops advanced ablation technologies including radiofrequency systems focused on patient care through cutting-edge temperature-controlled and thermal ablation solutions.
The competitive dynamics are further shaped by recent regulatory and product developments that signal shifting capabilities and market intentions. Abbott Laboratories received CE Mark approval in January 2026 for the TactiFlex Duo Ablation Catheter, Sensor Enabled, supporting both pulsed field and radiofrequency energy delivery with temperature control capabilities for atrial fibrillation treatment. Boston Scientific Corporation secured FDA 510(k) clearance in August 2025 for the GX1 Radiofrequency Generator Kit as a product line extension of the G4 RF Generator, featuring continuous power monitoring and control based on temperature and impedance measurements. Additionally, NeuroOne Medical Technologies Corp. obtained FDA 510(k) clearance in August 2025 for OneRF Trigeminal Nerve Radiofrequency Probes to be used with the OneRF Ablation System. These milestones illustrate the pace of innovation and the regulatory pathways companies are leveraging to expand their addressable indications.
Regulatory, Reimbursement, and Market Dynamics
The regulatory environment plays a defining role in shaping the commercialization landscape for temperature-controlled RF ablation technologies. Devices in this category are subject to established classification frameworks that govern their clearance and market access. For instance, the Boston Scientific GX1 RF Generator is classified as Class II under 21 CFR 882.4400, designated as a Radiofrequency Lesion Generator with product code GXD, and is cleared via the 510(k) pathway with continuous temperature and impedance-based power control. Similarly, the NeuroOne OneRF Trigeminal Nerve Radiofrequency Probes are classified as Class II under 21 CFR 882.4725 with product code GXI. These classifications underscore the importance of demonstrating safety and effectiveness through robust performance data, particularly when introducing new generators, catheters, or probes that modify temperature control algorithms or energy delivery profiles.
Thermedical's Ablation System using saline-enhanced RF is also 510(k) cleared for the coagulation and ablation of soft tissue during percutaneous, laparoscopic, and intraoperative surgical procedures, reflecting the breadth of procedural settings where temperature-controlled ablation is gaining acceptance. Beyond device clearance, reimbursement considerations significantly influence adoption. Medtronic, for example, provides specific coding and payment guidance resources for the OsteoCool Radiofrequency Ablation System used in the treatment of painful bone tumors. Such resources help healthcare providers navigate the financial aspects of procedural adoption, reducing barriers to implementation and supporting broader utilization.
Market concentration also offers strategic insight. The industry exhibits a notable degree of consolidation among top players, with the top three companies accounting for approximately 62.45 percent of market share and the top five reaching about 81.3 percent. This concentration suggests that scale, portfolio breadth, and established clinical evidence are significant advantages in securing hospital contracts and influencing guideline-driven adoption. However, it also indicates that specialized innovators can find opportunities by targeting underserved indications, offering differentiated technology, or forming strategic partnerships to access distribution channels. The interplay between regulation, reimbursement, and competitive concentration creates a complex environment where success depends on aligning product capabilities with clinical needs and procurement realities.
Strategic Implications for 2026 Decision-Making
For organizations operating in or entering the temperature-controlled RF ablation market, the 2026 landscape presents several actionable imperatives. First, the emphasis on real-time temperature measurement and control is no longer a premium feature but a baseline expectation in many high-value applications. Companies must ensure their product development roadmaps prioritize thermal accuracy, impedance feedback, and integration with mapping or imaging systems where relevant. The recent clearances for generators with continuous power monitoring and catheters with embedded thermocouples illustrate the direction of technological evolution and the expectations of electrophysiologists, oncologists, and pain specialists.
Second, multi-indication portfolios offer resilience and growth potential. Leading competitors are leveraging temperature-controlled RF platforms across cardiac, oncology, pain, and vascular segments, allowing them to cross-sell within hospital systems and capture value from diverse procedural volumes. Organizations should evaluate whether their current pipeline supports this breadth or whether targeted acquisitions, licensing, or partnerships could accelerate their ability to serve multiple end markets. The segmentation data suggests that cardiac catheters remain a strong revenue anchor, while oncology and pain management systems offer growth avenues that may respond well to focused marketing and clinical education efforts.
Third, regional strategy must be tailored to local regulatory and reimbursement dynamics. North America and Europe remain core markets with established procurement processes and high procedural volumes, but Asia Pacific and other emerging regions present opportunities for companies that can navigate local clearance requirements, build clinical evidence, and establish distribution partnerships. Reimbursement support, such as coding guidance and payment resources, can be a decisive factor in accelerating adoption, particularly for procedures involving bone tumors or chronic pain where financial clarity reduces friction for providers.
Fourth, competitive intelligence must go beyond product specifications to understand the broader strategic moves of incumbents and challengers. Recent regulatory clearances and product line extensions signal where companies are investing and which indications they prioritize. Monitoring these developments, alongside shifts in market concentration and the emergence of new entrants, enables proactive positioning. Companies should assess how their offerings compare on temperature control precision, procedural efficiency, and total cost of ownership, and then craft value propositions that resonate with both clinical and administrative stakeholders.
Finally, the forecast trajectory indicates that the market will continue to expand at a double-digit CAGR through 2032. This long-term growth underscores the importance of sustainable investment in clinical evidence generation, physician training, and service support. Organizations that can demonstrate reliable lesion formation, reduced complications, and seamless integration into existing workflows will be best positioned to capture share as the market scales. The combination of strong macro growth, technological differentiation, and evolving regulatory and reimbursement frameworks creates a dynamic environment where informed, data-driven decisions will determine competitive outcomes.
Conclusion and Access to Full Intelligence
The worldwide temperature-controlled RF ablation technology market stands at a pivotal juncture, characterized by robust growth, advancing technology, and intensifying competition. Historical performance from 2020 through 2025 has established a strong foundation, while the forecast through 2032 points to continued expansion fueled by clinical demand and innovation. The competitive landscape is shaped by major medtech players with broad portfolios and specialized innovators pushing the boundaries of thermal ablation across cardiac, oncology, pain, and vascular applications. Regulatory classifications, reimbursement support, and market concentration further define the pathways to commercial success.
For executives, investors, and strategic planners, a high-level view is valuable but insufficient for precise decision-making. The full depth of segmentation, regional dynamics, end-user behavior, pricing structures, and competitive maneuvers requires a comprehensive analysis that our Worldwide Temperature-Controlled RF Ablation Technology Market report delivers. The complete study provides detailed data on market size and growth by segment, a thorough competitive profiling of key companies, analysis of recent regulatory and product developments, and actionable recommendations tailored to 2026 and beyond. We invite you to access the full report to retrieve the granular intelligence necessary to inform your strategy, identify high-priority opportunities, and navigate the evolving temperature-controlled RF ablation landscape with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Temperature-Controlled RF Ablation Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global Transparent Ice Maker Market Worth USD 495.3 Million in 2025 to Reach USD 811.52 Million by 2032 at 7.31 CAGR
By PW Consulting, 2026-09-02
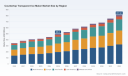
The Clarity Edge: Strategic Intelligence for the Worldwide Countertop Transparent Ice Maker Market Through 2032
The countertop transparent ice maker segment has quietly evolved from a niche luxury accessory into a strategically significant category within the broader small appliance landscape. As consumer expectations around homebar experiences, beverage quality, and compact appliance design continue to escalate, decision-makers across consumer electronics, white goods, and foodservice-adjacent channels require a disciplined, forward-looking view of where value is being created and where concentration risk is building. Our newly released Worldwide Countertop Transparent Ice Maker Market research study is designed to provide exactly that: a structured, data-grounded intelligence framework for executive planning, product portfolio decisions, channel strategy, and competitive positioning through the end of the decade.
Worldwide Countertop Transparent Ice Maker Market
This report is not a superficial scroll of headlines. It is a decision-ready market architecture built for leaders who need to understand how transparent ice manufacturing at the countertop level is reshaping demand patterns, supplier competition, product engineering priorities, and regulatory expectations across multiple end-use environments. What follows is a strategic preview of the analytical depth contained in the full study, along with the market logic that makes this category increasingly relevant for 2026 planning cycles and beyond.
Worldwide Countertop Transparent Ice Maker Market
Why This Category Matters Now
Few appliance subsegments combine aesthetic aspiration, functional specialization, and compact-form engineering as intensely as countertop transparent ice makers. The appeal is no longer limited to bartenders or premium hospitality environments. Home entertainment spaces, boutique cafes, specialty beverage retailers, and even premium office break areas are increasingly treating crystal-clear ice as part of the sensory experience rather than a simple cooling utility. That shift changes the economics of the category. It pushes manufacturers to optimize for appearance, melt behavior, cube geometry, and user-facing convenience features, rather than treating ice output as a commodity specification.
Worldwide Countertop Transparent Ice Maker Market
Our research captures this transition by framing the market as a space where consumer willingness to pay is being repositioned around quality perception, speed-to-first-cube, design integration, and easier maintenance. For strategic planners, that means the category cannot be evaluated through the lens of traditional volume-driven appliance competition alone. It requires an understanding of how product storytelling, visual performance, and compact engineering intersect with purchasing behavior in both residential and small commercial settings.
Macro Trajectory: A Market Built on Sustained, Not Speculative, Growth
The overall market trajectory examined in this study reflects a category that has already passed the early-adoption experimentation phase and is now consolidating around repeatable demand. Drawing on historical data from 2020 through the 2025 base year, the analysis tracks a consistent expansion path that carries the market well into the 2026 to 2032 forecast period. The growth profile is meaningful for planners because it indicates durable momentum rather than a temporary promotional spike.
For decision-makers, the strategic implication is straightforward: scale opportunities exist, but they are unevenly distributed across product architectures, use cases, and geographic demand centers. That is precisely why broad market narratives are insufficient. A company evaluating entry, expansion, or portfolio rebalancing needs to know where growth is structurally reinforced and where apparent opportunities may be crowded by concentration, channel complexity, or regulatory friction. The full report addresses those questions through a layered segmentation lens while preserving analytical discipline around the factors that actually drive share movement.
What the Report Delivers: Operational Intelligence, Not Just Market Description
The study is structured to support concrete business decisions rather than high-level awareness. It integrates market sizing, segmentation logic, competitive positioning, product evolution patterns, and regulatory context into a single planning framework. The objective is to help leaders translate market signals into action across product strategy, marketing emphasis, channel selection, and risk monitoring.
Inside the report, readers will find:
- A comprehensive sizing and forecast architecture that connects historical performance with the 2026 to 2032 outlook, allowing leadership teams to benchmark current assumptions against a consistent analytical baseline.
- A segmentation framework that separates demand by region, product type, and application, giving strategists a structured way to assess where portfolio focus is likely to generate the strongest return on development and commercialization effort.
- Competitive profiling of leading manufacturers and brand players, including product philosophy, engineering orientation, and positioning cues that illuminate how value is being claimed in the market.
- A review of recent product launches and preview events that signals where design, capacity, and user-experience priorities are heading in the near term.
- An integrated discussion of regulatory and safety considerations that can influence sourcing, consumer trust, and channel readiness, especially for players expanding across multiple markets.
- Practical interpretive guidance for planning teams that need to translate market structure into pricing, feature prioritization, distribution strategy, and launch timing.
Each section is written with the assumption that the reader is preparing for a real commercial decision, not simply reading for general context. That is why the report consistently links market patterns to operational consequences: what they mean for product roadmap choices, how they affect competitive vulnerability, and where they create openings for differentiated positioning.
Market Structure: What the Numbers Reveal About Competitive Reality
One of the most strategically important contributions of this study is its treatment of market concentration. The transparent countertop ice maker category is not evenly contested. A meaningful share of revenue is captured by a relatively compact set of players, and that has direct implications for new entrants, existing challengers, and even established brands evaluating expansion into adjacent forms or features.
For executives, concentration matters because it shapes bargaining dynamics, channel access, marketing efficiency, and the credibility required to win in premium segments. When a substantial portion of market value is held by a limited group of companies, the strategic question is not simply how large the market is, but how accessible profitable pockets remain and what distinguishes the leaders from the rest. The report examines that landscape with enough granularity to help teams assess realistic positioning pathways without reducing the category to a simplistic leader-versus-challenger narrative.
The segmentation logic further reinforces this point. Demand does not distribute itself uniformly across product types or usage environments. Different customer groups evaluate transparent ice makers through different lenses: some prioritize convenience and rapid production, others emphasize cube quality and drink presentation, and still others weigh ease of cleaning, footprint, and integration into compact spaces. Similarly, regional demand reflects distinct purchasing habits, channel structures, and product expectations. The report preserves that complexity so that strategy teams can avoid the common mistake of treating the category as a single battlefield when it is, in practice, several overlapping ones.
Competitive Landscape: Who Is Shaping the Category and How
The competitive set in this space combines large appliance-oriented brands, portable-appliance specialists, and smaller innovators focused on premium drink experiences. What distinguishes the leading players is less any single specification than the way they translate technical capability into a clear user promise. In this category, that promise often revolves around clarity, melt resistance, compactness, and the perceived quality of the beverage experience.
NewAir has established a recognizable position through countertop clear ice makers built around cascading water technology, emphasizing bubble-free, slow-melting cubes suited to cocktails and premium beverages. Its product logic highlights how engineering details can be used to support a premium-drink narrative rather than merely maximize output. Luma Comfort has focused on portable countertop units that combine relatively strong daily output with fast first-cube production, an appealing value proposition for home and small commercial settings where speed and convenience matter. Euhomy Technology Inc. has been actively extending its portable-appliance portfolio with premium-oriented clear and crescent ice options, signaling at recent industry events that design differentiation and drink-experience enhancement remain central to its roadmap.
GE Appliances, through its GE Profile Opal series, has built strong recognition in countertop and portable ice making with a focus on high-output, chewable ice formats. While its mainstream association is with nugget-style products, its broader innovation footprint and compact model expansion have positioned it as a force influencing consumer expectations across the countertop ice category. Frigidaire, distributed widely through Curtis International Ltd., contributes countertop models that combine transparent viewing features with square or clear ice production and self-cleaning functionality, reinforcing convenience as a competitive differentiator. Igloo Products Corp. addresses the portable countertop segment with compact systems aimed at home and outdoor use, broadening the context in which clear or standard ice production is considered part of lifestyle equipment rather than solely bar or kitchen infrastructure.
Silonn continues to compete in the consumer appliance space with countertop clear ice cube makers emphasizing efficient, self-cleaning designs for home and office environments. Klaris, through its Craft Klaris offering, takes a more specialized approach by focusing on large, crystal-clear cubes for cocktails using directional freezing in a compact footprint, an example of how a narrow premium use case can support a distinct brand identity. Hoshizaki Corporation brings commercial-grade credibility into the conversation, with gourmet cube and specialty clear ice options that bridge high-end foodservice expectations and countertop or undercounter applications. Together, these players illustrate a market where competition is shaped by product philosophy, audience targeting, and the ability to connect ice quality with a broader beverage experience.
2026 Developments: Where Product Strategy Is Heading
Recent product activity provides an early signal of how manufacturers are refining their countertop ice strategies. At CES 2026, Euhomy Technology Inc. premiered four new portable ice makers, including the Luna Pro Crescent Clear Ice Maker and Rock Pro Sphere, both oriented toward crystal-clear ice production. That launch underscores how clearly visible ice quality and format variety are becoming part of the premium portable-appliance conversation. In parallel, GE Appliances previewed the Opal Mini Nugget Ice Maker and Opal Mini Pro at KBIS 2026, introducing compact countertop models with enhanced nugget output. Even where the primary format is not transparent cube ice, the move matters because it reflects an industry-wide push toward compact, high-output, design-conscious countertop appliances that reshape consumer expectations across the segment.
These developments are not isolated product news. They reveal a pattern: manufacturers are competing on a combination of footprint, speed, presentation quality, and user-facing convenience, while also using trade-show visibility to reinforce premium positioning. For strategists, the implication is that product planning in this category increasingly requires coordination between engineering, design language, and brand storytelling. A specification advantage alone is rarely enough if the broader experience does not reinforce the intended market position.
Regulatory and Safety Context: A Strategically Underappreciated Driver
Market discussions often treat regulation as a compliance footnote. In countertop ice makers, however, safety and material standards can influence consumer confidence, retail readiness, and product design choices in ways that directly affect commercialization speed and brand reputation. Recent recall activity in adjacent small-appliance categories has underscored how important it is for manufacturers and distributors to maintain rigorous attention to electrical safety, component durability, and material selection.
For example, prior regulatory action involving household countertop nugget ice makers highlighted laceration hazards associated with auger blade integrity. In a separate case, a recall of ice crushers addressed potential fire hazard concerns. While these actions do not define the transparent ice maker category itself, they illustrate the broader risk environment in which countertop appliances operate and why safety engineering is not optional surface-level detail. At the same time, general compliance expectations around electrical safety and material standards, including BPA-free components in many consumer models, continue to shape product specifications across U.S. and EU markets.
Strategic planners should read this context as a commercial variable, not merely a legal one. Products that are designed with safety, durability, and transparent consumer communication in mind can reduce downstream friction in retail, support brand credibility in premium segments, and lower exposure to recall-related disruption. The report incorporates these considerations so that teams can factor them into sourcing, design review, and market-entry decisions with appropriate seriousness.
Strategic Takeaways for 2026 Decision-Making
For leadership teams planning around this category, several strategic imperatives emerge from the market structure and competitive dynamics examined in the study.
- First, transparent ice quality is increasingly a positioning engine, not just a technical feature. Companies that treat clarity, cube geometry, and melt behavior as central to the customer experience are better placed to command premium perception and defend margin.
- Second, the market rewards differentiated use-case targeting. Residential home bars, small commercial cafes, specialty beverage settings, and compact premium kitchens do not buy for the same reasons. Portfolio strategy should reflect that reality rather than assuming a single product narrative can carry multiple audiences.
- Third, concentration in the category means that share gains are unlikely to come from broad generalizations. They are more likely to come from identifying underserved pockets, improving convenience or design integration, or establishing a credible premium promise that existing leaders are not fully addressing.
- Fourth, product launches and preview activity suggest that compact form, speed-to-first-cube, and visual quality will remain central battlegrounds. Roadmap decisions should be evaluated against those competitive priorities, not against legacy appliance metrics alone.
- Fifth, safety and regulatory readiness should be integrated into strategic planning as an enabler of market confidence. In a category where premium positioning depends on trust and user experience, weak safety architecture can undermine even strong product concepts.
Taken together, these implications point to a market where success is increasingly defined by the ability to align engineering, design, audience targeting, and risk management in a coherent commercial story. That is exactly the kind of environment in which disciplined market intelligence can create an outsized advantage.
Why the Full Study Is Built for Action
The preview above is intended to demonstrate the analytical stance of the report, not to replace it. The full study goes further by providing the structured segmentation context, competitive interpretation, and planning-oriented discussion that teams need when they are deciding where to invest, how to position, and which risks to monitor. It is designed to support conversations in product management, strategy, sales leadership, and channel development, with a clear link between market evidence and executable conclusions.
Readers who engage with the complete report will find a market view that is detailed enough to inform real choices and disciplined enough to avoid the trap of overgeneralized growth narratives. In a category where competitive positioning, consumer perception, and regulatory context all interact, that combination is not a luxury. It is a practical requirement for 2026 planning and for the years of forecast development that follow.
For organizations seeking to map out portfolio direction, assess competitive vulnerability, or prepare for targeted expansion, this research offers a comprehensive foundation. The macro trajectory signals opportunity. The segmentation structure clarifies where that opportunity lives. The competitive and regulatory context explains how to pursue it responsibly. The full report brings those elements together in a form built for decision-makers who need more than a market snapshot—they need a strategic operating perspective.
For detailed analysis of this topic, please visit the official page: Worldwide Countertop Transparent Ice Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Global Driverless Dump Truck Market to Reach USD 6414.73 Million by 2032 Growing at 15.12 Percent CAGR
By PW Consulting, 2026-09-02
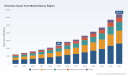
The Autonomous Haulage Revolution: Strategic Insights for the Worldwide Driverless Dump Truck Market 2026–2032
The global mining and heavy construction sectors stand at an inflection point. As operational margins tighten, labor availability constrains growth, and decarbonization mandates accelerate across jurisdictions, fleet operators are increasingly turning to autonomous haulage as a structural solution rather than a tactical experiment. The Worldwide Driverless Dump Truck Market has evolved from isolated pilot programs into a commercially scaling ecosystem, driven by proven safety records, compelling productivity gains, and the integration of battery-electric powertrains with OEM-agnostic control systems. Our newly released market research provides a comprehensive, decision-ready intelligence framework designed specifically for executive leadership, capital allocation committees, and technology procurement teams navigating this transformation from 2026 through 2032.
Worldwide Driverless Dump Truck Market
This introduction outlines the strategic architecture of the study, highlights the operational depth embedded in its analytical models, and demonstrates how executives can translate macro market trajectories into actionable deployment roadmaps, partnership strategies, and risk mitigation frameworks. The full intelligence package contains granular market sizing, competitive positioning matrices, regional adoption curves, and end-use segmentation that go beyond the high-level synthesis presented here. Readers seeking the complete dataset, scenario modeling tools, and procurement-level specifications are directed to the full report portal.
Worldwide Driverless Dump Truck Market
Market Trajectory and the 2026 Decision Context
The commercial trajectory of driverless dump trucks has passed the proof-of-concept threshold. Historical adoption data from 2020 through 2025 reveals a consistent acceleration curve, with the total addressable market expanding from approximately $1.215 billion to nearly $2.394 billion over that five-year window. This growth has been fueled by parallel deployments across surface mining, underground operations, and large-scale civil construction, alongside regulatory clarity on functional safety standards and operational readiness requirements for autonomous mobile machinery.
Worldwide Driverless Dump Truck Market
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate of 15.12 percent, positioning the global market on a path toward revenue levels exceeding $6.4 billion by the end of the decade. This trajectory is not merely a function of incremental automation adoption; it reflects a structural shift in how hauling operations are engineered. Fleet managers are increasingly evaluating total cost of ownership through the lens of continuous 24/7 cycle optimization, fuel and energy efficiency, reduced human exposure to high-risk environments, and the long-term alignment with zero-emission procurement mandates.
For 2026 decision-makers, the immediate strategic priority lies in distinguishing between short-term operational efficiency gains and long-term competitive positioning. Early movers who integrate autonomous haulage into broader mine planning, site logistics, and energy infrastructure roadmaps are building operational moats that will compound as the technology normalizes across extraction and construction verticals. The market research synthesizes the historical momentum, the forward-looking growth envelope, and the structural drivers that will separate leadership positions from reactive adoption through 2032.
Structural Segmentation and Operational Demand Drivers
The commercial landscape for autonomous dump trucks is defined by clear operational boundaries that shape purchasing behavior, technology selection, and deployment pacing. Payload capacity remains one of the most critical differentiators, as hauling requirements vary dramatically between ultra-class mining operations, mid-tier open-pit sites, and aggregate or construction applications. The market naturally bifurcates into heavy-class, mid-class, and lighter-capacity autonomous haulage segments, each with distinct technical requirements around duty cycle, terrain navigation, load handling, and integration with existing site infrastructure.
End-use application is equally determinative. Surface mining represents the dominant commercial context, where continuous haulage loops, large fleet coordination, and high-volume throughput justify the capital intensity and integration complexity of autonomous control systems. Underground mining deployments introduce additional constraints around ventilation, confined navigation, real-time collision avoidance, and system redundancy, but they also offer compelling value propositions in environments where human operator exposure to hazards must be minimized. Large-scale construction and quarry operations represent a rapidly emerging frontier, where mixed-OEM fleet compatibility, vision-centric sensing architectures, and shorter deployment timelines are reshaping traditional procurement logic.
Regional deployment patterns further illustrate the market's geographic diversity. Asia Pacific continues to anchor substantial commercial activity, reflecting the scale of mining and infrastructure investment across major industrial economies. North America maintains a strong presence driven by advanced quarry operations, western US and Canadian mining jurisdictions, and active partnerships between technology providers and large construction material producers. Latin America, the Middle East and Africa, and Europe each present distinct regulatory frameworks, site characteristics, and adoption timelines that influence how quickly autonomous haulage systems transition from pilot to full commercial operation.
The research isolates these structural dynamics without reducing them to static percentages, instead mapping how payload requirements, end-use intensity, and regional operating conditions interact to shape procurement cycles, deployment sequencing, and vendor selection criteria.
Competitive Landscape and Strategic Positioning
The autonomous dump truck ecosystem is anchored by a concentrated group of established equipment manufacturers, specialized autonomy providers, and emerging OEMs that are rapidly expanding their commercial footprints. Market concentration remains high, with the leading cohort commanding a disproportionate share of deployed units, operational hours, and proprietary haulage system integration. This concentration reflects both the capital intensity of mine-grade autonomy and the importance of proven safety records, fleet integration expertise, and long-term service support in procurement decisions.
Caterpillar has extended its Cat MineStar Command for hauling framework across multiple truck classes, from mid-capacity models demonstrated in aggregate operations to large-scale mining trucks in high-volume production environments. With hundreds of autonomous trucks already in operation and billions of tons hauled globally, Caterpillar's deployment base provides a reference architecture for fleet-wide cycle optimization, remote dispatch coordination, and integration with mine planning systems. Recent demonstrations in the aggregates sector signal a broader application footprint beyond traditional mining.
Komatsu's FrontRunner Autonomous Haulage System represents one of the most mature commercial AHS platforms, integrated deeply into its haul truck series and supported by a substantial deployed fleet. The system's scale of operation, cumulative tonnage moved, and global presence across open-pit mining sites underscore the value of proprietary OEM integration, where haulage control, truck hardware, site communications architecture, and maintenance workflows are engineered as a unified ecosystem.
Pronto.ai has differentiated itself through an OEM-agnostic autonomy stack designed for retrofit deployment across Caterpillar, Komatsu, and mixed fleets. This approach addresses an important commercial reality: many operators are managing heterogeneous fleets and require a pathway to autonomy that does not demand full fleet replacement. Recent milestone achievements, including fully autonomous mixed-OEM quarry operations and tiered product editions that combine vision, LiDAR, and radar for all-weather performance, illustrate how autonomy providers are expanding from mining into aggregates and construction applications with faster deployment cycles and modular sensing configurations.
Volvo Autonomous Solutions has pursued a transport-as-a-service model centered on autonomous heavy-duty trucks with virtual driver capabilities, emphasizing continuous operation in quarry and mining partnerships. This service-oriented approach reflects a broader industry shift toward outcome-based commercial models, where operators evaluate autonomy not only through equipment procurement but also through operational availability, uptime guarantees, and integration with site logistics workflows.
Hitachi Construction Machinery has built a substantial operational record with its autonomous haulage system, demonstrating compatibility in mixed-fleet environments and maintaining a documented zero-incident safety trajectory across extended working hours and mileage. Liebherr has positioned its autonomous haulage solution around large mining trucks and battery-electric variants, including high-profile agreements for zero-emission autonomous deployments, aligning haulage automation with the electrification strategies of forward-looking mining groups.
Chinese OEMs are expanding their autonomy and electrification footprints simultaneously. XCMG has delivered operational autonomous electric mining truck fleets in partnership with energy and technology ecosystem players to support zero-carbon haulage, while SANY has progressed on autonomous and electric mining truck agreements with global construction material producers. These developments indicate that autonomy and electrification are increasingly bundled as integrated value propositions, particularly in regions where energy transition commitments and cost competitiveness intersect.
Technology Architecture, Electrification, and Operational Readiness
Autonomous haulage adoption is no longer solely a software or sensing challenge; it is an integrated engineering problem spanning vehicle propulsion, site communications, fleet management, functional safety, and operational change management. The research examines how technology architectures differ across OEM-integrated systems, retrofit autonomy stacks, and service-based delivery models, and how those differences shape procurement timelines, customization requirements, and long-term scalability.
Battery-electric autonomous haul trucks represent a critical convergence point between decarbonization strategy and automation. Large-capacity battery modules, charging infrastructure planning, thermal management, and duty-cycle optimization all influence whether electric autonomous trucks can match the throughput expectations of diesel-electric equivalents in continuous mining operations. The study analyzes these technical trade-offs and maps them against regional energy availability, site infrastructure constraints, and operator decarbonization commitments.
Operational readiness is equally central. Industry guidelines and regulatory frameworks increasingly emphasize risk assessment processes aligned with established functional safety standards, system validation protocols, change management for site personnel, and clear operational responsibilities across autonomy providers, equipment OEMs, and site operators. The research integrates these compliance and readiness considerations into the deployment analysis, ensuring that executives can evaluate not just technical feasibility but also the operational, safety, and organizational prerequisites for sustained commercial performance.
Recent product launches and deployment milestones reinforce this convergence. Tiered autonomy editions that combine multiple sensing modalities for all-weather performance, mixed-OEM fleet demonstrations surpassing significant tonnage thresholds, and aggregate-sector autonomous deployments all signal that the market is expanding both in technical sophistication and in application breadth.
Regulatory, Safety, and Sustainability Context
Policy and safety frameworks are shaping adoption velocity as much as technology is. Functional safety standards for autonomous and semi-autonomous machine systems provide a common reference point for risk assessment, system design, and operational validation in mining environments. Regional codes of practice, particularly in jurisdictions with active large-scale mining, further address implementation, operational readiness, and change management for autonomous haulage. These frameworks reduce ambiguity for procurement teams and create a more predictable environment for scaling deployments.
Safety performance data from leading deployments continues to support the commercial case for autonomy. Extended operational hours without safety incidents, reduced human exposure to hazardous environments, and measurable improvements in cycle consistency and fuel or energy efficiency collectively strengthen the business rationale. The research synthesizes these outcomes within a broader evaluation framework that allows operators to compare autonomy providers, deployment models, and site-specific readiness requirements against their own operational priorities.
Sustainability is no longer a parallel discussion to autonomy; it is increasingly inseparable from it. Zero-emission haulage strategies, energy infrastructure planning, and the integration of autonomous control with electrification roadmaps are shaping long-term capital decisions. Operators that align autonomy adoption with decarbonization commitments are positioning themselves for regulatory resilience, energy cost management, and stakeholder expectations around operational emissions.
Strategic Recommendations for 2026–2032 Decision-Makers
The research translates market intelligence into decision frameworks across several executive priorities:
- Procurement sequencing and fleet strategy: evaluate OEM-integrated autonomy versus retrofit or service-based models based on existing fleet composition, site infrastructure, desired deployment speed, and long-term asset strategy.
- Total cost of ownership modeling: incorporate continuous operation benefits, energy efficiency improvements, reduced exposure risk, maintenance implications, and integration costs into a multi-year financial assessment rather than an equipment-purchase view.
- Partnership and vendor selection: assess autonomy providers and OEMs on proven deployment scale, functional safety alignment, mixed-fleet compatibility, service support geography, and electrification roadmap integration.
- Site readiness and change management: prioritize operational training, control-room integration, communications infrastructure, and safety governance to ensure that technology deployment translates into sustained productivity gains.
- Regional and end-use alignment: match deployment pacing to regulatory clarity, energy infrastructure availability, site geometry, and application intensity, recognizing that surface mining, underground operations, construction, and quarry contexts require distinct evaluation criteria.
Executives who approach autonomous haulage as a system-level transformation—rather than an isolated equipment upgrade—will be best positioned to capture the compounding advantages of safety, efficiency, decarbonization alignment, and operational resilience as the market scales through 2032.
Research Scope and How to Access Full Intelligence
This study delivers a multi-dimensional intelligence package designed for strategic planning, capital allocation, procurement evaluation, and technology roadmap development. The full report encompasses historical market sizing from 2020 to the base year, a detailed 2032 forecast trajectory, segmentation analysis across payload capacity, end-use application, and regional deployment patterns, competitive profiling of leading autonomy providers and OEMs, recent deployment milestones and product launches, technology architecture comparisons, electrification and infrastructure considerations, regulatory and functional safety frameworks, and scenario-based evaluation tools for procurement and partnership decisions.
Readers seeking detailed regional breakdowns, payload-class revenue distributions, end-use commercial splits, company-level positioning matrices, and site-deployment benchmarks are encouraged to access the complete report through our research portal. The full document provides the granular data, comparative tables, and executive decision models required to convert market intelligence into concrete 2026 investment, procurement, and partnership strategies.
The Worldwide Driverless Dump Truck Market is entering a phase where strategic timing, integration discipline, and vendor selection will define competitive advantage. This research equips decision-makers with the structural understanding and operational context necessary to navigate that transition with confidence, while the complete dataset and analytical tools offer the precision required for execution-level planning.
For detailed analysis of this topic, please visit the official page: Worldwide Driverless Dump Truck Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


