



Category: market research
PW Consulting Projects Worldwide Coconut Oil Fat Powder Market to Reach 1073.64 Million by 2032 Growing at 6.6 CAGR
By PW Consulting, 2026-09-02
Navigating the 2026 Landscape: Strategic Insights from the Worldwide Coconut Oil Fat Powder Market Research
The global supply chain for specialty ingredients is undergoing a period of profound recalibration. As consumer preference shifts toward clean-label formulations, plant-based nutrition, and functional cosmeceuticals, Coconut Oil Fat Powder has emerged as a critical enabler for product developers across multiple verticals. For executives navigating procurement, R&D pipeline management, and market expansion strategies in 2026, understanding the trajectory of this ingredient class is no longer optional—it is a board-level imperative.
Worldwide Coconut Oil Fat Powder Market
Our newly released Worldwide Coconut Oil Fat Powder Market research report provides a comprehensive, data-driven blueprint of the industry landscape. This analysis is designed to serve as a strategic compass, offering decision-makers the granular intelligence needed to anticipate supply fluctuations, regulatory shifts, and competitive repositioning. Below, we preview the core dimensions of this study and outline why it represents an essential asset for corporate strategy teams operating in the current fiscal year and beyond.
Worldwide Coconut Oil Fat Powder Market
The Macro Trajectory: Sizing the Opportunity Through 2032
The market has demonstrated remarkable resilience and growth momentum over the past half-decade. Drawing on historical data spanning 2020 through 2025, the sector has consistently expanded, with valuations climbing from approximately USD 512.4 million in 2020 to an estimated USD 686.37 million by 2025. This upward trajectory reflects a compound annual growth rate that positions the ingredient class as a high-priority category for ingredient suppliers, food technologists, and nutritional formulators alike.
Worldwide Coconut Oil Fat Powder Market
Looking ahead, the forecast period from 2026 to 2032 projects sustained expansion, with the market anticipated to reach USD 1,073.64 million by the end of the forecast horizon. This represents a steady CAGR of 6.6 percent, underpinned by rising demand in developed and emerging markets alike. The growth is not merely a function of population expansion; it is fueled by structural shifts in how manufacturers approach fat functionality, shelf stability, and clean-label positioning. Coconut oil fat powders offer a unique combination of thermal stability, emulsification properties, and consumer-friendly branding that aligns with modern formulation priorities.
However, translating these top-line figures into actionable strategy requires a deeper dive. The aggregate numbers mask significant variation across product specifications, regional supply chains, and application-specific performance requirements. This is precisely where our research delivers its highest strategic value: by deconstructing the headline metrics into decision-ready frameworks that help procurement leaders, pricing strategists, and R&D directors allocate capital with precision.
Decoding the Segmentation Architecture
The Coconut Oil Fat Powder market is not a monolith. It is a multi-dimensional ecosystem where product type, end-use application, and geographic footprint interact to create distinct profit pools and risk profiles. Our report segments the market across these three critical axes, enabling clients to identify where their product offerings, supply networks, and customer targeting strategies intersect with the highest-growth corridors.
At the product specification level, the market divides between standard formulations and organic-certified variants. The regular category continues to anchor volume demand, particularly in industrial food processing and large-scale supplement manufacturing where cost efficiency and supply reliability remain paramount. Meanwhile, the organic segment has carved out a premium positioning, driven by consumer sensitivity to sourcing transparency, pesticide-free assurances, and clean-label certification requirements. The interplay between these two streams creates a bifurcated pricing environment that manufacturers must navigate carefully, particularly when raw material cost volatility enters the equation.
From an application standpoint, the market is anchored by three dominant use cases. The Food and Beverage sector represents the largest consumption channel, where coconut fat powders are leveraged for their flavor neutrality, mouthfeel enhancement, and compatibility with vegan and dairy-free formulations. Dietary Supplements constitute the second pillar, with manufacturers utilizing micro-encapsulated and standardized fat powders to deliver energy, immunity, and metabolic health benefits in convenient dosage formats. The Cosmetics and Personal Care segment, while smaller in absolute volume, demonstrates strategic importance due to its higher margin profile and the growing consumer emphasis on plant-derived emollients in skincare and haircare formulations.
Geographically, the market distribution reveals a complex tapestry of supply origin and demand concentration. The Asia Pacific region commands the largest share of market activity, reflecting both production capacity and regional consumption patterns. North America and Europe follow as mature, high-value markets where clean-label mandates, sustainability credentials, and premium pricing tolerance create attractive entry and expansion opportunities. Latin America and the Middle East and Africa regions, while smaller in current scale, represent emerging vectors where dietary transition trends and localized manufacturing investments could accelerate demand growth over the forecast period.
Competitive Dynamics: Mapping the Strategic Battlefield
The competitive landscape for Coconut Oil Fat Powder is characterized by a mix of regional specialists, globally integrated suppliers, and ingredient-formulation experts who have built their reputations on technical performance, certification portfolios, and supply chain reliability. Market concentration data indicates that the top three players account for approximately 38.45 percent of total market revenue, while the top five entities control roughly 52.6 percent. This moderate concentration level suggests that while leading incumbents hold meaningful market power, the space remains accessible to agile manufacturers and niche formulators who can differentiate through specification customization, regulatory compliance, and application engineering.
Our research profiles a comprehensive roster of key companies that define the current competitive equilibrium. India-based manufacturers, including Vinayak Ingredients India Pvt Ltd and Ace International, have established strong positions as export-oriented suppliers, with product lines tailored for food and nutraceutical applications. Ace International has distinguished itself through the use of acacia fibre stabilization technology, delivering high-solubility formats that meet vegan and HALAL certification standards, while Vinayak Ingredients has built reputation on consistent 50 percent fat-content formulations aimed at both food and supplement markets. Zeon Lifesciences further strengthens the India-origin supply cluster with premium-grade, free-flowing powders designed specifically for energy and immunity supplement formulations.
The United States contributes specialized capability through Connoils LLC, which operates as a bulk supplier of organic coconut oil powders targeting international supplement, food, and nutraceutical channels. This US-based footprint provides a critical bridge between North American formulation demand and global sourcing flexibility. Across the Pacific, China's manufacturing ecosystem is represented by NEW ELEMENT Bio-Tech and Xi'an Healthful Biotechnology Co., Ltd. (HSF Biotech). NEW ELEMENT Bio-Tech offers high-specification natural coconut oil powder at 70 percent fat content, supported by FSSC22000, ISO 9001, HALAL, and Kosher certifications, while HSF Biotech brings annual production capacity of 600 MT and a focus on micro-encapsulated formats with dual KOSHER and HALAL credentials. These Chinese manufacturers have become integral to global supply chains, particularly for buyers seeking cost-competitive, certification-backed volumes at scale.
European and Southeast Asian players add further depth to the competitive matrix. FrieslandCampina Professional, operating under its Kievit brand, produces high-fat powder variants including coconut-based formulations reaching up to 80 percent fat content, positioned for bakery, dessert, and beverage applications through its Vana-Grasa and Vana-Crema product lines. Malaysia's Eramas Group employs spray-dry processing to deliver high-fat-load coconut powders up to 80 percent for soups, sauces, snacks, and bakery channels, leveraging regional proximity to raw material origin. Taiwan's Ming Chyi Biotechnology Ltd. (MCB Group) has built a global reputation in micro-encapsulated nutritional fat and oil powders, offering coconut variants that address stability and bioavailability requirements in food and nutrition solutions.
Additional players round out the supply ecosystem with specialized value propositions. The Coconut Company, based in the United Kingdom, supplies bulk coconut oil powder at 70 percent fat with acacia fibre, targeting food manufacturers seeking European-sourced reliability. Australia's A S Harrison & Co Pty Limited serves as a distributor and provider of encapsulated coconut oil fat powders across a 30 to 70 percent fat range, including MCT variants, serving food, pharmaceutical, and cosmetic applications. These companies, among others profiled in the report, illustrate the diversity of business models, geographic footprints, and technical specializations that define the current competitive environment. Understanding how these players interact—through capacity allocation, pricing behavior, certification strategies, and regional partnerships—is critical for any firm seeking to defend or expand its market position.
Raw Material Dynamics and the 2025-2026 Supply Equation
No strategic assessment of the Coconut Oil Fat Powder market would be complete without addressing the upstream commodity dynamics that directly influence cost structures, margin sustainability, and procurement planning. The period from 2025 through early 2026 has been marked by notable volatility in global coconut oil pricing, with implications that ripple through every tier of the fat powder value chain.
Global coconut oil prices experienced a sharp escalation in 2025, climbing from approximately USD 1,978 per metric tonne in January to a peak of USD 2,841 by July, before moderating to around USD 2,323 by December. This trajectory was driven by a combination of weather-related supply disruptions, limited production growth, and inventory tightening across key origin countries. Earlier in the same year, between January and April, coconut oil prices jumped 31 percent to USD 2,587 per metric tonne, underscoring the speed at which supply-side shocks can translate into cost pressures for downstream processors and formulators.
Looking into 2026, projections from Food Additives Asia indicate that global crude coconut oil production is expected to stabilize at approximately 3.5 million metric tonnes, with prices hovering in the range of USD 2,050 to USD 2,300 per metric tonne. This stabilization offers a degree of predictability that manufacturers can use to lock in forward contracts and structure production planning. However, the memory of the 2025 volatility serves as a cautionary reminder that weather patterns, geopolitical factors, and trade flow disruptions can rapidly alter the cost baseline.
The supply picture is further complicated by regional production dynamics. Philippine coconut oil exports, a key reference point for global trade flows, declined by 25.75 percent in volume between January and August 2025 due to El Niño-induced drought conditions. Paradoxically, export value rose by 42.35 percent over the same period, driven by the higher unit prices that accompanied the volume contraction. This decoupling of volume and value metrics illustrates the complex risk-reward calculus that procurement teams must navigate: lower physical availability does not necessarily translate to proportionally lower cost exposure when price escalation is substantial.
These raw material dynamics directly affect the economics of Coconut Oil Fat Powder production. Fat powders are typically manufactured through spray-drying or micro-encapsulation processes that incorporate carrier agents such as acacia fibre, maltodextrin, or starch to stabilize the oil fraction and ensure flowability. When base oil costs surge, manufacturers face a dual pressure: rising input costs compress margins unless offset by price pass-through mechanisms or specification adjustments, while end customers may push back on price increases depending on contract structures and alternative ingredient availability. Our report provides frameworks for assessing these cost pass-through dynamics, evaluating the elasticity of demand across different application segments, and modeling procurement strategies that balance price exposure with supply security.
Regulatory Tailwinds and Sustainability Narratives
Beyond commodity volatility, the Coconut Oil Fat Powder market operates within an evolving regulatory and sustainability landscape that creates both opportunities and compliance obligations for market participants. In 2026, one particularly significant development is the explicit exclusion of coconut oil from the European Union's Deforestation Regulation (EUDR). This regulatory carve-out positions coconut oil as a sustainable alternative to palm oil within European markets, where deforestation-linked sourcing concerns have driven stringent compliance requirements and consumer scrutiny.
For manufacturers and brand owners targeting European distribution channels, this regulatory distinction carries strategic weight. It reduces the compliance burden associated with traceability documentation and deforestation-risk assessments, while simultaneously strengthening the sustainability narrative that can be leveraged in marketing and procurement communications. Formulators seeking to reformulate away from palm-derived fats may find coconut oil fat powders to be an attractive technical and regulatory-friendly substitute, particularly in applications where texture, flavor profile, and clean-label positioning intersect.
This regulatory context interacts with broader certification trends that define market access and premium positioning. HALAL, Kosher, FSSC22000, ISO 9001, and organic certifications are not merely compliance badges; they function as market-entry credentials that determine which supply chains can serve specific customer segments, dietary preferences, and geographic markets. Our research maps the certification portfolios of key suppliers and analyzes how certification differentiation influences pricing power, customer acquisition, and competitive moats. Understanding which certifications command the highest market returns, and where certification gaps create vulnerability, is essential for companies evaluating supplier partnerships or preparing their own product lines for international expansion.
What the Report Delivers: Actionable Intelligence for Strategic Teams
The Worldwide Coconut Oil Fat Powder Market research is structured to move beyond descriptive market narratives and deliver operational intelligence that can be integrated directly into corporate planning processes. The report encompasses a wide array of analytical components designed to support decision-making across multiple functional areas.
At the core of the study is a detailed market sizing and forecasting framework that quantifies historical performance and projects future trajectories across the key segmentation dimensions. These forecasts are constructed using rigorous methodology that accounts for supply-side constraints, demand-side consumption patterns, pricing dynamics, and macroeconomic indicators that influence ingredient purchasing behavior.
Competitive profiling is another essential pillar of the research. Each key company is analyzed across dimensions including manufacturing capacity, product specifications, certification footprints, geographic reach, and strategic positioning. This competitor intelligence enables clients to benchmark their own capabilities, identify potential partnership or acquisition targets, assess supplier risk concentrations, and anticipate competitive responses to market developments.
The report also provides deep-dive analysis of the raw material supply environment, including production trends, price trajectory modeling, weather-related risk factors, and trade flow dynamics. This upstream intelligence is critical for procurement teams that need to structure hedging strategies, negotiate long-term supply agreements, or reconsider their sourcing mix in response to evolving cost and availability conditions.
Application-specific insights are offered to help R&D and product development teams understand how formulation requirements, regulatory expectations, and consumer preference trends differ across Food and Beverage, Dietary Supplements, and Cosmetics and Personal Care channels. These insights inform ingredient selection, specification targeting, and market-entry prioritization decisions.
Finally, the research incorporates strategic scenario analysis that helps leadership teams stress-test their plans against potential shifts in raw material pricing, regulatory evolution, competitive entry or exit, and regional demand acceleration or deceleration. This forward-looking dimension ensures that clients are not merely reacting to current conditions but are prepared to navigate a range of plausible futures with confidence and agility.
Conclusion: Positioning for the 2026 Decision Cycle
The Worldwide Coconut Oil Fat Powder Market is entering a phase where growth potential is matched by complexity. Raw material volatility, regulatory differentiation, certification-driven market access, and a competitively layered supplier landscape all demand that corporate strategy teams move beyond surface-level intelligence to access the kind of granular, forward-looking analysis that enables decisive action. Our research report is built to meet that demand.
By combining rigorous market sizing, segmentation intelligence, competitive profiling, raw material dynamics, and regulatory context into a single integrated framework, the study equips procurement leaders, R&D directors, pricing strategists, and executive teams with the insights needed to allocate resources efficiently, mitigate supply risk, capture premium positioning opportunities, and anticipate competitive shifts before they materialize.
For organizations seeking to deepen their understanding of the Coconut Oil Fat Powder market and translate that understanding into 2026 strategic advantage, the full report provides the comprehensive, actionable intelligence required to make informed, confident decisions. We invite you to access the complete research to explore the detailed segmentation data, competitive assessments, and strategic frameworks that will guide your planning through the forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Coconut Oil Fat Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Shows Worldwide Surgical Saw Blades Market Valued at $485.5 Million in 2025 Projected to Reach $703.91 Million by 2032 with 5.45% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for 2026: Unpacking the Global Surgical Saw Blades Market
The global surgical landscape is undergoing a profound transformation, driven by an aging population, the rise of robotic-assisted procedures, and an uncompromising focus on infection control. For executive leadership teams, procurement officers, and strategic planners, understanding the nuances of the surgical saw blades market is no longer optional—it is a critical component of operational readiness and competitive positioning. As we move through 2026, the intersection of material science, regulatory frameworks, and clinical efficiency is reshaping how medical facilities acquire and utilize these essential instruments.
Worldwide Surgical Saw Blades Market
PW Consulting is pleased to introduce our latest comprehensive market research report, Worldwide Surgical Saw Blades Market. This document serves as a definitive guide for stakeholders navigating the complexities of this vital medical device sector. The following analysis outlines the strategic value of this research, highlighting key macroeconomic trends, competitive dynamics, and operational shifts that will define the industry trajectory through 2032.
Worldwide Surgical Saw Blades Market
Market Trajectory and Macroeconomic Foundations
The financial footprint of the surgical saw blades sector demonstrates resilient growth, underpinned by steady surgical volumes and technological adoption. Historical data from 2020 through 2025 indicates a consistent upward trend in market revenue, recovering robustly from global disruptions and accelerating into the current fiscal year. Looking ahead, the market is projected to expand from an estimated 508.41 million USD in 2026 to approximately 703.91 million USD by 2032. This growth path reflects a compound annual growth rate of 5.45 percent over the forecast period.
Worldwide Surgical Saw Blades Market
Such macroeconomic stability offers a fertile ground for investment, yet it also invites intense competition. Decision-makers must recognize that this growth is not uniform; it is distributed across varying product types, usage models, and clinical applications. Our report deconstructs these layers without oversimplifying the reality on the ground. We examine how hospitals are balancing budget constraints with the need for high-performance tools, and how manufacturers are responding to the demand for precision and safety.

Product Diversity and Clinical Integration
The market is segmented by product type, usage model, and application, each carrying distinct implications for supply chain management and clinical outcomes. Oscillating blades currently hold a significant share of the market value, driven by their widespread utility in general bone cutting procedures. Sagittal and reciprocating blades serve specialized niches, often associated with specific orthopedic and spinal interventions. Understanding the volume and value distribution across these categories is essential for vendors forecasting demand and for hospitals optimizing their instrument trays.
The usage model debate between single-use and reusable blades remains a pivotal strategic decision point. Single-use blades are increasingly preferred in many healthcare settings to mitigate cross-contamination risks and reduce sterilization overhead. Reusable blades continue to serve high-volume centers that prioritize long-term cost efficiency and possess robust sterilization infrastructure. Our analysis provides a granular view of adoption rates and cost-benefit profiles for each model, helping stakeholders align their procurement strategies with clinical priorities and infection control mandates.
Application-wise, orthopedic surgery dominates the consumption landscape, reflecting the high frequency of joint reconstructions, trauma repairs, and sports medicine procedures. Cardiothoracic surgery, neurology and ENT, and other applications represent important secondary segments where specialized blade requirements and precision demands command premium positioning. The report details how these application segments interact with reimbursement frameworks and surgical volume trends.
Regulatory and Reimbursement Landscapes
Compliance and payment structures are critical filters through which market strategies must be designed. Surgical saw blades are subject to rigorous international standards, including ISO 8828 for powered surgical instruments and ISO 16061 for sterile single-use devices. Manufacturers must ensure that product development and quality management systems are continuously aligned with these evolving requirements to maintain market access. Regulatory scrutiny is intensifying, and non-compliance can result in significant delays and reputational damage.
In the United States, the reimbursement environment adds another layer of complexity. Surgical saw blades are generally encompassed within MS-DRG codes 515-517 for musculoskeletal procedures, which operate under bundled payment models. This means that the cost of blades is often integrated into broader episode-of-care payments, influencing how hospitals evaluate value versus price. Strategic buyers are increasingly looking for solutions that demonstrate clinical efficacy and cost efficiency within these bundled frameworks. Our report explores how reimbursement policies are shaping procurement behaviors and product innovation across major markets.
Material Science, Sourcing, and Operational Resilience
The physical and economic foundations of surgical saw blades are heavily influenced by material science and supply chain dynamics. Medical-grade stainless steel 440C and carbide tips dominate the industry, valued for their durability and cutting performance. However, recent sector analysis indicates that costs for these materials have risen by 8-12 percent due to supply chain pressures on cobalt and tungsten. These inflationary trends are compressing margins and forcing manufacturers to reconsider sourcing strategies and pricing models.
Furthermore, sterilization protocols for reusable blades are strictly regulated, requiring steam autoclaving at 132-134°C for 3-4 minutes, validated per AAMI ST79 standards. Compliance with these sterilization requirements is not merely a technical detail; it is a critical operational parameter that affects turnaround times, asset utilization, and overall cost of ownership. Single-use options circumvent these sterilization demands but introduce different logistics and waste management considerations. Our research evaluates these operational trade-offs to assist facilities in making informed decisions that balance safety, efficiency, and sustainability.
Competitive Landscape and Strategic Maneuvers
The market exhibits a concentrated competitive structure, with the top three companies accounting for approximately 58 percent of the market share and the top five representing over 74 percent. This concentration underscores the dominance of established medical device giants with deep integration into hospital procurement systems and clinical workflows. Leading players include Stryker Corporation, DePuy Synthes, Zimmer Biomet, B. Braun, Medtronic, Smith & Nephew, Integra LifeSciences, and BD. Each competitor brings a distinct portfolio and strategic focus, from sagittal and oscillating systems to high-torque powered solutions and specialized neurosurgical blades.
Recent developments highlight the agility and innovation focus of these key players. Stryker has expanded its precision offerings with next-generation sagittal saw blades for total knee arthroplasty. Medtronic has secured regulatory clearances for expanded indications in neurosurgery via its Midas Rex systems. Zimmer Biomet has integrated disposable oscillating blades into its ROSA robotics portfolio, signaling the convergence of saw technology with robotic assistance. DePuy Synthes has bolstered its distribution reach through multi-year supply agreements with healthcare group purchasing organizations. These moves illustrate how incumbents are defending their positions through product differentiation, regulatory wins, and strategic partnerships.
For emerging entrants or companies seeking to gain share, the path is challenging but not impossible. Success often requires targeting underserved niches, offering superior single-use options, or leveraging cost advantages in specific applications. Understanding the competitive intensity, patent landscapes, and channel dynamics is vital for any market entry or expansion strategy.
Strategic Imperatives for 2026 and Beyond
As organizations plan for the remainder of the decade, several strategic imperatives emerge from the data and trends outlined in our report. First, product portfolio optimization is essential. Companies must decide where to invest in high-growth applications and usage models while rationalizing legacy offerings. Second, supply chain resilience must be prioritized, given the volatility in raw material costs and the critical nature of sterile device availability. Third, clinical value proposition must be sharpened, demonstrating how specific blade types improve surgical outcomes, reduce operative time, or lower total cost of care within bundled payment environments.
Procurement leaders in healthcare facilities should use this intelligence to negotiate better terms, evaluate vendor stability, and assess product mix alignment with their clinical volume and infection control policies. Investors and analysts can leverage the concentration metrics and growth forecasts to assess market attractiveness and competitive risks. Manufacturers can use the segmentation and application data to identify white spaces and refine go-to-market strategies.
About the Worldwide Surgical Saw Blades Market Report
The Worldwide Surgical Saw Blades Market report is designed as a practical, data-rich resource for informed decision-making. It provides a comprehensive analysis of market size, segmentation, competitive dynamics, and industry context, spanning historical data from 2020 to 2025 and a detailed forecast through 2032. The report includes actionable insights on product types, usage models, applications, and regional distributions, alongside a deep dive into regulatory standards, reimbursement frameworks, raw material trends, and sterilization requirements.
Readers will find detailed company profiles, recent product launches, regulatory clearances, distribution deals, and strategic initiatives that illuminate the competitive landscape. FAQs and industry context notes offer quick reference points on compliance, infection control preferences, and operational standards. This report is an indispensable tool for executives, strategy teams, procurement professionals, and market analysts who require a rigorous, up-to-date understanding of this critical medical device sector.
To access the full dataset, detailed segmentation breakdowns, and complete competitive intelligence, we invite you to explore the source webpage. The complete report offers the granular data and proprietary analysis needed to turn market insight into strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting 2025 Global Ball Clays Market Report Forecasts 4.35% CAGR to $849.03 Million by 2032 as Asia Pacific Leads with $295.02M Regional Share
By PW Consulting, 2026-09-02
Strategic Intelligence in a Maturing Commodity Landscape: Introducing the Worldwide Ball Clays Market Research 2026
The global industrial minerals sector stands at a critical inflection point. For stakeholders involved in the extraction, processing, and application of ball clays, the period spanning 2026 through 2032 promises to be defined less by explosive volume growth and more by strategic consolidation, regulatory adaptation, and value optimization. As supply chains recalibrate following recent geopolitical and economic shifts, the need for precise, forward-looking intelligence has never been more acute. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Ball Clays Market, designed to equip senior leadership with the analytical rigor required to navigate this complex landscape.
Worldwide Ball Clays Market
This report is not merely a collection of historical data points. It is a strategic roadmap built on a foundation of granular primary research and rigorous secondary validation. Our objective is to illuminate the structural forces shaping the market, allowing decision-makers to distinguish between transient market noise and durable secular trends. By focusing on the interplay between supply constraints, demand-side evolution in key ceramic sectors, and the competitive maneuvers of established players, this study provides the context necessary to formulate robust corporate strategies for the remainder of the decade.
Worldwide Ball Clays Market
Market Trajectory and Structural Shifts
Understanding the trajectory of the ball clays market requires looking beyond simple headline figures. Our analysis tracks the market revenue evolution from 2020 through the forecast horizon ending in 2032. The data reveals a narrative of consolidation and steady expansion. After reaching an estimated global revenue baseline of 630.2 million USD in 2025, the market is projected to advance toward a valuation of 849.03 million USD by 2032. This growth path corresponds to a Compound Annual Growth Rate (CAGR) of 4.35 percent over the forecast period.
Worldwide Ball Clays Market
Such growth, while steady, is not linear. The historical data from 2020 to 2025 shows fluctuations that reflect the sensitivity of the sector to broader construction and manufacturing cycles. The forecast period suggests a recovery and expansion phase, driven by sustained demand in core application areas. However, the rate of growth implies that market share gains will likely come through strategic positioning rather than riding a broad tidal wave of demand. Companies must therefore look closely at where value is being created.
Our segmentation analysis dissects this revenue pool across three critical dimensions: Region, Type, and Application. While specific percentage splits are reserved for the full deliverable to maintain competitive integrity, the hierarchy of value is evident. Regionally, the market is distributed across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, with distinct regional dynamics influencing pricing power and supply security. In terms of product type, the market encompasses shredded, nooled, and air-floated ball clays, each catering to specific processing requirements within the ceramics industry. On the demand side, the application landscape is anchored by ceramic tiles, sanitaryware, tableware, refractories, and other industrial uses. The relative weight of these segments dictates where investment in capacity or technology yields the highest return.
Furthermore, global production volumes provide a counterpoint to revenue data. Sector analysis indicates that global ball clay production was estimated at approximately 5.2 million metric tons in 2024, with significant volume flowing into sanitaryware and floor tiles. This volume context is crucial for understanding supply tightness. When production volumes are considered alongside revenue forecasts, the implication is clear: price realization and premiumization of product grades will be key drivers of the projected revenue growth, compensating for potential volume constraints in certain mature basins.
Competitive Dynamics and Corporate Strategy
The ball clays market is characterized by a moderate level of concentration, where scale and access to high-quality deposits confer significant advantages. Our analysis of market concentration indicates that the top three players hold approximately 38.4 percent of the revenue share, while the top five control around 54.6 percent. This structure suggests that while there is room for niche players, the market leaders possess substantial influence over pricing standards and supply availability. Understanding the strategies of these key entities is essential for any new entrant or existing player seeking to defend their position.
The competitive landscape is populated by a mix of global industrial minerals giants and specialized regional producers. Imerys, headquartered in Paris, France, stands as a global leader with extensive mining and processing operations spanning the UK, France, Thailand, and the United States. Their portfolio focuses on high-plasticity ball clays tailored for sanitaryware and ceramics. Similarly, Sibelco, based in Antwerp, Belgium, operates premium deposits in Devon, UK, offering refined products like SANBLEND for global ceramics markets.
In North America, the competitive field is dense with specialized producers. Covia Holdings LLC supplies branded grades such as PREMIERE and VANTAGE, mined in Texas and Indiana, catering to ceramic pressing and extrusion needs. Other significant US-based entities include Old Hickory Clay Company in Kentucky, Gleason Clay Company in Tennessee, Thiele Kaolin Company, and KaMin LLC. These companies form the backbone of the domestic supply chain, often navigating specific regional regulatory environments and logistics networks.
The Asian market presents a different competitive dynamic, with players like Ashapura Minechem Ltd. and Gujarat Mineral Development Corporation Ltd. (GMDC) in India supplying fine-grained, highly plastic clays primarily for whiteware and sanitaryware. GMDC operates mines at Rajpardi and Bharuch, positioning itself as a key supplier for the region's robust ceramics manufacturing base. Additionally, 20 Microns serves as another Indian supplier of premium ball clay for the ceramics industry. In Europe, Stephan Schmidt KG in Germany and G&W Mineral Resources in South Africa add further layers to the global supply network, ensuring diverse sourcing options for downstream manufacturers.
Recent corporate activities highlight the volatility and strategic realignment occurring within this group of key companies. In July 2025, Imerys executed a divestiture of its Artemyn mining division, which included certain ball clay and kaolin assets across the Americas, Europe, and Asia. Such moves signal a potential strategic refocusing on core assets or a response to margin pressures in specific geographies. Conversely, Stephan Schmidt Group demonstrated expansionary intent in April 2025 by acquiring Saarfeldspatwerke GmbH & Co., broadening its portfolio in industrial minerals. These contrasting moves—divestiture versus acquisition—illustrate the fragmented strategic approach currently prevalent in the sector.
Pricing dynamics also remain a critical focal point for competition. In March 2025, Thiele Kaolin Company announced a price increase effective March 1, citing input cost pressures for clay products including ball clay grades. This action reflects the broader industry challenge of managing cost inflation while maintaining customer relationships. Our report details how these pricing shifts propagate through the supply chain and impact the competitive positioning of firms that choose to absorb costs versus those that pass them on.
Operational Realities and Regulatory Headwinds
Strategic planning in the ball clays sector cannot be undertaken in a vacuum. It must account for the physical and regulatory realities of extraction and processing. Ball clay is a sedimentary clay primarily composed of kaolinite, typically ranging from 20 to 80 percent, along with mica and quartz. This composition contributes to its high plasticity and binding properties, which are indispensable for ceramics. However, accessing these resources involves significant operational complexity.
The mining and processing of ball clay face increasingly stringent global environmental regulations. This is particularly true for open-pit operations, which can impact land degradation, water pollution, and local habitats. Compliance now requires substantial investments in pollution control and land reclamation. These regulatory costs act as a barrier to entry for new projects and can compress margins for existing operators if not managed efficiently. Our market dynamics section delves into how these regulatory frameworks vary by region, affecting the comparative advantage of mining jurisdictions in North America versus Asia or Europe.
In the United States, specific tax provisions also influence the economic viability of production. USGS data indicates that the depletion allowance for ball clay is 14 percent for domestic and foreign sources under US tax provisions for clay used in manufacturing. This fiscal detail, while technical, forms part of the broader cost structure that influences long-term investment decisions in US-based operations.
Furthermore, supply chain security is becoming a priority. USGS Mineral Commodity Summaries from 2024 highlight that US ball clay production forms part of the broader clays category, with leading companies including Covia Holdings LLC, Gleason Clay Co., Imerys, and Old Hickory Clay Co. The concentration of production among these entities underscores the importance of supply chain resilience. For downstream ceramic manufacturers, understanding the stability of these suppliers is as critical as understanding the end-market demand. Any disruption in these key production hubs can ripple through the global supply chain, affecting lead times and pricing for ceramic tiles and sanitaryware manufacturers.
Scope of Analysis and Strategic Utility
The Worldwide Ball Clays Market report is structured to serve as a decision-support tool for multiple functions within an organization. Whether you are in strategic planning, procurement, investment analysis, or competitive intelligence, the depth of data provided is tailored to support high-stakes decisions.
The report provides a comprehensive overview of the market status and trend forecast for the period 2026 to 2032. It includes detailed historical data from 2020 to 2025, allowing for trend analysis and baseline validation. The base year for the study is 2025, ensuring that the forecast methodology is grounded in the most recent available economic reality.
Key components of the research include:
- Market Size and Growth Forecasting: Detailed revenue projections across the forecast period, enabling budgeting and revenue modeling.
- Segmentation Analysis: Deep dives into regional, type, and application segments to identify high-growth pockets and saturated niches.
- Competitive Landscape: Profiles of key companies, including their headquarters, operational focus, and recent strategic developments such as mergers, acquisitions, or divestitures.
- Industry Context and Dynamics: Analysis of regulatory impacts, raw material characteristics, and production trends that influence market stability.
- Recent Developments Tracking: Timely updates on price adjustments, corporate restructuring, and portfolio expansions that signal shifting market sentiments.
By integrating these elements, the report allows stakeholders to benchmark their performance against market averages and key competitors. For investors, the concentration ratios and growth forecasts provide a basis for valuing assets or assessing potential acquisition targets. For manufacturers, the segmentation data helps in aligning product development with the most promising end-use sectors, such as the robust demand in sanitaryware versus the specific requirements of tableware.
The inclusion of specific recent developments, such as the pricing actions taken in early 2025 and the asset reallocation seen in mid-2025, ensures that the intelligence is current. In a market where margins can be squeezed by input cost pressures, knowing who raised prices and why is vital intelligence for procurement negotiations and pricing strategy formulation.
Conclusion: Navigating the Next Phase of Growth
As the worldwide ball clays market moves toward a projected valuation of over 849 million USD by 2032, the path forward will be defined by the ability to adapt to regulatory constraints, manage cost pressures, and capitalize on specific regional demand drivers. The steady CAGR of 4.35 percent suggests a healthy market, but one that rewards precision over brute force expansion.
The divergence in corporate strategies observed among key players like Imerys and Stephan Schmidt indicates that there is no single playbook for success. Some are shedding non-core assets to streamline operations, while others are acquiring to broaden their mineral portfolios. Simultaneously, pricing adjustments by producers like Thiele Kaolin highlight the ongoing tension between cost recovery and market share retention.
Access to granular data on regional splits, specific application growth rates, and detailed company profiles is essential to decode these signals fully. While this overview establishes the macro environment and the key actors, the full intelligence required to execute specific strategic moves resides within the complete report. Stakeholders who equip themselves with this level of detail will be best positioned to mitigate risks associated with regulatory compliance and supply volatility while capturing the value available in the evolving ceramics and industrial minerals landscape.
PW Consulting invites industry leaders, investors, and policymakers to engage with this research to secure a comprehensive understanding of the forces shaping the ball clays market. The data is ready; the strategic imperative is clear.
For detailed analysis of this topic, please visit the official page: Worldwide Ball Clays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report Projects Worldwide Cathodic Acrylic Market to Reach 926.89 Million USD by 2032 Growing at 5.2 Percent CAGR
By PW Consulting, 2026-09-02
Strategic Imperatives in the Worldwide Cathodic Acrylic Market: Navigating Growth From 2026 to 2032
The global coatings industry stands at a critical inflection point, where performance requirements, regulatory pressures, and supply chain recalibrations are reshaping the competitive landscape for cathodic acrylic electrodeposition systems. As automotive manufacturers accelerate lightweighting initiatives, as industrial metal finishers demand higher corrosion resistance with lower environmental footprints, and as raw material cost structures continue to oscillate across key chemical building blocks, the ability to make forward-looking investment and procurement decisions depends on access to rigorously modeled, strategically framed intelligence. PW Consulting’s latest Worldwide Cathodic Acrylic Market research study has been designed precisely for this moment: a data-rich, decision-oriented intelligence platform that equips executives, procurement leaders, R&D directors, and market strategy teams with the analytical scaffolding they need to act confidently throughout the 2026-2032 forecast horizon.
Worldwide Cathodic Acrylic Market
This introduction outlines the strategic architecture of the study, demonstrates how macro-level growth trajectories and structural dynamics have been integrated into a cohesive analytical narrative, and previews the actionable frameworks contained within the full report. The objective is not to enumerate every figure, but to establish why this research serves as a critical decision-support asset for organizations operating in, supplying to, or competing within the cathodic acrylic value chain.
Worldwide Cathodic Acrylic Market
Macro Growth Trajectory: What the Numbers Signal for 2026 Decision-Making
Over the historical review period from 2020 through 2025, the worldwide cathodic acrylic market demonstrated resilient expansion, recovering from early-cycle disruptions and then compounding at a pace that reflects both structural demand and incremental technology adoption. The market’s revenue trajectory climbed from approximately 505.35 million USD in 2020 to 650.0 million USD by the 2025 base year, establishing a firm foundation for the forward-looking forecast window. Moving into the projected period, the analysis models sustained growth that carries the market from an estimated 692.91 million USD in 2026 through to 926.89 million USD by 2032.
Worldwide Cathodic Acrylic Market
These figures are not isolated snapshots. They represent the output of a demand-driven modeling methodology that triangulates downstream application requirements, substrate transition trends, coating formulation evolution, and regional production capacity dynamics. A compound annual growth rate of 5.2 percent anchors the forecast pathway, signaling a market that is expanding at a measured but consistent clip—one that rewards disciplined capacity planning, targeted formulation innovation, and strategic customer alignment rather than speculative volume plays.
For enterprise decision-makers, this trajectory carries several implications. First, it confirms that cathodic acrylic systems remain a foundational primer technology across multiple metal-finishing workflows, with demand dispersed across automotive, industrial, and appliance segments rather than overly concentrated in a single vertical. Second, the moderate growth rate suggests that margin capture will increasingly depend on formulation differentiation, service responsiveness, and regulatory compliance capability rather than sheer scale alone. Third, the forecast window spans enough years to require multi-cycle capital and inventory planning, meaning that organizations need scenario-aware inputs rather than static point estimates.
The full report unpacks how these trajectory assumptions were constructed, what sensitivity variables were stress-tested, and which demand drivers carry the greatest weight in shaping the 2026-2032 pathway. It also maps how historical recovery patterns from 2020-2025 inform confidence intervals around the forward projections, giving leadership teams a more nuanced basis for budgeting, capacity allocation, and customer forecasting.
Structural Dynamics Shaping the Cathodic Acrylic Landscape
Behind the headline revenue curve lies a set of operational and regulatory forces that actively redistribute value across the supply chain. The cathodic acrylic market is not simply expanding; it is evolving in character, and that evolution has direct consequences for sourcing strategy, formulation roadmaps, and market-entry timing.
Regulatory frameworks continue to exert downward pressure on volatile organic compound content across industrial and automotive coating applications. Directives that mandate lower VOC thresholds for industrial coatings have accelerated the transition toward low-emission cathodic electrodeposition formulations, reinforcing the strategic relevance of acrylic-based resin architectures that can deliver corrosion protection while remaining compliant with tightened environmental standards. At the same time, chemical registration and restriction programs in major markets have placed ongoing scrutiny on certain acrylic monomers and sensitizer-related substances, compelling formulators and resin suppliers to reconfigure raw material portfolios and validate alternative pathways without sacrificing performance.
Raw material cost behavior has added another layer of complexity. Acrylic acid and butyl acrylate, two foundational inputs for acrylic resin production, have experienced periods of pronounced price volatility during the recent recovery cycle. Contract price movements in European markets and spot price dynamics in Asian trading hubs have underscored how tightly coating economics are coupled to petrochemical feedstock conditions and regional supply-demand balances. For procurement teams and formulation engineers, this means that resin cost structures are not static; they fluctuate with logistics recovery, plant utilization rates, and regional availability, which in turn affects margin planning and pricing negotiation leverage.
Trade policy adds a further dimension. Tariffs on certain acrylic resin imports into the United States have influenced sourcing patterns and cost structures for downstream finishers and OEMs that rely on cross-border material flows. These duties do not uniformly affect all market participants, but they do create asymmetric cost environments that reward regional supply chain design, localized formulation capability, and strategic inventory positioning.
The study devotes substantial attention to these dynamics because they are not background noise; they are decision variables. Organizations that understand how regulatory change, feedstock pricing, and trade exposure interact with cathodic acrylic demand can better anticipate formulation shifts, renegotiate supply agreements from a position of insight, and align product development with the compliance and cost parameters that customers will increasingly require.
Competitive Landscape: Differentiated Positions Among Leading Players
The cathodic acrylic market has reached a moderate level of concentration, with the top three participants accounting for a meaningful share of total revenue and the top five collectively representing a majority of the market. This structure reflects the technical barriers inherent in formulating high-performance cathodic electrodeposition primers: resin architecture, crosslinking chemistry, bath stability, application robustness, and corrosion performance all matter, and incumbents have built advantage through long-standing automotive validation, global supply networks, and continuous formulation refinement.
Among the companies analyzed in depth within the report, several positions stand out for their strategic relevance. Axalta Coating Systems maintains a global footprint in cathodic electrodeposition primers, with acrylic-based AquaEC systems positioned around automotive corrosion protection. Its profile illustrates how established coating suppliers leverage integrated product platforms and OEM relationships to sustain market presence across multiple regions. PPG Industries produces cathodic acrylic electrocoats such as its Powercron range, specifically deployed as primers in automotive OEM and industrial metal finishing contexts; this illustrates the dual-use nature of many cathodic acrylic formulations and the importance of application-specific validation.
BASF SE offers CathoGuard cathodic electrodeposition coatings built on acrylic resin technology for high-performance corrosion resistance, reinforcing the role of large chemical and coatings integrators in providing performance-differentiated primer solutions. Allnex contributes from a specialty chemistry angle, supplying resins and crosslinkers used to formulate cathodic acrylic electrodeposition coatings, which highlights the upstream-but-critical layer of the value chain where formulation enablers shape what downstream finishers can achieve. Kansai Paint Co., Ltd. and Nippon Paint Holdings Co., Ltd. extend the competitive field through global supply of cathodic acrylic ED coatings for automotive and industrial applications, including primer-layer solutions such as NP Catolyte, demonstrating how established paint manufacturers continue to scale internationally and compete on both technical capability and regional service coverage.
These companies are not simply competitors; they represent different access points into the same market. Some compete primarily at the formulated coating level, others at the resin and crosslinker layer, and others through regional distribution and service infrastructure. Understanding these positions matters because it clarifies where value is captured, where entry barriers are highest, and which types of partnership or procurement strategies will be most effective for a given organization’s role in the chain.
The full report goes beyond descriptive profiles. It examines how these players are positioned relative to demand segments, what kinds of formulation or supply chain moves would alter their competitive standing, and where consolidation pressure or white-space opportunity is most likely to emerge over the forecast period. For executives evaluating supplier strategy, partnership options, or potential market entry, this competitive mapping provides the context needed to interpret market signals accurately rather than react to them generically.
What the Study Delivers: Operational Content Built for Action
A market study earns its place in executive planning only when it translates analysis into usable structure. The Worldwide Cathodic Acrylic Market research was built with that standard in mind. Rather than stopping at high-level revenue estimates, the report delivers a layered set of analytical components designed to support multiple decision workflows.
The study provides a comprehensive historical reconstruction and forward forecast that ties base-year positioning to the 2026-2032 pathway, allowing readers to trace how past recovery patterns and current demand signals inform future projections. It frames the market through multiple analytical lenses so that users can evaluate growth from the standpoint most relevant to their role: resin and crosslinker suppliers can focus on formulation enablers and input cost exposure; coating manufacturers can concentrate on application validation and customer segmentation; OEMs and finishers can prioritize supply stability, compliance readiness, and performance trade-offs.
Detailed segmentation analysis is included to illuminate where demand is concentrated and how different structural categories shape revenue distribution. This includes breakdowns by region, by resin type, and by application, presented in a way that reveals relative scale and strategic emphasis without reducing complex market behavior to oversimplified percentages. The intent is to help users understand which segments anchor the market, where growth momentum is strongest, and how allocation decisions should be calibrated to reflect real demand geography and end-use priorities.
Competitive intelligence is structured to support benchmarking and positioning analysis. Company-level assessments connect product portfolios, geographic reach, and technology emphasis to market share realities and strategic posture. This allows readers to interpret who is leading in which contexts, what capabilities are being emphasized, and how the concentration structure may evolve as demand patterns shift or as new formulation approaches gain traction.
The report also embeds market dynamics analysis that connects regulatory mandates, raw material cost behavior, and trade policy to practical operating consequences. By integrating these factors into the analytical framework rather than treating them as separate side notes, the study enables users to evaluate how compliance requirements, feedstock volatility, and tariff exposure influence cost structures, formulation choices, and regional competitiveness.
In addition, the research provides scenario-aware framing that helps organizations test assumptions. Forecast pathways are not presented as fixed certainties; they are constructed with an explicit appreciation of variables that can accelerate, moderate, or redirect growth. That design choice matters for planning teams that need to align capital deployment, inventory strategy, and supplier commitments with a range of plausible outcomes rather than a single deterministic line.
Throughout, the emphasis remains on operational usability. The content is organized so that strategy, procurement, R&D, and commercial teams can locate the inputs most relevant to their responsibilities and use them as part of a broader planning process. The objective is to reduce the gap between reading the analysis and acting on it.
Why This Research Matters for 2026 Enterprise Decisions
The 2026 decision environment will be shaped by the interaction of steady market expansion, evolving compliance expectations, and continued sensitivity in raw material and trade conditions. In that setting, organizations that rely on generic industry narratives or outdated snapshots risk misjudging both opportunity and exposure. A dedicated, methodologically transparent study offers a more reliable foundation for action.
For capacity and investment planning, the forecast trajectory and segmentation structure help leadership assess where demand is likely to accumulate and whether existing production or supply capabilities are aligned with that distribution. For procurement and supply chain strategy, the integration of raw material pricing behavior, regulatory constraints, and trade exposure provides context for renegotiating terms, evaluating sourcing alternatives, and building resilience against input volatility. For product development and formulation teams, the analysis of resin types, application contexts, and competitor positioning clarifies which performance and compliance targets are gaining priority and where differentiation can be most effectively pursued.
For commercial and market-entry strategy, the combination of regional demand emphasis, application-level focus, and competitive concentration analysis helps organizations identify where customer priorities are strongest, which supplier relationships matter most, and how to position offerings in a market where incumbents have meaningful technical and validation-based advantages.
Ultimately, the value of the study lies in its ability to connect macro growth signals to operational decision variables. The worldwide cathodic acrylic market is expanding at a pace that rewards informed planning, and the forces shaping that expansion are specific enough to require detailed analysis rather than broad generalization. Organizations that equip themselves with structured, forward-looking intelligence will be better prepared to allocate resources, manage risk, and capture share in a market where technical and regulatory sophistication increasingly separate leaders from followers.
Accessing the Full Intelligence
This introduction has outlined the strategic rationale, structural dynamics, competitive context, and operational content that define the Worldwide Cathodic Acrylic Market research. The full report extends well beyond this overview, offering the detailed segmentation analysis, company-level assessment, dynamic market drivers, and forecast construction that enterprise decision-makers need to act with confidence.
To access the complete dataset, segmentation breakdowns, competitive profiles, and scenario-based forecast detail, readers are encouraged to obtain the full research publication through the official PW Consulting market study portal. The complete version provides the depth required to translate high-level trajectory signals into precise planning inputs, supplier evaluations, and strategic positioning decisions across the 2026-2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Cathodic Acrylic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Worldwide Fieldscope Market to Grow at 4.65% CAGR to USD 618.58 Million by 2032 Surpassing 2025 Base of USD 450 Million
By PW Consulting, 2026-09-02
Strategic Intelligence for the Fieldscope Market: Navigating Growth from 2026 to 2032
In an era where precision optics define competitive advantage across observation, hunting, and surveillance sectors, understanding the trajectory of the global Fieldscope market is not merely an academic exercise—it is a strategic imperative. As enterprises confront shifting consumer preferences, tightening export regulations, and rapid product innovation cycles, comprehensive market intelligence becomes the cornerstone of resilient decision-making. This article introduces our latest Worldwide Fieldscope Market research, a rigorously structured study designed to equip executives, product planners, and investment strategists with the contextual depth and actionable frameworks needed to navigate the 2026–2032 forecast horizon.
Worldwide Fieldscope Market
The optical sports equipment landscape has entered a phase of steady maturation. After navigating pandemic-era supply chain disruptions and subsequent demand recalibrations, the Fieldscope segment has demonstrated consistent revenue recovery and moderate expansion. Our analysis situates this momentum within a broader macro trajectory, offering decision-makers a calibrated view of where growth will materialize, which product architectures will dominate, and how leading manufacturers are positioning themselves amid intensifying competition. Rather than presenting isolated statistics, this study weaves historical performance into forward-looking strategic narratives, enabling organizations to stress-test their portfolios against realistic market evolution.
Worldwide Fieldscope Market
Historical Trajectory and Baseline Positioning
Market evaluation begins with a clear understanding of where the industry has been. Drawing on historical data spanning the early 2020s through the base year of 2025, our research maps the revenue evolution of the global Fieldscope sector with a focus on structural inflection points rather than short-term volatility. The historical window reveals a market that experienced initial growth acceleration, followed by a period of stabilization as supply chains normalized and consumer demand settled into a more predictable pattern. By the base year, the broader market had re-established a firm upward trajectory, creating a reliable foundation for forward projections.
Worldwide Fieldscope Market
This historical baseline is not presented in isolation. It serves as the diagnostic lens through which we evaluate pricing strategies, channel distribution efficiency, and regional demand maturation. Executives reviewing product roadmaps can use this retrospective analysis to distinguish between temporary demand spikes and sustainable category growth. The study deliberately avoids over-indexing on single-year fluctuations, instead emphasizing multi-year trend lines that expose the underlying health of the Fieldscope ecosystem. Such an approach ensures that strategic plans are anchored in durable market behavior rather than transient market noise.
Forecast Horizon: Mapping the 2026–2032 Growth Arc
Looking ahead, the forecast period captures a market entering a phase of measured but consistent expansion. The overall revenue trajectory projects a compound annual growth rate of 4.65 percent across the 2026–2032 window, reflecting a balance between steady end-user demand and incremental innovation-driven upgrades. This growth rate signals a market that is no longer in a hyper-expansion phase but remains structurally attractive for companies that can align product development with evolving application requirements and regional purchasing power.
The forecast architecture underpinning this study is built to answer the questions that matter most to enterprise strategy: How will total market volume compound over the next seven years? Which product formats are gaining momentum as users prioritize portability, optical fidelity, or durability? How do application-specific demand patterns shape manufacturing and distribution priorities? By modeling these dimensions in an integrated framework, the research provides a navigable roadmap rather than a static snapshot. Decision-makers can use the forecast layers to scenario-plan inventory allocation, prioritize market entry timing, and calibrate R&D investment toward the segments most likely to deliver sustained returns.
Segment Architecture: Type, Application, and Regional Dynamics
A market of this scale and maturity cannot be understood through aggregate figures alone. The study dissects the Fieldscope landscape across three foundational dimensions: product type, end-use application, and geographic distribution. Each dimension reveals distinct consumption behaviors, pricing sensitivities, and competitive intensities that directly influence go-to-market strategy.
On the product architecture side, the market is shaped by the interplay between angled-body and straight-body designs. These two configurations serve different ergonomic preferences and observational use cases, influencing everything from retail placement to accessory bundling strategies. The research examines how manufacturers are optimizing optical designs, eyepiece interchangeability, and housing durability to meet divergent user expectations. Rather than treating these formats as interchangeable, the analysis highlights the strategic implications of design choices on customer retention, cross-sell potential, and premiumization pathways.
Application-wise, the Fieldscope ecosystem spans birdwatching and nature observation, hunting, and surveillance and photography. Each application vertical carries its own performance thresholds and purchasing cadence. Observation-focused users typically prioritize optical clarity, color fidelity, and long-term reliability, while hunting applications demand ruggedness, rapid deployment, and field-ready ergonomics. Surveillance and photography use cases introduce additional considerations around image capture compatibility and digital integration. By mapping these application profiles, the study equips product teams with the contextual intelligence needed to tailor feature sets, warranty structures, and marketing positioning without diluting brand focus.
Geographically, the market exhibits a distributed demand profile that reflects varying levels of outdoor recreation maturity, optical product literacy, and retail channel development. The research addresses regional demand patterns as part of a broader strategic assessment, enabling executives to evaluate where distribution partnerships, localized product variants, or channel expansion would generate the strongest marginal returns. The report intentionally withholds granular regional percentages and absolute sub-market valuations in this overview, reserving that level of detail for subscribers who require precise market-sizing inputs for budget allocation and territory planning.
Competitive Landscape: Strategic Positioning of Leading Manufacturers
No market analysis is complete without a rigorous examination of the players shaping it. The Fieldscope sector is characterized by a blend of established optical engineering houses, specialized outdoor equipment brands, and diversified sports-optics portfolios. Our research profiles the competitive field through a structured lens that evaluates product architecture, brand positioning, warranty and service models, and recent market activity.
Nikon Corporation continues to anchor its Fieldscope offering with a comprehensive lineup that spans premium and mid-tier segments. Its portfolio integrates ED glass technology, field-flattening optics, and waterproof construction across multiple series, reinforcing a strategy that balances optical performance with practical field durability. Recent catalog releases and related sports-optics announcements indicate an ongoing commitment to refreshing specifications and supporting the broader observation ecosystem.
Swarovski Optik occupies a premium niche defined by exceptional optical clarity and build quality. Its high-end spotting scope platforms are positioned for users who prioritize resolution and craftsmanship, often in hunting and nature observation contexts where performance justification supports higher price points. Carl Zeiss AG brings a parallel premium engineering lineage, leveraging precision manufacturing and advanced optical design to serve wildlife observation and hunting applications where reliability and image fidelity are non-negotiable.
Vortex Optics has built a strong reputation around practical field performance and customer assurance, including lifetime warranty backing that resonates with hunters and outdoor observers who value long-term usability. Bushnell Corporation, operating across multiple price segments, extends Fieldscope accessibility through product lines designed for hunting, shooting, and general outdoor use, broadening the addressable market beyond specialist buyers. Celestron contributes with ED-glass spotting scopes that support birding, wildlife observation, and digiscoping, while Kowa maintains a strong optical-performance identity focused on birding and nature observation.
Leica Camera AG reinforces the premium German-optics segment with products designed for nature observation and hunting, while Opticron offers a value-and-performance angle through field-ready configurations that appeal to birdwatching and observation users seeking reliable performance without premium-tier pricing. Meade Instruments rounds out the competitive picture by supplying spotting scopes that serve both astronomical and terrestrial observation use cases, illustrating the cross-pollination between precision optics categories.
This competitive mosaic is not static. The study integrates recent development activity, including updated product catalogs, new accessory and ecosystem announcements, and independent field evaluations of leading models. These developments matter because they signal where manufacturers are investing in differentiation: optical coatings, ergonomic refinements, waterproof and rugged construction, and complementary product ecosystems that extend the utility of Fieldscope platforms. Competition in this space increasingly hinges on the ability to deliver consistent optical quality while maintaining field-ready durability and clear value proposition alignment with specific user communities.
Industry Dynamics: Regulations, Materials, and Field-Ready Engineering
Strategic planning in the Fieldscope market must account for the operational realities that shape product design, trade compliance, and end-user expectations. One critical dynamic involves export control considerations. Certain optical products, including Fieldscopes, may be subject to export control laws that require appropriate procedural compliance in the exporting country. For manufacturers, distributors, and multinational buyers, this regulatory layer influences inventory routing, international sales strategy, and documentation requirements. Organizations that integrate compliance foresight into their market-entry and distribution planning reduce the risk of disruption and build more resilient cross-border operations.
At the product level, premium Fieldscopes increasingly rely on extra-low dispersion glass to compensate for chromatic aberration and enhance resolution and color contrast. This material choice is not merely a technical specification; it is a competitive signal that shapes perceived value, upgrade justification, and segmentation strategy. The research examines how ED glass adoption influences pricing architecture and how manufacturers communicate optical benefits to different user groups without overcomplicating the purchase decision.
Field-use durability remains another defining dynamic. Waterproof construction and ruggedized housing are no longer optional features for many observation and hunting applications; they are baseline expectations. Certification and construction standards that demonstrate resistance to moisture, impact, and variable field conditions directly affect brand trust and repeat purchase behavior. By tying engineering choices to real-world usage scenarios, the study helps product and marketing teams align feature positioning with the practical demands that drive purchasing decisions.
What the Worldwide Fieldscope Market Report Delivers
This market research is constructed to function as a working strategic asset rather than a high-level summary. It is organized to support a range of enterprise use cases, from portfolio planning and competitive benchmarking to channel strategy and demand forecasting. The report integrates quantitative market modeling with qualitative competitive and regulatory analysis to create a decision-ready framework.
The scope of coverage includes historical market sizing that establishes baseline performance, forward-looking revenue projections that extend through the 2032 forecast window, and structured breakdowns that illuminate how type, application, and regional demand patterns interact. Rather than presenting these elements as isolated tables, the study contextualizes them within the operational realities of optical manufacturing, outdoor recreation demand cycles, and evolving user expectations. This integrated approach allows readers to trace how market-level trends translate into segment-level implications.
In addition to market sizing and segmentation, the report provides a competitive landscape assessment that maps the strategic posture of key manufacturers. Each profile is evaluated not only for product breadth but also for positioning discipline, ecosystem support, and responsiveness to recent product and market developments. The research also incorporates industry-context factors that affect strategic execution, including trade compliance considerations, optical material selection, and ruggedization requirements. Together, these components create a comprehensive view of the environment in which Fieldscope companies operate and compete.
For enterprise users, the practical value lies in the study’s ability to connect market structure with decision levers. Product managers can use the segmentation analysis to refine feature prioritization and price-band strategy. Commercial leaders can draw on the regional and application insights to evaluate channel expansion, partnership focus, and demand concentration. Executive teams can rely on the forecast architecture to align capital allocation with the segments most likely to generate durable growth. By presenting this intelligence in a structured, commercial-ready format, the report reduces the time required to move from information consumption to strategic action.
Strategic Implications for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the Fieldscope market face a set of interconnected decisions. The first is portfolio alignment: does the current product mix adequately address the diverging requirements of observation-focused users, hunting applications, and surveillance or photography use cases? The second is competitive positioning: are premium optical features, ruggedization, warranty assurance, or accessible price points being used deliberately to differentiate, or is the brand relying on broad positioning that may dilute conversion efficiency? The third is geographic and channel strategy: where should distribution effort intensify, and how should compliance and trade considerations shape international expansion plans?
The growth trajectory projected for the 2026–2032 period suggests that success will depend less on chasing volume alone and more on capturing value through informed segmentation and disciplined execution. Companies that understand how type preferences, application demands, and regional maturity interact will be better positioned to allocate resources efficiently. Likewise, organizations that incorporate regulatory and material dynamics into product and supply-chain planning will be more resilient when market conditions shift.
This study is designed to support precisely those decisions. It provides the analytical scaffolding needed to evaluate where opportunity is concentrated, how competitors are positioning themselves, and which structural factors will influence performance over the forecast window. By focusing on the relationships between market size, segmentation behavior, and competitive action, the research enables leaders to construct strategies that are both grounded and adaptable.
Conclusion: Turning Market Intelligence into Strategic Advantage
The global Fieldscope market is entering a period in which clarity of strategy matters as much as clarity of optics. Steady compound growth, diversified application demands, and a competitive field defined by optical engineering heritage and field-ready durability create both opportunity and complexity. Organizations that approach this environment with structured intelligence will be better equipped to prioritize product development, sharpen positioning, and deploy commercial resources with confidence.
Our Worldwide Fieldscope Market research translates this complexity into an actionable view of the market’s past, present, and future. It provides the historical context necessary to interpret current momentum, the forecast architecture required to plan ahead, and the competitive and regulatory analysis needed to execute with precision. The overview presented here is intended to demonstrate the depth and practical orientation of the study while preserving the detailed segment-level intelligence that subscribers rely on for precise planning.
For executives and strategists who require full access to segment breakdowns, regional and application-level market sizing, and comprehensive competitive profiles, the complete report offers the granular data and structured analysis needed to support high-stakes decisions. This introduction serves as a prelude to that deeper intelligence—an invitation to move from strategic awareness to informed execution as the Fieldscope market continues its measured evolution through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Fieldscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Silver Salt Market to Hit USD 2,192.66 Million by 2032 with 5.08% CAGR
By PW Consulting, 2026-09-02
Strategic Imperatives in the Global Silver Salt Market: Navigating Growth, Supply Dynamics, and Competitive Shifts Through 2032
The global silver salt market stands at a critical inflection point. As industrial demand intensifies, regulatory frameworks tighten, and raw material costs reshape margin structures, enterprises across photovoltaics, healthcare, electronics, and specialty chemicals must look beyond short-term procurement tactics. The newly released Worldwide Silver Salt Market research by PW Consulting is designed to equip decision-makers with the structural intelligence needed to navigate the 2026-2032 horizon with confidence. This overview outlines the macro trajectory, the operational anatomy of the study, the evolving competitive landscape, and the external forces that will define strategic positioning in the coming years.
Worldwide Silver Salt Market
Macro Trajectory and the 2026 Decision Window
Over the historical review period from 2020 through 2025, the market demonstrated steady expansion, with consolidated revenue climbing from approximately US$1.18 billion to an estimated US$1.55 billion by the base year of 2025. The forward forecast window extending to 2032 indicates continued upward momentum, anchored by a compound annual growth rate of 5.08 percent. By the close of the projection period, total market revenue is positioned to approach the US$2.2 billion threshold, reflecting sustained demand absorption across multiple end-use verticals and an evolving supply chain ecosystem.
Worldwide Silver Salt Market
These figures are not merely headline numbers; they represent a structural shift in how silver salts are deployed across high-value applications. The 2026-2032 interval is particularly consequential for capital allocation, capacity planning, and supply contracting. A mid-single-digit growth trajectory may appear moderate at first glance, but in a market characterized by high concentration, feedstock sensitivity, and regulatory friction, even incremental volume expansion translates into meaningful share renegotiation and pricing power contests. Our research isolates the inflection points where procurement strategy, technology adoption, and regional sourcing decisions will diverge, enabling leadership teams to model scenarios rather than react to lagging indicators.
Worldwide Silver Salt Market
What the Worldwide Silver Salt Market Study Delivers
PW Consulting's Worldwide Silver Salt Market analysis is structured as an operational intelligence asset rather than a static sizing exercise. The report maps the ecosystem across multiple analytical layers, connecting demand-side application dynamics, supply-side manufacturing profiles, pricing sensitivity, and competitive positioning into a unified decision framework. The core content is organized to support three primary use cases: strategic market entry or expansion evaluation, supply chain reconfiguration and sourcing optimization, and competitive benchmarking against established incumbents.
The study dissects market architecture across chemical type categories, capturing the relative scale and trajectory of each segment and highlighting where volume concentration and margin profiles diverge. It further segments demand by application, examining how photovoltaics, medical and healthcare, photography and imaging, and electronics and industrial catalysts each contribute to overall consumption patterns, pricing elasticity, and future growth vectors. Regional coverage spans Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, with attention to local manufacturing capacity, trade flows, and policy environments that shape market accessibility.
Beyond segmentation, the report integrates a detailed company landscape covering leading global producers, specialized chemical manufacturers, and regional scale-up players. Each profiled entity is evaluated through operational footprint, product breadth, quality positioning, and end-market focus. The analysis also extends to market concentration dynamics, providing context on how consolidated revenue distribution influences bargaining power, pricing transparency, and entry barriers. Decision-makers will find practical outputs including procurement sensitivity considerations, feedstock linkage analysis, regulatory exposure mapping, and scenario-ready growth indicators that can be directly embedded into internal forecasting models.
Segment-Level Strategic Signals
The architecture of demand across chemical types reveals a clear hierarchy in revenue contribution and application breadth. Silver nitrate continues to anchor a substantial portion of market value, reflecting its entrenched role in industrial, pharmaceutical, and analytical use cases. Silver chloride and silver bromide occupy smaller but strategically significant positions, with demand tied to specialized imaging, electronic, and chemical synthesis pathways. Silver iodide and other silver salts represent more niche but technically differentiated demand pockets, where performance specifications and purity thresholds often command premium positioning.
On the application side, the consumption base is diversified but unevenly weighted. Photovoltaics represents a major demand engine, leveraging silver-based compounds in high-specification manufacturing workflows where material performance directly influences end-product efficiency. Medical and healthcare applications form another substantial pillar, supported by antimicrobial applications, pharmaceutical synthesis, and clinical-grade supply requirements. Photography and imaging maintain a legacy but still relevant demand footprint, while electronics and industrial catalysts contribute meaningfully through specialized process chemistry, surface treatment formulations, and catalyst-enabled manufacturing chains.
Importantly, the interplay between these segments is not static. Substitution pressures, purity requirements, and regional sourcing preferences can shift relative demand intensity over short- to medium-term horizons. The research isolates these sensitivity points so that procurement and product strategy teams can assess which segments carry the greatest volume resilience, which are most exposed to feedstock price volatility, and where application-specific qualification cycles may create temporary supply constraints or entry opportunities.
Competitive Landscape: Concentration, Capability, and Global Footprint
The competitive structure of the worldwide silver salt market is moderately concentrated, with the top three players accounting for approximately 41.8 percent of revenue and the top five expanding that share to roughly 57.5 percent. This concentration level signals a market where established incumbents hold meaningful scale advantages, yet where specialized manufacturers and regional processors can still capture differentiated positions through purity assurance, application support, and localized service models.
At the premium end of the spectrum, Heraeus Holding and Merck / Sigma-Aldrich exemplify high-purity, application-oriented positioning. Heraeus operates from a strong precious metals foundation, supplying high-quality silver salts for industrial, pharmaceutical, and electronics applications with an emphasis on consistent specification and broad technical support. Merck / Sigma-Aldrich addresses the research, analytical, and high-purity laboratory segment, supporting R&D pipelines and specialty formulations where reproducibility and documentation are paramount.
Johnson Matthey and Umicore extend the competitive field into precious metal chemistry and advanced materials platforms. Johnson Matthey's silver salt capabilities are embedded within its broader catalysis and electronics portfolio, giving it direct relevance in high-performance industrial and medical applications. Umicore contributes through its precious metals group profile, serving surface technology, catalysis, and electronics demand with an integrated materials mindset.
The Americas supply base is reinforced by American Elements, Ames Goldsmith Corporation, Alfa Aesar (Thermo Fisher Scientific), and GFS Chemicals. American Elements stands out for its breadth across silver nitrate, silver sulfate, silver chloride, and specialty organic silver salts, supporting customers from research quantities to bulk high-tech demand. Ames Goldsmith Corporation maintains a focused presence in silver nitrate and related salts for photography, electronics, and chemical synthesis. Alfa Aesar provides silver compounds for research, development, and industrial scale-up, while GFS Chemicals concentrates on high-purity silver nitrate and salts targeting laboratory, pharmaceutical, and specialty chemical channels.
India's manufacturing footprint adds important scale and regional agility through Pheonix Industries, Macsen Laboratories, and Texchem Industries. Pheonix Industries has built its operations around industrial silver salts since 2006, particularly silver nitrate and related compounds. Macsen Laboratories operates as an ISO-certified manufacturer and supplier of silver carbonate and other silver salts for pharmaceutical and industrial consumption. Texchem Industries contributes additional production capacity for industrial-grade silver salt applications. These players illustrate how regional scale, certification frameworks, and cost-efficient processing can support both domestic demand and export-oriented supply chains.
In China, Chenzhou Jingui Silver Industry Co Ltd operates within nonferrous metals operations to produce silver nitrate and silver-based compounds. Its position reflects the broader linkage between primary metal processing and downstream specialty chemical output, a connection that becomes especially relevant when trade policy and export licensing frameworks change.
Recent market intelligence reinforces the diversification of this competitive field. A July 2025 industry report estimated the global silver sulfate market at approximately US$1.9 billion in 2024, with projections pointing toward US$2.2 billion by 2030. In January 2026, analyst commentary highlighted silver nitrate market estimates reaching around US$6.2 billion by 2030 across medical, pharmaceutical, and industrial applications. More recently, in March 2026, technical developments involving silver dendrite growth structures directed toward sulfate ions drew attention to evolving materials science pathways that could influence downstream processing and application design. Together, these developments underscore that silver salt markets are not only shaped by traditional chemical supply dynamics but also by parallel innovation in material architectures and adjacent product categories.
Market Dynamics: Feedstock, Regulation, and Cost Pressure
A realistic strategic assessment of the silver salt market must place feedstock linkage and cost structure at the center of the analysis. Silver metal remains the primary upstream feedstock for silver salt production, meaning that mine supply trends, secondary recovery, and broader precious metals cycles transmit directly into manufacturing economics. Global mined silver supply reached approximately 846.6 million ounces in 2025, anchoring the upstream base for primary production. At the same time, all-in sustaining costs for silver are projected to rise by 3.8 percent in 2026, moving from US$22.59 per ounce in 2025 to US$23.44 per ounce. Even where primary silver does not pass through a salt manufacturer's balance sheet directly, the broader cost environment affects availability, secondary market pricing, and margin negotiation across the value chain.
On the procurement side, sensitivity to input cost changes has already been visible. Silver nitrate pricing in the second half of 2024 was notably influenced by shifts in both silver metal and nitric acid feedstock prices, demonstrating how chemical manufacturing costs can pivot on multiple commodity vectors at once. For buyers and producers alike, this dual exposure means that supply contracts, inventory timing, and hedging strategies must account for correlated cost pressures rather than treating silver salts as isolated chemical commodities.
Regulatory developments introduce an additional layer of strategic complexity. Effective January 2026, China implemented a tighter silver export licensing system, approving only 44 companies for exports. This policy shift directly affects the flow of silver-based materials from one of the world's most consequential production and processing regions. For downstream users dependent on cross-border supply, the impact can manifest through altered lead times, changed supplier qualification requirements, and re-weighting of sourcing portfolios toward alternative domestic or third-country suppliers. For manufacturers operating within the approved exporter framework, the change can reshape competitive access to international markets, particularly where regional pricing gaps and qualification cycles create temporary advantages or constraints.
The combined effect of feedstock cost pressure, chemical input volatility, and export licensing constraints creates a market environment where static procurement assumptions quickly erode. Strategic value in 2026 will accrue to organizations that can integrate these dynamics into scenario-based sourcing models, diversify exposure across supplier types and geographies, and align procurement timing with anticipated shifts in primary supply and policy enforcement.
Implications for 2026 Strategy and Sourcing Decisions
The 2026-2032 outlook rewards proactive strategic positioning. Enterprises that treat silver salts as commoditized inputs risk underpricing risk and overcommitting to single-source pathways. By contrast, organizations that build a segmented view of demand drivers, supplier capabilities, and regional policy exposure can convert market complexity into negotiation leverage and supply resilience.
Several strategic priorities emerge from the current market architecture. First, application-specific qualification requirements and purity specifications will continue to separate suppliers that compete on documentation and technical support from those competing primarily on price. Second, the mid-concentration structure of the market means that share leadership does not automatically equate to universal supply advantage; specialized manufacturers and regional processors can still win on service responsiveness, local regulatory alignment, and tailored product grades. Third, upstream cost trajectories and export policy changes are likely to drive periodic re-pricing and reassignment of supply relationships, making contract flexibility and multi-supplier readiness essential.
The Worldwide Silver Salt Market study provides the evidentiary foundation to support these priorities. It equips strategy teams with a clear map of where volume is concentrated, how demand is distributed across applications and regions, which companies hold what strategic positions, and how external dynamics such as mining economics, chemical input costs, and regulatory frameworks interact with market behavior. More importantly, it is built to translate these insights into actionable procurement and growth decisions rather than high-level commentary.
Why This Research Matters for 2026 Decision-Making
In a market moving at a mid-single-digit growth pace but shaped by material cost sensitivity and tightening regulatory access, the value of a detailed intelligence asset lies in its ability to reveal leverage points before they become obvious in price lists or supply disruptions. PW Consulting's Worldwide Silver Salt Market research offers precisely that orientation. It integrates historical performance, forward forecast structures, segmentation depth, competitive profiling, and dynamic external context into a single analytical reference.
For executives evaluating market entry, capacity expansion, sourcing network redesign, or product-grade strategy, the report reduces ambiguity at the point of decision. It clarifies where growth is structurally supported, where margins are most exposed, and which players are positioned to influence price and availability over the forecast horizon. It also frames the strategic questions that matter most: how to balance purity and cost, how to allocate sourcing across regions under changing export rules, how to anticipate feedstock-linked volatility, and how to position against a moderately concentrated but capability-diverse competitive set.
The complete analysis contains the detailed segmentation data, regional breakdowns, application-level demand context, company profiles, and scenario-ready indicators needed to build internal forecasts and sourcing models at the granularity required for 2026 execution. To access the full dataset, regional and application-level intelligence, and the complete competitive landscape supporting this outlook, decision-makers should consult the source report directly. In a market where timing, specification, and supply access increasingly determine outcomes, the difference between reactive procurement and strategic positioning is access to precise intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Silver Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Business Networking App Market to Surpass USD 15 Billion by 2032 Driven by 10.64 Percent CAGR
By PW Consulting, 2026-09-02
The Worldwide Business Networking App Market: Strategic Intelligence for the 2026 Decision-Maker
Executive Overview: A Market at the Inflection Point
The global business networking application landscape is undergoing a structural transformation. What was once a supplement to traditional professional outreach has evolved into a core infrastructure layer for talent acquisition, partnership formation, and commercial intelligence. Our latest Worldwide Business Networking App Market research captures this shift with precision, offering a multi-year view that stretches from historical baselines through 2032. For executives, investors, and product leaders navigating 2026, the study functions as a strategic compass: it quantifies the trajectory, maps the competitive terrain, and surfaces the operational and regulatory variables that will define winners and laggards in the years ahead.
Worldwide Business Networking App Market
The market has demonstrated consistent upward momentum. From a baseline exceeding 4.2 billion USD in 2020, revenue climbed to approximately 7.55 billion USD by 2025, reflecting a compounding growth pattern that underscores durable demand across enterprise and independent professional segments. The forward trajectory projects the market to surpass 8.6 billion USD in 2026 and continue its ascent toward roughly 15.3 billion USD by 2032, sustained by a compound annual growth rate of 10.64 percent. These figures are not abstract statistics; they signal a market that has moved past early-adoption volatility and entered a phase where scale, retention, and monetization design determine competitive endurance.
Worldwide Business Networking App Market
Yet macro growth alone does not illuminate where value concentrates, how platform economics diverge, or which strategic moves will compound advantage. This research was designed to answer those questions. It integrates historical performance, segmentation architecture, competitive profiles, and the regulatory and infrastructure dynamics reshaping deployment conditions. The following overview previews the analytical layers contained in the full report while preserving the granular breakdowns that decision-makers will need to access directly for planning precision.
Worldwide Business Networking App Market
Growth Architecture and the 2026–2032 Trajectory
The decade-long arc captured in this study reveals a market that has consistently expanded its revenue base while diversifying its use cases. The progression from 2020 through 2025 shows a market that weathered shifts in remote work patterns, professional content consumption, and enterprise networking budgets, emerging with stronger monetization foundations. By 2025, the overall market reached 7.55 billion USD, and the forecast window indicates that growth will not merely continue but accelerate in structural terms as organizations embed networking applications into broader talent, sales, and partnership workflows.
The 10.64 percent compound annual growth rate across the 2026–2032 forecast period reflects more than user acquisition. It captures the maturation of revenue models, the deepening of enterprise adoption, and the emergence of AI-assisted matching and personalization as differentiators rather than novelties. Importantly, this growth is unevenly distributed across platforms, regions, and monetization strategies, which is precisely why high-level totals must be paired with segmented analysis. The report dissects these layers to show where scale is being generated, which revenue mechanisms are gaining share, and how regional dynamics are influencing deployment priorities.
For 2026 planning, the strategic implication is clear: the market is large enough to support multiple viable business models, yet concentrated enough that positioning, partnership strategy, and regulatory readiness will separate sustainable operators from transient entrants. Executives who rely on aggregate numbers alone risk misallocating product investment, overlooking regional readiness, or underestimating the monetization shifts already reshaping competitive benchmarks.
Segmentation: Platform, Revenue Model, and Regional Dynamics
Platform Economics and User Access Patterns
The market’s platform composition reflects divergent user behaviors, development constraints, and monetization potentials. iOS and Android each command substantial revenue share, but their dynamics differ in ways that affect product strategy, audience targeting, and lifetime value optimization. The report examines how platform preferences interact with feature delivery, in-app engagement, and enterprise versus individual user flows. Rather than treating mobile operating systems as neutral distribution channels, the analysis frames them as strategic variables that shape acquisition cost, retention design, and revenue realization.
Decision-makers will find detailed comparisons that illuminate how platform-specific usage patterns influence feature prioritization, subscription conversion, and advertising inventory performance. These insights are essential for teams deliberating cross-platform investment, feature rollout sequencing, and audience segmentation strategies in 2026 and beyond.
Monetization Architecture: Subscription, Advertising, and Transactional Revenue
Revenue model composition is one of the most consequential dimensions of this market. Subscription-based revenue represents the largest share, reflecting a broader industry tilt toward recurring relationships and sustained engagement. Advertising revenue forms a substantial secondary pillar, particularly where scale, content consumption, and professional discovery create inventory value. A smaller but strategically important portion of the market derives from in-app purchases and event-driven transactions, often tied to specialized communities, gig-based collaboration, and premium access features.
The report does not merely list these splits; it interprets them. It explores how subscription dependence influences churn management and feature roadmaps, how advertising revenue interacts with user experience and data practices, and how transactional models create niche advantages for platforms targeting freelancers, founders, and event-oriented networking. For executives evaluating expansion, partnership, or monetization shifts, these distinctions are critical. A strategy that works for a subscription-led professional network may misfire in an advertising-heavy environment, and vice versa.
Regional Distribution and Deployment Context
Geographic distribution shapes both opportunity and execution complexity. North America, Europe, and Asia Pacific each represent significant revenue contributions, while Latin America and the Middle East and Africa reflect smaller but strategically relevant footprints. The full report examines how regional factors influence adoption pacing, enterprise readiness, localization requirements, and regulatory exposure.
Rather than reducing regions to single percentages, the analysis connects geographic performance to underlying drivers: enterprise concentration, professional culture, mobile ecosystem maturity, and data compliance expectations. This framing helps organizations assess where to prioritize go-to-market resources, how to calibrate partnership strategies, and which compliance investments are likely to protect or enable growth in specific territories.
Competitive Landscape: Incumbents, Specialists, and AI-Enabled Entrants
The business networking app market is defined by a concentrated core of established players and a broadening periphery of specialized and AI-driven platforms. Our research profiles the leading companies shaping this environment, examining how their positioning, feature sets, and audience focus influence competitive pressure and partnership opportunities.
LinkedIn remains the dominant global professional networking application, anchored in career development, job searching, business connections, company pages, and professional content sharing for both individuals and enterprises. Its scale and ecosystem breadth set the market’s reference point for enterprise integration and professional identity. Xing reinforces the importance of regional specialization, serving German-speaking countries and Europe with an emphasis on job opportunities, events, and business connections. Its continued relevance illustrates how localized networks can sustain strong positions even within a globalizing market.
On the startup and entrepreneurial side, AngelList connects founders, investors, and talent through job applications, company following, and specialized profiles tailored to the startup ecosystem. Polywork targets creative and freelancer-oriented professionals with multi-project portfolios, collaboration opportunities, and opportunities boards designed for gig-based work. These platforms demonstrate that segmentation by professional identity and work mode can create durable niches even as broader networks expand.
AI-enabled matching is increasingly reshaping engagement models. Lunchclub pairs users for one-to-one video meetings based on shared interests and goals, while Intch serves a large, globally distributed user base with AI-matching focused on the future of work and recommendation-driven connections. Bumble Bizz introduces swipe-based matching into a business networking mode, extending a familiar consumer interaction pattern into professional contexts. Alignable concentrates on small business owners, enabling local connection, advice sharing, and partnership formation. Fishbowl offers an anonymous professional networking environment where employees at similar levels or companies can discuss candid advice and analysts’ insights. Meetup complements app-based networking with event-based professional and interest communities, facilitating in-person and virtual meetups for career and business connections.
The strategic lesson is not simply that competition is intense. It is that competitive advantage now arises from the alignment of matching logic, audience specificity, monetization design, and compliance posture. Platforms that generalize too broadly risk dilution; those that specialize too narrowly risk ceiling effects. The report maps this tension in detail, providing the comparative context needed to evaluate positioning, partnership, and potential consolidation scenarios.
Regulatory and Infrastructure Dynamics Reshaping Market Conditions
Market growth does not occur in a vacuum. Recent regulatory and infrastructure developments are altering the operating environment for business networking applications, affecting data handling, content delivery, user acquisition, and cost structures. The research integrates these variables so that strategic plans reflect current realities rather than outdated assumptions.
Data privacy and broker regulation are expanding in scope. Multiple U.S. states, including California, Oregon, Texas, and Vermont, maintained or amended data broker registration and compliance requirements in 2025, broadening definitions to include entities that process or transfer personal data without direct consumer relationships. For networking applications that aggregate professional profiles, infer interests, or facilitate connections across organizational boundaries, these developments raise important questions about data classification, consent design, and disclosure practices.
At the federal level, the U.S. Department of Justice Bulk Data Rule took effect in April 2025, with additional requirements introduced in October 2025. The rule imposes cybersecurity controls and record-keeping obligations on certain transactions involving bulk sensitive personal data with foreign or covered persons. This creates a new compliance layer for platforms that handle substantial volumes of professional data, particularly where international users, cross-border data flows, or enterprise integrations are involved.
Network governance has also shifted. The U.S. Court of Appeals for the Sixth Circuit struck down the FCC’s 2024 Safeguarding and Securing the Open Internet Order in January 2025, ending federal net neutrality regulations via FCC authority. While the direct business impact varies by deployment model, the change introduces uncertainty around traffic management, content delivery priorities, and the cost of maintaining reliable access for data-intensive features such as video meetings, rich media profiles, and real-time matching.
Infrastructure cost pressures add another dimension. U.S. residential electricity prices rose more than 36 percent from 12.76 cents per kilowatt-hour in 2020 to 17.44 cents per kilowatt-hour in February 2026, with data centers contributing to demand pressures. Data centers accounted for 4 percent of total U.S. electricity use in 2024, and demand is expected to more than double by 2030, prompting state-level debates on ratepayer protections and infrastructure costs. For application providers relying on cloud-hosted matching engines, media processing, and continuous engagement features, energy and hosting dynamics can influence operating costs and regional deployment decisions.
These dynamics do not uniformly affect every segment, but they influence risk allocation, compliance investment, and infrastructure planning across the market. The full report places these factors in context, helping leaders anticipate where regulatory exposure is most acute and where infrastructure costs may shape margin expectations.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is built for practical use. Beyond high-level market sizing, it provides a structured set of analyses that support product, commercial, and compliance decisions. The report’s scope includes:
- Historical market performance from 2020 through 2025, establishing a verified baseline for trend interpretation and scenario planning.
- Forecast projections from 2026 through 2032, enabling multi-year resource allocation, investment prioritization, and competitive benchmarking.
- Segmentation analysis across platform, revenue model, and region, revealing where growth is concentrated and how monetization patterns differ.
- Company profiles covering dominant incumbents, regional specialists, startup-ecosystem platforms, AI-matching services, small business networks, anonymous discussion apps, and event-based networking communities.
- Competitive concentration context, including market share dynamics that clarify the balance between dominant players and specialized entrants.
- Regulatory and infrastructure developments that affect data handling, network reliability, hosting costs, and compliance obligations.
- Strategic framing for partnership, expansion, monetization, and risk management decisions in a market that is simultaneously scaling and fragmenting.
Each section is designed to move beyond description into interpretation. The objective is to help leaders answer actionable questions: Where should product investment be directed to capture durable retention? Which monetization pathways align with target audiences? How should regional rollout be sequenced given compliance and enterprise readiness? What competitive responses are plausible as AI-assisted matching and niche professional networks continue to evolve?
Strategic Implications for 2026 Decision-Makers
The most important takeaway from this research is that the business networking app market has entered a phase where growth is available, but advantage is earned through precision. Aggregate expansion justifies attention, but it does not dictate strategy. The organizations that will benefit most are those that align their product, commercial, and compliance decisions with the market’s internal structure.
First, monetization strategy must be evaluated against the audience it serves. Subscription-led models require sustained engagement and clear value differentiation; advertising-led models depend on scale, content flow, and user experience balance; transactional and event-driven models thrive in specialized communities and project-oriented workflows. The report’s segmentation analysis helps leaders match monetization assumptions to the realities of each segment rather than extrapolating from market averages.
Second, competitive positioning must account for both scale and specialization. Dominant global networks set user expectations and enterprise integration standards, while regional platforms and AI-enabled matching services open opportunities in localization, relevance, and connection quality. The presence of small business networks, anonymous discussion environments, and event-driven communities further illustrates that professional networking is no longer a single use case. Leaders need to decide whether to compete broadly, partner selectively, or anchor in a defensible niche.
Third, regulatory and infrastructure conditions are becoming strategic variables, not background noise. Data broker registration expansions, bulk data controls, shifts in network governance, and rising infrastructure demand all affect how applications can scale, where they can operate efficiently, and what compliance investments are necessary to protect growth. The report integrates these factors so that strategy accounts for operational risk as well as market opportunity.
Finally, the market’s concentration dynamics suggest that partnership and ecosystem decisions matter as much as product features. In a market where a small number of firms hold a large share of revenue, access to enterprise relationships, professional content flows, and matching intelligence can be as valuable as standalone user acquisition. The research provides the context needed to evaluate where partnerships may accelerate reach, where they may create dependency, and where independent positioning remains the stronger option.
Accessing the Full Intelligence
The overview presented here is intentionally selective. It establishes the market’s direction, introduces the competitive and regulatory context, and previews the analytical depth available in the complete study. To support concrete decisions, however, leaders need the full segmentation breakdowns, regional interpretations, company profiles, concentration analysis, and scenario-ready forecasts that the complete report provides.
PW Consulting’s Worldwide Business Networking App Market research is designed to serve as a working intelligence asset rather than a static summary. It gives executives, investors, and product teams the structured evidence required to make 2026 decisions with confidence, while preserving enough granularity to support planning across multiple strategic paths. For those who need the detailed figures, comparative profiles, and segment-level interpretation that underpin the conclusions outlined here, the full report offers the complete dataset and analysis necessary to translate market momentum into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Business Networking App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Global Aircraft Tire Retreading Market to Reach $847.47 Million in 2032 at 4.2% CAGR
By PW Consulting, 2026-09-02
# Worldwide Aircraft Tire Retreading Market: Strategic Intelligence for 2026 and Beyond
The global aviation industry stands at a critical juncture where operational efficiency, cost management, and sustainability mandates converge. For stakeholders in the aerospace supply chain, understanding the nuances of the aircraft tire retreading market is no longer optional—it is a strategic imperative. As we move into 2026, the dynamics shaping this sector are influenced by volatile raw material costs, increasingly stringent regulatory frameworks, and a pressing industry-wide goal to reduce environmental footprints. This article serves as a strategic overview of the current landscape, drawing upon comprehensive market intelligence to highlight the opportunities and challenges that define the Worldwide Aircraft Tire Retreading Market.
Worldwide Aircraft Tire Retreading Market
Market growth in this sector is not merely a function of fleet expansion but is deeply tied to the economic logic of reuse. The shift from virgin tire production to retreaded solutions is accelerated by both financial incentives and regulatory pressure. Our latest research provides a granular look at these trends, offering a roadmap for executives, investors, and operational leaders to navigate the complexities of the next forecast period.
Worldwide Aircraft Tire Retreading Market
Executive Summary and Market Trajectory
The Worldwide Aircraft Tire Retreading Market has demonstrated resilient growth over the past half-decade, recovering robustly from pandemic-era disruptions and continuing to expand as air travel demand normalizes and accelerates. Analysis of historical data from 2020 through 2025 indicates a clear upward trajectory in revenue generation, positioning the market for sustained expansion through 2032. The total market valuation crossed the 600 million USD threshold in the base year 2025, reflecting a significant recovery and growth phase compared to the 2020 baseline.
Worldwide Aircraft Tire Retreading Market
Looking ahead, the forecast period from 2026 to 2032 projects a steady compound annual growth rate (CAGR) of 4.2 percent. This growth rate suggests a mature but steadily evolving market where incremental gains are driven by technological improvements in retreading processes and increased adoption rates in specific aviation sectors. By 2032, the market revenue is projected to reach approximately 847.47 million USD. This forecast underscores the long-term viability of retreading as a core component of aircraft maintenance, repair, and overhaul (MRO) strategies.
Segmentation Dynamics and Operational Insights
To truly leverage market intelligence, decision-makers must understand where value is concentrated. Our report dissects the market across three critical dimensions: tire type, aircraft type, and region. While specific percentage splits are detailed in the full dataset, the broader structural shifts are evident and crucial for strategic planning.
Tire Type Segmentation
The market is primarily divided between radial tires and bias tires. Radial tires continue to dominate the landscape, reflecting the broader industry shift toward radial technology in commercial aviation due to superior durability and fuel efficiency. The revenue generated from radial tire retreading significantly outpaces bias tires, driven by the prevalence of these tires in large commercial fleets. However, bias tires maintain a substantial presence, particularly in niche applications and older aircraft models where replacement cycles differ. Understanding the lifecycle management of each type is essential for MRO providers planning their capacity and tooling investments.
Aircraft Type Segmentation
Commercial aircraft represent the largest share of the retreading market. The high utilization rates of commercial jets necessitate frequent tire replacement and retreading cycles, making this segment the primary revenue driver. Military aircraft form the second significant pillar, where durability and specific operational requirements often dictate specialized retreading protocols. General aviation contributes a smaller but vital portion of the market, often characterized by different service level agreements and turnaround time expectations. The interplay between these segments affects pricing strategies and service level commitments across the value chain.
Regional Analysis
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America stands out as a prominent hub, reflecting the high density of commercial and military aviation activity in the region. Europe also commands a significant share, driven by stringent environmental regulations and a mature MRO infrastructure. The Asia Pacific region is emerging as a key growth engine, correlating with the rapid expansion of airlines in that territory. Latin America and the Middle East and Africa, while smaller in total volume, present specific opportunities for localized service centers to reduce logistics costs and turnaround times for operators in those regions.
Competitive Landscape and Strategic Positioning
The aircraft tire retreading market is characterized by a high degree of concentration, with a few key players commanding the majority of the market share. This consolidation implies that competitive moves by top-tier companies can ripple through the entire ecosystem. Our analysis identifies five primary entities that define the current competitive structure.
- Michelin Aircraft Tire Services: Headquartered in Clermont-Ferrand, France, Michelin remains a dominant force, providing retreading services for both commercial and military aircraft. Their expertise spans Hot Cap and cold retreading processes, and they maintain rigorous certifications under FAA TSO-C62f and EASA Part 145.
- Goodyear Aviation Tires: Based in Akron, Ohio, USA, Goodyear leverages its extensive network of authorized service centers to offer retreading for radial and bias-ply tires. Their compliance with FAA and military specifications ensures they remain a preferred partner for diverse operator types.
- Bridgestone Aircraft Tire (USA) Inc.: Operating out of Nashville, Tennessee, Bridgestone delivers services for business, commercial, and military aircraft through its Firestone Aircraft Tire division. Their FAA-approved processes solidify their position in the North American and global markets.
- Dunlop Aircraft Tyres (Sumitomo Rubber Industries): Located in Birmingham, UK, Dunlop specializes in civil and military tire retreading. Their approvals from EASA, FAA, and UK CAA make them a critical player in the European and transatlantic supply chains.
- Continental Tires Aircraft Division: Based in Hanover, Germany, Continental provides retreading for general aviation and commercial aircraft through certified partners. Their adherence to FAA TSO and EASA standards highlights the importance of certification in maintaining market access.
Recent Corporate Developments
Strategic agility is evident in recent corporate activities. In mid-2024, Michelin received FAA recertification for expanded retreading capabilities specifically on wide-body aircraft tires, signaling an enhancement in their service scope for large carriers. Earlier in 2023, Goodyear showcased retreaded tire technologies focused on sustainable aviation at the NBAA-BACE trade show, emphasizing the industry's pivot toward green technologies. Furthermore, in early 2024, Bridgestone secured a significant U.S. Air Force contract for retreading military transport aircraft tires, illustrating the steady demand within the defense sector. These events highlight how certification updates, sustainability marketing, and defense contracts are key levers for growth among top competitors.
Industry Dynamics and External Influences
Market performance does not occur in a vacuum. Several external factors are currently reshaping the economics and operations of aircraft tire retreading. These dynamics must be integrated into any forward-looking strategic plan.
Regulatory Environment
Safety and compliance remain the bedrock of this industry. The FAA Advisory Circular AC 145-9A mandates strict non-destructive testing and tread depth verification for all retreaded aircraft tires. This regulation ensures safety but also introduces operational overhead that impacts service pricing and turnaround times. Compliance is not merely a legal requirement but a competitive differentiator; firms that can demonstrate superior adherence to these standards often secure preferential contracts with major airlines and military bodies.
Sustainability Pressures
Environmental considerations are increasingly driving procurement decisions. ICAO sustainability goals target a 5 percent reduction in aviation tire waste by 2030. This mandate boosts the adoption of retreading over virgin tire production, as retreading significantly extends the life of the tire casing and reduces landfill waste. Operators are under growing pressure to report on their environmental metrics, making retreaded tires an attractive option for meeting carbon reduction targets. This shift is transforming retreading from a cost-saving measure into a sustainability imperative.
Cost Drivers and Raw Materials
The economics of retreading are sensitive to input costs. Natural rubber prices, which are key for aircraft tire retreading compounds, averaged 1,800 USD per metric ton in Q4 2025 amid supply chain stabilization. Fluctuations in this commodity directly affect the margin structures of retreading providers. Additionally, labor costs play a crucial role. Skilled tire retreading technicians in the U.S. command average wages of 28 USD per hour, driven by aviation safety certification requirements. This labor intensity means that automation and process efficiency are critical areas for investment to maintain profitability.
Strategic Implications for 2026 Decision-Making
For executives and strategic planners, the data points toward several key areas of focus for the 2026 fiscal year and beyond. The interplay between market growth, regulatory compliance, and cost management creates a complex environment where generic strategies are insufficient.
Supply Chain Resilience
Given the volatility in raw material pricing and the specialized nature of certified components, supply chain resilience is paramount. Companies must evaluate their sourcing strategies for rubber compounds and ensure that their logistics networks can handle the specific requirements of transporting aircraft tires across regions without compromising integrity. The concentration of the market among top players also suggests that partnerships or acquisitions could be viable strategies for smaller entrants looking to scale quickly.
Investment in Certification and Technology
With regulations like AC 145-9A tightening oversight, investment in quality control technology and certification maintenance is non-negotiable. Firms that integrate advanced non-destructive testing capabilities may gain a competitive edge by reducing failure rates and improving turnaround speed. Furthermore, as sustainability goals become more binding, technologies that maximize the number of retread cycles per casing will offer distinct economic advantages.
Regional Expansion vs. Consolidation
While North America and Europe remain mature markets, the growth forecast suggests that Asia Pacific offers the highest potential for volume increases. However, entering these markets requires navigating local regulatory environments and establishing trust with regional carriers. Conversely, in mature markets, consolidation may yield efficiencies. Strategic managers must decide whether to pursue geographic expansion or deepen market penetration in existing strongholds based on their specific organizational capabilities.
Conclusion and Access to Full Intelligence
The Worldwide Aircraft Tire Retreading Market is poised for steady growth, underpinned by the essential nature of aircraft maintenance and the evolving demands of sustainability. The projected CAGR of 4.2 percent through 2032 indicates a healthy market environment, but success will depend on navigating regulatory hurdles, managing input costs, and aligning with the strategic priorities of major aircraft operators and military bodies. The concentration of market share among leading players like Michelin, Goodyear, Bridgestone, Dunlop, and Continental underscores the importance of competitive intelligence in this space.
This article provides a high-level strategic overview, but the complexities of market entry, specific segment valuations, and detailed competitor benchmarking require deeper analysis. The nuances of regional pricing differences, specific application rates across commercial versus military sectors, and granular competitor market share percentages are critical for granular planning. To access the complete dataset, including detailed segmentation splits, comprehensive competitor profiles, and scenario-based forecasting models, we invite you to explore our full market research publication.
Our comprehensive report offers the actionable intelligence needed to make informed investment and operational decisions in 2026. By securing access to the full study, your organization can move beyond general trends and leverage specific data points to optimize your strategy in the global aircraft tire retreading landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Tire Retreading Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Wired Flat Panel Detectors Market to Reach USD 1,219.47 Million by 2032 Amid 3.4 Percent CAGR Driven by Medical Imaging Segment
By PW Consulting, 2026-09-02
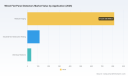
Strategic Imperatives in the Wired Flat Panel Detector Market: A 2026 Decision-Maker's Perspective
The global diagnostic imaging landscape is undergoing a structural realignment, and nowhere is this more evident than in the wired flat panel detector segment. For executives steering capital allocation, product roadmaps, and market entry strategies in 2026, this is no longer a peripheral hardware discussion. It is a core determinant of throughput, compliance readiness, and clinical adoption velocity. The Worldwide Wired Flat Panel Detectors Market study from PW Consulting distills over a decade of historical tracking and seven years of forward projection into a decision-grade intelligence asset. What follows is a strategic preview of the market architecture, the forces reshaping competitive positioning, and the operational content embedded in the full report.
Worldwide Wired Flat Panel Detectors Market
Macro Trajectory: Grounding Strategy in a Measured Growth Curve
Wired flat panel detectors have evolved from expensive early-adopter technologies into standardized clinical and industrial imaging components. Our historical series captures this maturation. The market generated 820.5 million USD in revenue in 2020, experienced a mild contraction to 816.35 million USD in 2021 as supply chains recalibrated, then accelerated through 868.73 million USD in 2022 and 881.54 million USD in 2023. The 2024 figure reached 977.68 million USD, reflecting post-pandemic capacity normalization and renewed capital investment in fixed installation upgrades. The 2025 baseline softened slightly to 965.0 million USD, consistent with a maturing base and selective procurement cycles.
Worldwide Wired Flat Panel Detectors Market
The forecast window from 2026 through 2032 describes a measured but structurally persistent expansion. We project a compound annual growth rate of 3.4 percent, with revenue climbing from 1023.56 million USD in 2026 through to 1219.47 million USD in 2032, passing intermediate benchmarks of 1040.81 million USD in 2027, 1058.43 million USD in 2028, 1156.13 million USD in 2029, 1130.62 million USD in 2030, and 1137.23 million USD in 2031. For a 2026 strategic planner, this curve is informative precisely because it is not hyperbolic. It signals steady institutional demand, not speculative replacement cycles. Capital deployment should therefore prioritize reliability, lifecycle support, and compatibility with existing fixed radiography and fluoroscopy infrastructure rather than chase aggressive volume assumptions.
Worldwide Wired Flat Panel Detectors Market
It is equally important to recognize where the growth originates. The overall market is shaped by regional procurement rhythms, material specificity, and application mix, but the full study deliberately holds back granular percentage splits and exact regional or application-level dollar figures so that leadership teams engage with the complete analytical architecture before committing to plan-specific forecasting. In this preview, the strategic takeaway is straightforward: the revenue base is broad enough to support multiple playbooks, but the dispersion across geographies, scintillator materials, and end-use verticals requires navigation on a segment-by-segment basis. The report provides precisely that navigation without oversimplifying the dispersion.
The Operating Frame: Standards, Reimbursement, and Procurement Realities
A 2026 decision is never purely technical. In the wired flat panel detector space, the operating environment is bounded by standards, reimbursement mechanics, and procurement constraints that alter total cost of ownership and go-to-market timelines. Market participants must address compliance requirements tied to diagnostic X-ray imaging equipment, including the IEC 62220-1-1:2020 framework for medical electrical equipment. This standard shapes validation testing, documentation, and post-market surveillance obligations, which in turn affect vendor qualification cycles for hospital procurement teams.
In the United States, reimbursement alignment provides a critical demand anchor. Wired digital radiography detectors fall under defined hospital outpatient payment pathways, and awareness of the relevant coding structure allows manufacturers and systems integrators to frame value propositions in clinical-finance terms rather than in sensor specifications alone. Procurement officers increasingly evaluate detector selection through the lens of installation permanence, service intervals, and workflow compatibility rather than peak resolution alone, which is why wired deployments continue to hold a stable position in fixed suites despite broader industry curiosity about cordless alternatives.
Material economics further modulate strategy. For example, amorphous selenium panels used in certain wired detector configurations carry unit costs that climb significantly with size, meaning that larger-format fixed-room deployments demand different financial modeling than compact or modular installations. At the same time, regulatory guidance clarifies usage boundaries: wired flat panel detectors are constrained to fixed installations and are not approved for patient-contact use in sterile fields without encapsulation. This is not a marginal footnote. It defines where wired architectures are viable, where service protocols must be designed, and where vendor documentation must preempt clinical questions. The full report weaves these dynamics into a risk-and-readiness matrix that helps product and commercial teams anticipate friction before it appears in a procurement cycle.
Segment Architecture: Reading Between the Headlines
Segment analysis is where most executive summaries fail. They either flatten the market into a single number or provide partial percentage breakdowns that appear precise but lack operational context. The PW Consulting study avoids both traps. It maps the wired flat panel detector market through three lenses that matter to 2026 planners: geographic dispersion, scintillator material selection, and application orientation.
Geographic Dispersion and Procurement Heuristics
Regional revenue is anchored by a handful of large clusters, with Asia Pacific and North America carrying substantial weight, followed by Europe, Latin America, and the Middle East and Africa. The exact dollar contributions and percentage allocations are reserved for the complete report, but the strategic implication is visible at the surface: procurement in high-volume regions tends to be driven by hospital consolidation, retrofit cycles in established radiography rooms, and regional tender structures, while smaller regions often reflect selective upgrades and project-based installations. For 2026, the value lies not in assuming uniform growth but in matching commercial motion to region-specific buying behavior. The study provides region-by-region demand patterns, seasonality tendencies, and procurement conductor profiles that let teams design pricing and service bundles that fit local reality rather than global averages.
Material Pathways: Cesium Iodide and Gadolinium Oxysulfide
Scintillator material differentiation shapes image quality, dose sensitivity, cost structure, and application fit. Two material families dominate the current wired detector universe: Cesium Iodide and Gadolinium Oxysulfide. One material pathway is associated with stronger gain characteristics and high-demand clinical use cases, while the other is linked to mature cost-performance profiles and broad deployment stability. Their revenue contributions are substantial, with Cesium Iodide-related volumes totaling 606.96 million USD and Gadolinium Oxysulfide-related volumes totaling 358.04 million USD across the market base, but those numbers are best interpreted alongside format size, detector architecture, and application requirements. In this preview, the strategic point is that material choice is not a generic specification; it is a commercial signal. The report connects material selection to workload profiles, sensitivity considerations, and cost-per-scan reasoning so that engineering teams and commercial leaders can align specifications with the economics of the environments they target.
Applications: Medical Imaging as the Demand Core
Application orientation reveals where demand density concentrates. Medical imaging sits at the center of the market, with associated revenue of 812.95 million USD, reflecting broad deployment in radiography and fluoroscopy rooms, digital upgrade programs, and multi-room hospital imaging departments. Industrial non-destructive testing contributes 115.19 million USD, driven by fixed-line inspection setups, precision weld and casting checks, and continued investment in quality assurance assets. Veterinary medicine adds 36.86 million USD, a smaller but growing niche shaped by specialized imaging suites and expanding animal care infrastructure. The study addresses the exact allocation and growth pace of these verticals in detail; what matters in a 2026 preview is that medical imaging is the anchor, industrial NDT is the diversification lever, and veterinary medicine is the incremental expansion path that often benefits from adjacent clinical detector platforms. Leaders who understand these layers can stagger product support, service SLAs, and ecosystem partnerships accordingly.
Competitive Landscape: Eight Players, Distinct Modes of Competition
The wired flat panel detector market is not a winner-take-all arena. It is a structured competitive space in which device heritage, detector architecture, service coverage, and clinical validation define positioning. The following companies represent the core competitive field captured in our research base.
Varex Imaging
Headquartered in the United States, Varex Imaging is a leading provider of wired flat panel detectors for medical X-ray imaging systems, with a-Si and CMOS-based models supporting radiography and fluoroscopy. Its 2024 product launch of a high-resolution wired flat panel detector for cardiac imaging applications demonstrates a pattern of targeting niche clinical requirements with higher specification hardware, a move that increases relevance in specialized suites where image fidelity directly affects workflow confidence.
Trixell
Trixell operates as a joint venture of Thales, Philips, and Siemens, and supplies wired digital flat panel detectors for general radiography, fluoroscopy, and dental applications. Its presence reflects the advantage of consortium backing in integration, service reach, and clinical trust. The 2024 showcase of the Pixium 4700 wired detector at ECR for interventional radiology highlights a continued emphasis on fixed-room performance and interventional workflow compatibility.
Canon Medical Systems
Based in Japan, Canon Medical Systems offers the CXDI series of wired flat panel detectors using CMOS technology for portable and fixed X-ray systems in medical diagnostics. Its June 2024 FDA 510(k) clearance for a CXDI-710C wireless-capable wired flat panel detector upgrade is instructive: the market is expanding compatibility and upgrade paths even within wired architectures, giving existing customers migration flexibility without forcing full replacement.
Konica Minolta
Konica Minolta produces wired AeroDR and REGIUS flat panel detectors for CR/DR systems in healthcare radiography. Its positioning is anchored in workflow maturity and broad deployment familiarity, which supports replacement demand and retrofit programs in hospitals already running Konica or compatible CR/DR infrastructure.
Fujifilm
Fujifilm manufactures the FDR D-EVO series of wired flat panel detectors for digital radiography in hospitals and clinics. Its strategy illustrates how detector lines can be integrated into wider imaging ecosystems, enabling vendors to compete not only on detector specs but also on image processing and department workflow alignment.
Rayence
Rayence, based in South Korea, produces wired CMOS flat panel detectors such as the XAR series for medical X-ray imaging equipment. Its November 2023 IEC 62220-1 Class A certification for the XAR-HD wired flat panel detector underscores the importance of formal compliance attestation as a commercial enabler, particularly in markets where procurement teams require documented certification before qualification.
iRay Technology
iRay Technology, headquartered in China, supplies wired digital flat panel detectors for X-ray systems in medical and industrial applications. This dual-use orientation is strategically relevant because it creates cross-demand resilience and expands the addressable installation base beyond hospital imaging alone.
Agfa HealthCare
Agfa HealthCare, headquartered in Belgium, offers wired DR solutions including MUSICA flat panel detectors for direct digital radiography. Its presence demonstrates the enduring role of detector-plus-image-processing integration in fixed-room settings, where departments prioritize consistent image rendition and reading-room compatibility.
The broader competitive insight is not simply who competes, but how. The market exhibits a concentration profile in which the top three players account for approximately 45.5 percent of revenue and the top five for approximately 62.3 percent. That tells a 2026 planner two things at once: incumbents hold meaningful share and established relationships matter, but enough fragmentation remains to allow targeted wins in application niches, regional tenders, and material-specific deployments. The full report maps share dynamics, partnership patterns, and development signals so that strategy teams can identify where incumbency is a barrier and where it is an entry vector.
Recent Developments as Strategic Signals
Market intelligence gains value when it converts discrete events into forward indicators. Several 2023 and 2024 developments in the wired flat panel detector sector are especially relevant for 2026 planning.
- Varex Imaging's October 2024 launch of a high-resolution wired flat panel detector for cardiac imaging points to continued specialization in high-stakes clinical applications, indicating that premium specifications will be rewarded in select suites.
- Canon Medical Systems' June 2024 FDA clearance for a CXDI-710C wireless-capable wired flat panel detector upgrade shows that wired platforms are being extended through hybrid compatibility and upgrade pathways rather than treated as static assets.
- Trixell's March 2024 showcase of the Pixium 4700 wired detector at ECR for interventional radiology reinforces the continued relevance of wired detectors in procedure-adjacent environments where fixed positioning matters.
- Rayence's November 2023 IEC 62220-1 Class A certification for the XAR-HD wired flat panel detector illustrates how formal attestation supports market access and procurement qualification, particularly in regulated hospital purchasing cycles.
These events are not isolated news items. They reveal a competitive tempo in which specification upgrades, regulatory clearances, and workflow showcases are being used to reinforce installed-base retention, open narrow application markets, and preserve relevance in fixed-room environments. The study tracks this tempo systematically so that product planning teams can synchronize development milestones with the rhythm of competitor and customer expectations.
What the Full Study Delivers: A Practical Intelligence Toolkit
A preview can establish the landscape, but it cannot replace the scaffolding that makes a market study actionable. The complete PW Consulting Worldwide Wired Flat Panel Detectors Market report is built to be used in quarterly strategy reviews, capital planning sessions, and product-governance discussions. It is organized around content that converts analysis into decisions.
Forecast Architecture and Scenario Framing
The study provides a 2026-to-2032 forecast that extends the historical 2020-to-2025 series, allowing teams to evaluate multiple forward paths against observed momentum. Revenue projections are accompanied by monitoring indicators that help planners test sensitivity to changes in procurement cycles, hospital capital budgets, and industrial inspection spending. Exact segment-level allocations and detailed dollar splits are included in the full edition, but the preview intentionally withholds them to preserve the analytical integrity of the complete model.
Segment-by-Segment Navigation
Regional, material, and application segmentation is presented with the context required for commercial use. Planners do not receive decontextualized percentages; they receive the logic that explains why demand is distributed the way it is, which sub-segments are sensitive to installation format, and where material economics alter purchase decisions. This is the difference between knowing a number and knowing what to do with it.
Competitive and Development Monitoring
The report includes company-level profiles, recent development tracking, and share concentration analysis. That structure enables teams to benchmark their own roadmap against observable competitor moves, anticipate qualification pressure points, and identify windows where a focused application or regional entry can be timed effectively.
Regulatory, Reimbursement, and Usage Boundaries
Compliance frameworks, coding considerations, and usage restrictions are analyzed as practical constraints rather than background trivia. The study connects these factors to procurement timelines, installation planning, and total cost of ownership, so that commercial and service teams can build operating assumptions that hold up under hospital and industrial buyer scrutiny.
FAQ and Deployment Reality Checks
The report incorporates a focused FAQ section that addresses recurring practical questions about installation permanence, sterile-field restrictions, integration considerations, and procurement qualification requirements. This helps internal teams prepare consistent responses and reduces the risk of misalignment during sales cycles or internal approvals.
Strategic Use Cases for 2026 Decision-Making
For executives and planners, the study is most valuable when it is placed directly into operational decision loops. The following use cases illustrate how the intelligence translates into action.
- Capital allocation decisions can be stress-tested against a 3.4 percent CAGR trajectory and a 2032 revenue horizon of 1219.47 million USD, preventing both overcommitment to aggressive replacement assumptions and underinvestment in installed-base retention.
- Product roadmaps can be aligned with material and application signals, helping engineering teams decide where to prioritize Cesium Iodide or Gadolinium Oxysulfide support, which formats deserve longer lifecycle commitments, and how upgrade compatibility can extend product relevance.
- Market entry and partnership strategies can draw on regional demand patterns and competitor concentration data, allowing teams to identify where incumbency is strong and where specialized applications or industrial NDT use cases provide a more accessible entry point.
- Regulatory and reimbursement readiness can be integrated into launch planning, ensuring that certification timelines, documentation requirements, and coding awareness are addressed before commercial execution rather than after.
- Service and installed-base strategies can be calibrated to the fixed-installation nature of wired detectors, emphasizing on-site support, calibration cadence, component availability, and upgrade pathways that protect customer value over long deployment cycles.
Why This Study Belongs in 2026 Planning Now
The wired flat panel detector market is not defined by dramatic disruption. It is defined by disciplined continuity, technical refinement, and a procurement environment in which fixed installations, compliance readiness, and workflow compatibility continue to matter. That makes it a steady but demanding market for strategic planning. The Worldwide Wired Flat Panel Detectors Market study is designed to meet that demand with analysis that is specific enough to guide action and structured enough to withstand cross-functional scrutiny.
In this preview, we have outlined the macro trajectory, the operating constraints that shape demand, the segment architecture that determines where growth concentrates, the competitive field that defines positioning, and the practical toolkit that turns analysis into planning. What we have not done is substitute a partial view for the full analytical model. The complete report includes the full segment allocations, the detailed regional and application breakdowns, the deeper competitive share analysis, and the extended monitoring framework that decision-makers need before they commit capital, set product priorities, or lock in market-entry assumptions.
For teams preparing 2026 strategies, the next step is to engage the full study and map its findings directly to your planning calendar. The intelligence is built for that transition: from awareness to architecture, and from architecture to action.
For detailed analysis of this topic, please visit the official page: Worldwide Wired Flat Panel Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Cardiac Pressure Monitors Market to Hit USD 2,253.28 Million by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-02
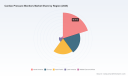
Decoding the Global Cardiac Pressure Monitors Market: Strategic Intelligence for the 2026–2032 Horizon
The global landscape for cardiac pressure monitoring is entering a decisive phase of transformation. As healthcare systems worldwide confront rising cardiovascular disease burdens, aging populations, and persistent cost containment pressures, the demand for precise hemodynamic assessment has evolved from a niche critical-care requirement into a foundational pillar of modern cardiovascular management. PW Consulting’s latest Worldwide Cardiac Pressure Monitors Market study delivers a comprehensive, data-rich foundation for executives who must navigate this accelerating transition with precision. Built on a rigorous bottom-up methodology and calibrated against verified industry trajectories, this report translates complex clinical, regulatory, and commercial forces into actionable intelligence. The following analysis outlines the structural drivers, competitive architectures, and operational considerations that will shape enterprise strategy through 2032, while demonstrating why comprehensive segmentation data, company-level benchmarks, and forward-looking scenario models reside exclusively within the full publication.
Worldwide Cardiac Pressure Monitors Market
The Macro Trajectory: Growth Foundations and Structural Inflection Points
The worldwide cardiac pressure monitors market has demonstrated consistent expansion across the historical analysis window, reflecting steady adoption of hemodynamic assessment technologies across acute, transitional, and decentralized care environments. Revenue scaled from approximately USD 1,050 million in 2020 to USD 1,243 million by 2022 and reached USD 1,288 million in 2023, before continuing its upward arc to USD 1,348 million in 2024 and an estimated USD 1,450 million in the 2025 base year. This sustained trajectory is not merely a reflection of incremental device replacement cycles; rather, it captures a fundamental broadening of clinical use cases, deeper integration of pressure-derived parameters into routine patient monitoring, and growing institutional recognition of hemodynamic precision as a lever for reducing adverse events and shortening length of stay.
Worldwide Cardiac Pressure Monitors Market
Looking ahead, the forecast horizon projects a compound annual growth rate of 6.5 percent, steering aggregate revenue toward USD 1,561 million in 2026, USD 1,663 million by 2027, and sustained expansion through the early 2030s. By the close of the forecast window in 2032, total market revenue is positioned to exceed USD 2.25 billion. It is important to emphasize that these headline figures represent aggregated market behavior across product architectures, end-user configurations, and geographic ecosystems. The underlying dispersion across those dimensions—where growth concentrates, where adoption lags, and which sub-segments carry disproportionate margin or volume implications—is precisely where strategic advantage is built or lost. Detailed segment-level revenue contributions, regional growth differentials, and product-type share dynamics are systematically mapped within the full report to ensure decision-makers can align portfolio priorities with empirically validated pathways rather than generalized market narratives.
Worldwide Cardiac Pressure Monitors Market
A structural reality that shapes competitive positioning is the degree of market concentration. The consolidated landscape reflects a relatively mature competitive environment, with the top three participants capturing a notable share of total revenue and the top five firms commanding an even larger proportion of the addressable market. This concentration pattern matters for strategic planning: it signals that supply-side dynamics, pricing negotiations, procurement relationships, and technology standardization efforts are increasingly influenced by incumbent scale, installed-base depth, and the ability to bundle hemodynamic solutions with broader monitoring or data infrastructure. At the same time, the presence of a long tail of specialized manufacturers, regional distributors, and clinically oriented innovators indicates that differentiation remains feasible for players who can demonstrate measurable performance advantages, regulatory clarity, or workflow integration benefits.
Competitive Architecture: Incumbents, Innovation Entrants, and the Strategic Meaning of Recent Moves
The competitive field for cardiac pressure monitors is populated by organizations with deep clinical engineering heritage, expansive hospital distribution networks, and increasingly sophisticated software and analytics capabilities. Major established players span multinational device conglomerates, specialized hemodynamic technology providers, and integrated patient monitoring groups. Their combined portfolios encompass invasive pressure transduction systems, pulmonary artery catheter platforms, advanced hemodynamic consoles, and noninvasive or minimally invasive measurement approaches that extend monitoring beyond the intensive care unit.
Several of the most consequential commercial entities illustrate the breadth of strategic approaches currently shaping the market. Edwards Lifesciences, now operating within the broader BD ecosystem, has long anchored its hemodynamic franchise on pulmonary artery catheter technologies and advanced monitoring consoles that support cardiac pressure and flow assessment in high-acuity settings. BD itself has reinforced its hemodynamic monitoring narrative through platforms that emphasize predictive analytics and clinical decision support, integrating algorithmic guidance into hemodynamic instability management. Medtronic contributes a comprehensive acute-care hemodynamic portfolio, emphasizing cardiac output and pressure parameter instrumentation designed for critical care workflows. ICU Medical, including the legacy pressure transducer capabilities associated with Smiths Medical, maintains a strong position in invasive pressure measurement systems and transducer kits that support direct cardiac pressure monitoring at the bedside.
The competitive equation extends well beyond traditional monitoring specialists. Koninklijke Philips N.V. embeds hemodynamic and cardiac pressure capabilities within enterprise telemetry and vital signs platforms, positioning pressure measurement as one element of a connected clinical information environment. GE Healthcare delivers hospital-grade monitoring systems with integrated cardiac pressure measurement functionality, aligning hemodynamic instruments with broader patient surveillance architectures. Drägerwerk and Getinge both supply hemodynamic monitoring and pressure instrumentation tailored for cardiac and critical care environments, reflecting sustained European engineering and clinical service depth. Nihon Kohden reinforces the Asia-based competitive landscape through patient monitoring systems that incorporate hemodynamic and cardiac pressure modules. Masimo has expanded its monitoring footprint through advanced noninvasive and hemodynamic technologies, including solutions built around pressure-related and cardiac output parameters. Retia Medical, meanwhile, has pursued an accessible, low-cost hemodynamic monitoring approach through cardiac output instrumentation that incorporates pressure-derived parameters, illustrating how focused innovation can open differentiated positioning even within a concentrated market.
Recent commercial and regulatory developments provide concrete signals about where value creation is accelerating. In April 2025, BD introduced an advanced hemodynamic monitoring platform incorporating predictive AI-based algorithms designed to address blood pressure instability and optimize flow management in critical care, a move that underscores the industry’s pivot toward algorithm-enabled decision support. In June 2025, Cardinal Health launched a multi-system continuous monitoring solution for cardiac activity and other vital signs within a single-patient-use design, highlighting growing attention to workflow simplification and infection-control-oriented product architecture. On the regulatory front, the U.S. Food and Drug Administration cleared a wearable ambulatory blood pressure monitor in February 2026, expanding the feasibility of out-of-hospital pressure tracking. Earlier in 2025, another developer received clearance for a cuffless blood pressure monitoring system intended for over-the-counter availability in the United States beginning in 2026, signaling progress toward consumer-accessible and decentralized monitoring pathways. Additionally, a non-invasive central venous pressure measurement system earned FDA Breakthrough Device Designation in early 2026, pointing toward emerging interest in noninvasive surrogates for parameters historically accessed through invasive instrumentation.
For executives, these developments are not isolated product launches; they are indicators of shifting clinical expectations, reimbursement alignments, and competitive infringement points. Companies that can connect regulatory clearance, clinical utility evidence, and workflow integration into a cohesive value proposition will be best positioned to convert technological momentum into durable share gains. The complete report dissects these company-specific trajectories alongside detailed competitive benchmarking, partnership and distribution analyses, and assessments of where each major participant’s portfolio strength aligns—or clashes—with the dominant demand centers in the market.
Technology and Clinical Dynamics: Invasive Precision, Noninvasive Expansion, and the Hybrid Road Ahead
Clinical adoption of cardiac pressure monitoring has historically been anchored by invasive instrumentation, particularly in environments where direct pressure waveforms, dynamic response characteristics, and real-time hemodynamic interpretation are essential to managing complex cardiovascular instability. Invasive cardiac pressure monitors continue to represent a substantial share of total market revenue, reflecting their entrenched role in critical care, perioperative medicine, and specialized cardiac suites. Their enduring presence is reinforced by clinical workflows that depend on precise pressure transduction, reliable catheter-based measurement, and compatible monitoring consoles that translate raw physiological signals into interpretable parameters for bedside decision-making.
At the same time, noninvasive cardiac pressure monitors constitute a meaningful and growing portion of the market. This category encompasses a widening spectrum of technologies, from externally applied measurement systems to algorithmic estimation approaches and cuffless monitoring concepts. The appeal of noninvasive modalities is obvious: reduced procedural risk, broader deployability across general ward and ambulatory settings, and greater alignment with decentralized and home-based care models. As evidence bases mature and devices demonstrate acceptable accuracy thresholds in target populations, noninvasive solutions are increasingly viewed not as full replacements for invasive instrumentation in all contexts, but as complementary tools that extend the reach of hemodynamic awareness beyond the most acute environments.
The practical implication for manufacturers and purchasers is that the product landscape is not converging toward a single dominant modality. Instead, it is evolving into a layered ecosystem in which invasive systems sustain high-acuity, high-fidelity use cases, noninvasive systems broaden monitoring coverage and enable earlier or more continuous assessment, and hybrid clinical pathways determine which technology is appropriate for which patient profile, care setting, and economic constraint. Report segmentation captures these distinctions explicitly, mapping revenue behavior across product types and linking them to end-user demand patterns. Because the balance between invasive and noninvasive adoption differs dramatically by region, hospital type, and clinical program, the granular segment data within the full study is essential for avoiding overgeneralized technology forecasts.
End-User Fragmentation and the Redistribution of Demand Across Care Settings
Where cardiac pressure monitors are purchased, deployed, and utilized has become just as important as what technologies are used. Hospital and clinic environments remain the dominant demand center, reflecting the concentration of acute cardiovascular care, surgical services, and specialized monitoring programs within institutional settings. These facilities continue to drive substantial volume for both invasive and integrated noninvasive solutions, while also placing a premium on interoperability, service infrastructure, consumables supply reliability, and clinician training. The installed-base economics in hospital environments also create sticky relationships, meaning that initial procurement decisions often influence replenishment, upgrade, and expansion cycles over multiple years.
Ambulatory surgical centers represent a second, increasingly distinct end-user pathway. As procedural complexity and patient acuity shift partially toward outpatient surgical environments, hemodynamic monitoring requirements within these settings must balance clinical safety with operational efficiency, space constraints, and turnover demands. Monitoring solutions in ambulatory surgical contexts are therefore evaluated not only on technical performance but also on portability, setup speed, ease of integration with existing surgical workflows, and alignment with the center’s scope of services.
Homecare settings form a third and strategically significant demand vector. Home-based and transitional care models are expanding pressure monitoring from a predominantly facility-bound activity into a more continuous, patient-centric practice. This shift is supported by broader telehealth adoption, evolving reimbursement frameworks for remote physiologic monitoring, and growing recognition that cardiovascular status can be managed more proactively when pressure trends are observed beyond episodic clinic visits. For manufacturers, the homecare segment introduces distinct product requirements: usability for non-specialist users, connectivity for data transmission, durability for non-clinical environments, and clarity around which parameters are appropriate for decentralized interpretation. The full report assesses how revenue is distributed across these end-user environments and identifies the operational and commercial implications of demand migration, without oversimplifying the heterogeneity within each setting.
Regulatory, Reimbursement, and Standards Alignment: The Operational Skeleton of Market Growth
Commercial success in the cardiac pressure monitors market depends heavily on the alignment between device classification, regulatory clearance pathways, coding structures, and reimbursement realities. Invasive blood pressure monitoring systems and transducers are regulated as Class II devices under relevant U.S. premarket notification requirements, with clearance typically pursued through the 510(k) pathway. This regulatory framework matters for product roadmaps because it shapes development timelines, documentation burdens, predicate selection strategy, and the speed with which iterative design improvements or accessory expansions can reach market.
Reimbursement architecture further influences adoption patterns. Certain invasive hemodynamic monitoring procedures, including right heart catheterization for monitoring purposes using flow-directed catheters, are reported under designated procedural coding, which directly affects how hospitals and clinicians account for the cost and reimbursement of monitoring services. In parallel, pulmonary artery pressure monitoring approaches for heart failure management have dedicated Medicare coverage and reimbursement coding resources, reinforcing the economic viability of specific monitoring programs in chronic disease management. More broadly, remote physiologic monitoring treatment services—including those that encompass blood pressure parameters—utilize updated coding structures with defined national average reimbursement rates, indicating that payers continue to refine payment mechanisms for continuous or intermittent physiologic data collection outside traditional facility walls.
Regulatory and safety oversight also continues to tighten around measurement validity. Public safety communications have cautioned against the use of unauthorized blood pressure measuring devices lacking appropriate marketing authorization, reinforcing the importance of regulatory compliance for manufacturers, distributors, and healthcare purchasers alike. For companies expanding into consumer-accessible or decentralized monitoring concepts, demonstrating that a device meets the appropriate regulatory expectations is not merely a legal requirement; it is increasingly a market-access prerequisite, since procurement and prescribing decisions are influenced by perceived clinical reliability and regulatory standing.
These dynamics create a layered operational landscape. Product strategy must account for clearance status, intended-use definitions, documentation readiness, and compatibility with existing coding frameworks. Commercial strategy must incorporate reimbursement literacy, particularly where new monitoring programs depend on billability to sustain adoption. Procurement and clinical strategy must weigh whether the evidentiary basis for a device matches the reimbursement and regulatory environment in which it will be deployed. The complete market study integrates these considerations into a unified view of market dynamics, enabling readers to see how regulatory and reimbursement forces interact with technology adoption rather than treating them as separate background factors.
2026–2032 Strategic Imperatives for Market Participants
As the forecast period unfolds, successful market participants will need to make deliberate choices across several strategic dimensions. First, technology roadmaps must clarify the intended clinical positioning of each product family. Solutions positioned for high-acuity invasive monitoring require sustained attention to measurement fidelity, catheter and transducer reliability, service responsiveness, and compatibility with critical care workflows. Solutions positioned for broader deployment, including ward-based and home-based monitoring, require equal attention to usability, connectivity, data interpretability, and the clinical evidence needed to justify monitoring outside traditional intensive environments.
Second, competitive differentiation will depend increasingly on the integration of monitoring hardware with software intelligence. Predictive algorithms, trend interpretation, alarm optimization, and clinical decision support are becoming central to value propositions because they address the operational challenge of converting continuous or frequent measurements into actionable clinical insight. Companies that can demonstrate reproducible performance improvements, reduced alarm fatigue, or clearer thresholds for intervention will strengthen their standing with clinical buyers and procurement teams.
Third, commercial strategy must align product portfolios with the realities of end-user fragmentation. Hospital-centered sales models, ambulatory surgical center outreach, and home-based distribution pathways each require different pricing structures, service offerings, training approaches, and evidence packages. A portfolio that performs well in one setting may underperform in another unless commercial execution is tailored to the specific purchasing drivers, clinical staffing profiles, and operational constraints of that environment.
Fourth, geographic strategy must reflect uneven regional dynamics. Demand maturity, procurement structures, clinical practice patterns, reimbursement conditions, and regulatory expectations differ substantially across regions, and these differences influence both the pace and the shape of adoption. Organizations that rely on single-region assumptions risk misallocating resources or underpricing the effort required to enter or expand in less familiar markets. Detailed regional revenue behavior, demand concentration patterns, and growth differentials are mapped within the full study to support precise geographic prioritization.
Finally, strategic planning should consider the long arc of consolidation and partnership activity. Given the market’s concentration profile, acquisitions, divestitures, distribution agreements, and technology alliances can reshape competitive positions quickly. Executives should therefore monitor not only product launches and regulatory milestones, but also organizational restructuring, portfolio rationalization, and changes in the ownership or distribution architecture of key hemodynamic technology assets.
What the Full Study Delivers
PW Consulting’s Worldwide Cardiac Pressure Monitors Market report is structured to convert high-level industry awareness into decision-grade intelligence. The publication traces historical revenue performance from 2020 through the 2025 base year and extends a disciplined forecast across the 2026–2032 period, providing the numerical scaffolding needed to benchmark internal expectations against market-wide behavior. It examines market structure through multiple segmentation lenses, connecting product-type dynamics, end-user demand patterns, and regional performance into a coherent explanatory framework. This multi-dimensional segmentation is presented in detail so that readers can identify where growth is concentrated, where adoption constraints persist, and how different market slices contribute to overall revenue progression.
The competitive analysis component profiles the major participants shaping the industry, integrates recent product launches, regulatory clearances, and designations, and provides context around the strategic significance of each development. Rather than treating these events as isolated news items, the report situates them within broader trends in algorithm-enabled monitoring, decentralized measurement, workflow simplification, and noninvasive parameter expansion. In parallel, the study incorporates the regulatory and reimbursement architecture that governs market access, including relevant device classification considerations, procedural coding references, remote monitoring coding updates, and publicly communicated safety expectations.
Importantly, the report deliberately avoids superficial market summaries. The objective is to supply executives, product leaders, investors, and clinical-commercial strategists with sufficiently granular segmentation detail, company-level profiles, and forward-looking scenario context to support resource allocation, portfolio planning, pricing strategy, and market-entry evaluation. The headline numbers and directional narratives described here establish the strategic backdrop; the full study supplies the segment-level precision, competitive depth, and operational context needed to convert that backdrop into executed strategy.
Closing Perspective
The worldwide cardiac pressure monitors market is moving through a period in which clinical utility, regulatory clarity, reimbursement alignment, and technology integration will jointly determine which organizations capture disproportionate value. The aggregate growth path is clear, but the strategic opportunities within that path are highly differentiated by product architecture, care setting, region, and competitive positioning. PW Consulting’s study is designed for leaders who need more than a top-line forecast: it is built to illuminate the structural drivers behind the numbers and to provide the segmentation fidelity, competitive context, and market-dynamics analysis required to act with confidence. For organizations preparing decisions in 2026 and beyond, the full report offers the complete intelligence architecture necessary to align innovation, commercial execution, and market access strategy with the realities of an increasingly sophisticated hemodynamic monitoring landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Cardiac Pressure Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


