



Category: market research
PW Consulting: Residential Solar Market Poised for 14.02% CAGR Through 2032
By PW Consulting, 2026-07-13
Residential Solar Power Solution Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As governments, utilities and homeowners accelerate distributed energy adoption, the residential solar market has moved from niche system installs to a mainstream capital and policy battleground. Our updated market model shows the global residential solar power solutions market nearly doubling from an estimated USD 61.4 Billion in 2020 to USD 128.19 Billion in 2025, and continuing on a robust trajectory under our base-case assumptions. We forecast an average compound annual growth rate of 14.02% into the 2026–2032 period, with a projected market size exceeding USD 320 Billion by 2032. These headline numbers frame why 2026 is a pivotal year for positioning: momentum is clear, but the competitive and regulatory environment is shifting rapidly enough to reshape winners and losers.
Residential Solar Power Solution Market
Why this research matters for boardrooms in 2026
- Timing of strategic moves: With multi-year expansion built into the market, incremental capacity additions alone will not secure sustainable margin expansion. Boards must decide whether to invest in scale, vertical integration, product premiumization, or services-led models—each path requires different near-term capital and partnership choices.
- Regulatory inflection points: Policy changes and trade measures are already altering cost dynamics and supply choices. Our research isolates the commercial impact of recent tax and trade developments and quantifies alternative scenarios so executives can price risks into contracts and capital plans.
- Channel and consumer economics: As rooftop buyers shift expectations (tariff arbitrage, resilience, total cost of ownership), companies that redesign sales funnels and after-sales services will capture disproportionate value. This report provides the decision-grade evidence to prioritize those investments.
Market trajectory and the assumptions that matter
Between 2020 and 2025 the residential solar market more than doubled in revenue terms, a reflection of improving panel and inverter economics, rising homeowner interest in energy independence, and policy-driven deployment in multiple markets. Our projections for 2026–2032 incorporate three linked assumptions: continued module efficiency gains and cost declines, progressive electrification of homes, and a mixed regulatory environment that includes trade remedies and episodic subsidy adjustments. Under these assumptions the market sustains a mid-teens CAGR—translating into a market more than two times its 2025 size by the end of our forecast window.
Residential Solar Power Solution Market
Importantly, our modelling layers in scenario sensitivity for raw-material shocks, subsidy removal, and tariff disruptions—each of which can compress or expand near-term revenue by material margins. For executives, the practical implication is that capital allocation must be flexible and hedged against policy swings and input-price volatility.
Residential Solar Power Solution Market
Key industry dynamics shaping 2026 strategic choices
- Input cost volatility: Polysilicon spot prices rose materially in early 2025, reflecting supply constraints and cyclical demand. The knock-on effect is visible across module pricing and OEM margins—our scenario analysis shows how short-term spikes can reallocate margin pools across the value chain.
- Shifting subsidy and tax landscapes: Notable policy shifts—such as the termination of the U.S. residential tax credit for systems placed in service after December 31, 2025—reconfigure project economics for a significant buyer cohort. Our regulatory impact matrix quantifies which customer segments and geographies suffer most and where commercial models must pivot (e.g., lease-to-own, community-shared models, or bundled storage incentives).
- Trade and duties: Quotas and duty measures, including recent CBP actions and preliminary antidumping determinations affecting certain supply routes, are already influencing procurement strategies. Our procurement playbook outlines how to re-route sourcing, negotiate volume protections, and structure long-term supply contracts under elevated trade risk.
- System cost benchmarks: Recent independent benchmarks indicate U.S. residential system pricing clustered in a narrow band of $3.2–$4.2/Wdc in 2025. When combined with local tariff and cross-border cost impacts, those unit economics translate directly into regional payback windows and finance availability. We model financeable IRRs for a variety of buyer profiles in the full report.
Competitive landscape — who to watch and why
The residential solar ecosystem blends module manufacturers, inverter and power electronics specialists, energy storage integrators, and vertically integrated home-energy brands. Market concentration remains moderate: the top three players control roughly 34.5% of the market by revenue, while the top five account for about 42.8%. This structure produces both opportunities for scale-driven incumbents and niches where differentiated technology or service plays can thrive.
- High-volume module leaders: Firms with massive module shipments and vertically integrated wafer-to-module capabilities are competing aggressively on price and efficiency. Their continued investment in N-type and high-efficiency monocrystalline technology is lowering levelized cost of energy for rooftop systems and imposing pressure on smaller module suppliers.
- Performance and integration players: Companies focused on inverter optimization, microinverters, and integrated storage-plus-control stacks are creating higher-value propositions for homeowners. These firms are winning on customer experience and O&M economics, not just upfront price.
- Premium systems brands: A subset of providers combines differentiated panel tech, branded storage, and a direct-to-consumer sales channel to capture higher margins—appealing to customers prioritizing aesthetics, performance, and integrated software services.
In the detailed company profiles we benchmark product roadmaps, production footprints, channel strength, and balance-sheet resilience. That analysis highlights which suppliers are best positioned to expand share organically, and which present attractive M&A targets for system integrators seeking supply assurance or vertical capability.
What the full PW Consulting report delivers
This research is designed to be operational from day one for corporate strategists, M&A teams, and commercial leaders. Key deliverables include:
- Proprietary market model with annualized revenue estimates from 2020 through 2032 and scenario toggles for raw-material, trade and policy shocks;
- Actionable segmentation framework by product architecture, connectivity (on-grid vs hybrid/off-grid), and commercial channels with clear implications for pricing and unit economics (note: we intentionally withhold the granular segment tables in this preview);
- Competitive benchmarking covering technology, manufacturing scale, and channel reach for leading module and inverter makers, plus supplier scorecards and supplier risk heatmaps;
- Go-to-market playbooks by region for installers, utilities and new entrants, including customer acquisition cost benchmarks and financing structures optimized for 2026 realities;
- Regulatory and trade impact matrices that translate recent CBP, DOC, and tax policy developments into revenue-at-risk and contingency actions;
- M&A and partnership roadmaps including target archetypes, valuation sensitivities, and integration checklists;
- Operational checklists for procurement, inventory hedging and inventory-to-order conversion strategies under volatile polysilicon and upstream pricing.
Strategic implications and recommended executive actions for 2026
- Hedge supply but prioritize flexibility: Locking in component volumes via long-term agreements can stabilize margins, but overly rigid contracts increase exposure to efficiency improvements and price declines. Structure agreements with price collars, capacity options and pass-through clauses tied to vetted indices.
- Pivot to value beyond modules: Margins are migrating toward system-level integration—software, storage and lifecycle services. Invest selectively in customer-facing software, O&M platforms, and bundled financing to capture lifetime value.
- Adopt a multi-scenario playbook: Given policy volatility, develop at least three go-to-market plans (accelerate, defend, consolidate) calibrated to subsidy and trade outcomes. Each plan should have predefined trigger points tied to regulatory announcements or commodity movements.
- Targeted M&A to fill capability gaps: Use M&A to acquire software, storage, or distribution capabilities rather than duplicating expensive manufacturing scale unless compelling cost synergies exist.
- Customer segmentation by economics, not geography: Prioritize buyer segments with favorable payback periods and financeability. We show how to re-rank territories based on end-customer economics rather than headline install volumes.
How to use this preview
This preview is intentionally selective: it demonstrates the analytical depth and strategic framing PW Consulting provides, while reserving the granular segment tables, detailed company scorecards, and downloadable data models for the full report package. If your 2026 plans depend on precise segment forecasts, supplier risk scores, or deal-level valuation sensitivities, the full dataset and model controls will be required to operationalize the scenarios we outline here.
Next steps and where to find the full intelligence
For executives ready to move from insight to action, PW Consulting offers a suite of advisory options: bespoke scenario workshops, procurement and hedging playbook execution, and diligence-led M&A support. To access the full Residential Solar Power Solution Market report, including downloadable Excel models, segmentation tables, and the complete competitive scorecards, please visit our report page. The full package contains the detailed intelligence necessary to convert the strategic implications above into execution-ready plans for 2026.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Phenolic Resin Market at USD 7,411.35M in 2025; 5.01% CAGR (2026–2032)
By PW Consulting, 2026-07-13
Liquid Phenolic Resin Market 2026: Strategic Compass for Executive Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on the Liquid Phenolic Resin market that frames the strategic choices facing manufacturers, downstream integrators, investors and policy teams in 2026. This is a forward-looking, decision-focused synopsis designed to show the analytical depth of our full study while preserving the detailed segment tables and proprietary models that drive prescriptive action. Consider this a high-resolution map with the detailed coordinates available in the full report.
Liquid Phenolic Resin Market
Why this market matters to 2026 strategy
Liquid phenolic resins sit at an intersection of durable-goods manufacturing, construction materials, automotive lightweighting and high-temperature industrial processing. Between 2020 and 2025 the global market expanded materially, reflecting recovery in construction and targeted industrial demand. Our base-year sizing indicates a market of USD 7,411.35 Million in 2025. Looking forward, our forecast model projects the market will grow at a compounded annual rate of 5.01% across the 2026–2032 horizon, reaching approximately USD 10,435.47 Million by 2032. That growth trajectory creates a multi-year runway for strategic investment but also raises stakes around feedstock exposure, regulatory compliance and competitive positioning.
Liquid Phenolic Resin Market
Five structural dynamics shaping decision trade-offs
-
Demand diversification vs. concentration risk. End-use demand drivers (construction, insulation, foundry, laminates/coatings and friction materials) are uneven in cyclical sensitivity and margin profile. Firms must balance investments toward higher-growth structural uses—such as advanced composites for automotive lightweighting—with the steady base provided by traditional wood product and refractory markets.
Liquid Phenolic Resin Market -
Raw material volatility and cost pass-through. Phenol is the principal upstream feedstock. Pricing signals through early 2026 demonstrate renewed tightening: Northeast Asia phenol spot prices reached about USD 1.01/kg in March 2026 (an 8.6% increase from December 2025 and a 3.1% monthly rise), pressured by maintenance outages and stronger downstream resin operating rates. These dynamics mean feedstock hedging, bilateral supply agreements and flexible formulation strategies are now core commercial capabilities.
-
Regulatory and sustainability premium. Stricter formaldehyde emission standards and related air quality regulations are elevating compliance costs—our synthesis of region-level regulatory impact models indicates compliance-driven cost increases in the neighborhood of 8–12% for producers of conventional formulations. Concurrently, buyers increasingly prize certified low-emission and circular-material variants, creating a dual imperative: regulatory compliance and product differentiation through sustainability credentials (e.g., ISCC PLUS).
-
Supply-chain fragmentation and geopolitics. The sector shows moderate aggregation at the top: our concentration analysis indicates the market remains neither fully consolidated nor atomized (three-company concentration and five-company concentration metrics point to a moderate-leading-player landscape). Tariff actions, such as U.S. reciprocal measures implemented in 2025 that affected certain resin-related imports, can abruptly shift cost competitiveness and reroute trade flows, incentivizing nearshoring and multi-regional footprints.
-
Product and process innovation as margin lever. Incremental improvements—lower-emission resoles, waterborne systems, and process yields—translate directly into commercial share when paired with robust application development (e.g., adhesives with reduced formaldehyde release for engineered wood). Certification achievements and validated sustainability claims materially accelerate buyer adoption in Europe and premium segments.
Competitive landscape: strategic implications for incumbent and new entrants
The competitive set combines global chemical integrators, regionally specialized producers and technically focused toll manufacturers. Key strategic archetypes we analyzed include:
-
Global integrators: Companies with large-scale, vertically integrated chemical platforms and global distribution capability are positioned to absorb feedstock volatility, invest in low-emission product lines and offer bundled solutions to large OEMs. Their strategic options include selective capacity expansion in growth corridors and value-capture via downstream formulation licensing.
-
Regional specialists: European-focused and Asia-specialized players emphasize proximity to key customers and regulatory competence. Their competitive edge is speed-to-market for region-specific formulations and certification services; their primary strategic vulnerabilities are feedstock import exposure and limited scale when competing for global OEM contracts.
-
Custom and toll producers: Dedicated contract manufacturers and ISO-certified tollers provide flexible small-batch supply and rapid formulation iteration—an attractive route for engineering houses and mid-sized firms seeking lower capital intensity. Scaling these relationships into longer-term partnerships is an underutilized strategy for premium capture.
Representative firm-level observations from our review:
-
Hexion Inc. – Broad resoles capability and global reach make it a natural supply partner for multi-national wood and composites OEMs. Strategy: deepen value-added adhesive platforms and negotiate long-term phenol-offtake arrangements to shield margins.
-
Prefere Resins Holding GmbH – European specialization gives it regulatory fluency; prioritize certification-led differentiation and selective capacity to serve higher-margin construction and insulation segments.
-
Sumitomo Bakelite – The company’s ISCC PLUS certification (achieved in late 2025 for some operations) is a strategic advantage in European sustainability-conscious markets; accelerate certified-supply commercialization and target automotive electronics and coatings customers that value circularity.
-
BASF and DIC – Large-scale integration enables aggressive product development; opportunity lies in leveraging BASF’s downstream formulation assets and DIC’s Asian expansions to capture premium industrial applications.
-
Capital Resin, Georgia-Pacific Chemicals, Bakelite Synthetics, Jinan Shengquan, SI Group – These players represent a mix of contract manufacturing strength, regional volume supply and technical niche expertise. Their strategic move sets include expanding tolling footprint, consolidating regional supply agreements, and aligning product roadmaps with OEM decarbonization goals.
What our full study delivers (practical, transaction-ready content)
The PW Consulting report is structured to convert insight into action. Key operational and strategic deliverables include:
- Validated market sizing and multi-scenario forecasts (base and upside iterations) covering 2020–2032 with our 2025 base year and 2026–2032 projection horizon.
- Feedstock price modeling and sensitivity matrices showing margin exposure across pricing, tariff and regulatory shock scenarios.
- Regulatory impact assessment and compliance-cost playbooks for major jurisdictions—detailing engineering, formulation and certification pathways to meet formaldehyde and related standards.
- Competitive benchmarking with playbook recommendations by strategic archetype (scale integrator, regional specialist, toll manufacturer).
- Deal pipeline: prioritized M&A targets and partnership hypotheses, screening using synergies, capacity fit and regulatory exposure.
- Commercial go-to-market templates for premium positioning (sustainability certification, low-emission claims, co-development with OEMs).
- Operational recommendations on capacity siting, tolling partnerships, and raw material logistics hedging.
Note: This preview deliberately omits granular regional and application-split tables and the proprietary unit economics that underpin our buy/sell recommendations—these are available in the full report and interactive data annex.
Actionable recommendations for 2026 planning cycles
-
Hedge and diversify phenol exposure. Lock incremental phenol volumes through multi-year contracts in tandem with flexible formula options to protect margins during episodic price spikes.
-
Prioritize low-emission formulations and certification. Dedicate R&D and capital to bring ISCC PLUS–compatible and low-formaldehyde product lines to market; certification accelerates market access in Europe and premium OEM segments.
-
Reassess footprint under tariff risk. Evaluate nearshoring or regional manufacturing agreements in response to trade measures that can impose up to meaningful tariff levels; consider tolling partnerships to maintain customer continuity.
-
Use M&A and partnerships to buy capabilities. Acquire or partner for formulation know-how, certification pipelines and local regulatory expertise rather than relying solely on organic development—this shortens time-to-revenue.
-
Implement dynamic pricing linked to feedstock indices. Where contract structures allow, adopt transparent indexation to pass-through material cost swings while preserving customer relationships.
Closing perspective
The liquid phenolic resin market presents a balanced risk-reward profile for 2026 decision-makers: predictable, mid-single-digit growth aggregated at the global level but with concentrated value creation available to players who manage feedstock volatility, regulatory compliance and product differentiation. Our full PW Consulting market study converts the broad opportunities highlighted above into executable strategies, quantified scenarios and a prioritized action plan tailored to your role—supplier, OEM, investor or policy advisor. For the numerical tables, segment-level economics and the interactive decision-support model that power the tactical recommendations in this brief, please consult the full report via PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Precision Copper Foil Market — USD 21,167.3M by 2032, 8.64% CAGR
By PW Consulting, 2026-07-13
High Precision Copper Foil Market — Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s High Precision Copper Foil Market study provides a strategic compass for companies that must make decisive capital, procurement and product choices in 2026. Using 2025 as the base year, our top‑line market model shows an industry that has grown materially through the 2020–2025 historical window and is forecast to continue expanding at a compound annual growth rate (CAGR) of 8.64% across the 2026–2032 horizon. In revenue terms (USD, Million), the market moves from a substantial 2025 base toward a materially larger addressable opportunity by 2032 — underpinning both near‑term tactical choices and multi‑year strategic investments.
High Precision Copper Foil Market
Why this study matters in 2026
-
Demand structuralization: The market is being reshaped by simultaneous secular forces — electrification of mobility, miniaturization and density increases in printed circuit boards, the growth of advanced AI and communications hardware that require ultra‑smooth, low‑roughness foils, and the continuing adoption of lithium‑ion and next‑generation battery formats. These trends are durable and create differentiated value pools for specific foil technologies.
High Precision Copper Foil Market -
Supply fragility and cost volatility: Raw material dynamics—most notably copper feedstock price volatility—are exerting a visible influence on cost structures and commercial behavior across the value chain. Producers have already signaled price adjustments in 2026, and upstream treatment/refining charge swings are introducing asymmetric risk to producers and buyers alike.
High Precision Copper Foil Market -
Regulatory and sustainability pressures: Advanced jurisdictions have tightened environmental requirements, pushing manufacturers to invest in emissions‑reduction measures, renewable energy sourcing and recycled copper usage. Compliance choices now directly affect capital planning, cost competitiveness and market access for certain high‑end applications.
-
Consolidation and niche specialization: The competitive landscape shows a mix of global leaders investing in ultra‑smooth and ultra‑thin technologies alongside regional specialists focusing on battery grade and flexible circuit applications. The market is neither a pure monopoly nor atomized: concentration metrics point to meaningful leadership but with room for differentiated entrants.
What PW Consulting’s report delivers (practical, decision‑ready content)
Our research is designed to be operationally useful to procurement, product leadership, corporate strategy and M&A teams. Key deliverables include:
-
An audited market‑size model (base year 2025) and a point‑by‑point forecast through 2032 with scenario variants tied to copper price paths, EV penetration curves and board design cycles.
-
Cost‑to‑produce and break‑even curves for electrodeposited versus rolled foil pathways, including sensitivity analysis to cathode price swings and energy cost assumptions.
-
Supplier heatmaps and capability matrices highlighting technology differentiators (ultra‑thin foils, ultra‑smooth surfaces, precision thickness control), facility footprints and recent capacity moves.
-
Commercial playbooks for procurement teams: hedging trigger points, contract structures, acceptable lead‑time buffers and escalation clauses to protect against rapid raw material-driven price moves.
-
Regulatory and sustainability impact matrix: capital expenditure implications of emissions requirements, recommended carbon reduction investments and payback estimates under multiple policy regimes.
-
M&A and partnership diagnostic: target profiles, valuation sensitivities and integration checklists for buyers seeking either vertical integration into rolling/electrolytic production or bolt‑on specialty capability.
-
Go‑to‑market playbooks for technology owners: product positioning, co‑development pathways with OEMs (batteries, AI accelerators, HDI boards) and specification negotiation templates.
Competitive landscape — what leading players signal for 2026
The industry map is populated by long‑established materials houses and focused specialty suppliers. Leading firms distinguish themselves through IP in ultra‑smooth and ultra‑thin foil production, control of critical process steps, and targeted capacity investments.
-
Mitsui Mining & Smelting (Mitsui Kinzoku) continues to pursue premium MicroThin and ultra‑smooth product strategies and has signaled commercial price increases in early 2026 while rolling out capacity expansions for its proprietary VSP™ technology. These moves underscore a willingness to defend margins and to scale proprietary, high‑value products.
-
JX Nippon and Furukawa maintain technology‑led positions in both electrodeposited and rolled foils, emphasizing precision thickness control and high‑frequency performance—areas where end‑users are increasingly willing to pay for demonstrable technical advantage.
-
European and regional specialists such as Circuit Foil Luxembourg, Wieland (rolled foil) and Solus are doubling down on tight‑tolerance and ultra‑low roughness niches, supporting high‑frequency and AI accelerator applications where surface quality is a commercial differentiator.
-
Asian manufacturers, including established and emerging Chinese, Korean and Taiwanese firms, are strategically important to global supply given their large manufacturing footprints and accelerating capability upgrades directed at both battery grade and high‑precision electronics segments.
Market concentration metrics indicate a moderate-but-meaningful level of aggregation among the top players. This structure produces competitive dynamics where technology leadership and commercial agility matter as much as scale—creating opportunities for focused entrants to win niche premium positions while larger players protect broadscale OEM relationships.
Recent market signals executives must heed in 2026
-
Price actions by major suppliers in early 2026 reflect immediate margin pressure from raw material and labor costs; commercial teams should expect further supplier‑initiated repricing unless copper feedstock trajectories moderate.
-
Capacity investments announced by technology leaders indicate a deliberate move to capture growing volumes in ultra‑smooth and ultra‑thin segments; late entrants should assess the risk of downward pressure on premium spreads if capacity growth outpaces niche demand.
-
Product portfolio refreshes and updated catalogs point to rapid iteration in tolerance and surface finish specifications—buyers must update qualification processes to avoid supply constraints on next‑generation designs.
Strategic imperatives & recommended actions for 2026
To translate market intelligence into competitive advantage, executive teams should prioritize a mix of defensive and offensive moves:
-
Build a procurement “early warning” system tied to raw material and supplier signals. Define contract escalation clauses and a hedging playbook tied to specific copper price thresholds and supplier liquidity signals.
-
Reassess product roadmaps: accelerate co‑development with foil suppliers on ultra‑thin/ultra‑smooth specifications where willingness‑to‑pay is demonstrable; defer commoditized transitions where margin erosion risk is high.
-
Calibrate capacity investments to scenario outcomes. Use PW Consulting’s demand‑by‑application scenarios to time capacity additions and to size them for premium versus commodity mixes.
-
Pursue supply diversification and dual‑sourcing for critical specifications. Where performance risk is high (AI accelerators, certain battery foils), secure qualification of at least two geographically diverse suppliers.
-
Embed sustainability as a commercial differentiator: investments in recycled copper sourcing and renewable energy not only mitigate regulatory risk but are increasingly requested by OEM procurement teams.
-
Explore targeted M&A to acquire specialty capabilities rather than broadscale volume. The most accretive deals in the near term will be technology or specification plays that shorten time‑to‑market for premium applications.
How to use this study in 90 days
-
Procurement: implement the supplier scorecard and commence renegotiation pilots with top suppliers using the price‑trigger templates in the report.
-
R&D/Product: run a technical gap analysis against the foil technology roadmaps and prioritize two co‑development projects for ultra‑thin/ultra‑smooth foils.
-
Corporate Strategy: model two M&A scenarios using the report’s valuation sensitivities and target lists; commence discreet outreach if criteria match.
Next steps and access to the full intelligence
The analysis above demonstrates the type of strategic depth PW Consulting brings to high precision copper foil decisions in 2026. The full report contains proprietary, transaction‑grade intelligence — including detailed segmentation by application and region, supplier scorecards, precise cost curves, and downloadable scenario models — intentionally withheld here to preserve the commercial utility of our subscription offering.
Reach out to PW Consulting to obtain the full dataset, supplier benchmarking tables, and the model templates you can deploy immediately to stress‑test 2026 investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steering Wheel Adjustment Motors — USD 2,110.88M by 2032 at 6.19% CAGR
By PW Consulting, 2026-07-13
Automotive Steering Wheel Adjustment Motor Market — Strategic Preview for 2026 Decision-Makers
As vehicles evolve from mechanical assemblies to integrated smart cabins, the humble steering wheel adjustment motor is becoming a strategic component. Our latest PW Consulting study positions this market as a distinct growth node within the broader vehicle electrification and human-machine interface (HMI) wave: the global market stood at approximately USD 1.39 billion in 2025 and is forecast to expand to roughly USD 2.11 billion by 2032, growing at a compound annual growth rate (CAGR) of 6.19% through the 2026–2032 forecast window. For corporate leaders planning investments, procurement strategies, product roadmaps or M&A activity in 2026, this study delivers the actionable context needed to convert opportunity into advantage.
Automotive Steering Wheel Adjustment Motor Market
Why this market matters for 2026 strategic choices
-
Convergence of cabin electrification and advanced driving functions: Steering adjustment actuators are no longer a convenience feature; they play a role in automated ingress/egress, memory-based personalization, and even steer-by-wire architectures that reshape interior packaging. Decisions on motor topology, control integration and supplier relationships now affect vehicle architecture and customer experience.
Automotive Steering Wheel Adjustment Motor Market -
Commodity and supply-chain inflection points: Compact high-torque motors increasingly rely on NdFeB rare-earth magnets. Recent 2025 developments — including domestic NdPr supply agreements and qualification of U.S.-produced NdPr oxide into automotive-grade magnet production — materially change sourcing calculus for OEMs and tier suppliers in 2026.
Automotive Steering Wheel Adjustment Motor Market -
Consolidation and competitive positioning: The market exhibits moderate concentration; the top three players control a meaningful share, and the top five consolidate a clear majority. That dynamic creates windows for strategic partnerships, volume-driven pricing plays, and selective M&A to secure capability or margin.
-
Regulatory and safety lift: Emerging standards for steer-by-wire systems (notably ISO 19725 under publication during 2024–2025) mean that 2026 product and supplier selections must account for system-level validation and compliance timelines, not just component cost and performance.
What PW Consulting’s report delivers — practical content for 2026 action
-
Forward-looking market sizing and scenario modelling: A base-year anchor in 2025 with forecasts to 2032, including high/medium/low adoption scenarios that map directly to EV penetration, autonomous driving feature sets and regional OEM program timelines.
-
Technology and design decision framework: A detailed assessment of motor topologies (brushed vs brushless), actuation form-factors (linear vs spindle/hollow-shaft), control electronics integration, and crash- and noise-performance trade-offs — presented as decision matrices tailored to OEM, tier-1, and supplier use cases.
-
Supplier benchmarking and playbooks: Comparative scorecards covering capability, program wins, manufacturing footprint, and integration expertise. Benchmarks are presented with recommended sourcing strategies — direct supply, JV/strategic equity, or multi-source backup — depending on strategic priorities.
-
Materials and procurement risk module: Analysis of NdPr/NdFeB supply pathways, price-sensitivity scenarios and mitigation tactics including long-term offtakes, vertical integration, and design options that reduce rare-earth intensity without compromising torque density.
-
Regulatory and systems safety checklist: Compliance pathways for emerging standards (including steer-by-wire safety requirements), recommended testing programs and timelines to align product launches with certification milestones.
-
Commercial models and pricing sensitivity: Templates for total cost of ownership (TCO) including integration costs, warranty exposure and program allocation that allow procurement and product teams to stress-test supplier proposals.
-
Deal and portfolio playbook: M&A targets, partnership archetypes and integration plans built from scenario analysis — enabling rapid decision-making in 2026 when consolidation windows open.
Market dynamics to watch in 2026
-
Material sovereignty and magnet markets: 2025 transactions and technical milestones — such as domestic NdPr supply agreements and the commercialization of U.S.-produced NdPr oxide into automotive-grade NdFeB magnets — have reduced single-source risk. Nevertheless, price volatility remains a core purchasing risk into 2026; our procurement module models price bands and hedging strategies to protect margin.
-
Shift to more integrated actuator subsystems: OEMs increasingly seek suppliers capable of delivering not just motors but validated actuator subassemblies with embedded controls, memory functions and diagnostics. This trend favors suppliers with cross-domain system competence or those willing to partner with electronics specialists.
-
Regulatory gating for steer-by-wire adoption: As ISO 19725 becomes authoritative for certain vehicle classes, OEMs that plan to introduce steer-by-wire features must prioritize suppliers with documented system-safety engineering processes and demonstrable compliance roadmaps.
-
Program cadence and volume timing: The market’s projected expansion from the 2025 base through 2032 at a 6.19% CAGR is not linear across vehicle segments or geographies. Program award timing and first-fit positions in vehicle platforms will determine which suppliers capture disproportionate share of incremental revenue. Our report maps those program windows to OEM roadmaps to help teams prioritize 2026 engagement plans.
Competitive landscape — players to know and why they matter
-
Johnson Electric (Hong Kong) — strengths: dedicated steering adjuster motors with automatic linear and height adjustment, and user-centric modes (intelligent/welcome) that align with smart-cabin and EV applications. Their product focus makes them a go-to for OEMs prioritizing seamless entry/egress experiences.
-
Bosch Mobility (Germany) — strengths: broad electric drive portfolio (including hollow-shaft and spindle solutions) offering mature functions such as easy entry/exit, memory, low-noise designs and crash resistance across 12/24V platforms. Bosch’s systems expertise positions it well for safety-critical and integrated solutions.
-
NSK (Japan) — strengths: engineered tilt and telescopic columns using advanced plastic technologies for impact energy absorption and position memory. NSK’s materials and mechanical know-how are attractive to programs where crash performance and weight savings are prioritized.
-
thyssenkrupp (Germany) — strengths: infinitely variable electrical height/length adjusters for luxury segments, utilizing lightweight aluminum/magnesium and high crash-safety designs. Their premium positioning serves high-margin vehicle lines seeking sophisticated user features.
-
Brose (Germany) — strengths: integration of motorized adjusters within a broader electric motors & drives portfolio, with a track record of providing compact, integrated solutions for steering columns.
-
Nexteer Automotive (United States) — strengths: systems-level steering columns and intermediate shafts with capabilities for steer-by-wire and stowable columns. Nexteer is notable for supplying architectures that enable novel interior layouts and automated driving features.
-
JTEKT (Japan) — strengths: steering systems with electronic power steering and adjustment-related tuning expertise; attractive to OEMs seeking tight integration between steering feel and adjustment mechanics.
Collectively, the top three and top five suppliers wield concentrated market influence — an important fact when negotiating volume, intellectual property sharing and platform commitments. Our study’s competitor scorecards and negotiation playbooks provide program-specific guidance without publishing commercially sensitive detail in this preview.
Strategic plays we recommend for 2026
-
Lock early on magnet supply paths: Negotiate offtake or strategic partnerships with magnet producers or qualified converters, or design product variants that reduce rare-earth intensity. Time-to-contract in 2026 will materially affect component cost curves into 2027 and beyond.
-
Prioritize system-capable suppliers: Favor partners who can deliver validated actuator subassemblies with software and diagnostics — this reduces integration risk and compresses vehicle validation timelines.
-
Define compliance and testing milestones in supplier contracts: Embed ISO 19725-aligned milestones and third-party verification into early-stage contracts to de-risk steer-by-wire program timelines.
-
Use modular sourcing to balance innovation and security: Combine strategic single-sourcing for performance-critical variants with second-source agreements for mainstream volumes to maintain resilience without sacrificing capability.
-
Monitor consolidation targets: With market concentration favoring a handful of suppliers, 2026 is likely to see partnership and M&A activity — be prepared with criteria for when to pursue bolt-on acquisitions versus technology partnerships.
How to use this preview and next steps
This article is a strategic preview designed to highlight why the steering wheel adjustment motor market deserves board-level attention in 2026. It showcases the depth of the PW Consulting analysis — including scenario-based forecasts, supplier scorecards, materials risk models, and compliance playbooks — while intentionally omitting the granular segment tables and program-level numeric matrices that are reserved for the full report.
For procurement leaders, product chiefs and corporate strategists planning 2026 actions, the full study provides the playbooks and financial models needed to make decisive moves: secure material pathways, prioritize supplier engagements, specify safety and validation milestones, and assess M&A opportunities against quantified demand scenarios. Accessing the complete report will unlock the segmented forecasts, program-timing maps and vendor negotiation templates that convert the strategic directions outlined here into executable plans.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Adjustment Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Motor Control Centers (MCC) Market — Strategic Outlook for 2026 Decision-Makers
As boardrooms finalize 2026 capital allocation and digitalization roadmaps, Motor Control Centers (MCC) sit at the intersection of electrical power distribution, industrial automation and operational resilience. PW Consulting’s latest MCC Market study (base year 2025) synthesizes five years of historical dynamics with a robust forecast to 2032. Headline positioning: the global MCC market is estimated at USD 7,200 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.2%, reaching an expected market value of approximately USD 10,970 Million by 2032. This briefing explains why the study is strategically critical for 2026 decisions — and what senior executives must know now, without giving away the granular segmentation that makes the full report a necessary purchase.
Motor Control Centers Mcc Market
Why MCCs Matter in 2026: Strategic Imperatives and Market Forces
-
Industrial digitalization and control convergence: The push for Industry 4.0 is changing what an MCC must deliver. A growing share of new MCC installations are specified with IoT connectivity and real-time diagnostics built-in, turning MCCs from passive switchgear into active data and asset management nodes. For 2026, this elevates requirements for open architectures, edge-to-cloud data models and cybersecurity hardening in procurement criteria.
Motor Control Centers Mcc Market -
Regulatory and safety demands: Global standards have tightened arc-flash protection requirements and formalized testing and certification pathways for MCCs. Compliance is no longer a checklist exercise — it is a design constraint that materially affects engineering choices, supplier selection and retrofit budgets.
Motor Control Centers Mcc Market -
Input-cost volatility and supply-chain stress: Recent cycles of raw-material price inflation and constrained supply of key conductor materials have compressed vendor margins and increased lead times. Procurement strategies that ignore material-price sensitivity or make single-source commitments are exposed to cost creep and schedule risk through 2026.
-
Labor and service economics: Rising skilled-labor costs and scarcity of qualified electrical technicians are changing the calculus toward modularity, withdrawable units and designs that reduce on-site labor intensity for installation and maintenance.
-
Market structure dynamics: The MCC industry displays meaningful concentration among leading suppliers, which impacts pricing power, product roadmaps and aftermarket ecosystems. Understanding not just capability but competitive positioning is essential for strategic sourcing.
What PW Consulting’s MCC Report Delivers — Actionable, Not Decorative
This study goes beyond high-level narration to provide operational intelligence that procurement, engineering and strategy teams can apply immediately. Key deliverables include:
-
Validated market sizing and forecast model (2020–2032) with transparent assumptions and scenario buckets — enabling you to stress-test demand against economic, regulatory and technology shocks.
-
Granular segmentation by region, product type and application with demand drivers and elasticity indicators. (Note: this executive preview omits the granular split figures; the full dataset is included in the report.)
-
Supplier benchmarking and concentration analysis that quantify competitive positioning and reveal where platform plays, niche specialists and vertically integrated suppliers create strategic battlegrounds.
-
Procurement and CAPEX playbooks: RFP templates, TCO calculators, and standardized acceptance test plans tailored for modern MCCs (digital-enabled, arc-compliant, and service-ready).
-
Cost-sensitivity and BOM impact models that tie copper and other conductor price movements to unit economics, enabling hedging and contract clauses that protect margins and schedules.
-
Technology adoption matrix and retrofit pathways — showing where to prioritize upgrades (connectivity, motor management, predictive maintenance) and where to preserve CAPEX for high-return deployments.
-
Regulatory compliance roadmaps, mapping IEC and regional safety requirements against product specifications and installation practices.
-
Use cases and implementation case studies across industrial manufacturing, utilities and energy sectors — demonstrating measurable OEE, safety and lifecycle-cost improvements.
Competitive Landscape — Who Matters and How They Compete
The MCC vendor ecosystem blends global platform suppliers with strong engineering credentials and regional specialists. Our competitive analysis synthesizes product capabilities, go-to-market strategies and recent strategic moves to assess where each player is likely to win in 2026:
-
ABB (Zurich, Switzerland) — positioning: system integrator and platform innovator. Recent showcases emphasized AI-driven predictive maintenance embedded in MCC platforms, signaling a push to monetize services and software-driven uptime guarantees.
-
Siemens (Munich, Germany) — positioning: motor management and industrial-grade digitalization. New motor-management product releases emphasize diagnostics and cybersecurity enhancements, making Siemens attractive to asset-heavy industrial clients with rigorous safety and data-integrity needs.
-
Schneider Electric (Rueil-Malmaison, France) — positioning: modular, certified platforms for heavy and utility applications. Recent certification progress indicates a focus on compliance-sensitive customers and large-scale renewals.
-
Eaton (Dublin, Ireland) — positioning: safety and renewables-ready MCCs. Demonstrations at industry shows underscore integration with distributed generation and resilience features that appeal to infrastructure projects.
-
Rockwell Automation (Milwaukee, USA) — positioning: control-centric MCCs with tight PLC and automation integration, appealing where MCCs are part of bigger automation estates.
-
GE Vernova (Cambridge, USA) — positioning: ruggedized solutions and advanced metering for harsh environments, a choice where uptime in severe conditions is critical.
-
Mitsubishi Electric (Tokyo, Japan) — positioning: integrated PLC and control-function MCCs for brownfield automation upgrades.
Market concentration metrics from our analysis indicate a material share controlled by the top three and top five suppliers — a dynamic that shapes negotiation leverage, lead-time risk and innovation diffusion. For procurement teams, knowing whether to opt for a dominant-platform strategy or a best-of-breed assembly is a central strategic question; our report provides the quantified inputs and decision trees to choose.
Practical Recommendations for 2026 Planning
-
Specify digital readiness as a procurement filter. Require open communication protocols and demonstrable cybersecurity features in RFPs; include acceptance tests for data integrity and latency.
-
Account for higher baseline O&M costs driven by labor inflation through modular designs that minimize on-site labor and enable remote diagnostics and firmware-managed maintenance.
-
Embed arc-flash compliance and certification verification in supplier evaluation criteria to avoid retrofit costs and regulatory penalties.
-
Negotiate supply-agreement clauses that mitigate raw-material price swings — use indexed pricing bands, advance buy options, and multi-source commitments for critical conductor components.
-
Prioritize pilot deployments of predictive maintenance and digital motor management on high-value lines; use measured KPI improvements to build the business case for scaling digital MCCs across sites.
-
Model lifecycle costs, not just purchase price. Our TCO templates reveal when premium, service-enabled MCCs deliver lower total cost over typical asset lives.
How Senior Executives Should Use This Report in 2026
For C-suite and functional leaders, the study is structured to support three immediate uses:
-
Capital planning: feed the report’s scenario-driven forecasts directly into multi-year CAPEX plans to size spending under conservative, base and accelerated automation scenarios.
-
Strategic sourcing: use supplier scorecards and concentration analysis to craft negotiation strategies and diversify supply where risk exposure is high.
-
Operational transformation: use the retrofit pathways and ROI templates to sequence deployments that maximize uptime and minimize disruption to production.
What This Preview Hides — and Why You Need the Full Study
This briefing intentionally demonstrates the analytical rigor and strategic framing of PW Consulting’s MCC Market study while withholding the granular split tables and proprietary segment-level forecasts that operational teams require for procurement and engineering specification. The full report contains downloadable data tables, interactive forecast models, supplier scorecards and executable RFP templates that translate insight into action. If your 2026 plan involves MCC procurement, retrofits, or service-partners, those tables form the difference between a defensible strategy and a speculative bet.
PW Consulting’s MCC Market study is designed as a short-list tool for decision-makers: diagnose risk, prioritize investments, and execute with procurement-grade instruments. For access to the full datasets, scenario models and supplier-by-supplier technical appendices that underpin the headline CAGR and market sizing above, consult the PW Consulting report page and request the complete report package.
For detailed analysis of this topic, please visit the official page: Motor Control Centers Mcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rosin Modified Phenolic Resin Market — USD 1,936.8M in 2025, 4.18% CAGR
By PW Consulting, 2026-07-13
Rosin Modified Phenolic Resin Market: Strategic Imperatives for 2026 Decision‑Makers
Executive preview — why PW Consulting’s new study matters now
As the chemicals landscape stabilizes after pandemic-era shocks and raw material volatility, Rosin Modified Phenolic Resin (RMPR) is reasserting itself as a strategically important specialty resin for inks, adhesives, coatings and a range of industrial applications. Our PW Consulting market study — anchored on a 2025 base year and a detailed 2026–2032 forecast — provides the rigorous, actionable intelligence senior executives need to make high‑stakes decisions in 2026: capacity commitments, pricing strategy, procurement hedging, M&A screening and product portfolio resets.
Rosin Modified Phenolic Resin Market
Key macro anchors from the study: the RMPR market reached roughly USD 1.94 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 4.18% over the 2026–2032 forecast window. Under our central scenario the market climbs to roughly USD 2.58 billion by 2032. Those topline numbers matter — but the real value for executives is translating them into operational and strategic moves. This preview explains how.
Rosin Modified Phenolic Resin Market
What this analysis delivers for 2026 strategy
- A working market map: Practical segmentation across product types, applications and regions that clarifies where demand is volume‑driven versus margin‑driven. (Segment‑level tables and company revenue splits are intentionally reserved for the full report.)
- Demand drivers and timing: A prioritized list of growth pockets by application (printing inks, adhesives/sealants, coatings, road marking, etc.), with adoption curves and near‑term catalyst schedules.
- Supply chain playbook: Supplier benchmarking, feedstock exposure matrices and a raw material sensitivity model that quantifies EBITDA impact under alternate gum‑rosin and phenol price paths.
- Regulatory & ESG risk register: VOC and emissions overlays by geography, compliance cost estimates and operational mitigations for resin producers and formulators.
- Commercial levers: Pricing frameworks, channel segmentation and go‑to‑market templates for premium versus commodity RMPR grades.
- M&A and partnership screening tools: A shortlist of capability gaps, likely targets and valuation ranges using multiples calibrated to RMPR margins and concentration dynamics.
Market dynamics to watch in 2026
Three structural forces will shape decision windows this year:
Rosin Modified Phenolic Resin Market
- Feedstock volatility and raw material concentration: Gum rosin remains the primary upstream feedstock for RMPR production; historical swings in gum‑rosin availability and price have translated rapidly into downstream cost pressure for printers and formulators. Our supply scenario analysis models both acute shocks and protracted price regimes, enabling procurement teams to quantify the value of hedging, long‑term contracts and vertical integration.
- Regulatory tightening and formulation shifts: Growing restrictions on VOCs and stricter environmental standards in key markets are accelerating demand for reformulated RMPR grades and low‑VOC binders. This dynamic creates a premium niche for producers who can demonstrate compliance without compromising key performance attributes — e.g., adhesion, gloss and drying speed.
- Market concentration and competitive tension: The RMPR market sits in a middle ground between fragmentation and consolidation — the top three players account for a meaningful portion of capacity, while the top five increase that footprint materially. That structure produces periodic pricing and capacity imbalances that can be exploited with disciplined commercial strategies and targeted capacity deployment.
Competitive landscape — who matters and why
Our competitive review synthesizes company capabilities, route‑to‑market models and technology differentiators for manufacturers that materially influence market dynamics:
- Tridev Resins (India) — A focused manufacturer and exporter whose strengths lie in customer co‑development for printing‑ink applications and regional distribution networks. Their playbook demonstrates how mid‑market vendors can defend margins through formulation partnerships.
- Atul Polychem (India) — Notable for R&D in synthetic resins and formulation support for demanding industrial use cases. Their approach highlights the value of technical sales teams in premium segments.
- Foreverest Resources Ltd. (China) — A producer leveraging condensation polymerization routes and emphasizing high‑polymer binders for inks. Their technical positioning underscores the role of process expertise in performance differentiation.
- DRC Resins (India) — Known for Grade‑specific offerings (e.g., Dropol™ series) that target print performance; an example of productization as a commercial moat.
- Bluebell Polymers, Sanvy Resins, Resin Chemicals, Komo Tac, Baolin Chemical, Shuanghe Chemical — Together these suppliers showcase the diversity in production scale, certification focus (e.g., ISO), and route‑to‑market emphasis (domestic sales, export orientation, specialty product lines).
The full report includes a calibrated competitive matrix with benchmarking against technical specs, margin bands, geographic reach and customer concentration — information that matters when sizing acquisition targets or negotiating long‑term supply agreements.
Recent industry moves and near‑term implications
- Price signals: Early‑2026 actions by select phenolic resin producers — including announced price increases — suggest margins will be sensitive to feedstock swings in the coming quarters. Our models show that even modest phenolic moves can materially affect spot pricing for RMPR grades unless pass‑through mechanisms are in place.
- Operational and compliance activity: Safety and certification events from major regional suppliers indicate a continued focus on operational resilience and regulatory compliance — a non‑negotiable for buyers in regulated end‑markets.
For procurement and operations leaders, these signals are a call to update risk registers, re‑test supplier backup plans and reweight inventory policies to balance service levels against working capital objectives.
How to convert PW Consulting insights into 2026 actions
Below are priority actions we recommend companies take this year, and how our report supports them:
- Revise procurement strategies: Use the report’s raw‑material sensitivity matrices to determine the optimal mix of spot, term and backward integration. The internal NPV templates quantify payback periods for seizing upstream supply stakes versus signing multi‑year purchase agreements.
- Reprice with discipline: Implement the report’s pricing playbook that links performance tiers to elasticity estimates by application. This reduces margin leakage in inflationary phases and captures upside in premium segments arising from low‑VOC or high‑temperature grades.
- Prioritize R&D investment: Apply the product roadmap framework to focus R&D dollars on formulations likely to win share under tightening VOC rules and increasing demand for sustainable chemistries.
- Screen M&A and JV targets: Leverage the deal‑screening checklist and valuation ladder to identify targets that close capability gaps (e.g., high‑melting grades, specialty ink binders) while fitting tolerance for integration complexity.
- Update commercial channels: Reassess distributor economics and direct‑sell opportunities in fast‑growing regional corridors identified in our market mapping exercise.
What the full PW Consulting report contains (practical contents)
- Comprehensive market sizing and growth scenarios (2020–2032), including base, upside and downside cases.
- Segment and regional analytics with granular demand forecasts, historical trends and market share models (note: detailed segment‑level revenue tables and exact company shares are available only in the full study).
- Supplier and feedstock deep dive, including gum‑rosin availability, price correlation analysis and a phenol‑price pass‑through model.
- Regulatory and ESG impact assessment with compliance cost estimates by jurisdiction.
- Competitive benchmarking, product attribute matrices, and company profiles with strategic positioning and suggested counter‑strategies.
- Commercial playbooks: pricing, channel and product strategies tailored to printing inks, adhesives, coatings and specialty applications.
- M&A readiness pack: target screening, integration checklist and financial sensitivity models for valuation stress‑testing.
Final perspective — positioning for optionality
In 2026 the RMPR market will reward firms that convert macro clarity into operational optionality. That means combining disciplined supply management with targeted technical investment and sharper commercial segmentation. Our study provides the decision support and playbooks to execute against those objectives while protecting downside through scenario planning and hedging strategies.
PW Consulting’s full report contains the empirical tables, company revenue splits and model workbooks that executives and deal teams will need to finalize plans. This preview is designed to demonstrate the analytical depth and direct operational utility you can expect — for access to the complete datasets, segment‑level allocations and company‑by‑company financial proxies, please consult the full report.
For detailed analysis of this topic, please visit the official page: Rosin Modified Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beard Shave Formula Market to Hit USD 11,719.4M by 2032 with 4.85% CAGR
By PW Consulting, 2026-07-13
Beard Shave Formula Market — Strategic Briefing for 2026 Decisions
PW Consulting’s Beard Shave Formula Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames a rapidly maturing category that blends legacy mass‑market players, heritage wet‑shaving artisans, and digitally native beard‑care specialists. At the macro level the market demonstrates stable expansion — growing from roughly USD 6.6 billion in 2020 to about USD 8.4 billion in 2025, and projected to reach approximately USD 11.7 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 4.85% over the forecast window. This briefing distils the strategic implications of those trends for corporate decision‑makers in 2026 while intentionally withholding granular regional and application breakdowns to preserve the full report’s role as a primary source for transaction and product planning.
Beard Shave Formula Market
Why this report matters for 2026 strategic choices
- Capital allocation: Budgeting for R&D, supply‑chain resilience, and targeted distribution experiments (DTC, retail, professional channels) should be informed by the market’s mid‑single‑digit growth profile and the premiumization occurring within the category.
- Portfolio strategy: The combination of scale incumbents and agile niche players means incumbents must decide whether to defend mass channels or selectively invest in premium/natural formulations while challengers must prioritize scalability and margin capture.
- M&A and partnerships: The competitive concentration metrics in the study indicate meaningful room for consolidation and bolt‑on acquisitions to secure capabilities (formulation science, DTC fulfillment, barber channel relationships).
- Regulatory & operational risk: Recent changes in grooming policy across military services and ongoing natural‑oil supply volatility require proactive scenario planning for demand shocks and margin pressure.
Market trajectory and what the numbers tell you
The category’s steady expansion through 2025 underscores resilient end‑user demand for beard‑specific shave preparations and ancillary grooming products. From a strategic viewpoint, two macro takeaways are critical: first, growth is consistent but not explosive — the market rewards targeted differentiation over broad heavy CAPEX bets on volume alone. Second, market concentration is meaningful but not prohibitive: the top three firms account for a material share of the market, while the top five accumulate a clear majority, leaving definable pockets of opportunity for focused entrants and incumbents pursuing adjacent premium or natural segments.
Beard Shave Formula Market
For executives, the implication is clear: incremental share gains remain attainable through product innovation, channel optimization, and brand positioning, but these moves must be calibrated against realistic growth expectations and disciplined margin management. The market’s projected climb to the low double‑digit billions by 2032 means long‑term value creation, but it will be unevenly distributed — the premium and specialty niches are likely to expand faster than commoditized segments.
Beard Shave Formula Market
Segmentation shape without the minutiae
The beard shave formula category is usefully decomposed along product form (gels, creams, foams, oils and soaps), end‑use (individual consumers, professional barber services, hospitality/other institutional uses), and regional dynamics. These axes drive very different product requirements — from performance‑centric formulations designed to soften coarse beards and minimize irritation, to botanically driven premium products prioritizing natural sourcing and skin protection.
Rather than publish detailed regional and application shares here, this briefing emphasizes decision‑relevant distinctions: product form factors dictate R&D and packaging choices; channel mix dictates marketing, pricing, and fulfillment models; and regional regulatory environments influence claims, testing, and labeling requirements. The full report contains the granular segmentation matrices and historical series required for rigorous SKU‑level P&L modeling.
Key dynamics and tail risks shaping 2026 strategy
- Regulatory shifts: Changes issued across U.S. military services in 2025–2026 tighten the scope for long‑term medical shaving waivers and reinforce clean‑shave standards in certain duty contexts. These moves create short‑to‑medium‑term demand variability in institutional channels and emphasize the need for manufacturers to diversify channel exposure.
- Raw‑material volatility: Premium formulations increasingly rely on natural oils (e.g., argan, jojoba). Supply chain volatility for these inputs is ongoing and can materially compress margins for products marketed on natural‑ingredient credentials unless procurement and pricing strategies are adjusted.
- Premiumization & consumer behavior: Elevated willingness to pay for natural, performance, and skin‑sensitive products drives faster growth at the premium end. Consumers are also demonstrating loyalty to brand experiences (barber partnerships, subscription replenishment models) more than to commodity price points.
- Retail & DTC dynamics: Traditional retail still moves high volumes, but subscription DTC and curated bundles are proving to be higher margin growth engines for smaller and digitally native brands, forcing incumbents to reconcile channel conflict with margin uplift opportunities.
Competitive landscape—what incumbents and challengers are doing
The market reflects a classic multi‑channel competitive structure: global CPG giants leverage scale and retail reach; premium heritage brands trade on craft and ritual; and indie DTC players capture premium mindshare with authentic storytelling and ingredient claims. Highlighting a cross‑section of players illustrates strategic variety:
- Procter & Gamble (United States) — Leverages household brands and extensive distribution to defend mass and performance segments. Scale R&D and shelf presence remain core advantages, particularly for broad reach and cost management.
- Unilever (U.K./Netherlands) — Combines mainstream strength with digital playbooks (including subscription models via acquired platforms). Their strategic posture emphasizes multi‑brand ownership to cover both value and premium spaces.
- L'Oréal Group (France) — Focused on technical formulations and skin‑centric claims under specialist men’s grooming lines; strength lies in formulation science and professional channel partnerships.
- The Art of Shaving (United States) — A luxury, ritualized approach to shave preparation and in‑store services; competitive moat exists in experiential retail and premium pre‑shave portfolios.
- Beiersdorf AG (Germany) and Edgewell Personal Care (United States) — Represent well‑positioned incumbents balancing mass skin‑comfort claims with targeted innovations for sensitive or coarse beard care.
- Clarins (France) and other premium cosmetic houses — Prioritize botanical and skin‑health narratives, appealing to consumers seeking premium natural credentials backed by established beauty credibility.
- Independents (e.g., Honest Amish, Beardbrand, Proraso, Cremo) — Capture niche audiences via authenticity, heritage, or performance messaging. These brands are natural acquisition targets for scale players seeking premium or DTC capabilities.
Strategically, incumbents must weigh defensive investments (price, placement, private label competition) against offensive plays (acquisitions of indie brands, targeted premium launches). For challengers, the path to scale runs through differentiated formulations, razor‑thin fulfillment economics for subscriptions, and selective retail partnerships that preserve brand premium.
What the full PW Consulting report delivers (operationally focused)
Our comprehensive report is designed to convert insight into action. Highlights include:
- Market sizing and growth scenarios at global, regional, and channel levels (historical series and 2026–2032 projections).
- Product‑level and channel segmentation frameworks with SKU‑level implication maps for R&D and pricing.
- Supply‑chain and raw‑material risk maps, including stress tests for natural‑oil price increases and mitigation playbooks.
- Competitor dossiers with positioning matrices, route‑to‑market strategies, and acquisition target lists (including valuation heuristics for M&A screening).
- Regulatory heat maps and scenario planning templates addressing grooming policy changes and labeling/compliance risks in key markets.
- Actionable go‑to‑market playbooks for incumbents and challengers — DTC subscription pilots, retail assortment optimization, and barber/pro channels monetization.
- Five prioritized strategic imperatives and a 12‑month execution roadmap tailored for management teams evaluating investments or portfolio pivots in 2026.
The body of the report includes the detailed tables, regional splits, and unit economics that are intentionally not reproduced in this brief to preserve analytical value for subscribers and project partners.
Practical recommendations for 2026 — five priority moves
- Lock in strategic raw‑material arrangements: Negotiate multi‑year supply contracts or joint‑ventures for volatile natural oils; consider formula reformulation buffers where feasible to protect margins.
- Segmented product architecture: Build distinct SKUs for performance, skin‑sensitive, and botanical premium buyers — but centralize R&D to reduce duplication and accelerate claim validation.
- Channel‑tailored go‑to‑market: Pilot premium DTC subscription bundles while maintaining defensive retail shelf presence; establish barber partnerships as both revenue and R&D labs for product validation.
- Regulatory & institutional scenario planning: Quantify exposure to military and institutional channels and diversify to consumer channels in regions where grooming policies tighten.
- M&A & partnership focus: Use tuck‑ins to acquire DTC capabilities, artisanal formulations, or sustainable sourcing expertise — prioritize deals that accelerate margin recovery and brand credibility.
Closing — why access the full report
This briefing surfaces the strategic crossroads facing players in the beard shave formula market as they plan for 2026. The category offers predictable aggregate growth and compelling pockets of premium expansion, but value will accrue to organizations that combine supply‑chain foresight, disciplined product architecture, and channel agility. PW Consulting’s full report supplies the granular regional splits, product‑form revenue tables, scenario models, and competitive benchmarks necessary to convert the insights above into executable plans and rigorous investment theses.
For boards and leadership teams preparing 2026 budgets, product roadmaps, or M&A screens, the full dataset and playbooks are essential. Contact PW Consulting to obtain the complete report, download the interactive models, and schedule a strategy session tailored to your firm’s exposure in this evolving category.
For detailed analysis of this topic, please visit the official page: Beard Shave Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Consumer IoT Market 2026: Strategic Imperatives and Actionable Intelligence
Executive snapshot
Between 2020 and 2025 the consumer IoT market more than doubled in scale, reflecting rapid adoption across smart home, wearables, personal electronics and in-vehicle consumer interfaces. Our base-year analysis (2025) places the global market at USD 208.5 Billion. From 2026 the market is forecast to expand at a compound annual growth rate (CAGR) of 14.85% through 2032, driving total market value to roughly USD 550 Billion by the end of the forecast window. This pace is transformational: it converts adjacent consumer electronics markets into platform- and service-led businesses and raises the strategic stakes for product, channel and regulatory positioning in 2026 and beyond.
Consumer Iot Market
Why this research matters for 2026 decisions
-
Timing: 2026 is a pivot year. With a high-growth runway ahead, incumbents and challengers must choose whether to double down on hardware differentiation, migrate to software-and-service models, or pursue hybrid plays that lock consumers into ecosystems.
Consumer Iot Market -
Regulatory inflection: New regulatory requirements—most notably EU-level cyber resilience rules with phased compliance and local US/California laws governing device security—mean product roadmaps and compliance budgets must be reconciled now, not later.
Consumer Iot Market -
Consolidation pressure: Market concentration is meaningful but not prohibitive—top-three vendors control roughly one-third of the market while top-five approach one-half—creating windows for focused challengers and M&A-driven scale plays.
-
Interoperability and standards: Matter and other certification programs have matured rapidly; interoperability is shifting from a convenience play to a baseline market expectation. Device makers who are late to certify will face distribution frictions and higher returns costs.
What leaders need to know — five strategic implications
-
Reframe product portfolios around services and recurring revenue. As unit growth accelerates, lifetime value and retention will increasingly separate winners from losers. Hardware alone no longer delivers defendable margins; subscription and bundled services (cloud features, AI enhancements, extended warranties) are decisive.
-
Design for regulatory-first security. With regional laws mandating baseline security controls and disclosures, security-by-design will be essential to market access. Companies should prioritize secure boot, timely OTA updates, vulnerability disclosure processes, and Supplier Security SLAs to avoid being locked out of major markets or facing reputational and financial risk.
-
Prioritize interoperability and developer enablement. The proliferation of certified Matter devices and the widening ecosystem of thread/low-power connectivity demand a developer-friendly platform strategy. Investing in SDKs, clear developer documentation, and partner certification accelerates channel adoption and reduces customer friction.
-
Optimize BOM and channel economics without sacrificing differentiation. Emerging wireless standards and next-generation silicon create cost-and-performance trade-offs that impact pricing strategy. Product teams must balance advanced connectivity and on-device AI with yield-sensitive component choices and scalable manufacturing partners.
-
Hone go-to-market (GTM) segmentation and partnerships. The effective GTM mix will be a hybrid of DTC, retail alliances, telco-bundling and retail-embedded experiences. Strategic partnerships (CE retailers, telcos, platform vendors) will accelerate reach while reducing customer acquisition costs for software-driven services.
Competitive landscape—positions and near-term moves to watch
The market is populated by strong platform incumbents and a vibrant set of category specialists. Leading players leverage ecosystems, distribution, brand and developer scale—while smaller, focused companies compete on price, niche features and speed-to-market. Key strategic observations on major vendors:
-
Amazon: Deep strengths in voice, retail distribution and cloud services give Amazon a structural advantage for platform-led monetization. Recent wearable and AI upgrades signal intent to expand user touchpoints beyond the living room into daily personal devices.
-
Google: Integration with the broader Android and services stack, plus continued investment in Matter support, positions Google to be the interoperability anchor for many OEM partners. Platform openness remains a double-edged sword—accelerating adoption but diluting direct monetization levers.
-
Apple: A privacy-first positioning and tight hardware-software integration continue to justify premium pricing and loyalty. Expansion of third‑party Thread/HomeKit support creates opportunities for embedded partners but also raises expectations for strict privacy and certification compliance.
-
Samsung: Strength in appliances and a broad device portfolio makes Samsung a natural integrator of multi-category experiences. Investments in next-generation connectivity (Wi‑Fi 7 readiness) are aimed at preserving leadership in high-throughput home applications.
-
Category specialists (Philips/Signify, Sonos, iRobot, Arlo, Wyze, TP‑Link): These firms are bifurcating into two strategic archetypes—(1) product-first premium specialists who monetize via brand and service extensions, and (2) value incumbents who scale through low-cost BOM and distribution. Their agility makes them key M&A targets for platform players seeking category fill.
Macro tailwinds, headwinds and risk matrix for 2026
-
Tailwinds: Strong consumer replacement cycles, rising acceptance of subscription models, and enhancements in on-device AI will drive both unit volumes and ARPU.
-
Headwinds: Compliance costs, escalating support/resolution expectations, and macro-driven component pricing volatility can compress margins—especially for hardware-first models.
-
Regulatory risk: Non-compliance with regional cybersecurity and product safety rules can restrict market access, incur fines and increase return rates; conversely, early compliance can be a commercial differentiator.
-
Concentration risk: While major platforms control significant share, there remains space for vertical specialists and regional champions—timing and partnership selection determine success.
What the PW Consulting report delivers (practical, transaction-ready outputs)
Our full study is built for decision-makers who need executable guidance, not just high-level signals. Deliverables include:
-
Top-down market-sizing and growth scenarios (base, upside, downside) through 2032, with sensitivity analysis on price, penetration and replacement cycles.
-
Vendor landscape and strategic positioning maps, including vendor scorecards that evaluate product breadth, platform strength, developer ecosystem, monetization capability and regulatory readiness.
-
Commercial playbooks: GTM archetypes, channel economics templates, pricing simulations and subscription packaging options tailored to consumer segments.
-
Compliance and security roadmaps aligned with EU, US and subnational regulations—practical checklists for product teams and sample contractual clauses for supplier security obligations.
-
M&A and partnership target screening: criteria-driven shortlists for bolt-on acquisitions, JV structures and OEM co-development frameworks.
-
Technology deep dives: connectivity standards roadmap, edge vs cloud AI trade-offs, lifecycle OTA strategies and cost engineering levers for BOM reduction.
-
Operational playbooks: support and reverse-logistics modeling, warranty and repair economics, and CX design templates to minimize churn.
How to use this intelligence in 90‑, 180‑ and 365‑day plans
-
90 days: Conduct a rapid compliance gap assessment against regional security standards, prioritize Matter/Thread certification paths, and run a topline ARPU sensitivity to subscription price points.
-
180 days: Finalize GTM partner agreements (telco bundles or retail exclusives), pilot bundled subscription offers, and lock component supply agreements to hedge near-term cost volatility.
-
365 days: Scale platform investments, execute targeted M&A or strategic alliances to fill portfolio gaps, and migrate installed base customers to service-led revenue streams.
Why PW Consulting’s analysis is different
We combine rigorous, transparent market modeling with practitioner-grade playbooks and legal/compliance checklists. Our methodology triangulates vendor disclosures, primary interviews, component-level BOM analysis and certification registries—yielding forecast scenarios that are both defensible and operationally actionable. Importantly, while this briefing surfaces critical strategic directions and macro metrics (historic and forecast totals, CAGR, concentration indicators), we intentionally withhold certain granular segmentation metrics and proprietary regional allocations in public summaries to preserve the analytical value of our full dataset.
Next steps — access to the full dataset and custom briefings
If your 2026 strategy depends on precise regional mix, application demand curves, OEM-level unit economics or bespoke scenario runs, our full report and custom consulting engagements provide the detailed segmentation, downloadable datasets and interactive models you need. The full intelligence package includes the complete breakdown across components, applications and regions, plus the vendor-level revenue and share estimates used to build our strategic recommendations.
Visit our report page to download the executive report and request a tailored briefing—PW Consulting will help you convert the market’s growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Consumer Iot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trial Process Management Market to Reach USD 6,880.83M by 2032 (13.18% CAGR)
By PW Consulting, 2026-07-13
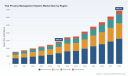
Trial Process Management System Market: Strategic Briefing for 2026 Decision-Makers
As organizations recalibrate clinical development strategies in 2026, Trial Process Management (TPM) systems have shifted from “nice-to-have” operational tools to strategic infrastructure that directly impacts time-to-decision, regulatory risk, and trial economics. This briefing—drawn from PW Consulting’s latest market research—summarizes the high-level market trajectory, competitive dynamics, regulatory forces, and the pragmatic decision framework executive teams should use this year. It is designed to demonstrate the report’s analytical depth while preserving the proprietary segmentation and scoring that unlocks tactical plans in the full study.
Trial Process Management System Market
Market Trajectory: Scale and Growth Expectations
TPM adoption has accelerated through the 2020s. On a macro basis, the global TPM market more than doubled from its early‑decade baseline and reached nearly USD 2.9 billion in 2025 (base year). Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of around 13.2% over the 2026–2032 forecast window, reaching the mid‑single‑digit billions by the end of the period. That growth is being driven by a combination of platform modernization, cloud migration, regulatory tightening around data protection and electronic records, and the emergence of AI-enabled orchestration layers that promise to compress study build and execution cycles.
Trial Process Management System Market
Why This Matters for 2026 Decisions
- Cost-to-Operate vs. Speed-to-Market: With sponsors and CROs under pressure to shorten development timelines, TPM systems are now a lever both for operational cost control and schedule risk mitigation. The right platform choice influences monitoring frequency, query resolution times, and protocol adherence—metrics that materially affect study economics.
- Regulatory & Cyber Requirements: Emerging regulatory expectations (including tighter HIPAA security requirements and evolving GDPR guidance on data protection by design) make platform security and privacy engineering a board-level procurement criterion. Validation, encryption, and auditability are non‑negotiable.
- Vendor Differentiation through AI and Site Enablement: Vendors that combine core CTMS capabilities with AI for study build, risk-based monitoring, and virtual trial orchestration are moving from feature vendors to strategic partners.
- Integration as a Competitive Filter: Interoperability with EDC, EHR, safety databases, and finance systems determines whether a TPM investment delivers expected efficiency gains or becomes another silo that increases integration cost.
What the Full Report Delivers (Actionable Modules)
- Market sizing and a transparent forecast methodology (historical 2020–2025; forecast 2026–2032; base year 2025; USD, revenues in Millions).
- Segmented demand analysis across deployment modes, end‑user types, and regional markets—presented with scenario modelling and sensitivity to regulatory and technology shocks.
- Vendor landscape and comparative benchmarking: capability matrices, go‑to‑market positioning, integration readiness, product roadmaps, and M&A/partnership tracking.
- Implementation playbooks for sponsors, CROs, and sites: procurement checklists, validation timelines, pilot designs, change management templates, and TCO models that incorporate labor and cloud hosting realities.
- Risk register and compliance checklist aligned to current regulatory expectations (e.g., FDA 21 CFR Part 11, GDPR Art.25, HIPAA Privacy and Security Rule updates), plus recommended vendor contract clauses and BAA considerations.
- Commercial intelligence: pricing models, licensing benchmarks, and recommendations for outcome‑based contracting and vendor consolidation strategies.
Competitive Landscape: Strategic Positions and Near‑Term Moves
The TPM market is characterized by a mix of large platform integrators, specialized CTMS vendors, and service-heavy CROs that bundle TPM capabilities into broader offerings. Leading providers are pursuing distinct strategies that matter to buyers:
Trial Process Management System Market
- Veeva Systems —Continuing its enterprise platform focus, Veeva’s site‑oriented product introductions signal a dual approach: maintain strong sponsor/CRO footprint while enabling site adoption and data flow efficiency. Site-centric offerings that lower site burden can materially influence enrollment and source document timelines.
- Medidata (Dassault Systèmes) —An aggressive AI and orchestration strategy positions Medidata as a hub for study simulation, build automation, and real‑time optimization. Recent strategic partnerships and AI ecosystem announcements demonstrate a push to embed predictive and prescriptive intelligence across lifecycle stages.
- Oracle —With established enterprise implementations and recognized integration strengths, Oracle remains a default choice for organizations prioritizing depth of integration across EHR/EDC and regulatory compliance scaffolding.
- Advarra —Focused on academic and site networks, Advarra’s enhancements emphasize financial management, regulatory automation, and reporting—areas with immediate ROI for institutions that run high volumes of investigator‑initiated and academic trials.
- Parexel, IQVIA, Clario, RealTime, ArisGlobal, MasterControl —Each brings differentiated value: Parexel and IQVIA pair TPM with CRO services and broad data platforms; Clario targets endpoint and device-focused workflows; RealTime and Advarra strengthen site workflows; ArisGlobal and MasterControl cater to compliance‑heavy, regulated environments.
Recent vendor moves—strategic AI partnerships, product launches focused on site enablement, and enhanced analytics—signal a competitive phase where platform orchestration, AI augmentation, and site economics will determine leadership. Buyers should treat vendor roadmaps and AI safety guardrails as procurement deal‑breakers.
Regulatory and Operational Dynamics that Shape Vendor Selection
- Data Protection & Security: Proposed HIPAA Security Rule updates introduce mandatory encryption, routine vulnerability scanning, and annual penetration testing for entities processing ePHI—raising validation and continuous compliance costs for both cloud and hybrid implementations.
- Data Protection by Design: GDPR Article 25 increasingly constrains how TPM vendors manage identifiable health data. Buyers must require documented pseudonymization strategies, access minimization, and built‑in privacy controls in vendor due diligence.
- HIPAA Privacy Requirements: Expect more rigorous expectations around BAAs, minimum‑necessary access, and disclosure documentation when TPM vendors handle data on behalf of covered entities.
- Regulatory Records & Auditability: Standards such as FDA 21 CFR Part 11 and EMA guidelines remain central—platforms must support electronic signatures, secure audit trails, and validated system life‑cycle management.
- Operational Cost Drivers: Primary cost contributors are specialized labor for configuration, validation, and compliance monitoring, alongside cloud hosting fees that scale with data volume and integration complexity. These must be fully captured in TCO and ROI models.
Practical Guidance: Procurement & Implementation Priorities for 2026
- Adopt a risk‑based procurement scorecard that weights interoperability, AI maturity (with auditability), site ergonomics, and regulatory evidence over feature checklists.
- Build validation and compliance costs into budget cycles from Day‑1. Plan for continuous validation activities tied to security patching, AI model updates, and integration changes.
- Pilot for impact: run short, instrumented pilots focused on enrollment speed, query cycle time, and monitoring‑efficiency metrics. Use these to derive evidence for scaling and price negotiations.
- Negotiate outcome‑oriented terms where practical (e.g., migration credits tied to user adoption thresholds, service credits for integration SLAs, or shared savings for workflow automation gains).
- Prioritize vendors that publish explainability and monitoring tools for AI components—regulators and auditors increasingly expect governance artifacts for autonomous decision support.
- For site networks and academic centers, seek site‑friendly licensing and deployment models that minimize administrative burden and support multi‑sponsor collaboration.
Strategic Questions PW Consulting Helps Clients Answer
- Which TPM architecture (cloud‑native, hybrid, or on‑premise) minimizes TCO while satisfying near‑term compliance milestones?
- How to structure a phased rollout that delivers measurable operational wins within the first 12 months?
- What vendor partnership model—best‑of‑breed integrations vs. single‑vendor platforms—best aligns with our portfolio strategy and clinical complexity?
- How to score vendor AI propositions for safety, auditability, and real‑world impact on trial timelines?
- Which contract terms and KPIs should be non‑negotiable in an era of tighter data protection rules?
Our full Trial Process Management System Market report provides granular answers to these questions—complete with segmented demand tables, vendor scorecards, pricing benchmarks, implementation timelines, and downloadable procurement templates. The analysis blends quantitative market projection with qualitative vendor due diligence to support actionable 2026 roadmaps.
Next Steps
For executive teams planning TPM investments in 2026, the immediate priority is to align clinical, IT, privacy, and procurement stakeholders around a single, measurable set of objectives—then use that charter to evaluate vendors against the priorities and risks outlined above. PW Consulting’s full report and advisory engagements are designed to convert those objectives into negotiation strategies, validated implementation plans, and measurable KPIs that preserve study timelines while controlling compliance risk and operational cost.
Contact PW Consulting’s Life Sciences practice to access the complete market study, vendor benchmarks, and tailored advisory services that translate the market’s projected growth and vendor dynamics into a practical 12–36 month execution plan.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Satellite Control Market to Hit USD 35,470M by 2032 at 7.45% CAGR
By PW Consulting, 2026-07-13
Satellite Control Service Market: Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Industry Lead, I present an executive preview of our Satellite Control Service Market study — a pragmatic guide designed to orient corporate strategy, procurement, and investment decisions in 2026. The market for satellite control services has moved from niche operations to a core component of commercial space value chains. Our baseline analysis shows the market expanding from roughly USD 15.2 billion in 2020 to about USD 21.45 billion in 2025, and we forecast continued growth to an estimated USD 35.47 billion by 2032 at a compound annual growth rate (CAGR) of approximately 7.45% across the forecast horizon. For leaders planning capital allocation, partner selection, or M&A activity in 2026, the choices made this year will determine who captures durable operational value as this market doubles in scale.
Satellite Control Service Market
Why 2026 Is a Strategic Inflection Point
Several concurrent forces converge in early 2026 to make this a decisive year for satellite control strategies:
Satellite Control Service Market
- Regulatory recalibration: major jurisdictions are moving to simplify licensing, widen spectrum access, and harmonize approvals for satellite infrastructure — creating windows for faster deployments and cross‑border commercial models.
- Operational economics: capital intensity for ground infrastructure remains high, but shared ground-station and GSaaS (Ground Station as a Service) models are rapidly maturing as a cost mitigation pathway for operators and new entrants.
- Technology and mission diversity: multi-orbit architectures and mixed constellations (LEO/MEO/GEO and beyond) increase complexity for telemetry, tracking and command (TT&C), driving demand for integrated ops platforms and resilient network fabrics.
- Competitive consolidation: market concentration metrics show a meaningful presence of scale incumbents alongside a growing cohort of specialist GSaaS providers and defense primes — creating both partner and competitor dynamics that must be navigated deliberately.
Taken together, these dynamics make 2026 the year to pivot from opportunistic experiments to repeatable operating models and resilient supplier strategies.
Satellite Control Service Market
What PW Consulting’s Study Delivers — Practical, Transaction‑Ready Intelligence
This report is built for operators, infrastructure investors, systems integrators, and advanced users of satellite services who need actionable outputs rather than abstract predictions. Key deliverables include:
- Market sizing and growth drivers: rigorous top‑down and bottom‑up models covering the market from 2020 through our 2026–2032 forecast window, with scenario variants reflecting regulatory, spectrum, and technology outcomes.
- Decision frameworks: procurement scorecards, supplier shortlisting criteria, and risk‑weighted TCO models that let you compare GSaaS versus in‑house station builds under multiple mission profiles.
- Operational blueprints: recommended architectures for multi‑orbit control, resilient TT&C routing, and disaster recovery for mission‑critical operations.
- Commercial playbooks: go‑to‑market templates for service bundling, pricing levers, and partnership structures tailored to commercial, government/military, and civil/scientific use cases.
- Vendor diagnostics: structured vendor scorecards and negotiation playbooks to quantify service coverage, latency, security posture, and escalation SLA tradeoffs.
- M&A and investment toolkit: due‑diligence checklists, synergy quantification models, and three stress‑test scenarios to evaluate targets and alliances.
- Regulatory tracker and spectrum impact map: an integrated view of near‑term regulatory proposals and their operational impact on licensing, spectrum availability, and infrastructure approvals.
The study combines quantitative forecasts with hands‑on tools you can adapt directly to purchasing cycles, board deliberations, and program roadmaps.
Competitive Landscape — Who Matters, and How to Position
The market exhibits a mix of incumbent operators, integrated systems houses, and specialized ground‑network providers. Concentration is material but not prohibitive — the largest three players control a meaningful share of market activity while the top five increase that presence further. This creates both power centers and plenty of tactical openings for niche providers and partnerships.
- Global ground‑network specialists (examples include leading regional GSaaS players): these firms anchor multi‑orbit TT&C and data acquisition through dense ground footprints and are advancing capability for lunar and deep‑space missions. Their strategic advantage is reliable, geographically diversified access and operational experience across mission profiles.
- Integrated satellite operators (major fleet operators and commercial broadcasters): these organizations leverage end‑to‑end control capabilities tied to their fleet economics. They trade some flexibility for strong coordination between flight operations and services monetization.
- Defense and prime systems houses (large aerospace and defense firms): these players bring hardened telemetry, security architectures, and mission assurance — a preferred option for government and military programs where compliance and continuity are decisive.
- New‑wave GSaaS and boutique operators : agile providers focus on API‑first access, developer support, and low‑friction on‑ramping for small satellite constellations. They are winning business where speed and integration matter more than legacy scale.
Recent industry moves underline these patterns: a leading GSaaS operator announced continued network expansion in early 2026 to reinforce multi‑orbit TT&C; an integrated operator released a results update reaffirming its global control capabilities; a major managed connectivity vendor secured a five‑year renewal supporting military network operations; and a constellation operator accelerated gateway deployments in late 2025 — all evidence of active investment on both infrastructure and service fronts.
Strategic Plays for 2026 — Practical Steps
- Adopt hybrid GSaaS/in‑house operating models. For most organizations, blended models deliver the best risk/return: outsource routine coverage and burst capacity, retain mission‑critical control and security domains in‑house.
- Lock-in regulatory and spectrum pathways. Prioritize engagements with regulators and spectrum holders now — policy changes in major markets are time‑sensitive and will materially affect deployment timelines and operating economics.
- Design for resilience and cyber‑assurance. Insist on hardened routing, cross‑provider redundancy, and end‑to‑end encryption and key management as preconditions for supplier selection.
- Use supplier scorecards to avoid lock‑in. Scorecards should quantify service diversity (multi‑orbit, multi‑antenna), restoration SLAs, and interoperability with third‑party mission control systems.
- Be opportunistic on M&A and partnerships. Look for acquisitions that add geographic ground coverage, API integration capability, or spectrum access; pursue commercial alliances to accelerate go‑to‑market while minimizing CAPEX.
How to Use This Study in Your 2026 Planning
Use the report as the single source of truth for three critical activities in 2026:
- CapEx and OpEx planning — use our TCO models to evaluate build vs buy under multiple utilization curves and spectrum scenarios.
- Supplier selection and contract design — apply our procurement templates and SLA matrices during RFQs to capture service continuity and upgrade pathways.
- Portfolio and M&A strategy — leverage our scenario analyses and vendor diagnostics to prioritize targets and quantify post‑merger integration risk.
Beyond the executive summary and trend narrative, the full study includes interactive dashboards, downloadable financial models, and a regulatory timeline you can embed into board materials and investment memoranda.
Closing — Where This Preview Leaves You
2026 is not a year to wait. The satellite control services market is scaling predictably and structurally — supported by policy shifts, GSaaS maturation, and mission diversity. Our study synthesizes these dynamics into decision‑ready outputs: models, scorecards, and roadmaps that help you move from strategy to execution without losing optionality.
This preview deliberately surfaces the analysis framework, headline market scale, and strategic recommendations while reserving the granular sub‑segment and regional split data for the full report. To access the segment‑level allocations, regional and service type breakdowns, vendor scorecards, and the interactive scenario models that underpin our recommendations, please consult the full report materials on the PW Consulting research page.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


