



Category: market research
PW Consulting: Smart TV-led TV Market to Reach USD 364.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
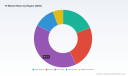
TV Market 2026: Strategic Preview for Corporate Decision‑Makers
PW Consulting’s latest TV Market research is built as a decision‑grade tool for boards, corporate strategy teams, and product leaders planning for 2026 and beyond. This preview synthesizes the highest‑value strategic conclusions from the full study: the macro trajectory, the operational and regulatory dynamics that will shape winners and losers, competitive posture of leading OEM integrators, and the pragmatic, near‑term priorities every executive should adopt. The full dataset, granular regional/type/application splits, and our financial model are available on the report landing page — this article intentionally surfaces interpretation and implications while withholding core segment detail to preserve the full report’s commercial value.
TV Market
Macro trajectory you can build a plan around
Using 2025 as the base year, the global TV Market sits at approximately USD 228.61 Million (revenue unit: Million) and has expanded consistently since 2020. From a solid historical baseline, the market enters a forecast window (2026–2032) with an expected compound annual growth rate (CAGR) of 6.98%, reaching roughly USD 364.77 Million by 2032 under our central case. That growth profile is robust enough to justify near‑term capex and product investment, yet not so rapid as to eliminate the need for disciplined portfolio prioritization — companies must choose where to concentrate R&D, manufacturing footprint, and channel investments to capture disproportionate value.
TV Market
Why 2026 is a strategic hinge year
- Acceleration of integration-led value: Automotive and large‑format use cases have shifted the competitive frontier from panel commodities to integrated display systems that combine hardware, software, and services. Decisions made in 2026 about platform architecture and supplier partnerships will lock in customer experience for multiple product generations.
- Regulatory and safety inflection: Functional safety, electromagnetic compatibility, and in‑vehicle light emissions standards are converging into mandatory engineering constraints that materially affect time‑to‑market and BOM design choices.
- Supply and technology squeeze: Incremental demand for higher‑quality displays coincides with capacity constraints in advanced panel fabs and a premium on integration expertise — creating a window for early movers to capture margin expansion.
Core dynamics shaping strategy
- From panels to experiences: Value is migrating away from raw panel supply to system‑level solutions — curved and panoramic systems, integrated infotainment, multi‑zone UX, and bundled content/services are where margins and differentiation now aggregate.
- Regulatory-driven product risk: UNECE standards for retro‑reflective materials and electromagnetic compatibility (R43 and R10), rules on blue light intensity (UNECE R65), and global expectations for FMVSS/ECE testing add both cost and certification timelines. Concurrently, ISO 26262 (functional safety) and ISO 21434 (cybersecurity) are gating factors for any in‑vehicle display deployment.
- Consolidation and supplier leverage: The market exhibits high concentration among a limited group of OEMs and Tier‑1 integrators. That structural reality increases negotiating power for established suppliers but also elevates entry barriers for specialist challengers who lack integration footprints.
- Software as a defensible moat: The platformization of displays — OTA update ecosystems, integrated media/content apps, and secure communication channels — creates recurring revenue and stickiness that hardware alone cannot replicate.
Competitive landscape: what the major manufacturers signal
Several automotive OEMs have become focal points for display innovation, and their public product strategies telegraph where investments are meaningful:
TV Market
- Tesla, Inc. (Austin, TX): Favors large‑format integrated displays and vehicle infotainment convergence. Their approach highlights the commercial opportunity for high‑integration suppliers who can deliver turnkey hardware plus content aggregation and connected services.
- BMW AG (Munich): Investing in panoramic vision systems that emphasize luxury UX and high fidelity displays — signaling demand for premium panel technologies coupled with advanced HMI software.
- Mercedes‑Benz Group AG (Stuttgart): Commercializing hyperscreen and curved display experiences that blend multiple zones and advanced graphics, underscoring the need for cross‑disciplinary systems engineering (mechanical, thermal, and software).
- Audi AG (Ingolstadt): Driving innovations around virtual mirrors and high‑resolution cluster systems, illustrating a move to replace mechanical components with software‑defined displays.
- General Motors Company (Detroit): Emphasizing large infotainment and instrument clusters across broad model portfolios, which increases scale opportunities for suppliers that can meet volume, cost and certification targets simultaneously.
The strategic takeaway: OEMs are no longer just customers of display glass — they act as integrators and product designers. Suppliers that can align to OEM systems‑integration roadmaps (hardware + software + compliance) will command superior terms.
Practical contents of the full PW Consulting report
For teams preparing investment memos, product roadmaps, or procurement strategies, the report provides action‑oriented deliverables, including:
- Market sizing and forecast with scenario variants (central, upside, downside) and an integrated financial model (2020–2032).
- Go‑to‑market playbooks for hardware OEMs, Tier‑1 suppliers, and software/service providers, keyed to three commercialization windows: 0–12 months, 12–36 months, and 36+ months.
- Competitive benchmark matrix covering capability, integration posture, route‑to‑market, and certification readiness for leading OEMs and supplier archetypes.
- Regulatory and standards impact assessment with compliance cost estimates and timeline implications tied to UNECE and ISO requirements.
- Supplier mapping and risk heatmap for component concentration, capacity constraints, and alternate sourcing scenarios.
- M&A and partnership shortlists generated by strategic fit algorithms and synergy modeling for multiples and integration costs.
- Templates for RFPs, acceptance tests, and contract clauses that protect IP, ensure cybersecurity, and allocate certification risk.
Actionable recommendations for 2026 corporate planning
- Prioritize system‑level investments: Redirect a portion of hardware R&D budgets into software platforms, UX toolchains, and OTA infrastructure. Even conservative scenarios in our model show higher lifetime margins for integrated offerings versus panel supply.
- Fast‑track certification planning: Begin ISO 26262 and ISO 21434 workstreams now; regulatory tests (UNECE R43/R10/R65 and FMVSS/ECE checks) add lead time and rework risk if started late. Allocate both budget and program management resources accordingly.
- Design for modularity and supplier optionality: Create product families with modular display units to enable multi‑supplier sourcing and mitigate capacity or technology disruptions.
- Forge content and services partnerships: Secure content aggregation and app partners early to populate integrated infotainment systems and capture recurring revenue streams.
- Use M&A tactically: Acquire small software teams or UX studios to accelerate capability-build; pursue bolt‑on purchases for niche certification expertise rather than large‑scale consolidation unless pursuing clear scale economics.
- Monitor KPIs that matter: Track time‑to‑certification, mean time to OTA deploy, supplier concentration ratio by BOM value, and software ARPU (for service‑enabled models).
Scenario sensitivities and what to watch next
Two main scenario levers will re‑shape forecasts and should be embedded in any investment decision: technology substitution pace (how quickly panels migrate to newer architectures and in‑vehicle standards evolve) and regulatory tightening (new testing requirements or cross‑jurisdictional harmonization). Our model provides sensitivity tables for both levers — those granular outputs and regional split analyses are held in the full report.
How to use this report in boardroom decision cycles
- Q1 2026 (Immediate): Baseline portfolio triage — classify SKUs into “must invest,” “maintain,” and “sunset” buckets based on integration fit and certification readiness.
- Mid‑term (12–24 months): Execute supplier consolidation or dual‑sourcing playbooks, begin certification projects, and run pilots with software/content partners.
- Longer term (24–60 months): Scale platform rollouts, integrate recurring service pricing, and evaluate M&A targets to pick up missing capabilities.
Final note — what you won’t find in this preview
This article deliberately omits granular regional, type and application splits and the full competitive scorecards that underpin our valuation and scenario outputs. Those segmentation tables, contract‑level margin assumptions, and downloadable Excel workbooks are accessible on the report page and are essential for transaction due diligence or financial planning. If your team needs a tailored workshop (portfolios, procurement, or M&A screening), PW Consulting offers bespoke modules that operationalize the report into executable projects.
In a market that moves from commodity panels to integrated display experiences, 2026 will separate companies that merely sell components from those that own customer journeys. Use the next 12 months to lock in integration partners, accelerate certification, and build software moats — the full PW Consulting TV Market report gives you the granular maps and executable templates to do exactly that.
For detailed analysis of this topic, please visit the official page: TV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lateral Flow POC Reader Market to Hit USD 701.17M by 2032 at 3.0% CAGR — PW Consulting
By PW Consulting, 2026-07-12
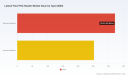
Lateral Flow POC Reader Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest Lateral Flow Point-of-Care (POC) Reader Market briefing is designed as a strategic decisioning tool for executive teams, corporate development groups, and investors planning commitments in 2026. The market is no longer a peripheral accessory business: it is maturing into a measurable, device-driven diagnostic segment with steady growth, rising regulatory scrutiny, and new commercial architecture. This article synthesizes the report’s most decision-relevant insights while preserving the detailed, proprietary segmentation and model outputs for subscribers.
Lateral Flow POC Reader Market
Executive snapshot: Why this matters right now
- The lateral flow POC reader market is established and growing. After notable expansion in the early 2020s, the global market reached an estimated USD 575.0 Million in 2025 (base year) and is projected to continue expanding through our 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 3.0%.
- Growth that persists in a low-single-digit band signals a shift from a pandemic-driven spike to structurally driven, incremental adoption — driven by reimbursement shifts, regulatory clarity, and platform convergence across immunoassay and molecular point-of-care modalities.
- Competitive dynamics are consolidating: the top three players capture roughly half of the market, and the top five around two-thirds, creating meaningful scale advantages for incumbents while leaving pockets of opportunity for agile specialists and OEM partners.
Market trajectory: data-driven context without giving away the map
PW Consulting’s historical series traces market value from 2020 through the 2025 base year and projects through 2032. The trajectory shows a recovery from the volatility of the pandemic years into a steady mid-single-digit expansion path. By 2026 the market crosses a new threshold, reflecting the interplay of recurring POC demand and replacement cycles for both benchtop and handheld readers. By 2032 our consolidated forecast indicates continued expansion, driven by incremental penetration in routine clinical workflows, new reimbursement categories, and incremental product upgrades that emphasize quantitation, connectivity and regulatory compliance.
Lateral Flow POC Reader Market
Importantly for 2026 planning: the modest but persistent CAGR means strategic options that rely on scale and margin expansion (pricing discipline, consumables lock‑in, bundled service contracts) compound value meaningfully over a multi-year horizon; conversely, one-off tactical plays without a path to either recurring revenue or channel ownership will struggle to achieve acceptable returns.
Lateral Flow POC Reader Market
Forces shaping the market — what to watch this year
- Regulatory momentum and product eligibility: Recent clearances and CE/IVDR activity are reducing uncertainty. Examples include new FDA clearances and CLIA waivers in early 2026 for POC molecular platforms that sit adjacent to lateral flow diagnostics, and established IVDR pathways for quantitative readers. Regulatory clarity is reducing time-to-market for platform upgrades but increasing the need for compliance investment early in the product lifecycle.
- Reimbursement reclassification: Several European markets have moved reimbursement codes that recognize digital diagnostics as diagnostic devices rather than mere accessories. This reclassification elevates the commercial profile of readers (and the economic value of digital quantitation) and will materially affect purchasing decisions among hospital networks and primary care chains.
- Platform convergence and partnering: Expect continued horizontal integration across molecular and lateral-flow modalities. Strategic supply agreements and M&A in early 2026 underscore vendor emphasis on offering broader POC portfolios rather than single-use readers alone.
- Channel economics and OEM demand: Manufacturers of assays continue to weigh OEM reader partnerships versus app-based smartphone solutions. The economics of consumables, service, and software subscriptions increasingly dictate the most attractive GTM approaches.
Competitive pulse: who’s moving and why it matters
The market comprises established vendors, specialist OEMs, and emerging platform players. PW Consulting’s competitive analysis spotlights a set of companies with differentiated strategic postures:
- QuidelOrtho Corporation (San Diego, USA) — A leading integrated diagnostics firm that combines lateral flow readers with immunoassay and molecular POC assets. Recent strategic moves include a supply agreement with analyzer platform partners and an acquisition that expands their ultra-fast PCR portfolio. These actions indicate a deliberate pivot from single-product offerings to platform breadth and channel depth — a blueprint for scale-driven defensibility.
- Lumos Diagnostics (Australia) — Focused on clinical-grade LDX readers optimized for lateral flow assays in POC settings. Their positioning emphasizes clinical integration and performance, targeting adoption in ambulatory and decentralized testing sites.
- Axxin (Sweden) — Known for benchtop quantitative readers with strong regulatory positioning (CE, IVDR compliance and active FDA submissions). Axxin’s approach highlights technical robustness and compliance as enablers for partnerships with assay manufacturers seeking expedited market access in regulated jurisdictions.
- Detekt Biomedical (UK) — A supplier of OEM and custom reader platforms, operating in the niche between in-house development and off-the-shelf procurement. Their value proposition centers on customization and rapid integration for POC programs.
- Gold Standard Diagnostics (USA) — Markets quantitative readers for infectious disease and allergen testing. Their RapidScan line demonstrates that vertical specialization combined with quantitation capability remains a viable route for differentiation.
- Operon (Spain) — Offers off-the-shelf readers targeting POC immunoassay quantification. Operon’s strategy is to serve fragmented demand with accessible devices and streamlined procurement.
Collectively, these firms illustrate three viable strategic archetypes in 2026: platform consolidators (broad portfolios and channel reach), compliance/quality specialists (regulatory and performance differentiation), and OEM/integration players (customization and partnership-driven growth).
Strategic implications for 2026 decisions
- For medical device incumbents: If your objective is share expansion, prioritize platform breadth through targeted partnerships or tuck-in acquisitions that add complementary POC modalities and consumables. The economics of recurring consumables and service contracts will drive long-term value more than one-time device sales.
- For diagnostics innovators and assay developers: Validate two GTM pathways in parallel — an OEM partnership route (to access regulated, blue‑chip customers) and a direct, device‑agnostic digital approach (to accelerate adoption in low-barrier markets). Reimbursement wins in Europe make the OEM route increasingly attractive for clinical-grade assays.
- For private equity and strategic investors: Market concentration presents buy-and-build opportunities but requires disciplined playbooks to integrate regulatory, software, and service capabilities. Look for targets with established regulatory filings or modular platforms that can be cross‑sold into larger installed bases.
- For hospital networks and large buyers: Negotiate bundled contracts that lock in consumables and remote device management. Reimbursement changes increase the case for capital procurement, but buyers should insist on interoperability and upgrade pathways to mitigate obsolescence risk.
- For companies considering market entry: Avoid broad country-by-country rollouts. Prioritize geographies and channels where reimbursement and regulatory frameworks are favorable, and where distribution partners can deliver rapid access to clinical decision-makers.
What the PW Consulting report delivers (practical, operational outputs)
The full report is built for executives who must convert insight into action. It includes:
- A validated historical market series (2020–2025) and a forward-looking financial model (2026–2032) with scenario analysis and sensitivity tables.
- Proprietary segmentation across region, product type (benchtop vs. handheld), and end-use application, with demand drivers and tipping points per segment (note: detailed segment tables are reserved for subscribers).
- Competitive profiles and capability maps for the market’s leading vendors, with an assessment of product roadmaps, regulatory posture, and channel strategy.
- A regulatory and reimbursement tracker that identifies near-term risks/opportunities and quantifies their impact on adoption timing.
- Commercial playbooks — GTM scenarios, pricing levers, and an M&A/partnership matrix with likely synergies and integration risks.
- An executable 36‑month migration plan for buyers and vendors focused on product upgrades, procurement strategies, and IT/interop considerations.
- An interactive Excel model that allows you to run your own scenarios and test assumptions on penetration, pricing, and consumables attachment.
Recommended next steps for 2026
- Commission a rapid opportunity assessment (6–8 weeks) to quantify your addressable market under the new reimbursement rules and regulatory timelines.
- Prioritize one or two strategic partnerships to fast-track platform breadth; use supply agreements or white‑label OEM deals to bridge capability gaps rather than building from scratch.
- Fast‑track regulatory planning: lock in CE/IVDR compliance and establish a clear FDA engagement plan if the United States is a target market.
- Design commercial pilots that capture recurring revenue (consumables + software) and gather real-world health-economic data to support reimbursement submissions.
- Where M&A is on the table, prefer targets that bring either regulatory clearances or significant consumables attachment rates — those provide the most immediate value accretion.
Closing — how PW Consulting can help
The lateral flow reader market has transitioned from episodic growth into a structurally interesting segment with predictable returns for disciplined players. PW Consulting’s full Lateral Flow POC Reader Market report provides the granular segmentation, competitive intelligence, and executable playbooks needed to convert 2026 strategy into measurable outcomes. This article is a strategic preview: the report retains the proprietary segmentation tables, full company profiles, and the detailed financial model that corporate executives and investors require to make capital allocation decisions with confidence.
For teams preparing 2026 budgets, portfolio pivots, or acquisition screens, our report distills where to commit capital, where to partner, and where to wait for clearer signals. Contact PW Consulting or visit our report page to unlock the detailed model and the complete set of operational recommendations.
For detailed analysis of this topic, please visit the official page: Lateral Flow POC Reader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surgical Gowns Market to Hit USD 284.42 Million by 2032 at 5.8% CAGR — PW Consulting
By PW Consulting, 2026-07-12
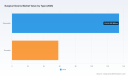
Surgical Gowns Market — Strategic Outlook for 2026: A PW Consulting Structural Brief
As healthcare providers, device manufacturers, distributors, and private equity sponsors plan their 2026 roadmaps, the surgical gowns market presents a measured growth story with concentrated pockets of opportunity and regulatory inflection points that demand strategic clarity. This brief distils the high-level implications from PW Consulting’s newest Surgical Gowns Market study (base year 2025, historical 2020–2025, forecast 2026–2032) to help executives prioritize choices that will materially affect competitiveness through the next planning cycle.
Surgical Gowns Market
Executive snapshot
In 2025 the global surgical gowns market stood at approximately USD 192.6 Million (revenue unit: Million). Under a central-case trajectory, we model a compound annual growth rate (CAGR) of 5.8% for the 2026–2032 forecast window, reaching the high hundreds of millions by 2032. Market concentration is meaningful: the three largest players account for roughly 42.3% of the market, while the top five control about 52.7% — a structure that creates both predictable competitive behaviour and openings for challenger brands that execute precisely on differentiation and channel strategy.
Surgical Gowns Market
Why this research matters for 2026 decisions
- Timing of investment and capacity expansion: With mid-single-digit CAGR ahead, capacity investments must be disciplined. Players who front-load automation and quality systems aligned to new standards can compress time-to-market for premium, higher-margin products.
- Portfolio positioning: The market’s growth is driven by shifts in clinical practice, regulatory thresholds and procurement economics. Firms that align product tiers with clearly defined hospital procurement levers will capture disproportionate share.
- M&A and partnership targeting: Given moderate concentration and fragmented mid-market supply, 2026 is a high-conviction year for bolt-on acquisitions that accelerate sterile supply capability, regional access, or differentiated barrier technologies.
- Regulatory compliance as a market moat: Upcoming standards and reimbursement signals reframe compliance from cost center to strategic protector of price realization and contracting leverage.
Market trajectory: what the headline numbers conceal
The market progression from the historical window into our forecast reflects steady demand renewal driven by surgical volumes, infection-control protocols, and an enduring tilt toward single-use disposables in many settings. However, beneath the headline CAGR lie three dynamics that materially influence winners and losers:
Surgical Gowns Market
- Standard and test-method upgrades: Updated performance standards force suppliers to revalidate materials and production flows. Early adopters of the new test regime will enjoy first-mover status in premium tenders.
- Procurement economics and unit-price pressure: Even with market growth, buyer consolidation and value-based purchasing compress margins in commoditized categories. Companies that quantify total cost of ownership (TCO)—including infection avoidance and reprocessing costs—will defend price.
- Clinical and sustainability trade-offs: Hospitals balance clinical protection, staff comfort, and environmental goals. Suppliers that can credibly demonstrate barrier performance without compromising throughput or recyclability will open higher-margin pathways.
What the report delivers — practical, transaction-ready outputs
PW Consulting’s full report is structured to move executives from insight to action. Core, executable deliverables include:
- Market sizing and scenario stacks (base, conservative, upside) for 2026–2032 with sensitivity to surgical volume trends and unit-price shifts.
- Regulatory and standards matrix mapping impact by geography and product class, including compliance timelines and recommended mitigation steps.
- Go-to-market playbooks tuned to acute-care procurement processes, private-label strategies, and distributor partnership models.
- Supplier and capability heatmaps highlighting manufacturing, sterilization, and testing bottlenecks tied to lead-time and margin implications.
- Commercial models: channel economics, margin waterfalls, and TCO calculators designed for bid teams and pricing committees.
- M&A diligence kit: target screening criteria, precedent valuation ranges, integration playbooks, and a short-list of targets informed by strategic fit and operational synergies.
- Risk register and contingency levers covering raw-material shocks, regulatory rework, and payor/reimbursement uncertainties.
Competitive landscape: players, positioning, and tactical moves
The market is anchored by several established manufacturers and diverse regional suppliers. PW Consulting’s competitive assessment focuses on product capability, regulatory credentials, channel reach, and innovation velocity. Key companies profiled in the study include:
- Medline Industries — Northfield, Illinois, USA ( https://www.medline.com). Known for high-barrier Level 4 surgical gowns with features such as breathable sleeves and reinforced fabrics. Recently secured FDA 510(k) clearance in early 2025 for a Level 4 gown meeting the latest ANSI/AAMI PB70 barrier specifications (K242844), reinforcing their premium clinical positioning.
- Cardinal Health — Dublin, Ohio, USA ( https://www.cardinalhealth.com). Offers a range of AAMI Level 3/4 gowns including breathable models and practical design elements such as instrument pockets—an advantage in workflow efficiency-focused tenders.
- Halyard Health — Atlanta, Georgia, USA ( https://www.halyardhealth.com). Specializes in tri-layer isolation and surgical gowns designed for advanced barrier performance, catering to infection-prevention mandates in higher-acuity settings.
- 3M Company — St. Paul, Minnesota, USA ( https://www.3m.com). Produces a spectrum of disposable surgical gowns covering BASIC to REINFORCED categories aligned to ANSI/AAMI PB70 standards; benefits from broad clinical trust and global distribution networks.
- Yadu Medical (Henan) Co., Ltd. — Changyuan, Henan Province, China ( https://www.yadugroup.com). A sterile gown manufacturer cleared by FDA for Level 3 gowns in late 2025 (K250564), strengthening the competitive set among cost-advantaged sterile suppliers.
Recent regulatory clearances and product refreshes emphasise how certification timelines now influence commercial windows. The report includes a competitive action matrix showing who is primed to win specific contract archetypes and why.
Regulatory and reimbursement inflections executives cannot ignore
- Regulatory class: Surgical gowns are Class II devices under the FDA product code FYA and require 510(k) premarket notification as codified in 21 CFR 878.4040. Suppliers must preserve robust design history files and clinical or bench evidence aligned to the latest guidance.
- Standards update: The new NF EN 13795-1:2025 standard tightens physical-property and test-method expectations for single-use surgical drapes and gowns. This elevates testing investment for any supplier planning on selling into markets that adopt EN 13795-1:2025 verbatim.
- Reimbursement signal: The 2026 Medicare Physician Fee Schedule proposed rule introduced a specific reimbursement pathway for surgical gowns (CPT-coded SB028 at a unit value of $5.13 in the proposed 2026 MPFS). Where implemented, reimbursement can catalyse procurement shifts toward higher-cost, higher-performance products if clinical-economic value is demonstrated.
Strategic implications and recommended 90–180 day actions
- Manufacturers: Prioritize certification projects for products aligned to premium tenders; accelerate validity testing to avoid rework windows when standards are adopted. Run a SKU rationalization to concentrate R&D and quality spend on high-opportunity items.
- Distributors and private-label partners: Re-evaluate supplier scores using the updated standards matrix. Negotiate conditional pricing tied to certification milestones and add clauses for rapid volume increases tied to pandemic-like demand shocks.
- Hospitals and large group purchasers: Incorporate TCO models into RFPs and pilot higher-barrier gowns in procedures with the highest downstream-cost impacts (e.g., infection-related readmissions). Consider reimbursement capture strategies where MPFS reimbursement applies.
- Investors and M&A teams: Use the report’s diligence kit and target short-list to prioritize deals that deliver vertical control over sterilization and testing capabilities or expand branded presence in high-growth clinical niches.
How to use this brief and next steps
This document is intentionally diagnostic: it demonstrates analytical rigor and actionable line-of-sight without disclosing every granular split or segment figure. PW Consulting’s full Surgical Gowns Market report contains the detailed segmentation, price ladders, regional demand curves and contract archetype models required to operationalize the strategies sketched above — including downloadable bidder-ready templates and a prioritized M&A short-list.
For organizations preparing budgets and capex decisions for 2026, rushing to commit without a targeted read of the full study introduces execution risk. PW Consulting can provide custom briefings, scenario workshops, and rapid-scope due diligence tailored to your strategic priorities.
Concluding note
Between incremental market growth and structural regulatory shifts, 2026 is a decision year: firms that recalibrate product portfolios, lock in certification pathways, and leverage procurement economics will convert steady market expansion into durable advantage. PW Consulting’s full study supplies the granular intelligence and executable tools to do exactly that — enabling leadership teams to move from observation to informed action with speed and confidence.
For detailed analysis of this topic, please visit the official page: Surgical Gowns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Central Gateway Module Market to hit USD 6,110M by 2032; 6.7% CAGR
By PW Consulting, 2026-07-12
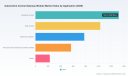
Automotive Central Gateway Module Market — Strategic Primer for 2026 Decision-Makers
As vehicle architectures evolve from federated to zonal and domain-oriented topologies, the central gateway module (CGM) has emerged from a component-level consideration to a strategic control point for automotive OEMs, tier‑1s, and semiconductor suppliers. Our PW Consulting Automotive Central Gateway Module Market study (base year 2025) synthesizes market dynamics, technology trajectories, supplier economics and regulatory imperatives into a single decision-grade briefing designed to inform boardroom choices and capital allocation in 2026.
Automotive Central Gateway Module Market
Why this study matters for 2026 strategies
-
Macro trajectory — The CGM market has moved from roughly USD 2.85 billion in 2020 to about USD 3.93 billion in 2025, and is forecast to grow to approximately USD 6.11 billion by 2032 under a mid‑cycle CAGR of ~6.7% for the forecast period. That pace is sufficient to drive sustained supplier consolidation and to justify multi‑year platform investments, but not so rapid as to remove the premium on disciplined program costing and modularity.
Automotive Central Gateway Module Market -
Strategic inflection — 2026 marks the first operational year when UNECE R155 and ISO/SAE 21434 related requirements for cybersecurity and functional safety are expected to materially affect supplier selection, bill of materials (BOM) design and software update strategies. Compliance is no longer an engineering checkbox; it is a commercial differentiator that alters total cost of ownership, warranty exposure and residual value assumptions.
Automotive Central Gateway Module Market -
Concentration & bargaining dynamics — The market is moderately concentrated: the top three players control nearly half of the market, and the top five account for roughly two‑thirds. For OEMs and Tier‑1s this creates an environment where strategic partnerships can secure preferred access to secure silicon and software stacks, while for smaller suppliers it raises the bar for design-to-cost and niche technical differentiation.
What the report delivers — action over description
Designed as an executable playbook rather than a reference catalogue, the full PW Consulting report blends quantitative forecasting with operational tools you can apply immediately in procurement, product planning and M&A diligence. Key deliverables include:
-
Verified market sizing and scenario-based forecasts (2026–2032) anchored on our 2025 base year and stress-tested against semiconductor cycles, EV penetration scenarios and regulatory shock cases.
-
Technology roadmaps that map CGM functional stacks (communication fabrics, compute and security engines, OTA support) to platform architectures commonly adopted by global OEMs, highlighting where Ethernet and high‑bandwidth backbones become mission‑critical.
-
A procurement risk matrix detailing supplier concentration, single‑sourcing exposure, and raw material / silicon supply vulnerabilities, with recommended mitigation actions for component hedging and multi‑sourcing.
-
Competitive benchmarking and supplier scorecards built around technology readiness, cybersecurity maturity, software update ecosystems and cost-to-serve metrics — tailored for use in RFQs, partner selection and Tier‑1 negotiations.
-
Regulatory compliance playbook that translates UNECE R155 and ISO/SAE 21434 mandates into product requirements (e.g., hardware security module integration, secure boot, intrusion detection and encrypted comms) and verification checkpoints required during 2026 program starts.
-
Investment and M&A frameworks that identify profiles of tuck‑ins, bolt‑ons and platform bets likely to generate near-term margin expansion or strategic lock‑in for OEMs and Tier‑1 integrators.
Market dynamics and drivers you must integrate into 2026 plans
-
Regulatory compliance is now engineering. UNECE R155 and ISO/SAE 21434 have escalated the need for embedded hardware security modules (HSMs), secure boot chains and intrusion detection in gateway products. These requirements increase per-unit complexity and create a recurring software‑driven services revenue opportunity (patching, vulnerability management) that must be priced into supplier contracts.
-
Bandwidth & compute reallocation. The shift toward Ethernet backbones and zonal ECUs increases input/output and compute demand at the gateway. This is accelerating demand for higher‑performance processors, real‑time virtualization, and deterministic Ethernet stacks — affecting BOM composition and thermal/EMC design considerations.
-
Supply‑side coupling. Semiconductor availability, raw material constraints and the need for close collaboration between component makers and raw material suppliers are shaping program timelines. Long lead components and qualification cycles can add 3–6 months to project schedules unless procurement hedges are in place.
-
Software-defined economics. As OTA capabilities become table stakes, CGMs are evolving into continuous service gateways. This changes lifetime economics — suppliers that can offer secure update frameworks, vulnerability monitoring and analytics capture will command premium margins and closer OEM engagement.
Competitive landscape — what distinguishes winners
The market combines established automotive electronics integrators with semiconductor leaders that supply the foundational building blocks. Success in 2026 will hinge on three capabilities: systems integration (hardware + middleware + cybersecurity), supply resilience, and software lifecycle services.
-
Systems integrators — Companies with deep vehicle systems expertise and global program management capabilities remain advantaged. Their ability to deliver cross‑domain connectivity, validate functional safety cases and scale production globally keeps them at the center of tiered supply chains.
-
Semiconductor and IP suppliers — Foundational silicon vendors that tightly couple processor performance with security IP and automotive-grade peripherals are shaping the BOM and locking in design wins earlier in platform cycles. Their roadmap cadence directly impacts module capabilities and cost curves.
-
Regional challengers and fast followers — Localized players are competing on cost and speed to market for regional OEMs; however, as compliance and cybersecurity requirements rise, these challengers must invest materially in security architectures to remain competitive.
Representative names in the ecosystem include historic automotive electronics leaders, global tier‑1 integrators and semiconductor suppliers. Each brings distinct strengths: deep vehicle integration and cybersecurity features (for global tier‑1s), connectivity stacks and ADAS integration experience, as well as processor and security IP from semiconductor vendors. For program evaluators, comparing supplier capabilities across integration depth, security compliance and long‑tail software support is essential.
Strategic playbook for 2026 — recommended actions
-
Reprice programs to reflect compliance costs: Build UNECE R155 / ISO 21434 compliance into target costs and supplier KPIs. Expect a step‑function increase in initial engineering hours and recurring vulnerability management fees.
-
Lock in secure silicon early: For new platform launches, prioritize early access to validated processors and HSM partners. Where possible secure multi‑year allocation agreements to avoid late‑cycle program slippage.
-
Design for software monetization: Treat the gateway as a subscription enabler. Define clear responsibilities for OTA infrastructure, data ownership and revenue sharing before production sign‑off.
-
Pursue focused M&A to plug capability gaps: Target bolt‑ons that bring certified cybersecurity stacks, OTA management platforms or advanced Ethernet switch expertise rather than broad horizontal acquisitions that dilute integration focus.
-
Stress test supply chains: Run 18‑month scenario analyses on single‑source components and validate second‑source paths for critical silicon. Incorporate escalation clauses and buffer inventory strategies in supplier contracts.
How to use our report in 2026 program cycles
Procurement teams will find the supplier scorecards and cost models immediately actionable during RFP rounds. Systems engineering will value the technology roadmaps and regulatory checklists for architecture decisions and validation planning. M&A and corporate strategy teams can use the scenario forecasts and concentration analytics to prioritize targets and quantify upside. Importantly, our scenario analyses are parameterized so you can rerun projections with your own EV penetration, ADAS adoption or semiconductor pricing assumptions.
What we intentionally withhold in this primer — and why
To preserve the commercial value of the underlying research and to ensure readers obtain the full, verifiable datasets needed for program-level decisions, this introduction omits core segment‑level tables and granular regional/application splits. The full report contains detailed segmentations, market share tables, unit‑level BOM breakdowns and downloadable vendor scorecards that are indispensable for bid modeling and contract negotiations. Think of this article as the strategic trailer: it maps the terrain and points to the exact datasets you will need to execute in 2026.
Closing guidance — a checklist for decision-makers
-
Embed UNECE R155 / ISO 21434 into supplier RFQs and program KPIs.
-
Prioritize early silicon commitments and multi‑source strategies for high‑risk components.
-
Redesign commercial terms to capture lifecycle software and security service revenues.
-
Use market concentration metrics to inform negotiation stance and M&A prioritization.
For teams preparing bids, signing strategic supply agreements or shaping 2026 product roadmaps, the full PW Consulting Automotive Central Gateway Module Market report provides the empirical backbone and practical instruments required to convert market growth into defensible margin improvements and strategic lock‑in. Visit our research portal to access the complete dataset, supplier scorecards and implementation templates necessary to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Automotive Central Gateway Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AI for Edge Devices Market to Expand at 23.5% CAGR — PW Consulting Insight (2026–2032)
By PW Consulting, 2026-07-12
Artificial Intelligence for Edge Devices Market — Strategic Preview for 2026 Decision-Makers
As enterprises prepare capital allocation, product roadmaps, and regulatory compliance strategies for 2026, the edge AI landscape demands a different kind of market intelligence: one that couples robust macro forecasts with executable playbooks and vendor-level nuance. This PW Consulting briefing introduces the firm’s latest market research on Artificial Intelligence for Edge Devices. It highlights the strategic takeaways that should shape boardroom decisions, while preserving the granular segment-level intelligence for the full report where practitioners can access detailed spreadsheets, vendor scorecards, and scenario models.
Artificial Intelligence for Edge Devices Market
Market snapshot: scale, trajectory, and concentration
Edge AI is moving from niche deployments to a mainstream infrastructure layer. Our base-year analysis (2025) positions the global market at approximately USD 11.8 Billion, with a compound annual growth rate (CAGR) of 23.5% through the forecast horizon (2026–2032). By 2032, the market trajectory points to multi‑dozen billion scale, reflecting the cumulative effect of on-device inference adoption across mobile, industrial, automotive, healthcare, and consumer segments.
Artificial Intelligence for Edge Devices Market
Competitive dynamics are moderately fragmented: the top three players account for roughly one-third of the market, while the top five capture just over two-fifths. That concentration profile creates room for specialist challengers and systems integrators to capture differentiated value through software, services, and verticalized solutions.
Artificial Intelligence for Edge Devices Market
Why this matters to 2026 enterprise strategy
- CapEx and procurement timing: With rapid compound growth, procurement windows for edge compute hardware and integrated platforms will compress. Enterprises that delay standardizing architectures risk higher migration and integration costs as vendors accelerate product refresh cycles and raise the bar for security and compliance.
- Vendor selection as strategic choice: Edge AI suppliers are not interchangeable parts. Hardware optimizations, developer ecosystems, and software toolchains materially affect time‑to‑value for pilots and scale-ups. Selecting a partner is simultaneously a technology and a go‑to‑market decision.
- Regulatory and sustainability externalities: New requirements around energy reporting, data sovereignty, and device certification will alter total cost of ownership models. Forward-looking procurement must bake in compliance pathways, not retrofits.
Dynamics shaping the edge AI market in 2026
- Energy and performance tradeoffs: Power consumption remains the central engineering constraint for edge compute. Innovations that enable DRAM‑less architectures and aggressive power reduction are altering BOM and operational models. For technology buyers, this translates into new ROI horizons: lower energy draw can reduce device-level operating costs and enable deployments where previously infeasible.
- Standards and certification: Governments and standards bodies are converging on frameworks for transparency and interoperability. New guidance for evaluating AI standards and certification catalogs for edge systems are emerging as de facto purchasing criteria for enterprise procurement teams.
- Policy-driven demand flows: Public financing and strategic assistance programs are beginning to direct capital toward secure, resilient edge solutions in geopolitically sensitive regions. This creates pockets of accelerated demand for vetted platforms that meet security and compliance thresholds.
- Platformization vs. specialization: The market is bifurcating into broad platform providers that offer verticalized suites and specialized accelerators optimized for particular inference workloads (vision, audio, low-latency control). Both plays can be profitable—what matters is alignment between workload economics and partner capabilities.
Technology and vendor landscape — how to read the field
Leading semiconductor and systems companies each bring distinct value propositions that influence enterprise architectures. Market leaders offer high-performance platforms and robust software ecosystems, enabling use cases from robotics to automotive. Mobile and consumer device incumbents embed AI capabilities at device scale, while a cohort of startups and semiconductor specialists focuses on ultra‑low power accelerators and MLSoCs designed for embedded vision and inference.
- High-performance platform providers: Companies delivering integrated edge platforms for robotics, industrial automation, and autonomous systems emphasize throughput, developer tooling, and ecosystem partnerships. Their products are favored in use cases that require sustained inference performance and complex model support.
- Mobile and consumer AI suppliers: Providers that embed on‑device AI into phones and personal devices prioritize energy‑efficient designs and tightly integrated software stacks to deliver end‑user capabilities with minimal latency.
- Specialist accelerators and MLSoCs: Emerging players focus on power-efficient, low-footprint accelerators tailored to vision and inferencing tasks where BOM and thermal constraints dominate design decisions.
Because vendor selection is consequential, the full report provides a practical competitor matrix and vendor profiles that evaluate partner readiness across performance, power, software ecosystem, security posture, and go‑to‑market alignment.
Recent developments that will matter in 2026
- Public funding initiatives targeting secure edge-enabled devices are mobilizing procurement budgets and creating new buyers—especially where national security and resilience are core requirements.
- Product launches and expanded developer ecosystems from major chipset vendors have shortened the prototype-to-deployment pathway, reducing integration friction for enterprises that adopt reference stacks.
- Strategic partnerships between systems integrators and chipset providers are producing compliant, certified edge platforms tailored for regulated markets—accelerating enterprise confidence in rollouts.
These dynamics combine to form a market environment where technology performance and policy compliance jointly determine supplier attractiveness. Organizations that evaluate both axes simultaneously will have a decisive advantage.
Where enterprise value will be captured
- Software and services around hardware — Integration, lifecycle management, secure update mechanisms, and model management are sustainable revenue pools that yield higher margins than commodity hardware. For buyers, service-level agreements and remote management capabilities are critical differentiators.
- Verticalized solutions — Industry-specific stacks (industrial vision, edge-enabled healthcare monitoring, automotive ADAS) convert throughput into measurable business outcomes. Successful vendors combine domain expertise with optimized inference stacks.
- Operational efficiency — Energy-aware architectures and optimized inference pipelines reduce operational expenditure in distributed deployments, affecting TCO calculations for large-scale pilots and global rollouts.
What the PW Consulting report delivers (practical components)
PW Consulting’s full study is designed for executives who need to translate market intelligence into executable decisions. The report contains:
- Detailed market sizing and forecast methodology (base year 2025; forecast period 2026–2032) with scenario analyses tailored for conservative, baseline, and aggressive adoption cases.
- Vendor benchmarking across technology, software ecosystem, security posture, developer support, and vertical go‑to‑market readiness.
- Use-case value calculators and ROI templates that model real-world deployments (pilot-to-scale economics, CapEx/Opex tradeoffs, and energy impact assessments).
- Procurement and integration playbooks: architecture decision trees, procurement RFP templates, vendor evaluation scorecards, and deployment checklists to accelerate safe, compliant rollouts.
- Regulatory mapping and compliance pathways aligned to current standards and guidance, including energy reporting expectations and certification resources applicable to distributed edge systems.
- M&A and partnership tracker highlighting strategic moves, financing, and alliances that shift supplier landscapes and accelerate access to capabilities.
How to use this intelligence in 2026
- Align procurement with compliance roadmaps: Require suppliers to demonstrate compliance readiness and productized pathways to meet energy and transparency obligations—doing this during vendor selection minimizes retrofit costs later.
- Prioritize pilot-to-scale economics: Use the report’s ROI templates to stress-test business cases across geography and edge topology. Pilot success metrics must map to scaled operational models, not vanity metrics.
- Design modular architectures: Build on interoperable stacks and open toolchains to avoid lock-in as silicon and software rapidly iterate. Modularization reduces migration cost and facilitates selective upgrades.
- Allocate budget for lifecycle services: Expect most value capture to shift into software, monitoring, and managed services. Budgeting for these capabilities is essential for sustained performance and security.
Final counsel — what 2026 leaders should do today
Edge AI is no longer an experimental add‑on—it's an infrastructure inflection. Boards and technology leaders must move from exploratory pilots to disciplined portfolio management: standardize reference architectures, codify compliance requirements, and select partners that align with long-term operational and governance objectives. The macro growth trajectory is compelling, but the devil is in implementation detail: energy constraints, standards adherence, and vendor ecosystems will determine who wins the operational and financial upside.
This preview outlines strategic priorities and the practical intelligence needed to act in 2026. For the granular segmentation, regional and application breakdowns, vendor scorecards, and model-level forecasts that underpin these recommendations, consult the full PW Consulting Artificial Intelligence for Edge Devices Market report. The full study contains the detailed data and worksheets enterprises require to commit capital, negotiate supplier SLAs, and design compliant deployment programs.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence for Edge Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advocacy Software Market to Hit USD 730.45M by 2032 at 10.12% CAGR
By PW Consulting, 2026-07-12
Advocacy Software Market 2026: Strategic Preview for Enterprise Leaders
As PW Consulting’s lead industry analyst, I present a strategic preview of our Advocacy Software Market research — a pragmatic guide for enterprise decision-makers preparing vendor, product, and investment choices in 2026. The space has moved beyond simple petition pages and email blasts; it is now a data‑driven, AI‑infused layer of civic engagement, public affairs, and social impact technology. Our benchmarking shows the global market expanding at a compounded annual growth rate of approximately 10.12% from the recent historical baseline, nearly doubling in scope across the upcoming forecast window. These macro dynamics create both opportunity and strategic risk for procurement, program teams, and C-suite leaders who must balance reach, compliance, and operational scalability.
Advocacy Software Market
Why this study matters for 2026 decisions
-
Timing and momentum: The advocacy market crossed an inflection point over 2020–2025 as organizations shifted budgets toward digital constituent engagement and policy intelligence. With continued double‑digit CAGR, 2026 is the year many buyers move from tactical pilots to enterprise rollouts — making vendor selection, data governance, and integration choices consequential for multi‑year programs.
Advocacy Software Market -
AI and automation are operational imperatives: Leading vendors are embedding agentic AI capabilities and automation into workflows that historically consumed disproportionate staff time (e.g., legislative monitoring, petition routing, and supporter triage). Organizations that treat AI as a strategic enabler — not just a feature checkbox — will compress time‑to‑value and materially reduce labor costs in advocacy operations.
Advocacy Software Market -
Regulatory and reputational exposure: Heightened privacy regulation (GDPR, CCPA) and a measurable rise in sector breaches have forced a rethink of vendor risk assessments. By 2026, privacy‑centric architectures and demonstrable security postures are procurement gating items, not negotiation levers.
Market dynamics and the business implications
-
Growth drivers: Digital-first campaigning, expanded fundraising and supporter engagement channels, and the adoption of AI for policy monitoring collectively drive sustained market growth. Expect vendors to accelerate investment in embedded analytics, predictive segmentation, and real‑time action orchestration.
-
Consolidation and concentration: The competitive landscape shows a moderate level of concentration among established players, while a healthy long tail of niche and open‑source options retains tactical appeal. This hybrid structure creates room for both platform consolidation and point-solution sourcing depending on organizational risk appetite and functional depth requirements.
-
Security and compliance as differentiators: Data breaches and regulatory scrutiny mean that vendors who can demonstrate privacy‑by‑design, comprehensive audit capabilities, and robust anonymization processes will win larger enterprise agreements. Procurement teams must bake compliance verification into RFPs and pilots.
-
Cost and accessibility: Entry-level pricing tiers remain available for grassroots and smaller organizations, but enterprise buyers face a different calculus — total cost of ownership, integration overhead, migration costs, and the staff resources required to operationalize sophisticated features.
Competitive landscape: strategic profiles and implications
Our coverage examines established platform families, specialist vendors, open‑source projects, and adjacent policy intelligence suppliers. A concise, comparative read of the key players provides insight into where functional strengths and go‑to‑market plays are concentrated:
-
Blackbaud — Traditionally strong in nonprofit fundraising and constituent engagement, Blackbaud has moved decisively into AI, launching an AI agent and an industry coalition to accelerate embedded intelligence for social impact work. For enterprise buyers, Blackbaud signals a platform‑level approach to combining fundraising, analytics, and agentic automation — attractive for organizations seeking an integrated supplier with scale.
-
NationBuilder — With the recent introduction of NationBuilder Engage, the company is sharpening its multi‑channel advocacy and volunteer mobilization capabilities. NationBuilder’s pricing accessibility at the entry level makes it a durable option for organizations that need quick deployments and community organizing tools, while the new product line aims to compete more directly for larger campaign requirements.
-
Salsa Labs and EveryAction — Both vendors remain viable choices for nonprofits focused on supporter engagement, fundraising, and canvassing. Their strengths lie in action toolkits and campaign orchestration, with EveryAction’s integration into broader ecosystems offering cross‑product leverage for organizations that prefer vendor ecosystems over point solutions.
-
CiviCRM — As an open‑source option, CiviCRM remains compelling where customization, cost control, and community‑driven development matter most. It is particularly attractive to organizations with internal development capacity or constrained budgets that need CRM and advocacy functionality without vendor lock‑in.
-
Quorum , FiscalNote — These suppliers occupy the public affairs and legislative intelligence niche. Their focus on policy monitoring, stakeholder mapping, and compliance support makes them primary choices for organizations whose advocacy is tightly bound to legislative outcomes. FiscalNote’s application of AI to policy signals faster, higher‑fidelity insights for teams that require real‑time tracking.
-
NGP VAN , Action Network , CallHub — These vendors serve campaign and grassroots mobilization requirements with strengths in political campaign workflows, action tracking, and telephony/canvassing integrations. They remain mission‑critical for high‑tempo campaign environments where rapid supporter activation is the metric of success.
Recent vendor movements and their strategic meaning
-
Blackbaud’s October 2025 unveiling of an AI Agent and an AI Coalition for Social Impact signifies a platform strategy to embed agentic workflows across fundraising, advocacy, and operations. For buyers, this trend means assessing not just feature lists, but the vendor’s roadmap for AI governance, explainability, and embedded compliance.
-
NationBuilder’s January 2026 launch of NationBuilder Engage highlights the competitive race for multi‑channel orchestration and volunteer management. Expect vendors to either broaden horizontal capabilities or double down on deep vertical specialization (e.g., political campaigns vs. nonprofits).
What our full report delivers (practical, implementation‑ready content)
This research is designed as an operational tool for 2026 planning cycles. Key deliverables include:
- Market sizing and forward scenario modeling to support budgeting and portfolio planning.
- Vendor scorecards and a decision matrix tuned for functionality, security posture, AI maturity, and integration cost.
- RFP templates and pilot frameworks that embed privacy, auditability, and data portability clauses.
- Implementation playbooks and change management checklists tailored to advocacy workflows (fundraising-to-action conversion, volunteer mobilization, legislative tracking).
- ROI and TCO models that quantify labor savings from automation, incremental revenue from digital actions, and risk reduction from improved compliance.
- Strategic M&A and partnership maps showing where consolidation and co‑innovation are most likely over the forecast horizon.
Note: while this preview shares the market’s overall trajectory and vendor dynamics, detailed regional and application breakdowns, as well as granular vendor financials and pricing comparisons, are deliberately withheld in this summary to preserve analytical depth for subscribers and buyers who access the full dataset.
Practical 2026 playbook — recommended executive moves
-
Start with a compliance‑first procurement: Require demonstrable GDPR/CCPA controls, incident response SLAs, and anonymization routines in every shortlist. Schedule security proof‑points as part of pilots, not just post‑contract audits.
-
Adopt phased AI pilots with measurable KPIs: Test agentic workflows on constrained use cases (e.g., legislative sentiment tagging, supporter qualification) and measure labor reduction, accuracy, and supporter experience before scaling platform‑wide.
-
Design for composability: Favor platforms that offer modular APIs and prebuilt connectors to CRM, DMP, and analytics stacks. This reduces lock‑in risk and preserves optionality as the market consolidates or new specialist entrants appear.
-
Consolidate where it creates value: For organizations with broad advocacy and fundraising needs, consolidation can reduce integration overhead. For mission‑specific workflows (legislative tracking or high‑tempo campaign ops), maintain specialized suppliers that excel in vertical capabilities.
-
Build a governance and talent plan: Technical capability is necessary but not sufficient. Create cross‑functional teams (legal, IT, comms, program) to oversee vendor governance, content policies, and ethical AI use.
How to use PW Consulting’s research in procurement and M&A
Procurement teams should use our vendor scorecards and pilot templates to convert market insight into contractual advantage — negotiating clear data portability clauses and phased payments tied to delivery milestones. For corporate development and private equity, the report identifies white‑space adjacencies, potential bolt‑on targets, and the valuation implications of AI roadmaps and compliance investments.
Conclusion — strategic value proposition
In 2026, advocacy software is no longer a marginal tool; it sits at the intersection of civic influence, brand reputation, and regulated data custody. Our market study equips executives with the macro view (growth trajectory and concentration dynamics), the competitive context (who leads where and why), and the tactical instruments (RFPs, pilots, governance frameworks) to make confident, defensible decisions. For organizations that must balance rapid supporter activation with privacy and compliance, the next 12–24 months will determine whether advocacy capability becomes a competitive advantage or a source of operational risk.
For a complete breakdown of regional, type, and application sub‑segments, granular vendor comparisons, and the downloadable implementation toolkit, please consult the full PW Consulting Advocacy Software Market report.
For detailed analysis of this topic, please visit the official page: Advocacy Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Multi‑functional Printer (MFP) Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new Multi‑functional Printer (MFP) Market study (base year 2025; forecast period 2026–2032). This companion article is a “trailer” — deliberately rich in directional insight and practical implications, while withholding the granular segmentation tables and proprietary scorecards that appear in the full report. Our aim: give technology, procurement, and corporate strategy teams the confidence to act in 2026 while motivating deeper engagement for transaction‑level decisions.
Multi-functional Printer Market
Big picture: growth trajectory and why 2026 is an inflection year
The MFP market has moved beyond replacement cycles and is now a convergence point of digitization, sustainability regulation, and new consumption models. Measured in USD (revenue in Million), the market expanded through the 2020–2025 period and, using our base year 2025, is projected forward across 2026–2032 at a compound annual growth rate (CAGR) of about 5.8%. This growth reflects steady demand for enterprise and SMB printing solutions, accelerated adoption of cloud‑native features, and renewed spending as organizations rationalize on‑premise fleets for hybrid work.
Multi-functional Printer Market
For executives, the takeaway is simple: 2026 is not a “do nothing” year. Market momentum and external pressure (regulatory and ESG) create both risk and opportunity for those who move early on procurement strategies, vendor engagement, and portfolio redesign.
Multi-functional Printer Market
Why this research matters to 2026 corporate decisions
- Procurement and TCO optimization: Our study equips procurement teams to move beyond sticker price and evaluate lifecycle cost: device acquisition, consumables, service, energy, and end‑of‑life obligations.
- Compliance and sustainability alignment: Stricter regulations (notably the European ESPR and EU Ecodesign extensions, as well as ENERGY STAR purchasing mandates for U.S. government buyers) are altering product spec sheets and total cost. Action in 2026 will be required to avoid stranded assets and procurement noncompliance.
- Security and data governance: With enterprise MFPs now integrated into cloud workflows, adherence to standards such as ISO 27001 and GDPR controls is table stakes; the report outlines practical controls and vendor assessment criteria.
- Service and business model transformation: Subscription‑based consumables, managed print services (MPS), and outcome‑based contracts continue to reshape vendor economics. The study offers templates for designing pilot MPS arrangements and evaluating vendor margin impact.
- Product and channel strategy: R&D roadmaps and channel incentives must be reassessed against trends in inkjet economics, laser performance, and integrated cloud platforms; the study highlights where to prioritize investment for 2026–2028.
What’s inside the full PW Consulting report (practical, executable outputs)
- Market sizing and forward scenario modeling (base year 2025; forecast to 2032) with sensitivity runs for macroeconomic and component‑supply shocks (figures reported in USD Million).
- Scenario playbooks: three actionable pathways for OEMs, channel partners, and enterprise buyers — “Optimize & Consolidate,” “Cloud‑first Modernization,” and “Sustainability‑led Replacement.”
- Vendor assessment framework and scorecards for security, service economics, cloud capability, and sustainability compliance (designed for fast insertion into RFPs).
- TCO and ROI calculators with configurable inputs for device mix, print volumes, energy costs, consumables pricing, and service levels.
- Commercial model templates for subscription and outcome‑based contracts, including margin/phasing illustrations and negotiation playbooks.
- Go‑to‑market modules for channel leaders: partner segmentation, incentive design, and field enablement for selling hybrid MFP + cloud services bundles.
- Regulatory compliance checklist and repairability/sustainability readiness assessment aligned to ESPR, ENERGY STAR, ISO 27001, and GDPR.
- Acquisition screening matrix for strategic M&A and bolt‑on services — what to buy (technology, service capability) and how to value recurring revenue streams.
- Executive one‑page action plans for 90/180/365 day horizons to convert insight into measurable outcomes.
Competitive landscape — strategic implications for 2026
The market is characterized by a mix of established OEMs and vertically integrated service providers. Each competitor brings distinct positioning that should inform vendor selection, partnership decisions, and competitive moves.
- HP Inc. (Palo Alto, CA) — Strengths: broad enterprise portfolio across laser and inkjet MFPs, deep cloud and security integrations. Strategic posture: emphasize managed services and SaaS‑layer tie‑ins. Implication: prioritize HP for cloud‑native rollouts where security certifications and scale are primary selection criteria.
- Canon Inc. (Tokyo) — Strengths: strong A3/A4 lineups with an emphasis on energy efficiency and hybrid workflows. Strategic posture: product efficiency and enterprise imaging solutions. Implication: consider Canon for energy‑constrained estate rationalizations and mixed‑workload environments.
- Seiko Epson Corporation (Tokyo) — Strengths: inkjet models optimized for low cost per page and high‑volume operations. Strategic posture: push high‑efficiency ink systems into SMB and volume‑sensitive workflows. Implication: Epson is a high‑leverage choice when consumables economics are the primary total cost driver.
- Brother Industries (Nagoya) — Strengths: hybrid laser/ink models and subscription consumables. Strategic posture: channel friendly with strong SMB appeal. Implication: use Brother where flexible commercial models and predictable consumable spend are priorities.
- Ricoh (Tokyo) — Strengths: cloud workflow platforms and intelligent automation; recent launches expanded cloud‑ready IM Series (January 2026). Strategic posture: workflow‑centric engagements targeting enterprise process automation. Implication: Ricoh is attractive for organizations seeking document workflow modernization tied to print consolidation.
- Konica Minolta (Tokyo) — Strengths: collaboration tools and team workflow integrations within bizhub series. Strategic posture: focus on office collaboration and team productivity. Implication: strong fit for office environments prioritizing integrated collaboration hardware and software.
- Kyocera Document Solutions (Kyoto) — Strengths: reliability, low maintenance, and high throughput (TASKalfa series). Strategic posture: industrial reliability for heavy print loads. Implication: ideal for operations where uptime and low service frequency are essential.
- Xerox Holdings (Norwalk, CT) — Strengths: managed print services and enterprise security capabilities. Strategic posture: packaging of MPS and security to capture recurring revenue. Implication: favored where vendor‑managed environments and security SLAs are decisive.
- Sharp Corporation (Osaka) — Strengths: MFPs integrated with interactive whiteboards and collaborative features; recent compact color MFP launch in India (May 2025). Strategic posture: convergence with meeting room technology. Implication: consider Sharp for hybrid meeting‑space ecosystems.
- Lexmark (Lexington, KY) — Strengths: workflow automation and sustainability messaging. Strategic posture: targeted enterprise workflow automation coupled with sustainability credentials. Implication: strong option for sustainability‑driven procurements.
Regulatory and industry guardrails — what to act on immediately
- ESPR and Ecodesign requirements in Europe are reshaping product roadmaps: durability, reparability, and recyclability features should be validated in vendor RFPs.
- U.S. federal purchasing rules continue to favor ENERGY STAR certified devices for government buyers; factor certification timelines into procurement schedules.
- Information security standards (ISO 27001) and privacy rules (GDPR) require both device‑level controls (encryption, authentication, audit trails) and vendor contractual commitments. Validate both technical and contractual compliance before signing multi‑year service agreements.
Opportunities, risks and practical playbooks for 2026
- Opportunities: Monetize services and consumables with subscription tiers; differentiate via integrated cloud workflows and verticalized attachments (healthcare, education). Use pilot bundles to demonstrate quick ROI.
- Risks: Non‑compliance with new environmental laws, under‑priced service models eroding margin, and underestimating security controls leading to breach exposure tied to MFP endpoints.
- Playbook (90/180/365 days):
- 90 days: Run an estate audit, map high‑risk devices, and shortlist three vendors using our vendor assessment framework.
- 180 days: Pilot a mixed‑model (subscription + managed services) in two facilities, enforce ISO/GDPR control requirements, and lock in energy‑efficiency clauses.
- 365 days: Scale successful pilots, renegotiate consumables pricing with volume triggers, and execute phased replacement aligned with ESPR timelines.
Next steps — where the full report adds value
This article is a strategic preview: it surfaces the growth outlook (base 2025, forecast 2026–2032 at ~5.8% CAGR in USD Million), competitive dynamics, regulatory imperatives, and immediate playbooks. The full PW Consulting report provides the proprietary segmentation datasets, regional and application breakdowns, downloadable scorecards, and the interactive TCO model you’ll need to operationalize these insights. For procurement teams, R&D leaders, and corporate strategists preparing for 2026, the complete study is the decision‑support tool to move from intent to contract with confidence.
To review the complete dataset, scenario outputs, and executable templates, contact PW Consulting or visit our Multi‑functional Printer Market report page to access the full findings and tools required for implementation.
For detailed analysis of this topic, please visit the official page: Multi-functional Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Brik Shape Aseptic Packaging to hit USD 230.3M by 2032 at 4.13% CAGR
By PW Consulting, 2026-07-12
Brik Shape Aseptic Packaging Market — Strategic Outlook for 2026 Decision-Makers
Executive preview
PW Consulting’s latest market study on Brik Shape Aseptic Packaging positions the sector as a stable, mid-single-digit growth market with measurable consolidation at the supplier level and accelerating sustainability-driven product innovation. Using 2025 as the analytical base year, our bottom-up model shows the global market expanding from approximately USD 112.5 Million in 2020 to USD 172.5 Million in 2025, with a projected climb to roughly USD 230.3 Million by 2032. The forecast window (2026–2032) is modeled at a compound annual growth rate (CAGR) of 4.13%.
Brik Shape Aseptic Packaging Market
Why this study matters for 2026 corporate decisions
- Capital allocation: With predictable, modest growth and concentrated supplier power (CR3 ≈ 46%; CR5 ≈ 65%), capex and procurement choices require a multi-year view. This report maps where to prioritize filling-line investments, retrofit budgets, and service contracts to protect throughput and ROI.
- Portfolio strategy: Companies evaluating product innovation (e.g., reduced carbon footprint SKUs, long-life dairy, plant-based beverages) need scenario-tested demand curves and profitability thresholds. Our study translates market growth and durability expectations into go/no-go financial checkpoints.
- Supplier and M&A playbooks: The mid-market concentration means partnership, co-development and selective M&A are viable levers. Our vendor fabric—paired with deal archetypes—enables buyers to calibrate integration versus supplier diversification strategies.
- Sustainability certification and packaging compliance: Regulatory momentum toward recyclable and paper-based barriers is reshaping material choices. We quantify how these trends affect total cost of ownership (TCO) across filling lines and shelf-life trade-offs, enabling compliance-forward product launch timelines.
What the market numbers tell us (high-level interpretation)
The historical series and our forecast show a resilient expansion path driven by steady demand for ambient liquid foods and beverages that require aseptic protection. The step-up from 2020 to 2025 reflects both base-market recovery after pandemic dislocations and penetration gains in places where cold-chain logistics remain expensive or unreliable. From a strategic standpoint, the predictable growth trajectory (4.13% CAGR through 2032) reduces macro volatility risk for long-lead investments such as filling equipment, automated case-handling and secondary packaging.
Brik Shape Aseptic Packaging Market
Key dynamics shaping 2026 strategies
- Sustainability as product and procurement driver — New paper-based barrier technologies are maturing. Leading suppliers are launching formats that reduce or eliminate aluminum barriers and substantially increase renewable content. For product owners, this means revisiting material specifications and supplier scorecards to account for recyclability, consumer perception and extended producer responsibility (EPR) obligations.
- Technology-led differentiation — Improvements in barrier chemistry and laminate engineering are enabling slimmer, lighter packs without compromising shelf life. Early adopters that align innovation with marketing claims gain premium shelf positioning; laggards risk losing both on-shelf space and premium pricing.
- Capital intensity and operational cadence — Aseptic brick packaging demands specialized high-speed aseptic filling lines and rigorous maintenance regimes. Our operational models quantify the incremental OPEX and maintenance exposure associated with different fill-rate targets and help prioritize investments in automation versus labor.
- Regulatory and standards convergence — Regulatory preferences in several markets are converging on uncoated paperboard and easily recyclable structures. Compliance timelines vary by jurisdiction, but the direction is clear: companies must plan material reformulation and supply-chain audits well in advance of labeling-change deadlines.
Competitive landscape — what to watch in 2026
The sector is dominated by a handful of global systems suppliers and a tier of regional converters. The operating model is a two-speed game: global technology platforms compete on fill-system compatibility and full-stack solutions, while regional converters compete on price, lead times and customization.
Brik Shape Aseptic Packaging Market
- Tetra Pak International S.A. (Pully, Switzerland) — A category architect with a broad installed base and ongoing product programs that emphasize renewable-material content and integrated service models. Their recent product introductions demonstrate how incumbent scale and co-development partnerships can accelerate adoption of paper-based barriers.
- SIG Group AG (Neuhausen am Rheinfall, Switzerland) — An innovator in full-barrier solutions, with recent launches that push the envelope on non-aluminum barrier options. SIG’s trajectory highlights how product differentiation can unlock new co-pack and private-label opportunities.
- Elopak ASA (Oslo, Norway) — Focused on dairy and plant-based fluid segments with packaging formats that appeal to sustainability-conscious buyers. Their regional strengths and channel relationships give them an edge in certain retail and foodservice segments.
- Greatview Aseptic, IPI Srl, WINTIPAK AG, UFlex Limited — Regional and global converters that supply roll-fed and brick-shaped material compatible with major filling systems. These players are key partners for private-label manufacturers and regional brand owners seeking flexible MOQ and localized lead times.
Recent vendor moves — such as SIG’s mid-2025 launch of a 1-liter full-barrier carton without aluminum, and Tetra Pak’s late-2025 introduction of a paper-based barrier 200 ml slim carton — underscore a competitive pivot toward reducing embedded aluminum and increasing renewable content. These product introductions are not merely marketing statements; they reshape supplier evaluation criteria and create windows for early-adopter advantages.
Practical contents of the report — operational assets in the PW playbook
PW Consulting’s deliverable is designed for executives, product and procurement leads, and corporate development teams who must take decisions in 2026 with a three-to-five-year horizon. The report balances market intelligence with executable frameworks:
- Market sizing & validated growth scenarios: base-case, sustainability-driven uptake, and faster-innovation adoption scenarios across our forecast period.
- Unit economics models for typical SKU families: TCO sensitivity to material mix, fill-line speed, scrap and logistics.
- Filling-line and capex decision tool: investment thresholds, payback modeling and retrofit vs replacement matrices.
- Supplier matrix and negotiation playbook: capability maps, service-level comparators, and contract terms to mitigate concentration risk.
- Commercial go-to-market templates: SKU rationalization, premiumization roadmaps, and retailer engagement scripts tailored to sustainability claims.
- M&A and partnership screening criteria: target archetypes, valuation levers and integration risks for bolt-on converters or upstream material suppliers.
- Regulatory and compliance roadmap: jurisdictional timelines, labeling and recyclability thresholds, and recommended mitigation steps.
- Case studies and pilot blueprints: three anonymized implementation examples that demonstrate real-world impacts on cost, lead time and consumer perception.
Strategic implications and recommended 90–180 day actions
- Supply assurance audits — Immediately initiate dual-sourcing pilots for any single-supplier critical material or finished pack where lead times exceed tolerance thresholds. Given the CR3/CR5 concentration, alternate supplier qualification is tactical insurance.
- Sustainability prioritization — Commission a product-material convergence study to identify 12–24 SKUs for material transition pilots that align with retailer ESG scorecards and upcoming regulation windows.
- Capex sequencing — Defer non-critical line expansions in favor of targeted retrofits that enable new barrier materials; the retrofit option often delivers faster time-to-market for sustainability claims.
- Commercial proof points — Prepare a two-phase launch plan for any “paper-barrier” SKU: (1) trade and OOH validation with key retailers; (2) consumer trial supported by comms that emphasize lifecycle benefits, not just recyclability.
- M&A and partnership scouting — Shortlist 6–8 regional converters and material innovators for deeper diligence. Our framework prioritizes technical compatibility, installed-base overlap and price-to-service trade-offs.
Methodology & confidence
The study synthesizes proprietary shipment telemetry, supplier public disclosures, trade interviews, and PW’s bottom-up costing models. Where market opacity exists—particularly around private-label contract terms and converter margins—we apply triangulation and conservative assumptions. The report includes sensitivity bands and scenario overlays so that strategy teams can stress-test plans against raw-material shifts and regulatory accelerations.
Closing — how to use this intelligence
For 2026, decisions in procurement, product design and capital planning will hinge on an informed balance between innovation (paper-based barriers and polyester alternatives), supply resilience, and cost control. PW Consulting’s Brik Shape Aseptic Packaging Market study equips decision-makers with the quantitative backbone—growth trajectory, concentration metrics and scenario models—and the practical playbooks to act confidently. To preserve the commercial integrity of our client-grade models, detailed regional and application split tables, full vendor scorecards and the granular financial model are available only in the complete report and interactive dataset.
Next step
- Download the full report and interactive model to access the complete segment-level intelligence, supplier benchmarking matrices and downloadable financial templates (link provided in the official release).
- Contact PW Consulting to commission a tailored workshop that maps this market intelligence directly to your capex plan, supplier strategy and sustainability roadmap.
For detailed analysis of this topic, please visit the official page: Brik Shape Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: OBC market to reach USD 325M by 2032, growing at 7.88% CAGR
By PW Consulting, 2026-07-12
Olefin Block Copolymer (OBC) Market — 2026 Strategic Preview for Corporate Decision-Makers
PW Consulting’s latest market study on Olefin Block Copolymer (OBC) delivers a focused, decision-grade perspective for executives preparing strategic moves in 2026. Built on a 2025 base year and a 2026–2032 forecasting window, the analysis quantifies a clear growth trajectory for the OBC market — underpinned by a multi-year compound annual growth rate of 7.88% — and projects material expansion from the 2025 baseline through 2032. For companies facing capital allocation decisions, product roadmaps, or supply-chain reconfigurations next year, this research converts market momentum into operational priorities and investment guardrails.
Olefin Block Copolymer (OBC) Market
Why this research matters in 2026
-
Timing of capacity investments. Producers and converters considering new lines, debottlenecking, or backward integration need an independent forward view of demand growth and grade migration to avoid overcommitment or missed opportunities.
Olefin Block Copolymer (OBC) Market -
Shifting application content. Electrification, packaging performance demands, and lightweighting are altering polymer specifications. Understanding which grade attributes command a premium is essential for product positioning and pricing strategy.
Olefin Block Copolymer (OBC) Market -
Supplier strategy and risk. Feedstock volatility, regulatory shifts on recyclability and chemical restrictions, and recent capacity announcements make supplier selection and contracting structure high-priority items for procurement teams.
-
M&A and partnership scouting. With established polymer majors and specialized innovators both active in the space, 2026 will be a year to choose between bolt-on acquisitions, JVs, or licensing arrangements to capture differentiated value.
What this PW Consulting study delivers — practical, transaction-ready outputs
-
Robust market sizing and forward forecast built from a bottom-up model calibrated to primary interviews, company disclosures, and trade flows. We provide topline numbers for the 2020–2025 historical window and a detailed projection through 2032 to support strategic planning horizons.
-
Demand-driver analysis that links macro trends (mobility electrification, packaging format shifts, adhesives performance needs, and consumer durables design) to grade-level uptake and willingness-to-pay.
-
Supply-side mapping with plant-by-plant capacity overlays, announced expansions, and technological differentiators. Notable public inputs — such as producer disclosures of existing INFUSE™ production capacity and recent expansion programs — are integrated into our capacity-utilization scenarios.
-
Price and margin modelling that stresses test outcomes across raw-material swings, grade mix evolution, and competitor pricing tactics. These transparent models are provided in Excel format for client-side sensitivity runs.
-
Competitive scorecards and playbooks. Each leading supplier is profiled on technology platform, go-to-market posture, typical end-use relationships, and likely near-term strategic moves. M&A targets and licensing candidates are highlighted for acquirers and strategic partners.
-
Scenario planning and a decision matrix tailored for 2026 actions — from greenfield investments to tiered off-take agreements — enabling rapid prioritization under multiple demand and supply futures.
-
Regulatory and sustainability impact assessment, covering recyclability requirements, circular-economy pathways, and disclosure obligations that influence product acceptance in regulated end-markets.
Competitive landscape — incumbents, challengers, and capability clusters
-
Dow Inc. (Midland, Michigan, United States) — A focal supplier with an established INFUSE™ OBC portfolio targeting soft-touch, sealing and flexible applications. Public signals around production capacity and announced expansions position Dow as a volume leader with an expansive grade slate. Recent capacity expansion announcements and earlier capacity declarations have important implications for regional supply balance and pricing dynamics.
-
Mitsui Chemicals, Inc. (Tokyo, Japan) — A technology-led player with NOTIO™ grades focused on automotive soft-touch and sealing. Strong OEM linkages in passenger vehicle supply chains and reported OBC volume growth through 2024–2025 tie Mitsui closely to vehicle platform content trends.
-
LG Chem Ltd. (Seoul, South Korea) — Pursuing metallocene-derived elastomers that compete with OBC in packaging and consumer goods. Planned commercial introductions position LG Chem to capture growth in flexible packaging and higher-volume consumer segments.
-
ExxonMobil Corporation (Irving, Texas, United States) — With Vistamaxx™ performance polymers that overlap the OBC value proposition, ExxonMobil continues to push into performance niches; a recent premium-grade launch for waterproof membranes in construction underscores product diversification within the family of performance olefins.
-
Borealis AG (Vienna, Austria) , LyondellBasell Industries N.V. (Rotterdam, Netherlands) , SABIC (Riyadh, Saudi Arabia) , and Eastman Chemical Company (Kingsport, Tennessee, United States) — These players offer complementary product lines or OBC-adjacent elastomers and bring regional strength, film- and molding-focused grade sets, and integration advantages. Collectively, the competitive set blends large polymer majors with specialty innovators, producing differentiated grade stacks and commercial models.
Recent industry developments and their strategic implications
-
Capacity and capability moves: Several producers have publicly signalled capacity increases and expanded product families, shifting the supply curve and accelerating the commercialization of higher-performance grades. These expansions necessitate closer attention to timing: new tonnes arriving in-market can depress spot spreads even while average selling prices for premium grades hold.
-
Product innovation: New premium grades pitched at construction membranes and other specialty outlets expand the addressable market for OBC-type polymers beyond traditional applications. This increases the strategic value of portfolio breadth and application development capabilities for securing long-term contracts.
-
OEM-driven adoption: Automotive manufacturers remain a critical growth vector, with some producers already embedded in OEM platforms. This relationship-driven demand creates differentiated opportunities for companies that can meet automotive qualification and scale supply reliably.
-
New entrants and adjacent technologies: Metallocene-derived elastomers and proprietary performance olefins challenge incumbents on cost and performance in selected applications, raising the bar for continuous product development and customer proof-points.
Market dynamics — where margins will be made in 2026
-
Grade premiumization: Expect the clearest margin opportunities in specialized grades that solve well-defined performance gaps (e.g., sealant adhesion, waterproofing membranes, and high-elasticity footwear components). Commodity-grade competition will be driven by scale, feedstock integration, and logistics efficiencies.
-
Geography of cost and access: Regional feedstock availability, existing cracker integration, and plant footprint decisions will determine who can sustainably supply low-cost volumes versus who must play the specialty/technical-service card.
-
Customer co-development: Firms that embed technical service, rapid qualification capabilities, and joint cost-to-serve models will secure longer-term contracts and reduce the churn associated with spot-sourced supply.
-
Risk vectors: Volatility in olefin feedstock prices, regulatory shifts around polymer recycling, and the pace of EV adoption introduce upside and downside scenarios that materially alter the ROI calculus for 2026 investments.
How to use this research for 2026 decision-making
-
Board-level capital allocation: Use our scenario outputs to stress-test greenfield timing and scale, identify break-even price curves, and set go/no-go triggers tied to realized demand and feedstock outcomes.
-
Product portfolio prioritization: Align R&D and commercialization spend with grade attributes that command premium adoption in target applications; deprioritize commoditized grade development where scale players dominate.
-
Commercial contracting: Negotiate supply agreements with volume-flex mechanisms and indexed pricing that protect against short-term feedstock shocks while preserving upside participation in premium-grade uptake.
-
M&A and partnerships: Leverage our target screens and scorecards to identify acquisition candidates that fill technological gaps, accelerate market entry, or offer advantaged regional footprints.
Next steps — where the full intelligence sits
This preview frames the strategic choices that will matter in 2026, but the operational details and the proprietary models that turn foresight into executable initiatives are contained in the full PW Consulting OBC Market report. The complete package includes granular regional and application demand splits, company-level market shares, plant-level capacity schedules, price and margin ladders by grade, and an editable Excel model for bespoke sensitivity analysis. For executive briefings, tailored scenario workshops, or to license the underlying dataset and commercial templates, contact PW Consulting to schedule an engagement.
For detailed analysis of this topic, please visit the official page: Olefin Block Copolymer (OBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Grade Nitric Acid Market to Reach USD 153.48M by 2032 at 5.5% CAGR
By PW Consulting, 2026-07-12
Electronic Grade Nitric Acid Market — Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our comprehensive Electronic Grade Nitric Acid Market study (base year 2025). This briefing demonstrates the analytic depth we bring to procurement, supply-chain, and corporate-strategy teams while deliberately withholding the granular segment tables and regional breakdowns that comprise the full intelligence product. If your 2026 capital allocation, sourcing, or M&A decisions depend on dependable, scenario-tested insights, the follow-on report contains the operational detail required to act with confidence.
Electronic Grade Nitric Acid Market
Market snapshot — trajectory and context
The electronic grade nitric acid market has shown steady expansion through the recent cycle. Our historical model tracks an increase in total market revenue from USD 80.72 Million in 2020 to USD 105.5 Million in 2025. Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of 5.5% across the 2026–2032 forecast window, reaching roughly USD 153.48 Million by 2032 under our baseline scenario.
Electronic Grade Nitric Acid Market
- Underlying drivers: rapid semiconductor fabrication capacity additions, tighter purity requirements across advanced nodes, and parallel demand from solar and specialty display fabs.
- Upstream sensitivity: ammonium nitrate remains the primary feedstock; its supply and input pricing materially affect variable costs for producers.
- Policy tailwinds and headwinds: targeted industrial subsidies and national CHIPS-style initiatives are accelerating localized demand, while environmental and nitrate-related regulatory tightening in some jurisdictions adds compliance costs and potential production constraints.
Why this matters for 2026 strategic planning
Five strategic realities should shape board-level and procurement decisions in 2026:
Electronic Grade Nitric Acid Market
- Timing and phasing of capacity: given steady mid-single-digit CAGR and episodic demand surges tied to wafer fab ramp cycles, firms that synchronize capacity investments with customers’ node transitions capture superior utilization and margin outcomes.
- Supplier risk is not binary: purity requirements create meaningful barriers, but the supplier base remains a mix of global and regional specialists. That creates opportunities for targeted partnerships, exclusive supply agreements, and localized JV structures to secure continuity.
- Raw-material and logistics volatility matters: procurement teams must build feedstock hedges and logistics contingency plans that convert volatility into manageable cost-of-goods-sold exposure rather than margin erosion.
- Regulatory foresight is an economic lever: early compliance investment and permitting roadmaps reduce time-to-market for capacity expansions in environments where nitrates and emissions controls are becoming more prescriptive.
- M&A and co-investment economics are attractive — selectively: the market’s structural growth and technical entry barriers make bolt-on acquisitions and capacity co-investments effective ways for chemical producers and strategic buyers to accelerate access to premium-quality product lines.
What the PW Consulting report delivers (operationally focused)
This study is built for action. The full deliverable blends market modeling with hands-on tools that procurement, operations and strategy teams can apply immediately:
- Proprietary demand models forecasting grade- and application-level requirements across the 2026–2032 horizon, with scenario toggles for fab ramp speed and policy interventions.
- Supplier and capacity maps showing technology footprints, purification routes, and logistics corridors — optimized for contract negotiation and contingency planning.
- Commercial playbooks for buyers and sellers: contract structures, price-index strategies, and lead-time guarantee mechanisms tailored to ultra-pure chemical procurement.
- Regulatory impact matrices that quantify permitting timelines, expected compliance costs, and mitigation levers across key jurisdictions.
- CapEx prioritization templates and IRR sensitivity tables for new purification lines or on-site generation, helping CFOs sequence investments with the highest risk-adjusted returns.
- Risk registers and scenario-based decision trees for supply disruptions, feedstock shocks, and abrupt regulatory changes — with tactical mitigations and cadence for board-level readiness reviews.
Competitive landscape — strategy implications from leading players
The market comprises both large diversified chemical manufacturers and specialized regional producers. Key players exemplify differentiated strategic positions that inform competitive dynamics:
- UBE Corporation (Tokyo, Japan) — A technology-led incumbent with a focus on high-purity nitric acid for electronics. UBE’s recent capacity expansion demonstrates a playbook focused on anticipating semiconductor customer growth and capturing premium pricing through scale and certified purity processes. For competitors and customers, UBE’s move signals the commercial imperative of matching lead-times and documentary rigor expected by fabs.
- Columbus Chemicals (Columbus, Wisconsin, USA) — A North-American specialist concentrating on ultra-high-purity products and localized supply. Their capabilities underscore the commercial value of proximity to fabs and the intangible trust premium that onshore delivery affords in geographies prioritizing semiconductor sovereignty.
- Suzhou Crystal Clear Chemical (Suzhou, China) — A regional champion producing EL-grade nitric acid at extremely high purities, supporting multiple wafer fabs across East China. The company typifies the vertically integrated, cost-competitive model that regional fabs favor when speed and localized service matter more than global brand scale.
Additionally, investments by larger chemical conglomerates in ultra-pure facilities (e.g., new ultra-pure acid capacity announcements in Europe) indicate mainstreaming of electronic-grade chemistries within broader portfolios, increasing competitive intensity for mid-sized specialized suppliers. The combined landscape is best characterised as fragmented—regional champions with deep technical know-how coexist with global players scaling capacity for broader coverage.
Supply chain and regulatory dynamics to watch in 2026
- Feedstock chain visibility: ammonia-derived intermediates remain a single-thread risk. Buyers should require parity reporting on feedstock sourcing and implement contractual pass-throughs or capped exposure mechanisms.
- Compliance-as-a-service: with nitrate-related regulations tightening in certain markets, suppliers that can deliver „regulation-ready” product and documentation will command contracting advantages. Expect permitting lead times to be a gating factor on new plant build-outs.
- Policy-driven demand pockets: public incentives and domestic production programs accelerate localized fab construction and thereby create regional demand spikes that may outpace global supply until new capacity comes online.
- Purity and traceability requirements will tighten with advanced nodes: technical differentiation — filtration, distillation train configuration, and analytics for trace-metal monitoring — will be a commercially significant capability.
Practical 2026 playbook — five immediate moves
- Align procurement KPIs with purity and continuity metrics, not just unit price. Introduce supplier audits focused on analytical capability and change-control discipline.
- Secure conditional capacity options early. For buyers, short-term capacity reservations tied to ramp milestones protect against fab-related surges; for suppliers, convertible contracts de-risk greenfield investments.
- De-risk feedstock through diversified sourcing and indexed purchase agreements; examine vertical integration or long-term offtake for ammonium nitrate where economics permit.
- Invest in regulatory and permitting playbooks; pre-emptive engagement with permitting authorities materially shortens timelines for expansions in jurisdictions increasingly sensitive to nitrate management.
- Pursue targeted partnerships and bolt-ons. For chemical producers seeking entry, smaller regional purifiers and niche analytics providers represent high-impact acquisition targets that accelerate market access without the long lead time of greenfield builds.
How to use the full PW Consulting study
The full report delivers the granular segmentation, supplier scorecards, regional demand matrices, and pricing tables omitted from this preview. It includes downloadable modelling tools that allow you to re-run demand and margin scenarios against alternate fab-ramp and regulatory outcomes. Use it to quantify the trade-offs associated with investment timing, supplier selection, and M&A targets — and to prepare board-ready scenarios for 2026 capital allocation.
We’ve structured the intelligence product to be actionable: executives receive both the strategic narrative and the operational templates to move from decision to execution in weeks, not months.
Next steps
If your 2026 planning cycle requires validated demand curves, supplier risk heat maps, or a prioritized list of acquisition and partnership targets in the electronic grade nitric acid value chain, PW Consulting can provide the full study and a tailored advisory engagement. The public preview demonstrates the rigorous foundation of our analysis while preserving the detailed segment-level data that underpins confident commercial action. Contact our industry desk to access the full report and schedule a strategy workshop tailored to your role — procurement, operations, or corporate development.
For detailed analysis of this topic, please visit the official page: Electronic Grade Nitric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


