



Category: market research
PW Consulting: DOTP Market to Hit USD 3,129M by 2032 with 5.55% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Dioctyl Terephthalate (DOTP) Market — Strategic Outlook for 2026 Decision‑Making
Executive preview
As companies prepare capital, sourcing and product strategies for 2026, DOTP is moving from niche replacement chemistry toward mainstream industrial adoption. Our base‑year synthesis (2025) frames a market that has expanded from an estimated USD 1,631.5 million in 2020 to roughly USD 2,150 million in 2025, and—under our central forecast—continues to grow at a compound annual growth rate of about 5.55% through the 2026–2032 window to reach nearly USD 3,129 million by 2032. Those headline numbers understate the complexity behind supply chains, regulatory pressure, and product differentiation that will determine winners and losers over the next 18–36 months.
Dioctyl Terephthalate (DOTP) Market
Why this research matters for decisions you must make in 2026
-
Timing: Procurement cycles, contract renegotiations and planned capacity projects initiated in 2024–25 will come to a head in 2026. Strategic clarity on supply, duty exposure and product-spec compliance will materially affect COGS and market access.
Dioctyl Terephthalate (DOTP) Market -
Regulatory turnarounds: DOTP’s broad confirmation for food‑contact and medical indirect uses under major frameworks provides commercial opportunity — but also requires rigorous documentation and supplier qualification to realize value without unexpected recalls or non‑compliance costs.
Dioctyl Terephthalate (DOTP) Market -
Competitive positioning: The industry is mid‑consolidation. Leading producers combine differentiated feedstock strategies, technical grades and route‑to‑market strength. Understanding concentration and capability is a prerequisite to commercial planning and M&A prioritization.
Market dynamics shaping DOTP through 2026
-
Demand substitution and end‑use adoption: Industry momentum toward non‑phthalate plasticizers has driven broad adoption across flexible PVC, cables, automotive interiors and packaging. This is a structural trend rather than a short impulse; manufacturers that secure qualified DOTP supplies and fast‑track compatibility testing will capture outsized value.
-
Regulatory and trade signals: Two sets of developments materially alter the trade and pricing environment. First, DOTP has been explicitly affirmed compatible with FDA 21 CFR 177.2600 migration rules and EU REACH for relevant food‑contact and medical uses, creating a pathway for food/medical applications where documentation and chain‑of‑custody matter. Second, trade enforcement activity in the U.S. — including antidumping investigations and a subsequent determination of material injury for certain DOTP imports — introduces duty and quota risk that can re‑route volumes and raise landed costs for U.S. buyers. Firms active in North American supply chains must build duty‑scenario contingencies into 2026 contracts.
-
Feedstock and cost structure dynamics: The chemistry is straightforward but the economics are sensitive to PTA and 2‑ethylhexanol (2‑EH) availability and pricing. Stoichiometrically, about 1.000 kg of PTA combined with 1.568 kg of 2‑EH produces roughly 2.352 kg of DOTP per theoretical ton basis — a simple fact that can be modelled into per‑ton cost curves, yield assumptions and working capital needs. Vertical integration or preferred sourcing of 2‑EH (or captive production) is a clear defensive move for producers seeking margin protection.
-
Supply concentration and investment cadence: The market shows moderate concentration at the top (our CR3 and CR5 metrics signal that the top suppliers together control a meaningful portion of capacity without offering monopoly pricing). That structure supports selective pricing power but also generates vulnerability: a single plant outage, capacity ramp or regulatory action can move regional balances rapidly. New product introductions and incremental capacity announcements by established players indicate an environment of measured expansion rather than a free-for-all buildout.
-
Technology and grade segmentation: Producers differentiate by purity, volatility, and thermal performance (e.g., high‑temperature grades for cable applications vs. high‑compliance grades for food/medical). Customers who require cross‑grade qualification early can avoid costly reformulations down the line.
Competitive landscape — what matters to buyers, integrators and investors
Across global suppliers, we observe distinct strategic postures:
-
Producers with technical‑grade offerings and flexible delivery (drums, totes, bulk) position themselves as reliable contract suppliers for film, sheet and conventional PVC downstream processors. Their commercial playbook emphasizes fast qualification and supply flexibility.
-
Large regional players that control upstream feedstock (or dedicated esterification lines) can protect margin via integrated supply and higher technical reliability for high‑spec applications such as cables and automotive interiors.
-
Specialist manufacturers focused on regulatory compliance and product stewardship target food‑contact and medical markets where traceability and certification unlock price premiums and long‑term contracts.
Representative company developments illustrate these dynamics: a major EU producer has celebrated a decade of its flagship DOTP brand while confirming stable production and feedstock integration; a technical supplier in Italy has introduced a higher‑performance DOTP grade for flexible packaging; several Chinese suppliers emphasize high‑temperature and bulk supply for cable and synthetic leather markets. Each move should be evaluated through the lens of your 2026 procurement timeline, technical acceptance windows and cross‑border trade exposure.
What the PW Consulting DOTP report contains — operationally actionable deliverables
We designed this study to move beyond thematic commentary into executable guidance for 2026 decisions. The report bundles the following tools and outputs, each built on primary interviews, plant‑level capacity mapping, trade flow reconstruction and modeled price scenarios:
-
Forward demand engine to 2032 with scenario branches for high substitution, duty‑shock and slower adoption — built to integrate customer‑side product qualification timelines.
-
Supplier scorecards and capacity overlays that link technical grade, feedstock integration, geographic footprint and delivery modality to commercial risk indicators.
-
Bottom‑up cost‑to‑produce models (PTA/2‑EH linkage), logistics and landed cost calculators so buyers can simulate supplier bids under multiple duty scenarios and freight shocks.
-
Regulatory matrix and trade‑policy heatmap that flags jurisdictional compliance thresholds and antidumping/duty exposure for sourcing strategies.
-
Commercial playbooks and contract language templates for 12–36 month offtakes, qualification checklists for food/medical use, and a supplier‑diversification decision tree tuned to 2026 planning cycles.
-
M&A and investment screening: target shortlists, valuation sensitivities and a red‑flag checklist for technical liabilities and environmental compliance.
Note: To preserve the strategic value of granular segmentation and proprietary supplier volumes, this preview deliberately omits region‑by‑region and application‑level percentage breakdowns. The full report contains the detailed tables, regional flows and per‑application forecasts necessary for transactional work.
How to use these insights in 2026 — practical recommendations
-
Procurement and sourcing: Lock in multi‑year contracts with flexibility for duty pass‑throughs and put options that reflect likely enforcement scenarios. If your cost model is exposed to PTA/2‑EH volatility, negotiate indexation clauses or co‑sourcing arrangements that include feedstock pass‑through terms.
-
Product and regulatory strategy: Fast‑track DOTP grades requiring food/medical certification with prioritized supplier audits — regulatory compliance is a gatekeeper to premium segments and long‑term contracts.
-
Portfolio and pricing: Create tiered product offerings aligned to grade performance. In parallel, stress‑test pricing models against a 5–8% duty shock (historical outcomes from trade cases provide a reference) to understand margin absorption and end‑customer pass‑through capacity.
-
Capacity and investment: Favor incremental capacity additions or tolling agreements over greenfield builds unless you can secure feedstock and off‑take. Vertical integration into 2‑EH or strategic partnerships with feedstock suppliers materially improves resilience and ROIC.
-
M&A and partnerships: Prioritize targets that close supply gaps (geography or grade) and offer documented regulatory compliance for high‑value applications. Avoid assets with opaque feedstock provenance or unresolved duty exposure.
Final note — what you get from the full PW Consulting study
This executive preview demonstrates the analytical scaffolding and decision levers we use to counsel clients active in the DOTP value chain. The complete study delivers the numeric and scenario granularity you will need to operationalize the recommendations above — including region/application forecasts, supplier volume tables, price trajectories and duty‑scenario P&L impact matrices. We have intentionally withheld those segmented tables here to preserve the report’s marketplace value and to encourage a direct engagement where we can map our findings onto your commercial cadence and risk tolerances.
For procurement teams, product leaders, investors and corporate strategists planning for 2026, the question is no longer whether DOTP will play a pivotal role — it is how you will position your firm to capture margin and protect access. PW Consulting’s full DOTP market study translates that strategic imperative into tactical action plans and modeled outcomes ready for board and transaction use.
For detailed analysis of this topic, please visit the official page: Dioctyl Terephthalate (DOTP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CCS market to reach USD 329 Million by 2032 at a 10.5% CAGR
By PW Consulting, 2026-07-12
Carbon Capture and Storage Market 2026: Strategic Preview for Corporate Decision-Making
As governments sharpen net-zero timelines and industrial emitters face both tightening regulation and new commercial incentives, carbon capture and storage (CCS) is transitioning from demonstration-stage engineering into mainstream capital planning. PW Consulting’s latest Carbon Capture and Storage Market study — anchored on a 2025 base year and extending through 2032 — synthesizes market sizing, competitive intelligence, technology economics, regulatory trajectories and implementation playbooks tailored for executives making high-stakes decisions in 2026.
Carbon Capture and Storage Market
Executive snapshot: market momentum and what it means
Across 2020–2025 the CCS market expanded convincingly from its early-adopter base, and our base-year dataset (2025) captures a market size that reflects maturing projects, new offtake structures and growing policy support. From 2026 through 2032 we model a compound annual growth rate of 10.5%, which drives the market to roughly double over the forecast window. That trajectory is not linear: waves of project commissioning, policy milestones and infrastructure builds create discrete investment windows and distinct risk-return profiles for different investor types.
Carbon Capture and Storage Market
What this means for corporate leaders in 2026 is straightforward: the next 18–36 months will determine whether your organization secures favourable commercial terms, occupies preferred supply-chain positions, or is forced into higher-cost retrofits later. The market is expanding, but competitive and regulatory dynamics are creating asymmetric opportunities for first movers and well-prepared fast followers.
Carbon Capture and Storage Market
Why this research matters to 2026 decisions
-
Capital allocation: Our scenario-based sizing and cashflow modelling lets CFOs assess break-even timelines for capture retrofits, new-build integrations and storage-lease agreements under realistic policy and carbon-price paths.
-
M&A and partnerships: The market concentration metrics in our analysis indicate significant clustering among established EPC, technology licensor and operator players — knowledge that's essential when structuring JV terms, earn-outs, or strategic carve-outs.
-
Procurement and supply-chain strategy: We map key bottlenecks — from specialty alloy lead times to offshore transport complexity — so procurement teams can prioritize long-lead vendor engagements with quantifiable impact on schedule risk and cost overruns.
-
Regulatory and commercial risk management: With important policy reviews underway (notably an EU ETS review expected in mid-2026), our regulatory matrix helps business development and government-relations teams prepare scenario playbooks and lobbying priorities.
What the PW Consulting report delivers — practical, transaction-ready tools
-
Proprietary market model: A dynamic financial model calibrated to historical 2020–2025 activity and stress-tested across policy, price and technology adoption scenarios for 2026–2032.
-
Technology and CapEx benchmarks: Comparative economics for major capture technologies (amine-based, oxy-fuel, pre-combustion variants and emerging solid sorbents), including unit-level cost drivers and sensitivity to input prices such as electricity and high-grade alloy materials.
-
Project bankability playbooks: Standardized documentation checklists, commercial term templates for CO2 offtake and transport, and lender/investor due-diligence scorecards tailored to CCS-specific exposures.
-
Regulatory impact matrix: Line-by-line assessment of near-term policy changes (including frameworks under review within the EU ETS), fiscal incentives, and market-based mechanisms that affect project returns and counterparty credit.
-
Supply-chain and construction risk maps: Vendor concentration assessments, labour and freight sensitivity analysis, and mitigation strategies for long-lead items such as corrosion-resistant steel components.
-
Competitive intelligence pack: Annotated profiles, capability maps and recent transaction-level intelligence for leading suppliers and operators (EPCs, licensors and integrated oil & gas players).
-
Executive decision frameworks: Prioritised action checklists for CEOs, CTOs, and CFOs — from go/no-go investment triggers to staged contracting approaches that preserve optionality.
Competitive landscape — who shapes the market and how
The CCS value chain is populated by a mix of technology licensors, engineering contractors, industrial operators and oil & gas majors that increasingly provide integrated capture-transport-storage services. There is notable clustering at the top: the largest three players account for a substantial share of market activity, and the top five drive a majority of project execution capacity. This concentration influences pricing power, access to storage assets and the speed at which large-scale projects progress.
-
Linde plc (Woking, UK) — A leading supplier of large-scale post-combustion capture systems and industrial-gases integration, Linde has strengthened its position through long-term commercial agreements covering not just capture equipment but also transport and storage services. Their model is attractive to heavy industrial emitters seeking bundled solutions.
-
Mitsubishi Heavy Industries (Tokyo, Japan) — With longstanding experience deploying amine-based post-combustion systems, MHI brings repeatable delivery models and global reference plants. Their installed-base expertise reduces technology execution risk for complex retrofits.
-
Shell CANSOLV (Montreal, Canada) — The CANSOLV amine process is positioned as a high-removal-efficiency option for post-combustion capture, and Shell’s licensing approach emphasizes modular deployment and proven operational performance.
-
Aker Solutions (Fornebu, Norway) — Specialising in EPC for capture plants and CO2 terminals, Aker brings offshore and onshore integration capabilities that are critical where transport and storage infrastructure must be built in parallel with capture facilities.
-
ExxonMobil (Irving, Texas, USA) — As an operator of integrated CCS projects, ExxonMobil offers end-to-end services including long-term storage operations. Their commercial deals with industrial emitters demonstrate the scale opportunity for third-party storage providers.
-
Fluor Corporation (Irving, Texas, USA) — An EPC heavyweight that has pivoted resources towards full-scale CCS project delivery, Fluor is a frequent partner for industrial asset owners seeking turnkey retrofits.
-
SLB (Schlumberger) (Houston, Texas, USA) — SLB is deploying capture and subsurface technologies, leveraging its subsurface expertise to support integrated capture-to-storage solutions and pilot-to-commercial scaling.
Recent market activity underscores momentum: industry bodies have formed new partnerships to accelerate sector adoption (e.g., a mid-2026 MOU between the cement and CCS institutes), and leading operators have moved from pilot to commercial operations, with multiple project start-ups and storage operations commencing in 2025–2026. These events are reshaping supply signals and accelerating commercialization.
Regulatory, cost and infrastructure dynamics to watch in 2026
-
Policy inflection points: The EU’s review of ETS rules — with findings expected in July 2026 — introduces material upside or downside to commercial incentives, particularly if permanent removals are formally integrated or new sectors are included. Our regulatory scenarios quantify the effect of each plausible outcome on project IRRs.
-
Allowance and revenue mechanisms: New allocations and set-asides in market mechanisms can materially alter project cashflows and reduce reliance on high initial carbon prices. Corporate buyers should structure contracts to capture these second-order benefits.
-
CapEx pressure points: Harsh chemical environments necessitate expensive alloys for certain process streams; this remains a recurring cost driver in our equipment-level benchmarks and is a core consideration for lifecycle costing.
-
Transport and storage economics: Offshore transport and storage consistently show higher unit costs versus onshore alternatives; decisions about shared infrastructure versus dedicated pipelines materially change the project value proposition.
-
Input cost variability: Labour, freight and energy price differences across jurisdictions create wide cost bands. Our procurement playbooks translate these into actionable hedging and contracting strategies.
Practical recommendations for executives in 2026
-
Lock long-lead items now: If your 2026–2028 plans include capture or retrofit work, initiate procurement for corrosion-resistant materials and engineering hours in the coming 6–12 months to avoid schedule slippage and cost inflation.
-
Pursue staged contracting: Use EPC contracts that separate FEED, modular supply and balance-of-plant phases. This preserves flexibility while securing vendor capacity.
-
Negotiate integrated offtake-storage packages: Where possible, secure bundled agreements that provide storage access and price stability; integrated offers from major operators shorten execution timelines and de-risk financing.
-
Stress-test project economics against policy scenarios: Build decision triggers tied to key policy milestones (e.g., EU ETS amendments). Our scenario outputs map those triggers to go/no-go moments.
-
Explore collaboration to share infrastructure: Consider co-investment in transport or terminal assets with regional partners to achieve scale and lower unit costs, especially in regions where offshore storage is the only viable long-term option.
Conclusion — why PW Consulting’s preview should shape your 2026 playbook
The CCS market is larger and growing faster than the narrowly focused public debate suggests. Yet scale alone does not guarantee favourable returns: timing, vendor selection, contract structure and policy-readiness determine winners. PW Consulting’s report combines market-scale forecasting (anchored to 2025 data and a 10.5% CAGR outlook through 2032), rigorous supplier and competitor analysis, and transaction-grade playbooks. It’s designed to convert high-level climate ambition into executable capital and commercial plans for 2026 and beyond.
For executives preparing capital plans, joint-venture structures, or procurement strategies this year, the full intelligence set — including the complete model, vendor scorecards, and project-level case studies — is accessible through our report portal. The preview above highlights direction and implications; the report itself contains the datasets and templates you will need to operationalize strategy with confidence.
For detailed analysis of this topic, please visit the official page: Carbon Capture and Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Optic Cable Assembly Market to Reach USD 11,130M by 2032 at 6.9% CAGR
By PW Consulting, 2026-07-12
Fiber Optic Cable Assembly Market — A Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused, executive‑grade preview of our new Fiber Optic Cable Assembly Market study. This briefing highlights the strategic lines of force that will determine winners and losers through 2026 and beyond, while deliberately preserving the granular segmentation tables and proprietary scorecards that deliver competitive advantage — those are reserved for the full report.
Fiber Optic Cable Assembly Market
Why this research matters in 2026
The fiber optic cable assembly market is no longer a niche component market: it is a foundational enabler for data‑rich economies, defense systems, and decarbonization infrastructures. In our base year (2025), the market sized at USD 7,000 Million. After recovering steadily from 2020 levels, the industry enters a period of sustained expansion; our forecast (2026–2032) projects a compound annual growth rate of 6.9%, taking the market to roughly USD 11,130 Million by 2032. These macro dynamics — combined with regulatory shifts and concentrated pockets of technological differentiation — make 2026 a decisive year for capital allocation, sourcing strategy, and M&A activity.
Fiber Optic Cable Assembly Market
Analytical framework and what's inside the full report
- Proven methodology: demand‑side and supply‑side triangulation using bottom‑up vendor modelling, project pipelines, and installation cost curves.
- Historical baseline (2020–2025) and forward scenarios (2026–2032) with sensitivity to CAPEX cycles, component shortages, and tariff events.
- Practical deliverables: supplier heatmaps, procurement negotiation templates, total cost of ownership (TCO) calculators for prefabricated vs. field‑terminated assemblies, and a manufacturing checklist for ISO 5–ISO 7 cleanroom readiness.
- Vendor due diligence materials: comparable scorecards, margin benchmarks, and a shortlist of acquisition targets by strategic objective.
- Regulatory and policy playbooks: compliance checklists and scenario responses for emerging rules affecting safety, export controls, and subsea security.
Note: this executive summary surfaces the strategic insights you need to steer 2026 decisions. Detailed regional and application‑level tables, unit economics, and proprietary vendor rankings are excluded here to protect the commercial value of the study; access to the full dataset is available through our report portal.
Fiber Optic Cable Assembly Market
Key themes shaping strategies in 2026
- Volume growth with asymmetric value pools. Aggregate demand is expanding steadily, but value accrues unevenly: high‑precision assemblies for defense, space, and hyperscale datacenters command premium margins relative to commodity patch cords.
- Manufacturing quality and regulatory qualification are strategic differentiators. Cleanroom assembly (ISO 5–ISO 7) and validated qualification pathways are increasingly mandatory for mission‑critical applications; early compliance investments lower certification risk and speed time‑to‑contract.
- Infrastructure projects drive localized demand spikes. Public works and transportation projects are catalyzing installation activity in specific corridors, producing opportunities for contractors and preterminated solutions that reduce field labor.
- Geopolitics and trade policy fragment sourcing choices. Tariffs and new government programs focused on subsea security and supply‑chain resilience raise the cost of single‑region sourcing and tilt procurement toward diversification and nearshoring.
- Market structure: a fragmented core with specialist leaders. Market concentration remains modest — the top three firms account for roughly one quarter of market value, with the top five reaching about thirty percent — leaving substantial room for vertical specialists and regional champions to thrive.
Competitive landscape — who matters and why
The supplier set spans full‑spectrum manufacturers, precision boutique producers, ruggedized specialists, and broad‑reach distributors. Understanding each type is essential for aligning sourcing and partnership strategy.
- Optical Cable Corporation (Roanoke, VA) — A pioneer in military/tactical and enterprise assemblies, OCC’s breadth includes pre‑terminated and custom variants. Its recent strategic collaboration (July 2025) with a systems partner underscores an intent to expand into enterprise and data‑center verticals through combined product and channel plays.
- Diamond SA (Switzerland) — Recognized for high‑precision interconnects and cleanroom production, Diamond is an archetype for firms that command premium pricing in space, aerospace, and laboratory markets where contamination control and traceable processes are contract prerequisites.
- L‑com Global Connectivity (North Andover, MA) — Focused on ruggedized, pre‑terminated assemblies and patch cords, L‑com is positioned where industrial reliability and rapid deployment matter, particularly in verticals that value plug‑and‑play field solutions.
- Fiber Instruments Sales, Inc. (USA) — A distributor and manufacturing support player, this firm is valuable for buyers seeking breadth of catalog, fusion‑splice capability and field‑installable options, reducing lead times on low‑to‑mid complexity requirements.
- fiberone, llc (USA) — A specialist in custom multi‑fiber assemblies; its updated 2026 product catalog highlights the importance of configurability and rapid prototyping for bespoke customer requirements.
Strategic takeaway: partnering with a single global vendor is rarely optimal in 2026. A modular supplier strategy — pairing high‑precision producers for mission‑critical assemblies with regional fabricators or distributors for scale and responsiveness — reduces certification risk and shortens lead times.
Regulatory and geopolitical developments that change the playbook
- Certification and safety standards. New regulatory guidance for qualification of fiber components in safety‑critical systems raises the bar for suppliers wishing to compete in nuclear, aviation, and energy markets. Early adoption of qualification programs converts into long‑term contract advantages.
- Subsea security and export controls. Legislative attention to subsea cable security and maintenance elevates national‑interest considerations, potentially altering who can bid on sensitive projects and increasing the role of government stakeholders in procurement decisions.
- Trade policy and tariffs. Persistent tariffs on certain imports remain a non‑trivial cost factor for sourcing strategies; procurement teams must model tariff scenarios into landed cost and supplier total cost analyses.
Concrete actions for executives in 2026
- Chief Procurement Officer: Implement a three‑tier sourcing model (strategic/qualified partners; regional fulfillment partners; contingency suppliers) and adopt TCO calculators that incorporate tariffs and qualification lead times.
- Head of Network/Infrastructure: Prioritize pre‑terminated assemblies for new buildouts to lower field labor exposure; require supplier qualification evidence for safety‑critical segments.
- Head of Manufacturing/Operations: Evaluate targeted investments in cleanroom capability (or contract partnerships with certified facilities) to access high‑value aerospace/defense contracts.
- Corporate Strategy & M&A: Screen acquisition targets that fill capability gaps (cleanroom production, specialty multi‑fiber designs, or regional fulfillment) and favor targets with validated customer qualifications.
- Compliance & Legal: Build a watchlist of regulatory developments (safety qualification guides, subsea policy, trade actions) and design contractual clauses that allocate certification and tariff risks appropriately.
Why purchase the full PW Consulting report
This preview explains the strategic stakes but omits the detailed segmentation, unit economics, and proprietary vendor scoring that you need to execute with confidence. The full study delivers:
- Detailed breakouts by region, type, and application with historical and forecasted values;
- Vendor financial and capability benchmarking, including contract references and supply‑risk ratings;
- Installation cost plots and TCO models by project type; and
- Playbooks for procurement negotiations, qualification programs, and M&A integration.
Purchasing the full report gives you the defensible data to justify capital budgets, the supplier matrices to rapidly identify preferred partners, and the scenario models to stress‑test strategic plans in the face of tariff and regulatory volatility.
For 2026, the central strategic question for executives is simple: will you treat fiber assemblies as a commodity to be optimized on price, or as a strategic lever that secures differentiated performance and recurring revenue? Our work shows that companies taking the latter view — investing selectively in qualification, modular sourcing, and cleanroom capability — are the most likely to capture outsized returns as the market scales toward USD 11,130 Million by 2032.
To access the complete dataset, vendor matrices, and tactical playbooks, visit the PW Consulting report page and download the full Fiber Optic Cable Assembly Market study.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Piano Market to Hit USD 2,025 Million in 2025, Poised for 5.0% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Digital Piano Market 2026 — Strategic Preview for Corporate Decision-Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present an executive preview of our Digital Piano Market study (base year: 2025). This piece is designed as a high-fidelity “trailer”: it surfaces the evidence-based trends, competitive dynamics, and decision levers that should shape boardroom priorities in 2026, while preserving the granular segmentation and proprietary datasets that drive transaction-level decisions for subscribers of the full report.
Digital Piano Market
Market snapshot — trajectory and scale
Our market model—anchored on historical performance from 2020–2025 and a detailed forecast through 2032—shows the digital piano market continuing a steady expansion at a compound annual growth rate of approximately 5.0% over the forecast window. All figures in this article are expressed in USD Million. After recovering from early-decade disruption, the global market recorded robust growth into 2025 and moves into 2026 with upward momentum. The market value in 2025 provides the strategic baseline for planning; our scenario-driven forecasts point to sustained scale-up through the early 2030s, reflecting steady demand across consumer learning, entertainment and performance use cases and ongoing product innovation.
Digital Piano Market
Key modelling levers: macro consumer spending trajectories, channel evolution (bricks-and-clicks), product cycle refresh rates, and supplier cost dynamics. These inputs combine to produce a forward view that is constructive but nuanced—growth is consistent rather than explosive, which means 2026 will be a year for strategic positioning rather than an all‑out market grab.
Digital Piano Market
Why this study matters for 2026 decisions
Five strategic implications should guide executive agendas this year.
- Product tiering and R&D allocation. With demand growth steady, the highest ROI will come from clear differentiation: premium sound engines and hybrid actions for high-end buyers, and durable, affordable designs for entry-level segments. Investment should prioritize perceptible features—acoustic modeling, expressive key action, and software integration—that influence purchase decisions and justify price premiums.
- Pricing governance and response capability. The market is sensitive to pricing moves from incumbents. Notably, a recent price adjustment by a major player in mid‑2026 underscores how strategic repricing can resegment value perceptions and open share opportunities for agile competitors. Companies must establish rapid competitive reaction frameworks and test elasticities by channel and SKU.
- Channel mix optimization. Omnichannel orchestration (direct-to-consumer, specialty retailers, institutional sales to schools and conservatories) will determine share shifts. Digital-first marketing and software-mediated product demos are increasingly decisive for conversion and aftermarket monetization.
- Supply chain resilience and compliance. Operational continuity hinges on vendor diversification, environmental certification, and duty-aware logistics. HS code clarity and absence of new export controls in 2026 reduce tariff uncertainty, but manufacturers should maintain ISO 14001 alignment and monitor component inputs (acoustic woods, specialized electronic components) for sourcing concentration and quality risk.
- M&A and partnership playbooks. With top-three concentration that is meaningful but not dominant and a top-five footprint that controls a majority of the market, there is room for targeted acquisitions, white-label partnerships, and OEM/ODM strategies to accelerate scale—particularly for entrants seeking distribution depth or for incumbents looking to bolt on technology or cost advantages.
What the full PW Consulting report delivers (practical outputs)
This study is structured to convert market intelligence into executable plans. Highlights include:
- Proprietary market size and growth model (historical 2020–2025, forecast 2026–2032) with scenario sensitivities and policy shock simulations.
- Segment-level playbooks: market opportunity maps by type, channel, and application with prioritized initiatives and quick-win tactics (note: full segment tables and numeric splits are available only in the subscriber report).
- Competitive scorecards and capability matrices for leading manufacturers, complemented by product benchmarking across sound engines, key action technology, software ecosystems, and price tiers.
- Go-to-market templates tailored for OEMs, D2C brands, and specialty retailers—covering assortment strategy, channel incentives, digital trials, and service propositions.
- Supply chain heatmaps and supplier risk dashboards showing component concentration, environmental compliance checkpoints, and logistic scenarios.
- Investment and M&A dossiers—target identification criteria, valuation heuristics, and integration red flags for acquirers or JV partners.
- Regulatory and sustainability tracker: duty classifications, certification requirements, and environmental management expectations for manufacturing operations.
Competitive landscape — what to watch
The market’s competitive architecture is characterized by a handful of established players with strong brand equity and technological IP, meaningful mid‑tier specialists, and a broad base of entry-level OEM/ODM manufacturers. Market concentration metrics indicate that the top three firms collectively hold a notable share of industry revenues while the top five cross the majority threshold—this creates a balance between incumbent strength and margin for challengers with the right playbooks.
- Yamaha Corporation (Hamamatsu, Japan) — Signature offerings such as Clavinova and Arius combine sophisticated sound engines with seamless app ecosystems. Yamaha’s pricing and positioning moves have immediate spillover effects across premium and education channels; the supplier’s May 2026 price change is an example of how legacy brands can reshape competitive dynamics and margin pools.
- Roland Corporation (Hamamatsu, Japan) — The FP and GP series emphasize portability and immersive acoustics via PureAcoustic technologies. Roland’s early-2026 collaboration with Karimoku (artisan cabinetry) to launch artisan digital pianos signals a focused premiumization strategy that blends heritage craftsmanship with modern electronics, increasing differentiation in the upper-end market.
- Kawai — Known for Harmonic Imaging and refined key actions, Kawai is a technical stalwart in the high-fidelity segment. The firm’s investments in acoustic emulation warrant attention from competitors seeking parity in expressive performance.
- Casio — Competes on price-performance with innovations in hybrid hammer action and compact form factors. Casio’s technology focus makes it a persistent threat in volume channels and in emerging digital-native buyer cohorts.
- Korg and Clavia (Nord) — Korg’s portable lines and Clavia’s AI sampling/modeling strengths cater to niche performers and studio professionals; both underscore the importance of software and modeling excellence as points of differentiation.
- Williams and Lida — Williams leverages US distribution and value-focused console design, while Lida (China-based OEM/ODM) plays a critical role in cost-competitive entry segments and private-label supply. Their positioning highlights the bifurcation of the market between brand-led premium and cost-efficient volume supply chains.
Regulatory, materials and operational considerations
Operational decision-makers should note four practical dynamics:
- Customs and duty stability: the HS classification for digital pianos provides clarity for cross-border logistics; no targeted tariff updates were identified in 2026, reducing one axis of near-term trade risk.
- Environmental management: ISO 14001 continues to be a de facto expectation for manufacturing sites; buyers and institutional customers increasingly require documented environmental management practices.
- Raw material complexity: premium models depend on acoustic woods and specialized soundboard materials. While no new material controls emerged in 2026, procurement teams should maintain supplier diversification and monitor availability/quality variance.
- Compliance discipline: absence of new export controls is positive, but firms must keep legal and supply teams aligned with shifting national requirements and voluntary sustainability standards demanded by key retail partners.
Strategic playbook for 2026 — five priority actions
- Execute a two-track product strategy: accelerate premium feature rollouts for affluent and institutional buyers while protecting margins on entry models through cost engineering and bundled services.
- Recalibrate pricing helmets and elasticities; use targeted promotions and differentiated finance options rather than blunt across-the-board discounts.
- Invest in software ecosystems and subscription services (lesson: hardware differentiation is necessary but not sufficient; recurring revenue enhances lifetime value).
- Strengthen supply chain visibility with a dual-sourcing mandate for critical components and a supplier scorecard tied to environmental metrics.
- Scan the acquisition landscape for capability gaps—particularly in modeling engines, voice/sound IP, and distribution assets—where tuck-ins can accelerate market access at lower risk than greenfield builds.
Conclusion — positioning for measured growth
2026 is a year to consolidate strategic positioning rather than chase unsustainable volume. The market’s steady 5.0% growth profile rewards disciplined investment in perceived value drivers—sound authenticity, action realism, and integrated digital experiences—while cost and supply chain management protect margins. Competitive moves by legacy brands and specialty entrants will continue to create localized dislocations; success will go to players who combine product excellence, nimble pricing, and a resilient, compliant supply base.
To convert these insights into executable plans, access to the full PW Consulting Digital Piano Market report is required—the subscription edition contains the complete segment-level datasets, regional and application splits, detailed competitor scorecards, and the reproducible financial model that underpins our forecasts. Those datasets are intentionally withheld here to preserve the report’s commercial value and to ensure decision-makers have a single authoritative source for transactional use.
For inquiries about licensing the dataset, custom benchmarking, or a tailored decision workshop based on the report, PW Consulting’s strategy team is available to support immediate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Digital Piano Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Conductive Polymers Market to Hit $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-07-12
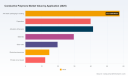
Conductive Polymers Market: Strategic Briefing for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to frame why the conductive polymers market deserves board-level attention in 2026. This sector—bridging advanced materials science, electronics, textiles, and packaging—has evolved from a niche specialty to a strategically important category with clear commercial inflection points. Our new market study (base year 2025) synthesizes five years of historical performance (2020–2025) and provides a forward-looking roadmap through 2032 that is designed to inform investment, M&A, procurement, and innovation choices in the coming 18–36 months.
Conductive Polymers Market
Why this market matters in 2026
Conductive polymers are no longer an academic curiosity. Over the past half-decade the global market expanded materially—from an estimated USD 163 million in 2020 to about USD 215 million in 2025—driven by diversified end-use adoption across electronics, medical devices, smart textiles, and anti-static packaging. Our modelling projects continued growth through 2032, reaching roughly USD 345 million by the end of the forecast window, underpinned by a compound annual growth rate of approximately 7% during the forecast period. This pace positions conductive polymers as a high-value, mid-scale materials market where targeted investments can yield disproportionate strategic returns.
Conductive Polymers Market
For corporate leaders evaluating capital allocation in 2026, conductive polymers present three convergent opportunities: (1) product differentiation in high-growth electronics and wearable segments; (2) supply chain advantage through early control of specialty monomers and formulation expertise; and (3) value creation via M&A or strategic partnerships with technology-specialist suppliers.
Conductive Polymers Market
What the PW Consulting study delivers (practical, transaction-ready insights)
- Actionable market sizing and scenarios: A validated baseline (2020–2025) and three demand scenarios (conservative, baseline, accelerated) for 2026–2032 to stress-test capex and revenue plans without exposing our proprietary subsegment allocations.
- Commercial playbooks: Go-to-market strategies tailored to product players, compound formulators, and OEMs—covering pricing levers, tiered value propositions, and channel economics.
- Supply chain and sourcing diagnostics: Raw material risk matrices, alternative sourcing routes, and inventory/hedging strategies to protect margins against volatile monomer markets.
- Regulatory and sustainability roadmaps: Compliance pathways for REACH, Ecodesign/ESPR-related restrictions, and best-practice lifecycle reporting that minimize market access risk.
- Technology and IP landscape: Comparative R&D roadmaps, leading material platforms, and patent activity heatmaps to guide licensing and R&D collaboration choices.
- M&A and partnership targets: A short-list of acquisition and JV archetypes, plus valuation heuristics and integration checklists focused on rapid scale and capability acquisition.
- Commercial due diligence kits: Data room templates, key vendor interview guides, and a forensic checklist for validating supplier claims on conductivity, durability, and process repeatability.
Competitive landscape: what leading players are doing
The market shows moderate concentration: the top three suppliers account for a meaningful but not overwhelming share of the market, and the top five collectively hold roughly 30%—a structure that favors both specialized incumbents and nimble entrants. Several firms illustrate contrasting strategic postures that should be instructive to executives considering market entry or partnership.
- Premix Group (Finland) — Moving fast on scale and digital operations. Recent investments include a new U.S. manufacturing facility and deployment of an AI/ML platform (PERTTI 3.0) used to optimize recipes and enable real-time process control. These moves signal a playbook focused on supply chain proximity, automation, and data-driven quality assurance.
- Heraeus (via Heraeus Epurio, Germany) — Technology-driven incumbent with advanced conductive polymer platforms (notably PEDOT-based chemistries). The group’s expansion in China and emphasis on analytics-enabled capacity point to a dual strategy: protect premium electronics and display customers while scaling cost-effectively in APAC.
- Eeonyx Corporation (United States) — Specialist coatings and process know-how for e-textiles and industrial fabrics. Firms like Eeonyx underscore the importance of process competence (coating, deposition) alongside chemistry.
- Agfa-Gevaert Group (Belgium) — Supplier of conductive inks and films; representative of companies that combine materials science with printing/processing mastery to address flexible electronics and optical applications.
- SABIC (Saudi Arabia) — Major polymer conglomerates are entering the value chain through conductive blends and engineered compounds, offering scale advantages and distribution reach for industrial applications.
Recent corporate activities illustrate the near-term templates for success: capacity expansions in APAC, AI-enabled process control, and new high-performance grades showcased at leading industry exhibitions. These actions are not random—they reflect three strategic priorities that buyers and investors should internalize: proximity to growth markets, digitalization of formulation and production, and product-grade differentiation.
Market dynamics that will shape 2026 decisions
- Raw material and feedstock risk: The economics of conductive polymer manufacturing are sensitive to a small set of specialty monomers. For example, high-purity EDOT for PEDOT derivatives commands a premium and can materially affect unit economics. Volatility in aniline and other specialty monomer markets exerts acute short-term pressure—especially on APAC production nodes—requiring procurement strategies that include hedging, alternative chemistries, and supplier partnerships.
- Regulatory tailwinds and constraints: REACH registration requirements and the EU’s Ecodesign/ESPR frameworks are increasing the cost of market entry for chemically complex formulations. Companies that build compliant ingredient registries and circularity claims now will face lower commercial friction in 2027–2030.
- Manufacturing as a competitive moat: Investments in automation, inline conductivity monitoring, and recipe libraries (the kind illustrated by PERTTI 3.0 deployments) shorten time-to-spec and reduce scrap—translating into margin expansion for manufacturers that industrialize formulation science.
- Application diversification: While electronics and anti-static packaging remain core buyers, growing demand from wearables, electroluminescent devices, and energy storage niches is broadening the demand base and changing performance benchmarks (mechanical flexibility, long-term stability, and lower-temperature processing).
Implications for strategic choices in 2026
Executives should treat 2026 as an inflection year. The combination of revenue growth velocity (projected mid-single-digit CAGR across the forecast window), evolving regulatory constraints, and supplier digitization creates multiple decision points:
- Procurement and sourcing: Move from spot-based buying to strategic raw material partnerships or tolling arrangements for high-purity monomers. Consider regional stocking hubs to mitigate short-term supply shocks.
- Capex and capacity: Prioritize flexible, digitally instrumented capacity that can accommodate multiple conductive formulations. Greenfield expansion should be measured against tolling and JV options with established formulators.
- R&D and differentiation: Invest in formulation IP that targets the mechanical and environmental performance attributes demanded by next-generation wearables and flexible electronics. Shared R&D consortia can accelerate pre-competitive work while spreading cost.
- M&A and partnerships: Pursue bolt-on acquisitions that provide process know-how (coating, printing), regulatory dossiers, or access to proprietary monomers. Small-to-mid acquisitions can quickly lift both capability and customer access in a market where scale is balanced by specialized know-how.
- Regulatory and sustainability positioning: Build registries and lifecycle datasets now to avoid market access bottlenecks in the EU and to meet procurement thresholds from multinational OEMs.
How PW Consulting’s study supports your 2026 actions
The report is structured to be a working tool—suitable for corporate strategy teams, corporate development, procurement, and R&D leadership. It combines rigorous top-down market sizing with bottom-up checks, supplier intelligence, regulatory impact analysis, and a transaction-focused annex including diligence templates and valuation frameworks. Importantly, while the study demonstrates where growth pockets are developing, it purposely limits public disclosure of our granular segment-by-segment maps to preserve the commercial edge for subscribers.
In short: the conductive polymers market is entering a phase of professionalization. The winners will be those who align advanced materials IP with resilient supply chains, regulatory foresight, and digitally enabled manufacturing. Our analysis shows the pathway to capture value—whether through targeted partnerships, disciplined capacity plays, or selective M&A—without overpaying for surface-area growth.
Next steps
- Contact PW Consulting to schedule a tailored briefing and scenario workshop for your leadership team.
- Request the subscriber edition of the report to access detailed subsegment analyses, supplier scorecards, and the M&A target short-list.
We designed this briefing to give you directional clarity for 2026 while reserving the granular intelligence that will enable executable strategies. For companies seeking to translate the projected market momentum into defensible commercial advantage, the window to act is now.
For detailed analysis of this topic, please visit the official page: Conductive Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BNNT Market to Reach USD 215.0 Million by 2032 at 9.8% CAGR
By PW Consulting, 2026-07-12
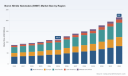
Boron Nitride Nanotubes (BNNT) Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise but forward‑looking introduction to our new BNNT Market study — designed specifically to inform executive decisions in 2026. This briefing demonstrates the analytical depth and practical frameworks underpinning the full report while preserving the core segmented intelligence that subscribers rely on to make procurement, investment, and product‑strategy choices.
Boron Nitride Nanotubes (BNNT) Market
Market snapshot — a capital‑allocation lens
The BNNT market has moved beyond the laboratory: total market revenue expanded from USD 87.45 Million in 2020 to USD 112.5 Million in 2025 and is forecast to accelerate through the coming decade. Under our base assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of 9.8% over the forecast window, reaching roughly USD 215.0 Million by 2032. That trajectory reflects a confluence of industrial adoption, new high‑value applications, and accelerating commercial scale‑up among a small set of specialized producers.
Boron Nitride Nanotubes (BNNT) Market
For 2026 decision cycles this snapshot matters: the market is large enough to support multiple commercial models (premium‑grade suppliers, volume producers, and integrated systems players) yet still concentrated enough to create meaningful strategic leverage for early movers and scale investors.
Boron Nitride Nanotubes (BNNT) Market
Why this report should be on your 2026 agenda
- Investment prioritization: Where to deploy capital between scale (manufacturing) and capability (application development) to capture asymmetric returns as the market crosses commercial thresholds.
- Supply security & procurement: How upstream raw‑material volatility and premium grades affect margin and contract structures for OEMs and materials integrators.
- Commercialization timing: Evidence‑based roadmaps for product launches and channel development, including which value chains reach payback earliest under realistic adoption curves.
- Regulatory & quality preparedness: Practical checklists for certifications and audit readiness that materially speed qualification in aerospace, healthcare, and electronics.
What the full report delivers — actionable, not academic
We designed the study as a practitioner’s toolkit. Highlights include:
- Integrated demand forecast and scenario models (2026–2032) calibrated to technology adoption curves, price elasticity, and supply constraints.
- Cost and pricing models that trace input‑cost sensitivity (including boron feedstock and processing energy) to finished BNNT price bands and margin outcomes.
- Supply chain mapping and vendor scorecards covering production technologies, scale matrix, reliability, and IP posture.
- Application playbooks with commercial case studies: how BNNTs change value propositions in composites, thermal management, electronics, and medical use cases.
- Regulatory and standards roadmap, including audit and certification pathways that reduce time‑to‑qualification in key end markets.
- Deal and partnership templates for licensing, toll‑manufacturing, JV structures, and M&A valuation heuristics tailored to the BNNT landscape.
- A buyer’s negotiation kit: recommended contracting structures (price‑indexing clauses, quality acceptance tests, supply‑security covenants) to mitigate raw‑material and production risk.
Note: the above is a selective preview. The full report contains the granular regional, product and application splits, proprietary price curves, and supplier scorecards that underpin these tools.
Competitive landscape — profiles and strategic implications
The BNNT competitive set is compact but diverse — ranging from start‑ups with IP‑protected processes to established materials companies offering industrial‑scale volumes. Market concentration is meaningful: the top three suppliers account for a substantial share of industry revenue, and the top five consolidate an even larger portion, creating a market where scale, quality, and certification matter greatly.
- BNNT Materials, LLC (Newport News, VA) — Position: premium‑quality BNNTs optimized for R&D and high‑value commercial applications. Strategic strengths include focused product quality and market reputation. For buyers this supplier is a go‑to for rapid prototyping and early qualification; for investors they represent a differentiated margin profile but limited near‑term scale unless capitalized for volume expansion.
- BNNano, Inc. (Burlington, NC) — Position: commercial manufacturing with patented NanoBarb™ enhancements. Recent developments: announced capacity expansion in January 2026 to lower cost and increase throughput, and reported a second consecutive profitable year in 2025. These moves signal a transition from niche supplier to industrial partner — a critical inflection for OEMs seeking predictable supply and price improvement.
- Tekna Advanced Materials Inc. (Sherbrooke, QC) — Position: large‑scale production using induction plasma for aerospace‑grade supply. Strategic engagement with standards bodies and participation in audit criteria development are noteworthy: this company is positioning quality and certification as a core competitive moat, attractive for aerospace and regulated sectors.
- Naieel Technology (Daejeon, South Korea) — Position: industrial‑grade BNNTs combined with thermal application expertise. Reported production and application breakthroughs position Naieel to capture thermal management segments where integration know‑how matters.
- BNNT Technology Pty Ltd (Brisbane, Australia) — Position: Australian‑based supplier that achieved kilogram‑scale production in 2021 and competes on price and format flexibility. This firm is worth watching for regional supply diversification and aggressive pricing strategies that pressure commodity tiers.
- Nanoshel LLC (Columbus, OH) — Position: commercial supply with claims of ultra‑high purity (>99.9%). This purity focus makes them a candidate supplier for sensitive research and biomedical applications where material purity reduces qualification risk.
Strategic implication: alliances between application integrators and producers that combine scale, certification, and materials science capabilities will determine which companies capture the early volume premium.
Dynamics and risk drivers you must model in 2026
- Raw‑material cost pressure: Boron prices climbed to roughly USD 780/MT in December 2025, and boron nitride feedstock premiums for high‑purity grades have remained firm into 2026. These trends increase input cost sensitivity and favor suppliers that can vertically integrate or lock long‑term supply contracts.
- Standards and audit regimes: Industry participants are actively engaging with the Performance Review Institute to develop NADCAP audit criteria relevant to metallic powder materials — a capability that will shorten qualification times for certified suppliers and raise the bar for new entrants.
- Scale vs. quality tradeoffs: Achieving kilogram‑scale production is necessary but not sufficient. Buyers will increasingly insist on traceability, certificate‑of‑analysis consistency, and functional validation, which privileges those who invested early in QA/QC and certification pathways.
- Market concentration risks: The current supplier pool and concentration metrics imply that supply shocks or rapid capacity additions by one player can meaningfully swing pricing and availability. Scenario planning for both demand surges and supplier disruptions is essential.
Practical playbook for 2026 — recommended executive moves
- Secure upstream: Negotiate staged, indexed offtakes for boron feedstock or co‑invest in upstream capacity to dampen input volatility.
- Pursue selective partnerships: Co‑development agreements with certified producers accelerate qualification while limiting capital exposure.
- Differentiate through application validation: Fund third‑party testing and system‑level validation (thermal, structural, biocompatibility) to command premium pricing.
- Prepare for audit regimes: Allocate resources to NADCAP/accreditation readiness if targeting aerospace, defense, or regulated medical markets.
- Build an acquisition watchlist: Target bolt‑on producers with complementary production technologies, strong QA systems, or regional supply footprints to accelerate market entry.
- Use our scenario models: Apply our forecast variants (base, accelerated adoption, and delayed commercialization) as decision triggers for capex, hiring, and partner commitments.
Next steps — where to get the intelligence that shifts outcomes
This introduction maps the strategic terrain. If your 2026 priorities include securing supply, sizing investments, or accelerating product commercialization using BNNTs, the full PW Consulting report provides the detailed segmentation, pricing ladders, supplier scorecards, and downloadable scenario models you need to act with confidence.
Contact our research team or download the full report for the proprietary datasets and tactical playbooks that convert opportunity into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: Boron Nitride Nanotubes (BNNT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Legal Practice Management Market Poised for 11.5% CAGR Through 2032
By PW Consulting, 2026-07-12
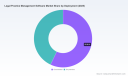
Legal Practice Management Software Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market research positions Legal Practice Management Software (LPMS) as a high-growth enterprise software vertical with clear implications for law firms, technology vendors, and investors heading into 2026. Using 2025 as the base year, our top-line market model estimates the global LPMS market at approximately USD 2.68 Billion and projects expansion to roughly USD 5.74 Billion by 2032, representing a compound annual growth rate of 11.5% over the forecast horizon. This trajectory reflects accelerating cloud adoption, embedded AI, and renewed attention to automation across revenue operations and trust accounting.
Legal Practice Management Software Market
Why this research matters for 2026 strategic decisions
-
Timing: 2026 is a strategic inflection point. Buyers are moving from pilot deployments to firm-wide rollouts of cloud-native, AI-enabled platforms; vendors must convert feature parity into defensible platform value; and investors must evaluate consolidation potential within a market that remains moderately fragmented (our concentration metrics indicate meaningful presence of leading vendors but substantial room for consolidation).
Legal Practice Management Software Market -
Risk calibration: The interplay of regulatory expectations (data privacy, SOC 2, and jurisdictional ethics on AI) and operational risk (trust accounting, billing errors, client data security) creates a narrow window where technology choices materially affect regulatory exposure and client trust.
Legal Practice Management Software Market -
Value capture: Organizations that align product selection, vendor partnerships, and change management to measurable KPIs—billing cycle time, realization rates, client intake velocity, and administrative FTE reduction—stand to capture outsized ROI within 12–24 months.
Market dynamics — what is driving growth and disruption
The LPMS market growth is being driven by a combination of structural and tactical forces.
-
Cloud acceleration: The American Bar Association’s 2025 legal technology survey confirms widespread migration to cloud-based tooling. The effect is twofold: faster feature velocity from vendors and reduced capital friction for smaller firms that previously could not justify on-premises investments.
-
AI as a multiplier: Adoption of AI-driven features—automatic time capture, document summarization, precedent extraction, and predictive tasking—has jumped noticeably. ABA trend data shows AI usage among legal professionals rising sharply during 2024–2025, shifting AI from novelty to productivity enabler across practice sizes and specializations.
-
Operational pressure: Rising labor cost and the imperative to improve margin per partner push firms to automate billing, trust accounting, and matter workflows. Automated billing and integrated trust accounting reduce reconciliation errors and accelerate client collections; these operational gains translate directly into working capital improvements.
-
Regulatory overlay: Cloud platforms are increasingly evaluated on their compliance posture—SOC 2, data residency controls, and jurisdictional ethics guidelines for AI-assisted legal work. Vendors that bake in auditability and role-based controls create a durable commercial advantage, especially with mid-size and enterprise clients.
Competitive landscape — positioning the leaders and challengers
The LPMS vendor ecosystem in 2026 is a mix of specialist platforms, broader practice suites, and verticalized AI players. Below we summarize strategic profiles of the core vendors we evaluated.
-
Clio — A cloud-first incumbent that has moved aggressively to broaden platform scope through inorganic growth and premium product extensions. Clio’s recent acquisition of legal research capabilities and the launch of an enterprise-tier platform signal a shift from SMB dominance toward competing for larger, process-driven firms. Strategic implication: Clio is consolidating modular value into a platform play, increasing the importance of integration strategy for partners and customers.
-
MyCase — Positioned as an all-in-one, mid-market practical suite focused on ease of use and rapid time-to-value. Its strengths are customer experience and straightforward operational workflows; its challenge is defending against AI-enabled feature sets and deep integrations offered by larger platforms.
-
Rocket Matter — Having reimagined its product surface, Rocket Matter emphasizes modern UX and advanced practice management. The vendor is competing on performance and workflow sophistication, aiming to capture firms seeking an alternative to legacy incumbents.
-
Filevine — A serious contender on analytics and workflow orchestration. Filevine’s combination of case management and embedded analytics positions it well for practices that want operational intelligence alongside case handling.
-
Smokeball — Known for automatic time capture and document automation, Smokeball targets firms where granular matter-level productivity metrics drive fee capture. It exemplifies how task-level automation converts into higher realization.
-
PracticePanther , Centerbase , LeanLaw — These vendors skew toward specific segments: PracticePanther with broad SMB appeal, Centerbase toward mid-market integrated finance functions (recent AP automation partnership highlights this), and LeanLaw with a focused revenue operations approach built on QuickBooks integration.
-
Specialists (Lexzur, Supio, Caseflow) — Verticalized or practice-specific plays are gaining traction by automating highly repetitive litigation workflows, personal-injury workflows, or by providing in-house matter-management features that larger suites under-serve.
Recent market signals and what they reveal
-
Platform convergence: Major deals and feature rollouts during 2024–2025 show vendors layering research, advanced analytics, and enterprise-grade modules on top of core practice management—indicating vendors are moving from point-solution competition to platform differentiation.
-
Partnerships over point acquisitions: Some vendors prefer embedding third-party fintech capabilities (e.g., accounts payable, payments, or bank-feeds integration) through partnerships, accelerating time-to-market while preserving capital for strategic M&A.
-
Ethics and compliance as product features: New regulatory guidance around AI use in legal practice is driving demand for explainability, audit trails, and configurable human-in-the-loop gates. Vendors that explicitly productize compliance features reduce buyer friction.
What PW Consulting’s report contains — practical deliverables
Our report is designed for executives who need actionable insights rather than academic description. Key contents include:
-
A validated top-down and bottom-up market-sizing model (base year 2025) with scenario analysis across adoption rates, pricing evolution, and cloud migration curves.
-
Market structure and concentration assessment with implications for M&A, partnership, and go-to-market strategies.
-
Detailed vendor scorecards that map product capability, go-to-market fit, enterprise readiness, and integration posture—highlighting where each vendor wins and where they are vulnerable.
-
Commercial playbooks for buyers (evaluation checklists, procurement negotiation levers, change-management templates) and for vendors (partner ecosystems, pricing playbooks, API strategies).
-
Regulatory and ethics companion notes, detailing compliance checkpoints—particularly for trust accounting, client data security, and AI governance.
-
Forecast scenarios and an interactive model for subscribers, enabling “what-if” analysis around adoption, pricing, and consolidation waves.
Strategic implications and prioritized actions for 2026
Whether you represent a law firm, a vendor, or an investor, the following actions should be prioritized in 2026:
-
For law firms: Treat LPMS procurement as an enterprise transformation. Define success metrics tied to cash flow and realization, require SOC 2 and clear AI governance in contracts, and budget for a 12–18 month adoption program that includes workflow redesign and staff reskilling.
-
For vendors: Differentiate via platform interoperability and compliance-as-a-feature. Invest selectively in domain AI where you can demonstrate measurable FTE or margin improvement; pursue partnerships for finance automation rather than duplicative build efforts.
-
For investors and M&A teams: Look for target profiles that combine sticky customer bases, recurring revenue models, and modular APIs that facilitate ecosystem plays. The market’s fragmentation means bolt-on M&A can be value-accretive if integration risk is managed.
Data, methodology, and the limits of this preview
Our model synthesizes vendor disclosures, buyer surveys, pricing benchmarks, and primary interviews. The base year is 2025 and forecast granularity covers 2026–2032. Concentration metrics indicate a moderate degree of vendor dominance but significant pockets of opportunity for vertical specialists.
In line with our “preview” approach, this article presents the high-level market sizing, growth trajectory, competitive trends, and strategic recommendations. Detailed regional and application splits, vendor scorecard matrices, and full scenario model inputs are intentionally reserved for subscribers and report purchasers. Those datasets include the granular breakdowns, vendor revenue estimates, and adoption curves that are essential for transactional diligence and procurement negotiation.
Next steps — how to use this insight
-
If you are a buyer: Request the buyer’s checklist and the vendor comparison appendix to shorten procurement cycles and quantify expected ROI under your firm’s utilization assumptions.
-
If you are a vendor: Use our partner-readiness and API-maturity checkpoints to accelerate enterprise deals and reduce churn.
-
If you are an investor: Access the full forecast model and vendor valuation framework to stress-test acquisition scenarios across multiple deployment and pricing assumptions.
PW Consulting’s full Legal Practice Management Software Market report provides the granular metrics, vendor-by-vendor analysis, and downloadable models needed to convert the trends outlined here into executable strategies. For access to the model and the complete set of appendices, contact our research services team or visit the report page.
For detailed analysis of this topic, please visit the official page: Legal Practice Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diabetes Drugs Market to Reach USD 117.7B by 2032, 6.5% CAGR
By PW Consulting, 2026-07-12
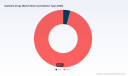
Diabetes Drugs Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our Diabetes Drugs Market study — a decision-useful briefing designed to orient senior executives, investment committees, and policy teams as they shape plans for 2026 and beyond. This is a “trailer” of the full study: it illustrates the analytical depth and line of inquiry we used, highlights the material strategic inflection points shaping the market, and explains how the full report converts those insights into executable options. Core, granular segment breakdowns are intentionally withheld here to preserve the value of the complete dataset and to guide you to the full report for transaction-grade intelligence.
Diabetes Drugs Market
Why this market matters in 2026
The diabetes drugs market is entering a new phase of scale and complexity. Our baseline model — built on historical trends through a 2025 base year and a detailed forecast covering 2026–2032 — projects the market to grow from an estimated USD 75.9 billion in 2025 to roughly USD 117.7 billion by 2032, at a compound annual growth rate of approximately 6.5%. That trajectory is driven by a mix of continuing demand for chronic glycemic management, the rapid commercialisation of incretin-based therapies, and evolving payer dynamics that are reshaping affordability and access.
Diabetes Drugs Market
What changes in 2026 will determine winners and losers
-
Payer architecture and affordability levers: 2026 marks the operational rollout of several novel reimbursement mechanisms that materially affect patient access and manufacturer pricing strategies. The U.S. Medicare “GLP‑1 Bridge” programme — which introduces a standardized low copay structure for eligible Part D beneficiaries — is emblematic. Programs of this type alter channel economics, accelerate demand among insured populations, and force manufacturers to redesign launch and lifecycle pricing plans. Companies that can model and operationalise these programmes will capture outsized share gains; those that cannot will face utilization and margin pressure.
Diabetes Drugs Market -
Regulatory and clinical inflection points: The cycle of approvals and label expansions continues to reshape competitive dynamics. A salient example: in early 2026 the FDA approved a once-weekly basal insulin (Awiqli / insulin icodec) for type 2 diabetes. Approvals like this change therapy sequencing, influence prescribing behaviour, and create new commercial battlegrounds between legacy insulin franchises and next‑gen agents. For strategy teams, the implications are multifold: procurement forecasting, patient support programme design, and competitive clinical messaging must be retooled rapidly.
-
Supply‑chain and raw material concentration risk: Upstream vulnerabilities are now first‑order strategic risks. Recent industry reviews indicate that a substantial portion of critical starting materials for essential medicines is concentrated in very small numbers of supplier countries; similarly, a large share of API regulatory filers originate from a single country cluster. These facts translate into real operational exposures: sudden site disruptions, export controls, or geopolitical frictions can cause acute production shocks and pricing volatility. Board-level playbooks must therefore include supplier redundancy, strategic inventories, and nearshore sourcing assessments.
-
Market concentration and competitive intensity: The diabetes drugs market exhibits a high degree of concentration at the top. The three largest firms account for roughly half of market revenue, and the top five for about two-thirds. That structure drives intense innovation-and-defense strategies: incumbents use scale to defend channels and drive formulary positioning, while challengers seek niche clinical advantages, service differentiation, or M&A as routes to scale.
How the full report helps 2026 decision-making
-
Actionable market model and scenario framework: We provide a flexible financial model with deterministic and scenario branches calibrated to policy changes, pricing shocks, and clinical outcomes. The model is the working asset for commercial planning, enabling sensitivity runs for pricing, market access, and competitor moves.
-
Commercial playbooks keyed to payer pathways: The study maps concrete go‑to‑market options for launch, scale, and defence under alternative reimbursement regimes. These playbooks include tiering strategies, discount schedules, hub-and-spoke patient support models, and contracting templates designed for value-based arrangements and bridge programmes.
-
Risk heatmaps and supplier due diligence toolkits: We translate upstream concentration metrics and API sourcing footprints into operational risk heatmaps, with mitigation roadmaps that span near‑term tactical measures and medium‑term strategic sourcing initiatives.
-
Competitive landscape and capability gaps: The report synthesises corporate positioning across innovation pipelines, manufacturing footprints, commercial capabilities, and partnership networks. For each major competitor we profile strategic intent, recent regulatory milestones, and plausible next moves — then translate those into countermove options for clients.
-
M&A and partnership diagnostics: We identify target archetypes and valuation drivers for bolt-ons, capacity plays, and strategic collaborations — with acquisition case modelling that reflects the market’s projected growth path and concentration dynamics.
Competitive snapshot — what to expect from the major players
The competitive field is a blend of large diversified pharma and specialised biologics firms. Each major player pursues a distinct mix of product, channel, and clinical strategies:
-
Novo Nordisk A/S: A global leader with deep capabilities in insulin and incretin-based therapies. Recent regulatory success in 2026 has reinforced its clinical portfolio and extended its commercial runway. Novo’s scale in delivery innovation and patient support remains a barrier to entry for many challengers.
-
Eli Lilly and Company: Aggressively expanding in the incretin/GIP space with a portfolio that spans glucose control and obesity‑related indications. Lilly’s dual focus on therapeutic innovation and rapid market execution positions it as a principal growth engine in the category.
-
Sanofi: Maintains a core franchise in long‑acting insulins and is focused on lifecycle management and cost‑effective delivery. Sanofi’s strategic options include manufacturing optimisation, biosimilar positioning, and targeted partnerships.
-
Boehringer Ingelheim and Janssen Pharmaceuticals: Both firms play important roles in the SGLT2 and related segments, deploying differentiated clinical evidence to maintain access in the face of payer scrutiny. Their strategies emphasise outcome data and integrated care models to preserve formulary placement.
Strategic implications by function
-
Commercial leaders: Must re‑architect segmentation and targeting to account for payer programme mechanics (e.g., low‑copay bridge programmes). Sales force deployment, channel incentives, and digital patient engagement must be aligned with new utilization patterns.
-
Medical & RWE teams: Should prioritise comparative‑effectiveness evidence and real‑world studies that address payer endpoints — hospitalization reduction, adherence durability, and total cost of care — to secure favourable coverage and rebates.
-
Manufacturing & procurement: Need to move beyond cost optimisation to resilience planning: dual sourcing, qualified backup APIs, strategic inventory policies, and regionalisation where feasible.
-
Corporate development: Will find 2026 a fertile window for bolt-ons that provide capacity or complementary modalities; however, valuation discipline is critical because premium multiples are attached to proven commercial execution in this concentrated market.
Scenarios to stress-test in 2026 planning
-
Accelerated uptake under favorable reimbursement: Rapid adoption of supportive payer mechanisms that lower out‑of‑pocket costs, increasing volume but compressing list price realisations; value capture shifts to service‑based contracts and volume agreements.
-
Supply shock scenario: An upstream disruption in a critical API or starting material creates temporary shortages, favouring manufacturers with diversified supply chains and excess capacity.
-
Clinical substitution dynamic: New approvals or landmark RWE that change prescribing patterns between insulins and incretin agents, altering therapy mix and channel economics.
How PW Consulting turns insight into action
Our full Diabetes Drugs Market report goes beyond high-level narrative. It delivers a calibrated financial model, stratified scenario outputs, competitor playbooks, procurement and supply‑chain diagnostics, and practical templates for commercial negotiations and payer dossiers. Each section includes an executive decision matrix that maps options to risks, investments required, and near‑term KPIs for monitoring. This is structured to support quarterly board deliberations and 12‑ to 36‑month strategic plans.
Next steps
If your 2026 plan depends on optimally navigating reimbursement reforms, supply‑chain shocks, or competitive launches, the full PW Consulting report is the operational asset your team should build decisions on. The public preview you have read establishes the lines of analysis; the detailed dataset, forecasting model, and playbooks — which include granular segmentation and market-share analytics — are available in the comprehensive study and accompanying client workshop. Contact our industry practice to schedule a briefing or to commission bespoke scenario runs tailored to your portfolio.
PW Consulting’s Diabetes Drugs Market research is designed to convert complexity into clear choices. Use it to sharpen 2026 budgets, prioritise investments, and define the tactical moves that will secure sustainable growth in a market that is large, concentrated, and rapidly evolving.
For detailed analysis of this topic, please visit the official page: Diabetes Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Paper Pallets 2026: Strategic Imperatives from PW Consulting’s Market Brief
This briefing introduces PW Consulting’s in-depth Paper Pallet Market research (base year 2025), designed to inform executive decisions across procurement, logistics, packaging innovation, and corporate strategy as you plan for 2026 and beyond. The study synthesizes a five‑year historical review (2020–2025) with a rigorous forecast horizon of 2026–2032. Our topline quantified view shows a compact but consistently expanding market, with a compound annual growth rate (CAGR) of 5.48% across the forecast window. All monetary figures in this research are reported in USD (Million) and calibrated to 2025 as the base year.
Paper Pallet Market
Why this briefing matters for 2026 decision cycles
-
Operational levers are shifting beyond cost-per-pallet. Sustainability, cross-border compliance, and total landed cost (including reverse logistics and recycling) have moved to the top of procurement scorecards. Paper pallets now sit at the intersection of those priorities—lightweight, recyclable, and exempt from ISPM‑15 wood treatment regimes—making them strategically relevant to global shippers.
Paper Pallet Market -
Market maturity is manifesting unevenly: while absolute market value is expanding steadily, concentration remains modest. The three- and five‑firm concentration ratios indicate a fragmented competitive field, which creates opportunity windows for captive sourcing programs, regional champions, and proprietary product platforms.
Paper Pallet Market -
Material and product innovation—corrugated constructions, molded pulp forms, honeycomb cores, and novel paper wraps—are changing performance tradeoffs between single‑use plastic, treated wood, and reusable platforms. Early adoption pilots in 2024–2025 have generated measurable lifecycle benefits for targeted categories of goods.
What the macro numbers tell strategy teams
-
Observed growth through 2025 and our modeled trajectory to 2032 reflect steady demand migration into paper‑based load‑support solutions, driven by sustainability targets and regulatory clarity on packaging materials. The market’s projected CAGR of ~5.5% is sufficient to justify medium‑term investments in supply capacity and product R&D for companies with adjacent capabilities.
-
Because the market remains fragmented—with the three‑firm concentration well below levels typical of heavy industrial pallets—both incumbent packaging groups and nimble specialists retain room to pursue share via differentiated value propositions: cost parity, compliance simplicity, lighter weight, or circularity features.
-
For financial sponsors, the market scale today is meaningful for bolt‑on acquisitions and platform consolidation plays that prioritize distribution reach and technical IP over sheer manufacturing footprint.
Regulatory and logistics dynamics shaping 2026 choices
-
Regulatory advantage: Paper pallets are exempt from ISPM‑15 requirements applicable to wood packaging (a persistent friction for international shipments). This simplification materially lowers operational barriers for global routing and reverse logistics, especially for fast‑moving consumer goods and export‑oriented food & beverage flows.
-
Return logistics and circularity: Paper pallet designs that enable compact return folding or efficient pulping at end of life reduce reverse logistics cost per cycle and improve effective CO2 metrics—two KPIs corporate sustainability teams will continue to press in 2026.
-
Complementary innovations: The market is seeing a wave of product extensions—paper‑based pallet wraps and lightweight protective wraps—that reduce reliance on single‑use plastics. These launches demonstrate adjacent product routes for incumbent corrugated and paper manufacturers seeking higher value per pallet equivalent.
Competitive landscape — who matters and why
The ecosystem mixes large corrugated groups with specialized innovators and regionally focused manufacturers. Key companies included in our competitive study offer different strategic models:
-
Smurfit Kappa Group (Dublin, Ireland): Strong emphasis on integrated corrugated systems and end‑to‑end packaging solutions; recent product launches position them to bundle paper pallet options with broader packaging contracts.
-
DS Smith Plc (London, UK): Industrial R&D focus on patented fiber‑based pallet technology enables differentiated performance claims and customer lock‑in via design IP.
-
International Paper Company (Memphis, USA): Combines scale in corrugated and molded paper solutions with established distribution channels to FMCG and industrial clients.
-
Sonoco Products Company (Hartsville, USA): Offers integrated paper pallet systems and a route to replacement products for traditional packaging clients through existing commercial relationships.
-
PALLITE Limited (UK) and ATTA Pallet (Hungary): Specialist manufacturers focused on honeycomb and assembled paper pallet forms—these players operate at the technical frontier for lightweight, high‑strength designs and often act as OEM suppliers to larger groups.
-
EcoDuro Inc. (Canada): Molded pulp and paper‑based pallets that appeal to cold‑chain and single‑use scenarios where contamination control and compostability are prioritized.
Competitive implications: incumbents will defend via integrated offers and scale economics; specialists win by pushing technical performance and service models (rapid prototyping, testing programs, and co‑development contracts). For buyers, supplier portfolios that combine national scale with local technical support often offer the best risk‑adjusted outcomes.
Recent developments that accelerate adoption
-
Product launches in 2024–2025 have broadened solution sets beyond the pallet itself into wraps and load‑stabilization products, enabling broader substitution away from plastics in outbound logistics.
-
These innovations reduce barriers to pilot programs—shippers can now test a paper pallet + wrap system with demonstrable environmental and handling outcomes rather than evaluating isolated component swaps.
What the full PW Consulting report delivers (operationally actionable)
- -
-
Top‑down and bottom‑up market sizing (historical 2020–2025 and forecast 2026–2032 with the stated CAGR), including scenario variants for accelerated sustainability adoption and slower conversion cases.
- -
Supply‑chain stress tests that model cost sensitivity to fuel, pulp prices, and recycling yields—useful for procurement hedge design.
- -
Carrier and packaging compatibility matrices that show handling constraints, fork‑truck cycle impacts, and racking compatibility for common warehouse setups.
- -
Commercial playbooks: procurement tenders, pilot specifications, KPI scorecards, and unit economics templates broken down to a level that supports contract negotiations.
- -
Competitive profiles and go‑to‑market strategies for the principal suppliers, including partnership and M&A archetypes.
- -
Regulatory and sustainability risk matrix covering cross‑border compliance, ISPM‑15 exemptions, and lifecycle carbon accounting approaches suitable for Scope 3 reporting.
- -
Buyer decision frameworks for selecting between reusable wood/plastic platforms and paper‑based single/triple‑use solutions, reflecting total landed cost and CO2 per shipment metrics.
Note: to preserve the value of the primary research and encourage direct engagement, granular regional and application segmentation tables, unit‑price ladders by configuration, and customer‑level adoption curves are presented exclusively in the complete report and dataset.
How to convert insight into 2026 actions
-
Procurement teams should run a two‑track sourcing process: (1) short‑term trials for high‑volume SKUs where reverse logistics are controlled, and (2) strategic RFPs for long‑term programs with lifecycle pricing and recycling commitments.
-
Operations should incorporate paper pallet handling simulations into warehouse slotting exercises; verify racking compatibility and fork engagement under load cases representative of your product mix before scaling.
-
Sustainability and reporting leads can accelerate Scope‑3 reductions by prioritizing categories with high outbound weight and frequent export routing (where ISPM‑15 exemption creates incremental value).
-
M&A and corporate development should screen targets that add technical IP (patents on fiber construction), proprietary distribution, or strategic regional coverage—these are the premium value drivers in a fragmented market.
-
R&D and product teams should prioritize modular pallet designs that enable multipurpose use (transit protection, stackability, return compaction) and evaluate adjacent product extensions such as paper‑based wraps that complete the sustainability story for buyers.
Final orientation and next steps
For companies planning capital allocation and sourcing strategies in 2026, the paper pallet market presents a pragmatic decarbonization lever with operational upside—provided decisions are grounded in robust unit‑economics, validated handling trials, and a clear supplier evaluation framework. PW Consulting’s full report delivers the data tables, scenario models, and supplier scorecards required to act with confidence. If your team needs a tailored briefing or a pilot design workshop aligned to your SKU set, our analyst team is prepared to translate the research into executable programs.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Ultrasonic Cleaners Market to Hit USD 1,980.9M by 2032 (6.8% CAGR)
By PW Consulting, 2026-07-12
Medical Ultrasonic Cleaners Market — Strategic Briefing for 2026 Decision Makers
As PW Consulting’s lead industry analyst, I present an executive-level preview of our full Medical Ultrasonic Cleaners Market study. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory drivers and strategic options that will matter most to executives planning capital allocation, product strategy, and go-to-market moves in 2026. It intentionally showcases the analytical depth behind our work while reserving detailed segment-level matrices for the full report so you have a compelling reason to access the primary resource for procurement-grade inputs.
Medical Ultrasonic Cleaners Market
Market at a Glance: Growth Trajectory and Structural Signals
Our base-year analysis (2025) and historical review (2020–2025) show a market that has moved from recovery into steady expansion. Measured in USD (Million), the global market size reaches an estimated 1,273.5 million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 6.8% over the projection window (2026–2032), reaching approximately 1,980.9 million by 2032. This is not an episodic spike driven by one-off purchases; the path we model reflects durable drivers—regulatory tightening, continued automation of sterile processing, and growing demand for reproducible cleaning processes across hospitals, clinics, and device manufacturing lines.
Medical Ultrasonic Cleaners Market
Two structural features are worth flagging for strategic planning:
Medical Ultrasonic Cleaners Market
- Market concentration remains modest: the combined share of the top three and five firms (CR3: 28.5%; CR5: 35.2%) indicates room for differentiated competitors to scale through innovation, channel development and services-led models rather than through outright monopolistic control.
- Growth is broad-based but nuanced: expansion is supported by recurring replacement cycles, retrofit opportunities tied to compliance upgrades, and installed-base aftersales—areas that favor firms with strong service networks and validation capabilities.
Why 2026 Is a Pivotal Year for Strategic Choices
Three converging pressures make 2026 a decision point rather than a routine planning year:
- Regulatory clarity and enforcement: MDR-conformant devices and reproducible cleaning validation standards are now practical procurement filters for hospital systems and contract manufacturers. Procurement teams increasingly require documented process reproducibility and validation-ready equipment.
- Operational economics in sterile processing: Ultrasonic systems continue to deliver measurable labor savings versus fully manual cleaning processes. Hospitals and central sterile departments are prioritizing investments that reduce throughput time while preserving regulatory compliance.
- Sustainability and procurement policy shifts: New product introductions emphasizing biodegradable agents and lower life-cycle environmental impact are gaining traction among health systems seeking to meet institutional ESG targets.
These pressures translate into three strategic imperatives: embed validation and compliance into product value-propositions; design aftermarket and service models to capture recurring revenue; and accelerate product variants that meet both clinical performance and sustainability requirements.
Competitive Landscape: Who’s Setting the Agenda
Our landscaping of active participants reveals a mix of specialist firms, industrial suppliers and established OEMs pursuing adjacent medical opportunities. Below are high-level strategic profiles of the key players we track and what their recent moves imply for market competition.
- Crest Ultrasonics (Trenton, NJ)
Strengths: Precision-focused product engineering for healthcare workflows and multi-cycle, digitally controlled units tailored to sterile processing departments. Strategic partnerships with hospital systems (notably a recent 2025 collaboration) position Crest to co-develop clinical workflows that reduce procurement friction.
Strategic posture: Focus on customized integrated solutions and service contracts that lock in installed base. For competitors, emulating Crest requires investments in clinical relationships and configurable software interfaces for validation.
- Elma Schmidbauer GmbH (Singen, Germany)
Strengths: Modular systems and explicit MDR compliance credentials; early adoption of eco-friendly cleaning chemistries. Product introductions in 2025 reinforced a regulatory-first product narrative.
Strategic posture: Leading on regulatory positioning and “green” product differentiation. Competitors should anticipate higher procurement thresholds where MDR-compliant documentation and lifecycle impacts are procurement criteria.
- Branson Ultrasonics (Danbury, CT)
Strengths: Broad R&D capability in digital controls and surgical-instrument-specific solutions. The 2025 product line announcement underlines their intent to capture pre-cleaning and validation workflows within hospitals.
Strategic posture: Technical depth coupled with brand recognition in controlled environments. Rival firms must match or exceed user experience and verification ease to compete on total cost of ownership.
- Ultrasonic Power Corporation (New Britain, CT)
Strengths: Combines industrial-grade robustness with medical-grade hygiene standards, including bespoke systems for precision cleaning in pharmaceutical settings.
Strategic posture: Positioned to serve OEM and contract-manufacturing customers requiring high throughput and custom engineering—an attractive niche as device complexity rises.
- Ultrasonic LLC (United States)
Strengths: Flexibility to handle small-batch and complex component cleaning across healthcare and aerospace verticals.
Strategic posture: Competitive in specialized, high-mix environments; success depends on rapid customization and service responsiveness.
Recent Industry Developments and What They Mean
- Strategic partnerships between vendors and hospital networks are becoming a higher-value route to procurement adoption. These alliances shorten the evidence-collection phase for clinical buyers and create an upgrade channel for new features and services.
- Product launches emphasizing biodegradable agents and MDR compliance materially alter procurement criteria. By 2026, sustainability and regulatory alignment coexist as procurement filters—companies lacking either will find growth constrained.
- Digital controls and process validation are now baseline expectations for larger hospital systems and medical device manufacturers. Vendors that provide reproducible, auditable cleaning cycles capture both procurement preference and price resilience.
Operational and Supply-Chain Considerations
High-capacity stainless steel tanks remain an industry standard for instrument pre-cleaning. This creates concentrated demand for certain raw materials and precision fabrication—factors that increase the importance of supply-chain resilience. In your 2026 planning horizon, consider three operational levers:
- Supplier diversification for grade-A stainless and electronic controls to mitigate lead-time spikes.
- Modular manufacturing designs that allow rapid reconfiguration between benchtop and higher-capacity units to balance mix risk.
- Scaled validation tooling and documentation templates that reduce time-to-procurement for hospital systems and OEM customers.
Where Value Will Be Captured—Strategic Playbook
Based on our model and competitive analysis, successful firms will pursue a blended value capture strategy across product, software, and services:
- Product Leadership: Invest in MDR-compliant product portfolios and digital control platforms that simplify validation. Customers increasingly buy on the basis of auditable outcomes, not just hardware specs.
- Aftermarket Services: Build validation-as-a-service, consumables programs (eco-friendly chemistries), and uptime guarantees. Recurring service revenues will materially increase lifetime customer value.
- Channel and Partnerships: Establish clinical co-development arrangements with hospital systems and device OEMs to accelerate adoption curves and create switching costs.
- Sustainability Differentiation: Prioritize biodegradable chemistries and lifecycle analyses to win tenders where ESG plays a role in procurement decisions.
Decision Framework for 2026 Allocations
Executives reviewing capital and commercial investments for 2026 should evaluate initiatives against three scorecard dimensions:
- Revenue Resilience: Will the investment increase recurring revenue or shorten sales cycles in regulated procurement environments?
- Regulatory and Reputational Risk Mitigation: Does the initiative reduce buyer friction by delivering compliant, validated workflows and documented outcomes?
- Operational Scalability: Can manufacturing and service delivery scale without linear increases in working capital or supply-chain concentration risk?
High-priority 2026 investments typically pass at least two of these tests—examples include modular product platforms with cloud-enabled validation logs, service network build-outs in high-density hospital regions, and partnerships that provide clinical evidence for cleaning outcomes.
Report Contents — Practical Outputs You Can Use
The full PW Consulting report provides operationally focused deliverables designed for immediate use in planning cycles and procurement negotiations. Key inclusions are:
- Detailed market model (historical and forecast) by year—ready for integration into financial planning tools (USD, Million).
- Scenario-based forecasts with sensitivity to replacement cycles, regulatory adoption timing and price pressure.
- Tactical go-to-market playbooks for vendors, including segmentation strategies, pricing levers and sales enablement assets tailored to hospital purchasing groups and OEMs.
- A validation checklist and template set that can be adapted by suppliers to accelerate RFP wins with clinical buyers.
- Competitive intelligence dossiers on the leading suppliers, their product roadmaps, and likely next moves—plus identified white spaces for entrants.
These outputs are structured to support board-level investment approvals and operational rollouts in 2026. Note that the full report also includes the granular segmentation and regional matrices that are intentionally consolidated here to maintain this briefing’s “trailer” orientation.
Next Steps for Executives
If you are evaluating capital deployment, M&A, or a product launch in the medical ultrasonic cleaner space for 2026, we recommend three immediate actions:
- Request the full PW Consulting dataset to incorporate our year-by-year revenue model into your financial planning tools.
- Run a quick pilot with a strategic hospital partner to validate feature sets (digital logs, eco-chemistry compatibility) and quantify labor and throughput benefits within 90–120 days.
- Audit your supply base for critical inputs (stainless fabricators, electronics) and define dual-sourcing plans to avoid single-point failure during scale-up.
Closing — Why This Matters
The medical ultrasonic cleaners market is maturing into a sector where outcomes (validated cleaning cycles, regulatory alignment, and sustainability) increasingly trump pure hardware differentiation. With a forecast CAGR of 6.8% and a near-doubling in market size from 2025 to 2032 under our central scenario, there is material value to be built—provided companies align product development, service models and channel strategies to the new procurement reality.
For procurement-grade segment tables, regional prioritization matrices, and the full competitive annex—along with our financial model you can plug into 2026 budgets—access the complete PW Consulting report. The full dataset is the operational asset your leadership team needs to move from strategy to execution in 2026.
For detailed analysis of this topic, please visit the official page: Medical Ultrasonic Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


