



Category: market research
Organic Cocoa Market to Reach USD 984M by 2032 with a 6.98% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Organic Cocoa Market — Strategic Preview for 2026 Decision-Makers
As consumer demand for certified, traceable and sustainably produced ingredients intensifies, organic cocoa has moved from niche to strategic input for food manufacturers, ingredient traders and agribusiness investors. PW Consulting’s Organic Cocoa Market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) synthesizes commercial realities, regulatory shifts and supply-side constraints into a pragmatic decision toolkit for 2026. This short briefing highlights the report’s strategic value, the principal market forces you must plan around, and the practical levers companies can deploy—while reserving the full, actionable segment and regional detail for subscribers.
Organic Cocoa Market
Market trajectory at a glance
-
Market scale and momentum: The organic cocoa market has expanded materially over the last half-decade — rising from roughly USD 452 Million in 2020 to USD 620 Million in 2025 (Million, USD, base year 2025). Our forecast model projects sustained growth through 2032, reaching an estimated USD 984 Million by the end of the forecast period.
Organic Cocoa Market -
Growth rate: The market’s compound annual growth rate (CAGR) for the forecast window (2026–2032) is 6.98%, reflecting a blend of premiumization, product adoption in value-added applications, and expanding certified supply chains.
Organic Cocoa Market -
Market structure: Concentration is material. The top three firms control a dominant share of the market, and the top five further consolidate supplier influence — dynamics that shape pricing power, certification access and buyer negotiation strategies.
Why this matters for 2026 strategy
-
Risk and opportunity confluence: 2026 will be the year when regulatory stringency, certification bottlenecks and premium consumer demand collide with structural supply constraints. Companies that prepare now can capture outsized margins in premium channels while avoiding supply disruptions.
-
Regulatory inflection points: European organic regulations and tightened audit and operator-group rules have increased compliance costs and raised barriers to market access for many smallholder producers. This accelerates consolidation and creates premium sourcing opportunities for supply chain players that can manage compliance end-to-end.
-
Traceability and provenance as premiums: Buyers increasingly pay for verifiable origin, regenerative practices and Fairtrade-style premiums. Investments in traceability and farmer engagement are no longer “nice to have” — they are required to defend shelf space in premium categories.
Key market dynamics shaping 2026 choices
-
Supply-side fragmentation vs. buyer concentration: Smallholder-dominated origins remain the backbone of organic cocoa production, but a significant portion of producer organisations currently struggle to meet new group-of-operators and segregation standards. This creates short- to medium-term supply squeezes for fully certified, audit-ready volumes.
-
Certification & development partnerships: Multilateral and development agency initiatives are actively reshaping the supplier base—partnering with cooperatives to upgrade governance, agroforestry practices and organic certification. These programs both expand long-term supply and create near-term winners among cooperatives that successfully upgrade.
-
Processing capacity and product mix: Processors with dedicated organic lines and segregated facilities capture higher-value volumes. Vertical integration—from bean sourcing through processing to ingredient sale—remains a primary route to margin capture and traceability assurance.
-
Premiumization of applications: While confectionery remains a core outlet, beverage, bakery and specialty ingredient applications are expanding demand for certified organic derivatives. Portfolio choices (e.g., focusing on butter versus powder versus liquor) and co-manufacturing partnerships dictate margin profiles.
-
Concentration risks: With a high CR3/CR5, buyer choices are constrained by a small set of large suppliers; strategic buyers should prepare contingency sourcing plans and invest in supplier development to reduce vulnerability.
What PW Consulting’s report delivers (practical, actionable)
-
Proprietary market model: An Excel-ready model projecting demand and supply across 2026–2032 with scenario toggles for price shocks, accelerated certification rollouts and attrition of smallholder volumes.
-
Decision-grade playbooks: Supply-side and commercial playbooks for manufacturers, ingredient traders and investors covering supplier due diligence, contract structures, and premium capture strategies.
-
Regulatory and compliance roadmap: A concise compliance checklist and timeline for EU organic regulations and audit readiness, including mitigation pathways for smaller suppliers and cooperative onboarding templates.
-
Risk matrix and stress-tests: Identified failure modes (regulatory non-compliance, climate-related yield shocks, logistics interruption) with quantified P&L impacts under three probability scenarios.
-
Supplier scorecards and sourcing tender templates: Practical templates to evaluate processors and cooperatives on traceability, segregation capability, certification maturity, processing capacity and commercial terms.
-
M&A and partnership pipeline: Candidate screening criteria and indicative value drivers for bolt-on acquisitions, joint ventures and long-form offtake agreements—tailored to capture premium organic value pools.
-
Sustainability KPIs and farmer engagement playbook: Pragmatic metrics and field interventions that drive yield uplift, reduce input costs through agroforestry and deliver certified volumes within defined timelines.
Competitive landscape: strategic implications for incumbents and challengers
The market features a mix of specialized organic traders/processors, global ingredient giants with organic lines, and mission-driven specialty brands. Each group faces different strategic choices:
-
Specialized organic processors and traders (e.g., firms focused exclusively on certified organic supply and processor integration) have the advantage in credibility and farmer relationships. Their strategic priority is scaling certified throughput without compromising segregation practices and audit trails.
-
Large global suppliers and agribusinesses use integration and procurement scale to securitize supply and offer wide product portfolios. Their strategic play involves investing in dedicated organic processing capacity and leveraging sustainability programs to secure long-term feedstock.
-
Premium chocolate brands and specialty ingredient companies win on provenance and consumer storytelling. For them, direct sourcing, transparency and premium positioning justify higher unit economics—but their scalability depends on securing reliable certified supplies.
Notable market participants exemplify these archetypes: established organic processors with direct farmer-cooperative sourcing; Swiss and European processors running large dedicated organic facilities; global agribusiness groups with segregated organic lines; and mission-first brands that monetize traceability. Competitive moves to watch in 2026 include capacity investments for segregated processing, expanded cooperative certification programs, and consolidation via selective M&A to secure certified volumes.
Priority actions for 2026 — a tactical roadmap
-
Secure certified throughput: Lock in multi-year offtake or forward purchase agreements with certified suppliers and cooperatives, coupled with supplier development clauses that underwrite certification upgrades.
-
Invest in traceability: Allocate budget for digital traceability pilots (blockchain or interoperable ledgers) tied to sustainability claims; convert traceability into price premiums and procurement leverage.
-
Segregation capacity & flexibility: Evaluate the economics of dedicating processing capacity versus contract manufacturing with certified partners. Short-term lease or tolling arrangements can reduce capital exposure.
-
Regulatory compliance program: Implement the report’s compliance roadmap immediately—focus on group-of-operators governance, audit-readiness and segregation controls to avoid market access loss, especially into Europe.
-
Scenario planning: Build three modular scenarios—“Certification Ramp-up,” “Origin Shock,” and “Premium Compression”—and stress-test P&L, working capital and logistics for each.
-
Partnerships with development agencies: Co-invest in producer organization upgrades and agroforestry programs (which often unlock matching donor or FAO-supported funds), de-risking supply growth and improving ESG credentials.
-
Value-chain integration assessment: For mid-sized players, run an M&A and build-vs-buy decision framework focused on acquiring processing capability or locking in origin relationships rather than commoditized bean trading.
-
Commercial segmentation: Define a two-track commercial approach—premium track (traceable, single-origin, regenerative) and scale track (cost-competitive, certified bulk)—with distinct margin models and sales channels.
How to use this research in the next 90 days
-
Immediate: Use the compliance checklist to audit your supplier base for EU readiness and identify high-risk contracts.
-
30–60 days: Run the report’s stress-tests on your procurement and hedging models; engage top suppliers on certification roadmaps and secure targeted offtakes.
-
90 days: Implement traceability pilots and finalize a prioritized shortlist for either capacity investment or M&A based on the report’s supplier scorecards.
Next steps and access to full detail
This briefing highlights priorities and strategic implications. PW Consulting’s full Organic Cocoa Market report contains the granular regional and application breakdowns, supplier-level benchmarking tables, model files and acquisition-target profiles necessary for transaction and operational execution. Core segment-level tables and regional splits have intentionally been omitted from this preview to preserve the commercial integrity of the analysis—subscribers receive the full dataset, downloadable models and customizable playbooks.
For executive briefings, model walkthroughs or to license the full dataset and templates, PW Consulting’s industry team is available to tailor the findings into a bespoke implementation plan for your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Organic Cocoa Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Road Transport Refrigeration Market to Reach USD 6.65M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-12
Road Transport Refrigeration Equipment: Strategic Imperatives for 2026 — A PW Consulting Preview
As global supply chains continue to recalibrate in the wake of pandemic-era disruptions, stricter emissions regulation, and accelerating electrification, the road transport refrigeration equipment (TRU) market is entering a decisive phase. PW Consulting’s upcoming market study—anchored on a 2025 base year and covering 2020–2025 historically with a 2026–2032 forecast horizon—frames that phase with actionable analysis for executives planning investments, fleet transition strategies, and product development roadmaps in 2026.
Road Transport Refrigeration Equipment Market
Why 2026 is a Strategic Inflection Point
-
The market has shown steady expansion: our assessment documents a compound annual growth rate (CAGR) of 5.8% across the forecast window, reflecting a combination of demand growth in perishables logistics, regulatory-driven replacement cycles, and uptake of electric TRU technologies.
Road Transport Refrigeration Equipment Market -
Underpinning that growth is a clear trajectory: the overall market value rises from the early-2020s baseline through the 2025 base year and continues upward into the early 2030s, validating multi-year investment for manufacturers, fleet operators, and service networks.
Road Transport Refrigeration Equipment Market -
Regulatory timelines and enforcement actions that become binding in 2025–2026 (notably state-level zero-emission mandates and refrigerant restrictions) create mandated replacement and retrofit windows. For many stakeholders, 2026 is the year to move from pilots and selective deployments to scaled rollouts or strategic hedging.
What This Preview Offers — and What It Withholds
We present a high-level synthesis of market dynamics, competitive posture, technology economics, and regulatory risk so that C-suite leaders and investment committees can prioritize decisions for 2026. Consistent with the “trailer” intent of this briefing, we deliberately omit the granular segmentation tables and proprietary split data that inform supplier selection, pricing negotiation, and site-by-site deployment economics. Those datasets and scenario models are available in the full PW Consulting report.
Key Market Dynamics Shaping 2026 Decisions
Regulatory Acceleration and Operational Impact
-
State-level emission regimes—most prominently California’s Transport Refrigeration Unit (TRU) Airborne Toxic Control Measure (ATCM) amendments—are moving from rulemaking into implementation. Amendments require progressively higher proportions of zero-emission TRUs in subject fleets by the end of 2025 and 2026, and CARB’s 2025 implementation updates broaden enforcement tools to include registration, reporting, and operating fees. The U.S. EPA’s partial waiver in early 2025 clarifies enforcement jurisdiction, reinforcing the practical force of these timelines.
-
Refrigerant policy is another lever: limits on global warming potential (GWP) for newly manufactured TRUs are already in force, pushing OEMs and aftermarket providers to validate lower-GWP chemistries or non-fluorinated alternatives in their platforms.
Technology Economics: Electrification vs. Diesel
-
Electric TRUs are moving beyond niche use. Operational modeling in our study shows that, on an hourly basis, electric systems consume measured electrical energy in the single-digit kW range versus diesel flow measured in fractions of a gallon per hour—yielding tangible hourly fuel/energy savings (we model average hourly savings that become compelling over total lifecycle horizons when paired with predictable electricity pricing and reduced maintenance).
-
However, total cost of ownership is context dependent. Charging infrastructure availability, route duty cycles, ambient extremes, and capital financing terms materially alter payback timelines. PW Consulting’s scenario engine quantifies break-even for common duty profiles; these outputs are a core deliverable in the full report.
Supply-Chain Volatility and Component Risk
-
Steel and other commodity inputs used in TRU housings and components are exposed to global metal-market volatility. Procurement strategies that previously focused on price are now being rebalanced to secure continuity of supply and minimize production lead-time risk.
-
For OEMs, this means dual-sourcing strategies, inventory buffering, and supplier partnership models tied to shared risk-reward metrics. For fleets, it justifies multi-vendor service agreements to avoid single-source downtime risk.
Competitive Landscape — Who’s Setting the Pace
The TRU market is characterized by a mix of long-established OEMs, regional specialists, and an expanding set of technology-focused entrants. Market concentration is moderate: the top three players account for a substantial share of the market, with the top five representing a clear majority—an environment where scale affords R&D and distribution advantages, but niche differentiation remains viable.
Profiles and Strategic Moves
-
Thermo King (Wood Dale, Illinois) : Continues to anchor its portfolio across diesel, hybrid, and all-electric TRUs. Recent launches targeted urban and light-duty segments with modular nose-mount solutions optimized for box trucks—an explicit play for last-mile and regional distribution fleets.
-
Carrier Transicold (Minneapolis, Minnesota) : Advances in reduced-maintenance, lower-operating-cost platforms signal a push to protect legacy diesel revenue while accelerating electrified product lines for center-divide trailer applications.
-
Guchen Thermo (China) : Expanding capability across diesel, electric, and battery-assisted TRUs for medium and heavy trucks positions Guchen for both domestic scale and export opportunities as global buyers seek competitive price-performance trade-offs.
-
Zanotti (Italy; Daikin subsidiary) : Focuses on refrigerated van and truck conversions with engineering depth in system integration—appealing to markets where retrofits and conversions remain cost-effective alternatives to full vehicle replacement.
-
Kingtec Group (US) and Hubbard Products (UK) : Both play crucial roles in complementary segments—trailers, RVs, and cold rooms—and demonstrate the importance of regional service networks and aftermarket parts availability.
Recent product introductions and sector benchmarks further crystallize market directions. Thermo King’s mid-2025 nose-mount unit responds to a growing demand for compact, precise-control systems in urban logistics. Carrier’s Vector 8811MT emphasizes lifecycle cost reduction—an explicit counterpoint to electrification narratives by retaining relevance for diesel-centric operators who prioritize uptime and maintenance economics. Industry benchmarking by the North American Council for Freight Efficiency (published in late 2024) provides the first independent efficiency baselines for transport refrigeration performance, enabling apples-to-apples comparisons and accelerating procurement discipline.
Practical, Actionable Guidance for 2026
For OEMs and Component Suppliers
-
Prioritize modular architectures: design platforms that can accept multiple powertrain options (diesel, hybrid, electric) and alternative refrigerants with limited airframe rework. This reduces the obsolescence risk tied to rapid rule changes.
-
Invest in service networks and digital diagnostics: reduced downtime and predictive-maintenance capabilities are increasingly decisive purchase criteria for large fleet operators.
-
Secure supply continuity: institutionalize commodity risk management and consider contractual hedges or long-term supplier agreements for critical metals and electronics.
For Fleet Operators and 3PLs
-
Shift from pilot mode to prioritized scaling by establishing a triage framework: identify routes and vehicle types where electric TRUs yield the shortest payback and prioritize those for conversion early in 2026.
-
Negotiate comprehensive service and performance contracts that align incentives for uptime, energy efficiency, and refrigerant stewardship.
-
Plan for compliance costs and administrative requirements: CARB-style registration, reporting, and operating fees necessitate new operational workflows and potential third-party compliance support.
For Investors and Strategic Buyers
-
Focus due diligence on software-enabled players and OEMs with clear electrification roadmaps and service ecosystems; these assets differentiate value beyond hardware.
-
Consider staged capital deployment tied to regulatory milestones and infrastructure rollouts to manage transition risk and preserve optionality.
What the Full PW Consulting Report Delivers
Beyond this executive preview, the full market study provides the operational detail required to execute 2026 strategies: market sizing and forecast models by vehicle type and application, supplier benchmarking with capability matrices, a scenario-based total-cost-of-ownership (TCO) engine for common duty cycles, regulatory impact models for major jurisdictions, and procurement playbooks for OEMs and fleets. Importantly, the full dataset includes the granular splits, unit shipment models, and pricing sensitivities that firms need to model deployment, yet are intentionally excluded from this preview to preserve the research’s proprietary value.
Final Advisory
For decision-makers planning 2026 investments, the message is clear: the TRU market is both growing and converging around a new set of success factors—regulatory compliance, electrification economics, service excellence, and supply-chain resilience. Acting early to secure the right mix of hardware, software, and partner agreements will convert regulatory risk into competitive advantage. PW Consulting’s full report equips executives with the data and playbooks to make those choices with confidence.
To convert this strategic preview into operational plans for 2026, stakeholders should prioritize scenario modeling tied to their specific route profiles, capital constraints, and compliance jurisdiction. Our team stands ready to run customized configurations derived from the full market dataset and to support procurement and fleet-transition roadmaps.
For detailed analysis of this topic, please visit the official page: Road Transport Refrigeration Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lignin Products Market to Top USD 978.1M by 2032 (4.28% CAGR)
By PW Consulting, 2026-07-12
Lignin Products Market: Strategic Intelligence for 2026 Decision-Makers
Executive preview
As sustainability continues to move from niche demand to mainstream procurement criteria, lignin — the largest renewable aromatic polymer on earth — is shifting from a low-value by-product to a platform feedstock for differentiated commercial applications. Our 2026-focused study positions lignin products as a steady-growth market: the global market is projected to expand from a base-year value in 2025 to just under one billion USD by 2032, growing at a compound annual growth rate of approximately 4.28% through the 2026–2032 forecast horizon. Market concentration is meaningful: the top three suppliers account for more than half of market share (CR3 ~51.5%), and the top five control roughly two-thirds (CR5 ~68.2%).
Lignin Products Market
This article summarizes the strategic value of the PW Consulting Lignin Products Market study for executives planning capital allocation, commercial launches, partnerships, or M&A in 2026. Following a “trailer” principle, we expose the analytical depth and commercial insights that underpin our recommendations while withholding the granular segmented tables and proprietary company-level revenue breakdowns — access to those is available in the full report.
Lignin Products Market
Why 2026 is an inflection year
-
Regulatory clarity is converging with commercialization readiness. Recent feed-safety certifications and re-authorisations in major jurisdictions have materially reduced regulatory execution risk for lignin in animal feed and related agricultural uses.
Lignin Products Market -
Technical maturation is enabling higher-value applications beyond traditional dispersants and binders. Oxidation and functionalisation pilots that reached demonstration scale in early 2026 are enabling formulations for performance markets such as adhesives, resins, and engineered rubber.
-
Industry consolidation and scale economics are creating space for premium differentiation. With a moderately concentrated supplier landscape, incumbents are leveraging backward integration, feedstock control, and technical partnerships to defend margin pools, while challengers focus on niche specialities or regional reach.
Market dynamics at a glance — what drives growth
-
Demand pull from sustainable product mandates and circularity targets. End-markets increasingly favour bio-based modifiers — especially in agriculture, building materials, and specialty chemicals — creating predictable demand corridors for lignin derivatives.
-
Feedstock and processing pathways determine product economics. Sulfite-based lignosulfonates and kraft lignin follow different downstream value maps; processing capital intensity and co-product integration drive differentiated margin outcomes for producers.
-
Regulatory and certification tailwinds unlock premium channels. Inclusion of lignin sulfonates on permitted organic production lists and recent feed certifications reduce go-to-market friction for agricultural applications and create near-term commercial expansion potential.
-
Scale and technology convert low value into specialty returns. Pilot plants for controlled oxidation and functional fillers represent the critical step to price segmentation: commodity lignosulfonates compete on volumes, while oxidized and engineered lignins target performance price premiums.
Competitive landscape — who matters and why
The competitive map is multi-modal: large integrated pulp and biochem players dominate supply, while specialized marketers and regional manufacturers win on distribution and formulation expertise. The report profiles established leaders and strategic challengers and assesses competitive positioning across four axes: feedstock control, downstream processing capability, route-to-market, and regulatory approvals.
-
Borregaard LignoTech (Sarpsborg, Norway) — A leader in lignosulfonates and lignin-based biopolymers with strong application knowledge in agriculture. Regulatory re-authorisations and product approvals in recent years reinforce their advantage in feed-related applications and institutional trust among buyers.
-
Domsjö Fabriker (Örnsköldsvik, Sweden) — Focused on sulfite lignin products with solid traction in agricultural binders and construction admixtures. Their product portfolio aligns with value chains that prioritize product performance and sustainability credentials.
-
UPM Biochemicals (Vantaa, Finland) — Moving beyond commodity lignin into engineered functional fillers; strategic product launches in partnership with downstream OEMs demonstrate a route to higher-margin, specification-driven markets.
-
Stora Enso (Helsinki, Finland) — Leveraging kraft lignin production and pulp integration to address wood panel resins, feed binders, and structural applications where vertical integration with forest raw material matters.
-
LignoStar International B.V. (The Hague, Netherlands) — A distribution and marketing specialist for calcium lignosulfonates; excels at channel development and formulation support for agricultural pellet binders and soil amendments.
-
Green Agrochem / LigninCorp (Beijing, China) — Regional champion focused on fertilizer binders, pesticide dispersants, and animal feed applications in high-volume agricultural markets; benefits from local downstream demand and nimble product promotion.
Recent developments underscore strategic vectors: feed safety certifications (e.g., Sappi Europe’s October 2024 certification) and Borregaard’s EU re-authorisation in 2024 reduce buyer hesitancy and open institutional procurement. UPM’s collaboration to demonstrate a tire concept shows how engineered lignins can penetrate performance supply chains. The VTT-supported LigniOx pilot that entered demo operation in early 2026 is representative of the step-change in technical capability that will dictate winners and losers over the next five years.
Commercial plays and where to focus in 2026
-
Agricultural formulations: Pellet binders, fertilizer dispersants, and soil amendments are near-term revenue drivers. Regulatory acceptance and demonstrable operational savings (e.g., lower pelleting energy, improved pellet durability) make this a pragmatic entry point for producers and formulators.
-
Construction and building materials: Admixtures and resin modifiers can absorb incremental value if performance parity or improvement can be proven in field trials — certification and standards alignment are pivotal.
-
Specialty chemicals and engineered fillers: Oxidized and functionalized lignins target adhesives, thermoset resins, and composite fillers. These require higher R&D intensity but can command meaningful price premiums and strategic OEM partnerships.
-
Geographic and channel plays: Scale-driven suppliers will defend commodity channels; smaller players and marketers will succeed by coupling technical service with localized distribution in fragmented agricultural markets.
-
M&A and strategic partnerships: Bolt-on acquisitions that add processing technologies (oxidation, fractionation), certification status, or channel access accelerate market entry without waiting for organic scale.
Risk map — what keeps executives up at night
-
Feedstock shifts: Changes in pulping mix or pulp industry economics can quickly alter supply abundance and relative pricing between sulfite and kraft-derived lignins.
-
Regulatory reversals or fragmented approvals: While recent certifications are constructive, variability across jurisdictions still creates go-to-market complexity for exporters and multinational buyers.
-
Technology scale-up risk: Demonstration plants reduce but do not eliminate execution risk for oxidation and functionalization pathways that underpin high-margin segments.
-
Competitive pricing pressure: Commodity segments remain price-sensitive; producers who cannot differentiate on function or cost efficiency will be exposed as the market evolves.
What the PW Consulting report delivers (practical content)
For executives needing to act in 2026, the full report supplies the following operational tools and deliverables:
-
Granular market sizing and forward-looking demand scenarios by source, product type and application (note: proprietary segment tables and regional splits are provided in the full report).
-
Supplier scorecards and revenue concentration analysis, including CR3/CR5 dynamics and supplier strategies.
-
Technical pathways assessment mapping process readiness, scale requirements, and unit economics for key upgrading technologies.
-
Regulatory matrix and certification playbook covering organic production lists, feed safety pathways, and region-specific compliance steps.
-
Go-to-market modules: channel design, pricing frameworks, sample commercial term sheets, and pilot-to-scale roadmaps.
-
M&A and partnership typology with prioritized acquisition targets and diligence checklists informed by primary interviews and plant-site data.
Actionable recommendations for 2026
-
Prioritise regulatory clearances and certifications as market-entry enablers. The commercial upside from feed and organic-channel approvals is immediate and measurable.
-
Invest in at least one pilot or demo partnership for oxidation/functionalization if targeting specialty markets. The ability to prove technical scalability will be a decisive differentiator.
-
Secure feedstock optionality and supply agreements. Controlling or hedging access to pulp streams increases resilience against pulp-market volatility and improves margin visibility.
-
Build downstream commercial capabilities rather than relying solely on commodity sales. Technical service, co-development with end-users, and tailored logistics unlock premium opportunities in agriculture and construction.
-
Use M&A selectively to buy capability: prioritize targets that deliver certification, customer access, or proprietary processing technology rather than only incremental volume.
Concluding note — the strategic value of our 2026 lens
For leaders considering capital deployment, commercial expansion, or portfolio rebalancing in 2026, the lignin products market offers a portfolio of opportunities with differentiated risk-return profiles. The market’s steady CAGR and near-term certification tailwinds create attractive windows for strategic moves, but victory will go to players who combine technical execution with commercial discipline and regulatory foresight.
PW Consulting’s full Lignin Products Market report contains the underlying datasets, segmented forecasts, supplier revenue estimates, and executable playbooks needed to convert insight into action. To review the complete segment tables, company revenue breakdowns, and bespoke scenario models, consult the full report on our website or contact PW Consulting for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Lignin Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Security Screening Systems Market to grow at 7.8% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Security Screening Systems Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations and public agencies re-evaluate physical security postures in the wake of shifting threat vectors, the Security Screening Systems market is transitioning from point solutions to integrated, data‑driven platforms. PW Consulting’s new market research—anchored on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon—shows a market that expanded from roughly USD 6.0 billion in 2020 to USD 8.5 billion in 2025 and is projected to grow at a 7.8% CAGR into the decade, approaching the mid‑teens of billions by 2032. For executives making procurement, R&D, and partnership decisions in 2026, the implications are clear: scale matters, but speed, integration capability and governance will determine who captures value.
Security Screening Systems Market
Why this research matters for 2026 strategy
-
Timing and investment planning: The reported 7.8% CAGR and the multi‑year trajectory provide planning envelopes for capital and operating budgets. Whether you are an airport authority contemplating checkpoint CT rollouts, a border agency evaluating non‑intrusive inspection (NII) capacity, or a systems vendor prioritizing product roadmaps, these macro trajectories set fiscal guardrails.
Security Screening Systems Market -
Vendor selection and competitive dynamics: The market remains meaningfully fragmented (our concentration metrics indicate the top three and top five firms together do not dominate the market), which creates both procurement choices for buyers and M&A optionality for vendors seeking scale.
Security Screening Systems Market -
Operational integration risk: The next wave of procurements prioritizes not only detection performance but the ability to integrate AI analytics, remote screening workflows, and cyber‑secure data handling—capabilities that separate platform leaders from legacy equipment suppliers.
High‑level market anatomy (what we reveal — and why we withhold)
Our analysis synthesizes the market’s overall growth, vendor concentration, regulatory environment and technology adoption patterns to produce forward‑looking strategic guidance. To preserve the tactical value of the full study for subscribers and clients, granular splits by region, product and application are deliberately withheld in this summary. What we do make available here are the decisive market forces, real‑world supplier moves and practical decision frameworks that will shape procurement and investment through 2026 and beyond.
Key market dynamics shaping decisions in 2026
-
Technology convergence: Computed Tomography (CT), advanced X‑ray, millimeter‑wave (mmWave) imaging, and AI‑enabled analytics are converging into interoperable screening platforms. Buyers increasingly evaluate systems for throughput, false‑alarm reduction via AI, and remote screening capability that enables centralized interpretation centers.
-
Regulatory and safety constraints: Radiation and RF safety standards remain binding design constraints for suppliers and buyers. For example, X‑ray full‑body screening systems are governed by effective dose limits; mmWave solutions are subject to RF exposure standards. Procurement teams must bake compliance testing and documentation into RFP requirements to avoid deployment delays.
-
Procurement follows funding cycles: Public‑sector allocations—such as the 2026 federal budget priorities for checkpoint CT systems—create time‑bound windows for large procurements. Private venue operators and infrastructure owners similarly concentrate upgrades around financing and capital planning cycles.
-
Data governance and cross‑border operations: Remote screening and centralized image interpretation introduce complex privacy and cybersecurity requirements. Deployments that transnationally transmit imagery must reconcile local data protection laws and the security protocols of receiving agencies—an issue underscored by recent international remote baggage screening implementations.
-
Service and lifecycle economics: Buyers are shifting attention from capital cost alone to total cost of ownership—service, spare parts, software subscriptions including AI model updates, and cybersecurity patches drive lifecycle economics and supplier lock‑in.
Competitive landscape — what strategic patterns we observe
The vendor ecosystem comprises legacy industrial OEMs, specialized imaging firms, and software‑centric entrants. Strategic moves over the past 18 months highlight three themes:
-
Platformization by legacy OEMs: Established imaging leaders continue to extend hardware portfolios with AI and remote screening services, creating vertically integrated offerings to lock in long‑term service and analytics revenue.
-
Order flow and contract wins: Mid‑sized inspection specialists are capitalizing on high‑volume, near‑term procurements for cargo and vehicle inspection, underscoring the importance of a service footprint and rapid deployment capabilities.
-
Strategic alliances and consolidation: Expect continued JV formation and partnerships that pair imaging hardware with enterprise software and systems integration capabilities to offer turnkey detection ecosystems.
Illustrative vendor signals (recent developments and strategic implications)
-
Operationalized remote screening: A leading UK‑based OEM recently deployed an international Remote Baggage Screening System connecting airports and government agencies, demonstrating the operational feasibility—and compliance complexity—of cross‑border image transmission. For buyers and system integrators, this is a proof point for remote models; for privacy officers, it is a reminder to harden data protection and access controls.
-
Contract momentum among NII specialists: Several recent multi‑million dollar orders for cargo and vehicle inspection systems reflect durable demand from logistics and border security stakeholders. Vendors that couple hardware with rapid commissioning and local lifecycle support gain an advantage in these procurements.
-
Alliance‑driven product development: A newly announced joint venture between a systems integrator and an imaging specialist signals a trend toward combining enterprise software, analytics and advanced imaging technologies into unified offerings—shortening time‑to‑market for solutions that meet enterprise‑grade IT and security requirements.
Operational and procurement recommendations for 2026
-
Adopt a platform‑first evaluation: Prioritize suppliers offering modular, software‑driven architectures that decouple hardware refresh from analytics subscriptions. This reduces future rip‑and‑replace risk while enabling continuous performance improvements via AI updates.
-
Embed compliance and cyber in the RFP: Require demonstrable adherence to radiation and RF safety standards, and demand third‑party cybersecurity attestations and data‑handling procedures for any remote screening capability.
-
Model true lifecycle costs: Build TCO models that include software licensing, model retraining, remote monitoring, service SLAs and parts availability. Use scenario analysis to stress‑test budgets against higher‑than‑expected service demand and supplier consolidation risk.
-
Pilot with measurable KPIs: Shortlist vendors for pilot deployments with prespecified throughput, detection efficacy and false alarm metrics, plus operational KPIs for integration effort and latency for remote interpretation workflows.
-
Prioritize suppliers with local service networks: For border and cargo inspection, local commissioning and spare‑parts logistics materially affect uptime—an essential consideration when evaluating bids.
-
Prepare for procurement windows tied to public budgets: Map capital budgets and single‑point regulation changes (e.g., checkpoint CT allocations) to procurement timelines to avoid missing critical funding cycles.
Risk map — what could derail plans
-
Regulatory tightening: Changes in safety or data laws can increase compliance costs or necessitate hardware redesigns.
-
AI performance variability: Overreliance on vendor‑provided AI without in‑house validation frameworks can expose programs to detection degradation in the field.
-
Vendor concentration shifts: Although current concentration metrics indicate space for competition, selective consolidation or strategic partnerships could shift bargaining power and increase switching costs.
-
Supply‑chain and geopolitical constraints: Hardware components and cross‑border service models are sensitive to trade and export controls; contingency sourcing is prudent.
What the full PW Consulting study contains (practical deliverables)
The comprehensive report equips leaders with a playbook to act in 2026 and includes:
-
Detailed market forecast models and scenario analyses through 2032, with sensitivities tailored to funding, regulatory and technology adoption pathways.
-
Vendor scorecards and capability maps that assess imaging performance, AI maturity, service footprint, integration APIs, and cyber/data governance posture.
-
Procurement templates—RFP language, compliance checklists, pilot KPI definitions and TCO modeling templates—to accelerate decision cycles and reduce procurement execution risk.
-
Hands‑on guidance for pilots and scale deployments, including integration sequencing, data sovereignty playbooks, and governance frameworks for remote screening operations.
-
Strategic M&A and partnership playbooks outlining where scale, capabilities and geographic reach create the best value for acquirers and partners.
Concluding guidance — a practical checklist for Q1–Q2 2026
-
Map your immediate capital availability against the market’s growth trajectory and funding windows relevant to your sector.
-
Shortlist vendors based on integration readiness and evidence of operational deployments—not only lab performance.
-
Require transparent AI validation and an auditable data governance framework as non‑negotiable contract elements.
-
Plan pilots with rapid decision gates tied to measurable reductions in false alarms and lifecycle cost projections.
-
Assess M&A or JV opportunities to accelerate capability acquisition versus organic development where time‑to‑market is critical.
PW Consulting’s Security Screening Systems Market study provides the quantitative backbone and the executable playbooks to make those checklist items operational. For access to the full dataset—including regional and product breakdowns, vendor market shares, and downloadable procurement templates—consult the full report or contact our advisory team to arrange a bespoke briefing and scenario run for your organization.
For detailed analysis of this topic, please visit the official page: Security Screening Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Torsional Vibration Damper Market at USD 1,800M in 2025, 5.5% CAGR
By PW Consulting, 2026-07-12
Torsional Vibration Damper Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a focused, decision-oriented briefing on the global torsional vibration damper (TVD) market. This is the executive “trailer” for our full market research: you will find rigorous frameworks, actionable implications and evidence-based directionality here — but selective numerical detail from core segment tables is intentionally withheld to preserve the urge to access the full report for definitive project-level inputs.
Torsional Vibration Damper Market
Market snapshot (base year 2025; forecast 2026–2032)
-
Historical base: our tracked period (2020–2025) shows a recovery and accelerating demand profile, with total market size rising from roughly USD 1.2 billion in 2020 to USD 1.8 billion in the 2025 base year.
Torsional Vibration Damper Market -
Outlook: the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.5% over the 2026–2032 forecast window, reaching roughly USD 2.8 billion by 2032 under the central scenario.
Torsional Vibration Damper Market -
Concentration: the market remains moderately fragmented; the three- and five-firm concentration ratios indicate that specialist OEM suppliers and integrated powertrain suppliers coexist — offering both differentiated technology and aftermarket scale. This structural profile creates opportunity for technology-driven consolidation and targeted partnerships.
Why this matters for corporate decision-making in 2026
-
R&D and product roadmaps: as internal combustion engine (ICE) architectures evolve (downsizing, higher specific torque) and hybrid powertrains proliferate, torsional dynamics become more complex. Firms must prioritize multi-mode damping solutions and material science investments now to avoid late-cycle rework.
-
Procurement and raw-material strategy: volatility in petrochemical markets has materially impacted elastomer and silicone-fluid costs. Strategic sourcing, hedging contracts, and qualification of material substitutes will determine margin resilience through 2026 and beyond.
-
Aftermarket vs. OEM playbook: aftermarket demand remains a stabilizer for suppliers facing compressed OEM pricing. Decisions on channel focus, inventory allocation and warranty exposure will affect near-term cash generation and long-term OEM leverage.
-
M&A and partnership targeting: given moderate concentration levels, bolt-on acquisitions of niche viscous or elastomer specialists — or JVs with precision spring/steel manufacturers — can buy technology differentiation faster than greenfield development.
-
Regulatory and NVH compliance: accelerating noise, vibration and harshness (NVH) and emissions certification protocols are increasing test and validation overheads. Capital allocation for testing labs and early-stage certification support is a 2026 must.
What the full report contains — practical, transaction-ready deliverables
-
Actionable market sizing and modeling: up-to-date total market and dynamic forecast models (adjustable inputs for fuel mix, global vehicle production scenarios, and aftermarket consumption) that plug directly into corporate planning tools.
-
Scenario analysis and sensitivity tables: three stress-tested scenarios (baseline, downside commodity-shock, and accelerated electrification) with P&L and working-capital impacts for supplier and OEM archetypes.
-
Supply-chain risk map: tiered supplier heatmaps, single-source dependency flags, and lead-time variability scores to prioritize dual-sourcing and qualification programs.
-
Technology readiness and IP landscape: comparative assessment of elastomeric, viscous and spring-based architectures, roadmap timing for multi-stage solutions, and inventor/portfolio mapping for M&A screening.
-
Competitive benchmarking toolkit: supplier scorecards across cost-to-produce, quality/qualification heritage, OEM presence, aftermarket channels and service capability — ready for vendor negotiations.
-
Commercial playbooks: win themes for OEM tenders, aftermarket bundling options, pricing levers and warranty covenant templates proven in recent negotiations.
-
Integration checklists for M&A and JV: operational due-diligence checklists emphasizing validation labs, test rigs, and elastomer chemistry quality systems.
Competitive landscape — who matters and why
The TVD supplier landscape combines large integrated powertrain suppliers and focused specialists. The following profiles are oriented to strategic posture rather than exhaustive corporate disclosure:
-
Vibracoustic SE — a technology leader in pressed and vulcanized elastomer and fluid dampers, with strong OEM and aftermarket channels. Recent advancements in multi-stage elastomer engineering (announced early 2026) indicate an intent to reframe multi-frequency damping for downsized, high-torque applications.
-
Vibratech TVD (Fluidampr) — renowned for viscous/fluids-based dampers and a strong presence in high-performance, off-highway and stationary-power segments. Their recent technical webinar underscores a capability to optimize viscous damping for hybridized torque profiles.
-
Schaeffler AG — pursues centrifugal-pendulum absorbers and arc-spring solutions embedded into transmissions, targeting powertrains where compactness and shift-quality are critical.
-
ZF Friedrichshafen AG — leverages dual-mass flywheel know-how to provide integrated decoupling systems with deep transmission integration expertise.
-
Continental AG — combines broad OEM access with a competitive aftermarket franchise, positioning for cross-selling NVH packages.
-
Hasse & Wrede GmbH — a global leader for viscous shear dampers in heavy-duty engines and compressors; active product introductions and system integrations for reciprocating compressors have reinforced their sectoral dominance.
-
Dayco Incorporated — aftermarket-focused, expanding severe-duty portfolios in response to specific heavy-duty engine platforms and fleet requirements.
-
American Engineering Group (AEG) , Geislinger GmbH , BorgWarner Inc. , Trelleborg AB , Valeo SA , Sumitomo Riko and LuK GmbH — each contributes distinct competencies from dual-elastomer systems to tuned steel-spring dampers and integrated driveline solutions. Collectively they shape the competitive set for OEM contract bids and aftermarket coverage.
Recent industry activity is instructive: Vibratech’s September 2025 webinar signaled heightened OEM interest in viscous solutions tailored for downsized high-torque ICEs and hybrids; Vibracoustic’s February 2026 product unveiling confirms elastomer multi-stage commercialization is accelerating; Dayco and Hasse & Wrede’s 2025 product initiatives illustrate continuing investment in severe-duty and compressor-specific applications. These moves highlight supplier strategies of product differentiation, channel expansion and vertical specialization.
Market dynamics and risk accelerators
-
Raw-material volatility: engineered elastomers and silicone-based fluids are sensitive to petrochemical price swings. Cost pass-through mechanisms are limited in OEM contracts, creating potential margin squeeze for suppliers without hedging strategies or material substitutes.
-
Regulatory tightening: NVH and emissions testing protocols are intensifying — in several mature markets regulatory testing burdens have been increasing at near-double-digit rates. This raises certification costs and extends lead times for new damper introductions.
-
OEM price pressure: sustained price-reduction programs in high-volume automotive contracts compress supplier margins; scale and differentiation are increasingly decisive competitive advantages.
-
Technology transition: electrification and hybridization change torsional-frequency spectra and torque-management requirements. While full BEV architectures reduce some damper needs, hybrid systems and high-efficiency ICEs expand demand for specialized damping — creating non-linear winners and losers by segment.
Practical 90/180/365-day actions for executives
-
90 days: run a targeted supplier risk audit (top five critical parts), initiate raw-material hedging conversations, and prioritize qualification slots for alternative elastomer suppliers.
-
180 days: field-test multi-stage prototypes with prioritized OEMs and fleet partners; mobilize aftermarket bundling pilots on two geographic platforms to stabilize aftermarket revenue.
-
365 days: execute one inorganic play (bolt-on viscous or elastomer competency) or formalize a technology JV; lock in certification roadmaps for new NVH/emissions requirements and embed test-lab investments into capital planning.
Closing provocation — what this briefing does not disclose (and why)
We have deliberately presented the strategic architecture, competitive map and operational playbooks while omitting the granular split tables that drive deal-level valuations (regional and application-specific revenue bridges, tiered margin models and segment-level unit economics). These core datasets — including fully modeled regional and application segmentation, vendor-specific revenue allocations and granular pricing matrices — are included in the full PW Consulting report and are essential for transaction diligence, sourcing RFPs and capex allocation decisions.
To convert the directional advantages outlined above into executed decisions in 2026, access to the full data pack and vendor scorecards is necessary. PW Consulting’s full TVD market study contains the downloadable models, supplier scorecards and bespoke scenario runs you will deploy in boardrooms, procurement negotiations and R&D portfolio meetings.
For an accelerated readout or to commission custom modeling keyed to your product, region or OEM portfolio, please contact PW Consulting’s industry research team via our corporate research page to obtain the full report and supporting datasets.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Boat Insurance Market Forecasted at 5.85% CAGR Through 2032
By PW Consulting, 2026-07-12
Boat Insurance Market — 2026 Strategic Prelude
As organizations map their 2026 strategic agendas, the boat insurance segment presents a blend of steady expansion, concentrated competitive dynamics, and policy-driven inflection points that require deliberate, data-backed responses. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — positions the market at approximately USD 335 million in 2025 and forecasts growth at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon, guiding the market toward roughly USD 475 million by 2032. This briefing synthesizes the strategic implications of those macro trends and previews the practical deliverables embedded in the full report, while intentionally reserving the granular splits and proprietary scenario outputs for subscribers.
Boat Insurance Market
Market trajectory: steady expansion with concentrated supply
Between 2020 and 2025 the market demonstrated durable expansion driven by a mix of recreational demand recovery and steady activity in commercial marine segments. That momentum continues into the forecast window and is underpinned by two structural features that will shape 2026 decisions.
Boat Insurance Market
- Growth momentum: The mid-single-digit CAGR reflects predictable, insurance-driven uplift rather than episodic boom — a profile that favors disciplined underwriting and incremental product innovation over speculative capacity expansion.
- Concentration dynamics: Market share is clustered among a small number of incumbents, creating a landscape in which three firms account for a majority slice of business while the top five extend that dominance further. These concentration metrics raise the stakes on distribution control, pricing power, and product differentiation for both incumbents and challengers.
Where demand and risk meet: drivers insurers must model in 2026
Underwriting profitability in the near term will hinge on how carriers adapt to four interlocking drivers:
Boat Insurance Market
- Climate and extreme weather exposure: Insurers face rising storm and surge volatility in coastal corridors. Reinsurance cost pressures and episodic losses are already being reflected in pricing actions across high-exposure geographies.
- Regulatory interventions: New state-level mandates altering minimum liability requirements or proof-of-insurance regimes will reshape addressable risk pools and distribution friction. For example, recent legislative activity in certain jurisdictions is increasing the minimum liability coverage required for certain classes of watercraft — a change that has immediate implications for product design and compliance workflows.
- Distribution evolution and consumer behaviors: Digital-first quoting, membership-based models, and bundling with auto/home lines continue to change customer acquisition economics. Average annual premiums for many recreational buyers remain modest, making scale and cost-to-serve a critical profitability lever.
- Segmentation of fleet economics: Commercial operations such as fishing and shipping display different loss drivers and lifetime values than the recreational segment; translating that into differentiated underwriting scorecards and premium architectures is a near-term imperative.
Competitive landscape: strategic postures and playbooks
The competitive field includes long-established multiline insurers, specialty marine underwriters, and nimble insurtech entrants. The incumbents’ public positioning and recent moves illuminate likely strategic plays for 2026:
- Large multiline carriers (digital scale + bundling): Organizations with established auto and homeowners footprints leverage cross-sell and digital quote engines to reduce acquisition costs. Expect continued focus on streamlined purchasing journeys and integrated policy bundles targeting customers whose boats are insured alongside other household assets.
- Specialty carriers and MGAs (product depth + bespoke underwriting): Firms that emphasize yacht and commercial vessel capabilities maintain underwriting flexibility, tailored endorsements, and loss-mitigation services. Their strength is customization for higher-value craft and complex liability exposures.
- Insurtechs and program managers (speed + niche focus): New entrants are proving the value of focused product innovation, rapid expansion into high-potential states, and partnerships with distribution platforms. Recent market moves show targeted geographic expansion into major boating markets and tailored admitted/excess capacity strategies.
Sample company archetypes reflected in the market: consumer-focused online quoters; fleet and commercial specialists; high-net-worth yacht underwriters; and membership-oriented providers leveraging partner underwriters. Each archetype implies different investment priorities — from scale-oriented digital marketing to actuarial investments in catastrophe modeling.
Regulation and pricing: tactical consequences for product teams
New regulatory actions imposing minimum liability limits or proof-of-insurance at registration points materially change the distribution environment. Where jurisdictions introduce mandatory liability thresholds, expect a structural uplift in addressable premium and administrative complexity around registration and enforcement. Simultaneously, data indicates that in coastal-intensive markets insured premiums are already experiencing meaningful upward pressure as reinsurers reprice catastrophe exposure. Together, these forces create both risk and opportunity: higher premiums can improve margins if loss ratios are managed, but they can also accelerate customer churn if carriers fail to articulate clear value.
Actionable playbook for 2026
Insurers and investors should prioritize a balanced program of quick wins and strategic investments. PW Consulting’s practical recommendations include:
- Short-term (0–12 months): Reprice exposures in high-frequency coastal corridors; launch targeted marketing for homeowners-to-boat cross-sells; implement claims triage automation to contain loss adjustment expense; and update compliance checklists for new state liability mandates.
- Medium-term (12–36 months): Invest in refined catastrophe and hull risk models, develop parametric storm cover options to accelerate claims payment, expand program distribution partnerships with marina groups and OEMs, and pilot telematics/usage-based endorsements for high-value recreational craft.
- Capital and reinsurance: Reassess reinsurance attachment strategies in light of rising coastal volatility; consider layered protections and alternative capital instruments to smooth earnings and support competitive quoting in peak seasons.
- M&A and partnerships: Use a market-concentration-informed approach to evaluate tuck-in acquisitions that enhance distribution or modeling capabilities; deploy minority investments to secure distribution exclusivity with tech platforms or membership organizations.
What the full PW Consulting study delivers — practical, executable intelligence
The depth of the full report is designed for decision-makers who need executable outputs rather than academic summaries. Highlights include:
- Proprietary market sizing and validated historical trajectory from 2020–2025, plus scenario-based forecasts to 2032 that stress-test demand under varying climate, regulatory, and economic permutations.
- Competitive playbooks and capability benchmarks tied to public and private players — mapping which organizations compete on price, product breadth, or service-led differentiation.
- Practical underwriting tools: scorecards, loss-driver matrices, and a claims-operations checklist tailored to recreational, commercial fishing, and commercial shipping classes.
- Regulatory impact models that quantify the operational and premium implications of recent and proposed state statutes, including proof-of-insurance mechanics and minimum liability changes.
- Pricing sensitivity and profitability dashboards that allow scenario toggling for premium elasticity, reinsurance cost shocks, and claim frequency shifts.
- M&A target shortlist and diligence templates keyed to market concentration dynamics, integration risk, and near-term premium accretion potential.
- Implementation roadmaps and KPI scorecards for the first 24 months post-launch of new products or distribution initiatives.
Strategic takeaways for 2026 planning
For executive teams setting 2026 priorities, our analysis yields three clear strategic imperatives:
- Control distribution economics. Scale-enabled distribution and low acquisition cost remain the strongest defensive moats. Whether by bundling, digital direct-to-consumer channels, or exclusive program agreements, reducing cost-to-acquire is a primary lever on 2026 P&Ls.
- Differentiated risk selection and product innovation. With premium pressure rising in exposed geographies, carriers that can segment more accurately, offer parametric options, or underwrite fleet exposures with precision will hold the margin advantage.
- Proactive regulatory readiness. Anticipate and operationalize around state-level liability changes and registration enforcement. Carriers that can seamlessly validate coverage at point-of-registration or offer compliant product wrappers will capture displaced buyers and reduce frictional churn.
Why this study matters now
As 2026 planning cycles compress, leadership teams need more than broad directional insight — they need templates, tested scenarios, and competitor intelligence that directly feed underwriting models and GTM plans. PW Consulting’s research is structured to convert market forecasts and concentration analytics into prioritized actions: where to reprice, where to underwrite, whom to partner with, and which regulatory shifts to treat as strategic opportunities rather than compliance costs.
For decision-makers seeking the underlying segment-level data, regional demand curves, and the full set of proprietary modelling outputs that informed this strategic synopsis, the complete report and its annexes contain the granular intelligence required to operationalize these recommendations. Access to those proprietary splits, scenario models, and deal-level diligence materials is available via our full report portal.
In an environment where policy change, climate exposure, and digital distribution converge, the 2026 winners will be those who translate macro trends into tight underwriting action plans, nimble distribution plays, and defensible product differentiation—before premium cycles force reactive moves. PW Consulting’s Boat Insurance Market study is designed to be that bridge from insight to execution.
For detailed analysis of this topic, please visit the official page: Boat Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Data Centers to Hit USD 109.88B by 2032 at 17.11% CAGR
By PW Consulting, 2026-07-12
Modular Data Centers Market: Strategic Imperatives for Enterprise Decisions in 2026
Executive snapshot
The modular data center market is entering a phase of accelerated maturation and strategic importance for enterprise IT and infrastructure planners. From a historical footprint that expanded from 16.51 Billion USD in 2020 to 36.37 Billion USD in the base year of 2025, our forecast shows continued rapid expansion through the 2026–2032 horizon—reaching 109.88 Billion USD by 2032 at a compound annual growth rate of 17.11% (revenue unit: Billion USD, currency: USD). For C-suite leaders and infrastructure decision-makers preparing 2026 budgets and roadmaps, this trajectory creates a set of discrete opportunities and measurable risks: speed-to-service, modular scalability for AI/HPC, supply-chain resilience, and regulatory and standards-driven compliance requirements.
Modular Data Centers Market
Why 2026 is an inflection point
- AI-driven demand intensity: The performance and density requirements of modern AI and HPC workloads are reshaping what “modular” must deliver—higher power density per rack, integrated liquid-cooling options, and factory-integrated IT stacks ready for rapid turn-up.
- Edge and distributed deployments: Enterprises and service providers are shifting from purely centralized builds to distributed modular footprints that reduce latency and expand availability while lowering time-to-market.
- Standards and safety converge: Recent updates to safety and performance frameworks (notably the revised UL 2755 outline for prefabricated modular systems) and community-driven standardization efforts such as Open Compute Project’s modular sub-project are creating clearer technical baselines—reducing vendor lock-in risk but increasing the compliance bar for providers.
- Commercial consolidation with room for niche leaders: Market concentration metrics show that the top three firms hold a meaningful share (~42.5% CR3) and the top five ~55.2% (CR5), signifying a landscape where scale matters but specialized capabilities and speed-to-market still create advantage for agile suppliers and system integrators.
- Supply-chain and construction economics: Prefabrication and factory-controlled fabrication reduce onsite labor and schedule risk in regions with constrained labor supply and logistics challenges—making modular deployments a preferred risk-managed route for many projects.
What PW Consulting’s Modular Data Centers Market study delivers
- Precision market sizing and a transparent forecast model (base year 2025; historical coverage 2020–2025; forecast 2026–2032) that incorporates demand drivers across cloud, colocation, edge, and enterprise segments.
- Practical decision frameworks for procurement, site selection, and vendor qualification that tie technical choices (cooling architecture, prefabrication level, power distribution topology) to financial KPIs.
- Vendor capability mapping and competitive scenario analysis—covering product roadmaps, integration risk, deployment velocity, and after-sales support models—structured to support RFP and pilot-selection processes.
- Regulatory and standards impact assessment (UL 2755:2025, OCP modular efforts) and a compliance checklist to accelerate approvals and insurance underwriting.
- TCO and ROI templates that model capex/opex trade-offs under different density, utilization, and energy-price scenarios—delivering an enterprise-grade view of breakeven horizons for modular versus traditional builds.
- A risk-adjusted route-to-deployment playbook that addresses supply-chain volatility, factory acceptance testing (FAT) best practices, and commissioning timelines for AI/HPC and edge workloads.
Note: The report contains granular segment-level data and proprietary split analyses that are not published in this prospectus. Access to the full dataset and interactive models is available via our research portal.
Modular Data Centers Market
Competitive landscape — strategic signals to watch
The modular market is being shaped by a mix of global infrastructure incumbents, systems integrators, and specialized modular fabricators. Strategic buyers should watch three broad vendor archetypes: scale integrators with end-to-end lifecycle services, engineering-centric suppliers with deep factory-prefab capabilities, and high-velocity providers focused on AI/edge time-to-service.
Modular Data Centers Market
- Vertiv (Lewisville, Texas) — Vertiv’s prefabricated modular solutions emphasize integrated power, cooling, and IT modules targeted at AI/HPC and high-density applications. Their modular megawatt-scale approach is designed for rapid scaling; enterprises targeting high-density clusters should evaluate Vertiv for turnkey performance and global service footprints.
- Schneider Electric (Boulogne-Billancourt, France) — Schneider’s EcoStruxure modular offerings prioritize adaptable designs for heterogeneous environments. Their strength lies in management integration and broad systems compatibility—an advantage for enterprises seeking a standardized control plane across multiple sites.
- ABB (Zurich, Switzerland) — ABB positions itself around modular, scalable solutions that accelerate colocation deployment and ROI. Their industrial automation expertise can be decisive where flexible power and distribution schemes are key to phased growth.
- Eaton (Dublin, Ireland) — Eaton’s SmartRack modular solutions marry rack-level integration with power and cooling enclosures. A recent product expansion (Jan 2026) in collaboration with Flexnode targeted rapid AI factory deployments, claiming significant compressions in deployment schedules—a strategic signal for buyers needing fast, validated rollouts.
- Flex (Sunnyvale, California) — Flex’s pre-engineered AI infrastructure platforms emphasize accelerated deployment timelines (vendor claims of up to ~30% faster delivery). Their strength is in manufacturing scale and integration velocity for compute, power, and cooling.
- Dell Technologies (Round Rock, Texas) — Dell’s modular approaches focus on modularized racks and integrated compute stacks for edge and high-density contexts, useful where vendor-managed compute and infrastructure lifecycle services are required.
- M.C. Dean (Alexandria, Virginia) — M.C. Dean brings specialized rack and overhead electrical configuration expertise and has strengthened its IP portfolio (patent issuance for a modular support rack system in mid-2026), making them an attractive partner for large campus or distributed installations with complex cabling and electrical requirements.
- Haskell Modular Solutions (Greenville, South Carolina) — Haskell’s factory-controlled fabrication model supports highly customized modular builds with predictable quality and shortened onsite schedules—an option for enterprises with bespoke site constraints.
Recent product and standards developments to factor into vendor selection
- Eaton’s January 2026 expansion (product collaboration with Flexnode) signals continued vendor focus on rapid AI deployment stacks and compressed schedule guarantees; buyers should insist on validated FAT outcomes and SLA-backed delivery timelines.
- Vertiv’s 2025 OneCore announcement highlights an industry trend toward modular architectures that scale from megawatt to hyperscale blocks optimized for AI/HPC; technical interoperability and cooling choices will define performance differentials.
- Siemens’ mid-2025 turnkey edge announcement underscores the growing marketplace for fully integrated, rapid-deployment edge modules suited to both permanent and interim operations.
- Regulatory and standards shifts (UL 2755:2025; OCP modular sub-project) are tightening the compliance envelope—enterprises should require vendor certification and third-party verification as part of procurement criteria.
Operational playbook for procurement and deployment in 2026
- Define workload-first requirements: quantify power-per-rack, expected scaling cadence, and service-level needs tied to application classes (AI training, inference, latency-sensitive edge services).
- Prioritize factory acceptance and modular integration testing: require FAT reports, documented thermal and acoustic performance, and validated interconnect tests for multi-module clusters.
- Embed standards and compliance clauses: ensure vendor commitments to current safety outlines and to any relevant OCP or interoperability frameworks.
- Contract for schedule and risk: include milestone-based payments, liquidated damages for deployment slippage, and options for phased scalability tied to business KPIs.
- Mitigate supply-chain volatility: diversify module suppliers for critical components, secure long-lead items under separate contracts, and evaluate local assembly hubs where lead times or logistics are constraining.
Financial considerations and TCO framing
With the market expanding at a high-teens CAGR and total addressable demand moving toward triple-digit billions by 2032, enterprises must reframe capital planning around modularity as a financial lever: faster time-to-service converts to earlier revenue capture or operational savings; factory-quality controls reduce rework and change-order risk; and standardized modules simplify long-term maintenance and part-procurement. Our report provides scenario-based TCO models that translate density, utilization, and energy-efficiency choices into payback timelines and NPV sensitivities—valuable inputs for 2026 capital allocation and site-portfolio strategies.
Key strategic questions for the C-suite in 2026
- Are we optimizing for speed-to-market (prefabricated/all-in-one modules) or for highest possible customization and futureproofing?
- How will our AI/HPC roadmap change rack-level power, cooling, and footprint requirements over the next 24–48 months?
- Do our procurement and contracting templates require updates to capture factory acceptance, interoperability certification, and regulatory compliance for modular systems?
- Which vendors align to our geographic, lifecycle, and service objectives—do we need vendor diversity to manage concentration risk?
- Have we stress-tested capital plans against the high-growth scenario reflected in market forecasts to 2032, and what is our phased investment trigger?
Conclusion: 2026 will be a year of decisive builds and strategic pilots. The modular data center market’s strong growth profile (17.11% CAGR across 2026–2032) and accelerating product innovation create an environment where early, well-structured decisions can materially alter an enterprise’s infrastructure cost curve and service agility. PW Consulting’s full Modular Data Centers Market report contains the segment-level insights, vendor scorecards, financial models, and procurement templates needed to convert the macro opportunity into executable 2026 programs. For access to the complete dataset, interactive models, and procurement playbooks, please refer to our research portal.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bike Racks Market — Strategic Outlook for 2026: A PW Consulting Brief
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a concise strategic introduction to our full Bike Racks Market research suite. The market has demonstrated steady, resilient growth through the first half of the decade — expanding from roughly USD 1.2 billion in 2020 to about USD 1.64 billion by the 2025 base year — and is forecast to continue this trajectory into the next planning horizon, reaching close to USD 2.5 billion by the end of the 2026–2032 forecast window at a compound annual growth rate of 6.2%. For corporate leaders preparing capital allocation, product roadmaps, or M&A strategies in 2026, this report crystallizes where value will appear and which operational and regulatory levers must be managed to capture it.
Bike Racks Market
Why this research is a must-read for 2026 strategic decisions
-
Market momentum is measurable and multifaceted. Growth is being driven by urban cycling infrastructure investments, accelerating adoption of e-bikes, shifting consumer preferences for active leisure, and continuing demand from vehicle-mounted transport solutions for both recreational and utility use.
Bike Racks Market -
Timing matters. 2026 is the inflection point for firms that must convert steady market growth into durable share gains. The next 18–24 months are the window for refining product portfolios, securing strategic partnerships, and locking in public procurement and OEM relationships to benefit from the mid-cycle upswing.
Bike Racks Market -
Risk and regulatory hygiene are non-negotiable. Recent safety campaigns and recall events have raised the bar for compliance and aftermarket support. Companies that anticipate these pressures and translate them into product design, quality assurance, and communication strategies will preserve brand equity and protect margins.
What the PW Consulting report delivers — practical, decision-ready content
-
Robust market sizing and demand models calibrated to 2020–2025 historical data and disaggregated forecasts for 2026–2032 — enabling financial planning and TAM/SAM/SOM exercises for new product launches and geographic expansion.
-
Go‑to‑market playbooks tailored to commercial (public/institutional), consumer aftermarket, and OEM channels — including pricing archetypes, margin ladders, and distribution economics.
-
Competitive benchmarking and capability maps that assess product portfolios, manufacturing footprint, distribution reach, and channel strategies for the leading suppliers in the space.
-
Supply chain and cost‑to‑serve analysis that identifies commodity exposure, single‑source vulnerabilities, nearshoring opportunities, and inventory strategies to preserve service levels during demand spikes.
-
Regulatory and standards navigator — practical checklists and testing roadmaps for compliance with dynamic safety and certification regimes (including authoritative vertical fatigue and dynamic testing standards), plus a mitigation playbook for recall scenarios.
-
Scenario-based strategic options and M&A target screens — from tuck‑ins that fill technical gaps (e.g., lightweight materials, e‑bike load systems) to roll‑up strategies in fragmented subsegments.
-
Actionable implementation roadmaps covering product R&D priorities, service & warranty frameworks, and five prioritized strategic initiatives for 12‑ and 36‑month horizons.
Competitive landscape — profile and strategic implications
The competitive set spans specialist commercial suppliers, consumer-oriented equipment brands, and vehicle-transport specialists. Key players include Madrax, RockyMounts, Dero, Thule, Kuat, Yakima, Saris, Hollywood Racks, North Shore Racks, Wagner Companies, Huntco, and SteadyRack. Each brings differentiated strengths:
-
Commercial parking and municipal-focused providers (examples: Madrax, Wagner Companies, Huntco) dominate infrastructure engagements with product lines engineered for durability, anti-theft features, and ease of installation across public works projects.
-
Aftermarket vehicle-mounted specialists (examples: Thule, Yakima, Kuat, RockyMounts, Saris, Hollywood Racks, North Shore Racks) compete on fit-for-vehicle integration, installation speed, and accessory ecosystems. Premium engineering and integrated locking/security features are primary purchase drivers for higher-margin segments.
-
Innovative niche suppliers (examples: Dero, SteadyRack) are expanding into adjacent installation and storage solutions, offering two-tier and space-saving systems targeted at multifamily, workplace, and institutional buyers.
Strategically, the market remains sufficiently fragmented that targeted product differentiation, channel prioritization, and service commitments can convert modest share gains into meaningful revenue growth. Firms with scale in manufacturing and distribution can still amplify returns by reducing lead times and increasing aftermarket revenue through accessories, spare parts, and maintenance contracts.
Regulation, safety and standards — risk and opportunity
-
Recall and safety events have been salient industry signals. Recent national safety campaigns and product recalls tied to latch mechanisms and pivot hardware have imposed direct costs on manufacturers and eroded consumer confidence for some brands. These events make robust validation programs and traceable supply chains essential corporate priorities.
-
Compliance with validated test standards — particularly vertical dynamic fatigue and related mechanical performance tests — is increasingly referenced in procurement specs and commercial tenders. Proactive certification is now a procurement prerequisite in many institutional contracts.
-
Regulatory scrutiny creates a competitive advantage for companies that can demonstrate superior test credentials, rigorous supplier audits, and rapid-response aftermarket service operations. Conversely, firms that deprioritize quality assurance risk product withdrawals, warranty liabilities, and reputational damage.
Market dynamics and product trends shaping 2026 decisions
-
E‑bike proliferation: Higher average bike mass and new battery‑carry requirements are reshaping product design criteria. Buyers increasingly demand racks and carriers explicitly rated for e‑bike loads as a baseline feature.
-
Vehicle electrification and range sensitivity: Lightweight materials and aerodynamic packaging for roof-mounted systems are more valued as EV adoption increases, influencing material and product engineering priorities.
-
Urban infrastructure funding: Local and regional grant programs (a recent example being school-route and community-safe-routes grants awarded in 2025–2026) are accelerating public procurement cycles for commercial bike parking — a predictable source of near-term volume for compliant suppliers.
-
Product innovation cadence: Leading consumer brands continue to iterate quickly (notably product launches and previews from major platform players), increasing emphasis on modularity, tool-free installation, and integrated security features.
Priority strategic moves for 2026
-
Certify for tomorrow, not yesterday: Prioritize conformance to recognized dynamic and fatigue standards across new product introductions and retrofit kits. This lowers bid rejection in institutional procurement and shortens sales cycles.
-
Design for e‑bike realities: Re-engineer hitch and roof platforms for higher static and dynamic loads, and offer clearly documented user instructions and compatibility guides to reduce misuse and liability.
-
Lock in public-sector flows: Build a targeted procurement funnel for grant-funded programs and municipal tenders. Establish pre-qualified vendor status and templated compliance packages to accelerate contract awards.
-
Service as a differentiator: Create bundled service agreements, spare-part programs, and rapid-response recalls remediation capabilities. These lift lifetime value and become a defensible moat against low-cost competitors.
-
M&A and partnerships: Pursue bolt-on acquisitions that bring complementary material technologies, testing capabilities, or commercial sales footprints. Consider strategic partnerships with vehicle OEMs and large rental fleets to secure recurring volumes.
-
Channel rebalancing: Accelerate direct-to-consumer channels for premium products while strengthening retail and installer networks to preserve reach for volume SKUs. Use data from DTC channels to inform product development and warranty provisioning.
How PW Consulting can accelerate your 2026 plan
Our full report contains the granular segmentation, competitive scorecards, price ladders, and regional go-to-market models that operational teams need to translate insights into execution. It also includes scenario-based cash-flow impact modeling for price and volume shocks, detailed supplier risk matrices, and M&A target prioritization lists aligned with five distinct corporate archetypes (market consolidator, technology consolidator, premium niche player, channel integrator, and full-spectrum incumbent).
If your 2026 planning cycle requires a data-driven roadmap — from product engineering and certification sequencing to channel economics and M&A due diligence — our full Bike Racks Market study provides the playbook and the primary-source verification to act with confidence. The executive summary above outlines the landscape and the levers; the full intelligence package contains the segmented market figures, competitive scorecards, and financial models you will need to finalize budgets and board-level recommendations.
Next steps
-
Download the full report to access the detailed segmentation, regional and application breakdowns, and executable 12–36 month implementation plans.
-
Engage PW Consulting for a tailored workshop: in 2–4 weeks we can map your product roadmap to the highest-probability growth corridors and deliver a prioritized action list for 2026 investment.
PW Consulting delivers research that informs decisive action. In a market growing predictably yet punctuated by regulatory and technological inflections, the difference between participation and leadership will be determined by who moves first to operationalize certification, e‑bike readiness, and service-based differentiation. Our full analysis equips leaders to do exactly that.
For detailed analysis of this topic, please visit the official page: Bike Racks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Leather Market to Reach USD 1,138 Million by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
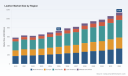
Leather Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive preview
As companies set strategy for 2026, the leather sector sits at an inflection point. Our Leather Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies both the resilience and the disruption potential of the industry. The global market expanded from a mid‑single‑hundred million base in 2020 to roughly USD 732 million by 2025, and our model projects a compounded growth trajectory (CAGR) of approximately 6.5% through 2032—reaching just over USD 1.13 billion by the end of the forecast horizon. These headline dynamics underline a market that is neither static nor hyper‑consolidated: our concentration metrics show modest top‑player share (CR3 ≈ 24%, CR5 ≈ 28%), indicating ample room for scale plays, vertical integration, and niche premiumization.
Leather Market
Why this matters for 2026 corporate choices
- Regulatory timing is forcing capital choices: With major regulatory changes phasing in during 2026–2027, procurement, compliance and product development budgets will need reallocation now to avoid disruptive retrofits later.
- Growth is material but selective: A steady mid‑single‑digit CAGR creates attractive returns for firms that combine cost control with differentiated product and traceability propositions; undifferentiated commodity players will face margin pressure.
- Fragmentation creates opportunity: The relatively low concentration enables M&A roll‑ups and bolt‑on strategies for manufacturers and distributors seeking scale or route‑to‑market acceleration.
Market trajectory and structural drivers
Our bottom‑up forecast layers demand drivers—luxury and premium footwear/fashion resilience, automotive and furniture cyclical rebounds, and expanding specialty applications—against supply‑side constraints including raw hide availability, energy and chemical cost volatility, and tightening environmental compliance. The net is a steady market expansion path that rewards operational excellence and compliance readiness. Crucially, the growth is not uniform: premium, traceable, and compliance‑certified leather grows faster than blended or low‑trace commodity offerings. For this reason, strategic positioning—premium vs. scale commodity—will determine share and margin trajectories through 2026 and beyond.
Leather Market
Regulatory and trade dynamics altering the playing field
- EU Deforestation Regulation (EUDR): The inclusion of cattle hides and prepared leather within EUDR scope (effective December 2026) fundamentally raises the bar for origin proof and due‑diligence across EU supply chains. Companies selling into or sourcing through Europe must operationalize traceability now.
- OEKO‑TEX and voluntary standards: Industry standards are pre‑empting regulation by demanding delivery‑level provenance documentation from slaughterhouses and tanneries—compliance can become a market access enabler, not merely a cost.
- Chemical restrictions: Recent revisions to REACH‑style restrictions in major markets (effective June 1, 2026 in the U.S. federal notices) require immediate reassessment of finishing chemistries and supplier declarations.
- Standards and national policy moves: Draft standards consultations (e.g., India's BIS) and promotional programs are reshaping how sourcing and export promotion are managed in key producing countries.
- Trade volatility: Short‑term export slippage (e.g., a modest decline in U.S. leather exports in FY26) demonstrates how geopolitics and tariffs can affect near‑term revenue and channel strategies.
Competitive landscape — strategic implications from leading players
The sector features a diverse set of competitors ranging from artisanal tanneries to global brand manufacturers. Key archetypes and strategic takeaways:
Leather Market
- Artisanal premium tanneries (e.g., Horween Leather Company): These firms command premium pricing through provenance, craftsmanship and consistent product performance. Strategy implication: invest in brand partnerships and small‑batch traceable supply chains to capture high margin pockets.
- Brand‑led footwear and apparel manufacturers (e.g., Wolverine Worldwide): Brand owners control downstream margins and have the leverage to demand supplier compliance and innovation. Strategy implication: focus on supplier scorecards, long‑term contracts, and collaborative R&D to secure preferred supply.
- Traditional finished‑leather manufacturers (e.g., Weinheimer Leder): Technical tanning expertise and process control are their competitive moats. Strategy implication: upgrade process automation, chemical use optimization and energy efficiency to defend margins under regulatory pressure.
- D2C premium goods (e.g., Saddleback Leather Co.): Direct channels and lifetime warranty models illustrate premium durability plays. Strategy implication: brands can monetize storytelling about provenance, and after‑sales services can extend customer lifetime value.
- Contract furniture and upholstery specialists (e.g., American Leather Holdings): Custom, high‑value segments remain attractive for specialised suppliers with fast customization capabilities.
- Large emerging‑market manufacturers and exporters (e.g., A.V. Thomas, Bhartiya International): Scale, labor efficiency and export focus drive growth. Strategy implication: these players are positioned to capture volume growth but must compress compliance and traceability costs to maintain competitiveness.
Recent industry signals to watch in 2026
- Design and export fairs (e.g., major international leather fairs and talent showcases) are accelerating innovation diffusion and buyer‑seller matchmaking—use these as a live market‑testing channel for product pilots.
- Regulatory submissions and consultations indicate near‑term tightening; treat policy news as leading indicators rather than background noise.
- Industry promotional funding moves—public agencies reallocating budgets to market development—create windows for co‑funded expansion into select markets.
What the full PW Consulting Leather Market report delivers (practical, executive‑ready content)
We designed the report to be actionable for boardrooms and operating teams. Highlights include:
- Revenue and demand models (2020–2032) with scenario sensitivities and a 6.5% central CAGR;
- Segment and channel analyses with decision trees for premium vs. commodity strategies (note: detailed segment line items and regional/application splits are intentionally withheld here to preserve the report’s strategic value);
- Proprietary supplier risk matrix and a traceability checklist you can apply to Tier‑1 and Tier‑2 suppliers;
- Regulatory compliance playbook (EUDR, chemical restrictions, voluntary standards), including a one‑page executive checklist for procurement and legal teams;
- Commercial playbooks—pricing levers, SKU rationalization templates, and retail vs. D2C margin simulations;
- M&A and partnership framework—target screens and integration checklists tailored to acquire scale or capability (e.g., tanning tech, finishing chemistries, traceability platforms);
- Ten actionable near‑term moves and a 24‑month roadmap to operationalize traceability, reduce chemical risk, and capture premium price realization.
Immediate actions for 2026 planning cycles
To convert the market view into decisions this year, companies should prioritize the following:
- Compliance audit within 90 days: Map supplier documentation against EUDR and OEKO‑TEX requirements; implement corrective action plans for any documentation gaps.
- Traceability pilot: Deploy a focused chain‑of‑custody pilot with a core SKU or product family to test data capture, verification and cost impact.
- Re‑price for compliance: Run margin sensitivity analyses that incorporate incremental compliance and testing costs and reprice contracts where indexation is feasible.
- Supplier diversification and contracting: Secure multi‑source arrangements for critical hides and negotiate clauses for shared compliance investments.
- Capex prioritization: Delay non‑strategic brownfield expansion; prioritize investments in finishing processes that reduce chemical exposure and energy consumption.
Monitoring dashboard for leadership
Track these KPIs monthly to maintain strategic control:
- Raw material availability and unit cost variance;
- Traceability compliance rate across active SKUs;
- Regulatory exposure index (jurisdictions + product lines affected);
- EBITDA margin by product family (pre‑ and post‑compliance cost);
- Order book conversion from premium categories vs. commodity categories.
Closing perspective and next steps
The leather market in 2026 is a study in managed transition: stable headline growth and fragmented supply create both runway and pressure. Companies that treat compliance, traceability and product differentiation as strategic levers—not just cost centers—will capture disproportionate share as buyers and regulators raise the bar. The full PW Consulting Leather Market report contains the segmented intelligence, supplier lists, procurement templates and valuation playbooks you need to operationalize these insights; this introduction purposefully omits detailed sub‑segment tables to preserve the report’s utility for subscribers and clients.
To convert insight into action, senior teams should prioritize a rapid compliance audit, a traceability pilot, and a supplier contracting review in Q1–Q2 2026. PW Consulting stands ready to accelerate any of these workstreams with bespoke modeling, vendor due diligence, and M&A advisory support.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hemodialysis Concentrates Market to Reach USD 3,560M by 2032 — PW Consulting
By PW Consulting, 2026-07-12
Hemodialysis Concentrates Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our Hemodialysis Concentrates Market study designed to inform executive choices in 2026. The market reached an estimated USD 2,350 Million in our base year (2025) after steady expansion from 2020, and our scenario modelling projects it to reach roughly USD 3,560 Million by 2032, reflecting a compounded annual growth rate of 6.2% across the 2026–2032 forecast window. These headline figures frame the commercial context; the full study supplies the granular segmentation, scenario tables and playbooks necessary for executable strategies. This article highlights why that intelligence matters and how senior teams should use it without disclosing the detailed segment-level figures reserved for the full report.
Hemodialysis Concentrates Market
Why this research matters for 2026 strategies
- Triage capital allocation: The market’s mid-single-digit CAGR signals durable demand — yet pockets of higher growth and margin exist. The report helps prioritize R&D and manufacturing capex toward those pockets so investment returns exceed the market average.
- Mitigate regulatory and quality risk: Recent Class 2 recalls and amplified quality scrutiny have made regulatory readiness a competitive differentiator; the report includes a regulatory-risk heatmap and remediation playbook.
- Decompress supply-chain vulnerability: Material-cost volatility and single-sourcing risk for medical-grade inputs require structured hedging and supplier strategies; our procurement models quantify trade-offs between cost, resilience and lead-time.
- Inform M&A and partnership decisions: An industry structure with concentrated market shares among leading players creates specific opportunities for bolt-on acquisitions, capacity deals and strategic alliances — the study ranks targets and synergies by ROI horizon.
- Commercial strategy optimization: Pricing, reimbursement and channel mix differ materially by setting (clinic vs home dialysis). The report combines reimbursement mapping with price-elasticity scenarios to guide contract negotiations and tender strategies.
What the full report contains — operational modules for immediate use
- Transparent market architecture: Historical sizing (2020–2025), forecast scenarios (2026–2032), and sensitivity analyses built on demand drivers and supply constraints. High-level market numbers are presented here; granular regional, type and application splits are available in the full dataset to support market-entry and valuation work.
- Segment playbooks: Actionable strategies for acid vs bicarbonate concentrates, premixed vs dry formats and clinic vs home care deployment — each with product, pricing and channel recommendations tailored to execution in 12–36 month horizons.
- Competitive benchmarking: Detailed company profiles, capability matrices, and a 360° view of R&D, manufacturing footprint, regulatory posture and commercial reach for primary market participants.
- Manufacturing and cost modeling: A factory-level cost model calibrated to medical-grade materials, water purification costs, labour and compliance overheads — enabling build vs buy decisions.
- Regulatory & quality playbook: Practical steps to meet evolving device and chemical quality expectations, FDA engagement templates, and corrective action frameworks influenced by recent recall case studies.
- Supply-chain resilience matrix: Supplier concentration scoring, inventory policy optimisation and contingency sourcing pathways for critical inputs.
- Commercial and reimbursement templates: Tender response playbooks, hospital and homecare contracting guides, and KPI dashboards for post-deal integration.
- M&A and partnership screening: A prioritized list of inorganic targets and partnership archetypes aligned to strategic growth paths — from bolt-ons for manufacturing scale to technology tie-ups for digital/IoT-enabled concentrates.
Market dynamics shaping 2026 decisions
- End-user demand drivers: Demographic trends, CKD prevalence and expanded home-dialysis programs underpin structural demand. The net effect is steady volume growth coupled with rising interest in solution formats that simplify administration and reduce clinic burdens.
- Format innovation and product differentiation: Single-use bicarbonate cartridges and other pre-measured delivery systems are reducing point-of-care complexity and contamination risk. These innovations change buying criteria, switching costs and lifecycle economics for providers.
- Quality and regulatory pressure: Multiple FDA Class 2 device recalls in recent periods illustrate that quality lapses are financially and reputationally costly. Organizations with robust quality systems and rapid corrective-action capabilities gain negotiating leverage and lower recall exposure.
- Cost and input volatility: Medical-grade water systems, electrolytes and acid components remain exposed to supply-chain bottlenecks and regional infrastructure constraints. The report quantifies how these input cost swings translate into gross-margin sensitivity by production model.
- Consolidation and concentration: The market exhibits a high level of concentration among leading players, reinforcing scale advantages in manufacturing, distribution and regulatory compliance. Our competitive index shows the top-three players command a substantial share of the market, with the top five controlling an even larger portion — an important consideration for new entrants and suppliers.
- Reimbursement and procurement complexity: Payer policies and procurement practices vary by jurisdiction, affecting the total addressable revenues realized by manufacturers. The study’s reimbursement appendix decodes major markets and identifies pragmatic pathways to favorable contracting.
Competitive landscape — strategic positioning of core players
- Fresenius Medical Care (Bad Homburg, Germany): A mature global manufacturer with integrated product-and-service offerings, recently advancing digital integration through a unified platform that facilitates concentrate-device interoperability. Their scale supports robust regulatory and distribution capabilities, making them a benchmark for competitors and potential partner or acquirer targeting clinical channels.
- B. Braun Melsungen (Melsungen, Germany): Positions concentrates within broader dialysis systems, leveraging system-level bundling to protect margins and retention. Their integrated approach raises entry barriers for standalone concentrate vendors seeking to displace incumbent suppliers in integrated clinics.
- Nipro Corporation (Osaka, Japan): Focused on machine-compatible concentrates and a strong presence in APAC markets. Their technical compatibility with regional device standards and emphasis on manufacturing quality make them a resilient competitor in price-sensitive markets.
- Rockwell Medical (Wixom, Michigan, USA): Innovator in single-use cartridges and dry/sterile formats, actively commercializing new product types and maintaining visibility through prominent conferences. Recent product introductions and trade-show activity demonstrate a playbook centered on technical differentiation and specialty channel penetration.
- Renacon Pharma (Karachi, Pakistan), Farmasol (Kayseri, Turkey) and Pollet Medical Group (Belgium): These players illustrate regional and vertical-integration strategies: local production scale, niche formulations and acquisition-driven expansion. The 2025 acquisition of Farmasol by Pollet Medical Group exemplifies consolidation aimed at securing supply and manufacturing capacity.
What this means for corporate strategy in 2026 — recommended actions
- Prioritize quality systems now: Invest in pre-emptive validation and traceability protocols. The cost of doing so is significantly lower than the combined financial and commercial impact of a recall.
- Diversify supplier and manufacturing footprints: Reconfigure sourcing to reduce single-point risks for medical-grade water treatment and key electrolytes; consider small-scale localized production to service home-care growth corridors.
- Accelerate format-led R&D: Allocate R&D spend to formats that reduce clinic time and contamination risk (e.g., single-use bicarbonate cartridges), as these command premium pricing in tender processes focused on total cost of care.
- Negotiate integrated value propositions: Bundle concentrates with ancillary services or device connectivity to capture higher-margin, longer-duration contracts with dialysis providers.
- Use M&A strategically: Target acquisition candidates that provide manufacturing scale, regulatory dossiers or geographic access rather than solely top-line accretion; the market’s concentration amplifies the benefit of scale-aligned deals.
- Embed scenario planning in procurement and pricing: Deploy the report’s sensitivity matrices to stress-test commercial plans against recalls, raw-material shocks and reimbursement shifts.
How PW Consulting’s study supports boardroom decisions
- We convert market dynamics into actionable options: where to invest, where to partner, and what to divest — each tied to quantified revenue and margin outcomes under multiple regulatory and supply scenarios.
- Our deliverables include ready-to-use slides and financial models for investment committees and M&A teams, plus operational checklists for manufacturing and quality leaders.
- We provide a tailored decision map for three archetypal players — global OEMs, regional manufacturers and pure-play concentrate specialists — so you can adopt the competitive moves most relevant to your role in the value chain.
This briefing is a strategic extract designed to demonstrate the depth and applicability of the full Hemodialysis Concentrates Market study. The dataset behind our headline market sizing, the segmentation by region, type and application, the company-level revenue and performance matrices, and the scenario-specific models are intentionally retained in the complete report to preserve their proprietary value and to enable secure client-level licensing. For executives preparing investment decks, procurement negotiations, product roadmaps or M&A diligences in 2026, the full report supplies the granular evidence and executable templates to move from strategy to measurable outcomes.
Hemodialysis Concentrates Market
Contact PW Consulting through our research portal to access the full report, licensing options and tailored advisory packages that translate these insights into a 12–36 month execution plan aligned to your risk tolerance and strategic objectives.
Hemodialysis Concentrates Market
For detailed analysis of this topic, please visit the official page: Hemodialysis Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


