



Category: market research
PW Consulting: Alkyl Catalyst Market Hits $125.28M in 2025, Poised for $155.69M by 2032 (3.1% CAGR)
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Alkylation Catalysts Market
In an era where refining margins and environmental mandates intersect, the alkylation catalysts market represents a critical nexus for petrochemical and downstream fuel producers. As global energy transitions accelerate and regulatory frameworks tighten, decision-makers require more than surface-level estimates. They need forward-looking intelligence that maps technological shifts, competitive maneuvers, and demand trajectories with surgical precision. Our latest market research on alkylation catalysts delivers exactly that, positioning corporate strategy teams, procurement leaders, and R&D directors to act decisively throughout the 2026–2032 forecast horizon.
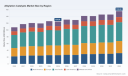
The global alkylation catalysts market reached an estimated 125.28 million USD in 2025, reflecting a nuanced trajectory from its 2020 baseline of 108.15 million USD. Looking ahead, our analysis projects steady expansion, with the market anticipated to reach approximately 130.67 million USD in 2026 and continue its upward path toward 155.69 million USD by 2032. This translates to a compound annual growth rate of 3.1 percent over the forecast period, underscoring a market defined not by explosive volatility but by measured, regulation-driven adoption and incremental process optimization. For enterprises planning capital allocation, technology roadmaps, or supply chain restructuring, understanding the velocity and direction of this growth is non-negotiable.
Why This Research Matters for 2026 Decision-Making
The 2026 operating environment will test refining and petrochemical organizations on multiple fronts simultaneously. Stricter environmental regulations are intensifying pressure to replace legacy hydrofluoric acid and sulfuric acid processes with solid acid zeolite alternatives that reduce hazardous emissions and align with evolving gasoline blending limits. At the same time, macro trends toward HF-free alkylation are accelerating, driven by incident avoidance mandates from OSHA and EPA standards and reinforced by ISO 9001:2015 and API certification requirements that now govern catalyst suppliers across global refinery networks. These dynamics reshape procurement criteria, technology licensing strategies, and long-term capacity planning.
Our report was engineered to translate these macro forces into actionable intelligence. It does not simply chart historical revenue lines; it isolates the structural drivers that will determine competitive outcomes over the next seven years. Readers will gain clarity on how shifting refinery configurations, regional regulatory pacing, and catalyst formulation innovations converge to create both risk and opportunity. The study maps demand pathways across key application segments, evaluates the performance and commercial readiness of competing catalyst architectures, and dissects the strategic positioning of leading technology providers. By embedding 2026-specific regulatory updates, including forthcoming REACH and TSCA standard revisions that mandate lower sulfur catalysts, the analysis equips executives with the foresight required to anticipate compliance costs, retrofit timelines, and procurement lead times before they become operational bottlenecks.
Inside the Report: Practical Intelligence for Strategy and Operations
This publication is structured as a decision-support toolkit rather than a static market snapshot. Each section is designed to answer the practical questions that arise in boardrooms, engineering reviews, and procurement committees. The report provides a comprehensive evaluation of catalyst types, dissecting performance characteristics, lifecycle economics, and compatibility with existing alkylation units. It examines application pathways across ethylbenzene and cumene production, alkane upgrading, and emerging specialty uses, drawing clear connections between catalyst selection and downstream product specifications. Regional demand patterns are contextualized through the lens of refining capacity expansion, regulatory adoption curves, and infrastructure readiness, allowing readers to identify where growth will materialize and what supply chain implications follow.
Beyond market sizing, the study delivers a competitor intelligence framework that evaluates how major players differentiate their technology portfolios, shape licensing strategies, and respond to evolving compliance landscapes. Each profiled organization is assessed on its core catalyst offerings, recent technology milestones, and strategic posture within the broader alkylation value chain. The report also incorporates an in-depth analysis of recent commercial developments, including new product launches, process innovation milestones, capacity expansions, and operational technology upgrades that have reshaped competitive dynamics in the past year. By linking these events to broader market forces, the research reveals how technology roadmaps and corporate execution are influencing the pace of adoption across the industry.
Readers will also find structured assessments of market concentration, technology licensing trends, and supply-side constraints that directly affect pricing negotiations, vendor selection, and long-term contract strategies. The report integrates qualitative insights on certification requirements, safety standards, and environmental compliance pathways, ensuring that procurement and engineering teams can align catalyst specifications with both operational and regulatory objectives. All findings are presented with sufficient granularity to support scenario planning, while deliberately preserving the highest-resolution data for stakeholders who require definitive commercial intelligence.
The Competitive Landscape: Leaders Defining the Next Generation of Alkylation Technology
The alkylation catalysts market is characterized by a concentrated set of technology leaders whose proprietary processes and catalyst formulations heavily influence industry standards. Honeywell UOP stands at the forefront with its ISOALKY ionic liquid catalyst and established HF and sulfuric acid alkylation processes, delivering high-octane alkylate performance tailored for complex refinery configurations. Its recently commissioned EcoZeal low-temperature catalyst in Belgium demonstrated the viability of modular alkylation systems operating at reduced thermal loads, while subsequent pilot testing validated an 18 percent energy consumption reduction—a development that signals the growing commercial relevance of low-temperature catalyst architectures.
Chemical Catalyst Market
ExxonMobil continues to shape the competitive field through its EMRE technology and zeolite catalyst portfolio designed for sulfuric acid alkylation, emphasizing reliability and integration with existing refinery infrastructure. Albemarle Corporation has carved a distinct position with its AlkyClean process and AlkyStar catalyst, which deliver sulfur-free, high-octane gasoline outputs aligned with tightening emissions standards. In 2025, Albemarle introduced a new environmentally friendly zeolite catalyst specifically engineered for high-octane gasoline production, and simultaneously implemented real-time catalyst analytics across four facilities, achieving a 9 percent improvement in operational uptime. These initiatives illustrate how data-driven catalyst management is becoming a competitive differentiator.
Sinopec has expanded its influence through silica-modified zeolites and zeolite catalysts optimized for commercial alkylation units, scaling up its modified catalyst formulations for broader refinery deployment. Meanwhile, Zeolyst International provides specialized solutions through its ATA-41 and broader zeolite series, supporting trans-alkylation and paraffin isomerization applications where selectivity and catalyst longevity are paramount. Together, these organizations reflect a market where technological differentiation, process integration, and compliance readiness determine market share trajectories. With a combined concentration that highlights the dominance of a handful of major technology providers, the landscape rewards organizations that can align their procurement and licensing strategies with the most resilient and forward-compatible catalyst architectures.
Market Dynamics: Regulation, Technology, and the Push Toward Safer Refining
The alkylation catalysts market is being reshaped by a convergence of regulatory, environmental, and technological forces that collectively redefine what refineries demand from catalyst suppliers. Stricter environmental regulations are accelerating the shift toward solid acid zeolites, which reduce hazardous emissions from alkylation units and align with increasingly stringent gasoline blending limits. This transition is not incremental; it represents a structural reorientation of catalyst procurement priorities, with safety, emissions performance, and regulatory compliance now competing alongside cost and throughput in vendor selection criteria.
The push toward HF-free alkylation has gained significant momentum as organizations seek to mitigate operational risk under OSHA and EPA incident avoidance mandates. Supply chain and engineering teams are increasingly prioritizing catalyst systems that minimize hazardous material handling, reduce worker exposure, and simplify permitting processes. Certification frameworks such as ISO 9001:2015 and API standards have further elevated the bar for catalyst suppliers, ensuring that product consistency, traceability, and quality management systems meet the rigorous expectations of global refinery operators.
Looking toward 2026, updates to REACH and TSCA standards will introduce additional compliance layers by mandating lower sulfur catalysts to meet evolving gasoline specifications. These regulatory milestones will influence not only catalyst formulation but also procurement cycles, validation timelines, and retrofit planning. Organizations that understand the sequencing of these requirements will be better positioned to negotiate long-term supply agreements, manage inventory buffers, and coordinate engineering readiness for catalyst transitions. The market is therefore moving toward a model where regulatory foresight and technology selection are inseparable components of operational strategy.
Alkylation Catalysts Market
Positioning Your Organization for the 2026–2032 Horizon
Navigating the alkylation catalysts market successfully requires a clear understanding of how regulatory timelines, catalyst technology evolution, and competitive behavior intersect. The 3.1 percent CAGR projected through 2032 suggests a market where incremental gains are secured through operational efficiency, compliance readiness, and strategic alignment with technology leaders who can deliver durable performance improvements. Enterprises that integrate market intelligence into their capital planning, vendor negotiations, and process modernization roadmaps will be best equipped to protect margins and capture value as the industry transitions toward safer, cleaner, and more efficient alkylation architectures.
Our full market research report provides the detailed segmentation analysis, competitive benchmarking, regulatory impact modeling, and forward-looking scenario frameworks necessary to make these decisions with confidence. To access the complete dataset, detailed segmentation breakdowns, and comprehensive strategic recommendations, visit the source page for the full report and equip your team with the intelligence needed to lead in the evolving alkylation catalysts landscape.
For detailed analysis of this topic, please visit the official page: Alkylation Catalysts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Hydrosulfide Market to Hit $620M by 2032 with 4.2% CAGR
By PW Consulting, 2026-09-16
Sodium Hydrosulfide Market Strategic Outlook 2026: Navigating Volume Growth and Regulatory Friction
The global sodium hydrosulfide market is entering a pivotal phase where steady volume expansion collides with tightening environmental oversight and fluctuating input costs. For industrial strategists, procurement leaders, and corporate development teams, the 2026 operating environment demands more than backward-looking revenue tracking. It requires a clear understanding of how regional supply architectures, type-specific demand shifts, and application-side procurement behaviors will evolve across the forecast horizon. Our latest Sodium Hydrosulfide Market research publication is engineered to deliver exactly that operational clarity. Drawing on a structured base year of 2025 and a historical review spanning 2020 through 2025, the report extends its analytical lens to 2026–2032, providing decision-makers with a defensible framework for capacity planning, contract negotiations, and competitive positioning.
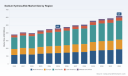
At the macro level, the market trajectory reflects measured but consistent growth. Revenue moved from 380.0 million USD in 2020 to 432.67 million USD in 2023, then continued its upward path to 449.38 million USD in 2024 and 460.0 million USD in 2025. The forecast arc projects this momentum through the end of the decade, with revenues expected to reach 476.99 million USD in 2026 and climb to approximately 620.0 million USD by 2032. This progression translates to a forecast period CAGR of 4.2 percent, a rate that signals durable demand rather than speculative surges. For executives, that growth profile carries a specific strategic implication: sodium hydrosulfide is not a niche volatile chemical, but a workhorse industrial input whose procurement and supply decisions compound over multi-year horizons. The report contextualizes these headline figures within the underlying demand engine, showing where volume is structurally accumulating and where margin exposure is intensifying.
Why 2026 Decision-Making Requires a Different Analytical Lens
The 2026 landscape is defined by a convergence of operational pressures that historical benchmarks alone cannot resolve. Sulfur-based chemical supply chains are navigating stricter transport protocols, closed-loop sulfur handling expectations, and low-emission production requirements. Environmental compliance under REACH and EPA frameworks is no longer a peripheral compliance cost; it is reshaping logistics economics, site selection logic, and supplier qualification standards. At the same time, raw material volatility remains a persistent threat to manufacturing economics. Price movements in sulfur dioxide, sodium hydroxide, and zinc—particularly for zinc-based production routes—can compress margins quickly during commodity spikes, making procurement timing and hedging strategy central to profitability.
Compounding these dynamics, market pricing signals are already showing sensitivity to broader commodity cycles. In the United States, pricing for sodium sulfide products, including sodium hydrosulfide, eased to 518 USD per metric ton in November 2025, reflecting a modest month-over-month decline and a more pronounced year-over-year pullback. While such movements can temporarily relieve procurement budgets, they also mask underlying structural risks: environmental scrutiny of sulfur dioxide emissions as a process byproduct, the generation of sulfite and thiosulfate residues in wastewater streams, and the operational hazards associated with transport and handling. These pressures are especially acute in Europe and North America, where regulatory intensity is reshaping acceptable sourcing models and pushing manufacturers to differentiate on safety, traceability, and environmental performance.
This is where the new report adds decision-grade value. Rather than presenting a flat growth curve, it breaks down the forces that will determine which companies capture share, which procurement teams secure supply resilience, and which operators navigate margin compression without sacrificing service quality. The analysis is designed for teams that must act in 2026 with incomplete visibility into the next seven years, giving them a structured way to test assumptions, prioritize investments, and align commercial strategy with evolving regulatory and operational realities.
What the Report Delivers: Operational Intelligence Over Abstract Trends
The publication is built around actionable modules that connect market structure to business decisions. It begins with a rigorous demand-and-supply framework that maps how sodium hydrosulfide flows across major industrial ecosystems and where procurement behavior is shifting. Instead of stopping at top-line projections, the report unpacks the structural drivers behind volume formation, helping readers understand which demand centers are expanding on fundamentals and which are being shaped by substitution risk, process optimization, or regional compliance costs.
A central strength of the study is its segmentation logic, which translates market complexity into operational categories that procurement, sales, and strategy teams can use directly. The analysis examines the liquid and solid forms of sodium hydrosulfide as distinct value propositions, reflecting the different handling requirements, end-user preferences, and application fit that define purchasing decisions. It also maps demand across core industrial uses, including pulp and paper processing, mining operations, leather and tanning workflows, and water treatment applications. For each segment, the report explores the operational rationale for adoption, the factors influencing specification requirements, and the procurement dynamics that will shape sourcing behavior over the forecast period. This structure allows readers to move quickly from high-level market size to the specific demand pockets most relevant to their portfolios.
Equally important, the report integrates a regulatory and operational risk overlay that many market summaries overlook. It evaluates how environmental compliance, transport constraints, and production-side emissions management are altering the economics of sodium hydrosulfide supply. Rather than treating regulation as a static barrier, the analysis frames it as a competitive variable: firms that invest early in safer handling, closed-loop sulfur systems, and lower-emission processes are building negotiating leverage and customer trust, while those that rely on legacy logistics models face rising friction. For buyers, this distinction influences supplier selection, contract structure, and total cost of ownership assessments. For producers, it shapes capital priorities and product positioning.
The forecast architecture is deliberately built for scenario use. Readers are given the analytical scaffolding to test how changes in raw material costs, regional compliance intensity, and application-side procurement timing could shift outcomes across the 2026–2032 window. This is not a single-point prediction exercise; it is a decision-support tool that helps teams prepare for multiple plausible paths, identify early warning signals, and align internal planning with market realities. The report is structured so that strategy, supply chain, and commercial teams can extract directly applicable insights without wading through disconnected data points.
Competitive Landscape: Consolidation, Differentiation, and the Race for Operational Credibility
The sodium hydrosulfide market is characterized by a moderately concentrated competitive structure, where scale, geographic reach, and application-specific expertise determine who can compete effectively across multiple end-use sectors. With a CR3 of 48.5 percent and a CR5 of 65.2 percent, the market shows meaningful concentration at the top, yet still leaves room for specialized players to win on purity, logistics reliability, and sector-focused service models. In this environment, competitive advantage is increasingly defined not just by output volume but by the ability to deliver consistent specification quality, compliant handling, and dependable supply across long procurement cycles.
Several leading suppliers anchor the market and illustrate the different routes to competitive relevance. Nouryon, based in Amsterdam, Netherlands, manufactures and supplies sodium hydrosulfide solution as a reactive sulfur chemical building block, serving mining, pulp and paper, and polymer production. Its positioning reflects the importance of integrating NaSH supply into broader chemical value chains where consistency and reactive performance matter. Solvay, headquartered in Brussels, Belgium, offers sodium hydrosulfide alongside high-grade sodium sulphide for industrial applications, including mining and chemical intermediates, emphasizing the role of multi-product portfolios in meeting diversified industrial demand. Tessenderlo Kerley, Inc., operating from Phoenix, Arizona, United States, produces and supplies sodium hydrosulfide solution with a focus on mining, the Kraft process, and leather dehairing, highlighting how application-specific expertise can anchor a supplier’s commercial footprint.
Regional specialization and product differentiation continue to shape the competitive field. Moleko, based in Australia, supplies high-purity ekoSURE Sodium Hydrosulfide solution for copper and molybdenum flotation, Kraft process operations, leather tanning, and specialty chemicals. In July 2025, Moleko officially launched a new brand identity for its high-purity sodium hydrosulfide solution, repositioning it as ekoSURE and emphasizing investments in purification technologies, traceability, and environmentally responsible production. That move is instructive: it signals a market where purity, documentation, and sustainability credentials are becoming commercial differentiators rather than optional enhancements.
In China, Shandong Aojin Chemical Technology Co., Ltd., located in Zibo City, Shandong, manufactures sodium hydrosulphide and sodium hydrosulfide for mining, paper making, leather processing, and textile production, illustrating the role of integrated regional manufacturing in serving multiple industrial sectors. Quadra Chemicals Ltd., based in Canada, supplies mining-grade sodium hydrosulfide solution for industrial and mining applications, reinforcing the importance of grade consistency and sector-focused distribution in markets where operational reliability is paramount. BOINTE ENERGY Co., Ltd., operating from Tianjin, China, functions as an active exporter and supplier of sodium hydrosulfide with logistics organized for global shipments, showing how export-oriented players compete on reach, coordination, and supply continuity. Together, these companies reflect a competitive landscape where geographic presence, product grade, application alignment, and logistics capability all influence market standing.
The report evaluates these players within a broader structural context, helping readers understand where concentration creates pricing and supply resilience dynamics, and where fragmentation leaves openings for differentiated entrants. It examines how suppliers are responding to the same operational pressures facing buyers—transport safety, emissions management, raw material exposure, and compliance burden—and how those responses are reshaping competitive advantage. For executives assessing partnerships, sourcing diversification, or market entry, this competitive mapping provides a practical foundation for evaluating who is positioned to sustain supply, who is investing in future-ready production, and where vulnerability may emerge under tighter regulatory or cost conditions.
Liquid Sodium Hydrosulfide Market
Turning Market Intelligence into 2026 Advantage
The strategic value of this research lies in its ability to connect market structure to executable decisions. For procurement teams, the report supports more informed sourcing strategies by clarifying where demand is structurally durable, where specification expectations are tightening, and where compliance and logistics risks will influence total cost of ownership. For producers and distributors, it offers a framework for prioritizing capacity, grade development, and regional positioning in a market where margin protection increasingly depends on operational discipline and differentiated service. For investors and corporate development groups, the analysis provides a grounded view of where consolidation pressures, application growth, and regulatory-driven barriers may shape future competitive dynamics.
The 2026–2032 outlook is not merely a projection exercise. It is a decision architecture for managing a chemical market that is growing at a steady pace while becoming more complex to serve. The report translates that complexity into structured insight: how the market is sized, how it is segmented, who competes and why, and which operational forces will matter most over the forecast period. By integrating historical performance, forward estimates, competitive mapping, and regulatory context into a single analytical package, the study gives teams a practical basis for aligning procurement, production, and commercial strategy with the realities of the next phase of market development.
Sodium Hydrosulfide Market
For organizations that need to move from high-level awareness to actionable intelligence, the full report provides the deeper segmentation detail, competitive benchmarking, and scenario-ready analysis necessary to support confident 2026 decision-making. The macro direction is clear; the strategic edge comes from understanding where to act, what to weigh, and how to prepare for the operational and regulatory shifts already reshaping the sodium hydrosulfide market.
For detailed analysis of this topic, please visit the official page: Sodium Hydrosulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Content Market Hits $191.55B in 2025, Projected to Reach $761.75B by 2032
By PW Consulting, 2026-09-16
Navigating the Surge: A Strategic Framework for the Digital Content Market Through 2032
The global digital content ecosystem is undergoing a structural transformation that demands immediate strategic attention. As we move deeper into the 2026 fiscal cycle, enterprise leaders face a complex intersection of accelerating addressable demand, evolving regulatory expectations, and rapid technological substitution across creation, distribution, and monetization layers. At PW Consulting, we have synthesized multi-year historical performance with forward-looking structural indicators to deliver a comprehensive assessment of how this market will evolve through 2032, and what disciplined capital allocation and capability investment require in response.
The opportunity set is substantial, but it is not uniformly distributed. Organizations that continue to treat content as a tactical output channel will find themselves outpaced by competitors who recognize it as a core infrastructure investment. This research note outlines the macroeconomic trajectory, competitive fault lines, regulatory friction points, and operational leverage points that should shape board-level discussion in the coming quarters.
Market Trajectory and the 2026 Inflection Point
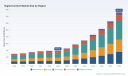
The historical record from 2020 through 2025 reveals a market that experienced rapid expansion followed by a period of measured correction and consolidation. Revenue climbed from a baseline of 149.4 billion USD in 2020 to a peak near 193.12 billion USD in 2024, before settling at approximately 191.55 billion USD in 2025. This 2025 adjustment reflects a combination of macroeconomic recalibration, platform-level monetization optimization, and early cost-reduction pressures from automation adoption. Rather than signaling demand erosion, this phase represents a maturation inflection where volume-driven growth gives way to value-driven growth.
Looking forward, the forecast period from 2026 through 2032 projects a sustained upward arc, starting at 227.63 billion USD in 2026 and scaling toward 761.75 billion USD by 2032. The implied compound annual growth rate of 5.1 percent over the forecast horizon may appear measured on the surface, yet it understates the structural reallocation occurring beneath the aggregate figure. Growth will not be evenly distributed across formats, channels, or geographies. Certain content modalities will capture disproportionate share as production economics shift, while legacy consumption patterns face compression from agentic workflows and AI-native generation pipelines.
For decision-makers, the critical takeaway is timing. Entering new content investment cycles without segmentation intelligence risks capital misallocation into formats or platforms that will face margin erosion within the forecast window. Conversely, organizations that align capability building with the segments showing durable monetization resilience can capture both top-line expansion and operating leverage.
What the Research Delivers: Actionable Intelligence Beyond the Headline
This study is designed as a decision-support instrument, not a static size-and-growth summary. It translates market architecture into operational implication across multiple planning horizons. The report framework is organized to answer four questions that recur in boardrooms and strategy functions alike: where is value accumulating, who controls the enabling infrastructure, what constraints will reshape cost and compliance structures, and how should a portfolio of content initiatives be sequenced.
The segmentation architecture maps content types, application environments, and regional demand profiles to identify where scale advantages and growth momentum diverge. Rather than presenting undifferentiated totals, the analysis isolates structural drivers such as production cost curves, audience engagement durability, platform dependency risk, and monetization pathway maturity. This allows strategy teams to distinguish between segments that are expanding on the strength of fundamental consumption shifts and those that are temporarily inflated by promotional cycles or platform subsidy dynamics.
The competitive landscape review examines the strategic positioning, technology roadmaps, and ecosystem leverage of leading platform and creation-oriented players. The assessment focuses on how each organization is shaping the supply side of content production, the degree to which integrated toolchains are creating switching costs, and where emerging interoperability or licensing models may alter competitive moats. This lens is particularly important for enterprises evaluating partnership structures, vendor consolidation, or build-versus-buy decisions for content operations.
The report also incorporates cross-cutting industry dynamics that influence execution risk. Regulatory developments around accessibility, content transparency, and platform accountability are not peripheral compliance issues; they are becoming design constraints that affect development timelines, cost structures, and market access. By mapping these requirements against current capability maturity, the research enables teams to forecast implementation burden and prioritize remediation or redesign efforts before they become growth bottlenecks.
Finally, the study integrates recent commercial and intellectual property developments that signal how the infrastructure layer of content delivery, rights management, and creator compensation is being reconstituted. These developments matter because they alter the downstream economics of distribution and monetization, influencing how value is captured once content reaches end users.
Digital Notes Market
Competitive Architecture and the Battle for Creation Leverage
The competitive field is increasingly defined by organizations that can compress the distance between idea, production, and distribution while preserving quality and brand consistency. Several platform-scale players are extending their influence through integrated creation suites that combine workflow tooling, storage, versioning, and AI-assisted generation within a single operational environment.
Microsoft Corporation has positioned its suite around productivity and content operations, embedding creation, storage, and management capabilities across familiar interface environments. Its strategy emphasizes continuity between professional documentation, presentation, and video editing workflows, which reduces friction for enterprise content teams that already operate within its productivity ecosystem. The integration of assistant-oriented creation features further accelerates draft-to-final timelines for internal and external content assets.
Digital Content Market
Alphabet Inc. has pursued a parallel path through collaborative workspace tooling and video production assistance, emphasizing AI-supported editing and management within cloud-native environments. Its approach leverages widespread adoption of its collaboration and communication infrastructure, aiming to make content creation a natural extension of daily operational workflows rather than a separate production discipline.
Adobe Inc. continues to anchor its position in professional-grade content creation, with a focus on high-fidelity visual production, compositing, and managed asset workflows. The integration of generative capabilities into its core creative environment is reshaping production economics by reducing manual iteration cycles, particularly for creative teams working under cost and turnaround pressure. Adobe's trajectory signals a market where professional creation tools are becoming more accessible through AI augmentation, expanding the producer base while simultaneously raising the bar for differentiated output quality.
Canva Inc. has expanded its relevance beyond lightweight graphic design into broader content generation, including video and conversational, agentic design workflows. Its recent introduction of a foundation-model-driven design layer reflects a broader industry shift toward prompt-mediated production with layered, editable outputs. This lowers the skill threshold for content creation, which expands participation but also intensifies competition for audience attention in already saturated channels.
Beyond these established players, the infrastructure and rights-management layer is beginning to attract targeted innovation. Recent patent activity and structured commercial intake initiatives from emerging infrastructure-oriented providers indicate growing attention to verified content delivery, stateful media handling, and rights-controlled access. These developments suggest that the market is moving toward more explicit mechanisms for tracking delivery, enforcing access conditions, and aligning creator compensation with verifiable consumption. For content-dependent enterprises, this infrastructure evolution may eventually influence platform selection, licensing strategy, and revenue-sharing expectations.
Structural Dynamics Shaping Cost, Compliance, and Content Design
Market growth does not occur in a regulatory vacuum. A series of accessibility and content-accountability mandates is reshaping how digital content must be designed, deployed, and monitored. In the United States, accessibility standards adopted by federal health and justice agencies established expectations aligned with web content accessibility guidelines at a defined compliance level for web and mobile content. This creates a durable design requirement that affects user interface decisions, media asset preparation, and testing workflows across content operations.
In parallel, the European accessibility framework introduced compliance obligations for digital products and services, including websites and applications, with deadlines that have already come into force for relevant organizations. For companies operating across multiple jurisdictions, these requirements introduce a multi-layered compliance map that must be reconciled during product and content development rather than retrofitted afterward. Failure to internalize these constraints early can lead to rework, delayed launches, and elevated assurance costs.
Beyond accessibility, content accountability expectations are expanding. Policy guidance from child health and development authorities has emphasized the importance of transparent metrics around content intended for younger audiences, signaling a likely trajectory toward more structured reporting and content governance in specific segments. For platforms and brands with significant youth-facing content exposure, this introduces an additional governance and disclosure layer that should be factored into operating models.
Production economics are also shifting. Recent industry analysis from a major creative software provider highlights growing demand for AI-augmented workflows aimed at reducing creation time and cost. This is not merely a productivity narrative; it is a structural pressure on the cost base of content production. Teams that successfully integrate assisted generation, asset reuse, and automated iteration can expand output volume without proportionate headcount growth. Teams that do not adapt risk margin compression as production expectations rise while budget constraints remain tight.
Strategic Priorities for 2026 Decision-Making
Translating these dynamics into action requires a disciplined approach that balances growth ambition with execution realism. The following priorities should anchor near-term planning.
- Align content investment with segment-level resilience rather than aggregate market momentum, since growth concentration varies materially across formats and application environments
- Evaluate creation and distribution toolchains for integration depth, switching cost exposure, and AI workflow compatibility, recognizing that vendor selection increasingly shapes long-term operating economics
- Build accessibility and content governance requirements into design and development cycles from the outset, treating them as product constraints rather than retrospective compliance tasks
- Assess licensing, rights management, and delivery-verification developments as potential sources of future monetization structure, particularly where content distribution depends on third-party platforms or partner networks
- Sequence capability investments so that AI-assisted production enhances differentiation rather than merely compressing cost, since lower production barriers will intensify competition for audience attention
- Monitor competitive moves in both creation tooling and delivery infrastructure, because shifts in either layer can alter the economics of content reach, retention, and revenue capture
The 2026 planning cycle is not simply a matter of forecasting demand; it is a matter of positioning portfolios, partnerships, and operating models against a market that is expanding while simultaneously reorganizing itself around automation, regulation, and infrastructure change. Organizations that approach the market with segmented intelligence, compliance-aware design, and strategic clarity on where value will accrue will be better placed to convert growth into durable advantage.
The complete analysis, including detailed segmentation trajectories, competitive positioning matrices, and regional demand breakdowns, is available through our full Digital Content Market research release. We encourage strategy and commercial leadership teams to review the full dataset to inform capital allocation, platform strategy, and content operating model decisions for the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Digital Content Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTFE Venting Membrane Market to Reach $2.69B by 2032, Growing at 5.2% CAGR
By PW Consulting, 2026-09-16
Strategic Venting: Navigating the PTFE Membrane Market in 2026
The global industrial landscape is undergoing a profound transformation, driven by electrification, stringent safety regulations, and evolving material science demands. At the intersection of these trends lies the critical role of PTFE venting membranes. These specialized components are no longer mere accessories; they are essential enablers of battery safety, sterile medical environments, and durable structural systems. As we move through 2026, understanding the trajectory of this market is not just an academic exercise—it is a strategic imperative for stakeholders across the value chain. This analysis draws from our latest comprehensive market research to outline the opportunities and risks defining the sector over the next decade.
The market has witnessed a robust trajectory over the past five years, recovering from global supply chain shocks and accelerating towards new highs. Historical data from 2020 through 2025 indicates a steady upward curve, culminating in a valuation that sets the stage for significant growth in the forecast period. Our analysis projects the global market value to reach approximately 2,050 million USD in 2026, up from 1,883.5 million USD in the base year of 2025. This momentum is expected to continue, with revenues climbing towards 2,689.9 million USD by 2032. Such figures underscore a compound annual growth rate (CAGR) of 5.2 percent during the forecast period from 2026 to 2032. This growth is not linear; it is punctuated by technological shifts and regional dynamics that require nuanced strategic planning.
PTFE Venting Membrane Market
Market Dynamics and Supply Chain Pressures
While the top-line growth figures are promising, the underlying dynamics present a complex picture for procurement and manufacturing leaders. The cost structure for PTFE venting membranes is heavily influenced by raw material volatility. High-grade PTFE resins exhibit price volatility driven by global supply chain disruptions, a trend that analysts have flagged as persistent throughout 2025 and into 2026. This volatility is compounded by geopolitical factors affecting the fluorspar supply chain. Sovereign fluorspar policies in China, which supplies a significant majority of global output, are raising landed costs for North American and European converters by double-digit percentages.
These regulatory and logistical headwinds are forcing adjustments in production planning. Several European compounders have been observed idling a portion of their nameplate PTFE capacity during the first quarter of 2026 to preserve liquidity in response to tightening export licensing and shipment volumes. China's export licensing tightened 2025 shipments to levels below previous years, creating a squeeze on availability for downstream manufacturers. For companies operating in this space, the ability to hedge against raw material price variations—which can fluctuate by a significant margin annually—is becoming a key differentiator in maintaining margin integrity. Our report delves deep into these cost structures, offering models for supply chain resilience that go beyond simple procurement tactics.
Segmentation and Application Drivers
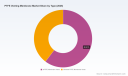
The demand for PTFE venting membranes is not uniform across all sectors. It is being pulled by specific high-value applications that prioritize performance and safety. The report segments the market by type, distinguishing between ePTFE Membrane Vents and Sintered PTFE Membrane Vents. Each type serves distinct functional requirements, with expanded PTFE gaining traction in applications requiring high breathability and chemical resistance, while sintered variants are critical where structural integrity under pressure is paramount.
In terms of application, the breadth of use cases illustrates the material versatility of PTFE. The electric vehicle (EV) battery sector remains a primary growth engine, driven by the absolute necessity for thermal runaway protection and pressure equalization in battery packs. Alongside this, the medical sector continues to demand high-purity venting solutions for sterile devices and drug delivery systems. The automotive industry, broader than just EV batteries, utilizes these membranes for under-the-hood components and lighting systems to protect against moisture and contaminants. Electronics packaging and industrial uses further diversify the revenue base. Chemical packaging and food and beverages packaging represent niche but high-compliance segments where barrier properties are non-negotiable. Understanding the specific growth rates and revenue contributions of each of these segments is crucial for targeting investment, and our full study provides the granular breakdown required to prioritize these verticals effectively.
Geographically, the market is distributed across key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific currently represents a substantial portion of the volume, reflecting the concentration of manufacturing and electronics production. However, North America and Europe maintain strong positions driven by high-value automotive and medical applications. The report analyzes the revenue distribution across these regions without revealing specific percentages in this overview, but the full publication details the regional revenue contributions and growth trajectories, highlighting where local manufacturing capabilities are aligning with demand centers.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established material science giants and specialized converters. Market concentration remains moderate, with the top three players holding a combined share in the low twenties and the top five accounting for slightly less than thirty percent of the market. This fragmentation suggests opportunities for consolidation or for niche players to secure strong positions through differentiation.
Key companies shaping the industry include Gore & Associates, Inc., known for leading production of expanded PTFE venting membranes for automotive and medical applications. Donaldson Company, Inc. continues to be a pivotal supplier of advanced filtration and venting solutions, recently expanding production capacity in late 2024 to support rising demand from life sciences and industrial processing. Saint-Gobain Performance Plastics has also moved to expand fluoropolymer materials processing capability in early 2025 to address rising specialty filtration demand.
In Asia, Nitto Denko Corporation and Sumitomo Electric Industries, Ltd. are key providers of engineered PTFE membranes for electronics and automotive OEMs. Porex Corporation introduced advanced porous polymer and membrane solutions in mid-2024, targeting medical and industrial customers. Other significant players include Zeus Industrial Products, Marian, Inc., Poly Fluoro Ltd, and Membrane Solutions, LLC, each contributing to the supply chain through conversion, customization, or specialized property engineering such as hydrophobic and oleophobic coatings. The report profiles these entities in detail, analyzing their strategic partnerships, capacity investments, and R&D focus areas to help clients identify potential suppliers or competitors.
Strategic Value of the 2026 Research
For corporate strategists, investors, and product developers, this market research offers more than just historical data. It provides a forward-looking lens calibrated for the 2026 decision-making cycle. The study includes actionable insights on capacity planning, helping manufacturers anticipate where bottlenecks might occur given the current idling of European capacity and tightening of exports. It evaluates the regulatory environment, offering compliance roadmaps for companies navigating fluorspar policies and export licensing changes.
Furthermore, the report assesses the technological roadmap. As EV battery architectures evolve and medical devices become more complex, the specifications for venting membranes are tightening. The research identifies which technical properties are becoming standard versus premium, allowing R&D teams to align their development pipelines with market needs. The segmentation analysis enables precise market sizing for new product launches, ensuring that capital is deployed into the highest potential application areas. Whether you are evaluating entry into the ePTFE space or assessing the risk of raw material price hikes on your sintered product lines, the detailed data tables and forecast models in the full study provide the quantitative backing needed for confidence in your strategy.
Industrial Venting Membrane Market
Conclusion
The PTFE Venting Membrane Market is at a critical juncture where growth potential is high, but so are supply chain risks. The projected expansion to nearly 2,690 million USD by 2032 represents a significant opportunity for those who can navigate the complexities of raw material sourcing and regional regulatory shifts. Companies that leverage detailed intelligence on competitive moves, such as the capacity expansions by Donaldson and Saint-Gobain, will be better positioned to anticipate market shifts. By understanding the specific demands of the EV, medical, and packaging sectors, stakeholders can tailor their offerings to capture value in the most resilient segments. This research serves as a foundational tool for executing that strategy, ensuring that decisions made in 2026 are built on a comprehensive understanding of the market landscape. The full report contains the specific data points, regional splits, and company profiles necessary to operationalize these insights.
For detailed analysis of this topic, please visit the official page: PTFE Venting Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dry Ice Machine Market to Reach $344.8M by 2032, 5.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Cold Front: Strategic Insights for the Dry Ice Machine Market Through 2032
The global industrial landscape is undergoing a silent but significant transformation, driven by the need for sustainable cleaning solutions, stringent cold chain requirements, and the relentless pursuit of operational efficiency. At the heart of this shift lies the Dry Ice Machine Market. As enterprises face increasing pressure to adopt eco-friendly technologies while maintaining rigorous safety standards, understanding the trajectory of dry ice production and blasting equipment becomes not just an option, but a strategic imperative. Our latest market research provides a comprehensive roadmap for stakeholders looking to capitalize on these emerging opportunities between 2026 and 2032.
In an era where data transparency dictates competitive advantage, decision-makers require more than surface-level estimates. They need a granular understanding of how market forces interact, how regulatory frameworks evolve, and where the capital flows are heading. This introduction serves as a high-level overview of the intelligence contained within our full study, designed to equip senior leadership with the context needed to interpret the broader market signals before diving into the specific methodologies and breakdowns available in the complete report.
Macro Economic Trajectory and Growth Signals
Historical data suggests a resilient upward trend for the dry ice machine sector, reflecting broader industrial adoption rates and the substitution of traditional abrasive cleaning methods with cryogenic alternatives. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a solid foundation for forecasting the period extending to 2032. The market has demonstrated consistent expansion, moving from a valuation of approximately 163.15 million USD in 2020 to a projected 215.0 million USD by 2025. This trajectory underscores a mature yet accelerating adoption curve.
Dry Ice Machine Market
Looking forward, the forecast period indicates sustained momentum. The market is expected to reach 231.45 million USD in 2026, climbing steadily to 344.8 million USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 5.5 percent over the forecast horizon. Such a rate suggests a balanced expansion where technological innovation meets steady demand across key verticals. For investors and manufacturers, this CAGR signals a stable environment for capital deployment, albeit one that requires careful monitoring of regional nuances and operational costs.
It is crucial for strategists to recognize that these aggregate figures mask complex underlying drivers. The revenue growth is not uniform across all product categories or geographic zones. While the top-line numbers indicate a healthy market, the distribution of value across different machine types and application sectors varies significantly. Our full report dissects these variations to reveal which specific segments are outpacing the average growth rate and which are facing headwinds due to saturation or regulatory constraints.
Segmentation Landscape: Types and Applications
The market is diversified across several machine types, each catering to distinct production needs and output specifications. The landscape includes pellet dry ice production machines, block dry ice production machines, and slice dry ice production machines. Each type serves a unique function within the supply chain, influencing everything from storage logistics to end-user application efficiency. Understanding the revenue contribution of each category is essential for manufacturers deciding where to focus R&D resources.
Dry Ice Market
Similarly, the application sector drives significant demand variance. Key verticals include food and beverage, cold chain logistics, industrial cleaning, and medical and pharmaceutical uses. The food and beverage sector often leads in volume due to the critical need for temperature control during processing and transport, while industrial cleaning sees strong uptake due to the environmental benefits of dry ice blasting over sand or chemical blasting. Medical applications, though smaller in volume, command high compliance standards that impact machine specification requirements.
However, precise revenue splits and percentage contributions for these segments are sensitive competitive intelligence. In our complete market study, we detail exactly how these segments compare in terms of market share and growth velocity. Access to this level of detail allows procurement officers and product managers to benchmark their internal portfolios against the broader industry standard. Without this granular view, companies risk misallocating resources to slower-growing niches while missing high-potential opportunities in emerging applications.
Regional Market Dynamics and Distribution
Geographic distribution plays a pivotal role in shaping market strategy. The global landscape is divided into key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique mix of regulatory environments, industrial density, and cold chain infrastructure maturity. Historically, North America and Asia Pacific have shown robust activity, reflecting strong industrial bases and varying degrees of adoption in logistics and cleaning sectors.
Europe continues to maintain a significant presence, driven by strict environmental regulations that favor dry ice blasting over chemical alternatives. Meanwhile, emerging markets in Latin America and the Middle East and Africa represent areas of potential expansion, though they come with distinct infrastructural challenges and varying raw material availability. The interplay between these regions creates a complex trade flow and supply chain dynamic that affects pricing and availability of equipment.
Detailed regional revenue figures and growth rates are central to our full analysis. These metrics help multinational corporations determine where to prioritize sales channels and where local manufacturing might offer a competitive edge against imports. For a precise understanding of which regions are contributing the most to the global revenue pool and how their growth rates compare to the global average, stakeholders are encouraged to refer to the complete regional breakdown provided in the full report. This ensures that expansion strategies are grounded in accurate local market intelligence rather than generalized assumptions.
Competitive Landscape and Key Incumbents
The market features a mix of established players and specialized innovators, operating across multiple continents. Concentration levels indicate a moderately fragmented environment, with the top three companies holding approximately 24.6 percent of the market and the top five reaching 26.2 percent. This structure suggests that while there are dominant forces, there is still room for niche players to compete on technology or regional specialization.
Key companies shaping the industry include Cold Jet, LLC based in San Marcos, Texas, known for advanced dry ice production pelletizers and blasting equipment focusing on energy-efficient CO2 utilization. CRYONOMIC in Belgium offers hydraulic drive solutions for crystal-hard pellets and sticks in semi-automated industrial settings. ASCO Carbon Dioxide Ltd from Switzerland specializes in automatic pelletizers capable of multiple thicknesses for food-grade and industrial use. Other notable entities include Artimpex nv and IceTech in the United States, Alfred Kärcher SE & Co. KG in Germany, TOMCO2 Systems, Aquila Triventek, and Ziyang Sida Cryogenic Machine Co., Ltd. in China.
Recent industry movements highlight the dynamic nature of this competition. For instance, Cold Jet has been particularly active, launching a new line of dry ice blasting machines for the food processing industry in August 2025, followed by the introduction of the PR750H industrial pelletizer in November 2025 and the PE 80 High-Efficiency Pelletizer in February 2026. These launches demonstrate a clear focus on efficiency and versatility across pellet sizes. Meanwhile, CRYONOMIC appointed Multico svl. as a distributor for Romania in November 2025, and ICS exhibited at Auto Exotica 2026 in April, signaling ongoing efforts to expand distribution networks and brand visibility in specific verticals like automotive.
Competitor profiling in our full report goes beyond product listings. It analyzes market positioning, recent strategic moves, and the implied focus areas based on public announcements. For investors, understanding the cadence of product launches and distribution expansions provides clues about where each company sees the highest growth potential. This intelligence is vital for partnership due diligence or for identifying acquisition targets that align with long-term strategic goals.
Critical Market Dynamics and Operational Considerations
Beyond pure economics, the dry ice machine market is heavily influenced by regulatory and operational factors that impact total cost of ownership and deployment feasibility. Safety and compliance are not merely checkboxes; they are structural components of the market that define where and how equipment can be utilized. Our research integrates these dynamics to provide a realistic view of market barriers and facilitators.
Regulatory Frameworks and Safety Protocols
Operators must navigate a complex web of safety standards when deploying dry ice production and blasting equipment. A primary requirement is the use of equipment only in properly ventilated spaces that comply with local and national regulatory standards. This constraint impacts facility design and limits the types of environments where dry ice blasting can be implemented without significant infrastructure upgrades.
Exposure limits are another critical factor. Guidelines often dictate that exposure to dry ice must follow specific occupational safety standards, such as maintaining CO2 levels below certain thresholds over an 8-hour workday with continuous monitoring. For example, adherence to OSHA guidelines regarding 5,000 ppm limits requires facilities to invest in monitoring systems, adding to the capital expenditure associated with dry ice technology adoption.
Transportation and logistics also face strict oversight. All dry ice transportation containers must meet DOT regulations for hazardous materials labeling and emission controls. This affects the downstream logistics of companies utilizing dry ice for shipping or cleaning, influencing the choice of production machines that can integrate smoothly with compliant packaging and distribution workflows. Additionally, safety protocols for blasting equipment include the use of insulated containers and compliance with federal regulations on hazardous materials, ensuring that both operators and the environment are protected during industrial cleaning processes.
Raw Material Economics and Supply Chain Volatility
The economics of dry ice production are intrinsically linked to the availability and pricing of CO2 feedstock. Raw material expenses remain subject to fluctuations in CO2 supply, which can be influenced by seasonal demand in other sectors, such as beverages or welding, and broader industrial production cycles. This volatility introduces a variable cost element that manufacturers must factor into their pricing models and long-term contracts.
Current sector analysis indicates that average pellet prices can range significantly, reflecting the interplay between supply constraints and regional demand spikes. For machine operators, this means that the efficiency of the production machine—measured in yield and energy consumption per pound of dry ice—is a critical metric for profitability. Machines that optimize CO2 utilization can mitigate some of the impact of raw material price swings, offering a competitive advantage to operators who invest in higher-efficiency technology.
Our full report delves into the sensitivity analysis regarding raw material costs and how they impact the overall market revenue projections. By understanding the correlation between CO2 pricing trends and machine utilization rates, businesses can develop more robust financial models. This level of insight is necessary for forecasting operational budgets accurately and avoiding margin erosion during periods of supply tightness.
Strategic Implications for 2026 and Beyond
For enterprises operating in or adjacent to the dry ice machine market, the period from 2026 to 2032 offers both challenges and opportunities. The projected growth suggests that demand will not vanish, but the competition for market share will intensify. Success will depend on the ability to interpret data correctly, anticipate regulatory shifts, and align product offerings with the specific needs of high-growth applications.
Strategic decision-makers should consider the following implications based on the macro trends identified:
- Technology Investment: With new product launches focusing on high-output and multi-size capabilities, R&D should prioritize flexibility and energy efficiency to match evolving customer requirements in food processing and industrial cleaning.
- Compliance Integration: Safety regulations are tightening. Equipment that integrates monitoring and ventilation compliance features directly into the production system may gain preference in regulated industries like pharmaceuticals and food safety.
- Regional Strategy: While global growth is steady, regional disparities require tailored approaches. Distributors and sales teams need localized data to identify regions where infrastructure supports dry ice adoption versus those hindered by supply chain or regulatory hurdles.
- Supply Chain Resilience: Given the volatility in CO2 feedstock prices, partnerships with reliable gas suppliers and investment in machines with high conversion efficiency will be key to maintaining margins.
Ultimately, navigating this market requires more than a glance at the headline CAGR. It demands a deep dive into the segmentation splits, competitive maneuvers, and regulatory undercurrents that define the daily operations of the industry. Our comprehensive market research report is designed to provide that depth. It offers the specific breakdowns, detailed company profiles, and forward-looking risk assessments necessary to build a resilient strategy.
To access the full suite of data, including precise regional valuations, detailed application segment sizes, and complete competitive benchmarking, we invite you to review the full publication. The insights contained within are crafted to support informed decision-making, ensuring that your organization is prepared to lead rather than follow in the evolving landscape of dry ice production and blasting technology.
For detailed analysis of this topic, please visit the official page: Dry Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vehicle Roadside Assistance Market to Hit $42.77B by 2032, 5.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Vehicle Roadside Assistance Market: A 2026 Outlook
The vehicle roadside assistance industry stands at a critical inflection point as it moves through 2026. Driven by shifting consumer expectations, the electrification of fleets, and an increasingly complex regulatory environment, the sector is undergoing a transformation that demands precise, data-backed strategic planning. For executive leadership teams, investors, and operational decision-makers, navigating this landscape without granular intelligence is no longer viable. Our newly released Vehicle Roadside Assistance Market research report provides the comprehensive analytical framework required to turn market volatility into competitive advantage.
This analysis is not merely a retrospective of market performance. It is a forward-looking strategic instrument designed to inform capital allocation, partnership structuring, geographic expansion, and technology investment decisions through 2032. By synthesizing historical performance data with rigorous forecasting models, the report reveals the structural forces that will define winners and laggards in the coming years.
Market Trajectory: From Historical Resilience to Forecasted Expansion
The global vehicle roadside assistance market has demonstrated consistent growth over the past half-decade, reflecting the essential nature of emergency mobility services in modern transportation ecosystems. Historical data from 2020 through 2025 illustrates a steady upward trajectory, with the market expanding from a baseline revenue of 22.8 billion USD to 29.7 billion USD. This compound growth reflects enduring demand across both consumer and commercial segments, even as the industry contended with supply chain disruptions, labor market tightness, and evolving safety protocols.
Looking ahead, our forecast period spanning 2026 to 2032 projects continued expansion, with the market expected to reach 42.77 billion USD by the end of the forecast window. This growth is anchored by a forecasted compound annual growth rate of 5.3 percent, signaling a mature yet dynamically evolving industry. The midpoint of this trajectory, with 2026 revenue projected at 32.26 billion USD and 2027 at 32.95 billion USD, underscores a market that is not experiencing a transient spike but rather sustaining a methodical climb. For strategic planners, this persistence suggests that roadmap decisions made in 2026 will compound in significance as the market approaches the 40 billion USD threshold toward the decade's end.
Crucially, these top-line figures represent only the surface layer of our analysis. The report deconstructs the underlying drivers, volume-to-value shifts, and regional asymmetries that shape these totals, providing the depth required for actionable strategy. Decision-makers who rely on aggregate numbers alone risk missing the nuanced opportunities hidden within service type dynamics, application-segment behaviors, and geographic growth pockets. The full intelligence is detailed within the complete report, where segmented projections and sensitivity analyses equip leaders to model multiple scenarios with precision.
Industry Dynamics: Labor, Regulation, and Operational Risk
The market does not operate in a vacuum. Several macro-level forces are actively reshaping cost structures, compliance obligations, and service delivery models across the roadside assistance value chain. Understanding these dynamics is essential for building resilient operational strategies that can withstand external shocks.
Labor costs represent a persistent pressure point. According to data released by the U.S. Bureau of Labor Statistics in April 2026, private industry worker compensation costs rose 3.4 percent over the year ending March 2026. For roadside assistance operators, whose business models depend heavily on skilled field personnel, tow truck operators, and dispatch coordinators, rising compensation expenses directly impact margins. Companies that fail to integrate workforce cost escalation into their pricing strategies, route optimization algorithms, or automation roadmaps will find their profitability eroding. Our report examines how leading operators are responding, from technology-enabled dispatch efficiencies to strategic fleet partnerships that redistribute labor intensity.
Regulatory scrutiny is simultaneously intensifying across key jurisdictions. In the United States, Colorado now requires towing carriers to submit operational towing data for the previous calendar year by February 1, 2026, reflecting a broader trend toward data transparency and regulatory oversight. Meanwhile, Maine's working group concluded in January 2026 that formal regulation is needed for the statewide towing and roadside assistance industry under the Board of Motor Vehicle oversight. These developments signal a shift from informal industry self-governance toward structured compliance frameworks. In California, towing and roadside assistance operations are separately classified under code 7227 for insurance reporting purposes, a nuance with significant implications for risk assessment, coverage structuring, and inter-state operational planning. Our report maps these and other regulatory currents, helping organizations anticipate compliance costs and align their operational footprints accordingly.
Operational safety remains a non-trivial concern. Research from the AAA Foundation for Traffic Safety in 2024 highlighted the elevated risk roadside assistance providers face of being struck by vehicles while assisting stranded motorists. This safety dimension influences insurance premiums, workforce retention, and the design of service protocols. Companies that invest in enhanced safety training, improved vehicle visibility technologies, and digital coordination tools that minimize on-site exposure are better positioned to manage both human and financial risk. The report explores how safety-driven innovation intersects with customer experience and cost management.
24 Hour Emergency Roadside Assistance Market
Competitive Landscape: Ecosystem Players and Strategic Positioning
The competitive architecture of the vehicle roadside assistance market is multifaceted, encompassing traditional consumer service providers, white-label digital platforms, insurance-integrated offerings, OEM ownership programs, and specialized networks for niche vehicle segments. This diversity creates both collaboration opportunities and competitive friction, and understanding where each player fits is critical for partnership strategy and market entry decisions.
In North America, AAA remains a primary provider of consumer roadside assistance, leveraging a combination of in-house fleets and independent service providers to deliver emergency towing, tire changes, lockout services, and minor repairs. Its brand recognition and broad membership base position it as adefault reference point in the consumer segment. Alongside AAA, insurance carriers such as Allstate, GEICO, and Progressive offer roadside assistance as optional or integrated coverage within auto insurance policies, embedding emergency services into the broader risk management ecosystem. This insurance-led model creates a distinct value proposition centered on policyholder convenience and bundled pricing.
The digital transformation of roadside assistance is perhaps most evident in the rise of platform operators like Agero, Inc. As a leading white-label digital roadside assistance platform and network operator, Agero serves insurance companies, fleets, and OEMs, processing more than 14 million annual dispatches while integrating deeply into vehicle policies and mobility programs. Agero's strategic momentum in 2026 underscores this direction: in May 2026, the company renewed its multi-year partnership with Hagerty to deliver premium roadside assistance services tailored to enthusiast vehicles through the Hagerty Drivers Club, and simultaneously completed the acquisition of Urgently to expand its tech-driven network across automotive, fleet, rental, and insurance markets. These moves illustrate how platform players are scaling through both partnership depth and consolidated network reach.
Across Europe, the competitive landscape is characterized by network operators and integrated service providers with strong OEM and fleet ties. ARC Europe SA, headquartered in Belgium, operates a European roadside assistance network focused on OEM and fleet digital platforms, providing towing, lockout, and minor repair services with an emphasis on real-time information and electrification compatibility. In February 2026, ARC Europe published analysis on 2026 driver expectations for transparency, real-time ETA visibility, and digital communication, citing electrification as a key driver of changing service requirements. Viking Assistance Group AS, based in Norway, provides roadside assistance including heavy-duty and commercial vehicle support across Europe, with a focus on fleet and insurance partnerships. In Denmark, SOS International A/S delivers global roadside assistance and recovery services primarily for commercial and fleet vehicles, while Falck A/S offers full-service roadside assistance including towing, battery service, and subscription-based vehicle support across Northern Europe. Allianz Partners, headquartered in France, rounds out the European contingent by embedding integrated roadside assistance solutions within insurance and mobility programs, coordinating towing, mechanical assistance, and claims processes.
OEMs represent another strategic axis. Ford Motor Company offers 24/7 roadside assistance and support benefits to owners through warranty and ownership programs. Nissan Motor Corporation provides nationwide 24/7 assistance for vehicle owners, including towing, jump starts, and emergency lockout service. Hyundai Motor Company guarantees five-year 24/7 roadside assistance coverage under its Hyundai Assurance program. Lincoln Motor Company delivers lifetime 24/7 assistance for qualifying vehicles, including fuel delivery and emergency support. Mazda Motor Corporation offers complimentary roadside assistance for new vehicles, covering three years of flat tire, lockout, and towing services. Subaru Corporation provides 24-hour nationwide assistance for owners, covering towing, jump starts, flat tire changes, and gas delivery. These OEM programs illustrate how vehicle manufacturers use roadside assistance as a value-added differentiator, strengthening brand loyalty and ownership experience.
Finally, specialized networks such as Good Sam Enterprise, LLC address underserved segments, providing roadside assistance tailored to RV, marine, and specialty vehicle owners through insurance and membership programs. This segmentation highlights how niche focus can command premium positioning and foster deep customer relationships outside the mainstream passenger and commercial vehicle segments.
Report Scope: Operational Intelligence for Strategic Execution
To translate market awareness into executable strategy, leaders require more than high-level trends. The Vehicle Roadside Assistance Market report delivers a structured, operationally relevant body of intelligence designed for immediate application in planning cycles. The report's architecture ensures that every section serves a decision-making purpose.
Key components of the report include:
- Comprehensive historical market sizing from 2020 through 2025, establishing a validated baseline for trend analysis and model calibration
- Forward-looking revenue forecasts segmented across the 2026 to 2032 horizon, enabling scenario planning and investment prioritization
- A detailed breakdown of service type dynamics, including towing services, tire replacement services, and other service categories, with qualitative and quantitative insights into demand drivers and service mix evolution
- An application-segment analysis covering passenger cars, commercial vehicles, and other application areas, with attention to usage patterns, fleet composition shifts, and commercial versus consumer demand differentials
- A regional assessment that evaluates market maturity, growth catalysts, and competitive intensity across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa
- A competitive landscape review that profiles core companies, maps their strategic positioning, and analyzes recent developments such as partnerships, acquisitions, and industry analyses that signal future market direction
- An in-depth examination of industry dynamics, including labor cost trajectories, regulatory developments, safety considerations, and their combined impact on operational design and margin management
- Strategic recommendations tailored to distinct stakeholder roles, including service providers, platform operators, insurers, OEMs, fleet managers, and investors
Each section is built to stand alone as a reference for specific functional teams while also integrating into a cohesive strategic narrative. The report's segmentation analysis, in particular, provides the granularity needed to identify where growth is concentrated, which service categories are gaining relative share, and how application-level demand is shifting in response to vehicle technology evolution and fleet composition changes. These insights are deliberately developed to support resource allocation decisions, partnership targeting, and market entry sequencing.
Why This Intelligence Matters for 2026 Decision-Making
The 2026 operating environment rewards organizations that can align strategic vision with empirically grounded market intelligence. Several factors make this report particularly timely for current decision-making cycles.
First, the convergence of digitalization, electrification, and regulatory change is restructuring how roadside assistance is delivered, priced, and integrated into broader mobility and insurance ecosystems. Organizations that understand these interconnections can design offerings that anticipate rather than react to market shifts. The report's analysis of recent developments, such as Agero's partnership renewal with Hagerty and its acquisition of Urgently, alongside ARC Europe's published analysis on driver expectations and electrification, provides concrete reference points for how industry leaders are positioning themselves in real time.
Second, the forecasted growth trajectory to 2032 creates a window for strategic investment in network expansion, technology infrastructure, and partnership development. However, the distribution of growth is not uniform. Segments and regions will outperform or lag based on structural factors that aggregate numbers cannot reveal. Accessing the full segmentation analysis allows decision-makers to direct capital and operational effort toward the highest-probability opportunities while avoiding areas where competitive saturation or regulatory headwinds may compress returns.
Third, the competitive landscape's breadth means that partnership strategy has become as important as organic capability building. Whether an organization is an insurer seeking embedded assistance solutions, an OEM designing ownership benefits, a fleet manager optimizing total cost of ownership, or a platform operator pursuing network consolidation, identifying the right partners and understanding their strategic incentives is essential. The report's company profiles and recent developments section equip teams to evaluate potential alliances with a clear view of each player's capabilities, market focus, and momentum.
Finally, the operational pressures surrounding labor costs, compliance, and safety are not transient. They represent structural components of the cost and risk equation that must be factored into pricing strategy, service design, and technology investment Roadside assistance providers face elevated risk of being struck by vehicles while assisting stranded motorists, a reality that influences everything from insurance costs to workforce planning. Meanwhile, the 3.4 percent rise in private industry worker compensation costs and the emergence of new regulatory reporting requirements in jurisdictions such as Colorado and Maine demonstrate that cost and compliance management are becoming increasingly sophisticated disciplines. The report translates these dynamics into strategic considerations, helping organizations build operating models that are both efficient and resilient.
Vehicle Roadside Assistance Market
Conclusion: Access the Full Strategic Picture
The vehicle roadside assistance market in 2026 is defined by steady growth, structural transformation, and an intensifying competitive agenda. The headline figures, a market moving from 29.7 billion USD in 2025 toward 42.77 billion USD by 2032 at a compound annual growth rate of 5.3 percent, tell a story of sustained opportunity. But the real strategic value lies beneath the surface, in the segmentation patterns, regional asymmetries, competitive maneuvers, and operational dynamics that determine where value is created and captured.
This article has previewed the scope and strategic relevance of our Vehicle Roadside Assistance Market research. It has outlined the market trajectory, the industry dynamics shaping cost and compliance, the competitive landscape spanning consumer providers, digital platforms, insurers, OEMs, and specialty networks, and the operational intelligence embedded in the full report. What remains are the precise segmentation figures, regional breakdowns, and detailed forecasts that enable confident, specific decision-making.
For executives who need to move from market awareness to executable strategy, the complete report provides the depth, structure, and actionable insight required. We invite you to access the full research to explore the comprehensive segmentation analysis, competitive profiles, regulatory mapping, and forward-looking forecasts that will inform your 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Vehicle Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-Destructive Testing Instruments Market to Reach $30.7B by 2032, 9.3% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Non-Destructive Testing Instruments Market: Navigating Growth Through 2032
The global landscape for non-destructive testing instruments is undergoing a profound transformation, driven by escalating safety mandates, infrastructure aging, and the rapid integration of digital technologies. As industrial sectors worldwide prioritize asset integrity and operational reliability, the demand for advanced inspection solutions has accelerated beyond historical trajectories. Our latest comprehensive analysis, Non-Destructive Testing Instruments Market, provides a critical roadmap for stakeholders aiming to align their strategies with the compounding opportunities projected through 2032. This article outlines the strategic value of this research, synthesizing macroeconomic indicators, competitive dynamics, and emerging industry shifts to underscore why informed decision-making is paramount in the current fiscal year and beyond.
For enterprise leaders, investors, and product strategists, the overarching market narrative is defined by sustained expansion and evolving technological prerequisites. Historical data reveals a consistent upward momentum, with the market valuation climbing from 11.6 billion USD in 2020 to an estimated 16.5 billion USD by 2025. This trajectory is not merely a reflection of post-pandemic recovery but indicative of a structural shift in how industries approach quality assurance and risk mitigation. The forecast period anticipates a robust compound annual growth rate of 9.3 percent, propelling the market valuation toward 18.62 billion USD in 2026 and surpassing the 30 billion USD threshold by 2032. Such figures underscore a fertile environment for capital allocation, product development, and strategic partnerships. However, realizing value within this ecosystem requires navigating a complex web of regional variances, technological bifurcation, and regulatory tightening that only deep-dive intelligence can adequately decode.
Deconstructing the Market Architecture
A superficial glance at aggregate numbers offers limited strategic utility. True competitive advantage lies in understanding the granular mechanics that drive revenue streams across different modalities, end-user sectors, and geographic territories. The research provides a multi-dimensional segmentation analysis that illuminates where growth is concentrated and which sub-markets are maturing versus those poised for disruption.
Technological Modalities and Adoption Curves
The industry is characterized by a diverse array of testing methodologies, each serving distinct operational needs and capital constraints. Ultrasonic testing continues to command significant attention, reflecting its versatility in detecting internal flaws across a wide range of materials without causing damage. Radiographic testing maintains its relevance, particularly in scenarios demanding high-resolution imaging for complex geometries. Simultaneously, magnetic particle testing, eddy current testing, and emerging alternative types cater to specialized applications where surface defects, conductivity variations, or specific material properties are the primary concern.
Non-Destructive Testing Instruments Market
The strategic nuance here is not just in identifying the dominant techniques but in understanding the shifting cost-benefit analyses that influence procurement decisions. High upfront costs associated with advanced instruments, such as phased array ultrasonic and digital radiography systems, remain a barrier for small and medium enterprises. Yet, the pressure on component and sensor pricing is reshaping the affordability landscape. Our analysis dissects these pricing dynamics, average selling price trends, and the subtle trade-offs between capital expenditure and long-term inspection efficacy, enabling organizations to forecast budget requirements and technology roadmaps with precision.
Sectoral Demand Drivers
Demand for NDT instruments is inextricably linked to the operational intensity and safety criticality of downstream industries. The oil and gas sector remains a pillar of consumption, driven by the need to monitor pipelines, refineries, and offshore structures under harsh conditions. Power generation facilities, encompassing both traditional and renewable energy assets, rely heavily on inspection technologies to ensure grid stability and prevent catastrophic failures. Aerospace applications impose the most rigorous standards, where the margin for error is non-existent and regulatory compliance is absolute. Manufacturing, as a broad category, continues to expand its footprint, integrating NDT into production lines for real-time quality control. Other applications further diversify the revenue base, capturing niche but high-growth opportunities in automotive, rail, and marine sectors.
The report delves into the specific demand catalysts within each vertical, highlighting how operational downtime costs, regulatory penalties, and the push for predictive maintenance are reshaping procurement behaviors. By mapping these application-specific drivers, decision-makers can identify high-engagement segments and tailor their value propositions accordingly.
Geographic Value Distribution
Regional dynamics play a pivotal role in shaping market opportunities. North America and Europe represent mature markets with established regulatory frameworks and high adoption rates of advanced technologies. Asia Pacific, while currently reflecting a different scale of valuation, is emerging as a critical growth engine fueled by rapid industrialization, infrastructure development, and increasing awareness of quality standards. Latin America and the Middle East and Africa contribute distinct regional profiles, often tied to resource extraction, energy projects, and localized manufacturing hubs.
The research avoids generic regional summaries, instead providing a nuanced view of how economic policies, trade dynamics, and local industrial priorities influence market penetration. Understanding these geographic nuances is essential for multinational corporations seeking to optimize their distribution networks and for regional players aiming to capture cross-border opportunities.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated structure, with a select group of leading entities commanding a significant share of total revenue. The top three competitors account for approximately 65.5 percent of the market, while the top five collectively hold around 82.2 percent. This concentration indicates the presence of established incumbents with strong technological portfolios, extensive service networks, and deep customer relationships. However, the remaining market share is distributed among a diverse array of specialized firms, creating a dynamic environment where innovation and niche expertise can disrupt traditional hierarchies.
Profiles of Key Industry Participants
The competitive arena is populated by organizations that have carved out distinct identities through technological specialization, geographic reach, and service integration. Mistras Group, Inc., headquartered in Princeton Junction, New Jersey, stands as a leading provider of NDT instruments and field inspection solutions, offering ultrasonic and advanced testing equipment tailored for industrial applications. Olympus Corporation, based in Shinjuku, Tokyo, is a major manufacturer focusing on ultrasonic phased array and thickness measurement systems, leveraging decades of imaging and sensing expertise.
Nikon Metrology NV, located in Tricht, Belgium, supplies X-ray and computed tomography instruments that cater to precision NDT applications, appealing to sectors where detailed internal visualization is paramount. Sonatest Ltd, operating from Hertfordshire, UK, produces portable ultrasonic and eddy current NDT instruments, addressing the need for field-deployable and flexible testing solutions. Acuren Corp., based in Markham, Ontario, Canada, provides advanced NDT equipment and inspection services, with a specialization in phased array and digital radiography instruments that bridge hardware and expertise.
Eddyfi Technologies, from Quebec City, Quebec, develops eddy current and remote NDT instruments specifically designed for pipeline and industrial use, emphasizing reliability in critical infrastructure monitoring. Zetec Inc., situated in San Jose, California, manufactures eddy current and magnetic particle NDT instruments, serving a broad customer base with robust and proven technologies. YXLON International GmbH, headquartered in Hamburg, Germany, produces X-ray NDT instruments and modules, contributing to the radiographic testing ecosystem with high-performance solutions. Fischer Technology Inc., located in Windsor, Connecticut, supplies coating thickness and material analyzers used in NDT contexts, addressing surface measurement and material verification needs. TWI Ltd, based in Cambridge, UK, provides advanced NDT testing instruments and systems for research and industrial use, acting as a bridge between cutting-edge development and practical deployment.
Recent Corporate Developments and M&A Activity
The competitive landscape is further shaped by a series of strategic moves that signal shifting priorities and consolidation trends. In April 2026, NDT Systems launched the BondHub Imaging Bond Tester with C-scan imaging capability, a product release that enhances composite inspection capabilities and reflects the growing emphasis on advanced imaging for non-metallic structures. This development underscores the industry's pivot toward multi-modal inspection tools that deliver actionable data faster.
Earlier in the forecast window, SGS introduced a new AI-driven inspection platform in November 2025, designed to enhance NDT accuracy through machine learning algorithms and automated defect recognition. This launch highlights the accelerating integration of artificial intelligence into inspection workflows, promising to reduce human error and increase throughput. In October 2025, Bureau Veritas executed an acquisition of a regional competitor to expand its advanced ultrasonic testing capabilities, a move that illustrates the strategic value of consolidating technological strengths and expanding service footprints.
Intertek entered a strategic partnership in September 2025 with a technology firm to develop a remote digital NDT inspection platform, signaling the industry's embrace of connectivity and remote monitoring. Such collaborations are becoming increasingly common as organizations seek to leverage external expertise and accelerate digital transformation. Additionally, Previan Technologies realigned Eddyfi Technologies and NDT Global as independent industrial-technology leaders in June 2026, a corporate restructuring that aims to sharpen focus and enhance agility within specialized segments of the market.
X-ray Non-destructive Testing Equipment Market
Industry Dynamics and Headwinds
Regulatory Evolution and Compliance Costs
Regulatory frameworks are tightening, with direct implications for both equipment suppliers and inspection service providers. The new ISO 9712-2025 standard, issued by ISO Technical Committee 135 in January 2026, increases the certification renewal frequency for NDT personnel to every three years, mandating compulsory retraining on advanced methods. This shift ensures that the workforce remains proficient with evolving technologies but also introduces recurring compliance costs and administrative burdens. Similarly, the EN 4179:2026 standard establishes updated minimum requirements for the qualification and certification of NDT personnel in aerospace applications, reinforcing the sector's demand for highly credentialed inspectors.
These regulatory changes elevate the importance of instrumentation that supports efficient training, certification, and documentation. Instruments that integrate with digital record-keeping systems or offer intuitive interfaces for complex procedures gain a competitive edge in an environment where compliance is non-negotiable. Furthermore, certification renewal changes in 2026 require more frequent retraining, driving up labor costs for qualified NDT personnel, as noted by industry sources in late 2025. This labor cost pressure incentivizes the adoption of tools that maximize inspector productivity and reduce the time required per inspection.
Cost Pressures and Adoption Barriers
Despite the favorable growth outlook, cost remains a pivotal factor influencing market penetration, particularly among smaller enterprises. The high upfront cost of advanced NDT instruments, including phased array ultrasonic and digital radiography systems, continues to limit adoption among small and medium enterprises. This barrier creates a bifurcation in the market, where large industrial players can accelerate their digital and advanced testing transformation, while smaller entities may rely on traditional methods or shared service models.
On the pricing front, averaged selling price trends for ultrasonic testing techniques showed increases through 2024, with ongoing pressure from component and sensor pricing in 2025. These dynamics suggest that manufacturers are navigating a delicate balance between maintaining margins and offering competitive pricing in a supply-constrained environment. Our analysis examines how these cost structures affect downstream pricing strategies and the total cost of ownership for end-users, providing clarity on where economies of scale can be leveraged and where value-added services can offset hardware costs.
Strategic Value of the Research for 2026 Decision-Making
In an environment defined by rapid technological change, regulatory evolution, and intense competitive maneuvering, access to granular, forward-looking intelligence is a strategic necessity. This research equips decision-makers with the analytical framework required to navigate uncertainty and capitalize on emerging opportunities.
Capital Allocation and Investment Strategy
For investors and corporate strategy teams, the forecast trajectory offers a compelling basis for portfolio decisions. The projected growth from 18.62 billion USD in 2026 to over 30 billion USD by 2032 indicates sustained demand across multiple cycles. Understanding which segments are expanding at higher rates, which technologies are gaining share, and which geographic regions are accelerating adoption allows for targeted investment in high-potential areas. The report's segmentation analysis helps identify where capital can be deployed with the highest return potential, whether in product innovation, market expansion, or strategic acquisitions.
Product Development and Technology Roadmapping
For manufacturers and technology developers, the research provides critical insights into the evolving requirements of end-users. The shift toward AI-driven platforms, remote digital inspection capabilities, and advanced imaging solutions signals where R&D efforts should be concentrated. By analyzing recent product launches and corporate realignments, organizations can benchmark their own innovation pipelines and identify gaps in the market. The discussion of cost pressures and pricing trends further informs go-to-market strategies, helping companies position their offerings to address both the premium segment seeking cutting-edge performance and the cost-conscious segment requiring accessible solutions.
Market Entry and Competitive Positioning
For companies considering market entry or expansion, the competitive landscape analysis offers a realistic assessment of the barriers and opportunities. The concentration of market share among top players highlights the importance of differentiation, whether through technological novelty, specialized application focus, or regional expertise. The profiles of key companies and recent strategic developments reveal the tactics that incumbents are employing to defend and grow their positions. Armed with this knowledge, new entrants can identify underserved niches, form strategic alliances, or develop disruptive business models that challenge the status quo.
Risk Management and Regulatory Compliance
For operators and service providers, the regulatory updates represent both a challenge and an opportunity. The increased frequency of certification renewals and the heightened requirements for advanced methods underscore the need for robust training programs and compliant instrumentation. The research integrates these regulatory dynamics into the broader market context, helping organizations anticipate compliance costs, plan workforce development, and select tools that streamline certification and documentation processes. By proactively addressing these factors, companies can mitigate operational risks and maintain their competitive standing in regulated industries.
Conclusion: The Path Forward
The Non-Destructive Testing Instruments Market is at an inflection point, where historical growth patterns are being amplified by technological innovation, regulatory tightening, and the imperatives of asset integrity across critical industries. The data landscape reveals a market on a robust growth trajectory, yet the true value for decision-makers lies in the strategic insights that connect macroeconomic trends to actionable business implications. This research serves as a comprehensive guide for navigating the complexities of the market, offering the depth and precision required to make informed investments, drive product innovation, and secure a resilient competitive position.
To fully capitalize on the opportunities outlined in this analysis, stakeholders are encouraged to access the complete report. The full study provides the detailed segmentation data, granular regional breakdowns, company-level assessments, and forward-looking scenarios that form the backbone of a winning strategy. By integrating this intelligence into your planning processes, you can transform market uncertainty into a structured pathway for sustainable growth and leadership in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-Destructive Testing Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Unlocking Growth in the Cetirizine Hydrochloride Market: Strategic Insights for 2026 and Beyond
The global pharmaceutical landscape for antihistamine therapies is undergoing a significant transformation, driven by rising prevalence of allergic conditions, evolving regulatory frameworks, and shifting supply chain dynamics. For stakeholders operating within the Cetirizine Hydrochloride sector, understanding the nuanced trajectory of this market is no longer optional; it is a strategic imperative. Our latest comprehensive market research study delves deep into the operational, financial, and competitive layers of the Cetirizine Hydrochloride industry, providing a robust foundation for decision-making throughout the forecast period extending to 2032.
This article serves as a strategic overview of the key findings contained within the full report. It is designed to highlight the macroeconomic trends and competitive pressures that define the current landscape, while outlining the specific analytical depth available to subscribers who seek to leverage this intelligence for commercial advantage.
Macroeconomic Trajectory and Market Valuation
The financial outlook for the Cetirizine Hydrochloride market demonstrates sustained growth momentum, reflecting both steady demand from established markets and expanding penetration in emerging regions. Based on historical data tracking from 2020 through the base year of 2025, the market has shown a consistent upward trend in revenue generation. The valuation started at a significant baseline in 2020 and has climbed steadily, reaching an estimated 3980.0 Million USD by 2025.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is anticipated to reach approximately 4408.89 Million USD in 2026, with growth accelerating towards a valuation of 6250.0 Million USD by the end of the forecast window in 2032. This trajectory underscores a Compound Annual Growth Rate (CAGR) of 6.98 percent during the forecast period. Such growth rates indicate a healthy elasticity in demand, suggesting that despite generic competition and pricing pressures, the core utility of Cetirizine Hydrochloride in managing allergic conditions remains robust.
These figures represent more than just top-line revenue; they signal the scale of opportunity available for manufacturers, distributors, and investors. However, realizing this potential requires a granular understanding of where value is being created and eroded within the value chain, which is a core focus of our detailed analysis.
Segmentation Dynamics and Consumption Patterns
The market is fragmented across several key dimensions, each presenting unique challenges and opportunities for market participants. Our report dissects these segments to reveal shifting consumption patterns that are critical for product portfolio strategy.
Dosage Forms and Patient Preferences
The form factor in which Cetirizine Hydrochloride is delivered plays a pivotal role in market share distribution. Tablets continue to dominate the landscape, reflecting their convenience and established patient preference in adult demographics. However, the report highlights significant activity in liquid formulations, including syrups and solutions, which are essential for pediatric and geriatric populations who may have difficulty swallowing solid dosage forms. The balance between these forms influences manufacturing complexity, packaging requirements, and regulatory pathways, particularly concerning flavorings, preservatives, and sugar content in pediatric formulations.
Therapeutic Applications Driving Demand
Clinically, the demand for Cetirizine Hydrochloride is anchored primarily in the treatment of allergic conditions. Allergic Rhinitis remains the largest application segment, driven by environmental factors and increased diagnosis rates globally. Other significant applications include Allergic Conjunctivitis and Eczema, where antihistamines play a supportive role in symptom management. Understanding the specific growth rates within each therapeutic area allows companies to tailor their marketing messages and clinical support materials to the conditions with the highest unmet need or fastest growing prevalence.
Geographic Revenue Distribution
Geographically, the market exhibits a diverse revenue mix. While North America and Europe represent mature markets with established reimbursement pathways and high brand recognition, the Asia Pacific region emerges as a critical volume driver. The region's growth is supported by increasing healthcare access, rising disposable incomes, and a large patient base. Latin America and the Middle East and Africa also contribute to the global total, though often with different dynamic characteristics related to pricing regulations and import dependencies. Our analysis avoids simple regional rankings, instead focusing on the specific growth drivers and barriers within each territory to guide market entry or expansion strategies.
Competitive Landscape and Corporate Strategy
The Cetirizine Hydrochloride market is characterized by a mix of large multinational pharmaceutical corporations and specialized generic manufacturers. Market concentration data indicates a moderately consolidated environment, where a handful of key players command a significant portion of the market share. This structure creates a competitive arena where pricing power, regulatory approval speed, and supply chain reliability are key differentiators.
Key companies active in this space include major generic producers and API manufacturers such as Granules India Limited, Aurobindo Pharma Limited, Cipla Limited, and Mylan (Viatris). These entities compete not only on price but on regulatory compliance and supply consistency. For instance, Teva Pharmaceutical Industries Ltd. and Apotex Inc. maintain strong positions in finished dosage forms, leveraging long-standing FDA approvals and established distribution networks.
Recent activity among these competitors highlights the intensity of the race for market access and product differentiation. Strategic moves often involve securing new approvals to extend portfolio depth or entering specific geographic markets where demand is underserved. Our report provides detailed profiles of these key companies, analyzing their recent developments, strategic positioning, and potential impact on market pricing and availability.
Regulatory and Supply Chain Volatility
One of the most critical aspects of the current market environment is the volatility introduced by regulatory changes and supply chain constraints. These factors can materially impact profit margins and product availability, making real-time intelligence vital for risk management.
Regulatory Developments
Regulatory bodies are increasingly scrutinizing safety profiles and pricing structures. In May 2025, the FDA issued a Drug Safety Communication requiring revised labeling for cetirizine and levocetirizine products. This update warned about rare but severe pruritus upon long-term use and abrupt discontinuation. Such labeling changes can influence prescribing habits and patient adherence, requiring manufacturers to update communication strategies and potentially manage adverse event reporting more rigorously.
Furthermore, pricing regulations remain a potent force, particularly in emerging markets. In January 2026, the National Pharmaceutical Pricing Authority (NPPA) of India capped the retail price of cetirizine hydrochloride ophthalmic solution. Price controls of this nature directly affect revenue projections and require companies to adjust their cost structures or volume expectations to maintain profitability in controlled markets.
Supply Chain and Raw Material Dynamics
Supply chain resilience has become a focal point for industry participants. In March 2026, U.S. spot prices for cetirizine dihydrochloride API rose approximately 11.8 percent. This increase was attributed to constrained supply from Indian and Chinese sources, compounded by seasonal demand spikes and logistical pressures. Such fluctuations highlight the dependency on specific geographic hubs for API production. Companies that rely heavily on single-source suppliers or specific regions face heightened risk, whereas those with diversified sourcing strategies may find opportunities to capture margin improvements during periods of constrained supply.
Quality and Recall Incidents
Quality assurance remains a non-negotiable standard. In March 2025, specific lots of Cetirizine Hydrochloride Tablets were recalled due to potential manufacturing quality issues identified by the FDA. Incidents like these serve as reminders of the operational risks inherent in pharmaceutical manufacturing. They can lead to temporary supply shortages, reputational damage, and increased regulatory oversight. Our report examines these incidents not merely as news items, but as case studies for understanding systemic risks and the importance of robust quality management systems.
Recent Developments Shaping the Foreground
The period leading into 2026 has seen specific product launches and approvals that refine the competitive landscape. These developments often signal where companies are placing their bets for future growth.
Notably, Preferred Pharmaceuticals Inc. received FDA approval in March 2026 for a Cetirizine Hydrochloride Oral Solution USP specifically formulated for pediatric use. The product is sugar-free and dye-free with a grape flavor, targeting children two years and above. This move addresses a specific niche within the liquid dosage form segment, focusing on palatability and safety concerns for younger patients.
Cetirizine Hydrochloride Market
Loratadine Market
Simultaneously, Aurohealth LLC received FDA approval in February 2026 for Cetirizine Hydrochloride as an over-the-counter human drug, expanding the availability of generic OTC options. Indoco Remedies Limited also secured final USFDA approval in October 2025 for their 10 mg tablets. These sequential approvals indicate a continuous pipeline of generic entrants seeking to capture share in the OTC and prescription segments, intensifying competition but also ensuring supply stability for consumers.
The Strategic Value of Deep-Dive Intelligence
While the macroeconomic trends and competitive moves outlined above provide a high-level view, successful strategic planning requires access to granular data that lies beneath the surface. The full market research report offers actionable intelligence that goes beyond general observations.
Subscribers to the complete study gain access to detailed segmentation revenue splits, allowing for precise identification of high-growth niches within dosage forms and therapeutic applications. The report provides deep-dive profiles of key companies, including their financial health, recent strategic partnerships, and specific regional strengths. This level of detail enables competitive benchmarking and helps identify potential acquisition targets or partnership opportunities.
Furthermore, the analysis of market dynamics includes a thorough examination of raw material sourcing risks, regulatory timelines, and reimbursement trends. Understanding the interplay between API price volatility and finished product pricing strategies is essential for margin protection. The report also addresses frequently asked questions regarding market barriers, entry strategies, and the impact of recent regulatory changes on long-term profitability.
For investors and corporate strategists, the ability to model different scenarios based on accurate historical data and robust forecast methodologies is invaluable. The report provides the foundational data required to build financial models, assess risk exposure, and validate market entry assumptions. Whether the goal is to expand production capacity, launch a new formulation, or enter a new geographic region, the insights contained in this study serve as a critical decision-support tool.
Navigating the Future Landscape
As the Cetirizine Hydrochloride market moves through the forecast period towards 2032, the interplay of growth drivers, regulatory constraints, and competitive pressures will continue to evolve. The projected CAGR of 6.98 percent suggests that the market will expand significantly, but the distribution of this growth will not be uniform. Companies that can navigate supply chain complexities, adapt to regulatory labeling requirements, and differentiate their products through formulation innovation or strategic pricing will be best positioned to capture value.
The recent approvals for pediatric solutions and new OTC entrants indicate that the market remains dynamic, with room for innovation even in a mature therapeutic class. However, challenges such as API price volatility and pricing caps in key markets require vigilant management. Access to comprehensive, up-to-date intelligence is the key to turning these challenges into opportunities.
We invite industry stakeholders to explore the full findings of our Cetirizine Hydrochloride Market research. The complete report provides the detailed segmentation data, company profiles, and dynamic analysis necessary to formulate a winning strategy in this evolving landscape. Access the full intelligence to ensure your decisions are grounded in rigorous data and expert analysis.
For detailed analysis of this topic, please visit the official page: Cetirizine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phloroglucinol Market Sees 5.85% CAGR Toward $280.7M by 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Global Phloroglucinol Market Through 2032
The global phloroglucinol market stands at a pivotal inflection point, shaped by tightening regulatory frameworks, expanding pharmaceutical applications, and a highly concentrated supply chain. For executives, procurement leaders, and strategic planners, understanding the trajectory of this critical intermediate is no longer optional—it is a prerequisite for resilient sourcing, capacity planning, and competitive positioning. Our latest comprehensive study, spanning historical performance through 2032, delivers the structured intelligence required to transform market uncertainty into actionable strategy.
Over the past half-decade, the market has demonstrated steady expansion, reflecting sustained demand from pharmaceutical formulation and specialty chemical synthesis. Current valuations position the industry at a substantial baseline, with forward projections indicating continued value accumulation through the end of the decade. The compound annual growth rate across the forecast horizon registers at 5.85 percent, a figure that encapsulates both organic demand growth and the market's sensitivity to capacity adjustments, regulatory shifts, and pricing dynamics. This growth trajectory is neither linear nor uniformly distributed; it is mediated by regional manufacturing ecosystems, grade-specific procurement patterns, and the strategic maneuvers of a tightly knit competitive field.
At the core of this analysis lies a rigorous reconstruction of supply and demand mechanics. The report dissects historical consumption patterns, maps production capacity expansions, and evaluates the structural drivers that will dictate market behavior through 2032. Readers will find granular examinations of how pharmaceutical-grade dominance shapes overall revenue composition, how industrial and research-grade segments carve out specialized niches, and how application-level demand responds to clinical adoption, manufacturing scale-up, and downstream chemical integration. Each dimension is contextualized within pricing environments, raw material volatility, and compliance requirements that collectively determine margin profiles and sourcing feasibility.
Decoding Competitive Dynamics and Strategic Positioning
The phloroglucinol landscape is characterized by pronounced concentration. The top three players command more than half of total market share, while the top five extend their footprint to approximately two-thirds of total revenue. This concentration is not accidental; it reflects the capital intensity of pharmaceutical-grade production, the regulatory overhead required for API and injection-grade compliance, and the incremental barriers that separate bulk suppliers from high-purity specialists. The report provides a detailed competitive mapping that moves beyond simple market-share rankings to analyze operational footprints, supply reliability, quality certification pathways, and strategic alliances that define leadership positions.
Phloroglucinol Market
Worldwide P-chlorophenol Market
Among the manufacturers under scrutiny, several Chinese enterprises have built formidable positions by aligning production capabilities with domestic pharmaceutical demand and export-oriented API supply. Entities such as Taixing Yinxin Chemical, Jiangsu Dingye Pharmaceutical, Beijing Wisdom Chemicals, Hebei Jianxin Chemical, Shouguang Fukang Pharmacy, Kaifeng Mingren Pharmaceutical, Clent Chemical, and Sinopharm Guorui Pharma each occupy distinct roles within the value chain, ranging from bulk and specialty chemical supply to high-purity pharma-grade output and approved injection formulations. Their collective activities illustrate how regional manufacturing clusters are consolidating technical capability, expanding throughput, and responding to both domestic procurement cycles and international demand signals.
On the global stage, established multinational players continue to reinforce their positioning through targeted acquisitions and supply-chain integration. Merck KGaA, for instance, has moved to secure stable access to phloroglucinol API and intermediates by acquiring the pharmaceutical chemicals division of Shaanxi Sciphar HiTech Industry, a move that underscores the strategic premium placed on supply continuity and quality assurance. Meanwhile, Aarti Industries maintains a globally oriented production footprint that supports pharmaceutical customers with consistent API supply. These developments are not isolated incidents; they are symptomatic of a broader industry pattern in which leading firms prioritize upstream security, capacity alignment, and regulatory readiness as foundational elements of long-term competitiveness.
The report systematically evaluates how these competitive forces interact with pricing structures, order Book stability, and customer-switching behavior. By tracing recent operational milestones—including Sinopharm Group's strategic partnership with Nantong Acetic Acid Chemical to expand production capacity and Merck KGaA's acquisition activity in early 2025—the analysis isolates the mechanisms through which capacity adjustments and M&A transactions reshape supply availability, regional balance, and pricing expectations. Readers gain clarity on which moves represent tactical short-term optimizations and which signal structural shifts likely to influence procurement strategy over the next several years.
Market Dynamics: Regulation, Pricing, and Supply Resilience
Regulatory visibility and pricing transparency are the twin pillars upon which procurement decisions now rest. The industry operates within an environment where compliance documentation, safety reporting, and substance recognition directly affect market access and buyer confidence. Phloroglucinol's inclusion in official substance databases, its recognition through FDA UNII identifiers, and its presence in EMA periodic safety update reports for marketed medicines collectively reinforce its regulatory standing and facilitate cross-border procurement. These signals matter because they reduce ambiguity for formulators, wholesalers, and contract manufacturers seeking reliable, auditable supply sources.
Pricing dynamics remain highly sensitive to raw material cost fluctuations, production batch sizing, and grade-specific purity requirements. As of early 2026, bulk pharmaceutical-grade phloroglucinol has been observed trading within a range reflecting these pressures, with price dispersion driven by contract structures, order volume, and regional logistics costs. The report translates these observed price bands into a structured framework for scenario planning, enabling buyers and suppliers to model margin sensitivity, evaluate contract terms, and anticipate the impact of raw material volatility on overall cost of goods. This is especially critical for organizations that rely on steady API input for antispasmodic formulations, specialty synthesis pipelines, or dye manufacturing workflows where cost predictability directly affects product economics.
Regulatory developments also intersect with capacity strategy. The approval of phloroglucinol injection for marketing by Sinopharm Guorui Pharma exemplifies how product-level regulatory milestones can catalyze demand shifts, stimulate downstream procurement, and incentivize upstream capacity expansion. The report assesses how such milestones propagate through the value chain, influencing not only volume expectations but also quality-system requirements, documentation burdens, and the competitive positioning of manufacturers that can demonstrate consistent compliance. By mapping these intersections, the study equips decision-makers with the foresight needed to anticipate supply tightness, evaluate alternative sourcing options, and time procurement commitments to align with anticipated capacity releases.
Inside the Report: Tools for Decisive Action
This study is designed as an operational asset rather than a static reference. Its architecture supports a range of internal use cases, from strategic sourcing reviews and capacity-investment justification to competitive benchmarking and risk assessment. The report integrates historical reconstructions, forward-looking forecasts, and structural analysis into a cohesive decision-support toolset. Key components include:
- A comprehensive market sizing framework that traces revenue evolution across historical years and projects growth through the forecast period, providing a consistent baseline for scenario modeling and investment appraisal.
- Segment-level analysis covering type classifications, application domains, and regional distribution patterns, presented in a way that highlights relative share, growth behavior, and demand drivers without obscuring the structural relationships that underpin them.
- A competitive landscape evaluation that profiles leading manufacturers, maps their operational strengths and supply characteristics, and examines recent strategic moves that signal positioning shifts.
- An integrated assessment of regulatory developments, pricing behavior, and raw material dynamics, linked to practical frameworks for procurement planning, contract negotiation, and supply continuity management.
- Forward-looking insights that connect market concentration, capacity expansion activity, and product-level regulatory milestones to medium-term supply expectations and competitive reordination risks.
Throughout the analysis, emphasis is placed on interpretability and applicability. Data points are contextualized within operational realities, and projections are accompanied by the assumptions and sensitivities that shape them. This approach ensures that readers can translate high-level trends into specific, defensible actions—whether that means reevaluating supplier portfolios, assessing the strategic value of long-term contracts, or prioritizing internal investments in quality systems and compliance infrastructure.
Turning Intelligence into Advantage
Markets characterized by moderate growth, concentrated supply, and regulatory sensitivity reward organizations that combine analytical rigor with operational discipline. The phloroglucinol market is no exception. Its trajectory through 2032 will be shaped by the interplay of capacity expansion, compliance readiness, pricing sensitivity, and the strategic choices of a relatively small group of influential manufacturers. For executives navigating this environment, timely and well-structured intelligence is the difference between reactive adjustment and proactive positioning.
Our full report delivers the depth, granularity, and strategic framing required to make informed decisions with confidence. It provides the segmented breakdowns, competitive profiles, pricing frameworks, and forward scenarios that executives need to align sourcing strategies, evaluate investment opportunities, and anticipate the competitive moves that will define the next phase of market evolution. To access the complete analysis and integrate it into your planning cycle, visit our official report page for the full Phloroglucinol Market research.
For detailed analysis of this topic, please visit the official page: Phloroglucinol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Encryption Key Management Market Hits $3.8B in 2025, Projects 12.8% CAGR to $8.83B by 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Encryption Key Management Market: A 2026 Outlook
As organizations navigate an increasingly complex data security landscape, the management of cryptographic keys has evolved from a technical afterthought to a core strategic priority. The Encryption Key Management Market stands at a pivotal inflection point in 2026, driven by converging forces: tightening regulatory frameworks, the rapid adoption of cloud-native architectures, and the looming transition toward post-quantum cryptographic standards. For enterprise decision-makers, understanding the trajectory of this market is no longer optional; it is a foundational requirement for building resilient, compliant, and future-proof data protection strategies.
Our latest comprehensive research report on the Encryption Key Management Market offers a meticulously structured analysis designed to inform high-stakes 2026 planning. Spanning historical performance from 2020 through 2025 and projecting forward to 2032, the study maps the market's evolution with precision. In 2020, the global market generated approximately 2.08 million USD in revenue. By 2025, this figure had climbed to 3.8 million USD, reflecting sustained enterprise investment in centralized cryptographic controls. Looking ahead, the forecast period from 2026 to 2032 is projected to deliver a compound annual growth rate of 12.8 percent, with market revenue expected to surpass 8.8 million USD by the end of the outlook window. These headline trajectories are more than statistical milestones; they signal a structural shift in how organizations allocate security budgets, modernize legacy infrastructure, and evaluate vendor ecosystems.
Market Dynamics Reshaping Key Management Strategies
The acceleration of the Encryption Key Management Market is being propelled by a confluence of regulatory, technological, and operational dynamics. Chief among these is the ongoing evolution of government and industry standards. In December 2025, NIST released the initial public draft of SP 800-57 Part 1 Revision 6, updating foundational recommendations for cryptographic key management. With public comment open through February 2026, this revision signals a heightened emphasis on lifecycle governance, algorithmic agility, and alignment with emerging threat models. For compliance and architecture teams, these updates will directly influence procurement criteria, audit readiness, and the design of internal key governance frameworks.
Simultaneously, the quantum computing horizon is forcing a reevaluation of long-term cryptographic investments. Utimaco's 2025 PQC Readiness Report, which surveyed more than 200 IT security professionals, underscored an urgent industry consensus: organizations must begin embedding post-quantum cryptographic capabilities into their key management roadmaps now, rather than treating them as a distant future concern. This sentiment is echoed in recent product and partnership movements. Utimaco's launch of a Post Quantum Security App Package in April 2025 and its subsequent integration into the VAST Cosmos ecosystem in March 2026 demonstrate how vendors are translating quantum readiness from theoretical discussion into deployable, infrastructure-grade solutions. The implications for enterprise architects are clear: key management platforms must already be evaluated for crypto-agility, algorithm swapping capabilities, and compatibility with external hardware security module ecosystems.
Operational complexity continues to compound these regulatory and technological pressures. As enterprises expand across hybrid and multi-cloud environments, the administrative overhead associated with fragmented key inventories, inconsistent rotation policies, and disparate access controls has become a material bottleneck. Modern key management solutions are increasingly judged not only on cryptographic robustness but also on their ability to provide unified operational visibility, automated policy enforcement, and seamless integration with existing cloud service provider toolchains. Reducing the human and procedural burden of key lifecycle management has emerged as a decisive factor in vendor selection and platform consolidation efforts.
Report Scope: Operational Content for Executive Decision-Making
The report is structured to move beyond high-level market sizing and deliver actionable intelligence that can be directly plugged into enterprise planning cycles. Readers will find a detailed examination of deployment models, procurement pathways, and integration requirements that reflect the actual operating conditions of modern security teams. The analysis breaks down the market across multiple functional dimensions, allowing decision-makers to isolate the segments most relevant to their organizational context without getting lost in undifferentiated aggregates.
Key components of the research include:
- A rigorous historical reconstruction of market performance from 2020 to 2025, establishing baseline trajectories and highlighting inflection points where investment patterns shifted in response to cloud migration, regulatory changes, and vendor consolidation.
- A forward-looking forecast model extending through 2032, built on scenario-informed assumptions that account for regulatory uptake, cloud adoption curves, and the gradual mainstreaming of advanced cryptographic capabilities.
- A structured segmentation analysis that disentangles the market by deployment type, functional application, and geographic concentration. This enables readers to identify which solution categories are absorbing the most enterprise spend, which use cases are driving platform selection, and how regional maturity profiles differ across major economic zones.
- A deep competitive landscape assessment that profiles the leading platforms, maps their strategic positioning, and evaluates how recent product launches, partnership announcements, and standards alignment are reshaping vendor differentiation.
- An integrated regulatory and standards timeline that cross-references NIST guidance, industry readiness reports, and enterprise compliance requirements, helping teams anticipate audit expectations and align procurement cycles with forthcoming guidance updates.
Throughout the document, qualitative insights are anchored to verifiable data points and recent industry events, ensuring that strategic recommendations are grounded in observable market behavior rather than speculative projections. The report is designed to serve chief information security officers, enterprise architects, procurement leaders, and risk compliance officers who need a shared, evidence-based reference point for multi-stakeholder 의사결정에.
Competitive Landscape: Leaders, Innovators, and Strategic Positioning
The Encryption Key Management Market is characterized by a pronounced concentration of enterprise revenue among a select group of platform providers, while a broader field of specialized and cloud-native players competes on integration depth, cryptographic agility, and regional compliance capabilities. Market concentration metrics highlight the dominance of established vendors, with the top three firms collectively capturing a substantial share of total revenue and the top five extending that footprint further. This consolidation reflects the enterprise preference for platforms that offer comprehensive lifecycle management, proven cloud integrations, and clear alignment with external compliance frameworks.
Among the most influential players, AWS Key Management Service continues to anchor a large portion of cloud-native deployments. Its centralized creation, storage, rotation, and access control capabilities support encryption, signing, and multi-cloud hybrid deployments, making it a default consideration for organizations already invested in Amazon's ecosystem. Recent product enhancements, such as the April 2025 integration enabling server-side encryption for Amazon S3 Tables using customer-managed keys, illustrate how platform vendors are continuously expanding the scope of managed key use cases to cover structured data workloads and analytics pipelines.
Google Cloud's Cloud Key Management Service offers a parallel trajectory, emphasizing generation, management, and external linking of keys across Google Cloud services. Its external key management support extends the platform's reach for organizations that prefer to retain certain cryptographic controls with third-party managers, a configuration that is increasingly relevant for regulated industries and sovereignty-sensitive deployments.
On the enterprise security side, Thales has reinforced its position through the CipherTrust Data Security Platform and CipherTrust Cloud Key Management, which deliver centralized lifecycle management for cloud-native, bring-your-own-key, and hold-your-own-key models across public clouds. This breadth of deployment models appeals to organizations navigating complex data residency requirements and hybrid architectures that span on-premises infrastructure and multiple cloud providers.
Utimaco has emerged as a particularly dynamic force in the market, combining hardware security module support with software-defined key management and a strong emphasis on post-quantum preparedness. Its Enterprise Secure Key Manager and Secure Server offerings provide crypto-agile key management with unified on-premises and cloud control, directly addressing the administrative consolidation needs flagged by security teams. The company's recent activity underscores a dual focus on standards alignment and ecosystem expansion: the April 2025 Post Quantum Security App Package, the March 2026 VAST Cosmos partnership for AI data infrastructure compliance, and the February 2025 PQC Readiness Report collectively position Utimaco as a vendor bridging immediate operational needs with longer-term cryptographic resilience.
Fortanix complements this landscape with a data security manager that delivers HSM-grade key management, full lifecycle controls, bring-your-own-key management capabilities, and integration for multi-cloud and hybrid environments, including support for external key management models on Google Cloud Platform. IBM continues to reinforce its enterprise data protection portfolio through key management solutions and data security services that emphasize bring-your-own-key configurations and cloud integration, catering to large organizations with stringent governance requirements.
Regional and cloud-native entrants are also shaping competitive dynamics. Alibaba Cloud's Key Management Service provides scalable, compliant key generation, storage, and envelope encryption with webhook and customer-managed key configurations, aligning with the needs of organizations operating within its cloud ecosystem. KakaoCloud's Key Management Service offers secure, systematic key management for its cloud environments with automated encryption controls, reflecting the broader trend of regional cloud providers embedding cryptographic governance directly into their service layers.
The competitive narrative in 2026 is increasingly defined not by raw feature count but by the ability to operate seamlessly across deployment boundaries, accommodate evolving cryptographic standards, and reduce the operational friction associated with key sprawl. Vendors that can demonstrate clear migration paths, transparent audit trails, and forward compatibility with emerging algorithmic requirements are gaining decisive advantage in enterprise evaluations.
Commercial Encryption Products Market
Strategic Takeaways for 2026 Enterprise Decisions
For organizations mapping their security investments in 2026, the Encryption Key Management Market presents both a consolidation opportunity and a resilience imperative. The most consequential decisions will revolve around platform selection criteria that balance immediate operational efficiency with long-term cryptographic adaptability. Enterprises that treat key management as a static compliance checkbox risk accumulating technical debt as regulatory expectations evolve and cloud architectures grow more distributed.
Several strategic priorities emerge from the current market trajectory:
Encryption Key Management Market
- Align procurement cycles with forthcoming standards updates, particularly those stemming from NIST's evolving key management guidance, to ensure that selected platforms can accommodate revised lifecycle and governance expectations without disruptive re-architecture.
- Evaluate vendor roadmaps for post-quantum readiness, including the availability of algorithm agility, hybrid cryptographic modes, and integration pathways with hardware security modules or external key management services.
- Prioritize unified operational visibility across on-premises and cloud environments, as the administrative burden of fragmented key inventories continues to be a primary driver of platform consolidation and budget reallocation.
- Assess multi-cloud and hybrid deployment compatibility early in the selection process, since environments that span multiple cloud providers or combine managed services with self-managed infrastructure increasingly require portable key management models and consistent policy enforcement.
- Consider the concentration dynamics of the vendor landscape when planning for vendor risk, support continuity, and negotiation leverage, recognizing that a small number of platforms account for a significant share of enterprise adoption while specialized providers compete on niche cryptographic and compliance capabilities.
The broader implication is that key management is becoming a strategic architecture layer rather than a discrete utility. Enterprises that embed cryptographic governance into their cloud migration, data classification, and incident response planning will be better positioned to absorb regulatory changes, operational complexity, and emerging cryptographic threats without sacrificing agility.
Conclusion: Accessing the Full Intelligence Picture
The Encryption Key Management Market is entering a phase of accelerated structural change, where growth rates, competitive positioning, and regulatory expectations intersect to reshape how organizations protect their most sensitive data assets. The headline trajectory of the market reflects sustained enterprise commitment to cryptographic governance, but the real value for decision-makers lies in understanding the segmentation patterns, vendor movement, and operational dynamics that will determine which platforms deliver durable value over the next several years.
This report provides the analytical framework needed to evaluate those dynamics with precision. By integrating historical performance, forward-looking forecasts, detailed segmentation breakdowns, and a granular competitive assessment, it equips enterprise teams with a shared reference point for budgeting, vendor evaluation, and architecture planning. The complete dataset, including the full regional, type-based, and application-level segmentation splits, as well as the in-depth competitive profiles and scenario-informed forecasts, is available through the full report. Organizations seeking to translate these market signals into concrete 2026 action plans are encouraged to access the complete study for a comprehensive view of the strategic opportunities and risks shaping the Encryption Key Management Market.
For detailed analysis of this topic, please visit the official page: Encryption Key Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


