



Category: market research
PW Consulting: Photocatalyst Market Hits $2.2B in 2025, Forecasts 9.6% CAGR to $4.18B by 2032
By PW Consulting, 2026-09-16
The Photocatalyst Market in 2026: A Strategic Compass for Industrial Transition
The global photocatalyst market stands at a pivotal inflection point. After a decade of incremental adoption driven by niche environmental applications, the sector is now accelerating under the combined weight of regulatory pressure, urban air-quality mandates, and next-generation construction standards. Our latest market research delivers a comprehensive, forward-looking assessment of this landscape, designed specifically to equip corporate strategists, R&D directors, and investment committees with the operational intelligence needed to navigate decision-making in 2026 and beyond.
By consolidating five years of historical performance with a seven-year forecast horizon, the study maps how demand is structurally shifting across material classes, end-use sectors, and regional ecosystems. More importantly, it translates macro trajectories into actionable strategic frameworks—covering supply-chain resilience, regulatory compliance pathways, competitive positioning, and innovation roadmaps. This is not a static sizing exercise. It is a decision-support architecture for enterprises that must anticipate where capital, technology, and policy will converge over the next cycle.
A Market Accelerating Under Structural Tailwinds
Photocatalysis has evolved from a laboratory-scale environmental concept into a commercially embedded technology set. The sector’s valuation trajectory over the past half-decade reflects a clear acceleration, with revenue compounding steadily from the early 2020s through the current base year. That momentum is projected to intensify as the forecast window unfolds, supported by a compound annual growth rate that places the industry among the faster-growing segments within advanced materials and environmental technologies.
The underlying drivers are multifaceted and mutually reinforcing. Stricter indoor-air VOC and NOx emission standards worldwide are pushing facility operators, architects, and municipal authorities toward photocatalytic air-purification and self-cleaning materials. Simultaneously, the European Green Deal’s circular-economy provisions are channeling subsidies into sustainable construction materials that incorporate photocatalytic glazing and surface treatments. These policy signals are not isolated; they are compounding with corporate sustainability commitments, urbanization pressures, and a growing recognition that passive environmental remediation can deliver measurable operational savings over asset lifecycles.
Precious Metal Catalyst Market
Yet growth is not uniform, and the strategic implications vary sharply by material type, application architecture, and geographic footprint. This is precisely where high-level headlines fall short and granular, structured analysis becomes essential. Our research dissects the market’s composition without exposing the margin for guesswork, allowing leadership teams to evaluate where their portfolios align with the steepest growth vectors and where exposure to slower-moving segments requires defensive repositioning.
Photocatalyst Market
From Macro Trajectories to Operational Strategy
The study is structured to bridge the gap between top-line market direction and on-the-ground execution. Rather than presenting a single aggregate figure, the report builds a layered view of demand dynamics, pricing behavior, and technology substitution patterns across the forecast horizon. It examines how input-cost volatility—particularly within high-purity titanium dioxide feedstock supply chains, where production remains concentrated among a limited number of global suppliers—shapes margin structures and procurement strategies for downstream formulators and coating manufacturers.
Supply-chain visibility is a recurring theme. The analysis maps the sensitivity of photocatalytic product economics to upstream raw-material availability, logistics bottlenecks, and regional production capacity. It also evaluates how vertical integration moves by key feedstock and intermediate suppliers influence stability of supply and cost predictability for industrial buyers. For procurement and operations teams, these insights translate into more resilient sourcing frameworks and better-informed make-versus-buy decisions for specialty formulations.
On the demand side, the report traces how application adoption curves diverge across sectors. Air purification, water purification, and self-cleaning surfaces each follow distinct commercialization rhythms, shaped by local regulatory timelines, public-sector procurement cycles, and building-material integration requirements. Anti-fogging and anti-soiling coatings, alongside other emerging use cases, occupy a different risk-reward profile, typically requiring longer validation periods but offering higher differentiation potential once performance thresholds are met. The study outlines the commercial milestones, testing protocols, and certification pathways that govern market entry, helping R&D and product management teams sequence development pipelines against realistic adoption windows.
The forecast framework extends through the end of the decade and into the early 2030s, enabling scenario planning under varying assumptions for regulation, feedstock costs, and regional investment intensity. By modeling how different policy or cost environments could alter demand pacing, the report equips strategy teams to stress-test capital allocation, capacity expansion, and partnership choices well ahead of market inflection points.
Competitive Architecture and the Players Shaping the Next Cycle
The competitive landscape in photocatalysis is defined by a blend of material science specialists, large chemical conglomerates, and application-focused innovators. Concentration metrics indicate that the top three and top five participants command a meaningful share of commercial activity, underscoring the importance of understanding not just who leads today, but how incumbency advantages, differentiation strategies, and partnership ecosystems are evolving.
Kronos Worldwide, Inc. remains a specialist in photocatalytic titanium dioxide grades tailored for self-cleaning surfaces and building materials, positioning its portfolio around architectural and infrastructure demand. Cristal Global, operating through its CristalACTiV platform, has advanced ultrafine titanium dioxide formulations for photocatalytic coatings and NOx abatement applications, with recent product development centered on air-quality improvement use cases. TOTO Ltd. supplies photocatalytic coatings spanning self-cleaning surfaces as well as air and water purification, with a strong footprint in construction and healthcare environments. Ishihara Sangyo Kaisha, Ltd. contributes high-purity titanium dioxide photocatalysts aimed at environmental and industrial applications, while Nippon Soda Co., Ltd. develops and supplies photocatalytic formulations and binders that enable downstream integration.
On the broader materials and environmental catalysis side, BASF SE provides photocatalytic materials for air purification and environmental catalysis, leveraging its scale and cross-sector distribution capabilities. In the innovation frontier, Puralytics LLC has developed PuraMesh photocatalyst technology for advanced oxidation and water/air purification, while Nanoptek Corp. supplies visible-light titania photocatalysts and pigments that address performance limitations in lower-light conditions. Daicel Miraizu continues as a manufacturer of photocatalytic materials and coatings, and the International Photocatalyst Standards Test Centre in the UK serves as an independent testing and certification provider, underpinning market credibility through ISO-aligned evaluation protocols.
Recent corporate activity reinforces the strategic direction of the sector. In early 2026, Cristal Global advanced its CristalACTiV TiO2 products for NOx abatement applications targeting air-quality improvement, signaling continued emphasis on pollution-mitigation endpoints. Around the same period, Tronox highlighted photocatalytic applications within its specialty TiO2 products in its sustainability reporting, while also advancing vertical integration in its TiCl4 supply chain to stabilize TiO2 production. These moves illustrate a broader pattern: leading participants are aligning product development with regulatory tailwinds, while simultaneously working to insulate production from feedstock volatility.
The report examines how these competitive dynamics translate into market access barriers, partnership opportunities, and differentiation strategies. It evaluates where scale, where formulation expertise, and where application validation create durable advantages, and where new entrants or collaborative models may compress incumbency moats over the forecast period.
Why 2026 Is a Decision Window, Not Just a Forecast Year
For corporate decision-makers, 2026 functions as a strategic checkpoint. The convergence of tighter emission standards, subsidy mechanisms for sustainable construction, and evolving testing and certification expectations is reshaping the criteria by which photocatalytic products win commercial adoption. Enterprises that treat this year as a passive continuation of prior trends risk misaligning product roadmaps, sourcing strategies, and go-to-market priorities with the market’s actual direction.
Notable structural forces now shaping that direction include the ongoing influence of environmental compliance on specialty TiO2 product portfolios, with sustainability reporting and regulatory expectations encouraging broader adoption of photocatalytic NOx abatement technologies. In parallel, European frameworks are directing financial support toward circular-economy-aligned building materials, strengthening the economic case for photocatalytic glazing and surface solutions. At the same time, global indoor-air quality standards are tightening, expanding the addressable base for photocatalytic air-purification and self-cleaning materials. Regulatory approvals from bodies such as the European Chemicals Agency have also enabled the commercial launch of new photocatalytic products for air purification, widening the field for innovation-led entrants while raising the bar for compliance-ready product design.
These conditions create a market environment where strategic timing matters as much as technical capability. Companies that understand the interplay between feedstock cost dynamics, regional regulatory pacing, and application-specific certification requirements are better positioned to prioritize investments, negotiate supply agreements, and structure partnerships. The study is built to surface those interdependencies clearly, giving leadership teams a shared analytical baseline for cross-functional planning.
What the Report Delivers for Strategy, R&D, and Commercial Teams
The research is organized to support a wide range of internal use cases. For strategy and corporate development teams, it provides a market-level orientation that ties growth trajectories to competitive positioning, enabling more informed evaluation of adjacency opportunities, M&A targets, and geographic expansion priorities. For R&D and product teams, it maps technology substitution patterns, formulation considerations, and performance-testing expectations, helping calibrate development timelines against market readiness. For commercial and sales leadership, it outlines application-specific demand drivers, procurement contexts, and the regulatory and certification factors that influence buying decisions in construction, environmental services, and industrial settings.
The report also includes practical coverage of market-concentration dynamics, supply-chain sensitivity, and recent corporate developments that shape near-term competitive behavior. It integrates sector-level signals around regulation, raw-material availability, and sustainability reporting trends, translating them into implications for sourcing, pricing, and product positioning. By combining historical context, forecast direction, and qualitative intelligence on the companies and institutions actively shaping the market, the study offers a consolidated reference point for decision-making across functions.
Importantly, the analysis is designed to remain useful beyond the immediate planning cycle. Because photocatalytic adoption is influenced by long-duration assets such as buildings, infrastructure, and industrial facilities, today’s product and sourcing choices have multi-year consequences. The forecast horizon and scenario frameworks included in the research help organizations connect near-term actions to longer-term outcomes, reducing the risk of short-horizon optimization that undermines competitive positioning later in the decade.
Accessing the Full Intelligence Suite
Our Photocatalyst Market study is intended for teams that need more than directional commentary. It provides a structured, data-informed foundation for evaluating where the market is heading, which actors are shaping the pace of change, and how enterprise strategy should respond in 2026 and through the coming forecast years. The complete report includes detailed segmentation analyses, competitive profiles, regulatory and supply-chain assessments, and forecast scenarios that together form a comprehensive decision-support toolkit.
To explore the full segmentation detail, company-level positioning, regional demand architecture, and scenario-based forecasts, request access to the complete market research. The full intelligence suite is available through our official research portal, where strategy, procurement, and innovation teams can retrieve the complete dataset and analytical modules needed to ground 2026 planning in a rigorous, forward-looking view of the photocatalyst market.
For detailed analysis of this topic, please visit the official page: Photocatalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ball Mill Mining Market Hits $4.35B in 2025, Projected to Reach $6.86B by 2032
By PW Consulting, 2026-09-16
Ball Mill (Mining) Market 2026: Navigating the Efficiency Imperative in a $4.6 Billion Industry
The global mining equipment landscape is undergoing a structural transformation, and at the heart of this shift lies the ball mill. As the workhorse of mineral processing, the ball mill remains indispensable for reducing ore to fine particles suitable for downstream extraction. Yet, the operational context surrounding this machinery is changing rapidly. Rising energy costs, stricter environmental regulations, and the relentless pursuit of throughput optimization are reshaping procurement strategies, capex planning, and long-term fleet management for mining enterprises worldwide.
PW Consulting’s latest market research on the Ball Mill (Mining) Market is designed to cut through this complexity. Built on a rigorous historical dataset spanning 2020 through 2025 and extended with a comprehensive forecast period through 2032, this report provides the strategic intelligence required to make high-stakes decisions in 2026 and beyond. The market has demonstrated consistent momentum, with overall industry revenue climbing from 3171.89 million USD in 2020 to an estimated 4353.5 million USD by the base year of 2025. The forward trajectory points to continued expansion, positioning the sector at a projected 4606.46 million USD in 2026, with growth compounding toward 6859.45 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 6.9 percent, reflecting sustained investment in mining infrastructure, the commissioning of new processing plants, and the modernization of aging grinding circuits.
For executives, engineers, and procurement leaders, these aggregate figures serve as a critical baseline. They signal that demand for grinding equipment is not merely cyclical but structurally supported by the global need for processed minerals across industrial, technological, and energy-transition applications. However, aggregate size alone does not dictate strategy. The true value of this research lies in its ability to translate macro trends into actionable frameworks, helping organizations allocate capital, evaluate vendor partnerships, and anticipate regulatory or supply-chain disruptions before they impact operations.
The Strategic Value of Granular Intelligence for 2026 Decision-Making
2026 represents a pivotal planning year for mining organizations. Capital allocation decisions made now will determine operational competitiveness over the next several years, particularly as companies balance throughput targets with escalating energy costs and compliance requirements. The PW Consulting report is structured to support these decisions with field-ready analysis rather than abstract commentary. Readers will find detailed breakdowns of equipment types, end-use applications, and regional deployment patterns, all contextualized within the broader market trajectory.
The research dissects the market across multiple dimensions that matter directly to procurement and engineering teams. Equipment segmentation covers wet grinding ball mills, dry grinding ball mills, and other specialized configurations, allowing readers to understand where demand is concentrating and how technological preferences are evolving. Application-level analysis examines use cases across metal mining, mineral mining, and other processing verticals, highlighting where throughput requirements, liberation size targets, and circuit configurations differ. Geographic coverage spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing a global view of where development activity, mine expansions, and equipment replacement cycles are most active.
Importantly, the report does not simply present data points in isolation. Each segment is examined through the lens of operational relevance, helping decision-makers understand why certain configurations are favored in specific contexts, how application requirements drive specification choices, and which geographic markets are experiencing the most intense competition for supply and installation capacity. This approach ensures that readers can map market intelligence directly onto their own asset planning, vendor negotiations, and risk management frameworks.
Competitive Landscape: Established Leaders and Emerging Pressures
The ball mill market is characterized by a moderately concentrated competitive environment, with the top three players accounting for approximately 33.5 percent of market share and the top five collectively capturing around 48.2 percent. This structure creates a landscape where established multinational suppliers compete on technology, reliability, and global service networks, while regional and specialized manufacturers carve out positions through cost efficiency, customization, and responsiveness to local project requirements. Understanding this dynamic is essential for organizations evaluating supplier partnerships, negotiating procurement contracts, or assessing the availability of spare parts and technical support over the lifespan of a grinding circuit.
Several core companies define the current competitive baseline. Metso, headquartered in Finland, has strengthened its position through its Premier and Select horizontal ball mill offerings, emphasizing energy-efficient grinding solutions that can deliver up to 30 percent energy savings compared with conventional ball mills. This focus on efficiency aligns with broader industry mandates and appeals to operators seeking to reduce operating expenditures while maintaining throughput. FLSmidth, based in Denmark, complements this landscape with high-throughput ball mills and its Tower Mill technology for secondary and fine grinding. The company’s push to replace conventional ball mills in iron ore beneficiation, with documented energy reductions in the 25 to 50 percent range, underscores a strategic emphasis on alternative grinding architectures that can outperform traditional designs in specific applications.
KHD Humboldt Wedag, operating from Germany, continues to serve the market with traditional ball mill designs and upgrade packages for existing grinding circuits, targeting stable and efficient performance in mining environments. Sepro Mineral Systems, from Canada, addresses small and medium capacity operations with tyre-drive rotary grinding mills suitable for ball, rod, and pebble charges, offering a practical solution for operators where flexibility and manageable scale are priorities. On the capacity and throughput side, CITIC Limited in China supplies large-capacity ball mills for mining and mineral processing, with an emphasis on high throughput and reliability. Hongxing Machinery, also based in China, provides standard and energy-saving ball mills for ore re-crushing in mineral processing, reflecting the continued importance of cost-competitive equipment in high-volume segments.
Recent market developments illustrate how competitive and project dynamics are evolving in real time. In September 2025, Deccan Gold Mines Limited launched the Altyn Tor Gold Project in Kyrgyzstan, incorporating a ball mill as part of its gold extraction processing infrastructure. This type of project execution signals sustained demand for grinding equipment in gold and base metal operations, particularly where new facilities are being commissioned or existing circuits are being expanded. In July 2025, Gold Rock Projects introduced a new ball mill designed specifically for gold producers, equipped with digital monitoring sensors for real-time performance tracking and automated load control. This development highlights the growing integration of digital instrumentation and automation into grinding equipment, enabling operators to optimize mill performance, reduce manual intervention, and respond more quickly to changes in feed characteristics or circuit conditions.
Competitive pressure is also coming from adjacent technologies. Metso reported record sales of stirred mills in 2025, with more than 20 Vertimill units sold, demonstrating sustained demand for energy-efficient alternatives to conventional ball mills. This trend does not diminish the role of the ball mill, but it does reinforce the need for operators to evaluate the full spectrum of grinding options when designing or upgrading circuits. Decision-makers must weigh capital cost, energy consumption, maintenance requirements, and product size distribution against the specific demands of their ore bodies and processing goals.
Market Dynamics: Efficiency, Regulation, and Supply Chain Volatility
The operational environment for ball mill procurement and deployment is shaped by a convergence of technical, regulatory, and macroeconomic forces. Energy efficiency mandates and sustainability initiatives across the mining sector are accelerating the adoption of energy-efficient grinding systems and automation. Organizations are increasingly scrutinizing the total cost of ownership of grinding equipment, recognizing that energy consumption during operation can dominate lifecycle costs. The projected 25 to 50 percent energy reduction achievable when replacing conventional ball mills with more efficient alternatives has become a compelling value proposition, particularly for operators facing rising power prices or operating in regions with strict carbon and emissions expectations.
Regulatory frameworks are adding further complexity. OSHA noise exposure limits and the EU Occupational Safety and Health Framework Directive establish strict permissible exposure levels for ball mill operations, conditions that are frequently exceeded without mitigation measures. These requirements are driving interest in engineering controls, enclosure improvements, and operational protocols that reduce noise and vibration at the source. At the same time, compliance pressures are encouraging adoption of ISO 14001 environmental management systems, as mining companies seek to standardize their approach to environmental performance, hazard control, and continuous improvement. Equipment suppliers that can support these compliance objectives through design features, documentation, and service integration are likely to gain preference in competitive tenders.
Supply chain volatility presents another critical consideration. Steel grinding media raw material costs account for 55 to 70 percent of manufacturing costs for forged balls used in ball mills, and these costs have experienced volatility of over 25 percent year-on-year in recent years. Such fluctuations directly affect consumable expenses, which are a significant component of grinding circuit operating costs. Operators must factor media cost volatility into their budgeting, negotiate procurement agreements with appropriate flexibility, and evaluate whether certain mill designs or operating strategies can reduce media consumption or extend media life. The interplay between equipment selection, operating parameters, and consumable costs is a central theme in the report’s analysis, helping readers build more resilient cost models.
Forged Steel Grinding Balls Market
Why This Research Matters Now
The ball mill market is not defined solely by equipment sales; it is shaped by the intersection of ore characteristics, processing objectives, energy economics, regulatory compliance, and competitive technology alternatives. The 6.9 percent CAGR reflected in the forecast period signals that demand will continue to grow, but growth alone does not guarantee optimal outcomes for any individual organization. The strategic question for 2026 is not whether the market is expanding, but how to position within it with the right equipment specifications, supplier relationships, and operational strategies.
Ball Mill (Mining) Market
This research provides the analytical foundation to answer that question. It combines historical validation with forward-looking projections, embeds competitive and project-level developments in context, and addresses the operational dynamics that influence procurement and performance. By connecting market size trends with segmentation insights, regulatory drivers, and supply-chain realities, the report equips readers to make decisions with greater confidence and precision.
For organizations planning capital expenditures, evaluating grinding circuit upgrades, or preparing for new project commissions, the full report offers the depth required to move beyond general market awareness into targeted strategy. Explore the complete analysis, including detailed segmentation, competitive profiles, and operational dynamics, by accessing the full market research at the source page.
For detailed analysis of this topic, please visit the official page: Ball Mill (Mining) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnesium Carbonate Market Hits USD 307.71 Million in 2025, Poised for 4.7% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Magnesium Carbonate Market: Navigating Growth Through 2032
Executive Overview
The global magnesium carbonate market stands at a pivotal juncture. As of 2025, the sector has demonstrated steady resilience, recovering from minor fluctuations observed in the early 2020s to establish a robust revenue baseline. For enterprise leaders and strategic planners, understanding the trajectory of this essential industrial mineral is no longer optional; it is a critical component of supply chain security, product development, and competitive positioning.
This article serves as a strategic precursor to the comprehensive Magnesium Carbonate Market Research Report published by PW Consulting. Our analysis covers the historical performance from 2020 through 2025 and projects market behavior through the forecast period ending in 2032. The objective is to equip stakeholders with the macroscopic perspective needed to allocate capital efficiently and anticipate regulatory shifts. However, the granular data required for precise operational modeling is reserved for the full intelligence subscription.
Magnesium Carbonate Market
Market Trajectory and Growth Dynamics
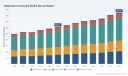
The market has exhibited a consistent upward trend over the past half-decade. Revenue valuations have progressed from approximately 248.5 million USD in 2020 to an estimated 307.71 million USD in 2025. This growth reflects the material's entrenched position in pharmaceuticals, personal care, and industrial manufacturing. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, albeit at a measured pace typical of mature commodity markets.
Key macroeconomic indicators derived from our modeling include a projected valuation of 321.45 million USD in 2026, escalating to 424.39 million USD by 2032. This progression implies a Compound Annual Growth Rate (CAGR) of 4.7 percent over the forecast horizon.
- Historical Stability: The market navigated post-pandemic supply chain adjustments between 2020 and 2023, stabilizing at 281.02 million USD by 2023.
- Forecast Momentum: Growth is expected to accelerate slightly in the late forecast period, with significant valuation jumps observed in the 2030 to 2032 window.
- Revenue Scale: All valuations are denominated in USD Millions, providing a standardized metric for cross-regional comparison.
While these headline figures provide a top-down view of market health, they do not reveal the underlying drivers of regional disparity or application-specific demand spikes. Understanding where the growth originates requires a deeper dive into segmentation that only the full report provides.
Segmentation Insights: Type and Application
Magnesium carbonate is not a monolithic commodity. Its utility varies significantly based on physical properties, specifically the distinction between light and heavy grades. Light magnesium carbonate, known for its high porosity and oil absorption capabilities, typically commands a different market dynamic compared to heavy magnesium carbonate, which is often preferred for specific industrial densities and pharmaceutical fillers.
Our analysis indicates that both types contribute substantially to the overall revenue pool. Light magnesium carbonate maintains a significant share of the global revenue, driven by its versatility in personal care and specialty chemical applications. Heavy magnesium carbonate complements this by serving specific industrial and technical requirements. The interplay between these two types dictates pricing strategies and inventory planning for manufacturers.
On the demand side, the application landscape is diverse. The pharmaceutical sector remains a cornerstone consumer, utilizing the material for antacids, laxatives, and tablet excipients. Simultaneously, the rubber and plastic industry leverages magnesium carbonate as a functional filler to enhance durability and processing characteristics. Personal care and cosmetics represent a high-value segment where purity standards are stringent, while the remaining broader industrial applications provide a stable baseline demand.
Calcium Carbonate Market
Note: Precise revenue splits for each type and application segment are proprietary data points within our full database. Stakeholders requiring specific volume or value allocations for these segments to build financial models are encouraged to access the complete segmentation tables in the final report.
Regional Landscape and Trade Flows
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region typically exhibits the highest aggregate volume due to the concentration of manufacturing capacity and raw material availability. North America and Europe maintain mature markets with high demand for high-purity pharmaceutical and food-grade variants.
Trade dynamics play a crucial role in shaping regional supply. For instance, natural magnesium carbonate imports into Japan from China have shown significant valuation in recent trade data, highlighting the interdependence of Asian supply chains. Meanwhile, regulatory frameworks in the United States continue to influence market entry costs and classification standards.
- North America: A mature market with strong regulatory oversight regarding chemical safety and purity.
- Europe: Focuses on high-value specialty grades, with Germany serving as a hub for production and trading.
- Asia Pacific: Dominates in terms of volume and raw material processing, particularly involving magnesite derived from natural sources.
- Rest of World: Emerging demand centers in Latin America and Africa offer niche opportunities for industrial expansion.
Detailed regional revenue contributions and growth rates are critical for determining market entry strategies. Our full report breaks down the specific valuation and forecast for each region, allowing clients to assess local competitiveness without relying on industry averages.
Competitive Landscape and Key Players
The magnesium carbonate market is characterized by a moderately fragmented structure with a concentration of expertise among specialized manufacturers. The top three players hold a combined market share of approximately 23.5 percent, while the top five entities control around 28.0 percent of the revenue. This suggests that while large players exist, there is significant room for specialized niche providers and traders.
Several key companies define the competitive edge through product purity, capacity expansion, and supply chain integration.
Leading Manufacturers and Traders
- Dr. Paul Lohmann GmbH & Co. KGaA (Germany): A premier producer offering high-purity light, heavy, medium heavy, and specialty grades. Their focus spans pharmaceutical, food, and industrial applications, setting a benchmark for quality consistency.
- Kyowa Chemical Industry Co., Ltd. (Japan): Known for pharmaceutical-grade and high-purity light and heavy magnesium carbonate. Their recent product catalog releases emphasize enhanced purity focus for food additives and personal care.
- Konoshima Chemical Co., Ltd. (Japan): Produces multiple grades including plate-shaped variants, catering to specific chemical and industrial use cases that require unique morphological properties.
- Lehmann & Voss & Co. KG (Germany): A significant supplier and trader. Recent updates include enhanced technical selling capabilities and supply chain optimizations for mineral fillers, positioning them as a key logistics and sourcing partner.
- Grecian Magnesite S.A. (Greece): A major producer leveraging natural magnesite. Their recent commissioning of a second X-ray-based mineral processing line at Yerakini Mines signals a strong commitment to capacity expansion and processing efficiency.
- Yingkou Magnesite Chemical (China): A large-scale producer utilizing natural magnesite, playing a critical role in the global supply volume, particularly for industrial grades.
- Others: Additional players such as Naikai Salt Industries, SCORA S.A.S., and Buschle & Lepper S.A. contribute to the ecosystem with specific focuses on food, nutraceutical, bakery, and refractory applications.
The competitive dynamic is not just about production volume. It is about the ability to navigate regulatory changes and supply chain disruptions. The recent developments observed in late 2025, such as portfolio updates and processing line commissions, indicate that incumbents are actively fortifying their positions against potential market volatility.
Regulatory and Industry Context
External factors significantly influence market fluidity. Regulatory status varies by jurisdiction and application, affecting everything from import duties to product certification.
In the United States, magnesium carbonate is listed under the Harmonized Tariff Schedule Chapter 25, with no specific duties applied in the current framework, facilitating relatively smooth trade flows for imported grades. However, compliance remains key. The material was delisted from U.S. color additive certification requirements in recent regulatory updates, simplifying its use in certain cosmetic applications. Conversely, it remains approved in Codex Alimentarius standards as INS 504(i), ensuring its continued legitimacy in global food supply chains.
Raw material economics also factor into strategic planning. Conservation policies, such as depletion allowances for magnesite and magnesium carbonate, can impact cost structures for domestic producers in regions like the U.S. Understanding these fiscal nuances is essential for accurate margin forecasting.
Our report integrates these regulatory and raw material factors into a holistic market view, analyzing how policy shifts in 2026 and beyond might alter cost bases or demand elasticity.
Strategic Value for 2026 Decision-Making
For C-suite executives, procurement officers, and strategy analysts, the Magnesium Carbonate Market Report offers more than just numbers. It provides a framework for action. The period from 2026 to 2032 is expected to see evolving demands in high-purity sectors alongside steady industrial consumption.
Why this intelligence matters now:
- Supply Chain Resilience: With capacity expansions occurring in Europe and production scaling in Asia, knowing where supply is tightening or easing helps mitigate procurement risk.
- Product Portfolio Alignment: As regulations shift, such as changes in color additive certifications or food safety standards, companies must align their product offerings with compliant grades. Our analysis highlights which grades are gaining regulatory favor.
- Investment Timing: The forecast suggests a notable acceleration in market valuation toward the end of the decade. Identifying the catalysts for this growth allows investors to time market entry or capacity expansion correctly.
- Competitive Benchmarking: Knowing the market concentration and the strategic moves of key players like Grecian Magnesite or Kyowa Chemical allows firms to position themselves defensively or offensively.
The data provided in the summary above serves as a validation of market health. However, the specific drivers—such as exact growth percentages per application segment, detailed regional supply deficits, or proprietary pricing models—are contained within the full intelligence suite. Relying on aggregate data alone can lead to suboptimal strategic decisions in a market where purity premiums and regional logistics costs vary widely.
Conclusion
The magnesium carbonate market is poised for steady growth, underpinned by essential demand in pharmaceuticals, industrial manufacturing, and personal care. With a projected CAGR of 4.7 percent and a total market value expected to exceed 424 million USD by 2032, the opportunity for strategic expansion is clear.
However, success in this market requires more than a view of the top-line numbers. It demands an understanding of the interplay between light and heavy grades, the nuances of regional trade flows, and the strategic maneuvers of key competitors. The PW Consulting Magnesium Carbonate Market Research Report is designed to provide this depth.
We invite stakeholders to utilize this overview as a foundation for their strategic planning. For the detailed segmentation data, comprehensive competitor profiles, and actionable forecasts required to navigate 2026 and beyond, we recommend accessing the full report. This ensures that your decisions are based on complete intelligence rather than partial visibility.
PW Consulting remains committed to delivering clarity in complex markets. For further inquiries or to acquire the full dataset, please contact our research team.
For detailed analysis of this topic, please visit the official page: Magnesium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Hemodialyzer Market to Hit $6.3 Billion by 2032, 6.5% CAGR
By PW Consulting, 2026-09-16
Strategic Blueprint for the Hemodialyzer Market: Navigating a $6.3 Billion Horizon Through 2032
The global hemodialysis ecosystem stands at a decisive inflection point. As patient volumes expand, reimbursement frameworks tighten, and membrane technologies diverge toward higher solute clearance, corporate strategy can no longer rely on legacy volume assumptions or static procurement models. Our newly released market intelligence study on hemodialyzers supplies the analytical architecture required to convert structural tailwinds into executable decision pathways. Covering a historical window from 2020 through 2025 and projecting forward to 2032, the analysis translates macro-level expansion into actionable intelligence for product planning, procurement, pricing architecture, and competitive positioning.
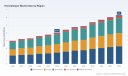
The overarching trajectory is unambiguous. Market value, measured in USD billions, has consistently advanced across the past half-decade and is projected to sustain that momentum through the end of the forecast period. Base-year positioning in 2025 translates into a 2026 opening that sets the stage for a measured yet compounding expansion cycle, culminating in a multibillion-dollar endpoint by 2032. The implied compound annual growth rate across the forecast horizon signals a market that is not merely scaling but progressively re-rating itself around clinical performance, membrane selection, and therapy modality differentiation. For executives, this is not a story of passive demand growth; it is a signal that product architecture, supply continuity, and clinical value propositions will increasingly determine share capture.
Why This Study Matters for 2026 Decision-Making
The 2026 operating environment introduces a layered set of strategic variables that demand more than top-line market sizing. Reimbursement calibration, regulatory classification pathways, water-quality compliance standards, and raw-material cost structures are reshaping the economics of dialyzer procurement and therapy configuration. Our study is engineered to place each of these forces into a single decision-ready framework so that leadership teams can move from awareness to action without stitching together fragmented inputs.
Dialyzer Market
For procurement and supply-chain leaders, the analysis provides the segmentation lenses needed to evaluate where demand is consolidating, where alternative membrane configurations are gaining traction, and how regional deployment patterns influence inventory planning. For commercial and R&D teams, the study maps the divergence between high-flux platforms and lower-flux alternatives, giving product strategists a clearer understanding of where clinical differentiation, therapy expansion, and portfolio alignment are likely to create durable advantage. For corporate development and investor-facing teams, the concentration profile of the competitive landscape offers a benchmark for assessing consolidation risk, partnership logic, and market-entry realism.
Crucially, the study avoids static projection and instead frames growth as a function of therapy adoption, membrane material economics, and regulatory-driven product classification. This allows decision-makers to test scenarios: what happens if expanded solute removal therapies scale faster in outpatient settings? What happens if reimbursement adjustments alter facility economics and shift purchasing behavior? The research is built to support those stress tests with structured evidence rather than anecdotal narrative.
Market Scale, Trajectory, and the Investment Signal
The historical arc establishes a clear baseline. Between 2020 and 2025, market value climbed in a stepwise pattern, reflecting both steady dialysis volume expansion and incremental upgrades in device selection. The 2025 base year anchors the analysis in a market that has already absorbed years of incremental demand and is now positioned for the next phase of structural expansion. From that base, the 2026 forecast opens a meaningful growth step, and the sequential trajectory through 2032 maps a market that continues to widen rather than plateau.
This path matters because it reframes hemodialyzers from commoditized disposables into clinically and economically differentiated inputs. As therapies evolve toward broader solute removal profiles and higher-efficiency modalities, the value captured by each procedure is increasingly linked to the membrane, the device class, and the compatibility of the delivery system. The study highlights that market growth is not solely a volume story; it is also a composition story. The mix shift toward higher-performance configurations is a critical variable for pricing strategy, contract negotiation, and product roadmap prioritization.
For executives, the strategic takeaway is straightforward: planning around a single aggregate figure obscures the real decision points. What matters is the convergence of therapy trends, reimbursement dynamics, and product-class differentiation, all of which determine where margin, share, and operational resilience will be won or lost.
Segment Architecture and Decision Value
The report dissects the market along multiple strategic axes that directly inform commercial, procurement, and clinical-strategy discussions. Type-based segmentation distinguishes among high-flux dialyzers, low-flux dialyzers, and other device configurations, giving R&D and commercial teams a structured view of where performance-based differentiation is concentrated and where price-sensitive purchasing may dominate. This distinction is particularly relevant as therapy protocols continue to evaluate trade-offs between clearance targets, membrane compatibility, and cost-per-procedure economics.
Application-focused analysis clarifies the dominant clinical context in which hemodialyzers are deployed, anchoring demand patterns to the core hemodialysis procedure environment. This lens matters because outpatient facility economics, session frequency, and modality mix directly influence procurement volume, device lifespan assumptions, and contract structures. Understanding how the application environment shapes usage is foundational for forecasting demand stability and evaluating whether growth is being driven by volume expansion, therapy upgrade, or both.
Regional segmentation is presented as a geographic demand map rather than a static share table, enabling supply-chain and market-entry teams to see where deployment intensity, clinical infrastructure, and purchasing environments diverge. This regional perspective supports more precise capacity planning, localization decisions, distributor strategy, and risk assessment around logistics or regulatory variation. The study intentionally preserves this segmentation at a strategic level so that readers can identify where to focus commercial attention without being distracted by superficial percentage-based breakdowns.
Hemodialyzer Market
In parallel, the analysis integrates raw-material context, emphasizing that polyethersulfone-based membrane systems constitute the primary material foundation for high-flux configurations, with cost behavior tied to medical-grade extraction and processing requirements. For procurement and product-cost strategists, this linkage between membrane material and device economics is essential for scenario modeling around input-cost volatility, supplier qualification, and margin protection.
Competitive Landscape: Scale, Differentiation, and Consolidation Signals
The competitive environment reflects both entrenched incumbents and specialized players pursuing differentiated membrane technology, therapy compatibility, and regional distribution strength. Market concentration metrics indicate that a relatively small group of leading participants commands a substantial share of total industry value, while a broader field of manufacturers competes on product design, membrane quality, and therapeutic alignment. This dual structure has direct implications for pricing power, partnership opportunity, and entry feasibility.
Fresenius Medical Care AG & Co. KGaA remains a dominant force in high-flux device supply and high-volume hemodiafiltration-compatible configurations, with reported dialyzer distribution volumes that underscore its scale advantage and global reach. Baxter International Inc. continues to position around advanced therapy membranes and expanded solute removal platforms, including class II device profiles associated with broader clearance targets. Nipro Corporation has advanced its ELISIO membrane platform with a focus on middle-molecule toxin removal, reinforcing the competitive relevance of membrane engineering as a differentiation vector. Asahi Kasei Corporation supplies high-flux product lines that align with performance-oriented dialysis workflows, while B. Braun Melsungen AG maintains a presence through polyethersulfone-based high-flux configurations.
Toray Industries, Inc. contributes advanced membrane technology to the high-flux segment, and Nikkiso Co., Ltd. supports the ecosystem through delivery-system compatibility that intersects with dialyzer usage. Outset Medical, Inc. represents a different competitive angle, integrating hemodialyzer components into a consolidated hemodialysis platform and illustrating how device-plus-system designs can alter procurement and adoption dynamics. Medica S.p.A. offers both high-flux and low-flux polyethersulfone options for global distribution, and Vantive US Healthcare, LLC extends the THERANOVA device family through distribution and sales activity aligned with expanded solute removal therapy.
The competitive base also includes regional and specialized manufacturers such as Kawasumi Laboratories, Inc., JMS Co., Ltd., Shandong Weigao Group Medical Polymer Co., Ltd., Allmed Medical Care Holdings Limited, Farmasol, WEGO Group, and Dialife SA, each contributing to supply diversity, regional coverage, and segment-specific product positioning. For strategic planners, the relevant insight is not simply who is present, but how product architecture, therapy compatibility, and geographic reach shape competitive resilience. Scale players can pressure pricing and supply reliability; specialized players can win on membrane performance, clinical fit, or regional responsiveness.
Industry Dynamics Shaping the 2026 Operating Environment
Multiple external forces are compressing decision timelines and raising the cost of strategic lag. On the regulatory side, hemodialyzers associated with expanded solute removal profiles are classified under Class II with special controls, a designation that shapes product development pathways, documentation burden, and market-access timing. This classification environment means that product differentiation must be paired with regulatory readiness; clinical promise alone does not guarantee commercial velocity.
On the standards side, water-quality and reprocessing requirements continue to anchor operational compliance. AAMI-aligned expectations for bacterial counts and endotoxin thresholds in dialysate preparation and device reprocessing create a compliance floor that affects facility operations and, indirectly, device selection and service models. For manufacturers and suppliers, these standards reinforce the importance of consistency, traceability, and compatibility with reprocessing or water-treatment workflows.
Reimbursement dynamics add another layer of strategic pressure. Updated ESRD PPS payment parameters for 2026 adjust the base rate and recalibrate how dialysis service payments relate to device usage in outpatient settings. Because reimbursement logic influences facility economics, it also influences procurement behavior, contract negotiation, and the willingness of providers to adopt higher-cost, performance-differentiated devices. Strategy teams that ignore the reimbursement-to-purchasing link risk misreading demand durability and pricing tolerance.
In parallel, raw-material cost behavior remains a sensitive variable for high-flux manufacturing, particularly where medical-grade polyethersulfone extraction drives input economics. This connects directly to margin planning, supplier diversification, and procurement hedging. Recent corporate activity reinforces the competitive intensity of this environment: broader commercialization of high-volume hemodiafiltration-compatible systems, launches optimized for middle-molecule toxin removal, introductions of expanded solute removal devices under HDx-oriented therapy frameworks, and catalog expansions of polyethersulfone-based high-flux and low-flux configurations all indicate that firms are actively competing on clinical utility, therapy compatibility, and global availability.
What the Report Delivers: Operational Intelligence, Not Just Market Sizing
This study is structured to support execution rather than simply describe the market. It combines historical baselines, forward projections, segmentation lenses, competitive profiling, and dynamic factor analysis into a decision framework that can be used across commercial, procurement, R&D, and corporate strategy functions. The report's value lies in its ability to connect market expansion to the operational questions that determine performance: which device classes are gaining strategic relevance, where demand is being shaped by therapy evolution, how competitive concentration affects pricing and negotiation leverage, and which regulatory or reimbursement shifts deserve active monitoring.
Readers will find structured coverage of the market's expansion path, the composition of demand across device types and application contexts, and the geographic distribution of opportunity and risk. Competitive profiles are presented not as static company summaries but as strategic snapshots that highlight scale, product focus, and recent commercialization activity. The study also integrates the compliance, reimbursement, and raw-material forces that influence both supply economics and purchasing behavior. By tying these elements together, the report gives decision-makers a coherent basis for scenario planning, portfolio alignment, and market-entry evaluation.
What Remains Inside: Accessing the Full Strategic Picture
The overview presented here is deliberately designed to establish analytical credibility while reserving the complete segmentation detail, regional deployment patterns, application-level demand structures, and precise market-value breakdowns for the full report. Those components are essential for procurement modeling, product-roadmap calibration, contract strategy, and competitive benchmarking, but they are most useful when examined in the full analytical context rather than as isolated figures.
For teams ready to move from directional insight to actionable planning, the complete study provides the depth required to support quantitative scenario work, regional prioritization, and competitive positioning decisions. The aggregate trajectory tells leaders that the market is expanding and re-rating around performance; the full report tells them exactly where to concentrate resources, which segments justify closer scrutiny, and how the competitive field is likely to behave as therapy formats, reimbursement rules, and membrane economics continue to evolve.
In a market moving toward a multi-billion-dollar endpoint over the forecast period, the organizations that outperform will be those that treat hemodialyzers as a strategic interface between clinical performance, purchasing economics, and regulatory reality. This study is built to help leadership make that transition with discipline, precision, and a clear line of sight from market intelligence to operational decision-making.
For detailed analysis of this topic, please visit the official page: Hemodialyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mobile App Testing Market Hits $7.7B in 2025, Projected 17.09% CAGR to $23.23B by 2032
By PW Consulting, 2026-09-16
The Mobile Application Testing Services Market: A Strategic Imperative for 2026
The digital ecosystem of 2026 no longer tolerates performance gaps, security lapses, or fragmented user experiences. As mobile applications become the primary interface for commerce, healthcare, finance, and enterprise operations, the discipline of validating these applications has evolved from a post-development checkpoint to a continuous, strategic capability. Our latest Mobile Application Testing Services Market research captures this inflection point. It provides decision-makers with a structured, forward-looking view of market trajectory, competitive positioning, and operational dynamics that will shape procurement, partnership, and investment choices throughout the forecast horizon.
The market has already demonstrated a clear upward momentum. Measured in billions of USD, valuation climbed from 3.5 in 2020 to 7.7 in 2025, reflecting sustained enterprise investment in quality engineering and the mainstream adoption of structured testing programs. Projections extend this arc to 8.72 in 2026, 10.61 in 2027, and onward to 23.23 by 2032. Sustained at a compound annual growth rate of 17.09 percent across the 2026 to 2032 forecast period, this expansion signals more than incremental demand. It reflects a structural reallocation of operational budgets toward testing ecosystems that can keep pace with device fragmentation, regulatory scrutiny, and user expectations for seamless performance. The figures themselves tell a story of maturation, but the strategic implications lie beneath the surface—in how service models are reorganizing, where cost structures are concentrating, and which operational capabilities will separate resilient providers from commoditized vendors.
Game Testing Service Market
Decoding the Structural Drivers
Several interlocking forces are reshaping demand. Labor remains the primary operational cost in mobile application testing services, with specialized human expertise in manual and automated testing driving day-to-day economics. Labor regulations in key regions continue to influence how organizations build, scale, and source QA teams, making workforce strategy as critical as technology selection. At the same time, compliance requirements are no longer peripheral considerations. Testing for GDPR, HIPAA, and PCI-DSS in mobile environments requires dedicated frameworks that protect data privacy and security across regulated sectors such as healthcare and finance. Enterprises are increasingly mandating ISO 29119-aligned processes to standardize quality assurance and mitigate risk, embedding testing standards directly into procurement criteria.
Infrastructure trends are equally consequential. Cloud-based device labs and real-device infrastructure have become standard for scalable testing, allowing teams to manage device fragmentation and frequent OS updates without accumulating heavyweight in-house hardware fleets. Consumer expectations continue to escalate: users now demand consistent performance across a widening array of screen sizes, network conditions, and operating system versions. This reality raises the cost of post-launch defects and amplifies the value of comprehensive testing programs that catch issues before they reach production. Together, these dynamics create a market in which testing services are evaluated not only on defect detection rates but also on compliance readiness, deployment speed, and the ability to absorb volatility in device and platform landscapes.
Demand is distributed across a balanced set of service categories and delivery models. Manual and automated approaches each hold substantial share, reflecting a pragmatic blend in which exploratory, UX-sensitive validation coexists with repeatable, high-velocity automation pipelines. The application spectrum spans native, web, and hybrid environments, each introducing distinct validation challenges around platform-specific behaviors, cross-browser consistency, and integrated architecture complexity. Regional activity reflects similarly diversified engagement, with testing demand concentrated across major economic corridors and emerging adoption zones. While headline figures illuminate the scale of the opportunity, the operational reality is more nuanced: procurement teams must weigh service depth, tooling integration, compliance coverage, and geographic delivery capacity against their own development cadence and risk profile. These are precisely the trade-offs our research quantifies and contextualizes.
Inside the Research: Practical Intelligence for Decision Makers
This report is designed as an operational reference rather than a high-level survey. It maps the market across the dimensions that matter to strategy, procurement, and investment teams, translating macro trends into actionable decision inputs.
The analysis covers market sizing and forward projections with a clear view of how growth compounds across the forecast window. It breaks down the market by testing type, by application category, and by region so that readers can align their own footprint with broader demand patterns without getting lost in fragmented metrics. The segmentation structure is paired with concentration analysis that shows how market share distributes across leading participants, offering a realistic picture of competitive saturation and whitespace. Total market concentration indexed by CR3 and CR5 highlights the extent to which leadership is consolidated or dispersed, helping stakeholders gauge incumbent influence and entry dynamics.
Beyond sizing, the report delivers practical content that supports execution. It examines how service providers structure offerings across functional, performance, security, usability, accessibility, and localization testing. It evaluates automation maturity, real-device and cloud-based testing capabilities, and the role of AI-assisted quality engineering in accelerating validation cycles. It also addresses procurement-relevant considerations such as outsourcing models, compliance alignment, certification standards, and the operational implications of labor-intensive QA workflows. For organizations comparing vendors, building internal centers of excellence, or assessing market entry, the study provides a structured lens for evaluating fit, scalability, and long-term defensibility.
Competitive Landscape: Who Shapes the Market and How
The mobile application testing services arena is defined by a diverse set of operators whose differentiating strengths span geography, delivery model, and technological specialization. Understanding how these players position themselves is essential for interpreting pricing dynamics, partnership options, and service reliability.
DeviQA, headquartered in Warsaw, Poland, focuses on end-to-end mobile app testing for iOS and Android. Its profile emphasizes functional, performance, security, and automation testing, with particular attention to AI-powered QA and outsourcing models. This positioning makes it relevant for organizations seeking integrated service delivery with an eye toward efficiency gains through intelligent automation. TestingXperts operates with global reach and regional hubs, including the Philippines, and delivers full-stack mobile testing that spans functional, usability, performance, security, localization, and cloud or real-device validation. Its emphasis on AI-led automation aligns with enterprises looking to scale testing coverage while managing cycle time. pcloudy offers a cloud-based testing platform that supports more than 5000 real devices for both manual and automated testing on Android and iOS, augmented by AI agents and integrations. Its platform orientation appeals to teams that prioritize device diversity, infrastructure elasticity, and tooling interoperability.
BrowserStack maintains a global footprint centered on real-device cloud testing for mobile apps across more than 2000 iOS and Android devices. Its support for automated testing via Appium and custom device labs positions it as a strong fit for engineering teams that require broad device coverage and programmable test execution. a1qa, based in Decatur, Georgia, provides mobile testing on real devices with functional, performance, and QA services, alongside crowdsourced and automation options. This hybrid model is useful for organizations balancing controlled QA environments with broader, scenario-rich validation. Qualitest, headquartered in London, delivers end-to-end mobile and web testing that incorporates security, performance, and accessibility, with a focus on AI-powered quality engineering. Its breadth makes it relevant for enterprises seeking unified assurance across multiple digital touchpoints.
Testriq, operating from Mumbai, India, emphasizes iOS and Android QA with performance testing, security pen-testing, and ISO 29119-compliant services. Its standards-aligned approach supports clients in regulated or risk-sensitive contexts. TestMatick, with a New York base and a Ukraine office, verifies apps under real-life conditions and leverages AI-driven automation, an approach that resonates with teams prioritizing realistic usage simulation and automation-led efficiency. ScienceSoft, based in McKinney, Texas, covers the full range of mobile app testing including functional, performance, security, usability, and accessibility, supported by ISTQB-certified engineers. Its certification-oriented talent model appeals to organizations that value formalized QA competency and consistent service quality.
Taken together, these players illustrate a market that rewards specialization without sacrificing breadth. Providers differentiate through real-device scale, automation maturity, compliance expertise, geographic delivery capacity, and the ability to combine human judgment with AI-enhanced workflows. For buyers, the strategic question is not simply who offers the lowest cost but which provider can integrate into existing development pipelines, meet sector-specific compliance demands, and sustain quality as application portfolios grow more complex.
Strategic Implications for 2026 Decision Making
Entering 2026, organizations must treat mobile application testing not as a discretionary expense but as a core enabler of product reliability, regulatory compliance, and customer retention. Several strategic implications emerge from the current market trajectory.
- Budget allocation should reflect the blended nature of demand. As manual and automated testing both hold meaningful share, investment plans need to support exploratory validation and repeatable automation in proportion to release cadence, user sensitivity, and risk exposure.
- Compliance readiness is becoming a procurement discriminator. With GDPR, HIPAA, and PCI-DSS requirements shaping testing for regulated applications, buyers should prioritize providers that can demonstrate structured privacy and security validation rather than treating compliance as a downstream checklist.
- Infrastructure strategy directly affects scalability. The normalization of cloud-based device labs and real-device infrastructure means that organizations can expand coverage without proportionate hardware investment, but they must still evaluate tool integration, data security, and device representativeness.
- Labor economics remain central. Because specialized QA labor accounts for the primary operational cost, workforce planning—whether through in-house hiring, outsourced partnerships, or managed services—should be modeled alongside automation roadmaps to avoid bottlenecks and cost escalation.
- Standards adoption is a signal of operational maturity. ISO 29119 alignment and ISTQB-certified engineering capabilities offer tangible indicators of process discipline, which matters when quality assurance must be auditable and repeatable across multiple product teams.
- Competitive selection should weigh delivery model fit. Some providers emphasize platform scale and real-device coverage, others focus on AI-assisted automation, and still others build advantage through compliance depth or regional delivery capacity. The right choice depends on the organization’s release rhythm, risk profile, and integration requirements.
Why This Research Matters Now
Market growth at a 17.09 percent CAGR through 2032 is not merely a statistical headline; it is a signal that testing services are moving from supportive function to strategic investment area. As valuation expands from 8.72 in 2026 toward 23.23 by 2032, the stakes for selecting the right testing strategy, provider, and operating model rise in tandem. Enterprises that delay structured evaluation risk higher defect exposure, slower release cycles, and weaker compliance posture. Those that act early can align procurement with demand patterns, optimize cost structures, and build quality capabilities that compound over time.
Mobile Application Testing Services Market
This research captures the market at a moment when device diversity, regulatory pressure, and user expectations are all intensifying simultaneously. It is designed to help leaders navigate that complexity with clarity. The complete study provides the detailed segmentation, concentration metrics, competitive profiles, and forward projections needed to support procurement decisions, partnership strategies, internal capability planning, and investment assessments. For decision-makers who need more than surface-level market color, the full report offers the depth required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Mobile Application Testing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Padlock Market Reaches $2B in 2025, 5.9% CAGR ≈ $3.1B by 2032
By PW Consulting, 2026-09-16
Strategic Insights: The Padlock Market Trajectory and Decision Framework for 2026
The global security hardware landscape is undergoing a structural transformation, and nowhere is this more evident than in the padlock market. As organizations recalibrate their physical security postures in response to evolving regulatory environments, supply chain volatility, and rising threat vectors, the padlock sector has emerged as a critical barometer of industrial resilience and commercial confidence. This article serves as a strategic preview of our latest comprehensive market research, designed to equip executives, procurement leaders, and security architects with the analytical rigor required to navigate the forecast period from 2026 through 2032.
Over the past half-decade, the market has demonstrated a consistent upward trajectory, recovering from the contractionary pressures of the early 2020s and establishing a robust growth foundation. Total market revenue reached approximately USD 2.137 billion in 2026, reflecting a compound annual growth rate of 5.9 percent across the forecast horizon. This expansion is not merely a function of post-pandemic normalization; it is driven by foundational shifts in how businesses and institutions approach asset protection, regulatory compliance, and operational continuity. Understanding these underlying currents is essential for any organization seeking to optimize capital allocation, mitigate supply chain exposure, and align security procurement with long-term strategic objectives.
Macroeconomic Foundations and Growth Catalysts
The revenue progression from 2020 through 2025 tells a story of adaptive resilience. After starting at roughly USD 1.502 billion in 2020, the market expanded steadily, surpassing the USD 2.0 billion threshold by 2025. This growth has been underpinned by sustained demand across commercial security deployments, residential protection upgrades, and industrial applications where lockout/tagout protocols and heavy-duty access control remain non-negotiable. The forecast period extending to 2032 projects a market valuation approaching USD 3.116 billion, signaling that the sector has moved beyond cyclical recovery into a phase of structural expansion.
Padlock Market
Several interlocking factors are accelerating this trajectory. First, the modernization of physical security infrastructure in mid-market commercial real estate and logistics facilities is creating consistent replacement and upgrade cycles. Second, residential security spending has matured beyond basic deterrent models toward integrated, higher-tolerance hardware that complements smart home ecosystems. Third, industrial and institutional buyers are increasingly standardizing on certified, auditable locking solutions that satisfy insurance requirements and occupational safety mandates. These demand drivers are compounding, and they interact with macroeconomic variables that our research quantifies through scenario-based modeling and sensitivity analysis.
Regulatory and Supply Chain Dynamics Shaping Procurement Strategy
The padlock market does not operate in a vacuum. Recent regulatory interventions have introduced new cost structures and compliance considerations that directly influence manufacturing economics and downstream pricing. The Department of Commerce initiated the Section 232 Steel and Aluminum Inclusions Process in April 2025, with determinations issued within a 60-day window. This action has had immediate implications for raw material inputs, particularly for steel-bodied and laminated padlocks prevalent in construction, industrial, and municipal applications. Subsequent expansions to the tariff list in August 2025 added hundreds of product categories to the steel and aluminum duty framework, raising component costs and reinforcing the need for strategic sourcing flexibility.
Lock Market
Simultaneously, the Harmonized Tariff Schedule underwent revision in 2026, with updated classifications for imported padlocks affecting duty calculations for manufacturers supplying North American and broader US channels. These classification adjustments require procurement teams to reassess landed cost models, evaluate alternative supplier geographies, and consider inventory timing strategies that account for duty volatility. Our research maps these regulatory touchpoints against pricing elasticity and supply chain reconfiguration scenarios, providing decision-makers with a structured view of how policy shifts translate into operational risk and opportunity.
On the standards side, the CEN classification framework continues to serve as the authoritative reference for security ratings across global markets. Manufacturers such as ABUS maintain active alignment with BS EN12320 testing protocols, which define low, medium, and high security tiers. Commercial insurers, facility managers, and government procurement offices increasingly reference these ratings during vendor selection, making certification status a strategic differentiator rather than a passive compliance checkbox. Understanding which manufacturers have sustained validated ratings, and how those ratings map to end-use risk profiles, is a recurring theme throughout our analysis.
Competitive Architecture: incumbents, specialists, and the certification moat
The competitive landscape is characterized by a mix of globally scaled manufacturers, family-owned specialists, and regional players that compete on distinct value propositions. Concentration metrics indicate that the top three firms command approximately 55 percent of market revenue, while the top five collectively hold around 62 percent. This level of concentration suggests that scale advantages in distribution, certification portfolios, and OEM integration are meaningful, yet ample room remains for differentiated players to capture niche demand through specialized product architectures and relationship-driven channels.
Within this architecture, several manufacturers have established recognizable positions. Master Lock Company LLC operates a broad portfolio spanning combination, laminated, high-security, lockout/tagout, and smart-connected models, serving home, commercial, and industrial channels with a globally recognized distribution footprint. Wilson Bohannan Lock Company LLC, a seventh-generation family enterprise, has built its reputation on solid brass construction, high-security interchangeable core designs, and door-key compatible configurations tailored for utility, industrial, military, and government deployments. ABUS August Bremicker Söhne KG maintains a strong European and global presence in premium padlock segments, with particular relevance in commercial, industrial, and safety applications where certified security ratings carry weight.
In the North American manufacturing base, Pacific Lock Company has drawn attention through its focus on government-standard field service hardware and medium-to-low security padlocks for military and Department of Defense applications. Its recent achievement of Department of Defense approval for the PL951 high-security padlock, following successful certification under MIL-DTL-43607J, positioned it as the first and only US manufacturer certified to all three military padlock grades. This milestone illustrates how certification depth can function as a competitive moat, particularly in segments where procurement specifications are stringent and substitution is limited. Wilson Bohannan and other US-based specialists similarly emphasize interchangeable cores, custom OEM solutions, and utility-grade durability, expanding the menu of options available to buyers who require traceable supply chains and configurable hardware.
Asian manufacturers contribute additional capacity and product diversity. SINOX, for example, produces heavy-duty key and combination padlocks targeting school, gym, toolbox, club, and industrial locker environments, with resettable and key override features that address practical operational needs. Federal Lock Company and other regional producers supply padlocks tailored to security and industrial requirements, broadening the supplier base for cost-sensitive and application-specific deployments. Meanwhile, Brady Corporation reinforces the lockout/tagout safety segment, providing safety padlocks and employee protection solutions that intersect physical security with occupational health compliance. These varied profiles underscore a market where segmentation by material, mechanism, security tier, and end-use application creates multiple distinct playing fields rather than a single commoditized arena.
Report Scope: Operational Intelligence for Procurement and Strategy Teams
Our research is structured to move beyond headline figures and deliver actionable intelligence across the dimensions that matter most to enterprise decision-making. The report opens with a detailed market sizing framework that traces historical revenue performance and projects forward through the forecast period, enabling readers to benchmark their own growth assumptions and identify divergence points between macro trends and segment-level behavior. Revenue models are expressed in millions of USD and are accompanied by scenario analysis that accounts for regulatory cost impacts, material price volatility, and demand elasticity across application categories.
A central component of the study is the segmentation architecture, which disaggregates revenue by type, application, and geographic region. This framework is designed to help procurement and product strategy teams understand where value concentrates, which sub-segments exhibit higher growth momentum, and how regional demand patterns interact with manufacturing and logistics footprints. The analysis also examines material composition trends, including the relative positioning of steel, brass, and other body constructions, alongside mechanism differentiation that ranges from traditional keyed systems to rotating disc cylinder technologies and smart-connected variants. These structural insights are paired with qualitative assessment of how certification status, insurance alignment, and OEM integration influence share dynamics.
The competitive profiling section extends beyond descriptive summaries. Each key enterprise is evaluated across manufacturing capability, certification portfolios, channel reach, and recent strategic moves that signal shifting priorities. The report captures notable developments such as military-grade certification achievements, trade show participation that signals market expansion intent, and product-line extensions that address emerging use cases. By contextualizing these events within broader industry cycles, the analysis helps readers distinguish between one-off announcements and structural shifts that warrant attention in sourcing and partnership decisions.
In addition, the study integrates a regulatory and standards watch module that tracks tariff classifications, trade policy adjustments, and testing standards that affect compliance and cost. This module is intended for teams that need to anticipate changes before they impact landed costs or vendor eligibility. The report also includes a framework for evaluating supplier risk, covering concentration exposure, geographic dependency, and the implications of raw material tariff regimes for steel and aluminum-intensive product lines. Together, these components form a decision-support toolkit rather than a static market snapshot.
Strategic Implications for 2026 and Beyond
For executives navigating 2026, the padlock market presents a clear mandate: treat physical security hardware as a strategic input rather than a commoditized purchase. Several implications follow directly from the data and dynamics outlined in our research.
- Certification alignment is a procurement accelerator. Buyers whose specifications reference recognized security ratings and military or industrial certifications can streamline vendor qualification, reduce substitution risk, and strengthen audit readiness. Manufacturers with validated certifications across multiple tiers are better positioned to support regulated environments and insurance-driven compliance requirements.
- Material cost volatility demands sourcing diversification. Recent tariff developments around steel and aluminum content have reshaped cost structures for laminated and steel-bodied padlocks. Organizations should evaluate multi-source strategies, alternative material configurations where operationally acceptable, and inventory planning that accounts for duty cycles and classification updates.
- Segment strategy should match risk profile to product architecture. Commercial security, residential protection, and industrial applications each impose distinct performance, durability, and compliance expectations. A portfolio approach that aligns product selection with end-use risk, rather than defaulting to uniform specifications, yields better total cost of ownership and fewer downstream failures.
- Competitive concentration creates both stability and opportunity. While a concentrated top tier provides established distribution and certification depth, specialized manufacturers continue to compete effectively through customization, OEM integration, and niche certification portfolios. Evaluating both scale players and specialists enables buyers to balance reliability with flexibility.
- Standards and classification monitoring should be institutionalized. Changes to tariff schedules, testing standards, and security rating frameworks can alter vendor eligibility and landed costs. Embedding regulatory surveillance into procurement workflows reduces surprise and supports more resilient contracting terms.
The market is not merely growing; it is evolving in ways that reward organizations who can read the interplay between regulation, material economics, certification, and application-specific demand. Our research is designed to make that interplay legible, providing the analytical scaffolding needed to convert market intelligence into procurement strategy, capital planning, and risk mitigation.
Accessing the Full Intelligence Package
This article has outlined the strategic contours of the padlock market and highlighted the decision frameworks that our latest research brings into focus. The complete study goes further, delivering the granular segmentation detail, competitive benchmarking, scenario models, and regulatory tracking that enterprise teams require to move from awareness to action. Core figures, segment-level revenue splits, regional demand patterns, and application-specific growth breakdowns are available in the full report, alongside detailed profiles of the manufacturers shaping the competitive landscape and an expanded view of the regulatory developments influencing cost and compliance.
For decision-makers ready to translate market dynamics into concrete sourcing, pricing, and portfolio choices, the full research package provides the depth and specificity needed to sharpen strategy across the 2026 to 2032 horizon. We invite you to access the complete report to explore the segmentation architecture, competitive analysis, and scenario frameworks that underpin the insights summarized here.
For detailed analysis of this topic, please visit the official page: Padlock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dipropylene Glycol Market Hits USD 4.9B in 2025, Projects 4.14% CAGR Through 2030
By PW Consulting, 2026-09-16
Strategic Intelligence in the Dipropylene Glycol (DPG) Market: Navigating the 2026-2032 Forecast Period
The global Dipropylene Glycol (DPG) market stands at a critical inflection point as we move deeper into 2026. For procurement leaders, supply chain strategists, and market expansion teams, understanding the trajectory of this essential chemical intermediate is no longer just a matter of cost optimization; it is a strategic imperative. The DPG market, valued at 4.9 billion USD in the base year of 2025 and projected to reach 6.51 billion USD by 2032, presents a complex landscape shaped by feedstock volatility, evolving regulatory frameworks, and shifting end-user demand. This comprehensive market research study offers the granular intelligence required to make informed decisions in this dynamic environment.
Our latest report provides a deep dive into the historical performance and future outlook of the DPG sector. With a historical review spanning 2020 to 2025 and a detailed forecast period extending from 2026 to 2032, the study is designed to equip stakeholders with the foresight necessary to mitigate risk and capitalize on emerging opportunities. The compound annual growth rate (CAGR) of 4.14 percent underscore a steady, yet nuanced, expansion trajectory. However, headline figures only tell part of the story. To truly navigate the market, one must understand the underlying forces driving these numbers, from regional supply dynamics to grade-specific demand shifts.
Market Trajectory and Growth Dynamics
Analyzing the historical data reveals a resilient market foundation. After reaching 4.0 billion USD in 2020, the market witnessed a consistent upward trend, accelerating to 4.63 billion USD by 2024 and settling at 4.9 billion USD in 2025. This growth reflects the compound's versatility across diverse industrial applications. Looking ahead, the forecast period suggests continued expansion, with market size anticipated to hit 5.28 billion USD in 2026. However, astute analysis reveals that growth is not always linear. Strategic fluctuations noted in the forecast data highlight the sensitivity of the market to external pressures such as raw material costs and production scheduling, making real-time intelligence crucial for capacity planning and procurement timing.
The projected growth to 6.51 billion USD by 2032 indicates a robust long-term outlook. Yet, the path to this figure is influenced by several macroeconomic and microeconomic variables. Our research dissects these variables to provide a clear view of where value is being created and where margins might be under pressure. Understanding the interplay between supply chain constraints and demand generation is key to leveraging these forecasts effectively.
Supply Chain Pressures and Raw Material Dynamics
One of the most significant factors influencing the DPG market in 2026 is the cost of raw materials, specifically propylene oxide. As a co-product of monopropylene glycol production, DPG manufacturing is intrinsically linked to the availability and pricing of upstream feedstocks. Recent data indicates that propylene oxide prices in North America rose 7.5 percent quarter-over-quarter to 1.14 USD/KG by March 2026. This upward pressure on feedstock costs directly impacts DPG manufacturing economics, prompting strategic adjustments across the value chain.
These cost pressures have already manifested in market behavior. In April 2026, Industry leaders Dow Chemical and Monument Chemical announced price increases on Dipropylene Glycol and related glycol products. Dow Chemical specifically targeted DPG LO+ and related glycol products, citing exposure to propylene oxide feedstock pressures. Such moves signal a tightening margin environment that buyers must anticipate. Our report provides detailed analysis on how these cost pass-through mechanisms affect different regions and application sectors, enabling buyers to negotiate from a position of strength.
Technological Innovation and Sustainability Trends
Sustainability is no longer a peripheral concern in the DPG market; it is becoming a core driver of procurement decisions. Leading producers are increasingly integrating bio-based and recycled feedstocks into their portfolios to meet the growing demand for sustainable chemicals. Dow Inc.'s marketing of Dipropylene Glycol-REN LO+ with at least 50 percent ISCC PLUS certified bio-based material via the Ecolibrium mass-balance approach serves as a prime example. This innovation allows customers in personal care and industrial applications to reduce their carbon footprint without compromising product performance.
Such developments require buyers to evaluate not just the chemical properties but also the lifecycle credentials of the DPG they source. Our research assesses the availability and scalability of these sustainable grades against traditional petrochemical routes. We examine how mass-balance certification and bio-circular feedstocks are reshaping the competitive landscape and influencing customer preferences, particularly in regions with stringent environmental regulations.
Regional and Segment Growth Opportunities
The Asia Pacific region continues to command a significant share of global DPG consumption, reflecting the broader growth of chemical-intensive industries in the region. Similarly, North America and Europe remain substantial demand centers, driven by established industrial bases and high standards for product quality and safety. Our report breaks down market dynamics across these key geographies, analyzing how local production capacities, import-export balances, and regional regulatory environments shape supply availability and pricing structures. By understanding regional nuances, stakeholders can optimize their sourcing strategies and identify untapped markets or underserved segments.
Beyond geography, the composition of the DPG market by type and application reveals critical growth vectors. Technical grades hold a prominent position, catering to broad industrial needs such as solvents and coupling agents. Pharmaceutical and electronics grades also command significant value, driven by stricter purity requirements and niche applications. The analysis covers Functional Fluids, Polyurethane and Polyester Resins, and Personal Care and Pharmaceuticals, highlighting how demand patterns differ across these verticals. For instance, while functional fluids represent a large volume segment, the personal care sector drives demand for high-purity, low-odor variants. Understanding these segmentation dynamics allows companies to tailor their product development and marketing strategies to the most lucrative opportunities.
Competitive Landscape and Industry Consolidation
The DPG market is characterized by a moderately concentrated competitive structure. Our analysis identifies a CR3 of 51.0 percent and a CR5 of 62.0 percent, indicating that the top five players hold a substantial portion of the market. This concentration suggests that major producers have significant influence over pricing, supply stability, and innovation directions. Key companies profiled in the research include Dow Inc., BASF SE, LyondellBasell Industries, Shell Chemicals, and ExxonMobil Chemical.
Each of these players brings distinct capabilities and strategic focuses to the market. Dow Inc., based in Midland, Michigan, is a primary producer of DPG Regular Grade and specialized grades such as DPG-CIR LO+, DPG-REN LO+, as well as DPG LO+ and DPG JSQI variants. Dow supplies fragrance-grade, industrial-grade, and sustainable options, leveraging its co-product status from monopropylene glycol production to offer a wide array of solutions for solvents, coupling agents, and personal care. BASF SE, headquartered in Ludwigshafen, Germany, offers DPG as a by-product of monopropylene glycol production and provides grades for use as solvents in fragrances, inks, semiconductors, leather, and hydraulic fluids, along with Care-grade humectant and solubilizer formulations.
Propylene Glycol (PG) Market
LyondellBasell Industries, with its operations in Houston, Texas, manufactures both industrial grade and fragrance-grade DPG, supplying the polyester synthesis, urethane, personal care, and industrial sectors. Shell Chemicals, based in London, United Kingdom, focuses on supplying DPG LO (low-odor) and standard grades for perfumery, cosmetics, and industrial solvents, supported by comprehensive product stewardship summaries. ExxonMobil Chemical, located in Spring, Texas, produces and supplies DPG as part of its broader glycol portfolio, serving chemical intermediates, coatings, and personal care applications. The report provides in-depth competitive profiling, examining each company's product portfolio, regional footprint, and strategic moves to help clients benchmark their position and identify partnership or acquisition opportunities.
Regulatory Compliance and Operational Safety
Operating in the DPG market requires strict adherence to regulatory standards and product stewardship protocols. Dipropylene Glycol production is a by-product of monopropylene glycol manufacturing, subjecting it to specific regulatory oversight. For instance, strict REACH registration requirements govern the safety data sheets and handling of DPG in European markets. Additionally, industrial grade DPG requires compliance with the Globally Harmonized System for transport and handling, as outlined in stewardship bulletins from major producers like LyondellBasell. These regulatory frameworks impact not only the cost of compliance but also the flow of goods across borders and the ability to enter certain markets. Our report details the regulatory landscape, providing guidance on how to navigate these requirements efficiently while maintaining operational continuity.
Executive Takeaways and Strategic Recommendations
For executives and decision-makers, the insights contained in this report translate into actionable strategies. The 4.14 percent CAGR and the projected market size of 6.51 billion USD by 2032 suggest ample opportunity, but realizing this value requires precise navigation of the complexities outlined above. Procurement teams should consider locking in supply agreements or diversifying sources in light of the April 2026 price increases and ongoing feedstock volatility. R&D and product development units can leverage the growth in sustainable grades and specialty applications to differentiate offerings. Furthermore, understanding the competitive concentration and the specific capabilities of key players like Dow, BASF, and LyondellBasell can inform partnership strategies and market entry plans.
Dipropylene Glycol (DPG) Market
The DPG market is evolving. The transition from high-volume industrial consumption to more specialized, value-driven applications, coupled with the push for sustainability and the realities of raw material cost fluctuations, demands a sophisticated approach to market intelligence. This study is designed to be that compass, offering the depth and breadth of analysis needed to thrive in the 2026-2032 period. By illuminating the hidden drivers of market performance and forecasting, we empower our clients to move beyond reactive adjustments and toward proactive, strategic growth. To access the full scope of data, detailed segmentation breakdowns, and comprehensive company profiles, we invite you to explore the complete market research report.
For detailed analysis of this topic, please visit the official page: Dipropylene Glycol (DPG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Bentonite Market Hits $178.1M in 2025, Projects 4.7% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Sulphur Bentonite Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
The Sulphur Bentonite Market stands at a critical inflection point. As agricultural demand intensifies and regulatory frameworks evolve across key producing and consuming regions, manufacturers, investors, and supply chain strategists require more than surface-level projections. PW Consulting’s latest market research delivers a comprehensive, forward-looking assessment designed to equip decision-makers with actionable intelligence for the 2026–2032 horizon. This report does not merely chart historical trajectories; it decodes the structural forces shaping value creation, margin dynamics, and competitive positioning in a market experiencing steady, technology-driven expansion.
Market Trajectory: A Data-Backed Foundation for Strategic Planning
Building on a clear historical baseline, the Sulphur Bentonite Market has demonstrated consistent upward momentum across the 2020–2025 evaluation window. Total market valuation climbed from approximately 140.5 million USD in 2020 to an estimated 178.1 million USD by 2025, reflecting sustained adoption of bentonite-sulphur formulations across agricultural and industrial applications. This trajectory is projected to accelerate into the forecast period, with the market anticipated to reach 184.9 million USD in 2026 and expand further to 242.72 million USD by 2032. The compound annual growth rate of 4.7 percent throughout the 2026–2032 forecast window underscores a market characterized by moderate but reliable expansion, driven by soil health initiatives, micronutrient integration requirements, and evolving fertilizer blend architectures.
Revenue streams have consistently been denominated in USD million, providing a standardized metric for cross-regional benchmarking and investment allocation. Rather than relying on static snapshots, this research maps the inflection points where capacity expansions, raw material price realignments, and policy-driven demand shifts converge. For executives calibrating production schedules, pricing architectures, or geographic market entries, these projections establish a disciplined foundation for scenario modeling and resource deployment.
Report Scope and Operational Content: What Decision-Makers Will Gain
PW Consulting’s Sulphur Bentonite Market study is structured to translate macro-level indicators into operational clarity. The report opens with a rigorous segmentation analysis that isolates demand patterns by product specifications, regional consumption profiles, and end-use applications. Each segment is evaluated through the lens of volume drivers, substitution risks, and pricing elasticity, enabling readers to identify where margin expansion is structurally achievable versus where competitive intensity will compress returns.
Sulphur Bentonite Market
Beyond segmentation, the research delivers a granular competitive landscape assessment. It maps enterprise positioning, manufacturing footprints, product portfolio strategies, and recent capacity deployment initiatives. The analysis goes further by integrating supply chain vulnerability mapping, evaluating how molten sulphur feedstock availability, energy cost fluctuations, and logistics constraints influence production economics. Regulatory and environmental compliance requirements are also examined in depth, particularly their impact on dust control protocols, emission standards, and plant-level operating expenditures.
To ensure strategic relevance, the report incorporates a comprehensive dashboard of recent industry developments. These timelines capture manufacturing expansions, facility inaugurations, product line extensions, and regional demand interventions that have already altered market dynamics. By contextualizing these events within broader pricing cycles and policy trajectories, the research provides a working framework for forecasting near-term supply responses and identifying windows of competitive advantage.
Competitive Landscape: Key Players and Strategic Positioning
The Sulphur Bentonite sector exhibits a moderately consolidated structure, with the top three firms commanding approximately 48.0 percent of market share and the top five reaching 58.0 percent. This concentration level suggests that scale, distribution networks, and formulation expertise remain decisive competitive moats. Yet the market continues to attract targeted expansions from both established producers and regional specialists, indicating room for differentiation through product customization, organic certification, and micronutrient integration.
Among the leading participants, several enterprises illustrate distinct strategic orientations. In Gujarat, India, Maruti Corporation has positioned itself as an active manufacturer and exporter of 90 percent sulphur bentonite, alongside micronutrient-enhanced variants incorporating zinc and copper. Its export-oriented model and focus on blended formulations reflect a strategy aimed at capturing emerging market demand for customized nutrient delivery. In Edmonton, Alberta, Keg River has built a reputation around premium bentonite sulphur fertilizers, including its Keg90S and Keg 85S lines, with particular emphasis on pastille form factors and dust mitigation. The company’s OMRI-listed organic offerings further signal a strategic pivot toward compliance-driven and sustainability-conscious buyer segments.
Globally, Tiger-Sul operates as a recognized leader in sulphur bentonite production, maintaining a broad footprint across multiple regions and emphasizing micronutrient-enhanced sulphur products. Its scale and distributionreach provide a benchmark for market positioning. In the Middle East, the National Sulphur Fertilizer Company, based in Qatar’s Messaied Industrial Area, has structured its core plant nutrient offering around high-quality sulphur bentonite, targeting substantial production capacity as part of its regional supply strategy. Meanwhile, Istanbul-based Sulfert Chemical has carved a specialized role in organic bentonite sulphur manufacturing, aligning product development with regulatory and certification preferences in export markets.
India’s Coromandel International Limited continues to expand its dedicated bentonite sulphur fertilizer manufacturing footprint, reinforcing its position within a market increasingly shaped by domestic soil health programs and import demand dynamics. In Dubai, Amarak Chemicals has advanced its portfolio beyond standard formulations to include zincated and boronated sulphur bentonite variants, recently launching a fully automated production facility designed to enhance throughput and consistency. These company profiles collectively illustrate a market where product engineering, certification pathways, and capacity agility are becoming as important as baseline volume output.
Recent Developments and Structural Industry Shifts
Several high-impact developments since early 2025 have already begun reshaping capacity allocation and regional supply balances. In March 2025, Coromandel International Limited inaugurated a second sulphur manufacturing plant at its Visakhapatnam facility, effectively doubling its bentonite sulphur capacity to 50,000 tonnes per annum. This expansion directly addresses rising domestic and export demand, while also signaling India’s broader push toward self-sufficiency in sulphur-based fertilizer inputs.
By February 2026, Amarak Chemicals commenced operations at a fully automated sulphur bentonite facility within the Jebel Ali Free Zone in Dubai, with a 60,000 tonnes per annum capacity target. The launch underscores accelerating investment in Middle Eastern production hubs, where logistics advantages and export-oriented infrastructure are being leveraged to serve both regional agricultural demand and overseas distribution channels. These capacity additions arrive against a backdrop of fluctuating molten sulphur feedstock availability, where refinery maintenance schedules and export restrictions in key producing regions have periodically constrained supply for bentonite sulphur producers.
Simultaneously, raw material pricing dynamics have introduced meaningful volatility into production economics. Average global sulphur prices have fluctuated between roughly 70 and 130 USD per metric ton through mid-2025, compelling manufacturers to recalibrate hedging strategies, inventory buffers, and pass-through pricing mechanisms. Energy cost variability and input price swings have further pressured production economics in key manufacturing zones, particularly in India and China, where cost structures are highly sensitive to feedstock and utility pricing.
Environmental and regulatory developments are equally consequential. Stricter emissions standards and dust control requirements during bentonite sulphur fertilizer production have elevated operational expenditures for manufacturers, prompting investments in closed-system processing, dust suppression technologies, and compliance-driven process upgrades. In India, government-backed fertilizer support programs and widespread soil health card distribution have amplified sulphur bentonite import volumes and domestic demand, creating an additional growth catalyst that interacts with global supply reallocations and pricing cycles.
Strategic Implications for 2026 and Beyond
For executives operating in or adjacent to the Sulphur Bentonite Market, the convergence of steady top-line growth, moderate competitive concentration, and evolving input cost dynamics demands a disciplined strategic posture. The 4.7 percent CAGR through 2032 suggests that broad market expansion will continue, but revenue capture will increasingly depend on segment selection, formulation differentiation, and supply chain resilience. Companies that can align capacity deployment with regional demand signals, manage sulphur feedstock exposure through contractual and inventory strategies, and navigate environmental compliance without sacrificing throughput will be best positioned to defend margins.
Sulphur Recovery Market
The competitive landscape also indicates that scale alone is no longer a sufficient differentiator. Enterprise strategies that incorporate micronutrient enhancement, organic certification readiness, dust control advantages, and automation-driven consistency are emerging as meaningful value drivers. Regional dynamics further complicate the equation: policy interventions in key agricultural markets, refinery-driven sulphur supply constraints, and logistics infrastructure variations require firms to maintain flexible sourcing architectures and scenario-aware production planning. In this environment, intelligence that connects macro forecasts with segment-level demand behavior, competitor capacity moves, and regulatory cost trajectories becomes a critical asset rather than a supplementary report.
How to Access the Complete Intelligence Package
This overview provides a structured preview of the market forces, competitive dynamics, and developmental milestones shaping the Sulphur Bentonite Market through 2032. However, the full research deliverable extends significantly beyond these highlights. Readers seeking detailed segment-level valuations, regional consumption mappings, pricing scenario models, competitive share analyses, and operational benchmarking frameworks will find the complete PW Consulting market study designed specifically for strategic planning, investment evaluation, and supply chain optimization. To access the full dataset, granular forecasts, and executive decision matrices, visit the official market research page and secure the complete intelligence package built for 2026-facing strategy teams.
For detailed analysis of this topic, please visit the official page: Sulphur Bentonite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 4K Ultra HD TV Market Hits $118.85M in 2025, Projected 24.38% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Horizon: Navigating the 4K Ultra HD TV Market in 2026 and Beyond
The 4K Ultra HD television market stands at a critical inflection point as of 2026. Driven by an accelerating compound annual growth rate of 24.38 percent, the sector has transformed from a mature consumer electronics category into a high-velocity growth arena fueled by display innovation, smart ecosystem integration, and shifting viewer behaviors. Our latest 4K Ultra HD TVs Market study compresses the historical trajectory of 2020 through 2025 and extends a disciplined forecast window to 2032, delivering the analytical architecture executives need to calibrate capital allocation, product roadmaps, and supply chain resilience in an increasingly volatile landscape.
For strategic decision-makers, the overarching narrative is clear: market revenue has climbed from 56.22 million USD in 2020 to an estimated 118.85 million USD in 2025, positioning the base year as a springboard for exponential expansion. Looking forward, the forecast period maps a steep upward curve, projecting revenue to reach 147.92 million USD in 2026, 178.42 million USD in 2027, and accelerating toward 541.36 million USD by 2032. This trajectory is not merely a statistical projection; it is a structural signal that the next wave of growth will be captured by organizations that align product strategy with regional demand patterns, display technology adoption, and application-driven usage models. The purpose of this preview is to illuminate the analytical depth awaiting buyers of the full study, while deliberately withholding the granular breakdowns that only the complete report can provide.
Decoding the Growth Trajectory: From Recovery to Accelerated Expansion
The historical window of 2020 to 2025 reveals a market that has consistently outgrown the broader consumer electronics average. Revenue climbed to 64.76 million USD in 2021, advanced to 76.68 million USD in 2022, and held steady growth at 86.68 million USD in 2023. The acceleration became more pronounced in 2024, when revenue reached 105.39 million USD, before culminating in the 2025 base-year figure of 118.85 million USD. This progression underscores a market that has successfully navigated post-pandemic demand normalization, channel rebalancing, and the early adoption of premium display technologies.
The forecast window from 2026 through 2032 is where strategic planning becomes decisive. Starting at 147.92 million USD in 2026, the market is projected to scale to 228.87 million USD by 2028, then 351.99 million USD by 2030, and ultimately 541.36 million USD by 2032. This stepped expansion signals a market in which technological differentiation, smart-platform monetization, and regional penetration rates will increasingly determine competitive positioning. Executing on this opportunity requires more than a top-line growth assumption; it demands a comprehensive understanding of how product segmentation, regional dynamics, and end-use applications interact over time. The full study unpacks these interactions with a level of granularity that enables scenario planning, market-entry prioritization, and investment sequencing.
Segmentation Architecture: Where Growth Will Concentrate
A market moving at this pace cannot be managed through aggregate figures alone. The report disaggregates the landscape across three critical dimensions, each carrying distinct strategic implications for product planning, pricing architecture, and channel strategy. Understanding how display types compete, how applications evolve, and how regional markets behave is essential for translating a 24.38 percent CAGR into actionable forecasts.
Display Technology Dynamics
The competitive battleground for 4K Ultra HD televisions is increasingly defined by the interplay of advanced display technologies. The study examines OLED, QLED, and LED architectures as distinct value pools, mapping their adoption curves, pricing tiers, and performance positioning. Each technology offers a different value proposition, from premium contrast and color performance to cost-efficient scalability and smart-feature enablement. The analytical framework inside the full report isolates the demand drivers that will determine which technology segments capture share, how pricing pressure evolves, and where manufacturers can secure margin resilience. Because these technology shares are shifting rapidly with new panel supply and consumer preference, the detailed splits and growth trajectories are disclosed only within the complete study.
Application-Driven Demand
Modern 4K Ultra HD TVs are no longer passive display devices; they are content hubs, gaming platforms, and smart-ecosystem endpoints. The report evaluates application categories including Smart TV and Gaming TV environments, alongside other specialized use cases. This segmentation is vital because application mix directly influences feature requirements, connectivity expectations, and retail positioning. Smart TVs, for instance, require deep integration with operating systems, streaming partnerships, and AI-driven user experiences, while gaming-focused models emphasize refresh rates, low latency, and HDR alignment. The study maps demand intensity and growth prospects across these applications, equipping product teams with a demand-side blueprint. Specific proportion breakdowns and revenue attribution by application are reserved for the full report to preserve the precision of the underlying model.
Regional Growth Profiles
Geographic demand is unevenly distributed and increasingly shaped by regulatory conditions, infrastructure readiness, and local pricing dynamics. The research partitions the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each presenting a distinct value-creation path. Asia Pacific represents the largest value concentration, reflecting scale demand and rapid technology adoption, while North America and Europe contribute structurally significant volumes with higher average unit pricing in premium segments. Latin America and the Middle East and Africa present growth opportunities tied to infrastructure expansion, digital content availability, and evolving retail ecosystems. The complete study provides a region-by-region examination of market size trajectories, demand catalysts, and competitive intensity without publishing the detailed regional percentages here, so decision-makers are encouraged to consult the full report for the exact geographic splits required to build accurate regional plans.
Competitive Landscape: Strategic Positioning and Innovation Pressure
The 4K Ultra HD TV market is defined by a dense field of global manufacturers, each pursuing differentiated strategies in display technology, smart-platform integration, and pricing architecture. The report profiles leading enterprises including Samsung Electronics, LG Electronics, Sony Corporation, Hisense, TCL Corporation, Panasonic Corporation, VIZIO, and Skyworth. These companies anchor the market through distinct value propositions: Samsung and LG leverage advanced QLED, OLED, and AI-enhanced smart features; Sony competes on premium picture quality and BRAVIA platform integration; Hisense and TCL push Mini-LED and QD-Mini LED architectures into broader consumer segments with Google TV and smart ecosystem alignment; Panasonic combines OLED and 4K LCD panels with Fire TV integration; VIZIO focuses on accessible 4K UHD smart TVs with Dolby Vision and HDR support; and Skyworth delivers HDR-enabled 4K UHD models targeting value-conscious segments.
Beyond the established incumbents, market dynamics are being reshaped by new entrants and platform-driven expansion. Notably, Amazon announced the W70B Series Smart TV as a core 4K UHD model, emphasizing sleek design and immersive viewing, signaling how platform players are entering the hardware space to deepen ecosystem lock-in. This kind of product launch matters strategically because it intensifies competition for share of attention, smart-services revenue, and retail shelf presence. The full study goes beyond company profiles to map competitive interaction patterns, including how brand portfolios are structured, where pricing pressure is building, and which segments are most vulnerable to disruption. Given the consolidated nature of the industry, competitive analysis must also consider market concentration, and the complete research provides the exact concentration metrics needed to assess barrier-to-entry conditions and pricing power.
Industry Dynamics: Supply Chain Constraints, Regulatory Headwinds, and Cost Volatility
No strategic assessment of the 4K Ultra HD TV market is complete without confronting the operational and regulatory pressures that shape cost structures and supply continuity. As of April 2025, China placed export restrictions on seven categories of medium and heavy rare earths, including dysprosium, samarium, and terbium, which are essential for permanent magnets used in 4K TV displays and components. These restrictions were part of a broader response to tariff escalations and have introduced material price volatility and supply chain uncertainty across electronics production. Further analysis from early 2026 indicates that these controls will continue to affect component availability and cost planning, with additional foreign direct product rule extensions shaping procurement strategies.
The practical implication for manufacturers and channel partners is that cost forecasting can no longer rely solely on historical component pricing. Rare earth constraints and raw material volatility have become structural variables in the cost stack, influencing margin planning, sourcing diversification, and manufacturing geography. The report integrates these dynamics into a broader sustainability and supply chain risk framework, helping executives anticipate where bottlenecks may emerge, how pricing architectures may need to adapt, and which product tiers are most exposed to input-cost fluctuations. Because the precise impact varies by component, component substitution pathways, supplier diversification options, and regional sourcing implications differ across product segments, the complete study supplies the operational detail necessary to translate these macro risks into procurement and product decisions.
Inside the Report: Operational Content Built for Executive Action
This market study is designed to move beyond descriptive trends and deliver decision-grade intelligence. The full version includes product and technology assessments, application-level demand analysis, regional market mapping, and competitive positioning evaluations. It is structured to support multiple functional needs: product managers can use it to prioritize feature roadmaps and display mix decisions; sales and commercial teams can align go-to-market plans with regional demand signals; supply chain and sourcing leaders can evaluate material exposure and supplier diversification paths; and strategy teams can build investment scenarios grounded in forecast-period growth paths.
In addition to the core segmentation and forecast content, the study synthesizes recent industry developments and regulatory milestones, including export control actions and platform-driven product launches, into a practical context for near-term planning. The report is built for readers who need a single analytical reference that connects market size, growth trajectory, competitive intensity, and supply-side risk into one consistent framework. Readers seeking exact regional percentages, application splits, type-based revenue shares, and company-level concentration figures will find those details only in the full release, which is why this preview deliberately highlights the architecture and advisory value without disclosing the embedded figures.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a market view that is simultaneously optimistic about growth and disciplined about risk. A compound annual growth rate of 24.38 percent over the forecast period signals an exceptional opportunity, but capturing that opportunity requires a precise understanding of where growth is concentrated, how competitive pressures are evolving, and which external shocks can alter cost and availability assumptions. The 4K Ultra HD TVs Market study provides that integrated view, linking historical momentum, forecast expansion, segmentation dynamics, and competitive context into a single strategic frame. It is intended to help leadership teams answer the practical questions that shape capital allocation, product portfolio strategy, regional prioritization, and risk mitigation in the year ahead.
For organizations building their 2026 plans, the full report offers the depth required to convert a high-level growth story into actionable strategy. The preview above demonstrates the analytical approach, the scope of coverage, and the strategic context embedded in the research, while preserving the segmented data and competitive metrics for the complete edition. To access the full market size progression by year, the detailed segmentation splits, the comprehensive company profiles, and the operational dynamics analysis, readers are encouraged to obtain the full study from the source page, where the complete intelligence package is available for decision-making across product, commercial, and supply chain functions.
4K Ultra HD TVs Market
UHD TV Market
For detailed analysis of this topic, please visit the official page: 4K Ultra HD TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Corporate Travel Insurance Drives 14.75% CAGR in $648.4M Market
By PW Consulting, 2026-09-16
Strategic Imperatives in the Business Travel Insurance Market: A 2026 Outlook
Introduction: The New Risk Landscape for Corporate Travel
Corporate travel has fundamentally transformed over the past half-decade. As organizations navigate a complex environment defined by geopolitical volatility, evolving regulatory frameworks, and heightened duty of care obligations, the business travel insurance market has emerged as a critical component of enterprise risk management strategies. Our latest comprehensive market research provides decision-makers with the intelligence needed to navigate this rapidly expanding landscape through 2032.
The base year analysis (2025) reveals a market that has demonstrated remarkable resilience and growth momentum. Historical data from 2020 through 2025 illustrates consistent upward trajectory, with revenues expanding from 129.74 million USD to 249.8 million USD—a reflection of both increased travel volumes and heightened awareness of comprehensive coverage needs. This growth pattern establishes a robust foundation for the forecast period extending through 2032, where compound annual growth rates are projected at 14.75 percent.
Market Trajectory and Growth Catalysts
The forecast period from 2026 to 2032 presents compelling expansion opportunities that warrant immediate strategic attention. Market valuations are expected to progress from approximately 285.26 million USD in 2026 to reach 648.4 million USD by 2032. This trajectory underscores the accelerating demand for specialized coverage solutions as corporations reassess their travel risk postures in an uncertain global environment.
Structural Market Dynamics and Segment Evolution
Understanding which coverage categories command the largest share of corporate spending provides essential insight for product development teams and procurement strategists. Within the type-based segmentation, Corporate Travel Insurance represents the dominant category, valued at 186.73 million USD, while Individual Business Trip Insurance accounts for 63.07 million USD. This distribution highlights the strong preference among enterprises for comprehensive group-based solutions that streamline administration and ensure consistent protection across teams.
The application-based analysis further illuminates corporate priorities. Medical and Health Coverage stands at 95.62 million USD, Accident and Liability at 92.19 million USD, and Trip Cancellation and Delay at 61.99 million USD. These figures affirm that health protection and liability management remain paramount concerns for risk managers, while trip disruption coverage continues to gain prominence as travel schedules become increasingly complex and subject to interruption.
Regional deployment patterns reveal distinct maturity profiles across global markets. North America leads with 100.35 million USD in market value, followed by Europe at 74.6 million USD and Asia Pacific at 62.42 million USD. Latin America contributes 12.43 million USD, while the Mideast and Africa region represents an emerging frontier with significant growth potential. These regional distributions correspond closely with corporate travel volumes and maturity of local insurance infrastructure.
Market concentration data indicates that the top three players command 55.2 percent of total market share, while the top five firms control 68.4 percent. This concentrated structure suggests both competitive intensity among established leaders and opportunities for specialized providers to differentiate through niche capabilities, digital innovation, or tailored service models.
Regulatory Environment and Compliance Imperatives
Regulatory considerations increasingly shape procurement decisions within the business travel insurance sector. No federal statute mandates business travel insurance in the United States; however, employers maintain a duty of care obligation under OSHA Section 5(a)(1), creating a compliance-driven rationale for maintaining adequate coverage programs. This obligation extends to organizations operating internationally, where local labor laws and host-country requirements may impose additional expectations.
The ISO 31030:2021 standard for travel risk management provides a framework that requires organizations to document insurance as one control within their broader risk management architecture. Corporations seeking to demonstrate mature risk governance increasingly reference this standard when evaluating provider offerings and structuring their travel protection programs. Adoption of such frameworks correlates strongly with the purchasing patterns observed in larger enterprises.
Evolving data privacy requirements under GDPR and related regulations compel providers to enhance cybersecurity protocols for policyholder data embedded within corporate plans. Organizations must evaluate vendor capabilities not only on coverage breadth and pricing but also on data handling maturity, particularly when policies encompass multinational travel across jurisdictions with divergent privacy expectations. Specialized human labor for claims processing and risk advisory services represents a primary operational cost for business travel insurance providers, a factor that influences both pricing structures and service quality differentiation across the competitive landscape.
Competitive Landscape and Strategic Positioning
The competitive arena features established multinational insurers and specialized providers, each pursuing differentiated value propositions. Allianz, headquartered in Munich, Germany, specializes in Allianz Travel and Allianz Global Assistance business travel insurance plans with digital app-based claims processing, emergency assistance, and corporate/group programs. AXA, based in Paris, France, provides AXA Assistance corporate and digital business travel insurance platforms with multi-trip coverage and real-time traveler support features, emphasizing technology-enabled service delivery.
Travel Insured International, located in Morristown, New Jersey, USA, offers specialized business travel insurance solutions with coverage for trip cancellation, interruption, medical emergencies, and business equipment protection—catering to organizations with diverse asset protection needs. Seven Corners, headquartered in Bloomington, Minnesota, USA, delivers annual multi-trip business travel insurance plans with high limits and features tailored for frequent business travelers and corporate groups, addressing the segment of employees with elevated travel frequency.
International Business Travel Insurance Plans Market
HTH Worldwide, based in Scottsdale, Arizona, USA, provides corporate business travel insurance with long-term and international coverage options for business travelers, serving organizations with extended-duration assignments. Zurich Insurance Group, headquartered in Zurich, Switzerland, offers Zurich Business Travel Solution and Zurich Travel Assist for group business travel insurance with dedicated account management and global claims processing, emphasizing relationship-driven service for complex corporate accounts.
Chubb, also based in Zurich, Switzerland, supplies Chubb Business Travel Insurance plans with group coverage, target market determinations, and integration with corporate risk management—appealing to organizations seeking seamless alignment between travel insurance and broader enterprise risk frameworks. Marsh, headquartered in New York, USA, delivers business travel insurance solutions as part of its risk advisory services, including group plans and corporate risk management integration, positioning insurance within a holistic advisory context.
Aon, based in London, UK, provides Aon Business Travel Insurance solutions with focus on corporate travel programs and integrated risk management services, leveraging its global advisory platform. Berkshire Hathaway Travel Protection, located in Fairfield, Connecticut, USA, specializes in business travel insurance with robust coverage for corporate travelers and group programs, drawing on the financial strength and reputation of its parent organization.
Recent industry developments underscore the evolving governance landscape. In March 2026, the US Travel Insurance Association named a new president to guide the association focused on travel insurance standards, signaling heightened attention to industry self-regulation and best practice dissemination. In February 2026, USTIA released updated resources on why 2026 is the year to travel smart, reinforcing the strategic emphasis on informed coverage decisions as travel activity accelerates.
Report Framework and Analytical Depth
Our market research delivers actionable intelligence across multiple analytical dimensions designed to support evidence-based decision-making. The report structure encompasses comprehensive market sizing with historical baselines and forward-looking projections, segmentation analysis across type, application, and regional dimensions, and granular competitive profiling of key market participants.
Operational cost analysis examines the role of specialized human labor in claims processing and risk advisory services, illuminating cost structures that influence pricing strategies and margin profiles. Coverage architecture assessments evaluate how medical, liability, and trip disruption protections are bundled and priced across different corporate segments, revealing optimization opportunities for procurement teams seeking to align coverage with actual risk exposure.
Business Travel Insurance Market
Technology adoption trends are explored in the context of digital claims processing, real-time traveler support platforms, and integrated risk management dashboards that connect travel insurance data with broader corporate risk ecosystems. The analysis of regulatory developments—including OSHA duty of care obligations, ISO 31030:2021 framework expectations, and GDPR-driven cybersecurity requirements—provides compliance leaders with structured guidance for vendor evaluation and policy design.
The report also incorporates scenario analysis that enables organizations to stress-test their coverage strategies against potential disruptions, from geopolitical events to public health crises and natural disasters. By mapping coverage gaps against plausible disruption scenarios, risk managers can prioritize enhancements that deliver the greatest resilience improvement relative to incremental cost.
Strategic Recommendations for 2026 Decision-Makers
Organizations approaching business travel insurance procurement in 2026 should prioritize several strategic actions. First, assess current coverage alignment with duty of care obligations and ISO 31030:2021 documentation requirements, ensuring that policy structures satisfy both legal expectations and internal governance standards. Second, evaluate provider capabilities in digital claims processing and real-time traveler support, as these service dimensions increasingly differentiate vendor value propositions and influence employee experience during incidents.
Third, consider the integration potential between travel insurance platforms and existing corporate risk management systems, recognizing that seamless data flow enhances both operational efficiency and risk visibility. Fourth, examine regional coverage adequacy in light of expanding travel footprints, particularly as organizations increase engagement with Asia Pacific and Latin American markets where insurance infrastructure continues to mature.
Fifth, benchmark pricing and coverage structures against the competitive landscape, leveraging the detailed vendor analysis provided in this report to identify opportunities for renegotiation or provider diversification. The market concentration data indicates that while large players dominate, specialized providers offer differentiated features that may better suit specific organizational profiles, travel patterns, or risk appetites.
Conclusion: Accessing Comprehensive Market Intelligence
The business travel insurance market stands at an inflection point where growth, regulation, and technology converge to reshape enterprise risk management practices. Our full market research report provides the detailed quantitative analysis, competitive assessments, and strategic recommendations necessary for informed decision-making throughout the 2026–2032 forecast horizon. The insights presented here represent a curated preview of the comprehensive analysis available in the complete study.
Decision-makers seeking granular segmentation data, detailed vendor benchmarking matrices, scenario modeling outputs, and region-specific procurement guidance are invited to access the full report through our platform. The complete intelligence package delivers the depth required to construct resilient, cost-effective, and compliant business travel insurance strategies aligned with organizational objectives.
As corporate travel continues its recovery and expansion trajectory, the organizations that invest in sophisticated risk management frameworks—supported by comprehensive insurance coverage and informed by rigorous market intelligence—will be best positioned to navigate uncertainty while enabling their teams to travel with confidence. We invite you to explore the full research to strengthen your strategic positioning in this dynamic market.
For detailed analysis of this topic, please visit the official page: Business Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


