



Category: market research
Navigating the Next Wave: Strategic Intelligence for the Autoclaved Aerated Concrete Market (2026–2032)
The built environment is undergoing a structural realignment. Decarbonization mandates, shifting material cost dynamics, and an accelerating preference for lightweight, high-thermal-performance solutions have propelled Autoclaved Aerated Concrete (AAC) from a niche alternative to a mainstream strategic consideration. As corporate decision-makers plan capital allocation, supply chain positioning, and geographic expansion for 2026 and beyond, the AAC market has emerged as a critical intersection of construction demand, regulatory tailwinds, and operational efficiency gains. Our latest research publication provides a comprehensive, decision-grade mapping of this trajectory across the forecast horizon through 2032.
The foundation of this outlook is built on a clear historical arc. From a base of USD 178.5 Million in 2020, the market progressed to USD 227.8 Million by 2025, reflecting compounding annual growth even amid intermittent supply chain friction and raw material price volatility. Moving into the forecast period, the trajectory accelerates into a robust growth corridor, with the market expected to cross the USD 244.0 Million threshold in 2026, continue upward through the mid-to-late 2020s, and approach USD 359.4 Million by 2032. Underlying this expansion is a forecast-period CAGR of 6.98 percent, a figure that signals sustained, structurally supported demand rather than a short-lived cyclical spike. For executives evaluating capacity planning, technology licensing, distributor partnerships, or regional entry strategies, these macro indicators establish the baseline for scenario modeling and investment prioritization.
Yet macroeconomic aggregates alone do not dictate competitive success. The strategic value of this research lies in its translational architecture: rather than presenting abstract totals, the study decomposes growth drivers into actionable dimensions that align with corporate planning cycles. Decision-makers are guided through a structured evaluation of how market momentum bifurcates across product formats, end-use applications, and regional ecosystems, enabling targeted positioning instead of broad, unfocused exposure. The report is designed to bridge the gap between market observation and execution, translating demand signals into procurement roadmaps, capacity expansion logic, and partnership criteria.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This publication is structured as an operational toolkit rather than a passive market summary. The analytical framework is engineered to support cross-functional teams—strategy, operations, supply chain, and business development—in validating assumptions and stress-testing strategic initiatives. Key components include:
- Historical Reconstruction and Baseline Calibration: A granular review of market evolution from 2020 through 2025, isolating inflection points, recovery patterns, and the structural factors that shaped volume and value trends. This retrospective anchors all forward-looking estimates and establishes the credibility of the forecast model.
- Forecasting Architecture for 2026–2032: A multi-variable projection framework that incorporates demand-side drivers, supply-side capacity dynamics, and regulatory pacing. The forecast does not rely on linear extrapolation; instead, it integrates sector-specific momentum to map a realistic growth corridor for the next seven years.
- Segment-Level Strategic Decomposition: Detailed analysis across product categories and application verticals, enabling readers to identify where value creation is concentrating, which formats are scaling most efficiently, and how end-use demand patterns are shifting in response to construction practices and building performance expectations.
- Regional Ecosystem Mapping: An assessment of how geographic markets differ in maturity, adoption intensity, regulatory influence, and competitive saturation. The analysis clarifies where demand is emergent, where it is consolidating, and where strategic entry or expansion may yield disproportionate returns.
- Competitive Positioning and Capability Benchmarking: A panoramic view of the operating landscape, including established manufacturers, technology providers, licensed plant operators, and distribution-focused players. Profiles are evaluated against production tenure, geographic footprint, product breadth, and strategic moves that signal future competitive intent.
- Industry Dynamics and Vulnerability Mapping: Targeted examination of the forces shaping margins and operational resilience, including raw material pricing behavior, policy interventions, and certification-driven procurement shifts. These insights allow organizations to anticipate cost pressure, evaluate substitution trends, and align sourcing strategies accordingly.
Collectively, these elements form a decision-support ecosystem. Rather than leaving readers with isolated data points, the report constructs a continuous logic chain: from historical evidence, through structural drivers, to competitive reality, and finally to strategic implication. The objective is to enable leaders to ask sharper questions—about capacity timing, product mix optimization, distributor alignment, and regional prioritization—and to answer them with evidence that withstands scrutiny.
Market Dynamics: Regulatory Acceleration, Material Realities, and Demand Reconfiguration
The AAC market's expansion is not occurring in a vacuum. It is being reshaped by intersecting forces that alter both the demand curve and the cost structure of production. One of the most consequential shifts involves regulatory and certification environments. In several advanced construction markets, green building certification frameworks have increasingly favored materials that combine structural utility with lightweight characteristics and thermal insulation performance. This has translated into higher procurement visibility for AAC within project specification processes, particularly where energy efficiency targets are tightening and where building envelopes must satisfy stricter performance thresholds. Parallel policy mechanisms in parts of Europe have further reinforced this trajectory, as energy codes and retrofit mandates effectively position AAC as a pragmatic solution for both new builds and renovation programs seeking measurable thermal gains.
At the same time, material-side dynamics are introducing a more complex operating environment. The core input architecture of AAC manufacturing—dependent on cement and lime as primary binding agents—remains exposed to pricing volatility. Seasonal fluctuations, regional supply constraints, and broader commodity cycles have periodically pressured input costs, affecting margin stability across block and panel producers. This has elevated the importance of sourcing strategy, formulation flexibility, and vertical coordination for manufacturers seeking to protect unit economics. In certain markets, policy-driven substitution initiatives have begun reshaping input dependency by encouraging alternative material pathways, lowering embodied carbon intensity and altering the traditional cost equation for AAC production. These regulatory and material intersections are not peripheral concerns; they are central to understanding where competitive advantage will be earned or eroded over the forecast period.
Autoclaved Aerated Concrete (AAC) Market
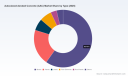
On the demand side, the configuration of end-use adoption is evolving as construction priorities shift. Residential applications continue to reflect substantial demand, supported by housing activity cycles and the material's suitability for efficient wall systems. Commercial development contributes a distinct demand layer, where speed of assembly, weight reduction, and building performance specifications influence material selection. Infrastructure and industrial applications, while representing smaller share tiers in aggregate, introduce specialized requirements that reward product consistency, durability, and tailored engineering profiles. The report evaluates these demand streams not merely as volume contributors, but as strategic segments where specification influence, purchasing behavior, and competitive differentiation diverge meaningfully.
Competitive Landscape: Established Players, Regional Expansion, and Strategic Signaling
The competitive architecture of the AAC market reflects a blend of long-entrenched manufacturers, technology-and-licensing operators, distribution-centric participants, and newer entrants expanding capacity to capture demand momentum. In North America, the landscape is anchored by producers with substantial operational tenure and established supply relationships. One of the region's oldest manufacturers has built a multi-decade presence in AAC blocks and panels, reinforcing channel depth and regional familiarity. Alongside it, another significant North American supplier has sustained production and market participation for over two decades, contributing to a competitive base that values reliability and specification acceptance. More recent activity has also brought newer manufacturing capacity into the region, with production commencing in 2022, signaling that market growth is attracting additional investment rather than consolidation alone.
In Europe, the competitive picture is shaped by a mix of manufacturers, structural system suppliers, and technology providers operating through licensed plant networks. A major Northern European producer has established scale across Estonia and Latvia, positioning itself as a leading regional manufacturer of blocks and panels. In Poland and broader Eastern Europe, additional producers are reinforcing regional supply, while in the UK, a manufacturer and supplier continues to extend structural wall system offerings across domestic and international channels. Technology-and-licensing operators also play an important role, enabling production capacity beyond the boundaries of vertically integrated manufacturers and expanding the market's geographic reach through partnership-based models.
Asia introduces a different dynamic, characterized by capacity expansion and diversified participation. In India, the sector has seen meaningful manufacturing scale-up, with one major producer completing a phased capacity expansion to a substantial annualized volume for blocks, bricks, and panels. Another significant player has moved into AAC production through a dedicated product line launched in 2025, reflecting the strategic use of broader cement and building materials portfolios to enter or deepen participation in lightweight concrete segments. Additional Indian manufacturers continue to build out block and panel output, underscoring the region's role as a focal point for both volume growth and operational scaling.
Distribution-focused participants further complicate and enrich the competitive fabric. In several markets, distributors act as critical intermediaries, sourcing and supplying AAC blocks and panels to construction projects where manufacturing presence may be limited or where project-specific procurement logistics favor intermediary scale. This dual structure—manufacturers building capacity and distributors extending reach—creates multiple pathways for market participation and complicates simplistic views of competitive intensity. The report evaluates these roles in context, highlighting where manufacturing control, technology licensing, or distribution capability constitutes the more decisive strategic asset.
Strategic Implications for 2026 Planning
For organizations entering 2026 with AAC exposure or considering it, the strategic implications fall into several priority areas. First, the growth trajectory justifies disciplined capacity and supply chain planning, but only when paired with segment-specific demand intelligence. Broad market growth does not automatically translate into uniform opportunity across product types or application verticals. Decisions regarding which formats to prioritize, which applications to target, and where to locate or expand production should be informed by the segmentation patterns revealed in the full study.
Second, competitive positioning will increasingly depend on how well firms manage the tension between demand tailwinds and input cost variability. Companies that can stabilize cost structures, optimize formulation strategies, or align sourcing with regional pricing behavior will be better positioned to preserve margins while scaling. Similarly, firms that understand where regulatory and certification pressures are converting into procurement preference will be able to align product specifications and marketing positioning more effectively.
Third, the competitive landscape suggests that market access is not uniform. In some regions, established manufacturing presence, specification history, and channel relationships create meaningful barriers. In others, licensed production models, distributor networks, and new capacity additions are loosening those barriers and opening room for strategic entry. Evaluating which pathway is most viable—direct manufacturing, technology partnership, or distribution alignment—requires a clear view of regional saturation, demand cadence, and incumbent behavior, all of which are examined in depth in the complete report.
Closing Perspective: The Case for Full Intelligence
The AAC market is entering a phase in which strategic advantage will belong to those who can interpret momentum with precision rather than approximation. The headline growth path outlines an attractive opportunity, but the real decision architecture lies beneath it: in the interplay of segment concentration, regional heterogeneity, regulatory pacing, input cost volatility, and competitive maneuvering. This research is built to expose those layers systematically, giving leadership teams a structured basis for planning capital, refining product strategy, and choosing where to commit operational resources.
The analysis presented here is intended as a strategic preview. It establishes the scale, direction, and structural logic of the market, and it highlights the operational realities that will shape execution in 2026 and beyond. For the full segmentation breakdown, regional demand mapping, competitive benchmarking detail, and the complete forecast tables that support internal modeling, we invite you to access the full report. The complete study provides the depth required to convert market visibility into concrete, defensible action.
Worldwide Cellular Concrete Market
For detailed analysis of this topic, please visit the official page: Autoclaved Aerated Concrete (AAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrofusion Fittings Market to Reach $2.18B by 2032, 6.99% CAGR
By PW Consulting, 2026-09-16
Strategic Intel: Why the Electrofusion Fittings Market Outlook Matters for 2026 Decision-Makers
As infrastructure priorities shift toward resilience, safety, and faster deployment, the electrofusion fittings market is entering a decisive phase for capital allocation and product strategy. Our latest market research unpacks the commercial dynamics shaping polyethylene (PE) joining systems across water, gas, industrial, and emerging energy applications. This overview frames the strategic value of the study for executives planning 2026 investments, while pointing toward the full report for the granular intelligence needed to act with precision.
From Recovery to Sustained Expansion: Quantifying the Opportunity
The global electrofusion fittings market has moved beyond post-pandemic normalization into a structured growth trajectory. Revenue climbed steadily from 2020 through 2025, reaching a base of approximately 1,360.0 million USD, and our forecast model projects continued expansion at a compound annual growth rate of 6.99 percent through 2032. The trajectory is not uniform: near-term growth reflects catch-up installation activity, infrastructure replacement programs, and steady procurement cycles, while the later forecast years indicate a compounding effect driven by material substitution, stricter leakage standards, and expanding utility networks.
For corporate planners, this shape matters. It signals that the market is large enough to justify dedicated go-to-market investment, yet segmented enough that broad-brusf strategies will leave margin on the table. The study maps where value is accumulating, how growth is distributed across product families and end uses, and which regions are converting demand into durable procurement patterns. Rather than presenting static snapshots, the analysis connects historical momentum to forward-looking scenarios so leadership teams can pressure-test revenue assumptions against realistic adoption curves.
What the Study Delivers: Operational Intelligence, Not Just Headlines
A market overview can confirm direction; only a structured research product can translate direction into operational choices. This report is built around decision-ready modules that cover the full electrofusion fittings value chain and the commercial environment surrounding it.
- Market sizing and forecast framework covering historical performance through 2025 and a detailed outlook from 2026 to 2032, expressed in consistent USD million terms for executive modeling.
- Segment-level analysis across fitting types and application categories, identifying where demand concentrates, where substitution risk is higher, and which product families show the strongest pricing and volume dynamics.
- Regional evaluation that distinguishes mature distribution markets from high-growth territories, highlighting procurement habits, channel structures, and local compliance influences.
- Competitive landscape profiling of leading manufacturers and suppliers, with attention to product ranges, certification positioning, equipment ecosystems, and recent commercial moves.
- Industry dynamics including regulatory updates, labor availability pressures, raw material volatility, standardization activity, and application-level installation trends that shape both cost structures and project timelines.
The report also integrates recent developments that can alter short-term competitive positioning. These include refreshed product catalogs, updated generic joining procedures, new fitting launches with transition couplings and threaded options, and exhibition-level visibility around hydrogen distribution use cases. By placing such events inside the broader market framework, the study helps teams separate signal from noise and anticipate which developments are likely to affect procurement, specification, or channel behavior in 2026 and beyond.
Competitive Landscape: How Leading Players Are Shaping the Field
The electrofusion fittings market is not dominated by a single universal solution provider; it is shaped by a set of specialists, regional strongholds, and application-focused suppliers. The research profiles companies that are actively influencing specification, availability, and quality expectations across water, gas, and industrial piping systems.
Electrofusion Fittings Market
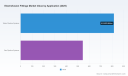
Plasson Ltd. continues to reinforce its position through PE100 electrofusion fittings and related fusion equipment for water, gas, and industrial piping, alongside an updated 2026 catalog and tooling listings. This kind of catalog refresh matters because it signals active product stewardship and keeps specifiers current on couplers, tees, elbows, and saddles. Georg Fischer Central Plastics Company remains relevant for pressure applications by supplying HDPE electrofusion fittings aligned with ASTM F1055, supported by training materials and large-diameter options that appeal to processors seeking repeatable parameter setting. Integrity Fusion Products has carved out a recognizable niche with its IntegriFuse brand HDPE electrofusion couplers across multiple diameter ranges and SDR options, emphasizing injection-molded, pressure-rated construction and controlled quality standards.
International and regional suppliers add further differentiation. Radius Systems Limited specializes in electrofusion fittings and welding equipment for PE pipe systems and supports generic fusion procedures for municipal and industrial work. Pipelife International has expanded visibility for its GeoFusion couplers and fittings, including reduced-cycle-time models with substantial deployment in Europe, an indicator of how installation speed can become a competitive differentiator. Agru Kunststofftechnik GmbH supplies couplers and saddles for pressure and drainage applications, while Egeplast focuses on pressure-rated HDPE electrofusion products for water and gas distribution. Strongbridge Inc. emphasizes large-diameter capability with offerings up to 63 inches and high-pressure classes, targeting projects where fitting performance under demanding service conditions is critical. Kimplas Piping Systems Private Ltd., operating within NORMA Group, demonstrates how electrofusion fittings can become integral to large-scale gas distribution supply chains, with significant annual unit volumes supporting British gas distribution projects.
Recent corporate and sector developments reinforce the strategic relevance of these profiles. Updated catalog releases, the approval of revised generic electrofusion joining procedures, new product introductions featuring steel-PE transition couplings and thread options, and high-profile exhibition activity around hydrogen distribution all point to a market where product specifications, installation standards, and application expansion are evolving together. The full study examines how such developments influence competitive positioning rather than treating them as isolated news items.
Market Dynamics: The Forces That Will Define 2026 Execution
Growth rates and market size are necessary context, but the practical challenges of 2026 will be determined by the environment in which fittings are specified, manufactured, and installed. The research integrates multiple dynamic factors that affect cost, speed, compliance, and competitive differentiation.
Installation discipline is receiving renewed attention. The approval of the third edition of MAB-1 in late 2025 establishes a more uniform electrofusion joining procedure for PE pipe installations in the field, which can reduce variability across contractors and improve specification confidence for utilities and engineering teams. At the same time, standardization activity continues to shape equipment and process expectations, including updated performance requirements for electrofusion control units used with polyethylene fittings. These moves do not simply adjust paperwork; they influence which products are easier to specify, which installation crews can work more efficiently, and how manufacturers position training and support.
Labor constraints remain a practical brake on project execution. In 2025, a significant share of utility contractors reported difficulty finding qualified workers for specialized processes such as electrofusion, contributing to project delays. This environment raises the strategic value of fittings and equipment that reduce installation complexity, support faster cycle times, and fit more cleanly into trained workforces. Suppliers that align product design with field usability can convert labor scarcity into a competitive advantage rather than treating it as an external inconvenience.
Input cost volatility also demands attention. Polyethylene resin price fluctuations have been material, with manufacturers reporting substantial variability that affects electrofusion fittings production economics. When resin costs move sharply, pricing discipline, inventory strategy, and product mix decisions become more important than headline volume growth. The study places these cost dynamics alongside segment and regional data so planners can evaluate where margin resilience is strongest and where exposure needs active management.
Application-level momentum further shapes the outlook. In Europe, gas distribution projects installed a markedly higher number of electrofusion joints in 2024 compared with the prior year, reflecting continued investment in pipeline infrastructure and replacement activity. Equally notable is the growing visibility of electrofusion solutions in emerging energy contexts, where distribution-focused projects are beginning to explore PE-based joining for new fluid transport needs. These trends broaden the conversation beyond traditional water and gas pipelines and invite suppliers to think in terms of application expansion rather than static category boundaries.
What Is Held Back—and Why Full Access Changes the Decision
The executive preview above establishes direction, but it deliberately omits the precise splits that conversion planning requires. The full report provides the detailed segmentation data across fitting types, application categories, and regions, along with the numerical market values that support forecasting, channel planning, and scenario modeling. It also includes the structured competitive profiles and recent-devaluation timeline needed to benchmark positioning, anticipate specification shifts, and assess where supplier moves are likely to influence procurement behavior.
Electro-fusion Coupler Market
This design is intentional. High-level growth narratives can inform strategy, but they cannot replace the segmented intelligence required to answer questions such as where demand is most durable, which product families show the strongest pricing power, how regional procurement differs in practice, and which competitor actions warrant a response in 2026. By offering the framework in this preview and reserving the detailed numbers and segmentation for the complete study, we create a clear path from awareness to action.
How to Use This Research for 2026 Planning
For product leaders, the study supports portfolio decisions by connecting segment dynamics to realistic demand patterns and competitive responses. For commercial teams, it helps prioritize regions and channels where procurement behavior is most likely to reward focused investment. For operations and supply chain planners, it frames the impact of resin volatility, labor constraints, and installation standardization on cost and delivery assumptions. For corporate development and investor relations, it provides a defensible market structure that links historical performance to forward projections through 2032.
The report is not intended as a passive reference document. It is structured to support scenario testing: what happens if installation standardization accelerates adoption in one region, if labor scarcity pushes buyers toward faster-cycle products, if resin volatility reshapes margin expectations, or if new application areas expand the addressable market beyond current boundaries. Each of these questions benefits from the segmentation and competitive context held in the full study.
Accessing the Complete Intelligence
If your 2026 planning depends on knowing not just that the market is growing, but where the value is accumulating and how competitors are positioning themselves, the full Electrofusion Fittings Market research provides the detail required to move from strategy to execution. The complete report contains the segmentation figures, regional evaluations, company profiles, and dynamic-factor analysis needed to build more precise forecasts, allocation plans, and competitive responses. The overview presented here is designed to establish credibility and context; the full intelligence is where confident decisions are made.
For detailed analysis of this topic, please visit the official page: Electrofusion Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air Source Heat Pumps Market Hits $49.2B in 2025, Forecast 7.2% CAGR to 2032
By PW Consulting, 2026-09-16
Unlocking Strategic Value in the Air Source Heat Pumps Market: Why 2026 Decisions Require Premium Intelligence
The global air source heat pumps market is entering a decisive growth phase, with total industry revenue projected to surpass USD 51.64 billion in 2026 and continue its upward trajectory toward an estimated USD 80.45 billion by 2032. This sustained expansion, driven by a compound annual growth rate of 7.2 percent across the forecast horizon, reflects a structural pivot in building decarbonization, energy security imperatives, and rapid electrification of thermal systems. For executives, investors, and market strategists, navigating this landscape requires more than headline figures. It demands precise, forward-looking intelligence that translates macroeconomic momentum into actionable market positioning.
Our latest comprehensive study on the air source heat pumps market is purpose-built for that reality. Serving as both a baseline diagnostic and a strategic roadmap, the report equips leadership teams with the analytical rigor necessary to allocate capital, refine product portfolios, anticipate regulatory inflection points, and outperform in an increasingly competitive manufacturing and distribution ecosystem. This overview demonstrates how the study translates complex market signals into operational intelligence, while preserving the granular breakdowns that only the full publication delivers.
The Macro Trajectory: Translating Historical Momentum into 2026–2032 Decision Frameworks
The market has evolved from an estimated USD 34.25 billion in 2020 to USD 49.2 billion in 2025, demonstrating consistent year-over-year expansion across a period marked by volatile energy pricing, tightening carbon mandates, and early-stage electrification incentives. The forecast period from 2026 through 2032 maps a deliberate acceleration curve, with annual revenue crossing USD 60.96 billion by 2028 and reaching USD 71.25 billion by 2030. Such progression is not uniform across product architectures, application segments, or geographic territories. Rather, it emerges from converging technology maturation, regional policy differentiation, and supply chain realignment.
Strategic decision-making in 2026 hinges on recognizing that historical growth is not merely descriptive; it is diagnostic. The baseline trajectory reveals how capacity investments, refrigerant transitions, and installer ecosystem readiness have compounded over the past half-decade. Our report contextualizes these dynamics within a structured analytical framework, enabling clients to identify where volume expansion will be concentrated, which technological pathways will command pricing premiums, and how regional policy cycles will influence uptake velocity. The full publication contains the detailed decomposition required to align corporate roadmaps with these shifting demand vectors.
Regulatory and Technology Inflection Points Reshaping Competitive Positioning
Market expansion is being simultaneously accelerated and recalibrated by a wave of regulatory and technological shifts. The EU F-Gas regulation mandates a global warming potential below 150 for new split air conditioning and heat pump equipment starting in 2027, compelling manufacturers to accelerate migration toward low-GWP refrigerants such as R32 and R290. In the United States, the Department of Energy finalized amended energy conservation standards for air-cooled commercial package air conditioners and heat pumps, with compliance becoming effective January 1, 2029. Meanwhile, Japan revised its HFC quota management framework in 2025, pushing R-410A costs upward by more than three times relative to R-32, fundamentally altering regional cost structures and product planning.
These regulatory vectors are intersecting with proactive industrial initiatives. Mitsubishi Electric Corporation committed USD 143.5 million to retrofit a U.S. manufacturing facility for variable-speed compressor production, targeting an October 2027 operational start. Simultaneously, the New England Heat Pump Accelerator introduced a USD 450 million program designed to supercharge cold-climate air source heat pump adoption through midstream incentives, reducing per-unit deployment costs by USD 500 to USD 700. In the Northeast high-performance HVAC market, air source heat pumps now account for 32 percent of residential HVAC equipment demand, underscoring how regional specialization is reshaping equipment mix and channel economics.
Our report dissects how these interventions alter competitive advantage. It evaluates the timing of compliance deadlines against product development cycles, assesses the commercial implications of midstream incentive architectures, and projects how refrigerant pathway decisions will influence long-term serviceability, component sourcing, and after-market economics. Executives seeking to prioritize R&D investments, align capacity additions, or restructure commercial partnerships will find the regulatory impact mapping essential to avoiding stranded investments and capturing first-mover advantage in transitioning segments.
Competitive Landscape: Consolidation Dynamics and Strategic Differentiation
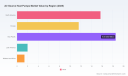
The market exhibits meaningful concentration, with the top three participants collectively commanding approximately 45.2 percent of industry revenue and the top five holding an estimated 62.8 percent share. Such concentration reflects decades of engineering heritage, cold-climate performance differentiation, inverter technology leadership, and global distribution scale. Yet concentration also masks rapid competitive evolution, as regional champions, technology specialists, and vertically integrated appliance manufacturers expand their footprint through targeted product launches and strategic capacity investments.
Prominent market participants include Daikin Industries, Ltd., recognized for high-efficiency inverter platforms and cold-climate monobloc and split solutions spanning residential and commercial applications; Mitsubishi Electric Corporation, distinguished by ductless and multi-split systems with Hyper-Heating technology and variable refrigerant flow architectures; and Carrier Global Corporation, offering residential and commercial platforms built around Infinity and Greenspeed inverter technology. Trane Technologies plc delivers broad split-system and packaged offerings with high-efficiency inverter configurations. From the Asian manufacturing corridor, LG Electronics, Inc. and Samsung Electronics Co., Ltd. contribute air-to-air and air-to-water lines emphasizing high coefficient of performance and residential-to-light-commercial versatility. Gree Electric Appliances Co., Ltd. and Fujitsu General Limited reinforce efficiency-focused residential and commercial portfolios, while Hitachi, Ltd. and Panasonic Corporation maintain established residential and light-commercial heat pump lines. In Europe, Bosch Thermotechnology GmbH markets air-to-air and air-to-water platforms under multiple brand architectures, and NIBE Industrier AB specializes in cold-climate residential heating and domestic hot water systems.
The competitive analysis within our report goes beyond corporate profiling. It evaluates how product architecture focus, refrigerant strategy, cold-climate engineering capability, and regional manufacturing footprint translate into share resilience or vulnerability under evolving standards. The full document provides the comparative benchmarking, segment positioning matrices, and strategic response scenarios required to assess partnership opportunities, potential acquisition targets, and defensive positioning in high-growth sub-segments.
What the Full Study Delivers: Operational Intelligence for Strategy, Capital, and Execution
This market research is engineered to support end-to-end strategic execution. It combines quantitative forecasting, structural segmentation, regulatory mapping, and competitive intelligence into a unified analytical platform. The publication is structured to help leadership teams answer the questions that determine 2026 success: where demand growth will be most durable, which technology pathways will attract premium pricing, how regulatory timelines will reshape product economics, and which competitive moves will determine market access.
Key analytical dimensions include a comprehensive historical-to-forecast revenue trajectory, enabling clients to benchmark internal performance against market momentum and identify inflection points in demand expansion. The study presents rigorously defined segmentation architecture, allowing teams to isolate the segments with the strongest growth elasticity, highest margin potential, and most favorable policy tailwinds. Regional demand mapping clarifies where capacity deployment, distributor expansion, and service infrastructure investment will generate the highest strategic return. Competitive profiling and concentration analysis equip strategists with the intelligence required to anticipate share shifts, evaluate barrier-to-entry dynamics, and refine go-to-market positioning.
Worldwide Absorption Heat Pumps Market
Beyond structural analysis, the report integrates forward-looking operational considerations. It assesses how midstream incentive frameworks alter installed-cost economics and influence buyer behavior. It maps the timing and commercial implications of refrigerant transitions relative to product lifecycles and component supply chains. It examines how efficiency standard revisions will affect competitive parity across residential and commercial equipment categories. These elements are synthesized into scenario-based guidance, enabling decision-makers to test strategic assumptions against plausible regulatory and market pathways rather than relying on static projections.
The full study also provides the detailed quantitative backing necessary for internal validation. Executive teams can use the underlying decomposition to align sales forecasting, production planning, channel investment, and R&D prioritization with verified market trajectories. Investors and corporate development professionals gain a structured basis for evaluating segment attractiveness, competitive durability, and capital allocation efficiency across the forecast horizon.
Strategic Imperatives for 2026: Aligning Decision-Making with Market Reality
As the market advances toward the 2026 revenue milestone and continues its expansion through the early 2030s, several strategic imperatives will separate resilient players from reactive competitors. First, product planning must integrate refrigerant pathway decisions with long-term compliance timelines, ensuring that portfolio architectures are aligned with low-GWP migration without sacrificing performance or service economics. Second, capacity and manufacturing investments need to account for variable-speed compressor demand, cold-climate performance requirements, and regional standards timelines, particularly as major industrial retrofits reshape supply availability. Third, commercial strategy should recognize that incentive structures and regional policy momentum create uneven demand curves, requiring differentiated market entry, pricing, and channel approaches rather than uniform global execution.
Fourth, competitive positioning must reflect the reality that concentration masks rapid product-level and segment-level disruption. Organizations that depend solely on historical share as a proxy for future resilience risk underestimating the impact of efficiency standards, cold-climate performance differentiation, and regional technology convergence. The companies that will capture disproportionate value are those that combine engineering discipline with proactive regulatory anticipation and flexible commercial architecture.
Our report is designed to support each of these imperatives. It provides the analytical scaffolding necessary to convert high-level market growth into detailed strategic action, while preserving the proprietary breakdowns, comparative matrices, and scenario analyses that require full access to the publication. Readers evaluating the air source heat pumps opportunity for capital deployment, product planning, M&A assessment, or channel expansion will find the complete study essential for informed, forward-looking decision-making.
Air Source Heat Pumps Market
Next Steps: Accessing the Full Intelligence Architecture
The macro trajectory, regulatory shifts, competitive concentration, and incentive dynamics described here represent only the entry point to a far more granular analytical framework. The complete market study delivers the segment-level resolution, regional demand mapping, competitive benchmarking, and scenario-based forecasting required to translate market momentum into executable strategy. For organizations preparing 2026 investment decisions, portfolio adjustments, or market-entry plans, the full report provides the evidence base needed to prioritize with confidence and act ahead of inflection points.
Access the complete analysis to obtain the detailed market size decomposition, strategic segmentation insights, competitive positioning frameworks, and forward-looking regulatory impact assessments that will shape your 2026–2032 decision architecture.
For detailed analysis of this topic, please visit the official page: Air Source Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Petroleum Needle Coke Market Hits $215M in 2025 With 6.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Carbon Matrix: Strategic Imperatives in the Petroleum Needle Coke Market Through 2032
The global petroleum needle coke sector stands at a critical inflection point. As graphite electrode demand aligns with grid-scale steelmaking and lithium-ion battery supply chains accelerate, the underlying feedstock architecture is undergoing a structural realignment. For executives, procurement leaders, and capital allocators, the 2026–2032 horizon presents both margin compression risks and premium positioning opportunities. This guide synthesizes the core market architecture, competitive vectors, and operational dynamics that will shape strategic decision-making in the coming cycle. It is designed to function as a strategic compass—grounded in verified market trajectories, yet deliberately scoped to preserve the granular intelligence required for enterprise-grade execution.
Macro Trajectory: Navigating a 6.7% CAGR Across a Reshaped Demand Base
Over the 2020–2025 historical window, the petroleum needle coke market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting a compound trajectory driven by electrode manufacturing intensification and the early-stage integration of battery-grade carbon materials. The forward arc, projected through 2032, extends this momentum with a steady CAGR of 6.7 percent, carrying the aggregate valuation toward the mid-340 million USD range by the close of the forecast period. This growth is not merely linear accumulation; it is structurally uneven, shaped by feedstock pricing volatility, regional capacity recalibration, and a widening divergence between traditional graphite electrode applications and emerging energy storage pathways.
The base year of 2025 serves as a calibration anchor, capturing post-restriction market normalization and the initial absorption of environmental compliance investments. From 2026 onward, the expansion curve reflects compounding capacity additions, qualification cycles for lower-carbon coke variants, and the gradual migration of high-performance anode materials into mainstream battery architectures. Decision-makers evaluating capex timing, supplier diversification, or vertical integration must anchor their models to this trajectory while recognizing that the underlying segmentation shifts will dictate where value actually accrues.
Importantly, the market’s concentration profile underscores a highly consolidated supply environment. A small cohort of integrated producers commands the majority of electrode-grade and battery-grade output, creating both pricing discipline and vulnerability to localized operational disruptions. Understanding how this concentration interacts with regional regulatory acceleration and feedstock availability is essential for anyone mapping supply chain resilience or negotiating long-term tolling and offtake arrangements.
Segmentation Architecture: Where Volume Meets Value
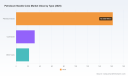
The market’s structural composition reveals three interlocking dimensions that collectively determine margin exposure and growth velocity. The type split highlights the dominance of petroleum-derived needle coke relative to coal-based and other variants, with petroleum routes capturing the bulk of premium-grade electrode and anode production. This hierarchy is not static; it is being actively reshaped by lifecycle emissions considerations, feedstock accessibility, and processing maturity.
Application-wise, graphite electrodes continue to anchor the largest share of consumption, reflecting their entrenched role in electric arc furnace steelmaking and specialty carbon applications. Simultaneously, lithium-ion battery usage represents a smaller but rapidly scaling segment, driven by anode material innovation and the push for higher energy density and faster charge cycles. The remaining application pool serves niche industrial and composite manufacturing requirements.
Regional dispersion further complicates the picture. Supply and demand nodes span North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each exhibiting distinct consumption intensity, regulatory posture, and feedstock logistics. Capacity additions, export flows, and localized compliance requirements interact to create pockets of tightness and surplus that rarely align with headline aggregates. For strategic planning, this means that aggregate sizing alone is insufficient; the actionable intelligence lies in how segment dynamics intersect with regional supply constraints, qualification lead times, and downstream manufacturing capacity pipelines.
Competitive Landscape: Integrated Producers, Strategic Moves, and Positioning Vectors
The competitive field is defined by a mix of refinery-integrated operators, specialty coke producers, and regionally anchored suppliers whose processing capabilities and customer qualification networks determine market access. Several entities stand out for their operational footprint, product-grade versatility, and recent strategic interventions.
- Phillips 66 Company (Houston, Texas, United States) operates through integrated delayed-coking infrastructure, including its Lake Charles refinery complex, delivering both electrode-grade and battery-grade material. Its recent trajectory reflects a deliberate alignment with energy storage demand, underscored by a multi-hundred-million-dollar capacity expansion in Louisiana and a long-term supply agreement supporting a large-scale graphite-anode plant in North Carolina.
- GrafTech International Ltd. (Brooklyn Heights, Ohio, United States) maintains a vertically integrated supply position via its Seadrift facility, serving ultra-high-power graphite electrode and specialty carbon markets. Its product portfolio expansion into lower-carbon needle coke variants signals a strategic response to demand-side environmental qualification requirements.
- ENEOS Corporation (Tokyo, Japan) leverages Japanese refining and coking assets to produce premium petroleum-based needle coke, supplying graphite electrode and battery anode manufacturers with a focus on consistent grade quality and reliability.
- Seadrift Coke L.P. (Seadrift, Texas, United States) converts Gulf Coast refinery residues into petroleum needle coke, supported by calcination capability for anode-grade material and a logistics profile aligned with North American downstream demand.
- Petrocokes Japan Ltd. (Tokyo, Japan) operates within the Sumitomo Corporation group ecosystem, concentrating on electrode and specialty applications with a regional supply orientation.
- C-Chem Co., Ltd. (Japan) serves regional electrode manufacturers, maintaining a focused production profile aligned with Asian downstream manufacturing needs.
- Chinese Petroleum & Chemical Development Company (CPCDC) (Taiwan) supports regional graphite electrode supply chains, positioning itself within East Asian demand networks that continue to scale electrode consumption.
Beyond individual profiles, the competitive vector is increasingly shaped by three operational levers: capacity expansion timing, feedstock flexibility, and product qualification for lower-emission or recycled-feedstock routes. Recent industry developments illustrate this shift. Capacity investments are being directed toward battery-grade output streams; product launches are emphasizing reduced lifecycle carbon intensity through alternative feedstock blending; and long-term supply agreements are locking in offtake for anode-scale manufacturing footprints. These moves are not isolated. They signal a market where incumbent positioning will be tested by the ability to secure consistent aromatic-rich feedstocks, navigate qualification cycles, and align with downstream decarbonization mandates.
Market Dynamics: Feedstock Volatility, Regulatory Pressure, and the Petroleum Advantage
The operating environment is defined by a set of interacting forces that repeatedly reshape cost structures, capacity utilization, and product-grade competitiveness.
- Feedstock volatility remains a primary margin variable. Petroleum needle coke production depends on highly aromatic decant oil and pitch feedstocks, and the price behavior of these streams is closely tied to crude oil and coal tar market fluctuations. FCC decant oil, derived from slurry oil after particle removal, serves as the primary aromatic-rich feedstock, making refinery throughput patterns and slurry handling economics directly relevant to coke cost curves.
- Environmental regulation is actively restructuring supply geography. Stricter regulatory frameworks in China have constrained a meaningful share of graphite electrode capacity and restricted output across multiple provinces, tightening regional availability and redirecting procurement patterns. At the same time, tightening EU carbon-footprint rules increasingly favor petroleum-based needle coke with lower lifecycle emissions relative to coal-tar routes, altering competitive dynamics in export-sensitive and compliance-driven markets.
- Qualification and downstream alignment are becoming gating factors. As battery-grade applications scale, supplier qualification cycles, consistency requirements, and traceability expectations are increasingly influential. Producers that can demonstrate stable grade performance, auditable feedstock provenance, and alignment with low-carbon or recycled-feedstock pathways are gaining preferential access to long-term agreements and premium pricing tiers.
Collectively, these dynamics create a market where cost leadership alone is no longer sufficient. Competitive advantage is increasingly a function of feedstock security, regulatory adaptation, and the ability to deliver qualified product into both traditional electrode and emerging battery value chains.
The Report: What Decision-Makers Will Find Inside
The complete Petroleum Needle Coke Market study is structured to convert high-level trajectory awareness into executable strategy. Rather than presenting static sizing alone, the report maps the operational and commercial levers that determine where growth, margin, and risk concentrate across the 2026–2032 period.
- Market sizing and forward modeling that anchor planning to verified historical baselines and forecast trajectories, enabling scenario testing around feedstock cost shifts, capacity additions, and application mix evolution.
- Segment-level structure analysis covering type partitions, application channels, and regional dispersion patterns, with emphasis on how volume distribution translates into pricing power, supply security, and qualification risk.
- Competitive profiling and strategic event tracking that examine capacity expansions, product launches, supply agreements, and regional positioning moves, highlighting how incumbents are reallocating capital and reorienting product portfolios.
- Dynamic context integration that connects raw material volatility, regulatory interventions, and carbon-intensity qualification trends to practical procurement, sourcing, and capacity-planning implications.
- Actionable framing for commercial and operational teams seeking to evaluate supplier resilience, entry timing, vertical integration logic, and long-term offtake strategy in a market where concentration and qualification barriers increasingly shape access.
The report is designed for executives who need to move beyond headline aggregates and understand the structural drivers that will determine competitive outcomes in the next investment cycle. It provides the evidentiary scaffolding required to test assumptions, pressure-test supply strategies, and align portfolio decisions with the most consequential market shifts.
Strategic Takeaway for 2026 Planning
As the petroleum needle coke market advances through its 6.7 percent CAGR window, the strategic question is no longer whether demand will expand, but where value will be captured and which supply chains will be rewarded with preferential access, premium pricing, and durable contracting relationships. The convergence of feedstock economics, regulatory recalibration, capacity concentration, and battery-grade qualification is creating a market in which operational precision and forward positioning matter more than ever.
This research study is built to help leadership teams navigate that complexity. It preserves the analytical depth required for credible strategy formulation while guiding readers toward the full dataset, segment architecture, and competitive intelligence needed for enterprise-level execution. For organizations preparing 2026 sourcing strategies, capacity commitments, or market-entry evaluations, the complete report provides the structured intelligence necessary to convert market trajectory into defensible commercial advantage.
Petroleum Needle Coke Market
Needle Coke Market
For detailed analysis of this topic, please visit the official page: Petroleum Needle Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogenated DLC Coating Market to Hit $217.9M by 2032, 5.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Future of Surface Engineering: Strategic Insights into the Hydrogenated Diamond-Like Carbon Coating Market
The landscape of industrial surface engineering is undergoing a profound transformation, driven by the relentless demand for durability, efficiency, and performance across critical sectors. At the forefront of this evolution is the Hydrogenated Diamond-Like Carbon (DLC) Coating market, a niche yet pivotal segment within the broader advanced materials industry. As we move deeper into the decade, understanding the trajectory of this market is no longer optional for industry leaders; it is a strategic imperative. This article serves as a precursor to our comprehensive market research study, designed to equip stakeholders with the intelligence needed to navigate the complexities of the 2026 to 2032 forecast period.
Our latest analysis provides a rigorous examination of the market dynamics, offering a clear view of where value is being created and where challenges lie. By integrating historical data from 2020 through 2025 with robust forward-looking projections, we illuminate the path ahead. The following insights highlight the strategic value embedded in our full report, outlining why this intelligence is critical for decision-making in the current fiscal landscape.
Market Trajectory and Financial Outlook
The financial health of the Hydrogenated DLC Coating market reveals a story of steady resilience and measured growth. Our research indicates that the global market reached approximately 146.8 million USD in 2025, building upon a recovery trajectory that began after the volatility experienced in the early 2020s. Looking ahead, the market is projected to expand to 150.73 million USD in 2026, signaling a continued positive momentum as industries resume full-scale operations and invest in longevity-enhancing technologies.
The long-term forecast suggests a compelling value proposition for investors and manufacturers alike. By 2032, the market is expected to reach 217.9 million USD. This expansion reflects a Compound Annual Growth Rate (CAGR) of 5.85 percent over the forecast period. Such growth is not accidental; it is underpinned by the increasing adoption of DLC technologies in applications where friction reduction and wear resistance are paramount. For corporate strategists, this growth rate represents a stable opportunity for capital allocation, provided that entry strategies and product positioning are informed by granular data.
It is crucial to note that while the aggregate numbers provide a macroeconomic view, the real strategic advantage lies in understanding the velocity of adoption across different segments. Our report dissects these movements without relying on superficial averages, ensuring that stakeholders understand the specific drivers contributing to the 5.85 percent CAGR. This level of detail allows for precise budgeting and capacity planning over the next seven years.
Segmentation and Application Drivers
The versatility of hydrogenated DLC coatings is evidenced by their widespread application across diverse industrial verticals. Our analysis categorizes the market into key types and application areas, revealing where the highest demand intensity resides. In terms of coating type, the market is divided among hydrogenated variants, non-hydrogenated variants, and other coating solutions. The dominance of specific types in the current landscape underscores the preference for hydrogenated amorphous carbon structures in scenarios requiring superior tribological performance.
On the application front, the demand is distributed across Automotive Components, Tools and Dies, Medical Devices, and other specialized uses. The automotive sector remains a primary engine of growth, driven by the need for enhanced component longevity and fuel efficiency. Similarly, the tooling industry continues to rely on these coatings to extend tool life and maintain precision in manufacturing processes. Medical device manufacturers are also increasingly integrating these coatings to ensure biocompatibility and wear resistance in implantable and surgical instruments.
However, the relative weighting of these segments shifts over time based on technological breakthroughs and regulatory changes. Our full report provides a detailed breakdown of these segmentation splits, allowing clients to identify high-growth niches. Instead of relying on broad industry assumptions, stakeholders can leverage our data to pinpoint which application areas are poised for the most significant expansion in the 2026 to 2032 window. This granularity is essential for R&D prioritization and marketing strategy formulation.
Geographical Distribution and Regional Dynamics
Geographic diversification is a key consideration for any company operating in the global coatings market. Our study maps the revenue distribution across major regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of opportunities and regulatory environments that influence market penetration and growth rates.
Currently, North America and Europe hold significant shares of the market, reflecting established industrial bases and high adoption rates of advanced surface technologies. Asia Pacific represents a dynamic growth zone, fueled by expanding manufacturing capabilities and increasing local demand for high-performance components. Emerging markets in Latin America and the Middle East and Africa also contribute to the global revenue pool, albeit at different scales.
Understanding the regional nuances is vital for supply chain optimization and market entry strategies. Our report avoids generic regional summaries, instead offering specific insights into the revenue contributions and growth trajectories of each area. This enables multinational corporations to tailor their regional strategies effectively, ensuring resources are allocated to markets with the highest potential return on investment. Stakeholders seeking to expand their footprint will find the regional analysis within our full study indispensable for mitigating risk and maximizing reach.
Competitive Landscape and Key Players
The market is characterized by a mix of established industrial giants and specialized coating providers. Our analysis profiles the key companies shaping the competitive environment, assessing their technological capabilities, market presence, and strategic positioning. The competitive landscape is moderately concentrated, with the top three players holding a significant portion of the market share, while the top five collectively control a larger fraction. This structure suggests a competitive environment where differentiation through technology and service quality is paramount.
Prominent players such as Oerlikon Balzers and IHI Group / Ionbond are recognized for their robust portfolios in PVD and PACVD-based coating solutions. Oerlikon Balzers, headquartered in Liechtenstein, provides hydrogenated amorphous carbon coatings essential for automotive and aerospace wear resistance. Similarly, IHI Group and Ionbond, operating across Switzerland and Japan, offer comprehensive DLC solutions for tools and precision components. These companies set the benchmark for quality and technological integration.
Hydrogenated Diamond-Like Carbon Coating (DLC) Market
In the United States, companies like Calico Coatings, IBC Coatings Technologies, and Acree Technologies specialize in hydrogenated a-C:H coatings for commercial, industrial, and medical applications. Calico's CERTESS CARBON line and IBC's Ceratough D coating exemplify the focus on specific industrial needs, including military and testing compliance. Meanwhile, European entities like Miba Group / Teer Coatings in Austria and CemeCon in Germany continue to supply advanced coatings for engines, transmissions, and toolmaking. The presence of these diverse players ensures a dynamic competitive environment where innovation is continuously driven by the need to outperform rivals in wear resistance and coating durability.
Our report goes beyond simple company profiles. It analyzes the strategic moves, technological pipelines, and market influence of these key entities. By understanding the strengths and weaknesses of competitors, businesses can identify gaps in the market and formulate strategies to capture untapped value. This competitive intelligence is a cornerstone of our research offering.
Report Scope and Operational Content
To support informed decision-making, our comprehensive study offers a deep dive into operational and strategic content. The report is structured to provide actionable intelligence rather than just theoretical data. It includes a detailed examination of the industry chain, covering raw material suppliers, coating service providers, and end-user integration. This value chain analysis helps stakeholders identify bottlenecks and opportunities for vertical integration or partnership.
Furthermore, the report addresses the technological landscape, detailing the processes involved in depositing hydrogenated DLC coatings and the parameters that influence coating performance. This technical depth is crucial for R&D teams looking to optimize production or develop next-generation coating solutions. We also explore the regulatory environment and standardization requirements that govern the use of these coatings in sensitive sectors like medical and aerospace.
Cost structure analysis is another critical component. By understanding the cost drivers associated with production and application, managers can better control expenses and improve margins. The report also includes scenarios and sensitivity analysis, allowing clients to test their strategic assumptions against various market conditions. This holistic approach ensures that the final deliverable is a practical tool for strategic planning, not just an academic exercise.
Strategic Imperative for 2026 Decision-Making
As we enter 2026, the decisions made today will define competitive positioning for the remainder of the decade. The Hydrogenated DLC Coating market offers a stable growth environment, but success requires more than just observing the headline numbers. It demands a nuanced understanding of where the growth is coming from, who is driving it, and how external factors might influence the trajectory.
Diamond-Like Carbon Coating Market
Investing in surface engineering technologies without accurate market intelligence is akin to navigating without a map. Our research provides the necessary coordinates. Whether the goal is to enter a new geographic market, launch a specialized coating product, or optimize an existing supply chain, the data within our full report serves as the foundation for evidence-based strategy. The 5.85 percent CAGR is an invitation to grow, but capturing that growth requires precise execution informed by detailed insights.
We invite industry leaders, investors, and strategic planners to review the full findings of our Hydrogenated Diamond-Like Carbon Coating Market Report. The executive summary provided here offers a glimpse into the depth of analysis available, but the complete study contains the specific data points, regional breakdowns, and competitive assessments necessary to finalize your strategic roadmap. Accessing the full intelligence will ensure your organization is prepared to capitalize on the opportunities within the 2026 to 2032 forecast period.
For detailed analysis of this topic, please visit the official page: Hydrogenated Diamond-Like Carbon Coating (DLC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Food Grade Calcium Chloride Market to Hit USD 760M by 2032, 6.8% CAGR
By PW Consulting, 2026-09-16
Navigating the Calcium Chloride Food Grade Market: Strategic Intelligence for 2026 Decision Makers
The global food ingredient supply chain is entering a phase of structural recalibration, and calcium chloride food grade sits at a critical intersection of regulatory compliance, processing efficiency, and consumer-driven quality standards. As manufacturers, distributors, and strategic investors map their roadmaps for 2026 and beyond, understanding the underlying market architecture is no longer optional—it is a competitive necessity. Our newly released Calcium Chloride Food Grade Market research report delivers the granular intelligence required to navigate this evolving landscape with confidence.
Worldwide Food Grade Ammonium Chloride Market
Drawing on a rigorous historical analysis spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, this report provides a comprehensive baseline for strategic planning. The market has demonstrated consistent momentum over the review period, with total revenue expanding steadily from a baseline in 2020 to a projected trajectory that crosses the half-billion USD threshold in 2026. The compound annual growth rate across the forecast horizon is positioned at 6.8 percent, reflecting a market that is maturing but still capable of meaningful expansion. By the end of the forecast window in 2032, overall revenue is projected to approach the 760 million USD mark, underscoring the sustained commercial relevance of this essential food additive.
What distinguishes this analysis is not merely the macro trajectory, but the depth of operational and competitive context layered beneath it. The following sections outline the strategic architecture of the report and explain why it serves as an indispensable decision-support tool for executives operating in food processing, ingredient supply, procurement, and market development.
The Strategic Imperative for 2026 Planning
Corporate strategy in the food ingredients sector has shifted decisively toward proactive scenario planning. Regulatory frameworks, raw material sourcing constraints, certification requirements, and regional demand shifts are no longer peripheral concerns; they are central drivers of margin structure, supply continuity, and market positioning. For organizations that rely on or distribute food-grade calcium chloride—whether as a firming agent, preservative, texture modifier, or processing aid—the 2026 decision window demands clarity on three fronts: where growth is structurally concentrated, how competitive dynamics are evolving, and which operational levers will determine long-term resilience.
This report is designed explicitly to answer those questions. Rather than presenting a static snapshot, it maps the interplay between historical performance patterns and forward-looking demand signals. The forecast period, running from 2026 through 2032, is structured to support capacity planning, market entry evaluations, and portfolio allocation decisions. By anchoring analysis in a detailed historical baseline and extending it through a disciplined projection methodology, the report enables stakeholders to stress-test strategic assumptions against multiple market trajectories.
Importantly, the research avoids the trap of oversimplified aggregation. Instead, it dissects the market through multiple analytical lenses—type, application, and region—while maintaining strict attention to the certification, compliance, and quality-assurance requirements that govern food-grade supply chains. The result is a decision-ready intelligence framework that can be integrated directly into commercial planning, procurement strategy, and competitive benchmarking.
Inside the Report: Operational Depth and Executive Relevance
The research is built around a structured, multi-dimensional analytical model that translates market data into actionable strategy. Below is a preview of the core components included in the full report:
- Historical and Forecast Revenue Architecture: A year-by-year reconstruction of market revenue from 2020 through 2025, followed by a projected trajectory through 2032. This framework supports growth benchmarking, market-share modeling, and investment timing analysis.
- Type-Based Market Segmentation: A detailed breakdown separating the market into calcium chloride dihydrate and anhydrous forms. The analysis examines how form-specific demand patterns, processing requirements, and application preferences shape revenue distribution and supply-chain priorities.
- Application-Driven Demand Mapping: A thorough examination of how calcium chloride food grade is deployed across beverage production, dairy processing, meat processing, bakery and confectionery operations, and fruits and vegetables. The report evaluates adoption drivers, formulation considerations, and end-use growth dynamics without reducing the analysis to superficial category labels.
- Regional Market Structure: A geographic assessment that positions demand, supply capacity, and strategic opportunity across major global regions. The segmentation provides context for sourcing decisions, distribution planning, and market-entry prioritization.
- Competitive Landscape and Company Profiles: In-depth profiles of leading producers and distributors, including operational focus, product certifications, jurisdictional strengths, and recent strategic moves. The report also evaluates market concentration indicators to clarify the balance between established incumbents and emerging suppliers.
- Regulatory and Certification Framework: A practical synthesis of the compliance environment governing food-grade calcium chloride, including GRAS status under U.S. FDA regulations, EU food additive ordinance alignment, FCC and USP/EP specifications, and kosher/halal certification expectations. This section serves as a reference for procurement, quality assurance, and export strategy.
- Raw Material and Supply Chain Dynamics: An assessment of feedstock considerations, particularly the role of natural brine sourcing in high-purity production, and how supply-side factors influence cost structure, availability, and regional production advantages.
Each section is structured to provide both strategic context and operational specificity. The goal is to equip readers with a clear understanding of not only where the market is moving, but also what it takes to participate effectively in that movement.
Competitive Landscape: Who Is Shaping the Market
The food-grade calcium chloride sector is characterized by a mix of specialized chemical manufacturers, broad-line industrial suppliers, and regionally focused producers. Market concentration metrics indicate that a relatively small group of major players commands a significant share of total revenue, while a wider field of regional and product-focused companies competes through certification differentiation, application specialization, and supply reliability.
Several leading organizations define the current competitive shape of the market. TETRA Technologies, Inc., based in Houston, Texas, produces and supplies NSF-certified, kosher food-grade calcium chloride in anhydrous flakes and liquid formats, aligned with Food Chemicals Codex and E509 standards for food processing, brewing, and dairy applications. In 2025, the company completed a production expansion at its El Dorado, Arkansas facility to support increased demand across industrial and municipal applications, including specialized food-grade grades.
OxyChem, headquartered in Dallas, Texas, offers a recognized portfolio of food-grade calcium chloride products, including BRINERS CHOICE® Food Grade Anhydrous 94-97% Pellets and Liquidow® food-grade calcium chloride solution. Its offerings are kosher and halal certified for food additive use in canning, meat processing, and preservation. In mid-2025, OxyChem launched anhydrous calcium chloride 96% ultra-pellets designed for fast-acting performance across de-icing, dust control, and industrial applications, reflecting continued investment in purity and solubility optimization.
In Europe, nedMag B.V., based in Venlo, Netherlands, supplies nedMag Ca® food-grade calcium chloride in liquid 34% and prill forms, certified to EU Food Additive Ordinance 231/2012 for cheese production, vegetable processing, and food ingredient applications. Solvay S.A., headquartered in Brussels, Belgium, manufactures food-grade and pharmaceutical-grade calcium chloride dihydrate certified to EN 233, BP/USP pharmacopoeia, and E509 standards. In early 2025, Solvay commercially launched an expanded food-grade and pharmaceutical-grade calcium chloride dihydrate line from its Rheinberg facility, targeting dairy processors and excipient buyers.
North American distribution and specialty supply also play a significant role. Hill Brothers Chemical Co., based in Atlanta, Georgia, produces and supplies 77-80% food-grade calcium chloride flakes meeting FCC and USP specifications for food processing and preservation. Hawkins, Inc., headquartered in Minneapolis, Minnesota, distributes food-grade calcium chloride solutions at 30% and 32% concentrations under FDA CFR Title 21 §184.1193, with kosher and halal certification. CoreChem Inc., located in Knoxville, Tennessee, supplies mini-pellet food-grade calcium chloride in FCC grade for turkey processing, vegetable canning, and food additive applications.
On the global supply side, several Chinese manufacturers contribute significantly to export-oriented supply. Weifang Bell Chemical Co., Ltd. and Weifang Haibin Chemical Co., Ltd., both based in Shandong Province, produce food-grade calcium chloride flakes and granular forms meeting FCC and E509 standards for international food processing markets. Qingdao Huadong Calcium Chloride Co., Ltd. produces food-grade calcium chloride under international purity specifications, while Jiangsu Kolod Food Ingredients Co., Ltd. supplies food-grade calcium chloride at high purity levels for food additives and processing.
This competitive mosaic matters because procurement decisions in food-grade markets are rarely driven by price alone. Certification breadth, supply consistency, regional proximity, application expertise, and regulatory alignment often determine supplier selection. The report examines these dynamics in greater detail, providing a structured basis for supplier evaluation and competitive positioning.
Regulatory, Quality, and Supply Chain Dynamics
Food-grade calcium chloride operates within a tightly governed compliance environment. In the United States, it is generally recognized as safe for food use under the FDA Code of Federal Regulation Title 21, Section §184.1193, with conditions of use specified for food processing and additive applications. It is also recognized under USDA organic regulations without annotation for certain non-synthetic uses in food processing. These regulatory foundations create a stable but stringent operating environment in which product specifications, certification documentation, and batch consistency carry direct commercial weight.
For international markets, alignment with Food Chemicals Codex standards, EU food additive ordinance requirements such as E509 under Ordinance 231/2012, and kosher/halal certification is often essential. In North America and Europe, USP/EP and NSF certifications are commonly mandatory for liquid and anhydrous food-grade calcium chloride sold for pharmaceutical and food applications. The report integrates these regulatory parameters into the broader market analysis so that readers can assess how compliance requirements influence market access, supplier qualification, and regional demand patterns.
Supply-side considerations are equally important. Natural brine feedstock sourced from Michigan brines remains the dominant raw material basis for high-purity food-grade calcium chloride production, supporting operations by major producers and contributing to regional supply advantages. This feedstock reality shapes cost structures, production geography, and the strategic positioning of suppliers with access to consistent brine resources. Understanding these material flows is critical for organizations evaluating sourcing resilience, price sensitivity, and long-term supply security.
Why This Research Matters for 2026 and Beyond
Market research in the food ingredients space is most valuable when it connects high-level trends to operational reality. This report is designed with that principle in mind. It does more than report historical numbers or project future totals; it frames the market in terms that executives, planners, and analysts can use immediately.
Calcium Chloride Food Grade Market
For procurement and supply-chain leaders, the research provides context on certification pathways, supplier differentiation, and feedstock dynamics that influence purchasing strategy. For commercial and business-development teams, it offers a structured view of application demand patterns and regional opportunity sets. For investors and corporate strategists, it supplies the kind of disciplined market sizing, concentration context, and competitive mapping needed to evaluate entry points, expansion timing, and portfolio risk.
The forecast horizon through 2032 is particularly relevant for organizations making multi-year commitments. Capacity planning, product-line decisions, regional distribution investments, and supplier partnerships all benefit from a forward-looking view that is grounded in verifiable historical performance and clearly articulated projection logic. By integrating macro market sizing with segmentation structure and competitive context, the report enables readers to move from awareness to action.
Access the Full Intelligence Framework
This overview provides a strategic preview of the market environment and the analytical scope of the full report. However, the complete research deliverable contains the detailed segmentation data, regional breakdowns, company-level benchmarking, and forward-looking scenario structures that decision-makers need to translate insight into execution.
The full report offers a comprehensive, decision-ready dataset and interpretive analysis designed for professional use across procurement, commercial strategy, competitive intelligence, and investment planning. For teams operating in 2026 and beyond, access to this level of structured market intelligence can meaningfully improve strategic clarity and reduce uncertainty in high-stakes planning processes.
To explore the complete findings, detailed segmentation, competitive profiles, and forecast architecture, access the full report and equip your organization with the market intelligence needed to act decisively in the evolving calcium chloride food grade landscape.
For detailed analysis of this topic, please visit the official page: Calcium Chloride Food Grade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Recycling Market to Hit $5.88B by 2032 with 5.66% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Circular Economy: Unlocking Value in the Global Glass Recycling Market 2026–2032
The global transition toward circular economic models is no longer a theoretical ambition; it is a operational imperative reshaping supply chains, regulatory compliance, and capital allocation across the materials sector. For executives navigating the glass manufacturing and waste management landscapes, the coming years present a complex matrix of opportunity and risk. PW Consulting's latest comprehensive study on the Glass Recycling Market is designed to convert this complexity into actionable strategic clarity. As organizations prepare their capital plans and operational roadmaps for the 2026 fiscal year and beyond, understanding the granular mechanics of this market is essential to securing competitive advantage.
Plastic Recycling Market
This market research report serves as a critical decision-support tool, offering a data-rich examination of an industry poised for steady expansion. The underlying narrative is one of maturation. Drawing on historical data from 2020 through 2025, the analysis establishes a baseline of robust growth that continues into the forecast period extending to 2032. In 2020, the global market valuation stood at approximately 2.05 billion USD. By the base year of 2025, this figure had climbed to 4.01 billion USD, reflecting a compound annual growth rate of 5.66 percent over the analyzed historical window. Looking forward, the trajectory suggests continued momentum, with projected revenues reaching 4.2 billion USD in 2026 and advancing toward 5.88 billion USD by 2032. These figures are not merely statistics; they represent the scale of investment required, the volume of feedstock in motion, and the financial magnitude of the opportunity awaiting stakeholders who can navigate the technical and regulatory nuances of glass recovery.
Navigating the Core Dynamics and Operational Challenges
While the headline numbers indicate growth, the strategic value of this research lies in its dissection of the underlying dynamics. The glass recycling ecosystem is not a monolith; it is a fragmented network of collection infrastructure, processing technology, and end-market demand, all influenced by a tightening regulatory environment. A primary focus of the report is the infrastructure bottleneck that currently limits the efficiency of material recovery. Industry data indicates that only 40 percent of glass recycling is accepted at material recovery facilities, largely due to commingling in single-stream systems. This infrastructure constraint creates significant variance in feedstock quality and availability, directly impacting the economics of downstream manufacturers.
Simultaneously, the regulatory landscape is accelerating the demand for recycled content. In Europe, the Packaging and Packaging Waste Regulation 2025/40 entered into force on 11 February 2025 and is generally applicable from 12 August 2026, mandating glass packaging recycling targets at 70 percent by 2025. Such mandates force a reevaluation of procurement strategies for packaging firms, making reliable access to high-quality cullet a critical compliance and operational requirement. In the United States, the glass container recycling rate was recorded at 31.3 percent in 2018, with 3.1 million tons recycled from 12.3 million tons generated. While legislative efforts in states like California have supported increased recycled glass use in packaging, the gap between generation and recovery remains a key area of strategic focus. Furthermore, the economic case for recycling is reinforced by operational efficiencies; for every 10 percent increase in cullet in the batch, furnace energy needs drop by nearly 3 percent. This energy dynamic is a crucial lever for margin improvement in an era of volatile energy prices, and the report deep-dives into how this variable influences regional competitiveness.
Glass Recycling Market
Segmentation and Application Realities
To deploy capital effectively, leaders must understand where value is generated within the value chain. The report provides a rigorous breakdown of the market by product and application, revealing the dominance of specific segments while highlighting the emerging potential of niche applications. Recycled glass cullet remains the cornerstone of the industry, commanding a significant share of the market revenue due to its direct application in container and fiberglass manufacturing. The processing of glass into powder and crushed glass forms represents additional vectors of value creation, catering to specialized industrial needs ranging from abrasives to fillers.
On the demand side, glass containers continue to be the primary driver of recycled material consumption, reflecting the packaging sector's reliance on sustainable inputs. However, the analysis also scrutinizes other critical applications, including flat glass for construction and automotive sectors, and fiber glass for insulation and reinforcement. Smaller but strategically distinct segments such as highway beads, abrasives, and fillers offer diversification opportunities for processors looking to optimize yield and reduce waste. The report avoids superficial aggregation, instead offering a detailed view of how volume flows through these different channels, helping clients identify which applications offer the highest margins, the most stable demand, and the best alignment with their existing operational capabilities. It is important to note that while the report quantifies these market shares with precision, the full depth of regional and application-specific revenue data is reserved for the complete deliverable to ensure stakeholders derive maximum value from the proprietary analysis.
Competitive Landscape and Strategic Consolidation
The competitive architecture of the glass recycling market is characterized by a mix of established multinational players, specialized regional processors, and vertically integrated manufacturers. The market concentration metrics indicate that the top three companies hold a combined share of 42 percent, while the top five account for 51 percent of the market. This level of concentration suggests a mature industry where scale and network density are significant barriers to entry, yet sufficient fragmentation remains for strategic M&A and partnership activity to reshape the landscape.
Key players are actively positioning themselves to capture this growth through expansion, partnerships, and acquisitions. Sibelco, headquartered in Houston, Texas, stands as a dominant force, producing and supplying high-quality recycled glass cullet with a global capacity exceeding 5 million tons annually, including 2 million tons in North America, supported by over 60 facilities. In a significant move to expand its footprint, Sibelco acquired Strategic Materials, Inc. in December 2025, a transaction designed to expand the glass recycling network across North America. Strategic Materials itself is a critical node in the ecosystem, processing and supplying recycled glass cullet as high-quality feedstock for container and fiberglass production.
Other major entities are pursuing parallel strategies to secure their supply chains and enhance sustainability credentials. Owens-Illinois, Inc., based in Toledo, Ohio, operates the Glass4Good program, which recycled 392 metric tons in 2025, representing a 24 percent increase, with cullet processed into new glass bottles and jars. Vetropack Holding AG, headquartered in Meyrin, Switzerland, processes and supplies recycled glass cullet for container manufacturing and other glass applications, reinforcing the European supply base. Ardagh Group, based in Dublin, Ireland, has focused on partnerships for glass recycling services and cullet supply in container production. In April 2025, Ardagh Glass Packaging partnered with CAP Glass to establish advanced glass recycling services across the U.S. for high-quality cullet supply, signaling a strong push into the North American market. Momentum Recycling, LLC, operating out of Utah, processes glass recycling with a focus on cullet production for manufacturing and aggregates, illustrating the role of specialized regional players in optimizing local loops.
Recent developments further underscore the dynamic nature of this competitive field. In March 2025, Glass Half Full opened a new 10,000-square-foot recycling facility in Chalmette, Louisiana, with a capacity of 300,000 pounds per day, marking a 30-fold increase in processing capability. Such expansions demonstrate the rapid scaling potential in regions where infrastructure has been lacking, and the report analyzes the implications of these capacity additions for regional pricing and supply stability.
The 2026 Decision Framework
As organizations finalize their strategies for 2026, the insights contained in this report provide a framework for addressing the most pressing questions facing industry leaders. How should procurement teams structure contracts to mitigate the risk of cullet shortages driven by regulatory targets and infrastructure limitations? Where do the highest growth opportunities lie for processors looking to invest in new fractionation or processing technologies? How does the energy efficiency gain from cullet substitution translate into competitive pricing power in the container and flat glass markets? And perhaps most critically, how should companies evaluate the strategic fit of potential acquisitions or partnerships in a market where consolidation is accelerating, as evidenced by recent moves from major players?
The report equips decision-makers with the analytical tools to answer these questions. It moves beyond generic industry commentary to provide specific, data-backed assessments of market drivers, restraints, and opportunities. By integrating historical performance with forward-looking forecasts, it allows for scenario planning that accounts for regulatory shifts, energy price volatility, and changing consumer preferences. The analysis also highlights the interplay between regional dynamics and global market forces, ensuring that strategies are robust whether they are deployed in mature markets with high recycling rates or emerging regions where infrastructure is being built out.
Conclusion: A Catalyst for Sustainable Growth
The glass recycling market is at an inflection point. The convergence of regulatory pressure, energy economics, and corporate sustainability commitments is driving demand for recycled glass at a pace that outstrips the current capacity of many supply chains. For companies operating in this space, the margin for error is narrowing. Success in 2026 and beyond will belong to those who can secure reliable feedstock, optimize processing efficiency, and align their product portfolios with the most value-intensive applications.
PW Consulting's in-depth Glass Recycling Market research is more than a data repository; it is a strategic asset designed to inform high-stakes decisions. By revealing the structural forces shaping the market and profiling the competitive maneuvers of key players, the report empowers stakeholders to act with confidence. To access the full spectrum of analysis, including detailed segmentation data, regional breakdowns, and comprehensive competitor profiling, stakeholders are encouraged to explore the complete report. The intelligence contained within is essential for turning the challenges of the circular transition into a durable source of growth and resilience.
For detailed analysis of this topic, please visit the official page: Glass Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: White Fused Alumina Market Hits $200M in 2025, Projects 4.01% CAGR Through 2032
By PW Consulting, 2026-09-16
White Fused Alumina Market 2026: Strategic Intelligence for Industrial Decision-Makers
As industrial manufacturing enters a new cycle of material optimization and cost discipline, White Fused Alumina has emerged as a critical component across abrasives, refractories, and technical ceramics. The global market has demonstrated consistent expansion over the past five years, growing from 150.0 Million USD in 2020 to 200.0 Million USD in 2025, with revenue projections indicating a continued upward trajectory through the end of the decade. Our latest White Fused Alumina Market research is built to translate this trajectory into executable strategy, giving procurement leaders, product developers, and market planners a precise, evidence-based view of where value is being created and where competitive pressure is intensifying.
This analysis is not a static snapshot. It is a forward-looking strategic instrument calibrated for the 2026 decision window. By combining historical performance from 2020 through 2025 with a structured forecast spanning 2026 to 2032, the report enables stakeholders to test assumptions, align supply commitments, and prepare for shifting demand patterns without relying on fragmented secondary sources or outdated industry narratives.
Market Trajectory and the Strategic Meaning of the Growth Curve
The market's evolution reflects more than incremental volume growth. The progression from 159.67 Million USD in 2021 to 170.69 Million USD in 2022, followed by acceleration toward 185.97 Million USD in 2023 and a measured 187.12 Million USD in 2024, shows a sector that has absorbed supply disruptions, raw material volatility, and regional demand rebalancing while still advancing ahead of broader industrial benchmarks. The 200.0 Million USD baseline in 2025 reinforces a market that has stabilized around quality differentiation, application-specific grading, and more disciplined inventory management.
From a strategic planning perspective, the forecast period tells its own story. Revenue is expected to reach 215.16 Million USD in 2026, followed by 217.06 Million USD in 2027 and 229.1 Million USD in 2028. The projection continues into 2029 at 231.99 Million USD, approaches 248.89 Million USD by 2030, and then moves toward 245.29 Million USD in 2031 before reaching 263.29 Million USD in 2032. These are not arbitrary numbers. They are planning inputs that help organizations gauge capacity timing, contracting windows, and the pace at which high-performance grades may capture additional share as downstream users demand better wear resistance, thermal stability, and polished surface outcomes.
The overall growth profile supports a compound annual growth rate of 4.01 percent across the forecast horizon, indicating a market that rewards companies able to align product specifications with end-use performance requirements rather than competing solely on commoditized volume. For 2026 planning, this means the strategic question is less about whether demand will advance and more about how to position specifications, supply agreements, and regional sourcing decisions to capture margin in a market where performance credibility increasingly determines customer retention.
Report Architecture: What Decision-Makers Will Find Inside
The study is organized to convert market complexity into operational clarity. Rather than offering a high-level overview alone, the report maps the market across type, application, and regional demand structures so that readers can align internal assumptions with external evidence. The segmentation logic is designed for practical use: it helps teams understand where white fused alumina is being specified, which grade structures are gaining emphasis, and how application requirements are reshaping procurement priorities.
Fused Magnesia Market
Inside the report, stakeholders will find:
- A full market size reconstruction from 2020 through 2025, providing a verifiable historical baseline for internal forecasting and board-level review.
- A detailed 2026 to 2032 outlook that translates growth momentum into planning-relevant signals for capacity, sourcing, and product roadmap decisions.
- Type-level analysis that distinguishes among refractory, abrasive, and ceramic-grade demand patterns, supporting product positioning and specification strategy.
- Application-level evaluation that examines how refractories, abrasives, and ceramics usage shapes volume flows and customer requirements.
- Regional demand mapping that reveals where consumption is concentrated and how geographic dynamics influence pricing, logistics, and sourcing strategy.
- Competitive profile coverage of the leading producers, including operational focus, product offerings, and strategic positioning within the white fused alumina value chain.
- Synthesis of industry dynamics that connects supply-side realities with downstream performance expectations, giving readers context for scenario planning and risk assessment.
The report is intended for teams that need more than directional commentary. It provides a structured foundation for budgeting, segment prioritization, customer strategy, and competitive positioning in a market where small specification advantages can translate into long-term contract value.
Competitive Landscape: Who Shapes the Market and How
The white fused alumina market is defined by a mix of established industrial suppliers and regionally influential producers, each bringing a different balance of purity, scale, application focus, and geographic reach. Our analysis examines the companies that materially influence pricing behavior, grade availability, and supply reliability, allowing readers to benchmark their own positioning against the actors most likely to affect purchasing decisions in 2026 and beyond.
Washington Mills operates with a clear emphasis on high-purity output, manufacturing white fused alumina grains, powders, and bubbles via electric arc fusion of Bayer-processed alumina. With material purity exceeding 99 percent Al2O3, the company supports demanding uses in refractories, ceramics, abrasives, and polishing applications. For customers where consistency and purity are non-negotiable, this profile signals a supplier orientation toward performance-sensitive segments rather than volume-only competition.
Imerys brings a broad, globally distributed production footprint to the market. With 12 global production sites, the company produces fused alumina, including white fused alumina, under the Alodur brand for abrasives, refractories, and technical ceramics. That scale and brand architecture matter in procurement environments where supply continuity, multi-region coverage, and application versatility are weighed alongside price.
Rusal contributes to the landscape through large-scale electric arc furnace production of white fused alumina from pure alumina at its Boksitogorsk Alumina Refinery. The company's integration with upstream alumina resources gives it a distinct supply-chain posture, which can influence cost structure, volume reliability, and the ability to serve industrial users seeking stable baseline supply.
U.S. Electrofused Minerals positions white fused alumina within a broader fused oxides portfolio for industrial applications. Its approach reflects a practical, application-oriented supply model in which white fused alumina is part of a wider materials offering, allowing customers to consolidate sourcing across related oxide products where specification alignment is possible.
MOTIM Electrocorundum provides another important European reference point, producing high-quality white fused alumina for refractories and abrasives. Its specialization reinforces the market's split between performance-driven and cost-sensitive purchasing channels, as well as the continued relevance of regional manufacturers that combine technical consistency with proximity to key industrial users.
In the Asia-Pacific supply structure, Zhengzhou Yufa Group stands out as a large-scale producer with a strong emphasis on cost-efficient supply for global abrasives and refractories. Henan Ruishi Renewable Resources Group similarly supplies white fused alumina grains and powders for industrial use, adding to the region's manufacturing depth and reinforcing the competitive importance of volume capability, logistics efficiency, and pricing agility.
Together, these players illustrate a market where concentration creates both opportunity and caution. The sector's structure indicates that a limited number of producers account for a substantial share of revenue, while still leaving room for specialized suppliers to compete on grade, purity, and service. For 2026 strategy, that means competitive intelligence cannot stop at product specs; it must also address supplier reliability, regional coverage, and the ability to respond to application-specific demand shifts.
Industry Context and Strategic Implications for 2026
The market intelligence in this study is grounded in current industrial realities. White fused alumina demand does not evolve in isolation. It is shaped by how abrasives manufacturers balance surface-finishing performance against cost, how refractory producers evaluate thermal endurance and service life, and how ceramics users align material characteristics with component requirements. At the same time, supply-side considerations such as energy intensity, raw alumina availability, furnace operation efficiency, and logistics constraints influence how reliably producers can meet specification-sensitive orders.
For 2026 planning, these dynamics create several strategic priorities. Companies need to evaluate whether their product and sourcing strategies are aligned with the growing importance of high-consistency grades. Procurement teams must weigh whether multi-supplier structures or consolidated partnerships better serve their risk and performance requirements. Market leaders need to determine where differentiation is sustainable, particularly in applications where wear life, polish quality, and thermal behavior directly affect downstream economics.
The report also supports scenario-based thinking. Because the forecast extends through 2032, organizations can use it to test how changes in regional demand strength, application mix, or grade adoption might alter revenue potential and competitive intensity. That forward visibility is especially valuable for capital planning, long-term contracts, and product development roadmaps where premature commitments can erode flexibility and delayed moves can cede share to more responsive competitors.
White Fused Alumina Market
Why This Research Matters Now
The white fused alumina market is entering a phase where informed decisions will separate resilient operators from those forced to react to supply and pricing shifts after the fact. With a 2025 baseline of 200.0 Million USD and a forecast that points toward 263.29 Million USD by 2032, the market offers meaningful expansion, but it also demands sharper segmentation insight, supplier benchmarking, and application-level understanding. Organizations that enter 2026 with only generic market narratives will be at a disadvantage when negotiating with producers, specifying grades for sensitive applications, or deciding where to invest in capability and coverage.
This White Fused Alumina Market research is designed to close that gap. It translates verified historical data, forward projections, and competitive profiling into a usable strategic framework for 2026 decision-making. The full intelligence set, including deeper segmentation detail, regional demand analysis, and complete company profiles, is available through the complete report. For teams that need precise market estimates, actionable segmentation, and a clear view of who is shaping the competitive environment, the full study provides the depth required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: White Fused Alumina Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Titanium Diboride Market Hits $44.1M in 2025, Set to Grow at 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Titanium Diboride Market: Strategic Intelligence for 2026 Decision-Makers
The global landscape for advanced ceramics is undergoing a quiet but fundamental transformation. At the center of this shift lies titanium diboride (TiB2), a material whose unique combination of hardness, electrical conductivity, and thermal stability is reshaping demand patterns across defense, semiconductor, and industrial manufacturing sectors. As organizations finalize their capital allocation and product roadmaps for 2026 and beyond, access to granular, forward-looking intelligence is no longer a luxury—it is a prerequisite for sustainable competitive advantage.
Our latest Titanium Diboride Market study, published by PW Consulting, is designed to meet this imperative. Spanning a historical analysis from 2020 through 2025 and a comprehensive forecast extending to 2032, this research translates complex market signals into an actionable strategic framework. Below, we outline the core architecture of the analysis, highlight the competitive dynamics currently reshaping the value chain, and explain why deepening your understanding of this niche—but rapidly evolving—market is a critical exercise for executive teams planning their next phase of growth.
Market Trajectory: From Steady Expansion to Strategic Inflection
The titanium diboride market has demonstrated resilient, compounding growth over the past half-decade. In 2020, total global market revenue stood at approximately 32.0 million USD. By 2025, that figure had climbed to 44.1 million USD—a trajectory that reflects both organic industrial adoption and the material's successful penetration into high-performance end-use segments. Looking ahead, our baseline forecast projects continued expansion, with market revenue expected to reach 45.28 million USD in 2026 and advance steadily toward 60.2 million USD by 2032. This long-view projection is anchored by an anticipated compound annual growth rate (CAGR) of 4.5 percent across the 2026-to-2032 forecast horizon.
These macroeconomic figures tell an important story, but they are only the starting point. The real strategic value lies in understanding how this growth is distributed across product types, application verticals, and geographic corridors—exactly the dimensions where competitive positioning can be won or lost. Market analysis at this level must move beyond headline numbers to examine the structural drivers: the maturation of bulk-grade production against the accelerating uptake of nanostructured formulations, the shifting allocation of demand across cutting tools, wear-resistant coatings, armor materials, refractory applications, electrodes and electrical contacts, composite materials, thermal barrier coatings, nuclear applications, and aerospace components, as well as the divergent growth tempos across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each of these segments carries its own pricing logic, supply constraints, and technology adoption curves, and our study maps them with precision.
Importantly, the market's growth profile is not uniformly distributed, and concentration patterns underscore this reality. The top three participants command a combined market share of 62.0 percent, while the top five extend that figure to 76.0 percent. This level of consolidation signals a market where scale, technology moats, and long-term customer relationships carry disproportionate weight—and where new entrants or expanding players must navigate an already crowded field with clear differentiation strategies.
Inside the Report: An Operational Playbook, Not a Static Snapshot
PW Consulting's Titanium Diboride Market study is structured to serve as a working reference for strategy, procurement, product development, and investment teams. Rather than offering a single trajectory, the report builds a multi-dimensional view of the market that connects demand fundamentals with supply-side realities, competitive behavior, and the broader industrial environment.
Key components of the analysis include:
- Segment-level deep dives: Detailed evaluation of how each product type and application category is evolving in terms of volume, value, technology requirements, and end-user adoption incentives. The analysis highlights where premium-grade materials are unlocking higher margins and where cost-optimized bulk supplies remain the dominant commercial vehicle.
- Regional market architecture: A geographically disaggregated assessment that examines demand intensity, manufacturing presence, trade flows, and localized supply constraints across all major regions. This section is designed to inform capacity siting decisions, partnership targeting, and market-entry prioritization.
- Competitive profiling and strategic positioning: In-depth company assessments that go beyond corporate descriptions to evaluate each player's product focus, geographic footprint, technology emphasis, and apparent strategic direction. The report contextualizes how established specialists and emerging capacity additions are reshaping share dynamics.
- Supply chain and input cost context: Examination of the material ecosystem that underpins titanium diboride production, including the role of boron-based feedstocks, energy intensity, and the operational impact of logistics and freight conditions on cost structures.
- Regulatory and environmental overlay: Analysis of how environmental considerations, mining and processing constraints, and compliance dynamics influence both upstream feedstock availability and downstream manufacturing economics.
- Technology and application horizon scanning: Identification of emerging use cases—such as additive manufacturing grades, advanced electronic sputtering targets, and next-generation armor and aerospace ceramics—that are expanding the addressable market and creating new value pools.
- Forecast scenarios and decision frameworks: Structured projections through 2032 that allow readers to stress-test assumptions around demand growth, competitive intensity, and input cost evolution, supporting both short-term operational planning and longer-range investment evaluation.
This integrated approach ensures that the study functions as more than a data repository. It is built to help decision-makers translate market signals into concrete actions: whether that means prioritizing a specific application vertical for product development, evaluating a potential partnership or acquisition, calibrating pricing strategy in a consolidating market, or assessing the viability of new capacity in a specific geographic corridor.
Competitive Dynamics: Specialists, Subscale Disruption, and Strategic Consolidation
The titanium diboride market is defined by a set of specialized producers whose capabilities are tightly aligned with specific end-use requirements. Understanding who these players are—and how they are positioning themselves—offers essential context for any strategic assessment of the market.
Europe remains home to several high-purity, technology-focused producers. Treibacher Industrie AG, based in Althofen, Austria, stands as a leading European source of high-purity titanium diboride powders and related hard material powders, serving industrial, aerospace, and electronics applications. Alongside it, H.C. Starck GmbH, part of the Mitsubishi Materials Group and headquartered in Goslar, Germany, is a prominent European producer of high-purity TiB2 powders and sputtering targets, with a strong presence in semiconductor, aerospace, and specialty chemistry markets. In a recent strategic move, H.C. Starck launched a new grade of titanium diboride powder tailored for additive manufacturing applications, with improved properties aimed at aerospace and automotive end-use sectors—a development that underscores the growing intersection between advanced materials and next-generation manufacturing processes.
In North America, the competitive picture blends established industrial material strength with specialized high-performance applications. 3M Company, through its Ceradyne subsidiary based in St. Paul, Minnesota, operates as a dominant supplier of TiB2-based defense armor, aerospace ceramics, and advanced materials, supported by long-standing military procurement relationships. Materion Corporation, headquartered in Mayfield Heights, Ohio, concentrates on high-purity TiB2 sputtering targets and specialty powders for semiconductor and thin-film deposition markets across North America and Europe—an application space where purity specifications and consistent quality are critical differentiators.
Japan continues to play a central role in specialty-grade material supply. Japan New Metals Co., Ltd., based in Toyonaka, Osaka, supplies specialty-grade TiB2 powders designed for electronics, precision tooling, semiconductor, and other high-value-added applications, with both domestic demand and export markets in scope.
China's manufacturing base adds significant volume and breadth to the global supply picture. Shandong Pengcheng Advanced Ceramics Co., Ltd., located in Zibo, Shandong, operates as a major Chinese producer of TiB2 ceramics, powders, and conductive ceramics, with applications spanning aluminum smelting cathodes, industrial cutting tools, and armor protection. Dandong Chemical Engineering Institute Co., Ltd. (DCEI), based in Dandong, Liaoning, produces titanium diboride alongside hexagonal boron nitride and amorphous boron powders, leveraging advanced processing technologies for a range of industrial applications. Together, these producers illustrate the dual nature of the market: a high-value, purity-sensitive segment driven by electronics, aerospace, and defense requirements, and a volume-oriented segment anchored in industrial tooling, wear applications, and cathode materials.
Worldwide Military Grade Titanium Disilicide Powder Market
Capacity and geographic expansion are already reshaping the competitive landscape. In July 2025, Kyocera Corporation acquired a titanium diboride ceramics manufacturing facility in South Korea, a move aimed at expanding production capacity and strengthening its market presence in the region. Such initiatives signal that established materials manufacturers are actively investing in geographic diversification and production scale, reinforcing the market's growth trajectory while simultaneously raising the bar for competitive differentiation.
Input Costs, Logistics, and Regulatory Currents: The Forces Shaping Margins
No strategic assessment of the titanium diboride market is complete without examining the upstream and environmental forces that influence both cost structures and supply reliability. Boron-based feedstocks sit at the heart of TiB2 production economics, and recent market intelligence points to several interconnected dynamics that buyers and producers alike must monitor.
Global boric acid prices exhibited a slightly declining trend in the first quarter of 2026, with spot prices in China recorded at 1,146 USD per metric ton in December 2025 amid relatively stable supply conditions. While a softening in feedstock pricing can ease input cost pressure in the near term, it does not eliminate the structural sensitivities that define this supply chain. Environmental regulations and mining costs continue to shape boric acid supply-side conditions for boron-based materials, introducing a persistent layer of uncertainty into cost forecasting. At the same time, supply chain disruptions and logistical challenges have influenced boric acid price movements across North America, Asia Pacific, and Europe, while environmental restrictions and freight rate fluctuations remain key factors affecting the overall cost structure of boron feedstock destined for TiB2 production.
For market participants, these dynamics carry direct strategic implications. Procurement teams must evaluate supplier resilience, inventory buffers, and geographic sourcing diversification in light of freight volatility and regulatory constraints. Producers need to factor energy intensity, environmental compliance, and logistics exposure into capital planning and pricing architecture. And executives designing market-entry or capacity-expansion strategies must account not only for demand momentum but also for the evolving complexity of the input cost environment that will ultimately determine margin sustainability.
Why This Research Matters for 2026 Strategy
As organizations move from planning cycles into execution, the titanium diboride market presents a clear case for informed, data-grounded decision-making. The combination of a consolidated competitive structure, differentiated application demand, evolving manufacturing technologies, and a feedstock environment shaped by logistics and regulatory pressures creates a setting where strategic clarity matters more than ever.
This study is designed to give executives, analysts, and operational leaders the kind of market visibility that supports confident action. It connects high-level growth trajectories with the granular segment and competitive intelligence required to build realistic scenarios, identify priority opportunities, and anticipate the shifts that will redefine value creation through 2032. Whether your focus is on expanding product portfolios, securing supply, evaluating partnership or acquisition targets, or positioning for geographic growth, the report offers the structured insight needed to move forward with precision.
For a complete view of the market size, segment dynamics, competitive profiles, and forward-looking forecasts underpinning this analysis, we invite you to access the full Titanium Diboride Market research. The detailed intelligence within is built to support the decisions that will define your organization's trajectory in the years ahead.
Titanium Diboride Market
For detailed analysis of this topic, please visit the official page: Titanium Diboride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Tubing Set Market Hits $1,027.5M in 2025 with 4.12% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Blood Tubing Set Market: Navigating Growth and Regulation in 2026
The global medical device landscape is undergoing a period of nuanced transformation, and few segments illustrate this complexity better than the Blood Tubing Set Market. As healthcare systems worldwide grapple with aging demographics, rising prevalence of chronic kidney disease, and increasingly stringent regulatory frameworks, the demand for reliable, high-performance extracorporeal blood circuits has never been more critical. For executives, procurement leaders, and investment analysts, understanding the trajectory of this market is not merely an academic exercise—it is a foundational requirement for strategic planning in 2026 and beyond.
At PW Consulting, we have released a comprehensive new study designed to cut through the noise and provide actionable intelligence. This article serves as an introduction to those findings, highlighting the strategic value the research offers to enterprises operating within or adjacent to the dialysis and blood transfusion ecosystems. While we preview the macro trends and competitive dynamics here, the full depth of segment-level analysis, regional breakdowns, and proprietary forecasts is reserved for our detailed report. Readers seeking to benchmark their position or identify high-yield opportunities are encouraged to consult the complete intelligence package.
Blood Collection Tubes Market
Market Trajectory and Core Financial Indicators
The Blood Tubing Set Market has demonstrated steady, predictable growth over the past half-decade, reflecting the essential nature of the products involved. Analysis of historical data from 2020 through 2025 reveals a consistent upward trajectory in revenue, moving from a baseline of approximately 812.35 million USD in 2020 to 1,027.5 million USD by 2025. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Blood Tubing Set Market
Our forecast models indicate that the market will continue to expand, driven by volume growth in dialysis procedures and incremental improvements in tubing set durability and biocompatibility. The projected compounding annual growth rate (CAGR) for the forecast period stands at 4.12 percent. This rate suggests a mature but resilient market environment, where growth is less about explosive disruption and more about steady volume expansion, technological refinement, and strategic consolidation. By the end of the forecast horizon in 2032, total market revenue is anticipated to reach significant new thresholds, offering clear pathways for stakeholders who can navigate supply chain complexities and regulatory compliance effectively.
For decision-makers in 2026, this trajectory implies several strategic imperatives. First, the market is not poised for volatile spikes but rather for sustained, manageable growth, requiring long-term capacity planning rather than short-term speculation. Second, the financial metrics underscore the importance of cost efficiency in manufacturing and procurement, particularly given the material cost dynamics inherent in medical-grade production.
Product Segmentation and Clinical Applications
Understanding where value is generated within the Blood Tubing Set Market is critical for targeted strategy. The market is broadly segmented by patient demographics, distinguishing between adult and pediatric applications. Given the higher prevalence of end-stage renal disease in adult populations, the adult segment naturally commands the majority of revenue share. However, the pediatric segment, while smaller in volume, often commands different specifications regarding priming volume, biocompatibility, and safety features. A successful product portfolio must address both segments with appropriate engineering and positioning.
Application-wise, the market is anchored by two primary channels: dialysis centers and hospitals & clinics. Dialysis centers represent the dominant setting for blood tubing set utilization, reflecting the chronic nature of hemodialysis treatments and the high frequency of disposable circuit replacement required per patient per week. Hospital and clinic environments also constitute a vital channel, particularly for acute dialysis scenarios, surgical procedures requiring extracorporeal circulation, and specialized care units. Each channel presents distinct procurement cycles, reimbursement pathways, and regulatory oversight requirements.
Our report provides granular analysis of these segmentation splits, helping organizations identify which sub-segments offer the best alignment with their manufacturing capabilities or distribution strengths. Rather than applying a one-size-fits-all strategy, the data suggests that tailored approaches based on application setting and patient age group yield significantly better margins and customer retention.
Competitive Landscape: Key Players and Strategic Moves
The Blood Tubing Set Market is characterized by a concentrated competitive environment where established medical device manufacturers leverage specialized product portfolios and regulatory expertise to maintain market share. Several key companies define the landscape, offering machine-specific and system-agnostic solutions that cater to the diverse needs of hemodialysis providers.
Nipro Corporation, headquartered in Osaka, Japan, has established a strong presence through its NiproSet blood tubing sets. These products are notable for being machine-specific for hemodialysis, featuring FDA-tested components that emphasize compatibility and safety. Nipro’s strategy highlights the value of close integration with dialysis equipment manufacturers, ensuring that tubing sets perform optimally within specific system configurations.
B. Braun Melsungen AG, based in Melsungen, Germany, offers the Streamline Airless System Hemodialysis Bloodlines and DiaStream bloodline systems. These solutions focus on reducing air embolism risks and improving hemodynamic stability during treatment. B. Braun’s approach underscores the importance of engineering innovations that directly reduce clinical risks, a key selling point in procurement decisions made by hospital administrators and nephrology directors.
Fresenius Medical Care AG, with headquarters in Bad Homburg vor der Höhe, Germany, provides the CombiSet SMARTECH and other blood tubing sets tailored for hemodialysis machines. As a global leader in dialysis care, Fresenius leverages its extensive clinical network and integrated service model to promote its consumables, reinforcing brand loyalty and standard-setting within care facilities.
Recent developments in the competitive and regulatory space underscore the need for vigilance. In April 2026, B. Braun Medical Inc. issued an urgent medical device correction regarding the Streamline Airless System Hemodialysis Bloodlines and B3 Low Volume Bloodlines. The correction addressed potential microbubble and leakage risks, with updates issued following FDA MedWatch alerts. Such events serve as a stark reminder that even mature products require continuous quality monitoring, rapid response protocols, and transparent communication with the regulatory community. For competitors and customers alike, these corrections influence purchasing confidence and may shift volume toward alternative suppliers who can demonstrate robust quality management systems.
Regulatory Environment and Clinical Compliance
The Blood Tubing Set Market operates within a tightly regulated framework that shapes product development, market entry, and ongoing compliance. Hemodialysis blood tubing sets are classified as Class II devices, subject to FDA 510(k) requirements for demonstrating substantial equivalence to existing predicates. This regulatory pathway demands rigorous documentation, clinical performance data, and quality system adherence, creating barriers to entry that protect established players while ensuring patient safety.
Reimbursement dynamics also play a pivotal role in market behavior. Hemodialysis blood tubing sets are covered under Medicare Part B reimbursement codes for dialysis procedures, linking device utilization directly to federal payment structures. Changes in coverage policies or coding updates can ripple through demand patterns, affecting volume projections and pricing strategies. Stakeholders must stay attuned to Centers for Medicare & Medicaid Services (CMS) national coverage determinations, which remain active and influential throughout 2026.
International standards further complicate the compliance landscape. Blood tubing sets must comply with ISO 10993 biocompatibility standards for blood contact, ensuring that materials do not induce adverse immune or thrombotic responses. Additionally, all blood tubing sets are single-use devices sterilized via gamma irradiation or ethylene oxide prior to market release, as mandated by FDA premarket notification guidance. These sterilization requirements impact production logistics, facility design, and cost structures, particularly regarding the medical-grade PVC tubing that forms the core of many sets. Unit costs for such tubing can vary between 5 and 15 USD per set depending on volume and customization, adding a layer of financial sensitivity that procurement teams must manage carefully.
Strategic Insights for 2026 Decision-Making
The intersection of market growth, competitive dynamics, and regulatory requirements creates a complex environment where strategic foresight is paramount. For manufacturers, the key challenge lies in balancing innovation with compliance, ensuring that new product features do not inadvertently trigger additional regulatory scrutiny or quality issues. For distributors and healthcare providers, the focus shifts to supply chain resilience, vendor reliability, and cost optimization without compromising patient safety.
Several actionable themes emerge for 2026:
- Portfolio Optimization: Companies should assess whether their tubing set offerings adequately address the divergent needs of adult versus pediatric patients and the specific requirements of dialysis centers versus hospital settings. Consolidating around high-performing, compliant products while phasing out underperforming SKUs can sharpen competitive positioning.
- Regulatory Preparedness: With Class II classification and ISO 10993 compliance as baseline requirements, organizations must maintain robust documentation and quality management systems. Proactive engagement with regulators and continuous monitoring of safety alerts, such as the 2026 B. Braun correction, can mitigate reputational risk and inform product improvement cycles.
- Cost and Supply Chain Management: Given the material cost variability in medical-grade PVC and the sterilization requirements, procurement strategies should factor in volume commitments, supplier diversification, and logistics stability. Long-term contracts with reliable raw material suppliers can help smooth out unit cost fluctuations.
- Reimbursement Alignment: Understanding how Medicare Part B codes and CMS determinations affect demand is essential for revenue forecasting. Aligning product features with reimbursable procedure codes can enhance market access and encourage adoption in cost-sensitive care settings.
What the Full PW Consulting Study Delivers
The insights outlined above represent only the opening chapter of our comprehensive Blood Tubing Set Market research. The full report goes much deeper, offering a level of granularity that enables precise strategic planning and investment analysis. Readers who access the complete study will find detailed segmentation breakdowns by region and type, forward-looking revenue forecasts through 2032, and a thorough examination of market concentration metrics. The report also includes analysis of industry context, covering regulatory shifts, reimbursement updates, material cost trends, and sterilization practices that impact total cost of ownership.
Furthermore, the study provides an in-depth competitive benchmarking section, profiling key players, their product specifications, recent developments, and strategic positioning. This allows companies to benchmark their own offerings, identify gaps in their portfolios, and anticipate competitor moves with greater accuracy. The research is designed to serve a wide range of stakeholders, from product managers and supply chain directors to investors and policy analysts, delivering a cohesive narrative backed by rigorous data analysis.
Conclusion
The Blood Tubing Set Market in 2026 is a landscape of steady growth, concentrated competition, and rigorous compliance demands. For organizations operating in this space, the ability to interpret market signals, anticipate regulatory changes, and align product strategies with clinical and reimbursement realities will determine long-term success. PW Consulting’s latest market research provides the strategic intelligence needed to navigate this environment with confidence, transforming raw data into clear, actionable directions. To unlock the full spectrum of insights, segmentation details, and competitive analysis, we invite you to explore the complete report and integrate its findings into your 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Blood Tubing Set Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


