



Category: market research
PW Consulting Report: Luxury Packaging Market to Hit $253.71M by 2032 Amid 5.23% CAGR
By PW Consulting, 2026-09-16
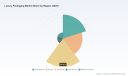
Strategic Horizons: Navigating the Luxury Packaging Market in 2026 and Beyond
The luxury packaging sector stands at a critical inflection point. As consumer expectations evolve and regulatory pressures intensify, brands are no longer treating packaging as a mere container but as a strategic asset that communicates value, reinforces sustainability commitments, and protects brand equity. Understanding the trajectory of this market is essential for executives making capital allocation, product development, and supply chain decisions in 2026. This publication presents a comprehensive analysis of the luxury packaging landscape, offering the intelligence required to navigate an increasingly complex environment.
Worldwide Luxury Cosmetics Packaging Market
The global luxury packaging market has demonstrated consistent growth over the past half-decade. Valued at approximately 143.92 million USD in 2020, the sector expanded steadily to reach 178.23 million USD by the base year of 2025. Looking forward, the market is projected to climb to 186.79 million USD in 2026, continuing its upward trajectory through the forecast period ending in 2032, where it is expected to surpass 253.71 million USD. This expansion is underpinned by a compound annual growth rate of 5.23 percent, reflecting sustained demand across high-end consumer segments. However, aggregate figures only tell part of the story. The real strategic opportunities lie in understanding the structural shifts, material innovations, and regional dynamics that are reshaping competitive positions.
Our latest market research goes beyond top-line projections. It provides a granular examination of the forces driving growth, the constraints limiting expansion, and the strategic maneuvers required to capture value in a fragmented yet consolidating industry. For decision-makers operating in 2026, this report serves as a vital compass, illuminating pathways for investment, partnership, and innovation.
Decoding the Competitive Landscape
The luxury packaging ecosystem is characterized by a mix of established multinational players and specialized niche manufacturers. Our analysis maps the strategic positioning of key companies that are defining the market's direction, examining their operational focus, geographic reach, and innovation pipelines.
Market Leaders and Specialized Innovators
Several prominent organizations are setting the pace for the industry. DS Smith plc, headquartered in London, has cemented its reputation through a strong focus on paper-based luxury rigid boxes and premium packaging solutions. Similarly, Smurfit Westrock plc, based in Dublin, continues to advance paperboard and rigid luxury packaging while integrating sustainability innovations into its core offerings. In Milan, Pusterla 1880 S.p.A. specializes in luxury rigid boxes and premium cardboard packaging, catering to brands that demand both aesthetic excellence and structural integrity.
The Asia-Pacific region contributes significant manufacturing capabilities, exemplified by Topsion Packaging in Dongguan, China, which focuses on structurally complex rigid boxes for premium luxury applications. European fiber-based solutions are championed by Stora Enso Oyj in Helsinki, whose emphasis on circular solutions aligns with growing environmental mandates. International Paper Company, operating from Memphis, USA, provides premium paperboard and secondary paper luxury packaging at scale. Mondi plc, also headquartered in London, drives the market forward with advanced materials and designs tailored for luxury packaging. Complementing these larger entities are specialized firms such as HH Deluxe Packaging Ltd. in London, which concentrates on high-end luxury packaging and presentation solutions, and Winter and Company AG in Zug, Switzerland, known for luxury gift boxes and premium packaging. BDMO, based in Belgium, rounds out this competitive cohort with a focus on luxury cardboard packaging for cosmetics and gifts.
The competitive landscape is moderately consolidated. The top three players command a combined market share of 24.6 percent, while the top five extend their influence to 26.2 percent. This concentration indicates that while dominant players hold significant sway, substantial room remains for specialized competitors and regional leaders to carve out profitable niches. Understanding the specific strengths and strategic vulnerabilities of each competitor is essential for positioning your own offerings effectively.
Market Dynamics and Structural Shifts
Material Economics and Supply Chain Pressures
The cost environment for luxury packaging materials has become increasingly volatile. Paper prices remain elevated due to sustained global demand, higher energy costs for production, and increased reliance on recycled fibre. This pressure is compounded by regulatory and market forces affecting alternative materials. Plastic prices have risen notably, with contract increases of nearly 20 percent for polyethylene and polypropylene used in packaging. These cost dynamics directly impact margin structures and force brands to make difficult trade-offs between material choice, aesthetic quality, and cost efficiency.
Regulatory Headwinds and Opportunities
Regulatory frameworks are reshaping the operational landscape. The European Union's Packaging and Packaging Waste Regulation targets over-packaging with mandates for reduced material use in luxury segments. Compliance is no longer optional; it is a strategic imperative that influences design specifications, material sourcing, and end-of-life considerations. In the United Kingdom, Extended Producer Responsibility fees for 2025-2026 set producer charges at 192 pounds per tonne for glass and 196 pounds per tonne for paper and card. These fee structures incentivize material optimization and circular design approaches, rewarding companies that can reduce weight without compromising perceived quality.
Innovation in Action: Recent Developments Defining the Market
The pace of innovation in luxury packaging is accelerating, driven by sustainability mandates, consumer demand for experiences, and technological advancements. Recent milestones highlight the industry's commitment to redefining what luxury packaging can achieve.
Showcasing Circular Solutions
At the Luxe Pack Shanghai trade show in May 2026, Stora Enso showcased innovative fiber-based packaging solutions redefining circular luxury. This demonstration underscored the growing viability of sustainable materials that do not sacrifice the tactile and visual qualities expected in premium segments. Meanwhile, Luxe Pack New York returned with record-breaking figures, featuring premium materials, smart packaging, and a strong sustainability focus. These events signal that the intersection of luxury and sustainability is no longer a niche interest but a mainstream expectation.
Investment in Capabilities
Infrastructure investments are reinforcing the industry's innovation capacity. In April 2026, Mondi inaugurated a new innovation center in Milan dedicated to advanced materials and designs for luxury packaging. This facility will serve as a hub for developing next-generation solutions that meet evolving brand and regulatory requirements. Earlier in the year, in January 2026, James Cropper secured funding to expand production capacity for luxury packaging papers, addressing the growing demand for high-quality fiber-based substrates. These developments illustrate that leading players are committing significant resources to staying ahead of market trends.
Strategic Implications for 2026 Decision-Makers
The luxury packaging market offers substantial growth potential, but realizing that potential requires more than passive observation. Executives must adopt a proactive stance, leveraging data-driven insights to inform strategy across multiple dimensions.
Aligning Material Strategy with Regulatory and Cost Realities
With raw material costs under pressure and regulations tightening, brands must reassess their material portfolios. The shift toward fiber-based and recycled solutions is gaining momentum, but the transition must be managed carefully to maintain premium perception. Understanding the cost implications of different material choices, including regulatory fees and supply chain risks, is critical for maintaining profitability while meeting sustainability targets.
Capitalizing on Regional and Application-Specific Opportunities
Growth is not uniform across all segments. Certain applications and regions are outpacing others, driven by consumer wealth, brand investment, and cultural preferences. Identifying where demand is concentrated and which customer segments are most willing to pay for premium packaging enables more targeted product development and marketing efforts. The ability to tailor offerings to specific luxury sub-segments, whether in cosmetics, fashion, or premium beverages, can significantly enhance competitive differentiation.
Leveraging Competitive Intelligence for Strategic Positioning
The moderately consolidated nature of the market means that both large players and specialized firms have opportunities to thrive. Understanding competitor capabilities, innovation pipelines, and strategic focus areas allows companies to identify gaps in the market and position themselves effectively. Whether through partnerships, acquisitions, or organic innovation, strategic Positioning requires a clear view of the competitive terrain.
Preparing for the Future
The forecast period extending to 2032 suggests that the luxury packaging market will continue its expansion, but the composition of that growth will evolve. Companies that invest now in flexible manufacturing capabilities, sustainable material portfolios, and customer-centric design processes will be best positioned to capture long-term value. Those that delay adaptation risk being squeezed by cost pressures, regulatory constraints, and shifting consumer expectations.
Why This Research Matters Now
In a market defined by rapid change, incomplete information is a liability. The insights contained in this report are designed to equip executives with the knowledge needed to make confident, forward-looking decisions. From material economics and regulatory impacts to competitive dynamics and innovation trends, every aspect of the luxury packaging ecosystem is examined with the rigor required for high-stakes strategy development.
The data presented here represents only a fraction of what is available. Our full market research provides detailed segmentation analysis, granular regional breakdowns, application-specific growth drivers, and comprehensive competitor profiles. It includes actionable recommendations for supply chain optimization, product portfolio strategy, and market entry or expansion planning. For organizations serious about competing in the luxury packaging sector, this depth of intelligence is indispensable.
Your Next Step
The luxury packaging market is evolving at an accelerating pace. The decisions made in 2026 will shape competitive positioning for years to come. To access the complete analysis, including detailed segmentation data, regional market sizes, application breakdowns, and in-depth competitor evaluations, we invite you to explore our full market research report. Equip your organization with the strategic intelligence needed to navigate this dynamic landscape and capture the value that lies ahead.
Luxury Packaging Market
For detailed analysis of this topic, please visit the official page: Luxury Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pool Cleaners Market Hits $115M in 2025, Set to Hit $197.09M by 2032, Growing at 6.23% CAGR
By PW Consulting, 2026-09-16
Navigating the Blue Economy: Strategic Insights from the 2026 Pool Cleaners Market Intelligence Report
The landscape of aquatic maintenance is undergoing a profound transformation, driven by converging technological innovations and shifting consumer expectations. As industry leaders prepare for the remainder of the decade, access to precise, forward-looking intelligence is no longer merely advantageous; it is essential for sustained competitive advantage. This article serves as a strategic preview of our latest comprehensive research initiative, designed to equip stakeholders with the analytical clarity required to navigate the Pool Cleaners Market through 2032. By synthesizing historical performance with forward-looking projections, this report constructs a robust framework for capital allocation, product development, and market positioning.
Pool Cleaners Market
Macro Trajectory and Structural Growth Dynamics
The global pool cleaning equipment sector has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical analysis reveals a consistent upward trajectory, with market valuation climbing from 85.0 million USD in 2020 to approximately 115.0 million USD by the 2025 base year. This growth reflects broader macroeconomic trends, including rising disposable incomes in mature markets, increased installation of private swimming facilities, and a growing emphasis on automated home maintenance solutions. Looking ahead, the forecast period spanning 2026 through 2032 indicates sustained momentum, with the market projected to reach 197.09 million USD by the terminal forecast year. This expansion corresponds to a compound annual growth rate of 6.23 percent, signaling a stable, moderately paced growth environment rather than a speculative boom.
It is important to recognize that such aggregate figures represent more than simple linear expansion. They embody a structural evolution in how consumers and facility managers approach water quality, chemical reduction, and time allocation. The steady CAGR underscores a mature yet innovation-driven ecosystem where incremental improvements in engineering, user experience, and energy efficiency compound over time. For executive teams, understanding this trajectory means recognizing that market share gains will increasingly depend on product differentiation, brand trust, and the ability to anticipate regional purchasing behaviors rather than on volume-driven price competition alone.
Technological Inflection Points and Product Evolution
The past eighteen months have witnessed a pronounced shift toward intelligent, connected, and highly autonomous cleaning systems. CES 2026 served as a visible showcase for this evolution, with multiple industry participants unveiling next-generation platforms that leverage artificial intelligence, advanced navigation protocols, and hybrid power architectures. These product launches are not isolated marketing events; they reflect a broader industry consensus that the next phase of value creation will be captured by manufacturers who successfully integrate smart diagnostics, adaptive cleaning patterns, and user-centric design into mainstream offerings.
Pool Chemical Market
Robotic systems have emerged as a particularly dynamic segment, increasingly favored for their operational efficiency and reduced reliance on external plumbing or manual intervention. Simultaneously, traditional suction and pressure-side categories continue to evolve, benefiting from refined filtration compatibility and enhanced durability. The interplay between these product architectures creates a complex but highly actionable landscape for engineering leaders and product managers. Our research dissects the innovation cadence across these categories, analyzing how feature adoption curves align with consumer willingness to pay, installation complexity tolerances, and long-term maintenance expectations.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with the top three participants collectively commanding approximately 42.5 percent of total revenue and the top five entities holding roughly 58.0 percent. This concentration suggests an environment where established brands leverage distribution networks, service infrastructure, and brand recognition to maintain defensive moats, while newer entrants and specialized manufacturers pursue aggressive differentiation through software-driven features and cordless form factors. Understanding the equilibrium between incumbent stability and challenger agility is critical for businesses evaluating partnership opportunities, acquisition targets, or internal R&D prioritization.
Key players such as Maytronics Ltd., operating from its Israeli headquarters with a strong focus on its Dolphin-branded residential and commercial robotic systems, continue to invest heavily in navigation and propulsion refinements. Hayward Industries, Inc., based in North Carolina, maintains a broad portfolio spanning robotic and traditional cleaning categories, often emphasizing brand versatility and installer familiarity. Pentair plc, headquartered in Minnesota, provides a comprehensive suite of cleaning solutions that integrate seamlessly with wider aquatic ecosystems. Fluidra S.A., headquartered in Barcelona, leverages a portfolio encompassing Polaris, Zodiac, and Aquabot offerings, with a particular emphasis on European and global distribution channels. Aiper Intelligent LLC, operating from the United States, has positioned itself at the forefront ofcordless and AI-assisted robotic cleaners, emphasizing smart navigation and consumer usability. Meanwhile, NingBo Poolstar Pool Products Co., Ltd., based in China, functions as a significant OEM/ODM partner, supporting both branded and private-label demand across multiple product categories.
Recent product activity reinforces the intensity of this competitive environment. In January 2026, Aiper Intelligent LLC introduced the Scuba V3 and Scuba V3 Pro platforms at CES, highlighting advanced artificial intelligence and smart operational capabilities. During the same event, Maytronics Ltd. launched the Dolphin EON robotic cleaner, featuring JetIQ propulsion technology, SmartMap navigation, and a hybrid power configuration. By February 2026, iGarden, under the Fairland Group umbrella, released the M1 Pro Max bionic dual-vision robotic cleaner, an initiative that was subsequently recognized as a CES 2026 Innovation Award honoree. These developments illustrate a market where engineering differentiation, rather than pure scale, increasingly determines premium positioning.
Regulatory Pressures and Supply Chain Considerations
Beyond product innovation and competitive maneuvering, external macro-forcing mechanisms are actively reshaping cost structures and sourcing strategies. As of March 2025, the United States implemented new tariff measures affecting imported raw materials and chemicals, including a twenty-five percent tariff on steel and aluminum and a ten percent tariff on Chinese-origin imports. These policy adjustments have direct ramifications for pool equipment manufacturers, component suppliers, and assembled product importers, introducing volatility into input costs and prompting strategic reevaluation of domestic versus overseas production footprints.
Such regulatory dynamics interact with broader supply chain considerations, including freight logistics, alternative material substitution, and regional manufacturing flexibility. Companies that proactively map these cost drivers into their pricing architectures, inventory planning, and vendor diversification strategies will be better positioned to preserve margins without sacrificing market accessibility. Our analysis incorporates these external pressures into a holistic assessment of market resilience, enabling decision-makers to model scenarios that account for tariff impacts, currency fluctuations, and shifting sourcing patterns.
Probing Beyond the Surface: What This Research Delivers
While the macroeconomic trajectory and competitive framing provide a necessary foundation, the true strategic value of this research lies in its granular, decision-oriented architecture. The full study is engineered to support cross-functional teams with actionable intelligence across multiple dimensions. Key components include:
- A comprehensive segmentation analysis that isolates performance drivers across product architectures, installation environments, and geographic demand clusters, allowing leadership to identify high-conviction growth pathways without relying on generic market narratives.
- Detailed demand behavior profiling that examines purchase frequency, feature prioritization, installer influence, and post-sale service expectations, helping product and marketing teams align development roadmaps with real-world adoption patterns.
- Competitive intelligence mapping that evaluates brand positioning, innovation pacing, distribution reach, and strategic response patterns among leading manufacturers and emerging challengers, enabling precise benchmarking and gap identification.
- Supply chain and cost-structure assessments that contextualize input volatility, component dependency, and regional manufacturing considerations, supporting procurement and financial planning under varying tariff and logistics scenarios.
- Scenario-based forecasting frameworks that translate historical performance and forward indicators into actionable revenue expectations, capacity planning inputs, and market entry timing assessments.
Each analytical module is designed to answer specific strategic questions: Which product developments command premium acceptance in high-growth demand clusters? How are incumbent brands defending share against software-led entrants? Where do distribution partnerships and regional service networks create the most durable competitive advantages? By addressing these questions with methodological rigor and clearly sourced data, the study transforms raw market signals into executable strategic guidance.
Implications for 2026 Decision-Making
Entering the second half of the decade, businesses operating in or adjacent to this sector face a defining set of choices. The convergence of artificial intelligence-driven cleaning routines, cordless engineering, tariff-sensitive supply chains, and evolving consumer expectations creates an environment where reactive strategies will be quickly outpaced by proactive, data-informed positioning. Organizations that treat market intelligence as a continuous input rather than a periodic report will be better equipped to time product launches, allocate marketing spend, negotiate supplier contracts, and evaluate partnership or acquisition opportunities.
This research publication is specifically structured to serve that purpose. It provides executive teams, strategy directors, product leaders, and investment analysts with a consolidated, high-fidelity view of market mechanics, enabling them to separate structural growth from temporary noise. By grounding strategic planning in clearly delineated trend lines, competitive benchmarks, and segment-level demand dynamics, stakeholders can construct more resilient operating plans and reduce the uncertainty associated with capital deployment.
Strategic Access and Forward Engagement
The complete research deliverable extends well beyond the high-level trajectory outlined here. It contains the detailed segmentation breakdowns, competitive playbooks, regional performance context, and forecasting methodologies necessary to translate awareness into execution. For organizations seeking to calibrate product roadmaps, refine pricing architectures, evaluate market entry timing, or benchmark against the most active industry participants, the full report offers the depth required to make those decisions with confidence.
This preview demonstrates the analytical rigor and strategic orientation embedded in our research methodology. To access the complete segmentation matrices, company-specific competitive assessments, scenario-driven forecasts, and the full spectrum of data-driven insights, we invite you to visit the official source webpage and obtain the complete Pool Cleaners Market research publication. In a market defined by steady expansion, accelerating technological iteration, and shifting regulatory cost structures, precision intelligence is the most effective differentiator for businesses committed to long-term growth and market leadership.
For detailed analysis of this topic, please visit the official page: Pool Cleaners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
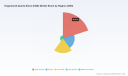
Navigating the Engineered Quartz Stone Market: Strategic Intelligence for 2026 and Beyond
The global demand for engineered quartz stone (EQS) has transitioned from a niche luxury preference to a mainstream standard in residential and commercial surface solutions. As we move through 2026, industry stakeholders face a complex landscape defined by robust growth trajectories, shifting regulatory frameworks, and intense competitive maneuvering. PW Consulting's latest market research provides a comprehensive navigational chart for executives, investors, and supply chain leaders seeking to capitalize on these dynamics. This executive briefing outlines the strategic value of our analysis, synthesizing historical performance, forward-looking projections, and critical market intelligence to inform high-stakes decision-making.
Market Trajectory: From Recovery to Sustained Expansion
The engineered quartz stone sector has demonstrated remarkable resilience and growth over the past half-decade. Our analysis tracks revenue performance from 2020 through the base year of 2025, capturing the market's recovery from global supply chain disruptions and its subsequent acceleration. The market valuation has climbed steadily, surpassing the 120 million USD threshold in 2025. This historic performance sets a robust foundation for the forecast period extending through 2032.
Projections indicate a continued upward trajectory, with the market expected to reach valuation levels exceeding 195 million USD by the end of the forecast window. This growth is underpinned by a compound annual growth rate (CAGR) that reflects sustained investment in surface materials across key sectors. For strategic planners, these figures are not merely statistics; they represent the total addressable market expansion that will dictate capacity planning, capital allocation, and geographic focus over the next seven years. Understanding the inflection points within this timeline allows organizations to time their market entry, product launches, and scaling initiatives with precision.
Structural Segmentation: Identifying High-Yield Opportunities
A superficial view of the EQS market obscures the nuanced value pools that drive profitability. Our research deconstructs the market across critical dimensions, providing leaders with the granularity needed to prioritize resource deployment. The analysis examines product types, application verticals, and regional performance, revealing where demand is most concentrated and where growth vectors are emerging.
Within product classifications, the market is dominated by specific formats that align with prevailing construction and renovation trends. The research details the revenue contribution and growth potential of quartz slabs, tiles, and other emerging formats. By mapping the adoption curves of these product types against buyer preferences in different end-use scenarios, firms can refine their manufacturing mixes and inventory strategies. Similarly, the application landscape is dissected to highlight the primary drivers of consumption. While certain applications remain the predominant revenue generators, the research identifies ancillary segments that offer diversification benefits and emerging opportunities for product innovation.
Regional analysis is equally critical. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents distinct demand drivers, regulatory environments, and competitive intensities. For instance, mature markets may offer stability and high per-capita consumption, while developing regions may present higher growth rates driven by urbanization and infrastructure development. Our segmentation analysis equips clients with the insights necessary to tailor regional go-to-market strategies, balancing risk and reward across their global footprint.
Engineered Quartz Stone (EQS) Market
Competitive Landscape: Dynamics Among Key Players
The EQS market features a mix of established global giants and agile regional manufacturers, creating a competitive environment where differentiation is paramount. PW Consulting's report profiles the strategies, capabilities, and market positions of leading entities that are shaping industry standards. Understanding the moves of these key players is essential for benchmarking, partnership evaluation, and competitive positioning.
In North America, family-owned and domestic manufacturers are leveraging local production and strong brand equity to capture market share. Companies such as Cambria have built reputations around high-performance slabs and lifetime warranties, appealing to consumers and contractors who prioritize durability and trust. Similarly, MSI Surfaces has expanded its portfolio significantly, offering a wide array of styles produced through advanced machinery and patent-protected processes at its domestic facilities. These firms illustrate the importance of manufacturing proximity and design variety in securing customer loyalty.
On the global stage, pioneer brands continue to drive innovation in design and sustainability. Caesarstone, a longstanding leader since the late 1980s, maintains a strong presence through continuous product development and adaptation to regional demands. Recent capacity expansions by Caesarstone highlight the strategic focus on supporting growing demand in residential and commercial construction across major markets. Concurrently, the company has responded to industry pressures regarding worker safety by launching innovative quartz surfaces with reduced crystalline silica content, signaling a proactive approach to regulatory compliance and product safety.
European and international players are also advancing the market through technological breakthroughs and global distribution networks. The Cosentino Group stands out as a global leader, with its Silestone brand introducing HybriQ+ technology designed to lower crystalline silica content while maintaining aesthetic and performance standards. VICOSTONE, based in Turkey, has established itself as a leading manufacturer of premium quartz products for residential and commercial use, leveraging extensive collections to meet diverse design requirements. In Asia, manufacturers are expanding their reach and production capabilities. Hanwha L&C and LG Hausys represent major South Korean conglomerates producing high-quality engineered stone surfaces, with Hanwha operating facilities in both South Korea and the United States to serve local and export markets. In India, Techstone Quartz operates as an integrated manufacturer and exporter, focusing on high-quality slabs and prefabricated countertops. Meanwhile, LT Quartz in China specializes in professional quartz surfacing production and marketing, catering to a broad spectrum of applications.
Recent developments underscore the intensity of capacity and product strategy adjustments. Pokarna Limited, for example, announced significant investments to expand its engineered quartz slab production capacity, driven by rising export demand from North American and European construction sectors. These expansions, including new production lines operational in early 2026, reflect the industry's response to market growth and the strategic importance of scaling supply to meet international orders. Our competitive analysis synthesizes these developments to reveal trends in M&A activity, capacity investments, product launches, and sustainability initiatives, providing a holistic view of how the competitive battleground is evolving.
Regulatory and Operational Dynamics: Risk and Adaptation
Market growth cannot be decoupled from the regulatory and operational environment. The EQS industry is currently navigating a period of heightened scrutiny regarding health and safety, particularly concerning crystalline silica exposure during fabrication and installation. Regulatory bodies in key markets are advancing rulemaking and enforcement actions that could fundamentally alter manufacturing processes, product specifications, and liability landscapes.
In California, regulators have moved to prohibit the fabrication of artificial stone countertops with more than one percent crystalline silica, a measure driven by concerns over silicosis cases among workers. Cal/OSHA has tightened silica safety requirements and continues to enforce emergency temporary standards, compelling manufacturers and fabricators to adapt their operations. Australia has taken an even more stringent approach, banning the manufacture, supply, processing, and installation of engineered stone benchtops, panels, and slabs effective mid-2024, with prohibitions on imports added in early 2025. These regulatory shifts create both challenges and opportunities. Companies that proactively develop low-silica or silica-compliant products can turn compliance into a competitive advantage, securing contracts in markets where safety certifications are becoming a prerequisite for doing business.
Beyond regulation, cost dynamics remain a critical factor. Fluctuations in the prices of essential raw materials, such as polyester resins and quartz aggregates, directly impact profit margins. Our report analyzes these cost drivers and their volatility, offering insights into supply chain resilience and pricing strategies. Leaders must understand how material cost fluctuations interact with regional demand and competitive pricing to maintain margin integrity. The research provides frameworks for monitoring input costs, hedging strategies, and optimizing procurement to mitigate margin erosion.
Strategic Frameworks for 2026 Decision-Making
PW Consulting's Engineered Quartz Stone Market report is designed as a practical tool for execution, not just a repository of data. The study integrates quantitative forecasts with qualitative insights to support specific strategic actions. Clients will find detailed 분석의 of market drivers, restraints, and opportunities, enabling them to validate investment theses and identify whitespace. The report includes comprehensive profiles of key companies, analyzing their product portfolios, geographic reach, recent developments, and strategic positioning. This allows competitors to benchmark against industry leaders and new entrants to assess market barriers.
Furthermore, the analysis covers the entire value chain, from raw material sourcing to manufacturing technologies, distribution channels, and end-user preferences. By mapping the value chain, organizations can identify bottlenecks, partnership opportunities, and areas for vertical integration or diversification. The report also examines the impact of macroeconomic factors, construction trends, and consumer behavior shifts on demand patterns. For example, the growing emphasis on sustainable building materials and health-conscious design choices is influencing product development and marketing narratives. Our research highlights how EQS products can be positioned to align with these broader trends, such as through innovations in low-silica content, recycled content integration, and energy-efficient manufacturing processes.
The segmentation data provided in the report allows for precise targeting. Whether a firm is focusing on the dominant application segments or exploring niche applications with high growth potential, the research supports data-driven segmentation strategies. Regional breakdowns enable the calibration of market entry strategies, resource allocation, and risk management plans tailored to local conditions. The inclusion of recent industry developments ensures that the intelligence is current and actionable, capturing the latest capacity expansions, product launches, and regulatory updates that could impact business outcomes.
Engineered Stone Market
Conclusion: The Imperative for Comprehensive Intelligence
As the engineered quartz stone market accelerates toward the 2030s, the margin for strategic error narrows. The convergence of robust demand growth, evolving regulatory requirements, cost volatility, and intense competition demands a holistic and up-to-date understanding of the industry. PW Consulting's market research delivers this intelligence, combining rigorous data analysis with deep industry expertise. By revealing the underlying dynamics of market segmentation, competitive behavior, and operational risks, the report empowers stakeholders to make informed decisions that drive sustainable growth. We invite industry leaders to leverage this comprehensive analysis to navigate the opportunities and challenges of the EQS market with confidence, ensuring their strategies are aligned with the realities of 2026 and the trajectory toward 2032.
For detailed analysis of this topic, please visit the official page: Engineered Quartz Stone (EQS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Hose Market Hits $14.35B in 2025 with 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
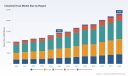
Industrial Hose Market Outlook 2026: Strategic Intelligence for Enterprise Decision Makers
The industrial hose market stands at a critical inflection point as the global economy navigates shifting supply chain dynamics, evolving regulatory frameworks, and sustained capital investment across heavy industry. Our latest comprehensive market research, Industrial Hose Market Analysis 2026, delivers the strategic intelligence needed to navigate this complex landscape. This report is not merely a data compilation, but a decision-support engine designed for executives, procurement leaders, and strategic planners who require actionable foresight rather than retrospective summaries. With a forecast horizon extending through 2032, our analysis captures both the immediate pressures shaping 2026 operations and the structural shifts that will define competitive advantage over the next half-decade.
Market Trajectory and Structural Growth Patterns
The industrial hose sector has demonstrated consistent revenue expansion over the past half-decade, with historical performance data from 2020 through 2025 establishing a clear trajectory of resilience and demand acceleration. Total market valuation has progressed from a baseline of 10,278.0 million USD in 2020, reaching 11,011.88 million USD in 2021, and advancing through 11,654.77 million USD in 2022, 12,007.18 million USD in 2023, 13,227.84 million USD in 2024, before culminating at 14,352.0 million USD in 2025. This historical arc reflects sustained capital deployment across fluid transfer infrastructure, equipment modernization cycles, and infrastructure development initiatives globally.
The forecast period from 2026 through 2032 projects continued expansion, anchored by a compound annual growth rate of 6.98 percent. Revenue is expected to reach 14,864.94 million USD in 2026, scaling toward 16,623.63 million USD by 2027, 18,166.93 million USD in 2028, 18,307.89 million USD in 2029, 20,276.98 million USD in 2030, 21,952.85 million USD in 2031, and ultimately 23,169.0 million USD by 2032. These figures represent nominal market size in USD millions, reflecting the aggregate value of hose products, assemblies, and associated fluid handling components across all industrial applications. The sustained growth rate underscores a market that continues to expand beyond cyclical recovery, driven by underlying industrial activity and technological modernization.
Importantly, our methodology isolates growth drivers from noise, enabling stakeholders to distinguish between temporary demand spikes and durable structural expansion. The 6.98 percent CAGR encompasses multiple interacting variables, including raw material cost volatility, geographic supply chain reconfiguration, regulatory compliance costs, and the ongoing shift toward high-performance composite and thermoplastic materials. executives who rely solely on headline growth figures risk misallocating resources; our analysis deconstructs these layers to reveal where sustainable value creation resides.
2026 Strategic Context: Pricing Pressures, Standards, and Operational Realities
The current operating environment is defined by intersecting cost and compliance pressures that directly influence procurement budgets, manufacturing margins, and product specification decisions. As of early 2026, stainless steel prices have stabilized near 1,995 USD per ton, a level that directly impacts hydraulic hose production costs and influences the economics of metal-reinforced assemblies. Simultaneously, natural rubber benchmark pricing has fluctuated between approximately 1.61 and 2.23 USD per kilogram, while synthetic rubber FOB pricing in China registered around 2,267 USD per ton in January 2026. These input cost dynamics do not merely affect short-term pricing; they reshape the competitive positioning of material categories, forcing manufacturers and buyers alike to reevaluate specification strategies, inventory management approaches, and total cost of ownership calculations.
Regulatory and standards evolution adds another critical dimension. The newly defined EN 854:2026 specifications establish updated requirements for textile reinforced rubber hydraulic hoses and assemblies intended for industrial and commercial applications, creating a compliance imperative that will influence product selection, certification processes, and market access for suppliers who have not aligned their portfolios accordingly. Concurrently, OSHA regulations continue to set binding workplace safety rules for hose handling and pressure systems in industrial settings, reinforcing the operational importance of durable, compliant assemblies that reduce incident risk and support audit readiness. These standards are not peripheral considerations; they embed themselves into procurement criteria, supplier qualification processes, and liability frameworks across multiple sectors.
Industrial Hose Market
Worldwide Industrial Flexible Hose Market
Trade show activity during early 2026 further illustrates the industry's active engagement with these dynamics. Companies including Salem-Republic Rubber Company, NRP Jones, Tubes International, and Elastohose have all maintained visible booth presences at major industry gatherings such as CONEXPO-CON/AGG 2026 and FLUID POWER 2026, showcasing product innovations, engaging with end-users, and signaling strategic priorities around durability, material advancement, and application-specific engineering. This sustained exhibition activity reflects an industry in active dialogue with its customer base, adapting to technical requirements and competitive expectations in real time.
Core Research Dimensions: What the Report Delivers
Our analysis is structured to provide immediate tactical value alongside long-term strategic orientation. Rather than presenting isolated data points, the report integrates quantitative benchmarking with qualitative assessment to produce a decision framework applicable across corporate functions.
Quantitative Benchmarking and Historical Reconstruction
The research reconstructs historical market performance from 2020 through 2025, calibrating base-year 2025 figures before projecting forward through 2032. This structure allows users to validate internal assumptions against audited market trajectories, identify periods of outperformance or underperformance relative to industry trends, and model scenario-based forecasts with confidence in the underlying baseline. All figures are expressed in USD millions, ensuring consistency with global financial reporting conventions and facilitating direct integration into strategic planning models.
Application and Product Category Landscape
The report maps revenue distribution across hydraulic hoses, air and water hoses, suction and discharge hoses, chemical hoses, and food and beverage hoses, while simultaneously tracking demand intensity across oil and gas, construction and infrastructure, automotive, agriculture, mining, chemicals, and food and beverage applications. By presenting these dimensions as interlocking rather than independent, our analysis reveals how material selection, performance requirements, and end-market purchasing cycles interact to shape revenue concentration and growth velocity within each product and application stream. Readers gain visibility into which categories are structurally positioned for sustained expansion and which face margin compression, substitution risk, or regulatory headwinds.
Geographic Demand Architecture
Market activity spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa region, each exhibiting distinct procurement patterns, infrastructure development pacing, and industrial output profiles. Our geographic assessment avoids simplistic ranking exercises in favor of examining how regional industrial structures, trade flows, and local manufacturing capacity interact to produce divergent growth paths. This regional layering enables multinational operators to prioritize market entry timing, distribution investments, and localized product strategies with greater precision.
Competitive Position Mapping and Strategic Posture Assessment
The competitive landscape includes established multinational manufacturers and specialized fabricators whose strategic positioning, product breadth, and regional reach vary considerably. Our analysis profiles organizations including Parker Hannifin Corporation, Gates Corporation, Danfoss, Continental AG, Kuriyama of America, Inc., Flexaust Inc., Southeastern Hose, Inc., and NRP Jones, examining their product portfolios, operational focus areas, and apparent strategic emphasis on fluid transfer, pressure systems, and specialized industrial applications. Rather than providing static company descriptions, we assess how each player's portfolio architecture and market orientation suggest vulnerability to pricing pressure, capacity to capture premium specification opportunities, and likelihood of influencing industry standards adoption.
Supply Chain, Procurement, and Cost Drivers
Recognizing that input costs and logistics realities fundamentally affect commercial outcomes, the report integrates raw material pricing intelligence, production cost considerations, and procurement cycle dynamics into its strategic recommendations. By linking stainless steel and rubber pricing movements to segment margins and product substitution patterns, we equip procurement teams and finance leaders with the context needed to negotiate with suppliers, time purchases, and evaluate make-versus-buy decisions more effectively.
Competitive Dynamics: Concentration, Differentiation, and M&A Potential
Market concentration metrics indicate a moderately fragmented but increasingly competitive environment, with CR3 at 24.6 percent and CR5 at 26.2 percent. These figures signal that while no single entity commands dominant market control, the top tier of suppliers collectively holds meaningful share, and the distance between leading players and the broader tail of manufacturers remains structurally significant. For strategic planners, this concentration profile suggests several actionable implications. First, pricing power is unlikely to be exercised uniformly across the market, meaning that differentiation through application engineering, certification compliance, delivery reliability, and technical support will likely determine which suppliers succeed in capturing premium positions. Second, the moderate concentration leaves room for consolidation, partnership formation, and vertical integration moves that could alter competitive balances over the forecast horizon. Third, smaller and mid-tier fabricators that specialize in custom assemblies, oilfield applications, or niche material configurations may find opportunities to compete on responsiveness and engineering service rather than price alone, particularly as end-users increasingly prioritize specification integrity and operational safety.
The strategic posture of leading and mid-tier players reflects the broader tension between scale economies and specialization. Multinational manufacturers typically compete on portfolio breadth, international distribution reach, and alignment with major industrial standards, while regional or application-focused fabricators often emphasize custom engineering, rapid turnaround, and proximity to specific end markets. Our analysis examines how these strategies are likely to perform as raw material volatility persists and as regulatory updates such as EN 854:2026 raise the baseline for compliance. Companies that have invested in material science capabilities, certified manufacturing processes, and application-specific testing infrastructure are better positioned to defend margins and capture share from less differentiated competitors.
2026 Decision Framework: Translating Market Intelligence into Action
The report is designed to answer the strategic questions that matter most to enterprise decision makers in 2026 and beyond. Rather than offering generic observations, we structure the analysis around actionable decision points.
- Where should procurement and sourcing investments be directed given current raw material pricing, input volatility, and compliance-driven specification requirements?
- Which product categories and application segments present the most attractive risk-adjusted growth exposure over the 2026 to 2032 window, and how should capital allocation reflect those opportunities?
- How do geographic demand patterns affect distribution strategy, local manufacturing decisions, and market entry timing for both incumbent operators and new entrants?
- What competitive vulnerabilities and strengths are embedded in current supplier portfolios, and how should that assessment inform partnership, sourcing, and potential acquisition evaluations?
- In what ways do evolving standards and safety regulations reshape the total cost of ownership calculus for industrial hose systems, and which suppliers are best positioned to support compliance-driven purchasing requirements?
Each of these questions is addressed through integrated quantitative data, qualitative market assessment, and competitive profiling that together provide a coherent basis for strategic planning. Our objective is to enable leaders to move from uncertainty to structured decision making, using evidence that accounts for both near-term operating realities and longer-term structural trends.
Concluding Perspective
The industrial hose market in 2026 is defined by durable growth momentum, material cost complexity, regulatory refinement, and an active competitive landscape that rewards differentiation and technical capability. The trajectory from a 14,352.0 million USD base in 2025 toward an estimated 23,169.0 million USD by 2032 reflects an industry where sustained capital spending, infrastructure development, and fluid handling modernization converge to support demand. Yet beneath these headline figures lies a richer analytical environment, one in which product category dynamics, application-specific demand intensity, regional variation, cost-driven substitution, and competitive positioning collectively determine where value is created and retained. Our full Industrial Hose Market report delivers the detailed segmentation analysis, scenario modeling, competitive profiling, and procurement intelligence required to act on this complexity with confidence. For executives and strategic planners who need more than macro-level summaries, the complete study provides the resolution necessary to inform sourcing strategy, investment prioritization, partnership evaluation, and risk management through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pipe Joints Market Hits $228.6M in 2025, Projected to Reach $327.9M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Pipe Joints Market 2026-2032: Navigating Growth, Competition, and Regulatory Shifts
The global pipe joints market stands at a pivotal juncture as organizations prepare for the 2026 fiscal year and beyond. Infrastructure spending, industrial expansion, and evolving safety regulations are converging to reshape demand patterns across multiple sectors. For executives, procurement leaders, and strategic planners, the ability to anticipate these shifts is not merely an advantage, it is a necessity. Our latest Pipe Joints Market research delivers a comprehensive, data-driven blueprint designed to inform capital allocation, product positioning, and competitive strategy through 2032.
This insight briefing outlines the macro trajectory, competitive architecture, and emerging dynamics that will define the market landscape. It is structured to demonstrate the analytical rigor and actionable depth embedded in the full report, while intentionally reserving granular segmentation figures, regional breakdowns, and application-specific revenue allocations for the complete dataset available on our platform.
Macro Trajectory: A Resilient Growth Arc Across the Forecast Horizon
Drawing on historical performance from 2020 through 2025 and extending into a seven-year forecast period spanning 2026 to 2032, the market demonstrates a consistent upward trajectory. The overall revenue base, measured in USD millions, has progressed from 173.5 in 2020 to 181.33 in 2021, 187.78 in 2022, and 209.06 in 2023. The pace of expansion accelerated notably in 2024 and 2025, with recorded revenues of 209.42 and 228.6 respectively, reflecting stronger industrial activity, renewed construction momentum, and recovering supply chain conditions.
The forecast window projects sustained growth, with the market expected to reach 243.46 in 2026, followed by 255.59 in 2027, 269.9 in 2028, 290.04 in 2029, 293.41 in 2030, 308.93 in 2031, and a projected 327.9 by 2032. This pathway corresponds to a compound annual growth rate of 5.35 percent across the forecast horizon, signaling a market that is expanding at a steady, investable pace rather than experiencing volatile spikes. For strategic planners, this CAGR provides a reliable baseline for capacity planning, inventory forecasting, and long-term partnership structuring.
Importantly, the absolute scale of the market and the consistency of its growth underscore the foundational role that pipe joints and couplings play across critical infrastructure and industrial ecosystems. As organizations map their 2026 objectives, understanding how this trajectory aligns with regional development cycles, application-specific demand surges, and material cost normalization becomes a central component of scenario planning.
What the Report Delivers: Operational Content Designed for Execution
The full Pipe Joints Market study goes beyond top-line projections to equip decision-makers with structured, implementation-ready intelligence. The report is organized around several core analytical pillars, each calibrated to support distinct enterprise functions:
- Market sizing and forward modeling: Historical baselines and forecast pathways are presented with methodological transparency, enabling teams to anchor budgeting and demand planning in validated trajectories rather than speculative estimates.
- Segmentation architecture: The analysis dissects the market across product types, application verticals, and geographic regions. While aggregate growth signals are clear, the report provides the segmented context necessary to identify where demand is concentrating, which product categories are outpacing the broader curve, and how application-driven procurement patterns differ across industries.
- Competitive landscape and concentration metrics: Market structure is evaluated through concentration indicators, revealing the degree of fragmentation versus consolidation. This framework helps organizations assess entry barriers, partnership opportunities, and the strategic implications of operating in a market where the top three players hold a measured share and the top five maintain a slightly broader but still moderate footprint.
- Pricing and cost environment analysis: Unit economics are examined in the context of material inputs, manufacturing complexity, and specification tiers. The report situates price ranges for standard metal and alloy fittings within broader cost dynamics, giving procurement and pricing teams a reference frame for negotiations, margin planning, and make-versus-buy decisions.
- Regulatory and compliance mapping: Emerging codes and installation mandates are tracked to highlight how policy shifts influence material selection, approval workflows, and project timelines. This section is particularly relevant for firms operating in jurisdictions where nonmetallic joint specifications and manufacturer installation protocols are becoming more stringent.
- Recent industry developments and event intelligence: Product launches, trade show activity, and supplier announcements are synthesized to provide a live pulse on innovation cadence and market engagement. This ensures that strategy teams are aware of near-term product introductions and industry gatherings that may influence competitive positioning or procurement cycles.
Competitive Landscape: Key Players and the Structure of Market Participation
The pipe joints sector is characterized by a mix of established manufacturers, specialized engineering firms, and regional suppliers, each competing on dimensions such as joint integrity, installation efficiency, diameter range, and application-specific performance. The report profiles several core companies whose product portfolios and recent moves illustrate the competitive dynamics shaping the market.
Northwest Pipe Company, headquartered in Bellingham, Washington, focuses on engineered steel water pipe solutions with watertight joint systems, including its InfraShield® platform and custom mechanical couplings designed to preserve pipeline integrity under demanding service conditions. Victaulic, based in Easton, Pennsylvania, manufactures grooved mechanical pipe couplings and joining systems that emphasize faster, safer installation across industrial applications, and has continued to expand its fire protection portfolio with recent coupling introductions targeting rigid pipe joints in sprinkler systems. Teekay Couplings, operating from the United Kingdom, produces mechanical pipe couplings spanning a wide diameter range, with an emphasis on space, weight, and installation efficiency for diverse project requirements.
American Cast Iron Pipe Company, located in Birmingham, Alabama, offers restrained joint solutions such as Flex-Ring and Field Flex-Ring designs for ductile iron pipe, addressing endwise separation risks under thrust conditions. Holz Rubber Company, based in the United States, manufactures custom and standard expansion joints that absorb thermal movement and accommodate misalignment in piping systems, supporting reliability across variable operational environments.
These profiles are not isolated company snapshots; they are embedded within a broader concentration analysis that quantifies how market share is distributed and what that distribution implies for competitive strategy. In a market where the top three participants collectively hold approximately 22.8 percent and the top five reach roughly 28.5 percent, the landscape remains relatively fragmented at the top, leaving meaningful room for specialized players, regional specialists, and innovation-driven entrants to compete on performance, service, and application focus rather than scale alone.
Recent activity reinforces this dynamic. In early 2026, Victaulic introduced its style 009v FireLock coupling for rigid pipe joints in sprinkler systems, reflecting continued product development in fire protection and mechanical coupling segments. On the industry engagement front, Iran PIVEX held a January 2026 trade show featuring pipe joints and fittings from international suppliers, while the TUBE Trade Fair in Düsseldorf, scheduled for April 2026, is expected to showcase a broad array of pipe joints and coupling exhibitors. These events signal active supplier participation and sustained interest in cross-border sourcing, technology demonstration, and partnership formation.
Market Dynamics and Contextual Forces Shaping 2026 Decision-Making
Beyond sizing and competition, the research integrates the contextual forces that influence how the market behaves in practice. One notable development is the normalization of raw material costs. Steel prices for pipe joints and couplings are moderating in 2026 following earlier declines, as base metal costs stabilize. This shift has direct implications for manufacturing margins, supplier pricing strategies, and procurement timing, particularly for organizations that delayed purchasing decisions during periods of price volatility.
Pipe Joints Market
Artificial Joints Market
Regulatory evolution is equally consequential. The 2025 Ohio Fire Code mandates that nonmetallic pipe joints must be approved and installed in accordance with manufacturer instructions, reinforcing the importance of compliance documentation, approved product listings, and installer training. For firms operating in or supplying to jurisdictions with similar code trajectories, this type of requirement can affect product selection, project approval timelines, and the relative attractiveness of metallic versus nonmetallic joint solutions in specific applications.
Cost structures also vary meaningfully across specification tiers. General steel or metal pipe joints typically range from approximately USD 30 to over USD 200 per unit, while high-specification alloy fittings can reach between USD 500 and USD 2,000. These ranges illustrate how performance requirements, material grades, and application criticality drive pricing dispersion. For strategic planners, the key insight is that average market growth does not imply uniform profitability across all product categories; instead, value capture often depends on positioning within higher-specification segments, optimizing supply chain efficiency, or differentiating through installation reliability and joint performance.
Together, these dynamics create a market environment where growth is broad-based but execution is highly segmented. Companies that succeed in 2026 and beyond will be those that align their product portfolios with application demand, monitor material cost trends closely, and maintain agility in response to code changes and installation standards.
Why This Research Matters for 2026 Enterprise Decisions
As organizations finalize 2026 strategies, the pipe joints market presents both opportunity and complexity. The projected expansion from 243.46 in 2026 toward 327.9 by 2032, supported by a 5.35 percent CAGR, indicates that demand will continue to grow at a meaningful pace. however, growth at the aggregate level masks important variation across regions, product types, and end-use sectors. Without segmented visibility, companies risk overcommitting to underperforming categories, underestimating regional demand intensity, or misaligning pricing and inventory strategies with actual procurement behavior.
This research is designed to reduce that uncertainty. By combining macro forecasting with structured segmentation, competitive profiling, concentration metrics, and contextual intelligence on materials, regulation, and recent industry activity, the report provides a decision-ready framework for multiple functional teams:
- Strategy and corporate development: Evaluate where to invest, which application verticals offer the strongest near-term tailwinds, and how market concentration shapes partnership and acquisition logic.
- Sales and commercial leadership: Identify high-potential segments, tailor value propositions around joint integrity, installation efficiency, and compliance readiness, and align go-to-market plans with regional demand patterns.
- Procurement and supply chain: Time purchases in response to material cost normalization, assess supplier diversity and concentration risk, and benchmark unit economics against specification tiers.
- Product and engineering: Prioritize development toward mechanical coupling innovations, restrained joint technologies, expansion joint solutions, and fire protection systems where recent launches and trade show activity indicate active market interest.
The full report also contains the detailed regional and application-level segmentation data, granular revenue allocations, and deeper competitive benchmarking that are essential for precise planning. Those specifics are intentionally reserved for the complete dataset, ensuring that teams accessing the full study receive the uncompromised intelligence needed for targeted execution.
Looking Ahead: Positioning for Durable Advantage
The pipe joints market is not simply expanding; it is evolving in ways that reward precision, compliance awareness, and application-specific engineering. As steel costs stabilize, fire and installation codes tighten, and major suppliers continue to introduce specialized coupling and joint technologies, the competitive edge will belong to organizations that can translate market-level growth into segment-level action.
Our Pipe Joints Market research provides the foundation for that translation. It equips leadership with the historical context, forecast confidence, competitive structure, and dynamic intelligence required to make informed decisions throughout 2026 and across the remainder of the forecast period. For teams ready to move from high-level outlook to detailed planning, the complete report offers the segmentation depth, regional specificity, and application-level revenue context necessary to operationalize strategy with precision.
The 2026 market environment will reward those who prepare with data, act with segmentation discipline, and monitor the regulatory and material shifts that shape real-world demand. This study is built to support that preparation from the first strategic review through to execution.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the 2-in-1 Laptop Market: Navigating Growth, Disruption, and Competitive Realignment in 2026
The 2-in-1 laptop category has evolved from a niche premium segment into a foundational hardware architecture for modern computing. As form factors continue to blur the boundaries between productivity, creativity, and mobile workflows, enterprise buyers, channel partners, and OEM strategists require more than surface-level trend summaries. They need structured, forward-looking intelligence that connects macroeconomic trajectories, component-level disruptions, and competitive maneuvering into actionable decision frameworks. PW Consulting's latest market research on the 2-in-1 Laptops Market is built precisely for that purpose: to convert complex industry signals into clear strategic direction for 2026 and beyond.
The Strategic Imperative of a Data-Backed Market View
Over the past half-decade, the category has demonstrated consistent expansion, moving from a baseline of approximately 2,590 million USD in 2020 to an estimated 3,340 million USD in 2025. That progression reflects more than incremental demand; it signals a structural shift in how organizations and individual users evaluate device versatility, input flexibility, and display interactivity. The forecast window extending through 2032 projects a compound annual growth rate of 7.0 percent, with market valuation anticipated to reach roughly 5,357 million USD by the end of the period. These figures are not abstract statistics. They represent the scale of capital allocation, product roadmap prioritization, and regional capacity planning that stakeholders must address in the current planning cycle.
For executives evaluating portfolio investments, inventory commitments, or channel strategies, the key question is no longer whether the 2-in-1 category will continue to expand, but how growth will be distributed across architectures, use cases, and supply ecosystems. A 7.0 percent CAGR in a mature hardware segment suggests sustained transition rather than speculative hype. It implies that convertible and detachable designs are becoming default considerations in specific procurement segments, while also rewarding manufacturers that can align processor roadmaps, display technologies, and service models with evolving user expectations. PW Consulting's research translates this trajectory into a structured lens for scenario planning, allowing decision-makers to test assumptions against validated historical patterns and forward projections.
Report Architecture: From Macro Trajectory to Operational Readiness
The research is organized to support both strategic oversight and tactical execution. Rather than presenting a single narrative arc, the report decomposes the market into analyzable layers that reflect how real organizations make hardware decisions. The foundation rests on historical tracking from 2020 through the 2025 base year, followed by a forecast horizon spanning 2026 to 2032. This dual structure enables readers to benchmark recent performance, identify inflection points, and calibrate medium-term expectations with confidence.
Beyond top-line sizing, the report examines the architecture split between convertible and detachable designs, mapping how each form factor addresses distinct usage profiles, thermal constraints, and input preferences. It also assesses demand patterns across consumer and commercial environments, highlighting where procurement cycles, total cost of ownership calculations, and device longevity requirements diverge. Regional coverage is integrated as a strategic layer rather than a static table, allowing readers to understand how localized purchasing behavior, distribution maturity, and policy environments shape deployment velocity.
The analytical framework further incorporates competitive positioning, supply chain sensitivity, and technology adoption timing. Readers will find structured evaluations of product line breadth, feature differentiation, and go-to-market emphasis across leading manufacturers. Equally important, the report connects these commercial signals to upstream realities such as display and touch integration, semiconductor sourcing pressures, and tariff-driven cost dynamics. The objective is to give strategists a complete operating picture: what is selling, why it is selling, where production risk is accumulating, and which capabilities are most likely to determine market share in the next planning cycle.
Competitive Landscape: Architectural Diversification and AI-Enabled Positioning
The 2-in-1 laptop arena is defined by a concentrated group of established OEMs that are competing simultaneously on hardware versatility, display quality, processor integration, and software-enabled productivity. Market concentration remains high, with the top firms collectively commanding a substantial share of category revenue. This concentration does not imply stagnation. Instead, it reflects an intense competition over micro-differentiation: hinge engineering, touch and pen responsiveness, battery endurance, screen resolution and color accuracy, and increasingly, the integration of AI-centric processing capabilities.
Dell continues to maintain a broad convertible portfolio across mainstream and performance-oriented segments, pairing touch and pen-ready configurations with current-generation Intel Core Ultra platforms. Its lineup illustrates a pragmatic approach to the category: multiple screen sizes and price tiers, consistent enterprise serviceability, and clear positioning for users who need convertible flexibility without abandoning traditional laptop ergonomics.
HP has emphasized the intersection of manageability, display quality, and AI features, particularly in business-facing convertible lines. By combining OLED touchscreen options with AI-forward branding and enterprise-grade chassis design, HP targets procurement teams that want device versatility alongside security, manageability, and visual quality for presentation-heavy or content-review workflows.
ASUS has pursued a more segmented strategy, spanning creative-oriented convertibles, lightweight gaming-capable flip systems, business flip models, and Chromebook options. The breadth of its portfolio reflects a deliberate effort to capture different purchase motivations under one roof, from color-accurate displays for professional creators to 360-degree hinge designs for education and general productivity environments.
2-In-1 Laptops Market
Acer's presence in the category highlights value-conscious engineering and, more recently, a focus on next-generation processor platforms. Its convertible offerings span budget-friendly spin designs, business travel models, and AI-branded flip systems. This range demonstrates how aggressively the category is being extended into multiple price and performance bands, making 2-in-1 configurations accessible to a wider set of buyers.
Lenovo has leaned into the convergence of design refinement, OLED touchscreen adoption, and AI PC narratives. Its convertible and detachable-oriented lines target both premium consumer segments and commercial buyers seeking balanced ergonomics and modern input experiences. The emphasis on Copilot+ features and OLED implementation shows how manufacturers are using software and display quality as leverage in a category where hardware form factors are increasingly familiar to consumers.
Samsung has positioned its Galaxy Book 360 lineup around high-end display technology and integrated ecosystem appeal. With Super AMOLED touchscreens and Intel Core Ultra platforms, these devices reinforce the idea that 2-in-1 devices can serve as premium productivity and media tools rather than merely compromise form factors. The strategy aligns with a broader push toward visually rich, AI-capable devices that perform well in both tablet and laptop modes.
Microsoft remains a defining presence through its Surface line, particularly with detachable-oriented devices powered by advanced silicon options. Its high-end detachable offerings underscore the enduring relevance of detachables in scenarios where tablet-first usage, portability, and pen-based interaction take priority. At the same time, the broader competitive conversation shows that detachable and convertible designs are not interchangeable; each serves distinct workflow assumptions and purchase criteria.
Taken together, these players reveal a market where success depends less on announcing a new form factor and more on executing consistently across display quality, battery performance, thermal management, support ecosystems, and supply reliability. PW Consulting's research evaluates these competitive signals in a way that helps stakeholders identify where differentiation is genuine and where product narratives risk blending into commodity positioning.
Industry Dynamics: Supply Chain Realignment, Component Innovation, and Tariff-Driven Economics
The category's growth trajectory is unfolding against a backdrop of meaningful operational friction. Recent sector analysis points to tariff-related pressures and export restrictions affecting advanced semiconductor components, prompting manufacturers to diversify sourcing and accelerate localization strategies. These developments are not incremental conveniences; they reshape cost structures, lead-time expectations, and regional production planning. For 2-in-1 laptops, which depend on integrated display, touch, and processing ecosystems, any disruption in component availability can cascade quickly into product timing and margin performance.
Tariff actions and retaliatory measures from trade partners have added further complexity by raising production costs for consumer goods, including 2-in-1 laptops, with estimates indicating cost increases in a broad double-digit range. Alongside that, supply chain disruptions have become a recurring risk factor rather than an occasional exception. Semiconductor and display sourcing remain especially sensitive, and the U.S. General Services Administration has noted that such disruptions have translated into longer lead times and higher costs for critical laptop components. In a category where hinge design, touch integration, and thin-chassis thermal constraints already demand precise component coordination, these pressures can influence everything from bill-of-material planning to channel inventory strategy.
Gaming Laptop Market
Despite these headwinds, component-level innovation continues to open differentiation opportunities. Himax Technologies' move into mass production of OLED Touch IC for IT applications is a notable example. By enhancing integrated display and touch performance with industry-leading characteristics, such component advances can improve the user experience that manufacturers rely on to justify premium pricing and reinforce product identity. At the device level, recent introductions such as AI-focused convertible systems powered by next-generation Snapdragon platforms illustrate how manufacturers are translating NPU capability, extended battery life, and multi-monitor support into tangible value propositions. These product developments matter because they show that the category is still evolving in ways that go beyond hinge rotation or screen size alone.
For strategic planners, the implication is clear: market expansion is real, but it is being filtered through a more complicated operating environment. Revenue opportunity must be weighed against sourcing resilience, tariff exposure, logistics risk, and the cost of localizing or dual-sourcing critical inputs. PW Consulting's report addresses these tensions directly, giving readers a structured way to evaluate where demand is durable and where execution risk may erode expected returns.
Why This Research Matters for 2026 Decision-Making
In 2026, hardware strategy is no longer about forecasting a single growth curve. It is about aligning product mix, channel behavior, procurement expectations, and supply chain options within a market that is simultaneously expanding and fragmenting in its competitive logic. The 2-in-1 laptop category exemplifies this challenge. It offers clear long-term demand support, yet it also requires careful interpretation of form-factor preferences, commercial versus consumer buying patterns, regional purchasing conditions, and component-level constraints.
This research is designed to reduce uncertainty at exactly those decision points. It provides a disciplined framework for interpreting historical performance, evaluating forward projections, and understanding how competitive and operational variables interact. Readers gain clarity on where the market is heading in aggregate, how major players are positioning themselves, and which structural pressures are most likely to influence cost, availability, and differentiation in the near term. Just as importantly, the report is built to support internal discussion: it gives product leaders, procurement teams, channel strategists, and investors a common reference point for debating scenario outcomes and prioritizing investments.
The full study goes further than the overview presented here. It contains the detailed segmentation logic, competitive profiles, regional interpretations, and operational risk analysis needed to convert high-level market direction into executable plans. To access the complete dataset, segmentation breakdowns, and strategic recommendations underpinning this analysis, visit the source report page and obtain the full intelligence package. In a market where timing, positioning, and supply resilience determine competitive outcomes, that deeper view is the difference between reactive planning and confident strategic action.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports 5.55% CAGR for Progressing Cavity Pumps Market to Reach $2,036.03 Million by 2032
By PW Consulting, 2026-09-16
Navigating the Future of Fluid Handling: Strategic Insights from the Progressing Cavity Pumps Market Forecast 2026-2032
The global industrial landscape is undergoing a profound transformation driven by efficiency demands, regulatory shifts, and the relentless need for reliable fluid management solutions. For stakeholders in the progressing cavity pump (PCP) sector, the period from 2026 through 2032 represents a critical window of opportunity and challenge. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip leadership teams with the actionable intelligence required to navigate this evolving terrain.
As enterprises finalize their strategic roadmaps for the upcoming fiscal years, understanding the macroeconomic currents shaping the PCP market is no longer optional—it is imperative. This briefing serves as an introduction to our deep-dive analysis, outlining the trajectory of market growth, the competitive dynamics at play, and the operational variables that will define profitability in the years ahead. While this article provides a high-level overview of the strategic landscape, the full report contains the granular segmentation and proprietary data necessary for precise capital allocation and market entry strategies.
Market Trajectory and Growth Horizons
The progressing cavity pump market has demonstrated resilience and steady expansion over the past half-decade. Our analysis tracks performance from 2020 through the base year of 2025, providing a robust historical foundation for forecasting future trends. The market has grown consistently, driven by increased industrialization and the expanding application of PCP technology in demanding environments ranging from heavy oil extraction to precise food processing.
Looking toward the forecast period of 2026 to 2032, the momentum is expected to continue. The market is projected to reach significant revenue milestones by the end of the forecast window. This growth is not merely a function of inflation but reflects genuine adoption rates and technological modernization across key sectors. The compound annual growth rate (CAGR) indicates a steady upward trajectory, suggesting that demand for specialized fluid handling equipment will outpace broader industrial sluggishness in certain segments.
For strategic planners, these figures underscore the importance of timing. Entering or expanding within this market requires alignment with the growth curves identified in our study. The data suggests that while the early years of the forecast period may see moderate expansion, the later years present accelerated opportunities as infrastructure projects mature and new technologies gain widespread acceptance. Understanding the inflection points in this revenue curve is essential for optimizing inventory, production capacity, and investment timelines.
Segmentation Dynamics and Operational Drivers
The versatility of progressing cavity pumps is reflected in their diverse deployment across various configurations and end-use industries. Our research dissects the market into critical dimensions, including pump type and application sector. This segmentation is vital because growth is not uniform across all categories. Some configurations are experiencing faster adoption due to specific industry trends, such as the shift toward more efficient artificial lift methods in oilfields or the increasing stringent hygiene standards in food processing.
-
Technological Configurations
The market is categorized by stage configurations, each serving distinct performance requirements. Single-stage, double-stage, and four-stage pumps cater to different pressure and viscosity needs. Our analysis reveals how the balance among these configurations is shifting. For instance, higher-stage configurations may see increased demand in applications requiring greater head pressure, while single-stage units remain vital for specific low-pressure, high-flow scenarios. The choice of configuration directly impacts maintenance schedules and operational expenditure, making this segment analysis crucial for product portfolio planning.
-
Industry Applications
End-user application is a primary driver of demand. Key sectors include Oil and Gas, Water and Wastewater, Chemical and Petrochemical, Food and Beverage, and Others. Each sector presents unique challenges and regulatory requirements. The Oil and Gas sector continues to be a major contributor, particularly in artificial lift solutions where reliability in harsh downhole conditions is paramount. Simultaneously, the Water and Wastewater sector is gaining traction due to environmental regulations and the need for handling abrasive slurries and viscous fluids without degradation.
The Food and Beverage industry represents a high-growth niche where hygienic designs compliant with international standards are non-negotiable. Chemical processing also remains a steadfast consumer of PCP technology, driven by the need to handle shear-sensitive materials. Our report details the revenue contributions and growth rates of each application area, helping clients identify which verticals offer the highest return on investment for their specific capabilities.
Competitive Landscape and Strategic Positioning
The global PCP market is characterized by a mix of specialized manufacturers and diversified industrial giants. Market concentration metrics indicate a moderate level of consolidation, with the top three players holding a significant share, though ample room remains for niche competitors and regional specialists. Understanding the competitive hierarchy is essential for benchmarking performance and identifying partnership or acquisition opportunities.
Process Gas Compressor Market
Key Market Participants
Several companies define the current competitive landscape, each bringing distinct strengths to the table:
- PCM Group (France): A leader in progressing cavity pumps with a global presence in over 90 countries. Their portfolio includes the EcoMoineau MX, HyCare, and Moineau A series. Recent activities highlight their focus on oily water treatment and hygienic meat transfer solutions, showcasing adaptability across industrial and sanitary applications.
- NETZSCH Pumps & Systems (Germany): Recognized as a global leader in NEMO progressing cavity pumps. They serve chemical, environmental, mining, and oil and gas sectors. Recent innovations focus on hermetic seal upgrades that allow safer handling of toxic liquids without maintenance, addressing critical safety regulations.
- SEEPEX (Germany): A specialist in standard progressive cavity pumps, hopper pumps, and API 676 models. They are notable for integrating digital control systems, catering to abrasive, shear-sensitive, and viscous fluids across multiple industries.
- NOV Process & Flow Technologies (United States): Providers of Mono and Moyno technologies. Their emphasis lies in oilfield artificial lift, heavy oil, and high-sand applications, positioning them strongly within the energy extraction segment.
- Weatherford International (United States): Suppliers of PCP systems and artificial lift solutions tailored for oil and gas wells. They offer material options designed to withstand harsh downhole conditions, competing directly in the upstream energy space.
- ChampionX Corporation (United States): Developers of PCP pumping systems including SMARTEN VSD and HiCone models. Their focus is heavily oriented toward oilfield applications and artificial lift technologies.
- Sulzer Ltd (Switzerland): Providers of progressing cavity pump solutions for chemical processing, energy, and industrial sectors, leveraging a broad engineering heritage.
- Roto Pumps Limited (India): Manufacturers of high-pressure progressive cavity pumps for chemical, mining, wastewater, and power plant applications, representing strong growth potential in emerging markets.
- ITT Bornemann GmbH (Germany): Suppliers of Bornemann progressing cavity pumps focused on hygienic, sanitary, and industrial fluid handling, competing in the high-sanitation niche.
- Nova Rotors Srl (Italy): Producers of Diamond progressing cavity pumps and related grinders. Recent participation in food and beverage exhibitions underscores their commitment to this sector.
- Flexon-All Srl (Romania): Manufacturers of custom progressive cavity pumps with 22 standard types, offering flexibility for flows ranging from 1.6 to 135 m³/day.
Beyond the established giants, the landscape includes regional players who compete on customization and cost-efficiency. Strategic decisions regarding partnerships or market entry must consider the specific strengths of these competitors, such as NETZSCH's recent advancements in hermetic seals or PCM's focus on reducing maintenance downtime through maintenance-in-place designs.
Industry Dynamics and Risk Factors
No strategic plan is complete without a thorough assessment of the external forces that could impact operations. Our report integrates several critical dynamics that are currently shaping the PCP market environment. These factors influence not only the cost of goods sold but also the regulatory compliance burden and the overall value proposition offered to customers.
Supply Chain and Material Volatility
One of the most significant challenges facing manufacturers is the volatility of raw materials. The elastomer raw materials and specialized polymers used in stators are subject to price swings that can impact the bottom line. Industry data suggests these fluctuations can cause annual price variations touching double digits. Since stator costs can form a significant portion of the total pump value, even minor changes in material pricing can ripple through to final equipment costs. Furthermore, quarterly fluctuations of up to 15% in elastomeric stator materials have been observed due to supply chain factors. Effective procurement strategies and supplier diversification are therefore critical competencies for maintaining margin stability.
Regulatory and Safety Standards
Regulatory pressure is mounting, particularly regarding safety and hygiene. New hermetic seal upgrades for progressing cavity pumps are enabling safer handling of toxic liquids and gases without the need for frequent maintenance. This innovation aligns with stricter occupational health and safety regulations in chemical and energy sectors. Additionally, in the food and beverage sector, hygienic and sanitary progressing cavity pumps must comply with EHEDG and FDA standards. Compliance is not just a legal requirement but a competitive differentiator. Companies that fail to adapt to these standards risk losing access to high-value market segments.
Operational Efficiency and Labor Costs
Labor costs and downtime are persistent concerns for operators. Maintenance-in-place designs, such as those highlighted by PCM Group, reduce pump removal downtime and associated labor requirements. In an environment where skilled labor is increasingly scarce and expensive, equipment that minimizes intervention offers a compelling economic advantage. This trend is driving purchasing decisions toward technologies that promise longer service intervals and easier onsite maintenance. Strategic planners must weigh the initial capital expenditure against these long-term operational savings when evaluating market opportunities.
Strategic Implications for 2026 Decision Makers
As organizations move into 2026, the insights derived from this market research will inform several key strategic pillars. First, market entry and expansion decisions must be data-driven. Knowing which regions and applications are growing fastest allows for targeted marketing and distribution efforts. Second, product development roadmaps should align with the shifting demand between single-stage, double-stage, and four-stage configurations, as well as the increasing integration of digital controls and hermetic seals.
Progressing Cavity Pumps Market
Third, risk management strategies need to account for raw material volatility. Hedging strategies or long-term supply contracts may become necessary to protect margins. Finally, M&A activity remains a viable path for consolidation. With a moderate concentration level, there is potential for acquiring niche players to gain access to specific regional markets or application expertise, such as the hygienic food processing sector or high-sand oilfield applications.
Conclusion and Access to Full Intelligence
The Progressing Cavity Pumps Market is poised for steady growth, underpinned by industrial expansion and technological innovation. However, realizing value in this market requires more than a superficial understanding of global totals. It demands a deep grasp of segmentation shifts, competitive maneuvers, and the nuanced dynamics of supply chains and regulations.
This article has outlined the strategic framework and high-level trends defining the sector. Yet, the full depth of our analysis contains the specific segmentation data, regional breakdowns, and detailed company profiles necessary to build a robust business case. The complete report offers the granular intelligence required to validate assumptions and finalize investment decisions with confidence.
For executives and analysts seeking to secure a competitive advantage in the 2026-2032 period, PW Consulting's full market research report provides the essential toolkit. We invite you to access the complete study to unlock the detailed forecasts, segmentation splits, and strategic recommendations that will drive your organization's success in the evolving landscape of progressing cavity pump technology.
For detailed analysis of this topic, please visit the official page: Progressing Cavity Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Playground Turf Market Hits $187.7M in 2025, 7.54% CAGR to $309.6M by 2032
By PW Consulting, 2026-09-16
Beyond the Green Carpet: Strategic Insights for the Playground Artificial Grass Turf Market in 2026
Introduction: The Strategic Imperative for 2026
As the global landscape for recreational infrastructure evolves, the playground artificial grass turf market stands at a pivotal juncture. For stakeholders ranging from municipal planners to private manufacturers, understanding the trajectory of this sector is no longer optional; it is a critical component of risk management and capital allocation strategy. PW Consulting's latest market research study offers a comprehensive examination of this industry, designed to equip decision-makers with the intelligence required to navigate the complexities of the 2026 to 2032 forecast period.
This report is not merely a collection of figures. It is a strategic roadmap intended to clarify growth vectors, regulatory hurdles, and competitive pressures. By analyzing historical performance from 2020 through 2025 alongside forward-looking projections, organizations can better position themselves to capitalize on emerging opportunities while mitigating potential downsides. The following analysis highlights the key themes explored in our full study, demonstrating why this intelligence is vital for corporate strategy in the coming fiscal year.
Macro Market Overview: Growth Trajectory and Historical Context
The playground artificial grass turf sector has demonstrated remarkable resilience and expansion over the past half-decade. Historical data indicates a steady climb in market revenue, reflecting increased adoption rates across various recreational and educational settings. From a base market size in 2020, the industry has progressed through 2021 and 2022, continuing its upward trend into 2023, 2024, and reaching a significant valuation in 2025. This historical performance sets a robust foundation for the current outlook.
Looking toward the immediate future, the projected market size for 2026 represents a substantial increase from the previous year, signaling continued momentum. The forecast extends through 2032, offering a long-term view for infrastructure planning. The compound annual growth rate (CAGR) calculated for the 2026 to 2032 period stands at 7.54 percent. This growth rate is a key indicator of market health, suggesting that investment in this sector remains attractive despite broader economic fluctuations. Such top-line growth underscores the necessity for businesses to secure their supply chains and refine their product offerings to meet escalating demand.
Segmentation Dynamics: Type, Application, and Regional Nuances
Understanding where growth originates is just as important as knowing how much the market is growing. Our research dissects the market into primary segmentation categories, including product type and end-user application. While specific percentage breakdowns are reserved for the full dataset, we observe that certain synthetic materials dominate the landscape. The industry is primarily characterized by the use of polyolefin and polyester films, with other specialized types comprising a smaller portion of the total mix. The dominance of polyolefin film highlights the industry's preference for durability and safety features inherent in this material class.
In terms of application, the market is driven significantly by school playground installations. This segment represents a major revenue contributor, followed by public playground initiatives and other miscellaneous applications. The distinction between school and public sector demand is crucial for companies targeting specific procurement channels. Government-led public projects often have different bidding requirements compared to private school districts or residential complexes. Additionally, the report analyzes regional performance, noting that North America, Europe, and Asia Pacific represent the largest revenue centers. Each region presents unique growth drivers, from demographic shifts to urban development projects. Latin America and the Middle East and Africa also contribute to the global total, offering emerging opportunities for expansionist strategies.
Artificial Grass Turf Market
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is defined by a mix of established manufacturers and specialized producers who focus on certified quality and safety standards. Higher market concentration can be observed through metrics such as the CR3 and CR5 values, indicating that while the market is not a monopoly, key players hold significant influence. To achieve success, companies must differentiate themselves through product certification, innovation, and supply chain reliability.
Several core companies exemplify the standards required to thrive in this environment. Controlled Products, headquartered in Dalton, Georgia, operates as a vertically integrated manufacturer. They are known for producing IPEMA-certified playground artificial grass turf products. Their standard lines, such as PL929 and PL981, utilize specific thatch systems and fiber shapes like Omega and S-shaped fibers. They also offer private-label options for commercial playground applications, allowing partners to brand products appropriately. This vertical integration provides them with control over quality and cost structures.
Another significant player is XGrass, based in the United States. They specialize in manufacturing IPEMA-certified artificial grass playground surfacing systems. Their product portfolio includes lines such as XGrass Prime, Ultra Natural, and Premier Natural. A key feature of their offerings is the inclusion of PolyGreen shock-absorbing foam padding and antimicrobial infill. These features address critical safety and hygiene concerns, which are paramount for facilities hosting children.
Smart Turf is also a prominent manufacturer in the space, with operations in the USA. They focus on playground artificial grass turf featuring built-in Microban antimicrobial technology. This is specifically designed for heavy-traffic contact sports and playground areas. The inclusion of antimicrobial technology responds to growing health and safety expectations, making their products suitable for high-use environments. These companies illustrate the market demand for certified, safety-focused products that withstand rigorous use.
Industry Dynamics: Regulation, Materials, and Standards
Dynamic regulatory changes are reshaping the operational landscape for manufacturers and suppliers. Compliance is no longer a static requirement but an evolving process that requires constant monitoring. A critical regulation involves IPEMA certification, which is required for commercial playground surfacing systems using artificial grass to meet ASTM F1292 impact attenuation standards. This standard ensures that the surfacing adequately cushions falls, reducing the risk of serious injury. Manufacturers must maintain this certification to access commercial contracts, making compliance a gatekeeper for revenue streams in the public and institutional sectors.
On the materials side, the construction of playground artificial grass turf is primarily based on polyethylene fibers. This material choice is driven by performance characteristics and cost considerations. Industry data suggests that polyethylene-based playground turf materials cost between $2.20 and $4.10 per square foot. Managing raw material costs within this range is essential for maintaining margin health. Fluctuations in raw material pricing or supply availability can directly impact the final cost to consumers and the profitability of installers and manufacturers.
Recent developments highlight the increasing focus on chemical safety and standardized testing. In May 2026, the Synthetic Turf Council published a new ASTM F3782-26 standard for sampling and testing synthetic turf fiber and fabric for the presence of PFAS. This certification achievement represents a shift toward greater transparency and environmental responsibility. The standard provides a standardized practice for sampling and testing synthetic turf for these per- and polyfluoroalkyl substances. Compliance with ASTM F3782-26 will likely become a differentiator for brands seeking to appeal to environmentally conscious consumers and regulators. Businesses must anticipate how these testing protocols will affect production processes and supply chain sourcing.
Strategic Value for Decision Makers
Access to detailed market intelligence provides a distinct advantage in strategic planning. For corporate leaders and investors, the full report offers proprietary data that goes beyond public summaries. The value of this research lies in its granularity and actionable insights. While high-level figures provide context, the detailed segmentation splits and company-specific analyses allow for precise scenario planning.
Understanding the specific revenue contributions of regions like North America or Asia Pacific, along with the exact market shares of application segments such as school versus public playgrounds, enables targeted marketing and distribution strategies. Knowing the precise market concentration metrics helps in evaluating market entry barriers and merger acquisition opportunities. Furthermore, the detailed breakdown of material costs and regulatory timelines allows operations teams to budget more accurately for the 2026 fiscal year and beyond.
Playground Artificial Grass Turf Market
The report also serves as a benchmark for performance. Companies can compare their internal growth metrics and regional penetration against the industry averages provided. This benchmarking is essential for setting realistic KPIs and adjusting strategic goals. In a market growing at nearly 8 percent annually, missing a trend or misinterpreting a regulatory shift can result in lost market share. The insights contained in this study are designed to prevent such oversights.
Conclusion: Navigating the Future
The playground artificial grass turf market presents a landscape of opportunity tempered by regulatory complexity. With a forecast period extending to 2032 and a strong growth trajectory established from 2020 to 2025, the sector is poised for continued expansion. However, success in 2026 and beyond will depend on the ability to adapt to new standards like ASTM F3782-26, manage material costs, and compete effectively against landscape leaders.
PW Consulting's Playground Artificial Grass Turf Market Research delivers the depth required to make informed decisions. By integrating historical data, future projections, and a detailed analysis of competitive and regulatory dynamics, this study provides the comprehensive view necessary for long-term planning. For organizations ready to move beyond surface-level information, the full report offers the critical intelligence needed to harness the momentum of this evolving market. We invite you to explore the complete findings to secure the strategic advantage you need.
For detailed analysis of this topic, please visit the official page: Playground Artificial Grass Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: UHPC Market to Hit $831 Million by 2032, Growing at 7.6% CAGR
By PW Consulting, 2026-09-16
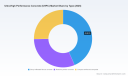
Strategic Intelligence Report: The Ultra-High Performance Concrete (UHPC) Market Outlook 2026-2032
Executive Summary: Navigating the Next Frontier in Construction Materials
The construction materials sector is undergoing a paradigm shift where performance metrics dictate strategic investment more than ever before. As we move into 2026, the Ultra-High Performance Concrete (UHPC) Market stands at a critical inflection point, driven by infrastructure modernization, sustainability mandates, and the growing demand for durable, high-strength materials. PW Consulting's latest comprehensive study, Ultra-High Performance Concrete (UHPC) Market, offers a definitive guide for stakeholders aiming to capitalize on this evolution. This article serves as a strategic preview, outlining the macro-economic currents and competitive dynamics that will define the sector, while underscoring the necessity of deep-dive data for precise decision-making.
Market Trajectory: From Resilience to Robust Growth
Understanding the historical context is vital for forecasting future potential. The UHPC market has demonstrated remarkable resilience and consistent expansion over the past half-decade. Starting from a base of approximately 340.0 Million USD in 2020, the market has navigated supply chain complexities and economic fluctuations to reach an estimated 500.0 Million USD by 2025. This historical trajectory underscores a compound annual growth rate momentum that stakeholders cannot ignore.
Looking ahead, the forecast period from 2026 to 2032 projects an even more aggressive expansion curve. The market is anticipated to surpass the 552.99 Million USD mark in 2026, gradually accelerating towards a projected value of 831.0 Million USD by 2032. This growth narrative is underpinned by a CAGR of 7.6% throughout the forecast window. Such figures indicate not just recovery, but a structural shift in how critical infrastructure and high-performance building projects are specified and executed. For corporate strategists, these macro-indicators signal a widening window of opportunity, though the specific allocation of capital across regions and applications requires granular analysis available in the full report.
Segmentation Dynamics: Types, Applications, and Geography
The UHPC ecosystem is not monolithic; it is a complex tapestry of specialized technologies and diverse use cases. The market is segmented by type, reflecting the varying technological formulations that engineers and contractors select based on specific project requirements. Key categories include Slurry-infiltrated fibrous concrete, Reactive powder concrete, and Compact reinforced composite. Each type offers distinct advantages in terms of compressive strength, durability, and ease of application, influencing procurement strategies across different sectors.
Fiber Reinforced Concrete (FRC) Market
Applications further diversify the market landscape. Road and bridge construction remains a dominant driver, leveraging UHPC for its longevity and load-bearing capabilities. Building construction follows as a significant segment, where architectural aesthetics and structural safety converge. Additionally, niche but high-value sectors such as military construction and other specialized industrial applications contribute to the overall demand mix. Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. While aggregate figures suggest a balanced global interest, regional infrastructure spending bills, regulatory environments, and local manufacturing capabilities create unique micro-markets that require detailed scrutiny to identify high-yield entry points.
Competitive Landscape: Key Players and Strategic Positioning
The UHPC market is characterized by a moderately concentrated competitive structure, with major players leveraging proprietary technologies and extensive distribution networks. Our analysis identifies several key companies that are shaping the industry standards and consumer preferences. Holcim, through its Ductal brand, maintains a strong focus on proprietary UHPC solutions for bridge preservation, precast elements, and architectural applications, utilizing patented fiber-reinforced formulations. Similarly, Sika AG offers a robust UHPC pre-blend product line specifically tailored for bridge and infrastructure construction, emphasizing reliability and ease of use for contractors.
BASF SE continues to be a pivotal force with its Master Builders Solutions, providing UHPC admixtures and specialized mixes for high-performance applications. In the United States, GCP Applied Technologies focuses on specialty admixtures enabling UHPC production for infrastructure and precast segments. RAMPF Holding GmbH & Co. KG differentiates itself with EPUDUR® UHPC systems designed for machine beds, components, and high-precision applications, catering to industrial needs beyond traditional construction.
Other notable contenders include Cor-Tuf LLC, a licensed producer using American-made formulations for infrastructure, precast, and utility projects, and Densit ApS, which provides engineered UHPC solutions like Ducorit® for industrial strengthening, oil & gas, and offshore applications. CeEntek Pte Ltd is gaining attention for UHPC 2.0™ with carbon nano-fiber enhancement, targeting low-carbon, cost-effective production for bridge connections and architectural panels. In the Middle East, Gulf Precast Concrete Co. LLC supplies UHPC concrete products for bridges and architectural cladding, while Steelike UHPC focuses on all-white UHPC for architectural, ballistic, and non-bridge applications with enhanced durability.
The competitive dynamics are further intensified by recent strategic moves. For instance, LafargeHolcim has recently launched Ductal Eco UHPC with approximately 40% lower carbon footprint, signaling a strong industry pivot towards sustainability without compromising performance. Such developments highlight the need for stakeholders to monitor not just pricing, but also technological innovation and environmental compliance as key differentiators.
Market Dynamics: Regulations, Innovations, and Recent Developments
Regulatory frameworks and standardization bodies play a crucial role in legitimizing and accelerating UHPC adoption. In July 2025, ASTM International published a proposed test method standard to determine whether FRC or UHPC mixtures meet the required quality for their intended structural performance. This standardization effort reduces ambiguity for engineers and insurers, potentially lowering barriers to entry for broader application.
Government-led initiatives are equally influential. Under the EDC-6 initiative, the Federal Highway Administration promoted UHPC for bridge preservation and repair, including steel beam end repairs, link slabs, and bridge deck overlays. A notable milestone occurred in February 2025, when the Virginia Department of Transportation executed the first U.S. sprayable UHPC application for bridge abutment repair on the I-495 Capitol Beltway. This event, promoted under EDC-6 for bridge preservation, validates sprayable technologies as a viable method for rapid rehabilitation.
Technological innovation remains rapid. In December 2025, LafargeHolcim introduced spray-applied UHPC technology via its UHPC Technologies division for rapid bridge rehabilitation, complementing its earlier eco-friendly product launch. These developments suggest a dual trend: the push for faster construction methods and the imperative for lower carbon emissions. For investors and project managers, these dynamics imply that supply chains must adapt to new delivery formats and performance criteria.
Ultra-High Performance Concrete (UHPC) Market
Strategic Implications for 2026 Decision Makers
As we enter 2026, the strategic implications of the UHPC market growth are profound. The projected revenue growth from 552.99 Million USD in 2026 to over 831.0 Million USD by 2032 indicates a maturing market where early movers can secure significant market share. However, success depends on nuanced understanding rather than broad assumptions. The concentration of the market, with CR3 percent around 62.8 and CR5 percent at 74.5, suggests that while large players dominate, there is room for specialized entrants who can address specific regional or application-based needs.
Decision-makers must consider how sustainability mandates will alter procurement criteria. The shift towards lower carbon footprint formulations, as seen with recent product launches, will likely become a standard requirement rather than a differentiator. Furthermore, the adoption of sprayable technologies opens new logistical and application service opportunities. Companies involved in infrastructure maintenance, precast manufacturing, or architectural design must evaluate their supply chain readiness for these advanced material forms.
Risk management also comes into play. Dependence on key regions or specific application sectors without diversification could expose firms to volatility. The detailed segmentation analysis in our full report provides the granular data necessary to mitigate such risks, revealing which sub-segments offer the highest stability and growth potential.
Conclusion: The Value of Deep-Dive Intelligence
The Ultra-High Performance Concrete (UHPC) Market is poised for significant expansion, driven by a confluence of infrastructure needs, technological innovation, and regulatory support. While the macro indicators point to a healthy 7.6% CAGR and a market value approaching 831.0 Million USD by 2032, the true strategic value lies in the details. Understanding the specific growth rates of slurry-infiltrated versus reactive powder concrete, or the nuanced demand shifts in bridge construction versus architectural panels across different continents, requires access to the full dataset.
PW Consulting's report goes beyond these headlines to provide actionable intelligence. It dissects the competitive maneuvers of key players like Ductal, Sika, BASF, and emerging innovators, offering a roadmap for positioning your enterprise. It analyzes the impact of ASTM standards and FHWA promotions on market velocity. For leaders who need to move beyond general trends and into specific investment planning, product development, or market entry strategies, this research is an indispensable tool. We invite you to explore the full study to unlock the comprehensive data tables, regional breakdowns, and competitive profiles that will refine your 2026 roadmap.
For detailed analysis of this topic, please visit the official page: Ultra-High Performance Concrete (UHPC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Audio Speakers Market to Reach USD 10,270M by 2032 with 7.21% CAGR
By PW Consulting, 2026-09-16
Navigating the Sonic Shift: Strategic Intelligence for the Global Car Audio Speakers Market (2026–2032)
The automotive sound landscape is undergoing a structural transformation. No longer confined to premium afterthought installations, car audio speakers have evolved into a critical interface between vehicle architecture, electrification, and consumer expectations for immersive in-cabin experiences. As OEMs reconfigure cabin layouts for battery packs and digital cockpits, and as aftermarket buyers demand plug-and-play fidelity, the strategic imperative for suppliers, distributors, and automotive tier-1s has never been clearer. Our latest Car Audio Speakers Market research was built to cut through cycle-driven noise and equip leadership teams with decision-grade intelligence for the 2026–2032 horizon.
The historical trajectory through 2025 establishes a resilient upward arc, with the market expanding from a baseline of approximately $4,150 million in 2020 to an estimated $6,310 million by the base year. This progression reflects sustained consumer spending on cabin personalization, iterative OEM integration programs, and the gradual migration of high-fidelity audio architectures into mainstream vehicle segments. Looking forward, our forecast models project the market to reach roughly $6,776 million in 2026 and continue ascending toward the $10,270 million mark by 2032, supported by a compound annual growth rate of 7.21%. These figures are not isolated rallying points; they are calibrated indicators of how macroeconomic demand, vehicle electrification, and component-level innovation are converging. For executives, the strategic value lies in understanding what drives that trajectory at the granular level—where volume grows, where margin pressure accelerates, and where competitive positioning must shift before consensus forms.
Architectural Shifts and Product Portfolio Mapping
Modern vehicle cabins are being re-engineered around acoustic performance as a differentiator. The transition toward digital signal processing, active noise management, and higher-amp electrical architectures in electrified platforms is reshaping speaker requirements. Our report dissects the product taxonomy that suppliers and buyers are currently negotiating, including component architectures engineered for discrete placement and acoustic precision, coaxial configurations favored for space-constrained retrofits and factory integration, and dedicated low-frequency reinforcement units that anchor premium listening profiles. Each branch carries distinct engineering trade-offs, installation complexity, and value-chain economics. Rather than treating these categories as static buckets, the research maps their adoption curves against vehicle platform types, retrofit versus OEM supply chains, and regional installation customs. This allows product planners to anticipate which form factors will absorb incremental demand, where crossover opportunities exist, and how to sequence R&D investments without overcommitting to trailing technologies.
Regional Demand Vectors Without the Noise
Geography remains a decisive variable in pricing power, channel reach, and competitive intensity. The analysis segments the global footprint into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, treating each not as a uniform revenue pool but as a distinct operating theater. Asia Pacific’s scale reflects the compounding effect of vehicle production volume, urban mobility transitions, and rapidly maturing aftermarket ecosystems. North America and Europe continue to anchor premium upgrade demand and regulatory-driven cabin refinement programs, while Latin America and the Middle East & Africa present specialized growth pockets shaped by fleet composition, import-channel dynamics, and localized installation cultures. Our methodology deliberately avoids flattening these markets into simplistic share percentages. Instead, the report pairs demand density assessment with channel-access friction, regulatory readiness, and supplier footprint strategy, enabling regional directors to prioritize go-to-market sequencing and inventory placement with greater fidelity.
Competitive Architecture and the Tactical Response Window
The market is concentrated enough to reward disciplined positioning but fragmented enough to punish reactive strategies. Top-tier players hold meaningful share, yet the remaining landscape is defined by specialized engineering pedigrees, channel leverage, and speed of platform integration. The research profiles the strategic posture and product signaling of defining organizations, including Pioneer Electronics Corporation’s tiered speaker families built for factory and upgrade pathways; Alpine Electronics Inc.’s integration-focused series designed to bridge factory radios and aftermarket upgrades; Rockford Fosgate’s high-power handling lines engineered for clean sound reproduction; JL Audio’s high-power, durability-oriented speaker options with marine-grade lineage; Sony Corporation’s high-resolution mobile audio offerings emphasizing clarity and accurate bass response; Focal JM Lab’s plug-and-play high-fidelity integration systems for OEM and aftermarket vehicles; and Hertz Car Audio’s premium lines emphasizing timbre accuracy, power handling, and refined sound quality. These profiles are not static brochures; they are competitive coordinates. The report evaluates how each player’s portfolio architecture aligns with shifting OEM requirements, aftermarket installer preferences, and pricing tolerances.
Recent product and pricing signals reinforce the need for faster decision cycles. In March 2026, Pioneer Electronics announced a flagship SPHERA car audio system with updated speaker integration aimed at total interior refresh programs. By mid-2026, Hertz Audio expanded its HEX family with new 4-inch models tailored for compact installations while preserving full HEX performance characteristics, and introduced HMX SPORT.2 models featuring advanced sports audio tuning. In the prior year, Sony Corporation broadened its GS car speaker and subwoofer lineup, extending model coverage across multiple form factors and power classes. Together, these moves illustrate an industry accelerating toward differentiated acoustic tuning, form-factor optimization, and platform-specific integration. The market study translates such announcements into strategic implication: where competitors are likely to contest share, which performance attributes are becoming table stakes, and where white space remains for suppliers willing to invest ahead of the curve.
Car Amplifiers Market
Trade Policy, Supply Pressure, and Pricing Architecture
External environment shifts are no longer peripheral; they are now embedded in cost structures and channel strategy. Leading suppliers have adjusted pricing as tariff exposure and trade-policy volatility affect import economics for automotive electronics. Raised pricing on car audio products, tariff refunds arriving alongside new imposed measures, and higher effective duties on components of certain origins have all contributed to elevated landed costs for downstream products. Simultaneously, supply-chain pressure on critical component categories has prompted additional price adjustments across multiple suppliers. These dynamics create a pricing environment where cost pass-through strategies, sourcing diversification, and inventory timing can determine margin retention. Our report does not stop at describing these pressures. It connects them to scenario-based pricing models, margin sensitivity analysis, and sourcing risk mapping so that procurement leaders and commercial teams can simulate exposure, stress-test price ladders, and identify where contractual or channel adjustments may protect profitability during volatile import cycles.
Report Roadmap: Operational Tools for 2026 Decision Cycles
The intelligence in this study is structured for immediate deployment. Beyond macro sizing and forecast lines, the report delivers an operational toolkit designed for cross-functional use. Core deliverables include:
- Product and technology mapping across speaker categories, with emphasis on integration readiness, installation complexity, and performance differentiation
- Demand-driver analysis by vehicle type, linking passenger vehicle cabin upgrades, commercial vehicle fleet considerations, and electrified platform acoustic requirements to volume potential
- Channel and pricing dynamics assessment, including tariff impacts, landed-cost shifts, and supplier pricing responses across key distribution pathways
- Competitive posture reviews that connect product portfolio moves, recent launches, and integration positioning to likely share contests and white-space opportunities
- Scenario planning modules that test growth trajectories under alternative supply, trade, and adoption conditions, helping teams size risk and adjust investment sequencing
Each section is built to answer a practical question: where should R&D capital be allocated, which OEM and aftermarket segments warrant deeper channel investment, how should commercial teams adjust pricing and sourcing in response to external cost shocks, and what time horizon should be used to evaluate competitive threats before they become visible in market share data. The research is calibrated for executive review, product strategy sessions, and commercial planning workshops alike.
Car Audio Speakers Market
Why This Matters Now
The 2026 decision window is defined by convergence. Electrification is altering cabin architecture and power availability. Digital signal processing and tuning sophistication are raising the performance floor. Trade and sourcing disruptions are compressing margin flexibility. And consumer expectations are increasingly shaped by high-fidelity listening experiences that do not stop at the factory floor. In this environment, organizations that rely on lagging indicators or fragmented assumptions risk misallocating resources into declining niches while competitors claim positioning in higher-growth, higher-margin segments. Our report is designed to replace inference with evidence, narrative with analytical structure, and reaction with preparation. The headline trajectory to 2032 is clear. The operational pathway to capturing disproportionate value within that trajectory requires deeper segmentation, competitive benchmarking, and scenario-tested strategy. That is precisely what this study is built to provide.
For leadership teams evaluating product roadmaps, channel investment, and commercial positioning in the current cycle, the full report offers the granular segmentation, competitive mapping, and strategic scenarios necessary to move from awareness to action. The complete intelligence package, including detailed segmentation analysis, company profiles, pricing-tariff implications, and scenario planning tools, is available through the full market study available on our site.
For detailed analysis of this topic, please visit the official page: Car Audio Speakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


