



PW Consulting: Face Recognition Market Hits $3.65B in 2025, Projects 14.5% CAGR to $9.36B by 2032
By PW Consulting, 2026-09-16
Navigating the Face Recognition Systems Market: Strategic Intelligence for Enterprise Decision-Makers in 2026
Executive Perspective
The face recognition systems market has transitioned from an emerging technology category into a foundational infrastructure layer for enterprise security, identity verification, and operational efficiency. As organizations across sectors reassess their technology portfolios in the wake of shifting regulatory frameworks and accelerated AI maturity, the need for precise, forward-looking market intelligence has never been more critical. This industry insight introduces our latest comprehensive study on the Face Recognition Systems Market, a research product designed specifically for executives who must align technology investment with strategic growth trajectories through 2032.
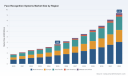
The macroeconomic trajectory underscores the magnitude of this opportunity. From a base valuation of $3.65 billion in 2025, the market is projected to exceed $9.36 billion by 2032, expanding at a compound annual growth rate of 14.5 percent. These figures represent more than raw revenue projections; they signal a structural shift in how enterprises deploy biometric identification, allocate capital toward hardware-software integration, and navigate an increasingly complex competitive landscape. The research accompanying this overview translates these high-level trends into actionable intelligence, enabling leadership teams to separate signal from noise and make informed commitments in a crowded technology ecosystem.
Macro Demand Landscape and Growth Drivers
Market expansion over the past half-decade has been consistently robust. Revenue climbed from $1.8 billion in 2020 through successive annual increases, surpassing the $3 billion threshold by 2024 and reaching $3.65 billion at the 2025 mark. The momentum is expected to maintain its upward trajectory, with forward estimates indicating sustained double-digit growth each year through the end of the forecast window. This growth profile reflects the compounding effect of multiple reinforcing demand drivers rather than reliance on a single deployment vertical.
Enterprise adoption is being accelerated by the convergence of three core catalysts. First, organizations are prioritizing physical access control and identity verification as part of broader zero-trust security architectures. Second, public sector programs continue to expand facial recognition deployments for border management, law enforcement support, and national identity initiatives, creating durable procurement pipelines that stimulate both hardware and software innovation. Third, algorithmic accuracy improvements, supported by standardized evaluation frameworks and computational advances, are lowering the perceived risk profile for enterprise consumers who previously hesitated due to performance or demographic bias concerns.
Hardware and computational requirements add another layer of strategic consideration for procurement teams. High-accuracy identification workflows increasingly depend on GPU or NPU acceleration to sustain performance at scale, while CPU-only configurations are generally constrained to lightweight models with reduced matching fidelity. Understanding where a given deployment falls on this hardware spectrum directly affects total cost of ownership, integration timelines, and long-term scalability. Our research examines these technical interdependencies in detail, providing IT architects and procurement leaders with the context needed to evaluate vendor proposals against realistic infrastructure assumptions.
Regulatory Architecture and Compliance Realities
Any forward-looking market strategy must account for the evolving regulatory environment that shapes procurement approvals, deployment boundaries, and data governance obligations. Regulatory activity across major jurisdictions has intensified, and the cumulative effect is reshaping how vendors position their platforms and how enterprises structure their risk assessments.
In the United States, the Facial Recognition Act of 2025 requires law enforcement agencies using facial recognition technology to undergo annual accuracy and bias testing conducted by NIST, establishing a new baseline for accountability in public sector deployments. State-level mandates add further complexity, such as Virginia law requiring approval for facial recognition technology utilization by local governments, effective July 1, 2026. These domestic requirements create a patchwork that enterprise vendors must navigate carefully, particularly when offering cross-jurisdictional services or multi-agency platforms.
International frameworks introduce additional compliance dimensions. The European Union AI Act classifies real-time facial recognition in public spaces for law enforcement as high-risk, with prohibitions unless authorized for important public security reasons, effectively shaping market participation rules for vendors operating in or serving EU territories. Meanwhile, China's Provisions on Security Management in the Application of Facial Recognition Technology took effect June 1, 2025, establishing data security requirements that influence product design, data handling protocols, and partnership structures within one of the world's largest deployment markets.
Our analysis treats regulatory dynamics not as peripheral background information but as strategic variables that affect pricing power, go-to-market timelines, and competitive differentiation. Companies that integrate compliance readiness into their product roadmaps and contract structures can convert regulatory complexity into barriers to entry, while those that treat it as an afterthought risk stalled deployments and reputational exposure.
Competitive Field and Differentiation Vectors
The competitive environment reflects a mix of specialized biometric technology providers, large industrial technology firms, and AI-native algorithm developers. Market concentration remains pronounced, which has direct implications for procurement leverage, partnership options, and the feasibility of vendor diversification strategies. Understanding the positioning of leading players helps organizations assess where consolidation pressure is strongest and where niche differentiation still creates room for specialized suppliers.
Several firms illustrate the diversity of competitive strategies currently shaping the market. Clearview AI provides facial recognition platforms and commercial access to large-scale image databases for law enforcement, border control, and investigative applications. Its recent track record includes a one-year contract valued at $225,000 with U.S. Customs and Border Protection for facial recognition services in border screening and tactical targeting, alongside a SOC 2 attestation with zero exceptions validating data security and privacy standards. These developments reflect a dual emphasis on operational scale and compliance credibility.
Face Recognition Device Market
NEC Corporation offers NeoFace facial recognition systems and platforms for public safety, law enforcement, and national ID programs. Its technology has been recognized as ranked the world's most accurate in the latest NIST FRTE 1:N identification test using a 12 million person database, an achievement that highlights the competitive importance of benchmark performance in government and high-stakes enterprise procurement. IDEMIA, headquartered in Paris, delivers biometric identification solutions including facial recognition for border control, law enforcement, and government identity programs, while Thales Group provides facial recognition and biometric systems for law enforcement, aviation security, and public safety applications. These two European-based organizations underscore the strategic role of government-adjacent identity infrastructure in sustained demand.
On the industrial and machine vision side, Cognex Corporation manufactures and sells machine vision and 3D vision systems integrated with facial recognition for industrial, security, and access control uses, demonstrating how recognition capability is increasingly embedded within broader automation ecosystems. Panasonic supplies facial recognition hardware and software solutions for surveillance, access control, and border security, reinforcing the hardware-software integration thesis across multiple deployment settings.
AI-native companies are pursuing differentiation through algorithmic precision and responsible deployment framing. Paravision develops and commercializes AI-powered facial recognition algorithms optimized for accuracy and ethical deployment in enterprise and security sectors, a positioning that aligns with growing procurement emphasis on bias performance and governance assurances. On the Asia-Pacific side, SenseTime Group offers facial recognition and AI vision systems deployed in smart cities, law enforcement, and public security applications, while Megvii Technology develops Face++ facial recognition technology and platforms for identity verification, security, and commercial use. Both illustrate how regional deployment ecosystems and large-scale public security programs shape product roadmaps and commercial scale.
Testing Benchmarks and Performance Standards as Market Signals
Independent evaluation frameworks increasingly function as market signals that influence purchasing decisions, vendor comparisons, and product development priorities. NIST activity in 2026 underscores the centrality of standardized testing to market confidence. In January 2026, NIST issued an FRTE 1:1 report with comprehensive accuracy metrics including demographic performance and provisional duration updates for algorithms submitted since September 2025. In May 2026, NIST released an updated FRTE 1:1 Verification report with participation statistics and performance benchmarks across algorithms. These recurring updates give procurement teams and technical evaluators a structured basis for comparing vendor claims against reproducible performance data.
For enterprise strategists, benchmark performance is not merely a technical metric; it is a procurement catalyst that can shorten evaluation cycles, support internal approval processes, and reduce perceived deployment risk. At the same time, performance claims must be evaluated in the context of specific use cases, population demographics, environmental conditions, and matching configurations. Our research dissects how testing outcomes translate into commercial messaging, where benchmark leadership translates into procurement advantage, and where gaps between test conditions and operational realities create opportunities for differentiated positioning.
Applied Deployment Domains and Segment Considerations
Demand is distributed across multiple functional applications, each with distinct performance requirements, procurement rhythms, and integration constraints. Access control remains a dominant use case, driven by organizations seeking to replace or augment physical credentialing systems with biometric verification that reduces credential leakage and streamlines entry workflows. Security and surveillance applications extend recognition capability into broader monitoring and situational awareness contexts, where throughput, false-positive tolerance, and operator support requirements shape system selection. Face identification use cases, including 1:1 verification and 1:N identification workflows, introduce different computational demands and accuracy expectations, and they often intersect with compliance frameworks that vary by jurisdiction and end-user type.
Technology architecture choices further influence competitive positioning and procurement decisions. Decision-makers must evaluate the trade-offs across recognition modalities and understand how each maps to cost, accuracy, and deployment environment. The shift from single-modality deployments to multi-layered recognition strategies is becoming more visible as organizations seek redundancy, improved resilience, and broader coverage across lighting, distance, and pose variation conditions. Segmentation choices also affect hardware procurement, integration complexity, and long-term maintenance commitments, all of which should be factored into enterprise budgeting and vendor evaluation.
What the Research Delivers
This study is structured to provide executive and technical audiences with actionable intelligence rather than abstracted trend summaries. The report combines quantified market sizing, forward forecasts, and segment-level analysis with qualitative assessments of competitive behavior, regulatory exposure, and technology adoption patterns. Readers will find detailed coverage of demand drivers, deployment contexts, hardware and algorithmic considerations, and the strategic implications of benchmark performance and compliance requirements.
The analysis is designed to support multiple decision contexts. Product leaders can use the findings to align roadmaps with demand concentration and performance expectations. Procurement teams can leverage the competitive and segment analysis to sharpen evaluation criteria and negotiation positioning. Investment and strategy functions can draw on the forecast trajectory and market concentration insights to assess growth pathways and consolidation risk. Policy-aware organizations can use the regulatory mapping to anticipate approval friction, data handling obligations, and the operational implications of jurisdiction-specific mandates.
Strategic Imperatives for 2026 and Beyond
The face recognition systems market presents a rare combination of expanding demand, performance-driven competition, and regulatory recalibration. For enterprises planning capital allocation and technology strategy in 2026, the strategic question is not whether facial recognition will continue to gain adoption, but how to engage with the market in a way that balances growth opportunity against compliance exposure, integration complexity, and competitive dependency.
Face Recognition Systems Market
Organizations that approach this market with structured intelligence can make more disciplined choices about vendor selection, deployment sequencing, hardware investment, and compliance readiness. They can also better anticipate where consolidation, benchmark leadership, and regulatory pressure will reshape supplier dynamics over the next several years. The full study expands on these themes with detailed market projections, segment analysis, competitive profiling, and scenario considerations intended to support concrete planning decisions.
This overview has been crafted to provide a credible, professional foundation for understanding the market's direction and the strategic stakes involved. To access the complete dataset, segment-level breakdowns, competitive mapping, and forward forecasts that support enterprise planning through 2032, we invite decision-makers to consult the full market research publication.
For detailed analysis of this topic, please visit the official page: Face Recognition Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Current Sensing Resistor Market to Reach $265.1 Million by 2032, CAGR 5.59%
By PW Consulting, 2026-09-16
Strategic Intelligence Report: The Current Sensing Resistor Market Outlook 2026–2032
As the global electronics industry accelerates toward electrification and smarter power distribution, the role of precision current sensing has evolved from a passive compliance requirement to a critical enabler of system efficiency, safety, and performance. PW Consulting presents this executive briefing on the Current Sensing Resistor Market, drawing on comprehensive historical tracking from 2020 through 2025 and detailed forward-looking projections spanning 2026 to 2032. This analysis is designed to equip strategic leaders, procurement directors, and R&D planning teams with the contextual depth needed to navigate supply chain complexities, technology transitions, and competitive shifts in the coming years.
Market Trajectory and Structural Growth Signals
The historical record from 2020 to 2025 reveals a consistent upward trajectory in global revenue for current sensing resistors, reflecting sustained capital investment in power electronics, automotive electrification, and industrial automation. After reaching a baseline level in 2020, the market steadily expanded through 2022 and 2023, driven by early-cycle adoption in automotive battery management systems and data center power infrastructure. By 2024, demand acceleration entered a more pronounced phase, with 2025 closing the historical window at a significantly elevated revenue mark.
Our forecasting model projects continued expansion through 2032, with a compound annual growth rate of 5.59 percent across the full forecast horizon. The progression from the 2025 baseline into the mid-2020s suggests that incremental capacity additions, alongside the phasing in of next-generation powertrain architectures and industrial motor drives, will sustain revenue momentum. As the timeline extends further toward the early 2030s, the growth curve reflects the compounding effect of platform migrations in electric vehicles, the scaling of renewable energy inverters, and the continuous miniaturization of high-power shunt elements. It is important to note that these are structural, ecosystem-level signals: the detailed breakdown of how this growth distributes across specific regional corridors, product architectures, and end-use verticals remains a core deliverable of the full report.
Technology Transitions and the Shift Toward High-Density Shunt Architectures
A defining theme of the 2026–2032 period is the ongoing migration from conventional thick-film platforms toward higher-performance metal-based and sintered shunt technologies. Industry data points to sintered metal current sense chip resistors achieving power dissipation levels significantly above traditional thick-film equivalents while preserving low temperature coefficient of resistance. This material-level advancement allows designers to increase current-carrying capacity within shrinking board footprints, a constraint that has become central to automotive module packaging and compact industrial power supplies.
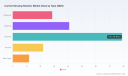
At the same time, metal foil and metal strip architectures continue to hold relevance where ultra-low TCR and long-term stability are non-negotiable, particularly in precision instrumentation and high-reliability automotive traction environments. Wirewound and thin-film solutions occupy adjacent niches, each carrying distinct trade-offs in inductance, power handling, and manufacturing economics. The strategic question for component engineers is no longer which technology dominates in absolute terms, but rather which platform aligns with a given application's thermal, electrical, and qualification requirements at acceptable total cost of ownership. The complete study maps these technology trade-offs against actual design requirements and quantifies the relative revenue share each type commands across the broader product landscape.
Competitive Landscape: Differentiation Through Qualification and Platform Strategy
The current sensing resistor market remains moderately fragmented, with top-three concentration levels indicating that while scale players exert meaningful influence, specialized mid-tier manufacturers retain significant footholds through technical differentiation and regional distribution strength. The competitive battleground has shifted decisively from pure price competition toward qualification readiness, power-density innovation, and application-specific portfolio breadth.
Bourns, Inc. has reinforced its automotive and power electronics positioning with the launch of its CSS4C-1216 Series 4-terminal current sense resistors, designed to meet AEC-Q200 expectations with up to 5 watts of power handling, low inductance, and a compact form factor. This family complements the company's Riedon shunt portfolio, which spans metal strip and thick-film elements tailored for EV battery management and industrial power conversion. In parallel, Vishay Intertechnology, Inc. has expanded its Power Metal Strip lineage with the WSLF1206 and WSBE families, delivering 5-watt capability within a 1206 footprint while maintaining low resistance values optimized for high-efficiency EV power systems and board-space-sensitive designs.
ROHM Co., Ltd. has drawn attention with its UCR10C Series sintered metal shunt resistors, which push rated power to 1.25 W within a 2012 metric size and carry AEC-Q100 qualification for automotive motor control and power electronics applications. This product direction underscores a broader industry trend toward sintered metal platforms as credible alternatives to traditional thick-film offerings in thermally constrained environments. TT Electronics has similarly advanced its SMT shunt portfolio with the LRMAK Series, a 4-terminal family qualified to AEC-Q200 standards, offering resistances down to 500 µΩ and up to 2 watts of power for automotive motor control and industrial current sensing.
Beyond these headline developments, the competitive fabric includes Ohmite Manufacturing Co., whose LVK and PCS Series address low-resistance, high-power, and chip current sense applications with precision thick-film and metal implementations. TE Connectivity Ltd. contributes CGS Series metal chip resistors and high-current shunts positioned for automotive and industrial sensing architectures. KOA Speer Electronics, Inc. maintains a focus on precision low-ohm applications through its KDV and PSJ2 Series metal film and power shunt offerings, while Caddock Electronics, Inc. emphasizes accuracy and stability in precision thick-film current sense resistors intended for instrumentation and power monitoring. In the European precision segment, Isabellenhütte Heusler GmbH & Co. KG supplies precision shunt resistors and metal-based current sensors engineered for high-accuracy demands in EV and power electronics environments.
Collectively, these players illustrate a market where product qualifications, package density, and application-specific support are becoming the primary vectors of differentiation. The full report provides a deeper comparative assessment of competitive positioning, recent product cadence, and the strategic implications of these launches for procurement prioritization and second-source planning.
Regulatory, Qualification, and Supply Chain Considerations as Strategic Filters
Automotive-grade qualification has emerged as one of the most consequential filters shaping demand patterns in the current sensing resistor segment. AEC-Q200 compliance is no longer a peripheral bonus; it is increasingly a prerequisite for participation in EV battery management, traction inverter, and frequency converter designs. This qualification dynamic is visible across multiple recent product introductions, from Bourns' CSS4C-1216 family to TT Electronics' LRMAK Series and Vishay's Power Metal Strip platforms, all of which are positioned with explicit automotive reliability expectations.
Environmental and material compliance further shapes the competitive field. Recent sintered metal shunt introductions, including ROHM's UCR10C Series, are fully lead-free and RoHS compliant, with automotive-grade temperature cycle durability integrated into the product claim set. For supply chain and compliance teams, these specifications reduce integration risk in regions with stringent environmental mandates and simplify multi-source qualification where suppliers must demonstrate equivalent regulatory alignment.
On the commercial side, material cost dynamics are beginning to influence device selection decisions. The emergence of sintered metal current sense chips capable of delivering up to 2x higher power dissipation than traditional thick-film equivalents while maintaining low TCR is prompting a reevaluation of thermal derating margins and board-area budgets. As these products mature into volume production, the cost-per-watt-per-cubic-millimeter calculus may tilt in favor of advanced shunt architectures in high-power applications, even if initial unit pricing remains elevated. The complete study dissects these shifting cost-performance trade-offs and their implications for make-versus-buy, design-in prioritization, and inventory strategy.
Current Sensing Resistor Market
Worldwide Precision Resistors Market
Findings and the Strategic Case for Detailed Market Intelligence
A market growing at a mid-single-digit CAGR over a seven-year horizon does not move by accident. It is propelled by interlocking forces: electrification roadmaps in automotive original equipment manufacturing, the scaling of industrial motor drives and renewable inverters, the push for higher power density in consumer and telecommunications power supplies, and the relentless requirement for more accurate current measurement in closed-loop control architectures. Each of these forces exerts a distinct pull on product type selection, qualification requirements, and regional sourcing patterns.
Yet the headline market trajectory only tells part of the story. The strategic decisions that separate resilient portfolios from vulnerable ones depend on operational intelligence: which product types are gaining share in which applications, how regional demand differs in cadence and qualification emphasis, which manufacturers are converting product launches into validated design wins, and how material and qualification constraints will reshape total cost structures. These are precisely the dimensions that our full Current Sensing Resistor Market research unpacks with granular segmentation, revenue allocations, and forward-looking scenario modeling.
For procurement leaders, the value lies in anticipating qualification shifts, identifying credible second sources before supply constraints materialize, and understanding where thermal-performance breakthroughs are likely to displace incumbents. For R&D and application engineering teams, the value lies in mapping technology trade-offs to actual system requirements and avoiding over-investment in architectures that are losing share in key verticals. For executive planning teams, the value lies in aligning capacity, tooling, and supplier relationships to the demand waves that the forecast period will bring.
PW Consulting's full market study transforms these strategic questions into structured answers. It integrates historical performance, projected revenue paths, segmentation detail across resin types, applications, and regional demand centers, and a competitive profile of the manufacturers reshaping the segment. The report is designed to be immediately usable: a reference foundation for design-in strategy, supplier evaluation, pricing negotiations, and long-range capacity planning.
To access the complete segmentation detail, competitive benchmarking, and full forecast tables that underpin this briefing, please visit the PW Consulting market research portal. The full edition extends well beyond these introductory findings, providing the quantitative and qualitative depth required to convert market trajectory into actionable corporate strategy.
For detailed analysis of this topic, please visit the official page: Current Sensing Resistor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Steel Round Bars Market: Strategic Intelligence for 2026 Decision-Makers
The global steel round bars market stands as a critical backbone for industrial infrastructure, yet its complexity often obscures clear navigational paths for executives. As we move deeper into 2026, understanding the interplay between historical performance and future trajectory is no longer optional—it is essential for maintaining competitive advantage. PW Consulting presents this comprehensive market study to decode these dynamics, offering a granular view of an industry projected to evolve significantly over the next decade.
Market intelligence in this sector must go beyond surface-level trends. Stakeholders require precise data on valuation, growth inhibitors, and competitive maneuvering to allocate capital effectively. This article serves as a strategic preview of our latest deep-dive analysis, outlining the macroeconomic contours and the specific operational insights contained within the full report. The goal is to equip leadership teams with the context needed to validate internal assumptions against external market realities.
Market Trajectory and Valuation Horizons
The financial scale of the steel round bars industry underscores its significance in the global materials landscape. Based on historical data spanning from 2020 through the base year of 2025, the market has demonstrated substantial resilience and expansion. The total revenue generated by this sector has grown from approximately 180.0 USD Billion in 2020 to an estimated 230.0 USD Billion in 2025. This upward trajectory reflects sustained demand across core industrial verticals despite fluctuating economic conditions.
Looking forward, the forecast period from 2026 to 2032 suggests continued growth, with the market size projected to reach 247.98 USD Billion in 2026 alone. The analysis indicates a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast horizon, signaling steady consolidation and expansion. By the end of the forecast period in 2032, valuations are expected to climb significantly higher, reflecting long-term confidence in infrastructure development and manufacturing output.
However, raw valuation numbers only tell part of the story. The nuances of year-over-year performance, such as the slight contraction observed in 2024 before recovering in 2025, highlight the volatility inherent in commodity-driven markets. Our study dissects these fluctuations to identify whether they represent temporary supply chain disruptions or structural shifts in demand. Understanding these patterns allows procurement managers and investors to time their entries and exits with greater precision.
Industry Dynamics and Material Flows
Current market dynamics are being reshaped by a confluence of regulatory changes, raw material cost pressures, and logistical adjustments. Recent developments in early 2026 illustrate the volatility that buyers must account for. In April 2026, major producers such as Nucor Bar Mill Group announced price increases for commercial long products and certain large structural sections. Similarly, Gerdau Long Steel North America implemented merchant bar and structural section price increases around the same period. These moves signal upstream pressure on pricing structures that will likely ripple through the supply chain.
Logistical costs are also under scrutiny. In March 2026, Norfolk Southern issued a public tariff announcement adjusting market-based rates for iron, steel, and scrap metal commodities, effective July 1, 2026. Such regulatory adjustments directly impact the landed cost of materials, influencing regional competitiveness and margin structures for downstream manufacturers.
On the raw material front, market intelligence indicates shifting cost bases. As of May 2026, iron ore prices reached levels around 114.7 USD per ton CFR, representing a month-over-month increase. Concurrently, billet prices rose by 10 to 20 USD per ton in regional markets during May 2026. These input cost hikes challenge manufacturers to maintain price stability without eroding profitability. Conversely, long-term forecasts from institutions like the World Bank suggest iron ore prices may decline further in 2026–27, potentially falling below 2019 levels due to expanding supply. This divergence between short-term spikes and long-term outlooks creates a complex environment for hedging strategies.
Furthermore, international trade policies are tightening. Multiple countries, including the EU and Uzbekistan, have introduced export duties or quotas on ferrous scrap in 2025–2026. These restrictions alter the availability of recycled raw materials, impacting electric arc furnace operations and cost structures for producers reliant on scrap feedstocks. Our report details how these regulatory shifts are segmenting regional markets and altering competitive advantages for key players.
Competitive Landscape Overview
The steel round bars market features a diverse mix of global giants and specialized regional distributors, creating a multifaceted competitive environment. Consolidation metrics indicate a moderately concentrated market, with the top three companies holding approximately 38.5 percent of the share, while the top five account for 45.2 percent. This structure suggests that while large players drive significant volume, there remains ample room for niche operators to compete on service, specification, and regional availability.
Leading global entities such as Nucor Corporation and ArcelorMittal continue to anchor the market. Nucor, based in Charlotte, North Carolina, produces and supplies Merchant Bar Quality round steel bars using electric arc furnace technology with high recycled content. ArcelorMittal, headquartered in Luxembourg, operates as a global producer across carbon, stainless, and alloy grades for construction, automotive, and machinery sectors. Their strategies often set the tone for pricing and capacity utilization across regions.
In Asia, major manufacturers like Nippon Steel Corporation and Tata Steel play pivotal roles. Nippon Steel focuses on stainless and carbon round steel bars with an emphasis on high-strength grades for industrial use. Tata Steel, based in Jamshedpur, India, supplies premium round steel bars including specialized series with enhanced machinability for automotive and structural applications. POSCO, from Seoul, South Korea, also supplies round steel bars from carbon to high-alloy grades for global markets, reinforcing the region's manufacturing dominance.
European producers maintain strong positions in specialty segments. Thyssenkrupp AG provides stainless and alloy round steel bars through an integrated production and distribution network, while Outokumpu Oyj remains a leading producer of stainless steel round bars for corrosion-resistant applications in chemical, energy, and food processing. SSAB AB supplies high-strength round steel bars specifically for heavy equipment and construction, catering to demanding engineering requirements.
The Americas host a robust network of distributors and specialized suppliers. Eaton Steel Bar Company in Cleveland specializes in hot-rolled and cold-drawn round steel bars for defense and heavy industry. Gerdau S.A., based in Sao Paulo, manufactures merchant bar quality round steel bars for structural and industrial uses. US-based entities such as Jade Sterling Steel, Chatham Steel, Ohio Bar & Metal, North Shore Steel, Summit Steel Corp, and TW Metals provide critical distribution and processing services, often catering to specific ASTM specifications or defense-related needs. Smaller specialized producers like Virwadia Steels and Vishwa Stainless Pvt. Ltd. in India further diversify the supply base for stainless grades.
Report Scope and Functional Analysis
The complete PW Consulting market study offers significantly more depth than the high-level overview provided here. It delivers a navigational map of the steel round bars ecosystem, breaking down performance metrics without exposing every sensitive figure in this public summary. The report is engineered for practical application by strategy teams, procurement officers, and investors who need actionable intelligence rather than generic trends.
Structural Steel Market
Key components of the full document include a detailed segmentation analysis that isolates performance drivers across different material types and end-use industries. The study examines how specific grade requirements influence supply chain decisions and pricing power. It also provides a comprehensive regional breakdown, evaluating how local industrial policies, infrastructure spending, and manufacturing capacity affect market penetration and growth potential in different geographies.
Segmentation Drivers and Technology Trends
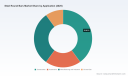
Understanding the split between material types is crucial for sourcing strategies. The market encompasses carbon steel, alloy steel, and stainless steel round bars, each serving distinct functional requirements. Carbon steel remains a workhorse for general structural and industrial applications, while alloy steel offers enhanced mechanical properties for specialized machinery. Stainless steel caters to environments requiring corrosion resistance, such as chemical processing and food manufacturing.
Technological advancements in production methods are also reshaping the landscape. The shift toward electric arc furnace technology, as utilized by producers like Nucor, emphasizes sustainability through high recycled content. This aligns with broader environmental, social, and governance (ESG) mandates that are increasingly influencing procurement decisions. The report analyzes how green manufacturing initiatives are impacting cost structures and customer preference patterns across major consuming sectors.
Regional Nuances and Application Sectors
Regional dynamics vary significantly due to local infrastructure projects, automotive production rates, and energy sector activities. The study provides insights into how regions like North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are performing relative to global averages. It examines the flow of materials across borders and how tariffs, such as those recently adjusted by Norfolk Southern, impact inland logistics and final delivery costs.
Application-wise, the market serves construction, automotive, manufacturing and industrial, and oil and gas sectors. Each vertical presents unique demand cycles and specification requirements. Construction demand is often tied to government infrastructure spending, while automotive and manufacturing sectors are more sensitive to economic cycles and consumer demand. The oil and gas segment relies heavily on high-grade materials capable of withstanding extreme conditions. The full report delineates how these sectors interact with supply constraints and price volatility.
Strategic Recommendations for Stakeholders
Given the projected market size and growth rate, stakeholders must adopt proactive strategies rather than reactive measures. Procurement teams should consider hedging against raw material price volatility, especially in light of recent billet and iron ore price movements. Diversifying supplier bases across different regions can mitigate risks associated with localized trade restrictions or logistical bottlenecks.
For investors and competitors, monitoring the pricing actions of major players like Nucor and Gerdau provides early signals of margin shifts. Understanding the concentration of market share among top players helps in assessing potential M&A opportunities or identifying vulnerable niche segments. The report includes scenario planning tools to help organizations model the impact of varying input costs and demand fluctuations on their bottom lines.
Steel Round Bars Market
Access to the complete dataset and proprietary analysis models is available through our full market research document. This resource provides the detailed numerical breakdowns, competitor profiling, and risk assessment frameworks necessary to make informed strategic decisions.
The steel round bars market offers substantial opportunities for those equipped with the right intelligence. By leveraging detailed insights on growth rates, competitive moves, and material dynamics, organizations can position themselves to capitalize on the projected expansion through 2032. We invite you to explore the full report to unlock the specific data points and strategic recommendations tailored to your operational needs.
For detailed analysis of this topic, please visit the official page: Steel Round Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reclaimer Market Hits $630M in 2025, Projects 5.8% CAGR to $975M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Why the Reclaimer Market Demands Executive Attention
As industrial infrastructure enters a phase of accelerated renewal, the reclaimers market has emerged as a critical lever for operational resilience. PW Consulting’s newly released Reclaimer Market research provides a comprehensive, forward-looking intelligence framework designed specifically for enterprise decision-makers navigating 2026 and beyond. This report is not a retrospective data compilation; it is a strategic navigation tool that connects capital allocation, technology adoption, and competitive positioning to measurable market trajectories. For executives, procurement leaders, and infrastructure strategists, the research delivers a clear line of sight from historical performance to the forecasted landscape that will shape procurement, partnership, and expansion decisions throughout the decade.
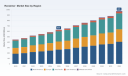
The baseline data establishes a market with sustained upward momentum. In 2020, the global market stood at 450.0 million USD, progressing to 475.47 million USD in 2021, 523.06 million USD in 2022, 551.32 million USD in 2023, 585.73 million USD in 2024, and reaching 630.0 million USD in the 2025 base year. This consistent expansion reflects deepening integration of reclaiming equipment across bulk material handling, road rehabilitation, and heavy industrial infrastructure. From 2026 through 2032, the market is projected to follow a calculated growth trajectory, with 2026 opening at 654.65 million USD, advancing through 713.33 million USD in 2027, 758.88 million USD in 2028, 803.36 million USD in 2029, 858.19 million USD in 2030, 884.14 million USD in 2031, and peaking at 975.0 million USD in 2032. The compound annual growth rate across the forecast period is evaluated at 5.8 percent, a figure that signals durable demand expansion rather than speculative volatility. For strategy teams, this trajectory translates into a predictable window for capital planning, vendor evaluation, and technology readiness investments.
What separates this research from conventional market summaries is its operational emphasis. The study maps procurement pathways, deployment considerations, and strategic trade-offs that determine whether capital is locked into legacy configurations or aligned with next-generation efficiency standards. Readers will find structured analysis of equipment architectures, application-specific deployment logic, and regional adoption patterns that influence total cost of ownership. The report is built to answer the questions that surface in boardrooms and engineering reviews: which equipment profiles match specific throughput requirements, where modernization thresholds create the strongest return, and how procurement timing interacts with supply chain and labor dynamics. Instead of leaving executives to extrapolate from fragmented data points, the research consolidates the decision variables into a single strategic framework.
The competitive environment demands equally rigorous scrutiny. The report profiles a concentrated field of established manufacturers whose capabilities set the operational benchmarks for the market. FLSmidth & Co. A/S, headquartered in Copenhagen, Denmark, specializes in bucket wheel and scraper reclaimers with advanced automation and digital monitoring for bulk material handling in mining, cement, and power sectors. thyssenkrupp Industrial Solutions, based in Essen, Germany, offers boom bucket wheel stacker-reclaimers and integrated stockyard systems, with over 328 units installed globally since 1970. Metso Corporation, operating from Espoo, Finland, provides bucket wheel stacker reclaimers and repairs and upgrades with automation features for high-throughput stockyard operations. TAKRAF GmbH in Leipzig, Germany manufactures dual-purpose stacker-reclaimers and bucket wheel reclaimers for high-capacity applications up to 10,000 t/h. Kawasaki Heavy Industries, Ltd., headquartered in Kawasaki, Japan, develops gantry-crane-derived stacker-reclaimers for ironworks, power plants, ports, and mines, drawing on comprehensive material handling expertise. NHI Global, based in Nanjing, China, supplies circular overpile stacker reclaimers and integrated stacking and reclaiming systems for bulk materials. Caterpillar Inc., from Irving, Texas, USA, offers road reclaimers and related machinery for asphalt stabilization and bulk material processing. Liebherr Group, headquartered in Biberach an der Riss, Germany, provides high-capacity stacker-reclaimer models with enhanced handling efficiency for large-scale bulk terminals. BEUMER Group, based in Beckum, Germany, delivers bucket wheel reclaimers and circular stacker-reclaimers for coke, anthracite, and other bulk materials. Bruks Siwertell, from Stockholm, Sweden, focuses on fully automated stacker reclaimers and slew bearing replacements for bulk material operations. Bedeschi S.p.A., headquartered in Milan, Italy, manufactures bucket wheel stacker-reclaimers for port and bulk material handling with commissioning and modernization services. Richmond Engineering Works, L.L.C., based in Richmond, Virginia, USA, supplies stacker reclaimers for port authorities and bulk handling facilities. This roster illustrates a market where engineering heritage, regional reach, and automation maturity intersect, and where vendor selection directly influences long-term performance and service availability.
Recent commercial activity further clarifies how the competitive field is moving. In February 2025, Metso Corporation was awarded an order to provide repairs and upgrades for a bucket-wheel stacker reclaimer at a customer stockyard operation in Africa, underscoring the sustained value of lifecycle support and modernization in established installations. In September 2025, Bruks Siwertell secured a turn-key project to replace a critical slew bearing on a fully automated stacker reclaimer for a U.S. operator, reflecting the growing importance of precision component replacement in maintaining uptime across automated systems. In May 2025, Bedeschi S.p.A. participated in the WAMPEX Exhibition in Accra, Ghana, and the company is scheduled to exhibit again at WAMPEX 2026 in Accra, Ghana, from 3 to 5 June 2026, signaling continued engagement with port, bulk handling, and infrastructure procurement networks in Africa. In December 2024, Richmond Engineering Works, L.L.C. was awarded a major contract by a U.S. port authority for the production of two new stacker reclaimers, reinforcing the ongoing demand for purpose-built equipment in high-capacity terminal operations. Together, these developments point to a market where new equipment orders, lifecycle upgrades, and component replacement programs are all active revenue channels, and where strategic sourcing decisions must account for both initial capital outlay and long-term service continuity.
Beyond competitive positioning, the research integrates the operational dynamics that are reshaping procurement and deployment logic. Material specifications remain a decisive factor in equipment durability and maintenance planning. Bucket wheel components rely on high tensile steel plates, such as SAILMA 350HI plates, alongside wear-resistant liners such as Hardox 400, which directly influence wear profiles, replacement intervals, and lifecycle cost modeling. Regulatory expectations are also evolving. EPA-Certified Refrigerant Reclaimers require specific certification standards for equipment used in refrigerant recovery, adding a compliance layer that affects selection criteria in relevant applications. Infrastructure design continues to define performance boundaries, as stockyard systems for bulk materials rely on rail-mounted and portal designs to handle materials including coal, iron ore pellets, and coke, shaping layout planning and throughput assumptions. Labor dynamics introduce another strategic variable, since heavy equipment operations in mining and ports face labor shortages for stacker reclaimer operators, increasing the value proposition of automation and reduced crew dependency. Energy considerations are equally relevant, as modern stacker-reclaimers incorporate automation and digital monitoring to reduce energy consumption in bulk handling, linking sustainability goals with operating cost reduction. The report synthesizes these forces so that decision-makers can weigh material durability, compliance requirements, labor availability, and energy performance as interconnected variables rather than isolated concerns.
Reclaimer Market
Concentration data provides additional strategic context for competitive and procurement planning. The market structure reflects meaningful consolidation among leading suppliers, with the top three firms accounting for approximately 48 percent of market share and the top five firms representing roughly 55 percent. This concentration pattern has practical implications for sourcing strategy, negotiation leverage, and supply continuity. For enterprises evaluating long-term partnerships, the research uses this concentration environment to frame questions about vendor reliability, service coverage, product roadmap alignment, and post-sales support capacity. Rather than treating supplier selection as a purely price-driven exercise, the analysis connects market structure to operational risk management and strategic resilience.
The segmentation architecture is designed to clarify where investment logic diverges across equipment families and deployment contexts. The study examines mechanical road reclaimers, hydraulic road reclaimers, and other equipment categories, connecting performance characteristics to application environments and total cost of ownership. It also maps demand across road construction, airports, wharves, public engineering, mining, oil, agriculture, and other end-use settings, helping readers understand how throughput requirements, environmental conditions, and operational cadence influence equipment choice. This structure is particularly valuable for organizations that operate across multiple sectors or are evaluating diversification, because it reveals where equipment standards overlap and where application-specific customization justifies differentiated procurement strategies.
Worldwide Reformer Unit Market
For 2026 planning cycles, the report’s strategic value lies in its ability to convert market signals into actionable decision paths. Executives can use the research to align capital expenditure timing with the forecasted growth curve, prioritize automation and monitoring investments where labor constraints and energy efficiency gains are most pronounced, and evaluate vendor alternatives against concentration-driven supply realities. Engineering and procurement teams can apply the segmentation and dynamics analysis to refine specification sheets, reduce lifecycle risk, and build service agreements that protect uptime in demanding operating environments. Portfolio and expansion planners can use the regional and application mappings to identify where demand intensity and infrastructure renewal cycles create the strongest entry or growth opportunities. The research is structured to support all of these use cases without forcing every organization into a single template.
Because the full study contains proprietary segmentation detail, application-level deployment logic, regional adoption nuance, and granular vendor comparison frameworks, the complete intelligence package is reserved for readers who require decision-grade depth. The teaser presented here demonstrates the analytical rigor, scope, and practical orientation of the research, but the underlying breakdowns, scenario-based procurement guidance, and comprehensive market structure analysis are developed for engaged stakeholders ready to convert insight into execution. To access the complete Reclaimer Market research, including the full segmentation architecture, competitive benchmarking detail, and forecast methodology designed for 2026 strategy sessions, please visit the source page and secure the complete report package.
For detailed analysis of this topic, please visit the official page: Reclaimer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DJ Software Market Set to Hit $219.75M by 2032, Growing at 5.25% CAGR
By PW Consulting, 2026-09-16
Navigating the Digital Turntable: Strategic Intelligence for the DJ Software Market (2026-2032)
Executive Summary: The Rhythm of Change
The global DJ Software Market is undergoing a transformative phase, driven by the convergence of artificial intelligence, streaming integration, and evolving live performance demands. For enterprises operating within the music technology sector, understanding these shifts is not merely an academic exercise but a critical component of strategic planning. Our latest comprehensive market study offers a granular look at the revenue trajectories, competitive dynamics, and technological adoption curves defining this landscape through 2032.
This introduction serves as a strategic overview, highlighting the macro-economic indicators and structural shifts identified in our full report. While specific segmentation data is reserved for the complete intelligence package, the broader trends indicate a steady expansion fueled by professional adoption and consumer-grade innovation. Decision-makers requiring precise forecasts for investment, product development, or market entry should consider this document a precursor to the detailed financial models and competitive benchmarking available in the full submission.
Market Trajectory: A Decade of Expansion
The financial architecture of the DJ Software Market demonstrates resilience and consistent growth. Analyzing the data from historical baselines through the forecast horizon reveals a compound annual growth rate that underscores the sector's maturity. The market valuation has progressed from a base of approximately 120.5 million USD in 2020 to an estimated 155.75 million USD in 2025. This historical performance sets a robust foundation for the forecast period extending to 2032.
Projecting forward, the revenue stream is expected to climb to 162.22 million USD in 2026 and continue its ascent toward 219.75 million USD by the end of the forecast window. This trajectory translates to a CAGR of 5.25 percent, signaling steady demand rather than volatile spikes. For stakeholders, this consistency suggests a market where long-term infrastructure investments can yield reliable returns. However, realizing these returns requires an understanding of where the revenue is generated and how value is captured across different user segments.
It is crucial to note that while the top-line figures provide a health check, the underlying drivers vary significantly across use cases and geographies. The full report dissects these variations, offering a multi-dimensional view that goes beyond aggregate revenue to explore the specific engines of growth within the ecosystem.
Industry Dynamics and Technology Drivers
Several key technological and operational factors are reshaping the value proposition of DJ software. These dynamics are not just features; they are becoming table stakes for market participation.
-
Hardware Compatibility and Ecosystem Lock-in: Professional DJ software platforms now support over 100 controllers and mixers from major manufacturers such as Pioneer DJ, AlphaTheta, and Allen & Heath. This broad compatibility ensures that software remains agnostic enough to attract a wide user base while deeply integrating with specific hardware ecosystems to drive loyalty.
-
Streaming Integration: The integration of direct streaming services like Apple Music and Spotify into DJ software represents a paradigm shift. It allows for seamless library management and access to millions of tracks without local storage constraints, fundamentally changing how DJs prepare for live sets and manage digital assets.
-
AI and Computational Creativity: Advanced software suites are increasingly incorporating AI for stem separation, harmonic mixing, and automix functions. These features enhance real-time performance capabilities and lower the barrier to entry for complex mixing techniques, appealing to both professionals seeking efficiency and amateurs seeking polish.
-
Infrastructure Requirements: As features become more computationally intensive, the demand for high-performance hardware rises. Current sector analysis indicates that optimal operation requires laptops or desktops with minimum 16GB RAM and fast processors, creating a secondary market effect that influences hardware partnerships and consumer upgrade cycles.
-
Cross-Platform Ubiquity: Leading solutions are no longer confined to desktop environments. Availability across macOS, Windows, iOS, Android, and even Vision Pro ensures that DJs can mix and perform seamlessly across devices, blurring the lines between practice, production, and live execution.
These drivers collectively expand the total addressable market by lowering technical barriers and enhancing the utility of the software in various contexts, from private mixing to large-scale event production.
Competitive Landscape: Architects of the Digital Sound
The market is characterized by a moderately concentrated competitive environment. The top three companies hold a combined market share of 41.3 percent, while the top five players extend their influence to 56.7 percent. This concentration suggests that while there is room for innovation and niche players, the bulk of market value is contested by established entities with robust ecosystems.
DJ Software Market
Our analysis profiles key incumbents who are defining the standard of care for DJ software:
-
Serato Limited (Auckland, New Zealand): Known for Serato DJ Pro, a professional platform emphasizing cloud streaming integration, stem separation, and broad hardware compatibility. Their recent update released in May 2026 expanded support for older Pioneer DJ mixers, demonstrating a commitment to legacy hardware longevity.
-
AlphaTheta Corporation (Japan): A pivotal player through its Pioneer DJ software ecosystem, specifically Rekordbox. They focus on library management, CDJ compatibility, and streaming integrations. In 2026, AlphaTheta has been particularly active, introducing the DJM-V5 mixer and releasing firmware updates for the OPUS-QUAD standalone system. Their acquisition of DJ Monitor's technology in May 2026 further strengthens their KUVO capabilities, signaling a strategic push into advanced tracking and interaction technologies.
-
Native Instruments GmbH (Berlin, Germany): With Traktor, they offer a blend of DJ and music production software. Their strategy includes stems, hardware integration, and entry-level variants like Traktor Play, catering to a spectrum from hobbyists to touring professionals.
-
Algoriddim GmbH (München, Germany): Creators of djay Pro, an award-winning solution recognized for real-time effects, multi-platform support, and AI-assisted mixing. Their focus on cross-platform accessibility aligns with the industry trend toward device agnosticism.
-
inMusic Brands Inc. (Cumberland, United States): Through the Engine DJ ecosystem, they provide desktop library tools and controller support tailored for professional DJing, leveraging their broader portfolio of music hardware brands.
-
Atomix Productions (Dubai, UAE): VirtualDJ remains a long-standing contender with a massive library and streaming features, maintaining relevance through continuous updates and a strong user community.
-
DJ.Studio (Netherlands): Focusing on AI-powered mix production, they offer stem separation, timeline editing, and seamless library integration specifically optimized for mashups and radio shows, carving a niche in production-focused workflows.
-
Mixvibes (Paris, France): Their Cross DJ offering emphasizes cross-platform functionality with real-time stem separation and effects, competing aggressively on feature parity and accessibility.
These companies are not merely selling software licenses; they are managing ecosystems. Competitive advantage often lies in the depth of hardware integration, the quality of AI features, and the reliability of streaming partnerships. The full report provides a detailed benchmarking of these players against financial performance, user sentiment, and strategic movements.
Video Editing Software Market
Report Content and Operational Sections
To support complex decision-making, the full market study is structured to provide actionable intelligence across multiple dimensions. This document is designed for product managers, investors, and strategy teams who need to validate assumptions with data.
The comprehensive analysis includes an in-depth examination of market segmentation by type, application, and region, though specific splits are detailed within the secure download. The report also covers supply chain dynamics, pricing strategies, and the impact of regulatory changes on software distribution. Furthermore, it provides a forecast model that accounts for various scenarios, allowing stakeholders to stress-test their strategies against potential market shifts.
Operational sections delve into the adoption rates of specific features such as AI stems and streaming proxies, correlating these with user retention and upgrade cycles. This level of detail enables clients to prioritize feature development roadmaps based on verified market demand rather than speculation.
Strategic Meridian: Timing and Decision Maturity
The timing of this report coincides with a period of significant activity in the sector. With recent product updates from AlphaTheta Corporation and Serato Limited occurring in early 2026, the competitive field is actively realigning. The acquisition activities and firmware enhancements observed in the first half of the year suggest a period of consolidation and capability enhancement.
For enterprise decision-makers, the data suggests that the window for entering the market with a generic solution is narrowing. Differentiation increasingly requires deep integration with hardware ecosystems or superior AI-driven creative tools. The forecast period through 2032 offers a long enough horizon to justify R and D investments, but the CAGR of 5.25 percent indicates that growth will be competed for rather than easily captured.
Understanding the specific regional demands and application-based preferences is essential for market entry or expansion strategies. For instance, while the aggregate data shows consistent growth, the intensity of adoption varies across professional live performance contexts versus recording and production use cases. The full report elucidates these nuances, providing the granularity needed to allocate resources effectively.
Conclusion: From Insight to Action
The DJ Software Market is poised for continued evolution, anchored by stable growth metrics and driven by rapid technological innovation. The journey from 2026 to 2032 will be defined by how well companies can integrate AI, streaming, and hardware compatibility into a cohesive user experience. For organizations looking to navigate this landscape, access to precise, validated data is the most critical asset.
This overview provides the strategic context and macro-validation necessary to appreciate the value of the full study. To access the complete segmentation splits, detailed company profiles, regional forecasts, and the full financial model, we invite you to engage with the complete market research report. Secure your competitive advantage with intelligence that moves beyond trends to deliver actionable foresight.
For detailed analysis of this topic, please visit the official page: DJ Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Automotive Armrest Market: Navigating Growth Through 2032
The automotive interior landscape is undergoing a quiet but profound transformation. What was once considered a utilitarian component—fixed, functional, and largely overlooked—is now emerging as a critical touchpoint for comfort, sustainability, and modular design. As seating systems evolve from passive ergonomics to active user experiences, the automotive armrest has captured the attention of OEMs, tier suppliers, and aftermarket strategists alike. This shift is not merely aesthetic; it reflects deeper structural changes in vehicle architecture, consumer expectations, and regulatory frameworks. For executives navigating the 2026–2032 horizon, understanding the trajectory of this segment requires more than surface-level market estimates. It demands a disciplined, forward-looking analysis that connects material innovation, competitive consolidation, and regulatory pressure to actionable portfolio decisions.
Our latest research publication on the automotive armrest market is designed precisely for that purpose. Built on a rigorous historical baseline spanning 2020–2025 and extended through a comprehensive forecast window to 2032, the study provides a structured lens into how revenue, adoption patterns, and competitive positioning are being reshaped. The market has demonstrated consistent upward momentum over the past half-decade, with steady expansion across product architectures and material choices. As organizations prepare their strategic roadmaps for the 2026 fiscal year and beyond, this intelligence serves as a critical calibration tool—helping leaders separate cyclical noise from genuine structural inflection points.
Why 2026 Marks a Pivotal Inflection Point
The automotive supply chain enters 2026 under a fundamentally different operating environment than the one that defined the early 2020s. Electrification platforms continue to reconfigure interior packaging constraints, consumer preferences increasingly reward tactile comfort and personalized control surfaces, and regulatory bodies are tightening requirements around component safety, material sourcing, and lifecycle footprints. Within this context, armrest systems have moved from being treated as commodity trim pieces to becoming integrated elements of broader cockpit architecture.
Several forces converge to make this year particularly consequential for strategic planning. First, modular interior architectures are gaining traction across multiple vehicle segments, allowing sliding, folding, and adjustable configurations to be tested and deployed at scale. Second, the push toward lightweight, bio-sourced, and recycled material inputs is accelerating across seating supply chains, creating new performance benchmarks and procurement trade-offs. Third, regulatory developments—including UN Regulation No. 17 requirements for locking systems on comfort devices and updated safety guidelines issued by major oversight agencies in late 2024—are reshaping design validation cycles and compliance cost structures. These dynamics do not operate in isolation. They interact with manufacturing footprints, supplier partnerships, and regional demand rhythms in ways that can materially alter margin profiles and time-to-market assumptions. For decision-makers, the margin for guesswork has narrowed. What is needed is a research framework that connects macro trends to segment-level realities without over-simplifying the complexity on the ground.
A Research Framework Built for Execution
This market study is structured to bridge strategic inquiry and operational execution. Rather than presenting high-level aggregates in isolation, the report is organized around the dimensions that matter most to product planning, procurement, and competitive positioning teams. By integrating historical baselines with a forward-looking projection horizon through 2032, the analysis provides a continuous narrative that leaders can use to stress-test assumptions across multiple scenarios.
The report delivers actionable intelligence across several practical dimensions:
- Comprehensive sizing and trajectory analysis that contextualizes recent performance within long-term growth trends, helping organizations separate baseline expansion from segment-specific accelerations or decelerations.
- A structured breakdown of product architectures and functional configurations, enabling engineering and product teams to evaluate which form factors are gaining traction and under what usage conditions.
- Material and manufacturing pathway analysis that maps the shift toward sustainable inputs, recycled content, and lightweighting strategies, including the performance and cost implications of bio-sourced alternatives and energy-absorbing foam systems.
- Channel and go-to-market dynamics that distinguish how volume flows through integrated OEM supply relationships versus independent aftermarket ecosystems, with emphasis on the operational implications of each pathway.
- Competitive landscape profiling that examines how leading suppliers differentiate through seating system integration, modular console mechanisms, ergonomic component specialization, storage-enabled designs, and heated or comfort-enhanced variants.
- Regulatory and compliance context that translates safety standards and vestigial rule updates into practical implications for design validation, locking mechanisms, and component injury-risk considerations.
Each section is designed to answer the kinds of questions that surface in cross-functional planning sessions: where is demand consolidating, which material transitions are nearing commercial maturity, how are regional demand patterns reshaping sourcing priorities, and what does competitive differentiation look like when armrests are treated as part of a broader interior system rather than a standalone component. By presenting these insights in a cohesive framework, the study equips teams to move from observation to action with greater precision.
Automotive Headrest Market
Competitive Dynamics and the New Differentiation Playbook
The supplier landscape for automotive armrests is characterized by a mix of established interior specialists, seating system integrators, and regional players with deep manufacturing and engineering capabilities. Market concentration remains measured, with a handful of firms holding meaningful share and a broader field competing through engineering differentiation, regional partnerships, and material innovation. In such an environment, the ability to anticipate which competitive moves will compound over the next several years is as important as understanding current positioning.
Several leading companies illustrate the strategic directions currently shaping the market. Adient continues to expand its integrated seating systems capability, including armrest and console integration, reinforced by recent operational moves such as the acquisition of a seating foam plant that strengthens component production continuity and vertical coordination. FORVIA Faurecia has been advancing modular interior concepts, including on-demand center console systems with sliding mechanisms that enhance armrest and console functionality while incorporating sustainable materials and surface activation technologies. Grammer AG occupies a position centered on consoles and armrests for passenger vehicle interiors, with an emphasis on ergonomic components and complementary headrest solutions. TACHI-S Co., Ltd. brings manufacturing depth in seating assemblies that encompass armrest components as part of broader seat architectures. Piston Interiors focuses on practical feature differentiation, including fold-away options, storage integration, and durable latch systems for armrests and center consoles. Yanfeng Automotive Interiors extends its reach across door panels, floor consoles, and armrests, including comfort-oriented heated variants, reflecting the broader trend of treating interior surfaces as multi-functional user interfaces.
These profiles are not static. Competitive advantage is increasingly defined by how effectively suppliers can align engineering roadmaps with sustainability targets, modular design flexibility, and regional manufacturing responsiveness. The report maps these dynamics in greater detail, providing the comparative context needed to evaluate partnership opportunities, supply chain resilience, and technology adoption timing.
Recent industry developments reinforce how quickly the competitive landscape can shift. Strategic acquisitions that expand component production capability, alongside the unveiling of modular console systems with sliding armrest functionality, signal a broader movement toward integrated, adaptable interior architectures. These moves matter because they alter not only who competes, but how value is created—shifting emphasis from discrete part manufacturing toward system-level integration, comfort engineering, and material performance. For organizations assessing their own positioning, understanding the cadence and intent behind such moves is essential.
Regulatory, Material, and Operational Currents
No strategic assessment of this market is complete without addressing the operational currents that shape design choices, cost structures, and launch timelines. Regulatory requirements are one of the most influential of these currents. UN Regulation No. 17 introduces locking-system expectations for comfort devices when their presence could introduce additional injury risk, while updated oversight guidance issued in late 2024 has continued to refine how interior components are evaluated under evolving safety expectations. These frameworks do not merely impose compliance obligations; they influence architecture decisions, validation cycles, and the feasibility of certain mechanical configurations.
At the same time, material strategy is becoming a central competitive variable. Automotive seat armrest production increasingly relies on precise multi-step processes that incorporate bio-sourced and recycled inputs to reduce weight and CO2 footprint, while maintaining the durability and comfort performance expected by end users. In parallel, seat foam production continues to depend on high-density closed-cell materials engineered to meet energy-absorbing and non-flammability requirements relevant to occupant protection. Together, these material shifts create a more complex sourcing environment—one where sustainability, regulatory compliance, and functional performance must be balanced rather than treated as separate workstreams.
For procurement and engineering leaders, this means that armrest strategy is no longer confined to dimensional tolerances or cosmetic finishes. It extends into material traceability, energy-absorption performance, locking reliability, weight targets, and lifecycle impact. The research study provides the structured context needed to navigate these intersecting priorities, linking technical requirements to market-level implications.
Translating Intelligence into Strategic Action
As organizations prepare their 2026 planning cycles, the value of disciplined market intelligence lies in its ability to reduce uncertainty without oversimplifying reality. The automotive armrest market is expanding within a broader interior systems transformation, and the companies that succeed will be those that can interpret growth signals accurately, align product roadmaps with material and regulatory shifts, and position themselves relative to a competitive set that is increasingly defined by integration, modularity, and comfort engineering.
This study is designed to support that effort. It offers the historical grounding, forward-looking projections, and segment-level context necessary to evaluate investment priorities, sourcing strategies, product differentiation, and partnership structures. More importantly, it is built to help leaders ask better questions: which product configurations are gaining durable traction, where do material transitions create cost or performance trade-offs, how do regulatory developments shape design feasibility, and what competitive moves should be monitored as leading indicators rather than retrospective events.
Automotive Armrest Market
The complete analysis goes further, providing the detailed market sizing, trajectory modeling, competitive benchmarking, and segment-level context that decision-makers need to convert market signals into executable strategy. For teams responsible for seating systems, interior components, procurement planning, or competitive intelligence, the full report offers the depth required to act with confidence across the 2026–2032 horizon. Those seeking the complete dataset, regional and application-level breakdowns, material pathway comparisons, and in-depth competitive profiling are encouraged to access the full study directly through our research portal, where the complete intelligence package is available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automotive Armrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Education Software Market Hits $89.3M in 2025, Poised for $190.8M by 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Education Software Market (2026–2032)
The global education software landscape is undergoing a structural transformation that demands more than passive observation from enterprise leaders. As digital learning ecosystems mature, the convergence of adaptive technologies, regulatory scrutiny, and shifting institutional procurement models is redefining competitive advantage. PW Consulting’s latest market intelligence study on the Education Software Market is engineered to equip executives, investors, and product strategists with the analytical clarity required to navigate this inflection point. Rather than offering a static snapshot, this research delivers a forward-looking operational framework calibrated to the decision cycles of 2026 and beyond.
Industry participants today face a dual mandate. They must scale technology deployments while simultaneously defending against rising compliance costs, data governance risks, and intensifying vendor consolidation. The market has already demonstrated considerable momentum, with global revenue climbing from approximately 52.3 million USD in 2020 to an estimated 89.3 million USD by 2025. More importantly, the trajectory ahead points to sustained expansion at a compound annual growth rate of 11.5 percent through 2032. Such growth is not uniform across all cohorts. It is increasingly concentrated among organizations that can integrate data-driven personalization, responsible artificial intelligence, and resilient security architectures into their core offerings. Enterprises that treat these capabilities as optional enhancements will find themselves structurally disadvantaged as procurement standards tighten and end-user expectations accelerate.
The strategic value of this publication lies in its refusal to simplify complexity. By anchoring analysis in rigorous historical baselines and forward projections, the report translates macro-level momentum into actionable Go-to-Market considerations. Leaders evaluating product roadmaps, partnership portfolios, or regional expansion strategies will find a structured lens for weighing trade-offs between rapid innovation and long-term defensibility. The following sections outline the analytical architecture of the study and demonstrate how each component maps directly to the operational priorities shaping 2026 decision-making.
Decoding the 2026–2032 Growth Trajectory
Market expansion in education software is no longer driven by routine digitization alone. It is being reoriented by pedagogical shifts, institutional budget reallocations, and the maturation of cloud-native delivery models. The report’s historical analysis establishes a clear baseline, tracing revenue progression across the 2020–2025 window before projecting sustained acceleration through 2032. This longitudinal view is essential for executives who must distinguish between temporary demand spikes and durable structural growth. A double-digit CAGR environment rewards organizations that can align product cadence with institutional procurement cycles, while penalizing those that over-invest in features without clear instructional or administrative utility.
Forward projections in this study are structured to support scenario planning rather than rigid forecasting. Executives gain visibility into how growth may propagate across different deployment models, usage contexts, and buyer archetypes. This granularity matters because aggregate numbers obscure the operational realities that determine execution success. By mapping demand patterns to underlying adoption drivers, the analysis enables leadership teams to anticipate where procurement emphasis will shift, which performance metrics will gain prominence, and how pricing architectures may need to evolve under increasing competitive pressure.
Education Software Market
Crucially, the report also addresses the cost dynamics that frequently erode projected margins. Ongoing software maintenance, security patching, and continuous functionality updates typically add between fifteen and twenty-five percent of original development expenditure each year. For product organizations and institutional buyers alike, this recurring burden reshapes total cost of ownership calculations and influences long-term vendor selection. The study integrates these operational realities into its strategic assessment, ensuring that growth narratives are grounded in the economics of sustained delivery rather than initial market entry.
Navigating Regulatory Pressures and Competitive Realignment
The sector’s growth trajectory is unfolding against a backdrop of intensifying regulatory scrutiny and restructuring competitive dynamics. Data protection has moved from a compliance checkbox to a strategic differentiator. Recent enforcement actions highlight the reputational and operational stakes involved. For example, the Federal Trade Commission reached a settlement with Illuminate Education requiring the implementation of a comprehensive information security program and the deletion of unnecessary data following a breach that exposed personal information of more than ten million students. Simultaneously, the U.S. Department of Education issued a formal inquiry to Instructure Holdings to verify compliance with the Family Educational Rights and Privacy Act. These developments underscore a broader reality: institutions and enterprise buyers are increasingly evaluating vendors through the lens of data stewardship, security maturity, and procedural transparency.
At the same time, the competitive landscape remains moderately concentrated, with a handful of established players commanding a substantial share of total market revenue. This concentration does not imply stagnation. Instead, it signals a market where differentiation is increasingly derived from pedagogical depth, integration capability, and responsible technology deployment rather than raw feature volume. Several leading organizations are already pivoting toward AI-enhanced learning support, personalized instruction pathways, and credentialing ecosystems that bridge academic and professional outcomes. Recent corporate activity reinforces this direction: one major publisher introduced new AI-driven capabilities within its digital course solution for higher education, emphasizing responsible deployment, real-time student support, and tailored reading experiences. Another prominent language and learning platform reported annual bookings surpassing one billion USD while authorizing a significant share repurchase program, reflecting both commercial scale and strategic confidence. Meanwhile, a personalized K-12 teaching and learning provider garnered multiple industry recognitions for its multilingual, cross-subject instructional solution, highlighting the premium that institutions place on adaptability and breadth of coverage.
These developments are not isolated signals. They illustrate a market where competitive advantage is shifting toward organizations that can harmonize innovation with accountability, demonstrate measurable instructional impact, and sustain trust across highly regulated buyer environments. Executives evaluating partnership opportunities, acquisition targets, or competitive positioning must therefore look beyond headline market share and assess the underlying capabilities that determine long-term resilience.
Inside the Report: Analytical Depth Designed for Execution
This publication is structured to function as a working reference for cross-functional strategy teams rather than a high-level commentary. The analytical architecture spans multiple interconnected dimensions, each designed to answer a specific class of executive question. Readers will encounter a detailed segmentation analysis that decomposes demand patterns across solution categories, deployment contexts, and institutional adoption profiles. Rather than treating these dimensions in isolation, the report examines how they intersect, enabling leaders to identify where value creation is most concentrated and which buyer segments are likely to drive incremental spend.
The competitive and vendor landscape assessment goes beyond organizational profiling to evaluate strategic positioning, capability alignments, and recent developmental moves that indicate future trajectory. By mapping organizational focus areas against evolving procurement priorities, the study helps teams anticipate which vendors are likely to strengthen their hold on key segments and which may face pressure to reposition. Regional analysis is similarly contextualized, offering leaders a comparative view of demand maturity, institutional procurement behavior, and expansion feasibility without reducing complex markets to oversimplified rankings.
Beyond structural analysis, the report incorporates practical execution considerations. It addresses the total cost implications of sustained software delivery, the operational requirements of responsible AI integration, and the compliance expectations that increasingly shape procurement decisions. These elements are woven into strategic recommendations so that product, commercial, and risk functions can align on a shared operating posture. For organizations evaluating market entry, portfolio expansion, or partnership strategy, the document provides a disciplined basis for comparing opportunity against execution complexity.
Translating Intelligence into 2026 Strategic Action
Market intelligence delivers value only when it informs concrete decisions. For executive teams operating in the education software sector, the 2026–2032 window will reward organizations that can synchronize product strategy with institutional procurement behavior, regulatory expectations, and the economics of long-term service delivery. The study is designed to support that synchronization by converting trend observation into prioritized action pathways. Leaders can use the analysis to stress-test product roadmaps against emerging buyer requirements, evaluate whether current positioning will hold under intensifying competition, and determine where investment should be concentrated to capture durable demand rather than transient attention.
The report also serves as a shared analytical foundation for cross-functional alignment. Commercial teams can calibrate messaging around measurable impact and compliance readiness. Product organizations can benchmark development priorities against the capabilities that are gaining institutional traction. Risk and governance functions can integrate data stewardship expectations into vendor evaluation and internal deployment standards. When these functions operate from a common evidence base, strategic decisions become more coherent, resource allocation more disciplined, and market response more agile.
Ultimately, the Education Software Market will not be defined solely by the speed of technological advancement. It will be shaped by the organizations that can pair innovation with operational discipline, align their offerings with real instructional and administrative needs, and navigate an environment where trust and transparency are becoming core commercial assets. This study provides the structured intelligence necessary to make those judgments with confidence.
Access the Complete Strategic Assessment
The insights summarized here represent only the opening layer of a far broader analytical effort. The full report expands on segmentation dynamics, competitive positioning, regional demand patterns, procurement behavior, and the operational cost structures that shape long-term profitability. It also includes detailed company profiles, recent developmental milestones, and scenario-based considerations that help executives translate market momentum into executable strategy.
Educational and Training Software Market
For organizations preparing investment decisions, product roadmap adjustments, or market-entry evaluations in 2026, the complete publication offers the depth required to move from informed perspective to decisive action. Readers seeking the full dataset, granular segmentation analysis, and extended competitive intelligence are encouraged to access the complete report through the official PW Consulting research portal. The complete assessment is designed to function as a standalone strategic resource, enabling leadership teams to extract the precise intelligence needed for their specific decision context while maintaining a clear line of sight to the broader market trajectory.
For detailed analysis of this topic, please visit the official page: Education Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
OLED Lighting Panels Market to Hit $127.13M by 2032, PW Consulting Reports
By PW Consulting, 2026-09-16
Illuminating the Future: Strategic Insights into the OLED Lighting Panels Market Through 2032
The transition from traditional illumination to advanced organic light-emitting diode (OLED) technology represents more than a technological upgrade; it signifies a fundamental shift in how industries approach design, efficiency, and user experience. As we navigate the complexities of the global lighting landscape in 2026, understanding the trajectory of OLED lighting panels is critical for stakeholders aiming to capitalize on emerging opportunities. Our latest market research study provides a comprehensive analysis of this evolving sector, offering the data-driven intelligence necessary to formulate robust strategies for the coming years.
This report serves as a definitive guide for executives, investors, and product developers who need to navigate the interplay between technological innovation, regional demand shifts, and competitive dynamics. By examining historical performance from 2020 through 2025 and projecting forward to 2032, we uncover the underlying forces shaping the market value and growth potential. The following analysis highlights the strategic value of this research and outlines the key themes that will define the industry landscape in the immediate future.
Market Trajectory and Growth Horizons
The global OLED lighting panels market has demonstrated resilient growth over the past half-decade, recovering from initial deployment challenges to establish a steady upward curve. Our analysis tracks revenue progression from approximately 67.1 million USD in 2020 to an estimated 87.7 million USD in 2025. This historical baseline provides crucial context for understanding the momentum entering the forecast period. The market is projected to continue its expansion through 2032, driven by increasing adoption in commercial, automotive, and specialized industrial applications.
Forecast data indicates a compound annual growth rate (CAGR) of 5.56 percent during the 2026 to 2032 period. This growth rate suggests a mature yet expanding market environment where incremental gains are driven by technological refinements and broader acceptance rather than volatile speculation. By 2032, the market revenue is expected to reach significant milestones, reflecting the cumulative effect of investment in manufacturing capacity and the penetration of OLED solutions into mainstream lighting sectors. Understanding these top-line figures is essential for capacity planning and investment timing, but the true value lies in dissecting the drivers behind these numbers.
Worldwide LED Panel Lights Market
Segmentation Dynamics and Application Shifts
The market is not monolithic; it is defined by distinct segments that exhibit varying growth characteristics and strategic priorities. Our research dives deep into the breakdown of the market by type and application, revealing where the highest value creation is occurring. For instance, the balance between flexible and rigid panel technologies highlights the industry's pivot toward design versatility. The data suggests that flexible solutions are capturing a substantial share of the landscape, reflecting the demand for form factors that can be integrated into curved surfaces and innovative architectural designs. Rigid panels continue to hold significant ground, particularly in applications where structural stability and uniform illumination are paramount.
Application-wise, the landscape is diversifying. Traditional lighting remains a core pillar, yet the most dynamic growth vectors are emerging from specialized sectors. Automotive lighting represents a key area of expansion, fueled by the broader trend of vehicle electrification and the consumer demand for personalized interior and exterior lighting experiences. Beyond these primary categories, a significant portion of the market is attributed to other specialized uses, indicating that OLED technology is finding niches in industrial inspection systems and high-color-rendering commercial installations. Our report details these splits without obscuring the strategic implications, allowing decision-makers to identify which segments align with their core competencies.
Regional Analysis and Global Supply Chains
Geographical distribution of demand and production capacity plays a pivotal role in shaping market strategy. The Asia Pacific region stands out as a dominant force in the global landscape, reflecting the concentration of manufacturing infrastructure and rapid adoption rates in key economies. North America and Europe follow as significant markets, driven by stringent energy efficiency regulations and a strong focus on sustainable design in commercial spaces. Emerging regions, including Latin America and the Middle East and Africa, present nascent opportunities that may offer higher growth rates from a smaller base, though they require tailored market entry strategies.
Our analysis examines how these regional disparities influence supply chain logistics and pricing power. The concentration of manufacturing capabilities in specific zones underscores the importance of understanding local regulatory environments and labor dynamics. For example, while advanced production lines offer high precision, they also face challenges related to specialized labor availability and cost structures. By mapping the geographical revenue distribution, companies can better assess where to locate production facilities, where to focus sales efforts, and how to mitigate risks associated with regional economic fluctuations.
Competitive Landscape and Key Industry Players
The OLED lighting panels market is characterized by a mix of specialized manufacturers and large-scale display technology giants. The competitive environment is moderately concentrated, with the top three companies holding a significant share of the market revenue, while the top five players command a majority of the industry value. This structure suggests that while there is room for innovation from smaller players, scale and technological leadership are critical determinants of success.
Several key companies are setting the pace for innovation and commercialization. OLEDWorks, based in Rochester, NY, continues to lead in automotive applications, particularly with its Atala-series panels used for rear lighting and interior personalization. Their focus on high-performance solutions positions them well as vehicle electrification increases the demand for custom lighting profiles. LG Display, headquartered in Seoul, South Korea, brings immense production capacity to the table, with mass production capabilities exceeding 900,000 units annually. Their ability to scale production makes them a formidable player in the commercial lighting space.
In Japan, a cluster of companies is driving technological advancement and material science innovation. Konica Minolta is actively expanding its production capabilities, recently announcing the construction of a new roll-to-roll pilot coating line within its Hino facility in Tokyo. This move signals a commitment to improving manufacturing efficiency and throughput. Lumiotec, located in Yonezawa City, specializes in commercial panels with high color rendering index options, catering to applications where light quality is as critical as efficiency. Kaneka focuses on niche applications, including industrial inspection systems, demonstrating the versatility of OLED technology beyond general illumination.
Furthermore, the supply chain ecosystem is vital. Sumitomo Chemical, also based in Tokyo, provides polymer OLED materials that enable solution-processed panel production using printable ink technology. This material science capability underpins the ability of downstream manufacturers to create flexible and cost-effective panels. NEC Lighting rounds out the competitive landscape by providing panels for commercial and architectural installations, emphasizing the aesthetic and functional integration of OLEDs in built environments.
Recent Developments and Technological Advances
The pace of innovation in 2026 has been particularly brisk, with major players announcing significant milestones that will shape the market for years to come. In March 2026, Konica Minolta unveiled its plans for a new roll-to-roll pilot coating line, a development that promises to enhance production flexibility and potentially lower costs through advanced coating techniques. This infrastructure investment highlights the industry's focus on scaling manufacturing processes to meet growing demand.
May 2026 saw LG Display present next-generation tandem OLED technologies at the SID Display Week. Tandem structures are widely recognized for their potential to improve brightness, efficiency, and lifespan, addressing some of the historical limitations of OLED lighting. This presentation underscored the company's commitment to pushing the boundaries of performance. Following this, in June 2026, OLEDWorks announced advancements in high-performance multi-stack OLED technology. These parallel developments in tandem and multi-stack architectures indicate a industry-wide race to optimize light output and energy consumption, which are critical metrics for both regulatory compliance and consumer acceptance.
Drivers, Restraints, and Market Dynamics
Several macro and micro factors are influencing the market trajectory. Energy efficiency mandates are increasingly driving the adoption of low-power OLED lighting panels in commercial spaces. As governments and building management organizations impose stricter standards on energy consumption, the inherent advantages of OLED technology, such as low heat generation and directional light emission, become more valuable. This regulatory pressure acts as a catalyst for replacing older lighting infrastructure with newer, compliant solutions.
Simultaneously, the automotive sector is undergoing a transformation that benefits OLED lighting. The electrification of vehicles increases the demand for custom OLED lighting panels, as electric vehicle platforms offer more design freedom and require sophisticated lighting signatures for branding and safety. Consumers are increasingly viewing lighting as a key element of vehicle personalization, creating a premium market segment that rewards high-quality, flexible OLED solutions.
OLED Lighting Panels Market
However, challenges remain. The average market price for OLED lighting panels remains a consideration for mass adoption, with industry data indicating prices around 1,600 USD per square meter in 2025. While costs are expected to decrease with scale and process improvements, price sensitivity in certain applications may slow penetration. Additionally, specialized manufacturing faces labor shortages in advanced production lines, which can constrain capacity expansion and increase operational costs. Addressing these constraints requires strategic workforce development and automation investments.
Strategic Recommendations for 2026 and Beyond
For organizations operating in or entering the OLED lighting panels market, the insights from this research point to several actionable strategies. First, understanding the specific needs of high-growth segments is essential. Companies should evaluate whether their portfolios align with the demands of automotive personalization or high-efficiency commercial installations, as these areas show strong momentum. Second, monitoring the technological race between tandem and multi-stack solutions is crucial. Early adoption of next-generation architectures could provide a competitive edge in performance and efficiency, distinguishing products in a crowded marketplace.
Third, supply chain resilience must be prioritized. Given the concentration of manufacturing in specific regions and the reliance on specialized materials from key suppliers, diversifying sourcing and investing in vertical integration where feasible can mitigate risks. Finally, keeping a close watch on regulatory developments regarding energy efficiency will allow companies to anticipate demand shifts and position their products as compliance-ready solutions.
Conclusion
The OLED Lighting Panels Market is at an inflection point where technological maturity meets expanding application scope. The projected growth through 2032 offers substantial opportunities for those equipped with the right intelligence. Our comprehensive market research study provides the detailed segmentation data, competitive profiles, and forward-looking analysis required to make informed decisions. We invite industry leaders to explore the full report to gain access to the granular data and strategic frameworks that will define success in this illuminating sector.
For detailed analysis of this topic, please visit the official page: OLED Lighting Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


