



PW Consulting: Auto Aluminium Wheel Market Hits $165M in 2025, Projected CAGR 2.8% to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Automotive Aluminium Alloy Wheels Market: Navigating 2026 and Beyond
Executive Overview
The automotive aluminium alloy wheels market stands at a critical inflection point in 2026. As original equipment manufacturers accelerate platform electrification, pursue aggressive lightweighting targets, and navigate an increasingly fragmented tariff and raw-material landscape, the strategic importance of wheel supply chain intelligence has never been higher. This report provides a comprehensive, data-driven roadmap for executives, product planners, procurement leaders, and investors who must align their portfolios with structural shifts rather than short-term market noise. By synthesizing five years of historical performance with a seven-year forward outlook, the analysis equips decision-makers with the contextual clarity required to allocate capital, prioritize engineering roadmaps, and recalibrate regional exposure.
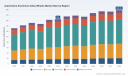
The market has demonstrated resilient recovery patterns following pandemic-era disruptions, with global revenue climbing from approximately 142.3 million USD in 2021 to a projected 175.3 million USD in 2026. Over the full forecast horizon through 2032, the sector is expected to expand at a compound annual growth rate of 2.8 percent, reflecting steady demand from passenger and commercial vehicle segments compounded by regulatory tailwinds and material substitution trends. While headline figures suggest moderate growth, the underlying dynamics reveal significant variation in profitability, capacity utilization, and competitive positioning across manufacturing processes, vehicle architectures, and geographic corridors. Understanding where margin compression concentrates and where premium differentiation can be sustained requires granular segmentation analysis that extends well beyond aggregate market sizing.
Market Trajectory and Structural Growth Drivers
Historical data from 2020 through 2025 illustrates a sector that has rebounded unevenly but decisively. After a brief contraction in 2023, revenue reaccelerated through 2024 and 2025, establishing a foundation for the 2026 to 2032 forecast window. The compound annual growth rate of 2.8 percent reflects a market transitioning from volume-led expansion toward value-driven optimization. Lightweight construction requirements, particularly within passenger vehicles and high-performance SUVs, continue to anchor baseline demand. Simultaneously, commercial vehicle fleets face mounting pressure to reduce total cost of ownership and meet fleet-level efficiency mandates, gradually shifting procurement preferences toward alloy wheels where durability and load ratings justify premium positioning.
The forecast trajectory accounts for both organic end-market growth and structural supply-side adjustments. Regional capacity additions, evolving OEM sourcing strategies, and the gradual reallocation of production toward low-pressure casting and forged architectures influence how value is distributed across the forecast period. Notably, the market does not follow a linear expansion curve; phases of capacity rationalization and technology adoption create inflection points that reward participants with flexible manufacturing footprints and disciplined raw-material hedging strategies. Executives evaluating regional exposure or plant utilization targets must therefore interpret growth projections through the lens of process maturity, contract visibility, and tariff-adjusted landed costs rather than relying on a single blended growth assumption.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a concentrated but highly differentiated supplier base. Global market structure analysis indicates a relatively modest concentration profile, with the top three participants capturing roughly 25.5 percent of total revenue and the top five reaching approximately 29.2 percent. This fragmentation reflects the coexistence of large-scale integrated producers, regional specialists, and aftermarket-focused brands that serve distinct customer segments with varying performance, aesthetic, and cost requirements.
CITIC Dicastal operates as the world's largest producer and exporter of automotive aluminium alloy wheels, supplying OEMs globally with high-volume cast and forged products. Its technological breadth spans LPDC, CPC, spinning, and forging processes, enabling scale advantages in high-volume passenger vehicle programs. Borbet, a family-owned German manufacturer, emphasizes quality, style, and off-road applications across light alloy wheels for cars, caravans, campers, and commercial vehicles. Ronal Wheels positions itself as a premier global supplier of forged and multi-piece alloy wheels, spanning passenger cars, SUVs, commercial vehicles, and premium or racing-oriented lines. Maxion Wheels and Iochpe-Maxion reinforce the southern hemisphere's strategic importance, with Maxion supplying steel and aluminium alloy wheels across passenger, commercial, and specialty segments through global production networks, while Iochpe-Maxion leverages its leadership in aluminium wheels and structural components with targeted expansion in South America for light-vehicle applications.
Aluminum Alloy Wheels Market
The aftermarket and performance segments introduce a parallel competitive layer. Enkei supplies major Japanese and global automakers with lightweight OEM and aftermarket alloy wheels, while American Racing delivers performance, custom, and vintage designs with strong aftermarket credibility. Wheel Pros functions as a designer and marketer of aftermarket alloy wheels that is actively expanding into forged and high-performance luxury segments. Alcoa Corporation maintains its position as a global leader in forged aluminium wheels, emphasizing sustainable, low-carbon solutions for premium and OEM applications. MAK Wheels rounds out the competitive field as an Italian manufacturer of custom alloy wheels for cars, SUVs, 4x4, and heavy-duty applications, with recent dedicated model development for major OEMs.
Recent product activity underscores the pace of innovation and brand differentiation. In early 2026, MAK Wheels introduced its 2026 collection, including the KULT and AURUM models dedicated to BMW and Mercedes-Benz programs alongside the LEGEND model developed for 4x4, heavy-duty, and camper applications. Earlier in 2025, MAK launched the Stark flagship alloy wheel targeting Volkswagen Group vehicles and broader SUV and car segments, while American Racing announced the TTF II drag-inspired wheel designed for high-performance trucks. These launches reflect a dual strategy across the industry: OEM program exclusivity that secures volume stability, and aftermarket or specialty positioning that supports premium pricing and brand affinity.
Demand Architecture Across Vehicles, Channels, and Processes
Demand segmentation analysis reveals how revenue is distributed across vehicle types, sales channels, and manufacturing methodologies, providing essential context for capacity planning and product mix optimization. Passenger vehicles account for the larger share of total market revenue, while commercial vehicles represent a substantial secondary pool driven by fleet durability, total cost of ownership considerations, and heavy-duty load requirements. The channel split between OEM and aftermarket demand further clarifies where volume stability and margin flexibility intersect. OEM relationships deliver multi-year program visibility but introduce price compression cycles and technical qualification burdens. Aftermarket demand offers faster response to design trends and regional customization, though it remains more exposed to discretionary spending cycles and retail channel dynamics.
Manufacturing process segmentation adds another layer of strategic relevance. Casting remains the dominant process by revenue, reflecting its cost efficiency and suitability for high-volume passenger vehicle programs. Forging contributes a meaningful share associated with strength-to-weight advantages and premium positioning, particularly in performance and light-duty commercial applications. Flow forming occupies a more specialized role, often bridging cost and performance objectives for targeted applications. Because each process carries distinct capital intensity, cycle time, material yield, and qualification requirements, participants must evaluate their process portfolios against the specific growth profile of their target segments rather than treating process capability as a generic competitive lever.
Automotive Aluminium Alloy Wheels Market
Operating Environment: Cost Volatility, Tariffs, and Regulatory Acceleration
The operating environment in 2026 and beyond is shaped by three interlocking forces: raw-material cost volatility, evolving trade policy, and tightening emission regulations. Aluminium prices represent a dominant share of production costs in automotive aluminium alloy wheels, and annual price fluctuations in the range of 18 to 22 percent continue to exert pressure on manufacturer margins. Suppliers without integrated procurement strategies, long-term supply agreements, or effective hedging programs face structural disadvantage when market conditions shift suddenly. Recruitment of low-carbon and recycled aluminium content is increasingly viewed as a dual-purpose response, supporting both cost resilience and sustainability commitments while opening access to 고객에게 preferred supplier status in OEM networks.
Trade policy developments have introduced new complexity to cross-border sourcing. Tariff actions on aluminium articles have raised the cost of imported wheels and parts, directly affecting landed-cost calculations for distributors, retailers, and OEM supply chains that rely on international procurement. At the same time, proposed and implemented tariff escalations on goods from key trading partners create uncertainty around supply continuity and shift the attractiveness of regional production footprints. Companies that previously optimized solely for unit cost must now incorporate tariff exposure, logistics flexibility, and customs-resolution timelines into their sourcing models. The result is a market in which tariff-aware capacity placement and dual-sourcing strategies are becoming baseline requirements rather than optional safeguards.
On the regulatory side, tightening CO2 emission targets for passenger cars are accelerating OEM demand for lighter aluminium alloy wheels as one component of broader fleet efficiency improvement programs. Weight reduction contributes directly to fuel economy and electric range performance, making alloy wheel specifications a tangible lever within multi-parameter engineering optimization. This regulatory push reinforces long-term demand for lightweight structures and supports premium positioning for suppliers that can demonstrate measurable weight savings, consistent quality, and compliance with OEM specifications. As vehicle architectures evolve, especially within electrified platforms, wheel design requirements may also shift toward thermal management, load distribution, and integration with suspension and braking systems, creating opportunities for suppliers with advanced engineering capabilities.
Sustainability, Recycling, and Strategic Capacity Evolution
Sustainability expectations are reshaping procurement priorities and capacity investment decisions. Recycled aluminium content in wheels is increasing as manufacturers seek to align with corporate environmental goals and customer-facing sustainability commitments. New production line investments in markets such as Mexico and Brazil are expanding capacity for low-pressure cast aluminium wheels while supporting the broader transition toward lower-carbon material inputs. This evolution is not merely a compliance exercise; it affects supplier qualification, brand positioning, and long-term cost structure as recycled material availability and processing efficiency improve.
For OEM-facing suppliers, sustainability credentials increasingly intersect with commercial competitiveness. Programs that can demonstrate traceability, reduced embedded carbon, and consistent mechanical performance are better positioned to win and retain high-value contracts. For aftermarket players, sustainability messaging can support premium pricing in segments where customers value environmental responsibility alongside aesthetics and performance. However, the operational reality is that sustainability investments must be paired with disciplined cost management and process reliability. Otherwise, the margin impact of raw-material volatility can quickly offset the strategic benefits of greener sourcing.
Strategic Implications for 2026 Decision-Making
Translating this landscape into actionable strategy requires a disciplined focus on several priority areas. First, portfolio alignment should distinguish between volume stability in OEM programs and margin opportunity in aftermarket and performance segments, ensuring that capacity and commercial resources reflect the distinct economics of each channel. Second, process configuration must be reviewed against segment growth profiles, with casting supporting high-volume cost competitiveness, forging enabling premium differentiation, and flow forming addressing targeted performance niches. Third, supply chain architecture should incorporate tariff-aware sourcing, regional flexibility, and raw-material risk management, given the persistent volatility of aluminium prices and the ongoing evolution of trade measures.
Fourth, sustainability and lightweighting should be treated as interconnected strategic priorities rather than separate initiatives. The same engineering capabilities that reduce weight can often be paired with lower-carbon material strategies and recycling pathways that strengthen OEM qualification and aftermarket positioning. Fifth, competitive intelligence should go beyond headline market shares to assess process mix, program pipeline visibility, regional footprint, and brand strength within specific vehicle types and customer segments. In a market where the top three participants collectively account for just over a quarter of revenue, the ability to capture differentiated value depends on precision positioning rather than scale alone.
What the Full Report Delivers
This summary frames the strategic questions that matter most entering 2026, but the complete report provides the detailed segmentation, competitive benchmarking, and scenario analysis required to convert direction into execution. The full study breaks down market size and growth trajectories by region, vehicle type, OEM versus aftermarket channels, and manufacturing process, enabling precise identification of where growth is concentrated and where margin pressure is most acute. It examines competitive positioning for key global suppliers, incorporating recent product launches, technology focus, and regional expansion patterns, while contextualizing operating dynamics through raw-material cost volatility, tariff developments, and regulatory demand drivers. The analysis also explores sustainability trends and capacity evolution, offering practical frameworks for evaluating sourcing strategy, product mix, and program prioritization.
For executives responsible for capital allocation, product planning, procurement, or market entry, the complete report functions as a decision-support tool that turns market complexity into structured insight. The full dataset, segmentation detail, and competitive profiles are available through the source market research page, where readers can access the complete intelligence package designed to support 2026 strategy formulation and execution.
For detailed analysis of this topic, please visit the official page: Automotive Aluminium Alloy Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Piano Market Hits $2,025M in 2025, Eyeing 5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Digital Piano Market 2026-2032
The global musical instrument sector stands at a compelling inflection point, and within it, the digital piano market emerges as a high-value consolidation play. For executives, supply chain leaders, and product strategists, the transition from 2026 onward demands more than historical benchmarking. It requires a forward-looking, data-anchored map of demand shifts, technological substitution rates, regional consumption patterns, and competitive maneuvering. Our latest Digital Piano Market research report delivers precisely that blueprint, translating multi-year macroeconomic tracking and granular segmentation modeling into actionable intelligence tailored for enterprise decision-making in 2026.
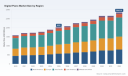
Built on a rigorous historical foundation spanning 2020 to 2025, this analysis traces a clear trajectory of sustained commercial expansion. The market crossed the 2,025 million USD threshold in the base year, reflecting durable demand resilience despite macroeconomic volatility and evolving retail channels. Moving forward, our forecast horizon runs through 2032, anchoring enterprise planning around a projected CAGR of 5.0 percent. This growth path is not a flat extrapolation; it captures nuanced acceleration and stabilization phases, regional maturity differentials, and product-cycle timing that will directly shape capital allocation, inventory strategy, and market-entry sequencing. By publishing this intelligence now, we equip leadership teams with the temporal advantage required to act ahead of pricing resets, product launches, and channel realignments that typically define mid-decade industry cycles.
The 2026 Decision Architecture: How This Research Informs Strategy
Strategic planning in 2026 rarely succeeds through isolated data points. It requires contextual modeling that connects market sizing with operational realities. This report is structured around that need. Instead of presenting static snapshots, we embed market value evolution within a continuous analytical framework, enabling readers to benchmark internal performance against market rhythm, evaluate investment timing, and test sensitivity scenarios across product categories, distribution pathways, and consumer usage behaviors.
The strategic value of this publication lies in its ability to convert broad market momentum into targeted guidance. For manufacturers, the analysis clarifies where capacity expansion, SKU rationalization, or premium-tier positioning will likely generate the strongest return profile. For distributors and retailers, it illuminates category velocity, purchase intent dispersion, and the changing weight of different end-use environments. For investors and corporate development teams, the study offers a structured lens on concentration patterns, competitive resilience, and the scalability of regional demand centers. Throughout, the report preserves analytical discipline: it surfaces directional magnitude and structural behavior while intentionally reserving the most precise segmentation estimates for the full edition, where interactive tables, scenario overlays, and region-specific breakdowns can be evaluated in context.
Piano (Pianoforte) Market
Inside the Report: Operational Intelligence Beyond Top-Line Growth
The depth of this research reflects a deliberate focus on practical application. The full report is organized to support cross-functional teams, with content designed to feed pricing strategy, product roadmapping, channel negotiation, and competitive response planning. Key analytical components include:
- Longitudinal market tracking that connects historical performance with forward estimates, allowing readers to evaluate momentum consistency and identify inflection intervals across the forecast window.
- Segment-level structural analysis covering product architectures and usage contexts, with emphasis on how each category contributes to overall market composition and where performance divergence is expected to widen or narrow.
- Regional demand mapping that distinguishes mature consumption environments from higher-growth territories, informing localization priorities, entry timing, and channel-mix strategies without reducing complexity to oversimplified rankings.
- Competitive benchmarking that examines corporate positioning, offering architecture, and differentiation models across both established premium manufacturers and value-oriented producers.
- Market concentration evaluation, helping stakeholders gauge consolidation pressure, competitive moat durability, and the strategic implications of leadership-group scale.
- Regulatory and compliance context analysis, including customs classification norms, environmental management expectations in production ecosystems, and the current absence of new export or environmental restrictions that could disrupt supply continuity.
- Material and engineering considerations relevant to premium-tier instruments, including acoustic-wood integration, soundboard construction, and the broader implication of material choices on cost structures and brand positioning.
This structure ensures that the report functions as an operational reference rather than a passive overview. By weaving together market sizing, structural segmentation logic, competitive behavior, and compliance context, the study provides a decision-ready environment for scenario modeling and internal alignment.
Competitive Landscape and the 2026 Rearrangement
The digital piano market remains characterized by a concentrated leadership group, yet the competitive dynamic is far from static. Industry leaders continue to invest in sound-engine refinement, hybrid action technologies, app connectivity, and design differentiation, while a second tier of manufacturers competes through accessibility, OEM/ODM flexibility, and targeted entry-level positioning. Our analysis highlights how these strategic postures shape pricing power, brand loyalty, and channel leverage across different customer segments.
Among the firms examined, several stand out for their distinct product philosophies and ongoing innovation cadence. Yamaha Corporation continues to anchor its offering around the Clavinova and Arius lines, with attention to advanced sound engines and app integration that reinforce its premium and mid-tier appeal. Roland Corporation pursues a parallel high-performance strategy, drawing on its FP and GP series alongside PureAcoustic technology to bridge portable and grand-model expectations. Kawai Musical Instruments Manufacturing Co., Ltd. emphasizes Harmonic Imaging technology across its ES, MP, and CX series, reinforcing tonal fidelity as a central differentiator. Casio Computer Co., Ltd. extends its reach through the Celviano and Privia series, leveraging Grand Hybrid sound concepts and Smart Hybrid Hammer Action to appeal to both aspirational and practical buyers. Korg Inc. contributes a focused portable and compact portfolio through its Liano and LP series, prioritizing high-quality piano sounds in accessible form factors. Further north, Clavia DMI advances a technology-forward identity with the Nord Piano series, employing AI sampling and advanced modeling to address players seeking expressive nuance. In the United States, Williams Pianos supports broader accessibility with portable and console models built around 88-note weighted action. Meanwhile, Lida Electronic Co., Ltd. addresses entry-level and portable demand with hammer-action keyboards and strong OEM/ODM capabilities, reflecting the importance of manufacturing flexibility in the value segment.
What makes the 2026 environment especially significant is the velocity of visible corporate action. Recent developments already hint at product-cycle intensity and pricing recalibrations that may influence broader market behavior. In January 2026, Roland Corporation announced the KIYOLA KF-20 and KF-25 artisan digital pianos, developed in collaboration with Karimoku in Japan, a move that signals continued interest in elevating craftsmanship perception and domestic design integration. Later in the year, Yamaha Corporation announced a price increase on Clavinova digital pianos, effective May 4, 2026, a development that is particularly relevant for channel planning, margin forecasting, and competitive response analysis.
These moves should not be read in isolation. They align with a broader environment in which premium instruments continue to incorporate soundboard materials and acoustic woods, reinforcing the link between material selection and perceived value, even as specific price trends for such inputs remain variable. At the same time, the regulatory backdrop has remained comparatively stable: digital pianos and keyboards fall under HS Code 92071030, with ERGA OMNES duty application across regions and no targeted tariff updates identified. ISO 14001 environmental management certification continues to be maintained within relevant manufacturing facilities, and no new environmental restrictions or export controls have been imposed on digital piano production or shipping. This regulatory continuity matters because it reduces near-term uncertainty for cross-border planning while preserving the importance of established compliance disciplines.
Market Dynamics, Concentration, and Strategic Opportunities
One of the most strategically relevant features of this market is the balance between concentration and segmentation opportunity. The leadership group commands meaningful share, and that concentration shapes negotiation dynamics, retailer relationships, and brand visibility. Yet the market is large enough, and diverse enough in usage contexts, to sustain differentiated strategies across learning environments, entertainment applications, performance settings, and other specialized use cases. This diversity is precisely where more detailed segmentation analysis becomes indispensable, because the strategic implication of each segment depends not only on size, but also on purchasing cadence, sensitivity to feature upgrades, and responsiveness to pricing shifts.
Our report addresses that complexity by separating magnitude from mechanism. Readers gain a clear view of how the market is composed and where structural pressure is building, while reserving the most precise numerical breakdowns for the complete dataset. This approach preserves interpretive clarity while avoiding premature reduction of nuanced segment behavior into static numbers. For 2026 planning, that distinction is critical. A company evaluating whether to expand into a higher-growth region, reposition a portable line, or strengthen institutional learning-channel partnerships needs to see the shape of demand before committing to specific allocations. This publication provides that shape, and the full report delivers the precision needed to convert it into execution.
Beyond concentration and segmentation, the market presents several recurring strategic themes that our analysis brings into sharper focus. First, the interaction between product design and ecosystem integration continues to influence buyer preference, especially where app connectivity, sound modeling, and action response are treated as integrated value propositions rather than isolated features. Second, the tension between craftsmanship signaling and mass-market accessibility is intensifying, with companies pursuing both artisan collaboration and entry-level scalability in the same competitive landscape. Third, supply coherence remains essential in an environment where premium materials, manufacturing certifications, and stable customs classification continue to define operational expectations. Each of these themes carries implication for pricing, channel mix, and product roadmaps, and each is examined with enough granularity in the full edition to support concrete planning choices.
Digital Piano Market
Conclusion: Turning Market Intelligence into 2026 Action
The digital piano market is entering a phase where historical consistency and forward momentum coexist with rapid product evolution, selective pricing adjustments, and sustained competitive investment. That combination creates both opportunity and risk for organizations that must decide where to align resources, how to position portfolios, and when to respond to competitor moves. Our Digital Piano Market research report is designed to reduce the ambiguity around those decisions by offering a coherent analytical narrative anchored in verified historical data and disciplined forward estimates.
For teams preparing for 2026 and beyond, the strategic imperative is not simply to know that the market is growing, but to understand how growth is distributed, where competitive intensity is rising, and which operational and regulatory conditions will shape execution. This publication opens that window. It presents the structural logic of the market, contextualizes recent corporate developments, and frames the questions that leadership teams should be asking now. To access the full segmentation breakdowns, region-specific estimates, and scenario-ready detail that support precise investment and planning decisions, we invite you to explore the complete report on our website. The highest-value intelligence is there, ready to be translated into strategy.
For detailed analysis of this topic, please visit the official page: Digital Piano Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isothermal Packaging Market Hits $91.4M in 2025, Set for 5.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Isothermal Packaging Market: Navigating the 2026 Decision Landscape
The isothermal packaging sector stands at a critical inflection point. As global supply chains tighten and temperature-sensitive logistics become increasingly complex, the ability to maintain controlled temperatures without relying entirely on active refrigeration is no longer a tactical convenience; it is a strategic imperative. PW Consulting understands that executive teams require more than high-level market summaries. They need structural clarity, competitive positioning, and forward-looking intelligence that can be immediately applied to capital allocation, product development, and partnership strategy. Our latest comprehensive market research on the Isothermal Packaging Market is built precisely for that purpose, offering decision-makers a rigorous foundation to act with confidence throughout 2026 and beyond.
The narrative emerging from the full report is one of disciplined expansion, material innovation, and regulatory maturation. Gross revenue has progressed from 68.5 million USD in 2020 to 91.4 million USD in 2025, reflecting both sustained demand and the sector’s gradual ability to absorb higher compliance costs and sustainability expectations. Looking ahead, the forecast window tracked in the study extends through 2032, with the trajectory anchored by a projected compound annual growth rate of 5.7 percent. By 2032, total market revenue is positioned to reach 134.8 million USD. These headline figures are not abstract indicators; they frame a market that is large enough to reward focused investment yet fragmented enough to penalize undifferentiated strategy. The real question for leadership teams is not whether isothermal packaging will grow, but which segments, capabilities, and partnerships will convert that growth into durable competitive advantage.
Why This Research Matters for 2026 Decision-Making
Over the past five years, historical data shows a market that has consistently advanced in step with broader cold chain complexity. Revenue moved from 74.78 million USD in 2021 through 76.69 million USD in 2022, 79.64 million USD in 2023, and 87.09 million USD in 2024 before crossing the 90 million USD threshold in 2025. That path matters strategically because it signals a market that has moved past isolated growth spurts into a more predictable, structurally supported expansion phase. For 2026, this means planning cycles can no longer rely on assumption-driven growth estimates or generic trend commentary. Corporate strategy requires evidence-based segmentation, competitor benchmarking, and a clear read on the operational forces shaping adoption.
The forecast period from 2026 to 2032 further underscores the value of disciplined foresight. Starting from an estimated 94.8 million USD in 2026, the projected climb to 102.62 million USD in 2027, 108.95 million USD in 2028, 113.39 million USD in 2029, and 121.09 million USD in 2030 reflects an environment where demand is broadening across end-use categories while supply-side innovation is steadily reshaping cost structures and performance specifications. Executives evaluating M&A, capacity expansion, service-line extensions, or geographic entry will find that the study provides a reasoned framework rather than a static snapshot. In fast-moving life sciences and temperature-controlled logistics markets, the difference between a reactive decision and a strategically timed one often comes down to how well an organization understands the forces shaping the next several quarters, not just the current quarter.
Equally important, the research is designed to support practical decisions around product architecture and operational footprint. Isothermal solutions are increasingly judged not only on thermal performance, but also on reusability, reverse logistics, material sourcing, and compliance readiness. As a result, strategy teams need insight that connects market size and growth to operational realities, including how manufacturers are adapting to evolving standards, what raw materials are gaining prominence in packaging construction, and where sustainability expectations are beginning to influence procurement and design choices. The full report is structured to help leaders translate these dynamics into concrete actions, whether that means refining a product roadmap, reassessing supplier relationships, or identifying where differentiation can be built into both engineering and service models.
How the Study Is Structured for Actionable Intelligence
This research is organized to serve multiple internal audiences at once. It is detailed enough for strategy, product, and supply chain teams that need granular context, while remaining clear enough to inform board-level discussions about market positioning, investment priorities, and risk exposure. Rather than presenting a single aggregated story, the study breaks the market down across meaningful structural dimensions so that executives can identify where growth is concentrated, where competitive pressure is most intense, and where long-term differentiation is most achievable.
Refrigeration Packaging Market
By type, the market includes distinct material and design pathways, each with its own cost, performance, and sustainability profile. The study examines how these categories compete on functionality and customer preference, and where engineering trade-offs influence adoption. In practice, the type landscape matters because it determines not only what is being purchased, but why it is being purchased. Performance requirements tied to heat retention, weight constraints, reusability, and end-of-life handling can shift demand between materials and designs, which means product strategy must account for both technical compatibility and procurement behavior.
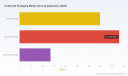
By application, isothermal packaging serves multiple high-stakes sectors, each with different compliance burdens, shipment patterns, and tolerance thresholds. The report explores how demand diverges across these usage contexts and why some applications are more sensitive to innovation in reusable systems, monitoring integration, and sustainable material substitution. Application-level insight is especially valuable in 2026, because buyer expectations are no longer limited to basic temperature control; they increasingly include assurance, transparency, and evidence of environmental or operational responsibility throughout the product lifecycle.
By region, the analysis reflects the uneven pace of adoption and the differing regulatory environments that shape local demand. Geography is not treated as a decorative layer of data, but as a strategic lens for understanding where volume, competitiveness, and market entry barriers differ. This regional framing helps companies evaluate distribution models, localization requirements, and partnership opportunities with the nuance they require, particularly when deciding whether to serve a market through existing infrastructure or build a dedicated presence. Regional dynamics can also reveal where certain materials or packaging formats gain traction more quickly, which can influence sourcing, service design, and expansion timing.
Beyond segmentation, the study connects the market to an evolving operating environment that is shaping how players compete. Regulatory expectations are becoming a more active force in packaging design and procurement, especially where temperature-sensitive shipments must satisfy stringent handling standards. At the same time, producer responsibility frameworks are increasingly influencing how packaging components are evaluated at end-of-life, pushing attention toward recyclable and reusable configurations. Raw material choices are also part of the conversation, with certain insulation structures continuing to play a central role in isothermal packaging construction while recycled inputs are making measurable inroads into more sustainable shipper designs. These forces are not peripheral; they are reshaping cost structures, product roadmaps, and customer selection criteria. Understanding them in context is essential for any organization that wants to anticipate change rather than simply respond to it.
Competitive Dynamics That Define Strategic Positioning
The competitive landscape is shaped by a specialized set of manufacturers and solution providers whose capabilities span thermal engineering, compliance, sustainability, and logistics support. The report provides company-level context that helps leaders understand how incumbents are positioning themselves and where the market may be vulnerable to new entrants or partnership-driven disruption.
-
EMBALL'ISO specializes in high-performance passive isothermal packaging solutions for life sciences, including vaccines and biologics, with reuse and reverse logistics services.
-
Sofrigam designs, manufactures, and deploys lightweight, sustainable isothermal packaging for pharmaceutical, biotech, and healthcare temperature-sensitive products.
-
Cryopak provides complete cold chain packaging solutions including insulated containers, gel packs, phase change materials, and sustainable reusable programs.
-
Peli BioThermal offers reusable and single-use thermal packaging solutions for pharmaceuticals, clinical trials, and life sciences cold chain distribution.
-
Cold Chain Technologies delivers sustainable thermal packaging including reusable pallet and parcel solutions with digital monitoring for life sciences.
-
Intelsius manufactures environmentally sustainable temperature-controlled packaging and sample transport solutions compliant with UN regulations.
-
Isovation manufactures innovative isothermal packaging for healthcare, food, and logistics to maintain controlled temperatures.
-
Zfoam supplies foam materials and solutions for isothermal packaging in food, pharma, and industrial applications.
What distinguishes this group is not only the breadth of their technical offerings, but the strategic directions embedded in them. Several players are leaning into reusable and reverse logistics models, suggesting that the market is beginning to reward lifecycle thinking over single-transaction product sales. Others are emphasizing lightweight construction and sustainable materials, aligning product design with procurement expectations around environmental impact. Some are integrating monitoring and digital capabilities into thermal packaging programs, which points to a broader shift toward visibility and assurance as part of the value proposition. For decision-makers, this matters because competitive advantage may increasingly depend on how well a company can combine thermal reliability, compliance readiness, and sustainable service design in a single coherent offering.
Market structure also suggests that concentration is meaningful, but not absolute. The study examines concentration indicators that help explain where scale, reputation, and integrated service capabilities matter most. In markets with meaningful share held by a limited set of established providers, new entrants often have to compete through differentiated design, niche application expertise, or a stronger sustainability and logistics narrative. In that context, understanding competitor profiles is not about memorizing company names; it is about recognizing capability clusters, identifying where incumbents are stretched, and assessing which buyer segments are most open to alternative solutions.
What Strategic Leaders Should Watch in 2026
As isothermal packaging moves further into a period of material and regulatory evolution, several themes warrant close attention. The first is the increasing importance of compliance as a design constraint. Temperature-sensitive shipments involving biological and medical materials must align with recognized handling standards, which means packaging is no longer a passive shell but a regulated component of the logistics chain. Companies that treat compliance as a late-stage requirement risk rework, delayed adoption, and weaker customer confidence.
The second theme is the pressure to reduce environmental footprint without sacrificing thermal performance. Extended producer responsibility considerations and broader sustainability expectations are influencing how packaging components are sourced, used, and recovered. At the same time, post-industrial recycled inputs are being integrated into more sustainable shipper designs, signaling that circularity is moving from aspiration to engineering practice. For manufacturers and buyers alike, this trend raises practical questions about trade-offs between reuse, recyclability, weight, insulation effectiveness, and total cost.
The third theme is the role of insulation material choices in shaping both performance and market positioning. In many isothermal packaging structures, polyurethane foam insulation remains a core raw material, reinforcing the importance of material availability, consistency, and innovation in product development. Yet the broader landscape is not static; demand is also shaped by alternatives and hybrid approaches that aim to balance thermal reliability with weight, cost, and sustainability goals. Companies that understand these material dynamics can make more informed decisions about sourcing, product architecture, and differentiation.
Isothermal Packaging Market
The fourth theme is the rise of service-oriented value. Reuse and reverse logistics, digital monitoring, and program-based deployment models are becoming more visible in the market, indicating that buyers increasingly value outcomes over components alone. This shift has strategic implications for pricing, customer retention, and competitive differentiation. It also means that companies evaluating their market position should consider not only what they sell, but how they support it across the shipment lifecycle.
Why the Full Study Is Built for Decision-Makers
This research is designed to help leadership teams convert market intelligence into decisions that are defensible, timely, and specific. The complete report provides deeper segmentation analysis, competitor context, regulatory and materials dynamics, and forecast pathways that support planning across 2026 and the 2026–2032 horizon. It is intended for strategy, operations, product, and investment teams that need to assess where the market is heading and how their organization can respond with precision.
Because isothermal packaging sits at the intersection of performance, compliance, sustainability, and logistics, isolated data points are rarely enough. Decision-makers benefit most from a structured view that links market size, growth trajectory, segmentation behavior, and competitive posture into a single coherent narrative. That is the purpose of the full study: to give executives a reliable foundation for prioritizing investments, refining product and service strategy, and anticipating the forces that will shape demand in the coming years.
If your team is preparing for 2026 planning cycles, evaluating market entry or expansion, or assessing how thermal packaging strategy should evolve alongside regulatory and sustainability expectations, the complete report offers the depth required to move from broad awareness to actionable insight. The full analysis goes beyond summary figures to examine the structural forces that will determine where growth concentrates and how competition intensifies. For organizations that rely on temperature-controlled distribution, this is the kind of intelligence that can help shape decisions before the market shift becomes obvious to everyone else.
The complete PW Consulting study on the Isothermal Packaging Market is available through our research portal, where you can access the full segmentation framework, competitive profiles, regulatory and materials context, and the extended forecast view that supports strategic planning well beyond the 2026 horizon. For teams seeking a clear, evidence-based path through a market that is both expanding and becoming more demanding, this report is built to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Isothermal Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DOTP Market Hits $2.15B in 2025, Projects 5.55% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Dioctyl Terephthalate (DOTP) Market: Strategic Foresight for 2026 and Beyond
The global chemicals landscape is undergoing a structural shift, driven by tightening regulatory frameworks, evolving downstream performance requirements, and a recalibration of supply chain geographies. At the center of this transformation sits Dioctyl Terephthalate (DOTP), a high-performance, non-phthalate plasticizer that has steadily gained traction as a critical enabler for flexible PVC applications across multiple end-use sectors. For procurement leaders, R&D directors, and strategic planners, the 2026 operating environment demands more than incremental forecasting. It requires a precise, forward-looking intelligence architecture that connects macroeconomic trajectories, regulatory inflection points, and competitive positioning into actionable strategy.
Our newly released Dioctyl Terephthalate (DOTP) Market research report is engineered to serve as that architecture. Spanning a rigorous historical baseline from 2020 through 2025 and extending into a forward-looking forecast window from 2026 to 2032, this study translates complex market signals into a coherent decision-making framework. The analysis is anchored in verified revenue trajectories, measured in USD millions, and calibrated to a long-term growth profile that reflects both near-term momentum and structural maturation. As we move deeper into the forecast period, the market is projected to expand to approximately 2.35 billion USD in 2026, continuing its upward trajectory toward a 2032 valuation that underscores sustained industrial demand. This growth is underpinned by a compound annual growth rate of 5.55 percent, a figure that captures the balance between volume expansion, pricing dynamics, and the gradual substitution of legacy phthalate-based additives.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a unique convergence of challenges and opportunities. On one side, manufacturers are navigating raw material procurement volatility, where the stoichiometric relationship between terephthalic acid and 2-ethylhexanol must be carefully optimized to balance cost efficiency with yield stability. On the other side, regulatory scrutiny has intensified, particularly in key import markets where trade remedy investigations have reshaped duty landscapes and altered competitive accessibility. Companies that treat these dynamics as isolated operational issues risk strategic misalignment. Those that integrate them into a unified market intelligence model can anticipate margin pressure points, identify compliant sourcing pathways, and align capacity investments with genuine end-use demand shifts.
This report is structured to bypass superficial trend commentary and deliver operational precision. It examines how material specifications, compliance certifications, and supply chain logistics intersect with regional demand patterns and application-specific performance thresholds. By mapping the interplay between production scalability, product grade differentiation, and regulatory validation, the study equips stakeholders with a clear lens through which to evaluate partnerships, sourcing strategies, and market entry or expansion scenarios. The narrative deliberately avoids granular percentage breakdowns or isolated regional revenue figures, focusing instead on the structural forces that will define competitive advantage throughout the forecast horizon.
Report Architecture: From Macro Trajectory to Operational Execution
The research is organized into a multi-layered framework designed for cross-functional utility. At the top level, the historical and projected revenue arc provides a validated baseline for scenario modeling. This is not a static curve; it is contextualized by capacity evolution, grade positioning, and the shifting economics of non-phthalate plasticizer adoption. The analysis tracks how market participants have navigated the transition from volume-driven growth to value-driven differentiation, particularly as downstream sectors demand materials that balance flexibility, thermal stability, and regulatory compliance.
A core component of the report delves into supply chain architecture and material dynamics. The production pathway for DOTP relies on precise feedstock integration, where the theoretical mass ratio of terephthalic acid and 2-ethylhexanol determines output yield per ton of processed material. Understanding this stoichiometric foundation is essential for evaluating cost structures, feedstock sensitivity, and the operational leverage available to integrated producers versus specialty formulators. The report examines how variations in feedstock procurement, synthesis guidance, and bulk supply arrangements influence competitive positioning, particularly for manufacturers that offer technical-grade formulations tailored to film, sheet, gaskets, molding, automotive interiors, floor coverings, cable insulation, and protective coatings.
Regulatory and compliance mapping forms another critical pillar. The study traces how food-contact migration limits, medical device standards, and children's article restrictions have become baseline expectations rather than niche differentiators. Products that meet established FDA indirect food additive migration thresholds and EU REACH requirements are no longer optional; they are table stakes for markets that demand versatility across packaging, synthetic leather, and consumer-facing applications. The report analyzes how compliance validation intersects with product launch cadence, capacity expansion milestones, and long-term supply reliability, ensuring that strategic planners can assess risk exposure with precision rather than speculation.
Competitive Positioning and Market Concentration Dynamics
The competitive landscape reveals a market characterized by moderate concentration, with the top three participants collectively representing a substantial share of total revenue, while the top five extend that footprint into a broader but still consolidated structure. This concentration pattern reflects the capital intensity of dedicated production assets, the importance of feedstock control, and the value of established regulatory clearances. The report profiles the strategic posture of leading market participants, examining how each has carved out operational advantages through product differentiation, geographic reach, and application-specific technical support.
Among the profiled organizations, several illustrate the diverse pathways to competitive relevance. A U.S.-based specialist emphasizes technical-grade formulations designed as non-phthalate PVC plasticizer alternatives, distributed across drums, totes, and bulk channels to serve film and sheet manufacturing, gasket production, molding operations, automotive components, floor coverings, cable systems, and coating applications. A China-based manufacturer focuses on high-temperature-resistant DOTP grades tailored for cable applications, automotive interiors, food packaging, and synthetic leather, complemented by synthesis guidance and scalable bulk supply capabilities. Another China-based producer positions its DOTP plasticizer around PVC flexibility and durability, targeting automotive, construction, consumer goods, and medical applications while maintaining compliance with REACH and FDA standards. A Poland-headquartered producer operates as the largest EU-based manufacturer, leveraging a dedicated plant that utilizes proprietary 2-ethylhexanol feedstock to deliver a flagship non-phthalate plasticizer for PVC cables, automotive segments, flooring, and flexible packaging, with product validation extending to food-contact materials, children's articles, and medical devices.
Beyond static profiling, the report integrates recent market developments that signal how competitive dynamics are evolving. A major European producer marked the anniversary of its flagship DOTP launch, highlighting a decade of production stability and quality consistency alongside a capacity increase initiated in 2018 that underscores long-term commitment to non-phthalate plasticizer expansion. Separately, an Italian specialty manufacturer developed and introduced a high-performance grade engineered for flexible PVC packaging, emphasizing low volatility, enhanced flexibility, and environmental compliance. These developments are not isolated announcements; they reflect strategic responses to shifting downstream requirements, regulatory expectations, and the growing premium on application-specific performance attributes. The study synthesizes these activities into a forward-looking competitive assessment, enabling readers to gauge which operational models are scaling effectively and where market share reallocation is likely to occur.
Regulatory Inflection Points and Trade Dynamics
No strategic assessment of the DOTP market is complete without a rigorous examination of the regulatory and trade environment that shapes market access, cost structures, and competitive parity. The report provides a detailed timeline of trade remedy actions, mapping the progression from initial investigations through determinations of material injury and the subsequent issuance of antidumping duty orders. These developments have direct implications for import pricing, supply diversification strategies, and the relative competitiveness of domestically produced versus imported material.
The analysis traces how U.S. trade authorities evaluated imports originating from multiple jurisdictions, determining that material injury had occurred from shipments sold at less than fair value. This determination triggered antidumping duty orders that have reshaped the commercial calculus for both suppliers and buyers. The report contextualizes these actions within a broader regulatory enforcement pattern, noting that investigations were initiated by the U.S. Department of Commerce in mid-2024 and culminated in formal determinations by early 2025. For strategic planners, the critical insight lies not merely in the existence of duties but in how they interact with feedstock dynamics, capacity geography, and downstream compliance requirements. The study examines how market participants are adapting sourcing strategies, evaluating alternative supply corridors, and aligning product positioning with regulatory realities to preserve margin integrity and supply continuity.
Dimethyl Terephthalate (DMT) Market
Simultaneously, the report emphasizes that regulatory compliance is not solely a defensive function. Products validated under established food-contact migration limits and REACH frameworks are increasingly leveraged as competitive differentiators, particularly in applications where indirect food contact, medical device integration, or consumer safety standards dictate material selection. The study maps how compliance validation supports premium positioning, enables access to restricted downstream segments, and reduces qualification friction for new product introductions. By connecting regulatory milestones to commercial outcomes, the report provides a practical lens for assessing which product grades and supply partnerships are best positioned to capture value in a compliance-driven market environment.
Strategic Takeaways for Forward-Looking Planning
As organizations prepare their 2026 strategies, the DOTP market presents a clear mandate: success will belong to those who align operational execution with structural market intelligence. The convergence of sustained demand growth, moderate market concentration, evolving trade remedy frameworks, and rising compliance expectations creates a landscape where generic sourcing strategies and reactive procurement models are insufficient. Companies must evaluate feedstock integration, grade differentiation, capacity scalability, and regulatory validation as interconnected variables rather than isolated operational concerns.
Dioctyl Terephthalate (DOTP) Market
This report is designed to serve as a strategic compass. It translates historical performance data into forward-looking scenarios, contextualizes recent product launches and capacity expansions within competitive dynamics, and maps regulatory developments onto commercial implications. By focusing on the forces that will shape pricing, availability, and market access throughout the forecast window, the study enables stakeholders to make informed decisions about supplier partnerships, capacity investments, market entry timing, and product positioning. The narrative deliberately withhold granular segment-level breakdowns and isolated regional revenue figures, reserving those details for the full intelligence package that subscribers and purchasers can access directly through the source portal.
For executives, analysts, and strategic planners who require more than surface-level trend commentary, this research delivers the depth, structure, and operational relevance necessary to navigate the next phase of market evolution. The full study extends beyond the macro trajectory and competitive snapshots presented here, offering detailed segmentation analysis, application-specific demand mapping, regulatory compliance pathways, and scenario-based forecasting models calibrated to the 2026 through 2032 horizon. Readers seeking complete quantitative breakdowns, proprietary competitive benchmarking, and integrated strategic recommendations are encouraged to access the full report through the official research portal, where the complete intelligence architecture is available to support rigorous, data-driven decision-making.
For detailed analysis of this topic, please visit the official page: Dioctyl Terephthalate (DOTP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Distillation Packings Market to Reach $1,456.41M by 2032 at 6.0% CAGR
By PW Consulting, 2026-09-16
Navigating the Distillation Packings Market: Strategic Intelligence for 2026 Decision-Making
Executive Overview: A Market at an Inflection Point
The global distillation packings market stands at a critical juncture as industrial separation processes demand higher efficiency, lower energy consumption, and stricter compliance with environmental standards. Our latest market research report provides a comprehensive examination of this evolving landscape, offering corporate strategists, procurement leaders, and engineering executives the data-driven foundation needed to make confident decisions in 2026 and beyond.
Building on a historical analysis spanning 2020 through 2025, our forecast model projects sustained growth through 2032, anchored by a compound annual growth rate of 6.0 percent. The market, valued at approximately 965.22 million USD in the 2025 base year, is expected to reach 1,019.74 million USD in 2026 and continue its upward trajectory toward 1,456.41 million USD by 2032. These figures reflect more than incremental expansion; they signal a structural shift in how industries approach mass transfer equipment, driven by technological advancement, regulatory pressure, and regional capacity realignment.
This article serves as a strategic preview of our full Distillation Packings Market report. It highlights the analytical framework, competitive intelligence, and operational dynamics that decision-makers must understand to position their organizations advantageously. Core segmentation data, regional revenue breakdowns, and application-specific valuations are reserved for the complete publication, where they are presented with the granularity required for actionable planning.
Distillation Packings Market
Market Trajectory: From Recovery to Sustained Expansion
The five-year historical window from 2020 to 2025 reveals a market that has consistently outpaced initial projections. Revenue climbed from 750.15 million USD in 2020 to 965.22 million USD by 2025, reflecting a recovery trajectory that accelerated as petrochemical and chemical processing facilities resumed capital expenditure programs following earlier disruptions. The steady year-over-year progression underscores durable demand for distillation internals across multiple processing sectors.
Our forecast period, covering 2026 through 2032, models a continuation of this momentum. The market is projected to surpass the 1 billion USD threshold in 2026 and reach 1,090.35 million USD by 2027. Subsequent years show compounding growth, with valuations of 1,165.98 million USD in 2028, 1,249.42 million USD in 2029, and 1,305.96 million USD in 2030. The latter half of the forecast window reflects moderating but still robust expansion, culminating in a 1,456.41 million USD market size by 2032. This trajectory is supported by ongoing capacity additions in emerging industrial corridors, retrofits of aging distillation columns, and the gradual substitution of conventional trays with advanced packing solutions that deliver superior theoretical stage efficiency.
It is important to note that these aggregate figures provide the macro foundation for our analysis. The complete report dissects the underlying drivers segment by segment, enabling clients to identify which product categories, material specifications, and end-use verticals are contributing most significantly to growth. This layered approach ensures that strategic planners can align procurement timelines, capacity investments, and partnership decisions with the segments that match their operational priorities.
Structural Dynamics: Technology, Regulation, and Operational Realities
Several interconnected forces are reshaping the distillation packings landscape and will continue to influence purchasing behavior throughout the forecast period. First, the technical differentiation between structured and random packing architectures remains a central consideration for process engineers. Structured packings, with their engineered surface area and controlled flow distribution, are increasingly favored in applications where pressure drop minimization and high separation efficiency are paramount. Random packings continue to occupy a significant share of the market, particularly in scenarios where cost-effectiveness, ease of installation, and tolerance for uneven liquid distribution are prioritized. Grid packings and other specialized variants address niche requirements, including high-capacity vacuum operations and temperature-sensitive distillations.
Material selection is another critical determinant of market behavior. Metal packings, typically fabricated from stainless steel or specialty alloys, dominate segments requiring corrosion resistance, mechanical strength, and long operational life. Plastic packings serve applications where chemical compatibility, weight reduction, and lower initial cost are decisive factors. Ceramic packings, while representing a smaller portion of overall demand, remain essential in highly corrosive environments and specific chemical processing contexts. The interplay between material performance, fabrication complexity, and total cost of ownership creates a nuanced decision matrix that our report analyzes in detail.
Regulatory and operational dynamics are equally influential. Environmental regulations targeting volatile organic compound emissions in chemical plants are accelerating the preference for low-emission structured packings in distillation applications. These regulations are not merely compliance checkboxes; they are reshaping engineering specifications and prompting facility operators to reevaluate existing column internals. At the same time, the skilled labor cost differential for precision installation and maintenance of structured packings, which averages 15 percent higher than for random packings, introduces a practical consideration that procurement and operations teams must weigh against long-term efficiency gains.
Supply chain and fabrication considerations further complicate the landscape. Custom corrosion-resistant packings designed for aggressive chemical processes require specialized surface treatments that increase fabrication time by approximately 20 percent compared to standard metal media. Meanwhile, raw material pricing dynamics, such as the current unit price of stainless steel wire gauze for structured packings at approximately 45 USD per cubic foot, directly affect margin structures and pricing strategies. These factors are integrated into our market dynamics analysis to provide a realistic picture of cost pressures, lead time implications, and negotiation leverage.
Competitive Landscape: Key Players and Strategic Positioning
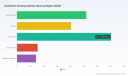
The distillation packings market exhibits moderate concentration, with the top three companies holding a combined market share of 55.5 percent and the top five accounting for 62.3 percent. This concentration reflects the technical barriers to entry, the importance of established engineering relationships, and the value of proprietary packing designs that have been validated across decades of industrial operation. Our report provides a thorough competitive assessment of the organizations shaping this landscape.
Sulzer AG, headquartered in Winterthur, Switzerland, is recognized as a core provider of Mellapak series structured packings and BXPlus gauze packings for distillation columns. The company emphasizes low pressure drop and high efficiency in chemical and petrochemical separations, and its January 2025 introduction of the MellapakEvo structured packing demonstrates a continued commitment to performance enhancement. Koch-Glitsch, based in Wichita, Kansas, USA, offers FLEXIPAC HC structured packings and INTALOX ULTRA random packings, along with the Montz Pak line, optimized for crude vacuum distillation and high-capacity applications. Their portfolio reflects a strong focus on processing conditions that demand robust mechanical design and flexible capacity scaling.
Raschig AG, located in Ludwigshafen, Germany, develops and supplies Raschig Super Ring random packings and metal structured packings for distillation, with a clear emphasis on high-performance mass transfer media. Julius Montz GmbH, also based in Germany, specializes in Montz-Pak wire gauze structured packings tailored for vacuum and temperature-sensitive distillations, delivering low pressure drop per theoretical stage. These European incumbents maintain strong positions through engineering heritage, consistent product innovation, and deep integration with global process design firms.
The competitive field also includes several manufacturers with significant regional presence and growing international reach. Finepac India, headquartered in Pune, manufactures FP series and wiremesh structured packings for distillation columns, prioritizing corrosion resistance and broad application range. Goel Impex, based in New Delhi, supplies high-performance structured packings for distillation, absorption, and stripping, with an emphasis on customized chemical resistance solutions. Ambani Metals, located in Ahmedabad, produces advanced structured packings for efficient separation in distillation and related processes, supported by global export capabilities. These organizations illustrate the expanding influence of manufacturers outside the traditional European and North American core, particularly as cost-competitive engineering and material expertise become increasingly valued.
Chinese suppliers such as Pingxiang Xingfeng Chemical Packing Co., Ltd. and Jiangxi Kelley Chemical Packing Co., Ltd., both based in Pingxiang, Jiangxi, contribute meaningfully to the market. Pingxiang Xingfeng supplies metal random packings including Pall rings for distillation columns, serving petrochemical and chemical industries, while Jiangxi Kelley provides tower packing and structured packings with a focus on high-efficiency random and metal media. In the United States, Mach Engineering, headquartered in Houston, Texas, manufactures X and Y corrugated structured packings for distillation columns, offering both custom and off-the-shelf options. The presence of these diverse players underscores the importance of evaluating suppliers not only by brand recognition but by alignment with specific process requirements, lead time expectations, and regional service capabilities.
Report Contents: Operational Intelligence for Strategic Planning
Our Distillation Packings Market report is structured to deliver practical value at every stage of the decision-making process. Rather than presenting abstract market narratives, the publication focuses on actionable intelligence that can be integrated into capital planning, supplier evaluation, product development, and competitive positioning. The report includes the following core components:
Mass Transfer (Distillation) Market
- Historical and Forecast Revenue Analysis: A detailed examination of market size evolution from 2020 through 2025, followed by a year-by-year forecast extending to 2032. This section provides the quantitative backbone for scenario planning and investment timing.
- Segmentation Framework: A systematic breakdown of the market by type, material, application, and region. Each segmentation dimension is analyzed to reveal growth patterns, share dynamics, and the strategic implications of shifting demand.
- Competitive Profiling: In-depth company assessments covering product portfolios, technological focus, geographic reach, and recent developments. Profiles are designed to support supplier selection, partnership evaluation, and competitive benchmarking.
- Market Dynamics and Cost Drivers: An integrated discussion of raw material pricing, labor cost differentials, fabrication complexity, regulatory influences, and infrastructure considerations that affect total cost of ownership and procurement strategy.
- Strategic Recommendations: Actionable guidance for navigating capacity investments, technology adoption, supplier diversification, and regional market entry, tailored to the needs of engineering firms, processing companies, and equipment manufacturers.
By combining quantitative rigor with qualitative industry context, the report enables clients to move beyond high-level trends and into the specifics that determine project success. Whether the objective is to optimize a distillation column retrofit, evaluate a new supplier relationship, or anticipate demand shifts in a target region, the analysis is organized to support evidence-based decisions.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle presents a unique set of considerations for organizations operating in or adjacent to the distillation packings market. On one hand, the projected growth trajectory suggests expanding opportunity across multiple segments and geographies. On the other hand, the concentration of market share among a limited number of established players, combined with evolving regulatory requirements and cost pressures, demands a disciplined approach to strategy. Our report is designed to help decision-makers navigate this environment with clarity.
For procurement and engineering leaders, the report offers a structured basis for comparing packing types, materials, and supplier capabilities against specific process conditions. The segmentation analysis clarifies where performance advantages are most pronounced and where cost-driven considerations may justify alternative selections. For corporate strategists and investors, the forecast data and competitive profiling provide a foundation for assessing market entry opportunities, partnership potential, and long-term demand visibility. For product development teams, the discussion of operational dynamics, including fabrication time implications and environmental regulation trends, highlights the innovation areas most likely to influence future purchasing criteria.
Importantly, the report does not treat the market as a monolithic entity. It recognizes that the drivers of demand in petrochemical processing differ from those in chemical manufacturing, pharmaceutical applications, and oil and gas operations. Similarly, regional variations in industrial activity, regulatory frameworks, and supplier ecosystems require tailored strategic responses. By preserving the granularity of segmentation data within the full publication, we ensure that clients can extract the precise insights relevant to their operational context without relying on generalized assumptions.
Conclusion: Turning Market Intelligence into Strategic Advantage
The distillation packings market is characterized by steady growth, meaningful technological differentiation, and a competitive structure that rewards organizations capable of aligning product capabilities with process requirements. Our comprehensive report translates this complexity into a clear, data-supported framework that decision-makers can use to reduce uncertainty, prioritize investments, and strengthen their competitive position.
The macro trajectory, from a 965.22 million USD market in 2025 to a projected 1,456.41 million USD by 2032, provides the broad context. The detailed segmentation, competitor analysis, and dynamics assessment provide the precision needed to act confidently. For leaders who require a complete view of the market, including the specific regional, application, and product-level data that underpin our forecasts, the full Distillation Packings Market report is available for immediate review. We invite you to access the complete publication to obtain the full intelligence package and begin integrating these insights into your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Distillation Packings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flavor Enhancer Market Hits $6.8B in 2025, 6% CAGR to $10.06B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Food Flavor Enhancer Market: Navigating Growth and Complexity Through 2032
The global food flavor enhancer industry is entering a decisive phase of transformation. As consumer preferences shift toward cleaner labels, functional nutrition, and reduced sodium profiles, manufacturers across the value chain face a critical window to align product portfolios with emerging demand signals. PW Consulting's latest Food Flavor Enhancer Market research provides a rigorous, data-grounded framework to support executive decision-making through the 2026-2032 forecast horizon. This report is structured not as a static snapshot, but as a living strategic asset designed to inform capital allocation, competitive positioning, and supply chain resilience in a market that continues to evolve at a measured yet unmistakable pace.
Food Flavor Enhancer Market
Drawing on verified historical data and forward-looking modeling, the analysis traces a market that expanded from approximately 5.5 billion USD in 2020 to an estimated 6.8 billion USD in 2025, with a projected trajectory toward roughly 10.1 billion USD by 2032. The forecast points to a compound annual growth rate of 6.0 percent over the forecast period, reflecting steady volume expansion supported by industrial food processing, retail convenience formats, and ongoing reformulation efforts in mature and emerging economies alike. Base-year calibration for 2025 anchors the modeling to current operating conditions, while the projection window captures the intersection of consumer behavior shifts, regulatory recalibration, and technological optimization within the flavor ingredients ecosystem.
Market Structure and the Strategic Signal Within the Data
Understanding the architecture of this market requires looking beyond headline revenue figures. Historical movement between 2020 and 2025 reveals how external pressures, commodity dynamics, and product mix adjustments shaped year-over-year performance, including periods of compression and recovery that tested supply chain discipline. The forecast period from 2026 through 2032 maps a sequence of incremental gains, with year-by-year estimates calibrated to reflect realistic adoption curves, capacity announcements, and pricing sensitivity across major end-use channels.
The analytical depth within the full report decomposes these trajectories across the core dimensions that matter to strategy teams: product type, application category, and geographic footprint. Rather than offering generic statements, the study isolates where momentum is concentrating, which segments exhibit structural durability versus cyclical vulnerability, and how category leadership is likely to shift as ingredient platforms mature. Critically, the segmentation analysis is designed to inform product roadmap decisions, pricing strategy, and regional Go-to-Market prioritization without exposing sensitive competitive signals prematurely. Executives seeking the complete set of segment-level estimates, share distributions, and growth attribution breakdowns will find them within the full publication, where each figure is cross-referenced with demand drivers and supply-side constraints.
Competitive Landscape: Consolidation, Differentiation, and the Playbook of Leading Players
The flavor enhancer space is characterized by a concentrated core of globally active ingredient and flavor companies, complemented by regional specialists that compete on formulation expertise, sourcing proximity, or application-specific performance. Concentration metrics within the study indicate that a small group of established players commands a substantial share of total market revenue, underscoring the importance of differentiation through innovation, sourcing reliability, and regulatory readiness. At the same time, the presence of multiple competitors across glutamate-based systems, yeast-derived ingredients, hydrolyzed vegetable proteins, and specialty taste modulation solutions signals a market where technical capability and customer intimacy remain decisive.
Several companies stand out for their scale, technological breadth, and geographic reach. Ajinomoto Co., Inc. remains closely associated with monosodium glutamate production rooted in fermentation-based processes using plant-derived feedstocks, while also expanding its operational footprint in key producing markets. Givaudan SA continues to advance plant-derived and natural alternative platforms, increasingly emphasizing speed-to-market through digital and consumer-insight tools. Kerry Group plc has built a strong position around natural umami and yeast-derived systems suited to processed and savory applications. International Flavors & Fragrances Inc. offers a broad portfolio spanning synthetic and natural enhancement solutions for food processing environments, and Sensient Technologies Corporation supplies integrated flavor systems that support multiple beverage and food categories. Mane SA and Takasago International Corporation contribute specialized ingredient capabilities, while Biospringer by Lesaffre, Ohly, and Angel Yeast Co., Ltd. represent a strong yeast-based value chain that spans both traditional umami enhancement and clean-label positioning. Firmenich SA and Symrise AG round out a competitive set that blends taste modulation science with application-focused formulation support.
Beyond these anchor names, the landscape includes additional suppliers such as American International Foods, Inc., which maintains a strong MSG supply orientation, and Actus Nutrition, whose whey protein-based ingredient portfolio adds another functional dimension to flavor enhancement discussions. Rather than treating this roster as a static directory, the report evaluates each company's strategic posture in terms of capacity decisions, platform launches, geographic expansion, and response to regulatory change. This company-level intelligence is essential for benchmarking, partnership assessment, and competitive threat mapping.
Recent Developments Shaping the 2026 Decision Calendar
Recent operational moves and innovation announcements signal where the industry is placing its bets. In late 2025, Ohly opened a new spray drying tower in Hamburg, Germany, expanding production capacity for yeast-based flavor enhancer products and reinforcing the strategic importance of yeast extract platforms in natural enhancement strategies. Around the same period, Ajinomoto expanded its MSG production footprint across Brazil, Vietnam, and Thailand, a move that strengthens global supply resilience and positions the company closer to demand centers in multiple regions. In the spring of 2025, Fufeng Group introduced a new plant-based MSG product line at a major food additives expo, targeting clean-label and vegan applications and reflecting the broader industry push toward label-friendly presentation without abandoning performance expectations.
Flavor and Fragrance Market
Innovation cadence also accelerated through platform launches and trade show activity. Givaudan showcased Myromi and Consumer Foresight platforms at VivaTech 2025, designed to compress innovation cycles and connect sensory science with consumer trend intelligence. Ajinomoto Health & Nutrition introduced Salt Answer and Palate Perfect platforms aimed at sodium reduction and taste optimization, directly addressing one of the most persistent reformulation challenges in savory and processed food categories. These developments illustrate a market in which competitive advantage is increasingly tied to formulation agility, messaging precision, and the ability to translate scientific advances into commercial-ready solutions.
The full report situates each of these events within a broader strategic context, assessing their implications for capacity utilization, regional supply balance, and the pace of substitution between traditional and alternative enhancer systems.
Regulatory and Supply-Side Dynamics That Cannot Be Ignored
No forward-looking strategy in this sector is complete without accounting for the regulatory environment and feedstock realities that influence cost structures and market access. In early 2026, the U.S. Department of Commerce conducted antidumping duty administrative reviews and released preliminary results concerning imports of monosodium glutamate from China, while the U.S. International Trade Commission subsequently determined that revoking existing antidumping orders on MSG from China and Indonesia would likely lead to continuation or recurrence of material injury. These actions create a complex trade environment with direct implications for pricing, sourcing decisions, and the cost competitiveness of imported versus domestically sourced or regionally produced material.
On the regulatory front, the U.S. Department of Health and Human Services directed the FDA in 2025 to explore rulemaking that could affect the self-affirmed GRAS pathway for food ingredients, including flavor enhancers. Although MSG continues to maintain GRAS status and remains subject to standard ingredient-panel labeling requirements, any tightening or clarification of the pathway for ingredient recognition would have ripple effects across product development timelines, documentation burdens, and the speed at which new enhancer systems can reach market. The report analyzes these dynamics not as isolated headlines, but as structural variables that shape portfolio risk, compliance strategy, and market entry sequencing.
Supply-side considerations are equally important. Corn starch remains the primary feedstock for monosodium glutamate production in China, accounting for a substantial majority of usage in 2025, which ties producer economics to agricultural commodity trends, regional availability, and input cost volatility. For companies dependent on glutamate-based systems, feedstock exposure is a strategic variable that influences both margin stability and geographic sourcing strategy. The study integrates these raw material dynamics into its segment discussion, highlighting where input sensitivity is most acute and where alternative feedstock routes or ingredient platforms may offer greater resilience.
What the Report Delivers: An Action-Oriented Blueprint
PW Consulting's Food Flavor Enhancer Market research is designed to convert complex market information into executable strategy. The publication provides a full historical and forecast series anchored to 2025 base-year conditions and extended through 2032, enabling scenario modeling for revenue planning, capacity planning, and long-cycle investment decisions. The segmentation framework covers the primary type categories, major application domains, and regional markets, with discussion of the demand logic, competitive intensity, and development patterns that differentiate each segment. Rather than offering undifferentiated growth numbers, the analysis connects each segment to the operating conditions that drive performance, giving readers a practical basis for prioritizing resources.
The competitive section combines company profiles, recent development tracking, and strategic interpretation to help readers assess relative positioning, risks, and opportunities across the market. Regional and application-level insights are paired with regulatory and supply-side context so that strategy teams can evaluate not only where growth is happening, but also what conditions must be managed to capture it. This integrated approach is especially valuable for organizations evaluating new formulation platforms, considering geographic expansion, or weighing exposure to trade policy and ingredient recognition changes.
Importantly, the report functions as a decision-support system rather than a standalone dataset. It enables users to test assumptions about category substitution, sodium-reduction reformulation, clean-label positioning, and supply chain localization. By linking market size evolution to underlying drivers, the study helps executives distinguish between temporary fluctuations and durable structural shifts, reducing the risk of overreacting to short-term noise or underestimating longer-term transitions.
Why This Research Matters for 2026 Decision-Making
The 2026-2032 window is shaping up to be a period in which disciplined strategy will separate durable performers from reactive followers. A 6.0 percent CAGR may appear moderate at the headline level, but the composition of that growth matters immensely. Different product types, applications, and regions are advancing at different speeds, and the companies that succeed will be those able to combine technical credibility with supply resilience, regulatory readiness, and sharp customer insight. Recent capacity investments, platform launches, and trade-policy developments already demonstrate that the boardroom agenda in this market extends well beyond volume growth alone.
Executives using this report will be better positioned to answer several critical questions: where to concentrate innovation resources, how to anticipate regulatory and trade-related disruptions, which ingredient platforms offer the strongest long-term alignment with label and health trends, and how to interpret competitor activity without losing sight of proprietary positioning. The complete segmentation data, regional breakdowns, application-level estimates, and company-level intelligence are essential to turning these questions into concrete plans.
For decision-makers who require the full granularity necessary to set budget priorities, define market-entry strategies, and evaluate competitive threats, the complete Food Flavor Enhancer Market research provides the depth and structure needed to act with confidence. The teaser figures and directional insights presented here establish the strategic frame; the full report delivers the operational intelligence required to execute within it.
For detailed analysis of this topic, please visit the official page: Food Flavor Enhancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Loyalty Management Market to Hit $10.25 Billion in 2025, Surging to $23.21 Billion by 2032
By PW Consulting, 2026-09-16
Global Loyalty Management Market Intelligence: Strategic Imperatives for 2026 and Beyond
As organizations navigate an increasingly complex customer retention landscape, the global loyalty management market stands at a critical inflection point. Having been carefully tracked from 2020 through 2025 and projected forward across a 2026-2032 forecast horizon, this sector demonstrates a sustained growth trajectory that underscores shifting consumer expectations, technological maturation, and intensifying competitive dynamics. The most recent comprehensive analysis from PW Consulting reveals a market that expanded from approximately 5.4 billion U.S. dollars in 2020 to an estimated 10.25 billion in 2025, with forward calculations projecting continued acceleration toward 11.47 billion in 2026 and extending to a projected 23.21 billion by 2032. This represents a compound annual growth rate of 12.4 percent across the forecast window, positioning loyalty management as one of the more resilient and strategically vital technology domains in the broader customer experience ecosystem.
The Convergence of Scale and Strategic Necessity
What makes these aggregate figures particularly instructive for enterprise decision-makers is not merely the magnitude of expansion but the structural forces driving it. Historical data from 2020 through 2025 reflects a market that weathered macroeconomic volatility while maintaining steady adoption curves across industries. The transition from isolated point solutions to integrated loyalty ecosystems has fundamentally altered how organizations allocate budget, design program architecture, and measure return on customer retention investments. As we look toward 2026, the compounding effect of AI-enabled personalization, omnichannel orchestration, and heightened regulatory scrutiny on data practices creates a decision environment where tactical program adjustments are insufficient. Leadership teams require structural intelligence that maps technology pathways against consumer behavior shifts, competitive benchmarks, and compliance calendars.
Regulatory Realignment and Consumer Value Expectations
The 2026 operating environment introduces regulatory and behavioral pressures that directly reshape loyalty program design. Effective January 1, 2026, California Consumer Privacy Act regulations classify loyalty programs offering points, rewards, or other financial incentives as triggers for mandatory consumer disclosures. Businesses must now provide clear notices detailing material program terms, categories of implicated personal information, and the perceived data value exchanged before consumers opt into data collection. This regulatory layer compounds existing GDPR obligations around transparency in data processing and mandates Data Protection Impact Assessments for higher-risk loyalty activities.
Simultaneously, consumer motivation patterns are recalibrating around immediate economic benefit. Industry studies published in early 2026 indicate that approximately 85 percent of Quick-Service Restaurant loyalty participants prioritize cost-saving benefits as their primary engagement driver in an inflationary environment. This behavior signals a broader market shift where value-focused program structures, transparent reward economics, and frictionless redemption paths are becoming baseline expectations rather than competitive differentiators. Organizations that fail to align program architecture with these dual forces of regulatory clarity and consumer value sensitivity risk elevated opt-out rates, diminished lifetime value capture, and reputational exposure around data practices.
Competitive Landscape Architecture
The loyalty management vendor ecosystem now spans established enterprise platforms, cloud-native engagement suites, and specialized retail or sector-focused solutions, each occupying distinct positioning along orchestration depth, integration complexity, and deployment modality. Salesforce delivers cloud-based loyalty management capabilities that emphasize real-time insights and integrated customer profile analytics within broader marketing technology workflows. Oracle embeds loyalty functions within CRM and ERP architectures to support personalized retention strategies at enterprise scale, while SAP focuses on large-scale customer engagement programs driven by structured data and enterprise-grade reward management. Adobe contributes creative and data-driven platform capabilities with emphasis on journey orchestration and personalization for retention outcomes.
Loyalty Management Market
In the specialized and mid-market segments, several vendors have carved differentiated positions. Capillary Technologies concentrates on enterprise-focused, AI-powered omnichannel programs spanning retail, travel, and automotive verticals with an increasingly explicit posture toward privacy-first loyalty design. LoyaltyLion targets e-commerce and retail organizations with streamlined program setup and analytics-focused tooling. Yotpo integrates loyalty mechanics with reviews, referrals, and user-generated content to deepen engagement loops. Annex Cloud and Ignite Retail Technology both emphasize omnichannel engagement and scalable analytics, with Ignite notably extending its unified platform footprint through recent retail and convenience-channel deployments. Zinrelo and Open Loyalty differentiate through multi-channel program flexibility, gamification mechanics, and API-first or headless design philosophies that support bespoke program construction. TrueLoyal positions around combined rewards and fan club mechanisms to drive retention and brand advocacy across channels. GROWERS applies AI-enhanced loyalty architecture to agriculture retail, enabling customized rewards and predictive insights for retailers and producers.
This competitive spread reflects a market in which no single solution archetype dominates all use cases. Rather, enterprises face a segmentation challenge in matching organizational maturity, data infrastructure readiness, channel complexity, and compliance posture to appropriate platform classes. PW Consulting's market study maps these vendor archetypes against deployment patterns, solution types, and organizational sizing to support more defensible selection and investment reasoning. The analysis also highlights market concentration dynamics that indicate meaningful share distribution among leading providers while leaving substantial openness for specialized and emerging entrants in targeted verticals.
Operational Intelligence Within the Full Research Scope
The complete PW Consulting loyalty management market research extends well beyond headline sizing and growth rates. Executive and strategy readers can expect a structured examination of solution architecture classifications, deployment preference evolution, organization-size adoption curves, and industry vertical demand patterns that together reveal where investment momentum is concentrating and where white-space opportunities are forming. By solution orientation, the study distinguishes platform-based, API-based, and services-led delivery models and examines how each maps to enterprise integration requirements, speed-to-program timelines, and ongoing management burdens. Deployment analysis compares on-premise and cloud-anchored adoption trajectories, including the operational and governance implications of each path under evolving data-handling expectations.
Retail Bank Loyalty Program Market
The research also breaks down organization-size dynamics to differentiate large enterprise program strategies from small and mid-sized enterprise adoption constraints and acceleration paths. Vertical-level viewing captures demand intensity across BFSI, retail, consumer goods, hospitality, travel, healthcare, IT and telecom, and adjacent sectors, illustrating where loyalty programs are evolving from promotional vehicles into core retention and data-strategy assets. Importantly, the study intentionally withholds granular percentage splits and dollar-level breakdowns of these segments within this preview to preserve analytical exclusivity; full segment matrices, cross-tabulations, and forward demand allocations are reserved for the complete report and accompanying data appendices.
Recent Market Movements and Their Strategic Signals
Several recent developments provide early indicators of how vendor capabilities and enterprise adoption are co-evolving. In late 2025, Ignite Retail Technology announced a platform partnership through which a major convenience retailer transitioned loyalty operations to its unified platform for enhanced analytics and multi-channel engagement, signaling growing enterprise appetite for consolidated loyalty-and-analytics architectures rather than fragmented point tools. Earlier in the year, GROWERS launched AI-driven enhancements to its agriculture-focused loyalty offering, enabling predictive insights for retailers and farmers and demonstrating how sector-specific loyalty technology is moving toward forward-looking decision support rather than retrospective reward tracking. Mid-2025 saw Capillary Technologies publicly emphasize privacy-first loyalty strategies amid evolving regulations, reinforcing the market-wide recognition that compliance-aware design is now a core capability rather than a peripheral legal consideration. In early 2026, Alchemer released a Quick-Service Restaurant study reinforcing the consumer cost-sensitivity trend, further validating the strategic importance of value-aligned loyalty economics.
Strategic Decision Framework for 2026 Planning
For leadership teams constructing 2026 technology roadmaps, loyalty management now demands evaluation across three interlocking lenses. First, architecture and integration readiness determine whether loyalty data can feed broader customer profiles, personalization engines, and enterprise analytics with sufficient latency and fidelity. Second, compliance and data-value transparency must be designed into program mechanics from inception, particularly as incentive-linked data collection triggers expanded disclosure duties in key jurisdictions and as cross-border privacy expectations continue to harden. Third, program economics and consumer motivation alignment require explicit testing of reward structures, redemption friction, and perceived value against current inflationary behavior patterns, especially in high-frequency verticals where immediate savings increasingly outweigh abstract points accumulation.
The most effective 2026 strategies will treat loyalty platforms not as standalone promotional utilities but as structural components of customer data infrastructure, lifetime value optimization, and regulatory resilience planning. That shift requires decision-makers to evaluate vendors and deployment pathways against operational outcomes rather than feature checklists, and to incorporate segment-specific demand signals rather than relying on generic adoption narratives.
Accessing Complete Market Intelligence
A disciplined approach to loyalty investment in 2026 begins with access to the full dataset, competitive benchmarking, vertical demand mapping, and solution-deployment cross analysis that only the complete PW Consulting research provides. The detailed report delivers precise segment allocations, forward demand projections by organization size and industry vertical, solution-type growth reasoning, deployment trajectory commentary, and vendor positioning frameworks that together support procurement, product strategy, and board-level investment rationale.
The full study, accompanying executive summaries, and segment-level intelligence are available through the source research portal. Readers seeking complete quantitative matrices, competitive profiles, regulatory-impact scenario mapping, and actionable planning templates are encouraged to access the full report directly to obtain the granular intelligence necessary for high-stakes strategic decisions.
Conclusion: From Tactical Loyalty to Structural Retention Advantage
The loyalty management market's sustained double-digit growth trajectory through 2032 reflects a durable transition in how enterprises conceive retention: from transactional reward distribution toward integrated, data-rich, compliance-aware engagement infrastructure. For 2026 decision-makers, the strategic opportunity lies in selecting platforms, program architectures, and governance practices that convert regulatory complexity and consumer value sensitivity into differentiated retention advantage. PW Consulting's market research provides the foundational intelligence needed to make those choices with confidence, while the complete report preserves the segment-level detail and competitive depth that executive planning demands.
For detailed analysis of this topic, please visit the official page: Loyalty Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Running Watches Market Hits $7.4B in 2025, 9.4% CAGR to $13.9B by 2032
By PW Consulting, 2026-09-16
Navigating the Next Horizon: Strategic Intelligence for the Global Running Watches Market (2026–2032)
The athletic wearables sector has matured rapidly over the past five years, transforming from a niche enthusiast category into a core component of the broader performance technology ecosystem. As we approach the mid-decade inflection point, organizations operating across manufacturing, retail, investment, and strategic planning require a disciplined lens into the structural forces shaping the Running Watches Market. PW Consulting’s latest industry analysis provides a comprehensive, boardroom-ready examination of the landscape from a 2025 base year through a 2032 forecast horizon, translating historical momentum into actionable intelligence. The study maps a clear trajectory from a 4.74 billion USD valuation in 2020 to a projected 13.95 billion USD by 2032, anchored by a compound annual growth rate of 9.4 percent. This document outlines the strategic architecture of the report and demonstrates how decision-makers can leverage its frameworks to navigate competitive intensity, supply chain volatility, and accelerating consumer demands.
A Decade of Acceleration: Mapping the Revenue Trajectory
Historical performance across the 2020 through 2025 window reveals an unbroken expansion curve, with annual valuations climbing from 4.74 billion to 7.43 billion USD. The progression from 5.28 billion in 2021, 5.85 billion in 2022, and 6.11 billion in 2023 demonstrates sustained demand absorption, while the subsequent jump to 6.90 billion in 2024 and 7.43 billion in 2025 confirms that growth has decoupled from post-pandemic recovery dynamics. Looking forward, the forecast model positions 2026 at 8.33 billion USD and extends steadily upward, reaching 9.06 billion in 2027, 9.82 billion in 2028, 10.73 billion in 2029, 11.65 billion in 2030, 12.86 billion in 2031, and ultimately 13.95 billion by 2032. These figures are not isolated projections; they reflect modeled demand elasticity, product cycle cadence, and the structural migration of mainstream fitness consumers toward performance-grade instrumentation. Crucially, the research isolates the primary velocity drivers without oversimplifying the underlying complexity. Readers will find explicit analysis of how GPS-enabled precision, physiological monitoring integration, and multi-sport versatility are reshaping purchase criteria across different user cohorts. The narrative deliberately avoids fragmenting the outlook by slicing the market into isolated regional or application-level percentage shares, because executive strategy demands a first-principles understanding of interaction effects, capacity allocation, and portfolio prioritization rather than static tabular breakdowns.
Portfolio Architecture and Product-Level Innovation
The report dissects the product ecosystem along a structured type framework that captures the full spectrum of running-centric instrumentation. This segmentation spans GPS-native devices, standalone pedometer-focused instruments, dedicated heart-rate monitoring watches, and hybrid GPS plus heart-rate models optimized for continuous athletic tracking. The analysis demonstrates how each architecture serves distinct positioning tiers and how manufacturers are engineering feature convergence to capture overlapping demand pools. Parallel to this, the application landscape is mapped across running, biking, cardio training, climbing, and adjacent use cases, revealing how cross-training behavior, outdoor endurance pursuits, and structured fitness programming are influencing SKU rationalization and platform investment. Rather than presenting these dimensions as disconnected columns, the study examines how product architecture, sensor suites, and software ecosystems must be aligned with consumer use patterns to protect margin profiles and reduce inventory risk. Strategic readers will gain clarity on where engineering investment yields the strongest competitive differentiation, which feature combinations are becoming table-stakes, and how platform modularity is enabling faster iteration cycles without compromising cost discipline.
Running Watches Market
Competitive Architecture and Strategic Positioning
Market concentration remains pronounced, with the top three participants commanding roughly 72.4 percent of aggregate revenue and the top five consolidating approximately 88.0 percent. This concentration underscores the importance of understanding not merely who leads the category, but how incumbents defend share while emerging and adjacent players pursue differentiated value propositions. Garmin continues to anchor the premier performance tier through a disciplined lineup built around the Forerunner 970 and Forerunner 570, alongside the Fenix 8 and Enduro 3 series. Their strategy emphasizes precise training metrics, advanced navigation, and athlete recovery instrumentation, reinforcing a positioning that appeals to serious runners and triathletes who treat their wearables as performance management platforms. COROS has carved a distinct identity in the ultralight endurance space, leveraging the Pace 4, Apex 4, and NOMAD to deliver multi-sensor navigation, extended battery life, and rugged outdoor construction. In August 2025, COROS expanded this footprint with the NOMAD outdoor GPS watch, introducing dual-frequency navigation, detailed mapping, rugged construction, and an Adventure Journaling capability that broadens its utility beyond conventional running sessions. Suunto maintains a strong presence through multisport and running GPS devices, including the Vertical 2, Run, and 9 series, where dive-rated durability, precise heart rate capture, and performance data delivery under extreme conditions differentiate its engineering narrative. Polar approaches the category through advanced physiological monitoring and training optimization, exemplified by the Vantage M3, Street X, and broader Vantage lineup, which integrate heart rate and GPS running capabilities into structured performance feedback loops. Meanwhile, Amazfit represents an increasingly influential affordability-and-functionality axis, with T-Rex 3 Pro, T-Rex Ultra 2, and Active series offerings that balance GPS accuracy, battery endurance, and fitness tracking at accessible price points. In May 2026, iRunFar updated its best GPS running watches guide to reflect the latest 2026 lineup, validating pricing and availability while incorporating models such as the Amazfit T-Rex Ultra 2, signaling how independent verification and consumer media continue to shape purchase consideration.
The research does more than profile product portfolios; it evaluates go-to-market posture, brand equity durability, channel leverage, and innovation cadence. The report examines how premium players protect hardware margins while layering subscription-adjacent services, how mid-tier challengers leverage material efficiency and sensor commoditization to narrow capability gaps, and how value-oriented entrants use packaging, battery longevity, and GPS reliability to defy entry-level stigma. These strategic lenses enable clients to benchmark their own positioning, assess vulnerability to competitive encroachment, and prioritize partnership, acquisition, or product roadmap investments with greater precision.
Smartwatch Market
Structural Shifts: Supply Dynamics and Regulatory Undercurrents
No forward-looking market assessment is complete without addressing the material and policy environments that shape production economics and long-term resilience. In 2025, the U.S. Geological Survey recommended adding copper, silicon, silver, rhenium, and lead to the List of Critical Minerals, directly elevating supply disruption risk for semiconductors, sensors, and precision components embedded in running watches. This development is particularly consequential for manufacturers who depend on tightly integrated electronic assemblies, advanced navigation chipsets, and sensor-grade materials. The same agency’s 2025 methodology for the Critical Minerals List assesses probability-weighted net decreases in U.S. GDP from foreign trade disruptions, prioritizing the monitoring of semiconductor and electronics supply chains. For the running watches sector, this framework signals heightened attention to sourcing diversification, inventory buffering, component substitution feasibility, and geopolitical exposure in downstream electronics manufacturing. The study integrates these supply-side realities into a broader dynamics assessment, showing how raw material classification, trade flow sensitivity, and component lead times can alter cost structures, delay product introductions, and recalibrate competitive advantage for firms that lack flexible procurement architectures. Beyond materials, the analysis considers how ecosystem software, data privacy expectations, firmware update sustainability, and device longevity expectations are becoming structural differentiators. Companies that treat hardware as the entire product are increasingly exposed, while those designing integrated hardware-plus-software experiences with durable update pathways are building more defensible customer relationships and lower churn profiles.
What the Full Research Delivers: Operational Intelligence for 2026 Decision-Making
This report is engineered to function as a working strategic asset rather than a static summary. It combines quantitative modeling with qualitative competitive assessment to support planning cycles across R&D, sourcing, sales, and investment functions. The complete study provides a structured examination of market sizing and forward projections grounded in a consistent 2025 base year and 2032 forecast framework. It details the evolution of product architectures and application demand patterns, helping teams align platform roadmaps with actual usage migration rather than speculative trend narratives. The competitive review places primary emphasis on how leading players structure their value propositions, manage innovation cadence, and defend market share in a concentrated environment. The dynamics section translates critical mineral designations, semiconductor supply considerations, and regulatory monitoring frameworks into implications for procurement strategy, cost planning, and resilience design. The report also addresses how pricing architecture, channel composition, and brand positioning interact to shape profitability, and it maps the practical consequences of independent review cycles and retail validation for launch timing and promotional strategy. Throughout, the analysis is designed to support scenario planning: clients can use the frameworks to test capacity expansion assumptions, evaluate portfolio additions, stress-test supply dependencies, and refine messaging strategies for different consumer tiers. By focusing on the mechanisms that drive the 9.4 percent compound growth trajectory, the study equips teams to make decisions that are robust under multiple demand and cost conditions rather than dependent on a single baseline outcome.
Closing the Intelligence Gap
The Running Watches Market is entering a period in which competitive advantage will be determined less by product availability than by strategic precision. Firms that understand where growth is structurally concentrated, how product architectures are converging, and which supply and regulatory pressures will reshape cost economics will be better positioned to allocate capital, time product introductions, and defend margins. The macro arc from 7.43 billion USD in 2025 toward a 13.95 billion USD endpoint in 2032 is clear, but the strategic value lies in the operational insight beneath that headline: how concentration shapes pricing power, how sensor and navigation innovation changes demand, how material classifications alter sourcing strategy, and how competitive portfolios evolve under sustained scrutiny from both consumers and independent reviewers. PW Consulting’s complete analysis is built to convert these dynamics into executable strategy. Organizations ready to move from observation to decision will find the full dataset, segmentation logic, competitor deep dives, and scenario frameworks essential to shaping their 2026 programs and beyond.
For detailed analysis of this topic, please visit the official page: Running Watches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


