



PW Consulting: Global Sunglasses Market to Reach $310M by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-07
The 2026 Sunglasses Market: Strategic Imperatives in a Consolidating Landscape
The global sunglasses market stands at a critical inflection point. Over the past half-decade, revenue has expanded from 120.0 million in 2020 to an estimated 190.0 million in 2025, reflecting a compound trajectory that underscores both resilient consumer demand and a structural shift in how eyewear is designed, distributed, and differentiated. Our newly published Sunglasses Market study isolates the forces shaping the 2026-2032 forecast window, delivering a decision-ready framework for brand leaders, retail strategists, and supply chain executives who must navigate rising concentration, evolving material economics, and intensifying product specialization.
Helicopter Aerial Photography Services Market
This article provides a strategic preview of the report's architecture and the analytical rigor behind it. It is designed to surface the dimensions that matter most for 2026 planning while reserving the granular segmentation, regional revenue splits, and company-level market share calculations for the full intelligence suite. For executives who require precise quantification to support capex allocation, inventory planning, and competitive positioning, the complete dataset is available through the official report portal.
Metal Powder Gas Atomizer Market
Macro Trajectory and the 2026 Baseline
The sunglasses category has proven remarkably durable through a period of volatile input costs, shifting consumer spending patterns, and accelerated channel reconfiguration. Historical performance from 2020 through 2025 reveals a consistent upward arc, with revenue climbing from 120.0 million to 190.0 million. That expansion sets a robust platform for the forecast period, during which the market is projected to advance from 208.13 million in 2026 toward 310.0 million by 2032, sustaining a compound annual growth rate of 6.5 percent.
Roto-Molded Spray Box Market
This growth profile is not merely a function of baseline consumer demand. It reflects a convergence of product innovation, category blending, and strategic consolidation that is reshaping the competitive field. The 2026 snapshot of 208.13 million serves as a pivotal reference point for scenario modeling: it captures post-tariff cost realignment, early-cycle adoption of sustainable material platforms, and the initial market response to newly announced brand portfolio expansions. Decision-makers who anchor their planning to this baseline, rather than to historical averages alone, will be better positioned to calibrate production schedules, channel commitments, and promotional calendars.
The forecast arc from 2027 onward—progressing through 214.71 million, 244.01 million, 253.97 million, and ultimately 263.27 million in 2030 before reaching 297.96 million in 2031 and 310.0 million in 2032—signals an acceleration profile that rewards early-mover advantage in product architecture and supply chain resilience. Organizations that treat the 6.5 percent CAGR as a directional signal rather than a mechanical extrapolation will uncover specific pockets of outperformance that the full report quantifies in detail.
Structural Shifts Defining the 2026 Competitive Arena
Behind the aggregate numbers lies a market that is consolidating around a small set of dominant players while simultaneously fragmenting in product nuance. The concentration profile is pronounced: the top three firms command approximately 65.0 percent of market revenue, and the top five extend that control to roughly 80.0 percent. This dual characteristic—high concentration at the top, diverse specialization below it—creates a strategic environment where scale advantages in manufacturing, brand licensing, and distribution coexist with acute pressure to differentiate on lens technology, material provenance, and lifestyle alignment.
For 2026 planning, this structure has three practical implications. First, premium and lifestyle-driven segments are increasingly anchored by a limited number of multi-brand platforms, which means licensing strategy, co-brand architecture, and retail partnerships carry outsized weight. Second, mid-tier and performance-oriented players are competing on functional specificity rather than broad brand recognition, elevating the importance of lens engineering, fit ergonomics, and use-case marketing. Third, channel dynamics are being reshaped by cost pressures that originate upstream in raw material inputs and trade policy, requiring executives to model margin sensitivity across both domestic and cross-border sourcing routes.
The report dissects these dynamics through a structured lens that connects product architecture, application orientation, and geographic distribution to operational decision points. Rather than presenting static snapshots, the analysis maps how each structural layer interacts with pricing strategy, inventory turnover, and brand portfolio mix, enabling readers to identify where concentration confers advantage and where it creates vulnerability.
Product and Application Architecture: Where Value Is Created
The sunglasses category is no longer a single product class. It is a portfolio of specialized sub-segments, each with distinct engineering requirements, consumer expectations, and margin structures. The report organizes this complexity into type-level and application-level frameworks, revealing how polarized optics, mirrored aesthetics, and photochromic adaptability compete for consumer attention and retailer shelf priority.
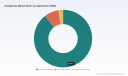
Polarized lenses anchor the largest value pool within the type segmentation, driven by their dual appeal in both lifestyle and performance contexts. Their dominance reflects a broad consumer familiarity with glare reduction and visual comfort, as well as a growing emphasis on outdoor activity and travel-oriented apparel coordination. Mirrored sunglasses occupy a smaller but strategically significant position, leveraging fashion-forward reflectivity and brand-adjacent styling to capture attention in premium and trend-sensitive channels. Photochromic sunglasses represent a more specialized niche, appealing to consumers who value adaptive lens behavior across changing light conditions and who prioritize convenience in transitional environments.
On the application side, the market's value distribution is heavily weighted toward fashion and lifestyle use cases, which reflect the category's enduring role as both a functional accessory and a style expression. Sports and outdoor applications form a smaller but highly engaged segment, where product specifications such as impact resistance, comfort during extended wear, and lens clarity directly shape purchase decisions. Professional and safety-oriented use cases, while comparatively limited in revenue contribution, carry distinct regulatory and procurement requirements that reward reliability, certification compliance, and institutional purchasing relationships.
The full report quantifies each of these segments with precise revenue estimates and growth trajectories, allowing readers to assess where their product portfolios align with category momentum and where reallocation may be warranted. For 2026 decision-making, this segmentation is especially valuable because it connects directly to inventory planning, promotional targeting, and channel mix. Executives who understand which application domains are expanding fastest, and which lens types are gaining retail placement velocity, can prioritize SKU development and markdown strategy with far greater confidence.
Geographic Dispersion and the Regional Playbook
Geographic distribution is another layer where the report provides decision-grade clarity. The market's revenue is spread across a set of regional pools, each with its own consumer behavior patterns, channel maturity, and sensitivity to trade and materials dynamics. North America, Europe, and Asia Pacific collectively represent the largest revenue bases, while Latin America and the Middle East and Africa contribute smaller but strategically meaningful volumes.
Rather than treating geography as a static map, the analysis frames each region as a distinct operating environment with specific implications for assortment planning, pricing architecture, and distribution strategy. In mature markets, growth is increasingly tied to premiumization, brand storytelling, and retail experience quality. In emerging or mid-maturity markets, volume expansion is often supported by broader accessory adoption, growing outdoor recreation participation, and expanding retail footprints. The interplay between these regional profiles and the global concentration structure means that multinational producers and licensing platforms must carefully calibrate which brands, lens technologies, and price tiers are prioritized in each market.
The report's regional decomposition is designed to support this kind of market-by-market calibration. It isolates the revenue contributions and directional trends that help executives answer practical questions: which regions merit deeper brand investment, where distribution partnerships should be strengthened, and how assortment breadth should be adjusted to match local demand signals. The detailed regional figures and growth rates are reserved for the full publication, where they can be cross-referenced with channel data, brand-level performance, and tariff-impact scenarios.
Material Economics, Trade Policy, and Cost Architecture
One of the most immediate pressures shaping 2026 strategy is the evolving cost environment around raw materials and trade policy. Industry reporting indicates that additional duties on Chinese-origin materials, effective in February and March 2025, have disrupted eyewear production costs and supply chains. At the same time, tariffs on goods from Mexico and Canada at 25 percent, also effective in March 2025, are expected to increase production costs and require supply chain adjustments for optical products. Further pressure comes from steel and aluminum duties at 25 percent, effective March 12, 2025, which affect material inputs for eyewear manufacturing.
These policy shifts do more than raise input prices. They alter the relative attractiveness of different sourcing routes, influence the economics of frame construction and lens assembly, and change the cost-benefit calculus for nearshoring versus offshore production. For category participants, the practical challenge is to incorporate these cost dynamics into margin planning, pricing strategy, and inventory timing without losing responsiveness to consumer demand signals.
Sustainability is intersecting with this cost architecture in ways that are becoming commercially meaningful. One notable example involves the rollout of eco-frame collections using over 60 percent recycled inputs, which has driven a 12 percent unit mix shift toward sustainable SKUs in EMEA retailers during peak seasons. This is not merely a branding exercise; it reflects a measurable change in what retailers and consumers are selecting within the assortment, and it signals that material provenance is increasingly part of the purchasing decision. The report examines these developments within the broader context of production economics, showing how sustainability commitments can align with cost management, retailer engagement, and product differentiation when they are executed with operational precision.
Competitive Landscape: Scale, Specialization, and Portfolio Choreography
The competitive field in sunglasses is defined by a small group of large-scale platforms and a set of specialized players that compete on product performance, brand identity, and use-case authority. Understanding how these companies position themselves is essential for 2026 planning, because their strategies shape retail assortments, consumer expectations, and the pace of innovation across lens technology and frame design.
EssilorLuxottica operates as a dominant force through premium brands including Ray-Ban, Oakley, Costa, and Oliver Peoples, with extensive global production of polarized and photochromic lenses. Its scale allows it to influence category standards in lens engineering, distribution reach, and brand licensing. Kering Eyewear offers sunglasses under Maui Jim, Gucci, and other luxury brands, emphasizing polarized lenses and adventure-oriented collections. Its strategy blends heritage luxury positioning with performance-oriented lens technology, creating a bridge between style-driven and activity-driven consumer segments.
Safilo Group produces and distributes sun and optical frames with a strong emphasis on lifestyle, sport, and performance sunglasses. Its portfolio orientation makes it a significant player in the middle and upper tiers of the market, where brand relevance and product versatility are key. De Rigo Vision specializes in eco-friendly and high-performance sunglasses, including frames with recycled inputs and lifestyle collections, positioning sustainability as a core differentiator rather than an adjunct attribute. Marcolin manufactures sunglasses for licensed brands including Tom Ford, Adidas, and Timberland, focusing on fashion and performance, and thereby operates at the intersection of brand licensing and product execution.
Beyond the large platforms, several specialized companies illustrate the value of use-case authority. Maui Jim provides polarized sunglasses for fishing, outdoor sports, and adventure, with proprietary lens technology that reinforces its credibility in performance contexts. goodr produces affordable, fun, and polarized active sunglasses designed for no-slip and no-bounce performance, targeting a more value-conscious but activity-focused consumer. Bajio Sunglasses focuses on premium polarized sunglasses for fishing and water sports, emphasizing adventure and outdoor use, and demonstrating how a narrow application focus can support a distinct brand identity and loyal customer base.
Recent Strategic Moves and What They Signal for 2026
The competitive landscape is not static. Recent developments provide a live readout of how major participants are positioning for the forecast period. In February 2025, Maui Jim unveiled the Color You Can Feel 2 global advertising campaign for its Ekolu spring-summer collection, highlighting adventure and connection themes. This move underscores the continued importance of narrative-driven marketing in outdoor and lifestyle sunglasses, where emotional association and activity context amplify product relevance.
In May 2026, Safilo Group signed a binding agreement to acquire Spy+ and Serengeti, expanding its sunglasses portfolio. This acquisition signals a deliberate push to broaden brand coverage and strengthen the company's foothold across lifestyle and performance niches. Also in May 2026, EssilorLuxottica showcased future-ready eyewear solutions at Vision Expo 2026, reinforcing its focus on product innovation and forward-looking category leadership. Together, these moves highlight a market where portfolio expansion, brand acquisition, and technology showcasing are being used to lock in share and shape consumer perception ahead of the forecast window.
For decision-makers, the strategic takeaway is clear: consolidation and brand-building are accelerating, and the companies that define the category's next phase will be those that can combine scale with credible specialization. The report's competitive analysis goes beyond event tracking to assess how these moves alter channel leverage, assortment diversity, and the bargaining position of retailers and licensees. The full study provides the company-level context needed to evaluate where competitive pressure is intensifying and where strategic whitespace remains.
What the Full Study Delivers for 2026 Planning
This preview is built to establish the analytical frame behind our Sunglasses Market research. The complete report extends this foundation into a detailed, decision-oriented instrument that connects market sizing, segmentation, competitive profiling, and industry dynamics to executable strategy. It is designed for teams that need to move from high-level understanding to specific action in product planning, channel strategy, sourcing, and brand positioning.
Readers who engage with the full study will gain access to precise segmentation values across type, application, and region; company-level context that maps strategic positioning and recent developments; and structured analysis of how trade policy, raw material costs, and sustainability adoption are reshaping production economics. The report also integrates historical performance from 2020 through 2025 with the 2026-2032 forecast, enabling scenario comparison and sensitivity testing around growth assumptions, cost pressure, and portfolio mix.
For executives preparing 2026 plans, the strategic value lies in the report's ability to translate market structure into operational choices. That means understanding not only how large the market is, but where the value is concentrated, which product and application segments are gaining momentum, how regional demand signals differ, and how the competitive field is being reconfigured through acquisitions, brand campaigns, and technology showcases. The complete intelligence suite is available through the official report page, where the full dataset, segmentation detail, and competitive analysis can be reviewed in context.
Closing Perspective
The sunglasses market in 2026 is defined by resilient demand, high concentration, and a growing premium on specialization. Growth from 190.0 million in 2025 to a forecast of 208.13 million in 2026, and ultimately toward 310.0 million by 2032 at a 6.5 percent CAGR, creates opportunity for organizations that can act with precision. But opportunity in a concentrated, cost-sensitive, and brand-driven market rewards those who can see beyond headline numbers and understand the structural forces shaping product, channel, and competitive outcomes.
Our Sunglasses Market study is built to provide that structural clarity. It is designed to help leaders make informed decisions about where to invest, what to emphasize in assortment and messaging, how to respond to material and tariff pressures, and how to position against a competitive set that is both consolidated and rapidly evolving. For teams that need the full segmentation detail, regional revenue figures, and company-level intelligence to support 2026 commitments, the complete report is available through the source page, where the full depth of the analysis can be accessed and applied directly to strategic planning.
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gantry/Cartesian Robots Market to Grow at 9.4% CAGR, Reaching $5.9B by 2032
By PW Consulting, 2026-09-07
Strategic Horizon: Navigating the Gantry and Cartesian Robots Market Through 2032
The industrial automation landscape is undergoing a structural transformation, driven by the need for precision, scalability, and cost-efficiency in manufacturing environments. At the forefront of this shift is the Gantry and Cartesian Robots Market, a sector witnessing robust expansion as industries seek to optimize material handling, assembly, and processing workflows. PW Consulting's latest comprehensive study provides a critical roadmap for stakeholders aiming to capitalize on this growth trajectory. With a forecast period extending through 2032, this research moves beyond superficial market sizing to offer actionable intelligence on competitive dynamics, technological shifts, and regional deployment nuances.
Worldwide Medium Voltage Submarine Cable Market
For enterprise decision-makers, the value of this report lies not merely in historical validation but in its predictive capacity. The market has demonstrated resilience and consistent upward momentum, evolving from a niche automation solution to a cornerstone of modern factory architecture. By analyzing the interplay between raw material fluctuations, regulatory frameworks, and technological innovation, this study equips leaders with the insights necessary to mitigate risk and identify high-value opportunities in a crowded competitive field.
Worldwide Dry Type Cylinder Liner Market
Market Trajectory and Growth Vectors
The historical performance of the Gantry and Cartesian Robots Market underscores a clear trend of accelerating adoption. Between 2020 and 2025, the market revenue climbed steadily, reflecting a compound annual growth rate that signals sustained investor confidence and industrial demand. This growth is not accidental; it is the result of converging factors including labor shortages in key manufacturing hubs, the push for higher throughput in logistics, and the increasing complexity of production lines requiring precise multi-axis movement.
Mobile Application Testing Tools Market
Looking forward, the forecast period from 2026 to 2032 projects a continued expansion at a significant CAGR. This trajectory suggests that the market will more than double its value over the forecast horizon, driven by underlying demand across diverse application segments. The report details how specific use cases are fueling this demand, highlighting the dominance of material handling and palletizing operations while noting the rising interest in specialized welding and assembly applications. However, the true strategic value for your organization lies in understanding the velocity of this growth across different robotic configurations. Whether evaluating one-axis solutions for simple tasks or multi-axis gantry systems for complex payloads, the research delineates where capital allocation will yield the highest return on investment.
It is crucial for stakeholders to recognize that this growth is not uniform. Regional disparities play a significant role in shaping market access strategies. The report provides a granular breakdown of revenue contributions across major geopolitical zones, allowing companies to tailor their go-to-market strategies based on local industrial maturity and automation readiness. While some regions exhibit mature, saturated markets requiring differentiation strategies, emerging economies present greenfield opportunities where automation adoption is just beginning to accelerate. Understanding these regional nuances is essential for supply chain planning and sales force deployment.
Competitive Landscape and Strategic Positioning
The competitive environment within the Gantry and Cartesian Robots Market is characterized by a mix of specialized niche players and established industrial giants. Market concentration metrics indicate a moderately fragmented landscape, suggesting that while major players hold significant sway, there is ample room for specialized solution providers to capture value through innovation and targeted application expertise. PW Consulting's analysis profiles key entities that are defining the pace of this market, offering insights into their strategic focus and capacity for innovation.
Germany remains a powerhouse for engineering excellence in this sector, with firms like igus leading the charge in maintenance-free plastic linear robots. Their focus on cost-effective pick-and-place and palletizing solutions addresses a critical pain point for operations seeking to reduce lifecycle costs. Similarly, Festo continues to strengthen its position with ready-to-install Cartesian robots and 3D gantries based on linear and slide drives, emphasizing ease of integration for system integrators. Another German entity, Dunkermotoren, is carving out a niche with gantry systems utilizing ServoTube linear motors, specifically targeting high-speed packaging and electronics assembly where precision and speed are paramount.
In Japan, the competitive landscape is defined by robust factory automation capabilities. Yamaha Motor Co., Ltd. offers the XY-X series Cartesian robots, catering to high-performance factory automation needs with both moving arm and gantry types. IAI Automation complements this with compact 2- to 6-axis Cartesian robots featuring linear drives and parallel kinematics, appealing to applications where footprint size and flexibility are critical. Janome Industrial Equipment rounds out the Japanese contingent with standard Cartesian robots focused on cost-effective industrial handling, ensuring a broad entry point for manufacturers with budget constraints but high volume requirements.
Switzerland contributes high-precision heavy-load capabilities through Güdel Group AG, whose FP-5 and gantryRobot series are designed for handling loads up to several tonnes with high precision. This positions Güdel uniquely in sectors requiring substantial payload capacity without sacrificing accuracy. Across the Atlantic, the United States hosts a diverse set of competitors. Physik Instrumente (PI) USA specializes in precision modular XY/Z and XYZ gantries with air bearings and linear motors, targeting high-value sectors like semiconductor manufacturing and 3D printing. Nordson EFD focuses on 3-axis Cartesian systems for adhesive dispensing and material handling, addressing specific process requirements in assembly and packaging. Promation offers tabletop Cartesian robots for soldering and electronics assembly, catering to the nuanced needs of the electronics production ecosystem.
Recent strategic developments among these key players highlight the dynamic nature of the market. In late 2025, Yamaha Motor Co., Ltd. established TY ROBOTICS Co., Ltd. through a joint venture with Taiwanese partner TOYO Automation. This move aims to transfer single-axis and Cartesian robot production starting in early 2026, intended to expand lineups and reduce lead times. Such vertical integration and partnership strategies are critical indicators of where supply chain bottlenecks may be alleviated and where pricing power might shift. Furthermore, in early 2026, Festo introduced a GripperAI AI-based gripper solution compatible with Cartesian systems. This innovation enables mixed-product handling and faster deployment without brand lock-in, signaling a broader industry trend toward modularity and software-defined hardware capabilities. Meanwhile, the International Federation of Robotics featured Güdel's FP-5 gantry robot in a 3D concrete printing application, demonstrating real-world heavy-load precision in the construction industry, thereby validating the technology's expansion beyond traditional manufacturing into infrastructure.
Industry Dynamics and Operational Realities
Navigating the Gantry and Cartesian Robots Market requires a clear understanding of the headwinds and tailwinds shaping operational feasibility. The report delves deep into the macro-environmental factors that influence procurement, deployment, and long-term reliability. One of the most pressing issues analyzed is the volatility in raw material costs. Since 2022, prices for steel and rare-earth magnets have fluctuated significantly year-on-year. This volatility exerts direct margin pressure on manufacturers of linear guides and ball screws, which are core components of gantry systems. The research quantifies how these variations have compressed gross margins in standard-grade segments, providing a basis for more robust negotiation strategies with suppliers and more accurate cost forecasting for internal budgets.
Regulatory compliance represents another critical dimension of market dynamics. Strict regulatory standards and safety requirements, particularly in North America, impose significant restraints on the deployment of heavy industrial robots, including gantry systems. The report outlines how these constraints affect implementation timelines and total cost of ownership. Updated standards from 2025, including ISO and ANSI requirements, now necessitate comprehensive risk assessments for collaborative applications involving gantry robot cells. For compliance officers and plant managers, understanding these evolving mandates is not optional; it is a prerequisite for avoiding costly retrofits or operational shutdowns. The study provides a framework for interpreting these regulations in the context of Cartesian systems, helping organizations stay ahead of compliance curves.
Conversely, energy efficiency is emerging as a powerful driver for adoption. Manufacturers are increasingly integrating energy-efficient designs into robotic systems to minimize power consumption during intensive operations like heavy material handling. As energy costs rise and sustainability mandates tighten, the Total Cost of Ownership (TCO) calculation for automation equipment is shifting. Systems that offer lower energy consumption per cycle are gaining preference over those that prioritize speed alone. The report analyzes how leading vendors are responding to this demand through design innovations, allowing buyers to factor energy efficiency into their ROI calculations alongside acquisition costs.
Segmentation and Application Depth
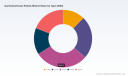
A core strength of this market research is its detailed segmentation analysis, which goes beyond surface-level categories to explore the specific drivers within each segment. The market is categorized by type, application, and region, providing a multi-dimensional view of demand. In terms of robotic configuration, the demand varies significantly based on the complexity of the task. From single-axis systems used for simple linear transfers to complex multi-axis gantries capable of intricate manipulation, the report maps the revenue contribution and growth potential of each configuration. This allows engineering teams to align their technology roadmaps with market realities, ensuring that internal R&D efforts are directed toward configurations with the highest commercial viability.
Application-wise, the market is driven largely by material handling and palletizing, which account for a substantial portion of revenue. However, the report also highlights the growing sophistication in welding and other specialized applications. For instance, the use of Cartesian systems in adhesive dispensing and electronics assembly is creating new revenue streams for vendors who can offer specialized end-effectors and control systems. The analysis covers how different industries are adopting these technologies at varying rates. Logistics and warehousing continue to be strong adopters due to the need for speed and accuracy in order fulfillment, while heavy industry sectors are leveraging gantry systems for tasks that require significant payload capacity and repeatability. By understanding which application segments are most resilient to economic downturns and which are most sensitive to technological disruption, companies can diversify their portfolio risks effectively.
Strategic Implications for 2026 and Beyond
The insights provided in this report are designed to inform critical decisions in 2026 and the subsequent forecast period. For procurement leaders, the data on raw material trends and margin pressures offers a basis for strategic sourcing and inventory management. understanding the cost structures of key competitors can empower negotiation teams to secure better terms and lock in pricing stability amidst volatile markets. For product managers and R&D directors, the analysis of recent product launches and joint ventures provides a benchmark for innovation. The shift toward AI-enabled grippers and modular systems suggests that future competitiveness will depend on software integration and flexibility as much as on mechanical hardware.
Sales and marketing teams will find significant value in the regional segmentation and application breakdowns. Knowing where demand is concentrated allows for targeted campaign spending and distributor partnership selection. For example, recognizing the stringent safety regulations in North America helps sales teams prepare compliant solution packages that address customer concerns proactively, shortening the sales cycle. Conversely, identifying emerging regions with growing automation needs allows companies to establish a foothold before the market becomes saturated.
Furthermore, the report serves as a vital tool for investment strategy. Whether considering M&A opportunities, partnerships, or capacity expansion, the market concentration data and growth forecasts provide the necessary context to evaluate potential returns. The identification of key players and their recent strategic moves, such as production transfers via joint ventures or the launch of AI-compatible hardware, signals where industry consolidation or capability upgrades may occur. Investors and corporate strategists can use this intelligence to anticipate market shifts and position their assets accordingly.
Conclusion: The Intelligence Advantage
In a market growing at a robust pace with significant complexity in technology and regulation, information asymmetry is a competitive disadvantage. PW Consulting's Gantry/Cartesian Robots Market research eliminates this disadvantage by providing a unified, data-driven view of the landscape. From the macroeconomic drivers influencing overall market size to the micro-level details of competitor product offerings and regulatory constraints, this study covers the full spectrum of factors that define success in this sector.
The forecast to 2032 indicates that the growth story is far from over. As industries continue to digitize and automate, the demand for precise, reliable, and efficient linear motion solutions will only intensify. However, capturing this growth requires more than just participation; it requires strategic clarity. This report offers that clarity, enabling leaders to distinguish between transient trends and structural shifts.
We invite you to explore the full depth of this analysis. The insights summarized here are drawn from a comprehensive dataset that includes detailed segmentation splits, regional revenue breakdowns, and extensive competitor profiling. To access the complete intelligence required for your specific strategic planning, including granular data on market concentration and detailed case studies of recent industry developments, please visit the full report page. Secure your organization's competitive edge with the precise data needed to navigate the future of industrial automation.
For detailed analysis of this topic, please visit the official page: Gantry/Cartesian Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Horizons: Navigating the 2-Hydroxyethyl Methacrylate Market in 2026 and Beyond
The global specialty chemicals landscape is entering a decisive inflection point, where material science innovation intersects with evolving regulatory frameworks and shifting end-user demands. At the center of this transformation sits 2-Hydroxyethyl Methacrylate, a versatile monomeric building block whose applications span from high-performance automotive coatings to advanced biomedical hydrogels. As industry leaders prepare their capital allocation and product roadmaps for 2026, understanding the structural forces shaping this market has moved from optional intelligence to operational necessity.
Vacuum Bagging Breather Fabric Market
This executive briefing introduces the latest PW Consulting market research on the 2-Hydroxyethyl Methacrylate sector, crafted specifically to equip decision-makers with a forward-looking, data-anchored perspective. The following analysis outlines the macro trajectory, competitive architecture, and regulatory-material dynamics that will define strategic choices over the coming planning cycle, while preserving the granular segmentation intelligence that only the full report delivers.
Worldwide Steel Radiator Market
A Market in Measured Expansion: Framing Growth for the 2026 Planning Cycle
Over the historical review window from 2020 through 2025, the 2-Hydroxyethyl Methacrylate market has demonstrated consistent, compound-driven expansion. Revenue progression over this period reflects a sector that has absorbed raw material volatility, supply chain disruptions, and regional demand rebalancing while maintaining a fundamentally upward trajectory. By the close of the base year, total market revenue had climbed to a level that underscores the material's entrenched role across multiple industrial value chains.
Intra-city Logistics Market
Looking forward, the forecast horizon running from 2026 through 2032 signals a continuation of this momentum. The market is projected to reach approximately 550.99 million USD in 2026, building on a 2025 base of 531.0 million USD. This represents a notable step-up in absolute terms and sets the stage for sustained growth through the end of the decade. By 2032, the sector is anticipated to approach the 700 million USD threshold, reflecting the cumulative effect of capacity investments, application diversification, and the gradual penetration of higher-purity grades in quality-sensitive verticals.
Underlying this trajectory is a compound annual growth rate of 4.2% across the forecast period. For strategic planners, this figure is more than a historical abstraction—it is a baseline for scenario modeling. It informs decisions around production scaling, inventory positioning, pricing architecture, and partnership structures. A growth rate in this band suggests a market that is neither stagnant nor hyper-heated, but rather one where disciplined execution, grade specialization, and regional demand alignment will separate high-performing operators from those locked into commoditized competition.
The full report unpacks this trajectory with detailed year-by-year revenue modeling, allowing readers to stress-test their internal forecasts against our multi-scenario projections. What remains critical at this stage is recognizing that the headline growth figure masks a layered reality: different purity tiers, application segments, and geographies are expanding at divergent speeds, and the strategic implication of that divergence is precisely what our deeper analysis illuminates.
The Structural Anatomy of Demand: Purity Tiers, Application Verticals, and Regional Weighting
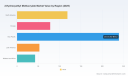
One of the most operationally significant dimensions of the 2-Hydroxyethyl Methacrylate market lies in how demand fractures across purity specifications. Not all end-use environments tolerate the same molecular consistency, and the price-quality trade-off is a decisive lever in formulation engineering. Our research tracks three principal purity bands, each serving a distinct set of performance requirements and cost constraints.
Mid-tier and high-tier purity grades continue to anchor a broad swath of industrial consumption. Applications where clarity, reproducibility, and regulatory compliance are less stringent can operate effectively with specifications that balance cost efficiency against acceptable performance envelopes. At the other end of the spectrum, ultra-high-purity variants are becoming an increasingly strategic differentiator, particularly in segments where optical clarity, biocompatibility, or long-term stability dictate formulation architecture. The emergence of grades pushing toward and beyond 99% purity signals that downstream formulators are willing to absorb premium pricing when the material directly enables product performance or regulatory passage.
On the application side, demand fragmentation tells a story of both concentration and diversification. Coatings represent the largest single consumption channel, reflecting the monomer's foundational role in film formation, adhesion promotion, and surface engineering. Reactive resin systems occupy the second tier of consumption, where the monomer's chemistry enables cross-linking architectures critical to three-dimensional printing, casting applications, and advanced composite fabrication. Adhesives form another substantial pillar, leveraging the material's bonding characteristics across industrial assembly, medical device construction, and specialty packaging. Beyond these core verticals, a residual category captures specialty and emerging uses that collectively contribute meaningful incremental demand.
Regionally, the market exhibits a decidedly global footprint, but one where Asia Pacific carries disproportionate weight in absolute consumption. This concentration aligns with the region's expansive manufacturing base, growing formulation capacity, and accelerating adoption of high-performance materials across electronics, medical, and industrial segments. North America and Europe each command meaningful shares, driven by mature industrial ecosystems, stringent quality expectations, and sustained investment in specialty coatings and biomedical applications. Latin America and the Middle East and Africa regions, while smaller in absolute terms, present growth pockets where industrial modernization and localized formulation capacity are steadily expanding the addressable user base.
Crucially, our report does not treat these segmentation layers as static snapshots. It maps how purity preferences migrate across regions and applications over time, how regulatory pressure reshapes grade selection, and where substitution risk or premium-grade migration is most likely to alter share balances. The strategic implication is clear: companies that position themselves solely on a global average view of the market will miss the localized grade shifts and application re-rating events that actually drive margin outcomes.
Voice of the Market: Competitive Posture and Company-Level Strategic Moves
The competitive landscape for 2-Hydroxyethyl Methacrylate is shaped by a mix of regional suppliers, specialized chemical manufacturers, and downstream-oriented formulators that influence grade standards and application specifications. Market concentration metrics indicate a moderately consolidated environment, with three major players accounting for a substantial share of total revenue and the top five firms extending that control further. This structure creates a market where scale, grade capability, and customer intimacy all matter, but where focused players can compete effectively by owning specific purity niches or application alliances.
Several companies stand out for their active positioning in the 2-Hydroxyethyl Methacrylate value chain. Shakti Chemicals, headquartered in Mumbai, operates as a trader and supplier supporting polymer chemistry applications across Asia, providing a commercial bridge between production capacity and regional formulation demand. In China, Qingdao RENAS Polymer Material Co., Ltd. has established itself as a manufacturer and supplier focused on polymer materials and specialty chemicals, aligning its product line with the country's expanding materials ecosystem. Nantong Chem-land Co., Ltd. similarly functions as an active trader and supplier, offering high-purity grades tailored for industrial and specialty use. Yancheng Green Chemicals Co., Ltd. rounds out this group as a manufacturer supplying polymer synthesis and advanced chemical applications, reflecting the breadth of production-oriented entrants in the region.
Beyond these core suppliers, the broader competitive narrative is increasingly defined by product innovation and application co-development among larger multinational and specialty chemical players. Recent industry activity underscores how grade engineering and end-use collaboration are becoming central to competitive differentiation rather than raw volume expansion alone.
Recent Developments as Strategic Signals
A notable product introduction occurred in mid-2025, when Chemical United launched HEMA HISS, an ultra-pure grade reaching 99.5% specification. The formulation was optimized for high-clarity applications in soft contact lenses, three-dimensional printing resins, medical hydrogels, and high-gloss coatings. This launch illustrates a market trend in which purity advancement is directly tied to performance claims that matter in regulated and quality-sensitive verticals. Delivering a grade with that level of specification is not merely a technical achievement—it is a commercial signal that the demand ceiling for premium HEMA is extending into biomedical and optical applications where tolerance for impurities is minimal.
In late 2024, Dow pursued an application development collaboration with an automotive manufacturer centered on a new HEMA-based coating for electric vehicle batteries. The project focused on enhancing thermal management and extending battery life, linking the monomer's surface and film-forming properties to a high-priority automotive engineering challenge. This type of collaborative development is telling: it shows that 2-Hydroxyethyl Methacrylate is being evaluated not just as a commodity component, but as an enabling element in advanced mobility solutions where thermal resilience and coating durability directly affect product performance.
Earlier in 2024, Evonik introduced VISIOMER HEMA-P 100, a phosphate methacrylate monomer derived from 2-Hydroxyethyl Methacrylate. The offering targeted improved flame retardancy, adhesion, and corrosion resistance in coatings and composites, expanding the functional utility of HEMA-derived chemistry into performance-enhanced material systems. By extending the monomer's value chain into derivative formulations, Evonik demonstrated how innovation can create premium downstream markets even as base monomer demand follows its own growth rhythm.
These developments collectively reinforce a central insight: competitive advantage in this market is increasingly derived from specification leadership, application co-engineering, and derivative innovation rather than pure production volume. The full report provides a structured examination of how each profiled company positions itself across these dimensions, including capability mapping, commercial orientation, and the likely strategic implications of their respective market postures.
Regulation, Raw Materials, and Environmental Boundaries as Strategic Variables
No strategic assessment of the 2-Hydroxyethyl Methacrylate market would be complete without accounting for the regulatory and operational constraints that shape the playing field. These factors do not merely set compliance baselines; they influence grade architecture, market access, formulation substitution, and the relative attractiveness of different application verticals.
Raw material dependency remains a foundational variable. HEMA production relies on ethylene glycol as a key upstream feedstock, and the price behavior of that input is closely tied to crude oil and natural gas cycles. This linkage means that margin planning cannot be isolated from energy market volatility. Suppliers and buyers alike must contend with cost fluctuations that ripple through procurement contracts, pricing strategies, and inventory timing. In a market where growth is steady but not explosive, raw material cost management can be as decisive as volume growth in determining profitability.
Regulatory divergence across regions introduces additional complexity. In the European Union, the Cosmetics Regulation has placed specific constraints on 2-Hydroxyethyl Methacrylate in nail cosmetics, limiting its use to professional applications only. The framework mandates specific labeling requirements and bars non-compliant products from market entry, a rule that has been actively enforced since September 2021. This regulatory posture narrows the accessible consumer-facing segment in Europe and shifts opportunity toward professional channels and alternative chemistries where appropriate. Meanwhile, the United States maintains a more permissive stance for certain medical and dental applications, allowing use in dental adhesives, medical tapes, and wound dressings without equivalent professional-use restrictions. This contrast creates an uneven regulatory terrain in which product positioning and market entry strategies must be tailored by jurisdiction rather than assumed globally uniform.
Environmental considerations further shape operational planning. HEMA is subject to hydrolysis into methacrylic acid and ethylene glycol, and producers are required to monitor and treat effluent to limit release to approximately 0.02 tonnes per year per plant. While this parameter originates from long-standing chemical assessment reporting, it remains relevant as a benchmark for environmental management and as a reminder that production compliance is tied to continuous effluent control. In an era where sustainability reporting and chemical stewardship are increasingly scrutinized, environmental management is not just a regulatory obligation but a reputational and operational consideration.
For high-purity applications, technical standards add another layer of discipline. ISO requirements for grades at or above 99% purity are in place for biomedical and pharmaceutical applications, mandating rigorous distillation and testing protocols. This means that accessing premium biomedical demand requires demonstrable process control and quality assurance capability, which in turn influences which suppliers can credibly compete in that segment.
Together, these dynamics create a market environment where strategic planning must incorporate regulatory monitoring, raw material risk hedging, and quality infrastructure investment. The full report integrates each of these factors into the broader market outlook, allowing readers to evaluate how they may affect regional demand, grade selection, and competitive accessibility over the forecast horizon.
What the Full Research Delivers for 2026 Decision-Making
This market study is designed to serve as a working intelligence asset rather than a static reference document. For executives, commercial leaders, and strategy teams preparing 2026 plans, the report provides the analytical scaffolding needed to translate macro trends into actionable positioning. The following elements represent the core operational value of the full research:
- A complete revenue trajectory spanning the historical review period and the full 2026 through 2032 forecast window, enabling year-by-year benchmarking against internal projections and investment cases.
- Detailed segmentation mapping across purity grades, application verticals, and regional markets, giving readers the ability to identify where growth is most concentrated and where competitive exposure is most acute.
- A structured competitive landscape assessment covering key suppliers and specialty players, including company positioning, commercial focus, and the strategic meaning of recent product and application developments.
- An integrated analysis of raw material dependencies, regulatory distinctions, and environmental constraints, framed specifically in terms of their impact on pricing dynamics, market access, and grade strategy.
- Scenario-ready context for capacity planning, partnership evaluation, and product roadmap decisions, helping teams connect market signals to concrete strategic options.
The intent of this briefing has been to demonstrate the analytical rigor and strategic relevance of the study while preserving the detailed segmentation and company-level intelligence that constitute the full value of the report. Headline figures and structural themes provide a necessary orientation, but the decisions that matter most—grade portfolio choices, regional entry or expansion plans, supply chain risk mitigation, and application-focused innovation—are best informed by the deeper, segmented evidence base contained in the complete publication.
Conclusion: Positioning for a Market Defined by Precision and Adaptation
The 2-Hydroxyethyl Methacrylate market is entering 2026 with a clear growth baseline, a maturing competitive architecture, and an expanding set of performance-driven applications. The combination of steady compound growth, increasing emphasis on higher-purity grades, and active innovation in both end-use formulations and derivative chemistries points to a sector where precision, compliance capability, and application partnership will increasingly determine commercial success. Raw material volatility and regulatory divergence will continue to test operational discipline, rewarding companies that treat these variables as strategic inputs rather than external noise.
For organizations seeking to align their 2026 decisions with the market's actual contours rather than broad generalizations, the full PW Consulting research offers the depth required to move from awareness to action. By translating macro trends into segmented evidence and competitive context, the report supports more confident planning across supply strategy, commercial positioning, and product development. The complete analysis is available in our latest market research release, where the full set of figures, segmentation breakdowns, and company evaluations can be reviewed in detail.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
2032 Luxury Sunglasses Market Forecast Hits $19.78B as PW Consulting Reports 4.59% CAGR
By PW Consulting, 2026-09-07
The Luxe Lens: Navigating the 2026 Luxury Sunglasses Market with Strategic Precision
The global luxury sunglasses market stands at a pivotal intersection of heritage craftsmanship, brand prestige, and rapid structural transformation. As we move deeper into 2026, the sector is no longer defined solely by seasonal runway cycles or discretionary consumer spending. It is now shaped by macroeconomic realignment, tariff-induced supply chain recalibration, and the quiet but decisive consolidation of design houses under vertically integrated groups. At PW Consulting, we recognize that the executives navigating this landscape cannot afford broad directional narratives. They require granular, forward-looking intelligence that connects historical baselines, structural shifts, and competitive positioning into actionable strategic roadmaps. Our newly released Luxury Sunglasses Market research report is built precisely for that mandate.
PEGylation Technology Market
Drawing on our 2025 base-year analysis and a historical dataset spanning 2020 through 2025, this study projects the market trajectory through 2032. The overall revenue landscape, measured in billions of USD, traces a clear compound annual growth rate of 4.59 percent across the full forecast horizon. This expansion is neither linear nor uniformly distributed. Rather, it reflects deliberate portfolio optimization by dominant players, evolving consumer preferences across fashion and performance segments, and jurisdictional pricing dynamics that are actively reshaping margin structures. What follows is a strategic preview of how this report equips leadership teams with the analytical architecture needed to make high-conviction decisions in 2026 and beyond. The numbers shared here are directional; the complete intelligence is anchored in the full report.
Spanish Signs Market
The Arc of Growth: What the Macro Trajectory Signals for 2026 Decision-Making
Market expansion in the luxury eyewear space is rarely a story of volume alone. It is a story of value capture, brand equity leverage, and distribution discipline. The historical baseline illustrates steady revenue progression from the early 2020s through 2025, with the aggregate market reaching a meaningful scale that sets the stage for the 2026–2032 horizon. At the 2025 anchor point, total market revenue sits at a level that underscores both the resilience of premium consumer spending and the structural role of sunglasses as both functional armor and symbolic accessory. From there, the forward projection envisions continued ascent, culminating in the late 2031 to 2032 band where the market crosses into the next revenue tier.
Gallium Nitride Ultra-Thin Charger Market
For executive teams, this trajectory is not merely a backdrop. It is a planning scaffold. A sustained growth rate across a multi-year window implies that demand drivers are durable rather than cyclical spikes. It suggests that brand owners must invest in capacity alignment, assortment logic, and channel configuration well before the demand materializes. It also signals that pricing power, when executed with precision, can be sustained—but only when paired with rigorous cost management, transparent trade policy monitoring, and disciplined promotional architecture. The report translates this macro arc into scenario framing: how growth concentrates across product formats, how application demand shifts between lifestyle fashion and active-performance use cases, and where regional weighting creates both headwinds and tailwinds for sourcing, fulfillment, and localized brand building. We deliberately withhold the granular regional and application-level share breakdowns in this preview so that the complete segmentation logic, sensitivity ranges, and cross-tabulation matrices remain a proprietary asset within the full research suite.
Competitive Gravity: How the Market Structure Is Rewiring Strategic Options
No luxury category thrives without a clearly defined competitive architecture, and the luxury sunglasses market is notable for the concentration of capability among a relatively tight circle of players. Our analysis captures this through the lens of market concentration, where the top three participants command nearly half of total revenue and the top five extend that share into the mid-60 percent range. In practical terms, this means that category leadership is not fragmented across dozens of independent artisans or boutique labels alone. It is anchored by entities that combine design authority, manufacturing scale, licensed brand portfolios, and global distribution networks.
EssilorLuxottica, headquartered in Paris, exemplifies this integrated model. The group owns and manufactures iconic lines such as Ray-Ban and Oakley while also managing licensed luxury eyewear for brands including Tom Ford, Oliver Peoples, and Dolce & Gabbana. This duality—owning both mass-recognized leisure brands and high-end licensed fashion houses—gives the group remarkable portfolio breadth and the ability to cross-pollinate design language, supply chain efficiencies, and retail presence across tiers. Marcolin Group, based in Italy, operates with a similarly strategic posture, producing and distributing Tom Ford eyewear and a broader roster of designer luxury sunglasses that rely on strong fashion credibility and controlled distribution. De Rigo Rem, also Italian, manufactures and licenses luxury eyewear under the Police and Lozza names, leveraging brand heritage and specialty retail relationships to sustain premium positioning. Safilo Group continues to produce licensed luxury sunglasses, most notably for Gucci, aligning closely with fashion house calendars and brand imagery.
Alongside these large-scale operators, a distinct tier of independent and specialty craftsmanship players reinforces the category’s premium narrative. Garrett Leight, based in the United States, designs and sells handcrafted luxury sunglasses with premium materials, emphasizing material integrity, artisanal finishing, and differentiation through tactile quality rather than volume. Oliver Peoples, also U.S.-based and operating under EssilorLuxottica ownership, offers premium luxury sunglasses that marry historical design references with contemporary manufacturing standards, reinforcing the appeal of understated sophistication within the luxury segment.
For 2026 planning, the strategic implications are immediate. When concentration is high, competitive advantage often comes from portfolio orchestration rather than raw capacity. It comes from timing co-brand launches, controlling channel exclusivity, and managing the tension between accessibility and scarcity. It also comes from anticipating how rival groups respond to macro shocks. The full report maps these company profiles and their specific luxury offerings into a competitive benchmarking framework, allowing your team to compare portfolio composition, licensing dependencies, material strategies, and distribution footprints without the fragmentation that typically clouds eyewear market intelligence. The detailed competitive scoring, capability matrices, and positioning maps are included in the full study, where the analysis is calibrated for direct application to portfolio reviews and go-to-market planning.
Market Dynamics Under Pressure: Tariff Realignment, Pricing Strategy, and the Pause-Calibration Cycle
Strategic clarity in 2026 cannot be divorced from the regulatory and trade environment. The luxury sunglasses market is particularly sensitive to import structures, manufacturing geography, and duty architecture because a significant share of frames and components traverses multiple borders before final assembly, fulfillment, and retail placement. In April 2025, The Vision Council documented a substantial shift in U.S. import duties on optical products sourced from China. For sunglasses, the combined rate reached a striking 154.5 percent, aggregating base duties, Section 301 tariffs, and reciprocal duties enacted during that period. This escalation fundamentally altered the cost calculus for importers reliant on Chinese-sourced components or finished goods, forcing a rapid re-evaluation of landed cost, margin tolerance, and assortment composition.
The response from market leaders was swift and pragmatic. EssilorLuxottica, for example, implemented price increases in the U.S. market specifically to offset tariff impacts on imports originating from China and Thailand. This is not merely a pricing event; it is a strategic signal. It demonstrates how vertically integrated and portfolio-rich groups can recalibrate consumer-facing pricing while attempting to preserve brand equity and demand elasticity. It also highlights the need for scenario planning around sourcing diversification, regional fulfillment logic, and the balance between absorbing cost pressure and passing it through to end consumers.
At the same time, the trade policy landscape remains fluid. President Trump announced a 90-day pause on newly implemented country-specific reciprocal tariff increases for countries that have not retaliated, effective in April 2025. For market strategists, such pauses introduce both relief and uncertainty. They provide breathing room for supply chain reconfiguration and inventory positioning, but they also require ongoing monitoring because the pause does not reset the underlying tariff architecture for affected categories. The interplay between base duties, Section 301 measures, and reciprocal tariffs means that the effective cost of goods can shift quickly if negotiating positions evolve or retaliation dynamics change.
The full market research report integrates these dynamics into a structured analysis of the forces shaping demand, supply, pricing, and channel behavior. Rather than treating tariffs as an isolated regulatory note, we embed them within the broader dynamics section, examining how they interact with regional sourcing strategies, category pricing tiers, and the competitive positioning of brands that rely on specific manufacturing or component pathways. The objective is to give your team a framework for anticipating margin pressure, planning assortments with duty-aware logic, and evaluating which partners or sub-brands are structurally more exposed to trade volatility. As with the segmentation data, the detailed duty sensitivity analysis and region-specific implications are reserved for the complete report, ensuring that the most operationally sensitive intelligence is delivered in its full context, with the accompanying assumptions and scenario ranges.
What’s Inside: An Action-Oriented Research Architecture
Executive research is only as valuable as its usability. Our Luxury Sunglasses Market report is constructed to move beyond descriptive commentary and toward decision-ready structure. It is organized to support multiple use cases: annual strategic planning, portfolio review, competitive benchmarking, pricing and assortment optimization, and risk assessment related to trade and sourcing volatility. The architecture includes a historical baseline that contextualizes the 2020–2025 progression, an anchor analysis around the 2025 base year, and a forward projection covering 2026–2032 that extends to the late 2031 and 2032 horizon. Throughout, the narrative connects the aggregate revenue arc to the structural forces shaping category evolution.
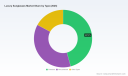
The segmentation logic is built to reveal where demand concentrates, how product formats perform relative to each other, and how application use cases diverge in their purchasing drivers. The report examines the polarization of product types, exploring the role of polarized lenses in premium consumer preferences and the continued relevance of non-polarized offerings within specific luxury positioning strategies. It also accounts for other type categories that serve niche demands and specialty retail placements. The application analysis distinguishes between fashion-led consumption, where sunglasses function primarily as an accessory statement, and sports-oriented usage, where performance optics, frame durability, and fit become central to brand selection. A third application group captures residual demand scenarios, specialty use, and evolving categories that may gain relevance as consumer habits shift. The regional analysis frames where market activity is strongest and where growth potential is most strategically meaningful, without reducing the findings to simplistic share rankings. The complete segmentation splits—covering regional distribution, type breakdown, and application composition—are delivered in the full report with the underlying cross-tabs and scenario discussion required for precise planning.
The competitive section presents company profiles and recent developments in a format designed for strategic comparison. It maps how leading groups structure their luxury offerings, manage licensed brand relationships, and respond to category-level events. Recent developments included in the research highlight the pace and precision of strategic action. In March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana for the development, production, and worldwide distribution of prescription frames and sunglasses, reinforcing the strategic value of enduring brand partnerships. Also in March 2026, EssilorLuxottica unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses, handmade in Japan—an indication of how luxury positioning is being elevated through material differentiation, limited-run craftsmanship, and designer collaboration. The same period saw EssilorLuxottica expand its AI glasses portfolio with new Ray-Ban Meta optical styles for prescription wearers, available for pre-order in the U.S., demonstrating how the company is threading wearable technology into a brand ecosystem that spans both fashion and function. The report ties these events to broader implications for portfolio strategy, brand collaboration cadence, material innovation, and premiumization pathways.
Implications for 2026 Strategic Decisions
The convergence of steady market expansion, high concentration among capable incumbents, and a volatile trade and pricing environment creates a clear mandate for 2026 strategy. Leadership teams should approach the year with five operational priorities in mind, each grounded in the analysis our report provides.
- Portfolio orchestration must be deliberate. With concentration anchored by groups that blend owned and licensed luxury brands, the ability to sequence launches, manage exclusivity, and align fashion calendars with premium demand cycles will differentiate performers from followers. The full report’s company profiles and brand-architecture analysis are intended to support portfolio gap analysis and collaboration prioritization.
- Pricing architecture requires scenario discipline. Tariff-induced cost escalation has demonstrated that pricing is not a static lever but a strategic response to supply chain structure. The research frames how major players have adjusted U.S. pricing to offset import impacts and what that implies for margin management, promotional restraint, and consumer perception.
- Sourcing and fulfillment logic must be re-examined through a duty-aware lens. The combined tariff environment for certain import pathways has reshaped landed cost assumptions. The full report’s dynamics section is designed to help teams evaluate exposure, compare sourcing pathways, and think through regional fulfillment options in a way that preserves premium positioning while protecting margin integrity.
- Product formulation should balance style statements with functional credibility. Polarized versus non-polarized preferences, along with sports-oriented performance demands, require assortment strategies that reflect the distinct drivers of fashion-led and activity-led purchase behavior. The segmentation analysis helps teams identify where intensity of demand justifies deeper investment and where niche formats warrant controlled exploration.
- Competitive monitoring must extend beyond revenue share to capability and brand leverage. Understanding which players hold licensed relationships, which emphasize handcrafted premium materials, and which are integrating technology-forward styles is essential for anticipating market moves. The report distills these capability signals into structured comparative analysis, enabling sharper positioning decisions.
Importantly, the report is not just a retrospective on where the market has been. It is a forward-looking instrument for sensitivity testing. Because the forecast period extends through 2032, leadership teams can use it to evaluate whether current investments are aligned with the pace and shape of growth, to stress-test assortment plans against changing regional and application demand, and to assess whether pricing and sourcing strategies remain robust under shifting trade conditions. The strategic value lies in the integration: macro growth, structural concentration, competitive behavior, and regulatory dynamics are not presented in isolation. They are connected so that the executive can see how a licensing extension, a material innovation, or a tariff pause might ripple through revenue potential, competitive positioning, and channel execution.
Why This Report Belongs in Your 2026 Decision Stack
In a category where brand heritage, material quality, licensed partnerships, and distribution control all contribute to premium value, information asymmetry is a competitive risk. The organizations that outperform in 2026 will be those that can translate market structure into portfolio choices, that can anticipate the margin implications of trade shifts before they become reactive pricing events, and that can read competitive moves as signals of broader strategic intent rather than isolated product launches. Our Luxury Sunglasses Market research is built to reduce that information asymmetry without oversimplifying the complexity underneath.
The report delivers a directional macro view grounded in a 2025 base year and a historical 2020–2025 trajectory, extended by a 2026–2032 forecast that maps the market toward its next revenue tier. It frames competitive concentration and company-specific luxury capabilities in a way that supports benchmarking and positioning review. It embeds the most recent trade and pricing developments into a dynamics analysis that connects regulation, sourcing exposure, and strategic response. And it keeps the most operationally sensitive data—precise regional composition, type and application share breakdowns, and detailed concentration figures—within the full research environment so that the intelligence remains actionable, protected, and ready for direct application to your planning process.
For executives who need to decide where to invest, which partnerships to extend, how to structure pricing in a duty-sensitive environment, and how to read the competitive field with confidence, this research is an essential input. The full report provides the complete segmentation detail, the full competitive benchmarking framework, the scenario ranges, and the integrated dynamics discussion that transform high-level growth trends into precise strategic guidance. Access the complete intelligence at the source page, where the full segmentation splits, company profiles, recent developments, and regulatory context are presented in their complete analytical form.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Sensor Market Hits $2.12B in 2025, 6.15% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Automotive Door Handle Sensors Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
The automotive door handle sector has evolved far beyond a passive mechanical interface. As electric vehicle architectures prioritize aerodynamic efficiency, silent operation, and seamless user experiences, door handle sensors have become critical enablers of keyless access, gesture-driven interaction, and fail-safe egress. The latest Automotive Door Handle Sensors Market research from PW Consulting synthesizes five years of historical performance with a seven-year forward trajectory, offering decision-makers a structured view of how this niche component market is scaling, consolidating, and reshaping itself around regulatory and technological inflection points.
Split-Type Colloid Mill Market
For executives planning capital allocation, supplier qualification, platform sourcing, and compliance roadmaps in 2026, this report functions as a decision-grade reference rather than a static data table. It connects macro growth signals to grounded competitive behavior, maps technology adoption pathways to application demand, and highlights how the intersection of safety regulation and consumer expectations will redefine acceptable design boundaries. The following overview outlines what the research delivers, why it matters for 2026 planning cycles, and which structural forces analysts should monitor as the market accelerates through the end of the decade.
Peripheral Drug Eluting Stent Market
Why This Research Matters for 2026 Decision-Making
Automotive component planning in 2026 requires more than observing headline growth; it demands clarity on timing, adoption intensity, and the operational implications of shifting standards. The market for door handle sensors entered a period of measurable expansion between 2020 and 2025, with annual revenue climbing from approximately USD 1.65 billion in 2020 to around USD 2.12 billion in 2025. This progression reflects sustained OEM interest in integrated access systems and a growing reliance on sensor-based touchpoints in both premium and volume-segment vehicles.
Centrifugal Carbon Capture Compressor Market
Compounding this historical momentum is a forecast period that points to continued expansion, with projected revenue reaching nearly USD 2.32 billion in 2026 and continuing upward through 2032. Across the forecast window, the overall market is expected to advance at a compound annual growth rate of 6.15 percent. While the aggregate trajectory is constructive, the real strategic value lies in understanding the rhythm of adoption: which application categories are pulling demand forward, which sensor modalities are gaining design wins, and how regional manufacturing and compliance environments shape sourcing strategies. The full segmentation detail, regional deployment patterns, and application-level revenue mapping are developed in the complete study, where the numbers are contextualized against platform volume, vehicle mix, and supplier readiness.
For 2026 specifically, the report is designed to support several planning objectives:
- Evaluating when to commit to sensor architectures for upcoming vehicle programs and platform refresh cycles
- Assessing supplier capabilities in proximity detection, low-power wake-up functions, gesture recognition, and false-trigger mitigation
- Gauging the operational impact of new safety requirements on hidden, flush, and electronically actuated door handle designs
- Determining where to prioritize qualification efforts across capacitive, infrared, ultrasonic, and hybrid detection approaches
- Aligning sourcing and localization decisions with regional volume concentration and regulatory timelines
What the Report Covers: A Practical Playbook for OEMs, Suppliers, and Investors
The study is structured to move from market foundation to execution-relevant analysis. Rather than presenting an isolated forecast, it ties revenue evolution to technology choices, application pull, competitive behavior, and regulatory drivers. The result is a reference that can be used for product planning, supplier evaluation, M&A scouting, and capital planning.
At the core of the research is a comprehensive market sizing and forecast model grounded in historical data from 2020 through 2025 and extended across the 2026 to 2032 forecast period. The analysis translates consolidated revenue into a forward view that highlights where growth is likely to intensify and where incremental adoption will be shaped by platform cycles and regulatory compliance. The full report unpacks this trajectory by type, application, and region, allowing readers to understand not just how large the market is becoming, but where value is being captured and by what mechanisms.
The segmentation framework is developed with a sharp focus on decision utility. By sensor type, the research examines how capacitive, infrared, ultrasonic, and other detection technologies compete on integration complexity, power consumption, environmental robustness, and user-experience performance. By application, the analysis follows the demand originating from keyless entry systems, power door systems, and gesture control systems, distinguishing between mainstream convenience features and premium or emerging interaction modes. Regional analysis is provided to help teams interpret where demand is most concentrated and how local vehicle production, safety mandates, and supplier ecosystems shape procurement strategy.
In addition to segmentation, the report delivers competitive and operational intelligence. Market concentration metrics are evaluated to clarify how revenue and design influence are distributed across the supplier base, giving readers a realistic view of consolidation risk, negotiation leverage, and dependency exposure. Company profiles are included for organizations with established or emerging roles in automotive door handle sensing, covering their technology orientation, integration strengths, and stated directions in compact, low-power, and application-specific solutions. The report also tracks recent developments that are reshaping the near-term landscape, including product introductions and regulatory actions that directly affect design priorities and compliance timing.
Key Dynamics Reshaping Demand and Design Strategies
Several forces are converging to make door handle sensors a strategically important subsystem in the broader vehicle access architecture. The first is the ongoing electrification and aerodynamic optimization of exterior body panels. Hidden or flush handle designs can improve drag coefficients and visual minimalism, but they also change how users interact with the vehicle and how reliably egress can be achieved in emergency scenarios. As a result, sensor solutions must balance convenience, detection accuracy, low-power wake-up behavior, and fail-safe performance.
The second force is the rising expectation for seamless keyless access. Drivers and passengers increasingly expect vehicles to recognize presence, respond to proximity cues, and support contactless interaction without compromising security or creating false activations. This expectation is pushing development toward sensor stacks that can deliver reliable detection with minimal power draw and stable performance across a wide range of environmental conditions. The report analyzes how this demand is reflected across keyless entry systems, power door systems, and gesture control applications, and where adoption is likely to accelerate as platforms mature.
The third force is regulatory action, which is becoming a defining factor in design feasibility. In early 2026, Chinese automotive safety regulators approved the mandatory national standard GB 48001-2026, Safety Technical Requirements for Automotive Door Handles. The standard introduces technical requirements intended to enhance safety, with particular attention to hidden or flush handle designs in electrified vehicle architectures. New vehicle type approvals are required to comply fully from January 1, 2027, with a transition period extending to January 1, 2029 for vehicles previously approved. This regulatory timeline matters because it intersects directly with development cycles, validation schedules, and the availability of sensor solutions capable of meeting stricter safety and reliability expectations.
Parallel scrutiny is emerging in other markets. In the United States, federal regulators are investigating multiple Tesla models for potential defects in electronic door releases, with incident reports tied to cases where doors would not open after crashes. Whether or not these investigations lead to direct mandates, they contribute to broader engineering caution around electronically dependent egress systems and reinforce the value of robust detection, redundancy, and fault-tolerant control strategies. These developments are discussed in the report not only as risk signals, but also as indicators of where future validation expectations may become more demanding across global programs.
Competitive Landscape: Technology Positioning and Recent Moves
The supplier landscape is characterized by a mix of semiconductor specialists, Tier-1 system suppliers, and component manufacturers with distinct technology strengths. The report profiles several companies whose solutions are shaping design choices around proximity sensing, wake-up functionality, gesture recognition, and integrated handle systems. Collectively, these players illustrate how the market is moving toward more tightly integrated, application-tuned sensing modules rather than generic discrete components.
NXP Semiconductors is positioned around automotive NFC door handle reference designs and solutions optimized for compact integration. Melexis offers Hall effect and low-power sensor solutions, including door handle wake-up switches and e-door handle applications. Continental AG develops capacitive door handle sensor modules that emphasize gesture recognition and enhanced false-trigger resistance. Valeo SA supplies ultrasonic-based flush handle sensor systems aimed at hands-free door activation across luxury and mass-market vehicles. Infineon Technologies contributes through microcontrollers and sensor ICs that support proximity and position sensing within door handle detection and control architectures. NMB Technologies Corporation manufactures vehicle door handle systems with integrated sensor solutions for OEM customization, including sensing and lighting. ADAC Companies provides vehicle access systems featuring integrated sensing technologies, capacitive sensors, and microswitches in exterior door handles and trim.
These company profiles are placed in the context of broader market concentration, where a meaningful share of revenue is associated with a limited number of influential suppliers. The report uses concentration indicators to help readers interpret negotiation dynamics, supply continuity risk, and the practical implications of relying on a small group of design leaders. For procurement and engineering teams, this is especially relevant when evaluating platform dependency and long-term sourcing resilience.
Recent industry activity underscores how quickly product expectations are changing. Continental AG introduced a new capacitive door handle sensor module featuring integrated gesture recognition and improved false-trigger resistance for premium EV platforms. This type of advancement matters because it reflects a dual priority now driving development: richer user interaction and more reliable behavior under real-world conditions. At the same time, the approval of GB 48001-2026 in China demonstrates that safety regulation is no longer a background consideration. It is becoming a direct determinant of which handle designs can move forward, when they can be approved, and which sensing approaches are best positioned to meet stricter performance requirements.
Taken together, these competitive and regulatory developments point to a market in which technical differentiation, compliance readiness, and system-level reliability are increasingly intertwined. The complete study goes further by mapping these dynamics against regional volume patterns, application demand, and sensor-type adoption, which helps readers distinguish between short-term product wins and longer-term structural shifts.
What 2026 Planning Should Prioritize
Given the growth trajectory, the technology mix, and the emerging regulatory calendar, several priorities stand out for organizations operating in or dependent on this market. First, teams should treat sensor selection as a platform-level decision rather than a late-stage component substitution. Detection modality, power behavior, integration form factor, and false-trigger performance can influence development risk, validation effort, and long-term uniformity across vehicle lines.
Second, compliance readiness should be factored into technical roadmaps early. With safety standards now introducing explicit requirements for automotive door handles and with phase-in timelines aligned to vehicle type approval cycles, engineering teams need to understand which sensor and actuator architectures are most compatible with anticipated safety expectations. The report's regulatory analysis provides context for where authorities are focusing attention and how compliance obligations may influence both hidden and conventional handle designs.
Third, sourcing strategies should account for market concentration and the pace of innovation among leading suppliers. As leading semiconductor and Tier-1 players continue to refine compact, low-power, and application-specific solutions, procurement teams should evaluate not only current sample performance but also roadmap alignment, qualification support, and the ability to meet future functional and safety requirements. This is particularly important for programs that depend on sensor-integrated door handles as a defining feature of the customer experience.
Finally, investors and strategy teams should use the forecast and segmentation structure to separate durable demand drivers from temporary platform cycles. The overall expansion from 2026 onward reflects underlying shifts in vehicle access interaction, electrification-driven body design, and safety-driven engineering discipline. Yet the distribution of growth across applications and technologies is likely to vary by region and by vehicle segment. The report is designed to make those distinctions visible so that decisions are based on differentiated insight rather than aggregate growth alone.
Accessing the Full Intelligence
This overview is intended to establish the strategic frame and demonstrate the depth of the underlying research. The complete Automotive Door Handle Sensors Market study extends the analysis into detailed segmentation, regional revenue distribution, application-level demand mapping, technology adoption patterns, competitive positioning, and regulatory impact assessment. It also provides implementation-oriented commentary for sourcing, engineering qualification, and plan-of-action development across the 2026 to 2032 horizon.
For executives who need to make 2026 commitments with confidence, the full report offers the granularity required to compare sensor pathways, interpret supplier capabilities, and align program timing with regulatory and market realities. The aggregate growth signals are strong, but the decisive advantages will come from understanding where exactly value is being created, which design choices are becoming standard, and how safety expectations will reshape what is commercially and technically viable.
PW Consulting's full market research provides that level of operational clarity. The complete edition is available through our official report page, where the segmented data tables, competitive evaluations, and strategic recommendations can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Automotive Door Handle Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Concrete Fibers Market Hits $215M in 2025, Projects 6.5% CAGR to $344.8M by 2032
By PW Consulting, 2026-09-07

Strategic Imperatives in the Synthetic Concrete Fibers Market: A 2026 Outlook
As global infrastructure priorities pivot toward accelerated construction timelines, reduced reliance on primary steel reinforcement, and enhanced durability standards, the synthetic concrete fibers market has emerged as a critical nexus for construction materials strategy. At PW Consulting, we have compiled a comprehensive market intelligence report that examines the structural shifts, competitive dynamics, and forward-looking revenue trajectories shaping this sector. This article provides a strategic preview of the research, emphasizing the analytical dimensions that decision-makers will need to navigate the 2026–2032 period with confidence.
Worldwide Sun Tube Market
While the broader construction chemicals and fiber reinforcement landscape has historically been characterized by fragmented regional activity and application-specific substitution patterns, recent developments indicate a convergence of demand drivers, raw material volatility, and product innovation that warrants a more coordinated commercial approach. Our study is designed not merely as a retrospective data exercise, but as a decision-support instrument that maps probable market pathways, competitive positioning, and procurement sensitivity to macroeconomic and feedstock fluctuations. Readers seeking the full set of quantitative segmentation, regional breakdowns, and proprietary strategic assessments will find the complete report at our source platform, where the entire intelligence framework is available for institutional review.
Round-Type Drop Optical Fibre Cable Market
The market sizing embedded in our analysis reflects a sustained expansion trajectory. Drawing on historical baselines that track installed volume and value realization across multiple end-use environments, the market has demonstrated steady accumulation, moving from a base reflecting the 2020 period to a substantially larger revenue position by 2025. The forward projection extends through the 2032 horizon, capturing the anticipated compound annual growth implied by infrastructure modernization programs, industrial flooring upgrades, and recurring substitution of steel mesh and rebar in slab and precast applications. This growth cadence is neither linear nor uniform across segments; rather, it reflects a layered set of adoption curves where certain applications and geographies accelerate ahead of others, creating both first-mover advantages and supply-demand mismatches that require careful operational planning.
Overhead Bins Market
A defining feature of the current market era is the intersection of supportive end-use demand with persistent feedstock price variability. Synthetic fiber economics are closely linked to the cost and availability of polymer inputs, particularly polypropylene, which serves as the backbone for a majority of macro and micro synthetic reinforcement products. Recent market intelligence indicates that polymer price levels have experienced notable volatility, with regional benchmarks showing meaningful divergence across Northeast Asia, North America, and Europe. For fiber manufacturers, converters, and downstream concrete producers, these price movements influence not only input cost structures but also the timing of procurement contracts, inventory strategies, and pricing architecture for finished reinforcement solutions. Our report examines how this raw material sensitivity propagates through the value chain and what operational responses are emerging among leading participants.
At the same time, the competitive field is consolidating practices even as it retains a broad set of international and regional players. Market concentration metrics indicate that a limited group of firms accounts for a meaningful share of total revenue, yet the sector still accommodates a diverse ecosystem of specialty manufacturers, technology-driven entrants, and application-focused suppliers. This structure creates a competitive environment where differentiation is increasingly determined by technical service, product consistency, performance certification, and the capacity to support large-scale infrastructure and commercial projects with reliable supply. The companies that are gaining strategic visibility are doing so not solely through volume expansion, but by aligning product portfolios with specific substitution scenarios, such as replacing welded wire mesh, enhancing crack control, and improving impact resistance in demanding floor regimes.
Within this competitive landscape, several established participants illustrate the strategic directions that are shaping the broader market. Sika AG continues to reinforce its position through macro and micro synthetic fiber offerings designed to substitute steel reinforcement in slabs, industrial flooring, and precast applications, while simultaneously expanding production capacity in the United States to address growing demand from industrial flooring, mining-related construction, and sustainable building requirements. That capacity expansion signals an important strategic posture: aligning manufacturing footprint with regional demand centers and project pipelines. Mapefibre by MAPEI S.p.A. represents a parallel emphasis on crack control and steel replacement through macro and micro synthetic fibers, with blended resin formulations developed to optimize performance in concrete dosage and structural behavior. Euclid Chemical Company has advanced the narrative of application-anchored growth through technology that targets replacement of welded wire mesh and steel in floors and industrial applications, reinforced by recent supply partnerships tied to new manufacturing construction projects. FORTA Corporation has built recognition around virgin copolymer macro synthetic fibers intended for crack control, impact resistance, and steel replacement across slabs and infrastructure, while also extending its portfolio into micro and monofilament solutions for shrinkage crack control and micro-reinforcement. GCP Applied Technologies Inc. has focused on post-crack protection functionality and digital enablement, notably through updated mobile-based tools that improve analysis, cost evaluation, and submittal workflows for synthetic macrofibers.
Beyond these principal actors, the competitive set reaches into specialized and regionally embedded providers. BarChip Inc. emphasizes engineered high-performance macro and micro synthetic fibers with structural reinforcement credentials and project-level deployment in global infrastructure. Fabpro Polymers contributes specialized high-performance synthetic fibers for reinforced concrete, with application coverage spanning macro and micro types. Polyfibers maintains a broad product line of micro and macro synthetic fibers with technical support oriented toward global concrete reinforcement. Mighty Shield Sdn Bhd positions its macro and micro synthetic fibers around crack bridging, flexural resistance, and diversified use cases in shotcrete, precast, and pavement environments. Adfil has developed a portfolio spanning floors, precast, pattern-imprinted concrete, and tunneling applications, reflecting the breadth of end-use contexts in which synthetic fibers are being specified. Belgian Fibers likewise participates across macro and micro reinforcement scenarios, adding further depth to a market that is increasingly defined by application specialization rather than commodity substitution alone.
Recent developments provide a practical lens on how strategy is being enacted on the ground. In mid-2025, Euclid Chemical Company moved forward with a partnership to supply macro synthetic fiber for concrete reinforcement at a new automotive manufacturing and vehicle assembly plant, demonstrating how product placement is increasingly tied to landmark construction projects that serve as reference cases for specification and adoption. In parallel, Sika AG announced an increase in synthetic macro-fiber production capacity at its Tennessee facility, targeting industrial flooring, mining applications, and sustainable construction outcomes. These actions illustrate two complementary approaches: securing strategic project wins that expand reference coverage, and investing in regional capacity to reduce supply-chain friction and improve responsiveness. A third illustrative move occurred when GCP Applied Technologies Inc. introduced an updated version of its synthetic macrofiber mobile application solution, enhancing analytical speed, cost analysis features, and PDF-format submittal packages. This type of digital tooling is not merely a convenience layer; it reduces specification friction, accelerates engineering reviews, and strengthens the commercial case for fiber-based reinforcement by improving transparency around performance and cost trade-offs.
These developments must be read against the backdrop of raw material dynamics that have introduced new complexity into procurement and pricing. Polypropylene-linked costs have experienced significant movement, with year-to-date increases recorded in early 2026 and regional benchmarks that reflect disparity across major markets. Price levels observed in Northeast Asia, North America, and Europe have at various points diverged enough to influence sourcing logic, margin planning, and regional competitiveness. More recent observations also point to intermittent downward adjustments over short horizons, even as longer-term comparisons remain elevated relative to prior-year baselines. For market participants, this environment underscores the importance of hedging strategies, contract structuring, formulation efficiency, and value-engineering engagement with concrete producers who must balance performance requirements against total installed cost. Our research framework addresses these sensitivity points by mapping the interplay of input price behavior, regional manufacturing economics, and application-level demand intensity.
From a commercial standpoint, the synthetic concrete fibers market is shaped by three reinforcing themes. First, substitution momentum remains the central growth engine: the drive to reduce steel dependency in slabs, precast elements, and industrial flooring continues to expand the addressable space for both macro and micro synthetic fibers. Second, specification quality is becoming a differentiator: technical documentation, performance reliability, certification credibility, and digital support tools increasingly influence procurement decisions alongside unit price. Third, regional execution capability matters more than ever, because large-scale projects and infrastructure programs reward suppliers who can deliver consistent quality, project-level technical support, and supply continuity across geographies. These themes do not simply describe the market; they define the conditions under which competitive advantage is created and sustained.
Against that backdrop, our report provides a multi-layered examination of the market structure, demand architecture, competitive positioning, and forward trajectory. The analysis begins with historical market evolution, using a documented value progression across the 2020 to 2025 interval to establish a credible baseline for forward-looking modeling. It then examines the projected period from 2026 through 2032, where growth assumptions are anchored in continued infrastructure spend, industrial flooring modernization, and ongoing steel-replacement adoption. To support strategic interpretation, the research disaggregates the market by type, application, and region, enabling clients to isolate the segments that matter most to their commercial objectives. Instead of presenting segmentation as a static list of shares, the report evaluates the structural logic behind volume distribution, the relative attractiveness of each demand pool, and the operational implications of serving them at scale.
The study also examines the competitive environment in detail, including the role of market concentration in shaping pricing behavior, supplier bargaining power, and the strategic room available to mid-tier and specialty players. Rather than merely identifying top participants, the report interprets how their product strategies, project targeting, capacity decisions, and digital-service initiatives contribute to differential positioning. Recent company-level developments are integrated into this analysis to show how strategic moves are translating into market presence and supply chain advantage. In doing so, the research provides a practical template for assessing where competitive intensity is rising, where differentiation opportunities are expanding, and where risk concentrations may warrant strategic mitigation.
Equally important is the report’s treatment of raw material and cost-side dynamics. Because synthetic fiber offerings are closely tied to polymer feedstock economics, understanding the trajectory of input costs and regional price dispersion is essential for forecasting margins, shaping procurement policy, and evaluating supplier resilience. Our analysis connects observable price behavior with broader implications for formulation strategy, contract timing, regional sourcing decisions, and downstream pricing adaptability. This dimension is especially relevant for organizations that must respond to project specifications while maintaining cost competitiveness in an environment where feedstock benchmarks can shift materially over relatively short intervals.
The report further includes actionable strategic frameworks designed for corporate planning teams, product managers, procurement leaders, and investment analysts. These frameworks address questions such as which applications offer the strongest near-term adoption potential, how regional demand patterns differ in their growth drivers and specification maturity, what capacity and partnership strategies are most effective under current competitive conditions, and how firms can navigate feedstock volatility without compromising technical credibility or service quality. By tying market data to operational decision logic, the research is intended to support both strategic planning and near-term execution, rather than functioning purely as a high-level market overview.
There is also a clear emphasis on sustainability and performance rationale. The move toward synthetic fibers is not solely a cost-driven substitution story; it is increasingly aligned with broader construction objectives related to durability, crack mitigation, reduced steel consumption, and application flexibility across precast, floor, shotcrete, and tunneling environments. Suppliers that can articulate and validate these performance benefits with credible technical support and repeatable product quality are better positioned to capture specification share, especially in projects where long-term performance and lifecycle considerations weigh heavily in material selection. Our analysis evaluates how these value propositions are being communicated, where they are gaining traction, and what evidence standards are becoming expected by engineering and procurement teams.
Ultimately, the intent of this research is to provide a precise and usable understanding of how the synthetic concrete fibers market is likely to evolve, where competitive value will accrue, and what operational choices will determine commercial success through the late 2020s and into the early 2030s. The study presents a structured synthesis of market size progression, segmentation logic, competitive positioning, and raw material sensitivity, while leaving room for tailored interpretation based on each organization’s product focus, geographic exposure, and customer base. For decision-makers who require the full complement of segmented figures, regional trajectories, concentration analysis, and company-level strategic detail, the complete report is available through our research portal, where the entire dataset and accompanying strategic commentary can be reviewed in depth.
In a market where growth is real but uneven, and where raw material behavior, regional manufacturing footprints, and project-based specification patterns all influence outcomes, the organizations best positioned to succeed will be those that combine demand insight with disciplined execution. This report is designed to support that combination: giving leadership teams a credible view of market direction, competitive pressure points, and actionable priorities, while preserving the depth of segmentation and company-level analysis needed for precise strategic planning. For the full intelligence package, including complete segmentation data and proprietary strategic assessments, please access the full report on our source platform.
For detailed analysis of this topic, please visit the official page: Synthetic Concrete Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Floor Drains Market to Reach USD 2,133.1 Million by 2032 Amid 3.6% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for 2026: Navigating the Stainless Steel Floor Drains Market
The global infrastructure landscape is undergoing a subtle but significant transformation, driven by stringent hygiene protocols, evolving construction standards, and renewed investment in public utilities. For stakeholders in the built environment, the stainless steel floor drains market represents a critical intersection of sanitary engineering and material durability. As we move into 2026, understanding the trajectory of this sector is not merely about tracking sales volumes; it is about anticipating compliance shifts, supply chain volatility, and competitive positioning.
Worldwide Roll Feeders Market
Our latest market research study offers a comprehensive examination of this sector, providing the granular intelligence required to make informed capital allocation and product development decisions. This article serves as a strategic overview, highlighting the macro-economic currents and competitive tensions that define the landscape, while outlining the depth of analysis available in the full report. The data presented here reflects a thorough analysis spanning historical performance from 2020 through 2025, with a detailed forecast period extending to 2032.
MW-class Wind Power Pitch Slip Ring Market
Market Trajectory and Growth Dynamics
The stainless steel floor drains market has demonstrated resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend in revenue, reflecting the material's growing preference over traditional alternatives due to its corrosion resistance and longevity. In 2020, the market revenue stood at approximately 1,378.7 million USD. By 2025, this figure has evolved to 1,656.0 million USD, signaling a robust compound annual growth rate over the historical period.
Data Center Magnetic Levitation Compressors Market
Looking ahead, the forecast period from 2026 to 2032 projects further consolidation and growth. The market is anticipated to reach 1,757.32 million USD in 2026, with a forecast CAGR of 3.6 percent through 2032. This growth is not linear; it is punctuated by specific demand drivers related to infrastructure modernization and hygienic design requirements. While the overall trajectory is positive, industry participants must navigate fluctuating raw material costs and varying regional adoption rates to capitalize on these opportunities.
It is important to note that while the aggregate numbers suggest stability, the underlying segmentation reveals distinct pockets of volatility. The demand structure is influenced heavily by the type of drainage system required for specific environments, ranging from traditional water seals to specialized gravity-based systems. Furthermore, the application spectrum varies significantly, with commercial and municipal sectors often driving volume differently than household or industrial segments. Understanding the weight of each segment is crucial for targeting marketing efforts and production capacity, details of which are fully unpacked in the complete study.
Regulatory Pressures and Industry Context
The operating environment for stainless steel floor drain manufacturers and purchasers is increasingly shaped by regulatory frameworks. In 2025 and heading into 2026, compliance has become a primary differentiator. For instance, commercial kitchen drains must meet NSF/ANSI 14 and NSF/ANSI 51 standards, in addition to ASME A112.6.3 for performance. These standards are not optional; they are gatekeepers to entry in high-value commercial and foodservice markets.
Beyond general plumbing codes, specific industries are subject to rigorous hygienic design principles. Foodservice and commercial applications are subject to HACCP hygienic design principles and EHEDG guidelines for sanitary requirements. This regulatory layer adds complexity to product design and certification processes. Manufacturers who can demonstrate compliance effectively gain a competitive moat, whereas those lagging risk exclusion from key supply chains, particularly in pharmaceutical and food processing sectors.
On the infrastructure front, government spending continues to play a pivotal role. In 2025, the Infrastructure Investment and Jobs Act continued channeling billions into wastewater management and public facility refurbishment. This inflow of capital supports demand for municipal used drainage systems, providing a stable baseline for market growth regardless of private sector fluctuations. However, reliance on public funding cycles requires strategic timing in sales and deployment strategies.
Material costs also remain a critical variable. Stainless steel price per pound in 2025 depends on nickel costs and market trends, with 304 grade ranging from $1.45 to $2.06 per pound. This volatility impacts margins for manufacturers and final pricing for buyers. Strategic procurement and hedging strategies are becoming essential competencies for leading firms to maintain profitability amidst these input cost swings.
Competitive Landscape and Key Players
The market structure is characterized by a mix of specialized manufacturers and larger diversified entities. Market concentration metrics indicate a relatively fragmented landscape, with a CR3 of 24.6 percent and a CR5 of 26.2 percent. This suggests that while there are dominant players, there is significant room for niche specialists and regional competitors to thrive.
Several key companies define the current competitive arena. Josam Company, based in Elkhart, Indiana, offers 304/316L stainless steel floor drains, trench drains, cleanouts, and retrofit liners with fabricated and cast options for commercial and industrial hygienic applications. Their recent activity highlights a focus on specific high-profile installations, such as the Royal Winery Project in February 2025 and the Venn Brewing Project in January 2025, demonstrating their penetration into specialized facilities requiring high hygiene standards.
AWI Manufacturing, located in Montgomery, Alabama, manufactures stainless steel floor drains, hub drains, and related systems used in food, dairy, and commercial settings for over 50 years. Their long tenure suggests deep institutional knowledge regarding sanitary requirements in sensitive processing environments. Similarly, Jay R. Smith Mfg. Co., also headquartered in Montgomery, Alabama, produces stainless steel floor drains, sanitary drains, and specialty drainage products for commercial applications, reinforcing the strength of the US manufacturing base in this sector.
On the industrial and high-traffic end, Zurn Industries, based in Saginaw, Michigan, manufactures high-grade stainless steel floor drains, floor sinks, and trench drains for industrial and high-traffic environments. Their strategic moves are notable; in 2025, Zurn expanded its hygienic drainage product line specifically targeting pharmaceutical and food processing applications. This move signals a strategic pivot towards higher-margin, regulation-intensive segments.
The landscape also includes global players and custom specialists. Blucher, part of Watts Water Technologies and based in Vildbjerg, Denmark, is a global manufacturer of stainless steel drainage systems, including floor drains and channels. Their geographic reach provides a counterbalance to US-centric manufacturers. CustomDrains, operating out of the United States, specializes in custom stainless steel floor drain systems and accessories for commercial, industrial, food processing, and pharmaceutical facilities. Their focus on customization allows them to serve complex project requirements that off-the-shelf solutions cannot meet. Finally, Sioux Chief Manufacturing Company, based in Sioux Falls, South Dakota, provides residential and commercial stainless steel floor drains and related drainage products, covering the lower end of the market spectrum where volume and cost-efficiency are paramount.
Understanding the strategic moves of these entities is vital. Whether it is Josam's project-based references, Zurn's product line expansion, or CustomDrains' specialization, each maneuver reshapes the value chain. The full report provides a detailed profiling of these companies, including their specific product portfolios, regional strengths, and strategic positioning relative to the market segments discussed earlier.
Report Scope and Strategic Value for 2026
This market research study is designed to be a practical tool for decision-makers. It goes beyond surface-level observations to provide actionable intelligence. The scope covers a base year of 2025 and historical years from 2020 to 2025, ensuring that recent trends are fully contextualized before looking forward. The forecast period extends from 2026 to 2032, allowing for long-term planning cycles.
One of the core strengths of this analysis is the detailed segmentation. The report breaks down the market by region, covering key areas such as North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. This regional breakdown is essential for identifying export opportunities, assessing local competition, and understanding regulatory variations. For example, while North America and Europe represent significant portions of the market value, the growth dynamics in Asia Pacific or the infrastructure spending in Latin America may offer different risk-reward profiles for investors and manufacturers.
The product type segmentation is equally critical. The study distinguishes between Traditional Water Seal Floor Drains, Spring-type Floor Drains, Suction Stone Floor Drains, Gravity Floor Drains, and Others. Each type serves different functional requirements and price points. Knowing which type is gaining traction in specific applications can guide R&D priorities. For instance, the demand for hygienic applications might favor specific seal technologies over gravity-based systems in certain contexts.
Application segmentation further refines the view, categorizing usage into Household Used, Commercial Used, Municipal Used, Industrial Used, and Marine Used. The commercial sector often drives significant volume, but the industrial and municipal sectors may offer higher stability or value per unit due to infrastructure contracts. The report analyzes the revenue contribution and growth potential of each application, helping stakeholders align their sales pipelines with the most promising end-use markets.
For corporate strategists, the competitive landscape analysis offers benchmarks against key players. By comparing market share, product breadth, and recent developments, companies can identify gaps in the market or areas for consolidation. The inclusion of recent developments, such as project references and product line expansions, ensures that the competitive intelligence is current and relevant to the 2026 operating environment.
Implications for Decision Makers
In the context of 2026 planning, several strategic implications emerge from this market overview. First, compliance is no longer a back-office function; it is a front-line competitive advantage. Firms that integrate NSF, ASME, HACCP, and EHEDG standards into their design philosophy early will capture market share in regulated industries like food processing and pharmaceuticals. Second, raw material volatility requires agile supply chain management. With stainless steel prices fluctuating based on nickel markets, long-term contracts and diversified sourcing may be necessary to protect margins.
Third, the infrastructure spending landscape provides a tailwind, but it requires patience and relationship building. The continued flow of funds from acts like the Infrastructure Investment and Jobs Act means public sector projects will remain active. However, capturing this demand requires navigating procurement processes and demonstrating longevity and compliance. Fourth, the market concentration suggests that partnerships or niche positioning can be effective strategies. With a CR5 below 30 percent, there is no single dominant force controlling the entire market, allowing for strategic entry or expansion in specific regions or segments.
Finally, the regional dynamics suggest that a one-size-fits-all approach is insufficient. The market behavior in North America may differ significantly from Asia Pacific or Mideast and Africa due to varying construction rates, regulatory maturity, and income levels. A granular understanding of regional revenue splits and growth rates is necessary to allocate resources efficiently. The full report provides these specific regional and segment comparisons, enabling precise geographic targeting.
Conclusion
The stainless steel floor drains market stands at a juncture where material science, regulatory compliance, and infrastructure investment converge. The projected growth to 2,133.1 million USD by 2032 underscores the long-term viability of the sector, but the path to capturing this value is fraught with competitive and operational complexities. Companies that rely on aggregate data alone risk missing the nuances of segment performance, regional disparities, and competitor moves.
This market research report is engineered to close that gap. It transforms raw data into strategic narrative, offering clarity on where growth is concentrated, who is leading the charge, and what external factors will shape the next cycle. For executives, investors, and product leaders planning for 2026 and beyond, the detailed insights contained within this study provide the foundation for robust strategy formulation. We invite you to explore the full proprietary analysis to secure the comprehensive data sets, detailed competitor profiles, and segment-specific forecasts necessary to navigate this evolving market with confidence.
For detailed analysis of this topic, please visit the official page: Stainless Steel Floor Drains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microcrystalline Wax Market to Reach USD 1,934M by 2032 with 4.15% CAGR
By PW Consulting, 2026-09-07
Navigating the Microcrystalline Wax Market in 2026: A Strategic Imperative for Forward-Looking Enterprises
The global microcrystalline wax market stands at a critical inflection point. As industries balance growing demand for high-performance specialty waxes against escalating regulatory complexity and raw material volatility, the margin for strategic guesswork has effectively disappeared. For executives, procurement directors, and R&D leaders operating in 2026 and beyond, understanding the structural forces shaping this sector is no longer a peripheral exercise—it is a core component of resilient, profitable planning.
Insulin Analog Market
The market recorded steady expansion throughout the late 2010s and early 2020s, with revenue climbing from approximately $1.13 billion in 2020 to an estimated $1.43 billion by the close of 2025. The trajectory through the coming forecast window reflects a compound annual growth rate of roughly 4.15 percent, driven by sustained industrial utilization, formulation innovation, and shifting supply-chain architectures. While the aggregate figures provide a reliable baseline, the real strategic value lies in decoding how regional demand concentrations, application-specific consumption patterns, grade differentiation, and competitive positioning interact to create both opportunity and risk. This article outlines the landscape as it stands today and demonstrates why a granular, data-backed market research framework has become indispensable for enterprise decision-making in 2026.
Worldwide Aircraft Crew Rest Modules Market
Structural Shifts Reshaping the Market Environment
Microcrystalline wax has evolved from a relatively commoditized petroleum derivative into a performance-critical input across a diverse portfolio of end-use industries. Its value proposition rests on a combination of hardness control, viscosity regulation, surface protection, and compatibility with complex formulations. That versatility has made it attractive to formulators in cosmetics, personal care, candle manufacturing, adhesive systems, packaging engineering, rubber compounding, and specialty coatings. Yet the same versatility means that demand signaling is increasingly fragmented, and companies that rely on blunt, top-line forecasts quickly find themselves misaligned with real procurement behavior.
Worldwide Marine Whistles Market
Several concurrent dynamics are compressing the timeline for strategic action. On the regulatory front, policymakers across multiple jurisdictions have begun explicitly incorporating mineral waxes into broader trade, security, and compliance frameworks. Recent amendments to the Special Economic Measures Act in Canada, effective in mid-2025, placed paraffin wax, micro-crystalline petroleum wax, and slack wax within the scope of targeted import restrictions. In parallel, U.S. trade authorities have advanced Section 301 actions that extend forced-labor import bans and proposed supplemental ad valorem duties into the mineral wax category, including microcrystalline wax obtained by synthesis or other processes. Additional tariff classifications under the Harmonized Tariff Schedule further complicate landed-cost modeling for importers and distributors. These instruments are not isolated technicalities; they are structural levers that reshape sourcing feasibility, compliance overhead, and regional pricing differentials.
At the same time, raw material economics have introduced fresh volatility into production cost structures. Rising crude oil benchmarks and persistent refinery constraints pushed average microcrystalline wax prices upward in the first quarter of 2026, with global averages rising by more than five percent as feedstock expenses climbed. That pressure has been compounded by broader geopolitical instability affecting chemical feedstock flows. Disruptions linked to conflict in the Middle East have intensified price volatility across naphtha, LPG, and natural gas derivatives, transmitting cost fluctuations directly into wax manufacturing economics. In this environment, procurement strategies that assume stable input pricing or linear cost pass-through are increasingly fragile.
Competitive Landscape: Strategic Positioning and Differentiated Offerings
The market is moderately concentrated, with the top three players accounting for a meaningful share of total revenue and the top five extending that coverage further. This concentration matters because it shapes pricing power, supply reliability, and the pace at which innovation diffuses through the value chain. The leading participants are not competing on identical axes. Instead, each is carving out defensible positions through grade specialization, application-focused value propositions, and selective sustainability investments.
ExxonMobil Corporation continues to leverage its Prowaxx™ portfolio of fully refined, semi-refined, and slack microcrystalline wax grades across packaging, adhesives, construction, personal care, and rubber applications. Its recent expansion into high-purity microcrystalline wax lines for specialty plastics and coatings reflects a broader push to capture formulators seeking tighter impurity thresholds and reproducible performance in technically demanding substrates. Sasol Limited has taken a different route, emphasizing micronized-grade differentiation and reduced environmental intensity. Its SASOLWAX LC Spray 30 G and LC Spray 30 G-EF grades, marketed with a meaningfully lower product carbon footprint, target coatings, inks, plastics, and specialty manufacturing where surface protection and sustainability messaging both carry commercial weight.
Calumet Specialty Products Partners L.P. anchors its position in intermediate and microcrystalline waxes, with a substantial portion of its capacity directed toward hard grades for industrial adhesives, packaging, and consumer products. That capacity allocation signals how critical hard-wax performance characteristics remain for adhesive bonding, structural packaging, and durable consumer applications. Sonneborn LLC has built a reputation around Multiwax™ grades that meet U.S. FDA compliance requirements, making its product lines relevant to lipstick, cold creams, ointments, food packaging, and hot melt adhesives—an intersection where regulatory compliance and performance must operate simultaneously.
The International Group, Inc. (IGI Wax) focuses on dedicated microcrystalline wax production and blending across multiple physical forms, from bulk liquid to granule, pellet, and slab formats, serving cosmetics, food-grade, industrial, and coatings applications. That flexibility allows customers to align material form with manufacturing process constraints, a relatively subtle but operationally significant advantage. Sinopec Corporation contributes scale and geographic reach, with production and supply capabilities that include small-package delivery into European markets for industrial and downstream uses, highlighting the growing importance of cross-border fulfillment flexibility. Paramelt B.V. pursues a sustainability-led positioning, offering microcrystalline waxes that support sustainable and bio-based alternatives in coatings, adhesives, and plastics—an increasingly relevant differentiator as formulators face pressure to reduce fossil-derived content without sacrificing performance. Kahlwax GmbH rounds out the leadership set with industrial-grade microcrystalline wax serving plastics, rubber, and specialty manufacturing, reinforcing the persistent demand for consistent, application-ready industrial inputs.
These strategic orientations are not static. Recent product launches and portfolio expansions in early to mid-2025 indicate that incumbents are actively adjusting their offerings to capture higher-value segments, improve process compatibility, and respond to sustainability expectations. For customers and investors, the practical implication is clear: the competitive map is shifting around grade-level performance, regulatory readiness, and carbon and feedstock resilience, not simply around volume and price.
Segmentation Dynamics: Where Value Actually Accumulates
A market of this size and growth profile can appear uniformly attractive at a high level, but enterprise-level opportunities are won or lost in the segmentation layer. The broad demand split between flexible and hard grades underscores how differently these materials behave in end-use formulations, and how much that behavioral difference matters to specifiers. Hard grades remain central where structural integrity, thermal stability, and controlled hardness are non-negotiable. Flexible grades, meanwhile, support formulations that require tighter integration with binders, polymers, and emollient systems, particularly in personal care and select adhesive architectures.
Application-level demand reflects a similarly nuanced picture. Cosmetics and personal care, alongside candles, represent substantial consumption centers, but the drivers behind those figures are not interchangeable. In cosmetics and personal care, microcrystalline wax is valued for texture modulation, product stability, and formulation compatibility in items such as lipsticks, cold creams, and ointments. In candle manufacturing, the material’s burn characteristics, fragrance retention, and structural behavior create distinct specification priorities. Adhesives and packaging form another meaningful demand cluster, with adhesives requiring controlled hardness and compatibility with hot-melt and pressure-sensitive systems, while packaging applications depend on moisture resistance, surface finish, and sealing performance. Rubber and a broader set of specialty applications round out the consumption base, each with its own performance thresholds and substitution dynamics.
Regional demand patterns add another layer of complexity. The market’s revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa reflects different industrial densities, formulation traditions, regulatory environments, and trade exposure. For a company planning capacity, inventory positioning, or go-to-market strategy in 2026, treating these regions as homogeneous blocks would be a serious misjudgment. The strategic question is not simply where demand is largest, but where specification alignment, compliance feasibility, and supply chain reliability intersect most favorably with a given product portfolio.
Because the margin between a useful estimate and a precise, decision-grade segmentation view can be substantial, organizations that rely on approximate splits risk overcommitting to the wrong grade mix, the wrong application messaging, or the wrong regional footprint. That is precisely why the detailed segmentation architecture in our full study is built for operational use rather than high-level orientation.
Regulatory, Trade, and Cost Volatility: A 2026 Planning Reality
The regulatory and trade developments now intersecting the microcrystalline wax sector are too material to treat as peripheral risk factors. For importers, distributors, and formulators with multi-region exposure, the practical challenge is to integrate compliance logic directly into sourcing strategy, rather than handling it as a separate legal review after procurement decisions are made. The scope of recent instruments—spanning targeted import restrictions, forced-labor-related import measures, and specific tariff treatment for mineral wax categories—means that country-of-origin dynamics, documentation completeness, and supplier transparency have moved to the center of total-cost modeling.
On the cost side, the first-quarter 2026 price increase driven by rising feedstock expenses is a reminder that microcrystalline wax economics are tightly coupled to refinery behavior and crude benchmarks. When feedstock constraints and geopolitical disruption intersect, cost volatility can escalate quickly, and the lag between raw-material movement and finished-grade pricing can be frustrating for procurement teams that have already committed to fixed-price arrangements or inventory plans. Sustainable cost management in this context depends less on timing the market and more on constructing a sourcing architecture that can absorb shock: diversified grade sourcing, flexible contract structures, regional fallback pathways, and early visibility into formulation substitutions that preserve performance while reducing exposure to specific feedstock-dependent grades.
Formulators and end-product manufacturers are also facing increasing pressure to reconcile performance requirements with sustainability expectations. That pressure does not automatically translate into simple feedstock substitution, because microcrystalline wax’s functional role often depends on precise wax properties that are difficult to replicate without reformulation. The companies that are gaining traction are those that address sustainability as a specification problem—offering grades with lower associated carbon intensity, improving process compatibility, and maintaining regulatory compliance—rather than treating it solely as a marketing claim.
Why This Research Matters for 2026 Decision-Making
Enterprises entering 2026 need more than a market snapshot. They need a structured, evidence-based view that connects market size and growth trajectory to the operational realities of grade selection, application targeting, regional sourcing, regulatory exposure, and competitive positioning. A study that stops at aggregate revenue and a headline CAGR can support scenario discussion, but it cannot reliably inform capacity commitments, product-portfolio emphasis, supplier qualification, or pricing strategy in a market where segmentation spreads and regulatory overlays are this pronounced.
The full Microcrystalline Wax Market research is designed to bridge that gap. It integrates historical performance from 2020 through the 2025 base year with a forward forecast extending through the end of the decade, allowing readers to examine how demand evolved under different industrial and economic conditions and how the growth path is likely to unfold as feedstock, regulatory, and application dynamics continue to shift. Beyond the top-line trajectory, the study provides a detailed segmentation framework that allows decision-makers to isolate the demand drivers, grade preferences, and regional consumption characteristics that matter most to their specific strategic posture.
Equally important, the research situates the competitive landscape within the context of actual product offerings, capacity orientations, and recent market actions. Rather than cataloguing companies in abstraction, it examines how leading participants structure their microcrystalline wax portfolios around flexible and hard grades, application-specific requirements, compliance readiness, and sustainability positioning. That approach allows readers to interpret competitive moves as strategic signals—where incumbents are reinforcing mature demand centers, where they are experimenting with higher-value specialty grades, and where new product launches signal emerging specification expectations.
The study also builds regulatory and trade developments into the analytical architecture, so that sourcing and market-access considerations are evaluated alongside demand and competitive factors. This integrated lens is essential in a period when import restrictions, tariff treatment, and compliance conditions are actively reshaping the cost and feasibility of moving material across borders. For procurement, sales, and strategy teams, the value lies not merely in knowing that regulations exist, but in understanding how they interact with grade selection, regional supply bases, and landed-cost assumptions.
Finally, the research is constructed for practical application. It supports questions such as: Which grade families offer the strongest alignment with current formulation requirements and regional compliance constraints? Where are demand signals strongest enough to justify targeted sales engagement or distribution investment? Which competitive moves indicate shifting specification expectations that could affect future product planning? How should sourcing strategies adapt to continued feedstock volatility and trade-related cost variability? The answers to these questions are rarely visible in summary-level data, but they are exactly the answers that determine execution quality in 2026.
What the Full Report Unlocks
For teams ready to move from directional awareness to actionable intelligence, the complete study provides the depth required to connect market structure to enterprise strategy. The report delivers a detailed segmentation analysis that allows readers to examine demand distributions across regions and applications without relying on blanket assumptions. It provides a comprehensive competitive assessment that ties company profiles to specific microcrystalline wax offerings, grade strategies, and recent product activity. It incorporates the regulatory, trade, and raw-material forces that are actively shaping pricing, sourcing, and compliance exposure. And it frames the entire analysis within a forecast architecture that supports planning across multiple time horizons.
The objective is not to overwhelm with data, but to equip decision-makers with a defensible basis for choices that will shape cost structure, market access, product positioning, and competitive resilience. In a market where concentration, segmentation, regulation, and feedstock dynamics all interact at once, the organizations that outperform will be those that treat market intelligence as a core input to commercial and operational design, not as a background briefing.
Conclusion
The microcrystalline wax market in 2026 is defined by a combination of steady demand growth, pronounced grade and application differentiation, active regulatory and trade intervention, and continued feedstock-driven cost pressure. These forces reward companies that can translate market structure into specific decisions about grade mix, application focus, regional sourcing, and compliance readiness. Aggregate market figures provide the starting point, but the strategic advantage belongs to those who can work from a more granular, integrated view of how demand, competition, and risk are actually distributed.
For executives and strategy teams seeking that level of clarity, the full Microcrystalline Wax Market research offers a focused, operationally relevant foundation. It is built to support the decisions that matter most in the current environment: where to emphasize, where to diversify, how to price and source with greater confidence, and how to interpret competitive moves as signals rather than noise. The detailed segmentations, competitive profiles, regulatory overlays, and forward forecasts contained in the complete study are intended to convert market complexity into a practical decision framework for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Microcrystalline Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


